



Category: market research
PW Consulting: Worldwide Vanadium Slag Market to Reach USD 1.681B by 2032 at a 7.52% CAGR — Asia-Pacific Leads with USD 619.3M
By PW Consulting, 2026-08-18
Worldwide Vanadium Slag Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Vanadium Slag Market (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes commercial intelligence, regulatory signals, technology trends and hard market modeling to equip executives making capital allocation, supply‑chain and M&A decisions in 2026. Our top‑line model shows the global vanadium slag market expanding from approximately USD 684 million in 2020 to USD 1,011.9 million in 2025, with a forecast rise to about USD 1,681.0 million by 2032 — a compound annual growth rate of 7.52% across the 2026–2032 projection window. Market concentration is material: the three‑firm and five‑firm concentration ratios (CR3 and CR5) underscore a market where a relatively small group of integrated players capture a majority of production and processing capacity.
Human Plasma-like Medium Market
Why this preview matters for 2026 planning
Vanadium slag sits at the intersection of steelmaking co‑products, critical mineral supply chains and emerging demand from grid-scale energy storage (vanadium redox flow batteries). The result is a market with both entrenched incumbents and rapid pockets of change driven by regulatory shifts, tariff regimes and processing innovations. For corporate leaders in 2026, strategic questions cluster around: Where to secure low‑cost, secure feedstock; which processing and recycling technologies to adopt; what off‑take and tolling structures reduce price and supply volatility; and how to position for demand coming from energy storage and specialty chemical markets.
Antibacterial Lubricant Gel Market
What PW Consulting’s report delivers (operational, decision‑ready content)
- Transparent, audit‑ready market model (USD, millions) with yearly historical datapoints and a seven‑year forecast, enabling scenario comparisons and sensitivity testing for price, recovery and demand shocks.
- Actionable supplier risk matrix and counterparty profiles that rank and stress‑test upstream steel co‑producers, primary vanadium miners and specialty processors on production resilience, regulatory exposure and ESG credentials.
- Practical commercial tools: standardized off‑take/tolling template clauses, benchmarking of processing costs, and an indexed approach to V2O5 price pass‑through in long‑term contracts.
- Technology pathway assessments: comparative recovery efficiencies, capital and operating cost curves for hydrometallurgical vs. aluminothermic flows, and an evaluation of closed‑loop recycling systems.
- Regulatory and trade scenario playbooks—mapping likely outcomes from import bans, tariff adjustments and permitting delays to help prioritize acquisitions or build projects in alternative jurisdictions.
- Deal readiness checklists for M&A and joint ventures, including legal, environmental, metallurgical and offtake diligence points.
Key market dynamics shaping 2026 decisions
- Feedstock dominance and supply geometry: Vanadium slag remains the dominant feedstock for global vanadium production — accounting for the majority of primary supply — which ties vanadium availability directly to steelmaking cycles and ore grades (USGS and industry reporting). That linkage drives correlated volatility in years of steel output swings and plant outages.
- Regulatory reshaping of flows: Recent policy shifts — notably the restriction on vanadium slag imports enacted by China — have materially re‑allocated processing activity and forced international feedstock strategies to evolve. Concurrent tariffs and trade measures in major consuming markets further change cost and logistics calculations for importers and processors.
- Price signal implications: The observed V2O5 price levels and their volatility in 2024–2025 are pivotal inputs to capex decisions on new processing capacity and to decisions on whether to internalize slag processing or rely on tolling agreements.
- Processing gains and material efficiency: Emerging plant trials and zero‑waste systems are already delivering step‑change recovery improvements. Case trials have demonstrated near‑double‑digit percentage gains in recovery efficiency while reducing tailings volumes — an operational improvement that translates directly into margin uplift for processors and lower feedstock intensity for battery makers.
Competitive landscape — strategic implications
The vanadium slag market is characterized by vertically integrated steelmakers that generate slag as a co‑product, dedicated processors that convert slag to high‑purity vanadium chemicals, and dedicated primary vanadium miners exploring slag as a complementary feedstock. Below we summarize strategic positions of leading players covered in the report and how they are likely to shape the competitive map in 2026.
Thyristor Dimming Power Supply Market
- Pangang Group Vanadium & Titanium Resources (China) : A major integrated co‑producer with strong upstream access to titanomagnetite ores. Their strength is feedstock security and scale; potential strategic moves include expanding tolling services and licensing processing technology to third parties affected by import restrictions.
- HBIS Group / Chengde Steel (China) : Large steel producers with slag production embedded in steelmaking operations. Their advantage is low incremental cost of feedstock; strategic options in 2026 will likely focus on downstream integration and captive offtake arrangements with chemical processors.
- EVRAZ KGOK / EVRAZ plc (Russia) : An integrated miner‑producer with downstream ferrovanadium operations. EVRAZ’s vertical integration provides a hedge against price swings but increases exposure to geopolitical and sanction risk — an important strategic variable for counterparties contemplating long‑term contracts.
- AMG Vanadium LLC (United States) : A specialist processor and recycler with expertise in converting residues, ashes and spent catalysts into ferrovanadium. AMG’s recycling capabilities and access to spent catalysts make it a strategic partner for companies seeking to diversify away from slag‑only feedstocks.
- U.S. Vanadium LLC (Arkansas, USA) : Focused on converting steel slag and other vanadium‑bearing materials into high‑purity V2O5 and chemicals. Its location and product slate position it as a critical supplier for North American specialty markets, particularly where tariffs and logistics raise the cost of imports.
- Largo Inc. (Canada/Brazil operations) : A primary producer with growing by‑product handling capability; recent operational updates show continued V2O5 production momentum and active management of slag streams — a company to watch for strategic expansions into slag‑derived products and long‑term offtakes (recent Q1 2026 and FY2025 production disclosures reinforce operational scale and trajectory).
- Bushveld Minerals (South Africa) and other regional players: These firms hold strategic regional importance and can be attractive partners for offtake, local processing partnerships and fundable expansions tied to regional supply security.
- Desheng Group and other Chinese processors : Advancing zero‑waste and higher‑recovery processing trials that materially improve margin per tonne processed — a trend likely to compress the cost curve for efficient processors and raise the bar for legacy facilities.
- Czech Vanadium and Beijing Jianlong : Examples of smaller scale or specialized producers with metallurgical niches (aluminothermic processes, integrated steel/vanadium operations) important for buyers seeking specific product forms or shorter lead times.
Notable recent developments you need to factor into 2026 planning
- Offtake arrangements and project tie‑ups are accelerating: Recent offtake term sheet activity targeting slag streams indicates growing interest in securing high‑grade slag feedstock through early contractual commitments (April 2026 corporate announcements underline this trend).
- Production momentum at primary vanadium operations: Public reporting from sizable producers shows continued V2O5 output and active management of associated slag/by‑product streams — a reminder that primary mine expansions and by‑product handling remain key determinants of near‑term supply.
- Policy and tariff actions continue to rewire trade flows: Import bans and tariff adjustments have immediate commercial consequences for where processors choose to invest or partner, particularly for companies exposed to North American or Chinese markets.
How to use the PW Consulting report in your 2026 decision cycle
Executives should use PW Consulting’s market study as a decision‑support tool across several common 2026 use cases:
- Procurement strategy: calibrate the tradeoffs between long‑term offtake, tolling and spot purchase based on our supplier risk rankings and scenario price curves.
- Capex prioritization: use the report’s cost‑curve analysis and recovery efficiency scenarios to select between retrofitting existing plants, building a new hydrometallurgical facility or investing in recycling capacity.
- M&A and JV diligence: deploy our deal readiness checklists and counterparty profiles to accelerate diligence and reduce execution risk on time‑sensitive transactions.
- Regulatory playbooks: adopt the report’s scenario playbooks to anticipate policy shocks and create contingency plans for feedstock re‑routing or rapid domestic processing scale‑up.
- Market entry and product strategy: map product specifications and customer segments using our demand forecasts (including energy storage trajectories) to prioritize high‑value chemical and battery supply pathways.
Final note — what you will not find in this preview
This article highlights the strategic contours and practical utility of PW Consulting’s full study while intentionally withholding the detailed regional and application‑level split tables and specific contractual clause language that constitute the core commercial IP of the report. Those proprietary cell‑level market splits, supplier exposures by jurisdiction, and the interactive financial model are available exclusively through the full report package and our consulting engagements.
Next steps for executives
If your 2026 capital allocation or supply strategy will be influenced by vanadium availability, processing technology or trade policy, schedule a briefing with PW Consulting. We will walk you through the model, run customized scenarios for your supply chain, and map an execution blueprint that converts market intelligence into defensible, time‑sensitive decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Vanadium Slag Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Perfumes Market to Reach USD 87.11 Billion by 2032, Growing at a 5.85% CAGR (Base Year 2025)
By PW Consulting, 2026-08-18
Worldwide Perfumes Market 2026: Strategic Preview for Executive Decision-Making
Why 2026 is a Pivotal Year — and What This Preview Delivers
PW Consulting’s latest Worldwide Perfumes Market report (base year 2025; historical window 2020–2025; forecast 2026–2032) provides senior executives with a sharp, decision-focused view of an industry resuming robust expansion. At a compound annual growth rate of 5.85% across the forecast horizon, the global perfumes market is projected to expand from an estimated USD 58.5 billion in 2025 to approximately USD 87.11 billion by 2032. That trajectory creates both opportunity and strategic risk for brand owners, ingredient suppliers, and retail partners — and 2026 will be the year many companies must choose between defensive optimization and offensive investment.
Induction Furnace Power Transformers Market
Key Strategic Implications for 2026
-
Portfolio prioritization: With steady market growth, portfolio rationalization should be guided by clear value metrics. Brands must differentiate where premiumization and innovation deliver margin uplift and where scale and distribution drive volume. The coming 18–24 months favor targeted premium launches supported by experiential marketing rather than a broad volume push across underperforming SKUs.
Immunological Agents Market -
M&A and alliance timing: The market’s expansion and continuing fragmentation create windows for strategic combinations that achieve distribution scale or brand depth. Merger and acquisition activity will accelerate around assets that offer prestige credentials, proprietary formulations, or direct-to-consumer capability. Executives planning transactions in 2026 should model scenarios that stress-test travel-retail exposure and regulatory reform risk.
Worldwide Sponging Machines Market -
Supply-chain and ingredient strategy: Rising demand for natural, traceable ingredients and evolving regulatory constraints require end-to-end transparency in sourcing. Procurement strategies in 2026 must combine multi-source security for critical naturals with longer-term partnerships for sustainable supply — including contract structures that smooth price volatility and ensure compliance.
-
Regulatory readiness: Companies must move from ad-hoc compliance to regulatory resilience. Recent IFRA amendments and expanded transparency lists have shortened reform windows; in 2026, firms without a prioritized reform roadmap for ingredient substitution and product communication will face margin erosion and launch delays.
-
Channel mix optimization: The recovery pattern across travel retail, department stores, and e-commerce remains uneven. Leaders should re-weight channel investment based on scenario-tested elasticity of demand and the brand’s experiential needs, while developing quick-response promotional plays to capture shifting seasonal peaks.
Market Trajectory — A Snapshot for Strategy Teams
Our modeling shows the perfumes market continuing a consistent expansion from the mid-2020s into the early 2030s. After an estimated market size of USD 58.5 billion in 2025, the market is forecast to reach roughly USD 61.9 billion in 2026 and to approach the high eighties by 2032 under the base-case CAGR of 5.85%. This steady growth masks structural change: premiumization of consumer demand, greater demand for natural and sustainable inputs, and a channel mix shifting toward digital-first experiences and selective travel-retail recovery. Strategy teams must therefore translate headline growth into prioritized actions that close the gap between top-line opportunity and bottom-line capture.
Competitive Landscape — Who Matters and Why
The market comprises a mix of large beauty conglomerates, luxury houses, regional leaders, and specialized ingredient creators. Instead of enumerating market shares, our analysis emphasizes strategic positions and vectors of competitive advantage:
-
Large Beauty Conglomerates (scale + portfolio breadth): Global groups with deep distribution networks and multi-brand portfolios hold advantage in cross-channel rollout and co-marketing synergies. Their challenge is preserving prestige credentials while extracting operating leverage.
-
Luxury Houses (heritage + rarity): Iconic fashion and luxury houses maintain pricing power through storytelling and craftsmanship, making them preferred partners for aspirational launches and selective retail placements.
-
Licensed & Mass Fragrance Operators (reach + license management): Companies combining owned and licensed brands can rapidly scale new concepts but must manage license complexity and promotional pressure in mass channels.
-
Ingredient & Creation Houses (innovation enablers):strong> Suppliers that control formulation capability and sustainable sourcing can accelerate partner go-to-market timing and shape future scent trends.
Our competitive profiles focus on strategic options and execution risk for leading firms — where to invest, what to divest, and how to structure partnerships. Recent industry moves underline the point: high-level merger discussions between major groups could reshape market dynamics, while new prestige entries and specialized trade events signal that product innovation and ingredient storytelling remain front and center.
Recent Industry Signals and Strategic Responses
-
Consolidation conversations among large players are a clear signal to executives to reassess both defensive and offensive M&A options. A well-structured acquisition can accelerate entry into a premium niche or shore up geographic distribution — but integration plans must account for channel exposure and product portfolio overlap.
-
New premium brand launches continue to capture consumer attention; incumbents should expect to compete not just on scent but on provenance, experiential marketing, and service models (e.g., bespoke and refill systems).
-
Trade shows and ingredient showcases are now critical strategic forums: they accelerate access to sustainable raw materials, novel encapsulation technologies, and scent personalization platforms. Companies that deploy scouting teams and fast-track pilots will capture first-mover advantages.
-
Regulatory changes and ingredient transparency requirements compress R&D cycles. Brands must proactively adapt formulations and consumer communications, turning a compliance mandate into a brand-differentiating transparency offer.
What the PW Consulting Report Contains — For the Executive Who Must Act
The full report delivers an actionable toolkit tailored for 2026 strategic planning cycles. Key deliverables include:
-
Global market sizing and forecast model (2020–2032) with scenario switches and sensitivity tests to calibrate strategic options against downside shocks and upside acceleration.
-
Commercial playbooks for premium and mass segments, including pricing corridors, promotional elasticity estimates, and channel-specific go-to-market checklists.
-
Competitive position maps and executable M&A screening frameworks that prioritize targets by strategic fit, integration complexity, and expected time-to-synergy.
-
Supplier and ingredient risk matrix, incorporating sustainability risk scores, substitution pathways, and time-to-compliance for recent regulatory changes.
-
Consumer insight capsules: trend narratives, segmentation archetypes, and media-to-purchase attribution guidance for digital-first and omnichannel activations.
-
Scenario playbooks for channel disruptions (including travel retail variability), with quantified impact ranges for annual planning and contingency budgets.
-
Executive briefings and a slide-ready summary for board-level decision sessions, designed to accelerate approvals for 2026 investment and restructuring choices.
Actionable Recommendations — A Four-Point Roadmap for 2026
-
Implement a two-speed product strategy: concentrate R&D and marketing investment on a smaller set of premium launches while optimizing the mass portfolio for cost-to-serve and distribution efficiency.
-
Negotiate supply contracts that prioritize traceability and volume flexibility. Locking in sustainable naturals through multi-year agreements with shared sustainability KPIs reduces formulation risk.
-
Run rapid M&A readiness exercises: prepare diligence templates, early-warning integration playbooks, and post-merger value-capture plans so you can move decisively when opportunities arise.
-
Upgrade regulatory and consumer-facing transparency: convert compliance costs into brand differentiation by publicly documenting ingredient sourcing and reformulation timelines.
Why PW Consulting’s Intelligence Matters Right Now
2026 is a year when strategic clarity will compound into competitive advantage. Our report combines a rigorously stress-tested forecast (covering 2026–2032), regulatory horizon-mapping, supplier ecosystem analysis, and actionable commercial playbooks to help leaders translate market growth into defensible margin gains. We show where to be bold, where to consolidate, and where to hedge — while deliberately reserving the granular regional and product breakdowns that are essential for transaction and channel-specific decisions to the full report.
Next Steps
Executives seeking the full data set — including detailed regional and product splits, model files, and executive workshops — can access the complete report and advisory engagement options via PW Consulting’s Worldwide Perfumes Market page. For leadership teams planning strategy sessions in 2026, we offer expedited briefings that align the report’s implications with your financial and commercial calendar.
Contact PW Consulting to schedule an executive briefing and obtain the full market dataset that underpins the analysis summarized here.
For detailed analysis of this topic, please visit the official page: Worldwide Perfumes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Concentrated Tomatoes Market to Reach USD 14,424.93 Million by 2032, Expanding at a 5.6% CAGR
By PW Consulting, 2026-08-18
PW Consulting Releases Worldwide Concentrated Tomatoes Market Report — Strategic Imperatives for 2026
PW Consulting today publishes its definitive market study, Worldwide Concentrated Tomatoes Market: 2020–2032 Outlook, offering senior executives, procurement leaders, and investors an operational playbook to navigate a complex, higher‑velocity environment in 2026. Built on a base year of 2025 with historical analysis across 2020–2025 and a forecast window spanning 2026–2032, the report quantifies a market that reached USD 9,850.5 Million (revenue unit: Million, currency: USD) in 2025 and is projected to grow at a 5.6% CAGR through 2032 to USD 14,424.93 Million. This release summarizes the report’s strategic value while deliberately withholding the granular segment tables and region/application breakouts; those datasets are available in the full report on our site.
Worldwide Licensed Merchandise Retail Market
Why 2026 Is a Decision Point
-
Macro momentum: After recovering from the early‑decade disruption, the concentrated tomatoes market has exhibited steady expansion—from USD 7,485.6 Million in 2020 to USD 9,850.5 Million in 2025—creating a window for scale investments and margin capture in 2026.
Worldwide Melaleuca Oil Market -
Regulatory inflection: New reporting and due‑diligence requirements will materially affect supply‑chain economics beginning late 2025, altering sourcing, certification, and cost pass‑through models.
Worldwide Metal Lathes Market -
Trade and protection dynamics: A combination of antidumping tariffs and evolving trade barriers requires strategic repositioning of export footprints and supplier portfolios.
What the Report Delivers (Practical, Actionable Content)
-
Forecast engine: Integrated market model (Excel) with scenario toggles for raw material price, processing yield, and end‑market demand elasticity—enabling forward P&L and ROI simulations for 2026 capital plans.
-
Decision frameworks: Procurement playbook for hedging raw‑material exposure, contract farming structures, and supplier segmentation by risk and cost to serve.
-
Regulatory playbook: Step‑by‑step compliance and supplier diligence checklists tailored for EUDR and major export markets, including operational templates for traceability and due‑diligence auditing.
-
Competitive landscaping: Strategic profiles and capability matrices for leading global producers, plus a prioritized list of acquisition targets and JV candidates by strategic fit and integration complexity.
-
Operational benchmarks: Processing yield, energy intensity, and capital expenditure ranges for greenfield and brownfield expansion—derived from primary interviews and plant‑level benchmarking.
-
Risk heatmaps and mitigation blueprints: Coverage of raw‑material volatility, recall/food‑safety exposure, tariff scenarios, and logistical bottlenecks with contingency playbooks.
Note: This communiqué intentionally refrains from publishing granular region‑by‑region, application, and sub‑type tables; the full downloadable appendices contain the detailed segment splits and vendor‑level data essential for transaction diligence and site‑level planning.
Competitive Landscape — What Leading Players Reveal About the Next Wave of Consolidation
The concentrated tomatoes market shows moderate top‑end concentration: the largest three companies account for about 32.5% of market share (CR3), and the largest five about 45.2% (CR5). That structure creates opportunities for both scale players to extend margin advantage and for nimble specialists to exploit premium niches.
-
Morning Star Company (Woodland, CA, USA) — World’s largest independent producer with deep vertical integration and contracting expertise. Morning Star’s scale and processing footprint make it the benchmark for low‑cost, high‑volume supply to industrial processors; its capabilities set the bar on efficiency and cold‑chain logistics.
-
Ingomar Packing Company (Newman, CA, USA) — A major industrial supplier with strong ties to US food processors. Ingomar’s customer intimacy in industrial food processing makes it a strategic partner for downstream formulators seeking supply security and product customization.
-
Mutti S.p.A. (Basilicanova, Parma, Italy) — A premium‑positioned brand with emphasis on provenance and varietal quality. Mutti exemplifies the premiumization pathway—higher ASPs, strong brand equity, and direct retail/foodservice channels—attractive to those seeking margin insulation from raw‑material swings.
-
Conserve Italia (San Giovanni in Persiceto, Italy) — Cooperative structure that provides resilience in sourcing and community‑anchored supply networks—an important model where EUDR and provenance traceability are prioritized.
-
Kiril Mischeff Ltd. (Dobrich, Bulgaria) — Europe’s major paste manufacturer and a leader in aseptic concentrate exports, illustrating how technology investments (aseptic lines) expand addressable markets without proportional increases in logistics costs.
-
COFCO Tunhe Tomato Co., Ltd. (Shihezi, Xinjiang, China) — Asia’s production leader and a key example of how vertically integrated state‑backed supply chains can scale quickly; however, exporters face trade‑policy headwinds in some markets.
Industry Dynamics: Raw Materials, Regulation and Trade
-
Raw material exposure: Processing tomato economics remain sensitive to farmgate prices and processing yields. California grower prices averaged roughly USD 90.10 per ton in 2023 and California crush volumes reached 11.4 million tons in 2023—figures that underscore how concentrated production basins can influence global availability and short‑term price spikes.
-
Regulatory pressure: The EU Deforestation Regulation (EUDR) requires enhanced due‑diligence for tomato supply chains beginning December 2025, pushing buyers to operationalize traceability, chain‑of‑custody systems, and supplier audits. For companies selling into EU markets, failure to adapt will raise compliance costs and restrict access.
-
Trade frictions: US antidumping duties on tomato paste imports from China range substantially (158.01% to 412.35%), materially altering trade flows and making near‑sourcing and regionalization strategies economically attractive for US buyers.
-
Food safety and brand risk: Recent recalls, such as the FDA‑recorded Conti Foods recall for undeclared wheat allergen, reinforce the financial and reputational cost of lapses in allergen control and labeling—driving demand for tighter supplier qualification and end‑to‑end traceability.
Strategic Actions for 2026 — What Leaders Should Be Doing Now
-
Prioritize traceability investments: Implement supplier‑level traceability, chain‑of‑custody records, and digital audit trails to meet EUDR requirements and reduce recall exposure. Fast movers will benefit from lower compliance margins and improved market access.
-
Rebalance sourcing portfolios: Reduce tariff and trade concentration risk by diversifying sourcing across homologous basins and contract farming arrangements. Short‑term spot buying should be complemented by multi‑year offtakes with price‑index clauses to smooth P&L volatility.
-
Invest selectively in aseptic technologies: Aseptic concentrates reduce logistics costs and expand market reach; consider CapEx for modular aseptic lines where incremental margin and volume growth justify the investment.
-
Define premium vs industrial product strategies: Segment commercial routes-to-market: protect premium channels with varietal sourcing and branding while optimizing low‑margin industrial supply through scale and process efficiencies.
-
Make M&A playbooks ready: Given the market’s mid‑level concentration, strategic tuck‑ins and regional consolidations can deliver rapid scale and access to proprietary supply contracts; prepare integration playbooks now.
-
Stress‑test scenarios: Use the report’s scenario models to run 2026 capital and sourcing plans against raw‑material spikes, abrupt tariff changes, and accelerated regulatory compliance cost curves.
How PW Consulting Supports Execution
Beyond the published report, PW Consulting offers tailored advisory services to translate insights into executables: custom M&A due diligence, procurement transformation, implementation of traceability tech stacks, and workshop‑driven scenario planning for board readiness. Our proprietary database and benchmarking tools allow clients to fast‑track valuations, identify integration synergies, and map supplier risk exposures down to the field level.
Closing — The Value of the Full Report
This press release outlines the strategic contours you need to evaluate and act in 2026. For commercial teams planning capital allocation, procurement leaders restructuring supplier portfolios, and private‑equity sponsors vetting platform deals, the full Worldwide Concentrated Tomatoes Market report provides the granular tables, vendor‑level intelligence, and downloadable models required for transaction‑grade decisions. We intentionally withheld subsegment and regional tables from this summary to preserve the report’s value as a decision‑support asset—access the complete dataset, appendices, and implementation templates on our website.
For inquiries about licensing the dataset, commissioning a deep‑dive on a specific basin, or booking a strategy workshop, contact PW Consulting’s Food & Agriculture Practice.
For detailed analysis of this topic, please visit the official page: Worldwide Concentrated Tomatoes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Industrial Kneader Market (Base Year 2025) at USD 1,280.5 Million — Forecast (2026–2032) to Reach USD 1,816.35 Million at 5.12% CAGR; Asia Pacific (USD 515.6M) and Sigma Blade Kneaders (USD 553.3M) Lead
By PW Consulting, 2026-08-18
Worldwide Industrial Kneader Market — Strategic Outlook for 2026
Executive summary
PW Consulting’s latest Worldwide Industrial Kneader Market report (base year 2025) delivers a boardroom-ready synthesis of where the kneader industry stands as companies finalize capital plans and product roadmaps for 2026. Our analysis shows a market that is growing steadily: the industry-wide revenue base reaches USD 1,280.5 Million in 2025 and is projected to approach USD 1,816.35 Million by 2032, implying a compound annual growth rate of 5.12% over the 2026–2032 forecast window. Market concentration remains low — the top three and top five suppliers cumulatively hold modest shares (CR3 ≈ 18.45%; CR5 ≈ 27.8%) — underlining a fragmented supplier landscape that rewards differentiation and local service capability.
Worldwide Casting & Release Paper Market
Why this report matters to decision-makers in 2026
-
CapEx prioritization: Companies planning equipment investments in 2026 face competing pressures — decarbonization objectives, EV-driven new material requirements, and steel-driven cost volatility. Our report translates market sizing and scenario modeling into pragmatic investment gates and timing guidance for procurement committees.
Flow-Through Immersion Coolers Market -
Supplier strategy: With a fragmented market, supplier selection is as much about risk management and aftermarket capability as it is about headline price. We provide a practical supplier-comparison framework to reduce procurement cycle time and lock in service-level performance.
Worldwide Parcel Audit Software Market -
Portfolio and product development: R&D leaders targeting high-viscosity and battery-materials segments will find our technology and application mapping useful for product roadmaps that prioritize modularity and thermal management.
Market trajectory and underlying assumptions
Our topline projection is rooted in historical performance (2020–2025) and an explicit set of demand drivers extending through 2032. The industry grew from under a billion dollars in 2020 to a 2025 base of USD 1,280.5 Million and, under our central scenario, reaches USD 1,816.35 Million by 2032. This trajectory reflects an annualized growth of 5.12% during the forecast window and incorporates the following core modeling assumptions:
-
Steady replacement and modernization cycles in rubber, plastics, and chemical processing industries.
-
New demand pockets arising from electrification supply chains, specifically battery electrode paste and related high‑viscosity processing.
-
Material cost pass-through and engineering redesigns prompted by elevated steel input prices and elevated tariff regimes.
Market dynamics shaping 2026 decisions
-
EV battery manufacturing as a catalyst: The electrification trend has become a tangible demand generator for specialized kneaders used in electrode paste and other high‑viscosity processes. Firms that can demonstrate process control for fine-particle dispersions and thermal stability will gain early-adopter advantage in supplier selection processes for battery plants.
-
Raw-material cost pressure and tariff impacts: Steel input costs and trade policy are no longer peripheral. Recent market indicators show upward movement in hot-rolled coil and benchmark steel prices, and higher U.S. tariffs on steel imports (notably changes effective in mid‑2025) materially affect OEM component costs. Buyers should bake localized sourcing, advanced yield engineering, and steel-efficient mechanical designs into procurement specifications.
-
Aftermarket and servitization premium: Given the capital intensity and uptime sensitivity of kneaders, clients are increasingly willing to pay for rapid spare parts availability, predictive maintenance, and outcome-based service contracts. Service capability is now a differentiator in an otherwise fragmented supplier field.
-
Regulatory and sustainability drivers: Energy efficiency, solvent emissions controls, and refrigerant management in cooling-intensive kneaders are becoming procurement filters for corporates with aggressive Scope 1/2 targets. Compliance-readiness and demonstrable lifecycle analysis are table stakes for vendor selection in 2026.
Competitive landscape — where incumbents and specialists stand
The kneader equipment market is characterized by a mix of global engineering houses, regionally focused manufactures, and niche specialists. The CR3 and CR5 metrics indicate room for consolidation but also opportunities for regional champions and technology-focused entrants. Key vendor archetypes identified in the report include:
-
Technology leaders with deep materials know‑how: European and Japanese firms that emphasize engineering for mixed viscosities, precision tolerances, and high-durability designs for elastomers and specialty polymers.
-
Niche specialists and scale operators: Companies that excel in a small set of applications — e.g., dispersion technologies or continuous kneading — and which supplement equipment sales with local spares networks and retrofit services.
-
Cost-competitive OEMs from established manufacturing hubs, offering solid value propositions for standard-capacity units while competing aggressively on lead times.
Representative players profiled in the full report (with HQ and capability summaries) include long-standing regional specialists and global engineering groups that supply Banbury, sigma, continuous, and internal mixer technologies. Our competitive profiles evaluate product portfolios, aftermarket networks, R&D investment, and strategic positioning — delivering a practical guide for sourcing managers and corporate strategists.
What the full report contains — actionable content for practitioners
To convert insight into action, PW Consulting’s report is structured around operational decision-making tools rather than academic segmentation tables. Notable components include:
-
Investment playbook: A step-by-step guide for CAPEX approval including TCO templates, payback scenarios under varying throughput and energy-price conditions, and retrofit vs. replace decision trees.
-
Procurement checklist and supplier scorecard: Standardized RFP language, critical technical clauses (e.g., thermal control, torque curves, product contact materials), and an evidence-based scoring matrix to compare vendors on technical, commercial, and service dimensions.
-
Operational readiness and maintenance blueprint: Preventive and predictive maintenance schedules, recommended spare parts kits by equipment class, and a service-level agreement (SLA) playbook tailored to reduce mean time to repair in distributed manufacturing contexts.
-
Application mapping and specification templates: High‑level processing parameter sets for common industry applications (rubber, chemicals, food, battery pastes, etc.) to accelerate pilot testing and line qualification. Note: detailed segment allocations and confidential unit volumes are intentionally withheld from the public summary.
-
M&A and partnership radar: A shortlist of strategic deals and partnership types that can densify aftermarket networks, add adjacent technologies (e.g., inline coating and extrusion), or enter battery-materials workflows.
Strategic recommendations for 2026
-
For buyers (manufacturers and processors): Emphasize modularity and serviceability in specs. Where possible, negotiate outcome-based components of service contracts (uptime guarantees, spares pooling) to mitigate lead-time and tariff risks.
-
For equipment OEMs: Invest selectively in thermal management and process analytics to differentiate on performance for high‑value emerging segments such as battery materials. Expand localized aftermarket footprints in growth markets to capture service revenue streams.
-
For investors and corporate development teams: Target smaller regional specialists with strong aftermarket penetration and product differentiation as acquisition targets. The fragmented market profile offers roll-up economics if combined with a centralized service and parts platform.
-
For R&D and product teams: Prioritize energy efficiency, modular cooling solutions, and digital monitoring (torque, temperature, viscosity proxies) to win early tenders in battery and high‑viscosity chemical applications.
Recent market signals and near-term risks
-
Trade shows and factory visit programs in early 2026 continue to generate supplier‑buyer engagement, signaling healthy project pipelines in tire and rubber adjacent sectors.
-
Industry publications and vendor guides are increasingly referencing EV battery applications as a structural demand driver — companies should treat battery-related kneader specifications as a cross-functional requirement (R&D + procurement + quality).
-
Input-cost volatility (notably steel) and tariff shifts remain the most immediate margin risk. Practical mitigation includes design for steel efficiency, local sourcing, and contract clauses that allow limited cost pass-throughs.
Methodology and limitations
Our modeling is based on a bottom-up synthesis of historical demand (2020–2025), primary interviews with manufacturers and end users, and price and policy signals available through early 2026. The forecast period runs from 2026 to 2032 and reflects a central-case macro outlook. The public-facing executive highlights intentionally avoid granular regional and application-specific allocations — these are provided in detail within the full dataset and proprietary appendices.
Next steps and how to access the full intelligence
PW Consulting’s Worldwide Industrial Kneader Market report is designed to be immediately operational for 2026 planning cycles. For access to the full dataset, segmented demand matrices, vendor scorecards, and downloadable financial models that power our CAPEX and procurement playbooks, please visit the report landing page. The public summary serves as a strategic “trailer” — it demonstrates the rigor and practical orientation of our work while reserving the granular, permissioned datasets that corporate decision-makers rely on for transaction-level choices.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Kneader Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Toluic Acid Market Valued at USD 248.5 Million in 2025, Forecast to Reach USD 331.22 Million by 2032 at a 4.19% CAGR (2026–2032)
By PW Consulting, 2026-08-18
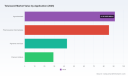
Worldwide Toluic Acid Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s new Worldwide Toluic Acid Market briefing offers an executive-grade preview of the structural shifts that will shape commercial strategy in 2026 and beyond. Our analysis synthesizes historical performance (2020–2025), a detailed outlook for 2026–2032, and scenario-driven playbooks that translate market intelligence into executable moves. The total market rose from USD 201.2 Million in 2020 to USD 248.5 Million in the base year 2025 and, under our central scenario, is expected to grow to roughly USD 331.2 Million by 2032 — a compound annual growth rate (CAGR) of approximately 4.19% over the forecast period. This note highlights how PW Consulting’s report equips executives to convert that macro trajectory into durable commercial advantage while intentionally withholding segment-level proprietary figures to preserve the full strategic value of the complete report.
Worldwide Metal Lathes Market
Why 2026 Is a Decision Inflection Point
-
Feedstock volatility is changing supply economics. Toluene — the primary upstream feedstock for industrial toluic acid production — showed marked price tightness in early 2026. PW Consulting’s market surveillance recorded Northeast Asia toluene at about USD 1,058/MT FOB in March 2026, and regional spot quotations in April 2026 around USD 1.08/kg in Northeast Asia and USD 1.06/kg in Europe, with recent regional uplifts in the high single- to low double-digit percent range. These moves materially affect operating margins for oxidation-based producers and shift the calculus for hedging, tolling and backward-integration decisions.
Worldwide Excavator Multi-Processors Market -
Regulatory scrutiny and trade classifications are tightening. Key toluic acid isomers are captured in major compliance frameworks — for example, m-toluic acid carries a specific U.S. HS subheading under aromatic monocarboxylic acid derivatives, and p-toluic acid is subject to TSCA listings and EU REACH requirements. Expect heightened documentation needs for cross-border flows and growing due diligence expectations from large downstream users in pharma and agrochemical supply chains.
16 Slice CT Scanner Market -
Consolidation and capacity reshuffling are accelerating. Recent transactional activity — notably a 2025 regional acquisition by Hanwha Chemical to bolster pharmaceutical intermediate capacity — signals a trend toward strategic bolt-on acquisitions and capacity consolidation in regions where premium-grade intermediates are in demand. Market concentration metrics show a moderate level of aggregation (CR3 and CR5 indicate that the top firms collectively control a meaningful but non-dominant portion of supply), creating both localized power centers and opportunities for nimble challengers.
What PW Consulting’s Report Delivers (Operationally Focused)
This report is designed as more than an industry summary — it is a toolkit for executives, procurement leads, and corporate development teams. Key practical deliverables include:
-
Top-line market model (2020–2032) with baseline, upside and downside scenarios and an interactive Excel workbook to stress-test price, demand and margin sensitivity.
-
Supply chain and cost-stack maps differentiating feedstock exposure, energy intensity, and logistics premiums by manufacturing archetype.
-
Regulatory and trade compliance matrix (TSCA, REACH, HS classifications and country-specific controls) with recommended documentation pathways for cross-border suppliers and buyers.
-
Commercial playbooks: supplier scorecards, negotiation scripts, contract structures (term vs. spot, indexation clauses tied to toluene), and an RFP template tailored for industrial and pharma-grade intermediates.
-
M&A and partnership toolkit: target screening criteria, valuation sensitivities to feedstock and purity premia, and integration risk checklists informed by recent transactions.
-
Operational checklists: quality & compliance KPIs for GMP and research-grade manufacturing, logistics continuity plans, and a capital-expenditure tracker for greenfield vs brownfield options.
Strategic Implications for Different Market Actors
-
Producers: Prioritize feedstock risk mitigation. With toluene price volatility feeding directly into cost of goods sold, producers should evaluate hedging programs, long-term offtake agreements with feedstock suppliers, and selective backward integration where feasible. Distinguish product portfolios by grade — premium pharmaceutical intermediates remain a value shield against commoditization.
-
Buyers and formulators: Move from transactional sourcing to strategic supplier partnerships. The current environment favors buyers who secure capacity through medium-term contracts that include price-indexation and quality-assurance clauses. Establish dual-sourcing in geographically diverse hubs to hedge supply-chain shocks.
-
Investors and M&A teams: Look for bolt-on targets that add regulatory-complaint, high-purity capacity or unique downstream access. The market’s concentration profile suggests room for value creation via consolidation in specific value pools rather than broad market domination.
-
Policy and compliance officers: Upgrade documentation and testing regimes to ensure REACH registration completeness and TSCA compliance, and to shorten approval lead times for new product lines in regulated markets.
Competitive Landscape — Snapshot (Companies You Need to Monitor)
The toluic acid supply base is a mix of regional specialists and global specialty suppliers. PW Consulting’s report profiles the leading firms, their operational footprints, and their strategic positioning:
-
Evergreensino Chemical Co., Ltd. (Dalian, China) — A vertically integrated Chinese manufacturer offering the three primary isomers and derivative intermediates with a focus on DEET and other industrial downstreams. Strengths: integrated oxidation know-how and regional logistics optimization.
-
Hefei TNJ Chemical Industry Co., Ltd. (Hefei, China) — Bulk supplier with industrial-scale m-toluic acid offerings and high-purity grades for intermediates. Strengths: scale manufacturing and competitive bulk pricing for commodity flows.
-
Kaival Chemicals Pvt. Ltd. (Vadodara/Ahmedabad, India) — GMP-certified producer targeting pharmaceutical and fragrance intermediates. Strengths: regulatory readiness and niche pharma interfaces.
-
Muby Chemicals (Mubychem Group) (India) — Export-oriented supplier of high-purity o- and p-isomers, with established logistics channels to global specialty markets. Strengths: export compliance and quality control for lab/industry use.
-
Ottokemi (Otto Chemie Pvt. Ltd.) (Mumbai, India) — OEM manufacturer supplying lab and industrial customers with high-purity grades and global shipping capabilities. Strengths: broad product catalogue and distribution reach.
-
Merck KGaA (via Sigma-Aldrich) (Darmstadt, Germany) — Global specialty supplier focused on research and analytical grades with rigorous quality controls. Strengths: brand trust in R&D and specialty markets.
-
Tokyo Chemical Industry Co., Ltd. (TCI) (Tokyo, Japan) — Supplier of laboratory to industrial grades with strong service offerings for research customers. Strengths: R&D channel and premium product support.
-
Triveni Chemicals / Triveni Interchem Pvt. Ltd. (Vapi/Gujarat, India) — Industrial supplier with a focus on domestic and regional industrial applications. Strengths: local market penetration and cost-efficient production.
Notable transactional signal: Hanwha Chemical’s February 2025 acquisition of a regional production facility underlines strategic moves to secure pharmaceutical-grade intermediates and align upstream capacity with downstream demand — a pattern likely to recur as firms pursue supply security over spot exposure.
Practical Next Steps for 2026
-
Run a 12–24 month procurement stress-test using our market model to quantify the EBITDA impact of different toluene-price trajectories and contract structures.
-
Audit top-tier suppliers for regulatory completeness (REACH dossiers, TSCA listings, GMP status) and integrate audit outcomes into a supplier risk-adjusted scoring model.
-
Evaluate selective capacity investments or tolling partnerships in regions where premium intermediate demand is insulated from commodity cyclicality.
-
Prepare an M&A shortlist of targets that can immediately add high-purity volumes or proprietary downstream channels, and run confidential valuations using our sensitivity templates.
Conclusion — How the Full Report Helps
PW Consulting’s Worldwide Toluic Acid Market report is a decision-focused product: it pairs quantified baseline and scenario forecasts (2026–2032) with the operational tools required to act — not just to know. We provide the empirical backbone (historical series and our 4.19% CAGR forecast), a regulatory and raw-material context (toluene price dynamics and compliance frameworks), and the playbooks buyers, sellers and investors need to deploy in 2026. To access full segment-level analytics, supplier scorecards, the interactive financial model, and transaction-grade diligence templates, please visit our report landing page or contact your PW Consulting representative for a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Toluicacid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Probiotic Ingredients for Animal Use Market to Expand at 8.21% CAGR, Reaching USD 2,631.81 Million by 2032
By PW Consulting, 2026-08-18
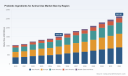
Worldwide Probiotic Ingredients for Animal Use Market — 2026 Strategic Outlook (PW Consulting)
As the animal nutrition industry accelerates its pivot away from antibiotic growth promoters and toward biological solutions, PW Consulting’s new market study — Worldwide Probiotic Ingredients for Animal Use — provides a timely, pragmatic playbook for commercial, R&D, regulatory and M&A decisions in 2026. Our base-year assessment finds the global market reached USD 1,515.9 Million in 2025 and, under the central scenario, is forecast to expand at a compound annual growth rate (CAGR) of 8.21% through 2032, reaching USD 2,631.8 Million by the end of the forecast horizon. These headline metrics underline both the scale and the investment momentum shaping supplier strategies, channel economics and upstream value chains over the next three to five years.
Worldwide Social Engineering Attack Defense Solution Market
Why this report matters for 2026 decision-making
-
Timing: 2026 marks an inflection in adoption curves — regulatory clarity in major markets and product innovations are turning probiotics from niche supplements into core feed ingredients for many production systems.
Worldwide Disc Grinder Market -
Risk management: With AGP restrictions entrenched as policy in multiple jurisdictions and strain‑level approvals becoming the norm, businesses must align product development, registration roadmaps and commercial trials to avoid market access surprises.
Worldwide E-Notary Software Market -
Capital allocation: The forecast trajectory and concentration dynamics call for refined capital deployment — whether building internal strain libraries, acquiring specialty producers, or scaling contract manufacturing to secure supply.
-
Go-to-market design: Channel economics and farm-level adoption drivers differ materially across animal categories. Fast followers and incumbents can extract margin through formulation, demo data and service‑based commercial models.
What the PW Consulting report delivers — practical, transaction-ready content
-
Transparent market sizing and multi-scenario forecasts to stress-test investment cases and pricing strategies for 2026–2032.
-
Actionable segmentation layers (ingredient family, animal application, and regional demand) mapped to commercial KPIs — presented with clear methodologies and reproducible assumptions. Note: detailed segment tables and raw datasets are included in the full report and are gated for subscribers.
-
Supply-chain and manufacturing heatmaps identifying technical pinch points (strain production, drying and QA bottlenecks, stability during feed processing) and supplier dependency matrices for procurement teams.
-
Regulatory tracker and dossier playbook: jurisdictional requirements, dossier templates and timelines for strain approvals and post-market surveillance obligations.
-
Commercial playbooks and trial design templates — from pilot farms to commercial step‑up — that shorten validation cycles and reduce execution risk for product launches.
-
M&A and partnership intelligence: validated target screening criteria, valuation sensitivities and integration checklists specific to probiotic ingredient businesses.
-
Competitor benchmarking and supplier scorecards integrating product portfolios, route-to-market strategies and recent innovation activity.
Market dynamics and technical drivers that will shape 2026 outcomes
-
Regulatory catalysts: Global restrictions on antibiotic growth promoters remain a primary adoption driver; recent regulatory activity — including EFSA evaluations of lactobacilli and bifidobacteria — is creating clearer pathways for product registration but increasing the emphasis on robust, strain‑specific efficacy data.
-
Technical survival and formulation: Feed processing (notably steam pelleting) remains a major technical constraint. Spore‑forming Bacillus strains repeatedly demonstrate superior survival through high-heat processes, which explains their prevalence in certain production systems. Commercial formulators must therefore align strain selection to processing and storage realities.
-
Performance proof as a commercial moat: Buyers increasingly procure on a risk‑adjusted basis — paying premiums for documented outcomes in feed conversion, pathogen mitigation and resilience under stress events. Standardized trial protocols and independent field data are becoming de facto commercial currency.
-
Concentration and competitive balance: The market shows a moderate level of concentration; leading groups collectively hold a meaningful share, but there remains material space for specialized entrants with novel strains, differentiated formulations (e.g., water‑soluble formats) or compelling service models.
Competitive landscape — who is shaping the market and how
-
Large, diversified ingredient houses (e.g., global specialty feed and ingredients groups) are integrating probiotics into broader animal nutrition portfolios to offer bundled solutions and secure distribution scale. These players leverage global supply chains and broad customer access.
-
Specialized microbial companies focus on strain development, formulation science and targeted applications — investing in dossiers and performance trials that underpin premium positioning. They are preferred partners for OEM feed formulators and specialty distributors.
-
Notable players profiled in the report include a mix of both archetypes: firms that emphasize proprietary Bacillus technologies and rapid‑action formats; global feed conglomerates that embed probiotics alongside enzymes and acids; and microbial specialists focusing on postbiotic and strain‑driven claims. Recent product activity — such as a major probiotic enhancement showcased late in 2025 and a multi-strain DFM launch mid‑2025 — signals intensified competition around faster onset of activity and robustness under production stress.
-
For executives evaluating partners or targets, our competitive profiles illuminate R&D pipelines, route-to-market strategies and IP positioning — enabling defensible commercial and M&A decisions in 2026.
Strategic implications and recommended priority actions for 2026
-
Prioritize strain portfolios that match processing realities: If your customers require pelleted feeds or high-temperature applications, give precedence to spore‑forming strains and invest in pelleting survivability testing.
-
Accelerate dossier-driven development: Build regulatory dossiers in parallel with efficacy trials to shorten time-to-market after positive performance signals. Consider pre-submission engagements with authorities in priority markets.
-
Design commercial pilots for rapid readouts: Standardize trial protocols to generate comparable KPIs (FCR, mortality, pathogen load, resilience under stress) that buyers and regulators recognize.
-
Use M&A selectively to acquire capability gaps: Targets that offer proven strains, manufacturing scale or market access can offer faster ROI than greenfield R&D — but insist on transparent, audited trial and stability data during diligence.
-
Differentiate on service and evidence: Companies that combine microbiology expertise with on-farm support and economics-of-use models will outcompete in procurement cycles that reward demonstrable ROI.
-
Secure supply continuity: Identify single‑source and high-risk nodes in your ingredient supply chain and develop contingency plans — tolling relationships, dual sourcing, or nearshoring where appropriate.
How commercial teams, R&D leaders and investors should use this report
-
Commercial leaders: Use the report’s demand-side scenarios and buyer segmentation to re-allocate sales resources, design pricing tiers, and negotiate value-based contracts tied to farm-level outcomes.
-
R&D and operations: Leverage our technical appendices and stability matrices to optimize strain selection, refine downstream processing and reduce manufacturing loss during pelleting and storage.
-
Regulatory and quality teams: Adopt the included dossier templates and submission timelines to accelerate approvals in priority jurisdictions while maintaining compliance with emerging strain‑specific requirements.
-
Investors and M&A teams: Apply our valuation sensitivity analyses and target scorecards to prioritize targets that fill capability gaps and to set realistic earn‑out milestones linked to commercial adoption.
PW Consulting’s Worldwide Probiotic Ingredients for Animal Use market study is intentionally designed as a decision‑ready resource for 2026. It combines transparent forecasts and market concentration analysis with practical execution tools — trial protocols, dossier templates, supply‑chain maps and competitor intelligence — to reduce uncertainty and speed project delivery. For readers seeking the full segmented datasets, regional and animal-type splits, and company-level financial implications, the detailed tables and proprietary models are available in the complete report and accompanying data package.
To discuss how the findings apply to your portfolio, bespoke scenario modeling, or a rapid commercial due diligence in support of an acquisition or product launch, PW Consulting’s industry team is available for advisory engagements that translate these insights into executable 90–180 day plans.
For detailed analysis of this topic, please visit the official page: Worldwide Probiotic Ingredients for Animal Use Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Hydrogel Bioink Market to More Than Double from USD 120 Million in 2025 to USD 291.18 Million by 2032 at a 13.5% CAGR
By PW Consulting, 2026-08-18
PW Consulting Strategic Brief: Worldwide Hydrogel Bioink Market — Actionable Intelligence for 2026 Decision-Making
Executive summary
Our new market study on the Worldwide Hydrogel Bioink Market arrives at a pivotal moment. After a rapid ramp from the low‑double‑digit millions in 2020 to USD 120.0 Million in 2025 (base year), the market is forecast to expand at a compound annual growth rate (CAGR) of 13.5% over the 2026–2032 horizon, reaching north of USD 290 Million by 2032 under the central scenario. This trajectory reflects accelerating adoption across tissue engineering, drug discovery and translational research, while exposing suppliers, developers and investors to a concentrated set of operational and regulatory inflection points that will define winners in 2026 and beyond.
Worldwide Job Boards Software Market
Why this report is a strategic asset for 2026
- Decision-ready intelligence: Our deliverable translates market growth projections into concrete, prioritized initiatives—R&D roadmaps, manufacturing scale plans, supply‑chain resilience programs and regulatory pathways—framed for calendar‑year 2026 execution.
- Risk calibration: We quantify exposure across the value chain—from raw material volatility and freight surcharges to evolving toxicology rules—and translate those into mitigation playbooks calibrated to three investment risk profiles.
- Competitive clarity without information overload: The study synthesizes public and proprietary intelligence into competitor profiles, capability matrices and scenario P&Ls, enabling rapid benchmarking and M&A screening without leaking the granular market allocations that live in the full dataset.
Market structure and concentration — what matters
The hydrogel bioink sector remains moderately fragmented: the top three suppliers account for roughly one‑third of the market and the top five less than half. This structure creates attractive pockets for specialized entrants and strategic investors, particularly where differentiated chemistry platforms or validated clinical use cases exist. Fragmentation also implies opportunities for consolidation in 2026 as larger players seek to accelerate vertical integration (formulation → biofabrication services → regulated product pipelines).
Worldwide Cloud Financial Planning and Analysis Solution Market
What the full report contains (practical, executable content)
- Forward-looking financial model: historic (2020–2025) P&Ls and a forecast spine (2026–2032) with sensitivity toggles for price shock, supply disruption and regulatory delay scenarios.
- Technology and formulation playbook: independent evaluation of natural, synthetic and hybrid hydrogel platforms, including handling/printability matrices, crosslinking strategies, cell‑compatibility tradeoffs and scale‑up constraints. Each technology is scored against manufacturability and translational readiness.
- Manufacturing and scale checklist: unit operations, QC specifications, recommended analytical assays, and a GMP readiness roadmap that prescribes minimum steps to move research‑use formulations toward clinical submission.
- Regulatory navigator: practical steps for 510(k) strategy in the U.S., EU compliance considerations (including restrictions on certain photoinitiators), and templates for biocompatibility testing pathways—critical for teams planning clinical translation in 2026.
- Supply‑chain risk register and procurement playbook: raw material sourcing maps, dual‑sourcing templates, contractual clauses to protect margin under price shocks, and logistics options (including the operational impact of recent temperature‑controlled freight surcharges).
- Commercial go‑to‑market (GTM) playbooks: differentiated value propositions for academic, pharma/biotech and clinical research customers, channel strategies (direct vs distributor), pricing architectures and sample-to-purchase conversion best practices.
- Competitive intelligence annex: concise profiles of the leading suppliers, product roadmaps, partnership footprints and recent strategic moves to inform M&A and alliance decisioning.
Competitive landscape — actionable takeaways
The market is populated by a mix of specialized bioink formulators, bioprinter platform providers and biotech firms pursuing proprietary biomaterials. Our analysis highlights several archetypes:
Liquid Form Cryogenic Hydrogen Storage System Market
- Platform formulators with deep chemistry IP and catalog breadth: These vendors maintain portfolios that span GelMA, alginate derivatives and hyaluronic‑based systems, emphasizing reproducibility and ease of integration with extrusion and light‑based printers.
- Specialist proprietary collagen and recombinant platforms: Firms leveraging recombinant human collagen or other bio‑engineered proteins are positioning for translational use cases where immunogenicity and human‑origin signals matter.
- Precision synthetic suppliers: Companies offering PEG‑based and thiol‑ene chemistries are differentiating on tunability and high‑resolution encapsulation, attractive for drug‑screening and organ‑on‑chip initiatives.
Key players profiled in the report (selected):
- Allevi Inc. (USA) — a focus on GelMA and stem‑cell‑oriented formulations; recent product updates emphasize enhanced crosslinking for improved cell retention and print fidelity.
- Bioink Solutions (USA) — modular, customizable formulations including collagen and alginate bases targeting translational research labs and service providers.
- BICO / Cellink (Sweden/Group) — a broad hydrogel portfolio designed for both extrusion and light‑based bioprinting; recent launches address printability for complex vascular models.
- CollPlant (Israel) — recombinant human collagen platform advancing toward clinical certification, including recent biocompatibility certification milestones.
- Gelomics (UK) — GelMA and synthetic hydrogel formulations tuned for high‑resolution applications.
- Prometheus Biosciences (BICO, Netherlands) — precision PEG hydrogels targeting defined cell encapsulation use cases.
- Advanced BioMatrix (USA) — hyaluronan‑ and thiol‑modified collagen kits that bridge 3D cell culture and early translational workflows.
Recent developments that should shape 2026 plays
- Product innovation continues: major groups launched improved ink series and crosslinking upgrades in 2024–2025, which accelerates adoption in complex tissue models and raises the bar for new entrants.
- Regulatory and certification milestones matter: ISO/biocompatibility certifications for recombinant collagen platforms reduce clinical translation friction and materially affect strategic valuation.
- Operational pressures persist: raw‑material supply constraints and price volatility have emerged as recurring supply risks; teams must embed procurement stress tests into product costing models now.
Industry dynamics and immediate risks
- Raw materials: Periodic supply disruption in algal feedstocks has driven double‑digit percentage increases in alginate pricing in recent cycles—an input‑cost risk that directly compresses margin if not hedged or passed through.
- Regulation: EU chemical restrictions have tightened the acceptable scope of certain photoinitiators; product teams should re‑test formulations for compliant alternatives to avoid market access delays.
- Reimbursement and device classification: U.S. guidance increasingly treats hydrogel bioinks used in clinical research as regulated device constructs with 510(k) expectations; preparing a regulatory dossier in 2026 is non‑negotiable for firms targeting clinical use.
- Logistics: New temperature‑controlled freight surcharges on transatlantic lanes materially change landed cost economics for cold‑chain bioinks and should be factored into distributor agreements and pricing models.
- Clinical translation guardrails: Materials marketed as “research use only” cannot be implanted without GMP conversion—an operational pivot that demands upfront investment if a commercial pathway to clinic is intended.
2026 playbook — recommended priorities for executives
- Short term (0–12 months): Harden supply chains (dual‑source critical biopolymers), prioritize formulation swaps for restricted chemistries, and complete GMP gap assessments for products intended for translational use.
- Medium term (12–24 months): Execute targeted product upgrades (printability + validated crosslinking paths), secure key certifications that accelerate clinical acceptance, and lock strategic partnerships with bioprinter OEMs and CROs.
- Capital and M&A posture: Pursue tuck‑ins that add either a validated raw material supply or a complementary chemistry platform; for investors, prioritize assets with demonstrable translational milestones and certification progress.
- Commercial moves: Reprice contract portfolios to reflect freight and input cost inflation, while introducing tiered product lines (research vs bridging/GMP) to capture both early‑stage and translational demand.
Scenario planning — three actionable frames for 2026 decision cycles
- Base case: Market follows the 13.5% CAGR, enabling moderate organic growth for incumbents with strengthened supply chains and regulatory readiness; prioritize certification and channel expansion.
- Downside (supply shock + regulatory delay): Double‑digit input inflation and a staggered approval environment compress margins and elongate time‑to‑revenue; shift to conservative inventory strategies and option‑based supplier contracts.
- Upside (rapid clinical adoption): Accelerated translational wins trigger premium pricing for validated bioinks and favor vertically integrated players; scale manufacturing capacity and expedite GMP conversions.
How to use this study in your 2026 planning
The report is built as an operational decision tool: use the financial model to stress‑test your product roadmap under the three scenarios, deploy the regulatory navigator to build a 510(k) timeline, and leverage the supplier matrix to reconfigure procurement. The full dataset contains granular regional and application splits, channel economics and per‑segment demand curves that are intentionally withheld from this brief to protect strategic confidentiality—these are available in the complete report for clients and subscribers.
About PW Consulting
PW Consulting provides strategic market intelligence and transaction support to life‑science technology firms and investors. Our hydrogel bioink study combines primary interviews, proprietary datasets and in‑house technical assessment to deliver executable guidance for 2026 decision cycles.
Call to action
For enterprise licenses, bespoke scenario workshops or to access the full dataset and annexes (including supplier tables, granular regional and application allocations, and the underlying financial model), contact our Worldwide Biofabrication practice or visit the PW Consulting report page for subscription details and executive briefing availability.
For detailed analysis of this topic, please visit the official page: Worldwide Hydrogel Bioink Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Auto-fill Humidification Chamber Market Poised for 6.45% CAGR Through 2032
By PW Consulting, 2026-08-18
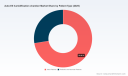
Worldwide Auto-fill Humidification Chamber Market: Strategic Preview for 2026 Decisions
PW Consulting’s latest market intelligence on the Worldwide Auto-fill Humidification Chamber market is released as an executive-grade briefing designed to inform strategic choices through 2026 and beyond. This preview summarizes the strategic implications of our full 2025-base-year study (historical 2020–2025; forecast 2026–2032), highlights regulatory and commercial inflection points, and teases the practical tools and frameworks in the full report that senior leaders will use to convert insight into action.
Intelligent Ultrasonic Bird Repellent Market
Market trajectory and what it means for 2026 planning
The global market for auto-fill humidification chambers has moved from a modest medical-supplies category into a core respiratory-support adjunct with sustained commercial momentum. Our topline sizing shows growth from roughly USD 475 million in 2020 to about USD 642 million in 2025, and a projected rise toward approximately USD 994 million by 2032 — an implied compound annual growth rate of 6.45% across the forecast window. That trajectory reflects interacting demand drivers: expanded respiratory therapy outside acute care, increased adoption of heated-humidifier-based ventilation protocols, rising standards for infection control, and vendor-led innovation around compatibility and automated fluid management.
Worldwide Polypropylene (PP) Lined Pipes Market
For decision makers in 2026, the headline implications are straightforward: this is not a stagnant consumables line — it is a mid-growth medical supply market with margins, regulatory constraints, and consolidation dynamics that reward early clarity on channel, product differentiation, and regulatory timing.
Worldwide Oxidized PAN Fiber Market
Why PW Consulting’s 2026 lens matters
- Decision-focused analysis: We translate market sizing and scenario forecasts into practical decision levers — from procurement cadence for large hospital systems to product launch pacing for device OEMs.
- Regulatory and reimbursement clarity: The report synthesizes device-class pathways, typical 510(k) considerations for the US, and reimbursement levers that affect purchasing economics (including commonly referenced HCPCS billing approaches).
- Commercial playbooks: We provide vendor scorecards, channel strategies, and tender-response templates that procurement and BD teams can use immediately to improve win rates.
- M&A and partnership diagnostics: For corporate development teams, the study includes target-screening criteria, valuation sensitivities tied to recurring consumables revenue, and integration red flags unique to sterile single-use respiratory adjuncts.
Competitive landscape — concentrated but active
The auto-fill humidification chamber market is commercially concentrated, with a narrow set of established respiratory-device suppliers dominating supply relationships with large hospital systems and ICU OEMs. Our concentration metrics underscore a market where the top three players hold the majority of market share and the top five capture most of the rest. This concentration accelerates the importance of compatibility claims, regulatory track records, sterile manufacturing capacity, and established distribution networks.
Key vendors profiled in the full report (selected highlights below) include manufacturers with proven product families, clearance histories, and global supply footprints — each offering different routes to market and partnership opportunity:
- Fisher & Paykel Healthcare (Auckland, New Zealand) — Well-known for the MR290 series and integration across MR-series humidifiers and myAirvo systems. Their dual-float auto-refill mechanism and overfill prevention features are positioned for both adult and pediatric ventilation applications. ( https://www.fphcare.com)
- Intersurgical (Wokingham, United Kingdom) — Offers dual-float autofill chambers with sterile variants and fill set compatibility for a broad range of heated humidifiers used across ICU and CPAP to full mechanical ventilation modes. ( https://www.intersurgical.com)
- Flexicare (Mountain Ash, United Kingdom) — Markets sterile and double-valve variants for BiPAP use, emphasizing low water volume for faster warm-up and compatibility with heated-wire systems. ( https://flexicare.com)
- GaleMed Corporation (Taiwan) — Produces the Humi.AIDE™ family with neonatal and adult models; notable for mechanisms that permit sterile water refill without interrupting ventilation. ( https://www.galemed.com)
- Vadi Medical Technology (Taoyuan City, Taiwan) — Offers both disposable and reusable auto-feed systems compatible with major humidifier brands, addressing cost-sensitive and high-utilization settings. ( https://www.vadi-medical.com)
- Yaxin Medical (Suzhou, China) — Focuses on disposable chambers engineered for ICU ventilator compatibility and standardized connector interfaces, optimized for scale manufacturing. ( https://www.yaxinmed.com)
- Vyaire Medical (AirLife) (Mettawa, Illinois, USA) — Sells AirLife autofill chambers as part of integrated heated humidifier solutions and has pursued regulatory filings emphasizing prior technology predicates. ( https://www.vyaire.com)
Recent regulatory milestones — such as FDA clearances and 510(k) submissions — are shaping competitive positioning. Notable examples include a 2022 FDA clearance for a major supplier’s NIV/NHF circuit kit that referenced autofill chamber functionality, and a 2023 510(k) submission by another leading vendor referencing legacy autofill technology. These actions emphasize that 510(k) strategy and predicate selection remain central to US market access planning.
Regulatory, clinical and supply dynamics that will shape 2026 outcomes
- Device classification and pathways: Auto-fill humidification chambers are generally regulated as accessories under respiratory gas humidifier device classifications (US CFR pathways), which means most commercial contestants pursue the 510(k) route where predicate selection, bench testing of fluid-handling safety, and documentation of sterility claims are decisive.
- Infection control and single-use norms: Clinical guidance and manufacturer instructions strongly favor single-patient disposable use to avoid cross-contamination — a behavior that supports recurring consumables revenue while forcing logistics and waste-management optimization in hospitals.
- Materials and sterilization: Clear polycarbonate constructions in sterile packaging are the de facto market standard. Product differentiation therefore often comes from functional elements (dual floats, overfill protection, low-volume warm-up designs) and documented compatibility with heated-wire breathing circuits.
- Reimbursement levers: In certain jurisdictions, humidification supplies are billed through miscellaneous DME supply codes — a factor that influences hospital procurement policies and group purchasing negotiations.
- Supply chain resilience: For 2026, sourcing flexibility for sterile injection molding, validated assembly, and logistics for sterile single-use products will be a competitive differentiator, particularly under surge scenarios and in regions where import constraints persist.
What the full report contains — operationally actionable elements
Beyond top-line market modeling, the report is structured to be used at the working-table level by product, commercial, regulatory, and M&A teams. Core deliverables include:
- Detailed methodology, assumptions, and base-year (2025) dataset in USD (Millions) and scenario variants through 2032.
- Primary-research intelligence: interview excerpts with procurement leads, respiratory therapists, and OEM clinical engineers to validate real-world use patterns and procurement constraints.
- Vendor scorecards and a reproducible vendor-selection matrix that weighs compatibility, sterile manufacturing capacity, regulatory status, and commercial terms.
- Channel economics and sample tender terms (GPO playbook) to accelerate negotiations in 2026 procurement cycles.
- Regulatory playbooks for 510(k) strategy, bench testing templates, and a timeline for filings aligned with product development milestones.
- M&A diagnostics including target screening filters, integration risk checklists, and revenue-synergy modeling templates tied to consumables attachment rates.
- Risk register and mitigation playbook covering supply interruption, adverse-event reporting pathways, and recall readiness.
Practical recommendations for leaders planning in 2026
Translate the market movement and regulatory context into clear near-term actions:
- Prioritize compatibility-first product development: ensure new chamber designs validate heated-wire and common humidifier-system interfaces early to shorten hospital adoption cycles.
- Lock in sterile manufacturing partners with capacity buffers and validated processes to avoid single-source exposure.
- Map procurement calendar windows for large public health systems and GPOs — aligning tender-ready product dossiers with these windows materially improves win probability.
- For market entrants, consider niche neonatal or home-health variants with compelling clinical evidence to avoid head-to-head competition in the core ICU consumables segment.
- For incumbents, explore bundling strategies (humidifier + autofill chamber) to protect attachment rates and blunt third-party disposable encroachment.
- Regulatory teams should prioritize predicate analysis and bench-test plans now to de-risk US market clearance timelines through 2026.
- Corporate development should use the vendor scorecard in the full report to triage acquisition targets that immediately improve sterile manufacturing footprint or channel reach.
How to use this preview
This briefing is a strategic “trailer” — it surfaces the core trends, regulatory context, competitor dynamics, and the specific decision playbooks that will matter in 2026. The full PW Consulting report contains the detailed segment tables, pricing curves, vendor scorecards, raw interview excerpts, and downloadable tender templates that procurement, product, regulatory, and corporate development teams will need to operationalize the recommendations summarized here.
To access the full dataset, including segment-level analysis, region and end-user breakouts, and the complete vendor benchmarking, please consult the PW Consulting report page. Our team is available to run bespoke workshops that translate the report’s models into 90–180 day action plans tailored to your organization’s role in the ecosystem — OEM, distributor, hospital system, or private-equity sponsor.
Contact PW Consulting for access and to schedule a strategic briefing that aligns the report’s insights with your 2026 investment and market-entry calendar.
For detailed analysis of this topic, please visit the official page: Worldwide Auto-fill humidification chamber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Solvent-based Organoclay Market to Reach USD 1,020.15 Million by 2032 on a 4.75% CAGR
By PW Consulting, 2026-08-18
Worldwide Solvent-based Organoclay Market: Strategic Signals for 2026 Decision-Makers
PW Consulting’s new market study on the worldwide solvent-based organoclay market synthesizes seven years of historical performance and a forward-looking forecast (2026–2032) to deliver actionable guidance for commercial, technical, and M&A leaders preparing for 2026. The sector is entering a measured expansion phase: after recovering from mid-cycle volatility, total market value expanded from the mid-2020s base and reached approximately USD 737.6 Million in our 2025 baseline. Under the central scenario the market is projected to grow at a compound annual growth rate (CAGR) of 4.75% across 2026–2032, trending toward a market size just above USD 1.02 Billion by 2032. These macro dynamics—and the structural forces that underlie them—shape a narrow window of strategic choices for the coming 18–30 months.
Small Popcorn Machine Market
Why 2026 Is a Strategic Inflection Point
-
From stabilization to selective acceleration: The period through 2025 shows a market that has absorbed raw-material interruptions and demand swings across paints, coatings and oilfield services. The 2026–2032 trajectory implies steady, not explosive, demand growth—favoring companies that can convert mid-single-digit CAGR into margin expansion through product differentiation, channel optimization, and operational efficiency.
Worldwide Time Series Databases Software Market -
Concentration-driven opportunities: Market concentration is meaningful but not prohibitive—leading suppliers consolidate significant share while a diverse group of regional players remains competitive on cost, specialty grades and local service. This structure rewards both scale (for R&D and global distribution) and nimbleness (for tailored formulations in regional end-markets).
Electric Vehicle Graphene Battery Market -
Regulatory and raw-material regime shifts: Compliance with REACH-type requirements and tighter environmental oversight, combined with reliance on montmorillonite (bentonite) and quaternary ammonium modification chemistries, makes supply-chain control and technical-compliance capability strategic assets.
Core Strategic Questions for 2026
-
How should producers allocate R&D and CapEx between low-cost commodity grades and premium, application-specific organoclays (e.g., thixotropic, anti-settling, or low-polarity-optimized chemistries)?
-
What is the optimal near-term M&A posture—bolt-on specialty grades, regional distribution networks, or upstream bentonite assets that secure feedstock and quality control?
-
How will formulators and end-users hedge compliance and supply risk while maintaining formulation performance and cost targets?
What Our Report Delivers (Practical, Executable Outputs)
-
Scenario-based demand modelling: A primary forecast that maps baseline, upside, and downside cases for 2026–2032, enabling procurement and sales leaders to stress-test budgets and inventory strategies against macro and sectoral shocks.
-
Supplier & capability matrix: A panoramic assessment of global and regional manufacturers, mapped by technical capabilities (e.g., low vs. high polarity optimization, easy-dispersible vs. pre-gel technology), production footprint, and vertical integration level—designed to support sourcing decisions and supplier segmentation.
-
Regulatory compliance playbook: Practical guidance on aligning organoclay grades and manufacturing processes with REACH and EPA-like frameworks, including recommended monitoring metrics and incremental formulation shifts that reduce regulatory exposure without sacrificing performance.
-
Raw-material risk and pricing outlook: A structured assessment of montmorillonite supply dynamics, the effect of mine-level integration on cost and quality, and scenarios for near-term input-price volatility that inform contract length and pass-through strategies.
-
Commercial and product strategies: Go-to-market recommendations for distributors, co-packers and producers—including SKU rationalization, premiumization levers, and channel-specific packaging/technical-support models that improve sell-through in paint, coatings and industrial end-uses.
-
Financial benchmarking and M&A due diligence templates: Standardized models to evaluate target economics, synergies, and integration risk—tailored to organoclay’s mix of commodity and specialty revenue streams.
Competitive Landscape: Who Matters—and Why
The market’s competitive structure blends global specialty chemical players, vertically-integrated miners, and regional manufacturers focused on export and import-substitution. Understanding each archetype clarifies where transaction and partnership value will appear in 2026.
-
Vertically integrated manufacturers —those that own bentonite sources and control modification processes—enjoy advantages in cost control, quality consistency, and the ability to develop grade families targeted at different solvent polarity windows. These players are well positioned to protect margins when feedstock availability tightens and are attractive partners for formulators seeking secure supply.
-
Global specialty suppliers leverage brand, technical-service reach, and a portfolio approach: they can bundle organoclays with additive systems, provide global technical support for OEMs, and rapidly commercialize novel hectorite versus bentonite chemistries. Their scale supports multi-market R&D investments.
-
Regional innovators and cost competitors capture value by aligning to local supply chains, offering fast lead times, and competing on price for standard grades. They are often the first choice for cost-sensitive formulators or local manufacturers seeking import substitution.
Key industry players exemplify these archetypes and highlight strategic priorities for 2026:
-
Manufacturers with owned bentonite deposits and ISO-aligned processes demonstrate the economics and risk mitigation of vertical integration; such companies typically emphasize grade consistency and supply security.
-
Large specialty chemical suppliers focus on product-development depth—offering both bentonite- and hectorite-based grades, and positioning brands as problem-solving partners for thixotropy and anti-settling performance.
-
Regional producers show the market’s capacity for decentralized competition: lower-cost grades and export-focused strategies remain significant in many end-markets, particularly where proximity to coatings and drilling customers matters.
Market Dynamics That Will Drive Outcomes in 2026
-
Feedstock quality and sourcing: Montmorillonite commodity characteristics create a technical hurdle—small differences in clay mineralogy can materially affect organoclay performance after quaternary-ammonium treatment. Control of feedstock, either through ownership or long-term partnerships, reduces supply and quality risk.
-
Product differentiation through formulation science: The continuing shift toward easy-dispersible grades and performance-tuned chemistries increases the value of application R&D. Suppliers who can translate lab-scale rheology improvements into plant-level performance gains will capture premium pricing.
-
Regulatory and sustainability pressures: Compliance considerations—especially for export to regulated markets—are already shaping product portfolios. The most commercially successful firms will combine compliance with clear claims around lifecycle performance and handling safety.
-
Channel and end-market evolution: Demand patterns in paints & coatings, drilling fluids, greases, and inks will diverge by region and application. Suppliers that align go-to-market models to the commercial cadence of each channel secure conversion and stickier contracts.
Recommended 90–180 Day Roadmap for 2026 Planning
-
Immediate (30–60 days): Conduct an internal SKU and margin audit to identify commodity versus specialty revenue, and begin supplier scorecarding against quality, delivery, and regulatory compliance metrics.
-
Near-term (60–120 days): Stress-test contracts and inventory policies against the report’s baseline and downside scenarios; initiate technical trials with at least two alternative organoclay suppliers for critical formulations.
-
Medium-term (120–180 days): Finalize a portfolio strategy (e.g., premiumization vs. cost leadership) and align CapEx or M&A priorities—evaluate targets that add feedstock control, complementary grade technology, or market access.
How to Use This Study
This report is intended as a decision-enabling toolkit for commercial and technical executives. It is not a descriptive catalog: it blends market-sizing certainty with scenario-driven guidance and tactical templates so that procurement, R&D, and corporate development teams can plan for 2026 with clarity. To preserve competitive advantage for our clients we present deep supplier and SKU-level intelligence inside the full report; the public summary intentionally omits granular split tables and detailed regional/application percentages to protect proprietary market structures and drive direct engagement for customized deliverables.
For executives preparing budgets, negotiating supplier contracts, evaluating M&A targets, or reconfiguring product portfolios for compliance and performance, PW Consulting’s Worldwide Solvent-based Organoclay Market study converts market signals into executable next steps for 2026. For access to the full dataset, detailed supplier profiles, and our custom scenario models, visit the PW Consulting report page or contact our sector team for a briefing tailored to your strategic horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Solvent-based Organoclay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Riding Floor Scraper Market Poised for a 5.82% CAGR During 2026–2032
By PW Consulting, 2026-08-18
Worldwide Riding Floor Scraper Market — Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s new market study on the Worldwide Riding Floor Scraper Market synthesizes primary interviews, OEM product-level analysis, and a validated forecasting model to deliver the strategic intelligence that equipment manufacturers, rental fleets, large contractors, and private equity investors need to act with conviction in 2026. The market reached USD 332.45 Million in 2025 and is projected to expand at a compound annual growth rate of 5.82% through our 2026–2032 forecast window, reflecting a predictable but evolving demand profile shaped by productivity pressures, emissions-driven equipment choices, and material supply dynamics.
Worldwide Vibraphones Market
Why this market matters in 2026
-
Operational leverage in renovation and industrial surface-preparation projects. Mechanized ride-on scrapers materially reduce site labor hours and schedule risk on high-intensity flooring-removal tasks—an increasingly valuable attribute in the face of persistent trades labor shortages and rising wage baselines.
Worldwide Reservoir Analysis Market -
Regulatory and ESG tailwinds accelerating technology substitution. Occupational health and indoor air quality considerations—together with local emission regulations—are tilting demand toward battery and low-emission equipment for confined commercial and institutional environments.
Short Drama Promotion Authorization Platform Market -
Supply-chain and raw-material sensitivity. The segment’s core consumable—carbon and hardened steel scraper blades—and structural steel inputs create observable exposure to raw-material cost inflation and sourcing volatility (global steel benchmarks, for example, were trading at 3,103 CNY/T in early April 2026), which in turn affects OEM margin engineering, spare parts pricing, and aftermarket service economics.
-
Consolidation potential coexists with segmented demand. Market concentration metrics highlight a mid-market dominated by a handful of global and regional specialists (the top three players account for just over 40% of the market; the top five approach 60%), but significant whitespace remains for targeted product and channel strategies.
Core report deliverables — actionable, not academic
PW Consulting structured the analysis to be operationally useful for executives making 2026 capital and product decisions. Key components include:
-
Robust market-sizing and scenario-driven forecasting: transparent base-year calibration (2025) and a detailed 2026–2032 projection suite with upside/downside scenarios tied to labor-cost trajectories, steel-price shocks, and regulation-driven product substitution.
-
Go-to-market playbooks for OEMs and distributors: channel segmentation, rental-vs-sale decision frameworks, and a prioritized set of customer archetypes for early adoption of battery-powered scrapers.
-
Comprehensive competitive dossiers: strategic and product-level profiles for the principal market participants (including Bartell Global’s Terminator line, National Flooring Equipment’s broad model range, Onsite Equipment Manufacturing’s Workhorse products and recent battery-model launches, OEM Products Inc.’s hydrostatic/zero-turn line, and Husqvarna Construction’s professional-grade options). Each dossier contains capability maps, manufacturing footprints, recent product moves, and implications for partner or competitor strategies.
-
Practical commercial tools: total-cost-of-ownership (TCO) calculators with configurable inputs for utilization, fuel/energy costs, blade wear rates, and labor savings; procurement negotiation templates; spare-parts service-level agreements; and operator-safety and indoor-air-quality compliance checklists.
-
M&A and investment intelligence: target screening criteria tuned to market concentration dynamics, integration risk matrices, and post-acquisition value-capture playbooks for adding scale in distribution, rental fleets, or adjacent surface-preparation portfolios.
Competitive landscape — who to watch and why
The universe of ride-on floor scraper suppliers combines long-tenured specialists and global construction-equipment incumbents. Our report does not simply catalogue product SKUs; it assesses defensibility and go-forward options across three dimensions: product modularity (battery retrofits, attachments), manufacturing and supply resilience, and channel depth (OEM-direct vs dealer vs rental networks).
-
Bartell Global (Innovatech) — The originator of the Terminator platform remains an innovation anchor. Its multi-fuel approach and legacy installed base create aftermarket and retrofit opportunities, but sustained competitiveness will depend on quicker roll-out of high-cycle battery platforms and telematics.
-
National Flooring Equipment — A broad portfolio and distribution footprint make this player central to contractor buying patterns. Portfolio breadth is a strength for channel control, with implications for price architecture and spare-parts logistics.
-
Onsite Equipment Manufacturing (Workhorse) — Workhorse’s patent-backed mechanical design and recent moves into Lithium-Ion battery models (notably the 500e announced in October 2025) signal the kind of product innovation that pressures legacy propane and corded-electric incumbents to accelerate electrification roadmaps.
-
OEM Products Inc. — The company’s hydrostatic-drive, zero-turn platforms and the latest ultra-efficient battery models position it well for applications that require heavy-duty performance with low operational emissions.
-
Husqvarna Construction — As a large global player, Husqvarna’s product reliability standards and channel scale matter most in institutional and large infrastructure projects where single-vendor procurement and global service consistency are decisive.
Strategic implications and recommended moves for 2026
Executives who use the report as a decisioning tool will be able to translate market signals into concrete 12–24 month actions. Our recommendations are pragmatic and prioritized by expected ROI and execution complexity:
-
Prioritize battery and low-emission product programs for institutional and indoor commercial channels. Given tightening QA regulations around indoor air and operator exposure, early-bird advantages accrue to OEMs that can demonstrate lifecycle cost parity and clear emissions credentials.
-
Design retrofitability and attachment ecosystems. For manufacturers, creating bolt-on electrification kits or universal attachment platforms accelerates fleet migration without requiring customers to replace entire machines.
-
Embed TCO and utilization telemetry into product offerings. Fleets and rental houses prefer machines that provide utilization data and predictive maintenance alerts; these features unlock higher utilization rates and secondary-market value.
-
Hedge raw-material exposure with procurement strategies. Steel-price sensitivity affects blade replacement margins and unit economics; multi-sourcing and hedging contracts should be part of commercial planning for 2026 CAPEX cycles.
-
Align product and channel incentives around service and refurbishment. On-the-ground advantages accrue to organizations that bundle operator training, consumables, and refurbishment services, turning a hardware sale into a predictable annuity.
-
Consider inorganic options to capture distribution or rental scale. With the top-five firms collectively holding a significant share but meaningful niche demand remaining fragmented, bolt-on acquisitions in regional distribution or rental assets can be an efficient path to scale.
Evidence-based sensitivity analysis — what keeps margins and adoption rates fluid
PW Consulting’s scenario work isolates three high-impact variables for 2026 decisions: steel and consumable blade pricing, local labor-cost inflation, and the pace of emission-driven product substitution. Each variable influences adoption and pricing differently—high labor inflation increases total cost savings from mechanization, whereas spikes in steel prices raise short-term OEM input costs and accelerate aftermarket blade-price sensitivity. Our model provides stress-tested outcomes so CFOs and product leaders can quantify the trade-offs of accelerating battery programs versus protecting margins.
What this briefing omits (and where to get it)
This newsroom-style summary highlights the strategic takeaways and practical frameworks executives need to prioritize in 2026. In keeping with our “teaser” approach, we are intentionally withholding the granular regional, application, and power-source revenue splits and other proprietary tables that underpin our forecasts. Those detailed segmentations—plus model-level unit economics and dealer-level channel share matrices—are available in the full PW Consulting report and accompanying data workbook.
For decision-makers who require executable insight—budget-ready three-year product roadmaps, procurement negotiation playbooks, and M&A screening lists—PW Consulting’s full deliverable turns market projection into operational execution. Contact PW Consulting or visit our Worldwide Riding Floor Scraper Market report page to request an executive briefing and a sample of the data workbook.
For detailed analysis of this topic, please visit the official page: Worldwide Riding Floor Scraper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


