



Category: market research
PW Consulting: Worldwide Ultra Long Endurance UAV Market Set to Expand at a 12.15% CAGR During 2026–2032
By PW Consulting, 2026-08-12
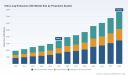
Worldwide Ultra Long Endurance UAV Market — Strategic Insights for 2026 Decision‑Makers
PW Consulting’s new market study on Worldwide Ultra Long Endurance (ULE) Unmanned Aerial Vehicles (UAVs) synthesizes macro trajectories, technology inflection points, competitive dynamics and regulatory catalysts to inform capital allocation and go‑to‑market strategies in 2026. The market has accelerated from a multi‑hundred‑million dollar niche in 2020 to a mature multi‑billion dollar industry by 2025, and is forecast to continue expanding at a compound annual growth rate (CAGR) of 12.15% through 2032 — reaching roughly 7.7 billion USD by the end of the forecast period. That growth and the structural shifts behind it make 2026 a pivotal year for product roadmaps, industrial partnerships and capability investments.
Worldwide IP Geolocation Software Market
Why 2026 is a Strategic Inflection Point
Three concurrent dynamics converge in 2026 to create unique strategic opportunities and hazards for suppliers, operators and investors:
Heavy Duty Bariatric Beds Market
- Technology maturation: breakthroughs in energy storage, silicon‑anode batteries, lightweight composites and hydrogen fuel cells are translating into demonstrable, mission‑scale endurance records and commercial prototypes.
- Operational validation: several high‑profile flight campaigns and mission‑representative tests have moved long‑endurance concepts from lab to operational proof points, enabling commercialization conversations with national authorities and large service customers.
- Regulatory and market enablement: targeted type approvals and national service pilots are clearing the path for commercial service offers at stratospheric and high‑altitude layers, creating addressable markets outside traditional defense procurement cycles.
For executives planning 2026 budgets, this combination means decisions will have asymmetric outcomes: timely investments in the right propulsion, autonomy and payload integration platforms can secure multi‑year revenue streams, while late entrants risk being consigned to low‑margin retrofit or niche roles.
Worldwide Signal Conditioners Market
Market Trajectory: What the Numbers Tell Us
The ULE UAV market’s expansion is not linear; it reflects technology stacking and diverse value pools — from persistent ISR to communications relay and environmental sensing. Our top‑level model shows a compound expansion consistent with significant reinvestment across product classes, with year‑on‑year acceleration as HAPS, solar‑electric and hybrid propulsion systems scale. Market concentration metrics indicate that while a handful of incumbents hold influential positions, the ecosystem remains open to technology disruptors and vertically integrated service providers: the CR3 sits in the low‑forties and the CR5 in the low‑sixties, signaling meaningful leader advantage without insurmountable barriers to entry for differentiated offers.
Competitive Landscape: Positioning and Recent Proof Points
The competitive map is heterogeneous — spanning boutique endurance specialists, legacy defense primes and emerging commercial HAPS players. Key strategic observations:
- Specialist endurance OEMs are demonstrating operational breakthroughs. Platform Aerospace and DZYNE Technologies have delivered record‑setting endurance tests for Group 3 and Group 5 classes respectively, validating both the tactical persistence model and the viability of higher‑altitude, long‑range missions.
- HAPS and solar‑electric entrants are shifting the perimeter of the addressable market. AALTO HAPS (Airbus subsidiary) and Skydweller Aero have executed sustained stratospheric and prolonged solar‑electric flights that materially change assumptions about persistent connectivity and continental coverage models.
- Defense primes and established UAV manufacturers remain relevant through systems integration, certification experience and scale for complex payload and strike‑capable platforms. Their strength is in program delivery and customer relationships, not always in technology novelty.
- Tactical long‑endurance players continue to innovate in payload modularity and affordability, securing opportunities in maritime patrol, border security and commercial services where rapid deployment and operational cost matter.
Recent industry milestones captured in the research are important decision inputs for 2026 plans: DZYNE’s 60‑hour Group 5 mission‑representative flight at 25,000 ft (Feb 2026) sets a new benchmark for persistent ISR at that class; AALTO’s Zephyr achievements (including multi‑week/67‑day stratospheric flights tested in 2025) underpin imminent commercial HAPS service offers; Skydweller’s multi‑day solar‑electric demonstrations with naval partners highlight maritime ISR and communications roles. These events collectively validate multiple commercial and defense use cases that were previously theoretical.
Technology and Supply‑Chain Dynamics
Decisions about propulsion and structural architectures will dominate R&D and procurement debates in 2026. While internal combustion platforms remain attractive for certain payload and endurance cost tradeoffs, solar‑electric and hydrogen fuel‑cell hybrids are moving rapidly from experimental to operational as battery energy density and composite manufacturing scale. Materials and supplier risk are non‑trivial: large solar‑wing platforms rely on advanced carbon‑fibre composites, and high‑energy batteries depend on specialized cell chemistries. Our report maps supplier concentration, critical raw material exposure and second‑source strategies so firms can de‑risk multi‑year production plans.
Regulatory and Commercialization Pathways
Regulatory milestones are unlocking commercial models. Type approval campaigns and national HAPS trials — some targeting service introductions from 2026 — mean companies must be ready not only with flying prototypes but with operations, spectrum coordination and service level agreements. For 2026, executives should treat regulatory engagement and standards participation as core to product roadmaps rather than optional advocacy.
How PW Consulting’s Report Converts Insight into Action
Our study is designed as a practical playbook for 2026 decision cycles. Core deliverables and tools included in the report are:
- Top‑level market sizing and validated forecasts (2020–2032) with scenario variants tied to regulatory timelines and technology adoption curves.
- Commercial readiness indices for propulsion families and altitude classes to prioritize near‑term R&D and partnership investments.
- Company benchmarking matrices and capability maps that identify where incumbents hold durable advantages and where disruptive entrants can exploit gaps.
- Go‑to‑market playbooks for defense programs, telecom connectivity services, maritime and environmental customers — including contracting archetypes, pricing levers and SLAs for endurance‑based services.
- Decision frameworks for make/buy/partner choices, with financial templates that stress‑test capital intensity, operating cost per flight‑hour and time‑to‑revenue under multiple commercialization timetables.
- M&A and partnership scouting lists with shortlists of target archetypes (technology owners, systems integrators, service operators) and valuation heuristics tuned for the endurance market.
- Risk registers and mitigation plans covering supply chain, certification, spectrum contention and mission safety, plus recommended governance for program delivery in multi‑stakeholder environments.
We deliberately present the high‑level outcomes here while the report itself contains the full segmentation tables, granular regional and application breakouts, and downloadable financial models that enable forensic stress‑testing of in‑house assumptions. This release follows our “trailer” approach: present decisive insights to inform immediate planning while directing stakeholders to the full dataset for execution‑grade decisions.
Actionable Recommendations for 2026
Executives and investors should consider the following priority actions this year:
- Prioritize modular payload architectures and open interfaces — endurance advantages compound when payloads can be rapidly swapped without airframe redesign.
- Accelerate partnerships on energy‑system technologies (battery, fuel‑cell, solar arrays) to secure preferential supply and co‑develop application‑specific power management solutions.
- Engage early with regulators and national pilots where HAPS or stratospheric services are being trialed; regulatory seat‑time translates directly into market access advantages.
- Run live operational pilots with end customers (defense, telco, maritime) in 2026 to validate lifecycle OPEX and to collect the operational telemetry required for insurance and certification.
- Include concentration metrics and market share scenarios in strategic planning — targets and partnerships should reflect the moderate leader advantage seen across the industry rather than assuming winner‑takes‑all dynamics.
Conclusion — Use This Moment Wisely
ULE UAVs are transitioning from a technology frontier into a commercially material industry segment. The combination of improving energy systems, successful flight validations, and near‑term regulatory openings creates a window in 2026 where bold, well‑timed decisions can secure durable market positions. PW Consulting’s report equips leaders with the market intelligence, operational templates and risk frameworks necessary to convert technological promise into sustainable business performance. For those preparing budgets, procurement plans or M&A strategies this year, the strategic choices made in 2026 will set the competitive map for the remainder of the decade.
Accessing the Full Intelligence
This press summary highlights the strategic implications and programmatic actions our clients are using in 2026. The full report contains the detailed segmentations, company scorecards, and model workbooks necessary for transaction diligence and product planning. To access the complete dataset, scenario models and company benchmarking, please visit the PW Consulting report page (Worldwide Ultra Long Endurance UAV Market) or contact our advisory desk for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Ultra Long Endurance UAV Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Valeryl Chloride Market to Reach USD 105.45 Million by 2032 at a 5.15% CAGR; Asia‑Pacific Commands 38.5% as Pharmaceutical Intermediates Drive Growth
By PW Consulting, 2026-08-12
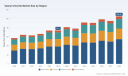
Worldwide Valeryl Chloride Market — Strategic Outlook for 2026: A PW Consulting Intelligence Brief
As companies prepare capital allocation and supply-chain decisions for 2026, PW Consulting’s latest market study on Valeryl Chloride (n‑Pentanoyl chloride) delivers a compact, decision‑grade perspective that connects chemistry, compliance and commercial strategy. Our analysis synthesizes historical performance (2020–2025), a proprietary demand‑supply model and scenario-based forecasts through 2032, showing that the global market expanded from the mid‑tens of millions of USD in 2020 to approximately USD 74.2 million in 2025 and is projected to grow to roughly USD 105.5 million by 2032 at a compound annual growth rate (CAGR) of about 5.15% over the 2026–2032 forecast window.
Disposable Anti Reflux Drainage Bag Market
Why this matters for 2026 planning
-
Budgeting and procurement: The industry’s steady mid‑single‑digit CAGR masks important short‑term volatility driven by raw‑material and regulatory shocks; procurement teams must move beyond fixed‑price spot buying to blended strategies that combine long‑term supply agreements, indexed pricing and conditional call‑offs.
Structured Illumination Microscopy Market -
Regulatory and risk mitigation: Regulatory compliance (including REACH and equivalent regimes) and hazardous‑materials handling impose non‑trivial cost and operational constraints — capital planning for compliance upgrades is a 2026 priority.
Worldwide AR Automation Software Market -
M&A and partnerships: The market’s structure concentrates supply among a small number of specialist producers. Buyers, toll manufacturers and ingredient companies should approach M&A or JV opportunities with a narrow set of technical, logistical and regulatory due‑diligence criteria to accelerate time‑to‑value.
Market dynamics: synthesis, supply sensitivity and handling realities
Valeryl Chloride production is fundamentally tied to the chemistry of pentanoic acid conversion (commonly via reagents such as thionyl chloride or phosphorus trichloride). This upstream linkage creates two notable dynamics for 2026 decision makers: first, product pricing and availability remain sensitive to valeric acid supply and the cost of chlorinating reagents; second, regulatory and safety requirements materially affect landed cost and usable capacity.
From an operational standpoint, Valeryl Chloride is a corrosive, flammable liquid with well‑documented hydrolysis and migration risks during storage and transit. Best practices — including the use of lined or fluorinated drums, controlled‑atmosphere handling, and validated storage stability checks — are no longer optional. Buyers that factor packaging and handling into total-cost-of‑ownership models capture a competitive advantage in reliability and compliance.
Competitive landscape — profiles and strategic implications
Our report includes a focused provider analysis of market participants that are active across manufacturing, custom synthesis and research supplies. Key company archetypes and strategic plays include the following:
-
Large Chinese suppliers with integrated manufacturing platforms — firms operating from major chemical hubs supply commercial volumes and often combine commodity pricing with localized logistical reach. Their scale supports custom synthesis and rapid order fulfillment, but buyers should scrutinize quality management systems and export‑compliance practices when relying on high‑volume suppliers for regulated markets.
-
Specialty western producers — producers offering research‑grade or ≥99% purity product lines position themselves on technical documentation, material safety information and niche packaging options (e.g., fluorinated 190 kg drums). These suppliers are attractive to customers with stringent specification or traceability needs; they often command premium pricing but reduce technical risk.
-
Indian contract manufacturers and exporters — companies that combine cost‑competitive production with export orientation are effective partners for mid‑sized pharmaceutical and agrochemical customers. Their strategic value depends on demonstrated quality systems (COA, batch traceability) and validated export logistics.
In short, market control is tilted toward a small number of specialized producers — the top tier captures the majority of commercially traded supply, while a handful of additional firms round out most available capacity. This concentration influences negotiation dynamics, lead times and contingency planning for buyers and investors alike.
What PW Consulting’s report delivers — practical, executable content
We designed the study as an operational toolkit for 2026 decisions rather than a purely descriptive market narrative. Key deliverables inside the full report include:
-
Demand‑supply thermals and a proprietary pricing model that translates feedstock scenarios into landed price trajectories under multiple energy and reagent cost assumptions;
-
Scenario analyses (optimistic, base, stressed) incorporating raw‑material shocks, regulatory tightening and logistics disruptions — each mapped to likely outcomes for contract terms, inventory days and working capital;
-
Supplier scorecards and a short‑list methodology that combines technical capability (e.g., purity grades, custom synthesis), regulatory footprint, logistics readiness and financial stability metrics — formatted for rapid inclusion in RFPs and sourcing playbooks;
-
Step‑by‑step compliance and handling checklist derived from current regulatory frameworks and best practices, including packaging, storage stability testing and documentation templates required for cross‑border movement;
-
M&A and partnership screening matrices that highlight where bolt‑on capacity, tolling arrangements or backward integration make economic sense depending on end‑use exposure (pharmaceutical intermediates, agrochemicals, flavors/fragrances);
-
Pricing and contract templates (indexation clauses, minimum‑take commitments, force majeure triggers adapted to chemical supply realities) and a model to quantify the P&L impact of different contracting strategies;
-
A capital expenditure playbook — including CAPEX sizing, expected payback intervals, and operating parameter sensitivities for firms contemplating local production versus long‑term procurement contracts.
Strategic moves for 2026 — practical recommendations
-
Adopt hybrid procurement: Combine multi‑year framework agreements with agile spot and call‑off instruments. This reduces exposure to feedstock spikes while preserving optionality as demand shifts between applications.
-
Invest in compliance early: Prioritize REACH and equivalent validations for suppliers and contract manufacturers. Early investment in compliance lowers the probability of disruptive delisting or shipment quarantines.
-
Segment product strategy by purity needs: Different customers tolerate different grade and documentation requirements. Align product flows (high‑purity streams versus research‑grade supply) to optimize margins and reduce cross‑contamination risk.
-
Build redundancy into logistics: Secure packaging qualified suppliers (e.g., fluorinated or lined drums) and validated carriers experienced with corrosive chemicals to cut transit failure rates and claims.
-
Leverage supplier scorecards for M&A diligence: When evaluating acquisitions or JVs, emphasize technical documentation depth, HSE record, and customer retention over headline capacity numbers.
Where the market can surprise in 2026
Two disruption vectors deserve monitoring. First, sudden feedstock constraints (valeric acid or chlorinating reagents) can produce rapid price inflation and reroute volumes to the most reliable suppliers. Second, regulatory or trade policy changes in major manufacturing hubs can compress available export capacity for months. Both vectors favor buyers and investors who maintain clear contingency plans and supplier diversification strategies.
About the competitive set covered
PW Consulting’s study profiles a cross‑section of established producers and regional specialists, providing technical summaries and strategic positioning notes for each. The companies covered include long‑standing Chinese producers with integrated platforms, US specialty chemical companies that emphasize high‑purity lines and detailed TDS support, and Indian exporters focused on cost‑effective supply to pharmaceutical and agrochemical customers. For each company we map technical capabilities (including available packaging, typical purity grades and custom synthesis capacity), geographic reach and likely strategic role in the market.
Next steps — how to extract maximum value
For procurement, R&D and corporate development teams preparing decisions for 2026, we recommend three immediate actions:
-
Request a tailored supplier short‑list using PW Consulting’s scorecard to validate incumbent suppliers against compliance and operational readiness criteria;
-
Run sensitivity testing on the report’s pricing model under your feedstock contract terms to quantify working capital exposure for your product lines;
-
Use our scenario playbooks to stress‑test M&A or tolling arrangements under accelerated regulatory tightening or a short‑term supply shock.
PW Consulting’s full Worldwide Valeryl Chloride Market report contains the detailed segment economics, supplier market‑share tables, and granular regional and application forecasts that underpin the executive recommendations summarized here. This brief is intentionally high‑signal and non‑exhaustive: download the full analysis to access the data tables, supplier scorecards and actionable templates required to execute on 2026 strategies with confidence.
Contact PW Consulting to request an excerpted supplier short‑list, bespoke scenario runs, or a workshop that will translate the report’s insights into a prioritized action plan for your procurement, manufacturing and M&A teams.
For detailed analysis of this topic, please visit the official page: Worldwide Valeryl Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Polyester Coating Market Poised for 5.35% CAGR in 2026–2032, New Report Shows
By PW Consulting, 2026-08-12
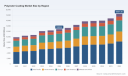
Worldwide Polyester Coating Market: Strategic Imperatives for 2026 — PW Consulting Official Brief
PW Consulting’s latest market study on the Worldwide Polyester Coating Market (base year 2025; historical review 2020–2025; forecast period 2026–2032) delivers an actionable, decision-grade view for executives preparing capital allocation, commercial strategy, and supply-chain resilience plans for 2026. At a macro level the global polyester coatings market was approximately USD 12.8 billion in 2025 and — under our base-case assumptions — is expected to grow at a compounded annual growth rate (CAGR) of 5.35% through the 2026–2032 forecast window, reaching the mid-to-high teens in billions by 2032. This briefing synthesizes the report’s strategic takeaways while intentionally reserving detailed segment-level tables and regional splits for the full report.
Worldwide Higher Education Learning Management Systems Market
Why this report matters for 2026 decision cycles
- Investment timing and scale: The market’s steady mid-single-digit CAGR and the observed capacity investments by leading suppliers create distinct windows for brownfield expansions versus greenfield projects. Executives deciding on 2026 CAPEX will need the report’s plant-level economics and scenario P&L to pick the right timing.
- Portfolio positioning: Demand drivers (durability, sustainability, regulatory shifts) are altering value capture across powder, liquid, water-borne, and specialty polyester offerings. Our analysis identifies where margin compression is structural versus temporary.
- Supply-chain exposure: Feedstock volatility and regional cost differentials materially affect coatings competitiveness. The report translates commodity risk into hedging and sourcing playbooks for procurement teams.
- M&A and partnerships: With a moderately fragmented competitive landscape, there are opportunistic niches and consolidation targets — we map those by capability, geography, and customer adjacency.
What the report contains — practical, transaction-ready modules
- Executive summary with scenario-led market sizing (2026–2032), downside/upside drivers, and sensitivity to key inputs.
- Methodology appendix describing data sources, primary interview program (manufacturers, formulators, major end-users), and our pricing and volume modeling logic.
- Supply-side analysis including resin feedstock flows, major upstream capacity changes, contract structures, and logistics constraints that affect coated metal and component supply chains.
- Demand-side segmentation by end-use and formulation family with growth vectors, buyer economics, and adoption timelines for low-VOC and recycled-content solutions (note: detailed segment revenue tables are in the full report).
- Competitive benchmarking: capability maps, technology differentiation, and a proprietary clustering of players by strategic posture (scale incumbents, specialist innovators, regional champions).
- Implementation playbooks: 24–36 month action plans for procurement, R&D, sales, and operations tailored to OEMs, coil coaters, and industrial finishers.
- Transaction support materials: valuation ranges for strategic targets, synergy estimates, and integration risk checklists.
Key market dynamics shaping 2026 strategies
- Feedstock volatility and regional cost divergence: Purified terephthalic acid (PTA) — a critical feedstock for polyester resins — has shown significant regional pricing spreads and short-term spikes. North American PTA traded near notable highs in late 2025 and early 2026, with short-term weekly surges observed in early 2026 linked to upstream oil and paraxylene disruptions. By contrast, other regional PTA markets have been materially lower, creating persistent arbitrage opportunities and influencing where resins are produced and coatings formulated. For procurement leaders, this means active hedging and diversified sourcing are non-negotiable in 2026.
- Regulatory push toward low-VOC and recycled content: Evolving EU rules and a growing number of national measures are accelerating the shift from solvent-borne systems to powder and high-performance water-borne polyester solutions in industrial and architectural applications. Simultaneously, leading formulators are commercializing recycled-content powder systems; manufacturers that cannot demonstrate compliance or sustainability credentials will face increasing customer scrutiny and potential access constraints to certain OEM platforms.
- Capacity rebalancing among incumbents: Major suppliers have signaled and executed capacity expansions and targeted product launches in 2024–2025. These moves — from doubling resin capacity in key Asia sites to automation-led coil line expansions — will influence regional margin convergence and create pockets of excess supply in specific formulation families. Our report evaluates each announced expansion for realistic ramp timelines and downstream absorptive capacity.
- Fragmented competitive structure: Market concentration metrics point to a moderately fragmented industry: the top three players do not dominate, and even the top five collectively represent a minority share. This distribution preserves room for specialized players, regional champions, and startup innovators to capture value through technical differentiation and customer intimacy.
Competitive landscape — strategic implications
Our benchmarking covers global leaders and regional specialists. Major coating and resin companies continue to pursue differentiated plays: sustainability-focused product launches, capacity expansion in high-growth demand corridors, and automation investments to reduce unit costs and improve quality consistency.
Topical Antifungals Market
- Leading global formulators are commercializing recycled-content powder ranges and advancing low-VOC liquid and powder platforms. These product moves are as much about market access as they are about incremental margin preservation.
- Resin suppliers with upstream integration are leveraging scale to offer bundled resin-plus-formulation solutions, increasing switching costs for downstream coaters. Investment in lab-to-line scale-up capability has become a key competitive moat.
- Recent corporate actions — new product introductions and capacity expansions announced in 2024–2025 — materially alter regional competitive dynamics and should be factored into 2026 commercial planning and contractor sourcing.
Operational playbook for 2026 (three priorities)
- Secure feedstock optionality: Lock in diversified PTA supply agreements, consider tolling arrangements in advantaged regions, and implement dynamic pass-through clauses for customers where commercial conditions allow.
- Accelerate conversion to low-emission formulations: Prioritize reformulation of high-volume SKU families to powder or water-borne platforms where feasible; use pilot commercialization with anchor customers to derisk rollouts and capture first-mover premiums.
- Rationalize capacity with digital supply-chain tools: Use near-real-time demand signals and plant-level cost curves to determine whether to invest further in automation or pursue contractual alliances with regional coaters to avoid underutilized fixed cost exposure.
Commercial and M&A vantage points
Given the market’s growth profile and fragmentation, 2026 is likely to be active for bolt-on consolidation and technology acquisitions. Buyers should prioritize targets that offer:
Worldwide Short Term Insurance Market
- Proven low-VOC or recycled-content formulations with shortened scale-up lead times;
- Access to strategic end-markets (e.g., coil, appliance, automotive components) where long-term replacement cycles support predictable volumes;
- Geographic footprint that mitigates feedstock cost exposure or provides advantaged logistics to key customers.
For sellers, demonstrating a credible path to integrate sustainability credentials and stable supply agreements will meaningfully expand buyer interest and valuation multiples.
Scenario outlook and what to watch in 2026
Our scenario framework models three plausible paths to 2032: base-case (the published CAGR), a downside where prolonged feedstock inflation and trade barriers depress investment, and an upside where accelerated adoption of sustainable formulations and industrial restocking lift volumes. For 2026 specifically, key monitoring indicators include:
- PTA price trajectory and spread differential across regions;
- Implementation timelines of major announced plant expansions and their actual ramp rates;
- Regulatory developments affecting VOC limits and recycled-content mandates in primary markets;
- OEM specifications shifting to validated low-VOC or recycled-content systems, which accelerate procurement cycles for winners.
How PW Consulting’s report supports executable decisions
This study is structured to move executives from insight to action. Beyond headline market sizing, the full report contains plant-level cost benchmarks, formulary transition playbooks, customer economics for each major end-use, and a prioritized list of acquisition targets with preliminary valuation ranges. For procurement and operations teams, we provide sample RFP language and contracting templates that reflect current feedstock volatility and trade-policy risk.
Conclusion — the strategic choice for 2026
The global polyester coatings market offers a predictable growth runway but is being reshaped by feedstock volatility, regulatory pressure, and a sustainability-driven reconfiguration of product economics. For leaders planning 2026 initiatives, the choice is between reactive short-term fixes and proactive repositioning: those who secure feedstock optionality, accelerate low-VOC/recycled solutions, and align capacity to near-term commercial traction will capture outsized share as the market grows. PW Consulting’s full report delivers the granular, transaction-grade intelligence required to execute that repositioning — including scenario P&Ls, plant-specific breakeven analyses, and a prioritized M&A pipeline.
For the detailed segment-level tables, regional splits, and downloadable appendices that support 2026 board-room decisions, access the full Worldwide Polyester Coating Market report on the PW Consulting website or contact our strategy team to arrange a bespoke briefing and licensing of the model.
For detailed analysis of this topic, please visit the official page: Worldwide Polyester Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Ethane Market Poised for a Steady 5.02% CAGR Through 2032
By PW Consulting, 2026-08-12
Worldwide Ethane Market 2026: Strategic Imperatives — PW Consulting Insight
Executive snapshot
PW Consulting’s new Worldwide Ethane Market report (base year 2025) synthesizes five years of historical observation (2020–2025) with a multi‑year forecast (2026–2032). The market’s upward trajectory — from its early‑decade baseline through an estimated USD 36.8 billion in 2025 and a projected rise to approximately USD 51.9 billion by 2032 — implies a compound annual growth rate of about 5.02% across the forecast window. Market concentration is meaningful but not monopolistic: the three largest firms account for just under 40% of visible market share, and the leading five for roughly 56%.
Golf Course Mangement Solutions Market
This briefing is written for C‑suite executives, commercial directors, and infrastructure planners who must set, validate, or accelerate 2026 strategies. It highlights the strategic choices implied by our analysis while deliberately withholding granular segment and regional tables — those curated datasets and underlying models are available in full with the report.
Main Distribution Frame Market
Why ethane will be a decisive strategic variable in 2026
-
Feedstock economics are re‑shaping petrochemical value chains. The gradual but persistent market growth that we project through 2032 reflects not only demand for ethylene derivatives but also structural shifts in feedstock preference across major consuming regions. For trading desks and procurement teams, this means ethane price dynamics will increasingly drive margins at ethylene crackers and downstream chains.
Worldwide Technical Skills Screening Software Market -
Export infrastructure is unlocking new trade flows. The commissioning of new export terminals and expansions in the United States has already altered logistics optima, and additional capacity coming online through 2026 will change shipment patterns and contracting horizons for exporters and importers alike.
-
Midstream and integrated players are repositioning. The structure of the market — moderate concentration among a handful of large, integrated players combined with active midstream project development — creates asymmetric opportunities for both scale players and nimble niche participants.
Operational and commercial playbook for 2026
For executives preparing 12–36 month plans, the following action areas should be prioritized. Each recommendation is grounded in our market model and scenario analysis (methodology details and granular outputs are contained in the full report).
-
Recalibrate feedstock sourcing strategies. Producers that lock in flexible offtake arrangements, or who secure blended contracts (spot + indexed) across multiple supply corridors, will preserve margin optionality as export volumes and regional demand patterns shift.
-
Accelerate logistics-readiness. With recent terminal start‑ups and pipeline expansions changing capacity and transit time dynamics, firms should audit terminal access, vessel availability, and timeslot contracting practices. Those with integrated logistics or long‑term capacity rights will enjoy competitive resilience.
-
Embed scenario triggers into capex calendars. Rather than irreversible large‑scale expansions, consider staged capacity buildouts tied to verified utilization and price thresholds. Real options in plant design and modular LNG/NGL handling can materially reduce downside risk.
-
Update commercial contracting playbooks. Standardized term sheets that include flex volumes, force majeure definitions aligned to ethane handling, and price collars will become essential. Counterparties should negotiate for transparent indexation clauses and explicit arbitration pathways to reduce friction during price dislocations.
-
Prioritize downstream integration where it enhances margin capture. Value‑chain integration remains attractive for operators who can internalize ethane supply security, but only when logistics and commercial terms are de‑risked.
-
Strengthen risk and treasury frameworks. Emerging export growth amplifies balance sheet and trade finance requirements. Hedging strategies must be calibrated to the volatility profile implied by accelerating international flows and by periods of maintenance or turnaround at key crackers.
Competitive dynamics — what the market structure means for strategy
The market’s leading firms occupy distinct, sometimes overlapping, strategic roles: integrated international majors who are both producers and consumers; midstream specialists focused on extraction, fractionation and export; regional champions investing in import capacity and cracking; and growth‑stage exporters targeting new trade routes. A few illustrative patterns from our analysis:
-
Integrated oil & chemical majors continue to leverage integrated value chains to optimize feedstock flows into crackers and downstream derivatives. Their strategic levers include captive supply optimization, joint ventures on crackers, and coordinated logistics deployment.
-
Midstream operators have become the tactical enablers of export expansion. Recent terminal commissions and pipeline upgrades have materially changed exportable capacity and timing, making midstream access a commercial bottleneck in many planning scenarios.
-
New and expanding importers in Asia and elsewhere are reshaping global flows by building receiving infrastructure and pre‑positioning fleet capacity to secure U.S. ethane volumes. This demand pull has a direct bearing on pricing, shipping cycles, and contracting norms.
Key commercial milestones and industry movements that informed our forecasts include recent terminal commissioning and expansion projects in North America, a projected step‑change in U.S. net exports in the mid‑2020s, targeted feedstock conversions by large downstream producers in Asia, and the scheduled start‑up of new crackers in Europe and Asia. These events collectively accelerate trade formation and increase the premium on logistics and contractual rigor.
Scenarios to use in 2026 planning
We recommend three base scenarios that should be stress‑tested across capital planning, offtake contracting, and procurement playbooks. Each scenario is calibrated to the market growth envelope implied by our core forecast (5.02% CAGR) and to plausible deviations driven by infrastructure timing and feedstock substitution dynamics.
-
Baseline: steady infrastructure roll‑out and demand growth aligned with our central forecast — prioritize flexible contracting, staged capex, and enhanced logistics coordination.
-
Acceleration: faster export capacity utilization and stronger feedstock conversion in consuming markets — accelerate long‑term offtake negotiations, secure berthing/slot rights, and evaluate opportunistic upstream or terminal investments.
-
Constrained: delays in key terminals or a temporary demand slowdown — focus on liquidity preservation, short‑term storage solutions, and renegotiation frameworks for large contracts.
Contents and practical deliverables in the full PW Consulting report
Clients who subscribe to the full Worldwide Ethane Market study will receive:
-
A transparent market model covering 2020–2032 with downloadable inputs and a customizable scenario engine.
-
Risk heatmaps for supply, demand, logistics and regulatory variables, with quantified trigger thresholds for strategic decision‑making.
-
Commercial playbooks and contract templates tailored to exporters, importers, and midstream companies.
-
Detailed company profiles and strategic assessments for major market participants, mapped to potential partnership and M&A implications.
-
Interactive dashboards that let users view alternative regional and application splits; note that these granular splits are intentionally withheld from public summaries to preserve the integrity of the underlying datasets and to ensure users consult the full report for transactional decision support.
How to translate insight into 2026 decisions
Four immediate steps will materially de‑risk near‑term plans:
-
Run a 90‑day sourcing and logistics audit to align contractual terms with the new export cadence and terminal availability.
-
Reprice medium‑term contracts using scenario indices and optionality clauses rather than fixed long‑term flat prices.
-
Reassess capex milestones with embedded go/no‑go triggers tied to utilization and market prices, rather than calendar deadlines.
-
Engage with midstream partners to secure capacity options or to explore joint investments that reduce basis and logistic risk.
Final perspective
Through 2026 and beyond, ethane will be both a commodity and a strategic lever — influencing petrochemical competitiveness, trade balances, and infrastructure economics. PW Consulting’s analysis demonstrates that the market is growing at a reliable clip, that export and logistics developments are shifting trade geographies, and that competitive advantages will accrue to organizations that combine contractual sophistication with operational flexibility.
For executives who need to convert these structural insights into executable 2026 strategies, the full Worldwide Ethane Market report provides the detailed regional and application splits, the transactional datasets, and the decision tools necessary to act with conviction. Visit the PW Consulting Worldwide Ethane Market report page to access the complete study, request a tailored briefing, or license our interactive model.
For detailed analysis of this topic, please visit the official page: Worldwide Ethane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Benign Positional Vertigo Treatment Market Hits USD 989.49 Million in 2025, Poised for 5.38% CAGR Through 2032
By PW Consulting, 2026-08-12
Worldwide Benign Positional Vertigo Treatment Market — Strategic Insights for 2026 Decision-Makers
PW Consulting’s latest market research briefing on the Worldwide Benign Positional Vertigo (BPPV) Treatment Market synthesizes historical performance, near-term volatility and a multi-scenario outlook to equip executive teams with the intelligence required to make confident 2026 investment and commercialization decisions. Built on a detailed base-year of 2025 and a forecast window through 2032, this briefing balances rigorous market quantification with practical playbooks that address reimbursement, regulatory pathways, supply resilience and competitive positioning.
Acoustic Magnetic Electronic Article Surveillance (EAS) System Market
Market snapshot: tempo, scale and trajectory
The global BPPV treatment market—measured in USD Million and indexed to a 2025 base year—has demonstrated steady expansion over the past five years, and our modeling projects an aggregate compound annual growth rate of 5.38% through the 2026–2032 forecast horizon. While the market encounters short-term noise and occasional year-to-year blips, the multi-year trend points to growing demand for diagnostic precision, ambulatory and home-based repositioning solutions, and integrated vestibular rehabilitation services.
3D Bio-Printer Market
Importantly for 2026 planning, PW Consulting’s scenario suite highlights a modest near-term correction before recovery into the latter half of the forecast period. That pattern underscores two operational realities: (1) resource allocation decisions taken in 2026 should emphasize optionality and staging; and (2) winning commercial strategies will be those that preserve investable capital while positioning for the resumption of mid-single-digit growth later in the decade.
Worldwide Disposable Dialyzers Market
Why this report matters to C-suite and corporate development teams
-
Actionable sizing and scenario logic: We provide not just a point estimate but alternative scenarios driven by reimbursement shifts, regulatory timing and supply shocks—so finance teams can stress-test investment cases under credible contingencies.
-
Commercial playbooks for 2026: The briefing translates market signals into go-to-market options—prioritized channel plays, pricing levers, and bundling strategies—tailored for device OEMs, hospital systems, diagnostics manufacturers and telehealth/service providers.
-
M&A and partnership roadmap: The report contains an M&A heat map that identifies capability and portfolio gaps commonly targeted in recent transactions, supporting faster diligence and clearer valuation hypotheses.
-
Regulatory and reimbursement navigation: We map device classifications, expected 510(k) trends, and payer dynamics to reduce time-to-market risk and improve early revenue visibility.
Competitive landscape — who to watch and why
The BPPV ecosystem blends diagnostic specialization, device innovation, and an expanding set of home-care enablements. Market concentration metrics show a moderate level of consolidation, with the top-three and top-five firms capturing a meaningful share of value—enough for incumbents to influence pricing and channel dynamics, but still leaving space for focused entrants with differentiated technology or distribution strategies.
Highlighted industry participants in our coverage include:
-
Entellus Medical (now Stryker) — Plymouth, MN, USA. Now integrated into Stryker, the business brings minimally invasive ENT device expertise and navigation-enabled systems that intersect with repositioning workflows. Recent product updates center on enhanced navigation and procedure integration, improving clinician confidence in complex cases.
-
Interacoustics — Middelfart, Denmark. A leader in diagnostic chairs and video-goggle systems, noted for recent CE Mark renewals that emphasize patient safety enhancements. Their positioning makes them a natural partner for clinics seeking turnkey diagnostic-to-treatment pathways.
-
Natus Medical (Natus Neurology) — Middleton, WI, USA. Known for vHIT and videonystagmography platforms, the company’s next-generation systems improve canal identification and treatment verification—a critical differentiator as payers and providers demand demonstrable outcomes.
-
Bernafon (WS Audiology) — Bern, Switzerland. Offers vestibular testing and rehabilitation devices that support particle repositioning therapy; strategic strength lies in integrating testing data into rehabilitation programs.
-
Beurer GmbH — Ulm, Germany. Focused on consumer-facing, portable Epley devices and home-use vertigo kits. Their presence highlights a parallel commercial runway: self-care products and remote monitoring for post-procedural follow-up.
Each of these firms illustrates a distinct route-to-value: device-enabled procedural enhancements (Stryker/Entellus), diagnostic clarity (Interacoustics, Natus), structured rehabilitation (Bernafon) and consumer decentralization (Beurer). PW’s competitive scorecards in the full report evaluate these capabilities across clinical efficacy, channel reach, regulatory maturity and margin profile.
Regulatory, reimbursement and input-cost dynamics
-
Regulatory framework: BPPV-related diagnostic systems and repositioning chairs are generally classified as Class II devices in the U.S., requiring 510(k) clearance. Timing and evidentiary expectations for clearance influence product launch sequencing and clinical trial design.
-
Reimbursement influences: Procedural reimbursement remains a practical lever. For example, the commonly billed canalith repositioning procedure carries an average Medicare reimbursement that materially affects clinician throughput economics—an important consideration for pricing and KOL engagement strategies.
-
Supply-side pressures: Raw material cost increases—medical-grade silicone and polymer resins—have raised component costs by mid-teens in recent quarters. Manufacturers should consider longer lead contracts, multi-sourcing and design-for-material-replacement initiatives to protect margins.
-
Labor and service cost considerations: Specialist reimbursement and ambulatory labor economics influence where procedures are performed (hospital vs. outpatient clinic vs. home-support). Labor cost dynamics should therefore inform channel investments and service bundling.
-
Therapeutic landscape: There are currently no approved systemic pharmacotherapies for BPPV; standard-of-care remains physical maneuvers and vestibular rehabilitation. That clinical reality shapes product roadmaps—digital therapeutics, remote-guided maneuvers and diagnostic precision will drive value, not drug development pipelines.
What the full PW Consulting report delivers (practical contents)
-
Detailed market sizing and forecast models (2020–2032) with scenario toggles for regulatory delays, reimbursement shifts and supply shocks.
-
Regional demand drivers and end-user adoption curves (hospital, diagnostic center, outpatient and home-care channels), with sensitivity analyses but without publishing clients’ proprietary account-level data.
-
Provider economics and procedure-level margin models that translate CPT and DRG inputs into practice-level ROI for device adoption.
-
Supplier and input-cost heat maps (materials, components, contractual strategies), including recommended sourcing playbooks to manage polymer and silicone price volatility.
-
Competitive scorecards and acquisition target shortlists, with financial proxies and integration risk indicators to accelerate DD processes.
-
Commercial launch templates and a 90–180 day tactical plan for new product introductions, including KOL engagement calendars and reimbursement submission trackers.
Strategic guidance — six imperatives for 2026
-
Prioritize diagnostic certainty: Investments in objective vestibular testing (vHIT, video nystagmography) reduce repeat visits and improve procedural ROI. Commercial teams should align pricing to demonstrable time-to-diagnosis improvements.
-
Design for multi-channel delivery: Expect a mix of ambulatory, diagnostic-center and home-based demand. Modular product architectures that support clinic and at-home workflows will capture greater lifetime value.
-
Hedge input cost risk: Negotiate longer-term supply agreements for critical polymers, qualify alternate materials and pursue design optimizations to reduce silicone dependencies.
-
Align clinical evidence with reimbursement strategy: Early engagement with payers and clearly documented post-procedure outcomes will shorten reimbursement cycles and improve uptake among high-volume clinics.
-
Build partnership-based access: OEMs should pursue strategic alliances with diagnostic centers and telehealth platforms to embed device use into referral pathways rather than relying solely on direct sales.
-
Preserve optionality in capital allocation: Given the projected short-term adjustment in 2026, stage investment tranches and preserve runway for accelerated scale when the market resumes its multi-year growth trajectory.
Conclusion — how to use this briefing in 2026 planning
For boards, corporate development teams and commercial leadership, PW Consulting’s briefing provides a decision-ready mix of market scale, competitive dynamics and execution playbooks tailored for the 2026 environment. The combination of steady multi-year growth with episodic near-term disruption favors nimble strategies that pair diagnostic-led value propositions with supply-resilient product designs. Executives who use our scenario-based framework will be better positioned to time investments, structure partnerships and negotiate with payers—minimizing downside while retaining upside optionality.
To access the full dataset, regional breakdowns, detailed vendor scorecards and downloadable financial models—tools required to operationalize the recommendations above—please visit the PW Consulting report page. The full report contains the granular segmentation and tables intentionally omitted here to preserve the tactical insights that buyers of the complete study rely on for competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Benign Positional Vertigo Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Small Bulldozers Market to Expand at 4.82% CAGR Through 2032
By PW Consulting, 2026-08-12
Worldwide Small Bulldozers Market: Strategic Outlook 2026 — PW Consulting Issues Actionable Intelligence for C-Suite Decision-Making
PW Consulting today released a forward-looking industry briefing derived from its forthcoming Worldwide Small Bulldozers Market report (base year 2025). The analysis synthesizes historical performance from 2020–2025 and presents a clear-growth scenario for 2026–2032, with the global small bulldozer market sized at USD 1,345.7 Million in 2025 and a compound annual growth rate (CAGR) of 4.82% across the forecast window. By 2032, our centralized forecast trajectory reaches roughly USD 1,870.9 Million under baseline assumptions.
Enterprise Email Security Platforms Market
Executive snapshot — why this matters for corporate strategy in 2026
- Market momentum is steady but non-linear: post-pandemic recovery and a sequence of macro shocks produced variability between 2020 and 2025. These dynamics create both short-term tactical pressures and medium-term strategic openings for manufacturers, dealers, and fleet owners.
- Concentration and competitive scale are meaningful: the market displays mid-range concentration where the top three to five players collectively command a plurality of demand — enough to shape technology adoption, channel economics, and pricing behavior.
- Input cost volatility and trade policy are active risk factors: steel price behavior and changing tariff regimes are already affecting cost structures and supplier strategies; responses in 2026 will set margin trajectories for the medium term.
What this report gives you — practical deliverables for 2026 decision cycles
PW Consulting’s market study is structured to move beyond descriptive charts and towards operational decision-support. Key deliverables include:
Worldwide Portals Software Market
- Scenario-based demand modeling and demand-shock stress tests calibrated to 2026 procurement cycles, enabling procurement teams to simulate lead times, price pass-through, and timing of fleet expansions or replacements.
- Supplier and OEM scorecards that benchmark engineering, telematics, total cost of ownership (TCO), and parts availability — enabling commercial teams to prioritize partner negotiations and warranty / aftermarket contracts.
- Cost-structure impact frameworks that link raw material price trajectories and tariff changes to BOM cost, gross margin sensitivity, and suggested pricing levers for OEMs and dealers.
- Product roadmap heatmaps and technology adoption timelines (including automation, precision grading systems, and electrification pathways) to help R&D and portfolio managers prioritize investments with payback windows tuned to 2026–2028 demand.
- Go-to-market playbooks for rental companies and small-operator channels that define fleet mix, maintenance contracts, and financing/leasing propositions to capture faster-growing demand pockets.
- Risk matrices and mitigation action plans covering supply-chain concentration, single-sourced components, and regulatory exposure across primary markets.
Macro dynamics shaping the 2026 operating environment
Three macro vectors will disproportionately influence competitive outcomes in 2026:
Agriculture Accounting Software Market
- Input-cost volatility: steel markets have moved materially in the 2024–2026 window. Manufacturers face higher steel and fabricated-steel component costs; combined with recent tariff adjustments, this compresses near-term margins unless OEMs and distributors proactively adjust pricing strategies or reengineer inputs.
- Infrastructure-led demand: continued public and private infrastructure programs in many markets sustain baseline unit demand for small bulldozers, while the pace and geography of projects drive equipment specification choices and aftermarket services.
- Technology and operator expectations: precision-control suites, telematics, and operator comfort are no longer premium differentiators in many mature segments — they are expected. The commercial prize rests with firms that can deliver integrated systems with demonstrable uptime and TCO advantages.
Strategic implications for 2026 decision-makers
- Procurement and inventory timing: use the report’s short-cycle price-pass-through models to time purchases, component hedges, and supplier contracts. A calibrated approach to inventory (safety stock versus just-in-time) mitigates price spike exposure without locking excessive working capital.
- Product portfolio prioritization: prioritize models that balance ease of service, modular electronics, and fuel efficiency — these factors produce outsized value in both rental and contractor channels in the 2026 environment.
- Supply-chain diversification: accelerate qualification of alternate stamped-steel and subassembly suppliers in lower-cost regions to reduce tariff-driven cost exposure and strengthen on-shore options for critical components.
- Aftermarket and service monetization: commercialize uptime guarantees, predictive-maintenance bundles, and extended warranties — our TCO simulations show aftermarket revenue can materially stabilize margins when new-vehicle pricing is constrained.
- Channel and pricing strategy: for OEMs with regional ambitions, consider differentiated pricing and financing offers tied to local market conditions and infrastructure program timetables to preserve volume while protecting margins.
Competitive landscape — who to watch in 2026
The market is characterized by a mix of global OEMs and regional challengers. PW Consulting profiles the principal competitors and recent moves that signal strategic intent for 2026:
- Caterpillar Inc. (Irving, Texas, USA): continues to advance integrated precision and fuel-efficiency features on its small/compact crawler lines, focusing on operator ergonomics and site-development productivity.
- Komatsu Ltd. (Tokyo, Japan): doubling down on intelligent machine control and incremental automation, positioning new generation models for higher grading productivity on road and site work.
- Deere & Company (John Deere) (Moline, Illinois, USA): pushing SmartGrade and E‑Drive technology across its small-to-mid offering to capture productivity-conscious buyers and rental fleets seeking lower operating costs.
- Case Construction Equipment (CNH Industrial) (Racine, Wisconsin, USA): launched a refreshed N‑Series family with operator-centric improvements, signaling an intent to consolidate share in utility and tight-site applications.
- Liebherr Group (Bulle, Switzerland): emphasizing engineering robustness and lifecycle durability for demanding construction use cases.
- Major Chinese OEMs (e.g., Shantui, LiuGong, SDLG, XCMG): competing on value, parts availability, and localized channel networks — these players are pivotal in emerging markets and increasingly competitive in mature markets via targeted feature upgrades.
- Hyundai Construction Equipment (Seoul, South Korea): expanding its footprint with models designed for precise earthmoving and competitive service programs.
Recent market actions reinforce this competitive dynamic. Notable industry events through early 2026 include product launches and trade‑show previews from multiple OEMs that indicate accelerated technology refresh cycles and targeted investments in cab comfort, control systems, and fuel-efficiency improvements.
Raw materials, policy, and the near-term margin outlook
Input-cost pressure is a tangible near-term challenge. Steel-price movements and trade policy shifts have increased the emphasis on procurement strategy and design-for-cost programs. PW Consulting’s cost-sensitivity analyses show that a sustained uptick in steel and tariff-influenced import costs can erode manufacturer gross margins unless offset by pricing actions, engineering substitutions, or absorption into aftermarket pricing. These levers require cross-functional alignment and pre-planned contract strategies to execute in a tight 2026 procurement window.
How C-suite teams should use this report in Q1–Q4 2026
- CEOs and strategy leads: use the scenario suite to stress-test M&A and geographic expansion plans, focusing on whether target profiles enhance technology, service reach, or raw-material resilience.
- CFOs and procurement heads: adopt the report’s price-pass-through and hedging templates to set procurement cadence and capital allocation for 2026 capex.
- Product and R&D leaders: apply the technology adoption timelines and product heatmaps to rationalize feature rollouts and prioritize modular architectures that minimize variant proliferation.
- Sales and channel executives: operationalize the go-to-market playbooks to tailor rental, dealership, and direct-sales mixes by customer segment, and to design financing incentives that accelerate order conversion in 2026.
Teaser — what we intentionally withhold here (and why)
To preserve the commercial and practical edge for subscribing organizations, this press briefing intentionally omits granular segmentation value tables and region/application revenue splits contained in the full report. Those detailed segment matrices — including model-level economics, region-by-application sizing, and dealer-channel share analytics — are provided exclusively in the full PW Consulting report along with downloadable tools and supplier scorecards to enable immediate operational deployment.
Next steps — obtaining the full intelligence package
Organizations planning procurement, product-cycle launches, or capital allocation in 2026 should obtain the full Worldwide Small Bulldozers Market report. The complete deliverables include interactive forecasting models, a supplier matrix with operational KPIs, proprietary TCO calculators, and scenario planners tuned to tariff and steel-price sensitivities — all designed to convert market insight into executable strategy.
For access to the full report, bespoke briefings, or a demonstration of our forecasting toolset, PW Consulting’s industry team stands ready to support executive workshops and tailored advisory engagements for the 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Small Bulldozers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Over-the-Horizon Radar Market Poised for a 6.5% CAGR During 2026–2032PW Consulting Forecasts Worldwide Fecal Occult Testing Market to Reach USD 1.50 Billion in 2025, Growing at a 5.96% CAGR Through 2032
By PW Consulting, 2026-08-12
Worldwide Over-the-horizon Radar Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
Executive snapshot
As strategic competition accelerates across maritime and high-latitude approaches, over-the-horizon radar (OTHR) has moved from niche capability to core national infrastructure. PW Consulting’s forthcoming Worldwide Over-the-horizon Radar Market report (base year 2025) synthesizes seven years of historical observation and a seven-year forecast to offer a decision-ready, operational playbook for program managers, prime contractors, suppliers, and sovereign procurement authorities as they plan through 2032.
Worldwide Police Scanner Market
Market trajectory: the numbers that matter
Our macro analysis shows the global OTHR market reached approximately USD 1,128.5 million in 2025 and is projected to expand to roughly USD 1,226.5 million in 2026, tracking toward an estimated USD 1,753.6 million by 2032. That growth path implies a forecast compound annual growth rate (CAGR) of 6.5% across the 2026–2032 period, continuing an observable expansion since 2020. The historical series (2020–2025) demonstrates steady year-on-year scale-up as defense modernization, Arctic domain awareness, and wide-area maritime surveillance priorities converged.
Worldwide Underwater Connectors Market
Why 2026 is a strategic inflection point
- Procurement windows are opening. Several national programs are moving from concept and validation phases into construction and acquisition. The timing of environmental reviews, budget requests, and multi-year operations-and-maintenance (O&M) contracts creates discrete decision gates for prime contractors and subsystem suppliers in the next 12–36 months.
- Capital and lifecycle costs shape vendor selection. Long lead items (high-power transmitters, large-scale antenna arrays, site foundations) and multi-decade sustainment profiles mean procurement decisions made in 2026 will determine cost and capability envelopes well into the 2030s.
- Interoperability and networked sensing are non-negotiable. Modern OTHR deployments are increasingly evaluated as components of a layered sensing architecture that must integrate with airborne, space-based, and coastal sensors—an integration challenge as much as a procurement one.
Competitive landscape: who sets the tempo
The market is moderately concentrated with a small set of system integrators and established defense primes driving program wins and upgrades. Leading providers include globally recognized primes and specialized radar firms whose technologies and program delivery footprints shape bidding strategies and partner selection.
Raman-AFM Market
- RTX Corporation (Raytheon) — Long-standing systems integrator with relocatable OTHR heritage and multi-decade sustainment experience for naval and homeland systems. Recent program awards and ongoing ROTHR upgrades underscore Raytheon’s operational depth in large-scale deployments.
- Lockheed Martin — Major systems integrator with breadth across surveillance radar and integration capabilities for long-range detection and tracking.
- Northrop Grumman — Developer of radar systems and sensor-network integration solutions that support wide-area surveillance architectures.
- BAE Systems — Enterprise partner in JORN-derived programs and a key provider of software, control systems, and upgrade pathways for both skywave and surface-wave configurations.
- Thales, Leonardo, Saab, Israel Aerospace Industries (IAI), Aselsan — Regional and international suppliers offering modular radar subsystems, signal-processing IP, and regional program partnerships.
Our concentration metrics indicate that the top three providers account for a substantial portion of market activity, while the top five capture a clear majority—conditions that favor consortium bidding, strategic supply agreements, and targeted M&A for mid-tier suppliers seeking scale.
Recent program activity and geopolitical drivers
- Domestic procurement and budget allocations in North America are accelerating OTHR deployments for homeland defense and northern approaches; construction starts and environmental milestones will be decisive in 2026–2028 timelines.
- Canada’s selection of a consortium for Arctic OTHR validation and procurement, leveraging JORN technology partnerships, signals a renewed focus on high-latitude domain awareness and cross-national technology transfer opportunities.
- Tactical and expeditionary OTHR installations in Indo‑Pacific areas underscore demand for flexible, multi-mission systems that can be installed with constrained infrastructure and rapid deployment timelines.
- Recent contract awards and subsystem procurements (including transmit subsystem actions and multi-year O&M packages) indicate prime contractors are locking in supply chains and sustainment models—developments that will shape pricing, lead times, and competitive dynamics for the rest of the decade.
Technology and capability trends shaping supplier strategy
- Signal processing and AI-enabled detection: Advances in clutter rejection, adaptive filtering, and machine learning-based classification are turning OTHR from raw long-range detection into actionable intelligence for maritime and air domain awareness.
- Modularization and transportability: Demand for relocatable and staged deployments is driving modular transmitter/receiver architectures and more rigorous installation playbooks for foundation and power subsystems.
- Power systems and transmitter modernizations: Upgrades to transmit chains remain a programmatic priority; vendors that can reduce lifecycle power costs and extend operational uptime will have a competitive edge.
- Systems-of-systems integration: OTHR suppliers are increasingly evaluated on their ability to integrate with national command-and-control, ISR, and allied data-sharing frameworks rather than on radar performance alone.
Strategic implications by stakeholder
- Defense planners and program offices: Treat 2026 as a procurement window—finalize secure interoperability requirements, de-risk site environmental processes, and align budgets to multi-year sustainment commitments.
- Prime contractors: Prioritize supply chain lock-in for transmitters and antenna components while building software and sensor-fusion capabilities to win platform-level contracts.
- Subsystem suppliers and mid-tier firms: Target partnerships and technology licensing with primes to secure predictable order flow; demonstrate cost-to-operate improvements as a procurement differentiator.
- Investors and M&A teams: Look for consolidation opportunities among high-skill subsystem suppliers and analytics firms that can accelerate primes’ delivery timelines and expand aftermarket revenue streams.
- Regional governments: Balance sovereign capability development with partnership models that bring transfer of know-how and onshore sustainment capacity.
What PW Consulting’s report delivers (preview)
Our full report is engineered as an operational tool for decision-makers. Highlights include:
- Comprehensive market sizing (2020–2032) and scenario-based forecasts that quantify procurement demand and sustainment spending across multiple adoption pathways.
- Acquisition and deployment timelines that map environmental reviews, site construction, and capability handover windows for imminent programs.
- Vendor scorecards and capability matrices covering technical maturity, delivery risk, sustainment footprint, and partnership posture for the leading system integrators and specialist suppliers.
- Contract-tracking and event timelines for recent awards, subsystem procurements, and strategic consortiums—enabling near-term business capture planning.
- Operational playbooks for site selection, infrastructure design, and lifecycle cost optimization—built from primary interviews and program documentation.
- Risk frameworks and mitigation checklists that translate technical, environmental, and geopolitical uncertainty into executable program actions.
Per the “trailer” approach of this release, the public preview demonstrates our analytic depth while reserving the full segmentation tables, per-region and per-application splits, and unit-level procurement schedules for report subscribers and the report landing page.
Action checklist for 2026 decision-makers
- Lock in interoperability requirements with allied partners to ensure procurement options remain open for coalition-enabled deployments.
- Prioritize lifecycle and sustainment cost metrics when scoring bids—initial acquisition price does not reflect decades of power, maintenance, and upgrade expenditures.
- Engage early with transmit-subsystem and antenna suppliers to de-risk long lead components and secure capacity commitments.
- Assess potential consortia partners for capability gaps and delivery track record—consortium structure will materially affect schedule risk.
- Plan for staged capability insertion: validate a minimum viable OTHR capability early, then iterate with software and sensor-fusion upgrades tied to performance-based milestones.
Conclusion: why this matters for 2026
The OTHR market is entering a phase of programmatic crystallization. Macroscale demand trends and a projected CAGR of 6.5% through 2032 indicate sustained investment, but the near-term winners will be defined by who best manages supply chains, demonstrates integration competence, and converts legacy program experience into modern, software-driven capability roadmaps. PW Consulting’s full Worldwide Over-the-horizon Radar Market report equips stakeholders with the market intelligence and acquisition playbooks they need to convert 2026 procurement windows into durable strategic advantage.
To access the full dataset, vendor scorecards, and the complete set of segment-level forecasts and procurement schedules, please visit the PW Consulting report landing page for the Worldwide Over-the-horizon Radar Market.
For detailed analysis of this topic, please visit the official page: Worldwide Over-the-horizon Radar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Metal Scavenging Agents Market Set to Expand at a 6.85% CAGR Through 2032PW Consulting: Worldwide Aerospace Galley Trolley Market to Rise from USD 326.25 Million in 2025 to USD 462.79 Million by 2032 at a 5.12% CAGR
By PW Consulting, 2026-08-12
Worldwide Metal Scavenging Agents Market — Strategic Insights for 2026 Decision-Makers
PW Consulting’s latest market intelligence brief — the Worldwide Metal Scavenging Agents Market Report (base year 2025, forecast 2026–2032) — delivers a rigorous, transaction-ready view of an often-overlooked but commercially critical segment of the chemical-purification value chain. The global market reached approximately USD 245.0 Million in 2025 and, driven by tightening regulatory limits on metal residues, expanding catalytic process routes and increasing demand for high-purity outputs, is projected to grow at a compound annual growth rate (CAGR) of 6.85% across our forecast window. Under our central scenario the market expands to roughly USD 278.2 Million in 2026 and continues to strengthen toward the end of the decade.
Why this matters for corporate strategy in 2026
-
Regulatory and quality pressure: Pharmaceutical and fine-chemical manufacturers are reducing allowable trace-metal thresholds while auditors are expecting repeatable, validated purification solutions. That creates recurring demand for validated scavenging workflows — not only as a lab-scale fix but as a scalable production control.
-
Commercial recovery and circularity: Industrial players are treating metal scavengers as both cost centers and potential recovery vectors. Opportunities to monetize recovered precious metals, or to reduce catalyst procurement and disposal costs, are reshaping procurement and R&D priorities.
-
Supplier economics and concentration: The market’s competitive structure is neither fully consolidated nor atomized — the top three suppliers account for a meaningful share, and the top five are responsible for a majority market presence (CR3 ~42.5%; CR5 ~58.2%). This dynamic creates space for premium positioning by incumbents and targeted entry by specialists.
Report deliverables — practical, transaction-ready content
This report was built to inform commercial decisions in 2026 — from capex allocation and procurement frameworks to M&A screening and technical partnerships. Key operational deliverables include:
-
Market-sizing and demand-modeling workbook: a transparent, auditable build-up from end-demand drivers through to point-of-use consumption for the period 2020–2032, with scenario toggles for regulatory tightening and catalyst-recovery economics.
-
Segmentation intelligence: material-class, application and regional decompositions (note: detailed sub-segment tables and downloadable data are provided in the full report).
-
Supply-side playbook: plant-level capacity mapping, supplier scorecards, lead-time benchmarking and a supplier-risk heat map designed for procurement negotiations and dual-sourcing strategies.
-
Commercial diligence kit for M&A: target screening criteria, valuation multiple guidance, synergy levers (capex deferment, cross-selling into pharma accounts), and a 100‑day integration checklist tailored to scavenger businesses.
-
Technical annexes for R&D and process teams: lab protocols for efficacy testing, recommended analytical methods for residual-metal quantification, and guidelines for scale-up from bench to multi-ton processing.
-
Sustainability assessment: lifecycle footprints for main product classes, recommended recycling pathways and an ROI model for implementing metal-recovery loops at different scales.
Competitive landscape — profiles and strategic positioning
We evaluated suppliers across technical capability, manufacturing scale, route-to-market and customer concentration. The report includes in-depth profiles of market-leading and specialty players, including:
-
SiliCycle Inc. (Quebec City, Canada) — recognized for its SiliaMetS functionalized silica portfolio and multi-ton manufacturing capability; positions itself as a partner for high-purity pharmaceutical customers requiring validated, scalable scavengers.
-
Johnson Matthey (London, UK) — a diversified materials supplier offering macroporous polymer and silica-based scavengers, with product lines designed for both organic and aqueous streams and a broad industrial customer base.
-
Biotage (Uppsala, Sweden) — brings a strong pharma-focused toolkit and application know-how, including scavengers optimized for palladium and other transition metals, complemented by purification workflows.
-
PhosphonicS (Abingdon, UK) — a specialist in functionalized materials that targets both impurity removal and value recovery in process and waste streams.
-
BASF SE and Merck KGaA — global chemical majors with metal-scavenging offerings embedded in broader portfolios, enabling cross-selling into established B2B channels and advantaged logistics.
-
Fuji Silysia Chemical Ltd , United Chemical Technologies (UCT) and Apollo Scientific — regional and specialty players that supply high-purity silica-based materials, often winning business on technical customization, rapid response and niche application expertise.
Across suppliers, recurring differentiators are validated application data, multi-ton manufacturing capability, and end-user support (e.g., process qualification packages). The report’s supplier scorecards rate each company on those dimensions as well as on pricing transparency and sustainability credentials.
Strategic imperatives for 2026 — four actions for executives
-
Convert purity and compliance into competitive differentiation. Firms that can provide validated end-to-end purification packages (scavenger + analytical validation + process guidelines) command pricing power and accelerate qualification cycles for large pharma customers.
-
Operationalize metal recovery. Invest in pilot programs to recover and re-sell precious metals or to reduce catalyst spend — the total cost-of-ownership case for scavengers can shift dramatically when recovery economics are captured.
-
Hedge supply and secure technical partnerships. Establish dual- or multi-source supply agreements with short-list suppliers and include technical collaboration clauses for product customization and co-development.
-
Embed sustainability metrics into procurement. Procurement teams should require lifecycle and disposal-impact data as part of RFQs; progressive buyers can prioritize suppliers with recycling or take-back programs.
Tactical playbook highlights — ready-to-use items from the report
-
Due-diligence checklist for sourcing: specification templates, validation test panels, recommended contract clauses (warranty on residual-metal removal performance) and minimum analytical reporting requirements.
-
Pilot-to-scale decision tree: go/no-go criteria for moving from bench screening to production qualification, including sample throughput, contact time, and regeneration/reuse metrics.
-
Procurement scorecard: a weighted scoring model that balances price, lead time, technical support, sustainability and recovery potential.
-
M&A screening matrix: 30+ target attributes spanning IP robustness, customer stickiness, manufacturing footprint and synergy potential.
Risks, blind spots and investment guardrails
No market is without risk. Our sensitivity analysis identifies three near-term pitfalls to monitor: (1) sudden shifts in catalyst technologies that reduce demand for certain scavenger chemistries; (2) a race to the bottom on commoditized products that compresses margins; and (3) regulatory fragmentation across key manufacturing jurisdictions that increases qualification complexity. The report outlines mitigation options for each, including diversification of product portfolio, development of proprietary functionalized scavengers, and regional qualification roadmaps.
Why PW Consulting’s analysis is different
Two qualities distinguish this work. First, the report integrates technical validation data with commercial intelligence: lab-standard efficacy testing is cross-walked to commercial consumption models so decision-makers can see the financial impact of technical choices. Second, the deliverables are operational: along with narrative analysis we provide decisioning tools — models, scorecards and checklists — that can be deployed immediately in procurement, R&D and corporate development workflows.
Our high-level market projection shows a resilient growth trajectory into the late 2020s underpinned by regulatory and quality demands; yet competitive dynamics leave room for both incumbents and well-positioned challengers. For leaders planning capital allocation, strategic partnerships, or bolt-on acquisitions in 2026, this report converts a technically complex domain into actionable commercial options.
Next steps and access
This press piece intentionally presents a strategic preview. The full report contains granular regional and application splits, downloadable model files, detailed supplier scorecards, and the technical annexes required to run a pilot or to complete commercial due diligence. For access to the complete dataset, scenario workbooks and proprietary appendices, please visit PW Consulting’s report page or contact our industry team directly.
For detailed analysis of this topic, please visit the official page: Worldwide Metal Scavenging Agents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Traumatic Brain Injuries Assessment and Management Devices Market Valued at USD 4,173.89 Million in 2025, Poised for Further Growth
By PW Consulting, 2026-08-12
Worldwide Traumatic Brain Injuries Assessment And Management Devices Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
PW Consulting’s new market study, with a 2025 base year and a 2026–2032 forecast horizon, crystallizes the commercial, clinical and regulatory inflection points that will determine winners and losers in the traumatic brain injury (TBI) devices landscape over the next decade. The global market expanded from approximately USD 2,750.4 million in 2020 to USD 4,173.9 million in 2025 and is forecast to reach USD 7,581.2 million by 2032, representing a compound annual growth rate (CAGR) of 8.9% across the projection period. Market concentration metrics (CR3 = 42.5%; CR5 = 58.8%) signal a marketplace that is neither wholly fragmented nor locked by an entrenched oligopoly—creating meaningful runway for both incumbent expansion and targeted entrants.
Cord Blood Collection Kits Market
Why this report matters for 2026 strategy
- Timing: 2026 will be a year of accelerated clinical validation and regulatory activity for point-of-care diagnostics, biomarker assays and neuromonitoring systems. Companies must align product development, evidence generation and commercial rollout plans to capture early-adopter demand.
- Capital allocation: With sustained double-digit growth potential, investment decisions in R&D, M&A and field infrastructure will determine relative market share gains. Our study translates market growth into actionable investment levers and risk-adjusted returns across realistic time horizons.
- Policy and payer sensitivity: Recent reimbursement trends and clinical evidence developments require a structured approach to value demonstration. Firms that integrate reimbursement pathway planning with clinical development will unlock the fastest routes to scale.
Market dynamics — what is driving growth and where uncertainty remains
Three broad forces are shaping demand: technological convergence (imaging + digital biomarkers + AI), care‑pathway decentralization (point-of-care and outpatient assessment), and evolving clinical evidence for neurocritical monitoring. Adoption of portable EEG, eye-tracking and blood‑based biomarker tests is creating layered decision-support workflows that mirror emergency, outpatient and military use cases. Simultaneously, hospital-based neurocritical care continues to demand robust ICP and brain tissue oxygen monitoring solutions supported by neurosurgical and ICU ecosystems.
Worldwide Vibraphones Market
Key structural uncertainties that buyers and investors must stress‑test in 2026 include the pace of clinical outcome evidence for PbtO2-guided management (recent trials and meta-analyses updated through 2025 have reshaped the debate), the robustness of reimbursement for TBI-related procedures (historical Medicare trends show muted reimbursement and falling procedural volumes), and the degree to which regulatory clarity around blood‑based biomarkers and AI-enabled decision aids will standardize adoption across markets (note: the U.S. Department of Defense maintains an evolving list of FDA-cleared devices relevant to head injury assessment).
Smart Home Extended Warranty Market
Competitive landscape — positioning and strategic playbooks
Our vendor taxonomy and therapeutic-technology mapping capture three archetypes: (1) diagnostic innovators delivering point-of-care triage tools; (2) neuromonitoring incumbents entrenched in the neuro‑ICU; and (3) systems integrators offering imaging and platform-level solutions. Representative players and their strategic postures include:
- BrainScope Company Inc. — differentiated on an EEG-based handheld platform and AI/ML biomarkers for point-of-care assessment. Its regulatory traction and handheld form factor target pre-hospital and ED workflows.
- Abbott Laboratories — leveraging a laboratory and bedside platform strategy with rapid blood‑based TBI assays to capture triage and early diagnostic use cases; positioning emphasizes speed-to-result and integration with existing i‑STAT infrastructure.
- Oculogica and SyncThink — advancing eye‑tracking as an objective adjunct for concussion assessment; their regulatory clearances reflect a maturing niche that complements other modalities rather than replacing them.
- InfraScan and similar NIRS device makers — playing to fast hematoma detection in resource-limited or tactical environments where CT access is delayed.
- Integra LifeSciences, RAUMEDIC and Natus — legacy neuromonitoring and catheter manufacturers entrenched in the neurocritical care pathway; their enterprise relationships and hospital install base remain a powerful moat for severe TBI management solutions.
- Large platform vendors (Philips, GE HealthCare, Elekta) — competing at the systems and imaging layer, enabling interoperability and enterprise procurement deals that favor integrated monitoring + imaging workflows.
Recent regulatory and product developments bolster these dynamics. Notable events include multiple FDA 510(k) clearances for point-of-care and eye-tracking devices (2024–2026) and a Breakthrough Device designation for a neurostimulation therapy addressing episodic memory loss after moderate‑to‑severe TBI. These milestones illustrate two market realities: regulatory pathways are navigable with focused evidence packages, and therapeutic adjuncts (e.g., neurostimulation) are beginning to enter the commercialization funnel—creating new adjacencies for device companies and service providers.
What the report contains — practical deliverables for corporate teams
PW Consulting’s study is intentionally execution-oriented. The deliverables are structured to be directly usable by commercial, clinical development and corporate strategy teams:
- Market sizing and growth scenarios: bottom-up and top-down models with sensitivity testing across optimistic, base and conservative adoption curves for device classes, with clear assumptions so clients can re-run models against proprietary inputs.
- Go-to-market playbooks: customer segmentation, channel economics, pricing guidance and sales force design templates tailored to hospitals, diagnostic centers and point-of-care channels.
- Clinical evidence blueprints: recommended trial designs, endpoints, comparator selection and health economics analyses aligned to payer expectations and regulatory submissions.
- Regulatory and reimbursement maps: country-by-country regulatory pathways for devices and biomarkers, plus pragmatic reimbursement strategies and coding playbooks to accelerate coverage discussions.
- Competitive benchmarking and vendor profiles: strengths-weaknesses-opportunities-threats analyses for leading players, including IP positioning, partnership fit, and licensing opportunities.
- M&A and partnership frameworks: target screening criteria, synergies quantification and deal-structuring guidance for strategic and financial buyers.
- Risk-adjusted financial models and ROI calculators: modular templates to evaluate product launches, geographic rollouts and acquisition scenarios under multiple adoption timelines.
Strategic imperatives for 2026
- Prioritize evidence that matters: invest early in pragmatic endpoints—time-to-decision, avoided CTs, and triage accuracy—in addition to traditional clinical outcomes. Payers and hospital procurement increasingly demand health system-level impact, not just diagnostic accuracy.
- Design for interoperability: systems that integrate with hospital EMRs, imaging archives and bedside monitors reduce clinical friction and accelerate procurement approvals.
- Hybrid commercial models: combine direct enterprise sales for neuro‑ICU products with channel partnerships and hosted-service models for point-of-care diagnostics to optimize reach and unit economics.
- Plan for regulatory modularity: build evidence packages that support both diagnostic aid claims and broader clinical decision support functions, anticipating tighter scrutiny on standalone diagnostic claims for biomarkers and AI tools.
- Watch the clinical trial landscape: outcomes from PbtO2 monitoring studies and other neurocritical trials will materially affect adoption of invasive monitoring; incorporate alternative scenarios in portfolio planning.
How clients should use this research
For executives and investors, the report is not a static snapshot—it is a decision tool. Use it to prioritize R&D spend, identify partnership candidates, and stress-test M&A targets against realistic adoption curves. For product teams, the evidence blueprints and reimbursement playbooks de-risk clinical development strategies. For commercial leaders, the customer segmentation and channel economics modules translate market opportunity into executable sales and marketing plans.
Final note — a “trailer” that points to the full intelligence
This briefing highlights the macro trends, competitive contours and strategic choices that will shape the TBI devices market in 2026 and beyond. In keeping with PW Consulting’s “trailer” approach, we have intentionally shown the analytical depth and the frameworks you need to act while reserving the detailed segmented tables, region- and application-level forecasts, and proprietary vendor scoring to the full report. Those deliverables include granular scenario models and downloadable financial templates that allow you to run bespoke simulations for specific device classes and markets.
To access the full dataset, detailed segment analytics and the vendor scorecards that underlie our conclusions, please visit the official report page or contact PW Consulting directly for a licensed copy and a tailored briefing session.
For detailed analysis of this topic, please visit the official page: Worldwide Traumatic Brain Injuries Assessment And Management Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Lysosomal Acid Lipase Deficiency Treatment Market Set to Expand at 6.25% CAGR, New Report Shows
By PW Consulting, 2026-08-12
Worldwide Lysosomal Acid Lipase Deficiency (LAL‑D) Treatment Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s new market study on treatments for Lysosomal Acid Lipase Deficiency (LAL‑D) is designed as an operational intelligence tool for executives preparing decisions in 2026. Built on a transparent modelling framework (historical: 2020–2025; base year: 2025; forecast: 2026–2032), the report combines a granular commercial playbook with high‑fidelity demand and revenue scenarios. At a macro level the market follows a steady expansion path — delivering a compound annual growth rate (CAGR) of 6.25% through 2032 — with market value moving from an estimated USD 196.7 Million in 2025 to roughly USD 300.7 Million in 2032. That trajectory underpins a wide range of strategic moves from capacity investments to M&A and pricing negotiations.
Worldwide Physical Resource Management Market
Why this study matters for 2026 strategy
- Timing matters: 2026 is the inflection point for many too‑late/too‑early choices. Our forecast period (2026–2032) is calibrated to show when revenue and patient‑identification headwinds transition into durable uptake — enabling accurate ROI windows for launch and capacity decisions.
- High concentration, concentrated risk and opportunity: The market is highly concentrated (CR3 ≈ 88.5%, CR5 ≈ 94.2%), which means incumbents retain pricing leverage but also that competitive moves (a new approval, a supply disruption, or an innovative modality) can rapidly re‑shape value capture.
- Practical, executable guidance: This is not an academic exercise — the report gives step‑by‑step checklists and model outputs you can immediately use in 2026 budgeting, tendering, and regulatory planning cycles.
Key dynamics shaping near‑term decisions
- Ultra‑rare epidemiology with uneven detection: LAL‑D remains an ultra‑rare condition; prevalence estimates place it in the rare‑disease band, which creates both high per‑patient economics and chronic under‑diagnosis. A recurring theme in our interviews and modelling is the untapped diagnostic pool — addressing it changes the top line materially but requires investment in awareness and testing programs.
- Regulatory and exclusivity tailwinds: The current approved enzyme replacement therapy benefited from orphan‑drug pathways and priority review, and incumbents enjoy meaningful regulatory protections in established markets. Understanding the remaining effective exclusivity window is a critical lever for timing licensing, partnerships and launch sequencing.
- Pricing and reimbursement realities: Annual treatment costs in established markets reflect orphan pricing dynamics and payer willingness to fund transformative therapies. These economics support attractive unit economics for suppliers but also create payer scrutiny and pressure points for contracting in 2026 and beyond.
- Manufacturing as a strategic constraint: Manufacturing for the leading enzyme replacement therapy utilizes an avian‑based production platform. This approach yields clinical product advantages but introduces distinctive capacity constraints and cost drivers — making supply‑chain investment decisions a material determinant of market access and margin.
- R&D and modality shifts: While enzyme replacement remains the incumbent standard, the pipeline includes differentiated approaches (e.g., gene therapy, next‑generation biologics). Our scenario work shows that even a single successful alternative modality can change pricing dynamics and patient flows within a narrow time window.
Competitive landscape — practical implications
The market leader for LAL‑D treatment is a large integrated biopharma that markets the only currently approved enzyme replacement therapy for both pediatric and adult patients. That incumbent benefits from a proven clinical profile, established payer relationships and an integrated manufacturing approach. For market entrants and investors, the report evaluates the incumbent’s defensibility across five vectors: regulatory exclusivity, clinical differentiation, manufacturing scale and resilience, payer contracting history, and specialist centre networks.
Worldwide Livescan Devices Market
Because concentration is high, the strategic playbook is not limited to "go or no‑go" on clinical development — it extends to non‑dilutive commercial approaches: co‑development with diagnostic providers, targeted access programs to accelerate identification and uptake, and manufacturing partnerships to de‑risk supply. Our intelligence highlights how incumbency advantages can be neutralized through focused execution on diagnostics, real‑world evidence (RWE) and payer‑linked outcomes agreements.
Cryogenic Hydrogen Storage System Market
Report contents — what you will receive
The report was structured to be directly actionable for commercial, clinical development, regulatory and corporate development teams. Key deliverables include:
- Market model (Excel): patient‑flow and revenue scenarios across the 2020–2032 horizon, sensitivity levers and scenario toggles for pricing, diagnosis rates and new entrant timelines.
- Go‑to‑market playbooks: segmented GTM options for incumbent and new entrants, including hospital‑led vs home‑care deployment strategies, specialty centre engagement, and payer negotiation templates.
- Payer & HTA intelligence: synthesis of reimbursement precedent, likely dossier requirements in major markets, and modeled budget‑impact statements for use in 2026 submissions.
- Manufacturing & supply guidance: detailed assessment of current production platforms, consent‑ready supplier lists, capital expenditure profiles and time‑to‑scale scenarios to mitigate avian‑platform constraints.
- Regulatory timelines & exclusivity maps: consolidated view of orphan, priority review and conditional approval mechanisms — and how they translate into commercial exclusivity across key jurisdictions.
- RWE and diagnostic acceleration playbook: program designs to increase diagnostic yield, economic models showing patient identification payback, and implementation roadmaps for 12‑ to 36‑month horizons.
- M&A and partnership screening tool: prioritized target archetypes, valuation frameworks reflecting market concentration and near‑term cash flow profiles, and an execution checklist for deal teams.
How the report supports the 2026 decision agenda
- Portfolio prioritization: Use our demand curves and NPV scenarios to decide whether to accelerate programs targeting LAL‑D or re‑allocate to adjacent ultra‑rare indications. The CAGR and base‑case growth help set realistic revenue hurdles for internal IRR targets.
- Launch sequencing & market access: Our payer dossiers and HTA scenarios let you prioritize initial launch territories and pricing strategies that maximize early patient access without undermining long‑term price realization.
- Manufacturing investment & risk mitigation: Given the idiosyncrasies of avian‑based manufacture, the report sets out when and how much to invest in redundant capacity, fill‑finish partnerships, or technology transfers to ensure uninterrupted supply.
- M&A and partnering timing: Concentration levels mean a small set of strategic deals can change competitive dynamics. The study flags acquisition and licensing windows that align with exclusivity expiries and expected pipeline readouts.
- Commercial contracting & outcomes models: We provide contracting templates and modeled outcomes‑based agreements that reflect payer risk tolerance and the clinical course of LAL‑D, enabling earlier negotiation and faster access.
Real‑world constraints and mitigation strategies
Three pragmatic constraints repeatedly influenced our modelling and recommendations: limited diagnosis, manufacturing specificity, and payer scrutiny on high‑cost orphan products. For each we present mitigations: targeted screening programs to lift diagnosis rates efficiently; staged capital plans and contract manufacturing strategies to neutralize single‑platform risk; and evidence generation designs aligned to payer decision criteria. Each mitigation is tied to measurable KPIs and a short checklist for 90‑ to 180‑day implementation.
Next steps and how to use the accompanying assets
PW Consulting’s report is intentionally structured as a decision support package for 2026: downloadable models, payer dossiers, negotiation playbooks and a 12‑month implementation roadmap. The public summary above is designed to outline the strategic value; the full intelligence pack contains the detailed segmentation, market shares, regional scenarios and line‑item revenue forecasts necessary for transaction due diligence, launch planning, or portfolio rebalancing.
To access the complete dataset, including the full segmentation breakdown and downloadable Excel model supporting the 6.25% CAGR projection and the 2025–2032 revenue curve, visit our report page or contact PW Consulting’s healthcare strategy team. The complete report is the only source of the detailed regional, treatment‑type and end‑user splits required for transactional analysis and granular market entry planning.
Conclusion
By 2026, executives who combine a clear view of epidemiology, pragmatic manufacturing plans, and payer‑centric evidence strategies will capture disproportionate value in the LAL‑D market. PW Consulting’s Worldwide LAL‑D Treatment Market report converts that competitive logic into executable plans and financial models calibrated to the real constraints of ultra‑rare therapy commercialization. Reach out to obtain the full report and the working model that will make your 2026 decisions measurable, defendable, and outcome‑oriented.
For detailed analysis of this topic, please visit the official page: Worldwide Lysosomal Acid Lipase Deficiency Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


