



Category: market research
PW Consulting: Worldwide Consumer Electronic Biometrics Market to Grow at 15.7% CAGR, Hitting USD 76.22 Billion by 2032 as Smartphones and Fingerprint Tech Dominate
By PW Consulting, 2026-08-05
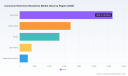
Worldwide Consumer Electronic Biometrics Market: Strategic Outlook for 2026 — PW Consulting Report Preview
PW Consulting’s new market study on Worldwide Consumer Electronic Biometrics delivers an evidence-backed strategic road map for commercial leaders planning moves in 2026. Built from a five-year historical base and a seven-year forecast horizon, the report synthesizes market-scale dynamics, supplier positioning, technology trajectories, regulation and supply-chain risk into actionable choices for device OEMs, semiconductor suppliers, platform companies, payment networks and private equity investors. This preview highlights the report’s strategic value while preserving the granular segment-level findings for subscribers and clients.
Worldwide Consumer Electronic Biometrics Market
Market trajectory and macro drivers
The consumer electronic biometrics market has shifted from a niche security add-on into a foundational layer for user experience, payment authentication and device safety. PW Consulting’s topline model shows a sustained acceleration: the market expanded rapidly through 2020–2025 and reached approximately USD 27.5 billion in 2025. Under our base forecast, the market steps into a stronger growth phase in 2026 and is projected to exceed USD 76 billion by 2032 — reflecting a compound annual growth rate (CAGR) of 15.7% across the forecast period.
Worldwide Consumer Electronic Biometrics Market
Three structural forces underpin this growth: (1) continued premiumization of consumer device security tied to payment and identity use-cases, (2) rapid diffusion of multimodal biometrics across new form factors (cards, wearables, home devices and notebooks), and (3) a software-driven upgrade cycle — where liveness, anti-spoofing and privacy-preserving architectures drive new monetizable services. Each of these forces creates distinct investment and competitive implications that we unpack in dedicated chapters of the report.
Worldwide Consumer Electronic Biometrics Market
What the report delivers — practical, transaction-ready outputs
- Dynamic market model: a granular, time-series top-down and bottom-up model (2020–2032) with scenario sensitivity to penetration, ASP and replacement cycles.
- Competitive scorecards: independent assessments of module and platform suppliers across technology, cost, IP depth, go-to-market reach and integration risk.
- Supplier risk matrix: concentrated wafer and component exposures, dual-sourcing stress tests and contingency playbooks for 2026 procurement cycles.
- Regulatory impact assessments: calibrated scenarios for export controls, privacy law fragmentation and EMVCo’s ‘Biometric on Card’ initiative — translated into compliance costs and time-to-market impacts.
- Go-to-market playbooks: OEM commercialization timelines for biometric-enabled product launches, recommended partner structures and monetization pathways (SaaS verification, identity-as-a-service, transaction risk reduction).
- M&A and partnership pipeline: target prioritization based on technology adjacencies, capability gaps and likely valuation multiples within the current consolidation window.
- IP and technology roadmap: mapping of optical, ultrasonic, capacitive, camera-based 3D, iris and behavioral stacks — and the likely winners by cost curve and integration friction.
Strategic imperatives for 2026 decision-makers
As leaders draft plans for 2026, the report crystallizes five imperatives that should guide capital allocation and commercial strategy.
- Design for resilience, not just cost: With component production concentrated in specific wafer foundries, procurement teams must incorporate geopolitical and export-control stress tests into supplier selection. Dual-sourcing and qualified second-source roadmaps should be budgeted and executed in 2026 to avoid single-point failures.
- Prioritize software and services monetization: Hardware differentiation is narrowing. Device makers and platform owners should reallocate investment towards liveness detection, continuous authentication, privacy-preserving templates and identity services that enable recurring revenue and stickiness.
- Align with standards early: EMVCo’s ‘Biometric on Card’ and evolving national export controls imply non-trivial compliance lead times. Product teams that embed standards-aligned architectures now will avoid costly rework and secure first-mover advantage for payment-related use cases.
- Adopt a portfolio approach to modality: Single-modality bets expose companies to competitive displacement as optical and camera-based solutions evolve. Our analysis recommends a prioritized blend of fingerprint, face and behavioral modalities matched to form-factor economics and end-user friction targets.
- Use M&A and partnerships to fill capability gaps: The current consolidation window presents opportunities to acquire niche sensor technologies, advanced algorithms or regional go-to-market assets. Strategic buyers should focus on targets that remove integration risk and accelerate monetizable services.
Competitive landscape — who matters and why
The market structure is moderately concentrated: PW Consulting’s competitive concentration analysis indicates that the top three players account for a meaningful plurality of supplier influence, while the top five together extend majority share — a dynamic that shapes pricing power, standards influence and channel reach.
Several vendor archetypes are visible:
- Platform integrators and consumer OEMs (e.g., Apple Inc., Samsung Electronics) — these firms embed proprietary biometric stacks and control the largest distribution channels, making them natural gatekeepers for platform-level security features.
- Chipset and SoC suppliers (e.g., Qualcomm Technologies) — they influence reference architectures and enable scale by integrating sensors onto mobile platforms.
- Module and sensor specialists (e.g., Goodix, Synaptics, Fingerprints, Egis) — these suppliers drive cost and differentiation at the device level through sensor variety (capacitive, optical, ultrasonic) and integration support.
- Specialist system providers and software houses (e.g., IDEMIA, NEC, Suprema, IDEX Biometrics) — focused on enterprise-grade algorithms, payment-card integrations and biometric middleware.
Recent market moves reinforce these archetypes and the momentum toward consolidation and capability stacking: a global award recognizing a major supplier’s leadership in biometric innovation, cross-border acquisitions that combine public-security and consumer-authentication assets, the emergence of novel optical and metalens-based contactless modules, and the entry of local champions in large addressable markets. Each event accelerates integration complexity for OEMs and changes the calculus for partners and investors assessing 2026 opportunities.
Regulation, supply chain and product dynamics: practical consequences
- Export controls and AI model constraints: Revision of advanced computing export rules and controls on certain AI model weights materially affect where high-performance biometric processing can be developed and deployed. We quantify compliance lead times and re-hosting costs in the full report.
- Wafer and component concentration: Dependence on a narrow set of foundries for sensor ICs creates a persistent supply-side vulnerability. Our supplier-risk framework translates that vulnerability into scenario-specific revenue-at-risk and procurement playbooks.
- Standards-led product shifts: Initiatives like EMVCo’s biometric-on-card push accelerate demand for ultra-thin, low-power fingerprint modules and create new certification costs and gatekeepers for payment use-cases.
- Scale in adjacent volumes: With consumer device shipments embedding biometric modules at scale, incremental unit declines in ASP or slight penetration gains produce outsized P&L effects for module suppliers — a sensitivity analysis provided in the report helps quantify which levers matter most.
How investors and corporate strategy teams should use this preview
This preview is designed to orient 2026 planning. PW Consulting’s full study converts these insights into decision-ready outputs: acquisition target shortlists with indicative valuation ranges, supplier scorecards to inform long-lead sourcing decisions, region- and form-factor-specific go-to-market playbooks, and a live model that lets executives test “what-if” scenarios for device adoption, pricing and regulatory outcomes.
Examples of immediate, high-value actions recommended for C-suite and investment committees:
- Execute a prioritized validation program to qualify secondary sensor suppliers and reduce single-source exposure within the next two quarters.
- Allocate R&D budget to liveness and template protection technologies that can be productized as subscription services within 12–18 months.
- Define a standards-compliance roadmap aligned with EMVCo and regional export-control timelines to avoid delayed product certifications.
- Screen small-to-midcap acquisition targets that provide either unique modality IP or quick integration pathways into payment credential ecosystems.
Why read the full report
PW Consulting’s full report goes beyond this strategic preview. It contains the underlying models, proprietary segmentation, interactive dashboards and vendor-level metrics necessary to convert insight into execution. For boards, procurement leads and deal teams preparing for 2026, the report is a practical toolkit: it tells you not just where the market is going, but how to sequence investments, mitigate supplier risk, and capture recurring revenue from biometric-enabled experiences.
To obtain the full dataset, benchmarking modules and bespoke advisory support, contact PW Consulting. Our team can provide tailored briefings, deep-dive workshops and scenario runs calibrated to your portfolio or product roadmap.
For detailed analysis of this topic, please visit the official page: Worldwide Consumer Electronic Biometrics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Child-Resistant Blister Lidding Film Market to Hit USD 1,559.1 Million by 2032, Driven by a 6.94% CAGR
By PW Consulting, 2026-08-05
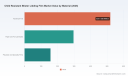
Worldwide Child Resistant Blister Lidding Film Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market research briefing on the Worldwide Child Resistant Blister Lidding Film market is designed as a strategic primer for executive teams preparing 2026 roadmaps. The global market has demonstrated steady expansion over the last half‑decade and, under a baseline scenario, is projected to continue growing at a mid‑single‑digit compound annual growth rate (CAGR) through the forecast window. This release highlights the actionable intelligence and decision frameworks embedded in the full report, while preserving the granular proprietary tables and splits that are available on our website for clients and subscribers.
Worldwide Child Resistant Blister Lidding Film Market
Why this market matters in 2026
Child resistant (CR) blister lidding films sit at the intersection of pharmaceutical safety, regulatory compliance, and packaging sustainability. With aging populations in core markets, persistent regulatory tightening, and pharmaceutical packaging increasingly required to balance barrier performance with recyclability, CR lidding films have become a strategic lever for time‑to‑market and product stewardship. From an investor and operations standpoint, the segment offers predictable revenue growth and defensible margins — but not without technical, regulatory and supply‑chain complexities that require deliberate choices in 2026.
Worldwide Child Resistant Blister Lidding Film Market
Market trajectory at a glance
-
Historical momentum: The market has expanded consistently across the 2020–2025 period as pharmaceutical unit volumes recovered and safety specifications tightened.
Worldwide Child Resistant Blister Lidding Film Market -
Near‑term baseline: Our model uses 2025 as the base year and anticipates the market continuing its expansion into 2026 and beyond under a central scenario; the projected multi‑year CAGR is in the high single digits, reinforcing medium‑term growth visibility for incumbent producers and new entrants alike.
-
Longer horizon: By the end of the forecast window the market is expected to be meaningfully larger than in 2025, driven by a combination of regulatory-driven upgrades, premiumization toward higher‑barrier and recyclable constructions, and incremental uptake across geographies.
What the full report delivers — practical, transaction‑ready intelligence
The PW Consulting report goes beyond high‑level trends to equip commercial, product and M&A teams with actionable deliverables, including:
-
Market sizing and forecast models built from 2020 through a multi‑year forecast period, with scenario sensitivity (base, downside, upside) to stress test strategic choices.
-
Go‑to‑market playbooks targeted at manufacturers, converters and pharmaceutical contract packagers: product positioning matrices, price band analysis, and win‑loss implication frameworks.
-
CapEx and capacity planning guidelines assessing thermoforming and foil conversion footprints, tooling lead times, and break‑even utilization thresholds for new lines.
-
Regulatory compliance checklists and engineering tradeoffs comparing peel‑push, peel‑open and tear‑open approaches for mixed adult usability and child resistance.
-
Supply‑chain risk maps, highlighting raw‑material exposure, alternative sourcing strategies and inventory levers to mitigate volatility.
-
Commercial benchmarking and vendor scorecards that help procurement teams operationalize supplier selection and qualify technical claims.
To honor the “trailer” principle of this briefing, we outline the type and strategic value of granular content without reproducing proprietary split tables and line‑item values. Clients will find the embedded spreadsheets and scenario tools indispensable for board‑level decisions.
Competitive landscape — who matters and why
The CR lidding film market shows a balance: several global platform players with integrated R&D and manufacturing capabilities, plus regional specialists and converters that compete on customization and speed. The competitive dynamic favors organizations that can combine regulatory know‑how, barrier technologies, and increasingly, demonstrable sustainability credentials.
-
Amcor plc (Melbourne, Australia) — A global packaging platform known for supplying CR lidding films for pharmaceutical blisters across a range of peelable and push‑through formats. Recent product development is oriented toward recyclable constructions, reflecting both customer demand and regulatory pressure.
-
Constantia Flexibles (Vienna, Austria) — Specialist in multi‑layer aluminium and film laminates with a strong presence in high‑barrier pharmaceutical applications. Active participation in major trade shows signals continued emphasis on design and client collaboration.
-
Tekni‑Plex (Wayne, PA, USA) — Focuses on thermoformable lidding technologies and user‑centric designs that balance child resistance with senior accessibility. Certification and protocol compliance are central to their value proposition.
-
Winpak Ltd. (Winnipeg, Canada) — Emphasizes puncture‑resistant constructions and reliability for medical markets, where supply continuity and quality control are premium concerns.
-
Alpine Packaging Inc. (North Salt Lake, UT, USA) — A custom converter targeting OTC and Rx niches with flexible aluminum/polymer laminates tailored for brand differentiation.
-
ProAmpac (Cincinnati, OH, USA) — Positions itself around sustainable and recyclable flexible lidding solutions, aligning material innovations to circular‑economy requirements.
-
Hood Packaging Corporation (Madison, MS, USA) — Known for proprietary peel‑reseal features that support secondary use cases and consumer convenience without compromising child resistance.
-
Sonoco Products Company (Hartsville, SC, USA) — Integrates thermoformed lidding films with high barrier properties for global pharmaceutical customers, leveraging a broad packaging portfolio.
Recent corporate developments underscore where competitive advantage is being created: product launches emphasizing recyclability, tradeshow reveals that translate to new partnerships, and certifications that validate protocol compliance. These moves point to two strategic priorities for competitors in 2026 — secure regulatory assurance and deliver demonstrable sustainability without surrendering barrier performance.
Dynamics and risks shaping 2026 strategies
-
Raw material exposure: Aluminium foil (typical gauge ranges used in lidding) remains the primary substrate in many CR constructions. Recent reference pricing indicates notable price sensitivity; procurement strategies that diversify suppliers or hedge critical purchases will materially affect margin stability.
-
Regulatory constraints: Compliance regimes such as the U.S. CPSC child resistance testing protocol and European standards for elderly usability are non‑negotiable. The CPSC protocol requires a very low success rate in opening attempts by young children, while legacy EU testing mandates adult usability demonstrations (e.g., repeated openings by older adults). These standards drive both R&D cycles and qualification lead times.
-
Sustainability regimes: Policy instruments are already influencing design choices. For instance, plastic packaging levies and recycled content mandates in certain jurisdictions create a two‑front challenge: meeting end‑use functional requirements while aligning with minimum recycled content thresholds and tax regimes that penalize low‑recycled content.
-
Tax and cost headwinds: Specific packaging taxes can introduce non trivial cost increments on conventional constructions, creating incentives to reformulate or pass costs through the commercial chain. Companies that can quantify total landed cost impacts and present alternative low‑tax constructions will command negotiating leverage.
-
Consolidation and differentiation: Competitive intensity is increasing as incumbents pursue scale while niche providers compete on customization and speed. Moderate market concentration exists — sufficient to support margin pools for disciplined players but permissive for successful targeted entrants.
Strategic playbook for 2026 — decisions that matter
For C‑suite and strategy teams preparing near‑term plans, the report recommends focusing on three coordinated moves:
-
Prioritize regulatory‑first product roadmaps. Invest in third‑party testing and adult/usability validation early in the NPI process to compress time‑to‑market for pharmaceutical customers that require validated CR performance.
-
Redesign procurement for input volatility. Implement dual sourcing for aluminium and polymer layers, explore long‑term offtakes or metal hedging mechanisms, and build buffer strategies for critical thin‑gauge foil to avoid costly line downtime.
-
Separate sustainability and functionality in commercial conversations. Develop modular constructions that allow a de‑risked migration path to higher recycled content, and quantify tax exposures to offer customers transparent total cost of ownership comparisons.
Executives should treat these moves as an integrated program: procurement, R&D and commercial functions must coordinate KPIs to ensure that sustainability commitments do not undermine child‑resistance performance or lead to unfavorable margin erosion.
Transactions, partnerships and innovation hotspots
2026 is shaping up to be an active year for bolt‑on M&A and strategic partnerships. Targets of interest include converters with captive pharma relationships, technology owners of patented peel mechanisms, and regional players that provide faster local service for pharmaceutical contract packagers. Investors should evaluate targets not only on revenue growth but also on their technical validation pipelines and ability to meet evolving recycled‑content requirements.
How to use the full PW Consulting report
The full report is structured as a decision toolkit: integrated financial models, supplier scorecards, product comparison matrices, compliance checklists and scenario playbooks. It is made for commercial negotiations, board‑level investment assessment, and operational planning. Subscribers gain access to downloadable spreadsheets and step‑by‑step guides that translate market scenarios into near‑term tactical actions for sales, procurement and manufacturing teams.
Conclusion — the strategic value proposition
As 2026 planning cycles commence, the child resistant blister lidding film market offers a clear mixture of predictable growth and structural complexity. Companies that can operationalize regulatory compliance, secure raw‑material continuity and present credible sustainability pathways will outperform. PW Consulting’s full report supplies both the quantified market backdrop and the execution playbooks required to convert insight into measurable outcomes. For executives seeking to validate capital proposals, inform product roadmaps, or prioritize M&A targets, the report provides the empirically driven inputs and the scenario tools necessary to make confident decisions.
To review the granular datasets, proprietary segment analyses and downloadable scenario models referenced in this briefing, please visit the PW Consulting report page or contact our client services team to arrange a briefing with the research authors.
For detailed analysis of this topic, please visit the official page: Worldwide Child Resistant Blister Lidding Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Lock with Cat's Eye Market Hits USD 1,550.0 Million in Base Year 2025, Set to Grow at 13.5% CAGR to USD 3,760.99 Million by 2032 — Asia‑Pacific Leads (USD 849.6M), Residential Dominates; Market Remains Fragmented (CR3 32.5%)
By PW Consulting, 2026-08-05
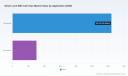
Worldwide Smart Lock With Cat's Eye Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive summary
PW Consulting’s latest market study on the Worldwide Smart Lock With Cat's Eye Market synthesizes five years of historical performance and a seven-year forecast to deliver a decision-grade view for corporate leaders, product teams, investors, and policy-makers. The market has moved from an early-stage IoT niche into a mainstream security and convenience category: total market value expanded materially between 2020 and 2025 and — under current trajectories — is expected to continue a strong compound annual growth rate through the 2026–2032 forecast window. This preview highlights the strategic value of the full report for 2026 planning cycles while intentionally omitting granular segment tables and proprietary model outputs to encourage direct access to the full intelligence package.
Worldwide Smart Lock With Cat's Eye Market
Market trajectory: growth, momentum, and what it means
Key macro dynamics are unambiguous. From the pandemic-era recovery and accelerating smart-home adoption, the smart-lock-with-cat-eye market has recorded multi-year growth, with the base year set at 2025 in our analysis. Our forecast model projects sustained expansion over the 2026–2032 period at a mid-teens CAGR, reflecting a convergence of three durable trends: (1) consumer demand for integrated visual verification and remote access, (2) rapid feature convergence between home-security incumbents and telecom/OEM entrants, and (3) falling component costs for cameras, sensors, and secure connectivity stacks.
Worldwide Smart Lock With Cat's Eye Market
For corporate strategists, two practical takeaways are immediate. First, product roadmaps that integrate reliable video capture, robust privacy controls, and interoperable cloud services capture disproportionate buyer preference. Second, channel strategies must account for both platform-enabled OEM partnerships and direct-to-consumer experiences; the latter are increasingly shaped by bundled services from larger smart-home ecosystems.
Worldwide Smart Lock With Cat's Eye Market
Why this report matters for 2026 decision-makers
- Timing: Boards and product committees preparing 2026 investment cycles need a clear view of where to allocate R&D and go-to-market spend — our forecast horizon aligns with typical three-year planning cadences and highlights inflection points for scaling production, pricing, and partnerships.
- Competitive positioning: The market sits at a crossroads between hardware differentiation (camera angle, night vision, facial recognition) and software/platform ownership (device management, firmware security, cloud video services). Our analysis isolates which competitive levers yield defensible margin expansion versus those that are easily replicated.
- Risk triage: Supply chain fragility, regulatory uncertainty, and data-privacy exposure create asymmetric downside. The report quantifies scenario impacts and provides mitigation playbooks tailored to different company archetypes — OEMs, firmware vendors, platform players, and legacy lock manufacturers.
Report contents — practical, operational, and transaction-ready
The full PW Consulting report is structured to be directly usable in board decks, investment memos, and product roadmaps. Highlights include:
- Market model and assumptions: Transparent base-year inputs (historical 2020–2025) and a probabilistic forecast engine for 2026–2032, with scenario toggles for adoption curves, component deflation, and regulatory cost impacts.
- Go-to-market playbooks: Channel prioritization matrices for direct retail, installer networks, institutional procurement, and subscription-led service models. Each playbook contains revenue levers, unit-economics sensitivities, and sample KPIs for first 24 months post-launch.
- Product benchmarking: A specification matrix comparing real-world product features — camera field-of-view, night vision performance, biometric modalities, indoor interface ergonomics, and battery longevity — mapped to perceived value by buyer persona.
- Privacy & compliance toolkit: Practical checklists and contract language templates to support deployment in heterogeneous jurisdictions, including guidance on data minimization, retention policy, consent flows, and breach-response playbooks.
- Supply chain and manufacturing risk maps: Component concentration analysis, alternative sourcing strategies, and cost arbitrage modeling to inform sourcing and nearshoring decisions.
- M&A and partnership dossiers: Target screening criteria, valuation checkpoints, and integration roadmaps for platform acquisitions, camera-IP buys, and regional distribution rollups.
Competitive landscape: who is shaping the category and how
The current competitive field blends entrenched lock-makers, consumer electronics giants, and platform/ODM specialists. Market activity in 2024–2025 has been dominated by two parallel dynamics: consumer-electronics brands pushing high-feature models with rich in-home interfaces, and platform orchestration players enabling a multitude of OEMs through white-label solutions.
- Xiaomi — Leveraging its consumer-electronics playbook, Xiaomi has delivered iterations emphasizing large indoor displays, wide-angle cat-eye cameras, AI-driven human detection, and an array of unlocking methods. These moves focus on user experience and ecosystem stickiness; expect Xiaomi to continue prioritizing price-performance and integrated services to increase lifetime value.
- Huawei — Huawei’s strategy centers on integrated surveillance-grade optics and AI detection, positioning products as secure, high-performance smart-locks within broader smart-home bundles. Its emphasis on multi-modal unlocking and camera fidelity indicates an attack on the premium segment.
- Yale (ASSA ABLOY) — As a legacy security brand, Yale is converting trust equity into feature-rich digital locks with cat-eye visualization. The brand is playing to strengths in mechanical integrity and firmware reliability while incorporating visual verification to retain relevance in modern smart-home ecosystems.
- Tuya Inc. — As a platform enabler, Tuya’s value proposition is interoperability and rapid OEM time-to-market. Their platform enables numerous white-label manufacturers to ship WiFi/APP-controlled devices integrated with cat-eye functionality; this reduces entry barriers and accelerates market fragmentation at the lower end.
- Specialist OEMs (e.g., PuXin, Locstar, Botin) — These vendors are iterating on camera performance, 3D facial recognition options, and integrations with mainstream platforms. Their agility in hardware development makes them attractive partners for brands seeking speed-to-shelf without heavy R&D investment.
Recent product launches in 2025 — from larger indoor screens and extended battery life to 160°+ viewing angles and AI human detection — signal that competitive differentiation is increasingly feature-led rather than channel- or brand-led. This shifts the battleground to firmware update cadence, privacy assurances, and post-sale service experiences.
Regulatory and privacy dynamics: a strategic blindspot for many
Regulatory pressures are one of the least appreciated strategic risks. Three regulatory themes require executive attention:
- Standards gap: Some major markets still lack unified technical standards for camera-enabled locks, leaving product makers to navigate an uneven patchwork of mechanical safety rules and ad-hoc privacy guidance. This creates both compliance risk and an opportunity for first-movers to adopt best-practice voluntary standards that become de facto market expectations.
- Data protection law: In jurisdictions governed by comprehensive frameworks (e.g., GDPR-equivalent regimes), visual data from cat-eye devices is tightly constrained — use must be for private purposes, sharing is limited, and camera orientation that captures public spaces or neighbors can be restricted. Product and legal teams must bake privacy-by-design into firmware and UX flows.
- Local tenant protections: Subnational regulations (for example, tenant privacy laws in major cities) impose operational constraints — consent mechanisms, physical key provisions, and retention limits — that materially affect leasing and multi-dwelling unit (MDU) sales strategies.
Strategic recommendations for 2026
- Prioritize privacy engineering: Adopt a default-minimization approach to video capture, provide transparent retention controls to users, and embed consent flows into installer and property-management interfaces. These moves reduce legal risk and create customer trust advantages.
- Differentiate beyond optics: While camera FoV and resolution matter, the sustainable differentiator is post-capture value: edge analytics, false-positive reduction, local-first processing options, and seamless firmware update mechanisms.
- Design channel-specific SKUs: Residential and institutional buyers have distinct needs on SLAs, deployment, and lifecycle services. Create SKU and service bundles tailored to each channel rather than a one-size-fits-all product.
- Use platform partnerships strategically: Partner with platform players to accelerate distribution, but protect margin and data access through contractual controls and co-branding strategies where appropriate.
- Prepare for consolidation: The market’s competitive breadth and moderate concentration make it ripe for consolidation. Maintain an M&A playbook that prioritizes access to camera-IP, regional distribution, or cloud-video capabilities.
How to get the full intelligence
This briefing is a strategic trailer designed to demonstrate the depth and operability of PW Consulting’s analysis while preserving the detailed segmentation, model outputs, and proprietary company scorecards that drive transactional decisions. The full report includes downloadable spreadsheets, sensitivity models, vendor scorecards, and recommended contract language for privacy and OEM agreements.
For executive teams preparing 2026 budgets, product leaders defining roadmaps, and M&A teams screening targets, the full Worldwide Smart Lock With Cat's Eye Market report provides the granular evidence and operational tools needed to convert insight into action.
Contact
To request the complete report, model access, or a tailored briefing for your executive team, please visit the PW Consulting research portal or contact our market intelligence team directly. Accessing the full content will unlock the granular segmentation, regional projections, and product-level benchmarking that underpin the strategic conclusions summarized here.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Lock With Cat's Eye Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Dispute Advisory and International Arbitration Market Projected to Expand at a 6.35% CAGR Through 2032
By PW Consulting, 2026-08-05
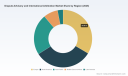
PW Consulting: New Worldwide Dispute Advisory and International Arbitration Market Report — Strategic Imperatives for 2026
PW Consulting today publishes its definitive market study, Worldwide Dispute Advisory and International Arbitration Market (base year 2025), delivering an actionable compass for corporate counsel, arbitration practitioners, dispute advisory firms, and in-house risk teams preparing strategy for 2026 and beyond. Grounded in a six-year historical series (2020–2025) and a seven-year forecast horizon (2026–2032), the report models a global market that we estimate at USD 24,850.5 Million in 2025, rising to USD 27,007.1 Million in 2026 and growing at a compound annual growth rate (CAGR) of 6.35% through 2032 to reach an anticipated USD 38,238.2 Million. While this press release highlights the study’s strategic takeaways, the full dataset, granular segmentation and interactive dashboards are reserved for the report and associated intelligence portal.
Worldwide Dispute Advisory and International Arbitration Market
Why this report matters for decisions made in 2026
-
Timing and resource allocation — The projected mid-single-digit CAGR signals sustained demand for dispute advisory services. Organizations that realign budgets in early 2026 to shore up dispute preparedness and expert capacity will be better positioned to avoid value erosion when disputes crystallize.
Worldwide Dispute Advisory and International Arbitration Market -
Structural shifts in spend — The study identifies where advisory spend is migrating (by service type and industry vertical), enabling counsel and procurement teams to benchmark third-party engagements against emerging market norms and negotiate more effectively.
Worldwide Dispute Advisory and International Arbitration Market -
Vendor and capability strategy — For law firms and consultancies, the analysis pinpoints which capability bundles (forensics, delay analysis, strategic advisory, legal counsel) are becoming table stakes versus differentiators, guiding M&A, alliance, and hiring priorities.
-
Regulatory and technological risk planning — With disputes increasingly intersecting with data privacy, cybersecurity, AI, crypto and tariff-related matters, the report translates macro trends into prescriptive compliance checklists and escalation protocols for 2026.
-
Enforcement and forum selection — The evidence base in the report supports more defensible seat selection and enforcement strategies in cross-border matters, informed by recent institutional caseloads and market concentration dynamics.
What the report contains — practical, operational, and decision-ready
-
Comprehensive market sizing and forecasting: A transparent methodology that reconciles historical casework, institutional statistics, and advisory billing trends to produce top-line market estimates and scenario-based forecasts for 2026–2032.
-
Segmentation with pragmatic lenses: Multi-dimensional segmentation (region, service type, industry vertical) is presented alongside use-case matrices and service bundling maps to help clients translate market trends into procurement and delivery choices. Note: detailed segment tables are included in the full report to preserve the precision necessary for contracting and budgeting.
-
Competitive capability maps: Firm-level profiling and capability heatmaps (including global law firms, boutiques and Big Four advisory practices) let buyers and competitors identify capability gaps, potential partners and acquisition targets.
-
Operational playbooks and toolkits: Actionable checklists, RFP templates for dispute advisory services, expert selection scorecards, and cost-sensitivity models tailored for high-value cross-border matters.
-
Case studies and benchmark scenarios: Representative anonymized engagements illustrating successful dispute containment, cost management, and enforcement strategies across common dispute archetypes.
-
Regulatory tracker and tech impact assessment: A living annex that synthesizes data protection guidance (including the ICCA-IBA Task Force perspectives), AI tooling adoption paths for evidence review, and the practical implications of evolving tariff and crypto disputes.
Market dynamics shaping arbitration and advisory in 2026
-
Globalization of disputes remains strong. Institutional statistics released in early 2026 show continued cross-border intensity in arbitration filings and party diversity, underscoring why multinational parties must prioritize enforcement planning and venue defensibility when structuring transactions (International Chamber of Commerce, February 2026).
-
Technology is moving from augmentation to integration. AI tools for document review, chronology building, and damages modelling are reducing time to evidentiary readiness while raising new procedural and evidentiary questions—requiring firms to adopt hybrid workflows that pair algorithmic speed with expert oversight (Cleary Gottlieb Trends, January 2026).
-
Data privacy and cybersecurity are operational imperatives. GDPR constraints and task-force guidance on electronic evidence mean that cross-border evidentiary strategies must be built into case budgets and timelines from day one.
-
Geopolitics, tariffs and novel asset classes (crypto) are driving new dispute types. Parties and advisors must build capability to navigate sanctions, sovereign countermeasures and digital-asset valuation challenges that increasingly appear on arbitral dockets.
-
Labor and delivery models are evolving. Specialized human capital remains the primary cost driver for high-stakes advisory work; the most successful providers are blending distributed expert networks with centralized project management to control margins while maintaining quality.
Competitive landscape — what leading firms are prioritizing
The market remains fragmented: the combined share held by the three largest players (CR3) is modest relative to many professional services sectors, and even a five-firm concentration (CR5) leaves substantial room for boutiques and specialist practices to capture mandate flow. Our study profiles a cross-section of market leaders and innovators, and distils strategic positioning relevant to 2026 decision-makers:
-
Full-service global firms (e.g., Freshfields Bruckhaus Deringer, White & Case, Baker McKenzie) are leveraging integrated platforms to deliver seamless cross-border litigation, arbitration and transactional advice. Their emphasis is on pre-contentious strategy, enforcement corridors and multi-forum coordination.
-
Regional and sector specialists (e.g., Herbert Smith Freehills Kramer, King & Spalding) are differentiating by concentrating high-value mandates in energy, construction and infrastructure where industry knowledge materially affects outcome and pricing.
-
Boutiques and elite counsel (e.g., Three Crowns LLP, Quinn Emanuel) are capturing marquee mandates by combining focused expertise in public international law and high-stakes advocacy with flexible resourcing models that appeal to sophisticated claimants and respondents.
-
Forensic and consulting players (e.g., PwC) continue to deepen technical offerings—damage quantification, forensic accounting, and expert witness services—operating in tight coordination with counsel to shorten timelines and sharpen narrative control.
Recent industry developments reinforce these dynamics: institutional caseload releases, recognition in global rankings, and trend publications by leading practices underscore both the scale of opportunity and the increasing sophistication of clients’ expectations (ICC statistics, Chambers Global 2026, Cleary Gottlieb trends, Quinn Emanuel awards, LCIA casework reports).
Practical implications and recommended actions for 2026
-
For in-house legal teams: adopt a dispute-readiness matrix that integrates enforcement profiling, data protection contingencies, and early expert triage. Use the report’s procurement templates to test supplier claims against market benchmarks.
-
For law firms and advisers: invest in integrated service bundles that couple forensic capability with arbitration advocacy, and develop demonstrable AI governance frameworks to satisfy tribunals and clients alike.
-
For investors and corporate strategists: incorporate dispute scenario analysis into transaction diligence, particularly for projects exposed to geopolitical risk, tariff volatility, or novel digital-asset considerations.
-
For boutique specialists: leverage focused domain expertise and flexible resourcing to pursue higher-margin niche mandates while partnering with global platforms on enforcement and jurisdictional reach.
What we deliberately leave to subscribers — and why
True to our “trailer” principle, this release communicates the report’s strategic thrust, operational offerings and high-level market metrics, while reserving full granular tables, regional and service-type breakdowns, firm-level revenue mapping, and the interactive forecast models for the full report and subscriber portal. Those detailed segmentations are essential for contracting, budgeting and competitor analysis and are therefore delivered as part of the report package to ensure users have the complete, auditable dataset needed to act with confidence in 2026.
How to use the report
-
Start with the executive dashboard to align senior stakeholders on market trajectory and the specific cost drivers that will affect 2026 budgets.
-
Deploy the vendor scorecards and RFP templates in tandem to compress procurement cycles and secure demonstrable SLAs on dispute staffing and deliverables.
-
Apply the scenario models to at least three downside and upside dispute outcomes in transaction and project planning, and stress-test enforcement assumptions under divergent geopolitical scenarios.
PW Consulting’s Worldwide Dispute Advisory and International Arbitration Market report synthesizes institutional caseload signals, firm behaviour, regulatory developments and technology adoption to provide a single source of truth for dispute strategy in 2026. For access to the full report, datasets and the interactive intelligence portal, please visit the PW Consulting research page.
About PW Consulting: We are a global strategy and advisory firm specialising in market intelligence, commercial litigation economics and transaction risk. Our multidisciplinary teams combine legal industry experience, forensic economics, and scenario-based modelling to help clients convert complex market signals into executable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Dispute Advisory and International Arbitration Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Food‑Grade Ammonium Chloride Market to Reach USD 268.04 Million by 2032, Expanding at a 4.12% CAGR
By PW Consulting, 2026-08-05
Worldwide Food Grade Ammonium Chloride Market — Strategic Outlook for 2026: What Senior Executives Need to Know
PW Consulting’s latest market brief on the Worldwide Food Grade Ammonium Chloride Market (base year 2025) offers boardroom-ready intelligence designed to influence capital allocation, sourcing strategy, and regulatory planning as companies prepare for 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the report synthesizes quantitative market sizing with actionable playbooks — enabling commercial, supply chain, and regulatory leaders to convert insight into immediate decisions.
Worldwide Food Grade Ammonium Chloride Market
Market trajectory: a measured, resilient expansion
The food grade ammonium chloride market has demonstrated steady growth through the early 2020s, expanding from approximately USD 164 million in 2020 to just over USD 200 million in 2025. Our forecast model — reflecting demand drivers across bakery, confectionery, seasonings, and pharmaceutical excipient segments — anticipates continued expansion through 2032, reaching an estimated USD 268 million and implying a compound annual growth rate of 4.12% over the 2026–2032 forecast period. This trajectory signals neither a hyper-growth bubble nor stagnation; rather, it defines a stable market where differentiated quality, regulatory alignment, and supply reliability will determine winners and losers.
Worldwide Food Grade Ammonium Chloride Market
Why the 2026 decision window matters
- CapEx and capacity optimization: With forecasted moderate growth, investments in plant expansions or debottlenecking should be calibrated to expected demand upticks and to risk scenarios related to feedstock volatility. Our scenario-based capacity planning tools help prioritize projects that protect margins under multiple raw material price paths.
- Sourcing and supplier consolidation: Market concentration is mid-range — our analysis shows the top three suppliers capture a significant share of supply, and the top five control a majority slice of the market. For procurement leaders, this means negotiating leverage exists but is asymmetrical; strategic partnerships and dual-sourcing strategies reduce disruption risk without over-capitalizing on inventory.
- Product and quality strategy: Food manufacturers evaluating ingredient substitution or reformulation will face choices between high-purity and standard grades. Quality certification, supply-chain traceability, and formulation guidance can be decisive in capturing incremental share in food and pharmaceutical channels.
- Regulatory timing: New and extended authorizations in key jurisdictions mean companies that align dossiers and compliance roadmaps early will enjoy first-mover advantage for new applications or export markets.
What the report delivers — practical, transaction-ready intelligence
Beyond headline sizing and forecasts, our report is designed as an operational toolkit for 2026 planning. Key deliverables include:
Worldwide Food Grade Ammonium Chloride Market
- Integrated market model: A granular forecast engine that combines demand-side drivers (category growth, substitution risk, price elasticity) with supply-side constraints (production routes, feedstock dependence, capacity cycles). This model supports what-if scenarios for M&A, greenfield projects, and contract renegotiations.
- Strategic supplier profiles: Actionable dossiers on incumbent and emerging suppliers, including manufacturing footprints, capability maps for food/pharma grades, certifications, and logistics channels. These profiles allow procurement teams to shortlist partners based on capability and risk appetite.
- Commercial playbooks: Segmented GTM playbooks for ingredient formulators, food manufacturers, and feed/pharma ingredient marketers. Each playbook contains channel economics, margin benchmarks, and target customers where premium grades yield a measurable price premium.
- Regulatory compliance matrix: A jurisdiction-by-jurisdiction guide to permissible uses, labelling, and documentation requirements — plus a prioritized roadmap to achieve export-ready certifications within 6–12 months.
- Price and margin simulation suite: Inputs and templates for corporate FP&A teams to model upstream ammonia and hydrochloric acid volatility into finished product margins and contracted pricing commitments.
- Risk & resilience framework: A short-list of operational risk mitigations (inventory buffers, toll manufacturing agreements, geographic diversification) and an accelerated incident-response protocol for supply interruptions.
Competitive landscape: profiles, strategic moves, and implications
The food-grade ammonium chloride market combines international chemical majors with regional specialty producers. The competitive map is characterized by established players with strong quality credentials alongside nimble regional manufacturers focusing on cost-competitive supply or specialized food/pharma grades.
- BASF SE (Ludwigshafen, Germany): A global chemicals major, BASF offers food and pharma-compliant grades and has recently expanded capacity and upgraded quality controls. Their scale and certification portfolio make them a preferred partner for multinational food manufacturers seeking global supply consistency.
- Jiangsu Khonor Chemicals Co., Limited (Jiangsu, China): A supplier with a broad range of grades for food, feed and pharma. Their integrated cost base and regional logistics strength make them a key source for buyers in search of competitive pricing, subject to quality and compliance validations.
- Muby Chemicals / Mubychem Group (Mumbai, India): Known for a portfolio of pharmacopeial grades and anti-caking variants, this player is important where technical grade differentiation and batch-to-batch consistency matter.
- Indian heavyweights (e.g., Tata Chemicals, Tuticorin Alkali): These manufacturers combine scale with regional distribution expertise, important for food manufacturers sourcing within South Asia or seeking alternative supply sources.
- Specialty European suppliers (e.g., CFL Chemische Fabrik Lehrte, Macco Organiques): They serve niche applications where close regulatory alignment, traceability, and documentation are critical for pharmaceutical and specialty food sectors.
Recent industry moves — including commercial launches of food-grade products compliant with updated international purity standards and capacity expansions at established plants — underscore a market where quality certification and operational scale are actively being used as competitive levers. For buyers and investors, this means premium payoffs for validated, traceable supply and for sellers, an imperative to invest in compliance and quality systems.
Industry dynamics shaping 2026 strategy
- Feedstock and cost dynamics: Production economics are tightly coupled to ammonia and hydrochloric acid inputs. Price volatility in these upstream commodities has a direct pass-through effect on production costs, and firms must model multiple feedstock scenarios when negotiating multi-year supply contracts or planning capacity investments.
- Production routes and byproduct flows: Ammonium chloride is commonly manufactured via direct reaction between ammonia and hydrochloric acid and can also be produced as a byproduct in certain soda ash manufacturing routes. Understanding local production footprints and byproduct flows is essential to assessing supply flexibility and opportunistic sourcing.
- Regulatory environments: In major markets, regulatory clarity supports stable use-cases — for example, the recognition of ammonium chloride as a permissible processing aid and flavoring adjunct in food in key jurisdictions. Additionally, extended authorizations for feed uses in major economic regions create planning certainty through the next regulatory cycles.
- Concentration and consolidation: The market exhibits a moderate level of concentration: the top three players hold a meaningful share and the top five collectively control a majority of the market. This structure creates an environment where scale advantages coexist with opportunities for regional specialists to capture niche premium segments.
Actionable recommendations for 2026 planning
- Procurement leaders: Adopt a dual-track sourcing strategy combining a core long-term partner for baseline volumes with flexible regional suppliers to buffer price or supply shocks. Use the report’s supplier assessment tools to qualify second-source partners rapidly.
- R&D and formulation teams: Prioritize validation studies that quantify performance and cost trade-offs between high-purity and standard grades. Documented equivalence studies and supplier quality agreements will accelerate adoption where substitution is feasible.
- Commercial leaders: Develop tiered pricing that captures margin from customers requiring higher certification or traceability while protecting volumes in cost-sensitive channels. The commercial playbooks provide ready templates for contract design and negotiation levers.
- Investment and corporate development: Use our scenario-driven valuation model to screen potential acquisitions or joint ventures. Targets that combine regional cost advantages with certifiable quality systems are likely to deliver the best risk-adjusted returns.
- Regulatory & compliance teams: Fast-track dossiers and audits where export growth is a strategic priority. The regulatory matrix highlights jurisdictions where gaining approvals yields the largest market access benefits within a 12–18 month window.
Conclusion — the strategic premium is in quality, traceability, and resilience
For 2026, the strategic opportunity in the food grade ammonium chloride market is not in betting on volume alone; it is in capturing the premium that accrues to suppliers and manufacturers who can demonstrably deliver certified purity, end-to-end traceability, and supply resilience. PW Consulting’s market model and operational playbooks equip decision-makers to allocate capital, structure supply agreements, and prioritize compliance activities in a way that protects margins and positions businesses for steady growth over the coming cycle.
Next steps
- Download the executive summary or contact our team to arrange a bespoke workshop that applies our forecast and supplier assessment tools to your 2026 planning scenarios.
- Access the full report for the complete dataset, regional demand curves, grade-level economics, and pro forma transaction models — necessary for transaction execution and detailed supplier negotiations.
PW Consulting — helping chemical and food sector leaders translate market intelligence into profitable operational strategies.
For detailed analysis of this topic, please visit the official page: Worldwide Food Grade Ammonium Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Market Insights: Worldwide Face & Voice Biometric Market Set to Reach USD 18,719.61 Million by 2032
By PW Consulting, 2026-08-05
Worldwide Face Voice Biometric Market — 2026 Strategic Preview
PW Consulting’s latest market study, covering 2020–2025 as the historical baseline and forecasting through 2026–2032, frames a rapidly maturing global market for combined face and voice biometrics. The market reached a sizable enterprise scale by the 2025 base year and is projected to grow at a compound annual growth rate (CAGR) of approximately 14.0% over the forecast horizon. By 2032 the market is expected to be multiple times larger than the mid‑decade base, reflecting accelerated adoption across identity proofing, contact centers, mobile banking, border control, and enterprise access use cases.
Worldwide Face Voice Biometric Market
Why this report matters for 2026 enterprise decision‑makers
-
High‑velocity procurement cycles require clarity. Security, privacy, and regulatory risk are converging with commercial opportunity — technology choices made in 2026 will determine cost trajectories, compliance exposure, and user‑experience differentiation for at least the next half decade.
Worldwide Face Voice Biometric Market -
Operationalization is the new frontier. Early wins have shifted from vendor pilots to large‑scale rollouts; enterprises need deployment playbooks that reconcile accuracy, liveness, latency, and privacy constraints in production environments.
Worldwide Face Voice Biometric Market -
Investment and M&A signals are increasingly visible. With a market concentration profile that shows the top three vendors holding a meaningful but not overwhelming share (CR3 ~32.45%) and the top five approaching half the market (CR5 ~48.9%), strategic buyers and corporate development teams must prioritize rigorous vendor diligence.
What the PW Consulting report delivers — practical, operational intelligence
-
Market sizing and validated growth scenarios: a defensible topline view for budget planning and investor diligence built from bottom‑up vendor coverage, demand modeling and macro adoption drivers.
-
Deployment playbooks and TCO templates: step‑by‑step migration paths for greenfield and brownfield projects, including hardware sizing, edge vs cloud tradeoffs, and latency budgets for real‑time matching.
-
Regulatory & standards compliance toolkit: alignment matrices mapping EU AI Act obligations, GDPR implications for biometric processing (notably profiling and special‑category data considerations), ISO/IEC 30107‑3 PAD protocols, and NIST evaluation touchpoints.
-
Vendor scorecards and functional comparators: side‑by‑side evaluation of multi‑modal capabilities (face, voice, behavioral fusion), liveness detection maturity, integration toolkits (SDKs/APIs), and enterprise features such as SSO and mobile SDK support.
-
Security testing recipes: adversarial and presentation‑attack test plans, recommended metrics for FAR/FRR calibration, and remediation prioritization to address the most likely real‑world attack vectors.
-
Commercial playbook and procurement templates: RFP language, SLAs keyed to latency and accuracy requirements, and pricing archetypes for software, hardware and managed services engagements.
-
M&A diagnostic and partnership heatmap: indicators to qualify targets for strategic acquisition versus technology partnership, derived from capability gaps and market concentration dynamics.
Key market dynamics shaping 2026 strategies
-
Regulatory pressure and compliance engineering. The EU AI Act’s classification of certain biometric systems as high‑risk creates a compliance bar that will increase certification costs and lengthen procurement cycles in regulated sectors. Complementary data protection requirements (e.g., GDPR's restrictions on biometric data processing) demand privacy‑first architectures, consent frameworks, and data minimization by design.
-
Standardization and testing. ISO/IEC 30107‑3 remains central to presentation attack detection protocols and is increasingly referenced in procurement mandates. NIST’s continuing evaluations (including recent FRVT updates) add an independent performance context that enterprises should reference when benchmarking vendors.
-
Operational performance constraints. Production systems are no longer judged only by accuracy metrics but by latency, robustness to environmental variations, and liveness guarantees. Edge inference using modern NPUs is increasingly necessary to meet sub‑100ms matching windows for responsive UX; hardware selection therefore becomes a first‑order architectural decision.
-
Ethics and customer trust. Public and regulatory scrutiny over biometric use requires verifiable consent workflows, transparent error handling, and redress processes. These non‑technical design elements materially affect adoption and litigation risk.
-
Attack surface evolution. Spoofing, voice‑synthesis attacks, and deepfake threats motivate investment in multi‑modal fusion and robust PAD. Certification achievements and independent lab results (e.g., iBeta levels) are increasingly used by procurement to triage vendor shortlists.
Competitive landscape — vendors to watch and strategic posture
-
NEC Corporation (Tokyo, Japan) — A long‑standing leader in large‑scale biometric deployments. NEC couples facial analytics (NeoFace) with voice biometrics to support real‑time surveillance and enterprise banking use cases. Recent product launches have emphasized integrated real‑time multi‑modal surveillance capabilities.
-
Aware Inc. (Bedford, MA, USA) — Focused on SDK/embedded solutions for mobile and desktop authentication, Aware’s Knomi stack targets government and financial institutions seeking flexible integration into client apps. Strategic partnerships for platform integration have broadened deployment avenues.
-
ID R&D (Neurotechnology) (Cambridge, MA, USA) — Notable for liveness detection and anti‑spoofing in voice and face; products such as IDVoice and IDLive Face are used in call centers and access control. Certification milestones underscore PAD maturity.
-
Daon Inc. (Reston, VA, USA) — The IdentityX platform emphasizes identity proofing and multi‑modal fusion for fintech and government KYC contexts. Real‑world pilots with banks highlight practical integration paths for mobile verification flows.
-
Voice Biometrics Group (VBG) (Redmond, WA, USA) — Specialist voice‑centric vendor with facial integration options; strong in contact center fraud prevention and remote authentication scenarios.
-
Thales Group (Paris, France) — Offers multi‑modal biometric solutions for border control and national identity projects, integrating face/voice into established digital identity portfolios.
-
HID Global (Austin, TX, USA) — Focuses on mobile authenticators and enterprise physical/logical access, pairing biometric capabilities with identity lifecycle management.
-
Verint Systems (Melville, NY, USA) — Strong play in contact center authentication and workforce management, combining voice biometrics with facial recognition to streamline customer journeys.
Recent vendor moves reinforce the market’s operationalization phase: product launches integrating voice into real‑time facial surveillance, SDK integrations into major mobile platforms, and lab certifications for PAD. These developments accelerate procurement readiness but also raise the bar for compliance and interoperability.
Six strategic actions for 2026
-
Adopt a compliance‑first architecture: mandate conformity checkpoints for high‑risk classification, map data flows for GDPR compliance, and require transparency/consent mechanisms in user journeys.
-
Prioritize multi‑modal fusion plus PAD: combine face and voice with behavioral signals to reduce false accepts and increase resilience to synthetic attacks.
-
Define latency and edge requirements early: include NPU/edge inference requirements in RFPs when sub‑100ms response is required; quantify network fallbacks for degraded connectivity.
-
Insist on independent certification and third‑party benchmarking: reference ISO/IEC PAD protocols and NIST evaluation outcomes as pass/fail criteria in shortlist gating.
-
Instrument pilot programs with operational KPIs: measure time‑to‑authenticate, abandonment rates, fraud reductions, and regulatory audit readiness rather than pure accuracy numbers.
-
Build an M&A watchlist informed by capability gaps: prioritize targets that fill PAD, edge inference, or identity proofing shortfalls rather than purely incremental accuracy improvements.
How to use this briefing and next steps
This preview synthesizes the report’s strategic implications for 2026 planning: accelerating adoption, evolving regulation, and the transition from pilots to enterprise rollouts. PW Consulting’s full report contains the supporting data tables, region‑and‑application level splits, granular vendor benchmarking, financial models, and downloadable procurement templates that are intentionally omitted here to preserve the value of the complete analysis.
For technology leaders, procurement teams, and corporate strategists preparing 2026 budgets or M&A plans, the report offers the playbooks and metrics needed to de‑risk deployment and capture value from multi‑modal biometrics. Access to the full dataset and annexes will enable precise localisation of opportunity, vendor selection, and a compliance roadmap tailored to your sector and jurisdiction.
PW Consulting remains available to brief executive teams on how the report’s findings translate into a 12‑ to 36‑month implementation roadmap specific to your organization’s risk profile and commercial objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Face Voice Biometric Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Concrete Densification Polishing Material Market to Grow at a 6.15% CAGR During 2026–2032
By PW Consulting, 2026-08-05
Worldwide Concrete Densification Polishing Material Market — Strategic Preview for 2026 Decision‑Makers
Executive summary
PW Consulting’s forthcoming market study on the Worldwide Concrete Densification Polishing Material Market synthesizes five years of historical performance and a seven‑year forecast to deliver the decision‑grade intelligence that senior executives, procurement leads, and investment committees need for 2026 planning. The market has shown a resilient upward trajectory — expanding from the mid‑hundreds of millions in 2020 to just under one billion USD in 2025 — and our models project continued expansion through the 2026–2032 forecast window at a compound annual growth rate of approximately 6.15%. By 2032 the market reaches the high‑hundreds-of-millions / low‑billions threshold, reflecting structural demand for durable, low‑maintenance concrete finishes across new construction and retrofit activity.
Worldwide Concrete Densification Polishing Material Market
Why this matters for 2026 strategic decisions
-
Portfolio prioritization: Manufacturers and distributers must choose whether to double down on product chemistry (e.g., silicate families, colloidal silica) or to build systems capability (polishing + densifier + coatings) that command higher lifetime value.
Worldwide Concrete Densification Polishing Material Market -
Procurement and margin management: Raw material and energy volatility have created recurring margin pressure. Understanding cost pass‑through levers and hedging options for soda ash, silica feedstocks, and intermediates will be a board‑level priority this year.
Worldwide Concrete Densification Polishing Material Market -
Sales channel reconfiguration: Demand is increasingly driven by integrator and design‑spec channels where product EPDs and whole‑system warranties influence specification decisions—an important commercial implication for 2026 bidding and tender strategies.
-
Regulatory and sustainability alignment: With green building standards tightening, manufacturers that can demonstrate life‑cycle impact reductions through Environmental Product Declarations and GWP‑aligned products will access premium projects and faster specification cycles.
What the PW Consulting report delivers (practical, actionable contents)
This report is designed as a deployment playbook for 2026. Beyond headline sizing and trend charts, the study contains:
-
Transparent methodology and audited source mapping so teams can reproduce our base case and stress test assumptions against their internal data.
-
Cost‑model templates that isolate raw material, energy, logistics, and formulation complexity to quantify margin impacts under different feedstock price scenarios.
-
Buyer personas and specification decision‑trees (architects, general contractors, flooring contractors, facility managers) to support targeted commercial programs.
-
Supplier scorecards and capability matrices that rate players on formulation breadth, sustainability credentials, system integration, and distribution reach.
-
Go‑to‑market playbooks for new product introductions, including channel incentives, training programs for polishing contractors, and specification cadences for design teams.
-
M&A screening filters: cash‑flow bands, technology gaps, and geographic footprints that highlight attractive bolt‑on and transformational targets.
-
Signal trackers and a near‑term monitoring dashboard that lists the specific data feeds and leading indicators procurement, sales and strategy teams should monitor weekly and monthly.
Competitive landscape — who matters and why
The supplier universe is structurally fragmented: the three‑ and five‑firm concentration ratios indicate that no single incumbent dominates the market, leaving room for regional specialists, chemistry innovators, and system providers to expand. Our proprietary supplier framework evaluates each firm across four vectors: chemistry & R&D, system & service capability, sustainability credentials, and route‑to‑market strength.
-
Curecrete Distribution, Inc. — legacy brand strength and product recognition from the original densifier give strong specification pull, particularly where installers value tried‑and‑tested chemistries and training programs.
-
W. R. Meadows — positions itself as a systems vendor, packaging densifiers into integrated polished flooring solutions that simplify procurement for large commercial and industrial customers.
-
Sika AG — global R&D and product breadth enable rapid response to regional specification demands and broader portfolio bundling with other construction chemicals.
-
The Euclid Chemical Company and LATICRETE — strong in contractor and infrastructure channels, with deep relationships in large commercial projects and renovation markets.
-
PROSOCO — recent strategic move to publish Environmental Product Declarations (January 2026) is a game‑level differentiator. EPDs accelerate acceptance in LEED v5 or GWP‑sensitive tenders and illustrate how transparency can be converted into procurement advantage.
-
Technology disruptors (Adhesives Technology Corporation / Convergent’s silica‑free STRiON:Fortify; colloidal silica specialists such as Ecolab and Rio Floor) — these suppliers represent the innovation edge by redefining performance tradeoffs (penetration depth, cure speed, reflectance) and by responding to sustainability-driven substitution pressures.
-
Equipment and service integrators (e.g., Xtreme Polishing Systems, Hyper Grinder) — these players increase switching costs by selling the installer ecosystem (tools, abrasives, training) alongside consumables, creating resilient recurring revenue.
Supply chain and raw‑material dynamics
Raw‑material volatility is a persistent operational risk in 2026. Feedstock dynamics — notably the cost and availability of sodium silicate, soda ash, silica sand, and intermediates used to produce colloidal silica — have driven episodic jumps in production cost. Regional divergences in feedstock pricing and energy input costs create margin differentials that are not easily arbitraged in the short run. In addition, logistics bottlenecks and energy price swings in 2024–2025 materially pushed up production costs for silicate‑based chemistries, and these pressures continue to reverberate into contracting cycles.
Strategic implications: manufacturers should implement active sourcing strategies (dual‑sourcing, local feedstock partnerships), update cost pass‑through clauses in contracts, and accelerate R&D pathways that reduce dependence on the most volatile inputs.
Regulation, sustainability and procurement
Environmental transparency is now a procurement requirement in many institutional projects. The appearance of certified Environmental Product Declarations among suppliers is not merely a marketing event — it is a procurement gate for LEED v5 and GWP‑focused tenders. Suppliers that publish credible EPDs gain earlier specification windows and reduce procurement friction in sustainability‑driven projects. Expect to see more product‑level lifecycle disclosures and supplier scorecards incorporated into tender evaluation matrices in 2026.
Strategic priorities for 2026 — a checklist for executives
-
Short‑term: implement a raw‑material hedging and sourcing playbook (cover 6–12 months of exposure) and renegotiate pass‑through language on multi‑year contracts.
-
Commercial: create specification tools and install training programs to lock in design‑and‑install economics with major contractor groups.
-
R&D: prioritize formulations that either reduce high‑volatility inputs or enable clear lifecycle GWP reductions that can be certified through EPDs.
-
Portfolio: consider premium, systemized offerings where installers and facility owners pay for lifetime performance, not unit price.
-
M&A: target adjacent capabilities—colloidal silica production, contractor networks, or equipment/service integrators—that accelerate route‑to‑market and increase recurring revenue.
-
Risk: maintain flexible manufacturing footprints and logistics contingencies to mitigate regional feedstock shocks.
Scenario planning & leading indicators
We present three scenarios in the full report: a Baseline aligned with the 6.15% forecast CAGR, an Upside driven by accelerated green construction and specification shifts, and a Downside driven by sustained raw‑material shocks or a macro construction slowdown. For board‑level monitoring in 2026, track these leading indicators weekly or monthly:
-
Spot and contract prices for sodium silicate and soda ash;
-
Number of published EPDs and procurement tenders specifying product‑level lifecycle credits;
-
Major project awards in commercial, industrial, and public infrastructure segments;
-
M&A activity among regional players and technology startups;
-
Installer availability and equipment sales as a proxy for refurbishment cycles.
How to use the full PW Consulting report (trailer)
This article is a strategic preview: it surfaces the most consequential commercial and operational implications we identified, but intentionally omits the granular breakdowns, granular regional and application segment numbers, and the full supplier scorecards to encourage a deeper evaluation. The complete report contains the full segmentation, scenario models with downloadable spreadsheets, supplier heatmaps, and templates you can use directly in 2026 budget and procurement cycles.
For strategy teams preparing CAPEX, procurement, or M&A decisions for 2026, the full deliverable translates market trends into executable initiatives, prioritizes investment trade‑offs, and supplies the data‑driven templates required to accelerate decisions with confidence.
Next steps
Download the full Worldwide Concrete Densification Polishing Material Market report from PW Consulting to obtain the underlying datasets, sensitivity models, and supplier dashboards referenced here. If you would like a tailored briefing for your executive team, request our 60‑minute strategic workshop where we map the report’s findings to your portfolio and produce a prioritized 100‑day action plan.
PW Consulting — Senior Industry Analysis, Concrete & Construction Materials
For detailed analysis of this topic, please visit the official page: Worldwide Concrete Densification Polishing Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Consumer & Enterprise Hearables Market Set to Surge from USD 68.6 Billion in 2025 to USD 155.0 Billion by 2032 at a 12.35% CAGR, Led by Asia Pacific
By PW Consulting, 2026-08-05
PW Consulting: Strategic Brief — Worldwide Consumer and Enterprise Hearables Market (Base Year 2025)
Executive snapshot
PW Consulting today publishes an executive briefing derived from our full Worldwide Consumer and Enterprise Hearables Market report (base year 2025, forecast 2026–2032). The headline: hearables are transitioning from an overwhelmingly consumer-driven audio accessory market to a multi-dimensional platform spanning communications, health, and enterprise productivity. Our analysis finds the market has more than doubled since 2020 and is projected to maintain a double‑digit compound annual growth rate (CAGR) through the 2026–2032 forecast window, offering both scale and strategic inflection points for vendors, enterprise buyers, and investors planning 2026 initiatives.
Worldwide Consumer and Enterprise Hearables Market
Why this briefing matters for 2026 decision-making
- Investment prioritization: identify which product architectures, sensor suites, and software stacks will deliver defensible margins and recurring revenue into 2028–2032.
- Go-to-market timing: determine which partnerships with platforms, unified‑communications providers, and health systems unlock early enterprise adoption without cannibalizing consumer sales.
- Supply‑chain resilience: integrate near‑term component risk and tariff scenarios into sourcing strategies to avoid costly manufacturing bottlenecks in 2026.
- M&A and partnership screening: use our concentration and competitive diagnostics to focus diligence on targets that complement platform or clinical capabilities.
What the full report contains (practical, action‑oriented deliverables)
- Proprietary market model and forecast (2026–2032) with downloadable worksheets that let you run your own scenarios using alternative CAGR and pricing assumptions.
- Vendor scorecards and go‑to‑market playbooks: product, channel, pricing and ecosystem tactics mapped to buyer personas (consumer, enterprise IT, health providers).
- Technology roadmap and component tracker: timelines for ANC, low‑power ML, sensor fusion, and battery improvements plus supplier risk heatmaps.
- Procurement and integration toolkit for enterprise buyers: procurement checklists, TCO templates, pilot design, and UC/endpoint interoperability matrices.
- Regulatory and materials risk assessment: scenario planning for tariffs, raw‑material constraints, and compliance pathways in major markets.
- Case studies and ROI models for enterprise deployments across frontline workforces, contact centers, and clinical hearing programs.
Data‑driven highlights you can act on
Our macro view shows the hearables market expanded rapidly between 2020 and 2025, driven by consumer TWS adoption, premium ANC headphones, and an accelerating convergence with clinical hearing categories. The 2025 market baseline in our model is a substantial USD‑denominated annual turnover figure (reported in millions), and our forecast demonstrates sustained expansion through 2032 under a central scenario that assumes continued product innovation, broader enterprise adoption, and a steady maturation of hearing‑health integrations.
Worldwide Consumer and Enterprise Hearables Market
Key modeling inputs include historical unit shipment trajectories, ASP (average selling price) trends, sensor and IC cost curves, and enterprise procurement cycles. The market concentration analysis shows a meaningful presence of global platform players and premium incumbents — the top three and top five firms together account for a clear plurality of revenue (moderate concentration that still leaves room for meaningful disruption by emerging players and regional specialists).
Worldwide Consumer and Enterprise Hearables Market
Competitive landscape — strategic positioning and tactical implications
- Platform integrators (example: Apple Inc.): dominate consumer convenience and ecosystem lock‑in. Their devices are now extending into health and enterprise use cases through firmware and software features. Tactical implication: competitors should prioritize differentiated services (enterprise management, specialized sensors, privacy contracts) instead of direct feature parity.
- Mobile OEMs and Android ecosystem partners (example: Samsung Electronics): focus on cross‑device continuity and enterprise mobility. Tactical implication: enterprise offerings that exploit Android enterprise APIs and device management capabilities can unlock channel partnerships with these OEMs.
- Premium audio specialists (examples: Sony, Bose, Sennheiser): maintain a margin moat on high‑fidelity audio and ANC. Tactical implication: bundle premium audio with enterprise collaboration features (certified UC profiles) to capture corporate buyers who equate audio quality with professional performance.
- Hearing‑health leaders (examples: Demant, Starkey, WS Audiology): bridge clinical credibility and consumer form factors. Tactical implication: partnerships with health systems and real‑world validation studies create barriers to entry for consumer‑only players aiming at health markets.
- Enterprise communications vendors (examples: Jabra, Poly): leverage certification, managed services and integration with UC suites. Tactical implication: services and lifecycle management (secure provisioning, fleet management) become as important as hardware design.
- Value players (examples: Xiaomi, LG): expand global reach via aggressive price/performance. Tactical implication: expect margin pressure at the mid‑market; premium and enterprise segments can be insulated by differentiated services and validated outcomes.
Recent market signals support these dynamics: platform firms continue to ship significant TWS volumes while adding health and AI features through firmware updates; trade shows highlighted new form factors and immersive audio; and several entrants are commercializing scene‑aware tuning and edge ML for personalized experiences.
Supply‑chain, materials and regulatory dynamics that will shape 2026
- Component concentration and raw‑material volatility: MEMS microphones and select semiconductor materials remain pinch points. Recent industry notes flag MEMS microphone supply and cobalt volatility as material risks; extreme weather events have also stressed certain quartz supplies tied to semiconductor lead times.
- Tariff and trade policy uncertainty: evolving tariffs in key markets create near‑term margin pressure and have accelerated regional manufacturing and dual‑sourcing strategies among tier‑1 vendors.
- Advances in componentization: new parts tailored to hearables (for example, accelerometers with built‑in voice activity detection) reduce system complexity and open new low‑power on‑device capabilities — a critical differentiator for always‑on health and voice features.
Strategic responses we recommend: (1) execute supplier‑diversification playbooks and second‑source qualification in 2026; (2) renegotiate long‑lead contracts with embedded resilience clauses; (3) invest modestly in bill‑of‑materials redesigns to reduce exposure to constrained commodities.
Enterprise buyer and investor playbook for 2026
- For CIOs and procurement leads: pilot with outcomes‑focused metrics (productivity, call quality, safety). Insist on managed lifecycle services and secure provisioning; budget for device management and certification costs in year‑one TCO estimates.
- For health system and clinical leaders: require clinical validation and data governance from vendors before wide deployment in hearing‑health programs. Use staged rollouts to measure adherence and clinical outcomes.
- For investors and M&A teams: prioritize targets with proven enterprise revenue motion, recurring software or services revenue, and defensible supply‑chain contracts. Use our vendor scorecards to triage opportunities that strengthen platform reach or clinical differentiation.
What the full report will give you that this briefing does not
- Granular regional and end‑use segmentation with interactive charts and downloadable data tables (reserved for the full report to protect proprietary segmentation logic).
- Vendor financial proxies, benchmark ASP trajectories, and unit‑shipment curves for modeling acquisition and product‑pricing scenarios.
- Operational playbooks: detailed procurement RFP templates, deployment checklists, and sample SLAs for enterprise fleet management and clinical integrations.
- Scenario toolkits allowing you to re‑run forecasts under alternative tariff, materials and adoption assumptions.
This briefing follows the “trailer” principle: we surface the strategic signals and ready‑to‑use recommendations you need to make confident 2026 decisions while reserving the full segmented detail, underlying spreadsheets, and vendor scorecards for subscribers to the full report.
How to prioritize action in Q1–Q3 2026
- Immediate (0–3 months): run a supplier concentration stress test and initiate second‑source qualification for critical components; begin pilot selection for enterprise endpoints aligned to business outcomes.
- Near term (3–9 months): finalize enterprise procurement frameworks and deploy small‑scale pilots with integrated lifecycle management; negotiate conditional pricing tied to volume and support.
- Medium term (9–18 months): lock in strategic partnerships (platform, UC vendors, health systems) and allocate R&D spend toward sensor fusion and edge ML capabilities validated by pilot outcomes.
Closing — why PW Consulting’s work matters
Hearables are no longer just a consumer accessory — they are a cross‑cutting endpoint that embeds sensing, local compute, and connectivity into people‑facing workflows. For executives making 2026 investments, the right combination of product architecture, supply‑chain resilience, and validated enterprise outcomes will determine who captures the high‑growth corridors of this market. PW Consulting’s full market report provides the granular data, vendor diagnostics, and practical playbooks to convert this strategic potential into measurable results. To access the complete dataset, vendor scorecards, and downloadable scenario models, please visit PW Consulting’s report page.
For detailed analysis of this topic, please visit the official page: Worldwide Consumer and Enterprise Hearables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 5.48% CAGR for Worldwide Radiator Flushing Chemicals Market Through 2032
By PW Consulting, 2026-08-05
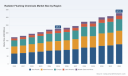
Worldwide Radiator Flushing Chemicals Market: Strategic Outlook and Action Plan for 2026
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present an executive preview of our latest Worldwide Radiator Flushing Chemicals Market study — a practical intelligence product built to shape high‑stakes decisions in 2026. This briefing synthesizes the report’s most consequential, data‑driven conclusions and lays out the strategic choices executives and investors should prioritize this coming year. In keeping with our "trailer" principle, we demonstrate analytical depth and direction while reserving proprietary segmentation matrices and paid models for report subscribers.
Worldwide Radiator Flushing Chemicals Market
Market trajectory: steady growth, measurable upside
The radiator flushing chemicals market has moved beyond simple cyclicality and entered a phase of steady expansion. Our base-year analysis shows the market expanded from USD 172.4 Million in 2020 to USD 225.5 Million in 2025. Under our central scenario the market is projected to grow through the 2026–2032 forecast window at a compound annual growth rate of 5.48%, reaching roughly USD 327.6 Million by 2032.
Worldwide Radiator Flushing Chemicals Market
Why this matters for 2026 planning: a predictable mid-single-digit CAGR creates a planning horizon where disciplined investment in product reformulation, channel partnerships and supply‑chain resilience can deliver compound returns without the binary risk profile of early‑stage markets. Companies that treat 2026 as a year for operational tightening and selective growth will outperform peers in both top‑line and margin metrics.
Worldwide Radiator Flushing Chemicals Market
Market structure and competitive dynamics
The market shows moderate concentration. The top three players capture a meaningful share of industry revenue, and the top five deepen that concentration — a structure that favors well‑executed national brands and nimble regional specialists. That said, the market still includes a broad set of independent formulators and chemical suppliers, leaving room for targeted M&A and localized differentiation.
- Household and legacy brands: Established names with extensive distribution networks continue to monetize brand trust and service‑bay relationships. Their strength is reliability: technician familiarity and aftermarket channel reach.
- Performance and formulation innovators: Specialist formulators are competing on chemistry (acidic vs. non‑acidic, biodegradable blends, and fast‑action vs. maintenance products) and claims that resonate with professional service providers.
- Regional players and marine/industrial suppliers: These firms leverage niche technical expertise and localized service agreements to defend pockets of demand where OEM/cycle characteristics differ materially from passenger automotive norms.
What leading suppliers are doing (strategic playbook)
We analyzed the market actions of core industry participants and synthesized observable strategic patterns.
- Brand consolidation and service integration: Major aftermarket brands are deepening technician loyalty by bundling flushing chemistries with service programs and diagnostic advisories — a move that raises switching costs for professional customers.
- Product differentiation through chemistry: Several players are emphasizing acid‑free and biodegradable formulations, or specialty acid blends that promise rapid descaling without metal damage. These technical distinctions are becoming primary purchase drivers among shop networks and fleet operators.
- Channel breadth and digital commerce: Leading manufacturers balance traditional wholesale and automotive aftermarket channels with direct e‑commerce, enabling rapid promotional experimentation and higher margin capture.
- Geographic playbooks: Global firms combine centralized R&D with region‑level regulatory and supply‑chain adaptations — a hybrid model that accelerates product approvals and reduces time‑to‑market for tailored formulations.
Representative company observations (non‑exhaustive): household names leverage scale and distribution; specialist formulators emphasize chemistry claims and quick‑action products; regional suppliers lean on service contracts and technical support. Our full report profiles each major competitor with win/loss analysis, channel maps and M&A appetite signals.
Supply‑side dynamics and raw‑material exposure
Raw material price behaviour and availability are now core strategic variables. Ethylene glycol — a primary upstream feedstock for many coolant formulations — displayed notable volatility through 2025: an initial price surge, a weakening phase and a late‑year rebound. Our 2026 baseline assumes more balanced availability with prices residing in a relatively narrow band versus the sharp swings seen historically. That creates an operational window for manufacturers to normalize procurement strategies, but the risk of episodic spikes remains.
Phosphoric acid and other specialty intermediates also experienced subtle regional variance in early 2026. While these movements are not currently destabilizing, they increase the value of multi‑source contracts, inventory optimization and formula flexibility (e.g., switching between phosphate‑centric and organic acid‑based chemistries where product claims and regulations permit).
Regulatory and policy tailwinds / headwinds
Regulatory shifts are indirectly reshaping demand patterns. Stricter U.S. rules on reclaimed refrigerants and the 2025 updates to California’s building and EV charging codes — effective in 2026 — alter maintenance intervals, vehicle fleet composition and that sector’s service workflows. For radiator flushing chemicals, the immediate implications are twofold:
- Greater emphasis on documented environmental performance and compatibility claims; purchasers increasingly demand clear data on biodegradability, heavy‑metal absence and neutralization requirements.
- Opportunities to capture new service volumes as fleet electrification and building electrification evolve service routines — while also managing transitional declines in some legacy vehicle segments.
Strategic imperatives for 2026 decision‑makers
Based on our synthesis of market dynamics, competitor moves and supply‑chain signals, PW Consulting recommends the following prioritized actions for executives planning 2026 budgets and strategic initiatives:
- Hedge and diversify feedstock sourcing: Lock tiered contracts for ethylene glycol and specialty acids; add alternative suppliers and local buffer inventories to limit margin erosion during price spikes.
- Refine product portfolio for clarity and claims: Prune overlapping SKUs; invest in two clear pillars — a technician‑grade, fast‑action offering and a maintenance line with strong environmental credentials.
- Deepen service partnerships: Build bundled commercial models with national service chains and fleet operators (fixed price per service + chemistry refill) to increase recurring revenues.
- Pursue targeted M&A and licensing: Acquire niche formulators or regional distributors to accelerate access to high‑value channels; license environmentally differentiated chemistries where rapid scale matters.
- Upgrade commercial analytics: Deploy pricing and promotion elasticity testing across distribution nodes to capture margin while maintaining technician loyalty.
What PW Consulting’s report delivers (practical contents)
The full report is designed as an operational playbook for 2026. Key deliverables include:
- Granular market sizing (historical 2020–2025 and forecast 2026–2032) with modeled sensitivity scenarios.
- Competitive profiles and decision‑grade benchmarking on product portfolios, channel strategies and recent strategic moves.
- Supply‑chain heat maps, raw material cost‑pass‑through analysis and recommended procurement contracts.
- Regulatory impact matrix and compliance checklists tailored to North America, Europe and APAC operating models.
- Investor and M&A playbook with candidate lists, valuation heuristics and integration risk assessments.
- Interactive financial model (TAM/SAM/SOM) and go‑to‑market roadmaps by go‑to channels, with prioritization scoring for 2026 investments.
Importantly, to preserve commercial confidentiality and maximize strategic leverage, we have intentionally withheld the report’s full segmentation tables and price‑sensitive matrices from this preview. Those elements are central to tactical execution and are available exclusively through our subscriber portal.
Concluding perspective: use 2026 to convert stability into advantage
The radiator flushing chemicals market in 2026 is neither a sprint nor a stalled sector — it is a medium‑growth industry where operational excellence, chemistry differentiation and channel orchestration determine winners. With a baseline CAGR of approximately 5.5% and a trajectory that extends to roughly USD 327.6 Million by 2032, the path to outsized returns runs through supply‑chain clarity, targeted product investment and disciplined commercial execution.
If your 2026 agenda includes geographic expansion, margin stabilization or M&A, our report provides the decision‑ready analytics required to prioritize initiatives and quantify trade‑offs. For the complete intelligence package — including the proprietary segmentation matrices, interactive models and company‑level diagnostics essential for execution — visit the PW Consulting report page or contact our commercial team to arrange an in‑depth briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Radiator Flushing Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Mini-Program Short Drama Market Poised for Rapid Expansion — 13.93% CAGR Expected Through 2032
By PW Consulting, 2026-08-05
Worldwide Mini Program Short Drama Market: Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused preview of our new market study, Worldwide Mini Program Short Drama Market (base year 2025). This briefing distills the strategic implications that matter most to executives planning budgets, product roadmaps, and partnerships for 2026 — while preserving the full, proprietary segmentation and financial models for readers who access the full report.
Worldwide Mini Program Short Drama Market
Executive summary: Why 2026 is an inflection year
The mini program short-drama ecosystem has evolved from an experimental distribution channel into a mainstream commercial market within five years. From a modest base in 2020 it expanded exponentially through 2025, reaching a multi-billion-dollar industry by our 2025 base year. Our forecast (2026–2032) projects sustained expansion at a compound annual growth rate of 13.93%, with the market more than doubling over the forecast horizon under the central scenario. That trajectory creates both scale opportunities and strategic complexity for content owners, platforms, and advertisers entering or reallocating resources for 2026.
Worldwide Mini Program Short Drama Market
What this means for corporate decision-making in 2026
-
Allocate a dedicated mini-program short-drama playbook: Treat mini-program distribution as a distinct channel, not merely an extension of long-form streaming. Expect unit economics, audience behaviors, and production cadence to differ materially from legacy formats.
Worldwide Mini Program Short Drama Market -
Rebalance investment toward modular production and rapid iteration: The market favors short, serialized micro-episodes with fast feedback loops. Investment in lightweight production pipelines and template-driven creative reduces time-to-market and enables A/B testing at scale.
-
Prioritize integrated monetization stacks: Successful operators combine direct monetization (microtransactions/episode paywalls), subscription layers, and efficient advertising formats. 2026 winners will be those who optimize blend and sequencing across these models.
-
Embed regulatory and content-compliance workflows up-front: Platforms and producers must operationalize filing, reporting, and takedown readiness in content pipelines to avoid fines, removals, and churn. Recent enforcement waves demonstrate the cost of non-compliance.
Market trajectory and strategic nuances (high level)
Key macro facts to guide corporate strategy in 2026:
-
The market experienced explosive growth from 2020 to 2025, reaching a multi-billion USD scale by the report’s base year (2025), driven by platform integrations, in-app monetization mechanics, and rising consumer engagement with short serialized formats.
-
Our forecast through 2032 models a protracted expansion with a 13.93% CAGR under the central scenario — signaling persistent platform monetization, internationalization efforts, and continued creative experimentation.
-
Growth drivers include platform-driven distribution via mini programs, integrated social payment and sharing mechanics, and cross-border appetite for compact, mobile-first storytelling.
Competitive landscape: strategic roles and moves
The competitive map is a mix of mega-platforms, specialized streaming services, and nimble overseas aggregators. High-level takeaways for 2026 planning:
-
Platform incumbents (e.g., Tencent, ByteDance, Kuaishou): These companies control primary distribution channels and user acquisition levers. Tencent integrates mini-programs tightly with social and payment ecosystems. ByteDance leverages short-video virality and has pushed international variants. Kuaishou’s strategic retrenchments highlight the risk of platform-level pivoting.
-
Streaming and studio players (iQIYI, Youku/Alibaba, Bilibili, Mango TV): Traditional streamers are incubating micro-drama divisions and creator tools to capture younger viewers. Youku’s launch of a “Mini-Drama Studio” demonstrates the shift toward tooling and creator enablement as a competitive lever.
-
IP and production partners (China Literature, studios): IP owners are central to speed-to-audience and localization economies. Converting serialized IP into vertical micro-drama formats has become a repeatable playbook.
-
International and specialty platforms (Mega Matrix / FlexTV, Snail / Interactive Films, ReelShort, DramaBox): These players accelerate globalization through partnerships and localized products; recent MOUs and co-productions show an appetite to combine Chinese production methodologies with global distribution strategies.
Notable 2024–2025 developments that shape 2026 strategy:
-
Cross-border production and distribution MOUs (e.g., Snail / Mega Matrix) signal investment in AI-driven personalization and immersive formats for global markets.
-
Major content partnerships (e.g., WeTV and Lionsgate co-productions) establish first-window strategies that prioritize mini-program premieres alongside platform exclusives.
-
Platform product launches (Youku’s Mini-Drama Studio; ByteDance’s regional products) emphasize creator tooling, analytics, and integrated monetization as the frontier for scaling creator ecosystems.
Regulation, content quality, and audience behavior — risks and levers
Regulatory interventions in 2024–2025 introduced filing and review regimes and active enforcement across major platforms. These developments have three immediate implications for 2026:
-
Compliance as competitive advantage: Firms that standardize cost reporting, filing workflows, and rights documentation gain distribution certainty and reduce moderation risk.
-
Quality-first content gating: Platforms are shifting from quantity to quality; producers must match platform-defined content standards to secure shelf space and promotion.
-
Consumer scale and stickiness: The user base for micro-drama formats is now measured in hundreds of millions in certain markets, and engagement patterns differ by episode cadence and social mechanics. Understanding micro-metrics — completion rates, re-engagement windows, micro-transaction conversion funnels — is essential for modeling revenue and retention.
What PW Consulting’s full report delivers (practical content)
Our report is intentionally operational. It includes:
-
Proprietary market-sizing and scenario-based forecasts (TAM/SAM/forecast) calibrated to platform, content form, and monetization mix for 2026–2032.
-
Actionable GTM playbooks for platforms, studios, and IP owners covering launch sequencing, cross-promotion tactics, creator monetization splits, and subscription coupling strategies.
-
Production and cost playbooks that outline low-latency pipelines, episode templates, talent contracting models, and unit-economics benchmarks — with sensitivity analysis for production scale and region/mode of distribution.
-
Regulatory and compliance checklists and implementation timelines tailored to platform filing regimes and content safety requirements.
-
Partner and competitor matrices (global and regional), including capability heatmaps for distribution, creator tooling, analytics, IP conversion, and localization — mapped to potential strategic moves for 2026.
-
Data-driven KPI dashboards and analytical templates for monitoring live campaigns and series launches — from micro-conversion funnels to lifetime revenue curves per IP.
-
Strategic investment playbooks and VC-facing memos assessing M&A, content co-production, and platform partnerships using 3-phase deployment scenarios (conservative, central, aggressive).
Recommended strategic moves for 2026 (priority checklist)
-
Establish a centralized mini-program center of excellence to standardize creative, compliance, and analytics — reduce time-to-scale and defend margins.
-
Pilot hybrid monetization experiments (micro-payments layered with episodic subscriptions and native advertising) and instrument them with rapid analytics to identify the optimal mix per market.
-
Negotiate first-window optionality with platform partners: secure promotion in exchange for shared production risk or exclusive mini-program premieres.
-
Invest in AI-backed recommendation and creative optimization to increase episode-level completion and micro-transaction conversion.
-
Build contingency and compliance reserves: factor regulatory takedown and filing timelines into launch schedules and cash-flow forecasts.
Final note — the “trailer” for the full intelligence package
This briefing demonstrates why the Worldwide Mini Program Short Drama Market has matured into a strategic priority for platform owners, studios, and global distributors in 2026. The market reached multi-billion USD scale by 2025 and is forecast to grow at a mid-teens CAGR through 2032 — creating both scale and complexity across monetization, compliance, and creative production.
To preserve the competitive integrity of the full analysis and to support actionable planning, we have omitted granular regional and content-split tables from this preview. The complete report includes the detailed segmentation, financial models, and proprietary scenario outputs you need to finalize 2026 budgets and partnership commitments.
Access the full Worldwide Mini Program Short Drama Market report via PW Consulting’s research portal for the complete data package, downloadable models, and a tailored executive briefing for your organization.
For detailed analysis of this topic, please visit the official page: Worldwide Mini Program Short Drama Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


