



Category: market research
PW Consulting: X-ray Inspection Market Set to Grow at 5.73% CAGR to USD 3.86B by 2032
By PW Consulting, 2026-08-02
X-ray Inspection Systems Market: Strategic Imperatives for 2026 — An Executive Preview
PW Consulting presents a focused industry primer to accompany our full X-ray Inspection Systems Market study. This briefing is designed to orient senior leaders — CEOs, heads of product, BD and regulatory affairs — to the forces that will shape capital allocation, M&A, and go-to-market decisions in 2026. It highlights why the market matters, where strategic risks and opportunities concentrate, and how our full report turns data into executable choices.
X-ray Inspection Systems Market
Why this market matters in 2026
X-ray inspection systems sit at the intersection of quality assurance, regulatory compliance, and production automation. Across medical devices, pharmaceuticals, automotive, and electronics manufacturing, X‑ray technologies (from high-resolution micro-CT to inline 2D imaging) are shifting from “nice-to-have” validation tools to mission‑critical production controls. The commercial signal is clear: after growing from under USD 2.0 Billion in 2020 to approximately USD 2.61 Billion by the 2025 base year, the market is projected to continue expanding through the forecast window. By 2032 total industry revenues approach the high‑single‑digit billions under a mid‑cycle CAGR of approximately 5.73%. That steady, technology-driven expansion creates predictable runway for targeted investments while exposing firms to differentiated competitive and regulatory pressures.
X-ray Inspection Systems Market
What the full PW Consulting study delivers (practical, action-oriented)
- Market sizing and validated forward curves (historical 2020–2025; forecast 2026–2032) calibrated to real equipment replacement cycles and factory automation roadmaps.
- Scenario-based demand models that translate macro drivers into unit-volume and service-revenue outcomes under three realistic adoption trajectories.
- Regulatory and reimbursement impact assessments (including recent FDA and Medicare shifts) with decision trees and compliance-cost estimates tied to product classes.
- Vendor landscaping with competitive positioning maps, capability heatmaps (hardware, software/AI, services), and M&A readiness scoring.
- Commercial playbooks for incumbents and challengers: channel strategies, bundling recommendations, and pricing levers optimized for capital equipment and recurring service economics.
- Procurement and supply‑chain resilience diagnostics, including lead-time stress tests and single‑sourcing risk matrices.
- Operational KPI dashboards and a step‑by‑step implementation guide for piloting inline and CT inspection solutions in high-mix production lines.
- Appendices: primary interviews, methodology, and an anonymized database of procurement tenders and equipment spec-level requirements across end markets.
Key market dynamics shaping 2026 choices
- Technology convergence. Higher-resolution detectors, faster reconstruction algorithms, and on-device AI are increasing the scope of defects that can be automated for real‑time reject decisions. This improves throughput but requires tighter integration across hardware, edge compute, and MES/ERP systems.
- Regulation is tightening. The U.S. Quality Management System Regulation (QMSR), effective February 2, 2026, embeds ISO 13485:2016 into device CGMP expectations — raising the bar for validation, traceability and supplier audits for solutions used in medical device inspection.
- Reimbursement and care‑delivery models matter for portable systems. Pending Medicare analyses tied to HCPCS codes for portable X‑ray services will materially influence buyer economics for mobile units used in remote care and hospital-at-home settings.
- Concentration and value capture. The market shows a moderate to high degree of concentration at the top — a structural feature that favors firms with integrated product-service offerings and global support footprints. This has implications for pricing power, partnership strategies, and M&A valuation multiples.
- End-market divergence. Demand drivers in medical device QA, consumer electronics, and automotive are asynchronous: medical adoption is regulatory-bound but high-value per unit; electronics and automotive prioritize throughput and inline integration. Effective product roadmaps will segment offerings accordingly.
Competitive landscape — who matters and why
The competitive field blends specialized inspection innovators with large industrial automation and metrology players. Leading manufacturers remain differentiated on three axes: imaging physics (microfocus, CT vs. 2D), software/analytics (3D recon & AI detection), and aftermarket support (service, calibration, training). Notable incumbents profiled in our study include:
X-ray Inspection Systems Market
- North Star Imaging — a specialist in industrial CT and non‑destructive testing for micro-components and implants, with deep application engineering for 3D imaging challenges.
- Nikon Metrology — offers large‑envelope CT capacity and microfocus tubes tailored to implantables and additively manufactured parts, leveraging optics and precision engineering heritage.
- Nordson Corporation — provides both manual and automated series inspection platforms with strong integration options for production lines.
- YXLON International — microfocus X‑ray and CT systems focused on medical device QA for small parts and implants.
- Mettler Toledo — supplies X‑ray systems tuned for pharmaceutical and medical device packaging integrity and contaminant detection.
- Viscom AG — specializes in 3D AXI and MXI systems for series inspection of medical electronics and modules.
- HEUFT Systemtechnik — delivers pulsed X‑ray systems optimized for inline foreign object and package-quality detection.
Recent regulatory milestones — such as FDA 510(k) clearances for advanced stationary and portable systems — are accelerating market entry for new device classes and expanding clinical use cases. Our competitive assessment emphasizes relative strengths (e.g., clinical approvals, service network breadth, software ecosystems) rather than headline revenue figures; the full report includes an actionable vendor selection matrix for procurement teams.
Strategic implications for decision-makers in 2026
For leaders making budget and product decisions in 2026, three high‑priority implications emerge from our analysis:
- Prioritize regulatory alignment and documentation now. With QMSR effective in early 2026 and ongoing FDA device clearances reshaping clinical use, firms should accelerate ISO-aligned quality programs, supplier audits, and traceability systems to avoid market access delays.
- Design product portfolios along two axes — high-value, compliance-heavy systems (medical & pharma) and high-volume, throughput-optimized inline solutions (electronics, automotive). Each requires distinct sales motions, support economics, and upgrade paths.
- Monetize services and data. As installed bases grow, service, calibration, and software subscriptions become the main margin lever. Build remote diagnostics and predictive maintenance into contracts and consider outcome-based pricing pilots for tier‑1 OEMs and system integrators.
Recommended immediate moves (first 90–180 days)
- Run a regulatory gap assessment mapped to QMSR/ISO 13485 for all inspection products and supply partners.
- Initiate a channel and partner audit to identify weaknesses in aftersales coverage and spare‑parts logistics for priority markets.
- Test a bundled hardware+software offering in one pilot customer segment (medical QA or electronics inline) to quantify churn reduction and service ARPU uplift.
- Establish a reimbursement monitoring cell focused on HCPCS code developments and hospital procurement trends for mobile X‑ray adoption.
- Screen strategic M&A targets using our five‑factor readiness score (technology fit, service footprint, regulatory posture, customer overlap, cultural compatibility).
What the full report will let you do
Accessing PW Consulting’s full X-ray Inspection Systems Market study gives you the granular inputs and executable tools you need to convert insights into decisions: procurement scorecards, supplier shortlists, capex sensitivity matrices, and a prioritized roadmap of product changes keyed to regulatory timelines. We deliberately preserve confidential sub‑segment tables and client-level data in the paid report to protect commercial value; the executive summary here surfaces the strategic signals without releasing those granular splits.
How PW Consulting supports execution
Beyond analysis, we offer hands-on engagement packages tailored to the typical 2026 agenda: compliance readiness sprints, go‑to‑market pilots, M&A diligence and integration playbooks, and field service optimization projects. Our approach couples the market intelligence in this report with implementation teams that translate recommendations into measurable P&L outcomes.
Closing — the decision moment
For executives evaluating capital allocations in 2026, the choice is framed by predictability and differentiation. The market’s steady compound growth provides a reliable horizon for investment; the differentiator will be how quickly firms align product roadmaps to regulatory shifts, convert installed bases into service revenue, and embed AI-enabled analytics into inspection workflows. PW Consulting’s full report gives you the actionable detail to prioritize investments, de‑risk execution, and capture the greatest value as the X‑ray inspection market enters its next growth chapter.
To obtain the full dataset, proprietary segmentation tables, and vendor selection tools referenced in this preview, please contact PW Consulting for access to the complete X-ray Inspection Systems Market report and advisory services.
For detailed analysis of this topic, please visit the official page: X-ray Inspection Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Traffic Marking Paints market to reach USD 321.9 Million by 2032 (5.2% CAGR)
By PW Consulting, 2026-08-02
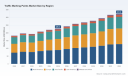
Traffic Marking Paints Market: Strategic Outlook for 2026 Decision-Making
As cities accelerate infrastructure renewal, highways demand higher durability, and sustainability rules tighten, the traffic marking paints market occupies an outsized role in municipal planning, highway concession economics, and coatings portfolios. PW Consulting’s latest study—anchored on a 2025 base year and projecting through 2032—provides the strategic intelligence executives need to act decisively in 2026. The market, measured in USD (Million), has shown a resilient recovery across 2020–2025 and is projected to grow at a compound annual growth rate (CAGR) of 5.2% from 2026 onwards, reaching an anticipated market size by 2032 that makes the category a non-trivial contributor to specialty coatings growth agendas.
Traffic Marking Paints Market
Why this intelligence matters for corporate strategy in 2026
- Resource allocation and portfolio prioritization. With predictable mid-single-digit growth, senior management can set capital allocation rules for R&D, production upgrades, and market-entry pilots with greater confidence. The report translates growth trajectories into investment thresholds that preserve margin while enabling product differentiation.
- Procurement and supply-chain resilience. Volatility in key inputs—most notably titanium dioxide and specialty resins, which together can represent a dominant share of manufacturing cost—means procurement strategies materially impact gross margin. Our analysis converts raw-material exposure into hedging and vendor diversification playbooks.
- Regulatory and sustainability positioning. Stricter low-VOC expectations in many jurisdictions require actionable reformulation and compliance roadmaps. The study maps regulatory trajectories against product portfolios to highlight where incremental reformulation investments yield outsized market access benefits.
- M&A and commercial plays. The market’s competitive structure supports both bolt-on consolidation and regional roll-up strategies. Our scenario models help identify the economic thresholds at which acquisition creates immediate scale economics versus when organic growth is superior.
What the report delivers: practical, action-oriented modules
Beyond forecasting, our study is organized to facilitate decision-making across functions. Key operational and strategic deliverables include:
Traffic Marking Paints Market
- Dynamic market model: a buildable model that converts macro drivers and scenario levers (e.g., urbanization rates, highway capex, VOC regulation timelines) into demand and revenue outputs.
- Cost-sensitivity and margin diagnostics: SKU-level margin maps that isolate the impact of titanium dioxide, resin type, and glass bead quality on unit economics, plus suggested pricing ladders across product lifecycles.
- Regulatory readiness checklist: jurisdiction-by-jurisdiction actions tied to R&D timelines for low-VOC and waterborne technologies, including recommended testing protocols and certification roadmaps.
- Competitive scorecards: comparative analyses of incumbent and challenger suppliers on technical performance, channel coverage, production footprint, and innovation trajectories—designed to inform partner selection and M&A prioritization.
- Go-to-market playbooks: tender and specification strategies for winning public contracts, trial deployment plans for long-life thermoplastic solutions, and specification language that procurement teams can use to capture total cost of ownership advantages.
- Implementation-ready pilot designs: practical testing frameworks for proving long-life or low-VOC products on a municipal scale, with KPI templates and failure-mode monitoring.
Competitive landscape: actionable insights on leading players
The traffic marking paints sector combines global coatings majors with specialized regional manufacturers and system providers. Our analysis synthesizes recent strategic moves and capability sets of the most consequential participants to outline threats, opportunities, and likely next moves in 2026:
Traffic Marking Paints Market
- Global coatings leaders: Companies with broad coatings portfolios bring compelling advantages in distribution, R&D scale, and raw-material procurement. Recent product launches focused on extreme-weather durability and longer service life demonstrate their intent to push premium-priced, differentiated lines that reduce life-cycle repainting needs.
- Specialist marking companies: Niche players that concentrate on thermoplastic systems or zone-marking products retain strong customer intimacy and technical know-how, making them natural partners for joint innovation or attractive targets for roll-up strategies that deliver immediate route-to-market benefits.
- Technology and material innovators: Suppliers expanding eco-friendly waterborne solutions and enhanced retroreflective thermoplastics are engineering the next performance bar. Portfolio expansions and product launches during 2025–2026 signal a two-track market: premium durability claims and low-VOC sustainability claims will compete for procurement preference.
Notable industry moves tracked in the study include launches of high-durability and eco-friendly product lines as well as targeted market expansions tied to smart-city and highway modernization projects. These developments highlight an industry actively reshaping product value propositions around durability, environmental impact, and retroreflective performance.
Market structure and strategic implications
The market displays moderate fragmentation: leading firms do not yet command very high concentration ratios, leaving room for strategic consolidation and local leadership plays. This structure creates a dual strategic pathway for incumbents and entrants alike—either invest to capture premium segments through product differentiation or pursue geographical/segment roll-ups to achieve scale benefits in procurement and distribution.
Raw-material price dynamics and margin pressure
Raw-material inputs are a dominant determinant of manufacturing economics. Independent data points indicate that titanium dioxide and specialty resins can account for a large share of total costs, and thermoplastic formulations exhibit a wide price band driven by resin quality and glass-bead specifications. The practical implications for 2026 are clear:
- Price volatility in TiO2 and resins can rapidly compress margins; companies should operationalize cost pass-through clauses for public tenders and institute flexible pricing mechanisms for private contracts.
- Product engineering focused on reducing TiO2 intensity or substituting with lower-cost binders—without sacrificing retroreflectivity—can produce durable competitive advantage.
- Vertical partnerships with glass-bead suppliers and resin producers can stabilize supply and enable joint value propositions emphasizing longevity and safety performance.
Strategic imperatives and a 12-month action plan for 2026
To convert market visibility into commercial advantage, the following priority actions are recommended for the next 12 months:
- Launch targeted pilot programs for waterborne and low-VOC lines in jurisdictions signaling stricter environmental norms; use early wins to secure specification language in municipal tenders.
- Institute a raw-material risk dashboard that ties TiO2 and resin exposure to product margin by SKU and flags hedging or inventory actions when risk thresholds are crossed.
- Develop an M&A filter: target specialty producers with strong regional contracts or unique thermoplastic recipes that materially extend repaint cycles.
- Redesign tender bid templates to emphasize total cost of ownership (TCO) and service-life metrics rather than lowest upfront price; back claims with third-party durability data from controlled pilot deployments.
- Invest in product certification and lab capacity to accelerate time-to-market for eco-friendly and high-retroreflective products; consider co-funded demonstration projects with cities and highway authorities.
- Create channel partnerships with road-services contractors and airport operators to embed products into lifecycle service agreements, increasing recurring revenue and near-term adoption.
KPIs to monitor through 2026
- Market share movement in targeted geographies and application verticals (tracked quarter-on-quarter).
- Average service life improvements (months or years) attributable to premium formulations.
- VOC intensity per SKU and compliance milestones achieved versus regulatory timelines.
- Gross margin resilience against raw-material price shocks; frequency and efficacy of price pass-throughs.
- Number and size of specification wins in municipal and highway tenders linked to product pilots.
What we intentionally withhold in this preview
To preserve the commercial utility of the full intelligence package, this article omits granular, segment-level revenue tables, region-by-region split figures, individual SKU price matrices, and detailed supplier revenue shares. The complete report contains those datasets, alongside interactive modeling tools that allow clients to test bespoke scenarios (e.g., different reformulation investment levels, tender-win rates, and raw-material cost projections) and receive tailored P&L impacts.
Next steps: how to use this study in board-level decision cycles
For boards and executive teams planning 2026 actions, the report is structured to slot directly into strategic reviews. Use it to:
- Inform capital allocation decisions for coatings R&D and production line upgrades;
- Define procurement risk tolerances and contract language for raw-material supply;
- Prioritize markets and product categories for M&A and organic investment;
- Set measurable KPIs for sustainability and specification wins in public infrastructure projects.
In a market growing at an expected mid-single-digit CAGR and presenting both margin pressure from raw-material exposure and upside from premium performance claims, 2026 represents a tactical window to re-engineer product portfolios, secure specification-led revenues, and lock in long-term partnerships. PW Consulting’s full Traffic Marking Paints Market study is designed to move teams from insight to implementation—equipping leaders with the models, scorecards, and playbooks necessary to convert the sector’s trajectory into realized competitive advantage.
For detailed analysis of this topic, please visit the official page: Traffic Marking Paints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High-Selenium Yeast Market Poised for 4.8% CAGR Through 2032
By PW Consulting, 2026-08-02
High Selenium Yeast: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive snapshot
As the High Selenium Yeast market moves from niche supplement to strategic ingredient across animal nutrition and functional foods, 2026 will be a pivotal year for executives who must reconcile regulatory complexity, supply-chain constraints and product premiumization. PW Consulting’s forthcoming full report — built on a base year of 2025 and an explicit forecast horizon of 2026–2032 — shows a steady, investment-grade market trajectory with compound annual growth of 4.8%. The market has expanded consistently through 2020–2025 and our models project continued growth into the early 2030s, underscoring predictable upside for companies that align R&D, regulatory and commercial execution now.
High Selenium Yeast (High-Selenium Yeast) Market
Why this matters for 2026 decision-makers
2026 will be the year when strategic moves crystallize into structural advantage. Several dynamics that have been maturing across the supply chain and regulatory landscape converge to make near-term decisions high-leverage:
High Selenium Yeast (High-Selenium Yeast) Market
- Regulatory clarity: Recent authorizations and government recognitions in major markets have reduced a key source of uncertainty that previously inflated go-to-market timelines.
- Demand articulation: The ingredient’s transition from an ancillary micronutrient to a differentiated technology input (for antioxidant support, animal health and human functional foods) is driving higher-margin opportunities.
- Supply-side normalization: Raw-material cost volatility has eased relative to earlier cycles, enabling predictable procurement and more confident margin modeling.
Market trajectory in context
PW Consulting’s topline model tracks the market through a full five-year historical run (2020–2025) and delivers scenarios into 2032. The market has shown stepwise expansion year-over-year and our baseline forecast envisions steady growth through the forecast window at an annualized rate of 4.8%. For commercial leaders, this predictability enables multi-year investments in formulation, route-to-market and brand positioning that previously would have been considered premature.
High Selenium Yeast (High-Selenium Yeast) Market
Key growth drivers and headwinds
- Premiumization of feed and functional food formulations: As nutritionists and formulators seek higher bioavailability and traceability, demand is shifting toward standardized, well-documented yeast-based selenium solutions that can be justified on health outcomes and feed efficiency metrics.
- Regulatory momentum: Recent official recognitions and approvals in geographies that previously required lengthy local data packages have shortened commercialization windows for compliant suppliers.
- Clinical and translational evidence: A modest but growing corpus of peer-reviewed and industry-sponsored studies supports claims for bioavailability and functional benefits, encouraging adoption in targeted applications.
- Supply-chain steadiness: After periods of commodity-driven input volatility, selenium supply and logistics have stabilized, lowering one barrier to scale. However, capacity constraints for high-selenium yeast manufacturing still demand strategic supplier relationships and contingency planning.
- Commercial fragmentation: The competitive field remains fragmented enough to favor focused players with technical differentiation, but concentrated enough in some subsegments that partnerships and alliances remain meaningful routes to scale.
Competitive landscape — strategic takeaways
Our competitive analysis focuses on incumbent ingredient specialists and vertically integrated animal-nutrition firms. The following are synthesis-level insights drawn from company profiles, product positioning and recent regulatory events; detailed market-share and segment-level metrics are available in the full report.
- Lallemand Inc. (Montreal, Canada): Lallemand’s high-selenium yeast offering has achieved regulatory traction in key jurisdictions and is positioned as a premium, standardized additive with assured selenomethionine content. The company’s strength lies in regulatory know-how and a track record of gaining approvals across complex markets — a capability that shortens commercialization timelines for customers who value compliance certainty.
- Alltech Inc. (Nicholasville, USA): Alltech couples proprietary yeast technology with extensive feed and farm channel relationships. Their product emphasis on animal well-being and antioxidant support reflects an integrated go-to-market that leverages farm-level outcomes and nutritional consulting — a model that drives adoption where advisors influence procurement.
- Cypress Minerals Inc. (Fresno, USA): Cypress positions a standardized, gluten-free high-selenium yeast product that has been used in clinical settings. The company’s differentiation is technical purity and use-case specificity, attractive to functional food formulators and clinical researchers seeking controlled inputs for trials.
Recent regulatory developments — notably the authorization of Lallemand’s premium product in European markets and regulatory green lights in large Asian markets — materially change the competitive calculus. These events make regulatory readiness a table-stakes capability for 2026.
What PW Consulting’s full report delivers (practical content)
The full PW Consulting study is designed as an operational playbook for executives. It includes:
- Detailed market-size modeling (historical series and scenario-based forecasts), with embedded sensitivity analyses to test price, adoption and regulatory timing assumptions.
- Go-to-market matrices that map channel economics across feed, dietary supplements and functional food pathways — highlighting margin pools, lead times and typical buyer decision cycles.
- Supply-chain diagnostics that identify concentration risks at raw-material and manufacturing stages, and prescribe procurement hedges and inventory-buffer strategies.
- Regulatory heat maps and pathway playbooks for prioritized jurisdictions, including dossier templates, expected timelines and evidence requirements for feed and food approvals.
- Competitive benchmarking and M&A scouting: profiles of incumbent suppliers, assessment of technological differentiators, and transaction criteria for bolt-on acquisitions to accelerate capability gaps.
- Commercial test-and-learn pilots and an A/B playbook for pricing, claims architecture and distributor incentives — enabling rapid validation with measurable KPIs.
Actionable strategic moves for 2026
Executives should view the coming 12–18 months as a window to build asymmetric advantages. Recommended moves we articulate in the report include:
- Prioritize regulatory “fast tracks”: Allocate resources to secure authorizations in jurisdictions where approvals materially expand addressable demand — engage early with regulators, and pre-position robust safety and efficacy dossiers.
- Lock in supplier partnerships: Negotiate multi-year offtake and capacity agreements with certified manufacturers to protect margins and ensure continuity as demand scales.
- Invest in clinical evidence selectively: Fund targeted trials that align with high-value use cases (e.g., reproductive performance in livestock, specific functional-food endpoints) to unlock premium pricing and label claims.
- Design go-to-market pilots with outcome-based pricing: Partner with lead customers to co-finance pilots that tie price to observable improvements (e.g., feed conversion ratios or biomarker improvements), lowering buyer risk and accelerating adoption.
- Evaluate bolt-on capabilities: Use M&A to acquire critical capabilities — such as specialized fermentation, analytics for organic selenium speciation, or niche distribution networks — where time to scale via build is prohibitive.
How to use the report in your 2026 planning cycle
Use our report as the central input to three enterprise processes:
- Commercial planning: Translate demand scenarios into SKU-level revenue plans and distributor incentive structures.
- R&D roadmapping: Prioritize formulations and analytic investments that maximize differentiation and reduce regulatory friction.
- Corporate development: Define acquisition screens and partnership scorecards focused on technical fit, regulatory dossiers and channel access.
Why PW Consulting’s approach matters
We combine macro forecasting with practical, executable playbooks. The market’s steady compound growth and improving regulatory clarity reduce structural investment risk, but success hinges on execution across three dimensions: regulatory foresight, manufacturing certainty and clinical differentiation. Our preview here surfaces directional insights; the full study contains the granular models, scenario matrices and action templates that your leadership team will need to operationalize these strategies.
Next steps
This article follows the “preview” principle: it demonstrates the analytical depth needed to build confidence while preserving the report’s proprietary segmentation, granular regional and application-level forecasts, and downloadable model files for subscribers. For those preparing 2026 budgets and strategic initiatives, access to the full report will translate high-level conviction into executable plans with quantifiable ROI.
To obtain the complete High Selenium Yeast market study with detailed segment economics, regulatory playbooks and transaction scouting lists, please visit the PW Consulting publication page.
For detailed analysis of this topic, please visit the official page: High Selenium Yeast (High-Selenium Yeast) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: CNG ISO Tank Market to Reach USD 266.96M by 2032 at 5.63% CAGR
By PW Consulting, 2026-08-02
CNG ISO Tank Container Market — Strategic Imperatives for 2026
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present a focused strategic primer on the compressed natural gas (CNG) ISO tank container market intended to orient executive decision-making for 2026. This piece synthesizes our quantitative outlook, competitive reading, and actionable playbooks without disclosing the proprietary, granular splits and scenarios contained in the full study. Consider this the trailer: enough insight to recalibrate strategy and priorities now, but intentionally reserved to drive engagement with the full PW Consulting deliverable for transaction‑grade detail.
CNG ISO Tank Container Market
Market snapshot: trajectory and structural signal
Our base-year analysis (2025) and historical review (2020–2025) show a market that has grown steadily and is positioned for continued expansion through our forecast window (2026–2032). The global CNG ISO tank container market reached a meaningful milestone in 2025, having advanced materially since 2020, and we model a compound annual growth rate (CAGR) of 5.63% over the forecast period. Under PW Consulting’s central scenario, the market expands progressively into the early 2030s—driven primarily by rising CNG adoption across vehicle fleets and industrial propulsion, coupled with incremental modernization of intermodal transport assets.
CNG ISO Tank Container Market
Two structural signals emerge from the top-line analysis. First, demand is broadening: buyers are no longer concentrated in a single application niche but are increasingly deploying standardized, high-pressure ISO solutions across multiple use-cases. Second, supply-side consolidation and product differentiation are intensifying, creating both scale advantages and distinct technology/IP vectors for leading vendors.
CNG ISO Tank Container Market
Why this matters for 2026 decision-making
-
CapEx and capacity planning: With a predictable mid-single-digit CAGR and clear seasonality in procurement cycles, manufacturers and fleet operators must sync investment timetables with the market’s multi‑year ramp. A delayed capacity investment can mean missed market share; an oversized bet risks underutilized assets. Our modeling helps you size phased expansions and decide between in-house production vs. contract manufacturing.
-
Product strategy & differentiation: Safety and pressure-handling capabilities have emerged as product axes. New higher-pressure designs and safety-focused architectures are moving from R&D to commercialization. Winning vendors will balance incremental innovation with certification time — the latter can materially affect go-to-market timing.
-
Sourcing and cost resilience: Carbon steel remains the dominant raw material due to its strength and cost profile. Price volatility in steel markets therefore transmits directly to unit economics. Procurement teams should establish dual-sourcing, indexed contracts, and forward-purchase strategies; operations leaders should evaluate design changes that reduce steel intensity without compromising safety or certification.
-
Regulatory compliance as a market gate: ISO 1496-series compliance and related testing for intermodal transport govern market access. Certification timelines materially affect time-to-revenue and should be built into product launch plans and acquisition due diligence.
-
M&A and partnership timing: With mid-to-high market concentration and clear global leaders, strategic acquisitions and OEM partnerships remain viable routes to scale and geographic expansion. However, premium multiples for proven certification, backlog, and manufacturing capacity can compress the arbitrage window; acting in 2026 requires pre-validated integration playbooks and regulatory checklists.
What PW Consulting’s full study delivers (practical, transaction‑ready tools)
The PW Consulting CNG ISO Tank Container study combines a transparent forecasting engine with pragmatic execution tools designed for corporate leadership, investors, and supply-chain managers. Highlights include:
- Scenario-based demand models (base, upside, downside) covering 2026–2032 with editable assumptions so your team can stress-test strategies under alternative energy and macro setups.
- Comprehensive TCO (total cost of ownership) models for owner-operators and lessors that incorporate capital, certification, maintenance, and logistics components.
- Supplier scorecards and manufacturing benchmarking packs to accelerate vendor selection and audit prioritization.
- Regulatory heatmaps and certification timelines keyed to ISO 1496 and relevant regional approvals, with a practical checklist to compress approval cycle time.
- CapEx planning templates and sensitivity analyses, including steel-price pass-through levers and margins under different procurement arrangements.
- Go‑to‑market and commercial playbooks for OEMs, integrators, and leasing businesses (pricing guidance, bundling strategies, and channel design).
- Targeted M&A screening methodology and a confidential shortlist workflow to identify and value bolt-on manufacturing, IP, or channel assets.
Competitive landscape — concentration, players, and tactical moves
The market exhibits moderate-to-high concentration: our concentration metrics indicate material share aggregation among the top three and top five suppliers. That concentration produces asymmetric advantages in pricing, certification throughput, and channel relationships, but it also opens exploitable niches for nimble competitors focused on specific product attributes or service models.
Profiles of representative, strategically significant suppliers illustrate current competitive dynamics:
-
TGE Gas Engineering (France) — Specialist in high‑pressure, safety‑optimized ISO tank solutions. Recent product launches targeted at higher-pressure applications and sustained trade-show engagement (notably in 2024–2025) signal a deliberate commercialization push to capture premium segments.
Website: https://tge-gas.com
-
SinoCleansky Technologies Corporation (China) — Focused on long-tube skid containers and ISO-certified tank units for transport and storage. The company’s certification breadth (ISO/ASME) supports export orientation and competitive participation in global supply pools.
Website: https://www.sinocleansky.com
-
Luxi New Energy Equipment Group (China) — Manufacturer of long-tube skid and ISO-compliant tanks with strong domestic manufacturing scale. Their product mix accentuates cost competitiveness in volume applications.
Website: https://www.luxixny.com
Strategic implication: incumbents with integrated certification capabilities and demonstrated product evolution will increasingly command higher margins. New entrants must either find narrow, defensible niches (e.g., ultra-high safety platforms, leasing-as-a-service) or partner with established players to achieve scale rapidly.
Supply‑chain and raw‑material playbook
Carbon steel’s predominance creates a predictable vulnerability: when steel swings, unit economics do too. Practical mitigations that we recommend and that are modeled in the full report include:
- Indexed supply agreements and capped corridor pricing to smooth cost volatility.
- Design-to-cost initiatives to reduce steel intensity while preserving certification and safety margins.
- Geographic diversification of fabrication footprints to balance freight, labor, and tariff exposure.
- Strategic inventory buffering calibrated to working-capital cost and lead-time risk tolerance.
Regulatory & standards context — operational levers
ISO 1496-series standards and related intermodal testing are not administrative hurdles but determinant commercial factors. Certification timelines should be explicitly accounted for in go‑to‑market sequencing, and compliance-driven design choices will frequently determine which customer segments a product can serve. For 2026 launches, the executives we advise build certification paths in parallel with prototype testing to compress the overall commercialization schedule.
Recommended execution roadmap: 90‑day and 12‑month priorities
-
90‑day (stabilize & prioritize): validate backlog and orderbook quality, secure critical steel forward positions for the next two quarters, initiate certification pre-submissions for any new pressure-class product, and run a rapid supplier scorecard to identify single‑source risks.
-
12‑month (scale & differentiate): complete pilot runs of higher-pressure containers with concurrent third-party certification; finalize at least one strategic partnership (manufacturing or channel) to accelerate market access; deploy TCO-based commercial pilots with key fleet customers to lock in early-adopter references.
Conclusion — what to do next
The CNG ISO tank container market presents a clear, measurable growth runway through 2032 underpinned by rising CNG adoption and structural supply-side consolidation. For 2026, the strategic priority is simple: marry disciplined capacity and procurement decisions with accelerated certification and customer‑facing TCO tools. That alignment converts favorable market growth into sustained competitive advantage.
PW Consulting’s full study provides the granular segmentations, interactive models, and asset-level diligence materials needed to operationalize these priorities. To access the complete market dataset, regional and application splits, and bespoke scenario tools that inform transaction-level decisions, contact our advisory team or visit the PW Consulting report page for a confidential briefing.
For detailed analysis of this topic, please visit the official page: CNG ISO Tank Container Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Lead‑Acid Battery Market: USD 359.81M by 2032, 5.28% CAGR — PW Consulting
By PW Consulting, 2026-08-02
Lead‑Acid Battery Market: A 2026 Strategic Preview for Decision‑Makers
As PW Consulting’s lead industry analyst, I present a concise, high‑impact preview of our comprehensive Lead‑Acid Battery Market study designed to inform capital allocation, supply‑chain strategy, and commercial positioning through 2026 and beyond. Grounded in a rigorous base year of 2025 and a historical lens from 2020–2025, our model projects the market to continue expanding at a steady compound annual growth rate (CAGR) of 5.28% across the 2026–2032 forecast window — lifting aggregate market value from USD 252.0 million in 2025 toward a substantially larger industry by 2032.
Lead-Acid Battery (Lead-Acid Batteries) Market
Why this report matters for 2026 decisions
-
Timing: 2026 is a pivot year for lead‑acid players as legacy demand centers (automotive starter batteries, industrial motive power) intersect with renewed opportunities in stationary backup, renewable integration, and telecom infrastructure. Our study synthesizes demand signals to identify where near‑term investments will compound by 2032.
Lead-Acid Battery (Lead-Acid Batteries) Market -
Risk management: Raw material cycles, regulatory pressure on recycling and disposal, and labor cost shifts are converging to reshape competitive economics. We quantify scenario outcomes so procurement, manufacturing, and treasury leaders can stress‑test strategies against plausible shocks.
Lead-Acid Battery (Lead-Acid Batteries) Market -
Competitive clarity: While the sector is neither highly consolidated nor atomized, leading firms are actively repositioning via product, channel, and geographic moves. Understanding the directionality and tempo of those moves is essential to formulate defensive and offensive plays.
Snapshot: growth trajectory and macro context
The lead‑acid market’s recovery and steady growth from 2020 through 2025 — where our base year value sits at USD 252.0 million — underpin a resilient sectoral outlook. At a modeled CAGR of 5.28% for 2026–2032, the market’s expansion is driven by incremental demand in backup power for data centers and telecom, continued replacement cycles in automotive and industrial applications, and selective growth in renewable‑adjacent stationary storage. PW Consulting’s forecast maps this pathway in quantitative scenarios that reflect differing technology substitution rates and regulatory interventions.
Dynamics shaping the near term (operational and regulatory)
-
Recycling and circularity: Policy frameworks in the U.S. and key export markets continue to incentivize battery recycling through consumer core charges, state‑level disposal bans, and public‑private collection schemes. Industry data indicates exceptionally high recycling rates for lead‑acid chemistry, creating both a supply advantage (recycled lead feedstock) and a compliance imperative for manufacturers and retailers.
-
Raw material and labor considerations: Domestic manufacturing benefits from high shares of recycled content, which moderates exposure to global lead price swings but raises the importance of domestic collection and reclamation infrastructure. Labor cost dynamics and automation trends in assembly and recycling will influence where new capacity is sited.
-
Regulatory complexity: Across major markets, extended producer responsibility, transportation rules, and safety standards for stationary installations alter total cost of ownership calculations. Our report translates these into actionable pass‑through and investment assumptions for CFOs and procurement teams.
What the PW Consulting report contains (practical deliverables)
-
Market sizing and validated forecasting framework — base year 2025, historical 2020–2025, forecast 2026–2032 — with demand scenarios tied to adoption curves for VRLA, flooded, and emerging lead‑acid variants.
-
Supply‑chain mapping and vulnerability heat map — from lead feedstock and processed lead to cell assembly, recycling loops, and logistics bottlenecks — with mitigation playbooks for suppliers and OEMs.
-
Pricing and margin model — stress‑tested against raw material swings, labor inflation, and compliance costs, enabling corporate finance teams to model EBITDA sensitivity by strategy.
-
Commercial playbook — go‑to‑market segmentation, channel optimization, OEM partnership frameworks, and tendering strategies for stationary vs. motive power customers.
-
Investment and M&A scorecards — capital intensity profiles, target screening criteria, and integration checklists for bolt‑on acquisitions focused on recycling, specialty VRLA, or high‑cycle motive power niches.
-
Scenario planning annexes — three discrete futures (baseline, accelerated EV‑penetration, and aggressive substitution) with timeline triggers and decision‑point recommendations for executives.
-
Competitive intelligence dossier — curated profiles of leading incumbents, recent strategic moves, technology positioning, and suggested partnership/arbitration strategies.
Competitive landscape: what we observe and why it matters
The competitive set in lead‑acid remains populated by legacy manufacturers who combine deep channel access with specialized product portfolios. Our study devotes individual strategic profiles to seven core firms, examining where each player is investing, retreating, or pivoting.
-
EnerSys (Reading, PA): continuing to emphasize advanced energy storage and industrial backup; recent organizational realignment signals a sharper focus on high‑margin sectors such as data centers and telecommunications UPS solutions.
-
GS Yuasa (Kyoto, JP): maintains a diversified industrial and automotive footprint with public investor communications underscoring long‑term product roadmaps and global scale advantages.
-
Exide Industries (Kolkata, IN): actively promoting VRLA and flooded solutions into grid‑tied and infrastructure projects; recent project wins and trade‑show presence reflect a strategy of capturing large institutional tenders in emerging markets.
-
East Penn Manufacturing (Duncannon, PA): leveraging strong distributor channels and recent customer‑facing digital guidance to better capture EV/hybrid and replacement demand.
-
Clarios (Redwood City, CA): focused on AGM and low‑voltage solutions for automotive and powersports; their product development cadence merits attention for any OEM engagement strategy.
-
C&D Technologies (Blue Bell, PA): emphasizing specialized flooded and VRLA variants for critical infrastructure, with investments in pure‑lead and nano‑carbon technics for UPS applications.
-
Hoppecke (Brilon, DE): a strong player in industrial and rail applications — their positioning in high‑current and rail systems provides a blueprint for premium product strategies.
Recent corporate actions underline the strategic themes: EnerSys’s segment realignment (May 2026) reveals an industry shift toward specialist commercial units; Exide’s project participation and contract wins in early‑2026 demonstrate demand persistence in large infrastructure tenders; East Penn’s customer navigation tools (late‑2025) indicate increased emphasis on digital sales enablement.
Strategic plays for 2026 (recommended priorities)
-
Secure feedstock resiliency: prioritize contracts and partnerships with domestic recycling and reclamation operators to stabilize input costs and ensure compliance with evolving EPR frameworks.
-
Differentiate through channel and service: build value beyond cells — warranty programs, reverse‑logistics, and uptime‑guarantees are decisive in the stationary and telecom segments.
-
Right‑size R&D and product mix: balance investment between low‑cost flooded products and higher‑margin VRLA/AGM offerings tailored to data‑center, telecom, and rail segments.
-
Pursue targeted M&A: evaluate bolt‑on acquisition opportunities that expand recycling capacity, add specialty chemistries, or secure strategic distribution in growing regional markets.
-
Embed scenario discipline: institute decision gates tied to regulatory and EV adoption milestones so capex and commercial commitments remain reversible within governance constraints.
How PW Consulting delivers value
Our Lead‑Acid Battery Market study combines proprietary field interviews, plant‑level cost modeling, and cross‑reference datasets to produce an actionable roadmap for executives. We deliberately present a high‑level view here to demonstrate the analytic depth and strategic thinking embedded in the full deliverable while protecting the granular segmented outputs that are most valuable for competitive planning.
In short: if your 2026 playbook requires quantified scenarios for procurement, a prioritized pipeline of inorganic targets, and a defensible commercial strategy in a market growing at a mid‑single digit CAGR, PW Consulting’s full report supplies the templates and the decision rules to act with confidence.
Next steps
-
For a guided walk‑through of the models, scenario triggers, and M&A scorecards, PW Consulting offers tailored briefings that map the report’s implications directly onto your balance sheet and commercial plans.
-
If you are evaluating capital allocation, alliance formation, or supply‑chain de‑risking in the lead‑acid value chain for 2026, the timing to align strategy with forecast momentum is now.
Punchline: the lead‑acid sector is not stagnant legacy tech — it is a resilient industrial chemistry with clear niches of sustained growth. Our research equips executives to convert that resilience into profitable, defensible positions; the full report contains the granular segmentation, pricing curves, and proprietary scoring that operationalize these strategic priorities.
For detailed analysis of this topic, please visit the official page: Lead-Acid Battery (Lead-Acid Batteries) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Grain & Seed Cleaning Equipment Market to Grow at 4.92% CAGR
By PW Consulting, 2026-08-02
Grain and Seed Cleaning Equipment: Strategic Outlook to 2032 — A PW Consulting Industry Brief
Executive preview
The Grain and Seed Cleaning Equipment market is entering a phase of steady, technology-enabled expansion. Our baseline review (base year 2025) demonstrates a market that has recovered and rebalanced across commodity cycles and is forecast to grow at a compound annual growth rate of approximately 4.9% through the 2026–2032 horizon. This growth is neither speculative nor uniform; it is shaped by converging forces — automation, energy efficiency mandates, shifting farm structures, and differentiated demand between large-scale processors and on-farm operators.
Grain and Seed Cleaning Equipment (Grain & Seed Cleaning Equipment) Market
Why this research matters for 2026 corporate decisions
-
Timing and capital deployment: As OEMs and investors set budgets and M&A agendas for 2026, the trade-off between investing in high-capacity, integrated lines and modular/mobile units will determine market share capture. Our study maps where productivity investments yield the highest ROI within the forecast window.
Grain and Seed Cleaning Equipment (Grain & Seed Cleaning Equipment) Market -
Product roadmap prioritization: Technology inflection points — particularly in optical sorting, AI-enabled defect detection, and low-energy air handling — are creating differentiation that materially affects replacement cycles and service economics. Understanding which capabilities convert to premium pricing is critical for 2026 product choices.
Grain and Seed Cleaning Equipment (Grain & Seed Cleaning Equipment) Market -
Channel and service strategy: The split between centralized processing plants and on-farm/portable demand has implications for distribution, aftermarket services, and parts economics. For 2026 planning, firms must optimize inventory, retrofit programs, and remote diagnostic offerings to protect margins.
-
Regulatory and sustainability risk: Energy efficiency and emissions considerations are moving from voluntary to commercially consequential. Suppliers that can credibly lower drying and airflow energy intensity will gain negotiation leverage with large grain handlers and exporters.
Market trajectory and financial context (what the numbers imply)
From a PW Consulting vantage, the aggregate market size has shown a clear recovery from 2020 through the 2025 base year and continues on a steady upward path through 2032. The mid-single-digit CAGR embedded in our forecast reflects a market driven by gradual replacement, selective capacity expansion, and increasing value-add per unit (sensors, automation, and energy systems). While headline growth is not hyperbolic, the quality of growth — driven by technological upgrades and higher-ticket integrated solutions — creates strategic opportunities for margin expansion for the right incumbents and entrants.
Importantly, the market’s growth is lumpy at the segment and geography levels. That unevenness produces pockets of rapid adoption (e.g., optical sorting retrofits, energy-efficient drying retrofits) alongside slower-moving replacement cycles in cost-sensitive channels. The PW Consulting report disaggregates these dynamics to guide where 2026 investment will compound value versus where it simply preserves share.
Key strategic implications by stakeholder
-
OEMs and component suppliers: Prioritize modular platforms that can be upsold with sensor and AI packages. Invest in partnerships (or acquisitions) that fill gaps in machine vision, predictive maintenance, and energy-efficient air handling to accelerate time-to-market for integrated systems.
-
Grain and seed processors: Focus CapEx on front-end quality control (pre-cleaning and optical sorting) to protect downstream processing margins. Evaluate retrofit pathways that reduce energy and labor while improving throughput — the economics often favor staged upgrades over full-line replacement.
-
Dealers and service networks: Redesign service contracts around uptime and data-driven performance guarantees. For 2026 negotiations, position aftermarket analytics as a revenue stream; customers increasingly accept premium pricing for measurable yield and quality improvements.
-
Private equity and strategic buyers: Seek targets that combine durable aftermarket revenues, product differentiation (e.g., AI-enabled sorters, low-energy fans), and distribution footprints in underserved markets. Consolidation opportunities exist, but the market remains fragmented — integration plans must focus on margin harmonization and cross-selling.
Technology and sustainability as competitive levers
Two technological vectors will disproportionately influence winners and losers over the next planning cycle. First, optical sorting and AI-driven defect detection are moving from novelty to baseline expectation for premium quality streams; recent product introductions illustrate this trajectory. Second, energy-efficient drying and airflow systems are rapidly becoming procurement priorities as operators internalize energy cost volatility and regulatory pressures. Suppliers that can demonstrate reliable energy savings and improved throughput will be favored in tender processes in 2026 and beyond.
Case in point: leading suppliers have already introduced next-generation systems that employ deep learning for impurity detection and novel fan architectures for lower energy consumption. These developments are changing the calculus of total cost of ownership (TCO) and are central to our recommendations on product positioning and retrofit offerings.
Competitive landscape — what the report reveals (select profiles)
-
Bühler Group (Uzwil, Switzerland): A full-line supplier with strengths in optical sorting and integrated cleaning lines. Their moves into AI-enhanced sorters and end-to-end line solutions position them as a go-to partner for processors seeking quality-driven yield improvements.
-
Westrup A/S (Slagelse, Denmark): Known for precision seed-cleaning machinery and modular high-capacity systems. Their focus on lab-to-industrial scalability makes them attractive where seed purity commands premium value.
-
Cimbria A/S (Thisted, Denmark): A leader in screen cleaners and recently launched fan series that demonstrably lower drying energy intensity — an example of product-led sustainability that shifts procurement preferences.
-
PETKUS Technologie GmbH (Wutha-Farnroda, Germany): Specializes in intensive cleaning and calibration systems, often bundled into seed conditioning packages for commercial seed houses.
-
North American specialists (Lewis M. Carter, ArrowCorp, Bench Industries, Seedburo, Flaman, A.T. Ferrell, GCS): Collectively, these firms serve the broad spectrum from lab and boutique seed cleaning to portable, on-farm solutions. Their strength is in niche customization, rapid service, and accessibility to smaller operators — segments that are strategically important despite lower average unit values.
Recent moves to watch
-
Major product introductions in 2025 illustrate where R&D dollars are heading: advanced optical sorters employing deep learning and fan systems geared to cut drying energy by large margins. These are not incremental updates — they alter TCO and procurement criteria for many buyers.
-
Market structure remains moderately fragmented: large global firms are complemented by regional specialists that own relationships, service networks, and local product fits — a dynamic that favors alliances, selective acquisitions, and distribution partnerships rather than single-channel dominance.
What the PW Consulting report delivers — practical modules for 2026 action
-
Collectible intelligence: granular demand-side diagnostics across plant-scale, on-farm, and depot operations (note: specific regional and application splits are available in the full report).
-
Supplier scorecards: capability maps, product roadmaps, and aftermarket economics for the leading manufacturers, with benchmarking against technology and service metrics.
-
Scenario-based financial models: TCO calculators for retrofit versus replacement decisions, sensitivity analyses for energy and labor cost swings, and budgeting templates for CapEx prioritization.
-
Go-to-market playbooks: channel, pricing, and service strategies tailored for OEMs, distributors, and equipment financiers preparing 2026 commercial plans.
-
M&A and partnership due diligence packs: target screening criteria, integration risk matrices, and projected synergies for prioritized acquisition themes.
How to use this intelligence in 2026
-
Short term (0–12 months): Use our TCO and retrofit matrices to accelerate aftermarket offers in tenders where energy and quality premiums are decisive.
-
Medium term (12–36 months): Prioritize product investments that embed AI sorting and low-energy air systems; pilot bundles with financing and uptime SLAs to reduce buyer friction.
-
Long term (36+ months): Pursue consolidation or alliance plays that stitch together complementary capabilities — optical sorting, industrial drying, and digital service — to create defensible integrated solutions.
Limitations and the “trailer” approach
In this brief we intentionally showcase directional findings and strategic implications while withholding certain granular segment tables and regional/application-specific numeric splits to preserve the value of the full subscription report. PW Consulting’s full Grain and Seed Cleaning Equipment Market study contains the detailed breakouts, proprietary demand models covering historical (2020–2025) and forecast (2026–2032) periods, and downloadable financial templates that companies will need to finalize 2026 budgets and M&A screens.
Next steps
For executives setting strategy, R&D heads planning product roadmaps, and investors sizing targets in 2026, this research is designed to be operational: it converts market trends into prioritized initiatives, investment sizing, and risk mitigations. Access the complete PW Consulting report to obtain the full datasets, region-application matrices, supplier scorecards, and scenario models needed to make definitive capital and commercial decisions in 2026.
For detailed analysis of this topic, please visit the official page: Grain and Seed Cleaning Equipment (Grain & Seed Cleaning Equipment) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Camphene Market 2026: Strategic Primer for Decision‑Makers
As companies plan budgets, supply‑chain realignments, and M&A activity for 2026, our Camphene Market study at PW Consulting delivers the macro clarity and executable insight required to convert uncertainty into competitive advantage. The camphene landscape is small by headline revenue but rich in strategic leverage: between 2020 and our base year (2025) the market expanded materially, and our forecast through 2032 anticipates steady growth driven by specialty end‑uses and substitution dynamics. The model embedded in the full report projects a compound annual growth rate (CAGR) of approximately 5.45% over the 2026–2032 forecast window, producing a meaningful uplift from the 2025 baseline into 2032.
Camphene Market
Why this matters for 2026 strategic planning
- Portfolio decisions: Camphene is a low‑volume, high‑impact input for perfumery, aroma chemicals, and selected industrial intermediates. Small shifts in supply or purity requirements can move supplier economics and product roadmaps materially—an important consideration when prioritizing R&D and procurement spend in 2026.
- Trade and sourcing risk: Recent tariff actions and evolving exclusions have already re‑shaped landed cost assumptions. Firms that delay systematic sourcing diversification risk margin compression or supply interruptions at precisely the moment commodity and specialty chemical markets tighten.
- M&A and partnerships: With market concentration remaining low (CR3 ~24.6%, CR5 ~26.2%), there is clear room for consolidation and roll‑up strategies that can create scale in logistics, quality control, and route‑to‑market—especially for premium grades.
Market overview — what the headline numbers tell you
Our historical analysis shows a recover‑and‑reinforce pattern: the camphene market grew from the low‑hundreds (USD Million) in 2020 to a noticeably higher base by 2025, reflecting both recovering demand in fragrance and steady uptake in industrial applications. The forecast horizon to 2032 models compound growth of ~5.45% driven by incremental gains in formulated consumer products, increased substitution toward higher‑purity grades, and selective industrial uses that value camphene’s chemical attributes. While the absolute market size remains modest compared with mainstream petrochemicals, its economic significance for certain value chains (perfume houses, flavor houses, specialty chemical converters and some pharma intermediates) is disproportionate.
Camphene Market
Dynamics shaping 2026 decisions
- Trade policy and tariff volatility: Policy shifts since late 2024—most notably USTR adjustments that raised duties on select chemical intermediates—have altered landed cost math for natural intermediates. Extensions of tariff exclusions through mid‑2025 were limited and temporary, and the resulting uncertainty persisted into subsequent sourcing cycles. More recently, authorities clarified duty treatment: certain natural camphene feedstocks classified under essential oils/resinoids retain an MFN duty, while additional surcharges have been applied to certain origins. These developments make a one‑size‑fits‑all sourcing playbook untenable for 2026.
- Feedstock and production choices: Natural camphene is commonly derived from pine oleoresin and related streams, while synthetic routes (e.g., alpha‑pinene isomerization) provide high‑purity, tariff‑insulated alternatives. The availability of synthetic production offers a tactical lever to mitigate trade exposure and stabilize quality—albeit at different cost and carbon footprints.
- Fragmented supply base: The supplier universe spans regional specialists, listed manufacturers, and global distributors. This fragmentation underpins opportunistic supplier consolidation, strategic contracting, and value capture through forward integration into purification or formulation services.
Competitive landscape — strategic reading of key players
The camphene supplier set is diverse: specialist terpene manufacturers, pine‑derivative processors, multinational specialty chemical houses, and regional distributors. Each segment presents different partnership economics and risk profiles.
Camphene Market
- Indian producers and listed manufacturers (example: established organic/terpene firms based in India) tend to offer scale on natural derivatives and competitive pricing for standard grades. Their strengths lie in raw‑material access to oleoresin feedstocks and established trade channels into perfumery and aroma markets. For western buyers, they present reliable volume options but expose buyers to regional trade dynamics.
- European and North American intermediates producers (example: specialty chemical houses and German manufacturers) bring tight quality control, regulatory compliance capabilities, and proximity to high‑value fragrance and flavor customers. They are often the go‑to for high‑purity or specialty‑functional camphene grades and for co‑development of tailor formulations.
- Chinese suppliers and traders provide scale and competitive pricing but are exposed to trade restrictions (including elevated duties in some destinations). They remain critical to global supply, especially when distributors or formulators require cost‑competitive natural grades.
- Distributors and niche specialists (US‑based distributors, UK aroma houses) add commercial reach and service layers—packaging, logistics, regulatory paperwork, and specialty blending. They are pivotal for market access in regions where producers lack sales footprints.
Across this universe, our competitive scoring matrix in the full report evaluates quality control systems, regulatory track record, capacity flexibility, margin structure, and customer concentration to identify the most attractive partners for different buyer archetypes.
Regulatory and trade signals you cannot ignore in 2026
- Tariff stack effects: Official announcements since December 2024 have raised duties on select intermediate chemicals; exclusions have been periodically re‑issued but with limited windows. Notably, some Chinese‑origin natural intermediates have attracted significant additional surcharges—creating scenarios where synthetic or alternate‑origin sourcing is cost‑advantageous despite higher raw‑material costs.
- Duty classifications: Natural camphene feedstocks often fall under essential oil/resinoid HTS classifications and can incur MFN duties; this paperwork nuance affects landed cost modeling and supplier selection.
- Mitigation pathways: The development of synthetic camphene routes and availability of alternative global suppliers offer actionable mitigants to tariff exposure—these are explored in the report’s procurement playbook and scenario models.
Practical, operational intelligence inside the report
Our deliverable is intentionally operational. We marry macro sizing and scenario forecasts with hands‑on tools your trading teams, procurement leads, and strategy groups can immediately apply:
- Detailed bottom‑up demand and supply model (2020–2032) with sensitivity switches for feedstock costs, tariff scenarios, and adoption rates of synthetic grades.
- Supplier matrix with graded assessments on purity capability, traceability, capacity elasticity, and commercial terms—designed to accelerate supplier qualification and reduce time‑to‑safety stock.
- Cost‑to‑serve and landed cost models incorporating duty permutations (including MFN and Section 301‑type scenarios) so procurement can compare total landed economics, not just FOB pricing.
- Commercial playbooks: contracting templates, hedging checklists, and negotiation levers that procurement and business development teams can use to lock favorable terms in 2026.
- M&A and partnership shortlists: target archetypes that create scale or supply‑chain resilience, along with preliminary synergy estimates and integration cautions based on observed industry consolidation patterns.
- Regulatory risk register and monitoring cadence: an actionable watchlist tied to likely policy trigger points that can materially alter margin assumptions in a quarter.
2026 playbook — recommended moves by horizon
- Immediate (0–6 months): Run a duty‑sensitivity review for current contracts; qualify at least two non‑correlated suppliers (one synthetic route, one natural origin) to de‑risk trade exposure; renegotiate minimum take contracts to increase flexibility.
- Medium term (6–18 months): Invest in small‑scale purification or formulation capability to capture margin on premium grades; pursue strategic alliances with regional distributors to shore up last‑mile service in priority markets.
- Strategic (18–36 months): Evaluate targeted roll‑ups in fragmented supply pockets to capture scale benefits and supplier consolidation premiums; consider CAPEX for synthetic route adoption if long‑run tariff structures persist.
Scenarios that matter
The report models three practical scenarios—stable trade environment, intermittent tariff spikes, and structural protectionism—each with implications for pricing, supplier selection, and capital allocation. Our recommendation: embed scenario triggers into procurement SLAs and capital budgeting so that when policy or feedstock shocks occur, actions are pre‑aligned to protect margin and continuity.
Conclusion — what leaders can take away for 2026
For executives making 2026 strategic choices, camphene is emblematic of small markets with outsized operational and commercial risk. The opportunity lies in treating camphene not as a commodity to be purchased on price alone, but as a strategic lever: diversity of supply, tariff‑aware sourcing, targeted vertical moves, and selective product differentiation can convert a modest revenue stream into a source of margin resilience and product innovation.
PW Consulting’s full Camphene Market report contains the granular segmentation, supplier scorecards, downloadable models, and transaction homework that operational teams need to execute these recommendations. For firms that demand both market depth and immediate operational playbooks, the report is designed to be a one‑stop strategic toolkit for 2026.
Next step
Access the full study to unlock the segmentation tables, per‑grade pricing scenarios, and the supplier due‑diligence pack that we intentionally hold back here to protect the value of the primary research. Our desk is available for bespoke briefings, acquisition screens, or to build a tailored procurement migration plan aligned to your 2026 budget cycle.
For detailed analysis of this topic, please visit the official page: Camphene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Edible Fungus Market to Reach USD 5,650 Million by 2032 (7.25% CAGR)
By PW Consulting, 2026-08-02
Edible Fungus (Edible Products) Market — Strategic Outlook for 2026 Decision-Making
PW Consulting’s latest Edible Fungus market primer synthesizes the commercial logic, competitive dynamics, and regulatory volatility that will shape corporate strategy in 2026 and beyond. Anchored on a base year of 2025 and a detailed historical series from 2020–2025, our forecast extends through 2032. The global market is projected to continue a steady expansion from an estimated USD 3,475 Million in 2025 toward a multi‑billion dollar opportunity by 2032, reflecting a compound annual growth rate (CAGR) of 7.25% over the forecast window. This preview explains why that trajectory matters for boardroom decisions in 2026, what strategic choices it forces, and how the full PW report equips executives to convert macro momentum into defensible value.
Edible Fungus (Edible Products) Market
Why this research matters for 2026 strategic choices
-
Timing of investments: A sustained mid‑single digit CAGR implies that near‑term capacity and capability investments must be selective — focused on segments and channels with above‑market growth or margin expansion potential.
Edible Fungus (Edible Products) Market -
Portfolio prioritization: Companies must decide whether to double down on core fresh mushroom supply, pursue higher‑margin specialty and value‑added products, or accelerate entry into adjacent applications such as nutraceuticals and ingredient sales for plant‑based formulations.
Edible Fungus (Edible Products) Market -
Regulatory and certification risk: 2025 regulatory activity (notably actions by the USDA) has created uncertainty around organic standards and labeling that directly affect premium positioning and export eligibility — decisions in 2026 must therefore embed regulatory scenario planning.
-
M&A and consolidation planning: Market concentration metrics indicate meaningful consolidation at the top end of the market, making strategic acquisitions an attractive route to scale, channel access, or geography‑specific capability in 2026.
Market direction and underlying demand drivers
The market’s growth is not accidental — it is driven by a confluence of structural and tactical forces. Consumers’ ongoing tilt toward healthful, protein‑complementary foods, expansion of ready‑to‑cook and convenience meal formats, and rising interest in functional mushroom applications underpin sustained demand. On the supply side, tighter cost control through automation, indoor cultivation technologies, and scaling of value‑added processing create margin expansion opportunities for forward‑thinking players.
Operational evidence from major production markets reinforces the narrative: recent official crop reporting for the United States shows large output volumes and pricing patterns that reshape raw material economics and contract negotiation levers for processors and retailers. Specialty mushroom segments are registering faster growth than commodity categories, reflecting premiumization and differentiated product strategies that are actionable now for 2026 planning.
Competitive landscape — structure, players, and implications
The market exhibits measurable concentration at the top. Aggregate share of the three largest participants indicates near‑term influence by leading producers, while the five‑firm concentration underscores the presence of several firms with systemic scale. For strategy teams, this means competitive battles will be played across three fronts: cost/scale, differentiated product innovation, and channel control.
-
Monterey Mushrooms Inc. (Watsonville, CA, USA) — An integrated grower/processor with capabilities spanning fresh and processed formats across North America and Mexico. Strengths: end‑to‑end supply chain integration and scale in common varieties.
-
Monaghan Mushrooms (Monaghan, PA, USA) — Major grower/packer focused on food service and retail. Strengths: logistics and retail partnership depth.
-
Greenyard NV (Lutèce) (Gavere, Belgium) — European leader in both fresh and processed mushroom distribution. Strengths: multi‑country footprint and processor network.
-
Bonduelle Group (Lille, France) — Global canned and frozen mushroom producer with established private‑label and branded channels. Strengths: processing scale and international trade experience.
-
Okechamp S.A. (Belgium) — Specialist button mushroom grower/packer with export capabilities. Strengths: focused product expertise and packing technology.
-
The Mushroom Company (United Kingdom) — Fresh mushroom producer for UK and European markets. Strengths: market adjacency and retail relationships.
-
Shanghai Finc Bio‑Tech Inc. (Shanghai, China) — Leading Chinese edible fungi manufacturer with value‑added product focus. Strengths: large domestic market access and cost advantage in cultivation.
-
CMP Mushrooms (United States) — North American grower and supplier across fresh and processed segments. Strengths: regional serviceability and contract fulfillment.
-
Costa Group (Melbourne, Australia) — Australasian supplier with presence in food service and retail. Strengths: regional distribution and category management.
Each firm displays distinct strategic playbooks — from Monterey’s integration to Bonduelle’s processing and Greenyard’s distribution — offering blueprints for how different competitive advantages translate into profitable outcomes. The full report provides deeper diagnostics on capex intensity, margin bands, and channel economics for each named player.
Regulatory and production developments that will shape 2026
-
USDA activity: In early 2025 the USDA delayed the effective date for organic mushroom standards clarification, and in May 2025 proposed rescinding a 2024 rule relating to organic standards and certain labeling. These regulatory moves create short‑term premium certification uncertainty and could reconfigure cost/payoff calculations for producers targeting the organic premium in 2026.
-
Crop reporting: USDA NASS reporting for the 2024–2025 season documented large crop volumes and an aggregate crop value signal that informs contract pricing and bargaining positions between growers and processors going into 2026.
-
Specialty segment momentum: Specialty mushroom sales have shown material upticks in recent seasons, indicating an opportunity for margin expansion via product innovation and branded positioning.
Actionable strategic playbook for 2026
Based on our analysis, executives should prioritize a set of integrated actions that convert market growth into durable advantage:
-
Segment focus and SKU rationalization: Narrow immediate product portfolios to highest margin SKUs and channels where you can achieve a top‑three position; defer broader expansion until value‑added capabilities are proven.
-
Supply‑chain resilience: Invest selectively in controlled environment cultivation and automation to reduce yield volatility and unit costs — structure supplier contracts with price‑review mechanisms tied to published crop reports.
-
Regulatory scenario planning: Embed at least three regulatory scenarios (business‑as‑usual, organic‑premium contraction, organic standards tightening) into 2026 budgeting and certification decisions.
-
M&A and partnerships: Target tuck‑ins for channel access and capability (processing, canning, freezing) rather than geography alone; small bolt‑on acquisitions can materially accelerate margin improvement if they de‑risk seasonality.
-
Channel and route‑to‑market optimization: Prioritize food service and e‑commerce partnerships for premium and specialty formats while protecting core retail shelf positions through collaborative promotions and co‑pack agreements.
-
Data‑driven pricing: Use production volumes and price indexes (as captured in the report) to create dynamic pricing models that protect margins during harvest surges.
-
Brand‑led premiumization: For firms able to command brand equity, invest in certification, traceability, and ingredient storytelling — immediate small investments here can yield outsized price premiums.
What the full PW Consulting report delivers (operational and decision‑grade content)
-
Comprehensive historical dataset (2020–2025) and a fully modeled forecast (2026–2032) with base case and sensitivity cases tied to yield, price, and regulatory shifts.
-
Granular segmentation by geography, product type, and application with reconciled market tables and interactive charts (note: this preview intentionally omits the raw sub‑segment numbers).
-
Company scorecards for major players, including capacity maps, margin proxies, and strategic intent assessments.
-
Transaction and partnership tracker with recent deals, valuation multiples, and integration risk checklists.
-
A regulatory tracker that documents USDA developments and other jurisdictional updates, plus recommended compliance and lobbying playbooks for 2026.
-
Commercial playbooks: go‑to‑market scripts for retail, food service, and ingredient channels; private‑label negotiation templates; and contract structuring clauses for growers and processors.
-
Operational model and cost curve analyses to support investment cases for automation, processing lines, and CAPEX timelines.
Closing — converting insight into 2026 advantage
The edible fungus market presents a classic strategic inflection: stable, mid‑single digit growth at the aggregate level combined with pockets of rapid premiumization and consolidation. 2026 will be the year that separates leaders — those who move early on capacity, channel, and regulation — from laggards who react to price and compliance shocks. PW Consulting’s full market study provides the datasets, scenario models, and tactical playbooks to make those choices with confidence.
For boards, investors, and executive teams preparing 2026 budgets and strategic plans, the prudent next step is to review the full report’s segmented forecasts, company diagnostics, and actionable implementation guides. Access the complete intelligence to convert the market trajectory and regulatory inflection points into quantifiable value.
For detailed analysis of this topic, please visit the official page: Edible Fungus (Edible Products) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ambient Air Quality Monitoring Market to Reach USD 634.02M by 2032 at 6.5% CAGR
By PW Consulting, 2026-08-02
Ambient Air Quality Monitoring System Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting presents a focused strategic preview of the Ambient Air Quality Monitoring System market to inform executive decision-making in 2026. Built on a base of validated market modelling (base year 2025) and forward-looking scenario planning (forecast period 2026–2032), this briefing synthesizes the macro trajectory, competitive dynamics, regulatory tailwinds, and operational constraints that will determine where capital, talent, and product focus must go next. The market’s broad direction is compelling: total market value rose from roughly USD 300 million in 2020 to about USD 411.5 million by 2025 and is projected to exceed USD 450 million in 2026, growing to an estimated USD 634 million by 2032 at a compound annual growth rate of 6.5% across the forecast window. This preview demonstrates the study’s strategic value while reserving the granular segmental matrices for the full report.
Ambient Air Quality Monitoring System Market
Why this study matters for 2026 decisions
- Capital allocation with confidence: The market’s mid-single-digit CAGR and expanding absolute size create a predictable backdrop for multi-year investments in product development, network rollout, and M&A — but only if procurement and deployment trade-offs are modeled correctly.
- Procurement and deployment optimization: Decisions about reference-grade stations versus distributed low-cost sensors hinge on real-world TCO modeling, lifecycle O&M, and spatial coverage trade-offs. Our research aligns those trade-offs to typical municipal, industrial, and corporate procurement cycles in 2026.
- Regulatory readiness: With sustained regulatory emphasis on continuous monitoring of PM, NO2, and O3 and standards governing cleanroom and industrial air quality, the study provides compliance roadmaps that integrate monitor selection, QA/QC routines, and data acceptance protocols.
- Commercial strategy and partnerships: The market demands new go-to-market models combining hardware, data services, and financing. The research identifies which partner archetypes (reference analyzer OEMs, low-cost sensor suppliers, systems integrators, and data platform providers) are decisive for scaling networks in 2026.
What the report delivers (practical, executable content)
- Actionable decision frameworks: procurement playbooks for public agencies, industrial operators, and large enterprises, including bid evaluation templates and scoring rubrics.
- Deployment blueprints: hybrid network architectures that balance reference stations and sensor grids, with scenario-driven sensor densities and maintenance cadences.
- Financial tools: TCO and ROI templates, capex/opex tradeoff calculators, and grant-funding capture strategies tailored to common funding models used across 2026 procurement cycles.
- Vendor assessment: standardized vendor scorecards and negotiation playbooks that collapse technical specs, service-level expectations, and lifecycle support into procurement-ready criteria.
- Data governance and QA/QC: practical data pipelines, validation workflows, and documentation checklists to satisfy regulatory reporting and stakeholder transparency demands.
- Use-case playbooks: urban exposure mapping, industrial emissions control, mobile monitoring studies, and cleanroom compliance — each with step-by-step pilot-to-scale templates.
- Scenario stress tests: sensitivity analyses reflecting commodity price shocks, labor shortages, and regulatory tightening to stress-test investment decisions.
Macro signals and interpretation (selected high-level metrics)
The market’s trajectory is clear at the aggregate level: from roughly USD 300 million in 2020 to approximately USD 411.5 million in 2025, with a projected near-term step to ~USD 451 million in 2026 and continued expansion to an estimated USD 634 million by 2032 at a 6.5% CAGR over the forecast window. These aggregates reflect three concurrent phenomena:
Ambient Air Quality Monitoring System Market
- Regulatory acceleration: Ongoing enforcement of continuous monitoring for major pollutants is driving persistent demand for both reference-grade analyzers and expanded sensor networks for spatial resolution.
- Network densification: Cities and states are moving from sparse regulatory sites toward denser sensor grids and mobile monitoring programs to capture hyperlocal exposure patterns, creating opportunity for modular, interoperable offerings.
- Technology layering: A two-tier market is emerging—high-accuracy reference instruments for compliance and hybrid arrays of low-cost and portable sensors for coverage and community engagement. Success in 2026 depends on packaging these layers into integrated service propositions rather than selling devices alone.
Competitive landscape — who matters and why
The market is shaped by a mix of specialist manufacturers, industrial conglomerates, and instrumentation leaders. Our competitive analysis in the full report profiles each major player, their strategic strengths, and the adjacencies they are likely to pursue. Select strategic impressions:
Ambient Air Quality Monitoring System Market
- Aeroqual (New Zealand) — Deep expertise in integrated, real-time ambient monitoring with near-reference accuracy positions Aeroqual well for municipal and mid-sized network deployments seeking a balance of accuracy and cost. Their product portfolio supports turnkey sensor-network rollouts when calibrated against reference stations.
- Vaisala (Finland) — Strong in atmospheric science and compact transmitters, Vaisala is a natural partner for urban networks and industrial ambient monitoring where robustness and sensor longevity matter. Expect emphasis on sensor calibration, service contracts, and network-level solutions.
- Teledyne Technologies (United States) — Reference-grade analyzers and proven compliance-grade systems make Teledyne a go-to supplier for regulatory monitoring, laboratories, and industrial emissions control where traceability and accreditation matter.
- Horiba (Japan) and Thermo Fisher Scientific (United States) — Both firms supply regulatory instrumentation and have the service ecosystems to support long-term monitoring obligations, making them strategic choices for public agencies and corporate compliance teams.
- Ecotech (Australia) and Testo (Germany) — Specialists in particulate monitoring and portable devices respectively, these players are important in expanding coverage and providing mobile or campaign-style monitoring options.
- Siemens, Emerson Electric, and 3M — Industrial and systems integrators with broader portfolios, these companies can embed air monitoring into building management, industrial control systems, and filtration solutions, enabling cross-selling into existing enterprise relationships.
Strategically, market entrants and incumbents are converging on three vectors: (1) platformization of sensor data and value-added analytics, (2) service-based models that reduce upfront capex for public-sector buyers, and (3) partnerships that combine reference instrumentation with low-cost sensor grids and data validation layers.
Recent market movements shaping 2026 tactics
- New product launches and upgrades from emerging vendors are expanding the options for dense, low-power sensor grids and improving data fidelity in non-reference devices.
- Municipal and state deployments — including large-scale solar-powered sensor networks and planned mobile monitoring studies — validate hybrid architectures and create repeatable procurement templates.
- Public funding patterns remain crucial: many air monitoring networks continue to rely on federal and state grant mechanisms, which places a premium on vendors that can partner on grant writing, bundled financing, and lifecycle service contracts.
Risks and structural constraints
- Infrastructure and cost barriers: Reference-grade stations remain expensive and infrastructure-intensive; this limits pure reference deployment at scale and increases the importance of hybrid architectures and remote maintenance strategies.
- Funding volatility and labor costs: Operational budgets and skilled labor availability are recurring constraints for public networks. Organizations must plan for multi-year O&M funding or choose models that minimize ongoing staffing requirements.
- Standards and compliance complexity: Regulatory obligations (including national ambient air quality requirements and technical standards governing testing and documentation) require disciplined QA/QC programs and vendor solutions that support certified workflows.
Recommended 90-day priorities for 2026
- Run a rapid asset and needs audit to map existing monitoring coverage gaps and regulatory obligations.
- Pilot a hybrid network (one reference site + contiguous sensor grid) with defined acceptance criteria and a 6–12 month validation window.
- Negotiate vendor pilots with explicit data access, calibration, and SLA terms; require transparent QA/QC methods and data pipelines.
- Align funding pathways — prioritize projects with grant eligibility and create bundled O&M options to reduce fiscal-year dependency.
- Invest in data governance and staff training to ensure monitoring outputs are defensible for regulatory and community use.
Next steps — where to find the full intelligence
This briefing surfaces the strategic contours that matter for 2026. PW Consulting’s full Ambient Air Quality Monitoring System Market report contains the granular decision-support materials that procurement teams, product leaders, and mergers & acquisitions professionals need: regional and application splits, vendor scorecards with comparative metrics, downloadable TCO tools, deployment templates, and interactive scenario models. The granular segmentation and financial matrices are intentionally excluded from this preview to protect the operational detail that drives competitive advantage. For teams preparing budgets, RFP specifications, or go-to-market plays in 2026, accessing the full report will convert these strategic directions into executable plans.
For detailed analysis of this topic, please visit the official page: Ambient Air Quality Monitoring System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: IVIg Market to Reach USD 21,320M by 2032 at 6.98% CAGR (2026–2032)
By PW Consulting, 2026-08-02
Intravenous Immunoglobulin (IVIg) Market: Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a forward-looking, executive-grade preview of our new IVIg market study. This is a tactical briefing designed to clarify how the IVIg landscape will shape high-stakes decisions in 2026 — from capacity investments and M&A prioritization to product strategy and reimbursement engagement. The goal: demonstrate the analytic depth and commercial utility of our work while preserving the granular segmentation and proprietary models that form the core value of the full report.
Intravenous Immunoglobulin (IVIg) Market
Executive summary — why this matters in 2026
The IVIg market has transitioned from a stable therapeutic niche into a strategically critical and capital-intensive segment of immunology and rare-disease care. Our market model, built on a 2025 base year and covering historical performance from 2020–2025 with scenario-driven forecasts through 2032, shows the market expanding from the low‑teens of USD billions in 2025 to a materially larger market by the end of the forecast horizon. The forecast compound annual growth rate (CAGR) we model for the 2026–2032 period is approximately 6.98% — a pace that creates both attractive commercial opportunity and mounting pressure on supply chains, raw-material sourcing, and reimbursement strategies.
Intravenous Immunoglobulin (IVIg) Market
Concentration metrics reinforce why competitive positioning is paramount: top-tier firms collectively command a substantial share of market revenue (CR3 ~62%; CR5 ~75%), meaning market leadership decisions by a handful of players will continue to set pricing, capacity, and access dynamics.
Intravenous Immunoglobulin (IVIg) Market
What this preview reveals — and what it deliberately withholds
-
Revealed: macro trajectory, sector concentration, structural cost drivers, regulatory and reimbursement inflection points, and the strategic implications for 2026 boardroom decisions.
-
Withheld: the granular revenue splits by individual regions, indications, and product formulations — these form the “map” of micro-opportunity and competitive risk that we preserve for clients who access the full dataset and models.
Market trajectory and the decision window
Key topline dynamics from our modeling:
-
Resilient baseline demand driven by core indications and expanding off-label usage in immuno-inflammatory disorders; steady adoption curves underpin the multi-year growth path.
-
Unit-cost pressure from raw-material supply remains the dominant margin lever. Our analysis reaffirms an industry fact: plasma feedstock accounts for a material majority of finished-goods cost, and volatility here cascades through pricing and gross margins.
-
Regulatory and reimbursement timing — including near-term changes in coding and Medicare payment windows — create discrete, short-term inflection points that materially affect 2026 commercial rollouts and contracting strategies.
Together, these forces mean 2026 is a make-or-break year for capital allocation and competitive positioning: firms that secure supply, clarify reimbursement pathways, and accelerate differentiated value propositions will capture disproportionate upside as the market grows at roughly a 7% CAGR to 2032.
Practical strategic implications for 2026 decisions
-
Capacity and plant investment: Delay-free investment in plasma collection and fractionation capacity can serve as a long-term strategic moat. Our scenario analysis quantifies payback thresholds across three capex timelines — conservative, base, and accelerated — providing board-level ROI cases tied to supply-realization risk.
-
M&A and partnership screen: Given measurable market concentration, targeted acquisitions of mid-sized plasma collectors and specialty manufacturers are high-impact ways to secure feedstock and incremental market share. We provide a ranked shortlist of acquisition archetypes and an integration-risk checklist.
-
Pricing and contracting: With top players setting benchmark rates, winning contracts in 2026 will require flexible pricing frameworks linked to verifiable supply commitments and performance-based reimbursement models. Our commercial playbooks include template clauses and negotiation strategies informed by projected Medicare coding windows.
-
Regulatory sequencing: New product launches and label expansions hinge on donor-screening, pathogen-inactivation, and facility-approval timelines. Strategic timing of submissions — coordinated with capacity ramp plans — minimizes time-to-market and optimizes return on regulatory spend.
-
Clinical and pipeline prioritization: For firms with multiple IVIg or alternative immunomodulatory programs, our value-of-delay and comparative clinical-utility models indicate which indications and formats deliver the most defensible commercial returns under different reimbursement regimes.
Report contents — operational and actionable
Our full IVIg study is built for executives and deal teams who need to act in 2026. Highlights of the deliverables include:
-
A granular market model (historical 2020–2025; forecast 2026–2032) with scenario toggles to test price, volume, and supply shocks.
-
Cash-flow and NPV analyses for plant expansions, plasma-collection investments, and contract manufacturing partnerships.
-
Reimbursement-impact modules that map coding, coverage, and payment timelines to revenue outcomes under multiple payer scenarios.
-
Commercial playbooks for tender wins, hospital formulary adoption, and specialty pharmacy engagement — including win/loss drivers and contract language templates.
-
Regulatory pathway matrices for label expansions and new formulation approvals, with recommended submission timing to align with business milestones.
-
Competitive benchmarking and product-lifecycle scoring across leading IVIg portfolios; capability heat maps for manufacturing, plasma collection, and geographic reach.
-
A risk and mitigant matrix covering plasma supply, pathogen concerns, pricing pressure, and geopolitical exposures, with prioritized mitigation actions.
Competitive landscape — what leaders are doing
The IVIg arena remains dominated by a small group of established biologics companies. Our competitive analysis emphasizes capability vectors rather than raw market shares alone: portfolio breadth (ready-to-use vs. lyophilized formats), plasma sourcing and vertical integration, regulatory track record, and commercial infrastructure in high-value channels.
-
CSL Behring continues to leverage a broad product set focused on primary humoral immunodeficiency and related indications, combining scale manufacturing with sustained market access efforts.
-
Takeda has fortified its offering through ready-to-use, low-IgA formulations and regulatory approvals that enhance product differentiation in immunodeficiency and CIDP segments.
-
Grifols and Octapharma sustain competitive pressure via manufacturing scale and clinical program breadth, while select regional players are increasingly active in targeted launches.
-
Smaller and emergent suppliers — including newly commercial entrants — are pursuing narrow, differentiated plays (e.g., pediatric approvals, low-IgA products) and selectively contesting hospital formularies.
Recent industry events in 2025–2026 illustrate how quickly competitive advantage can shift: regulatory approvals and commercial launches have accelerated portfolio refreshes and intensified procurement competition in the United States market. These developments underscore why market timing and reimbursement alignment are now core strategic imperatives.
Market dynamics and risk signals
Four structural dynamics require special attention in 2026:
-
Raw material economics: Plasma feedstock accounts for a dominant share of production cost. Our sensitivity modeling shows that modest spikes in plasma acquisition cost compress margins materially unless offset by price adjustments or procurement hedges.
-
Reimbursement cadence: Short-term coding and payment windows — including recent Medicare billing updates — create discrete revenue timing impacts. Our payer model quantifies these timing effects and prescribes tactical interventions for commercial teams.
-
Regulatory standards: Stringent donor-screening and pathogen-inactivation requirements create high barriers to entry but also supply brittleness. Compliance investments are non-negotiable and should be treated as strategic assets.
-
Supply concentration: A significant share of IVIg supply depends on donor plasma sourced via FDA‑approved facilities. This dependency limits rapid scale-up and elevates country- and facility-level operational risk.
How PW Consulting helps executive teams act in 2026
Our engagement model turns the report’s insights into executable programs:
-
Board-level briefings translating forecast scenarios into capital allocation decisions.
-
Deal support — target screening, diligence playbooks, and post-merger integration plans tailored to plasma- and biologics-specific complexity.
-
Commercial execution: bespoke contracting templates, payer engagement roadmaps, and field-level messaging calibrated to payer and hospital procurement pain points.
-
Manufacturing and supply strategy: supplier due diligence, buffer-inventory modeling, and contingency playbooks to reduce single-point-of-failure exposures.
Next steps — what you can do right now
If your 2026 plan includes capacity commitments, portfolio launches, or acquisition activity in IVIg, the most valuable next step is to review the full market model and competitor benchmark appendix. The compact intelligence in this preview points to clear strategic levers, but the highest-confidence decisions require the report’s granular regional, indication, and product-split forecasts — the exact datasets we preserve for clients and subscribers.
PW Consulting is ready to provide an executive debrief, tailor the model to your balance-sheet assumptions, or run a confidential acquisition-screening of potential targets. For teams preparing 2026 operating plans, the difference between a good and a decisive year will be access to the granular inputs and scenario tooling contained in the full study.
Closing note
The IVIg market’s steady growth profile — underpinned by meaningful structural complexity — rewards disciplined, data-driven strategy. With an expected mid‑single-digit-to-high‑single-digit CAGR into the early 2030s, companies that align supply, regulatory timing, and payer strategy in 2026 will disproportionately capture future value. Our full IVIg report supplies the models, benchmarks, and playbooks necessary to convert market opportunity into realized performance.
For detailed analysis of this topic, please visit the official page: Intravenous Immunoglobulin (IVIg) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


