



Category: market research
PW Consulting Predicts Worldwide Cloud VPN Market to Surge at 15% CAGR from USD 15.85B in 2025 to USD 42.16B by 2032
By PW Consulting, 2026-07-16
Worldwide Cloud VPN Market 2026: Strategic Insights for Enterprise Decision‑Makers
Executive summary
As enterprises finalize networking and security roadmaps for 2026, cloud VPN architecture is moving from tactical remote‑access fix to a strategic building block of hybrid and multi‑cloud operations. PW Consulting’s latest Worldwide Cloud VPN Market report (base year 2025, forecast 2026–2032) shows the market at an inflection point: total industry revenue reached approximately USD 15.9 billion in 2025 and is forecast to expand at a 15.0% compound annual growth rate (CAGR) into the forecast window. By 2032 the market is expected to exceed USD 42 billion, underscoring continued investment momentum from global enterprises and cloud providers alike.
Worldwide Cloud VPN Market
Why this matters for 2026 decisions
For CIOs, CISO teams, and infrastructure procurement leaders preparing budgets and architectures for 2026, the tactical choices made this year will influence security posture, operational cost, and regulatory compliance for the next technology cycle. The report frames three immediate decision vectors:
Worldwide Cloud VPN Market
- Architecture consolidation vs. best‑of‑breed: As Secure Access Service Edge (SASE) and Zero Trust approaches converge with traditional VPN offerings, organizations must decide whether to consolidate under a single integrated vendor or combine specialized ZTNA and cloud VPN components. Each path carries distinct operational and contract management tradeoffs.
- Operational cost management under infrastructure strain: Rising data center electricity demand, localized spikes in wholesale power prices, and material impacts to colocation economics require procurement teams to model total cost of ownership (TCO) under stressed infrastructure scenarios rather than relying on static cloud transit fees.
- Compliance‑first networking: New and expanding data sovereignty and bulk‑data transfer restrictions mean that VPN routing, encryption, and edge processing decisions are now compliance controls. Enterprises must embed regulatory constraints into network design from the outset.
Market trajectory and concentration — what the headline numbers conceal
The headline market trajectory — a mid‑teens CAGR and a more than doubling of market size through 2032 — captures broad momentum but masks nuanced pressures. Market concentration is meaningful: the top three vendors collectively account for roughly one‑third of global revenue, and the top five approach half the market. That level of concentration creates both dependency risks and negotiation leverage for large buyers. Our analysis highlights pockets of rapid innovation outside the dominant players, particularly among cloud‑native security providers and specialist gateway vendors.
Worldwide Cloud VPN Market
Competitive landscape — strategic positioning of core vendors
The 2026 competitive map blends hyperscaler scale with network‑security incumbency and a new wave of cloud‑native challengers. Our report profiles leading vendors and distills strategic implications for enterprise buyers:
- Cisco Systems, Inc. — Leverages integrated SASE and SD‑WAN portfolios to offer cloud‑delivered VPN capabilities that appeal to customers seeking appliance‑to‑cloud continuity and a familiar support model. Cisco remains a default choice for broad enterprise footprints, especially where managed services and legacy integration are priorities.
- Microsoft Corporation — Through Azure VPN Gateway, Microsoft embeds site‑to‑site and point‑to‑site connectivity deep in its cloud stack, simplifying hybrid architectures for Azure‑centric estates and appealing to enterprises prioritizing cloud‑native tooling and identity integration.
- Amazon Web Services, Inc. — AWS has extended its connectivity portfolio with recent innovations (notably a VPN Concentrator introduced late 2025) to better support many‑site, low‑bandwidth topologies via Transit Gateway integrations, reducing per‑site overhead for distributed deployments.
- Google LLC — Google Cloud VPN emphasizes performance and dynamic routing for hybrid and multi‑cloud use cases. It is positioned for workloads where predictable throughput and cloud backbone performance are decisive.
- Huawei Technologies Co., Ltd. — Provides a suite of cloud VPN features within a broader enterprise networking and cloud portfolio; relevant for customers focused on integrated vendor stacks in certain geographies.
- Palo Alto Networks, Inc. — With Prisma Access, Palo Alto blends VPN functionality into a cloud‑delivered security platform that supports ZTNA principles, attractive to organizations prioritizing unified security policy enforcement across distributed users.
- Fortinet, Inc. — Fortinet’s cloud VPN and virtual appliances offer an operational continuity play for customers seeking firewall‑plus‑VPN integration under a single vendor and often a single support contract.
- Zscaler, Inc. and Cloudflare, Inc. — Represent the cloud‑native insurgent category: Zscaler’s Zero Trust Exchange and Cloudflare’s Zero Trust/WARP push VPN replacement or augmentation models that shift connectivity from network‑centric to application‑centric constructs.
- Check Point, Oracle, Array Networks — Serve distinct niches: Check Point’s integrated security gateway approach, Oracle’s cloud‑to‑cloud/site VPN strategy for OCI customers, and Array’s focus on application delivery and secure access gateways.
Recent product and partnership signals
Market movement in late 2025 and early 2026 validates the dual trend of hyperscaler capability expansion and cloud‑native security partnerships. Notably, AWS’s November 2025 launch of a VPN Concentrator signals hyperscaler attention to multi‑site efficiency, while Cloudflare’s February 2026 partnership with Mastercard demonstrates an expanded focus on application security and critical‑infrastructure defenders. These signals should inform vendor shortlists and proof‑of‑concept (PoC) scopes in 2026.
Regulatory and infrastructure dynamics shaping demand
Regulation and localized infrastructure economics are becoming primary decision variables:
- Compliance constraints: The U.S. Department of Justice Bulk Data Rule (effective 2025) and regional data sovereignty regimes require architects to model VPN traffic paths as part of data residency and transfer controls. Financial services in the EU must also design for DORA’s operational resilience obligations, which place auditability and continuity requirements squarely on cloud VPN solutions.
- Energy and cost pressure: Projections of rapid growth in electricity demand for U.S. data centers, and observed wholesale price volatility in data‑center heavy regions, mean that cloud egress and peering strategies must be modeled under energy‑stress scenarios. The result: a higher weight on efficiency, edge processing, and contract clauses that share or mitigate infrastructure cost exposure.
What the PW Consulting report delivers — practical, procurement‑ready assets
The report is built for operational use by IT and security teams, not just market watchers. Deliverables include:
- Validated market sizing with year‑on‑year historicals (2020–2025) and a 2026–2032 forecast informing budget planning horizons.
- Vendor profiles and capability maps that align product features to procurement criteria (performance, management, compliance, and TCO).
- Use‑case‑driven deployment templates (site‑to‑site, remote access, transit gateway topologies, ZTNA hybrid models) with pros/cons and migration dependencies.
- Regulatory impact assessments that map major jurisdictions’ rules to design controls and contractual clauses.
- Procurement checklist, negotiation playbook, and sample RFP language to shorten vendor selection cycles.
- Operational runbooks for observability, incident response, and capacity planning tuned to cloud VPN architectures.
To preserve commercial sensitivity and drive actionable engagement, the report deliberately reserves detailed segment and regional line‑items for the full document and accompanying data workbook available on PW Consulting’s report page.
How to use this research in 2026 planning cycles
Buyers should treat the findings as a decision accelerator. Practical next steps we recommend:
- Rebaseline your networking TCO with scenarios that include higher power costs and constrained colocation capacity; prioritize pilots that demonstrate measurable bandwidth efficiency gains.
- Reconcile security policy with routing topology: ensure that ZTNA rollouts do not create blind spots for regulated data flows or complicate audit trails required by DORA and similar frameworks.
- Shortlist vendors for PoC based on integration risk and exit economics rather than feature checklists alone; use PW Consulting’s vendor capability matrix to create a 6–9 month evaluation roadmap.
- Negotiate elasticity clauses and transparency on cloud transit and peering costs; include service credits for resilience and clearly defined responsibilities for cross‑border traffic handling.
Investment thesis and risk matrix — at a glance
The investment case for expanding cloud VPN capabilities in 2026 rests on three pillars: enabling secure hybrid operations, reducing remote‑access friction for distributed workforces, and achieving regulatory‑aligned control over data flows. Key risks include vendor lock‑in, sudden infrastructure cost inflation, and compliance misalignment due to evolving jurisdictional rules. The report provides a risk‑weighted decision framework and a phased migration plan to mitigate these exposures while accelerating time‑to‑value.
Conclusion and next steps
Cloud VPN is no longer a commodity adjunct to corporate firewalls; it is an architectural lever with implications across cost, compliance, and operational resilience. Our analysis shows substantial growth ahead, concentrated vendor influence, and intensifying regulatory and infrastructure pressures that will shape procurement and architecture decisions throughout 2026. PW Consulting’s full Worldwide Cloud VPN Market report contains the detailed regional/segment tables, vendor financials, and downloadable scenario models necessary for procurement and architecture teams to act with confidence.
To access the full report, detailed datasets, and executable tools referenced in this briefing, visit PW Consulting’s Worldwide Cloud VPN Market report page and download the data workbook and procurement templates.
For detailed analysis of this topic, please visit the official page: Worldwide Cloud VPN Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Classified Circuit Breaker Market to Grow from USD 540.0 Million in 2025 to USD 811.96 Million by 2032 at 6.0% CAGR — North America, Miniature Circuit Breakers and Residential Renovation Lead the Charge
By PW Consulting, 2026-07-16
Worldwide Classified Circuit Breaker Market: Strategic Insights for 2026 Decision‑Makers
Executive summary
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise preview of our new Worldwide Classified Circuit Breaker Market report — a tactical resource designed to inform high‑stakes corporate decisions in 2026. The classified circuit breaker segment is on a steady growth trajectory: the market reached approximately USD 540 million in our 2025 base year and is projected to grow at a 6.0% CAGR over the 2026–2032 forecast period, driving the addressable market well beyond USD 800 million by 2032.
Worldwide Classified Circuit Breaker Market
This release follows the “trailer” principle: it communicates the analysis depth and strategic value embedded in the full study while intentionally withholding core segment-level numbers and proprietary tables. Use this briefing to understand the forces shaping the market in 2026 and to recognize the types of operational playbooks, scenario plans, and prioritization frameworks that the full report delivers.
Worldwide Classified Circuit Breaker Market
Why this matters for 2026 decision windows
-
Investment timing: With a predictable mid‑single‑digit CAGR and an observable step‑up from 2025 into 2026, the market offers a balance of steady demand growth and targeted upside from grid modernization and smart electrification projects. Capital allocation decisions (R&D, capacity expansion, M&A) should be sequenced to capture near‑term retrofit demand while positioning for medium‑term digital product adoption.
Worldwide Classified Circuit Breaker Market -
Competitive positioning: The market demonstrates measurable concentration — our analysis indicates the top three firms account for roughly 52.4% of market value and the top five near 68.2% — implying that scale, channel reach, and classified compatibility are meaningful barriers. Niche entrants can still succeed, but only with clear differentiation or local supply advantages.
-
Value chain risk management: Key raw material dependencies (copper, steel, engineering polymers) and recent regional moves to localize assembly underline the need for supply‑chain scenario planning now, not later. Procurement strategies refined in 2026 will determine margin resilience through the forecast period.
Core market dynamics shaping strategy
-
Regulatory and interchangeability framework: UL‑classification continues to be the fulcrum for third‑party compatibility in residential and light‑commercial loadcenters. This regulatory architecture enables a competitive replacement market but also imposes certification timelines and testing costs that must be baked into product roadmaps and pricing models.
-
Grid modernization and renewables integration: Distributed energy resources and higher electrification rates are changing load profiles. Circuit breaker features that support selective coordination, fault analytics, and integration with inverters and energy management systems will command strategic attention.
-
Digital transformation: Electrification is converging with connectivity — smart breakers with remote monitoring and trip‑forensics are shifting value from pure hardware to recurring software and services revenue. Firms that can operationalize after‑sales telemetry and predictive maintenance stand to improve lifetime customer value.
-
Materials and cost pressure: Exposure to copper, steel, and specialty polymers creates input cost volatility. The report includes sensitivity analyses showing how material price swings translate to margin erosion under different pass‑through assumptions, and offers hedging and dual‑sourcing templates applicable in 2026 procurement cycles.
Competitive landscape — what the market leaders and challengers are doing
Our competitor analysis synthesizes public product portfolios, compatibility strategies, and recent business developments to create executable market maps for potential entrants and incumbents.
-
Eaton Corporation (Dublin): Maintains one of the broadest lines of UL‑Classified breakers with deep compatibility across multiple loadcenter brands. Eaton’s scale and cross‑compatibility strategy serve as a model for defending retrofit channels and locking in aftermarket replacement flows.
-
Siemens (Munich): Leverages global footprint and standard breaker portfolios while offering classified replacements for specific panel systems. Their mix of global engineering and regional channel partners illustrates a dual approach for markets with different certification landscapes.
-
ABB Ltd (Zurich) and Schneider Electric (Rueil‑Malmaison): Both companies combine wide voltage‑range offerings with strong activity in industrial and utility segments. Their strategic playbooks emphasize integrated solutions and systems sales, rather than discrete replacement components.
-
General Electric (GE Vernova) and regional heavyweights such as Mitsubishi Electric , LS Electric , and Fuji Electric : These firms compete on breadth, global service networks, and legacy relationships with large commercial and industrial customers. Their presence makes large project wins a function of systems capability and lifecycle service economics.
-
CHINT Group (China): Active in international trade shows and moving toward localized assembly in key emerging markets — a development that illustrates the importance of regional manufacturing footprint as a competitive lever for cost and lead‑time advantage.
-
Specialist UL‑classified suppliers and smaller manufacturers: These players frequently target replacement and retrofit channels with compatible breakers and focused channel relationships. Their strategies include faster certification cycles, aggressive channel promotions, and selective geographic focus to avoid head‑to‑head scale battles.
Recent industry movements (what to watch in 2026)
-
CHINT’s expanded exhibition and local assembly announcement in Brazil signals intensifying competition via regional supply‑base localization.
-
Prototype showcases of digitally enabled breakers at major exhibitions (e.g., Hager, CNC Electric) point to an expected commercialization wave for smart breakers contingent on certification timelines and integration standards.
-
Ongoing UL‑classification practices continue to enable third‑party compatible replacements; firms should track certification roadmaps closely to avoid time‑to‑market misalignment.
What the PW Consulting report delivers — practical, execution‑oriented assets
The full report is designed as a playbook for corporate teams making 2026 decisions. Highlights include:
-
A validated top‑down market model (2020–2025 historical, 2026–2032 forecast) with sensitivity scenarios for demand drivers and price environment.
-
Competitive diagnostics and product compatibility matrices that map UL‑classification relationships and channel implications.
-
Supply‑chain risk maps, raw‑material sensitivities, and procurement optimization templates prioritized for 12–24 month implementation.
-
M&A target screening criteria and a shortlist of fit candidates by capability and geography, accompanied by valuation heuristics and integration risk flags.
-
Go‑to‑market playbooks: channel segmentation, pricing levers, and service offerings tailored for retrofit, new‑build, and industrial applications.
-
Regulatory and certification roadmap with time and cost estimates for UL‑classification and cross‑jurisdictional approvals.
-
Actionable 90‑, 180‑, and 360‑day implementation plans for product, commercial, and supply‑chain initiatives to be executed beginning in 2026.
Strategic implications and recommended actions for 2026
-
Prioritize certification velocity: If your product roadmap includes classified replacements, accelerate UL‑classification activities now to align launch windows with mid‑term retrofit cycles.
-
Embed digital services early: Field data and remote diagnostics convert one‑time hardware sales into ongoing revenue streams; pilot smart breaker rollouts with strategic channel partners in 2026 to validate monetization models.
-
Reassess manufacturing footprint: Use the report’s scenario toolkit to evaluate the tradeoff between localized assembly and centralized scale—particularly for markets showing strong policy or tariff signals.
-
Prepare for consolidation: Given the market concentration dynamics, consider bolt‑on acquisitions to secure aftermarket channels or to acquire certification breadth rather than building organically.
-
Hedge raw‑material exposure: Execute dual‑sourcing and indexed purchasing clauses where practical to protect margins against copper and polymer volatility highlighted in our sensitivity analyses.
How to use this intelligence in boardroom discussions
Translate the report’s quantitative scenarios into decision briefs: frame choices as option value exercises (build vs. buy vs. partner), support requests for incremental R&D and certification funding with quantified NPV profiles, and sequence operational moves (procurement, pilot deployments, channel contracts) into near‑term sprints with measurable milestones. Our implementation templates convert market forecasts and competitive metrics into board‑ready KPIs for 2026.
Next steps and where to get the full study
This article previews the strategic contours of the Worldwide Classified Circuit Breaker Market and highlights the actionable intelligence executives need for 2026. To preserve analytical integrity and to protect proprietary segmentation, we have withheld detailed region, type, and application splits from this summary. The full report includes those granular data, scenario models, and executable templates referenced above.
For the complete dataset, interactive models, and step‑by‑step implementation playbooks, visit our report page or contact PW Consulting’s market team to schedule a briefing. The full study is calibrated for 2026 decision timelines and includes live Excel models you can run through your own assumptions.
PW Consulting — turning market insight into operational advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Classified Circuit Breaker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Photosensitive Resin Market to Expand at a 12.45% CAGR Through 2032
By PW Consulting, 2026-07-15
PW Consulting: Worldwide Photosensitive Resin Market — Strategic Preview for 2026 Decisions
Executive summary
The worldwide photosensitive resin market is entering a phase of accelerated commercialisation and technical differentiation. Our new market model shows the industry expanding from approximately USD 3,885 million in 2020 to USD 6,750.5 million in 2025, and—at a compound annual growth rate (CAGR) of 12.45% for the 2026–2032 forecast window—reaching an estimated USD 15,348.14 million by 2032. For executives preparing capital plans, product roadmaps, or partnership strategies in 2026, these topline dynamics create both opportunity and near‑term complexity: strong demand tailwinds are met by raw‑material volatility, tightening regulatory regimes, and intensifying competition among specialist and incumbent suppliers.
Worldwide Photosensitive Resin Market
Why 2026 is a strategic inflection point
-
Demand inflection across applications: Additive manufacturing, precision electronics and medical device sectors continue to drive volume and higher‑value resin formulations. The market is no longer a niche consumable market; it is maturing into a portfolio of premium, regulated and high‑performance products that require differentiated R&D, certification and supply capabilities.
Worldwide Photosensitive Resin Market -
Sourcing and price volatility: Acrylate monomers and certain photoinitiators remain supply‑sensitive. Historical swings—most notably a roughly 40% price volatility event observed in 2023 for acrylate monomers—underscore the need for procurement hedging, strategic stock policies and supplier diversification in 2026.
Worldwide Photosensitive Resin Market -
Regulatory and sustainability pressures: Stricter environmental and safety standards in major markets (US/EU) are accelerating adoption of lower‑toxicity formulations, recyclability requirements and biomass‑derived chemistries. Recent industry R&D headlines around biomass photoresists illustrate that sustainability is moving from peripheral R&D to commercial decision‑making.
-
Supply capacity and cost dynamics: Capacity expansion, particularly in Asia Pacific, expanded UV‑curable resin output materially in 2025—contributing to moderation in some raw material costs even as specialised chemistries command premium pricing. The net effect is a bifurcated market: commodity‑like grades under pricing pressure and high‑performance/specialty grades with expanding margins.
What the PW Consulting report delivers (practical, transaction‑grade intelligence)
-
Topline market sizing and forward scenario models: multi‑scenario forecasts through 2032 under alternative demand, raw‑material and regulatory assumptions, with a base case aligned to the 12.45% CAGR noted above.
-
Competitive positioning matrix: supplier profiles, technology stacks, go‑to‑market capabilities and a quantified market concentration view (the industry displays moderate concentration; top‑three and top‑five shares indicate meaningful but not prohibitive incumbency).
-
Technology & materials playbook: evaluation of monomers, photoinitiators, oligomer backbones, and two‑photon polymerisation chemistries that matter to applications such as ultrafast high‑resolution printing and medical‑grade parts.
-
Regulatory & certification roadmap: practical checklists for achieving medical, dental and electronics clearances in the US and EU, including timelines, testing nodes and expected cost buckets.
-
Commercial blueprints: pricing strategies, channel structures and contractual clauses (supply guarantees, force majeure, indexation) tailored to both staple and specialty resin supply.
-
Supplier risk and resiliency heatmap: concentration of raw materials, single‑source dependencies, logistical risk points and recommended mitigations by priority.
-
M&A and partnership targets: screening filters for bolt‑on candidates across geographies and capability sets (formulation depth, regulatory file libraries, specialty monomer inventory).
Competitive landscape — patterns, not numbers
The photosensitive resin value chain is populated by three distinct archetypes: high‑volume formulators with broad geographic manufacturing footprints, specialised innovators serving demanding niche applications, and legacy chemical majors supplying high‑value photoresists for advanced electronics. Each archetype brings strategic levers that buyers and investors should evaluate differently.
-
Asia‑based formulators and manufacturers (examples include Resione, UnionTech, Zicai Chemical and U‑Sunny): their strengths are application‑oriented R&D for 3D printing, tight cost structures and rapid local scale‑up. These companies are decisive suppliers for fast‑growing additive manufacturing segments and are increasingly competing on specialty formulations.
-
Western and European innovators (Formlabs, Liqcreate, UpNano, 3D Systems): they differentiate on application certification, OEM partnerships and high‑precision chemistries (e.g., two‑photon polymerisation resins). Regulatory clearances and an established installed base in medical/dental end markets give them premium pricing power in those categories.
-
Japanese chemical majors and electronics materials specialists (Asahi Kasei, Tokyo Ohka Kogyo, JSR, Shin‑Etsu, Fujifilm): these players dominate high‑value photoresist and semiconductor‑grade photosensitive chemistries. Their strengths—technical depth, IP, and close ties to semiconductor and display ecosystems—make them essential partners for electronics OEMs pursuing advanced patterning and EUV innovations.
Market structure metrics show a moderate level of concentration: the largest suppliers together control a meaningful share of the market, but there remains sizeable room for specialist entrants and regional champions to capture niche growth. That topology favours both disciplined M&A by incumbents and focused organic expansion by innovators.
Signals from recent industry developments
-
Commercial expansion and new channels: leading producers report expanded UV‑curable resin channels and growth in specialty segments—evidence that manufacturers are monetising product breadth beyond commodity grades.
-
Sustainability and circularity: reported growth in recycled (PCR) resin volumes and focused product development on biomass‑derived photoresists signal structural change in feedstock sourcing and product positioning.
-
Regulatory wins accelerate commercial adoption: regulatory clearances for medical/dental grades lower adoption friction and shift commercial conversations from proof‑of‑concept to procurement and scale‑up.
Key risks and pragmatic mitigations for 2026 planners
-
Raw material volatility — mitigate with dual‑sourcing, long‑term offtake contracts indexed to transparent drivers, and strategic inventory management that balances working capital and service levels.
-
Regulatory uncertainty — build a certification roadmap early, invest in third‑party labs or co‑fund testing with OEM partners, and prioritise markets where regulatory approval yields pricing premium.
-
Technology obsolescence — allocate R&D budget defensively across photoinitiators, oligomer backbones and emerging two‑photon chemistries; consider licensing agreements with specialist innovators to accelerate time‑to‑market.
-
Competitive margin compression in commodity grades — pursue product segmentation: reserve direct selling for high‑value grades while leveraging distribution partners for commoditised SKUs.
Actionable strategic recommendations for 2026
-
Rebalance portfolio towards specialty and regulated grades that command higher margins and create stickier customer relationships (medical, dental, electronics patterning).
-
Invest in sustainability differentiation (biomass and PCR content) to meet procurement mandates in the EU and US and to pre‑empt incoming regulation.
-
Pursue targeted alliances with equipment OEMs and end‑market integrators to co‑develop formulation and certification roadmaps—this reduces time‑to‑adoption and lowers technical risk.
-
Evaluate bolt‑on M&A to secure specialty monomers, photoinitiators or regulatory dossiers rather than broad scale capacity additions that may commoditise returns.
-
Operationalise supply risk controls: supplier scorecards, stress test scenarios and a procurement nexus that ties pricing to objective indices where possible.
-
Deploy pricing architecture by product family: subscription/consumable models for OEM partners, spot‑price pass‑through for commodity feeds, and value‑based pricing for certified medical/electronics grades.
How PW Consulting supports 2026 decision execution
PW Consulting combines market modelling, supplier due diligence and executable commercial playbooks into a single engagement. For clients preparing investment memoranda, negotiating supply agreements, or planning R&D roadmaps, we deliver: custom scenario models, counterparty risk dossiers, prioritized M&A target lists, and step‑by‑step certification timelines. The full Worldwide Photosensitive Resin Market report contains the granular inputs—segmental forecasts, supplier scorecards and downloadable Excel models—that mature strategy and execution plans require.
In short, the macro story is clear: robust growth, technical differentiation and regulatory pressure will reshape competitive advantage in photosensitive resins through 2032. Leaders who combine material science investment with disciplined commercial execution and supply‑chain resilience will capture disproportionate share of value as the market doubles from mid‑decade levels. PW Consulting’s report is designed to convert that macro view into operational priorities and measurable actions for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Photosensitive Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Rail Components Market to Reach USD 99.6 Billion by 2032 on a 4.65% CAGR
By PW Consulting, 2026-07-15
Worldwide Rail Components Market: Strategic Insights for 2026 Decision-Makers
Executive summary
As rail operators, OEMs, investors and policy-makers set budgets and strategies for 2026, the components ecosystem that underpins rolling stock and infrastructure is at an inflection point. PW Consulting’s latest Worldwide Rail Components Market report provides a pragmatic, scenario-based assessment of this environment, combining a rigorous historical baseline (2020–2025) with a forward-looking forecast (2026–2032). The headline: the global rail components market expanded from roughly USD 58.1 billion in 2020 to USD 72.5 billion in 2025, and our modelling projects a compounded, mid-single-digit recovery and growth trajectory—a 4.65% CAGR over 2026–2032 that pushes the market toward approximately USD 100 billion by 2032.
Worldwide Rail Components Market
Why this matters for 2026 decisions
-
Capital allocation needs to be fact-based. The market’s return to growth in 2026, after uneven investment over prior years, creates a window for targeted capex that must be timed to component life cycles, regulatory timelines, and supply-chain constraints.
Worldwide Rail Components Market -
Regulatory and standards shifts are tightening time horizons. Mandates for advanced signaling baselines and next-generation train control in major markets compress deployment schedules for onboard and wayside systems—and create near-term demand for component upgrades, integration services, and retrofit solutions.
Worldwide Rail Components Market -
Raw materials and trade policy will recalibrate sourcing and localization strategies. Energy-driven steel cost inflation and carbon-focused border mechanisms are changing the economics of cross-border procurement and making supply resilience a strategic priority.
Market dynamics shaping supplier and buyer strategies
Three macro dynamics dominate the 2026 planning landscape:
-
Technology acceleration. Automation (including driverless platforms), digital fleet management, and the integration of ERTMS/CBTC-class signaling demand closer coupling between mechanical components (bogies, wheelsets, brakes) and digital control systems. Component suppliers who can offer integrated hardware‑software bundles or validated interfaces will secure premium positions in procurement dialogs.
-
Regulation-driven refresh cycles. Upcoming interoperability mandates and safety baselines create predictable retrofit opportunities for signaling, braking and train control subsystems. Procurement teams should model compliance-driven replacement waves into 5–7 year capital plans.
-
Supply-chain economics and decarbonization pressure. From raw steel to specialized alloys, suppliers face margin pressure from material price spikes and carbon tariffs. Buyers and suppliers alike will need dual strategies: (a) near-term hedging and supplier diversification to manage cost volatility; (b) medium-term investment in low-carbon materials and repatriated manufacturing to mitigate tariff and compliance risk.
Competitive landscape: practical takeaways
The rail components market is neither atomized nor monopolized: market concentration indicates room for scale plays and focused innovation. The top three players control a meaningful but not dominant share, and the top five approach half the market—an environment that favors well-capitalized incumbents and ambitious challengers.
-
Integrated system players (e.g., established OEMs and large mobility divisions) leverage end-to-end portfolios—electrification, traction, signaling and rolling-stock components—to offer turnkey solutions. Their advantage is in system-level validation and rapid deployment for major transport authorities.
-
Specialist component manufacturers (braking systems, wheels, rails) maintain margin strength through materials expertise and regulatory certifications. Certification wins and niche proprietary metallurgy retain premium pricing power, particularly for high-speed and heavy-haul applications.
-
Mid-sized regional suppliers and component integrators can capture retrofit and replacement markets by offering rapid customization, local manufacturing footprints, and risk-sharing contracting models tied to lifecycle performance.
Recent corporate moves underscore these dynamics: new automation platforms and signaling products signal an acceleration toward driverless and GoA4-capable fleets; strategic acquisitions are being used to densify product portfolios in metro and commuter segments; and certification wins for premium rails and components open commercial doors in heavy-haul corridors. Long-term contract awards for digital fleet optimization highlight the rising value of software-enabled maintenance and fuel/energy savings.
What PW Consulting’s report delivers — operationally useful content
Designed as a decision-grade toolkit for 2026 planning cycles, the report blends high-level foresight with actionable modules you can use inside procurement, product, and M&A processes. Highlights include:
-
Market sizing and vintage growth analysis (2020–2025) plus probabilistic forecasts to 2032 that allow you to stress-test investment cases under different demand and price environments.
-
Policy and standards impact assessments — mapping regulatory milestones to component demand waves and compliance costs so you can prioritize retrofits vs. new-build specifications.
-
Supply‑chain vulnerability mapping — a supplier risk heatmap that integrates raw-material exposure, regional trade barriers, and manufacturing concentration to inform dual-sourcing and onshoring decisions.
-
Technology adoption roadmaps and interoperability matrices — practical guidance for integrating traction, braking, and signaling subsystems with digital fleet management platforms.
-
Commercial playbooks — supplier negotiation templates, lifecycle total-cost-of-ownership models, and maintenance‑capex optimization frameworks to reduce whole-life costs.
-
M&A and partnership scouting dossiers — candidate lists and valuation heuristics for bolt-on acquisitions or joint development agreements that accelerate capability gaps (e.g., compact brake calipers, advanced wheel metallurgy, or autonomous train control elements).
-
Scenario-based CapEx plans and investment triggers keyed to lead indicators (orderbooks, certificate approvals, raw material price bands) so 2026 decisions can be phased and reversible.
Strategic imperatives for 2026
-
Prioritize integration-ready suppliers: choose partners who can demonstrate validated hardware‑software interfaces and provide lifecycle performance guarantees aligned with digital fleet programs.
-
Embed regulatory compliance into product roadmaps: align releases and retrofit programs with the timelines of major interoperability baselines to avoid last-minute design rework.
-
Hedge materials exposure while investing in low‑carbon sourcing: combine short-term procurement contracts and financial hedges with medium-term investments in alternative steels and recycled alloys.
-
Design procurement for flexibility: use modular contracts, option windows, and performance-based payments to navigate the mid‑cycle demand variability suggested by our forecasts.
-
Accelerate digitization of maintenance: quantify TCO gains from digital prognostics and remote upgrade paths and prioritize pilots where fleet heterogeneity is greatest.
-
Use M&A selectively to fill capability gaps: target assets that shorten your route to certification or expand localized manufacturing in regulated markets.
How senior leaders should use this report in 2026 planning
Procurement chiefs should extract supplier heatmaps and TCO models to redesign sourcing panels for the next three procurement rounds. Chief engineers and product leaders should adopt the interoperability matrices to de-risk multi-supplier integrations before mass production. Corporate development teams should employ the M&A dossiers to shortlist targets that offer rapid scale or tech differentiation. Finally, CFOs should fold the probabilistic scenarios into rolling forecasts to keep capital commitments flexible across 2026–2028.
Competitive snapshot — what to watch from market leaders
Expect incumbents and specialists to pursue divergent but complementary strategies. Some players will double down on system integration and digital platforms to capture higher-margin services. Others will pursue targeted acquisitions and certifications to secure heavy-haul and high-speed contracts where materials and engineering excellence remain the differentiator. Watch for:
-
Product launches in driverless and automation platforms that accelerate deployment windows for transit authorities.
-
M&A and portfolio consolidation in braking and compact component niches that serve high-density metro markets.
-
Certifications and material approvals that unlock access to large corridor projects and shift supplier selection criteria from price to proven performance.
Closing — the strategic value of the PW Consulting report
For 2026, the rail components market offers both predictable retrofit demand driven by regulation and uneven greenfield opportunities tied to national transport spending. The difference between winners and laggards will be how well they translate foresight into procurement architecture, supplier partnerships, and targeted investments in digital and low-carbon technologies. PW Consulting’s Worldwide Rail Components Market report equips executives with the scenarios, tools and playbooks required to make those choices with clarity — while preserving the detailed segment-level intelligence for subscribers and clients who require transaction-grade data.
For full access to the dataset, segmented forecasts, supplier scorecards and executable templates that support 2026 decision cycles, please visit our report landing page and contact our engagement team to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Rail Components Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Waterproof Phone Pouch Market to Expand at a 5.8% CAGR During 2026–2032, New Report Reveals
By PW Consulting, 2026-07-15
Worldwide Waterproof Phone Pouch Market — Strategic Briefing for 2026 Decisions
Executive snapshot
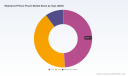
PW Consulting’s latest market study on the Worldwide Waterproof Phone Pouch market establishes a clear, actionable line of sight for executives planning through 2026 and beyond. Using 2025 as the base year and a historical window from 2020–2025, the research benchmarks recent performance and forecasts the market through 2032. The market expanded from a mid‑three‑hundreds million USD base in 2020 to roughly USD 450 million in 2025, and our forward view projects steady expansion to the high six‑hundreds million USD range by 2032 — implying a mid‑single‑digit compound annual growth rate (CAGR) of about 5.8% for the forecast period. Market concentration remains low, with the top three and top five firms controlling modest shares of overall industry revenue, underscoring an open competitive environment with ample room for disruption and consolidation.
Worldwide Waterproof Phone Pouch Market
Why this report matters for 2026 corporate strategy
-
Fast‑maturing, durable demand signals: The market’s trajectory reflects a mix of sustained consumer adoption (leisure and daily protection) and pockets of professional demand where specification and certification drive purchase decisions. For product and commercial leaders, this means the opportunity is near‑term certain but differentiated by product positioning and channel execution.
Worldwide Waterproof Phone Pouch Market -
Margin pressure and sourcing choices: Material and labor dynamics are already influencing gross margins. PVC input costs have moved appreciably higher year‑over‑year and manufacturers in primary sourcing hubs are facing wage inflation pressures. These cost trends elevate the importance of material selection, supplier contracts, and design decisions that reduce bill‑of‑materials exposure without impairing waterproof performance or compliance.
Worldwide Waterproof Phone Pouch Market -
Regulation and quality risk as strategic levers: New chemical controls (notably restrictions on certain plasticizers) and a visible history of zipper or seal failures that led to multi‑model recalls in recent years make regulatory and QA investments essential. Firms that move early to certify phthalate‑free solutions, adhere to recognized ingress‑protection standards, and demonstrate third‑party testing will have a credible go‑to‑market advantage in 2026.
-
Innovation vectors that trade up value: Recent product developments—battery‑integrated pouches, enhanced buoyancy designs, and extended IP/ MIL standards—show that feature innovation continues to create new premium tiers. Strategists should assess whether to compete on price, on differentiated features, or via vertically integrated propositions (bundled accessories, certified ecosystems).
Report contents — what you will find (and what we intentionally withhold here)
PW Consulting’s report is built for decision makers. It combines a quantitative core with pragmatic toolkits:
-
A validated market time series (2020–2025) and a detailed, scenario‑based forecast (2026–2032) that support revenue planning and target setting.
-
A proprietary demand model that synthesizes device penetration, outdoor and travel trends, and replacement cycles — enabling bottom‑up revenue sensitivity testing under alternate assumptions.
-
A supplier and materials map that ranks component cost exposure, sourcing risk, and regulatory sensitivity — including PVC and alternative polymer pathways.
-
A channel and pricing playbook covering direct‑to‑consumer, retail partnerships, and B2B procurement strategies; retail markdown and subscription models are stress‑tested for margin impact.
-
Go‑to‑market readiness checklists, certification roadmaps (IP/ MIL/ ASTM), and an M&A screening framework for tuck‑ins and capacity plays.
-
Competitive benchmarking and scenario case studies that illuminate how feature innovation, certification, and supply agility translate into share gains.
To preserve the strategic value of the research and to encourage direct engagement, we have intentionally excluded full public disclosure of the underlying sub‑segment tables and regional/application splits in this release. Those granular splits — essential for channel, regional investment, and SKU decisions — are accessible in the full report.
Competitive landscape — positioning and practical implications
The competitive set spans established premium brands headquartered in North America that emphasize performance, certification and premium retail presence, alongside agile Shenzhen‑based suppliers that compete on breadth, price and OEM/ODM capabilities.
-
Premium incumbents (examples): Pelican Products, OtterBox, Lifeproof and Catalyst consistently lean on certified protection, recognized IP/MIL ratings, and retail/enterprise distribution. Their product plays in 2024–2025 show investment in buoyancy and integrated feature sets — signals that premiumization is a deliberate growth route and that partnerships with outdoor and marine brands can extend reach.
-
Value and volume players (examples): Select Shenzhen manufacturers remain influential in global e‑commerce and white‑label supply. Their scale and factory flexibility make them the natural partners for retailers and fast‑moving consumer lines. For firms evaluating margin versus scale tradeoffs, leveraging these suppliers for mainstream SKUs while reserving premium innovations for branded channels can be an effective dual‑track.
-
Recent company moves underscore strategic choices: Pelican’s 2025 launch of buoyancy‑optimized cases, OtterBox’s product previews tied to flagship device launches, and Lifeproof’s certified power‑integrated pouch illustrate divergent ways to expand wallet share — either by technical differentiation, device‑aligned compatibility, or by adding utility through power and accessories.
Key dynamics and operational priorities for 2026
-
Materials strategy: Re‑engineering toward phthalate‑free formulations and alternative polymers will be financially material. Expect suppliers to pass through some cost increases; long‑term contracts and strategic raw‑material hedging can stabilize COGS.
-
Quality and certification: Buyers increasingly demand validated ingress performance. Investment in third‑party testing, factory quality assurance and traceability prevents costly recalls and supports premium pricing.
-
Channel segmentation: Differentiate SKUs by channel — highly certified, higher‑margin SKUs for specialty and enterprise channels; cost‑optimized variants for mass e‑commerce and private label. Align logistics and warranty support accordingly.
-
Product roadmaps: Integrate features that solve real use‑case friction points (e.g., touch usability when wet, buoyancy, integrated power, AR‑friendly transparency) rather than pursuing gimmicks; ensure backward compatibility with major device form factors.
-
M&A and partnership screen: Small bolt‑on acquisitions that bring testing labs, IP on seals/closures, or marine‑grade materials expertise provide asymmetric value given the low top‑tier concentration.
Strategic playbook — three recommended actions for 2026
-
Short term (0–6 months): Audit product lines for regulatory compliance and recall exposure; prioritize certification of flagship SKUs and implement an accelerated QA program for closure systems.
-
Medium term (6–18 months): Reconfigure sourcing to reduce PVC cost exposure and lock in manufacturing capacity for peak selling seasons; pilot premium differentiated SKUs in targeted geographic and channel pockets where consumers pay for engineering and certification.
-
Long term (18+ months): Evaluate inorganic opportunities that compress time‑to‑market for certified, ruggedized solutions or bring proprietary sealing technologies in house; pair M&A with a branded‑ecosystem strategy that bundles accessories and service.
Methodology and confidence
Our analysis integrates vendor interviews, trade channel scans, customs and shipment data, price and cost inputs, and third‑party testing outcomes. The base year is 2025; historical data cover 2020–2025, and forecasts run 2026–2032. Given available inputs and transparent assumptions, the modeled range and central case are robust for strategic planning. Sensitivity bands are included in the full report to stress‑test capital allocation and pricing scenarios.
Next steps — how to use this intelligence
-
For product leaders: Use the report’s certification roadmaps and supplier risk heat maps to prioritize R&D and QA spend.
-
For commercial teams: Apply the channel playbook and demand model to set SKU rationalization and promotional cadence for 2026.
-
For corporate development: Use the M&A screening framework to identify targets that accelerate access to certification, engineering IP or margin improvement.
Access the full dataset and tools
This briefing is a high‑value extract designed to orient strategic choices. The full PW Consulting report contains the complete regional, type and application splits, supplier-by-supplier revenue estimates, downloadable forecasts, and executable templates referenced here. To obtain the full intelligence package and accompanying scenario models, please visit the PW Consulting report page or contact our research team for a briefing and tailored executive summary.
For detailed analysis of this topic, please visit the official page: Worldwide Waterproof Phone Pouch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Taxi & Limousine Market to Surge from USD 312.45 Billion in 2025 to USD 572.74 Billion by 2032, Backed by a 9.04% CAGR
By PW Consulting, 2026-07-15
PW Consulting: Strategic Imperatives for 2026 — Worldwide Taxi and Limousine Services Market Outlook
Executive summary
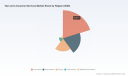
PW Consulting today publishes its authoritative market brief—Worldwide Taxi and Limousine Services Market—which frames 2026 as an inflection year for operators, platforms, OEMs, airports and corporate travel buyers. Our analysis uses 2025 as the base year, tracks 2020–2025 historical performance, and delivers scenario-based forecasts across 2026–2032. The market expanded from the low‑hundreds of billions of USD in 2020 to an estimated USD 312.45 Billion in 2025 and is projected to advance to roughly USD 341.47 Billion in 2026, with a compound annual growth rate of 9.04% across the 2026–2032 forecast window. Market concentration remains meaningful—our concentration metrics indicate that the top three and top five firms account for material, but not dominant, portions of global demand—creating both competitive pressure and strategic openings for focused regional and product plays.
Worldwide Taxi and Limousine Services Market
Why 2026 is an inflection point
-
Regulatory acceleration: 2026 is the first year in which multiple regulatory milestones and compliance deadlines converge. Notable regulatory drivers include clean-mobility standards (for example, requirements that transportation-network companies report and progressively electrify vehicle miles) and jurisdictional zero‑emission mandates targeting 2030–2035. These create near-term capital planning and compliance imperatives.
Worldwide Taxi and Limousine Services Market -
Fleet modernization and accessibility: City regulators and commissions are actively funding fleet upgrades—2025 reporting from major municipalities shows significant increases in charging infrastructure and accessibility conversions—forcing operators to reassess fleet mix, procurement cadence, and total cost of ownership models.
Worldwide Taxi and Limousine Services Market -
Service segmentation and quality expectations: Demand for premium, security-conscious limousine and chauffeured services from corporate clients is rising concurrently with mass-market ride-hailing. This bifurcation intensifies the need for differentiated go-to-market and pricing strategies.
-
Operational economics under pressure: Fuel and energy cost volatility, higher vehicle acquisition costs (particularly EVs), and evolving labor and insurance frameworks require new operating models and financial structures to preserve margins.
Implications for decision-makers in 2026
Our report translates these dynamics into direct, prioritized actions for six stakeholder groups.
-
Platform operators and taxi companies — Recast fleet strategies around fast-forward electrification and accessibility targets. Prioritize depot charging and dynamic dispatch optimization to protect unit economics; pilot subscription and contract bundles for corporate clients to stabilize revenue.
-
OEMs and vehicle fleet managers — Offer integrated EV procurement and financing packages, warranty/telemetry services and retrofit pathways for WAV conversions. Work closely with local regulators to co-design incentive-eligible solutions.
-
Airports and ground handlers — Leverage strong service recognition to renegotiate concession frameworks that incentivize cleaner and higher-quality ground transport, and invest in curbside and holding-area electrification to reduce dwell times.
-
Corporate travel and security teams — Re-evaluate supplier mixes to meet rising safety and privacy requirements; negotiate performance-based contracts for premium chauffeur and airport transfer services with clear SLAs around vehicle specs and driver vetting.
-
Investors and M&A teams — Focus on deals that accelerate electrification, last‑mile reliability, and corporate travel exposure; target assets that combine operating scale with proprietary routing, payments and compliance capabilities.
-
Policymakers and regulators — Deploy predictable incentive structures and phased compliance timelines to avoid displacing incumbent services; fund WAV adoption and depot infrastructure to create equitable access outcomes.
Competitive landscape: leaders, challengers and regional specialists
The market exhibits a hybrid structure: global technology-enabled platforms coexist with deep regional champions and legacy chauffeur providers. Our competitive review profiles leading players and strategic archetypes:
-
Global app platforms — Firms such as Uber Technologies Inc. and Lyft Inc. leverage scale, platform economics and diversified service tiers (from on-demand taxi equivalents to premium black-car offerings) to defend urban markets and enterprise accounts. Their strategic focus in 2026 is balancing electrification investments with network utilization to sustain profitability.
-
Regional super-apps and dominant local players — Companies like Didi Chuxing, Grab and Ola maintain commanding positions in their home markets and adjacent geographies. Their advantages are extensive local supply, tailored payment ecosystems and regulatory relationships; their 2026 priority is translating scale into profitable, low-carbon fleets.
-
Cost-focused challengers — Bolt and similar providers continue to press on affordability and market penetration, particularly in price-sensitive urban corridors and emerging markets.
-
Premium and corporate-focused operators — Blacklane, Addison Lee, Gett, EmpireCLS and Carey represent the security, compliance and high‑touch end of the spectrum, where customers are willing to pay a premium for vetted drivers, higher safety standards and airport/meet-and-greet capabilities.
-
Public and municipally backed fleets — Government-backed operators and regulated taxi authorities remain critical anchors for airport connectivity and access-focused services, and are often the first adopters of WAV conversion and fleet electrification programs.
Collectively, the market structure supports both platform consolidation in urban cores and durable niches for high‑service, regionally entrenched operators. Our concentration metrics—while indicating that top firms control meaningful share—also highlight significant room for well‑executed regional or product-focused strategies.
What the PW Consulting report delivers (operationally focused)
Beyond top-line forecasts, our deliverables are designed for immediate operational use by C‑suite and business-unit leaders:
-
Scenario-based demand forecasts and sensitivity testing across fuel, energy and regulatory pathways to quantify upside / downside exposures for 2026–2032.
-
Fleet transition models that compare total cost of ownership for legacy ICE fleets, hybrid mixes and full EV outcomes—integrating capex, charging infrastructure and utilization assumptions.
-
Regulatory compliance playbooks that map major jurisdictional timelines (including phased clean‑miles standards and zero‑emission mandates) to procurement and capital deployment calendars.
-
Operational blueprints for depot charging, driver scheduling, WAV integration and dynamic pricing to sustain margins during transition periods.
-
Commercial and RFP templates tailored to airports, corporates and government agencies to accelerate contracted revenue while meeting service-level and accessibility requirements.
-
Investment and M&A screening tools—valuation multipliers adjusted for electrification risk, regulatory exposure, and defensibility of customer relationships.
-
Competitive playbooks that benchmark leading players’ product mixes and go‑to‑market tactics and identify pragmatic partnership opportunities (e.g., OEM‑fleet, airport concession, corporate travel integrators).
Priority actions and timing for 2026
We translate strategy into an actionable timeline that executives can adopt immediately.
-
0–6 months: Complete a regulated‑zone compliance audit; secure conditional financing or OEM partnerships for first-wave EV procurement; launch WAV pilot routes supported by public grants; negotiate pilot contracts with key airport and corporate accounts.
-
6–18 months: Ramp depot charging deployments; implement driver retraining and vetting programs for premium services; roll out subscription and enterprise bundles; initiate focused M&A or strategic alliances to shore up urban supply density.
-
18–36 months: Consolidate operational analytics and dynamic pricing across fleets; achieve measurable reductions in fleet GHG intensity in line with jurisdictional milestones; scale premium, security-focused limousine services for corporate and VIP channels.
Closing: the strategic edge for 2026
2026 will separate leaders who adapt back-office economics, electrification and accessibility into commercial advantage from followers who react to compliance pressures at the margin. The PW Consulting Worldwide Taxi and Limousine Services Market report is purpose-built to convert regulatory and operational complexity into executable roadmaps—combining market foresight, granular fleet and depot analytics, and competitor intelligence to support board-level decisions and field-level execution plans.
For organisations that must prioritise capital, manage regulatory risk and preserve margin while growing service quality, our report provides both the evidence base and the playbook. To access the full set of proprietary datasets, regional and service-level granularity, and downloadable toolkits referenced above, please visit our report page—where the complete intelligence package and subscription options are available.
For detailed analysis of this topic, please visit the official page: Worldwide Taxi and Limousine Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Natural Aroma Chemicals Market Poised to Grow at a 6.8% CAGR During 2026–2032
By PW Consulting, 2026-07-15
Worldwide Natural Aroma Chemicals Market — 2026 Strategic Preview
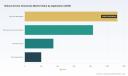
As companies map out investment, procurement, and R&D agendas for 2026, PW Consulting’s latest market study on the Worldwide Natural Aroma Chemicals Market offers a focused, decision‑grade vantage point. Built on a 2020–2025 historical base (base year 2025) and a 2026–2032 forecast horizon, the study demonstrates that the global natural aroma chemicals market has moved from roughly USD 1.84 billion in 2020 to about USD 2.50 billion in 2025 and is on a steady trajectory toward nearly USD 4.0 billion by 2032, driven by a compound annual growth rate of 6.8% across the forecast window. This preview highlights the report’s strategic value for 2026 planning while deliberately reserving detailed segment tables and proprietary model outputs for report subscribers.
Worldwide Natural Aroma Chemicals Market
Why 2026 Represents an Inflection Point
- Regulatory pressure and reformulation dynamics: Global compliance frameworks (notably IFRA and REACH) continue to shape ingredient selection and force reformulation choices across fragrance and personal care portfolios. Companies will need regulatory‑aware product roadmaps to avoid costly late‑stage changes.
- Sustainability claims are becoming a competitive necessity: Buyers and brand owners increasingly demand lower‑carbon, traceable natural ingredients. Early movers in reduced product carbon footprint (rPCF) labeling and biotech‑derived naturals are already securing premium shelf space and preferred supplier status.
- Feedstock and trade volatility: Essential oils — the primary feedstock for many natural aroma chemicals — remain an economic and supply risk; the broader essential oils market was valued at roughly USD 28.3 billion in 2025 and continues to show year‑on‑year movement. New tariff regimes and commodity price swings require more sophisticated procurement strategies.
- Technology adoption reshapes supply economics: Precision fermentation and other biotech routes are shifting the cost, lead‑time and sustainability calculus for certain aroma molecules. 2026 will be the year many organizations choose between in‑house capability build, strategic partnerships, or long‑term sourcing contracts with biotech suppliers.
High‑Level Findings (What Every Executive Should Know)
- Market momentum is solid: The market’s post‑pandemic recovery accelerated through 2023–2025 and, on current trajectories, supports mid‑single‑digit to high‑single‑digit growth over the coming half decade.
- Concentration and competitive shape: The market is neither a pure commodity arena nor a closed oligopoly. A mix of global ingredient giants and specialized regional players coexist; the largest firms collectively control a material but not dominant share, leaving space for agile niche players and vertical integrators.
- Demand composition is evolving: Traditional end uses remain important, but shifts toward clean‑label flavors, sustainable fragrance ingredients, and botanical traceability are changing the premium structure and win criteria for suppliers.
- Risk vectors matter more than ever: Raw material price swings, sudden regulatory adjustments, and localized supply disruptions are the principal downside risks to baseline growth — and these are quantifiable within our scenario models.
What the Full Report Delivers — The Practitioner’s Toolkit
- Proprietary global market sizing and growth scenarios (2020–2032), with interactive upside/downside pathways that translate macro drivers into P&L sensitivities for ingredient manufacturers, brands and distributors.
- Top‑line and bottom‑line impact models for raw material shocks, tariff scenarios, and carbon‑pricing sensitivities — including procurement playbooks and hedging guidance.
- Supplier benchmarking and capability heatmaps covering global leaders and regional specialists, with assessments of technology readiness (fermentation, isolation, extraction) and sustainability credentials.
- Regulatory impact matrix and a reformulation playbook aligned to IFRA/REACH developments, enabling R&D and regulatory teams to prioritize substitutions and claim pathways.
- Commercial strategies and route‑to‑market blueprints for ingredient firms: pricing levers, value‑added services, and co‑innovation models for brand partnerships.
- M&A and alliance scorecards identifying targets for capability acquisition (biotech, botanical sourcing, fractional synthesis) and recommended deal structures across 2026–2028.
- Case studies illustrating strategic responses from different stakeholder perspectives — CPO, Head of R&D, Head of Sustainability — and a set of board‑level decision templates for near‑term capital allocation.
Competitive Landscape — Who’s Setting the Pace
The competitive field combines global ingredient houses, specialized natural extractors, and agile contract manufacturers. Key players shaping the market include long‑standing flavor and fragrance leaders as well as pure‑play naturals suppliers. Their strategic moves provide a clear roadmap for competitive positioning in 2026:
Worldwide Natural Aroma Chemicals Market
- Givaudan: Global leader with a wide natural portfolio and a strong emphasis on sustainable botanical sourcing and co‑development with brand owners.
- Symrise: Deep capabilities across biotech and plant‑based molecules with an emphasis on scalable, supply‑secure solutions for personal care and flavors.
- IFF: Large multinational integrating biotechnology and clean‑label natural strategies to meet evolving consumer expectations.
- BASF: Advancing fermentation‑based aroma ingredients and rPCF labeling (recent launches underscore a commercial push into traceable, lower‑carbon ingredients).
- DSM‑Firmenich (Firmenich): Investing in bio‑sourced production lines and new facilities to support pine‑based and biodegradable musk alternatives.
- Regional and niche specialists: Companies such as Takasago, Mane, Robertet and a cohort of suppliers from India, the U.S. and Europe remain critical partners for provenance, essential‑oil extraction expertise, and price‑sensitive supply.
Recent product and capacity moves — from rPCF‑labeled menthol launches to new pine‑based production facilities — signal that incumbents are prioritizing sustainability claims and technology levers to preserve margin and market share. These developments are discussed in depth in the report’s competitor playbooks and scenario impact tables.
Worldwide Natural Aroma Chemicals Market
Strategic Imperatives for 2026
- Reassess the sourcing mix: Move beyond spot markets to layered contracts combining long‑term supply agreements, strategic reserves, and biotech‑sourced alternatives to balance cost, lead time and sustainability goals.
- Invest in verifiable sustainability: Prioritize traceability platforms and third‑party carbon accounting for key molecules — these investments increasingly unlock premium placement with brand customers.
- Accelerate technology partnerships: Evaluate precision fermentation pilots and strategic equity in biotech providers as insurance against feedstock volatility and as a lever to secure lower‑carbon claims.
- Integrate regulatory foresight into product roadmaps: Build timely reformulation pipelines and a regulatory impact dashboard to prevent disruptive compliance costs.
- Adopt a market‑segmented commercial playbook: Align sales strategies to the evolving buyer priorities — provenance and sustainability for premium brands, cost and consistency for mass‑market players.
- Prepare M&A and JV frameworks: Define clear investment criteria for acquiring upstream botanical capacity, biotech IP, or downstream consumer access to accelerate time to market.
How PW Consulting Supports Execution
Our practice combines market economics, supply‑chain analytics, regulatory intelligence and hands‑on commercial playbooks. The full Worldwide Natural Aroma Chemicals Market report includes the proprietary dataset, scenario models, supplier heatmaps, and the operational toolkits summarized above. For organizations that require implementation support, we offer bespoke advisory packages: procurement transformation, technology scouting and diligence, regulatory strategy, and post‑merger integration for aroma ingredient deals.
Please note: in keeping with the “trailer” approach of this preview, we have summarized the core strategic takeaways and withheld the detailed segment‑level tables, region/application breakouts and downloadable model files. These proprietary deliverables — including molecule‑level supply‑demand curves and price sensitivity matrices — are available only in the full report and through our advisory engagements.
For executives making capital, procurement and innovation choices in 2026, the right mix of scenario planning, supplier rebalancing, and targeted technology investment will separate leaders from followers. PW Consulting’s full report and tailored advisory services provide the concrete data, decision‑ready models and implementation pathways required to translate the market’s 6.8% CAGR and near‑term volatility drivers into competitive advantage. Contact PW Consulting to access the complete study and begin turning insights into actions.
For detailed analysis of this topic, please visit the official page: Worldwide Natural Aroma Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Glass Fiber Sizing Agent Market Forecast to Reach USD 1,059.21 Million by 2032
By PW Consulting, 2026-07-15
Worldwide Glass Fiber Sizing Agent Market: Strategic Insights for 2026 Decision-Makers
Executive preview — why PW Consulting’s latest market study matters to your 2026 strategy
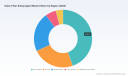
PW Consulting’s new Worldwide Glass Fiber Sizing Agent Market report (base year 2025; forecast period 2026–2032) equips executives with the sector-level intelligence required to make confident commercial and technical decisions in 2026. Our analysis synthesizes historical performance (2020–2025), a rigorous forecast model (2026–2032) with an expected compound annual growth rate (CAGR) of 6.18%, and an evaluation of market concentration that highlights competitive levers and consolidation risk. The market is clearly on an upward trajectory; however, the strategic opportunities and execution risks are nuanced and require more than headline numbers. This preview outlines the practical choices the report supports and the ways it helps management teams convert macro momentum into defensible growth.
Worldwide Glass Fiber Sizing Agent Market
Market snapshot: growth trajectory and competitive posture
-
Growth context — After a steady expansion through 2020–2025, our model projects continued growth into 2032, underpinned by demand from composites-intensive sectors and increasing regulatory pressure to move toward lower-VOC, waterborne technologies.
Worldwide Glass Fiber Sizing Agent Market -
Scale and momentum — The market size measured at our 2025 base and projected through 2032 provides both a sizing lens and a set of scenarios (base, downside, upside) that reflect raw material shocks, regulatory shifts, and downstream demand cycles.
Worldwide Glass Fiber Sizing Agent Market -
Concentration — The market exhibits moderate concentration: the three largest suppliers account for a meaningful share of industry revenue, with the top five reaching a majority share. That structure creates both opportunity for premium positioning and vulnerability to supply-side disruption.
Why this matters for 2026 strategic decisions
In 2026, companies face a confluence of choices: accelerate product innovation, secure feedstock on favorable terms, reposition pricing, or pursue M&A to secure scale and technical capability. Our report translates market-level forecasts into decision-ready guidance across five priority streams:
- Product roadmap prioritization — The move to waterborne polyurethane dispersions and low-VOC film formers is not a binary choice but a staged migration. The report shows which chemistries and formulation attributes will capture premium positioning among thermoplastic and thermoset composite makers, and where investment in R&D will deliver the highest margin uplift.
- Procurement and raw-material hedging — Sizing formulations use a predictable basket of inputs (water, silane coupling agents, film formers, surfactants, antistatic additives, and rheology modifiers). Our raw-material scenarios quantify exposure to price swings and propose hedging and supplier segmentation strategies tailored to different cost structures.
- Commercial segmentation and go-to-market — The market is driven by a relatively concentrated set of end-markets with distinct technical requirements. The report offers actionable account-tiering guidance, margin-to-volume trade-offs, and recommended channel plays for specialty formulators and commodity suppliers alike.
- Regulatory compliance and product claims — EU REACH and food-contact directives are reshaping acceptable formulations. Our compliance matrix maps regulatory constraints to formulation options and recommended certification pathways, enabling faster time-to-market without sacrificing performance claims.
- M&A and partnership scouting — Given the market’s mid-range consolidation, there are high-value plays for both bolt-on acquisitions (to secure proprietary film formers or silane technologies) and strategic partnerships (to co-develop sizing tuned to OEM composite processes). The report provides an M&A heat map and synergy assessment framework.
Practical contents of the PW Consulting report
This is a practitioner’s deliverable, designed to be directly operationalizable by strategy, product, procurement, and business development teams. Highlights include:
- Proprietary demand model with scenario drivers and sensitivity analysis for key inputs (raw-material price, resin market penetration, and production capacity).
- Product and formulation decision matrices showing which chemistries and film-former technologies align with specific end-market performance parameters.
- Supply-chain stress tests and supplier segmentation to prioritize sourcing and mitigate single-source risk.
- Regulatory impact assessment, including compliance pathways for REACH and relevant EU food-contact standards, and recommended product positioning language to support sales.
- Commercial playbooks and pricing templates for launching new low-VOC or food-contact-compliant grades.
- M&A target shortlisting criteria and integration risk checklists calibrated to preserve production continuity and technology transfer.
Competitive landscape — who matters and why
The report profiles the leading suppliers whose technical depth and distribution footprint shape commercial outcomes. Key company insights include:
- Celanese (United States) — A benchmark supplier offering emulsion polymers designed for thermoset reinforcement. Celanese’s Resyn® and Vinamul® platforms are recognized for improving handling and composite properties, and their portfolio serves as a quality standard in multiple geographies.
- Michelman (Cincinnati, OH, United States) — Known for Hydrosize® film-forming dispersions and an integrated set of binders and lubricants tailored to both chopped and continuous fibers. Michelman’s recent launch (February 2026) of a single-sizing solution designed to serve both fiber forms exemplifies product consolidation that can cut downstream complexity for fiber producers.
- Evonik Industries (Germany) — A leader in silane coupling chemistries (DYNASYLAN®) and VPS additives that reduce breakage in high-speed production and enable robust bonding with polymer matrices.
- BYK (ALTANA Group, Germany) — Focused on MAH-grafted polymer film formers and low-VOC solutions that address the most exacting polyolefin composite requirements.
- Covestro (Germany) — Supplier of Baybond® waterborne polyurethane dispersions and crosslinkers; provides grades engineered for protection, adhesion and regulatory compliance in food-contact scenarios.
- Great Eastern Resins Industrial (GRECO, Taiwan) — Specializes in high-solid-content aqueous polyurethane dispersions with low viscosity and strong weather resistance, addressing particular needs in humid-production environments.
- Emsland Group (Germany) — An innovative player in bio-based starch sizing solutions for pre-sizing and warp sizing in textile-related glass fiber applications.
Collectively, these suppliers illustrate the market’s technical diversity: film formers, silane chemistries, and specialty additives are viable paths to differentiation. The top-tier firms capture a significant share of revenue while mid-sized specialists provide the niche technologies that OEMs increasingly demand. Our report includes detailed supplier scorecards and a partner-selection rubric to aid vendor choices without exposing confidential benchmarking data in this preview.
Regulatory and raw-material dynamics shaping product strategy
Two regulatory levers are materially shaping the sector. First, longstanding EU REACH obligations continue to accelerate reformulation toward compliant chemistries. Second, food-contact and low-VOC requirements push formulators toward waterborne systems, especially in products that interface with sensitive end-uses. On the materials side, sizing formulations depend on a defined set of inputs — water, silane coupling agents, film formers, surfactants, and a small suite of performance additives — and applied at low percentages of composite weight. This predictability enables focused supplier strategies but also concentrates risk when a single raw-material class faces disruption. Our report’s raw-material playbooks identify resilient sourcing strategies and alternative chemistries for rapid substitution.
How leading companies should use this intelligence in 2026
- CEOs and corporate strategists — Use the market scenarios to set investment priorities and M&A budgets; quantify potential returns from targeted consolidation versus organic R&D.
- R&D and product management — Apply the formulation decision matrices to accelerate low-VOC/waterborne product launches with credible claims and roadmaps for regulatory approval.
- Procurement — Implement supplier segmentation and hedging strategies to protect margins in the event of raw-material price shocks.
- Commercial teams — Adopt the go-to-market playbooks to target high-priority OEM segments, emphasizing technical claims that buyers value and are willing to pay a premium for.
- M&A teams — Use the M&A heat map and integration checklists to prioritize acquisition targets that bring scale or unique formulation capability without undue execution risk.
What is intentionally withheld in this preview
Consistent with our “trailer” approach, this press release demonstrates the depth and practical focus of PW Consulting’s analysis while withholding detailed tables and granular splits by region, application, and micro-segments. Subscribers to the full report receive downloadable models, segmented revenue forecasts, pricing curves, and supplier-level performance metrics that support transaction diligence and capex planning.
Next steps — converting insight into action
For leaders preparing budgets, negotiating supply contracts, or planning product launches in 2026, the full PW Consulting report provides the quantitative models, supplier assessments, and regulatory roadmaps necessary to act decisively. If your team needs a tailored briefing — scenario runs aligned to your supply base, a competitor deep-dive, or a product commercialization checklist calibrated to the latest regulatory thresholds — PW Consulting can deliver an accelerated executive workshop built on the report’s proprietary outputs.
PW Consulting’s Worldwide Glass Fiber Sizing Agent Market study is a practical, strategy-focused tool: it reveals the market forces, competitive dynamics, and regulatory constraints you must address in 2026 while preserving the detailed segment data that supports high-confidence decisions for those who engage further.
For detailed analysis of this topic, please visit the official page: Worldwide Glass Fiber Sizing Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide PDMAT Market to Reach USD 638.73 Million by 2032, Expanding at a 7.5% CAGR
By PW Consulting, 2026-07-15
Worldwide PDMAT Market: Strategic Intelligence for 2026 — PW Consulting Insight Brief
Executive summary
As semiconductor nodes push below 22 nm and copper interconnect scaling intensifies, Pentakis(dimethylamino)tantalum (PDMAT) has moved from a niche precursor to a critical supply-chain element for advanced TaN barrier films. PW Consulting’s new Worldwide PDMAT Market report (base year 2025; historical 2020–2025; forecast 2026–2032) equips senior procurement, process development, and corporate strategy teams with the actionable intelligence needed to make high-consequence decisions in 2026.
Worldwide PDMAT Market
Headline market view
Our quantitative model shows the global PDMAT market reached USD 385.0 Million (USD Million unit) in 2025. Under our central scenario, the market expands at a compound annual growth rate (CAGR) of 7.5% across the forecast window, reaching approximately USD 638.7 Million by 2032. The market exhibits a high degree of supplier concentration (CR3 ≈ 65.5%; CR5 ≈ 82.2%), a structural feature that shapes commercial leverage, qualification timelines, and risk allocation.
Worldwide PDMAT Market
Key takeaways for 2026 decision-makers
- PDMAT is a specialty, high-barrier precursor whose demand tracks advanced logic and memory capacity growth, not general chemical consumption — expect demand drivers to be technology-node and foundry-capacity dependent.
- The market is consolidating: a small group of specialized suppliers controls the majority of accessible product, making supplier selection and qualification a strategic, not tactical, procurement activity.
- Upstream chemistry and packaging choices materially affect downstream yield: synthesis routes, multi-stage purification, and inert packaging can be decisive for HVM qualification.
- Procurement timelines are long. Qualification cycles, custom packaging qualification (ampoules, bubblers), and safety approvals require 9–18 months in many cases; early engagement matters.
- Risk management must combine technical and commercial measures: dual sourcing where possible, strategic stockpiles aligned to qualification status, and supplier development agreements to secure capacity.
Why this report matters for 2026 planning
2026 will be a turning point for several reasons. First, foundry and IDM capital allocations made in 2023–2025 begin to translate into HVM demand for advanced barrier films. Second, incremental improvements in ALD/CVD tool throughput and purity requirements push PDMAT manufacturers to upgrade purification and packaging. Finally, regulatory and handling constraints—PDMAT’s air- and moisture-sensitivity and its classification for R&D use only—mean that operational readiness (inert handling, qualified bubblers/ampoules, controlled logistics) becomes an explicit part of supplier selection. Our report synthesizes these drivers into pragmatic scenarios that connect supply-side dynamics to procurement KPIs and technology roadmaps.
Worldwide PDMAT Market
Market sizing & trajectory (strategic highlights)
Using a bottom-up build aligned with foundry capacity forecasts and thin-film consumption models, we estimate the PDMAT market grew to USD 385.0 Million in 2025. Under a base-case adoption curve tied to sub-22 nm device ramp and PVD/ALD technology adoption, the market is projected to grow at a 7.5% CAGR during 2026–2032, reaching roughly USD 638.7 Million by 2032. This trajectory assumes steady secular growth in advanced packaging and logic nodes, with downside scenarios linked to alternative barrier chemistries or unexpected supply disruptions.
Competitive landscape — who matters and why
The supplier universe blends large specialty chemical houses with regional high-purity manufacturers. Competition is shaped by depth of purification capability, packaging options for ALD/CVD systems, geographical service footprint, and long-term HVM supply commitments. Key players profiled in the report include:
- Merck KGaA (EMD Group) — a global supplier with extensive distribution and high-purity PDMAT offerings tailored for TaN barrier deposition across major semiconductor markets.
- Ereztech — a US-based supplier that differentiates on flexible order sizes, custom packaging (glass ampules, metal bubblers), and responsiveness to ALD process qualification needs.
- Strem Chemicals (Ascensus Specialties) — positions as a trusted research-grade supplier with deep experience in organometallic precursors for CVD/ALD R&D streams.
- Nanmat Technology, TOPCO Scientific, PentaPro Materials — Taiwan-based manufacturers with vertically integrated precursors portfolios and proximity advantages to Asian fabs.
- Argosun and Sinocompound — Chinese suppliers focused on high-purity PDMAT for local and regional fabrication ecosystems.
- DOCK Chemicals — European supplier known for ultra-high-purity product lines tailored to semiconductor precursor specifications.
Our competitive analysis evaluates each firm across nine dimensions (purity control, HVM capacity, packaging systems, regional logistics, regulatory compliance, technical service, price competitiveness, scale-up capability, and partnership willingness). The report includes supplier scorecards and negotiation playbooks to accelerate selection and contracting.
Supply chain and technical dynamics
PDMAT synthesis is typically carried out via metathesis between tantalum pentachloride (TaCl5) and lithium dimethylamide (LiNMe2), followed by multi-stage purification to reduce chloride and oxygen impurities to parts-per-million or lower for HVM use. The industry continues to invest in purification innovations to meet sub-22 nm yield requirements; ultra-low chloride (<10 ppm) and oxygen control are table stakes for qualified product. PDMAT’s air- and moisture-sensitivity, and its R&D-classified handling, require end-to-end inert-gas logistics, controlled packaging (glass ampoules, metal bubblers), and in-situ delivery systems on ALD/CVD tools.
To put physical scale into perspective, independent industry estimates indicate global PDMAT volume was in the low-tonne range in 2024 (roughly 1,869 kg) with an average selling price in the multiple-thousand-USD-per-kilogram range. These characteristics create a market where small changes in physical-kilogram demand can result in significant revenue shifts and supply tightness.
Operational and regulatory nuances
- PDMAT is supplied in specialized formats—glass ampules, bottles, or metal bubblers—each with distinct qualification and safety pathways. Packaging choice influences qualification cycles and tool uptime.
- Regulatory constraints and safety data sheets designate PDMAT as moisture- and air-sensitive and largely intended for R&D/industrial applications; shipment and handling must align with hazardous-material protocols and fab safety systems.
- Qualification for HVM typically requires collaborative process optimization between precursor supplier and fab process engineers; expect multi-stage pilot runs and tight defect-density gating.
Strategic recommendations for 2026 (practical playbook)
- Begin supplier qualification cycles now. With typical timelines stretching 9–18 months across packaging, safety, and process qualification, firms targeting 2026 supply must engage suppliers immediately.
- Adopt a hybrid sourcing strategy: secure long-term supply agreements with at least one strategic partner and maintain a secondary qualified supplier or toll-manufacturing option to mitigate single-source risk.
- Invest in inbound logistics and handling. Facilities must be validated for inert receiving, temporary storage under controlled atmosphere, and safe feed to ALD/CVD systems.
- Negotiate performance-linked contracts. Include clauses for on-time delivery, impurity thresholds, and joint scale-up milestones tied to price adjustments and capacity reservations.
- Allocate resources to analytics and failure analysis. Early detection of trace impurities (chloride, oxygen) prevents yield excursions; embed analytic acceptance criteria into procurement requirements.
- Plan capacity with scenario stress-tests. Our report models multiple downside and upside scenarios (technology substitution, supplier outage, accelerated demand) to inform buffer stock levels and CAPEX timing.
What the PW Consulting report contains (actionable sections)
- Market sizing and forecast model (base year 2025; historical 2020–2025; forecast 2026–2032) with scenario sensitivity and downside/upside cases.
- Supplier landscape: nine detailed vendor profiles, capability scorecards, and negotiation playbooks.
- Procurement playbook: qualification timelines, packaging decision matrix, technical checklists, and contract language templates.
- Technology & process review: synthesis routes, purification technologies, and implications for sub-22 nm nodes.
- Supply chain risk matrix and mitigation toolkit: dual-sourcing pathways, toll-manufacture options, and inventory sizing guidance.
- Regulatory and safety annex: handling standards, shipping class considerations, and packaging compliance requirements.
- Appendices with raw data tables, forecast assumptions, and methodological notes (note: detailed regional and end-use splits are available in the full report to subscribers).
Conclusion — how to use this insight
For organizations that rely on advanced TaN barrier films, PDMAT is not a commodity to be sourced at the last minute. The combination of structural supplier concentration, stringent purity requirements, and constrained physical volumes means that sourcing, qualification, and process integration decisions taken in 2026 will materially influence unit cost, yield, and time-to-volume for product roadmaps through 2032. PW Consulting’s Worldwide PDMAT Market report delivers the quantitative trajectory, supplier intelligence, and operational playbook to turn these risks into strategic advantage.
Next steps
Executives and procurement leads should review the executive-level scenario models and supplier scorecards in the full PW Consulting report to finalize 2026 sourcing strategies. For access to the complete dataset, detailed regional and application splits, and supplier scorecards, please consult the PW Consulting report portal and contact our industry team for a guided briefing.
For detailed analysis of this topic, please visit the official page: Worldwide PDMAT Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Pt Paste for Gas Sensor Market Valued at USD 110.0 Million in 2025 to Reach USD 170.38 Million by 2032 — 6.45% CAGR, Asia Pacific Commands Nearly 48% Share
By PW Consulting, 2026-07-15
Worldwide Pt Paste for Gas Sensor Market — Strategic Outlook to 2026 and Beyond
PW Consulting’s new market study on the Worldwide Pt Paste for Gas Sensor Market delivers a focused, decision-grade roadmap for corporations planning capital allocation, procurement, R&D and M&A in 2026. Anchored on a detailed base-year assessment (2025) and a 2026–2032 forecast horizon, the report quantifies market value, tracks structural concentration, and models supply-side risk tied to platinum group metal (PGM) dynamics. At the macro level the market is expected to expand from approximately USD 110.0 million in 2025 to about USD 170.4 million by 2032, implying a compound annual growth rate of roughly 6.45% over the forecast period.
Worldwide Pt Paste for Gas Sensor Market
Why this report matters for 2026 decisions
2026 will be a pivotal year for organizations that depend on platinum pastes for gas sensors. The market sits at the intersection of three accelerating trends: (1) continued demand growth for sensing applications across automotive emissions control, industrial monitoring and consumer safety; (2) heightened raw-material risk due to persistent PGM supply constraints and commodity price volatility; and (3) technology-driven differentiation from paste formulations, firing processes and substrate integration that determine sensor performance and cost. Our research synthesizes quantitative forecasts with qualitative supplier intelligence so leaders can decide whether to hedge, vertically integrate, pursue strategic partnerships or accelerate materials R&D.
Worldwide Pt Paste for Gas Sensor Market
Market structure and competitive posture
The Pt paste market for gas sensors shows a moderate-to-high level of concentration with the largest three suppliers commanding a material share of the market and the top five controlling a substantial majority. This concentration creates both risks and advantages: established vendors offer scale, multi-region supply chains, and technical validation; meanwhile smaller specialists can move faster on bespoke formulations and forge close OEM relationships. The competitive landscape is bifurcated between traditional PGM processors and specialty ceramic/thick-film formulators — an architecture that favors firms with integrated PGM sourcing, process engineering and sensor-system know-how.
Worldwide Pt Paste for Gas Sensor Market
-
TANAKA Precious Metals (Japan) — Strengths include a broad Pt-paste portfolio tailored to electrodes and heaters, high-temperature firing know‑how (notable 1,450°C processes), and certified RoHS2, making it a primary partner for automotive and high-reliability industrial sensor programs. TANAKA’s product diversity (including porous reactive electrodes and Pt alloy variants) underlines a strategy of selling differentiated, application‑tuned pastes rather than commodity metal.
-
Heraeus Electronics (Hanau, Germany) — A leader in thick-film conductor pastes with versatile Pt-containing formulations, Heraeus focuses on high conductivity and solderable chemistries for fuel- and oxygen-sensor architectures. Recent technical datasheet updates (Feb 2026) demonstrate iterative product refinement aimed at automotive and industrial OEMs seeking solderable, chemically resilient conductor layers.
-
Dycotec Materials (UK) — Specializes in screen-printable fritted platinum conductor pastes that enable fine-line printing and dense fired layers for ceramic circuits and zirconia sensors. Dycotec’s lower-temperature firing options provide flexibility for manufacturers balancing thermal budgets against substrate choice.
-
Ferro Corporation, Johnson Matthey, Umicore — These incumbents contribute scale, PGM market insight and cross-industry customer reach. Johnson Matthey’s 2025 PGM market reporting highlighted structural supply deficits that directly influence paste sourcing economics. Umicore’s recycling and engineered‑materials capabilities position it uniquely in closed‑loop strategies.
-
MANA Metal (China) & American Elements (USA) — Represent regional and application-focused suppliers delivering screen-printable pastes for flat oxygen sensors, SOFCs and other niche sensor platforms, enabling local sourcing alternatives that can shorten lead times and reduce logistics risk.
Supply-side realities: platinum as the gating factor
Platinum metal remains the dominant upstream feedstock and the primary driver of cost and availability for Pt paste manufacturers. Industry reporting indicates a notable supply shortfall in 2025 and a steep price response — platinum prices rose markedly during the year, driven by geopolitical risk, reduced above-ground stocks and lower primary output in major producing regions. For buyers and manufacturers, this elevates the importance of multi-layered procurement strategies: contract diversification, recycled-PGM sourcing, forward hedging and supplier-level due diligence on feedstock provenance and material efficiency.
Report scope: actionable deliverables
PW Consulting’s study is built for practitioners. Beyond headline forecasts, the report supplies the tools companies need to turn insight into action:
- Bottom‑up market sizing and a seven-year forecast model by product architecture and application class (segmentation detail available in the full report).
- Supply-chain mapping that traces PGM flow from primary producers through refining, paste manufacturing and sensor OEMs, highlighting single‑point-of‑failure nodes.
- Price‑sensitivity and margin-health models that quantify the impact of platinum price scenarios on paste and finished-sensor economics.
- Supplier scorecards with capability matrices (formulation breadth, firing process, qualification pedigree, RoHS compliance, geographic footprint).
- Procurement playbooks: contract structures, inventory policies, and recycled-PGM program templates.
- Technology watch and R&D diagnostic covering low‑Pt alloy strategies, conductive-frit innovation, and integration with LTCC/HTCC processes.
- M&A and partnership candidate shortlists aligned to strategic archetypes (secure feedstock, broaden formulation set, gain regional manufacturing).
- Regulatory and sustainability impact summaries, including compliance checklists for RoHS2 and ESG reporting considerations.
Key strategic implications for 2026
-
Prioritize feedstock resilience: With platinum market deficits and sharp 2025 price moves still reverberating, organizations should secure multi-sourced, contractually protected PGM supply and evaluate recycled-supply channels. Short-term procurement should be complemented by medium-term investments in recycling partnerships and on-site reclaim capabilities.
-
Differentiate via materials engineering: Suppliers that can reduce required Pt loading through alloying, microstructure control or process integration will create durable cost advantage. OEMs should incentivize co-development projects that target identical or superior sensing performance at lower Pt intensity.
-
Negotiate smarter contracts: Cost‑pass-through, price collars, volume-flex clauses and currency hedges are table stakes. Procurement teams must align contract design with forecast sensitivity models supplied in the report.
-
Segment prioritization: Not all sensor applications carry the same margin or volume risk. Focusing growth investments on application segments with the most favorable combined outlook for volume expansion and premium pricing will maximize ROI.
-
Capitalize on supplier concentration: The market’s concentration (top-three and top-five vendor dominance) creates opportunities for selective partnerships and strategic exclusivities, but also elevates systemic risk if one of the major processors faces feedstock disruption. Balance partnership depth with alternative-supplier development.
-
Keep regulatory and sustainability levers active: RoHS2 conformity and emerging ESG expectations mean product chemistry and recycling programs are increasingly procurement criteria. Early alignment reduces qualification delays and protects market access.
How to use this study in your 2026 planning cycle
Leaders should treat this analysis as a resource for three planning horizons:
- Immediate (0–12 months): Implement procurement risk mitigations, re-price forecasts against current PGM curve scenarios, and begin sensitive supplier audits.
- Near term (12–36 months): Launch co-development programs to reduce Pt intensity, invest in recycling/joint reclamation partnerships, and execute targeted supplier diversification.
- Strategic (36+ months): Evaluate vertical integration or M&A opportunities to secure feedstock and proprietary paste technologies, especially where sensor performance is a decisive product differentiator.
Closing perspective
For executives navigating the Pt paste for gas sensor market, the central strategic question in 2026 is not merely how large the market will be, but how resilient and competitive your position will be in the face of raw-material shocks and accelerating technical differentiation. PW Consulting’s report provides the scenario-tested intelligence, supplier diagnostics and tactical playbooks that procurement chiefs, product leaders and corporate development teams need to make those calls with confidence.
To access the full dataset, supplier scorecards, scenario models and the granular segmentation tables that underpin the headline projections, request the complete Worldwide Pt Paste for Gas Sensor Market report from PW Consulting. The report is structured to plug directly into your 2026 budgeting, sourcing and innovation roadmaps while preserving the commercial confidentiality of supplier- and segment-level metrics.
For detailed analysis of this topic, please visit the official page: Worldwide Pt Paste for Gas Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


