



Category: market research
PW Consulting: Worldwide Veterinary Glucometers Market to Reach USD 926.01 Million by 2032, Expanding at a 7.85% CAGR
By PW Consulting, 2026-07-15
Worldwide Veterinary Glucometers Market — Strategic Imperatives for 2026
PW Consulting’s newest market study on the Worldwide Veterinary Glucometers Market synthesizes five years of historical performance and a seven‑year forecast to 2032, delivering a market view that is both data‑rigorous and directly actionable for executive decision‑making. The global market is projected to expand from a 2025 base of approximately USD 545.6 Million to just over USD 926.0 Million by 2032, reflecting a compound annual growth rate (CAGR) of roughly 7.85%. Market concentration is material — the top three and five suppliers together account for a clear majority of revenue — an attribute that shapes pricing, channel, and M&A dynamics through 2026 and beyond.
Worldwide Veterinary Glucometers Market
Why this report matters to 2026 strategic planning
-
Timing: 2026 will be a pivotal year for veterinary diagnostics, as new continuous glucose monitoring (CGM) entrants complete regulatory and manufacturing validation while incumbent players consolidate channel relationships. Our forecast period (2026–2032) is therefore aligned to the window in which product relaunches, distribution changes, and reimbursement practice evolution will most strongly influence share shifts.
Worldwide Veterinary Glucometers Market -
Actionability: The study translates market movement into clear decision levers — product investment priorities, channel build vs. partnerships, pricing architecture, and M&A criteria — so that commercial and corporate development teams can convert insight into near‑term actions.
Worldwide Veterinary Glucometers Market -
Risk‑adjusted planning: The veterinary glucometer market sits at the intersection of medtech accuracy requirements, species‑specific validation needs, and an increasingly digital, clinic‑to‑home continuum of care. Our scenarios explicitly model regulatory friction, channel concentration, and adoption rates for clinic‑direct CGMs versus home testing solutions to inform contingency planning for 2026 operational budgets.
Market trajectory and structural takeaways
After a steady expansion through 2020–2025, the market enters a higher‑growth phase driven by two convergent themes: (1) the maturation and clinical acceptance of pet‑oriented CGMs and enhanced meter algorithms calibrated for species‑specific physiology; and (2) broader digitization of the veterinary patient record and remote monitoring workflows that raise demand for interoperable measurement devices. Our base‑case projects continued mid‑single‑digit to high‑single‑digit growth through 2032 — a profile that rewards timely investments in product differentiation and channel access.
Concentration indicators show the market is not a fragmented long tail: leading manufacturers capture concentrated shares that enable them to move distribution and pricing quickly. This creates both opportunities for disruptive entrants with clinically‑validated technology and challenges for smaller incumbents that lack scale in manufacturing, distribution partnerships, or post‑market clinical evidence.
Competitive landscape — what to watch in 2026
The competitive map combines traditional veterinary diagnostics specialists, medtech players extending into animal health, and dedicated pet CGM innovators. Key companies profiled in our study include established large animal health players, specialist glucometer manufacturers, and CGM‑first startups. Across the competitor set, three themes deserve attention:
-
Species‑specific calibration and clinical validation: Vendors with robust, published validation against laboratory reference methods in dog, cat (and where relevant, equine) matrices are carving out trust advantages with veterinarians.
-
Platform and data strategy: Devices that support clinic workflows — data sharing between pet owners and veterinarians, multi‑pet profile management, and clinic‑level dashboards — are gaining traction over one‑off meters that merely display a value.
-
Channel and distribution sophistication: Exclusive or preferential relationships with major animal health distributors materially accelerate market access for devices positioned as clinic‑direct CGMs or vet‑recommended home meters.
Representative vendor snapshots included in the report (each with strategic implications and suggested partner/competitive responses) are:
-
Zoetis (Parsippany, NJ): Continues to leverage brand trust and a product ecosystem calibrated for companion animals. Recent device iterations emphasize small sample volumes and integrated mobile apps to strengthen clinic‑to‑home continuity.
-
i‑SENS (Seoul): Focuses on veterinary‑calibrated meters with an emphasis on straightforward clinic and home use; competitive on unit economics and global distribution reach.
-
Nova Biomedical (Waltham, MA): Addresses both companion and herd applications by extending glucose and ketone measurement capability, positioning around multi‑use clinical value.
-
Universal Biosensors (Rowville): Emphasizes multi‑pet profile management and handheld point‑of‑care usability for clinical settings.
-
ALR Technologies / GluCurve (Singapore / USA): A CGM‑focused entrant that has announced re‑validation and relaunch plans — a development that could reshape clinic CGM adoption timelines if commercial roll‑out meets projected accuracy and distribution targets.
-
Adapet Medical, UltiMed/Advocate, MAI Animal Health, Woodley Equipment: Each brings differentiated mixes of portability, dual analyte testing (glucose + ketone), and clinical distribution footprints; collectively they form the tactical competitive field for mid‑market clinic and home segments.
Notably, recent developments — including a late‑2025 product relaunch announcement from a CGM vendor and earlier major meter upgrades by established players — signal that 2026 will be the year when product claims, clinic validation, and distribution activation converge to produce measurable share movement.
Regulation, clinical validation and technology implications
Regulatory and validation dynamics are central to commercial strategy. Veterinary glucometers are judged not only by ease of use but by species‑specific accuracy validated against laboratory reference methods. Where applicable, ISO 15197 performance benchmarks and animal‑matrix verification are increasingly referenced in procurement and clinical guideline decisions. In practice this means that new product launches without rigorous animal‑specific validation face slower adoption and greater discounting pressure.
Operational implications for suppliers include investment needs for veterinary clinical studies, documentation for distributor qualification, and engineering for small sample volumes consistent with ear or paw capillary sampling. Meanwhile, the ongoing off‑label use of certain human flash glucose monitors in veterinary practice underscores both an unmet clinical need and an addressable regulatory gap for dedicated veterinary CGMs.
What the PW Consulting report delivers (practical, non‑theoretical outputs)
We designed the study to support tactical decisions in 90–180 day planning cycles as well as to inform three‑year strategic roadmaps. Key deliverables include:
-
Comprehensive market model: historical series and scenario‑based forecasts through 2032, with modular drivers so teams can re‑run outcomes under alternative adoption, pricing, and regulatory scenarios.
-
Segment and channel playbooks: go‑to‑market blueprints for clinic‑direct CGMs, clinic‑recommended home meters, and herd/large‑animal solutions.
-
Competitive battlecards: validated strength/weakness matrices, product claims comparison, and distributor maps for each major competitor.
-
Evidence and regulatory checklist: recommended study designs, sample size guidance, and pathways for animal‑matrix validation to meet purchaser expectations.
-
M&A and commercial partnership scoring: a rational, repeatable framework to prioritize targets by technology fit, distribution access, and scale economics.
-
Financial templates and price sensitivity analysis: margin and payback models calibrated to typical veterinary channel mixes.
To honor the “trailer” principle and preserve the strategic value of the full dataset, this release intentionally omits core segment tables and granular regional or product‑level figures. The report itself contains complete segmentation by product type, animal category, end‑user channel, and region, together with downloadable models for internal use.
Recommendations for executives in 2026
-
Manufacturers with clinical validation: Shift from feature‑led marketing to evidence‑led commercial programs. Prioritize clinic key opinion leader (KOL) engagement and distributor exclusivity pilots that tie reimbursement or purchasing incentives to demonstrated accuracy in veterinary matrices.
-
SME device makers: Consider partnerships or selective licensing with larger animal health distributors to overcome channel friction. Evaluate bolt‑on acquisitions that can close gaps in clinical evidence or manufacturing scale.
-
Private equity and corporate development: Target assets that combine validated CGM algorithms, regulatory dossiers, and existing distributor agreements; avoid technology‑only assets lacking clinic validation unless a clear, well‑funded clinical program is part of the deal thesis.
-
Veterinary groups and networks: Implement standardized device evaluation criteria based on species‑specific performance and data integration capability before endorsing home monitoring kits to clients.
Next steps and how to access the full intelligence
PW Consulting’s full Worldwide Veterinary Glucometers Market report contains the complete numerical backbone — segmented market sizes, pricing ladders, and the financial model that underpins our 7.85% CAGR projection. For procurement teams, corporate strategy groups, and investor due diligence teams preparing for 2026 initiatives, the dataset and playbooks in the full report are designed to fast‑track execution while reducing clinical and commercial risk.
Contact PW Consulting to request the full report, the underlying market model (editable), and our executive briefing package. For organizations seeking a short engagement, we offer a 4‑week strategic sprint that converts the report’s insights into a tailored 90‑day action plan and a prioritized list of pilot or M&A opportunities.
For detailed analysis of this topic, please visit the official page: Worldwide Veterinary Glucometers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide LARC Market Valued at $5.61B in 2025, Forecast to Reach $8.66B by 2032 at a 6.4% CAGR
By PW Consulting, 2026-07-15
Worldwide LARC Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence
Executive preview — why this report matters to leadership teams planning for 2026
As healthcare payers, device manufacturers, and strategic investors set budgets and pipelines for 2026, the long‑acting reversible contraception (LARC) market presents a mix of predictable growth and accelerating structural change. PW Consulting’s latest Worldwide LARC Market report (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes market size, technology evolution, regulatory inflection points and competitive dynamics into an actionable playbook. At a macro level the global LARC market approached USD 5.6 billion in 2025 and is forecast to grow at a compound annual growth rate of 6.4% through our 2032 horizon, illustrating both steady demand and clear upside for differentiated strategies.
Worldwide Long-Acting Reversible Contraception(LARC) Market
High‑level takeaways for 2026 decision cycles
-
Moment of product lifecycle opportunity: recent regulatory wins extending the approved duration of implantable options, combined with the entrance of next‑generation, lower‑copper IUD designs, are reshaping lifetime value calculations for existing portfolios.
Worldwide Long-Acting Reversible Contraception(LARC) Market -
Consolidation and concentration: the market remains concentrated among a small group of established players, making targeted alliances, licensing and selective M&A high‑impact levers for faster scale and channel access.
Worldwide Long-Acting Reversible Contraception(LARC) Market -
Policy and reimbursement tailwinds: recognition of LARC’s superior efficacy and favorable long‑term cost profile is increasingly reflected in reimbursement frameworks — but payer uptake timelines differ by market and program structure.
-
Supply chain and raw material risks: innovations that materially reduce copper content create risk/reward tradeoffs for manufacturers reliant on traditional copper‑IUD supply models and for procurement agencies.
What’s new in the competitive landscape (select highlights)
-
Product lifecycle extensions: One incumbent obtained regulatory approval in early 2026 to extend the labeled duration of an etonogestrel subdermal implant, shifting the competitive calculus around replacement cycles and follow‑on product economics. This kind of extension raises the bar for clinical evidence packages required from rivals and generics.
-
New entrants and licensing activity: The licensing of a next‑generation hormone‑free copper IUD to a major global vendor in 2026 — following earlier regulatory authorization of that device in 2025 — is accelerating commercialization plans for “low‑copper” designs that claim comparable efficacy with smaller metal loads and preloaded inserter ergonomics.
-
Public‑sector and low‑cost manufacturing: Established WHO‑prequalified implants and domestically scaled copper IUD producers remain critical suppliers for donor‑funded and national procurement, sustaining distinct demand channels where price and supply continuity matter most.
-
Regulatory and clinician requirements: For certain implants, regulator‑mandated training and certification for insertion and removal remain binding operational constraints; these influence adoption curves and drive demand for training services and digital support tools.
Report scope — what PW Consulting delivers
This report is designed as an operationally focused, strategy‑grade tool for corporate strategy, commercial planning, R&D prioritization and investor due diligence. Key inclusions are:
-
Market sizing and seven‑year forecasts (2026–2032) at a global level, with scenario modelling that quantifies sensitivity to adoption rates, duration extensions and price erosion.
-
Multi‑angle segmentation frameworks (by device type, geography and end‑user channel) and a reproducible methodology (bottom‑up market build corroborated with primary interviews and vendor validation). Note: the press summary intentionally omits detailed segment revenue tables — full segment datasets are available in the complete report on our website.
-
Practical go‑to‑market playbooks covering pricing, reimbursement engagement, tender strategy, and product launch sequencing for both branded and lower‑cost entrants.
-
Vendor profiles and scorecards — covering regulatory status, pipeline, manufacturing footprint, pricing posture and partnership appetite — calibrated to support M&A screening and commercial partnerships.
-
Supply‑chain risk matrix and mitigation options focusing on raw material exposure, contract manufacturing dependencies and scale‑up timelines for new inserter or frame technologies.
-
Regulatory and policy tracker with likely near‑term inflection points that can compress or expand addressable markets, including training/REMS requirements and public procurement policy shifts.
-
Appendices containing primary interview transcripts, unit cost models, and a reproducible sensitivity model clients can adapt for bespoke scenarios.
Strategic implications and recommended actions for 2026
-
Prioritize evidence-generation that targets duration and non‑inferiority claims. Clinical dossiers that demonstrate extended duration of effectiveness materially change lifetime revenue and substitution dynamics; sponsors should evaluate accelerated or adaptive trial pathways now to capture label extensions.
-
Pursue selective licensing and co‑commercial deals to accelerate access in markets where in‑country regulatory or procurement barriers are high. Licensing a differentiated, lower‑copper device or a preloaded inserter can rapidly expand channel presence without capex‑intensive manufacturing investments.
-
Design tender strategies aligned to public‑sector buying cycles. Manufacturers supplying public programs should model multi‑year demand and include contingency for price compression from generic entrants post‑patent expiry.
-
Hedge raw material risk. For companies exposed to copper price and supply volatility, develop alternative sourcing, vertical inventory strategies, and R&D plans that can validate lower‑metal formulations without compromising clinical outcomes.
-
Invest in training and services. Regulatory requirements for clinician certification create a stable revenue opportunity for training programs, digital insertion aids, and remote proctoring — all of which can accelerate uptake and reduce adverse event rates.
-
Prepare for intensified competition following patent expiries. Companies should map likely generic entrants, assess applicator patent coverage windows, and develop defensive strategies including product‑differentiation, patient support services, and locked‑in procurement contracts.
Competitive watchlist — who to monitor
The market is shaped by a mix of multinational pharmaceutical/device companies and regionally focused manufacturers. A small group of incumbents holds dominant share and extensive channel reach, while agile niche players are introducing clinically differentiated designs and lower‑cost supply options. Recent public moves — including device approvals, licensing deals and duration‑extension approvals — are concentrated among both global brands and specialist women’s health manufacturers. Our full report contains scored profiles, comparative matrices and likely partner/opportunity maps for each major player.
Risk scenarios that change the 2026 playbook
-
Accelerated generic entry following patent expirations could depress prices in private markets and compress margins unless sponsors secure service differentiation or protected applicator designs.
-
Slower than expected public procurement uptake or prolonged reimbursement negotiations could shift demand from premium branded options to lower‑cost alternatives, particularly in price‑sensitive markets.
-
Regulatory requirements that tighten insertion/removal training could slow adoption in ambulatory channels but create downstream commercial opportunities for accredited training providers and bundled service offerings.
-
Raw material shocks — for example, copper supply disruption or sudden price spikes — would advantage lower‑copper technologies and manufacturers that diversified sourcing early.
Why PW Consulting’s analysis is a strategic asset for 2026
Executives tell us they need intelligence that goes beyond point estimates — they need a playbook that links clinical evidence, regulatory timing, procurement mechanics and competitor intent to concrete commercial choices. This report is built to answer “what‑if” questions that matter in boardrooms and M&A committees: what happens to unit economics if a leading implant’s label is extended; where will procurement buyers shift if a lower‑copper, preloaded system achieves broader approvals; which suppliers are most exposed to copper price swings. We combine top‑down macro scenarios with bottom‑up primary research and vendor engagement so clients can model realistic outcomes and prioritize investments in 2026.
Next steps
This press preview highlights the strategic contours of PW Consulting’s Worldwide LARC Market report. It intentionally omits granular segment allocations and detailed vendor market shares to preserve the commercial value of the full dataset. For market participants preparing budgets, pipeline decisions, or M&A screening for 2026, the complete report delivers the data tables, scored vendor profiles, downloadable models and primary research transcripts necessary to move from insight to action.
For detailed analysis of this topic, please visit the official page: Worldwide Long-Acting Reversible Contraception(LARC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Worldwide Reusable Food Wrap Market to Reach USD 397.3 Million by 2032, Fueled by 7.15% CAGR
By PW Consulting, 2026-07-15
Worldwide Reusable Food Wrap Market — Strategic Preview for 2026 Decision-Makers
Executive summary
As sustainability moves from consumer preference to regulatory requirement, the reusable food wrap market has shifted from a niche lifestyle segment to a strategic category for consumer goods, retail and foodservice operators. Our new PW Consulting report (base year 2025) quantifies this transition: the worldwide market expanded from roughly USD 173 million in 2020 to USD 245 million in 2025 and is forecast to approach USD 397 million by 2032, representing a compound annual growth rate of approximately 7.15% over the 2026–2032 forecast window. That trajectory reflects a convergence of policy-driven demand, improving unit economics for reusable products, and technology-enabled distribution models.
Worldwide Reusable Food Wrap Market
Why this briefing matters for 2026 strategy
For executives preparing budgets, portfolios and M&A pipelines in 2026, reusable food wraps are no longer an optional sustainability exercise: they are a defensible growth lever and a reputational hedge against accelerating single-use bans and procurement mandates. This preview highlights the actionable insights our full report provides — including scenario-tested forecasts, supplier scorecards, and go-to-market playbooks — while preserving the proprietary, segment-level intelligence available in the full dataset.
Worldwide Reusable Food Wrap Market
Market snapshot (macro view)
The category’s recovery and growth across 2020–2025 demonstrate resilience: a post-disruption rebound in consumer spending on eco-friendly kitchenware, and expansion into commercial channels. Looking ahead, our 2026–2032 base forecast anticipates steady expansion driven by regulatory tailwinds, retail channel evolution and product innovation. The market’s compound growth profile points to sizable upside for firms that capture distribution breadth, certification-led premiumization, and manufacturing scale.
Worldwide Reusable Food Wrap Market
What the full report delivers (practical, transaction-ready content)
Organizations purchasing the full PW Consulting study will receive a toolbox designed for immediate operationalization and board-level decision support. Key deliverables include:
- Bottom-up demand models by region, channel and product type (sensitive assumptions and scenarios included).
- Price and margin benchmarking across product types and geographies, with historical trajectories and short-term elasticity estimates.
- Supplier and OEM/ODM scorecards combining capacity, certifications (e.g., LFGB, REACH, FDA compliance), lead times and quality metrics.
- Regulatory impact matrix mapping near-term policy changes to addressable demand by channel and compliance risk.
- Commercial playbooks: D2C and retail launch templates, pricing ladders, subscription and refill mechanics, and private-label considerations for grocery and foodservice accounts.
- M&A and partnership shortlist: accretive targets identified using strategic fit, manufacturing footprint and brand equity filters.
Regulatory and demand dynamics shaping 2026
Regulation is the most visible accelerant. State-level mandates in the United States and similar moves globally are creating explicit commercial incentives to shift away from single-use packaging. Notable developments that feed directly into 2026 opportunity sizing include California’s extended producer responsibility and recyclability requirements, as well as state bans and limits on single-use food service ware that are coming online regionally. These policies are prompting foodservice buyers and retail procurement teams to re-evaluate packaging specifications and to pilot reusable alternatives — a procurement channel that will be decisive for broader adoption.
Supply-side realities and raw material dynamics
Margins and procurement strategy hinge on raw material dynamics. Beeswax — a core input for many traditional reusable wraps — has shown price volatility in visible transactions, underlining a procurement risk for producers reliant on mono-commodity supply chains. Global export price benchmarks and transaction-level trades in 2024–2025 indicate material cost pressures that will alter supplier economics unless firms diversify formulations (e.g., plant-based or silicone alternatives), lock in long-term supply agreements, or pursue vertical integration. Our full study includes a procurement playbook with hedging simulations and alternative-material sensitivity analyses to inform 2026 sourcing decisions.
Competitive landscape — what incumbents and manufacturers are doing
The market combines heritage artisan brands, digitally native challengers and cost-driven manufacturers. Established brands such as Bee’s Wrap and Abeego have leveraged certification, storytelling and premium retail placement; digitally native and zero-waste labels (including several Canadian and U.S.-based players) capitalize on direct-to-consumer familiarity and subscription models. At the same time, larger-scale manufacturers in Asia have built capacity for compliant OEM/ODM production, offering cost advantages and scale for private-label initiatives.
Strategic implications we observe from competitive movements:
- Brand differentiation is migrating from aesthetics and materials claims toward verifiable sustainability credentials and supply-chain transparency; brands without certified claims risk commoditization.
- Silicone and other non-beeswax formulations are expanding the set of addressable customers (including vegan and high-temperature use cases), creating an adjacent product innovation frontier.
- OEM/ODM partners with regulatory certifications and flexible minimums are enabling retailers and CPGs to test private-label offerings rapidly — an effective route to scale for buyers seeking margin capture.
Sector risk profile for 2026
Decision-makers must weigh three principal risks:
- Input-cost risk — material price volatility can compress margin if not actively managed through supply agreements or formulation diversification.
- Quality & safety risk — inconsistent product quality or lack of regulatory compliance can trigger reputational and legal exposure, particularly for foodservice partnerships.
- Market fragmentation risk — a proliferation of low-cost imports and undifferentiated private labels can depress prices and erode brand equity unless companies secure distribution advantages or IP-based differentiation.
Playbook for 2026 — recommended actions by capability
PW Consulting recommends a calibrated set of actions depending on your role and risk appetite:
- For consumer brands: accelerate certification and third-party testing, introduce a mid-tier silicone offer to capture new use cases, and pilot subscription replenishment to increase lifetime value.
- For retailers: pursue private-label rollouts in foodservice and grocery categories with limited-risk test-and-learn assortments; prioritize suppliers with proven compliance and scalable capacity.
- For manufacturers and OEMs: invest in traceability systems and lab certifications to win B2B contracts; evaluate forward-integration to capture a greater share of value.
- For investors and M&A teams: focus on targets that combine brand equity, supply resilience and attractive unit economics — and conduct diligence on raw material contracts and certification history.
What we’re watching in 2026
Near-term inflection points include the pace at which foodservice buyers implement reusable program pilots, the emergence of standardized certification frameworks for reusable packaging, and how quickly premium retailers convert regulatory pressure into category resets. We are also monitoring supply-chain consolidations and the entry of larger, multi-category sustainability brands that can cross-sell into reusable kitchenware.
Competitive profiles — illustrative, non-exhaustive
The full report contains vendor-by-vendor analysis and scored profiles. Examples of the types of players covered include:
- Heritage artisan brands with certification-led positioning and established retail distribution.
- Digitally native zero-waste labels that focus on direct-to-consumer growth and community-driven retention.
- Large-scale Asian OEM/ODM players offering certified manufacturing and flexible private-label services, capable of supporting rapid scaling for retail and foodservice customers.
Conclusion — the strategic window for 2026
Reusable food wraps sit at the intersection of regulation, consumer preference and supply-chain economics. For companies looking to make material progress on sustainability while protecting or expanding margin pools, 2026 is a pivotal year to translate pilots into scaled programs. The macro trajectory is favorable: the market has shown sustained growth from 2020–2025 and, under our central case, continues its expansion toward a substantially larger market by 2032. However, the pace and quality of that capture will be determined by firms’ choices on certification, sourcing and channel strategy.
Next steps
PW Consulting’s full Worldwide Reusable Food Wrap Market report provides the granular market maps, supplier scorecards, and executable playbooks needed to turn strategy into results. For procurement teams, business-unit leaders and investors that need transaction-grade analysis for 2026 planning, our database and advisory services can be deployed to produce tailored models, supplier negotiations support, and acquisition diligence briefs.
Contact PW Consulting to request the full dataset, scenario models, and proprietary supplier scorecards to inform your 2026 strategy and operational plan.
For detailed analysis of this topic, please visit the official page: Worldwide Reusable Food Wrap Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Smart Lock With Cat's Eye Market to Reach USD 3,760.99 Million by 2032 at 13.5% CAGR — Asia Pacific Leads with USD 849.6 Million
By PW Consulting, 2026-07-15
Worldwide Smart Lock With Cat's Eye Market: Strategic Outlook for 2026 — PW Consulting Release
PW Consulting's latest market study, "Worldwide Smart Lock With Cat's Eye Market," equips senior leaders with the empirical context and strategic frameworks required to make high-consequence decisions in 2026. The market has moved from a nascent niche toward a scale opportunity: global revenues expanded materially through 2020–2025 and, with a modeled compound annual growth rate (CAGR) of 13.5% across our forecast horizon, are projected to roughly double again by the early 2030s. This press brief summarizes the report’s strategic value, core dynamics, competitive positioning, regulatory headwinds, and 2026-ready playbooks — while intentionally withholding granular segment-level figures to preserve our subscriber-first intelligence model.
Worldwide Smart Lock With Cat's Eye Market
Why this report matters for 2026 decision-making
-
Timing: 2026 is a pivotal inflection year. Early high-growth adoption of visual-integrated smart locks (cat's eye devices) has transitioned the segment from product innovation to commercialization and regulatory scrutiny. Executives who align product, channel, and compliance strategies now will capture asymmetric market share as mainstream adoption accelerates.
Worldwide Smart Lock With Cat's Eye Market -
Signal-to-noise optimization: The report synthesizes five years of historical market performance with a 2026–2032 forecast built on bottom-up adoption curves, device-level ASP trajectories, and platform integration economics. That allows procurement, product, and M&A teams to distinguish durable structural trends from transient hype.
Worldwide Smart Lock With Cat's Eye Market -
Operational levers: Beyond market sizing, PW Consulting provides executable playbooks — from GTM segmentation and OEM partnerships to device lifecycle cost models — enabling teams to convert market opportunity into measurable P&L outcomes.
Market trajectory: What the macro numbers reveal
Our macro analysis shows the smart lock with cat's eye market has grown substantially since 2020. Using USD-denominated revenues, the market more than doubled in the first half of the decade as early adopters embraced video-integrated access solutions. Our modeling indicates that by 2026 the market continues to expand at a double-digit pace and, under baseline assumptions, will scale meaningfully through 2032 as hardware costs decline, AI-driven features improve conversion, and retrofit cycles for multifamily and single-family housing accelerate.
Importantly, market concentration metrics indicate a moderately fragmented vendor landscape: the three largest players hold a meaningful but not dominant share, while the top five consolidate additional reach. For corporates this means attractive windows exist for scale-focused entrants with distribution advantages or for incumbents to pursue bolt-on acquisitions that improve margins and platform stickiness.
Competitive dynamics: product, platform, and channel
The competitive set is heterogeneous, spanning multinational device OEMs, platform enablers, and specialized device integrators. Leading device manufacturers increasingly embed wide-angle visual capture, AI-based human detection, night vision, and multi-modal unlocking to differentiate on convenience and perceived safety. Platform providers are moving upstream by offering standardized SDKs, cloud services, and white-label solutions that accelerate go-to-market for OEMs and installers.
-
Xiaomi and Huawei: These consumer-tech incumbents emphasize vertical integration — combining wide-angle cat's eye cameras, AI detection, and large indoor displays to deliver a unified home security experience. Rapid product cycles and ecosystem bundling (smart home hubs, cameras, and voice assistants) are their competitive strengths.
-
Global legacy brands (e.g., Yale under ASSA ABLOY): These firms blend mechanical access credibility with digital features, targeting trust-conscious buyers through channel partnerships and certified installer networks.
-
Platform and ODM players (e.g., Tuya): Platform players enable OEM scale by providing firmware, cloud connectivity, and app ecosystems across multiple manufacturers — lowering time-to-market but introducing differentiation challenges.
-
Specialists and regional OEMs: Niche manufacturers are advancing cost-efficient camera modules, local-language UX, and retrofit-friendly mechanical interfaces for diverse housing stock.
Recent product launches in 2024–2025 underscore these dynamics: several major vendors introduced new cat's eye-enabled smart locks with expanded viewing angles, enhanced indoor screens, and AI detection suites — signaling a shift from novelty features to baseline customer expectations.
Regulatory and privacy dynamics shaping commercial risk
Smart locks with integrated cameras sit at the intersection of consumer safety and data protection, and regulators are reacting at different speeds across jurisdictions. Several regulatory vectors have immediate strategic implications for 2026:
-
Data minimization and retention: Jurisdictions with robust privacy regimes treat video captured by door devices as highly sensitive. Product roadmaps must include configurable retention policies, on-device anonymization modes, and explicit consent flows to avoid non-compliance risks.
-
Positional privacy and scope: Rules that prohibit cameras from pointing at neighboring units or public thoroughfares require engineering and installation controls — both in hardware mechanical design and in commissioning processes for installers.
-
Tenant protections: Urban tenant protection laws are increasingly mandating physical-key options, data minimization, and transparent notice and consent procedures — influencing multi-dwelling unit (MDU) deployment strategies.
Notably, some national standards remain narrowly focused on mechanical safety and lag in defining consistent requirements for recording, triggering, and storage practices of visual-enabled door devices. This regulatory patchwork creates first-mover advantages for vendors that can offer compliance-by-design solutions and installer training programs for complex markets.
Report deliverables: what PW Consulting provides (high level)
Our full report is designed as an operational toolkit for corporate strategy, product, and M&A teams. Key components include:
-
Market sizing and forward-looking demand models (historical 2020–2025 and forecast 2026–2032) with scenario analysis reflecting alternative macro, component-cost, and regulatory outcomes.
-
Investment-grade competitor dossiers covering product roadmaps, channel strategies, and recent launches — enabling rapid benchmarking and opportunity mapping.
-
Commercial playbooks: pricing frameworks, installer economics, subscription vs. one-time revenue models, and partner co-investment structures that accelerate adoption in target end markets.
-
Technology and component deep dives: camera modules, edge-AI compute, battery strategies, and trade-offs for on-device versus cloud inference in latency and privacy-sensitive contexts.
-
Regulatory risk matrices by major jurisdiction and a compliance checklist for product and installation teams to operationalize privacy-by-design for 2026 deployments.
-
M&A and partnership screening templates with priority targets, integration playbooks, and a valuation sensitivity grid to expedite diligence.
To preserve the actionable value of the report for subscribers, detailed segment and regional breakdowns, channel-level unit economics, and company-specific revenue splits are reserved for report access.
Strategic recommendations for 2026
Based on our synthesis, we advise executive teams to pursue a three-track strategy in 2026: invest in product defensibility, orchestrate channel scale, and harden privacy governance.
-
Product defensibility: Prioritize edge AI and privacy-preserving features (on-device person detection, selective recording) to reduce cloud dependency while meeting privacy expectations. Differentiate through user experience touchpoints — large indoor displays, low-latency alerts, and robust onboarding for installers.
-
Channel orchestration: Build hybrid distribution strategies. Retail and e-tail channels serve mainstream consumers; certified installer networks and strategic MDU partnerships unlock higher ACV customers. Consider white-label partnerships with platforms to expedite reach in markets where brand recognition is nascent.
-
Privacy and compliance as market access: Treat regulatory compliance as a market-entry enabler rather than a cost. Invest in modular compliance stacks and installer certification to pre-empt local regulations and win procurement opportunities in privacy-sensitive segments such as MDUs and commercial real estate.
Where PW Consulting adds unique value
PW Consulting combines rigorous quantitative models with practitioner-focused deliverables. Our strength is translating device-level technical decisions into P&L and risk-exposure outcomes — enabling boards and executive teams to make rapid, defensible decisions. We also provide bespoke scenario analysis during diligence or strategic planning cycles, isolating the economic impact of feature choices (e.g., inclusion of on-device storage vs. cloud subscription) under different regulatory regimes.
Next steps and how to access the report
For leaders preparing budgets, product roadmaps, or M&A pipelines in 2026, this report functions as a decision-grade resource. PW Consulting has intentionally reserved detailed regional, application, and type-level figures within the subscriber report to maintain the report’s commercial integrity and to ensure clients receive the most relevant, tailored intelligence.
To download the complete report, including the data tables, regional and application splits, and full competitor annexes, please visit our report page. Clients can also request a tailored briefing with our analysts, who will walk through scenario models and recommend action paths aligned with your corporate priorities.
Closing observation
The smart lock with cat's eye market is no longer purely experimental. By 2026, it will be judged on how well vendors balance convenience-driven features with robust privacy controls and installer-centric economics. For companies that move early to codify compliant product architectures, scale distribution partnerships, and embed privacy-by-design, the next three years offer structural growth and consolidation opportunities. PW Consulting’s report is crafted to be the operational compass for that journey.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Lock With Cat's Eye Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Mosquito Repellent Water for Pregnant Women Market to Reach USD 456.24 Million by 2032 at a 7.5% CAGR; Asia Pacific Leads with USD 126.21M
By PW Consulting, 2026-07-15
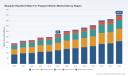
Worldwide Mosquito Repellent Water For Pregnant Women Market — Strategic Outlook for 2026
PW Consulting’s latest market study on the Worldwide Mosquito Repellent Water for Pregnant Women market (base year 2025, forecast period 2026–2032) delivers a focused, decision-ready view for executives planning 2026 strategies. The global market—estimated at USD 275.0 Million in 2025—is projected to expand to roughly USD 303.6 Million in 2026 and follow a 7.5% CAGR through the forecast window, reflecting accelerating demand driven by health guidance, product innovation and shifting channel economics. This briefing synthesizes the study’s strategic implications while reserving granular segment-level tables and proprietary model outputs for subscribers of the full report.
Worldwide Mosquito Repellent Water For Pregnant Women Market
Why this market matters to leadership teams in 2026
-
Clear regulatory tailwinds: Public health authorities (CDC, EPA, ACOG and related bodies) have continued to clarify safety guidance for pregnant women, explicitly endorsing specific EPA-registered actives when used as directed. That clarity reduces consumer hesitation and creates a stable platform for evidence-based marketing and clinical communication.
Worldwide Mosquito Repellent Water For Pregnant Women Market -
Health risk awareness and preventative healthcare: As vector-borne disease risk remains a prominent public-health concern in numerous geographies, pregnant women and caregivers are a priority buying cohort—one that values demonstrated efficacy and safety above anecdotal "natural" claims.
Worldwide Mosquito Repellent Water For Pregnant Women Market -
Product innovation is differentiating: Manufacturers combining proven repellents (picaridin, DEET, IR3535 and PMD/OLE where appropriate) with skin-care adjuncts (e.g., humectants and hyaluronic agents) are achieving higher trial and repurchase among sensitive-skin users—an important competitive lever in the maternity category.
-
Channel transformation: Evolving retail dynamics—especially omnichannel and subscription models—are reshaping how pregnant consumers discover and repurchase repellents; 2026 will be a year where digital-first pilots must demonstrate unit economics to scale.
What PW Consulting’s report delivers (practical, transaction-ready content)
-
Robust market-sizing and forward-looking forecast model calibrated to 2020–2025 historicals and stress-tested across three macro scenarios for 2026–2032.
-
Granular segmentation frameworks (product formulation, distribution channel, and use-case archetypes) and proprietary consumer-insight clusters that reveal purchase triggers, channel preferences, and messaging sensitivities for pregnant consumers and their influencers.
-
Regulatory and safety dossier mapping: a compliance playbook that translates CDC/EPA guidance into label claims, clinical support strategies, and risk-mitigation checklists for packaging and marketing.
-
Supply-chain and sourcing heat map focused on active-ingredient availability, single-supplier risks, and formulation inputs (including trends toward combining synthetic actives with skin-conditioning agents).
-
Competitive benchmarking and value-pool analysis, including CR-level concentration metrics, channel profitability matrices, and a prioritized list of white-space opportunities for SKUs, packaging and service bundling.
-
Go-to-market playbooks by distribution archetype and a tactical marketing roadmap with measurable KPIs for 6-, 12- and 24-month horizons.
-
M&A screening templates, deal-values sensitivity checks (revenue and margin accretion scenarios), and post-merger integration quick wins for bolt-on acquisitions in formulation, contract manufacturing and digital retail capability.
Competitive landscape — strategic read on core players
-
PARA'KITO (France; with notable U.S. operations): Positioned as a family-oriented brand, PARA'KITO leverages an approachable product design and claims that balance everyday usability with risk/benefit messaging for sensitive groups. Their strength lies in consumer-facing packaging and cross-border brand recognition; the primary strategic imperative is to convert awareness into repeatability via proven efficacy claims and stronger clinical positioning for pregnant users.
-
Sawyer Products (United States): Known for Picaridin and DEET portfolios, Sawyer occupies a performance-first niche with explicit safety communication targeted at pregnant women. Their technical credibility is a competitive advantage; success for Sawyer in 2026 will depend on scaling consumer messaging and building trust in mainstream retail channels beyond outdoor-enthusiast cohorts.
-
SC Johnson — OFF! brand (United States): A legacy mass-market incumbent with wide distribution, OFF! benefits from scale, EPA-registered formulations and a well-known brand name. The strategic challenge is to modernize maternal safety narratives and capture premiumization opportunities without diluting brand equity.
-
Repel (Spectrum Brands, United States): Offers high-concentration DEET products and positions safety guidance prominently. Repel’s opportunities lie in diversifying formulations toward skin-compatible actives and expanding into curated maternity bundles and clinical channels.
-
MURO (South Korea): A regional innovator combining icaridin (picaridin) with skin-care additives like sodium hyaluronic acid. MURO exemplifies the new-product archetype that fuses efficacy with dermal comfort—an increasingly important differentiator for pregnant consumers and caregivers.
Overall market concentration is moderate: the top three and top five players capture material shares, but the field remains contestable for differentiated products and channel specialists. The CR3 and CR5 metrics in the report quantify this dynamic and underpin tactical recommendations for both incumbents and new entrants.
Regulatory and safety dynamics — practical implications
-
Authoritative guidance now frames the market: EPA-registered repellents with certain actives are deemed safe and effective for pregnant women when used according to label instructions. This removes ambiguity and enables evidence-based product positioning.
-
DEET (up to commonly registered concentrations) retains a strong efficacy and safety profile in peer-reviewed literature; however, perception risks around "chemical" ingredients persist among some consumer segments—requiring clear, science-backed communication.
-
Labeling, clinical support and health-professional outreach will be decisive. Compliance teams should prioritize harmonized labeling, pregnancy-safety FAQs, and targeted clinician engagement programs to convert institutional endorsement into retail traction.
Formulation and product trends to watch in 2026
-
Hybrid formulations that pair proven repellents (picaridin, low-concentration DEET, IR3535) with humectants and gentle skin conditioners are achieving higher acceptance among pregnant consumers and those with sensitive skin.
-
Manufacturers will increasingly invest in clinical comfort studies (dermal tolerance, pregnancy-specific safety substantiation) to support premium pricing and to enable pharmacy and prenatal-clinic distribution partnerships.
-
Natural or "citronella-only" claims remain attractive for a subset of buyers but carry efficacy trade-offs; strategic players will focus on bundling education with products rather than relying on natural positioning alone.
Commercial playbook: prioritized actions for 2026
-
Product: Release a maternity-tier SKU set with clear, evidence-backed safety claims and skin-care benefits; validate with small-scale clinical or tolerability studies to support clinician endorsements.
-
Channel: Pilot subscription and prenatal-bundle offers via digital channels while deepening presence in pharmacy and obstetric clinic networks through professional education and sampling.
-
Marketing & Communication: Lead with authoritative guidance (CDC/EPA) in consumer-facing content, employ testimonial evidence, and invest in targeted educational campaigns to reduce perceived chemical risk.
-
Supply & Risk: Secure multi-source supply for key actives, prioritize contract manufacturing relationships that meet regulatory audit standards, and institute raw-material price-hedging where appropriate.
-
M&A: Look for bolt-on assets that bring formulation IP, clinical data, digital-direct-to-consumer capabilities, or regional distribution strength that accelerates market access.
How PW Consulting can help
For leadership teams evaluating product launches, portfolio prioritization or deal activity in 2026, PW Consulting offers implementation-focused advisory: tailored market-entry roadmaps, acquisition screening and diligence support, pricing-architecture models, and clinician-outreach playbooks derived from our proprietary consumer cluster data and forecast scenarios.
Next steps — where to find the full intelligence
This press summary is designed as a strategic preview. The full PW Consulting Worldwide Mosquito Repellent Water For Pregnant Women Market report contains the complete forecasting model, segmented demand curves, regional and channel tables, competitor scorecards, and downloadable Excel workbooks that underpin the conclusions summarized above. For access to the complete dataset, proprietary segmentation, and bespoke advisory engagements for 2026 planning, please consult the report landing page and contact PW Consulting for an executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Mosquito Repellent Water For Pregnant Women Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects 6.94% CAGR as Global Child-Resistant Blister Lidding Film Market Expands Through 2032
By PW Consulting, 2026-07-15
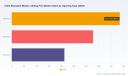
Worldwide Child Resistant Blister Lidding Film Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market study on the Worldwide Child Resistant Blister Lidding Film Market provides a forward-looking, actionable briefing for executives planning strategic moves in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecasting horizon, the report quantifies an established global market that expands at a steady compound annual growth rate (CAGR) of 6.94%. Our baseline analysis pegs the market at approximately USD 975 million in 2025 with a projected rise to roughly USD 1,559 million by 2032. Beyond headline figures, the research synthesizes regulatory shocks, raw-material dynamics, supplier concentration, and innovation vectors that will define competitive advantage over the next planning cycle.
Worldwide Child Resistant Blister Lidding Film Market
Why this matters for 2026 strategy
Child-resistant blister lidding films sit at an intersection of healthcare safety, regulatory compliance, sustainability mandates, and material science. For corporate strategists, procurement heads, R&D leaders and M&A teams, the market offers three immediate strategic inflection points in 2026:
Worldwide Child Resistant Blister Lidding Film Market
- Regulatory-driven product spec escalation — CPSC and European standards continue to tighten performance and usability constraints, forcing redesigns that affect cost, bill-of-materials and supplier qualification time.
- Supply-side cost pressure and recycling mandates — aluminum remains a critical raw input and its price dynamics, together with recycled-content rules, materially affect life-cycle cost and product architecture choices.
- Consolidation and capability concentration — the market reveals a mid-level concentration where a handful of players account for a disproportionate share of specialized capability, creating both partnership and competitive risk for new entrants.
Core market dynamics shaping 2026 decisions
Four forces will dominate boardroom conversations next year:
Worldwide Child Resistant Blister Lidding Film Market
- Regulatory compliance as a product requirement, not a checkbox. North American and European child-resistance protocols (including CPSC Protocol 1700.20 and EN 14375) collectively raise the bar for both child-test failure rates and adult usability durability. Compliance timelines and repeat-certification cycles are shortening, driving demand for pre-validated film systems and contract test services.
- Materials and cost volatility. Primary lidding constructions continue to rely on thin-gauge aluminum foil laminated to polymers. Aluminum pricing remains a material lever — our reference datasets show recent market pricing pressure that must be modeled explicitly in procurement and product-cost scenarios. Packaging tax regimes and recycled-content mandates in key jurisdictions further complicate cost-to-serve calculations.
- Sustainability and regulation converge. Extended producer responsibility (EPR) and packaging waste directives are pushing customers to request recyclable or mono-material solutions. Manufacturers that can demonstrate viable, certified recyclable constructions will gain access to procurement panels and tenders where environmental criteria are weighted heavily.
- Supplier concentration and capability clusters. The market displays moderate concentration: the top three suppliers capture a meaningful share of specialty capability while the top five increase that footprint substantially. This creates a supplier landscape where strategic partnerships, dual-sourcing and qualification speed are material competitive levers.
Competitive landscape — who matters and why
Our competitive assessment highlights several global and regional players who set technical, commercial and compliance benchmarks. PW Consulting’s report profiles each firm with a focus on capability, strategic intent, and tactical implications for customers and competitors:
- Amcor plc (Melbourne). A leader in compliant child-resistant lidding films, Amcor’s development of recyclable child-resistant solutions positions it well with sustainability-focused pharmaceutical customers. Expect them to leverage scale in commercialization and regulatory documentation to win larger tenders.
- Constantia Flexibles (Vienna). Constantia’s strength in high-barrier aluminum lidding foils and multi-layer constructions makes them a go-to for high-spec Rx blister programs. Their visibility at major trade shows signals continued investment in product portfolio and market positioning.
- Tekni-Plex (Wayne, PA). Tekni-Plex’s thermoformable solutions and documented compliance work for senior-friendly and CPSC protocols make them attractive for customers prioritizing usability alongside child safety. Continued certification updates indicate a focus on regulatory alignment as a selling point.
- Winpak Ltd. (Winnipeg) and Sonoco Products Co. (Hartsville). Both companies emphasize high puncture resistance and integrated barrier films, serving medical and pharmaceutical segments where durability and shelf life are paramount.
- Alpine Packaging, ProAmpac, Hood Packaging. These regional and specialty suppliers differentiate on customization, sustainable laminates and patented peel/reseal or peel-push mechanics, offering customers tailored solutions for OTC and Rx portfolios.
Recent corporate events — from product launches of recyclable CR lidding films to trade-show demonstrations and certification milestones — confirm that incumbents are executing both incremental innovation and market signaling strategies that materially affect procurement timelines and qualification hurdles.
What PW Consulting’s report provides — practical, not academic
This is not a product catalogue. The report is structured to be used by decision-makers on the move. Key operational deliverables include:
- Forward-looking scenario models calibrated to 2020–2025 history and stress-tested through 2032, enabling CFOs to model capex, COGS and margin impact under multiple aluminum-price and regulatory regimes.
- A supplier risk-and-opportunity matrix that scores vendors on technical capability, regulatory documentation, sustainability roadmap and commercial flexibility to inform dual-sourcing and preferred-supplier strategies.
- Practical procurement playbooks for rapid supplier qualification, including test-bench templates for verifying CPSC and EN compliance and recommended timelines for sample-to-qualification cycles.
- R&D and packaging-engineering roadmaps that prioritize material substitution, recyclability pathways and adult-usability optimization to reduce rework and reduce recall risk.
- M&A and partnership decision frameworks that identify where bolt-on acquisitions versus strategic alliances deliver the fastest route to capability ownership.
Regulatory and cost levers — what you must model now
Our analysis underscores two modeling imperatives for 2026 planning cycles:
- Simulate regulatory-compliance cost trajectories. CPSC Protocol 1700.20 and EN 14375 impose both child-safety thresholds and adult-usability durability tests; design changes to meet those thresholds often carry material cost and cycle-time implications that procurement must forecast into multi-year contracts.
- Incorporate packaging taxation and recycled-content mandates into product cost and portfolio rationalization. Regional tax instruments — for example, penalties for low recycled content in plastic packaging — and 2030 recycled-content milestones materially change the attractiveness of polymer-rich constructions. These should be embedded in TCO models rather than treated as peripheral risks.
Actionable recommendations for 2026 (short list)
- Prioritize supplier pre-qualification now. Shortlist suppliers that offer pre-validated CPSC/EN compliant constructions and request accelerated qualification programs tied to contract pricing.
- Run material-substitution pilots with explicit tax and recycling constraints. Select two test SKUs to re-engineer for recyclable mono-materials or reduced polymer content and track cost, yield and certification timelines.
- Negotiate flexible pricing clauses linked to primary raw-material indices. Given aluminum price volatility, include indexation or shared-cost mechanisms to avoid margin erosion during price spikes.
- Design procurement scorecards that value regulatory documentation speed and sustainability roadmaps. Do not chase lowest initial price at the expense of time-to-market and compliance burden.
- Assess M&A targets for complementary technical patents and test-facility ownership. Small acquisitions that reduce qualification time can produce outsized returns during product rollouts.
Methodology, data integrity and market concentration
PW Consulting’s study consolidates primary interviews with packaging engineers and procurement heads, supplier financials, trade-show intelligence, regulatory standards, and commodity-price inputs. The market exhibits measurable concentration: the top three suppliers command a meaningful portion of specialized capability, and the top five increase that footprint considerably. This concentration pattern should inform deal diligence, contingency sourcing and commercial negotiation strategies.
What we intentionally omit here — and why
In keeping with a “trailer” approach, this briefing purposefully demonstrates analytical depth while withholding certain granular segment-level figures and region-by-region application breakdowns. Those specifics are embedded in our full report and model sets to ensure licensed access control and to support confidential use by client teams. Executives who need the detailed segmentation, supplier scoring matrices, unit-cost build-ups and downloadable scenario models will find them in the complete PW Consulting report.
Next steps — how to use this intelligence in Q1 2026
For immediate action in the first quarter of 2026, we recommend three parallel tracks: (1) run a two-SKU pilot to test recyclable constructions and new supplier engagement; (2) update procurement contracts to include commodity-indexation clauses; and (3) initiate a short-list and RFP process focused on suppliers with documented CPSC and EN compliance pathways. These steps convert market insight into defensible commercial action.
Access the full analysis
PW Consulting’s full Worldwide Child Resistant Blister Lidding Film Market report contains the complete datasets, downloadable financial models, supplier profiles and compliance playbooks needed to move from insight to execution. For licensing and access details, or to commission a tailored executive briefing that maps the findings to your product portfolio, please visit our publication page or contact our industry practice team.
For detailed analysis of this topic, please visit the official page: Worldwide Child Resistant Blister Lidding Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Turbocharger Bearing Market Poised to Reach USD 3,075.89 Million by 2032 at 5.25% CAGR — Asia Pacific Leads with USD 860 Million
By PW Consulting, 2026-07-15
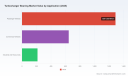
Worldwide Turbocharger Bearing Market: Strategic Imperatives for 2026 Decision-Makers
PW Consulting today publishes an industry-grade briefing accompanying our full market research on the Worldwide Turbocharger Bearing Market. Built on a 2025 base, five-year historical review (2020–2025) and a robust forecast horizon (2026–2032), the report translates technical and commercial complexity into decision-ready intelligence. At a macro level, the market has shown steady expansion—from approximately USD 1,940 Million in 2023 to USD 2,150 Million in 2025—and our modelling points to continued growth through the forecast period, reaching an estimated USD 3,075.89 Million by 2032 at a compound annual growth rate (CAGR) of 5.25% (2026–2032).
Worldwide Turbocharger Bearing Market
Why this market matters in 2026
The turbocharger bearing market sits at the intersection of several disruptive forces that will shape supplier economics and OEM product strategies in 2026 and beyond. Stricter emissions regulations (notably Euro 7 and EPA Phase 3 heavy-duty standards) are accelerating demand for higher-efficiency turbocharging systems, which in turn raises the technical bar for bearings—lower friction, higher-speed stability, and improved thermal performance. At the same time, raw material volatility—illustrated by recent price pressure on high-strength alloy steels and copper—has increased cost-side uncertainty for bearing manufacturers and their tiered suppliers. Geopolitical trade measures and tariff dynamics compound these pressures, incentivizing localization and supply-chain redesign.
Worldwide Turbocharger Bearing Market
For executives, these dynamics mean that bearing portfolio decisions are no longer purely engineering choices: they are strategic levers that influence vehicle fuel-efficiency compliance, supplier footprints, and aftermarket positioning. The PW Consulting report quantifies these dynamics, translates them into scenario-tested forecasts, and offers practical pathways for capture and defense of margin.
Worldwide Turbocharger Bearing Market
What the report delivers: practical, actionable intelligence
-
Proprietary market model (USD, Million) with historical baselines (2020–2025) and a granular forecast (2026–2032), including sensitivity runs tied to raw material and regulatory scenarios.
-
Technology-pathway assessments that compare journal, ball, roller, foil/air and hybrid ceramic solutions across performance, cost, and manufacturability dimensions.
-
Supply-chain stress-testing templates that model tariff, freight, and input-price shocks, and recommend mitigation levers (inventory strategy, dual-sourcing, regionalization).
-
OEM-supplier engagement playbooks for embedding bearing technology into turbocharger qualification cycles and aftermarket rollouts.
-
Commercial playbooks for pricing, margin defense, and aftermarket monetization—focused on converting engineering improvements into realized revenue.
-
An M&A and partnership decision framework tailored to the market’s competitive profile and technology roadmaps.
To preserve the strategic value of the research, this overview intentionally omits the detailed segment-level tables, regional splits, and company-level shares that appear in the full report. Those datasets are available on the source page and are the primary reason many clients use the full deliverable as the foundation for 12–36 month investment planning.
Competitive landscape: established incumbents and focused specialists
The sector is characterized by a mix of global bearing conglomerates and niche specialists that own unique technology platforms. Market concentration is meaningful but not insurmountable—our concentration metrics show a moderately consolidated structure, with the top three firms holding a significant share and the top five consolidating an even larger portion of the market. This structure creates a dynamic where scale confers advantages in global OEM contracts and platform-level design wins, while smaller specialists compete on high-differentiation technologies and service intimacy.
-
Schaeffler Group (Herzogenaurach, Germany): A leader in journal and foil air bearings, with active demonstration of next-generation foil bearings for electric turbochargers. Schaeffler’s approach pairs bearing innovation with system-level integration—an important trend as OEMs seek tightly-coupled turbocharger solutions.
-
SKF AB (Gothenburg, Sweden): Known for hybrid ceramic and air foil bearings optimized for high-speed operations. SKF’s recent product introductions emphasize extended durability for heavy-duty applications, signaling a push to capture efficiency-driven retrofit and OEM programmes.
-
NTN Corporation (Nara, Japan): A mass-market specialist producing a wide range of rolling element solutions, with a focus on low-friction designs for downsized turbochargers. NTN’s exhibition activity underlines its effort to remain visible where passenger-vehicle volumes still matter.
-
NSK Ltd. (Tokyo, Japan): Focused on high-temperature angular contact ball bearings that address shaft stability and durability at the upper extremes of turbocharger operating envelopes.
-
The Timken Company (North Canton, Ohio, USA): Brings expertise in tapered roller and super-precision bearings for industrial and automotive turbochargers where load capacity and precision are differentiators.
-
RBC Bearings Incorporated (Plainview, New York, USA): A specialist in foil air bearings and thrust bearings, with customer footprints in aerospace and high-performance automotive segments.
-
JTEKT Corporation (Osaka, Japan): Produces Koyo-branded needle roller and ball bearings tailored to turbocharger demands—an important player in Asian OEM supply chains.
-
Waukesha Bearings Corporation (Waukesha, Wisconsin, USA): Supplies hydrodynamic journal and tilt-pad bearings for power generation and marine turbocharger uses—illustrating the cross-industry demand drivers for bearing technologies.
Recent corporate moves—such as Schaeffler’s demonstration of foil bearings at IAA Mobility and SKF’s introduction of higher-durability hybrid bearings—underscore two strategic directions: (1) performance-driven innovation for regulatory and downsizing imperatives; and (2) product lifecycle plays targeting heavy-duty and aftermarket segments where retrofit demand can accelerate adoption.
Market dynamics that will shape supplier strategies
-
Regulatory acceleration: Euro 7 and EPA Phase 3 create deterministic demand for higher-efficiency turbocharger subsystems; bearings that reduce parasitic loss will be required inputs to compliance strategies.
-
Raw material pressure: Price shocks in high-strength steels and copper alloys increase bill-of-material volatility and favor suppliers with integrated sourcing or hedging capabilities.
-
Geopolitical and trade friction: Tariff differentials have pushed companies to reconsider centralized manufacturing models in favor of regional footprints and near-shore sourcing.
-
Technology bifurcation: The market will bifurcate between high-volume rolling-element solutions optimized for cost and specialized air/foil or ceramic systems optimized for performance and thermal tolerance.
-
Aftermarket opportunity: As fleets pursue emissions compliance, a sizeable upgrade and retrofit window opens for differentiated bearing solutions—an attractive route to margin extension for manufacturers and distributors.
Priority actions for 2026 planning
-
Align R&D roadmaps to emissions timelines: Tie bearing development milestones directly to OEM Euro 7 and EPA Phase 3 qualification calendars to maximize timing of design wins.
-
Pursue technology partnerships: Short-term partnerships with ceramics and foil suppliers can accelerate entry into high-performance niches without the full capital intensity of in-house development.
-
Stress-test supply chains: Deploy PW Consulting’s supply-chain stress-testing templates to understand margin sensitivity under raw-material and tariff scenarios, and implement prioritized hedging or dual-sourcing actions.
-
Localize selectively: Where tariff or logistics dynamics materially increase landed cost, consider localized production cells to preserve competitiveness for regional OEMs.
-
Leverage aftermarket pathways: Build retrofit kits and service programs that convert regulatory-driven engine upgrades into recurring revenue streams.
-
Consider targeted consolidation: Given market concentration and technology economies, selective M&A can accelerate access to specialized platforms and established OEM relationships.
Concluding perspective and next step
For executives preparing budgets and capital plans in 2026, turbocharger bearing decisions will be strategic inflection points that influence product compliance, supply-chain resilience, and EBITDA trajectories. The market’s steady growth—anchored by a 5.25% CAGR across the forecast window—creates both opportunities and risks that are highly contingent on technology choices and sourcing strategies. PW Consulting’s full report delivers the segment-level detail, company benchmarking, and scenario models that operational leaders and corporate strategists need to convert these market signals into concrete decisions.
Access to the full dataset—including detailed regional and application splits, company-level positioning, and downloadable model files—is available through PW Consulting’s report portal. The release is designed as a hands-on toolkit for 2026 planning: deep enough to build investment cases, and practical enough to guide execution.
For detailed analysis of this topic, please visit the official page: Worldwide Turbocharger Bearing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Optoelectronic Safety Laser Scanner Market Set to Climb from USD 585.5 Million in 2025 to USD 949.45 Million by 2032, Growing at a 7.15% CAGR
By PW Consulting, 2026-07-15
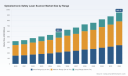
Worldwide Optoelectronic Safety Laser Scanner Market — Strategic Preview for 2026 Decision‑Makers
PW Consulting’s newest market research brief on the Worldwide Optoelectronic Safety Laser Scanner Market uses 2025 as its base year and offers a comprehensive forecast through 2032. At the macro level the market is sizable and expanding steadily — the industry reached approximately USD 585.5 Million in 2025 and, on the trajectory defined in our model, grows at a compound annual growth rate of 7.15% to approach roughly USD 949.5 Million by 2032. These headline metrics frame a marketplace that is mature in its safety foundations yet dynamic in technology, supply‑chain risk and competitive repositioning — making 2026 a pivotal year for procurement, product strategy and M&A.
Worldwide Optoelectronic Safety Laser Scanner Market
Why this report matters for 2026 strategic choices
-
Actionable timing: 2026 is where long‑lead upstream constraints (semiconductor wafer supply, substrate lead times) intersect with accelerating demand for 3D perception and outdoor‑grade solutions. Executives who act this year convert constrained supply into competitive advantage.
Worldwide Optoelectronic Safety Laser Scanner Market -
Regulatory inflection: Revisions to positioning and safety‑distance guidance (notably EN ISO 13855:2024) and ongoing certification expectations around IEC and ISO safety frameworks are increasing integration complexity — not just for sensors but for system validation, documentation and liability management.
Worldwide Optoelectronic Safety Laser Scanner Market -
Competitive consolidation and product differentiation: Market concentration is meaningful — the top three suppliers capture a majority share and the top five command roughly three‑quarters of the market — creating both barriers and predictable partnership pathways for new entrants and niche specialists.
Key strategic implications from our analysis
-
Supply‑chain resilience is now a strategic priority. Export controls, export policy shifts and extended lead times for GaAs/Germanium substrates have materially increased volatility in laser‑diode availability and pricing. Organizations must map GaAs exposure, assess alternative wavelength strategies, and secure multi‑tier suppliers or buffered inventory where economics justify.
-
Technology bifurcation: 2D safety laser scanners continue to be the backbone for many stationary and mobile safety applications, but the emergence of certified 3D perception units — including new outdoor‑capable LiDARs with safety certification — is re‑shaping solution architectures. Buyers must evaluate not only sensor performance but verification workflows, software stacks and integration costs.
-
Standards and certification complexity increases total cost of ownership. Newer 3D products are being certified at different performance levels, and standards updates introduce nuanced placement and distance calculation obligations that impact installation time, documentation and retrofit viability.
-
Concentration creates strategic leverage for both suppliers and customers. Large vendors can scale validation labs, bundle safety controllers and offer networked diagnostics; smaller vendors compete on form‑factor, rapid customization and price. For acquirers, the CR3/CR5 dynamics sharpen targets for consolidation and bolt‑on capability acquisition.
-
Channel and systems integration matter more than ever. Products are only part of the value chain: network protocols (PROFINET, EtherNet/IP/CIP Safety, PROFIsafe), embedded cameras, on‑device diagnostics and simplified commissioning decide winners in real deployments.
Competitive landscape — what to watch among leading vendors
-
SICK AG: A clear technology leader with breadth across 2D safety scanners and an aggressive move into certified 3D LiDAR for outdoor/mobile applications. Their multiScan100‑S demonstrates how premium vendors are leveraging multi‑echo returns, higher ingress protection and safety certification to address cranes, AGVs and mixed indoor/outdoor fleets.
-
Leuze electronic: Focused on compact form factors and tight‑space integration; recent product launches emphasize the design tradeoff between footprint and protective field, making them a go‑to for AGVs and constrained machine environments.
-
Pilz: Strengthening network integration and application tooling (e.g., Profinet support, updated safety calculators aligned to EN ISO 13855:2024) — positioning Pilz as a practical choice for customers prioritizing standards alignment and ease of commissioning.
-
Keyence and OMRON: Both push higher detection ranges, integrated sensing (cameras, diagnostics) and strong global service footprints. Their strategy centers on system‑level differentiation — integrated safety networking and robust field performance.
-
North American and niche players (Banner, Rockwell/Allen‑Bradley): Emphasize ecosystem integration and enterprise network compatibility, appealing to OEMs and system integrators embedded in large automation stacks.
-
European and Italian specialists (Pepperl+Fuchs, Reer, Datasensing, Fiessler, Turck): Compete on application‑specific robustness, certification support and regional service models, often forming the backbone for OEM machine safety offers.
-
Japanese suppliers (Hokuyo, IDEC): Known for compact, reliable devices with specific strengths in mobile and industrial machine applications.
Report contents — what PW Consulting delivers (practical and tactical)
-
Proprietary market model with historical reconstruction (2020–2025) and scenario‑based forecasts (2026–2032) that isolate demand vectors by form factor, end‑use archetype and deployment topology.
-
Supply‑chain stress tests that quantify exposure to GaAs/Germanium constraints, alternative sourcing timelines, and supplier concentration impacts under multiple geopolitical scenarios.
-
Vendor benchmarking and a commercial scorecard covering product breadth, certification status, integration capabilities, service footprint and go‑to‑market velocity.
-
Standards impact assessment — mapping steps required to remain compliant with ISO/IEC and revised EN guidance, and a practical checklist for installers and OEMs to reduce audit risk.
-
Product selection playbooks for different buyer personas (OEMs, end users, integrators, fleet operators) including deployment templates, TCO calculators and risk‑adjusted procurement strategies.
-
M&A and partnership intelligence: prioritized target lists by capability gap, acquisition defensibility, and integration effort (technical and commercial).
-
Commercial negotiation guidance: contract structures, recommended clause language for long‑lead items, and hedging approaches for raw material price volatility.
Concrete recommendations for 2026
-
Immediate (0–6 months) — Operationalize supply‑chain visibility: perform a supplier exposure audit for GaAs and compound semiconductor wafers, begin dual‑sourcing critical laser diode families, and renegotiate key‑component lead‑time SLAs with price/volume collars.
-
Short to medium term (6–18 months) — Run technology pilots: validate a small fleet or cell with 3D safety LiDAR where environmental conditions require it, and compare lifecycle integration effort and verification costs versus upgraded 2D systems. Use pilot outcomes to inform a three‑year procurement roadmap.
-
Strategic (18–36 months) — Align product roadmaps and M&A: for incumbents, prioritize investments in networked diagnostics and certification labs; for investors, focus on targets that plug perceptual gaps (3D safety, outdoor IP‑rated sensors) and offer defensible installation ecosystems.
-
Cross‑cutting — Compliance first: require suppliers to demonstrate compliance mapping to IEC 61496, ISO 13849 and relevant EN updates, and insist on documented installation‑level safety calculations as a condition of acceptance.
How PW Consulting’s report accelerates your 2026 moves
-
Decision‑ready intelligence: our models convert macro forecasts into procurement volumes, supplier concentration metrics and scenario outcomes you can use directly in board‑level CapEx discussions.
-
Implementation templates: from safety‑distance calculation checklists to supplier negotiation playbooks and integration acceptance test scripts — the deliverables reduce time from decision to deployed outcome.
-
Independent vendor scorecards and risk maps: reduce vendor selection risk and speed RFP design with our validated comparative framework.
-
Advisory support: clients can commission targeted deep dives (e.g., GaAs supply contingency planning, certification readiness audits, or acquisition due diligence) based on the report’s findings.
PW Consulting’s briefing is intentionally a “trailer” — it provides the strategic thesis, validated forecasts and the operational levers that executives need to act this year while preserving the granular segmentation, vendor scorecards and contract‑level insights for the full report. If your 2026 plan depends on securing perception hardware, managing certification risk, or using sensor strategy as a competitive moat, this is the intelligence foundation you should build from.
Access the full Worldwide Optoelectronic Safety Laser Scanner Market report for detailed tables, vendor scorecards, scenario models and implementation playbooks — or contact PW Consulting for a tailored workshop to convert the findings into an executable 12–36 month roadmap.
For detailed analysis of this topic, please visit the official page: Worldwide Optoelectronic Safety Laser Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Condensation Cure Silicone Rubber Market to Reach USD 3,132.81 Million by 2032, Driven by 4.82% CAGR
By PW Consulting, 2026-07-15
Worldwide Condensation Cure Silicone Rubber Market: Strategic Outlook for 2026
Executive summary
PW Consulting’s latest Worldwide Condensation Cure Silicone Rubber Market report (base year 2025) delivers a decision-grade synthesis for executives planning resource allocation, product roadmaps, procurement, and M&A activity in 2026. The market—measured in USD Million—shows steady recovery and expansion after cyclical pressures, with a compound annual growth rate (CAGR) of 4.82% across our 2026–2032 forecast window. By 2032 the market is projected to exceed the three‑billion USD mark, underscoring durable demand across mold making, construction, electronics potting, and general industrial maintenance applications.
Worldwide Condensation Cure Silicone Rubber Market
Why this report matters for 2026 corporate strategy
-
Timing for capex and manufacturing footprint decisions: With material cost volatility and regional regulatory shifts intensifying in 2025, 2026 will be the year to decide whether to localize production, hedge supply, or consolidate formulating operations. Our report quantifies the trade-offs between localized supply chains and centralized scale for condensation-cure systems.
Worldwide Condensation Cure Silicone Rubber Market -
Product portfolio prioritization: Condensation (tin-cured) systems remain preferred for many mold making and certain architectural uses due to formulary flexibility and cost profile. The report maps where technical differentiation (e.g., rapid cure grades, high‑tear formulations, tailored thixotropy) can command premium positioning versus cost-leader offerings.
Worldwide Condensation Cure Silicone Rubber Market -
M&A and partnership scouting: The market’s moderate concentration—three-leading-firm share and five-leading-firm share metrics demonstrate available room for bolt-on consolidation—creates windows for vertical integration (raw material capture) and horizontal scale (geographic expansion). Our competitive intelligence flags targets with complementary IP, channel access, or regional manufacturing capability.
-
Procurement and risk mitigation: Raw-material pressures and regulation in supply hubs are already reshaping cost structures; procurement strategies built on multi‑sourcing, formula adaptation, and selective inventory buffering will materially reduce margin erosion in 2026.
Market sizing and near-term trajectory
Using 2025 as the base year, our model synthesizes historic performance (2020–2025) and overlays demand drivers, raw-material cost trends, and regulatory scenarios to produce a 2026–2032 forecast. The market expands at a mid-single-digit CAGR (4.82%), propelled by steady replacement and aftermarket demand in tooling and construction sealant segments, and gradual adoption in specialty electronics potting where thermal and dielectric stability are prioritized.
Dynamics shaping 2026 decisions
-
Raw-material cost inflation: Feedstock constraints and price movements in organosilicon monomers and cyclic siloxanes have materially raised input costs during 2024–2025. Notably, D4 prices rose sharply in 2025—this single factor has amplified manufacturing cost sensitivity across condensation cure producers and favors formulary optimization that reduces volatile intermediate usage.
-
Regulatory and environmental pressure: Stricter environmental policies in key production geographies have increased compliance and capital expenditure needs. Firms with diversified, lower‑emission production processes or earlier investments in waste-stream management will face fewer regulatory headwinds in 2026.
-
End‑market mix resilience: Traditional mold-making and construction-related uses provide a predictable demand base, while growing specialty applications (e.g., high‑temperature stable grades, custom potting compounds) offer margin expansion. The report parses these demand profiles and highlights where product R&D should focus to capture higher-value niches.
-
Price realization vs. volume trade-offs: Manufacturers will confront choices between preserving volume through competitive pricing and protecting margin by shifting sales toward performance-differentiated formulations. Our scenario analyses clarify breakeven points for both strategies under different cost-pass‑through assumptions.
Competitive landscape: what the leading players reveal about strategy
The condensation cure silicone rubber space exhibits a moderate level of concentration. The top three players account for a meaningful share of the market, and the top five firms increase that share further—this structure produces both stability and opportunity. Below we outline the strategic positions of the core firms covered in our report and the implications for competitors and customers.
-
Smooth‑On, Inc. (Macungie, PA, USA) — Known for a diverse Mold Max and OOMOO portfolio, Smooth‑On’s strength lies in product breadth and well‑established channels into hobbyist, prototyping, and small‑batch industrial customers. Strategy implication: focus on channel depth, service offerings (formulation support), and brand-led premiumization.
-
Polytek Development Corp. (USA) — Emphasizes high tear strength and cure reliability for flexible molds. Strategy implication: exploit formulation advantages when cure inhibition tolerance and part fidelity matter, especially in specialty casting processes.
-
Silicones, Inc. (USA) — Longstanding manufacturer of tin-catalyzed RTV‑2 systems with custom formulation capability. Strategy implication: custom contract manufacturing and application engineering will be key defensive levers against commodity pricing pressure.
-
CHT Group (Germany) — Supplies both materials and modification chemistries (catalysts, thixotropes), representing an upstream play. Strategy implication: companies that control modifier chemistry can influence downstream differentiation and pricing.
-
BBN Materials (China) — Competitive on cost and customization for crafts and construction segments. Strategy implication: low‑cost regional players will continue to pressure prices in volume‑driven segments unless premium technical propositions are emphasized.
-
Silpak, Inc.; Elkem Silicones; Shin‑Etsu; Momentive — Each brings a mix of global reach, specialized grades (rapid cure, high‑thermal stability), and scale. Strategy implication: incumbents with global logistics, IP in high‑performance grades, or access to feedstocks are positioned to win in higher‑margin engineering applications.
Strategic recommendations for executive teams in 2026
-
Rebalance product portfolios: Shift emphasis toward higher‑value, differentiated grades (rapid cure, high‑thermal stability, low‑shrink) where competition from commodity suppliers is weakest.
-
Secure feedstock diversity: Prioritize contracts or partnerships that mitigate single‑source exposure to D4 and other cyclic siloxane volatility; consider captive intermediate production where scale economics make sense.
-
Invest selectively in compliance and sustainability: Allocate capital to emissions control and waste reduction in regions tightening environmental rules—this preserves operating continuity and can be a marketable advantage to buyers with ESG mandates.
-
Use M&A for capability gaps: Target small- to mid‑sized firms with complementary formulations, application know‑how, or regional routes to market rather than large bolt‑on capacity that adds commodity exposure.
-
Enhance application engineering: Bolster customer-facing technical services to translate raw formulation advantages into faster adoption and premium pricing—especially for industrial, electronics potting, and specialized tooling customers.
What’s inside the PW Consulting report (practical components)
Our report is designed as an operational playbook for 2026. Key inclusions:
-
Market sizing and multi-scenario forecasts (2026–2032) with sensitivity to raw‑material costs and regulatory scenarios.
-
Demand-driver analysis by application families and decision frameworks for portfolio allocation (without disclosing proprietary sub-segment revenue shares in this summary).
-
Detailed competitive profiles and capability matrices of leading vendors with strategic positioning maps.
-
Supply‑chain heatmaps and procurement playbooks that link feedstock movements (including D4) to landed cost modeling.
-
Advisory-ready M&A screen and value creation blueprints for integration or partnership scenarios.
-
Regulatory and environmental risk assessment with mitigation pathways and compliance cost estimates.
How to use this intelligence in Q1–Q2 2026
Use the report to shape board-level decisions in Q1 2026—specifically for capital allocation, procurement contracts, and R&D prioritization. The scenarios and breakeven analyses allow rapid assessment of whether to: (a) normalize prices to protect share; (b) push into differentiated, higher-margin grades; or (c) pursue targeted acquisitions to close capability gaps. Each path has distinct implications for working capital, customer retention, and margin resilience.
Closing: converting insight into competitive advantage
Condensation cure silicone rubber continues to be a backbone material for tooling, construction, and selected specialty industrial uses. The 2026 inflection point will be defined less by end‑market growth alone and more by how companies manage feedstock volatility, regulatory shifts, and product differentiation. PW Consulting’s report packages quantitative forecasts, tactical playbooks, and competitive maps into an executable platform for senior leaders who need to make consequential choices in 2026.
Access the full report
This press release intentionally omits granular segment figures and regional/application-specific revenue breakdowns to preserve the value of the full diagnostic. For the complete dataset, interactive models, and the downloadable advisory playbook, please visit the PW Consulting report page and request the Worldwide Condensation Cure Silicone Rubber Market report for 2026 strategic planning.
For detailed analysis of this topic, please visit the official page: Worldwide Condensation Cure Silicone Rubber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Surgical Tray Market Tops USD 540.2 Million in 2025 as Reusable Trays Drive Demand
By PW Consulting, 2026-07-15
Worldwide Surgical Tray Market — Strategic Preview for 2026 Decisions
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I am pleased to present a strategic preview of our latest Worldwide Surgical Tray Market study. This briefing distills the report’s most consequential, decision-ready insights for executive teams preparing capital allocation, product strategy, and M&A decisions in 2026. The analysis synthesizes five years of historical performance to a 2025 base, then projects the market through 2032 using scenario-ready forecasting and proprietary supplier economics. While this preview showcases the report’s analytical depth, core segmented datapoints and model outputs are intentionally reserved for the full report to preserve the “trailer” experience and drive deeper engagement.
Worldwide Surgical Tray Market
Market at a Glance: Scale, Momentum, and What It Means
-
Trajectory and scale: The surgical tray market exhibited steady expansion through the first half of the decade, reaching a 2025 market size of USD 540.2 Million (revenue unit: Million, base year 2025). Our baseline projection applies a compound annual growth rate (CAGR) of 5.81% over the 2026–2032 forecast window, culminating in a material market uplift by 2032 under the base scenario.
Worldwide Surgical Tray Market -
Growth drivers: Demand dynamics are driven by rising surgical volumes, expansion of ambulatory care delivery models, infection-control imperatives, and the life-cycle replacement cadence for reusable assets. Simultaneously, suppliers face rising expectations around sterilization compatibility, modularity, and procurement transparency.
Worldwide Surgical Tray Market -
Market structure: The market exhibits moderate concentration with leading players capturing significant but not dominant shares (CR3 and CR5 metrics indicate room for both scale-driven competition and targeted consolidation strategies). This structure creates opportunity for disciplined roll-up strategies and for regional challengers to scale via specialized product differentiation.
Why This Report Matters for 2026 Strategy
-
Decision timing: 2026 will be a pivotal year for procurement cycles, capital refresh programs in central sterile processing departments, and contract renegotiations tied to hospital networks’ five-year sourcing plans. Our report maps the timing of these commercial inflection points against demand forecasts to inform optimal entry, exit, or expansion timing.
-
Risk-adjusted investment: We provide scenario-based valuation bridges that quantify upside and downside to unit economics under alternative raw-material and regulatory assumptions. This is critical when stainless-steel and polymer input prices—along with sterilization-compliance investments—can materially affect margin profiles.
-
Regulatory and reimbursement alignment: The study integrates current standards and payer dynamics—such as moist heat sterilization validations (ISO 17665-1), FDA device-class pathways (Class II, 510(k) considerations), and inclusion in CMS DRG payments—to help stakeholders avoid policy-driven revenue surprises.
Report Contents — Practical Tools for Executives
-
Proprietary market model: A calibrated, auditable forecast engine spanning 2020–2032, with scenario toggles for sterilization-capital cycles, reusable vs. disposable adoption curves, and raw-material price shocks.
-
Go-to-market playbooks: Tactical recommendations for suppliers and buyers, including contract structures, total-cost-of-ownership calculators, and adoption roadmaps for modular tray systems and procedure kits.
-
Supplier scorecards and capability maps: Comparative analysis across manufacturing footprint, sterilization compatibility, product modularity, and aftermarket services—designed to support vendor selection and strategic sourcing.
-
Unit economics and pricing ladder: Benchmarks for cost-to-produce by material family and sterilization-method sensitivity, with customizable inputs so procurement teams can model contract-level impacts.
-
M&A & partnership heatmap: Identification of high-probability targets and partnership archetypes (technology accretors, regional distribution platforms, and sterilization service integrators) aligned to multiple return-on-investment horizons.
-
Operational playbook for central sterile processing (CSPD): Best-practice protocols mapped to AAMI ST79 guidance for validated cleaning and bioburden control, with KPIs for throughput and compliance monitoring.
Competitive Landscape: Who Matters and Why
The market’s competitive set combines global scale suppliers, specialty device firms, and distributors with integrated supply-chain services. Key firms profiled in the report include established players that command procurement leverage and innovation partners that influence product design standards:
-
Cardinal Health, Inc.: A global leader in custom sterile procedure trays, with expansive contract coverage across large hospital systems. Cardinal’s scale and integrated supply-chain offer a template for defensive contracting and bundled-service models.
-
Medline Industries, LP: A manufacturer with broad capabilities across reusable stainless-steel and disposable-plastic trays. Medline’s catalog and product modularity illustrate how SKU rationalization and sterilization compatibility drive buyer preference.
-
B. Braun Melsungen AG: A European engineering-centric supplier known for modular stainless-steel systems designed for steam and EO sterilization—demonstrating the premium end of performance-focused trays.
-
Steris plc: Supplier of rigid sterilization containers and the recent Harmony product family highlights how product-led sterilization efficiency can create differentiation for hospital CSPD workflows.
-
Teleflex (Pilling), Integra LifeSciences, Becton Dickinson (BD), Mölnlycke Health Care: Each brings specialized capabilities—from perforated instrument trays and neurosurgical/orthopedic sets to bundled procedure kits and wound-care procedure trays—showing the spectrum of horizontal and vertical specialization in the market.
Recent corporate moves we track include targeted product launches, large system contract awards, and catalog expansions that influence competitive dynamics. These developments underscore a market where vendors compete on service, sterilization compatibility, and supply-chain resiliency as much as on price.
Operational and Regulatory Realities
-
Standards & validation: Compliance with ISO 17665-1 for moist heat sterilization and adherence to AAMI ST79 cleaning-validation guidelines are non-negotiable for market access and for minimizing infection-risk liabilities.
-
Regulatory pathway: The majority of instrument trays fall under Class II device guidance requiring 510(k) notifications in the U.S.—a procedural and timing consideration for new product introductions and design changes.
-
Raw-material sensitivity: Medical-grade 316L stainless steel remains a cost driver—industry data indicates an approximate band for input costs. Suppliers with supply agreements or alternative material strategies will exhibit superior margin resilience under price volatility.
-
Reimbursement context: Inclusion of tray-related costs within DRG payments in certain jurisdictions makes total-cost-of-care negotiation an essential part of provider-supplier conversations.
Strategic Recommendations for 2026
-
For incumbent manufacturers: Double down on sterilization-validated modular platforms and service bundling. Invest in CSPD-focused tools that reduce turnaround time and support lifecycle tracking—these create sticky, defensible revenue streams.
-
For distributors and hospital systems: Move from unit-price procurement to TCO/availability contracts. Require suppliers to demonstrate compliance with ISO 17665-1 and validated cleaning per AAMI ST79 as sourcing prerequisites.
-
For private equity and corporate development teams: Prioritize bolt-on acquisitions that fill capability gaps (e.g., sterilization tech, regional distribution) rather than broad geographic consolidation. The market’s concentration metrics suggest attractive niches for consolidation-driven margin expansion.
-
For new entrants and tech startups: Focus on interoperability—design trays and containers that simplify sterilization workflows, integrate with CSPD inventory systems, and offer measurable throughput improvements backed by clinical validation.
-
Supply-chain resilience: Hedge raw-material exposure through multi-sourcing, long-term purchase agreements, and material-efficiency engineering to protect margins from stainless-steel price swings.
What You Will Gain from the Full Report
-
Access to an interactive model that lets you stress-test scenarios relevant to your business case (pricing, sterilization capital cycles, geographic rollouts).
-
Granular segmentation by material, tray type, end-user, and region—presented with supplier-level exposure and demand elasticity insights (note: these segmented outputs are intentionally not disclosed in this preview).
-
Executable procurement templates, CSPD KPI dashboards, and a prioritized M&A target list with fit / value scoring that executives can act on immediately in 2026.
Final Observations
The surgical tray market presents a balanced mix of steady demand growth and structural change. With a baseline CAGR in the mid-single digits, the market supports both organic and acquisitive growth strategies—provided firms align product capabilities to sterilization and CSPD efficiency demands. For executive teams, 2026 will be a year to convert market visibility into competitive advantage: lock in supplier terms that reflect TCO, invest selectively in sterilization-validated modular platforms, and pursue M&A targets that shore up last-mile distribution or technical differentiation.
PW Consulting’s full Worldwide Surgical Tray Market report is designed as a practical decision-support toolkit for 2026. It contains the segmented datasets, supplier scorecards, scenario models, and operational playbooks needed to move from insight to execution. To access the complete dataset, interactive model, and bespoke advisory options, please visit the report landing page referenced in our release materials.
For detailed analysis of this topic, please visit the official page: Worldwide Surgical Tray Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


