



Category: market research
PW Consulting: Worldwide Retort Cartons Market Poised for Robust Growth — 7.6% CAGR Through 2032
By PW Consulting, 2026-07-15
Worldwide Retort Cartons Market: Strategic Brief for 2026 Decision-Makers
Executive summary
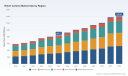
PW Consulting’s latest market study — base year 2025, historical window 2020–2025, and a forecast horizon 2026–2032 — synthesizes commercial, technical and regulatory intelligence that will shape winning strategies in the retort cartons sector. The global market for retort cartons and related high-barrier formats expanded from USD 585.4 Million in 2020 to USD 842.5 Million in 2025 and is projected to grow at a 7.6% CAGR across 2026–2032, reaching approximately USD 1,406.9 Million by 2032. Market concentration is high: the leading three suppliers account for more than four fifths of industry revenue (CR3 ≈ 82.4%), and the top five approach near-total dominance (CR5 ≈ 89.2%).
Worldwide Retort Cartons Market
Why this report matters for 2026 decisions
-
Capital allocation and plant footprint. Companies planning investments in retort-capable filling lines, sterilization capacity, or co-manufacturing relationships need a forward-looking picture of absolute market scale and growth momentum to justify multi-year capex.
Worldwide Retort Cartons Market -
Procurement and raw material risk. Paperboard supply dynamics and pricing volatility, combined with aluminum and polymer markets, make targeted procurement strategies and hedging essential in 2026.
Worldwide Retort Cartons Market -
Product and packaging innovation. Evolving recyclability mandates and Extended Producer Responsibility (EPR) requirements are changing feature trade-offs between mono-material designs, fiber-based cartons, and high-barrier laminated structures.
-
M&A and partner selection. High concentration and differentiated technology roadmaps among incumbents create distinct opportunities for complementary acquisitions, JV models and toll-manufacturing agreements.
Market trajectory and the numbers that matter
Our analysis traces a clear recovery and acceleration pattern: absolute market size rose materially between 2020 and 2025, and our baseline scenario projects continued expansion to roughly USD 925.6 Million in 2026 and onward to USD 1,406.9 Million by 2032. The 7.6% CAGR embeds sector-specific tailwinds (premiumization of shelf-stable meals, pet food demand, and adoption of carton-based alternatives to cans) while accounting for headwinds such as raw material inflation and increasingly stringent recyclability standards.
These headline figures form the backbone for three operational use cases this year: (1) sizing new filling lines and bottlenecks in sterilization throughput; (2) quantifying the commercial upside from launching retort-enabled SKUs in retail and e‑commerce channels; and (3) stress-testing P&L impact from paperboard and polymer cost cycles.
Competitive landscape — who’s setting the pace
The market is dominated by established converters and system providers that combine packaging material know‑how with filling and sterilization systems. Our vendor view profiles strategic positioning, technical differentiators and commercial moves for the principal players:
-
Tetra Pak (Pully, Switzerland) — A pioneer with the Tetra Recart family and filling systems such as the R2 line; emphasizes high fiber content (up to 71% renewable paperboard in certain formats) and offers small-format capabilities tailored to premium pet food and shelf‑stable meals. ( https://www.tetrapak.com)
-
Amcor (Zürich, Switzerland) — Focused on high-barrier solutions across carton and flexible formats; recent product launches signal expansion into small-volume retort bottles and novel low-acid beverage applications. ( https://www.amcor.com)
-
SIG Combibloc (Neuhausen, Switzerland) — Supplies retort-compatible carton systems that emphasize integrated aseptic and retort processing for extended shelf life. ( https://www.sig.biz)
-
Mondi (Weybridge, UK) — Expanding food packaging portfolio with sustainability-aligned solutions and mono-material concepts suitable for retort conditions. ( https://www.mondigroup.com)
-
Huhtamaki (Espoo, Finland) — Develops fiber-based and mono-material retort options aimed at recyclability and thermal resilience. ( https://www.huhtamaki.com)
-
Sonoco Products Company (Hartsville, SC, USA) — Broad retort packaging manufacturing capability, with exposure to both cartons and flexible forms. ( https://www.sonoco.com)
-
ProAmpac (Cincinnati, OH, USA) — Innovates in high-barrier flexible and carton hybrid solutions for ready meals and pet food. ( https://www.proampac.com)
-
Constantia Flexibles (Vienna, Austria) — Specializes in retort laminates and mono-PP solutions targeting heat resistance and recyclability. ( https://www.constantia-flexibles.com)
-
Coveris (Vienna, Austria) — Supplies flexible and rigid retort formats with emphasis on thermal processing robustness. ( https://www.coveris.com)
-
NaturPak Pet (Janesville, WI, USA) — Co-manufacturer using Tetra Pak Recart tech, notable for small-format premium pet food production capacity and localized fill-and-sterilize services. ( https://naturpakpet.com)
Recent strategic moves reinforce the competitive profile above: NaturPak Pet validated volume capability on R2 lines for small‑format premium pet food; Amcor introduced a novel 2oz retort bottle for shelf‑stable beverages; Mondi and Constantia extended portfolios with sustainability-compliant and mono-material retort options. These developments are cataloged and analyzed in the report with implications for customer switching costs, co-manufacturing scale and service models.
Industry dynamics shaping strategy in 2026
-
Regulatory pressure: Extended Producer Responsibility (EPR) programs in multiple U.S. states and EU packaging directives press for higher recycled content and full recyclability targets by 2030. Companies must reconcile barrier performance with recyclability thresholds to avoid compliance costs and loss of access to key retail customers.
-
Raw material volatility: Paperboard and polymer price moves materially affect margin math for carton-based versus flexible retort structures — early 2026 price adjustments announced by major paperboard producers underscore the urgency of supplier risk management and index-linked contracts.
-
Technology trade-offs: Multi-layer structures (including aluminum foil barriers and multiple PP layers) deliver proven retort performance; mono-PP and high-fiber constructions offer sustainability benefits but require validated sterilization protocols and potential changes in line equipment and sealing technologies.
-
Channel shifts: Growth in ready-to-eat and premium pet foods, coupled with e-commerce packaging requirements, is accelerating demand for differentiated pack sizes and formats that balance shelf life, convenience and sustainability claims.
What’s inside the PW Consulting report (operational highlights)
-
Proprietary market-sizing methodology and three forecast scenarios (base, upside, downside) with sensitivity to paperboard and polymer price trajectories.
-
Supply-side mapping and capacity assessment for retort-capable filling systems, co-packers and tooling constraints.
-
Raw material analysis covering pricing drivers, contract structures, and technical implications for barrier design (aluminum foil grades, polymer layer choices and fiber content thresholds).
-
Regulatory audit and compliance roadmap focused on EPR, recyclability targets and recycled-content thresholds relevant to 2026 procurement and design cycles.
-
Commercial playbook: GTM options for brand owners, SKU prioritization framework, launch economics for pet food and ready meals, and retailer acceptance criteria.
-
Competitive benchmarking and vendor scorecards with capability matrices, partnership archetypes and M&A target filters.
-
Scenario-based ROI models and capex calculators for filling-line decisions and retrofits to support retort processes.
Strategic recommendations — what to do in 2026
-
Prioritize dual-track product development: validate at least one mono-material/recyclable retort format while maintaining a high-barrier incumbent SKU for near-term shelf-life certainty.
-
Lock conditional supply agreements with paperboard and film suppliers that include price collars or indexation to mitigate announced cost shocks and maintain predictable gross margins.
-
Assess co-manufacturing and tolling options with providers that already operate retort R2 lines to reduce time-to-market and capital exposure for new SKUs.
-
Embed regulatory scenario planning into NPD timelines: ensure product roadmaps include pathways to meet 2030 recyclability mandates and state-level EPR compliance to avoid late-stage redesigns.
-
Use concentrated vendor market structure to negotiate bundled commercial terms (tooling, service, training, co-marketing) that create switching friction for competitors.
How PW Consulting accelerates your decisions
The report functions as a decision-grade toolkit: it converts headline market trajectories into operational levers, providing the analytics to size investments, choose partners, and quantify regulatory exposure. We combine primary interviews, plant-level inspections and cost modeling to produce executable recommendations — but in keeping with our “trailer” approach, the full segmentation tables, region- and application-level splits, supplier scorecards and downloadable models are available only in the complete report and subscriber portal.
Next steps
If you are evaluating capacity investments, negotiating long-term raw material contracts, planning M&A, or redesigning packaging to meet 2030 recyclability targets, PW Consulting’s Worldwide Retort Cartons Market report provides the actionable inputs you need in 2026. For the complete dataset, granular segment breakdowns, and our vendor scorecards, please consult the full report on our website or contact the PW Consulting research desk for a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Retort Cartons Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Automotive FPC Market Poised to Accelerate at a 16.0% CAGR, Driving Next‑Gen Vehicle Electronics
By PW Consulting, 2026-07-15
Worldwide Automotive Flexible Printed Circuit (FPC) Market — Strategic Outlook for 2026
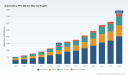
PW Consulting’s latest market intelligence brief on the Worldwide Automotive FPC market delivers an evidence-based, decision-ready roadmap for automotive leaders preparing strategy in 2026. The study synthesizes emerging technology trends, supplier dynamics, regulatory drivers, and supply‑chain vulnerabilities to show where value migration will occur through the 2026–2032 planning horizon. Our bottom-line finding: the market has already accelerated into a high-growth phase — rising from roughly USD 1.05 billion in 2020 to USD 2.61 billion in 2025 — and is forecast to grow at a compound annual growth rate (CAGR) of 16.0% through 2032, targeting a market size north of USD 7.3 billion by 2032. This trajectory is reshaping how OEMs, tier suppliers, and new entrants should allocate R&D, procurement, and capital in 2026.
Worldwide Automotive FPC Market
Why this report matters for 2026 decisions
-
Timing: 2026 will be the year many OEMs move from pilot to scale for EV, ADAS, and cockpit-electronics programs that depend on automotive-grade FPCs. Procurement windows, qualification cycles, and multi-year supply contracts initiated in 2026 determine capacity and cost profiles well into the next decade.
Worldwide Automotive FPC Market -
Capital allocation: Given the market’s projected 16% CAGR and projected near-tripling of market size within the forecast period, mis-timed investments in capacity or technology risks meaningful opportunity cost. Our scenario analyses show asymmetrical ROI between early investments in multilayer/high-density capabilities and late, catch-up expansions.
Worldwide Automotive FPC Market -
Supplier selection and risk: With the market moderately concentrated among established specialists — making the top-3 and top-5 suppliers material partners for large OEM programs — strategic supplier selection and co-investment models will be key to securing high-reliability supply and favorable commercial terms.
-
Regulatory and material pressure: Converging pressures — from functional safety standards to input-cost volatility (notably copper foil and specialty polymers) — are compressing margins and changing the calculus on localization, inventory strategy, and vertical integration.
Market snapshot and trajectory (headline metrics)
-
Historical momentum: The market more than doubled from 2020 to 2025, driven by electrification, ADAS proliferation, and increasing electronics content per vehicle.
-
Forecast growth: A 16.0% CAGR is projected for 2026–2032, reflecting sustained demand across battery management, sensing, high-speed data links, and advanced displays.
-
Concentration: Competitive intensity is moderate — a modest number of specialist suppliers command a meaningful share of the market, making strategic supplier relationships and capability mapping essential for OEMs and tier‑1s seeking to de‑risk programs.
Strategic implications: five actions every executive should consider in 2026
-
Re-baseline procurement strategy toward capability, not just cost. With higher complexity in multilayer and rigid‑flex FPCs and the expanded use of FPCs in safety-critical functions, procurement playbooks must prioritize supplier qualification, long‑lead cycle management, and shared qualification investment. Our supplier scorecards and total cost of ownership (TCO) models in the report enable negotiation levers that go beyond unit price.
-
Invest selectively in modular design and standardization. Reducing SKU complexity through modular FPC architectures lowers qualification burden and shortens time-to-production across vehicle platforms. The report includes design-for-manufacturing checklists and a prioritized set of architecture choices that balance performance with supplier scalability.
-
Harden supply chains against raw-material shocks. Recent input-cost trends — including material inflation for copper foil and polyimide films — and labor shortages in key assembly geographies materially affect landed costs. Our scenario-based sensitivity analyses quantify breakeven points for localizing supply, holding strategic safety stock, or negotiating cost pass-through clauses.
-
Embed regulatory and cybersecurity compliance early in product roadmaps. Standards such as ISO 26262 and regional cybersecurity rules are increasingly enforced for electronic substrates used in safety- and connectivity‑critical subsystems. The report’s compliance matrix maps functional safety and cyber requirements against typical FPC applications and supplier certification paths.
-
Explore partnership and M&A plays to secure differentiated capabilities. Given the market dynamics, strategic M&A, joint ventures, or capacity co-investments with established FPC specialists can accelerate time-to-market for advanced applications while limiting execution risk. Our deal-screening framework highlights where scale, IP, or geographic reach deliver the most strategic value.
Report deliverables — what you get
PW Consulting’s Worldwide Automotive FPC market report is structured to convert insight into action. The report bundle includes:
-
High‑fidelity demand model with SKU-level drivers, adoption curves for EV/ADAS/infotainment, and scenario toggles for adoption rates (note: this press release intentionally omits detailed segment tables; full segmentation and downloadable data are available in the report portal).
-
Supplier heat maps and capability matrices covering manufacturing process maturity (single-sided, double-sided, multilayer, rigid‑flex), reliability performance, and scale economics.
-
Supply‑chain risk register listing critical single-sourced inputs, price sensitivity, and actionable mitigations — including alternative material pathways and dual sourcing playbooks.
-
Regulatory compliance checklist linked to common FPC use cases, and an engineering checklist for satisfying ASIL/B and cybersecurity requirements during supplier qualification.
-
Commercial playbook for procurement teams: negotiation templates, scorecard KPIs, and a 24‑month supplier engagement roadmap to secure production slots.
-
M&A and partnership screening tool: valuation benchmarks, integration risk scoring, and modelled synergies for common deal archetypes.
Competitive landscape — profiles and near-term dynamics
The automotive FPC market is anchored by several established electronics-materials and interconnect specialists. PW Consulting’s competitor analysis blends firm-level profiling with program-specific signals to identify winning suppliers and emergent challengers. Key market participants examined in the report include:
-
Nitto Denko Corporation (Japan) — A longstanding supplier of flexible printed circuits for instrument panels, safety systems, and sensors. Recent launches point to a strategic focus on EV battery monitoring applications calibrated to automotive reliability standards.
-
Sumitomo Electric Industries, Ltd. (Japan) — Provider of high-density FPCs used in ECUs, infotainment, and ADAS. Supplier nominations in 2025 underscore momentum in next‑generation sensing and compute platforms.
-
Nippon Mektron, Ltd. (Japan) — Specialist in multilayer FPCs for camera, LIDAR, and battery management sensor stacks. Joint development activities with OEMs signal a prioritized role in autonomous‑sensor integration.
-
Flexium Interconnect, Inc. (Taiwan) — Known for automotive-grade FPCs supporting displays, lighting, and connectivity modules; well-positioned for cockpit electronics trends.
-
Interflex Co., Ltd. (South Korea) — Supplies FPCs for touch panels and power distribution; a regional player that bridges assembly and sensor module capabilities.
-
Zhen Ding Technology Holding Limited (Taiwan) — A strategic partner for EV battery pack FPC integration and high-speed in-vehicle data transmission; recent validation milestones with solid-state battery programs highlight its relevance to EV roadmaps.
-
Multi-Fineline Electronix, Inc. (MFLEX) (USA) — Offers custom FPCs for wearable integration and ADAS; strength in bespoke design and integration services.
-
Fujikura Ltd. (Japan) — Focused on wire-harness replacement and high-frequency transmission substrates; relevant for OEMs targeting weight reduction and signal integrity improvements.
Recent company developments — product launches, supplier nominations, joint development agreements, and validation successes — validate strategic moves by incumbents to capture rising content in EV and autonomy programs. Our competitive-play analysis maps these events to program adoption curves and supply risk to highlight which supplier relationships will be most strategic for 2026 contract cycles.
Supply‑side pressures and regulatory tailwinds
-
Materials volatility: Input-price inflation is non-trivial. Copper foil prices rose materially due to mining disruptions, and polyimide feedstock experienced elevated cost pressure in 2025. These inputs are core to FPC economics and amplify the value of material-efficiency design choices.
-
Labor and capacity constraints: Skilled labor shortages in Asia-Pacific assembly lines increased effective production costs in 2025, influencing near-term capacity sourcing decisions and justifying automation investments in certain geographies.
-
Regulation: Functional safety and cybersecurity rules (including updated ISO 26262 guidance and regional cybersecurity mandates) are reshaping supplier qualification. Embedding compliance early in FPC design reduces rework risk and shortens qualification timelines for high-voltage and safety-critical applications.
Methodology and credibility
Our findings combine primary interviews with OEM and tier‑1 engineering and procurement leads, supplier financials, proprietary shipment and bill-of-materials models, and a bottom‑up synthesis of program adoption rates across vehicle segments. Forecasts incorporate sensitivity analyses across raw-material price paths, supplier consolidation scenarios, and faster/slower EV adoption cases. Where the press release is intentionally silent on segment-level numeric detail, the full report provides downloadable models and segment tables for immediate incorporation into business planning.
Conclusion — positioning for 2026
For executives planning 2026 initiatives, the choice is between reacting to supplier-led constraints and proactively shaping supply and design strategies that capture the upside of a market growing at a mid‑teens CAGR. The PW Consulting report equips leaders with the operational playbooks, supplier maps, and financial models required to convert growth into durable margin and secure program wins. To review the full datasets, supplier scorecards, and scenario models — including downloadable tables and program-level forecasts omitted from this summary — access the full Worldwide Automotive FPC Market report on our portal.
For licensing, bespoke briefings, or to request the dataset for integration into your procurement and product development systems, contact PW Consulting through our website or request a 60‑minute executive briefing with the report team.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive FPC Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Insulinoma Market Poised to Expand at a 5.75% CAGR Through 2032PW Consulting Forecasts Worldwide Headless CMS Market to Grow at a 21.45% CAGR Through 2032
By PW Consulting, 2026-07-15
Worldwide Insulinoma Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting releases its latest Worldwide Insulinoma Market report (base year 2025; forecast 2026–2032), biopharma leaders, medtech strategists, and healthcare investors face a pivotal planning horizon. The market has demonstrated steady expansion from the early 2020s and, under our central forecast, is expected to continue a robust growth trajectory through 2032. This briefing highlights the strategic value of our research for decisions to be taken in 2026, outlines the competitive and regulatory inflection points that will shape near-term outcomes, and explains how the practical tools in the report translate raw market figures into actionable corporate choices.
Worldwide Insulinoma Market
Top-line market context you need to know
-
Historical momentum: Our time series shows the insulinoma market expanding across the 2020–2025 historical window, reflecting rising diagnostic capacity, incremental therapeutic innovation and more systematic capture of refractory cases.
Worldwide Insulinoma Market -
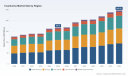
Near-term trajectory: The market base in 2025 stands at roughly USD 167 Million (revenue unit: Million USD). Under our base-case assumptions, the market is projected to grow at a compound annual growth rate (CAGR) of approximately 5.75% over the 2026–2032 forecast period, reaching roughly USD 247 Million by 2032. These macro figures frame the opportunity set for therapeutic developers, diagnostics vendors, and specialized service providers.
Worldwide Insulinoma Market -
Competitive concentration: Market concentration metrics indicate a moderately consolidated landscape (CR3 ~42% and CR5 ~57%), suggesting a mix of dominant incumbents and meaningful niche players — a structure that favors focused innovation strategies and selective partnerships.
Why this report matters for 2026 planning
-
Translating incidence to addressable opportunity: Insulinomas remain rare — with incidence estimates on the order of 1–4 cases per million per year — and a subset is clinically aggressive or metastatic. For industry strategists, the key is converting epidemiology into a realistic, reimbursable addressable population. Our report synthesizes epidemiology, diagnostic pathways and treatment attrition to produce a working patient-access model that supports go/no-go decisions on candidate assets and commercial launches.
-
Unblock development risk through regulatory insight: Recent regulatory alignment on trial design for novel therapies has immediate implications for development timelines and spend profiles. We interpret these alignments, model potential trial designs and provide scenario-based timelines that materially affect peak sales profiles and valuation multiples.
-
Commercial timing and resource allocation: Given the market’s modest absolute size but attractive growth rate, successful entrants must optimize scarce commercial resources. Our playbooks prioritize channel selection, KOL engagement cadence, and phased geographic rollouts that maximize return on limited commercial investment.
Competitive and clinical dynamics — spotlight on a lead program
Among pipeline competitors, one program merits special attention: Rezolute’s ersodetug (RZ358), an anti-insulin monoclonal antibody aimed at tumor-mediated hyperinsulinism, including malignant insulinoma and refractory hypoglycemia. In September 2025 Rezolute announced FDA alignment on a streamlined single-arm, open-label Phase 3 upLIFT trial for tumor hyperinsulinism with an approximately 16-patient cohort, and the company expects topline data in H2 2026. Importantly, the regulatory dialogue confirmed that positive results from a separate congenital hyperinsulinism Phase 3 trial (sunRIZE) may serve as supportive evidence for the tumor indication.
Why this matters strategically:
-
Trial design and regulatory precedent: A streamlined single-arm pathway with confirmatory supportive data compresses development timelines and lowers near-term randomized-control trial risk. For competitors and investors, this shifts the calculus of Phase 2/3 trial designs and valuation milestones.
-
Small but clinically urgent population: In the U.S., the initially addressable malignant insulinoma population is limited — our synthesis of company filings and clinical literature points to roughly 1,500 patients with malignant disease, and a meaningful fraction remain refractory to surgery and conventional medical management. That clinical urgency can support expedited regulatory pathways, but also requires tailored access and reimbursement strategies focused on high medical need.
-
Commercial ripple effects: A successful late-stage readout for a first-in-class mechanism could reshape treatment algorithms (e.g., for patients refractory to diazoxide and somatostatin analogs), influence diagnostic throughput, and trigger demand for specialized infusion and monitoring services. Our report models these downstream effects and quantifies possible uplift scenarios consistent with different uptake curves.
Regulatory and treatment standard dynamics
-
Standard of care and clinical pathways: Surgical resection remains the primary curative option for localized insulinoma. For inoperable or metastatic cases, diazoxide is commonly used as first-line medical therapy, with somatostatin analogs and other measures for refractory hypoglycemia. Any new therapy that meaningfully reduces hypoglycemic events in refractory patients will likely target a premium access pathway.
-
Regulatory strategy: The recent FDA alignment on using confirmatory congenital HI data to support tumor indications is notable. From a strategic perspective, this creates an argument for cross-indication development programs, where safety and pharmacology readouts in a broader congenital population can materially de-risk the tumor program and accelerate labeling timelines.
What’s in the full report — practical, transaction-ready outputs
PW Consulting’s Worldwide Insulinoma Market report is built for use in boardrooms, diligence processes and investor decks. Key deliverables include:
-
A detailed market-sizing model (historical and forecast 2020–2032) with scenario toggles for incidence, diagnostic penetration, treatment mix, and reimbursement uptake.
-
Company scorecards and pipeline dossiers that synthesize trial designs, regulatory status, and product positioning, including commercial readiness assessments.
-
Reimbursement and HTA intelligence with country-level decision triggers and pricing sensitivity analyses (multi-scenario ROI matrices suitable for valuation and negotiation planning).
-
Go-to-market playbooks for launch sequencing, KOL networks, patient support programs, and specialty pharmacy strategies tailored to orphan/ultra-orphan dynamics.
-
M&A and licensing heatmaps identifying likely strategic acquirers, partnership synergies and valuation benchmarks based on comparable small-population launches.
-
Operational readiness checklists for manufacturing scale-up, cold-chain logistics, and post-market surveillance obligations specific to biologics and antibody therapies.
How executives should use this report in 2026
-
Prioritize clinical investments with regulatory-readout timing in mind. If a competitor has a pivotal readout in 2026 (e.g., topline data expected H2 2026), sponsors should re-assess ongoing trials for design amendments, comparator selection and label-anchoring strategies.
-
Recalibrate valuation models to reflect faster de-risking paths. Streamlined single-arm designs with confirmatory external evidence change probability-of-success inputs and time-to-peak-sales assumptions — both critical for fundraising and licensing discussions in 2026.
-
Design commercial pilots that match patient flow realities. Given the small addressable populations, tight referral networks and specialized care settings will determine early uptake; our playbooks show how to structure pilots that prove prescriber economics and patient support ROI within 12–18 months.
-
Use the report’s scenario engine in negotiations. Whether setting price expectations with payers or evaluating partnership bids, our sensitivity analyses allow teams to present defendable financial ranges under conservative, base and aggressive adoption scenarios.
Limitations and deliberate information gating
Consistent with the “trailer” principle, this release surfaces high-confidence macro findings, regulatory inflection points and practical recommendations — but intentionally withholds granular segment-level tables and certain regional/application split values that are proprietary to the full report. PW Consulting’s detailed segmentation (by region, treatment type and end-user), patient-subsegment volumes and confidential interviews form the backbone of the full datasets available on the report page. This approach ensures executives receive both strategic insight here and the full operational toolkit when they access the report directly.
Final perspective — actionable next steps for 2026
-
Immediate due diligence: Teams with assets in preclinical or early clinical stages should update their development calendars and financial models to incorporate the latest regulatory precedents and potential competitive readouts in 2026.
-
Commercial readiness: Sponsors expecting to launch in the late 2020s should implement pilot access programs and begin payer dialogue now; small-population launches demand early, focused payer and provider engagement.
-
M&A timing: For acquirers, the next 18 months are a window to capture technology and footprint advantage if pivotal trials confirm safety and efficacy; our M&A heatmap identifies target profiles likely to command strategic premiums.
PW Consulting’s Worldwide Insulinoma Market report is designed as an operational playbook for 2026 strategy: a concise synthesis of epidemiology, clinical pathways, regulatory signals and commercial mechanics, paired with transaction-grade financial and operational models. For access to the complete datasets, segmentation breakdowns, and downloadable financial model, please visit the report page on the PW Consulting website. Our team remains available to present a private briefing tailored to your corporate questions and to run bespoke scenario analyses for board-level decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Insulinoma Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Off‑highway Wheels Market Poised for 5.6% CAGR in 2026–2032 Outlook
By PW Consulting, 2026-07-15
Worldwide Off‑Highway Wheels Market: Strategic Intelligence for 2026 Decision‑Makers
Executive summary
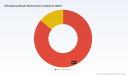
As capital cycles in agriculture, construction and mining begin to reset for the mid‑2020s, off‑highway wheels emerge as a strategic supply chain node where product design, materials inflation and OEM buying behavior converge. PW Consulting’s Worldwide Off‑Highway Wheels Market report (base year 2025; historical review 2020–2025; forecast 2026–2032) synthesizes hard market sizing with forward‑looking scenario analysis to equip executives with decision‑grade intelligence for 2026. The global market, measured in USD Million, expands from an estimated 8.4 billion in 2025 to a projected 12.3 billion by 2032, implying a steady compound annual growth rate of 5.6% through the forecast window. Concurrently, market concentration metrics indicate that the top three and top five suppliers control a meaningful share of market value — a structural fact that shapes strategic options from pricing to partnership.
Worldwide Off-highway Wheels Market
Why this matters for 2026 strategy
-
Timing of capital allocation: firms planning 2026 capex for manufacturing, tooling, or electrification‑compatible wheel systems must anchor budgets to realistic growth expectations and margin sensitivity. The reported CAGR provides the basis for multi‑year investment thresholding and ROI modelling.
Worldwide Off-highway Wheels Market -
Supplier and procurement strategy: given the industry’s moderate concentration, procurement teams need tailored playbooks — from preferred supplier lists to dual‑sourcing triggers — to preserve continuity without sacrificing cost or innovation access.
Worldwide Off-highway Wheels Market -
Product road‑mapping: OEMs and Tier‑1s should consider prioritizing lightweight and sensor‑ready wheel architectures now to stay aligned with electrification and sustainability mandates that crystallize through 2026.
Market trajectory and what the numbers mean
Our model quantifies an overall market trajectory that accelerates modestly post‑2025, reflecting recovering equipment cycles, ongoing infrastructural programs in multiple regions, and incremental pricing pressure from raw material movements. The headline growth — a mid‑single digit CAGR — masks divergent dynamics beneath the surface: steel remains the dominant raw material in volume and value, driving cost pass‑through behavior; meanwhile, aluminum and advanced composite solutions are gaining strategic interest where weight savings translate to fuel or energy efficiencies.
For boardrooms calibrating targets and covenant stress tests in 2026, the implication is straightforward: plan for growth that is steady but not explosive, and stress‑test scenarios for both raw material cost spikes and step‑function demand reductions tied to macro shocks. The report provides layered scenarios that translate the headline CAGR into cash‑flow and working capital implications across manufacturing footprints.
Competitive landscape — who matters and why
The competitive map remains anchored by legacy industrial manufacturers with integrated tire‑wheel portfolios and broad OEM relationships. Key global players profiled in the report include long‑standing steel wheel specialists and diversified wheel systems firms that supply OEMs and aftermarket channels. Our qualitative and quantitative analysis highlights three structural archetypes among these firms:
-
Global integrators: firms with extensive manufacturing footprints, deep OEM contracts, and aftermarket channels — they can defend scale pricing but face complexity in rapid product pivoting.
-
Specialist innovators: companies that compete through differentiated wheel architectures (e.g., multi‑piece flotation wheels, high‑durability mining wheels) and targeted OEM programs.
-
Regional champions and custom fabricators: smaller players that win by servicing extreme‑duty use cases or offering rapid bespoke solutions in localized geographies.
Recent market activity underlines how product innovation and visibility at trade shows continue to drive perception and order pipelines. For example, leading steel wheel manufacturers continued to publicize product launches and exhibition participation in early 2026, reinforcing their channel momentum and signaling incremental competitive pressure in high‑performance niches.
Dynamics shaping margins, supply and innovation
Several immediate operational factors will determine winners and losers through 2026:
-
Raw material volatility: steel is the predominant input for the majority of off‑highway wheels due to its cost‑to‑strength ratio. Price movements in structural steel — and regional spread differentials — will determine gross margin variability. Procurement playbooks that combine long‑term contracts, vendor financing, and regional hedging will outperform ad hoc buying strategies.
-
Regulatory and standards compliance: wheel and vehicle subsystem design must align with industry safety standards and regional regulations (for example, established SAE and OSHA‑referenced standards for braking systems on rubber‑tired machinery). Engineering teams should bake compliance checks into early‑stage designs to avoid costly reworks and certification delays.
-
Design trends: electrification of heavy equipment, a growing emphasis on operational efficiency, and an increasing focus on sustainability are pressuring designers toward lighter, sensor‑ready wheels. Firms that master material substitution without compromising durability will unlock new OEM programs and total cost of ownership advantages.
-
Aftermarket and service models: given the heavy‑duty nature of end use, aftermarket parts, refurbishment and field services represent high‑margin, recurring revenue opportunities. Companies with integrated aftermarket strategies and digitized service offerings can create defensible annuity streams.
Report contents — what PW Consulting delivers
The report goes beyond headline sizing to deliver actionable modules designed for commercial, product and supply chain teams:
-
Market sizing and forecast (2020–2032), including scenario analyses that adjust for commodity shocks, regulatory changes and demand curve inflections.
-
Competitive profiles and capability maps: deep dossiers on leading OEM suppliers, specialty manufacturers and regional fabricators, including strategic positioning, product portfolios, and recent go‑to‑market moves.
-
Procurement and sourcing playbooks: negotiation frameworks, dual‑sourcing decision trees, and recommended contract structures to mitigate raw material and logistics risks.
-
Technical adjacencies and product roadmaps: an assessment of material substitution pathways, integration of sensors and telemetry, and design implications for electrified drivetrains.
-
Aftermarket strategies and service economics: pricing guidance, refurbishment vs. replace economics, and field service digitalization templates.
-
Risk register and regulatory checklists: actionable compliance milestones tied to engineering and procurement workflows.
How executives should use this intelligence in 2026
-
Prioritize decisions that balance resilience with optionality. Example: secure medium‑term steel supply at competitive rates while retaining capacity to pivot to aluminum or advanced alloys where product economics permit.
-
Embed concentration awareness into contracting. With top suppliers controlling a material share of market value, teams should model the operational impact of supplier distress and prepare contingency sourcing and logistics plans.
-
Accelerate product feature roadmaps that are “electrification‑ready.” Investments in hub redesign, weight reduction, and sensor integration can convert into early OEM wins as vehicle platforms evolve.
-
Monetize aftermarket potential. Design services, refurbishment contracts and performance warranties can materially improve lifetime margins and smooth cyclical revenue swings.
Caveats and the research approach
PW Consulting’s conclusions are grounded in a mixed‑methods approach combining longitudinal market modeling, primary interviews with OEM and supplier executives, and on‑the‑ground factory and logistics audits. While the report discloses headline market sizes, growth rates and concentration metrics to support executive planning, we intentionally withhold certain segmented breakdowns in this public summary to protect the competitive intelligence value of our subscription product. Subscribers receive the full segmentation matrices and data tables, along with the underlying assumptions and source listings.
Practical next steps
-
For commercial leaders: use the report’s procurement playbooks to negotiate cost‑plus or indexed supply contracts during Q1–Q2 2026.
-
For product and engineering: schedule a design review in H1 2026 to evaluate weight and sensor retrofits against planned OEM platform refreshes.
-
For strategy and M&A teams: leverage our competitive dossiers to identify acquisition targets that fill capability gaps (e.g., specialty flotation wheels, heavy mining wheels, or integrated wheel‑tire systems).
Closing note — the decision horizon
As firms set budgets and strategic priorities for 2026, the off‑highway wheels market will reward disciplined, insight‑driven choices. A stable mid‑single digit growth profile creates space for targeted investment, but the twin pressures of raw material volatility and evolving vehicle architectures require proactive measures. PW Consulting’s Worldwide Off‑Highway Wheels Market report provides the calibrated, operationally relevant intelligence that executives need to convert market visibility into resilient competitive advantage.
How to access the full intelligence
The complete report includes the detailed segmentation, supplier scorecards, primary interview excerpts and downloadable data tables that underpin the summary presented here. Contact PW Consulting to obtain the subscription access and tailored briefings necessary to operationalize these findings in your 2026 plans.
For detailed analysis of this topic, please visit the official page: Worldwide Off-highway Wheels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide NBR Latex Market to Grow at 8.01% CAGR, Reach USD 4,476 Million by 2032
By PW Consulting, 2026-07-15
Worldwide Nitrile Butadiene Rubber (NBR) Latex Market: Strategic Directions for 2026 — PW Consulting Intelligence Brief
As companies plan budgets, procurement strategies and investment roadmaps for 2026, the nitrile butadiene rubber (NBR) latex market is moving from recovery into a structurally growth-oriented phase. PW Consulting’s latest Worldwide NBR Latex Market report (base year 2025) shows the global market reaching approximately USD 2,610 Million in 2025 and accelerating to roughly USD 2,885 Million in 2026, underpinned by an 8.01% compound annual growth rate across our 2026–2032 forecast horizon. These headline data points capture both the pace of expansion and the reconfiguration risks executives must manage in the coming 12–18 months.
Worldwide Nitrile Butadiene Rubber (NBR) Latex Market
Why this report matters for 2026 decision-making
-
Macro momentum with micro fragility: The market has demonstrated a volatile trajectory through 2020–2025, including demand shocks and a steep recovery. The 2026 inflection point is driven by a combination of sustained end-market demand (medical and industrial), capacity rebalancing and a re-rating of sustainability requirements.
Worldwide Nitrile Butadiene Rubber (NBR) Latex Market -
Feedstock and trade shocks are no longer discrete events: Butadiene and acrylonitrile pricing swings—tied to crude and regional supply constraints—have introduced cost volatility that directly affects margins and contract economics for downstream manufacturers. In parallel, regional trade measures and disruptions to shipping corridors have created availability premiums in critical sourcing hubs.
Worldwide Nitrile Butadiene Rubber (NBR) Latex Market -
Regulation and sustainability are now commercial levers: Regulatory drivers such as tighter VOC rules in Europe and buyers’ sustainability specifications in healthcare converge to make product-grade differentiation a revenue and risk-management instrument, not just compliance overhead.
What executives will find practical in the PW Consulting report
-
Transparent market architecture: a clear methodology documenting base-year sizing, historical trend reconciliation and our demand-supply model that reconciles plant-level capacity, utilisation and trade flows for the forecast period (2026–2032).
-
Scenario-based forecasts: upside/downside pathways that quantify the impact of feedstock shocks, accelerated adoption of bio-based NBR, and additional tariff/regulatory actions—each modelled with sensitivity matrices for price, volume and margin outcomes.
-
Supply-chain intelligence: a plant- and asset-level map with commissioning timelines, announced capacity additions and shutter risks. This is coupled with counterparty profiles to support supplier selection and risk mitigation.
-
Pricing and margin toolkit: a feedstock pass‑through model that links butadiene and acrylonitrile spot/contract movements to finished‑goods pricing bands under different contractual terms.
-
Commercial playbooks: tailored go‑to‑market approaches for glove manufacturers, industrial chemical buyers and specialty compounders—covering contract language, inventory strategies and innovation partnerships.
-
M&A and capex decision support: an acquisition heatmap, valuation multipliers adjusted for concentration dynamics, and a checklist for line integration and synergies.
-
Regulatory compliance and product transition guide: a stepwise pathway to lower‑VOC and bio‑based grades aligned with regional regulatory requirements and procurement tenders.
Competitive landscape — what matters strategically
The NBR latex supply base mixes global majors, regionally dominant players and focused specialist producers. The market concentration metrics in our analysis indicate a meaningful presence of top-tier producers while leaving room for mid‑sized players to carve differentiated positions (CR3 and CR5 are material, reflecting consolidated leadership and an active tier-two market). Key strategic takeaways:
-
Scale players with integrated footprints (including large producers in East Asia and integrated petrochemical groups) continue to shape global pricing and availability dynamics. Their strengths are reliable offtake for glove producers and the ability to manage feedstock sourcing vertically.
-
Innovation leaders that invest in specialized grades and sustainability (including early commercialisation of bio‑based NBR latex) are creating product premium pools, especially in healthcare and regulated markets.
-
Regional and specialist suppliers remain critical buffers for procurement teams seeking diversification and agility, particularly in regions prone to shipping disruptions or tariff exposure.
Among named industry actors, we profile vertically integrated chemical majors, Asian nitrile specialists and regional producers across the Americas and Southeast Asia. Recent market moves—such as the commissioning of new capacity in Asia and the launch of certified bio‑based NBR latex lines—illustrate the twin themes of capacity expansion and product differentiation. These developments reinforce both supply resilience and the margin bifurcation between conventional and sustainable grades.
Dynamics to watch in 2026
-
Feedstock price volatility and availability: Tightness in butadiene markets and crude-linked pricing on acrylonitrile will continue to produce asymmetric impacts across suppliers based on feedstock integration and contracting strategy.
-
Regulatory pressure and buyer requirements: Tighter VOC and sustainability criteria in key markets will accelerate migration to lower‑emission and bio‑based formulations, with first‑mover premium potential for compliant suppliers.
-
Trade and logistics risk: Shipping disruptions and tariff actions in recent years have shown how regional availability can diverge quickly; companies should build playbooks for rapid sourcing shifts and contractual flexibility.
-
Consolidation and strategic M&A: Capacity additions and strategic launches are prompting buyers and investors to re-evaluate portfolios. Expect selective M&A activity focused on capability densification (sustainable grades) and footprint rationalisation.
Three high-impact strategic plays for 2026
-
1) Supply Resilience Play — Multi‑tier Sourcing and Inventory Engineering: For manufacturers with tight time-to-market requirements (e.g., glove producers), adopt layered supplier contracts (primary, secondary, contingency), coupled with dynamic inventory buffers. Use the report’s plant-level availability signals to prioritise supplier relationships and contract durations.
-
2) Green Differentiation Play — Move Early on Bio-based NBR: Adopt a product roadmap that phases in lower‑VOC and bio‑based NBR grades for regulated and premium channels. The report provides a certification and cost-implementation checklist to quantify premium capture versus retrofit capex.
-
3) Margin Defence Play — Feedstock Hedging and Contract Re-architecting: Implement a hybrid pricing mechanism tied to a transparent feedstock index with periodic floors/ceilings, reducing margin leakage during feedstock spikes. Our pricing toolkit offers scenario outputs you can embed in customer and supplier contracts.
How different stakeholders should use the intelligence
-
C-suite and corporate strategy: Use the forecast scenarios to validate 2026 capex and M&A priorities, focusing on resilience-adjusted returns and regulatory readiness.
-
Procurement leaders: Leverage supplier and plant maps to redesign sourcing strategies, optimise contract tenors and set hedging policy thresholds.
-
R&D and product management: Apply the regulatory and sustainability transition guide to prioritise grade development and certification plans that align with high-value customers.
-
Investors and advisors: Use the M&A heatmap and concentration analysis to screen targets that offer defensible margins and complementary footprint exposure.
What we deliberately withhold in this brief — and why
This article is a strategic trailer: its purpose is to surface the insights decision-makers need to recognise urgency and prioritise next steps. To preserve the value of the full research product and to support confidential advisory engagements, we have intentionally omitted granular regional and application-level census figures, individual company volumetric shares and full price-by-grade tables. The complete report contains those segmented datasets, primary‑source reconciliations and an interactive model that enables bespoke scenario runs.
Next steps — getting the full intelligence
For executives preparing 2026 operating plans, PW Consulting’s full Worldwide NBR Latex Market report delivers the step-by-step inputs and templates needed to convert these strategic plays into executable programs. The report combines authoritative market sizing, supplier and asset mapping, price and margin mechanics, regulatory compliance modules and M&A decision frameworks—all calibrated to inform board-level and operating-level choices.
Contact PW Consulting to access the full report, request a tailored briefing, or commission the custom scenario modelling that aligns our baseline to your company’s asset position and commercial contracts. In a market shaped by feedstock cycles, regulatory shifts and sustainability transitions, this granular, actionable intelligence will be essential to preserve margins, secure supply and capture the premium opportunities that will define 2026 performance.
For detailed analysis of this topic, please visit the official page: Worldwide Nitrile Butadiene Rubber (NBR) Latex Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 14.28% CAGR for Worldwide Automotive Coolant Heaters Market
By PW Consulting, 2026-07-15
Worldwide Automotive Coolant Heaters Market: Strategic Insights for 2026 Decision-Making
PW Consulting today releases an executive briefing from its forthcoming Worldwide Automotive Coolant Heaters Market report — a forward-looking analysis designed to equip OEMs, tier‑1 suppliers, private equity investors, and procurement teams making strategic choices in 2026. Built on a robust historical series (2020–2025) and a detailed forecast window (2026–2032), the study synthesizes market sizing, competitive dynamics, technology trajectories, and regulatory risk into an actionable playbook for near-term and runway decisions.
Worldwide Automotive Coolant Heaters Market
Why this market matters in 2026
-
Thermal management has moved from a component-level cost conversation to a strategic systems issue as electrification accelerates. Coolant heaters — once primarily an ICE cold‑start accessory — are now integral to battery performance, cabin comfort, and range optimization across ICE, hybrid, plug‑in, and full‑battery vehicle architectures.
Worldwide Automotive Coolant Heaters Market -
Macro trajectories embedded in our analysis are unambiguous: the global coolant heaters market expands significantly from the 2025 base year and more than doubles toward the end of the forecast horizon, underpinned by a compound annual growth rate (CAGR) of 14.28% through 2032. This pace drives rapid change across supplier footprints, BOM composition, and engineering integration timelines.
Worldwide Automotive Coolant Heaters Market -
Regulatory pressure, customer expectations for range and comfort in cold climates, and the migration to 400V/800V electrical architectures together create a tightly coupled demand and technology evolution pathway that will determine winners and losers over the next 18–36 months.
Market sizing and strategic takeaways
PW Consulting’s modeling places the market at a clear inflection point in 2025, with a pronounced acceleration across the forecast period. Our bottom-up and top-down reconciled approach captures revenue movements driven by vehicle production mix, thermal system architectures, and increasing penetration of high‑voltage coolant heater solutions in xEV platforms. For decision-makers in 2026, the implications are straightforward:
-
Design and procurement cycles must shift earlier to reflect heated adoption curves — securing qualified thermal components is now a multi-year activity, not a supplier selection made at launch order.
-
Suppliers that can demonstrate scalable architectures compatible with both 400V and 800V systems, modular thermal integration, and reduced integration cost will command premium access to OEM programs.
-
Financing and M&A strategies should treat coolant heater capability as a lever for faster OEM qualification across EV platforms rather than a niche incremental revenue stream.
What PW Consulting’s report delivers (practical, non‑revealing summary)
-
Validated historical market sizing (2020–2025) and transparent forecasting methodology (2026–2032) with scenario bands for low-, base-, and high-adoption pathways.
-
Technology readiness assessment and roadmap for high‑voltage coolant heaters, resistive/PTC platforms, and hydronic solutions — including integration constraints with heat pump and battery thermal management systems.
-
Supplier benchmarking matrix with capabilities, program wins, manufacturing footprints, and go‑to‑market posture (note: the public briefing intentionally omits compartmentalized segment revenues to preserve report exclusivity).
-
Commercial playbooks for OEMs and tier‑1s: procurement negotiation levers, dual-sourcing strategies, cost‑to‑serve models, and time‑to‑production acceleration tactics.
-
Supply‑chain stress tests and raw‑material exposure mapping for PTC ceramics and other critical inputs, with mitigation strategies tailored to 2026 contracting cycles.
-
Regulatory impact mapping that aligns 49 CFR-like safety requirements and emissions-driven thermal mandates to product functional requirements and testing pathways.
Competitive landscape — who to watch and why
The industry is moderately concentrated, with the top three revenue holders capturing a significant share of the market and the top five firms representing a majority of revenues. This concentration presents both barriers and opportunities: established players bring OEM qualifications and scale; fast followers and regional specialists can win on cost, niche application expertise, and speed.
-
Webasto (Stockdorf, Germany) — Deep systems capability in conventional engine pre‑heating and increasingly in high‑voltage modules for hybrid/electric platforms. Webasto’s heritage in thermo systems positions it well for integrated HVAC integration projects and multi‑region serial production.
-
BorgWarner (Auburn Hills, USA) — A strategic front‑runner in HVCH technology with recent contract awards for both 400V and 800V variants. Their 2025 contract wins underscore an OEM preference for suppliers who can certify across voltage architectures and scale into high‑volume PHEV/EV programs starting late in the decade.
-
Valeo (Paris, France) — Focused on glycol heating solutions and heat‑pump compatible designs, Valeo’s portfolio targets HVAC‑centric system integration where cabin comfort and energy efficiency converge.
-
Eberspächer (Esslingen, Germany) — Strong in hydronic heaters and multi‑application platforms spanning passenger cars to commercial vehicles; an important player where legacy ICE support and new HVCH offerings intersect.
-
Hotstart, PTI, Hebei Nanfeng (NF), VVKB — A mix of specialized heavy‑duty/heavy‑equipment suppliers and regional PTC manufacturers that are increasingly relevant for non‑OEM channels, cold‑climate retrofit opportunities, and regional bus/coach markets.
Recent wins and program starts — notably multiple BorgWarner contract announcements in 2023 and 2025 — validate the market’s move toward standardized HVCH platforms and the necessity for suppliers to demonstrate multi‑voltage capability and high‑volume manufacturing readiness. For incumbents, defending share will require modular product families and tighter supply chain control; for new entrants, focus on niche applications or regional partnerships remains a pragmatic route to scale.
Key dynamics shaping supplier and OEM choices
-
Electrification architecture convergence: Adoption of 400V and 800V systems is driving design commonality and reducing the cost of goods for HVCH platforms configured to support both voltages. Suppliers must validate cross‑voltage performance early to remain eligible for multi‑platform programs.
-
Regulatory and certification demands: Emission reduction mandates and vehicle equipment standards raise the bar for functional safety, thermal reliability, and certification timelines. These requirements favor suppliers with integrated testing labs and pre‑certification roadmaps.
-
Materials and commodities: PTC ceramic availability and cost volatility are non‑trivial risk factors. Procurement teams that secure multi‑tiered supply agreements and invest in strategic inventory buffering will preserve launch timelines.
-
System integration premium: OEMs increasingly prefer fewer suppliers that can deliver thermal systems rather than standalone modules. This creates incentives for vertical integration, strategic partnerships, and selective M&A.
Actionable recommendations for 2026 decision-makers
-
For OEM program teams: Lock in thermal supplier selections earlier in the program cycle and require cross‑voltage validation clauses. Treat coolant heater architecture as a platform decision that drives downstream HVAC and battery pack thermal design.
-
For tier‑1 suppliers: Prioritize scalable HVCH architectures, pursue strategic partnerships for PTC supply, and invest in regional manufacturing to align with OEM localization requirements.
-
For investors and PE: Screen targets for HVCH IP, cross‑voltage validation, and OEM program backlog. Companies with hybrid hydronic/electric capability or modular designs command premium strategic value.
-
For procurement and supply‑chain leaders: Implement multi‑sourcing approaches for critical ceramics, include penalty/award clauses tied to test performance, and consider inventory hedging for 2026 contract awards that span to 2028 production ramps.
How PW Consulting’s report informs 2026 strategy (closing)
Our report equips decision-makers with the empirical market sizing (base year 2025), rigorous 2026–2032 scenarios, and a practical toolkit for negotiating and operating in a rapidly evolving landscape. The study’s market concentration analysis highlights a competitive field where technical validation, supply chain resilience, and program‑level agility determine access to high-growth EV and hybrid programs.
If your 2026 strategy requires clarity on supplier selection timing, technology bets (PTC vs resistive vs hydronic), or M&A prioritization — PW Consulting’s full report contains the proprietary segment-level analytics, supplier scorecards, and contract-level implications that will inform executable decisions. This briefing demonstrates the depth of our analysis while reserving the granular data tables and model outputs for authorized report access.
For organizations preparing budgets, awarding supplier contracts, or setting product roadmaps in 2026, the consequence is simple: treat coolant-heater strategy as an integral systems decision. Those who align product, procurement, and program engineering now will secure cost, performance, and market-share advantage as adoption accelerates through 2032.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Coolant Heaters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Medicine Packaging Adhesive Market Poised for 6.68% CAGR During 2026–2032
By PW Consulting, 2026-07-15
Worldwide Medicine Packaging Adhesive Market: Strategic Brief for 2026 Decision‑Makers
PW Consulting’s latest market study — Worldwide Medicine Packaging Adhesive Market — arrives at a pivotal time for executives steering operations, procurement, and product strategy in pharmaceutical and medical packaging. The global market, which reached an estimated USD 1,638.0 Million in 2025, is forecast to expand further into 2026 and beyond, reflecting a compounded annual growth rate of 6.68% over the forecast window. For boards and C‑suite leaders preparing 2026 budgets and three‑to‑five year roadmaps, this research is crafted as a practical decision support tool: it translates macro growth into actionable options while deliberately withholding sensitive granular datapoints to drive targeted engagement with our full report.
Worldwide Medicine Packaging Adhesive Market
Why this report matters in 2026
- Strategic timing: As regulatory, environmental, and supply‑chain vectors converge, adhesive selection and sourcing are rising from line‑item procurement concerns into strategic risk areas that affect product safety, sustainability disclosure, and recyclability claims.
- Market momentum: The market’s solid mid‑single‑digit CAGR indicates sustained demand driven by pharmaceutical packaging formats and increasing production automation — signaling both growth opportunities and operational stress points for high‑volume producers.
- Competitive dynamics: A moderately concentrated vendor landscape (CR3 ~38%, CR5 ~52%) creates a landscape where leading global players maintain meaningful share, yet mid‑market specialists and regional suppliers remain influential — an important context for M&A, partnership, and sourcing strategies.
Key thematic takeaways for 2026 strategy
- Regulatory differentiation will be a strategic axis. State‑level Extended Producer Responsibility (EPR) programs and evolving recycled content targets are influencing packaging design rules and supplier selection. Notably, several EPR frameworks recognize patient‑safety exemptions for certain pharmaceutical packaging, creating a nuanced compliance landscape where companies must balance sustainability mandates with regulatory and clinical safety constraints.
- Product safety and compliance remain non‑negotiable. Adhesives used in medicine packaging must align with food‑contact and pharmaceutical guidance (e.g., FDA 21 CFR 175.105, relevant EMA/EC standards). Suppliers that can demonstrate validated compliance pathways and supporting documentation will command preference in tender processes.
- Raw material volatility is an enduring procurement risk. Key adhesive chemistries still rely on petrochemical‑derived monomers, tackifiers, and specialty resins, making cost exposure sensitive to oil market dynamics and monomer availability. Procurement strategies should therefore include longer‑dated contracts, diversified feedstock sources, and index‑linked pricing triggers where appropriate.
- Innovation is bifurcating value creation. Advancements such as LED/UV‑curable chemistries, high‑performance hot melts for high‑speed lines, and water‑based laminating systems are enabling both operational efficiency gains and improved recyclability profiles. Early technical validation and pilot conversions can yield competitive advantage in high throughput production settings.
Practical playbook: five actions for leaders in 2026
- Define “safety‑first sustainability” criteria: Establish a cross‑functional decision matrix that ranks packaging adhesive options by patient safety compliance, recyclability impact, and total cost of ownership. Use that matrix to guide pilot programs and supplier pre‑qualification.
- Hedge raw material exposure: Implement a layered procurement approach combining strategic inventory buffers, staggered contract maturities, and partnerships with suppliers that offer feedstock‑diversification roadmaps (bio‑based or recycled polymer pathways where technically feasible).
- Prioritize line‑level trials for novel chemistries: Allocate dedicated CAPEX for validating LED/UV and advanced hot melt systems on production lines where throughput and tamper‑evidence requirements are most acute. Measure adhesive‑related downtime, changeover time, and packaging integrity metrics as part of pilot KPIs.
- Reassess supplier segmentation and negotiation levers: Given the market’s concentration dynamics, combine global incumbents for scale‑driven commodity purchases with qualified regional or specialist suppliers for innovation, contingency supply, and niche applications.
- Embed regulatory intelligence into sourcing: Require suppliers to deliver explicit compliance dossiers (migration testing, extractables/leachables, and contact‑safety certifications) as part of RFQ evaluation criteria — this shortens validation cycles and reduces time‑to‑market risk.
What the full PW Consulting report delivers (practical, actionable content)
- Proven procurement playbooks — templates for RFQs, contract clauses addressing raw material volatility, and sample SLAs that align adhesive performance with production uptime targets.
- Technology decision frameworks — side‑by‑side comparative evaluations (operation speed, thermal profile, curing footprint, recyclability implications) to prioritize adhesive classes for specific medicine packaging formats.
- Regulatory and sustainability impact assessments — scenario models that map emerging EPR requirements and exemptions against packaging choices, plus a checklist to streamline regulatory submissions and design dossiers.
- Commercial and M&A opportunity maps — identifying segments where consolidation delivers scale, and niches where vertical integration or strategic partnerships are likely to yield margin expansion.
- Operational conversion guides — step‑by‑step laboratory and line validation protocols, expected timeline templates, and sample cost‑benefit calculators tailored to pharmaceutical packaging lines.
- Primary‑research validated vendor profiles — pragmatic supplier comparisons that highlight validated use cases, global‑supply footprints, and innovation trajectories (note: detailed segment share tables are reserved for report subscribers).
Competitive landscape: what to watch among leading suppliers
The adhesive supply ecosystem for medicine packaging blends global majors with specialist innovators. Established multinationals retain advantages in scale, regulatory support, and global logistics; nimble specialists bring focused formulations and rapid co‑development capabilities.
Worldwide Medicine Packaging Adhesive Market
- Henkel AG & Co. KGaA – Strong in high‑speed pharmaceutical lines and tamper‑evident bonding with advanced hot melt and LED/curable portfolios. Recent product launches underscore a strategic push into fast‑curing, regulatory‑aligned chemistries that support device assembly and packaging integration.
- H.B. Fuller – Noted for medical‑grade and pharmaceutical packaging adhesives, including biocompatible hot melts for flexible packaging. Their positioning is attractive for makers seeking validated grade adhesives for sensitive surfaces.
- 3M Company – Offers broad packaging adhesive capabilities with emphasis on structural bonding and labeling solutions; 3M’s strength lies in systems thinking across adhesives, tapes, and converting technologies.
- Arkema / Bostik – Focused on laminating and hot melt solutions for flexible and high‑barrier applications; their R&D track record supports barrier integrity in complex laminate structures.
- Avery Dennison – A leader in pressure‑sensitive labeling — an increasingly strategic domain for traceability, serialisation, and tamper evidence in pharmaceutical packaging.
- Dow Inc. – Supplies heat‑sealable coatings and laminating adhesives suited to blister and flexible formats; operators seeking integrated film‑adhesive systems may find value in their portfolio.
- Specialists such as artimelt, Jowat, Capital Adhesives, and BC Adhesives – These players offer targeted hot melt and tamper‑evident formulations, often with strong support for line integration and rapid technical response — useful for contingency sourcing and niche applications.
Recent market activity underlines the divergence between incremental product refinement and step changes from novel chemistries: Henkel’s rollouts of LED‑curable and advanced hot melt lines, and Dymax’s visibility at medical device forums, point to an upcoming phase where curing speed and regulatory compliance converge as differentiators.
Worldwide Medicine Packaging Adhesive Market
Implications for M&A, sourcing, and R&D investments
- M&A: Mid‑market specialists remain attractive bolt‑on targets for players seeking to round out pharmaceutical portfolios or secure specialized formulations and regional channel access.
- Sourcing: Adopt a dual‑track sourcing model — secure scale supply with tier‑one partners while maintaining relationships with regional specialists for innovation and redundancy.
- R&D: Direct investment toward chemistries that reduce volatile‑content migration, improve recyclability metrics, and shorten curing cycles. Prioritize supplier co‑funded pilots to accelerate commercialisation with lower capital exposure.
How to use this brief and next steps
This document is designed as a strategic primer: it highlights the growth trajectory (market momentum visible through 2026 and consistent with a ~6.7% CAGR outlook) and frames the operational, regulatory, and competitive levers that executive teams must prioritize. PW Consulting’s full report contains the proprietary segment analytics, scenario models, and supplier scorecards that we deliberately summarize but do not publish here — these are essential for transaction diligence, capital allocation, and supplier negotiations.
- For procurement leaders: request the vendor scorecard appendix and procurement playbook to shorten RFP cycles and improve negotiation outcomes.
- For R&D and operations: obtain the conversion‑validation protocols and pilot KPI templates to de‑risk trials of new adhesive technologies on production lines.
- For strategy and M&A teams: access the opportunity map and valuation benchmarks to target acquisitions and partnerships with clear synergy pathways.
To access the complete dataset, proprietary segment breakdowns, and supplier benchmarking that underpin the recommendations above, please visit the PW Consulting report page for Worldwide Medicine Packaging Adhesive Market or contact our advisory desk for a tailored executive briefing. PW Consulting stands ready to support scenario planning, due diligence, and implementation roadmaps aligned with your 2026 strategic objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Medicine Packaging Adhesive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Acute Ischemic Stroke Market Set to Surge at a 7.82% CAGR Through 2032
By PW Consulting, 2026-07-15
Worldwide Acute Ischemic Stroke Market — Strategic Outlook for 2026
PW Consulting’s latest Worldwide Acute Ischemic Stroke (AIS) Market report is designed as a decision-grade playbook for executives, investors, health system leaders, and medtech strategists preparing for 2026. The global AIS market, estimated at USD 10,750 Million in 2025, is poised to expand at a compound annual growth rate (CAGR) of 7.82% through our forecast window. Our base-to-forecast mapping shows a clear inflection as clinical guidelines, reimbursement policy, and device innovation converge — creating tactical opportunities and strategic risks that require immediate attention.
Worldwide Acute Ischemic Stroke Market
Why this report matters for 2026 decision-makers
-
Actionable foresight: We translate macro drivers and microscale commercial levers into executable moves for 2026 planning cycles — from product roadmaps to regional market prioritization.
Worldwide Acute Ischemic Stroke Market -
Risk-calibrated scenarios: Instead of binary forecasts, the report offers stress-tested scenarios that quantify revenue, margin, and adoption impacts under alternative reimbursement, regulatory, and supply-chain shocks.
Worldwide Acute Ischemic Stroke Market -
Competition intelligence: A curated competitive matrix highlights capability clusters, innovation pipelines, and tactical plays by leading and fast-moving challengers, enabling defensible responses and M&A screening.
-
Go-to-market templates: Evidence-driven commercial models (pricing, hospital contracting, training and bundle strategies) are included to accelerate adoption while protecting price realization.
Executive snapshot — market dynamics shaping 2026
-
Clinical expansion: The AHA/ASA 2024 guideline extension of the thrombectomy eligibility window to 24 hours for selected patients materially expands the addressable population in most advanced systems and creates a lasting tailwind.
-
Epidemiology pressure: Population aging means AIS incidence is expected to rise sharply over the decade — major markets will see substantially higher procedure volumes into 2030, increasing demand for optimized devices and streamlined workflows.
-
Regulatory acceleration: The FDA’s increased use of Breakthrough Device Designation in 2025 signals faster pathways for novel thrombectomy systems; this accelerates competitive churn and compresses product life cycles.
-
Reimbursement recalibration: CMS updated NTAP reimbursement for eligible thrombectomy devices in FY2026 to $11,250 — a pivotal input for hospital procurement economics and pricing strategies in the U.S.
-
Supply-chain constraints: Rising tariffs on certain neurovascular components and geographic supply concentration raise non-trivial cost and resiliency issues in 2026 sourcing plans.
-
Market structure: Concentration metrics indicate an industry where the top three and top five players command a majority share; incumbents retain scale advantages but face targeted disruption from nimble innovators.
What the report contains — depth without the noise
-
Integrated market-sizing and forecasts: Detailed topline market trajectories from historical 2020–2025 performance through a segmented 2026–2032 forecast horizon, incorporating procedural volume models, device penetration curves, and pricing elasticity.
-
Segmentation architecture: Multi-dimensional splits by region, treatment type, and end-user designed for scenario modeling and prioritization (note: granular segment tables and downloadable model workbooks are reserved for the full report).
-
Clinical and evidence mapping: Comparative trial and registry reviews, technology differentiation matrices, and evidence-generation roadmaps to optimize reimbursement and adoption trajectories.
-
Regulatory and reimbursement playbooks: Country-specific pathways, HTA watchlists, and best-practice templates to accelerate approvals and secure favorable coverage terms.
-
Commercial execution modules: Hospital contracting levers, distributor segmentation, pricing strategies aligned with NTAP dynamics, and field-force deployment models calibrated by hospital type and procedure mix.
-
M&A and partnership screening: A prioritized list of inorganic targets and alliance archetypes — validated against technological fit, clinical evidence stage, and supply-chain footprint.
-
Operational risk & resilience: Supplier-mapping, tariff impact simulations, and inventory strategies to mitigate production and delivery shocks.
-
Data assets: Primary interviews with clinicians, procurement leads, and KOLs; procedure-level hospital datasets; and a transparent modeling appendix that underpins our forecasts.
Competitive landscape — who to watch and why
-
Stryker Corporation (Kalamazoo, MI, USA) — a leader in mechanical thrombectomy with flagship retrievers and catheter platforms. Recent product introductions for adjacent cerebrovascular conditions suggest a strategy of broadening procedural indications and reinforcing hospital relationships.
-
Medtronic plc (Dublin, Ireland) — strong in revascularization devices and aspiration systems; recent positive multi-year clinical readouts sustain market confidence in core platforms and extend lifetime value through evidence-backed retention.
-
Johnson & Johnson (Cerenovus, New Brunswick, NJ, USA) — focuses on next-generation devices for large vessel occlusion and has secured important regulatory milestones, tightening its grip on high-acuity segments.
-
Penumbra, Inc. (Alameda, CA, USA) — specialist aspiration player pushing speed and efficacy with cleared systems; regulatory wins have translated into faster adoption curves in centers prioritizing workflow efficiency.
-
Balt USA LLC (Irvine, CA, USA) — markets focused stent retrievers and continues to leverage niche engineering strengths to contest share in targeted markets.
-
Terumo Corporation (Tokyo, Japan) — supplies a broad neurovascular portfolio with strength in aspiration catheters and guidewires; OEM partnerships and distribution reach give it defensive breadth.
-
MicroVention, Inc. (Aliso Viejo, CA, USA) — offers integrated aspiration systems and is expanding in Europe following CE approvals, reflecting a playbook centered on regional regulatory leverage.
-
Rapid Medical (Yokneam, Israel) — an upstart developing active access platforms and differentiated catheter technologies, representing an innovation-led challenger with high partnership potential.
Recent competitive moves underscore the pace of change: product launches in late 2025, FDA clearances accelerating aspirational systems, multi-year clinical data reinforcing incumbent platforms, and CE Mark expansions enabling faster European plays. Together, these developments compress windows for market entry and raise the bar on clinical and economic evidence required to win contracts.
Strategic imperatives for 2026 — recommended actions
-
Prioritize evidence that matters: Invest in pragmatic, outcomes-focused studies tied to hospital economics (length-of-stay reduction, readmission avoidance) to unlock reimbursement levers and capture NTAP-driven premiums.
-
Optimize product mix by procedure workflow: Differentiate on device features that shorten procedure time, reduce consumables, and ease training burden — procurement teams increasingly value total procedure cost over unit price.
-
Accelerate regulatory & HTA alignment: Target Breakthrough pathways and early HTA engagement for novel systems to compress time-to-reimbursement and build payor confidence.
-
Defend supply chains tactically: Establish diversified sourcing, dual-sourcing for critical components, and tariff-mitigation strategies to protect margins in the face of geopolitical pressures.
-
Pursue selective M&A and partnerships: Look for tuck-ins that fill gaps in access platforms, evidence-generation capabilities, or regional distribution where scale synergies are immediate.
-
Deploy flexible commercial models: Consider value-sharing pilots, bundled-care contracts with high-volume centers, and training-as-a-service to reduce adoption friction.
Scenario planning & measurement — practical triggers for 2026
-
Adoption upside trigger: Faster-than-expected guideline uptake or broader emergency triage protocols — accelerate scale investments and expand manufacturing capacity.
-
Reimbursement pressure trigger: Negative HTA findings or payer resistance — pivot to cost-reduction initiatives and focus sales on centers with bundled reimbursement.
-
Competition disruption trigger: Rapid market entry by devices with breakthrough designation — prioritize evidence amplification and tactical pricing to protect share.
-
Supply shock trigger: Component tariffs or supplier failure — deploy contingency suppliers and pre-negotiated logistics ramps to avoid lost sales.
For each trigger, the report provides quantified impact ranges on top-line and margin, recommended mitigation playbooks, and a prioritized set of KPIs to monitor in real time.
How to access the full intelligence
The summary above is a curated preview of PW Consulting’s full report, which contains the granular models, segmented forecasts, downloadable datasets, detailed company profiles, and a full list of primary research sources that underpin our conclusions. To obtain the complete report, model workbooks, and a briefing with our AIS practice leads, please visit the official report page. The full document is essential for anyone who needs to convert 2026 market signals into investment-grade strategy and executable plans.
PW Consulting’s AIS team stands ready to support tailored strategy workshops, M&A diligence, and go-to-market buildouts informed by the proprietary data and scenario simulations contained in the complete report.
For detailed analysis of this topic, please visit the official page: Worldwide Acute Ischemic Stroke Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Inguinal Hernia Repair Mesh Market Hits USD 4,801.0 Million in 2025
By PW Consulting, 2026-07-15
Worldwide Inguinal Hernia Repair Mesh Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market intelligence on the Worldwide Inguinal Hernia Repair Mesh market synthesizes five years of historical performance (2020–2025) with an actionable seven‑year forecast (2026–2032). The study documents steady expansion through 2025 — the market increased from USD 3,820.5 Million in 2020 to USD 4,801.0 Million in 2025 — and projects continued growth at a compound annual growth rate (CAGR) of 4.8% across our forecast window. By 2032, the market is projected to approach USD 6.7 Billion (USD 6,665.9 Million). This release is designed as a strategic “preview” for corporate leaders preparing 2026 investment, product, regulatory and M&A plans: it demonstrates the depth of our analysis while preserving the proprietary granularity that drives competitive advantage.
Worldwide Inguinal Hernia Repair Mesh Market
Why this preview matters for 2026 planning
-
Timing and trajectory: With a mid‑single digit CAGR and a material base scale achieved by 2025, hernia mesh remains an investable medtech category rather than a niche. That trajectory creates a window for measured expansion — either by scaling core product lines or selectively acquiring complementary capabilities — but it also tightens execution risk for players who delay strategic moves until 2027–2028.
Worldwide Inguinal Hernia Repair Mesh Market -
Concentration dynamics: The market shows meaningful concentration among a handful of established medical device manufacturers. Our CR3 and CR5 indicators signal that top competitors together hold nearly half to two‑thirds of market value, underscoring the importance of competitive differentiation and channel strength for emerging entrants and mid‑market firms.
Worldwide Inguinal Hernia Repair Mesh Market -
Operational leverage: Manufacturers able to optimize raw material sourcing and implement value engineering will disproportionately benefit from margin expansion, given recent upstream cost volatility. Procurement strategy is therefore an immediate lever for 2026 P&L improvement.
Market trajectory and key uncertainties
Our topline numbers reflect a market that is resilient but not immune to shocks. The core growth drivers remain demographic trends, increasing elective procedure volumes in many healthcare systems, and ongoing shift toward minimally invasive techniques where clinically appropriate. However, three near‑term uncertainties will shape outcomes in 2026 and beyond:
-
Regulatory harmonization: In mid‑2025, the U.S. Food and Drug Administration issued draft guidance calling for standardized package labeling for hernia mesh devices. This initiative aims to improve clinical consistency and patient safety but will require suppliers to update labeling, clinician education materials and quality systems. Firms that move early to comply will face lower commercialization friction and may gain adoption advantages.
-
Raw material inflation: Medical‑grade polypropylene — the dominant substrate for many synthetic meshes — has experienced sharp price inflation since 2021. The sector saw an increase exceeding 35% in recent years, materially impacting manufacturing cost structures. Companies that secure alternative sourcing, implement material‑efficient designs, or pivot toward differentiated biomaterials will be better positioned to defend margins.
-
Reimbursement and coding shifts: Updated coding and national average payment rates (effective January 1, 2026) create both upside for optimized procedure bundles and exposure where device pricing is misaligned with payer expectations. Revenue capture strategies must therefore be aligned with local reimbursement architectures early in 2026.
Competitive landscape — what the preview reveals
Our competitive assessment identifies several incumbent strategies and tactical moves that will shape market share dynamics in 2026:
-
Becton Dickinson (BD) — From a product and regulatory standpoint, BD leverages a dual approach: established polypropylene solutions for tension‑free repairs and differentiated bioresorbable options for case‑specific soft tissue reinforcement. Recent European expansion of a prophylactic indication and new product sizes underline BD’s push to broaden clinical use cases and geographic registration. For competitors, BD’s move signals intensified competition in prophylaxis and reinforced focus on lifecycle management of mesh portfolios.
-
Medtronic (Covidien) — Medtronic’s portfolio emphasizes anatomically contoured and self‑fixating mesh technologies tailored to laparoscopic workflows. The company’s strength in clinician training and bundled systems offers defensibility in settings where procedural standardization and TAPP/TEP approach volumes are high. Expect continued investment in surgeon education and integrated procedural solutions.
-
Ethicon (Johnson & Johnson MedTech) — Ethicon couples legacy polypropylene platforms with partially absorbable constructs, aiming to balance long‑term reinforcement and early‑stage tissue integration. Their large commercial footprint and OR consumables channels allow for pull‑through adoption; competitors should anticipate pricing pressure in legacy segments and displacement attempts where Ethicon bundles products with sutures or fixation systems.
-
B. Braun (Aesculap) — B. Braun emphasizes portfolio breadth and technical nuance in mesh weight, elasticity and user familiarity. The company’s strength is clinical customization for repair techniques; market entrants should be aware that B. Braun’s clinician relationships in certain geographies can accelerate product uptake for materials that align with local surgical preferences.
-
W. L. Gore & Associates — Gore’s biomaterials and ePTFE‑based constructs position it as a specialist supplier focused on adhesion minimization and specific abdominal wall indications. Their R&D orientation and advanced polymer know‑how make them a logical partner or acquirer for companies pursuing differentiated biomaterial strategies.
-
Getinge (Atrium Medical) — Atrium’s historical synthetic lines, and the litigation context associated with legacy products, highlight the long tail of product liabilities in this sector. Risk management, post‑market surveillance and clear labeling strategies are essential controls for incumbent and new suppliers alike.
Regulatory, reimbursement and supply chain implications
Our analysis shows that regulation and reimbursement are now co‑equal strategic levers alongside product innovation. The FDA’s draft labeling guidance increases the bar for clinical documentation and post‑market communication — translating into programmatic investments in regulatory affairs, human factors and sales force enablement. Simultaneously, updated CPT/HCPCS guidance and national payment changes mean that sales and pricing strategies need to be coordinated with payer affairs to avoid revenue leakage.
On the supply side, medical‑grade polymer inflation has compressed gross margins for manufacturers that pass costs through contractually or cannot reengineer product inputs. For 2026, three mitigants emerge: (1) hedged and diversified polymer sourcing; (2) modular design lowering material intensity; and (3) near‑term pricing frameworks tied to demonstrable clinical differentiation (e.g., reduced recurrence, fewer complications).
What PW Consulting’s full report contains (practical, operational deliverables)
While this preview surfaces strategic direction and market kinetics, the full Worldwide Inguinal Hernia Repair Mesh report delivers the operational intelligence needed to act in 2026. Key deliverables include:
-
Proprietary financial model (Excel) with top‑down and bottom‑up modules allowing users to run scenario tests across price, volume, and material cost assumptions for 2026–2032.
-
Regulatory readiness checklist tied to the FDA draft guidance and major regional conformity requirements, including a step‑by‑step labeling update playbook and timeline.
-
Commercial playbooks for hospitals, ambulatory surgical centers and specialist surgical channels, with clinician segmentation, value messages, and recommended training investments.
-
M&A and partnership screen: a scored universe of targets by strategic rationale (technology, geography, cost synergies), with a recommended integration outline and three valuation scenarios.
-
Procurement and sourcing playbook focused on polymer hedging, alternative biomaterials sourcing, and contract negotiation templates for raw material volatility mitigation.
-
Granular datasets: regional and product‑type breakdowns, surgical approach forecasts, and end‑user demand matrices — intentionally withheld in this preview to preserve the proprietary value of the full report.
Recommended actions for executives in 2026
-
Prioritize labeling and clinical communication updates: ensure regulatory and commercial teams are synchronized to implement FDA and regional labeling standards early in the year.
-
Lock in raw material strategies: create a sourcing task force to negotiate multi‑tier contracts and evaluate material‑efficient design variants to protect margins.
-
Reassess portfolio playbooks: map products to updated payer environments and surgeon preferences; redeploy sales resources to high‑return channels (where our modelling shows the fastest conversion of incremental marketing spend to revenue).
-
Consider targeted M&A or partnerships: prioritize assets that provide biomaterial differentiation, regulatory depth, or OR systems integration that accelerate adoption curves where incumbents are strongest.
-
Invest in post‑market data: create or expand registries and real‑world evidence programs to support value claims and reimbursement positioning.
How to use this preview
This executive summary is intended to orient strategic planning for 2026. It highlights market scale, expected growth trajectory, concentration dynamics (CR3/CR5 indicators) and the competitive and regulatory developments that will matter to boards, corporate strategy teams and business unit leaders. If your priorities for 2026 include product launches, pricing redesign, capital allocation for M&A, or operational resilience against raw material shocks, the full PW Consulting report provides the actionable data, financial models and playbooks to execute with confidence.
To access the complete analysis, detailed regional and product breakdowns, and the downloadable toolset described above, please consult PW Consulting’s full report page. The full deliverable is structured to support planning sprints and board‑level decisions throughout 2026, providing both the evidence base and the execution templates senior teams require.
For detailed analysis of this topic, please visit the official page: Worldwide Inguinal Hernia Repair Mesh Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Distribution Power Regulator Market to Expand at a 6.0% CAGR Through 2032
By PW Consulting, 2026-07-15
Worldwide Distribution Power Regulator Market: Strategic Outlook and 2026 Imperatives
Executive snapshot
PW Consulting’s new market brief—Worldwide Distribution Power Regulator Market—presents a road-tested, decision-oriented view for executives planning capital allocation, product strategy, and supply-chain positioning in 2026 and beyond. The report projects that the global distribution power regulator market, measured at the base year 2025, stands at approximately USD 3.12 billion and is expected to expand to roughly USD 4.68 billion by 2032, representing a compound annual growth rate (CAGR) of about 6.0% over the 2026–2032 forecast window. These headline numbers set the backdrop for strategic planning: sustained, mid-single-digit growth underlines steady demand driven by grid modernization, renewable integration, and greater operational expectations on distribution assets.
Worldwide Distribution Power Regulator Market
Why 2026 is a strategic inflection point
-
Acceleration of distributed energy resources (DERs): Utilities and distributors are confronting two-way power flows and tighter voltage envelopes as rooftop PV, storage and microgrids proliferate, creating new functional requirements for regulators (including reverse power flow handling and more precise voltage control).
Worldwide Distribution Power Regulator Market -
Digitalization and interoperability: Communication standards and protocols (IEC 61850, IEC 60870, DNP3, MODBUS, among others) are moving from “nice-to-have” to procurement preconditions for many network operators who are integrating regulators into supervisory control and distribution automation stacks.
Worldwide Distribution Power Regulator Market -
Cost and commodity pressures: Raw material trajectories—copper in particular—are meaningful line-item risks for transformer- and regulator-intensive projects. Our synthesis of commodity outlooks points to higher-than-historical copper levels in 2026 under base-case assumptions, compressing supplier margins and elevating total cost of ownership (TCO) dynamics.
-
Standards and reliability expectations: Compliance with industry standards for performance and enclosure protection (for example, IEEE C57.15 and NEMA 4) and certifications for extended mechanical operations are central to procurement specifications, especially for utility-scale deployments.
What PW Consulting’s report delivers (practical content you can act on)
-
Quantitative market sizing and scenarios—historical (2020–2025) and forward-looking (2026–2032)—calculated on a consistent USD basis, with baseline, upside and downside scenarios that stress commodity and regulatory swings.
-
Investment-grade methodology: transparent forecast assumptions, unit economics, and sensitivity tables that quantify how changes in raw material costs, installation labor, and digital retrofits alter project IRRs and payback periods.
-
Competitive benchmarking—qualitative and strategic mapping of incumbent and aggressive new entrants across product architecture, control stacks, channel strategies and aftermarket capabilities.
-
Technology deep-dives—analysis of step voltage, ferroresonant and electronic regulator technologies focusing on application fit, upgradeability, and lifecycle cost trade-offs (note: detailed sub-segment figures and regional breakdowns are reserved for the full report).
-
Procurement and sourcing playbook—negotiation levers, specification templates (including interoperability clauses and testing regimes), and supplier scorecards to accelerate RFP cycles while protecting margin and lead-time exposure.
-
Supply-chain risk mapping—sensitivity to copper and other raw-material trends, single-source exposures, and recommended hedging and inventory strategies for 2026 procurement calendars.
-
Actionable M&A and partnership intelligence—criteria for evaluating targets (IP, installed-base service revenues, control-platform assets), plus a prioritized shortlist of archetypal target profiles to fit buy-or-partner strategies.
Competitive landscape—what leaders are doing
The market exhibits a moderate level of concentration: the top three players account for a material share of installed capacity, with the top five materially increasing that concentration. That structure creates both stability and opportunity: established vendors control crucial OEM relationships and aftermarket channels, while niche and regional players exploit vertical specialization and cost advantages.
-
ABB Ltd. (Zurich) positions regulators within a broader electrification and grid-solutions portfolio, leaning on systems integration capabilities to sell higher-value automation and service contracts.
-
Eaton Corporation Plc (Dublin) emphasizes single-phase and substation regulators with advanced controls under legacy brands, targeting utilities focused on reliability and long-term serviceability.
-
Siemens AG / Siemens Energy (Munich) brings deep engineering heritage and an emphasis on reliability and renewable integration to its regulator offerings—appealing where certification and long-term performance matter most.
-
GE Vernova (Boston) highlights compliance with IEEE performance standards and reverse-power operation for distributed generation scenarios, an increasingly important capability for modern distribution circuits.
-
Other notable players—Schneider Electric, Hitachi Energy, Howard Industries, Toshiba, Maschinenfabrik Reinhausen and a series of specialized regional manufacturers—compete on product variants, service models and local presence.
Recent product activity is instructive. For example, Hitachi Energy’s June 2025 launch of a compact line-voltage regulator integrated at the transformer level demonstrates the industry push toward more integrated, space- and cost-efficient devices that also support active voltage control—an attractive value proposition for retrofits and constrained urban feeders.
Regulatory, standards and interoperability—practical implications
-
Procurement specs must embed compliance: require IEEE C57.15-type performance guarantees and appropriate environmental/enclosure ratings (e.g., NEMA 4) upfront to reduce rework risk.
-
Communication and control: mandate protocol support and cybersecurity baselines at RFP stage—vendors offering native IEC 61850 or robust gateway strategies will materially ease integration costs.
-
Testing and longevity: where extended mechanical operations matter, insist on third-party reliability attestations (e.g., performance certifications that validate multi-million operation lifecycles).
Cost and supply-side risk: what to watch and how to respond
Commodity exposure is non-trivial. Industry consensus modeling points to copper remaining elevated in 2026 versus pre-pandemic averages, pressuring winding- and conductor-intensive products. That dynamic compresses vendor margins and can prompt lead-time or price escalation clauses. Our recommended mitigations for 2026:
-
Lock-in strategic supply agreements with indexed pricing collars to limit downside on volume buys while sharing some upside with suppliers.
-
Design-for-cost reviews—evaluate opportunities to substitute materials, leverage alternative winding approaches, or adopt modular architectures that allow partial field upgrades rather than full replacements.
-
Inventory optimization—use probabilistic lead-time hedging for key components rather than blanket stockpiling to manage working capital.
Actionable recommendations for corporate decision-makers in 2026
-
Re-align capex plans to the market growth posture: use the mid-single-digit CAGR as a baseline for phased rollouts, with upside allocations reserved for accelerated DER-driven hot spots.
-
Prioritize digital-ready specifications: require telemetry, standardized communications, and upgrade pathways in all new procurements to avoid early obsolescence.
-
Run targeted pilot projects that validate reverse-power handling, local voltage optimization algorithms, and two-way protection schemes before broad deployment.
-
Adjust supplier due diligence to include lifecycle service economics—ensuring aftermarket revenue profiles and field-service capabilities are part of the sourcing calculus.
-
Stress-test investment cases against commodity shocks and regulatory tightening; maintain a scenario folder that translates bench-level assumptions into portfolio-level P&L outcomes.
-
Consider bolt-on M&A for service-platform capabilities or software-enabled control modules rather than raw hardware manufacturers, where synergies can accelerate differentiation.
Why PW Consulting’s report is indispensable for 2026 planning
This study is purpose-built for decision-makers who need more than market color: it blends rigorous quantitative sizing with hands-on procurement templates, supplier checklists, and TCO models calibrated to contemporary commodity and regulatory realities. To preserve the integrity of tactical plans, we deliberately maintain the “trailer” approach in public summaries—showing methodology, directionality and practical conclusions while reserving granular regional and sub-segment data for the full report and client briefings.
For 2026 planning cycles—budget approvals, supplier negotiations, pilot funding, and M&A diligence—PW Consulting’s Worldwide Distribution Power Regulator Market report equips teams with the facts, scenarios and actionable frameworks required to make defensible choices under uncertainty. To access the complete dataset, sub-segment growth rates, regional splits, and downloadable procurement templates, please consult the full report on our publication page or contact PW Consulting’s energy practice.
For detailed analysis of this topic, please visit the official page: Worldwide Distribution Power Regulator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


