



Category: market research
PW Consulting Forecasts Automotive Connecting Rod Bush Market to Grow at a 3.82% CAGR Through 2032
By PW Consulting, 2026-07-13
Automotive Connecting Rod Bush Market — Strategic Preview for 2026 Decision-Making
PW Consulting’s latest market intelligence briefing offers a forward-looking, executive-grade appraisal of the global Automotive Connecting Rod Bush market. Built on a 2025 base year, our analysis synthesizes historical performance (2020–2025) and a granular forecast window (2026–2032) to translate market dynamics into actionable choices for OEMs, suppliers, aftermarket players and strategic investors. This preview highlights the report’s strategic value for calendar‑year 2026 planning while deliberately withholding the full segmented tables and proprietary model outputs to encourage review of the complete dossier.
Automotive Connecting Rod Bush Market
Market snapshot — what the headline numbers tell you
-
Market scale and trajectory: The global market stands on a steady expansion path. From a measured market value of USD 642.5 Million in our 2025 base year, the model projects growth at a 3.82% compound annual growth rate (CAGR) across 2026–2032, reaching an estimated USD 835.28 Million by 2032. The market is already showing consistent year‑on‑year gains in the 2023–2025 period that underpin our near‑term baseline.
Automotive Connecting Rod Bush Market -
Concentration and competitive structure: Market concentration is moderate. The top three firms collectively account for a meaningful share of industry revenues, and the top five raise that share appreciably — a structure that supports both scale advantages and pockets of regional/technical specialization.
Automotive Connecting Rod Bush Market -
Forecast horizon: Our scenario suite covers a central case (3.82% CAGR), conservative and upside cases, and sensitivity runs that stress raw‑material price shocks, accelerated electrification, and regulatory-driven replacement demand.
Why this report matters for 2026 strategy
-
Decision timing: 2026 is a pivotal year for capital allocation and product roadmaps. OEMs and Tier‑1/2 suppliers will finalize mid‑cycle product updates and capacity plans; our modeling quantifies the addressable market envelope and highlights where marginal investments deliver the highest ROI under plausible market paths.
-
Risk‑informed sourcing: Raw‑material composition and supply continuity materially affect margin and availability. The report’s procurement stress tests and supplier tiering allow procurement leaders to prioritize dual‑sourcing, hedging, or strategic inventory deployment ahead of potential material squeezes.
-
Regulatory contagion and aftermarket opportunity: Recent airworthiness directives and tightening emissions standards create both compliance costs and aftermarket demand pockets. The report maps regulatory events to demand pulses and prescribes commercial approaches to capture replacement and retrofit demand without compromising OEM channels.
Key strategic implications — recommended plays for 2026
-
Prioritize material and tribology innovation: Advances in bi‑metal and tri‑metal alloys, high‑tin aluminum formulations, and low‑friction surface treatments materially affect fuel efficiency and emissions. Suppliers with validated, low‑wear solutions are positioned to win OEM design‑ins and preferred aftermarket status.
-
Calibrate capacity expansion to regional demand drivers: Given the market’s moderate CAGR, capacity investments should be staged and linked to secured offtake or modular manufacturing strategies. Greenfield capacity is advisable only where long‑term contracts or differentiated technology protect utilization.
-
Leverage aftermarket channels as a margin and resilience lever: Regulatory-driven replacement mandates and repair kit rollouts create high-margin, short‑cycle revenue that can offset upstream cyclicality. A balanced OEM‑aftermarket go‑to‑market strategy reduces exposure to new‑vehicle cycles.
-
Embed regulatory intelligence into product lifecycles: Active monitoring of airworthiness and emissions directives — including recent directives that mandate replacement of specific bushings in certain engine families — should be integrated into product update timelines to preempt compliance disruptions.
-
Adopt flexible sourcing and alloy rationalization: Material mix (bronze, steel‑backed aluminum, brass, etc.) drives both performance and cost. Standardizing alloy families across platforms where performance permits simplifies procurement and improves supplier leverage.
Competitive landscape — tactical takeaways
Our competitive mapping synthesizes product portfolios, geographic footprints, and route‑to‑market strengths across leading incumbents and notable regional manufacturers. High‑level observations include:
-
Global engineering leaders (example: MAHLE GmbH) differentiate through deep OEM relationships, integration into engine systems, and investments in low‑friction, high‑durability bearings tailored to internal combustion platforms.
-
Legacy powertrain specialists (example: Federal‑Mogul / Tenneco) continue to extract value from aftermarket scale and aftermarket‑OEM crossovers, particularly where bi‑metal and tri‑metal technologies address high‑duty commercial engines.
-
High‑performance and niche specialists (example: King Engine Bearings, K1 Technologies) maintain premium positions through tolerance precision and proven performance under extreme loads — important for motorsport, performance aftermarket and heavy‑duty segments.
-
Regional champions and cost‑competitive producers (several Asia and India‑based manufacturers) compete on cost, speed to market, and catalog breadth. Many have upgraded quality systems (IATF/ISO certifications) to capture OEM and aftermarket share simultaneously.
For 2026 playbooks, the analysis recommends distinct approaches for scale players (protect OEM share, invest in materials tech), regional manufacturers (move up the quality curve, secure long‑term contracts), and aftermarket specialists (monetize regulatory replacement windows and repair kits).
Regulatory and materials context — dynamics to watch
-
Regulatory event impact: Recent airworthiness directives related to specific engine models illustrate how targeted regulatory action can create abrupt replacement demand and compliance costs. Our report includes a regulatory tracker that quantifies the near‑term demand uplift and the longer‑term compliance burden by engine family.
-
Material composition and supply risk: Connecting rod bushings remain primarily manufactured from bi‑metal steel‑backed bronze, high‑tin aluminum alloys and brass. Price and availability volatility in copper and aluminum markets, plus regional alloy processing constraints, are modeled to show margin sensitivity across supplier types.
-
Emissions and efficiency pressure: Stringent fuel efficiency and emission mandates globally are increasing the value of low‑friction bushing designs. Our friction‑reduction benefit model translates tribology improvements into measurable fuel and emission gains at fleet level — a key negotiation lever for OEMs and suppliers.
What’s inside the full PW Consulting report (actionable components)
-
Proprietary market model (USD Million base) with historical series (2020–2025) and forecast (2026–2032) under central, conservative and upside scenarios.
-
Segmentation frameworks by region, material type and vehicle class, with elasticities, growth drivers and leading indicators (note: full segment tables and discreet values are retained in the paid report).
-
Supplier scorecards and capability matrices covering engineering depth, capacity, quality certifications, lead times and aftermarket reach.
-
Manufacturing cost and margin benchmarks, including BOM-level sensitivity to alloy price movements and labor/capex assumptions.
-
Regulatory tracker and impact matrix that ties airworthiness directives and emissions mandates to near‑term replacement demand and long‑term design shifts.
-
Go‑to‑market playbooks for OEMs, Tier suppliers and aftermarket players: pricing strategies, contract terms, service propositions and M&A/opportunity heatmaps.
-
Scenario planning tools and a business‑case calculator designed for C‑suite and transaction teams to run quick valuations under different adoption, regulatory and material‑price paths.
How to use this preview in your 2026 planning cycle
-
For strategy teams: Run the report’s scenario suite against your product roadmaps to determine the marginal value of material upgrades or manufacturing capacity expansions.
-
For procurement: Use the supplier scorecards and material sensitivity runs to prioritize dual‑sourcing, strategic inventory, and alloy rationalization before contract renewals.
-
For M&A and corporate development: The concentration metrics and competitive profiles identify targets that either consolidate scale or fill technical gaps; our valuation tool helps quantify synergies under the central and upside cases.
Closing — an invitation to deeper intelligence
This preview demonstrates the analytical depth PW Consulting brings to the Automotive Connecting Rod Bush market: a calibrated market model, supplier and materials intelligence, regulatory foresight, and translated commercial actions. For teams making allocation, sourcing, product or M&A decisions in 2026, the full report supplies the proprietary segmented datasets, playbooks and financial models necessary to act with conviction.
Access to the complete report will provide the precise segment tables, regional and material‑type breakdowns, and downloadable model files that are intentionally withheld here. Contact PW Consulting or visit our report page to obtain the full market study and supporting tools for your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Automotive Connecting Rod Bush Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smoke Evacuation Tubing Market to Climb from USD 235.05 Million in 2025 to USD 380.4 Million by 2032 at a 7.12% CAGR
By PW Consulting, 2026-07-13
Smoke Evacuation Tubing Market 2026: Strategic Signals for Executive Decision-Making
Executive summary
PW Consulting’s new Smoke Evacuation Tubing Market report synthesizes five years of historical performance (2020–2025) and provides a forward-looking forecast through 2026–2032. The global market expanded materially from the start of the decade and reached USD 235.05 Million in our 2025 base year. Under our forecast scenarios, the market accelerates to roughly USD 380.4 Million by 2032, reflecting a compound annual growth rate (CAGR) of 7.12% across the 2026–2032 horizon. These macro dynamics create a multi-faceted strategic agenda for device manufacturers, distributers, hospital procurement teams, and private equity investors preparing critical decisions in 2026.
Smoke Evacuation Tubing Market
Why this market matters in 2026
-
Structural growth. The product category is no longer a niche accessory: consistent year-on-year expansion and healthy mid-single-digit-to-high-single-digit CAGR dynamics are turning smoke evacuation tubing into a predictable revenue stream that complements larger systems sales and disposable consumable portfolios.
Smoke Evacuation Tubing Market -
Regulatory momentum. Regulatory pressure—both statutory and institutional—has heightened the imperative to manage surgical plume. More than a third of U.S. states have enacted laws requiring smoke evacuation in operating rooms, and devices in this space fall under recognized FDA Class II requirements for electrosurgical accessories. Compliance cost and procurement timelines will be a central consideration for rollouts in 2026.
Smoke Evacuation Tubing Market -
Product innovation is shifting purchasing behavior. Design advances (e.g., tapered corrugated profiles, single-extrusion materials, integrated tubing kits) are improving usability and infection control, enabling suppliers to capture premium positions even as hospitals optimize consumable spend.
Market trajectory — the numbers you need to plan around
Executives planning budgets and M&A strategies for 2026 should anchor decisions to three high-level facts from our study: the market’s base size in 2025 (USD 235.05 Million), the immediate uplift in 2026, and the projected rise to approximately USD 380.4 Million by 2032. Those figures, combined with a 7.12% CAGR for the forecast window, provide a quantifiable foundation for scenario modelling—whether your focus is organic growth, bolt-on acquisitions, or strategic partnerships with OR systems vendors.
Key demand drivers and risk factors
-
Regulatory and institutional mandates. Rising legal and occupational-safety expectations are increasing baseline demand for compliant evacuation solutions, especially in jurisdictions with explicit requirements.
-
Shift toward disposables and integrated consumables. Hospitals balancing infection control and cost efficiency are selectively adopting integrated tubing kits and single-use options that streamline workflow with electrosurgical pencils and smoke evacuators.
-
Procurement rationalization. Larger health systems are centralizing purchasing; this favors suppliers who can offer validated compatibility across major smoke evacuator platforms and can demonstrate supply-chain resilience.
-
Price sensitivity vs. clinical preference. Devices with demonstrable usability or clinical benefit can command a premium; however, commoditization remains a real threat if suppliers compete only on price.
Competitive landscape — what to watch in 2026
The market exhibits moderate concentration: the top three vendors together account for a meaningful share of the market, while a broader set of manufacturers constitutes a substantial competitive tail. CR3 and CR5 metrics indicate room for consolidation and for service differentiation beyond price.
-
CONMED Corporation (Largo, Florida) — Strengths: breadth of portfolio, compatibility with established evacuator platforms, and a deep distribution network. Strategic play: leverage platform compatibility to negotiate formulary placements with large hospital systems and bundle tubing with consumable and capital equipment sales.
-
Medtronic plc (Dublin) — Strengths: productized RapidVac offerings and laparoscopic variants with control features. Strategic play: integrate tubing design with procedural workflows to drive higher share in electrosurgery-centric specialties and to cross-sell into existing installed bases.
-
CLS-Surgimedics (USA) — Strengths: sterile/non-sterile breadth and accessory ecosystem (pencil wands). Strategic play: emphasize specialty-specific solutions and direct-clinician engagement to defend margin against low-cost imports.
-
I.C. Medical, Inc. (Phoenix, Arizona) — Strengths: U.S.-based manufacturing and laparoscopic sterile sets. Strategic play: position “made-in-country” supply reliability as a procurement differentiator, especially for large health systems prioritizing supply resiliency.
-
DeRoyal Industries , Aspen Surgical , Stryker , CooperSurgical , and Buffalo Filter (CONMED) — Each brings unique channel relationships, system compatibility, or product integration capabilities. Notably, Stryker’s late-2024 regulatory clearance for a smoke-evacuation-enabled device underscores how system-level integration can shift demand toward vendors that can offer instrument-level evacuation solutions.
Strategic implications and recommended actions for 2026
Our analysis yields five pragmatic priorities for executives preparing 2026 roadmaps:
-
Re-seat product strategy around workflow outcomes. Buyers increasingly evaluate tubing on clinical workflow and staff time savings, not just unit cost. Product R&D should emphasize ease-of-use, connector compatibility, and packaging that reduces OR setup time.
-
Build compatibility and validation playbooks. Suppliers that can demonstrate validated compatibility with major smoke evacuators and electrosurgical systems will unlock preferred supplier agreements with integrated health systems.
-
Consider bolt-on consolidation selectively. Given the market’s moderate concentration, serial acquisitions of niche tubing and accessory makers can quickly increase share and margin if integration captures procurement synergies and reduces SKU complexity.
-
Operationalize regulatory and procurement readiness. Ensure product dossiers and 21 CFR compliance artifacts are complete and accessible; regulatory friction is a top source of tender disqualification in 2025–2026 procurement cycles.
-
Differentiate via supply-chain resilience and clinical evidence. Investments in redundancy, U.S.-based manufacturing options, and clinician-led evidence generation (time-in-OR, aerosol reduction metrics) materially improve contracting outcomes with large buyers.
Where the report provides operational advantage
This PW Consulting report is expressly designed as a decision-support tool for 2026. It contains:
-
Actionable market models and scenario tables that map unit-volume, ASP, and revenue sensitivities against regulatory and adoption scenarios (note: detailed segment-level tables and region/application splits are included in the full report and accessible through our data portal).
-
Competitive scorecards and vendor heat maps that evaluate product breadth, system compatibility, manufacturing footprint, and evidence base—constructed to support supplier selection and M&A screening.
-
Regulatory and procurement playbooks that translate FDA Class II device requirements and state-level legislative trends into checklists for product development, clinical trials, and tender responses.
-
Commercial playbooks with go-to-market tactics for three archetypal players—global OEMs, regional specialists, and private-label players—covering channel strategies, pricing levers, and partnership frameworks.
-
Supply-chain stress tests and contingency plans to quantify the cost of disruption and to prioritize domestic-sourcing investments versus offshore optimization.
Use cases where the report delivers immediate ROI
-
Procurement teams preparing 2026 contract renewals: use our compatibility matrices and TCO models to negotiate better terms and fewer SKUs.
-
Corporate development teams evaluating tuck-ins: apply our M&A screening criteria and synergies model to shortlist targets that move the needle on CR3/CR5 concentration and distribution reach.
-
Product and R&D leaders: leverage our usability and clinical evidence frameworks to prioritize product roadmaps that command price premiums.
-
Private equity sponsors: stress-test exit scenarios using our forecast range and sensitivity runs to set valuation and hold-period expectations.
Next steps for executives
For leaders planning capital allocation and commercial initiatives in 2026, the near-term priorities are clear: (1) reconcile product roadmaps with regulatory evidence needs, (2) codify compatibility and supply guarantees for large health-system clients, and (3) evaluate M&A candidates using the report’s revenue-per-SKU and channel-synergy models.
PW Consulting’s report functions as a short-cut to readiness—delivering actionable templates and data that accelerate decision cycles while preserving the granular segmentation and regional figures behind our paywall. If you are preparing a 2026 growth plan, procurement RFx, or acquisition thesis, integrating these market-calibrated inputs will materially reduce execution risk.
Conclusion
The smoke evacuation tubing market is transitioning from niche consumable to strategic portfolio asset. With a base of USD 235.05 Million in 2025 and a guided path toward approximately USD 380.4 Million by 2032 at a 7.12% CAGR, the category merits prioritized attention in 2026 planning cycles. PW Consulting’s report surfaces the competitive, regulatory, and product levers that determine who captures the growth and who competes on eroding margins. For the complete segmentation breakdowns, vendor matrices, and procurement-ready tools that support execution, download the full report from PW Consulting’s market intelligence portal.
For detailed analysis of this topic, please visit the official page: Smoke Evacuation Tubing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Photolithography Equipment Market to Reach USD 32.45 Billion in 2025 as EUV and Asia‑Pacific Dominate
By PW Consulting, 2026-07-13
Photolithography Equipment Market — Strategic Preview for 2026 Decision-Makers
Executive summary
As global semiconductor investment accelerates into AI, high-performance computing, and edge devices, photolithography equipment remains the most capital-intensive and strategically critical segment of the fab supply chain. PW Consulting’s forthcoming Photolithography Equipment Market Research (base year 2025; historical coverage 2020–2025; forecast period 2026–2032) synthesizes macro drivers, technology roadmaps, supplier capabilities and regulatory risk into an actionable framework for executives planning 2026 capital and partner strategies.
Photolithography Equipment Market Research
Key headline: the market is on a sustained expansion trajectory — growing from an already large installed and replacement base in 2025 to roughly double by the end of the forecast horizon — driven by node transitions, capacity buildouts and ongoing node scaling. Our model, built on a 10.45% compound annual growth rate (CAGR) for the 2026–2032 period, yields a 2025 market size of USD 32,450 Million (revenue unit: Million, currency: USD) and a projected market approaching USD 65,065 Million by 2032. These aggregates encapsulate system shipments, upgrades and services across EUV, DUV and complementary patterning technologies.
Photolithography Equipment Market Research
Why this preview matters to 2026 strategy
- Capital allocation: firms committing to 2026 fab investments must reconcile multi-year lead times for advanced lithography with uncertainty from export controls and localized supply initiatives.
- Supplier selection and risk mitigation: with very high market concentration among a handful of suppliers, a robust supplier-risk playbook is critical to avoid production bottlenecks and geopolitical exposure.
- Technology roadmap alignment: buyers and ecosystem participants must balance near-term throughput needs (DUV/ArFi) with medium-term High-NA EUV adoption and service footprints.
Market outlook and macro foundations
Our 2026 outlook is grounded in three measurable macro dynamics: fab capacity growth, node-driven replacement cycles, and regulatory constraints. Industry plans indicate a near-term wafer fab capacity expansion (notably driven by AI and HPC demand) that PW Consulting has incorporated into scenario models. These capacity expansions are front-loaded into the 2026–2028 period and exert outsized demand on immersion DUV and EUV tool availability, spares and service engineers.
Photolithography Equipment Market Research
Regulatory and supply risk layers materially shape deployment feasibility. Recent export control tightening by the US Bureau of Industry and Security on advanced photolithography tools below ~7nm raises both timing risk and potential for supply fragmentation. Concurrently, supplier-side resource constraints — for example, optics production and specialty gases used in EUV sources — have driven cost pressures and cadence uncertainty. Our base-case financial projection reflects these frictions while the upside case assumes eased export constraints and an accelerated High-NA EUV ramp.
Competitive landscape: what to watch in 2026
The photolithography market shows extreme concentration at the supplier level. A very small set of dominant vendors control nearly the entire technology stack for advanced nodes, and that concentration translates into bargaining power, differentiated service ecosystems and long technology lead times. The CR3 and CR5 metrics in our analysis underscore this reality: the top three and top five vendors collectively command the vast majority of supply and aftermarket services.
- ASML Holding N.V. (Veldhoven, Netherlands) — The undisputed leader in EUV and high-end DUV platforms, ASML’s roadmap toward High-NA EUV is central to industry scaling beyond 3nm. Recent product shipments of High-NA EUV systems for leading-edge process development illustrate how tooling availability governs node timelines. For buyers, ASML’s platform cadence and service footprint will dictate migration pathways and capex phasing.
- Nikon Corporation (Tokyo, Japan) — Nikon’s NSR-series and well-established DUV scanners remain strategic workhorses for logic, memory and specialty fabs at mature nodes. Nikon’s incremental system showcases at trade events reflect a play on stability and throughput optimization where EUV adoption is phased.
- Canon Inc. (Tokyo, Japan) — Canon’s focus on ArF immersion upgrades and complementary patterning techniques (including nanoimprint) positions it as a nimble provider for HVM upgrades and differentiated node strategies, particularly for fabs seeking cost-effective throughput gains.
- Shanghai Micro Electronics Equipment (SMEE) (Shanghai, China) — SMEE’s DUV immersion tools are a strategic enabler for domestic fab programs, aligned to China’s localization targets. While performance differentials versus leading-edge suppliers remain, SMEE’s roadmap matters for regional capacity and procurement diversification strategies.
Strategic implication: supplier selection is no longer a pure technical decision. It is a composite of technology fit, supply-chain sovereignty, regulatory exposure and long-term service partnerships. PW Consulting’s vendor-risk matrix in the full report ties supplier capabilities to discrete procurement playbooks for OEMs, IDMs and fabless/OSAT ecosystems.
Operational dynamics and system-level constraints
Behind the headline CAGR lie operational constraints that will determine realized outcomes in 2026:
- Optics capacity: advanced multilayer optics production — a critical input for EUV — has limited ramp cadence. Major optics manufacturers have been increasing capacity, but High-NA tooling targets remain constrained on an annual basis.
- Specialty consumables: supply bottlenecks in items like helium isotopes for EUV sources and specialty gases introduce variable OPEX and can delay tool acceptance.
- Regulatory gating: export controls can delay or reroute shipments, forcing alternative sourcing or second-source strategies and sometimes triggering requalification costs.
These operational realities amplify the importance of service contracts, spare-parts strategies and skills development in 2026 — not as optional extras but as core components of capital planning.
What the PW Consulting report contains (practical, actionable content)
PW Consulting designed the full Photolithography Equipment Market Research report as a decision-useful toolkit for 2026 planning. It includes:
- Market modeling: bottom-up and top-down models reconciled against supplier shipment disclosures, with scenarios for regulatory tightening, High-NA adoption rates and capacity variance. (Base year: 2025; forecast 2026–2032; CAGR 10.45% used for primary baseline.)
- Executive playbooks: procurement, supplier risk mitigation, upgrade vs. new-tool decision flows, and CAPEX phasing templates tailored for IDMs, foundries and advanced packaging players.
- Competitive profiles: deep vendor dossiers covering product roadmaps, installed base dynamics, aftermarket revenue levers and partnership ecosystems for the major suppliers.
- Operational annexes: spare-parts inventories, service-capacity mapping, qualification timelines and cost-to-serve benchmarks for EUV vs. DUV deployments.
- Regulatory and geopolitical scenarios: quantified impact matrices illustrating how export policy shifts and localization drives alter supplier choices, lead times and total cost of ownership.
- Supply-chain stress tests: sensitivity analyses for optics capacity, specialty gas pricing and skilled-service headcount shortages, with mitigation strategies and contingency playbooks.
Note: to preserve commercial confidentiality and to protect the strategic value of the analysis, detailed regional and application-level splits (the granular segmentation figures and percentage allocations) are intentionally summarized at a high level in this preview; full segment-level tables and interactive dashboards are available in the paid report.
Actionable recommendations for 2026
- Adopt a two-track procurement strategy: secure baseline DUV capacity for near-term volume while reserving optionality for EUV/High-NA placements tied to node confirmation and regulatory clearances.
- Prioritize service and spare-part contracts at the time of purchase: our scenario stress tests show that lifecycle availability and responsiveness materially affect effective throughput in years 1–3 post-installation.
- Develop geopolitical hedges: diversify supplier relationships and invest selectively in regionalized service capabilities where export risk is elevated.
- Stress-test supply chains: quantify the impact of key input constraints (optics, gases, skilled field engineers) on your factory ramp plans and incorporate buffer strategies into EBITDA forecasts.
- Engage in collaborative partnerships: consider co-development or long-term service agreements with leading suppliers to secure prioritized delivery windows and accelerated technology transfers where feasible.
Preview of recent industry movements relevant to 2026 execution
- ASML’s delivery of a commercial High-NA EUV system for advanced process development underscores the technology’s strategic role for sub-3nm node workstreams and the limited cadence of production-grade High-NA units.
- Major DUV vendors continue iterative product upgrades—reflecting a market that will sustain both advanced EUV investment and high-throughput DUV deployments for the foreseeable planning horizon.
- Upstream capacity and material news — including optics manufacturers scaling multilayer coating lines and documented specialty-gas supply constraints — should be treated as scheduling risk factors in any 2026 procurement calendar.
Final note — how to use this preview
This article provides a calibrated strategic lens on the photolithography equipment market, designed to inform board-level discussions, procurement cycles and R&D alignment for 2026. For procurement teams, the vendor playbooks and TCO models are immediately actionable. For strategy and corporate development teams, the regulatory scenarios and supply-chain stress tests enable robust M&A and partnership screening.
To access the complete, interactive dataset, detailed segmentation tables, regional and application-level forecasts, and downloadable procurement templates, visit the PW Consulting report landing page. The full report contains the granular intelligence necessary to convert the high-level strategies in this preview into executable 2026 plans.
For detailed analysis of this topic, please visit the official page: Photolithography Equipment Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pathogen Detection Market to Hit USD 9,499.07 Million by 2032 at 7.8% CAGR (Forecast 2026–2032), Led by PCR
By PW Consulting, 2026-07-13
Pathogen Detection Market Outlook: Strategic Imperatives for 2026 — PW Consulting Report Highlights
Executive snapshot
PW Consulting's Pathogen Detection Market Report (base year 2025; historical window 2020–2025; forecast period 2026–2032) provides a forward-looking, actionable foundation for enterprise decision-making heading into 2026. Our analysis finds the global market at approximately USD 5,615 Million in 2025, with a projected compound annual growth rate (CAGR) of 7.8% through 2032, when the market is expected to approach roughly USD 9,499 Million. Market concentration is moderate: the top three players account for a meaningful share of the market while the top five increase that concentration further — a structure that favors both scale-driven plays and targeted innovation by specialist entrants.
Pathogen Detection Market
Why this report matters for 2026 decision cycles
-
Translate macro momentum into executable initiatives: Our forecast and scenario analyses convert headline growth into sequenced priorities for product development, distribution, and commercial partnerships.
Pathogen Detection Market -
Bridge regulatory and reimbursement complexity: The roadmap we provide helps firms prioritize dossiers and payer engagements that materially affect near-term access and margins.
Pathogen Detection Market -
De-risk supply and margin pressures: Proprietary supplier-risk and cost-sensitivity modules identify where procurement and vertical integration yield the strongest returns under 2024–2026 supply volatility.
-
Benchmark competitive intent: Our competitor maps and capability matrices allow management teams to identify white-space opportunities and credible acquisition or partnership targets.
What the report delivers — practical, decision-ready tools
-
Five-year and long-range revenue forecasts aligned to multiple go-to-market scenarios, stress-tested against supply shocks and regulatory shifts.
-
Segment- and technology-level growth drivers and adoption curves (PCR, immunoassays, NGS, isothermal amplification, mass spectrometry and others) with use-case prioritization for clinical, food safety, pharmaceutical QC, and environmental testing.
-
Regulatory roadmap and payer-playbook: prioritized pathways for CLIA-waived and CE-IVD strategies, plus reimbursement impact assessments tied to representative CPT and national codes.
-
Supplier and raw-material heatmaps that quantify exposure to reagent and consumables price shocks and identify mitigation levers (dual sourcing, hedging, local manufacturing).
-
Commercial models that optimize hardware-to-consumables economics, including service-led frameworks and subscription-based reagent monetization.
-
M&A and partnership screen: a ranked list of tuck-in targets, strategic partner archetypes, and likely consolidation scenarios — with sensitivity to antitrust and regional regulatory constraints.
-
Executive playbooks and 90/180/365-day action plans for product, commercial, and regulatory teams designed to accelerate time-to-revenue.
Market dynamics shaping 2026 decisions
Three dynamics dominate near-term strategy: regulatory access, reimbursement design, and supply-chain cost pressure.
-
Regulatory access: Point-of-care expansion remains gated by specific regulatory statuses (e.g., CLIA-waived in the U.S.). Securing simplified-use clearances materially expands addressable channels (physician offices, urgent care, non-traditional sites) and shortens sales cycles for low-complexity diagnostics.
-
Reimbursement: Changes in reimbursement can shift clinical and commercial economics quickly. For example, updated payment codes and fee schedules for high-volume tests materially affect provider adoption thresholds and price elasticity in 2025–2026 planning.
-
Input-cost volatility: Medical-grade reagents and single-use plastics experienced notable cost escalation in recent years, elevating the importance of margin-protection measures such as local sourcing, supplier contracts indexed to volumes, and design-for-cost in consumables.
-
Global access and procurement: WHO prequalification expansion for rapid tests increases market opportunity in low-resource settings but also raises the bar for quality, supply assurance, and price-pressure from public tenders.
Competitive landscape — what to watch
The competitive field is composed of diversified diagnostics giants, specialized molecular-platform vendors, and nimble assay innovators. Each group brings distinct vectors of value and risk:
-
Large diagnostics OEMs (e.g., Roche, Abbott, Thermo Fisher, BD) — These firms combine installed instrument footprints, broad assay portfolios, and strong regulatory pathways. Their strategic moves focus on point-of-care marks, higher-throughput platforms, and bundled service contracts. Recent CE and clinical-readout milestones from major OEMs reinforce their ability to accelerate commercialization where regulatory clearance and reimbursement alignment exist.
-
Molecular-platform specialists (e.g., Danaher/Cepheid, Bio‑Rad, Qiagen) — Their strength is rapid molecular workflows and assay multiplexing. Regulatory clearances and targeted product launches in 2024–2025 show continued innovation at the platform assay interface; these firms remain prime partners or acquisition targets for organizations seeking rapid access to validated multiplex capabilities.
-
Assay innovators and isothermal/alternate-technology players (e.g., Meridian, Hologic, Luminex/DiaSorin) — Focused on niche pathogens and faster time-to-result, these players can command clinical adoption in focused indications and are often attractive for licensing or co-development with manufacturers seeking differentiated cartridge content.
Recent company milestones illustrate strategic trajectories that will influence 2026 competition: targeted FDA clearances for new on-demand assays, multiplex panel launches that expand clinical breadth, CE-IVD point-of-care authorizations, strong clinical trial readouts for sensitivity/specificity claims, and distribution deals that accelerate hospital adoption. These moves tighten the window for newcomers to establish clinical trust and payer coverage.
Strategic imperatives for 2026 — recommended plays by stakeholder
-
Instrument manufacturers : Prioritize CLIA-waived and decentralized-use design wins; bundle consumables with service/analytics to protect margins; accelerate modular cartridge strategies to broaden assay attach rates.
-
Reagent and consumables suppliers : Execute dual-sourcing and local-fill strategies in 2026 to reduce exposure to input-cost shocks; develop lower-cost formulations and SKU rationalization for high-volume assays.
-
Clinical lab networks and hospital systems : Model total-cost-of-ownership across on-site, POC, and reference testing pathways; negotiate volume-based reagent rebates and prioritize multiplex panels that reduce downstream workflow costs.
-
Public health and procurement bodies : Leverage WHO prequalification to consolidate tenders and incentivize manufacturers to align pricing and supply commitments for low-resource markets.
-
Private investors and corporate development : Target asset classes that combine high recurring-revenue consumables with differentiated platform lock-in; prioritize targets with clean regulatory pathways and demonstrated clinical utility data.
Immediate actions for Q1–Q4 2026
-
Fast-track regulatory filing strategies for point-of-care pathways and align clinical protocols to payer evidence requirements.
-
Complete supplier risk audits and implement selective near-shoring for critical reagent lines.
-
Negotiate pilot reimbursement arrangements or coverage-with-evidence development to de-risk market launches.
-
Initiate 90-day commercial pilots with integrated pricing and service bundles to prove unit economics before broad rollouts.
How PW Consulting supports your 2026 agenda
PW Consulting offers bespoke advisory services that translate this report’s insights into executable programs: custom market-sizing that reflects your product mix, regulatory-pathway design and dossier support, payer-engagement strategies tailored to national systems, supplier-risk remediation playbooks, and M&A due diligence and valuation for targeted assets. Our strategic workshops convert high-level findings into board-ready operating plans with KPI tracking for the first 12 months post-engagement.
Next steps — where to get the full intelligence
This release is an executive preview designed to surface the strategic logic and operational levers that will matter in 2026. The full PW Consulting Pathogen Detection Market Report contains granular regional and application-level forecasts, technology-specific adoption curves, detailed competitor profiles, and data tables that underpin the scenarios summarized here. To access the complete analysis, data tables, and downloadable playbooks, please visit the PW Consulting report page and request the full report.
For detailed analysis of this topic, please visit the official page: Pathogen Detection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Boc‑L‑Leucine Market Set to Expand at a 7.45% CAGR During 2026–2032
By PW Consulting, 2026-07-13
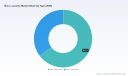
Boc L‑Leucine Market 2026 Strategic Outlook — PW Consulting Industry Brief
PW Consulting today publishes an advanced industry briefing accompanying our forthcoming Boc L‑Leucine Market report (base year 2025, forecast 2026–2032). This briefing distills the strategic implications of our full study for corporate decision‑makers planning investments, procurement, and product roadmaps in 2026. It highlights the structural drivers behind a resilient mid‑single‑digit to high‑single‑digit growth trajectory while intentionally reserving detailed segment tables and granular regional splits for report subscribers.
Boc L Leucine Market
Executive snapshot — why Boc L‑Leucine matters in 2026
Boc L‑Leucine sits at the confluence of peptide chemistry, pharmaceutical intermediate supply chains, and speciality amino‑acid markets. Our top‑level sizing shows a market that expanded steadily through 2020–2025, reaching an estimated USD 155.6 Million (revenue, 2025), and is projected to continue growing at a compound annual growth rate (CAGR) of 7.45% over the 2026–2032 forecast period. Under a set of plausible operational and pricing scenarios we model multiple upside pathways, with the market reaching the mid‑hundreds of millions by the early 2030s.
Boc L Leucine Market
Two structural facts underpin the thesis: first, Boc‑protection chemistry remains a standard route in peptide synthesis and pharmaceutical intermediate manufacture; second, the upstream feedstock market for L‑Leucine is large and evolving — our sector review cites a 2025 valuation for the global L‑Leucine market in the range of approximately USD 1.20–1.52 billion, with fermentation‑based production dominating the higher‑purity supply required for protected derivatives.
Boc L Leucine Market
Market dynamics shaping 2026 corporate choices
- Supply‑chain tightness and price volatility: Recent freight and logistics constraints have pushed US amino‑acid prices sharply higher (we note industry data reporting a ~24.06% increase in March 2026 for amino‑acid baskets). Such volatility flows through to Boc‑intermediates where margin sensitivity to feedstock and freight is material. Procurement teams should re‑price scenarios for 2026 accordingly.
- Quality segmentation and premiumisation: Pharmaceutical‑grade L‑Leucine carries a significant price premium versus feed‑grade equivalents (industry analyses indicate a premium band roughly in the 25–40% range). For players targeting regulated end markets, investments in quality assurance and traceability yield disproportionate commercial returns.
- Regulatory and handling standards: Boc L‑Leucine is largely marketed for research and peptide synthesis under controlled handling and ISO‑aligned quality systems. Compliance and supplier audits are increasingly non‑negotiable for buyers working with clinical or commercial peptide APIs.
- Concentration and supplier economics: The market exhibits a moderate degree of supplier concentration: our competitive concentration metrics show the top three players account for roughly 38.5% of market volume while the top five approach the mid‑50s percentile. That structure creates tangible procurement leverage but also implies that single‑source dependencies persist in some product lines.
Strategic implications for 2026 planning
Boards, corporate strategy teams, and procurement executives should treat Boc L‑Leucine as more than a commodity SKU. The product’s role as a protected amino‑acid intermediate creates cross‑cutting implications for sourcing policy, quality certification, and product roadmap timing. From our analysis, four near‑term imperatives emerge:
- Stress‑test supply chains against price shocks: Scenario modelling in the report quantifies P&L sensitivity to the dual inputs of L‑Leucine feedstock cost and logistics rates. Firms with thin cost buffers should prioritize alternative sourcing corridors and long‑lead buy strategies for 1H–2H 2026.
- Differentiate on quality and service rather than price alone: Given the premium for pharmaceutical‑grade L‑Leucine, value‑added services (certificate‑of‑analysis transparency, tailored packaging, smaller MOQ offerings for discovery labs) are commercial levers that reduce churn and improve realized margins.
- Prioritise regulatory alignment before scale‑up: For companies aiming to move from lab‑scale peptide synthesis to clinical supply, early investment in supplier audits, ISO/GMP readiness checks, and downstream impurity profiling shortens time‑to‑clinic.
- Consider bolt‑on M&A and contract hedging: The market concentration profile makes small acquisitions and long‑term tolling agreements an effective route to secure critical volumes. Our deal‑level scenarios show how modest capacity additions can de‑risk supply for high‑margin peptide programmes.
What the PW Consulting Boc L‑Leucine report delivers (practical contents)
Our full report is built for operators and strategists. It combines empirical market sizing, supply‑chain mapping, primary interviews, and financial stress tests into a deployable toolkit. Key deliverables include:
- Verified historical time series (2020–2025) and forward forecasts (2026–2032) with sensitivity overlays and scenario bands;
- Upstream cost model linking L‑Leucine feedstock input prices to finished Boc intermediate costs under alternate logistics assumptions;
- Supplier scorecards and procurement playbooks—covering quality, lead times, contract clauses, and audit checklists;
- Market concentration analysis and competitive benchmarks to support M&A or partnership diligence;
- Regulatory and compliance roadmap for transition from research supply to clinical manufacturing (including ISO/GMP triggers and documentation matrices);
- Commercial playbooks for manufacturers and distributors—including pricing strategies, packaging innovations, and channel segmentation;
- Primary research appendices containing anonymized transcripts and synthesis from interviews with C‑suite procurement, R&D heads, and third‑party logistics providers.
To preserve subscriber value our briefing emphasizes the structure and actionable outputs without reproducing the proprietary segment tables, regional percentages, or line‑by‑line revenue buckets—these are available exclusively in the full report package.
Competitive landscape — core players and positioning
The Boc L‑Leucine ecosystem is populated by an array of specialty chemical manufacturers, fine chemical distributors, and peptide reagent suppliers. Leading names we profile in depth include established Chinese producers, India‑based fine chemical exporters, and Western distributors that service peptide R&D markets. Representative company snapshots from our report:
- Fengchen Group Co., Ltd. (China): A manufacturer and global supplier of Boc‑L‑Leucine in BP/EP/USP grades, positioned for bulk peptide‑intermediate customers with an emphasis on high‑purity powder formats.
- Hangzhou Leap Chem Co., Ltd. (China): Specialist supplier offering custom and wholesale quantities, focused on supporting both research and industrial peptide applications.
- Wuhan Fortuna Chemical Co., Ltd. (China): Bulk manufacturer serving chemical synthesis and pharmaceutical segments with an emphasis on scale and price competitiveness.
- Central Drug House (CDH) (India): ISO‑certified exporter with breadth across laboratory and fine chemical channels, notable for regulatory documentation services to global customers.
- BLD Pharmatech (China), Chem‑Impex International (USA), Peptide.com (AAPPTec, USA), TCI Chemicals (Japan), Biosynth (Switzerland/UK), Sinochem Nanjing Corporation (China): These suppliers span distributor and manufacturer roles, offering a mix of research‑grade and higher‑purity intermediates with established channels into peptide synthesis markets.
Our vendor matrix in the report maps these players across capability (purity grades, batch volumes), service levels (lead time, secondary packaging), and regulatory credentials—enabling rapid short‑lists for procurement and technical due diligence.
Methodology and data integrity
PW Consulting’s Boc L‑Leucine modelling combines bottom‑up shipment and revenue reconstruction with primary supplier interviews, distributor sell‑through data, and feedstock cost triangulation. The study contextualises Boc demand within the broader amino‑acid complex (noting the sizeable L‑Leucine market) and overlays logistics cost scenarios that reflect the early‑2026 freight environment. We use industry‑standard concentration metrics to evaluate competitive dynamics and create rule‑based vendor scoring for procurement readiness. Detailed methodology, raw assumptions, and sensitivity parameters are supplied with the purchase package to enable in‑house model reconciliation.
How executive teams should use this briefing in 2026
- Procurement leads: use the report’s supplier scorecards and cost model to reprice 2026 procurement and establish hedging or long‑term agreements where necessary.
- R&D and CMC heads: align reagent sourcing strategies with clinical milestones—prioritise suppliers with GMP transition experience where applicable.
- Corporate development teams: leverage concentration insights and vendor economics to identify M&A targets or strategic partnerships that secure capacity for pipeline programmes.
- Risk & compliance officers: adopt the audit checklists and regulatory timeline templates to de‑risk supplier transitions and ensure traceability.
Next steps and access to the full report
This briefing is a strategic extract designed to inform immediate 2026 planning. The full PW Consulting Boc L‑Leucine Market report contains the granular regional splits, application‑level segmentation, downloadable vendor scorecards, and the complete set of financial models that organisations need to convert insights into executable decisions. To access the full study, data appendices, and bespoke consulting engagements, please visit our website or contact PW Consulting’s industry practice team.
PW Consulting — actionable intelligence for specialty chemicals and peptide supply chains. Our analysts combine sector‑specific depth with pragmatic, procurement‑ready deliverables so that commercial leaders can move faster and with more certainty in 2026.
For detailed analysis of this topic, please visit the official page: Boc L Leucine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Finds Hot Melt Glue Market Tops USD 10,018.89 Million in 2025
By PW Consulting, 2026-07-13
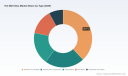
Hot Melt Glue Market — 2026 Strategic Brief (PW Consulting)
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a condensed strategic briefing derived from our full Hot Melt Glue Market study (base year 2025). This briefing is designed to equip executive teams with the vantage points needed to make high‑confidence decisions in 2026. It highlights macro trajectories, strategic inflection points, competitor moves, and concrete next steps — while reserving the full, actionable segment-level tables and models for the complete report.
Hot Melt Glue Market
Market Snapshot — the macro story you must anchor to
The hot melt adhesive market has transitioned from steady recovery into a structurally expanding market. Measured on a 2025 base, the global market sits at roughly USD 10.02 billion and is projected to grow at a compound annual growth rate (CAGR) of 6.2% across the 2026–2032 forecast window. Under the baseline scenario in our modelling, that trajectory points toward a market north of USD 15 billion by 2032.
Hot Melt Glue Market
For 2026 strategic planning, the implication is clear: demand expansion will be broad-based and persistent, driven by end‑use volumes recovering in packaging, hygiene, woodworking, and automotive retrofit cycles — even as product mix shifts toward higher‑value, specialty formulations and solutions. That combination creates simultaneous opportunities in volume, margin improvement, and differentiation through formulation and service.
Hot Melt Glue Market
Why this report matters for 2026 decision-making
- Aligns investment sizing with realistic demand curves: our forecast provides a tested baseline and two alternate scenarios (upside and disruption) that allow capital plans to be stress‑tested against raw material volatility and regulatory shocks.
- Translates industry noise into risk parameters: we map inputs such as recent ethylene tightness (EVA costs rising materially year‑over‑year) and elevated tackifier spot prices into margin stress matrices so procurement can prioritize hedging or supplier diversification.
- Prioritizes go‑to‑market choices: identifies where product innovation (bio‑based and metallocene chemistries) will command premium pricing versus where cost leadership will win.
- Supports M&A and partnership screening: our competitive concentration diagnostics and target archetypes let BD teams rapidly triage attractive bolt-on or capability acquisitions without overpaying for transient scale.
What the full report delivers (practical contents)
- Executive forecast model (2026–2032) with scenario toggles for raw material and regulatory shocks, and downloadable inputs for client stress‑testing.
- Commercial playbooks: go‑to‑market strategies by end‑use and by formulation family, including recommended pricing ladders and margin improvement levers.
- Procurement and feedstock playbook: supplier scorecards, contracting templates, and a raw‑material sensitivity dashboard that converts price moves into P&L outcomes.
- Technology and product roadmap: near‑term actionable R&D projects (e.g., bio‑based tackifiers, lower‑temperature PU systems) and a three‑year prioritization matrix for capex allocation.
- Regulatory and compliance map: jurisdictional risk ratings (including REACH and U.S. state‑level constraints) with compliance pathways and timelines.
- Competitive benchmarking and M&A scorecards: profile dossiers and valuation yardsticks for the relevant competitive set.
- Operational playbook for manufacturing footprint: capacity optimization, nearshoring vs. export scenarios, and private label/contract manufacturing decision trees.
Competitive landscape — what the market structure signals
The market exhibits moderate concentration with leading triad and quintet shares indicating neither tight oligopoly nor pure fragmentation. This structure creates a dual dynamic: established majors retain pricing and distribution advantages, while mid‑tier and specialized players can capture lucrative niches through formulation, sustainability credentials, and service models.
Key strategics to watch (representative competitive capabilities):
- H.B. Fuller — strength in packaging systems and rapid commercial launches; track record of targeted product introductions for e‑commerce packaging.
- Henkel — broad application footprint and recent capacity expansion, signaling commitment to volume and customized solutions in Europe.
- Bostik (Arkema) — leadership moves into metallocene and hygiene formulations; a good bellwether for nonwoven and consumer hygiene trends.
- 3M — industrial bonding and certification-driven positioning; sustainability and process quality are differentiators.
- Avery Dennison — niche scale advantage in pressure‑sensitive adhesive systems for labeling and tapes.
- Huntsman, Dow, Evonik, BASF — upstream players that influence formulation inputs and therefore margin dynamics for adhesive producers.
- Contract manufacturers (e.g., Texas Eastern Products) and regional specialists (e.g., Jowat, Sika) — relevant for private‑label strategies and regional supply resilience.
Recent corporate moves — new product launches, capacity expansions, and certifications — are consistent with a market pivoting toward higher performance, sustainability claims, and compliance-ready formulations. Use these signals as leading indicators when defining competitive responses.
Industry dynamics and the practical implications for 2026
- Raw material volatility: EVA copolymer supplies tightened recently, causing sizable year‑over‑year cost increases; hydrocarbon tackifier spot prices have also moved materially higher. Companies must model these inputs into pricing and procurement strategies — short‑term passthrough will not be fully acceptable to customers, so margin recovery plans are required.
- Regulatory pressure: new and expanding restrictions (including EU chemical controls and state‑level rules such as Proposition 65) are forcing reformulation timelines and labelling costs. Regulatory lead time must be a 2026 budget line item.
- Trade policy and tariffs: import duty regimes in key markets create nearshoring incentives for producers and can reorder global sourcing economics.
- Sustainability premium: buyers in hygiene and consumer packaging increasingly demand bio‑based or low‑emission solutions, creating a two‑tier market where premium formulations command higher margins.
Actionable recommendations — a 90‑day and 12‑month plan for 2026
- 90‑day priorities
- Run the raw‑material sensitivity module against your current product mix to quantify margin exposure and identify top three cost levers.
- Initiate supplier risk audits for critical feedstocks; secure medium‑term purchase commitments where price risk is unacceptable.
- Launch targeted application trials with select customers for higher‑value formulations (e.g., hygiene or e‑commerce packaging adhesives) to validate premium positioning.
- 12‑month priorities
- Decide on a manufacturing footprint optimization: invest to nearshore for tariff‑exposed SKUs or partner with regional contract manufacturers for flexibility.
- Accelerate one reformulation program to address imminent regulatory constraints and position for premium sustainable tenders.
- Pursue at least one bolt‑on acquisition or JV to acquire formulation capability, regional capacity, or a validated customer channel if organic growth cannot meet time‑to‑market needs.
Scenario planning — prepare for three plausible 2026 inflection events
- Base case: steady 6%+ growth with manageable raw material tailwinds; focus on premiumization and rationalized SKUs.
- Upside: accelerated demand in packaging and hygiene; prioritize capacity expansions and fast commercial rollouts of high‑value formulations.
- Disruption: sustained raw material shocks or regulatory bans; enact contingency plans including stepped reformulations, emergency sourcing lanes, and temporary price cushions.
How to use this briefing and the full report
Executives, procurement heads, R&D leaders, and corporate development teams should treat this briefing as a diagnostic lens and the full report as the operational playbook. The full report contains the proprietary models, validated supplier scorecards, and the M&A target filters you will need to convert insight into implemented actions.
Next steps — PW Consulting support
PW Consulting can: deploy a tailored 2‑week diagnostic using our financial and raw‑material models; run a half‑day executive workshop to align 2026 capex and product priorities; provide an M&A screening sprint to identify 3–5 high‑probability targets. If you want a hands‑on walkthrough of the models or an executive summary tailored to your company, contact our practice lead to schedule a briefing.
For access to the full dataset, interactive models, and the complete segment and regional breakdowns, please visit the PW Consulting Hot Melt Glue Market report landing page — the full report contains the tables and tools needed to operationalize the strategies summarized here.
Prepared by PW Consulting — actionable market intelligence to align your 2026 decisions with the structural growth and risk profile of the hot melt adhesive market.
For detailed analysis of this topic, please visit the official page: Hot Melt Glue Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Styrene Acrylic Market Poised for 6.02% CAGR Through 2026–2032
By PW Consulting, 2026-07-13
Styrene Acrylic Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As companies prepare strategy roadmaps for 2026, the styrene acrylic market presents a mix of steady expansion, regulatory complexity, and concentrated pockets of competitive intensity. PW Consulting’s latest market study — anchored on a 2025 base year and covering historical performance (2020–2025) and forward forecasts through 2032 — shows the market continuing its multi-year recovery and structural growth trajectory. The global market, which expanded from USD 9.5 Billion in 2020 to USD 12.5 Billion in 2025, is projected to grow at a compound annual growth rate (CAGR) of 6.02% over the forecast period, reaching approximately USD 18.81 Billion by 2032. These headline metrics are a useful north star for boardroom planning; the full report converts them into decision-grade implications for procurement, R&D, manufacturing and M&A.
Styrene Acrylic Market
Why 2026 Is a Critical Inflection Point
- Momentum meets uncertainty. Growth momentum is intact, but 2024–2025 supply shocks and regulatory shifts mean that near-term tactical choices will have long-term strategic ripple effects. Our analysis flags 2026 as the year when firms must convert resilience measures (short-term sourcing fixes, temporary capacity tweaks) into durable positioning (product portfolios, regional footprint, and compliance-by-design).
- Cost and supply volatility remains a board-level risk. Raw-material volatility — exemplified by episodes of sharp styrene and acrylic acid price swings in recent quarters — materially affects margins and product competitiveness. Our modeling shows that modest sustained price differentials in monomer inputs can erode margin pools unless offset by formulation innovation, price pass-through, or reshoring of feedstock-secure supply lines.
- Regulatory tightening is not hypothetical. New and updated rules — including EU restrictions on free styrene monomer content in consumer paints and tighter disclosure or labeling requirements in jurisdictions like California — require companies to embed compliance into product roadmaps, not just post-market remediation.
What the PW Consulting Report Delivers (Operationally Focused)
The full study is designed as an operational playbook for 2026 decision cycles. Key deliverables include:
Styrene Acrylic Market
- Multi-scenario demand forecasts (baseline, downside, upside) aligned to macro sectors such as paints & coatings, adhesives & sealants, construction chemicals, and paper/textiles.
- Forward-looking pricing and margin models that link raw-material scenarios to finished-goods pricing elasticity and pass-through timelines.
- Supply-chain heatmaps and supplier scorecards — assessing geopolitical, tariff, and feedstock exposure at plant and country level.
- Regulatory impact matrices and compliance templates for product reformulation and labeling strategies in major jurisdictions.
- Product and technology roadmaps with opportunity sizing for lower-VOC, low-free-styrene, and bio-based monomer blends, plus a comparative assessment of capex vs. licensing/formulation partnerships.
- M&A and partnership playbooks, including target prioritization typologies (technology owners, regional converters, feedstock-secure producers) and integration value capture mechanisms.
- An executable go-to-market playbook for commercial teams: segmentation, pricing cadences, distributor vs direct models, and tender strategy for large institutional buyers.
Note: This preview intentionally omits detailed segment-level tables and country-by-country breakouts. The full dataset and downloadable forecast models are available in the complete report.
Styrene Acrylic Market
Competitive Landscape: Who Matters and Why
The styrene acrylic space presents a hybrid structure: a handful of established chemical majors and specialty producers supply differentiated binders and emulsions, while regional players serve localized demand. Market concentration data indicate that the top three players collectively control roughly one-third of the market, while the top five approach but do not exceed the majority — a structural feature that creates room for focused scale plays and niche specialization.
- OMNOVA Solutions Inc. (Fairlawn, OH, USA) — strong in emulsions and copolymers for coatings, adhesives and textiles; recent launches targeted low-VOC textile coatings. Strategic implication: product-led differentiation around sustainability and regulatory compliance can command distributor preference and margin premium.
- Arkema S.A. (Colombes, France) — established portfolio of binders for paper coatings, paints and nonwovens. Strategic implication: legacy brands and formulation expertise make Arkema a natural partner for converters seeking fast compliance pathways.
- Synthomer PLC (London, UK) — focused innovation in emulsions for architectural coatings and graphic arts; recent new-grade introductions indicate R&D-led growth. Strategic implication: portfolio breadth in high-performance grades supports premium positioning in developed markets.
- BASF SE (Ludwigshafen, Germany) — strong integrated presence with expanded capacity investments in recent years. Strategic implication: incumbents with integrated upstream capability can use capacity and logistics scale to out-execute during episodic supply constraints.
- Dow Inc. (Midland, MI, USA) , Wacker Chemie AG (Munich, Germany) , Celanese Corporation (Irving, TX, USA) , and Trinseo PLC (King of Prussia, PA, USA) — each brings unique balance of branded grades, regional production, and end-market relationships. Strategic implication: for mid-sized players, aligning with one or two of these majors for co-development or supply agreements can accelerate route-to-market while mitigating feedstock risk.
Recent industry moves underline the competitive dynamics: product launches emphasize low-VOC formulations and high-performance grades; capacity expansions by established players are shifting the supply balance in certain regions; and smaller, focused suppliers continue to win share in niche applications through speed-to-market.
Dynamics That Will Drive Winning Strategies in 2026
- Regulatory-first product design. Stricter limits on free styrene in consumer-facing paints and heightened carcinogen labeling thresholds in key markets mean reformulation is now a baseline requirement. Companies that invest in low-free-styrene technologies and validate compliance pathways gain preferred-supplier status with large OEMs and retail chains.
- Tariff and localization playbooks. Trade measures that affect cross-border flows create an advantage for regionally located or tariff-exempt manufacturing. Nearshoring or tariff mitigation agreements should be part of commercial risk matrices for 2026 procurement plans.
- Raw material hedging and vertical relationships. The market’s sensitivity to styrene and acrylic acid price swings makes feedstock-secure sourcing — through long-term contracts, co-investment, or vertical integration — an immediate priority for margin protection.
- Targeted M&A and partnerships. With top-five share below 50% and pockets of specialty demand growing, bolt-on acquisitions for formulation technologies, regional distribution footprints, or feedstock access can deliver outsized ROI versus greenfield capex in 2026.
Actionable Recommendations for 2026 Planning
- Prioritize a three-tier supplier strategy: secure primary feedstock-linked partners, cultivate secondary regional suppliers for agility, and maintain a tertiary roster for spot-market access.
- Allocate R&D dollars to low-free-styrene chemistries and VOC-reduction that preserve rheology and performance — suppliers that validate performance equivalence reduce product substitution risk for customers.
- Embed tariff and regulatory scenarios into commercial pricing models and contract templates; seek clauses that allow dynamic price adjustments tied to feedstock indices.
- Run a rapid 90-day M&A readiness assessment if growth ambitions require inorganic moves — define target profiles (tech owner vs. regional consolidator), white-space maps, and integration playbooks upfront.
- Use our scenario models to stress-test EBITDA under different raw-material and regulatory assumptions; focus on cash-conversion improvements during the 2026 planning cycle to fund strategic investments without overleveraging.
How PW Consulting’s Study Supports Your 2026 Decision Calendar
For executive teams and functional leaders, our report is both a strategic compass and a tactical toolkit. It translates headline growth (CAGR of 6.02% to 2032) into actionable programs: which product grades to prioritize, where to site incremental capacity, how to price under cost volatility, and which M&A plays deliver defensible synergies. The research package combines quantitative forecast models, qualitative supplier and technology due diligence, and prescriptive playbooks that can be operationalized within 90–180 days.
To access the full dataset, regional and application-level breakouts, and the downloadable Excel model that powers our forecasts and sensitivity testing, please consult the complete PW Consulting Styrene Acrylic Market report. The detailed segmentation, country-level exposure maps, and supplier-level financial benchmarking are available there and are essential for executing on the programmatic steps outlined above.
Final Thought
2026 will separate companies that merely managed volatility from those that converted it into competitive advantage. With measured investment in compliance-ready formulations, feedstock-secure supply strategies, and targeted consolidation where it matters, players can capture disproportionate share as the market expands toward the USD 18.8+ Billion opportunity by 2032. PW Consulting’s full report equips leaders with the forecast fidelity and practical roadmaps needed to turn that opportunity into measurable, sustainable value.
For detailed analysis of this topic, please visit the official page: Styrene Acrylic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Phased Array Antenna Module Market Poised to Hit USD 12,769.18 Million by 2032 on a 17.15% CAGR — North America Leads with USD 1,655.63 Million in 2025
By PW Consulting, 2026-07-13
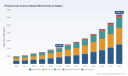
Phased Array Antenna Module Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting’s latest market study on Phased Array Antenna Modules delivers a forward-looking, decision-grade view for executives and investors preparing to act in 2026. Our bottom-up market model shows the segment expanding rapidly over the coming decade — growing from roughly USD 4.22 billion in 2025 to an expected USD 12.77 billion by 2032, a compound annual growth rate (CAGR) of 17.15% across the forecast period. The market remains moderately concentrated (top-3 firms account for approximately 43% of revenue, top-5 about 59%), a structure that creates both barriers and clear opportunity windows for challengers and adjacent players.
Phased Array Antenna Module Market
What the report delivers: actionable, executable intelligence
- Proprietary demand model and scenario analyses that translate macro drivers into addressable module demand across defense, satellite communications, telecom infrastructure, and automotive/industrial radar (note: detailed segment tables and granular regional splits are reserved for the full report).
- Vendor benchmarking and capability heatmaps covering RF front-ends, T/R modules (including GaN readiness), beamformer ICs, and system-level integration capabilities.
- Supply-chain mapping with single-point-of-failure diagnostics and mitigation playbooks for semiconductor, packaging, and assembly tiers.
- Technology roadmap and adoption timelines for enabling innovations (e.g., GaN-on-Si T/R modules, mmWave arrays, metamaterial flat-panel designs), with cost and thermal-efficiency trajectories modelled to 2032.
- M&A and partnership playbooks that prioritize inorganic routes to close capability gaps and accelerate time-to-market for mobile SATCOM, AESA upgrades, and 5G/6G-active arrays.
- Procurement and qualification checklists for procurement teams evaluating suppliers under export-control, IP and lifecycle-cost constraints.
Market dynamics: drivers, inflection points, and near-term catalysts
Several structural forces are driving the strong CAGR and the rapid re-shaping of industry economics. Defense modernization programs continue to demand higher-performance, modular AESA solutions with digital beamforming. Commercial SATCOM — driven by LEO constellation proliferation and the mobility market — is creating new requirements for electronically steerable flat-panel arrays. Telecom operators’ move toward densified, high-frequency 5G deployments (and early planning for 6G pathways) is expanding demand for compact, high-throughput modules. Simultaneously, advancements in GaN-on-Si and integration of RFIC beamformer chips are enabling higher power densities and more compact T/R architectures, accelerating miniaturization and cost-reduction curves.
Phased Array Antenna Module Market
Recent industry developments underscore these trends and the pace of innovation: a major U.S. defense prime announced continued production and a large contract modification for a modular AESA naval radar, demonstrating procurement scale and unit-cost reduction momentum; a leading system integrator completed a critical design review for a next-generation ground-based AESA with digital beamforming; several commercial vendors announced late-stage product developments in Ka- and Ku-band electronically steerable modules and flat-panel metamaterial antennas designed for mobile SATCOM. These events collectively act as both demand signals and technology validation for suppliers down the value chain.
Phased Array Antenna Module Market
Supply chain, regulation and material risks — and how to respond
The phased array module supply chain is multi-layered and exposed to several risks. RFIC and T/R chipsets rely on constrained specialty materials and process capacity (GaN, GaAs, silicon RFICs), and global semiconductor fragility translates directly into production lead-time risk. Geopolitical frictions and trade measures — notably export controls such as ITAR and EAR as well as tariff actions — add complexity to cross-border sourcing and customer access. There is also nascent pressure on rare-earth supply chains that can affect RF component production.
Mitigation strategies that senior procurement and operations leaders should prioritize in 2026 include:
- Dual-sourcing of critical RF components across geography and process nodes, combined with strategic inventory buffers for long-lead items.
- Selective vertical integration (packaging, T/R test capability) or JV structures to secure capacity without full capital exposure.
- Active engagement with policymakers and export-control counsel to shape compliant go-to-market approaches and maximize addressable markets.
- Investment in GaN qualification programs and thermal-management engineering to reduce lifecycle cost and accelerate platform adoption.
Competitive landscape — who matters and why
The competitive field is a blend of large defense primes, specialized antenna innovators, and semiconductor enablers. Key strategic profiles emerging from our analysis include:
- Raytheon Technologies (RTX): Deep systems integration strength and scale in modular naval AESA programs. Their ability to drive unit-cost reductions at scale makes them a preferred prime for large defense procurements.
- Northrop Grumman: Leadership in digital beamforming and integrated multi-mission radar systems for both ground and aerospace segments. Their ongoing next-generation radar programs indicate a strong roadmap position for long-range AESA applications.
- L3Harris Technologies and BAE Systems: Specialists in mission-focused phased arrays for electronic warfare, airborne and naval platforms, with advantages in multi-band and ruggedized module design.
- Lockheed Martin and Leonardo: Established integrators for airborne and government platforms, with strength in program management and platform certification pathways.
- Viasat, Kymeta, C-COM, Requtech and other SATCOM-focused players: Innovators in flat-panel and electronically-steered mobile SATCOM antennas; recent product launches and late-stage developments indicate accelerating commercialization of mobile broadband solutions.
- Analog Devices, Qorvo, Sivers and Kyocera: Critical semiconductor and component suppliers whose RF front-end and beamformer IC roadmaps determine module-level performance and manufacturability.
For commercial players, partnerships between system integrators and semiconductor specialists are increasingly the most efficient route to market. For defense primes, maintaining a secure and compliant supply chain while reducing per-unit cost remains the central competitive lever.
Strategic recommendations for executives preparing decisions in 2026
Based on scenario modelling and supplier assessments, PW Consulting recommends the following near-term actions for firms seeking to capture the market’s upside while managing risk:
- Prioritize GaN-on-Si adoption and co-invest in thermal management R&D. This drives a step-change in power density and unit economics for AESA and telecom arrays.
- Design product roadmaps around modular AESA architectures and software-defined beamforming to shorten integration cycles and support multi-mission upgrades.
- Target mobile SATCOM and enterprise mobility as a complementary commercial growth vector; seek partnerships with flat-panel innovators to accelerate field trials.
- Secure long-lead semiconductor capacity via strategic supply agreements, equity investments or long-term purchase commitments with RFIC suppliers.
- Implement a compliance-first export strategy: structure offerings into exportable and controlled tiers to preserve global market access while complying with ITAR/EAR constraints.
- Use targeted M&A to close capability gaps (e.g., beamformer ICs, metamaterials, system-level integration) rather than broad horizontal consolidation.
- Establish scenario-triggered investment gates — using supply-chain stress tests and procurement milestone signals — to pace CapEx while preserving optionality across 5G/6G and SATCOM pathways.
Why this preview — and why this report — matters to 2026 decision-making
This preview is designed to surface the strategic thrusts and risk factors that will shape capital allocation, partnership formation, and product roadmap choices in 2026. The full PW Consulting report converts these insights into operational tools: downloadable datasets, multi-scenario demand forecasts, supplier scorecards, and executable procurement/playbook templates. We intentionally treat detailed segment-level forecasts and regional splits as gated, high-value assets in the full report: executives who need to quantify addressable markets by region, technology, and application will find those granular datasets and the underlying assumptions in our complete release.
Next steps and how PW Consulting supports implementation
For leadership teams preparing budgets, R&D roadmaps, or M&A pipelines in 2026, PW Consulting offers tailored briefings and implementation workshops that translate the report’s findings into financial models, supplier RFP frameworks, and integration plans. Our consulting engagements typically include a workshop to calibrate the proprietary demand model to a client’s product mix, a supplier risk remediation plan, and a 12–36 month tactical roadmap aligned with procurement cycles and export-control timelines.
To explore the complete dataset, segment-level forecasts, and vendor scorecards, access the full report and associated tools on PW Consulting’s research portal. The phased array antenna module market is at an inflection: the window to establish technical leadership and secure supply chain control is narrow but well-defined. For organizations ready to act in 2026, the strategic choices made this year will determine who leads the next generation of RF-enabled systems.
For detailed analysis of this topic, please visit the official page: Phased Array Antenna Module Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Doubly Fed Induction Generator Market to Reach USD 20,950.0 Million in 2025, Poised for 6.8% CAGR from 2026–2032, Report Finds
By PW Consulting, 2026-07-13
Doubly Fed Induction Generator Market — 2026 Strategic Preview
Executive summary
PW Consulting’s new market intelligence note previews our forthcoming Doubly Fed Induction Generator (DFIG) Market Report and explains why its findings should drive capital allocation, technology choices, and M&A/sourcing decisions in 2026. Anchored in a full historical series (2020–2025) and a detailed forecast horizon (2026–2032), the research quantifies a resilient recovery and structural opportunity for DFIG technologies across utility-scale wind and repowering programs. This preview highlights the strategic implications, competitive dynamics, and regulatory/technology inflection points without disclosing the report’s proprietary segment tables — an intentional “trailer” designed to show rigor while directing decision-makers to the full dossier for transaction-grade detail.
Doubly Fed Induction Generator Market
Market outlook at a glance
-
Base year and historical window: Base year 2025 with historical coverage from 2020 through 2025, enabling multi-year trend validation.
Doubly Fed Induction Generator Market -
Current market scale: The global DFIG market reached approximately USD 20,950.0 Million in 2025 after a steady climb from the start of the historical window.
Doubly Fed Induction Generator Market -
Forecast trajectory: Across the PW Consulting forecast period (2026–2032) the market is projected to expand at a compound annual growth rate (CAGR) of 6.8%, reaching an estimated USD 33,203.42 Million by 2032 under our baseline scenario.
-
Concentration and competitive balance: Market concentration is meaningful — the top three suppliers together account for a material portion of installations, while the top five capture roughly two-thirds of the market by revenue — a structure that preserves scale advantages for incumbents but still leaves space for regional champions and differentiated entrants.
What’s in the full report (practical, transaction-ready deliverables)
-
Proprietary market sizing and demand-side forecasting engine (2026–2032) with scenario sensitivity to commodity shocks, repowering waves, and tender dynamics.
-
Supply-side modeling that maps manufacturing capacity, converter supply, and serviceable installed base by vendor — enabling bidders to size addressable opportunity and after‑sales revenue potential.
-
Vendor due diligence profiles with technology scorecards, reference installations, warranty & service frameworks, and balance‑sheet/operational risk flags.
-
Technology deep dives: DFIG topologies, converter architectures, cooling strategies, and retrofit compatibility analyses that quantify LCoE impact and integration complexity without disclosing proprietary performance curves in this preview.
-
Regulatory and grid-code mapping that translates evolving interconnection requirements into implementation checklists and procurement clauses.
-
Commercial playbooks for OEMs, tier‑1 suppliers, and developers — covering pricing strategies, partnership models, and M&A scenarios tuned for 2026 procurement cycles.
-
Supply-chain stress tests and mitigation roadmaps (rare-earth exposure assessment, converter semiconductors, and global logistics contingencies).
Competitive landscape — who matters and why
The DFIG competitive set combines long-standing electromechanical specialists, turbine OEMs with integrated drivetrain offerings, and large-scale engineering suppliers. Key players we analyze in depth include:
-
ABB (Zurich, Switzerland) — Modular DFIG platforms for 2–6 MW turbines; known for high nominal efficiencies and robust slip‑ring/serviceability designs. Recent strategic moves in power electronics materially expand ABB’s converter and aftermarket addressable base.
-
WEG S.A. (Brazil) — A vertically integrated electrical equipment player offering DFIG configurations among broader generator portfolios; positions on design compactness and insulation classes target longer service intervals.
-
Siemens Gamesa Renewable Energy (Spain) — Supplies geared DFIG technology across medium/low-wind onshore platforms; scale in large projects supports cost-out and LCoE leadership in select geographies.
-
GE Vernova (USA) — Leverages legacy DFIG expertise in variable-speed geared platforms and emphasizes grid integration and field reliability for developers seeking predictable output.
-
Ingeteam (INDAR, Spain) — Focused on high-power DFIG units and matching power-converter ranges, with strengths in grid-friendly control and LCoE optimization for retrofit work.
-
Winergy (Flender, Germany) — Specialist drivetrain supplier offering large-format double-fed asynchronous machines with proven installed base and modular cooling options.
-
CRRC & Shanghai Electric (China) — Regional champions supplying DFIGs across a broad power range with strong positioning for domestic repowering and coastal/offshore applications.
Recent competitive developments validate both consolidation and local innovation: ABB completed a material acquisition in late 2025 that substantially increases its converter and services footprint; Siemens Gamesa continues to secure large project orders deploying DFIGs; and new entrants and regional vendors are releasing higher‑voltage, water‑cooled converter solutions to press on performance and cost metrics. PW Consulting’s full vendor matrix links each development to estimated serviceable GW and aftermarket revenue potential.
Regulatory and technology dynamics redefining strategic priorities
-
Technology adoption: High-speed DFIG configurations maintain a dominant share of new wind installations in the onshore segment, underpinning continued demand for partial-converter architectures.
-
Grid functionality: DFIG systems retain an operational edge because they enable reactive-power contribution to the grid and achieve grid-code compliance through a partial converter (commonly a fraction of rated power). Emerging grid codes now emphasize low-voltage ride-through and soft‑ride characteristics — requirements that materially affect converter sizing and control strategies.
-
Raw material profile: Compared with permanent magnet synchronous machines, DFIG architectures use substantially fewer rare-earth materials, a structural advantage if rare-earth supply continues to show volatility or geopolitical risk.
Strategic implications for 2026 decisions (actionable guidance)
-
Prioritize techno-commercial clarity in RFPs. Specify not only nameplate power but converter topology, ride-through behavior, and serviceability metrics. Our report provides clause templates that convert technical requirements into enforceable procurement KPIs.
-
Weigh platform-level partnerships over point suppliers. Given vendor concentration dynamics, larger OEMs with integrated converter and nacelle offerings will win scale projects. For challengers, selective partnership with converter specialists can unlock competitive bids.
-
Use repowering windows strategically. The near-term expansion and replacement cycles create opportunities to capture upgrade-driven revenue. Investors should model mid-life retrofits versus full replacements using the lifecycle cost modules included in our full report.
-
Hedge component risk through dual-sourcing and forward purchasing. Semiconductor and insulation materials exposure can erode margins; our supply‑chain stress tests indicate which components are most likely to trigger project delays.
-
Invest in control-software differentiation. Meeting new ride‑through standards and offering grid-support services creates a premium aftermarket revenue stream. Control upgrades can be a low-capex route to justify longer service contracts.
-
Plan M&A and bolt‑on services around installed base economics. Aftermarket and service rights, converter exchange programs, and local O&M hubs often produce higher long-term margins than initial equipment sales.
How PW Consulting’s report reduces execution risk
The full DFIG Market Report is designed to be transaction-ready. It merges bottom-up equipment-supply modeling with top‑down demand scenarios, reconciles installation and decommissioning schedules, and overlays regulatory stress tests that translate technical codes into procurement design choices. For bidders, developers, and private capital, the report supplies sensitivity outputs (price, commodity, project delay) that can be exported into investment models to produce adjusted IRRs and payback timelines.
Next steps — where to get the full intelligence
This preview is intentionally non-exhaustive. The full PW Consulting Doubly Fed Induction Generator Market Report contains the granular segment tables, downloadable vendor profiles, model files, and procurement templates referenced above. Market participants preparing bids, planning capex for 2026, or assessing M&A opportunities should consult the complete report to convert the high-level insights here into executable plans.
Contact & access
-
To request the full report, data extracts, or a tailored advisory briefing for your portfolio or procurement pipeline, visit the PW Consulting publications page or contact the PW Consulting client services desk. Our analysts can produce a workshop that maps the report’s scenarios directly to your business case within two weeks.
PW Consulting — strategic clarity for the energy transition. Our DFIG market intelligence equips boardrooms and deal teams with the facts, scenarios, and playbooks they need to make 2026 count.
For detailed analysis of this topic, please visit the official page: Doubly Fed Induction Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting report forecasts 6.85% CAGR for the High-Speed Packaging Machine market through 2032
By PW Consulting, 2026-07-13
High‑Speed Packaging Machine Market — 2026 Strategic Preview from PW Consulting
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a high‑altitude, decision‑grade preview of the High‑Speed Packaging Machine market built to inform boardroom conversations and capital allocation choices in 2026. Our new market model uses 2025 as the base year and traces actuals across 2020–2025 before projecting demand through 2032. At the top line, the global installed and order pipeline expanded from approximately USD 13.3 billion in 2020 to about USD 18.5 billion in 2025. Our forecast anticipates continued expansion through 2032, reaching roughly USD 29.4 billion, driven by a compound annual growth rate of 6.85% across the 2026–2032 horizon.
High Speed Packaging Machine Market
Why this preview matters for 2026 decisions
2026 will feel like a pivot year for strategic buyers, OEMs, and investors in the packaging‑equipment ecosystem. Several simultaneous dynamics—supply‑chain normalization, sharper regulatory pressure on recyclability, renewed capital spending in food & beverage and pharmaceuticals, and accelerating e‑commerce throughput needs—combine to change the value equation for high‑speed machinery:
High Speed Packaging Machine Market
- Capital intensity versus agility: Buyers are balancing the unit economics of ultra‑high throughput lines with the operational flexibility of modular, reconfigurable platforms.
- Sustainability as a design constraint: Regulatory regimes and producer responsibility fees are increasingly shaping machine specifications and aftermarket services.
- Service and data monetization: As machines get faster, the aftermarket (predictive maintenance, upgrades, retrofits) becomes a critical lever for lifetime ROI.
What PW Consulting’s report delivers (practical, execution‑oriented)
We designed the full report to be more than a market map; it is a playbook for 2026 decisions. Key deliverables include:
High Speed Packaging Machine Market
- Proprietary market sizing and demand model (2020–2032) with scenario toggles for price shocks, regulatory tightening, and adoption curves for recyclability‑friendly technologies.
- Capital planning templates: TCO calculators, payback sensitivity matrices, and OEE uplift models tailored to high‑speed formats.
- Vendor evaluation and sourcing toolkit: decision matrices that weigh throughput, service coverage, retrofitability, energy profile, and compliance readiness.
- M&A and partnership scorecards: screening criteria for strategic buys, joint ventures, and minority investments focused on technology gaps and aftermarket potential.
- Supply‑chain risk map and mitigation playbook covering raw material volatility, single‑source components, and regional manufacturing dependencies.
- Technology adoption roadmap: modularization, servo and motion control evolution, in‑line quality inspection integration, and digital twin deployment timelines.
- Regulatory compliance checklist and design inputs for recyclable and recycled‑content packaging lines aligned to evolving EU/US/UK policies.
Interpreting the macro numbers without giving everything away
The headline growth trajectory — rising from USD ~18.5 billion in 2025 to nearly USD 29.4 billion by 2032 at a mid‑single‑digit CAGR — signals an industry large enough to reward scale, but also open enough to allow focused innovators to capture outsized pockets of value. Market concentration remains moderate: the top three global players account for roughly a third of market revenue, and the top five under half. That structure supports both continued organic competition and opportunistic consolidation, particularly in services, software layers, and platform modularity.
Competitive dynamics — what leading suppliers are doing now
Across the OEM landscape, winners are pursuing three mutually reinforcing plays: throughput leadership, platform modularity, and services/data monetization. Highlights from our competitive analysis and recent corporate developments:
- Syntegon (Bosch Packaging Technology) — Continues to lead on blister and precision pharma lines, investing in servo‑driven architectures for maximum speed and repeatability. Their 2025 Cyclone launch underscores how performance milestones can re‑price entire subsegments.
- IMA Group & Marchesini Group — Italian players remain strong in cartoning and monobloc integration, focusing on high throughput tailored to beverage, dairy, cosmetics, and pharmaceutical bottling and secondary packaging.
- Krones, Sidel, and Tetra Pak — Beverage and liquid packaging leaders continue to push filler and forming speeds while pairing hardware with line control software, sustainability certifications, and customer financing offers to reduce buyer friction.
- GEA, Multivac, Coesia, Ishida, Heat & Control, NJM (Romaco) — These suppliers have differentiated via niche capabilities (aseptic filling, thermoforming, high‑speed weighing, snack and case packing), and by deep aftersales networks that convert installation projects into recurring revenue.
- Recent corporate activity — new high‑speed launches, trade‑show demonstrations of 80k–120k bph fillers, updated sustainability certifications, and marquee installations in Asia‑Pacific — collectively illustrate that product and sustainability innovation remain the principal ways suppliers compete for tier‑one accounts.
Regulatory and input‑cost realities shaping machine design and procurement
Three non‑market forces stand out as determinative for 2026 planning:
- Regulation: Tighter rules on recycled content and extended producer responsibility in multiple jurisdictions are forcing OEMs and brand owners to re‑engineer both packaging formats and machine changeover sequences to support recyclable or recycled packaging streams.
- Raw‑material price volatility: Stabilization in plastics pricing after 2024 disruptions has reduced immediate cost shock risk, but energy and metal costs (notably aluminum) remain a vector of input volatility that impacts canning and metal‑forming equipment economics.
- Compliance costs: New producer fees and plastic taxes — already in effect in some markets — introduce variable per‑unit costs that change the ROI calculus for high‑speed mono‑format lines versus flexible, multi‑format lines.
Five strategic actions for 2026 (prioritized)
- Adopt modular platforms: Specify machines that can be reconfigured economically to protect against format obsolescence and to capture e‑commerce and premiumization opportunities.
- Embed sustainability as a performance metric: Require audited recyclability performance and retrofit pathways in RFQs; factor producer responsibility liabilities into TCO models.
- Lock in aftermarket economics: Negotiate multi‑year service contracts, digital‑data agreements, and upgrade paths that de‑risk uptime for ultra‑high throughput lines.
- Scenario plan CapEx: Use tiered IRR thresholds tied to regulatory scenarios and raw‑material shocks; prioritize projects with shorter payback or strategic optionality.
- Leverage partnerships: Where internal development is slow, use M&A, JV, or strategic partnerships to acquire software stacks, niche throughput technologies, or regional service footprints.
How to use this preview and where the full value lies
This article is intentionally a “trailer” — designed to demonstrate the depth of analysis and to surface strategic implications without publishing the granular regional, type, or application split tables that are essential for transaction work, procurement negotiation, and plant‑level investment. The full PW Consulting report includes interactive dashboards, downloadable CapEx models, supplier scorecards, and the granular segmentation data that operations, procurement, and M&A teams will require to finalize 2026 budgets and tactics.
If you are making capital commitments, drafting procurement specifications, or executing M&A in 2026, frame decisions around flexibility, sustainability readiness, and service economics rather than purely headline throughput. For many organizations, incremental investment in modular, connected equipment and aftermarket capabilities will deliver a superior risk‑adjusted return compared with single‑format, maximum‑speed installs.
Next steps
- For a detailed briefing, request PW Consulting’s full High‑Speed Packaging Machine Market report and the companion scenario models. The full package contains the regional and application detail that underpins the strategic recommendations above.
- For customized support — from CapEx modelling to vendor selection and transaction due diligence — contact our Strategy & Transactions team to schedule a tailored workshop and receive a bespoke excerpt of the dataset.
PW Consulting’s 2026 market intelligence is built to move from insight to action. Use it to test assumptions, stress‑test plans, and prioritize investments that create durability in throughput, compliance, and aftermarket value.
For detailed analysis of this topic, please visit the official page: High Speed Packaging Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


