



Category: market research
PW Consulting Forecasts Shadowless Lamps Market to Reach USD 4,633.2 Million by 2032 on a 5.5% CAGR
By PW Consulting, 2026-07-13
Shadowless Lamps Market 2026: Strategic Imperatives and Tactical Playbooks from PW Consulting
PW Consulting’s latest market research — Shadowless Lamps Market: Strategic Outlook 2026–2032 — delivers a concise, decision-grade synthesis for healthcare executives, medical device manufacturers, and investors preparing for the decisive procurement and product roadmap choices of 2026. The global market for shadowless lamps has matured from a solid growth trajectory in the early 2020s into a structurally expanding sector: from an observed market size in 2025 of USD 3,185 Million, the market is forecast to grow at a compound annual growth rate (CAGR) of 5.5% through 2032, reaching an estimated USD 4,633.2 Million by the end of the forecast window. These macro dynamics underpin the strategic recommendations below while the full report contains the granular segmentation, country-level dashboards, and supplier scorecards necessary to operationalize them.
Shadowless Lamps Market
Market Snapshot: Momentum and Structure
Historical performance (2020–2025) shows steady progression in both purchase volumes and average selling price uplift associated with next-generation LED and integrated systems. The market structure is moderately concentrated: the top three manufacturers account for a meaningful share of industry revenues and the top five consolidate a majority position — a context that favors innovation-led incumbents but leaves room for agile challengers, regional champions, and vertical integrators to pursue targeted growth.
Shadowless Lamps Market
- 2025 Market Size (base year): USD 3,185 Million
- Forecast Period: 2026–2032; CAGR: 5.5%
- Forecast 2032 Market Size: USD 4,633.2 Million
- Market concentration: CR3 and CR5 indicate a market where scale, service infrastructure, and channel reach matter materially
What’s Driving Strategic Decisions in 2026?
Five convergent forces will shape capital allocation and competitive positioning next year:
Shadowless Lamps Market
- Technology integration: The move from stand-alone lighting to systems that include 4K/HD in-light cameras, wireless OR connectivity, and interoperability with surgical workflows is accelerating. Buyers increasingly evaluate lighting not as a single-purpose asset but as a node in a digitized operating theatre.
- CapEx and life-cycle economics: Hospitals prioritize total cost of ownership (TCO) — lower heat, reduced energy draw, longer LED lifespan, and predictable maintenance are tipping decisions toward LED platforms and upgradeable architectures.
- Regulatory and safety compliance: Surgical lights are typically regulated as Class II medical devices requiring pathways such as FDA 510(k) and compliance with IEC 60601 electrical safety standards. Manufacturers must embed regulatory foresight into roadmaps to avoid time-to-market delays.
- Procurement practice: Lighting systems are procured as capital infrastructure rather than per-procedure items. This drives multi-year service contracts, leasing models, and bundled OR modernization projects that combine lighting with tables, pendants, and imaging.
- Clinical outcomes and ergonomics: Surgeons and perioperative teams place growing weight on color rendering, shadow management, and camera-ready illumination that supports minimally invasive and hybrid procedures.
Strategic Imperatives for Buyers (Hospitals, ASCs, Clinics)
For healthcare providers making 2026 procurement decisions, the following tactical playbook converts market insight into actionable steps:
- Shift evaluation criteria from one-time price to TCO and clinical value metrics: quantify energy savings, maintenance intervals, and upgrade paths for integrated cameras and data connectivity.
- Pilot with integration-first requirements: specify compatibility with room control systems, video capture standards, and cyber-security baselines before signing long-term contracts.
- Prioritize modular and upgradeable systems: require vendors to offer field-upgradeable optics/modules and clear decommissioning pathways to manage obsolescence risk.
- Negotiate outcome-aligned service contracts: include uptime guarantees, SLAs for replacement bulbs/modules, and metrics aligned to OR throughput.
- Use staged replacement strategies: combine selective LED retrofits with full-system upgrades as part of capital planning to smooth cash flows and benefit from incremental improvements in illumination and camera integration.
Strategic Imperatives for Manufacturers and Investors
Producers and private equity players looking to compete beyond price must align R&D, channel, and M&A strategies with the market’s evolving economics:
- Product roadmap discipline: invest in optical innovation (high CRI, glare control), active shadow compensation, and seamless in-light camera integration that supports the hybrid OR narrative.
- Service and software monetization: build recurring revenue through remote diagnostics, predictive maintenance, and software features (e.g., presets, camera overlays) sold via subscription or modular licenses.
- Strategic partnerships: collaborate with OR systems vendors, imaging suppliers, and software integrators to offer bundled solutions that simplify procurement decisions for hospitals.
- Manufacturing and supply resilience: diversify critical component sources (LED chips, optics) and localize assembly where reimbursement and procurement favor local content to reduce lead times and tariff exposure.
- M&A and alliance playbook: target tuck-ins that add digital capabilities, service infrastructure, or geographic reach. Given the market’s concentration profile, bolt-on acquisitions can rapidly improve CR capability without diluting brand equity.
Competitive Landscape: Reading the Field
The sector features a mix of global incumbents, specialized OEMs, and regional manufacturers. Key players exemplify distinct strategic postures:
- Stryker Corporation — a broad surgical solutions provider that leverages product breadth and systems integration. Recent platform introductions emphasize surgical visibility modes and modular upgrade paths.
- TRUMPF Medical (Hillrom/Baxter) — focuses on matrix optics and adaptive light management, leveraging precision engineering and a systems approach across care settings.
- STERIS plc — integrates high-fidelity lighting with OR-ready camera options and emphasizes 4K-capable systems for modern theatres.
- Getinge (Maquet) and KLS Martin — compete on clinical-grade optical performance, surgical ergonomics, and laser-safe features that appeal to tertiary centres and specialty ORs.
- Dräger — combines award-winning design with modularity and advanced optics, recently accelerating U.S. availability and capturing design accolades that enhance commercial positioning.
- Mindray, Heal Force, and other regional manufacturers — provide cost-competitive, rapidly configurable solutions for growth markets and price-sensitive channels; they increasingly close feature gaps through targeted R&D investment.
Recent product developments and accolades — for example, platform launches and design awards in 2024–2025 — underscore the sector’s technology cycle and the commercial importance of timely regulatory clearances and market launches.
Report Deliverables: What the Full Report Gives You
PW Consulting’s full report combines narrative insight with operational tools designed for immediate use in 2026 decision cycles. Deliverables include:
- A downloadable, scenario-driven market model (Excel) covering 2020–2032 with sensitivity options to test price erosion, LED adoption curves, and regional rollout timing.
- Supplier benchmarking and capability maps that score vendors on clinical performance, upgradeability, regulatory readiness, and after-sales service.
- Go-to-market playbooks for manufacturers: channel stratification, value-based contracting templates, and aftermarket service monetization strategies.
- Buyer checklists for procurement: technical specifications, cyber and interoperability clauses, and sample SLA clauses for capital projects.
- M&A target shortlist and valuation heuristics for investors focused on consolidation plays and digital capability tuck-ins.
How to Use This Research in 2026: A Tactical Sequence
Leaders can operationalize the report’s insight in a four-step sequence tailored to the 2026 planning calendar:
- Q1 — Strategic alignment: adopt the report’s market scenarios to set CapEx ceilings and prioritize OR modernization projects tied to surgical volume forecasts.
- Q2 — Pilot and procurement: run integration pilots with shortlisted suppliers that demonstrate camera, connectivity, and upgrade paths in live ORs.
- Q3 — Contract architecture: finalize multi-year, performance-based contracts with included upgrade rights and predictive maintenance terms.
- Q4 — Rollout and measurement: deploy phased upgrades and monitor KPIs (uptime, energy consumption, case throughput, clinician satisfaction) to validate ROI assumptions.
Closing: Why This Report Matters for 2026
As hospitals refocus capital on digital and procedural efficiency, shadowless lamps have evolved from commoditized fixtures to strategic OR assets that enable documentation, imaging, and surgeon-centric workflows. Our analysis quantifies the market’s expansion, illuminates the competitive and regulatory terrain, and delivers the practical tools procurement teams and product strategists need to make defensible, high-impact decisions in 2026. PW Consulting’s report intentionally showcases the insights and decision frameworks required for action while preserving the detailed segmentation and supplier-level data that empower precise deployment — available in the full report.
For executives preparing budgets, for product leaders crafting roadmaps, and for investors sizing opportunities, this research is designed to convert market understanding into measurable outcomes. Access the full dataset and interactive dashboards to unlock supplier scorecards, country-level demand drivers, and the granular segmentation that supports precise business cases.
For detailed analysis of this topic, please visit the official page: Shadowless Lamps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Hazardous Drug Disposal Service Market Reaches USD 1,354.12 Million in 2025, Set to Expand at a 7.34% CAGR from 2026–2032
By PW Consulting, 2026-07-13
Hazardous Drug Disposal Service Market — Strategic Imperatives for 2026 Decision-Making
PW Consulting’s new Hazardous Drug Disposal Service Market report provides senior executives and procurement leaders with the pragmatic intelligence required to make high-confidence decisions in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the study quantifies a market that expanded robustly through the first half of the decade and is projected to continue growing at a compound annual growth rate (CAGR) of 7.34%. With 2025 established as the report’s base year, our modeling shows sustained expansion through 2032, driven by regulatory tightening, healthcare delivery evolution, and service innovation.
Hazardous Drug Disposal Service Market
Why this report matters for 2026 strategy
- Actionable regulatory translation: We synthesize recent and near-term regulatory shifts (including broader state adoptions of EPA Subpart P and updated USP <800> guidance) into decision-ready checklist items for risk mitigation, procurement timing, and contract clauses.
- Procurement and vendor playbooks: Rather than surface-level vendor profiles, the report equips buyers with scoring matrices, cost-to-serve models, and scenario-based sourcing pathways to align supplier selection with organizational risk tolerance and sustainability goals.
- Capital and operating impact modeling: Our forecast shows clear revenue expansion from the base year into the late 2020s; the report translates that growth into likely capital and operating budget impacts for hospitals, long-term care, and outpatient networks under three adoption scenarios.
Market dynamics shaping 2026 choices
Three core dynamics will dictate supplier and buyer behavior in the coming 12–24 months:
Hazardous Drug Disposal Service Market
- Regulatory harmonization and enforcement: With multiple states moving to adopt EPA’s Hazardous Waste Pharmaceuticals framework (Subpart P) and continued emphasis on USP <800> compliance, healthcare operators face compressed timelines to implement compliant segregation, handling, and disposal workflows. The EPA’s early-2026 guidance on household medication and RCRA standards underscores that enforcement and clarity are evolving — not static.
- Operational decentralization of care: As care migrates outside the acute setting, the logistical complexity and traceability requirements for hazardous drug collection and disposal increase. Long-term care and retail pharmacy settings present unique compliance and chain-of-custody challenges that require tailored service models and contractual protections.
- Service innovation and cost pressure: Providers are evaluating hybrid models — centralized destruction versus on-site neutralization, third-party takeback programs versus in-house consolidation — to balance compliance, cost, and carbon footprint objectives. Competitive providers are differentiating through digital chain-of-custody, compliance-as-a-service offerings, and value-add clinical formulary optimization support.
Competitive landscape: what the market structure means for buyers
The sector displays a moderate level of concentration: leading incumbents collectively command a meaningful share of the market while a diverse group of regional and specialist providers compete on niche service attributes and local regulatory expertise. This structure creates negotiating leverage for sophisticated buyers but also heightens the importance of supplier selection and contingency planning.
Hazardous Drug Disposal Service Market
- Stericycle and large integrated players: Global leaders demonstrate strengths in compliance advisory, nationwide logistics, and integrated waste streams — capabilities that matter when organizations prefer single-vendor accountability across regulated medical and pharmaceutical waste. Recent moves by such firms to publish USP <800>-aligned guidance and support broader Subpart P adoption reflect how supplier strategy is reacting to regulatory signals.
- Hazardous-waste specialists and environmental services firms: Companies with deep hazardous waste treatment capabilities (including incineration and specialized destruction facilities) offer scale and technical competency for complex or high-volume waste streams. Their global networks are an advantage for multi-jurisdictional health systems.
- Healthcare-focused challengers: Providers that specialize in pharmacy-centric services, sharps management, and formulary consultancy compete on clinical integration, secure collection systems, and targeted compliance services for outpatient and long-term care settings.
Report contents — operational, commercial, and executable outputs
PW Consulting designed this report as a practical toolkit for executives who must act, not merely observe. Key deliverables include:
- Market-sizing and trend model: A transparent model with historical calibration and scenario-based forecasts through 2032, enabling buyers to stress-test budgets under different adoption and enforcement scenarios.
- Regulatory impact maps: Actionable impact matrices linking specific regulatory changes (e.g., state-level Subpart P adoptions, USP <800> clarifications, DEA-controlled substance protocols) to operational controls, compliance costs, and timeline urgencies by facility type.
- Vendor benchmarking framework: A reproducible scoring system that ranks suppliers on compliance coverage, geographic service footprint, treatment technology, digital traceability, and commercial terms (RFP templates included). The report summarizes strengths and strategic positioning of leading firms to inform sourcing strategy without disclosing proprietary share metrics.
- Procurement playbooks and contract language: Negotiation playbooks, sample SLAs, indemnity and audit clauses, and a decision tree for choosing between centralized vs. decentralized disposal models.
- Case studies and implementation checklists: Field-tested workflows and change-management templates covering staff training, segregation protocols, internal audit pathways, and incident-response procedures.
- Investment and M&A lens: Valuation heuristics and integration checklists for private equity and corporate development teams evaluating opportunities in hazardous pharmaceutical services, treatment assets, and technology-enabled traceability solutions.
Strategic recommendations for 2026 decision-makers
Organizations that treat hazardous drug disposal as a strategic operational function will mitigate risk and capture cost efficiencies. Our top recommendations:
- Prioritize compliance-first procurement: Use regulatory impact maps to set mandatory bid criteria. Contracts should require traceability, RCRA-compliant handling, and flexibility for state-level rule changes.
- Design hybrid operational models: Combine centralized processing capacity for high-volume streams with accredited local partners for remote sites. This reduces risk from single-point failures and improves reach into ambulatory and long-term care environments.
- Invest in digital chain-of-custody: Digital manifests and audit trails materially reduce administrative burden and exposure during inspections. Evaluate vendors on API readiness and integration with your EMR/pharmacy systems.
- Test on-site mitigation options strategically: For facilities with predictable waste profiles, validated on-site neutralization can lower lifecycle cost and transport risk — but only when paired with accredited validation and monitoring programs.
- Embed sustainability and cost transparency into RFPs: Require lifecycle carbon accounting and full-cost disclosure for destruction vs. neutralization pathways to align with corporate ESG and budget objectives.
- Plan for procurement windows tied to regulatory milestones: Use our scenario timelines to prioritize contracts that expire before known enforcement ramp-ups to preserve negotiating leverage.
Risks, watch points, and 90‑day actions
Key risks include uneven state adoption of federal rules, enforcement variability, price volatility tied to treatment capacity constraints, and the operational challenge of scaling compliant collection from non-acute sites. For the next 90 days we recommend:
- Conduct a rapid regulatory gap assessment against Subpart P and USP <800> milestones;
- Run an RFP readiness check using our vendor scoring template to identify near-term single-source risks;
- Pilot a digital manifest solution in a representative subset of sites to establish integration baseline and ROI evidence.
How to use this report
This study is deliberately structured as a decision-support instrument rather than a data dump. It combines a macro forecast (base year 2025; forecast period 2026–2032 with a 7.34% CAGR) and practical modules — from procurement templates to implementation checklists — that enable rapid translation from insight to action. To preserve competitive integrity and support live client engagements, the report omits granular public disclosure of our segment-level splits and proprietary vendor share tables in this press summary; these detailed appendices, price curves, and interactive models are available through the report landing page.
Next steps and where to get the full intelligence
For healthcare system CFOs, procurement heads, environmental compliance officers, and corporate development teams preparing for 2026, PW Consulting’s Hazardous Drug Disposal Service Market report provides the prioritized actions, negotiation levers, and regulatory timetables you need. To review segmented forecasts, detailed vendor scorecards, price sensitivity curves, and bespoke procurement templates, access the full report on our website. Our research team is also available for tailored briefings and procurement workshops to accelerate rollout and vendor rationalization.
PW Consulting — translating complex regulatory and market signals into executable strategies that protect patients, providers, and the bottom line.
For detailed analysis of this topic, please visit the official page: Hazardous Drug Disposal Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Dispensing Robot Market 2026: Strategic Insight Brief — PW Consulting
As healthcare providers and life‑sciences manufacturers move to resolve persistent labor shortages, accuracy requirements, and margin pressure, dispensing robotics have shifted from niche automation to strategic infrastructure. PW Consulting’s latest Dispensing Robot Market report (base year 2025) synthesizes five years of historical performance (2020–2025) and provides a 2026–2032 forecast built to inform boardroom decisions. The market’s macro trajectory — a compound annual growth rate (CAGR) of 9.24% in our forecast window — underpins a multi‑billion dollar opportunity that will materially affect capital allocation, M&A prioritization, and product roadmaps for the next three budget cycles.
Dispensing Robot Market
Market snapshot: momentum and medium‑term trajectory
Key headline metrics from the report set the strategic frame: global dispensing robot market value expanded from the low‑billion range in 2020 to an estimated USD 2.07 billion in 2025 (report base year). Our models project continued expansion into the forecast period, surpassing the mid‑range billions by the early 2030s. That growth, modeled at a 9.24% CAGR for 2026–2032, reflects accelerating adoption across hospital pharmacy operations, central fill facilities, specialty and retail pharmacy infrastructures, and specialised industrial uses such as semiconductor and electronics manufacturing.
Dispensing Robot Market
These topline dynamics mask important structural inflections that every executive should weigh in 2026: (1) capital intensity and procurement cadence are evolving with subscription and managed‑service offerings; (2) integration and software capability increasingly determine long‑term value; and (3) pockets of regulatory and reimbursement tailwinds are creating asymmetric pockets of near‑term demand.
Dispensing Robot Market
Why this report matters for 2026 decisions
- Capital planning and scenario modeling: With many health systems signaling constrained capex plans in 2026, the report translates forecast scenarios into three capital deployment pathways (conservative, base, accelerated) that CFOs can overlay on internal spend envelopes to identify optimal timing for phased automation.
- Procurement strategy and TCO: Beyond sticker price, we quantify operating lifecycle drivers — throughput, downtime, consumable costs, and software uplift — and provide a decision framework to compare capex buy versus robotics-as-a-service or managed‑service offers.
- Go‑to‑market and product positioning: For vendors, the report reveals where product differentiation (speed, footprint, integration APIs, compliance packaging) yields premium pricing and faster payback, helping prioritize R&D and channel investments in 2026.
- M&A and partnership screening: The forecast identifies capability gaps across incumbents and fast‑growing newcomers where bolt‑on acquisitions or technology partnerships deliver quick adjacency into central fill, IV compounding, or high‑volume retail channels.
- Regulatory and operational risk hedging: We map the interaction of hospital capex headwinds, pharmacy spending increases in specialty areas, and workforce pressures to help risk‑adjust deployment schedules and contractual terms.
What’s inside the report — practical, decision‑grade content
- Topline and scenario forecasts (2026–2032) with demand drivers mapped to business use cases and procurement cycles.
- Actionable total cost of ownership (TCO) models and payback calculators customizable to client inputs (throughput, labor rates, fill profiles).
- Vendor capability matrices evaluating hardware, software integration, service support, and compliance features — scoring vendors on criteria that matter to hospital pharmacies, retail chains, and central fill operators.
- Market entry and expansion playbooks for vendors and private equity, including channel strategies, pricing archetypes, and operational pilots designed to shorten sales cycles.
- Operational playbooks for providers showing stepwise implementation plans (pilot → scale → continuous optimization) and KPIs tied to safety, speed, and labor redeployment.
- Risk register and mitigation strategies including supply chain stretch scenarios, labor availability constraints, and reimbursement/regulatory shifts.
Competitive landscape — what executives must know
The competitive field spans established medical device and automation incumbents to specialized pharmacy‑automation vendors. The market remains characterized by multiple credible suppliers with differentiated value propositions rather than extreme concentration; in practice, that means procurement teams can drive competitive tension but must manage integration risk and lifecycle support commitments.
- Hospital and health‑system specialists: Companies with deep hospital workflow integrations and strong service networks stand out for complex deployments, including central pharmacy automation and IV compounding. Their advantage lies in EHR connectivity, clinical workflow expertise, and long service tails.
- Retail and outpatient focused vendors: Firms that have optimized for footprint, speed, and compliance packaging capture value in high‑velocity retail chains and outpatient clinics, where throughput and return on floor space dominate procurement decisions.
- Industrial and specialty players: For non‑clinical uses — e.g., electronics and semiconductor assembly — players emphasize precision dispensing, integration with downstream processes, and scalable linear/gantry architectures.
Notable vendor developments frame the near‑term competitive dynamic. For example, a major industry participant showcased an advanced high‑speed boxed medication dispensing robot with automated replenishment in late 2025, signaling intensified U.S. market efforts and an escalating emphasis on replenishment automation and throughput optimization. Such product introductions pressure competitors to accelerate integration, service offerings, and financing flexibility.
Market dynamics and external pressures
Three interlocking market forces will shape 2026 outcomes:
- Hospital capex realities: With a meaningful portion of health systems planning constrained or reduced capital spending in 2026, procurement windows are tightening and projects that demonstrate clear near‑term financial relief or regulatory necessity are prioritized.
- Pharmacy spend trends: Rising pharmacy spending — particularly from infusion and specialty channels — underpins demand for automation that improves throughput and compliance. Automation investments tied to specialty dispensing deliver differentiated ROI compared with commoditized unit‑of‑use scenarios.
- Labor and efficiency priorities: Automation to address staff shortages and burnout remains a major investment rationale. Around one‑third of health system leaders are prioritizing automation in response to financial pressures, making 2026 a year where demonstrable staff redeployment benefits can tip procurement decisions.
Practical recommendations for 2026 decision‑makers
- CFOs and procurement leads: Recast automation projects as operational transformation investments with explicit labor substitution and error‑reduction KPIs. Use the report’s scenario TCO models to negotiate outcome‑based contracts and service SLAs.
- Hospital pharmacy directors: Prioritize pilots that validate integration with existing medication management systems and demonstrate measurable time‑savings for pharmacy technicians within 6–9 months.
- Vendors and product leaders: Invest in modular, API‑first software and flexible financing models. Differentiate on total throughput and replenishment automation rather than purely hardware speed metrics.
- Private equity and M&A teams: Target tuck‑ins that fill software or service gaps (remote monitoring, spare parts, training) to enhance recurring revenue and reduce churn risk in hospital contracts.
- Operational leaders: Prepare workforce transition plans that combine retraining with redeployment into clinical tasks that increase patient value, thereby preserving headcount where needed and accelerating ROI realization.
How PW Consulting’s report de‑rIsks your 2026 roadmap
This report is designed as a practical playbook: it converts macro forecasts into executable steps for procurement, operations, and product strategy. Clients receive customizable TCO templates, negotiation playbooks, and pilot evaluation metrics that translate the market’s 9.24% CAGR into concrete investment cases. Critically, the report balances near‑term capital realities with longer‑term adoption curves so leaders can stage investments without losing strategic optionality.
Next steps — where to get the full intelligence
PW Consulting’s Dispensing Robot Market report contains the full set of segmentation tables, regional and application breakouts, vendor scoring matrices, and detailed financial models that underpin the executive guidance summarized here. To access the complete dataset, segmentation analyses, and downloadable TCO tools — which are intentionally omitted from this preview to preserve the report’s commercial value — visit our report page or contact our research team for a briefing and a tailored extract aligned with your operational inputs.
For boards, investors, and operating executives contemplating automation in 2026, the choice is not whether to engage — it is how and at what sequence to deploy capital and capability to capture the sizable upside while minimizing integration and financial risk. PW Consulting’s report provides the map; the decisions made this year will determine who wins the efficiency and safety dividends of the next decade.
For detailed analysis of this topic, please visit the official page: Dispensing Robot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Norbornane Diisocyanate Market Poised to Reach USD 355.52 Million by 2032, Growing at a 5.24% CAGR (2026–2032)
By PW Consulting, 2026-07-13
Norbornane Diisocyanate (NBDI) Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s forthcoming NBDI Market report (base year 2025; historical window 2020–2025; forecast period 2026–2032) provides a focused, decision-ready synthesis of a highly specialized chemical market. This preview outlines the high-level market trajectory, the competitive dynamics that will shape supplier strategy in 2026, practical decision frameworks for procurement and product development leaders, and the regulatory and feedstock considerations that materially affect near-term execution. The narrative intentionally demonstrates the analytical depth available in the full report while withholding core granular segment figures — a deliberate signal to industry stakeholders that the full dataset and proprietary scenario outputs are accessible in the complete study.
Norbornane Diisocyanate (NBDI) Market
Market trajectory at a glance
Norbornane Diisocyanate (NBDI) is a niche, high-value specialty isocyanate used in optical-grade polymers, high-performance coatings, elastomers and precision adhesives. Our market model — expressed in USD Million and incorporating historical performance — shows steady expansion through the forecast window, with the total market growing from the mid‑2020s base into the mid‑2030s. The model projects a compound annual growth rate (CAGR) of approximately 5.24% across 2026–2032, reflecting sustained demand from optics and specialty coatings segments and gradual adoption in high‑performance elastomers.
Norbornane Diisocyanate (NBDI) Market
Key macro takeaways:
Norbornane Diisocyanate (NBDI) Market
- The market demonstrates consistent, above‑commodity growth driven by product performance characteristics unique to the bicyclic norbornane molecular scaffold.
- The growth profile is steady rather than explosive — a pattern consistent with specialty chemical markets where substitution cycles and qualification timelines are multi‑year.
- Risk-adjusted upside exists where target end‑use industries (notably high‑precision optics and advanced coatings) accelerate capital spending or where regulatory shifts favor aliphatic diisocyanates over alternatives.
Why 2026 is a pivotal year for corporate strategies
For manufacturers, formulators, and large end users contemplating strategic moves in 2026, the market dynamics point to three converging decision windows:
- Supply security and long‑lead supplier qualification. Given manufacturing complexity and limited primary production capacity, contractual arrangements executed in 2026 will influence availability and price exposure for multiple years.
- Product development pipelines. Adoption in precision optical applications requires multi‑year qualification. Firms intending to launch optics‑grade systems in 2027–2029 must commit to development and scale decisions in 2026.
- Regulatory compliance and market access. Inventory listings and toxicological profile transparency are now table stakes; companies that proactively align regulatory dossiers and stewardship plans will avoid time‑to‑market bottlenecks in regional jurisdictions.
Competitive landscape and concentration insights
The market exhibits very high concentration: the combined share of the top three suppliers exceeds nine in ten units (CR3 ≈ 91.2%), and the top five approach near-total share (CR5 ≈ 96.5%). This structure has several practical consequences for strategic planning:
- Pricing power is structural. Buyers should anticipate periods of supplier leverage near capacity peaks and plan procurement strategies accordingly.
- Supplier climb‑down risk is meaningful. A production disruption at a leading producer can create immediate supply tightness; contingency sourcing and extended inventory strategies are prudent.
- Barriers to entry support incumbents. High fixed costs, complex synthetic routes and stringent product qualification create a moat for established producers.
Within this landscape, Mitsui Chemicals, Inc. (headquartered in Tokyo) is identified as the primary commercial producer and a market reference for NBDI (commercialized as NBDI™). Mitsui’s positioning — an emphasis on high‑performance aliphatic diisocyanates tailored for polyurethane elastomers, coatings and optical applications — serves as the market benchmark for pricing, technical specifications and supply reliability. Our full report profiles Mitsui’s publicly observable capabilities, asset footprint, and commercialization strategy, and overlays competitor archetypes to illustrate potential moves across pricing, capacity expansion and co‑development partnerships.
Feedstock and regulatory dynamics that matter in 2026
Two technical vectors are especially consequential for near‑term strategy:
- Feedstock pathway complexity. NBDI synthesis originates from norbornene‑based precursors; the bicyclic core typically arises via Diels–Alder reaction pathways involving cyclopentadiene derivatives. Feedstock availability, cost volatility of cyclopentadiene precursors, and process yield optimization materially affect delivered cost curves and effective margins. Companies investing in upstream integration or alternative synthetic routes can achieve defensible cost positions.
- Regulatory and safety profile management. NBDI is reported on major inventories (TSCA in the U.S., DSL in Canada, ECL in Korea) and has a documented toxicological dossier (including oral LD50 and irritation endpoints). Robust stewardship and transparent toxicology packages reduce market friction, particularly in regions with heightened chemical safety scrutiny. Early and proactive regulatory engagement shortens approval lead times for new formulations.
Both feedstock and regulatory factors are discussed in the full report with sensitivity analysis, scenario mapping, and practical checklists for implementation teams.
What the report delivers — practical, implementable content
PW Consulting’s full NBDI Market report is structured to convert insight into action. Key deliverables include:
- Market sizing and trajectory model (USD Million) covering historical 2020–2025 and a detailed forecast for 2026–2032 with scenario variants reflecting demand shocks and capacity changes.
- Supply‑chain risk heatmaps highlighting single‑point‑of‑failure facilities, logistical chokepoints and lead‑time distributions for common contract terms.
- Commercial playbooks for buyers and sellers: supplier selection criteria, contracting templates (volume vs. take‑or‑pay tradeoffs), and recommended hedging/stocking policies for 12–36 month horizons.
- Product commercialization timelines and qualification checklists for optical and coating applications — including recommended lab testing sequences and sample panel protocols to compress qualification time.
- Regulatory dossier templates and a regional roadmap for chemical inventory filings and stewardship obligations.
- Strategic M&A and investment indicators: a short list of capability gaps that would justify greenfield or brownfield investments, plus thresholds for pursuing JV or offtake arrangements.
Each of the above sections pairs analytics with executable next steps tailored for procurement heads, R&D leaders, corporate strategy teams and private equity investors evaluating specialty chemical exposure.
Strategic playbook — recommended actions for 2026
Based on our synthesis, firms should prioritize a compact set of initiatives in 2026 to convert market understanding into durable advantage:
- Secure multi‑tier supply: establish primary supply agreements with lead producers while qualifying secondary suppliers and plan safety stock to cover 2–4 months of throughput for mission‑critical applications.
- Accelerate optical qualifications: for firms targeting optics, compress parallel R&D and application trials into a coordinated program to allow market entry in the 2027–2029 window.
- Invest in feedstock optionality: evaluate backward integration (procurement equity or long‑term precursor contracts) or co‑development with incumbent producers to reduce input cost exposure.
- Formalize regulatory readiness: compile global inventory compliance packages and prioritize dossiers in jurisdictions where commercialization timelines are shortest.
- Monitor concentration and tactical M&A: given the high CR3/CR5 metrics, consider opportunistic M&A or strategic partnerships to secure capacity or accelerate market access rather than relying solely on spot procurement.
Why PW Consulting’s study is strategically unique
Three attributes differentiate our report from generic commodity analyses:
- Practitioner focus — every analytical module is tied to a decision input (e.g., contract term recommendations map directly to modeled price volatility and supplier concentration scenarios).
- Scenario depth — our forecast includes sensitivity strands that isolate the impact of feedstock shocks, regulatory delays and demand upticks in targeted end‑uses.
- Execution‑oriented outputs — templates, checklists and heatmaps are designed to be adopted immediately by commercial and technical teams.
Conclusion and next step
The NBDI market is a classic specialty chemical opportunity: predictable, engineering‑driven growth with outsized strategic implications for firms that act early on supply security, product qualification and regulatory readiness. The aggregated market trajectory (USD Million, CAGR ~5.24% through 2032) underwrites continued investment interest, but the high supplier concentration amplifies both opportunity and execution risk. Companies that build disciplined sourcing strategies, align R&D timelines with market qualification windows, and proactively manage regulatory dossiers will be best positioned to capture value as the market evolves.
To access the full dataset, segmented forecasts, supplier profiles and the operational playbooks referenced here — including downloadable contract templates and risk heatmaps — visit PW Consulting’s NBDI Market report page for the complete study and supplementary materials.
For detailed analysis of this topic, please visit the official page: Norbornane Diisocyanate (NBDI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Brine Preparation Systems Market to Climb from USD 528.4 Million in 2025 to USD 794.5 Million by 2032 at a 6.01% CAGR
By PW Consulting, 2026-07-13
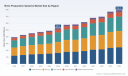
Brine Preparation Systems Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive teaser
As organizations prepare capital and operational plans for 2026, brine preparation systems are emerging from niche utility to strategic asset across food processing, municipal winter maintenance, and industrial water-treatment value chains. PW Consulting’s latest market study — with a 2025 base year and a 2026–2032 forecast horizon — quantifies a market that expanded materially through 2020–2025 and is expected to continue growing at a steady compound annual growth rate (CAGR) of 6.01% across the forecast period. This briefing outlines the report’s strategic value for corporate decision-makers and summarizes the competitive and regulatory landscape you need to factor into 2026 planning. To access the full dataset, vendor scorecards, and opportunity maps, please visit our report landing page.
Brine Preparation Systems Market
Market snapshot (why the numbers matter)
Our topline modelling shows the brine preparation systems market tracked durable growth in the 2020–2025 historical window and is projected to expand significantly by 2032 under a moderate-growth scenario. The mid-single-digit CAGR reflects a market driven by three converging forces: (1) ongoing modernization of food- and seafood-processing lines seeking consistency and hygiene; (2) municipal and highway agencies’ shift toward pre-wetting and liquid de-icing to optimize salt usage and operations; and (3) industrial process demand where brine is an input to chemical and water-treatment operations.
Brine Preparation Systems Market
For executives, the numeric story validates two propositions for 2026 planning: first, brine systems are no longer a one-off CAPEX item but part of recurring process optimization and sustainability programs; second, predictable growth enables multi-year supplier strategies — from vendor qualification and spare-parts provisioning to lifecycle service contracts and digitalization roadmaps.
Brine Preparation Systems Market
What this report delivers — practical, decision-ready outputs
- Proven market-sizing methodology and sensitivity scenarios: transparent assumptions, breakouts by end-use type and region (high-level), and upside/downside paths linked to raw-material and regulatory shocks.
- Procurement playbook and TCO templates: capital vs operating cost comparisons for automatic, semi-automatic and manual systems; vendor selection scorecards and warranty/service-performance KPIs.
- Operational performance benchmarks: cycle times, typical downtime drivers, energy and water footprints, and hygiene/cleanability checklists mapped to food-safety standards.
- Regulatory-impact matrix: how runoff controls, chloride limits, and environmental reporting requirements re-shape acceptable application mixes and procurement specifications.
- Risk register and mitigation playbooks: supply-chain bottlenecks for salt and key materials, contingency sourcing, and spare-parts stocking strategies to protect uptime.
- Investment and M&A compass: prioritized capability gaps, add-on acquisition profiles, and integration checklists for buyers seeking rapid scale or technology-led differentiation.
Competitive landscape — structure and implications
The brine-preparation vendor ecosystem is characterized by a mix of specialized equipment manufacturers, legacy industrial OEMs, and agile systems integrators. Our concentration analysis shows a moderate level of market aggregation: the combined revenue share of the three largest players indicates a market where leaders hold scale advantages in certain channels, while a broader long tail of suppliers captures niche, regional, and custom-work opportunities. The five-firm concentration metric underscores that strategic partnerships and dealer networks remain important routes to market.
Key firm archetypes and strategic priorities identified in the report:
- Specialist systems houses with deep vertical expertise — firms that design intelligent briners and bespoke systems for food and industrial customers. These providers emphasize engineering, multi-site manufacturing, and supply-chain logistics to serve large processors efficiently.
- Global industrial OEMs — organizations that bring strong hygiene and process-control credentials, and that sell integrated mixing and handling platforms to multinational food processors and chemical customers, often with well-developed aftermarket services.
- Seasonal/municipal-focused manufacturers — vendors that concentrate on winter-maintenance markets with automated salt-brine production and truck-filling solutions; these firms prioritize durability, ease-of-use, and regulatory compliance features.
- Modular and aftermarket suppliers — producers of tanks, agitators and retrofit controls for operators seeking incremental performance upgrades without full-system replacement.
Representative companies profiled in the study include both long-standing and emerging names across these archetypes. For example, several U.S.-headquartered specialists bring decades of domain experience and multiple manufacturing sites to optimize logistics. European OEMs contribute advanced mixing and hygiene-focused systems tailored to high-throughput food processors. A number of players concentrate on winter maintenance applications with automated, truck-ready brine makers and management platforms. Our vendor profiles synthesize technology differentiators, channel reach, product roadmaps, service economics, and partnership suitability for acquirers or strategic suppliers.
Market dynamics and near-term risks
- Raw-materials and supply-chain pressure: salt availability and logistics remain top-of-mind. Global trade flows and import dependence in certain markets affect landed costs and sourcing strategies for operators and suppliers alike.
- Regulatory and environmental headwinds: tighter rules on chloride runoff and contamination from de-icing operations are prompting municipalities and contractors to adopt precision application and brine-based pre-wetting, while also introducing compliance and reporting burdens.
- Technology adoption and digitization: buyers increasingly demand automated dosing, remote monitoring, and integration with maintenance-management systems. This creates opportunities for providers who bundle hardware with sensors and analytics as recurring-revenue services.
- Cross-industry demand shifts: growth in chemical manufacturing and water treatment (where brine is an intermediate input) adds a demand dimension that is less seasonal than winter maintenance but sensitive to broader industrial cycles.
These dynamics mean that 2026 planning must balance CAPEX timing with operational flexibility. Companies that lock into static equipment strategies risk higher lifecycle costs; those that adopt modular platforms and aligned service contracts can capture both efficiency and sustainability gains.
Strategic recommendations for corporate leaders (2026 playbook)
- Adopt lifecycle cost assessment as the procurement baseline. Move beyond headline CAPEX; require suppliers to model lifecycle energy, salt consumption, downtime risk, and service-level economics over a 7–10 year horizon.
- Prioritize modularity and retrofitability. Specify systems that support phased digital upgrades (sensors, remote monitoring) to avoid obsolescence and to enable future monetization of operational data.
- Embed regulatory scenario testing into project approvals. Stress-test plans for stricter runoff and chloride rules — this will affect dosing strategies and may favor closed-loop or additive-minimizing designs.
- Build strategic supplier partnerships with defined KPIs. Use pilot programs to validate durability and maintainability claims before enterprise-wide rollouts; require transparent spare-parts lead times and local servicing arrangements.
- Evaluate M&A and alliance options selectively. For industrial players and strategic buyers, acquiring niche automation or municipal-focused capabilities can accelerate entry into adjacent end markets and provide differentiated service bundles.
How to use the full PW Consulting report
This article is a strategic preview: it surfaces the key themes, vendor archetypes, and decision frameworks executives should use in 2026. The complete report contains the full numeric model, regional and application scenario tables, proprietary supplier scorecards, and downloadable TCO spreadsheets designed for immediate use in request-for-proposal and capital-approval processes.
If you are planning CAPEX, preparing procurement RFPs, evaluating acquisition targets, or setting service and sustainability KPIs for 2026, the full study delivers the granular evidence and templates required to move from strategy to execution while preserving confidentiality of sensitive segmentation intelligence.
About PW Consulting
PW Consulting advises industrial and food-processing leaders on growth, procurement, and M&A strategies. Our sector teams combine rigorous market modelling with hands-on implementation playbooks. The Brine Preparation Systems Market study is the product of primary interviews, equipment-level benchmarking, and supply-chain mapping conducted in 2024–2025 to inform planning for the 2026 decision window.
Next steps
- Request the executive dataset and vendor scorecards to support 2026 procurement rounds.
- Commission a tailored TCO assessment for a specific site or fleet to quantify short- and medium-term savings opportunities.
- Engage PW Consulting for an acquisition target screen or integration readiness review focused on brine-preparation capabilities.
Contact details and access to the full report are available on our website — the data and templates you need to turn 2026 uncertainty into actionable advantage are ready for deployment.
For detailed analysis of this topic, please visit the official page: Brine Preparation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Liquid Hazardous Waste Management Market Set to Surge from USD 48.5 Billion in 2025 to USD 73.34 Billion by 2032 at a 6.08% CAGR
By PW Consulting, 2026-07-13
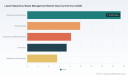
Liquid Hazardous Waste Management Market — 2026 Strategic Briefing
PW Consulting’s new market study on Liquid Hazardous Waste Management arrives at a pivotal moment for industrial generators, service providers, investors and regulators. The market has expanded steadily over the last half-decade — growing from a multi‑decade trough into a structurally larger sector — and now sits at an elevated base entering 2026. Our analysis shows the global market reached approximately USD 48.5 Billion in 2025 and is projected to continue expanding through the forecast horizon, reaching just over USD 73 Billion by 2032 on a compound annual growth rate of roughly 6.1% (2026–2032). This briefing highlights why the report is essential for decision-makers planning actions in 2026, what practical intelligence it delivers, and the competitive and regulatory dynamics that will shape priorities in the next 12–24 months.
Liquid Hazardous Waste Management Market
Why 2026 Is a Strategic Inflection Point
-
Regulatory modernization is accelerating. Major regulatory initiatives — including moves toward electronic-only manifests in the U.S., expanded treatment and classification of emerging waste streams (e.g., lithium batteries and PV panels), and tighter international shipment rules — are changing compliance workflows, traceability requirements, and cross-border movement economics. These changes shift commercial value toward operators with robust digital, compliance and logistics capabilities.
Liquid Hazardous Waste Management Market -
Permitting and capacity constraints are tightening in jurisdictions that have become more cautious about new or expanded treatment, storage and disposal facilities. Where moratoria or stricter siting rules are introduced, localized capacity imbalances emerge quickly and create near-term price and service-disruption risk for generators.
Liquid Hazardous Waste Management Market -
Consolidation and targeted capacity investments by major operators are reshaping access to high-temperature treatment and specialized processing for complex liquid streams. Strategic partnerships that guarantee access to new high-temperature facilities are already influencing feedstock routing and commercial terms.
-
Price pressure and unit disposal costs — particularly for common liquid streams such as contaminated solvents and antifreeze — remain material to operating margins for both generators and service providers, making cost benchmarking and outsource-vs-internalize decisions urgent boardroom topics.
What the Report Delivers: Actionable, Transaction-Ready Intelligence
This study is designed not as a theoretical taxonomy but as a practical toolkit for executives making 2026 decisions. Key deliverables include:
-
Bottom‑up market sizing and a transparent forecast model covering 2020–2032, reconciling generator flows, treatment capacity and price trajectories. We provide scenario-weighted demand curves to stress test strategic plans under alternative regulatory and capacity outcomes.
-
Treatment-technology assessments that compare cost-to-treat, environmental outcomes, operational risk, and capital intensity across prevailing options (e.g., high‑temperature incineration, physico‑chemical methods, recovery/recycling routes and deep-well injection). Each technology is ranked by commercial suitability for specific waste characteristics and regulatory environments.
-
Commercial benchmarking and unit-cost templates. The study includes benchmark benchmarks for collection logistics, treatment gate fees, and disposal economics to enable rapid financial modeling of in‑house versus third‑party strategies.
-
Permitting, regulatory and geopolitical risk matrices. We map the timing, probability and operational impact of major rulemakings, moratoria and international regulatory shifts and translate them into decision triggers for capex, M&A and contract renewals.
-
M&A and partnership playbook. The report provides a prioritized list of inorganic targets, valuation cross checks, integration risk checklists, and a diligence dashboard focused on liabilities, remediation history, and legacy‑waste exposures.
-
Procurement and tender-play templates designed for generators seeking resilient service contracts — including performance SLAs, pass-through risk clauses, and capacity‑reservation mechanisms for periods of constrained treatment availability.
-
Case studies and commercial archetypes showcasing how generators in high‑risk sectors restructured supply arrangements, invested in recycling/recovery pilots, or secured guaranteed treatment capacity through strategic partnerships.
Competitive Landscape — What to Watch in 2026
The market exhibits a dual structure: global integrated players investing at scale in treatment capacity and logistics, and specialized regional operators focused on niche or complex waste streams. Recent year-over‑year activity illustrates how the frontier of competition is shifting:
-
Large integrated operators are consolidating scale and capabilities. Recent acquisitions and multi‑year investments by global leaders have expanded access to high‑temperature treatment capacity and amplified their service footprints across key industrial markets. These moves improve national routing options for generators while raising the value of guaranteed‑access partnerships.
-
North American leaders remain focused on depth of service and emergency response capability. Firms with broad vacuum‑truck fleets, incineration assets and emergency response teams continue to compete on speed-to‑service and regulatory compliance expertise.
-
Specialists secure strategic advantages by focusing on complex or regulated niches — for example, mixed hazardous and radioactive liquid waste, or contractors with expanded permits for high‑volume mixed-waste processing. Capacity expansions at specialist sites materially alter regional service supply and are often underappreciated as catalysts for pricing power.
-
Smaller and mid‑tier players retain relevance through localized customer relationships, flexible contract terms and bespoke treatment offerings; fragmentation at the local level creates arbitrage opportunities for acquirers and strategic buyers.
Recent Industry Signals — Implications for Strategy
-
Large-scale acquisitions and facility expansions signal a push to secure treatment throughput and shift market share dynamics. These transactions create near‑term integration workstreams but longer-term advantages in routing and pricing.
-
Strategic partnerships that guarantee access to newly commissioned treatment capacity reflect an emerging commercial model: rather than owning every asset, firms are securing capacity under long-term arrangements to de‑risk generator supply chains.
-
Regulatory proposals to modernize manifests and extend regulatory coverage to new waste classes will raise compliance costs and increase demand for vendors offering end‑to‑end digital traceability.
Operational Imperatives for Generators and Providers in 2026
Executives should convert the macro picture into short-list operational actions. The choices below should be prioritized in 2026 planning cycles:
-
Audit and reconstruct commercial terms to include capacity reservation rights and escalation protections tied to regulatory-driven cost inputs.
-
Accelerate digitalization of chain-of-custody and manifest workflows to reduce administrative friction and comply with impending electronic-manifest mandates.
-
Invest selectively in on-site minimization and in-field separation to unlock recycling and recovery pathways that reduce disposal spend and environmental risk.
-
Run M&A and partnership scouting against a clarified set of liabilities and remediation thresholds; prioritize targets that deliver immediate capacity access or capability rather than challenger revenue alone.
-
Stress-test supply agreements for contingency routing in jurisdictions with potential permitting moratoria or constrained siting approvals.
Risk & Opportunity Map
The sector’s near-term upside is balanced by identifiable risks. Regulatory change and permitting constraints create both opportunities (for providers with compliant capacity and digital traceability) and threats (for generators and mid‑tier vendors facing route disruption). Cost volatility in disposal — particularly for heavily contaminated solvent streams and common antifreeze-like liquids — means that even small changes in gate fees materially affect manufacturing margins and operational budgets. PW Consulting’s scenario models quantify those inflection points and provide actionable thresholds for renegotiation and capex decisioning.
How PW Consulting’s Study Helps You Act in 2026
This report is designed to be immediately operational: decision-makers will find the downloadable financial models, vendor scorecards, permitting timelines, and tender templates necessary to execute within 60–120 days of purchase. We intentionally limit public disclosure of granular regional and application splits in this executive release to preserve the proprietary value of the underlying datasets; the full report and data portal contain the detailed regional, treatment-method and end‑user breakdowns, downloadable spreadsheets, and scenario-run libraries that corporate development, procurement and operations teams require for transaction execution and board-level strategy.
For executives who must translate market movement into actionable plans in 2026, PW Consulting’s Liquid Hazardous Waste Management Market report is built to be both a strategic briefing and an operational playbook — combining forward-looking market economics, detailed regulatory & permitting intelligence, and the commercial tools to act confidently under uncertainty.
Access the full report and the interactive data portal to retrieve the complete subsegment detail, regional maps, and downloadable financial models that support immediate deal, procurement and operational decisions.
For detailed analysis of this topic, please visit the official page: Liquid Hazardous Waste Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Poultry Farm Equipment Market Hits USD 5,213.6 Million in 2025, Poised for Continued Growth
By PW Consulting, 2026-07-13
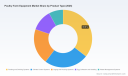
Poultry Farm Equipment Market 2026: Strategic Imperatives from PW Consulting
PW Consulting's new Poultry Farm Equipment Market report (base year 2025; forecast 2026–2032) delivers the forward-looking intelligence that senior executives, corporate strategy teams, and investors need to set winning agendas for 2026. The global market — which has expanded steadily through the 2020–2025 period and recorded a market size of approximately USD 5,213.6 Million in 2025 — is projected to continue growing at a compound annual growth rate (CAGR) of 5.2% through 2032, reaching roughly USD 7,434.4 Million by the end of the forecast horizon. These topline dynamics frame both opportunity and complexity: steady expansion supports disciplined investment, while increasing technological and regulatory complexity demands targeted execution.
Poultry Farm Equipment Market
Why this report matters for 2026 decision-making
-
Actionable capital planning: Our model translates the headline CAGR into scenario-tailored CapEx trajectories and payback expectations for greenfield and retrofit investments.
Poultry Farm Equipment Market -
Procurement and supply-chain risk mitigation: The report maps procurement levers — from component sourcing to vendor selection — against raw-material volatility and logistics constraints.
Poultry Farm Equipment Market -
Technology adoption roadmap: We benchmark automation, IoT sensing, and energy-efficiency solutions across farm types and lifecycle stages to prioritize initiatives that deliver measurable unit-cost reductions.
-
M&A and competitive positioning playbook: Market structure analysis and vendor profiles help investors and corporate development teams identify consolidation targets and partnership fits.
-
Regulatory and ESG alignment: Practical guidance aligns equipment strategy with animal welfare standards, energy regulations, and customer-facing sustainability claims.
Market dynamics that will define 2026 strategies
-
Labor shortages accelerate automation adoption — Across hatcheries and processing, persistent labor gaps and high turnover for repetitive tasks have pushed automation from optional to essential. Expect near-term capital allocation to favor sexing, catching, handling and automated feeding/watering systems that reduce labor dependency and error rates.
-
Raw-material volatility compresses supplier margins and shifts design choices — Fluctuating steel and component prices are forcing equipment manufacturers to re-evaluate material specifications, modular design approaches, and hedging strategies. Procurement teams should build cost-flex clauses and multi-sourcing contingencies into vendor contracts.
-
IoT and smart farming move from pilots to production — Sensors for temperature, ventilation, feed and water monitoring are now delivering repeatable operating efficiencies and traceability. Buyers should prioritize systems with open-data architectures and clear integrability with farm-management platforms.
-
Energy efficiency is both cost and compliance lever — Redesigns such as energy-efficient scalding and optimized climate control reduce operating expenses and support sustainability commitments. Energy performance should be a primary evaluation metric alongside upfront cost.
-
Supply concentration and fragmentation create strategic openings — The market exhibits a mixed structure with a handful of large, internationally recognized suppliers alongside numerous regional and OEM players. This configuration enables targeted partnerships, bolt-on acquisitions, and regional manufacturing strategies.
Competitive landscape: what leading players signal for 2026
The competitive map contains established global engineering houses, specialized automation firms, and a growing cohort of cost-competitive manufacturers from value regions. Several strategic themes emerge from company positioning and recent developments:
-
Product breadth and integrated systems: Companies such as Big Dutchman International (Germany, https://www.bigdutchman.com) and OFFICINE FACCO & C. Spa (Italy, https://www.facco.net) remain differentiated by turnkey offerings that span housing, feeding, ventilation and manure management. Their exhibitions and product launches indicate continued investment in integrated systems that simplify buyer decision-making and lock in maintenance revenue streams. Notably, Big Dutchman's January 2026 trade-show showcase — including a patented straight-line chain feeding innovation — underscores ongoing engineering-led differentiation.
-
Automation and farm-level intelligence: Vencomatic Group (Netherlands, https://www.vencomaticgroup.com), Petersime (Belgium, https://www.petersime.com) and Chore-Time (CTB, USA, https://www.choretime.com) are pushing deeper into automation and hatchery-process efficiency. These players are attractive to farms prioritizing labor substitution and traceability.
-
Specialist feeders and watering systems: Roxell (Belgium, https://www.roxell.com) and LUBING (Germany, https://www.lubing.com) highlight the margin and performance advantages in focused component markets — an important consideration for OEMs seeking best-in-class subsystems for integration.
-
Regional OEMs and cost providers: Chinese and Eastern European manufacturers (e.g., Hightop, Retech, TEXHA, and several Hebei suppliers) are increasing market share in cost-sensitive segments and export corridors. Buyers must balance initial equipment cost against lifecycle service, parts availability and technological openness.
-
Financial and operational momentum: Public and listed players are signaling resilience. For example, related portfolio and equipment businesses reported improved flows and synergy capture in late 2025, which suggests enhanced competition for large-scale projects and faster deployment of integrated solutions.
What PW Consulting’s report contains — practical, executable content
-
Robust market-sizing and trend analysis for 2020–2032, with scenario-based forecasts to support budget planning and sensitivity testing around key variables (labor costs, energy prices, raw materials).
-
Vendor benchmarking matrix: technical capability, service footprint, total-cost-of-ownership (TCO) scoring and integration risk assessments to fast-track procurement decisions.
-
Technology adoption playbook: evaluation criteria for automation, IoT, and energy systems; case studies showing realized returns and implementation pitfalls.
-
Supply-chain and sourcing toolkit: material-cost pass-through clauses, alternative sourcing strategies, and logistics contingency planning.
-
CapEx decision frameworks and payback models for retrofit vs greenfield investments, including recommended trigger points for investment under different market-growth scenarios.
-
M&A and partnership guide: target profiles, valuation considerations, and integration checklists tailored to the current market structure and concentration dynamics.
-
Regulatory, ESG and operational risk heatmaps with mitigation strategies aligned to animal welfare, emission targets and energy-use standards.
How executives should act in 2026 — practical next steps
-
Reframe CapEx around flexibility: favor modular equipment and upgradeable control systems that preserve optionality as raw-material and energy prices move.
-
Prioritize automation investments with measurable KPIs: target projects that reduce repetitive labor exposure and deliver sub-24-month paybacks under our median scenario; build phasing to derisk implementation.
-
Embed energy performance metrics into vendor selection: require lifecycle energy-use disclosures and warranty structures that support efficiency goals.
-
De-risk supply chains: diversify component suppliers, especially for critical subassemblies, and include indexed pricing where feasible to limit margin shock.
-
Use competitive structure to your advantage: with a moderately concentrated top tier and a broad long tail of regional suppliers, deploy a two-track sourcing strategy — strategic partnerships for core systems and competitive tenders for commoditized components.
-
Pursue targeted M&A: acquisitions that add automation capability, strengthen service footprints, or unlock regional manufacturing can accelerate growth and margin capture in a market that continues to expand at mid-single-digit rates.
Strategic caution — known risks and blind spots
-
Beware of total-cost myopia: low upfront prices from some OEMs can mask higher lifecycle costs due to parts scarcity and limited service networks.
-
Integration friction: legacy farms without standardized data architectures face longer timelines to realize IoT-driven efficiencies unless retrofits are planned holistically.
-
Regulatory shifts and welfare standards: rising expectations for animal welfare and environmental performance can strand assets if not anticipated in investment decisions.
Next step — where to find the intelligence you need
This release outlines the strategic contours and practical implications from PW Consulting’s Poultry Farm Equipment Market report. For procurement teams, operators, investors and corporate strategists who require the full decision-grade detail — including granular segment economics, supplier scorecards, and downloadable financial models — the full report contains the complete datasets and templates to execute in 2026. PW Consulting is available to deliver bespoke briefings, scenario workshops and integration planning support to help translate insights into immediate action.
Contact PW Consulting for access to the full report and to schedule a tailored executive briefing that aligns the analysis with your 2026 strategic priorities.
For detailed analysis of this topic, please visit the official page: Poultry Farm Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LDO Voltage Controllers Market Tops USD 5,240.4 Million in 2025, Eyes 5.81% CAGR Through 2026–2032 as Asia Pacific Commands USD 2,476.6 Million
By PW Consulting, 2026-07-13
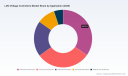
Ldo Voltage Controllers Market 2026: Strategic Imperatives for Corporate Decision‑Making
As PW Consulting’s senior industry analyst, I present a focused executive briefing distilled from our new Ldo Voltage Controllers Market research report (base year 2025, forecast 2026–2032). The market for LDO (low-dropout) voltage controllers has moved from steady utility to strategic linchpin in power-management roadmaps: after growing from USD 3,850.15 million in 2020 to USD 5,240.40 million in 2025, our model projects expansion to USD 7,776.13 million by 2032 — a compound annual growth rate (CAGR) of 5.81% across the forecast window. For leadership teams planning capital allocation, product roadmaps, or M&A in 2026, this profile matters: it reframes LDOs from component line items into competitive enablers for battery life, EMI/PSRR performance, and miniaturized system designs.
Ldo Voltage Controllers Market
Why this report matters to 2026 strategic choices
-
Decision timing: 2026 is a transitional year. Supply‑chain realignments, regulatory pressure on semiconductor exports, and renewed policy actions on critical minerals change the expected payoff timelines for capacity investments and supplier contracts.
Ldo Voltage Controllers Market -
Risk-adjusted allocation: LDOs are small in BOM cost but high in system value for a growing set of end-markets (automotive, portable consumer devices, telecom and industrial). Our report converts system-level benefits into quantitative portfolio scenarios to help prioritize R&D and procurement spend.
Ldo Voltage Controllers Market -
Commercial leverage: The LDO market exhibits a moderate level of vendor concentration with clear technology leaders; the report maps competitive moats and commercialization pathways so commercial teams can design targeted partnership or displacement plays.
Report contents — what executives will get
-
Market sizing and trajectories: historical series (2020–2025) and a bottom-up forecast (2026–2032) with scenario variants (base, supply-constrained, accelerated-adoption).
-
Technology and product taxonomy: benchmarking of single-channel, multi-channel and ultra‑low quiescent current architectures, including performance vectors (PSRR, dropout, noise, quiescent current, thermal packaging tradeoffs) to guide specification and sourcing decisions.
-
Commercial playbooks: go-to-market tactics for OEMs and suppliers, pricing elasticity analyses, and channel strategies tailored to automotive, consumer, telecom, industrial and medical customers.
-
Supply-chain and sourcing heatmaps: supplier tiering, lead‑time sensitivity analysis, and mitigation options (dual-sourcing, inventory strategies, geographic diversification) tied to real regulatory and raw‑material scenarios.
-
Competitive intelligence: executive profiles and capabilities matrices for the sector’s providers, product roadmaps, and acquisition appetites—framing targets for partnership or buy-side due diligence.
-
Risk & compliance playbook: regulatory impact scenarios (export controls, critical minerals policy) and operational checklists for export, import, and IP containment controls.
-
Client-ready assets: slide decks, executive summaries, and an editable financial model to integrate the forecast into corporate planning.
Market dynamics shaping 2026 choices
-
System-level demand drivers: Longer battery life, higher integration density, more stringent EMI/noise budgets, and wider adoption of multi-rail power architectures are shifting design emphasis toward higher-performance LDO solutions (high PSRR/low noise and ultra-low quiescent current variants).
-
Regulatory and geopolitical pressure: Continued export controls on advanced semiconductor manufacturing items and measures on critical minerals are driving buyers to treat supply as strategic. In 2025–2026 we have observed policy actions that increase the premium on supply-chain visibility and onshore or allied-sourced capacity.
-
Raw-material and process constraints: Controls on certain rare earths and the U.S. reliance on imports for several critical minerals create non-linear risk in some upstream packages and substrate stacks. Wafer and front-end capacity constraints remain a live risk for lead times across power-management ICs.
-
Product innovation cadence: Vendors are accelerating releases that combine automotive qualification, ultra-low Io, and compact packaging to target wearables, EV subsystems, and high-reliability telecom equipment.
Competitive landscape — who’s shaping the market
-
Texas Instruments: Broadest portfolio and scale. TI remains the default for a wide range of linear and LDO products, including automotive-qualified families. For firms focusing on breadth and long‑tail availability, TI is a reference supplier and a high-bar benchmark for quality and documentation.
-
Analog Devices: Performance‑oriented LDOs. ADI’s strength is precision and high-PSRR devices tailored to industrial and high-reliability systems. Their roadmap suits customers prioritizing signal integrity over price.
-
STMicroelectronics: Automotive and industrial focus. ST’s high-voltage input capability and AEC-Q100-qualified families make it a logical partner for automotive platforms and harsh-environment designs.
-
onsemi & Microchip: Low-power and controller expertise. Both companies offer low-Iq options and LDO controller variants that appeal to space-constrained or ultra-low power applications.
-
Renesas, Infineon, ROHM: System integration and automotive ecosystems. These vendors often bundle LDOs within larger power-management offerings, aiding customers who want turnkey power domains for vehicle or industrial platforms.
-
Specialists (Diodes, Toshiba, ABLIC, Nisshinbo): Niche innovation. These players push high-current, low-noise, and ultra-compact parts; recent product-level moves from ABLIC (product-line update, March 2026) and Nisshinbo (NP4271 automotive release, Aug 2024) illustrate continued innovation at the specialist end.
-
Recent operational signals: Product and process updates from Diodes Incorporated (labeling/traceability changes and portfolio reporting across 2025–2026) underscore the emphasis on regulatory compliance and supply transparency.
Strategic recommendations for 2026 (actionable, prioritized)
-
Rebalance supplier tiers: Reclassify LDO suppliers not only by cost but by traceability, qualification, and geographic resilience. Execute dual-sourcing for critical families and negotiate lead-time collars tied to volume commitments.
-
Product portfolio hygiene: Prioritize development of ultra-low quiescent and high-PSRR variants for battery-sensitive and signal-critical applications. For platform firms, commit to two multi-channel LDO families to consolidate BOM and simplify power sequencing.
-
M&A and partnerships: Target bolt-on acquisitions at the specialist end (ultra-low-Iq, automotive LDO brands, or small-package innovators) to accelerate time to market. Alternatively, pursue licensing/co-development with niche component suppliers to lock in IP and supply.
-
Regulatory-playbook implementation: Build an export-control dashboard and critical-minerals monitoring into procurement governance. Scenario-plan tariff impacts and enact contractual clauses to share raw-material risk with suppliers.
-
Value-based pricing and system ROI: Move commercial conversations from part-cost to system-value — demonstrate battery-life gains and EMI reduction as tangible customer savings to justify premium pricing on high-performance LDOs.
-
Operational readiness: Invest in design-for-supply practices (package standardization, PCB footprints, alternative-sourcing lists) and tighten NPI gates to include supplier risk checks.
What we are intentionally withholding (and why)
To preserve the research utility of the full PW Consulting report and to comply with our “trailer” principle for executive briefings, this press summary omits detailed regional and application percentage splits, granular revenue by product subtype, and the full vendor market-share table. Those data are central to tactical procurement negotiations and competitive positioning and are available in the full report package and our interactive dashboard.
Next steps — how to use this insight in 2026 planning
-
For CFOs: Use our bottom-line scenarios to stress-test capital projects and inventory policies against supply-constrained and tariff-impacted outcomes.
-
For CTOs and product leaders: Adopt the product benchmark matrix to rationalize the next 12–24 months of LDO selections for new platforms, prioritizing high-PSRR and ultra-low‑Iq options where system ROI is demonstrable.
-
For corporate development teams: Request the annotated competitor dossiers and M&A target shortlist to accelerate due diligence and valuation workstreams.
-
For procurement and operations: Implement the supply‑chain heatmap and supplier-risk framework included with the report to operationalize dual-sourcing and contractual protections.
PW Consulting’s full Ldo Voltage Controllers Market report includes the complete datasets, vendor scorecards, and an editable model that operationalizes the 2026 scenarios described above. To obtain the full report, request a briefing or schedule a tailored workshop, visit our website or contact your PW Consulting account representative. Our team stands ready to convert this market intelligence into a prioritized, executable plan for your 2026 capital and product decisions.
For detailed analysis of this topic, please visit the official page: Ldo Voltage Controllers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Magnetic Clamping Technology Market to Expand at 6.45% CAGR Through 2032, PW Consulting Forecasts
By PW Consulting, 2026-07-13
Magnetic Clamping Technology Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive summary
PW Consulting’s new market research brief on Magnetic Clamping Technology provides a practice-oriented roadmap for corporate decisionmakers preparing to act in 2026. Our analysis shows the global market expanded to approximately USD 585.5 Million in 2025 and is projected to progress to roughly USD 626.3 Million in 2026, with a 2026–2032 compound annual growth rate of about 6.45%, reaching an expected near-USD 907 Million by 2032. These headline figures mask important structural shifts — supply-side pressure from rare-earth materials, accelerating adoption of electro-permanent systems in automation and cleanroom environments, and a moderately concentrated vendor landscape (CR3 ≈ 42.2%; CR5 ≈ 58.4%) that is ripe for strategic repositioning.
Magnetic Clamping Technology Market
Why this brief matters to 2026 decision-makers
- Translate modest headline growth into differentiated returns: the market’s steady CAGR conceals pockets of rapid value creation tied to productization, services and integration with automation ecosystems.
- De-risk procurement and margin exposure: raw-material volatility and consolidation dynamics materially affect cost curves for OEMs and Tier‑1 suppliers.
- Prioritize R&D and capex: technology choices made in 2026 (electro-permanent vs. permanent vs. electromagnetic) will influence competitiveness across automation, injection molding and high-precision metalworking for the next decade.
- Plan M&A and strategic partnerships with clarity: mid-market specialists and modular technology providers represent high-conviction targets for bolt-on acquisition or collaboration.
Data-driven signals and strategic implications
Our model synthesizes historical performance (2020–2025) with scenario analysis for 2026–2032 to identify three decisive signals for 2026 strategy:
Magnetic Clamping Technology Market
- Technology-led premiumization: Electro‑permanent magnetic systems are increasingly valued for their maintenance profile (energy only during switching) and suitability for automation and cleanroom contexts. Firms that convert product capability into system-level value (faster mold changes, embedded clamping-force measurement, predictive maintenance) win pricing power.
- Raw-material and supply risk: Neodymium oxide and related rare earth inputs remain a key cost lever. Spot prices in 2026 exceeded historical norms, and the broader rare-earth market dynamics continue to be driven by EV and wind-power demand. Procurement and product design teams must integrate material scenarios into their 2026 planning cycles.
- Moderate market concentration and modular competition: The top three to five suppliers account for a majority share of market value, yet there is substantive room for specialized entrants and regional champions focused on customization, service or single-application dominance. This creates both acquisition targets and areas where incumbents must reinforce competitive moats.
Competitive landscape — who to watch and why
The market is populated by a mix of long-established industrial engineering leaders and specialized electro‑permanent innovators. Key competitive archetypes and representative firms include:
Magnetic Clamping Technology Market
- System integrators and precision toolmakers — firms that combine magnetic clamping with broader workholding systems and automation interfaces. These players compete on engineering depth and integration (example: providers offering five-sided machining solutions and zero-point integration).
- Injection-molding and quick-change specialists — companies emphasizing rapid mold exchange, active safety, and clamping-force diagnostics to shorten downtime for plastics processors.
- Electro-permanent innovators — vendors focused on low-energy switching, hybrid chucks and customized handling systems; they frequently derive value from intellectual property and OEM partnerships.
- Regional champions and custom shops — manufacturers that win on local service, aftermarket, and bespoke solutions for niche metalworking or lifting applications.
Recent market activity illustrates these dynamics: established European suppliers are showcasing integrated systems at major industrial shows; electro‑permanent manufacturers are extending partnerships and introducing hybrid chuck designs; and Asian producers are reinforcing global distribution networks. These events signal intensifying competition around modularity, safety features, and service offerings rather than pure price alone.
Regulation, materials and operational context
- Standards and safety: ISO 23582-1:2023 articulates essential safety requirements for magnetic clamping systems deployed on plastics and rubber machines. Compliance is now a commercial prerequisite for suppliers serving modern injection‑molding OEMs and Tier‑1 buyers.
- Cleanroom suitability: Electro‑permanent systems are meeting ISO Class 7–8 requirements for mould clamping in controlled environments, expanding opportunities in medical, micro‑components and high‑value polymer processing.
- Material markets: Neodymium oxide pricing and the broader rare‑earth market (valued at about USD 19.5 billion in 2024) are persistent drivers of component-level cost and innovation in magnet formulations.
What PW Consulting’s report delivers (practical components)
The brief that follows this teaser contains a full set of operationally focused deliverables designed for immediate use in boardrooms and planning cycles:
- Verified market sizing (2020–2025) and granular forecasting (2026–2032) with scenario toggles for material-price and adoption-rate sensitivities.
- Competitive benchmarking (strengths, commercial models, technology roadmaps) and CR-level analysis to inform M&A and partnership screens.
- Supply-chain maps and risk heatmaps including tiered supplier lists for magnets, cores and electronics, plus recommended mitigation actions and contract terms.
- Regulatory impact assessment (including ISO 23582-1 compliance pathways) and a product certification checklist.
- Go-to-market playbooks for product launches, channel expansion, rental and aftermarket service monetization.
- Commercial models and downloadable Excel tools for pricing, margin scenarios, and capex vs. opex tradeoffs when choosing magnetic technologies.
- Five actionable case studies and workshop modules to align sales, engineering and procurement on a 90‑ to 180‑day execution plan.
Strategic recommendations — a 2026 executive playbook
- Hedge and redesign for material risk: Secure multi-year supply agreements or collaborate on alloy substitution pilots. Reassess design tolerances to reduce dependence on costly rare-earth formulations where feasible.
- Prioritize electro‑permanent systems for automation plays: For OEMs targeting cleanroom or automated quick-change segments, invest in electro‑permanent product lines that enable predictive maintenance and integrate force-sensing capabilities.
- Monetize service and uptime: Develop rental, exchange and “clamping-as-a-service” offerings to capture recurring revenue and reduce buyer capital barriers.
- M&A and partnership targeting: Use the market’s concentration profile to identify bolt-on targets that add digital sensing, quick-change subsystems, or regional after-sales strength. Conversely, build defenses in high-value niches to deter entrants.
- Embed compliance as product differentiation: Turn ISO 23582-1 certification and cleanroom compatibility into go-to-market claims for medical and micro‑plastics applications.
- Run commercial pilots with OEM partners: Put validated performance metrics (setup time reduction, deformation avoidance, vibration reduction) into SLA-based trials that convert into platform contracts.
How to use this brief — and where to get the full intelligence
This article is a deliberate preview: it highlights the strategic levers and high‑impact recommendations that PW Consulting’s complete report supports with the full datasets, regional and application breakouts, vendor share tables, downloadable financial models, and supplier shortlists. The full report includes the exact segmentation tables, scenario-based revenue impacts, and ready-to-run workshop materials that boards and commercial teams need to convert insight into action.
Closing
For executives planning 2026 budgets, procurement teams renegotiating supplier agreements, and corporate development teams seeking inorganic growth, the magnetic clamping technology market offers a clear—but nuanced—opportunity. Growth is steady, but advantage will accrue to those who manage material risk, upgrade to system-level product propositions, and capture aftermarket and service monetization. PW Consulting’s full market study equips leaders with the empirical foundation and operational tools to make those choices with confidence.
For detailed analysis of this topic, please visit the official page: Magnetic Clamping Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Plastic Roof Cement Market Valued at USD 945.5 Million in 2025, Poised to Reach USD 1,317.15 Million by 2032 at a 4.85% CAGR
By PW Consulting, 2026-07-13
Plastic Roof Cement Market — Strategic Briefing for 2026 Decision Makers
PW Consulting’s latest market study on Plastic Roof Cement presents a concentrated, execution-focused roadmap for suppliers, distributors, and investors preparing strategic moves in 2026. Synthesizing five years of historical performance, forward-looking scenario models and supply-chain stress tests, the report quantifies market momentum and translates it into actionable choices for corporate leaders — while preserving the granular proprietary segment detail that subscribers access on our platform.
Plastic Roof Cement Market
Why this report matters for 2026 planning
After recovering from pandemic-era supply shocks, the global plastic roof cement market reached USD 945.5 Million (base year 2025). Our forecast models, calibrated across multiple oil-price, trade-policy and construction-demand scenarios, point to a 4.85% compound annual growth rate (CAGR) over the 2026–2032 horizon, with the market projection climbing into the mid-triple‑digit millions by 2032 (USD 1,317.15 Million). For executives making 2026 capital allocation and commercial strategy decisions, these topline dynamics imply:
Plastic Roof Cement Market
- Continued but modest volume expansion: opportunities to capture share through selective capex and product premiumization rather than broad-scale capacity expansion.
- Profitability sensitivity to raw-material cost swings — risk management of feedstock exposure must be prioritized alongside go-to-market investments.
- A fragmented supplier base that leaves room for M&A and differentiated brand plays, particularly in technical formulations and channel specialization.
What the report contains — practical, deal-ready deliverables
This study is designed as an operational toolset for 2026 execution. Key deliverables include:
Plastic Roof Cement Market
- Topline and bottom-up market sizing models (historical 2020–2025 and forecast 2026–2032) delivered in editable USD Million templates so teams can re-run scenarios with bespoke assumptions.
- Scenario planning suites that quantify revenue, margin and inventory outcomes under multiple bitumen/crude price pathways, trade-friction cases, and construction demand shocks.
- Actionable go-to-market playbooks for OEMs, distributors and retail channels: pricing buckets, bundling approaches, channel economics, and recommended KPIs for 12–24 month execution.
- Supplier and raw-material risk maps, including a prioritization of hedging strategies, alternative feedstock sourcing, and forward-buy thresholds tied to cashflow models.
- Regulatory and standards matrix (ASTM and Federal specifications) with compliance cost estimates and timelines for transitioning to low‑solvent, asbestos‑free formulations.
- M&A playbook and screening model: target attributes, valuation sensitivities, and integration checklists tailored to accession of regional manufacturing footprints, formulation expertise, or channel access.
- Competitive intelligence dossiers and benchmarking templates that allow teams to compare positioning, margin profiles and product portfolios against the principal market players.
Market dynamics and headwinds to model for 2026
Our research identifies three dynamics that will disproportionately shape profitability and strategy next year.
- Raw-material volatility. Bitumen and asphalt feedstock prices remain a primary driver of gross-margin variability. Recent trade data and price series show pronounced month-to-month moves in several key markets; procurement strategies that are agile and execution-ready will materially outperform static purchasing policies.
- Regulatory and product-compliance pressure. The sector continues to consolidate around low‑solvent, asbestos-free formulations compatible with ASTM D4586 Type I and Federal Spec SS‑153 Type I. This is changing product development roadmaps and marginal cost structures for formulators and private-label manufacturers.
- Fragmented competitive structure. Market concentration metrics indicate meaningful fragmentation — the top three and top five groups control a material yet non‑dominant share of demand — creating fertile ground for consolidation, regional roll-ups, and white-space specialization.
Competitive landscape — what the leading suppliers signal for 2026
The market’s incumbent manufacturers demonstrate a mix of product specialization, channel depth and brand equity. Strategic implications for market participants:
- Henry Company (El Segundo, CA — https://www.henry.com) : With premium trowel-grade, ASTM-compliant offerings focused on professional roofers and contractors, Henry underscores the value of specification-led sales and technical trust. For competitors, this signals the importance of technical service and code-level endorsements to win commercial business.
- GAF (Parsippany, NJ — https://www.gaf.com) : A legacy roof-systems player that markets general-purpose cold-applied cements, GAF leverages system selling and brand recognition. Strategy takeaway: integrated roof-system positioning and national distributor partnerships defends share against commodity pressure.
- Karnak Corp. (Clark, NJ — https://www.karnakcorp.com) : Seasonal grade offerings and heavy-consistency mastics illustrate product adaptation as a means to command price premia in climate-diverse markets. Product-grade segmentation is a defensible moat in regional rollouts.
- Gardner-Gibson (Tampa, FL — https://www.gardner-gibson.com) , Rust-Oleum (Vernon Hills, IL — https://www.rustoleum.com) and PrimeSource / Grip-Rite (Irving, TX — https://grip-rite.com) : These vendors highlight the retail and pro-retail continuum — from homeowner DIY cartridges to contractor-sized pails. Channel-tailored SKUs and packaging economics are pivotal for 2026 revenue growth.
- Polyglass U.S.A. (Deerfield Beach, FL — https://polyglass.us) and Tamko (Joplin, MO — https://www.tamko.com) : These makers emphasize system compatibility and specification compliance for asphalt roof repairs. Their approach reaffirms the premium customers place on ASTM validation and long-term warranty alignment.
Across these competitors, common strategic levers include formulation differentiation (fibered, solvent-reduced, or polymer-reinforced), channel segmentation (pro vs. retail), and service-adds (technical training, warranty management). For new entrants, focusing on one or two of these levers and executing rapidly is likely to be more effective than broad-spectrum entry.
Supply-chain and procurement playbook for 2026
Given the feedstock sensitivity, the report prescribes a procurement playbook that operationalizes risk into three practical steps:
- Quantify exposure. Map cost-pass-through on a per-SKU basis and estimate P&L swing for realistic price-change scenarios. Use the included stress-test templates to set hedging/deferment triggers that fit your balance-sheet tolerance.
- Diversify suppliers and logistics. Prioritize dual-sourcing for critical asphalt/bitumen inputs and evaluate regional tolling or co‑manufacturing to reduce freight and lead-time risk.
- Product and packaging levers. Reformulate or repackage high-volume SKUs to reduce unit raw-material intensity; introduce concentrated or cartridge SKUs where labor or logistics provide value to end-users.
Recommendations for executive action in 2026
For board-level and C-suite decision-makers, our prioritized recommendations are:
- Adopt a “selective growth” posture: prioritize margin-accretive segments and geographies identified in the report rather than across-the-board capacity investment.
- Invest 2–5% of expected 2026 revenue in formulation R&D to accelerate compliance with low‑solvent standards and to develop higher-margin polymer- or fiber‑reinforced products.
- Implement dynamic procurement policies tied to pre-defined market triggers and horizon-based hedging governed by the treasury function.
- Pursue bolt-on M&A that augments channel reach or provides formulation IP; use our screening model to prioritize targets that deliver immediate margin lift and scale synergies.
- Strengthen technical service and warranty programs for commercial customers — these intangible assets are generating outsized returns relative to incremental capex.
How PW Consulting’s report supports execution
Subscribers receive both the intelligence and the operational artifacts required to act in 2026: editable financial models, procurement stress-test tools, a regulatory compliance calendar, go-to-market playbooks, and company-level benchmarking dossiers. The research intentionally refrains from publishing proprietary segment line-item figures in public summaries; full segmentation, channel economics and company-level revenue mapping are available to subscribers and strategic clients who download the full report.
Next steps
Senior leaders evaluating 2026 budgets should use the report as a companion for three planning milestones: (1) a rapid 60–90 day implementation plan around procurement and pricing, (2) a 6–12 month product and channel execution calendar, and (3) an M&A screening and integration playbook for opportunistic consolidation. For full access to the detailed segmentation, company profiles, and the Excel toolkit, visit PW Consulting’s report portal or contact our industry practice to schedule a tailored briefing.
For detailed analysis of this topic, please visit the official page: Plastic Roof Cement Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


