



Category: market research
Polyurea Coatings Market — Strategic Briefing for 2026 Corporate Decision-Making
As PW Consulting’s Chief Industry Analyst, I present a compact, strategy-focused preview of our full Polyurea Coatings Market study. The sector’s structural growth and risk profile present a clear set of strategic choices for executives planning investments, partnerships, and go-to-market pivots in 2026. This briefing synthesizes the report’s most consequential insights — enough to shape near-term decisions while reserving the detailed segment-level tables, deal pipelines, and project-level maps for subscribers to the full study.
Polyurea Coatings Market
Market snapshot: trajectory and scale
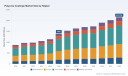
Polyurea coatings have moved from a niche high-performance material toward mainstream specification across infrastructure, industrial, and protective applications. Measured on a historical basis (2020–2025), the global market expanded from under USD 900 million to approximately USD 1.4 billion in our base year (2025). Looking forward across our forecast window (2026–2032), we model a steady compound annual growth rate of 6.33%, driving a market size north of USD 2.15 billion by 2032 under the base scenario.
Polyurea Coatings Market
That trajectory reflects a combination of accelerating adoption in high-value use-cases and incremental displacement of legacy coating technologies where lifecycle performance and regulatory compliance are decisive procurement criteria. Importantly for strategists, the market’s scale today is large enough to support specialization and global scale plays, yet concentrated enough that a small set of incumbent manufacturers and formulators continue to command meaningful share and influence.
Polyurea Coatings Market
Why this study matters for 2026 planning
- Timing of capacity and product decisions: With demand projected to grow at a mid-single-digit CAGR, capital deployment in manufacturing, application equipment, and technical service capabilities must be synchronized to avoid either stranded assets or missed share. Our report frames the optimal timing windows for capex and capacity expansion decisions across three realistic demand scenarios.
- Regulation-driven product specifications: Environmental compliance (VOC limits and lifecycle reporting) is shifting procurement toward 100% solids and low-VOC chemistries. Suppliers who pre-position low-emission product lines will find tender and project windows opening in regulated markets. The study quantifies the regulatory tailwinds and maps them to likely specification changes by buyer cohort.
- Supply chain and margin resilience: Volatility in feedstock pricing — notably isocyanates and specialty amines — is a high-probability, high-impact risk. The study offers pragmatic hedging frameworks, supplier contracting playbooks, and margin protection levers for both upstream manufacturers and downstream applicators.
- Competitive advantage playbook: We provide a decision matrix that links choice of strategic focus (vertical integration, niche premiumization, or geographic expansion) to realistic ROI timelines given current concentration and innovation dynamics.
Dynamics: forces shaping the market in 2026
- Performance economics: Buyers are increasingly valuing whole-life cost over first-cost. Polyurea’s cure speed, chemical resistance, and durability change project scheduling and maintenance economics — a factor we quantify under several asset-life assumptions.
- Environmental profile: Polyurea formulations are typically 100% solids and largely free of VOCs, a structural advantage as public-works and large private projects move toward stricter environmental specifications. Producers are also investing in solvent-free and lower-impact chemistries to align with upcoming regulation cycles.
- Raw material volatility: Fluctuating prices of isocyanates and amine resins present both a cost risk and an innovation incentive; firms that secure long-term feedstock agreements or develop alternative chemistries will enjoy asymmetric advantages.
- Concentration and customer power: Market concentration shows that a small group of suppliers capture a majority of commercial value; this creates opportunities for focused challengers to win by specialization, and for incumbents to consolidate adjacent value pools (formulation IP, application services, logistics).
Competitive landscape: what recent moves reveal
Our analysis pays close attention to a core set of market participants and their recent strategic moves — a reliable signal of where competition and margins will concentrate over the next 24 months.
- ArmorThane USA Inc. — aggressive programmatic wins: Recent contract announcements (including multiple blast mitigation awards) indicate a firm leveraging specialized performance credentials to win government and hardened-shelter projects. For competitors, the implication is clear: deep technical capabilities plus program-level relationships create high-barrier niches.
- BASF SE — capacity and sustainability bets: BASF’s capacity expansion in Asia signals a dual strategy: meet surging regional demand and advance sustainable chemistries that reduce VOCs and extend coating longevity. Big-chemical plays like this compress supply cycles and pressure smaller players to either differentiate or pursue partnering exits.
- Huntsman Corporation — product performance differentiation: Product launches touting measurable polymer performance improvements (e.g., intumescent technologies) show the market still rewards meaningful R&D-driven upgrades. Incremental performance gains translate to specification wins on projects where fire, corrosion, or longevity is mission-critical.
- Other notable players: System formulators and applicators (Sika, Covestro, Chemline, SPI, Polymer Nation) are clustering around specialization: waterproofing membranes, automotive systems, cast elastomers, and decorative/high-performance flooring. These positions highlight the two-tier market structure: platform-grade suppliers and highly focused applicators.
Taken together, incumbent moves suggest an emergent meta-strategy: verticalize where you can (formulation + application), out-innovate on sustainability and performance specs, or specialize into high-barrier niches where scale is less determinative.
What the full PW Consulting report delivers
- Validated market sizing and topline forecasts (historical analysis 2020–2025; base year 2025; forecast 2026–2032) with scenario modeling and sensitivity testing around raw material and regulatory shocks.
- Actionable go-to-market playbooks for manufacturers, applicators, and distributors — including pricing tactics, tender strategies, and installer economics.
- Comprehensive competitive profiles for leading suppliers, with M&A watchlists and a timeline of strategic moves mapped to capability gaps.
- Supply chain stress-testing and recommended contracting frameworks to mitigate isocyanate/amine price volatility and delivery risk.
- Technology roadmaps (chemistry, equipment, and integrative systems) that align R&D choices with addressable commercial value pools.
- Regulatory impact matrices that translate evolving VOC and sustainability rules into product-spec and procurement outcomes by buyer type.
Recommended 2026 executive actions
- Lock in strategic feedstock coverage: Secure multi-year or indexed supply agreements for critical intermediates; alternatively, pursue joint-ventures with chemical suppliers to share margin and risk.
- Prioritize low-VOC formulations and lifecycle claims: Move R&D and commercialization resources to formulations that deliver measurable LCA improvements — these products gain prioritized inclusion on public tenders and corporate procurement lists.
- Adopt a two-track growth approach: For scale players: pursue selective capacity expansion in geographies with near-term demand visibility. For challengers: double down on niche specialization (blast mitigation, intumescent systems, extreme-environment waterproofing) where technical differentiation yields pricing power.
- Invest in application ecosystems: Training, certified applicator networks, and bundled service models increase installed-base retention and margin capture. Our case studies quantify ROI on certification programs vs. pure product selling.
- Prepare M&A and partnership playbooks: Use 2026 as a window to acquire complementary formulation IP or regional applicator networks while valuations remain rational; our competitive concentration analysis highlights likely targets and valuation bands.
- Scenario-proof pricing: Adopt tiered pricing with raw-material pass-throughs and contractual hedges for long-duration projects; apply value-based pricing for whole-life cost propositions on large infrastructure accounts.
How to use this briefing
Treat this document as a strategic compass. If you are an executive evaluating capex, the key input is timing: align any greenfield capacity decisions with the demand scenarios in our full study to avoid overexposure to price shocks. If you are a product leader, use the regulatory and lifecycle insights to prioritize formulations that will be specified in tomorrow’s tenders. For M&A strategists, the competitive concentration and company profiles identify realistic acquisition corridors and partnership candidates.
PW Consulting’s full Polyurea Coatings Market report contains the underlying data tables, segmented forecasts, buyer-level procurement maps, and the transaction-ready annexes that operational teams need to execute on these recommendations. The critical, segment-level intelligence (regional and application split tables, project-level contract pipelines, and supplier cost models) are intentionally withheld from this preview to preserve competitive value and are available via our report portal.
Concluding perspective
In 2026, polyurea coatings represent a strategic growth corridor for materials and service companies that can move beyond commodity competition to offer demonstrable whole-life value and compliance certainty. The market is large enough, growing predictably, and concentrated in a way that makes both focused challenger plays and scale consolidation attractive. Executives who convert the insights above into concrete sourcing, product, and M&A moves this year will be well positioned for the next expansion phase through 2032.
For immediate access to the full dataset, segmented forecasts, and the playbooks described here, consult PW Consulting’s Polyurea Coatings Market report page or contact your PW Consulting account director.
For detailed analysis of this topic, please visit the official page: Polyurea Coatings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Computer Cart Market to Reach USD 344.8 Million by 2032 (6.98% CAGR)
By PW Consulting, 2026-07-09
Medical Computer Cart Market — Strategic Outlook for 2026
Executive snapshot
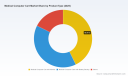
The medical computer cart market has matured into a reliable growth segment of healthcare infrastructure. Our PW Consulting baseline shows the market expanding from a mid‑single‑hundred million USD base in 2020 to an estimated USD 215.0 Million in 2025, and continuing at a compound annual growth rate (CAGR) of roughly 6.98% through the forecast window to 2032. That trajectory reflects steady uptake of point‑of‑care computing, the increasing digitalization of bedside workflows, and incremental product innovation around power management, ergonomics and clinical connectivity.
Medical Computer Cart Market
Why this report matters to 2026 decision‑makers
- Procurement and CAPEX planning: Hospitals and health systems that finalize multi‑year equipment budgets in 2026 need realistic, vendor‑level scenarios for total cost of ownership (TCO), lifecycle replacement and battery/maintenance costs—inputs that materially affect multi‑hospital purchasing strategies and leased vs. owned decisions.
- Product strategy for OEMs: Original equipment manufacturers must prioritize investment in battery management, UL/EN/IEC 60601‑1 electrical safety compliance and integrations for telehealth and medication administration. Timing product launches to capture the mid‑cycle upgrade wave will determine whether incumbents protect share or niche players gain footholds.
- M&A and partnership playbooks: Moderate concentration in the vendor landscape creates predictable consolidation dynamics. Strategic acquirers and private equity investors should use serviceable obtainable market (SOM) scenarios and vendor scorecards to identify tuck‑ins that deliver immediate synergies in service, distribution and product breadth.
What this PW Consulting study delivers (practical, operational value)
The report is designed as a hands‑on playbook for leaders who must convert market insight into executable plans in 2026. Highlights include:
Medical Computer Cart Market
- Validated historical demand (2020–2025) and base‑case through 2032 with sensitivity scenarios that stress-test adoption rates against staffing, reimbursement and regulatory change.
- Commercial frameworks for procurement teams: standardized vendor RFP templates, scoring matrices, and maintenance‑vs‑replace calculators to align capital planning with clinical KPIs.
- TCO and ROI templates that model battery servicing, battery life‑cycle replacement, warranties and predicted downtime impacts on nursing workflows.
- Deployment checklists for IT, clinical engineering and infection prevention teams that translate certification and safety standards into actionable procurement clauses (e.g., IEC 60601‑1 requirements, ISO quality controls).
- Vendor due diligence packs: technology fit maps, indirect spend leakage assessments, and price negotiation playbooks designed for hospital group purchasing organizations and national health services.
- A market consolidation watchlist and M&A valuation frameworks tuned to the segment’s concentration dynamics, service margins and installed base economics.
To maintain the tactical value of the report, we intentionally reserve full disaggregated tables, vendor scorecards and region‑by‑application revenue splits for the complete document and the online dashboard.
Medical Computer Cart Market
Competitive landscape — strategic positioning and implications
The market shows a mix of established incumbents and regional specialists. Three‑ and five‑firm concentration ratios are notable and suggest incumbent advantage in scale, service networks and certification coverage (CR3 ~62.5%; CR5 ~78.3%). Key players profiled in the report illustrate distinct routes to competitiveness:
- Capsa Healthcare (Canal Winchester, Ohio) — Known for integrated telehealth and mobile workstation platforms designed for EHR access, medication management and virtual consultations. Strategic implication: incumbency in telehealth‑enabled carts makes Capsa a preferred partner for hospitals seeking turnkey point‑of‑care telemedicine solutions.
- Ergotron (Eagan, Minnesota) — Differentiates on certified, ergonomic designs with integrated power systems and IEC/UL compliance. Strategic implication: strong suitability for acute care and imaging environments where certified electrical safety and adjustability are procurement must‑haves.
- RDP Health (Burgess Hill, UK) — Focuses on highly configurable workstations for NHS trusts with long warranties and workflow customization. Strategic implication: specialization in public health systems creates durable, contract‑based revenue and higher switching costs.
- Lund Industries / DataCart (Northbrook, Illinois) — Emphasizes customization, antimicrobial materials and warranties. Strategic implication: compelling for infection control‑focused buyers and institutions with unique clinical workflows that require tailored cart builds.
- Advantech (Taiwan / US & EU operations) — Provides integrated medical tablets and carts for medication administration and telehealth, with strength in compact computing platforms. Strategic implication: positions well where IT teams favor vendor‑managed electronics platforms and global supply chain scale.
- Parity Medical (Bromborough, UK) — UK‑designed and assembled carts for EPR and bedside clinical use. Strategic implication: local manufacturing and serviceability are attractive to public health customers prioritizing fast service turnaround and national compliance.
For buyers, these positioning differences translate into a short listing strategy: match cart platforms to the clinical environment first (acute ward vs. ambulatory vs. surgical center), then layer in service, warranty and electrical safety needs.
Regulatory, certification and reimbursement dynamics
- Electrical safety and product certification are non‑negotiable. Medical computer carts with active electrical systems must comply with UL/EN/IEC 60601‑1 standards; manufacturers and purchasers should validate certification documentation during procurement.
- Quality management frameworks such as ISO 13485:2016 and ISO 9001:2015 remain table stakes across active manufacturers and are a key filter in vendor selection due to traceability and post‑market surveillance needs.
- FDA 510(k) pathways are typically required when carts integrate diagnostic accessories or change their intended medical use—buyers should insist vendors clarify regulatory pathway and post‑market obligations in contract terms.
- On reimbursement: carts are generally accommodated within durable medical equipment (DME) and infrastructure categories under existing payment rules; we found no sweeping new CPT/DRG updates that would materially change reimbursement math, but local reimbursement nuance still affects total deployed economics.
Signals from the market — what to watch in 2026
- Product approvals and regulatory listings are a leading indicator of near‑term adoption. Recent FDA listings for advanced carts and platform upgrades reflect an incremental refresh cycle among hospital fleets.
- Upgrades focused on battery management and integrated power are appearing with greater frequency — expect battery technology and BMS features to become differentiators in procurement evaluations.
- Trade shows and industry exhibitions continue to be a primary channel for new product demonstrations and institutional presales engagements; vendors exhibiting broad power and mounting systems often secure larger enterprise contracts.
How to use this intelligence — prioritized 2026 actions
- For hospital procurement leaders: run an immediate inventory audit of deployed carts, align clinical owners on minimum safety certifications, and issue competitive RFPs that isolate battery management, warranty and service response as scored line items.
- For OEM product strategists: prioritize modular power management, telehealth integration and service‑friendly designs; validate IEC 60601‑1 conformance early in development to accelerate hospital adoption cycles.
- For investors and M&A teams: focus on target companies that offer installed base service contracts, regional distribution strength or specialized clinical workflows (e.g., pharmacy/med administration or phlebotomy) that create higher margin annuities.
- For system integrators and service providers: develop bundled managed‑service offers that include preventive battery maintenance, fast swap programs and data integration services with EHR vendors—these extend margins and deepen customer lock‑in.
Conclusion — the decisive value of nuanced market intelligence
As organizations finalize plans in 2026, the difference between a standard procurement and a value‑creating program will be the granularity of the market intelligence that informs vendor selection, product roadmaps and M&A prioritization. Our PW Consulting study couples validated macro forecasts with operational toolkits, vendor benchmarking and regulatory risk maps to enable executable decisions. The summary presented here highlights the strategic implications without exposing the granular segmentation and vendor scorecards that buyers and acquirers rely on to act with conviction.
For access to the full datasets, disaggregated scenarios, vendor scorecards and the practical toolkits referenced above, please consult the complete report and online dashboard provided by PW Consulting. Our team is available to deliver a tailored briefing and to support scenario modeling for your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Medical Computer Cart Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Shot Blasting Machines Market to Hit USD 2,310.27M by 2032 (6.32% CAGR)
By PW Consulting, 2026-07-09
Shot Blasting Machines Market 2026: Strategic Preview for Boardrooms and Capital Planners
As PW Consulting’s lead industry analyst, I present a concise strategic preview of our full Shot Blasting Machines Market study. This briefing synthesizes the macro trajectory, structural dynamics, competitive posture, and the practical decision tools that manufacturing executives, investors, and service providers will need to act confidently in 2026. It intentionally demonstrates analytical depth while reserving granular segment-level datapoints for readers who access the comprehensive report.
Shot Blasting Machines Market
Market snapshot — direction and scale
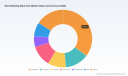
After a steady recovery and modernization cycle through the early 2020s, the global shot blasting machines market reached approximately USD 1,509 million in 2025 (base year). Our modelling shows continued expansion through the coming decade: the market is forecast to grow at a compound annual growth rate (CAGR) of 6.32% across the 2026–2032 period, reaching roughly USD 2,310 million by 2032. The trajectory reflects both replacement demand in mature manufacturing hubs and fresh capacity investments in growth markets where surface preparation is becoming industrialized.
Shot Blasting Machines Market
Why this study matters for 2026 decisions
- Timing of capital allocation: With mid-single-digit CAGR and a clear direction toward automation and digital retrofit spending, the next 12–18 months represent a crucial window to lock in suppliers, secure lead times, and negotiate lifecycle service agreements before suppliers reprice capacity expansions.
- Portfolio prioritization: For OEMs and tier-1 suppliers, choosing between fresh-line purchases, retrofits, or hybrid approaches requires integrated capex-opex modelling tied to line utilization and workforce availability — our study supplies those practical tools.
- Aftermarket and services playbook: With equipment lifecycles extending via retrofits and predictive maintenance, aftermarket services are becoming a primary margin engine. The report maps serviceable installed bases and identifies high-opportunity retrofit categories without exposing proprietary segment datapoints in this preview.
- Risk-adjusted valuation: Investors and M&A teams can use the study’s scenario matrices to stress-test valuations under raw-material shocks, regulatory tightening, and skilled-labor constraints.
Core market dynamics and operational implications
- Automation and digitalization: Machine OEMs are integrating IoT, predictive wear analytics, and MES connectivity. These features shift value from the capital sale to recurring data and service revenues. Decision-makers must re-evaluate procurement specs to prioritize systems with open integration standards and service APIs.
- Energy and efficiency focus: Energy efficiency and consumable optimization are now procurement differentiators — both for capital buyers aiming to lower TCO and for OEMs seeking product-market fit in regions with rising electricity costs.
- Consumables and raw-material volatility: Steel shot demand remains large — with global steel-shot consumption surpassing 6.8 million metric tons in 2025 — and prices have experienced significant swings as ceramic and glass bead substitutes compete for share. Procurement teams need hedging strategies and multiple-supplier contracts for abrasives to protect margins.
- Regulatory push on cleanliness and emissions: Tighter enforcement of surface cleanliness standards (for example, those applied in parts of the EU) and respiratory protection rules (OSHA/EPA in the U.S.) are accelerating conversions to enclosed, automated platforms fitted with advanced filtration and capture systems. Buyers that delay compliance-driven upgrades risk both fines and lost contracts with standards-conscious OEMs.
- Workforce availability and utilization constraints: Skilled-metalworking labor shortages — projected to create a multi-hundred-thousand technician gap in the U.S. by 2027 — are already constraining utilization. Practical implication: prioritize systems that reduce operator dependence, simplify frontline maintenance, and provide remote diagnostics.
- Fragmentation and regional supply dynamics: The competitive landscape remains fragmented (the top three and five firms account for modest shares of the market), creating opportunities for nimble specialists, service consolidators, and regional OEM partnerships. Fragmentation also means pricing heterogeneity and room for consolidation if macro conditions incentivize scale.
Competitive landscape — what leading suppliers are signaling
The vendor field combines global engineering leaders with regional specialists. Established players are differentiating along three vectors: end-to-end digital platforms, energy/consumable efficiency, and global aftermarket footprints.
Shot Blasting Machines Market
- Wheelabrator (UK): Maintains a strong reputation in wheel- and air-blast systems for continuous and batch processing. Their global service network remains a comparative advantage for high-volume industrial customers seeking single-vendor accountability.
- Rösler Oberflächentechnik (Germany): Positioning itself as a technology leader via Smart Blast® digitalization initiatives; recent product launches emphasize AI-driven abrasive consumption analytics and predictive wear monitoring — features that reduce TCO and enable outcome-based service agreements.
- Guyson Corporation (USA) and Sinto America (USA): Focused on niche precision, peening, and finishing systems where process control and validation are mission-critical, particularly in automotive and aerospace supply chains.
- C.M. Surface Treatment (Italy) and other European OEMs: Pushing energy-efficient, high-throughput solutions tailored to foundry and heavy-industry applications; their trade-show activity underscores targeting of export markets.
- Regional manufacturers (China, India, Slovenia, etc.): Competing on cost-competitive turnkey systems and rapid delivery cycles. Recent trade-show activity from Qinggong and others shows a push into intelligent machine controls for castings and forgings.
Recent industry signals to note:
- Rösler’s Smart Blast® 4.0 (Mar 2025) demonstrates how AI and MES connectivity are now productized rather than conceptual.
- Trade and innovation events through 2025–2026 (e.g., industry workshops, expos, and Winoa’s innovation day in 2026) show firms aggressively educating buyers on operational optimization rather than selling equipment alone.
- Capacity expansions in manufacturing hubs (notably in India) indicate supplier readiness to serve local and regional demand with shorter lead times and lower landed cost.
What the full PW Consulting report delivers (practical, action-oriented content)
- Transparent market sizing and methodology — base-year benchmarking (2025), historical 2020–2025 performance, and probabilistic forecasts to 2032.
- Scenario-based demand models that stress-test outcomes under raw-material price shocks, accelerated regulatory adoption, and labour-constrained utilization assumptions.
- Procurement playbooks — spec templates, total cost of ownership calculators, and decision trees for buy-vs-retrofit analysis adapted to plant size and throughput.
- Vendor scorecards and capability heatmaps — compact, decision-ready assessments of OEMs across technology, aftermarket reach, digital openness, and energy performance.
- Aftermarket and services playbook — retrofit opportunity mapping, spare-parts demand curves, SLA design, and service-margin expansion tactics.
- M&A and partnership intelligence — valuation multipliers, target profiles, and integration checklists for roll-ups, JV structures, and distributorship strategies.
- Regulatory and compliance compendium — practical compliance checklists and filtration/PEP design considerations tied to major jurisdictional requirements.
- Executive dashboards and workshop materials — ready-to-use slide decks and a 90-day action plan for procurement and operations teams.
Practical strategic recommendations for 2026
- Prioritize purchases and retrofits that reduce skilled-labor dependency: automated handling, remote diagnostics, and simplified maintenance packages will protect throughput under labor shortages.
- Lock in multi-year abrasives agreements and dual-sourcing strategies to mitigate price volatility and substitution risks in consumables.
- Specify openness and interoperability in procurement contracts to avoid vendor lock-in and to enable rapid integration with MES/ERP systems.
- Invest selectively in OEMs or service providers that can deliver outcome-based contracts (e.g., throughput or abrasive-consumption KPIs) to convert predictable operational improvements into financial-return commitments.
- Hedge regulatory exposure by accelerating filtration and enclosure upgrades where standards are tightening — this both preserves market access and can unlock new contracts with standards-driven OEM buyers.
- Use the fragmented competitive landscape to pursue bolt-on acquisitions if scale in aftermarket capability or regional service density is needed quickly.
Conclusion — how to use this preview
PW Consulting’s full Shot Blasting Machines Market report is intentionally practical: it equips procurement directors, plant managers, CFOs, and M&A teams with the quantitative models and implementation tools required to convert market trends into executable strategies in 2026. This preview outlines the directional facts and strategic implications; the comprehensive report contains the operational details, vendor scorecards, and scenario models that underpin confident capital and commercial decisions.
For executives ready to move — whether to re-spec a global tender, prioritize retrofit projects, or model an acquisition — the full dataset and playbooks are available through the PW Consulting portal. Accessing the complete report provides the segment-level intelligence, regional playbooks, and supplier matrices that this preview deliberately withholds to preserve the report’s commercial value and ensure you can execute with precision.
For detailed analysis of this topic, please visit the official page: Shot Blasting Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Outlook: Karl Fischer Titrators Market to Grow at 5.5% CAGR
By PW Consulting, 2026-07-09
Karl Fischer Titrators Market — Strategic Outlook for 2026: A PW Consulting Executive Brief
Executive snapshot
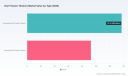
The Karl Fischer titrators market sits at the intersection of analytical precision, regulatory rigor, and incremental digital innovation. Our PW Consulting study — with a 2025 base year and a 2026–2032 forecast horizon — shows a market that expanded steadily through the early 2020s and is expected to continue growing at a mid-single-digit compound annual growth rate (CAGR) of 5.5%. Measured in USD (Million), the market grew from approximately 170 million in 2020 to roughly 230 million in 2025, and PW forecasts a continuation of that trajectory into the early 2030s. This brief explains why those macro dynamics matter for executive decisions in 2026, what tactical moves will likely create competitive advantage, and how to use the full report to operationalize strategy without revealing the granular segmentation tables we reserve for subscribers.
Karl Fischer Titrators Market
Why 2026 is a strategic inflection point
-
Regulatory pressure meets digital opportunity. Two trends converge in 2026: reinforced regulatory requirements for data integrity and cyber resilience in laboratory environments, and a rapid emergence of software-enabled instrumentation (AI-assisted calibration, remote diagnostics, secure connectivity). Compliance requirements such as FDA 21 CFR Part 11 and regional cyber rules are forcing instrument vendors and laboratory operators to rethink both instrument design and lifecycle management.
Karl Fischer Titrators Market -
Market scale supports focused investment. The market’s scale and predictable growth at a 5.5% CAGR create room for targeted R&D and bolt-on acquisitions. The overall market size trajectory (from low hundreds of millions in 2020 to a mid-three-hundreds projection by the end of the forecast) is large enough to justify investments in modular instrument platforms, reagent ecosystems, and software services that extend recurring revenue.
Karl Fischer Titrators Market -
Concentration shapes competitive tactics. The market displays a relatively high concentration at the top: the three largest suppliers hold a substantial majority of commercial volumes, and the top five dominate even further. This concentration creates both barriers and opportunities — scale advantages for incumbents, and whitespace for niche players that can deliver distinct value (e.g., field-ready analyzers, reagent sustainability, or tightly integrated LIMS/ERP connectivity).
What the full PW report delivers (practical contents)
-
Actionable market model: a bottom-up revenue model across historical (2020–2025) and forecast (2026–2032) horizons, with sensitivity scenarios tied to adoption rates of automated and portable solutions, reagent pricing, and regulatory-driven replacement cycles.
-
Decision-ready playbooks: tailored strategic options for vendors, OEMs, reagent suppliers, and laboratory groups — covering go-to-market, product development roadmaps, partnerships, and M&A priorities for 12–36 month timeframes.
-
Channel and pricing analysis: diagnostics on distributor economics, service and consumable margins, and recommended pricing levers to protect installed-base economics while accelerating consumables uptake.
-
Risk and compliance checklist: concrete steps to align instrument design and software stacks with data integrity and cyber regulations, including recommended controls for audit trails, user access, and secure telemetry.
-
Operational playbook for labs: practical protocols for reagent management, calibration cadences, sample handling, and instrument selection criteria for laboratories operating under GMP or in field conditions.
-
Competitive benchmarking: vendor scorecards across product breadth, automation level, reagent ecosystems, software capability, and service footprint — used to identify realistic partnership or acquisition targets.
Key dynamics that will shape purchasing and investment decisions in 2026
-
Data integrity and cyber-regulatory compliance: Vendors and lab managers must build towards compliance not just for validation but as a commercial differentiator. Instruments that provide secure telemetry, immutable audit trails, and configurable user roles will command premium positioning in regulated verticals.
-
Consumables and reagent economics: Routine reagent stability — for example, standard solvents used in volumetric titration — degrades over time and imposes recurring operational costs and QC burden. Our analysis includes operational scenarios where a typical solvent requires systematic titer checks and replenishment planning, affecting total cost of ownership and service models.
-
Shift to automation and field-capable devices: The release of compact and wireless analyzers opens new use-cases (on-site QC, in-line process monitoring). Vendors offering seamless handoff between lab-grade accuracy and field portability will capture incremental market share.
-
Software and AI-enabled measurement assurance: Recent product introductions with AI-assisted calibration and predictive maintenance capabilities reduce downtime and enhance reproducibility. Embedding these capabilities into service contracts increases recurring revenue and stickiness.
Competitive landscape — what incumbents and challengers are doing
The market contains long-established instrumentation leaders with comprehensive portfolios and multiple specialist players that address niche verticals. Notable vendors and their strategic postures include:
-
Metrohm AG — Swiss instrumentation leader focusing on both volumetric and coulometric titrators, increasingly integrating analytics and remote diagnostics into its product stack. Recent product introductions emphasize accuracy and compliance-friendly data handling.
-
Mettler Toledo — a US-headquartered incumbent pushing high-throughput automation, with oven autosamplers and algorithmic advances designed for regulated environments and large-scale QC labs.
-
Xylem Analytics — European player with a focus on modular automatic titrators that balance trace-level sensitivity with industrial robustness, positioning into process and lab workflows.
-
Regional and specialist players — manufacturers from Japan, China, and the US (including Hiranuma, KEM, Koehler, Hanon, Infitek, Hanna, Hach) who pursue vertical depth (petrochemicals, food, pharmaceuticals) or cost-competitive offerings and firmware-driven differentiation.
-
Recent moves — The competitive timeline through 2024–2025 showed multiple suppliers launching AI-enabled instruments, firmware upgrades for stability, reagent partnerships for greener chemistries, and the emergence of rugged portable analyzers suitable for field work.
Strategic implications and recommended actions for 2026
-
For vendors seeking growth: Adopt a two-track product strategy — (1) defend and expand installed-base value through software, services, and consumables; (2) pursue adjacent growth via portable/field instruments and reagent sustainability initiatives. Prioritize integrations that reduce laboratory friction (LIMS, ERP) and address CFR 21 Part 11 requirements out of the box.
-
For potential acquirers: Target niche players with unique IP in AI-assisted titration or proprietary reagent formulations. Given the market concentration, bolt-on acquisitions can rapidly improve scale in service coverage or expand a vendor’s consumables funnel.
-
For laboratory managers and end-users: Reassess procurement criteria to include lifecycle costs (reagents, calibration intervals, and software subscription fees) and cyber-compliance readiness. Operational playbooks that tighten reagent management (to counter solvent titer drift) will materially improve measurement consistency.
-
For reagent suppliers: There is a commercial opening for greener, more stable formulations and reagent-as-a-service subscriptions that reduce customer operational overhead and create recurring revenue streams.
Risk map — what to watch through 2026
-
Regulatory shock: Stricter regional cyber and data regulations could increase time-to-market for connected devices unless compliance is redesigned into product roadmaps early.
-
Supply and raw-material volatility: Periodic degradation of key solvents and the need for frequent re-titration create operational risk and cost pressure for laboratories, an area where improved reagent stability could be a decisive differentiator.
-
Incumbent entrenchment: High market concentration among top suppliers raises barriers for new entrants; therefore, differentiation through services and digital ecosystems becomes critical for challengers.
How to use this study to make decisions in 2026
-
Stage investments using scenario modeling provided in the report: map product launches and regulatory milestones to expected market-shift inflection points to prioritize R&D spend.
-
Translate vendor scorecards into partnership pipelines: use our benchmarking to identify best-fit OEM or reagent partners for joint go-to-market pilots targeted at high-value verticals.
-
Reframe commercial conversations toward life-cycle economics: position instruments not just on capex but on TCO, consumable attachment, and compliance risk reduction — the areas purchasers will value most in 2026.
Conclusion — the path forward
The Karl Fischer titrators market presents a classic strategic trade-off in 2026: stability in aggregate demand (supported by a clear historical growth path and a 5.5% CAGR projection) alongside accelerating functional disruption driven by software, reagent innovation, and regulation. Executives who prioritize modular product architectures, embed compliance-by-design, and convert consumables into recurring revenue will be best positioned to capitalize. For those ready to operationalize these insights, our full PW Consulting report contains the detailed segment matrices, vendor scorecards, and scenario models necessary to convert strategic intent into 12–36 month execution plans.
Next step
Access the full report to obtain the granular segmentation, regional and application breakdowns, and downloadable financial model that support acquisition screening, product roadmaps, and lab procurement policies. Our executive team is available to tailor a strategy session that maps the report’s findings to your organization’s priorities.
For detailed analysis of this topic, please visit the official page: Karl Fischer Titrators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electrical Steels to reach USD 39.65B by 2032 at 5.82% CAGR
By PW Consulting, 2026-07-09
Electrical Steels Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present this executive preface to our full Electrical Steels Market study. The analysis condenses the competitive, regulatory and technology forces that will shape procurement, investment and product strategies through the next investment cycle. Grounded in a 2025 base-year assessment and a detailed forecast out to 2032, the market remains on a steady expansion path — climbing from an estimated USD 20.4 billion in 2020 to approximately USD 26.5 billion in 2025, and projected to reach roughly USD 39.7 billion by 2032 at a compound annual growth rate of about 5.82% over the forecast horizon. This preface demonstrates how the study supports high-stakes 2026 decision-making without revealing the full, actionable segmentation data reserved for subscribers to the complete report.
Electrical Steels Market
Why this report matters in 2026
-
Critical input for electrification: Electrical steel sits at the intersection of mobility electrification (traction motors), power transmission (transformers) and industrial electrification. Demand trajectories for these end-markets are now diverging by geography and application, creating opportunities and risks for suppliers, OEMs and investors.
Electrical Steels Market -
Policy and trade are reshaping economics: Carbon-adjustment regimes, emissions trading reforms, and trade remedy actions have moved from policy drafts into implementation and enforcement. These shifts materially change the landed cost calculus for imported steel and the value proposition of localized production.
Electrical Steels Market -
Technology differentiation is profitable: Advances in non-grain-oriented and grain-oriented grades, ultra-thin laminations and coatings are unlocking efficiency gains in EV motors and low-loss transformers — and creating premium product pockets that reward scale and R&D commitment.
-
Timing matters for 2026 decisions: With mid-term capacity additions and investments announced through 2025 reaching commissioning windows in the 2026–2028 window, firms that act this year can secure supply arrangements, partnership terms and siting decisions that endure across the forecast period.
What the full PW Consulting report delivers (practical modules)
-
Market sizing & forecasts: Bottom‑up market value and volume estimates (historical 2020–2025 and detailed annual forecasts 2026–2032) calibrated to leading demand drivers and price pathways.
-
Demand archaeology: Application-level demand drivers and scenario blocks for motors, transformers and ancillary industrial uses — with sensitivity to EV adoption curves and renewable penetration rates.
-
Supply and capacity mapping: Global and regional plant inventories, recent greenfield and brownfield announcements, and a near-term commissioning calendar to highlight potential oversupply windows and chokepoints.
-
Raw-material and cost stack analysis: Inputs such as alloying metals and key ferrous inputs, price volatility case studies, and hedging/contracting playbooks for procurement teams.
-
Regulatory impact assessment: Actionable scenarios showing how carbon border adjustments, emissions-benchmarks and trade measures alter cost competitiveness and routing decisions.
-
Competitive benchmarking & supplier scorecards: Capability matrices covering product breadth (NOES/GOES and ultra-thin grades), low-carbon process credentials, geographic footprint and reliability metrics for major producers.
-
Strategic playbooks: M&A and greenfield decision frameworks, joint-venture term sheets, contract structures for long-term offtake, and innovation roadmaps linking metallurgy advances to end-user system gains.
-
Scenario simulations & stress tests: Tailored model outputs for different technology adoption, carbon price and trade regimes with clear trigger points for strategic decisions.
Competitive landscape — key themes and company positioning
The competitive map is a mix of global integrated steel giants, regional specialists and vertically integrated players serving automotive suppliers, transformer OEMs and industrial motor manufacturers. The full report includes supplier scorecards; below is a synopsis of strategic positions we consider most consequential for 2026 decisions.
-
ArcelorMittal (Luxembourg): A leading flat-rolled steel producer with a strategic push into non-grain-oriented electrical steel for mobility and grid applications. Recent moves show a clear aim to localize supply in priority markets and to couple capacity with low-carbon process credentials.
-
Nippon Steel & Sumitomo Metal Corporation (Japan): An incumbent in grain-oriented technology, with strong low-loss grades tailored to power transformers and grid modernization — a reliable partner for utilities and large transformer manufacturers.
-
POSCO (South Korea): Balanced capability across NOES and GOES, with product innovation emphasizing hyper-thin non-grain-oriented grades for electric vehicle traction applications.
-
Baosteel / Baowu (China): High-volume producer with a broad electrical steel portfolio positioned to serve rapidly growing domestic EV and smart-grid demand — a company to watch for export posture shifts as policies evolve.
-
JFE Steel (Japan): Focused GOES expansion via partnerships in fast-growing markets, seeking to capture domestic electrification and industrialization waves through localized manufacturing capacity.
-
thyssenkrupp Steel & voestalpine (Europe): European technology leaders combining carbon portfolio management with specialty electrical steel variants to serve mobility and utility markets under tightening decarbonization rules.
-
North American specialists (including NLMK, AK Steel, Cleveland‑Cliffs): Positioned to benefit from regional reshoring and trade protection dynamics, with product portfolios targeting both legacy transformer demand and emerging EV motor requirements.
-
Regional specialists (e.g., Stalprodukt): Niche players offering flexibility for OEMs seeking specialized grades or proximity supply for industrial motors and small-scale transformers.
Across these players, common strategic threads emerge: vertical integration, targeted product differentiation (loss-optimized alloys and thin-gauge NOES), and geographic redeployment in response to trade measures and carbon-pricing mechanisms.
Recent developments and what they signal for 2026 strategy
-
Greenfield and JV capacity announcements are clustering with commissioning windows in the late 2020s — a reminder that decisions made in 2026 on partnerships, land and offtake contracts will shape supply balances for the next decade.
-
Policy implementation is accelerating: carbon-related import adjustments and emissions-benchmark revisions are already shifting cost lines and will favor producers that can prove low-carbon supply chains.
-
Trade enforcement and antidumping activity are increasing market segmentation — beneficiaries will be local producers and those with defensible technology-led differentiation.
Top strategic implications — 2026 action checklist
-
For OEMs (EV and motor manufacturers): Secure multi-year offtake or strategic supply partnerships now to lock in access to ultra-thin NOES grades and to co-develop traction-steel specifications. Incorporate carbon and trade contingencies into total landed-cost models.
-
For utilities and transformer manufacturers: Prioritize supplier qualification for low-loss GOES variants and diversify sourcing to mitigate single-source risk where local policy exposure is high. Use procurement levers to pass through regulatory cost shifts.
-
For steel producers and investors: Accelerate capability investments where technical differentiation and low-carbon credentials can command premium pricing. Use scenario modeling to test the timing and scale of greenfield projects, JV structures and technology licensing.
-
For procurement and treasury functions: Implement raw-material hedging strategies for key alloy inputs and establish flexible contracting terms that protect margins under volatile ferrosilicon and alloy price regimes.
Risks that warrant active monitoring
-
Regulatory sequencing: Implementation speed and scope of carbon-adjustment policies and emissions benchmarks can materially affect regional competitiveness.
-
Input-price volatility: Alloy and additive price swings have disproportionate effects on thin-gauge and low-loss product economics.
-
Demand variability: EV penetration, transformer replacement cycles and industrial electrification do not move in lockstep across regions — mismatches between capacity additions and real demand can compress margins.
-
Trade frictions: Ongoing antidumping and countervailing activity can re-route trade flows rapidly, creating both supply opportunities and procurement headaches.
How to use this study in 2026 corporate planning
The PW Consulting Electrical Steels Market study is designed to be directly operational for senior leadership and functional teams: strategic planning can use the scenario matrices to set investment trigger points; procurement can adopt the supplier scorecards and cost-stack analyses to re-negotiate contracts; R&D and product teams can use the technology roadmaps to prioritize alloy and coating investments that unlock system-level gains in motors and transformers. The study’s models are modular — enabling you to run customized scenarios against the base-year (2025) and the forecast window to 2032.
Next steps — where the hidden data takes you
This preface intentionally surfaces the critical implications without publishing the granular segment-level splits and supplier-by-supplier metrics that are core to transaction execution. The full report provides those confidential tables, downloadable models, supplier scorecards and a step-by-step investment checklist tailored to your role. If your 2026 planning cycle includes procurement commitments, capacity investments or strategic partnerships in electrical steel, we recommend commissioning the full study and a short advisory sprint to translate the insights into binding commercial terms.
PW Consulting stands ready to conduct a focused workshop to map these findings to your portfolio and to stress-test your supply chain and investment options against the regulatory and market scenarios most likely to manifest through 2026–2032.
For detailed analysis of this topic, please visit the official page: Electrical Steels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fasteners Market to Reach USD 135.3B by 2032; 4.3% CAGR Forecast (PW Consulting)
By PW Consulting, 2026-07-09
Fasteners Market 2026: Strategic Playbook for Decision-Makers
As organizations reset priorities for 2026, the fasteners industry presents a mix of dependable growth and accelerating structural change. PW Consulting’s newest Fasteners Market research—benchmarked to 2025 with a historical lens covering 2020–2025 and forecasts through 2032—translates the market’s quantitative trajectory into executable strategy. Our base-year assessment shows a global market north of USD 100 billion in 2025, rising to a projected mid-130s billion by 2032, at a compounded annual growth rate near 4.3% across the forecast horizon. For executives planning capital allocation, sourcing strategies, or M&A activity this year, that steady macro expansion masks critical inflection points that demand calibrated responses.
Fasteners Market
Why this research matters for 2026 decisions
-
Signal vs. noise: The overall market growth is steady, but pockets of disruption—driven by regulation, geopolitics, and raw-material volatility—create asymmetric risks and opportunities. Leaders who rely on headline growth alone risk misallocating resources into structurally sub-optimal segments.
Fasteners Market -
Timing matters: With the market already above the USD 100 billion mark in 2025 and clear momentum into the late 2020s, 2026 is the year to convert strategy into execution: secure constrained inputs, test new product architectures, and rationalize manufacturing footprints.
Fasteners Market -
Decision-grade intelligence: The report couples a data-led market forecast with operational playbooks—allowing procurement, product, and corporate development teams to move from hypothesis to action without reinventing the wheel.
Market snapshot: growth, concentration, and material structure
Our assessment confirms a mature but evolving market. After recovering through the early 2020s, the global fasteners market recorded a meaningful step-up by 2025 and is forecast to continue expanding into 2032, consistent with a mid-single-digit CAGR. Market concentration is moderate: the top-three players account for a meaningful share, and the top-five consolidate about half of market capacity—indicative of scale advantages but also signaling room for specialist and regional challengers.
Material composition remains a defining structural factor. Metal-based fasteners—with steel as the primary backbone—dominate the raw-material mix, accounting for roughly three-quarters of industry consumption globally. This entrenched dependency makes the sector acutely sensitive to steel and non-ferrous metal cycles, and to trade and tariff regimes that affect cross-border flows.
Drivers and headwinds shaping 2026 strategy
-
Regulatory acceleration: Recent policy moves are not theoretical. Trade and product standards have been tightened across major markets—most notably a reintroduction of protective tariffs on base metals and targeted standards updates in seismic regions. These actions increase landed costs, complicate global Sourcing policies, and raise compliance costs for finished fastener assemblies.
-
Geopolitical tension and tariffs: Tariff escalation and differentiated duties on critical supply origins have materially altered the economics of cross-border procurement. Companies with exposure to regions subject to elevated duties are already re-evaluating second-source options and reshoring feasibility.
-
End-market dynamics: Automotive electrification, construction standards for seismic resilience, and aerospace certification cycles are driving divergent product demand—higher performance alloys and pretensioned systems in safety-critical applications; engineered polymer solutions in space- and weight-sensitive applications.
-
Innovation in installation and integration: Tooling, system-level fastening solutions, and integrated logistics are evolving—from single-use fasteners to fastening-as-a-service propositions that bundle hardware, software, and inventory management.
-
Raw-material inflation and input pass-through: Given the metal-intensity of the industry, price shocks in steel/aluminum remain the single largest input risk. Firms with hedging discipline and long-term supplier agreements enjoy a durable margin advantage.
Strategic imperatives for executive teams in 2026
-
Reassess sourcing through a tariff-aware lens. Update landed cost models to reflect current duties and potential near-term policy shifts. Where duty exposure is significant, prioritize validated second-source partners and regional capacity building.
-
Prioritize product-tiering and value capture. Separate commodity fasteners from engineered and performance-critical fasteners in commercial strategies. Focus R&D and sales coverage on higher-margin, certified fasteners tied to safety and durability specifications.
-
Invest in modular manufacturing. Flexible lines that can switch across materials and designs reduce the cost of responding to regulation or customer specification changes, and they increase the value of existing footprint investments.
-
Embed installation efficiency as a differentiator. Fastener manufacturers who can demonstrably reduce installation time or total lifecycle cost will unlock contractor and OEM adoption across construction and assembly markets.
-
Use M&A selectively to buy capability, not volume. Bolt-on acquisitions that provide engineering depth, certified production for aerospace/defense, or direct access to OEM programs are preferable to scale-only deals in a moderately concentrated market.
Competitive landscape: who to watch
The sector blends global platform players with specialized engineering houses. A non-exhaustive list of names featured in our analysis includes Würth Group (Germany), LISI Group (France), Nifco Inc (Japan), MW Industries (United States), Hilti (Liechtenstein), Illinois Tool Works (ITW, United States), Stanley Black & Decker (United States), Arconic (United States), Bossard Group (Switzerland), Bulten AB (Sweden), Howmet Aerospace (United States), Fastenal (United States), Hillman Group (United States), SFS Group (Switzerland), and Acument Global Technologies (United States).
Our competitive matrix goes beyond logos: it maps each company’s core capabilities (e.g., engineering fasteners for aerospace certification, polymer injection-molding proficiency, distribution and inventory services, or construction-focused system solutions), geographic strengths, and recent strategic moves. Recent market activity illustrates two clear trends—horizontal consolidation to secure distribution and direct market access, and focused product launches that increase installation speed and specialization:
-
Product innovation is active: multiple suppliers have introduced next-generation fastening systems designed to cut installation time and improve end-user productivity.
-
Targeted acquisitions have strengthened aerospace portfolios and European trading networks—moves that were executed to lock in certified production capability and regional customer channels.
What PW Consulting’s Fasteners Market report delivers
This research is designed as an operational decision-support tool—not just a market overview. Key, practitioner-oriented inclusions are:
-
Demand models linked to macro scenarios: scenario-driven forecasts (2026–2032) that let you stress-test volumes under different economic, policy, and raw-material pathways.
-
Cost-to-serve templates: modular landed-cost calculators that incorporate tariffs, freight, and input price pass-through for rapid sourcing comparisons.
-
Competitive playbooks: capability maps for major players and challenger profiles, plus M&A fit assessments to prioritize potential targets by strategic fit and integration effort.
-
Regulatory and standards tracker: an actionable digest of emerging standards and certification requirements across key jurisdictions—critical for planning product qualification and plant investments.
-
Go-to-market and productization frameworks: customer-segmentation strategies, pricing levers, and route-to-market playbooks for distributors, OEMs, and contractors.
-
Risk heatmaps and mitigation playbooks: supply-chain vulnerability assessments and recommended tactical mitigations for procurement, manufacturing, and logistics teams.
How to use this research in practice during 2026
-
Procurement: refresh your sourcing strategy immediately—use the report’s landed-cost models and tariff scenarios to decide whether to hedge, reshore, or index contracts.
-
Product and engineering: align development budgets toward fastening systems that meet rising performance and installation-efficiency demands, and prioritize certifications where regulators are tightening standards.
-
M&A and corporate development: deploy the competitive playbooks to shortlist targets that close capability gaps (engineering certifications, polymer technology, or regional distribution) rather than simply adding volume.
-
Operations: phase in modular manufacturing investments to preserve responsiveness across material and product cycles, while protecting margins against raw-material shocks.
-
Commercial teams: adopt a value-based pricing approach, emphasizing total installed cost and lifecycle benefits for safety- and performance-critical fasteners.
Final observation and recommended next steps
The fasteners market in 2026 is neither a static commodity space nor a landgrab for hyper-growth winners. It is a sector of steady overall growth where regulatory shifts, input-cost volatility, and product innovation create outsized advantages for firms that anticipate and adapt. PW Consulting’s report equips leaders with the quantitative forecast—anchored to a base-year assessment—and the operational templates required to act decisively in 2026.
To move from strategic intent to measurable outcomes, access to the full report is essential: it contains the granular segmentation, supplier matrices, and scenario spreadsheets that we deliberately omit from this preview to preserve its role as a decision-enabling resource. Contact PW Consulting for the full dataset, customized briefings, and workshops to translate insights into a tailored 100-day action plan for your organization.
For detailed analysis of this topic, please visit the official page: Fasteners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cochlear Implants Market — USD 1,850M in 2025, 7.5% CAGR (2026–2032)
By PW Consulting, 2026-07-09
Cochlear Implants Market 2026: Strategic Intelligence for High-Stakes Decisions
As PW Consulting’s Senior Industry Analyst, I present an executive preview of our forthcoming Cochlear Implants Market study — a practice-oriented strategic asset designed to inform boardrooms, corporate development teams, and market-access planners as they set course for 2026 and beyond. This preview synthesizes the macro trajectory of the market, highlights the competitive inflection points that will shape supplier economics, and spells out the specific decision levers where our full report delivers immediate operational value. To respect the “trailer” principle of this brief, we intentionally withhold granular regional and application-level splits from this summary; the full dataset and model access are available on the report landing page.
Cochlear Implants Market
Macro outlook: a growing, resilient market
The cochlear implants market has shown steady expansion over the first half of the decade, rising from USD 1,280 Million in 2020 to USD 1,850 Million in 2025 (base year). Our modeling projects continued momentum across the 2026–2032 forecast window, with the market expanding at a compound annual growth rate (CAGR) of 7.5% to reach approximately USD 3,064 Million by 2032. This trajectory reflects a combination of technology-driven replacement cycles, broadened clinical indications, and improving access pathways in multiple health systems.
Cochlear Implants Market
- Durable demand fundamentals: demographic tailwinds, rising diagnosis rates, and greater clinician familiarity are driving a predictable underlying growth rate that supports multi-year capacity planning.
- Upside from regulatory and indication expansions: recent approvals and label expansions are accelerating adoption in traditionally later-stage cohorts (notably younger pediatric populations).
- Structural margin pressure and price transparency: procurement programs and reimbursement dynamics are exerting downward pricing pressure in selected markets, necessitating productivity and value-capture responses from suppliers.
Why this matters for 2026 decision cycles
Corporate leaders must translate the market’s steady growth into prioritized investments and risk mitigations in 2026. The choice of where to allocate capital — R&D, commercialization, manufacturing scale, or M&A — will determine whether an organization captures disproportionate share and margin as the market matures.
Cochlear Implants Market
- Go-to-market timing: firms considering product launches or new clinical indications should align regulatory and commercialization calendars to capitalize on the forecasted expansion window. Our full report provides scenario maps linking approval timelines to revenue trajectories under several adoption curves.
- R&D Focus: with firmware/upgradability and patient-facing software emerging as differentiators, investments in modular, upgradable architectures can unlock recurring revenue and reduce product obsolescence risks. The report quantifies the potential aftermarket revenue pool and offers a staged investment roadmap.
- Market access and reimbursement playbooks: stable CPT coding and Medicare policies create a predictable foundation in key payor markets, but the advent of large-volume procurement initiatives in select geographies requires tailored pricing strategies. We provide playbooks that reconcile clinical value propositions with public procurement realities.
- Manufacturing and supply chain resilience: given rising volumes, decisions on capacity expansion versus contract manufacturing should be stress-tested against the forecast’s demand scenarios. The study includes a capacity-planning tool that ties unit economics to lead times and inventory policies.
Competition and concentration — what the data reveals
The cochlear implants market is concentrated, with the top three players capturing a clear majority of market revenue and the top five an even larger share. This concentration creates a dynamic where technology leadership and access play an outsized role in shaping competitive advantage. The competitive landscape is being influenced by several tactical developments in 2024–2025 that have structural implications for 2026 strategy.
- Technology differentiation: the introduction of implants capable of post-market firmware upgrades is a material inflection in product economics — enabling extended device lifecycles, differentiated service offerings, and new software-driven revenue models.
- Regulatory-driven addressable population growth: expanded pediatric indications remove a prior constraint on adoption in select markets, increasing absolute demand and altering the customer mix in clinical segments.
- Procurement participation: inclusion in government volume-procurement programs in high-volume markets materially alters tender dynamics and price elasticity — forcing incumbent suppliers to balance margin preservation with volume capture.
Profiles of strategic players to watch
- Cochlear Limited (Sydney, Australia) — Manufacturer of the Nucleus series, including the recently FDA-cleared Nucleus Nexa System (July 2025), which introduced on-field firmware upgrade capability. This capability reshapes aftermarket engagement and lifecycle value capture.
- MED-EL (Innsbruck, Austria) — Offers a broad portfolio including the Rondo, Sonnet, and Opus series. Notably, in November 2025 MED-EL secured expanded pediatric indications for younger infants, expanding its clinical reach and altering future pediatric cohort sizing.
- Advanced Bionics (Santa Clarita, CA; Sonova subsidiary) — Known for Naida, Neptune, and Harmony processors. The company’s selection in China’s volume-based procurement program signals a competitive posture in large public tenders and underscores the strategic importance of procurement participation.
These players’ moves illustrate two concurrent trends: first, product innovation is migrating toward software-enabled lifetime enhancement; second, payor and procurement mechanisms are forcing a strategic balance between price competitiveness and differentiated clinical/technical value.
Regulatory and reimbursement context — stability amid selective disruption
- Procedure coding stability: CPT code 69930 for cochlear device implantation remains in effect through 2025, providing predictability in procedure-level reimbursement and clinical coding workflows.
- Medicare coverage continuity: Medicare continues to cover cochlear implantation under the existing national coverage determination (NCD 50.3), which reduces reimbursement uncertainty for device suppliers targeting the senior population.
- Country-level procurement initiatives: selective government-led procurement programs are altering pricing norms in high-volume markets and require specific tender strategies; inclusion in these programs can materially accelerate unit uptake but typically compresses margins.
Report deliverables — what you get in the full study
Our full PW Consulting Cochlear Implants Market study is engineered to be immediately actionable for 2026 planning cycles. Key components include:
- Comprehensive market-sizing model (USD, Million) with historical 2020–2025 data and a 2026–2032 forecast. Models are provided in editable format so teams can run alternate scenarios.
- Segmentation by product type, patient cohort, and region (note: detailed segment data are available in the full report; summary indicators in this preview intentionally omit granular splits).
- Competitive benchmarking: product feature maps, patent landscaping, and a timeline of regulatory events tied to commercial impact assessments.
- Procurement and reimbursement playbooks: country-level reimbursement matrices, tender strategy templates, and payer negotiation playbooks calibrated for 2026 dynamics.
- Go-to-market execution guides: channel selection analysis, referral pathway optimization, and clinician adoption levers tailored for new-indication launches.
- M&A and partnership scoring tool: shortlists of potential tuck-ins and alliance targets, valuation sensitivity analysis, and integration-risk checklists.
- Risk register and mitigation blueprints: supply-chain stress tests, competitive response simulations, and regulatory change scenario planning.
How to use the study in 90/180/360-day planning horizons
- Next 90 days: Use our clinical-indication and reimbursement matrices to validate product claims and refine messaging for payor dossiers and clinician KOL engagement. Short-term actions include realigning commercial targets by facility type and initiating reimbursement discussions where label expansions open new patient cohorts.
- Next 180 days: Finalize capacity and supply-chain decisions using the model’s mid-case demand forecast; begin pilot launches in prioritized geographies where procurement and reimbursement signals align. Review potential partnership targets identified in our M&A tool.
- Next 360 days: Execute product-upgrade monetization strategies, roll out aftermarket software/service offers, and secure long-term contracts in key public procurement programs where feasible. Track the impact of pediatric indication expansions on device mix and training needs.
Strategic takeaways — what leaders must not overlook
- Software and upgradability are now strategic product pillars: organizations that lock into static hardware-only models will face increasing aftermarket disadvantage.
- Market concentration favors those who can combine clinical credibility with procurement-savvy pricing strategies: your competitor set is consolidated and able to shift market norms quickly.
- Regulatory and reimbursement stability provides a runway for investment — but targeted procurement programs can create asymmetric risk/reward profiles that must be modeled explicitly.
- Operational readiness — especially manufacturing flexibility and clinician training programs — will determine whether forecasted volume growth translates into higher share or simply fuels incumbents.
PW Consulting’s full Cochlear Implants Market report provides the granular segmentation, model access, and playbooks that senior teams need to convert the market’s steady growth into sustainable competitive advantage. For teams making allocation decisions in 2026, the difference between acting on headline growth and acting on calibrated, segment-level insights will be measured in share gains, margin resilience, and speed to market.
To access the complete dataset, interactive models, and the tactical playbooks referenced here, please visit our report page — where the full intelligence package is available for download and licensing.
For detailed analysis of this topic, please visit the official page: Cochlear Implants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Capecitabine Market to Reach USD 743.71 Million by 2032 (6.01% CAGR)
By PW Consulting, 2026-07-09
Capecitabine Market — Strategic Preview for 2026 Decision-Makers
Executive summary
As oncology portfolios and procurement strategies are rebalanced for a post‑pandemic, value‑conscious era, capecitabine’s established role as an oral fluoropyrimidine positions it at the intersection of clinical utility, policy pressure, and supply‑chain fragility. PW Consulting’s Capecitabine Market study (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes quantitative market trajectory—anchored with a mid‑single‑digit CAGR—and qualitative ecosystem changes that will determine winners and losers in 2026 and beyond.
Capecitabine Market
This preview distills the research’s strategic value for corporate leaders: why the market’s steady expansion (reported through 2025 and modeled into 2032 in USD millions) matters to portfolio prioritization, commercial planning, and risk management—while preserving the detailed segment matrices and price/volume scenarios that are available only in the full report.
Capecitabine Market
Market trajectory: what the headline numbers mean for strategy
Capecitabine demonstrated resilient growth through the early 2020s and, under conservative projection assumptions, continues to expand through 2032 at a projected compound annual growth rate consistent with a mature oncology small‑molecule product class. The base‑year view (2025) and our modeled path into the forecast window (2026–2032) highlight a market that is neither hyper‑volatile nor static: it provides a predictable revenue corridor that supports incremental investment in lifecycle management, manufacturing redundancy, and differentiated formulations.
Capecitabine Market
For executive teams, the practical takeaway from the aggregated market sizing is straightforward: capecitabine remains a stable revenue contributor with upside driven primarily by formulary positioning, label and guideline developments, and shifts in delivery channel mix. These are the levers that will determine whether a company captures a disproportionate share of the steady growth or is marginalised by competitors who move faster on access and risk mitigation.
Competitive landscape — concentrated but contestable
The competitive structure is characterized by a relatively low top‑tier concentration, suggesting room for agile players to scale through tactical wins. Market concentration metrics in the study (CR3 and CR5) point to a market in which originator brands coexist with multiple generic producers and regionally strong marketers. This configuration alters the calculus for entrants and incumbents alike: brand equity and regulatory stewardship matter, but so do supply reliability and distribution partnerships.
- Genentech, Inc. — The originator behind the well‑known branded formulation, retaining significant prescriber awareness and payer negotiation leverage in markets where branded reimbursement persists.
- CHEPLAPHARM Arzneimittel GmbH — Notable for its strategic acquisition of branded rights and for executing region‑specific commercialization tactics, especially in key high‑value markets.
- Indian manufacturers (Alkem, Hetero, Dr. Reddy’s, MSN Laboratories) — Supply‑chain scale and cost competitiveness underpin their roles as primary generic suppliers in multiple markets; partnerships with distribution specialists enable access to developed‑market channels.
- Sandoz and Viatris — Large generics platform players with established regulatory footprints and channel reach, competing on reliability, contract depth, and formulary access.
The full report contains actionable profiles and benchmarked supplier scorecards that quantify manufacturing capacity, regulatory history, and commercial reach—critical inputs when negotiating supply agreements or planning regional launches.
Regulatory and supply‑chain shocks driving near‑term strategy
2024–2025 saw several regulatory and operational events that materially change how organizations should approach capecitabine in 2026:
- Regulatory recalibration: A major regulatory authority completed a label modernization in late 2025 that updated dosing guidance and patient‑selection considerations, and introduced requirements for pre‑treatment genetic screening linked to drug metabolism risk. This change elevates the importance of diagnostics linkage and payer coding clarity.
- Supply interruptions: Market surveillance flagged significant supply interruptions in select developed markets during 2025 caused by unexpected demand surges and logistical incidents. Such episodes emphasize the ROI of dual‑sourcing strategies, buffer inventories for critical strengths, and transparent communication plans with health systems.
- Product security and distribution risk: High‑risk incidents affecting specific lots in certain geographies underline the reputational and regulatory consequences of transport and storage control weaknesses.
For 2026 planning, these signals translate into concrete operational priorities: accelerate DPYD/genotype testing collaborations, validate alternative API and finished‑dosage manufacturers, and update commercial contracting templates to include shortage and quality‑incident clauses. PW Consulting’s report models the financial and operational impact of these mitigants under alternative shortage and uptake scenarios.
Innovation pulse: incremental innovation and next‑generation approaches
While capecitabine is a legacy cytotoxic, clinical innovation is ongoing. Early‑stage programs aim to improve therapeutic index and pharmacokinetics, and initial clinical data presented for next‑generation capecitabine candidates show promise in modulating systemic 5‑FU exposure and safety profiles. Adaptive trial readouts already in progress will influence the competitive window for modified formulations or combination strategies.
Companies evaluating R&D or in‑licensing opportunities should treat these developments as asymmetric bets: low probability of displacement of the existing standard in the short term, but significant long‑term value if improved safety or convenience meaningfully increases use or allows label expansion.
Implications for commercial, R&D, and M&A decisions in 2026
Executives preparing budgets and M&A pipelines for the 2026 fiscal year should prioritize actions that capture near‑term market growth while protecting against downside shocks. Key strategic imperatives include:
- Market access and coding: Invest in payer engagement to ensure DPYD screening workflows are reimbursed and that updated labels do not become access blockers. Bundle diagnostics and drug contracting where feasible.
- Supply resilience: Implement tiered sourcing strategies that balance cost with redundancy. The economics of maintaining a second qualified finished‑dosage supplier are compelling when modeled against the revenue at risk in shortage scenarios.
- Portfolio optimization: Reassess the role of capecitabine within broader oncology portfolios—allocate commercial resources to strengths (formulary markets, hospital contracts) and consider divestiture or partnering where long‑term margins are structurally constrained.
- R&D and lifecycle management: Prioritize investments in formulation improvements or patient‑support programs that strengthen prescriber preference and adherence, and build a defensive moat while next‑generation entrants progress through trials.
- M&A and licensing: Use the current market concentration profile to identify bolt‑on targets that deliver complementary manufacturing capacity, geographic market access, or downstream distribution capabilities.
What the full PW Consulting report delivers (high‑value, execution‑oriented content)
Our comprehensive study blends proprietary modeling with primary interviews to support executable decisions. Highlights include:
- Granular demand and revenue scenarios across the 2026–2032 forecast horizon, denominated in USD (millions), with sensitivity runs tied to regulatory and supply events.
- Detailed competitive scorecards and supplier due‑diligence templates for manufacturers and distributors—designed to accelerate procurement negotiations.
- Commercial playbooks for hospital, retail, and online pharmacy channels that prioritize interventions by return on investment and operational feasibility.
- Regulatory risk matrices and a step‑by‑step DPYD testing implementation guide for market access teams.
- M&A target shortlists and valuation heuristics focused on capacity, regulatory standing, and channel strength.
Note: In keeping with the “trailer” principle, this preview intentionally limits publication of the report’s proprietary segmentation matrices—regional, indication, and distribution splits are summarized in the full report along with downloadable financial models, price sensitivity curves, and contract templates.
How to use these insights in your 2026 planning cycle
Senior leaders should use this research to structure cross‑functional planning workshops that align commercial, manufacturing, and regulatory levers. Practical next steps we recommend for 2026 decision cycles include:
- Immediate: Convene a cross‑functional rapid review of DPYD testing readiness and payer reimbursement pathways.
- Quarter 1: Run a supply‑risk simulation using the report’s scenario models to define minimum buffer inventory and second‑source qualification timelines.
- Mid‑year: Revisit contracting strategies with hospitals and specialty pharmacies to capitalize on channel shifts toward oral oncology care delivery.
- Strategic: Evaluate bolt‑on M&A and licensing opportunities against the report’s supplier scorecards to close capability gaps quickly.
Conclusion — why this study matters for 2026
Capecitabine will remain a strategically important asset class: stable in demand, sensitive to regulatory and supply events, and open to value capture by organizations that align commercial execution with operational robustness. For leaders tasked with 2026 budgets and strategic priorities, the core benefit of PW Consulting’s Capecitabine Market study is that it converts high‑level trends into prioritized, executable choices—backed by scenario‑tested financials and operational playbooks.
To access the full segmentation datasets, supplier scorecards, and the interactive forecasting models that power these recommendations, review the complete report or contact PW Consulting’s industry team to schedule a tailored briefing. The full intelligence is designed to accelerate decision cycles and reduce the downside risk of misallocated capital in a market where stability and timeliness are competitive advantages.
For detailed analysis of this topic, please visit the official page: Capecitabine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: ECMO Systems Market to Hit USD 450M in 2025, Growing at 4.5% CAGR
By PW Consulting, 2026-07-09
ECMO Systems Market 2026: Strategic Imperatives from PW Consulting’s Market Intelligence
As healthcare systems recalibrate capital allocation, clinical staffing and technology roadmaps for the post‑pandemic decade, extracorporeal membrane oxygenation (ECMO) has moved from niche tertiary care into a core capability for advanced hospitals and regional networks. PW Consulting’s latest ECMO Systems Market study (base year 2025, forecast 2026–2032) synthesizes clinical, commercial and regulatory dynamics to inform decisive investment and commercial strategies in 2026. The market totaled USD 450 Million (base year 2025) and, at a compound annual growth rate (CAGR) of 4.5% across our forecast window, is projected to expand materially through 2032—underscoring steady demand for devices, disposables, training and service models.
Extracorporeal Membrane Oxygenation (ECMO) Systems Market
Why this study matters for 2026 decision-makers
- Timing: 2026 will be the first full year after several industry inflection points (new product launches, revised training standards, and evolving reimbursement interpretations) have settled into operational practice. The report translates these inflections into tractable scenarios for procurement, capacity planning and go‑to‑market execution.
- Actionability: Beyond headline growth, the study provides ready‑to‑use decision tools—procurement scorecards, ROI run‑books, and scenario planning templates—that let hospital systems and device manufacturers convert macro forecasts into budgetary actions.
- Competitive clarity: Concentration metrics show a mature supplier landscape where a small set of global players influence price, technology roadmaps and channel dynamics. Our analysis explains competitive positioning and where sustainable differentiation can be created.
What the report contains (practical deliverables)
- Executive summary with 2020–2025 historicals and a 2026–2032 base‑case forecast (quantified market size and growth drivers in USD Million).
- Methodology appendix: data sources, triangulation techniques, and sensitivity testing for alternative epidemiology and utilization scenarios.
- Demand modelling: system, consumable and service revenue pools; adoption curves for adult, pediatric and neonatal uses; and centre‑level capacity models for tiered hospital systems.
- Regulatory & reimbursement playbook: pathway maps for major markets, recent changes affecting MS‑DRG assignment and billing, and payer negotiation strategies.
- Clinical & workforce dynamics: implications of the ELSO 2025 narrative guidelines for training, simulation programs, and competency‑based credentialing; assessment of nurse‑led versus perfusionist‑led staffing models.
- Commercial intelligence: competitor benchmarking, technology roadmaps, pricing pressure points, distributor/channel models and recommended commercial KPIs.
- M&A and partnership targets: screening criteria, valuation drivers and integration risk matrices for bolt‑on and capability acquisitions.
- Operational playbooks for hospital systems: procurement scoring, total cost of ownership (TCO) calculators, and rapid deployment blueprints for intra‑hospital and transport use.
Market dynamics shaping strategic choices in 2026
Several observable shifts are converging to make 2026 a pivotal year for ECMO strategy:
Extracorporeal Membrane Oxygenation (ECMO) Systems Market
- Product cycle and supply evolution: New console and oxygenator introductions have reset customer expectations for modularity, transportability and integrated monitoring. Recent launches have altered channel conversations and created opportunities for re‑procurement exercises across tier‑1 centres.
- Guideline and training standardisation: The ELSO 2025 narrative on training and competency has become an operational requirement for many centres seeking accreditation or payer support. This raises the practical bar for device vendors to include bundled training, simulation kits and competency assessment tools in commercial propositions.
- Reimbursement & billing nuance: Longstanding MS‑DRG assignments continue to affect hospital economics; nuanced interpretation of coding for peripheral VA and VV ECMO remains a lever that buyers and suppliers must actively manage with local payers.
- Workforce models and cost pressure: Evidence that nurse‑led advanced practice provider models can deliver comparable clinical outcomes to perfusionist‑led models while reducing personnel costs is accelerating interest in alternative staffing models—impacting service contracts and training revenues.
- Consolidation and concentration: The market exhibits meaningful concentration among a few global vendors. This creates both barrier‑to‑entry dynamics and tactical openings for challengers that can pair differentiated clinical evidence with compelling TCO advantages.
Competitive snapshot (implications for 2026 strategy)
The competitive field is anchored by established manufacturers with deep clinical relationships and broad product portfolios. Recent notable developments that will influence competitive dynamics in 2026 include:
Extracorporeal Membrane Oxygenation (ECMO) Systems Market
- Medtronic: European launch of a configurable single‑system ECMO platform has repositioned the company as a system integrator able to offer unified console–pump–oxygenator packages; this raises the stakes for differentiated value propositions around interoperability and service integration.
- Fresenius (Xenios): Regulatory approval of their next‑generation console has broadened device choices for centres that require neonatal‑to‑adult flexibility; suppliers will need to counter with evidence, lifecycle costs and service models.
- Getinge, LivaNova, Terumo: These incumbents continue to defend installed bases through incremental product improvements, transport solutions and surgical‑market relationships; tactical responses will center on bundled consumables, rapid deployment and training packages.
For manufacturers, the immediate commercial questions are: how to architect differentiated bundles that lock in consumable revenue, what service and training models will be most defensible, and where to prioritize limited development capital to capture growth pockets. For hospital systems, questions are focused on procurement cadence, capital allocation versus leasing, and workforce models that protect outcomes while optimising operating expense.
Strategic recommendations for 2026
- Manufacturers — prioritize integrated value offers: Combine hardware, disposables and accredited training into subscription or outcome‑linked contracts. Provide modular upgrade paths to protect hospital CAPEX and accelerate adoption.
- Manufacturers — evidence and reimbursement alignment: Invest in pragmatic trials and real‑world evidence that demonstrate TCO improvements under nurse‑led staffing models and reduced length of stay—evidence that payers and procurement teams will pragmatically value.
- Providers — adopt TCO procurement frameworks: Use the report’s procurement scorecards to compare TCO (device, disposables, training and service) rather than unit price. Model scenario-based capacity needs for regionalized ECMO networks versus in‑hospital readiness.
- Health systems — workforce transformation: Pilot competency‑based nurse/AP models aligned with ELSO 2025 guidance to lower operating costs and expand coverage hours. Pair workforce pilots with internal credentialing and simulation investments.
- Investors/M&A — look for capability adjacencies: Targets that provide training, digital monitoring, or consumable differentiation will deliver multiple levers for margin expansion in a concentrated market. Prioritize targets with recurring consumable revenue and strong clinical partnerships.
- Regulatory/reimbursement strategy: Map MS‑DRG impacts to service lines and develop payer playbooks that translate clinical protocols into reimbursable pathways; consider reimbursement pilots in priority markets to de‑risk adoption.
How PW Consulting’s report reduces strategic risk in 2026
Our study synthesizes primary vendor interviews, hospital procurement data, payer trend analyses and clinical guideline reviews into a single actionable intelligence product. Clients receive:
- Granular scenario models that convert macro forecasts into centre‑level capacity and budget implications.
- Negotiation playbooks that operational teams can use in vendor RFPs, complete with scoring rubrics and TCO comparators.
- Market entry and prioritisation matrices for manufacturers and investors, calibrated to regulatory timelines and evidence requirements.
Trailer — what we intentionally withhold here
In line with our “trailer” approach, this introductory brief surfaces the strategic thrusts you need to act now while reserving the granular segmentation tables, regional and modality breakdowns, and detailed supplier contract benchmarks for the full report. Those datasets include the fine‑grained regional, modality and application splits, price pools and unit‑level assumptions that underpin commercial decisions. If you are evaluating procurement options, planning capital investments, or building M&A casework for 2026, the full dataset is essential to operationalise the recommendations above.
Next steps
- For hospital procurement and operational leaders: request the TCO calculators and the rapid deployment playbook to accelerate capital decisions this fiscal year.
- For device manufacturers: engage our commercial team for a competitor threat assessment and a three‑year product and pricing playbook tailored to your portfolio.
- For investors: commission a focused diligence package that overlays the report’s valuation drivers with clinical adoption risk matrices.
PW Consulting’s ECMO Systems Market study offers the empirical foundation and pragmatic tools to convert the sector’s steady growth and doctrinal shifts into concrete 2026 decisions. To access the full report, segmentation datasets and bespoke advisory services, please visit our research page or contact our ECMO practice lead for a briefing tailored to your agenda.
For detailed analysis of this topic, please visit the official page: Extracorporeal Membrane Oxygenation (ECMO) Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: WiFi Thermostats Market Set for 21.07% CAGR Through 2032
By PW Consulting, 2026-07-09
WiFi Thermostats Market: Strategic Preview for 2026 Decision-Making
As organizations prepare strategic roadmaps for 2026, the WiFi thermostats market deserves renewed attention. Our latest PW Consulting market study—anchored on a 2025 base year and projecting through 2032—captures a market accelerating from a compact niche into a mainstream platform for energy management, building automation, and connected-home services. The report synthesizes a rigorous time series (2020–2025), forward-looking forecast (2026–2032) and primary-channel intelligence to help commercial executives, product leaders, utility program designers and investors prioritize initiatives that can materially influence ROI and market share over the next three to five years.
WiFi Thermostats Market
Why this market matters in 2026
Two macro dynamics make WiFi thermostats strategically consequential in 2026. First, device penetration continues to compound rapidly: the market has demonstrated sustained double-digit year-over-year expansion in recent history and PW Consulting projects a robust compound annual growth rate of 21.07% through the forecast horizon. Second, the product has evolved beyond a simple thermostat into a convergent node for energy optimization, indoor air quality sensing, occupant behavior analytics and third‑party services (utilities, insurers, property managers). Together these trends turn WiFi thermostats into both a distribution channel and a data asset.
WiFi Thermostats Market
Contextualizing growth: between 2020 and 2025 the overall market expanded visibly from single‑digit millions in USD to a larger base in our 2025 assessment (base year). The momentum continues into 2026 and beyond—our forecast shows pronounced scale by the early 2030s as device capabilities, standards alignment and incentive programs lower acquisition friction and increase perceived value for end users and program sponsors.
WiFi Thermostats Market
What matters to 2026 corporate decision-makers
- Platform versus product orientation: Companies must decide whether to compete primarily on hardware spec/price or on platform value—data services, AI-based control logic, and partner integrations. Our research shows that platform‑centric strategies materially increase lifetime value per install when coupled with subscription or service‑based monetization.
- Standards and interoperability investments: Matter and other interoperability frameworks are moving from optional differentiators to baseline expectations in premium and mid‑tier offerings. Prioritizing certified interoperability cuts friction in large‑scale residential and commercial deployments.
- Channel and installation models: Self‑install consumer channels are growing, but commercial and utility-backed programs still rely on trained installers to meet regulatory and performance requirements. Hybrid go-to-market models that mix direct retail, HVAC channel partnerships and utility programs will dominate short‑term growth.
- Utility and incentive alignment: With many utility programs and state incentives offering meaningful rebates for certified devices, alignment with program requirements (e.g., ENERGY STAR, state appendices) accelerates procurement cycles and lowers customer acquisition cost.
- Data governance and privacy: As thermostats collect occupancy, temperature, and sometimes air‑quality or radar data, robust privacy frameworks and transparent consent models are table stakes—especially for utility integrations and multi-occupant buildings.
Market structure and competitive positioning (high-level)
The market is moderately concentrated: the top three vendors capture a meaningful share, and the top five widen that concentration further—indicating healthy brand and distribution advantages but leaving room for agile entrants and differentiated niche plays. This concentration pattern suggests incumbents benefit from scale in product development, certification, and channel relationships; however, execution gaps—particularly in software experiences and partner ecosystems—create attack vectors for challengers.
Key vendor archetypes represented in the competitive set include:
- Legacy HVAC and controls players expanding into WiFi and smart-home integration: These firms leverage long-standing OEM and field service channels to secure installs at scale while modernizing their product suites for cloud-first services.
- Pure-play smart-thermostat innovators: Companies with differentiated sensing, AI or UX capabilities who push the category forward on features like occupancy sensing, air‑quality metrics and adaptive control.
- Platform and consumer‑electronics incumbents: Players who integrate thermostats into broader smart-home ecosystems and can offer cross‑product value and lifecycle engagement.
Representative examples from our vendor analysis (profiles included in the full report) are:
- Resideo Technologies, Inc. — a primary provider of Honeywell Home WiFi smart thermostats, noted for Matter compatibility, HVAC integration and expanding premium touchscreen offerings (notable launches in 2025 and 2025–2026 recognition in industry awards).
- ecobee Inc. — a firm recognized for advanced sensor suites, air quality monitoring and a focus on energy‑saving control logic across Essential and Premium product lines.
- Google (Alphabet Inc.) — Nest continues to push AI learning, geofencing and ecosystem playbooks that leverage Google services and Matter support to compete at scale.
- Emerson Electric Co. — a traditional controls and HVAC supplier modernizing with smart products designed for integrator channels and voice/control ecosystems.
Recent product and recognition milestones—particularly Resideo’s product launches and award recognition—underscore how incumbents are refreshing portfolios at the premium end while utilities and regulatory programs continue to shape adoption economics.
Regulatory and incentive dynamics that will shape 2026
Regulation and incentive programs are among the most tangible levers affecting market economics in 2026. A few notable dynamics bear direct operational significance:
- Certification requirements: Some jurisdictions now require occupant-controlled smart thermostats to meet specific certification standards for eligibility in energy‑efficiency programs. Compliance is non‑negotiable for vendors seeking utility program access.
- ENERGY STAR and program alignment: Updated ENERGY STAR specifications and program eligibility expand rebate pathways for compliant devices, and many programs channel rebates through retailers and installers—accelerating consumer uptake where rebate administration is seamless.
- State and regional rebates: Several established utility and state programs continue to offer financial incentives for qualified smart thermostats, often contingent on post‑installation registration or performance verification—an operational requirement that vendors and installers must bake into deployment processes.
For go‑to‑market teams, the implication is clear: certification timelines and rebate program eligibility should be prioritized in product roadmaps, and partnerships with program administrators can become a primary distribution funnel for scale.
Operational playbook: 6 actions to prioritize in 2026
- Fast‑track certification and compliance: Build certification timelines into R&D roadmaps and allocate resources to meet utility and jurisdictional requirements early enough to benefit from rebate windows.
- Design for install variability: Standardize self‑install experiences for mass retail while maintaining installer-friendly variants for commercial and program installs.
- Monetize data responsibly: Define clear commercial models for energy‑optimization services while implementing privacy-by-design to meet regulatory and consumer expectations.
- Partner on utility pilots: Use targeted pilots to validate demand response, peak shifting, and customer engagement value propositions before scaling across utility territories.
- Invest selectively in premium UX/AI: Differentiate on features that produce measurable energy savings or convenience (adaptive learning, radar occupancy, AQI integration) rather than incremental hardware specs alone.
- Plan regional go‑to‑market sequencing: Prioritize markets where incentive programs, regulatory clarity and channel readiness align—then scale outward once field operations and service models are proven.
What PW Consulting’s full report delivers (practical contents)
This preview encapsulates the strategic contours; the full PW Consulting WiFi Thermostats Market report delivers operationally actionable intelligence designed for immediate use by product, sales and strategy teams. Key deliverables include:
- Comprehensive market sizing and forecasting (2020–2032) with scenario analyses and sensitivity testing to stress‑test strategy under alternate adoption curves.
- Granular segmentation by region, price tier and end‑use, cross‑referenced with route‑to‑market and channel economics (note: detailed segment tables are reserved for the full report).
- Competitive dossiers and capability heatmaps for leading vendors, including product roadmaps, certification status, and partner ecosystems.
- Utility program and regulatory mapping with program-by-program qualification and rebate mechanics to support sales enablement and channel planning.
- Go‑to‑market playbooks, pricing heuristics, and customer acquisition cost benchmarks—plus templates for business cases and payback models tailored to residential, commercial and program deployments.
- Implementation risk register and mitigation pathways covering supply chain, interoperability, installation and post‑install verification.
The full dataset and appendices supply the numerical detail—regional and end‑use splits, price‑tier economics and downloadable time series—that decision teams require to model revenue scenarios, adjust product roadmaps and negotiate program agreements. Per our “trailer” principle, this executive introduction demonstrates analytical depth while directing practitioners to the complete report for the underlying segment-level intelligence necessary to execute.
Final note: timing and next steps
2026 represents a pivot point: many of the structural ingredients—standards alignment, incentive cadence and product maturation—are in place. Firms that align product certification, channel strategy and data‑service monetization over the next 12–18 months will convert growth tailwinds into defensible market positions. PW Consulting’s full study is designed to shorten that strategic decision cycle by providing the granular, executable data and playbooks leaders need to act this year.
For teams planning budgets, product roadmaps or partnership strategies for 2026, the full report is the single reference that ties market trajectories to near‑term tactical moves. Contact PW Consulting or visit our report page to access the complete dataset, vendor dossiers and implementation templates.
For detailed analysis of this topic, please visit the official page: WiFi Thermostats Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


