



Category: market research
PW Consulting: Intellectual Property Translation Services Market to Expand at a 6.5% CAGR, Driven by Rising Patent Translation Demand
By PW Consulting, 2026-07-02
Intellectual Property Translation Services Market — 2026 Strategic Outlook and Executive Briefing
As corporations and law firms near critical 2026 planning cycles, the demand for reliable, secure, and cost-efficient intellectual property (IP) translation services is a strategic linchpin for global IP programs. PW Consulting's new market study — synthesized from 2020–2025 historical data and a 2026–2032 forecast horizon — shows the IP translation market expanding at a steady mid-single-digit CAGR. This trajectory reflects sustained globalization of filings, larger multilingual litigation portfolios, and accelerating adoption of AI-assisted workflows. For executives evaluating sourcing, technology investment, or M&A in 2026, this report provides the actionable frameworks and go-to-market intelligence needed to convert translation capability into competitive advantage.
Intellectual Property Translation Services Market
Macro Snapshot (why this matters for 2026)
Our analysis quantifies a resilient market that has grown through pandemic disruptions, supply-chain volatility, and a wave of digital transformation within IP operations. The study's forecast period to 2032 models compound growth consistent with an overall market CAGR of 6.5%. Those topline dynamics underpin three strategic realities for 2026 decision-makers:
Intellectual Property Translation Services Market
- Translation spend is now a predictable line item in global filing budgets rather than an ad-hoc operational cost.
- Technology-enabled productivity gains (and new cost models) are creating differentiation between suppliers and shifting buyer expectations.
- Data security, regulatory compliance, and vendor integration capabilities are becoming procurement gatekeepers rather than nice-to-haves.
What the PW Consulting Report Contains (practical, executable content)
- Market sizing and forecast model (2020–2032) with scenario-based sensitivity analyses to support budget planning and stress-testing in 2026 decisions.
- Actionable vendor selection matrix: third-party assessment criteria, scoring rubrics, and a shortlist framework for buyers to evaluate providers against capability, scale, quality assurance, security, and integration readiness.
- Technology assessment toolkit: maturity maps for machine translation (MT), MT post-editing (MTPE), AI-assisted project scoping, and connectors into IP management platforms — including recommended pilot designs and expected productivity uplifts.
- Compliance and risk playbook: GDPR, ISO standards, data handling policies and contractual clauses that legal and procurement teams must enforce when engaging IP translation suppliers.
- Commercial benchmarks and contracting templates: procurement negotiation levers, SLA definitions, acceptance criteria for translated deliverables, and recommended escalation paths for quality disputes.
- M&A and partnership diligence checklist: templates to evaluate the strategic fit of translation providers, intellectual property around AI tooling, and operational integration risks.
- Executive decision-support dashboards and a buyer’s one-page checklist for 90-day implementation sprints.
Industry Dynamics Shaping 2026 Decisions
Three converging forces will drive procurement and investment choices this year:
Intellectual Property Translation Services Market
- Technology acceleration and the “AI-in-the-loop” imperative: Patent owners and law firms are rapidly piloting AI systems that identify reusable text, predict translation effort, and route content to the optimal mix of machine and human resources. Notably, patent filings for AI systems that reduce translation effort have emerged among incumbent providers — signaling a near-term shift from manual scoping to predictive pre-processing. Buyers must evaluate not only translation quality, but also the supplier’s IP around post-editing workflows and predictive analytics.
- Integration with IP lifecycle systems: Seamless connectors between translation engines and IP management platforms are shifting vendor selection toward providers that can embed into prosecution and docketing workflows. Recent product launches that integrate AI-assisted translation with IP management software underscore the operational value of end-to-end visibility and reporting.
- Regulatory and security-led procurement: Data protection and compliance obligations are non-negotiable. Translators handling patent applications, litigation documents, and prosecution materials are now routinely required to demonstrate ISO-level information security controls and contractually enforceable GDPR-aligned processes. Procurement teams must demand demonstrable evidence — including audits, DPA templates, and technical controls — as part of any RFP.
Competitive Landscape — who to watch and what they bring
The IP translation market is fragmented; our concentration metrics show that the top few global players account for a modest portion of total volume, leaving substantial room for specialist boutiques and regional providers. This fragmentation creates a nuanced supplier market where scale, domain expertise, and technology ownership create different forms of competitive advantage.
- Global incumbents with integrated IP services: Established firms that combine scale with IP-specialist linguists and corporate-grade security are positioned to support large filers and multi-jurisdictional programs. These providers often couple translation with prosecution support, portfolio analytics, and litigation services.
- Technology-forward vendors: Some market participants are patenting or building proprietary AI systems to reduce scoping effort and increase reuse detection at the authoring stage. This capability can materially lower total program costs over time and streamline national-phase and validation workflows.
- Specialist boutiques and regional experts: Firms that focus exclusively on IP translation or particular industry verticals (e.g., life sciences or semiconductors) retain premium positions for complex, high-risk work due to deep domain expertise and certified translator networks.
To make procurement actionable, PW Consulting’s vendor assessment profiles include governance maturity, technology roadmap, integration capabilities, ISO/GDPR evidence, and a practical “fit-for-purpose” score tailored to buyer archetypes. The report summarizes strengths and trade-offs across the competitive set without exposing client-sensitive commercial data.
Recent Market Developments with Strategic Implications
- Late-stage patents and product announcements from suppliers indicate an investment wave in AI that targets pre-translation effort reduction — an inflection point for buyers considering capex vs. opex trade-offs in 2026.
- Connector launches that integrate translation workflows into IP management suites are shortening project turnaround and improving auditability; organizations that mandate such integration will enjoy faster cycles and lower error rates.
- Public sector and multilateral tools expanding language coverage are increasing the volume of accessible patent literature — raising the bar for providers that must now handle diverse language pairs at scale.
Strategic Playbook for 2026 — four recommended actions
- Segment translation spend by risk and complexity: Move from a one-size-fits-all outsource model to a tiered supplier approach: high-risk filings and litigation work go to certified specialist vendors; high-volume, low-complexity tasks leverage MTPE with clear acceptance criteria.
- Require integration and traceability: Embed translation acceptance gates within IP management systems; demand APIs or connectors as a contractual requirement to ensure reproducibility and audit trails.
- Run short, measurable pilots: Test AI-assisted scoping and MTPE on representative workloads with matched quality metrics and TCO modeling; use these pilots to negotiate outcome-based pricing in 2026 contracts.
- Lock down compliance as a procurement non-negotiable: Insist on ISO audits, documented DPAs, and technical controls as pre-conditions to work commencement; include penalties and rapid-exit clauses for non-compliance.
How the Report Supports Board-Level and Operational Decisions
For boards and C-suite leaders, the report translates market dynamics into capital allocation and risk management questions: Should the organization invest in in-house MT+post-editing capabilities? Which suppliers should be strategically partnered versus tactically engaged? For IP operations leaders, the study delivers step-by-step procurement language, vendor scorecards, and a 90-day implementation plan that converts strategy into measurable outcomes.
Why this is a “must-read” prelude to 2026 planning
This briefing has been written to demonstrate PW Consulting’s methodology and the report’s practical utility while preserving the concentrated analytical insights that drive high-value decisions. The full report contains the complete regional and service-type segmentation, detailed vendor scorecards, pricing benchmarks, and modelled scenarios that underpin our recommendations. Those granular tables and the interactive forecast model are intentionally omitted here to protect the analytical work-product and to provide clients with a clear incentive to access the complete deliverable.
Next steps
- Download the full PW Consulting report and model to obtain the detailed regional/service splits, vendor scorecards, and pricing benchmarks that inform precise budgeting and vendor negotiation strategies for 2026.
- Schedule a bespoke briefing with our IP services practice to translate the findings into a customized 90-day supplier optimization plan.
PW Consulting’s Intellectual Property Translation Services Market report is designed to transform market data into operational certainty — enabling buyers, legal teams, and corporate strategists to act decisively in 2026 with confidence in quality, compliance, and cost predictability.
For detailed analysis of this topic, please visit the official page: Intellectual Property Translation Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Endosseous Implant Market to Hit USD 9,742.05 Million by 2032, Expanding at a 6.55% CAGR (2026–2032)
By PW Consulting, 2026-07-02
Endosseous Implant Market 2026: Strategic Preview from PW Consulting
Executive summary
As healthcare providers and device manufacturers prepare investment and go-to-market plans for 2026, PW Consulting’s latest Endosseous Implant Market report—based on a 2025 base year and a 2026–2032 forecast horizon—turns raw growth trends into actionable strategy. The market has expanded steadily through 2020–2025 and reached an estimated USD 6,248.5 Million in 2025, with our model projecting continued expansion to approximately USD 9,742.05 Million by 2032 at a compound annual growth rate (CAGR) of 6.55%. This preview outlines where the immediate strategic levers lie in 2026: product portfolio choices, regulatory positioning, channel and partner selection, and targeted clinical evidence investments. To preserve the competitive edge of our clients, we intentionally withhold granular subsegment tables here; the full report contains the detailed splits and scenario analytics that underpin the recommendations below.
Endosseous Implant Market
Why 2026 is a pivotal planning year
2026 sits at the inflection of several converging forces. Aging populations and rising elective restorative dentistry demand underpin a durable baseline growth trajectory. At the same time, technological shifts—implant surface science, material alternatives, and digital prosthetics workflows—are changing what customers value and how quickly they will adopt innovations. Regulatory landscapes and reimbursement mechanics are also tightening the pathway to market. For organizations making allocation decisions in 2026, the trade-offs between incremental product improvements, capacity investments, and M&A must be informed by a market model that anticipates both durable growth and episodic disruption. Our report distills that model into strategic prescriptions tailored to OEMs, distributors, and clinical networks.
Endosseous Implant Market
Market trajectory and the core growth narrative
-
Recent performance: The global endosseous implant market demonstrated robust resilience through the historical window, rising to an estimated USD 6,248.5 Million in 2025.
Endosseous Implant Market -
Near-term outlook: Our forecast indicates steady growth into 2026 and beyond, consistent with a 6.55% CAGR across 2026–2032, reflecting sustained clinical adoption, increasing case complexity, and incremental price and mix improvements driven by premium implant systems and value-focused alternatives.
-
Long-term scale: By 2032, the market is projected to approach the USD 10 billion scale, creating room for portfolio expansion, volume-driven manufacturing economics, and strategic consolidation.
Key market dynamics shaping 2026 decisions
-
Clinical innovation versus commoditization: Advances in surface technologies and immediate-load systems continue to differentiate premium offerings. At the same time, cost-sensitive channels are driving demand for lower-price, functionally adequate systems. Manufacturers must decide whether to compete on differentiated clinical endpoints or scale and cost.
-
Regulatory and standards pressure: Endosseous implants are regulated as Class II devices in major jurisdictions, with 510(k) pathways in the U.S. and Notified Body oversight under EU MDR in Europe. ISO standards on implant materials (e.g., Grade 4 titanium specifications) and sterilization protocols (sterility assurance via validated gamma irradiation doses) are non-negotiable design constraints with cost and time implications.
-
Reimbursement and clinical codes: Procedure codes covering implant placement influence adoption rhythms in insured populations. Understanding payer mix and coding dynamics is essential for pricing and commercial strategy in 2026.
-
Supply-chain and manufacturing resilience: Demand growth at the forecasted CAGR will stress component sourcing (e.g., titanium supply chains), sterilization capacity, and contract manufacturing bandwidth. Early 2026 investments to de-risk supply chains will pay dividends.
-
Digital and restorative integration: The proliferation of digital restorative planning and CAD/CAM prosthetics is shortening time-to-restore and enabling premium value capture for systems that integrate across the treatment chain.
Competitive landscape—what leading players signal
The market remains dominated by established global implant manufacturers and a cohort of regional specialists. Leading groups combine material science, proprietary surface technologies, and integrated restorative workflows to defend margin and share. Notable examples include long-standing global leaders known for proprietary alloy and surface platforms, multi-national firms offering evidence-backed tapered designs, strong regional champions from Asia with rapid international expansion, and a set of value-focused manufacturers targeting price-sensitive channels.
Recent developments among major participants illustrate two practical lessons for 2026 strategy:
-
Product breadth and incremental innovation continue to be core competitive weapons—companies are extending implant platforms with new diameters, lengths, and surface options to address immediate-load protocols and a wider patient mix.
-
Regulatory clearances and clinical publications materially impact commercial momentum—routine 510(k) activity and multi-year survival data releases remain decisive trust builders for clinicians and payers.
Our competitive chapter profiles each major vendor’s strategic positioning—technology differentiators, channel footprints, recent launches and regulatory milestones, and partnership patterns. For executives building 2026 offensive or defensive plans, these profiles clarify which competitors are most likely to compete on premium clinical claims, which will lean into price-led expansion, and where white-space opportunities remain.
Strategic implications and recommended actions for 2026
-
Portfolio prioritization: Segment your roadmap into “clinical differentiation” and “volume economics” tracks. Prioritize clinical studies and regulatory filings for platforms intended to capture premium pricing, while rationalizing SKU complexity in price-sensitive channels.
-
Clinical evidence investment: Allocate budget to targeted, high-yield clinical endpoints—immediate loading, marginal bone preservation, and soft-tissue stability. Five-year survival data and real-world registry evidence will be decisive purchase criteria for mid- and high-volume clinicians in 2026.
-
Regulatory acceleration: Construct parallel submission and post-market strategies. Anticipate Notified Body timelines and prepare preclinical dossiers aligned with ISO material and sterilization guidance to avoid downstream delays.
-
M&A and partnerships: Use 2026 to pursue tuck-ins that shore up digital restorative integration or add regional distribution strength. Smaller system providers with established distribution but limited R&D pipelines are attractive targets to accelerate access to growth pockets without diluting core engineering efforts.
-
Commercial model evolution: Develop bundled value propositions that combine implant systems, digital planning services, and prosthetic workflows. For distributors, prioritize clinical training and outcome-based marketing to build loyalty beyond price competition.
-
Operational resilience: Quantify capacity investments required to support projected volumes under the 6.55% CAGR scenario. Secure critical inputs and validated sterilization capacity early in 2026 to mitigate lead-time risk.
What the PW Consulting report contains (practical deliverables)
Our full report delivers the tactical intelligence teams need to operationalize the 2026 playbook:
-
Proprietary market model (historical 2020–2025 and 2026–2032 forecast) with scenario-switch capabilities for pricing, adoption rates, and clinical segmentation impacts.
-
Competitive intelligence dossiers for each major player, mapping product portfolios, recent launches, regulatory milestones, and partnership moves—plus likely near-term strategic trajectories.
-
Regulatory and standards matrix outlining submission pathways, essential preclinical and clinical endpoints, and compliance checkpoints across major jurisdictions.
-
Commercial playbooks for OEMs and distributors, including pricing sensitivity analysis, channel segmentation strategies, and recommended training and evidence-generation investments.
-
Acquisition candidate screen and valuation templates for inorganic growth strategies, emphasizing integration risk and value-capture levers.
-
Operational readiness checklist addressing manufacturing scale-up, sterilization accreditation, and supply-chain continuity planning.
Each deliverable is structured to be directly usable in board-level decision briefings and capital planning cycles for 2026.
Credibility and methodology
The analysis synthesizes primary interviews with clinicians, distributors, and device executives; proprietary shipment and pricing datasets; and public regulatory and clinical literature. We align our material and sterilization assumptions with prevailing standards and guidance—ISO material specifications, AAMI sterilization practices, and regulatory frameworks such as FDA 510(k) and EU MDR—ensuring our scenarios reflect compliance realities, not just theoretical upside.
How executives should use this preview
Consider this article a strategic trailer: it signals where competitive pressure will concentrate in 2026 and summarizes the pragmatic actions that separate winners from the also-rans. For teams drafting their 2026 operating plans, the decision levers to pull now are clear—prioritize clinical evidence where price elasticity is low, shore up regulatory and sterilization pathways, and pursue targeted partnerships to accelerate digital integration.
Next steps
PW Consulting’s full Endosseous Implant Market report includes the granular segmentation, regional forecasts, and company-level market shares that support executable budgets and M&A valuation models. For organizations seeking to convert the 6.55% CAGR opportunity into market leadership by 2026, the complete report, toolkit, and a bespoke briefing can be accessed through our research portal. Contact our team to schedule a tailored executive workshop that translates the findings into a 90-day action plan.
For detailed analysis of this topic, please visit the official page: Endosseous Implant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Embedded Wi‑Fi Modules Market Set for Explosive 13.59% CAGR During 2026–2032
By PW Consulting, 2026-07-02
Embedded Wi‑Fi Modules Market — Strategic Outlook for 2026 Decision‑Makers
As enterprises and device OEMs plan product roadmaps for 2026, embedded Wi‑Fi modules stand at a crossroads of technological acceleration, regulatory change, and supply‑chain tension. PW Consulting’s new market study — covering historical performance (2020–2025) and an actionable forecast through 2032 — provides the pragmatic intelligence executives need to convert connectivity trends into defensible commercial decisions. At the macro level, the market expands from a 2025 base to more than double by the end of our forecast window, with a compound annual growth rate of 13.59% across 2026–2032. This release is designed as a strategic “trailer”: it surfaces rigorous analysis and ready‑to‑use tools while reserving the full segmented datasets and company scorecards for report subscribers.
Embedded Wi Fi Modules Market
Why Embedded Wi‑Fi Modules Matter in 2026
-
Technology inflection. Wi‑Fi 6/6E has already reshaped expectations around throughput and spectrum use; Wi‑Fi 7 (IEEE 802.11be) is now driving a new wave of module redesigns that exploit wider channel bandwidths and multi‑link operation. The finalized R1 Wi‑Fi 7 spec and subsequent releases have created a short‑window advantage for early adopters who can certify and field products on time.
Embedded Wi Fi Modules Market -
Regulatory momentum. Policy shifts — notably expanded, conditional access to the 6 GHz band in multiple jurisdictions and the FCC’s recent authorization of geofenced variable power (GVP) devices — materially affect design margins and deployment strategies. Organizations that anticipate regional differences in 6 GHz access will avoid costly redesigns and certification delays.
Embedded Wi Fi Modules Market -
Supply‑chain friction. Semiconductor constraints, including localized memory shortages that disproportionately affect high‑performance Wi‑Fi 7 designs, are creating component lead times and price volatility. Strategic procurement and design flexibility are now essential risk mitigants.
-
Concentration and competition. The market exhibits moderate concentration among a handful of suppliers; the top three and five vendors account for a substantial share of revenue, underscoring the importance of supplier selection and partner risk management.
What PW Consulting’s Report Delivers — Practical, Transaction‑Ready Intelligence
This study is structured to bridge strategic foresight with immediate operational needs. Key deliverables include:
-
Robust market sizing and a transparent forecasting methodology anchored on our 2025 base year and a 2026–2032 forecast horizon (aggregate growth driven at a 13.59% CAGR). We document assumptions, sensitivity ranges, and scenario drivers so finance teams can plug figures into CapEx and revenue models.
-
Technology adoption timelines that translate standardization milestones (including Wi‑Fi 7 releases) into realistic certification and time‑to‑market estimates for embedded products.
-
Supply‑chain playbooks: multi‑sourcing checklists, component hedging tactics, and a 36‑month component price and lead‑time outlook tailored for Wi‑Fi module BOMs.
-
Commercial tools: supplier scorecards, negotiation levers, pricing sensitivity models, and a build‑vs‑buy framework that quantifies total cost of ownership for both turnkey module buys and in‑house SoC integration.
-
Risk matrices and regulatory readiness plans to align product roadmaps with regional 6 GHz policies, VLP/GVP regimes, and certification variants across major markets.
-
Executive summaries and investor‑grade briefings suitable for board discussions, M&A diligence, and capital allocation prioritization.
Note: In keeping with our “trailer” approach, granular regional and application‑level splits are deliberately omitted here; subscribers receive interactive dashboards that unlock those tables and exportable model sheets.
Competitive Landscape — Who Wins and Why
The embedded Wi‑Fi module ecosystem comprises chipset houses, module integrators, and specialty module manufacturers. Our qualitative and quantitative analysis highlights three archetypes of competitive advantage:
-
Cost and scale leaders: vendors with high‑volume, low‑cost silicon and optimized manufacturing that dominate high‑volume consumer and basic IoT segments.
-
Integration and miniaturization specialists: suppliers focused on certified, ultra‑compact modules and combo solutions for constrained form factors in consumer, automotive and wearables.
-
Performance and vertical‑certified partners: companies offering high‑throughput, secure chipsets and module platforms tailored to industrial and automotive safety certifications.
Representative players we profile in depth include embedded SoC and module suppliers with differentiated positions: Espressif (known for highly integrated ESP platforms popular in IoT), Murata (leading miniaturized, certified modules), Silicon Labs (low‑power multi‑protocol SoCs), Infineon and Broadcom (chipset performance and security), Texas Instruments and Microchip (industrial and certified modules), Qualcomm (micro‑powered, programmable IoT modules), Realtek and AzureWave (cost‑competitive module makers), and IoT module specialists such as Quectel and Telit. Our full report contains side‑by‑side assessments of product roadmaps, certification timelines, partner ecosystems, margin profiles, and a proprietary supplier risk score.
We also surface recent market moves that market participants should watch: a new industrial Wi‑Fi 7 M.2 module brought to market early in 2026, launches of long‑range, ultra‑low power Wi‑Fi HaLow modules late in 2025, fresh Wi‑Fi 7 SoC announcements tailored to IoT, and continued vendor presence at leading trade shows that signal go‑to‑market intent. Collectively these events indicate accelerating readiness for next‑generation embedded connectivity across industrial and consumer segments.
Strategic Imperatives for 2026
Our analysis crystallizes a short list of high‑impact actions executives should prioritize in 2026:
-
Accelerate certification and firmware readiness for 6 GHz operation where your target markets permit it. Anticipate different power and coordination regimes and design to modular RF front‑ends to keep SKU counts manageable.
-
Qualify at least two suppliers across chipset and module tiers to mitigate single‑source risk; use our supplier scorecards to weight technical, financial, and geopolitical risk factors.
-
Reserve high‑performance memory and critical components for flagship SKUs and explore re‑architecting non‑critical variants to use lower‑risk bill‑of‑materials options.
-
Map certification timelines into the product development calendar with a 6–12 month buffer for region‑specific regulatory divergence (e.g., varying 6 GHz access rules), and budget for firmware updates post‑release.
-
Embed security and secure provisioning into module selection criteria; secure boot, lifecycle update paths, and supply‑chain provenance are increasingly differentiating in industrial and healthcare segments.
-
Use scenario planning to stress‑test pricing and demand under different supply‑chain shock permutations; our downloadable stress‑test models give procurement teams a repeatable method for scenario scoring.
How PW Consulting Can Support Your 2026 Playbook
Companies subscribing to PW Consulting’s Embedded Wi‑Fi Modules Market report receive the full dataset, bespoke supplier scorecards, and a suite of executable assets — including a downloadable model, procurement negotiation templates, and a prioritized list of M&A and partnership targets. For teams preparing product launches in 2026, we offer rapid, custom workshops that translate market and regulatory scenarios into a two‑quarter implementation roadmap.
To access the complete intelligence — including regional and application segmentation, per‑vendor financial and roadmap diagnostics, and our exportable forecasting model — visit the PW Consulting report page or contact our industry team for a briefing. The headline numbers and strategic takeaways above indicate where value will accrue; the detailed levers and tactical tables in the full report show how to capture it.
In a market growing at a high‑teens CAGR and reshaped by standards, spectrum policy, and supply‑chain dynamics, the right partner intelligence in 2026 will determine who captures scale and who becomes a distant follower. PW Consulting’s Embedded Wi‑Fi Modules Market study is designed to make that choice less risky — and more profitable.
For detailed analysis of this topic, please visit the official page: Embedded Wi Fi Modules Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electrical Measurement System Market to Expand at 6.03% CAGR Through 2032, Propelled by Asia‑Pacific Demand
By PW Consulting, 2026-07-02
Electrical Measurement System Market — Strategic Briefing for 2026 Decision‑Makers
Executive summary
As organisations recalibrate capital allocation and product roadmaps for 2026, the electrical measurement system market presents a balanced mix of steady demand and structural disruption. PW Consulting’s latest market study shows the global market expanded through 2020–2025 and is forecast to continue growing at a compound annual growth rate (CAGR) of approximately 6.03% across 2026–2032, with the market size rising from the mid‑teens billion USD range in 2025 to an expected figure in the mid‑twenty billions by 2032. This briefing highlights the strategic implications of that trajectory, synthesises near‑term risks and opportunities, and summarises the practical, decision‑ready tools contained in the full report.
Electrical Measurement System Market
Why this matters for 2026 planning
Measurement equipment is both a bellwether and an enabler for capital‑intensive industries: test and measurement demand is driven by semiconductor cycles, automotive electrification, wireless infrastructure rollouts, and energy grid modernisation. In 2026 these drivers interact with non‑cyclical forces — supply‑chain fragility, regulatory intervention, and component scarcity — creating environments in which procurement timing, supplier selection, and product feature prioritisation materially affect P&L and time‑to‑market. For boards and executive teams, the key decision levers are:
Electrical Measurement System Market
- Aligning procurement cadence to product and test needs to avoid overstocks during a soft patch or shortages during surges;
- Investing selectively in modular, software‑defined test equipment that extends lifetime value and reduces upgrade cost; and
- Positioning partnerships and M&A to secure upstream criticality (components, firmware/IP) rather than only downstream distribution.
Market trajectory and what the headline numbers mean
PW Consulting’s forecast captures a resilient market: measured in USD, the industry demonstrates consistent expansion through the 2026–2032 forecast window. The mid‑single digit CAGR masks heterogeneity — pockets of rapid growth tied to next‑generation telecom test, EV powertrain validation, and grid‑edge monitoring coexist with slower volumes in legacy benchtop instruments. For strategic planning this means organisations should treat the market as structurally growing, but episodically volatile. Capital allocation that presumes steady linear growth risks either missed upside or inventory inefficiencies.
Electrical Measurement System Market
Key growth drivers (practical lens)
- Electrification of transportation and industrial processes — driving demand for power analyzers, high‑precision current/voltage measurement and automated test sequences for inverter and battery validation.
- Wireless and high‑speed digital ecosystems — necessitating RF, microwave and signal integrity instrumentation for design, certification and field troubleshooting.
- Energy transition and grid modernisation — creating long‑duration demand for deployed monitoring, power quality analysis, and preventive maintenance tools.
- Software and data monetisation — measurement platforms are increasingly sold as a bundle of hardware, analytics firmware and cloud services; lifecycle revenue models matter.
Supply chain, raw materials and regulatory dynamics to watch
2026 presents a markedly different upstream environment than 2020. Concentration of rare‑earth refining capacity, shifts in semiconductor export controls, and AI‑driven memory shortages have real, tangible impact on instrument makers. Practical takeaways for procurement and product teams:
- Expect episodic lead‑time extensions for analog ICs and passives; design teams should qualify alternate BOMs and increase modularity to decouple long‑lead subassemblies.
- Where magnets, precision components or bespoke RF modules depend on refined materials, scenario‑planning should assume periodic supply tightness tied to geopolitical actions.
- Regulatory changes in export controls can affect sourcing and aftermarket services — legal and trade teams should be engaged early in supplier selection and contract clauses.
Technology and product strategy implications
For R&D and product management leaders, the report emphasises three actionable shifts:
- Architect for software upgradability — instrumentation that decouples hardware refresh from feature updates preserves customer relationships and enables subscription revenues.
- Prioritise modularity and calibration ecosystems — field maintainability and traceable calibration remain differentiators for industrial and utility customers.
- Invest in automation and higher throughput test platforms — as semiconductor and EV testing needs scale, customers trade lower per‑unit speed for integrated automation and data‑centric validation.
Competitive landscape — what the major players are doing (and what it means)
The market displays moderate concentration: a group of well‑capitalised incumbents lead on technology breadth, brand and global service networks while a diverse set of regional and value players compete on price, niche features and fast local support. The practical competitive moves we observe and their implications are:
- Large instrumentation firms are leveraging their R&D budgets to integrate digital services and higher bandwidth capabilities, focusing on end‑to‑end validation stacks suitable for semiconductor and telecom OEMs. Expect premium pricing for end‑to‑end, software‑enhanced solutions.
- Established field‑tool specialists concentrate on ruggedisation, portability and broad distribution channels for industrial and utility customers — these capabilities sustain service revenue and aftermarket stickiness.
- Low‑cost entrants continue to pressure price‑sensitive segments, particularly in education and entry‑level industrial applications; incumbents respond by emphasising calibration, warranties and integrated service offerings.
- Scale plays and consolidation are visible in suites that bundle automated test platforms with software and data capture — vertical integration into semiconductor test systems remains an active strategic frontier.
Specific firm examples illuminate strategy archetypes: one segment leader focuses on high‑bandwidth R&D instruments and protocol‑centric solutions; other legacy handheld specialists double down on rugged field diagnostics and distribution partnerships; mid‑market companies compete with modular automated test systems and tailored power‑electronics rigs. For buyers, supplier selection should now be a multidimensional decision — balancing technical fit, software roadmap, supply reliability and service footprint rather than one‑dimensional price comparison.
Recent signals and near‑term events
Market participants should monitor product introductions and catalog refreshes that reveal supplier priorities. A February 2026 catalog release from a specialist highlighted ultra‑high sensitivity insulation testers targeting safety‑critical applications — a sign that precision and niche differentiation remain meaningful revenue drivers even as broader platforms evolve. Such product moves often presage follow‑on investments in calibration services and vertical‑market partnerships.
What PW Consulting’s report provides — practical contents for executives
The full Electrical Measurement System Market report is designed as an operational playbook for 2026. Key elements include:
- An integrated market model (2020–2032) with scenario sensitivity for component costs, lead times and regulatory regimes — enabling “what‑if” budgeting for procurement and capex committees.
- A supplier due‑diligence toolkit with templates for assessing manufacturing resilience, IP exposure, calibration service capacity and software roadmap maturity.
- Product‑level decision matrices that map instrument classes to buyer objectives: R&D speed, field robustness, total cost of ownership and recurring revenue potential.
- Deal playbooks for partnerships and M&A that identify value levers (access to channels, IP consolidation, vertical integration) and common valuation pitfalls in the sector.
- Actionable risk mitigation checklists covering alternative sourcing, inventory hedging and contractual clauses to address export controls and raw material shocks.
Recommendations for 2026 strategic moves
Based on the market outlook and practical constraints, we recommend executives focus on five priorities this year:
- Rebase supplier scorecards to include geopolitical and component‑specific risk metrics; require dual‑sourcing for critical subassemblies where feasible.
- Accelerate software enablement on existing installed bases to monetise lifecycle services and reduce sensitivity to hardware replacement cycles.
- Target partnerships for upstream control — whether through minority investments in niche component makers or long‑term supply agreements tied to joint roadmaps.
- Segment inventory strategy by instrument class: maintain buffer stock for long‑lead PCB assemblies while adopting just‑in‑time for commoditised mechanical parts.
- Evaluate selective M&A in automation and analytics capabilities — buyers can capture immediate synergies by bundling test hardware with data‑centric services.
How to use the report in boardroom and procurement cycles
Boards and executive teams should use the report as a rehearsal tool for 2026 decisions: run the scenario model in quarterly strategy reviews, require procurement to incorporate the supplier due‑diligence checklist before new contracts, and task product teams with a 90‑day plan to demonstrate at least one software‑driven upgrade path for a flagship instrument. For private equity and corporate development teams, the report’s deal playbooks and valuation caveats provide a faster pathway to identify and stress‑test targets.
Conclusion — the strategic posture for 2026
The electrical measurement system market in 2026 is not a binary bet on growth or decline; it is a portfolio of risks and opportunities. Companies that combine disciplined supply‑chain management, modular product design and a services‑centric commercial model will capture disproportionate value as the market expands at a mid‑single digit CAGR through 2032. The PW Consulting report gives decision‑makers the models, checklists and scenarios required to translate headline growth into defensible strategic moves — while deliberately withholding the granular segmentation tables and raw data that underpin those models until you access the full intelligence package.
Next steps
To access the detailed segmentation, regional and application breakouts, vendor benchmarking tables and the interactive forecast model, visit the PW Consulting report page. The full dataset and downloadable templates are available to subscribers and provide the operational detail necessary to execute on the recommendations outlined here.
For detailed analysis of this topic, please visit the official page: Electrical Measurement System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Steel Idler Rollers Market Reaches USD 4,200 Million in 2025, New Report Reveals
By PW Consulting, 2026-07-02
Steel Idler Rollers Market 2026: Strategic Imperatives for C-Suites and Procurement Leaders
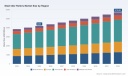
PW Consulting’s latest market brief on Steel Idler Rollers synthesizes five years of historical analysis (2020–2025) and a forward-looking forecast for 2026–2032 to equip executives with the evidence and playbooks required to make high-confidence decisions this year. At a macro level, the global steel idler rollers market reached approximately USD 4,200 Million in the base year 2025 and is projected to grow at a compound annual growth rate (CAGR) of 4.5% through 2032, reaching roughly USD 5,715 Million by the end of the forecast window. This briefing is designed as a strategic “trailer”: it surfaces the trends, risks, and levers that matter while reserving detailed subsegment tables and proprietary benchmarking for the full report.
Steel Idler Rollers Market
Why 2026 Is a Strategic Inflection Point
-
CapEx cycles and infrastructure programs are converging. Continued investment in ports, cement plants, and regional infrastructure—particularly in Southeast Asia and the Middle East—creates near-term demand pockets that suppliers and OEMs must convert into durable revenue.
Steel Idler Rollers Market -
Input-cost volatility raises margin risk. High-grade alloy steel price swings remain material—industry sources report year-over-year variability in the high teens—forcing manufacturers to revisit procurement, contract design, and product-cost engineering.
Steel Idler Rollers Market -
Regulation and safety continue to tilt purchasing decisions toward proven, durable solutions. Idler rollers’ role in worker safety, dust control, and compliance in heavy industries increases the value of lifecycle performance when clients select suppliers.
-
Operational digitization is moving from pilot to scale. Condition monitoring and predictive maintenance for conveyor components are rapidly becoming procurement priorities, changing the value proposition from parts-only to parts-plus-service.
What PW Consulting’s Report Delivers (Practical, Executable Content)
-
Validated market sizing and a 2026–2032 forecast model (USD, revenue unit: Million), including scenario runs for commodity shocks and infrastructure acceleration.
-
Segment frameworks by type, application and region with growth drivers annotated; our public summary intentionally withholds granular subsegment numbers to protect the competitive intelligence contained in the full dataset.
-
Supplier benchmarking: manufacturing footprints, lead-time mapping, quality-cost trade-offs, and spare-parts logistics analysis to support make-or-buy decisions.
-
Cost and margin playbook: bill-of-materials sensitivity, hedging templates for steel exposure, and price pass-through strategies for OEMs and distributors.
-
Technology and innovation roadmap: practical assessment of self-lubricating bearings, corrosion-resistant coatings, and smart idler integrations—what moves the needle on TCO and what remains experimental.
-
Aftermarket commercialization guide: warranty design, service-pack pricing, spare-part fulfilment, and commercial KPIs to drive recurring revenue.
-
M&A and partnership heatmaps: target archetypes, valuation sensitivity to raw-material volatility, and integration playbooks focused on aftermarket capture and sensor/analytics capabilities.
Key Strategic Recommendations for 2026
-
Hedge raw-material exposure proactively. Given the documented swings in alloy steel pricing, organizations should combine medium-term purchase agreements with indexed shorter-term buys and component-level cost reduction initiatives.
-
Prioritize service-led differentiation. Deploy pilot programs that bundle condition monitoring with spare-part fulfilment and SLAs; convert uptime improvements into premium pricing and longer contracts.
-
Modularize product design. Standardized shafts, bearings, and seals reduce SKU complexity, enable faster aftermarket fulfillment, and increase cross-sell potential across customer sites.
-
Invest selectively in digital sensors and edge analytics. Smart idler deployments (recent entrants are now moving from prototype to field trials) yield measurable reductions in unplanned downtime when paired with disciplined maintenance processes.
-
Reassess footprint and supplier strategies. Combine near-shore production for fast-moving SKUs with strategic low-cost sourcing for commoditized parts—while protecting quality through inspection regimes and supplier scorecards.
-
Price contracts for volatility. Introduce indexed clauses and passthrough terms in multi-year supply agreements to protect margins without sacrificing competitiveness.
Competitive Landscape — Who to Watch
The steel idler rollers market remains structurally fragmented: the three-largest players account for under a quarter of global revenue, while the top five capture roughly a third of market value. This dispersion creates opportunity for both scale players and agile regional manufacturers.
-
Rulmeca (Italy) — Global engineering-led supplier known for heavy-duty rollers and conveyor modules. Strengths: engineering brand, OEM-level relationships, and presence in ports and mining projects. Strategic implication: premium positioning in engineered installations.
-
Metso Outotec (Finland) — Mining-focused solutions provider emphasizing durability and low-maintenance designs. Strengths: deep mining domain expertise and aftermarket integration. Strategic implication: target for partnerships where value accrues to life-of-asset performance.
-
Continental (Germany) — Broad conveyor-systems footprint with integration across belts and rollers. Strengths: systems-level procurement advantages and cross-sell into industrial processing. Strategic implication: compete on systems economics, not parts alone.
-
ASGCO, Douglas Manufacturing, PPI, Martin Engineering, Superior Industries, Fenner Dunlop (USA / Australia / Netherlands) — These firms compete across heavy-industry applications with strong aftermarket channels and CEMA-aligned product lines. Strategic implication: aftermarket capabilities are a key differentiator.
-
HIC Universal (India), Melco (South Africa), GCS Conveyor (China) — Regional and cost-competitive manufacturers expanding export footprints. Strengths: price competitiveness and local-service models in emerging markets. Strategic implication: pressure on global players in price-sensitive segments.
Recent industry developments underscore two converging themes. First, materials and coatings innovations—self-lubricating bearings and corrosion-resistant finishes—are becoming commercially relevant for high-abrasion environments (industry reports, early 2026). Second, digitalization is accelerating: new smart idler products embedding real-time monitoring are moving from vendor press releases to customer pilots, signaling a shift in procurement criteria toward integrated condition-based maintenance.
Investment and M&A Signals to Monitor
-
Acquire niche aftermarket service providers with field networks and spare-part operations to accelerate cross-sell and shorten payback on CapEx.
-
Target sensor and analytics companies to capture data monetization opportunities and to lock in customers through predictive maintenance platforms.
-
Consider bolt-on acquisitions in low-cost production geographies to protect margin or to serve regional infrastructure programs more competitively.
How Strategic Leaders Should Use This Report in 2026
-
Procurement: use the cost-sensitivity models and hedging templates to redesign supplier contracts and to set KPIs that incorporate raw-material pass-throughs.
-
Operations: apply the manufacturing footprint analysis and SKU rationalization playbook to reduce lead times and working capital.
-
Commercial: pilot service bundles that combine condition monitoring, fast spares logistics, and performance-based pricing to increase wallet share.
-
Corporate Development: screen acquisition targets using the M&A heatmaps and integration checklists in the report to prioritize deals that accelerate aftermarket or digital capabilities.
-
Risk & Finance: run scenario models included in the report—covering commodity spikes, demand shocks, and accelerated infrastructure spending—to refine capital allocation and working-capital cushions.
Conclusion — The Strategic Edge in 2026
For executives deciding where to allocate capital, talent, and time in 2026, the Steel Idler Rollers market offers a classic combination of steady demand growth (4.5% CAGR) and structural change. Winners will be those that convert engineering credibility into service-led commercial models, shield margins from raw-material volatility, and deploy digital capabilities that demonstrably reduce customers’ total cost of ownership.
PW Consulting’s full Steel Idler Rollers Market report contains the granular regional and application breakdowns, company market shares, downloadable financial models, and operational playbooks referenced here. For procurement teams, product leaders, and corporate development executives seeking to turn the high-level strategic imperatives above into a 90- to 180-day operational plan, the complete dataset and tools are available on our report page.
For detailed analysis of this topic, please visit the official page: Steel Idler Rollers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Strategic Outlook — IoT MCU Market to 2032 and What Executives Must Act on in 2026
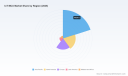
As enterprises plan product roadmaps and capital allocation for the coming 18–36 months, the IoT microcontroller (MCU) market is shifting from component-level optimization to platform-level competitiveness. PW Consulting’s latest IoT MCU Market report (base year 2025, forecast 2026–2032) provides an operationally focused playbook that translates a 9.0% CAGR and the market’s projected expansion from roughly USD 20.6 billion in 2025 to about USD 37.7 billion by 2032 into concrete strategic choices for 2026 decision-makers.
Iot Mcu Market
Why this report matters for 2026 planning
Three features make this analysis essential for executive teams preparing 2026 budgets and product milestones:
Iot Mcu Market
- Macro clarity: We synthesize demand-side momentum and supply-side constraints into a single, actionable narrative—aligning R&D, procurement, and GTM timelines with an expected market growth path over 2026–2032.
- Competitive differentiation: The study benchmarks vendor go-to-market postures, product roadmaps, and ecosystem strategies so product managers can prioritize partner engagements and architecture choices that reduce time-to-market and system-level cost.
- Compliance-led product readiness: Our regulatory and standards mapping identifies near-term compliance risks and opportunities (including voluntary labeling and ecosystem certifications) that will materially influence component selection and firmware roadmaps in 2026.
Top-line market view and what it implies
After an uneven recovery period through 2020–2025, the IoT MCU market is expected to accelerate into the next phase of growth. The report’s forecast trajectory—consistent with a 9.0% compound annual growth rate—signals that platforms and silicon suppliers able to bundle connectivity, security, and low-power performance will capture disproportionate value. For product teams, this means that 2026 choices about MCU architecture (bit-width and performance tier), connectivity stacks, and security primitives will directly affect roadmap scalability through the rest of the decade.
Iot Mcu Market
Concentration metrics are important for procurement and strategic risk: the top three suppliers control nearly half of the market, and the top five approach three-quarters. Those figures indicate a market that blends competitive innovation with structural supplier risk—requiring diversified sourcing strategies and platform-level approvals to avoid single-source vulnerabilities.
Dynamics shaping demand in 2026
- Platform consolidation: Increasing preference for MCUs that combine wireless connectivity, security hardware, and power management reduces BOM complexity but raises switching costs when architecture choices are entrenched. 2026 is a critical year to lock in software development kits (SDKs) and certification roadmaps if firms plan multi-year device fleets.
- Edge intelligence: Expanding on-device processing (edge AI/ML) will push buyers toward higher-performance 32-bit MCU families and hybrid SoC solutions for latency-sensitive use cases. This creates a strategic inflection for companies to balance compute capability against cost and power budgets.
- Regulatory momentum: New and emerging compliance frameworks (both voluntary and mandatory) will shape product acceptance in key markets—impacting connectivity interfaces, secure boot and OTA update requirements, and labeling. Firms must bake compliance into 2026 design cycles to avoid retrofit costs.
- Supply-side dynamics: While consolidation among leading vendors increases bargaining stability, lead-time variability and capacity constraints for specialized nodes mean procurement teams must adopt multi-sourcing, commit-to-volume contracts, or strategic allocation agreements.
Competitive landscape — where incumbents are positioning
Our vendor assessment focuses on technological differentiation, ecosystem presence, and go-to-market motions across a curated set of suppliers. The marquee players are executing differentiated strategies:
- NXP Semiconductors (Eindhoven) continues to push crossover MCUs with integrated connectivity and ecosystem certifications, targeting smart home and industrial interoperability advantages.
- STMicroelectronics (Geneva) leverages a broad STM32 portfolio and integrated low-power wireless stacks to defend diverse IoT endpoints, from consumer gadgets to industrial gateways.
- Infineon (Neubiberg) emphasizes secure, low-power platforms and power management integration, positioning for safety- and security-conscious industrial applications.
- Microchip (Chandler) has moved into higher-performance embedded analog and compute with recent launches tailored to math-intensive edge workloads, making it appealing for industrial automation and medical devices.
- Renesas (Tokyo) has accelerated its wireless MCU roadmap with dual-band Wi‑Fi 6 and BLE-capable parts, sharpening its play in connected home and gateway segments.
- Texas Instruments (Dallas), Silicon Labs (Austin), Espressif (Shanghai), Nordic (Trondheim), Broadcom, Analog Devices, Nuvoton, Holtek, and others each occupy well-defined niches—ranging from ultra-low-power sensors to high-throughput connectivity and mixed-signal precision.
Recent product introductions—such as higher-frequency, connectivity-rich MCUs from Renesas and Microchip’s high-speed analog-capable PIC32A family—are illustrative of the broader trend: vendors are building vertically integrated silicon/software stacks to accelerate design wins. For buyers, this makes 2026 a year to refine integration tests and certification timelines aligned to these new offerings.
Regulatory and standards landscape — compliance as strategy
The device compliance environment is tightening and diversifying across jurisdictions. Industry initiatives and government programs are converging on baseline security and interoperability expectations:
- Cross-industry certification programs are shaping interoperability expectations, pressuring silicon and SDK vendors to support standardized stacks and certification pathways.
- National-level standardization efforts are elevating terminal and transmission security expectations, directly influencing MCU design requirements for secure boot, cryptographic accelerators, and trusted update mechanisms.
- Voluntary labeling schemes and regional directives are creating market differentiation for consumer-facing devices; compliance investments can be monetized through reduced returns and higher consumer trust.
In practice, these dynamics mean compliance can no longer be an afterthought. Firmware architects and procurement leaders must co-design for standards alignment to reduce time-to-certification and avoid last-minute hardware revisions.
Operationally focused content in the PW Consulting report
This report is built for practitioners. It goes beyond descriptive market sizing and includes operational tools you can use immediately:
- Decision frameworks to prioritize MCU families by product archetype (battery-powered sensors, edge AI nodes, gateway devices, etc.), including trade-off matrices for performance, power, security, and cost.
- A vendor-selection playbook with negotiation levers for volume commitments, allocation assurances, and long-term roadmap alignment.
- Certification roadmaps mapping major standards and regulatory milestones to firmware and hardware integration tasks, with suggested timelines for 2026 product cycles.
- Scenario planning and sensitivity analysis linking silicon price and lead-time variability to product profitability under different go-to-market assumptions.
- Case studies documenting recent design wins and failure modes—practical lessons on firmware portability, SDK lock-in, and lifecycle management.
Practical recommendations for 2026
Based on our synthesis, we recommend five pragmatic actions for 2026 planning cycles:
- Commit to platform architecture decisions by Q2 2026. The market trajectory favors early architectural alignment to integrated connectivity and security stacks—delays increase the risk of costly mid-cycle redesigns.
- Negotiate supplier diversification with conditional allocations. Use the market’s concentration dynamics as leverage to secure supply while preserving alternatives for specialized nodes.
- Embed compliance gates into development sprints. Treat certification milestones (both voluntary labels and mandatory directives) as feature requirements that drive acceptance testing and release readiness.
- Invest in SDK abstraction layers. To mitigate vendor lock-in and accelerate OTA feature delivery, prioritize middleware that isolates application code from vendor-specific SDK changes.
- Pilot edge AI on representative device classes. Given the forecasted uptake of compute-capable MCUs, a controlled set of pilots will de-risk wider rollouts and clarify the TCO implications of on-device inference.
How PW Consulting’s analysis supports your execution
For leadership teams, this report functions as both a market compass and an execution kit. The combination of a defensible market trajectory, supplier benchmarking, regulatory mapping, and a library of tactical tools is designed to shorten decision cycles and improve the hit-rate of design wins in 2026.
We deliberately keep the most sensitive granular tables—detailed regional/application-level splits, unit-level pricing trajectories, and vendor-specific revenue curves—in the full report to preserve the necessity of direct engagement. That level of granularity is where procurement strategies and investment cases are built, and we reserve it for report subscribers and client engagements to ensure context-sensitive interpretation.
Next steps
Executives who prioritize time-to-market and regulatory resilience should request PW Consulting’s full IoT MCU Market report and our tailored advisory session. In a one-hour briefing we will walk through the data slices most material to your product portfolio, map supplier risk to your BOM, and produce a 90-day action plan aligned to 2026 milestones.
Contact PW Consulting to schedule a briefing and access the full dataset and appendices that contain the detailed segmentation, vendor scorecards, and actionable supply-chain tables required to execute with confidence.
For detailed analysis of this topic, please visit the official page: Iot Mcu Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: TFF Cassettes Market to Expand from USD 1,400M in 2025 to USD 2,319.9M by 2032 at 7.48% CAGR — North America, PES Membranes and Monoclonal Antibody Production Drive Growth as Top 3 Firms Control 62.45%
By PW Consulting, 2026-07-02
Tff Cassettes Market 2026 Strategic Preview: What Decision‑Makers Need Now
PW Consulting’s new Tff Cassettes Market study is the must‑read strategic briefing for executive teams planning 2026 moves in bioprocess filtration, downstream manufacturing, and bioproduct scale‑up. Drawing on a bottom‑up market model, primary supplier interviews, product‑level benchmarking, and regulatory validation mapping, the report translates quantitative growth trajectories into transaction‑ready recommendations — while reserving the granular tables and proprietary segment outputs for subscribers.
Tff Cassettes Market
Macro picture: a market with durable momentum
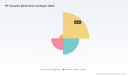
The tangential flow filtration (TFF) cassette market has moved from niche lab tooling to a core enabler of accelerated biologics manufacturing. Our base‑year analysis shows the global market expanding from approximately USD 1.05 billion in 2020 to USD 1.40 billion in 2025. With a forecast CAGR of 7.48% for the period 2026–2032, PW Consulting projects continued, above‑market growth through 2032 when the market is expected to exceed USD 2.3 billion. That combination of scale and steady growth creates predictable windows for capacity investments, supplier consolidation, and differentiated product launches.
Tff Cassettes Market
Why 2026 is a strategic inflection point
- Commercial scale‑up pressure: Biologics pipelines that matured during the pandemic era are entering late‑stage manufacturing, driving demand for validated, production‑grade TFF solutions. Procurement cycles that historically ran long are compressing — buyers expect validated supply in months, not quarters.
- Single‑use vs reusable calculus: The market is balancing the operational flexibility of single‑use cassettes against the cost efficiencies of reusable formats. The near‑term opportunity for vendors and end‑users is in hybrid strategies that pair single‑use lab and pilot cassettes with reusable production cassettes where lifecycle economics and regulatory validation support scale.
- Regulatory and validation gating: Increasing regulatory scrutiny on materials and particulate/endotoxin performance elevates vendors that can provide robust documentation and validated processes. Compliance with USP standards such as endotoxin and particulate testing is table stakes for 2026 procurement.
- Supplier concentration risk: The market exhibits measurable concentration among leading vendors, creating negotiation leverage for informed buyers but also supply risk if one or more suppliers face capacity constraints or quality events.
What PW Consulting’s report delivers — practical, actionable content
Our study is intentionally operable: beyond narrative insight, subscribers receive a toolkit designed to accelerate decision execution in 2026.
Tff Cassettes Market
- Market model with scenario runs: A base case and two alternative scenarios (conservative and high‑adoption) that let you model volume, revenue, and pricing sensitivity under different commercial assumptions.
- Supply chain and capacity map: Granular supplier capacity overlays, lead‑time analytics, and a three‑tier supplier risk heatmap supporting procurement contingency planning.
- Regulatory playbook: Checklist templates and acceptance criteria aligned to current USP and regulatory expectations, plus a validation timeline to shorten qualification windows.
- Buyer/supplier negotiation kit: Price benchmarking approach, contract terms to protect supply continuity, and a supplier selection matrix prioritizing technical fit, regulatory documentation, and manufacturing footprint.
- Technology adoption roadmap: Comparative assessment of membrane materials and cassette formats, with pragmatic recommendations for pilot validation, scale migration, and process economics (TCO) thresholds.
- M&A and investment playbook: Valuation heuristics, revenue synergy scenarios, and a prioritized target list for acquisition or partnership to strengthen membrane IP, fill capacity gaps, or enter adjacent geographies.
Competitive landscape: who matters and why
The TFF cassette market is served by a mix of multinational life‑science incumbents and specialized regional players. Several firms lead the technology road map and have active product introductions or regulatory deliverables that materially affect supplier selection in 2026:
- Sartorius AG (Göttingen, Germany): Offers a broad cassette portfolio across single‑use and reusable formats, with membrane platforms optimized for monoclonal antibody workflows and recent lab single‑use innovations aimed at accelerating small‑batch development.
- Repligen Corporation (Waltham, Massachusetts, USA): Positions single‑use and reusable cassette platforms alongside holder‑free self‑contained devices; recent regulatory documentation updates strengthen its appeal for customers requiring validated material declarations and endotoxin/particulate evidence.
- Cytiva / Danaher (Marlborough, Massachusetts, USA): Serves development to production needs with cassette and membrane pairings that prioritize scaleability and cross‑platform compatibility.
- Merck KGaA / MilliporeSigma (Darmstadt, Germany): Focuses on production‑grade cassettes, including single‑pass configurations used in high‑titer workflows — attractive to customers pursuing aggressive concentration strategies.
- Regional and niche suppliers (examples): Select Asian and specialist vendors supply competitive lab‑scale and production cassettes; their presence supports regional sourcing strategies and cost arbitrage, while also presenting quality and validation variance that buyers must quantify.
Market concentration among top suppliers is material — leading groups capture a substantial share of revenue — a dynamic that influences pricing power, service levels, and the strategic calculus for dual‑sourcing versus sole‑sourcing decisions.
Regulatory dynamics and quality as market differentiators
Regulatory readiness is a primary selection criterion for 2026. Vendors who can demonstrate cGMP manufacturing, validated materials, and compliance data (including endotoxin and particulate testing requirements) are advantaged. Recent vendor filings and catalog updates show an industry moving from product feature differentiation to documentation and validation as the primary competitive battleground.
For buyers, our report includes a practical validation checklist mapped to regulatory tests and acceptance criteria used by leading QA organizations — enabling faster qualification of new suppliers and reducing time‑to‑batch for process transfers.
Strategic playbook for executives planning 2026 actions
- Procurement leaders: Adopt a tiered sourcing strategy that pairs an incumbent global supplier with a validated regional alternative. Use the report’s supplier risk heatmap to structure backup capacity agreements and reduce single‑point‑of‑failure exposure.
- Manufacturing and process teams: Prioritize pilot‑to‑production migration plans that lock membrane and cassette formats early in process design. Leverage the TCO thresholds in the report to decide when reusable formats outweigh the operational flexibility of single‑use.
- R&D and product development: Design validation plans in parallel with supplier engagement. Our regulatory playbook shortens qualification timelines and clarifies the documentation vendors must provide to accelerate tech transfer.
- Corporate development and investors: Use the M&A playbook to screen targets that provide strategic membrane IP, manufacturing scale, or regional access — transactions that can materially de‑risk supply and accelerate growth capture.
Risks and mitigations we track for 2026
- Raw material bottlenecks: Membrane substrate constraints and thin‑film coating capacity can create lead‑time spikes. Mitigation: dual‑source critical membranes and secure advance purchase agreements.
- Regulatory qualification gaps: Suppliers lacking documented endotoxin/particulate data slow down transfers. Mitigation: prioritize vendors with published validation files and pre‑assembled regulatory kits.
- Market concentration shocks: High revenue shares among a few suppliers increase systemic risk. Mitigation: expand qualified vendor lists and invest in in‑house verification labs for faster onboarding.
- Technology obsolescence: Rapid improvements in membrane chemistries can shift economics. Mitigation: include upgrade clauses in long‑term contracts and stage capex to allow flexible migration.
How to use this report in your 2026 planning
PW Consulting’s Tff Cassettes Market study is designed to be directly operationalized into 2026 planning cycles. Senior teams typically use the report to:
- Set procurement KPIs and supplier SLAs informed by our lead‑time and capacity benchmarks;
- Quantify capex needs and timing for pilot vs production cassette inventories using our scenario model;
- Prioritize supplier due diligence lists based on regulatory readiness and product fit;
- Identify M&A or JV targets that close strategic gaps faster than organic development.
Next steps and access to full intelligence
This article previews the analysis and the strategic playbook inside PW Consulting’s full Tff Cassettes Market report. To access the complete dataset, interactive model, supplier scorecards, and downloadable validation templates that support rapid 2026 decision‑making, please visit our report page. The full report includes detailed segmentation tables, regional and application level forecasts, and the proprietary vendor benchmarking that we intentionally reserve for subscribers and clients.
For boards, investors, and senior operating teams evaluating entry or expansion in TFF filtration, the report provides both the evidence and the executable steps required to convert the market’s steady growth into sustainable advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Tff Cassettes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Residue Hydrodesulfurization Catalyst Market to Reach USD 5,343.01 Million by 2032, Expanding at a 4.61% CAGR (2026–2032)
By PW Consulting, 2026-07-02
Residue Hydrodesulfurization Catalyst Market: Strategic Imperatives for 2026 — PW Consulting Insights
PW Consulting today releases an executive briefing drawn from our forthcoming Residue Hydrodesulfurization (R-HDS) Catalyst Market report, designed to equip senior refinery executives, catalyst suppliers, M&A teams, and procurement leaders with the strategic context they need to make high‑consequence decisions in 2026. Our analysis synthesizes multi-year market sizing, supply‑chain risk mapping, technology differentiation, and competitor positioning to translate market dynamics into executable options — while reserving the granular regional and product split tables for subscribers of the full report.
Residue Hydrodesulfurization Catalyst Market
Market snapshot: stability with structural upside
After a period of post‑pandemic adjustment, the R‑HDS catalyst market stabilized near USD 3.9 billion in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of approximately 4.6% across the 2026–2032 horizon. Under our baseline scenario this translates into a material expansion of installed catalyst demand and service activity through the early 2030s, driven by continued ultra‑low sulfur legislation, refinery residue conversion initiatives, and strategic upgrading of heavy feed processing capacity.
Residue Hydrodesulfurization Catalyst Market
These headline numbers mask important nuance: growth is not uniformly distributed by technology or geography, and industry participants will see differentiated margin trajectories depending on their exposure to feedstock quality, technology mix (fixed‑bed, ebullated‑bed, slurry), and access to secured raw material streams. PW Consulting’s report exposes these risk/reward asymmetries and converts them into practical decision pathways for 2026 investments.
Residue Hydrodesulfurization Catalyst Market
Why 2026 is a strategic inflection point
-
Regulatory pressure continues to be the primary demand lever. Global acceleration toward ultra‑low sulfur fuels sustains demand for high‑activity NiMo and CoMo catalysts engineered to process sour, high‑boiling residues.
-
Feedstock economics and refinery configurations are evolving. Refiners are increasingly evaluating residue conversion not only for compliance but as a route to higher‑value products and improved complex margin capture.
-
Supply‑side stresses are amplifying procurement risk. Notably, molybdenum spot markets experienced volatility in the order of 18–22% across a 12‑month window in 2025, exerting direct pressure on manufacturing margins for residue catalysts. Concentrated mine and processing footprints (notably in Chile and China) mean that upstream disruptions translate rapidly into price and availability shocks for catalyst makers and their downstream refinery customers.
Practical, decision‑ready content included in the full report
PW Consulting’s R‑HDS Catalyst Market report is organized to move readers from context to action. Key deliverables include:
-
Proprietary market sizing and multi‑scenario demand forecasts (2020–2032) that quantify the revenue and volume pathways for the market under differing regulatory, crude slate, and fuel demand assumptions.
-
Technology & performance benchmarking for fixed‑bed, ebullating‑bed, and slurry systems — including service life, catalyst replacement cadence, and feedstock tolerance matrices — presented as operational decision trees for refinery planners.
-
Supply‑chain risk analytics: heatmaps of raw material concentration, supplier capacity, and single‑point failures that translate into prioritized mitigation measures and purchasing lead‑time recommendations.
-
Commercial playbooks for procurement and contract design, covering indexation strategies (including raw material pass‑throughs), hedging structures, and long‑term offtake constructs that preserve gross margins while securing supply.
-
M&A and partnership screening tools: a scored target list and diligence templates for buyers seeking inorganic scale or technology access, and for licensors evaluating joint ventures in high‑growth regional markets.
-
Case studies and model clauses for catalytic lifecycle management, digital monitoring adoption (predictive activity decay), and retrofit sequencing to minimize downtime and optimize AR/VR desulfurization outcomes.
To preserve competitive value for subscribers, we deliberately exclude detailed regional and application split tables from this briefing; those granular decompositions are available in the full report and underpin the operational models and contract templates referenced above.
Competitive landscape: concentration, capabilities, and consolidation
The market is moderately concentrated: our analysis shows that the top three players account for a substantial share of revenue, and the top five control well in excess of two‑thirds of market value. This structure creates both entry barriers and strategic windows — incumbents benefit from scale and integrated licensing, while nimble challengers can carve niches via specialty formulations, service intensity, or geographic proximity to raw material sources.
Core players and strategic differentiators to watch:
-
Axens SA — A technology‑led supplier with a comprehensive fixed‑bed RDS portfolio and advanced catalyst engineering approaches aimed at maximizing HDS, HDN, and RFCC feed compatibility. Axens’ track record in fixed‑bed resid HDS positions it as a preferred partner for refineries targeting predictable service intervals and integrated licensor offerings.
-
Advanced Refining Technologies (ART) — Historically a leading specialist in both fixed and ebullated bed resid applications; the company’s capabilities now sit under the ownership of W.R. Grace & Co. following a November 2025 acquisition. This consolidation strengthens Grace’s foothold in resid hydroprocessing and creates scale synergies in R&D and commercialization.
-
Albemarle Corporation, Haldor Topsoe, Honeywell UOP, Johnson Matthey, Shell (Criterion), and BASF — Each brings differentiated strengths across R&D depth, formulation science, and co‑development with licensors. Their portfolios emphasize high‑activity CoMo and NiMo systems tailored for heavy, sulfur‑rich streams and for minimizing selective poisoning.
-
Sinopec and CNPC — State‑backed producers with vertically integrated supply chains and domestic scale. Their presence shifts competitive dynamics in regional markets where domestic sourcing, government procurement preferences, and local content rules matter.
For vendors and refinery leaders alike, the acquisition activity and concentration metrics imply two strategic plays in 2026: consolidate capability where scale and licensor alignment are critical (for example, fixed‑bed systems tied to licensed process units), and selectively partner or source locally for bespoke resid formulations and rapid response service contracts.
Cost and raw‑material dynamics: actionable risk mitigations
Price and availability for key inputs are a near‑term operational reality. In 2025, base metal hydrodesulfurization catalysts were transacted in a price band approximately between USD 28–45 per kilogram for standard grades, with specialty formulations for resid applications commanding premiums in the 40–60% range. When combined with molybdenum supply volatility, these input cost dynamics materially affect supplier margins and, unless contract structures adapt, can compress refinery economics as well.
Practical mitigations we recommend for 2026:
-
Implement a two‑tier procurement strategy: tactical spot coverage for short windows and hedged long‑term supply for critical stream continuity, with explicit passthrough mechanics for metal cost swings.
-
Pursue strategic alliances or equity partnerships with catalyst producers that include guaranteed allocation clauses and co‑funded buffer inventory to insulate operations from upstream shocks.
-
Invest in predictive catalyst health monitoring and advanced analytics to extend run length where safe, and to optimize replacement timing — this reduces total catalyst consumption and dampens exposure to input price volatility.
Actionable recommendations for 2026 decision‑makers
-
For refiners: prioritize feedstock flexibility investments and catalyst lifecycle analytics. Contracts should shift from fixed‑price, short‑term spot buys toward hybrid structures that share metal cost risk and incentivize supplier innovation in high‑durability formulations.
-
For catalyst suppliers: accelerate development of residue‑grade specialty formulations while strengthening upstream raw‑material security. Consider regional manufacturing offsets and aftermarket service bundles to lock in customers where proximity and service responsiveness matter.
-
For investors and M&A teams: target assets that offer either licensor alignment (to capture process economics) or differentiated proprietary formulations with demonstrable run‑length improvements. The market rewards scale in R&D and manufacturing but also premium margins for formulation leadership.
-
For regulators and industrial policy makers: consider how local sourcing policies and strategic stockpiles for critical minerals like molybdenum influence refinery resilience and national fuel security. Coordination between energy policy and mineral policy is now a practical necessity.
Next steps: how PW Consulting helps
PW Consulting’s full Residue Hydrodesulfurization Catalyst Market report provides the underlying datasets, interactive scenario models, supplier scorecards, contract templates, and a prioritized 18‑month execution roadmap tailored for executives ready to act in 2026. If your 2026 plan requires defensible choices around sourcing, technology selection, or inorganic growth in the R‑HDS space, our analysis converts market complexity into clear options and quantified outcomes.
For access to the full report, proprietary tables, and modelled scenarios (including the detailed regional and application splits omitted from this briefing), please visit the PW Consulting report page or contact our industry team for a briefing and tailored extract relevant to your portfolio.
PW Consulting — translating catalytic market intelligence into operational advantage for the refining sector.
For detailed analysis of this topic, please visit the official page: Residue Hydrodesulfurization Catalyst Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High Precision Photomask Market Poised for 5.48% CAGR Through 2026–2032
By PW Consulting, 2026-07-02
High Precision Photomask Market 2026: Strategic Imperatives for Decision‑Makers
Executive summary
PW Consulting’s new High Precision Photomask Market report is designed as an operational compass for companies making critical capital, procurement, and partnership decisions in 2026. Our bottom‑up market model, calibrated across the 2020–2025 historical window, projects steady market expansion from a mid‑2020s base to the end of the forecast horizon. The industry is forecast to grow at a compound annual growth rate (CAGR) of approximately 5.48% through the 2026–2032 period, with total market value increasing substantially by 2032 under current policy and technology trajectories.
High Precision Photomask Market
Beyond headline growth, concentration metrics signal an industry where a small number of suppliers continue to command a majority of merchant mask volumes — an important structural fact for procurement, inventory strategy, and national technology planning. Our report distils these dynamics into actionable options for OEMs, IDM fabs, photomask suppliers, equipment vendors, investors, and policy teams.
High Precision Photomask Market
Why this report matters for 2026 decisions
-
CapEx timing: Align investments in lithography and mask‑writing capacity with mask supply lead times and blank availability rather than with wafer‑fab schedules alone.
High Precision Photomask Market -
Supply resilience: Build procurement strategies that explicitly account for concentrated blank supply, extended lead times, and premium pricing on advanced substrates.
-
Technology roadmap alignment: Prioritise mask technology (EUV, multi‑beam, nanoimprint readiness) consistent with node mix and defect‑tolerance targets for your product portfolio.
-
Regulatory & geopolitical risk mitigation: Integrate export‑control scenario plans into supplier selection and joint‑venture negotiations to avoid sudden capability gaps.
-
Competitive positioning: Use supplier scorecards and scenario modelling to evaluate insourcing, co‑development, or strategic minority investments.
Key market dynamics shaping the next planning cycle
-
Constrained blank capacity and extended lead times. Leading blank suppliers are operating at very high utilisation rates, translating into multi‑month lead times for high‑precision blanks. For any organisation depending on advanced photomasks, this changes the calculus on safety stocks and lead‑time buffers.
-
Price differentiation for advanced blanks. EUV and other advanced mask blanks attract a substantial price premium versus conventional DUV blanks due to complex multilayer coatings and defect‑control processes. Procurement strategies must move beyond lowest‑price bids to total cost and availability assessments.
-
Substrate and material bottlenecks. Key quartz‑substrate producers have limited near‑term expansion, affecting availability of ultra‑low‑expansion materials used in high‑precision masks. Buyers should expect phased capacity additions through the mid‑decade and plan accordingly.
-
Export controls and jurisdictional risk. Ongoing export‑control frameworks in multiple jurisdictions add uncertainty to cross‑border transfers of advanced photomask equipment and processes. Risk‑mitigation measures — from legal compliance to nearshoring — must be built into 2026 supply plans.
-
Consolidation and concentration. Market concentration is material: the top three and top five providers account for a disproportionate share of merchant photomask supply. This concentration amplifies single‑supplier risk and raises the value of strategic partnerships.
Competitive landscape — what we found (select players)
-
Tekscend Photomask (formerly Toppan Photomasks): A global merchant leader with deep capabilities across EUV and advanced optical masks. Recent initiatives include multi‑jurisdictional capacity expansion, targeted technology upgrades such as multibeam mask writers, and pilot investments in nanoimprint lithography. These moves indicate a deliberate strategy to broaden node coverage and regional footprint to meet customer demand for both advanced and mature nodes.
-
Photronics, Inc.: An established, geographically diversified manufacturer with a portfolio spanning leading‑edge reduction reticles to display masks. Photronics’ facility footprint and service model position it as a preferred partner for clients seeking geographic redundancy and multi‑node support.
-
Dai Nippon Printing (DNP): Focused on process development for the next generation of EUV masks, including multi‑electron beam writers and process controls for logic at the smallest nodes. DNP’s roadmap underscores the technical arms race around defect detection and yield‑driven mask manufacturing.
-
HOYA Corporation: A major supplier of mask blanks and finished masks, with strengths in both EUV blank technology and high‑precision flat panel display masks. HOYA’s position in the upstream blank market makes it a strategic counterparty for firms attempting to secure advanced blank supply.
-
Regional and specialist suppliers: A cohort of regional champions and niche specialists provide important capacity for specific node classes and display markets. Their roles as flexible partners, prototyping resources, or regional sources of supply should not be underestimated in contingency planning.
Recent developments to monitor
-
Targeted capacity and facility expansions by leading merchant providers, including new plants and equipment installations across North America, Europe and Asia — these change lead‑time geography and capacity availability for customers that strategically locate wafer fabs near mask supply.
-
Deployment of advanced mask writers (e.g., multibeam and next‑generation eBeam systems) in European and Asian facilities, enabling higher‑throughput production of complex masks and reducing per‑mask unit cost at scale.
-
Active development programs for 2nm‑generation EUV processes and adjacent techniques, reflecting industry commitment to pushing mask capability to meet future logic and memory demands.
What the PW Consulting report contains — practical, decision‑grade modules
-
Proprietary market forecast model (2020–2032) with scenario toggles for node mix, EUV adoption rates, and geopolitical shock events.
-
Supplier risk matrices and scorecards, including capacity maps, technology competence assessments, and contractual levers for securing priority supply.
-
Procurement playbooks: multi‑sourcing templates, safety‑stock calculators, vendor financing and consignment structures tailored for masks and blanks.
-
CapEx prioritisation framework for fabs and mask houses that aligns mask‑writing, blank procurement, and inspection tool investments to yield improvement targets and product roadmaps.
-
Scenario stress‑tests and contingency plans for export‑control escalations, material shortages, and sudden demand shifts — with clear triggers and recommended tactical responses.
-
Commercial benchmarking and valuation comps for strategic transactions — M&A, JV and minority stake assessments focused on capacity, IP, and customer contracts.
Strategic recommendations for 2026 planning
-
Secure diversified blank supply through a mix of long‑term contracts, strategic inventory pools, and regional dual‑sourcing to mitigate lead‑time risk.
-
Prioritise investment in mask‑writing and inspection co‑development with suppliers where product roadmaps require novel mask capability (e.g., EUV, multibeam, or NIL) — shared R&D reduces timing risk and spreads cost.
-
Embed export‑control scenarios into supplier and site selection. When feasible, design manufacturing flows to reduce chokepoints that are likely to be subject to export restrictions.
-
Adopt phased procurement and CapEx strategies that match mask capability investments to realistic node adoption timelines rather than aspirational wafer‑fab targets.
-
Negotiate operational flexibility in vendor contracts (priority lanes, capacity buyouts, options) to convert forecast uncertainty into manageable optionality.
-
For investors and M&A teams: prioritise targets that provide either differentiated technological IP in mask writing/inspection or strategically located capacity that reduces supply risk for key customers.
Implications by stakeholder
-
Chipmakers (IDMs and fabless): Treat mask procurement as a strategic capability. Early engagement, co‑funding of mask tool upgrades, and contractual priority are now legitimate levers to protect time‑to‑market.
-
Mask manufacturers: Invest selectively in multibeam and automated inspection to improve throughput and yield; pursue regional partnerships to defray regulatory risk.
-
Equipment vendors: Focus on throughput and defect‑control enhancements for advanced mask writers and blanks; support customers with financing and O&M packages that accelerate adoption.
-
Policy makers: Recognise masks as a choke‑point in the semiconductor value chain; targeted incentives for blank capacity and inspection tool deployment can yield outsized national resilience benefits.
Why PW Consulting — and what you can access next
PW Consulting’s High Precision Photomask Market report combines a deterministic market model with scenario‑based stress testing and operational playbooks. We draw on supplier disclosures, equipment rollouts, material‑supply intelligence, and regulatory mapping to turn market signals into executable options. The full report includes the granular segment models, interactive dashboards, supplier scorecards, and contract language templates that procurement, engineering and strategy teams need to act fast in 2026.
To preserve the value of these strategic levers for paying subscribers and to drive informed engagements, this release follows a “preview” approach: we have presented the macro trajectory, structural dynamics, and high‑level recommendations here, while detailed segment‑level valuations, region‑by‑region capacity maps, and proprietary company scorecards are available in the complete report. Contact PW Consulting or visit our report page to access the full dataset, interactive tools, and a tailored briefing for your organisation.
For detailed analysis of this topic, please visit the official page: High Precision Photomask Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sudan Red Dye Market to Reach USD 250.44 Million by 2032, Expanding at a 4.15% CAGR
By PW Consulting, 2026-07-02
Sudan Red Dye Market — Strategic Briefing for 2026 Decision-Making
PW Consulting’s newest market study on the Sudan Red dye sector (base year 2025; historical 2020–2025; forecast 2026–2032) delivers a decision-ready synthesis for executives navigating a compact but strategically complex market. With a 2025 market size of approximately USD 188.4 Million and a modeled compound annual growth rate (CAGR) of 4.15% across the 2026–2032 forecast window, this sector exhibits steady expansion accompanied by episodic volatility driven by regulatory interventions, raw-material swings and concentrated supplier structure (CR3 ≈ 31.4%; CR5 ≈ 44.85%). This briefing outlines why the study is material to 2026 strategy while intentionally preserving the granular segmentation that drives our premium analytics—access to which is available through the full report.
Sudan Red Dye Market
What makes Sudan Red strategically important in 2026?
- Regulatory intensity is increasing: Multiple jurisdictions expanded detection and enforcement capacity in 2025–2026, materially raising compliance risk for producers, downstream formulators and trade partners.
- Market scale is modest but concentrated: Absolute market value is measured in the low hundreds of millions of USD, creating opportunities for disciplined consolidation, premiumization and niche specialization rather than mass-market scale plays.
- Channel divergence: The product’s applications bifurcate into regulated end-uses (analytical, research, industrial components) and consumer-facing uses that are subject to outright prohibition in many markets—creating differential margin and compliance profiles.
- Supply-chain exposure: Upstream feedstock dynamics (notably aniline-linked supply and pricing) can shift unit economics rapidly; tactical sourcing and hedging matter to near-term margins.
- Legal and reputational tail risk: Recent fines and mandatory testing protocols have raised the cost of market entry and the severity of post-market remediation.
Data-driven headlines you can act on
Our modelling projects a continuation of mid-single-digit annual growth from a 2025 base of USD 188.4 Million to an estimated market value above USD 197.7 Million in 2026, progressing toward roughly USD 250.4 Million by 2032 under the base forecast. The growth profile contains non-linear episodes tied to regulatory enforcement and episodic demand shifts in specialty analytical and industrial channels; these create windows for margin expansion for compliant, certified suppliers and, conversely, downside risk for players exposed to banned consumer applications.
Sudan Red Dye Market
Market concentration metrics in the study show that the top three and top five suppliers control a material share of the value pool—sufficient to influence pricing and quality benchmarks, yet low enough to leave room for differentiated entrants and consolidation plays.
Sudan Red Dye Market
Key regulatory developments shaping 2026 strategy
- Regulatory authorities expanded detection methods and enforcement protocols in late 2025, including a specific analytical method issued by an Asia-Pacific regulator for Sudan I–IV in cosmetics. That method is already being integrated into customs and post-market surveillance in several markets, increasing both detection probability and enforcement speed.
- Several major markets retain explicit prohibitions on Sudan dyes for consumer and food uses; enforcement ranges from import alerts and fines to mandatory recalls. This drive toward more systematic testing transforms a previously low-probability audit risk into a near-term operational certainty for exposed portfolios.
- Penalties and recall costs are no longer theoretical: recent enforcement actions included fines, product recalls and expanded inspection regimes that increased compliance costs for supply-chains and importers.
What the full report contains—practical, executable assets
- Proprietary market-model (2020–2032) with scenario toggles for regulatory stringency, raw-material price shocks, and substitution adoption.
- Supplier scorecards and a five-tier risk matrix covering regulatory exposure, quality certification, logistical resilience, and traceability (chain-of-custody templates included).
- Regulatory compliance maps and playbooks for key jurisdictions, incorporating recent testing protocols and enforcement case studies.
- Raw-material sensitivity analysis focused on aniline and other azo-dye precursors, plus suggested hedging and procurement strategies.
- Commercial playbooks: go-to-market options for defending industrial channels, monetizing specialty analytical standards, and controlled exit strategies from banned end-uses.
- M&A and partnership screening framework to identify high-value targets for consolidation or capability acquisition, with illustrative scorecards (strategic fit, regulatory hygiene, accretion/dilution tests).
- Operational checklists and a 90-day remediation plan for firms subject to sudden enforcement or recall scenarios.
Competitive landscape—strategic reads on named players
The study profiles incumbent and specialist suppliers to outline strategic moves that will matter in 2026. Below is a synthesis of opportunity and risk for representative firms based on public profiles and PW Consulting’s interviews.
- Anmol Colorants Global (India) — A large-scale manufacturer serving industrial applications. Strengths include pricing flexibility and production scale; vulnerabilities include exposure to reputational risk if product stewardship lapses. Strategic options: pursue compliance certifications, lock in long-term feedstock agreements, and selectively upgrade toward higher-margin, regulated analytical channels.
- RX Marine — Identified as a major manufacturer with broad distribution reach. For players with diverse channel exposure, the key strategic lever is to segregate product lines and document end-use restrictions rigorously to avoid cross-contamination of volumes destined for consumer markets.
- Nanologica (Sweden) — Positioned in analytical chemistry and life-science consumables; high-margin, compliance-driven demand supports premium positioning. Opportunities include expanding certified reference material offerings and partnerships with pharmaceutical and diagnostic players requiring traceable standards.
- Otto Chemie Pvt. Ltd. (India) — Specialist supply to microscopy and research markets with global logistics capability. Their risk profile is tied to export controls and country-level testing; strategic focus should be on documentation, batch-level certification and targeted market segmentation.
- John Hogg & Co Ltd (UK) — A specialty dyes supplier serving fuels, lubricants and greases. Their heritage in regulated industrial uses is an asset; competitive differentiation will increasingly come from audit-readiness, product stewardship and service-led offerings (e.g., testing-as-a-service).
- Sigma-Aldrich / MilliporeSigma (US) — Global leader in certified analytical standards and research chemicals. Strengths include recognized quality and distribution networks. For manufacturers facing consumer-market exclusions, licensed supply of certified standards represents a reliable corridor to sustain volumes at premium margins.
Across this mix, common strategic levers are clear: upgrade traceability and certification, pivot volumes away from banned consumer end-uses, and pursue higher-margin specialty channels where regulatory compliance is a barrier to entry.
Immediate actions for leaders planning 2026 deployment
- Conduct a rapid portfolio audit to identify any exposure to consumer-facing uses that are regulated or prohibited in key export markets; execute divest or remediation options within a 90–180 day window.
- Institute mandatory pre-shipment testing and chain-of-custody certification for all export batches. Integrate the latest regional testing protocols into vendor agreements to reduce import-complication risk.
- Lock in strategic feedstock contracts and model raw-material sensitivity under multiple price scenarios; consider vertical partnerships where aniline exposure is material to cost structure.
- Prioritize route-to-market and product differentiation in specialty analytical and industrial segments where compliance acts as a moat; develop service bundles (testing, certification, custom formulations) to lift margins.
- For potential acquirers: focus on targets with clean regulatory histories, demonstrable QA systems, and niche access to life-science or industrial channels; avoid trophy deals with latent consumer-market liabilities.
Closing—the decision-making value in the full study
For executives crafting strategy in 2026, the Sudan Red dye market represents a focused value pool where disciplined regulatory hygiene, selective premiumization and supply-chain certainty determine winners. PW Consulting’s full market report delivers the models, supplier analytics, regulatory playbooks and executable roadmaps required to convert market dynamics into defensible revenue and margin outcomes. The executive summary above is deliberately selective: the report’s granular segmentation, proprietary scenario outputs and transaction-ready diligence templates are available through our research portal for organizations ready to act.
Contact PW Consulting or visit our report page to request the full Sudan Red Dye Market report and the supporting toolkits that will make your 2026 choices both timely and durable.
For detailed analysis of this topic, please visit the official page: Sudan Red Dye Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


