



Category: market research
PW Consulting: Compressor Type Car Refrigerator Market Hits $212.5M in 2025, 14.5% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Cold Chain Revolution: Strategic Intelligence for the 2026 Compressor Type Car Refrigerator Market
The global transportation and mobile cooling landscape is undergoing a structural shift, driven by evolving consumer lifestyles, stringent environmental regulations, and rapid electrification across automotive and recreational sectors. For executives, investors, and product strategists, the compressor type car refrigerator market represents a high-growth intersection of thermal engineering and mobile mobility. This article previews the strategic horizons outlined in our latest comprehensive market research, designed to equip decision-makers with the foresight required to navigate the forecast period through 2032.
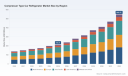
Drawing on a rigorous historical analysis spanning 2020 to 2025 and projecting forward to 2032, our research captures the velocity of this transformation. The market has demonstrated consistent resilience and expansion, with total revenues climbing from 138.75 million USD in 2020 to an estimated 212.5 million USD in the base year of 2025. This trajectory underscores a sustained adoption curve that is far from plateauing. As we look ahead, the forecast model indicates a robust compound annual growth rate of 14.5 percent, signaling that the industry is poised to scale significantly beyond its current baseline. By the close of the forecast window, the aggregate revenue landscape is expected to undergo a profound expansion, presenting both unprecedented opportunities and complex operational challenges for market participants.
However, macro-level growth figures alone do not constitute a winning strategy. The true value of this study lies in its granular dissection of the forces shaping competitive positioning, supply chain dynamics, and regional demand drivers. This preview offers a strategic teaser of the methodology and insights contained within the full report, emphasizing why accessing the complete intelligence framework is critical for 2026 decision-making.
Decoding the Growth Architecture: Beyond Aggregate Projections
Sustained market expansion is rarely uniform. It is the product of intersecting technological advancements, shifting application preferences, and geographically uneven regulatory adoption. The compressor type car refrigerator segment is no exception. Over the past half-decade, the industry has moved from niche automotive accessories to essential components in recreational vehicle ecosystems, commercial transport cooling, and high-performance outdoor mobility. This functional diversification has been accelerated by innovations in compressor miniaturization, improved energy efficiency, and the integration of advanced refrigerants that comply with tightening emissions standards.
Our analysis maps how these technological and application shifts are redistributing market share and value creation across different product architectures. While the broad category continues to grow, the allocation of demand across portable and built-in configurations reveals distinct usage patterns and consumer priorities. Portable units are capturing significant attention due to their flexibility and alignment with the growing mobility and outdoor recreation economy. Simultaneously, built-in solutions are seeing sustained integration in premium vehicle platforms and fixed RV installations, where reliability, space optimization, and continuous cooling performance command higher value propositions.
Similarly, application-level demand is being reconfigured by lifestyle evolution and commercial logistics requirements. Recreational vehicle deployments represent a major demand center, reflecting the broader global trend toward leisure travel and home-on-wheels lifestyles. Commercial and passenger vehicle applications form another substantial pillar, driven by fleet operators, transport companies, and passenger comfort mandates. A residual category of specialized use cases further diversifies the demand base, though it remains comparatively smaller in scale. Understanding the relative weight, growth pace, and strategic implications of these application streams is essential for manufacturers prioritizing product roadmaps and go-to-market strategies.
Regulatory Realignment and Supply Chain Pressures: The New Operating Environment
The competitive arena for compressor-based mobile refrigeration is no longer defined solely by performance metrics and price competition. Regulatory frameworks and raw material economics are actively reshaping cost structures, design specifications, and market entry barriers. A defining characteristic of the current cycle is the accelerated transition toward low-global-warming-potential refrigerants, with R1234YF now establishing itself as a standard across major compressor refrigerator models. This shift is not merely a technical specification; it is a direct response to emissions reduction mandates and evolving environmental compliance requirements that are reshaping product development timelines and component sourcing strategies.
Parallel regulatory pressures are emerging from energy efficiency mandates. Authorities in key markets, including the European Union and China, have instituted standards requiring substantially lower power consumption for new generations of compressor refrigerators. These directives force manufacturers to rethink thermal management architectures, optimize compressor cycles, and invest in next-generation control systems. For companies still relying on legacy designs, the compliance gap represents a material risk. For innovators, it offers a differentiation pathway that aligns sustainability with performance.
On the supply side, raw material volatility has introduced new cost management imperatives. Copper price fluctuations, exacerbated by import tariff dynamics in the United States, have directly impacted bill of materials costs for compressor windings and refrigeration tubing. These input cost pressures ripple through manufacturing margins and require strategic hedging, supplier diversification, and engineering efficiency improvements. Companies that treat supply chain resilience as a secondary concern will find themselves vulnerable to margin compression, while those that embed procurement agility into their product planning will protect profitability in an increasingly unpredictable materials environment.
Competitive Landscape and Strategic Positioning Dynamics
The market exhibits a moderately concentrated competitive structure, with a handful of established players commanding significant share and a broader field of regional and niche manufacturers competing on specialization, cost efficiency, and application-specific innovation. Concentration levels indicate that scale, brand recognition, and technological leadership remain powerful advantages, but they do not preclude agile entrants from capturing value in targeted segments. The presence of both globally recognized brands and regionally focused producers creates a multidimensional competitive matrix where differentiation is increasingly tied to refrigerant compatibility, energy performance, durability, and ecosystem integration.
Industry leaders are actively reinforcing their positions through product launches and catalog expansions that reflect the regulatory and performance trends shaping the market. Recent developments highlight how companies are aligning their innovation pipelines with the dual imperatives of compliance and efficiency. For example, the release of expanded compressor refrigerator catalogs featuring models with enhanced energy efficiency and next-generation refrigerant compatibility demonstrates how incumbents are leveraging portfolio breadth to address varying capacity requirements and vehicle integration needs. At the same time, the introduction of compact, high-performance portable units built around advanced micro compressors illustrates how manufacturers are targeting the demand for lightweight, versatile cooling solutions without sacrificing cooling power.
Regional and application-specific players are pursuing complementary strategies. Some focus on specialized DC compressor systems designed for trucks, recreational vehicles, and camping deployments, often with strong OEM partnership capabilities. Others concentrate on commercial vehicle and coach applications, where continuous operation, ruggedness, and fleet-level reliability are paramount. A further subset of manufacturers emphasizes off-road and outdoor use cases, integrating durable construction and lithium-compatible power options to serve demanding mobile environments. This fragmentation of strategic focus means that competitive advantage is rarely about being the largest player in every dimension; instead, it is about aligning product capabilities with the most attractive demand pockets while maintaining compliance readiness and supply chain flexibility.
What the Full Study Delivers: An Executive Toolkit for 2026 and Beyond
While the trends outlined above establish the strategic context, they only scratch the surface of the actionable intelligence required to make informed capital allocation, product development, and market entry decisions. The complete market research provides a multi-layered analytical architecture designed to convert high-level trends into executable strategy. At its core, the study delivers a detailed segmentation analysis that quantifies demand distribution across regions, product types, and application categories, enabling stakeholders to identify the highest-value opportunities and assess relative market saturation.
The report also constructs a comprehensive competitive profiling framework that goes beyond corporate descriptions to evaluate positioning, product portfolio strategy, recent development trajectories, and likely response patterns to regulatory and cost pressures. By mapping how leading companies are adapting their offerings and where gaps remain, the study helps manufacturers and investors anticipate competitor moves and identify whitespace for differentiation.
In addition to market sizing and competitive analysis, the research integrates a deep examination of market dynamics, including regulatory timelines, refrigerant transition pathways, energy efficiency mandates, and raw material cost drivers. These dynamics are analyzed not as isolated events but as interconnected forces that influence design cycles, sourcing strategies, pricing power, and regional competitiveness. The study further incorporates historical trend analysis to validate growth assumptions and provide a robust basis for forecasting, ensuring that projections are grounded in demonstrated market behavior rather than speculative extrapolation.
Operational and strategic utility is enhanced through coverage of demand drivers, constraints, and emerging use cases. The report explores how lifestyle shifts, vehicle electrification, fleet modernization, and outdoor recreation growth are reshaping end-user expectations. It also addresses barriers to adoption, including cost sensitivity, technical integration complexity, and compliance-related redesign requirements, offering a balanced view of where growth is most sustainable and where caution is warranted.
Compressor Type Car Refrigerator Market
Why This Intelligence Matters Now: Strategic Imperatives for 2026 Decision-Makers
The forecast window ahead will reward organizations that act on precise, forward-looking intelligence rather than reactive assumptions. With a projected growth trajectory that points toward substantial market expansion by the early 2030s, companies must decide where to invest, how to configure product portfolios, and which compliance and cost strategies will preserve margins. The temperature of competition is rising, and the window for establishing a differentiated position is narrowing as regulatory standards tighten and supplier cost structures evolve.
Access to the full report enables leadership teams to move from awareness to action. It supports scenario planning around refrigerant adoption, energy efficiency compliance, and raw material cost fluctuations. It informs portfolio prioritization by clarifying which product architectures and application segments offer the most compelling growth-to-risk ratios. It also strengthens competitive preparedness by revealing how incumbents and challengers are shaping their strategies in response to the same macro forces.
For investors and strategic partners, the study provides the evidentiary foundation needed to assess market attractiveness, competitive durability, and the scalability of participating firms. For manufacturers, it offers a roadmap for aligning engineering investments, supplier negotiations, and regional rollout plans with the most credible demand outlook available. In an environment where regulatory, technological, and economic variables are shifting simultaneously, such integrated insight is not optional; it is a strategic necessity.
Worldwide Miniature Refrigeration Compressor Market
Conclusion: Act on Intelligence, Not Assumption
The compressor type car refrigerator market is entering a phase of accelerated transformation, shaped by regulatory mandates, efficiency demands, material cost pressures, and expanding application diversity. The broad growth trajectory is clear, but the strategic winners will be those who understand the underlying structure of that growth and position themselves accordingly. This market research has been designed to deliver exactly that level of clarity, combining historical validation, forward-looking forecasting, competitive mapping, and dynamic risk analysis into a single decision-ready framework.
To fully leverage these insights for 2026 planning and beyond, stakeholders are encouraged to access the complete report, where detailed segment quantification, competitive profiles, regulatory impact assessments, and actionable strategic recommendations are presented in full. The macro currents are strong, but the precise navigation required to capitalize on them demands the depth and granularity that only the full study provides.
For detailed analysis of this topic, please visit the official page: Compressor Type Car Refrigerator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Emergency Power System Market Reaches $18.5M in 2025, Projected 6.1% CAGR Through 2032
By PW Consulting, 2026-09-16
Strategic Resilience: Navigating the Emergency Power System Market Through 2032
In an era where operational continuity is non-negotiable, the Emergency Power System Market stands as a critical infrastructure pillar for industries ranging from telecommunications to defense. As organizations face increasing volatility in grid stability and rising demands for uninterrupted power, the strategic allocation of capital toward emergency power solutions has shifted from a contingency plan to a core component of long-term business resilience. This article outlines the strategic landscape of the market, drawing on comprehensive research that tracks performance from 2020 through the forecast horizon of 2032.
For decision-makers operating in 2026, understanding the trajectory of this market is not merely about observing growth figures; it is about anticipating supply chain shifts, regulatory pressures, and the competitive maneuvers of key incumbents. The data indicates a steady upward trajectory, reflecting a global consensus on the necessity of robust backup power. Our latest market research provides the granular intelligence required to navigate this complex environment, offering a roadmap for stakeholders who must balance immediate procurement needs with long-term strategic positioning.
Emergency Power System Market
Market Trajectory: A Decade of Expansion
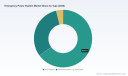
The market has demonstrated consistent resilience and growth over the past half-decade. Valued at approximately 13.76 billion USD in 2020, the sector has expanded steadily, reaching an estimated 18.5 billion USD by 2025. This historical performance underscores a compound annual growth rate that signals sustained investor and industrial confidence. Looking forward, the forecast period from 2026 to 2032 projects continued expansion, with revenue expected to climb toward 28.0 billion USD by the end of the forecast window.
This growth is not linear but is driven by specific macroeconomic and technological catalysts. The transition toward a 6.1 percent CAGR over the forecast period suggests that while the market is maturing, it remains far from saturation. Key drivers include the exponential increase in data center construction, stricter regulatory compliance regarding safety and continuity in industrial sectors, and the ongoing modernization of aging infrastructure in developed regions. For enterprise leaders, this trajectory implies that delaying investment in emergency power capabilities may result in higher costs and supply chain constraints later in the decade.
Segmentation Dynamics and Strategic Priorities
Understanding where value is generated within the Emergency Power System Market is crucial for targeted investment. The market is broadly categorized by type, application, and region, each presenting unique opportunities and challenges.
Technology and Application Drivers
In terms of technology, UPS Systems continue to dominate the landscape, reflecting the critical need for immediate, clean power protection for sensitive electronic infrastructure. Generator Systems remain a vital component, particularly for long-duration backup needs in industrial and commercial settings. The interplay between these technologies is evolving, with hybrid solutions gaining traction as organizations seek to optimize efficiency and reliability.
Application-wise, the Industrial sector represents the largest share of demand, driven by manufacturing plants that cannot afford production halts. Closely following is the demand from Data Centre and Telecommunication sectors, which is accelerating due to the digital transformation initiatives and the proliferation of cloud computing. Government and Defense applications also constitute a significant portion, where reliability is paramount and often dictated by stringent procurement standards. Commercial Construction Building projects are increasingly integrating emergency power systems at the design phase, influenced by green building codes and risk management protocols.
Regional dynamics further complicate the landscape. While established markets in North America and Europe maintain substantial share due to mature infrastructure and high replacement cycles, the Asia Pacific region is witnessing rapid adoption rates fueled by industrialization and urbanization. Emerging regions in Latin America and the Mideast and Africa are also beginning to prioritize emergency power infrastructure, albeit at a different pace, creating new avenues for expansion for companies with global reach.
Competitive Landscape and Recent Industry Movements
The market is characterized by a moderately concentrated competitive environment. The top three players hold a combined market share of approximately 25.4 percent, while the top five account for roughly 32.6 percent. This structure suggests that while dominance is held by major incumbents, there is sufficient space for specialized players and regional leaders to thrive.
Key Incumbents and Strategic Posturing
Several global corporations define the competitive edge in this sector. Eaton Corporation plc remains a central figure, offering leading backup power UPS and critical power solutions for data centers and enterprise applications. Their recent activity underscores a commitment to expanding capacity; in April 2026, Eaton broke ground on a new 50 million USD manufacturing facility in Henrico County dedicated to producing critical power management equipment. This move signals a long-term bet on infrastructure growth and supply chain localization.
Cummins Inc. continues to strengthen its position as a provider of robust power generation solutions. With a strong North American and international reach, Cummins reported record performance in its Power Systems segment in May 2026, citing increased demand for data center backup power and power generation solutions. Their Power Systems segment sales reached 2.0 billion USD, reflecting a 19 percent year-over-year increase, highlighting the surging demand for industrial-grade backup capabilities.
Generac Power Systems is another pivotal player, known for leading in home standby and commercial standby generators. In April 2026, Generac purchased a new facility in Sussex, WI to expand manufacturing of commercial and industrial backup power solutions, specifically targeting data centers and large-scale applications. This capacity expansion aligns with the broader market trend of scaling up to meet larger infrastructure requirements.
Other notable entities include Schneider Electric SE, which offers Smart-UPS and APC battery backup systems for IT and critical infrastructure protection, and Vertiv Holdings Co., which manufactures Liebert UPS systems and integrated critical power solutions for data centers. Kohler Co. specializes in durable commercial and industrial standby generators, while Atlas Copco provides efficient modular generators for data center and industrial emergency standby power. CyberPower Systems designs professional-grade UPS systems for IT professionals, and Myers Emergency Power Systems, LLC focuses on advanced backup power solutions including battery energy storage systems. Additionally, legacy brands like Powerware, now integrated into Eaton's portfolio, continue to influence the network and data center UPS solutions space. Firman Power Equipment also maintains a presence with portable generators for home and commercial emergency power needs.
Industry Dynamics and Operational Considerations
Navigating this market requires an understanding of the underlying dynamics that influence pricing, availability, and technology adoption. Regulatory frameworks play a significant role; for instance, as of December 2025, Eaton maintained the broadest range of ATS available in the critical power market for emergency power systems, setting a benchmark for compliance and interoperability that competitors must match.
Infrastructure development is another critical factor. The aforementioned manufacturing expansions by key players indicate a response to supply chain pressures and a desire to reduce lead times. However, labor costs and raw material availability remain variables that can impact production timelines and final pricing structures. The dependency on specific raw materials for generator and UPS production means that fluctuations in commodity markets can ripple through to the end user.
Furthermore, customer concentration is a notable aspect of the supply chain. As of December 2025, a significant portion of sales in the electrical segments was made to a concentrated group of large customers. This dynamic suggests that strategic partnerships and long-term contracts with major industrial or utility clients are essential for vendors seeking stability and volume growth.
Strategic Value for 2026 Decision-Makers
Why does this level of detail matter for your 2026 strategy? In a market projected to grow steadily but with complex segmentation and competitive maneuvering, generic market intelligence is insufficient. Decision-makers need to know not just the size of the market, but the velocity of specific segments, the capacity constraints of suppliers, and the strategic intent of competitors.
Our comprehensive research report goes beyond these high-level overviews. It provides detailed breakdowns of revenue streams by specific regions and application verticals, allowing you to benchmark your own performance against market averages. It analyzes the supply chain vulnerabilities that could impact procurement in the next 12 to 24 months. It also offers a deep dive into the financial health and strategic roadmaps of the key companies mentioned, helping you anticipate M&A activity or technology shifts that could alter the competitive landscape.
For investors, the report highlights the valuation implications of the 6.1 percent CAGR and the concentration risks associated with the top five players. For procurement managers, it identifies potential bottlenecks in UPS versus Generator supply chains. For strategists, it maps the expansion trajectories of players like Eaton and Cummins to predict where new capacity—and therefore potential market entry points—will emerge.
Worldwide Backup Power Market
Conclusion: Securing Power, Securing Future
The Emergency Power System Market is poised for significant growth through 2032, driven by the indispensable need for continuity in a digital and industrialized world. The data from 2020 to 2025 establishes a strong foundation, while the forecast period suggests that the demand curve will steepen rather than flatten. Companies that proactively align their strategies with these trends—whether through capacity investment, technology adoption, or strategic partnerships—will be better positioned to manage risk and capture value.
However, the nuances of regional performance, specific application growth rates, and the detailed financial metrics of competitors are critical pieces of the puzzle that require further examination. To access the full depth of this analysis, including the specific segmentation splits, detailed competitor profiles, and actionable recommendations tailored to your organization's needs, we invite you to explore the complete market research report. In a landscape where power equates to continuity, having the right intelligence is the first step toward ensuring resilience.
For detailed analysis of this topic, please visit the official page: Emergency Power System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the Steel Round Bars Market: Strategic Intelligence for 2026 Decision-Makers
The global steel round bars market stands as a critical backbone for industrial infrastructure, yet its complexity often obscures clear navigational paths for executives. As we move deeper into 2026, understanding the interplay between historical performance and future trajectory is no longer optional—it is essential for maintaining competitive advantage. PW Consulting presents this comprehensive market study to decode these dynamics, offering a granular view of an industry projected to evolve significantly over the next decade.
Market intelligence in this sector must go beyond surface-level trends. Stakeholders require precise data on valuation, growth inhibitors, and competitive maneuvering to allocate capital effectively. This article serves as a strategic preview of our latest deep-dive analysis, outlining the macroeconomic contours and the specific operational insights contained within the full report. The goal is to equip leadership teams with the context needed to validate internal assumptions against external market realities.
Market Trajectory and Valuation Horizons
The financial scale of the steel round bars industry underscores its significance in the global materials landscape. Based on historical data spanning from 2020 through the base year of 2025, the market has demonstrated substantial resilience and expansion. The total revenue generated by this sector has grown from approximately 180.0 USD Billion in 2020 to an estimated 230.0 USD Billion in 2025. This upward trajectory reflects sustained demand across core industrial verticals despite fluctuating economic conditions.
Looking forward, the forecast period from 2026 to 2032 suggests continued growth, with the market size projected to reach 247.98 USD Billion in 2026 alone. The analysis indicates a Compound Annual Growth Rate (CAGR) of 5.1 percent over the forecast horizon, signaling steady consolidation and expansion. By the end of the forecast period in 2032, valuations are expected to climb significantly higher, reflecting long-term confidence in infrastructure development and manufacturing output.
However, raw valuation numbers only tell part of the story. The nuances of year-over-year performance, such as the slight contraction observed in 2024 before recovering in 2025, highlight the volatility inherent in commodity-driven markets. Our study dissects these fluctuations to identify whether they represent temporary supply chain disruptions or structural shifts in demand. Understanding these patterns allows procurement managers and investors to time their entries and exits with greater precision.
Industry Dynamics and Material Flows
Current market dynamics are being reshaped by a confluence of regulatory changes, raw material cost pressures, and logistical adjustments. Recent developments in early 2026 illustrate the volatility that buyers must account for. In April 2026, major producers such as Nucor Bar Mill Group announced price increases for commercial long products and certain large structural sections. Similarly, Gerdau Long Steel North America implemented merchant bar and structural section price increases around the same period. These moves signal upstream pressure on pricing structures that will likely ripple through the supply chain.
Logistical costs are also under scrutiny. In March 2026, Norfolk Southern issued a public tariff announcement adjusting market-based rates for iron, steel, and scrap metal commodities, effective July 1, 2026. Such regulatory adjustments directly impact the landed cost of materials, influencing regional competitiveness and margin structures for downstream manufacturers.
On the raw material front, market intelligence indicates shifting cost bases. As of May 2026, iron ore prices reached levels around 114.7 USD per ton CFR, representing a month-over-month increase. Concurrently, billet prices rose by 10 to 20 USD per ton in regional markets during May 2026. These input cost hikes challenge manufacturers to maintain price stability without eroding profitability. Conversely, long-term forecasts from institutions like the World Bank suggest iron ore prices may decline further in 2026–27, potentially falling below 2019 levels due to expanding supply. This divergence between short-term spikes and long-term outlooks creates a complex environment for hedging strategies.
Furthermore, international trade policies are tightening. Multiple countries, including the EU and Uzbekistan, have introduced export duties or quotas on ferrous scrap in 2025–2026. These restrictions alter the availability of recycled raw materials, impacting electric arc furnace operations and cost structures for producers reliant on scrap feedstocks. Our report details how these regulatory shifts are segmenting regional markets and altering competitive advantages for key players.
Competitive Landscape Overview
The steel round bars market features a diverse mix of global giants and specialized regional distributors, creating a multifaceted competitive environment. Consolidation metrics indicate a moderately concentrated market, with the top three companies holding approximately 38.5 percent of the share, while the top five account for 45.2 percent. This structure suggests that while large players drive significant volume, there remains ample room for niche operators to compete on service, specification, and regional availability.
Leading global entities such as Nucor Corporation and ArcelorMittal continue to anchor the market. Nucor, based in Charlotte, North Carolina, produces and supplies Merchant Bar Quality round steel bars using electric arc furnace technology with high recycled content. ArcelorMittal, headquartered in Luxembourg, operates as a global producer across carbon, stainless, and alloy grades for construction, automotive, and machinery sectors. Their strategies often set the tone for pricing and capacity utilization across regions.
In Asia, major manufacturers like Nippon Steel Corporation and Tata Steel play pivotal roles. Nippon Steel focuses on stainless and carbon round steel bars with an emphasis on high-strength grades for industrial use. Tata Steel, based in Jamshedpur, India, supplies premium round steel bars including specialized series with enhanced machinability for automotive and structural applications. POSCO, from Seoul, South Korea, also supplies round steel bars from carbon to high-alloy grades for global markets, reinforcing the region's manufacturing dominance.
European producers maintain strong positions in specialty segments. Thyssenkrupp AG provides stainless and alloy round steel bars through an integrated production and distribution network, while Outokumpu Oyj remains a leading producer of stainless steel round bars for corrosion-resistant applications in chemical, energy, and food processing. SSAB AB supplies high-strength round steel bars specifically for heavy equipment and construction, catering to demanding engineering requirements.
The Americas host a robust network of distributors and specialized suppliers. Eaton Steel Bar Company in Cleveland specializes in hot-rolled and cold-drawn round steel bars for defense and heavy industry. Gerdau S.A., based in Sao Paulo, manufactures merchant bar quality round steel bars for structural and industrial uses. US-based entities such as Jade Sterling Steel, Chatham Steel, Ohio Bar & Metal, North Shore Steel, Summit Steel Corp, and TW Metals provide critical distribution and processing services, often catering to specific ASTM specifications or defense-related needs. Smaller specialized producers like Virwadia Steels and Vishwa Stainless Pvt. Ltd. in India further diversify the supply base for stainless grades.
Report Scope and Functional Analysis
The complete PW Consulting market study offers significantly more depth than the high-level overview provided here. It delivers a navigational map of the steel round bars ecosystem, breaking down performance metrics without exposing every sensitive figure in this public summary. The report is engineered for practical application by strategy teams, procurement officers, and investors who need actionable intelligence rather than generic trends.
Structural Steel Market
Key components of the full document include a detailed segmentation analysis that isolates performance drivers across different material types and end-use industries. The study examines how specific grade requirements influence supply chain decisions and pricing power. It also provides a comprehensive regional breakdown, evaluating how local industrial policies, infrastructure spending, and manufacturing capacity affect market penetration and growth potential in different geographies.
Segmentation Drivers and Technology Trends
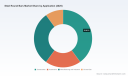
Understanding the split between material types is crucial for sourcing strategies. The market encompasses carbon steel, alloy steel, and stainless steel round bars, each serving distinct functional requirements. Carbon steel remains a workhorse for general structural and industrial applications, while alloy steel offers enhanced mechanical properties for specialized machinery. Stainless steel caters to environments requiring corrosion resistance, such as chemical processing and food manufacturing.
Technological advancements in production methods are also reshaping the landscape. The shift toward electric arc furnace technology, as utilized by producers like Nucor, emphasizes sustainability through high recycled content. This aligns with broader environmental, social, and governance (ESG) mandates that are increasingly influencing procurement decisions. The report analyzes how green manufacturing initiatives are impacting cost structures and customer preference patterns across major consuming sectors.
Regional Nuances and Application Sectors
Regional dynamics vary significantly due to local infrastructure projects, automotive production rates, and energy sector activities. The study provides insights into how regions like North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa are performing relative to global averages. It examines the flow of materials across borders and how tariffs, such as those recently adjusted by Norfolk Southern, impact inland logistics and final delivery costs.
Application-wise, the market serves construction, automotive, manufacturing and industrial, and oil and gas sectors. Each vertical presents unique demand cycles and specification requirements. Construction demand is often tied to government infrastructure spending, while automotive and manufacturing sectors are more sensitive to economic cycles and consumer demand. The oil and gas segment relies heavily on high-grade materials capable of withstanding extreme conditions. The full report delineates how these sectors interact with supply constraints and price volatility.
Strategic Recommendations for Stakeholders
Given the projected market size and growth rate, stakeholders must adopt proactive strategies rather than reactive measures. Procurement teams should consider hedging against raw material price volatility, especially in light of recent billet and iron ore price movements. Diversifying supplier bases across different regions can mitigate risks associated with localized trade restrictions or logistical bottlenecks.
For investors and competitors, monitoring the pricing actions of major players like Nucor and Gerdau provides early signals of margin shifts. Understanding the concentration of market share among top players helps in assessing potential M&A opportunities or identifying vulnerable niche segments. The report includes scenario planning tools to help organizations model the impact of varying input costs and demand fluctuations on their bottom lines.
Steel Round Bars Market
Access to the complete dataset and proprietary analysis models is available through our full market research document. This resource provides the detailed numerical breakdowns, competitor profiling, and risk assessment frameworks necessary to make informed strategic decisions.
The steel round bars market offers substantial opportunities for those equipped with the right intelligence. By leveraging detailed insights on growth rates, competitive moves, and material dynamics, organizations can position themselves to capitalize on the projected expansion through 2032. We invite you to explore the full report to unlock the specific data points and strategic recommendations tailored to your operational needs.
For detailed analysis of this topic, please visit the official page: Steel Round Bars Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Reclaimer Market Hits $630M in 2025, Projects 5.8% CAGR to $975M by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for 2026: Why the Reclaimer Market Demands Executive Attention
As industrial infrastructure enters a phase of accelerated renewal, the reclaimers market has emerged as a critical lever for operational resilience. PW Consulting’s newly released Reclaimer Market research provides a comprehensive, forward-looking intelligence framework designed specifically for enterprise decision-makers navigating 2026 and beyond. This report is not a retrospective data compilation; it is a strategic navigation tool that connects capital allocation, technology adoption, and competitive positioning to measurable market trajectories. For executives, procurement leaders, and infrastructure strategists, the research delivers a clear line of sight from historical performance to the forecasted landscape that will shape procurement, partnership, and expansion decisions throughout the decade.
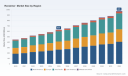
The baseline data establishes a market with sustained upward momentum. In 2020, the global market stood at 450.0 million USD, progressing to 475.47 million USD in 2021, 523.06 million USD in 2022, 551.32 million USD in 2023, 585.73 million USD in 2024, and reaching 630.0 million USD in the 2025 base year. This consistent expansion reflects deepening integration of reclaiming equipment across bulk material handling, road rehabilitation, and heavy industrial infrastructure. From 2026 through 2032, the market is projected to follow a calculated growth trajectory, with 2026 opening at 654.65 million USD, advancing through 713.33 million USD in 2027, 758.88 million USD in 2028, 803.36 million USD in 2029, 858.19 million USD in 2030, 884.14 million USD in 2031, and peaking at 975.0 million USD in 2032. The compound annual growth rate across the forecast period is evaluated at 5.8 percent, a figure that signals durable demand expansion rather than speculative volatility. For strategy teams, this trajectory translates into a predictable window for capital planning, vendor evaluation, and technology readiness investments.
What separates this research from conventional market summaries is its operational emphasis. The study maps procurement pathways, deployment considerations, and strategic trade-offs that determine whether capital is locked into legacy configurations or aligned with next-generation efficiency standards. Readers will find structured analysis of equipment architectures, application-specific deployment logic, and regional adoption patterns that influence total cost of ownership. The report is built to answer the questions that surface in boardrooms and engineering reviews: which equipment profiles match specific throughput requirements, where modernization thresholds create the strongest return, and how procurement timing interacts with supply chain and labor dynamics. Instead of leaving executives to extrapolate from fragmented data points, the research consolidates the decision variables into a single strategic framework.
The competitive environment demands equally rigorous scrutiny. The report profiles a concentrated field of established manufacturers whose capabilities set the operational benchmarks for the market. FLSmidth & Co. A/S, headquartered in Copenhagen, Denmark, specializes in bucket wheel and scraper reclaimers with advanced automation and digital monitoring for bulk material handling in mining, cement, and power sectors. thyssenkrupp Industrial Solutions, based in Essen, Germany, offers boom bucket wheel stacker-reclaimers and integrated stockyard systems, with over 328 units installed globally since 1970. Metso Corporation, operating from Espoo, Finland, provides bucket wheel stacker reclaimers and repairs and upgrades with automation features for high-throughput stockyard operations. TAKRAF GmbH in Leipzig, Germany manufactures dual-purpose stacker-reclaimers and bucket wheel reclaimers for high-capacity applications up to 10,000 t/h. Kawasaki Heavy Industries, Ltd., headquartered in Kawasaki, Japan, develops gantry-crane-derived stacker-reclaimers for ironworks, power plants, ports, and mines, drawing on comprehensive material handling expertise. NHI Global, based in Nanjing, China, supplies circular overpile stacker reclaimers and integrated stacking and reclaiming systems for bulk materials. Caterpillar Inc., from Irving, Texas, USA, offers road reclaimers and related machinery for asphalt stabilization and bulk material processing. Liebherr Group, headquartered in Biberach an der Riss, Germany, provides high-capacity stacker-reclaimer models with enhanced handling efficiency for large-scale bulk terminals. BEUMER Group, based in Beckum, Germany, delivers bucket wheel reclaimers and circular stacker-reclaimers for coke, anthracite, and other bulk materials. Bruks Siwertell, from Stockholm, Sweden, focuses on fully automated stacker reclaimers and slew bearing replacements for bulk material operations. Bedeschi S.p.A., headquartered in Milan, Italy, manufactures bucket wheel stacker-reclaimers for port and bulk material handling with commissioning and modernization services. Richmond Engineering Works, L.L.C., based in Richmond, Virginia, USA, supplies stacker reclaimers for port authorities and bulk handling facilities. This roster illustrates a market where engineering heritage, regional reach, and automation maturity intersect, and where vendor selection directly influences long-term performance and service availability.
Recent commercial activity further clarifies how the competitive field is moving. In February 2025, Metso Corporation was awarded an order to provide repairs and upgrades for a bucket-wheel stacker reclaimer at a customer stockyard operation in Africa, underscoring the sustained value of lifecycle support and modernization in established installations. In September 2025, Bruks Siwertell secured a turn-key project to replace a critical slew bearing on a fully automated stacker reclaimer for a U.S. operator, reflecting the growing importance of precision component replacement in maintaining uptime across automated systems. In May 2025, Bedeschi S.p.A. participated in the WAMPEX Exhibition in Accra, Ghana, and the company is scheduled to exhibit again at WAMPEX 2026 in Accra, Ghana, from 3 to 5 June 2026, signaling continued engagement with port, bulk handling, and infrastructure procurement networks in Africa. In December 2024, Richmond Engineering Works, L.L.C. was awarded a major contract by a U.S. port authority for the production of two new stacker reclaimers, reinforcing the ongoing demand for purpose-built equipment in high-capacity terminal operations. Together, these developments point to a market where new equipment orders, lifecycle upgrades, and component replacement programs are all active revenue channels, and where strategic sourcing decisions must account for both initial capital outlay and long-term service continuity.
Beyond competitive positioning, the research integrates the operational dynamics that are reshaping procurement and deployment logic. Material specifications remain a decisive factor in equipment durability and maintenance planning. Bucket wheel components rely on high tensile steel plates, such as SAILMA 350HI plates, alongside wear-resistant liners such as Hardox 400, which directly influence wear profiles, replacement intervals, and lifecycle cost modeling. Regulatory expectations are also evolving. EPA-Certified Refrigerant Reclaimers require specific certification standards for equipment used in refrigerant recovery, adding a compliance layer that affects selection criteria in relevant applications. Infrastructure design continues to define performance boundaries, as stockyard systems for bulk materials rely on rail-mounted and portal designs to handle materials including coal, iron ore pellets, and coke, shaping layout planning and throughput assumptions. Labor dynamics introduce another strategic variable, since heavy equipment operations in mining and ports face labor shortages for stacker reclaimer operators, increasing the value proposition of automation and reduced crew dependency. Energy considerations are equally relevant, as modern stacker-reclaimers incorporate automation and digital monitoring to reduce energy consumption in bulk handling, linking sustainability goals with operating cost reduction. The report synthesizes these forces so that decision-makers can weigh material durability, compliance requirements, labor availability, and energy performance as interconnected variables rather than isolated concerns.
Reclaimer Market
Concentration data provides additional strategic context for competitive and procurement planning. The market structure reflects meaningful consolidation among leading suppliers, with the top three firms accounting for approximately 48 percent of market share and the top five firms representing roughly 55 percent. This concentration pattern has practical implications for sourcing strategy, negotiation leverage, and supply continuity. For enterprises evaluating long-term partnerships, the research uses this concentration environment to frame questions about vendor reliability, service coverage, product roadmap alignment, and post-sales support capacity. Rather than treating supplier selection as a purely price-driven exercise, the analysis connects market structure to operational risk management and strategic resilience.
The segmentation architecture is designed to clarify where investment logic diverges across equipment families and deployment contexts. The study examines mechanical road reclaimers, hydraulic road reclaimers, and other equipment categories, connecting performance characteristics to application environments and total cost of ownership. It also maps demand across road construction, airports, wharves, public engineering, mining, oil, agriculture, and other end-use settings, helping readers understand how throughput requirements, environmental conditions, and operational cadence influence equipment choice. This structure is particularly valuable for organizations that operate across multiple sectors or are evaluating diversification, because it reveals where equipment standards overlap and where application-specific customization justifies differentiated procurement strategies.
Worldwide Reformer Unit Market
For 2026 planning cycles, the report’s strategic value lies in its ability to convert market signals into actionable decision paths. Executives can use the research to align capital expenditure timing with the forecasted growth curve, prioritize automation and monitoring investments where labor constraints and energy efficiency gains are most pronounced, and evaluate vendor alternatives against concentration-driven supply realities. Engineering and procurement teams can apply the segmentation and dynamics analysis to refine specification sheets, reduce lifecycle risk, and build service agreements that protect uptime in demanding operating environments. Portfolio and expansion planners can use the regional and application mappings to identify where demand intensity and infrastructure renewal cycles create the strongest entry or growth opportunities. The research is structured to support all of these use cases without forcing every organization into a single template.
Because the full study contains proprietary segmentation detail, application-level deployment logic, regional adoption nuance, and granular vendor comparison frameworks, the complete intelligence package is reserved for readers who require decision-grade depth. The teaser presented here demonstrates the analytical rigor, scope, and practical orientation of the research, but the underlying breakdowns, scenario-based procurement guidance, and comprehensive market structure analysis are developed for engaged stakeholders ready to convert insight into execution. To access the complete Reclaimer Market research, including the full segmentation architecture, competitive benchmarking detail, and forecast methodology designed for 2026 strategy sessions, please visit the source page and secure the complete report package.
For detailed analysis of this topic, please visit the official page: Reclaimer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DJ Software Market Set to Hit $219.75M by 2032, Growing at 5.25% CAGR
By PW Consulting, 2026-09-16
Navigating the Digital Turntable: Strategic Intelligence for the DJ Software Market (2026-2032)
Executive Summary: The Rhythm of Change
The global DJ Software Market is undergoing a transformative phase, driven by the convergence of artificial intelligence, streaming integration, and evolving live performance demands. For enterprises operating within the music technology sector, understanding these shifts is not merely an academic exercise but a critical component of strategic planning. Our latest comprehensive market study offers a granular look at the revenue trajectories, competitive dynamics, and technological adoption curves defining this landscape through 2032.
This introduction serves as a strategic overview, highlighting the macro-economic indicators and structural shifts identified in our full report. While specific segmentation data is reserved for the complete intelligence package, the broader trends indicate a steady expansion fueled by professional adoption and consumer-grade innovation. Decision-makers requiring precise forecasts for investment, product development, or market entry should consider this document a precursor to the detailed financial models and competitive benchmarking available in the full submission.
Market Trajectory: A Decade of Expansion
The financial architecture of the DJ Software Market demonstrates resilience and consistent growth. Analyzing the data from historical baselines through the forecast horizon reveals a compound annual growth rate that underscores the sector's maturity. The market valuation has progressed from a base of approximately 120.5 million USD in 2020 to an estimated 155.75 million USD in 2025. This historical performance sets a robust foundation for the forecast period extending to 2032.
Projecting forward, the revenue stream is expected to climb to 162.22 million USD in 2026 and continue its ascent toward 219.75 million USD by the end of the forecast window. This trajectory translates to a CAGR of 5.25 percent, signaling steady demand rather than volatile spikes. For stakeholders, this consistency suggests a market where long-term infrastructure investments can yield reliable returns. However, realizing these returns requires an understanding of where the revenue is generated and how value is captured across different user segments.
It is crucial to note that while the top-line figures provide a health check, the underlying drivers vary significantly across use cases and geographies. The full report dissects these variations, offering a multi-dimensional view that goes beyond aggregate revenue to explore the specific engines of growth within the ecosystem.
Industry Dynamics and Technology Drivers
Several key technological and operational factors are reshaping the value proposition of DJ software. These dynamics are not just features; they are becoming table stakes for market participation.
-
Hardware Compatibility and Ecosystem Lock-in: Professional DJ software platforms now support over 100 controllers and mixers from major manufacturers such as Pioneer DJ, AlphaTheta, and Allen & Heath. This broad compatibility ensures that software remains agnostic enough to attract a wide user base while deeply integrating with specific hardware ecosystems to drive loyalty.
-
Streaming Integration: The integration of direct streaming services like Apple Music and Spotify into DJ software represents a paradigm shift. It allows for seamless library management and access to millions of tracks without local storage constraints, fundamentally changing how DJs prepare for live sets and manage digital assets.
-
AI and Computational Creativity: Advanced software suites are increasingly incorporating AI for stem separation, harmonic mixing, and automix functions. These features enhance real-time performance capabilities and lower the barrier to entry for complex mixing techniques, appealing to both professionals seeking efficiency and amateurs seeking polish.
-
Infrastructure Requirements: As features become more computationally intensive, the demand for high-performance hardware rises. Current sector analysis indicates that optimal operation requires laptops or desktops with minimum 16GB RAM and fast processors, creating a secondary market effect that influences hardware partnerships and consumer upgrade cycles.
-
Cross-Platform Ubiquity: Leading solutions are no longer confined to desktop environments. Availability across macOS, Windows, iOS, Android, and even Vision Pro ensures that DJs can mix and perform seamlessly across devices, blurring the lines between practice, production, and live execution.
These drivers collectively expand the total addressable market by lowering technical barriers and enhancing the utility of the software in various contexts, from private mixing to large-scale event production.
Competitive Landscape: Architects of the Digital Sound
The market is characterized by a moderately concentrated competitive environment. The top three companies hold a combined market share of 41.3 percent, while the top five players extend their influence to 56.7 percent. This concentration suggests that while there is room for innovation and niche players, the bulk of market value is contested by established entities with robust ecosystems.
DJ Software Market
Our analysis profiles key incumbents who are defining the standard of care for DJ software:
-
Serato Limited (Auckland, New Zealand): Known for Serato DJ Pro, a professional platform emphasizing cloud streaming integration, stem separation, and broad hardware compatibility. Their recent update released in May 2026 expanded support for older Pioneer DJ mixers, demonstrating a commitment to legacy hardware longevity.
-
AlphaTheta Corporation (Japan): A pivotal player through its Pioneer DJ software ecosystem, specifically Rekordbox. They focus on library management, CDJ compatibility, and streaming integrations. In 2026, AlphaTheta has been particularly active, introducing the DJM-V5 mixer and releasing firmware updates for the OPUS-QUAD standalone system. Their acquisition of DJ Monitor's technology in May 2026 further strengthens their KUVO capabilities, signaling a strategic push into advanced tracking and interaction technologies.
-
Native Instruments GmbH (Berlin, Germany): With Traktor, they offer a blend of DJ and music production software. Their strategy includes stems, hardware integration, and entry-level variants like Traktor Play, catering to a spectrum from hobbyists to touring professionals.
-
Algoriddim GmbH (München, Germany): Creators of djay Pro, an award-winning solution recognized for real-time effects, multi-platform support, and AI-assisted mixing. Their focus on cross-platform accessibility aligns with the industry trend toward device agnosticism.
-
inMusic Brands Inc. (Cumberland, United States): Through the Engine DJ ecosystem, they provide desktop library tools and controller support tailored for professional DJing, leveraging their broader portfolio of music hardware brands.
-
Atomix Productions (Dubai, UAE): VirtualDJ remains a long-standing contender with a massive library and streaming features, maintaining relevance through continuous updates and a strong user community.
-
DJ.Studio (Netherlands): Focusing on AI-powered mix production, they offer stem separation, timeline editing, and seamless library integration specifically optimized for mashups and radio shows, carving a niche in production-focused workflows.
-
Mixvibes (Paris, France): Their Cross DJ offering emphasizes cross-platform functionality with real-time stem separation and effects, competing aggressively on feature parity and accessibility.
These companies are not merely selling software licenses; they are managing ecosystems. Competitive advantage often lies in the depth of hardware integration, the quality of AI features, and the reliability of streaming partnerships. The full report provides a detailed benchmarking of these players against financial performance, user sentiment, and strategic movements.
Video Editing Software Market
Report Content and Operational Sections
To support complex decision-making, the full market study is structured to provide actionable intelligence across multiple dimensions. This document is designed for product managers, investors, and strategy teams who need to validate assumptions with data.
The comprehensive analysis includes an in-depth examination of market segmentation by type, application, and region, though specific splits are detailed within the secure download. The report also covers supply chain dynamics, pricing strategies, and the impact of regulatory changes on software distribution. Furthermore, it provides a forecast model that accounts for various scenarios, allowing stakeholders to stress-test their strategies against potential market shifts.
Operational sections delve into the adoption rates of specific features such as AI stems and streaming proxies, correlating these with user retention and upgrade cycles. This level of detail enables clients to prioritize feature development roadmaps based on verified market demand rather than speculation.
Strategic Meridian: Timing and Decision Maturity
The timing of this report coincides with a period of significant activity in the sector. With recent product updates from AlphaTheta Corporation and Serato Limited occurring in early 2026, the competitive field is actively realigning. The acquisition activities and firmware enhancements observed in the first half of the year suggest a period of consolidation and capability enhancement.
For enterprise decision-makers, the data suggests that the window for entering the market with a generic solution is narrowing. Differentiation increasingly requires deep integration with hardware ecosystems or superior AI-driven creative tools. The forecast period through 2032 offers a long enough horizon to justify R and D investments, but the CAGR of 5.25 percent indicates that growth will be competed for rather than easily captured.
Understanding the specific regional demands and application-based preferences is essential for market entry or expansion strategies. For instance, while the aggregate data shows consistent growth, the intensity of adoption varies across professional live performance contexts versus recording and production use cases. The full report elucidates these nuances, providing the granularity needed to allocate resources effectively.
Conclusion: From Insight to Action
The DJ Software Market is poised for continued evolution, anchored by stable growth metrics and driven by rapid technological innovation. The journey from 2026 to 2032 will be defined by how well companies can integrate AI, streaming, and hardware compatibility into a cohesive user experience. For organizations looking to navigate this landscape, access to precise, validated data is the most critical asset.
This overview provides the strategic context and macro-validation necessary to appreciate the value of the full study. To access the complete segmentation splits, detailed company profiles, regional forecasts, and the full financial model, we invite you to engage with the complete market research report. Secure your competitive advantage with intelligence that moves beyond trends to deliver actionable foresight.
For detailed analysis of this topic, please visit the official page: DJ Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Education Software Market Hits $89.3M in 2025, Poised for $190.8M by 2032
By PW Consulting, 2026-09-16
Navigating the Next Wave: Strategic Intelligence for the Education Software Market (2026–2032)
The global education software landscape is undergoing a structural transformation that demands more than passive observation from enterprise leaders. As digital learning ecosystems mature, the convergence of adaptive technologies, regulatory scrutiny, and shifting institutional procurement models is redefining competitive advantage. PW Consulting’s latest market intelligence study on the Education Software Market is engineered to equip executives, investors, and product strategists with the analytical clarity required to navigate this inflection point. Rather than offering a static snapshot, this research delivers a forward-looking operational framework calibrated to the decision cycles of 2026 and beyond.
Industry participants today face a dual mandate. They must scale technology deployments while simultaneously defending against rising compliance costs, data governance risks, and intensifying vendor consolidation. The market has already demonstrated considerable momentum, with global revenue climbing from approximately 52.3 million USD in 2020 to an estimated 89.3 million USD by 2025. More importantly, the trajectory ahead points to sustained expansion at a compound annual growth rate of 11.5 percent through 2032. Such growth is not uniform across all cohorts. It is increasingly concentrated among organizations that can integrate data-driven personalization, responsible artificial intelligence, and resilient security architectures into their core offerings. Enterprises that treat these capabilities as optional enhancements will find themselves structurally disadvantaged as procurement standards tighten and end-user expectations accelerate.
The strategic value of this publication lies in its refusal to simplify complexity. By anchoring analysis in rigorous historical baselines and forward projections, the report translates macro-level momentum into actionable Go-to-Market considerations. Leaders evaluating product roadmaps, partnership portfolios, or regional expansion strategies will find a structured lens for weighing trade-offs between rapid innovation and long-term defensibility. The following sections outline the analytical architecture of the study and demonstrate how each component maps directly to the operational priorities shaping 2026 decision-making.
Decoding the 2026–2032 Growth Trajectory
Market expansion in education software is no longer driven by routine digitization alone. It is being reoriented by pedagogical shifts, institutional budget reallocations, and the maturation of cloud-native delivery models. The report’s historical analysis establishes a clear baseline, tracing revenue progression across the 2020–2025 window before projecting sustained acceleration through 2032. This longitudinal view is essential for executives who must distinguish between temporary demand spikes and durable structural growth. A double-digit CAGR environment rewards organizations that can align product cadence with institutional procurement cycles, while penalizing those that over-invest in features without clear instructional or administrative utility.
Forward projections in this study are structured to support scenario planning rather than rigid forecasting. Executives gain visibility into how growth may propagate across different deployment models, usage contexts, and buyer archetypes. This granularity matters because aggregate numbers obscure the operational realities that determine execution success. By mapping demand patterns to underlying adoption drivers, the analysis enables leadership teams to anticipate where procurement emphasis will shift, which performance metrics will gain prominence, and how pricing architectures may need to evolve under increasing competitive pressure.
Education Software Market
Crucially, the report also addresses the cost dynamics that frequently erode projected margins. Ongoing software maintenance, security patching, and continuous functionality updates typically add between fifteen and twenty-five percent of original development expenditure each year. For product organizations and institutional buyers alike, this recurring burden reshapes total cost of ownership calculations and influences long-term vendor selection. The study integrates these operational realities into its strategic assessment, ensuring that growth narratives are grounded in the economics of sustained delivery rather than initial market entry.
Navigating Regulatory Pressures and Competitive Realignment
The sector’s growth trajectory is unfolding against a backdrop of intensifying regulatory scrutiny and restructuring competitive dynamics. Data protection has moved from a compliance checkbox to a strategic differentiator. Recent enforcement actions highlight the reputational and operational stakes involved. For example, the Federal Trade Commission reached a settlement with Illuminate Education requiring the implementation of a comprehensive information security program and the deletion of unnecessary data following a breach that exposed personal information of more than ten million students. Simultaneously, the U.S. Department of Education issued a formal inquiry to Instructure Holdings to verify compliance with the Family Educational Rights and Privacy Act. These developments underscore a broader reality: institutions and enterprise buyers are increasingly evaluating vendors through the lens of data stewardship, security maturity, and procedural transparency.
At the same time, the competitive landscape remains moderately concentrated, with a handful of established players commanding a substantial share of total market revenue. This concentration does not imply stagnation. Instead, it signals a market where differentiation is increasingly derived from pedagogical depth, integration capability, and responsible technology deployment rather than raw feature volume. Several leading organizations are already pivoting toward AI-enhanced learning support, personalized instruction pathways, and credentialing ecosystems that bridge academic and professional outcomes. Recent corporate activity reinforces this direction: one major publisher introduced new AI-driven capabilities within its digital course solution for higher education, emphasizing responsible deployment, real-time student support, and tailored reading experiences. Another prominent language and learning platform reported annual bookings surpassing one billion USD while authorizing a significant share repurchase program, reflecting both commercial scale and strategic confidence. Meanwhile, a personalized K-12 teaching and learning provider garnered multiple industry recognitions for its multilingual, cross-subject instructional solution, highlighting the premium that institutions place on adaptability and breadth of coverage.
These developments are not isolated signals. They illustrate a market where competitive advantage is shifting toward organizations that can harmonize innovation with accountability, demonstrate measurable instructional impact, and sustain trust across highly regulated buyer environments. Executives evaluating partnership opportunities, acquisition targets, or competitive positioning must therefore look beyond headline market share and assess the underlying capabilities that determine long-term resilience.
Inside the Report: Analytical Depth Designed for Execution
This publication is structured to function as a working reference for cross-functional strategy teams rather than a high-level commentary. The analytical architecture spans multiple interconnected dimensions, each designed to answer a specific class of executive question. Readers will encounter a detailed segmentation analysis that decomposes demand patterns across solution categories, deployment contexts, and institutional adoption profiles. Rather than treating these dimensions in isolation, the report examines how they intersect, enabling leaders to identify where value creation is most concentrated and which buyer segments are likely to drive incremental spend.
The competitive and vendor landscape assessment goes beyond organizational profiling to evaluate strategic positioning, capability alignments, and recent developmental moves that indicate future trajectory. By mapping organizational focus areas against evolving procurement priorities, the study helps teams anticipate which vendors are likely to strengthen their hold on key segments and which may face pressure to reposition. Regional analysis is similarly contextualized, offering leaders a comparative view of demand maturity, institutional procurement behavior, and expansion feasibility without reducing complex markets to oversimplified rankings.
Beyond structural analysis, the report incorporates practical execution considerations. It addresses the total cost implications of sustained software delivery, the operational requirements of responsible AI integration, and the compliance expectations that increasingly shape procurement decisions. These elements are woven into strategic recommendations so that product, commercial, and risk functions can align on a shared operating posture. For organizations evaluating market entry, portfolio expansion, or partnership strategy, the document provides a disciplined basis for comparing opportunity against execution complexity.
Translating Intelligence into 2026 Strategic Action
Market intelligence delivers value only when it informs concrete decisions. For executive teams operating in the education software sector, the 2026–2032 window will reward organizations that can synchronize product strategy with institutional procurement behavior, regulatory expectations, and the economics of long-term service delivery. The study is designed to support that synchronization by converting trend observation into prioritized action pathways. Leaders can use the analysis to stress-test product roadmaps against emerging buyer requirements, evaluate whether current positioning will hold under intensifying competition, and determine where investment should be concentrated to capture durable demand rather than transient attention.
The report also serves as a shared analytical foundation for cross-functional alignment. Commercial teams can calibrate messaging around measurable impact and compliance readiness. Product organizations can benchmark development priorities against the capabilities that are gaining institutional traction. Risk and governance functions can integrate data stewardship expectations into vendor evaluation and internal deployment standards. When these functions operate from a common evidence base, strategic decisions become more coherent, resource allocation more disciplined, and market response more agile.
Ultimately, the Education Software Market will not be defined solely by the speed of technological advancement. It will be shaped by the organizations that can pair innovation with operational discipline, align their offerings with real instructional and administrative needs, and navigate an environment where trust and transparency are becoming core commercial assets. This study provides the structured intelligence necessary to make those judgments with confidence.
Access the Complete Strategic Assessment
The insights summarized here represent only the opening layer of a far broader analytical effort. The full report expands on segmentation dynamics, competitive positioning, regional demand patterns, procurement behavior, and the operational cost structures that shape long-term profitability. It also includes detailed company profiles, recent developmental milestones, and scenario-based considerations that help executives translate market momentum into executable strategy.
Educational and Training Software Market
For organizations preparing investment decisions, product roadmap adjustments, or market-entry evaluations in 2026, the complete publication offers the depth required to move from informed perspective to decisive action. Readers seeking the full dataset, granular segmentation analysis, and extended competitive intelligence are encouraged to access the complete report through the official PW Consulting research portal. The complete assessment is designed to function as a standalone strategic resource, enabling leadership teams to extract the precise intelligence needed for their specific decision context while maintaining a clear line of sight to the broader market trajectory.
For detailed analysis of this topic, please visit the official page: Education Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
OLED Lighting Panels Market to Hit $127.13M by 2032, PW Consulting Reports
By PW Consulting, 2026-09-16
Illuminating the Future: Strategic Insights into the OLED Lighting Panels Market Through 2032
The transition from traditional illumination to advanced organic light-emitting diode (OLED) technology represents more than a technological upgrade; it signifies a fundamental shift in how industries approach design, efficiency, and user experience. As we navigate the complexities of the global lighting landscape in 2026, understanding the trajectory of OLED lighting panels is critical for stakeholders aiming to capitalize on emerging opportunities. Our latest market research study provides a comprehensive analysis of this evolving sector, offering the data-driven intelligence necessary to formulate robust strategies for the coming years.
This report serves as a definitive guide for executives, investors, and product developers who need to navigate the interplay between technological innovation, regional demand shifts, and competitive dynamics. By examining historical performance from 2020 through 2025 and projecting forward to 2032, we uncover the underlying forces shaping the market value and growth potential. The following analysis highlights the strategic value of this research and outlines the key themes that will define the industry landscape in the immediate future.
Market Trajectory and Growth Horizons
The global OLED lighting panels market has demonstrated resilient growth over the past half-decade, recovering from initial deployment challenges to establish a steady upward curve. Our analysis tracks revenue progression from approximately 67.1 million USD in 2020 to an estimated 87.7 million USD in 2025. This historical baseline provides crucial context for understanding the momentum entering the forecast period. The market is projected to continue its expansion through 2032, driven by increasing adoption in commercial, automotive, and specialized industrial applications.
Forecast data indicates a compound annual growth rate (CAGR) of 5.56 percent during the 2026 to 2032 period. This growth rate suggests a mature yet expanding market environment where incremental gains are driven by technological refinements and broader acceptance rather than volatile speculation. By 2032, the market revenue is expected to reach significant milestones, reflecting the cumulative effect of investment in manufacturing capacity and the penetration of OLED solutions into mainstream lighting sectors. Understanding these top-line figures is essential for capacity planning and investment timing, but the true value lies in dissecting the drivers behind these numbers.
Worldwide LED Panel Lights Market
Segmentation Dynamics and Application Shifts
The market is not monolithic; it is defined by distinct segments that exhibit varying growth characteristics and strategic priorities. Our research dives deep into the breakdown of the market by type and application, revealing where the highest value creation is occurring. For instance, the balance between flexible and rigid panel technologies highlights the industry's pivot toward design versatility. The data suggests that flexible solutions are capturing a substantial share of the landscape, reflecting the demand for form factors that can be integrated into curved surfaces and innovative architectural designs. Rigid panels continue to hold significant ground, particularly in applications where structural stability and uniform illumination are paramount.
Application-wise, the landscape is diversifying. Traditional lighting remains a core pillar, yet the most dynamic growth vectors are emerging from specialized sectors. Automotive lighting represents a key area of expansion, fueled by the broader trend of vehicle electrification and the consumer demand for personalized interior and exterior lighting experiences. Beyond these primary categories, a significant portion of the market is attributed to other specialized uses, indicating that OLED technology is finding niches in industrial inspection systems and high-color-rendering commercial installations. Our report details these splits without obscuring the strategic implications, allowing decision-makers to identify which segments align with their core competencies.
Regional Analysis and Global Supply Chains
Geographical distribution of demand and production capacity plays a pivotal role in shaping market strategy. The Asia Pacific region stands out as a dominant force in the global landscape, reflecting the concentration of manufacturing infrastructure and rapid adoption rates in key economies. North America and Europe follow as significant markets, driven by stringent energy efficiency regulations and a strong focus on sustainable design in commercial spaces. Emerging regions, including Latin America and the Middle East and Africa, present nascent opportunities that may offer higher growth rates from a smaller base, though they require tailored market entry strategies.
Our analysis examines how these regional disparities influence supply chain logistics and pricing power. The concentration of manufacturing capabilities in specific zones underscores the importance of understanding local regulatory environments and labor dynamics. For example, while advanced production lines offer high precision, they also face challenges related to specialized labor availability and cost structures. By mapping the geographical revenue distribution, companies can better assess where to locate production facilities, where to focus sales efforts, and how to mitigate risks associated with regional economic fluctuations.
Competitive Landscape and Key Industry Players
The OLED lighting panels market is characterized by a mix of specialized manufacturers and large-scale display technology giants. The competitive environment is moderately concentrated, with the top three companies holding a significant share of the market revenue, while the top five players command a majority of the industry value. This structure suggests that while there is room for innovation from smaller players, scale and technological leadership are critical determinants of success.
Several key companies are setting the pace for innovation and commercialization. OLEDWorks, based in Rochester, NY, continues to lead in automotive applications, particularly with its Atala-series panels used for rear lighting and interior personalization. Their focus on high-performance solutions positions them well as vehicle electrification increases the demand for custom lighting profiles. LG Display, headquartered in Seoul, South Korea, brings immense production capacity to the table, with mass production capabilities exceeding 900,000 units annually. Their ability to scale production makes them a formidable player in the commercial lighting space.
In Japan, a cluster of companies is driving technological advancement and material science innovation. Konica Minolta is actively expanding its production capabilities, recently announcing the construction of a new roll-to-roll pilot coating line within its Hino facility in Tokyo. This move signals a commitment to improving manufacturing efficiency and throughput. Lumiotec, located in Yonezawa City, specializes in commercial panels with high color rendering index options, catering to applications where light quality is as critical as efficiency. Kaneka focuses on niche applications, including industrial inspection systems, demonstrating the versatility of OLED technology beyond general illumination.
Furthermore, the supply chain ecosystem is vital. Sumitomo Chemical, also based in Tokyo, provides polymer OLED materials that enable solution-processed panel production using printable ink technology. This material science capability underpins the ability of downstream manufacturers to create flexible and cost-effective panels. NEC Lighting rounds out the competitive landscape by providing panels for commercial and architectural installations, emphasizing the aesthetic and functional integration of OLEDs in built environments.
Recent Developments and Technological Advances
The pace of innovation in 2026 has been particularly brisk, with major players announcing significant milestones that will shape the market for years to come. In March 2026, Konica Minolta unveiled its plans for a new roll-to-roll pilot coating line, a development that promises to enhance production flexibility and potentially lower costs through advanced coating techniques. This infrastructure investment highlights the industry's focus on scaling manufacturing processes to meet growing demand.
May 2026 saw LG Display present next-generation tandem OLED technologies at the SID Display Week. Tandem structures are widely recognized for their potential to improve brightness, efficiency, and lifespan, addressing some of the historical limitations of OLED lighting. This presentation underscored the company's commitment to pushing the boundaries of performance. Following this, in June 2026, OLEDWorks announced advancements in high-performance multi-stack OLED technology. These parallel developments in tandem and multi-stack architectures indicate a industry-wide race to optimize light output and energy consumption, which are critical metrics for both regulatory compliance and consumer acceptance.
Drivers, Restraints, and Market Dynamics
Several macro and micro factors are influencing the market trajectory. Energy efficiency mandates are increasingly driving the adoption of low-power OLED lighting panels in commercial spaces. As governments and building management organizations impose stricter standards on energy consumption, the inherent advantages of OLED technology, such as low heat generation and directional light emission, become more valuable. This regulatory pressure acts as a catalyst for replacing older lighting infrastructure with newer, compliant solutions.
Simultaneously, the automotive sector is undergoing a transformation that benefits OLED lighting. The electrification of vehicles increases the demand for custom OLED lighting panels, as electric vehicle platforms offer more design freedom and require sophisticated lighting signatures for branding and safety. Consumers are increasingly viewing lighting as a key element of vehicle personalization, creating a premium market segment that rewards high-quality, flexible OLED solutions.
OLED Lighting Panels Market
However, challenges remain. The average market price for OLED lighting panels remains a consideration for mass adoption, with industry data indicating prices around 1,600 USD per square meter in 2025. While costs are expected to decrease with scale and process improvements, price sensitivity in certain applications may slow penetration. Additionally, specialized manufacturing faces labor shortages in advanced production lines, which can constrain capacity expansion and increase operational costs. Addressing these constraints requires strategic workforce development and automation investments.
Strategic Recommendations for 2026 and Beyond
For organizations operating in or entering the OLED lighting panels market, the insights from this research point to several actionable strategies. First, understanding the specific needs of high-growth segments is essential. Companies should evaluate whether their portfolios align with the demands of automotive personalization or high-efficiency commercial installations, as these areas show strong momentum. Second, monitoring the technological race between tandem and multi-stack solutions is crucial. Early adoption of next-generation architectures could provide a competitive edge in performance and efficiency, distinguishing products in a crowded marketplace.
Third, supply chain resilience must be prioritized. Given the concentration of manufacturing in specific regions and the reliance on specialized materials from key suppliers, diversifying sourcing and investing in vertical integration where feasible can mitigate risks. Finally, keeping a close watch on regulatory developments regarding energy efficiency will allow companies to anticipate demand shifts and position their products as compliance-ready solutions.
Conclusion
The OLED Lighting Panels Market is at an inflection point where technological maturity meets expanding application scope. The projected growth through 2032 offers substantial opportunities for those equipped with the right intelligence. Our comprehensive market research study provides the detailed segmentation data, competitive profiles, and forward-looking analysis required to make informed decisions. We invite industry leaders to explore the full report to gain access to the granular data and strategic frameworks that will define success in this illuminating sector.
For detailed analysis of this topic, please visit the official page: OLED Lighting Panels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Low-Speed Vehicle Market Hits $9.2B in 2025, Poised for 8% CAGR Through 2032
By PW Consulting, 2026-09-16
Strategic Horizons: Navigating the Low Speed Vehicle Market in 2026 and Beyond
Executive Overview: The Pulse of a Transformative Sector
The Low Speed Vehicle (LSV) sector has evolved from a niche auxiliary market into a structured component of the broader light electric mobility landscape. Between 2020 and 2025, the industry demonstrated remarkable structural resilience, expanding from a baseline of 6.3 billion USD to an estimated 9.2 billion USD by the close of 2025. This trajectory reflects more than incremental adoption; it signals a fundamental recalibration of how municipalities, commercial operators, and private communities integrate constrained-speed mobility solutions into daily operations. As we look toward the forecast window of 2026 through 2032, the market is projected to surpass 15.7 billion USD, driven by a compound annual growth rate of approximately 8.0 percent. For executive teams and capital allocators, the 2026 inflection point is particularly critical. It represents the convergence of regulatory clarity, supply chain recalibration, and shifting application demands that will define competitive positioning for the remainder of the decade.
PW Consulting’s latest Low Speed Vehicle Market study is designed not as a static data repository, but as a strategic navigation instrument. The report maps historical momentum against forward-looking operational variables, offering decision-makers a structured framework to align product roadmaps, partnership strategies, and regional deployment plans with the realities of an increasingly regulated and technologically maturing market. What follows is a preview of the analytical architecture underpinning this research, highlighting the dimensions that matter most as organizations prepare for the 2026 operating cycle and beyond.
Market Architecture: Historical Momentum and the 2026 Inflection Point
The market’s expansion over the past five years tells a story of consistent, compounding value creation. From 2020 through 2022, growth was characterized by measured adoption within established recreational and resort ecosystems. By 2023, however, the trajectory steepened as commercial and institutional buyers began recognizing the operational efficiencies of purpose-built low-speed platforms. The jump from 7.6 billion USD in 2023 to nearly 8.7 billion USD in 2024 underscores this shift, reflecting both volume expansion and the gradual premiumization of vehicle specifications. Entering 2025, the market closed at approximately 9.2 billion USD, positioning the sector at a threshold where scale, standardization, and supply chain maturity begin to interact in ways that reward strategic foresight.
Looking ahead, the forecast period reveals a sustained upward arc. By 2026, revenue is projected to reach nearly 10 billion USD, with the curve continuing its ascent through 2032. The 8.0 percent CAGR embedded in these projections is not merely a growth indicator; it is a structural signal. It implies that demand drivers are diversifying beyond traditional recreational use cases, regulatory frameworks are stabilizing around recognized safety benchmarks, and manufacturing footprints are adapting to both domestic protection measures and material innovation. Organizations that treat 2026 as a planning anchor rather than a static checkpoint will be best positioned to capture the value embedded in this expansion curve.
Competitive Dynamics: Incumbent Strategies and Recent Market Shifts
The competitive landscape in the LSV space remains moderately fragmented, yet concentration trends reveal clear patterns of consolidation and strategic positioning. Market leadership is distributed across a cohort of established manufacturers with deep roots in electric utility, golf, and neighborhood mobility segments. The top three players collectively account for approximately 24.6 percent of market revenue, while the top five extend that share to 26.2 percent. This distribution suggests that while no single entity commands dominant market control, recognized brands with certified product lines, established distribution channels, and compliance infrastructure retain meaningful advantages in procurement cycles and end-user trust.
Several core companies define the current competitive baseline. Club Car, headquartered in Auburn, Alabama, continues to manufacture street-legal Onward LSV models that align with NHTSA standards and SAE J2358 specifications, offering both electric utility and passenger variants. Textron Specialized Vehicles, operating out of Westerville, Ohio, sustains its presence through E-Z-GO and Cushman platforms engineered to meet FMVSS 500 and NHTSA LSV requirements for neighborhood and utility applications. GEM Products, based in Anaheim, California, assembles electric LSV models across the e2, e4, e6, and eL XD series, with certifications that include roof-crush protection and NHTSA-aligned safety standards. Yamaha Golf-Car Company, located in Cypress, California, leverages an exclusive North American agreement to distribute and support Pilotcar-branded electric LSV models, notably the PC-2 and PC-4 configurations, with street-legal certification. Bintelli Electric Vehicles, based in Charleston, South Carolina, assembles street-legal LSV and electric golf cart models within the United States, maintaining full compliance with federal LSV standards. American Landmaster, operating from Johnson City, Tennessee, produces domestically manufactured LSV and utility vehicle models certified under NHTSA low-speed vehicle classifications.
Recent market developments further illustrate how competitive positioning is being reshaped by partnership structures, regulatory determinations, and adoption trends. In early 2025, Yamaha Golf-Car Company announced exclusive North American distribution rights and wholesale operations for Pilotcar electric LSV models, effective from the first quarter of that year. This move expanded Yamaha’s product portfolio and reinforced its distribution leverage across the region. By the first quarter of 2026, broader industry data had identified a notable surge in street-legal LSV adoption, highlighting new profit opportunities for U.S. manufacturers. That momentum intersected with a significant trade determination in mid-2025, when the U.S. International Trade Commission issued an affirmative final determination in investigations concerning Chinese LSPTV imports, concluding that domestic LSV producers had been materially injured by unfair import practices. The outcome has structural implications for pricing, sourcing strategies, and competitive insulation for American-based manufacturers.
Regulatory and Technological Undercurrents
Regulatory compliance is no longer a peripheral consideration in LSV market strategy; it is a core requirement that shapes product design, certification pathways, and market access. LSVs must adhere to 49 CFR 571.500 FMVSS standards and SAE J2358 performance specifications, which establish baseline expectations for occupant protection, braking capability, and structural integrity. NHTSA certification labels and compliance with occupant protection and brake standards are mandatory for vehicles marketed under the low-speed classification, reinforcing the importance of documented conformity throughout the manufacturing and distribution chain. These requirements create a compliance barrier that favors established producers with mature quality assurance processes while raising the entry threshold for new market participants.
At the same time, material and powertrain transitions are redefining product economics. Lithium-ion batteries are increasingly specified in LSV models, offering extended range and reduced maintenance relative to traditional lead-acid alternatives. This shift affects total cost of ownership calculations, service interval planning, and resale valuation, making battery chemistry a strategic procurement variable rather than a purely technical specification. Complementary design choices also matter. Aluminum chassis components provide rust-proof durability and contribute to maintaining overall vehicle weight below the 3,000 lbs GVWR threshold required for LSV classification. These engineering considerations intersect with regulatory constraints, influencing both manufacturing cost structures and product longevity profiles.
Low Speed Vehicle Market
For strategists, the regulatory and technological landscape presents a dual reality. Compliance frameworks create predictability, enabling long-term capital planning and regional expansion modeling. Simultaneously, material and battery evolution introduce continuous improvement cycles that require manufacturers and buyers alike to stay current with specification shifts. The 2026 environment will reward organizations that integrate compliance readiness with technology roadmapping rather than treating them as separate functions.
What the Report Delivers: A Practical Intelligence Toolkit
This study is structured to move beyond high-level market sizing and into the operational dimensions that drive executable strategy. The analytical framework is organized to support cross-functional use, from product planning and procurement to sales positioning and partnership evaluation. Key components of the report include:
- Comprehensive historical tracking and forward projections that contextualize growth across the 2020 to 2032 window, with explicit attention to the 2026 decision horizon.
- Segmentation analysis that dissects market value across vehicle types, application environments, and regional demand patterns, enabling targeted go-to-market planning without relying on generic industry narratives.
- Competitive profiling of established manufacturers, including product certifications, geographic footprints, and recent strategic actions that illustrate how incumbents are adapting to regulatory and trade dynamics.
- Regulatory and standards mapping that translates FMVSS, NHTSA, and SAE compliance requirements into practical implications for sourcing, labeling, and market entry.
- Material and powertrain trend evaluation, with attention to battery chemistry adoption, chassis material selection, and their impact on weight classification, maintenance cycles, and total cost of ownership.
- Trade and policy context that connects domestic industry protection measures to sourcing strategies, pricing flexibility, and competitive insulation for U.S.-based production.
The objective is to provide decision-makers with a layered view of the market: enough structural context to validate strategic assumptions, and enough granular insight to inform budget allocation, product prioritization, and partnership selection. Readers who engage with the full report will find actionable frameworks rather than abstract trend statements, making the research suitable for use in board-level discussions, product committee reviews, and regional expansion planning.
Strategic Implications for 2026 Decision-Makers
As organizations prepare their 2026 plans, several strategic themes emerge from the market structure and recent developments. First, compliance capability is becoming a competitive differentiator. With clear NHTSA and FMVSS requirements governing occupant protection, braking performance, and certification labeling, manufacturers and distributors that institutionalize compliance verification will reduce time-to-market friction and strengthen credibility with institutional buyers. Second, trade policy is reshaping sourcing logic. The affirmative determination on Chinese LSPTV imports creates a protective environment for domestic producers, but it also requires careful evaluation of component sourcing, assembly footprints, and price architecture to fully capitalize on the shifting landscape.
Third, application diversification is accelerating. While golf courses and hotels and resorts continue to represent substantial demand centers, industrial facilities, airports, and other specialized environments are expanding their reliance on low-speed platforms for internal mobility, cargo movement, and personnel transport. Each application brings distinct operational requirements, service expectations, and procurement cycles. A segmented approach to product configuration and sales outreach will outperform one-size-fits-all positioning. Fourth, powertrain and material choices are influencing both economics and classification compliance. The transition toward lithium-ion batteries and aluminum chassis components is not merely an engineering preference; it affects vehicle weight, durability, maintenance planning, and lifecycle cost. Organizations that align procurement strategy with these shifts will gain advantages in total cost of ownership and end-user satisfaction.
Finally, the moderate concentration of the market, combined with active partnership activity and product portfolio expansion, suggests that 2026 will be a year of strategic realignment rather than passive growth. Companies that define clear positioning around compliance readiness, application specialization, and domestic production advantages will be better equipped to capture share in a market that is large enough to accommodate multiple winners but structured enough to reward discipline.
L7 and L6 Quadricycles Market
Closing Perspective
The Low Speed Vehicle market in 2026 stands at the intersection of regulatory maturation, material innovation, and expanding application demand. The projected trajectory from roughly 10 billion USD in 2026 toward more than 15.7 billion USD by 2032 reflects a sector that is consolidating its operational logic while continuing to open new revenue pathways. Success in this environment will depend on the ability to translate market scale into targeted execution: choosing the right compliance pathways, aligning product specifications with application realities, and positioning supply chains to benefit from the evolving trade and production landscape.
PW Consulting’s full Low Speed Vehicle Market study provides the depth, segmentation, and competitive intelligence required to make those decisions with confidence. The analysis presented here offers a structural preview, but the complete report contains the detailed breakdowns, company-level assessments, and forward-looking scenarios that equip leadership teams to move from awareness to action. For executives, planners, and investors seeking to navigate the 2026 landscape with precision, the full research deliverable is the essential next step.
For detailed analysis of this topic, please visit the official page: Low Speed Vehicle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Intelligence for the Boron Nitride Nanotube Market: Navigating Growth and Competition in 2026
The global materials landscape is undergoing a decisive shift. Advanced nanomaterials are moving from laboratory curiosity to industrial necessity, and among them, Boron Nitride Nanotubes (BNNT) stand out as a critical enabler for next-generation performance. At PW Consulting, our latest comprehensive market research on the BNNT sector is designed to equip executive leadership, R&D directors, and investment committees with the clarity needed to act decisively in 2026 and beyond.
This report is not merely a statistical compilation. It is a strategic roadmap built on rigorous primary and secondary research, calibrated to support high-stakes decisions across procurement, product development, market entry, and competitive positioning. As organizations confront tightening margins, accelerating technology cycles, and increasingly complex supply chains, understanding the BNNT market dynamics is no longer optional—it is foundational to sustainable growth.
The Market Trajectory: Setting the Baseline for 2026 Decision-Making
Drawing on a detailed historical baseline spanning 2020 through 2025, our analysis traces the market's evolution from an estimated 87.45 million USD to a projected 112.5 million USD by 2025. This progression reflects more than steady expansion; it signals a structural inflection as BNNT transitions from niche research applications into broader industrial adoption. Our forecast model projects continuation of this momentum through 2032, with the market reaching an estimated 215.0 million USD by the end of the period, underpinned by a compound annual growth rate of 9.8 percent.
These macro figures serve as the anchor for strategic planning. They indicate that demand is building on a sustainable trajectory, supported by cross-sector applications and maturing production capabilities. Yet numbers alone do not guide action. The true value of this research lies in its translation of top-line trajectory into actionable intelligence: where growth is concentrating, which performance attributes are becoming table stakes, and how supply-side evolution is reshaping purchasing power and risk exposure.
Report Coverage: What Decision-Makers Can Expect
Designed for executive consumption and operational deployment, the report delivers a complete view of the BNNT ecosystem through multiple analytical lenses:
- Comprehensive market sizing and forward-looking forecasts with structured scenario analysis that accounts for variations in adoption speed, raw material pricing, and manufacturing scale-up.
- Product segmentation that distinguishes between single-walled and multi-walled BNNT architectures, including their respective performance profiles, cost structures, and suitability for different end-use environments.
- Application-focused evaluation across structural composites, thermal management, electronic devices, and medical and biomedical applications, with qualitative discussion of value drivers, technical barriers, and commercialization maturity.
- Regional perspective that maps demand clusters, supply footprints, and localization dynamics across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
- Competitive landscape assessment with company profiles, strategic positioning, and an examination of how concentration levels shape pricing behavior, customer negotiation leverage, and barrier-to-entry dynamics.
- Market dynamics analysis covering raw material cost signals, regulatory developments, certification initiatives, and production milestones that are actively reshaping supply conditions in real time.
Segmentation at a Glance: Where Value Is Being Created
The BNNT market is not a monolith. Distinct product architectures and application requirements create divergent value pools, and understanding these differences is essential for aligning strategy with opportunity.
On the product side, both single-walled and multi-walled BNNT formats command significant share in the current market. Each offers unique electrical, thermal, and mechanical characteristics that appeal to different engineering priorities. The report examines how these formats interact with manufacturing economics, purity specifications, and application-driven performance thresholds, enabling buyers and producers to assess which segment aligns with their strategic objectives.
From an application standpoint, the market spans a broad spectrum of uses. Structural composites represent a substantial portion of current demand, reflecting BNNT's role in enhancing strength-to-weight performance and durability in demanding environments. Thermal management constitutes another major pillar, driven by the increasing need for efficient heat dissipation in high-power electronics, energy systems, and advanced manufacturing. Electronic devices add a complementary layer of demand, while medical and biomedical applications point toward a longer-term growth frontier as biocompatibility and functionalization capabilities advance.
Geographically, the market reflects a diversified footprint. North America and Asia Pacific stand out as substantial demand centers, while Europe maintains a meaningful position, supported by industrial manufacturing and materials research ecosystems. Latin America and the Middle East and Africa, though smaller in current scale, represent regions where localized production, import substitution, and emerging industrial demand could reshape the distribution of value over the forecast horizon. Rather than presenting isolated share percentages, the report connects regional conditions to supply chain logic, cost access, and end-market momentum, helping organizations prioritize where to focus commercial effort.
Market Dynamics: Raw Materials, Certification, and Scaling Reality
The trajectory of the BNNT market is influenced by forces that extend beyond end-product demand. Raw material economics, certification frameworks, and manufacturing achievements all shape the environment in which companies plan, price, and procure.
On the input side, boron-related pricing has been a relevant factor in market conditions. In the United States, boron prices reached approximately 780 USD per metric ton in December 2025, supported by improved downstream demand from glass and ceramics sectors. At the same time, boron nitride price levels have remained firm through 2026, with premiums for high-purity and tailored grades likely to persist. For BNNT buyers and producers alike, these signals matter: they affect cost planning, margin resilience, and the commercial viability of specialized grades that command higher value in performance-critical applications.
Regulatory and quality infrastructure is also becoming more defined. Market participants have actively engaged with the Performance Review Institute, Inc. to support development of NADCAP audit criteria for metallic powder materials. Such initiatives indicate an industry moving toward greater standardization and qualification discipline, particularly for sectors where material consistency, process control, and traceability are non-negotiable. This trend benefits established players with robust quality systems while raising the bar for new entrants seeking to gain customer confidence in demanding applications.
Boron Nitride Nanotubes (BNNT) Market
Production milestones further illustrate the market's evolution. Some participants have reached kilogram-scale production, an important step in demonstrating feasibility at volumes closer to commercial relevance. At the same time, multiple companies are investing in process innovation, capacity expansion, and product-grade differentiation. These developments suggest that the BNNT market is transitioning from proof-of-concept maturity toward competitive scaling, where cost efficiency, reproducibility, and application validation begin to separate leaders from followers.
Competitive Landscape: Differentiating Capability in a Concentrated Market
The BNNT sector remains relatively concentrated, with a meaningful share of market activity associated with a limited set of organizations. Concentration levels in the report underscore a market where a handful of players hold significant influence over pricing norms, customer relationships, and the pace of commercial adoption. For strategists, this means competitive intelligence is indispensable: understanding each player's technology approach, supply philosophy, and target application mix can reveal both risk concentrations and partnership opportunities.
Our research profiles the companies actively shaping the market, highlighting the distinct value propositions they bring:
- BNNT Materials, LLC, based in Newport News, Virginia, focuses on producing what it describes as some of the highest-quality BNNTs available, using innovative methods designed to support both research and commercial applications. Its positioning emphasizes performance and consistency for advanced R&D and specialized use cases.
- BNNano, Inc., headquartered in Burlington, North Carolina, is notable for having a commercially viable manufacturing process built around its patented NanoBarb enhanced tubes. The company targets industrial materials and applications, reflecting a focus on scalability and practical deployment rather than purely laboratory supply.
- Tekna Advanced Materials Inc., located in Sherbrooke, Quebec, emphasizes large-scale BNNT production via induction plasma technology. Its approach is oriented toward aerospace-grade requirements and high-volume supply, aligning with sectors where qualification and volume reliability are critical.
- Naieel Technology, based in Daejeon, South Korea, centers on high-quality industrial-grade BNNT and has reported breakthrough production milestones alongside thermal application technologies. Its profile suggests a dual emphasis on manufacturing progress and application-specific thermal performance.
- BNNT Technology Pty Ltd, operating from Brisbane, Queensland, has pursued Australian-made high-quality BNNT at reduced pricing for multipurpose formats across multiple industries. Its strategy reflects a cost-conscious, broad-application approach that may appeal to customers seeking accessible supply for diverse uses.
- Nanoshel LLC, headquartered in Columbus, Ohio, supplies BNNT with very high purity for research, academic, and industrial orders. Its offering is relevant for customers whose requirements center on purity standards and controlled materials sourcing.
Recent developments further illustrate how competitive dynamics are unfolding. In January 2026, BNNano announced a Q1 2026 capacity expansion aimed at reducing costs and improving quality, with significant growth expected in water purification and core materials. The same period saw the company report a strong and profitable 2025, including record net income and a second consecutive profitable year. These moves matter because they show how operational progress can translate into commercial momentum, strengthening a player's ability to compete on both price and performance while expanding into additional application domains.
For buyers, a concentrated landscape creates both advantages and vulnerabilities. Fewer dominant suppliers can mean deeper technical support, clearer qualification pathways, and stronger consistency, but it can also increase dependency risk and limit negotiating flexibility. For new entrants and investors, the concentration profile highlights the need to identify differentiated entry points—whether through production innovation, grade specialization, regional positioning, or application-specific validation—rather than attempting to compete solely on generic commodity terms.
Worldwide Halloysite Nanotubes Market
Strategic Implications for 2026 Enterprise Decisions
As organizations plan for 2026, the BNNT market presents several strategic imperatives. First, product and application strategy must be tied to real performance requirements rather than generic nanomaterial narratives. Whether the priority is structural composite enhancement, thermal management, electronic device integration, or biomedical exploration, the value case depends on grade suitability, process compatibility, and downstream validation. The report helps leaders differentiate among these pathways and avoid overcommitting to applications that are still nascent or technically misaligned.
Second, supply chain strategy needs to account for evolving cost structures and quality expectations. With boron-related inputs and boron nitride pricing showing firmness, and with premiums likely to persist for high-purity and tailored grades, procurement teams must evaluate supplier resilience, consistency, and qualification readiness. In sectors where certification and audit frameworks are gaining traction, supplier selection becomes as much about compliance and reliability as it is about price.
Third, competitive positioning should reflect both the concentration of the market and the diversity of player strategies. Organizations may benefit from partnerships with producers that match their application focus and scale needs, or from diversifying sourcing where feasible to reduce dependency. For companies considering entry or expansion, the report's competitive profiles and dynamic indicators provide a basis for assessing where differentiation is credible and where barriers remain high.
Finally, investment and planning decisions should incorporate scenario realism. A market growing toward a substantial 2032 scale does not imply uniform opportunity across all segments or regions. The most valuable use of this research is to align ambition with evidence: identify the subsegments where demand is strongest, the geographies where conditions are most favorable, and the competitive positions that are most defensible given current production and qualification realities.
Why This Research Matters Now
The BNNT market is entering a phase where insight translates directly into advantage. Companies that understand the interplay of product architecture, application maturity, regional demand, raw material dynamics, certification trends, and competitive differentiation will be better positioned to negotiate, source, develop, and expand with confidence. Those that rely on incomplete or outdated assumptions risk overpaying, under-qualifying, or misallocating resources into low-probability opportunities.
PW Consulting's BNNT market research is built for this moment. It offers the macro perspective needed for strategic planning and the operational depth required for execution. It is designed to support procurement strategy, product roadmapping, market entry evaluation, investment prioritization, and competitive benchmarking across a market that is becoming more structured, more scalable, and more strategically significant with every passing year.
The full report provides detailed market sizing, segmentation analysis, company profiles, regional perspectives, and dynamic indicators that together form a complete decision-support toolkit. For executives and analysts seeking to act with precision in 2026 and prepare for the years ahead, this intelligence offers the foundation needed to move from uncertainty to informed strategy.
For detailed analysis of this topic, please visit the official page: Boron Nitride Nanotubes (BNNT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Traditional Whiteboard Market to Reach USD 284 Million by 2032 Amid 3% CAGR
By PW Consulting, 2026-09-16
Traditional Whiteboard Market 2026: Strategic Intelligence for the Modern Enterprise
In an era dominated by digital collaboration tools and cloud-based workflows, the physical act of writing, erasing, and visualizing ideas on a traditional whiteboard remains a cornerstone of organizational communication. The Traditional Whiteboard Market has demonstrated remarkable resilience, evolving through material innovations and shifting workplace dynamics while maintaining its foundational role in education, commercial offices, and healthcare environments. As we enter 2026, decision-makers across sectors face a critical need to understand how this legacy market is positioned for sustained growth, competitive pressures, and strategic procurement. This newly released market research provides a comprehensive, data-driven roadmap designed specifically to inform enterprise strategy, supply chain planning, and facility investment decisions for the 2026–2032 horizon.
Why 2026 Demands a Reassessment of Traditional Whiteboard Strategy
The market has navigated a period of consolidation and moderate expansion. Following a compound annual growth rate of approximately 3.0% through the forecast period, revenue trajectories reflect a market that is neither stagnant nor explosively disruptive, but rather steadily maturing with predictable demand cycles. Base-year valuations anchored in 2025 establish a clear benchmark, while historical performance from 2020 through 2025 reveals how supply chain adaptations, educational infrastructure investments, and corporate workspace reconfigurations have collectively shaped consumption patterns. Entering 2026, procurement leaders and strategic planners must look beyond unit-cost considerations and evaluate how material durability, installation flexibility, and end-user workflow integration will dictate long-term value.
Our research deliberately avoids superficial market summaries. Instead, it delivers a structured analytical framework that maps revenue evolution, identifies structural demand drivers, and highlights the operational realities that influence purchasing decisions. By focusing on the interplay between product longevity, environmental conditions, and user behavior, the study equips executives with the context needed to align capital allocation with actual utilization patterns rather than speculative trends.
Navigating a Contained but Competitive Landscape
One of the most defining characteristics of the Traditional Whiteboard Market is its relatively fragmented yet concentrated competitive structure. The top three players collectively command a modest share of total industry revenue, while the top five extend their influence only slightly further. This concentration profile signals a market where regional specialization, product differentiation, and service-level commitments often outweigh pure scale advantages. For enterprises evaluating supplier partnerships or assessing market entry risks, understanding this distribution is essential to constructing resilient sourcing strategies and avoiding overreliance on a narrow supplier base.
Our analysis examines how established manufacturers leverage geographic manufacturing footprints, warranty structures, and application-specific engineering to maintain market positioning. We explore how companies operating across multiple verticals balance standardized production with customized configurations, and how warranty commitments and material certifications influence procurement confidence in institutional settings. The research also maps how competitive intensity varies across product categories, revealing where pricing pressure is most acute and where value-based differentiation remains viable.
Product and Application Realities Shaping Procurement Decisions
Material Choices and End-User Expectations
The market continues to be defined by distinct material categories, each with clear performance trade-offs that directly influence adoption in specific environments. Glass-based surfaces have gained traction in settings where aesthetic finish and long-term write clarity are prioritized. Melamine-based boards remain widely deployed due to their cost efficiency and broad compatibility with standard mounting systems. Porcelain steel surfaces appeal to high-traffic institutional and healthcare environments where surface integrity, chemical resistance, and frequent cleaning cycles are operational necessities. Rather than treating these categories as interchangeable, our research evaluates how each aligns with real-world usage intensity, maintenance expectations, and total cost of ownership considerations.
White Board Market
Where Demand Actually Materializes
Demand is not uniformly distributed across end-use environments. Educational institutions continue to represent the largest consumption base, driven by classroom configuration cycles, replacement schedules, and the pedagogical value of spontaneous visual collaboration. Commercial office environments follow as a substantial secondary demand center, where meeting-room renewal programs, hybrid workspace designs, and collaborative zone planning sustain steady procurement activity. Healthcare settings, while smaller in absolute volume, present specialized requirements around surface hygiene, compliance with cleaning protocols, and durability under rigorous maintenance routines. Our report dissects how these application segments differ in purchasing cadence, specification criteria, and vendor evaluation processes, enabling planners to tailor sourcing approaches rather than applying one-size-fits-all procurement models.
Regional Dynamics and Supply Chain Considerations
Geographic demand patterns reflect broader economic activity, institutional investment cycles, and local manufacturing capabilities. North American markets exhibit strong institutional procurement stability and a mature commercial office refresh environment. European demand is shaped by educational budget frameworks, workplace regulation trends, and a growing emphasis on sustainable product specifications. Asia Pacific presents a distinct profile influenced by rapid educational infrastructure development, expanding corporate real estate portfolios, and localized manufacturing ecosystems. Latin American and Middle East/Africa markets, while smaller in aggregate scale, offer targeted opportunities tied to specific institutional modernization initiatives and regional distribution partnerships.
Our research integrates these regional realities into a cohesive operational view. We examine how supply routes, import dependencies, domestic manufacturing capacity, and local service networks influence delivery reliability and post-installation support. For enterprises managing multi-site deployments or evaluating cross-border procurement, these insights help reduce friction in forecasting, inventory planning, and vendor selection.
Competitive Profiles That Matter for Strategic Sourcing
The competitive field includes manufacturers with distinct positioning strategies, ranging from education-focused product lines to broad commercial and healthcare portfolios. Several players have built recognition around specialized surface treatments, magnetic functionality, frameless designs, and freestanding configurations tailored to specific user environments. Others emphasize custom fabrication, long-duration warranties, or region-specific distribution models that strengthen their relevance in institutional procurement cycles.
Our report profiles leading participants and examines how their product architectures, branding approaches, and manufacturing commitments translate into market relevance. We assess how companies differentiate through write performance, surface durability, mobility options, and presentation integration features, and how these attributes resonate with education administrators, office facility managers, and healthcare procurement teams. The analysis also considers how warranty structures and domestic production claims influence buyer confidence, particularly in environments where long service life and low maintenance burden are prioritized over initial acquisition cost.
Traditional Whiteboard Market
What the Report Delivers: Operational Intelligence, Not Just Market Sizing
This research is designed to support concrete decision-making across multiple organizational functions. It goes beyond headline figures to provide an actionable structure that procurement teams, strategy planners, and facility leaders can apply directly to planning processes.
- Historical performance context from 2020 through 2025, establishing a clear baseline for interpreting near-term revenue movement and demand stability
- Forward-looking projections through 2032 that map expected market progression under baseline conditions, helping organizations align capital planning with realistic growth expectations
- Material and application segmentation analysis that clarifies where specification differences matter most and how end-use environments drive purchasing behavior
- Competitive landscape mapping that identifies concentration patterns, differentiation pathways, and supplier evaluation criteria relevant to enterprise procurement
- Regional demand framing that supports multi-market planning without reducing complex local dynamics to oversimplified rankings
- Operational context drawn from manufacturing activity, supply responses, and end-user behavior trends that illuminate how the market functions in practice
The study is structured to help readers answer practical questions: Which product attributes justify premium specification in high-use environments? How do replacement cycles differ across education, office, and healthcare settings? What supplier characteristics should be weighted most heavily in multi-site procurement programs? By addressing these questions within a consistent analytical framework, the report enables more disciplined planning and reduces reliance on anecdotal procurement assumptions.
Using This Intelligence to Strengthen 2026 Decision-Making
Strategic value emerges when market data is connected to operational realities. In the Traditional Whiteboard Market, that connection is especially important because purchases are often distributed across departments, budget cycles, and facility teams. A classroom replacement program, a corporate office refresh initiative, or a healthcare wing renovation may all involve whiteboard procurement, but each operates under different specification priorities, approval pathways, and usage expectations.
Our research helps unify these perspectives by showing how demand patterns, product characteristics, and competitive dynamics intersect in practice. Procurement leaders can use the findings to benchmark sourcing criteria, evaluate supplier proposals against market-consistent specifications, and anticipate how replacement and expansion needs may evolve over the forecast period. Strategy and operations teams can incorporate the market trajectory into broader workplace planning, ensuring that physical collaboration infrastructure is treated as a deliberate component of organizational design rather than an incidental facility expense.
For organizations considering supplier diversification, regional sourcing adjustments, or specification standardization across sites, the report provides the context needed to weigh trade-offs with greater confidence. It also supports scenario thinking by clarifying which market segments are structurally larger, which material categories align with particular operating conditions, and how competitive concentration shapes negotiation leverage and supply continuity considerations.
Access the Full Market Intelligence
This overview is intended to demonstrate the scope, rigor, and strategic relevance of the full study. The complete Traditional Whiteboard Market research contains the detailed segmentation analysis, competitive profiling, regional demand mapping, and forecast structures that enterprise decision-makers require for 2026 planning and beyond. Core data tables, segment-level breakdowns, company-specific strategic assessments, and operational context are developed in full within the report to support procurement modeling, facility planning, and market positioning exercises.
To access the complete dataset and apply these insights directly to your organization's planning processes, visit the source page for the full report. The detailed intelligence inside is structured to be immediately useful for strategy reviews, budget forecasting, supplier evaluations, and multi-site operational planning throughout the 2026–2032 forecast period.
For detailed analysis of this topic, please visit the official page: Traditional Whiteboard Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


