



Category: market research
Navigating the Next Wave: Strategic Intelligence for the Global Cement Boards Market (2026–2032)
The global construction materials landscape is undergoing a structural shift. As buildings demand higher performance, stricter fire safety, and greater environmental accountability, cement boards have emerged as a foundational material across residential, commercial, and industrial applications. At PW Consulting, we have just completed a comprehensive multi-year study of this sector, and the findings carry immediate implications for procurement leaders, product strategists, capital allocators, and competitive intelligence teams. This article previews the strategic contours of the report, frames the market trajectory through 2032, and explains why decision-makers should treat this intelligence as a core input to 2026 planning cycles.
Worldwide Tarp Tent Market
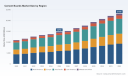
The cement boards market has demonstrated consistent expansion over the past half-decade, moving from a base of approximately 11,000 million USD in 2020 to an estimated 14,750 million USD in 2025. Our forecast model projects continued growth through the end of the decade, with the market reaching roughly 15,187 million USD in 2026 and climbing toward 23,150 million USD by 2032. Across the 2026–2032 horizon, the compound annual growth rate stands at 6.1 percent. These figures are not abstract benchmarks; they reflect a durable demand curve shaped by substitution away from legacy materials, accelerating build-out in emerging economies, and the built environment’s intensifying focus on durability, moisture resistance, and regulatory compliance.
Biomolecule Software Market
Yet aggregate numbers only tell part of the story. The real strategic challenge for 2026 lies in understanding how this growth is distributed across product architectures, application verticals, and regional corridors—and how competitive dynamics, input cost volatility, and certification requirements are reshaping margin profiles and go-to-market strategies. Our report is designed to convert high-level trends into actionable decision frameworks, allowing executives to prioritize investments, anticipate supply-side risks, and position product portfolios ahead of the next phase of market maturity.
Worldwide Epoxy Resin Diluent Market
Why 2026 Demands a Refresh in Market Intelligence
Several converging forces make the 2026 planning window particularly consequential for cement boards stakeholders. On the demand side, architects and contractors are increasingly specifying cement-based panels for siding, flooring, ceiling systems, roofing, and other critical envelope applications because these materials deliver a compelling combination of structural resilience, dimensional stability, and weather resistance. On the regulatory side, asbestos bans and tightening fire-safety requirements continue to accelerate the displacement of older, higher-risk alternatives, while green building certification programs are placing a premium on materials that can substantiate their environmental footprint with verified documentation.
This regulatory tailwind is not uniform, and compliance is becoming a competitive differentiator rather than a baseline checkbox. Our analysis highlights that fiber cement boards must satisfy evolving Environmental Product Declaration standards, including ISO 14025 and EN 15804, to support green building certifications across major markets. Companies that have already embedded environmental documentation, lifecycle transparency, and compliant formulations into their product strategy are gaining an edge in specification-driven procurement. Those that have not are facing longer sales cycles, greater scrutiny from design teams, and potential exclusion from bids tied to certified sustainable construction.
Simultaneously, the operating economics of cement board production are under pressure. Portland cement and cellulose fibers together account for roughly 50 to 60 percent of operating expenses in fiber cement board manufacturing, making input cost management a central lever for margin protection. In recent periods, cellulose fiber prices have experienced annual increases of up to 18 percent, driven by raw material volatility and supply chain constraints. These dynamics are reshaping cost structures across the value chain and forcing manufacturers and distributors to revisit pricing models, formulation optimization, hedging approaches, and regional sourcing strategies. In 2026, the winners will be those who integrate input-cost intelligence into product planning and procurement decisions, rather than treating it as a periodic purchasing issue.
The combination of these factors—a maturing demand base, stricter compliance expectations, and volatile input economics—creates a market where visibility matters more than ever. Executive teams need more than top-line growth estimates. They need a granular view of where value is being created, which segments are consolidating, which geographies are attracting capacity expansion, and how incumbents and challengers are re-positioning their portfolios. That is precisely the lens our report applies.
Macro Trajectory and the Shape of Growth
The historical trajectory from 2020 through 2025 shows a market that has navigated disruption and emerged with reinforced momentum. After moving through the pandemic-era fluctuations of the early 2020s, the sector rebounded with steady year-over-year expansion, reaching an estimated 13,712 million USD in 2024 before advancing to 14,750 million USD in 2025. The forecast period from 2026 to 2032 extends this path with disciplined, compounding growth, pointing toward a market size of approximately 20,731 million USD by 2030 and 23,150 million USD by 2032.
Importantly, this growth is not merely a function of broader construction activity. It is also being shaped by product-level substitution and application-level demand shifts. Fiber cement boards represent the dominant type segment in the current market structure, reflecting their widespread adoption in both exterior cladding and interior functional applications. Their advantage lies in fire resistance, moisture durability, and versatility across architectural finishes, which makes them the default choice in many specification workflows. Our report explores how this type-level dominance is being reinforced by product innovation, such as high-performance formulations designed for extreme weather resistance and new panel lines engineered to replicate concrete, wood, or stone aesthetics while preserving technical performance.
On the application side, the market is anchored by strong demand across siding, flooring, ceiling, roofing, and other use cases. Siding continues to be a primary demand driver, supported by both new residential construction and renovation activity that favors low-maintenance, long-life exterior materials. Flooring and ceiling applications contribute substantial volume as well, reflecting the material’s growing role in interior environments where moisture management and durability are critical. Roofing and other specialized applications round out the demand profile, with growth increasingly tied to regions where building codes and climate conditions reward resilient envelope solutions. Our analysis examines how these application segments are evolving in terms of specification patterns, project mix, and regional pull, without relying on static snapshot percentages that quickly become outdated.
Geographically, the market is diversified, with meaningful demand centers across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents a distinct combination of building activity, regulatory intensity, import dependence, and local manufacturing capacity. In some markets, established supply bases and mature distribution networks support stable growth; in others, capacity investments and import-substitution strategies are reshaping the competitive map. The report provides a regional framework that connects demand drivers, policy environments, and industrial capacity trends, enabling leaders to calibrate market-entry assumptions, export strategy, and local partnership decisions.
Competitive Dynamics and the Restructuring of Advantage
The competitive landscape in cement boards is characterized by a mix of global specialists, regional fabricators, and brand-driven exterior product companies. Our report profiles the firms that are defining the current battleground, including James Hardie, Nichiha, USG Corporation, American Fiber Cement Corporation, Allura, Cembrit Holding A/S, Etex Group, and Everest Industries. These companies illustrate the diversity of strategic postures in the market: some compete on high-density formulations and technical performance; others compete on aesthetic versatility, warranty strength, or distribution reach; still others compete by scaling capacity in high-growth geographies.
James Hardie, headquartered in Australia, continues to be closely associated with high-density fiber cement boards and panels for siding, cladding, and backer applications, with formulations engineered for fire and moisture resistance. Nichiha, based in Japan, has built a strong architectural panel position by replicating wood, stone, or concrete appearances for residential and commercial projects, and it has been actively extending its product lines in North America. USG Corporation, in the United States, is known for Durock and Solidrock cement boards with proprietary EdgeGuard technology, positioning its offerings around tile backer, water-durable, and mold-resistant performance. American Fiber Cement Corporation distributes and fabricates high-density fiber cement panels and boards, including Swisspearl and Patina series, for cladding and construction applications. Allura produces fiber cement siding panels and boards using Portland cement and wood pulp for exterior applications, backed by long-term warranties that reinforce buyer confidence. Cembrit Holding A/S, in Denmark, focuses on through-colored high-density fiber cement panels for facades and architectural cladding. Etex Group, headquartered in Belgium, markets fiber cement boards and panels under EQUITONE and Cedral brands for ventilated facades and roofing. Everest Industries, in India, manufactures fibre cement boards including SuperHD and ArteSeries for ceilings, walls, and partitions.
What matters strategically is not the list of names alone, but the patterns of behavior they reveal. Recent developments show a clear trend of targeted capacity expansion and product-line extension where demand prospects are strongest. For example, Nichiha expanded its Concrete Series with ConcreteBoard panels for a concrete-like appearance in the United States and Canada, and later introduced a new high-performance fiber cement siding product designed for extreme weather resistance in North America. Etex opened a new fiber cement board manufacturing facility in Santiago, Chile, expanding capacity for Latin American demand. In a parallel move, Shera invested substantially in a new fiber cement board plant in Thailand, aiming to reduce import dependence and create significant local employment. These moves signal where management teams see durable demand, where they believe local production can improve cost competitiveness or supply reliability, and where product differentiation can command specification share.
Market concentration also provides useful context for competitive strategy. The sector exhibits a meaningful degree of consolidation, with the top three firms accounting for approximately 55 percent of market revenue and the top five firms representing around 65 percent. This concentration suggests that scale, brand equity, distribution depth, and technical service capability are important advantages, while also leaving room for specialized players to compete in niche architectural applications or regional fabrication markets. Our report examines how this concentration interacts with regional fragmentation, product specialization, and the influence of large procurement channels, helping leaders assess where competitive intensity is rising and where there is room to build defensible positioning.
Inside the Report: Practical Content for Operating Decisions
The full study is structured to support not only strategic overview but also the operational decisions that follow from it. Rather than stopping at market sizing, the report translates demand, supply, and competitive signals into frameworks that teams can use immediately. Key areas of coverage include:
- A detailed market sizing and forecasting architecture that traces historical performance from 2020 through 2025 and extends the outlook to 2032, with a focus on the 2026–2032 growth path and the 6.1 percent CAGR trajectory.
- Analysis of type segments, centered on the dominance of fiber cement boards and the role of alternative cement board types, with attention to formulation trends, performance characteristics, and product substitution dynamics.
- An application-level review covering siding, flooring, ceiling, roofing, and other use cases, with an emphasis on specification drivers, end-use demand patterns, and the project environments that shape purchase decisions.
- A regional framework that connects demand centers with capacity investments, import dynamics, and local policy environments, helping businesses evaluate where growth is most durable and where exposure to volatility is highest.
- Competitive profiling of leading manufacturers and distributors, including product positioning, geographic focus, recent capacity and product moves, and the strategic implications of recent launches and plant expansions.
- A structural cost and supply analysis that addresses the influence of Portland cement and cellulose fibers on operating economics, including the sensitivity of margins to input price swings and the strategic options available for cost mitigation.
- A regulatory and certification lens that examines the growing importance of Environmental Product Declarations, fire-safety requirements, asbestos-related substitution, and the compliance pathways that influence specification and project eligibility.
- Scenario-oriented decision support that links market signals to practical questions around capacity planning, product mix, pricing strategy, procurement sourcing, and market-entry or expansion priorities.
This structure is intentional. Many market reports provide a single viewpoint and leave readers to reconcile conflicting signals on their own. Our approach integrates demand, supply, competition, regulation, and cost into one consistent analytical frame, so that product, sales, procurement, and strategy teams can use the same underlying logic when making 2026 decisions.
What Decision-Makers Should Take Into the 2026 Cycle
For executives planning the year ahead, several themes emerge from the evidence base. First, growth is real but uneven, and the value lies in identifying which application and regional pathways are most resilient under current regulatory and cost conditions. Second, input-cost volatility is not a temporary inconvenience; it is a structural factor that should be reflected in formulation strategy, supplier relationships, and pricing architecture. Third, compliance and environmental documentation are becoming part of market access, not just a reputational consideration, especially where green building certification and fire-safety performance influence specification. Fourth, the competitive field is being actively reshaped by capacity investments and product innovations in high-priority geographies, meaning that static competitive assumptions will quickly become obsolete.
In practical terms, these themes suggest that 2026 plans should be tested against a few core questions: Where does our portfolio align with the strongest specification trends, and where is it exposed to substitution risk? How sensitive are our margins to cellulose fiber and cement cost movements, and what levers do we have to protect profitability without sacrificing competitiveness? Do we have the documentation, product attributes, and technical support needed to win in specification-driven projects? Are we positioned relative to the recent capacity expansions and product launches that are changing regional supply and demand balances? The full report is built to help answer these questions with evidence rather than intuition.
Access the Full Strategic Assessment
This article has previewed the strategic logic behind our Cement Boards Market study and outlined the key forces shaping the 2026–2032 period. To support rigorous planning, the complete report goes further, offering the detailed segmentation analysis, company-level profiles, regional demand frameworks, cost-structure insights, and competitive benchmarking that operating teams need to make confident decisions. The market is expanding, but the real advantage will come from understanding where growth is most defensible, where costs are most exposed, and where competitors are placing their bets.
For the full dataset, the complete segmentation breakdown, and the extended competitive and regulatory analysis, please access the source report through the PW Consulting web portal. The detailed intelligence enclosed there is designed to serve as a working reference for 2026 strategy sessions, investment reviews, and procurement planning across the cement boards value chain.
For detailed analysis of this topic, please visit the official page: Cement Boards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cordless Vacuum Market Hits $1,758M in 2025, Projected 8.5% CAGR Through 2032
By PW Consulting, 2026-09-07
Unlocking the Future: Strategic Intelligence in the Cordless Vacuum Cleaner Market Through 2032
The home appliance sector is undergoing a profound transformation, driven by shifting consumer preferences toward convenience, advanced technology, and sustainable living. At the forefront of this evolution is the cordless vacuum cleaner market, a segment that has rapidly moved from a niche convenience product to a mainstream household essential. For industry leaders, investors, and strategic planners, understanding the trajectory of this market is no longer optional—it is a critical component of long-term business resilience and growth.
Smart Hand Dryer Market
PW Consulting's latest comprehensive study on the Cordless Vacuum Cleaner Market offers a definitive roadmap for navigating the complexities of this expanding landscape. This article serves as a strategic overview, highlighting the macro-economic trends, competitive dynamics, and regulatory forces shaping the industry from 2026 through 2032. It is designed to demonstrate the depth of intelligence available in our full report, empowering stakeholders to make evidence-based decisions that capitalize on emerging opportunities while mitigating potential risks.
Worldwide Modular Sterile Isolator Market
Market Trajectory and Growth Dynamics
The historical performance of the cordless vacuum cleaner market establishes a strong foundation of consistent demand. Between 2020 and 2025, the global market demonstrated robust expansion, reflecting a permanent shift in cleaning habits away from traditional corded appliances. This upward trajectory is projected to accelerate through the forecast period, underpinned by technological innovation, rising disposable incomes in developing economies, and an increasing emphasis on home hygiene.
Timing Power Optimization Tool Market
Historical Expansion and Future Projections
Analysis of market sizing data reveals a steady compound annual growth rate exceeding 8 percent over the forecast horizon. The market valuation has climbed significantly from the 1.25 billion USD mark in 2020 to an estimated 1.76 billion USD by the base year of 2025. This momentum is expected to carry the market valuation to nearly 1.9 billion USD in 2030, with continued growth pushing toward the 3 billion USD threshold by the end of the forecast period in 2032. Such figures illustrate a resilient category that is outperforming many broader consumer electronics benchmarks, driven by replacement cycles and first-time adopters alike.
The forecast period from 2026 to 2032 is characterized not just by volume growth, but by value creation through premiumization. As battery technology improves and smart features become more sophisticated, the average selling price in specific segments is adjusting, contributing to revenue growth that outpaces unit sales in mature markets. This dynamic suggests that revenue strategy must be balanced with volume targets, particularly as the market matures in regions with high penetration rates.
Key Drivers of Demand
Several structural factors are fueling this expansion. The proliferation of dual-income households has reduced the time available for traditional cleaning methods, increasing the reliance on quick, on-the-go cleaning tools that cordless vacuums provide. Furthermore, the miniaturization of high-efficiency motors and advancements in lithium-ion battery chemistry have extended run times and improved suction power, effectively removing the functional barriers that once hindered adoption.
Urbanization trends also play a pivotal role. As living spaces evolve, particularly in high-density urban environments, the maneuverability and storage efficiency of cordless units offer distinct advantages over bulky, corded alternatives. The integration of cleaning appliances into broader smart home ecosystems is another significant driver, appealing to tech-savvy consumers who value automation and connectivity.
Competitive Landscape and Strategic Positioning
The market structure is moderately concentrated, with the top three players holding a significant share of total industry revenue. The top five competitors collectively command a substantial portion of the market, indicating that scale, brand equity, and distribution networks remain critical barriers to entry. However, the presence of agile innovators from emerging markets has introduced fierce competition, forcing incumbents to continuously differentiate through product features, service ecosystems, and pricing strategies.
Profiles of Key Market Players
A diverse array of global manufacturers is vying for dominance, each leveraging unique strengths and regional advantages. Understanding the strategic positioning of these key companies is essential for benchmarking and identifying potential partnership or acquisition opportunities.
- Dyson: Headquartered in Singapore, Dyson continues to lead the premium segment with a focus on high-end cordless stick and canister vacuums. Their strategy centers on proprietary technology, including laser detection mechanisms for particle visualization and advanced filtration systems that appeal to health-conscious consumers. Dyson's brand equity allows for premium pricing, though they face pressure from competitors offering similar features at lower price points.
- SharkNinja: Based in the United States, SharkNinja has carved a strong position in the mid-to-premium tier with Shark-branded cordless upright and stick vacuums. Their value proposition often highlights powerful suction performance and convenient features like auto-empty stations, which address the pain point of frequent bin emptying. This focus on user experience has helped them gain significant shelf space and online traction.
- Bissell: Another United States-based giant, Bissell offers a broad portfolio of cordless stick and upright vacuums. Their Multi Reach models and self-emptying options cater to a wide demographic, balancing affordability with functionality. With a heritage spanning over a century, Bissell leverages deep trust in the home care category, though they continue to navigate product safety and quality assurance to maintain consumer confidence.
- Dreame Technology: Emerging from China, Dreame Technology is rapidly gaining recognition for cordless stick and wet-dry vacuums that incorporate AI navigation and flexible wands. Their approach blends cleaning performance with technological sophistication, targeting consumers who want versatility in a single device. The introduction of highly maneuverable designs reflects their responsiveness to user feedback and ergonomic demands.
- iRobot Corporation: While known primarily for robotic solutions, iRobot remains a key player in the broader cordless vacuum landscape through its Roomba cordless robot vacuums. Their offerings feature self-emptying stations and advanced mapping capabilities, integrating cordless cleaning into automated home routines. Their focus on software and connectivity differentiates them within the hardware-centric market.
- Tineco: Also based in China, Tineco specializes in cordless stick vacuums that combine wet-dry cleaning capabilities with smart AI features. Their products often emphasize intelligent sensing mechanisms that adjust suction based on floor type or debris load, appealing to the tech-forward segment of the market.
- Miele & Cie: The German manufacturer Miele & Cie emphasizes durability and filtration in their high-end cordless canister and stick vacuums. Their strategy targets the premium long-life appliance segment, where consumers are willing to pay for build quality and extended product lifecycles, aligning with a sustainability-minded purchase decision.
- Bosch: Bosch focuses on integrating cordless stick and canister vacuums with smart home ecosystems. Their approach leverages their broader brand recognition in home appliances and connectivity, aiming to create seamless interactions with other smart devices, which is increasingly relevant for connected home strategies.
- Electrolux: Based in Sweden, Electrolux offers cordless vacuums under various brands, including Eureka and AEG. Their designs prioritize lightweight construction and high performance, addressing the ergonomic needs of a diverse user base. Their multi-brand strategy allows them to cover different price points and regional preferences effectively.
- Eureka: A United States brand and part of the Midea Group, Eureka provides cordless stick and upright vacuums, notably through their ReactiClean series. They focus on accessible performance and practical features, capturing value in the mass-market and value-conscious segments.
- SEBO: The German company SEBO contributes to the market with cordless upright vacuums like the BALANCE A1, utilizing cyclonic technology and bagless operation. Their engineering focus on suction efficiency and dust containment resonates with consumers who prioritize cleaning efficacy and ease of maintenance.
Recent Developments and Innovation Cycles
The competitive landscape is further shaped by a continuous pipeline of product launches and strategic updates. In mid-2026, several key players executed notable initiatives that signal shifting priorities. SharkNinja introduced the Home Luxe Collection with new color options, indicating a move toward aesthetic customization and lifestyle branding to differentiate in a crowded market. Simultaneously, Dreame Technology launched the R10S Cordless Vacuum featuring a 180° bendable wand, directly addressing maneuverability challenges in tight spaces and under furniture. Additionally, Levoit entered the fray with the VortexIQ Cordless Vacuum Series, incorporating green light illumination for enhanced dust visibility, a feature that bridges functional utility with visual appeal.
These launches underscore a broader industry trend where hardware innovation is complemented by user-centric design elements. SEBO also previewed the Balance A1 PRO OCEAN cordless upright vacuum, reinforcing their commitment to cyclonic technology and bagless operation, while highlighting the importance of sustained R&D investment to maintain relevance. For stakeholders, tracking these development cycles is vital to anticipate feature standardization, price compression, and the potential for rapid obsolescence in specific product lines.
Segmentation Dynamics and Regional Nuances
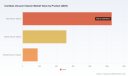
While the aggregate market figures provide a high-level view, the true strategic value lies in understanding how the market fragments across product categories and geographies. The cordless vacuum cleaner market is broadly defined by distinct product forms, each catering to specific use cases and consumer profiles. Stick vacuums represent the dominant product category, reflecting the widespread preference for lightweight, versatile cleaning tools that can transition between floors and surfaces. Robotic vacuums constitute a significant and growing portion of the market, driven by the automation trend and the convenience of scheduled cleaning, though they operate in a distinct sub-segment with different purchasing criteria. Handheld vacuums, while smaller in total share, serve niche applications such as automotive cleaning, stairs, and quick spot cleaning, offering an entry point for budget-conscious consumers or supplementary cleaning options.
Geographically, the market exhibits varied growth drivers and maturity levels. North America remains a substantial contributor to global revenue, supported by high consumer awareness, established distribution channels, and a culture of appliance ownership. The region's market dynamics are influenced by mature competition and a focus on premium features and smart integration. Europe presents a sophisticated market environment where regulatory standards and energy efficiency considerations play a heightened role in product design and consumer choice. The region's emphasis on sustainability and performance labeling shapes the competitive battlefield, favoring manufacturers who align with strict environmental benchmarks. Asia Pacific is characterized by rapid urbanization, a growing middle class, and a high appetite for technological adoption, creating a fertile ground for both volume growth and innovation. The region also hosts a dense concentration of manufacturing and R&D hubs, influencing global supply chain dynamics. Latin America and the Middle East and Africa represent emerging opportunities with distinct challenges related to infrastructure, affordability, and brand penetration, requiring tailored go-to-market strategies for success.
Strategic planning must account for these variations without relying on one-size-fits-all assumptions. Product mix, pricing architecture, and marketing messaging need to be calibrated to the specific demands and regulatory environments of each geography. The interplay between product segmentation and regional preferences creates a complex matrix that demands granular analysis to identify the most lucrative entry points and expansion pathways.
Regulatory and Industry Context Shaping Market Dynamics
The cordless vacuum cleaner market does not operate in a vacuum; it is increasingly influenced by regulatory frameworks and industry standards that affect product design, compliance costs, and consumer perception. These external factors are becoming integral to competitive positioning, as they can dictate market access, influence purchase decisions, and drive innovation in specific directions.
In the United States, the EPA ENERGY STAR certification program establishes energy and filtration performance benchmarks that influence purchase decisions in the mid-to-premium tier of cordless vacuums. Products that meet these standards can leverage the certification as a trust signal, appealing to consumers who prioritize energy efficiency and indoor air quality. This creates a competitive advantage for manufacturers who invest in meeting or exceeding these benchmarks, while also raising the bar for entry into the premium segment.
In the European Union, the regulatory landscape is even more prescriptive. The EU's Battery Regulation and mandatory energy performance labeling play a pivotal role in shaping cordless vacuum cleaner market dynamics. These regulations impact battery sourcing, recyclability, and energy consumption disclosures, requiring manufacturers to adapt their supply chains and product specifications. Furthermore, the European Commission's Ecodesign Regulation for household vacuum cleaners has increased consumer awareness of energy consumption and dust re-emission standards. This has led to a market environment where compliance is not just a legal necessity but a brand reputation imperative. Companies that fail to align with these standards risk losing credibility and market share in one of the world's most scrutinized appliance markets.
Beyond regulation, industry safety and trust remain paramount. Historical product issues, such as voluntary recalls of certain cordless models by major manufacturers, highlight the importance of rigorous quality control and transparent communication. Companies that maintain long-standing reputations for quality and address safety concerns proactively are better positioned to retain consumer trust in an era where product reliability is highly valued. The ability to navigate these regulatory and safety landscapes effectively is a key differentiator that can influence long-term brand equity and market resilience.
The Strategic Value of Comprehensive Market Intelligence
In a market defined by rapid technological shifts, evolving consumer behaviors, and complex regulatory requirements, relying on anecdotal evidence or outdated reports is a strategic liability. PW Consulting's Cordless Vacuum Cleaner Market research study provides the actionable intelligence required to make informed decisions with confidence. This report goes beyond high-level market sizing to deliver a deep, operational understanding of the forces at play.
What the Full Report Delivers
Our study is structured to support multiple facets of strategic planning, from market entry and product development to competitive benchmarking and investment analysis. The report includes detailed segmentation analyses that break down the market by product type, allowing stakeholders to identify growth pockets and assess the competitive intensity within each category. It provides a thorough examination of regional dynamics, offering insights into market maturity, consumer preferences, and distribution channels across key geographies, without exposing the granular data publicly. This ensures that clients gain a nuanced perspective needed for localized strategy formulation.
The competitive landscape section offers an in-depth profile of key market players, analyzing their product portfolios, strategic moves, and market positioning. This enables benchmarking against peers and identification of gaps in the market that may present opportunities for differentiation. The report also incorporates a detailed analysis of recent developments, including product launches, partnerships, and innovation trends, to help stakeholders stay ahead of the curve and anticipate future market shifts.
Furthermore, the study addresses the regulatory and macro-environmental factors that influence the industry, providing a comprehensive view of the risks and opportunities associated with compliance, sustainability, and consumer safety. By integrating these elements, the report serves as a single source of truth for understanding the interconnected dynamics of the cordless vacuum cleaner market. It equips executives, strategy teams, and investors with the data and analysis needed to formulate robust strategies, mitigate risks, and capitalize on the significant growth potential projected through 2032.
Conclusion: Positioning for Success in a Growing Market
The cordless vacuum cleaner market stands at a critical juncture, poised for sustained expansion driven by technological innovation, changing lifestyles, and global economic trends. With a projected growth trajectory that underscores the segment's resilience and potential, the opportunity for strategic gain is substantial. However, realizing this potential requires more than a superficial understanding of market size; it demands a deep, data-driven insight into the competitive landscape, regional nuances, regulatory pressures, and consumer behavior shifts.
PW Consulting's comprehensive market research offers the clarity and depth necessary to navigate this complex environment. By leveraging the intelligence contained in our full study, organizations can align their product development, marketing, and market entry strategies with the most promising avenues for growth. We invite industry stakeholders to access the complete report to unlock the full spectrum of analysis and data, ensuring their strategic decisions are grounded in the most current and reliable market intelligence available. The future of home cleaning is cordless, and the firms that prepare with precision today will define the market tomorrow.
For detailed analysis of this topic, please visit the official page: Cordless Vacuum Cleaner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Unsaturated Polyester Resins Market to Hit $206.7M by 2032 at 6.2% CAGR
By PW Consulting, 2026-09-07
Strategic Imperatives in the Unsaturated Polyester Resins Market: A 2026 Outlook
The global Unsaturated Polyester Resins (UPR) market stands at a critical inflection point as we move deeper into 2026. For stakeholders across the chemical value chain, the ability to navigate shifting demand drivers, raw material volatility, and evolving regulatory frameworks is no longer optional; it is a prerequisite for sustained profitability. This article provides a strategic preview of our latest market intelligence, designed to equip executive teams, procurement leaders, and strategic planners with the contextual depth required to make informed decisions in a rapidly evolving landscape.
Worldwide Electro-Hydraulic Brake (EHB) System Market
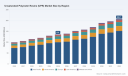
Drawing on a comprehensive dataset spanning historical performance from 2020 through 2025 and a forward-looking forecast horizon extending to 2032, our analysis maps the trajectory of a market that has demonstrated consistent expansion. The valuation recorded in 2025 established a robust baseline, and our projections indicate that the market will continue its upward momentum, reaching a substantially larger scale by the end of the forecast period. At the heart of this outlook lies a compound annual growth rate that underscores steady, compounding expansion across the assessment window. For organizations planning capacity investments, formulation upgrades, or geographic expansions, these macro-trajectories provide the foundational evidence needed to align operational roadmaps with market reality.
Worldwide MTB Helmet Market
The Strategic Calculus: Why 2026 Decision-Making Demands Granular Intelligence
Market-level aggregates tell only part of the story. In practice, the profitability and competitive positioning of UPR players are determined by how well they understand the interplay between resin typologies, application verticals, and regional demand centers. The UP consulting research framework goes beyond headline figures to dissect the structural forces shaping commercial outcomes. Companies that rely on generic industry narratives often misjudge capacity allocation, pricing strategies, or supply chain restructuring timelines. By contrast, decision-makers who access detailed segmentation intelligence can anticipate where demand will concentrate, which product architectures will command premium positioning, and how regional regulatory shifts will alter cost structures.
Worldwide Manual Feeding System Market
This report is structured to deliver actionable clarity across three interconnected dimensions. First, it provides a detailed breakdown of the market by resin type, revealing how orthophthalic, isophthalic, DCPD-based systems, and gelcoats each occupy distinct performance niches and price points. Second, it examines application-driven demand patterns, highlighting how building and construction, marine manufacturing, piping and tank systems, electrical and electronics, transportation, wind energy, and ancillary segments each exert unique pressure on formulation requirements and volume trajectories. Third, it maps regional demand geography, offering a nuanced view of where consumption is maturing, where it is accelerating, and where infrastructure or policy interventions are reshaping local supply dynamics.
Importantly, the segmentation analysis is not presented as static snapshots. Each split is contextualized within demand elasticity, substitute pressure, and feedstock availability, enabling readers to assess not just where the market is today, but how each subsegment is likely to evolve under different macroeconomic and regulatory scenarios. This layered approach ensures that strategic planners can stress-test their assumptions rather than relying on single-point forecasts.
Competitive Landscape: Positioning, Scale, and Strategic Moves
The UPR industry is characterized by a moderately concentrated structure, with a handful of diversified chemical and specialty materials players commanding a significant share of global capacity and innovation pipelines. Our analysis examines the strategic postures of leading organizations, evaluating how their product portfolios, manufacturing footprints, and recent corporate actions shape competitive dynamics.
Among the profiled players, Polynt Group has reinforced its reputation as a specialist in high-performance UPR and marine resins, leveraging a substantial sales volume that underscores its ability to serve demanding composite and marine end-markets at scale. BASF SE continues to position its UPR offerings within its broader performance materials portfolio, targeting composites and industrial applications where formulation consistency and technical service are critical differentiators. AOC, LLC has carved out a niche in specialty UPR and custom formulations, with an increasing emphasis on sustainable grades that align with downstream customers' environmental targets. UPC Technology Corporation maintains a focused manufacturing presence for industrial-grade unsaturated polyester resins, serving application segments that prioritize reliability and cost efficiency. Dow Inc. plays a distinct role in the value chain, producing DCPD resins and supplying key upstream components such as propylene glycol, thereby influencing feedstock availability and cost structures across the UPR ecosystem. Scott Bader Company Ltd. remains a recognized name in Crystic-branded UPR and composite solutions, with operational reach that extends into North America, supporting regional demand for specialized resin systems.
Beyond corporate profiles, recent market developments have introduced new variables into competitive calculations. The 2025 divestiture of INEOS Composites' UPR business to KPS Capital Partners, valued at approximately €1.7 billion, signaled a notable shift in ownership structures and portfolio priorities within the sector. Simultaneously, Ashland Inc announced the launch of new bio-based unsaturated polyester resins targeting automotive and construction applications, illustrating how sustainability-driven product innovation is becoming a commercial imperative rather than a peripheral initiative. Capacity expansion activity also featured prominently, with Reichhold extending its manufacturing footprint in the Asia-Pacific region to capture growing regional demand. More recently, pricing adjustments announced by AOC for EMEA and India markets have highlighted the sensitivity of regional margins to feedstock costs, logistics pressures, and localized demand-supply imbalances.
These events are not isolated incidents; they are indicators of broader strategic repositioning. The report contextualizes each development within the competitive landscape, helping readers understand which moves are likely to reshape market share, which signal technological redirection, and which may trigger pricing or capacity responses from competitors.
Demand Drivers and Application Dynamics
The resilience of UPR demand is anchored in the material's versatility, cost-effectiveness, and adaptability to fiber-reinforced composite architectures. However, the relative importance of individual application verticals is shifting as end-market priorities evolve. Building and construction continues to represent a dominant demand center, driven by infrastructure renewal, facade systems, and corrosion-resistant components that rely on UPR-based laminates and coatings. The marine sector sustains a steady requirement for hull components, recreational boat manufacturing, and repair-grade materials, with performance expectations increasingly tied to durability and reduced lifecycle maintenance.
Pipes and tanks, electrical and electronics, and transportation each contribute distinct demand profiles, often differentiated by specification requirements such as flame retardance, chemical resistance, thermal stability, or lightweighting objectives. Wind energy, while a smaller volume contributor in absolute terms, commands strategic attention because of its alignment with renewable energy expansion and the need for structurally robust blade materials. Ancillary applications further diversify the demand base, creating opportunities for customized formulations and niche-grade resins.
A critical insight from the report is that application demand cannot be evaluated in isolation from formulation economics. The same end-use may require different resin architectures depending on curing systems, fiber compatibility, processing conditions, and final mechanical properties. As a result, the report emphasizes the importance of mapping application requirements to resin type preferences, enabling suppliers to anticipate which product lines will see volume growth, which will face substitution pressure, and where technical service capabilities will become a decisive competitive factor.
Regional Dynamics, Feedstock Pressures, and Regulatory Realities
Regional market structures in the UPR sector are shaped by a combination of industrial density, downstream composite demand, logistics costs, and policy environments. Asia Pacific remains the largest demand hub, reflecting the concentration of manufacturing activity, construction volumes, and marine production capacity. North America, Europe, Latin America, and the Middle East and Africa each present distinct demand profiles, with growth trajectories influenced by local infrastructure cycles, industrial policy, and the maturity of composite supply chains.
Feedstock volatility continues to be a central operational challenge. Fluctuations in propylene glycol and phthalic anhydride prices compress producer margins and complicate volume-to-value forecasting. Maleic anhydride pricing has also exhibited variability linked to downstream UPR demand, reinforcing the need for proactive sourcing strategies and hedging consideration. Organizations that fail to integrate raw material sensitivity into their commercial planning risk margin erosion during periods of rapid input-cost movement.
Regulatory developments have added another layer of complexity. In Europe, new REACH digital product passport requirements have increased operational costs for UPR manufacturers, while the January 2025 update to the SVHC list required producers to adjust supply chain monitoring and strengthen compliance processes. In parallel, trade policy shifts have introduced cost pressures beyond feedstock dynamics; for example, U.S. tariffs on certain European steel and aluminum derivatives have reduced margins for EU UPR exporters by altering the cost competitiveness of derivative-based inputs. These regulatory and trade factors are not merely compliance exercises; they influence plant-level operating economics, export feasibility, and the relative attractiveness of regional sourcing strategies.
The report integrates these dynamics into a cohesive analytical frame, helping readers evaluate how regulatory exposure and feedstock risk vary by geography and by product architecture. This is particularly valuable for companies considering cross-border capacity deployment, export-oriented production, or reformulation initiatives designed to reduce compliance burden.
What the Full Report Delivers: A Practical Intelligence Toolkit
This preview offers a strategic orientation, but the full market research publication is designed to function as a decision-support toolkit rather than a static overview. The complete report provides detailed segmentation analysis across resin types, application verticals, and regional corridors, supported by historical data and multi-year forecasts that allow readers to model demand under different scenarios. It includes competitive profiling that goes beyond corporate descriptions to assess portfolio alignment, capacity implications, and strategic signaling derived from recent industry moves.
Operational and commercial teams will find practical value in the report's treatment of supply-demand balancing, pricing environment indicators, and feedstock sensitivity considerations. The inclusion of recent developments, such as acquisitions, product launches, capacity expansions, and price adjustments, is intended to help readers distinguish between transient events and structural shifts. Regulatory and trade context is embedded within the analysis so that compliance costs, passport requirements, substance-list updates, and tariff impacts can be evaluated alongside commercial planning assumptions.
For organizations preparing 2026 strategy cycles, the report is structured to support multiple use cases: capacity investment screening, market-entry assessment, product roadmap prioritization, supplier selection, and risk scenario planning. By combining macro trajectory evidence with segment-level granularity and competitive context, the research enables leadership teams to move from broad market awareness to specific, testable strategic actions.
Closing Perspective
The Unsaturated Polyester Resins market is entering a phase in which performance differentiation, regulatory adaptability, and feedstock management will matter as much as volume growth. The macro outlook reflects continued expansion, but the real strategic opportunities lie in understanding which resin types, applications, and regions will generate the strongest value creation under changing cost and compliance conditions. Companies that invest in detailed, scenario-aware intelligence will be better positioned to allocate resources efficiently, align product strategies with end-market evolution, and respond to competitive moves with greater confidence.
To access the full segmentation data, detailed company profiles, regional demand breakdowns, and scenario-based forecasts that underpin this analysis, we invite you to explore the complete report. The full publication provides the depth required to translate market direction into executable strategy for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Unsaturated Polyester Resins (UPR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Offshore Patrol Vessels Market Hits $223.42M in 2025, Eyes 4.65% CAGR Through 2032
By PW Consulting, 2026-09-07
Strategic Imperatives in the Offshore Patrol Vessels Market: A 2026 Decision-Making Framework
The global maritime security landscape is undergoing a structural transformation. As naval modernization programs accelerate, coastal states expand exclusive economic zone monitoring, and non-traditional security threats demand multi-mission operational flexibility, the Offshore Patrol Vessels Market has emerged as a critical investment domain for defense primes, shipbuilding consortia, and maritime procurement agencies. This market intelligence report is designed to equip corporate strategists, procurement directors, and investment analysts with a rigorous, forward-looking assessment of revenue trajectories, competitive positioning, and program-level execution dynamics through 2032. The following analysis outlines the strategic architecture of the study, demonstrates how macroeconomic indicators will be translated into actionable commercial insights, and explains why early-cycle visibility into vessel specifications, contract pipelines, and regulatory compliance requirements will separate proactive market participants from reactive observers.
Metaverse Virtual Platform Market
Understanding the Offshore Patrol Vessels Market requires moving beyond headline orders and isolated program announcements. Built within a base year of 2025 and supported by historical tracking from 2020 through 2025, the research framework maps a forecast horizon that extends to 2032. This longitudinal perspective enables decision-makers to evaluate inflection points where program backlogs, material cost pressures, certification timelines, and shipyard capacity intersect. Rather than providing a static snapshot, the study constructs a dynamic modeling environment that links historical delivery patterns to forward demand drivers. By anchoring the analysis in a consistent revenue measurement structure expressed in USD millions, the report maintains comparability across vessel categories, operational applications, and regional procurement ecosystems while preserving the analytical rigor required for capital allocation and competitive positioning decisions.
Worldwide Military Buckles Market
Macro Revenue Trajectory and Forecasting Architecture
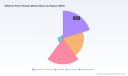
The historical record establishes a clear expansion pathway for offshore patrol vessel procurement and related lifecycle support activity. Revenue progression from 2020 through 2025 reflects sustained demand across navies, coast guard authorities, and maritime law enforcement agencies seeking platforms that balance endurance, patrol coverage, and mission adaptability. The forecast period from 2026 through 2032 extends this trajectory, projecting a compound annual growth rate of 4.65 percent. This rate is neither speculative nor linear; it emerges from an assessment of program backlog conversion cycles, incremental capability upgrades, replacement demand for aging hulls, and the steady broadening of patrol mandates that encompass maritime domain awareness, search and rescue coordination, fisheries enforcement, and pollution response readiness.
Worldwide Embedded Trash Can Market
Strategically, the growth rate signals a market that is expanding at a measured but persistent pace rather than experiencing volatile boom-and-bust cycles. That characteristic matters for operators and investors because it shapes inventory planning, engineering resource allocation, and partnership strategies. A steady expansion environment rewards firms that can standardize modular mission spaces, maintain repeatable production cadences, and align delivery schedules with customer certification and operational readiness milestones. It also rewards procurement teams that can sequence orders in a way that balances fleet renewal priorities with budget cycle constraints and multi-role capability requirements.
The forecast architecture underlying the analysis introduces a disciplined approach to uncertainty. Instead of offering a single deterministic outcome, the methodology isolates the variables most likely to alter program economics and delivery timing. These variables include steel and aluminum procurement cost behavior, labor availability within key shipyard clusters, emissions and safety certification pathways, and the pace at which advanced sensor integration and mission module configurations are adopted across different operational mandates. By structuring the forecast around such drivers, the report equips readers with the logic required to test sensitivity scenarios, rather than forcing reliance on a single point estimate. This approach is especially valuable in a sector where program adjustments, change orders, and multi-year delivery schedules frequently reshape commercial outcomes well after initial awards are announced.
Competitive Architecture and Strategic Positioning
The Offshore Patrol Vessels Market is defined by a concentrated yet internationally distributed competitive field. Leading organizations compete not only on vessel specifications and production capacity, but also on program management capability, lifecycle support integration, and the ability to tailor platforms to specific national or regional operational requirements. The market concentration profile reflects a landscape in which a relatively small group of established shipbuilders commands a substantial share of high-value programs, while regional and specialized yards continue to secure niche and repeat contracts through cost efficiency, localization advantages, and mission-focused design expertise.
Damen Shipyards Group, headquartered in Gorinchem, Netherlands, represents a design-and-build ecosystem centered on multi-mission versatility. Its offshore patrol vessel portfolio spans military and coast guard ranges built for border security, exclusive economic zone surveillance, search and rescue, and fishery operations. The strategic value of this approach lies in its modularity and operational breadth, which enable customers to adapt platforms across complementary mandates without fundamentally redesigning the vessel architecture. For procurement planners, such flexibility can translate into longer service life, broader crew utilization, and more efficient fleet commonality across vessel classes.
Lürssen, based in Lemwerder, Germany, has established a distinctive position through its PV80-class offshore patrol vessel designs intended for naval and coast guard applications. Its relevance in the market is reinforced by the participation of these designs in major international procurement programs, including advanced patrol platforms for defense and maritime security authorities. The competitive advantage here is rooted in engineered performance, rigorous production standards, and the capacity to execute complex shipbuilding programs that integrate advanced sensor and mission payloads. Organizations analyzing competitive positioning will find it useful to evaluate how such engineering-heavy programs balance performance requirements with cost discipline and delivery certainty.
Fincantieri, headquartered in Genoa, Italy, contributes a next-generation patrol vessel family designed to meet integrated operational mandates. Its PPX-derived offshore patrol vessel portfolio emphasizes coastal surveillance, exclusive economic zone protection, and anti-pollution operations. The strategic significance of this offering extends beyond hull construction; it reflects an integrated approach to mission-system integration, regulatory compliance, and naval acceptance standards. For analysts tracking technology adoption and operational readiness, the launch cycle and configuration choices associated with next-generation patrol families provide meaningful signals about how European naval procurement is weighting multi-role capability, emissions considerations, and mission modularity.
Austal, with its operational base in Fremantle, Australia, builds offshore patrol platforms that emphasize multi-role maritime security, border protection, and patrol missions. Its patrol boat family and related variants continue to be relevant for customers that prioritize rapid deployment, endurance, and adaptable mission profiles in regional maritime environments. Given the continued demand for patrol capacity in Indo-Pacific and other high-activity maritime zones, Austal’s production and program execution patterns are closely watched by buyers seeking proven, repeatable hull designs with established operational support frameworks.
Hyundai Heavy Industries, located in Ulsan, South Korea, has strengthened its market presence through offshore patrol vessel construction programs designed for long-endurance maritime patrol and multi-mission roles. Its delivery execution and program management capabilities are particularly relevant for buyers that require large-hull patrol platforms with extended range, sensor integration readiness, and mission module flexibility. The firm’s participation in international naval and coast guard programs highlights a competitive strategy centered on schedule adherence, technical integration, and the ability to support demanding operational endurance requirements.
Beyond these primary strategic players, additional shipbuilding entities contribute to regional patrol capacity through specialized programs and localized maritime security requirements. Jong Shyn Shipbuilding Company, operating in Taiwan, supports patrol fleet development through offshore patrol vessel production tailored to coast guard administration needs. OCEA Shipbuilding and Industries, based in France, supplies and constructs offshore patrol vessels for coast guard and maritime security applications, including charter and operational support activities. These participants illustrate how the competitive landscape extends beyond top-tier global yards to include organizations that win sustained relevance through regional mission alignment, cost-effective production models, and delivery reliability within specific procurement ecosystems.
Program-Level Developments and Market Momentum
Recent activity demonstrates that the market is not only forecast-driven but also shaped by live contract awards, vessel launches, and delivery milestones that alter backlog visibility and capability expectations. In early 2026, multiple developments reinforced the operational tempo and commercial seriousness of offshore patrol vessel procurement. Understanding these milestones is essential because they function as leading indicators of design acceptance, shipyard execution confidence, and customer preference for specific mission configurations.
One notable indicator is contract activity for additional patrol platforms awarded to established builders serving national border and maritime security mandates. Contract extensions and follow-on awards of this nature suggest that buyers are moving from one-off prototype procurement toward fleet standardization and repeat ordering. For market participants, such patterns carry direct implications for production forecasting, workforce planning, and the strategic value of securing design-derivative opportunities rather than competing solely on new bespoke configurations.
On the delivery side, the completion and handover of major offshore patrol vessel programs ahead of schedule have become meaningful signals of execution discipline. Early delivery is not merely a cost or schedule achievement; it reflects coordinated integration of naval acceptance standards, certification compliance, systems testing, and crew training pathways. When a builder delivers a representative vessel months ahead of the original timeline, the event communicates the organization’s ability to manage complexity across materials procurement, outfitting, testing, and program governance. For procurement agencies, these outcomes can influence future award decisions by demonstrating delivery certainty in a sector where operational readiness is often the decisive evaluation criterion.
Equally significant are launch-phase milestones for next-generation offshore patrol vessels. The debut of a first-of-class vessel designed around contemporary mission requirements provides a concrete reference point for assessing how designers are balancing endurance, sensor integration, mission module flexibility, and environmental compliance. Such launches often precede broader procurement waves, making them important indicators for analysts tracking technology evolution and emerging capability preferences within navy and coast guard customer bases. The timing of these events also matters because they can reveal how quickly new configurations are moving from design maturity to operational availability.
Together, these developments point to an active pipeline in which contract awards, deliveries, and launches are shaping market expectations in real time. The strategic takeaway is that offshore patrol vessel procurement is increasingly shaped by execution performance as much as by conceptual design. Buyers and competitors alike are watching who can convert specifications into operational hulls without compromising compliance, endurance, or multi-mission readiness. That reality elevates the importance of program-level intelligence in any market assessment that intends to support forecasting, competitive benchmarking, and long-range planning.
Regulatory, Technical, and Material Dynamics Shaping Demand
Offshore patrol vessel programs do not operate in a vacuum. They are embedded within regulatory frameworks, material procurement conditions, and technical integration requirements that influence both vessel design and commercial viability. As coastal operations extend across longer endurance ranges and broader mission sets, buyers and builders are increasingly aligning specifications with emissions standards, safety regulations, and operational certification expectations. Compliance is no longer a peripheral consideration; it is becoming a determinant of platform eligibility, procurement speed, and lifecycle cost.
One recurring theme across recent program activity is the integration of anti-pollution systems and mission capabilities that reflect evolving maritime authority standards. For navies and coast guard organizations, the inclusion of pollution response readiness alongside surveillance and patrol functions indicates a shift toward platforms that support both security and environmental operational mandates. This convergence influences interior layout, payload allocation, and crew workflow design, as well as the sensor and deployment equipment selected for field operations.
At the same time, advances in detection and mission module integration are reshaping the functional definition of a patrol vessel. Acoustic detection capabilities, surveillance payload integration, and adaptable mission spaces support anti-submarine awareness, coastal monitoring, and extended domain awareness tasks. Rather than treating these features as optional add-ons, forward-looking programs increasingly design them into the vessel architecture from the outset. That integration process affects hull form choices, power management, and aft or deck space planning, all of which carry implications for manufacturing complexity and total cost of ownership.
Material selection remains another critical dynamic. The use of steel and aluminum in offshore patrol vessel construction continues to support cost-efficient multi-mission platforms with extended operational ranges. Material strategy is closely tied to maintenance planning, corrosion management, weight distribution, and long-term repair availability. As procurement authorities evaluate total lifecycle economics, the balance between initial build cost, durability, and reconfiguration potential becomes a decisive factor in platform selection. This is especially relevant when buyers are weighing repeat orders across multiple vessels or coordinating fleet transitions across different mission types.
These dynamics interact with certification and maritime security standards that increasingly influence delivery schedules and acceptance criteria. Early delivery programs, for example, demonstrate not only production discipline but also adherence to updated security and operational certification requirements for long-endurance patrol missions. For industry participants, the practical implication is clear: competitive advantage increasingly depends on anticipating regulatory evolution rather than reacting to it after specifications are finalized. Companies that internalize compliance, emissions considerations, and mission system readiness within their design philosophy will be better positioned to maintain program continuity and secure follow-on demand.
Decision Architecture for 2026 and Beyond
As corporate leaders, procurement strategists, and investment teams prepare for the 2026 planning cycle, the Offshore Patrol Vessels Market presents both opportunity and execution risk. The strategic challenge is not simply to recognize growth, but to interpret where that growth will materialize, which vessel configurations will command sustained demand, and which competitive capabilities will differentiate reliable program delivery from speculative positioning. Effective decision-making in this environment requires a blend of macro awareness and granular program intelligence.
First, organizations must assess how backlog conversion, replacement demand, and new capability requirements will interact over the forecast horizon. A growing market rewards firms that can anticipate which operational mandates will expand, where fleet renewal pressure will intensify, and how multi-mission requirements will influence platform standardization. Strategic planners should evaluate whether their pipelines are aligned with repeat-order potential, derivative design opportunities, and customer preferences for endurance, modularity, and mission adaptability.
Second, competitive positioning must be evaluated in operational terms rather than in broad categorical labels. Shipbuilders and subsystem providers alike will need to understand how design families, production cadences, delivery schedules, and lifecycle support models affect customer selection. Buyers in particular are likely to weigh execution reliability heavily, especially where multi-year programs and certification pathways can delay operational availability. In that context, the ability to demonstrate repeatable delivery, compliant design, and integrated mission readiness can be as commercially significant as nominal price competitiveness.
Third, procurement and investment teams should incorporate sensitivity logic into their forecasting models. Material cost behavior, labor availability in shipyard clusters, certification timelines, and technology integration cycles can all alter program economics. Because the market expands at a moderate rather than abrupt pace, small changes in cost structure or delivery timing can have outsized strategic effects on margin, backlog visibility, and competitive positioning. A disciplined analytical framework that stress-tests these variables enables more robust capital planning and reduces exposure to surprise disruption.
Finally, the strategic value of market intelligence in this sector lies in its ability to connect macro growth with program-level execution. Revenue trends define the size of the prize; regulatory requirements and mission system integration define the rules of competition; contract awards, launches, and deliveries reveal who is already converting strategy into operational results. Organizations that integrate these layers of insight will be better positioned to shape procurement timing, prioritize engineering and production investments, and identify partnership or localization opportunities that strengthen long-term market participation.
What the Full Report Delivers
The complete Offshore Patrol Vessels Market research study is structured to provide decision-makers with an integrated intelligence package that bridges high-level market sizing with practical, program-relevant analysis. It translates historical revenue progression and forecast growth into a forward-looking market model, while preserving the analytical detail required to evaluate where demand will originate, how platforms will be specified, and which competitive capabilities will define execution success. The report combines market structure, competitive positioning, regulatory influence, technical evolution, and recent program milestones into a single strategic framework suitable for procurement planning, competitive benchmarking, and investment analysis.
Readers seeking a full understanding of demand segmentation, competitive capability comparisons, program-level case details, and sensitivity considerations will find the complete study designed to support those objectives without oversimplifying the underlying complexity. The analysis is intended to be actionable: it provides the context needed to interpret market growth, the competitive logic needed to assess rival positioning, and the operational awareness needed to anticipate regulatory and technical shifts that influence procurement outcomes. For teams preparing 2026 strategies and 2026–2032 investment or procurement roadmaps, the full report offers a structured foundation for evaluating opportunity, risk, and execution readiness across the offshore patrol vessel sector.
All underlying revenue figures, segmentation comparisons, concentration metrics, and program-level references are presented within the complete study to enable proportionate strategic evaluation while protecting the depth of proprietary analysis. Market leaders, naval procurement teams, shipbuilding strategists, and investors who require a complete picture of how offshore patrol vessel demand is forming—and where competitive advantage will be earned—will find the full research essential for disciplined planning in a market that rewards foresight, execution discipline, and mission-aligned design capability.
For detailed analysis of this topic, please visit the official page: Offshore Patrol Vessels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Photomask Market Valuation to Reach $384M by 2032, 8.2% CAGR
By PW Consulting, 2026-09-07
Navigating the Photomask Market: Strategic Intelligence for 2026 and Beyond
The photomask industry stands at a critical inflection point. As semiconductor nodes shrink below the 2nm threshold and display manufacturers push the boundaries of OLED and microLED architectures, the demand for precision lithography substrates has never been more complex or more lucrative. For enterprise leaders, investors, and supply chain strategists, understanding the trajectory of this market is not merely an academic exercise—it is a prerequisite for capital allocation, capacity planning, and competitive positioning. PW Consulting's latest Photomask Market research study provides the granular intelligence required to navigate this landscape with confidence. This article previews the strategic depth of that report, framing the macroeconomic currents and competitive tensions that will define the 2026-2032 forecast period.
Fire Anti Drug Mask Market
The Macro Trajectory: A Decade of Structural Growth
The photomask market has demonstrated remarkable resilience and expansion over the past half-decade. Historical data from 2020 through 2025 reveals a consistent upward curve, driven by the insatiable appetite for advanced logic chips, memory density improvements, and the proliferation of high-resolution display panels. The market closed the base year of 2025 with a total revenue valuation of 222.0 Million USD, a figure that underscores the sector's maturation beyond a niche enabler into a fundamental pillar of the global electronics supply chain.
Worldwide Smart Grammar Editor Market
Our forecast model projects this momentum to accelerate through the end of the decade. The compound annual growth rate (CAGR) is estimated at 8.2% across the 2026-2032 window. By 2026, market revenue is positioned to reach 237.65 Million USD, with subsequent years compounding toward a terminal valuation of 384.3 Million USD in 2032. This growth isn't merely linear; it is being reshaped by technological discontinuities. The transition to High-NA EUV lithography, the scaling of sub-2nm logic roadmaps, and the diversification of mask types to accommodate nanoimprinting and specialized defense applications are creating new revenue vectors that legacy models failed to capture. For decision-makers, this trajectory suggests that photomask procurement and investment can no longer be treated as a commoditized overhead line item. It is a strategic lever whose cost structure and availability will directly influence time-to-market for next-generation devices.
Worldwide Surface Antimicrobial Coating Market
Market Dynamics and Technological Disruption
The 2026 outlook is heavily influenced by the convergence of R&D breakthroughs and supply chain realignments. Several pivotal developments have already altered the operational baseline for manufacturers and foundry operators. In July 2025, the SPIE Photomask Technology + EUV Lithography Conference highlighted major milestones in advancing the single-print capabilities of High-NA EUV patterning. These advancements are designed to support the sub-2nm logic technology roadmap, effectively reducing the reliance on multiple patterning steps that have historically inflated complexity and cost. This shift places new performance requirements on photomask fabrication, demanding higher fidelity, tighter defect controls, and specialized pellicle integration.
Parallel to these lithography advancements, strategic partnerships are reinforcing the infrastructure required to sustain them. Imec and ZEISS extended their Strategic Partnership Agreement to 2029, a move that explicitly backs sub-2nm R&D and the NanoIC pilot line. This extended collaboration signals long-term commitment from the research and equipment ecosystems, de-risking the technology pipeline for mask makers and their foundry customers. On the supply side, Dai Nippon Printing began supplying evaluation EUV masks compatible with High-NA tools for beyond-2nm nodes as early as December 2024. Such moves indicate that the transition from research-grade prototypes to evaluable production-ready masks is already underway, compressing the feedback loop between mask suppliers and wafer fabs.
The broader innovation pipeline is also expanding rapidly. Over 60 new photomask variants were introduced globally targeting applications ranging from 3nm chips to large-area OLED panels. This variety reflects an industry moving away from one-size-fits-all solutions toward highly customized, node-specific, and application-specific mask architectures. Furthermore, readiness metrics indicate that approximately 37% of semiconductor foundries upgraded their EUV-compatible photomask production systems for sub-7nm chip manufacturing applications by early 2023. This foundational upgrade wave has now matured, meaning the fabs are increasingly demanding masks that can fully exploit these upgraded systems, raising the technical barrier to entry and rewarding suppliers with proven high-end process capabilities.
Competitive Landscape: Concentration and Differentiation
The photomask market is characterized by a high degree of concentration, a trait that carries significant implications for procurement strategy and M&A analysis. The top three players collectively command a CR3 of 65.4%, while the top five firms extend their grip to a CR5 of 82.3%. This concentration suggests that scale, technological IP, and long-term customer relationships create substantial moats. However, beneath this consolidated surface, competitive dynamics are being redefined by specialized capabilities, geographic footprints, and application diversification.
Leading the field is Tekscend Photomask Corp., headquartered in Tokyo, Japan. As a world premiere provider of photomasks for semiconductors, silicon stencil masks, and molds for nanoimprinting, Tekscend has positioned itself at the forefront of next-generation patterning technologies. Its involvement in nanoimprinting molds signals a strategic bet on alternative lithography pathways that may complement or eventually disrupt traditional optical masking in specific high-volume or specialized use cases.
Photronics, Inc., based in Brookfield, Connecticut, operates as a worldwide leader in photomask technologies and solutions for both semiconductor and flat panel display applications. Its dual-application footprint provides revenue diversification and cross-pollination of technical expertise, allowing the firm to serve logic, memory, and display customers with integrated capabilities. This breadth is particularly valuable as display manufacturing increasingly adopts finer resolution requirements that borrow from semiconductor mask-making know-how.
Dai Nippon Printing Co., Ltd., also headquartered in Tokyo, functions as an integrated supply chain provider of photomasks for semiconductors and displays. The company's integration across the supply chain, combined with its recent move into evaluation EUV masks for High-NA tools, demonstrates a capacity to scale advanced node solutions while maintaining end-to-end control over quality and delivery. In an environment where mask lead times and defectivity are critical bottlenecks, such integration can be a decisive competitive advantage.
Photo Sciences, located in Redlands, California, represents a different strategic archetype. As a specialized manufacturer of high-quality photomasks and custom components, it serves semiconductor, medical, and defense sectors. This diversification into medical and defense applications insulates the business from cyclical semiconductor downturns and opens access to high-margin, low-volume programs where precision and customization outweigh pure scale economics.
Compugraphics, based in Glenrothes, Scotland, focuses on precision semiconductor photomasks for wafer fabrication with an emphasis on cost optimization. In a market where foundry margins are perpetually pressured, suppliers that can deliver high-precision masks alongside cost-efficient processes occupy a vital niche. Compugraphics' positioning underscores that competitive differentiation isn't solely about pushing the bleeding edge; it's also about enabling customers to achieve performance targets economically.
Strategic Segmentation: The Dimensions of Demand
The market's growth is not evenly distributed across all product categories and demand sources. Our analysis decomposes the market into three primary segmentation axes, each carrying distinct risk-reward profiles for stakeholders.
By type, the market encompasses chromium-based masks, E-beam masks, and other specialized variants. Chromium-based masks continue to anchor high-volume production due to their established process compatibility and cost structure, but their dominance is being steadily challenged at advanced nodes where E-beam direct write and other precision methods become indispensable for feature complexity and resolution enhancement. The "other types" segment captures emerging formats, including those designed for nanoimprinting and specialized optical applications, which collectively represent a growing share of incremental revenue. The interplay between these types is shifting: as nodes advance, the mix tilts toward higher-complexity masks that command premium pricing but also require longer lead times and more sophisticated process control.
By application, semiconductor wafer manufacturing remains the dominant demand engine, absorbing the bulk of revenue as logic and memory scaling continue to drive mask complexity and volume. Display manufacturing constitutes a significant secondary pillar, fueled by the transition to high-resolution OLED and the emergence of large-area panel architectures that require precise mask alignment and defect management. The "others" application category includes medical, defense, and research-grade uses, which, while smaller in aggregate volume, often provide higher margin stability and longer program lifecycles.
Geographically, the market spans North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. The regional distribution reflects the underlying geography of semiconductor fabrication, display production, and research infrastructure. Asia Pacific remains deeply intertwined with the concentration of advanced node fab capacity, while North America and Europe host a mix of established mask houses, research institutions, and defense-related demand. Latin America and the Middle East and Africa represent emerging or specialized markets where incremental growth may be driven by specific industrial programs or partnerships. The strategic takeaway for executives is that regional exposure must be managed in the context of customer concentration, supply chain resilience, and the evolving footprint of fab investments.
The 2026 Strategic Imperative for Decision-Makers
Why does this research matter for 2026 planning? Because the photomask market is no longer a passive input to semiconductor and display production; it is a dynamic, technology-gated bottleneck that can accelerate or delay product roadmaps. The convergence of High-NA EUV adoption, sub-2nm node requirements, and the proliferation of mask variants means that procurement teams, capacity planners, and investors must look beyond headline growth rates. They need to understand which mask types will see margin expansion, which application segments will drive volume, and how regional shifts in fab capacity will alter supply-demand balances.
Our report is engineered to answer these questions with operational precision. It maps the revenue trajectory across the 2026-2032 forecast period, situating the 8.2% CAGR within the context of node transitions, display technology shifts, and regional capacity expansions. It dissects the competitive positioning of key players, analyzing how scale, specialization, and technological roadmaps influence market share and pricing power. It evaluates the impact of recent industry milestones—from the Imec-ZEISS partnership extension to the rollout of High-NA-compatible evaluation masks—on the near-term supply environment. And it provides actionable frameworks for assessing vendor viability, lead-time risk, and the cost implications of transitioning to advanced mask formats.
For semiconductor manufacturers and foundries, the insights enable more informed mask sourcing strategies, helping to balance the trade-offs between premium advanced-node masks and cost-optimized production masks. For display companies, the analysis clarifies how mask requirements are evolving with panel resolution and area scaling, supporting capex and supplier selection decisions. For investors and analysts, the report offers a structured view of concentration dynamics, growth vectors, and the technological moats that will separate winners from laggards in a market where the top five firms already control over four-fifths of revenue.
Inside the Report: Operational Depth and Executive Clarity
PW Consulting's Photomask Market study is designed to bridge the gap between high-level market narratives and the operational details that drive execution. The report delivers a comprehensive set of analyses and datasets, structured to support both strategic planning and tactical decision-making.
- Detailed market sizing and forecast across the full 2026-2032 period, with historical context from 2020-2025 to anchor trend analysis and validate model assumptions.
- Segmentation breakdowns by type, application, and region, presented with a focus on structural drivers, demand elasticity, and the shifting mix toward advanced-node and specialty masks.
- Competitive profiling of leading players, including headquarters positioning, product and service scope, and strategic implications of their market activities. The profiles extend beyond descriptive summaries to assess how each firm's capabilities align with near-term technology demands.
- Analysis of industry dynamics and technology milestones, integrating developments such as High-NA EUV patterning progress, strategic R&D partnerships, evaluation mask rollouts, and the introduction of new mask variants across logic and display applications.
- Assessment of concentration and market structure, highlighting the implications of a highly consolidated landscape for pricing, supply continuity, and entry barriers.
- Scenario-based considerations for how shifts in foundry upgrades, EUV-compatible system adoption, and downstream fab capacity expansions could alter mask demand patterns and supplier utilization.
- Executive summaries and visual frameworks designed for board-level review, investor presentations, and cross-functional alignment between procurement, engineering, and strategy teams.
The study is built to be referenced, not just read. Data is organized to support side-by-side comparison of segments, to stress-test assumptions about node transitions and display technology adoption, and to quantify the relative weight of different demand sources over time. By withholding only the most granular sub-segment figures in this preview, we ensure that the full report delivers the precise numbers and cross-tabulations required for internal modeling and investment committee review.
Conclusion: Turning Market Intelligence into Strategic Advantage
The photomask market will continue to be shaped by the relentless pace of semiconductor scaling, the evolving requirements of display manufacturing, and the technological barriers that separate leading-edge capability from mainstream production. With a historical trajectory that has carried the market from 148.75 Million USD in 2020 to 222.0 Million USD in 2025, and a forecast path that projects growth to 384.3 Million USD by 2032, the sector offers substantial opportunity—but only for those who can read its structural signals accurately. The concentration of revenue among a small group of established players, the rapid introduction of new mask variants, and the alignment of R&D partnerships around sub-2nm and High-NA EUV roadmaps all point to a market where expertise, precision, and strategic foresight are the true differentiators.
PW Consulting's Photomask Market research translates these dynamics into a clear, data-rich blueprint for 2026 and beyond. Whether your objective is to secure supply, evaluate competitive positioning, assess investment theses, or align internal roadmaps with external demand shifts, the report provides the intelligence foundation necessary to act with conviction. We invite you to explore the full study, where the complete segmentation detail, forecast tables, and competitive analysis are available to support your next strategic move.
For detailed analysis of this topic, please visit the official page: Photomask Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Online Beauty & Personal Care Market to Hit $561.2B by 2032 at 8.9% CAGR
By PW Consulting, 2026-09-07
Navigating the Digital Beauty Revolution: Strategic Imperatives for 2026 and Beyond
The global beauty and personal care industry stands at a critical inflection point. As digital transformation accelerates across consumer goods, the online segment has evolved from a supplementary sales channel to a primary driver of market expansion and brand equity. For executive leadership teams planning their strategic roadmap for 2026, understanding the nuanced dynamics of this sector is not merely an advantage—it is a necessity. The convergence of shifting consumer behaviors, regulatory evolution, and intense competitive maneuvering requires a data-backed approach to decision-making.
High Security Printing Market
Recent macroeconomic indicators suggest that the sector continues to demonstrate remarkable resilience despite broader economic headwinds. The trajectory from 2020 through 2025 has established a robust foundation for sustained growth. Industry valuations have climbed steadily, reflecting a compound annual growth rate that underscores the vitality of digital commerce in this space. As we look toward the forecast period extending to 2032, the momentum indicates a significant expansion in total market valuation. This growth is not uniform; it is shaped by specific technological adoptions, supply chain optimizations, and evolving regulatory frameworks that define the operational landscape for key players.
Worldwide Mobile Phone 3D Glass Display Market
PW Consulting has synthesized extensive primary and secondary research to produce a comprehensive analysis of the Online Beauty and Personal Care Products Market. This report is designed to equip stakeholders with the intelligence required to navigate the complexities of the coming years. The following insights provide a high-level overview of the market structure, competitive forces, and strategic considerations that will define success in 2026 and beyond.
Worldwide Industrial Grade Cholesterol Market
Market Trajectory and Growth Dynamics
The historical performance of the market from 2020 to 2025 reveals a consistent upward trend. Starting from a valuation of USD 208.5 billion in 2020, the market expanded to USD 310.2 billion by the base year of 2025. This growth reflects the heavy migration of consumers toward digital platforms for purchasing skincare, haircare, and cosmetics. The forecast period from 2026 to 2032 projects further acceleration, with the market expected to reach USD 326.42 billion in 2026 and continue climbing toward USD 561.2 billion by 2032.
This expansion is underpinned by a compound annual growth rate of 8.9 percent throughout the forecast horizon. Such growth rates indicate that digital channels are capturing share from traditional retail at an increasing pace. However, growth is not without friction. Industry executives have identified inflation and uncertain consumer appetite for perceived value as significant risks to industry growth. Approximately 54 percent of leaders surveyed cite these economic pressures as the greatest threat to sustained expansion. This sentiment highlights the need for brands to justify premium pricing through demonstrable value, efficacy, and enhanced digital customer experiences.
Furthermore, the structure of the market remains moderately fragmented despite the presence of dominant players. Market concentration metrics indicate that the top three firms hold a combined share of 25.4 percent, while the top five control 36.7 percent. This concentration level suggests that while major incumbents hold significant influence, there is ample room for niche players and new entrants to carve out specialized positions, particularly within specific product categories or geographic regions. Understanding the balance between consolidation and fragmentation is critical for mergers and acquisitions strategy as well as organic growth planning.
Segmentation and Channel Dynamics
A deep dive into the market structure reveals distinct opportunities across product types and distribution channels. While the overall market size is impressive, the composition of revenue across different segments dictates where investment capital yields the highest return. Skincare continues to represent the largest portion of the product mix, reflecting a global consumer shift toward health-conscious beauty routines and preventative care. Haircare follows as a significant contributor, driven by professional-grade products becoming accessible through online retail. Color cosmetics, fragrances, and oral care round out the portfolio, each with unique growth drivers tied to cultural trends and hygiene awareness.
Distribution channels remain a pivotal area of analysis. Online channels have secured a substantial position in the market hierarchy. In North America specifically, online channels accounted for over 35 percent of beauty and personal care sales in 2025. This statistic underscores the digital-first behavior of consumers in mature markets. However, traditional channels such as supermarkets and hypermarkets still command significant volume, indicating a hybrid shopping behavior where consumers research online but may purchase offline, or vice versa. Specialty stores and pharmacies also maintain strong footholds, particularly for products requiring professional endorsement or specific regulatory compliance.
Regional dynamics further complicate the landscape. North America remains a powerhouse, but the Asia Pacific region represents a critical growth engine with distinct consumer preferences. Europe maintains a steady presence with a focus on premiumization and regulatory adherence. Emerging markets in Latin America and the Middle East and Africa offer high-growth potential but come with logistical and infrastructural challenges. The report provides detailed mapping of these regional variances without exposing the specific valuation figures for each locale, ensuring that strategic partners must engage with the full data set to allocate resources effectively.
Regulatory Landscape and Compliance
The regulatory environment has become increasingly complex, directly impacting product launch timelines and market access strategies. In the United States, the Modernization of Cosmetics Regulation Act (MoCRA) has fundamentally changed the compliance landscape. The FDA expanded its cosmetic database from roughly 35,000 listings to nearly 590,000 by January 2025. This drastic increase reflects a heightened focus on transparency and safety tracking.
Implementation of MoCRA has strengthened compliance requirements and enhanced consumer trust in product safety. For online retailers and brand owners, this means that data integrity regarding ingredient sourcing, manufacturing processes, and adverse event reporting is now more critical than ever. Non-compliance carries significant reputational and financial risk. The report details the specific operational changes required to align with these new standards, offering a checklist for legal and compliance teams to mitigate exposure.
Beyond the US, other jurisdictions are introducing similar frameworks. Multinational companies must navigate a patchwork of regulations that affect labeling, marketing claims, and ingredient restrictions. The strategic implication is clear: regulatory agility is now a competitive differentiator. Brands that can navigate these complexities faster than their peers will gain first-mover advantage in key markets.
Competitive Landscape and Corporate Strategy
The competitive arena is populated by a mix of e-commerce giants, specialty retailers, and traditional beauty conglomerates adapting to digital commerce. Amazon.com, Inc. remains a dominant force, leveraging its massive marketplace to provide direct-to-consumer access to a wide range of beauty and personal care products. Its influence on pricing, visibility, and logistics sets the baseline for online retail expectations.
Specialty retailers like Sephora USA, Inc. and Ulta Beauty, Inc. compete through curation, brand experience, and loyalty programs. Sephora focuses on a curated selection of skincare, makeup, and personal care items, fostering a community-driven shopping environment. Ulta Beauty operates both online and in-store, offering private-label and third-party products with a strong e-commerce presence. In November 2025, Ulta Beauty launched an invite-only marketplace, increasing body care brands and products by 39 percent year-over-year. This move signals a strategic push to expand assortment breadth and capture niche demand within the digital ecosystem.
Sally Beauty Holdings, Inc. specializes in professional and retail beauty, personal care, and hair products with nationwide shipping. Their focus on professional-grade accessibility differentiates them from mass-market retailers. Meanwhile, major brand owners like The Estée Lauder Companies Inc. are actively optimizing their distribution partnerships. Recent developments show a concerted effort to expand presence on premium marketplace platforms. For instance, The Ordinary and Estée Lauder launched in the Amazon.com.mx Premium Beauty Store in late 2025, while Origins launched in the Amazon.ca Premium Beauty Store. These listings indicate a strategy to leverage high-traffic premium placements to drive incremental volume in key international markets.
Understanding the positioning of these key companies is essential for benchmark analysis. The report provides detailed profiles of these entities, analyzing their supply chain capabilities, digital marketing strategies, and recent tactical moves. However, the specific market share percentages and detailed financial metrics for these competitors are reserved for the full report to maintain the integrity of our proprietary analysis.
Strategic Value of the Full Market Report
While the overview above highlights the macro trends and competitive tensions, it merely scratches the surface of the intelligence available. For C-suite executives, investors, and strategy managers, the devil lies in the details. The strategic value of the complete PW Consulting report lies in its ability to convert high-level trends into actionable operational plans.
Actionable Intelligence for 2026 Decision-Making
Decisions made in early 2026 will lock in capacity, inventory, and marketing budgets for the remainder of the year. Relying on aggregate data is insufficient when competitive dynamics are shifting so rapidly. The full report offers granular insights that allow stakeholders to:
- Validate Market Entry Timing: Assess whether current market conditions favor launching new product lines or expanding into specific geographic regions based on detailed demand signals.
- Optimize Channel Mix: Determine the optimal balance between direct-to-consumer websites, marketplace participation, and traditional retail partnerships to maximize margin and reach.
- Mitigate Regulatory Risk: Implement proactive compliance measures based on a detailed breakdown of MoCRA and international regulatory requirements affecting online sales.
- Benchmark Competitive Performance: Compare internal performance metrics against industry standards and key competitor moves without relying on public disclosures alone.
- Identify High-Value Segments: Pinpoint specific product categories and consumer demographics that offer the highest growth potential relative to competitive intensity.
The report includes extensive segmentation analysis that breaks down the market by type, channel, and region. This data is essential for pricing strategy, promotional planning, and inventory management. By understanding the specific contributions of skincare, haircare, color cosmetics, fragrances, and oral care to the overall revenue pool, companies can allocate R&D and marketing spend more efficiently. Similarly, understanding the shift between online, supermarkets, specialty stores, pharmacies, and direct selling channels enables logistics teams to optimize distribution networks.
Integration of Macro and Micro Data
One of the unique strengths of this study is the integration of macroeconomic context with micro-level consumption data. We do not simply present numbers; we contextualize them within the broader economic environment. For example, knowing how inflation impacts discretionary spending on premium versus mass beauty products allows brands to adjust their value propositions. Understanding the specific impact of regulatory changes on online listings helps legal teams prepare for faster time-to-market.
The forecast period from 2026 to 2032 is modeled using scenarios that account for potential economic volatility. Executives need to know not just the baseline forecast but also the risk-adjusted outcomes. The full report provides these scenarios, enabling stress-testing of strategic plans against adverse conditions. This level of depth is crucial for risk management and long-term capital allocation.
Conclusion: The Cost of Inaction
The Online Beauty and Personal Care Products Market is poised for substantial growth, but the path to capturing value is fraught with complexity. The difference between success and stagnation in 2026 will likely come down to the quality of intelligence guiding strategic choices. Companies that rely on outdated models or incomplete data risk misallocating resources in a market that rewards precision and agility.
PW Consulting's comprehensive study offers more than just data; it offers a strategic framework for navigating the next seven years. From analyzing the impact of MoCRA on compliance workflows to evaluating the strategic implications of Ulta Beauty's marketplace expansion or The Estée Lauder Companies' premium store listings, the report connects the dots between industry events and commercial outcomes.
The full dataset includes detailed segmentation splits, regional analyses, and competitive profiles that are essential for building a robust 2026 strategy. Accessing the complete report ensures that your organization is not making decisions in the dark. We invite you to review the full findings to unlock the detailed intelligence required to lead in this dynamic market.
For stakeholders ready to move beyond surface-level insights, the complete report provides the depth needed to secure a competitive advantage. The market is moving fast; ensure your strategy is built on the most accurate and comprehensive foundation available.
For detailed analysis of this topic, please visit the official page: Online Beauty and Personal Care Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Soft Ice Cream Machines Market Hits $605M in 2025, Projected to Reach $990M by 2032
By PW Consulting, 2026-09-07
Strategic Outlook: The Soft Ice Cream Machines Market in 2026 and Beyond
The global soft ice cream machines market stands at a pivotal inflection point as it enters 2026. What was once a straightforward equipment sector driven primarily by casual dining and seasonal tourism has evolved into a technologically nuanced arena shaped by shifting consumer preferences, rigorous regulatory frameworks, and strategic consolidation among leading manufacturers. For executives, procurement directors, and investment analysts, understanding the trajectory of this market is no longer optional—it is a prerequisite for capital allocation, product positioning, and supply chain resilience.
Worldwide Line Chromatic Confocal Sensor Market
Drawing on a comprehensive historical review spanning 2020 through 2025 and a forward-looking forecast period extending to 2032, our latest market research publication offers a granular, decision-ready view of the soft ice cream machines landscape. The analysis captures how the sector has grown from a 2020 baseline of approximately 450 million USD to an estimated 605 million USD in 2025, and projects a measured expansion to roughly 990 million USD by the close of the forecast window. This translates to a compound annual growth rate of 5.2 percent over the projection period, a figure that reflects steady, not speculative, momentum. The following overview outlines the strategic architecture of the report, highlights the competitive forces reshaping the industry, and demonstrates why this intelligence matters for enterprise decision-making in 2026.
Worldwide Vitamin Analysis Service Market
Market Trajectory and Structural Drivers
The historical arc of the soft ice cream machines market reveals a sector that has weathered inflationary pressure, supply chain volatility, and abrupt changes in consumer behavior without losing its long-term growth orientation. Between 2020 and 2025, revenue expansion was supported by the gradual recovery of hospitality and service segments, the normalization of dairy commodity pricing, and the steady adoption of continuous freezers in both mid-sized and entry-level commercial operations. The forecast period from 2026 onward signals a more mature phase of growth, characterized by incremental volume gains, technology-led differentiation, and regional rebalancing rather than explosive headline expansion.
Industrial Marker Pen Market
Several structural drivers underpin this trajectory. First, the commercial soft serve ecosystem continues to benefit from the reinforcement of food safety and operational hygiene mandates. Regulatory bodies in major markets have tightened requirements around certified materials, automated sanitization cycles, and consistent temperature control, effectively raising the barrier to entry for sub-tier equipment and rewarding manufacturers that embed compliance into their core engineering. Second, the rising popularity of plant-based formulations—coconut milk, almond bases, and other non-dairy alternatives—has prompted equipment designers to rethink viscosity handling, cooling efficiency, and cleaning protocols. Machines that can accommodate alternative ingredient profiles without compromising output consistency are gaining preference among forward-looking operators.
Third, macroeconomic and fiscal developments in select regions have altered the effective cost structure of soft serve products. Recent adjustments to indirect taxation on ice cream categories, including a reduction in applicable GST rates from 18 percent to 5 percent beginning in late 2025, have lowered the tax burden on soft serve offerings in relevant markets. This shift, combined with the ongoing sensitivity to ingredient costs—such as the movement in dairy pricing reflected in recent agricultural market data—places greater emphasis on equipment efficiency, portion control, and total cost of ownership. Operators are increasingly evaluating machines not solely on upfront price but on energy consumption, yield reliability, and downtime minimization.
Finally, the sector is being reshaped by the cadence of innovation disclosures and trade activity. Recent product reveals at major industry gatherings, alongside new launches of automated and electronically controlled soft serve units, illustrate how manufacturers are responding to the demand for simpler operation, faster changeovers, and more consistent dessert quality. These developments are not isolated product news; they are indicators of a market moving toward integrated solutions that blend hardware performance with digital monitoring and service support.
Report Architecture and Operational Content
Our market research is structured to convert macro trends into actionable intelligence. Rather than presenting a single aggregate view, the study decomposes the market into logical segments that mirror how buyers evaluate equipment, how manufacturers allocate R&D resources, and how distributors prioritize inventory. The report covers the full historical baseline and forward forecast, but its real value lies in the layered breakdowns that expose where growth is concentrated and where competitive intensity is rising.
At the highest level, the analysis quantifies overall market size across the historical and forecast periods, establishing a consistent baseline for scenario planning. From this anchor, the study moves into segmentation dimensions that matter operationally:
- By region, the report examines how revenue is distributed across major geographic territories, highlighting where installed bases are expanding, where mature markets are stabilizing, and where emerging demand pockets are forming.
- By machine type, the study distinguishes between multi-cylinder configurations, single-cylinder units, and other equipment variants, capturing how form factor influences throughput, footprint, cleaning workflow, and suitability for different operating environments.
- By application, the analysis maps equipment deployment across catering operations, entertainment venues, retail shops, and other end-use settings, revealing which segments are driving procurement frequency and which are favoring higher-capacity or more specialized configurations.
Beyond segmentation, the report integrates a structured review of market dynamics that directly affect equipment purchasing and operating economics. This includes an assessment of raw material conditions relevant to dairy inputs, an evaluation of regulatory requirements imposed by food safety authorities and standards organizations, and a view of how packaging and taxation adjustments influence the broader soft serve value chain. Consumer habit shifts—especially the move toward non-dairy bases and healthier dessert positioning—are treated not as passing trends but as design inputs that manufacturers and operators must account for in product selection and menu planning.
The report also features a competitive landscape section that profiles the key companies shaping the market. Each profile focuses on the firm's specific offering within the soft ice cream machines segment, noting product lines, technological emphasis, and geographic positioning. This is complemented by a timeline of recent developments, including product reveals, launches, and trade show activity, which together provide a sense of the innovation velocity and market signaling patterns that decision-makers need to monitor.
Importantly, the publication does not merely describe the market; it translates findings into strategic questions. For a foodservice group evaluating fleet upgrades, the relevant question is whether to standardize on a single machine architecture or to diversify by application. For a manufacturer assessing market entry or expansion, the relevant question is where the concentration of demand intersects with regulatory and service requirements. For an investor, the relevant question is how the balance between established incumbents and agile new entrants will evolve under tightening compliance norms and changing ingredient economics. The report's segmentation, profiles, and dynamics sections are designed to support answers to these questions without resorting to generic commentary.
Competitive Landscape and Innovation Signals
The soft ice cream machines market is defined by a mix of long-established equipment specialists and regionally focused manufacturers, with a notable concentration of activity among a relatively small group of leading firms. Market structure indicators suggest a moderately concentrated environment, where a handful of producers account for a meaningful share of revenue while a broader tail of regional and application-specific suppliers serves niche demand. This structure has implications for pricing dynamics, service coverage, and the pace at which new features diffuse through the market.
Taylor Company, headquartered in Rockton, Illinois, represents a central force in the commercial soft serve segment. Its portfolio spans conventional soft serve freezers and frozen yogurt equipment, with the ICETRO by Taylor line extending the offering into heat-treated, high-productivity configurations. Recent activity, including a new soft serve unit exhibited in early 2026, underscores the company's continued focus on productivity and equipment versatility. ICETRO America, also under the Taylor umbrella, reinforces this direction with self-contained modular soft serve machines that incorporate automatic pasteurization and high production capacity, appealing to operators that prioritize consistent output and reduced handling risk.
Carpigiani, based in Bologna, Italy, occupies a premium position in the market, with soft serve machines tailored for ice cream vans, trucks, and retail environments. Its lineup covers single-flavor, twin-twist, and pump models, reflecting a focus on mobility, display, and multi-product flexibility. In parallel, Technogel has advanced its artisanal and industrial soft serve machines through electronic control of operating parameters, a development that aligns with the broader industry shift toward precision and repeatability. Tekno-Ice contributes to the higher-capacity end of the spectrum with Italian-made continuous freezers designed for semi-industrial and industrial soft serve production, addressing operators that require sustained output and process stability.
In the United States, Electro Freeze maintains a presence in commercial soft serve and frozen dessert equipment, with batch options and a service network that supports operators seeking local maintenance responsiveness. SaniServ, a long-standing name in the category, offers countertop and high-profit soft serve and yogurt freezers, emphasizing profitability and compact footprints for constrained service environments. On the supply side, Donper from China and Ningbo Sicen Refrigeration Equipment Co., Ltd. from Zhejiang provide commercial soft serve machines and large-capacity refrigeration-based equipment, respectively, contributing to the diversified sourcing landscape and offering alternatives for buyers balancing cost, capacity, and lead time.
Innovation signals from adjacent and complementary players also matter. A home-oriented automatic soft-serve line launched in early 2025 and a consumer-focused swirl machine with built-in freezing technology introduced around the same time illustrate how freezing and dispensing concepts are permeating different market tiers. While these are not direct replacements for commercial continuous freezers, they reflect a broader cultural and technological pull toward accessible, consistent frozen dessert experiences that can influence expectations in commercial settings as well. Meanwhile, scheduled trade activity and equipment exhibits continue to serve as focal points for product introductions and partner conversations, reinforcing the market's reliance on visible innovation cycles and industry gatherings.
Strategic Implications for 2026 Decision-Making
For enterprises operating in or adjacent to the soft ice cream machines market, the current environment demands a disciplined approach to strategy. The growth trajectory is constructive, but the sources of value are shifting from volume expansion alone to a combination of compliance assurance, operational efficiency, and product flexibility. Decision-makers should therefore orient their evaluations around several strategic dimensions.
First, equipment selection should be treated as a multi-year operating decision, not a one-time capital purchase. Regulatory expectations around hygiene, certified materials, and automated sanitization are increasing the cost of non-compliance and the reputational risk of inconsistent food safety performance. Machines that integrate these requirements by design reduce the operational burden on staff and simplify audit readiness. In a market where service coverage and parts availability influence uptime, the reliability of the supplier's support network is as important as the machine's nominal capacity.
Second, the economics of soft serve are increasingly sensitive to ingredient and energy dynamics. Dairy input pricing remains a variable that operators must monitor, and while fiscal adjustments in certain regions have eased some tax-related costs, the underlying pressure on margins persists. Equipment that supports consistent portioning, efficient cooling, and quick cleaning cycles can materially affect per-unit economics. The ability to handle non-dairy bases without major reconfiguration is becoming a differentiator for operators expanding their dessert menus or responding to local demand for plant-based options.
Third, the competitive landscape rewards clarity of positioning. With a moderate degree of concentration among leading producers and a long tail of regional and application-specific suppliers, buyers face a choice between broad-line providers that offer integrated support and specialized manufacturers that excel in particular form factors or end-use contexts. The strategic answer depends on the operator's footprint, throughput requirements, and service model. A standardized fleet may simplify training and maintenance, while a mixed deployment may better match diverse venue types. The report's segmentation detail helps decision-makers map these trade-offs to their own operating realities.
Fourth, innovation monitoring should be embedded into procurement and product planning cycles. Recent product reveals, electronic control enhancements, and modular dispenser options indicate that manufacturers are investing in ease of use, consistency, and configurability. Keeping pace with these developments allows operators to time upgrades advantageously and enables manufacturers to align R&D with demonstrable demand signals rather than speculative features. Trade shows and industry events remain valuable nodes in this monitoring process, offering concentrated views of new hardware, service programs, and partner ecosystems.
Finally, regional dynamics should inform expansion and sourcing strategies. The market's revenue distribution across territories reflects different maturity levels, regulatory environments, and consumption patterns. Operators entering new geographies or suppliers evaluating distribution partnerships need to understand where demand is stabilizing, where it is accelerating, and how local compliance and service expectations shape the viable equipment mix. This is particularly relevant in a market where the same machine family may need to be configured differently to meet region-specific hygiene standards, ingredient availability, and venue formats.
Why the Full Report Matters
This overview is intended to demonstrate the analytical rigor and strategic relevance of our Soft Ice Cream Machines Market research, while respecting the need for decision-makers to access the complete dataset before committing resources. The full report provides the underlying segmentation values, regional and type-level breakdowns, application-level deployment patterns, and company profiles that allow executives to move from directional confidence to precise planning. It also situates the market within the broader dynamics of ingredient costs, regulatory mandates, taxation shifts, and consumer habit changes, offering a single reference point for cross-functional alignment among operations, procurement, finance, and strategy teams.
In a market growing at a steady pace and undergoing simultaneous pressure from compliance, ingredient economics, and technology expectations, the cost of incomplete information is measurable. Procurement decisions made without a clear view of segmentation can lead to fleet mismatches. Investment theses built without a disciplined competitive map can overlook concentration risks or underappreciate the pace of feature diffusion. Operational plans that ignore regulatory and ingredient dynamics can underestimate total cost of ownership. Our research is designed to reduce these blind spots by combining historical continuity, forward visibility, and operational segmentation in one structured analysis.
For organizations preparing decisions in 2026—whether evaluating equipment standardization, assessing market entry, benchmarking competitors, or modeling margin sensitivity—the complete market intelligence offers a practical foundation. The report's segmentation splits, company profiles, recent development timeline, and dynamics review are built to support scenario analysis, procurement roadmaps, and competitive positioning exercises with minimal need for external supplementation.
Positioning for the Forecast Period
The soft ice cream machines market is entering a phase where disciplined execution will matter as much as market growth. The forecast period through 2032 points to continued expansion, but the distribution of that growth will be uneven across regions, machine types, and applications. Suppliers and operators alike will be rewarded for clarity: clear compliance posture, clear total cost of ownership, and clear alignment between machine capabilities and the way desserts are actually served in their target venues.
Our market research provides the structured visibility needed to navigate that complexity. By integrating historical performance, forward projections, segmentation detail, competitive profiles, and dynamic industry signals, the report equips decision-makers to distinguish between transient noise and durable shifts. For executives seeking to align capital, operations, and strategy with the realities of the soft ice cream machines market in 2026 and beyond, the full study offers the depth and specificity required to move from insight to action.
For detailed analysis of this topic, please visit the official page: Soft Ice Cream Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Methyl Diethanolamine Market to Reach $344.8M by 2032 with 6.98% CAGR
By PW Consulting, 2026-09-07
The Strategic Imperative of Methyl Diethanolamine: Navigating Growth, Supply Constraints, and Competitive Realignment Through 2032
Why 2026 Demands a Fresh Market Intelligence Framework
The Methyl Diethanolamine (MDEA) market is entering a decisive inflection point. Over the past half-decade, the sector has transitioned from a stable, back-office chemical supply chain into a dynamically priced, regionally fragmented, and capacity-constrained market where procurement timing, grade selection, and supplier diversification now directly influence operating margins and compliance posture. For executives planning capital allocation, sourcing strategies, and downstream product roadmaps in 2026, the question is no longer whether MDEA demand will grow, but how the interplay of feedstock volatility, logistics bottlenecks, and concentration-driven pricing power will reshape cost structures across gas treatment, textiles, and specialty applications.
Anti-Static Treadmill Mat Market
Our latest market research report is engineered as a decision-grade intelligence asset, not a static snapshot. It maps the trajectory from 2020 through a ten-year forecast horizon to 2032, converting historical demand signals into forward-looking strategic scenarios that boards, procurement leads, and R&D directors can operationalize immediately. The analysis is anchored in a measured compound annual growth rate of approximately 7 percent, reflecting a market that has consistently expanded from the low 160-million-dollar range in 2020 to a projected valuation exceeding 234 million dollars in 2026, and climbing toward 344 million dollars by 2032. This trajectory is not merely a function of volume growth; it is a composite of grade premiumization, application migration, and the strategic re-pricing of industrial amines in response to macro petrochemical pressures.
Integrated Stroller-Bike Market
What separates this study from conventional market summaries is its emphasis on structural drivers rather than headline figures. The report dissects the forces that will determine whether organizations can secure reliable supply at predictable cost points, where capacity expansions are most likely to shift regional availability, and which segments will absorb incremental demand versus those approaching saturation. By keeping the analytical lens on decision architecture, the research equips leaders to translate macro growth into actionable sourcing contracts, inventory buffers, and partnership strategies before price shocks or supply disruptions force reactive moves.
Worldwide Unmanned Vehicle Universal Chassis Market
Decoding the Trajectory: A Ten-Year Outlook Built for Scenario Planning
The forecast period from 2026 through 2032 is modeled around a growth environment that is steady in aggregate but highly differentiated underneath the surface. Starting from an estimated 2025 valuation of approximately 215 million dollars, the market is projected to step up to roughly 234 million dollars in 2026, then advance through subsequent years to reach 241 million dollars in 2027, 260 million dollars in 2028, 274 million dollars in 2029, 296 million dollars in 2030, 324 million dollars in 2031, and 344 million dollars in 2032. This progression reflects a market that is compounding without dramatic volatility, yet remains sensitive to input-cost cycles and capacity decisions made by leading producers.
Readers who rely on top-line growth alone risk misreading where value is being created and captured. The report deliberately avoids flattening the market into a single narrative. Instead, it separates trend signals from noise by examining how demand is distributed across application domains, how purity grades are becoming more consequential in procurement specifications, and how regional availability patterns are shifting as producers adjust logistics footprints and feedstock sourcing strategies. The objective is to help decision-makers identify which growth pockets are structurally supported and which are transient, enabling more precise capacity planning, contract negotiation, and risk hedging.
Importantly, the study translates these trajectories into practical scenario frameworks. Rather than presenting a single deterministic line, the analysis incorporates alternative pathways tied to raw material cost movements, transportation constraints, and demand intensity in core end-use sectors. This approach allows organizations to stress-test their MDEA exposure under different cost and supply assumptions, so that procurement policies and inventory strategies remain resilient even if input markets swing sharply.
- Historical demand patterns from 2020 to 2025 are used as calibration points, not just background data, so forecasts reflect how the market has actually responded to past cost and capacity shifts.
- The forecast model emphasizes grade-level relevance and application sensitivity, helping teams understand where pricing power is likely to concentrate and where substitution or spec adjustments can mitigate exposure.
- Regional and sectoral divergence is presented as a strategic map rather than a simple table, so readers can prioritize which markets warrant deeper due diligence before committing to long-term supply agreements.
What the Report Actually Delivers: A Practical Toolkit for Sourcing, Pricing, and Capacity Decisions
The MDEA market study is built for immediate operational use. It goes beyond aggregate growth figures to deliver a structured set of analyses that procurement, strategy, and operations teams can apply directly to sourcing plans, contract structures, and investment prioritization. The report is organized around real decision moments: securing volume at acceptable cost, selecting the right grade for a given process requirement, anticipating regional availability shifts, and evaluating which suppliers can reliably support long-term commitments.
One of the core components is a deep segmentation review that examines how the market breaks down across application domains and product grades, without reducing the analysis to simplistic share percentages. The report explains why certain application areas are absorbing incremental volume, what technical or regulatory drivers are shaping demand, and how purity specifications are influencing both pricing and supplier selection. This is especially valuable for organizations that must balance process performance with cost control, since the choice between different MDEA grades can have meaningful implications for absorption efficiency, handling requirements, and downstream performance in gas treatment workflows.
The study also includes a comprehensive competitive landscape assessment that profiles the principal manufacturers shaping global supply. Rather than simply listing company names, the report evaluates how each producer is positioned in terms of product breadth, specialty-grade capabilities, geographic footprint, and brand recognition in end markets such as oil and gas acid gas removal and industrial amine applications. This competitive mapping is paired with an analysis of concentration dynamics, giving readers a realistic view of how supplier power is distributed and where alternative sourcing options may be necessary to maintain negotiation leverage.
- Detailed company profiles covering leading global producers and regional manufacturers, including their core product lines, application focus, and strategic positioning in gas treatment and specialty chemical supply chains.
- A structured review of recent market-moving events, including pricing adjustments, logistics cost pressures, and feedstock-driven re-pricing actions that signal how quickly supplier strategies can shift.
- A concentration assessment that illustrates how supply is distributed among top players, helping organizations gauge dependency risk and identify where diversification could improve sourcing resilience.
- Application and grade-level analysis that connects technical requirements to procurement strategy, so teams can align product specifications with cost, performance, and availability considerations.
Beyond the segmented deep dives, the report provides a synthesis layer designed for executive consumption. It translates complex data into a coherent narrative about where the market is becoming more price-sensitive, where capacity constraints may emerge, and which structural factors are most likely to influence the next cycle of supplier behavior. This is intended to help leaders move from data recognition to action: adjusting contract terms, re-evaluating inventory policies, and aligning internal specifications with the realities of a market that is growing steadily but not uniformly.
Competitive Realignment: The Players Setting Price, Grade, and Supply Expectations
The MDEA market is defined by a relatively concentrated supplier base that includes large multinational chemical producers alongside regional manufacturers serving specific demand centers. This structure matters because it determines how pricing signals propagate, how quickly capacity adjustments can be made, and how much flexibility buyers realistically have when negotiating long-term supply. The report profiles the organizations that are most influential in shaping availability and cost expectations, from established European and North American producers to Indian, Chinese, and Russian manufacturers with regional supply strengths.
Among the globally recognized names, BASF SE stands out as a leading producer of alkylethanolamines, including MDEA, with a strong presence in gas treatment and petrochemical applications. Dow Inc. is similarly prominent through its UCARSOL brand, which is widely associated with acid gas removal in oil and gas operations. Huntsman Corporation supplies MDEA across gas-treating applications and offers specialty grades such as JEFFTREAT 783, while Eastman Chemical Company produces Amietol M12 for industrial and specialty uses. These companies illustrate the breadth of product strategies in the market, ranging from large-volume industrial supply to more technically differentiated grades targeting specific performance requirements.
At the same time, regional producers play an increasingly important role in balancing availability and price. Advance Petrochemicals Ltd. and Amines & Plasticizers Ltd. represent Indian manufacturing capacity oriented toward gas treatment and petrochemical supply, while Maoming Yunlong Industrial Development Co. Ltd. reflects Chinese production focused on industrial and gas treatment demand. Sintez OKA Group adds another layer through its regional supply orientation in oil and gas and specialty chemicals. The presence of this diverse supplier spectrum means that procurement strategy cannot rely on a single sourcing model; instead, it must evaluate which producers offer the right combination of grade consistency, geographic reach, and responsiveness to cost changes.
- Profiles of leading multinationals and regional manufacturers, with emphasis on how their product portfolios, brand positions, and application focus shape procurement options.
- An assessment of concentration dynamics that shows how the top suppliers collectively influence pricing stability and supply risk across the market.
- A competitive lens that helps buyers understand where differentiation is real versus nominal, so they can target suppliers whose capabilities match specific gas treatment, textile, or specialty process needs.
Recent market signals reinforce the importance of monitoring supplier behavior closely. In March 2026, BASF announced a planned price increase for amines, including MDEA, effective in early April, citing logistics and raw material feedstock cost increases. This kind of action is emblematic of the broader environment: MDEA pricing is increasingly tied to transportation costs, feedstock dynamics, and macro petrochemical pressures rather than to demand alone. The report uses such developments as reference points for understanding how quickly cost structures can shift and what that means for contract timing, inventory planning, and alternative supplier evaluation.
Pricing, Feedstocks, and the Emerging Cost Architecture of MDEA Supply
One of the most operationally relevant themes in the current market is the erosion of the assumption that MDEA cost will move predictably with volume alone. Prices are being shaped by a combination of feedstock economics, logistics friction, and supplier pricing discipline in a concentrated market. As a result, procurement teams need to think beyond unit price and consider total cost exposure, including transportation, grade suitability, and the risk of sudden re-pricing when input costs rise.
The study situates these pricing dynamics within the broader petrochemical context, where global market pressures and regional disruptions can influence feedstock availability and transportation costs. This is not a theoretical concern. When leading producers adjust pricing to reflect logistics and feedstock cost increases, the effect can cascade through downstream supply chains, especially for organizations that rely on just-in-time procurement or narrowly defined specifications. The report examines how these pressures interact with concentration in the supplier base, making it important for buyers to anticipate re-pricing cycles rather than react to them after contracts are locked.
At the same time, the analysis emphasizes that cost is not the only variable. Grade selection and application fit remain central to value creation. Higher-purity or specialty grades can carry different cost implications, but they may also reduce processing inefficiencies or improve performance in demanding gas treatment environments. The research helps organizations evaluate these trade-offs by connecting specification requirements to market availability, so that purchasing decisions are aligned with both technical needs and commercial realities.
- An evaluation of how feedstock and logistics pressures are reshaping supplier pricing behavior and what that means for contract timing and inventory strategy.
- A discussion of concentration-driven pricing influence, helping teams understand where negotiation flexibility is likely to exist and where alternative sourcing may be necessary.
- Practical guidance on integrating grade selection, application performance, and total cost considerations into a coherent procurement framework.
The Roles of Grade and Application: Where Value Is Captured and Where Constraints Bite
The report treats the market's segmentation as a strategic map rather than a passive classification. Across product types, the analysis looks at how different MDEA grades are positioned and why some specifications command more attention in procurement plans than others. The presence of multiple purity levels means that buyers often face trade-offs between performance, handling complexity, and cost, and those trade-offs can become more pronounced when supply tightness or re-pricing events occur.
On the application side, the study examines the demand environment across major end-use areas without reducing the picture to a single dominant narrative. Gas treatment remains a core demand driver given the continued importance of acid gas removal in oil and gas operations, but the report also considers how other application domains contribute to overall demand and where growth may be more selective. This balanced view is essential for organizations that need to understand not just where the market is expanding, but which segments are likely to offer stable, repeatable demand versus those that may be more sensitive to economic cycles or technical substitution.
By linking grade and application analysis to procurement outcomes, the report helps teams answer practical questions: which specifications are most critical for a given process, which segments are most exposed to price volatility, and where might spec adjustments or supplier diversification reduce risk without compromising performance. This kind of linkage is what turns industry data into business value.
- A focused look at how product grades influence pricing, specification decisions, and supplier selection in real procurement environments.
- An application-oriented assessment that distinguishes between structurally supported demand and more variable segments, helping leaders prioritize sourcing attention.
- A practical framework for aligning technical requirements with market availability, so that sourcing strategies are both cost-aware and performance-appropriate.
Using This Research to Convert Uncertainty into Advantage
The central value of this market study is its ability to convert a complex, cost-sensitive, and supplier-concentrated environment into a usable strategic framework. In 2026, organizations that rely on informal market knowledge or lagging price signals are likely to face avoidable exposure when feedstock costs rise, logistics constraints tighten, or leading producers adjust pricing. The report is designed to reduce that vulnerability by giving decision-makers a clearer view of where growth is coming from, how the supplier base is structured, and which levers can improve sourcing resilience.
For procurement teams, the research supports more informed contract timing, specification choices, and supplier diversification strategies. For strategy and planning functions, it provides a grounded basis for scenario modeling around cost trajectories and availability risk. For R&D and operations leaders, it clarifies how grade selection and application fit interact with market dynamics, helping to align internal requirements with external supply realities. In each case, the goal is the same: to enable proactive decisions rather than reactive mitigation.
The report also recognizes that complete confidence in any forecast is unrealistic in a market influenced by macro petrochemical pressures and logistics volatility. That is why the analysis emphasizes structural patterns, supplier behavior signals, and decision-relevant segmentation over rigid predictions. By focusing on what is most likely to shape buyer and supplier actions over the forecast horizon, the study gives organizations a practical way to prepare for multiple outcomes instead of betting on a single one.
- A decision-oriented synthesis that helps executives and operational leaders connect market structure to sourcing, inventory, and contract strategy.
- Signal-based monitoring guidance drawn from recent pricing and cost developments, so teams can track the indicators most likely to precede supplier re-pricing or availability shifts.
- A forward-looking lens for scenario planning, enabling organizations to test how different cost, supply, and demand assumptions would affect their MDEA exposure through 2032.
Get the Full Intelligence: The Data, Profiles, and Scenario Tools Behind This Overview
This article is an introduction to the depth available in the full Methyl Diethanolamine market research report. While the discussion above highlights the strategic logic, competitive structure, and pricing dynamics shaping the market, the complete study contains the granular segmentation detail, supplier profiles, concentration analysis, and scenario frameworks that leaders need to make precise sourcing and planning decisions. The full report is where the headline trajectory is connected to the operational details that determine whether a strategy will hold up under real market conditions.
For teams responsible for procurement, cost planning, or market positioning, the full report offers the level of specificity required to move from general awareness to targeted action. If your objective is to understand where MDEA demand is structurally headed, how supplier concentration affects pricing power, and which grade and application considerations should shape your sourcing posture, the complete research package provides the full analytical foundation.
The market is growing, but not uniformly. Costs are being repriced, supplier behavior is shifting, and application demand is distributed across segments with different risk profiles. In that environment, the organizations that perform best will be the ones that base their decisions on detailed, decision-grade intelligence rather than on surface-level metrics. The full report is built for exactly that purpose.
Discover the complete segmentation analysis, competitive profiles, concentration insights, and forward-looking scenario tools by accessing the full market research study. The detailed data and structured frameworks inside are designed to support the next cycle of procurement, strategy, and operational decisions across the MDEA value chain.
For detailed analysis of this topic, please visit the official page: Methyl Diethanolamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Intelligence: The Shellac Market Outlook for 2026 and Beyond
As we navigate the complex landscape of global commodity markets in 2026, few sectors offer the nuanced blend of heritage, regulatory scrutiny, and sustainable innovation quite like the natural resin industry. At PW Consulting, we have just completed a comprehensive deep-dive into the Shellac Market, delivering a forecast model that extends from 2026 through 2032. This report is not merely a collection of statistics; it is a strategic tool designed to inform procurement, investment, and operational decisions in a market characterized by concentrated supply chains and evolving consumer preferences.
Horizontal Fan Coil Units Market
The shellac industry stands at a critical juncture. Driven by the global shift towards natural ingredients and eco-friendly finishes, demand dynamics are reshaping how stakeholders approach sourcing and production. Our latest research encapsulates the trajectory of this market, providing a clear view of the growth corridors and the competitive forces that define them. For executives and strategists looking to secure their supply lines or identify new revenue streams, understanding the macro trends is only the beginning. The true value lies in the granular analysis of market segmentation, regulatory impacts, and competitor positioning that our full report provides.
Home Building Material E-Commerce Platform Market
Market Trajectory and Macro Economic Indicators
Our analysis begins with a rigorous examination of historical performance and future projections. The Shellac Market has demonstrated consistent resilience and steady expansion over the past five years. According to our data, the global revenue generated by the shellac industry has climbed from approximately 143.25 Million USD in 2020 to an estimated 170.28 Million USD in 2025. This historical progression sets a robust baseline for our forecast period, which spans from 2026 to 2032.
Worldwide Construction Vehicle Axle Market
Looking ahead, the market is projected to reach a valuation of 221.57 Million USD by the end of 2032. This growth trajectory implies a Compound Annual Growth Rate (CAGR) of 3.95 percent during the forecast period. While these aggregate figures provide a high-level view of economic health, the strategic implications run deeper. The steady upward momentum suggests a market that is not subject to volatile boom-and-bust cycles typical of some commodity sectors, but rather one driven by structural increases in consumption across specific application verticals.
It is important to note that while the overall market size is expanding, the distribution of value across different segments varies significantly. Strategic decision-makers must understand where the value is being generated. Our full report dissects these segments to reveal which regions and applications are outperforming the baseline CAGR, allowing clients to allocate resources more effectively. For instance, while the global aggregate grows steadily, certain regional markets exhibit higher sensitivity to raw material availability and regulatory changes, creating unique opportunities for localized supply chain optimization.
Supply Chain Dynamics and Regional Powerhouses
The structural integrity of the shellac supply chain is a paramount concern for any organization involved in its trade or utilization. Our research highlights a significant geographic concentration in the production and export of raw and refined shellac. India remains the dominant force in this arena, accounting for a substantial majority of the global lac resin supply. This dominance is rooted in the specific agro-climatic conditions of regions like Chhattisgarh, where the lac insect secretions are harvested.
The concentration of supply in a single geographic region presents both opportunities and risks. On one hand, it offers a consolidated sourcing hub for international buyers. On the other, it necessitates a deep understanding of the local labor dynamics and environmental regulations that govern production. Our industry context analysis indicates that the Indian shellac industry employs a significant workforce across hundreds of factories and processing units, known locally as bhattas. The stability of this labor force and the adherence to safety standards are critical variables that influence export reliability.
Furthermore, the geopolitical landscape plays a crucial role in trade flows. India's export strategy is heavily oriented towards key markets in Europe and the United States. Trade bodies and government agencies are actively facilitating these connections, recognizing the economic importance of this niche export sector. Recent initiatives have focused on connecting global buyers with Indian suppliers through dedicated expos and trade promotions. These events are not merely ceremonial; they are strategic interventions designed to secure long-term contracts and enhance the visibility of Indian shellac products in high-value markets.
Key Industry Developments and Trade Facilitation
In May 2026, significant activity was observed in the trade promotion sphere. SHEFEXIL, a key export promotion council, announced the second annual Bharat Nutraverse 2026 expo. This event, organized with the support of the Government of India, serves as a critical bridge between global buyers and Indian shellac and nutraceutical suppliers. Such initiatives underscore the government's commitment to elevating the quality and global reach of these products. For market participants, these events represent vital opportunities to forge new partnerships and stay abreast of regulatory updates concerning food-grade and pharmaceutical certifications.
Competitive Landscape and Player Positioning
The global shellac market is characterized by a mix of specialized manufacturers, exporters, and distributors. Our report provides a detailed competitive analysis of the key entities shaping the market. The competitive intensity is moderated by the specialized nature of the product, yet the market concentration ratios indicate that a handful of major players hold a significant share of the revenue. Specifically, the CR3 and CR5 metrics suggest a moderately concentrated market where scale and quality certification are key differentiators.
Leading the charge in India are several established manufacturers who cater to diverse global requirements. Companies such as D. Manoharlal (Shellac) Pvt. Ltd. and SK Shellac Company have built reputations on supplying top-grade shellac, dewaxed flakes, and refined products specifically tailored for food, cosmetic, and pharmaceutical coatings. Their ability to maintain consistent quality while scaling production is a critical factor in their market standing. Similarly, Vishnu Shellac Factory and Jagdamba LAC Factory focus on serving European and North American specialty markets, positioning themselves around heritage quality and food-grade compliance.
On the international front, European and American distributors and manufacturers play a pivotal role in refining and distributing these materials to end-users. Stroever Schellack Bremen (SSB) GmbH & Co. KG in Germany supplies premium shellac grades for food, pharmaceutical, and industrial applications, leveraging machine-made refining processes to ensure purity. In the UK, A.F. Suter and Co. Ltd operates as a key wholesaler and distributor, managing the import and export of high-quality shellac, waxes, gums, and resins. These entities often act as the crucial link between raw material producers and final formulation companies, adding value through logistics and quality assurance.
In the Asia Pacific region, beyond India, players like Chuxiong DES Shellac Co., Ltd. in China are notable for their emphasis on sustainable raw material base development and the production of food-grade high-purity refined shellac. Meanwhile, niche players like Shellac Finishes in Eastern India focus specifically on the woodworking and furniture restoration segments, importing and manufacturing fresh dewaxed shellac flakes. This segmentation of competitor focus allows for a targeted analysis of where competitive pressure is highest in specific value chains.
Strategic Implications for Competitive Intelligence
Understanding the profile of these competitors is essential for benchmark analysis. Our report goes beyond basic company profiles to analyze their strategic moves, capacity expansions, and certification statuses. For a procurement manager, knowing which supplier has the strongest foothold in pharmaceutical-grade certifications can mitigate supply risk. For an investor, identifying which manufacturers are aligning with sustainability trends can highlight long-term viability. The full deliverable includes detailed profiles of these key companies, offering a comparative view of their offerings and market reach.
Segmentation Analysis: Type, Application, and End-Use
One of the most valuable aspects of our research is the granular breakdown of the market by type and application. The shellac market is not monolithic; it is divided into distinct product categories such as waxed, dewaxed, bleached, and other variants. Each type commands a different price point and serves different functional requirements. For example, dewaxed shellac is often preferred for specific industrial and wood finishing applications where clarity and penetration are key, while waxed variants may find preference in other contexts.
Similarly, the demand drivers vary significantly across application verticals. The Food & Beverage sector represents a major consumption base, driven by the demand for natural glazing agents and coatings. Pharmaceutical applications require rigorous adherence to safety standards, creating a high-barrier entry point that benefits certified suppliers. The Cosmetics industry utilizes shellac for its natural properties in formulations, while the Woodworking sector relies on it for traditional finishes and restoration work.
Our analysis delves into the revenue contributions of each of these segments without losing sight of the interdependencies. A surge in demand for natural cosmetics, for instance, can ripple through to increase pressure on raw material availability, affecting pricing across the board. By understanding these linkages, clients can better anticipate cost fluctuations. However, the precise percentage splits and specific revenue contributions for each segment are detailed exclusively in the full report to maintain the depth of commercial confidentiality we offer our subscribers.
Regulatory and Quality Standards
Regulation is a defining force in the shellac market. As the product moves into food and pharmaceutical channels, compliance becomes non-negotiable. Organizations like SHEFEXIL support manufacturers in obtaining the necessary food-grade and pharmaceutical certifications under global safety standards. This regulatory support is vital for maintaining access to lucrative markets in Europe and North America. The cost of compliance and the time required to achieve certification are strategic factors that our report evaluates for each major region and company type.
Strategic Recommendations for 2026 Decision Makers
Based on our comprehensive analysis, we offer several strategic considerations for stakeholders operating in the Shellac Market in 2026.
- Diversify Sourcing Strategies: Given the high concentration of raw material production in India, companies should evaluate multi-sourcing strategies or secure long-term contracts to mitigate geopolitical or climate-related disruptions in the primary supply region.
- Invest in Certification: For players aiming to penetrate high-value segments like pharmaceuticals and premium food products, prioritizing regulatory compliance and certification is a direct pathway to margin expansion and market access.
- Monitor Sustainability Trends: The industry trend towards natural and eco-friendly solutions is accelerating. Manufacturers and brands that can verify the sustainability of their supply chain will gain a competitive advantage in marketing and procurement negotiations.
- Leverage Trade Events: Participation in industry-specific expos, such as the Bharat Nutraverse, provides direct access to innovation and networking opportunities that can lead to exclusive distribution agreements.
- Analyze Regional Nuances: While global averages provide a direction, regional dynamics differ. Strategies should be tailored to specific geographic markets, considering local consumption patterns and regulatory environments.
Conclusion
The Shellac Market is poised for continued growth, underpinned by a shift towards natural ingredients and steady demand across diverse industries. However, realizing the value of this growth requires more than just observing the headline numbers. It demands a deep understanding of the supply chain vulnerabilities, the competitive tactics of key players, and the regulatory frameworks that govern trade.
PW Consulting's full Shellac Market Report offers the detailed intelligence necessary to navigate this landscape with confidence. We have outlined the macro trajectory and the key players here, but the specific data points, regional splits, and competitor benchmarks that drive precise decision-making are contained within our comprehensive document. For organizations committed to strategic excellence in 2026 and beyond, accessing this level of detail is not optional; it is essential.
We invite you to explore the full findings of our study to uncover the specific opportunities that align with your organizational goals. The market is moving; ensure your strategy moves with it.
For detailed analysis of this topic, please visit the official page: Shellac Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Downlights Market to Hit $2.16B by 2032, Growing at 5.5% CAGR
By PW Consulting, 2026-09-07
Navigating the Downlights Market: Strategic Intelligence for 2026 Decision-Makers
The global lighting industry is undergoing a structural transformation, driven by energy efficiency mandates, rapid technological iteration, and shifting macroeconomic pressures. Within this landscape, the downlights sector represents a critical intersection of architectural design, commercial functionality, and residential aesthetics. As organizations plan their capital expenditures and product roadmaps for the remainder of the decade, relying on fragmented market signals is no longer sufficient. PW Consulting's comprehensive Downlights Market study offers a rigorous, data-backed foundation for strategic planning, providing executives with the clarity needed to navigate an increasingly complex environment.
Quartz Sand、Quartz Grit and Quartz Slab Market
This industry insight serves as a strategic preamble to our flagship research publication. It outlines the macroeconomic trajectory, competitive dynamics, and regulatory forces shaping the sector, while demonstrating the analytical depth embedded in the full report. The objective is to equip leadership teams with a nuanced understanding of where value is being created, where risks are concentrated, and how to position portfolios for sustainable growth through 2032.
Worldwide Twin Screw and Barrel Market
Market Trajectory and Structural Growth Drivers
The downlights market has demonstrated consistent expansion over the past half-decade, reflecting both mature adoption cycles and emerging demand vectors. Historical data from 2020 through 2025 reveals a sector that has successfully navigated supply chain disruptions, component cost inflation, and evolving end-user expectations. The global market reached a valuation of approximately 1,487.5 million USD in the base year of 2025, building upon steady year-over-year gains that trace back to the 1,200 million USD baseline established in 2020.
Multi-player Real-time Online Editing Market
Looking forward, the forecast period spanning 2026 to 2032 projects a compound annual growth rate of 5.5 percent. This trajectory suggests a market poised to exceed 2,159 million USD by the close of the forecast window. Such growth is not merely incremental; it reflects a convergence of structural factors that will redefine competitive positioning over the next seven years. Building renovation cycles, stringent energy codes, and the ongoing migration toward smart-integrated lighting ecosystems are all contributing to sustained demand across multiple end-use environments.
For executive teams, the implications of this trajectory are clear. Revenue planning cannot rely on linear extrapolation. Instead, strategic models must account for cyclical procurement patterns, regional tariff fluctuations, and the accelerating pace of product lifecycle compression. The full study deconstructs these variables into actionable modeling frameworks, enabling finance and strategy functions to stress-test assumptions against multiple macroeconomic scenarios.
Forecast Architecture and Scenario Planning
The forecast methodology underpinning our analysis integrates historical performance data with forward-looking indicators, including construction activity indices, regulatory compliance timelines, and semiconductor availability cycles. Rather than presenting a single-point projection, the report structures its outlook across baseline, optimistic, and conservative scenarios. This approach allows organizations to quantify exposure to key risk factors while identifying upside opportunities tied to specific product innovations or regional policy shifts.
Decision-makers will find particular value in the report's treatment of demand elasticity across different procurement environments. By mapping how pricing dynamics, lead times, and specification requirements interact with purchasing behavior, the study provides a practical lens for revenue forecasting, inventory optimization, and capacity planning. These insights are especially critical for organizations managing multi-year product portfolios or negotiating long-term supplier agreements in a volatile component market.
Competitive Landscape and Strategic Positioning
The downlights market is characterized by a moderately concentrated competitive structure, where scale, specification expertise, and brand credibility play decisive roles in capturing high-value contracts. Concentration metrics indicate that the top three participants command a combined share of approximately 52 percent, while the top five collectively account for 75 percent of total market revenue. This distribution underscores the importance of differentiated value propositions for mid-tier and emerging players seeking to expand their footprint without engaging in unsustainable price competition.
Several established manufacturers illustrate the strategic pathways available within this environment. Acuity Brands Inc, headquartered in Atlanta, Georgia, has built a prominent position through its Juno recessed LED downlight platform, serving residential, commercial, and retrofit applications with a focus on specification-grade reliability. JESCO Lighting Group LLC, based in Port Washington, New York, targets the architectural lighting segment with contemporary LED downlights designed for commercial, institutional, and residential environments, emphasizing aesthetic integration and performance consistency.
Ledra Brands Inc, operating out of Irvine, California under its Alphabet Lighting brand, offers the NU series downlights engineered for plenum spaces, with tamper-resistant and fire-rated configurations that address stringent safety requirements in high-specification projects. Satco Products, Inc., located in Brentwood, New York, has carved out a niche in commercial and slim-fit LED downlights featuring remote driver architectures and emergency backup capabilities, catering to applications where flexibility and code compliance are paramount. Signify Holding, based in Eindhoven, Netherlands, leverages the Philips brand to deliver professional LED downlights and recessed lighting systems, combining global distribution reach with well-established specification relationships. Zumtobel Group, headquartered in Dornbirn, Austria, provides architectural lighting solutions that integrate LED downlights and panels for professional interior applications, positioning itself at the intersection of design-led specification and building performance.
Product Innovation as a Competitive Differentiator
Recent product introductions highlight how leading participants are responding to evolving specification requirements and installation efficiency demands. In January 2026, Satco launched an LED Fire Rated Slimfit Downlight with remote driver and CCT selectable features, directly addressing the need for flexible color temperature options within code-compliant form factors. This followed a December 2025 introduction of LED Slimfit Downlights for the Performer series, which emphasized improved performance metrics for routine commercial and residential deployments.
In May 2026, Ultraleds announced an integrated LED downlight series featuring IP65 rating and fire-rated construction, targeting faster installation workflows in environments where durability and environmental protection are critical. Earlier in the cycle, in August 2025, Fluxwerx introduced the Speak series downlight with both fixed and adjustable options, positioning the product as a new paradigm for recessed lighting by offering design flexibility without compromising specification integrity. These developments illustrate a broader industry shift toward modular designs, configurable performance parameters, and installation-friendly architectures that reduce labor costs and accelerate project timelines.
The full report provides a detailed mapping of product positioning across these and other key participants, analyzing how feature sets, certification portfolios, and channel strategies influence competitive outcomes. Rather than offering a static company directory, the study evaluates strategic intent, identifying which organizations are prioritizing volume-driven segments, which are focusing on specification-intensive projects, and where convergence or divergence is likely to shape future market share dynamics.
Regulatory, Tariff, and Supply Chain Dynamics
No strategic assessment of the downlights market would be complete without a rigorous examination of the external forces that directly influence cost structures, compliance timelines, and competitive accessibility. Three interconnected dynamics deserve particular attention from leadership teams: regulatory mandates, tariff exposure, and semiconductor supply volatility.
On the regulatory front, the ENERGY STAR Downlights Specification Version 1.0, finalized on November 16, 2023, took full effect on January 1, 2025, establishing new performance thresholds for energy efficiency and operational consistency. This mandate has reshaped specification requirements for many procurement teams, particularly in commercial and public-sector projects where compliance documentation and validated performance data carry significant weight. Organizations that have aligned their product portfolios with these standards are better positioned to compete in regulated bidding environments, while those lagging in compliance face increasing friction in key channels.
Tariff exposure has introduced additional complexity to the cost landscape. The escalation of U.S.-China tariffs to a combined rate of 104 percent in 2025 has significantly affected component and fixture costs for lighting manufacturers, influencing sourcing strategies and pricing architectures across the value chain. Earlier in the cycle, U.S. tariffs on Chinese goods increased from 10 percent to 20 percent in February 2025, raising compliance and material costs for LED downlight production and prompting many participants to reevaluate supplier diversification, inventory buffering, and regional assembly strategies.
Supply chain dynamics have compounded these pressures. Persistent semiconductor supply-chain volatility extended lead times for LED drivers and control ICs to 12-16 weeks during peak periods in 2025, disrupting production scheduling and forcing manufacturers to make difficult trade-offs between inventory carrying costs and order fulfillment reliability. These lead-time extensions are not merely operational inconveniences; they affect quotation validity, project bidding timelines, and the ability to honor fixed-price contracts in environments where raw material and component costs can shift rapidly.
Pricing responses from major participants reflect these pressures. Acuity Brands implemented a third price increase for luminaires and electronics in July 2025, driven by new global tariffs and market volatility. Such moves illustrate how cost pass-through strategies are being calibrated in real time, and why procurement and finance teams must incorporate dynamic pricing assumptions into their planning models rather than relying on historical average costs. The full study quantifies these dynamics within dedicated analytical sections, providing a structured framework for evaluating tariff exposure, supplier concentration risk, and the financial implications of specification compliance across different segments.
Strategic Implications for Procurement and Product Planning
For organizations operating in or adjacent to the downlights market, the convergence of regulatory, tariff, and supply chain forces creates both risk and opportunity. On the risk side, reliance on narrow supplier bases, inflexible pricing contracts, or product lines that lag behind current compliance standards can erode margins and limit bidding competitiveness. On the opportunity side, manufacturers and distributors that proactively diversify component sourcing, integrate compliant performance characteristics early, and design for installation efficiency can capture advantage in specification-driven procurement environments.
The report's dynamics section goes beyond descriptive analysis to offer structured implications for sourcing strategy, inventory policy, and product portfolio management. By linking external events to operational and financial outcomes, the study helps teams translate macro-level disruptions into tactical decisions that preserve margin integrity and service reliability.
Application Segments and Regional Demand Architecture
Demand for downlights is distributed across multiple end-use environments, each with distinct specification priorities, procurement cycles, and price sensitivity profiles. Commercial applications represent the largest revenue share within the market, reflecting the ongoing intensity of workplace renovation, hospitality upgrades, and institutional project activity. Residential demand forms a substantial secondary pillar, supported by homeowner renovation cycles, new housing activity, and a growing preference for recessed lighting solutions that combine aesthetic subtlety with LED performance. Industrial applications, while smaller in absolute terms, contribute specialized demand tied to facility upgrades, safety-rated installations, and environments where durability and code compliance intersect.
Regional demand patterns further shape competitive strategy. North America, Europe, and Asia Pacific each represent significant revenue pools, but they differ markedly in terms of specification culture, code enforcement intensity, channel structure, and sensitivity to component cost fluctuations. Latin America and the Middle East and Africa constitute smaller but strategically relevant markets, often influenced by project-driven procurement, import dependency, and evolving building standards. Understanding how these regional contexts interact with product type, application requirements, and tariff exposure is essential for organizations deciding where to allocate sales resources, inventory, and product development effort.
The full study provides a structured analysis of how these regional and application dynamics interact, without reducing the landscape to simplistic share rankings. Instead, it focuses on the qualitative and quantitative factors that drive demand concentration, specification pull-through, and channel effectiveness in each context. This approach enables organizations to assess where their current capabilities align with market opportunity and where targeted investment may be required to capture growth effectively.
Why This Study Matters for 2026 Strategic Planning
The decisions made in 2026 will shape competitive positioning well beyond the current forecast horizon. Product portfolio investments, supplier agreements, pricing architectures, and channel strategies all require an evidence base that accounts for both historical performance and forward-looking disruption. PW Consulting's Downlights Market report is designed to serve as that evidence base, offering a level of analytical rigor that supports executive decision-making rather than merely describing market conditions.
Several attributes distinguish this study from broader industry summaries. First, it integrates historical data, base-year valuation, and multi-year forecasts into a coherent analytical narrative, allowing readers to evaluate growth sustainability rather than isolated data points. Second, it contextualizes competitive dynamics within the realities of product innovation, specification requirements, and channel behavior, helping organizations interpret market share movements in terms of strategic intent and capability alignment. Third, it embeds regulatory, tariff, and supply chain analysis directly into the market framework, ensuring that external volatility is treated as a core planning variable rather than an incidental footnote.
For strategy, finance, and product leadership, the report provides a foundation for scenario modeling, portfolio rationalization, and channel investment decisions. For sales and specification teams, it offers insight into the demand drivers and compliance requirements that influence procurement behavior across commercial, residential, and industrial environments. For supply chain and operations leaders, it frames the cost and lead-time dynamics that affect inventory policy, quotation strategy, and supplier diversification priorities.
The study also addresses the practical need for clarity in a market where terminology, specification standards, and product architectures evolve rapidly. By establishing a consistent analytical framework and defining the relationships between product types, applications, regions, and competitive forces, the report reduces the friction associated with cross-functional alignment. This is particularly valuable for organizations operating across multiple business units or geographies, where shared market intelligence can improve coordination and reduce interpretive variance.
What the Full Report Delivers
Beyond the macro-level context and competitive framing outlined here, the complete Downlights Market study provides detailed coverage designed to support operational and strategic execution. The report examines segmentation structures across product types, application environments, and geographic regions, enabling readers to evaluate where growth is concentrated and how demand characteristics differ across contexts. It includes concentration analysis that clarifies the competitive hierarchy and identifies the structural conditions that shape market entry, expansion, and retention strategies.
The publication also features company profiling that goes beyond basic corporate information to assess strategic positioning, product architecture, and the practical implications of recent launches and specification developments. Recent industry developments are integrated into the analysis to show how product introductions, regulatory milestones, and cost pressures are influencing near-term market behavior. In addition, the report incorporates structured treatment of industry context factors, including regulatory specifications, tariff developments, semiconductor supply dynamics, and pricing actions, linking each to its likely impact on market participants.
Readers will also find forward-looking analysis that connects market size and growth trajectory to the underlying drivers of demand, providing a basis for evaluating opportunity magnitude and planning resource allocation accordingly. The study is structured to support a range of use cases, from high-level strategic planning to more granular product and channel decisions, while maintaining a consistent analytical standard throughout.
Conclusion: Positioning for Informed Growth
The downlights market is not defined by a single trend or disruption. It is shaped by the interaction of regulatory mandates, tariff realities, supply chain behavior, product innovation cycles, and regional specification cultures. organizations that approach this environment with fragmented intelligence risk misallocating resources, underestimating compliance exposure, or misreading competitive intent. Those that invest in structured, data-grounded analysis are better equipped to align product portfolios, pricing strategies, and channel efforts with the realities of demand and cost.
PW Consulting's Downlights Market study is built to support that level of decision-making. By combining historical context, forecast architecture, competitive analysis, and dynamic industry factors into a single integrated framework, the report provides the intelligence necessary to plan with confidence across the 2026 to 2032 horizon. The overview presented here illustrates the scope and depth of the analysis, while leaving the core segmentation data, detailed company evaluations, and scenario-specific quantification for the full publication.
Leaders seeking to translate market complexity into actionable strategy will find the complete study an essential reference for 2026 planning and beyond. It offers the analytical precision required to evaluate growth opportunity, manage risk exposure, and position portfolios for durable performance in a sector where specification, compliance, and cost dynamics continue to evolve at pace.
For detailed analysis of this topic, please visit the official page: Downlights Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


