



Category: market research
PW Consulting: Blackout Curtains Market to Hit $344.8M by 2032, Growing at 6.98% CAGR
By PW Consulting, 2026-09-07
Strategic Intelligence for the Blackout Curtains Market: Navigating Growth, Innovation, and Competitive Dynamics in 2026
In an era defined by shifting consumer preferences, evolving regulatory standards, and rapid material innovation, the window treatments sector has emerged as a critical battleground for home goods manufacturers, commercial interior suppliers, and retail strategists. At the heart of this transformation lies the blackout curtains market, a segment that has quietly but steadily captured significant market share over the past half-decade. As enterprises prepare their portfolio expansions, channel strategies, and sustainability initiatives for the 2026-2032 horizon, understanding the underlying forces shaping this category is no longer optional. It is a strategic imperative.
Worldwide Centralized Monitoring Market
Our latest comprehensive market study delivers precisely the kind of actionable intelligence that executive teams, product developers, and commercial leaders require to make confident, forward-looking decisions. Built upon a rigorous five-year historical foundation and extended through a seven-year forecast window, this report maps the structural inflection points, competitive maneuvers, and demand-side shifts that will dictate profitability and market positioning in the years ahead. Below, we outline the strategic contours of the analysis and demonstrate why it serves as an essential reference for stakeholders operating across household, commercial, and specialized applications.
Special Zirconium Beads For Electronic Materials Market
Market Trajectory and the Macroeconomic Foundation
The blackout curtains market has demonstrated consistent upward momentum, reflecting a confluence of urbanization trends, heightened awareness of sleep health, energy efficiency mandates, and the growing premiumization of interior environments. Historical revenue patterns from 2020 through 2025 reveal a steady expansion trajectory, with the broader category advancing from approximately 163.15 million USD at the start of the period to a baseline valuation of 215.0 million USD by 2025. This compounding growth underscores a market that has successfully moved beyond cyclical volatility and established a durable demand base.
Worldwide Process Pressure Gauge Market
Looking ahead, the forecast period spanning 2026 through 2032 projects a sustained compound annual growth rate of 6.98 percent. Such a trajectory signals not merely incremental expansion but a structural re-rating of the category's commercial significance. By the close of the forecast window, the market is positioned to reach a substantially elevated revenue threshold, reflecting both volume-driven consumption and value-added pricing strategies enabled by material innovation, certification differentiation, and premium design positioning. For enterprises evaluating production scaling, inventory planning, or geographic rollout, this growth framework provides a reliable baseline against which to model capacity investments and channel allocation.
Critically, the expansion is not uniformly distributed across all demand vectors. The report disentangles the structural drivers that are accelerating adoption in specific end-use environments while identifying the friction points that moderate growth in others. Household applications continue to anchor the category, benefiting from residential renovation cycles, remote-work lighting adjustments, and heightened consumer sensitivity to light pollution and thermal comfort. Commercial deployments, meanwhile, are increasingly influenced by workplace wellness standards, hospitality renovation programs, and specialized facility requirements. Transportation and niche operational settings represent a more specialized but strategically important demand pool, often driven by performance specifications that go well beyond basic aesthetic considerations.
Competitive Architecture and Strategic Positioning
The competitive landscape of the blackout curtains market is characterized by a fragmented yet increasingly sophisticated player base. Market concentration metrics indicate a relatively dispersed structure, with the top three firms holding a combined share that reflects the absence of a single dominant gatekeeper. This fragmentation creates both opportunity and risk: it enables agile entrants to capture niche segments through specialization, while simultaneously compelling established manufacturers to invest continuously in product differentiation, channel access, and brand credibility.
Several companies have emerged as focal points of competitive activity, each pursuing distinct strategic pathways that illustrate the breadth of approaches available in this market. Sun Zero has built its positioning around a rigorous performance narrative, marketing specialty room-darkening and true blackout curtains that emphasize 100 percent light-blocking capability validated through independent laboratory testing. This commitment to third-party verification has become a differentiating asset in a category where consumer trust is frequently undermined by inconsistent product claims.
Eclipse has pursued a distribution-centric model, producing thermal and blackout curtain lines that are scaled through major retail partnerships. Its strategy highlights the enduring importance of shelf presence, brand recognition, and volume-oriented merchandising in segments where accessibility and price competitiveness remain decisive purchase drivers. Quince, by contrast, has carved a direct-to-consumer pathway that emphasizes material provenance and certification transparency, offering European linen and cotton true blackout curtains backed by OEKO-TEX certification. This approach resonates with consumers who prioritize non-toxic materials, sustainable sourcing, and minimalist design language.
Blackoutcurtains.com operates as a specialized provider targeting commercial and studio environments, where precise light-control requirements demand tailored solutions rather than standardized consumer-grade offerings. Sleepout has introduced a portable, instant-install concept that aligns with the growing mobility of living and work arrangements, while simultaneously differentiating itself through PFAS-free formulations and OEKO-TEX certification. The presence of manufacturing-focused players such as Zhuji Tenzo Textile Co., Ltd. illustrates the critical role of upstream fabric producers in supplying half-blackout and full-blackout textiles to a broader ecosystem of brand owners and private-label developers. At the broader premium end of the window treatments spectrum, Hunter Douglas Inc. continues to leverage its global production capabilities and established distribution networks to integrate blackout curtain lines within a more extensive portfolio of architectural shading solutions.
This diversity of strategic postures is not merely descriptive. It reflects the underlying economic logic of the market: performance claims, certification credibility, channel strategy, material composition, and end-use specialization are all levers that companies can adjust to capture disproportionate value within their chosen segments. The report analyzes how these levers interact, which combinations are proving most resilient under current market conditions, and where emerging entrants are most likely to disrupt incumbent positions.
Industry Dynamics Shaped by Certification, Material Innovation, and Consumer Expectations
One of the most consequential shifts shaping the blackout curtains market is the accelerating emphasis on health, safety, and environmental performance. Certification frameworks have evolved from peripheral marketing claims into decisive purchase criteria, particularly among household consumers, interior designers, and commercial procurement teams that operate under stringent indoor air quality and material safety requirements. Recent product documentation and independent testing data indicate that multiple leading offerings now carry OEKO-TEX certification, with several also achieving GREENGUARD Gold recognition or PFAS-free formulations. The convergence of these standards is reshaping competitive benchmarks, as manufacturers that fail to align with non-toxic and low-emission expectations face growing reputational and commercial headwinds.
Simultaneously, material science and textile engineering continue to expand the functional envelope of blackout products. Yarn-dyed woven constructions, flame-retardant variants, and high-customization light-blocking fabrics are increasingly visible at major trade exhibitions, signaling that performance differentiation is moving beyond simple opacity metrics. Recent exhibition activity has highlighted dedicated zones where manufacturers showcased 100 percent blackout fabrics, specialized flame-retardant formulations, and advanced woven structures designed for both aesthetic refinement and rigorous light control. These developments suggest that the category is maturing toward a more technical, specification-driven identity, particularly in commercial and institutional contexts where compliance and durability requirements are non-negotiable.
Consumer expectations are also being reshaped by the broader interior wellness narrative. Sleep quality, circadian lighting management, and thermal regulation are no longer niche concerns; they are increasingly central to residential purchasing decisions. This cultural shift amplifies the strategic relevance of products that can articulate clear, verifiable performance benefits. At the same time, it raises the stakes for brand communication, because the market is saturated with contradictory claims regarding light-blocking efficacy, fabric composition, and environmental safety. Companies that invest in transparent testing, recognizable certifications, and consistent product storytelling are better positioned to convert awareness into repurchase and recommendation behavior.
What the Report Delivers: Operational Intelligence for Decision-Makers
This study is designed to translate high-level market dynamics into a practical decision-support framework. Rather than stopping at aggregate trend commentary, the report constructs a multi-layered analytical architecture that enables stakeholders to evaluate opportunities, anticipate risks, and calibrate execution strategies with precision. The following elements represent the core operational value of the research:
- Comprehensive historical reconstruction and forward-looking revenue modeling that contextualizes past performance while projecting plausible growth pathways through the end of the decade.
- Granular segmentation analysis that isolates the structural drivers, demand intensity, and competitive characteristics shaping distinct product categories, application environments, and regional markets.
- End-use deployment insights that differentiate household purchasing behavior from commercial procurement logic and specialized operational requirements, enabling more targeted product development and channel planning.
- Detailed competitive profiling that examines how key participants position themselves across performance claims, distribution models, material sourcing, certification strategy, and pricing architecture.
- Certification and regulatory tracking that maps the evolving landscape of OEKO-TEX standards, PFAS-free formulations, GREENGUARD recognition, and other compliance frameworks influencing purchase decisions.
- Trade show and innovation monitoring that distills emerging fabric technologies, customization trends, and product launches into actionable signals for R&D and portfolio management.
- Market concentration and structural analysis that clarifies the degree of fragmentation, the influence of leading firms, and the strategic opening available to new entrants or niche specialists.
Each of these components is integrated into a cohesive narrative that connects demand-side behavior with supply-side execution. The objective is not simply to describe what is happening, but to explain why it matters, where the leverage points are located, and how organizations can align their strategies to capture durable advantage.
Strategic Applications for 2026 Executive Decision-Making
For organizations operating in or adjacent to the blackout curtains market, the 2026 decision environment presents a distinctive set of priorities. Capacity planning must account for sustained demand growth without assuming uniform expansion across all segments. Product roadmaps need to balance performance differentiation with cost discipline, especially as certification requirements and non-toxic material expectations become more entrenched. Channel strategy must reconcile the pull of major retail distribution with the precision targeting enabled by direct-to-consumer models and specialized commercial procurement pathways. Brand positioning must navigate an increasingly crowded field of performance claims by anchoring messaging in verifiable testing and recognized certifications.
The report is structured to support these decisions at multiple levels of organizational responsibility. Executive leadership can use the macro growth framework and structural analysis to validate investment theses and set long-range strategic direction. Product and innovation teams can draw on the segmentation and certification insights to prioritize development initiatives and ensure that new offerings align with emergent consumer and procurement criteria. Commercial and sales leaders can leverage the competitive profiling and end-use distinctions to refine targeting, adjust pricing architecture, and strengthen channel partnerships. Procurement and supply chain teams can benefit from the analysis of upstream fabric ecosystems and material trends that influence cost structures and availability constraints.
Why the Full Report Is Essential
While the strategic outline above captures the analytical direction of the study, the complete report contains the detailed segmentation data, regional demand patterns, application-specific revenue breakdowns, and company-level strategic assessments that transform high-level insight into execution-ready intelligence. The aggregate figures provide the necessary context, but the true strategic value lies in the disaggregated analysis that reveals where growth is concentrated, which competitive tactics are outperforming, and how certification and material innovations are reshaping purchase criteria across different customer groups.
Accessing the full report enables decision-makers to move beyond directional awareness and into precise strategic calibration. It offers the depth required to benchmark internal performance, evaluate market entry or expansion scenarios, and identify the specific segments where competitive differentiation can be most effectively established. For teams that need to justify resource allocation, prioritize product development, or restructure commercial approaches in response to evolving consumer expectations, the detailed intelligence within the complete study provides the evidentiary foundation necessary for confident action.
Conclusion: Positioning for the Next Phase of Market Evolution
The blackout curtains market is entering a phase in which growth is no longer the only measure of success. Differentiation, credibility, compliance alignment, and channel precision are becoming equally decisive in determining which companies capture sustainable value. The trajectory observed from 2020 through 2025, combined with the projected expansion through 2032, indicates that the category will continue to attract attention from both established players and emerging specialists. Yet the competitive advantage will belong to those who can translate market momentum into targeted execution, using verified performance claims, material innovation, and strategic positioning to stand out in a crowded field.
Our full market research study is engineered to support that transition from observation to action. By combining rigorous quantitative modeling with deep qualitative analysis of competitive behavior, certification dynamics, and end-use demand shifts, the report equips stakeholders with the intelligence required to make informed, resilient decisions in 2026 and beyond. For organizations ready to move from strategic awareness to strategic advantage, the complete analysis offers the comprehensive perspective necessary to navigate the next chapter of this evolving market with clarity and confidence.
For detailed analysis of this topic, please visit the official page: Blackout Curtains Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: ATC Equipment Market Hits $1.12 Billion in 2025, Surging 8.39% CAGR to $1.97 Billion by 2032
By PW Consulting, 2026-09-07
Navigating the Skies of Innovation: Strategic Insights for the 2026 Air Traffic Control Equipment Market
The global aviation infrastructure stands at a pivotal juncture. As airspace becomes increasingly congested and the demand for safer, more efficient travel grows, the backbone of this evolution lies in advanced Air Traffic Control (ATC) equipment. For stakeholders operating within the aerospace, defense, and aviation services sectors, understanding the trajectory of this market is not merely an academic exercise—it is a critical imperative for strategic planning in 2026 and beyond.
Commercial and Household Paper Shredder Market
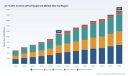
The ATC Equipment Market has demonstrated remarkable resilience and growth over the past half-decade. Valued at approximately 500 million USD in 2020, the sector has surged to an estimated 1,120 million USD by 2025. This trajectory underscores a compound annual growth rate (CAGR) of 8.39 percent projected through 2032, signaling a sustained expansion phase driven by technological modernization and regulatory mandates. This article serves as a strategic preview of our comprehensive market research, designed to equip decision-makers with the high-level intelligence needed to navigate the complexities of this evolving landscape. While we delve into the macro drivers and competitive forces here, the precise segmentation data and granular forecasts are reserved for our full report.
Worldwide Spinal Fusion Cage Market
The Macro Economic Trajectory and Growth Drivers
The growth narrative of the ATC equipment market is inextricably linked to the broader health of the global aviation industry. Following a period of disruption, the sector has rebounded with vigor. The market size climbed from 704.57 million USD in 2022 to 805.41 million USD in 2023, and further to 918.04 million USD in 2024. This consistent upward momentum suggests that investment in airspace management is being treated as a priority rather than a discretionary expenditure.
Worldwide Multi-Currency Checker Market
Looking toward the forecast period from 2026 to 2032, the market is expected to reach 1,967 million USD. This expansion is fueled by several converging factors. First, the aging infrastructure in major aviation markets requires urgent upgrades to maintain safety standards and operational efficiency. Second, the shift toward digitalization and remote tower technologies is opening new avenues for cost-effective management of air navigation services. Finally, regulatory bodies are increasingly mandating modern surveillance and communication systems to handle the integration of unmanned aircraft systems and increased flight densities.
For enterprise strategists, understanding these top-line figures is essential for capacity planning and investment allocation. However, the nuanced drivers behind regional performance and application-specific demand require a deeper dive. Our full analysis dissects these variables to provide a clear picture of where capital is flowing and which segments offer the highest return on investment in the coming cycle.
Regulatory Pressures and Infrastructure Modernization
Government policy and regulatory frameworks are among the most potent forces shaping the ATC equipment landscape. In the United States, the Federal Aviation Administration (FAA) has committed significant resources to modernization efforts. Notably, the FAA committed 6 billion USD by the end of 2025 for ATC upgrades under a 12.5 billion USD congressional authorization. This funding focuses heavily on telecommunications, radar surveillance, and data management systems. Such large-scale public investment creates a ripple effect across the supply chain, influencing vendor selection and procurement timelines globally.
However, challenges remain. Despite the authorization, FAA Facilities and Equipment account funding has remained approximately 3 billion USD annually, flat in real terms due to inflation. This constraint complicates the sustainment of legacy systems even as new technologies are deployed. Furthermore, reports indicate that aging National Airspace System (NAS) infrastructure risks service discontinuance by major carriers up to two years earlier than planned. This risk profile is prompting an accelerated transition to fiber and satellite networks to replace legacy copper infrastructure, aiming to support high-speed ATC data links and reduce obsolescence risks.
In April 2026, the FAA selected three AI-powered management system competitors, including Thales, for the SMART airspace routing trajectories program. This move highlights a clear strategic pivot toward intelligent automation and AI-driven routing to optimize traffic flow. For equipment manufacturers and system integrators, these regulatory signals are blueprints for product development and partnership opportunities. Our report details how these regulatory shifts specifically impact procurement cycles and technology adoption rates across different jurisdictions.
Competitive Landscape: Key Players and Strategic Moves
The ATC equipment market is characterized by a moderate level of concentration, with a CR3 of 24.6 percent and a CR5 of 26.2 percent. This fragmentation suggests that while major players dominate significant contracts, there is ample room for specialized innovators and regional partners to thrive. The competitive dynamics are defined by large-scale integrations, technology launches, and strategic partnerships aimed at securing long-term service agreements.
Several key companies are driving the industry forward. Thales Group, headquartered in Paris, provides integrated ATC systems including TopSky automation, radar surveillance, and digital towers for global air navigation service providers. In May 2025, Thales was awarded a modernization contract for nine ATC radar systems in Brazil by Omnisys, demonstrating its strong foothold in emerging markets. Similarly, L3Harris Technologies, Inc., based in Melbourne, Florida, offers FAA telecommunications infrastructure upgrades, ADS-B surveillance, tactical ATC systems, and digital voice solutions, positioning itself as a critical partner for US domestic upgrades.
Indra Sistemas S.A. from Madrid delivers air traffic management automation, surveillance radars, digital tower platforms, and airport operations systems. In a significant move toward cloud integration, Indra partnered with a major cloud provider in June 2025 for a scalable secure cloud platform supporting remote tower solutions. This partnership underscores the industry trend toward leveraging cloud computing for scalability and security in remote operations.
RTX Corporation (Collins Aerospace) in Arlington, Virginia, supplies STARS terminal automation, next-generation radars, digital tower systems, and common automation platforms. Their portfolio is essential for terminal area management. Meanwhile, Frequentis AG, based in Vienna, leads in ATC voice communication systems and integrated OneATM platforms supporting over 40 area control centres. In November 2025, Frequentis launched the TowerX unified automation platform to simplify tower operations with integrated modules, reflecting a push toward operational simplicity.
Leonardo S.p.A. from Rome provides ATC systems, integrated sensors, radars, and ground operations management for civil and military aviation, bridging the gap between defense and civil infrastructure needs. Beyond these incumbents, significant developments are reshaping the terrain. In December 2025, the FAA and DOT announced that Peraton was selected as the prime integrator for a Brand New Air Traffic Control System with 12.5 billion USD in modernization funding for radar replacement, fiber upgrades, and new centers. This massive contract award signals a new phase of procurement that favors large-scale system integration capabilities.
Understanding the specific contract values and market share nuances of these players is vital for competitive benchmarking. The full report provides a detailed competitive heat map that correlates company capabilities with regional demand spikes.
Technology Trends: Digital Towers and AI Integration
The technological frontier of the ATC market is defined by the move toward remote and digital tower modules and the integration of artificial intelligence. The shift from traditional concrete towers to remote digital solutions allows for centralized management of multiple airports, reducing operational costs and improving situational awareness for controllers. This transition is supported by the broader move to digital fiber and satellite networks replacing legacy copper infrastructure.
The integration of AI into airspace routing, as seen in the SMART program, represents a leap forward in efficiency. AI-powered systems can analyze vast datasets to predict congestion, optimize flight paths, and reduce fuel consumption. For equipment vendors, this means a shift in value proposition from hardware-centric solutions to software and service-oriented platforms. The ability to offer interoperable, software-defined systems is becoming a key differentiator.
Furthermore, surveillance technologies are evolving. ADS-B and next-generation radars are becoming standard requirements, pushing legacy surveillance equipment toward obsolescence. Companies that can offer seamless migration paths from legacy radar to modern surveillance suites will capture significant market share. These technological shifts are not uniform across all regions or application types. Our detailed segmentation analysis reveals which technologies are gaining traction in specific geographic zones and among different aircraft categories, providing a roadmap for R&D focus.
Strategic Implications for 2026 Decision Makers
For executives and strategy teams planning for 2026, the ATC equipment market offers both opportunities and risks. The clear growth trajectory suggests a favorable environment for sales and expansion. However, the complexity of procurement cycles, influenced by government funding timelines and regulatory approvals, requires careful navigation. Companies must align their product roadmaps with the specific modernization priorities outlined by bodies like the FAA and their international counterparts.
Supply chain resilience is another critical factor. With the accelerated transition to digital networks and the replacement of legacy infrastructure, the demand for specialized components and secure communication modules is rising. Delays in component availability can stall major modernization contracts. Additionally, the moderate market concentration implies that partnerships and consortiums may be necessary to bid for the largest system integration projects, such as the recent Peraton-led initiative.
Investment in AI and cloud capabilities is no longer optional for vendors aiming to remain competitive. The partnerships seen with Indra and the procurement preferences shown by the FAA indicate that scalability and intelligence are key purchase criteria. Firms that can demonstrate secure, scalable cloud integration for remote towers or AI-driven routing efficiencies will be better positioned to win contracts in the latter half of the decade.
Risk management also extends to geopolitical factors. Changes in defense spending and civil aviation budgets in key regions can alter the demand landscape quickly. Monitoring the balance between military and commercial aviation needs is essential, as many equipment suppliers serve both sectors. The interplay between these sectors often dictates the prioritization of dual-use technologies.
Conclusion: The Value of Deep Intelligence
The Air Traffic Control Equipment Market is undergoing a transformation defined by digitalization, AI integration, and massive infrastructure investment. The macro data indicates strong growth, but the real strategic value lies in understanding the underlying currents that drive this expansion. From regulatory funding constraints to the specific technological preferences of major prime contractors, the details matter.
This article has outlined the broad strokes of the market landscape, highlighting the key players, regulatory dynamics, and technological trends that define the 2026 outlook. However, to fully capitalize on these insights, organizations need granular data on segmentation splits, regional revenue distributions, and application-specific growth rates. The nuances of how commercial, military, and private aircraft sectors contribute to the total market volume require precise analysis to inform targeted strategies.
Our comprehensive report offers this depth. It moves beyond aggregate figures to provide actionable intelligence on market concentration, competitive positioning, and detailed forecast models. For organizations looking to secure a competitive advantage in the ATC equipment sector, access to this level of detailed intelligence is indispensable. We invite you to access the full market research study to unlock the specific data points and strategic recommendations necessary for informed decision-making in the year ahead.
For detailed analysis of this topic, please visit the official page: Air Traffic Control (ATC) Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cloud Database Market Hits $17.1B in 2025, 16.5% CAGR Forecasts $50B by 2032
By PW Consulting, 2026-09-07
Navigating the Cloud-Based Database Revolution: Strategic Intelligence for 2026 Enterprise Decisions
The landscape of enterprise data management has undergone a seismic shift in the first quarter of 2026. What was once considered an infrastructure utility has evolved into a critical strategic asset, driving everything from artificial intelligence integration to real-time regulatory compliance. As organizations worldwide accelerate their digital transformation agendas, the cloud-based database market stands at the forefront of this technological renaissance. PW Consulting recognizes that understanding the nuances of this market is no longer optional for C-suite executives and IT strategists; it is a fundamental requirement for sustainable growth.
Worldwide Industrial Pneumatic Brake Market
Our latest comprehensive market study, covering the historical trajectory from 2020 through 2025 and projecting forecast dynamics out to 2032, provides an unparalleled lens into this rapidly evolving sector. This article serves as an introduction to the depth of intelligence contained within the full report, highlighting the macro-level trends that define the industry while underscoring the operational specifics that only a detailed analysis can reveal. The numbers tell a compelling story of expansion, but the strategic implications lie in the intersection of technology, regulation, and competitive maneuvering.
B2B E-commerce Platform Tool Market
Market Trajectory and Growth Forecasts
The historical data from 2020 to 2025 illustrates a period of aggressive expansion for cloud-based database solutions. Starting at 8.85 billion USD in 2020, the market demonstrated resilience and upward momentum, reaching 10.17 billion USD in 2021 and continuing to climb through 2022 and 2023. By 2024, the market valuation had surged to 14.22 billion USD, reflecting the accelerated adoption of remote work infrastructures and the subsequent need for accessible, scalable data solutions. As we closed the base year of 2025, the market reached an estimated 17.1 billion USD, signaling a robust foundation for the forecast period.
Worldwide Energy Saving Air Conditioner Market
Looking forward to the forecast period of 2026 through 2032, the growth trajectory appears even more steep. The market is projected to reach 19.94 billion USD in 2026, followed by steady increments through 2027 and 2028, where valuations are expected to approach 27.31 billion USD. By the end of the decade in 2030, the market could touch 37.09 billion USD, culminating in a significant milestone of 50.0 billion USD by 2032. This expansion corresponds to a Compound Annual Growth Rate of 16.5 percent, a figure that underscores the high velocity of investment and adoption in this sector. Such growth rates are not merely statistical; they represent a fundamental restructuring of how enterprises store, manage, and derive value from their data assets.
However, raw market size and CAGR figures only scratch the surface. The true value for decision-makers lies in understanding the drivers behind this growth. Our full report dissects the contributing factors across different deployment models and database types, revealing which segments are fueling the bulk of this revenue expansion and which are poised for disruptive innovation. Readers of the complete study will find granular breakdowns that clarify where capital is flowing and where opportunity lies for both incumbents and new entrants.
Competitive Landscape and Key Players
The cloud-based database ecosystem is characterized by a high degree of market concentration, with a few dominant players commanding a significant share of the revenue. Our analysis indicates that the top three competitors hold approximately 65.0 percent of the market, while the top five extend their influence to 78.5 percent. This concentration suggests that while the market is growing, the battle for enterprise lock-in and multi-cloud interoperability is fierce among the leaders.
Amazon Web Services remains a pivotal force, leveraging a suite that includes Amazon Aurora, RDS for SQL Server, and DynamoDB to serve scalable relational, NoSQL, and serverless workloads. Their infrastructure continues to set the benchmark for availability and integration with broader cloud services. Microsoft competes closely with its Azure ecosystem, providing Azure SQL Database, Cosmos DB, and managed solutions for PostgreSQL and MySQL, often differentiating through built-in AI and security features that appeal to enterprise clients seeking integrated stacks. Google LLC has strengthened its position with Cloud SQL, Bigtable, Firestore, AlloyDB, and Spanner, focusing on cloud-native databases optimized for analytics, real-time applications, and deep AI integration.
Oracle Corporation continues to defend its stronghold in the enterprise relational space through Oracle Database Cloud Service, Autonomous Database, and Exadata on Cloud@Customer, now enhanced with AI capabilities. Meanwhile, Snowflake Inc. has carved a distinct niche with its cloud data platform, emphasizing native database and data sharing capabilities that allow for secure, scalable analytics without data movement. MongoDB, Inc. drives the NoSQL segment through MongoDB Atlas, a fully managed service designed for document-based workloads with multi-cloud support. IBM Corporation offers Db2 and Informix on Cloud, targeting hybrid environments that demand high availability and AI integration.
SAP SE provides SAP HANA Cloud for in-memory analytics and real-time business applications, crucial for large enterprises running ERP systems. Databricks, Inc. is gaining traction with its Lakehouse platform and integrated Delta Lake database, unifying data engineering and analytics in cloud environments. In the Asia-Pacific region, Tencent Cloud and Alibaba Cloud are significant players, offering TKEngine, Cloud Database services, RDS, and AnalyticDB tailored for regional enterprises and global scalability. Nutanix, Inc. and Couchbase, Inc. round out the competitive field with offerings focused on hybrid multicloud management and serverless NoSQL performance respectively.
The strategic moves made by these companies in early 2026 highlight the intensifying focus on AI integration. Google LLC announced managed, remote Model Context Protocol servers for its suite of databases, making them generally available for AI agents to connect securely to enterprise data as of April 2026. Oracle Corporation unveiled AI Database Agentic Innovations for Business Data and released enhancements for Oracle AI Database@Google Cloud in March 2026. Nutanix, Inc. released a complete agentic AI platform with Smart Tiering expansion in February 2026. These developments signal a shift from passive storage to active, intelligent data interfaces.
Segmentation Dynamics and Deployment Trends
Understanding how the market splits across different dimensions is crucial for targeting product strategies and investment decisions. The deployment landscape is divided among Public Cloud, Private Cloud, and Hybrid Cloud models. While the public cloud segment continues to capture the majority of attention due to its scalability and lower upfront costs, the hybrid and private cloud segments retain relevance for organizations with stringent data sovereignty or latency requirements. The full report provides specific revenue distributions across these deployment types, allowing strategists to gauge the relative maturity and growth potential of each model.
Similarly, the database type segmentation reveals the shifting preferences between Relational, NoSQL, and NewSQL technologies. Relational databases maintain a strong foundation, particularly for transactional integrity, but NoSQL solutions are expanding rapidly to handle unstructured data and high-velocity workloads. NewSQL represents an emerging frontier, promising the scalability of NoSQL with the consistency of SQL. Each type serves different use cases, and the revenue split between them indicates where developer preferences are trending.
End-user analysis further divides the market between SMEs and Large Enterprises. Large enterprises typically drive significant revenue due to the scale of their contracts and complex requirements, but SMEs represent a growing volume segment as managed services lower the barrier to entry. The report details the value contribution of each end-user category, offering insights into pricing strategies and service packaging that resonate with different organizational sizes.
Industry Dynamics and External Pressures
Market growth does not occur in a vacuum. Several external dynamics are shaping the cloud-based database market in 2026, creating both headwinds and tailwinds for industry participants. One significant factor is the labor market. Skilled database administrators and cloud infrastructure technicians command premium wages due to the rapid proliferation of managed cloud database deployments and AI-driven data processing demands. This labor cost pressure is influencing organizations to seek more automated, managed solutions that reduce the reliance on specialized human intervention, thereby feeding back into the demand for cloud-based database services.
Regulatory environments are also evolving rapidly. The EU Data Act, which came into force in September 2025, requires cloud providers to implement technical and organizational measures to prevent unlawful non-EU government access to non-personal data stored in Europe. This regulation impacts how providers architect their storage solutions and market their compliance capabilities to European clients. Concurrently, the U.S. CLOUD Act enables U.S. authorities to compel American cloud providers to provide access to data stored abroad, creating ongoing compliance challenges for European enterprises using these platforms. These cross-jurisdictional tensions require enterprises to carefully evaluate their cloud provider choices based on data residency and legal protection guarantees.
Infrastructure costs present another layer of complexity. U.S. data centers consumed 4 percent of total electricity in 2024, with demand projected to more than double by 2030 amid surging cloud database and AI workloads. This energy demand translates into operational costs and sustainability concerns that are increasingly becoming part of enterprise procurement criteria. Providers that can demonstrate energy efficiency or carbon-neutral operations may gain a competitive edge in specific segments of the market.
Security standards remain critical. ISO/IEC 27001 and related cloud security standards, along with 12 new global certifications achieved in 2025 for Oracle Database@Google Cloud, remain vital for enterprise adoption. Compliance is not just a checkbox; it is a currency of trust in the B2B market. Companies that fail to maintain or communicate their compliance posture risk losing ground to competitors who can guarantee higher levels of security assurance.
Strategic Value of the Full Report
While this overview provides a high-level map of the terrain, the full PW Consulting report offers the compass and detailed coordinates necessary for strategic navigation. The study goes beyond macro trends to offer actionable intelligence on pricing structures, vendor evaluation frameworks, and implementation roadmaps. For executives planning their 2026 budget allocations, the report provides the context needed to justify investments in cloud database migration or modernization.
The analysis includes deep dives into recent product releases and their implications. For instance, the launch of MariaDB Enterprise Platform 2026 in October 2025 as a unified cloud database platform uniting transactional, analytical, and AI vector workloads represents a significant consolidation trend. Understanding how such launches affect the competitive balance requires more than a press release summary; it requires an assessment of market reception and technical viability compared to established rivals.
Furthermore, the report addresses the supply chain and infrastructure constraints hinted at by energy consumption data. It explores how providers are mitigating risks associated with data center capacity and how enterprises can plan for potential latency or cost fluctuations driven by infrastructure scarcity. These operational details are critical for risk management strategies that extend beyond the IT department into supply chain and facilities planning.
Conclusion and Next Steps
The cloud-based database market in 2026 is defined by rapid growth, intense competition, and a complex regulatory environment. With a projected market size reaching 50.0 billion USD by 2032 and a CAGR of 16.5 percent, the sector offers substantial opportunities for organizations that can align their technology stacks with emerging trends. However, capitalizing on this growth requires more than general knowledge; it demands specific, data-backed insights into vendor capabilities, market share dynamics, and segment-specific growth rates.
PW Consulting's full market research report is designed to equip decision-makers with this precise intelligence. It transforms raw data into strategic narratives, helping organizations anticipate shifts in vendor dominance, regulatory compliance requirements, and technology adoption curves. For those ready to move beyond surface-level analysis and make informed, high-stakes decisions regarding their data infrastructure, the complete study is an essential resource. We invite you to access the full report to unlock the detailed segmentation data, competitor profiling, and forward-looking scenarios that will define the next era of cloud-based data management.
For detailed analysis of this topic, please visit the official page: Cloud-based Database Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Personal Dosimeter Market Hits $296.87M in 2025, Projects 7.06% CAGR to 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for Radiation Safety: Navigating the Personal Dosimeter Market Through 2032
The landscape of occupational radiation safety is undergoing a subtle but decisive transformation. As healthcare systems expand imaging capabilities, nuclear energy programs modernize legacy fleets, and industrial manufacturing adopts increasingly sophisticated containment protocols, the demand for precise, real-time personal dosimetry has shifted from compliance-driven procurement to strategic infrastructure investment. The newly released Personal Dosimeter Market study from PW Consulting maps this evolution across a seven-year forecast horizon, capturing the technical, regulatory, and commercial forces that will shape enterprise purchasing decisions through 2032.
Worldwide Cable Testing and Diagnostics Market
For executives navigating capital allocation, supply chain resilience, or product portfolio strategy, this report is designed less as a static reference and more as a decision operating system. It connects macro trajectory signals with on-the-ground procurement realities, translating historical inflection points into forward-looking procurement and R&D roadmaps. The analysis deliberately operates at the intersection of compliance architecture, clinical engineering priorities, and industrial safety economics, giving leadership teams a shared vocabulary for evaluating vendor partnerships, technology refresh cycles, and regional deployment sequencing.
Worldwide Thermoplastic Carbon Fiber Medical Composites Market
Why 2026 Represents a Structural Inflection Point
The personal dosimeter market has moved steadily upward over the past half-decade, with 2025 closing at approximately $296.87 million and 2026 projections reaching $319.14 million. This trajectory is not merely a function of incremental volume growth. It reflects a compounding set of operational realities: aging radiation protection frameworks requiring modernization, expanding occupational exposure monitoring mandates, and a gradual migration from passive badge-based workflows toward connected electronic systems capable of continuous dose logging, centralized analytics, and rapid incident response.
Worldwide Light Dump Trailer Market
The study's forecast period, spanning 2026 through 2032, positions leadership teams at a moment where procurement commitments made today will lock in exposure monitoring capabilities for the better part of a decade. The trajectory toward 2032, where market volume is projected to approach $477.22 million, signals an environment where dosimetry is increasingly embedded into broader radiation safety ecosystems rather than treated as isolated point solutions. Organizations that approach this window with granular vendor evaluation criteria, clear integration requirements, and realistic total-cost-of-ownership models will be better positioned to avoid fragmented deployments and vendor lock-in scenarios.
A compound annual growth rate of roughly 7.06 percent across the forecast horizon underscores both the resilience and the selectivity of this market. Growth will not distribute evenly across all product categories, application contexts, or geographies. The divergence between high-volume nuclear operations, broad-based clinical exposure monitoring, and specialized industrial use cases creates distinct purchasing cycles, different approval pathways, and varying sensitivity to price versus feature differentiation. This report's strategic value lies in clarifying where those divergences matter most for sourcing strategy and risk management.
What the Study Delivers: Operational Content Designed for Procurement and Product Teams
The report is organized to support translation from high-level market mapping to concrete procurement and product strategy. It does so by examining the ecosystem through three interlocking lenses: technology type, application environment, and deployment geography. Each lens is analyzed not simply for size, but for the operational dynamics that drive buying behavior, replacement cadence, and vendor evaluation criteria.
- Technology type coverage examines the functional trade-offs between electronic personal dosimeters, thermo luminescent badges, optically stimulated luminescence systems, film badge workflows, and emerging accessory types. The analysis connects measurement accuracy, read-out latency, reusability economics, and data management requirements to real procurement decisions in clinical and industrial settings.
- Application segmentation maps how exposure monitoring requirements differ across nuclear power operations, healthcare environments, industrial manufacturing sites, and specialized use cases. Each application context carries distinct compliance expectations, staffing models, and integration needs that influence whether organizations prioritize real-time alerting, archival dose records, multi-modal radiation detection, or streamlined badge exchange logistics.
- Regional deployment patterns are examined for how regulatory frameworks, procurement structures, and local radiation protection cultures shape demand. The report highlights where centralized hospital group purchasing, national nuclear operator standardization, and decentralized industrial safety programs create different competitive dynamics for suppliers and different negotiation leverage for buyers.
Beyond segmentation, the study includes a structured competitive landscape assessment, detailed profiles of leading manufacturers, and an operational scan of the regulatory and reimbursement environments that constrain or accelerate purchasing. These sections are intended to support vendor shortlisting, due diligence checklists, and internal business case development. The report also embeds raw material and capital expenditure context, including how hospital investment in radiation equipment and dosimetry integration frameworks influences product refresh timing and bundled procurement expectations.
Competitive Landscape: Ten Companies Shaping the Next Cycle
The market's competitive architecture is concentrated, with the top three and top five players each holding a substantial share of the overall landscape. That concentration does not imply a monolithic market, however. The field remains differentiated by product architecture, software integration depth, geographic service networks, and vertical specialization. The report profiles ten influential organizations whose product strategies and deployment footprints shape purchasing comparisons across medical, nuclear, and industrial environments.
Mirion Technologies, headquartered in Atlanta, Georgia, anchors its commercial emphasis on advanced wireless personal dosimetry with on-demand display capabilities and supporting dose management software. Its portfolio orientation illustrates the broader market drift toward connected read-out, centralized data workflows, and clinical-grade monitoring for X-ray, gamma, and beta environments. This product philosophy resonates in hospital and clinical procurement teams that prioritize rapid visibility and administrative workflow efficiency.
LANDAUER, based in Glenwood, Illinois, remains closely associated with optical and thermo luminescent badge ecosystems for occupational monitoring across medical, dental, and hospital facilities. Its market presence reflects the durability of badge-based programs where regulatory documentation, standardized exchange cycles, and long-established service relationships continue to drive repeat purchasing.
Tracerco, operating from Billingham in the United Kingdom, emphasizes real-time personal electronic dosimetry for gamma, beta, and neutron monitoring, with relevance across medical and life sciences applications. Its product direction highlights the growing importance of multi-modal detection in environments where exposure scenarios are less predictable and faster alarm response is operationally valuable.
Polimaster, from the Vilnius district in Lithuania, concentrates on active personal dosimetry for medical and healthcare settings. Its footprint demonstrates the continued regional diversification of supply options and the role of compact active monitoring tools in facilities seeking real-time staff dose awareness without full-scale system overhaul.
Unfors RaySafe, located in Hovås, Sweden, develops electronic personal dosimeters aligned with X-ray and gamma monitoring in medical imaging and clinical settings. Its positioning reflects the close coupling between imaging department workflow design and personal monitoring requirements, particularly where dose optimization initiatives place additional emphasis on accurate staff exposure tracking.
Thermo Fisher Scientific, headquartered in Waltham, Massachusetts, contributes to the market through electronic personal dosimetry platforms designed for gamma, beta, and neutron monitoring in hospital and medical contexts. Its broader instrumentation ecosystem gives it a distinct integration advantage in organizations that prefer aligning dosimetry purchases with existing laboratory, imaging, or safety infrastructure.
ATOMTEX, based in Minsk, Belarus, supplies personal dosimeters and radiation monitoring instruments with relevance in medical applications. Its presence in the profiled competitive set underscores the importance of understanding regional supplier capabilities, especially where service responsiveness, calibration logistics, and localized support influence vendor evaluation beyond spec-sheet comparisons.
Ludlum Measurements, from Sweetwater, Texas, focuses on personal radiation dosimeters and detectors for medical and hospital personnel exposure monitoring. Its profile reflects sustained demand for rugged, application-specific detection tools in settings where reliability and straightforward operational use remain decisive buying criteria.
Saphymo, operating from Massy, France, engages in radiation monitoring solutions including personal dosimetry for medical and nuclear medicine use. This positioning shows how specialized clinical workflows, especially in nuclear medicine, create requirements that differ from general radiology environments and often reward vendors with targeted workflow integration and isotope-aware monitoring approaches.
QuartaRad, based in Fair Lawn, New Jersey, offers compact personal Geiger counter and dosimeter solutions for medical and clinical radiation safety. Its inclusion in the competitive landscape highlights the enduring role of portable, point-and-read tools in supplemental monitoring, spot checks, and environments where simplicity and immediate feedback are prioritized.
Collectively, these companies illustrate a market where differentiation is less about presence versus absence and more about measurement modality, data integration, service model, and vertical fit. The study uses these profiles not as endorsements but as comparison scaffolding, enabling procurement teams to map product philosophies against internal requirements, compliance obligations, and long-term operating costs.
Regulatory Anchors and Reimbursement Realities Shaping Demand
Market growth in personal dosimetry does not happen in a vacuum. It is bounded and accelerated by regulatory expectations, occupational safety standards, and reimbursement or policy frameworks that influence how frequently monitoring is required, who bears the cost, and what documentation standards must be met. The report integrates these forces as live market dynamics rather than background footnotes.
In clinical settings, personal dosimetry is governed by a mix of employer obligations, occupational safety guidance, and device clearance requirements. FDA 510(k) clearances and CE Mark certifications continue to shape the commercial path for dosimeter devices sold in the U.S. and EU markets, affecting product launch timing, documentation burdens, and market access strategies for manufacturers. At the operational level, NIOSH and OSHA requirements influence how medical radiation environments structure monitoring programs, which in turn affects recurring demand for badges, electronic dosimeters, and supporting data management services.
Regulatory momentum is not static. Updated Ionizing Radiation Ordinance provisions have reinforced employer responsibilities for ensuring medical radiation workers wear personal dosimeters, which strengthens the compliance baseline for purchasing programs and narrows the window for informal or inconsistent monitoring practices. Such mandates matter strategically because they convert dosimetry from a discretionary safety enhancement into a defined operational obligation, making procurement continuity, calibration reliability, and service coverage more consequential than headline price comparisons.
Reimbursement constraints can also shape clinical demand indirectly. For example, certain provider policies limit basic radiation dosimetry calculation units over defined periods and constrain special dosimetry usage as well. While these policies do not eliminate monitoring requirements, they influence budgeting behavior, service intensity, and how clinical administrators justify equipment and monitoring spend. The study treats these dynamics as decision context, helping organizations distinguish between structural demand drivers and near-term administrative limits that may alter purchasing cadence without changing long-term necessity.
Implications for 2026 Enterprise Decision-Making
For leadership teams planning around 2026, the market's signals point toward several practical strategic priorities.
First, procurement strategy should be evaluated against integration requirements rather than device-only specifications. As dosimetry data becomes more central to radiation safety reporting, vendor selection increasingly depends on software interoperability, archiving practices, alerting logic, and the burden placed on safety officers and clinical staff. Products that offer cleaner data flow and simpler administrative handling often outperform on total operational value even when unit pricing appears less aggressive.
Second, the divergence between electronic and badge-based approaches should be assessed as a lifecycle question. Electronic personal dosimeters offer real-time visibility and stronger operational responsiveness, but their value depends on maintenance workflows, battery management, calibration cadence, and user adoption. Badge-based workflows remain relevant where documentation stability, standardized exchange programs, and long service relationships reduce administrative overhead. The right choice varies by site, staffing model, and the regulatory texture of the operating environment.
Third, regional procurement dynamics require differentiated sourcing strategies. In some markets, large centralized safety programs and institutional purchasing groups create volume leverage and standardization opportunities. In others, fragmented facility ownership and varied regulatory enforcement create a need for flexible service models and strong local support. The report's regional analysis is designed to help buyers anticipate where price competition is most intense, where service quality is the primary differentiator, and where compliance documentation requirements will dominate the evaluation process.
Fourth, capital expenditure planning should incorporate dosimetry as part of broader radiation equipment investment rather than as a standalone line item in isolation. Hospital budgets that sustain investment in radiation equipment increasingly expect dosimetry integration frameworks to align with imaging systems, safety programs, and personnel monitoring workflows. Vendors and buyers alike benefit from anticipating that linkage early, since it influences product selection, deployment sequencing, and multi-year service planning.
How to Use the Full Study
This preview is intended to demonstrate the analytical depth and decision relevance of the complete report while preserving the granular figures, segment breakdowns, and comparative employer-level insights for the full publication. The full study provides the detailed segment values, technology-level comparisons, region-specific demand patterns, and competitive positioning detail needed to support vendor shortlists, budget justifications, compliance planning, and product roadmap decisions.
Organizations evaluating radiation safety procurement for 2026 and beyond will find the complete edition useful for converting market direction into actionable criteria: which technology families align with specific application contexts, where regional dynamics create procurement advantages or risks, how the leading manufacturers differentiate their service and integration models, and what regulatory developments are likely to tighten or expand purchasing requirements.
The Personal Dosimeter Market report is built for teams that need more than aggregated growth numbers. It is designed to support decisions where accuracy, compliance durability, service reliability, and integration readiness determine whether a monitoring program delivers operational value over a multi-year horizon. For leaders preparing for 2026 commitments and planning toward 2032 capacity, the full study offers the structured intelligence required to move from market awareness to confident, evidence-based action.
For detailed analysis of this topic, please visit the official page: Personal Dosimeter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: High-Performance Electric Motorcycle Market to Hit $1.42 Billion by 2032, Growing at 11.8% CAGR
By PW Consulting, 2026-09-07
Navigating the High-Performance Electric Motorcycle Market: A Strategic Blueprint for 2026 and Beyond
The global mobility landscape is undergoing a paradigm shift, where performance is no longer the exclusive domain of internal combustion engines. High-performance electric motorcycles represent the vanguard of this transformation,merging exhilarating power delivery with sustainable technology. For industry stakeholders, investors, and strategic planners, understanding the trajectory of this segment is not merely an academic exercise; it is a critical imperative for navigating the opportunities and challenges of the coming years. Our latest market research publication offers a comprehensive dissection of the High-Performance Electric Motorcycle Market, providing the analytical rigor required to make informed decisions in 2026 and beyond.
Acoustics Service Market
This report serves as a strategic compass, designed to illuminate the path from the immediate present through the medium-term forecast horizon. By synthesizing historical performance data with forward-looking indicators, we equip decision-makers with the insights necessary to capitalize on emerging trends, mitigate risks, and identify high-value avenues for growth. The following overview encapsulates the depth, scope, and strategic utility of this analysis, offering a glimpse into the intelligence available within the full publication.
Three-proof Ruggedized Laptop Market
Market Trajectory and Growth Potential
The momentum behind high-performance electric motorcycles is underpinned by a robust upward trajectory in market revenue. Based on our extensive data modeling, the market has demonstrated consistent expansion over the historical review period, driven by technological breakthroughs in powertrain efficiency, battery energy density, and shifting consumer preferences toward zero-emission performance vehicles. In our base year, the global market generated approximately 0.65 billion USD in revenue, marking a significant step up from the estimated 0.37 billion USD recorded in 2020. This nearly doubling of market value over a five-year span highlights the accelerating adoption rates and the increasing commercial viability of premium electric two-wheelers.
Worldwide Hard Cover Making Machine Market
Looking ahead, the growth narrative remains compelling. The forecast period projects a sustained Compound Annual Growth Rate (CAGR) of 11.8 percent. This growth rate reflects a market that is maturing yet still possesses substantial room for expansion as infrastructure improves and product portfolios diversify. By the end of the forecast horizon in 2032, market revenue is projected to reach an estimated 1.42 billion USD. This trajectory suggests that the high-performance electric motorcycle segment is poised to transition from a niche enthusiast market to a more mainstream component of the broader electric mobility ecosystem, driven by continuous innovation and competitive pressure among leading manufacturers.
It is crucial to note that this growth is not uniform across all dimensions. The expansion is fueled by distinct dynamics in product types, application segments, and regional adoption patterns. While specific regional breakdowns and granular segment percentages are detailed within the full report to preserve the integrity of our proprietary analytics and to provide actionable nuance, the overarching theme is one of diversification. Demand is being shaped by a combination of individual consumer enthusiasm for thrill and speed, alongside commercial interests in fleet electrification and specialized utility applications, all of which are thoroughly analyzed in the study.
Product Segmentation: Performance Archetypes and Application Drivers
The high-performance electric motorcycle landscape is characterized by distinct product archetypes that cater to divergent rider expectations and usage scenarios. Our analysis categorizes the market based on vehicle type and application, revealing how manufacturers are tailoring engineering solutions to meet specific performance benchmarks. The market encompasses street-legal sportbikes designed for on-road dominance, as well as off-road machines engineered for rugged terrain, motocross, and enduro challenges. Each category demands unique approaches to power delivery, torque management, weight optimization, and suspension dynamics.
In the street segment, the focus is on rapid acceleration, top-speed capability, and advanced rider aids that integrate seamlessly with digital interfaces and connectivity features. These machines are competing directly with their gasoline-powered counterparts, offering instant torque and reduced maintenance requirements. The off-road segment, conversely, emphasizes agility, durability, and power-to-weight ratios that excel in technical environments. This includes trials, enduro, and dual-sport applications where electric powertrains offer advantages in packaging, low-end torque, and precise throttle control.
Application segmentation further delineates the market's growth vectors. Individual consumers remain a significant driver of demand, seeking high-performance machines for recreation, commuting, and brand affiliation. Simultaneously, commercial applications are emerging as a strategic growth pillar, encompassing uses such as specialized delivery, security patrols, and fleet operations where total cost of ownership, reliability, and operational efficiency are paramount. Our report provides a deep-dive analysis of these applications, evaluating the specific value propositions, purchasing criteria, and adoption barriers associated with each use case, enabling stakeholders to refine their market entry or expansion strategies.
Competitive Landscape: Innovation as the Primary Battlefield
The high-performance electric motorcycle sector is defined by a fiercely competitive environment where technological differentiation is the key to market leadership. The market structure exhibits a moderate level of concentration, reflecting the presence of established players leveraging brand equity and engineering heritage, alongside agile innovators disrupting the status quo with proprietary technologies. Our analysis profiles the key companies shaping this competitive arena, examining their strategic positioning, technological moats, and recent developments that signal future market directions.
Among the notable participants is Zero Motorcycles, headquartered in Santa Cruz, California. Zero has established itself as a pioneer in the electric performance space, utilizing its proprietary Z-Force electric powertrain combined with rigid, aircraft-grade aluminum frames. This engineering philosophy prioritizes lightweight construction and rapid off-the-line acceleration, delivering a superior riding experience that resonates with performance-oriented riders. Their continued focus on refining powertrain efficiency and frame integrity underscores a commitment to maintaining a competitive edge in the street and off-road segments.
Verge Motorcycles, based in Finland, represents the cutting edge of electric superbike engineering. The company has introduced patented hubless donut motors and claims first-to-market solid-state battery packs, technologies that enable record torque outputs and enhanced charging capabilities. By addressing critical pain points such as range anxiety and charging speed through proprietary hardware innovations, Verge is positioning itself as a leader in the high-end performance niche. Their approach highlights the importance of battery chemistry and motor design as differentiators in a market where performance specifications are increasingly scrutinized by sophisticated buyers.
Lightning Motorcycle, operating in the United States, has garnered attention for its high-performance sportbikes, including the LS-218 model. Engineered to rival the performance of gas counterparts, Lightning focuses on industry-leading fast charging capabilities and reduced maintenance needs. Their development trajectory emphasizes practicality alongside performance, targeting riders who demand the thrill of electric power without compromising on usability or downtime. This balance of performance and operational efficiency is a recurring theme among successful entrants in this market.
Energica Motor Company, based in Italy, specializes in high-performance electric motorcycles spanning superbike and sport models, such as the Ego Sport series. Energica's portfolio is characterized by zero-emission powertrains that deliver exceptional acceleration, with 0-60 mph times under 2.5 seconds for select models. Their expertise in high-output powertrains and comprehensive vehicle integration positions them as a benchmark for performance metrics in the European and global markets, appealing to enthusiasts who prioritize raw power and dynamic handling.
Harley-Davidson has entered the fray through its LiveWire division, bringing the weight of a legacy brand to the high-performance electric segment. The LiveWire S2 series exemplifies this approach, featuring advanced power delivery systems and modern connectivity features tailored for enthusiasts. By leveraging established manufacturing capabilities and brand recognition, Harley-Davidson is expanding the addressable market for electric performance motorcycles, bridging the gap between traditional motorcycle culture and electric mobility.
Stark Future, headquartered in Barcelona, Spain, focuses on motocross and dual-sport applications, emphasizing agile, torque-rich performance platforms. Their recent strategic partnership, announced in April 2026, with MOTOREX for lubrication expertise illustrates the nuanced collaborations required to optimize performance at racing, production, and product development levels. This move underscores the complexity of electric drivetrain lubrication and thermal management, areas where specialized knowledge can provide a tangible competitive advantage.
Electric Motion, based in Saint-Brès, France, specializes in high-performance electric motorcycles for trials, enduro, and off-road segments. Their focus on specialized powertrains and lightweight designs addresses the unique demands of off-road performance, where power-to-weight ratios and durability are critical. Electric Motion's presence highlights the vitality of the off-road niche, where electric propulsion is unlocking new possibilities for rider engagement and competitive racing formats.
These companies, among others, are engaged in a dynamic race to innovate, differentiate, and capture market share. Our report provides detailed competitive profiling, including headquarters locations, product strategies, and technological differentiators, offering a holistic view of the competitive ecosystem. Understanding the strengths, weaknesses, and strategic moves of these key players is essential for benchmarking, partnership identification, and competitive response planning.
Technological Dynamics and Market Enablers
The viability and growth of the high-performance electric motorcycle market are inextricably linked to advancements in raw materials, battery technology, and regulatory frameworks. Our analysis integrates these critical dynamics to provide a comprehensive understanding of the factors influencing market evolution. Battery technology remains the cornerstone of electric motorcycle performance, with lithium-ion and emerging solid-state battery packs playing a pivotal role in enhancing power-to-weight ratios, extending range, and reducing charging times. The transition toward solid-state batteries, as exemplified by developments in the industry, represents a potential breakthrough in energy density and safety, enabling longer ranges and higher performance without compromising vehicle weight.
Raw material sourcing and design innovations also contribute significantly to market capabilities. The use of aircraft-grade aluminum frames is a prevalent strategy for achieving lightweight construction, which is essential for high-performance handling and acceleration. Such material choices directly impact the overall vehicle architecture and performance characteristics, making supply chain resilience and material science advancements relevant considerations for manufacturers and investors.
Regulatory environments are increasingly shaping market incentives and product specifications. Standards such as EU Regulation 134/2014 Annex VII, which standardizes the measurement of electric motorcycle energy consumption and range, provide a framework for comparability and consumer transparency. Adherence to such regulations not only ensures market access but also drives manufacturers to optimize efficiency and accuracy in performance claims. Furthermore, zero-emission requirements and environmental regulations are accelerating the adoption of high-performance electric motorcycles, creating a supportive policy backdrop that aligns with sustainability goals and urban mobility strategies.
These technological and regulatory dynamics create a complex interplay that influences product development cycles, cost structures, and competitive positioning. Our report dissects these factors to reveal their implications for market growth, investment risks, and strategic opportunities, ensuring that readers are equipped with a nuanced understanding of the external forces at play.
Strategic Applications and Decision-Making Framework
The insights contained in this research report are designed to support a wide array of strategic applications for executives, investors, and product planners. Whether the objective is to enter the market, expand an existing product portfolio, identify partnership opportunities, or assess competitive threats, the analysis provides a solid foundation for evidence-based decision-making.
For manufacturers and technology providers, the report offers granular insights into segmentation drivers, consumer preferences, and performance benchmarks. This enables the refinement of product development roadmaps, ensuring that engineering investments align with market demand and competitive expectations. Understanding the relative importance of street versus off-road performance, the specific requirements of individual versus commercial applications, and the regional variations in adoption patterns allows for more targeted resource allocation and market prioritization.
Investors and financial analysts can leverage the market sizing, growth projections, and competitive landscape analysis to evaluate the potential return on investment and risk profile of ventures within the high-performance electric motorcycle sector. The detailed data on revenue trends, CAGR, and market concentration provides the quantitative basis for valuation models and scenario planning. Additionally, the identification of key technological and regulatory drivers assists in assessing the long-term viability and scalability of market participants.
For strategic planners within automotive and mobility organizations, the report serves as a tool for benchmarking and competitive intelligence. The profiles of leading companies, combined with an analysis of recent developments such as strategic partnerships and technological introductions, offer early warning signals of shifting competitive dynamics. This intelligence can inform M&A strategies, joint venture explorations, and positioning strategies to ensure relevance in an evolving market landscape.
It is important to emphasize that the full strategic value of this research lies in the depth and granularity of the data provided. While this overview highlights the macro-level trends and key players, the complete report contains essential details regarding regional market dynamics, precise segment shares, and specific application-driven demand factors. These elements are critical for fine-tuning localized strategies and uncovering niche opportunities that may not be apparent from aggregate figures alone. Access to the full dataset ensures that decision-makers have the complete picture required to execute with precision.
Why This Report is Essential for 2026 Strategic Planning
As we move through 2026, the high-performance electric motorcycle market is at an inflection point where acceleration in adoption, technological maturity, and competitive intensity are converging. Strategic decisions made now will have a lasting impact on market positioning and financial outcomes over the forecast period. This research report is structured to meet the demands of this critical juncture by delivering actionable intelligence that bridges the gap between high-level market trends and executable strategy.
The forecast period from 2026 to 2032 offers a substantial window for growth, but realizing this potential requires navigating a landscape characterized by rapid innovation and evolving consumer expectations. Companies must be agile in their response to technological breakthroughs, such as advancements in battery chemistry and motor design, while also addressing the practicalities of charging infrastructure, maintenance ecosystems, and regulatory compliance. Our analysis provides the context and data necessary to anticipate these changes and prepare accordingly.
Furthermore, the competitive landscape is dynamic, with new entrants and established players continually reshaping the battlefield through product launches, partnerships, and technological claims. Staying ahead requires a thorough understanding of who the key players are, what technologies they are pursuing, and how they are positioning themselves relative to the broader market. This report consolidates that intelligence, saving stakeholders the time and resources required to gather and synthesize disparate sources of information.
By integrating market sizing, segmentation analysis, competitive profiling, and technology assessment into a cohesive narrative, the report enables a holistic approach to strategy. It helps organizations align their internal capabilities with external opportunities, identify gaps in the market, and prioritize initiatives that offer the highest strategic return. Whether the focus is on product innovation, market expansion, or competitive defense, the insights provided serve as a catalyst for informed action.
Conclusion: Accessing the Full Intelligence Picture
The High-Performance Electric Motorcycle Market presents a compelling opportunity for stakeholders who are prepared to engage with its complexities and capitalize on its growth trajectory. With a projected CAGR of 11.8 percent and a market size poised to exceed 1.4 billion USD by 2032, the potential rewards for strategic foresight are significant. However, success in this environment demands more than a superficial understanding of trends; it requires detailed, data-driven insights that reveal the underlying mechanics of demand, competition, and technology.
This research publication is designed to be that definitive resource. It combines rigorous quantitative analysis with qualitative assessments of the competitive and technological landscape, offering a multi-dimensional view of the market. From the nuances of street versus off-road segmentation to the strategic implications of recent developments like Stark Future's partnership with MOTOREX, the report provides a level of detail that is essential for high-stakes decision-making.
To fully leverage the strategic value of this research, we invite you to access the complete report. The full publication contains the comprehensive data tables, detailed regional and segment breakdowns, in-depth company profiles, and forward-looking analysis that form the backbone of this overview. By obtaining the complete intelligence package, you will gain the clarity and confidence needed to navigate the high-performance electric motorcycle market with precision, identify the most promising avenues for growth, and secure a competitive advantage in the years to come.
The journey toward electrification in the performance two-wheeler sector is accelerating. Equip your organization with the insights necessary to lead, adapt, and thrive. Explore the full report to unlock the detailed market intelligence and strategic recommendations that will guide your path forward in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: High-Performance Electric Motorcycle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Memory Foam Mattress Market Hits $9.63B in 2025, Projected to Reach $14.26B by 2032 at 5.98% CAGR
By PW Consulting, 2026-09-07
The Memory Foam Mattress Market: Strategic Intelligence for 2026 and Beyond
The global sleep and therapeutic support surface industry stands at a critical inflection point. As consumer expectations around restorative sleep converge with rigorous clinical demands for pressure injury prevention, memory foam has evolved from a comfort novelty into a foundational material across residential, hospitality, and healthcare environments. For executives navigating supply chain realignments, product portfolio optimization, and channel expansion, understanding the trajectory of this sector is no longer optional. It is a core determinant of competitive positioning through the end of the decade.
Online E-book Services Market
This analysis introduces a comprehensive market research study designed specifically to equip leadership teams with the actionable intelligence required to make high-conviction decisions in 2026. Below, we outline the macro trajectory, competitive architecture, and operational dynamics that define the landscape, while demonstrating how the full report translates these forces into executable strategy.
Wall-flow Honeycomb Ceramic Carrier Market
Market Trajectory: Navigating the Growth Arc
Over the past half-decade, the memory foam mattress sector has demonstrated consistent, compounding expansion. Historical performance from 2020 through 2025 reveals a market that has steadily absorbed macroeconomic volatility while maintaining positive revenue momentum. What began as a niche material innovation has matured into a multi-billion-dollar global revenue stream, with 2025 closing near the 9.6 billion USD mark. The forward-looking trajectory extends this expansion through the early 2030s, driven by sustained procurement cycles in care facilities, rising disposable incomes in developing consumption markets, and a structural shift toward material technologies that balance durability, pressure redistribution, and user comfort.
Worldwide Wedding Car Rental Market
The compound annual growth rate projected across the forecast horizon underscores a steady, non-speculative expansion path. Rather than experiencing the boom-and-bust cycles characteristic of earlier consumer durables waves, the market is being shaped by institutional procurement standards, evolving clinical reimbursement frameworks, and a broadening consumer recognition of sleep quality as a health and productivity multiplier. For strategic planners, this implies that volume growth will be distributed across multiple demand engines rather than concentrated in a single geographic or application surge. Manufacturers and distributors that align their capacity planning, inventory positioning, and channel investments with this diversified growth profile will be better insulated against regional demand shocks and pricing compression.
The full report decomposes this trajectory into forward-looking volume and revenue pathways, mapping inflection points where capacity constraints, material cost fluctuations, or regulatory adjustments are likely to alter margin structures. Decision-makers will find scenario-based projections that isolate the contribution of each demand segment without exposing the granular figures in this executive overview. Accessing the complete dataset enables finance and operations teams to stress-test their 2026 budgets against realistic growth envelopes and to time capital expenditures in alignment with regional procurement calendars.
Competitive Architecture: Concentration, Differentiation, and Innovation Cycles
The competitive field is characterized by a moderate degree of concentration, where a limited number of established players hold meaningful shares of total revenue. This structure rewards companies that can simultaneously serve high-specification institutional channels and scale efficiently in consumer-facing retail. The leaders profiled in the study illustrate how strategic positioning diverges across clinical, therapeutic, and comfort-driven segments, and how recent corporate actions signal where capital and engineering resources are being deployed.
Among the core enterprises tracked are companies with deeply entrenched positions in therapeutic and pressure-redistributing sleep surfaces. Invacare, headquartered in Batesville, Indiana, has built its reputation around visco-elastic memory foam mattresses and overlays designed specifically for hospital and long-term care environments. Its Softform Premier Visco and SoftCloud ranges exemplify high-specification zoned pressure relief, targeting facilities that require validated performance in pressure redistribution alongside operational durability. Drive Medical, based in Schaumburg, Illinois, pursues a complementary strategy through therapeutic foam mattresses such as the Gravity series and Quickn-Comfort models. These products integrate hybrid visco-elastic memory foam layers for pressure redistribution across hospital and homecare settings, emphasizing accessibility, practical deployment, and cost-efficient clinical utility.
Moving into the medical-grade segment, Medtrica, operating from Canada, focuses on medical-grade memory foam mattresses and therapeutic replacement mattresses for hospital beds. Its product architecture emphasizes 100 percent medical-grade fabric and anti-fungal, anti-bacterial foam formulations, addressing infection control requirements that are increasingly prioritized in acute and post-acute procurement decisions. In Stockholm, Arjo has established itself as a significant force in pressure ulcer prevention and infection control for acute and community care. Its visco-elastic memory foam portfolio, including ConformX and TheraRest SMS Perimeter Plus VE, reflects a clinical engineering philosophy that links material performance directly to patient outcomes and staff workflow efficiency.
Recent corporate activity further illuminates where innovation capital is flowing. In October 2025, Arjo introduced the TheraRest SMS Perimeter Plus VE Mattress, featuring enhanced visco-elastic memory foam engineered for improved pressure redistribution and patient comfort in hospital settings. This launch signals continued investment in clinical differentiation rather than pure cost competition. In November 2025, Sinomax USA expanded the availability of its Vibe gel memory foam mattress into Walmart locations nationwide, spanning both in-store and online channels for premium comfort models. This distribution move highlights the growing convergence of premium consumer comfort features with mass-retail accessibility. Earlier, in February 2025, Americanstar Mattress announced in-house foam production at its Waco, Texas facility, aiming to accelerate proprietary comfort technologies tailored specifically for U.S. consumers. Such vertical integration decisions reflect a broader industry intent to capture margin, shorten development cycles, and protect intellectual property in a market where material formulations increasingly define brand equity.
The full report maps these competitive postures against share boundaries, partnership networks, and channel strategies, revealing where consolidation pressure is most likely to emerge and which capability gaps present entry or expansion opportunities. Leadership teams will be able to benchmark their product roadmaps against the engineering priorities and launch cadence of these incumbents, identifying whitespace where differentiated formulations, certification advantages, or service models can command premium positioning.
Regulatory, Reimbursement, and Quality Assurance Dynamics
No strategic assessment of this market is complete without addressing the regulatory and reimbursement terrain that shapes procurement eligibility, product classification, and risk exposure. The industry operates at the intersection of consumer goods standards and medical device expectations, a duality that creates both barriers to entry and defensible moats for compliant, well-documented manufacturers.
Regulatory classification remains a central force in market dynamics. Hospital-grade mattresses are subject to FDA classification as Class I and Class II medical devices, requiring Establishment Registration and Device Listing. This framework elevates the importance of quality management systems, documentation rigor, and post-market surveillance for any supplier targeting institutional buyers. Compliance is not merely a legal checkbox; it directly influences tender evaluations, formulary inclusion, and the speed at which new products can be deployed in care environments. Arjo’s mattresses, for example, have been tested to FDA 21 CFR Part 4 and CE marking standards for medical use, illustrating how certification portfolios are increasingly leveraged as commercial differentiators in tenders where clinical risk mitigation carries substantial weight.
Reimbursement structures further influence demand patterns, particularly in the healthcare segment. Medicare’s Durable Medical Equipment coverage extends to pressure-reducing mattresses that meet hospital bed criteria, and certain non-HCPCS coded memory foam mattresses may substitute under specific medical necessity guidelines. These reimbursement pathways create demand elasticity that is tied to documentation quality, clinical justification, and provider behavior. Strategic players monitor HCPCS updates and CMS guidance closely, because shifts in coding eligibility can rapidly alter the economics of product lines that were previously dependent on out-of-pocket consumer spending or facility capital budgets.
Quality and safety incidents, while not pervasive, reinforce the premium that procurement teams place on traceable manufacturing and durable seam integrity. The 2024 FDA Class II device recall involving seam tearing on a mattress cover serves as a cautionary reference point, reminding manufacturers and distributors that supply chain quality control and material validation carry reputational and operational consequences. No new recalls have been reported for other memory foam hospital products through 2025 and 2026, but the episode underscores why institutional buyers increasingly favor suppliers that can demonstrate consistent testing protocols and transparent failure-mode reporting.
The comprehensive study integrates these regulatory and reimbursement threads into a practical framework, helping product, legal, and commercial teams anticipate compliance milestones, align documentation with procurement requirements, and structure Go-to-Market plans that satisfy both clinical gatekeepers and consumer retail criteria. Readers who access the full report will find dedicated sections that translate these dynamics into operational checklists, tender-strategy guidance, and reimbursement-aware pricing considerations.
Application and Regional Demand Patterns: A Diversified Growth Engine
The market’s expansion is not the product of a single dominant driver. Instead, it reflects a diversified demand base spanning residential sleep upgrades, hospitality comfort standards, and healthcare therapeutic requirements. Residential applications constitute the largest share of revenue, reflecting sustained consumer interest in sleep quality, pressure relief, and material longevity. Hospitality continues to represent a meaningful demand stream, as hotels and residential-care operators seek surfaces that balance guest comfort with housekeeping durability and replacement cycles. Healthcare, while smaller in absolute volume relative to residential demand, commands disproportionate strategic attention because of its clinical performance thresholds, procurement formality, and reimbursement sensitivity.
Geographically, the market exhibits a multi-polar structure rather than reliance on a single dominant region. North America maintains a strong presence, supported by established healthcare procurement infrastructure, a mature consumer sleep market, and a robust retail distribution network. Europe contributes a substantial base shaped by clinical standards, regional reimbursement environments, and a consumer culture that increasingly values sleep wellness. Asia Pacific represents a large and growing revenue pool, driven by urbanization, expanding middle-class consumption, and the gradual professionalization of bedding retail and e-commerce channels. Latin America and the Middle East and Africa, while smaller in current scale, are tracked closely for their emerging procurement patterns and channel development potential.
What matters strategically is not merely the ranking of regions, but the interplay between regional material cost structures, logistics complexity, certification requirements, and channel maturity. A product configuration optimized for North American retail may require reformulation or packaging adjustments for European clinical tenders, while a hospital-grade offering destined for Asia Pacific may need to accommodate distinct procurement cycles and local distribution partnerships. The full report disentangles these regional and application nuances without reducing them to simplistic share percentages, instead providing scenario-based guidance on where capacity allocation, certification investment, and channel partnerships will yield the highest risk-adjusted returns.
How the Full Report Converts Intelligence into Execution
The strategic value of this study lies in its operational granularity and its explicit mapping of market forces to decision levers. Rather than stopping at high-level sizing and trend description, the report is structured to support concrete actions across product development, supply chain planning, pricing, channel strategy, and competitive positioning.
Throughout the document, readers will encounter detailed coverage of material technology trajectories, including how visco-elastic formulations, zoned pressure relief architectures, antimicrobial fabric integrations, and hybrid layer combinations are evolving in response to clinical and consumer feedback. The study evaluates the cost implications of these material shifts, highlights where proprietary formulations create durable differentiation, and identifies points at which commoditization risk increases for undifferentiated SKUs. This technical assessment is directly linked to product planning, enabling R&D and innovation teams to prioritize formulation investments that align with the most lucrative demand segments.
Pricing and margin architecture receive dedicated attention, with an examination of how institutional tenders, retail promotions, and reimbursement-aware purchasing behavior shape effective price realization. The report analyzes where premium positioning is sustainable, where value-tier competition compresses margins, and how manufacturers can structure SKU architectures to preserve profitability while meeting divergent performance expectations across residential, hospitality, and healthcare channels. Supply chain and manufacturing strategy are addressed through the lens of regional material sourcing, in-house versus outsourced foam production decisions, and the logistics implications of serving both bulky consumer freight and clinical delivery requirements. Recent moves toward in-house production and proprietary comfort technology development are contextualized within broader industry patterns, helping executives decide whether vertical integration, strategic supplier partnerships, or regional manufacturing footprints best fit their operating model.
Competitive benchmarking is built around real corporate profiles, product architectures, and documented recent developments rather than abstract market narratives. The study compares how leading players balance clinical credibility with retail reach, where they invest in certification and documentation, and how their launch cadence reflects differing strategic priorities. These comparisons are designed to inform both offensive moves, such as targeted product launches or channel acquisitions, and defensive maneuvers, such as strengthening tender documentation, improving service-level agreements, or differentiating on material longevity and infection-control features.
Finally, the report incorporates a structured FAQ and decision-support framework that translates complex regulatory, reimbursement, and procurement considerations into practical guidance. Readers will find clarity on device classification expectations, documentation requirements for institutional sales, reimbursement eligibility boundaries, and quality assurance practices that reduce recall and tender-failure risk. This section is particularly valuable for cross-functional teams that must align commercial ambition with compliance reality, ensuring that growth initiatives are grounded in feasible operational pathways.
What Decision-Makers Will Gain from the Complete Intelligence Package
Accessing the full report transforms macro awareness into executable strategy. Finance and strategy teams will be able to pressure-test 2026 resource allocation against forward-looking growth envelopes, identifying which applications and regions warrant incremental investment and which require defensive margin management. Product and R&D leaders will gain a technology roadmap that distinguishes between incremental comfort features and clinically meaningful performance improvements, reducing the risk of overinvesting in features that buyers do not value at premium price points. Commercial and sales executives will obtain channel-specific positioning guidance, enabling them to tailor messaging, packaging, and tender responses to the distinct evaluation criteria of retail consumers, hospitality buyers, and healthcare procurement committees.
Operational and supply chain leaders will benefit from a pragmatic view of manufacturing strategy, material sourcing, and logistics trade-offs, allowing them to anticipate cost pressures and capacity constraints before they become disruptive. Legal, regulatory, and quality functions will find a consolidated reference for device classification, certification expectations, and documentation standards, reducing ambiguity in product launches and institutional sales efforts. Taken together, these capabilities support a more coherent strategic posture: one that balances growth ambition with compliance discipline, differentiates on material and clinical value where it matters, and avoids the margin traps that arise from undifferentiated competition.
Conclusion: Positioning for Confident Decisions in 2026
The memory foam mattress market is entering a period in which success will be determined less by broad industry tailwinds and more by the precision with which companies align product architecture, channel strategy, compliance readiness, and regional execution. The growth path through the forecast horizon is solid, but it is also segmented, regulated, and increasingly competitive. Organizations that treat this landscape as a single homogeneous opportunity will underexploit high-value niches and overspend on low-return exposures. Those that adopt a segmented, intelligence-led approach will be better positioned to capture premium clinical and consumer demand, manage regulatory and reimbursement complexity, and time investments to the rhythm of regional procurement and retail cycles.
This introduction has outlined the strategic contours of the market and the competitive and operational forces shaping it. To move from awareness to execution, however, leadership teams need the full analytical architecture: detailed segmentation pathways, region-and-application-level scenario analysis, competitive benchmarking, material and manufacturing strategy guidance, and compliance-aware commercial playbooks. The complete market research study delivers that depth. It is designed to serve as a working strategic asset for executive teams, finance leaders, product planners, and commercial operators who need to make 2026 decisions with clarity, confidence, and evidence.
For organizations ready to convert market insight into actionable strategy, the full report provides the granular intelligence required to map opportunities, mitigate risk, and prioritize capital where it will generate the strongest returns. Accessing the complete dataset and analysis will ensure that your 2026 planning rests on a precise, operationally grounded understanding of where the memory foam mattress market is heading and how your enterprise can lead within it.
For detailed analysis of this topic, please visit the official page: Memory Foam Mattress Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Eye Anatomical Model Market Hits $355.74M in 2025, Projected 6.05% CAGR to 2032
By PW Consulting, 2026-09-07
Strategic Intelligence Report: The Eye Anatomical Model Market Outlook 2026–2032
In the rapidly evolving landscape of medical education and clinical training, precision tools are no longer optional—they are foundational. The Eye Anatomical Model Market stands at a pivotal inflection point, driven by advancements in surgical training, heightened demand for patient education, and the integration of next-generation manufacturing technologies. As organizations plan their capital allocation and product development strategies for the coming years, understanding the trajectory of this specialized sector is critical.
Metal Powder Gas Atomizer Market
This article serves as a strategic preview of PW Consulting's latest comprehensive market research study. It outlines the macroeconomic forces shaping the industry, highlights the competitive dynamics among key global players, and details the practical intelligence contained within the full report. Our goal is to equip stakeholders with the context needed to navigate the forecast period from 2026 to 2032, while demonstrating why deep-dive data is essential for informed decision-making.
Worldwide Autonomous Drone Station Market
Market Trajectory and Growth Vectors
The global demand for anatomical eye models has demonstrated consistent resilience and expansion over the past half-decade. Based on historical analysis from 2020 through 2025, the market has matured from a niche educational supply chain into a broader medical device support sector. The revenue trajectory indicates a steady climb, with the total market size reflecting significant investment in both physical training aids and digital-physical hybrid solutions.
Expedited Auto Transport Market
Looking forward, the forecast period suggests continued upward momentum. The compound annual growth rate (CAGR) projected for the sector underscores a healthy expansion environment, driven by increasing enrollment in medical programs and the need for specialized ophthalmic training tools. While specific regional breakdowns and segment-level revenue figures are reserved for the full intelligence dossier, the aggregate growth pattern signals a robust environment for manufacturers and distributors who can align with emerging educational standards.
Key macroeconomic drivers influencing this trajectory include:
- Educational Investment: Rising funding for medical and optometry schools is directly correlated with procurement cycles for high-fidelity anatomical models.
- Clinical Training Standards: Hospitals and specialized clinics are increasingly standardizing their training protocols, requiring durable, dissectible, and accurate models for resident education.
- Patient Communication: There is a growing trend in using enlarged anatomical models to explain complex conditions and surgical procedures to patients, enhancing informed consent processes.
It is important for stakeholders to recognize that while the overall market size is expanding, the composition of that growth varies significantly by model type and end-user application. The full report dissects these nuances, providing clarity on which specifications are driving volume versus value in the current fiscal cycle.
Competitive Landscape and Key Industry Players
The market structure is characterized by a mix of established manufacturers with decades of heritage and innovators introducing advanced manufacturing techniques. Market concentration metrics indicate a moderately fragmented environment, where leading firms hold significant share but there remains ample room for specialized niche players. The top five entities collectively represent a substantial portion of the market revenue, yet competition remains fierce on the grounds of anatomical accuracy, material durability, and technological integration.
Several core companies define the current competitive baseline:
- 3B Scientific GmbH (Germany): A dominant force in life-size and enlarged models, offering dissectible variants and pathological examples tailored for optometry and patient teaching.
- SOMSO Modelle GmbH (Germany): Renowned for high-quality enlarged models with detailed sagittal orbital sections, maintaining a strong reputation in anatomical education.
- GPI Anatomicals (United States): Focuses on oversized cut-away models that expose internal structures such as the retina and optic nerve, catering heavily to medical and pharmaceutical training.
- Erler-Zimmer GmbH & Co. KG (Germany): Provides models with augmented anatomy features, including orbit and eyelid variants that support detailed teaching scenarios.
- Stratasys (Israel): Represents the technological frontier, utilizing 3D printing and Digital Anatomy™ technology to create multi-layer replicas for surgical simulation.
Beyond these leaders, regional specialists play a crucial role in supply chain resilience. Manufacturers in Japan, China, and Australia contribute to the global supply by offering cost-effective and custom solutions. For instance, companies like Sakamoto Model Corporation and Xincheng Scientific Industries focus on anatomically accurate and giant PVC models respectively, while others target affordable dissectible versions for schools. This diversity ensures that different price points and specification requirements are met across the global value chain.
Understanding the specific capabilities, headquarters locations, and product portfolios of these entities is vital for partnership opportunities, competitive benchmarking, and supply chain risk assessment. The full report provides detailed profiles, including web presence and specific product lines, to assist in vendor selection and competitive analysis.
Technological Disruption and Product Innovations
The intersection of traditional manufacturing and advanced digital fabrication is reshaping the product landscape. While standard anatomical models have historically relied on materials like medical-grade PVC and SOMSO-PLAST®, recent developments indicate a shift toward high-fidelity simulation tools. Material costs for standard units vary widely depending on size and complexity, influencing procurement strategies for budget-conscious institutions.
A notable recent development highlights this technological shift. In November 2025, Stratasys demonstrated the first 3D-printed anatomical eye models for eyelid surgery training at Lid Summit Tirol in Austria. Powered by Digital Anatomy™ technology, these models offer multi-layer anatomical replicas of the eye and surrounding tissues. This innovation addresses a specific need in surgical training where tactile feedback and tissue layering are critical for competency development.
Furthermore, regulatory dynamics are evolving alongside these technologies. For educational use in controlled training settings, 3D-printed anatomical models for eyelid surgery training currently do not require regulatory clearance under FDA or EU MDR frameworks. This regulatory environment lowers the barrier to entry for simulation-based training tools, potentially accelerating adoption in residency programs and specialized workshops. However, stakeholders must remain vigilant as regulatory interpretations can shift with technological maturity.
Operational considerations also remain paramount. In clinical training environments, anatomical eye models often require standard hospital-grade sterilization methods, such as ethylene oxide or autoclave processes, between uses. This requirement impacts the total cost of ownership and influences material selection, as models must withstand repeated sterilization cycles without degrading anatomical fidelity.
Regulatory, Reimbursement, and Operational Dynamics
Navigating the operational landscape requires a clear understanding of classification and reimbursement realities. Anatomical eye models are typically classified under CPT code 76499, designated as an unlisted radiological procedure, within hospital settings. Crucially, there is no separate DRG reimbursement for these educational consumables. This financial reality means that procurement decisions are often driven by departmental budgets, grants, or educational funds rather than direct patient care reimbursement streams.
This classification impacts market demand in several ways:
- Budget Sensitivity: Since these items are often non-reimbursable consumables, price sensitivity among educational institutes and hospitals can be high.
- Value Proposition: Manufacturers must articulate clear educational outcomes and durability benefits to justify expenditures outside of direct reimbursement channels.
- Procurement Cycles: Purchasing decisions may align with academic fiscal years or training grant cycles rather than continuous clinical consumption.
Additionally, the cost of materials remains a significant factor in pricing strategies. Standard models utilizing medical-grade polymers can range significantly in unit cost based on complexity. Understanding these cost structures is essential for companies aiming to optimize their supply chains or for institutions negotiating bulk procurement contracts.
Synergy with Broader Medical Training Trends
The growth of the eye anatomical model market does not exist in isolation. It is intrinsically linked to broader trends in medical education and surgical specialization. As ophthalmic procedures become more intricate, the demand for realistic training models increases. This is particularly true for subspecialties involving retinal surgery, glaucoma management, and eyelid reconstruction.
Educational institutes continue to be a primary end-user segment, driving volume through foundational anatomy courses. However, hospitals and ophthalmic clinics are increasingly recognizing the value of these models for continuous professional development and patient interaction. The ability to physically manipulate a model enhances spatial understanding of complex orbital structures, which is difficult to achieve through digital screens alone.
The market is also seeing a divergence in model types. Small-sized models remain prevalent for individual study and desk reference, while large-sized models are critical for lecture halls and group demonstrations. Each segment serves a distinct pedagogical purpose, and procurement strategies should reflect the intended use case. The full research study provides precise segmentation data to help organizations identify which model types are gaining traction in specific contexts.
Strategic Recommendations for Stakeholders
For manufacturers, distributors, and institutional buyers, the upcoming forecast period presents both opportunities and challenges. Success will depend on the ability to interpret market signals correctly. We recommend the following strategic focus areas:
- Product Diversification: Consider expanding portfolios to include both traditional durable models and innovative 3D-printed simulation tools to capture different market segments.
- Regional Focus: While global growth is positive, regional demand drivers vary. Understanding local educational standards and procurement regulations is key to market entry or expansion.
- Compliance and Sterilization: Ensure product designs accommodate standard sterilization protocols to meet hospital-grade requirements, thereby widening the potential customer base.
- Educational Partnerships: Collaborating with medical schools and training centers can provide early feedback on product efficacy and secure long-term procurement relationships.
Stakeholders must also monitor the competitive intensity. With a moderate level of market concentration, there is potential for consolidation or for new entrants leveraging advanced manufacturing to disrupt established pricing models. Keeping abreast of competitor product launches and material innovations is essential for maintaining competitive parity.
Conclusion: The Value of Precision Intelligence
The Eye Anatomical Model Market is poised for steady growth, underpinned by enduring needs in medical education and clinical training. However, the surface-level trends only tell part of the story. True strategic advantage comes from understanding the granular details: the specific revenue contributions of model types, the precise allocation of end-user spending, and the nuanced performance of regions across the globe.
PW Consulting's full market research report delves into these depths, offering unparalleled visibility into the data that drives decisions. From detailed segmentation splits to competitive profiling and forecasted revenue paths through 2032, the complete study transforms raw data into actionable intelligence. Whether you are evaluating market entry, planning a product launch, or optimizing procurement strategies, the comprehensive analysis provided in the full report is an indispensable tool.
To unlock the full potential of your strategic planning, we invite you to access the complete Eye Anatomical Model Market research. Gain the clarity needed to navigate the complexities of the 2026–2032 forecast period with confidence.
For detailed analysis of this topic, please visit the official page: Eye Anatomical Model Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: UV Infection Control Market Hits $430M in 2025, Projects 6.15% CAGR to 2032
By PW Consulting, 2026-09-07
Strategic Horizons: Navigating the UV Infection Control Device Market in 2026 and Beyond
Executive Summary
The global healthcare landscape is undergoing a paradigm shift where infection prevention is no longer merely a compliance requirement but a core strategic imperative. As hospitals and healthcare facilities grapple with rising healthcare-associated infections (HAIs) and labor shortages, the adoption of ultraviolet (UV) infection control devices has moved from the periphery to the center of operational strategy. This article serves as a strategic overview of the UV Infection Control Device Market, drawing upon our latest comprehensive research to illuminate the pathways for enterprise decision-making in 2026.
Wide Temperature Desizing Enzyme Market
For executives, investors, and product leaders, understanding the trajectory of this market is critical. The transition from manual cleaning protocols to automated, technology-driven disinfection solutions represents a significant capital allocation opportunity. Our analysis indicates that the market is not only growing in size but also evolving in complexity, driven by regulatory frameworks, reimbursement updates, and technological advancements in UV-C LED and robotics. This insight piece outlines the macro-economic currents shaping the industry, the competitive dynamics at play, and the specific operational value propositions that define market success in the coming years.
Worldwide Lawn Mower Transmission Market
Readers will gain a high-level understanding of why the UV infection control sector is poised for sustained expansion and how recent regulatory clearances and labor cost dynamics are influencing adoption rates. However, the full granularity of segmentation data, region-specific revenue projections, and detailed company benchmarking is reserved for our in-depth market research report. This preview is designed to establish the strategic context necessary for stakeholders to appreciate the depth of intelligence available in the full study.
Split AR/XR Glasses Market
Market Trajectory and Historical Growth Patterns
The UV Infection Control Device Market has demonstrated resilience and consistent growth over the past half-decade. Based on historical data from 2020 through 2025, the industry has navigated post-pandemic normalization while cementing its role in standard healthcare protocols. The market revenue has shown a steady upward climb, reflecting the institutionalization of UV disinfection technologies beyond emergency pandemic responses.
Looking at the baseline figures, the market established a significant foothold in the early 2020s. The revenue trajectory from 2020 to 2025 illustrates a compound annual growth pattern that underscores the durability of demand. This growth is not merely a rebound effect but indicates a structural shift in how healthcare facilities manage microbial risks. The historical data suggests that once facilities integrate UV devices into their infection prevention workflows, retention and expansion of usage are high.
For the forecast period spanning 2026 to 2032, the outlook remains robust. Market projections indicate continued expansion, with revenue figures expected to reach new milestones by the end of the decade. The forecast period suggests a maturation of the market where early adopters are joined by a broader base of mid-sized healthcare providers seeking cost-effective infection control measures. The growth rate during this period is influenced by several key drivers, including the increasing burden of multidrug-resistant organisms and the ongoing need to optimize hospital room turnover times.
Strategic planners should note that the market size in the base year of 2025 sets a strong foundation for the forecast period. The progression from the 2025 baseline to the 2032 endpoint reflects a sustained commitment to expenditure on infection control technologies. This long-term view allows corporations to model return on investment over extended deployment cycles, considering both hardware acquisition and ongoing operational costs. The data implies that the market is moving beyond a niche segment to become a standard component of healthcare infrastructure capital budgets.
Segmentation Dynamics: Type, Application, and Regional Nuances
Understanding where the value lies within the market requires a nuanced look at segmentation. The market is broadly categorized by device type, application area, and geographic region. Each segment presents distinct opportunities and challenges for market entrants and incumbents alike. Our research delves deeply into these splits to provide actionable intelligence, but a high-level synthesis reveals the primary areas of focus for the industry.
In terms of device architecture, the market distinguishes between mobile and stationary solutions. Mobile type devices, which offer flexibility and can be moved between patient rooms, represent a significant portion of the market activity. These units are critical for facilities that require adaptable disinfection protocols without permanent infrastructure changes. Conversely, stationary type systems are integrated into fixed environments, such as air handling units or specific treatment rooms, offering continuous or scheduled disinfection capabilities. The balance between these two types often depends on the specific needs of the healthcare facility, with many larger institutions deploying a hybrid approach to maximize coverage and efficiency.
Application-wise, the market demand is distributed across water treatment, surface disinfection, and air treatment. Surface disinfection remains a primary driver, given the direct link between environmental surfaces and transmission of healthcare-associated pathogens. Water treatment applications address the need for safe water systems within healthcare facilities, while air treatment solutions are gaining traction for controlling airborne transmission risks. The interplay between these applications creates a comprehensive ecosystem where devices may be deployed in tandem to achieve a multi-layered defense strategy. Decision-makers must evaluate which application segment aligns best with their specific infection control goals and regulatory requirements.
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. While aggregate revenue figures show the total market contribution, the regional dynamics vary significantly based on healthcare infrastructure maturity, regulatory environments, and reimbursement landscapes. North America and Europe have historically been strong markets due to stringent infection control regulations and higher healthcare spending capacity. However, the Asia Pacific region is showing considerable momentum as healthcare infrastructure expands and awareness of infection prevention technologies grows. Latin America and the Middle East and Africa present emerging opportunities where pilot programs and targeted interventions are beginning to drive adoption. A detailed regional breakdown is essential for companies planning market entry or expansion strategies, as local compliance and distribution channels play a pivotal role in success.
Competitive Landscape and Key Industry Players
The competitive environment in the UV Infection Control Device Market is characterized by a mix of specialized manufacturers, innovative startups, and established medical device companies. Market concentration is moderate, with the top three companies accounting for a significant share of revenue, while the top five players command an even larger portion of the market. This structure suggests that while there is room for disruption, scale and established distribution networks provide considerable advantages.
Several key companies are shaping the industry through product innovation and strategic positioning. Xenex Disinfection Services, headquartered in San Antonio, Texas, is a notable manufacturer of the LightStrike+ autonomous whole-room UV-C microbial reduction robot, specifically targeting hospital surface disinfection. Their focus on robotics highlights the trend toward automation in infection control. Similarly, Blue Ocean Robotics from Denmark produces UVD Robots, which are autonomous UV-C disinfection robots designed for patient rooms and healthcare environments, emphasizing international collaboration and global deployment capabilities.
Surfacide, based in the United States, develops and sells the Helios+ UV-C system with triple emitters, designed for whole-room microbial reduction in healthcare facilities. This technology underscores the push for higher efficacy and comprehensive coverage within a single deployment. Tru-D SmartUVC provides intelligent UV-C room disinfection systems and has integrated with PDI Healthcare, illustrating the trend of partnerships between device manufacturers and broader hygiene service providers. American Ultraviolet and Lumalier Corporation are manufacturers of UV-C surface and air disinfection equipment, catering to medical and institutional use with a focus on reliability and established product lines.
In the specialized device segment, Germitec from Bordeaux, France, manufactures the Chronos UV-C high-level disinfection systems for ultrasound probes and endoscopes, addressing the critical need for reprocessing medical instruments. PuraCath Medical, located in Newark, California, developed the Firefly UV disinfection system for needleless connectors and catheter access sites, aiming to reduce central line-associated bloodstream infections. This focus on vascular access highlights the precision application of UV technology in preventing specific types of infections. AquiSense Technologies provides UV-C LED disinfection systems for air, surface, and water applications in healthcare, representing the shift toward LED technology which offers advantages in lifespan and form factor.
Other players such as UVC Cleaning Systems, Seal Shield, and Skytron also contribute to the competitive landscape. UVC Cleaning Systems provides portable and mobile UV-C disinfection systems for healthcare surface treatment. Seal Shield manufactures UV-C sanitization systems including the ElectroClave for medical device and surface disinfection. Skytron provides IPT UV-C disinfection robots for whole-room and infection prevention in healthcare. The presence of these diverse players indicates a vibrant ecosystem where competition drives innovation in efficacy, usability, and integration capabilities.
Regulatory Framework and Reimbursement Landscape
The regulatory environment is a critical determinant of market growth and product viability. Recent developments highlight the increasing scrutiny and formalization of UV disinfection devices within the healthcare regulatory framework. In December 2025, the FDA convened a General Hospital and Personal Use Devices Panel meeting focused on the Total Product Life Cycle evaluation and safety risks of germicidal UV devices for microbial reduction in healthcare. This meeting emphasized that all UV disinfection devices for pathogen reduction in medical settings are classified as Class II medical devices.
Furthermore, the FDA requires 510(k) clearance for whole-room UV-C microbial reduction devices marketed for healthcare use. The Advisory Committee on Germicidal UV Devices has also emphasized safety evaluation for the Total Product Life Cycle in hospital applications. These regulatory milestones signal to the market that safety and lifecycle management are paramount. Companies must ensure their devices not only meet efficacy standards but also adhere to rigorous safety protocols to mitigate risks associated with UV exposure to staff and patients. This regulatory clarity, while increasing barriers to entry, also stabilizes the market by ensuring that approved devices meet high-quality standards.
On the reimbursement front, recent CPT code updates support reimbursement for UV-C surface disinfection equipment in hospital infection prevention protocols. This development is significant because it directly impacts the financial viability of adopting these technologies for healthcare providers. When infection control equipment can be partially reimbursed through existing coding structures, the total cost of ownership for hospitals decreases, facilitating faster adoption rates. This reimbursement support aligns with the broader industry goal of reducing the economic burden of healthcare-associated infections, which often result in substantial costs for extended hospital stays and additional treatments.
Recent Developments and Product Innovations
The market has seen tangible product launches and regulatory clearances in late 2025 and early 2026 that signal the pace of innovation. In June 2025, Germitec announced the commercial launch of the Chronos R-Max UV-C high-level disinfection system for transesophageal echocardiography probes and endoscopes. This launch expanded the capabilities of high-level disinfection systems to cover a broader range of critical care instruments.
Moving into 2026, regulatory progress continued. In January 2026, UV Smart Technologies B.V. received FDA 510(k) clearance for the UV Smart D60 UV-C disinfection chamber device for high-level disinfection of medical equipment. This clearance validated the device's safety and efficacy profile, allowing for broader market access in the United States. Shortly thereafter, in February 2026, PuraCath Medical announced the launch of the FireFly UV disinfection system for needleless connectors and vascular access sites, achieving 99.99% germ reduction. These developments demonstrate the industry's commitment to addressing specific infection vectors with targeted technological solutions.
These product launches and clearances are not isolated events but part of a broader trend where manufacturers are increasingly focusing on niche applications and obtaining specific clearances to differentiate their offerings. The ability to demonstrate high-level disinfection for specific devices or achieving near-total germ reduction rates provides a competitive edge in procurement decisions. Stakeholders should monitor these emerging products as they may shift procurement preferences toward specialized, cleared devices that offer measurable clinical outcomes.
Operational Impact and Labor Dynamics
Beyond clinical efficacy, the economic argument for UV infection control devices is strengthened by operational efficiencies, particularly regarding labor costs. Sector analysis indicates that UV-C devices reduce labor needs in healthcare by automating surface disinfection, lowering cleaning staff time by up to 50%. In an environment where healthcare facilities face staffing shortages and rising labor costs, this reduction is a compelling value proposition.
Automation allows facilities to reallocate human resources to other critical tasks while ensuring consistent and reliable disinfection cycles. The consistency of UV treatment eliminates the variability inherent in manual cleaning processes. For hospital administrators, the ability to quantify labor savings provides a clearer path to ROI calculations. When combined with the potential for reduced infection rates and associated costs, the operational case for UV devices becomes robust. This labor dynamic is particularly relevant for large hospital systems where the cumulative time savings across multiple rooms can translate into significant operational improvements.
Strategic Implications for Decision Makers in 2026
For enterprises operating within or adjacent to the UV Infection Control Device Market, the 2026 landscape presents clear strategic imperatives. First, supply chain resilience and product reliability are paramount. With regulatory scrutiny increasing, maintaining compliance and ensuring device safety throughout the product lifecycle is essential. Companies must invest in quality assurance and post-market surveillance to align with FDA expectations regarding Total Product Life Cycle evaluation.
Second, differentiation through technology and application specificity is becoming increasingly important. As the market matures, generic UV solutions may face pressure from specialized devices that offer validated efficacy for specific use cases, such as instrument disinfection or vascular access protection. Innovators should focus on solving specific pain points within the infection control workflow and securing the necessary regulatory clearances to substantiate their claims.
Third, understanding the reimbursement environment is crucial for market access. As CPT code updates support reimbursement for UV-C surface disinfection equipment, manufacturers and service providers should align their messaging and product configurations to maximize eligibility for these financial incentives. This alignment can accelerate adoption among cost-conscious healthcare providers. Finally, regional expansion strategies should be data-driven. While aggregate market growth is positive, the opportunities in North America, Europe, and Asia Pacific differ in terms of regulatory hurdles, competitive intensity, and customer preferences. A nuanced regional strategy, informed by detailed market data, is necessary to optimize resource allocation.
Our comprehensive market research report provides the detailed segmentation data, competitive benchmarking, and forecast models required to execute these strategies effectively. The executive summary provided here underscores the direction of the market, but the specific revenue splits, growth rates by segment, and deep-dive company profiles are available in the full study. For organizations seeking to make informed capital investments or product development decisions in 2026, accessing the complete intelligence set is a strategic necessity.
Conclusion
The UV Infection Control Device Market is at a pivotal juncture where technology, regulation, and economics converge to drive sustained growth. The historical momentum from 2020 to 2025 has set a strong foundation, and the forecast period through 2032 suggests continued expansion driven by automation, regulatory clarity, and operational efficiency gains. Key players are innovating rapidly, with recent product launches and FDA clearances demonstrating the sector's vitality.
For stakeholders, the path forward involves balancing innovation with compliance, leveraging labor savings to build financial cases, and navigating a competitive landscape that rewards specialization. The strategic value of detailed market intelligence cannot be overstated in this complex environment. While this article provides a high-level overview of the market dynamics and key trends, the full depth of analysis requires access to the complete research dataset. We invite decision-makers to explore the full report to unlock the specific insights needed to navigate the opportunities and challenges of the UV Infection Control Device Market in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: UV Infection Control Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Micro EV Market Hits $3.71B in 2025, Projected to Hit $8.88B by 2032 at 13.3% CAGR
By PW Consulting, 2026-09-07
Navigating the Micro Electric Automotive Landscape: Strategic Insights for the 2026 Decision-Maker
The Macro Trajectory: A Billion-Dollar Shift in Urban Mobility
The global automotive sector is undergoing a fragmentation of mobility solutions, where the Micro Electric Automotive (Micro EVs) Market stands out as a high-growth niche with distinct strategic implications. Based on our comprehensive analysis covering historical data from 2020 through 2025 and a forecast period extending to 2032, the market demonstrates a robust upward trajectory. In 2020, the market valuation stood at 1.9 Billion USD, a figure that has steadily climbed to an estimated 3.71 Billion USD by the base year of 2025. This historical performance underscores a consistent compound annual growth rate, projecting the market size to reach 4.13 Billion USD in 2026 and accelerating towards 8.88 Billion USD by 2032.
Worldwide High-Filtration Mask Market
For enterprise strategists and investors, these numbers are not merely statistics; they represent a structural shift in how short-distance mobility is provisioned. The forecast CAGR of 13.3% indicates that micro EVs are outpacing many segments of the traditional automotive industry. This growth is not linear but is driven by specific inflection points in regulation, urbanization, and consumer preference for compact, electric mobility platforms. Our research indicates that the period from 2026 to 2032 will be defined by the transition from early adoption to mainstream integration in specific corridors, necessitating a clear understanding of where value is captured within the supply chain and end-use segments.
Worldwide Oscillating Bone Saw Market
Segmentation Dynamics: Product Mix and Application Horizons
Understanding the composition of this market is critical for resource allocation. The product landscape is primarily bifurcated between Quadricycles and Golf Carts, each serving different functional requirements yet competing for the same urban and semi-urban spaces. Our analysis details the revenue contribution of each type, highlighting how regulatory classifications in Europe versus utility standards in the Americas create divergent product pathways. Similarly, the application spectrum splits between Commercial Use, Personal Use, and Public Utilities. Commercial deployments are driving significant volume, particularly in last-mile logistics and campus mobility, while personal use remains a key growth vector in dense urban centers where parking and maneuverability are premium constraints.
Worldwide Metal Spinning Lathes Market
Decision-makers must recognize that these segments do not grow in isolation. The interplay between commercial fleet adoption and personal ownership models influences charging infrastructure requirements, battery chemistry demand, and after-sales service networks. We provide a granular breakdown of how these segments interact, revealing where saturation points may occur and where whitespace opportunities exist for new entrants or existing players looking to pivot. The data suggests that while personal use offers high visibility, commercial and public utility applications may offer stronger stickiness and volume stability in the mid-term forecast.
Competitive Forces: Who Defines the Market?
The competitive landscape is characterized by a mix of specialized micro-mobility innovators and established automotive giants leveraging their scale to capture niche segments. Market concentration is significant, with the top three players holding a substantial portion of market share and the top five commanding an even larger aggregate position. This concentration suggests barriers to entry related to homologation, brand trust, and supply chain security, but it also leaves room for disruptive designs that challenge incumbent assumptions about vehicle form factors.
Micro Mobility Systems AG , headquartered in Switzerland, represents the archetypal specialized innovator. Their focus on the Microlino L7e quadricycle emphasizes Swiss production quality, battery-electric drivetrains, and European homologation. Recent activities signal a strong push for geographic expansion; notably, in November 2025, Micro Mobility Systems AG announced a market expansion into Norway via a new local partnership, targeting compact urban mobility needs. Furthermore, the world premiere of the Microlino Spider at the Brussels Motor Show in May 2025 showcased their intent to evolve the product line as a future micromobility solution. These moves illustrate a strategy of leveraging regional partnerships to navigate fragmented regulatory environments while maintaining a distinct design identity.
SAIC-GM-Wuling Automobile Co., Ltd. , based in China, operates at a different scale with the Wuling Hongguang Mini EV series, recognized as the world's best-selling micro electric vehicle family. Their offering spans 4-door and 3-door variants tailored for urban personal and fleet use. In February 2026, the company unveiled a facelifted fifth-generation Wuling Hongguang Mini EV, featuring an updated compact design optimized for urban short-distance travel. This product refresh highlights the intensity of competition in the high-volume personal mobility segment and the necessity for continuous iteration to maintain market leadership. Wuling's ability to deploy such volumes influences component pricing and sets expectations for affordability in the broader micro EV category.
In the United States, Textron Inc. and Yamaha Golf-Car Company address the commercial, municipal, and recreational utility sectors. Textron's Cushman-branded electric micro vehicles and utility transporters serve commercial, municipal, and recreational applications, capitalizing on the demand for reliable, low-speed electric transport in controlled environments. Yamaha contributes with electric golf carts and small utility micro vehicles for recreational, residential, and commercial use. These players demonstrate that the "micro" definition extends beyond city streets to include campus logistics, resort mobility, and municipal fleets, where total cost of ownership and durability are paramount.
Polaris Inc. , also US-based, bridges the gap between recreational use and street-legal operation with its GEM and street-legal Neighborhood Electric Vehicles (NEVs). Their focus on urban corridors and recreational applications underscores the versatility of micro EV platforms when certified for specific road classes. Finally, Nissan Motor Co., Ltd. from Japan enters the fray with the Nissan Micra EV microcar platform, applying the engineering rigor and brand recognition of a major OEM to compact urban electric mobility. The presence of such diversified competitors indicates that success in this market requires a clear value proposition, whether through cost leadership, regulatory compliance expertise, or superior user experience.
Industry Dynamics: Regulation, Materials, and Technical Constraints
Strategic planning in the Micro EVs Market cannot occur in a vacuum; it must account for the external forces shaping supply and demand. Regulatory frameworks are a primary driver of market structure. From 2025, EU new vehicle CO2 emission targets require a 15% reduction from 2021 levels, imposing stricter safety and speed classifications on micro EVs in L6e and L7e categories. This regulatory tightening affects design parameters, testing costs, and time-to-market for manufacturers targeting the European region. Simultaneously, the market faces the challenge of fragmented regional classifications. Micro EVs must comply with distinct standards such as L6e/L7e quadricycles in Europe versus NEV standards under FMVSS 500 in the US. This dichotomy often requires separate redesigns for each market, impacting development budgets and platform scalability. Our report analyzes the cost implications of these compliance requirements and identifies strategies for managing multi-region product architectures.
On the supply side, material dynamics are exerting pressure on production costs. Lithium-ion battery systems accounted for a dominant share of the micro EV market composition in 2025, driven by higher energy density and charging performance. However, rising prices of lithium, nickel, and cobalt are increasing overall production costs for these battery systems. This cost pressure interacts with the regulatory push for electrification, creating a complex trade-off between performance, compliance, and margin preservation. Manufacturers are forced to innovate in battery management, packaging, and sourcing strategies to maintain competitiveness. We examine how leading companies are navigating these input cost fluctuations and what this means for pricing power and margin profiles across the forecast period.
Strategic Implications for 2026 and Beyond
For corporate leaders, the 2026 outlook presents a pivotal moment to align strategy with market realities. The convergence of regulatory shifts, cost pressures, and competitive intensity means that passive observation is no longer a viable strategy. Organizations must evaluate their positioning relative to the segmentation splits and the competitive actions of key players. For instance, the recent product launches and market expansions by companies like SAIC-GM-Wuling and Micro Mobility Systems AG demonstrate that speed to market and geographic agility are critical. Companies that can navigate the regulatory fragmentation between Europe and the US while managing battery cost exposure will be better positioned to capture the projected growth from 4.13 Billion USD in 2026 to over 8.88 Billion USD by 2032.
Moreover, the high market concentration suggests that partnership, acquisition, or niche specialization may be necessary for smaller players to gain traction. The differentiation between commercial and personal use applications also offers a lens for portfolio strategy; businesses might prioritize high-volume commercial contracts to stabilize cash flow while exploring personal use channels for brand extension. Understanding the specific regional revenue distributions and application mixes allows for more precise market entry decisions, capacity planning, and investment prioritization.
Deep-Dive Intelligence for Informed Decisions
This article provides a strategic overview, but the complexity of the Micro Electric Automotive Market demands a more granular examination. The data points highlighted here—the trajectory from 1.9 Billion USD in 2020 to the 2032 forecast, the segmentation by region, type, and application, and the specific moves by key competitors—are synthesized from a comprehensive dataset that includes detailed historical analysis, quantitative forecasts, and critical assessment of industry dynamics. To support robust decision-making, our full market research report offers an in-depth dive into the numbers and narratives that shape this landscape.
Stakeholders seeking to validate market entry strategies, benchmark against competitors, or refine product roadmaps will find the complete analysis indispensable. The full report unpacks the specific regional revenue contributions, the exact composition of the product mix, and the detailed application breakdowns that inform operational planning. It also provides a thorough competitive profiling of the key players, including their strategic positioning, recent developments, and potential future moves. Additionally, the full study explores the implications of raw material trends and regulatory changes with greater depth, offering scenarios and risk assessments that are essential for long-term planning.
We invite you to access the complete Micro Electric Automotive (Micro EVs) Market research to unlock the full spectrum of insights. The detailed intelligence contained within will empower your team to navigate the opportunities and challenges of this rapidly evolving sector with confidence. Visit our source page to download the comprehensive report and gain the actionable intelligence needed to drive your 2026 strategy forward.
For detailed analysis of this topic, please visit the official page: Micro Electric Automotive (Micro EVs) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fire Window Market Hits $881.42M in 2025, Projects 3.87% CAGR to $1.14B by 2032
By PW Consulting, 2026-09-07
Navigating the Fire Window Market: Strategic Intelligence for 2026 and Beyond
The built environment is undergoing a fundamental recalibration. Between tightening regulatory frameworks reactive to climate-driven wildfire risks and evolving commercial safety standards the fire-rated window sector is no longer a niche compliance category. It has become a critical infrastructure layer. For executives procurement leaders and investors navigating the 2026 decision cycle a clear dimensional view of where the market has been where it is heading and who controls the competitive rails is not optional. It is a prerequisite for capital allocation product planning and risk mitigation.
Online Video Parsing Software Market
This introduction frames the strategic posture of our latest Fire Window Market report. Rather than offering a static snapshot the analysis is engineered to translate historical trajectory into forward-looking operational intelligence. The following sections unpack the market baseline the forces reshaping supply and demand the competitive architecture and the practical toolkits embedded in the full study. Readers will see how the report is structured to support scenario planning supplier evaluation and regional rollout decisions. The granular breakdowns the proprietary matrices and the forward sensitivity models are reserved for the complete document so that leadership teams can move from awareness to action with a single directed step.
Worldwide Trisodium Acid Pyrophosphate (TSAPP) Market
Market Baseline and Growth Trajectory
The fire window category has demonstrated steady expansion through a period of regulatory turbulence and material supply volatility. Tracking data from 2020 through the base year of 2025 shows consistent upward movement with the market climbing from approximately 731.2 million USD to an estimated 881.42 million USD by 2025. That five-year arc establishes a durable foundation rather than a speculative spike and it sets the reference tone for any forward model.
PCE Superplasticizer Mother Liquor Market
Looking ahead the forecast window from 2026 to 2032 frames a market that compounds at a measured pace of 3.87 percent annually. The trajectory is not linear and that is precisely what makes strategic planning valuable. Growth is anticipated to step up visibly around 2028 before experiencing short-term normalization in the following year and then resuming a steeper climb into the early 2030s. By 2032 the market is projected to reach roughly 1.14 billion USD. This pattern matters because it signals how procurement cycles inventory planning and capacity investments should be staggered. Organizations that treat the category as uniformly flat risk misaligning production schedules or underinvesting in the windows of opportunity that open when regulatory mandates and commercial renovation programs converge.
The currency of analysis is USD and all projections are expressed in millions which standardizes comparability across regional revenue reporting and product-line valuations. The baseline dataset is anchored in 2025 historical tracking and then extended through a seven-year forward view. That structure allows decision-makers to test assumptions against both the recent recovery path and the longer horizon where code adoption curves and material substitution trends will dictate the pace of expansion.
Forces Reshaping Demand and Supply
The fire window market does not move in isolation. It is pulled by overlapping regulatory mandates material science advances and shifting construction economics. Our report maps these drivers as interconnected forces rather than isolated headlines so that strategy teams can see where compliance pressure becomes commercial opportunity and where supply risk becomes a sourcing imperative.
At the regulatory level the environment has grown more prescriptive. California has advanced wildfire resiliency requirements that effectively mandate dual-pane or multi-pane tempered glass in new and existing homes within the Wildland Urban Interface. Colorado has established statewide standards for fire-resistant construction that include window performance expectations. San Diego has moved toward Zone 0 fire safety rules effective in 2026 that call for fire-resistant materials including windows in newly constructed homes. In parallel NFPA 855 updates for 2026 introduce hazard mitigation analysis requirements for energy storage systems and those requirements cascade into commercial fire window applications where energy infrastructure and building envelopes intersect. The tariff environment adds another dimension. U.S. tariffs on Canadian steel and window products increased to 35 percent in 2025 with over-quota surtaxes layering additional cost pressure. That combination reshapes sourcing logic elevates the importance of qualification strategies and makes regional supply chain mapping a central component of any go-to-market plan.
On the demand side the commercial segment continues to anchor a large share of end-use consumption while residential construction influenced by wildfire zones and retrofit mandates is expanding its relative footprint. Industrial applications remain meaningful where specialized containment and safety specifications drive product selection. The report does not flatten these segments into a single narrative. Instead it treats them as distinct demand engines each with its own code pathway specification cadence and procurement rhythm. That segmentation logic is preserved in the full study so that readers can align product roadmaps with the specific demand profile most relevant to their portfolio.
On the supply side the market reflects a mix of vertically integrated manufacturers specialty fabricators and material specialists. Product innovation is concentrated where performance specifications meet aesthetic and energy-efficiency expectations. The emergence of lighter steel profiles polymer-based fire window systems and advanced glazing combinations indicates that differentiation is shifting from pure compliance to integrated value propositions. The report captures these dynamics through product-type and application lenses allowing teams to evaluate which materials and form factors align with future code expectations and which segments face substitution risk.
Competitive Architecture and Strategic Positioning
No market of this scale and regulatory intensity can be understood without mapping the competitive layer. The fire window landscape is moderately concentrated. The three largest players command roughly 54 percent of market share while the top five extend that reach to about 56 percent. That concentration pattern indicates that scale players hold meaningful influence over standard-setting and distribution channels yet a long tail of specialized manufacturers retains the ability to win on specification fit regional proximity and tailored compliance solutions.
The report profiles a broad set of strategic participants spanning multiple geographies and material categories. Among the leaders are internationally recognized names such as Assa Abloy headquartered in Sweden and positioned as a leading producer of fire-rated windows and integrated security solutions and Vetrotech based in India with a specialization in fire-resistant glass and fire window solutions. YKK AP operates from the United States with a focus on energy-efficient fire-rated windows and storefronts while Rehau Group from Switzerland provides polymer-based fire window systems. Sankyo Tateyama and Lixil both advance from Japan with fire-rated windows sliding systems and architectural window and door portfolios respectively. Schuco contributes from Germany with insulated fire-rated windows and façade systems and IMS Group provides fire safety windows and glazing systems in the United States. Van Dam from the Netherlands specializes in fire-rated glass and windows and Optimum Window produces fire-rated steel windows and doors. The roster extends further to include Safti First with vertically integrated fire-rated glass and framing Alufire from Poland with aluminum fire-rated windows and doors Promat from Belgium with broader fire protection systems Hope’s Windows with hot-rolled steel fire-rated windows and doors Aluflam with aluminum windows and glazing Hendry with fire-resistant windows and doors Fyre-Tec with code-compliant fire-rated windows Golden Glass with fire-rated glass and window systems Technical Glass Products as a leading North American manufacturer of fire-rated windows and storefronts and a set of regional specialists such as Fire Windows Direct and OWS Fire Rated in the United Kingdom with handmade and fabricator-led approaches Windows Latvia with timber fire-rated windows to the EN 16034 standard and the Fireproof Window Company with EI60 fire-rated windows. Chinese manufacturers including Hefei Yongtai Shandong Fire-proof Door and Nanchang Zhuohong Fire Equipment add depth to the global sourcing map with fire-proof window and door production and explosion-proof window capabilities alongside Hart & Co which combines aluminium and uPVC fire-rated windows with AOVs.
The competitive picture is not static. Recent activity illustrates how product launches and specification wins reshape positioning. In January 2026 Hope’s Windows launched the new Slightline 175 Series of custom hot-rolled steel windows a move that signals ongoing investment in aesthetic and performance differentiation within the steel category. The report tracks these developments as strategic signals rather than isolated press items so that readers can gauge which companies are expanding capability sets which are doubling down on specific material platforms and where partnership or acquisition logic may be forming.
Strategic positioning in this market depends on more than product availability. Companies compete on code familiarity specification support regional service density and the ability to navigate tariff and material cost volatility. The full report evaluates these dimensions through a structured competitive lens that highlights where scale creates advantage where specialization defends share and where customer-facing technical capability becomes the decisive factor in specification wins. By preserving the detailed scoring and comparative matrices for the complete document we ensure that buyers can use the study as a sourcing and engagement tool rather than a static directory.
Report Architecture: What Decision-Makers Get
The study is designed as an operational toolkit. It opens with a structured segmentation analysis that examines the market by region type and application without reducing any of those dimensions to a single headline figure. Instead it shows how demand distributes across construction categories how product types align with code pathways and where regional dynamics create divergent growth patterns. That layered approach allows readers to test their own assumptions against a consistent analytical framework.
The report then moves into a competitive deep dive. Company profiles are organized to surface capability scope geographic footprint and strategic orientation. The analysis does not simply list participants. It maps how each company fits into the concentration structure and where they are likely to compete for specification share. Recent developments are integrated into this view so that product launches compliance moves and partnership activity can be read as signals of forward intent.
A substantial portion of the study is devoted to market dynamics. Drivers and restraints are evaluated together so that teams can see not only what is pulling growth upward but what could slow it. Regulatory updates material cost shifts and sourcing constraints are treated as live variables. The report incorporates the most recent code actions tariff changes and safety standard updates so that the dynamics section reads as an operational briefing rather than a historical recap.
Forward modeling forms the analytical core. The forecast period from 2026 to 2032 is presented with enough structure to support scenario planning. Readers can use the trajectory to stage procurement decisions align production capacity and evaluate expansion timing. The model is built to be interrogated. It provides a baseline view and reserves sensitivity insights for the complete package so that leadership teams can explore how changes in code adoption pace material substitution or regional demand shifts would alter projected outcomes.
The report also includes practical appendices and reference material that support immediate use. These sections are designed for procurement specification and compliance teams that need to translate market intelligence into purchasing criteria vendor evaluation checklists and specification alignment notes. By embedding this operational layer the study moves beyond descriptive market intelligence and becomes a decision-support asset.
Translating Insight into 2026 Action
For 2026 planning the central challenge is not identifying that the market is growing. It is deciding where to place bets under conditions of regulatory acceleration and supply variability. The fire window category rewards organizations that can connect code timelines to product readiness and that can match sourcing strategies to regional demand clusters. The full report supports that work by providing the segmentation depth competitive context and forward modeling needed to convert high-level trends into specific operational choices.
Procurement and supply chain leaders can use the study to map qualification pathways evaluate substitute-material exposure and prepare for tariff and cost volatility. Product and development teams can use the segmentation framework to align roadmaps with the application categories most likely to expand under updated codes. Strategy and corporate development teams can use the competitive architecture to identify where consolidation sourcing partnerships or specification alliances may create advantage. Investors and market entrants can use the trajectory analysis to evaluate timing entry points and segment attractiveness without relying on oversimplified aggregates.
What distinguishes this study is its intention to serve as a working document. The core figures establish the scale and pace of the opportunity. The segmentation and competitive sections establish the structure. The dynamics and forecast sections establish the uncertainty range. The complete package then delivers the detailed breakdowns the comparative matrices and the sensitivity models that executive teams need to make precise decisions. That design reflects a deliberate editorial choice. The summary view builds confidence in the analytical rigor while the essential granular intelligence is reserved for readers who are ready to move from orientation to execution.
Where to Go Next
The fire window market in 2026 is defined by convergence. Regulatory pressure is intensifying material expectations are evolving and competitive positions are being tested by both scale advantages and specialized capability. Organizations that commit to a structured view of that environment will be better equipped to manage compliance exposure select suppliers and time investment with discipline.
This introduction has outlined the strategic logic behind the study and the categories of intelligence it contains. The complete Fire Window Market report expands every dimension discussed here into the detailed segmentation competitive profiling regulatory tracking and forward modeling required for precise planning. To access the full dataset regional and product breakdowns competitive scoring and scenario-ready forecasts please visit the source page and retrieve the complete research package.
For detailed analysis of this topic, please visit the official page: Fire Window Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


