



Category: market research
PW Consulting Reports Global Precision Swine Farming Market to Reach USD 840 Million in 2025 with 9.48 Percent CAGR Through 2032
By PW Consulting, 2026-09-02
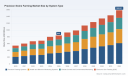
Precision Swine Farming: Navigating the 9.48% CAGR Growth Trajectory Toward 2032
Introduction: The Strategic Imperative for Precision Agriculture
The global swine industry is undergoing a fundamental transformation. Driven by escalating labor costs, stringent environmental regulations, and the critical need to optimize feed conversion ratios, precision swine farming has emerged as a cornerstone of modern agricultural strategy. As pork producers face margin compression and increased scrutiny on sustainability, the adoption of data-driven technologies is no longer optional—it is a competitive necessity. This article serves as a strategic preview of our comprehensive Worldwide Precision Swine Farming Market research, designed to equip executives and investors with the macro-level intelligence required to navigate the period from 2026 through 2032.
Worldwide Precision Swine Farming Market
Our analysis indicates that the market is poised for significant expansion. The total market revenue is projected to grow from a baseline of 840.0 Million USD in 2025 to 928.72 Million USD in 2026, eventually reaching 1583.51 Million USD by 2032. This trajectory reflects a Compound Annual Growth Rate (CAGR) of 9.48 percent. Such growth underscores a shifting paradigm where traditional husbandry is being replaced by integrated technological ecosystems. Understanding the drivers, segmentations, and competitive forces behind these numbers is essential for any stakeholder looking to capitalize on the next wave of agricultural modernization.
Worldwide Precision Swine Farming Market
2026 Market Landscape: A Decade of Compound Growth
The historical data from 2020 to 2025 reveals a resilient market structure that accelerated notably in 2024 and 2025. Starting at 540.2 Million USD in 2020, the market climbed steadily to 840.0 Million USD by the base year. This recovery and growth phase were fueled by post-pandemic supply chain stabilizations and an increased focus on biosecurity. However, the forecast period from 2026 to 2032 represents the true inflection point. The jump from 840.0 Million USD to 928.72 Million USD in the first forecast year suggests that adoption rates are crossing a critical threshold.
Worldwide Precision Swine Farming Market
Key industries are recognizing that precision farming is not merely about automation; it is about decision intelligence. The projected growth to 1133.98 Million USD by 2028 and further to 1342.39 Million USD by 2030 highlights the compounding effect of regulatory pressure and efficiency demands. For corporate strategists, this implies that investment in precision infrastructure today locks in competitive advantages for the remainder of the decade. The market is not just growing; it is maturing, with higher value segments gaining prominence over commoditized hardware solutions.
Segmentation Dynamics: Where Value Is Being Created
To understand where the growth is originating, one must look at the structural breakdown of the market. However, strategic decisions require more than just top-line numbers; they require an understanding of the technological pillars driving demand. Our research segments the market by System Type, Region, and Farm Size, each offering distinct strategic implications.
Precision Feeding Systems represent a substantial portion of the market value. With feed costs constituting 60 to 70 percent of total pork production expenses, technologies that optimize nutrient delivery and reduce waste are paramount. The market data reflects a heavy weighting toward systems that manage intake precision. This segment is driven by the dual pressure of cost reduction and environmental compliance regarding nutrient runoff.
Health and Behavior Monitoring Systems form another critical pillar. As regulations regarding antibiotic-free production tighten and animal welfare standards rise, the ability to detect illness early through biometric sensors and behavioral analytics is becoming a premium service. This segment is closely tied to the broader trend of digital health management in livestock.
Climate Control and Environmental Monitoring is seeing renewed interest due to regulatory updates. Specifically, the European Commission Industrial Emissions Directive revisions finalized in 2024 require continuous emissions monitoring in large livestock sites. This regulatory shift is directly increasing demand for precision swine farming technologies that can manage ventilation and emissions data in real-time.
Electronic Sow Feeding (ESF) remains a specialized but high-growth segment, particularly for operations focused on reproductive efficiency and individualized sow care. The interplay between these segments suggests that integrated solutions—those combining feeding, climate, and health—are likely to capture more value than standalone devices.
Geographically, the market shows distinct characteristics. The Asia Pacific region reflects the highest revenue contribution, driven by large-scale industrialization and government modernization initiatives. Europe follows closely, propelled by strict regulatory frameworks and high welfare standards. North America maintains a mature position with a strong focus on efficiency and labor reduction. Latin America and the Middle East and Africa represent emerging opportunities where precision adoption is in earlier stages but growing rapidly as infrastructure improves.
By Farm Size, the market is bifurcated. Large Scale Industrial Farms account for the majority of revenue, given their capacity to invest heavily in automation and their need to manage thousands of heads efficiently. Small and Medium Sized Farms represent a significant volume segment, often driven by the need to compete with larger entities through efficiency gains or by accessing premium markets that require traceability and welfare certification.
Competitive Landscape: Consolidation and Innovation
The market concentration indicates a moderately consolidated environment. The CR3 stands at 34.2 percent, and the CR5 reaches 51.5 percent. This suggests that while a few key players dominate the landscape, there is ample room for specialized innovators and regional champions to thrive. The competitive arena is characterized by a mix of established industrial giants and specialized technology providers.
Nedap N.V. from the Netherlands is a standout player, offering electronic sow feeding and individual pig monitoring integrated via their Livestock Connect platform. Their focus on data interoperability through Pigs Connections API positions them well in an ecosystem where data sharing between systems is becoming crucial. Similarly, CTB, Inc. in the United States, through brands like Chore-Time and Fancom, provides a broad suite of automated feeding, ventilation, and biometric systems. Their recent launch of the Chore-Time Barn Management Control System in March 2025 highlights their commitment to real-time monitoring capabilities.
Big Dutchman International GmbH from Germany supplies integrated pig house management systems, including precision climate control and welfare-focused barns like Havito and Xaletto. Their emphasis on digitalization tools for sow management and piglet rearing aligns with the industry's shift toward holistic barn management. In parallel, Hotraco Agri B.V. is pushing the boundary with AI-based predictive controls for swine barns, specializing in climate and feed automation.
Other notable competitors include VDL Agrotech BV , focusing on automation and housing technologies, and Fancom BV , which recently upgraded their eYeGrow weight monitor in September 2024 to achieve up to 98 percent accuracy for pigs between 25 and 130 kg. This upgrade enables daily growth tracking and feed cost optimization, directly addressing the feed cost challenge. Merck & Co., Inc. and Boehringer Ingelheim International GmbH are also entering the precision space by integrating health solutions with monitoring technologies, bridging the gap between animal health and farm management data.
On the hardware side, Roxell from Belgium has been active with recent product launches. In July and August 2025, they introduced the next-generation Discaflex feed transport system and the iQon Multifast batch feeding system upgrade. The iQon system integrates a smart control platform for precise weighing and mixing of up to 20 ingredients, directly targeting waste reduction. Guangzhou Yingzi Technology Co., Ltd. and Big Herdsman Machinery Co., Ltd. from China are providing precision technologies for feeding, environmental control, and monitoring, catering to the massive scale of Asian operations. Additional players like Jyga Technologies (GESTAL) , Skiold , WEDA Dammann & Westerkamp GmbH , and Osborne Industries, Inc. contribute to the diverse ecosystem of feeding, management, and housing technologies.
Industry Dynamics: Regulations, Costs, and Subsidies
Strategic planning in this sector must account for several macro-environmental factors that are accelerating market growth. Feed Costs remain the primary economic driver. Since feed represents 60 to 70 percent of total costs, any technology that improves feed conversion efficiency offers a rapid return on investment. Precision feeding systems are therefore not just technological upgrades but financial imperatives.
Labor Costs are another critical factor. Sector analysis indicates that precision swine farming technologies can deliver labor savings of 30 to 50 percent through the automation of monitoring, feeding, and climate control. In regions facing agricultural labor shortages, this benefit alone can justify capital expenditure. The ability to reduce manual intervention while increasing data accuracy allows farms to scale without proportional increases in headcount.
Regulatory Pressure is intensifying globally. Beyond the European Commission's emissions directives, stricter regulations on animal welfare and antibiotic-free production are driving adoption of precision monitoring. These regulations require detailed record-keeping and real-time health management, which manual processes cannot reliably provide. Consequently, the demand for traceability and automated health logging is rising.
Subsidies and Incentives play a significant role in market acceleration, particularly in Europe. Germany, Spain, and the Netherlands offer subsidies covering up to 40 percent of eligible precision hardware purchases. These financial incentives lower the barrier to entry for modernization projects and are expected to sustain demand even during periods of economic tightening. Understanding the specific eligibility criteria and application windows for these subsidies is a key component of successful market entry and expansion strategies.
Report Methodology and Depth
This article provides a high-level overview of the strategic landscape. However, the full Worldwide Precision Swine Farming Market study offers the granularity required for actionable decision-making. Our methodology combines rigorous secondary research with primary interviews from industry stakeholders, ensuring that both quantitative forecasts and qualitative insights are validated.
The report goes beyond headline figures to explore the nuances of adoption rates across different farm sizes and technological maturities. It examines the supply chain dynamics for critical components, such as sensors and control units, and assesses the risk factors that could influence market trajectory, including raw material price volatility and geopolitical shifts. The segmentation analysis provides a detailed look at how value is distributed across different system types and regions without relying on simplistic generalizations.
Furthermore, the competitive analysis profiles key companies not just by revenue, but by their strategic positioning, product pipelines, and recent developments. For instance, the report delves into how companies are integrating AI and machine learning into their offerings, moving from reactive monitoring to predictive management. This depth allows clients to benchmark their own technology roadmaps against industry leaders and identify potential partnership or acquisition opportunities.
Strategic Recommendations for Stakeholders
For equipment manufacturers, the focus should be on interoperability and data integration. As farms adopt multiple systems, the ability for these systems to communicate via open APIs will become a key differentiator. Manufacturers that offer closed ecosystems may face resistance from larger industrial farms seeking flexibility.
For investors, the growth in precision feeding and health monitoring segments offers attractive opportunities. The regulatory tailwinds in Europe and the industrialization trends in Asia Pacific create distinct regional investment theses. Subsidies in key European markets reduce investment risk, while the labor savings potential in North America drives organic adoption.
For pork producers, the message is clear: delaying precision adoption risks falling behind on efficiency and compliance. The data suggests that the cost of inaction—measured in feed waste, labor inefficiency, and regulatory non-compliance—will outweigh the capital investment required for modernization. Strategic planning should prioritize technologies that offer immediate ROI through feed savings and labor reduction, while building a data infrastructure that supports long-term health management and traceability.
Conclusion: The Path Forward
The Worldwide Precision Swine Farming Market is set to expand significantly over the next six years, driven by a confluence of economic, regulatory, and technological factors. The projected growth from 928.72 Million USD in 2026 to 1583.51 Million USD in 2032 represents more than just revenue; it represents a fundamental shift in how pork is produced globally.
Navigating this landscape requires detailed intelligence. While this preview outlines the macro trends and competitive dynamics, the full report provides the specific data points, segmentation splits, and regional forecasts necessary to formulate precise strategies. For organizations ready to move from observation to action, accessing the complete research intelligence is the logical next step. The window to capitalize on the early phases of this growth cycle is open, but it requires informed decision-making based on comprehensive data.
For detailed analysis of this topic, please visit the official page: Worldwide Precision Swine Farming Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report Projects 6.85 Percent CAGR For Worldwide Aircraft Sewage Truck Market Valued At 635 Million In 2025 Through 2032
By PW Consulting, 2026-09-02
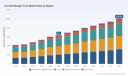
Beyond the Hangar: The Strategic Imperative of Global Aircraft Sewage Truck Market Intelligence for 2026
Introduction: The Hidden Engine of Airport Operations
Ground support equipment rarely captures headlines, yet it forms the operational backbone of every commercial and military airfield. Among these specialized machines, aircraft sewage trucks handle a function that is simultaneously unglamorous, highly regulated, and indispensable: the safe evacuation and replenishment of lavatory waste systems across modern aircraft fleets. As air traffic volumes recover and expand, as environmental mandates tighten around ramp emissions, and as fleet compositions shift toward larger wide-body aircraft with more complex waste management requirements, the market for aircraft sewage trucks has quietly entered a phase of structural transformation. For procurement leaders, operations directors, and long-term strategists, understanding this evolution is no longer optional. It is a prerequisite for resilient capital allocation and competitive positioning in the years ahead.
Worldwide Aircraft Sewage Truck Market
Our recently completed Worldwide Aircraft Sewage Truck Market study provides a comprehensive, forward-looking analytical framework designed specifically for enterprise decision-making in 2026 and beyond. Rather than offering a static snapshot, the report maps the historical trajectory that brought the industry to its current inflection point, quantifies the growth vectors that will define the next seven years, and dissects the competitive, technological, and regulatory forces reshaping procurement strategies across continents. This article outlines the strategic architecture of the research, demonstrates how its findings translate into actionable intelligence, and clarifies why institutional buyers, investors, and industrial planners should treat this market as a strategic priority in their 2026 planning cycles.
Worldwide Aircraft Sewage Truck Market
The Macro Trajectory: From Recovery to Sustained Expansion
The aircraft sewage truck sector has moved decisively past the volatility that characterized the early 2020s. Historical demand patterns reveal a steady, compounding expansion that outpaces many adjacent ground support segments. Between 2020 and 2025, global revenue in this market climbed from approximately 420.15 million to 635.0 million, reflecting a consistent upward curve driven by renewed flight schedules, aging equipment replacement cycles, and incremental capacity expansions at high-throughput hubs. That growth momentum does not plateau at the 2025 baseline. Instead, it accelerates into a projected valuation of 692.71 million in 2026, with the trajectory continuing upward through the end of the decade and into the early 2030s, ultimately approaching the one-billion threshold by 2032.
Worldwide Aircraft Sewage Truck Market
This expansion is underpinned by a forecast compound annual growth rate of 6.85 percent across the 2026 to 2032 horizon. Such a rate places the market in a distinct category of steady, structurally supported growth rather than cyclical spikes. For strategic planners, this compounding trajectory carries several immediate implications. First, it signals that demand will not be concentrated in isolated boom years but will instead unfold as a persistent pull across procurement budgets, fleet renewal schedules, and infrastructure investment programs. Second, it indicates that suppliers who delay capacity planning, service network expansion, or product modernization risk ceding long-term market share to competitors who align their roadmaps with this sustained growth curve. Third, it suggests that financing models, lease structures, and total-cost-of-ownership calculations will need to account for a market environment where replacement cycles shorten and utilization rates climb.
It is equally important to recognize that absolute market size is only one dimension of strategic relevance. The concentration of industry revenue among leading players remains moderately distributed, with the top three enterprises collectively representing roughly a third of total market value and the top five accounting for just under half. This competitive structure implies that while scale advantages exist, the market still accommodates differentiated positioning, regional specialization, and technology-led disruption. For buyers, this fragmentation offers leverage in negotiation, vendor diversification, and specification customization. For manufacturers and investors, it underscores the importance of clearly defined niches, service excellence, and operational reliability as primary competitive differentiators.
Segmentation Fundamentals: Where Demand Actually Materializes
A market research report gains strategic utility only when it helps decision-makers pinpoint where capital, engineering effort, and deployment resources will generate the highest returns. The aircraft sewage truck landscape is structured around three primary segmentation axes: equipment configuration, operational application, and geographic deployment. Each axis carries distinct procurement implications, and understanding their interplay is essential for building robust 2026 strategies.
On the equipment side, the market divides into self-propelled trucks and towed cart systems. The self-propelled category dominates the revenue base, reflecting the operational advantages of integrated mobility, faster turnaround cycles, and reduced dependency on tug vehicles during peak servicing windows. These units are engineered for direct ramp deployment, with stabilized lifting platforms, precise maneuvering profiles, and cabin ergonomics that minimize operator fatigue during high-frequency service rounds. Towed configurations, while representing a smaller share of total revenue, remain highly relevant for specific operational contexts. Airports with constrained ramp geometries, seasonal traffic patterns, or lower flight frequencies often favor towed units for their lower acquisition cost, simplified maintenance architecture, and flexibility in storage and deployment. The strategic takeaway is that fleet composition decisions cannot be reduced to a single platform preference; they must reflect runway layout, aircraft mix, shift intensity, and the balance between capital expenditure and operating flexibility.
Application segmentation further refines where demand concentrates and where future growth will crystallize. Commercial airports anchor the bulk of market activity, driven by the sheer volume of daily aircraft movements, the strict scheduling requirements of passenger-carrying flights, and the operational necessity of maintaining hygienic, compliant lavatory systems at scale. Military bases represent a distinct demand stream, characterized by procurement cycles tied to defense budgeting, specialized operational requirements, and often different validation standards for equipment deployment in austere or secured environments. General and business aviation constitutes a smaller but strategically meaningful segment, where procurement decisions frequently prioritize compact footprints, rapid servicing turnaround, and compatibility with VIP or corporate fleet specifications. Understanding how these application channels diverge in terms of procurement cadence, technical tolerances, and service-level expectations allows operators to avoid one-size-fits-all purchasing templates and instead tailor specifications to the actual utilization environment.
Geographic deployment patterns reveal additional layers of strategic complexity. Demand is not evenly distributed across regions, and the relative weight of each geography reflects underlying differences in air traffic density, airport infrastructure maturity, regulatory enforcement intensity, and local manufacturing or service ecosystems. North American operations sit within a market environment shaped by high-throughput hub networks, stringent safety and environmental expectations, and a mature aftermarket service landscape. Asia Pacific demand reflects rapidly expanding air travel infrastructure, new airport construction, and increasing adoption of standardized ground support protocols across both established and emerging carriers. European markets operate within a framework that increasingly emphasizes sustainability compliance, emissions reduction on the ramp, and harmonized operational standards across cross-border airline networks. Middle Eastern, African, and Latin American deployments present their own distinctive dynamics, often centered on airport modernization programs, regional carrier expansion, and equipment configurations adapted to local climate and operational conditions. The report maps these regional variations without reducing them to simplistic rankings, instead emphasizing how procurement timing, specification adaptation, and service-partner selection must be calibrated to local operating realities.
Competitive Architecture: Strategies, Differentiators, and Market Positioning
The competitive field in aircraft sewage trucks is defined by a mix of established European and North American manufacturers, growing Asian production capabilities, and specialized engineering firms that compete on technical refinement rather than sheer scale. Evaluating this landscape requires looking beyond brand recognition to understand how each player structures its value proposition, differentiates its engineering choices, and positions itself for the evolving regulatory and operational environment.
TLD Group has built its reputation around self-propelled lavatory and water service platforms that emphasize ramp visibility, low-profile architecture, and reduced environmental hazard exposure. Its product sequencing, including the LSP-900 series and electric LAV-900-E variants, reflects a deliberate focus on operational safety, interface precision, and minimized spill risk during waste handling. For procurement teams, TLD's approach illustrates how design philosophy can be aligned with airport risk-management priorities, particularly in high-density ramp environments where operator sightlines and containment integrity directly affect service reliability.
Miles GSE, operating from Istanbul, has concentrated on truck-mounted toilet service platforms that leverage vacuum evacuation principles for rapid and hygienic tank emptying. Its Miles 6022 configuration and related lavatory and garbage service vehicles are deployed in daily airport operations where throughput speed, contamination control, and crew ergonomics are critical. The company's engineering emphasis highlights how evacuation technology selection influences service duration, operator workload, and compliance with hygiene standards, making it a relevant reference point for operators evaluating total servicing time per turnaround.
Mallaghan, based in Northern Ireland, has positioned itself around self-propelled toilet service platforms with a growing emphasis on electrification and sustainability. The introduction of the fully electric eTSU model, featuring a 3000-liter tank, a 3-meter lifting platform, and 80-volt lithium-ion battery architecture, signals a strategic pivot toward zero-emission ramp operations. This product direction resonates with airport decarbonization targets and regulatory pressure to reduce ground-level emissions, making Mallaghan a useful case study for organizations assessing how electric propulsion affects range planning, charging infrastructure compatibility, and lifecycle operating costs.
Darmec Technologies, headquartered in Italy, specializes in both self-propelled and towed lavatory servicing units engineered for safety, reliability, and hygiene, with particular attention to operational performance in extreme cold climates. Its AS D series and associated configurations demonstrate how environmental hardening, material selection, and serviceability design can differentiate a platform in regions where temperature extremes and seasonal operational constraints would otherwise limit equipment effectiveness. For buyers operating in northern latitudes or high-altitude environments, such specialization directly affects uptime and maintenance scheduling.
On the Asian production side, Jiangsu Tianyi Aviation Industry Co., Ltd has developed a structured lineup of aircraft lavatory service trucks and sewage collection and filling vehicles, including the JSTY series and new-energy variants. These platforms integrate tanks, vacuum systems, and lifting mechanisms designed to serve both wide-body and narrow-body aircraft. The company's trajectory reflects broader industry dynamics in which Asian manufacturers combine standardized architectures with competitive pricing and expanding technical capability, increasing options for operators seeking balanced acquisition cost and functional coverage. Cartoo GSE similarly offers self-propelled lavatory service trucks configured for waste removal and clean water supply, with design compliance oriented toward CAAC and IATA standards, reinforcing the importance of regulatory alignment in platform selection.
Beyond these primary players, additional manufacturers contribute to a diverse supply ecosystem. Phoenix Metal Products emphasizes stainless steel tank construction and sanitary design principles aimed at reducing maintenance burden and improving containment reliability. Aviogei focuses on self-propelled lavatory service vehicles optimized for waste drainage on wide-body aircraft, while SCHRADER T+A FAHRZEUGBAU GMBH & CO. KG and Stinar LLC provide towed configurations that suit smaller airports and general aviation operations where footprint, storage simplicity, and lower acquisition thresholds are decisive. Together, these companies illustrate that competitive advantage in this market is not monolithic; it is distributed across engineering specialization, climate adaptation, electrification readiness, material durability, and application-specific fit.
Regulatory, Material, and Sustainability Dynamics Shaping Procurement
Market growth does not occur in a vacuum. The aircraft sewage truck sector is being reshaped by overlapping regulatory expectations, material science considerations, and sustainability mandates that together redefine what constitutes an acceptable, future-proof platform. For 2026 planning, these dynamics are not peripheral concerns; they are central to specification writing, vendor evaluation, and long-term asset strategy.
One of the most consequential shifts is the accelerating adoption of electric and hybrid lavatory service vehicles across airport and GSE operator fleets. This transition is driven by institutional decarbonization goals, local air-quality initiatives, and the operational desire to reduce ramp emissions in enclosed or high-traffic terminal environments. Electric platforms influence more than propulsion chemistry. They reshape energy management profiles, charging infrastructure requirements, shift planning, and total-cost calculations. Procurement teams evaluating electric variants must account for battery lifecycle, compatibility with existing airport charger standards, payload trade-offs, and the availability of service support for high-voltage systems. The market study addresses these considerations by mapping how electric configurations are penetrating different application channels and what operational adjustments accompany their deployment.
Regulatory compliance remains another defining constraint. Lavatory service equipment must align with IATA standards for safe and hygienic waste handling, aircraft interface compatibility, and design features that minimize environmental spill risk. These requirements affect tank sealing architectures, discharge protocols, operator protection systems, and documentation practices. Compliance is not merely a certification exercise; it directly influences fleet acceptance, audit readiness, and cross-airport interoperability. The report examines how manufacturers embed compliance into product architecture and how operators can verify that specified platforms will remain aligned with evolving service and safety expectations.
Material selection, particularly in tank construction, represents a quieter but operationally critical dynamic. Tanks are commonly fabricated from 304 stainless steel to provide corrosion resistance and maintain hygiene standards during repeated sewage handling cycles. This material choice affects not only containment integrity but also cleaning protocols, chemical compatibility, weight distribution, and long-term maintenance expense. Procurement specifications that overlook material-grade considerations risk higher repair frequencies, contamination liabilities, and shortened service life. By addressing material engineering as part of the broader product evaluation framework, the research ensures that buyers assess platforms on the full spectrum of durability and compliance rather than on initial sticker price alone.
Sustainability extends beyond electrification and regulatory checkboxes. It encompasses noise reduction on the ramp, optimized fluid management, spill prevention design, and service practices that reduce environmental exposure. As airports increasingly publish sustainability roadmaps and tie vendor selection to environmental performance criteria, aircraft sewage truck procurement becomes an instrument of broader institutional strategy. The report evaluates how different product architectures support or constrain these sustainability objectives, enabling operators to align equipment acquisition with published environmental commitments and stakeholder expectations.
What the Worldwide Aircraft Sewage Truck Market Study Delivers
The strategic value of this research lies in its operational specificity. Rather than stopping at high-level market sizing, the study is structured to guide procurement, engineering, finance, and investment decisions through a detailed, interconnected analytical framework. The report traces historical demand from 2020 through the 2025 base year, establishing the empirical foundation for forward projections that extend through 2032. It quantifies the growth path that carries the market from its current scale toward the approaching one-billion-dollar threshold, giving planners a reliable reference for budget timing, capacity planning, and scenario modeling.
The analysis segments the market along equipment type, application channel, and geographic deployment, allowing readers to isolate the demand drivers most relevant to their operational footprint. Each segmentation layer is examined for its implications on fleet mix, specification priorities, and procurement cadence. The competitive section profiles the leading manufacturers and contextualizes their engineering choices, regional strengths, and strategic positioning, providing a reference map for vendor evaluation, partnership selection, and benchmarking. Recent product developments, including the introduction of fully electric self-propelled toilet service platforms at major industry gatherings, are integrated into the analysis to show how technology roadmaps are resetting expectations around emissions, servicing speed, and operational flexibility.
Equally important, the study embeds the regulatory, material, and sustainability dynamics that will govern acceptable procurement standards in the coming years. It connects IATA-aligned hygiene and safety requirements to real-world specification decisions, links stainless-steel tank construction and corrosion resistance to maintenance economics, and frames electric and hybrid adoption within the broader airport decarbonization agenda. By weaving these threads together, the report gives decision-makers a coherent view of how compliance, engineering, and strategy intersect in a market that touches both operational reliability and institutional reputation.
Why 2026 Decisions Require This Intelligence
The 2026 planning horizon is not a routine annual budgeting exercise. It arrives at a moment when aircraft sewage truck demand is compounding at a sustained rate, when electric and hybrid platforms are moving from niche offerings toward mainstream consideration, and when regulatory and sustainability expectations are tightening around every aspect of ramp waste handling. Organizations that enter this period with incomplete market awareness risk overpaying for specifications they do not need, underestimating lifecycle costs, misaligning fleet mix with actual utilization patterns, or selecting vendors whose roadmaps do not match their operational timeline.
Conversely, organizations that ground their 2026 decisions in rigorous market intelligence can approach procurement with greater precision. They can calibrate fleet composition to actual application demands, prioritize platforms whose engineering aligns with environmental and compliance mandates, evaluate vendors against a clear map of technical differentiation and service capability, and time capital deployment to the growth rhythm of the market rather than to reactive replacement cycles. The study is designed to enable exactly this kind of informed, forward-looking decision-making.
Accessing the Full Strategic Picture
This article has outlined the analytical architecture, competitive context, and operational dynamics that make the Worldwide Aircraft Sewage Truck Market study a strategic asset for 2026 planning. It has traced the market's historical expansion, its projected growth path, the segmentation logic that shapes demand, the competitive differentiation among leading manufacturers, and the regulatory and sustainability forces that will define acceptable procurement standards in the years ahead. What remains beneath the surface are the precise regional breakdowns, the application-level revenue distributions, the detailed vendor benchmarking matrices, and the granular scenario analyses that transform broad insights into executable procurement and investment plans.
Those details are available in the complete report. For procurement leaders building fleet strategies, for operations executives aligning specifications with compliance and sustainability mandates, for investors assessing ground support exposure, and for industrial planners mapping regional deployment opportunities, the full study provides the structured intelligence needed to move from awareness to action. Accessing the complete research will enable your team to convert market momentum into procurement precision, align capital decisions with proven growth vectors, and position your organization to operate confidently in a market that is expanding steadily, electrifying selectively, and demanding higher standards of safety, hygiene, and environmental responsibility.
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft Sewage Truck Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Rapid Hygiene Monitoring System Market to Grow at 8.52 CAGR Reaching $515.96 Million by 2032
By PW Consulting, 2026-09-02
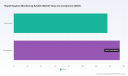
Strategic Intelligence for the Hygiene Monitoring Era: Executive Preview of the Worldwide Rapid Hygiene Monitoring System Market 2026-2032
Market Momentum and the Strategic Imperative for 2026 Decision-Makers
Global hygiene standards are no longer a compliance checkbox; they are a foundational pillar of operational resilience, brand protection, and public health security. As regulatory expectations tighten and consumer scrutiny intensifies, the rapid hygiene monitoring system market has transitioned from a niche sanitation tool to a core infrastructure investment across food, healthcare, pharmaceutical, and environmental sectors. Our newly released Worldwide Rapid Hygiene Monitoring System Market study captures this inflection point with forward-looking intelligence designed specifically to support enterprise planning for 2026 and beyond.
Worldwide Rapid Hygiene Monitoring System Market
The market trajectory over the past half-decade demonstrates consistent, compounding expansion. Global revenue climbed from approximately 195.4 million USD in 2020 to 291.1 million USD in 2025, reflecting an environment where rapid verification technologies have become embedded in daily operational workflows. Looking ahead through 2032, the market is projected to advance to 515.96 million USD, underpinned by a sustained compound annual growth rate of 8.52 percent. For executives, this trajectory signals more than top-line expansion; it reveals a structural shift toward continuous, data-driven hygiene verification that intersects with digital sanitation management, automated environmental monitoring, and rigorous audit readiness.
Worldwide Rapid Hygiene Monitoring System Market
The 2026 landscape introduces a decisive moment for strategy formulation. Organizations that treat hygiene monitoring as a static procurement activity risk falling behind competitors who are leveraging rapid ATP and bioluminescence systems as enablers of process optimization, regulatory defensibility, and operational transparency. This report is structured to convert that macroeconomic momentum into actionable intelligence, enabling leaders to align capital allocation, vendor selection, and regional deployment strategies with the realities of a consolidating, regulation-driven market.
Worldwide Rapid Hygiene Monitoring System Market
Report Scope and Actionable Analytical Architecture
Beyond headline figures, the study delivers a multi-dimensional examination of the rapid hygiene monitoring ecosystem, connecting market structure with operational context. The analysis covers the period from 2020 through 2025 for baseline historical performance, and extends forecast modeling through 2032 to support long-range planning. Revenue is assessed in USD million terms, with careful attention to component-level demand patterns, end-use deployment drivers, and regional growth dynamics.
The report is designed for practical decision support. It maps the market by component categories to clarify how instruments and consumables interact in real-world procurement cycles and recurring revenue models. It also evaluates end-use sectors to distinguish where rapid hygiene monitoring is becoming mission-critical versus where it remains an emerging best practice. Regional analysis further contextualizes where demand is maturing, where adoption curves are steepening, and where localized regulatory or operational conditions are shaping purchase behavior.
Each section is built to answer the questions that matter to strategy teams: which segments are generating durable growth, where does value accumulation appear strongest, and how should organizations interpret competitive positioning when market concentration is rising? Rather than presenting isolated statistics, the study integrates demand rationales, deployment patterns, and purchasing considerations so that readers can translate market signals into capacity planning, product roadmap decisions, and partnership strategy.
Market Dynamics: Regulation, Adoption, and Technology Convergence
The rapid hygiene monitoring market is being reshaped by an overlapping set of drivers that reinforce one another. Regulatory bodies including the FDA, EFSA, and WHO have implemented increasingly stringent guidelines for hygiene and sanitation in food processing and healthcare environments. These frameworks are compelling the adoption of rapid ATP hygiene monitoring systems as objective evidence of cleaning efficacy and contamination control. Similarly, International Organisation for Standardisation guidelines and FDA expectations emphasize mandatory hygiene verification in healthcare facilities, reinforcing demand for ATP consumables used in sterilization and cleaning validation.
As a result, hygiene monitoring is increasingly positioned as both a compliance mechanism and an operational training tool. ATP bioluminescence testing serves as a monitoring and training instrument for effective hospital cleaning, supporting infection prevention protocols and standardizing sanitation practices across complex care environments. In pharmaceutical production, cleanrooms, and sterile processing departments, rapid verification technologies are used to validate the cleaning of reusable medical devices and ensure consistency in high-risk workflows. This broadening application base is expanding the strategic relevance of the market beyond traditional food safety use cases.
At the same time, technology convergence is changing the purchasing calculus. Rapid hygiene monitoring is becoming more tightly integrated with sanitation management software, environmental monitoring programs, and quality-control portfolios. This integration supports faster decision loops, better data traceability, and stronger alignment between field operations and corporate compliance teams. For enterprises, the implication is clear: the value of a monitoring system is no longer limited to the hardware or single-test performance. Buyers are increasingly evaluating the full ecosystem, including software interoperability, consumables availability, training support, and the ability to generate auditable records across sites.
Competitive Landscape: Consolidation, Differentiation, and Strategic Positioning
The market is characterized by a concentrated competitive structure, with the top three companies accounting for approximately 58.42 percent of share and the top five firms representing about 72.15 percent. This concentration reflects both the maturity of core ATP-based monitoring technologies and the growing importance of scale, brand trust, and integrated solutions in competitive bidding. The report conducts a detailed profile assessment of leading participants to help readers interpret where advantages are being built and how competitive pressure is likely to evolve.
Hygiena, LLC operates from the United States and offers ATP-based rapid hygiene monitoring systems including EnSURE Touch, SystemSURE Plus, UltraSnap, and SuperSnap swabs for surface and water hygiene verification in healthcare, food, and pharmaceutical settings. Its recent acquisition of Nexcor Food Safety Technologies Inc. in December 2024 illustrates a deliberate move to strengthen its ATP and environmental monitoring product range with integrated sanitation management software, signaling an intent to compete on both measurement accuracy and workflow digitization.
3M Company provides Clean-Trace ATP hygiene monitoring systems and swabs for rapid verification of cleaning effectiveness, primarily in food processing and healthcare environments. Kikkoman Biochemifa Company, based in Japan, supplies the Lumitester Smart luminometer and LuciPac A3 series test kits that detect ATP, ADP, and AMP for highly sensitive rapid surface and water hygiene monitoring. Neogen Corporation markets the Clean-Trace Hygiene Monitoring System, including ATP tests and luminometers, for real-time environmental monitoring and sanitation verification in healthcare and food industries. Each of these players brings a distinct emphasis, whether in application breadth, sensitivity thresholds, or sector-specific deployment expertise.
The competitive field also includes internationally diversified contributors. Merck KGaA and Merck Millipore, headquartered in Germany, offer ATP and NAD rapid detection products for objective hygiene monitoring in manufacturing plants, including pharmaceutical and food sectors. Charm Sciences, based in the United States, develops PocketSwab Plus ATP tests and luminometers for rapid surface sanitation verification across food, healthcare, and environmental applications. Terragene, from Argentina, provides Chemdye PRO1 MICRO protein tests and Chemdye ATP-S1 systems specifically for monitoring cleaning of reusable medical devices in SPD/CSSD and healthcare settings. Bio-Rad Laboratories Inc., also United States-based, supplies hygiene monitoring solutions including ATP-based systems as part of a broader microbiology and quality control portfolio for healthcare and industrial applications.
This competitive mosaic matters because differentiation is increasingly determined by more than instrument performance alone. Vendors are competing on consumable supply reliability, regulatory alignment, software integration, and the ability to support standardized training and verification programs across multiple sites. For buyers, the strategic question is not simply which system performs best in isolation, but which provider can sustain consistent verification outcomes within a broader quality ecosystem.
Segmentation Intelligence: Where Value Is Being Created
The report provides a structured view of how demand is distributed across components and end-use categories to help organizations understand the mechanics of market growth. In the component view, the market reflects a balance between instruments and consumables, with each category carrying different procurement implications. Instruments anchor initial adoption and capital planning, while consumables drive recurring operational expenditure and long-term vendor relationships. This dynamic is particularly important for companies evaluating total cost of ownership, supply continuity, and multi-year contracting strategies.
In end-use terms, the analysis separates demand centers by operational context. Food and beverage applications represent a substantial share of market activity, reflecting the continued need for rapid sanitation verification in processing environments where contamination risk directly affects product safety and brand integrity. Healthcare and hospitals form another major demand axis, where hygiene verification intersects with infection prevention, regulatory inspection readiness, and patient safety programs. Pharmaceutical and biotech use cases add a further layer of complexity, with requirements shaped by cleanroom control, production integrity, and stringent validation expectations. Additional end-use applications extend the market's reach into broader environmental and industrial monitoring contexts.
Regional dynamics further influence how these segments develop. North America, Europe, Asia Pacific, and the Rest of World each present distinct demand profiles shaped by local regulatory emphasis, food safety infrastructure, healthcare procurement models, and manufacturing expansion patterns. The report contextualizes these regional variations without reducing them to simplistic rankings, instead focusing on how market maturity, adoption barriers, and growth catalysts differ by geography. This allows decision-makers to assess where to enter, where to deepen presence, and where to anticipate competitive intensity.
Importantly, the segmentation analysis is presented to illuminate strategic optionality. It supports questions such as whether to prioritize instrument-led entry strategies or consumables-driven recurring revenue models, how end-use focus affects sales cycle design, and which regional markets offer the most favorable combination of regulatory tailwinds and operational readiness. These insights are intended to inform product planning, go-to-market sequencing, and investment prioritization.
Using This Intelligence to Shape 2026 Strategy
For executives planning 2026 initiatives, the market study functions as a decision-support framework rather than a static reference document. The growth trajectory suggests that hygiene monitoring will remain a priority investment area, but the more nuanced strategic opportunity lies in understanding where margin, differentiation, and long-term competitive advantage will be created. Organizations evaluating market entry, expansion, or vendor consolidation can use the report to benchmark structural conditions, anticipate consolidation-driven pricing and supply dynamics, and identify the segments where adoption is accelerating fastest.
The findings are especially relevant for teams developing multi-year procurement strategies, building sanitation management capabilities, or integrating hygiene verification into broader quality and compliance systems. By linking market size and growth patterns to component and end-use behavior, the study helps leaders align operational assumptions with market realities. It also supports scenario planning by highlighting where regulatory pressure, software integration, and consumables demand are likely to reshape purchasing behavior over the forecast period.
Because the market is increasingly consolidated and regulation-sensitive, the cost of incomplete intelligence is rising. Companies that rely on generic market narratives risk misjudging competitive intensity, underestimating recurring consumable demand, or overlooking regional deployment factors that affect time-to-value. The full report is designed to reduce those blind spots by providing a comprehensive, evidence-based foundation for strategic planning.
Complete Intelligence Behind This Overview
This executive preview has outlined the structural forces, competitive dynamics, and strategic questions defining the worldwide rapid hygiene monitoring system market through 2032. The underlying study goes further, delivering detailed segmentation evaluation, regional demand interpretation, and company-level competitive profiling that cannot be fully reproduced in summary form. For teams that need precise market sizing, segment behavior, concentration analysis, and actionable recommendations for 2026 planning, the complete research package provides the depth required to move from awareness to decision.
Readers seeking the full analytical architecture, including the complete segmentation framework and extended competitive and regulatory analysis, are encouraged to access the source page for the Worldwide Rapid Hygiene Monitoring System Market report. The full study is structured to support immediate strategic use, offering the level of detail necessary to inform budgeting, vendor selection, market entry planning, and long-range operational strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Rapid Hygiene Monitoring System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Market Report: Worldwide Bunker Rake Industry Reaches 390.8 Million USD in 2025 with Projected 4.92 Percent CAGR to 2032
By PW Consulting, 2026-09-02
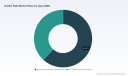
Strategic Intelligence for the Evolving Bunker Maintenance Landscape: Why the 2026 Outlook Demands Precision
The global bunker rake market is entering a decisive inflection point. As turf management operations face simultaneous pressure from tightening emissions standards, volatile input costs, and persistent labor constraints, leadership teams can no longer rely on historical procurement habits or generalized equipment forecasts. Our newly released Worldwide Bunker Rake Market study provides a structured, forward-looking intelligence framework designed specifically to support capital allocation, product strategy, and competitive positioning throughout the 2026-2032 horizon. This article previews the analytical architecture of the report, illustrates how the data connects to on-the-ground operational realities, and clarifies the strategic questions the full study is built to answer. Core segmentation values, regional revenue splits, and detailed breakouts are intentionally held back here to preserve the integrity of the commercial intelligence; interested decision-makers should consult the full report for the complete dataset and methodological breakdown.
Worldwide Bunker Rake Market
Market Trajectory and the Strategic Meaning of the Numbers
The bunker rake sector has demonstrated steady, compounding growth across the historical window, and the forward trajectory suggests continued expansion though not without structural friction. The broader revenue base has moved from a multi-year starting position above the three-hundred-million-dollar threshold in the early 2020s to a stronger base by 2025, and the forecast band extends upward into the mid-five-hundred-million range by the close of the decade. The compound annual growth rate anchored in the study sits near the high-four-percent mark, which signals durable demand rather than a speculative spike. For executives, that kind of growth cadence matters because it frames equipment investment as a multi-cycle decision rather than a single procurement event. A near-five-percent CAGR implies that capacity planning, inventory positioning, and service network design must be calibrated against sustained volume rather than short-term seasonal peaks.
Worldwide Bunker Rake Market
The trajectory also contains instructive inflection points. The forecast period does not follow a perfectly linear path; instead, it reflects the kind of market ebb and flow that strategic planners must anticipate. Intervals where revenue momentum temporarily moderates are just as informative as the upward strides, because they typically coincide with regulatory transition windows, input-cost recalibration, or shifts in end-user purchasing cycles. The study maps these intervals explicitly so that readers can separate cyclical softness from structural decline, a distinction that directly affects budgeting confidence and risk hedging.
Worldwide Bunker Rake Market
Currency consistency and base-year calibration further reinforce the report's utility for cross-functional planning. All revenue figures are expressed in U.S. dollars across a consistent measurement framework, which allows finance, procurement, and operations teams to align assumptions without reconciling conflicting currency or base-year adjustments. The historical series provides a verified reference point for trend validation, while the forecast period gives leadership a common timeline for scenario modeling. In practice, this means that a director of turf operations can test how a delayed fleet refresh, a shift in course renovation schedules, or a localized supply disruption would interact with the broader market path before committing capital.
Importantly, the study does not isolate the bunker rake category from its operating environment. Demand for bunker grooming equipment is tightly coupled with the health and composition of the facilities that depend on it. In the United States alone, golf facilities totaled over sixteen thousand at the close of 2024, creating a broad and relatively stable foundation for maintenance equipment consumption. That facility count is not merely a background statistic; it anchors expectations for recurring service cycles, replacement demand, and the scale of addressable opportunity for manufacturers and distributors alike. By embedding this facility-level context into the market narrative, the report helps readers interpret growth in terms of real operational footprints rather than abstract volume estimates.
Inside the Report: A Practical Toolkit for Decision-Makers
The Worldwide Bunker Rake Market study is structured as an operational reference rather than a passive data compilation. Its objective is to give strategy, sales, procurement, and product teams a shared evidentiary base that can be used immediately in planning cycles. The scope covers a defined historical window for trend validation and a multi-year forecast interval for forward planning, with consistent measurement conventions throughout. That design allows the report to function both as a retrospective benchmark and as a planning instrument for near-term and mid-term decisions.
A central feature of the study is its segmentation architecture. The analysis decomposes the market along multiple axes that matter to buyers and suppliers, including equipment configuration, end-use environment, and geographic footprint. Rather than presenting a single aggregate line, the report maps where volume and value concentrate, how different configurations compete for share, and which application environments drive recurring procurement rhythms. This is especially relevant for organizations that need to decide whether to prioritize self-propelled mechanical units, evaluate manual hand-held alternatives for specific maintenance scenarios, or align product portfolios with the distinct requirements of commercial golf operations, sports complexes and private clubs, and municipal parks or landscaping settings.
Beyond segmentation, the report integrates competitive intelligence that ties company positioning to operational capability. Profiles of leading manufacturers are built around product architectures, model-line differentiation, and the practical grooming outcomes their equipment is designed to deliver. The study examines how different builders approach contouring precision, sand handling efficiency, ride-on versus walk-behind ergonomics, and propulsion options across diesel, gas, and electric platforms. This competitor mapping is not limited to product catalogs; it is used to infer where each organization is likely to compete most aggressively, which customer segments they are best positioned to serve, and where substitution risk or partnership opportunity may emerge.
The study also incorporates a structured view of market concentration. By quantifying how revenue is distributed across the largest players, the report gives readers a clearer sense of competitive density and the degree to which share leadership translates into pricing influence, channel control, or service leverage. Concentration metrics matter because they shape expectations for new entrants, acquisition rationales, and the realism of displacement strategies. A market with meaningful share clustering will reward differentiated value propositions and disciplined channel execution, while a more fragmented environment may create room for regional specialization or niche application focus.
Operational decision-support is reinforced through scenario-ready framing. The forecast data is presented in a way that supports what-if analysis rather than simple extrapolation. Readers can use the structure to test questions such as how a delayed renovation pipeline would affect near-term demand, where fleet electrification might alter product mix preferences, or how regulatory compliance costs could shift total cost of ownership comparisons across propulsion types. The aim is to make the report usable in live planning conversations, not just as a reference document that sits on a shared drive.
Competitive Landscape: Positioning, Differentiation, and the Battle for Bunker Maintenance Share
The competitive field in bunker rake manufacturing is defined by a small group of influential players whose product strategies reflect different interpretations of what course maintenance teams value most. The study examines these organizations as strategic prototypes, each representing a distinct answer to the same core challenge: how to deliver consistent bunker conditioning with manageable labor input, reliable durability, and increasingly efficient propulsion.
The Toro Company stands out for its long-standing association with the Sand Pro series and its broad propulsion coverage across diesel, gas, and electric models. Its product narrative emphasizes precise bunker grooming and contouring, which positions the company as a reference point for operations that prioritize surface consistency and professional-grade presentation. From a strategy perspective, this product breadth allows the company to serve a wide spectrum of course sizes and maintenance philosophies while retaining a recognizable platform identity. Competitors and buyers alike watch Toro not only for model-level performance but also for signaling around electrification, service support, and the pace at which new grooming technologies are integrated into established lines.
Smithco Manufacturing approaches the category through a different lens, centered on ride-on efficiency and advanced grooming technology for sand bunker maintenance. Its Sterling series, including high-capacity ride-on configurations, reflects a focus on throughput and operator productivity. In markets where labor availability and time-per-task pressure are acute, that emphasis on ride-on performance can be decisive. Strategically, Smithco's profile illustrates how a manufacturer can compete by optimizing the ergonomics and output of bunker conditioning rather than by pursuing the broadest possible model portfolio. The implication for buyers is a more targeted value proposition: equipment designed to reduce manual effort and improve consistency across larger maintenance areas.
Billy Goat Industries contributes a third strategic posture, built around self-propelled, walk-behind bunker rakes that emphasize versatility and tighter operational maneuverability. Its SR series is associated with walk-behind operation and adaptable bunker conditioning, which appeals to settings that require responsive handling in varied layout conditions. From a competitive standpoint, this positioning underscores the continued relevance of smaller-footprint, highly maneuverable equipment in environments where access constraints, mixed maintenance tasks, or varied bunker geometries matter. Collectively, these three companies demonstrate that the bunker rake category is not a monolith; it is a field of competing design philosophies around propulsion, operator interaction, and grooming precision.
The study situates these competitors within the broader concentration context of the market. When a meaningful share of revenue is captured by a relatively small group of firms, strategic planning must account for the likelihood that incumbents will defend territory through brand equity, dealer relationships, parts and service networks, and incremental product upgrades. At the same time, concentration also reveals where differentiation is still possible. If the largest players compete primarily on grooming precision and ride-on efficiency, there may be room for specialized offerings that address labor reduction, localized service responsiveness, or application-specific configurations that larger portfolios do not optimize as closely. The report provides the framework to evaluate those opportunities with evidence rather than assumption.
Market Dynamics: Forces Reshaping Cost, Compliance, and Procurement Behavior
The bunker rake market does not move in isolation. It is shaped by overlapping forces that influence manufacturing economics, operating budgets, compliance requirements, and the practical realities of course maintenance staffing. The study weaves these forces into the analysis so that readers can interpret demand not just as a function of equipment preference, but as the outcome of a broader operating environment.
Raw Material and Manufacturing Cost Pressures
Input cost volatility remains a persistent variable in equipment manufacturing, and steel is a foundational material in bunker rake construction. During 2024, hot-rolled steel sheet pricing in the United States averaged around thirty-one dollars per hundredweight, underscoring the sensitivity of build costs to commodity cycles. This matters because steel exposure influences margin structure, pricing strategy, and the timing of product revisions. When material costs fluctuate, manufacturers must decide whether to absorb pressure, pass costs through, redesign components for material efficiency, or adjust production timing. For buyers, the same dynamic affects expected total cost of ownership, lead-time reliability, and the relative attractiveness of different procurement windows. The report uses this kind of contextual data to help teams anticipate cost-driven behavior on both sides of the transaction.
Trade policy adds another layer of manufacturing cost complexity. Ongoing U.S. Section 232 tariffs impose twenty-five percent duties on steel imports, directly affecting the cost structure of domestically manufactured equipment that relies on imported steel inputs. For organizations planning procurement or product development, the implication is that cost assumptions cannot be treated as purely market-driven; they must also account for policy-driven shifts that can alter the relative economics of domestic versus imported components. In a market where concentration and brand positioning already influence pricing power, tariff exposure can widen the gap between efficiently sourced competitors and those with greater input-cost vulnerability.
Labor Constraints and the Productivity Imperative
One of the most operationally significant dynamics in the sector is the challenge of staffing. In 2024, a substantial majority of golf course superintendents reported difficulty recruiting and retaining maintenance staff. That reality changes the calculus for bunker maintenance equipment. When skilled labor is harder to secure and retain, the value proposition shifts toward machines that reduce physical burden, improve consistency, and allow smaller crews to cover more ground efficiently. This is not simply a preference issue; it is an operational resilience issue. Facilities that depend on intensive manual processes face greater risk when staffing is unstable, while those that invest in equipment designed to reduce labor intensity can protect course conditions more reliably.
For manufacturers and solution providers, labor scarcity strengthens the argument for ergonomic improvements, self-propelled configurations, and technologies that make bunker conditioning more predictable with fewer hands on deck. For procurement leaders, it sharpens the evaluation criteria beyond sticker price, encouraging a broader comparison of training burden, maintenance complexity, operator fatigue, and seasonal coverage capacity. The study frames these labor-driven considerations as strategic inputs rather than peripheral concerns, because they directly influence which equipment categories are likely to see sustained preference growth.
Regulatory Direction and the Evolving Engine Equation
Compliance requirements are reshaping product design pathways, particularly for equipment powered by nonroad spark-ignition engines. EPA Phase 3 standards for nonroad spark-ignition engines under nineteen kilowatts apply across a 2024-2028 effective window, influencing engine design and, by extension, the configuration of equipment that depends on those powerplants. For bunker rakes that use gas or other spark-ignition propulsion, this regulatory sequence matters because it affects emissions performance, engine availability, service considerations, and the timing of product updates.
The practical significance for strategy is twofold. First, organizations evaluating current fleets need to understand how regulatory timelines interact with equipment lifecycles and replacement planning. Second, manufacturers and distributors need to anticipate how compliance-driven changes will influence buyer perceptions of future-proofing, especially as electrification continues to expand as an alternative. The study treats regulatory timing as a planning variable, helping readers assess whether near-term procurement should prioritize compliance readiness, whether transitional engine options create short-term advantages, and how electrification roadmaps may alter category preferences over the forecast period.
Facility Footprint and Steady Underlying Demand
A stable facility base supports consistent demand for maintenance equipment. The presence of over sixteen thousand U.S. golf facilities at year-end 2024 provides a substantial operational backdrop for recurring bunker upkeep. This does not guarantee uniform growth in every sub-segment, but it does establish a wide foundation of repeat maintenance activity. Bunkers are high-visibility course features, and their conditioning is closely tied to player experience and course reputation, which helps ensure that grooming remains a persistent priority rather than a discretionary expense. The report connects this facility-level reality to demand interpretation, helping readers distinguish between broad structural support for the category and narrower shifts in equipment mix or application preference.
Translating the Outlook into 2026 Strategic Actions
The 2026-2032 window is best approached as a period in which multiple transitions converge: equipment design adapts to emissions expectations, procurement decisions weigh labor productivity more heavily, and cost structures remain sensitive to material and trade policy. In that environment, the strategic value of the study lies in its ability to connect market direction with operational choice.
- Align procurement timing with regulatory and cost calendars. Replacement planning should consider how emissions standards, steel cost trends, and tariff exposure interact with fleet age and seasonal maintenance demands. The report's structure supports decisions about when to commit to current configurations versus when to wait for next-cycle designs.
- Evaluate equipment categories around labor reality, not just capability. With maintenance staffing under pressure, organizations should weigh how self-propelled mechanical units, manual hand-held options, and different propulsion types affect crew efficiency, training load, and seasonal coverage. The segmentation framework helps compare these tradeoffs in a disciplined way.
- Position product and channel strategy around concentration dynamics. Because meaningful revenue share is clustered among leading manufacturers, new entrants and incumbent challengers need clear differentiation in grooming precision, service responsiveness, application fit, or total cost of ownership. The competitive mapping in the study provides a base for targeting those openings.
- Use facility-level context to validate demand assumptions. Broad facility counts and recurring maintenance priorities support the case for sustained category demand, but local renovation pipelines, membership models, and municipal budget cycles will shape where growth is strongest. The report helps separate category-level trends from site-specific drivers.
These action themes are illustrative rather than exhaustive. The full study expands each into a more detailed analytical track, with segmentation breakdowns, regional context, and company-level profiles that allow teams to test specific hypotheses about market entry, product focus, pricing strategy, and channel investment.
Why the Complete Study Matters
The Worldwide Bunker Rake Market research is designed to serve as a decision-grade intelligence asset. It combines verified historical reference points, a forward forecast calibrated across a consistent measurement framework, segmentation views that reveal where value concentrates, and competitive profiles that translate product architecture into strategic positioning. It also integrates the operating forces that shape real procurement behavior, from material costs and trade policy to staffing constraints and emissions compliance.
For executives, product leaders, procurement professionals, and market strategists, the full report provides what a summary cannot: the detailed segmentation values, the regional and application-specific breakouts, the concentration metrics, and the structured competitor mapping needed to move from directional confidence to actionable planning. Those elements are held back from this preview by design, because the study's core strength is its completeness. Detailed figures and breakouts are available through the full report, where they can be used directly in planning models, investment memos, and competitive assessments.
If your 2026 decisions depend on understanding where bunker maintenance demand is heading, which equipment configurations are likely to gain preference, how leading manufacturers are positioning themselves, and what cost and compliance dynamics will shape buying behavior, this study is built to support that process with evidence and structure. The complete dataset and segmentation intelligence are available for review through the full Worldwide Bunker Rake Market report, where the full scope of the analysis can be put to work in your planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Bunker Rake Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Fermented Feed Ingredient Market to Hit USD 63,236.85 Million by 2032 with 8.45% CAGR
By PW Consulting, 2026-09-02
Navigating the Future of Animal Nutrition: Strategic Insights from the Global Fermented Feed Ingredient Market 2026-2032
The global animal nutrition landscape is undergoing a structural transformation driven by sustainability mandates, antibiotic restrictions, and the relentless pursuit of feed efficiency. At the center of this shift lies the fermented feed ingredient sector, a rapidly evolving segment where biotechnology meets agronomy to redefine how livestock, poultry, and aquaculture species receive essential nutrients. PW Consulting's latest comprehensive study, Worldwide Fermented Feed Ingredient Market, offers decision-makers a rigorous, data-backed roadmap through this complex ecosystem. This article previews the strategic architecture of the report, outlining why it is an indispensable tool for corporate planning in 2026 and beyond.
Worldwide Fermented Feed Ingredient Market
Market Evolution and Trajectory: A Decade of Resilient Growth
Over the past half-decade, the fermente feed ingredient market has demonstrated remarkable resilience and expansion. Historical data from 2020 through 2025 reveals a consistent upward trajectory, with total market revenue climbing steadily as producers across multiple continents integrate fermentation-based solutions into standard feeding protocols. The momentum has not plateaued; rather, it has accelerated into the forecast period spanning 2026 to 2032. Our analysis projects sustained double-digit absolute growth, with the market poised to exceed 63 billion USD by the end of the forecast window. This expansion is underpinned by a compound annual growth rate that reflects both structural demand shifts and technological maturation in fermentation processes.
Worldwide Fermented Feed Ingredient Market
The acceleration is not merely a function of volume. It represents a qualitative leap in how feed manufacturers and livestock integrators view ingredient functionality. Traditional protein and additive sources are being re-evaluated against metrics that include digestibility, gut microbiome modulation, immune support, and environmental footprint. Fermentation-derived ingredients score favorably across these dimensions, creating a compelling value proposition that extends well beyond price-per-ton comparisons. For corporate strategists, understanding the pace and shape of this growth is critical for capital allocation, supply chain design, and product portfolio prioritization.
Worldwide Fermented Feed Ingredient Market
Report Scope and Methodological Rigor: What Decision-Makers Will Find
The Worldwide Fermented Feed Ingredient Market study is designed as a practical intelligence asset rather than an abstract overview. It combines granular data collection with scenario-based forecasting to equip executives with actionable insights. The report's analytical framework covers multiple dimensions that directly influence strategic planning:
- Product-Type Landscape: The analysis dissects the market across key ingredient categories, mapping historical adoption patterns and forward-looking demand signals. Categories examined include amino acids, vitamins, enzymes, organic acids, and other specialized fermentation outputs. Each segment is evaluated for growth drivers, technological differentiators, and integration pathways within commercial feed formulations.
- Animal-Species Demand Profiles: Fermentation solutions are not applied uniformly across livestock sectors. The report breaks down consumption dynamics by animal type, including poultry, swine, ruminants, aquaculture, and other species. This segmentation reveals distinct nutritional priorities, regulatory pressures, and adoption curves that shape procurement strategies and R&D focus for ingredient suppliers and feed formulators alike.
- Regional Dynamics and Supply-Demand Networks: Geographic analysis explores how local feedstock availability, manufacturing infrastructure, trade flows, and policy environments influence market structure. The study identifies regions where production capacity is expanding, where import dependency creates opportunity for localized fermentation solutions, and where sustainability initiatives are accelerating ingredient substitution.
- Industry Context and Operational Cost Structures: Beyond headline revenue figures, the report integrates operational realities that affect competitiveness. For example, solid-state fermentation of agro-industrial wastes presents cost advantages of approximately 0.5 to 1 USD per kilogram of product compared to submerged fermentation ranges of 2 to 5 USD per kilogram, while consuming roughly 70 percent less water and achieving higher enzyme titers. These operational levers shape plant location decisions, feedstock sourcing strategies, and margin architecture.
Each section is supported by primary and secondary research, expert interviews, and validation exercises that ensure the findings withstand scrutiny in boardroom discussions. The output is structured to answer not only what is happening in the market but why it is happening and what it means for specific business decisions.
Competitive Arena: Major Players and Strategic Positioning
The fermented feed ingredient market features a diverse set of participants spanning global agri-processing giants, specialized biotechnology firms, and regional production leaders. Competitive intensity is shaped by differences in technology portfolios, vertical integration levels, and the ability to align product development with evolving regulatory and sustainability requirements. The report provides detailed company profiles that illuminate how leading organizations are positioning themselves within this dynamic environment.
Among the profiled entities, Cargill, Incorporated stands out through its Diamond V brand, which delivers microbial fermentation-derived postbiotic products, alongside Provisoy fermented soy protein solutions aimed at improving gut health, protein digestibility, and performance in swine, poultry, and aquaculture feeds. Archer Daniels Midland Company supports fermentation nutrient supply and yeast-based offerings such as Citristim, while also developing solutions that enhance rumen fermentation and gut health. Lallemand Inc. focuses on microbial fermentation solutions including silage inoculants, live yeast probiotics, and bacterial strains designed to optimize forage fermentation and microbiota balance across livestock species.
Angel Yeast Co., Ltd. operates as a major producer of yeast-based bio-feed ingredients, offering inactive yeast, yeast cultures, and microbial fermentation products that target gut health, immunity, and feed efficiency. Within the Cargill ecosystem, Diamond V specifically manufactures proprietary microbial fermentation postbiotic feed additives using distinct fermentation processes to support immune function, digestive health, and performance across livestock, poultry, and equine segments. Louis Dreyfus Company operates fermented soybean meal production lines that leverage synergistic probiotic fermentation technology to reduce anti-nutritional factors, enhance digestibility, and improve gut health. Evonik Industries AG contributes fermentation-derived amino acids and probiotic or gut health solutions integrated into animal nutrition for improved feed efficiency and sustainable livestock production.
dsm-firmenich develops and supplies fermentation-based probiotics, enzymes, and nutritional solutions that enhance performance and gut health while supporting efforts to reduce antibiotic use. BASF SE offers fermentation-derived enzymes, organic acids, and feed additives focused on optimizing nutrient utilization and animal health in fermented feed applications. CJ BIO, part of CJ CheilJedang, produces fermented soybean meal products and amino acids via fermentation, providing high-digestibility protein sources for livestock and aquaculture feeds. Nutraferma specializes in fermented soybean meal produced through proprietary fermentation processes that eliminate anti-nutritional factors and enhance nutritional value for animal diets.
The report also examines recent corporate activities that signal strategic intent and capacity expansion. In November 2025, Louis Dreyfus Company inaugurated a new specialty feed protein production line in Tianjin, China, with an annual capacity of 60,000 metric tons focused on fermented soybean meal using multi-strain probiotic fermentation technology to improve protein digestibility and gut health. In April 2026, multiple Chinese producers scaled the use of fermented feeds and synthetic amino acids derived from fermented corn starch to reduce soybean meal inclusion in diets, supported by government policy aimed at lowering soy dependency. Meanwhile, in October 2025, Lincoln University of Missouri conducted a field trial evaluating fermented soybean meal as an alternative protein source in aquaculture feeds compared with conventional soybean meal. These developments illustrate how capacity investments, commercial adoption, and scientific validation are converging to shape competitive dynamics.
Market Dynamics and Structural Shifts: Regulation, Sustainability, and Raw Material Innovation
The market does not evolve in a vacuum. Regulatory change, sustainability expectations, and raw material innovation are interacting to create both constraints and opportunities. In the United States and Canada, restrictions on antibiotic growth promoters have accelerated the adoption of fermented, probiotic-enriched feed solutions as alternatives to support gut health and performance. This regulatory environment continuously reshapes demand patterns, prompting ingredient suppliers and feed manufacturers to align product development with compliance requirements while differentiating on functional benefits.
Sustainability considerations are equally influential. Fermentation of agricultural by-products such as brewer's grains, citrus pulp, and fruit peels supports circular economy models, reducing waste while providing cost-effective nutrition in livestock diets. This aligns with broader corporate sustainability targets and consumer-facing branding strategies that increasingly value transparent, low-impact supply chains. In China, major dairy producers have reduced soymeal in cattle feed by approximately 20 percent through fermented alternatives, consistent with national efforts to decrease reliance on imported soy. Such shifts demonstrate how policy, resource security, and ingredient innovation can reinforce one another.
Raw material and process economics remain central to competitive advantage. Fermentation of soybean meal using multiple probiotic strains breaks down anti-nutritional factors, increasing small-molecule organic acids that support animal gut health and immunity. At the same time, producers are optimizing process selection to balance cost, water usage, and output quality. These technical choices influence not only unit economics but also the ability to scale sustainably and respond to fluctuating feedstock prices. The report analyzes how these dynamics affect margin potential, entry barriers, and long-term positioning for both incumbent players and new entrants.
Strategic Value for 2026 Decision-Making: Why This Study Matters Now
Corporate leaders face a set of interconnected decisions in 2026 that require precise, forward-looking intelligence. The fermented feed ingredient market is large enough to matter and dynamic enough to reward those who understand its nuances. The report is structured to support several high-stakes strategic activities:
- Portfolio and Product Investment: By mapping growth trajectories across ingredient types and animal segments, the study helps prioritize R&D spending, commercialization timelines, and acquisition targets. Executives can identify where functional differentiation is most valued and where commoditization risk is rising.
- Geographic and Supply Chain Strategy: Regional analysis clarifies where production capacity is expanding, where feedstock advantages exist, and where regulatory or trade conditions create friction or opportunity. This supports decisions on plant siting, sourcing contracts, and market entry or expansion.
- Competitive Positioning and Partnership Design: Detailed company profiles and recent development tracking reveal how peers are investing, collaborating, and differentiating. This enables more informed competitive responses, from product feature emphasis to partnership structures with feed integrators and livestock operators.
- Risk Assessment and Scenario Planning: The integration of regulatory trends, sustainability pressures, and process economics allows leaders to test strategies against plausible future conditions. The forecast framework supports sensitivity analysis around adoption speed, cost structures, and policy evolution.
In short, the study translates complex market signals into structured guidance. It is built for teams that need to convert uncertainty into a manageable set of options and commitments.
Concentration Patterns and What They Signal for Market Entry
Market structure matters as much as market size. The fermented feed ingredient sector exhibits a moderate level of concentration, with the top three players accounting for roughly 31.45 percent of revenue and the top five reaching approximately 42.8 percent. This concentration pattern indicates that while leading firms hold meaningful share, a substantial portion of the market remains accessible to specialized producers, regional players, and new technology-driven entrants. The report examines how this distribution affects pricing power, channel relationships, and the feasibility of differentiated positioning. It also explores where consolidation pressure is likely to intensify and where fragmentation may persist due to local feedstock advantages or species-specific application expertise.
For strategists, these structural insights help calibrate expectations around scale requirements, partnership needs, and the speed at which share can be gained or defended. Concentration is not static; it evolves with capacity investments, technology adoption, and regulatory shifts. The forecast period analysis tracks the forces that may alter this balance, enabling more realistic planning around competitive response and market access.
Preview of Segmentation Insights: Where Value Is Being Created
One of the report's core strengths is its ability to connect segment-level demand patterns with broader market forces without reducing the analysis to simplistic rankings. The ingredient-type view shows how amino acids, vitamins, enzymes, organic acids, and other categories each face distinct adoption drivers and competitive conditions. For example, amino acids remain central to precision nutrition strategies, while enzymes and organic acids are increasingly valued for their roles in nutrient utilization and gut environment modulation. Vitamins and other specialty outputs occupy important niches where formulation specificity and regulatory compliance influence purchasing decisions.
The animal-type perspective highlights how poultry, swine, ruminants, aquaculture, and other sectors differ in their nutritional priorities and adoption readiness. Poultry and swine operations often lead in integrating functional feed ingredients due to scale, throughput, and sensitivity to feed efficiency metrics. Ruminant applications involve unique fermentation and forage-related considerations, while aquaculture represents a growing frontier where alternative protein sources and gut health solutions are gaining traction through scientific validation and cost competitiveness. The report details how these sector-specific dynamics shape procurement behavior, formulation practices, and supplier engagement models.
Regional analysis complements these views by revealing how local feedstock availability, manufacturing capacity, and policy environments interact. Rather than presenting static regional shares, the study examines the direction and intensity of regional momentum, identifying where supply expansion is most active and where demand-side policy or sustainability drivers are accelerating ingredient substitution. This layered approach allows readers to understand not just where the market is today, but where structural advantages are forming.
How to Use This Intelligence: From Insight to Action
The report is designed to be operationalized. It supports a range of use cases, from annual planning and investment committee briefings to product roadmap development and supplier negotiation strategy. Teams can extract scenario-ready inputs for capacity planning, benchmark competitor moves against their own pipeline, and align commercial messaging with the functional benefits that buyers increasingly prioritize. The inclusion of recent developments, operational cost benchmarks, and regulatory context ensures that the data is not isolated from the realities of execution.
For organizations evaluating market entry, expansion, or portfolio rebalancing, the study provides a structured basis for comparing opportunities across ingredient types, animal segments, and regions. For incumbents, it offers a reference point for assessing whether current positioning remains aligned with the direction of demand and competition. In both cases, the objective is the same: reduce uncertainty enough to make confident, timely decisions.
Next Steps: Accessing the Full Strategic Picture
This article has outlined the conceptual framework, competitive landscape, and decision-Making value embedded in the Worldwide Fermented Feed Ingredient Market study. It has also highlighted the operational, regulatory, and sustainability forces that are shaping market evolution. Yet many of the most actionable details, including precise segment trajectories, regional demand nuances, and comparative positioning metrics, are developed in full within the complete report. Access to the full dataset and analysis enables teams to move from strategic orientation to implementation with greater confidence and specificity. For decision-makers preparing for 2026 and the forecast period through 2032, the complete study offers the depth required to translate market momentum into informed corporate action.
The fermented feed ingredient market is entering a phase where technological maturity, regulatory clarity, and sustainability imperatives are reinforcing one another. Organizations that understand not only the scale of this opportunity but also its structural drivers will be best positioned to capture value. PW Consulting's comprehensive study is built to provide that understanding, combining rigorous data with practical interpretation to support the strategic decisions that matter most.
For detailed analysis of this topic, please visit the official page: Worldwide Fermented Feed Ingredient Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Global Magnetorquer Rods Market Forecast 2026-2032 Reveals 10.21% CAGR and USD 154.9 Million Growth
By PW Consulting, 2026-09-02
Navigating the Orbital Infrastructure Boom: Strategic Insights into the Global Magnetorquer Rods Market
The satellite industry is currently undergoing a structural shift where the mass deployment of small satellites is meeting rigorous demands for reliable attitude control. As Low Earth Orbit (LEO) becomes increasingly congested with commercial constellations and scientific CubeSats, the reliance on propellant-free momentum management has elevated the strategic importance of magnetorquer rods. PW Consulting has compiled a comprehensive Worldwide Magnetorquer Rods Market study to dissect this evolving landscape. This article serves as an executive preview, highlighting the macroscopic economic indicators and competitive dynamics that define the sector through 2032, while underscoring the detailed intelligence available in the full report.
Worldwide Magnetorquer Rods Market
For stakeholders involved in space manufacturing, supply chain management, or investment within the aerospace sector, understanding the trajectory of magnetic torquers is not merely technical due diligence; it is financial imperative. As we move through the forecast period, the convergence of specialized material requirements, radiation tolerance standards, and scaling manufacturing capacities creates a complex decision matrix. The data presented herein offers a snapshot of the ground covered in our complete analysis, designed to equip leadership teams with the context needed to anticipate market contractions and expansions.
Worldwide Magnetorquer Rods Market
Macroeconomic Trajectory and Market Sizing
The global market for magnetorquer rods has demonstrated consistent resilience and growth over the past half-decade. Based on historical analysis from 2020 through the base year of 2025, the sector has transitioned from a niche component supply chain to a critical enabler of broader satellite deployment strategies. In 2020, the global revenue base stood at approximately $48.52 million. By 2025, this figure has expanded to $78.42 million, reflecting the accelerating adoption of small satellite architectures that prioritize cost-effective, non-chemical attitude control systems.
Worldwide Magnetorquer Rods Market
The growth narrative extends firmly into the forecast horizon. Our models project the market revenue to reach $88.78 million in 2026, continuing an upward trajectory to surpass $154.9 million by 2032. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 10.21% across the forecast period of 2026 to 2032. Such growth rates indicate a market that is not just recovering from post-pandemic supply chain adjustments but is fundamentally scaling alongside the proliferation of LEO constellations. The increasing demand for momentum dumping of reaction wheels, specifically in missions requiring low-power and propellant-free solutions, remains a primary driver of this sustained revenue momentum.
Segmentation Dynamics Without Data Leakage
While specific geographic revenue splits and application percentage breakdowns are reserved for the detailed tables in the full report, the qualitative segmentation trends are clear. The market is broadly categorized by the physical construction of the rods, primarily distinguishing between Iron Core Magnetorquers and Air Core Magnetorquers. Historically, iron core designs have dominated due to their high magnetic moment capabilities at lower power consumption, making them indispensable for missions with strict energy budgets. However, air core solutions maintain a significant foothold in specific radiation-sensitive or weight-constrained applications.
In terms of end-use, the market is heavily influenced by the rise of CubeSats and Nanosatellites, which have fundamentally altered the procurement volume and unit economics of the industry. Small Satellites represent another substantial share of demand, driven by commercial earth observation and communications networks. Medium and Large Satellites continue to utilize magnetic torquers for specific subsystem functions, though their lower unit volume contrasts sharply with the mass-production environment of the small satellite sector. The full study provides a granular mapping of these segments, allowing buyers to identify which specific value chain holds the most immediate opportunity for their portfolio.
Competitive Landscape and Key Players
The competitive environment for magnetorquer rods is characterized by a mix of specialized aerospace manufacturers and high-reliability coil producers. Market concentration metrics suggest a moderately consolidated environment, where a handful of established players hold significant influence, yet opportunities remain for agile manufacturers capable of meeting niche customization requirements. The following entities represent the core of the current supply landscape as analyzed in our report:
- NewSpace Systems (NSS) : Headquartered in Somerset West, South Africa, NSS stands as one of the largest global manufacturers with a strong emphasis on flight heritage. Their TAURUS series utilizes magnetic alloy rod cores to achieve high moments at low power. With over 7000 rods sold for international missions and involvement in more than 10 constellation programmes, they represent a benchmark for volume and reliability. Recent updates in late 2025 reinforced their position with datasheet revisions highlighting over 3500 units currently in orbit.
- ZARM Technik AG : Based in Bremen, Germany, ZARM Technik is a leading European manufacturer focused on efficient, optimized designs for Guidance, Navigation, and Control (GNC) actuators. Their offerings include customizable rods and radiation-tolerant electronic control units capable of withstanding up to 20krad TID. Supplying over 150 international missions with no reported failures, they emphasize TRL 9 qualification and robust environmental compliance.
- CubeSpace Satellite Systems : Operating out of Stellenbosch, South Africa, CubeSpace provides a compact, customizable range beneficial for CubeSats to microsatellites. Their CR series uses annealed/tempered high-performance ferrous cores with automated robotic winding to ensure repeatability and low cost. With radiation testing up to 24 kRad and carbon fibre protective sleeves, they cater to the high-volume needs of the nanosatellite sector.
- Tensor Tech : Based in Taiwan, Tensor Tech offers the TensorMTQ series, focusing on low power consumption (<1.5 W) and mass efficiency (<150 g). They provide both standalone rods and integrated MTQ boards, manufactured in ISO 7 cleanrooms with COMSOL analysis for magnetic performance. Their capability to scale from prototypes to mass production makes them a key partner for developing mission architectures.
- GomSpace : A major player in the Nordic region based in Aalborg, Denmark, GomSpace supplies the NanoTorque GST-600 (Mk2) 3-axis magnetorquer systems. Designed for 6U CubeSats and larger, these systems include air-torquers and feature high torque with low residual dipole. Updated specifications released in September 2025 highlight their continued commitment to CubeSat integration standards.
- Space Inventor : Also headquartered in Aalborg, Denmark, Space Inventor manufactures the MT-P4 series with annealed Alloy 79 cores and enameled copper windings. Their variants offer moments up to 6 Am² with options for integrated controllers or driver electronics suited for LEO momentum dumping. They emphasize redundant windings and supply options for enhanced mission safety.
- Custom Coils, Inc. : Established in 1978 in Alcester, South Dakota, USA, Custom Coils specializes in custom magnetorquers including air-core coils and rods. With over 45 years of experience, they focus on high-reliability aerospace-grade windings meeting ISO/NEMA/UL standards. Their recent technical publications in 2025 emphasized low-power, high-reliability designs and scalable manufacturing with vacuum/thermal testing.
The interplay between these competitors involves not just price competition but also differentiation through technology readiness levels, radiation hardening, and the ability to integrate control electronics directly with the rod assembly. The full market study provides a side-by-side capability comparison that aids in supplier selection and risk mitigation.
Industry Dynamics: Regulation, Materials, and Macro Trends
The operational environment for magnetorquer rods is dictated by stringent aerospace standards and material science advancements. A critical dynamic in the current market is the emphasis on Technology Readiness Level (TRL) 9 qualification. Manufacturers are increasingly expected to demonstrate radiation tolerance up to 24 kRad, alongside compliance with vibration, thermal vacuum, and shock testing standards exceeding 1500 g. These requirements are not merely regulatory hurdles but are fundamental to securing contracts for high-value constellation missions where failure is not an option.
Material science plays an equally pivotal role. The primary construction of modern magnetorquer rods relies on high-permeability magnetic alloy cores, such as annealed Alloy 79 or specialized ferrous alloys. These are combined with high-grade enameled copper magnet wire windings and protective carbon fibre sleeves. The choice of core material directly impacts the magnetic moment efficiency and thermal stability of the device, while the winding technique influences inductance and power consumption. As missions extend to higher radiation environments or require longer operational lifespans, the specification of these raw materials becomes a key differentiator in procurement strategies.
From a macro trend perspective, the industry is witnessing an increasing adoption of magnetorquer rods in small satellite constellations specifically for the momentum dumping of reaction wheels. This trend is driven by the demand for low-power, propellant-free attitude control systems in LEO missions. As satellites reach the end of their fuel or seek to minimize mass for launch cost reductions, magnetic torquers provide a passive method to manage angular momentum. This shift is reshaping the volume projections for the industry, favoring suppliers who can deliver high-reliability devices at a scale consistent with constellation deployment rates.
Strategic Value of the PW Consulting Report
In a market growing at double-digit rates with complex technical requirements, decision-makers require more than superficial summaries. The full PW Consulting Worldwide Magnetorquer Rods Market report offers a deep dive into the quantitative and qualitative factors that will influence investment and procurement decisions from 2026 through 2032. The study is designed to be an operational tool, providing the granular data necessary to build robust business cases.
Key areas covered in the full report include detailed historical revenue analysis from 2020 to 2025, offering a baseline for trend extrapolation. The forecast period analysis breaks down expected market sizes and growth rates with granularity that allows for scenario planning. Unlike high-level summaries, the comprehensive document includes specific segmentation analysis by region, enabling stakeholders to identify high-growth territories without ambiguity. Furthermore, the report contains a thorough examination of the supply chain, raw material price sensitivities, and the specific technical specifications that define competitive advantage among the key players.
Understanding the market concentration ratios and the specific capabilities of manufacturers like NewSpace Systems, ZARM Technik, and CubeSpace requires a level of detail that only the full dataset can provide. For instance, the ability to compare the radiation tolerance specifications of a CubeSpace CR series rod against a ZARM Technik unit involves analyzing test data and compliance certifications that are detailed in the complete intelligence package. Similarly, strategic decisions regarding entry into the North American versus European markets require nuanced insights into regional demand drivers and regulatory environments that are fully explored in the text.
Conclusion: The Path Forward
The Worldwide Magnetorquer Rods Market stands at the intersection of aerospace engineering and commercial scalability. With a projected market value exceeding $154 million by 2032 and a CAGR of 10.21%, the sector offers significant opportunities for manufacturers, integrators, and investors. However, capturing this value requires navigating a landscape defined by strict TRL requirements, specialized material dependencies, and a competitive set of established global suppliers.
PW Consulting's comprehensive study is the essential resource for stakeholders aiming to capitalize on these trends. By locking in the macroeconomic data, segmentation splits, and competitive profiles detailed in the full document, organizations can move from reactive observation to proactive strategy. The insights within this report are curated to reveal the specific opportunities hidden within the broader growth figures, providing the clarity needed to secure a strong position in the next generation of orbital infrastructure.
To access the complete segmentation data, detailed competitor profiles, and the full forecast tables necessary for your strategic planning, we invite you to request the full report. The depth of intelligence provided therein is tailored to ensure that your decisions are grounded in the most current and rigorous market analysis available.
For detailed analysis of this topic, please visit the official page: Worldwide Magnetorquer Rods Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reveals Worldwide Industrial Workbench Market to Reach USD 2,255.72 Million by 2032 with 4.56% CAGR Driven by Asia Pacific Leadership and Steel Segment Dominance
By PW Consulting, 2026-09-02
Strategic Intelligence for the Industrial Workbench Market: Navigating Growth and Supply Chain Dynamics in 2026 and Beyond
In the complex ecosystem of global manufacturing and industrial operations, the humble workbench serves as a critical node of productivity. It is where assembly happens, where maintenance is performed, and where precision engineering takes physical form. However, beneath the surface of this seemingly static equipment category lies a dynamic market driven by shifting material costs, evolving ergonomic standards, and broader macroeconomic forces such as reshoring and infrastructure development. PW Consulting has recently completed a comprehensive analysis of the Worldwide Industrial Workbench Market, providing stakeholders with the granular intelligence necessary to make informed decisions in 2026 and beyond.
Worldwide Industrial Workbench Market
This market research is not merely a collection of statistics; it is a strategic roadmap designed to help procurement leaders, supply chain managers, and corporate strategists navigate a landscape defined by volatility and opportunity. As we move through the forecast period extending to 2032, understanding the trajectory of market expansion and the competitive forces at play is essential for maintaining operational efficiency and cost control.
Worldwide Industrial Workbench Market
Market Trajectory and Growth Vectors
The industrial workbench sector has demonstrated resilient growth over the past half-decade, reflecting the broader health of the manufacturing and technical sectors. Our analysis covers a robust historical baseline from 2020 through 2025, establishing a clear pattern of recovery and expansion following global supply chain disruptions. Building on this foundation, the forecast period from 2026 to 2032 projects a continued upward trajectory, underscored by a compound annual growth rate that signals steady demand accumulation.
Worldwide Industrial Workbench Market
Revenue figures indicate a mature yet expanding market structure. The total market size has progressed consistently from approximately 1,325 million USD in 2020 to a projected 2,255 million USD by 2032. This growth is not linear but is influenced by specific inflection points related to industrial activity, capital expenditure cycles, and material availability. For decision-makers, this historical and forecasted data provides a benchmark for budgeting and long-term capacity planning. It highlights that while the market is stable, the rate of growth necessitates a proactive approach to inventory management and capital investment rather than a reactive stance.
The strategic value of this data lies in its ability to contextualize expenditure. By understanding the overall revenue unit progression in Million USD, organizations can better gauge the scale of potential opportunities or risks associated with dependency on this equipment category. Whether for direct procurement or as a component of broader facility planning, knowing the market's financial magnitude helps in aligning internal targets with external market realities.
Total Addressable Market and Revenue Projections
The core financial intelligence within our report focuses on the Total Addressable Market (TAM) as measured by revenue. The data reveals a market that has matured beyond its initial post-pandemic recovery spikes but continues to expand due to foundational industrial trends. The transition from the base year through the forecast horizon shows a market that is accumulating value steadily.
Key highlights from the revenue analysis include:
- Confirmed market valuation trends from the historical period of 2020-2025 which serve as a validation model for future projections.
- A forecast period extending to 2032 that allows for multi-year strategic planning and budgeting cycles.
- Revenue metrics tracked in USD Million, providing a standardized currency view for global comparison.
- Growth rates that reflect the underlying demand drivers without exposing short-term volatility that could mislead immediate tactical decisions.
For enterprise leaders, these figures are not abstract numbers. They represent the total pool of capital being deployed on workbench infrastructure globally. Understanding where this capital is flowing allows organizations to assess their own market share relative to the broader industry and identify gaps in their current procurement strategies.
Segmentation Dynamics: Material and Application Drivers
A deeper dive into the market structure reveals distinct segments that behave differently based on material costs and end-user requirements. Our report dissects the market by type, covering categories such as steel workbenches, stainless steel variants, wooden top options, and specialized laminate or ESD configurations. Each material type responds differently to raw material price fluctuations and specific industry hygiene or safety standards.
Simultaneously, the application segmentation underscores where the demand is originating. Key sectors including automotive and heavy manufacturing, electronics and semiconductors, pharmaceutical and healthcare, as well as educational and research labs, drive consumption. The interplay between these segments is critical. For instance, a surge in semiconductor fabrication capacity may disproportionately increase demand for ESD-safe workstations, while a boom in heavy manufacturing infrastructure may drive volume for heavy-duty steel benches.
By analyzing these splits without exposing sensitive proprietary data points prematurely, we allow clients to see the structural composition of the market. This helps in identifying which segments align with their specific operational needs and where the greatest growth potential lies. The report details the revenue contribution of each segment, allowing clients to prioritize their focus areas based on proven market volume.
Geographic Distribution and Regional Intelligence
Geographical analysis is another cornerstone of this study. The market is distributed across major regions including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique characteristics regarding manufacturing density, regulatory environments, and labor costs.
While we maintain the confidentiality of specific regional percentage splits in this overview, the full report provides a detailed breakdown of revenue performance by territory. This is vital for multinational corporations assessing where to locate manufacturing hubs or where to focus sales efforts. For example, regions with high manufacturing output naturally correlate with higher workbench consumption, but labor regulations regarding ergonomics may differ significantly between North America and Europe. Understanding these regional nuances allows for tailored market entry strategies or optimized supply chain networks.
Competitive Landscape and Key Players
The industrial workbench market is characterized by a mix of specialized manufacturers and broader industrial conglomerates. Market concentration is moderate, with the top three firms holding a specific share of the market and the top five firms commanding a slightly larger portion. This fragmentation suggests that while there are dominant players, there is still room for niche players to compete on specialization, customization, or regional service capabilities.
Our report provides detailed profiles of key companies that define the competitive boundaries. These profiles include headquarters, operational focus, and product capabilities. Notable players analyzed in the study include:
- LISTA: Based in Erlen, Switzerland, with North American operations in Holliston, MA. They offer modular heavy-duty workbenches with high capacity and integrated storage, focusing on high-precision industries.
- Treston (including IAC Industries): Headquartered in Turku, Finland, with IAC based in Goodyear, AZ. They specialize in ergonomic, customizable workstations with strong presence in electronics and lab applications.
- Pro-Line: Located in Haverhill, MA. Known for ergonomic modular workbenches with high capacity and flexible accessories emphasizing fast delivery.
- Durham Manufacturing: Based in Durham, CT. Produces heavy-duty steel workbenches with immense load capacities suitable for industrial maintenance environments.
- Bosch Rexroth: A Germany-based entity with US locations. Provides modular ergonomic workstations using aluminum extrusion framing with integrated drive and control systems.
- Formaspace: Operating out of Austin, TX. Focuses on custom-made industrial and lab workbenches with fully welded steel frames tailored to specific configurations.
Additional entities such as Borroughs Corporation, AFC Industries, Rousseau Metal, and Shure Manufacturing Corporation are also included in the analysis, each bringing specific strengths ranging from integrated storage solutions to enclosed heavy-gauge steel designs. Understanding the positioning of these competitors helps organizations benchmark their own requirements against the best available market solutions and anticipate pricing pressures or supply constraints driven by these key actors.
Recent Developments and Innovation Cycles
The market is not static; it evolves through product launches and strategic moves by key players. Our report integrates recent developments to show where the industry is heading in terms of innovation and market presence. These events signal shifts in technology or market focus that procurement teams should monitor.
Significant recent activities captured in the analysis include:
- 4Dock: In September 2025, the company presented a full lineup of heavy-duty industrial workbenches at PACK EXPO Las Vegas, highlighting durability for warehousing and assembly applications.
- Rockwell Automation: In November 2025, they introduced the FactoryTalk Design Workbench software tool, demonstrating the convergence of physical workbenches with digital design and automation tools at relevant industry events.
- Siegmund: In March 2026, the company showcased innovative workbench and welding table systems at HOLZ-HANDWERK 2026, targeting woodworking and industrial applications.
These developments illustrate a trend toward not just physical robustness but also integration with digital workflows and specialized application needs. Staying aware of such announcements helps organizations future-proof their infrastructure investments.
Macroeconomic Factors and Supply Chain Implications
No market analysis is complete without addressing the external forces that influence supply and cost. The industrial workbench market is particularly sensitive to raw material pricing, specifically steel, as well as regulatory changes and labor dynamics. Our report contextualizes these factors to help readers anticipate cost fluctuations and supply risks.
On the raw material front, global steel markets have shown stabilization in early 2026, though prices remain near the bottom of the current cycle in certain analyses. Chinese benchmark prices for steel rebar futures and hot-rolled coil have shown minor monthly gains amid overcapacity and demand factors. For manufacturers of steel workbenches, this translates to a complex cost environment where domestic production may be favored due to tariff structures, even if global spot prices are subdued.
Regulatory changes also play a pivotal role. For instance, US Section 232 steel tariffs increased to 50% on certain imports effective June 2025, with exceptions, supporting domestic producers. This directly influences material costs for US-manufactured industrial workbenches, potentially widening the price gap between domestically sourced and imported equipment. Organizations operating in the US must factor these tariffs into their total cost of ownership calculations.
Furthermore, macro trends such as data center expansion, infrastructure projects, and energy initiatives are driving steel and manufacturing activity in 2026. These broader economic engines create a ripple effect that sustains demand for industrial workbenches. Additionally, labor cost considerations are pushing the adoption of ergonomic design features. Modern workbenches are increasingly evaluated on their ability to reduce fatigue and injury in assembly and manufacturing environments amid ongoing workforce challenges. This shifts the purchasing criteria from purely price-based to value-based, considering long-term operational health and productivity.
Strategic Recommendations and Actionable Intelligence
The ultimate goal of the Worldwide Industrial Workbench Market research is to translate data into action. Based on the synthesis of market size, segmentation, competition, and macroeconomic factors, several strategic imperatives emerge for businesses operating in 2026.
First, procurement strategies should account for the divergence in material costs and regional availability. Understanding the impact of tariffs and steel price stabilization allows for more accurate forecasting of capital expenditure. Second, the segmentation data suggests that aligning workbench specifications with the specific growth sectors—such as electronics or healthcare—can yield better ROI than a one-size-fits-all approach. Third, the competitive landscape indicates that while large players dominate volume, specialized vendors may offer superior customization for niche requirements, which is critical for high-precision or specialized lab environments.
Finally, the inclusion of recent innovations and macro trends suggests that flexibility and ergonomics are becoming key differentiators. Investing in workstations that support ergonomic standards and potential digital integration may offer long-term benefits in workforce retention and productivity, outweighing initial cost savings from lower-tier equipment.
Conclusion: Accessing the Full Intelligence
The industrial workbench market is poised for continued growth, supported by robust infrastructure demands and evolving manufacturing needs. However, capitalizing on this growth requires more than general knowledge; it requires precise, validated data and a deep understanding of the competitive and macroeconomic landscape. This overview has highlighted the structural trends, key players, and external drivers that define the market, but the specific numbers, detailed regional splits, and proprietary analysis contained in the full report offer the granularity needed for definitive decision-making.
PW Consulting invites stakeholders to delve deeper into these findings. The complete report provides the full spectrum of data, from historical baselines to forecast endpoints, and detailed segmentation revenue figures that were summarized here. By accessing the full study, organizations can equip themselves with the comprehensive intelligence necessary to optimize their industrial workbench investments and maintain a competitive edge in a dynamic global market.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Workbench Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast Global Damping Slides Market to Reach $6098.69 Million by 2032 at 6.81% CAGR with Asia Pacific Dominating Region
By PW Consulting, 2026-09-02
Strategic Intelligence in Motion: Navigating the Global Damping Slides Market Through 2032
Executive Overview: The Silent Revolution in Furniture Hardware
The global damping slides market has entered a decisive growth phase, driven by an intersection of residential renovation cycles, premiumization trends in cabinetry, and an industrial shift toward precision motion control. As decision-makers evaluate their positioning for the 2026-2032 horizon, understanding the macro trajectory of this specialized hardware segment is no longer optional—it is a strategic imperative. Our latest Worldwide Damping Slides Market research provides a comprehensive, data-grounded blueprint for navigating this evolving landscape, translating complex demand signals into actionable intelligence for procurement, product development, and competitive strategy.
Worldwide Damping Slides Market
Since 2020, the market has demonstrated consistent expansion, with total revenue rising from approximately 2,850 million USD to roughly 3,846 million USD in 2025. The forward-looking trajectory suggests sustained momentum, with the market projected to reach over 4,019 million USD in 2026 and continue its ascent toward approximately 6,099 million USD by 2032. This represents a compound annual growth rate of 6.81 percent over the forecast period, a figure that underscores both the resilience of core furniture hardware demand and the accelerating adoption of damping technologies across adjacent application verticals. For enterprise leaders, these numbers are more than historical markers; they are baseline indicators of where capital allocation, supplier partnerships, and innovation roadmaps will yield the highest return over the next several years.
Worldwide Damping Slides Market
What distinguishes this research from conventional industry summaries is its deliberate focus on decision utility. Rather than offering superficial top-line figures, the analysis dissects the structural forces shaping supply chains, pricing dynamics, and competitive differentiation. The report is designed as a strategic companion for executives who need to anticipate market inflection points, assess vendor capabilities, and align product portfolios with emerging end-user expectations. Below, we outline the core dimensions of the study and why they matter for 2026 planning cycles.
Worldwide Damping Slides Market
Market Dynamics and Structural Drivers
The damping slides sector is being reshaped by several concurrent forces that directly influence how manufacturers, distributors, and furniture brands should position themselves. First, the premiumization of residential and commercial cabinetry continues to elevate consumer and specifier expectations around touch, noise, and perceived quality. Silent closing, controlled descent, and repeatable smooth operation have transitioned from optional luxuries to baseline requirements in many customer segments. This shift is reinforced by ongoing home renovation activity worldwide, which sustains demand for replacement hardware and new furniture assemblies alike.
Second, regulatory and safety expectations are reinforcing the value proposition of integrated damping mechanisms. Standards governing user safety, noise reduction, and operational reliability in residential and commercial furniture applications are creating additional incentives for hardware suppliers to demonstrate compliant, tested performance. Companies that can document consistent damping behavior, durability under repeated cycles, and stable operation across varying load conditions are better positioned to win specification lists and long-term supply agreements.
Third, raw material economics remain a critical variable in cost planning and pricing strategy. Damping slides are primarily manufactured using cold-rolled steel, and fluctuations in steel pricing directly impact production economics and final product pricing in the furniture hardware sector. In early 2026, cold-rolled steel in the United States continues to maintain a premium over hot-rolled coil due to additional processing requirements, a structural cost nuance that warrants careful monitoring by manufacturers and procurement teams. Understanding how these input dynamics propagate through tiered supply chains is essential for maintaining margin stability while responding to competitive price pressure.
These dynamics interact with broader macroeconomic and consumer behavior trends, creating a market environment where foresight and flexibility are rewarded. The research synthesizes these forces into a coherent framework, enabling stakeholders to prioritize investments in product engineering, supplier diversification, and market-specific positioning rather than reacting to short-term fluctuations in isolation.
Segmentation Architecture and Application Realities
A central strength of this study lies in its structured segmentation architecture, which moves beyond simplistic category labels to reveal how product types and application environments shape demand patterns, engineering priorities, and commercial strategy. The analysis examines the market through multiple lenses, including product architecture, regional distribution, and end-use application, while preserving the analytical discipline required to identify where growth is genuinely accelerating versus where volume is simply consolidating.
By product type, the market encompasses distinct design philosophies that serve different functional requirements. Undermount damping slides represent a substantial share of revenue, reflecting their widespread use in modern cabinetry and furniture platforms where clean aesthetics and concealed hardware are priorities. Side-mount ball bearing slides with damping functionality continue to hold strong relevance, particularly where load capacity, adjustability, and serviceability matter. Specialty roller damping slides occupy a more focused but strategically important niche, often selected for applications demanding specific motion characteristics, durability under specialized loads, or integration with unique furniture and equipment designs.
From an application perspective, the market is anchored by end-use environments that dictate performance expectations, cycle life requirements, and price-sensitivity thresholds. Residential furniture remains a dominant application domain, driven by the ongoing renovation wave, consumer preference for soft-close features, and the broader shift toward higher-quality home interiors. Office and commercial furniture forms a second major pillar, where reliability, consistent operation, and compliance with workplace environment standards influence purchasing decisions. Industrial and healthcare cabinet applications represent a growing vector, where controlled movement, hygiene considerations, and robustness under frequent use expand the role of damping slides beyond traditional furniture contexts.
Regional analysis in the study further contextualizes how local manufacturing capacity, trade dynamics, and end-market maturity shape competitive outcomes. The research maps revenue distribution across key geographies to reveal where demand density, supplier proximity, and specification influence create advantages for incumbents and entrants alike. Rather than presenting fragmented percentage tables, the narrative integrates regional insights into strategic implications, helping leaders assess which markets warrant deeper penetration efforts, where localized sourcing may reduce cost and lead-time exposure, and how regional preference patterns should inform product configuration and marketing emphasis.
Competitive Landscape and Strategic Positioning
The damping slides market features a diversified competitive field, with established European and North American hardware manufacturers sharing the stage with capable Asian producers and specialized niche players. Market concentration metrics indicate a moderately consolidated environment, with the top three competitors accounting for roughly 34.2 percent of revenue and the top five reaching approximately 49.5 percent. This structure suggests that while scale and brand recognition confer meaningful advantages, there remains substantial room for differentiated technology, regional strength, and application-specific expertise to drive share gains.
Several companies define the competitive frontier through distinct technical and commercial approaches. Hettich, based in Kirchlengern, Germany, offers a broad range of soft-close damping drawer slides spanning undermount and side-mount systems, with integrated silent-system damping designed for smooth, quiet operation in furniture and cabinetry applications. Häfele, headquartered in Nagold, Germany, positions its damping slides and soft-close mechanisms within comprehensive furniture hardware solutions, emphasizing high-quality silent closing drawer slides for residential and commercial use. Blum, from Höchst, Austria, specializes in premium soft-close damping slides such as the Tandem Plus Blumotion series, delivering integrated hydraulic damping for full-extension, silent drawer operation in high-end cabinetry.
Accuride International, located in Santa Fe Springs, California, manufactures precision ball-bearing and soft-close or ease-close damping slides for industrial, furniture, and heavy-duty applications, including models with controlled closing features. GRASS, also based in Höchst, Austria, supplies high-performance damping drawer slides and soft-close systems optimized for smooth movement and durability in furniture manufacturing. King Slide Works Co., Ltd., from Tainan, Taiwan, produces undermount and side-mount damping slides with soft-close technology, including SIMLEAD systems for silent operation in kitchen and wardrobe cabinetry. Knape & Vogt Manufacturing Company, in Grand Rapids, Michigan, offers ball-bearing drawer slides with damping or soft-close options for residential, commercial, and industrial storage solutions.
European and Asian specialization continues to broaden the field. Salice, based in Cantù, Italy, develops Progressa and other undermount soft-close damping drawer slides with advanced hydraulic mechanisms for premium furniture applications. Sugatsune, from Tokyo, Japan, provides high-quality damping and soft-close slides for furniture, focusing on silent and reliable performance. Formenti & Giovenzana S.p.A., also known as FGV, from Veduggio con Colzano, Italy, manufactures a variety of damping drawer slides and furniture hardware components for global markets. On the specialized end, Tianchang Jinlv Fire Equipment Co., Ltd., in Tianchang City, Anhui Province, China, produces specialized shockproof damping slides for tool drawers in fire trucks and emergency vehicles. BIMATEC SORALUCE, part of the Soraluce group in Limburg, Germany, incorporates hydromechanical damping slides in INA linear guiding systems for high-precision portal milling machines and heavy machinery.
Recent activity underscores how competitive intensity is evolving through visibility, demonstration, and direct customer feedback loops. In March 2026, KAV Hardware showcased ultra-smooth silent damping slides at Interzum and CIFF Guangzhou exhibitions, highlighting new connections and customer feedback on furniture hardware. In April 2026, SanyHore conducted a live demonstration of next-generation damping slides at CIFF 2026, focusing on eliminating sticking drawers in furniture applications. These events illustrate a market where technical refinement, user experience, and specification influence are increasingly decided in front of audiences that include designers, integrators, and procurement teams. The research evaluates such developments not as isolated news items, but as indicators of where product roadmaps, channel relationships, and branding investments are likely to create durable advantage.
Critical Intelligence for 2026 Decision-Making
For executives planning 2026 initiatives, the study translates market complexity into priority questions that directly affect sourcing, product strategy, and go-to-market decisions. One of the most important considerations is how to balance cost competitiveness with performance credibility. As damping features become more expected rather than exceptional, suppliers and furniture brands must articulate why their motion characteristics, cycle reliability, and finish quality justify preference in a crowded field. The report provides frameworks for assessing whether a given product lineage supports premium positioning or whether a more value-oriented architecture is better suited to specific customer segments.
Supply chain resilience is another focal point. Because cold-rolled steel and related processing inputs influence cost structures, the research examines how manufacturers can mitigate exposure through material strategy, supplier diversification, and design-for-manufacturability choices. The analysis also considers how regional cost environments interact with logistics, tariff considerations, and lead-time expectations, helping teams evaluate whether nearshoring, localized assembly, or long-haul sourcing best fits their target markets and volume profiles.
Application-specific demand forecasting plays a central role in the study's planning utility. Rather than treating all cabinetry and storage applications as a single pool, the report differentiates between residential, office and commercial, and industrial and healthcare contexts, each with distinct specification drivers and purchasing rhythms. This granularity supports more precise capacity planning, marketing alignment, and sales enablement. It also helps identify where adjacent product opportunities—such as complementary hardware, integrated mechanisms, or customized damping profiles—can extend value beyond the core slide component.
Finally, the research emphasizes the strategic importance of demonstration and validation. As seen in recent exhibition activity, stakeholders are increasingly looking for tangible proof of smooth operation, noise reduction, and consistent closing behavior. The study explores how companies can strengthen technical credibility through testing narratives, application case evidence, and specification support, turning performance claims into trusted decision criteria.
Inside the Report: What the Analysis Delivers
The Worldwide Damping Slides Market research is structured to serve as both a foundation for strategic planning and a reference for detailed market evaluation. The full study integrates historical performance tracking across the 2020-2025 period with a forward forecast extending through 2032, giving readers a continuous view of how revenue bases have evolved and where growth momentum is expected to concentrate. This historical-to-forward linkage is essential for validating assumptions, stress-testing growth plans, and aligning internal projections with externally observed trends.
Beyond top-line market sizing, the report provides a segmentation-based interpretation of demand by product type, application, and region, enabling readers to pinpoint where the most attractive opportunities and risks reside. The competitive landscape section profiles leading manufacturers and specialized participants, examining their product philosophies, geographic footprints, and areas of differentiation. This company-level context is paired with market concentration insights, helping stakeholders understand the balance between scale-driven competition and niche positioning.
The study also incorporates sector-level context on raw material dynamics, regulatory and safety influences, and macro demand trends, ensuring that market sizing is interpreted within the operational realities that shape pricing, availability, and specification behavior. By connecting these external factors to segmentation and competitive analysis, the report equips readers to evaluate not only what the market is doing, but why it is doing it, and what that implies for their own planning assumptions.
Operational utility is reinforced through a focus on decision-relevant detail. The research is designed to support scenario discussion around market entry, product portfolio optimization, supplier evaluation, and regional expansion. It helps identify where demand is structurally expanding, where competitive intensity is rising, and where differentiation through damping performance, material strategy, or application expertise can create defensible positioning. In short, the report functions as a strategic dashboard for organizations that need to move from reactive observation to deliberate market action.
Conclusion: From Insight to Action
The worldwide damping slides market is entering a period in which technical refinement, end-user expectations, and cost discipline will jointly determine competitive outcomes. With a projected CAGR of 6.81 percent and a revenue trajectory extending toward roughly 6,099 million USD by 2032, the segment offers meaningful growth potential, but only for organizations that can translate macro trends into precise product, sourcing, and positioning choices. The difference between generic optimism and executable strategy lies in the depth of the underlying intelligence.
This research was built to close that gap. It combines historical context, forecast discipline, segmentation clarity, and competitive analysis into a single strategic reference, while intentionally leaving the most granular breakdowns and proprietary interpretation for the full study. For teams preparing 2026 decisions—whether related to supplier selection, product roadmap priorities, regional expansion, or pricing strategy—the complete report provides the level of detail required to move with confidence.
To access the full segmentation data, company-level analysis, regional revenue distributions, and forward forecasts that support detailed planning, explore the complete Worldwide Damping Slides Market research. The source page contains the full dataset and interpretive depth needed to turn these strategic observations into operational advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Damping Slides Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Throw Flashlight Market to Reach 775.12 Million USD by 2032 Driven by 5.45 Percent CAGR
By PW Consulting, 2026-09-02
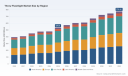
Strategic Illumination: Navigating the Worldwide Throw Flashlight Market in 2026
The global landscape for portable high-intensity lighting is undergoing a significant transformation. As organizations and professionals increasingly rely on specialized equipment for critical operations, the Worldwide Throw Flashlight Market has emerged as a vital sector within the broader illumination industry. For business leaders, investors, and strategic planners, understanding the trajectory of this market is no longer optional; it is a prerequisite for informed decision-making in 2026 and beyond.
Worldwide Throw Flashlight Market
This article serves as a precursor to the comprehensive Worldwide Throw Flashlight Market Research Report recently published by PW Consulting. Our analysis delves into the macroeconomic drivers, competitive intensity, and technological shifts defining this industry. While this overview provides actionable strategic context, the full report offers the granular intelligence required to execute precise market entries, optimize supply chains, and identify high-growth niches.
Worldwide Throw Flashlight Market
Market Trajectory and Historical Context
To understand where the market is going, one must first appreciate where it has been. The industry has demonstrated resilient growth over the past half-decade, recovering from pandemic-related supply chain disruptions and accelerating due to renewed emphasis on safety, outdoor recreation, and tactical readiness. Our historical analysis covers the period from 2020 through 2025, establishing a robust baseline for forecasting.
Worldwide Throw Flashlight Market
In 2020, the global revenue for throw flashlights stood at approximately USD 395.12 Million. By 2025, this figure climbed to USD 534.8 Million. This upward trend reflects a consistent compound annual growth rate (CAGR) of 5.45% projected through the forecast period ending in 2032. Such growth is not merely nominal; it represents an expanding addressable market driven by both replacement cycles and new adoption in professional sectors.
Looking forward, the forecast period from 2026 to 2032 suggests a continued expansion. The market is expected to reach significant milestones, surpassing the USD 600 Million threshold in the near term and advancing toward nearly USD 775.12 Million by 2032. This trajectory indicates a mature yet still growing industry where efficiency and specialization become the primary differentiators rather than mere volume.
Structural Segments and Value Distribution
The throw flashlight market is not a monolith. It is divided by technology type, application scenario, and geographic region. Each segment presents unique risk-reward profiles for stakeholders. Our research provides a detailed breakdown of these categories, but strategic overviews must highlight the structural weight of each component.
By technology, the market is dominated by LED Throw Flashlights, which command the largest share of revenue due to their energy efficiency, durability, and decreasing cost of production. However, specialized segments such as LEP (Laser Excited Phosphor) Flashlights and HID variants maintain a dedicated presence, particularly where extreme beam distance is prioritized over raw lumens. The interplay between these technologies is a key dynamic to watch, as hybrid solutions and next-generation LEDs begin to blur the lines between traditional categories.
In terms of application, demand is heavily influenced by professional and tactical requirements. Search and rescue operations remain a cornerstone of demand, alongside military and law enforcement use cases. Outdoor sports and hunting contribute a significant portion of the consumer-facing demand, while industrial inspection rounds out the professional sectors. Understanding the specific performance requirements for each application—such as beam distance, runtime, and durability—is essential for product positioning.
Geographically, the market is distributed across major global regions including North America, Europe, and the Asia Pacific region, with emerging contributions from Latin America and the Middle East and Africa. While North America and Asia Pacific represent substantial portions of the revenue base, regional nuances in regulatory compliance, consumer preference, and distribution channels require localized strategies.
Competitive Landscape and Strategic Positioning
The competitive environment in the throw flashlight market is characterized by a mix of established legacy brands and agile technology-focused manufacturers. Market concentration metrics indicate that the top three players hold approximately 38.45% of the market, while the top five control around 52.12%. This indicates a moderately consolidated market where brand loyalty and technological leadership play critical roles in maintaining share.
Several key companies define the current competitive frontier. Acebeam, headquartered in China, has positioned itself as a leader in high-performance long-throw devices. Their product lineup, including models capable of beam distances exceeding 2000 meters, targets search, rescue, and tactical applications. Their presence at major industry events like SHOT Show underscores their commitment to visibility and technological demonstration.
Fenix and Olight are other prominent Chinese manufacturers that have secured strong footholds. Fenix offers durable tactical and outdoor throw flashlights, such as the TK series, which are favored for law enforcement and professional use. Olight focuses on premium rechargeable options like the Marauder Mini 2 and Warrior series, blending high lumens with long-distance illumination for both tactical and everyday carry scenarios.
Nitecore continues to innovate with long-throw models like the P30i and MH25 PRO, targeting hunting and rescue professionals with beams reaching over 1000 yards. Meanwhile, American manufacturers maintain a strong presence in the high-end tactical segment. Streamlight manufactures reliable tactical and professional throw flashlights for law enforcement, firefighting, and industrial applications. SureFire focuses on high-end tactical illumination designed for demanding military and law enforcement environments, emphasizing durability and reliability.
Modlite, also based in the USA, focuses on professional-grade tactical throw lights like the PLHv2, emphasizing superior beam quality for military and law enforcement applications. On the enthusiast and value-driven side, companies like ThruNite, Speras, Lumintop, Wurkkos, and Imalent compete on specific performance metrics. ThruNite is known for the Catapult series optimized for beam distance and efficiency. Speras has positioned itself as an agile performer in 2026, emphasizing lumens versus candela optimization. Lumintop produces specialized throwers like the GT Nano series. Wurkkos delivers affordable high-performance options like the TS30S PRO. Imalent specializes in ultra-high output flashlights holding brightness records suitable for extreme scenarios.
Recent Developments and Industry Dynamics
The market is dynamic, with product launches and strategic shifts occurring regularly. In January 2026, Coast launched the Longshot L50R spotlight, capable of throwing 5000 lumens up to 1 km, featuring dual spotlight/flood modes and accessories for camp and search use. This launch highlights the trend toward multi-functionality in high-output devices.
Also in January 2026, Acebeam exhibited at SHOT Show 2026, showcasing new long-throw flashlight models including the W40 with next-gen LED and lens technology. This followed their participation in SHOT Show 2025, indicating a continuous pipeline of innovation. In March 2026, Speras updated its product positioning to emphasize agile performance in tactical throw flashlights, focusing on the optimization of lumens versus candela.
Beyond product launches, broader industry dynamics are shaping the market. Regulatory and safety compliance standards are driving participants to integrate USB-C rechargeable technology and improved LED efficiency. This shift reduces reliance on disposable batteries and aligns with broader sustainability goals in industrial and professional sectors.
Raw material costs remain a critical factor. LED and lithium-ion battery component costs influence margins in high-performance throw flashlights, especially given the demand for higher candela and lumen outputs. Supply chain stability for these components is a strategic vulnerability that manufacturers must manage.
Consumer habits are also evolving. Rising participation in outdoor recreational activities such as camping, hiking, hunting, and search & rescue drives demand for long-throw flashlights with focused beams exceeding 500-2000 meters. This trend blurs the line between consumer and professional gear, requiring manufacturers to design products that satisfy both durability needs and performance expectations.
Furthermore, tactical and professional models must meet stringent durability and performance requirements for law enforcement, military, and firefighting applications. Compliance with these standards often dictates design choices, materials, and testing protocols, creating barriers to entry for less established players.
Strategic Value of Comprehensive Market Research
For decision-makers in 2026, access to high-level trends is useful, but deep intelligence is transformative. The full PW Consulting Worldwide Throw Flashlight Market Report moves beyond general observations to provide the specific data architecture necessary for strategic execution.
Why this research matters now:
- Precision in Forecasting: While general growth rates provide direction, detailed segment-specific forecasts allow for accurate capacity planning and inventory management. Knowing exactly how demand shifts between LED and LEP technologies, or between tactical and outdoor applications, enables companies to allocate resources efficiently.
- Competitive Intelligence: Understanding the exact market share, revenue streams, and strategic moves of key competitors like Acebeam, Streamlight, and Nitecore allows companies to identify gaps in the market. Our report analyzes product positioning, pricing strategies, and technological roadmaps to help you anticipate competitor actions.
- Risk Mitigation: With fluctuating raw material costs and evolving regulatory standards, supply chain resilience is paramount. The report includes analysis of cost drivers and compliance requirements, helping organizations hedge against volatility in component pricing and regulatory shifts.
- Market Entry and Expansion: For companies looking to enter new geographic regions or application segments, granular data on regional revenue distributions and application-specific demand is crucial. Our segmentation analysis provides the insights needed to tailor go-to-market strategies effectively.
- Technology Roadmapping: As LED efficiency improves and new technologies like LEP mature, knowing the adoption curves and performance thresholds helps R&D teams prioritize development efforts. The report details the technological landscape to guide innovation priorities.
Conclusion and Next Steps
The Worldwide Throw Flashlight Market is poised for continued growth through 2032, driven by a combination of professional demand, recreational trends, and technological advancement. However, capturing value in this market requires more than a general understanding of growth rates. It demands a nuanced appreciation of segment dynamics, competitive maneuvers, and the operational realities of manufacturing high-performance lighting solutions.
This article has outlined the macro-environment and highlighted the key players shaping the industry. Yet, the specifics of revenue splits, exact regional valuations, and detailed application breakdowns remain essential for crafting a winning strategy. To access the complete dataset, detailed segmentation analysis, and comprehensive company profiles, we invite you to consult the full Worldwide Throw Flashlight Market Research Report .
Equip your organization with the intelligence needed to navigate the complexities of the flashight market in 2026. Download the full report to transform market uncertainty into strategic advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Throw Flashlight Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Worldwide Freezing Point Laser Hair Removal Market to Reach $1,165.04 Million in 2025 with 12.85 Percent CAGR Forecast to 2032
By PW Consulting, 2026-09-02
Strategic Intelligence for 2026: Navigating the Worldwide Freezing Point Laser Hair Removal Machines Market
As the global aesthetics industry accelerates into a new phase of commercialization and technological refinement, freezing point laser hair removal has emerged as one of the most consequential capital equipment categories for clinic operators, medical spas, and aesthetic distributors. PW Consulting has released an updated Worldwide Freezing Point Laser Hair Removal Machines Market research report covering the historical period from 2020 through 2025 and a forward-looking forecast window from 2026 to 2032. This study is designed as a decision-grade intelligence asset for executives who must evaluate equipment procurement, channel strategy, regulatory navigation, and competitive positioning in a market that continues to demonstrate strong structural momentum.
Worldwide Freezing Point Laser Hair Removal Machines Market
The total market revenue expanded from approximately 625.4 million USD in 2020 to 1,165.04 million USD in 2025, reflecting sustained adoption of contact cooling-based permanent hair removal platforms across professional clinic settings. The report models continued expansion through 2032, with 2026 projected at 1,295.63 million USD and growth compounding toward 2,715.51 million USD by the end of the forecast period. At the core of this trajectory sits a forecast CAGR of 12.85 percent, a rate that signals durable demand rather than a short-lived procurement cycle. For strategy leaders, the implication is clear: freezing point laser platforms are no longer a peripheral aesthetic offering. They are becoming an integral part of standardized service menus in skin and body clinics, which means equipment selection, supplier relationships, and compliance readiness must be treated as long-term strategic choices rather than isolated purchasing events.
Worldwide Freezing Point Laser Hair Removal Machines Market
This market research introduction is structured as a strategic preview. It highlights the analytical framework, market structure, competitive dynamics, and operational considerations embedded in the full report. Core regional revenue splits, detailed sub-segment proportions, and granular financial breakdowns are intentionally reserved for the complete publication. The objective is to provide executives with enough analytical context to understand why this dataset matters for 2026 planning, while preserving the full granularity for teams that require precise market modeling, pricing strategy, and product roadmap inputs.
Worldwide Freezing Point Laser Hair Removal Machines Market
Market Trajectory and the Strategic Value of the 2026 Forecast Window
The 2026 to 2032 forecast period is especially relevant for organizations that are currently finalizing capital expenditure plans, expanding into new geographies, or refreshing their clinical technology portfolios. The published market evolution shows a consistent upward path: 732.47 million USD in 2021, 799.17 million USD in 2022, 893.64 million USD in 2023, and 999.77 million USD in 2024. That progression establishes an important baseline. It indicates that demand growth did not depend on a single product cycle or regional surprise. Instead, it reflects broad-based uptake of laser-based hair removal systems built around freezing point cooling principles, where sustained comfort, repeatable treatment outcomes, and broader skin-type compatibility have become central purchase criteria.
From a strategy perspective, a 12.85 percent CAGR in this category suggests several distinct planning implications. First, the addressable demand base is expanding quickly enough that delayed procurement or outdated equipment choices can create competitive disadvantage in service delivery speed, patient comfort, and treatment throughput. Second, the growth rate is strong enough to justify disciplined investment in supplier evaluation, certification tracking, and after-sales service readiness, but not so speculative that it warrants unverified expansion assumptions. Third, the forecast horizon allows executives to benchmark internal revenue targets against published market momentum, helping to separate realistic capacity planning from aggressive top-line aspirations.
The full report extends the data series through 2032, which provides a long enough runway to assess whether current equipment portfolios will remain aligned with market demand or whether platform upgrades, wavelength diversification, and cooling technology refreshes will be required to maintain service competitiveness. For capital-intensive clinic models, this foresight is particularly valuable because the wrong platform decision can affect service perception, patient retention, and operational continuity for several years.
Market Structure and the Analytical Framework Inside the Report
The study is organized around the categories that matter most to commercial decision-makers: regional demand distribution, laser technology segmentation, and end-user deployment patterns. Rather than presenting these categories as isolated tables, the report integrates them into a working competitive map that shows how technology preferences, service channels, and regional procurement behavior interact. This approach allows readers to move beyond top-line market size and understand where demand is concentrated, how technology mix is shifting, and which end-user environments are driving equipment volume.
The regional framework captures demand across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region carries different purchasing dynamics, service expectations, and regulatory environments, and the report evaluates these differences in a way that supports market-entry planning and channel prioritization. The technology framework examines the three primary categories shaping the category: diode laser systems, alexandrite laser systems, and Nd:YAG laser systems. These technology tracks are central to product positioning because wavelength selection, cooling design, and treatment protocols directly influence clinical versatility and patient experience. The end-user framework breaks the market into medical spas and beauty clinics, hospitals, and home use devices, enabling an assessment of where professional capital equipment demand is strongest and how non-clinical channels are developing.
For executives, this structure matters because freezing point laser hair removal is not a uniform product category. It is a portfolio of solutions that must match the needs of different clinical settings, patient populations, and purchasing cultures. A system optimized for high-throughput beauty clinics may differ materially from one prioritized for hospital-based dermatology services or from a consumer-facing home device ecosystem. The report’s segmentation architecture is designed to help clients map their offerings to the correct demand pockets instead of relying on broad assumptions.
At the same time, the report preserves strategic discretion. It does not reduce the analysis to simplistic proportional comparisons or expose every sub-segment revenue figure in the overview. That design choice reflects the reality that market intelligence is most valuable when it supports internal modeling and confidential decision-making. Readers who need precise regional values, detailed technology shares, and exact end-user splits are directed to the full publication, where those figures are presented in a structured, actionable format.
Competitive Landscape: Positioning, Certification, and Technology Differentiation
The competitive environment in freezing point laser hair removal equipment is defined by a mix of established global players, China-based manufacturers with expanding export footprints, and specialist firms pursuing regulatory clearance and clinical differentiation. The report profiles leading companies and examines how they compete across wavelength versatility, cooling performance, certification status, and OEM/ODM capability. Rather than treating competition as a static ranking, the analysis frames it as a set of strategic choices about who serves which channel, with what clinical promise, and under which regulatory protections.
One of the most important competitive themes is the convergence of multi-wavelength diode platforms with continuous freezing point cooling. Several profiled manufacturers now emphasize systems built around 808/810nm diode output, with triple-wavelength combinations such as 755nm, 808nm, and 1064nm, and in some cases quadruple wavelength configurations. These setups are marketed to support broader skin-type coverage and more flexible treatment protocols, often supported by in-motion sliding technology, sapphire cooling tips, and low energy density approaches intended to improve patient comfort. For buyers, this shift raises the importance of understanding whether a platform’s technical claims are aligned with their clinical use cases, throughput targets, and after-sales support requirements.
Regulatory readiness is another defining competitive factor. Devices in this category commonly hold FDA 510(k) clearance or registration alongside Medical CE and ISO13485 compliance to support professional clinic and medical spa use. This regulatory layer is not merely administrative. It influences purchasing confidence, export eligibility, and the ability to position equipment as safe and suitable for professional environments. Recent developments reinforce that point. In late 2025, MLKJ, also associated with Weifang Mingliang Electronics Co., Ltd., unveiled a new commercial triple-wavelength diode laser hair removal machine developed with FDA compliance in mind for North American clinics, emphasizing safety and trust in aesthetic settings. Around the same period, Winkonlaser, also referenced as AresLite, received FDA 510(k) clearance for its DM40P non-crystal diode laser hair removal system for professional use. These actions illustrate how certification and market access are becoming strategic differentiators, especially for companies targeting regulated clinic channels.
The competitive set also includes firms with strong OEM/ODM orientations. For example, Beijing Superlaser Technology Co., Ltd. focuses on professional aesthetics and medical laser equipment under the Boslaser brand, with certifications including FDA, Medical CE, TUV, and ISO13485, positioning itself for broader channel partnerships rather than only direct brand sales. Other profiled manufacturers emphasize cooling stability and clinical comfort through compressor refrigeration, TEC cooling, sapphire head cooling, and skin-contact temperature control in the range of 0 to 5°C or lower. Alma Lasers, with global operations and Israeli headquarters, represents a different competitive layer through platforms such as the Soprano ICE and Titanium series, which combine ICE Plus continuous contact cooling with SHR in-motion technology and multi-wavelength diode laser approaches designed for all skin types.
Market concentration data further clarifies the competitive context. The report notes a CR3 of 41.25 percent and a CR5 of 56.8 percent, indicating that a relatively small group of suppliers accounts for a meaningful share of total market revenue, while still leaving substantial room for specialist entrants, regional players, and OEM-focused manufacturers. This structure matters for pricing negotiations, supply security, and partnership strategy. Companies evaluating suppliers must weigh the benefits of scale and established compliance support against the flexibility and customization potential offered by smaller or more specialized manufacturers.
Industry Dynamics Shaping Equipment Demand in 2026
Beyond equipment specifications and competitor profiles, the research incorporates broader industry dynamics that influence purchasing behavior and market growth. One important operational consideration is clinic startup economics. Industry modeling indicates that launching a laser hair removal clinic requires initial capital expenditure totaling approximately 570,000 USD, including equipment acquisition and a cash buffer of around 335,000 USD to support operations until break-even, which typically occurs in about six months. This type of financial context is directly relevant to equipment decision-making because capital intensity affects supplier selection, leasing vs. purchasing choices, and the pace at which a new clinic can build a treatment catalog around freezing point laser platforms.
Regulatory consistency also continues to shape market behavior. Devices in this category commonly rely on FDA 510(k) clearance or registration combined with Medical CE and ISO13485 compliance. These credentials support professional positioning and help reassure operators that the equipment is intended for clinical environments. At the same time, reimbursement realities remain an important constraint: laser hair removal for cosmetic indications is generally not covered under standard Medicare CPT/DRG codes and is treated as an out-of-pocket patient expense. That reimbursement posture reinforces the commercial importance of patient experience, perceived efficacy, and service convenience, since demand is driven by discretionary spending rather than insured treatment pathways.
Technology integration is another dynamic reshaping expectations. Multi-wavelength diode configurations combined with continuous sapphire or compressor-based freezing point cooling have become the standard framework for painless, all-skin-type hair removal in professional capital equipment. This standardization creates both opportunities and risks for buyers. On one hand, it improves the comparability of platforms and raises the baseline for clinical comfort. On the other hand, it means differentiation increasingly depends on service quality, warranty support, training, consumables access, and the credibility of technical claims. The full report evaluates these dynamics in greater depth so that readers can anticipate how competitive pressure may influence price, performance expectations, and channel behavior over the forecast period.
What the Full Report Delivers for Executive Decision-Making
While this introduction outlines the strategic arc of the market, the full PW Consulting report is built to support tangible planning tasks. It provides a structured basis for evaluating where freezing point laser hair removal equipment demand is strongest, which technology families are gaining relevance, and how competitive and regulatory forces are reshaping procurement priorities. The document is intended for teams that need more than narrative context: they require a usable reference for market sizing, segment mapping, and supplier benchmarking.
The report details how regional demand patterns differ, enabling readers to assess entry timing, distribution focus, and localized compliance considerations without relying on generic global assumptions. It examines technology segmentation in a way that helps organizations understand whether their product strategy should emphasize diode platforms, alexandrite systems, Nd:YAG solutions, or multi-wavelength combinations, depending on target patient populations and clinical workflows. It also analyzes end-user deployment across medical spas and beauty clinics, hospitals, and home use devices, which is critical for firms deciding whether to prioritize professional capital equipment, clinical service partnerships, or consumer-oriented channels.
In addition, the full study incorporates competitive profiling and recent regulatory and product developments so that readers can benchmark supplier credibility and monitor market-access moves that may change purchasing confidence. It places these findings in the context of market concentration, capital intensity, reimbursement limits, and technology standardization, giving executives a more complete view of the forces that will affect pricing, service expectations, and adoption speed through 2032.
For organizations planning 2026 investments, the report offers a structured way to test assumptions. It helps answer questions such as whether demand momentum is strong enough to justify expanded equipment portfolios, how much emphasis should be placed on cooling performance and wavelength flexibility, and which competitive or regulatory signals should be monitored closely before committing to a supplier or channel strategy. By combining market sizing, segmentation, competitive analysis, and operating dynamics in a single framework, the research is designed to reduce uncertainty in decisions that are expensive and long-lived.
How to Use This Research for 2026 Strategy
The most effective use of this market study is not passive reading. It is active alignment with internal planning processes. For product and procurement leaders, the report provides a reference point for evaluating whether current equipment specifications remain aligned with market expectations around comfort, skin-type coverage, and professional certification. For commercial and distribution teams, it supports decisions about which geographies and end-user environments deserve closer attention. For financial and executive teams, it offers a market-level growth benchmark that can be compared with internal sales targets, capacity plans, and investment thresholds.
Because the overview intentionally reserves detailed regional, technology, and end-user figures for the complete publication, organizations that need precise inputs for financial modeling, pricing decisions, or supplier shortlists are encouraged to access the full report. The strategic narrative presented here is intended to establish trust in the analytical approach and to make clear why the dataset is relevant, while leaving the complete quantitative detail for readers who require it for execution-level planning.
Closing Perspective
The Worldwide Freezing Point Laser Hair Removal Machines Market is entering a phase in which growth, technology maturity, and regulatory expectations are reinforcing one another. The 2020 to 2025 historical record demonstrates sustained expansion, and the 2026 to 2032 forecast profile points to continued double-digit momentum. For companies operating in aesthetic equipment, clinic services, or medical beauty distribution, the strategic question is no longer whether the category is expanding, but how to position products, partnerships, and compliance readiness to benefit from that expansion without overcommitting to assumptions that outpace market reality.
This PW Consulting research introduction has outlined the key structural elements behind that growth trajectory: a strong macro market path, a segmentation framework that reflects real commercial differences, a competitive landscape shaped by both scale and specialization, and operating dynamics that affect clinic economics and procurement choices. The complete report builds on this foundation with detailed market data and actionable analysis reserved for decision-makers who need precision intelligence. For teams preparing for 2026 commitments, that depth is where the strategic value becomes fully usable.
For detailed analysis of this topic, please visit the official page: Worldwide Freezing Point Laser Hair Removal Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


