



Category: market research
PW Consulting Forecasts Portable X-ray Market to Surpass USD 10 Billion by 2032 with 8.5 CAGR Driven by Digital Radiography and Home Healthcare
By PW Consulting, 2026-09-02
Navigating the Portable X-ray Horizon: Strategic Intelligence for 2026 and Beyond
The global medical landscape is undergoing a profound transformation, driven by aging populations, the decentralization of care, and an relentless pursuit of clinical efficiency. Within this shifting terrain, portable X-ray devices have emerged not merely as ancillary tools, but as critical infrastructure enabling point-of-care diagnostics, emergency responsiveness, and home-based patient management. As we step into 2026, the market for these devices stands at a pivotal inflection point, characterized by accelerating adoption, technological maturation, and a competitive environment that rewards foresight. PW Consulting's latest Worldwide Medical Portable X-ray Device Market study offers a rigorous exploration of this ecosystem, providing the strategic clarity executives need to navigate the complexities of the next growth cycle.
Worldwide Medical Portable X-ray Device Market
This analysis is not just a retrospective review of past performance; it is a forward-looking compass designed to inform capital allocation, product development, partnerships, and market entry strategies. The convergence of favorable macroeconomic indicators, evolving reimbursement frameworks, and a wave of regulatory approvals creates a dynamic environment where timing and precision are paramount. Understanding the underlying currents that will shape demand through 2032 is essential for any organization positioning itself in the medical imaging sector.
Worldwide Medical Portable X-ray Device Market
The Macro Trajectory: An Eight-Year Growth Window
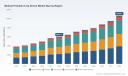
The baseline data paints a compelling narrative of sustained expansion. Building on a historical foundation from 2020 to 2025, the market has demonstrated resilience and consistent upward momentum. Revenue figures, expressed in USD Millions, reflect a trajectory where the collective value has grown substantially, moving from early base-year levels to a robust valuation in 2025. This historical performance sets the stage for a forecast period spanning 2026 to 2032, during which the market is projected to continue its ascent at a Compound Annual Growth Rate (CAGR) of 8.5%.
Worldwide Medical Portable X-ray Device Market
Such a growth rate signals more than incremental progress; it indicates a structural shift in how diagnostic imaging is deployed and reimbursed. The forecast extends to 2032, offering a long-horizon view that captures the full lifecycle of technology adoption curves and capital investment cycles. For strategic planners, this eight-year window is critical. It allows for the alignment of product roadmaps with anticipated demand surges, the anticipation of capacity constraints, and the evaluation of lifecycle profitability. The projection is not static; it is a living estimation that accounts for the interplay of drivers, restraints, and external shocks, providing a probabilistic framework for scenario planning.
Structural Dynamics and Demand Drivers
The growth narrative is underpinned by a confluence of operational and financial factors that are reshaping the healthcare delivery model. Recent intelligence regarding hospital capital expenditures reveals that executives surveyed in late 2025 anticipate a year-over-year increase in 2026 CapEx, driven predominantly by operational surplus, escalating patient volumes, and localized fiscal commitments. This willingness to invest in infrastructure creates a receptive environment for advanced imaging equipment. However, this investment appetite exists alongside significant pressure on operating margins. Data through early 2026 indicates that expense growth in drugs and medical supplies has outpaced revenue gains, resulting in challenging margin conditions. In this context, portable X-ray solutions that offer workflow efficiencies, reduced downtime, and superior dose management become highly attractive, as they directly contribute to operational leverage and cost containment.
Reimbursement dynamics further modulate market behavior. Proposed adjustments for 2026 Medicare allowances regarding portable X-ray transportation codes have been refined using specific inflation factors, with state-level rates reflecting normalized survey data and geographic cost indices. These adjustments influence the economics of mobile imaging services, particularly in fee-for-service and value-based care models. Organizations must understand how these coding nuances affect revenue cycles and the viability of portable deployment in various care settings. Simultaneously, the regulatory landscape is expanding the addressable market. A series of FDA 510(k) clearances between 2025 and early 2026 for systems from key players has opened new clinical indications and reinforced the safety and efficacy profiles of portable units. This regulatory activity reduces barriers to adoption and signals to the market that innovation in portability is being actively validated.
Segmentation Intelligence: Technology, Application, and Regional Nuances
While headline figures capture the scale of opportunity, the true strategic value lies in dissecting the market's architecture. The report provides a granular view across multiple dimensions, revealing where value is concentrated and where differentiation is most viable.
Technology Shifts: The Digital Dominance
The technology landscape is undergoing a decisive shift. Digital Radiography (DR) has established itself as the dominant modality, far outpacing Analog Radiography in revenue contribution. This divergence is not accidental; it reflects the clinical and operational advantages of digital systems, including faster image acquisition, superior workflow integration, wireless detector flexibility, and enhanced dose management capabilities. The trajectory suggests that analog solutions will increasingly serve niche or legacy roles, while growth capital and R&D focus will remain anchored in digital ecosystems. For manufacturers and investors, the implication is clear: competitive advantage is increasingly tied to the sophistication of digital interfaces, detector performance, and the seamless integration of imaging data into hospital information systems.
Application Spread: Where the Volume Lies
Demand is distributed across a spectrum of care settings, each with distinct purchasing drivers. Hospitals remain the primary anchor for volume, driven by the need for bedside imaging in critical care, emergency department throughput, and inpatient diagnostics. However, the market extends well beyond the hospital walls. Diagnostic centers, home healthcare providers, and ambulatory care centers represent significant and growing segments. The rise of home healthcare is particularly notable, reflecting a broader industry push toward aging-in-place solutions and decentralized care. Portable devices that offer ease of use, battery operation, and robust connectivity are well-positioned to capture this expanding application base. Understanding the specific requirements of each application segment is essential for tailoring product features and sales strategies.
Regional Landscape: Diversification and Intensity
Geographically, the market exhibits a complex pattern of distribution. North America continues to command a substantial share, supported by established reimbursement structures, high adoption rates of advanced imaging, and a mature competitive field. Europe maintains a strong presence, characterized by diverse healthcare systems and a focus on efficiency and standardization. Asia Pacific represents a dynamic and rapidly evolving region, where expanding healthcare infrastructure, rising middle-class populations, and increasing disease burdens are fueling demand. Latin America and the Middle East & Africa, while smaller in absolute terms, offer growth potential driven by healthcare modernization initiatives and the introduction of cost-effective solutions. The report delves into the specific nuances of these regional markets, identifying local competitive dynamics, regulatory pathways, and infrastructure readiness without exposing the precise breakdown of values, preserving the depth of insight for the full analysis.
Competitive Arena: Key Players and Strategic Postures
The market is defined by a competitive cohort of global and regional players, each pursuing distinct strategies to capture share and drive innovation. The concentration of the market is notable, with the top three players accounting for a significant portion of revenue, and the top five consolidating a substantial majority. This concentration suggests a landscape where scale, brand equity, and technological leadership provide defensive moats, yet it also leaves room for agile entrants and niche innovators to carve out positions through specialization.
GE Healthcare and Philips Healthcare represent established giants with comprehensive portfolios. GE's focus on high-image quality, AI integration, and dose management in series such as the Optima XR220 and XR240 underscores a commitment to clinical excellence and smart imaging. Philips emphasizes workflow efficiency and wireless detectors, with systems like the MobileDiagnost wDR designed to streamline bedside imaging in critical care environments. Siemens Healthineers continues to leverage its reputation for engineering precision with the Mobilett series, focusing on mobility and image quality in emergency and inpatient settings.
Carestream Health has built a strong presence with DRX-Revolution and similar portable digital systems, known for ease of use and suitability for emergency and bedside applications. Fujifilm Healthcare contributes with lightweight, high-resolution designs in the FDR Go series, targeting point-of-care needs. Canon Medical Systems offers reliable, dose-optimized solutions with platforms like RadPro, emphasizing clinical versatility. Shimadzu Corporation delivers high-speed imaging and dose efficiency through its MobileDaRt Evolution and MobileArt series. Samsung Medison has gained traction with compact, battery-operated systems like the GM85 and XGEO Mobile DR, highlighting portability and advanced digital imaging for point-of-care use.
Emerging and regional players are also reshaping the competitive landscape. Mindray from China targets cost-effective, high-performance solutions for hospitals and clinics globally. OXOS Medical has made waves with its ultra-portable MC2 system, featuring low radiation profiles, dynamic digital radiography, fluoroscopy, and specific pediatric indications, recently expanding its FDA clearance to include pediatric imaging. MinXray specializes in compact, durable systems for medical, veterinary, and field applications. Source-Ray manufactures high-output systems for mobile and clinical settings. DRGEM offers the PROMO Mobile X-ray System with FDA clearance for diagnostic imaging in hospital and clinic environments. United Imaging Healthcare rounds out the field with the uDR 380i Pro mobile X-ray system, utilizing digital radiography for versatile diagnostic use.
Recent regulatory and product developments highlight the pace of innovation. Throughout 2025 and early 2026, multiple manufacturers secured FDA 510(k) clearances for new or expanded indications. OXOS Medical achieved initial clearance for its MC2 system in January 2025, followed by an expansion for pediatric imaging in March 2026, underscoring the trend toward specialized, low-dose solutions. Poskom Co., Ltd. received clearance for its Airbile-100 Mobile X-ray Unit in December 2025. REMEDI Inc. and DK Medical Systems Co., Ltd. also secured clearances in mid-2025 for their respective portable systems. These approvals reflect a broadening of the market's technological and clinical boundaries, creating opportunities for differentiated positioning and accelerated adoption.
Strategic Imperatives for 2026 Decision-Makers
Translating market intelligence into action requires a disciplined approach. The report equips leaders with the insights necessary to address several critical strategic imperatives.
-
Portfolio Alignment and Technology Roadmapping : Decision-makers must evaluate their product portfolios against the accelerating shift toward digital radiography and the demand for features such as AI integration, wireless detectors, and dose optimization. Investment should be directed toward innovations that address workflow efficiency and clinical outcomes, ensuring that offerings remain aligned with the evolving expectations of hospital administrators and clinicians.
-
Market Entry and Expansion Strategies : For organizations considering geographic expansion or entry into new application segments, understanding regional nuances is vital. The disparity in market maturity, reimbursement environments, and competitive intensity across North America, Europe, Asia Pacific, and other regions demands tailored Go-to-Market strategies. The report provides the contextual intelligence needed to prioritize markets, identify partnership opportunities, and navigate local regulatory requirements.
-
Competitive Positioning and Differentiation : In a market with significant top-tier concentration, differentiation is key. Companies must assess their competitive standing relative to the capabilities of major players and the emerging threat of agile entrants. Strategies may include focusing on niche applications, leveraging cost advantages, enhancing service and support ecosystems, or pursuing strategic alliances and licensing agreements to access new technologies or distributions channels.
-
Capital Planning and Risk Management : With hospital CapEx trends indicating growth but operating margins under pressure, the value proposition of portable X-ray systems must be articulated in terms of total cost of ownership, utilization rates, and revenue impact. The report's analysis of reimbursement dynamics, expense trends, and regulatory changes helps leaders model financial scenarios and mitigate risks associated with policy shifts or economic volatility.
-
Regulatory Agility and Quality Assurance : The recent wave of FDA clearances illustrates the importance of maintaining a robust regulatory strategy. Organizations should monitor clearance trends and ensure their quality management systems are aligned with evolving standards, particularly as indications expand to include specialized populations such as pediatric patients or new anatomical areas.
Conclusion: Securing a vantage point in a dynamic market
The Worldwide Medical Portable X-ray Device Market is entering a phase of sustained expansion, driven by technological advancement, shifting care delivery models, and a complex competitive environment. For executives and investors, the ability to anticipate changes and act decisively will determine success. PW Consulting's comprehensive study offers a deep dive into the forces shaping this market, providing the data, analysis, and strategic perspectives needed to navigate the forecast period with confidence. By examining the interplay of macro trends, segmentation dynamics, competitive moves, and regulatory developments, this research serves as an indispensable tool for charting a course toward growth and resilience. The full intelligence contained in the report reveals the precise contours of opportunity, enabling stakeholders to make informed decisions that align with their long-term objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Medical Portable X-ray Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report Projects Worldwide New Energy Vehicle Fast Charging Market to Hit 32.8 Billion USD by 2025 with 28.45% CAGR
By PW Consulting, 2026-09-02
Global New Energy Vehicle Fast Charging Technology Market: Strategic Intelligence for 2026 Corporate Decision-Making
The worldwide transition toward electrified mobility has reached a critical inflection point. No longer confined to pilot deployments and policy-driven subsidies, the new energy vehicle ecosystem now demands charging infrastructure capable of matching vehicle throughput, grid constraints, and consumer expectations for speed and reliability. Our latest Worldwide New Energy Vehicle Fast Charging Technology Market research report provides the structural intelligence required to navigate this acceleration. Built on a historical baseline spanning 2020 through 2025 and extending a forward-looking forecast through 2032, the study translates macro-scale momentum into actionable frameworks for capital allocation, technology selection, channel strategy, and regulatory positioning. For executives operating in 2026, the difference between reactive investment and compounding advantage lies in understanding not just how large the market is becoming, but where value is concentrating, which technical architectures are displacing legacy systems, and how policy and input-cost dynamics will reshape unit economics over the next several years.
Worldwide New Energy Vehicle Fast Charging Technology Market
The market has expanded from an estimated 8.5 billion USD in 2020 to 32.8 billion USD in 2025, reflecting a sustained compound annual growth trajectory that underscores both demand intensity and supply-side readiness. Looking ahead, the forecast period projects a continued expansion arc, with market valuation expected to reach approximately 41.9 billion USD in 2026, advance toward 55.8 billion USD in 2027, and approach 112.1 billion USD by 2030, ultimately trending toward nearly 190 billion USD by 2032. These trajectories are anchored by a forecast compound annual growth rate of 28.45 percent, a figure that signals structural rather than cyclical growth. Such momentum is not evenly distributed across segments, geographies, or technology pathways. Rather, it reflects accelerating commercial deployment cycles, regulatory mandates that compress planning horizons, and the gradual standardization of high-power architectures that were once considered specialized or speculative.
Worldwide New Energy Vehicle Fast Charging Technology Market
Why 2026 Is a Defining Window for Strategic Planning
Entering 2026, decision-makers face a landscape where charging infrastructure has shifted from a supporting utility to a core competitive variable. Fleet operators weigh depot charging throughput against route utilization; public charging networks balance site acquisition costs with power availability; automakers align connector strategies and battery architectures with expected fast-charging availability; and equipment manufacturers navigate component pricing, thermal management demands, and interoperability requirements. The research report is structured to convert this complexity into a decision-ready architecture. It maps the historical growth trajectory that established baseline adoption patterns, then layers forward-looking analysis covering technology segmentation, power output tiers, regional deployment dynamics, and competitive positioning. By anchoring the analysis in a consistent methodology spanning both retrospective and prospective timeframes, the study enables organizations to benchmark internal assumptions, stress-test capacity plans, and identify the operational inflection points where early positioning compounds into durable advantage.
Worldwide New Energy Vehicle Fast Charging Technology Market
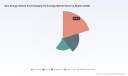
A central feature of the report is its cross-sectional segmentation architecture. Technology pathways are examined through the lens of commercial readiness, power architecture, and deployment context. DC fast charging has established itself as the dominant throughput backbone for public and corridor-based networks, while ultra-fast charging variants are increasingly targeted at high-traffic nodes where dwell time minimization carries direct commercial and user-experience value. Wireless fast charging, though currently representing a smaller share of aggregate activity, is tracked as a complementary pathway with distinct integration characteristics for controlled environments and specific fleet or destination applications. Power output segmentation further clarifies deployment logic, with mid-range output tiers addressing broader coverage requirements and higher output tiers reserved for corridors, hubs, and fleet operations where throughput and peak demand management justify greater capital and grid interconnection complexity. The report deliberately avoids flattening these distinctions into a single headline number. Instead, it quantifies how each segment contributes to overall momentum, where adoption curves diverge, and which structural factors will determine relative share shifts as the market matures.
Technology and Power Architecture Differentiation
Understanding fast charging technology evolution requires moving beyond nominal power ratings to the underlying engineering, economic, and operational trade-offs that shape real-world performance. Silicon carbide power modules have become a defining component for high-efficiency, high-power chargers, with pricing dynamics for these modules tracked at a meaningful cost per kilowatt of capacity as of late 2024. This input-cost environment influences not only equipment pricing but also the feasibility of modular scaling, site-level power budgeting, and the commercial viability of ultra-fast configurations in markets where utility interconnection and demand charges remain significant. Liquid-cooled architectures and advanced thermal management strategies are similarly central to sustaining output levels above traditional thresholds without compromising reliability or inflating maintenance exposure. The report examines how these engineering shifts are translating into product roadmaps, site design assumptions, and total-cost-of-ownership calculations across public networks, commercial fleets, and destination charging environments.
Simultaneously, the standardization landscape continues to reshape interoperability expectations and network economics. Bidirectional power transfer capabilities are being formalized within applicable international standards, extending the functional envelope of DC fast charging infrastructure beyond one-way energy delivery. This development carries implications for grid integration, energy management, and future service models that may link vehicle availability, stationary storage, and demand response. The research captures these standardization signals as part of a broader assessment of how technical specifications will constrain or enable business model flexibility as deployment scales. By connecting component-level trends, system-level architecture choices, and standard-setting trajectories, the report provides a coherent view of where technical differentiation is likely to persist and where commoditization pressure may intensify.
Competitive Landscape and Strategic Positioning
Market concentration data indicates that the fastest-moving portion of the industry is being shaped by a set of established and emerging players with distinct regional footprints, product philosophies, and deployment strategies. The top three participants collectively account for a substantial portion of market activity, while the top five extend that footprint further, reflecting both the scale advantages of integrated manufacturing and the specialized positioning ofmodular or regionally focused suppliers. The report profiles leading companies across Europe, North America, Asia-Pacific, and other active markets, mapping their product families, output capabilities, connector compatibility, and recent commercial milestones. These profiles are not intended as static company directories; they are structured to reveal competitive logic. Some suppliers emphasize modular architectures that allow output to scale with site requirements and fleet profiles. Others prioritize liquid cooling and high-efficiency power conversion to sustain elevated output levels in continuous operation. Still others focus on interoperability, network software integration, or targeted corridor and depot deployments that align with specific customer segments.
Recent operational developments illustrate how these strategies are translating into real-world deployment momentum. Major equipment orders tied to highway network expansion, commissioned satellite charging systems serving ferry and vessel-integrated electrification projects, grid-connected activations of high-power chargers at new public sites, and third-party-validated efficiency milestones for 350 kW-class chargers all point to a market in which proven performance, reliability, and contractual scale are becoming as important as nominal power ratings. The report contextualizes these events within broader competitive dynamics, highlighting where partnerships, order pipelines, and technology validation are reshaping expectations for market entry timing, capacity deployment, and customer acquisition. For organizations evaluating supplier relationships, partnership structures, or internal product strategy, this competitive mapping offers a basis for evaluating not only who currently leads in aggregate activity, but how leadership is being contested across segments and geographies.
Regulation, Subsidies, and Input-Cost Dynamics as Strategic Variables
Policy and input-cost environments are not peripheral considerations; they are core determinants of where and how fast charging infrastructure becomes commercially viable. European regulatory requirements mandating high-power charger deployment along core transport networks establish a clear spatial and temporal framework for corridor expansion, compressing the planning and execution cycle for infrastructure providers and creating predictable demand anchors in targeted geographies. In the United States, federal grant programs supporting fast charging corridor development carry domestic content expectations that influence sourcing strategies, supply-chain configuration, and project economics. These policy instruments do not operate in isolation. They interact with utility interconnection timelines, local permitting environments, land availability, and site-level power procurement costs to produce distinct regional deployment profiles.
On the input-cost side, material and component pricing trends introduce both risk and opportunity. Copper cable pricing relevant to high-output charging systems, silicon carbide module pricing, and broader power-electronics supply dynamics affect equipment cost structures and the marginal economics of scaling output. The report examines how these cost drivers intersect with supplier innovation, modular design, and efficiency improvements to shape the path of least resistance for deployment. Rather than treating subsidies or material costs as isolated headlines, the analysis positions them as variables within a broader decision framework. Organizations that incorporate regulatory cadence, content requirements, and input-cost trajectories into their site planning, vendor selection, and financing assumptions are better positioned to avoid stranded capacity, misaligned technology choices, or unfavorable unit economics as deployment scales.
Report Architecture and Practical Value for 2026 Decisions
The research is organized to move from market-scale context to segment-level intelligence, then to competitive and dynamic factors that influence execution. It begins with the historical growth record and forecast trajectory, establishing the scale and pace of expansion. From there, it disaggregates the market across technology pathways, power output tiers, and regional deployment patterns, quantifying how each contributes to overall momentum without reducing the analysis to oversimplified proportions. The segmentation logic is designed to help readers identify where growth is most concentrated, which configurations are gaining commercial traction, and how deployment contexts differ across public networks, fleet operations, and destination or workplace settings.
Beyond segmentation, the report provides actionable content on competitive positioning, product architectures, and recent market developments that signal near-term direction. Profiles of key companies are accompanied by an assessment of how their product strategies, order activity, and technical milestones relate to broader market trends. This enables readers to evaluate supplier fit, anticipate technology shifts, and understand where differentiation is likely to be durable versus where consolidation or price competition may intensify. The study also integrates regulatory mandates, subsidy frameworks, component pricing, and standardization developments into a unified view of market dynamics. This integration is critical because fast charging deployment decisions rarely hinge on a single variable; they depend on the interaction of policy timing, input costs, grid constraints, and technology readiness.
For 2026 decision-making, the report is intended to support several concrete use cases. Capital and capacity planners can use the forecast architecture to align investment horizons with realistic adoption curves rather than extrapolating from isolated site-level experience. Technology and procurement teams can reference the segmentation and competitive analysis to evaluate which output tiers, cooling approaches, and power-module strategies best match their operating context and cost targets. Strategy and market-entry teams can use the regional and dynamic analysis to identify where regulatory frameworks, subsidy structures, and deployment momentum create favorable conditions, and where fragmentation or input-cost pressure may require more cautious sequencing. Executives can use the concentration and competitive data to benchmark their exposure, assess partnership needs, and understand the strategic implications of a market in which a meaningful share of activity is being shaped by a relatively concentrated set of players with distinct technical and geographic strengths.
Approaching Complete Market Intelligence
A market moving at this pace demands more than a single aggregate figure or a static company list. It requires an integrated view that connects scale, segmentation, competition, policy, and input economics into a coherent basis for action. The Worldwide New Energy Vehicle Fast Charging Technology Market report is built for that purpose. It provides the historical grounding, forward forecast, segment architecture, competitive mapping, and dynamic context needed to replace assumption-driven planning with evidence-based strategy. The summary presented here is intended to demonstrate the depth and structure of the analysis while preserving the detailed segmentation values, regional and application splits, and granular competitive intelligence that constitute the full report.
Organizations seeking to translate market momentum into deliberate 2026 decisions will find the complete dataset, methodology notes, and segment-level breakdowns essential for precise planning. The full report enables readers to examine exact market size trajectories, segmentation contributions, concentration metrics, and the detailed profiles and recent developments that shape competitive positioning. It also provides the structured context needed to evaluate how regulatory mandates, subsidy programs, component pricing, and standardization developments interact with technology choice and deployment sequencing. For a landscape defined by rapid expansion and increasing technical differentiation, that level of detail is not optional; it is the foundation of decisions that hold up under execution.
The worldwide new energy vehicle fast charging technology market is no longer a speculative growth story. It is an operational reality with measurable scale, definable segments, identifiable competitive leaders, and policy and cost dynamics that directly influence deployment logic. The strategic question for 2026 is not whether the market will expand, but how organizations will position themselves within its structure to capture durable value. Complete market intelligence is the bridge between recognizing that opportunity and executing against it. The full research report delivers that intelligence in a form designed for executive review, investment planning, technology strategy, and competitive assessment. Accessing the full dataset and segment-level analysis will allow decision-makers to move from directional awareness to precise, evidence-backed action.
For detailed analysis of this topic, please visit the official page: Worldwide New Energy Vehicle Fast Charging Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Ultra-thin Copper Foils Market to Surge from USD 2,831.47 Million in 2025 to USD 6,259.49 Million by 2032 at 12.0% CAGR
By PW Consulting, 2026-09-02
Strategic Intelligence for the Next Decade: Inside the Worldwide Ultra-thin Copper Foils Market 2026–2032
In an era where miniaturization, signal integrity, and electrification are rewriting the rules of material science, ultra-thin copper foils have emerged as a critical enabler across high-growth electronics and energy storage markets. As we move deeper into 2026, the strategic imperative for leaders in PCB manufacturing, battery production, semiconductor packaging, and advanced materials sourcing has never been more acute. Our recently published Worldwide Ultra-thin Copper Foils Market research offers a meticulously constructed, data-driven roadmap spanning historical baselines from 2020 through 2032, delivering the analytical rigor required to navigate a highly concentrated and rapidly evolving value chain.
Worldwide Ultra-thin Copper Foils Market
The Macro Trajectory: A 12% CAGR Reshaping Material Expectations
The market’s expansion trajectory over the past half-decade has been nothing short of remarkable. From a 2020 baseline of approximately 1,650 million USD, the worldwide ultra-thin copper foils market advanced through successive growth phases, reaching roughly 1,912 million USD in 2021, 2,111 million USD in 2022, 2,379 million USD in 2023, 2,629 million USD in 2024, and settling at an estimated 2,831 million USD in 2025. This historical arc lays the foundation for a forecast period in which the market is projected to accelerate from 3,245 million USD in 2026 to 3,574 million USD in 2027, 4,070 million USD in 2028, 4,465 million USD in 2029, 4,969 million USD in 2030, 5,517 million USD in 2031, and ultimately approaching 6,259 million USD by 2032. Anchored by a compound annual growth rate of 12.0 percent, this trajectory reflects not merely cyclical demand but a structural realignment driven by device miniaturization, high-frequency signal requirements, and the relentless scaling of lithium-ion battery architectures.
Worldwide Ultra-thin Copper Foils Market
For executive teams planning capital allocation, capacity expansion, or supply chain diversification in 2026, this macro trajectory is more than a forecast—it is a strategic stress test. Growth at this pace demands clarity on margin dynamics, raw material volatility, regional capacity shifts, and the evolving specifications demanded by downstream OEMs. It also underscores why historical averages are insufficient: the market is bifurcating into commodity-grade volumes and high-value ultrathin specialties, each with distinct pricing power, technical barriers, and procurement risk profiles.
Worldwide Ultra-thin Copper Foils Market
Why This Study Matters for 2026 Decision-Making
The 2026 decision environment is characterized by intersecting forces: persistent copper price volatility, geopolitical trade adjustments, accelerated EV and ESS deployment cycles, and the relentless push toward finer-pitch circuitry in advanced packaging and high-density interconnect applications. Leaders who rely on fragmented market scans or outdated regional assumptions risk misallocating resources, overcommitting to suboptimal supply partnerships, or underestimating the technical moats that leading producers have built around sub-5-micrometer foil architectures.
Our Worldwide Ultra-thin Copper Foils Market research is engineered to close those intelligence gaps. It delivers an integrated view of market sizing, segmentation logic, competitive positioning, and material-market interdependencies, allowing stakeholders to translate macro trends into actionable procurement strategies, product roadmaps, and risk mitigation frameworks. The study is built for professionals who need more than directional commentary—they need a structured analytical foundation that can withstand boardroom scrutiny, investor due diligence, and multi-year capacity planning.
What the Research Delivers: Operational Depth for Strategic Execution
The report is structured to support both top-line strategic planning and granular operational decision-making. Rather than presenting a static snapshot, it maps the full evolution of demand patterns, technology requirements, and competitive behavior across multiple horizons. Key components include:
- Historical Reconstruction and Forward Forecast: A year-by-year sizing series from 2020 through 2032 that enables trend decomposition, growth driver attribution, and scenario modeling for finance and strategy teams.
- Segment-Level Architecture: Detailed breakdown across application categories, product type distinctions, and regional demand centers, with emphasis on where value is concentrating as specifications become more demanding.
- Competitive Positioning and Capability Mapping: A structured assessment of the leading manufacturers shaping the market, including their engineering focus, production specialization, and strategic posture in high-end ultrathin segments.
- Material Market Context: Integration of copper raw material dynamics, price behavior, and supply-side pressures that influence cost structures, negotiation leverage, and inventory strategy.
- Regulatory and Trade Overlay: Analysis of policy developments and cross-border considerations that can reshape sourcing strategies, regional advantage, and lead-time planning for electronics-grade materials.
- Forward-Looking Event Tracking: Coverage of technology demonstrations, certification milestones, and capacity-related developments that signal where the next wave of differentiation will emerge.
Each section is designed to feed directly into practical workflows: supplier selection, technology roadmap alignment, pricing strategy, risk hedging, and geographic diversification planning. The goal is not simply to describe the market, but to equip decision-makers with a usable framework for operating inside it.
Concentration, Capability, and the New Competitive Logic
One of the most strategically important features of this market is its concentration. With the top three players accounting for approximately 58.4 percent of market share and the top five holding roughly 74.15 percent, the competitive environment rewards scale, technical precision, and long-developed process expertise. The flip side is that high barriers to entry in ultra-thin product lines—particularly below 5 micrometers—create pockets of pricing resilience and customer lock-in that are not available in more commoditized material categories.
Leading participants illustrate how this competitive logic is playing out in practice. Mitsui Mining & Smelting Co., Ltd. (Mitsui Kinzoku) stands out as the world’s largest producer of electrodeposited ultra-thin copper foil at 5 micrometers or less, with a dominant global share in that segment and a portfolio that includes carrier-supported foils down to 1.5–5 micrometers for high-density interconnect PCBs and advanced electronics. Furukawa Electric Co., Ltd. focuses on ultra-thin foils that enable miniaturization in electronic devices, with specialty high-performance and flexible foils suited to fine-pitch circuits and high-frequency applications. JX Nippon Mining & Metals Corporation (JX Advanced Metals) supplies high-quality thin and ultra-thin foils, including electrodeposited varieties optimized for high-frequency signal integrity and semiconductor-related applications.
In Europe, Circuit Foil Luxembourg has built a reputation as a global manufacturer of high-quality electrodeposited copper foils spanning 1 to 210 micrometers, with a clear emphasis on high-end ultrathin products and a recent certification milestone that validates 100 percent recycled content in its ultrathin and doublethin lines. South Korea’s Solus Advanced Materials (SK Nexilis) has pushed capability boundaries with ultra-thin copper foil manufacturing technology down to roughly 1–2 micrometers, serving high-end PCB microcircuits and IC/USIM card foils, while also operating as an important European-based thin-foil manufacturing presence. Additional specialized players such as Fukuda Metal Foil & Powder Co., Ltd., Lotte Energy Materials, Nuode New Materials Co Ltd, Chang Chun Group, ILJIN Materials Co., Ltd., Advanced Copper Foil in the United States, and Proterial Metals, Ltd. further diversify the landscape with focused strengths in carrier-supported foils, battery-grade thin variants, very low roughness substrates, rolled ultra-thin alloys, and fine-line surface treatments.
This concentration is not merely a static market structure; it is a strategic signal. It means that procurement teams must evaluate suppliers not only on price, but on proven capability in the exact thickness, surface finish, and carrier or lamination configuration their products require. It also means that innovation events—such as advanced foil demonstrations at major industry showcases or the achievement of new sustainability certifications—can shift competitive expectations quickly, especially when they unlock access to new application verticals.
Forces Reshaping the Market Environment in 2026
No strategy for ultra-thin copper foils can be built in isolation from the broader material and policy environment. Copper price behavior has been a defining factor in recent months. LME Copper Grade A cash pricing reached levels around 12,880 USD per tonne in late April 2026, with the March 2026 monthly average near 12,529 USD/mt, reflecting ongoing volatility and prior record peaks above 13,000 USD/t earlier in the year. Copper prices also rose nearly 50 percent year-on-year in early 2026, driven by supply concerns alongside accelerating demand from electronics and energy sectors. For ultra-thin copper foil buyers and producers alike, this environment compresses margins, elevates the value of hedging and long-term supply agreements, and increases the importance of technical efficiency in material utilization.
Trade policy introduces an additional layer of complexity. In mid-2025, the U.S. considered imposing a 50 percent tariff on copper imports effective in early August, alongside discussions on potential exemptions for electronics-grade foils and laminates until domestic substitutes could be made available. Even where exemptions are debated, the prospect of tariff pressure alters sourcing calculations, delays, and regional cost comparisons. In practical terms, companies must assess not only the price of the foil, but the total landed cost, lead-time reliability, and the resilience of alternative sourcing pathways under shifting trade conditions.
At the same time, technology showcases and certifications are redefining what is commercially possible. In early 2026, SK Nexilis showcased a roll of 4 micrometer ultra-thin copper foil with 1,400 mm width and 5 km length at InterBattery 2026, highlighting capability for next-generation applications beyond EVs, including ESS, drones, robotics, defense, and aerospace. Elsewhere, Circuit Foil secured UL certificates validating 100 percent recycled copper foil supplier status for both its Ultrathin and Doublethin product lines. These developments matter because they link material performance to expanding application horizons and to sustainability requirements that are increasingly embedded in procurement specifications.
Strategic Questions This Study Helps Answer
For organizations operating in or adjacent to this market, the most valuable insights are often the ones that convert uncertainty into structured decision options. The research is designed to support that translation by helping teams address questions such as:
- Where is demand growth concentrating across application categories, and how should that influence product specification priorities and inventory planning?
- Which suppliers possess the technical and commercial profile to support sub-5-micrometer requirements, carrier-supported processing, low-roughness high-frequency needs, or battery-grade thin variants at scale?
- How should procurement strategies adapt to copper price volatility while maintaining supply reliability for high-specification applications?
- What regional dynamics are shaping cost, availability, and risk across key demand centers, and where do diversification opportunities exist?
- Which recent technology demonstrations, certifications, and trade-policy developments are likely to alter competitive positioning and sourcing logic over the 2026–2032 horizon?
These are not hypothetical concerns. They are the operational questions that separate reactive purchasing from strategic material leadership. By embedding market sizing, segmentation logic, competitive capability, and environmental context into one coherent analytical framework, the study provides a basis for more confident capital allocation, supplier negotiation, and technology roadmap planning.
How to Use the Full Report for 2026 Planning
The executive summary and market trajectory presented here are intended to demonstrate the scope and rigor of the full analysis. The complete Worldwide Ultra-thin Copper Foils Market research goes further by providing the detailed segmentation architecture, company-by-company capability assessment, market concentration context, and the material and regulatory overlays necessary for precise strategic work. For leaders responsible for electronics materials, advanced PCBs, IC substrates, battery supply chains, or broader advanced manufacturing portfolios, the full report functions as both an intelligence asset and a planning tool.
In a market expanding at a double-digit CAGR toward more than 6,250 million USD by 2032, the margin between assumptions and evidence can determine the difference between strategic advantage and strategic exposure. We invite decision-makers who require full segmentation detail, complete company-level profiles, and the supporting data series behind this overview to access the complete study through our official report page. There, the full analytical depth required to act with confidence in 2026 and beyond is available for review and integration into your internal planning process.
For detailed analysis of this topic, please visit the official page: Worldwide Ultra-thin Copper Foils Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Melatonin Gummies Market Valued at 787.42 Million in 2025 Forecast to Hit 1549.16 Million by 2032 With 10.15 Percent CAGR
By PW Consulting, 2026-09-02
Navigating the Sleep Revolution: Strategic Insights into the Global Melatonin Gummies Market (2026–2032)
The global landscape for sleep aids is undergoing a profound transformation, driven by rising consumer awareness of sleep hygiene, the destigmatization of supplement usage, and the preference for consumer-friendly delivery mechanisms. Within this shifting environment, melatonin gummies have emerged as a dominant force, bridging the gap between pharmaceutical efficacy and over-the-counter convenience. As we move into 2026, the strategic imperatives for stakeholders in this sector have never been clearer. This article serves as a precursor to our comprehensive market study, offering a high-level view of the trajectory while highlighting the critical intelligence required to navigate the coming years.
Worldwide Melatonin Gummies Market
Market Trajectory and Growth Fundamentals
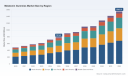
The financial momentum behind melatonin gummies is robust, reflecting a compound annual growth rate (CAGR) of 10.15% throughout the forecast period extending to 2032. This growth is not merely linear but indicative of a structural shift in how consumers approach sleep management. In 2025, the global market valuation stood at approximately USD 787.42 Million, a significant increase from the 2020 baseline of USD 485.6 Million. This trajectory suggests that by 2026, the market is poised to exceed the USD 900 Million threshold, reaching an estimated USD 903.27 Million.
Worldwide Melatonin Gummies Market
Looking further ahead, the expansion accelerates. Projections indicate that revenue will climb to USD 1.10 Billion by 2028 and continue its ascent to reach USD 1.55 Billion by 2032. This near-doubling of market size within a single decade underscores the category's resilience against economic fluctuations. For strategic planners, this signals that sleep health is no longer a niche wellness segment but a core component of the broader health and wellness economy. The consistent upward trend from 2020 through 2025 establishes a strong historical foundation, reducing the risk profile for new market entrants or product line extensions in 2026.
Worldwide Melatonin Gummies Market
Structural Pillars of Demand
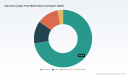
Understanding the drivers of this growth is essential for allocation of resources. The market expansion is supported by three primary pillars: dosage customization, distribution accessibility, and regional consumption patterns. Our analysis indicates that the 1mg to 3mg dosage strength segment currently commands the largest share of revenue, reflecting a consumer preference for gentle, nightly maintenance doses. However, the 5mg segment shows considerable volume, catering to those requiring stronger intervention for acute sleep onset issues. Meanwhile, the 10mg and above category, while smaller in total revenue contribution, represents a high-value niche for specialized formulations targeting severe sleep disruption.
Distribution channels play an equally critical role in market penetration. Pharmacies and drug stores remain the dominant revenue channel, leveraging consumer trust and pharmacist recommendation. Yet, online retail is closing the gap rapidly, driven by subscription models and direct-to-consumer marketing strategies. Supermarkets and hypermarkets provide mass-market visibility, while specialty stores cater to the premium and organic segments. Geographically, North America continues to lead in total revenue contribution, followed by Europe and Asia Pacific. However, growth rates in emerging regions suggest shifting dynamics that require localized regulatory and marketing strategies.
Competitive Landscape and Corporate Strategy
The market structure is moderately concentrated, with the top three players holding a combined share of 34.2% and the top five controlling 48.65%. This concentration leaves significant room for fragmentation and competition among mid-tier and emerging brands. Leading the pack is Natrol, headquartered in Chatsworth, CA, which has solidified its position as a producer of melatonin gummies ranging from 3mg to 10mg. Their recent introduction of fast-dissolve gummies in 10mg strength in June 2024 demonstrates a strategy focused on efficacy and speed of onset, targeting consumers seeking immediate relief.
Olly Nutrition, based in Oakland, CA, competes through flavor innovation and lifestyle branding, offering 3mg sleep gummies infused with botanicals. Their approach emphasizes the sensory experience of supplementation, appealing to younger demographics. Zarbee's, located in Sandy, UT, has carved a niche in the family segment, producing 1mg to 5mg gummies with natural flavors and honey-based formulations. Their acquisition of NSF certification for allergen-free lines in late 2023 highlights a strategic focus on safety and trust, particularly important given regulatory scrutiny on pediatric products.
Other key players include Vitafusion (Foothill Ranch, CA), which combines 5mg melatonin with L-theanine for relaxation; Nature Made (West Hills, CA), which leverages USP verification for quality assurance in 5mg and 10mg offerings; and NOW Foods (Bloomingdale, IL), which utilizes organic tapioca syrup bases to appeal to clean-label consumers. International presence is maintained by Jamieson (Toronto, ON) and Blackmores (Sydney, NSW), who distribute 5mg and 3mg formulations respectively across Canadian and Australian export markets. The competitive intensity suggests that differentiation through formulation, certification, and flavor profiling is necessary to capture market share beyond the dominant incumbents.
Regulatory Dynamics and Risk Management
Strategic planning in 2026 must account for a complex regulatory environment. In the United States, melatonin is classified as a dietary supplement under DSHEA, meaning it does not require pre-market approval but is subject to Good Manufacturing Practices (GMP). However, the regulatory landscape is tightening. In October 2024, the FDA issued a safety communication regarding pediatric melatonin gummies, citing overdose risks associated with packaging. This alert necessitates a review of packaging designs and dosage clarity, particularly for brands with family-oriented portfolios.
Quality control remains a persistent challenge. Between 2023 and 2024, multiple brands faced recalls due to undeclared allergens and inaccurate dosing. These incidents erode consumer trust and invite stricter enforcement. Furthermore, supply chain stability is a critical variable. The melatonin active pharmaceutical ingredient (API) is primarily sourced from China, with 2024 prices ranging between $150 and $200 per kilogram. While supply chains have stabilized, reliance on a single geographic region for API sourcing introduces vulnerability to geopolitical or logistical disruptions.
Internationally, export controls add another layer of complexity. The European Food Safety Authority (EFSA) requires melatonin gummies with dosages above 1mg to be labeled under Novel Foods if there is no history of consumption in the EU. This regulation impacts market entry strategies for European expansion and requires rigorous compliance documentation. Additionally, as an OTC supplement, melatonin gummies are not covered by insurance, with average retail prices hovering between $10 and $15 for a 60-count bottle of 5mg gummies. Pricing strategies must therefore balance affordability with the perceived value of quality and safety certifications.
Strategic Imperatives for 2026 Decision Making
For executives and strategic planners, the data points outlined above are merely the surface level. The true value of our upcoming Worldwide Melatonin Gummies Market research lies in the depth of actionable intelligence beneath these aggregates. To succeed in this environment, organizations must move beyond general market awareness to precise execution.
Key strategic questions that demand deeper analysis include:
- How should product portfolios be balanced between high-volume low-dose segments and high-margin high-dose specialties?
- What are the specific regional regulatory hurdles for each target market, particularly regarding EU Novel Food classifications and US pediatric safety guidelines?
- How can distribution channel mix be optimized to capture online growth while maintaining pharmacy shelf presence?
- What supply chain contingencies are necessary to mitigate API price volatility and sourcing risks?
- Which consumer demographics are driving the growth in specific dosage strengths, and how should messaging be tailored accordingly?
Our comprehensive report addresses these questions by providing detailed segmentation splits, historical data analysis from 2020 to 2025, and a granular forecast through 2032. We examine the competitive maneuvers of key players, analyze the impact of regulatory alerts on market share, and evaluate the financial implications of raw material costs. The report also includes scenario planning for potential regulatory shifts and supply chain disruptions, enabling leadership to build resilient strategies.
Conclusion: Accessing the Complete Intelligence
The melatonin gummies market offers substantial opportunity, but it is fraught with regulatory nuances, competitive intensity, and supply chain variables that require precise navigation. The aggregate growth figures confirm the sector's vitality, but the strategic winners will be those who understand the underlying mechanics of demand, distribution, and compliance.
This article has provided a strategic overview based on available macro data. However, the specific regional revenue splits, detailed dosage strength contributions, and channel-specific performance metrics are critical for budget allocation and market entry decisions. To access the full depth of our analysis, including the complete segmentation data, competitor profiles, and risk assessment frameworks, we invite you to explore the full Worldwide Melatonin Gummies Market research report. Equip your organization with the intelligence needed to lead in the sleep health sector throughout 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Melatonin Gummies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Micro Spray System Market to Reach USD 1,020.5 Million in 2025 with 9.25% CAGR Through 2032
By PW Consulting, 2026-09-02
Unlocking Precision: Strategic Imperatives in the Global Micro Spray System Market Through 2032
As the global agricultural and landscaping sectors confront intensifying pressure to optimize resource utilization, the Worldwide Micro Spray System Market has emerged as a critical nexus for innovation and efficiency. PW Consulting's latest comprehensive research, Worldwide Micro Spray System Market, offers a granular vision of an industry poised for substantial expansion. This analysis is not merely a retrospective of growth metrics; it is a strategic manual designed to guide enterprise decision-making through the forecast period extending to 2032. By examining the underlying dynamics, competitive maneuvers, and structural segmentation, stakeholders can position themselves to capture value in a market defined by precision and sustainability.
Worldwide Micro Spray System Market
The macro-economic landscape for micro spray systems presents a compelling trajectory of growth. Recent historical data indicates a robust expansion phase, with the overall market valuation reaching approximately 1020.5 Million USD in the base year of 2025. Looking forward, the consensus forecasts project the market to achieve a revenue volume of roughly 1104.88 Million USD in 2026, accelerating toward a projected valuation of 1895.67 Million USD by the end of the forecast period in 2032. This growth path suggests a Compound Annual Growth Rate of 9.25 Percent, signaling a sustained demand environment driven by technological adoption and regulatory shifts. For strategic planners, this trajectory underscores the necessity of aligning capital allocation and R&D investments with the upward momentum of the sector.
Worldwide Micro Spray System Market
Market Dynamics and Structural Drivers
The expansion of the micro spray system industry is not occurring in a vacuum. It is fueled by a confluence of macro trends, regulatory frameworks, and raw material realities that define the operational context for all market participants. Understanding these dynamics is essential for anticipating market shifts and mitigating risk.
Worldwide Micro Spray System Market
Regulatory and Environmental Catalysts
Environmental governance plays a pivotal role in shaping demand. Microirrigation is strictly defined under the ASABE/ICC 802-2014 Landscape Irrigation Sprinkler and Emitter Standard as systems discharging at flow rates less than 30 gallons per hour when operated at 30 psi. This technical definition, referenced in the U.S. Environmental Protection Agency WaterSense Program Guide, establishes a clear benchmark for compliance and performance that influences procurement strategies across North America and beyond.
Furthermore, the NRCS Conservation Practice Standard for Irrigation System - Microirrigation (Code 441), as outlined by the USDA NRCS in 2023, promotes the frequent application of small quantities of water as drops, tiny streams, or miniature spray. This standard is designed to improve water use efficiency and prevent contamination, directly incentivizing the adoption of micro spray technologies in conservation-focused agricultural programs. These regulatory anchors ensure that water scarcity, climate volatility, and environmental regulations continue to drive adoption of micro spray systems for efficient root-zone water application, reducing evaporation and runoff compared to traditional sprinklers.
Supply Chain and Material Considerations
On the supply side, the industry faces volatility linked to key components in micro-irrigation systems. Manufacturing costs are influenced by polymer and metal price volatility, specifically regarding polyethylene tubing, emitters, valves, and filters as noted in Industry Market Data from 2025. Strategic procurement functions must monitor these input costs closely, as fluctuations can impact margin structures and pricing strategies. Companies that secure resilient supply chains or innovate in material science to mitigate cost pressures will hold a distinct advantage in maintaining profitability throughout the forecast period.
Segmentation Insights: Navigating Product and Application Landscapes
The market is structurally divided across type and application verticals, each presenting unique value propositions and growth opportunities. While specific regional revenue figures and percentage splits are detailed in the full proprietary report, the overarching segmentation logic reveals where strategic focus should be directed.
Product Type Segmentation
The market is categorized into three primary technology types: Fixed Micro Sprayers, Rotating Micro Sprayers, and Micro Jets and Misters. Each segment serves distinct operational requirements. Fixed systems often dominate scenarios requiring uniform, low-velocity coverage, while rotating solutions provide broader radius coverage for specific crop geometries. Micro jets and misters cater to specialized humidity or cooling needs. The interplay between these technologies dictates equipment selection for end-users.
Application Verticals
Demand is distributed across key application areas including Orchards and Vineyards, Greenhouse and Nursery operations, Open Field Crops, and Landscaping and Turf. High-value perennial crops such as orchards and vineyards represent a significant demand center due to the critical need for precise water management to ensure yield quality. Greenhouse and nursery settings leverage micro spray for controlled environment agriculture, while open field crops increasingly adopt these systems to maximize water efficiency at scale. Landscaping and turf applications continue to drive consistent volume, particularly in municipal and commercial grounds maintenance where water conservation mandates are tightening.
Competitive Landscape and Strategic Maneuvers
The market structure exhibits moderate concentration, with the top three players holding a cumulative share of 32.4 Percent and the top five entities commanding 45.8 Percent. This indicates a landscape where dominant incumbents hold significant sway, yet sufficient fragmentation remains to allow agile competitors to gain traction through niche innovation or regional focus.
Key participants in this arena include global irrigation specialists such as Netafim, headquartered in Tel Aviv, Israel, which offers comprehensive micro-sprinklers and special emitters as part of a sprinkler irrigation portfolio, including the SuperNet series for precise low-volume water distribution in agriculture. Jain Irrigation Systems Ltd., based in Jalgaon, India, stands as a major global provider of micro-irrigation systems including micro spray and micro-sprinkler solutions for orchards, vineyards, and field crops with a focus on water efficiency.
North American manufacturers also exert strong influence. The Toro Company, located in Bloomington, Minnesota, provides micro-irrigation components and systems, including micro spray options for agricultural and landscape applications. Rain Bird Corporation, based in Azusa, California, supplies micro-irrigation products including micro spray nozzles and emitters designed for precise water application in agriculture and turf. Hunter Industries, headquartered in San Marcos, California, manufactures short-radius micro spray nozzles for controlled irrigation in small spaces, supporting robust micro spray systems with Pro-Spray pop-ups.
Further competitive pressure comes from entities like Nelson Irrigation in Walla Walla, Washington, which offers micro-irrigation solutions with a focus on sprinklers and sprays for agricultural water management, and Rivulis in Israel, specializing in micro and drip irrigation systems including micro spray components for efficient water use. Lindsay Corporation and Valmont Industries, both operating out of Omaha, Nebraska, provide irrigation systems incorporating micro-irrigation technologies and advanced irrigation equipment respectively. European and Asian players round out the ecosystem, including Irritec S.p.A in Italy, Antelco in Australia, Elgo Irrigation Ltd. in Israel, Mahindra EPC Irrigation Limited in India, and Chinadrip Irrigation Equipment Co., Ltd. in China.
Recent developments highlight the pace of innovation. Hunter Industries continues offering short-radius micro spray nozzles meeting ASABE/ICC 802-2014 micro-spray definition for precise low-flow irrigation in compact landscape spaces as of early 2026. Netafim made its full sprinklers and micro-sprinklers catalog available featuring SuperNet and other micro-sprinkler models for professional irrigation in April 2026. Additionally, cross-sector integration is evident, with FarmDroid introducing a new micro spray system on an autonomous solar-powered agricultural robot for precision spot spraying to reduce pesticide usage in October 2025.
Strategic Value for 2026 Enterprise Decision-Making
For executives and strategy directors, the value of this market research extends beyond observing growth numbers. The 2026 baseline and the forecast through 2032 provide a temporal framework for strategic planning. Decision-makers must assess where their organizations fit within the value chain—whether as equipment manufacturers, distributors, or end-users implementing irrigation infrastructure.
Investment and Innovation Roadmaps
With a projected CAGR of 9.25 Percent, capital deployment strategies should reflect confidence in the sector's long-term viability. However, the divergence between product types and application verticals suggests that a one-size-fits-all approach is insufficient. Investments should be targeted toward segments demonstrating the strongest alignment with regulatory incentives and water scarcity realities. For manufacturers, this may mean prioritizing R&D in emitter technology that meets evolving ASABE standards or developing modular systems that adapt to both orchard and turf requirements.
Competitive Positioning and Partnerships
Given the CR5 concentration of 45.8 Percent, new entrants or expanding players must identify white space. Partnerships with technology providers, such as integrating autonomous robotics with micro spray delivery as seen with FarmDroid, represent a frontier for value creation. Alternatively, focusing on regional strengths, such as the high volume potential in Asia Pacific or the established regulatory markets in North America and Europe, allows for tailored go-to-market strategies. Companies like Lindsay Corporation and Valmont Industries demonstrate how large-scale irrigation system providers can incorporate micro-irrigation technologies for field crop applications, suggesting that integration with broader irrigation portfolios is a viable growth lever.
Risk Management and Supply Chain Resilience
The influence of polymer and metal price volatility on manufacturing costs necessitates robust risk management frameworks. Strategic sourcing agreements and inventory hedging may become critical differentiators. Furthermore, as environmental regulations evolve, ensuring product compliance with standards like the WaterSense Program Guide and NRCS Code 441 protects against regulatory risk and enhances marketability to sustainability-conscious buyers.
Conclusion: Preparing for the Future of Precision Irrigation
The Worldwide Micro Spray System Market is at an inflection point where efficiency, regulation, and technology converge. The market size trajectory from 1020.5 Million USD in 2025 to a projected 1895.67 Million USD by 2032 underscores the magnitude of the opportunity. However, realizing this potential requires more than passive observation; it demands active strategic engagement with the segment dynamics, competitive forces, and regulatory environment detailed in this analysis.
PW Consulting's in-depth report provides the necessary intelligence to navigate this landscape. By offering detailed breakdowns of segmentation splits, comprehensive competitive profiles, and forward-looking forecasts, the research equips stakeholders with the clarity needed to make informed decisions. To access the full depth of data, including specific regional revenue contributions, granular application market sizes, and the complete competitive matrix, stakeholders are encouraged to explore the full study. The precision of your strategy depends on the precision of your data. Secure the complete intelligence today to lead the market tomorrow.
For detailed analysis of this topic, please visit the official page: Worldwide Micro Spray System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Global Insight: Worldwide Cosmetic Grade Centella Asiatica Extract Market Valued at 636.32 Million USD in 2025 Drives 7.65 CAGR Forecast Through 2032
By PW Consulting, 2026-09-02
Charting the Green Trajectory: Strategic Intelligence for the Global Cosmetic Grade Centella Asiatica Extract Market
The global beauty industry is currently navigating a paradigm shift where efficacy meets naturality. At the forefront of this evolution is Centella Asiatica, colloquially known as Cica, a botanical ingredient that has transcended its traditional roots to become a cornerstone of modern skincare formulations. For stakeholders operating within the cosmetic ingredient supply chain, understanding the magnitude and direction of this trend is no longer optional; it is a prerequisite for survival and growth. Our latest comprehensive study, the Worldwide Cosmetic Grade Centella Asiatica Extract Market, offers a definitive roadmap for navigating this complex landscape through 2032.
Worldwide Cosmetic Grade Centella Asiatica Extract Market
This research is not merely a collection of numbers. It is a strategic asset designed to inform critical investment decisions, supply chain optimizations, and product development pipelines in 2026 and beyond. By analyzing historical performance from 2020 to 2025 and projecting forward through 2032, we provide a clear lens into the market mechanics that drive value in this sector. The following analysis underscores the strategic value of this intelligence, highlighting the macro-economic drivers, competitive pressures, and operational nuances that define the current market environment.
Worldwide Cosmetic Grade Centella Asiatica Extract Market
Macro-Economic Trajectory and Revenue Pathways
The financial narrative of the cosmetic grade Centella Asiatica extract market is characterized by robust, sustained growth. Our analysis tracks a compelling revenue journey, beginning with a total market valuation of approximately 442.15 million USD in 2020. Over the subsequent five years, the market demonstrated resilience and acceleration despite global supply chain disruptions, culminating in a valuation of 636.32 million USD in 2025. This historical performance sets a strong foundation for the forecast period.
Worldwide Cosmetic Grade Centella Asiatica Extract Market
Looking ahead, the momentum shows no signs of abating. The market is projected to reach 718.28 million USD in 2026, marking a significant step up in value creation. As we extend the horizon to 2032, the trajectory points toward a valuation exceeding 1 billion USD, specifically reaching 1066.19 million USD. This expansion suggests a Compound Annual Growth Rate (CAGR) of 7.65 percent over the forecast period from 2026 to 2032. For executives and investors, these figures represent more than just top-line growth; they indicate a maturing market where scalability becomes a key differentiator. The consistent upward curve implies that demand drivers are structural rather than cyclical, rooted in changing consumer preferences and formulation science rather than fleeting trends.
Supply Chain Dynamics and Sourcing Vulnerabilities
A critical component of strategic planning in this sector involves understanding the upstream constraints that influence downstream availability. The supply of high-purity Centella Asiatica raw material for extraction relies primarily on cultivated sources in Asia. This geographic concentration creates a specific set of dynamics for global manufacturers. India, for instance, accounts for approximately 38 percent of global supply, making the cosmetic-grade extract inherently vulnerable to agricultural yield variations. Weather patterns, crop diseases, and local regulatory changes in sourcing regions can have outsized effects on global pricing and availability.
Furthermore, the industry is witnessing an increasing focus on traceability and sustainable farming practices. As brands face pressure to validate their natural claims, the provenance of the Centella Asiatica biomass becomes a competitive asset. Supply chain resilience is therefore not just about logistics; it is about securing relationships with cultivators who can guarantee consistency in biomass quality. Our report delves into these regional supply nuances without compromising sensitive commercial data, allowing procurement leaders to assess risk exposure in their current vendor networks. The interplay between agricultural output and industrial extraction capacity is a vital lever for cost management and product consistency.
Segmentation Strategy and Product Formulation Heterogeneity
The market is not a monolith. It is fragmented by extraction type, regional demand, and application utility. From a product perspective, the landscape includes distinct categories such as Madecassoside, Asiaticoside, Asiatic Acid, Madecassic Acid, and Standardized Mixed Extracts. Each of these chemical fractions offers different functional benefits, ranging from skin repair to soothing and anti-inflammatory properties. Understanding the relative market weight of these types is crucial for R&D teams deciding which active ingredient to prioritize for specific skin concerns.
Geographically, the demand distribution varies significantly, influenced by local beauty trends and regulatory environments. Similarly, the application landscape spans Skin Care, Hair Care, Makeup and Color Cosmetics, and Oral Care and Others. While skin care remains the dominant driver of demand, the diversification into hair and oral care represents an emerging frontier for growth. Strategic entrants must identify which segments offer the highest margin potential versus those that are volume-driven. Our analysis provides the framework to evaluate these segments based on growth velocity and competitive saturation, enabling companies to allocate resources where the return on investment is maximized. However, the specific percentage splits and revenue figures for these sub-segments are detailed exclusively within the full report to maintain analytical precision for our subscribers.
Competitive Intensity and Strategic Positioning
The competitive landscape is defined by a mix of established global chemical giants and specialized botanical extract manufacturers. Market concentration metrics indicate a moderately fragmented environment, with the top three companies holding a collective share that suggests room for consolidation or niche domination. With a CR3 of 31.45 percent and a CR5 of 42.8 percent, no single entity dominates the entire value chain, allowing specialized players to compete on quality, purity, and technical service.
Key players such as Indena S.p.A. and BASF SE leverage their extensive R&D capabilities and global distribution networks to maintain strong positions. Indena, based in Italy, focuses on high-purity botanical extracts including standardized Centella Asiatica extracts like TECA, emphasizing skin repair and soothing benefits. BASF, headquartered in Germany, incorporates these extracts into broader personal care portfolios, benefiting from synergies across multiple formulation types. Symrise AG and Croda International Plc similarly integrate Centella derivatives into their premium cosmetic offerings, with Croda utilizing its Sederma division to supply specialty ingredients for high-end formulations.
Regional specialization is also evident. In Asia, manufacturers like COSROMA and Wellgreen Technology Co., Ltd. in China are actively marketing high-triterpene contents, such as the Cosroma CICA-T80, catering to the demand for potent active ingredients. Botanic Healthcare in India leverages its proximity to raw material sources to supply extracts with specific asiaticoside concentrations for nutri-cosmetic applications. Meanwhile, companies like Seppic in France are differentiating through technical guidance, releasing detailed guides in late 2025 that emphasize precision and consistency in extracts to support the Cica trend. These recent developments, including product listings by Lipoid Kosmetik AG and new offerings from COSROMA, highlight the pace at which product portfolios are evolving. Understanding the specific strategic moves of these key companies is essential for benchmarking and identifying potential partnership or acquisition opportunities.
Regulatory Frameworks and Standardization Requirements
Compliance is a gatekeeper in the cosmetic ingredient industry. Cosmetic-grade Centella Asiatica extracts must comply with standardization requirements for triterpene content, including asiaticoside, madecassoside, asiatic acid, and madecassic acid. This standardization is critical to support consistent claims in skincare formulations. Without verified potency, marketing claims regarding barrier support or soothing efficacy can be challenged by regulators or scrutinized by informed consumers.
The regulatory landscape is evolving alongside consumer habits. There is a rising demand for natural, soothing, and barrier-repair ingredients in K-beauty, clean beauty, and sensitive skin products. This shift drives the incorporation of standardized cosmetic-grade Centella Asiatica extract. However, this demand also invites stricter scrutiny on ingredient provenance and safety. Our report assesses the regulatory hurdles across key markets, helping compliance officers and product managers anticipate changes that could impact formulation stability or market access. Navigating these requirements requires a partner who understands both the science of the extract and the legal framework of the destination market.
Strategic Imperatives for 2026 Decision Makers
As we move into 2026, the strategic implications for businesses operating in or entering this market are clear. First, supply chain security must be prioritized. Given the agricultural concentration risks, diversifying sourcing locations or investing in vertical integration could mitigate volatility. Second, product differentiation through standardization will be key. With multiple players offering extracts, the ability to guarantee and certify specific triterpene levels will become a primary value proposition.
Third, the expansion into adjacent application categories offers untrodden growth paths. While skin care dominates, the potential in hair care and other segments should not be overlooked. Finally, competitive intelligence must be continuous. The recent activity from major players in late 2025 signals an intensification of marketing and product development efforts. Companies need to stay ahead of these moves to protect their market share or find gaps to exploit.
This summary provides a high-level view of the market's health and direction, but the depth required for execution lies within the full data set. The macro trajectories, segmentation splits, and company profiles described here are merely the surface of a much deeper analytical ocean. To access the granular data necessary for precise forecasting, vendor selection, and market entry strategy, stakeholders are invited to explore the complete Worldwide Cosmetic Grade Centella Asiatica Extract Market research. The full intelligence packaged in this study is designed to convert uncertainty into actionable strategy, ensuring that your organization is positioned to capitalize on the green wave of Cica innovation.
For detailed analysis of this topic, please visit the official page: Worldwide Cosmetic Grade Centella Asiatica Extract Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report Forecasts Worldwide Sendust Core Market to Reach 1.12 Billion by 2032 with 9.2 Percent CAGR from 2026 to 2032
By PW Consulting, 2026-09-02
Navigating the Flux: Strategic Imperatives in the Worldwide Sendust Core Market Through 2032
The landscape of power electronics is undergoing a seismic shift, driven by the relentless demands of electrification, renewable energy integration, and high-frequency communication networks. At the heart of this transformation lies a critical component often overlooked until supply chains fracture: the Sendust core. As businesses navigate the complexities of 2026 and beyond, understanding the trajectory of the Worldwide Sendust Core Market is not merely an academic exercise—it is a strategic necessity for supply chain resilience, product design optimization, and competitive positioning.
Worldwide Sendust Core Market
Our latest comprehensive research, the Worldwide Sendust Core Market study, offers a granular view of this evolving sector. This article serves as a strategic preview, outlining the macro-economic forces, competitive tensions, and technological disruptions defined within the full report. We invite industry leaders to examine these insights as a foundation for deeper engagement with the complete intelligence package available on our source page.
Worldwide Sendust Core Market
The Trajectory of Growth: A Decade of Expansion
The Sendust core market has demonstrated robust resilience and growth over the past half-decade, establishing a strong baseline as we enter the forecast period. Between 2020 and 2025, the market evolved from a valuation of approximately 385.2 million USD to 605.15 million USD. This historical performance sets the stage for an ambitious forecast period spanning 2026 to 2032.
Worldwide Sendust Core Market
Our analysis projects a compound annual growth rate (CAGR) of 9.2 percent throughout this forecast window. By 2032, the market is anticipated to reach a valuation exceeding 1.1 billion USD. This trajectory reflects more than just incremental gains; it signals a structural expansion in demand drivers. The jump from the 2025 base year valuation of 605.15 million USD to the 2026 projection of 643.3 million USD indicates immediate momentum that stakeholders must capitalize on before the growth curve steepens further towards the end of the decade.
Such growth is not uniform. It is propelled by specific industrial shifts that require precise navigation. The full report dissects the velocity of this growth across different timeframes, identifying inflection points where investment or procurement decisions will yield the highest strategic return. Understanding the timing of these peaks is crucial for capacity planning and inventory management.
Supply Chain Dynamics and Material Realities
Strategic planning in the magnetic materials sector requires a clear understanding of the physical and regulatory constraints shaping production. Sendust cores, composed primarily of an alloy powder consisting of 85 percent iron, 9 percent silicon, and 6 percent aluminum, represent a specific niche within soft magnetic composites. This composition offers distinct advantages in terms of lower core losses and better thermal properties compared to traditional iron powder cores, making them indispensable for high-frequency applications.
However, the stability of this supply chain is subject to volatility. During 2023, iron-based feedstock prices for magnetic powder cores fluctuated by up to 15 percent, directly impacting production cost stability. For procurement managers, this historical volatility underscores the need for hedging strategies and diversified sourcing, details of which are modeled in our risk assessment section.
Regulatory environments are equally critical. Stringent environmental regulations in China and South Korea require a 20 percent reduction in emissions per ton of powder produced by the end of 2025 for metal magnetic powder core manufacturing. Compliance with these standards is not optional; it defines market access. Simultaneously, trans-Pacific trade dynamics have shifted dramatically. US Section 232 duties on steel and aluminum imports, including derivatives, increased to 50 percent effective June 2025. This includes tariff stacking for steel and aluminum content in products. For buyers in North America, this alters the landed cost calculus significantly, potentially favoring domestic or allied-nation suppliers over those subject to these duties.
The full report provides a detailed matrix of how these regulatory pressures interact with regional manufacturing capabilities, offering a roadmap for compliance and cost mitigation strategies that go beyond surface-level tariff analysis.
Application-Driven Demand: Where the Value Lies
The utility of Sendust cores spans several high-growth verticals. Our segmentation analysis identifies three primary pillars of demand that are driving the 9.2 percent CAGR.
Automotive and EV Electronics represent the largest share of current market value. As electric vehicles become more sophisticated, the need for efficient power conversion and magnetic components in inverters, DC-DC converters, and onboard chargers intensifies. The requirement for components that can handle high saturation levels while minimizing loss at high frequencies positions Sendust cores as a preferred solution.
Renewable Energy Inverters constitute the second major demand driver. The push for solar energy adoption necessitates inverters that operate efficiently at higher switching frequencies. Recent developments highlight this focus; for instance, Micrometals developed Sendust cores specifically for solar inverters that reduced power loss by 12 percent. Such technological improvements directly correlate with the expansion of this segment.
Telecommunications and 5G infrastructure form the third pillar. As networks densify and frequency bands expand, the magnetic components within base stations and network equipment must meet rigorous performance standards without compromising on size or thermal management.
While industrial power supplies remain a steady contributor, the explosive growth is concentrated in the first three categories. The report provides a comparative analysis of how these application segments interact with pricing structures and volume commitments, revealing where the highest margin opportunities exist for suppliers and where the most critical supply risks lie for OEMs.
The Competitive Arena: Incumbents and Emerging Players
The global competitive landscape for Sendust cores is characterized by a mix of established Western manufacturers and a robust cohort of Asian producers. Our market concentration data indicates a moderately consolidated environment, with the top three companies holding a combined market share (CR3) of 42.15 percent and the top five reaching 58.42 percent. This concentration suggests that while there is room for niche players, the bulk of market influence rests with key incumbents.
In the United States, Magnetics (Spang & Company) continues to emphasize quality and thermal properties, manufacturing high-quality Kool Mu (Sendust) powder cores. Similarly, Micrometals offers advanced variants like MS Sendust and SM SenMax, focusing on low loss and high saturation characteristics. Their recent development work on solar inverter cores underscores their commitment to the renewable energy segment.
The Asian manufacturing base is diverse and highly competitive. In China, companies like Pourleroi specialize in high DC Sendust cores and DPH-enhanced variants using fine-grain alloy powders for new energy applications. HSMAG focuses on toroid Sendust power cores for high-frequency applications above 8kHz. Other significant Chinese players include Shaanxi Magason-Tech, Shaanxi Gold-Stone Electronics (GS Magnetics), and Shinhom, all of which focus on various aspects of Sendust core production and customization.
South Korea contributes significant capacity through firms such as Chang Sung Corporation (CSC), which produces Sendust powder cores alongside MPP and High Flux materials. Samwha Electronics and Dongbu Electronic Materials also supply Sendust powdered cores for global applications, while CMSS Technology remains involved in production activities. Taiwan's ACME Electronics stands as a key player in the segment, and India's Vijaya Electronics serves as a manufacturer and exporter for electronic applications. In the US coil winding and specialized component space, Coil Winding Specialist, Inc. (CWS) offers Sendust toroidal cores for specific inductor and choke applications.
Strategic positioning in this market requires more than just identifying these players. It requires understanding their specific technological capabilities, certification statuses, and supply chain reliability. The full report includes detailed profiles and SWOT analyses for these key entities, providing the context needed to negotiate partnerships or assess single-source risks.
Technological Innovations and Certification Milestones
Innovation in the Sendust core market is not limited to material composition; it extends to manufacturing processes, environmental compliance, and product certification. Recent industry developments highlight the direction of travel.
In July 2025, TDK introduced eco-friendly coatings for powder cores, enhancing recyclability by 30 percent in industrial applications. This move aligns with the broader industry push towards sustainability and circular economy principles, potentially setting a new standard for component lifecycle management.
Certification is another critical battleground. In December 2025, Ole Wolff Elektronik A/S released the OWTC157xxxVS-xxx Sendust Toroid Choke series with RoHS, REACH, and AECQ-200 Grade 1 certifications tailored for ESS and PFC applications. Achieving AECQ-200 Grade 1 is particularly significant for automotive-related supply chains, as it validates the component for stringent automotive reliability standards.
These developments illustrate that market leadership is increasingly tied to sustainability credentials and certification breadth. Companies that fail to adapt to these evolving standards risk exclusion from high-value supply chains. Our report tracks these certification milestones and their implications for market entry barriers and competitive advantages.
Strategic Recommendations for 2026 Decision Makers
As organizations finalize their strategies for 2026, several key imperatives emerge from the data.
-
Supply Chain Diversification
Given the volatility in iron-based feedstock prices and the impact of US Section 232 duties, reliance on single-region sourcing is a heightened risk. Diversifying suppliers across different geopolitical zones can mitigate tariff shocks and material price fluctuations.
-
Focus on High-Growth Applications
Resource allocation should prioritize segments with the highest growth elasticity. Automotive EV electronics and Renewable Energy Inverters are projected to outpace general industrial demand. Aligning product roadmaps with these sectors ensures exposure to the strongest revenue streams.
-
Regulatory Compliance as a Value Proposition
With emissions reductions mandated in key manufacturing hubs like China and South Korea, compliance should be viewed as a competitive differentiator. Suppliers who can guarantee lower carbon footprints and adherence to local environmental laws will gain preference in sensitive supply chains.
-
Technology Adoption and Recycling
The introduction of eco-friendly coatings and improved loss-reduction technologies suggests a market trend towards efficiency and sustainability. Evaluating suppliers based on their adoption of these technologies can future-proof product designs against upcoming regulatory tightening.
These recommendations are derived from a synthesis of historical data, regulatory forecasts, and competitive intelligence. However, implementing them effectively requires access to the detailed segmentation splits, regional revenue breakdowns, and specific manufacturer market shares contained in the full study.
A Call for Deep-Dive Intelligence
The Worldwide Sendust Core Market is entering a phase of accelerated maturity. The confluence of electrification, renewable energy expansion, and stringent regulatory frameworks creates a complex environment where general market trends are insufficient for strategic success. Leaders need precise data on regional revenue splits, application-specific growth rates, and the nuanced positioning of competitors to navigate this terrain effectively.
This article has highlighted the macro trajectory, the key players, and the critical external factors influencing the market. Yet, it intentionally omits the granular data points necessary for immediate operational decision-making. The full report provides the specific revenue units for each segmentation, the detailed regional splits beyond the top-line figures, and the comprehensive competitive benchmarking that allows for apples-to-apples comparison of supplier capabilities.
For stakeholders ready to move beyond high-level overviews, the complete Worldwide Sendust Core Market research offers the detailed intelligence required to secure supply chains, identify partnership opportunities, and capture growth in this vital component sector. We invite you to access the full study via our source page to equip your organization with the precise data needed to drive 2026 strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Sendust Core Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Influencer Relationship Management Platform Market Hits $12.5 Billion in 2025 and Projects 26.04% CAGR Through 2032
By PW Consulting, 2026-09-01
Navigating the Influencer Economy: Strategic Imperatives for the IRMP Market in 2026 and Beyond
The influencer marketing landscape has matured from a discretionary brand experiment into a core revenue operations function. As social commerce, creator-led product launches, and algorithmic content distribution continue to reshape customer acquisition, enterprises are increasingly turning to Influencer Relationship Management Platforms (IRMPs) to systematize discovery, contracting, performance tracking, and long-term creator lifecycle management. PW Consulting’s newly released Worldwide Influencer Relationship Management Platform Market study is designed to equip executive teams, procurement leaders, and growth strategists with the structural intelligence needed to make informed technology investments, vendor selections, and capability-building decisions throughout the 2026–2032 forecast horizon.
Worldwide Influencer Relationship Management Platform Market
This market research is not a surface-level trend summary. It is a decision-grade intelligence asset built to help organizations cut through vendor noise, anticipate platform evolution, and align technology roadmaps with emerging regulatory and commercial realities. Below, we outline the strategic architecture of the study, the operational contents it delivers, and the competitive and regulatory forces that will define platform selection criteria in the coming years.
Worldwide Influencer Relationship Management Platform Market
Why IRMP Intelligence Matters for 2026 Decision-Making
By 2026, influencer marketing is no longer optimized through spreadsheets, ad-hoc outreach, or fragmented analytics dashboards. Scaling creator programs across product categories, regions, and campaign types requires a centralized system of record that can manage relationship touchpoints, compliance documentation, payment workflows, and multi-channel performance attribution. Organizations that treat IRMP adoption as a tactical software purchase rather than a strategic capability investment frequently encounter data silos, inconsistent creator onboarding, and opaque return measurement.
Worldwide Influencer Relationship Management Platform Market
The research underscores that platform selection in this category must be evaluated against three interconnected decision dimensions: operational scalability, data integrity, and ecosystem interoperability. Operational scalability determines whether a platform can support both micro-creator volume programs and enterprise-scale ambassador relationships without degradation in workflow efficiency. Data integrity governs how accurately platforms attribute engagement, validate creator authenticity, and surface fraud signals. Ecosystem interoperability reflects the degree to which a platform can integrate with e-commerce infrastructure, CRM systems, media planning tools, and payment gateways.
The study’s market trajectory analysis provides executives with the context needed to time these investments appropriately. The global influencer relationship management platform market reached an estimated revenue base of approximately $12.5 billion in 2025, expanding from roughly $2.85 billion in 2020. This growth trajectory reflects the compounding effect of creator-driven commerce, broader adoption of performance-linked influencer programs, and the structural shift toward managed relationship workflows rather than one-off sponsored placements. Looking forward, revenue is projected to continue its steep ascent through 2032, with a compound annual growth rate of 26.04 percent across the forecast period.
For decision-makers, this growth rate signals more than market enthusiasm. It indicates sustained platform investment, accelerating feature differentiation, and increasing pressure on legacy tools that cannot support AI-assisted discovery, automated contract management, or cross-channel relationship tracking. Organizations evaluating IRMP vendors in 2026 must therefore assess whether a platform’s roadmap is aligned with this pace of change or whether it is positioned for commoditization.
Inside the PW Consulting Research: Practical Intelligence for Execution
The study is structured to move beyond aggregate market commentary and deliver actionable, implementation-relevant content. It is intended for teams that need to justify budget allocation, compare vendor capabilities, and anticipate where the category is heading. The report’s architecture is built around several core components that directly support enterprise and mid-market planning cycles.
At the foundation of the analysis is a comprehensive market sizing and forecast framework that maps historical performance and forward-looking revenue trajectories across the 2026–2032 period. Rather than presenting isolated figures, the research embeds these numbers within a broader narrative about demand drivers, adoption maturity, and the transition from experimental influencer budgets to formalized creator relationship operations. This framing allows leadership teams to benchmark their internal timing assumptions against market-wide momentum.
The report also examines deployment-mode dynamics in detail. As organizations evaluate whether to prioritize cloud-based delivery or maintain on-premise infrastructure for sensitive campaign and contract data, the study analyzes how architecture choices affect integration flexibility, cost structures, and scalability. This is particularly relevant for enterprises managing large creator networks, multi-region compliance requirements, and complex data governance policies.
Organization-size segmentation is another critical dimension in the research. The analysis differentiates how large enterprises and small-to-medium enterprises approach IRMP adoption, including differences in workflow complexity, procurement behavior, and required feature depth. Large organizations typically demand enterprise-grade relationship orchestration, contract management, and multi-role access controls, while smaller teams often prioritize faster onboarding, cost efficiency, and streamlined discovery-to-outreach workflows. Understanding these divergent requirements helps buyers avoid either overbuying or under-specifying their platform.
Beyond sizing and segmentation, the report delivers practical operational coverage that can be applied directly to platform evaluation and internal rollout planning. This includes:
- Functional capability mapping across influencer discovery, relationship nurturing, campaign orchestration, gifting and product seeding workflows, payment and contract handling, affiliate and performance tracking, and analytics reporting.
- Vendor evaluation frameworks that translate feature claims into decision-relevant comparisons, helping procurement and marketing operations teams assess fit against internal use cases rather than marketing narratives.
- Implementation and adoption considerations that address integration complexity, internal workflow redesign, data migration, and cross-functional ownership between marketing, legal, finance, and operations.
- Procurement and licensing context designed to support negotiations around usage tiers, seat structures, API consumption, and enterprise service agreements.
The study is intentionally designed to help organizations convert market information into operational decisions. It provides the kind of structural clarity needed to assess whether a platform will support not only current campaign demands but also the next phase of creator program maturity, including cross-channel expansion, commerce integration, and automated relationship scoring.
Competitive Landscape: Differentiated Strategies Among Core Platforms
The IRMP category is shaped by a competitive set of vendors that have taken distinct strategic paths. Rather than converging on a single platform model, the market now reflects specialization across enterprise CRM depth, e-commerce integration, AI-assisted performance analytics, and workflow automation. The research analyzes this competitive architecture to help buyers understand not just who is in the market, but how each platform attempts to create value and where differentiation is most credible.
Aspire positions itself as a SaaS platform focused on influencer discovery, relationship management, campaign tracking, and performance analytics across social channels. Its trajectory in the market reflects an emphasis on end-to-end campaign visibility and channel-spanning analytics, appealing to teams that want a unified operational layer for creator programs.
CreatorIQ occupies a more enterprise-oriented position, offering CRM tools for relationship management, contracts, payments, and ROI measurement. The platform’s enterprise focus makes it particularly relevant for organizations that require formalized contracting, financial workflow integration, and structured return measurement across large creator networks.
Grin emphasizes influencer relationship management software that integrates discovery, outreach, gifting, and e-commerce tracking for brands. Its product direction reflects the growing importance of product seeding and commerce-linked creator programs, where the relationship lifecycle extends beyond content publication into product fulfillment and sales attribution.
Influencity brings an AI-powered approach to influencer discovery, CRM, campaign management, and real-time performance reporting. Platforms that center AI in their value proposition are responding to demand for faster creator identification, more dynamic performance monitoring, and improved prioritization of relationship opportunities.
Klear, operating within Meltwater’s broader suite, embeds influencer relationship management into a wider media and analytics ecosystem. Its positioning highlights discovery, engagement tracking, and analytics, appealing to organizations that want influencer workflows connected to broader listening, monitoring, and media intelligence capabilities.
Later Influence approaches the category through an influencer collaboration platform that combines relationship management, marketplace matching, and content approval workflows. This model is especially relevant for teams that need structured content review, brand safety controls, and collaborative approval processes in addition to relationship tracking.
Traackr focuses on influencer CRM for relationship nurturing, performance insights, and enterprise-scale campaign orchestration. Its enterprise orientation and emphasis on long-term relationship management differentiate it for organizations that treat creator programs as sustained partnerships rather than transactional campaigns.
Upfluence offers an all-in-one influencer platform with CRM features for discovery, outreach, payments, and affiliate tracking. Its broad feature set reflects the demand for consolidated workflows that can reduce tool sprawl across multiple stages of the creator engagement lifecycle.
The research situates these vendors within a broader competitive dynamic by examining how product launches, partnerships, and feature updates reshape evaluation criteria. Recent activity illustrates the pace of differentiation in the category. In October 2025, CreatorIQ launched AI-powered influencer fraud detection and relationship scoring enhancements, underscoring the growing importance of authenticity verification and relationship quality signals. In September 2025, Aspire announced integration with Shopify for streamlined influencer gifting and e-commerce tracking, reflecting closer ties between creator platforms and commerce infrastructure. In June 2025, Grin introduced automated contract generation and payment workflows in influencer CRM, signaling movement toward operational automation in creator contracting and compensation. In April 2025, Traackr expanded its platform with multi-channel relationship management for TikTok and YouTube Shorts, demonstrating continued adaptation to short-form video ecosystems and cross-channel relationship orchestration.
For enterprise buyers, these developments matter because they reveal where vendor attention is flowing. Fraud detection, commerce integration, automated contracting, and short-form video coverage are not isolated feature additions; they are indicators of the capabilities that the market increasingly expects as baseline requirements. The study helps organizations interpret these signals within a comparative framework, enabling more disciplined shortlisting and negotiation.
Market Dynamics and Structural Forces Shaping Platform Strategy
The IRMP market is not expanding in a vacuum. Several structural forces are reshaping how organizations design creator programs and how platforms must respond. The research integrates these dynamics to help buyers anticipate where compliance, cost, and creator strategy will influence technology decisions.
Regulatory pressure is one of the most consequential forces in the category. The EU Digital Services Act requires influencer platforms to disclose sponsored content and verify creator authenticity, introducing new obligations around transparency and identity validation. In parallel, FTC Endorsement Guides mandate clear disclosure of material connections in influencer relationships, reinforcing the need for platforms that can store, surface, and manage compliance documentation throughout the campaign lifecycle. These regulatory developments push IRMP adoption beyond convenience and into risk management, making contract storage, disclosure tracking, and authenticity verification more central to platform value.
Infrastructure and analytics costs also influence platform economics, particularly for AI-driven influencer analytics. Cloud computing costs for AI-driven influencer analytics average $0.05 to $0.20 per 1,000 API calls via AWS or GCP. While this cost range may appear modest at the unit level, it becomes strategically relevant when platforms scale high-volume discovery, sentiment evaluation, or performance modeling across large creator datasets. For organizations evaluating total cost of ownership, understanding how vendors manage API consumption, data storage, and compute intensity is essential to forecasting long-term operating expenses.
A third dynamic is the strategic shift in creator selection and relationship design. The market is increasingly shaped by a move toward micro-influencer relationships, with 70 percent of brands prioritizing creators under 100K followers. This trend increases platform demand for high-volume discovery, relationship triage, and workflow efficiency, because managing many smaller-scale relationships requires different operational tooling than managing a small roster of macro creators. Platforms that can support volume onboarding, automated outreach, lightweight contracting, and efficient performance monitoring are better positioned to serve this evolving brand preference.
Together, these dynamics create a market environment in which platform selection must balance compliance readiness, cost efficiency, and workflow scalability. The research addresses these forces not as isolated observations but as integrated inputs to a broader evaluation framework, helping organizations understand how regulatory requirements, infrastructure economics, and creator strategy will shape platform fit over the forecast period.
Market Concentration, Selection Discipline, and Strategic Timing
Despite rapid growth and expanding vendor activity, the IRMP market remains structured around a moderately concentrated competitive field. The research examines market concentration to help buyers understand the balance between established platform presence and ongoing room for specialization. This context is valuable because concentration levels influence pricing leverage, integration expectations, and the likelihood of future consolidation or platform bundling.
For 2026 decision-makers, the key implication is that vendor selection cannot be reduced to feature checklists alone. Enterprise buyers need to evaluate how each platform’s architecture, data handling, compliance support, and integration depth will perform as creator programs grow in complexity. Mid-market buyers must weigh speed of deployment and usability against the risk of outgrowing a platform as their creator strategy matures. In both cases, the study provides the comparative context needed to align vendor shortlists with organizational trajectory rather than short-term campaign needs.
The report also supports timing decisions. In a category expanding at a 26.04 percent CAGR, the cost of delayed evaluation can be significant. Organizations that postpone platform standardization may find themselves accumulating manual processes, fragmented performance data, and compliance gaps that become harder to unwind over time. Conversely, organizations that rush into platform adoption without clear workflow definitions or integration requirements may pay for unused capability or face costly reconfiguration later. The research is designed to help teams strike that balance by framing platform investment as a phased capability build rather than a one-time purchase.
What the Full Study Enables for Your Organization
The Worldwide Influencer Relationship Management Platform Market study is built to support a wide range of executive and operational use cases. It is intended to help strategy leaders understand where the market is going, procurement teams evaluate vendor claims with greater discipline, and marketing operations teams plan implementation in a way that reduces disruption and accelerates time to value.
Specifically, the full research equips organizations to:
- Benchmark internal platform requirements against market-wide adoption patterns and growth trajectories.
- Assess vendor differentiation across discovery, CRM, contract and payment workflows, analytics, fraud detection, and commerce integration.
- Anticipate how regulatory disclosure obligations and creator authenticity verification will affect platform selection and internal process design.
- Evaluate deployment-mode and organization-size fit in the context of integration needs, data governance, and scalability expectations.
- Frame procurement negotiations around realistic usage, API consumption, seat structures, and enterprise service requirements.
- Align influencer program roadmaps with platform capabilities so that relationship management evolves in step with campaign complexity and commerce integration.
Because the category is moving quickly, the most valuable decisions are those made with access to complete segmentation detail, forward-looking scenario context, and vendor-specific evaluation support. The published summary provides the strategic frame; the full report provides the operational depth required to convert that frame into a concrete purchasing and implementation plan.
Conclusion: From Market Awareness to Decisive Action
The influencer relationship management platform market is entering a phase in which technology choice has direct consequences for creator program efficiency, compliance readiness, and performance transparency. Growth has been strong, the competitive field is actively differentiating, and regulatory and operational forces are raising the stakes for platform selection. In this environment, organizations need market intelligence that goes beyond headline figures and supports practical, cross-functional decision-making.
PW Consulting’s Worldwide Influencer Relationship Management Platform Market study is designed for exactly that purpose. It combines market sizing, forecast trajectory, segmentation insight, competitive analysis, and regulatory context into a structured decision-support resource. For leaders responsible for marketing technology, creator programs, procurement, or growth strategy, the research offers a path toward more confident vendor evaluation and more disciplined investment timing.
To access the full segmentation detail, complete vendor profiles, and the full range of forward-looking market intelligence supporting these findings, visit the source page to retrieve the complete report.
For detailed analysis of this topic, please visit the official page: Worldwide Influencer Relationship Management Platform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Worldwide Vibration Detector Market to Hit 13080 Million by 2032 Growing at 9.33 CAGR
By PW Consulting, 2026-09-01
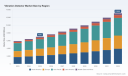
Strategic Imperatives in the Global Vibration Detector Market: Navigating the 2026 Landscape
The global industrial landscape is undergoing a seismic shift. No longer content with reactive repairs and scheduled downtime, enterprises are increasingly turning to condition-based monitoring and predictive maintenance strategies. At the heart of this transformation lies the vibration detector market, a critical enabler for asset integrity, operational efficiency, and safety across heavy industry. As we move through 2026, the strategic value of understanding this market extends far beyond simple procurement; it is about anticipating technological convergence, regulatory pressures, and competitive shifts that will define the next decade of industrial operations.
Worldwide Vibration Detector Market
PW Consulting has compiled a comprehensive Worldwide Vibration Detector Market study, designed specifically to equip decision-makers with the intelligence needed to navigate this complex ecosystem. This report is not merely a collection of statistics; it is a strategic roadmap derived from deep-dive analysis of historical trends, current market dynamics, and forward-looking projections. The following insights offer a preview of the critical themes shaping the industry, urging leaders to look beyond surface-level metrics and grasp the underlying forces driving growth.
Worldwide Vibration Detector Market
Market Trajectory and Financial Landscape
The financial magnitude of the vibration detector market underscores its importance as a strategic investment sector. Drawing from historical data spanning 2020 to 2025, the market has demonstrated consistent expansion, reflecting the growing reliance on sensor technology for machinery health assessment. In the base year of 2025, the overall market revenue reached approximately 7010.0 Million USD. This established foundation sets the stage for a robust forecast period extending from 2026 to 2032.
Worldwide Vibration Detector Market
Projections indicate a steady upward trajectory, with the market expected to climb to 7650.0 Million USD in 2026. By the end of the forecast period in 2032, revenue is anticipated to reach 13080.0 Million USD. This growth path translates to a Compound Annual Growth Rate (CAGR) of 9.33 percent over the forecast horizon. Such performance highlights the market's resilience and its integral role in industrial modernization. However, these aggregate figures represent only the tip of the iceberg. The true strategic value lies in understanding the velocity of growth across different vectors and the factors accelerating adoption in specific operational contexts.
Segmentation Dynamics: Type, Application, and Region
While the total market size provides a macro view, the segmentation data reveals where the opportunities and risks are concentrated. The market is divided across multiple dimensions, including sensor type, end-use application, and geographic region. Each segment presents unique value propositions and adoption curves that require tailored strategic approaches.
In terms of technology, the market encompasses a diverse array of sensor modalities. Piezoelectric accelerometers continue to hold a significant position, driven by their reliability in high-frequency vibration measurement. However, the landscape is increasingly competitive with the presence of piezoresistive vibration sensors, capacitive accelerometers, electromagnetic sensors, and optical laser vibration detectors. The choice of technology often depends on the specific environmental constraints and measurement requirements of the application, ranging from harsh industrial conditions to precision laboratory settings. Understanding the relative maturity and cost structures of these technologies is essential for product strategists and procurement leaders.
Application-wise, the demand is spread across several key industries. Industrial manufacturing remains a primary driver, leveraging vibration data for predictive maintenance of production lines. The automotive and transportation sector utilizes these sensors for vehicle dynamics and engine health, while aerospace and defense applications demand high-reliability solutions for critical components. Additionally, sectors such as oil and gas, energy and power, and medical and healthcare contribute to the demand profile. Each application vertical faces distinct regulatory and operational pressures that influence procurement cycles and technology preferences.
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Regional dynamics are shaped by local industrial bases, investment in automation, and the pace of digital transformation initiatives. While global averages provide a baseline, regional nuances regarding supply chain logistics, local manufacturing capabilities, and specific industrial policies play a crucial role in market entry and expansion strategies.
Competitive Landscape and Key Players
The vibration detector market is characterized by a mix of established industrial giants and specialized technology providers. The competitive environment is moderately concentrated, with the top three players holding a combined market share of approximately 32.4 percent and the top five companies accounting for 45.6 percent. This structure suggests a market where scale and brand reputation matter, yet there remains room for specialized innovators to capture niche segments.
Several key companies define the current competitive arena. SKF, headquartered in Gothenburg, Sweden, is a prominent provider of vibration sensors, analyzers, and monitoring systems, including the SKF Microlog series for predictive maintenance in industrial machinery. Emerson Automation Solutions, based in St. Louis, MO, USA, offers AMS wireless vibration sensors and CSI 2140 machinery analyzers for real-time vibration monitoring in rotating equipment. Fluke Corporation, located in Everett, WA, USA, manufactures handheld vibration meters such as the Fluke 805 and 810 for bearing and machinery health assessment.
Brüel & Kjær (HBK), with headquarters in Nærum, Denmark, supplies VIBROPORT and advanced vibration analyzers for condition monitoring in power plants and manufacturing. Honeywell International, based in Charlotte, NC, USA, delivers vibration monitoring systems including the HM500 series for aerospace and industrial applications. Siemens AG, from Munich, Germany, provides SIMATIC PCS 7 integrated vibration monitoring for process industries and turbine diagnostics. General Electric (GE Bently Nevada), located in Minden, NV, USA, specializes in 3500 series rack-mounted vibration monitoring systems for turbomachinery protection. PCB Piezotronics (IMI Sensors), in Depew, NY, USA, produces industrial accelerometers and vibration sensors like the 608A series for harsh environments. Metrix Vibration, based in Houston, TX, USA, offers proximity sensors and vibration transmitters for oil and gas and power generation equipment. National Instruments (NI), from Austin, TX, USA, develops modular vibration analysis systems using LabVIEW software for custom monitoring solutions.
Recent activities among these players signal the direction of the market. In October 2025, SKF launched the IMx-8 multi-channel vibration monitoring system for advanced predictive maintenance. Emerson showcased the AMS 2140 machinery health analyzer at the ACHEMA 2025 exhibition in June 2025. Fluke released an updated Fluke 805 Vibration Meter with an enhanced laser tachometer in April 2025. In March 2025, HBK achieved ATEX certification for the VIBROPORT 600 vibration analyzer for hazardous areas. These developments highlight a trend toward multi-channel capabilities, enhanced user interfaces, and expanded safety certifications, all of which are critical for operators in demanding environments.
Macro Drivers and Industry Dynamics
The growth of the vibration detector market is propelled by a confluence of macro-level drivers and industry-specific dynamics. A primary catalyst is the adoption of predictive maintenance strategies, driven by Industry 4.0 initiatives. Analysis suggests that predictive maintenance can reduce unplanned downtime by up to 50 percent, making the investment in vibration monitoring systems a compelling proposition for operations managers seeking to maximize asset utilization.
Additionally, regulatory frameworks play a significant role in shaping market demand. Standards such as ISO 20816-2016 govern vibration measurement and evaluation for machinery, requiring limits for rotating equipment. Compliance with these standards often necessitates the deployment of reliable vibration detection solutions, thereby creating a steady baseline demand in regulated industries.
Cost structures also influence market dynamics. On the raw material front, silicon MEMS accelerometer prices stabilized at 15 to 25 USD per unit in Q4 2025 amid a steady semiconductor supply. This stability provides a predictable cost environment for sensor manufacturers and integrators, allowing for more accurate pricing strategies and margin planning. Conversely, labor costs present a different pressure point. Skilled maintenance technician wages rose 4.2 percent year-over-year in the manufacturing sector to an average of 32 USD per hour in 2025. As labor costs increase, the economic case for automation and sensor-based monitoring becomes even stronger, as organizations seek to mitigate reliance on scarce and expensive skilled labor.
Report Structure and Operational Content
The PW Consulting Worldwide Vibration Detector Market study is structured to provide actionable intelligence for a wide range of stakeholders, from strategic planners to procurement specialists. The report delves into granular details that transform high-level market data into operational insights. Readers will find comprehensive analysis of market sizing, growth rates, and segmentation trends, supported by a methodology that ensures accuracy and relevance.
Key components of the report include detailed historical reviews and forecast models that account for various market drivers and restraints. The segmentation analysis breaks down the market by type, application, and region, offering a nuanced view of where growth is concentrated and where competitive intensity is highest. The competitive landscape section profiles major players, examining their product portfolios, strategic moves, and market positioning. This includes an assessment of recent product launches, partnerships, and certifications that indicate shifts in competitive advantage.
Furthermore, the report integrates industry context, including raw material trends, regulatory updates, and macroeconomic factors that influence market behavior. By synthesizing these elements, the study provides a holistic view of the ecosystem. The objective is to empower users to make informed decisions regarding market entry, product development, investment allocation, and risk management. The depth of analysis ensures that stakeholders can benchmark their performance against industry averages and identify gaps in their current strategies.
Strategic Takeaways for 2026 Decision-Makers
As leaders evaluate their strategies for 2026 and beyond, several critical takeaways emerge from the market analysis. First, the convergence of sensor technology with data analytics platforms is accelerating. Companies that can offer integrated solutions combining high-quality vibration detection with actionable insights will gain a competitive edge. Second, the emphasis on safety and compliance, evidenced by certifications like ATEX, is becoming a differentiator in hazardous environments, opening new markets for compliant solutions. Third, the stabilization of component costs combined with rising labor expenses strengthens the ROI narrative for predictive maintenance investments, suggesting a widening adoption base beyond early adopters.
Moreover, the moderate market concentration implies that while large players dominate, there is strategic room for targeted acquisitions or partnerships to enhance capabilities. Understanding the specific strengths of competitors such as SKF, Emerson, and Siemens, alongside specialized players like Fluke and HBK, allows organizations to identify whitespace opportunities. For instance, regions or applications where coverage is fragmented may present avenues for growth for agile entrants or those with localized support networks.
The forecast period through 2032 offers a long-term horizon for planning. With the market expected to grow from 7650.0 Million USD in 2026 to 13080.0 Million USD by 2032, the cumulative opportunity is substantial. However, realizing this value requires a nuanced understanding of the segmentation splits and the dynamics driving growth in each segment. Decisions made today regarding technology selection, supplier relationships, and market focus will have lasting implications as the market matures.
Conclusion and Access to Full Intelligence
The worldwide vibration detector market represents a dynamic intersection of industrial necessity, technological innovation, and economic efficiency. For enterprises operating in 2026, the ability to navigate this market with precision is a strategic imperative. The insights provided in this preview highlight the breadth and depth of the trends shaping the industry, from the growth trajectory and segmentation nuances to the competitive maneuvers of key players and the macro drivers influencing adoption.
However, the complexity of the market demands a level of detail that goes beyond summary observations. To fully leverage the data and analysis presented in the PW Consulting Worldwide Vibration Detector Market study, stakeholders are encouraged to access the complete report. The full document contains the granular segmentation data, detailed company profiles, regional breakdowns, and comprehensive forecast models necessary to build robust strategies. By accessing the complete intelligence, decision-makers can ensure their plans are grounded in the most accurate and up-to-date market evidence, positioning their organizations for success in an evolving industrial landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Vibration Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Worldwide Shaper Machine Market to Reach USD 1590.34 Million by 2032 with 3.5 Percent CAGR
By PW Consulting, 2026-09-01
Strategic Intelligence for the 2026 Capital Expenditure Cycle: Inside the Worldwide Shaper Machine Market
As manufacturing leaders finalize their capital allocation plans for the 2026 fiscal year, the precision metalworking landscape demands a clear-eyed assessment of where value will be created and where volatility threatens margins. The globally distributed shaper machine sector is entering a phase of measured expansion, shaped by industrial automation mandates, shifting labor economics, and incremental mobility toward smart manufacturing infrastructure. Our latest Worldwide Shaper Machine Market research study provides the analytical architecture required to navigate this environment. By anchoring decision-making in rigorously modeled historical performance and forward-looking demand drivers, procurement leaders, plant managers, and corporate strategists can move beyond reactive purchasing cycles and into proactive capacity planning.
Worldwide Shaper Machine Market
The report is designed as a decision-support instrument rather than a static statistical compendium. It maps the trajectory of the global shaper machine market from a 2025 baseline valuation of 1,250.0 million USD through a forecast horizon extending to 2032, where projected revenue reaches 1,590.34 million USD. Over the historical window spanning 2020 to 2025, the market demonstrated steady consolidation, with 2023 recorded at 1,165.2 million USD and 2024 climbing to 1,207.5 million USD. The forward-looking period from 2026 to 2032 reflects a compound annual growth rate of 3.5 percent, moving through 1,293.75 million USD in 2026, 1,339.03 million USD in 2027, and 1,385.90 million USD in 2028, before continuing a consistent upward path to 1,434.40 million USD in 2029, 1,484.60 million USD in 2030, 1,536.56 million USD in 2031, and ultimately 1,590.34 million USD in 2032. These figures are not abstract benchmarks; they represent the revenue baseline against which regional investments, technology adoption timelines, and competitive positioning must be calibrated.
Worldwide Shaper Machine Market
Why a 3.5 Percent CAGR Still Demands Precision in Capital Planning
A moderate growth rate in a mature industrial equipment category can easily be misread as a low-stakes environment. In reality, a 3.5 percent CAGR across a 2026 to 2032 window places an extraordinary premium on timing, segmentation discipline, and total cost of ownership calculations. Market participants who treat shaper machine procurement as a commodity purchase will find themselves exposed to equipment mismatch, underutilized capacity, and shifting compliance burdens. Conversely, organizations that align their acquisition strategy with granular demand segmentation, regional dynamics, and technology roadmap integration will capture disproportionate operational leverage.
Worldwide Shaper Machine Market
The forecast trajectory does not suggest explosive disruption; it indicates methodical expansion driven by replacement cycles, incremental modernization, and selective capacity additions in high-precision production environments. For decision-makers in 2026, this profile means that strategic value lies not in chasing volume alone but in optimizing the fit between machine capability, production cadence, and end-market demand. The research frames this challenge by breaking the market into actionable structural dimensions while deliberately keeping the most sensitive analytical layers reserved for the full study. This approach ensures that corporate planning teams can validate their internal assumptions before committing to multi-year capital programs.
Report Architecture: Operational Coverage for Procurement, Engineering, and Strategy Teams
The study is structured to serve multiple internal stakeholders simultaneously. For procurement and supply chain leaders, the report delivers a historically grounded view of pricing trajectories, capacity utilization signals, and procurement timing considerations. For engineering and manufacturing operations, it maps application-driven demand patterns across key production verticals, helping teams align machine specifications with part complexity, tolerance requirements, and throughput expectations. For corporate strategy and investor relations teams, the report provides a competitive landscape synthesis, market concentration context, and an assessment of the operational and regulatory forces shaping the industry’s medium-term evolution.
Core Analytical Modules
The research framework is organized around several interlocking modules, each built to convert raw data into executable strategy:
- Market size and trajectory modeling that anchors executive discussions in a validated baseline and transparent forward path, enabling budgeting teams to test scenarios against established revenue envelopes.
- Structural segmentation analysis that examines how different machine configurations and end-use environments are shaping demand, providing the basis for fleet planning, replacement scheduling, and product-mix optimization.
- Regional demand and intensity mapping that identifies where industrial activity, capacity investment, and modernization efforts are concentrated, giving multinational operators a platform for localized sourcing and deployment decisions.
- Competitive positioning and benchmarking that profiles established manufacturers, evaluates their product strategies, and contextualizes recent public activity within broader market momentum.
- Industry dynamics and external pressure assessment that quantifies the impact of material cost movement, labor cost escalation, regulatory compliance, and smart-manufacturing adoption on purchasing decisions and operating economics.
What the Study Is Built to Answer
The report is designed around the questions that repeatedly stall capital planning cycles: where should capacity be added first, which machine architectures best match near-term production requirements, how should organizations weigh automation and connectivity features against upfront cost, and what external cost pressures must be incorporated into lifetime value calculations. By addressing these questions within a single framework, the research removes the need for cross-functional teams to reconcile fragmented spreadsheets and disconnected forecasts.
Competitive Landscape: Dominant Manufacturers and the Battle for Precision Share
Market leadership in the shaper machine sector is not defined solely by historical reputation; it is increasingly determined by the ability to marry precision engineering with automation, connectivity, and application-specific customization. The competitive field reflects a strong concentration of advanced manufacturing capability among Japanese and European producers, complemented by regionally focused specialists that serve distinct end-use requirements. The study profiles the principal market participants and evaluates how their product portfolios, development cadence, and strategic signaling are shaping industry direction.
Leading Japanese Manufacturers and Integrated Precision Systems
Yamazaki Mazak Corporation continues to anchor its reputation around CNC shaper machines and multi-function machining centers engineered for precision metal shaping in automotive and aerospace applications. The company’s recent product trajectory signals a push toward integrated multi-tasking platforms designed to reduce part handling and streamline complex shaping workflows. DMG Mori Co., Ltd. similarly emphasizes horizontal and vertical shaper configurations paired with advanced CNC controls, targeting high-volume industrial production environments where consistency and throughput are paramount. Okuma Corporation distinguishes its offering through gear shapers and universal shapers tailored to gear manufacturing and heavy-duty metalworking applications, reinforcing a positioning around specialized tooling demands rather than generalized machining. Mitsubishi Heavy Industries Machine Tool Co., Ltd. supplies hydraulic shapers and precision shaping machines with a particular emphasis on shipbuilding and energy equipment fabrication, where large-scale structural integrity and controlled material removal are decisive factors.
Regional Specialists and Heavy-Industry Capabilities
Beyond the Japanese leadership cluster, a set of European and Korean manufacturers contributes differentiated capabilities to the competitive mix. Doosan Machine Tools manufactures CNC shapers for mold and die production with a clear emphasis on high-speed shaping capabilities, aligning its portfolio to tooling-intensive sectors where cycle time compression translates directly into margin performance. WaldrichSiegen GmbH & Co. KG specializes in large-scale portal shapers for heavy industry components such as turbine housings, addressing applications where footprint, rigidity, and load-bearing capacity shape purchasing criteria more than unit economics alone. Gretel Maschinen GmbH provides mechanical and CNC shaper machines for woodworking and metal shaping in furniture and toolmaking, bridging material categories with equipment flexibility. Soraluce S.A. develops traveling column shapers for milling and shaping operations in aerospace and energy sectors, emphasizing adaptable work envelopes and multi-axis integration for demanding fabrication requirements.
Recent Corporate Activity as a Signal of Product Momentum
Publicly visible product launches and trade show participation in the recent period provide useful signals about where manufacturers believe demand is heading. In April 2025, DMG Mori showcased a new CNC horizontal shaper model at Hannover Messe with enhanced automation features, underscoring the industry’s broader push toward reduced operator intervention and smoother line integration. In September 2025, Yamazaki Mazak introduced an Integrex shaper-integrated multi-tasking machine for complex part shaping, reinforcing a trend toward consolidating multiple operation types into a single platform to simplify workflow and improve part consistency. In November 2025, Okuma Corporation exhibited GENOS series shapers with AI-driven tool monitoring at IMTS Americas, demonstrating how intelligence and condition monitoring are moving from optional add-ons to core engineering priorities.
These developments are not isolated exhibition highlights. Together, they indicate that manufacturers are investing in automation readiness, process visibility, and integrated part handling as differentiators rather than peripheral upgrades. For corporate buyers in 2026, the strategic implication is clear: the ability to evaluate equipment not only on shaping accuracy but also on integration complexity, data output, and maintenance predictability will increasingly determine which procurement decisions generate long-term value.
Market Dynamics and the Cost Environment Shaping 2026 Decisions
A market forecast can outline where revenue is likely to move, but operational decisions are made inside a live cost and compliance environment. The research incorporates several external pressures that directly affect purchasing timing, equipment selection, and operating budget assumptions, including raw material pricing, labor economics, regulatory expectations, and industrial modernization mandates.
Input Cost and Labor Pressures
Structural cost pressures remain a central theme for equipment planning. Steel prices for machine tool frames rose by 8 percent to 850 dollars per metric ton due to supply chain constraints, a movement that directly affects the cost floor for heavy fabrication and long-lead manufacturing equipment. At the same time, global skilled machinist wages increased 5.2 percent year-over-year amid automation shortages in manufacturing. These two forces create a dual margin challenge: equipment acquisition costs are reacting to input cost inflation, while operators are also facing higher labor costs in environments where skilled technician availability constrains throughput. For planning teams, this means the business case for shaper machine investment increasingly depends on how effectively the equipment can offset labor intensity, reduce rework, and improve repeatable precision without requiring disproportionate post-purchase customization.
Regulatory and Standards-Based Compliance
Regulatory and standards frameworks add another layer of planning discipline. The ISO 230-2:2014 standard governs the test code for machine tools including shapers, requiring annual compliance verification. In practical terms, this pushes compliance from a one-time vendor selection checkpoint into an ongoing operational requirement. Organizations that deploy shaper machines without incorporating compliance verification into their maintenance and quality programs may face hidden risk in audit exposure, process qualification, and customer acceptance cycles. The study treats standards alignment as a recurring operational asset, not a static purchase criterion, and frames it as part of the broader total cost of ownership discussion.
Industry 4.0 and Smart Equipment Adoption
A separate structural driver is reshaping procurement priorities: industry 4.0 mandates are driving 15 percent adoption of smart shapers with IoT sensors by 2026. This shift is not uniform across segments, but it is materially influencing how manufacturers evaluate connectivity, data collection, predictive maintenance potential, and process visibility. Smart-shaping capability is increasingly treated as an enabler of uptime stability and process traceability rather than a premium feature. Buyers are therefore expected to weigh sensor integration, data architecture compatibility, and support pathways as part of the core equipment evaluation rather than as after-the-fact retrofits.
Market Concentration and the Strategic Implications of Fragmented Leadership
The shaper machine market continues to display competitive intensity with meaningful but not overwhelming consolidation. Market concentration remains structured around a moderate share held by leading manufacturers, with the top three players collectively holding 28.5 percent of the market and the top five expanding that share to 35.2 percent. This concentration profile indicates that while established manufacturers command significant influence over product direction and technology cadence, a substantial portion of market activity remains distributed across additional producers serving regional and application-specific niches.
For corporate strategy teams, this structure has two practical implications. First, competitive benchmarking must extend beyond the largest brands; in several application contexts, specialized manufacturers deliver decisive advantages in work envelope, material compatibility, or speed-to-deployment. Second, procurement leverage is best exercised through portfolio thinking rather than single-vendor dependency. Organizations that build multi-source relationships, validate alternative suppliers against technical fit, and maintain flexibility in vendor selection are better positioned to manage price, availability, and technology choice across a multi-year deployment horizon. The full study provides deeper competitive mapping and share context so that buyers can assess where supplier concentration creates risk and where it creates negotiation advantage.
How the Report Supports 2026 Capital Allocation and Procurement Strategy
The Worldwide Shaper Machine Market research is built to convert market context into near-term action. Its value lies in helping organizations align external demand conditions with internal planning needs across several critical dimensions:
- Budget timing and fleet planning grounded in a transparent revenue trajectory and historical context that reduces uncertainty around capacity additions and replacement cycles.
- Application-aligned equipment selection that connects demand distribution across end-use environments to machine specification decisions, helping teams avoid over-engineering or under-specifying for actual production requirements.
- Competitive and supplier evaluation that provides a structured way to assess manufacturers by product direction, application fit, and recent development signaling without relying on marketing narratives alone.
- Operating cost modeling inputs that incorporate input cost inflation, labor escalation, and smart-equipment adoption as variables in decision-making rather than treating them as background noise.
- Compliance and lifecycle management that frames standards adherence and maintenance predictability as value drivers tied to uptime and qualification risk.
The report does not replace internal engineering judgment or plant-level operational knowledge. Instead, it supplies the external market architecture that makes those internal decisions more defensible. By situating procurement, engineering, and strategy teams inside a shared set of market realities, the study shortens the distance between strategic intent and operational execution.
What the Full Study Reveals and Why the Complete Intelligence Matters
This overview is deliberately constructed to demonstrate analytical rigor while preserving the most decision-sensitive layers for the complete publication. The macro trajectory, structural segmentation, competitive profiles, and industry pressure points summarized here establish the context and credibility of the research. The full study extends far beyond that framework. It delivers the detailed segmentation layers, regional intensity breakdowns, application-level demand mapping, competitive share context, and scenario-ready planning inputs that corporate teams require when they move from strategic direction to procurement authorization.
For organizations preparing capital plans for 2026, the difference between a high-level market narrative and a fully integrated market research package is the difference between an informed discussion and a decision-ready brief. The complete report transforms headline figures into actionable segmentation, places competitive dynamics within operational reach, and equips teams to evaluate smart-equipment adoption, compliance readiness, and cost volatility as part of a single planning model.
Conclusion: Positioning for Measured Growth with Strategic Discipline
The worldwide shaper machine market is unfolding within a defined growth path, shaped by modernization mandates, cost pressures, and a competitive landscape that rewards precision, integration, and application-aware equipment selection. A 3.5 percent compound annual growth rate over the 2026 to 2032 period may appear moderate, but in a capital-intensive manufacturing environment it rewards those who plan with discipline and penalizes those who rely on assumptions. The research supply chain of data, segmentation, competitive intelligence, and industry dynamics assembled in this study is designed to support exactly that discipline.
For decision-makers evaluating where to allocate resources, which machine types to prioritize, and how to structure supplier relationships in 2026, the full version of the Worldwide Shaper Machine Market report provides the depth required to turn market awareness into procurement confidence. The complete intelligence framework remains available for teams that need to move from strategic context to specific planning actions, and it is that completeness that makes the study a practical asset for the year ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Shaper Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


