



Category: market research
PW Consulting: Worldwide Probiotic Ingredients for Animal Use Market to Expand at 8.21% CAGR, Reaching USD 2,631.81 Million by 2032
By PW Consulting, 2026-08-18
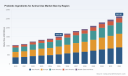
Worldwide Probiotic Ingredients for Animal Use Market — 2026 Strategic Outlook (PW Consulting)
As the animal nutrition industry accelerates its pivot away from antibiotic growth promoters and toward biological solutions, PW Consulting’s new market study — Worldwide Probiotic Ingredients for Animal Use — provides a timely, pragmatic playbook for commercial, R&D, regulatory and M&A decisions in 2026. Our base-year assessment finds the global market reached USD 1,515.9 Million in 2025 and, under the central scenario, is forecast to expand at a compound annual growth rate (CAGR) of 8.21% through 2032, reaching USD 2,631.8 Million by the end of the forecast horizon. These headline metrics underline both the scale and the investment momentum shaping supplier strategies, channel economics and upstream value chains over the next three to five years.
Worldwide Social Engineering Attack Defense Solution Market
Why this report matters for 2026 decision-making
-
Timing: 2026 marks an inflection in adoption curves — regulatory clarity in major markets and product innovations are turning probiotics from niche supplements into core feed ingredients for many production systems.
Worldwide Disc Grinder Market -
Risk management: With AGP restrictions entrenched as policy in multiple jurisdictions and strain‑level approvals becoming the norm, businesses must align product development, registration roadmaps and commercial trials to avoid market access surprises.
Worldwide E-Notary Software Market -
Capital allocation: The forecast trajectory and concentration dynamics call for refined capital deployment — whether building internal strain libraries, acquiring specialty producers, or scaling contract manufacturing to secure supply.
-
Go-to-market design: Channel economics and farm-level adoption drivers differ materially across animal categories. Fast followers and incumbents can extract margin through formulation, demo data and service‑based commercial models.
What the PW Consulting report delivers — practical, transaction-ready content
-
Transparent market sizing and multi-scenario forecasts to stress-test investment cases and pricing strategies for 2026–2032.
-
Actionable segmentation layers (ingredient family, animal application, and regional demand) mapped to commercial KPIs — presented with clear methodologies and reproducible assumptions. Note: detailed segment tables and raw datasets are included in the full report and are gated for subscribers.
-
Supply-chain and manufacturing heatmaps identifying technical pinch points (strain production, drying and QA bottlenecks, stability during feed processing) and supplier dependency matrices for procurement teams.
-
Regulatory tracker and dossier playbook: jurisdictional requirements, dossier templates and timelines for strain approvals and post-market surveillance obligations.
-
Commercial playbooks and trial design templates — from pilot farms to commercial step‑up — that shorten validation cycles and reduce execution risk for product launches.
-
M&A and partnership intelligence: validated target screening criteria, valuation sensitivities and integration checklists specific to probiotic ingredient businesses.
-
Competitor benchmarking and supplier scorecards integrating product portfolios, route-to-market strategies and recent innovation activity.
Market dynamics and technical drivers that will shape 2026 outcomes
-
Regulatory catalysts: Global restrictions on antibiotic growth promoters remain a primary adoption driver; recent regulatory activity — including EFSA evaluations of lactobacilli and bifidobacteria — is creating clearer pathways for product registration but increasing the emphasis on robust, strain‑specific efficacy data.
-
Technical survival and formulation: Feed processing (notably steam pelleting) remains a major technical constraint. Spore‑forming Bacillus strains repeatedly demonstrate superior survival through high-heat processes, which explains their prevalence in certain production systems. Commercial formulators must therefore align strain selection to processing and storage realities.
-
Performance proof as a commercial moat: Buyers increasingly procure on a risk‑adjusted basis — paying premiums for documented outcomes in feed conversion, pathogen mitigation and resilience under stress events. Standardized trial protocols and independent field data are becoming de facto commercial currency.
-
Concentration and competitive balance: The market shows a moderate level of concentration; leading groups collectively hold a meaningful share, but there remains material space for specialized entrants with novel strains, differentiated formulations (e.g., water‑soluble formats) or compelling service models.
Competitive landscape — who is shaping the market and how
-
Large, diversified ingredient houses (e.g., global specialty feed and ingredients groups) are integrating probiotics into broader animal nutrition portfolios to offer bundled solutions and secure distribution scale. These players leverage global supply chains and broad customer access.
-
Specialized microbial companies focus on strain development, formulation science and targeted applications — investing in dossiers and performance trials that underpin premium positioning. They are preferred partners for OEM feed formulators and specialty distributors.
-
Notable players profiled in the report include a mix of both archetypes: firms that emphasize proprietary Bacillus technologies and rapid‑action formats; global feed conglomerates that embed probiotics alongside enzymes and acids; and microbial specialists focusing on postbiotic and strain‑driven claims. Recent product activity — such as a major probiotic enhancement showcased late in 2025 and a multi-strain DFM launch mid‑2025 — signals intensified competition around faster onset of activity and robustness under production stress.
-
For executives evaluating partners or targets, our competitive profiles illuminate R&D pipelines, route-to-market strategies and IP positioning — enabling defensible commercial and M&A decisions in 2026.
Strategic implications and recommended priority actions for 2026
-
Prioritize strain portfolios that match processing realities: If your customers require pelleted feeds or high-temperature applications, give precedence to spore‑forming strains and invest in pelleting survivability testing.
-
Accelerate dossier-driven development: Build regulatory dossiers in parallel with efficacy trials to shorten time-to-market after positive performance signals. Consider pre-submission engagements with authorities in priority markets.
-
Design commercial pilots for rapid readouts: Standardize trial protocols to generate comparable KPIs (FCR, mortality, pathogen load, resilience under stress) that buyers and regulators recognize.
-
Use M&A selectively to acquire capability gaps: Targets that offer proven strains, manufacturing scale or market access can offer faster ROI than greenfield R&D — but insist on transparent, audited trial and stability data during diligence.
-
Differentiate on service and evidence: Companies that combine microbiology expertise with on-farm support and economics-of-use models will outcompete in procurement cycles that reward demonstrable ROI.
-
Secure supply continuity: Identify single‑source and high-risk nodes in your ingredient supply chain and develop contingency plans — tolling relationships, dual sourcing, or nearshoring where appropriate.
How commercial teams, R&D leaders and investors should use this report
-
Commercial leaders: Use the report’s demand-side scenarios and buyer segmentation to re-allocate sales resources, design pricing tiers, and negotiate value-based contracts tied to farm-level outcomes.
-
R&D and operations: Leverage our technical appendices and stability matrices to optimize strain selection, refine downstream processing and reduce manufacturing loss during pelleting and storage.
-
Regulatory and quality teams: Adopt the included dossier templates and submission timelines to accelerate approvals in priority jurisdictions while maintaining compliance with emerging strain‑specific requirements.
-
Investors and M&A teams: Apply our valuation sensitivity analyses and target scorecards to prioritize targets that fill capability gaps and to set realistic earn‑out milestones linked to commercial adoption.
PW Consulting’s Worldwide Probiotic Ingredients for Animal Use market study is intentionally designed as a decision‑ready resource for 2026. It combines transparent forecasts and market concentration analysis with practical execution tools — trial protocols, dossier templates, supply‑chain maps and competitor intelligence — to reduce uncertainty and speed project delivery. For readers seeking the full segmented datasets, regional and animal-type splits, and company-level financial implications, the detailed tables and proprietary models are available in the complete report and accompanying data package.
To discuss how the findings apply to your portfolio, bespoke scenario modeling, or a rapid commercial due diligence in support of an acquisition or product launch, PW Consulting’s industry team is available for advisory engagements that translate these insights into executable 90–180 day plans.
For detailed analysis of this topic, please visit the official page: Worldwide Probiotic Ingredients for Animal Use Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Hydrogel Bioink Market to More Than Double from USD 120 Million in 2025 to USD 291.18 Million by 2032 at a 13.5% CAGR
By PW Consulting, 2026-08-18
PW Consulting Strategic Brief: Worldwide Hydrogel Bioink Market — Actionable Intelligence for 2026 Decision-Making
Executive summary
Our new market study on the Worldwide Hydrogel Bioink Market arrives at a pivotal moment. After a rapid ramp from the low‑double‑digit millions in 2020 to USD 120.0 Million in 2025 (base year), the market is forecast to expand at a compound annual growth rate (CAGR) of 13.5% over the 2026–2032 horizon, reaching north of USD 290 Million by 2032 under the central scenario. This trajectory reflects accelerating adoption across tissue engineering, drug discovery and translational research, while exposing suppliers, developers and investors to a concentrated set of operational and regulatory inflection points that will define winners in 2026 and beyond.
Worldwide Job Boards Software Market
Why this report is a strategic asset for 2026
- Decision-ready intelligence: Our deliverable translates market growth projections into concrete, prioritized initiatives—R&D roadmaps, manufacturing scale plans, supply‑chain resilience programs and regulatory pathways—framed for calendar‑year 2026 execution.
- Risk calibration: We quantify exposure across the value chain—from raw material volatility and freight surcharges to evolving toxicology rules—and translate those into mitigation playbooks calibrated to three investment risk profiles.
- Competitive clarity without information overload: The study synthesizes public and proprietary intelligence into competitor profiles, capability matrices and scenario P&Ls, enabling rapid benchmarking and M&A screening without leaking the granular market allocations that live in the full dataset.
Market structure and concentration — what matters
The hydrogel bioink sector remains moderately fragmented: the top three suppliers account for roughly one‑third of the market and the top five less than half. This structure creates attractive pockets for specialized entrants and strategic investors, particularly where differentiated chemistry platforms or validated clinical use cases exist. Fragmentation also implies opportunities for consolidation in 2026 as larger players seek to accelerate vertical integration (formulation → biofabrication services → regulated product pipelines).
Worldwide Cloud Financial Planning and Analysis Solution Market
What the full report contains (practical, executable content)
- Forward-looking financial model: historic (2020–2025) P&Ls and a forecast spine (2026–2032) with sensitivity toggles for price shock, supply disruption and regulatory delay scenarios.
- Technology and formulation playbook: independent evaluation of natural, synthetic and hybrid hydrogel platforms, including handling/printability matrices, crosslinking strategies, cell‑compatibility tradeoffs and scale‑up constraints. Each technology is scored against manufacturability and translational readiness.
- Manufacturing and scale checklist: unit operations, QC specifications, recommended analytical assays, and a GMP readiness roadmap that prescribes minimum steps to move research‑use formulations toward clinical submission.
- Regulatory navigator: practical steps for 510(k) strategy in the U.S., EU compliance considerations (including restrictions on certain photoinitiators), and templates for biocompatibility testing pathways—critical for teams planning clinical translation in 2026.
- Supply‑chain risk register and procurement playbook: raw material sourcing maps, dual‑sourcing templates, contractual clauses to protect margin under price shocks, and logistics options (including the operational impact of recent temperature‑controlled freight surcharges).
- Commercial go‑to‑market (GTM) playbooks: differentiated value propositions for academic, pharma/biotech and clinical research customers, channel strategies (direct vs distributor), pricing architectures and sample-to-purchase conversion best practices.
- Competitive intelligence annex: concise profiles of the leading suppliers, product roadmaps, partnership footprints and recent strategic moves to inform M&A and alliance decisioning.
Competitive landscape — actionable takeaways
The market is populated by a mix of specialized bioink formulators, bioprinter platform providers and biotech firms pursuing proprietary biomaterials. Our analysis highlights several archetypes:
Liquid Form Cryogenic Hydrogen Storage System Market
- Platform formulators with deep chemistry IP and catalog breadth: These vendors maintain portfolios that span GelMA, alginate derivatives and hyaluronic‑based systems, emphasizing reproducibility and ease of integration with extrusion and light‑based printers.
- Specialist proprietary collagen and recombinant platforms: Firms leveraging recombinant human collagen or other bio‑engineered proteins are positioning for translational use cases where immunogenicity and human‑origin signals matter.
- Precision synthetic suppliers: Companies offering PEG‑based and thiol‑ene chemistries are differentiating on tunability and high‑resolution encapsulation, attractive for drug‑screening and organ‑on‑chip initiatives.
Key players profiled in the report (selected):
- Allevi Inc. (USA) — a focus on GelMA and stem‑cell‑oriented formulations; recent product updates emphasize enhanced crosslinking for improved cell retention and print fidelity.
- Bioink Solutions (USA) — modular, customizable formulations including collagen and alginate bases targeting translational research labs and service providers.
- BICO / Cellink (Sweden/Group) — a broad hydrogel portfolio designed for both extrusion and light‑based bioprinting; recent launches address printability for complex vascular models.
- CollPlant (Israel) — recombinant human collagen platform advancing toward clinical certification, including recent biocompatibility certification milestones.
- Gelomics (UK) — GelMA and synthetic hydrogel formulations tuned for high‑resolution applications.
- Prometheus Biosciences (BICO, Netherlands) — precision PEG hydrogels targeting defined cell encapsulation use cases.
- Advanced BioMatrix (USA) — hyaluronan‑ and thiol‑modified collagen kits that bridge 3D cell culture and early translational workflows.
Recent developments that should shape 2026 plays
- Product innovation continues: major groups launched improved ink series and crosslinking upgrades in 2024–2025, which accelerates adoption in complex tissue models and raises the bar for new entrants.
- Regulatory and certification milestones matter: ISO/biocompatibility certifications for recombinant collagen platforms reduce clinical translation friction and materially affect strategic valuation.
- Operational pressures persist: raw‑material supply constraints and price volatility have emerged as recurring supply risks; teams must embed procurement stress tests into product costing models now.
Industry dynamics and immediate risks
- Raw materials: Periodic supply disruption in algal feedstocks has driven double‑digit percentage increases in alginate pricing in recent cycles—an input‑cost risk that directly compresses margin if not hedged or passed through.
- Regulation: EU chemical restrictions have tightened the acceptable scope of certain photoinitiators; product teams should re‑test formulations for compliant alternatives to avoid market access delays.
- Reimbursement and device classification: U.S. guidance increasingly treats hydrogel bioinks used in clinical research as regulated device constructs with 510(k) expectations; preparing a regulatory dossier in 2026 is non‑negotiable for firms targeting clinical use.
- Logistics: New temperature‑controlled freight surcharges on transatlantic lanes materially change landed cost economics for cold‑chain bioinks and should be factored into distributor agreements and pricing models.
- Clinical translation guardrails: Materials marketed as “research use only” cannot be implanted without GMP conversion—an operational pivot that demands upfront investment if a commercial pathway to clinic is intended.
2026 playbook — recommended priorities for executives
- Short term (0–12 months): Harden supply chains (dual‑source critical biopolymers), prioritize formulation swaps for restricted chemistries, and complete GMP gap assessments for products intended for translational use.
- Medium term (12–24 months): Execute targeted product upgrades (printability + validated crosslinking paths), secure key certifications that accelerate clinical acceptance, and lock strategic partnerships with bioprinter OEMs and CROs.
- Capital and M&A posture: Pursue tuck‑ins that add either a validated raw material supply or a complementary chemistry platform; for investors, prioritize assets with demonstrable translational milestones and certification progress.
- Commercial moves: Reprice contract portfolios to reflect freight and input cost inflation, while introducing tiered product lines (research vs bridging/GMP) to capture both early‑stage and translational demand.
Scenario planning — three actionable frames for 2026 decision cycles
- Base case: Market follows the 13.5% CAGR, enabling moderate organic growth for incumbents with strengthened supply chains and regulatory readiness; prioritize certification and channel expansion.
- Downside (supply shock + regulatory delay): Double‑digit input inflation and a staggered approval environment compress margins and elongate time‑to‑revenue; shift to conservative inventory strategies and option‑based supplier contracts.
- Upside (rapid clinical adoption): Accelerated translational wins trigger premium pricing for validated bioinks and favor vertically integrated players; scale manufacturing capacity and expedite GMP conversions.
How to use this study in your 2026 planning
The report is built as an operational decision tool: use the financial model to stress‑test your product roadmap under the three scenarios, deploy the regulatory navigator to build a 510(k) timeline, and leverage the supplier matrix to reconfigure procurement. The full dataset contains granular regional and application splits, channel economics and per‑segment demand curves that are intentionally withheld from this brief to protect strategic confidentiality—these are available in the complete report for clients and subscribers.
About PW Consulting
PW Consulting provides strategic market intelligence and transaction support to life‑science technology firms and investors. Our hydrogel bioink study combines primary interviews, proprietary datasets and in‑house technical assessment to deliver executable guidance for 2026 decision cycles.
Call to action
For enterprise licenses, bespoke scenario workshops or to access the full dataset and annexes (including supplier tables, granular regional and application allocations, and the underlying financial model), contact our Worldwide Biofabrication practice or visit the PW Consulting report page for subscription details and executive briefing availability.
For detailed analysis of this topic, please visit the official page: Worldwide Hydrogel Bioink Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Auto-fill Humidification Chamber Market Poised for 6.45% CAGR Through 2032
By PW Consulting, 2026-08-18
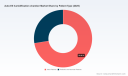
Worldwide Auto-fill Humidification Chamber Market: Strategic Preview for 2026 Decisions
PW Consulting’s latest market intelligence on the Worldwide Auto-fill Humidification Chamber market is released as an executive-grade briefing designed to inform strategic choices through 2026 and beyond. This preview summarizes the strategic implications of our full 2025-base-year study (historical 2020–2025; forecast 2026–2032), highlights regulatory and commercial inflection points, and teases the practical tools and frameworks in the full report that senior leaders will use to convert insight into action.
Intelligent Ultrasonic Bird Repellent Market
Market trajectory and what it means for 2026 planning
The global market for auto-fill humidification chambers has moved from a modest medical-supplies category into a core respiratory-support adjunct with sustained commercial momentum. Our topline sizing shows growth from roughly USD 475 million in 2020 to about USD 642 million in 2025, and a projected rise toward approximately USD 994 million by 2032 — an implied compound annual growth rate of 6.45% across the forecast window. That trajectory reflects interacting demand drivers: expanded respiratory therapy outside acute care, increased adoption of heated-humidifier-based ventilation protocols, rising standards for infection control, and vendor-led innovation around compatibility and automated fluid management.
Worldwide Polypropylene (PP) Lined Pipes Market
For decision makers in 2026, the headline implications are straightforward: this is not a stagnant consumables line — it is a mid-growth medical supply market with margins, regulatory constraints, and consolidation dynamics that reward early clarity on channel, product differentiation, and regulatory timing.
Worldwide Oxidized PAN Fiber Market
Why PW Consulting’s 2026 lens matters
- Decision-focused analysis: We translate market sizing and scenario forecasts into practical decision levers — from procurement cadence for large hospital systems to product launch pacing for device OEMs.
- Regulatory and reimbursement clarity: The report synthesizes device-class pathways, typical 510(k) considerations for the US, and reimbursement levers that affect purchasing economics (including commonly referenced HCPCS billing approaches).
- Commercial playbooks: We provide vendor scorecards, channel strategies, and tender-response templates that procurement and BD teams can use immediately to improve win rates.
- M&A and partnership diagnostics: For corporate development teams, the study includes target-screening criteria, valuation sensitivities tied to recurring consumables revenue, and integration red flags unique to sterile single-use respiratory adjuncts.
Competitive landscape — concentrated but active
The auto-fill humidification chamber market is commercially concentrated, with a narrow set of established respiratory-device suppliers dominating supply relationships with large hospital systems and ICU OEMs. Our concentration metrics underscore a market where the top three players hold the majority of market share and the top five capture most of the rest. This concentration accelerates the importance of compatibility claims, regulatory track records, sterile manufacturing capacity, and established distribution networks.
Key vendors profiled in the full report (selected highlights below) include manufacturers with proven product families, clearance histories, and global supply footprints — each offering different routes to market and partnership opportunity:
- Fisher & Paykel Healthcare (Auckland, New Zealand) — Well-known for the MR290 series and integration across MR-series humidifiers and myAirvo systems. Their dual-float auto-refill mechanism and overfill prevention features are positioned for both adult and pediatric ventilation applications. ( https://www.fphcare.com)
- Intersurgical (Wokingham, United Kingdom) — Offers dual-float autofill chambers with sterile variants and fill set compatibility for a broad range of heated humidifiers used across ICU and CPAP to full mechanical ventilation modes. ( https://www.intersurgical.com)
- Flexicare (Mountain Ash, United Kingdom) — Markets sterile and double-valve variants for BiPAP use, emphasizing low water volume for faster warm-up and compatibility with heated-wire systems. ( https://flexicare.com)
- GaleMed Corporation (Taiwan) — Produces the Humi.AIDE™ family with neonatal and adult models; notable for mechanisms that permit sterile water refill without interrupting ventilation. ( https://www.galemed.com)
- Vadi Medical Technology (Taoyuan City, Taiwan) — Offers both disposable and reusable auto-feed systems compatible with major humidifier brands, addressing cost-sensitive and high-utilization settings. ( https://www.vadi-medical.com)
- Yaxin Medical (Suzhou, China) — Focuses on disposable chambers engineered for ICU ventilator compatibility and standardized connector interfaces, optimized for scale manufacturing. ( https://www.yaxinmed.com)
- Vyaire Medical (AirLife) (Mettawa, Illinois, USA) — Sells AirLife autofill chambers as part of integrated heated humidifier solutions and has pursued regulatory filings emphasizing prior technology predicates. ( https://www.vyaire.com)
Recent regulatory milestones — such as FDA clearances and 510(k) submissions — are shaping competitive positioning. Notable examples include a 2022 FDA clearance for a major supplier’s NIV/NHF circuit kit that referenced autofill chamber functionality, and a 2023 510(k) submission by another leading vendor referencing legacy autofill technology. These actions emphasize that 510(k) strategy and predicate selection remain central to US market access planning.
Regulatory, clinical and supply dynamics that will shape 2026 outcomes
- Device classification and pathways: Auto-fill humidification chambers are generally regulated as accessories under respiratory gas humidifier device classifications (US CFR pathways), which means most commercial contestants pursue the 510(k) route where predicate selection, bench testing of fluid-handling safety, and documentation of sterility claims are decisive.
- Infection control and single-use norms: Clinical guidance and manufacturer instructions strongly favor single-patient disposable use to avoid cross-contamination — a behavior that supports recurring consumables revenue while forcing logistics and waste-management optimization in hospitals.
- Materials and sterilization: Clear polycarbonate constructions in sterile packaging are the de facto market standard. Product differentiation therefore often comes from functional elements (dual floats, overfill protection, low-volume warm-up designs) and documented compatibility with heated-wire breathing circuits.
- Reimbursement levers: In certain jurisdictions, humidification supplies are billed through miscellaneous DME supply codes — a factor that influences hospital procurement policies and group purchasing negotiations.
- Supply chain resilience: For 2026, sourcing flexibility for sterile injection molding, validated assembly, and logistics for sterile single-use products will be a competitive differentiator, particularly under surge scenarios and in regions where import constraints persist.
What the full report contains — operationally actionable elements
Beyond top-line market modeling, the report is structured to be used at the working-table level by product, commercial, regulatory, and M&A teams. Core deliverables include:
- Detailed methodology, assumptions, and base-year (2025) dataset in USD (Millions) and scenario variants through 2032.
- Primary-research intelligence: interview excerpts with procurement leads, respiratory therapists, and OEM clinical engineers to validate real-world use patterns and procurement constraints.
- Vendor scorecards and a reproducible vendor-selection matrix that weighs compatibility, sterile manufacturing capacity, regulatory status, and commercial terms.
- Channel economics and sample tender terms (GPO playbook) to accelerate negotiations in 2026 procurement cycles.
- Regulatory playbooks for 510(k) strategy, bench testing templates, and a timeline for filings aligned with product development milestones.
- M&A diagnostics including target screening filters, integration risk checklists, and revenue-synergy modeling templates tied to consumables attachment rates.
- Risk register and mitigation playbook covering supply interruption, adverse-event reporting pathways, and recall readiness.
Practical recommendations for leaders planning in 2026
Translate the market movement and regulatory context into clear near-term actions:
- Prioritize compatibility-first product development: ensure new chamber designs validate heated-wire and common humidifier-system interfaces early to shorten hospital adoption cycles.
- Lock in sterile manufacturing partners with capacity buffers and validated processes to avoid single-source exposure.
- Map procurement calendar windows for large public health systems and GPOs — aligning tender-ready product dossiers with these windows materially improves win probability.
- For market entrants, consider niche neonatal or home-health variants with compelling clinical evidence to avoid head-to-head competition in the core ICU consumables segment.
- For incumbents, explore bundling strategies (humidifier + autofill chamber) to protect attachment rates and blunt third-party disposable encroachment.
- Regulatory teams should prioritize predicate analysis and bench-test plans now to de-risk US market clearance timelines through 2026.
- Corporate development should use the vendor scorecard in the full report to triage acquisition targets that immediately improve sterile manufacturing footprint or channel reach.
How to use this preview
This briefing is a strategic “trailer” — it surfaces the core trends, regulatory context, competitor dynamics, and the specific decision playbooks that will matter in 2026. The full PW Consulting report contains the detailed segment tables, pricing curves, vendor scorecards, raw interview excerpts, and downloadable tender templates that procurement, product, regulatory, and corporate development teams will need to operationalize the recommendations summarized here.
To access the full dataset, including segment-level analysis, region and end-user breakouts, and the complete vendor benchmarking, please consult the PW Consulting report page. Our team is available to run bespoke workshops that translate the report’s models into 90–180 day action plans tailored to your organization’s role in the ecosystem — OEM, distributor, hospital system, or private-equity sponsor.
Contact PW Consulting for access and to schedule a strategic briefing that aligns the report’s insights with your 2026 investment and market-entry calendar.
For detailed analysis of this topic, please visit the official page: Worldwide Auto-fill humidification chamber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Solvent-based Organoclay Market to Reach USD 1,020.15 Million by 2032 on a 4.75% CAGR
By PW Consulting, 2026-08-18
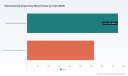
Worldwide Solvent-based Organoclay Market: Strategic Signals for 2026 Decision-Makers
PW Consulting’s new market study on the worldwide solvent-based organoclay market synthesizes seven years of historical performance and a forward-looking forecast (2026–2032) to deliver actionable guidance for commercial, technical, and M&A leaders preparing for 2026. The sector is entering a measured expansion phase: after recovering from mid-cycle volatility, total market value expanded from the mid-2020s base and reached approximately USD 737.6 Million in our 2025 baseline. Under the central scenario the market is projected to grow at a compound annual growth rate (CAGR) of 4.75% across 2026–2032, trending toward a market size just above USD 1.02 Billion by 2032. These macro dynamics—and the structural forces that underlie them—shape a narrow window of strategic choices for the coming 18–30 months.
Small Popcorn Machine Market
Why 2026 Is a Strategic Inflection Point
-
From stabilization to selective acceleration: The period through 2025 shows a market that has absorbed raw-material interruptions and demand swings across paints, coatings and oilfield services. The 2026–2032 trajectory implies steady, not explosive, demand growth—favoring companies that can convert mid-single-digit CAGR into margin expansion through product differentiation, channel optimization, and operational efficiency.
Worldwide Time Series Databases Software Market -
Concentration-driven opportunities: Market concentration is meaningful but not prohibitive—leading suppliers consolidate significant share while a diverse group of regional players remains competitive on cost, specialty grades and local service. This structure rewards both scale (for R&D and global distribution) and nimbleness (for tailored formulations in regional end-markets).
Electric Vehicle Graphene Battery Market -
Regulatory and raw-material regime shifts: Compliance with REACH-type requirements and tighter environmental oversight, combined with reliance on montmorillonite (bentonite) and quaternary ammonium modification chemistries, makes supply-chain control and technical-compliance capability strategic assets.
Core Strategic Questions for 2026
-
How should producers allocate R&D and CapEx between low-cost commodity grades and premium, application-specific organoclays (e.g., thixotropic, anti-settling, or low-polarity-optimized chemistries)?
-
What is the optimal near-term M&A posture—bolt-on specialty grades, regional distribution networks, or upstream bentonite assets that secure feedstock and quality control?
-
How will formulators and end-users hedge compliance and supply risk while maintaining formulation performance and cost targets?
What Our Report Delivers (Practical, Executable Outputs)
-
Scenario-based demand modelling: A primary forecast that maps baseline, upside, and downside cases for 2026–2032, enabling procurement and sales leaders to stress-test budgets and inventory strategies against macro and sectoral shocks.
-
Supplier & capability matrix: A panoramic assessment of global and regional manufacturers, mapped by technical capabilities (e.g., low vs. high polarity optimization, easy-dispersible vs. pre-gel technology), production footprint, and vertical integration level—designed to support sourcing decisions and supplier segmentation.
-
Regulatory compliance playbook: Practical guidance on aligning organoclay grades and manufacturing processes with REACH and EPA-like frameworks, including recommended monitoring metrics and incremental formulation shifts that reduce regulatory exposure without sacrificing performance.
-
Raw-material risk and pricing outlook: A structured assessment of montmorillonite supply dynamics, the effect of mine-level integration on cost and quality, and scenarios for near-term input-price volatility that inform contract length and pass-through strategies.
-
Commercial and product strategies: Go-to-market recommendations for distributors, co-packers and producers—including SKU rationalization, premiumization levers, and channel-specific packaging/technical-support models that improve sell-through in paint, coatings and industrial end-uses.
-
Financial benchmarking and M&A due diligence templates: Standardized models to evaluate target economics, synergies, and integration risk—tailored to organoclay’s mix of commodity and specialty revenue streams.
Competitive Landscape: Who Matters—and Why
The market’s competitive structure blends global specialty chemical players, vertically-integrated miners, and regional manufacturers focused on export and import-substitution. Understanding each archetype clarifies where transaction and partnership value will appear in 2026.
-
Vertically integrated manufacturers —those that own bentonite sources and control modification processes—enjoy advantages in cost control, quality consistency, and the ability to develop grade families targeted at different solvent polarity windows. These players are well positioned to protect margins when feedstock availability tightens and are attractive partners for formulators seeking secure supply.
-
Global specialty suppliers leverage brand, technical-service reach, and a portfolio approach: they can bundle organoclays with additive systems, provide global technical support for OEMs, and rapidly commercialize novel hectorite versus bentonite chemistries. Their scale supports multi-market R&D investments.
-
Regional innovators and cost competitors capture value by aligning to local supply chains, offering fast lead times, and competing on price for standard grades. They are often the first choice for cost-sensitive formulators or local manufacturers seeking import substitution.
Key industry players exemplify these archetypes and highlight strategic priorities for 2026:
-
Manufacturers with owned bentonite deposits and ISO-aligned processes demonstrate the economics and risk mitigation of vertical integration; such companies typically emphasize grade consistency and supply security.
-
Large specialty chemical suppliers focus on product-development depth—offering both bentonite- and hectorite-based grades, and positioning brands as problem-solving partners for thixotropy and anti-settling performance.
-
Regional producers show the market’s capacity for decentralized competition: lower-cost grades and export-focused strategies remain significant in many end-markets, particularly where proximity to coatings and drilling customers matters.
Market Dynamics That Will Drive Outcomes in 2026
-
Feedstock quality and sourcing: Montmorillonite commodity characteristics create a technical hurdle—small differences in clay mineralogy can materially affect organoclay performance after quaternary-ammonium treatment. Control of feedstock, either through ownership or long-term partnerships, reduces supply and quality risk.
-
Product differentiation through formulation science: The continuing shift toward easy-dispersible grades and performance-tuned chemistries increases the value of application R&D. Suppliers who can translate lab-scale rheology improvements into plant-level performance gains will capture premium pricing.
-
Regulatory and sustainability pressures: Compliance considerations—especially for export to regulated markets—are already shaping product portfolios. The most commercially successful firms will combine compliance with clear claims around lifecycle performance and handling safety.
-
Channel and end-market evolution: Demand patterns in paints & coatings, drilling fluids, greases, and inks will diverge by region and application. Suppliers that align go-to-market models to the commercial cadence of each channel secure conversion and stickier contracts.
Recommended 90–180 Day Roadmap for 2026 Planning
-
Immediate (30–60 days): Conduct an internal SKU and margin audit to identify commodity versus specialty revenue, and begin supplier scorecarding against quality, delivery, and regulatory compliance metrics.
-
Near-term (60–120 days): Stress-test contracts and inventory policies against the report’s baseline and downside scenarios; initiate technical trials with at least two alternative organoclay suppliers for critical formulations.
-
Medium-term (120–180 days): Finalize a portfolio strategy (e.g., premiumization vs. cost leadership) and align CapEx or M&A priorities—evaluate targets that add feedstock control, complementary grade technology, or market access.
How to Use This Study
This report is intended as a decision-enabling toolkit for commercial and technical executives. It is not a descriptive catalog: it blends market-sizing certainty with scenario-driven guidance and tactical templates so that procurement, R&D, and corporate development teams can plan for 2026 with clarity. To preserve competitive advantage for our clients we present deep supplier and SKU-level intelligence inside the full report; the public summary intentionally omits granular split tables and detailed regional/application percentages to protect proprietary market structures and drive direct engagement for customized deliverables.
For executives preparing budgets, negotiating supplier contracts, evaluating M&A targets, or reconfiguring product portfolios for compliance and performance, PW Consulting’s Worldwide Solvent-based Organoclay Market study converts market signals into executable next steps for 2026. For access to the full dataset, detailed supplier profiles, and our custom scenario models, visit the PW Consulting report page or contact our sector team for a briefing tailored to your strategic horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Solvent-based Organoclay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Riding Floor Scraper Market Poised for a 5.82% CAGR During 2026–2032
By PW Consulting, 2026-08-18
Worldwide Riding Floor Scraper Market — Strategic Imperatives for 2026 Decision-Makers
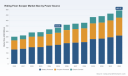
PW Consulting’s new market study on the Worldwide Riding Floor Scraper Market synthesizes primary interviews, OEM product-level analysis, and a validated forecasting model to deliver the strategic intelligence that equipment manufacturers, rental fleets, large contractors, and private equity investors need to act with conviction in 2026. The market reached USD 332.45 Million in 2025 and is projected to expand at a compound annual growth rate of 5.82% through our 2026–2032 forecast window, reflecting a predictable but evolving demand profile shaped by productivity pressures, emissions-driven equipment choices, and material supply dynamics.
Worldwide Vibraphones Market
Why this market matters in 2026
-
Operational leverage in renovation and industrial surface-preparation projects. Mechanized ride-on scrapers materially reduce site labor hours and schedule risk on high-intensity flooring-removal tasks—an increasingly valuable attribute in the face of persistent trades labor shortages and rising wage baselines.
Worldwide Reservoir Analysis Market -
Regulatory and ESG tailwinds accelerating technology substitution. Occupational health and indoor air quality considerations—together with local emission regulations—are tilting demand toward battery and low-emission equipment for confined commercial and institutional environments.
Short Drama Promotion Authorization Platform Market -
Supply-chain and raw-material sensitivity. The segment’s core consumable—carbon and hardened steel scraper blades—and structural steel inputs create observable exposure to raw-material cost inflation and sourcing volatility (global steel benchmarks, for example, were trading at 3,103 CNY/T in early April 2026), which in turn affects OEM margin engineering, spare parts pricing, and aftermarket service economics.
-
Consolidation potential coexists with segmented demand. Market concentration metrics highlight a mid-market dominated by a handful of global and regional specialists (the top three players account for just over 40% of the market; the top five approach 60%), but significant whitespace remains for targeted product and channel strategies.
Core report deliverables — actionable, not academic
PW Consulting structured the analysis to be operationally useful for executives making 2026 capital and product decisions. Key components include:
-
Robust market-sizing and scenario-driven forecasting: transparent base-year calibration (2025) and a detailed 2026–2032 projection suite with upside/downside scenarios tied to labor-cost trajectories, steel-price shocks, and regulation-driven product substitution.
-
Go-to-market playbooks for OEMs and distributors: channel segmentation, rental-vs-sale decision frameworks, and a prioritized set of customer archetypes for early adoption of battery-powered scrapers.
-
Comprehensive competitive dossiers: strategic and product-level profiles for the principal market participants (including Bartell Global’s Terminator line, National Flooring Equipment’s broad model range, Onsite Equipment Manufacturing’s Workhorse products and recent battery-model launches, OEM Products Inc.’s hydrostatic/zero-turn line, and Husqvarna Construction’s professional-grade options). Each dossier contains capability maps, manufacturing footprints, recent product moves, and implications for partner or competitor strategies.
-
Practical commercial tools: total-cost-of-ownership (TCO) calculators with configurable inputs for utilization, fuel/energy costs, blade wear rates, and labor savings; procurement negotiation templates; spare-parts service-level agreements; and operator-safety and indoor-air-quality compliance checklists.
-
M&A and investment intelligence: target screening criteria tuned to market concentration dynamics, integration risk matrices, and post-acquisition value-capture playbooks for adding scale in distribution, rental fleets, or adjacent surface-preparation portfolios.
Competitive landscape — who to watch and why
The universe of ride-on floor scraper suppliers combines long-tenured specialists and global construction-equipment incumbents. Our report does not simply catalogue product SKUs; it assesses defensibility and go-forward options across three dimensions: product modularity (battery retrofits, attachments), manufacturing and supply resilience, and channel depth (OEM-direct vs dealer vs rental networks).
-
Bartell Global (Innovatech) — The originator of the Terminator platform remains an innovation anchor. Its multi-fuel approach and legacy installed base create aftermarket and retrofit opportunities, but sustained competitiveness will depend on quicker roll-out of high-cycle battery platforms and telematics.
-
National Flooring Equipment — A broad portfolio and distribution footprint make this player central to contractor buying patterns. Portfolio breadth is a strength for channel control, with implications for price architecture and spare-parts logistics.
-
Onsite Equipment Manufacturing (Workhorse) — Workhorse’s patent-backed mechanical design and recent moves into Lithium-Ion battery models (notably the 500e announced in October 2025) signal the kind of product innovation that pressures legacy propane and corded-electric incumbents to accelerate electrification roadmaps.
-
OEM Products Inc. — The company’s hydrostatic-drive, zero-turn platforms and the latest ultra-efficient battery models position it well for applications that require heavy-duty performance with low operational emissions.
-
Husqvarna Construction — As a large global player, Husqvarna’s product reliability standards and channel scale matter most in institutional and large infrastructure projects where single-vendor procurement and global service consistency are decisive.
Strategic implications and recommended moves for 2026
Executives who use the report as a decisioning tool will be able to translate market signals into concrete 12–24 month actions. Our recommendations are pragmatic and prioritized by expected ROI and execution complexity:
-
Prioritize battery and low-emission product programs for institutional and indoor commercial channels. Given tightening QA regulations around indoor air and operator exposure, early-bird advantages accrue to OEMs that can demonstrate lifecycle cost parity and clear emissions credentials.
-
Design retrofitability and attachment ecosystems. For manufacturers, creating bolt-on electrification kits or universal attachment platforms accelerates fleet migration without requiring customers to replace entire machines.
-
Embed TCO and utilization telemetry into product offerings. Fleets and rental houses prefer machines that provide utilization data and predictive maintenance alerts; these features unlock higher utilization rates and secondary-market value.
-
Hedge raw-material exposure with procurement strategies. Steel-price sensitivity affects blade replacement margins and unit economics; multi-sourcing and hedging contracts should be part of commercial planning for 2026 CAPEX cycles.
-
Align product and channel incentives around service and refurbishment. On-the-ground advantages accrue to organizations that bundle operator training, consumables, and refurbishment services, turning a hardware sale into a predictable annuity.
-
Consider inorganic options to capture distribution or rental scale. With the top-five firms collectively holding a significant share but meaningful niche demand remaining fragmented, bolt-on acquisitions in regional distribution or rental assets can be an efficient path to scale.
Evidence-based sensitivity analysis — what keeps margins and adoption rates fluid
PW Consulting’s scenario work isolates three high-impact variables for 2026 decisions: steel and consumable blade pricing, local labor-cost inflation, and the pace of emission-driven product substitution. Each variable influences adoption and pricing differently—high labor inflation increases total cost savings from mechanization, whereas spikes in steel prices raise short-term OEM input costs and accelerate aftermarket blade-price sensitivity. Our model provides stress-tested outcomes so CFOs and product leaders can quantify the trade-offs of accelerating battery programs versus protecting margins.
What this briefing omits (and where to get it)
This newsroom-style summary highlights the strategic takeaways and practical frameworks executives need to prioritize in 2026. In keeping with our “teaser” approach, we are intentionally withholding the granular regional, application, and power-source revenue splits and other proprietary tables that underpin our forecasts. Those detailed segmentations—plus model-level unit economics and dealer-level channel share matrices—are available in the full PW Consulting report and accompanying data workbook.
For decision-makers who require executable insight—budget-ready three-year product roadmaps, procurement negotiation playbooks, and M&A screening lists—PW Consulting’s full deliverable turns market projection into operational execution. Contact PW Consulting or visit our Worldwide Riding Floor Scraper Market report page to request an executive briefing and a sample of the data workbook.
For detailed analysis of this topic, please visit the official page: Worldwide Riding Floor Scraper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide DECT Phone Market Contracts to USD 2,835.6 Million in 2025; Forecast Predicts −1.18% CAGR Through 2026–2032
By PW Consulting, 2026-08-18
PW Consulting: Worldwide DECT Phone Market — A 2026 Decision Playbook
PW Consulting today releases an executive briefing drawn from our full market study, "Worldwide DECT Phone Market (Base Year 2025; Forecast 2026–2032)". This strategic summary explains why DECT remains a mission‑critical consideration for enterprise technology and product leaders in 2026, how regulatory and standards momentum is re‑shaping opportunity windows, and where focused investments will produce differentiated returns. The full report contains the granular models, vendor scorecards, and segment‑level forecasts required to execute on the recommendations below.
Worldwide Agile and DevOps Services Market
Market at a glance — what the headline numbers mean for 2026
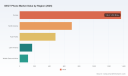
By our accounting the DECT phone market is a multi‑billion‑dollar industry. After a post‑2020 softening it stood at roughly USD 2.8 billion in 2025 (base year) and is forecast across 2026–2032 to follow a near‑flat to modestly contracting trajectory, with a compound annual growth rate of approximately –1.18% over the forecast window. The trajectory is not monotonic — the market shows short cyclical recoveries amid structural pressure from wireless substitution, unified communications, and shifting procurement priorities — creating tactical windows for vendors and buyers alike.
Worldwide Oil and Gas Back Office Software Market
Why this report matters for 2026 decision‑makers
- Strategy teams: pin down which DECT product archetypes remain strategically relevant for corporate mobility, healthcare, hospitality, and industrial automation as enterprises consolidate UC estates and rationalize device footprints.
- Product leaders & R&D: prioritize feature sets (security, ruggedization, multi‑cell scalability, NR+ capabilities) that materially improve lifetime value in cost‑sensitive segments.
- Channel & commercial leaders: align go‑to‑market motions around service‑led bundles and vertical partnerships where DECT maintains defensible advantages.
- M&A and corporate development teams: identify acquisition targets and bolt‑on categories that unlock cross‑sell in healthcare and industrial mobility while mitigating inventory and silicon supply risk.
Key dynamics reshaping the DECT ecosystem
- Regulatory and standards acceleration: A strengthened European regulatory framework (Implementing Decision 2025/2425) and active ETSI work on DECT‑2020 NR Release 2 are lowering barriers for DECT NR+ experimentation and local, licence‑exempt deployments in the 3.8–4.2 GHz range. Combined with a mature CAT‑iq certification ecosystem, these developments materially expand use cases in smart buildings, industrial automation and private wireless domains.
- Technology bifurcation: The market is splitting between classic consumer/analog DECT use cases and advanced IP‑DECT / DECT NR+ deployments that integrate with SIP/UC stacks, offer URLLC‑capable profiles, and support large multi‑cell topologies required by enterprises and healthcare providers.
- Vertical concentration: Healthcare, hospitality and certain industrial settings continue to value native DECT characteristics — predictable latency, rugged handsets, and established lifecycle support — even where general office mobility migrates to Wi‑Fi and cellular technologies.
- Industry consolidation and supplier concentration: Market concentration metrics indicate a meaningful presence of a small set of incumbent vendors, creating both partnership advantages and competitive pressure depending on your role in the value chain.
What the report includes — practical, actionable content
PW Consulting’s full market study is engineered for executable outcomes. Key deliverables include:
Worldwide Medication Dispensing Software Market
- Proprietary market size and forecast model (historical 2020–2025; outlook 2026–2032) with scenario toggles for adoption of DECT NR+, private wireless rollouts, and UC migration timelines.
- Go‑to‑market playbooks by buyer persona (IT buyer, procurement, facility manager, systems integrator) and by product archetype (consumer/analog, IP‑DECT, DECT NR+).
- Vendor benchmarking and supplier risk matrix that scores technology roadmap alignment, channel strength, certification posture, and supply chain resilience.
- Vertical use‑case blueprints for healthcare, manufacturing, and smart buildings — including deployment templates, security acceptance criteria, and service‑level engineering checklists.
- Financial templates: unit economics, TCO/ROI calculators, and pricing sensitivity analyses to inform commercial negotiations or acquisition diligence.
- Regulatory & standards playbook mapping regional spectrum constraints to practical deployment options and certification pathways.
We intentionally keep headline insights here; the full report contains the underlying tables, scenario assumptions, and segment‑level breakouts decision teams require to operationalize each recommendation.
Competitive landscape — how incumbent and specialist vendors are positioning
The vendor field is diverse: large consumer electronics firms, enterprise communications specialists, and niche OEM/chipset providers all have stakes. PW Consulting’s assessment groups these players by strategic roles and opportunities:
- Consumer incumbents (examples: Panasonic, VTech, Philips, Uniden, AT&T‑branded products) continue to dominate mass retail and home use through brand recognition, distribution, and cost efficiency. Their priority is maintaining ASPs and multi‑handset ecosystems as home voice demand softens.
- Premium and enterprise specialists (examples: Gigaset, Yealink, Poly/HP, Cisco, Avaya, Mitel, Snom, Grandstream, Alcatel‑Lucent Enterprise) are competing on integration with UC platforms, SIP interoperability, multi‑cell scalability and enterprise security. These players are best placed to capture DECT IP and NR+ adoption in campus and large‑site environments.
- Mission‑critical and vertical‑focused firms (examples: Ascom, Spectralink) continue to extract premium margins in healthcare and industrial settings where device resilience, service contracts, and regulatory compliance are non‑negotiable.
- Component and OEM enablers (example: RTX) underpin the ecosystem, and their roadmap alignment with NR+ and chip scarcity mitigation has outsized impact on device roadmaps.
Noteworthy dynamics and evidence points:
- Standards and product updates from major enterprise vendors (for example, updated IP DECT firmware and CAT‑iq security enhancements) are accelerating enterprise replacement cycles where justified by security and integration benefits.
- Interoperability demonstrations (notably the DECT NR+ smart building demo with major electrical systems suppliers) signal practical paths to new value pools beyond voice — sensing, low‑latency control and IoT aggregation.
- Independent product testing continues to matter for buyer choice; recognition of standout handsets and base station designs drives procurement decisions in conservative verticals.
Bottom‑line strategic recommendations for 2026
- Run targeted DECT NR+ pilot projects now: prioritize controlled smart building or industrial automation pilots with clear KPIs (latency, reliability, integration cost), and partner with systems integrators experienced in private wireless deployments.
- Defend enterprise footprints through UC integration: vendors should invest in plug‑and‑play SIP/UC adapters and a managed‑services subscription offering to extend hardware margins.
- Focus on vertical differentiation: healthcare and industrial customers will pay for certified, ruggedized, and securable solutions — build or acquire those capabilities rather than competing purely on price.
- Manage portfolio risk: balance legacy analog product cash flows with investment in IP‑DECT and NR+ roadmap items; use staged R&D funding tied to clear commercial milestones.
- Monitor regulatory windows: leverage harmonized spectrum rules to accelerate local pilots and capture first‑mover advantages in smart building corridors within Europe and similar jurisdictions.
- Pursue selective consolidation: buyers with strong channel access should evaluate bolt‑on acquisitions that add vertical expertise, service capabilities, or chipset relationships to accelerate go‑to‑market.
How to use this briefing — and what you’ll find in the full report
This briefing is designed to surface strategy‑level imperatives. For execution, teams will need the full dataset and tools we provide in the report, including:
- Interactive forecast models and sensitivity analyses (ability to switch adoption assumptions and see P&L impacts).
- Vendor scorecards with detailed capability scoring, go‑to‑market alignment matrices, and recommended diligence checklists for procurement teams.
- Complete regulatory mapping by jurisdiction and practical deployment guidance for NR+ trials and CAT‑iq certification milestones.
PW Consulting’s full Worldwide DECT Phone Market report is available through our insights portal. Accessing the full study provides the segment‑level tables, channel maps, and acquisition targets that underpin the recommendations above.
Concluding perspective
DECT is no longer merely “cordless voice” — it is an adaptable wireless substrate that, if deployed and supported correctly, can deliver low‑latency control, reliable voice, and IoT aggregation in verticals where Wi‑Fi and cellular do not sufficiently meet operational requirements. The next 12–18 months are a decisive period: regulatory clarity, standards consolidation, and a set of practical NR+ demonstrations are converging to create actionable commercial windows. Companies that pair disciplined portfolio management with targeted NR+ experimentation and strong channel orchestration will convert short‑term market softness into a sustainable competitive edge.
For the full dataset, vendor scorecards and the 2026 playbook required to make informed capital and product decisions, visit PW Consulting’s report page or contact our industry practice for a briefing.
Sincerely,
Senior Strategy Advisor & Chief Industry Analyst
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide DECT Phone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Room-Temperature Yogurt Market to Hit USD 11,480.83 Million in 2025; Asia-Pacific Leads with USD 6,874.4M as Market Eyes 6.5% CAGR (2026–2032)
By PW Consulting, 2026-08-18
Worldwide Room Temperature Yogurt Market: Strategic Briefing for 2026 Decision-Making
PW Consulting’s latest market study on the Worldwide Room Temperature Yogurt Market is designed as a practical intelligence brief for corporate leaders planning capital allocation, product roadmaps, and go-to-market strategies in 2026. This executive briefing distills the report’s most consequential, evidence-based trends and outlines immediate strategic moves — while preserving the granular segment-level data in our full report to encourage direct access to the proprietary models and dashboards.
Worldwide Flip Chip CSP Market
Executive snapshot
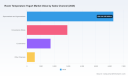
The room temperature (ambient) yogurt market has entered a structural growth phase. Our modeling — using 2020–2025 historicals and a 2026–2032 forecast horizon — projects sustained expansion at a compound annual growth rate (CAGR) of 6.5% for the forecast period. Market value climbed materially through 2025, and is projected to continue to rise in 2026 and beyond as manufacturers, retailers and foodservice operators converge around extended‑shelf products that reduce cold‑chain dependency.
Sapphire (Al2O3) Windows Market
Why 2026 is a strategic inflection point
- Scale and momentum: The market’s base year performance through 2025 shows sizable scale and positive acceleration into 2026. That momentum favors incumbents with established distribution, but it also opens meaningful white space for targeted entrants that pair technology with channel-focused execution.
- Supply‑side stressors and opportunities: Global dairy supply dynamics matter. USDA projections for overall milk production and recent upward movements in the FAO Dairy Price Index signal cost volatility for skim and whole milk powders — core inputs for ambient formulations. Firms that lock in cost advantages through long‑term contracts, ingredient hedging, co‑packing partnerships, or localized sourcing will secure margin resilience.
- Regulatory and process standardization: Ambient yogurt’s commercial viability is anchored in post‑fermentation heat treatment (secondary pasteurization) and aseptic processing to achieve multi‑month shelf stability. Regulatory expectations and packaging standards are converging; this creates a higher technical bar, favoring players that can invest in processing capabilities or strategic alliances with thermal‑processing and packaging technology providers.
- Consumer behavior and regional center of gravity: Cultural and logistical drivers — including high acceptance in several Asian markets where ambient yogurt is deeply embedded in consumption rituals and distribution systems — continue to shape demand patterns. These demand characteristics influence premiumization strategies, pack configurations, and promotional calendars.
Competitive landscape — what you need to know
The market structure is moderately concentrated: a handful of major dairy groups and targeted specialty players command a substantial portion of global ambient yogurt sales, while a dispersed set of innovators and regional brands pursue niche channels and formats. Leading players include large-scale dairy groups with integrated procurement, thermal processing and branded marketing, alongside nimble specialty manufacturers focused on extended‑shelf pouches and cups for foodservice and convenience channels.
Secondary DC Distribution Market
- Major integrated players: Established dairy giants have used their upstream milk sourcing, processing scale and brand recognition to roll out ambient lines. Their strengths are supply security, co‑branding, and access to mass retail chains — all important for national rollouts.
- International food conglomerates: Multinationals deploy ambient formats as part of broader dairy portfolios, often emphasizing formats that serve regions with constrained cold chains or where extended shelf life unlocks new channels (travel retail, humanitarian relief, remote foodservice).
- Specialty and innovation-led firms: Smaller companies are making targeted inroads with differentiated packaging and ultra‑long shelf‑life claims suited for schools, military and convenience formats. They are especially relevant if your strategy targets channels that prize portability and compliance with strict nutritional or logistical requirements.
Recent corporate developments reaffirm these dynamics: leading national producers have publicized advances in ambient production and sensory technologies; niche players launched school‑compliant, shelf‑stable cups; and adjacent product innovation in refrigerated Greek formats underscores broader category experimentation. Investors and strategy teams should monitor these signals for partnership or acquisition targets.
What the full report contains (practical deliverables for decision-makers)
Our full study translates market intelligence into implementable workstreams. Highlights include:
- Transparent market sizing and trend models (historical 2020–2025 and 2026–2032 forecasts) with scenario toggles for raw‑material prices, cold‑chain investment levels, and adoption curves.
- Unit‑economics and margin simulators by pack format and processing pathway that allow finance teams to stress‑test investment cases under different commodity price and capex scenarios.
- Channel playbooks showing differentiated go‑to‑market routes for supermarket, convenience, e‑commerce and institutional channels — plus trade promotion lift expectations and SKU rationalization guidance.
- Supply‑chain and co‑packing network maps identifying capacity bottlenecks, thermal processing technology gaps, and packaging partnerships to support multi‑month shelf life without refrigeration.
- Competitive positioning dossiers on core players, including manufacturing footprints, likely strategic priorities, and potential alliance or consolidation targets.
- Regulatory and product‑development checklists focused on secondary pasteurization, aseptic filling, and packaging integrity testing to maintain commercial sterility and sensory quality over targeted shelf‑life windows.
- Investment and M&A playbook with valuation heuristics for bolt‑on acquisitions, greenfield plants, and strategic minority investments in format innovators.
Strategic implications and near‑term actions for 2026
Leaders should translate the market outlook into a 12‑ to 18‑month operational agenda. We recommend the following priority moves:
- Accelerate format and pack innovation: Move beyond temperature as a selling point. Combine shelf‑stability with differentiated nutrition claims, single‑serve convenience, and premium sensory profiles. Pilots should test trade promotion elasticity by channel and by consumer cohort.
- Secure feedstock economics: Implement a layered procurement strategy that mixes long‑term supply agreements, spot market access and ingredient substitution where possible to protect gross margins against dairy price volatility.
- Invest tactically in processing capabilities: Evaluate whether to build, buy, or partner for thermal processing and aseptic filling. Smaller players without capital for full buildout can rapidly scale through contract manufacturing agreements with co‑packers that meet commercial sterility standards.
- Channel differentiation and pricing architecture: Design discrete price‑to‑value stacks for supermarkets, convenience and institutional buyers. Assume lower unit price tolerance in mass channels and capture premium in travel retail and gifting through bespoke multipacks and premium positioning.
- Sustainability as a commercial lever: Public reporting and supply chain transparency are becoming decision‑making variables for retail buyers and national procurement agencies. Sustainable packaging investments can accelerate retail acceptance and unlock new institutional contracts, particularly in markets where sustainability reporting is maturing.
- M&A and partnerships: Prioritize M&A targets that add capacity in strategic regions, proprietary formulations that extend shelf life without compromising taste, or packaging solutions that reduce logistics cost and breakage.
Risk factors and scenario planning
- Input cost swings: Commodity dairy price increases can compress margins rapidly. Stress‑test P&L under FAO/USDA‑aligned price trajectories and ensure working capital buffers for channel promotional cycles.
- Technical/regulatory setbacks: Any failure to meet sterility or shelf‑life claims can produce costly recalls and reputational damage. Build robust QA workflows and third‑party validation into launch timelines.
- Channel disruption: Changes in retail refrigeration footprint, trade promotion funding, or e‑commerce logistics can materially alter demand composition. Maintain flexible SKU strategies and dynamic promotional playbooks.
How to use this intelligence in 90 days
- Week 1–2: Run the PW Consulting market model against your SKU portfolio to identify underperforming SKUs and quick wins for SKU off‑load or repackaging.
- Weeks 3–6: Engage potential co‑packers and packaging partners that meet thermal processing and aseptic fill requirements; demand capability proofs and shelf‑life test data.
- Weeks 7–12: Finalize a prioritized investment list (capital and non‑capex), secure supply agreements, and launch a consumer pilot in a controlled channel to validate pricing and sensory acceptance.
Conclusion — the 2026 mandate
For 2026, executives should treat room temperature yogurt not as a niche subcategory but as a strategic lever to expand reach, diversify channel risk and extract margin from supply‑chain efficiencies. The market’s forecasted CAGR and the competitive dynamics create an environment where decisive investment in processing, procurement and packaging can deliver outsized returns — provided actions are grounded in rigorous scenario planning and validated by pilot learning.
PW Consulting’s full Worldwide Room Temperature Yogurt Market report contains the detailed datasets, segmented demand curves, and executable playbooks referenced here. For companies preparing capital plans, commercial launches or M&A pipelines in 2026, the report provides the models and due‑diligence materials that accelerate confident decision‑making. Visit our report landing page to access the complete study, proprietary dashboards, and advisory options.
For detailed analysis of this topic, please visit the official page: Worldwide Room Temperature Yogurt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Single‑Ply Roof Adhesives Market to Expand at a 5.5% CAGR During 2026–2032
By PW Consulting, 2026-08-18
Worldwide Single Ply Roof Adhesives Market: Strategic Imperatives for 2026
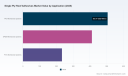
The single ply roof adhesives market is entering 2026 from a position of steady expansion and selective disruption. Our PW Consulting analysis—anchored on a 2025 base year and built from a 2020–2025 historical foundation—estimates the global market at approximately USD 1,150 million in 2025, with a base-case trajectory to roughly USD 1,673 million by 2032. The forecast period (2026–2032) is modeled at a compound annual growth rate (CAGR) of 5.5%, reflecting sustained demand in commercial roofing, retrofit activity and technology-led substitution toward low-VOC and solvent-free chemistries.
Intrinsic Safety Modules Market
Why this report matters to leaders making 2026 decisions
-
Actionable timing: 2026 will be a hinge year for manufacturers and specifiers as regulatory timelines, product launches and capacity expansions converge. The report translates market growth into tactical decision windows—when to scale production, when to prioritize low-VOC SKUs, and when to lock in raw material contracts.
Worldwide Anhydrous Borax Market -
Risk vs. opportunity mapping: We quantify exposure to feedstock volatility, regional regulatory tightening and seasonal application constraints, enabling finance and procurement teams to build realistic cashflow and margin scenarios for the next 18–36 months.
Urine Drug Testing Kit Market -
M&A and partnership playbooks: For acquirers and growth-stage firms, the study identifies value-creation levers (product portfolio rationalization, route-to-market consolidation, and intellectual property capture) and offers a prioritized short-list of inorganic targets based on capability gaps rather than headline market shares.
-
Commercialization readiness: Roofing adhesives are sold into installer networks and membrane system specifiers. Our report gives field-tested GTM approaches—training programs, specification capture strategies and installer economics—that move laboratory performance into real-world market share.
What the report delivers (practical scope)
-
Integrated demand model (USD Million units and revenue): scenario-driven forecasts at national and product-technology levels, with sensitivity levers for construction cycles, raw material pricing and VOC regulation trajectories.
-
Competitive intelligence pack: company profiles, strategic positioning maps, product-technology matrices and a supplier scorecard covering technical certification, manufacturing footprint and go-to-market strength.
-
Regulatory and standards matrix: compliance checklists for low-VOC/OTC requirements, certification pathways (UL/FM), and regional application constraints that affect install seasons and product adoption.
-
Operational playbooks: manufacturing site-siting guidance, capex sizing templates, raw-material hedging strategies, and logistics optimization for sticky and temperature-sensitive chemistries.
-
Commercial tools: spec-translation packs for product managers, value-based pricing frameworks for adhesives versus membranes, and installer economics models that demonstrate payback on higher-performing formulations.
-
Primary research appendix: anonymized installer surveys, OEM interviews, and lab-comparison summaries that substantiate performance claims and procurement preferences.
Note: The above description emphasizes the report’s practical orientation. To preserve competitive integrity and the ‘trailer’ nature of this release, detailed regional, application and type-level splits are available only in the full report and supporting datasets.
Market dynamics shaping 2026 strategy
-
Technology migration toward low-VOC and solvent-free chemistries. Demand-side pressure from regulatory bodies and sustainability-minded owners is accelerating specifications that favour water-based, low-VOC polyurethane and solvent-free bonding systems. This trend creates margin opportunities for formulators who can deliver parity in bonding strength and application window while reducing environmental compliance costs.
-
Raw material and performance trade-offs. Polyurethane systems continue to hold a significant position because their elasticity helps absorb deck movement and thermal cycling—important in single-ply assemblies. At the same time, solvent-based contact adhesives retain relevance for certain membrane types and installation environments, but they come with application temperature constraints and VOC obligations that limit year‑round usability in cooler geographies.
-
Regulatory gating and specification capture. OTC/VOC compliance remains a gating item in several U.S. jurisdictions and is becoming a purchasing criterion for major owners. Firms that proactively certify and document low-VOC performance gain an early advantage in specification-led procurement processes.
-
Seasonality and installation economics. Contact adhesives that require minimum application temperatures or have short open times impose labour and scheduling constraints for installers. Product formulation that extends application windows or simplifies installation yields direct share gains through reduced labour costs and rework.
Competitive landscape: how established players are positioning for 2026
The market is competitively balanced: a set of global formulators and system manufacturers provide both adhesives and membrane systems, while a cohort of nimble specialists produces highly differentiated chemistries and regional solutions. Aggregate concentration is moderate—our CR3 and CR5 metrics indicate that the top three firms control just under four in ten dollars of the market, while the top five approach a majority—pointing to space for targeted consolidation and specialty playbooks.
-
H.B. Fuller (St. Paul, MN) : Broad, product-led competitor with a push toward sustainability—illustrated by 2025’s introduction of Millennium PG-1 EF ECO 2, which eliminates chemical blowing agents by leveraging atmospheric gases. The company’s acquisition strategies (including regional brands) aim to broaden technical depth and installer reach.
-
Johns Manville (Denver, CO) : Integrates adhesives within a system-selling approach tied to insulation and membrane products. Strengths include product breadth (two-component foams, LVOC options) and channel relationships with commercial roofing specifiers.
-
GAF (Parsippany, NJ) : Leverages its position as a membrane supplier to push contact and specialty adhesives into commercial channels. Its formulations and technical guidance influence installer behaviour for TPO systems, particularly where compatibility and warranty alignment matter.
-
Tremco Roofing (Beachwood, OH) : Focuses on high-performance bonding systems and foam-based adhesives, with strong credentials in adhered single-ply systems and asset-level service capabilities.
-
Paramelt (Netherlands) : European leader with global operations, strong in PU and contact adhesives for EPDM/TPO/PVC. Their manufacturing footprint and materials know-how give them a rapid route to scale niche formulations across regions.
-
Sika (Baar, Switzerland) : Strategic investment in capacity and R&D—evidenced by a new technology and manufacturing facility in Pune (2025)—positions Sika to expand adhesive supply into fast-growth construction markets, coupling product innovation with local production economics.
-
Dove Technology, QDEK (Quin Global), Henry Company : Specialist and regional players that bring spray systems, low-VOC California‑compliant formulations and installer-focused solutions. Their agility makes them natural partners or targets for larger formulators seeking product breadth without lengthy internal development cycles.
Recommended strategic plays for 2026 (prioritized)
-
Product portfolio pivot to low-VOC and solvent-free chemistries: Prioritize a staged SKU rationalization that retires low-margin, regulatory-sensitive products and redeploys capex to high‑margin water-based PU and solvent-free systems.
-
Localized manufacturing nodes: Where freight and seasonality constrain applicator economics, build or partner for regional capacity—this is especially important in markets with fast installation windows or where temperature-sensitive logistics raise costs.
-
Installer economics and specification capture program: Invest in training, warranty-aligned product bundles and specification marketing to convert technical product advantages into repeat business.
-
M&A for capability acceleration: Target small to mid-sized formulators with differentiated low‑VOC or spray technologies to shorten time-to-market and expand distribution without diluting R&D focus.
-
Hedging and supplier contracts: Use the report’s raw-material exposure matrix to negotiate multi-year supply agreements for critical monomers and polyols, and to build pass-through clauses that protect margins in volatile feedstock environments.
How PW Consulting supports executive teams in 2026
Our report is structured to be immediately operational. Alongside the narrative we provide an integrated Excel model, a scenario workshop facilitation pack, detailed supplier scorecards and an M&A screening template that turns strategic options into executable plans. For corporate strategy teams, product managers and private-equity investors focused on the adhesives value chain, PW Consulting offers bespoke modeling support and target-validation engagements to de-risk 2026 execution.
To preserve the strategic advantage for subscribers, this public synopsis intentionally omits detailed regional, application and type-level breakdowns—these granular datasets and the primary-source evidence base are available in the full Worldwide Single Ply Roof Adhesives Market report and accompanying data room.
Contact PW Consulting or visit our report page to request an executive briefing, download the full dataset, or arrange a scenario planning session tailored to your portfolio. 2026 is a year for focused choices; this study turns market outlook into concrete moves.
For detailed analysis of this topic, please visit the official page: Worldwide Single Ply Roof Adhesives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Container Twistlock Market to Rise from USD 585.4 Million in 2025 to USD 830.34 Million by 2032 at a 5.12% CAGR, Led by Asia Pacific (~USD 300.04M)
By PW Consulting, 2026-08-18
Worldwide Container Twistlock Market — Strategic Briefing for 2026 Decision‑Makers
Executive snapshot
PW Consulting’s new market study on the Worldwide Container Twistlock Market provides an actionable, decision‑grade view for executives planning capital allocation and operational strategy in 2026. Built on a 2020–2025 historical foundation with a 2026–2032 forecast window, the report quantifies the market in USD Million (base year 2025) and models demand across macro drivers such as containerized trade flows, port automation, intermodalization, and regulatory compliance. At the portfolio level the market was estimated at USD 585.4 Million in 2025, and our scenario-led progression implies a steady expansion at a compound annual growth rate (CAGR) of 5.12% across the forecast period, reaching a projected market size in the higher hundreds of millions by 2032.
Power Electronics for Renewable Energy Market
Why this matters for 2026 strategy
- Capital allocation: The mid‑single digit CAGR and the market’s revenue trajectory justify selective investment in automation and high‑value product lines rather than broadscale capacity expansion. Capital planners should prioritize modular upgrades that can be scaled to fleet and terminal automation projects.
- Product roadmap alignment: The transition to semi‑automatic and fully automatic systems is no longer an optional improvement — it is a differentiator. Companies that align R&D and commercialization timelines with port modernization projects will capture a disproportionate share of incremental margin.
- Supply chain resilience: Raw‑material and standards pressures elevate procurement and quality assurance to strategic priorities. Procurement teams must integrate raw‑material volatility, certification lead times, and supplier concentration into contract and inventory design.
- M&A and partnership signals: Market concentration metrics show a market where leading players command a material share but room exists for focused challengers. Strategic partnerships and bolt‑on acquisitions that add automation, certification, or aftermarket capabilities are high‑impact moves in 2026.
What the report contains — practical, implementable outputs
This study is intentionally tactical in scope: it translates macro forecasts into operational pathways for manufacturers, port operators, OEMs, and investors. Key deliverables include:
Bone Cemented Elbow Prosthesis Market
- Market sizing and scenario models: A base case and two stress cases that reflect variations in container throughput, automation adoption rates, and raw‑material cost shocks. All models are provided in editable formats so teams can rerun scenarios with internal assumptions.
- Go‑to‑market playbooks: Product prioritization matrices, channel and aftermarket strategies, and time‑to‑market calendars tailored to semi‑automatic and fully automatic offerings versus manual legacy products.
- Procurement and risk templates: Supplier scorecards, hedging approaches for steel input cost exposure, and compliance checklists keyed to ISO standards and class‑society approvals.
- Commercial due diligence packages: Comparable transaction comps, margin laddering by product architecture, and integration checklists for M&A or JV negotiations.
- Field validation plans: Test protocols for automation retrofits, safety acceptance criteria, and stakeholder communication templates for rolling out new twistlock systems in live terminals or intermodal fleets.
Market dynamics shaping 2026 choices
Three structural dynamics are decisive for near‑term strategy:
Cable Squirrel Guard Market
- Automation acceleration — Port and terminal operators are accelerating the shift from manual handling toward semi‑automatic and fully automatic twistlocks to reduce human exposure and cycle time. This creates demand for electromechanical solutions that integrate with terminal operating systems and autonomous vehicle platforms.
- Standards and certification intensity — ISO 3874 and ISO 1161 remain the operational baseline for interchangeability and safety. Class society approvals (ABS, DNV‑GL, CCS) and railroad authorizations (AAR) are necessary market access levers in marine and intermodal segments respectively; certification timelines should be treated as gating factors for product launches.
- Input cost and supply chain sensitivity — Twistlock production depends on high‑strength forged or cast steels. Recent steel price behavior and spot volatility mean procurement strategies must combine longer contracts, strategic inventory buffers, and alternative alloys where feasible to protect margins.
Competitive landscape — positioning and strategic choices
The market is commercially competitive but not atomized: the leading three players together hold a material share of revenue, and the top five firms account for a clear majority of market value. This concentration profile creates both barriers and opportunities — scale players can mobilize certification, inventory and global service networks; specialist suppliers win on customization, speed and niche approvals.
Representative company dynamics (selected disclosures and observed moves):
- LOX Container Technology — Pushing automation at the product edge with electrified, retractable automatic twistlocks integrated for autonomous vehicles. Their Road Gen 2 launch shows the edge of demand where ports and logistics operators experiment with autonomy projects.
- Pacific Marine & Industrial and Delta Mark — Classic portfolio players that combine AAR and class society approvals, offering breadth across manual, semi‑automatic and automatic models and serving both marine and rail markets. Their value comes from compliance breadth and channel reach.
- Container Technics NV and SEC Ship's Equipment Centre — Focused on global stocking strategies and port‑centric distribution; they underscore the commercial advantage of regional inventory positioning for rapid replacement and retrofit programs.
- Mainland China and India manufacturers (GLS, Shanghai Metal Corporation, ITP, NDRAGOLD, Karma Steels) — Competitive cost structures and growing engineering sophistication. Several have moved up the value chain by adding larger seat variants and class‑approved marine models.
- MacGregor (Cargotec group) and other integrated OEMs — Bundling twistlocks into larger cargo‑handling systems, thereby shifting procurement discussions from discrete hardware purchases to system‑level investments that emphasize uptime and integrated safety.
Across these players, recent market activity shows two themes: first, product advancement focused on automation and electrification; second, a refresh of catalogs and compliance updates reflecting updated strength requirements and ongoing ISO alignment.
Risks and friction points to model in 2026
- Certification lead times: Gaining class society or AAR approvals can take months and materially affects time‑to‑market for new designs. Plan product roadmaps with certification gates as critical path items.
- Raw‑material price volatility: Steel price moves can compress margins quickly — plan multi‑scenario P&Ls with stress cases and working capital buffers. As a tactical example, teams should consider the impact of recent regional steel price movements on quoted bill‑of‑materials.
- Aftermarket service complexity: Warranty and retrofits in the installed base are often the most profitable channel, yet they require global logistics and trained technicians. Underinvesting here is a missed yield opportunity.
Actionable recommendations for 2026
- Manufacturers: Prioritize modular automation platforms that can be certified as families, reducing per‑variant certification cost. Invest in a service arm with regional stocking for rapid turnarounds.
- Ports and terminals: Pilot electrified automatic twistlocks in a limited number of berths tied to concrete KPIs (dwell time, labor hours saved, safety incidents reduced) before broad rollout.
- OEMs and system integrators: Bundle twistlocks with digital monitoring and predictive maintenance features to capture aftermarket margin and extend customer lock‑in.
- Investors and M&A teams: Seek targets that combine certification depth with aftermarket service networks rather than pure volume play; specialist automation firms with IP in electromechanical retractable designs are strategic bets.
How PW Consulting supports execution
Beyond the market model and playbooks, PW Consulting offers hands‑on execution support for 2026 initiatives: certification roadmaps, supplier contracting workshops, pilot design and oversight for automation deployments, and deal diligence for inorganic growth. Our supporting toolkits include editable financial models, procurement scorecards, and installation/commissioning checklists aligned with ISO and class‑society requirements.
Closing — the strategic value proposition
For decision‑makers preparing budgets, technology roadmaps, or deal pipelines in 2026, the twistlock market represents a measured growth opportunity driven primarily by automation adoption, regulatory compliance, and aftermarket services. The market size and mid‑single digit CAGR provide a reliable growth runway; the concentration of leading players and the rapid evolution of automation technologies create clear inflection points where timely investments and partnerships will differentiate winners from followers.
PW Consulting’s full report contains the detailed segment tables, regional and application splits, supplier scorecards, and the editable scenario models referenced here. To access the full dataset, granular segment forecasts, and the implementation playbooks that translate insight into action, please visit the PW Consulting report page or contact our industry team to request the complete Worldwide Container Twistlock Market study and execution toolkit.
For detailed analysis of this topic, please visit the official page: Worldwide Container Twistlock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Enzymatic Detergents Market to Reach USD 22,096.6 Million by 2032 at 5.45% CAGR — North America Leads with USD 5,388.5M
By PW Consulting, 2026-08-18
Worldwide Enzymatic Detergents Market — Strategic Outlook for 2026 Decision-Making
Executive snapshot
PW Consulting’s new market study shows the worldwide enzymatic detergents market reached approximately USD 15,240.5 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 5.45% through the 2026–2032 forecast window, reaching an expected USD 22,096.6 Million by 2032. The market exhibits a moderate level of concentration (CR3 ~38.4%; CR5 ~46.15%), underlining the presence of several influential technology leaders alongside a broad field of regional and specialist suppliers.
Urine Drug Testing Kit Market
Why this report matters for 2026 planning
-
Actionable timing: 2026 is the pivot year for multiple regulatory, pricing, and supply-chain shifts that will redefine competitive cost structures and claims around sustainability. Our analysis isolates the decision points that separate opportunistic growth from margin erosion.
Worldwide Gas Gravitometers Market -
Portfolio positioning: Enzymatic formulations are now central to product differentiation across household and institutional cleaning. R&D and procurement choices made in 2026 will determine who captures premium, environmentally conscious segments versus commoditized volume.
MRI Radiofrequency Coils Market -
Supply resilience: Raw material, trade-policy and fermentation feedstock volatility mean procurement strategies must be restructured. The report maps the scenarios procurement leaders should model this year to avoid disruption or costly re-sourcing later.
Market dynamics shaping strategic imperatives
-
Regulatory tightening and label integrity: Updated biodegradability testing requirements under the EU Detergent Regulation and expanded REACH authorization lists are effective around 2026. These create both compliance costs and market opportunities for suppliers that can certify eco-performance quickly.
-
Raw-material and input-price pressure: Fermentation feedstock and key enzyme classes experienced meaningful cost increases in late 2025. Buyers and formulators who do not implement disciplined cost-mitigation (e.g., hedging, alternate feedstocks, increased production efficiency) will see margin pressure through 2026.
-
Geopolitical supply impacts: Tariff and trade-policy dynamics — notably protection measures applied to certain imported microbial enzymes — have shifted supply chains and raised landed costs for a material portion of the global enzyme flow. Sourcing footprint and contingency inventory strategies require immediate reassessment.
-
Technology-led product substitution: Advances in cold-water active proteases, stabilized lipases, and engineered amylases continue to expand application envelopes for enzymatic detergents. New enzyme chemistries allow formulators to combine performance with lower temperature wash cycles, supporting energy and carbon-reduction claims.
Competitive landscape — who matters and why
The sector’s technology architecture favors specialized enzyme houses and incumbent chemical players with biotechnology capabilities. A small set of global leaders—developers of next-generation proteases, amylases, and lipases—drive formulation trends through platform R&D, global supply networks and co-development agreements with major detergent brands.
-
Innovation leaders: Companies that combine enzyme discovery with formulation know-how set the market benchmark. Recent next‑generation product launches and certification wins indicate a near-term advantage for those who can deliver higher cold‑water performance and validated sustainability claims.
-
Integrated chemical majors: Large players with broad portfolio and distribution reach are leveraging enzyme blends and brand relationships to accelerate adoption in mainstream channels.
-
Specialist challengers: Regional and specialty enzyme suppliers continue to win niche applications by optimizing stability, pH tolerance, and color-care properties for targeted geographies or use-cases.
The report provides detailed company profiles, R&D roadmaps, recent product developments, and a competitor action matrix that translates observed moves into likely next steps — essential intelligence for procurement, alliance, and M&A teams.
Strategic implications and recommended actions for 2026
-
Reassess supplier strategy now. Convert spot purchases into capacity-backed agreements with clear clauses for feedstock pass-throughs, regulatory support, and minimum supply guarantees. For critical enzyme classes, consider co-investment in local fermentation capacity or multi-source qualification to reduce tariff exposure and freight risk.
-
Prioritize regulatory readiness as a product feature. Build a certification roadmap (e.g., biodegradability testing, ecolabel approvals, REACH dossiers) into product launch timelines. Investments here can accelerate market access and premium pricing in regulated geographies.
-
Embed cost-to-serve modeling in every product development track. Given recent input-price volatility, cross-functional teams must be able to simulate margin outcomes under different feedstock and tariff scenarios before committing to large-scale launches.
-
Differentiate through demonstrable sustainability and performance. Claims alone will not win shelf space; validated tests, third-party certifications, and transparent LCA inputs are becoming table stakes for brand escalation in household and institutional channels.
-
Design modular portfolios. Mix flagship enzyme-enabled formulations with lower-risk legacy chemistries to manage transition risk. Offer upgrade pathways (e.g., add-on enzyme packs, premium concentrates) to capture upsell without disrupting core margins.
-
Accelerate commercial partnerships. Licensing, co-development, and exclusive regional supply agreements can secure preferential access to breakthrough enzymes and create barriers for competitors. Use early-stage commercial pilots to de-risk scale-up and validate consumer acceptance.
-
Evaluate opportunistic M&A and bolt-on plays. Target regional fermentation assets, specialty enzyme niches, or formulation houses that can be folded into a broader branded portfolio to quickly change cost structures or accelerate geographic reach.
What the PW Consulting report delivers (practical content)
We designed this study as a hands-on toolkit for executive and operational teams charged with 2026 planning. The report includes:
-
A robust forecasting model with base-year calibration, sensitivity scenarios (input‑price shocks, accelerated regulation, technology adoption curves) and downloadable model files to test custom assumptions.
-
Regulatory tracker and compliance playbook tailored to Europe, North America, and major Asia Pacific jurisdictions — including timelines, certification requirements, and recommended dossier roadmaps.
-
Procurement and supply-chain playbooks: supplier scorecards, negotiation term templates, regional risk heatmaps, and contingency inventory calculators.
-
Competitive intelligence dossiers: executive profiles, recent product and certification activity, patent landscapes and go-to-market assessments for leading enzyme and chemical companies.
-
Commercial launch blueprints and channel strategies mapped to household, institutional and industrial use-cases — including premiumization levers, pricing sensitivity, and promotional frameworks.
-
M&A and partnership playbooks: valuation frameworks, integration checklists, and a prioritized list of target characteristics to accelerate inorganic growth or capability acquisition.
-
Risk matrices linking regulatory, input-price, geopolitical and technological threats to mitigations that are actionable within 90, 180 and 360-day horizons.
To preserve the strategic value of the analysis and encourage direct engagement, the public release intentionally omits the granular subsegment revenue breakdowns and detailed regional/application splits. The full dataset—including enzyme-type, regional and application-level forecasts, and company-level share estimates—is available in the complete report and interactive dashboard.
Use cases: how leading teams are applying the analysis
-
R&D and product managers: prioritize enzyme platforms that deliver validated cold‑water performance and stability to match rising low-temperature laundry adoption.
-
Procurement: convert short-term savings into long-term resilience by reshaping contracts around capacity and feedstock risk sharing.
-
Commercial and brand teams: restructure claims architecture around certified biodegradability and LCA-backed sustainability to defend premium segments.
-
M&A teams: use the report’s target-screening criteria and financial sensitivity models to identify acquisition opportunities that close capability gaps while protecting EBITDA.
Concluding view — the 2026 inflection
The enzymatic detergents market is moving from a phase where biochemical performance dominated purchase decisions to a structure where regulatory compliance, supply resilience and validated sustainability claims are equally decisive. The 2026 planning cycle is the point at which companies either lock in leadership through targeted investments and partnerships or face escalating cost and access barriers. PW Consulting’s analysis provides the operational roadmaps and decision frameworks needed to navigate this transition with precision.
Next steps
For procurement, R&D, commercial or corporate-development teams preparing 2026 budgets and action plans, PW Consulting offers bespoke briefings, model licensing and scenario workshops to translate the report’s insights into executable 90‑ to 360‑day programs. Access to the full dataset, segmentation detail and interactive dashboards is available through our report page or by contacting our strategic advisory desk.
For detailed analysis of this topic, please visit the official page: Worldwide Enzymatic Detergents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


