



Category: market research
PW Consulting Forecast: Worldwide Fire-Resistant Fabrics Market to Rise from USD 5.28B in 2025 to USD 8.18B by 2032 at a 6.45% CAGR — North America Leads with USD 1.77B in 2025
By PW Consulting, 2026-08-18
Worldwide Fire Resistant Fabrics Market — Strategic Preview for 2026 Decisions
PW Consulting's latest market intelligence indicates that the global fire resistant (FR) fabrics market reached USD 5,282 million in 2025 and is on a steady trajectory, with a compound annual growth rate of 6.45% driving the market toward an estimated USD 8,181 million by 2032. For executive teams preparing 2026 operating plans, sourcing strategies, or M&A playbooks, these headline metrics are more than market color — they reframe priorities across R&D, procurement, channel strategy, and regulatory compliance.
Embryo Transfer Medium Market
Why this report matters for 2026
-
Timing: 2026 will be a year in which companies either lock in advantage through targeted capacity or lose margin defensibility to raw‑material shocks and regulatory shifts. The market growth profile gives a predictable top‑line backdrop against which to stress‑test investments.
Worldwide Music School Software Market -
Risk management: our analysis quantifies supply‑chain vulnerability pockets and maps supplier concentration, enabling procurement teams to prioritize dual‑sourcing, strategic inventory, and long‑term offtake agreements.
Fluorescence Endoscopy Camera System Market -
Product roadmap alignment: lightweight thermal protection, recyclable chemistries, and laminate systems are rapidly moving from “innovation projects” to commercial imperatives for premium growth segments.
What PW Consulting's Report Delivers (Practical, Actionable Content)
-
Robust market sizing and forward-looking base, upside and downside scenarios calibrated to mid‑cycle and stress events — including price shocks and regulatory tightening.
-
Supplier scorecards and heatmaps that benchmark capability across technology (inherent vs treated), scale, geographic footprint, and sustainability credentials.
-
Cost‑to‑serve and margin sensitivity models that link feedstock inputs to finished‑goods pricing under multiple forex and energy scenarios.
-
Commercial playbooks for OEMs, distributors and textile converters covering segmentation, route‑to‑market, and value capture strategies tailored to industrial safety, defense/public safety, transportation, and building textiles.
-
Compliance and certification matrix mapping major standards to product types and geographies, supporting engineering and regulatory teams preparing 2026 launches.
-
M&A and partnership decision frameworks with prioritized target archetypes and indicative valuation ranges (methodology disclosed; proprietary deal comps available within the full report).
Near‑term Dynamics Shaping 2026 Strategy
Three structural dynamics will dominate executive agendas next year: feedstock volatility, regulatory momentum toward non‑halogenated chemistries, and premiumization of performance fabrics.
-
Feedstock volatility: aluminum‑ and magnesium‑based flame retardants saw meaningful price moves in 2025 driven by upstream supply disruptions and energy constraints. Procurement organizations should expect elevated cost pass‑through negotiations during 2026 and should model at least one significant price shock scenario in capital and sourcing plans.
-
Regulatory and customer pressure: non‑halogenated flame retardants are already a majority of the revenue pool in the broader flame retardant market, growing at a material clip. This regulatory and customer preference shift favors suppliers that can certify non‑halogenated technologies while maintaining performance and cost targets.
-
Standards as blockers or enablers: NFPA and equivalent standards remain gatekeepers in core end markets. For buyers and specifiers, early engagement in standards testing shortens approval cycles and accelerates time‑to‑revenue.
Supply, Capacity and Competitive Posture
The market exhibits moderate concentration: leading global suppliers collectively account for a meaningful share of revenues, but a competitive long tail persists — creating room for differentiated plays. Strategic moves we are tracking include capacity expansions in Asia, targeted lightweight product launches, and cross‑sector partnerships that combine specialty fibers with advanced laminates and coatings.
Notable industry actions that should influence 2026 decisions:
-
Tier‑one fiber manufacturers are investing in capacity and material innovations to secure upstream control and accelerate delivery on higher‑value inherent FR fibers.
-
Specialty fabric houses and laminators are partnering with fiber innovators and chemistry providers to produce lighter, more breathable systems optimized for firefighter and industrial protective wear.
-
New entrants and niche players are gaining traction with recyclable and non‑PVC flame‑retardant constructions — a commercial signal that sustainability can be a viable route to differentiation rather than a cost center.
Competitive Landscape — Strategic Implications
Our qualitative benchmarking of primary participants highlights three differentiated business models in the competitive set: integrated fiber champions, specialty fabric system providers, and chemistry/treatment specialists.
-
Integrated fiber champions (examples include long‑standing aramid producers) leverage their proprietary polymers and scale to compete on inherent FR performance. These players are best positioned to capture premium, high‑performance segments and to control margin through vertical integration.
-
Specialty fabric system providers (brands known for high‑performance outer shells and laminates) win in use‑case sensitive categories such as firefighting and some defense applications where certification history and system performance trump commodity pricing.
-
C hemistry and treatment specialists (producers of flame‑retardant treatments and formulations) play a pivotal role where cost, retrofittability and standards compliance determine adoption. Regulatory shifts toward non‑halogenated chemistries increase their relevance — but also raise the bar on R&D investment.
Recent product and capacity events underscore how these business models are translating into commercial advantage: targeted product launches that combine enhanced thermal protection with reduced weight; capacity additions in growth regions; and strategic partnerships that combine best‑in‑class fibers with system suppliers to accelerate field adoption. For 2026, executives should profile competitors not only by revenues and locations but by certifiable system competencies and roadmaps to non‑halogenated, recyclable solutions.
Strategic Plays for 2026 — Practical Recommendations
-
Procurement & supply risk: accelerate dual‑sourcing for critical feedstocks and adopt hedging strategies informed by our cost sensitivity models; prioritize suppliers with demonstrated margin resilience and regional redundancy.
-
Product & R&D: prioritize lightweight, breathable, and recyclable FR solutions that meet evolving standards. Fast‑track field trials with key OEMs to compress adoption cycles.
-
Commercial: implement value‑based pricing for premium performance segments and develop bundled service propositions (testing, certification support, aftermarket traceability) to increase stickiness.
-
M&A and partnerships: pursue tuck‑ins that supply differentiated chemistries or niche recyclable constructions; structure deals with earnouts tied to certification and commercial milestones to bridge technology risk.
-
Regulatory & compliance: embed a standards roadmap into product launch timelines; secure pre‑certification trials for products targeted at firefighting and defense to avoid approval delays.
How to Use the Full PW Consulting Report
The full report contains granular tools and deliverables designed for direct use in annual planning cycles: detailed forecasting models, supplier scorecards, plant‑level capacity maps, cost build‑ups, scenario simulators, go‑to‑market playbooks and a prioritized list of de‑risking actions for procurement and engineering teams. Our methodology chapter discloses assumptions, data sources and the sensitivity levers used in the forecast so teams can re‑run scenarios against custom input sets.
We designed the report as an executable resource for product, procurement, commercial, and corporate development teams — not just a high‑level market narrative. That said, consistent with the “preview” purpose of this release, we have intentionally withheld segmented regional, application and price point tables from this summary; those detailed outputs are accessible via the full report and interactive dashboards.
Next Steps — For Executives Building 2026 Playbooks
Use the 2026 planning cycle to convert macro certainty into tactical advantage: lock in strategic supplier agreements for critical inputs, accelerate certification for next‑gen fabrics, and position the organization for selective consolidation or partnership. With market growth proceeding at roughly a mid‑single‑digit CAGR, the winners next year will be those who convert technical differentiation into faster spec adoption and tighter supply chains.
To access the full dataset, segment‑level forecasts, supplier benchmarking and the PW Consulting 2026 action checklist, please visit our report page and download the comprehensive Worldwide Fire Resistant Fabrics Market report. Our team is available for tailored briefings to help translate findings into a prioritized 90‑day implementation plan.
For detailed analysis of this topic, please visit the official page: Worldwide Fire Resistant Fabrics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Collision Mitigation System Market to Reach USD 10,850.5 Million in 2025 and Surge to USD 24,516.66 Million by 2032 at a 12.35% CAGR
By PW Consulting, 2026-08-18
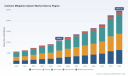
Worldwide Collision Mitigation System Market: Strategic Implications for 2026 Decision-Making
PW Consulting’s latest market study on the Worldwide Collision Mitigation System market — anchored on 2025 as the base year and projecting through 2032 — provides a compact, actionable intelligence package tailored for executive teams preparing strategic moves in 2026. The sector is at a pivotal inflection point: regulatory mandates, tougher safety-test protocols, and rapid sensor/platform innovation are converging to convert collision mitigation from a competitive differentiator into a near‑universal functional requirement. Our topline finding: the market stood at approximately USD 10,850.5 Million in 2025 and is forecast to more than double by 2032 to roughly USD 24,516.7 Million, implying a robust 12.35% CAGR over the 2026–2032 forecast window.
Aircraft Windshield Wiper System Market
Why this matters for 2026 corporate strategy
-
Regulatory certainty compresses time-to-market imperatives. With major jurisdictions moving from recommendation to mandate — for example, finalized U.S. rules requiring AEB on new light vehicles beginning compliance cycles and an EU regime that has already made AEB compulsory for new models — OEMs and Tier‑1s must align product roadmaps and certification programs to multi‑year compliance calendars.
Worldwide OCP Training Education Service Market -
Safety protocol evolution raises technical bar. Leading safety authorities updated test protocols (Euro NCAP, IIHS, etc.), broadening target scenarios and performance thresholds. This increases validation scope (motorcycles, junctions, elevated-speed front crash avoidance) and places a premium on systems that perform in degraded conditions.
Worldwide Home Console Market -
Technology complexity and differentiation have shifted upstream. Sensor fusion—combining radar, camera, and increasingly thermal or LiDAR inputs—has emerged as the practical route to robust performance across lighting and weather envelopes. This creates new architectural choices and supplier leverage points for sensor hardware, perception stacks, and domain controllers.
Market dynamics at a glance
-
Growth profile: The market’s projected compound annual growth rate of 12.35% (2026–2032) reflects accelerated adoption driven by regulation, OEM flagship programs, and retrofit opportunities in commercial fleets.
-
Concentration: The market exhibits moderate consolidation — our concentration analysis shows that the three largest players control roughly 42.5% of the market, while the top five account for about 58.8%. This structure preserves room for innovative challengers while rewarding scale and integration capability.
-
Technology stacking: Radar, image-based perception, and new modalities such as thermal LWIR are converging into multi‑sensor arrays; high‑performance perception silicon and software-defined safety stacks are becoming differentiation vectors.
Competitive landscape — what the leading suppliers are doing
-
Robert Bosch GmbH: Continues to leverage deep systems integration capabilities across radar, sensors, and control software. Recent upgrades to radar silicon and object-recognition algorithms indicate Bosch is optimizing detection range and false-positive performance to meet tougher test protocols.
-
Continental AG: Emphasizes sensor fusion and scalable ADAS platforms. Continental’s strategy centers on modular platforms that allow OEMs to tier features while maintaining integration economies for braking and actuation subsystems.
-
Denso Corporation: Focuses on high-reliability module supply, pairing radar and camera stacks with established OEM relationships — a play optimized for volume production and proven field reliability.
-
Aptiv PLC: Positions itself as a systems and software integrator, offering perception stacks and fusion middleware to accelerate OEM integration for both passenger and commercial vehicle programs.
-
Autoliv Inc.: Leverages its safety-system pedigree to push combined warning-and-braking solutions, focusing on occupant protection pathways and integrated testing regimes that align with new IIHS/Euro NCAP scenarios.
-
ZF Friedrichshafen AG: Offers end-to-end safety modules, from perception to braking control. ZF’s proposition is attractive for OEMs seeking single‑supplier responsibility across the safety chain.
-
Mobileye (Intel): Remains a leader in vision-first solutions and perception silicon. Its EyeQ processors and algorithmic approaches continue to scale across models, especially where cost-optimized camera-first setups can meet regulatory and test thresholds.
-
Valeo SA, Magna International, Hyundai Mobis, Bendix: Each of these firms plays a distinct role — sensor suppliers, integrators, or commercial-vehicle specialists — with product roadmaps that prioritize robustness, manufacturability, and fleet-oriented performance metrics.
Recent developments shaping near-term decisions
-
Product innovation: Thermal sensing has moved from lab to launch cycles. For example, the introduction of new thermal LWIR cameras designed for 360° ADAS reinforces how low-light and adverse-weather performance is becoming commercially viable for pedestrian AEB.
-
Semiconductor advances: Next‑generation RF-CMOS radar chips extend detection range and improve object classification — enabling more confident braking interventions at higher speeds.
-
Standards tightening: Safety authorities have tightened evaluation frameworks to include motorcycle and trailer targets and higher-speed front-crash prevention scenarios. Expect certification scope and validation investment to rise materially for systems claiming Top Safety Picks or equivalent awards.
What our full report contains — practical, operational deliverables
-
Integrated market model (USD Million, base year 2025) with scenario levers: price decline curves, regulation adoption timing, and component cost roadmaps — designed for rapid sensitivity testing across M&A, product pricing, and production ramp assumptions.
-
Strategic playbooks for OEMs, Tier‑1s, and semiconductor/sensor suppliers: timing recommendations for in-house development vs. partner sourcing, platform-level decisions for centralized vs. distributed domain controllers, and go‑to‑market sequencing for markets with staggered regulatory windows.
-
Vendor diligence framework: scorecards covering technical capability, production maturity, software quality processes, and IP positions—built to support sourcing and M&A screening without requiring bespoke consultancy engagement.
-
Regulatory and certification calendar: an operational checklist mapping global rules and test protocols to compliance milestones, test-facility needs, and sample volumes to inform 2026 program budgets.
-
Commercial vehicle annex: separate guidance on fleet retrofit economics, telematics integration, and uptime/maintenance models — recognizing that commercial fleets follow different procurement timelines and total-cost-of-ownership calculations.
Actionable recommendations for 2026 planning cycles
-
Prioritize robustness across environments. Investment in multi-sensor fusion and thermal/LiDAR augmentation is no longer optional for systems aiming to pass expanded Euro NCAP/IIHS regimes — plan validation budgets accordingly.
-
Lock down supplier scopes early. Given concentration that favors a handful of large Tier‑1s and the high cost of late-stage integration changes, strategic sourcing decisions and long‑lead procurement should be finalized in the first half of 2026 for programs targeting 2029 compliance windows.
-
Consider hybrid delivery models. For OEMs, a hybrid approach (core safety algorithms in-house + perception hardware from vetted Tier‑1s) balances IP control with production risk mitigation, especially where differentiated user experience is part of brand positioning.
-
Test for certification stringency. Product roadmaps must include edge-case testing (motorcycles, junctions, trailer scenarios) and degraded-sensor robustness to avoid re‑work when cert bodies tighten ratings.
-
Use the market model for M&A screening. The market’s strong CAGR and moderate consolidation create attractive windows for bolt-on acquisition of specialized perception firms or thermal-sensor startups — but diligence must emphasize software maturity and field validation data.
Why PW Consulting’s report is uniquely useful
Our study blends a granular, model-driven forecast with executable playbooks and a supplier diligence engine — an approach designed for leadership teams that need to translate market trajectories into resource allocation, R&D schedules, and M&A pipelines in 2026. We intentionally present headline market sizing and growth rates to anchor strategic prioritization while reserving the detailed segment-by-segment tables, granular region-by-application breakouts, and vendor-by-feature scoring matrices for the full report. This “preview” approach gives you the directional clarity to make board-level choices now, and a clear path to obtain the detailed data you’ll need for program implementation.
Next steps
-
For immediate strategic use: download our executive datasheet and scenario playbook to map how the 12.35% CAGR and regulatory timelines may affect your 2026 product and procurement budgets.
-
For operational planning: request the full report to access the complete market model (USD Million basis, 2025 base year), the vendor scorecards, and the certification calendar that will be essential for program scheduling and supplier negotiations.
-
For M&A and partnership teams: leverage our diligence checklist and target shortlist methodology to prioritize acquisition targets or OEM partnerships that fit into your 3–5 year roadmap.
As collision mitigation evolves from a differentiator to a compliance and safety imperative, 2026 is the year to align product architecture, supplier commitments, and validation investments. PW Consulting’s Worldwide Collision Mitigation System Market report provides the strategic compass and the operational instruments to convert market growth and regulatory pressure into defensible, executable advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Collision Mitigation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Polyolefin Battery Separator Films Market to Grow at a Robust 13.5% CAGR, New 2025 Insight Report Predicts
By PW Consulting, 2026-08-18
Worldwide Polyolefin Battery Separator Films Market — Strategic Outlook for 2026 Decisions
PW Consulting’s new market study on Worldwide Polyolefin Battery Separator Films delivers an actionable intelligence package designed to shape boardroom and operational decisions in 2026. The multi‑year story is unmistakable: the market has moved from a niche industrial commodity toward a foundational supply chain for electrification, scaling from roughly USD 3.85 billion in 2020 to about USD 7.97 billion in 2025, and our baseline forecast now projects growth to nearly USD 19.34 billion by 2032 at a 13.5% compound annual growth rate (CAGR). For executives weighing capex, offtake contracts, vertical integration, or M&A this year, these macro trajectories require immediate strategic responses rather than deferred planning.
Worldwide Automotive Retail Software Market
Why this report matters for 2026
Two practical takeaways define the report’s value to decision‑makers in 2026. First, the market scale and growth profile convert an operational product (microporous polyolefin films) into a strategic lever that affects battery pack costs, OEM sourcing strategies, and regional industrial policy. Second, the investment cycle entering full execution—large greenfield plants, integrated wet‑process capacity, and coated‑film lines—creates windows for first‑mover advantage but also material supply risk if timing or technology choices are misaligned. PW Consulting’s study turns these observations into executable options: supplier scorecards, cost curves, capex timelines, and regulatory-risk playbooks designed for teams preparing 2026 budgets and multi‑year roadmaps.
Data Recovery Equipment Market
Market trajectory and demand drivers
The headline numbers underscore a rapid secular transition: the market nearly doubled during 2020–2025 and is forecast to more than double again through 2032 under our central scenario. Demand momentum is underpinned by continued EV battery capacity build‑out, accelerating deployments in grid energy storage, and persistent replacement/upgrade cycles in consumer electronics. However, demand is not uniform—technical differentiation (wet vs. dry process, coated vs. uncoated films, ceramic or PVDF coatings, and shutdown/thermal‑stability features) is creating premium segments where safety, coating capability, and process control command differentiated commercial returns. In short, volume growth is substantial, but margin capture will depend on where suppliers and OEMs compete on technology and reliability.
Sit-Down Electric Counterbalance Forklift Market
Supply-side developments: capacity, concentration, and implications
- Industry consolidation is meaningful: the top three suppliers control a majority share of global capacity, and the top five are responsible for well over two‑thirds of the market by revenue—creating a market structure that favors incumbents but opens tactical windows for regional entrants and contract manufacturers that can offer local content and fast delivery.
- Capital intensity and strategic capex are rising. Recent, announced investments—large integrated wet‑process projects and multi‑phase greenfield plants—signal that the next 24–48 months will transform regional supply footprints. Several of these projects specifically target North American and Canadian production to address local content incentives and supply‑chain security.
- For 2026, the immediate implication is timing risk. Plants coming online in 2026–2028 will absorb a disproportionate share of demand growth, so late decisions on offtake or site selection may force expensive short‑term sourcing (spot imports, premium logistics, or expedited capacity) that can erode margins.
Raw material, cost volatility, and process selection
Polyolefin film economics remain tightly coupled to upstream polymer markets and petrochemical feedstocks. The industry continues to experience measurable price volatility—our review identifies near‑double‑digit swings in critical resin costs and documented multi‑month volatility patterns. These movements directly affect separator cost curves, and coated film variants amplify the effect because coating chemistries and ceramic additives add separate supplier risk and price sensitivity.
Practically, we advise companies to model at least three polymer‑price scenarios and to stress‑test contract structures against them. Tactical responses include resin off‑take agreements, strategic inventory buffering, selective vertical integration for upstream resin exposure, and flexible process investments that allow switching between wet and solvent‑free stretching technologies to minimize solvent‑related regulatory and cost risk.
Regulatory and safety forces shaping technology choices
Regulatory tightening and safety requirements are not theoretical constraints; they shape allowable process choices and operating costs. For example, proposed exposure limits for solvents used in some wet‑process base film production introduce potential compliance and capex implications for abatement systems and workforce hygiene. At the same time, OEM safety specifications (thermal runaway mitigation, shutdown behavior, ceramic coatings) are compelling suppliers to invest in higher‑value coated films and to validate performance under automotive testing regimes.
For 2026 capital planning, firms must incorporate regulatory compliance costs (air permits, solvent abatement, monitoring systems) into project NPV and consider solvent‑free or alternative processing technologies where feasible. Safety performance is increasingly a commercial differentiator—customers will pay for documented thermal stability and proven shutdown behavior when selecting long‑lead EV battery components.
Competitive landscape — what the major players are doing
The sector’s competitive map blends global incumbents with regionally focused challengers. Key strategic positions we highlight in the report include:
- Long‑established specialists offering both wet and dry technologies and emphasizing safety features in their product lines.
- Newer integrated entrants executing giga‑scale wet‑process builds to capture coated‑film economics and serve automotive OEMs with local content.
- Regional manufacturers investing in solvent‑free stretching and ceramic/PVDF coating capabilities to target high‑safety applications and differentiate on quality.
- Vertical players (chemical groups and battery suppliers) that use M&A and JV structures to secure supply and capture margin along the battery value chain.
These dynamics are reinforced by recent corporate actions—divestments, large greenfield investments, and capacity expansions—that we analyze for their competitive and timing implications. The combined picture points to an evolving but still concentrated market where strategic partnerships and timing of capacity entry matter as much as raw production volume.
PW Consulting’s 2026 strategic playbook
For executives and investment committees preparing decisive 2026 actions, our study recommends a prioritized set of moves:
- Secure near‑term supply through strategic offtake and tolling agreements rather than relying solely on greenfield timelines.
- Run polymer‑price and regulatory compliance stress tests across your product mix; hedge key inputs or pursue upstream partnerships where economics justify the capex.
- Invest in coating capability and qualification programs early—coatings (ceramic, PVDF) are becoming table stakes for high‑energy automotive cells.
- Evaluate flexible manufacturing lines that can alternate between wet and solvent‑free processes to limit regulatory exposure and broaden customer reach.
- Pursue M&A and JV opportunities selectively: consolidation can be value‑creating, but price discipline is essential in a capital‑intensive market with multi‑year lead times.
- Build a supplier‑risk scorecard that incorporates regional policy (local content incentives), environmental compliance, technology fit, and ramp risk to prioritize partners in 2026 contracting rounds.
What the report contains — practical tools for 2026 planning
PW Consulting’s report is structured as an execution toolkit for commercial, operations, and corporate development teams. Key deliverables include:
- An interactive demand model covering 2020–2032 with scenario toggles to test alternative EV/ESS trajectories.
- Plant‑level cost curves and break‑even maps for wet vs. dry processes and coated vs. uncoated film lines.
- Supplier scorecards and a ranked M&A shortlist based on production capability, technology differentiation, and regional supply security.
- Capex and ramp timelines with sensitivity to regulatory compliance costs and polymer price scenarios.
- A regulatory‑risk matrix and recommended compliance investment pathways (abatement, process substitution, monitoring systems).
- Commercial negotiation playbooks for offtake, tolling, and JV structures aligned to local content incentives and investment timelines.
In keeping with our “trailer” approach for this press summary, we intentionally omit the granular region‑by‑region and application‑by‑application tables and detailed line‑item segment forecasts from this release. These detailed spreadsheets, supplier benchmarking files, and the interactive model are available exclusively with the full report and client briefings.
Next steps for decision‑makers
2026 is a year for resolution: choose to secure supply, de‑risk feedstock exposure, and align technology choices with regulatory and OEM requirements—or accept higher spot costs and opportunistic sourcing. PW Consulting’s report equips you with the data‑driven scenarios, operational benchmarks, and transaction playbooks to execute those decisions. For access to the full dataset, interactive model, and tailored executive briefing, contact PW Consulting and reserve your analysis slot—timing matters as facilities come online and procurement windows close.
For detailed analysis of this topic, please visit the official page: Worldwide Polyolefin Battery Separator Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Glycosidases Market to Grow at a 6.18% CAGR During 2026–2032, Led by Food & Beverages Demand
By PW Consulting, 2026-08-18
Worldwide Glycosidases Market — Strategic Briefing for 2026 Decisions
Executive summary
PW Consulting’s latest Worldwide Glycosidases Market report (base year 2025) maps a market that has moved from niche enzymology into a broadly adopted toolset across industrial biotech, food processing, animal nutrition, biofuels and biopharma. Our analysis shows the global market expanding from roughly USD 1.12 billion in 2023 to an estimated USD 1.90 billion by 2032 at a compound annual growth rate (CAGR) of 6.18% over the 2026–2032 forecast window. For executives planning investments, partnerships, or product strategies in 2026, the key takeaway is simple: the market is sizable, predictable, and stratified — creating differentiated opportunities for scale players, specialized innovators, and downstream integrators.
Disposable Medical Anticoagulation Tube Market
Why this briefing matters for 2026 decision cycles
-
Capital allocation: Faster-than-average growth with mid-single-digit CAGR and a clear multi-year trajectory reduces the premium placed on near-term speculative bets. Firms should prioritise capital-efficient scaling and targeted R&D rather than broad, undifferentiated expansion.
Endotoxin Testing Kits Market -
Portfolio positioning: The enzyme marketplace rewards specialization that aligns with industry workflows — e.g., supply chains for food-grade enzymes, high-purity offerings for biopharma QC, and robust formulations for feed and industrial applications. 2026 planning should reweight product and go-to-market investments toward these workflow adjacencies.
Worldwide Expanded Polystyrene (EPS) Recycling Market -
Regulatory timing: With several glycosidases already affirmed under food-safety frameworks and specific feed enzymes authorized in key jurisdictions, firms can accelerate commercial roll-outs in regulated channels with an informed, compliance-first approach.
Market trajectory and structural dynamics
The glycosidases market shows a classic technology-to-platform maturation curve. Early volumes were driven by research and specialty reagents; a subsequent wave of adoption came from food & beverage process optimization and animal nutrition. Starting in the early 2020s, industrial biotechnology and biopharma quality control established steady, recurring demand. Our baseline size in 2025 provides an anchor for forecasting: visible year-on-year growth through 2032 underpinned by steady demand from both legacy and emergent applications.
Two structural forces drive this expansion. First, application diversification: downstream industries continue to embed glycosidases into production and analytical workflows, widening total addressable demand. Second, production economics: recombinant manufacturing platforms (notably E. coli and Pichia pastoris) have reduced cost-per-unit and improved consistency compared with native extraction, enabling broader penetration into price-sensitive segments.
Primary growth drivers (actionable lens)
-
Industrial and food process optimization — Enzymatic routes replace or augment chemical processing in many food and feed workflows. Expect adoption where enzymes lower ingredient costs, improve nutritional value, or provide regulatory and labeling advantages.
-
Analytical and QC demand in biopharma — As complex biologics and glycoprotein therapeutics proliferate, demand for high-purity glycosidases for glycan analysis and deglycosylation in QC workflows will remain robust. Procurement teams should treat enzyme supply as a mission-critical element of the QC supply chain.
-
Scale-enabled cost declines — The shift toward recombinant expression platforms has structural implications: lower marginal costs and more predictable supply enable new commercial models (e.g., subscription supply, bundled assay kits) and pricing pressure on low-differentiation products.
-
Regulatory endorsement in targeted channels — Where enzymes are affirmed as safe for food and authorized for feed, market adoption accelerates. Regulatory clarity reduces time-to-market and de-risks larger commercial commitments.
Key risks and headwinds
-
Commoditisation of standard enzymes — As recombinant production scales and new low-cost producers enter the market, commoditisation risk will compress margins for undifferentiated enzyme offerings.
-
Regulatory shifts — While several enzymes already enjoy favorable regulatory status in important markets, any tightening or regional divergence in safety evaluation could create time-lags and incremental compliance costs for entrants and incumbents alike.
-
Supply-chain concentration — Dependence on a limited number of expression platforms or reagent inputs could create vulnerability during bioprocess disruptions; de-risking through multi-sourcing and regional production redundancy is prudent.
Competitive landscape — what leading players signal
The market structure combines a set of well-capitalised life-science incumbents with specialist enzyme houses and agile niche providers. Market concentration metrics indicate the top three manufacturers capture a meaningful but not overwhelming share of industry revenue; the top five widen that footprint substantially. This leaves room for focused specialists and new entrants that can offer unique value propositions.
-
Merck KGaA (MilliporeSigma): A go-to supplier for research-grade glycosidases used in glycoprotein analysis and glycobiology. Their strength lies in breadth of catalog and integrated workflow positioning for laboratory markets.
-
Thermo Fisher Scientific: Broad portfolio and a strong channel presence for proteomics and biopharma QC. Thermo Fisher’s scale and instrument/consumable ecosystem support cross-selling opportunities and preferred supplier relationships.
-
New England Biolabs (NEB): Focus on recombinant glycosidases and high-throughput workflows. NEB’s rapid, application-oriented reagents appeal to labs pursuing throughput gains.
-
Roche and Takara Bio: Both bring pharmaceutical-grade enzyme offerings and regulatory know-how that suit drug-development and QC workflows; Roche also benefits from an established relationship network inside pharma.
-
Creative Enzymes, Worthington, Gold Biotechnology, and Neogen (Megazyme): These specialists supply targeted catalogs (industrial enzymes, food-grade products, and research reagents) and often compete on price-performance or application-specific validation.
Competitive advantage in 2026 will come from three interlocking capabilities: superior product validation for target applications (incl. stability, activity profile, and regulatory status), resilient manufacturing and supply chain, and integrated commercial models (kits, bundled services, or long-term contracts that lock in recurring revenue).
Regulatory and production context — implications for strategy
Regulation is not uniform, but it is predictable in important ways. Several glycosidases are affirmed as generally recognized as safe (GRAS) for food processes in key markets, and specific feed enzymes have pathway authorization under established EU frameworks. These regulatory endorsements are actionable: companies with compliant dossiers can accelerate commercial launches and obtain preferred-supplier status with major food and feed manufacturers.
On production, recombinant expression in E. coli and Pichia pastoris has become the dominant route because of scalability and cost-efficiency. Strategic planners should factor this into facility investments, partner selection, and supply continuity plans. For R&D teams, the dominance of recombinant platforms means that biologic engineering capabilities (e.g., strain development, fermentation scale-up, and downstream purification) are strategic differentiators.
What the PW Consulting report delivers — practical content for 2026 plans
-
Market sizing and multi-year forecast model anchored to 2025 that quantifies near- to medium-term growth trajectories and scenarios.
-
Actionable go-to-market playbooks mapped to verticals (food & beverage, animal feed, industrial biotech, biofuels, and biopharma) that prioritise where to deploy resources in 2026.
-
Competitive benchmarking that assesses incumbent strengths, product portfolios, channel reach and implications for potential M&A or alliance targets.
-
Regulatory mapping and a compliance readiness checklist to accelerate approvals and reduce time-to-revenue in regulated channels.
-
Supply-chain risk assessments and a manufacturing roadmap that helps C-suite leaders cost an onshore vs. offshore production mix and plan redundancy for critical inputs.
-
Commercial models and pricing guidance, including recommendations for subscription, bundling and value-based pricing strategies to defend margins in a maturing market.
Strategic recommendations for 2026
-
Prioritise validated, application-specific products over undifferentiated catalog expansion. Invest in stability data, regulatory dossiers, and co-validation studies with key customers to win preference.
-
Commit to recombinant capacity or secure long-term partnerships with established recombinant manufacturers. Manufacturing reliability is now a commercial differentiator, not just a cost lever.
-
Design hybrid commercial offers: combine enzymes with assay kits, technical support, and performance guarantees to build stickiness and predictable revenue.
-
Use M&A selectively to acquire gaps in workflow integration (e.g., assay providers, sample-prep kits) and to accelerate entry into regulated food and feed channels where approvals confer market access advantages.
-
Deploy scenario-based planning across regulatory and supply-chain stress cases so procurement and commercial teams can respond quickly to region-specific dynamics.
Conclusion — a trailer, not the full movie
The Worldwide Glycosidases Market is no longer an obscure corner of enzymology; it is a maturing market with clear structural growth and predictable demand signals. For leaders making 2026 capital, product, and partnership decisions, the right approach combines focused product validation, manufacturing resilience, and commercial models that capture recurring revenue. PW Consulting’s full report provides the granular segmentation, validated vendor matrices, and downloadable forecast model that boards and strategy teams need to move from intent to execution.
To obtain the detailed segmentation tables, company profiles, and the operating model templates referenced in this briefing, request the full report from PW Consulting — it contains the specific numbers and market-breakdown insights intentionally omitted from this overview to preserve the integrity of the research and to support client-level decision workstreams.
For detailed analysis of this topic, please visit the official page: Worldwide Glycosidases Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting report: Worldwide Glucose IV Bag Market set to expand at a 6.02% CAGR through 2032
By PW Consulting, 2026-08-18
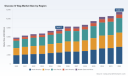
Worldwide Glucose IV Bag Market: Strategic Preview for 2026 — What Senior Leaders Must Know
Executive summary
PW Consulting’s latest market study on the Worldwide Glucose IV Bag Market — with a 2025 base year and a 2026–2032 forecast horizon — equips executives and procurement leaders to make high-confidence choices in 2026. The global market has expanded from approximately USD 5,824 million in 2020 to about USD 7,636 million in 2025 and is projected to grow at a steady compound annual growth rate (CAGR) of roughly 6.02% to exceed USD 11,496 million by 2032. These headline trajectories mask important inflection points in supply, regulation, and product design that will determine winners and losers across manufacturing, distribution, and hospital purchasing cycles in the year ahead.
Fiber Sensing Solution Market
Why this report matters for 2026 decisions
-
Timing capital and capacity investments: With demand growth accelerating and documented capacity additions from major players, 2026 will be a pivotal year to commit CAPEX or to seek strategic partnerships. The report models multiple demand scenarios and their effect on capacity utilization, cash flow, and payback timelines under conservative and upside assumptions.
Worldwide Practice Analytics Software Market -
De-risking supply chains: Recent large-volume parenteral (LVP) shortages and temporary regulatory import measures underscore the fragility of established supply chains. Our analysis quantifies exposure to single-source risks and prescribes prioritized mitigation steps for procurement and clinical teams.
Worldwide Diabetes Software Market -
Product and materials strategy: As hospitals shift to non-PVC, non-DEHP materials, decisions around transitioning SKUs, validating new packaging formats, and managing inventory obsolescence will be material to profitability. The report provides a phased roadmap for product-line conversion compatible with regulatory expectations.
-
Regulatory scenario planning: Ongoing emergency import authorizations and device clearances change the operational landscape for 2026. The study offers a regulatory tracker and playbook that prepare in-house regulatory affairs and quality teams for fast-moving concessions and post-market compliance obligations.
Market dynamics — what’s driving change
-
Demand fundamentals: Hospitals continue to rely on glucose/dextrose IV solutions for hydration, calorie provision, and as vehicles for drug administration. Aging populations and persistent acute-care needs provide a structural demand base, while episodic events (e.g., natural disasters, product recalls) create volatile spikes.
-
Supply shocks and management tactics: The sector has seen national shortages of LVP solutions, prompting conservation strategies such as prioritizing completion of partially infused bags and, in some jurisdictions, controlled compounding of 5% dextrose when packaging supply is constrained. Procurement teams must reconcile just-in-time inventory practices with strategic stockpiling and alternate-sourcing contracts.
-
Regulation as a supply lever: Authorities have, at times, authorized temporary importation of glucose injections labeled differently (e.g., anhydrous vs. USP dextrose), a nuance that affects interchangeability and clinical substitution. Manufacturers and hospitals must align labelling, clinician education, and substitution protocols to avoid clinical errors and compliance exposure.
-
Materials and product design shift: There is a clear migration toward multilayer polyolefin (non-PVC, non-DEHP) films and polypropylene bag technologies. These choices are driven by safety/regulatory demands and sustainability targets. Companies that can convert lines rapidly or offer validated legacy-to-new-material transition kits will capture share and trust.
Competitive landscape — who holds influence and how they’re moving
The market is moderately consolidated: top-three players account for a majority share, and the top-five capture a substantial portion of the market — a structure that enables both collaboration on surge capacity and competitive pressure on pricing for commoditized SKUs.
-
Baxter International Inc. remains the dominant flexible IV bag supplier with deep North American manufacturing footprint and broad clinical portfolio. Baxter’s scale provides supply reliability in normal cycles, but its exposure to regional disruptions makes it an important counterparty for strategic contracting rather than a sole-source provider.
-
B. Braun Melsungen AG and Fresenius Kabi AG compete strongly on sterile hospital-grade glucose solutions. Fresenius’ recent investment in a USFDA-registered freeflex production facility signals an aggressive capacity play and a strategic bet on non-PVC technologies; companies must anticipate increased competition for contracts that emphasize domestically produced supply.
-
ICU Medical (Otsuka ICU Medical LLC) is notable for its non-PVC, non-DEHP product options and recent regulatory clearances linked to aseptic transfer devices — incremental innovations that reduce downstream handling risk in hospitals. Such product adjuncts can be differentiators in tender processes that weight total cost of ownership and infection-control outcomes.
-
Grifols, Terumo, Otsuka and regional manufacturers maintain critical niche positions in national markets, and their product formulations, packaging choices (e.g., polypropylene bags), and regulatory relationships are essential considerations for buyers seeking redundancy without sacrificing clinical equivalence.
-
Suppliers of packaging and contract manufacturers such as SIPPEX, CDM Lavoisier, and outsourcing facilities like Assure Infusions are increasingly strategic. They provide ready-to-fill packaging and 503B sterile compounding capacity that supports rapid fill-and-finish and localized contingency supply plans.
Recent developments to watch
-
Device and transfer innovations — e.g., new 510(k) clearances for aseptic transfer devices — are reducing reconstitution risk and may shift purchasing priorities toward systems that reduce clinician handling time and contamination risk.
-
Major capacity expansions and facility openings, coupled with public disclosures about investments nearing USD 1 billion by significant incumbents, indicate that companies are pre-emptively addressing capacity constraints. Strategically, buyers should treat these announcements as opportunities to renegotiate terms or to establish long-term offtake agreements.
-
Regulatory flexibility such as temporary import authorizations will likely contract as supply stabilizes; therefore, buyers relying on emergency channels must plan transitions back to permanent, compliant sourcing streams to avoid clinical and legal risk.
What the PW Consulting report delivers — practical, action-oriented content
-
Proprietary demand models: scenario-driven forecasts (base, demand-shock, and accelerated-uptake cases) with month-by-month stress testing for 2026 planning cycles.
-
Supplier scorecards: a comparative matrix that weights capacity, regulatory footprint, material technologies, and contingency performance — designed for direct inclusion in RFP evaluation criteria.
-
Procurement playbooks: contract clauses and operational KPIs to secure priority allocation during shortages, plus dynamic inventory policies that balance working capital and clinical risk.
-
Regulatory and labeling tracker: timelines and decision trees to align sourcing choices with import authorizations, interchangeability guidance, and post-market surveillance obligations.
-
CapEx and conversion planner: a phased approach for manufacturers to convert PVC SKUs to non-PVC technologies with implied cost curves, validation steps, and recommended timelines tied to expected demand trajectories.
-
Clinical adoption maps: use-case analysis showing where higher-concentration dextrose products, bag volumes, and infusion adjuncts deliver differential clinical or economic value — framed as decision heuristics rather than raw share tables.
How to use this intelligence in 2026
-
Hospital supply officers: prioritize multi-vendor frameworks with capacity commitments for critical SKUs; implement rapid-switch protocols validated by clinicians to shorten time-to-substitution if a contracted SKU becomes unavailable.
-
Manufacturers: accelerate material-conversion roadmaps and establish co-investment models with key buyers to underwrite localized capacity; use the supplier scorecard to identify partnership targets for fill-finish or packaging capabilities.
-
Private equity and strategic investors: use the market’s forecasted growth and concentration metrics to find consolidation targets that can deliver scale synergies in packaging, sterile fill-finish, and regulation-savvy product portfolios.
-
Regulatory teams: build contingency protocols that translate temporary import allowances into validated clinical substitution pathways so that emergency supplies can be used without creating liabilities.
What we’re intentionally not publishing here — and why you’ll want the full report
In keeping with PW Consulting’s “trailer” approach, this release demonstrates the strategic depth of our findings while intentionally withholding granular regional and application-level breakdowns, specific segment revenues, and scenario-by-scenario SKU-level forecasts. Those detailed matrices — including per-region demand curves, concentration-and-material split tables, and supplier-by-SKU performance ratings — are available in the full report and are structured to be exported directly into procurement and financial models used by senior teams.
Immediate next steps
-
Secure executive briefings: schedule a 60–90 minute strategy session with our lead analysts to review tailored scenarios for your procurement footprint and manufacturing exposure.
-
Download the full dataset: obtain the comprehensive model that includes month-level forecasts, supplier scorecards, and the conversion planner to integrate into your 2026 budgeting and tender cycles.
-
Initiate tactical pilots: use our procurement playbook to run a 90-day pilot for dual-sourcing or validated compounding pathways to test operational resilience ahead of winter 2026 demand peaks.
PW Consulting’s Worldwide Glucose IV Bag Market report is designed for leaders who must convert market intelligence into executable programs in 2026. The global market’s steady growth, structural concentration, material-technology shift, and episodic supply shocks create both risk and opportunity — and the right intelligence can convert those into a defensible competitive advantage. For access to the full report, datasets, and an executive workshop, visit our report page or contact our market team directly.
For detailed analysis of this topic, please visit the official page: Worldwide Glucose IV Bag Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide UAV Propulsion Systems Market Set to Grow at a 12.85% CAGR — Electric Propulsion and North America Poised to Lead
By PW Consulting, 2026-08-18
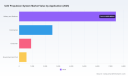
Worldwide UAV Propulsion System Market: Strategic Intelligence to Shape 2026 Decisions
PW Consulting announces a new industry briefing designed to guide C-suite and investment teams through an inflection point for UAV propulsion technologies
The propulsion systems that power unmanned aerial vehicles (UAVs) are no longer a niche engineering problem — they are a strategic fulcrum for defense programs, commercial logistics, and the emerging Advanced Air Mobility (AAM) economy. PW Consulting’s new Worldwide UAV Propulsion System Market report (base year 2025) synthesizes five years of historical performance and a multi-scenario forecast to 2032, delivering the decision-grade intelligence leaders need to prioritize R&D spend, shape M&A strategy, and harden supply chains in 2026.
Worldwide Orthopedic EMR Software Market
Market trajectory: a high-growth runway
Our modeling indicates the UAV propulsion market has moved from a global market measured in the low single-digit billions (USD, revenue unit: Million) in 2020 to a substantially larger base by 2025, reflecting accelerating adoption across military, commercial, and civil missions. The base-year 2025 estimate anchors our projections, which show continued robust expansion through the forecast period. Under our primary scenario, the market is projected to grow at a compound annual growth rate (CAGR) of 12.85% in the 2026–2032 window, culminating in a materially larger global market by 2032.
Worldwide Rotary Tablet Press Market
That growth trajectory is not uniform across technologies, geographies, or applications. Electric propulsion, hybrid architectures, micro-turbines, advanced piston and rotary designs, and fuel-cell integrations are each following distinct diffusion curves — and those differences are precisely what procurement, product and strategy teams must understand before committing capital in 2026.
Pooling RPCs (Reusable Packaging Container) Market
Why this matters for 2026 decision cycles
-
Portfolio prioritization: With R&D budgets under pressure, leadership teams must choose between incremental improvements to existing propulsion lines and strategic bets on disruptive architectures (e.g., native parallel hybrid systems, high-energy-density fuel cells). Our report maps payback horizons and break-even assumptions under multiple fuel, battery, and component-cost scenarios.
-
Supply chain resilience: The industry’s strong dependence on critical raw materials — lithium, nickel, cobalt, graphite, and rare-earth magnets — creates concentrated points of failure for electric propulsion and power electronics. Coupled with recent trade and export controls targeting alloys and specialized aerospace processing, supply-chain mitigation is a top-three procurement priority in 2026.
-
Regulatory alignment: Proposed performance-based regulations for beyond-visual-line-of-sight (BVLOS) operations and national strategies emphasizing domestic manufacturing are reshaping certification timelines. Programs that align propulsion-system robustness and redundancy with emerging regulatory thresholds will unlock earlier operational approvals and consequent revenue capture.
-
M&A and partnership timing: As mission requirements tighten around endurance and life-cycle cost, strategic M&A and JV activity will accelerate. Our scenario work shows where consolidation yields scale benefits (sourcing, testing, certification) versus where nimble specialist players retain premium margins.
Competitive landscape and what to watch in 2026
The vendor ecosystem spans established aerospace primes, dedicated propulsion specialists, and high-growth electric-native companies. Rather than a single category dominating, the market is evolving as a multi-modal competitive arena where incumbents and newcomers stake complementary claims.
-
Specialist OEMs: European and North American firms with deep combustion and rotary-engine expertise continue to serve high-end tactical and long-endurance missions. These players are investing in ruggedization, heavy-fuel compatibility, and integration packages for VTOL and fixed-wing ISR platforms.
-
Electric-native suppliers: Manufacturers of brushless motors, ESCs, and integrated power systems are scaling up to meet industrial and commercial drone fleets, focusing on thermal management and high-efficiency motor-control software.
-
Prime contractors and tier-one aerospace: Large aerospace groups and systems integrators are moving upstream through acquisitions and strategic partnerships to capture propulsion IP and qualification pathways required by defense customers and certificated civil platforms.
-
Hybrid innovators and fuel-cell entrants: A growing cohort of start-ups and small series suppliers is proving hybrid-electric and fuel-cell concepts that materially extend range while meeting platform weight constraints, attracting defense programs targeting greater stand-off and loiter capabilities.
Key companies highlighted in our analysis
Our competitive profiles include engineering capability, product roadmaps, certification posture, and commercial traction for leading names across the propulsion stack. Sample profiles include:
-
Sky Power GmbH (Germany) — A specialist in high-performance gasoline, heavy-fuel, two-stroke, and Wankel engines, Sky Power’s modular approach to carburetor and injection variants enables rapid OEM integration across diverse UAV missions.
-
Northwest UAV (United States) — As a major U.S. manufacturer of aviation-grade propulsion systems, Northwest emphasizes AS9100-compliant manufacturing and full-system integration for defense and commercial UAS customers.
-
UAV Propulsion Tech (United States) — Through partnerships with experienced European component makers, this company offers a mixed portfolio spanning piston engines, DC motors/generators, and micro-turbine options for integrators seeking single-supplier simplicity.
-
Rotron Power Ltd. (United Kingdom) — Focused on rugged rotary engines for VTOL and demanding defense use-cases, Rotron’s designs aim to combine power density with maintainability under austere conditions.
-
Plettenberg (Germany) and T‑MOTOR (China) — Representing the electric propulsion end of the market, these manufacturers provide EN 9100-certified motors, controllers, and integrated power systems for professional and industrial platforms.
-
Large aerospace groups (e.g., Honeywell, Safran, GE Aerospace, Rolls‑Royce) — Investing in hybrid-electric and micro-turbine efforts to leverage aerospace-grade certification expertise for defense and future commercial AAM applications.
-
Fuel-cell and hybrid specialists (e.g., Ballard Power Systems, Lowental Hybrid) — Demonstrating niche but high-impact solutions for extended-endurance tactical UAVs; recent contract awards and exhibition activity indicate accelerating defense interest.
Recent industry moves illustrate the tempo of change: acquisition activity to secure UAV-focused engineering capabilities, hybrid propulsion selections by defense primes, and exhibition-stage product launches demonstrating range and weight trade-offs. These events correlate with program-level procurement timelines we model in the report and should influence 2026 capital allocation and partnership strategies.
What the PW Consulting report delivers — practical modules for strategic teams
The report is organized around decision-centric deliverables rather than descriptive market statistics alone. Key modules include:
-
Global market sizing and forecast model (base year 2025) with drill-downs by propulsion architecture and application under multiple scenarios.
-
Technology roadmaps for electric, hybrid, piston, turboshaft/turboprop and micro-turbine systems, including maturity curves and recommended investment horizons.
-
Supply-chain risk heatmap covering critical raw materials, single-source components, and geopolitically sensitive inputs — with mitigation playbooks for sourcing diversification and nearshoring.
-
Vendor benchmarking and procurement scorecards built on engineering metrics, production capability, certification status, and program-level references.
-
Regulatory and certification tracker mapping proposed BVLOS and AAM rule changes to propulsion reliability, redundancy, and testing requirements.
-
M&A and alliance playbook: target selection criteria, valuation sensitivities, and integration checklists for acquiring propulsion IP or scaling manufacturing capacity.
-
Scenario-based investment cases capturing fuel and battery price volatility, export control regimes, and demand shocks related to defense procurement cycles.
Risk landscape and mitigation priorities
Three risk clusters demand board-level attention in 2026:
-
Raw-material concentration: Electric propulsion’s material intensity exposes programs to pricing and availability swings. Our procurement playbook prioritizes diversified sources, strategic inventory, and design choices that reduce rare-earth dependence where feasible.
-
Trade and export controls: Recent policy moves affecting specialized alloys and aerospace equipment have increased certification and logistics friction. The report provides a country-risk matrix and contract clauses to manage transfer limitations and compliance costs.
-
Regulatory uncertainty: Near-term certification pathways for BVLOS and AAM operations are evolving. We quantify the operational and revenue upside of meeting proposed performance-based requirements and recommend accelerated test campaigns for propulsion subsystems where the ROI justifies it.
How to use this intelligence in 90–180 day decision cycles
-
Procurement teams: Use the vendor scorecards and supply-chain heatmaps to reweight supplier panels and initiate dual-sourcing for critical components within the next quarter.
-
R&D and product management: Prioritize one or two propulsion architectures for fast-follower development based on program fit and certification velocity; align test schedules to anticipated regulatory milestones.
-
Corporate development: Deploy our M&A playbook to screen targets by technology complementarity and manufacturing footprint; set bid thresholds informed by scenario-driven valuations.
Next steps
PW Consulting’s Worldwide UAV Propulsion System Market report is intended as an operational tool: it goes beyond headline growth numbers to provide the playbooks and models procurement, engineering, and strategy teams need to act in 2026. The briefing intentionally previews market dynamics, vendor positioning, and risk vectors while reserving detailed segment-level datasets, regional breakdowns, and proprietary valuation matrices for the full report.
For organizations preparing budgets, negotiating supplier contracts, or evaluating acquisition targets in 2026, this report offers a concise bridge from market intelligence to executable plans. To access the full dataset, vendor benchmarking tables, and the scenario model behind the 12.85% CAGR projection for 2026–2032, please visit PW Consulting’s research portal to request the complete Worldwide UAV Propulsion System Market report and supporting Excel models.
For detailed analysis of this topic, please visit the official page: Worldwide UAV Propulsion System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Automotive Camera Sensor Market to Expand at a 16.02% CAGR, Reaching USD 22,523.2 Million by 2032
By PW Consulting, 2026-08-18
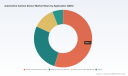
Worldwide Automotive Camera Sensor Market: Strategic Insights for 2026 Decision-Makers
The Worldwide Automotive Camera Sensor Market is at an inflection point. After accelerating through the early 2020s, the market reached a substantial valuation in 2025 and — under conservative baseline assumptions — is forecast to expand at a compound annual growth rate of 16.02% across 2026–2032, reaching a materially larger global footprint by the end of the period. For executives preparing 2026 roadmaps, capital allocation plans, or sourcing strategies, the implications are clear: camera sensors are no longer a discrete component purchase; they are a strategic enabler of vehicle safety, autonomy, and new value chains.
Worldwide CMO & CDMO Market
Why this report matters in 2026
- Strategic lens for executive decision-making: The report translates aggregate growth into board-ready scenarios that link sensor supply, SoC roadmaps, and regulatory timelines to P&L and product launch calendars.
- Actionable risk management: With semiconductor supply pressures and geopolitically driven reshoring incentives, our analysis presents practical mitigations for procurement and engineering leaders.
- Competitive posture intelligence: We map supplier strengths, integration strategies, and recent moves so OEMs and Tier-1s can define partnership and M&A plays without waiting for lagging public disclosures.
What the report delivers — practical, deployable outputs
- Market sizing and methodology: A transparent, reproducible model with base year 2025, 2020–2025 historical calibration, and 2026–2032 forecasts denominated in USD Million.
- Scenario-driven forecasts: Upside/downside cases that stress-test demand against regulatory acceleration, fab capacity constraints, and rapid SOC commoditization.
- Supplier evaluation framework: Vendor scorecards and a procurement-ready matrix covering technology competence, qualification lead times, scale, and integration risk.
- Technology roadmaps: Comparative timelines for HDR stacked CMOS, perception SoCs, camera-fusion architectures, and in-cabin monitoring solutions.
- Supply-chain playbook: Tactical measures for wafer risk, qualification pipelines, multi-sourcing, and inventory policies tied to lead-time elasticity.
- Commercial playbooks: Go-to-market options for Tier-1s and module houses — from value-added integration to licensing of perception IP — and example costing approaches without disclosing sensitive client numbers.
- Executive dashboards and scenario models: Ready-to-use tools for CFOs and CTOS to quantify capex, expected time-to-revenue, and margin impact under different technology adoption curves.
Competitive landscape — who matters and why
The market is concentrated: the three largest players command a clear majority of value, and the top five capture an even higher share. This concentration reflects the premium placed on automotive qualification, global manufacturing scale, and long-term OEM relationships. Against that backdrop, distinct strategic archetypes are emerging among the core players:
Worldwide Police Analytics Software Market
- Systems-focused Tier-1s — companies with deep vehicle-integration expertise are bundling cameras with perception software and ECU integration to protect margin and lock in vehicle architectures.
- Sensor specialists — CMOS foundry-aligned and image-sensor incumbents are competing on pixel performance, HDR capability, and automotive-grade qualification timelines.
- Software-native entrants — perception-stack and SoC providers are leveraging algorithmic differentiation to push camera-centric architectures up the stack toward autonomy use cases.
Representative firms span these archetypes. Leading Tier-1s supply multi-camera platforms for ADAS, surround view, and occupant monitoring; semiconductor incumbents deliver automotive-grade CMOS devices tuned for low-light and HDR; and software/SoC firms provide the perception engines that convert pixels into vehicle action. Recent developments underscore the dynamic competitive shifts: a major Tier-1 completed the integration of significant radar and camera assets in mid-2024 to expand production capacity; a leading image-sensor vendor launched a next-generation stacked CMOS optimized for low-light automotive use in early 2024; and a prominent sensor supplier secured nomination by a global OEM for next-gen ADAS programs in 2024. These moves collectively highlight the importance of scale, integration, and rapid qualification in 2026 supplier selection.
Worldwide Higher Education Student Information Systems Software Market
Market dynamics shaping 2026 strategy
- Regulatory acceleration: Safety rating bodies and regional regulations are elevating camera-based detection and occupant monitoring requirements. Compliance timelines have become de facto adoption deadlines for certain systems.
- Supply constraints and raw-material pressure: Automotive-grade silicon wafer pricing experienced notable increases in 2023, and fab capacity for high-end HDR stacked sensors remains a bottleneck — directly affecting ramp schedules.
- Geopolitical incentives: Subsidies and national semiconductor programs are altering investment calculus for localized manufacturing and qualification strategies.
- Technology bottlenecks: Demand for HDR stacked CMOS and integrated vision SoCs is outpacing high-end automotive fab availability, creating opportunities for those who secure capacity first.
Key risks and mitigations for executives
Risk-first planning is non-negotiable in 2026. The top risks we model include: extended lead times for qualified sensors, margin compression due to silicon price volatility, and timeline slippage on perception software that delays OEM launches. Tactical mitigations that have proven effective in our engagements include:
- Qualifying at least two sensor suppliers per critical camera SKU and maintaining a rolling six-to-nine month qualification pipeline;
- Negotiating capacity reservations with foundries and sensor houses, coupled with price-escrow mechanisms to share wafer-cost volatility;
- Pursuing strategic joint-ventures or minority investments to secure preferential access to next-generation sensor nodes and to accelerate local qualification;
- Designing modular camera platforms that enable sensor swaps without extensive ECU redesign, accelerating second-source adoption.
Strategic imperatives for 2026 corporate plans
- Embed camera roadmap decisions into platform-level architecture choices now; deferring integration decisions exposes teams to multi-quarter program delays.
- Prioritize HDR and low-light performance in camera-specification decisions for safety-critical functions; perception accuracy will increasingly determine competitive differentiation.
- Forge cross-functional procurement-engineering sprints to accelerate supplier qualification while negotiating capacity commitments tied to phased ramps.
- Balance vertical integration against flexible sourcing: owning sensor supply reduces exposure but increases capex and operational complexity.
- Quantify regulatory-compliance timelines in product release milestones and align testing budgets accordingly to avoid late-stage rework.
- Deploy TCO models that include wafer-price scenarios, qualification throughput, and end-of-line calibration costs to inform pricing and margin strategies.
Commercialization timelines and adoption curves
Camera applications show differentiated adoption velocities. Systems addressing active safety and driver monitoring are moving fastest due to regulatory and rating-body pressure. Surround view and parking assistance remain high-volume, addressable near-term revenue streams. Autonomy-related imaging for higher levels of SAE autonomy will expand over the forecast but requires concurrent advances in perception SoCs and sensor fusion. Our scenario suite presents granular timing for each application bucket, enabling program managers to align launches to supplier commitments and regulatory milestones.
How boards and C-suite teams should use this report
- CFOs: use our scenario dashboards to model capex phasing for vertical initiatives and to stress-test margin outcomes under silicon-price volatility.
- CTOs/Heads of Product: leverage the technology roadmaps and supplier scorecards to prioritize sensor qualifications and to design modular architectures that future-proof upgrades.
- Heads of Procurement: adopt the supplier-risk heatmaps and contract templates to secure capacity and to operationalize dual-sourcing strategies.
- Corporate Development: use the competitive analysis and M&A playbook to identify acquisition targets that accelerate time-to-market or shore up supply.
Report scope and how we protect the trailer
PW Consulting’s Worldwide Automotive Camera Sensor Market report is intentionally built as a decision-grade asset. It includes a transparent build of historicals (2020–2025), a detailed 2026–2032 forecast suite, and commercial tools denominated in USD Million. To maintain the "trailer" utility of this executive brief — demonstrating analytical depth while reserving the granular segmentation tables and proprietary supplier valuations for purchasers — we have purposefully withheld specific regional and application-level dollar splits in this release. The full report contains the detailed breakdowns, downloadable spreadsheets, supplier matrices, and model access for corporate licensing.
Next steps — what to do in Q1 2026
- Run a rapid internal alignment workshop using our executive checklist to identify program-year dependencies on camera supply and qualification milestones.
- Task procurement with immediate outreach to prioritized suppliers identified in the report and negotiate capacity-light options (NRE vs. volume commitments).
- Commission a sensor-selection proof-of-concept aligned with your perception stack vendor to validate HDR performance and calibration workflows in parallel with sourcing talks.
- Evaluate strategic tie-ups or minority investments where preferential capacity, co-development rights, or IP access will materially accelerate your roadmap.
For teams making capital and product bets in 2026, the path forward requires clarity on technology, supply, and regulatory timing. PW Consulting’s report converts those variables into operational decisions and commercial contingencies designed for immediate execution. To access the full dataset, vendor scorecards, and scenario models — including the region- and application-level breakdowns that inform program-level budgets — please visit PW Consulting’s report page to license the complete Worldwide Automotive Camera Sensor Market study.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Camera Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Motorized Operating Tables Market Poised to Reach USD 1,734.5 Million by 2032, Growing at a 6.38% CAGR
By PW Consulting, 2026-08-18
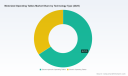
Worldwide Motorized Operating Tables Market: Strategic Insights to Guide 2026 Decision‑Making
PW Consulting today releases an executive briefing drawn from our comprehensive market research report on the Worldwide Motorized Operating Tables market. Built on a 2025 base year and a detailed historical window from 2020–2025, the report delivers forward-looking forecasts for 2026–2032. Our top‑line model projects the global market expanding from approximately USD 1.125 billion in 2025 to roughly USD 1.735 billion by 2032, reflecting a compound annual growth rate (CAGR) of 6.38% over the forecast period. These headline figures capture a market that is stable, technologically active, and strategically positioned at the intersection of surgical innovation, imaging penetration, and hospital capital cycles.
Worldwide Adapt Medical Adhesive Spray Market
Why this report matters for 2026 decision cycles
-
Capital allocation clarity: CFOs and procurement leads will find a year‑by‑year demand and ASP overlay that helps prioritize CapEx for operating room refreshes, imaging‑compatible table upgrades, and OR integrations.
DALI Dimming Power Supply Market -
Product strategy and R&D prioritization: Product managers can use our demand drivers and feature value‑maps to rank enhancements (e.g., carbon fiber radiolucent tops, bariatric load capabilities, integration with robotics and C‑arm ecosystems) by projected commercial ROI.
Worldwide Activated Alumina Sorbent Market -
M&A and partnership screening: Investors and corporate development teams gain a concentrated view of competitive positioning, deal catalysts, and consolidation dynamics — enabling targeted diligence for tuck‑ins or strategic alliances.
-
Risk & supply chain resilience: The report models component exposures (composites, actuators, control electronics) and identifies supplier dependency concentrations that matter for contingency planning in 2026 procurement strategies.
What the briefing contains (practical components)
-
Proprietary demand model: Annual market sizing from 2020 through 2032, with unit shipment estimates, ASP trend analysis, and scenario sensitivity to hospital procedure volumes and CapEx cycles.
-
Technology adoption maps: Roadmaps for electro‑hydraulic vs. electric platforms, radiolucent materials adoption, imaging and robotics integration, and feature value curves tied to willingness‑to‑pay by buyer type.
-
Commercial playbooks: Go‑to‑market recommendations for established OEMs and new entrants addressing channel strategies, service offerings, OEM/clinical training value propositions, and pricing tactics.
-
Regulatory & reimbursement intelligence: Practical compliance checklists (ISO 13485, EU MDR 2017/745, FDA Class II pathways), premarket strategy options, and guidance on clinical evidence generation where regulatory clarity amplifies commercial access.
-
Supplier & cost analysis: Bill‑of‑materials benchmarking, margin pressure scenarios reflecting component cost volatility, and cost‑reduction levers such as modular designs or localized manufacturing.
-
Commercial due diligence assets: Vendor scorecards, customer buying criteria matrices, and market concentration metrics to aid valuation and post‑acquisition integration planning.
Competitive landscape — who shapes the market and how
The market is characterized by a mix of well‑capitalized global incumbents, specialized niche players, and price‑competitive manufacturers scaling from Asia. Market concentration is meaningful but not opaque: the top three companies account for a material share of the market while the top five control a clear majority, leaving room for focused challengers and regional specialists to carve localized advantages.
-
Stryker Corporation — A strategy built on comprehensive product lines, high imaging compatibility, and ergonomic positioning. Stryker’s strength lies in cross‑selling within broad OR portfolios and in sustaining long‑cycle service revenues.
-
STERIS plc — Emphasizes durability, high load capacity, and integration into sterile workflow ecosystems. STERIS remains compelling to systems buyers looking for OR standardization and total cost of ownership stability.
-
Getinge (Maquet) — Premium engineering and complex‑procedure articulation define the Maquet position. Strong in cardiovascular and neurosurgical settings where precision and specialized features command premium pricing.
-
Hill‑Rom/Baxter (Trumpf Medical integration) — Patient‑centric positioning and a focus on safety features combined with OR workflow compatibility make this group attractive to large hospital systems and IDN rollouts.
-
Skytron, Mizuho OSI, Trumpf Medical — Each offers differentiated technical capabilities (e.g., modular tops, radiolucent designs, high‑precision positioning) that appeal to specific clinical pathways like orthopedics, spine, and trauma.
-
Mindray, Shandong Yuda, Infinium, ALVO, Inspital — These manufacturers supply competitive pricing, rapid local certification cycles, and flexibility for emerging markets or price‑sensitive buyers. Their presence intensifies price competition at the mid‑market tier and accelerates feature adoption timelines globally.
Recent market developments underscore strategic shifts that will influence 2026 decisioning: in early 2026, regulatory clearances and product launches (including an FDA/CE cleared urology table and a motorized imaging platform cleared for clinical use) show that integration between imaging systems and the operating table is now a fast track for differentiating offerings. Similarly, leading Chinese OEMs continue to fortify international certification and distribution, reshaping competitive benchmarks for price and functionality.
Dynamics shaping near‑term growth
-
Technology convergence — Operating tables are no longer stand‑alone devices. Integration with C‑arm imaging, surgical robots, and OR connectivity platforms is a primary value driver. Buyers increasingly assess tables as part of an integrated surgical ecosystem rather than an isolated asset.
-
Capital expenditure patterns — Hospitals prioritize upgrades that deliver multi‑procedure utility and imaging compatibility. This makes multi‑discipline tables and modular upgrade paths more attractive in procurement tenders.
-
Regulatory and clinical evidence — Compliance with ISO 13485, EU MDR, and FDA pathways remains table‑stakes; differentiated clinical studies demonstrating workflow efficiency or imaging benefits materially shorten sales cycles in sophisticated markets.
-
Materials and performance — Adoption of carbon fiber tops and high‑strength alloys improves intraoperative imaging and load capacity, enabling manufacturers to target specialized markets (e.g., bariatrics, orthopedics) with premium features.
-
Reimbursement context — Current reimbursement frameworks typically do not create new device‑specific codes for tables, so value must be demonstrated via procedure efficiency, throughput gains, or reduced complication rates to influence purchasing decisions.
Strategic recommendations for 2026 (actionable priorities)
-
For incumbents: double down on platform integration. Prioritize partnerships or OEM‑level integrations with major imaging and robotic vendors. Create bundled solutions and evidence packages that articulate ROI at the OR‑suite level.
-
For mid‑market players: specialize and commoditize smartly. Focus on regional certification speed, modularity, and service responsiveness. Use targeted clinical partnerships to validate performance in niche procedures where premium pricing is achievable.
-
For new entrants and Asian OEMs: invest in international regulatory footprints and after‑sales networks. Pricing will win initial share, but long‑term success in developed markets depends on clinical validation and service capabilities.
-
For investors and corporate development: screen targets for complementary technologies (imaging/robotics/connectivity), recurring service income, and sales channels into large IDNs. Use our vendor scorecards to prioritize acquisition targets that close capability gaps quickly.
-
For hospital systems and procurement teams: shift procurement metrics from purchase price to lifecycle value — uptime, interoperability, training, and upgradeability. Structured total cost of ownership (TCO) evaluations reduce long‑term operational surprises.
How the full PW Consulting report supports execution
The full report is designed as a practical toolkit for teams executing against 2026 plans. It includes downloadable models, supplier scorecards, clinical adoption roadmaps, and a prioritized list of strategic initiatives tailored to buyer types and regional contexts. Crucially — and by design — the document contains granular regional, technology and end‑user splits, unit and ASP curves, and detailed revenue waterfalls that underpin the headline forecasts. These granular datasets are not disclosed in this press briefing; they are provided in the paid report to preserve competitive confidentiality and to enable clients to run custom scenarios for their unique strategies.
Next steps
-
Procurement, strategy, and product teams interested in tailored walk‑throughs of the report’s models and vendor scorecards should contact PW Consulting to schedule a briefing.
-
We also offer bespoke scenario workshops that model hospital adoption by procedure mix, geographic expansion simulations, and M&A target stress‑testing to support 2026 board and investment committee cycles.
The motorized operating table market in 2026 is not a static hardware market; it is an integrative battleground where imaging, robotics, materials engineering, and service economics determine winners. PW Consulting’s worldwide analysis converts that complexity into operational priorities — allowing leaders to make defensible, evidence‑based decisions that align with both clinical demands and financial objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Motorized Operating Tables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Medical Textiles Industry Set to Skyrocket at a 23% CAGR, New Global Report Reveals
By PW Consulting, 2026-08-18
Worldwide Smart Medical Textiles Market — Strategic Preview for 2026 Decision-Makers
As organizations prepare strategic investment and product decisions for 2026, the smart medical textiles sector presents a rare combination of rapid growth, regulatory complexity, and technological convergence. PW Consulting’s new market study — base year 2025, historical coverage 2020–2025 and a forward-looking forecast to 2032 — shows the global market expanding from approximately USD 485.5 Million in 2020 to USD 1,280.0 Million in 2025, and accelerating into a multi‑billion-dollar opportunity by the end of the forecast window. Our model projects a compound annual growth rate of 23.0% (2026–2032), with the market expected to exceed USD 5.4 billion by 2032. This briefing summarizes the strategic implications for companies planning reallocations of capital, capability-build, or M&A activity in 2026, while intentionally reserving the report’s full segmentation and model outputs for subscribers and site visitors.
IP-Based Mobile Games Market
Why 2026 is a Strategic Inflection Point
-
Commercialization and Clinical Validation Converge — Technology readiness for biometric sensing textiles has matured; 2026 will be the year when clinical evidence and regulatory clearance increasingly determine commercial winners.
HBM Controller IP Market -
Scale vs. Specialization Trade-offs — Rapid market growth creates choices between vertically integrated scale plays and focused clinical‑use propositions with premium pricing. Decisions taken in 2026 about manufacturing footprints, strategic partners, and certification pathways will lock in cost structures for the next decade.
Gas Chromatography Detector Market -
Regulatory Gateways Determine Time-to-Revenue — Regulatory strategy (e.g., pursuing U.S. FDA 510(k) pathways, complying with EU MDR, and ISO 10993 biocompatibility expectations) will be a primary driver of product roadmaps, budget allocations, and trial design.
What the PW Consulting Report Delivers — Practical, Transaction‑Ready Intelligence
Our study is built for executives and corporate development teams who need executable guidance, not just descriptive analysis. Key deliverables include:
-
Market sizing and high‑frequency scenario models (base year 2025; forecast 2026–2032) that allow you to stress-test launches and acquisition paybacks against conservative, mid, and aggressive adoption curves.
-
Regulatory playbook and go‑to‑market timelines that translate MDR, FDA 510(k), ISO 13485, and ISO 10993 requirements into activity plans and cost estimates for clinical validation, submission, and post‑market surveillance.
-
Manufacturing and supply chain blueprint covering material inputs, scale economics, and vendor selection criteria — focused on reducing the specialty-material and complex-assembly cost burdens that currently affect a sizable portion of the supply base.
-
Technology evaluation framework that scores sensing modalities, washable integration approaches, power/energy options, and embedded electronics on clinical readiness and manufacturability.
-
Commercial playbooks: reimbursement pathways, HTA engagement strategies, pilot design for hospital networks, and channel maps for premium direct-clinic models versus consumer-facing preventative products.
-
M&A and partnership heatmaps highlighting archetypal targets (technology owners, vertical manufacturers, clinical-scale contract manufacturers), valuation drivers, and integration risk checklists.
-
Executive decision templates — board-level one-pagers, program roadmaps, and a prioritized list of 12 “must‑do” pilots to de‑risk 2026 launches.
Competitive Landscape — Who Matters Now
The sector’s competitive structure shows early clustering: a handful of technology and materials leaders control meaningful IP and partner networks, while a long tail of specialized manufacturers and clinical innovators populate the ecosystem. The three‑ and five‑firm concentration ratios in our market model indicate moderate consolidation pressure (CR3 ~32.5%; CR5 ~47.8%), meaning scale and partnerships matter but there remains room for focused specialists.
-
Sensoria Health Inc. (United States): A clinical‑oriented player using AI and textile‑integrated sensing in gait and rehabilitation solutions. Recent Series B funding in January 2025 strengthens its manufacturing scaling capability and clinical trial pipeline.
-
Hexoskin (Carré Technologies Inc., Canada): Established provider of washable sensor garments for continuous cardiopulmonary and activity monitoring with strong positioning in clinical research and remote monitoring projects.
-
Gentherm Inc. (United States): Brings advanced thermal management systems into medical settings and announced an FDA 510(k) submission in late 2025 for a surgical thermal management technology — a development we view as an indicator of incumbent industrial players moving into regulated clinical segments.
-
KOB GmbH (KARL OTTO BRAUN, Germany): Longstanding specialist in elastic medical textiles and sensor integration; active in standards work and closely aligned with clinical supply chains for wound care and rehabilitation.
-
Other meaningful contributors include innovators focused on conductive yarns, pressure‑mapping systems, and connected textile platforms — firms that provide critical enabling components or white‑label platforms to larger healthcare OEMs.
These companies exemplify different strategic archetypes: clinical systems builders, material and component specialists, thermal and safety incumbents, and platform integrators. For acquirers and partners, understanding which archetype aligns with your corporate model is a prerequisite for deal success.
Regulatory, Standards, and Cost Dynamics You Can’t Ignore
-
Regulatory frameworks are definitive commercial gatekeepers. Smart medical textiles intended for clinical use are subject to EU MDR 2017/745 and U.S. FDA device rules (including 510(k) pathways), with ISO 10993 expectations for biocompatibility. ISO 13485 remains the quality management baseline for device manufacturing.
-
Standards work is moving fast; participation in committees (for example, contributions from established textile specialists to IEC working groups) offers both technical influence and early visibility into interoperability expectations.
-
Production costs are structurally higher than comparable consumer wearables due to specialty materials, washable electronics, and regulated assembly processes. Our sector analysis indicates that a significant minority of producers face margin pressure from these inputs — a factor that will drive contract manufacturing consolidation and vertical partnerships in 2026.
Five Strategic Priorities for 2026
-
Design with Regulation in Mind — Embed regulatory milestones into product roadmaps. Early clinical protocol alignment and targeted ISO 13485 partnerships shorten time to clearance and reduce rework costs.
-
Choose a Manufacturing Stance — Decide whether to vertically integrate to protect IP and margins or to secure strategic CMOs with certified medical device lines. Each path has different capital and time implications reflected in our NPV scenarios.
-
Clinical Evidence as a Market Entry Tool — Prioritize randomized or real‑world evidence pilots that align with reimbursement and procurement decision points of major hospital systems; this materially accelerates adoption in clinical segments.
-
Data Security and Interoperability — Build data governance and cybersecurity into product architectures from the start; payor and provider procurement teams now list these as pass‑fail criteria.
-
Engage Standards and Ecosystem Partners — Active participation in standards work and early alliances with conductive yarn suppliers, pressure‑map specialists, or thermal systems vendors reduces technical risk and shortens certification timelines.
How PW Consulting’s Report Supports Tactical Decisions
The full study contains actionable modules designed to be deployed within 60–120 days of purchase: a playbook for regulatory filings, an RFP template for outsourcing manufacturing of Class II textile devices, a three‑scenario financial model calibrated to your product archetype, and a prioritized target list for acquisition or joint development. Importantly, the publicly available executive summary illustrates methodologies and headline outcomes; however, detailed segmentation tables, company-level share matrices, and the granular model downloadable files are reserved for report subscribers and are available via the report landing page.
Next Steps for Executives
-
Board Briefing: Use our one‑page risk and opportunity map to align executive focus areas for 2026 investment cycles.
-
Pilot Prioritization: Select two pilots — one clinical, one commercial — that target clear procurement decision-makers and can be executed within nine months.
-
Partner Audit: Run a rapid vendor scorecard against our supplier heatmap to identify resilient materials and CMO partners that comply with ISO 13485 and have experience with washable assemblies.
-
M&A Funnel: Shortlist targets according to the archetype that closes your capability gaps (sensing IP, materials, or regulatory experience) and request our confidential target dossiers as a next step.
PW Consulting’s Worldwide Smart Medical Textiles Market report is expressly built to convert market intelligence into operational programs and commercial outcomes for 2026. To access the full analysis, segmented model outputs, company share tables, and downloadable decision-support tools — and to obtain a tailored briefing for your leadership team — visit the report landing page or contact our industry desk. The executive summary is available immediately; detailed datasets and strategic annexes are provided to subscribers to preserve the commercial integrity of partners, suppliers, and clinical collaborators highlighted in the study.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Medical Textiles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Needle Scaler Market to Expand at a 4.81% CAGR Through 2032
By PW Consulting, 2026-08-18
Worldwide Needle Scaler Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s newest market study on the Worldwide Needle Scaler Market synthesizes five years of historical performance with a seven‑year forecast to 2032, delivering actionable intelligence for procurement chiefs, product managers, and corporate strategists preparing plans for 2026. Anchored on a 2025 base year and expressed in USD (revenue unit: Million), the analysis shows the market at a multi‑hundred million dollar scale in 2025 and tracking to grow at a steady compound annual growth rate (CAGR) of 4.81% through our 2026–2032 forecast horizon. The report blends rigorous market-sizing, competitor benchmarking, and operator‑level ergonomics/regulatory analysis into a playbook that supports near‑term capital allocation and three‑to‑five year product roadmaps.
Worldwide Plastic Microtube Racks Market
Why this study matters for 2026
- Preparation windows are short. Macro demand drivers — including a rebound in shipbuilding and a persistent emphasis on infrastructure maintenance — are already feeding tool purchase cycles in 2025 and will shape 2026 procurement lots. Buyers and sellers who align now will realize lower total cost of ownership and faster time‑to‑deployment.
- Regulatory and occupational health constraints are forcing product redesigns and operational changes. Updated vibration exposure limits, evolving site‑safety protocols, and emergent certification expectations are changing how fleet managers specify pneumatic and electric scalers.
- Supply‑side pressure on tool steel and component availability has increased input cost volatility. Firms that secure tiered supply agreements or invest in alternative materials will gain margin and delivery advantage in 2026.
What the PW Consulting report delivers — practical, executable outputs
- Market sizing and forward projections with documented methodology: historical series (2020–2025), a 2025 base, and a 2026–2032 forecast pathway that translates into procurement volumes and revenue expectations for planning cycles.
- Scenario modeling for demand drivers: three scenarios (conservative, base, accelerated) with sensitivity to shipbuilding activity, industrial maintenance spend, and commodity cost shocks — enabling CFOs to stress‑test CAPEX and inventory plans.
- Go‑to‑market playbooks for OEMs and distributors: channel segmentation, salesforce sizing heuristics, and aftermarket/service revenue strategies tailored to needle scalers (pneumatic and electric product families).
- Product benchmarking and ergonomic scorecards: cross‑brand comparisons on durability, vibration transmission, needle life, and operator comfort — linked to regulatory compliance thresholds and maintenance intervals.
- Supply chain and procurement guidance: risk maps for critical inputs, supplier audit checklists, and negotiation levers to protect margin against raw material and logistics volatility.
- M&A and partnership shortlist: high‑value acquisition targets and JV structures identified by capability gaps, service footprints, and product adjacencies — plus a diligence checklist for rapid evaluation.
Key market dynamics to factor into 2026 strategies
- Demand composition: End‑use drivers remain concentrated in heavy industrial sectors — shipyards, infrastructure maintenance, and energy — each with distinct duty cycles and procurement cadences. Equipment specifications and service models must be tailored accordingly.
- Regulatory environment: Updated occupational safety standards constrain acceptable vibration exposure for hand‑held scaling tools; OEMs face a dual mandate to reduce transmitted vibration and demonstrate compliance through testing and certification. This is a gating factor for public contracts and larger shipyard tenders.
- Input volatility: Tool steel and high‑strength consumable materials experienced notable price and availability pressure in recent years. Procurement strategies that incorporate multi‑sourcing, forward purchasing, or material substitution can materially protect gross margins.
- Labor and automation trends: Rising maintenance labor cost pressures have increased demand for higher‑throughput and lower‑operator‑strain solutions. Opportunities exist for integrating semi‑automated scaling rigs and service contracts that bundle tooling with skilled operator supply.
- Consolidation signals: Market concentration metrics indicate that incumbents command a meaningful share of revenue, but fragmentation persists. This creates windows for bolt‑on acquisitions focused on aftermarket service networks and regional distribution scale.
Competitive landscape — what the leading suppliers are doing (and why it matters)
The competitive map is a mix of global pneumatic specialists, industrial tool conglomerates, and regional manufacturers focused on maritime and heavy fabrication markets. PW Consulting’s qualitative and quantitative assessment highlights strategic postures and near‑term moves that buyers and investors should watch closely.
Worldwide Concrete Contractor Market
- Chicago Pneumatic (Saint‑Herblain, France) — a global pneumatic specialist whose CP89 series remains a preferred choice in high‑volume shipyard and foundry contexts. Recent product showcases emphasized improved needle durability and serviceability, signaling a continued focus on total cost of ownership rather than just unit price.
- Atlas Copco (Nacka, Sweden) — leans into ergonomics and operator safety. The refreshed PT15 model, promoted for reduced vibration, underscores a premium positioning that targets large industrial maintenance contracts where compliance and operator retention are priorities.
- Ingersoll Rand (Davidson, NC, USA) — continues to defend broad industrial accounts with heavy‑duty offerings and recent certification renewals for flagship models. Their certification progress is an important signal for procurement teams evaluating compliance risk in public and private tenders.
- Mirka (Jeppo, Finland) — known in metalworking circles for weld‑cleaning and surface‑prep solutions. Mirka’s product philosophy emphasizes modularity and consumable cost efficiency, attractive for fabrication shops seeking predictable operating spend.
- Titan Tool (Buffalo, NY, USA) — positions toward heavy cleaning applications in foundry and shipbuilding, focusing on ruggedness and needle change speed to minimize downtime in continuous operations.
- CS Unitec (Norwalk, CT, USA) — offers both electric and pneumatic variants and targets construction and civil‑works use cases, where non‑slip surface prep and ease of deployment are important differentiators.
- Alkin (Izmir, Turkey) — a regional manufacturer with strong ties to maritime and industrial refurbishing markets. Their footprint highlights the strategic importance of regional manufacturing hubs to service neighboring shipbuilding clusters.
Notable recent developments reinforce these trends: product launches centered on vibration reduction and needle durability, high‑visibility trade show debuts that emphasize maintenance economics, and certification updates that lower barriers to adoption in regulated work environments. For 2026, these vendor moves translate directly into procurement levers: specification language, warranty and service obligations, and contract KPIs tied to vibration and throughput.
Worldwide Network Monitoring and Visibility Tool Market
Actionable recommendations for 2026 planning
- Procurement teams: Introduce vibration and lifecycle performance metrics into RFPs. Move beyond unit pricing to evaluate warranty costs, needle consumable economics, and demonstrated compliance credentials. Include clauses for supply continuity and price‑adjustment triggers tied to documented commodity indices.
- OEMs and product teams: Prioritize investments in vibration dampening, modular needle systems, and predictive maintenance features that reduce downtime. Certification and independent testing will be market access prerequisites in several high‑value customer segments.
- Distribution and aftersales: Build service bundles that combine tool supply with consumables and certified operator training; these capture recurring revenue and increase switching costs for end users facing labor shortages and safety obligations.
- Corporate development teams: Target acquisitions that close capability gaps — specifically aftermarket service networks, rapid‑response field maintenance, and regional manufacturing near shipbuilding clusters. Valuations should consider incremental service revenue potential and integration synergies for product platforms.
- Risk managers: Hedge exposure to raw‑material shocks by negotiating multi‑year supply contracts and exploring alternative needle steels or coatings that deliver similar performance at lower cost volatility.
How PW Consulting’s report supports execution
We designed the report as a decision‑support tool, not merely an academic exercise. Its datasets and frameworks are optimized for real‑world use: downloadable forecast tables, supplier scorecards, RFP language templates, and a step‑by‑step M&A diligence checklist. Importantly, while this brief highlights directional findings, the detailed regional and application‑level splits, pricing curves, and named target financials are intentionally held within the full report to preserve the competitive advantage for subscribers and clients.
Next steps — where to go from here
- Procurement and product leaders should request a tailored briefing that overlays the PW Consulting forecast against your installed base and planned capital purchases for 2026.
- Investor and M&A teams can commission a rapid target screen using our vendor scoring model to prioritize due diligence on accretive add‑ons.
- Operational teams can adopt our ergonomic and compliance checklists to reduce project risk and accelerate tender qualification.
Pain points in the needle scaler space are tangible and addressable. The convergence of tighter safety standards, input cost volatility, and accelerating demand in targeted heavy industries creates a predictable opportunity window in 2026 for companies that align product innovation with robust supply strategies and service‑centric commercial models. PW Consulting’s Worldwide Needle Scaler Market report provides the data, the practical toolsets, and the strategic narrative to make those moves with confidence. For the full dataset, regional/application breakdowns, and downloadable toolkits, visit our report page and arrange a briefing with our lead analyst team.
For detailed analysis of this topic, please visit the official page: Worldwide Needle Scaler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


