



Category: market research
PW Consulting: Worldwide Security Software in Telecom Market Poised for Rapid Expansion at 13.01% CAGR During 2026–2032
By PW Consulting, 2026-08-12
Worldwide Security Software in Telecom Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting is publishing a focused industry briefing derived from our comprehensive market study, Worldwide Security Software in Telecom Market (base year 2025). The study synthesizes historical performance (2020–2025), near‑term market movements, and a forward-looking forecast (2026–2032) to provide operators, vendors, investors, and regulators with the strategic intelligence required to act with confidence in 2026. Our topline finding: the telecom security software market is re‑accelerating as operators monetize secure cloud, 5G, AI, and sovereign‑compliance offerings — growing from a 2025 base of USD 15,570 Million and expected to expand at a compounded annual growth rate of 13.01% through 2032, reaching an estimated market value in the low‑to‑mid USD 36,600 Million range by the end of the forecast.
Worldwide Higher Education Student Information Systems Software Market
Why this report matters for 2026 strategic choices
-
Timing and scale: The market’s 2026 inflection point combines increased operator investment in security‑enabled B2B services, vendor product cycles optimized for AI and 5G, and regulatory drivers that accelerate procurement timelines. The report quantifies this surge and models scenario outcomes that matter for budgeting, partnership selection, and M&A timing.
Data Center Renovation Service Market -
From CapEx to outcomes: Telecom buyers no longer purchase security as a discrete line item. They buy risk reduction, regulatory assurance, and business enablement. Our analysis translates market growth into actionable procurement levers, procurement timelines, and measurable KPIs for security projects aligned to revenue generation (enterprise connectivity, private networks, and managed security services).
105Ah LiFePO4 Battery Cell Market -
Vendor and technology roadmaps: The report identifies which technology classes and vendor archetypes will be pivotal in 2026 — from cloud‑native security platforms and SASE/SSE overlays to embedded 5G core security and AI‑driven threat detection — and maps sensible sourcing strategies for each.
What’s inside: practical, executable intelligence
-
Market sizing and robust forecasting: historical analysis (2020–2025) and probabilistic forecasts (2026–2032) with scenario sensitivity to regulatory shifts and technology adoption curves.
-
Go‑to‑market playbooks: vendor selection criteria, decision matrices for buy vs. build vs. partner, and RFP frameworks tailored to telecom operator procurement cycles and compliance needs.
-
Commercial models and TCO frameworks: CapEx/Opex modelling for cloud‑native vs on‑premise deployments, managed service cost comparisons, and revenue uplift scenarios for security‑augmented B2B offers.
-
Risk and regulatory impact assessment: actionable guidance on navigating digital sovereignty, data localization, trusted vendor policies, and emerging mandates such as the EU’s move toward quantum‑safe cryptography in critical communications.
-
Operator case studies and deployment templates: vetted implementation checklists for common telecom use cases (5G core protection, network slicing security, DDoS mitigation for mobile networks, secure edge and IoT onramps) and post‑deployment operational KPIs.
-
Vendor benchmarking and competitive playbooks: qualitative and quantitative scoring across performance, integration ease, roadmap, and compliance posture — designed for CISO and procurement decision support.
-
M&A and partnership signal matrix: identification of likely consolidation targets and partnership archetypes, underpinned by concentration metrics and vendor positioning insights to inform investment theses.
Key market dynamics shaping 2026 strategy
-
Cloud acceleration meets telecom specificity: Operators continue to migrate security functions to cloud‑native control planes while demanding telecom‑grade SLAs, low latency for edge security, and deterministic integration with OSS/BSS. Vendors that bridge cloud agility with carrier‑class reliability will capture share.
-
5G and AI are multiplying attack surfaces — and value: Network slicing, private networks, and AI‑driven network functions introduce both new vulnerabilities and new monetizable security services. The interplay between AI‑enabled network orchestration and AI‑driven security controls is a primary battleground in 2026.
-
Sovereignty, trusted stacks and quantum timelines: Policymakers are actively tightening requirements on vendor trust, data locality, and post‑quantum cryptography. Operators and vendors must plan for compliance pathways that are technology‑agnostic yet defensible in procurement reviews.
-
Persistent adversary activity: Independent threat intelligence indicates that telecom‑targeted campaigns observed in 2025 are persisting into 2026. Operators must prioritize threat hunting, telemetry fusion, and cross‑domain incident response capabilities.
-
Commercial convergence: Telecom providers are packaging security as a differentiator in B2B offers — bundling secure connectivity with managed detection, identity and access services, and security analytics to increase ARPU and stickiness.
Competitive landscape — who matters and why
The market exhibits balanced concentration: the three largest vendors command a meaningful share of market influence while the broader vendor tier provides specialized capabilities and regional strength. This structure creates strategic choice — align with broad‑portfolio incumbents for integrated delivery, or partner with focused specialists for rapid feature differentiation.
-
Cisco Systems — A go‑to provider for operators seeking integrated network security stacks and broad ecosystem interoperability. Cisco’s portfolio remains attractive for service providers that value deep routing and carrier‑grade security integration across RAN, transport, and core domains.
-
Palo Alto Networks — Positioning strongly around AI‑enabled security fabrics and sovereign AI protection frameworks. Recent partnership expansions showcased at industry events underscore a strategy to secure AI factories and operator AI deployments across multiple vendor ecosystems.
-
Fortinet — Focused on high‑performance security appliances and fabric integration. Recent OS releases emphasize AI controls and simplified SASE/SD‑WAN convergence, appealing to operators seeking consolidated management planes and performance at scale.
-
Ericsson & Nokia — As infrastructure incumbents, they embed security into 5G cores, RAN, and management stacks. Their strength lies in deep carrier relationships and turnkey integration for operators modernizing core and edge architectures.
-
Huawei — Continues to offer integrated security across cloud and network fabrics for operators in markets where its solutions remain viable on sovereign and commercial terms.
-
Check Point, Juniper, F5, Trend Micro — These vendors offer differentiated capabilities in perimeter security, high‑performance routing/security convergence, application delivery, and threat intelligence. Their modular approaches are attractive in multivendor operator deployments.
-
Specialists (Allot, P1 Security and others) — Niche vendors focused on telecom protocol security, DDoS mitigation, signaling protections, and attack simulation are critical for operators with advanced threat models and bespoke needs.
Recent market moves — including partnership expansions to protect AI factories, product releases that bake AI controls into security stacks, and independent threat advisories — reinforce that vendor roadmaps and threat trends are converging on AI and regulatory compliance as top priorities for 2026 procurement.
Strategic imperatives for telecom leaders in 2026
-
Adopt a layered, outcomes‑focused architecture: Combine cloud‑native detection with embedded core and RAN protections. Prioritize observability and telemetry fusion for rapid detection and automated remediation.
-
Embed compliance into procurement: Design vendor contracts and architecture choices to anticipate data localization, trusted vendor, and post‑quantum requirements — reducing rework and regulatory risk.
-
Monetize security: Build security bundles into enterprise connectivity and private network offers with clear SLAs and monetizable threat prevention or incident response services.
-
De‑risk supply chains via hybrid sourcing: Combine incumbents for scale and specialist partners for innovation. Use managed service pilots to accelerate time‑to‑value while controlling integration risk.
-
Plan for quantum migration now: Given EU and national targets for quantum‑safe transitions, include cryptographic migration pathways in network transformation roadmaps and vendor evaluations.
How to use our report and next steps
PW Consulting’s Worldwide Security Software in Telecom Market report is designed as an operational playbook for executives who must translate market trends into procurement, architecture, and investment decisions in 2026. The public briefing above highlights the strategic implications and vendor dynamics; the full report contains the granular scenarios, vendor scorecards, implementation checklists, and downloadable modelling spreadsheets that CISOs, CTOs, and strategic investors require.
To preserve the commercial value of our proprietary segmentation and vendor scoring, we have intentionally summarized insights here without publishing detailed regional or solution split figures. Organizations that require the full dataset, decision matrices, and bespoke advisory workshops can access the complete report and supporting deliverables on the PW Consulting website or contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Security Software in Telecom Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Okra Seeds Market Poised to Grow at 8.15% CAGR Through 2032, Signaling Strong Industry Upswing
By PW Consulting, 2026-08-12
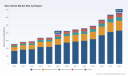
Worldwide Okra Seeds Market: Strategic Imperatives for 2026 — A PW Consulting Brief
PW Consulting today publishes an executive preview of our in-depth Worldwide Okra Seeds Market study (base year 2025, forecast 2026–2032). The global market has demonstrated sustained expansion through the first half of the decade, reaching an estimated USD 382.45 Million in 2025 and tracking a compound annual growth rate of approximately 8.15% into the forecast window. Our forward scenarios show continued momentum, with the market approaching the mid-to-high hundreds of millions of dollars by the end of the 2032 horizon. This briefing highlights the strategic insights in the full report that matter for board-level decisions and investment priorities in 2026 — without disclosing the granular segment tables contained in the paid study.
Worldwide Virtual IT Labs Software Market
Why this report matters for 2026 decision cycles
-
Timing: Seed companies, strategic investors, and institutional buyers are setting budgets and R&D roadmaps now for programs and planting seasons that will scale through 2027–2029. Understanding the macro trajectory and the drivers behind the 8%-plus CAGR is essential to avoid misallocation of capital.
Dual-Detector Gamma Camera Market -
Risk management: Fertilizer and input volatility, labor constraints in high-density producing regions, and accelerating regulatory approvals for new varieties are converging to create both near-term disruption and long-term opportunity. Our study maps these exposures to commercial outcomes.
Worldwide Convertible Jet Pumps Market -
Portfolio prioritization: As the market consolidates around a handful of global and regional champions, companies must choose where to compete (large-scale commercial supply chains vs. smallholder-focused varieties, protected vs. open-field use) — decisions that will lock in returns for multiple seasons.
Market dynamics shaping strategy in 2026
-
Demand and product mix: Hybrid varieties continue to drive productivity gains and adoption among commercial growers, supporting a healthy market expansion. At the same time, renewed varietal releases and public–private breeding programs are improving resilience and market acceptance in emerging production geographies.
-
Consolidation and competitive intensity: The sector displays moderate concentration. Leading multinational seed and agricultural groups command a meaningful share of commercial hybrid pipelines, while a diverse set of regional players fills local niches. M&A, strategic acquisitions, and breeding alliances are accelerating as firms seek scale in R&D and distribution.
-
Input and agronomy pressures: Fertilizer availability and cost, irrigation practices (notably supplemental watering schedules that materially influence yields), and labor constraints — particularly for women smallholders in several producing regions — are structural considerations that influence seed demand profiles and value propositions.
-
Regulatory and public-sector catalysts: Active public breeding programs and variety approvals are shortening commercialization timelines in priority countries. Institutional relaunches and working groups are creating coordinated pipelines of resilient varieties, widening the pool of bankable products for seed companies to commercialize.
Competitive landscape — positioning and strategic moves
The competitive set blends global agricultural leaders, specialized vegetable seed houses, and agile regional players. Below is a synthesized strategic reading of the principal competitors covered in our research.
-
Syngenta Group (Switzerland): Focused R&D in hybrid okra traits such as disease resistance and tropical adaptation positions it well for commercial vegetable production across large-scale value chains.
-
Bayer AG / Nunhems (Germany): Emphasizes quality, early-maturity and virus-resistant varieties; corporate strategy blends global breeding depth with targeted product launches for commercial supply chains.
-
Advanta Seeds / UPL (India): Strong presence in Asia and Africa with a broad hybrid portfolio; growth strategy leverages local adaptation and channel relationships with commercial and smallholder farmers.
-
Sakata Seed Corporation (Japan) & East-West Seed (Thailand): Both specialize in breeding for warm-climate performance and smallholder suitability; their offerings are notable for extended harvest windows and operational simplicity for growers.
-
Large European firms (e.g., Limagrain, Enza Zaden) and established Japanese and Indian companies (Takii, Mahyco, Nuziveedu, Kaveri, and several regional specialists): These firms provide product depth, distribution networks, and ongoing breeding investments that sustain competitive entry barriers.
-
Specialty and heirloom suppliers (e.g., Kitazawa, W. Atlee Burpee): Address the home-garden and niche culinary segments, an increasingly visible revenue stream as consumer interest in specialty produce grows.
Recent strategic events underscore the market momentum: corporate acquisitions that fortify vegetable seed portfolios, public-sector variety releases and program relaunches that broaden resilient trait availability, and commercial product rollouts targeted at key producing countries. These developments collectively accelerate commercialization timelines and shift the competitive salience toward companies that can integrate breeding, supply chain, and go-to-market execution swiftly.
What the PW Consulting report contains — practical modules for action
The full report is structured to be operationally useful for executive teams assessing near-term and medium-term bets. Key deliverables include:
-
Market sizing and forecast models (global and by commercial market archetypes) with sensitives and scenario outputs that can be toggled for alternative yield, price, and adoption assumptions.
-
Concentration and competitive benchmarking with capability heatmaps for breeding, distribution, and on-farm adoption reach.
-
Go-to-market playbooks for product launches: segmentation of buyer archetypes, channel economics, recommended pricing ranges, and sample promotional calendars tailored to planting cycles.
-
Supply chain stress tests and input-risk dashboards that translate fertilizer availability and labor dynamics into margin and volume impacts.
-
Farm-level adoption and ROI calculators designed for extension agents and commercial sales teams to accelerate farmer uptake trials.
-
M&A and partnership frameworks: target screening matrices, valuation comparators, and integration checklists for acquiring breeding assets or distribution footprints.
-
Regulatory and variety-tracker: approvals, public breeding outputs, and key policy levers that will affect commercialization speed in priority markets.
Note: The public preview purposefully omits line-item segment tables, regional share tables, and application-level revenue lines to preserve the report’s commercial data integrity. Those detailed inserts are available to subscribing clients and licensees.
High-level recommendations for 2026 action plans
-
Accelerate trait-led hybrid R&D focused on disease resistance and harvest window extension. Prioritize traits that demonstrably improve mechanization or reduce labor intensity — these attributes yield outsized commercial adoption in constrained labor markets.
-
Pursue targeted inorganic moves (selective acquisitions or minority investments) to secure breeding germplasm and regional seed multiplication capacity rather than broad geographic rollouts that dilute focus.
-
Lock in input supply and mitigate fertilizer cost exposure through strategic procurement partnerships and local production engagement; this reduces margin volatility for seed customers and supports adoption on smaller farms.
-
Deploy dual-channel strategies: maintain large-account commercial offerings for institutional buyers while designing simplified, lower-cost packs and agronomy support for smallholder and peri-urban growers.
-
Partner with public breeding programs and regional research centers to co-develop varieties that meet both yield and resilience goals — these collaborations shorten time-to-market and strengthen social license.
-
Invest in digital extension and distribution pilots that tie seed purchases to bundled advisory services, irrigation scheduling, and input financing to raise per-farmer lifetime value.
How PW Consulting supports your 2026 roadmap
-
Bespoke data subscriptions: full access to the report’s models, downloadable datasets, and periodic updates through 2032.
-
Strategic advisory: M&A due diligence, integration planning, portfolio optimization, and go-to-market activation.
-
Pilot design and field validation: localized adoption trials, ROI studies, and supply chain optimization workshops.
-
Regulatory and stakeholder navigation: support for variety registration strategies and public–private partnership frameworks.
Next steps: For teams shaping budgets, R&D investments, or M&A pipelines in 2026, the comprehensive models and playbooks in our full study will materially shorten decision cycles and reduce execution risk. The PW Consulting report brings together commercial intelligence, agronomic realities, and strategic playbooks so leadership teams can convert the favorable market tailwinds into sustained, defensible value.
We intentionally present a high-level strategic narrative in this preview. For full access to the segment-level data, regional breakouts, and downloadable financial models that underpin our recommendations, please contact PW Consulting to license the report or schedule a briefing with our industry practice leads.
For detailed analysis of this topic, please visit the official page: Worldwide Okra Seeds Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Automotive Engine Oil Additives Market Poised to Expand at a 3.21% CAGR Through 2032
By PW Consulting, 2026-08-12
Worldwide Automotive Engine Oil Additives Market: Strategic Outlook for 2026 — PW Consulting Preview
As PW Consulting publishes its latest market research on the Worldwide Automotive Engine Oil Additives market, this briefing synthesizes the strategic implications senior executives must weigh as they plan for 2026. Our full report provides granular, transaction-ready intelligence; the following preview highlights the high‑impact signals we expect to reshape supplier economics, product portfolios, and go‑to‑market plays without disclosing the proprietary segment-level datasets reserved for report subscribers.
Worldwide 5G Antennas Market
Market snapshot: measured expansion with structural pressures
After a period of steady recovery through the early 2020s, the global engine oil additives market is projected to continue expanding at a moderate compound annual growth rate (CAGR) of approximately 3.21% through the 2026–2032 forecast window. On an aggregate basis, the market crosses an important threshold in our base-year view, reflecting both the tailwinds from stricter performance and emissions standards and headwinds from raw material cost shocks and volatile base oil markets.
Worldwide Appraisal Service Market
PW Consulting’s model—built on bottom‑up SKU-level demand, OEM licencing calendars, and validated downstream blending activity—shows that market momentum entering 2026 is real but nuanced: growth is sustained, yet increasingly conditioned by regulation, vehicle fleet composition, and concentrated supplier dynamics that amplify both opportunity and risk.
Radio Tower Market
Why this matters for 2026 decision-makers
-
Standards-driven product re‑engineering is now mission‑critical. ILSAC GF‑7’s licensing and the simultaneous introduction of API SQ have created a multi‑track technical roadmap for passenger car and ultra‑low viscosity engine oils. Suppliers that can accelerate formulation platforms to meet fuel‑efficiency, low‑speed pre‑ignition (LSPI) mitigation, and piston cleanliness targets will win OEM and marketer share in 2026.
-
Price volatility in 2026 has changed commercial calculus. Early‑year base oil and additive cost increases—material suppliers publicly signalled finished‑goods price pressure in the mid‑teens percent range—mean margin management and purchasing strategy (including hedging and supplier diversification) will be board‑level priorities.
-
The market structure favors scale and technical breadth. With the top three suppliers accounting for a dominant portion of global revenue and the top five controlling an even larger share, the competitive environment rewards integrated technology providers and penalizes fragmented, low‑margin operators.
Competitive landscape: leaders, challengers, and what to watch in 2026
The industry’s competitive map is intentionally concentrated. PW Consulting’s competitive assessment confirms that global majors—companies with established additive platforms, OEM approvals, and broad IP portfolios—remain advantaged. These players combine formulation expertise (dispersants, VIIs, anti‑wear systems), recognized OEM relationships, and global manufacturing footprints that allow them to meet both performance and compliance timelines.
-
The Lubrizol Corporation: Renowned for additive packages aligned to passenger car and heavy‑duty diesel needs, Lubrizol’s recent rollouts targeting ILSAC GF‑7 compliance underscore its go‑to‑market agility. Expect continued pressure from Lubrizol on rapid formulation updates and customer trials in 2026.
-
Infineum: Backed by major oil‑company parents, Infineum’s focus on fuel efficiency and LSPI mitigation positions it well for GF‑7-era collaborations with OEMs and formulators seeking validated solutions for ultra‑low viscosity grades.
-
Afton Chemical and Chevron Oronite: Both firms balance broad product portfolios with deep OEM approval channels. Their strengths lie in translating regulatory requirements into scalable additive packages and securing approval timelines that matter to global oil marketers.
-
BASF, Evonik, LANXESS, Croda and Vanderbilt: These specialty chemical houses supply critical building blocks—antioxidants, viscosity index improvers, friction modifiers—creating a two‑tier dynamic where formulators purchase both complete packages and component technologies from multiple sources.
-
Regional producers and Chinese incumbents: Domestic manufacturers are growing relevance in certain markets through competitive pricing and localized supply chains, but they face a technology gap on new‑generation performance chemistries unless partnerships or licensing accelerate in 2026.
What this means: incumbency and technology ownership will remain the single biggest moat. However, nimble niche players can carve out durable positions by specializing in bio‑based additives, friction modifiers, or custom formulations for emerging fleet segments.
Regulatory timeline and operating risks
Regulatory updates are the dominant demand shaper for 2026. The ILSAC GF‑7 transition and API’s parallel category (API SQ) create an overlapping implementation timeline that extends into late 2026. PW Consulting’s regulatory matrix shows that the phased overlap was deliberately extended to provide the supply chain breathing room, but it also creates a strategic choice for additive suppliers: accelerate costly re‑formulation investment now for early adopter advantage, or stagger capital deployment and accept first‑mover disadvantages in select markets.
Other operating risks include geopolitical-driven raw material disruptions that have already pushed input costs materially higher. Suppliers and buyers who fail to lock in supply or establish cost‑pass‑through mechanisms will face margin erosion in 2026.
Practical report deliverables that inform 2026 execution
PW Consulting’s comprehensive market study offers a suite of practical tools and outputs for commercial, product, and corporate strategy teams:
-
Proprietary market sizing and forecast model (2026–2032) with scenario toggles for regulation, price shocks, and EV penetration.
-
Supplier benchmarking (technology, certifications, capacity, channel coverage) and a stratified supplier risk heatmap for procurement planning.
-
Regulatory implementation calendar mapped to product development lead times and OEM approval windows—actionable for R&D prioritization.
-
Price‑sensitivity and margin impact analysis tied to raw material movements and manufacturer pass‑through elasticity assumptions.
-
M&A and partnership scorecards identifying target profiles where scale, technology, or regional footprint would create immediate strategic leverage.
-
Playbooks for oil marketers and additive formulators covering launch sequencing, co‑marketing with OEMs, and sample‑to‑approval timelines by jurisdiction.
Note: The preview intentionally omits the full, segmented revenue tables by region, additive type, and vehicle application. These segment‑level numbers and the supporting transaction datasets are available exclusively in the full PW Consulting report.
Strategic recommendations for calendar‑year 2026
-
Make GF‑7 readiness a prioritized, cross‑functional program. R&D, regulatory affairs, and key account teams should collaborate on a six‑to‑nine‑month acceleration plan for API/ILSAC validation trials and customer pilots.
-
Institute dynamic purchasing and pricing strategies. Given recent base oil and additive price upticks, implement hedging, multi‑sourcing, and index‑linked pricing clauses to protect margins while remaining competitive.
-
Target OEM and leading oil marketers with proof‑point packs. Companies that can demonstrate LSPI mitigation, fuel‑economy gains, and piston cleanliness through independent labs will secure early adoption and sticky approvals.
-
Evaluate scale through partnerships. For mid‑sized specialty producers, strategic alliances or minority investments with technology leaders can fast‑track access to GF‑7 IP while avoiding large upfront capex.
-
Prepare operational contingency plans for supply disruption. Scenario playbooks addressing logistics constraints and alternative sourcing in the Middle East and Asia are essential.
Concluding perspective: choices and trade‑offs
2026 will be a year of accelerated technical change and commercial recalibration for the engine oil additives sector. The aggregate market outlook shows continued growth at a modest pace; yet, within that growth lie divergent outcomes determined by technology leadership, supply‑chain resilience, and regulatory alignment. Firms that move early to align formulation roadmaps with GF‑7/API SQ, that actively de‑risk inputs, and that deploy targeted commercial plays with OEMs and oil marketers will consolidate advantage.
PW Consulting’s full report converts these strategic imperatives into executable plans, complete with proprietary segment breakouts, supplier scorecards, and financial scenarios. For companies deciding their 2026 capital, R&D and commercial priorities, the report is designed to shorten decision cycles and reduce execution risk.
How to access the full intelligence
This preview is intended to orient senior leaders and shape 2026 planning conversations. To obtain the full Worldwide Automotive Engine Oil Additives Market report—including the segmented revenue tables, company‑level financial proxies, and the downloadable forecast model—please visit our official report page or contact PW Consulting’s industry practice.
PW Consulting will also be hosting a closed‑door webinar in early Q3 2026 to walk clients through model scenarios and bespoke implications for procurement and R&D roadmaps. Contact your client service representative to request an invitation.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Engine Oil Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Semiconductor Magnetic Sensor Market to Surge from USD 3,280 Million in 2025 to USD 5,995.97 Million by 2032 on a 9.0% CAGR
By PW Consulting, 2026-08-12
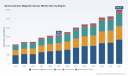
Worldwide Semiconductor Magnetic Sensor Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Semiconductor Magnetic Sensor Market synthesizes five years of historical performance (2020–2025) and a seven-year forecast (2026–2032) into an actionable strategic playbook for executives, product leaders, and investors. The industry enters 2026 from a position of renewed momentum: the market reached approximately USD 3,280 Million (base year 2025) and our bottom-up modeling projects a compound annual growth rate (CAGR) of roughly 9.0% through 2032, with the market approaching a near-doubling by the end of the forecast horizon. This briefing highlights the report’s strategic value without disclosing the proprietary granular splits — a deliberate “trailer” designed to show depth while directing readers to the full report for the detailed intelligence required for transaction-level decisions.
Worldwide Dimethyl Phosphite Market
Why this market matters in 2026
-
Critical enabling role: Magnetic sensors underpin a broad set of high-growth systems — from electrified powertrains and wide‑bandgap power conversion to advanced position, current and angle sensing in industrial automation and consumer devices. Their performance characteristics (bandwidth, sensitivity, size, power) are increasingly determinative of system-level outcomes.
Worldwide Search Engine Marketing (SEM) Tools Market -
Compelling macro momentum: After steady expansion through 2025, our forecasts show sustained double-digit tailwinds in select end-markets and accelerating adoption of high-performance technologies that support higher price realization and value-additive system integration.
Worldwide Retail Task Management Software Market -
Concentration and competitive dynamics: The market exhibits meaningful concentration at the top, creating a strategic calculus for mid‑market suppliers and OEMs contemplating vertical integration, exclusive supply contracts, or targeted M&A to secure capability or capacity.
What the report delivers — practical, transaction-ready outputs
-
Proprietary market sizing model calibrated to 2020–2025 historicals and validated by primary interviews with OEMs, tier‑1 suppliers, foundries and materials providers. The model supports ad-hoc scenario runs for pricing, volume shifts, and technology substitution.
-
Scenario-based forecasts (2026–2032) across demand shock, supply-constrained, and technology-adoption pathways to quantify revenue and margin sensitivities for strategic planning and valuation work.
-
Go‑to‑market playbooks for product managers and BD teams, detailing channel strategies, value-based pricing approaches, and use-case prioritization that materially shorten time-to-revenue for new sensor platforms.
-
Supplier & material risk scorecards that translate geopolitical, regulatory, and rare-earth exposure into quantifiable procurement stress metrics and recommended mitigation actions.
-
Comprehensive competitive benchmark and capability atlas mapping IP, manufacturing footprints, product families and adjacent solutions — designed to support M&A target screening, JV structuring, and licensing negotiations.
Key market signals shaping 2026 strategies
-
Technology premiumization: Adoption is shifting toward higher-performance magnetoresistive technologies and integrated multi-axis solutions that command price premiums and create differentiation opportunities for suppliers able to deliver system-grade references and supplier guarantee metrics.
-
System integration as strategic battleground: OEMs increasingly prize sensor suppliers that provide reference designs, certification-ready modules, and supply assurances — not just die-level components. This favors companies with cross-domain IP (sensor + analog front-end + system calibration).
-
Margin polarization: Cost deflation in adjacent subsystems (e.g., battery pack price declines) and rising value derived from electrification and automation are compressing margins on commodity sensors while expanding margins on high-speed, high-bandwidth and safety-critical solutions.
-
Geopolitical and raw material friction: Recent trade and export policy moves — and concentrated global processing capacity for certain rare earths — materially raise the probability of mid-cycle supply shocks. These dynamics necessitate active hedging, dual-sourcing, and material substitution strategies.
Supply chain and regulatory watch-list
-
Export controls and tariffs: Recent policy measures affecting semiconductor and related materials create new import/export complexity for multi-national supply chains. Companies should reassess sourcing clauses and contract language to reflect adjusted lead times, customs duties, and licensing requirements.
-
Concentration of critical processing: A high share of refined heavy rare earth processing remains geographically concentrated. For product lines that rely on high‑performance magnets or specialized alloys, procurement teams should quantify single‑point dependencies and develop decoupling options.
-
Commercial levers to mitigate risk: Stockpiling strategic components is costly; alternatives include design-for-substitutability, long-term offtake agreements with upstream refiners, and co-investment in alternate processing capacity.
Competitive landscape: how incumbent and emerging players are positioning
The competitive topology is a mix of specialized sensor houses, diversified semiconductor groups, and niche foundries that enable differentiated materials or integration approaches. The top-tier demonstrates both product breadth and deep application expertise, while mid-tier players are exploiting adjacent strengths and targeted innovations.
-
Specialist sensor manufacturers are deploying aggressive product roadmaps that combine advanced TMR/GMR technologies with application-specific analog front-ends and software calibration ecosystems. Their advantage is rapid time-to-market for higher-value use cases and tight OEM relationships.
-
Diversified semiconductor groups leverage scale, cross-divisional design capabilities, and global distribution to bundle magnetic sensing into multi-sensor portfolios for automotive and industrial customers, often providing certified reference designs and supply guarantees.
-
Foundry and materials partners that provide specialized process nodes (e.g., high-temperature GaN-compatible processes, TMR integration with CMOS) are emerging as strategic partners for performance-sensitive customers where in-house fabs are uneconomic.
To illustrate how strategy maps to players (without divulging proprietary rankings), the full report contains detailed company profiles and capability matrices for the leading participants in this sector — covering product architectures, commercial go‑to‑market motions, recent launches, and likely next moves. Recent public activity shows continued product innovation: new ultra‑low‑power 3-axis industrial designs, compact TMR angle sensors optimized for safety, and the first commercial 10 MHz TMR current sensors tailored to wide‑bandgap power electronics. These moves reflect a clear uptick in engineering investment toward higher-frequency, higher-accuracy, and systemized sensor solutions.
Implications for strategic choices in 2026
-
Product roadmap prioritization: If your portfolio includes commodity Hall-effect sensors, 2026 is the year to decide whether to move up‑market into magnetoresistive variants and integrated modules — or to double down on cost leadership with ultra‑low‑cost, high-volume manufacturing strategies.
-
M&A and partnership timing: With top‑tier concentration creating barriers to entry in certain subsegments, mid-size players should evaluate bolt-on acquisitions that add materials, foundry access, or software calibration stacks rather than pursuing organic scale exclusively.
-
Supply-chain restructuring: Design teams must incorporate alternative magnet and rare-earth sourcing into product specifications, and procurement should lock in multi-year agreements for vulnerable components. Consider co-investment vehicles with upstream suppliers to secure capacity and preferential pricing.
-
Commercial contracts and risk allocation: Revisit contractual risk allocation (force majeure, tariffs, export licensing) in new supplier agreements to reflect the elevated regulatory tail‑risk environment.
Who should read the full report
-
CEOs and corporate strategy teams evaluating M&A or vertical integration opportunities in sensors and power electronics.
-
Product and engineering leaders planning 3–5 year roadmaps that must reconcile performance requirements with realistic supply scenarios.
-
Procurement and supply-chain executives seeking prioritized mitigation actions and supplier scorecards tied to material risk exposure.
-
Investment professionals and corporate development teams requiring rigorous, auditable forecasts and scenario outputs to underwrite transactions.
Methodology snapshot and transparency
PW Consulting’s market model integrates bottom‑up bill-of-materials (BOM) analysis, aggregated shipment data, primary interviews, and public company disclosures reconciled to historical revenue. The base year is 2025 and the forecast window is 2026–2032. Our sensitivity suite allows users to re-run the forecast under alternative assumptions for technology substitution rates, material-cost pass-through, and end-market elasticity.
Next steps — how to act on this preview
-
Download the full report to obtain the granular segmentation, supplier rankings, and downloadable forecast model that support transaction diligence and product-strategy decisions.
-
Schedule a PW Consulting workshop to stress-test your 2026 product roadmap or M&A thesis using our scenario engine and supplier risk dashboards.
-
Engage our advisory team for a bespoke supplier risk audit or to develop a strategic sourcing playbook aligned with anticipated regulatory shifts and rare-earth supply volatility.
PW Consulting’s study provides the market-sizing, competitive intelligence, and pragmatic playbooks that senior teams need to make confident, time-sensitive decisions in 2026. The market’s trajectory is clear: sustained growth with differentiated value pools emerging for high-performance, system-oriented magnetic sensing solutions. For the granular segmentation and transaction-grade tables that underpin the strategic recommendations above, please consult the full report.
For detailed analysis of this topic, please visit the official page: Worldwide Semiconductor Magnetic Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Achondrogenesis Market to Grow at a 5.59% CAGR, Reaching USD 226.75 Million by 2032 (From USD 155.0 Million in 2025)
By PW Consulting, 2026-08-12
Worldwide Achondrogenesis Market: Strategic Imperatives for 2026 Decision-Makers
As health systems, diagnostic providers, biotechs, and specialty investors prepare plans for 2026, PW Consulting’s new Worldwide Achondrogenesis Market report offers a focused, pragmatic compass for navigating one of the most technically demanding and clinically sensitive rare-disease segments. Grounded in an updated market model with a 2025 base year and a six-year forecast horizon (2026–2032), the study synthesizes historical trends (2020–2025), scenario-driven forecasts and practical decision tools that leaders need to accelerate time-to-impact while managing commercialization risk.
Industrial Flash Memory Chip Market
Why this report matters for 2026 planning
Achondrogenesis is a low-incidence, high-need condition where every diagnostic and therapeutic decision has outsized clinical and economic consequences. Our analysis shows the global market value moving from USD 155.0 Million in 2025 to an estimated USD 226.75 Million by 2032, with an aggregate compound annual growth rate of 5.59% across the forecast window. The path between these anchor points is non-linear—reflecting episodic inflections from technology adoption, regulatory milestones and evolving care pathways—which makes tactical annual planning (not just extrapolation) essential for stakeholders aiming to optimize investment and operating choices in 2026.
Atomic Energy Batteries Market
Key market dynamics shaping near-term strategy
- Technology-driven detection gains: Continued advances in genomics, sequence interpretation and imaging integration are shortening diagnostic timelines. For organizations that can operationalize next-generation testing and post-analytic decision support, there is an opportunity to capture incremental diagnostic volume and to become preferred referral partners.
- Payor and reimbursement evolution: Reimbursement remains a gating factor. Our interviews and payment-mapping exercises indicate growing, but uneven, recognition of the value of early, definitive diagnosis—especially where it reduces downstream invasive procedures or inappropriate interventions. Strategic engagement with payors in 2026 will be decisive for uptake.
- Clinical pathway consolidation: Centers of excellence and academic networks are consolidating expertise, creating referral clusters and standardized protocols. Companies able to align with these networks—through clinical evidence, service-level agreements, or integrated diagnostics—will accelerate market penetration.
- Data and privacy constraints: The requirement for rare-disease registries and cross-jurisdictional data sharing is increasing. Organizations must balance data utility with compliance—investing early in governance frameworks will reduce time-to-launch risks for multisite initiatives.
- Concentration and competitive positioning: The market exhibits a mid-level concentration: the top three players account for a meaningful share of market revenues, while the top five capture just over half. This structure creates room for focused entrants and clinical innovators to carve sustainable niches if they apply clear differentiation and execution discipline.
What the report delivers — practical, execution-oriented content
We designed this report to be a working toolkit for executives, not just a descriptive monograph. Users receive:
Worldwide Manufacturing Intelligence Software Market
- Robust market model: An editable Excel model calibrated to historical activity (2020–2025) and populated with scenario branches for 2026–2032. The model supports sensitivity testing on key levers—diagnostic adoption rates, price points, reimbursement scenarios and referral routing—to generate bespoke forecasts for board-level decisions.
- Decision matrices and go-to-market plays: Field-tested playbooks that link product profiles to optimal commercialization paths (direct hospital partnerships, diagnostic lab networks, reference-center collaborations). Each play includes revenue levers, time-to-adoption estimates and implementation roadmaps tailored for 12–36 month horizons.
- Regulatory and reimbursement playbook: A practical checklist of filing pathways, evidence thresholds and payer engagement sequences with templates for economic dossier construction and real-world evidence strategies specific to prenatal and neonatal diagnostic contexts.
- Stakeholder maps and patient-journey analytics: Detailed maps of the referral and decision nodes that drive diagnostic utilization, with recommended interventions to reduce diagnostic delay and to increase appropriate test ordering among frontline clinicians.
- Risk-adjusted investment cases: Three archetypal investment models—conservative, base, aggressive—each projecting cash-flow timing, break-even horizons and upside triggers for investors and corporate development teams.
- Implementation checklists: Operational due-diligence templates for laboratory scale-up, quality systems, supply chain resilience and clinical trial site selection geared to rare-disease contexts.
Competitive landscape — strategic implications without divulging proprietary splits
Rather than replicate company-by-company revenue tables here, the report synthesizes competitive positioning across capability vectors—diagnostic breadth, clinical partnerships, service delivery, and evidence generation. The market’s concentration metrics indicate a competitive dynamics where the largest players drive volume and standard-setting, but where a credible technical differentiation or a compelling partnership can quickly change the playing field.
- Incumbent advantages: Scale players benefit from established network effects, validated lab processes and existing reimbursement relationships—advantages that compound in early-adopter markets.
- Mid-market opportunity zones: Mid-sized diagnostic innovators and academic spin-outs can capture share by specializing in integrated offerings (e.g., bundled genomic testing plus counseling) and by pursuing regional centers of excellence.
- Disruptor entry paths: New entrants should prioritize clinical evidence and operational reliability over broad geographic coverage. Focused clinical pilots that demonstrate utility and economic benefits are the fastest route to payer acceptance.
Scenario planning: seven plausible 2026 inflection scenarios
The report includes mapped scenarios that translate macro drivers into operational choices for 2026. Examples include:
- Accelerated-tech adoption: Rapid clinical acceptance of combined genomic-imaging protocols—favours diagnostic-first strategies and investments in high-throughput interpretation platforms.
- Reimbursement tightening: Conservative payor behavior shifts testing economics—favours bundled service offerings and risk-sharing agreements with payors and hospitals.
- Registry-enabled discoveries: International registry data yields new genotype-phenotype correlations, opening pathways for targeted therapeutic research collaboration.
Each scenario is coupled with tactical checklists—what to do in months 0–6, 6–18 and 18–36—enabling leaders to move from strategic intent to executable steps quickly.
How to use the report for 2026 decision cycles
- Portfolio prioritization: Use the scenario-adjusted financial model to re-score pipeline and diagnostic investment opportunities—identify which assets should be accelerated, which require de-risking, and which to shelve.
- Clinical partnership strategy: Map and prioritize center-of-excellence partnerships using our diagnostic referral and volume forecasts to maximize early patient identification and generate real-world evidence streams.
- M&A and partnering diligence: Employ the report’s valuation sensitivity tables and operational due-diligence checklists to test acquisition targets and alliance partners under multiple adoption and reimbursement outcomes.
- Regulatory timing and evidence sequencing: Follow the stepwise evidence plan to align regulatory filings, payer submissions and clinical publications—optimizing the sequencing to unlock revenue faster.
What we are intentionally withholding here — and why
True to the “trailer” principle, this public summary demonstrates the analytical depth and practical utility of the study while deliberately withholding core segmented figures and granular revenue splits. Those detailed data — including breakouts by geography, modality and end-user revenue — are included in the full report and interactive model only. This approach protects the immediacy and operational value of the report for subscribers and paying clients who require actionable, granular line-item analyses for investment and operational decisions.
Clients who will extract the most value
- Biotech and diagnostic companies developing next-generation prenatal and neonatal tests.
- Hospital systems and reference labs planning to expand rare-disease diagnostic services.
- Investors and corporate development teams evaluating targeted M&A or strategic partnerships.
- Policy-makers, payors and patient advocacy groups interested in optimizing care pathways for rare skeletal dysplasias.
Next steps and how to access the toolkit
For executive teams finalizing 2026 budgets and strategic plans, the PW Consulting Worldwide Achondrogenesis Market report functions as both a decision-accelerator and a governance resource. The full publication includes the downloadable market model (USD, revenue unit: Million), detailed segmentation, competitor landscaping, regulatory timelines and bespoke recommendation sets tailored to different stakeholder types.
Contact PW Consulting to arrange a walk-through of the model, obtain customized scenario outputs, or commission a rapid deep-dive tailored to your asset or market entry plan. For teams that need to move quickly: our 90-day implementation sprint combines the report outputs with hands-on advisory support to embed the findings into commercial and clinical launch plans.
In an environment where each diagnostic decision reshapes patient trajectories and commercial outcomes, robust, executable market intelligence isn’t optional—it’s mission-critical. PW Consulting’s report equips leaders with the insight and tools to turn 2026 uncertainty into strategic advantage while preserving the proprietary, high-value data that underpin confident execution.
For detailed analysis of this topic, please visit the official page: Worldwide Achondrogenesis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting report: Worldwide Outdoor Sound Barriers Market set to expand at a 5.06% CAGR through 2032
By PW Consulting, 2026-08-12
Worldwide Outdoor Sound Barriers Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study places the global outdoor sound barriers market at approximately USD 6,450 Million in the base year 2025, with a steady compound annual growth rate (CAGR) of 5.06% driving a projected rise to around USD 9,112 Million by 2032. This briefing distills the study’s strategic implications for executives planning capital allocation, product roadmaps, procurement strategies, and market entry during 2026 — while preserving the report’s proprietary, segment-level intelligence for subscribers.
Worldwide Police Software Market
Why this market matters to 2026 strategy
Outdoor sound barriers are no longer a niche civil-works afterthought. They have become an intersectional market where infrastructure capital, urban regulatory pressures, industrial noise compliance, and materials technology converge. For 2026, three forces make timely decisions critical:
Worldwide Surgical Scrub Market
- Predictable growth: mid-single-digit CAGR supports multi-year investments while leaving room for selective, higher-return plays in differentiated product segments.
- Cost and supply volatility: raw-material dynamics and modular manufacturing approaches are re-shaping supplier selection and total cost of ownership models.
- Regulatory tightening and standard updates that raise technical and reporting barometers for tender eligibility, performance warranties and lifecycle claims.
Executives who act in 2026 can lock in procurement frameworks, accelerate product upgrades, or reposition offerings ahead of regulatory harmonization and notable shifts in buyer specifications.
Hydrogen for Hydrogen Refuelling Stations Market
Market dynamics — what’s moving the dial
The report maps a layered set of drivers and headwinds that purchasers, OEMs and investors should internalize:
- Material cost pressures: engineering-market indices showed material price inflation through 2025 — notably for steel — increasing input cost risk for metal-based solutions. Price stabilization in certain geographies during 2025 provided short-term relief, but the underlying volatility means procurement strategies need to be more sophisticated than fixed-price contracting.
- Standards & regulation: recent updates to ISO 9613-2 and a suite of European rules on outdoor equipment noise measurement and reporting have raised the bar for how acoustic performance is specified, tested and documented. These changes are already influencing bid specifications and are likely to drive demand for validated, certifiable products.
- Product innovation & application breadth: advances in absorptive materials, transparent barrier technologies, and modular temporary systems have expanded use-cases (from highways to construction sites and energy projects). Buyers increasingly value documented dB attenuation under standardized test regimes plus considerations for durability, maintenance and aesthetics.
- Market structure: the market remains fragmented, with the top-three vendors accounting for a relatively small portion of global revenue. This fragmentation signals opportunity for consolidation, regional champions, and premiumization by differentiated suppliers.
Competitive landscape — positioning and recent moves
The competitive set mixes legacy fabricators, acoustics specialists and modular innovators. Our analysis highlights three strategic archetypes:
- High-performance absorptive specialists: Firms with deep acoustical engineering capabilities emphasize measured attenuation performance and turnkey design services. These players leverage decades of project experience to win larger infrastructure and industrial contracts, where specification and liability matter.
- Modular & temporary solutions providers: Companies offering portable, hire-and-purchase models target construction, events and short-term works. Their value lies in speed-to-deploy, reusability and lower capex entry for buyers that prefer operational flexibility.
- Systems integrators and retrofit specialists: Vendors focusing on retrofitting existing fences and infrastructure with absorptive inserts or hybrid panels appeal to municipal customers and facilities managers seeking rapid noise mitigation without full fence replacement.
Representative company signals and implications:
- Sound Fighter Systems (U.S.) — continues to foreground fully absorptive wall systems with corporate messaging focused on higher reduction ranges for highways and industrial projects. Their established engineering depth positions them well for spec-driven tenders where performance claims are scrutinized.
- AIL Sound Walls (Canada) — remains notable for turnkey municipal and residential solutions, reflecting sustained demand in public-sector projects that prize integrated design, warranty and service offerings.
- Echo Barrier (U.K.) — leads the portable/temporary segment, demonstrating the commercial traction of hire-and-buy models for construction and demolition markets; this model reduces procurement friction for short-duration needs.
- Kinetics Noise Control and IAC Acoustics (U.S.) — product updates and trade-show visibility indicate ongoing investments in panel systems and new product lines targeted at exterior and industrial applications, reinforcing that innovation cycles continue across material and modular configurations.
- Smaller niche players (e.g., Acoustic Sciences Corporation, Acoustiblok, and regional fabricators) — sustain market breadth by offering retrofit, fence-conversion solutions and specialty materials that cater to localized regulatory environments and retrofit demand.
Recent product releases, trade-show activity and product information updates from multiple incumbents demonstrate active competition on product performance, deployment flexibility and certification packages — all factors that will shape procurement outcomes in 2026.
Strategic implications for 2026 corporate decision-making
Informed by the report’s holistic modelling (historical analysis 2020–2025, base-year 2025 and forecasts through 2032), PW Consulting advises boards and executive teams to prioritize the following actions:
- Revise procurement playbooks to include material-escalation clauses, hedging options and flexible supply arrangements. Where steel exposure is material, adopt multi-sourcing and indexed contract terms tied to transparent indices.
- Invest in certifiable acoustic performance. With standards and measurement methodologies evolving, the ability to produce third-party validated attenuation data will convert tender opportunities into wins and reduce contractual disputes.
- Differentiate through service and lifecycle economics. Buyers are increasingly evaluating total cost of ownership — design for maintainability, replaceable absorptive inserts and modularity will command price premiums in many bids.
- Pursue targeted M&A or partnership plays in the modular/temporary segment. The hire-and-purchase model opens new commercial channels and recurring-revenue profiles attractive to investors seeking diversification within an otherwise project-driven market.
- Prepare region-specific compliance playbooks. Regulatory alignment (particularly in Europe) is accelerating; exporters and multinational vendors must be ready with compliance dossiers and testing evidence that align with the latest measurement methods.
What PW Consulting’s report delivers to subscribers
For decision-makers who require executable insight, the full study contains:
- Proprietary demand model (base 2025) with scenario analysis across the forecast horizon (2026–2032).
- Supplier scorecards and capability matrices to shortlist partners by technical competence, geographic reach and business model.
- Cost-sensitivity analyses reflecting raw-material trajectories, manufacturing mix and logistics exposures.
- Go-to-market playbooks with tender drafting language, warranty frameworks and performance-based contracting templates.
- Investment decision frameworks, including M&A target filters and integration checklists for bolt-on acquisitions in modular and retrofit niches.
- Case studies and implementation blueprints that translate acoustic performance requirements into engineering specifications and procurement tender clauses.
Importantly, the study provides granular regional and application splits, supplier-level revenue estimates and scenario-specific market sizing tables — proprietary elements that are intentionally reserved for report subscribers to protect actionable commercial intelligence.
Immediate tactical checklist for 2026
To convert insight into short-term action, PW Consulting recommends a focused 90-day plan for market-facing teams:
- Audit current tenders and contracts for exposure to steel and other commodity price movements; implement indexed or pass-through mechanisms where feasible.
- Identify two pilot projects to showcase certified absorptive performance and lifecycle cost reporting; use these as reference installations for public procurement bids.
- Engage with testing laboratories and certification bodies to pre-qualify product lines under the updated ISO method and applicable regional regulations.
- Screen potential partnerships with portable/modular providers to test hire-and-purchase offerings in a targeted regional market.
- Convene cross-functional war room (procurement, engineering, legal) to align contract language with updated measurement and reporting standards.
Closing — how PW Consulting supports your 2026 agenda
For leaders who must reconcile near-term cost pressures with medium-term growth opportunities, our Worldwide Outdoor Sound Barriers Market report is designed as an operational playbook as much as a market forecast. The macro numbers — USD 6.45 billion (2025 base) and a 5.06% CAGR to 2032 — quantify the opportunity. The differentiated insight we provide shows where to invest, partner and compete.
For full access to the proprietary regional and application breakdowns, supplier revenue analyses, and the complete set of implementation tools that underpin these strategic recommendations, please consult the full PW Consulting report or contact our industry specialists for a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Outdoor Sound Barriers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reveals Worldwide Percutaneous Nephroscope Market Valued at USD 557.24 Million in 2025
By PW Consulting, 2026-08-12
Worldwide Percutaneous Nephroscope Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market research on the worldwide percutaneous nephroscope market provides an evidence-based, decision-ready view for healthcare executives, device manufacturers, investors, and health systems preparing for 2026 and beyond. Our analysis shows a resilient market trajectory: from a base year of 2025, when the market size reached approximately USD 557 million, the sector is projected to grow at a compound annual growth rate (CAGR) of 6.19% over the 2026–2032 forecast horizon, reaching roughly USD 849 million by 2032. This growth is underpinned by procedure volume expansion, incremental device innovation, and evolving care settings.
Worldwide Display Ad Design Software Market
Why this report matters for 2026 strategy
-
Actionable timing: 2026 will be a pivotal year for capital allocation and product rollouts. The market momentum and regulatory cadence captured in our forecast window make 2026 the logical inflection point for launches, partnerships, and selective build-outs.
Worldwide Fume Filtration Systems Market -
Risk-managed investment: We quantify regulatory and reimbursement levers that materially affect revenue assumptions and provide scenario-based valuations for investment committees to incorporate into 2026 budgets.
Worldwide Blood and Fluid Warming Unit Market -
Competitive advantage: The market exhibits meaningful concentration among a handful of established firms (our CR3 and CR5 measures indicate a concentrated but contestable market). Our competitive playbook distills where incumbents are vulnerable and where disruptive entrants can win.
Market outlook — what the numbers imply
The mid-single-digit CAGR and the seven-year projection to 2032 signal steady, healthy expansion rather than a speculative boom. For corporate strategy teams, that profile favors disciplined, portfolio-based investments over aggressive, single-bet plays. Key demand drivers we identify include sustained procedure volumes for percutaneous nephrolithotomy (PCNL), incremental migration of selected interventions to ambulatory pathways, and continued replacement cycles for reusable capital equipment.
Importantly, the headline growth conceals meaningful heterogeneity by product type, channel, and region — our full report dissects these dynamics and quantifies addressable opportunity by segment and customer cohort. In this briefing we deliberately withhold detailed split data to preserve the incentive for deeper engagement with the full report; however, we outline the directional forces that matter for 2026 planning.
Practical takeaways for corporate leaders (2026 priorities)
-
Portfolio rationalization: Prioritize modular, optics-agnostic nephroscopy platforms that enable multi-procedure utility and lower total cost of ownership. Competitive advantage will accrue to designs that reduce turnover time and simplify sterilization pathways under existing AAMI guidelines.
-
Regulatory-first development: Build 510(k)-ready technical packages with clear predicate strategies for U.S. entry and parallel Notified Body strategies for EU MDR compliance. Delays in regulatory clearance materially shift launch timelines and NPV; treat regulatory resourcing as a core product roadmap constraint.
-
Reimbursement-informed pricing: Align commercial models with procedure-level reimbursement realities. For example, Medicare facility reimbursements for percutaneous nephrolithotomy remain an important benchmark for U.S. pricing strategies and payer conversations.
-
Channel and service economics: Evaluate hybrid service models that combine device sale with managed sterilization or refurbishment services. These models can both protect margins and address end-customer operational pain points tied to steam sterilization protocols and device longevity.
What’s inside the full PW Consulting report (practical scope)
-
Comprehensive market sizing and forecast (2020–2032), with scenario analysis and sensitivity to key variables such as procedure volume, device lifecycle, and price erosion.
-
Segment-level analytics covering product types, end-user channels, and regional demand drivers — with demand elasticity matrices to inform pricing and market-entry decisions.
-
Regulatory and reimbursement playbooks, including step-by-step checklists for 510(k) submissions, EU MDR preparation, and payer engagement strategies tailored to U.S. Medicare and major private payers.
-
Operational diagnostics for hospitals and ambulatory surgical centers: throughput optimization, sterilization workflow redesign per AAMI ST79 standards, and capital planning templates.
-
Competitive intelligence files on incumbent and emerging players, benchmarking on product portfolios, IP posture, recent launches, and go-to-market models.
-
Deal flow and M&A advisory: valuation frameworks, target screening criteria, and integration checklists specific to nephroscopy and adjacent urology device segments.
Competitive landscape — positioning and implications
The sector is characterized by a handful of established device manufacturers with deep clinical relationships, broad product portfolios, and recurring service revenue streams. Our competitive concentration metrics demonstrate that the top three and top five players command a material portion of market revenue, creating both entry barriers and predictable consolidation pathways.
-
Karl Storz SE & Co. KG — A leader in rigid nephroscopy platforms, Karl Storz continues to invest in imaging integration and procedural ergonomics. Recent trade-show activity showcased IMAGE1 S™-compatible upgrades that enhance visualization — a clear defensive move to protect share in high-volume PCNL centers. For competitors, Karl Storz’s strength underscores the importance of matching image-system interoperability as a minimum competitive requirement.
-
Olympus Corporation — Olympus’s catalog refreshes emphasize optics and size variants that allow clinical tailoring. Their incremental additions reflect a dual strategy: defend core markets while enabling cross-selling into endoscopy suites where Olympus enjoys installed-base advantages. New entrants should expect steep clinical credentialing hurdles in Olympus-dominated hospitals.
-
Richard Wolf GmbH — Compliance and certification investments — including recent EU MDR updates — indicate a quality-first approach. Their emphasis on continuous irrigation and procedural efficiency appeals to high-throughput settings. Competitors targeting European expansion must plan for comparable regulatory investments and documentation rigor.
-
PENTAX Medical (HOYA Group) — With a focus on rigid models designed for percutaneous access, PENTAX benefits from cross-modal optics expertise. Their strategy suggests opportunities for partnerships around image processing and fiber-optic durability.
-
Cook Medical — As a supplier of comprehensive nephroscopy kits and access systems, Cook’s role highlights the strategic value of complementary consumables and accessory sales. Market leaders that can bundle consumables with capital equipment will improve lifetime value per customer.
Recent company developments — from product launches to certification milestones — are indicative of the innovation and regulatory rhythms we expect to accelerate through 2026. Market participants who align product cycles with major urology congresses and certification timelines gain a disproportionate advantage in clinical adoption.
Regulatory, reimbursement, and operational guardrails
-
Regulatory classification: Percutaneous nephroscopes are regulated as Class II devices requiring 510(k) clearance in the U.S.; European market access requires Notified Body engagement under EU MDR. Early regulatory strategy must be integrated with R&D to avoid costly redesigns.
-
Reimbursement dynamics: Procedure-level reimbursements remain a strong determinant of hospital purchasing behavior. Device value messaging should be tied to measurable reductions in OR time, complication rates, or length of stay to influence hospital budget committees and payer evidence requirements.
-
Sterilization and materials: Reusable nephroscopes must tolerate validated steam sterilization cycles and are typically constructed using medical-grade stainless steels with rugged fiber-optic bundles. Procurement teams should demand lifecycle data and validated reprocessing protocols as part of supplier selection.
Go-to-market and M&A playbook for 2026
-
Partnerships over greenfield: For entrants, strategic alliances with established imaging or sterilization providers can accelerate acceptance while mitigating capital expenditures.
-
Adjacency buys: For incumbents seeking growth, tuck-in acquisitions of consumable or access-sheath specialists can expand wallet share rapidly and improve service-level margins.
-
Clinical evidence investments: Allocate at least two clinical trials or real-world evidence initiatives per major market to shorten hospital procurement cycles and support premium pricing.
-
Service-centric contracting: Offer bundled capital-and-consumables contracts with predictable per-procedure pricing to lock-in utilization and create recurring revenue.
Concluding perspective and next steps
The percutaneous nephroscope market presents a structurally attractive growth pathway for disciplined investors and manufacturers — steady expansion, clear technology-driven differentiation, and a procurement environment that rewards demonstrable clinical and operational value. As firms craft their 2026 strategies, the critical choices will center around regulatory timing, clinical evidence generation, and service-model design.
PW Consulting’s full report delivers the granular segmentation, competitor market-shares, regional and application-specific analyses, and executable playbooks referenced here. To translate the directional insights in this preview into transaction-ready intelligence and operational plans for 2026, request the full Worldwide Percutaneous Nephroscope Market report and our tailored executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Percutaneous Nephroscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Motorcycle Headlight Bracket Market to Reach USD 369.37 Million by 2032 at a 5.82% CAGR; Asia Pacific Leads with USD 112.59M
By PW Consulting, 2026-08-12
Worldwide Motorcycle Headlight Bracket Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
PW Consulting’s new market study on the Worldwide Motorcycle Headlight Bracket Market establishes a clear strategic frame for executives planning moves in 2026. The segment has shown steady recovery and expansion through the first half of the decade, with total industry revenues expanding from the low hundreds of millions of USD five years ago to roughly USD 248.6 Million in our 2025 base year. Our model projects continuation of growth into 2026 and beyond, with an expected year‑on‑year increase and a compound annual growth rate (CAGR) of approximately 5.82% over the 2026–2032 forecast window.
Worldwide Desktop KVM Switches Market
For leadership teams, procurement heads, product managers and private equity investors, the critical implication is that motorcycle headlight brackets are no longer a purely tactical hardware line item: they are a strategically material component influenced by materials markets, lighting electrification, regulatory regimes and a bifurcated channel structure. This briefing synthesizes the report’s strategic takeaways while preserving the granular datasets for subscribers — a trailer that highlights where to act and why, without disclosing the proprietary segment-level matrices reserved for the full report.
Worldwide Thermography Software Market
Why this matters in 2026
- Portfolio prioritization: Increased demand for aftermarket upgrades, combined with OEM platform refresh cycles, means bracket systems are a lever for both top-line differentiation and an accessory-driven P&L.
- Cost and sourcing sensitivity: Aluminum-driven manufacturing and steel alternatives create tangible margin levers that require active commodity risk management and supplier segmentation by capability.
- Regulatory and safety risk: Headlighting standards (including those comparable to FMVSS 108) are tightening in several markets, changing design verification, validation and aftermarket acceptance criteria.
- Consolidation opportunity: The market shows measurable fragmentation at the supplier level, with the top three and five vendors capturing meaningful but not overwhelming shares — a structure that favors strategic M&A and roll-up strategies in 2026.
Market dynamics shaping strategy
The headlight bracket market is being reshaped by a confluence of trends that matter directly to 2026 planning:
Worldwide Annealing Furnaces Market
- Electrification and lighting evolution: The shift to LED and adaptive lighting systems transforms bracket design requirements — thermal management, EMI considerations and integrated wiring channels are increasingly standard expectations for OEMs and sophisticated aftermarket offerings.
- Aftermarket momentum: Growth in custom builds, cafe‑racers, and electrified two-wheel platforms is expanding the aftermarket addressable base, while CNC-machined aluminum products are increasingly preferred for their cosmetic and functional attributes.
- Material economics and supply risk: Aluminum alloy dominates product engineering choices for its strength-to-weight profile and corrosion resistance, but price volatility and supply concentration can materially affect cost of goods sold and sourcing lead times.
- Regulatory headwinds and quality gating: Safety standards that influence headlamp performance indirectly impose requirements on bracket stiffness, durability and fixation methods — translating into longer development cycles and certification costs for OEM suppliers and aftermarket manufacturers who want to serve regulated markets.
- Channel divergence: The coexistence of OEM and aftermarket pathways requires distinct go-to-market models — selling to OEMs demands systems-level integration and long lead-time contracting; aftermarket success relies on modularity, aesthetics, and fast fulfillment.
Competitive landscape — strategic profiles & implications
The sector comprises a mix of precision boutique manufacturers, specialized lighting suppliers, regional fabricators and OEM captive production. Key archetypes and representative players include:
- Heritage European specialists (e.g., Tommaselli, Wunderkind‑Custom): These firms emphasize design-driven premium brackets, light‑damping engineering and high‑quality CNC aluminum finishes. Their strength: brand cachet and bespoke fitment for niche motorcycle communities. Strategic implication: attractive targets for licensing or brand-extension partnerships in premium accessory markets.
- North American custom and conversion specialists (e.g., Motodemic, Denali Electronics): Focused on performance conversions and LED integrations, they serve both OEM replacement needs and high-value aftermarket segments. Strategic implication: partnerships here accelerate product roadmaps for adaptive lighting and certified conversion kits.
- Asia-based contract manufacturers and volume suppliers (e.g., BrightstarTW, Chinese fabricators): Provide scale manufacturing, competitive pricing and rapid prototyping capabilities. Strategic implication: essential for cost optimization, but require disciplined quality assurance and IP protection to move up the value chain.
- OEM captive suppliers (e.g., Polaris / Indian, BMW Motorrad): Control design standards and part rationalization on volume platforms. Strategic implication: winning OEM slots offers predictable volumes but demands compliance, warranty programs and long design cycles.
- Regional artisans and small workshops (e.g., Baak Motocyclettes): Supply bespoke, small-batch components with strong local followings. Strategic implication: effective for limited-edition runs and community-driven co‑marketing.
Market concentration metrics indicate a moderately fragmented field: the top three and top five suppliers command a material portion of market revenue but leave substantial share for specialized and regional players — a dynamic that supports both organic growth and acquisitive consolidation strategies.
Operational levers — what procurement and engineering should prioritize in 2026
- Material strategy and hedging: Establish aluminum sourcing agreements with price‑adjustment clauses or dual-sourcing to manage volatility. For durability‑sensitive models, keep steel and stainless options in the design toolbox where justified by total lifecycle cost.
- Design modularity: Standardize mounting interfaces and create modular bracket families that serve both OEM platforms and aftermarket customization to reduce SKUs and accelerate time-to-market.
- Certification-ready productization: Invest in test fixtures and validation protocols aligned with lighting standards to shorten OEM approval cycles and minimize aftermarket warranty exposure.
- Supplier segmentation: Classify suppliers by capability (high‑precision CNC, high-volume stamping, materials expertise) and match them to product tiers to optimize margin and reliability.
- Inventory and lead-time strategies: For boutique and high-margin SKUs, embrace just-in-case buffers; for commoditized brackets, use lean replenishment linked to real‑time demand signals.
Go-to-market, M&A and partnership playbook for 2026
- OEM engagement: Prioritize engineering resources to meet platform integration requirements for OEMs, focusing on certification, corrosion resistance and NVH (noise, vibration, harshness) mitigation. Winning OEM business offers higher revenue certainty but requires longer investment horizons.
- Aftermarket acceleration: Rapidly release modular, visually differentiated brackets that facilitate LED retrofits and conversion kits; pair with targeted digital marketing to micro‑segments in the custom and e-bike communities.
- M&A criteria: Seek targets with differentiated IP (mounting systems, vibration-damping mounts), proven quality systems and complementary geographic footprints. Bolt‑on acquisitions can consolidate supply, capture channel relationships and add CNC capacity.
- Strategic partnerships: Align with lighting system providers to co-develop integrated lamp‑bracket systems that simplify OEM validation and increase barriers for pure‑play bracket suppliers.
What PW Consulting’s full report delivers
The full Worldwide Motorcycle Headlight Bracket Market report goes beyond this briefing to provide the actionable intelligence leaders need for 2026 execution:
- Validated market sizing and historic trends (2020–2025) and a detailed 2026–2032 forecast model incorporating scenario variants for material price shocks and regulatory tightening.
- Segmentation matrices across geography, material, sales channel and motorcycle type (note: this press briefing intentionally omits the proprietary segment breakdowns; the full datasets are included in the report).
- Detailed competitor dossiers for the primary OEMs, aftermarket champions and regional fabricators, with supplier scorecards, capacity maps and go‑to‑market positioning.
- Raw‑material exposure analysis with commodity stress tests and recommended hedging and sourcing strategies aligned to product portfolios.
- Regulatory compliance matrix, including implications of contemporary headlighting standards on mechanical design and certification timelines.
- Commercial playbooks for OEM sales, premium aftermarket launches and M&A screening templates tailored to acquirers and strategic buyers.
Actionable next steps for 2026 planners
- Commission a short, internal gap analysis comparing your current bracket portfolio against the certification and integration needs of prioritized OEM platforms and aftermarket segments.
- Run a supplier capability audit focused on CNC precision, materials traceability and testing capacity; identify two potential partners for pilot co-development of LED-integrated bracket assemblies.
- Evaluate acquisition targets that plug capacity or IP gaps; prioritize targets with documented quality systems and existing sales channels into the aftermarket communities you want to penetrate.
- Purchase the full PW Consulting report to unlock the proprietary segmentation datasets, granular regional demand curves and supplier scorecards needed to operationalize these recommendations.
In an industry at the crossroads of materials volatility, lighting technology change and evolving regulatory requirements, headlight brackets have graduated from commodity components to strategic assets. PW Consulting’s report equips executives with the evidence base and the implementation pathways to convert market momentum into defensible competitive advantage in 2026. For access to the full data tables, competitor models and downloadable forecasting tools, please visit our report page — the complete intelligence pack is available to subscribers and strategic partners.
For detailed analysis of this topic, please visit the official page: Worldwide Motorcycle Headlight Bracket Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Embedded Hypervisor Software Market to Rise from USD 565 Million in 2025 to USD 937.36 Million by 2032 at a 7.5% CAGR
By PW Consulting, 2026-08-12
Worldwide Embedded Hypervisor Software Market — Strategic Briefing for 2026 Decision Makers
PW Consulting’s latest market intelligence on the Worldwide Embedded Hypervisor Software market delivers a pragmatic, decision-oriented view for CTOs, product leaders, and procurement heads planning 2026 roadmaps. Built on a 2020–2025 historical baseline with 2025 as the reporting year and a 2026–2032 forecast horizon, the study documents a market that has expanded from mid‑hundreds of USD Million in 2020 to USD 565.0 Million in 2025 and is projected to approach roughly USD 937.4 Million by 2032 at a compounded annual growth rate (CAGR) of 7.5%. Alongside growth, the market exhibits measurable concentration — the top three vendors capture a majority share (CR3 ~54.8%), and the top five increase that footprint further (CR5 ~71.3%) — underscoring vendor-driven dynamics that matter to any buying or partnering strategy.
Worldwide Bibliographic Management Tool Market
Market dynamics in one paragraph
Embedded hypervisors are migrating from niche safety‑critical deployments into mainstream edge compute platforms as OEMs consolidate mixed‑criticality workloads, pursue functional consolidation in automotive ECUs and avionics, and add hardware acceleration for AI at the edge. The confluence of stricter certification demands (aviation and automotive), the arrival of new CPU architectures (Armv9, RISC‑V), and surging edge compute requirements is reshaping both buyer criteria and vendor roadmaps. At the same time, hardware constraints and certification obligations are raising the barriers to entry and favoring well‑capitalized suppliers with established safety toolchains and certification track records.
Portable Blood Tube Sealer Market
Why this report is strategically valuable for 2026
- Provides an evidence‑based growth outlook: clear topline trajectory and scenario implications through 2032 to inform multi‑year capital allocation and R&D prioritization.
- Translates compliance into a productization timeline: links DO‑178C DAL A, ISO 26262 ASIL D, ARINC 653 and IEC standards to practical implementation milestones and vendor selection criteria.
- Bridges architecture and procurement: clarifies how SoC choices (ARM with virtualization extensions, RISC‑V trends, or x86 VT‑x) materially affect partitioning strategy, real‑time determinism, and certification effort.
- Offers vendor and ecosystem insights: competitive positions and recent product moves that change integration risk and time‑to‑market.
What’s in the report (practical, actionable deliverables)
- Executive dashboards: topline market trajectories and concentrated vendor landscapes for boardroom briefings.
- Vendor scorecards and risk matrices: capability assessments across safety certification experience, real‑time determinism, multicore resource partitioning, supported architectures, and devtool ecosystems.
- Certification roadmaps: step‑by‑step cost, time and artifact requirements for DO‑178C, ISO 26262, IEC 62304 and IEC 61508 compliance when an embedded hypervisor is in scope.
- Hardware compatibility matrix: cross‑referenced virtualization extensions, SoC families, and recommended platforms for deterministic Type 1 partitioning.
- Migration playbooks: pragmatic approaches to move from legacy single‑OS ECUs or Type 2 host‑based virtualization to Type 1 separation kernels, including testbench templates and integration checkpoints.
- TCO and scenario models: three vendor‑agnostic total cost of ownership models (greenfield, brownfield, and safety retrofit) with sensitivity analyses on certification and SoC selection.
- Integration checklists: security hardening, partitioning validation, scheduling verification, and supply‑chain attestation requirements for procurement contracts.
- Go‑to‑market and partnership playbooks: prescriptive recommendations for ISVs, Tier‑1s, and semiconductor vendors seeking to accelerate adoption.
Competitive landscape — what the evidence shows
Our study profiles incumbent and specialist vendors and evaluates strategic moves that will affect 2026 supplier decisions. The market is dominated by established suppliers with deep certification credentials and productized toolchains, backed by a growing set of specialized entrants focused on narrow verticals or architectures.
Disposable Suture Grasper Closure Device Market
- Wind River — Long established in aerospace and defense, Wind River’s VxWorks 653 line remains a benchmark for DO‑178C projects. Recent product activity (VxWorks 653 v4) extends support to RISC‑V and Armv9, signaling vendor commitment to next‑gen silicon and enabling early adopters to evaluate migration paths off legacy architectures.
- Green Hills Software — With INTEGRITY‑178 and μ‑velOSity, Green Hills emphasizes determinism and partitioning for avionics and industrial systems. Their tooling tends to appeal to integrators that prioritize certifiability and a long tail of supported safety standards.
- Lynx Software Technologies — LynxSecure’s MILS‑style separation kernel is increasingly positioned for industrial and automotive use. Strategic partnerships with silicon vendors (e.g., NXP integration) strengthen its industrial applicability and shorten board bring‑up cycles.
- SYSGO — PikeOS presents a vertically diversified profile with certifications and product updates targeted at medical and industrial markets; a recent IEC 62304 Class C certification illustrates traction in regulated medical applications.
- Real‑Time Systems GmbH — Focuses on embedded virtualization across ARM and x86 with emphasis on real‑time partitioning, serving customers who require pragmatic, tightly coupled hypervisors for automotive and industrial IoT projects.
- BlackBerry QNX — QNX Hypervisor is a familiar choice for automotive platforms that require ISO 26262 ASIL D compliance and expanded support for heterogeneous system architectures — recent launches extend support for advanced edge accelerators.
- Mentor Graphics (Siemens EDA) — Offers virtualization tooling as part of a broader EDA and verification portfolio, attractive to aerospace and automotive OEMs looking to consolidate verification and hypervisor certification activities.
- ETAS (Bosch Group) — RTA‑Hypervisor targets multi‑OS automotive ECUs, with a strong ecosystem tie‑in to AUTOSAR and Bosch’s Tier‑1 relationships, making it a pragmatic pick for OEMs standardizing on AUTOSAR‑centric stacks.
Technology and regulatory guardrails that shape vendor choice
- Hardware prerequisites: Efficient Type 1 partitioning typically requires SoCs with virtualization extensions (e.g., Arm virtualization extensions such as those standardized around ARMv8/ARMv9 VE or equivalent RISC‑V extensions, or x86 VT‑x). In constrained devices, absent or partial hardware virtualization can nullify real‑time guarantees and complicate certification.
- Regulatory ceilings: Avionics projects remain governed by DO‑178C DAL A constraints for partitioning; automotive mixed‑criticality ECUs carrying safety functions must meet ISO 26262 ASIL D. These standards materially increase engineering overhead and favor vendors with prior certification artifacts and established toolchains.
- Standards for partitioning: ARINC 653 supplementation and time/space partitioning remain prescriptive for avionics, and vendors’ compliance with these API and partitioning models is a decisive procurement filter.
- Real‑time limitations of host‑based hypervisors: Type 2 hypervisors (hosted on a general‑purpose OS) exhibit scheduling latencies that routinely exceed strict sub‑millisecond deterministic requirements and are therefore unsuitable for hard real‑time functions without compensating architecture changes.
Topline strategic recommendations for 2026 planning
- Make certification a first‑class architectural constraint: choose vendors who can supply not just software but certification artifacts, gap analysis, and onboarding support to compress certification timelines.
- Lock hardware and hypervisor decisions early: the presence or absence of CPU virtualization extensions will drive partitioning strategy and test scope; evaluate Armv9 and RISC‑V pilots where long‑term silicon flexibility is a requirement.
- Prioritize vendors with broad ecosystem support: strong relationships with semiconductor suppliers, RTOS vendors, and AUTOSAR toolchains materially reduce integration risk.
- Use the report’s TCO scenarios to stress‑test procurement models: include long‑tail maintenance, safety patching, and certification revalidation costs in multi‑year budgets.
- Plan for a hybrid approach: for some programs a certified type‑1 hypervisor will be mandatory; for non‑safety compute on the same platform, consider hardened containers or secure enclaves to limit scope.
- Negotiate SLAs that reflect certification velocity: include vendor commitments on evidence delivery, support for audits, and indemnities where appropriate.
How to use the full PW Consulting report
This briefing intentionally omits granular regional and application splits and detailed per‑vendor scoring to preserve the utility of the full research package. The complete report includes the market segmentation by region, type and application, vendor benchmarking with weighted scoring, downloadable certification templates, hardware compatibility matrices, and editable TCO models intended for internal procurement and engineering teams. If your 2026 strategy depends on reliable timelines for certification, silicon selection, or supplier consolidation, the full dossier is designed as a plug‑and‑play resource into your product planning and sourcing processes.
To obtain the comprehensive dataset, vendor scorecards, and the operational playbooks referenced here, visit the PW Consulting report page or contact our industry practice. Our analysts stand ready to run a tailored supplier selection workshop or a certification readiness assessment aligned to your project calendars.
For detailed analysis of this topic, please visit the official page: Worldwide Embedded Hypervisor Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Worldwide Pseudomonas aeruginosa Treatment Market at USD 1,942.38 Million in 2025; Strong Growth Anticipated Through 2032
By PW Consulting, 2026-08-12
Worldwide Pseudomonas aeruginosa Infection Treatment Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Pseudomonas aeruginosa Infection Treatment Market delivers a rigorous, actionable intelligence package designed to support executive decision-making in 2026. Built on a harmonized dataset spanning 2020–2025 (base year 2025) and forward-looking projections through 2032, the report quantifies the market’s scale and trajectory — identifying structural growth drivers, competitive inflection points, and practical playbooks for market entry, portfolio prioritization, and M&A screening. In short: this is a strategy-first brief for those who must make bets on antibiotic portfolios, hospital supply chains, or specialist franchise expansion over the next 12–36 months.
Worldwide Polyurethane Elastomer Dispensing Equipment Market
Market Snapshot: Growth Trajectory and Concentration
The P. aeruginosa treatment market is mature yet dynamic. In 2025 PW Consulting estimates the global market size at approximately USD 1,942 million (base year). Our forecast models — incorporating demand-side drivers (hospital-acquired infection rates, antimicrobial stewardship policies, and adoption of novel agents) and supply-side realities (API availability, generics pressure, and reimbursement frameworks) — project compound annual growth of c. 5.5% over the 2026–2032 horizon. By 2032 the market is expected to be meaningfully larger than today, reflecting both persistent clinical need and gradual adoption of newer beta-lactam/beta-lactamase inhibitor combinations and novel siderophore cephalosporins in complex-care settings.
Worldwide Note-Taking Management Software Market
Market concentration is moderately high: the top three firms account for a substantial share of revenues, and the top five increase that share materially. This concentration underscores two realities for strategists: first, entrenched hospital relationships (formularies, stewardship committees, IV supply contracts) create defensible positions; second, innovators and generics players alike must pursue differentiated value propositions — whether through clinical evidence, unique formulations (e.g., inhaled or extended-infusions), or supply-chain resilience — to shift buying decisions.
Worldwide Amino Acetic Acid Market
What the Report Contains — Practical Modules for 2026 Planning
- Comprehensive market-size model from 2020 through 2032, including scenario testing against conservative, base, and accelerated adoption pathways (CAGR and sensitivity analyses furnished at the macro level to inform budgeting and valuation).
- Demand-driver analytics: incidence trends in hospital-acquired and community-associated P. aeruginosa infections, stewardship-influenced prescribing patterns, and country-level policy levers that materially affect uptake.
- Supply-side risk matrix mapping API concentration, route-to-market vulnerabilities for injectables and inhaled formulations, and cost-pressure scenarios for generics suppliers.
- Competitive playbooks synthesizing capabilities, pipeline awareness, and commercialization posture for the market’s leading players — enabling M&A prioritization, partnering windows, and defensive moves.
- Reimbursement and regulatory tracker that maps recent approvals, label expansions, and guideline shifts that have near-term impact on utilization.
- Actionable go-to-market roadmaps: formulary-access tactics, health-economics dossiers, and stewardship-aligned value-communication templates tailored to hospital pharmacy and infectious disease stakeholders.
Note: while the report demonstrates full granularity across regions, drug classes and indications to support tactical execution, this public summary intentionally omits core segment-level figures. Access to the detailed splits, product-level revenue forecasts, and granular regional scenario matrices is provided through the full report and associated data pack.
Strategic Implications for 2026
- Portfolio prioritization: Firms must weigh near-term revenue levers (generics and established beta-lactams) against longer-term value capture from novel agents. PW Consulting’s modelling shows that while generics sustain baseline volume, growth pockets center on agents positioned for difficult-to-treat resistant strains and on products backed by real-world evidence (RWE) in critical-care indications.
- Clinical evidence as a commercial differentiator: Recent real-world presentations and post-market surveillance (notably for newer siderophore and beta-lactamase inhibitor combinations) are accelerating formulary acceptance in complex-case pathways. Commercial teams should accelerate RWE generation and translate clinical narratives into stewardship-friendly economics.
- Supply resilience and manufacturing strategy: Given API concentration and the strategic role of injectable formulations in hospital supply chains, firms should secure backward integration options or multi-source suppliers and stress-test inventory policies to avoid costly product shortages that can erode hospital trust.
- Regulatory and guideline alignment: With IDSA guidance increasingly favoring newer β-lactam/β-lactamase inhibitors in difficult-to-treat cases, alignment of labeling, pharmacoeconomic evidence, and stewardship messaging will determine uptake velocity in tertiary-care centers.
Competitive Landscape — Who Matters and Why
The therapeutic landscape combines established multinationals with strong hospital channels, specialty developers of novel agents, and global generics manufacturers that sustain volume. PW Consulting’s qualitative and quantitative analysis highlights several archetypes and positioning opportunities:
- Large innovator pharmas (e.g., Pfizer, Merck, AstraZeneca, Novartis, Sanofi, Bristol Myers Squibb, Johnson & Johnson) : These firms retain advantages in hospital access, IV/inpatient marketing, and broad anti-infective portfolios. Their strategic choices — defensive line extensions, lifecycle management, or portfolio rationalization — will determine whether they maintain share or cede specialty niches to focused developers.
- Specialty antibiotic developers (e.g., Shionogi, AbbVie via Allergan portfolios) : These players are carving out differentiated positions with novel mechanisms (siderophore cephalosporins) and combination agents targeting carbapenem-resistant and difficult-to-treat phenotypes. Recent regulatory approvals and RWE presentations bolster their market narrative, particularly for stewardship committees evaluating alternatives to older agents.
- Generics and supply-chain specialists (e.g., Teva, Lupin, Baxter) : These firms underpin volume demand in many markets through established, cost-competitive offers for key antipseudomonal antibiotics and injectable delivery systems. Their importance will grow in price-sensitive settings, but competitive margin pressures require operational excellence and supply reliability.
Recent industry moves illustrate the strategic dynamics:
- Shionogi’s targeted real-world evidence campaigns (2025–2026) for cefiderocol have strengthened its clinical credibility in resistant Gram-negative contexts and underscored the commercial value of surveillance data in accelerating adoption.
- AbbVie’s regulatory traction for aztreonam–avibactam (EMBLAVEO) — including U.S. and European authorizations — expands the therapeutic toolkit for clinicians managing limited-option cases, reshaping therapeutic algorithms in tertiary centers.
- Regulatory approvals of generics for inhaled and injectable formulations (e.g., FDA approvals in 2025) underscore the persistent volume opportunity in chronic-care niches (e.g., cystic fibrosis lung infections) and reinforce pricing competition in mainstream hospital formularies.
Regulatory, Reimbursement and Guideline Forces
Regulatory clarifications and guideline endorsements are pivotal near-term determinants of product uptake. Recent regulatory activity — such as FDA recognition of CLSI standards for susceptibility testing and agency reassessments of polymyxin breakpoints — reduces clinical uncertainty and affects susceptibility reporting that clinicians rely on when selecting empiric therapy. Simultaneously, professional guideline bodies advocating preferential use of newer β-lactam/β-lactamase inhibitors in difficult-to-treat P. aeruginosa create commercial tailwinds for agents with robust coverage claims.
For payers and hospital procurement teams, the calculus is balancing higher up-front unit cost for novel agents against downstream savings from reduced length of stay, decreased mortality risk in complex infections, and avoided escalation to combination salvage therapies. The report provides templates for health-economic submissions to support formulary access and prioritizes metrics that stewardship committees find persuasive.
Practical Recommendations — What to Do in 2026
- For innovator firms: Accelerate RWE generation in defined clinical cohorts (e.g., hospital-acquired/ventilator-associated pneumonia, complicated intra-abdominal infections) and build stewardship-centered value propositions that quantify avoided escalation pathways.
- For generics players: Invest in manufacturing redundancy and tender-response capabilities; differentiate through service-level agreements to hospital pharmacies and bundled IV-care solutions.
- For private equity and M&A teams: Prioritize targets that provide either clinical differentiation (RWE-backed assets or novel mechanisms) or supply-chain control (API capacity, sterile injectable manufacturing). Use PW Consulting’s scenario models to stress-test post-deal value creation under pricing and adoption shocks.
- For hospital procurement and formulary directors: Employ the report’s decision frameworks to assess when to add newer agents for restricted use, and how to structure access criteria that align stewardship goals with clinical outcome improvements.
Why PW Consulting’s Report Matters for 2026
Executives must make near-term resource allocations in an environment of shifting clinical practice, regulatory nuance, and ongoing antimicrobial resistance pressures. This report translates those complexities into executable choices: prioritized investments, competitive defense and attack options, and concrete commercial tactics that align with stewardship frameworks. Our blended methodology — combining market-level forecasting, supplier-risk quantification, and competitor playbooks — provides actionable evidence without substituting for local clinical judgment.
To maintain the investigative “trailer” orientation of this release, we have showcased strategic takeaways and macro metrics (market scale in 2025 and CAGR through the forecast period) while reserving the detailed revenue-by-region, by-drug-class and by-indication matrices for subscribers to the full report. These granular datasets and downloadable model workbooks are the essential next step for teams that require pricing curves, country-level uptake timelines, and product-level revenue forecasts to finalize 2026 budgets and go-to-market plans.
Next Steps
Decision-makers ready to translate this insight into action can access the full report and data workbooks via PW Consulting’s official portal. The complete package includes the granular splits, customizable scenario tools, and an executive workshop option to align your commercial, medical affairs, and supply-chain leaders on a prioritized, 12–36 month plan.
Contact PW Consulting to schedule a briefing and receive a sample dataset excerpt that demonstrates the format of the full intelligence while preserving the confidentiality of proprietary segment detail.
For detailed analysis of this topic, please visit the official page: Worldwide Pseudomonas Aeruginosa Infection Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


