



Category: market research
PW Consulting: Worldwide Meso‑Micro Porous Carbon Materials Market Set to Expand at a 9.86% CAGR Through 2032
By PW Consulting, 2026-08-12
Worldwide Meso‑Micro Porous Carbon Materials Market — Strategic Insights for 2026 Decision‑Makers
PW Consulting’s new market study on Worldwide Meso‑Micro Porous Carbon Materials (base year 2025; forecast period 2026–2032) frames an actionable agenda for commercial leaders, technology strategists, and investors preparing for the next phase of industry evolution. The sector is moving from recovery to structural expansion: our model projects a compound annual growth rate (CAGR) of 9.86% across the 2026–2032 forecast window, with the market estimated at approximately USD 958.3 Million in 2025 and rising toward roughly USD 1,849.7 Million by 2032. These headline metrics reflect both demand acceleration in core end‑markets and ongoing supply‑side reconfiguration — a combination that will define winners and losers in 2026 and beyond.
Worldwide Chromium Sesquioxide Market
Why 2026 is a Strategic Inflection Point
-
Regulatory tightening and customer requirements are creating persistent, high‑value opportunities. Government actions on PFAS remediation and strengthened air emission standards have moved high‑performance adsorbents and engineered porous carbons from niche to strategic procurement items for municipal, industrial, and power‑sector buyers.
Embryo Holding Medium Market -
Raw material volatility that emerged through 2024–2025 (notably in coconut shell and coal feedstocks) continues to squeeze manufacturing margins and change sourcing calculus. At the same time, an industry pivot toward biomass‑derived precursors and specialty feedstock blends is already underway, reshaping cost curves and sustainability narratives.
Worldwide Media Monitoring Software Market -
Supply‑side investments and capacity moves announced in late 2025–early 2026 — including large reactivation/production expansions by incumbent suppliers — will relieve near‑term bottlenecks but introduce multi‑year timing risk. That creates a narrow window for commercially decisive actions such as offtake agreements, technology licensing, and targeted capex.
What this Report Delivers — Practical, Executable Intelligence
This is not a poster‑board survey. PW Consulting’s study combines proprietary bottom‑up modeling, supplier due diligence, and scenario stress‑testing to produce operational tools executives can use immediately. Key deliverables include:
-
A validated market size and forecast model (2020–2032) with scenario outputs calibrated to regulatory and feedstock pathways so you can stress‑test revenue and margin outcomes.
-
Segmentation frameworks (by geography, product type, and end‑use) with demand drivers and adoption curves mapped to technical requirements — presented to preserve strategic insights without disclosing tactical segment targets in this summary.
-
Supply‑chain cost modeling and a feedstock sensitivity engine that quantifies margin exposure to coconut, coal, and biomass inputs across grades and process routes.
-
An asset and capacity map covering announced expansions, reactivation potential, typical lead times, and commissioning risk profiles — enabling planning for production scarcity or surplus scenarios.
-
Vendor benchmarking scorecards (technical capability, quality control, regulatory readiness, specialty product suites), together with an M&A and partnership playbook that prioritizes targets and integration risks.
-
Commercial tools: customer procurement templates, pricing elasticity matrices, and product roadmaps tied to near‑term application pockets such as energy storage, catalysis, and water treatment.
Actionable Strategic Priorities for 2026
-
Secure feedstock optionality now. With feedstock price volatility and regional supply constraints, lock in diversified raw material channels and build contingency tariffs into procurement contracts. Our sensitivity tool shows how relatively modest input price changes propagate through to breakeven prices for key product grades.
-
Prioritize regulatory‑driven commercial plays. Treat PFAS remediation and tightened emission controls as multi‑year demand platforms where premium products can command a structural price premium — but ensure product qualification and regulatory documentation are in place before commercial outreach.
-
Revisit product portfolios through an application lens. The technical differentiation between highly ordered mesoporous carbon, template‑synthesized variants, and traditional activated carbons is material to buyers in energy storage and catalysis; prioritizing R&D investments that improve cycle life, throughput, and processability will unlock higher margins.
-
Use capacity announcements as timing signals — not guaranteed supply. Planned expansions reduce structural scarcity but are subject to feedstock and permitting risk. Contracts tied to milestone‑based supply guarantees are a pragmatic compromise for buyers and developers.
-
Build partnering options into commercialization plans. Licensing, joint R&D, and co‑development align risk and accelerate time‑to‑market for advanced electrode and membrane products; this is increasingly attractive to non‑traditional entrants seeking rapid exposure.
Competitive Landscape — Who to Watch and Why
The market features a mix of global incumbents and regional specialists with distinct strategic plays. Our report provides granular profiles; below is a concise strategic snapshot of leading participants and the moves shaping competitive dynamics.
-
Kuraray Co., Ltd. / Calgon Carbon Corporation — A top incumbent with broad product and channel reach. Recent capacity expansion commitments (announced early 2026) are explicitly aimed at drinking water and PFAS applications and will materially affect supply balances when brought online. Watch timing and reactivation yields closely.
-
Cabot Corporation (incl. Norit) — Deep experience in specialty carbons and engineered porous products, with a strong position in performance applications. Their R&D and formulation expertise make them a likely partner for advanced filtration and composite solutions.
-
Toyo Tanso Co., Ltd. — Differentiated by proprietary mesoporous platforms (CNovel®) and demonstrable battery‑electrode applications. Collaborative milestones with national laboratories and universities indicate a roadmap toward higher‑value, application‑specific membranes and electrodes.
-
Ingevity Corporation — Focused on high‑performance activated carbons and accelerating biomass feedstock pilots; their work highlights the economics of sustainable precursor integration.
-
Jacobi Carbons, Haycarb, Kureha, Donau Carbon, Carbotech, Carbon Activated Corporation — Regional specialists and niche suppliers that collectively provide the industry’s capacity diversity. Many maintain tight partnerships with local utilities, municipal buyers, and commodity chemical customers; they will be attractive consolidation targets for strategic buyers.
Cost and Supply‑Chain Dynamics to Monitor in 2026
-
Feedstock mix and availability: shifts from fossil to biomass precursors change both carbon yield and capex amortization profiles. Early movers who secure sustainable biomass sources will gain both margin resilience and marketing advantage.
-
Processing complexity vs. throughput: engineered mesoporous and template routes are capital‑intensive but command technical premiums. Optimization of process yield and reactivation cycles is where incremental profitability will be captured.
-
Tariffs and localization: policies encouraging domestic supply (including tariff‑free programs) will affect regional sourcing strategies and may favor localized manufacturing footprints for regulated end‑uses.
Where Value Will Be Created — Application‑Level Opportunities
Three application clusters will be the primary value engines through 2032:
-
Energy storage: demand for high‑surface, conductive mesoporous structures is rising as battery chemistries diversify. Breakthroughs in electrode fabrication (including self‑standing carbon membranes) are creating pathways from lab demonstration to commercial stacks.
-
Catalysis and chemical processing: controlled pore architectures improve active site accessibility and catalyst support performance—translating into process intensification and higher unit economics for specialty chemicals and refining applications.
-
Environmental remediation: industrial wastewater, municipal treatment, and air purification continue to be steady growth drivers where product qualification, regulatory validation, and certified supply chains matter more than price alone.
How Executives Should Use This Intelligence
-
Portfolio managers — deploy the report’s scenario suite to reweight R&D and capex pipelines against high‑probability regulatory and feedstock scenarios.
-
Procurement leaders — use the supplier scorecards and feedstock sensitivity analysis to renegotiate contracts and introduce indexed pricing clauses tied to validated raw material indices.
-
Corporate development teams — leverage the M&A playbook and target shortlists to accelerate inorganic moves in fragmented regional markets and to acquire technology gaps in ordered mesoporous carbons.
-
Product and commercialization teams — adopt the go‑to‑market templates and customer qualification checklists to shorten sales cycles in regulated verticals.
Final Notes — The Practical Edge PW Consulting Provides
This study is structured as a decision‑support toolkit rather than an academic catalog. It combines a validated market forecast (2020–2032), supplier‑level diligence, cost modeling, regulatory scenario analysis, and executable commercial playbooks designed to be integrated into 2026 strategic planning cycles. The narrative above intentionally highlights strategic inflection points while reserving the full segment‑level detail, vendor metrics, and downloadable modeling files for the complete report package.
For procurement models, supplier scorecards, and the complete dataset (including our downloadable Excel workbook and scenario drivers), consult the full report on the PW Consulting report page. Access to the proprietary datasets and the vendor‑level diagnostics will enable teams to move from strategy to executable tactics before market rebalancing accelerates later in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Meso-Micro Porous Carbon Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Data Center Optical Module Market to Soar from USD 16,479.05 Million in 2025 to USD 47,939.29 Million by 2032 at a 16.48% CAGR
By PW Consulting, 2026-08-12
Worldwide Data Center Optical Module Market — Strategic Preview for 2026 Decision‑Makers
PW Consulting’s latest market research, “Worldwide Data Center Optical Module Market (Base Year 2025): Strategic Outlook to 2032,” delivers a forward-looking synthesis intended to inform procurement, architecture, and investment decisions in 2026. The study frames a market that has transitioned from steady capacity upgrades to accelerated, AI‑driven refresh cycles: our model places the market at USD 16,479.1 Million in 2025 and projects expansion at a compound annual growth rate (CAGR) of 16.48% through the forecast horizon. By 2032 the market is forecast to surpass USD 47,900 Million — a scale that forces a fresh look at supplier strategy, supply‑chain resilience, and architecture trade‑offs for enterprises and hyperscalers alike.
Worldwide Candlenut Oil Market
Why this matters for 2026 strategy
-
Technology cadence is compressing. The migration to 400G, 800G and beyond (including pluggable 1.6T and coherent solutions) is no longer an over‑the‑horizon event — it is a procurement and design reality. Organizations that defer decisions on optical architecture face not only higher per‑port costs later, but also increased integration complexity as ports, optics, and switching fabrics evolve discontinuously.
Sustainable E-Fuel Market -
Capital allocation decisions must account for two correlated dynamics: steep unit performance improvements and a business environment that magnifies the cost of getting connectivity wrong (operational inefficiency, stranded assets, and regulatory friction). Our forecast quantifies the revenue trajectory that underpins these risks and opportunities, enabling CFOs and CTOs to stress‑test investment scenarios against realistic market growth paths.
Coupled Home Energy Storage Deployment Systems Market -
Supplier concentration and vendor roadmaps matter more. Leading vendors are investing aggressively in higher‑speed pluggables, coherent pluggables and DSP platforms — the competitive map is evolving from optics manufacturers to integrated silicon‑plus‑optics systems providers. Understanding that landscape is essential for long‑term sourcing and co‑development strategies.
Key market drivers and dynamics
-
AI workloads and hyperscale network densification: Training and inference clusters are driving higher lane rates, denser interconnects, and longer‑reach coherent deployments in some topologies. The result is faster adoption of higher‑bandwidth optics and pluggables designed for low latency and power efficiency.
-
Energy and operating cost pressures: Electricity routinely constitutes a material share of large data center operating expenses — industry analyses estimate energy can consume a very large portion of the operating budget, translating into millions in annual costs for large facilities. As optics influence total power per bit, optical module selection becomes a lever for both OPEX control and sustainability commitments.
-
Infrastructure and utility planning: Utilities in major markets are committing substantial capital to update grids in response to rising data center demand. That trend affects site selection timelines and long‑term operating assumptions for colocation and hyperscale operators.
-
Regulation and geopolitics: Export controls on advanced semiconductors and memories, coupled with data sovereignty policies, are reshaping sourcing and deployment strategies. Firms must overlay technology roadmaps with jurisdictional risk assessments to avoid costly retrofits or restricted markets.
Competitive landscape — what the report highlights (and what it withholds)
Our competitive analysis profiles the ecosystem across a spectrum: pure‑play optics manufacturers, photonics‑enabled semiconductor companies, integrated networking vendors, and system houses that bundle optics with racks and switching. Rather than publish exhaustive share tables in this executive summary, we emphasize strategic positions and capability sets that matter to buyers in 2026.
-
China‑based high‑speed optics leaders: Vendors with volume shipments into hyperscale cloud and AI clusters have moved from niche to mainstream, leveraging scale and close customer engagement to accelerate product iterations for 400G/800G and higher. Their commercial models and supply strategies have implications for global procurement and qualification timelines.
-
U.S. photonics and semiconductor incumbents: Companies that combine DSP, coherent technology and module assembly provide differentiated higher‑value solutions for long‑reach and high‑bandwidth interconnects. Recent platform expansions in 1.6T DSPs indicate an emerging class of vendor that can supply tightly integrated silicon‑to‑module stacks optimized for AI workloads.
-
Networking OEMs and system integrators: Network equipment vendors remain critical partners for enterprises seeking integrated optics that are qualified with switching platforms. Their role in standards, form‑factor adoption and lifecycle support should be a primary consideration in sourcing decisions.
-
Specialist single‑source suppliers: Several firms continue to win large, targeted orders for hyperscale customers, demonstrating the commercial importance of performance, service and supply predictability over simple price competition.
Illustrative recent developments from across the vendor landscape underline these dynamics: an upsized order for 800G single‑mode transceivers to support hyperscale AI workloads (April 2026); the expansion and sampling of next‑generation 1.6T optical DSP platforms (March 2026); demonstrations of higher‑lane‑rate TIAs and drivers and new pluggable modules aligned with PCIe 6.0 (OFC 2026); and announcements of upcoming 1.6T pluggable products targeted at AI and HPC clusters. Each development signals a step‑function improvement in available capacity and a compression of the vendor qualification cycle for early adopters.
Risks, constraints and non‑technical considerations
-
Supply‑chain and export controls: Advanced optics increasingly rely on high‑end semiconductor and photonic components subject to export controls. Procurement teams must integrate compliance reviews into vendor selection and consider dual‑sourcing or design‑win strategies that mitigate jurisdictional risk.
-
Power and sustainability constraints: The projected trajectory of data center electricity demand in major markets suggests infrastructure constraints could become a gating factor for deployment timing. Organizations need to coordinate optical upgrades with power supply plans and engage early with utilities and colocation partners.
-
Standards fragmentation and interoperability: The proliferation of form factors and lane‑rate options presents integration complexity. Enterprises should emphasize cross‑vendor interoperability testing in launch plans to reduce field failures and cascading upgrade costs.
-
Concentration of commercial power: Top vendors command meaningful commercial influence. Negotiation strategies must reflect not only price but roadmaps, co‑development options, and capacity commitments.
What PW Consulting’s report delivers for practitioners
This report is designed as an operational toolkit — not a theoretical essay. Key deliverables include:
-
Scenario‑driven demand models that map optical unit demand to server, switch and AI accelerator deployment plans (2026–2032), allowing you to stress test CapEx profiles against multiple performance trajectories.
-
Vendor capability maps and qualification checklists tied to procurement timelines — enabling procurement teams to prioritize interoperability tests, lead times and service‑level expectations.
-
Implementation playbooks for common transformation paths (incremental upgrade, targeted bolt‑on for AI pods, and full‑scale refresh), with stepwise checklists for validation labs, power planning and software integration.
-
Risk matrices that combine geopolitical, regulatory and energy constraints with mitigation options — from localized sourcing and capacity hedging to contractual protections and contingency inventory strategies.
-
Decision templates for C‑suite and board briefings that translate optical market trajectories into financial KPIs and ROI sensitivities.
Actionable recommendations for 2026
-
Adopt a modular optics strategy: Prioritize pluggable, vendor‑agnostic modules where feasible to reduce long‑term lock‑in and enable incremental upgrades aligned to compute density.
-
Integrate energy impact into procurement criteria: Evaluate optics on energy per bit and total system power, not only on unit price, to avoid hidden OPEX escalation and to meet ESG goals.
-
Pursue multi‑vector supplier engagement: Combine large incumbent vendors for long‑reach and coherent needs with agile suppliers for dense, short‑reach deployments. Contract language should address capacity assurance and export compliance.
-
Trigger early coordination with utilities and facility planners: Align optics upgrade timelines with confirmed power expansions and resilience plans to avoid schedule slippage and stranded costs.
-
Invest in interoperability validation: Allocate budget and lab cycles for cross‑vendor testing before scale rollout to shorten mean time to production and reduce integration risk.
How to use this preview
This release is a strategic preview designed to surface the implications of a rapidly expanding market — and to demonstrate the practical, transaction‑ready intelligence you will find in the full study. It highlights the macro trajectory (base year 2025, USD 16.48 billion; projected CAGR 16.48% through 2032) and outlines the vendor and operational themes that should inform boardroom and procurement decisions in 2026. Readers who require the detailed numeric splits, regional and application breakdowns, vendor share tables and downloadable decision templates should consult the full report on our website.
PW Consulting’s analysts are available to brief boards, procurement committees and systems architects on customized scenarios derived from the full model. Contact information and an executive summary download are available on the report page.
For detailed analysis of this topic, please visit the official page: Worldwide Data Center Optical Module Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Heated Fabric Market to Heat Up — Projected 13.62% CAGR Through 2032
By PW Consulting, 2026-08-12
PW Consulting Releases Strategic Brief: Worldwide Heated Fabric Market Outlook — Essential Intelligence for 2026 Decision-Making
Compressed insight. Actionable guidance. Data-led strategy — without giving away the playbook.
PW Consulting today publishes the executive brief for its new Worldwide Heated Fabric Market research, designed to equip senior leaders with the strategic perspective required to make high‑stakes product, investment, and supply‑chain decisions in 2026. The market for heated fabrics has moved from a niche technology to a commercially scaled platform across apparel, automotive interiors, medical devices, home textiles and industrial systems. Our analysis traces the market’s growth trajectory, the forces reshaping value chains, and the practical next steps for corporates and investors — while deliberately reserving the detailed segment matrices to the full report and downloadable datasets.
Ultra-Wideband Chip Market
Market trajectory: robust growth, increasing scale
Using a comprehensive historical base (2020–2025) and a focused forecast window (2026–2032), PW Consulting models the heated fabric market in USD (revenues expressed in Million). The market expanded rapidly through 2020–2025, and our base-year view (2025) captures a significant inflection point as manufacturing readiness, materials innovation, and product‑market fit converged.
Differential Interference Contrast Microscopy Market
- Our topline projection uses a compound annual growth rate (CAGR) of 13.62% across the forecast horizon and shows the market moving from a mid‑hundreds million USD sector in 2025 into the low billions by the end of the forecast period (revenues presented in Million USD in the full report).
- This pace reflects parallel drivers: more efficient heating element technologies, wider adoption in mobility and medical applications, and increasing availability of certified, series‑production ready components.
Why 2026 is a strategic inflection year
2026 sits at the junction of product maturation and adoption scaling. Three converging dynamics will determine winners and losers this year and beyond:
Worldwide Brand Data Management Software Market
- Material substitution and cost dynamics. Advances in conductive yarns, metal coatings, and low‑loading nanomaterials (including graphene integration) are changing product cost structures and design tradeoffs. These materials trends shorten time‑to‑market for differentiated thermal performance while shifting supplier risk upstream.
- Regulatory and safety certification. The emergence of certified, production‑grade heating elements has lowered a key barrier for inclusion in regulated segments such as medical devices and passenger vehicle interiors.
- Supplier concentration and modularization. The market shows a moderate level of top‑player concentration (our market concentration metrics indicate mid‑range CR3 and CR5 values), meaning strategic partnerships and supplier diversification will be critical for OEMs planning scale-up in 2026.
Practical report content — what leaders will find inside
PW Consulting’s full report is designed as a working tool for corporate strategists, R&D heads, procurement teams and investors. Key practical deliverables include:
- Topline market model (historical and forecast, 2020–2032) with downloadable time-series in Million USD and scenario variants for conservative, base, and accelerated adoption.
- Commercial playbooks for the most relevant end‑use vectors (apparel, mobility, medical, home and industrial), each with go‑to‑market options, unit economics templates, and product roadmaps tailored to differing regulatory regimes.
- Supply‑chain maps and supplier risk heatmaps — identifying strategic raw‑material exposures, qualifying criteria for manufacturing partners, and practical mitigation levers for 2026 procurement cycles.
- Technology assessment and TRL (Technology Readiness Level) grading for major heating approaches, including carbon‑based, metal‑based, and conductive polymer solutions; plus guidance on test protocols and design‑for‑manufacturability.
- Commercial diligence checklist for M&A, JV and licensing opportunities: what to validate in technical due diligence, IP mapping, and integration planning.
- Investor annex with valuation comparables, margin expectation bands, and a prioritized list of near‑term targets for strategic partnerships and bolt‑on acquisitions.
Note: while the brief above highlights the areas of analysis, we intentionally omit detailed micro‑splits (regional shares, type and application breakdowns, and per‑segment revenue tables) from this press release to preserve the research value of the full dataset available via PW Consulting’s portal.
Competitive landscape — who matters now
The heated fabric ecosystem is populated by a mix of specialist fabric engineers, e‑textile innovators, and component suppliers. Our competitive analysis focuses on firms that are shaping design standards, certification pathways, and high‑volume manufacturability:
- Embro GmbH (Falkenstein/Auerbach, Germany) — A specialist in custom heated textiles and smart e‑textiles with a strong series‑production orientation. Recent developments include VDE‑certified heating elements and flexible heating mats and tapes (April 2026), which materially improve electrical safety compliance and reduce time to production for OEMs targeting European and export markets.
- Gustav Gerster GmbH & Co. KG (Gerster TechTex; Biberach an der Riß, Germany) — Known for carbon‑fiber and copper solutions that emphasize fast heat‑up and high drapeability, making them attractive for embedded, form‑fitting applications where wearer comfort and uniform heating are priorities.
- LOOMIA Technologies Inc. (Brooklyn, NY, USA) — Developer of flexible electronic layers and TPU‑based resistive heaters. LOOMIA’s Gentoo Textile Heater (announced January 2025) and its subsequent push into energy‑efficient integration for automotive interiors (Feb 2026) illustrate a dual strategy: ruggedized performance for extreme environments and OEM‑friendly integration pathways for mobility clients.
- QuantumTex / UMATECO (Taiwan) — A vertically integrated supplier offering design‑to‑shipping services for wearable heated systems, useful for brands seeking rapid prototyping combined with manufacturing scale.
- Rockleigh Industries Inc. (USA) — Focused on graphene‑based conductive heating textiles with very low graphene loading, enabling lightweight, uniform heating solutions that are attractive where weight and flexibility are central constraints.
Strategic takeaway: 2026 winners will be those that combine certified, manufacturable heating modules with robust integration services, or those that control upstream conductive‑material supply to gain margin and differentiation.
Raw‑material and supply considerations to watch in 2026
Upstream markets are moving quickly and have direct implications for product costing and scalability. A few synthesis points from our upstream scan:
- Conductive textiles and electrically conductive fabric markets are expanding in parallel, creating both upstream demand competition and opportunities for vertically oriented players to capture margin. These upstream markets include metal‑coated yarns, silver plating, and carbon‑based solutions — each with distinct cost and performance tradeoffs.
- Nanomaterial and graphene integration at extremely low loading levels is enabling new form factors that were previously impossible; however, this also introduces quality control and sourcing nuances that must be managed through tightened incoming inspection and supplier qualification protocols.
- Certification regimes (electrical safety, flammability, laundering durability) are crystallizing buyer requirements in regulated applications. Manufacturers that can document certified heater modules will have a commercial edge in medical and mobility sectors.
How to use this research in 90 days
For executives preparing 2026 plans, PW Consulting recommends a three‑track approach that our report operationalizes with templates and prioritized action checklists:
- Quick wins (0–90 days): run supplier risk triage, validate critical raw‑material contracts, and initiate pilot certifications on targeted SKUs. Use our supplier qualification checklist to compress negotiation cycles.
- Mid‑term (3–9 months): lock in design‑for‑manufacturing decisions, pilot automotive or medical integrations with certified heater modules, and confirm volume pricing bands with multiple qualified vendors.
- Strategic (9–18 months): evaluate bolt‑on acquisitions for supply security or technical capability (especially in conductive yarns or graphene processing), and establish long‑term OEM partnerships for embedded heated interiors or medical device production.
Closing — the value proposition of PW Consulting’s heated fabric report
PW Consulting’s Worldwide Heated Fabric Market research delivers the market sizing, competitive intelligence, and operational tools executives need to make confident decisions in 2026. The analysis is intentionally structured as a “trailer”: we disclose the market trajectory, the strategic inflection points, and the practical actions you must consider — while reserving the granular segment tables and downloadable models for the full report package.
For access to the complete dataset, downloadable financial models, supplier lists, and tailored advisory engagements, follow the link to PW Consulting’s Heated Fabric Market page or contact our industry team for a briefing and bespoke scenario analysis.
For detailed analysis of this topic, please visit the official page: Worldwide Heated Fabric Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Furniture Installation & Relocation Services Market Poised to Grow at a 5.45% CAGR, New Insights Report Reveals
By PW Consulting, 2026-08-12
Worldwide Furniture Installation and Relocation Service Market: Strategic Outlook for 2026
PW Consulting’s latest market study — the Worldwide Furniture Installation and Relocation Service Market — provides a concise, action-oriented playbook for executives making 2026 investment, procurement, and operational decisions. Grounded in a 2025 base-year assessment and a detailed 2026–2032 forecast, the report projects continued expansion at a compound annual growth rate (CAGR) of 5.45%. The global market grew to approximately USD 1,650 Million in 2025 and is forecast to reach about USD 1,740.8 Million in 2026, with a steady climb toward an estimated USD 2,400.2 Million by 2032. These topline trajectories matter: they establish the scale of opportunity and the tempo at which strategy must evolve.
Worldwide Patient Relationship Management (PRM) Software Market
Why this report matters for 2026 decision-makers
- Translate macro growth into executable moves: the report connects market-level growth assumptions to concrete go-to-market and cost levers that alter near-term profitability.
- De-risk workforce and regulatory exposure: operators and buyers can test workforce models against regulatory scenarios that are now material to service economics.
- Identify high-impact digital and operational investments: the analysis prioritizes technology, process, and partner changes that deliver measurable ROI within 12–24 months.
- Support M&A and portfolio strategy: private equity and corporate development teams gain an evidence base for roll-up targets, valuation multiples, and integration roadmaps.
What the report delivers (practical, actionable content)
- Market sizing and scenario modelling — base-year 2025 benchmarks, 2026–2032 forecasts, and sensitivity runs for labor and fuel cost shocks.
- Buyers’ decision framework — procurement scorecards, SLA templates, and a total cost of ownership (TCO) calculator to compare incumbents, platforms, and asset-heavy providers.
- Vendor diagnostic — standardized scorecards and a decision matrix to evaluate platform marketplaces, franchise movers, and rental/installation specialists.
- Operational playbooks — step-by-step process maps for installation, in-store fulfilment, last-mile relocation, reverse logistics, and decommissioning.
- Workforce and compliance toolkit — recruitment and retention levers, training curricula, safety checklists aligned to prevailing standards, and scenario planning for gig-worker classification changes.
- Technology roadmap — prioritized investments across booking, dispatch, routing optimization, telematics, digital invoicing, and customer experience.
- M&A screening and integration checklist — criteria to identify platform+asset combinations, integration cost envelopes, and pressing post-close priorities.
Market dynamics shaping 2026 strategy
Three structural dynamics should shape every 2026 decision: labor economics, regulatory risk, and technology-driven productivity gains.
Biotin Binding Plate Market
- Labor economics — wage pressure is real and persistent. In the United States, hourly wages for furniture installers and movers averaged approximately USD 18.50 in 2024 (US Bureau of Labor Statistics). Operators that treat labor as the primary cost driver will see margin volatility if they cannot capture productivity gains or redesigno service delivery.
- Regulatory risk — classification and safety standards have material impact on operating models. For example, OSHA’s safe handling and storage rules are an operational baseline for injury prevention and insurance costs, and state-level employment classification rules (notably laws that reclassify gig workers) introduce legal and cost uncertainty into platform-based models.
- Automation and productivity — demand-side growth is accompanied by supply-side automation (routing, mechanized handling, and digital assembly guides). The US Bureau of Labor Statistics projects modest employment growth for furniture movers through the coming decade, as automation and efficiency reduce the labor intensity per transaction. Strategic adopters of productivity tools will widen the margin gap.
Competitive landscape: what incumbents and platforms are doing
The market remains structurally fragmented — concentration metrics show that the largest three and five providers capture a relatively small share of global revenues. This fragmentation creates both competitive pressure and consolidation opportunity.
Worldwide Laser Hair Loss Hat Market
- TaskRabbit (San Francisco) — a platform that connects local Taskers to consumers for assembly and installation. Strengths: flexible labor pool and strong consumer brand. Risks: exposure to worker-classification policy shifts and the need for stricter quality controls as enterprise demand grows. ( https://www.taskrabbit.com)
- Handy (New York) — an on-demand platform with an emphasis on urban coverage and recurring service flows. Strengths: urban penetration and booking convenience. Risks: margin sensitivity to gig economics and competition from hybrid models. ( https://www.handy.com)
- Thumbtack (San Francisco) — a marketplace for hiring local pros, with a focus on vetting and matching. Strengths: lead-gen model that scales with SEO and marketing. Risks: limited control over delivery quality without deeper platform integration. ( https://www.thumbtack.com)
- Angi (Denver) — an established directory and booking service for vetted contractors. Strengths: brand recognition and legacy local contractor relationships. Risks: transitioning legacy users to standardized digital SLAs. ( https://www.angi.com)
- CORT Furniture Rental & Delivery (Chantilly) — an asset-heavy rental and delivery player that bundles installation with rental contracts. Strengths: integrated revenue streams and predictable lifecycle management. Risks: capital intensity and geographic roll-out complexity. ( https://www.cort.com)
- Two Men and a Truck (Atlanta) — a large franchised moving network with deep local footprints. Strengths: extensive local capacity and established commercial moving capabilities. Risks: franchise consistency and digital uplift needed to remain competitive in urban last-mile services. ( https://twomenandatruck.com)
- Bellhop (Nashville) — a tech-enabled mover focusing on efficiency and customer experience in metro markets. Strengths: modern UX and optimized local operations. Risks: scale limitations outside dense US markets without capital investment or partnerships. ( https://www.getbellhops.com)
Strategic imperatives for 2026 — what leaders should do now
We distill the report’s recommendations into high-impact moves that shift outcomes within 6–18 months.
- Decide your labor model deliberately: pilot employee-based crews in select markets while keeping a vetted gig pool for overflow. Prepare contingency plans for gig-worker classification changes and quantify their P&L impact.
- Invest in routing and scheduling optimization first: modest tech investments in dispatch and load planning reduce mileage and labor hours materially and pay back faster than large capital outlays.
- Standardize productized service bundles: convert bespoke quotes into modular offerings with clear SLAs, pricing bands, and consumable parts lists to reduce quoting friction and speed execution.
- Prioritize safety and compliance as a competitive moat: adherence to material handling and workplace safety standards lowers insurance costs and protects brand reputation—embed this in procurement scoring.
- Pursue selective M&A and partnerships: consolidation opportunities exist where software-enabled platforms can be combined with local asset-heavy operators to capture both scale and margin.
- Design outcome-based contracts for large buyers: facilities and retail customers increasingly prefer outcome or subscription models (e.g., guaranteed install times, no-damage commitments) — build contractual playbooks and monitoring metrics.
- Embed sustainability and reverse logistics: circular-furniture flows and decommissioning services are differentiators for enterprise and public-sector buyers concerned with ESG targets.
A tactical 90-day plan for executives and investors
- Day 0–30: Run a quick P&L stress-test applying upside/downside wage and fuel scenarios from the report’s sensitivity models; identify two cost levers to protect margins.
- Day 30–60: Launch a one-market tech pilot (routing + mobile job aid) targeted at reducing average job time; measure delta in labor hours per job.
- Day 60–90: Negotiate a pilot enterprise contract with outcome-based SLAs and include a clause for joint data sharing; simultaneously screen three M&A targets using our roll-up rubric.
Conclusion — why now, and where to find the full playbook
Growth in the furniture installation and relocation market is steady and measurable: a clear multi-year runway exists, but it will be captured by firms that align labor strategy, regulatory planning, and targeted digitization. The market’s fragmentation and the projected mid-single-digit CAGR create both defensive and offensive strategic choices for 2026. PW Consulting’s full report supplies the granular segmentation, interactive models, and company scorecards necessary to convert these insights into executable plans.
For executives evaluating investment decisions, procurement leaders standardizing vendor programs, or private equity teams building roll-up strategies, the full report contains the detailed breakouts, proprietary vendor assessments, and downloadable tools that are intentionally withheld here to preserve source value. Visit PW Consulting’s report page to access the complete dataset, segmented forecasts, vendor scorecards, and downloadable TCO models that will inform your 2026 playbook.
For detailed analysis of this topic, please visit the official page: Worldwide Furniture Installation and Relocation Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Car Body Repair Market Set to Reach USD 263,010 Million by 2032
By PW Consulting, 2026-08-12
Worldwide Car Body Repair Market 2026 Outlook: Strategic Imperatives for Executive Decision-Making
PW Consulting’s latest market intelligence brief — the Worldwide Car Body Repair Market — provides an executive-grade, actionable roadmap for operators, suppliers, insurers, and private equity investors preparing for strategic allocation decisions in 2026. Drawing on a five‑year historical base (2020–2025) and a forward-looking forecast to 2032, the study combines market sizing, competitive diagnostics, cost-curve analysis, and operational playbooks to help leaders prioritize investments, M&A, and capability development as vehicle parc complexity and electrification accelerate service requirements.
Worldwide Automotive Shark Fin Antenna Market
Market at a Glance: macro trajectory and what it means for 2026
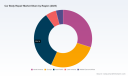
After navigating pandemic-era shocks and mid-cycle supply disruptions, the global car body repair market reached roughly USD 206 billion in 2025. Our modelling projects a steady compound annual growth rate of approximately 3.55% through 2032, taking the market toward the high‑$200 billions by the end of the forecast horizon. That moderate, sustained growth masks important structural shifts: rising repair severity driven by multi‑material bodies and ADAS complexity, upward pressure on refinish and consumables pricing, and an ongoing consolidation among multi-shop operators (MSOs) and franchised networks.
Worldwide L-Glutamic Acid Market
For 2026 planning cycles, those dynamics translate into three immediate strategic imperatives: (1) accelerate EV‑capable and ADAS recalibration readiness, (2) optimize network footprint and parts sourcing to defend margin against rising labor and materials costs, and (3) calibrate M&A and partnership activity to capture scale benefits while managing integration risk.
Worldwide Cleats Shoes Market
Why this report matters for 2026 decisions
- Data-driven trade-offs: The analysis quantifies the trade-offs between investing in specialized EV equipment and training versus pursuing scale through acquisitions or franchise expansion. We provide scenario modelling that maps incremental capex and operating cost reductions to margin outcomes across realistic demand trajectories.
- Operational playbooks: The report distils best-practice SOPs for ADAS calibration, high‑voltage system safety, and mixed-material structural repair — addressing both technician flow and liability controls that are essential to insurer and OEM relationships.
- Commercial levers: We outline contract templates and negotiation strategies for fleet and insurer partnerships that reflect current cost pressures (labour and refinish materials) while protecting service levels and warranty compliance.
- M&A & network optimization tools: Practical checklists and valuation frameworks help acquirers and sellers separate “scale with margin uplift” opportunities from add‑on deals that risk margin erosion due to legacy underinvestment in tooling and training.
Key industry dynamics shaping strategy in 2026
- Labor and repair economics: Labor rates and technician availability are central to repair economics. In the U.S., for example, average labor rates reached approximately $120–$160 per hour in 2025, with the typical collision job costing in the neighborhood of $4,700. These figures make labor productivity, cross‑training, and retention programs high‑yield focuses for operators and their investors.
- Raw material and refinish inflation: Paints and related materials experienced meaningful price inflation in early 2025 — suppliers announced increases in the order of mid‑single digits — shifting margin back to suppliers and requiring operators to rework pricing and inventory strategies.
- Vehicle complexity and EVs: Rising use of high‑strength steel, aluminum and composites — coupled with the rapid adoption of battery electric vehicles — is increasing repair severity and the requirement for specialized equipment and certification. OEM mandates for EV safe‑work procedures and ADAS recalibration are forcing shops to adopt new protocols or risk exclusion from OEM networks and insurer-approved panels.
- Regulatory and parts sourcing environment: Right‑to‑repair and state‑level aftermarket parts legislation continues to evolve, influencing parts-sourcing flexibility and the economics of used/recycled parts versus new OEM or aftermarket components.
Competitive landscape: what separates winners from followers
The market remains relatively fragmented with significant opportunity for scale economies. The competitive map includes three overlapping clusters:
- Large MSOs and consolidators: Networked multi-shop operators are pursuing roll-up strategies to capture standardized processes, centralized procurement advantages, and insurer relationships. Recent transactions — including major MSO-to-MSO deals and targeted acquisitions of specialty providers (for example, mobile repair assets) — reflect an acceleration of this consolidation trend.
- Franchised and independent networks: Franchise systems and independent shop chains emphasize local brand strength, fixed‑cost discipline, and standardized quality controls to retain insurer panels and fleet contracts. Their strategic choices are often between deeper franchisor support (training, digital tools) or selective alliances with suppliers and distributors to improve procurement terms.
- Material and technology suppliers: Refinish and consumables manufacturers, adhesive specialists, and parts distributors are repositioning from pure suppliers to integrated-service partners — offering training, certification programs, and digital color‑matching or inventory solutions to lock in long‑term demand.
Representative companies in the ecosystem illustrate these dynamics. Large MSOs and chains are actively growing through acquisitions and partnerships to capture capacity and fleet capability. Leading paints and materials companies continue to invest in formulations and systems for faster cure times and improved color matching — important operating levers for shops trying to increase throughput. Parts distributors and PDR specialists provide tactical capabilities that many operators use to reduce cycle time and claim severity.
Recent developments to watch
- Significant MSO acquisitions in late 2025 and early 2026 underscored the urgency for scale and fleet service capability — acquisitions included mobile and multi‑city operators that expand fleet servicing footprints.
- Industry forums in 2026 highlighted rapid adoption of AI tools, faster applied learning models for technicians, and the emergence of EV‑specific repair certification programs — all creating short windows for first‑mover advantage.
- Ongoing refinish price actions and evolving right‑to‑repair rules continue to alter gross margins and parts strategies; operators that lock in favorable supplier terms and master used-parts channels will retain a structural cost edge.
How the report translates into 2026 actions — a practical checklist
- Prioritize certification & safety investments: Create a two‑year roadmap for EV and ADAS readiness that sequences safety training, calibration infrastructure, and liability protocols so your sites qualify for OEM and insurer panels.
- Recast supplier partnerships: Renegotiate refinish and consumables contracts using volume‑based, demand‑smoothing structures and vendor training commitments to shield margins from raw material spikes.
- Sharpen pricing & segmentation: Implement differentiated pricing for complex, multi‑material repairs and for vehicles requiring high‑voltage or ADAS work; align commercial terms with insurers and fleet partners to preserve throughput incentives.
- Design M&A and integration playbooks: Use standardized due diligence templates focused on tooling, technician certification levels, and retrofit capex estimates; require integration plans that deliver realized procurement synergies within 12 months.
- Invest selectively in digital & AI tools: Deploy AI‑enabled estimating and scheduling platforms to reduce cycle time and improve capacity utilization, while piloting predictive maintenance offerings for fleet customers.
- Strengthen workforce pipelines: Create partnerships with technical schools and offer apprenticeship pathways tied to certification milestones to reduce hiring friction and lower training cost-per-technician.
Report contents — what executives will find inside
PW Consulting’s report blends strategic narrative with tools you can use immediately in board and operating reviews. Key deliverables include:
- Market sizing and validated demand scenarios through 2032, with sensitivity analyses tied to EV penetration and ADAS complexity assumptions.
- Competitive benchmarking and capability matrices for leading MSOs, franchisors, suppliers, and parts distributors, including M&A transaction profiles and integration risk checklists.
- Operational playbooks for EV-safe repairs, ADAS recalibration workflows, and rapid color refinish processes — each translated into capex and training templates.
- Commercial frameworks for insurer and fleet contracting, pricing playbooks for emerging high‑severity repairs, and distributor negotiation models to defend gross margin.
- Investor-focused dashboards: value creation levers, sensitivity to labor and materials inflation, and post‑deal integration milestones tied to return forecasts.
Conclusion — positioning for the next strategic inflection
The car body repair ecosystem is entering a transitional period where incremental investments in equipment, training, and digital tools will differentiate winners from followers. With a market that reached roughly USD 206 billion in 2025 and is projected to grow at a mid‑single‑digit CAGR through 2032, stakeholders who move decisively on EV readiness, network optimization, and supplier partnerships will secure durable margins and attractive growth vectors.
PW Consulting’s Worldwide Car Body Repair Market report is designed as a decision‑grade tool for 2026 strategy cycles: it delivers the strategic clarity, operational playbooks, and scenario models leaders need — while preserving proprietary granular splits and model assumptions for clients who require the complete dataset and customized advisory support.
To access the full dataset, regional and service-level breakouts, and bespoke advisory options, visit the PW Consulting report page or contact our industry team for a briefing and tailored implementation roadmap.
For detailed analysis of this topic, please visit the official page: Worldwide Car Body Repair Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Pet Food Delivery Market Poised to Hit USD 13,043.27 Million by 2032, Expanding at a 10.51% CAGR
By PW Consulting, 2026-08-12
Worldwide Pet Food Delivery Market — Strategic Briefing for 2026 Decision-Makers
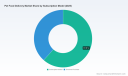
PW Consulting’s latest market study, the Worldwide Pet Food Delivery Market (base year 2025; historical 2020–2025; forecast 2026–2032), delivers the commercial intelligence senior leaders need to set strategy for the next three planning cycles. The market has demonstrated consistent expansion through the last half-decade and, with a compounded annual growth rate of 10.51% over the forecast period, is set to more than double in value by the end of 2032 versus the start of this decade. The data and analysis in this briefing synthesize that growth trajectory into clear, executable directions for product, channel and operational investments in 2026.
Worldwide Pre-lit Artificial Christmas Tree Market
Market snapshot and trajectory
Our bottom-up revenue model shows the pet food delivery market evolving from a nascent combination of subscription and ad-hoc channels into an integrated delivery ecosystem. Measured in USD million, the market nearly doubled between 2020 and 2025 and continues on an accelerated growth path through 2032. This expansion is underpinned by three durable shifts: (1) rising consumer willingness to pay for convenience and tailored nutrition; (2) improvements in cold-chain and fulfillment economics supporting fresh and refrigerated SKUs; and (3) channel convergence between direct-to-consumer brands, retail subscription offers and grocery/aggregator same‑day delivery.
Worldwide Pusher Furnaces Market
Competitive structure remains moderately fragmented: the top three firms account for roughly a third of market revenues while the top five approach the mid‑40s in percentage concentration, signaling both room for national-scale consolidation and attractive niches for digitally native challengers.
Biodegradable Magnesium Drug Eluting Stent System Market
Key demand and supply dynamics shaping 2026
- Subscription maturation: Cohort analysis shows that subscription models have moved beyond retention by discounting; leading programs now optimize replenishment cadence, bundling and personalization to increase lifetime value.
- Premiumization and personalization: Fresh, bespoke and veterinarian‑formulated offerings continue to outpace commodity kilos by margin, requiring new fulfillment strategies and SKU lifecycle management.
- Last‑mile economics and cold chain: Investment in refrigerated last‑mile capabilities is shifting from pilot to scale for firms that target premium fresh meals—an operational inflection that changes unit economics and capital requirements.
- Channel orchestration: Omnichannel partnerships (marketplaces, retail banners, grocery aggregators and D2C specialists) are creating hybrid go‑to‑market paths that accelerate customer acquisition but complicate margin governance.
- Input volatility and regulation: Raw material dynamics matter—global corn prices, for example, averaged approximately USD 198 per metric ton in late‑2025—while regulatory updates in major jurisdictions (e.g., EU labeling mandates and recent AAFCO nutrient guidance) are reshaping product labeling, claims and formulation risk.
- Trade & sourcing constraints: Remaining tariffs between major trading partners continue to influence sourcing choices and import economics for ingredient intensives SKUs.
Competitive landscape: incumbents, challengers and strategic moves
The competitive field is diverse: large online retailers and marketplaces, national pet‑care retailers with subscription programs, grocers and quick‑commerce players, and specialist D2C fresh‑food entrepreneurs. Key players we profile in the report include Chewy (Plantation, FL), Petco (San Diego, CA), PetSmart (Phoenix, AZ), Instacart (San Francisco, CA), Amazon (Seattle, WA), HelloFresh’s pet division (Berlin), Ollie (New York, NY) and Nom Nom (San Francisco, CA).
- Chewy has continued to extend its product scope into refrigerated fresh lines and recently announced partnerships and logistics capability enhancements to support refrigerated delivery at scale.
- Petco has moved to deepen membership economics by expanding free delivery options within its Vital Care program—an aggressive retention lever with implications for SKU assortment and promotional math.
- PetSmart’s Autoship and strategic partnerships enable broader access to fresh meal partners while smoothing inventory flows across retail and D2C channels.
- Aggregators like Instacart and platforms such as Amazon are compressing delivery times and competing on convenience—forcing brand owners to define clearer channel strategies and margin guardrails.
- Fresh‑food specialists (e.g., The Farmer’s Dog, Ollie, Nom Nom) continue to scale production capacity and refine formulation and subscription experiences, with targeted facility expansions to reduce lead times and unit costs.
Together, these moves illustrate a market in which scale players compete on convenience and price, while fast‑growing specialists compete on superior product and personalization. Our competitive benchmarking identifies where incumbent advantages exist—and where disruption risks are real.
What PW Consulting’s report delivers — actionable, implementable intelligence
This study is designed as a practical toolkit for executives preparing 2026 budgets, operating plans and M&A pipelines. Key deliverables include:
- Multi‑scenario revenue forecasts (base, upside, downside) for 2026–2032 with sensitivity to price, conversion and churn assumptions.
- Subscription economics models (LTV/CAC breakouts by channel and SKU archetype) enabling prioritization of acquisition and retention investments.
- Last‑mile and cold‑chain cost curves, with recommended routing density thresholds and capex vs. third‑party logistics decision trees.
- Supplier and ingredient risk heatmaps that combine price volatility, tariff exposure and substitution options.
- Regulatory compliance tracker covering major geographies (labeling, nutrient profiles and import controls) together with a practical checklist for product relabeling and claims management programs.
- M&A screening framework and a pre‑qualified list of target archetypes—manufacturing capacity, fulfillment hubs and complementary D2C brands—prioritized by strategic fit and integration complexity.
- Commercial playbooks for channel partnerships, private label strategy and omnichannel loyalty mechanics, supported by tactical sample roadmaps for the first 90, 180 and 360 days.
Note: the full report contains the granular regional and sub‑segment tables, SKU‑level elasticities and company‑level scorecards that form the basis of our recommendations. This briefing intentionally provides the strategic conclusions and playbook without reproducing every proprietary data slice.
Strategic imperatives for 2026 — five prioritized moves
- Rewire subscription economics: Move beyond simple discounts—use cadence optimization, mix incentives and service tiers to improve LTV while protecting gross margin.
- Invest selectively in cold chain: Only scale owned refrigerated last‑mile where density justifies capex; otherwise, lock strategic contracts with specialized 3PLs and shared hub models.
- De‑risk supply chains: Diversify ingredient sources and qualify substitutes to buffer against feed-cost and tariff shocks, and hedge critical ingredient exposure where feasible.
- Operationalize regulatory readiness: Prioritize labeling and formulation reviews in product roadmaps to avoid launch delays and geographic roll‑out friction.
- Pursue bolt‑on manufacturing or fulfillment assets: Target acquisitions that accelerate time‑to‑market for fresh SKUs or improve regional fulfillment economics rather than broad, brand‑only deals.
Risk scenarios & mitigations
The report includes stress‑test scenarios reflecting:
- Ingredient price shock: A sharp spike in commodity prices that compresses margins—mitigate with index‑linked contracts and pass‑through pricing triggers in subscription terms.
- Regulatory tightening: Faster adoption of stricter labeling or nutrient requirements—mitigate via pre‑emptive reformulation programs and tiered SKU rollouts.
- Channel commoditization: Same‑day delivery becomes table stakes—mitigate by differentiating on nutrition, convenience bundles and post‑purchase service.
- Logistics disruption: Capacity limitations for refrigerated transport—mitigate through hybrid hub strategies and prioritized SKU rationalization.
How to use this report in 2026 planning
- Start with the 90‑day diagnostic included in the report to quantify your subscription cohorts and identify margin leakages by channel.
- Use the 12‑month playbook to align product, supply chain and commercial teams around prioritized SKU launches and partner integrations.
- Deploy the M&A screening tool to build a 24‑month pipeline of capacity and capability targets, supported by our integration checklist to reduce execution risk.
For executives, the core value of the PW Consulting study is not only the directional forecast—this is a fast‑moving sector—but the operational levers and decision frameworks that convert growth into durable profit. The full report packages the models, dashboards and supplier scorecards needed to move from insight to execution.
Next steps & access
PW Consulting is scheduling a limited series of executive briefings and hands‑on workshops in Q1 2026 to translate the report’s findings into company‑specific roadmaps. To obtain the full report, supporting data tables, and to register for a briefing workshop, please visit our Worldwide Pet Food Delivery Market report page. The full package contains the region and sub‑segment level tables, SKU‑level elasticities and company benchmarking omitted from this briefing in order to preserve the utility of our proprietary modeling for subscribers.
In a market that is growing rapidly and becoming operationally complex, the right combination of subscription design, fulfillment strategy and regulatory foresight will determine which companies capture the majority of future value. PW Consulting’s study gives leaders the evidence‑based playbook to make those calls with conviction in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Pet Food Delivery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Vacuum Ovens Market Poised to Reach USD 411.25 Million by 2032, Growing at a 4.81% CAGR
By PW Consulting, 2026-08-12
Worldwide Vacuum Ovens Market — Strategic Outlook for 2026 Decision-Makers
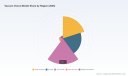
As organizations prepare capital plans, sourcing strategies, and product roadmaps for 2026 and beyond, the vacuum ovens segment is emerging from niche laboratory use into broader industrial and high‑value manufacturing workflows. PW Consulting’s new market study, which uses 2025 as its base year and projects through 2032, provides the actionable intelligence executives need to convert that transition into competitive advantage. The study sizes the global market at USD 296.0 Million in 2025 and models a compound annual growth rate (CAGR) of 4.81% over the 2026–2032 forecast horizon, reaching a modeled market value north of USD 411 Million by 2032.
Server Data Recovery Service Market
Why this matters for 2026 decisions
-
Capital allocation: Modest but steady growth and ongoing technology-driven adoption mean that discretionary capex in 2026 should be prioritized toward modular, scalable vacuum solutions that de‑risk future expansion without locking manufacturers into single‑purpose equipment.
Bulk Tote Dumpers Market -
Supply chain and procurement: Input cost dynamics and regulatory compliance are the primary levers affecting total cost of ownership. Procurement strategies that include supplier performance scorecards, multi‑sourcing for critical components, and long‑lead procurement for bespoke vacuum chambers will materially reduce program risk.
Worldwide Tomato Juice Market -
Product and process roadmaps: For R&D and operations leaders, the next 18–36 months are a window to introduce differentiated process controls (e.g., advanced outgassing protocols, integrated vacuum cycling) that translate into improved yields and certification advantages for sensitive applications.
Report scope — practical deliverables for executives
The report is designed as a decision‑support toolkit, not an academic exercise. Highlights of the deliverables that PW Consulting provides to subscribers include:
-
A validated market model and scenario engine (base year 2025, forecast period 2026–2032) that allows finance teams to stress-test revenue and margin outcomes under alternative adoption and pricing paths.
-
Buyer personas and procurement playbooks tailored to OEMs, contract manufacturers, and laboratory buyers — including RFP templates, evaluation rubrics and sample SLA language that emphasize safety, uptime and calibration traceability.
-
A supplier performance framework: technical criteria, service KPIs, and a pragmatic supplier scoring matrix to rank vendors on reliability, total cost, and compliance readiness.
-
Innovation and technology radar that maps near‑term product enhancements (vacuum insulation, integrated analytics, hybrid heating architectures) to commercial impact by 2028.
-
Regulatory and standards playbook covering machine safety, EMC/low‑voltage rules, and vacuum‑specific testing protocols — enabling product managers to accelerate certification timelines across major export markets.
-
M&A and partnership screening: a priority list of capability gaps and the archetypal targets (by capability and maturity) that would accelerate route‑to‑market or close technological gaps.
Competitive landscape — who shapes choices in 2026
The vacuum ovens space remains moderately fragmented: a mix of specialized European engineering houses, North American modular suppliers, and a number of highly focused US and Italian firms that serve both lab and production needs. Leading vendors distinguish themselves through product safety features, process repeatability, service networks and compliance capabilities. PW Consulting’s analysis profiles each key player along three dimensions — product architecture, channel & service model, and innovation roadmap — enabling buyers to map vendors to specific procurement objectives rather than generic brand recognition.
-
BINDER GmbH (Tuttlingen, Germany): A strong engineering heritage in controlled drying systems, positioned around safety for flammable solvents and precision thermal control — attractive to regulated laboratory and pilot production use cases.
-
Memmert GmbH + Co. KG (Schwabach, Germany): Known for energy‑aware designs and process versatility, with offerings that emphasize direct heating techniques and optimized vacuum cycles for powders and granulates.
-
Terra Universal, Inc. (Fullerton, CA): Focuses on cleanroom‑compatible and modular systems that integrate well into controlled environments, which benefits semiconductor and materials labs requiring contamination control.
-
WEISS TECHNIK North America (Grand Rapids, MI): Leverages a broader environmental simulation portfolio to offer high‑reliability vacuum drying systems to aerospace and automotive OEMs with stringent traceability requirements.
-
Across International and Cascade TEK (US providers): Compete on capacity range and automation options for industrial and materials processing segments; their strength is price‑performance for high‑throughput or specialized bake‑out processes.
-
Italvacuum S.r.l. and Carbolite Gero: Technology specialists with deep legacy expertise in industrial vacuum systems and high‑temperature processing, attractive to chemical and high‑temperature research users.
Strategic takeaway: the market favors suppliers who combine equipment performance with strong service and regulatory support. Our competitive matrices let procurement teams map each vendor to specific risk and value metrics (spare parts lead‑time, calibration support, ATEX/flam‑class handling, etc.) without the guesswork.
Market dynamics and input risks
-
Raw materials: Stainless steel remains the primary construction material for chambers and critical components. Broader stainless steel market dynamics — including alloy pricing and energy inputs — create a predictable component of unit cost. Buyers should bake metal price scenarios into their capex and procurement planning to avoid margin erosion during supplier contract periods.
-
Regulatory and standards pressure: Vacuum ovens used in electronics and aerospace workflows increasingly must conform to machine safety standards (e.g., ISO 12100), low‑voltage and EMC requirements for cross‑border markets, and process standards (e.g., ASTM E595 for outgassing). Early-stage compliance work reduces time‑to‑market and abstracted rework costs.
-
Energy efficiency and design trends: The industry is actively exploring vacuum insulation and alternative heating controls to meet tighter energy consumption targets in adjacent processing equipment segments. Adoption of those innovations will be an important differentiator for buyers seeking lower operating costs.
-
Market concentration: Competition is sufficient to keep supplier margins disciplined while enabling premium pricing for validated, field‑serviceable systems. Our report models concentration-related pricing dynamics and the implications for supplier negotiation strategies.
Recent industry signals to watch
-
Exhibitions and knowledge transfer remain active — several major trade shows in 2025 and 2026 showcased vacuum drying advances and underscored continued process innovation in pharma, semiconductors and heat treatment.
-
Manufacturers continue to highlight design optimizations for vacuum furnaces and ovens, with a focus on process efficiency and reduction of cycle times — an important trend for high‑throughput environments.
-
Raw material pricing in early 2026 showed range‑bound stainless steel pricing, reinforcing the need for procurement teams to lock favorable terms when possible without foregoing flexibility in manufacturing footprint decisions.
Strategic actions for 2026 — a pragmatic checklist
-
Prioritize modularity: Specify modular systems and serviceable subsystems to preserve future optionality; avoid bespoke, non‑scalable architectures unless justified by a high‑margin, long‑lived process.
-
Embed compliance early: Integrate safety and certification milestones into product and procurement timelines to avoid costly redesigns, especially when entering regulated verticals (pharma, aerospace, electronics).
-
De‑risk procurement: Use multi‑source strategies for long‑lead components (pumps, control systems, seals) and structure contracts with index‑linked clauses that balance supplier risk and buyer protection.
-
Invest in analytics: Add process monitoring and predictive maintenance to systems purchased in 2026 to reduce downtime and accelerate ROI; data‑rich deployments also create negotiating leverage with suppliers over lifecycle support.
-
Screen M&A and partnerships tactically: For firms seeking rapid capability expansion, prioritize acquisitions that bring service networks or proprietary vacuum control hardware rather than inventory‑heavy commodity plays.
How PW Consulting’s report supports your 2026 playbook
The report combines a transparent market model (base year 2025; forecast 2026–2032), a practical procurement toolkit, and vendor‑level strategic profiling so that your leadership team can convert market growth into quantifiable business outcomes. We deliberately structure the findings as an operational guide: financial model files for FP&A, RFP templates for procurement, and an implementation roadmap for operations and R&D.
To preserve the competitive value of the full dataset, this release highlights high‑level market sizing and directional insights while leaving the detailed segment breakdowns, contract‑level pricing benchmarks, and the full vendor scorecards available only in the full report. That detailed intelligence is mapped directly to the decision checkpoints most relevant to 2026 planning cycles.
Next steps
For executive teams preparing 2026 budgets, procurement leaders planning supplier negotiations, or R&D heads shaping product roadmaps, PW Consulting can provide the full research package and a tailored workshop to translate findings into a prioritized action plan. Contact our market research team for a briefing and a demonstration of the scenario engine and supplier scoring tools that underpin the study.
For detailed analysis of this topic, please visit the official page: Worldwide Vacuum Ovens Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Hip Orthosis Market to Grow at a 5.25% CAGR Through 2032
By PW Consulting, 2026-08-12
Worldwide Hip Orthosis Market Outlook 2026: Strategic Implications for Executive Decision-Making
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present an executive preview of our new Worldwide Hip Orthosis Market report. This briefing synthesizes the critical strategic takeaways global executives and investors must weigh in 2026. It highlights market trajectory, competitive dynamics, regulatory and reimbursement headwinds, and the practical, actionable intelligence contained in the full report — while deliberately reserving proprietary segment tables and granular splits to the report itself.
Solar Microinverter and Power Optimizer Market
Executive snapshot: a predictable, expanding market
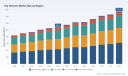
The hip orthosis market has demonstrated steady expansion through the 2020–2025 base period, rising from a mid‑three‑hundred million base to an estimated USD 542.4 Million in 2025. Our forecast model projects the market to continue growing throughout the 2026–2032 horizon, reaching roughly USD 776.0 Million by 2032, driven by a structural CAGR of approximately 5.25% over the forecast period. This trajectory is consistent with a durable, aging‑and‑activity‑driven demand profile that favors firms able to combine clinical efficacy with scalable manufacturing and clear reimbursement pathways.
Worldwide Home Health Software Market
Why this matters for 2026 corporate decisions
- Investment timing: The mid‑single digit CAGR signals a market that is not hyper‑explosive but reliably accretive. Firms making capital allocation decisions in 2026 should prioritize investments with a clear path to scale within the next 24–36 months (product platforms, modular manufacturing, and targeted clinical trials) rather than speculative category plays.
- Portfolio focus: Expect returns to favor product lines that demonstrate differentiated clinical outcomes (e.g., improved load distribution, controlled abduction mechanics, patient adherence) and low total cost of care. Margins will increasingly track the ability to deliver quantifiable value to payers and providers.
- M&A discipline: Consolidation opportunity exists but is selective. Market concentration metrics indicate meaningful but incomplete aggregation among top vendors, leaving room for bolt‑on acquisitions that bring clinical IP, channel reach, or manufacturing leverage.
- Reimbursement strategy: 2026 winners will be those who operationalize coding and fee‑schedule expertise into commercial playbooks — ensuring devices are aligned with existing billing codes or positioned for PDAC review where relevant.
Market structure and concentration
The market is characterized by a moderate level of concentration: the leading three firms collectively account for a substantive share of revenues, and the top five cover just over half the market. This structure produces a competitive landscape where national and regional players can still exert local influence, but larger firms set product and reimbursement benchmarks. For midsize players, the playbook in 2026 is clear: invest in niche clinical differentiation or partner with a national distributor to scale rapidly.
Flat Linear Motor Market
Competitive landscape — what the leading players are signaling
Our competitive analysis synthesizes product positioning, engineering approaches, and go‑to‑market execution across established suppliers:
- Össur (Reykjavik, Iceland): Focused on clinically differentiated solutions that optimize load dispersion and proprioceptive control. Products like osteoarthritis‑targeted unloader designs and post‑arthroscopy support demonstrate a strategy centered on evidence‑driven differentiation and patient comfort. For 2026, their playbook suggests continued emphasis on clinical publications and channel partnerships.
- Ottobock (Duderstadt, Germany): Balances therapeutic efficacy with user experience — breathable, stretch fabrics and easy don/doff designs enable use in ambulatory and pediatric populations. Their engineering‑led, user‑centric approach provides resilience in markets where adherence is a decisive outcome metric.
- Orthomerica (Orlando, USA) and Breg (Carlsbad, USA): Both emphasize postoperative stabilization and total‑contact comfort. These companies are well positioned where hospital supply contracts and post‑op protocols dictate device selection; agility in servicing institutional channels is their comparative advantage.
- Becker Orthopedic, Thuasne, RCAI, Fillauer, Aspen Medical Products: These firms represent a mix of prefabricated solutions, prescription braces, and complementary spinal/torso stabilization technologies. Their strategic options in 2026 include deeper partnerships with rehabilitation networks, co‑development arrangements with OEMs, or focusing on underserved clinical niches.
Collectively, these firms demonstrate two dominant strategic archetypes in 2026: (1) clinical differentiation through biomechanical innovation and outcomes evidence, and (2) channel dominance through hospital and prosthetics/orthotics networks. Successful scale requires combining both.
Regulatory and reimbursement dynamics executives cannot ignore
Regulatory and payment frameworks remain central determinants of commercial success in 2026. Key practical points drawn from our regulatory monitoring:
- HCPCS coding remains the operational backbone for hip orthosis billing in many major markets. Existing Level II HCPCS codes cover a range of hip orthosis designs and are updated through an annual process; there were no entirely new, standalone hip orthosis codes finalized in the 2025 biannual determinations beyond mapping to existing frameworks.
- Specific PDAC‑approved descriptors (for example, codes that describe postoperative abduction control orthoses) exist and are actively used by payers to determine coverage and reimbursement levels. Manufacturers should maintain PDAC engagement or equivalent local coding validation as part of product launch readiness.
- Discussions continue about potential off‑the‑shelf versus custom code delineations, mirroring long‑standing debates in orthotics. These coding conversations can materially affect price realization and are likely to surface again in payer negotiations and public forums in 2026.
In short, device design that aligns with established HCPCS descriptors, combined with robust coding claims support, materially reduces commercialization risk and accelerates uptake.
What PW Consulting’s report delivers for decision‑makers
For executives seeking to operationalize these insights, the full report provides pragmatic, decision‑facing assets (summarized here without exposing the proprietary segmentation matrices):
- A calibrated market model with historical tracking (2020–2025) and a bottom‑up forecast (2026–2032) that includes scenario variants for macro health spending, surgical volumes, and outpatient rehabilitation adoption.
- Reimbursement and regulatory playbooks mapping device archetypes to existing HCPCS codes, PDAC interactions, fee‑schedule sensitivities, and payer negotiation checklists.
- Competitive scorecards and capability heatmaps across product design, clinical evidence, manufacturing scale, and channel strength — enabling target selection for M&A, licensing, or JV activity.
- Go‑to‑market blueprints: pricing architecture, contracting templates for hospital and post‑acute networks, and a roadmap for payer pilots demonstrating cost‑offsets versus standard care.
- Operational modules: supplier risk assessment, manufacturing cost curves, and a 90‑, 180‑, and 360‑day implementation plan for rapid market entry or expansion.
Note: detailed split tables by region, product type, and clinical application are intentionally withheld from this preview to preserve the high value of the full dataset and modelling logic accessible in the report portal.
Priority actions for 90 days — tactical recommendations
- Audit product‑to‑code alignment: Conduct an immediate review of current and pipeline devices versus HCPCS descriptors and PDAC guidance. Prioritize any code validation gaps for corrective evidence generation.
- Targeted evidence generation: Allocate budget for 1–2 high‑impact clinical or real‑world evidence studies that quantify adherence, short‑term functional gains, or postoperative readmission reductions — outcomes that matter to purchasers.
- Channel optimization: Evaluate hospital contract opportunities and distributor partnerships where device comfort and easy don/doff features can be leveraged into preferred status.
- M&A screening: Use the report’s competitive scorecards to shortlist 3–5 acquisition or partnership targets that deliver immediate capability or geographic expansion without protracted integration risk.
Closing perspective
The hip orthosis market in 2026 presents a pragmatic growth story: stable expansion, clear niches for innovation, and measurable levers for commercial success. Market leaders will be those who translate biomechanical advantage into payer‑verified outcomes and who build distribution models that reduce friction for clinicians and patients alike. For investors and corporate strategy teams, the opportunity is not a binary bet on market size alone but on the ability to operationalize reimbursement strategy, evidence generation, and channel action within a 12–36 month window.
PW Consulting’s full Worldwide Hip Orthosis Market report contains the complete forecasting models, detailed segmentation tables, supplier scorecards, and executable playbooks referenced here. Visit our report page to access the complete dataset, annexes, and tailored advisory options for 2026 execution support.
For detailed analysis of this topic, please visit the official page: Worldwide Hip Orthosis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Cartridge Filters Market to Reach USD 10.4 Billion by 2032, Growing at a 6.15% CAGR
By PW Consulting, 2026-08-12
Worldwide Cartridge Filters Market: Strategic Outlook and Decision-Grade Insights for 2026
By PW Consulting — Senior Strategic Advisor & Chief Industry Analyst
Transfer Freezing Bag Market
Executive teaser
The cartridge filters market is navigating a period of steady expansion underpinned by regulatory pressure, material innovation, and continuing industrialisation of emerging markets. Our new Worldwide Cartridge Filters Market report (base year 2025, historical 2020–2025, forecast 2026–2032) quantifies that momentum: the global market is projected to grow from a 2025 baseline to an estimated market size exceeding USD 10.4 billion by 2032, at a compound annual growth rate (CAGR) of approximately 6.15% across the 2026–2032 forecast window. This press briefing outlines the strategic implications of that trajectory for market participants in 2026 — while deliberately withholding detailed segment-level figures to encourage direct engagement with the full report for transaction-grade data.
Worldwide Patient Scheduling Software Market
Why 2026 is an inflection year for buyers and investors
-
Consolidated but open: Market concentration metrics indicate the sector is neither a tight oligopoly nor a fragmented cottage industry. The top three companies account for a modest portion of the market, and the top five do not dominate to the extent of shutting out challengers. That structural dynamic creates high-leverage opportunities for nimble players and M&A-driven scale plays.
Worldwide Plastic Microtubes Market -
Regulatory tailwinds: Tightening environmental and potable water standards in major jurisdictions, together with industry-specific certifications for food, pharmaceutical, and high-purity processes, are accelerating replacement cycles and premium product adoption.
-
Raw-material sensitivity: The sector remains exposed to polypropylene resin price cycles and petrochemical capacity swings — a factor that materially affects margins for commodity-grade cartridges and gives an advantage to manufacturers that can engineer higher-value media or secure resilient sourcing.
Key themes shaping supplier and buyer strategies
-
Premiumisation and technical differentiation: End users in pharmaceuticals, food & beverage, and critical water treatment are migrating toward higher-precision media, membranes, and engineered metallic options that extend life and reduce total cost of ownership. Suppliers who can combine material science, validated performance, and regulatory support will capture disproportionate value.
-
Aftermarket and services as margin anchors: As hardware commoditisation persists at lower price tiers, installation, validation, field services, extended warranties, and consumables subscription models emerge as durable margin sources. Industrial OEMs and filtration specialists should accelerate service-embedded go-to-market pilots in 2026.
-
Supply-chain resilience and vertical integration: Given volatility in key feedstocks and geopolitical trade frictions, buyers will prioritize suppliers with multi-sourced resin contracts, regional production footprints, or backward-integration strategies that mitigate price and lead-time risk.
-
Innovation frontiers — membranes and metallic media: Advances in membrane chemistry and novel metallic membranes offer step-changes in fine-filtration performance and thermal/chemical robustness. Early commercialisation of such technologies will be a primary differentiator for premium-priced segments.
-
Sustainability and circularity: Regulations and corporate net-zero commitments are prompting lifecycle considerations: lower-energy manufacturing, recyclable housings, and longer-lasting cartridges that reduce replacement volumes. Suppliers that can credibly demonstrate lifecycle benefits will gain procurement preference.
What our report delivers — practical contents for decision-makers
PW Consulting’s Worldwide Cartridge Filters Market report is structured to move beyond high-level commentary and into decision-quality intelligence. Among the actionable elements included:
-
Verified market sizing and forward-looking forecasts (2026–2032) anchored to primary research and cross-validated supplier intelligence.
-
Scenario modelling that translates macro and micro drivers into probablistic revenue outcomes under different regulatory, raw-material, and adoption-rate assumptions.
-
Competitive landscaping with vendor scorecards, capabilities benchmarking, and go-to-market positioning for established multinationals and high-potential regional suppliers.
-
Commercial playbooks tailored to buyer and seller archetypes: procurement negotiation levers, aftermarket monetization blueprints, and channel optimisation strategies.
-
M&A and partnership screening matrices highlighting acquirability, strategic fit, and integration risk — complete with indicative valuation ranges and synergy levers (note: detailed target-level financials are available in the full report).
-
Technology and innovation roadmaps spotlighting membrane technologies, metallic media, and digital-enabled filtration assets (e.g., sensorized housings for predictive maintenance).
-
Regulatory and standards compendium to support compliance planning and certification timelines for critical end markets.
Competitive landscape: capabilities and likely strategic moves
The report includes granular company profiles and strategic assessments of leading players. Below is a synthesis of the competitive positioning and what to expect from named incumbents in 2026:
-
Pall Corporation — A global leader in separation and purification technologies with deep expertise in high-flow and membrane-based solutions. Expect Pall to double down on high-margin membrane portfolios and bioprocessing-certified products, using IP-rich offerings to defend premium segments.
-
Parker Hannifin — Leveraging a diversified process and hydraulic filtration footprint, Parker will likely pursue consolidation of complementary filtration businesses and expand its engineered filtration systems for industrial fluids.
-
3M Company — Materials science strength allows 3M to innovate on media formulations and roll out cost-effective high-performance cartridges. Its advantage will be rapid product development and channel breadth across industrial and commercial markets.
-
Eaton Corporation — With a tradition in fluid power and hydraulics, Eaton is positioned to commercialize integrated filtration offerings tied to powertrain and hydraulic subsystems.
-
Donaldson Company — Focused on air and dust collection as well as industrial process filtration, Donaldson is a go-to for heavy-duty site applications and will pursue OEM partnerships and dust-control regulatory-driven demand.
-
Pentair — Strong in water treatment, Pentair will focus on municipal and industrial water projects where regulatory compliance and lifecycle cost savings justify higher-spec cartridges and system sales.
-
Graver Technologies — A performance-specialist for liquid process and power generation, Graver will continue to capture niche, high-spec opportunities that demand advanced media and validation support.
-
Merck Millipore (Merck KGaA), Sartorius Stedim Biotech, Meissner Filtration Products — These firms collectively dominate biopharmaceutical and sterile-processing filtration. Expect further investment in single-use and validated cartridges, as well as service offerings tailored to GMP environments.
-
GKN Powder Metallurgy — Recent product launches point to an emphasis on metallic membrane cartridges for fine filtration; such innovations open new applications in downstream process stages and create separation advantages where polymer media underperform.
-
Regional manufacturers (e.g., LOONG Filtration, Brother Filtration, Gopani Filters) — Local suppliers will continue to undercut on price for standard cartridges, while also winning private-label and localized service contracts. These players are acquisition targets for global firms seeking cost footprint expansion.
Regulatory and raw-material risks — and how to hedge them
Compliance with standards for hydraulic systems, potable water contact, and food/pharma applications is non-negotiable in many end markets. Examples include internationally recognized filter testing standards and potable-water contact certifications. Simultaneously, exposure to polypropylene resin price movements and melt-blown media supply tightness has created margin volatility for commodity-focused SKU portfolios.
Strategic responses we recommend for 2026 decisions include:
-
Prioritise dual-sourcing and secured-offtake agreements for critical resins to stabilise costs.
-
Invest in R&D for alternative media and higher-value membranes to reduce dependence on commodity resin cycles.
-
Formalise regulatory-compliance pathways (pre-certifications, third-party validations) to shorten sales cycles into regulated end markets.
Go-to-market imperatives for 2026
-
Segment customers by value rather than volume: identify accounts where compliance needs, downtime costs, or quality sensitivity justify premium cartridges and lifecycle services.
-
Build outcome-focused commercial propositions: warranty bundles, performance SLAs, and consumable subscriptions accelerate locking in recurring revenue.
-
Pursue targeted M&A to acquire membrane capability, validated bioprocess technologies, or regional manufacturing footprints — especially where the market concentration profile leaves room for bolt-on consolidation.
-
Pilot digital-enabled filtration: sensorised housings and remote monitoring yield predictive maintenance use cases attractive to large industrial customers.
What readers should do next
For procurement heads, product leaders, and corporate development teams preparing for 2026, our report offers the operational playbooks and transaction intelligence needed to move from strategy to execution. This briefing intentionally omits specific split-level revenue figures and segment allocations to preserve the intelligence value of the full dataset; the complete report includes detailed, segment-level market sizing, regional breakout, application analysis, material-type economics, and vendor share models — essential for budgetary and M&A decision-making.
How to get the full intelligence
Reach out to PW Consulting to access the Worldwide Cartridge Filters Market report and accompanying data appendices. The full deliverable contains downloadable datasets, vendor scorecards, and customised scenario modelling templates we can tailor to your company’s portfolio or a targeted M&A thesis.
Closing perspective
Cartridge filtration is no longer a low-information, transactional market; it is a strategic arena where materials innovation, regulatory alignment, and digital services determine long-term value capture. With the market on a steady growth path into 2032 and competing forces reshaping cost and differentiation dynamics, 2026 represents a practical decision point: commit to premium, validated technologies and resilient supply chains — or compete on price in an increasingly volatile materials environment. PW Consulting’s report equips leaders to choose the winning path with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Cartridge Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Glucosamine Supplements Market Poised for a 4.85% CAGR During the 2026–2032 Forecast
By PW Consulting, 2026-08-12
Worldwide Glucosamine Supplements Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market intelligence brief on the Worldwide Glucosamine Supplements Market delivers a concise but high-resolution view of the sector’s trajectory as companies plan for the 2026 planning cycle. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the analysis synthesizes market-scale dynamics, regulatory pressure points, and supplier/brand activity to support practical choices on portfolio, sourcing, and go-to-market (GTM) investment.
Line Composite Insulator Market
High-level market signal: steady growth, structural opportunity
After recovering from pandemic-related consumption shifts, the global glucosamine market reached a base-year size of approximately USD 2.25 billion in 2025 (USD Million basis). Our forecast applies a conservative compound annual growth rate (CAGR) of 4.85% for the 2026–2032 horizon, projecting the market to exceed USD 3.13 billion by 2032. That pace signals durable demand driven by aging populations, ongoing self-care adoption among chronic-joint cohorts, and expanded distribution through e-commerce and mass-market channels.
Worldwide Duty Drawback Service Market
Two macro takeaways matter for 2026 planning. First, demand growth is broad-based but not explosive — implying that scale, cost discipline, and differentiated claims will determine winners. Second, market concentration remains moderate (CR3 ~28.5%, CR5 ~35.2%), meaning incumbents enjoy advantages but there is still meaningful space for specialist entrants and private-label expansion.
Worldwide Ball Joints Market
Why this report matters for 2026 strategic planning
- Risk-aware portfolio decisions — the report helps prioritize which glucosamine formats, delivery systems, and positioning strategies merit incremental investment versus those that should be deprioritized or exited.
- Sourcing and cost playbooks — raw-material volatility (notably shellfish-derived supply vs. vegetarian fungal substitutes) impacts margins; the analysis maps supplier risk profiles and cost-to-serve scenarios that feed 2026 budgeting and hedging choices.
- Regulatory and claims navigation — with heterogeneous rules across major markets, product claims and labeling strategies are a critical gating factor. The report distills how to frame science-backed structure/function language while avoiding regulatory overreach.
- Commercial channel optimization — the research identifies where brick-and-mortar, health-retailer, DTC, and e-commerce investments deliver different ROI profiles for mature versus niche formulations.
What we analyzed (and what we deliberately withhold here)
To remain a practical decision tool, the underlying report contains:
- Detailed market sizing by year (2020–2032) with scenario runs and sensitivity to raw-material price swings;
- Segmentation across regions, product types, and applications with demand drivers and growth vectors;
- Commercial benchmarking for core brands and private labels, including distribution footprints and retail pricing bands;
- Supplier mapping and a risk-graded matrix for raw-material sources, certifiers, and contract manufacturers;
- Regulatory and reimbursement dossiers for major jurisdictions with playbooks for compliant claims and label language;
- Actionable go-to-market recommendations tailored to three archetypes: incumbent branded manufacturers, private-label suppliers, and nutritional startups.
In keeping with the “trailer” principle of this release, we intentionally do not publish the granular regional splits, application percentages, or per-segment revenue amounts here. Those detailed tables, heat maps, and downloadable model files are available in the full PW Consulting report.
Competitive landscape: core companies and tactical patterns
The market remains a blend of legacy nutraceutical brands, value-driven private labels, and specialist formulators. Key players we profile include NOW Foods, Nature’s Bounty, Doctor’s Best, Jarrow Formulas, Thorne Research, Pure Encapsulations, Kirkland Signature (Costco), GNC, Swanson Health Products, Nutricost, Blackmores, and Nature Made. Each occupies a distinct strategic niche — from premium clinical positioning to mass-market value plays — and their recent moves illustrate three practical competitive templates:
- Product modernization and differentiation : Some market leaders are enhancing formulations (e.g., combining glucosamine with collagen matrices or MSM) to create differentiated structure/function narratives and extend shelf appeal. These are defensive but credible steps to sustain near-term ASPs.
- Third-party validation and certification : Certification and clinical evidence are being used selectively to defend premium price points. Certifications that verify purity, potency, or non-GMO/vegetarian sourcing are materially influencing procurement decisions among health-conscious segments.
- Geographic and channel extension : Established brands are extending into new retail corridors and digital-first models, while some regional players are driving expansion via partnerships to unlock growth in underserved geographies.
Recent public developments underline these dynamics: product relaunches that combine glucosamine with collagen biology, certification upgrades to reassure consumers and retailers, clinical studies supporting specific formulations, and distribution agreements expanding regional reach. For 2026, expect continued investment along these vectors as companies seek to protect margins and differentiate beyond commodity price competition.
Industry dynamics that will shape 2026 outcomes
- Regulatory posture: In the United States, glucosamine remains a dietary supplement under DSHEA (1994). That status reduces pre-market regulatory friction but increases the onus on manufacturers to meet Good Manufacturing Practices (GMP) and maintain label accuracy. In contrast, some jurisdictions restrict health claims more tightly — an operational reality for global launch strategies.
- Raw-material sourcing: Shellfish-derived glucosamine remains a cost-sensitive staple; alternative vegetarian sources command a premium. Our cost-model scenarios show raw-materials can swing gross margins materially, which makes supplier strategy and forward purchasing a central 2026 lever.
- Reimbursement limits: Most public and private payors do not reimburse glucosamine as a drug, constraining accessibility for certain patient groups and reinforcing the importance of value-based retail pricing and OTC channel innovation.
- Consumer behaviour: Usage is highly correlated with aging and self-management of osteoarthritis symptoms. Brand trust, third-party verification, and easy-to-understand dosing profiles are decisive purchase drivers, particularly in the 50+ cohort.
- Evidence and labeling: Historical regulatory opinions (e.g., EFSA) temper the claims landscape in some markets; companies must carefully design claims to survive regulatory scrutiny while still resonating with consumers.
Practical strategic recommendations for 2026
- Prioritize margin protection via sourcing diversification : Lock in a mix of conventional and alternative glucosamine suppliers, and evaluate tolling or co-manufacturing arrangements to reduce exposure to spot-price swings.
- Invest selectively in certification and clinical validation : For premium SKUs, targeted clinical endpoints or third-party certification can unlock distribution in health-retailer channels and justify premium positioning.
- Design channel-specific SKUs : Differentiate packaging and formulations for DTC, mass retail, and healthcare channels to optimize conversion and inventory velocity without proliferating costly SKUs.
- Embed label-compliance playbooks into product development : Make regulatory review a gating step for claims and marketing creative to avoid recalls or enforcement actions that can erode brand equity quickly.
- Monitor competitor concentration and M&A signals : Given the moderate concentration levels, M&A and private-label expansion will reshape competitive economics; build reconnaissance on distributor and retailer partnerships as part of your 2026 scenario planning.
How the PW Consulting report supports execution
The full report is a tactical kit for commercial, supply-chain, and regulatory leaders preparing 2026 strategies. It contains:
- Downloadable financial and scenario models that let you stress-test pricing, raw-material trajectories, and channel mixes;
- Step-by-step supplier risk matrices with contact profiles and certification checks;
- Marketing playbooks that translate clinical and certification signals into compliant claims and retailer-ready messaging;
- Customizable decision checklists for M&A diligence and private-label negotiation.
Next steps
PW Consulting’s briefing here provides the strategic backdrop you need to prioritize decisions in 2026 — but it is intentionally high level. To convert the insights into executable plans, access to the full dataset, segment-level demand curves, and the downloadable financial model is necessary. The full report provides those assets and the scenario tools that procurement, R&D, and commercial teams will use to lock in 2026 budgets and roadmaps.
For market-entry analysis, pricing simulations, supplier shortlists, or tailored briefings focused on your portfolio, contact PW Consulting to request the comprehensive Worldwide Glucosamine Supplements Market report and supporting advisory workshops.
For detailed analysis of this topic, please visit the official page: Worldwide Glucosamine Supplements Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


