



Category: market research
PW Consulting: Worldwide Sunlight Simulators Market Poised to Hit USD 890.5 Million by 2032
By PW Consulting, 2026-08-12
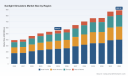
Worldwide Sunlight Simulators Market — Strategic Outlook for 2026 Decision‑Making
Executive summary
PW Consulting’s latest market study on Worldwide Sunlight Simulators is designed as an operational intelligence tool for C-suite executives, corporate strategy teams, R&D leaders, and investors preparing decisions in 2026. Built on a 2020–2025 historical baseline with a 2026–2032 forecast horizon, the study uses a transparent demand model to project market growth at a 7.0% compound annual growth rate (forecast period). The market size at the 2025 base year is established in the report, and the forecast points to materially larger installed and serviceable markets by 2032. This release summarizes the strategic conclusions and practical playbook items that derive from the full analysis while intentionally withholding the granular segment tables and vendor share details that are available in the full report.
Worldwide Composite Aerostructure Market
Why this market matters in 2026
Sunlight simulators sit at the intersection of multiple high‑growth technology vectors: advanced photovoltaics (including perovskite and tandem cells), space and aerospace testing (AM0 spectra), materials and cosmetics testing, and agricultural/biotech research. With increasing industrialization of next‑generation PV cell formats, stricter standards and certification requirements, and growing demand for lab throughput and automation, capital buyers and test‑service providers face complex tradeoffs between light‑source technology (LED, xenon, arc lamp), spectral fidelity, long‑term stability, total cost of ownership, and compliance with ASTM/IEC/JIS and sector‑specific rules.
Worldwide Liquor Store POS Software Market
What the report delivers — practical content for 2026 action
- Proven market-sizing methodology with transparent assumptions and scenario variants calibrated to observed procurement cycles and lab CAPEX timelines.
- Detailed demand model and forecasting engine (2026–2032) with runnable scenarios that stress test adoption curves for LED vs flash xenon, perovskite commercialization timelines, and defense/aerospace procurement surges.
- Operational supplier scorecards and vendor capability matrices that map product form factors, spectral performance classes, automation readiness, calibration support, and typical warranty/service models.
- Supply‑chain and component analysis covering LED emitter supply, driver electronics, thermal management, xenon lamp life and inventory risk, optical subsystems, and calibration instrument availability.
- Regulatory and standards playbook: how evolving ASTM, IEC and other specifications affect procurement requirements, lab accreditation, and product certification protocols.
- Go‑to‑market frameworks for OEMs and integrators: channel strategies, lab partnerships, service and calibration revenue models, and aftermarket differentiators.
- M&A and investment intelligence: acquisition targets, strategic partnership archetypes, valuation moats, and integration de‑risking checklists.
- Field case studies and procurement templates — RFP language, TCO calculators, test‑bed configuration examples and maintenance scheduling frameworks.
Market dynamics and strategic implications
The market is shifting from hardware‑only sales to systems delivered with lifecycle services and data. Buyers increasingly evaluate suppliers on three vectors: spectral accuracy over time, operational uptime (including ease and cost of calibration), and digital integration (automation, data capture, and test orchestration). These buyer priorities create opportunities for manufacturers and service providers to capture recurring revenue through calibration contracts, subscription access to test automation software, and managed test services.
Worldwide Stainless Steel Lunch Container Market
From an investment perspective, the market’s mid‑single digit midterm growth (7.0% CAGR across the forecast period) supports steady demand for new capacity and replacement cycles, while pockets of above‑average growth will be driven by large‑scale PV module validation, accelerated aerospace testing programs, and the emergence of commercial perovskite cell lines. Suppliers that can demonstrate field‑proven spectral stability and robust QA processes will command pricing premia and greater share of lab roll‑outs.
Competition: positioning and recent strategic moves
The competitive landscape is composed of specialist manufacturers, instrumentation incumbents, and nimble system integrators. Key players profiled in the report include leading LED tunable specialists, xenon flash suppliers, and research‑grade simulator producers. Our analysis highlights the following non‑confidential themes:
- Product differentiation is increasingly technical: tunable LED arrays that replicate AM0–AM1.5G spectra, long‑pulse LED systems for large‑area testing, and xenon flash units for IV testing each serve distinct buyer needs. Suppliers are investing in spectral control, temperature management, and automation interfaces to lock in enterprise customers.
- M&A and capability consolidation are accelerating. Notably, a significant 2025 acquisition combined LED‑based simulation know‑how with xenon‑based metrology expertise, signaling vendor strategies to offer broader, standards‑compliant portfolios that cover both steady‑state and flash IV testing requirements.
- Research and lab customers demand traceable calibration and compliance with international standards—vendors that can provide ISO‑grade calibration workflows and integrate with lab information management systems (LIMS) secure longer contracts.
- Service and aftermarket are differentiators. Successful vendors supplement hardware with onsite commissioning, remote diagnostics, predictive maintenance, and replacement part availability to minimize downtime for high‑value customers.
Profiles in strategic positioning (high level)
- Specialist LED manufacturers emphasize spectral tunability, long operational lifetimes, and automation interfaces tailored to PV and photochemistry research.
- Xenon‑based suppliers continue to retain relevance for high‑accuracy IV testing and flash‑based measurement standards in certain certification pathways.
- Instrument OEMs with broad optical portfolios leverage existing lab relationships to upsell solar simulation equipment for materials, cosmetics, and biotech applications.
- Custom integrators and engineering houses reinforce demand where unusual test envelopes (very large areas, space‑grade AM0 testing) are required, or when combined environmental chambers are needed.
Actionable recommendations for corporate decision‑makers in 2026
- Buyers — adopt a two‑track procurement strategy. For high‑throughput PV module lines, prioritize systems with automation and long‑term spectral stability; for specialized R&D or aerospace AM0 testing, secure access to both steady‑state LED and flash xenon capabilities. Use a weighted TCO approach that captures uptime, calibration downtime, and consumable replacement costs.
- OEMs — modularize product portfolios to offer hybrid solutions (LED + flash) via bundled sales or strategic partnerships. Monetize calibration and analytics as recurring revenue streams and standardize digital interfaces for integration into customer automation stacks.
- Service providers / labs — pursue accreditation and publish traceable calibration workflows. Differentiate on speed‑to‑test via automation and provide guaranteed throughput SLAs to capture premium lab contracts from PV manufacturers and aerospace customers.
- Component suppliers — prioritize supply security for critical parts (LED emitters, xenon bulbs, drivers, optics). Offer vendor managed inventory and consignment models for consumables to reduce customer procurement friction.
- Investors and M&A teams — target technology adjacencies that close capability gaps (e.g., a tunable LED maker acquiring flash/xenon metrology proficiency) and prioritize targets with sticky service contracts and documented calibration processes that reduce churn.
- R&D leaders — align internal testbeds and procurement calendars with industry standards updates. Invest in cross‑validation capability (ability to compare LED and xenon results) to future‑proof measurement protocols against evolving cell technologies.
Risk management and monitoring
Key risk vectors for 2026 include component availability (especially high‑performance LED emitters), regulatory or standard updates that change certification pathways, and the speed of commercialization for nascent PV technologies which could compress supplier product cycles. We recommend monitoring a short list of leading indicators monthly: procurement lead times for critical components, calibration cycle frequency and cost per lab seat, new large facility announcements in PV manufacturing, and changes to ASTM/IEC test method drafts.
Conclusion — how to use this analysis
For executives planning capital deployment, supplier negotiations, or M&A activity in 2026, PW Consulting’s sunlight simulators market report converts technical nuance into investment‑grade decision frameworks. The market trajectory supports disciplined expansion but rewards selective investment in automation, calibration services, and hybrid product portfolios. The full report provides the detailed segment tables, regional and application splits, vendor scorecards, downloadable models, and RFP templates required to execute on these strategies.
Next steps
To access the complete intelligence set — including the full segmentation breakdowns, vendor benchmarking data, downloadable forecast models, and our procurement playbook — please consult the report landing page listed in the official release. PW Consulting can also arrange a tailored briefing where our analysts will walk your team through scenario runs, vendor shortlists, and an executable 12‑month action plan aligned to your strategic objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Sunlight Simulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Vibration Isolation Systems Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study — the Worldwide Vibration Isolation Systems Market (base year 2025, historical review 2020–2025, forecast 2026–2032) — reframes how executives, product leaders, procurement heads, and corporate development teams should prioritize investment and operational choices in 2026. The market reached an estimated USD 5,276.13 Million in 2025 and, under our central scenario, is expected to expand at a compound annual growth rate (CAGR) of 6.51% through 2032, approaching USD 8,204.43 Million by the end of the forecast window. These topline dynamics mask important inflection points — regulatory updates, raw-material volatility, and technological shifts — that will determine winners and laggards in the next 18–36 months.
Consumer MCU Market
Why this report matters for 2026 strategy
-
Timing: 2026 is a pivot year. The combined effect of updated international vibration standards and new regional occupational rules creates near-term compliance and retrofit demand while raising the bar for next‑generation product specifications.
Worldwide Multiparameter Meters Market -
Capital allocation: With a steady mid-single-digit CAGR, the market rewards focused capital deployment — not broad, unfocused expansion. Our study supplies the investment cases, break-even timelines, and sensitivity analyses that CFOs need to prioritize projects with the highest risk-adjusted returns.
Elevator Hoistway Cables Market -
Procurement leverage: Raw-material dynamics and concentration profiles in the supplier base create windows for re‑negotiation, hedging, and dual-sourcing strategies. Procurement teams can convert insight into measurable bottom-line savings if they act before material price cycles and lead-times tighten further.
What the report contains — practical, transaction-ready analysis
-
Validated market sizing and scenario forecasts (base year 2025; 2026–2032 outlook) with upside/downside pathways and sensitivity to key inputs such as raw-material costs, regulatory adoption speed, and capital spending patterns.
-
Decision frameworks for product managers: technology roadmaps, feature-pricing matrices, and R&D prioritisation templates that translate market demand into development sprints and go-to-market sequencing.
-
Procurement playbooks and supplier risk heatmaps: supplier KPIs, alternative-material scorecards, and short/medium‑term hedging strategies tied to real-world sourcing calendars.
-
M&A and partnership scouting dossiers: target-screening criteria, valuation multiples observed in recent deals, and integration checklists tailored to acquiring vibration‑technology assets or forging OEM partnerships.
-
Compliance and retrofit action plans: gap analyses that map new standards and directives to product specs and field retrofit protocols, including estimated retrofit windows and cost buckets for capital planning.
-
Commercial playbooks for sales leaders: demand-creation templates for regulated sectors, tender-response accelerators, and lifecycle-service propositions that increase recurring revenue from installed base servicing.
Note: This briefing intentionally omits granular regional and application-level breakdowns to preserve the strategic value of the full report; clients who require segmented demand curves, pricing bands by region, and customer-level sizing should refer to the full study available through our distribution channels.
Market dynamics: drivers, headwinds, and short-term shocks
-
Regulatory tightening. ISO 10816-3:2025 introduced stricter vibration severity thresholds for industrial machines, while several regions have implemented more demanding operator exposure limits. In 2026 the EU Machinery Directive replaced previous guidance with a more prescriptive set of operator vibration exposure caps — a compliance imperative that will catalyze retrofits and specification upgrades across heavy industry and precision manufacturing.
-
Raw-material pressure and cost pass-through. Natural rubber experienced a notable supply shock in the recent cycle, with year‑over‑year price appreciation driven by weather disruptions in key producing regions. Manufacturers with high rubber-content products face margin compression unless they optimize formulations, raise prices or secure forward covers. By contrast, certain synthetic elastomer feedstocks have stabilized, creating selective cost relief for some product families.
-
Technology convergence. Hybrid approaches that pair elastomeric elements with pneumatic or active controls are moving from pilot to productization, enabling better low‑frequency isolation and dynamic adaptability. These hybrid systems and adaptive dampers will be high-priority R&D targets for incumbents and challengers alike.
-
Service and lifecycle monetization. As installed bases age and regulatory requirements tighten, aftermarket services — predictive maintenance, re-certification, and retrofitting — will become a material revenue pool. Firms that can package hardware with subscription-based monitoring and on-demand retrofit services will capture outsized lifetime value.
Competitive landscape — who to watch and why
The market exhibits moderate fragmentation; the leading three players together account for a material but far from dominant share, and the top five concentration indicates meaningful space for mid-size specialists to scale by specialization, geographic focus, or vertical integration.
-
Trelleborg AB (Sweden) — Strengths: deep engineering breadth across elastomer and air-spring technologies and strong OEM relations in precision manufacturing. Strategic implication: Trelleborg’s hybrid elastomer-air spring launch signals an aggressive push into higher-margin precision equipment segments; partners and competitors should expect incremental spec-wins in adjacent niches.
-
LORD Corporation (Parker Hannifin, USA) — Strengths: materials science and adaptive (magnetorheological) systems. Strategic implication: LORD’s recertification and continued investment in adaptive isolators position it well where regulatory thresholds demand active mitigation and where customers pay for on‑demand performance tuning.
-
Getzner Werkstoffe (Austria) — Strengths: proprietary low-frequency elastomer formulations used in civil and industrial projects. Strategic implication: innovations in low-frequency materials create defensible niches for infrastructure and large‑machine isolation projects — a playbook for premium pricing and specification-led procurement.
-
Hutchinson / Paulstra (France) — Strengths: broad product portfolio across automotive, aerospace, and industrial mounts. Strategic implication: a dual brand/organization strategy allows segmentation across high-volume automotive channels and lower-volume, higher-margin industrial applications.
-
Fabreeka (USA), Gerrymander (UK), Vibracoustic (Germany), Sumitomo Riko (Japan), Bridgestone (Japan) — Strengths: mix of niche materials, heavy‑load systems, and seismic solutions. Strategic implication: these players will be active in partnerships and co‑development agreements where regional codes or infrastructure projects create localized demand spikes.
Recent corporate moves underscore these trends: product launches of hybrid isolators and low-frequency elastomers (mid–late 2025), ISO recertifications for adaptive technology suppliers, and active trade-show commercialization of hybrid pads and low-frequency products. These activities point to accelerating product differentiation and the commercialisation of advanced materials and mechatronic solutions.
Implications for core functions — recommended 90‑ to 180‑day actions
-
CEOs / Corporate Development: Reassess M&A pipelines for targets that provide either technology differentiation (adaptive control, hybrid materials) or unique access to regulated verticals (semiconductor fabs, healthcare & life sciences). Use our report’s valuation benchmarks and integration checklists to fast-track diligence.
-
Product Leadership: Prioritize low-frequency performance and regulatory-proofing in next-generation roadmaps. Allocate a portion of R&D spend to validating hybrid architectures and to materials substitution strategies that reduce dependence on volatile natural rubber supply chains.
-
Procurement: Implement a two-track sourcing approach: (1) tactical hedging and dual-sourcing for short-term protection against elastomer price shocks; (2) strategic partnerships for long-term access to advanced compound formulations. Our supplier risk heatmaps highlight where to concentrate negotiation efforts.
-
Operations & Service: Build retrofit and lifecycle-service offerings now — regulatory-driven retrofit waves create opportunities for immediate revenue and improved margins. Deploy predictive-maintenance pilots in 2026 to validate subscription monetization.
-
Sales & Marketing: Re‑segment go-to-market plays by regulatory urgency and retrofit propensity rather than by traditional industry verticals alone. Tender-response accelerators in the report can reduce RFP turnaround and increase win rates.
Risks, uncertainties, and monitoring triggers
-
Material-price persistence: A prolonged spike in natural rubber could compress margins for elastomer-centric lines and accelerate substitution toward synthetics or hybrid designs.
-
Regulatory adoption pace: Faster-than-expected enforcement of vibration and operator-exposure rules would create an accelerated retrofit cycle; slower adoption would stretch investment payback periods.
-
Technological leapfrogging: Rapid scaling of active/adaptive systems may disrupt incumbents who rely on conventional passive products if they cannot commercialize competitive adaptive solutions quickly.
Next steps — how to use PW Consulting’s study in your 2026 playbook
-
Download the full report for detailed regional and application segmentation, customer-level sizing, and supplier financials that are intentionally excluded from this briefing to preserve the report’s transaction-grade value.
-
Request our executive workshop: a 2‑hour facilitated session where we translate the market scenarios into a tailored 12‑month action plan for your organization (R&D priorities, procurement actions, M&A screening).
-
Engage our diligence team for targeted M&A or JV evaluations — we can provide off-market intelligence and integration plans keyed to vibration-isolation assets or tech partners.
PW Consulting’s Worldwide Vibration Isolation Systems Market study combines quantitative forecasting (2026–2032), practical plug-and-play tools for procurement and product teams, and a competitive intelligence layer that shows not just who the incumbents are, but how they are likely to move in response to the regulatory and material shocks that will define 2026. For executives who must make durable decisions this year — about capital allocation, product roadmaps, supplier strategy, or M&A — the study is structured to convert market insight into decisive action.
To obtain the full report, including the segmented demand curves, supplier profiles, and downloadable decision templates, please visit our official distribution page or contact PW Consulting’s market access team.
For detailed analysis of this topic, please visit the official page: Worldwide Vibration Isolation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Paroxetine Market Set to Expand at a 4.12% CAGR Through 2026–2032
By PW Consulting, 2026-08-12
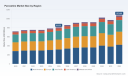
Worldwide Paroxetine Market — Strategic Outlook for 2026: A PW Consulting Preview
Executive summary
PW Consulting’s latest intelligence on the Worldwide Paroxetine Market positions paroxetine as a resilient, mid‑single‑digit growth therapeutic class through the 2026 strategic planning horizon. Our base‑year analysis (2025) places the global market at USD 810.25 Million (revenue, USD Million unit basis). After a period of modest volatility during 2020–2024, the market is forecast to expand at a compound annual growth rate (CAGR) of 4.12% across the 2026–2032 forecast window, reaching roughly USD 859.7 Million in 2026 and tracking toward an estimated USD 1,074.88 Million by 2032.
Worldwide In-Person Community Management Software Market
This preview highlights the tactical implications of those macro dynamics for corporate leaders preparing 2026 budgets, R&D roadmaps, commercial plans, and M&A screens. In keeping with the “trailer” approach, we expose the analytical frame, directional drivers, and decision‑grade recommendations while reserving detailed subsegment revenue tables, regional splits, and proprietary pricing matrices for the full report.
Genset Battery Market
Market trajectory and structural drivers
-
Historical resiliency: From USD 720.5 Million in 2020 to USD 810.25 Million in 2025, paroxetine demonstrates steady baseline demand tied to established clinical indications and inclusion on major essential medicines lists. Year‑to‑year fluctuations reflect episodic market events (supply interruptions and regulatory clearances) rather than a structural demand collapse.
Portable DC Load Bank Market -
Regulatory and product evolution: The class has seen ongoing lifecycle activity — approvals for extended‑release formulations and mesylate salt generics, plus multiple ANDA approvals in recent years — that create windows for entrants to capture incremental volume through differentiated dosage forms and bioequivalent generics.
-
Competitive intensity and concentration: Market concentration metrics indicate a moderately consolidated but still competitive environment. Leading branded and generics players co‑exist with a broad set of manufacturers supplying both API and finished doses, producing continuous price pressure in mature procurement channels.
-
Supply chain realities: Over 80% of paroxetine API supply originates from South Asia and East Asia, creating a persistent source‑country exposure that influences lead times, working capital needs, and procurement strategy.
Why this matters to 2026 corporate decisions
For commercial and manufacturing executives, the near‑term forecast and underlying dynamics translate into a specific set of decision levers for 2026. The PX market is no longer a “set and forget” legacy portfolio — it requires active strategic choices across sourcing, formulation, pricing, and partnerships. The key implications we surface for 2026 planning include:
-
Portfolio prioritization: Firms must decide whether to defend base volumes through high‑value channel contracts or to reallocate resources to differentiated formulations (e.g., controlled‑release, alternative salts) that command better margin resilience.
-
Manufacturing footprint and capacity investments: Given concentrated API supply patterns and periodic local disruptions, firms should reassess dual‑sourcing, onshore buffer capacity, and vendor qualification timelines targeted for 2026 ramp cycles.
-
Pricing and tender strategy: High generic competition has compressed unit economics in mature markets. Pricing approaches for 2026 must combine dynamic tender participation with selective direct contracting and value‑based negotiations in private pay and institutional segments.
-
Regulatory sequencing and filings: Recent ANDA approvals for extended‑release and mesylate capsule variants demonstrate the commercial payoff of timely filings. Companies with 2026 launch ambitions must accelerate bioequivalence packages and compliance roadmaps now to avoid multi‑quarter delays.
-
M&A and portfolio bolt‑ons: With a top‑end growth outlook that is steady but not explosive, M&A efforts should be disciplined — focused on scaling manufacturing capability, securing API supply, or acquiring differentiated formulations rather than pursuing commoditized volume alone.
Competitive landscape — what to watch in 2026
The competitive field includes a mix of originator brand players and a broad generics base. Key profiles and strategic positioning are summarized below to help executives assess competitor moves and partnership targets.
-
GlaxoSmithKline (GSK) — the originator and steward of branded formulations that retain recognition in certain markets. GSK’s continued focus on lifecycle management of branded names provides a benchmark for premium pricing windows and switch strategies.
-
Teva Pharmaceutical Industries — a large, global generics competitor with scale manufacturing and distribution capabilities; competes aggressively on breadth of strengths and channel reach.
-
Viatris (Mylan legacy) — leverages an extensive established generics portfolio and partner networks; a natural contender for tender wins and large‑volume contracts.
-
Indian manufacturers (Sun Pharma, Dr. Reddy’s, Lupin, Aurobindo, Zydus, Cipla, Alembic, Aurobindo) — collectively important for API supply and finished doses, with proven US/EU approvals and export capabilities. Several have secured ANDA clearances or approvals for ER/mesylate variants, intensifying competition in 2026.
-
Sandoz and Apotex — cross‑regional generics players providing distribution depth across Europe and the Americas, often serving as acquisition or distribution partners for price‑sensitive markets.
Recent regulatory events (e.g., new ANDA approvals and tentative approvals across multiple players) indicate continued opportunity for entrants that can execute regulatory filings efficiently. At the same time, concentration metrics suggest that forming strategic alliances or achieving scale remains a meaningful pathway to protect margins.
Supply chain, pricing and regulatory pulse
-
API sourcing concentration: With more than four‑fifths of API capacity located in India and China, 2026 strategies should prioritize contractual safeguards — minimum‑volume commitments, capacity reservations, and dual‑sourcing where feasible.
-
Pricing context: Generic paroxetine pricing in mature markets has stabilized at low wholesale acquisition costs; publicly available benchmarks in 2024 showed generic 20mg tablets in a narrow low‑cost band. Expect continued downward pressure in commoditized channels but pockets of premiumization for differentiated delivery systems.
-
Regulatory landscape: The patent cliff is a historical factor (original US patent expired in 2003), but lifecycle management via salts and ER formulations continues to yield commercial windows. Recent approvals for mesylate capsule generics and ER tablets underscore the significance of formulation patents and regulatory timing.
-
Market stability signals: Supply disruption episodes have diminished; paroxetine was removed from the US FDA drug shortage list after supply normalized in early 2023. However, episodic shortages remain a tail risk tied to API and manufacturing interruptions.
What PW Consulting’s full report delivers (practical takeaways)
Our comprehensive Worldwide Paroxetine Market report is designed as an operational toolkit for 2026 planning and includes:
- Granular market model with revenue build‑ups by formulation, channel, and scenario‑based forecasts (base, upside, downside).
- Pricing intelligence: historic transaction benchmarks, tender results, and unit cost curves that inform margin sensitivity analyses.
- Supply‑chain risk matrix: supplier concentration heat maps, lead‑time stress tests, and contract‑negotiation playbooks.
- Regulatory tracker and filing calendar: ANDA/MAA windows, patent landscapes for salts/formulations, and a prioritized filing strategy to secure first‑to‑market advantages.
- Competitive playbooks: benchmarking of 12+ participants across capabilities, go‑to‑market routes, and likely moves in tender markets for 2026.
- M&A screening models: valuation ranges, accretion/dilution stencils, and integration checklists for acquiring manufacturing scale or differentiated assets.
- Actionable recommendations and a 90‑day execution roadmap tailored to manufacturers, distributors, and private‑equity sponsors.
To preserve the strategic value of these diagnostic tools and support implementation, detailed line‑by‑line subsegment tables, raw data extracts, and our proprietary pricing model are accessible exclusively in the full report and the client portal.
Concise recommendations for 2026 planning
- Secure API continuity now — negotiate multi‑year supply agreements with capacity clauses and audit rights; identify a validated secondary source before Q3 2026.
- Prioritize differentiated formulations (ER, mesylate, alternate delivery) where clinical differentiation can justify premium pricing and reduce commoditization risk.
- Adopt hybrid tender strategies — combine selective participation in price‑competitive tenders with targeted direct contracts in specialty channels to protect margins.
- Accelerate regulatory filings for bioequivalence dossiers and prepare for expedited review pathways where available to capture early windows post‑approval.
- Use disciplined M&A to close capability gaps — target bolt‑ons that secure API feedstock, US/EU regulatory approvals, or niche formulation expertise rather than volume alone.
- Institute a quarterly supply‑chain stress test and margin sensitivity review as part of the 2026 operating cadence to respond quickly to price or supply shocks.
Next steps — where to get the full analysis
This preview is intended to inform strategic dialogue and prioritize 2026 initiatives. The full PW Consulting Worldwide Paroxetine Market report contains the detailed subsegment revenue breakdowns, regional and application tables, granular pricing curves, our complete competitive scorecards, and downloadable data packs for in‑house modeling. For immediate access, executive briefings, or tailored scenario runs for your portfolio, visit pw‑consulting.com/reports/worldwide‑paroxetine‑market or contact our commercial team to arrange a briefing and secure client access.
PW Consulting — translating market data into executable strategy for life sciences leaders preparing to win in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Paroxetine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Women's Non‑Athletic Footwear Market Tops USD 188,400 Million in 2025 — Asia Pacific Leads with USD 76,583.85 Million as Market Eyes 4.5% CAGR Through 2032
By PW Consulting, 2026-08-12
Worldwide Women's Non-athletic Footwear Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on the worldwide women's non-athletic footwear market delivers a forward-looking, execution-ready intelligence package tailored to executive teams planning resource allocation, product roadmaps, sourcing commitments, and M&A activity in 2026. The market reached approximately USD 188.4 billion in our 2025 base year and is projected to expand at a compound annual growth rate (CAGR) of 4.5% through the forecast window, approaching roughly USD 256.4 billion by 2032. These topline dynamics create both margin and volume opportunities — and corresponding risks — that require disciplined, near-term strategic choices.
Passive Direct Air Capture Market
Executive snapshot: Why this matters in 2026
-
Growth with constraint: Moderate, steady expansion creates room for investment but raises the bar for capital allocation. With mid-single-digit CAGR, winners will be those who convert modest market growth into outsized returns through operating leverage, premiumization, and channel optimization.
Worldwide B2B Chocolate Market -
Fragmented competitive structure: The market remains structurally fragmented; established luxury groups, accessible-luxury portfolios, and high-volume value players coexist with regional manufacturers and pure-play digital brands. This fragmentation drives opportunity for consolidators and for brand owners that can scale profitable distribution models.
Bus Processing Machines Market -
Input-cost pressure and sustainability regulation: Raw-material volatility and stronger environmental standards are reshaping sourcing, product design, and cost pass-through strategies — making near-term supplier and materials decisions material to 2026 P&L outcomes.
Market dynamics shaping 2026 strategic choices
Three interlocking dynamics will determine which firms lead to 2032: consumer preferences for comfort and style, input-cost and supply-chain resilience, and regulatory and brand-driven sustainability expectations.
-
Consumer behavior: Post-pandemic normalization has elevated demand for versatile, elevated-casual and occasion footwear. Buyers are trading up selectively for design or performance attributes, but remain price- and value-sensitive in many channels. This creates diverging playbooks for premium versus volume-first players.
-
Material and sourcing pressures: Leather and alternative materials are central to cost and differentiation strategies. In Q1 2025 wet‑blue leather prices jumped to around USD 2.80 per square foot — a near-term shock driven by drought-related supply constraints — while Indian leather export volumes slowed amid tighter water-use policies. These dynamics force sourcing diversification and increase the strategic value of synthetic and textile alternatives as cost-stabilizing levers.
-
Regulatory and greenwashing scrutiny: Standards such as ISO 14021 are receiving greater enforcement and marketplace attention, pushing brands to substantiate environmental claims. Firms that can operationalize traceable materials, verified labeling, and lifecycle assessments gain trust and reduce compliance risk.
Competitive landscape: implications for positioning and playbooks
The competitive set spans luxury conglomerates, accessible-luxury portfolios, trend-driven fashion brands, comfort-focused manufacturers, and high-volume global retailers. Each cluster has a distinct set of strategic priorities and vulnerabilities.
-
Luxury houses (e.g., brands under large fashion groups): These players leverage heritage craftsmanship, runway influence, and high price elasticity. Their primary levers are design exclusivity, limited editions, and controlled distribution to protect margin, but they face challenges scaling sustainably and responding rapidly to raw-material shocks.
-
Accessible-luxury and lifestyle groups: Brands in this category compete on aspirational styling and wider distribution. Their 2026 priorities should include optimizing product lifecycles, strengthening DTC channels, and adopting selective premiumization to protect margins without sacrificing volume.
-
Mass and value producers: Firms focused on volume gain from broad geographic reach and low-cost sourcing. Their structural risk is concentrated supplier exposure and limited ability to capture price increases without losing market share.
-
Comfort and performance-focused manufacturers: Brands emphasizing comfort technologies and materials can command loyal repeat customers but must make timely investments in material science and supply-chain capabilities to maintain differentiation.
Recent product and collection activities — runway showcases, targeted collection launches, and design-led product introductions — demonstrate how incumbent brands are both defending share and experimenting with new materials and silhouettes. These market signals should inform decisions on assortment, inventory cadence, and brand collaboration strategies in 2026.
What PW Consulting’s report provides (practical, actionable content)
This report is intentionally designed as a strategic toolkit for 2026 planning cycles, not just a readout of historic data. It combines market-sizing rigor with executable playbooks and scenario tools that translate ambiguity into prioritized actions.
-
Topline and scenario modeling: A transparent, bottom-up market model updated to a 2025 base year, with three demand scenarios showing how variations in material costs, consumer sentiment, and channel mix affect revenues and margin pools through 2032.
-
Material and supplier stress-tests: Playbooks to quantify the P&L impact of raw-material shocks (including leather and synthetic input cases), plus mitigation options — alternative materials, forward purchasing, and nearshoring simulations.
-
Assortment and SKU optimization framework: Methods to rationalize travel, seasonal, and perennial SKUs against margin contribution and inventory capital, including an elasticity-informed markdown algorithm.
-
Go-to-market and digital benchmarks: Channel-performance scorecards, DTC vs wholesale scenario outcomes, and conversion benchmarks for omnichannel assortments — enabling tailored channel investments that align with brand economics.
-
M&A and partnership screeners: Criteria and valuation heuristics for targeted acquisitions, JV structures with regional manufacturers, and strategic minority stakes that accelerate capacity or channel access.
-
Compliance and sustainability playbook: Practical steps to operationalize ISO-aligned labeling, lifecycle assessments, and supplier audits to mitigate reputational and regulatory risk.
Strategic priorities for executives in 2026
From our analysis, five priorities should feature prominently in executive agendas this year:
-
Sourcing resilience and material mix optimization — diversify leather supply chains, hedge exposure with synthetic alternatives, and invest in supplier partnerships that offer traceability and preferred pricing.
-
SKU and cadence rationalization — reduce low-velocity SKUs, focus on versatile silhouettes with higher turnover, and align production cycles to demand signals rather than calendar fashion alone.
-
Channel margin management — sharpen the economics of DTC conversion vs. wholesale reach; invest selectively in owned digital experiences where lifetime value justifies higher acquisition costs.
-
Sustainability as a margin protector — adopt verifiable environmental claims and circularity pilots that build brand trust and pre-empt regulation-driven costs.
-
M&A and portfolio pruning — use acquisition capital to fill capability gaps (e.g., material science, digital-first brands, regional manufacturing) while pruning underperforming low-margin segments.
How to use this report in a 2026 planning cycle
PW Consulting’s study is structured to be integrated directly into board-level and operating-review discussions:
-
Use the scenario toolkit to stress-test planned product investments against possible raw-material price paths and demand shocks; quantify the EBITDA sensitivity to each.
-
Apply the supplier stress-test and sourcing matrix when finalizing 2026 raw-material contracts; our recommended thresholds will help determine when to lock volumes and when to pursue flexible purchasing terms.
-
Deploy the SKU optimization playbook during assortment planning cycles to free working capital and accelerate profitable replenishment strategies.
-
Leverage the M&A screeners as a short list for inorganic growth that improves unit economics or accelerates entry into high-opportunity channels.
Closing — the strategic value of full intelligence
As boards and executive teams finalize budgets and strategic initiatives for 2026, the difference between a defensive and a value-creating plan will be the ability to convert macro market stability into micro-level margin gains while containing supply-side risk. PW Consulting’s report offers the models, scenario analyses, and hands-on playbooks to do exactly that.
For executives seeking the detailed subsegment matrices, supplier lists, and interactive dashboards that underpin these recommendations, the full report and downloadable spreadsheets are available on the PW Consulting publication page. The public overview you have read here is designed to demonstrate the analytical depth and practical focus of our work while reserving the granular inputs and proprietary models for subscription access — the same tools your team can use directly in 2026 planning sessions.
For detailed analysis of this topic, please visit the official page: Worldwide Women's Non-athletic Footwear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Specialty Ink Market to Reach USD 6.47 Billion by 2032 at 5.24% CAGR — Asia Pacific Leads with USD 1.85B and UV‑Curable Inks Dominate in 2025
By PW Consulting, 2026-08-12
Worldwide Specialty Ink Market: Strategic Imperatives for 2026 — PW Consulting Release
Executive preview from PW Consulting’s senior strategy team and lead industry analyst
Our new PW Consulting report, Worldwide Specialty Ink Market (Base Year: 2025), provides a decision-grade roadmap for executives who must balance growth, margin protection, and regulatory compliance in an increasingly volatile raw-material and geopolitical environment. The specialty ink market — valued at approximately USD 4.52 billion in 2025 — is poised to grow at a compound annual growth rate (CAGR) of 5.24% through the 2026–2032 forecast window, reaching a materially larger addressable market by 2032. This release summarizes the strategic takeaways that should shape boardroom and procurement actions in 2026, while preserving the granular datasets and proprietary segment models for subscribers to the full report.
Generation Management Systems Market
Why this report matters for 2026 decision cycles
-
Near-term cost shocks have become structural testcases for pricing power. In early 2026 leading producers implemented across-the-board surcharges and price adjustments in response to energy-market volatility and feedstock constraints (e.g., Sun Chemical and Flint Group announcements in March 2026). Our analysis quantifies how different commercial strategies — from contract renegotiation to index-based pricing clauses — protect margins across multiple business models.
Worldwide Disinfectants For Haemodialysis Market -
Regulatory complexity is accelerating product strategy risk. Continuing regulatory action (including ongoing U.S. EPA activity on certain pigment chemistries and national-level PFAS approaches) creates both compliance costs and innovation windows for low-risk formulations. The report maps regulatory scenarios to product roadmaps and near-term compliance cost ranges so product and legal teams can prioritize mitigation investments.
Worldwide Quantum Dot Films Market -
Supply resilience has moved from operational nicety to strategic requirement. Disruptions in chemical feedstock flows driven by geopolitical tensions and regional conflicts in 2025–2026 have exposed single-supplier and single-region dependencies. PW Consulting’s supply-risk matrix gives procurement leaders the tools to stress-test sourcing strategies and accelerate near-term dual-sourcing or strategic inventory programs.
Market dynamics: what the high-level numbers tell you
From 2020 through 2025 the specialty ink market registered steady expansion, culminating in an estimated market size of roughly USD 4.52 billion in 2025. Our baseline projection assumes a 5.24% CAGR from 2026 through 2032, with scenario models that reflect slower-growth and faster-growth pathways depending on raw material trends, regulatory outcomes, and adoption rates of energy-curable and functional ink technologies. The market concentration is moderate: the combined share of the top three firms is under 40%, and the top five account for just over half of global revenue — an architecture that supports both incumbent scale plays and targeted consolidation through M&A.
Importantly, the headline CAGR masks differentiated growth and margin profiles across product technology families and applications. The full report provides the granular, client-only breakdowns that allow product and commercial leaders to size serviceable addressable markets (SAMs) for specific formulations and to model price elasticity and margin trajectories under alternative input-cost scenarios.
Practical content included in the report (operational playbooks and tools)
-
Proprietary market-sizing and forecasting models (2020–2032) with downloadable Excel scenarios for stress-testing price and volume assumptions.
-
Supplier scorecards and capability maps — technical, geographic, financial and sustainability criteria — to inform dual-sourcing and strategic partnership decisions.
-
Regulatory impact matrix mapping key jurisdictions to formulation restrictions, likely timelines, and cost-of-compliance ranges.
-
Commercial playbooks: price-index clause templates, channel segmentation tactics, and go-to-market bundles that protect margins while preserving share in key accounts.
-
CapEx and capacity strategy models that link expansion decisions to lead times, working capital needs, and unit economics under multiple demand scenarios.
-
M&A heatmaps and integration checklists focused on technology tuck-ins (e.g., conductive or functional inks), geographic fill-ins, and bolt-on capabilities such as deinkability and low-migration chemistry portfolios.
Competitive landscape: how incumbents are reacting and where disruption is likely
The industry sits at the intersection of scale, formulation know-how, and regulatory credentialing. Legacy majors (Sun Chemical / DIC, Flint Group, Siegwerk, Toyo Ink and others) retain strong distribution networks, formulation IP and customer trust — assets that matter when customers demand validated low-migration, mineral-oil-free, or deinkable solutions. Recent company moves illustrate the strategic playbook in motion:
-
Sun Chemical (DIC) implemented price adjustments in March 2026 citing feedstock and logistics pressures, and continues to advance energy-curable product lines (e.g., a high-speed press UV ink launched in 2025). These twin actions highlight a dual focus on margin protection and technology differentiation.
-
Flint Group’s March 2026 pricing actions reflect similar cost-pass-through dynamics; the company’s emphasis remains on packaging and energy-curable formulations where customers tolerate premium pricing for performance and compliance benefits.
-
Toyo Ink has been active on both certification and capacity: its mineral-oil-free inks achieved recognized deinkability certification in January 2026, while capacity expansion in India (announced November 2025) signals a strategic bet on faster-growing end-markets and localized production economics.
-
Regional and specialist players — from INX International to Marabu and Nazdar — are leveraging targeted product portfolios (digital, UV LED, conductive, security inks) and faster NPD cycles to capture share in niche applications and white-space segments.
For buyers, suppliers showing both technical differentiation and resilient supply footprints will command premium terms. For sellers, demonstrating validated compliance (deinkability, mineral-oil-free formulations, PFAS avoidance) is increasingly the ticket to preference in large retail and packaging accounts.
Regulatory and raw-material headwinds: strategic implications
Ongoing regulatory initiatives — from pigment-specific risk management activity to broader PFAS scrutiny — create asymmetric incentives: compliance can raise short-term costs but also erect longer-term barriers to entry. At the same time, pigment and intermediate price volatility and regional feedstock disruptions have compelled firms to revisit inventory strategies, hedging, and vertical integration options. Our report provides a playbook that links regulatory scenarios to concrete P&L outcomes and recommends mitigation levers for procurement, R&D, and pricing teams.
Actionable strategic recommendations for 2026
-
Implement immediate pricing governance: adopt tiered indexation clauses for new contracts and backbook renewals; model customer-level elasticity to avoid unnecessary volume loss.
-
Prioritize formulation investments that address both regulatory tail risk and customer sustainability requirements — certified deinkability and PFAS-free assurance are differentiators.
-
Advance regional manufacturing footprints selectively to shorten lead times and reduce exposure to shipping and customs volatility; consider captive intermediate procurement where economics justify.
-
Deploy our M&A heatmap to pursue small, technology-led acquisitions (conductive, security, or rapid-curing chemistries) that accelerate route-to-market and broaden high-margin portfolios.
-
Convene cross-functional war rooms that use the report’s scenario models to stress-test budgets, capex, and hiring plans across three regulatory and three raw-material cost scenarios.
How to use this report in your 2026 planning cycle
Executives should view this PW Consulting study as an operational toolkit as much as a market brief. Use the downloadable forecasting models to align commercial targets, baseline procurement strategies on our supplier risk scores, and adapt product roadmaps using the regulatory impact matrix. The report’s confidential appendices contain the granular segment-by-segment tables, regional demand models, and supplier-led value-chain economics we intentionally withheld from public summaries to preserve analytical integrity and client exclusivity.
Next steps and where to find the full intelligence
This preview outlines the strategic contours that will define success in specialty inks through 2026 and beyond. PW Consulting’s full Worldwide Specialty Ink Market report includes the underlying datasets, segment-level forecasts, supplier scorecards, and downloadable scenario models essential for tactical implementation. For licensing, tailored briefings, or to access the full report with client-exclusive appendices, please visit our report page or contact your PW Consulting account lead. Access to the full dataset will enable you to apply the report’s tools directly to your company’s P&L and operating plan for 2026.
PW Consulting remains available to run bespoke workshops, integrate the model into enterprise planning systems, and support M&A diligence with rapid-turn valuation and synergy assessments. In an industry where formulation expertise, supply resilience, and regulatory positioning determine competitive advantage, executives who move early and with validated scenarios will capture disproportionate value as the market continues its steady expansion.
For detailed analysis of this topic, please visit the official page: Worldwide Specialty Ink Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Alfalfa Feed for Horse Market Hits USD 8.51 Billion in 2025, Poised to Grow at a 5.8% CAGR Through 2032
By PW Consulting, 2026-08-12
Worldwide Alfalfa Feed for Horse Market — Strategic Imperatives for 2026
PW Consulting’s newest market study on Worldwide Alfalfa Feed for Horse provides boards, commercial executives, and supply-chain leaders with a decision-grade roadmap for 2026. Anchored on a 2025 base year and a forecast horizon extending through 2032, the market model projects a sustained recovery and expansion at a 5.8% CAGR. By 2025 the market reached approximately USD 8.51 billion and, under our central scenario, approaches roughly USD 12.63 billion by 2032. These headline dynamics frame practical choices firms must make this year to protect margin, secure supply, and capture premium equine demand.
Worldwide Email Verification Software Market
What this PW Consulting report delivers — practical outputs, not platitudes
- High-resolution market sizing and validated growth scenarios (2026–2032) that translate macro demand into actionable sales and procurement targets.
- A layered supply-side map tracing farm gate economics through processing, storage, and cross-border logistics, with heatmaps for water, fuel, and fertilizer exposure.
- Regulatory risk frameworks covering basin-level groundwater restrictions, export controls, and feed-safety requirements—scored by likelihood and commercial impact.
- Buyer/supplier playbooks for structured long-term contracting, including sample clauses, price-adjustment mechanisms, and quality-assurance KPIs tailored to alfalfa products (hay, pellets, cubes, and chaff).
- Operational tools: ROI calculators for pelletizing and cube-compression investments, CapEx timelines for drying and storage, and farm-level break-even sensitivity models reflecting input-cost volatility.
- Competitive scorecards and acquisition screens built from primary interviews and shipment flows—designed to identify roll-up targets, partner fit, and white-space opportunities.
In short: the report is a playbook for executives who must convert market growth and structural risk into a year-one execution plan for 2026—without asking teams to rebuild analytics from scratch.
Worldwide Psychiatry EMR Software Market
Macro dynamics that will determine winners in 2026
Three structural forces compress choice and amplify risk as the industry enters 2026. First, water and irrigation policy is reshaping production footprints. Basin-level restrictions—exemplified by California’s groundwater allocation programs and tighter irrigation permitting in the U.S. Southwest—are producing measured contractions in irrigated alfalfa acreage and shifting cost curves for irrigated farms.
Worldwide Workload Automation Software Market
Second, input inflation has materially changed farm economics. Across major production states, university cost-of-production studies show that real input costs (water, fertilizer, labor, fuel, and machinery) are 20%–35% higher than 2020 levels, even as average yields have been effectively flat near historical norms. Those combined dynamics raise the effective marginal cost of new supply and make short-cycle production responses slower than in past cycles.
Third, technology and product innovation are creating new commercial pathways. Investments in seed genetics, forage-processing equipment, and quality-preserving machinery (for example, new reel-style tedders and knowledge centers focused on forage optimization) are beginning to change the calculus on value-added processing vs. raw-bale export. Early movers will capture grading premiums, reduce spoilage, and win integrated buyer relationships.
Demand-side patterns shaping 2026 positioning
Demand remains resilient and increasingly sophisticated. Horse owners, training facilities, and equine nutritionists are prioritizing traceability, consistent nutrient profiles, and convenience formats (pellets and cubes) that simplify feeding programs and biosecurity. Distribution channels are likewise evolving—traditional bulk buyers continue to matter, but specialty equine retailers and online channels are accelerating premiumization. Companies that can package reliability and provenance into a branded offer, rather than competing solely on price per ton, will command above-market margins.
Supply-side constraints and operational implications
Producers and processors face constrained upside in 2026 unless they actively manage three levers: water-use efficiency, logistics resilience, and vertical capture of processing value.
- Water risk: Regions facing enforced pumping reductions and curtailed irrigation allocations require transition plans—either through cultivar changes, deficit-irrigation protocols, or relocation of acreage into less-stressed basins.
- Logistics and seasonality: Compressed harvest windows and reliance on ocean freight for export-oriented businesses mean investment in drying/storage and flexible freight contracts are now strategic—not tactical—expenses.
- Processing arbitrage: Adding pelletizing or cube-compression capacity can both stabilize seasonal supply and open premium channels, but capex discipline and throughput utilization are critical to ensure that processing uplifts margin rather than erases it.
Competitive landscape — fragmentation, specialization, and where scale helps
The market remains fragmented: top-three and top-five concentration metrics show that no single cluster of incumbents dominates the global feed-for-horse arena. This fragmentation yields two realities for strategic decision makers in 2026.
- Opportunity for roll-ups and supply consolidation. Because market concentration is relatively low, well-timed M&A can materially increase bargaining power with logistics providers and large institutional buyers, and can accelerate access to export channels and processing assets.
- Room for differentiated premium plays. Many established players—ranging from established U.S. exporters to specialized European and Australian producers—have successfully carved niche positions by focusing on quality grading, non-GMO certification, or dedicated equine product lines. These firms illustrate an alternative growth path: depth over breadth.
Profiles in strategic contrast among leading firms show the practical range of playbooks available in 2026. Some companies combine export scale with commodity-grade bales and international distribution networks; others focus on premium, traceable alfalfa products for performance horses and boutique retailers. Select processors and traders have invested in pellet and cube capacity to capture year-round demand and reduce exposure to bale-quality seasonality. Recent industry moves—like new product knowledge centers and innovations in hay-preservation machinery—underscore how operational know-how is becoming a competitive asset.
Strategic actions for corporate leaders in 2026 (prioritized)
- Rebalance procurement toward secured multi-year offtake agreements with tiered pricing that reflect water and fuel pass-throughs—link contract tenure to capacity upgrades that reduce spoilage.
- Invest selectively in processing (pellets/cubes) where utilization models demonstrate positive IRR under conservative throughput assumptions; favor modular technologies that scale with demand.
- Pursue targeted M&A to close logistical gaps (storage, bulk handling) and to consolidate regional supply hubs; prioritize targets with proven quality-control systems and export documentation.
- Implement a water-risk dashboard for every sourcing region: link regulatory timelines, deficit-irrigation exposure, and local cost inflation to sourcing decisions and contingency acreage plans.
- Elevate product differentiation via certified traceability, nutrient-profile guarantees, and route-to-market exclusives with specialty equine retailers and veterinary channels.
- Negotiate freight and storage contracts with flexibility clauses to manage seasonal spikes; explore blended modal strategies to reduce ocean-vessel dependence during peak windows.
- Engage proactively on regional water policy and basin-management forums to shape allocation processes and avoid surprise curtailments in key sourcing basins.
How PW Consulting’s dataset and tools accelerate 2026 execution
Clients that deploy the full PW Consulting report gain immediate access to scenario-tested playbooks and operational templates: farm-level cost models that incorporate the latest university cost-of-production inputs; procurement scorecards keyed to quality, traceability and water exposure; and a policy-heatmap aligned to basin-level irrigation restrictions. We also provide an M&A screening tool calibrated to identify targets that offer EBITDA uplift through processing synergies or logistics consolidation.
Importantly, this article intentionally omits granular regional and product-split tables: those detailed segmentations—including region-by-region volumes, product-form mix, and channel shares—are preserved in the full report and our interactive online dashboards to protect client value and to enable tailored benchmarking.
Final perspective — positioning for 2026 and beyond
The alfalfa feed-for-horse market is maturing. Growth is real and measurable; our 5.8% CAGR forecast to 2032 creates optionality for firms that act decisively in 2026. But growth will not be distributed evenly: it will accrue to companies that manage water exposure, capture processing uplift, and translate provenance into premium pricing. Fragmentation means both opportunity and risk—late movers that remain commodity-centric will face margin pressure from rising input costs and tighter supply. Early movers who combine operational upgrades, disciplined contracting, and strategic consolidation will be the ones able to convert the coming market expansion into sustained, defensible profit.
For a complete breakdown of regional flows, product-form economics, and the proprietary company scorecards that underpinned our recommendations, access the full PW Consulting Worldwide Alfalfa Feed for Horse Market report and interactive annex on our website.
For detailed analysis of this topic, please visit the official page: Worldwide Alfalfa Feed for Horse Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Insights: Worldwide Blood-Thinning Drugs Market Poised to Grow at an 8.5% CAGR Through 2032
By PW Consulting, 2026-08-12
Worldwide Blood Thinning Drugs Market — Strategic Outlook to 2026: A PW Consulting Preview
Executive summary
PW Consulting’s latest market study on the worldwide blood thinning drugs market presents a focused, decision-grade perspective designed for executive teams planning their 2026 strategies. Using 2025 as the base year and a forecast window stretching from 2026 to 2032, the analysis frames an industry growing at a compound annual growth rate (CAGR) of 8.5%. The total market — which expanded from approximately USD 43,492.11 Million in 2023 to USD 47,188.94 Million in 2024 and reached USD 51,200.0 Million in 2025 — is projected to cross the USD 90 billion threshold by 2032 (USD 90,631.29 Million), reflecting sustained clinical demand, therapeutic migration to oral agents, and continuing innovation.
Worldwide Ecological Contractor Market
Why this report matters for 2026 corporate decisions
2026 is a pivot year for industry participants: patent cliffs, regulatory movements, and supply fundamentals converge to reshape competitive dynamics. PW Consulting’s report synthesizes these forces into actionable guidance. Our objective is to equip senior leaders with the scenario intelligence needed to prioritize investments across R&D, manufacturing resilience, commercial motion, and M&A.
Worldwide Embedded Database System Market
-
Timing and prioritization: With established molecules facing landmark IP and exclusivity events in 2026, strategic repositioning — including defensive lifecycle management and coordinated generics strategies — becomes urgent.
Common Mode Inductor Core Market -
Commercial posture: Reimbursement and access shifts driven by generic entry and payor negotiations will alter pricing leverages. Our report maps likely payer scenarios and prepares companies to defend margin while securing volume.
-
Risk mitigation: Supply chain fragilities — notably for heparin and low-molecular-weight heparin raw materials — demand immediate diligence; the report includes supplier risk matrices and contingency pathways.
Market dynamics and near-term catalysts
Several notable events and longer-term trends are recalibrating the sector:
-
Regulatory and safety developments: The voluntary withdrawal of a major reversal agent in late 2025 after safety signal reassessment has elevated the regulatory oversight profile for acute-care interventions. This event underscores the need for rigorous post-market surveillance strategies and communications planning for both originators and new entrants.
-
Patent expiries and generic competition: European exclusivity expirations and prior approvals of key generics have accelerated the entry of lower-cost alternatives into major markets. PwC-consistent modelling anticipates material sales displacement for affected brands in 2026, creating windows for generic manufacturers and pricing pressure for originators.
-
Therapeutic migration: Adoption of direct oral anticoagulants (DOACs) continues to outpace legacy vitamin K antagonists due to simplified monitoring and improved safety profiles. This secular trend supports above-market growth in aggregate volumes and shifts where innovation and margin pools are concentrated.
-
Supply-chain realities: Heparin production remains dependent on biological feedstocks with concentrated supply nodes. Companies holding vertical integration or secured long-term supply agreements possess a tangible competitive advantage in 2026.
Competitive landscape — reading between the logos
The blood thinning drugs market remains concentrated. Our market concentration metrics underline this: the top three firms account for approximately 68.5% of market volume, while the top five control around 82.3%. Such concentration informs both the battlegrounds and the levers available to challengers.
Key players span diversified global pharmaceutical houses, specialty injectables manufacturers, and large generic producers. Strategic takeaways include:
-
Integrated multinational originators: Companies co-commercializing leading DOACs continue to leverage combined clinical programs and global sales infrastructures. Their near-term strategy will emphasize tender defense, lifecycle management, and selective geographic prioritization as exclusivities lapse.
-
Generic and contract manufacturers: Firms with large-scale API and injectable capabilities are positioned to capture rapid share as patents expire, particularly in hospital-administered heparinoids and established oral agents. Speed-to-market, regulatory dossier robustness, and supply reliability will determine winners.
-
Specialty injectables and hospital-supply players: Providers focused on injectables and critical care formulations benefit from institutional procurement pathways. These firms should leverage clinical relationship depth and operational resilience to defend margins.
-
Diagnostics and biologics adjacencies: Companies offering complementary diagnostics or biologic therapies can create differentiated offerings around care pathways (e.g., peri-procedure risk stratification), opening partnerships and bundling opportunities.
Our competitive assessment in the report profiles leading firms across these archetypes, detailing headquarters, portfolio positioning, and tactical options — from co-commercialization adjustments to prioritization of geographic launches and tender strategies.
What the PW Consulting report delivers — practical content for immediate action
We designed the report to be a working toolkit for commercial and corporate development teams. Highlights include:
-
Proprietary market sizing and forecast model (base year 2025; forecast 2026–2032) with scenario toggles that reflect alternative uptake and pricing assumptions.
-
Regulatory and IP timeline: a consolidated tracker of expected expiries, regulatory decisions, and notable safety considerations that will materially affect market access and lifecycle strategies through 2032.
-
Reimbursement and payer-playbook: segmented payer scenarios, negotiation roadmaps, and a pricing sensitivity matrix to support formulary strategies and tender defense.
-
Supply-chain risk and mitigation matrix: supplier concentration mapping, substitution pathways, and inventory-management best practices for biologically-derived anticoagulants.
-
M&A and alliance screen: prioritized target lists and valuation heuristics for bolt-on acquisitions, tech licensing, and contract manufacturing partnerships.
-
Commercial launch-readiness checklist and go/no-go decision templates tailored for both originator label extensions and generic rollouts.
-
Executive dashboards and investor-ready summaries suitable for Board-level planning and capital allocation discussions.
Strategic playbook for 2026 — recommendations for each stakeholder
Below are distilled actions for sponsors, generics manufacturers, and institutional buyers heading into 2026:
-
Originators: Prioritize lifecycle management where exclusivity is eroding. Invest in evidence gaps that preserve premium pricing (real-world safety, comparative effectiveness) and ready contingency pricing models for regions where generic entry is imminent.
-
Generics and API suppliers: Accelerate regulatory filings in high-opportunity geographies, ensure QC rigor for biologically-sourced APIs, and secure long-term offtake contracts with hospital systems.
-
Hospital systems and payers: Reassess tender frameworks to incorporate total cost of care and reversal-agent dynamics post-safety signals; secure multi-source supply agreements to mitigate single-supplier risk.
-
Investors and BD teams: Use concentrated market structures to your advantage — pursue selectively priced assets that offer supply leverage or fast-follow generic margins, and prioritize targets with validated manufacturing quality systems.
Our confidence bounds and the need for tailored scenario planning
While our central forecast is anchored on a robust historical base and an 8.5% CAGR through 2032, multiple exogenous factors — regulatory reversals, unexpected safety findings, sudden supply disruptions, or accelerated generic uptake in priority markets — can shift trajectories meaningfully. PW Consulting’s full deliverable includes sensitivity analyses that quantify these impacts and propose responsive playbooks under alternative outcomes.
How to use the report in your 2026 planning cycle
Executives should consider the following pragmatic next steps to operationalize insights from the PW Consulting study:
-
Integrate our payer and pricing modules into the 2026 commercial budget exercise to stress-test margin scenarios.
-
Run rapid due diligence guided by our M&A screening tools to expedite potential bolt-on acquisitions before competitors consolidate scale.
-
Commission a supply-chain gap assessment using our supplier risk templates to pre-empt shortages tied to biological feedstocks.
-
Adopt our launch-readiness checklist for any product slated for market entry or relaunch in 2026 to minimize regulatory and commercial slippage.
Closing perspective
The blood thinning drugs market is entering a period of amplification and reallocation: enduring clinical demand and therapeutic shifts are intersecting with concentrated competitive dynamics and discrete regulatory inflection points. PW Consulting’s report offers the structured intelligence and practical tools that leaders need to make confident, timely decisions in 2026. For teams preparing budgets, assessing M&A, or defending franchise value, this is the operating manual to translate macro momentum into defensible advantage.
To access the full dataset, proprietary models, and company-level playbooks referenced in this preview, please visit our official report landing page or contact PW Consulting’s Healthcare Strategy team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Blood Thinning Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Aircraft Fire Systems Market to Grow at a 4.85% CAGR Through 2026–2032
By PW Consulting, 2026-08-12
Worldwide Fire System Aircraft Market — Strategic Preview for 2026 Decisions
Executive summary
PW Consulting’s latest market study on the Worldwide Fire System Aircraft Market synthesizes seven years of observed performance (2020–2025) and provides a scenario-driven forecast for 2026–2032. The global market reached approximately USD 2,185.5 Million in the base year 2025 and is projected to continue expanding at a compound annual growth rate (CAGR) of 4.85% across the forecast window. By 2032, our base forecast puts the total market above USD 3.0 billion, reflecting steady demand driven by regulatory compliance programs, retrofit cycles in commercial and cargo fleets, and technology substitution initiatives tied to environmental and battery-fire mitigation requirements.
Worldwide Network Sandboxing Tools Market
Why this report matters for 2026 strategic planning
-
Regulatory inflection points are compressing decision timelines. EASA’s halon replacement guidance and enforcement deadlines, ICAO cut-offs for certain halon-based systems, and updated SAE/FAA guidance on powerplant fire protection create near‑term compliance needs that have clear CAPEX and product-selection consequences for airlines, MRO networks, and OEMs.
Worldwide Biogas Compressors Market -
Supply‑side shifts are real and measurable. Transition to fluorine‑free foams and alternative clean agents, combined with the emergence of encapsulator technologies for lithium-ion incidents, is changing the materials and supplier roster for aircraft fire protection products. These changes affect certification roadmaps, sourcing strategies, and spare‑parts lifecycles.
Worldwide Embalming Fluid Market -
Market scale and trajectory provide a reliable backdrop for investment and procurement choices. With a 2025 market size north of USD 2.1 billion and a mid-single-digit CAGR to 2032, buyers and investors can model multi-year ROI for retrofits, product development, and strategic partnerships with a high degree of confidence—while still needing segment-level intelligence to prioritize targets.
Market snapshot (what the headline numbers tell you)
Observed growth from 2020 through 2025 reflects a combination of core fleet maintenance demand, retrofit waves in freighter and passenger conversions, and accelerated replacements tied to environmental regulation and battery-related fire risks. The projected expansion through 2032 is driven by ongoing fleet renewals, tightening certification expectations, and the roll‑out of next‑generation suppression agents. PW Consulting’s forecast modeling—anchored to a 4.85% CAGR—captures both steady organic growth and episodic regulatory-driven investment cycles.
Competitive landscape — who matters and why
The aircraft fire systems sector shows moderate concentration: the top three suppliers account for nearly half of market share while the top five capture just under six-tenths—levels that combine established incumbent strength with meaningful space for specialized and niche players. This structure produces a competitive environment where scale, certification depth, and programme management capability determine contract outcomes.
-
Collins Aerospace (RTX) — A broad portfolio across detection, suppression, and integrated safety systems positions the company as a first-choice partner for OEMs and large operators. Their engineering depth supports certified automatic solutions across occupied compartments, engines and auxiliary units.
-
Meggitt PLC — Deep heritage in aircraft fire suppression with in-house R&D focused on threat‑zone-specific applications. Meggitt’s ability to deliver certified solutions across commercial and military platforms keeps it highly competitive for both OEM-fit and aftermarket retrofit programmes.
-
AMERON / AMETEK MRO — Strong OEM manufacturing capabilities, especially in high‑pressure cylinders and pyrotechnic initiation systems, make AMERON critical in the supply chains for both fixed‑wing and rotorcraft platforms.
-
Specialist and modular players (Ventura Aerospace, H3R Aviation, Amerex, PacSci EMC, Parker Aerospace, Hazard Control Technologies, Perimeter Solutions) — These firms bring niche advantages such as FAA-certified Class E compartment solutions, Halon replacements for portable extinguishers, advanced extinguishing cartridges, and next‑generation foam/clean agent chemistries. Their agility and focused certification track records create commercial opportunities in retrofit, regional, and military segments.
Regulatory and technology dynamics shaping 2026 choices
-
Halon phase‑out and Halon replacements: Regulatory action—notably EASA guidance and enforcement timelines—has crystallized replacement timetables for portable Halon 1211 and established constraints on new installations of certain halon-based systems. OEMs and operators that delay selection of compliant alternatives face narrowing retrofit windows and potential operational limits in EASA jurisdictions.
-
Standards and certification updates: Recent SAE releases updating powerplant fire protection guidance, plus FAA/EASA attention on lithium‑ion battery fire mitigation, raise the technical bar for systems intended for new-type certification or retrofit into critical compartments. Suppliers with demonstrated test and certification programmes will secure early wins.
-
Agent transitions and material risk: The move to fluorine-free foam concentrates and clean agents such as Novec-1230 or engineered blends impacts long-term sustainment, storage, and logistics. Operators should factor lifecycle availability, environmental compliance, and agent-handling training into procurement decisions.
-
Lithium battery fire mitigation: Encapsulator technologies and hybrid suppression approaches are being evaluated and in some cases qualified for aviation battery‑fire scenarios. This is an emergent product category that intersects with cargo compartment design and electronic device policies.
Practical, decision‑ready content inside the full report
PW Consulting’s full study is intentionally practical and structured to support immediate 2026 program decisions. Key deliverables included are:
-
Scenario-based market forecasts (conservative, baseline, and accelerated regulatory adoption paths) that let procurement, R&D and finance teams stress-test investment cases.
-
Vendor scorecards assessing certification footprint, technology maturity, aftermarket strength, and programme delivery risk—useful for supplier selection and JV partner screening.
-
Retrofit and upgrade playbooks that outline realistic timelines for certification, spares provisioning, and MRO capacity planning under different regulatory scenarios.
-
Supply‑chain risk heatmaps and mitigation options, including materials sourcing, agent availability, and strategic inventory recommendations for high‑impact components (pressure vessels, cartridges, specialized foams/agents).
-
Commercial models and pricing benchmarks that support contract negotiations and capex budgeting (note: granular segment-level financials and regional allocations are contained in the full report).
-
Regulatory compliance checklists and audit templates tailored to EASA/ICAO/FAA regimes, designed to streamline operator and MRO compliance projects.
How chief executives, CFOs, fleet managers and investors should use this intelligence in 2026
-
CEOs / Strategy leads: Use the report to align product and M&A roadmaps with regulatory timing. The market’s concentration profile suggests selective bolt‑on acquisitions or partnerships with niche specialists will accelerate access to compliance-ready technologies at lower time-to-certification risk.
-
CFOs / Investors: Model capital deployment against the report’s scenario outputs. The mid-single-digit CAGR supports staged investments in manufacturing capacity or certification programmes, but due diligence should prioritize certification timelines, supplier concentration and agent supply security.
-
Fleet and maintenance chiefs: Prioritise retrofits and spares-forward buying in follow-on waves identified in the report’s retrofit playbooks. Focus initial asset allocation on aircraft and compartments exposed to the most immediate regulatory deadlines.
-
R&D and procurement teams: Use vendor scorecards to fast-track partner selection for agent transitions and lithium-battery mitigation technologies; incorporate maintenance and logistics implications into TCO calculations rather than treating agent swaps as purely product substitutions.
What we deliberately withhold here — and why you should get the full report
In keeping with PW Consulting’s “trailer” approach, this public summary provides the full strategic context, headline market sizing, concentration metrics, and the regulatory and technology signals you need to prioritise decisions in 2026. However, we do not disclose here the segment‑level revenue breakdowns, region-by-region allocations, or the detailed company revenue splits and contract-by-contract assessments that underpin our competitive scoring. Those datasets and the underlying models are included exclusively in the full report because they are the actionable assets purchasers need to execute procurement, M&A and certification strategies with confidence.
Next steps
Organisations planning material spend, certification programmes, or strategic investments in 2026 should treat the full PW Consulting report as a working tool rather than a descriptive document. It is structured for use in board-level decision sessions, procurement RFPs, and certification gap analyses. For executives seeking a tailored briefing, PW Consulting offers customised deep-dive workshops that map the report’s outputs to your fleet, product roadmap, or investment thesis.
For access to the complete dataset, vendor scorecards, and downloadable retrofit playbooks, visit our official report page and request the full Worldwide Fire System Aircraft Market study. Timely access will materially reduce regulatory execution risk and help convert the market’s projected growth into measurable business outcomes for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Fire System Aircraft Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Wearable Inertial Sensors Market to Surge from USD 1,450 Million in 2025 to USD 3,413.25 Million by 2032 at a 13.01% CAGR
By PW Consulting, 2026-08-12
Worldwide Wearable Inertial Sensors Market — 2026 Strategic Outlook (PW Consulting)
Executive snapshot
PW Consulting’s new market study on worldwide wearable inertial sensors frames a decisive window for corporate strategy in 2026. The market for wearable inertial sensing — driven by continued MEMS miniaturization, embedded sensor fusion and edge AI — is expected to expand materially over the coming decade. Our modelling shows the market growing from an estimated USD 1.45 billion in 2025 to reach roughly USD 3.41 billion by 2032, representing a compound annual growth rate (CAGR) in the low double digits. For executives planning product roadmaps, partnership strategies, or M&A activities, this level of growth creates both opportunity and urgency: captureable market segments are emerging quickly, and first-mover advantage in productized sensor-fusion and regulatory-compliant solutions will matter.
Worldwide Ultraman Peripheral Market
Why wearable inertial sensors are central to 2026 strategies
-
From consumer electronics to clinical-grade devices, inertial sensing is the foundational modality for motion-aware systems. Improvements in low-power MEMS, tighter sensor fusion and the offloading of inferencing to application-specific hardware are expanding the role of inertial sensors beyond motion detection — into contextual understanding, biometric authentication and continuous clinical monitoring.
Wearable Smart Wristbands Market -
The convergence of embedded AI and inertial hardware is creating discrete value pools: device manufacturers can reduce downstream data costs and latency by moving classification and anomaly detection onto the sensor platform, while cloud and analytics players can monetize higher-value services for long-term monitoring and outcomes analytics.
Worldwide Storage Area Network Solution Market -
Regulatory clarity is evolving and will affect go-to-market timelines. In 2026, regulators are more clearly distinguishing low-risk wellness wearables from sensor-based digital health technologies (sDHTs) that make medical claims. This bifurcation creates differentiated paths to market and different investment profiles for compliance and clinical validation.
What the PW Consulting report delivers — practical content for 2026 decision cycles
-
Robust market model and scenario engine: forward-looking revenue projections through 2032, plus alternative scenarios that stress-test assumptions on device penetration, price erosion and new application adoption.
-
Actionable segmentation maps: granular splits by sensor type, packaged IMU configurations, end-application, and regional demand patterns — presented with sensitivity testing so planners can align R&D and sales targets without guessing.
-
Vendor intelligence and scorecards: comparative assessments of suppliers across product performance, power profile, embedded-processing capabilities, regulatory track record and supply-chain resilience.
-
Go-to-market playbooks: tailored strategies for OEMs, system integrators, clinical research organizations and platform providers, including pricing levers, channel choices, and partnership archetypes.
-
Regulatory and standards roadmaps: mapping EU MDR, FDA guidance, IEC/ISO standards and relevant certification paths to product development stages, with templates for clinical evidence dossiers and quality system alignment.
-
M&A and partnership pipeline analysis: deal appetite by buyer type, valuation multiples observed in adjacent hardware/software transactions, and due-diligence checklists specific to sensor IP, firmware, and data governance.
-
Technical deep dives and integration guidance: recommendations on sensor selection, sensor-fusion architectures, power budgeting and wireless integration for constrained wearable form factors.
Strategic implications for enterprise leaders in 2026
-
Product strategy — choose your axis: Decide early whether your product competes on sensor performance, embedded intelligence, data services or regulatory positioning. The capital and time required to certify a device for medical use are substantial; for some players, partnering with certified platform providers is the higher-return path.
-
Supply chain and component selection — think resilience and differentiation: Leading MEMS suppliers emphasize power, size and integrated fusion capabilities. Locking into a supplier based solely on unit price risks future capability gaps as sensor-embedded AI becomes a differentiator. Multi-sourcing, long-lead component agreements and co-development arrangements are prudent for 2026 procurement strategies.
-
Regulatory & clinical planning — start early: The regulatory bifurcation between wellness and medical devices reduces uncertainty for many wearables, but those targeting diagnostic or therapeutic claims must begin clinical validation and quality system workstreams now. Our report provides template timelines showing when to initiate pivotal studies to meet intended 2027–2028 market entry targets.
-
Commercial partnerships — move beyond components: Sensor suppliers increasingly offer software toolchains, cloud connectors and certification assistance. Partnerships that bundle hardware, firmware and evidence-generation services accelerate time-to-market and reduce execution risk for device makers.
-
Data & services monetization — lock the data-to-insights loop: Beyond one-time device sales, subscription models for analytics, real-world evidence, and clinician-facing dashboards will be primary margin drivers as sensor data matures into validated outcomes signals.
-
IP and defensive strategy — protect algorithmic value: Embedded sensor fusion and motion-classification models represent core intellectual property. Enterprises should evaluate patents, trade secrets and data exclusivity as part of product valuation and M&A diligence.
Competitive landscape and what it means for partners and acquirers
The wearable inertial sensor ecosystem spans component-focused MEMS suppliers, IMU specialists, and vertically integrated wearable platform providers. Established MEMS vendors continue to push low-power, highly integrated inertial measurement units optimized for consumer and hearable applications. Companies supplying higher-performance IMUs and system-level motion-capture solutions compete on precision, latency and the maturity of their sensor-fusion stacks. At the same time, medically oriented wearable providers and turnkey research platforms differentiate with regulatory experience and clinical validation capabilities.
-
Bosch Sensortec: recognized for low-power smart IMUs tailored to wearables and hearables; their emphasis is on sensor fusion and energy-efficient operation for consumer-scale integration.
-
STMicroelectronics: evolving MEMS roadmaps with IMUs that incorporate embedded AI processing to support activity classification and robustness under high-impact events — a recent product release underscores this embedded-AI trajectory.
-
TDK InvenSense and Analog Devices: positioned around high-performance MEMS IMUs and precision sensors that feed higher-accuracy applications and device tiers requiring superior angular-rate and linear-acceleration fidelity.
-
Movella (Xsens) and 2M Engineering (QSense Motion): focus on research-grade motion capture and wireless IMU platforms that serve biomechanics, entertainment and developer ecosystems where fidelity and multi-sensor synchronization are critical.
-
Shimmer, Noraxon, BTS Bioengineering, ActiGraph and 221e: these vendors occupy the intersection of clinical research, rehabilitation and validated monitoring — offering platforms with prior certification experience and clinical use-cases that reduce time-to-evidence for medical claims.
Recent market activity — for example, new IMUs with embedded AI announced in 2025 and granted patents around biometric interaction in 2026 — illustrates two concurrent currents: hardware vendors are embedding more application logic into the sensor stack, and platform innovators are protecting differentiated system-level behaviors. Both trends elevate the importance of IP diligence and integration capability when evaluating partners or acquisition targets.
Regulatory and standards context — operational impacts
Regulation and standardization are active constraints on strategy in 2026. Authorities are clarifying expectations for non-medical wellness devices versus sensor-based digital health technologies. EU MDR, IEC 60601, ISO 14971 and ISO 13485 remain central frameworks for medical-grade wearables; conversely, recent guidance reduces the regulatory burden for clearly non-medical fitness wearables. For device manufacturers, these distinctions should determine product labeling, evidence programs, and QA investments from day one. Additionally, documented CE certifications for some IMU-based systems underscore the importance of third-party validation as a market-entry accelerant.
Risks and scenario considerations
-
Component concentration and supply disruption: MEMS fabrication is capital-intensive; constrained supply can slow new device launches and favor incumbents with deep supplier relationships.
-
Standards and interoperability fragmentation: Without common data and calibration standards, platform lock-in and costly integration projects will reduce adoption velocity.
-
Regulatory reclassification: Should regulators tighten the interpretation of medical claims around sensor-derived biomarkers, market access timelines could lengthen and development costs rise.
-
Data privacy and security requirements: As sensors capture more granular behavioral data, compliance with privacy regimes and secure firmware update mechanisms becomes a differentiator and a cost center.
How to use this report in your 2026 planning
-
Product leaders: use the scenario engine to stress-test hardware choices and estimate the timing and cost of achieving clinical-grade evidence.
-
Commercial teams: align sales and channel strategies to the report’s application maps and vendor scorecards to prioritize the highest-probability verticals for 2026–2028.
-
M&A teams: apply the due-diligence checklist and valuation benchmarks when assessing sensor-platform targets; look for verified clinical evidence and clean IP stacks as premium attributes.
-
Procurement and operations: adopt the supply-chain resilience templates and multi-sourcing frameworks to reduce exposure to single-vendor bottlenecks.
PW Consulting’s full report provides the granular breakouts, vendor-level financial proxies, and downloadable modelling that enterprises need to translate these strategic implications into execution plans. The summary above intentionally highlights the high-level findings and strategic pathways while reserving the full segmentation tables, vendor scorecards and downloadable scenario models for the published report. For access to the detailed datasets, benchmarking matrices and the scenario model files that support board- and investor-level decisions in 2026, visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Worldwide Wearable Inertial Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Food‑Grade Polyvinyl Acetate Market to Grow at a 4.9% CAGR Through 2032
By PW Consulting, 2026-08-12
Worldwide Polyvinyl Acetate (Food Grade) Market — Strategic Outlook and Tactical Playbook for 2026
PW Consulting’s new market brief on the Worldwide Polyvinyl Acetate (Food Grade) market (base year 2025; forecast 2026–2032) synthesizes hard data, supply-chain intelligence and regulatory context into an operationally focused guide for executive decision-making in 2026. The global food‑grade PVAc market is on a steady expansion path: valued at USD 219.11 Million in 2025 and projected to reach USD 306.26 Million by 2032, representing a compound annual growth rate of 4.9% over the forecast window. This release previews the report’s analytical architecture and strategic implications while intentionally reserving detailed sub-segment tables and region-by-application breakdowns for the full study.
Serial NAND Flash Market
Why PVAc (Food Grade) demands boardroom attention in 2026
Polyvinyl acetate for food-contact applications occupies a narrow but strategically significant niche within food additives. The compound remains the material of choice for core applications such as chewing gum bases and selected fruit, vegetable and cheese coatings, where regulatory acceptance, technical performance, and supply reliability are non-negotiable. For producers, ingredient suppliers, and private-equity investors, the market offers a combination of predictable, consumption-driven demand and episodic margin pressure tied to upstream feedstock cycles — a profile that favors deliberate, data-driven strategic moves over opportunistic reactions.
Phase Contrast Microscopy Market
Reading the macro trend: measured growth underpinned by structural demand
The market’s mid-single-digit CAGR reflects two complementary dynamics. First, stable end-market consumption in traditional applications continues to underpin baseline growth. Second, incremental value is being captured through product-grade differentiation (food‑grade certifications, low-odour grades, tailored molecular-weight distributions) and premiumization in specialty applications. Historical data through 2025 show periods of short-term volatility as supply and feedstock conditions fluctuated, but the long-term trajectory is upwards — an important consideration for capital allocation and capacity planning decisions.
Worldwide Smartphone Screens Market
Supply-chain and raw-material realities that will shape 2026 outcomes
-
VAM as the strategic choke point. Vinyl Acetate Monomer (VAM) is the key upstream feedstock for PVAc production. Its availability and pricing dynamics directly influence producer margins and the attractiveness of different sourcing strategies.
-
Tightness and regional spreads. Early‑2026 market intelligence pointed to tightened spot availability in several markets and regionally varied pricing. In the United States, reported late‑March 2026 spot tightness produced a noticeable price uptick. These conditions compel manufacturers to re-evaluate procurement levers — longer-term contracts, regional hedging, or partial vertical integration.
-
Implications for operations strategy. Companies must model margin sensitivity to VAM movements, optimize inventory-to-contract mixes, and consider backward-integration or strategic tolling agreements where scale and balance-sheet allow.
Regulatory clarity — a commercial advantage
Food‑grade PVAc benefits from established regulatory pathways. It is listed among approved basic polymers for indirect food additives under the U.S. Code of Federal Regulations (21 CFR Part 177) and appears in relevant FDA inventories for substances added to food under defined conditions. For manufacturers and downstream formulators, this status reduces regulatory friction but raises the bar for documentation, traceability, and certification rigor. Firms that demonstrate robust compliance frameworks — with materials safety data, migration testing, and documented control of food-contact specifications — gain a commercial edge, particularly with global branded food companies increasingly focused on supplier audits and transparent ingredient supply chains.
Competitive landscape: concentrated yet opportunistic
The market exhibits meaningful concentration but leaves space for well-positioned challengers. The top three players control approximately 58% of market share, and the top five account for roughly 71%. This structure produces a dual strategic dynamic:
-
Incumbent economies of scale and channel relationships favor large suppliers with established food-grade brands and regional production footprints.
-
At the same time, certification-led differentiation (e.g., HACCP, Halal, and other food-safety credentials), specialty low-odour or molecular-weight grades, and nimble customer service models open opportunities for regional specialists and new entrants.
Illustrative company reads from our competitive review:
-
Wacker Chemie AG — A global leader with well-known food‑grade PVAc brands and dedicated production assets in Asia. Their combination of recognized brands and regional production capacity makes them a headline competitor in chewing gum base and other high-volume food applications.
-
Nitchen New Material Co., Ltd. — A certified, specialist supplier with a focus on gumbase and food-contact grades; certifications and targeted product formats (granules, flakes) support niche customer relationships.
-
Regional producers such as Jiangsu Yinyang Gumbase Materials, ElephChem Holding, and Muby/Aadhunik Industries — These firms compete on local market knowledge, compliance credentials, and export cost structures, and are attractive partners or acquirers for firms seeking rapid market access.
What the PW Consulting report delivers — practical, deal-ready intelligence
Beyond high-level trend charts, the full report is structured as an operational playbook for 2026 decisions. Key practical deliverables include:
-
Proprietary market-sizing and a bottom‑up demand model tied to application-specific consumption drivers and seasonality; scenario variants incorporate different VAM-price pathways and post‑pandemic demand normalization.
-
Supply‑side mapping that identifies capacity nodes, single‑source vulnerabilities, and logistic friction points for each production cluster.
-
Margin and pricing models that simulate pass‑through mechanics under short-term spot shocks, contract renegotiation timelines, and regional tariff regimes.
-
Regulatory compliance checklist and migration-risk scoring for food-contact applications, designed for procurement and quality teams to operationalize in supplier audits.
-
Commercial playbooks: go-to-market recommendations for incumbents (defend via integrated service offers), challengers (narrow-focus premiumization), and new investors (bolt-on M&A plus capacity optimization).
-
M&A and partnership shortlist: a curated set of targets and partnership archetypes keyed to geography, certification portfolio, and production scale.
Recommended strategic moves for 2026
-
Lock in feedstock stability: prioritize a blend of multi-year supply contracts and spot coverage; where feasible, evaluate tolling or partial backward integration into VAM to reduce exposure to acute spot tightness.
-
Differentiate on certified quality: invest in HACCP, Halal, and recognized food-contact documentation; this reliably shortens sales cycles with major food manufacturers.
-
Optimize product mix toward higher-value food-grade specifications: deploy R&D to engineer grades that meet low-migration, low-odour, or tailored molecular-weight requirements demanded by specialty formulators.
-
Decide footprint with precision: favor regional production where logistics and regulatory alignment deliver total-cost advantage; consider flexible, smaller-scale lines to serve niche demand pockets.
-
Embed scenario-based commercial planning: produce rolling models that stress-test price shocks, raw-material squeezes, and trade-disruption events to inform contract length and inventory policy.
-
Prepare for consolidation and partnership opportunities: use the present market concentration and certification barriers to identify attractive bolt-on acquisitions or joint ventures that accelerate market access.
-
Invest in traceability and sustainability storytelling: even in this commodity-adjacent market, verified claims on traceability and lower-carbon production are increasingly important in commercial negotiations.
How executives should use this intelligence in 2026
For C-suite leaders and investment committees, the report translates to three immediate actions: (1) update procurement and margin-sensitivity models using the provided supply-demand scenarios; (2) review certification and audit readiness for all food-contact product lines; and (3) prioritize a short list of strategic options — tactical contracting, selective capacity expansion, or targeted M&A — each backed by the report’s quantitative due diligence templates.
We present a robust, actionable evidence base while intentionally omitting granular regional and application split tables in this preview. Those detailed subsegment matrices, supplier scorecards and deal models are provided exclusively in the full report and its interactive data annex.
Next steps
PW Consulting’s Worldwide Polyvinyl Acetate (Food Grade) Market report is designed to convert market knowledge into executable strategy in 2026. For companies preparing procurement cycles, capital budgets, or M&A pipelines in the coming 12 months, the report functions as both a risk-heatmap and a deal playbook. For access to the complete dataset, modeling files and the vendor-by-vendor benchmarking appendices, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Worldwide Polyvinyl Acetate (Food Grade) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


