



Category: market research
PW Consulting: Worldwide Military Protective Gear Market Poised for 4.5% CAGR During 2026–2032
By PW Consulting, 2026-08-05
Worldwide Military Protective Gear Market: Strategic Outlook for 2026 — A PW Consulting Preview
As geopolitical tensions, procurement modernization and material innovation converge, the global market for military protective gear is entering a period of steady growth and strategic realignment. PW Consulting’s latest market study — covering 2020–2025 historical performance and providing a 2026–2032 forecast — equips defense suppliers, prime contractors and policy-makers with the actionable insights they need to make high-conviction decisions in 2026.
Worldwide Military Protective Gear Market
Headline market trajectory
After a multi-year expansion, the market reached an estimated USD 16,850.5 Million in 2025 and is forecast to grow at a compounded annual growth rate (CAGR) of 4.5% over the 2026–2032 period. Under the baseline scenario modeled in this report, the market advances further in 2026 and continues its steady climb toward the end of the forecast horizon. This trajectory reflects a blend of sustained defense spending, incremental capability upgrades, and technology-driven refresh cycles rather than episodic, demand-driven spikes.
Worldwide Military Protective Gear Market
Why this matters for 2026 decision-makers
- Timing of investment and capacity decisions: The market’s steady CAGR favors measured capacity expansion and strategic partnerships over aggressive greenfield investments. For OEMs and advanced-materials suppliers, 2026 will be a pivotal year to align manufacturing scale with validated, multi-year contract pipelines.
- Product roadmap prioritization: Incremental improvements in mobility, weight reduction and integrated sensor/connectivity features are outcompeting large, single-step disruptive bets. Procurement organizations should prioritize modularity and upgradeability in contract requirements to maximize lifecycle value.
- Supply chain risk management: Premium ballistic raw materials remain a key cost and delivery risk. Firms that lock in diversified sourcing and co-develop supply agreements will gain margin and delivery advantages in competitive bid environments.
What the report delivers — operational, actionable intelligence
PW Consulting’s report is engineered as a practitioner’s toolset rather than a theoretical exercise. Core deliverables include:
Worldwide Military Protective Gear Market
- Quantified market-sizing and scenario-based forecasting through 2032, providing a defendable baseline for budgeting and business planning;
- Trade-off matrices for material choices (aramids, UHMWPE, composite layups) that map ballistic performance, weight, cost and manufacturability for system integrators;
- Supplier landscaping with capability heatmaps, program-fit guidance and tiered risk scoring to accelerate vendor selection and joint-development decisions;
- Contracting and procurement playbooks tailored to common defense acquisition models, including practical RFP language for modularity, interoperability and export-compliance clauses;
- Investment due diligence templates for private equity and strategic buyers assessing accretive M&A or bolt-on acquisition opportunities.
Market dynamics to watch in 2026
- Material economics: Advanced aramid fibers and UHMWPE composites continue to command premium pricing due to high processing costs and R&D for lightweight, multi-hit capabilities. This dynamic sustains margin pressure for lower-tier suppliers and creates incentives for vertically integrated material-to-system strategies.
- Certification and export controls: Stringent international ballistic testing standards and third-party validation remain gating factors for cross-border sales. Concurrently, regulatory controls such as ITAR constrain transferability for certain technologies, shaping partner selection and localization strategies.
- Geopolitical procurement preferences: NATO spending commitments and regional sourcing policies are driving localized manufacturing and supplier development programs—presenting both a market-access hurdle and an opportunity for firms that can establish compliant, regional footprints.
- Integration and digitalization: The warfighter’s kit is increasingly conceived as a systems-of-systems problem. Helmet-integrated communications, augmented-reality visors and sensor-fused protective ensembles are differentiators in competitive bids, elevating firms that bridge mechanical protection with electronics and software.
Competitive landscape — established primes and emerging challengers
The market displays moderate concentration: the three largest firms account for a meaningful share of global revenues, and the top five bring additional cumulative heft. This structure results in competitive dynamics where innovation and program wins can rapidly shift supplier prominence.
Leading defense and materials firms continue to set technical and procurement benchmarks:
- 3M Company (St. Paul, MN) — Known for lightweight composite ballistic helmets and integrated personal protective systems, 3M’s emphasis on multi-threat solutions positions it well for program-level bids that prize integration and lifecycle support. ( https://www.3m.com)
- BAE Systems (London, UK) — A systems integrator with modular armor and advanced materials expertise; BAE leverages scale and global program management in multi-domain procurements. ( https://www.baesystems.com)
- Gentex Corporation (Carbondale, PA) — A prime developer of communication-integrated helmets and AR visors, Gentex remains a key partner for modernization programs in allied markets. Recent contract extensions underscore its role in sustainment-phase production. ( https://www.gentexcorp.com)
- DuPont and Honeywell International — As critical material suppliers, both firms influence cost curves and technical ceilings through aramid and Spectra/UHMWPE offerings, respectively. ( https://www.dupont.com; https://www.honeywell.com)
- Specialist manufacturers such as Point Blank Enterprises, Avon Protection, Revision Military, ArmorSource and Safariland — These firms compete on responsiveness, customization and program-level qualifications for DoD and allied procurements.
- Regional suppliers such as MKU Limited and several established manufacturers in Asia and LATAM — They are increasingly important for export markets and localized procurement strategies.
Recent deal and program signals (implications for strategy)
- Contract continuations on helmet programs and delivery orders for protective plates indicate strong demand for sustainment and incremental upgrades. Suppliers able to demonstrate cost-efficiency in production and rapid delivery will be favored in follow-on buys.
- Acquisition activity among small- to mid-sized suppliers shows ongoing consolidation in tactical protection, often driven by the need to broaden product portfolios and secure program-ready credentials quickly.
- These moves suggest near-term opportunities for strategic buyers to acquire qualified production capacity and for primes to shore up supply chains via minority investments or JV arrangements.
Recommended 2026 playbook — five pragmatic actions
- Prioritize modular, upgradeable platforms: Structure product offers and contracts around modularity to capture lifecycle upgrades and reduce total cost of ownership for customers.
- Lock-in strategic material partnerships: Negotiate long-horizon supply-and-development agreements with aramid and UHMWPE producers to stabilize costs and co-develop next-generation fibers.
- Invest selectively in integration capability: Allocate R&D budgets to helmet and vest integration (communications, AR, CBRN interoperability) where margin expansion and competitive differentiation are highest.
- De-risk exportability early: Build export-compliance expertise and product variants that meet non-ITAR routes to market, enabling access to allied procurement programs.
- Use M&A selectively to buy capabilities: Target acquisitions that accelerate certification, scale production or secure regional market access rather than pursuing generalized consolidation.
What we deliberately withhold here — and why you should read the full report
In line with PW Consulting’s “trailer” approach, this preview communicates the market’s macro trajectory, key dynamics and clear strategic imperatives while intentionally withholding granular segment-level allocations, regional share breakdowns, and unit-level pricing models. Those granular data points are the operational inputs procurement teams and corporate strategy units require to build bid models, forecast revenue by product line, and finalize capacity plans — and they are contained in the full report.
Report components and practical tools included
- Full historical and forecast market tables (by year through 2032) and scenario-sensitivity analyses;
- Go-to-market playbooks tailored to primes, tier-1 suppliers, materials producers and private equity investors;
- Supplier diligence templates, technical comparison matrices and procurement-ready RFP language;
- Risk assessment matrices covering regulatory/ITAR constraints, raw-material pinch points, and delivery lead-time scenarios;
- Case studies summarizing recent program awards and supplier responses with lessons for strategic planners.
Final assessment — what 2026 will likely determine
The 2026 calendar year is less likely to be decisive for headline demand and more likely to determine competitive positions for the rest of the decade. Firms that use 2026 to secure material partnerships, demonstrate integrated-system capabilities, and lock in supplier or regional footprints will be best positioned to capture the upside embedded in a market growing at a mid-single-digit CAGR. Conversely, firms that delay certification roadmaps or treat raw-material sourcing as a tactical concern risk margin compression and exclusion from multi-year programs.
For program managers, strategic buyers, and senior procurement officials who need the full empirical foundation and executable templates to act in 2026, PW Consulting’s comprehensive Worldwide Military Protective Gear Market report provides the necessary depth — from validated market sizing to contract-level implications. To review the complete dataset, segmentation tables, and procurement checklists, visit the PW Consulting report page and request the full study.
For detailed analysis of this topic, please visit the official page: Worldwide Military Protective Gear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Chain Door Guard Market Poised for 4.51% CAGR Growth Through 2032
By PW Consulting, 2026-08-05
Worldwide Chain Door Guard Market — Strategic Briefing for 2026 Decision-Makers
Executive preview from PW Consulting’s Senior Industry Analysis Desk
PW Consulting’s new market intelligence on the Worldwide Chain Door Guard Market delivers a sharpened strategic lens for executives planning budgets, product roadmaps, sourcing arrangements, or M&A activity in 2026. Built on a comprehensive base year of 2025 and a forecast window through 2032, the study translates macro momentum into practical options: the global market size stood at approximately USD 487.15 Million in 2025 and, at a compound annual growth rate (CAGR) of 4.51% from 2026 to 2032, is projected to expand materially by the end of the forecast. This briefing outlines the strategic value of the full report for four critical stakeholder groups while preserving the granular segment-level details that are accessible in the full publication.
Worldwide Chain Door Guard Market
Why this market matters in 2026
-
Resilient, steady growth: After recovery and normalization in the early 2020s, demand for chain door guards is stabilizing into a multi-year growth trajectory. The market’s structural expansion is visible in the leap from the lower end in 2020 to the mid‑2020s baseline and the steady climb foreseen through 2032.
Worldwide Chain Door Guard Market -
Fragmented competitive landscape: Market concentration remains low, underscoring an industry of many specialized players and local champions. Our concentration metrics show that leading suppliers do not dominate the landscape — an important signal for players seeking organic expansion or roll-up strategies.
Worldwide Chain Door Guard Market -
Regulatory and standards pressure: Standards such as TS 003 (UK) and Secured By Design approvals are reshaping product specifications and procurement preferences. Compliance is no longer optional for those targeting regulated markets or institutional channels.
-
Input-cost volatility: Raw material price swings — notably in stainless steel, zinc and brass — are exerting immediate margin pressure and creating strategic sourcing opportunities for vertically integrated or geographically diversified suppliers.
Market dynamics that will shape 2026 decisions
-
Standards-driven differentiation: High-performance door chains that meet TS 003 requirements and similar testing regimes are carving out a premium niche. Buyers — from social housing specifiers to institutional procurement teams — are increasingly demanding certified options, which raises entry barriers for commodity suppliers but creates margin upside for certified product lines.
-
Product innovation and positioning: Recent launches emphasize a blend of strength, aesthetics and user experience (e.g., anti-swing magnetic systems and low-profile designs for modern door sets). These attributes influence channel strategy: specifiers and installers prioritize proven designs; DIY channels respond to finish variety and ease-of-installation.
-
Supply chain and cost management: Metal price volatility amplifies the value of hedging strategies, supplier diversification and localized sourcing. Companies that re-engineer product bills-of-materials or shift to alternative alloys without compromising compliance capture near-term margin gains.
-
Channel and constructal shifts: Institutional and commercial procurement cycles respond to building starts and retrofit waves; residential demand links to housing market health and retrofit programs. As these cycles diverge regionally, winning companies will align inventory and promotional cadence with channel-specific lead times.
Competitive landscape — who to watch and why
The market is characterized by long-standing regional specialists alongside global hardware brands. Our competitive mapping highlights six types of market participants: OEM/ODM specialists, heritage industrial brands, consumer DIY suppliers, security-focused premium brands, building products conglomerates, and niche designers focused on compliance and aesthetics.
-
D&D Hardware and D&D Builders Hardware: Strong OEM/ODM capabilities and a product range that includes zinc alloy and brass designs position these manufacturers as prime partners for distributors and door-makers seeking customized solutions and cost-effective manufacturing footprints.
-
ABUS: A security-first European player with broad international reach; its product focus demonstrates how certification and brand trust unlock apartment and multifamily channels where burglary protection is a primary purchase driver.
-
Prime-Line Products: An example of a North American channel-oriented supplier leveraging SKU breadth and finish options to serve mass‑retail, e‑commerce and contractor markets simultaneously.
-
UAP Limited: Recent product introductions that combine slim profiles and magnetic hold are emblematic of how design-led differentiation can be paired with compliance targets. The July 2025 launch illustrates speed-to-market for upgraded performance attributes.
-
Schlage (Allegion) and National Hardware (ASSA ABLOY): Legacy hardware brands remain influential through strong distribution relationships, cross-selling into adjacent door security product categories and leveraging brand trust for institutional procurement.
What the PW Consulting report delivers — practical, actionable content
-
Decision-ready financial models: Scenario-based revenue and margin projections keyed to metal-cost scenarios, certification premium assumptions and channel mix shifts.
-
Commercial playbooks: Tailored GTM templates for manufacturers, distributors and retailers that translate compliance, finish and installation attributes into SKU rationalization, pricing, bundling and promotional strategies.
-
Procurement and sourcing templates: A prioritized supplier-risk scorecard and negotiation levers to manage alloy exposure and logistics costs — ready to be deployed by procurement teams in 60–90 day cycles.
-
Compliance and testing checklist: A practical mapping of relevant standards (including TS 003 and Secured By Design pathways), test endpoints that materially affect product design, and an implementation timeline for certification-driven product upgrades.
-
M&A and partnership shortlists: A curated set of acquisition or JV archetypes — from small regional producers to specialized OEMs — aligned to strategic objectives (capacity, channel access, product diversification), plus a valuation framework sensitive to fragmentation and consolidation opportunities.
-
R&D and product roadmaps: Prioritized innovation themes (anti-swing mechanics, low-profile security, modular installation kits) and a staged investment timetable to capture premium segments growing through 2026 and beyond.
Strategic recommendations for 2026 — prioritized actions
-
For manufacturers: Invest selectively in TS 003-type certification and product redesigns that enable access to institutional and social-housing tenders. Parallel initiatives should focus on cost-to-produce reductions through design-to-cost and alternative alloy trials.
-
For distributors and retailers: Rebalance assortments toward certified, design-led SKUs in markets where standards are enforced. Use finish and installation simplicity as merchandising levers to increase average order value.
-
For investors and M&A teams: Target tuck-in acquisitions in regions with durable demand and strong local relationships. Given the industry’s low concentration, roll-up strategies can generate scale economics, but careful integration of quality and compliance processes is critical.
-
For procurement and real-estate specifiers: Embed certification clauses into tender documents and adopt a supplier-rating system that captures compliance testing, supply resilience and price hedging capabilities.
Decision-support evidence: what you will find in the full report
The full PW Consulting report provides the granular analytics decision-makers need — from regional demand drivers and end-user channel forecasts to finish and material trend analysis — accompanied by downloadable models and checklists. It combines quantitative forecasts (built atop a 2020–2025 historical series and a 2026–2032 forecast horizon) with qualitative interviews and supplier benchmarking to create a single reference for 2026 strategy cycles.
Closing: use this briefing as the first step
For executives entering 2026 with goals to expand, consolidate, or defend their positions in the chain door guard market, the strategic question is not whether the market will grow — it will — but how to capture the premium segments and protect margins amid rising standards and raw-material volatility. PW Consulting’s Worldwide Chain Door Guard Market report turns that macro certainty into operational playbooks and financial scenarios that are immediately applicable. Our analysis shows that companies who align product certification, cost engineering and channel execution in the coming 12–18 months will be the primary beneficiaries of the market’s projected mid-single-digit CAGR and the expansion visible through 2032.
To access the full breakdown, supplier profiles, country-level forecasts and the decision-ready toolkits referenced above, consult the complete PW Consulting report on the Worldwide Chain Door Guard Market. The detailed segment splits and downloadable models are available exclusively in the full publication.
For detailed analysis of this topic, please visit the official page: Worldwide Chain Door Guard Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Optoelectronic Safety Laser Scanner Market to Reach USD 949.45 Million by 2032, Expanding at a 7.15% CAGR
By PW Consulting, 2026-08-05
Worldwide Optoelectronic Safety Laser Scanner Market — Strategic Outlook for 2026 Decision-Making
Executive Summary
The optoelectronic safety laser scanner market has moved from niche machine-guarding components into a strategic technology that underpins the safe scaling of autonomous intralogistics, mobile robotics, and outdoor mobile machinery. Our analysis at PW Consulting shows the market expanding from an estimated USD 420.4 Million in 2020 to USD 585.5 Million in the base year 2025, with a projected compound annual growth rate (CAGR) of 7.15% through the 2026–2032 forecast horizon. By 2032 the global market is expected to approach roughly USD 949.5 Million. For corporate leaders planning capital allocation, product roadmaps, or supply-chain hedging in 2026, this trajectory argues for prioritized investment in sensor-enabled safety architectures, modular certification pathways, and selective supplier partnerships rather than scattershot procurement.
Worldwide Optoelectronic Safety Laser Scanner Market
Why This Report Matters for 2026
-
Decision timing: 2026 is a pivot year where more deployments shift from pilot to scale — particularly for AMRs, AGVs, and mixed human-robot environments. Procurement cycles and certification timelines mean choices made in 2026 determine field performance and retrofit costs for the next 3–5 years.
Worldwide Optoelectronic Safety Laser Scanner Market -
Risk management: Component concentration and geopolitics are raising upstream risk premia. Strategic sourcing decisions taken in 2026 can materially reduce exposure to lead‑time shocks and price volatility on compound-semiconductor inputs.
Worldwide Optoelectronic Safety Laser Scanner Market -
Standards harmonization: Recent and ongoing standards and normative updates (including the EN ISO 13855:2024 revisions and continuing IEC/ISO safety frameworks) will influence allowed system architectures and engineering labor costs — firms that plan for re-certification now will save significant time-to-market later.
Practical, Actionable Content in the Report
PW Consulting designed this market study to be more than a forecast: it is a playbook for executives, procurement leads, and systems architects. The report package includes:
-
Forward-looking market scenarios and sensitivity analysis calibrated to semiconductor supply stress, regulatory tightening, and accelerated AMR penetration — enabling CFOs to stress-test CAPEX plans under three plausible trajectories.
-
Vendor scorecards that evaluate performance across functional range, certification breadth, integration ease (industrial networking protocols), and service footprint — built for sourcing shortlists and RFP templates.
-
Certification and compliance roadmap templates tied to IEC 61496 and ISO 13849 families, with practical checklists for device selection, documentation, and audit readiness.
-
Supply-chain heatmaps and procurement mitigation playbooks addressing GaAs/GaN wafer and laser-diode concentration, extended lead times, and contingency sourcing strategies.
-
Integration blueprints and total-cost-of-ownership (TCO) calculators that factor in installation, commissioning, lifecycle recertification, and retrofit allowances specific to stationary vs mobile deployments.
-
Commercial models and go-to-market playbooks for solution providers wishing to bundle sensors with safety controllers, functional safety services, and managed monitoring contracts.
Market Dynamics That Will Drive 2026 Choices
Three structural dynamics will dominate boardroom discussions in 2026: regulatory evolution, semiconductor supply concentration, and the migration from 2D to safety-capable 3D perception in selected outdoor and mobile applications.
-
Regulatory and standards pressure: The EN ISO 13855:2024 revision introduces refined safety-distance calculations for orthogonal, parallel, and complex reaching scenarios, together with Z supplements addressing measurement inaccuracy and brake wear. These changes increase engineering rigor for protective device placement and may require product or system redesign in some deployments. Parallel developments in IEC 61496-1/-3 and ISO 13849 continue to define the performance baselines for Type 3 ESPE devices and PL/SIL targets.
-
Upstream supply concentration: A handful of suppliers control most of the GaAs wafer capacity and advanced laser-diode production. Historic export dynamics and policy shifts have extended lead times and elevated spot prices, and companies without diversified procurement strategies will face elongated fulfillment cycles. Our report quantifies the operational impact of multi-month lead-time shifts and offers procurement levers — including component hedging and strategic stocking thresholds.
-
Perception evolution: Manufacturers are expanding product lines from classic 2D safety scanners into 3D LiDAR-like devices with safety certifications for outdoor and mobile contexts. These innovations raise the technical bar on sensor validation, introduce new firmware and sensor-fusion testing needs, and create market differentiation opportunities for vendors that can certify 3D safety at acceptable cost and complexity.
Competitive Landscape — Strategic Mapping of Core Vendors
The market exhibits moderate concentration: the top three players account for a majority share, and the top five approach three-quarters of the market by revenue. That structure creates a two-tier competitive field: established industrial automation champions with broad product portfolios and newer, more specialized entrants polarised around size, range, and integration features.
-
SICK AG (Waldkirch, Germany): A portfolio leader that combines traditional 2D safety scanners with an aggressive push into safety-certified 3D perception. Recent product introductions reinforce SICK’s strength in certified, ruggedized solutions for outdoor mobile use and complex mobile platforms. Strategy implication: SICK is a natural partner for firms seeking end-to-end certified solutions and global service coverage.
-
Leuze electronic (Owen, Germany): Competes on compactness and fit-for-purpose design, targeting space-constrained AGV and AMR installations with ultra-compact footprints. Their emphasis on mechanical integration and simplified mounting makes them attractive where mechanical retrofits are limiting factors.
-
Pilz (Ostfildern, Germany): Combines safety-science credibility with practical tools like updated safety calculators and network-friendly interfaces (e.g., Profinet enhancements). Pilz’s offering is especially relevant for integrators needing deterministic diagnostics and multiple configurable protection zones.
-
Japanese firms OMRON, KEYENCE, Hokuyo, IDEC: Each brings differing strengths — from extended warning ranges and integrated vision to high environmental resistance and industrial networking. These vendors often appeal to high-performance OEMs with demanding detection-range or environmental requirements.
-
North American and other European vendors: Banner Engineering, Rockwell Automation (Allen‑Bradley), Pepperl+Fuchs, Datasensing, and a set of specialized suppliers fill out portfolios with application-specific scanners and strong channel relationships. Rockwell and Banner are often selected where control-system harmonization or enterprise-level vendor alignment is a procurement priority.
Recent Movements Worth Watching
Product launches and interface updates through 2024–2025 signal three tactical moves by leading vendors: certify up-market (3D safety), shrink the footprint for dense integrations, and simplify network integration. These are not cosmetic changes — each has downstream impacts on system architecture, certification scope, and service models. Companies planning 2026 rollouts should map vendor roadmaps against in‑house skills for system validation and lifecycle recertification.
Tactical Recommendations for 2026
-
Prioritize supplier dual-sourcing for laser diode subcomponents and negotiate lead-time visibility clauses. Spot-price shocks in 2023–2024 demonstrate the value of advance visibility and contractual flexibility.
-
Fast-track certification planning: align product choices with updated EN ISO 13855 guidance and build certification buffers into project timelines, especially when integrating 3D safety devices into mobile platforms.
-
Invest in in-house functional-safety competence or secure long-term engineering partnerships. The incremental costs of external recertification and required computational testing for 3D devices can erode margins if not anticipated.
-
Adopt modular architectures and over-the-air update strategies where fielded safety firmware updates are expected. This reduces retrofit friction and shortens incident remediation cycles.
-
Use TCO modeling — not unit cost — as the procurement benchmark. Integration time, downtime during retrofits, and lifetime recertification dominate the economics for safety systems.
What PW Consulting’s Report Does Not Reveal Here (and Why)
In this “trailer” briefing we intentionally show the analytical framework, the dynamics that matter in 2026, and vendor strategic stances — while withholding detailed subsegment revenue breakdowns, region/application-level percentages, and the full underlying data tables. Those granular splits are central to deployment‑level sourcing strategies and are included in the full report package to ensure licensed recipients can execute targeted procurement and product decisions with confidence.
How to Use the Full Report in Your 2026 Planning
Executives and functional leads will find immediate utility in the full study: scenario outputs to align board-level CAPEX timing; vendor scorecards to shorten RFP cycles; and supply‑chain mitigations to secure continuity for pilot-to-scale transitions. If your 2026 plan hinges on fleet-wide AMR deployments, outdoor mobile automation, or cross‑border manufacturing rollouts, the detailed segmentation and the operational checklists in the full report will materially reduce program risk and accelerate time-to-value.
Closing Note
The safety laser scanner market is maturing, but its growth is neither uniform nor risk-free. The market’s steady ascent to nearly USD 950 Million by 2032 at a 7.15% CAGR masks important inflection points driven by standards updates, upstream supply concentration, and a fast-evolving product landscape moving into 3D certified perception. In 2026, organizations that combine careful supplier strategy, active regulatory alignment, and investment in functional-safety capability will convert market growth into sustained competitive advantage. PW Consulting’s full Worldwide Optoelectronic Safety Laser Scanner Market report provides the data, templates, and vendor intelligence necessary to make those choices with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Optoelectronic Safety Laser Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Occlusion Spray Market to Grow from USD 115.45 Million in 2025 to USD 165.72 Million by 2032 at a 5.28% CAGR (2026–2032)
By PW Consulting, 2026-08-05
Worldwide Occlusion Spray Market — Strategic Preview for 2026 Decision-Making
PW Consulting’s new market brief on the Worldwide Occlusion Spray market offers senior executives and corporate strategy teams an actionable, intelligence-led foundation for high-stakes decisions in 2026. This executive preview synthesizes the report’s macro dynamics, competitive posture, regulatory considerations, and the practical toolset we deliver to clients — while deliberately reserving detailed segment-level figures and proprietary models for the full report. Think of this as the trailer: substantive enough to validate investment in the full briefing, but calibrated to drive follow-up access to the source intelligence.
Worldwide Occlusion Spray Market
Key market trajectories: what the numbers tell strategic leaders
Occlusion spray — the niche but mission-critical consumable used across dental prosthetics, clinics and industrial scanning workflows — has demonstrated steady expansion through the mid-2020s. Our modelling, anchored on a 2025 base year, shows the market progressing from the early‑2020s recovery phase into a structurally higher-growth cycle. In concrete macro terms, global market revenue reached an estimated USD 115.45 Million in 2025, following a multi‑year rise from the low‑100 millions in the preceding years, and is projected to grow to roughly USD 165.72 Million by 2032. That trajectory reflects a compound annual growth rate of approximately 5.28% across the 2026–2032 forecast window.
Worldwide Occlusion Spray Market
Two implications for strategy teams are immediate: first, the market is large enough to merit sustained commercial attention but small enough that focused interventions (product innovation, channel optimization, selective M&A) can meaningfully shift competitive share. Second, the mid-single-digit CAGR signals consistent demand drivers rather than boom-or-bust volatility — an environment suited to disciplined, ROI-oriented investments rather than speculative plays.
Worldwide Occlusion Spray Market
Why this report matters for 2026 planning cycles
- Portfolio prioritization: The market’s steady growth means firms should evaluate occlusion spray products as either core margin generators or strategic adjuncts to broader prosthetics and digital-dentistry portfolios. Our analysis helps you decide which products to scale, which to retire, and where to invest in formulation upgrades.
- M&A and partnership intelligence: With market concentration metrics pointing to a moderately consolidated market (CR3 and CR5 levels indicate meaningful leader presence but also room for bolt-on acquisitions), the report identifies acquisition archetypes and integration risk profiles suited to private equity and corporate buyers.
- Regulatory and go-to-market sequencing: Timing approvals and channel expansions matters. The report translates regulatory permissibility and regional distribution realities into tactical launch calendars for 2026–2028.
- Digital dentistry alignment: As digital scanning and CAD/CAM workflows mount, spray products that are compatible with digital scanning or designed for hybrid physical/digital workflows become strategic differentiators. We map product attributes to buyer value propositions across clinical and laboratory use cases.
What the full report delivers — a pragmatic, execution-ready toolkit
PW Consulting built this study to inform boardroom decisions and commercial execution. Key deliverables include:
- Transparent market-size model with historical series and scenario-based forecasts (base year 2025; forecast horizon 2026–2032), enabling topline and sensitivity analysis for different demand and price assumptions.
- Segment-playbook templates that translate demand drivers into concrete product, pricing and channel initiatives — from premium intra‑oral formulations to economy aerosol SKUs for high-volume labs.
- Competitive intelligence dossiers on leading suppliers, including product feature matrices, regulatory status, distribution footprints, and R&D focus areas.
- Go-to-market roadmaps for direct, distributor, and digital-channel strategies — including recommended KPIs, account penetration plans, and promotional mechanics tailored to dental labs, clinics, and industrial scanning customers.
- Regulatory impact assessment and checklist for intra‑oral approvals, labeling, and environmental/propellant considerations.
- M&A playbook and valuation framework calibrated to market concentration, margin profiles and integration synergies.
- Supply-chain and manufacturing gap analysis that identifies critical inputs, packaging opportunities, and quality controls to reduce time-to-market.
Competitive landscape — positioning and threats
The occlusion spray market blends legacy dental-supply players with specialized aerosol and consumables vendors. Our competitive review highlights several strategic patterns:
- Established dental manufacturers with product depth: Firms with long-standing dental portfolios bring trusted brands and deep distribution in labs and clinics. Their plays typically emphasize clinical safety, color consistency, and product range.
- Technical differentiators: A number of companies distinguish themselves by product attributes — intra‑oral approval for direct clinical use, water‑soluble formulas for easy cleanup, color options for visibility on different substrates, and sprays that serve dual purposes as digital scan primers.
- Regional strongholds and export strategies: Several European and North American players maintain concentrated footprints in professional dental channels, while niche vendors leverage distribution partnerships to reach broader industrial scanning customers.
Representative company observations drawn from our proprietary profiling:
- Pascal International, Inc. (Bellevue, WA, USA): Offers an intra‑orally approved aerosol used for precise occlusal contact marking across restorations; the product’s clinical approval status is a key asset when competing for direct clinic accounts.
- Dr. Jean Bausch (Cologne, Germany): Markets multi‑color articulating sprays noted for leaving a thin, removable film — a useful trade-off between visibility and model preservation that resonates with labs and clinicians focused on rework reduction.
- Renfert GmbH (Hilzingen, Germany) and YETI Dentalprodukte GmbH (Engen, Germany): Emphasize high‑visibility colorants and water-solubility characteristics that optimize identification of high spots on prosthetic work across wet/dry conditions.
- DFS Diamon GmbH (Riedenburg, Germany): Differentiates with formulations that resist certain solvents and avoid discoloration of plaster models — features attractive to labs concerned about model integrity.
- Vacalon (USA) and Indenco Dental Products (USA): Offer products that straddle clinical and digital-scanning use cases; suppliers that successfully position sprays as compatible with optical scanning can secure disproportionate share as digital adoption accelerates.
Collectively, market concentration measures indicate that the leading firms control a substantial portion of demand — creating both barriers and acquisition opportunities for challengers. The market is neither a fragmented free-for-all nor a closed oligopoly; it rewards disciplined product differentiation and distribution excellence.
Regulatory and product landscape: what to watch
A nuanced regulatory picture shapes commercialization choices. Certain occlusion spray formulations are permitted for intra‑oral use under prevailing FDA guidance for dental articulating materials, while select European products comply with the medical device framework historically embodied by Directive 93/42/EEC. Environmental considerations (propellant selection) and ingredient safety profiles are increasingly salient in procurement decisions among institutional buyers.
On the product side, common commercial realities persist: typical aerosol packaging formats center around 75 ml canisters, with alternative sizes available for specific applications; multiple color variants remain standard to meet visibility needs across substrates. Importantly, the convergence of spray formulations with digital-scanning workflows is an emergent product axis: sprays that do not interfere with scanning optics — or that double as scan primers — command a premium in certain channels.
Strategic imperatives for 2026
- Prioritize clinical approvals where relevant: If your 2026 strategy targets direct clinic revenue, securing or evidencing intra‑oral permissibility materially accelerates adoption and pricing power.
- Invest in digital compatibility: R&D resources allocated to scan‑friendly formulations will yield a growing return as CAD/CAM and intraoral scanning penetrate further into standard workflows.
- Optimize packaging and cost-to-serve: Reassess SKUs and packaging economics to match the procurement profiles of labs vs. clinics and to reduce logistics overhead.
- Targeted M&A and distribution deals: Use the report’s M&A playbook to identify bolt-ons that expand technical capability or channel reach while preserving margin profiles.
- Scenario-based resource allocation: Use the included alternative demand scenarios to stress-test investments — particularly around product development timelines and commercial rollouts — before committing capital in 2026.
Concluding note — where to get the full intelligence
This preview provides the strategic contours PW Consulting uses to guide clients through 2026 planning, but it intentionally omits the granular segment splits, supplier-by-sku economics, and our full valuation tables that drive transaction decisions. Senior teams that require executable plans — including deal lists, executable GtM playbooks, and the full sensitivity models — should consult the complete Worldwide Occlusion Spray Market report.
To access the detailed segmentation, competitive dossiers, and the proprietary forecast model that underpins these recommendations, please visit PW Consulting’s market reports page or contact your PW Consulting engagement lead. The full deliverable equips commercial, product and M&A teams with the evidence and playbooks they need to convert the mid‑single-digit CAGR environment into sustainable competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Occlusion Spray Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Multi-Point Ground Flares Market Poised to Reach USD 539.12 Million by 2032
By PW Consulting, 2026-08-05
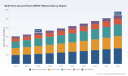
Worldwide Multi-Point Ground Flares (MPGF) Market — Strategic Preview for 2026 Decision Makers
PW Consulting’s latest industry briefing previews the full Worldwide Multi-Point Ground Flares (MPGF) Market study and distills the specific, actionable intelligence that senior executives, project sponsors, EPC firms, and investors need to prioritize through 2026. This article follows a “trailer” approach: it demonstrates the methodological depth and strategic insights contained in the full report while intentionally preserving core segment and regional detail to drive qualified traffic to the source for complete data and annexes.
Worldwide Multi-Point Ground Flares (MPGF) Market
Market snapshot — where the opportunity stands
At the macro level, the MPGF market is in an unmistakable growth phase. Using 2025 as the report’s base year, our modeled market size stands at USD 346.48 Million. Our forecast, based on historical trends (2020–2025), industry project pipelines, regulatory trajectories, and technology adoption rates, projects a compound annual growth rate (CAGR) of 6.52% across the 2026–2032 horizon, with the global market reaching approximately USD 539.12 Million by 2032.
Worldwide Multi-Point Ground Flares (MPGF) Market
This steady expansion is driven by converging forces: heightened regulatory scrutiny on flaring emissions and visible plumes; operational imperatives for smokeless, low-visibility solutions at high and variable waste-gas flow rates; continuing petrochemical and LNG infrastructure development; and increasing demand for turnkey, low-footprint, and remotely monitored flare systems. The market dynamics favor established OEMs with proven smokeless combustion technologies, reliable staging and ignition systems, and the capacity to deliver project-level guarantees under strict environmental and safety specifications.
Worldwide Multi-Point Ground Flares (MPGF) Market
What the full report delivers (practical, transaction-grade content)
- Robust market sizing and a transparent forecast model (base year 2025), including sensitivity scenarios tied to oil & gas CAPEX cycles, LNG project sanctions, and tightening emissions limits.
- Vendor benchmarking and a decision matrix that scores suppliers across 60+ criteria: technical performance, turndown range, smokeless/noise/radiation controls, lifecycle O&M burden, spare-parts lead times, and service footprint.
- Procurement playbook for owners and EPCs — standard RFP language, warranty formulations, performance guarantees, and contract de-risking clauses specific to MPGF deployment and retrofits.
- Techno-economic models that juxtapose capital expenditures, operating fuel/assist gas consumption, and lifecycle emissions costs to quantify payback under multiple regulatory regimes.
- Compliance and monitoring framework aligned to ISO/API standards and U.S. regulations (including references to legacy AMEL approvals and 40 CFR requirements) to reduce approval friction and accelerate permitting.
- Site selection and retrofit decision trees that help prioritize where MPGF delivers highest value versus alternative flaring solutions.
- Risk register and mitigation playbook — from ignition reliability and assist-gas logistics to community visibility, noise, and radiant heat management.
- M&A and partnership playbook highlighting where strategic acquisitions, JV structures, or licensing can secure aftermarket revenues and shorten market entry timelines.
Regulatory and standards context — a non-negotiable constraint
Regulation is a primary adoption lever for MPGFs. Notable precedents — such as EPA’s Alternative Means of Emission Limitation (AMEL) approvals for pressure-assisted MPGFs at major petrochemical sites — demonstrate that regulators will accept alternative flare technologies when accompanied by rigorous monitoring, performance guarantees, and documented destruction efficiency. In parallel, ISO/API standards (including ISO 23251 / API 521 references and other applicable API standards) frame design and operational expectations, while U.S. rules such as 40 CFR 60.18 remain operational touchstones for flare control and reporting. Manufacturers and buyers must design procurement and commissioning strategies around this regulatory envelope to avoid costly rework or permit delays.
Competitive landscape — vendor positioning and strategic bets
The MPGF vendor field is dominated by a mix of specialized combustion firms and wider industrial suppliers that have integrated MPGF offerings into broader process portfolios. Our qualitative assessment in the full report covers capability gaps, product roadmaps, and go-to-market strategies for tier-one and niche providers. Highlights:
- Zeeco, Inc. ( https://www.zeeco.com) — Zeeco positions MPGF as a solution for highly variable waste-gas volumes with a focus on safe, smokeless, and low-visibility flaring. Their strength lies in proven combustion engineering and site-specific customization for pressure, flow, radiant heat, and noise control. Recent product promotions emphasize these attributes, reinforcing their brand in operator-oriented sales cycles.
- John Zink Hamworthy Combustion ( https://www.johnzink.com) — John Zink’s LRGO™ MPGF lineup competes on demonstrated destruction efficiency, high turndown via staged systems, and turnkey delivery. Their product messaging emphasizes reliability and lifecycle performance, which resonates with risk-averse owners seeking long-term O&M predictability.
- Aereon (part of Cimarron) ( https://aereon.com) — Aereon focuses on array-enclosed configurations for very large flows with multi-stage operation and assist gas strategies for smokeless performance at low regimes. Their technical emphasis is attractive for projects with extreme variability in waste gas.
- Honeywell UOP Callidus ( https://uop.honeywell.com) — Honeywell’s strength is integration: staged high-pressure burners and controls that align with upstream and midstream process automation, aimed at large gas and petrochemical applications where systemic interoperability and reduced radiation are priorities.
- Encore Combustion ( https://encorecombustion.com) — Encore’s enclosed combustion MPGF offerings target ground-based smokeless combustion for large hydrocarbon volumes, leveraging proprietary burner designs and a focus on reliable ignition and maintenance simplicity.
Recent market moves illustrate the interplay of vendor marketing, operator vigilance, and project execution. Examples include Zeeco’s mid-2025 emphasis on MPGF capabilities, operator-led monitoring upgrades (an owner in Pennsylvania added an additional camera to MPGF monitoring in early 2025), and recent large-scale project supplies by specialty providers. These actions confirm two trends: operators are increasingly focused on continuous monitoring and visibility control, and vendors are commercializing turnkey and service-led propositions rather than stand-alone hardware.
Strategic implications for 2026 decision cycles
For executives setting 2026 priorities, the MPGF market presents distinct choices that will affect CapEx scheduling, vendor selection, and operational risk profiles:
- Owners and operators should treat MPGF procurement as a system buy — specifying performance-based outcomes (visibility, destruction efficiency, noise/radiation limits) rather than detailed component lists. This creates accountability and incentivizes vendor innovation on assist gas, staging, and remote diagnostics.
- EPCs must integrate MPGF selection early in FEED to avoid costly layout and utilities rework. Pre-approved vendor lists and standardized interface packages reduce bogging at tender stage.
- OEMs and suppliers should prioritize modular, serviceable designs and expand remote-monitoring as-a-service offerings. Aftermarket services and spare-parts subscriptions will be pivotal revenue streams as site operators seek to minimize downtime and guarantee compliance.
- Investors and project financiers should require demonstrable compliance paths and vendor performance guarantees as conditions precedent to funding — particularly where permitting relies on alternative emission limitation approvals.
- Regulators and community engagement teams should expect MPGFs to be evaluated against the same transparency principles applied to other emission control assets: continuous monitoring, public-friendly data disclosure, and traceable destruction-efficiency metrics.
How buyers should use PW Consulting’s report
The full PW Consulting MPGF report is built to be operational: not just market numbers but buy-side decision support. Subscribers will receive downloadable procurement templates, vendor scorecards, risk-mitigation checklists, and techno-economic spreadsheets calibrated to multiple gas quality and flow variability scenarios. The annexes contain vendor contact matrices, compliance checkpoints mapped to international standards, and worked examples that show when retrofits dominate over new-build MPGF procurement from a total-cost-of-ownership perspective.
Because this piece is a strategic preview, core segment-level splits and granular regional allocation tables are intentionally omitted here. Those detailed worksheets, sensitivity tables, and raw model files are included exclusively in the licensed report and the online data portal.
Concluding guidance — three action steps for 2026
- Prioritize compliance-first specifications: make performance guarantees and monitoring requirements the primary procurement levers to reduce approval and operational risk.
- Adopt a modular supplier strategy: combine a primary OEM with a validated secondary source for critical spares and commissioning support to mitigate single-source risk.
- Monetize the aftermarket: suppliers should launch service subscription models for remote monitoring, predictive maintenance, and regulatory reporting to capture recurring revenue and differentiate bids.
PW Consulting’s full Worldwide MPGF Market report provides the quantitative templates, vendor-level assessments, and regulatory mapping that decisionmakers need to operationalize these steps. For procurement teams, finance committees, and strategic planners preparing for 2026, the report is designed to shorten decision cycles and reduce execution uncertainty. To access the complete data, supplier scorecards, and downloadable procurement toolkits, visit our report portal and license the full study.
For detailed analysis of this topic, please visit the official page: Worldwide Multi-Point Ground Flares (MPGF) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Agriculture Micro‑Irrigation Market to Nearly Double from USD 13.85 Billion in 2025 to USD 26.14 Billion by 2032, Riding a 9.5% CAGR
By PW Consulting, 2026-08-05
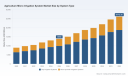
Worldwide Agriculture Micro Irrigation System Market — Strategic Imperatives for 2026
PW Consulting’s newest market research brief on the Worldwide Agriculture Micro Irrigation System market is timed for a pivotal moment. The sector has moved from niche efficiency plays into core agricultural strategy: our analysis finds the global market expanding from a 2025 base of USD 13,850 Million (USD Million revenue unit) and tracking toward more than USD 26,100 Million by 2032 at a 2026–2032 compound annual growth rate of 9.5%. With historical coverage from 2020–2025 and scenario modelling across 2026–2032, this report is designed to convert market data into operational choices for executive teams, investors, policy designers and scale-up founders in 2026.
Worldwide Agriculture Micro Irrigation System Market
Why this report matters for 2026 decisions
-
Investment prioritization: The market’s double-digit growth trajectory makes micro irrigation a high-conviction arena for capital allocation. Our research translates headline growth into forward-looking demand corridors that link product roadmaps to likely addressable markets under multiple adoption scenarios.
Worldwide Agriculture Micro Irrigation System Market -
M&A and partnership strategy: Consolidation signals are visible — the top-three and top-five vendor groups account for significant shares of installed capability — and incumbents are accelerating product-service bundling. The report identifies vendor archetypes and deal triggers that matter to buyers and sellers now.
Worldwide Agriculture Micro Irrigation System Market -
Product and R&D roadmaps: Electrification, digital fertigation, and precision dosing are moving from lab pilots to field-proven releases. Our analysis isolates capability gaps where product investment produces the strongest margin and adoption impact in 2026.
-
Supply-chain and cost management: Raw-material exposure (notably polyethylene for tubing and emitters) and standards-driven component requirements materially affect unit economics. The research provides sensitivity modelling for polymer price swings and regulatory compliance costs.
-
Go-to-market and financing models: Subsidy programs and public investments are accelerating replacement cycles in targeted markets. We translate policy design into practical channel and financing plays that capture subsidy-driven demand without compromising margins.
Macro drivers reshaping the sector
Three intersecting forces are re-defining micro irrigation as a strategic category rather than a point product. First, water scarcity and efficiency mandates are converting system adoption into risk mitigation and yield optimization; pressurized irrigation systems have seen rapid penetration in key producing regions, altering farm-level capital allocation. Second, regulatory and standards frameworks are tightening — for example, international standards now set implementation and performance expectations for pressurized drip systems — which raises the bar for product certification and procurement. Third, public investments and subsidy programmes are accelerating replacement and first-time adoption in critical geographies: targeted government spending and direct farmer subsidies are converting long-run potential into short-run demand surges.
Technology is an accelerant. Advances in embedded sensors, AI-driven dosing, and connectivity (including 5G‑enabled solutions) are enabling systems to deliver agronomic outcomes — not just water — and creating recurring software and service revenue potential for suppliers. Our scenario work shows that combining hardware sales with subscription-based advisory and control services materially increases lifetime value compared with hardware-only models.
Competitive landscape: what separates winners from the rest
The market exhibits moderate concentration: the CR3 is roughly 42.5% and the CR5 about 56.8%, indicating space for regional challengers and technology specialists to scale. Across the vendor field — from pioneering drip system manufacturers to precision-software providers — four capability clusters are emerging as decision criteria for 2026:
-
Integrated systems and digital agronomy: Vendors who combine drip or micro-sprinkler hardware with fertigation control and cloud-based crop-optimization tools are realizing higher customer stickiness. Established pioneers with long product pedigrees are moving aggressively into AI-enabled dosing and connected fertigation platforms.
-
Manufacturing footprint and supply agility: Near-market production and localized assembly are becoming competitive advantages, especially where lead times and logistics impact planting calendars. Recent factory expansions in North America are a direct response to these pressures.
-
Certification and subsidy alignment: Compliance with standards and local subsidy program rules (including country-specific component marking and testing) is a commercial prerequisite for large-scale adoption in several major programmes. Firms that streamline subsidy eligibility for farmers win faster adoption.
-
Channel & service model sophistication: Successful players increasingly offer financing, installation, maintenance, and data-driven advisory services — converting one-time hardware sales into multi-year relationships.
Illustrative vendor profiles shed light on how market leaders are positioning for 2026. Long-standing innovators who built the category are leveraging digital tools and new product architectures to protect market share while capturing higher-margin services. Vertically integrated suppliers in high-adoption countries are optimizing for low-energy and crop-specific solutions. Component specialists and greenhouse solution providers emphasize clog-resistance and filtration to reduce O&M headaches for growers. New product introductions and factory investments across the vendor set illustrate a common playbook: combine product innovation with supply‑chain resilience and software-enabled services.
Policy, subsidies and standards — sources of both demand and complexity
Public programmes and standards are acting as both demand multipliers and market filters. Subsidy schemes that provide large upfront support for micro irrigation can rapidly expand addressable markets — but they also introduce compliance requirements (for example, component marking and product certification) that increase time-to-market for exporters and OEMs. Large national investments to modernize irrigation infrastructure are similarly transformative, yet procurement rules and local content expectations change the commercial calculus for international suppliers.
For strategy teams, this duality creates an imperative: engineering product and commercial flows to be subsidy-aware (e.g., certification-ready, modular delivery, and local service capabilities), while building flexible pricing and financing structures that capture farmers’ cash-flow realities without eroding margins.
What PW Consulting’s report delivers — practical chapters and toolkits
-
Market sizing and credible forecast scenarios (base year 2025, historical 2020–2025, forecast 2026–2032) with sensitivity to adoption rates, policy shifts, and raw-material cost paths.
-
Detailed go-to-market playbooks tailored to vendor archetypes — from global OEMs to regional roll‑outs — including channel economics and subsidy-capture workflows.
-
Vendor capability scorecards and a curated list of M&A targets calibrated to strategic intent (scale, tech, channel access), plus diligence checklists for deal teams.
-
Commercial models and ROI tools: farmer-level total cost of ownership comparators, subscription pricing templates, and lender-friendly cash-flow models for asset financing.
-
Supply-chain and raw-material risk matrices that quantify exposure to polymer price volatility and recommend hedging and sourcing strategies.
-
Regulatory & subsidy mapping across priority markets, with implementation guides that reduce time-to-revenue for subsidy-dependent programs.
These deliverables are intentionally practical: we provide editable templates, pilot budgets and KPI frameworks that allow commercial teams to convert insight into action within 60–90 days. The report also contains granular segment-level datasets and regional demand breakdowns — we intentionally withhold certain granular splits here to preserve the strategic value of the full dataset available on the report page.
Implications by stakeholder
-
Investors: Prioritize companies demonstrating integrated hardware+software monetization, localized manufacturing or low-cost supply strategies, and validated route-to-subsidy channels.
-
Manufacturers: Certify product lines against major standards, design for modularity to meet subsidy rules, and bundle installation and monitoring to increase stickiness.
-
Agribusinesses and cooperatives: Deploy pilots that link micro irrigation to advisory services and yield verification to access finance and public funds.
-
Policymakers: Structure programmes to reward outcomes (water saved and yield uplift) rather than hardware alone; incorporate verification technology to prevent leakage and optimize public ROI.
90‑day playbook to capture 2026 upside
-
Week 1–3: Diagnostic — run an internal capability assessment using our vendor scorecard and subsidy-eligibility checklist.
-
Week 4–6: Pilot planning — select 2–3 farmer cohorts and design bundled hardware+monitoring pilots, with a plan to leverage local subsidy schemes.
-
Week 7–10: Supplier and manufacturing alignment — secure supply contracts for PE components with contingency clauses for polymer-price movements and qualify assembly partners for compliance marks.
-
Week 11–12: Commercial launch — roll a targeted channel campaign, deploy financing offers, and implement M&V (measurement & verification) to capture performance data for scaling.
Conclusion — a strategic decision window for 2026
Micro irrigation is no longer a peripheral sustainability investment — it is a strategic lever for yield optimization, water risk management and revenue diversification across agribusiness value chains. With the global market poised to nearly double in size over the next decade at a 9.5% CAGR (2026–2032), 2026 represents a decision window: scale now to capture the coming wave, or watch competitors consolidate key channels and service relationships.
PW Consulting’s Worldwide Agriculture Micro Irrigation System Market report equips leaders with the datasets, playbooks, and executable templates needed to translate sector growth into measurable enterprise outcomes. For the full segmentation, granular regional and application-level forecasts, vendor scorecards and the downloadable toolkits, access the complete report on our publications page.
For detailed analysis of this topic, please visit the official page: Worldwide Agriculture Micro Irrigation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Robust 7.2% CAGR for Worldwide Amino Acid Metabolism Disease Market Through 2032
By PW Consulting, 2026-08-05
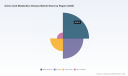
PW Consulting Strategic Brief: Worldwide Amino Acid Metabolism Disease Market — 2026 Outlook
PW Consulting today releases a strategic preview of our forthcoming Worldwide Amino Acid Metabolism Disease Market report. Built on an audited base year of 2025 and a rigorous forecast through 2032, the study models a market expanding at a compound annual growth rate (CAGR) of 7.2% — from a 2025 baseline market size of USD 2,990.75 Million toward a projected market of USD 4,865.39 Million by 2032. This briefing highlights the report’s practical value for senior executives, portfolio managers, corporate development teams, and public policy stakeholders who must make high‑stakes decisions in 2026 without compromising commercial optionality.
Worldwide Amino Acid Metabolism Disease Market
Why this report matters for 2026 decision-making
-
Near‑term inflection: The market’s acceleration into 2026 and beyond is driven by a confluence of diagnostic expansion, incremental therapeutic innovation (from medical foods and enzyme replacement to small molecules and advanced gene therapies), and evolving reimbursement dynamics. Executives planning product launches, licensing deals, or capital allocation in 2026 will need a forward‑looking evidence base that translates these forces into quantifiable commercial scenarios.
Worldwide Amino Acid Metabolism Disease Market -
Regulatory and IP milestones create asymmetric risk/reward windows in the next 3–7 years. Orphan exclusivity, patent expiries, and label expansions will re‑shape incumbent economics and new entrant pathways; a decision made in 2026 without mapping these timelines can be value‑destructive.
Worldwide Amino Acid Metabolism Disease Market -
Supply‑chain and raw material dependencies—especially for specialized APIs—are a recognized chokepoint. Companies that shore up supply or integrate contract manufacturing capabilities in 2026 can materially improve launch resilience and margin profiles.
What the full report delivers (practical and decision‑ready)
-
Transparent market model: top‑down and bottom‑up reconciled sizing, with sensitivity scenarios and unit economics for 2026–2032.
-
Patient‑flow and prevalence modeling: diagnosis, treatment uptake curves, and attrition assumptions calibrated to recent registry and claims data.
-
Commercial scenarios: pricing, reimbursement, and revenue simulations under multiple payer paradigms for strategic planning and negotiation playbooks.
-
Supply‑risk heatmap: supplier concentration, critical API pathways, and mitigation options (dual sourcing, toll manufacturing, backward integration).
-
Regulatory and IP matrix: orphan designations, patent expiry timelines, exclusivity windows and associated commercial impact scenarios.
-
Competitive and pipeline tracker: company profiles, mechanism of action mapping, clinical stage updates and go‑to‑market readiness scoring.
-
M&A and partnering blueprint: prioritized target lists, valuation sensitivities, and integration risk checklists.
-
Decision tools: executive one‑pagers, investor briefing slides, and operational KPI dashboards to accelerate board and investor approvals in 2026.
Note: This preview intentionally excludes granular sub‑segment revenues by region, disease type or treatment channel. Those core splits are delivered exclusively in the full report and accompanying data annex to preserve actionable insight for paying subscribers.
Key market dynamics shaping 2026 strategy
-
Therapeutic modality mix continues to evolve. Traditional medical foods and dietary management remain foundational, while enzyme replacement therapies and small molecules sustain incremental revenue growth. Parallel investment in gene therapy platforms creates optionality for disruptive, one‑time treatment economics — but practical commercialization remains gated by regulatory and clinical realities.
-
Regulatory shaping: Orphan Drug designations and label expansions materially influence time‑to‑monetization. For example, recent orphan designation activity confers multi‑year exclusivity that must be factored into licensing and launch timing decisions.
-
Payer engagement is tactical. Coverage policies and utilization management (e.g., prior authorization thresholds and step therapy for certain agents) are active levers in major markets. Early, evidence‑driven payer dialogues improve access and reduce launch risk.
-
Supply chain concentration: At least one core API pathway currently rests on a patented synthesis process with no anticipated generic entry in major markets until the end of the decade. Securing raw material access and contingency capacity is an immediate 2026 operational priority.
-
Market concentration: The industry shows moderate concentration, with the top three and top five players accounting for meaningful shares of market value — a dynamic that influences pricing power, partnership bargaining leverage, and M&A strategy.
Competitive landscape — what to watch in 2026
The therapeutic landscape combines established rare‑disease specialists, mid‑cap players pursuing lifecycle extensions, and biotech innovators advancing advanced modalities. Core commercial and pipeline actors profiled in our analysis include industry names that span enzyme replacement, small molecules, medical foods, and emerging gene therapies. Recent, strategically significant developments underscore both opportunity and timing risk:
-
BioMarin expanded label dynamics in late 2024 that facilitate patient self‑administration for an approved therapy targeting phenylketonuria, a move that alters channel economics and adherence profiles.
-
Travere’s late‑stage program updates in 2024 signal potential spillover effects for related rare amino acid conditions, illustrating how progress in adjacent rare disease spaces can inform clinical and commercial hypotheses.
-
Chiesi’s regulatory approval of an oral pediatric formulation earlier in 2024 highlights formulation strategy as a differentiator in pediatric and lifetime‑care markets.
-
PTC initiated a pivotal trial in 2024 for a candidate in phenylketonuria; such pivotal starts materially de‑risk future revenue streams but require careful forecasting around trial readouts and label scope.
-
On the gene therapy front, major pharmas advancing AAV‑based programs through acquisitions or internal development expand the strategic set for partnerships, but commercial deployment remains subject to regulatory constraints and trial‑only restrictions in several jurisdictions as of 2026.
Actionable strategic recommendations for 2026
-
Prioritize supply‑chain security: Initiate contractual or equity‑based ties with critical API suppliers in 1H‑2026 to lock pricing and capacity or develop parallel sourcing strategies. Supply risk is a tangible, near‑term commercial disruptor.
-
Map IP cliffs to product and R&D strategy: Use our IP timeline scenarios to decide whether to accelerate lifecycle investment, pursue follow‑ons or prepare defensive measures for anticipated patent expiries.
-
Adopt a tiered commercialization strategy: For high‑value, late‑stage assets consider hybrid launch models (center‑of‑excellence + hub‑and‑spoke) to manage payer negotiations and patient access simultaneously.
-
Engage payers early with real‑world evidence plans: Proactively define the evidence package and registries you will offer to payers to shorten the path from label to sustained reimbursement.
-
Position for strategic M&A: Use our M&A heatmap to identify targets that deliver immediate manufacturing or distribution scale, clinical pipeline breadth, or unique platform technologies ahead of anticipated market inflection points.
-
Design adaptive clinical development plans: Given regulatory nuances around gene therapies and the evolving natural history data for many amino acid disorders, adopt adaptive designs and surrogate endpoints to de‑risk pivotal programs.
Risk factors and mitigation
-
Regulatory timing: Orphan designations can both create opportunity and slow competitive entry; scenariobuilding should include conservative approval timelines.
-
Reimbursement volatility: Payers may tighten access through utilization management; plan for multi‑tier pricing and value‑sharing arrangements.
-
Clinical constraints: Advanced modalities face unique safety and long‑term follow‑up requirements; build post‑launch evidence budgets into launch forecasts.
-
Manufacturing/RAW: Single‑source API situations require active mitigation via contracts, technology transfer, or in‑house capacity investment.
How to use PW Consulting’s full report
-
Executive teams: Fast‑track board deliberations with pre‑packaged decision decks and scenario outputs tailored to 2026 capital plans.
-
BD&L and investors: Screen targets and structure term sheets using our valuation sensitivities and exclusivity maps.
-
Commercial leaders: Design launch sequencing and payer engagement plans with our reimbursement playbooks and channel economics.
-
R&D and clinical operations: Reconcile pipeline prioritization against market windows and patient population dynamics informed by our prevalence modeling.
PW Consulting’s Worldwide Amino Acid Metabolism Disease Market report is deliberately engineered as a decision‑support product for 2026. It provides the quantitative backbone and qualitative context required to convert scientific promise into sustainable commercial outcomes — while protecting the confidential, transaction‑grade segment detail that drives competitive advantage. For full access to the dataset, sub‑segment tables, and interactive scenario models, please visit the PW Consulting report page or contact our client services team to schedule a briefing.
About PW Consulting: We are a strategy advisory firm combining life‑science market analytics, commercial due diligence, and pragmatic implementation support. Our rare disease practice helps clients make faster, better calibrated choices where timing and evidence matter most.
For detailed analysis of this topic, please visit the official page: Worldwide Amino Acid Metabolism Disease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Robotic Scope Holder Market Poised to Reach USD 514.3 Million by 2032, Growing at a 7.5% CAGR (2026–2032)
By PW Consulting, 2026-08-05
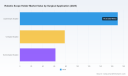
PW Consulting — Strategic Preview: Worldwide Robotic Scope Holder Market Report (Base Year 2025)
Executive snapshot
PW Consulting today releases a strategic preview of its forthcoming Worldwide Robotic Scope Holder Market report. Anchored on a 2025 base year with a five‑year historical window (2020–2025) and a forward view to 2032 (forecast period 2026–2032), the analysis quantifies a market that has expanded from roughly USD 216 million in 2020 to approximately USD 310 million in 2025, and is projected to continue growing at a compound annual growth rate (CAGR) of 7.5% through the forecast horizon. By 2032 the market opportunity is modeled to reach beyond half a billion USD—highlighting an enduring expansion driven by surgical automation, hybrid robotic workflows and accelerating clinical acceptance.
Worldwide Robotic Scope Holder Market
Why this preview matters to 2026 decision-makers
-
Strategic timing. The 7.5% CAGR we model for 2026–2032 signals a transition from early-adopter to scaling dynamics. For hospital groups, device OEMs and private equity investors, 2026 marks a critical inflection point where pilot programs and limited rollouts must convert into scalable deployment strategies to capture the majority of lifetime value.
Worldwide Robotic Scope Holder Market -
Consolidation and purchasing power. Our concentration metrics indicate a market where a small cohort of established vendors command the majority of installed base and channel influence. This concentration creates bargaining asymmetries, but also creates acquisition levers for entrants seeking rapid scale.
Worldwide Robotic Scope Holder Market -
Technology interoperability is now a procurement differentiator. Platforms that deliver seamless integration with established surgical robots and endoscopic suites, combined with intuitive control modalities (voice, foot pedals, haptic overrides), are the highest-conviction investments for systems integrators and procurement teams in 2026.
-
Regulatory and reimbursement clarity improves the investment calculus. IEC electrical-safety compliance, existing CPT reimbursement pathways for computer-assisted navigation, and the prevalent Class II FDA pathway for these devices materially reduce time-to-adoption risk for commercial strategies that prioritize regulatory alignment from product conception.
Report contents — practical, action-oriented deliverables
This report is built as an operator’s toolkit rather than an academic monograph. Highlights include:
-
Market sizing and demand modeling—validated across multiple data sources and triangulated with equipment placements, hospital adoption wave modeling and clinical activity indicators. (High-resolution, segment-level revenue tables and share matrices are included in the full report.)
-
Go-to-market playbooks—tailored for OEMs, systems integrators and hospital procurement. Each playbook includes channel mapping, pricing scripts, bundling strategies, and pilot-to-scale conversion workflows.
-
Vendor scorecards and competitive positioning frameworks—objective performance scoring across clinical compatibility, regulatory posture, service economics and integration flexibility.
-
Total cost of ownership (TCO) models—multi‑year lifecycle cost templates that incorporate capital, consumables, sterilization cycles, maintenance, and training. These templates are configurable to hospital size and surgical caseload.
-
Clinical adoption roadmaps—evidence‑backed scenarios that tie technology features to procedure-level uptake, surgeon acceptance thresholds and reimbursement levers.
-
Supply chain and manufacturing risk heatmaps—material availability and sterilization constraints (including considerations for medical‑grade stainless steel and titanium alloys and autoclave requirements) are modeled by risk tier to inform sourcing and dual-sourcing strategies.
-
Regulatory and reimbursement playbook—detailed mapping of IEC 60601‑1 implications, the 510(k) pathway for devices classified as Class II by the FDA, and the operational impacts of CPT coding on hospital billing and case economics.
Competitive landscape — what the leading suppliers reveal about the market
The sector is dominated by a mix of specialist robotic-surgery equipment firms and larger medtech players that have absorbed innovative start-ups. Our competitive review focuses on proven players that shape innovation and buyer expectations:
-
Mitaka Kohki (Tokyo): Known for the MS‑51 and MS‑6A systems, Mitaka emphasizes multi‑axis articulation and hands‑free controls (including voice activation) and is actively enhancing AI‑assisted positioning. Their product updates point to a mid‑market strategy of deep clinical integration with higher‑end robotic suites.
-
FreeHand Surgical (London): The FreeHand 2.0 portfolio highlights voice-activated control and surgeon ergonomics. The company’s recent presence at surgical society conferences has focused on hybrid procedures and live integration demos—signaling a go‑to‑market that emphasizes surgeon confidence and intraoperative workflow continuity.
-
EndoControl (now part of Medtronic, Rennes): The ViKY system’s acquisition and subsequent regulatory updates illustrate an acquirer strategy—use established distribution to accelerate technology reach while maintaining clinical support and OEM partnerships for endoscope compatibility.
-
Olympus (Tokyo): As an integrated endoscopic systems provider, Olympus positions robotic positioning as part of a broader surgical ecosystem—emphasizing device compatibility with its visualization platforms and hospital purchasing simplicity.
Across the vendor set we observe two clear strategic archetypes: boutique innovators that compete on feature differentiation (e.g., AI‑assisted positioning, voice control ergonomics), and platform incumbents that compete on integration, support network and bundled visual/robotic systems. The interplay between these archetypes shapes M&A, channel partnerships and OEM licensing negotiations.
Dynamics that will shape 2026 market moves
-
Standards and safety. Compliance with IEC 60601‑1 and sterilization protocols remains non‑negotiable; product roadmaps that bake in these constraints achieve faster institutional acceptance.
-
Reimbursement pathways. Existing CPT codes that capture computer‑assisted navigation materially improve the case for hospital investment when paired with demonstrated OR throughput gains and documented reductions in assistant labor.
-
Clinical evidence requirements. Decision-makers increasingly expect robust real‑world evidence—procedural time savings, reduced staff exposure, and consistent imaging alignment—before committing to system-wide rollouts.
-
Materials and sterilization economics. Design choices around medical‑grade stainless steel vs. titanium, and autoclave compatibility constraints, have downstream impacts on service intervals and sterilization throughput in high-volume ORs.
-
Regulatory predictability. The pathway for these devices is well‑trodden (Class II/510(k)), and recent device histories show no major recall patterns—reducing systemic regulatory risk for market entrants who adhere to established processes.
Actionable guidance for stakeholders in 2026
-
Hospital systems — pilot with procurement‑grade KPIs: Run bundled procurement pilots that track OR turnover time, surgeon satisfaction, and consumable spend to build a business case for enterprise procurement.
-
OEMs — prioritize interoperability and service economics: Product roadmaps should prioritize plug‑and‑play compatibility with the dominant visualization and robotic platforms, and service models that reduce total cost over a 5‑ to 7‑year lifecycle.
-
Investors — seek roll‑up targets among profitable niche players: Given market concentration dynamics, acquisitive consolidation focused on complementary IP and installed base monetization creates promising exit pathways within a 3–5 year horizon.
-
Regulators & payers — align clinical evidence to reimbursement triggers: Early engagement to validate outcomes tied to existing CPT pathways will speed payer acceptance and reduce adoption friction.
What we intentionally withhold in this preview
In keeping with the report’s role as a commercial intelligence product, detailed segment-level revenue splits, granular regional share tables and specific competitive revenue comparisons are reserved for the full report and client deliverables. This preview outlines the structural drivers, vendor dynamics and pragmatic playbooks; the proprietary, high-resolution tables and scenario models that convert these insights into executable strategies are available through PW Consulting’s report portal.
Next steps and how to access the full intelligence
Decision-makers planning capital allocation, rollouts or M&A activity in 2026 should obtain the full report for access to: facility-level deployment models, configurable TCO spreadsheets in USD (revenue unit: Million), vendor negotiation templates and an interactive scenario builder covering the 2026–2032 forecast period. To request the report, bespoke briefings or an executive workshop tailored to your organization’s role in the surgical ecosystem, contact PW Consulting’s Healthcare Technology practice.
PW Consulting’s Worldwide Robotic Scope Holder Market report is designed to be the single strategic source that aligns commercial, clinical and regulatory stakeholders around a clear path to value capture as the market scales through 2032.
For detailed analysis of this topic, please visit the official page: Worldwide Robotic Scope Holder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Steady 5.12% CAGR for Worldwide Cotton Bedsheets Market in 2026–2032
By PW Consulting, 2026-08-05
Worldwide Cotton Bedsheets Market: Strategic Preview for 2026 — Actionable Insights from PW Consulting
Executive summary
As the global bedding landscape rebalances in the aftermath of pandemic-era demand shifts and a renewed focus on sustainability and premium consumer experiences, our latest PW Consulting Worldwide Cotton Bedsheets Market report provides the operational intelligence executives need to make decisive moves in 2026. The global market — estimated at approximately USD 18.65 billion in 2025 — is forecast to expand at a compound annual growth rate (CAGR) of roughly 5.12% over the 2026–2032 forecast window, reaching the neighborhood of USD 26.45 billion by 2032. These headline figures capture a market that is growing steadily but remains structurally fragmented, creating differentiated opportunities for scale players, niche premium brands, and vertically integrated suppliers.
Worldwide Cotton Bedsheets Market
Why this matters for 2026 decision-makers
-
Timing and posture: A mid-single-digit CAGR does not imply uniform risk or opportunity. The market’s steady growth conceals pockets of rapid premiumization, sustainability-driven demand, and hospitality re-stocking cycles that will determine winners in 2026.
Worldwide Cotton Bedsheets Market -
Cost and supply volatility: Raw material dynamics — including global cotton production and pricing behavior — will materially affect margins and sourcing strategies over the next 12–18 months. Procurement leaders must re-evaluate their exposure to spot markets and futures positions as a near-term priority.
Worldwide Cotton Bedsheets Market -
Policy and trade: Shifts in trade policy and tariff treatments combine with logistic re-alignment to reshape nearshoring economics and supplier selection, forcing commercial teams to re-run landed-cost scenarios for major SKUs.
Core market dynamics — what we highlight in the report
-
Demand drivers and segmentation: We synthesize macro demand drivers — premium household consumption, accelerating direct-to-consumer channels, hospitality recovery, and healthcare procurement requirements — and map them against product attributes (source cotton variety, weave, finish) and go-to-market models.
-
Supply chain pressure points: The report analyses global cotton supplies and consumption balances (notably elevated production projections versus consumption in recent seasons), farm-gate price trends, and futures behavior that create both hedging needs and sourcing windows for buyers and manufacturers.
-
Regulatory and trade overlays: We interpret how tariff shifts and classification regimes (bed linen HS classifications and HTSUS treatment) influence supplier strategy, customs planning, and regional sourcing choices.
-
Commercial playbook: Practical modules include pricing models, landed-cost calculators, private-label vs. branded margin simulations, and channel-specific assortment tactics for 2026 season planning.
Macro raw-material and trade context
Two supply-side signals deserve immediate attention. First, global cotton supply estimates for recent seasons point to a production vs. consumption balance that changes the negotiating leverage between growers, merchants, and mills; this is visible in season-level production forecasts that exceed consumption in certain cycles. Second, pricing signals remain volatile: while official season-average farm prices may sit at mid-range levels, cotton futures have demonstrated sharp upward movement (notably approaching near two-year highs in early 2026). For procurement teams and risk managers this means: layer hedging strategies, maintain diversified origination options, and stress-test product pricing at multiple cotton-price scenarios.
On trade, tariff adjustments and expired exclusions under major measures (including U.S. Section 301 actions relevant to certain textile inputs) continue to alter landed-cost math for cross-border supply chains. Compliance with HTS and customs regimes for cotton bed linen remains a daily operating consideration for importers and distributors.
Competitive landscape — who to watch (and what they signal)
The cotton bedsheets market is characterized by a mix of large, vertically integrated manufacturers, hospitality-focused suppliers, and consumer-facing premium brands. Market concentration remains low — top-three and top-five combined shares are modest — underscoring fragmentation and buyer power. Our report contains detailed profiles and strategic assessments of key players, including:
-
Welspun Living Limited (India): Global scale and distribution are core advantages. For 2026, expect continued push on cost leadership, expanded private-label capabilities, and increased leverage into hospitality chains seeking consistent global supply.
-
Trident Limited (India): Vertical integration and sustainability investments position it to capture hospitality and institutional contracts where traceability and scale matter.
-
Indo Count Industries (India): A premium and export-focused manufacturer with advanced finishing and quality control — attractive to brands seeking higher margins and consistent quality for value or premium tiers.
-
Standard Textile and WestPoint Hospitality (United States): These firms exemplify the hospitality-focused supplier model where durability, lifecycle cost, and serviceability trump unit price. Strategic play: deepen service contracts and textile-as-a-service offerings for large hotel groups.
-
Boll & Branch (United States): Direct-to-consumer premium positioning, strong sustainability credentials, and traceability. For 2026, DTC brands will continue to grow relevance among premium urban consumers and influence wholesale assortment norms.
-
1888 Mills and American Textile Company (United States): Domestic manufacturers with brand and co-branded product launches — recent 1888 Mills product introductions emphasize the market appetite for trusted trademarks and affordability at scale.
Each competitor profile in the report includes strategic posture, margin levers, supplier networks, and near-term scenarios for expansion, consolidation, or repositioning.
Strategic implications and recommended actions for 2026
Across corporate profiles — from CPOs and heads of product to BD leads and CEOs — we recommend a focused set of actions that balance immediate margin protection with medium-term growth positioning:
-
Protect margins through dynamic hedging and multi-origin sourcing: Adopt a layered procurement approach (short-term spot, medium-term forwards, long-term contracts) and qualify alternative cotton origins to reduce single-source exposure.
-
Invest in traceability and verified sustainability claims: Consumers and institutional buyers increasingly demand certified and traceable cotton. Prioritize investments that create verifiable supply-chain narratives — these translate into premium pricing lift and channel access.
-
Optimize product portfolio by channel: Separate assortments for DTC premium, retail value, and hospitality/institutional specifications. Rationalize SKUs using margin-at-risk analysis and focus innovation where it unlocks higher ASPs.
-
Consider nearshoring and hub strategies: Re-run landed-cost models with updated tariff and logistics assumptions. For some buyers, a North America/Europe regional hub strategy will offset a portion of tariff exposure and improve service lead times.
-
Pursue partnerships and bolt-on M&A selectively: Acquisition targets that add differentiated finishing, certification capability, or regional manufacturing presence can accelerate time-to-market and protect margins in a cyclical raw-material environment.
-
Monetize hospitality demand with service-centric contracts: Suppliers who can offer linen-as-a-service, lifecycle management, and operational guarantees can secure higher-margin, recurring revenue streams from hotels and healthcare institutions.
Report contents — practical modules included
-
Executive dashboards: headline market size, forecast scenarios, and sensitivity to cotton-price movements.
-
Segmentation architecture: by region, material type, and end-user with qualitative demand mapping and category economics (detailed splits and proprietary datasets are available in the full report).
-
Supply-chain maps: origination flows, logistics nodes, and landed-cost models under different tariff and freight scenarios.
-
Competitive due diligence kits: company profiles, capability heatmaps, and deal-screening templates for strategic partnerships or M&A.
-
Commercial playbooks: channel-specific assortment strategies, pricing frameworks, and promotional elasticity guidance calibrated to 2026 market conditions.
-
Risk matrix and contingency plans: practical checklists for procurement, regulatory compliance, and product safety/labeling for major export markets.
What is intentionally withheld in this preview
Consistent with our “trailer” approach — showing the shape of opportunity while reserving the granular intelligence that drives direct competitive advantage — this press release omits chapter-level numeric splits and proprietary segment-level revenue tables. The full report contains the detailed regional and end-user revenue breakdowns, material-type shares, scenario-modeled P&L sensitivities, and the complete dataset that underwriting teams and commercial leads use to finalize 2026 budgets and capital allocation.
Next steps — how to use this intelligence
-
For C-suite and strategy teams: Use the headline forecasts and competitive positioning to stress-test 2026 budget allocations and prioritize investments in traceability, finishing capability, and regional logistics.
-
For procurement and operations: Begin immediate scenarios for hedging, multi-origin qualification, and contingency logistics to insulate 2026 product launches from cotton-price spikes and tariff shocks.
-
For commercial and product teams: Re-segment assortments by channel and pilot differentiated premium and sustainable ranges with clear margin targets and SKU rationalization plans.
About this PW Consulting publication
The Worldwide Cotton Bedsheets Market report is a PW Consulting flagship release that combines primary interviews with manufacturers, distributors, and brand leaders, proprietary shipment and pricing databases, trade-flow analysis, and scenario-modeled forecasts. It is designed as a practical playbook for decision-makers planning 2026 strategies who require both high-level foresight and executable tools.
Access and contact
Executives and teams seeking the complete dataset, segment-level schedules, and the actionable annexes should consult the full report and proprietary dashboards on our website. PW Consulting’s industry specialists are available to deliver bespoke briefings, scenario workshops, and custom modeling to align the insights to your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Cotton Bedsheets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Student Microscopes Market Forecast to Expand at a 5.1% CAGR Through 2032
By PW Consulting, 2026-08-05
Worldwide Student Microscopes Market: Strategic Intelligence for 2026 Decision-Making
Executive summary
As education systems and informal learning ecosystems continue to invest in hands-on STEM experiences, the worldwide student microscopes market stands at an inflection point. PW Consulting’s new market study—anchored on a 2025 base year and built from a 2020–2025 historical foundation with a 2026–2032 forecast horizon—projects continued, steady expansion at a compound annual growth rate of 5.1%. Our topline model anticipates the market growing from approximately USD 751.5 Million in 2025 to more than USD 1.06 Billion by 2032 under the base scenario. For executives planning procurement cycles, product road maps, or channel strategies in 2026, these macro dynamics create both clear opportunities and important trade-offs.
Worldwide Student Microscopes Market
Why this report matters for 2026 strategy
- Timing of investments: With predictable mid-single-digit growth, capital allocation toward product upgrades, digital imaging integration, and teacher training programs can be phased to match expected market expansion without over-capacity risk.
- Portfolio prioritization: Procurement teams and product managers can use our scenario outputs to decide whether to accelerate digital/USB offerings or reinforce durable, low-cost analog lines for high-volume educational buyers.
- Channel optimization: The market’s structure favors firms that combine direct institutional sales with online retail and distributor partnerships. Our go-to-market sensitivity analysis identifies the revenue elasticity across those channels.
What the PW Consulting report delivers (practical, actionable content)
We built this study to be a working tool for decision-makers. Key practical deliverables included with the report are:
Worldwide Student Microscopes Market
- Pro forma market-sizing models (historical and forecast) with adjustable assumptions for adoption rates, price points, and replacement cycles—enabling "what-if" modeling for 2026 budget planning.
- Buyer archetypes and procurement playbooks for K–12 districts, higher-education labs, and home/hobbyist channels, each with procurement triggers and typical purchase timelines.
- Pricing and margin matrices that illustrate the impact of feature bundling (optics, illumination, digital imaging, accessories) on realized margins across regions and channels.
- Supply-chain resilience maps, highlighting where material and labor constraints create lead-time risk and where near-shoring or dual-sourcing delivers measurable benefits.
- Competitor benchmarking dashboards (qualitative and quantitative) that synthesize product portfolios, distribution strengths, recent product launches, and R&D focus areas—designed for rapid strategic response.
Market trajectory and implications
The market’s projected steady expansion through 2032 offers a planning horizon that favors iterative innovation over speculative moonshots. A predictable CAGR of 5.1% translates into a meaningful cumulative expansion by the end of the decade—enough to justify investments in modular product platforms and digital enablement while avoiding the hyper-competition of saturated consumer gadgets.
Worldwide Student Microscopes Market
For 2026, this means organizations should prioritize three types of investments:
- Incremental product enhancements with demonstrable classroom benefits (e.g., improved optics, LED illumination, ruggedized frames);
- Low-friction digital add-ons (USB/digital imaging, simple Wi-Fi adapters, teacher-oriented software) that increase per-unit realized value without substantially raising procurement complexity; and
- Channel capabilities—training distributors and leaning into institutional tender expertise to shorten sales cycles and increase repeat purchases.
Competitive landscape—how the leading players are positioning
The student microscopes market remains moderately fragmented: the largest three players occupy a significant share but do not dominate. This creates room for established life-science optics firms and well-targeted entrants to capture niche growth pockets.
Our report profiles the leading manufacturers and synthesizes strategic moves observed across 2023–2024:
- AmScope (Irvine, CA): A category stalwart focused on student-grade compound and stereo microscopes. Recent product refreshes emphasize improved LED illumination and classroom-suitable ergonomics—moves that strengthen appeal to K–12 and homeschool markets.
- OMAX Microscopes (Irvine, CA): Targets value-conscious lab buyers with extended magnification ranges and a widening digital portfolio, including Wi‑Fi-enabled models aimed at integrating imagery into lab workflows.
- Celestron (Torrance, CA): Leverages consumer optics heritage to offer entry-level classroom microscopes; recent cordless and portable iterations indicate a strategy prioritizing classroom flexibility.
- Swift Microscopes (San Jose, CA): Positions on classroom durability and science-lab reliability—trade show activity and product rollouts emphasize ruggedized designs.
- National Optical & Scientific Instruments (Skokie, IL), Meiji Techno (Japan), Euromex (Netherlands), Motic (China), Leica Microsystems (Germany), and Olympus/Evident (Japan): Collectively, these vendors span the spectrum from low-cost, high-volume suppliers to premium educational brands. Their combined activity—catalog updates, digital-capable models, and ergonomic enhancements—reflects a market balancing cost sensitivity with increasing demand for imaging and connectivity features.
Recent product and catalog activity (through late 2024) shows investment in: LED lighting, cordless operation for field and portable classroom use, broader digital connectivity (including Wi‑Fi and USB imaging), and classroom-hardened mechanical designs. These moves are direct responses to procurement feedback captured in our primary interviews and tender analyses.
Regulatory, supply and cost dynamics that will shape 2026 choices
- Standards and certification: Educational optics must satisfy safety and biocompatibility standards; compliance regimes (including established ISO guidance and regional product safety marks) should be incorporated early in product development to avoid go-to-market delays.
- Material and manufacturing pressure: Optical glass quality and consistent lens supply are key inputs. Even modest volatility in lens availability or pricing can affect lead times and ASPs; procurement strategies should include contingency plans for critical optical components.
- Labor and production footprints: High-volume assembly locations remain cost-effective, but rising labor expectations and logistics complexity increase the attractiveness of partial near-shoring or higher automation for mid-tier suppliers.
- Certification-driven barriers: Regional conformity marks (electrical safety and EMC in some markets) are non-negotiable for institutional buyers; companies that front-load certification can shorten procurement cycles and gain preferred-vendor status.
Strategic recommendations for executive action in 2026
Based on our modeling and primary research, PW Consulting recommends the following priority actions for stakeholders preparing 2026 plans:
- For manufacturers: Adopt a modular-development approach—core optical platforms with optional digital modules and education-focused software—to address diverse buyer needs without proliferating SKUs. Pre-certify new variants for major markets to accelerate institutional adoption.
- For distributors and resellers: Invest in demonstration and teacher-training assets that reduce perceived implementation risk. Bundle service offerings (warranty extensions, rapid-replacement programs) to differentiate in tender processes.
- For institutional buyers (school districts, universities): Leverage predictable market growth to negotiate multi-year procurement contracts that lock volume discounts and ensure refresh cycles align with curriculum timelines. Prioritize devices that reduce total cost of ownership through modular upgrades rather than full replacements.
- For investors and OEMs considering entry: Focus on adjacent tech-enabled supplements (digital imaging, cloud-based lab reporting, augmented lesson plans) where margin expansion is achievable without competing on low-cost hardware alone.
Scenario planning and risk mitigation
Our report includes three actionable scenarios—base, upside (accelerated digital adoption), and downside (supply disruption). Each scenario quantifies revenue and margin outcomes based on alternate adoption speeds and price elasticity assumptions. Key sensitivities include adoption of digital imaging in classrooms, procurement budget cycles in major education systems, and raw-material bottlenecks.
For 2026 planning, the most probable operational risk is procurement lag: budget timing in school districts can create quarter-to-quarter revenue volatility. The strongest mitigant is to couple product availability with clear training and curricular integration—products that demonstrate classroom time-savings and pedagogical value achieve higher conversion during tight budget years.
Methodology and depth of analysis
PW Consulting’s study synthesizes primary interviews with procurement officers, educators, distributor executives, and manufacturing suppliers, combined with bottom-up shipment modeling and price-track analysis. We validated inputs against company disclosures and trade-catalog activity through 2024, and stress-tested forecasts with scenario analysis through 2032.
How PW Consulting can help you act on these insights
- Custom market-sizing adjustments for your product portfolio or geography, recalibrated for your pricing, mix, and channel assumptions.
- Procurement playbooks and tender templates designed to accelerate district-level approvals and shorten sales cycles.
- Competitor war‑rooms—rapid-response briefings that synthesize new rival product entries and recommended tactical responses.
Closing and next steps
The student microscopes market in 2026 is neither speculative nor static: it is a predictable-growth market with pockets of innovation around digital imaging, connectivity, and classroom durability. PW Consulting’s report equips executives with the models, playbooks, and competitive context required to make confident 2026 decisions—while preserving optionality for upside adoption scenarios.
To access the full dataset, detailed segmentation tables, and downloadable modeling tools that underlie these conclusions, please visit our report landing page. The executive summary presented here is intended to demonstrate the depth and operational focus of our work while reserving the detailed sub-segment data for report subscribers and clients who need it to execute their 2026 strategies.
For detailed analysis of this topic, please visit the official page: Worldwide Student Microscopes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


