



Category: market research
PW Consulting Forecast: Financial Services App Market to Surge from USD 165.2B in 2025 to USD 400.84B by 2032 at 13.5% CAGR
By PW Consulting, 2026-08-05
Worldwide Financial Services App Market: Strategic Imperatives for 2026 — PW Consulting Release
Executive preview
PW Consulting today publishes an executive preview of its forthcoming Worldwide Financial Services App Market report, providing senior executives and investors with the strategic framework required to navigate one of the fastest‑growing technology markets. The report uses 2025 as its analytical base year and presents a forward-looking forecast for 2026–2032. At the macro level, the market expanded rapidly through the early 2020s — rising from the mid‑double digits in 2020 to an estimated USD 165.2 Billion in 2025 — and is projected to continue growing at a compound annual growth rate (CAGR) of 13.5% through 2032, reaching roughly USD 400.8 Billion by the end of the forecast horizon. These headline figures underline the strategic urgency for firms to re-evaluate product roadmaps, operating models, and regulatory readiness in 2026.
Worldwide Financial Services App Market
Why this report matters for 2026 decision‑making
Executives allocating capital, signing partnerships, or building platform capabilities this year require more than high‑level optimism. They need playbooks that translate macro growth into executable initiatives with clear near‑term deliverables and measurable ROI. PW Consulting’s report is designed as an operational bridge between strategy and execution: it couples quantitative market sizing and scenario modelling with vendor scorecards, integration blueprints, and regulatory checklists that are immediately usable by product, engineering, and compliance teams.
Worldwide Financial Services App Market
What the report contains — practical, board‑level to bench‑level tools
- Strategic market mapping and scenario forecasts (base year 2025; forecast period 2026–2032) that stress‑test topline assumptions against macroeconomic and regulatory inflection points.
- Vendor evaluation matrices and "buy vs build" TCO models tailored to different go‑to‑market routes (bank incumbents, fintech challengers, platform providers).
- Integration and API blueprints for embedded finance, instant payments, and custody/stablecoin rails, complemented by sample contract clauses and SLAs to accelerate procurement cycles.
- Operational playbooks for fraud prevention, incident response, and resilience engineering aligned with emerging regulation and real‑world network threats.
- Commercial models and M&A scenarios including synergy capture frameworks and sensitivity analyses to inform valuation and post‑deal integration planning.
- Customer segmentation and UX benchmarks derived from proprietary behavioral datasets to help prioritize spend across onboarding, retention, and monetization levers.
Competitive landscape — how incumbents and challengers are positioning
The market is evolving as a dynamic mix of super apps, infrastructure providers, payment networks, and fintech specialists. Our qualitative assessment highlights three converging strategic plays.
Worldwide Financial Services App Market
- Super apps and consumer platforms (examples include established pan‑regional mobile financial platforms) continue to deepen engagement through embedded finance features — payments, lending, and investment — converting transactional relationships into broader lifetime value.
- Payment infrastructure firms and gateways are expanding up‑market: payment orchestration and programmable payment rails are now a core battleground as merchants and banks seek tighter integration between payments, reconciliation, and data analytics.
- Core banking and cloud platform vendors are accelerating modularization. Cloud‑native cores, coupled with composable front‑end stacks, are reducing time‑to‑market for new app features while amplifying third‑party ecosystem opportunities.
Selected illustrative company profiles in the report (not an exhaustive list) provide actionable insights about strategic positioning, partnership vectors, and execution risk. For instance, mobile super apps that combine payments, FX, and micro‑investing continue to leverage high engagement to cross‑sell financial products; payments and networks focus on tokenization and merchant orchestration; core platform providers push cloud migration and API enablement to win bank transformation deals. Each profile maps to tactical implications for potential partners and competitors — from channel economics to integration complexity and regulatory posture.
Regulatory and infrastructure dynamics shaping 2026 choices
Regulation and infrastructure trends in late 2024–2026 materially change risk profiles and operational requirements for app owners and their technology partners. Key elements summarized in the report include:
- Operational resilience and security mandates that increase compliance overheads and product development timelines. The EU’s Digital Operational Resilience rules and parallel regulatory initiatives globally force finance app operators to codify resilience testing, third‑party oversight, and incident reporting.
- Consumer data portability and API access requirements that shift control over account data and create interoperability opportunities — and competitive threats — between incumbents and new entrants as open data frameworks mature.
- Local data processing and sovereignty laws that necessitate differentiated product architectures and cloud footprints by jurisdiction, impacting latency, cost, and legal risk for multinational deployments.
- Energy and infrastructure cost pressures. Rising data center electricity prices, particularly in mature markets, are increasing the marginal cost of cloud‑hosted services and changing the economics of compute‑intensive features such as real‑time analytics and fraud detection.
Combining these forces, the report models three regulatory‑infrastructure scenarios and their impacts on capex, opex, time‑to‑market, and margins — enabling CFOs and CTOs to stress‑test investment proposals under plausible near‑term shocks.
Technology trends and commercial implications
Several technology trends accelerate both demand and complexity for financial services apps. Notable among them are programmable money and tokenized deposits, real‑time payment rails, and advanced fraud detection powered by network intelligence. Corporates should consider the following implications:
- Tokenization and programmable assets create pathways to new products (e.g., embedded deposits, instant settlements) but require careful partner selection for custody, liquidity, and compliance functions.
- Real‑time account‑to‑account payment networks are lowering friction in settlement and creating product opportunities (merchant‑initiated billing, request‑for‑payment flows), but also necessitate investment in settlement reconciliation and real‑time risk controls.
- Fraud detection is becoming proactive and networked; buyers should prioritize vendors that combine behavioral signals, device telemetry, and cross‑platform intelligence to detect emerging fraud rings earlier and at scale.
Five strategic imperatives for 2026
- Prioritize composability. Adopt modular, API‑first architectures that allow selective replacement of payments, KYC, and ledger functions without wholesale platform rewrites.
- Build regulatory flexibility. Design product flows and data architectures that can be scope‑limited per jurisdiction to meet sovereignty and operational resilience mandates while preserving a common codebase.
- Partner for speed and control. Strike hybrid partnerships — combining fintech agility with incumbent balance‑sheet and compliance capabilities — to accelerate time‑to‑market while limiting systemic exposure.
- Make security and energy costs part of product economics. Include resiliency and data processing cost assumptions in P&L and ROI models so that pricing, feature sets, and channel strategies reflect true lifetime costs.
- Elevate fraud and trust as product differentiators. Invest in real‑time, cross‑platform fraud intelligence and transparent customer remediation flows to protect margins and brand equity as transaction volumes rise.
Actionable timelines — what to do now versus next 12–36 months
For 2026, we recommend a staged approach:
- 0–6 months: Conduct a supply‑side audit and rapid vendor scorecard focused on integration risk, compliance readiness, and TCO. Lock pilot partnerships for tokenization and real‑time payments where strategic.
- 6–18 months: Execute modular migrations (e.g., payment orchestration, KYC gateways) and launch pilot products in controlled markets that validate economics under realistic regulatory constraints.
- 18–36 months: Scale successful pilots, transition to production‑grade resiliency practices, and pursue M&A or strategic alliances to fill capability gaps exposed during pilots.
Why PW Consulting’s methodology matters
The report combines bottom‑up quantitative modeling with qualitative diligence: primary interviews with senior product and engineering leaders, transaction level analysis of payment and transaction flows, vendor architecture reviews, and scenario stress‑testing against regulatory and energy cost shocks. This blended approach produces not only a credible market forecast, but also the practical artefacts that teams can bring into procurement, product planning, and board deliberations.
Next steps — how to access the full intelligence
This executive preview is intentionally directional. The full report contains detailed regional and segment breakdowns, proprietary vendor scorecards, downloadable integration templates, and raw datasets that underpin the forecasts. PW Consulting has prepared an executive briefing package and workshop options to help management teams convert insight into a three‑quarter execution roadmap.
To obtain the full report, datasets, and to schedule an executive briefing, please visit our report landing page or contact PW Consulting’s Financial Services Apps practice. The complete publication provides the granular visibility that boards and operating committees require to make confident investments during 2026’s critical planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Financial Services App Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 5.85% CAGR for Worldwide Nuclear-Grade LED Lighting Market Through 2032
By PW Consulting, 2026-08-05
Worldwide Nuclear Grade LED Lighting Market — Strategic Outlook for 2026 Decision-Making
Executive snapshot
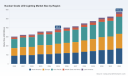
PW Consulting’s new market study on Worldwide Nuclear Grade LED Lighting synthesizes five years of historical evidence and a seven-year forecast to deliver a pragmatic roadmap for technology procurement, regulatory alignment, and supplier selection. The nuclear-grade LED lighting market expanded from approximately 302.15 Million USD in 2020 to 385.5 Million USD in 2025, continuing into a forecast trajectory that reaches roughly 402.45 Million USD in 2026 and 573.94 Million USD by 2032 — reflecting a compounded annual growth rate (CAGR) of 5.85% over the forecast window. Market concentration is meaningful but not prohibitive: the top three vendors account for about 38.5% of revenues while the top five cover roughly 52.4%, indicating an environment where specialist suppliers coexist with diversified system integrators.
Worldwide Nuclear Grade LED Lighting Market
Why this report matters for 2026 strategy
-
Procurement precision: Utilities, plant operators, and EPC contractors face increasing pressure to justify capital expenditures with resilient lifecycle economics. The report translates aggregate market growth into procurement-relevant insights — supplier risk profiles, qualification scorecards, and long-term availability forecasts — so decision-makers can move from vendor promises to verifiable performance baselines.
Worldwide Nuclear Grade LED Lighting Market -
Regulatory alignment: Nuclear lighting is inseparable from safety compliance. Our study maps lighting performance to seismic (IEEE-344), emergency illumination and post-incident requirements (e.g., extended-duration emergency illumination and 10CFR50 Appendix B quality frameworks), LOCA compatibility, and radiation testing regimes — enabling immediate incorporation of compliance checklists into 2026 RFPs and retrofit scopes.
Worldwide Nuclear Grade LED Lighting Market -
Risk-managed modernization: With many plants pursuing life-extension and refurbishment programmes, the timing, scope, and vendor selection for LED upgrades materially affect outage duration and operating costs. This report provides scenario modeling that ties LED selection to outage risk, maintenance burden, and operational resilience under high-radiation and post-accident conditions.
-
Supply-chain foresight: Component sourcing for radiation-hardened luminaires (stainless housings, radiation-tolerant drivers and CoB/LED dies, purpose-built optics) is specialized. The study highlights single-source dependencies, lead-time sensitivities, and recommended contingency inventories to avoid program slippage in 2026 purchasing cycles.
What the report delivers — practical content for implementers
-
Methodology and datasets: Transparent explanation of the 2020–2025 historical base, assumptions used for 2026–2032 forecasts, sensitivity ranges, and scenario variants keyed to regulatory change, reactor fleet activity, and new-build timelines.
-
Specification playbooks: Ready-to-adopt technical specification templates for high-, moderate- and low-radiation zones that include verification tests (gamma dose, LOCA-behaviour, seismic qualification), acceptance criteria, and documentation checklists for procurement teams.
-
Supplier qualification & scorecards: Comparative evaluations across design maturity, in-house manufacturing controls, radiation certifications, emergency-duration claims, seismic testing credentials, and quality-program compliance (10CFR50 Appendix B alignment where applicable).
-
Lifecycle cost and maintenance models: Integrated CAPEX/OPEX models reflecting installation, maintenance cycles, spare-parts provisioning, and outage-hour costs — enabling NPV-driven decisions between retrofit options and full replacement strategies.
-
Testing & commissioning protocols: Step-by-step commissioning scripts and on-site verification tests (photometric, thermal, driver stability under radiation, EMC testing for control interfaces) to avoid late-stage rejection and rework.
-
Case playbooks: De-identified case studies that expose common failure modes and successful mitigation strategies observed in recent retrofits and new-builds across global facilities.
Competitive landscape — who matters in 2026
The nuclear-grade lighting sector is populated by highly specialized manufacturers and integrators whose differentiation rests on tested radiation tolerance, mechanical robustness, and certification alignment. Key players profiled in the study include:
-
DITO Lighting d.o.o. (Gorica pri Slivnici, Slovenia) — Known for ultra radiation-resistant H-, N- and L-Series luminaires designed for both air and underwater deployment. Notable strengths: integrated driver architectures, LOCA compatibility, and verticalized in-house design and manufacturing. Recent 2025 developments include a U-50 upgrade with custom CoB LEDs and a consolidation of A-Series technology into an L-25 designation to streamline platform deployment.
-
Luminos Nuclear / Nanocut d.o.o. (Hrastnik, Slovenia) — Focuses on gamma-hardened LED luminaires with documented gamma testing to high dose levels (example test benchmarks include studies conducted at specialized facilities). Offers stainless-steel and emergency variants with in-house mechanical and electronics capabilities, underpinned by rigorous testing protocols.
-
Ahlberg Cameras (Sweden) — Supplies radiation-tolerant LED lights validated for pool and containment applications, often paired with visual inspection and CCTV systems in hot cells and radioactive pools.
-
BIRNS, Inc. (Oxnard, CA, USA) — Offers high-tolerance floodlights and emergency fixtures with seismic qualifications and high Gy tolerance benchmarks used in containment and high-ceiling applications; emergency fixture runtimes are a competitive differentiation for post-event illumination planning.
-
AO Sosny R&D Company (Dimitrovgrad, Russia) — Specializes in lighting for hot cells and maintenance facilitation areas, focusing on higher-input power fixtures specified for shielded environments.
-
G&G Industrial Lighting (Malta, NY, USA) — Produces compact luminaires for accelerator-level radiation environments with ruggedized, zero-maintenance designs.
-
Homewood Energy Services (USA), Martek Lighting (New Jersey, USA), and LED Lighting Supply (USA) — These suppliers are notable for North American compliance experience (including 10CFR50 Appendix B program adherence, seismic qualifications, and EMC considerations) and for offering tailored emergency and retrofit solutions for utilities and plant operators.
Collectively, these suppliers illustrate the blend of niche expertise and regulatory-focused engineering required by buyers. Our supplier profiles evaluate claims against independent test references, field records, and quality-program documentation to produce defensible supplier shortlists suitable for 2026 procurement cycles.
Regulatory and technical dynamics shaping vendor selection
-
Seismic and structural qualification: IEEE-344 remains the de facto benchmark for seismic qualification in many jurisdictions; buyers must ensure fixture-level and anchor-system validation rather than relying solely on generic product labels.
-
Emergency illumination & quality programs: Extended-duration emergency lighting expectations (commonly 24–40 hours for certain containment applications) and quality-program alignment with 10CFR50 Appendix B require careful matching of battery systems, maintenance regimes, and procurement documentation.
-
Radiation and LOCA performance: Gamma testing to certified dose levels and LOCA compatibility testing are non-negotiable for equipment in high-exposure zones. Some products advertise tolerance to very high cumulative doses; however, equivalence in driver design and optics must be validated in vendor-supplied test reports.
-
Materials & decontamination: Stainless-steel housings and smooth, decontaminable surfaces are standard design expectations to meet maintenance and ALARA considerations; raw-material sourcing and weld quality are often differentiators in long-term performance.
-
EMC & systems interoperability: Lighting controls interfacing with safety and monitoring systems require EMC validation to avoid interference with sensitive instrumentation — a gap frequently observed in rushed retrofits.
Five decisions to prioritize in 2026
-
Adopt specification templates from the report and mandate vendor compliance evidence (test certificates, seismic reports, LOCA results) as pass/fail criteria in RFPs.
-
Establish multi-year spare-part agreements with at least two qualified suppliers to reduce single-source exposure and ensure fast replacement during outages.
-
Require field trials or staged installations in non-safety-critical zones prior to mass rollouts to validate in-situ thermal, photometric and radiation behaviour.
-
Integrate lifecycle cost modelling into capital approvals — prioritize total cost of ownership and outage-avoidance value over simple unit-price comparisons.
-
Budget for independent verification testing during commissioning and for mid-life requalification checks where fixtures are subject to cumulative radiation or post-accident stresses.
Conclusion — how PW Consulting helps you act in 2026
For utilities, plant owners, and systems integrators preparing 2026 budgets and project scopes, the nuclear-grade LED lighting market offers predictable growth but demands specialist procurement discipline. Our study provides the technical, regulatory, and commercial intelligence needed to de-risk procurement, shorten qualification cycles, and align vendor commitments with operational resilience. We deliberately present a high-resolution view of market structure, supplier capabilities, and regulatory mapping while reserving the full segmented datasets, price matrices, and supplier scorecards for the comprehensive report.
Accessing the full report will provide the granular segmentation, downloadable spreadsheets, vendor scorecards and procurement-ready specification kits referenced in this summary. For teams preparing 2026 decisions, these deliverables materially shorten time-to-decision and elevate negotiation leverage with suppliers whose offerings must perform under the most demanding nuclear conditions.
For detailed analysis of this topic, please visit the official page: Worldwide Nuclear Grade LED Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Niraparib Market Set to Expand at a 12.43% CAGR, Driven by Surging Ovarian Cancer Demand
By PW Consulting, 2026-08-05
Worldwide Niraparib Market 2026: Strategic Implications and Executive Playbook — PW Consulting Preview
As PW Consulting’s chief industry analyst, I present a focused preview of our newest market research: the Worldwide Niraparib Market. This briefing outlines why niraparib will be a strategic inflection point for oncology portfolios in 2026, and why executive teams should align R&D, commercial, and supply-chain decisions with the macro dynamics we identify. The full report contains the granular matrices, scenario models, and proprietary market splits that underpin the conclusions below — data we intentionally reserve for subscribers and bespoke engagements.
Worldwide Niraparib Market
Market snapshot: size, trajectory and concentration
Niraparib’s market has evolved from an emerging maintenance therapy to a multi-indication commercial category. Using 2025 as our base year, PW Consulting quantifies the total addressable market at USD 1,180.5 Million and models a robust compound annual growth rate (CAGR) of 12.43% across the 2026–2032 forecast window. Under our central-case assumptions, the market more than doubles from the 2025 base to reach approximately USD 2,680.5 Million by 2032, driven by indication expansion, regulatory approvals, companion diagnostics uptake, and broader adoption in later lines of therapy.
Worldwide Niraparib Market
Two structural features are most salient to strategy teams: high market concentration and durable IP protection. Our concentration analysis shows the top three competitors account for well over 90% of market value, and the five largest players capture nearly the entire market — a dynamic that both stabilizes near-term revenues and raises the stakes of any label, pricing, or safety event affecting a principal holder. Complementing concentration, core U.S. patents underpinning composition and formulation extend into the late 2030s, providing a runway for premium pricing and controlled lifecycle management; generics were not approved as of April 2026.
Worldwide Niraparib Market
Regulatory and diagnostic inflection points to watch
- Late-2025 regulatory action enlarged the prostate cancer opportunity set: a December 12, 2025 FDA approval brought a niraparib-containing regimen (AKEEGA) into use for a BRCA2-mutated metastatic castration-sensitive prostate cancer indication, reflecting an acceleration of PARP inhibitor application beyond ovarian oncology.
- Companion diagnostics have matured: the FDA approved a validated HRD companion diagnostic for niraparib in early 2026, altering the economics of patient identification and reimbursement negotiation.
- Label refinements and safety communications in 2025 updated prescribing guidance for the originator product, reinforcing the importance of pharmacovigilance programs and targeted medical affairs investments.
Combined, these regulatory and diagnostic shifts materially change the commercial calculus: the addressable patient population becomes more precisely defined, payers demand companion diagnostic evidence, and formulary positioning depends on comparative efficacy in biomarker-defined subgroups.
Competitive landscape: players, positions and tactical implications
The market is anchored by an incumbent originator with broad global reach, complemented by strategic licensees and regional commercialization partners, as well as a compact ecosystem of API suppliers. Key competitive positions and implications include:
- GlaxoSmithKline (GSK): As the originator and primary marketer of the flagship product, GSK controls lifecycle levers — label, pricing, and global commercialization outside certain partnered territories. Its demonstrated global revenue performance positions it to invest in indication expansion and real-world evidence (RWE) initiatives. For third parties, GSK’s dominance means partnership or differentiation strategies are essential.
- Janssen Biotech (Johnson & Johnson): Holding exclusive rights (outside Japan) to the niraparib-based AKEEGA regimen in prostate cancer, Janssen has turned niraparib into a backbone for combination strategies. Its recent regulatory milestones validate combination approaches and increase the competitive threshold for single-agent positioning.
- Regional partners — Zai Lab and Takeda: Licensing and commercialization partnerships in Greater China and Japan respectively create geographically specific go-to-market dynamics. These partners will determine uptake speed, pricing corridors, and local data generation — crucial variables for multinational strategy teams.
- API and CDMO ecosystem: A compact set of active pharmaceutical ingredient (API) manufacturers provides manufacturing options but also concentration risk in supply. Firms active in manufacturing supply chains — including established generics and specialty API players — are critical nodes in launch and scale plans.
For companies contemplating entry or adjacent investments, the competitive map implies three routes: partner with incumbents to access channels and data, develop differentiated combinations or formulations to create clinical separation, or focus on supply-chain and cost leadership to enable competitive pricing strategies post-patent.
Operational and commercial risks that matter in 2026
- Regulatory dependency risk: Approvals for combination regimens and companion diagnostics shift market share rapidly toward the first mover; delays in sNDA approvals or diagnostic reimbursement create local access gaps.
- Concentration and single-supplier risks: Market concentration amplifies the commercial impact when supply chain disruptions or label updates occur. Companies should stress-test sourcing strategies and dual-source critical APIs.
- Payer and HTA volatility: The growing use of companion diagnostics increases per-patient cost and invites stricter health-technology assessment (HTA) scrutiny; payer outcomes will hinge on demonstrated biomarker-stratified benefit and budget impact models.
- Intellectual property timing: Patent cliffs are distant enough to justify premium pricing in the near-to-mid term, but lifecycle planning must already model post-exclusivity competition pathways.
What PW Consulting’s Worldwide Niraparib Market report delivers to executives
Our full study converts the high-level trends above into operational tools for 2026 decision-making. Deliverables include:
- Comprehensive market model (historical 2020–2025; base year 2025) and scenario-based forecasts to 2032 with sensitivity toggles for indication expansion, diagnostic adoption, and price erosion.
- Competitive intelligence dossiers on originator, licensees, and key API suppliers — including strategic intent mapping, revenue benchmarking, and a patent-timeline heatmap.
- Go-to-market playbooks tailored for: (a) new entrants seeking regional partnerships, (b) mid-sized firms optimizing manufacturing-to-market readiness, and (c) incumbents looking to defend share via combination strategies and RWE investment.
- Actionable supply-chain risk matrix and dual-sourcing templates to reduce single-point supplier exposure for APIs and finished-dose manufacturing.
- HTA and payer evidence blueprints tied to the companion diagnostic pathway, plus templated pharmacoeconomic models and rebuttal dossiers for formulary negotiations.
- M&A and licensing scorecards for target prioritization, with financial impact simulations and integration risk assessments.
We intentionally withhold detailed regional and indication split tables from this preview to safeguard the competitive value of the report. Subscribers receive the full segmentation and downloadable modeling files that drive the strategic recommendations summarized here.
Strategic recommendations for executives in 2026
- Prioritize biomarker-aligned evidence generation: invest in trials and RWE that demonstrate differentiation in diagnostic-defined subpopulations to win formulary access and premium reimbursement.
- Lock down supply resilience now: establish dual API sources and qualify alternative CDMOs before launch volumes scale to avoid revenue drag from capacity constraints.
- Negotiate companion diagnostic pathways collaboratively with diagnostic vendors and payers to streamline patient identification and reduce time-to-treatment.
- Consider combination development or label-seeking partnerships to expand addressable indications where single-agent economics are challenged by payer resistance.
- Use patent longevity to front-load lifecycle investments — safety surveillance, patient support programs, and geographic expansion — while modeling post-exclusivity scenarios now.
- Monitor concentration-sensitive scenarios: develop contingency plans for rapid market-response if a dominant player faces regulatory or safety setbacks.
Why this matters for 2026 planning cycles
2026 is a decisive year because regulatory approvals, diagnostic validation, and recent label actions have materially re-scoped niraparib’s commercial universe. Firms that integrate diagnostic-driven commercialization, build resilient supply chains, and align payer evidence strategies will capture outsized returns as the market compounds at an annualized rate above 12% through 2032. Conversely, organizations that wait for clearer signals risk paying a premium — or losing negotiating leverage — when incumbents and strategic partners monetize first-mover advantages.
Next steps and how to access the full intelligence
PW Consulting’s Worldwide Niraparib Market report is designed to be both strategic and operational: it informs board-level prioritization while supplying the tactical templates commercial teams need to act in 2026. For access to the full dataset, segmentation tables, downloadable models, and bespoke advisory support, visit our report page or contact a PW Consulting engagement lead. Our team can also deliver an executive workshop to translate the report’s scenarios into a six-month implementation roadmap tailored to your organization.
For detailed analysis of this topic, please visit the official page: Worldwide Niraparib Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 8.45% CAGR for Worldwide Cell Controller Market Through 2032
By PW Consulting, 2026-08-05
Worldwide Cell Controller Market: Strategic Insights for 2026 Decision-Makers
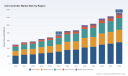
PW Consulting’s latest Worldwide Cell Controller Market report is the reference playbook for executives making high-stakes decisions in 2026. Drawing on a rigorous historical baseline (2020–2025) and an empirically grounded forecast through 2032, this analysis translates market momentum into clear choices for product strategy, supplier selection, regulatory compliance, and M&A. The market is expanding at a sustained pace — our modeled compound annual growth rate (CAGR) through the forecast period is 8.45% — and total industry revenue grows from a mid‑2025 baseline to a materially larger market by the end of the decade (figures expressed in USD Million). This press release outlines the strategic value of the report for boardrooms, product teams, and corporate development groups while preserving proprietary segment-level detail to incentivize access to the full study.
Worldwide Cell Controller Market
Executive summary: why this matters in 2026
Cell controllers sit at the intersection of electrification, safety regulation, and systems-level optimization. They are no longer component-line items: they are strategic enablers for automakers, energy-storage OEMs, industrial integrators, and semiconductor suppliers. Our baseline analysis captures the market’s transformation through 2025 and projects a continued upward trajectory into 2032, reflecting accelerating adoption across electric vehicles (including high-voltage traction systems), stationary energy storage, and industrial battery solutions.
Worldwide Cell Controller Market
For corporate leaders preparing budgets and roadmaps in 2026, the critical questions are not whether the market is growing, but how to position for competitive advantage. Should you deepen in-house IC development, pursue licensing or partnership models, accelerate testing and functional-safety certification, or prioritize acquisitions that fill capability gaps? The report translates macro growth into those operational decisions.
Worldwide Cell Controller Market
Market trajectory and concentration: what the numbers imply
-
Market growth: The cell controller market demonstrates robust expansion from our 2025 baseline into the forecast horizon (data in USD Million), underpinned by a projected CAGR of 8.45%. This pace reflects both unit growth in electrified platforms and increasing per-pack electronics complexity (safety diagnostics, individual-cell monitoring, and advanced balancing architectures).
-
Competitive concentration: Market concentration is moderate—our CR3 and CR5 metrics show that leading suppliers hold meaningful share but that the market remains contestable for focused entrants. This structure favors nimble players with differentiated technical capabilities (e.g., functional-safety ready ICs, scalable daisy-chain communications, or virtualization-enabled testing ecosystems) and strategic acquirers seeking consolidation opportunities.
Market dynamics shaping 2026 strategy
Several convergent dynamics will govern boardroom decisions in 2026:
-
Regulatory and functional-safety requirements: Automotive standards such as ISO 26262 (and related vehicle electrification standards) are driving product architectures that embed diagnostics, fault-tolerant balancing, and fail-safe communication. Compliance is no longer a checkbox; it is a gating factor for supplier selection and time-to-market.
-
Standardization of communications and isolation: Industry momentum toward isolated daisy‑chain communications and transformer-based physical layers supports high-cell-count strings and robust EMC performance. Suppliers that offer proven physical-layer solutions and reference implementations lower integration risk for OEMs.
-
Testing and virtualization: Increased reliance on virtualized test environments—illustrated by suppliers providing Cell Controller Virtualization (CCV) for multi-vendor validation—reduces prototype cycle time and enables earlier safety validation. Investment in virtual test benches is now a core part of product development budgets.
-
Technology differentiation: Key product differentiators include per-channel ADCs, integrated balancing topologies, hardware alarm interfaces, and certified ASIL/SIL levels. Suppliers that combine hardware robustness with software toolchains for diagnostics and fleet telemetry are capturing higher-value OEM relationships.
Competitive landscape — what to watch
The market is characterized by a small set of established semiconductor suppliers and a growing ecosystem of software/tooling providers and test specialists. Our competitive assessment focuses on product depth, functional-safety posture, go-to-market models, and ecosystem interoperability.
-
NXP Semiconductors (Eindhoven, Netherlands) — NXP’s portfolio exemplifies a vertically integrated strategy focused on automotive-grade cell controller ICs with explicit ASIL readiness, daisy-chain comms, and per-channel monitoring features. Recent product launches have intensified NXP’s relevance in high-voltage traction and stationary energy storage systems by addressing both performance and certification timelines.
-
Texas Instruments (Dallas, Texas, USA) — TI remains a foundational supplier of battery management ICs and cell controller building blocks. Its approach emphasizes scalable device families suitable for automotive and industrial packs, with strong distribution channels for system integrators.
-
Analog Devices (Wilmington, Massachusetts, USA) — Analog Devices competes on precision and integration, with device families targeted at high‑voltage, high‑channel‑count systems. Their strength is in signal integrity, isolation technology, and solutions that integrate seamlessly into high‑reliability BMS architectures.
-
dSPACE (Paderborn, Germany) — dSPACE operates in the adjacent ecosystem, offering Cell Controller Virtualization (CCV) and test platforms that accelerate multi-vendor validation and homologation. Virtualization providers are becoming strategic partners for OEMs that need to compress development timelines while preserving functional-safety validation rigor.
Taken together, supplier capabilities map onto different parts of the value chain: silicon suppliers drive device-level innovation and certification; tooling and virtualization providers reduce integration risk and cost of validation; systems integrators synthesize components into validated packs. Our report provides a vendor-readiness matrix that links these capabilities to common OEM procurement criteria.
What the PW Consulting report contains (practical, actionable chapters)
We designed the report for decision-makers who need immediately actionable intelligence. Highlights include:
-
Top-line market model: a transparent, traceable market-sizing model with historical and forecast revenue (USD Million), scenario variants, and sensitivity testing around key assumptions (EV penetration, energy-storage deployments, semiconductor supply dynamics).
-
Regulatory and standards matrix: a concise mapping of ISO 26262 and related ISO 12405 guidance to product requirements and certification workflows, including recommended test cases and timelines for ASIL/SIL compliance.
-
Supplier benchmarking: capability heatmaps covering product features (channel count, per-channel ADC, balancing architectures), safety certifications, integration support, and maturity of software toolchains.
-
Testing and validation playbook: recommended virtualization and hardware-in-the-loop (HIL) strategies, with vendor pairings (e.g., virtualization providers aligned with specific IC families) to compress homologation cycles.
-
Commercial and procurement playbook: go-to-market scenarios, distributor strategies, sourcing policies for dual-sourcing vs. single-sourcing, and contractual clauses to mitigate supply volatility.
-
M&A and partnership framework: identification of capability gaps that are best filled by partnership, acquisition, or in‑house development; valuation checklists for target selection; integration risk matrices and post‑deal value capture levers.
-
Technology roadmap: recommended R&D priorities for 2026–2028 across silicon, system firmware, and test automation, aligned to expected regulatory changes and OEM program timelines.
Strategic recommendations for 2026
Our report translates analysis into a concise set of strategic moves that executives can deploy in 2026. Key recommendations include:
-
Prioritize safety-first architectures: Commit near-term capital to ensure device and system-level compliance with automotive and industrial functional-safety regimes. This includes early engagement with certification bodies and investment in traceable development artifacts.
-
Invest in virtualization and HIL ecosystems: Organizations that accelerate virtualization gain measurable reductions in validation lead times and homologation risk. Plan a 12–18 month roadmap to integrate CCV/HIL platforms into product development workflows.
-
Adopt a tiered sourcing strategy: Balance the cost and integration advantages of leading silicon vendors with contingency suppliers to mitigate supply-chain shocks. Use the supplier-readiness framework in the report to operationalize dual-sourcing without proliferating SKUs.
-
Target modular system architectures: Design cell-controller modules to be decoupled from specific cell chemistries and pack designs. Modularization reduces time-to-adapt for new programs and enables software-driven differentiation (over-the-air diagnostics, advanced balancing algorithms).
-
Consider bolt-on acquisitions for tooling and test capabilities: For OEMs and Tier-1s, acquiring virtualization and test providers can shortcut competency development and secure early access to multi-vendor test benches.
How to use the full report
The press release intentionally summarizes the report’s strategic contours while preserving segment-level and vendor-specific intelligence for subscribers. The full PW Consulting report contains the granular regional and application splits, vendor-level market shares, pricing curves, and downloadable models needed to execute on the recommendations above. These details are provided in an interactive dashboard that can be customized to your internal scenarios and program timelines.
For 2026 planning cycles, we recommend executive teams convene a cross-functional cell-controller working group (R&D, procurement, safety/regulatory, legal, and corporate development). Use the report as the common analytical baseline to align trade-offs—time-to-market vs. certification cost, integration depth vs. supplier risk, and organic R&D vs. M&A—and to translate the 8.45% CAGR macro into concrete investment cases for the next fiscal year.
Contact and next steps
Access to the complete Worldwide Cell Controller Market report, the interactive financial model, and the supplier-readiness matrix is available through PW Consulting’s research portal. The full deliverable is designed to be used as a live decision-support tool in 2026 program reviews and M&A diligence. For executive briefings, tailored workshops, or to request sample excerpts of the methodology and model, contact our industry team—PW Consulting will coordinate a targeted session aligned to your strategic horizon.
PW Consulting’s cell-controller study equips leaders with the analytical foundation to make pragmatic, defensible decisions in a market that is growing, competitive, and heavily shaped by safety and testability requirements. We invite decision-makers to leverage the report as the strategic north star for 2026 planning.
For detailed analysis of this topic, please visit the official page: Worldwide Cell Controller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide IR Carbon Sulphur Analyzers Market Poised for 4.85% CAGR Through 2032
By PW Consulting, 2026-08-05
Worldwide IR Carbon Sulphur Analyzers Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest Worldwide IR Carbon Sulphur Analyzers Market report (base year 2025) is timed for executives, procurement leaders, and R&D strategists planning capital allocation and product roadmaps in 2026. The market has expanded steadily through the early 2020s — rising from a global revenue base in 2020 to a larger, more diversified industry by 2025 — and our forecast projects continued growth through 2032 at a compound annual growth rate (CAGR) of 4.85% (forecast period 2026–2032). This release is meant to serve as a strategic “preview”: it surfaces the operational levers, competitive dynamics, and structural risks that will determine winners in the next three years while guiding readers to the full report for transaction-level and segment-specific intelligence.
Worldwide IR Carbon Sulphur Analyzers Market
Why this market matters in 2026
-
Critical measurement function: Carbon and sulfur analyses remain central quality-control activities across metals, cement, minerals, and emerging battery materials. Analytical reliability often directly correlates with downstream yield, product performance and regulatory compliance.
Worldwide IR Carbon Sulphur Analyzers Market -
Steady market expansion: After recovering and consolidating through the first half of the decade, the overall market entered 2026 from a solid revenue base and is on a trajectory to add meaningful incremental spend through 2032. That predictability creates windows for targeted capex and service-model investments.
Worldwide IR Carbon Sulphur Analyzers Market -
Consumables and service as margin drivers: Beyond instrument sales, consumables (crucibles, accelerators) and maintenance/service contracts represent recurring revenue opportunities. Securing supply of high-purity tungsten accelerators and ceramic crucibles is a non-trivial procurement risk that manufacturers and end-users need to plan for.
What the report delivers (practical components)
-
Actionable market sizing and trend model — our model traces historical performance (2020–2025) and presents a 2026–2032 revenue forecast with scenario sensitivity to raw material disruption, regulatory tightening, and industrial capex cycles.
-
Buyer’s decision playbook — procurement frameworks, TCO templates, validation protocols, and service-contract negotiation checklists tailored for lab managers and corporate purchasers.
-
Competitive scorecards — calibrated assessments of instrument portfolios, service footprints, price bands, and aftermarket compatibility. Each vendor profile highlights technical differentiators (furnace type, detector architecture, throughput characteristics, and ease-of-use factors).
-
Consumables and supply-chain risk map — identification of critical inputs (including ceramic crucibles and tungsten-based accelerators), single‑source exposures, and suggested mitigation tactics such as strategic vendor stocking and qualification of secondary suppliers.
-
Regulatory and standards monitoring — implications for method validation, laboratory accreditation, and cross-border trade in analytical equipment and accessories.
-
Investment and M&A playbook — valuation heuristics for asset transactions, integration checklists for bolt-on service providers, and synergy targets for cross-selling consumables and service.
Competitive landscape — who to watch and why
The IR carbon–sulfur analyzer market is characterized by a few established instrument OEMs with deep installed bases, followed by regional and niche suppliers. Market concentration metrics indicate a market where the top three vendors capture a majority of revenue, with the top five controlling an even larger share — a structure that favors scale in manufacturing, service networks, and consumables logistics.
-
HORIBA, Ltd. — Renowned for the EMIA series, HORIBA combines robust high-frequency induction combustion with NDIR detection, focusing on throughput and user ergonomics. Recent documentation and user-centric refinements make HORIBA a strong choice for operations prioritizing uptime and sample throughput under varying sample matrices.
-
ELTRA GmbH (Verder Scientific) — ELTRA’s ELEMENTRAC family exemplifies portfolio breadth through single and dual-furnace architectures (induction + resistance). Their strategy emphasizes method flexibility across organic and inorganic matrices, which appeals to labs that serve multi-industry clients or require method consolidation.
-
LECO Corporation — With a legacy in combustion analysis, LECO’s multi-series offering spans dedicated and dual-purpose analyzers. Recent application notes underscore efforts to better serve cement and construction material producers with high-throughput process-control solutions.
-
Elementar Analysensysteme GmbH — Elementar focuses on rapid, high-precision instruments with modular detection options; attractive to labs that prioritize analytical fidelity for both inorganic and organic matrices.
-
Bruker Corporation — Combining high-frequency induction furnaces with advanced detection electronics, Bruker’s platforms aim at high-precision, high-throughput industrial labs and metallurgical applications.
-
Regional and niche players (Labtron, Torontech, BIOBASE, JIEBO) — These vendors compete on price-to-performance and regional service availability. They play an important role in localized markets where proximity and rapid spare-part provisioning matter more than global brand premium.
Recent vendor activity underscores two parallel themes: 1) incremental product enhancements that improve throughput and user experience, and 2) targeted application pushes into segments such as cement, battery materials, and process control where rapid, reliable carbon/sulfur data deliver measurable operational value.
Emerging operational and strategic themes for 2026
-
Method consolidation vs. specialization — Labs are balancing the economics of multi-matrix analyzers (to consolidate equipment base) against the higher accuracy and lower maintenance of single-purpose systems for critical applications. The right choice depends on test-volume mix and regulatory constraints.
-
Consumables security as a board-level issue — High‑purity tungsten accelerators and specific ceramic crucibles are small-dollar items that can stall production lines if unavailable. Forward-buying, dual-sourcing and in-region qualification are now essential tactical levers.
-
Service and digitalization as differentiators — Remote diagnostics, preventive maintenance subscriptions, and predictive spare-parts logistics are becoming decisive factors in procurement decisions.
-
Adjacent-market expansion — Vendors that can credibly cross-sell into battery materials, cement process control, and advanced alloys stand to capture above-market growth.
-
Regulatory-driven demand spikes — Stricter emissions and materials regulations in certain jurisdictions will periodically drive demand for validated carbon/sulfur testing, creating cyclic upticks.
Recommendations for corporate leaders and investors
-
Procurement leaders: Prioritize total cost of ownership analyses that include service uptime guarantees and consumable lead times. Negotiate multi-year spare‑parts and consumable agreements, and require minimum response times for critical regions.
-
R&D and product strategy teams: Invest in usability and method-reproducibility features (auto-sample handling, robust accelerators handling, and simplified calibration workflows). Consider modular detectors and furnace swaps to address both organic and inorganic testing without duplicative footprints.
-
Operations and supply-chain managers: Map single‑sourced consumables and implement redundancy—especially for tungsten accelerator supplies and ceramic crucibles. Validate alternative material suppliers proactively and include qualification timelines in procurement cadences.
-
Investors and M&A teams: Look for acquisition targets with strong service networks or consumables franchises; these assets compress payback periods and create recurring revenue streams.
How to use this preview in 2026 planning
This preview equips leaders to ask sharper questions in 2026 procurement rounds: Are vendors offering guaranteed consumable availability? Do their instruments integrate with plant MES or LIMS for closed‑loop process control? Can the vendor demonstrate method transfer and validation across the specific matrices your operations use?
For strategic purchasers contemplating capex in 2026, the full PW Consulting report includes a reproducible TCO model, scenario-based procurement timing recommendations, and a vendor short‑list generator based on your lab profile (volume, matrices, geographic spread). These tools are engineered to turn market-level insight into immediate, defensible decisions.
Next steps
-
Executive briefing — Schedule a tailored 60–90 minute briefing with PW Consulting to map the report’s recommendations to your organization’s testing footprint and capex cycle.
-
Access full segmentation and vendor profiles — The comprehensive report contains the detailed By-Region, By-Type and By-Application breakdowns, instrument-level comparisons, and the granular competitive intelligence that we intentionally reserved from this public preview.
-
Operational readiness checklist — Download our complementary checklist for consumables qualification and service-level agreement (SLA) negotiation to use immediately in vendor discussions.
PW Consulting’s Worldwide IR Carbon Sulphur Analyzers Market report is designed to convert macro visibility into operational advantage. The industry’s predictable mid-single-digit CAGR, combined with recurring consumables and service opportunities, creates a landscape where disciplined procurement, supply‑chain resilience, and targeted technology investments will yield outsized returns in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide IR Carbon Sulphur Analyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Industrial Wiping Cloth Market Poised to Expand at a 5.15% CAGR Through 2032
By PW Consulting, 2026-08-05
Worldwide Industrial Wiping Cloth Market: Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s newest market study — Worldwide Industrial Wiping Cloth Market (base year 2025, historical 2020–2025, forecast 2026–2032) — provides a focused, decision‑ready view of a sector that is quietly consolidating its role as a mission‑critical input across manufacturing, maintenance, and hygiene ecosystems. The global market was estimated at USD 4,520.0 Million in 2025 and, under our central scenario, is projected to expand at a 5.15% compound annual growth rate through 2032, reaching roughly USD 6.42 Billion. For procurement leaders, product strategists, private equity investors and operations managers, this study reframes wiping cloths from a commodity purchase to a strategic lever for margin, risk and sustainability outcomes in 2026.
Worldwide Industrial Wiping Cloth Market
Why this report matters for 2026 planning
- Actionable sizing and trend signals: the study reconciles manufacturer shipments, distribution flows and demand pull from key end markets over a comprehensive 2020–2025 historical run, and translates those dynamics into scenario outputs for 2026–2032 that inform capacity, sourcing and pricing decisions.
- Risk and resilience guidance: it maps raw‑material exposure (cotton rags, polyester blends, spunlace and meltblown nonwovens, recycled textile feedstocks) against supplier concentration and logistics constraints — enabling stress‑testing of procurement strategies for 2026 supply disruptions and cost inflation.
- Commercial playbooks: the report provides go‑to‑market blueprints for private label, branded and service models (including rental/consignment programs), showing where margin shifts are most realistic when moving from unit pricing to value‑based contracts.
- Sustainability ROI: it quantifies practical levers for circularity and recycled content strategies that preserve performance while reducing total cost of ownership and compliance risk in regulated end markets.
Report contents in practice — what you’ll use on Monday morning
- Consolidated market model calibrated to supplier, distributor and end‑user activity — designed for scenario sensitivity (price shocks, raw material substitution, demand shocks by industry).
- Supplier benchmarking and capability matrices that rank manufacturers by product technology (nonwoven, woven/knit, microfiber), service model (rental, stocking, direct ship), geographic footprint and critical‑use credentials.
- Procurement playbooks with RFP templates, total cost of ownership (TCO) calculators and inventory replenishment triggers tuned to wiping products’ consumption profiles.
- Investment decision frameworks for capex (nonwoven capacity, slitting/roll converting, finishing lines) and for M&A (bolt‑on targets, integration risk checklists and quick‑win synergies).
- Regulatory and standards monitoring: summary of current compliance pressures and an events calendar of industry forums that shape technical requirements and sustainability expectations in 2026.
- Case studies and commercial pilots from manufacturers and end users that demonstrate levers to improve absorbency, reduce waste and monetize service offerings.
Market dynamics shaping 2026 strategy
Three structural dynamics deserve explicit attention for any 2026 strategic plan:
Worldwide Industrial Wiping Cloth Market
- Material and process innovation — Advances in nonwoven technologies (spunlace, airlay, meltblown blends) and microfiber finishing continue to shift value toward engineered wipes for critical applications. Firms that can match performance with consistent quality command premium pricing in semiconductor, healthcare and aerospace end markets.
- Sustainability and circularity — The reuse and cascading of recycled textile materials into wiping products is well‑established practice. But the commercial opportunity in 2026 is selective: brands that can demonstrate chain‑of‑custody, consistent performance and quantifiable lifecycle benefits will secure differentiated contracts, particularly with corporate procurement teams and industrial laundries.
- Service and business‑model differentiation — Rental and managed‑service models (periodic pickup and replacement) are growing in relevance, especially where uptime and traceability matter. Service models convert a low‑margin disposable sale into recurring revenue with higher lifetime value.
Competitive landscape — fragmented, regional and ripe for selective consolidation
The industrial wiping cloth market remains a fragmented industry with modest aggregate concentration: the top three firms account for under one fifth of market share while the top five remain below 30% — a signal that national and regional players continue to control local channels and specialized niches. This fragmentation creates clear strategic windows in 2026 for buyers, integrators and investors who can execute disciplined consolidation or carve out differentiated, service‑enabled positions.
Worldwide Industrial Wiping Cloth Market
Key competitor archetypes identified in our study include:
- Regional manufacturing and wholesale specialists: companies with deep distributor relationships and broad SKU catalogs that serve traditional industrial and janitorial channels.
- Engineered wipes providers: firms focused on mission‑critical, high‑specification products for controlled environments (e.g., semiconductor, bio/pharma) who leverage tighter quality control and traceable materials.
- Direct‑to‑end‑user suppliers and private‑label consolidators: operators who compete on price, logistics and scale for manufacturing and automotive maintenance demand.
- Service‑oriented rental players: providers offering pickup/replacement services and wash cycles, which compete on convenience, total cost and sustainability claims.
Representative names analyzed in the report include long‑established manufacturers and distributors, engineered‑wipes specialists, China‑based exporters with competitive cost positions, and rental/service providers. Our company profiles synthesize public disclosures, product portfolios, distribution footprints and investment signals to show where each firm is positioned on a risk‑return matrix relevant to 2026 buyers and investors.
Events and signals to watch in 2026
- Industry conferences such as World of Wipes and The Clean Show remain focal points for standards development, product trials and distributor networking — expect these events in 2026 to accelerate pilot programs for sustainable materials and nonwoven processing innovations.
- Raw‑material cost trajectories (cotton waste streams, polyester and polypropylene nonwovens) and logistics constraints will be the short‑cycle drivers of price volatility — monitor monthly indices and supplier lead times for tactical purchasing advantage.
- Procurement policies from large manufacturers in automotive, electronics and food processing are evolving to include circularity and TCO criteria; early alignment with these buyers will create differentiated demand streams.
Strategic actions recommended for 2026
- Prioritize supplier capability audits over cost benchmarking. Focus on quality control, traceability and conversion capacity to avoid production shocks in critical applications.
- Pilot a managed‑service or rental model with a subset of customers to validate unit economics and lock in recurring revenue before scaling.
- Target selective vertical integration or strategic partnerships for recycled feedstock sourcing to stabilize input costs and secure sustainability claims.
- Deploy a dual‑track procurement strategy: secure base inventory under multiyear agreements while maintaining a smaller flexible pool to exploit spot opportunities and price dislocations.
- Use M&A to acquire capability (e.g., engineered nonwoven finishing) rather than raw volume alone; discipline on accretion thresholds will protect margins.
- Invest in product qualification for regulated end markets (semiconductor, healthcare): faster qualification cycles translate directly into pricing power.
- Create a data dashboard linking usage patterns, inventory turnover and wash/replacement cycles to reduce working capital and improve fill‑rates.
Conclusion — positioning for value rather than volume
For 2026, the strategic imperative is clear: industrial wiping cloths are no longer a pure commodity input. Performance differentiation, service models and sustainability credentials will drive where value accrues in the next three years. Our market model and competitive analysis show an expanding but still fragmented market — an environment that rewards disciplined investment in capability, selective consolidation and commercially grounded sustainability initiatives.
PW Consulting’s full report contains the detailed regional and application segmentation, supplier scorecards, pricing models and downloadable scenario models referenced here. Access to the full dataset and executable playbooks is available through the report page — consult the PW Consulting research portfolio to download the complete study and supporting Excel models for your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Wiping Cloth Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Ammonium Polyvanadate Market Poised for Robust Growth — 8.9% CAGR Forecast Through 2032
By PW Consulting, 2026-08-05
Worldwide Ammonium Polyvanadate (APV) Market: Strategic Imperatives for 2026
PW Consulting’s latest market study on Worldwide Ammonium Polyvanadate (APV) synthesizes five years of historical performance and seven-year forward-looking scenarios to equip corporate leadership, investors, and supply-chain managers with the insight required to make confident, commercially material decisions in 2026. Built on a 2025 base year with historical coverage from 2020–2025 and a forecast window extending 2026–2032, this report quantifies the APV market in USD Million while pairing that quantitative backbone with actionable frameworks, risk matrices, and transaction-ready analyses.
Worldwide Ammonium Polyvanadate (APV) Market
Market trajectory you cannot ignore
The APV market has demonstrated a steady expansion from 2020 through 2025, culminating in a market size of USD 455.12 Million in 2025. Our baseline projections indicate a continuation of that trend into the forecast horizon: the market is expected to grow to USD 826.67 Million by 2032, implying a compound annual growth rate (CAGR) of 8.9% from 2026 through 2032. These dynamics reflect structural demand drivers across metallurgical, chemical, and emerging energy-storage applications, and they present discrete windows of opportunity for new entrants, midstream consolidators, and technology-focused downstream players.
Worldwide Ammonium Polyvanadate (APV) Market
Why this report matters for decisions in 2026
-
Precision for capital allocation: The report aligns revenue and demand scenarios with operational cost benchmarks and capex schedules, enabling CFOs and strategy teams to prioritize expansions, brownfield upgrades, or brownfield-to-greenfield conversions with quantified payback periods under multiple commodity and logistics assumptions.
Worldwide Ammonium Polyvanadate (APV) Market -
Supply-chain resilience: APV is materially exposed to upstream vanadium feedstocks. Our modelling layers supply-side production shocks, logistics disruptions, and regulatory interventions to estimate shortfalls and price pressure under adverse scenarios—essential input for procurement and inventory strategy in 2026.
-
Commercial and contracting strategy: For offtake-driven projects, the report provides negotiation playbooks, indexation templates, and margin sensitivity matrices that translate market-level forecasts into practical contract structures.
-
M&A and partnership screening: Using coverage of market concentration and firm-level positioning, the study identifies consolidation corridors and JV archetypes that routinely deliver the strongest strategic returns in APV value chains.
Key market dynamics shaping 2026 decisions
Three structural dynamics dominate near-term strategy:
-
Raw material and production geography: Vanadium supply underpins APV economics. Global vanadium output and the geographic distribution of that output create concentration risk for APV upstream feedstocks. Recent data show a significant portion of contained vanadium production is concentrated in a small number of producing countries, a fact that exacerbates vulnerability to country-specific policy shifts and operational disruptions.
-
Geopolitics and trade policy: Recent geopolitical developments and sanctions have already affected production volumes in certain regions, altering trade flows and elevating logistics and counterparty risk for APV exporters and importers alike.
-
Strategic regulation: Vanadium is now recognised in several jurisdictions as a critical raw material, prompting industrial policy responses intended to secure domestic supply chains. Expect procurement preferences, traceability requirements, and potential incentives for local processing to influence project economics and sourcing decisions in 2026.
What the PW Consulting report delivers (practical, non-theoretical)
-
Top-line market model with scenario outputs for 2026–2032, including high/medium/low demand pathways and their fiscal sensitivities.
-
Supply-demand dashboards mapping feedstock availability, processing capacity, routing constraints, and short-cycle bottlenecks that materially affect APV availability.
-
Regulatory and ESG risk matrix with mitigation playbooks—covering emissions, waste-handling, and chemical safety compliance in key markets.
-
Price-driver decomposition and elasticity profiles tailored to different procurement horizons (spot, short-term contract, long-term offtake).
-
Commercial playbooks: contracting templates, inventory governance protocols, and recommended margin carve-outs for trading intermediaries.
-
M&A screening toolkit: valuation anchors, synergy capture roadmaps, transaction due-diligence checklists, and integration timing milestones.
-
Factory benchmarking and unit-cost curves for APV production routes—enabling rapid CAPEX/OPEX trade-off analysis for brownfield expansions and greenfield placement.
-
Supplier and feedstock scoring framework designed for procurement teams to rank counterparty reliability across technical, financial and geopolitical dimensions.
To preserve commercial sensitivity and to adhere to the “trailer” principle of this release, we have intentionally omitted detailed regional and application-level splits from this summary. The full report contains the granular tables, interactive charts and downloadable datasets required to operationalize decisions; access details are provided at the end of this release.
Competitive landscape — who matters and why
Market concentration metrics show that the top three players control a meaningful portion of the market (CR3 approximately 42.15%), while the top five account for a majority share (CR5 approximately 58.4%). This structure points to a market with clear incumbent advantages but still substantial room for strategic repositioning.
-
EVRAZ plc (Moscow, Russia) — A vertically integrated producer with significant downstream exposure to ferrovanadium and steelmaking applications. EVRAZ’s asset base offers scale advantages in feedstock processing and product placement for metallurgical markets. However, geopolitical constraints and trade frictions increase counterparty and logistics risk for its international customers; procurement teams should evaluate alternative supply contingency plans if depending on Russian-origin volumes.
-
Panzhihua Iron and Steel Group Vanadium Titanium New Material Technology Co., Ltd. (Panzhihua, China) — An integrated player leveraging domestic magnetite resources to feed both APV and downstream V2O5/ferrovanadium production. The company’s integration along the value chain diminishes feedstock variability risk and positions it to capture margin across stages; buyers should anticipate competitive pricing strategies in regional markets.
-
Chengde Xinhua Hebei Vanadium Products Co., Ltd. (Chengde, China) — Specialist in APV from vanadium slag with a focus on chemical and metallurgical end-uses. Firms seeking tailored chemical-grade APV for catalyst or specialty applications will find such suppliers attractive, especially where product quality and process history matter.
-
Hebei Jianlong Vanadium Products Co., Ltd. (Qian'an, China) — Concentrates on supplying APV as an intermediate for high-purity vanadium pentoxide. Jianlong’s positioning makes it a natural partner for downstream refineries or producers targeting high-purity downstream products.
-
Treibacher Industrie AG (Althofen, Austria) — European-based supplier focused on commercial and specialty-grade APV for catalysts and chemical applications. Treibacher’s proximity to European chemical markets and regulatory acumen offer a supply advantage for customers facing traceability and compliance constraints within the EU.
Strategic plays for 2026
Based on our integrated scenario work and company-level analysis, the following plays merit top priority for stakeholders looking to capture value in the APV market over 2026–2028.
-
Producers: Prioritize feedstock security via long-term ore contracts and diversified logistics corridors. Accelerate yield-improvement projects and deploy modular processing units that can be scaled with demand.
-
Downstream manufacturers (ferroalloy, chemical, battery sectors): Lock in multi-year offtakes with staged volume flexibility and put-call features—coupled with joint investment into filtration and purification capacity to de-risk quality variability.
-
Traders and distributors: Adopt inventory tiering—segregating high-purity and commercial grades—and implement dynamic hedging strategies tied to vanadium feedstock indices and FX exposure.
-
Investors and corporates exploring M&A: Target bolt-on assets that close the feedstock-to-finished product loop or provide geographic diversification away from concentrated production basins. Focus on deals that deliver immediate margin uplift via logistics or processing synergies.
Operational checklist for 90-day action
-
Run a supplier stress-test for your current APV sourcing set under at least three disruption scenarios.
-
Quantify the cash-flow impact of price moves implied by an 8.9% medium-term CAGR and prepare a staged tariff/premium pass-through policy.
-
Initiate commercial dialogues with at least two non-core-origin suppliers to diversify counterparty exposure.
-
Map regulatory and ESG compliance gaps across your value chain and prioritize capital for the highest-return mitigation measures.
Conclusion and next steps
APV occupies a strategically important and fast-evolving node in modern industrial chemistry and metallurgical supply chains. With a clear growth trajectory and concentrated upstream risk, 2026 will be a year when allocation of capital, choice of partners, and diligence on feedstock sourcing will determine winners and laggards. PW Consulting’s Worldwide APV Market report—anchored to a 2025 base year, covering 2020–2025 history and projecting 2026–2032—combines the market sizing you need (reported in USD Million) with the qualitative and transactional tools to translate that sizing into executable strategy.
For corporations preparing budgets, boards considering M&A, and procurement teams renegotiating offtakes, the full report contains the granular regional, grade and application splits, downloadable datasets, and executable templates intentionally omitted from this briefing. Access the complete study and supporting models through our website to obtain the in-depth tables, interactive dashboards and bespoke advisory options that will turn this market insight into 2026 competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Ammonium Polyvanadate (APV) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 6.42% CAGR for Worldwide Picrorhiza Extract Market Through 2032
By PW Consulting, 2026-08-05
Worldwide Picrorhiza Extract Market — 2026 Strategic Briefing
Executive summary
The global Picrorhiza extract market has entered a phase of sustained, measured expansion. After growing from a global market value of roughly USD 34.6 million in 2020 to approximately USD 48.7 million in the report base year of 2025, our modeling indicates a continued upward trajectory through the 2026–2032 forecast window. PW Consulting projects the market to expand at a compound annual growth rate (CAGR) of 6.42% during 2026–2032, reaching an estimated market value above USD 80 million by 2032 under the baseline scenario. For executives planning resource allocation, product roadmaps, procurement strategies or M&A activity in 2026, these macro contours create a clear strategic runway — but with important supply-side and regulatory caveats that must be actively managed.
Worldwide Picrorhiza Extract Market
Why this briefing matters for 2026 decision makers
-
Actionable timing: 2026 is a pivotal year to lock in supply arrangements, pilot cultivation partnerships and translate early-stage science into differentiated product claims before broader market adoption accelerates.
Worldwide Picrorhiza Extract Market -
Risk-adjusted growth: a mid-single-digit CAGR signals steady demand growth but not runaway expansion; success will hinge on securing high-quality, compliant raw material and demonstrating clinical or formulation advantage.
Worldwide Picrorhiza Extract Market -
Fragmented supplier landscape: concentration metrics show that market share is dispersed — domination by a few incumbents is limited, creating windows for agile entrants, strategic consolidations and premium differentiation.
Market dynamics shaping near-term strategy
Three structural themes define the Picrorhiza extract market in 2026: constrained raw material supply, evolving regulatory oversight tied to conservation, and a shifting application landscape driven by modern formulation science.
-
Supply scarcity and geography: Picrorhiza kurroa is a high-altitude Himalayan species whose commercial value rests in roots and rhizomes harvested from remote elevations. Historical industry reporting highlights a persistent gap between demand and supply, which has driven interest in organized cultivation and supply-chain interventions. For procurement teams, this means price and availability volatility remain material risks unless supply strategies are diversified.
-
Conservation-led regulation: Picrorhiza kurroa has long been subject to international conservation controls and national restrictions in harvest regions. International listings and national conservation policies continue to influence export eligibility, certification requirements and traceability expectations. Firms without robust compliance mechanisms face operational and reputational exposure.
-
Science and formulation trends: recent scientific work — including early 2026 publications exploring Picrorhiza as a prebiotic adjunct in synbiotic formulations — signals potential new value propositions beyond traditional herbal uses. This research trajectory creates near-term R&D and commercialization opportunities for companies that can move quickly to validate benefits and secure intellectual property or supply exclusivity.
Competitive landscape: incumbents, capabilities and strategic levers
The supplier ecosystem is diverse, with established exporters and regional producers offering a mix of crude powders, standardized extracts and liquid preparations. Key market participants include established Indian exporters and processors, leading Chinese producers focused on botanical applications, and a number of specialized suppliers operating in or sourcing from Himalayan regions.
-
Value propositions observed across providers: quality assurance (including organic and standardized actives), bulk B2B export capability, packaging and shelf-life optimization, and origin traceability. These capabilities determine which buyers win premium formulations versus commoditized supply deals.
-
Market concentration is low: top-three and top-five supplier groups account for minority shares of the market, indicating fragmentation and room for consolidation or differentiation. This presents tactical opportunities for buyers to negotiate favorable long-term contracts, pursue strategic alliances with cultivators, or execute roll-up strategies to secure scale.
-
Notable supplier profiles: several Indian manufacturers and exporters occupy a strong position in premium supply chains and international compliance; Chinese producers maintain capacity for herbal applications; regional Himalayan suppliers are critical to origin authenticity and community-based sourcing strategies. Each supplier archetype brings distinct trade-offs — price, traceability, scalability and regulatory risk — which buyers must balance against product positioning and channel strategy.
Regulatory and sustainability headwinds
Conservation listings and national regulations materially affect market access. Picrorhiza kurroa’s regulatory status and restrictions on wild collection in source countries increase compliance complexity for international buyers. For corporates, this elevates the importance of certified cultivated sources, chain-of-custody documentation and proactive engagement with sourcing communities to de-risk supply.
For sustainability-focused players, there is a window to convert conservation risk into commercial advantage by investing in cultivation projects, farmer training, and certification programs that guarantee supply while supporting local livelihoods. Such investments also reduce exposure to reactive policy shifts that can interrupt supply or increase costs.
What PW Consulting’s report delivers (practical, actionable components)
Our full market study combines quantitative modeling with practical toolkits designed to support 2026 decision-making. Key deliverables include:
-
Proprietary market-sizing and forecast model (2026–2032) with scenario modules that test regulatory tightening, cultivation scale-up and accelerated adoption of novel applications.
-
Demand–supply gap analysis and commodity flow maps that identify sourcing bottlenecks and near-term exposure points.
-
Supplier scorecards and a due-diligence framework assessing quality, compliance, traceability and scale readiness (confidential supplier rankings are included in the full report).
-
Regulatory & sustainability tracker with alerts on international listings, national harvest restrictions and required certifications.
-
Commercial playbooks tailored to buyer profiles — from formulators seeking standardized actives to ingredient traders prioritizing volume and cost — including contract templates, escalation pathways and negotiation levers.
-
Scenario planning tools and a risk dashboard enabling CFOs and procurement leaders to stress-test pricing and availability under adverse and accelerated-growth scenarios.
Strategic actions to prioritize in 2026
-
Secure diversified, multi-year supply: negotiate tiered contracts that include commitments to cultivated material and contingency clauses for regulatory disruptions.
-
Invest in cultivation partnerships: capital infusion into organized cultivation programs in source regions reduces long-term scarcity risk and can create preferred supplier status.
-
Build certification & traceability capabilities: implement chain-of-custody systems and third-party certification to safeguard market access and support premium positioning.
-
Fast-follow science-to-market opportunities: prioritize R&D programs to test synbiotic and other novel formulations flagged by 2025–2026 research, securing first-mover advantages on claims and formulations.
-
Pursue selective consolidation: use M&A or strategic partnerships to acquire upstream capacity or unique supplier relationships in fragmented supply chains.
Scenario outlook — planning parameters for 2026
Our modeling presents three core scenarios to inform strategic contingency planning:
-
Baseline: steady demand growth aligned with the 6.42% CAGR assumption; constrained but manageable supply as cultivation projects begin to scale.
-
Tight-regulation: accelerated conservation enforcement leads to restricted wild trade and short-term price spikes; buyers with cultivated and certified sources maintain continuity.
-
Acceleration: breakthroughs in organized cultivation and broader application adoption (e.g., synbiotic products) accelerate growth and favor suppliers who invested early in scale and quality systems.
Conclusion — the strategic value of acting in 2026
For companies engaged in nutraceuticals, herbal pharmaceuticals, and personal care, the Picrorhiza extract market in 2026 is better characterized as an opportunity gated by quality, compliance and supply resilience rather than by simple market size alone. The mid-single-digit CAGR provides predictable demand growth, but conservation-driven regulation and a persistent supply gap make strategic sourcing, cultivation partnerships and science-driven product differentiation the decisive factors for outperformance.
PW Consulting’s Worldwide Picrorhiza Extract Market report synthesizes quantitative forecasting with hands-on commercial playbooks and supplier intelligence to help executives convert these market dynamics into defensible business outcomes. The full dataset, granular segmentation analysis, supplier rankings and scenario model are available in the complete report — designed for procurement leaders, R&D heads, and corporate strategists preparing for 2026 and beyond.
To access the full report and the accompanying toolkits, visit the PW Consulting report page or contact our strategy team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Picrorhiza Extract Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide External Power Supplies (EPS) Market to Reach USD 12,200 Million in 2025, Growing at a 5.85% CAGR Through 2032
By PW Consulting, 2026-08-05
Worldwide External Power Supplies (EPS) Market — 2026 Strategic Preview: Growth, Regulation, and Competitive Playbooks
PW Consulting’s latest market study on the Worldwide External Power Supplies (EPS) market furnishes senior executives and investment teams with the strategic intelligence needed to make high-confidence decisions in 2026. Built on a 2020–2025 historical database and a 2026–2032 forecast horizon, the analysis quantifies a clear growth trajectory (compound annual growth around 5.85% through the forecast window) while translating regulatory shifts, supply-chain friction, and technology transition into actionable moves for suppliers, OEMs, channel partners and private-equity investors.
Worldwide External Power Supplies (EPS) Market
Why this preview matters to 2026 decision-making
2026 is a hinge year. The EPS market is large and expanding — our model places the market well into double-digit billions (USD, revenue units in Million) at the 2025 benchmark and projects consistent expansion through 2032 — yet growth is uneven and contingent on regulatory alignment, component availability, and tech adoption rates. For executives, the imperative is twofold: (1) secure product and compliance roadmaps that insulate revenue from regulatory and tariff shocks; and (2) convert efficiency and power-density improvements into differentiated, profitable product lines before commoditization accelerates.
Worldwide External Power Supplies (EPS) Market
Market outlook: measured growth, concentrated pockets of opportunity
The market’s macro picture is straightforward: after a recovery phase in the early 2020s, demand stabilizes into a sustained growth pattern through 2032 driven by continual replacement cycles in consumer electronics, rising requirements in networking and telecom (notably PoE and high-power edge devices), and increased medical and industrial EPS spending where reliability and certification command premium pricing. The forecast CAGR of roughly 5.85% embodies this steady expansion and underpins multiple strategic plays: premiumization, platform consolidation, and targeted geographic diversification.
Worldwide External Power Supplies (EPS) Market
Two structural observations matter for strategy:
- Market concentration remains moderate. The top-three and top-five manufacturer concentration ratios indicate room for scale advantages without complete market dominance — enabling mid-sized specialists to pursue vertical niches while larger players push platform economics and global distribution.
- Regulatory tailwinds and headwinds operate simultaneously. New ecodesign standards and evolving DOE requirements create both compliance costs and opportunities for product differentiation based on efficiency and lifecycle performance.
Regulatory environment and implications for product roadmaps
Regulation is a top-three strategic risk for 2026. Two developments require immediate incorporation into product and go-to-market planning:
- European ecodesign update: Regulation (EU) 2025/2052 formally updates EU requirements for external power supplies and related products, with implementation phased in through late 2028. The regulation raises the bar for energy performance and places a premium on lifecycle documentation — manufacturers must plan design-for-compliance timelines now to avoid product delistings and market access delays.
- U.S. DOE regulatory revision: In April 2026 the U.S. Department of Energy finalized revisions that remove certain reporting requirements for exempt consumer EPS under the EPS Service Parts Act of 2014. While this reduces administrative burden in some consumer segments, DOE’s overall efficiency program (including Level VI and successor expectations) remains in force and continues to shape technical specifications for exports and multinational product lines.
Strategic prescription: align design cycles with regulatory milestones; prioritize modular platform designs that can be updated to meet regional efficiency bands without full redesigns; and invest in compliance automation to reduce certification lead times.
Supply-chain and technology dynamics — where margins will be won or lost
Supply-side volatility is the dominant near-term operational constraint. Component lead times in early 2026 remained unpredictable due to fluctuating demand patterns and allocation issues. Geopolitical friction continues to elevate sourcing risk for magnetics, capacitors, semiconductors and GaN devices — the very inputs that determine cost, manufacturability and power-density.
- GaN and power-density: GaN adoption accelerates premium product segments (higher power densities, smaller form-factors, improved thermal performance). Companies that pair GaN with system-level EMI and thermal solutions will extract higher ASPs.
- Contract manufacturing and near-shoring: Manufacturers should reassess allocation of strategic BOM items and explore multi-sourcing or near-shoring to reduce single-country exposure and expedite time-to-market for regulated product lines.
- Service and warranty economics: As device longevity expectations and replacement cycles shift, service-based models (e.g., extended warranties, spare-parts-as-a-service) become durable revenue streams that offset hardware margin compression.
Competitive landscape — player archetypes and tactical opportunities
The report profiles the global competitive set and maps firms into strategic archetypes. Highlights include:
- Platform leaders (e.g., Delta Electronics): large-scale manufacturers with broad portfolios, deep R&D in efficiency compliance (DOE Level VI and EU ecodesign), and global manufacturing footprint. Their scale supports cost leadership and rapid compliance rollouts.
- Design-focused challengers (e.g., Lite-On Technology, CUI Inc., XP Power): firms emphasizing compactness, high efficiency, and medical/industrial-grade certifications. XP Power’s recent product introductions in the 65W–140W range exemplify targeted portfolio expansion into high-reliability segments.
- Niche specialists and cost innovators (e.g., Mean Well Enterprises, Phihong, Salcomp, Adapter Technology): these players target industrial, PoE, and mobile charging markets with deep application expertise and fast time-to-market for application-specific adaptations, including GaN-enabled, high-density designs.
- Regional OEMs and suppliers (e.g., Chicony, Acbel, FSP Group, TDK-Lambda, Artesyn): companies with strong ties to adjacent product ecosystems (PCs, servers, industrial modules) that can cross-sell EPS as part of broader systems.
Market concentration metrics reinforce the conclusion that scale matters but specialization wins in several sub-segments. The top-three and top-five concentration ratios in our study indicate a market where both global champions and nimble specialists can be commercially successful — provided their strategy tightly aligns with either platform economics or deep application differentiation.
What PW Consulting’s EPS report delivers (operational, not academic)
This is not a high-level narrative. The report is purposely operational and designed for executives who must act in 2026. Deliverables include (illustrative list):
- Demand and revenue scenarios through 2032 with sensitivity to regulatory implementation timelines and GaN adoption curves.
- Regulatory impact matrices by jurisdiction and product class, showing compliance cost and market access timelines.
- Supplier scorecards that benchmark technical capability, certification breadth, and supply-chain resilience for key EPS manufacturers.
- Component lead-time and risk heatmaps, plus tactical sourcing corridors to mitigate geopolitical exposure.
- Monetization playbooks: modularization, aftersales services, and channel strategies to protect margins amid commoditization.
- M&A and partnership frameworks identifying the most accretive targets by capability gap (GaN expertise, medical certifications, localized manufacturing).
Note: In keeping with our “preview” approach, this release outlines the scope and strategic value of the data without reproducing the proprietary segmentation tables and regional/application shares available in the full report. For the full set of granular splits (regional, output-power bands, and application-level revenue breakdowns), please consult the complete report package.
Strategic recommendations for 2026
Four priority moves for 2026 emerge from our research:
- Operationalize regulatory intelligence: create an agile regulatory team that maps product SKUs to jurisdictional timelines and integrates certification checkpoints into the NPI gating process.
- Pursue selective premiumization via GaN: prioritize GaN integration where ASP uplift and size/weight savings create clear value propositions (e.g., high-density adapters, medical-grade EPS). Couple this with IP and supplier contracts to secure supply.
- Harden supply chains with layered sourcing: implement multi-sourcing and local buffer strategies for critical active/passive components; negotiate capacity commitments with CM partners to lock in production windows for regulated SKUs.
- Monetize service and certification: convert certification investments into commercial assets by offering certified reference designs, white-label compliance services, and extended warranty packages that create sticky revenue streams.
For investors and M&A teams
EPS is a fertile ground for bolt-on acquisitions that either amplify platform coverage (adding medical/industrial certifications or GaN know-how) or secure distribution channels in high-growth end-markets. Valuation discipline should emphasize recurring-revenue potential from service extensions and the buyer’s ability to integrate supply-chain advantages that materially shorten product-to-market timelines under tightening regulatory regimes.
Closing: the tactical advantage of data-driven foresight
As 2026 unfolds, the EPS market will reward companies that convert regulatory and technological complexity into strategic advantage. PW Consulting’s Worldwide External Power Supplies market study equips leaders with the forecasted market scale, risk matrices, and executable playbooks needed to protect margins and accelerate growth across the forecast horizon. The preview you’ve just read highlights directionality and the highest-impact levers; the full report contains the granular segmentation, supplier benchmarking, and scenario models necessary to operationalize these insights.
Contact PW Consulting to access the full report and bespoke advisory services that translate these findings into prioritized 90/180/360-day action plans tailored to your role — supplier, OEM, distributor, or investor.
For detailed analysis of this topic, please visit the official page: Worldwide External Power Supplies (EPS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Classified Circuit Breaker Market to Rise from USD 540 Million in 2025 to USD 812 Million by 2032 at 6% CAGR — Miniature Breakers Command ~70% Share, North America Leads with USD 234.44 Million
By PW Consulting, 2026-08-05
Worldwide Classified Circuit Breaker Market — Strategic Outlook for 2026 (PW Consulting Preview)
Executive snapshot
PW Consulting’s forthcoming Worldwide Classified Circuit Breaker Market report provides decision-grade intelligence tailored for executive teams preparing strategy and investment decisions in 2026. Built on a 2025 base year with a historical series from 2020–2025 and a detailed forecast through 2032, the study quantifies the market’s recovery and structural growth: the market reached USD 540.0 Million in 2025, is projected to rise to approximately USD 578.6 Million in 2026 and to USD 811.96 Million by 2032, reflecting an expected compound annual growth rate (CAGR) of 6.0% over the 2026–2032 forecast window. This preview outlines the report’s strategic value without disclosing the full segment-level tables — those proprietary outputs are available in the full report.
Worldwide Classified Circuit Breaker Market
Why this matters for 2026 decision-makers
- Investment prioritization: The steady mid-single-digit CAGR signals a market that rewards focused product innovation (digital/smart breakers) and supply-chain investments more than broad-volume bets.
- Product strategy: Interchangeability standards (UL-classified listings) and loadcenter compatibility remain force-multipliers for market access. Manufacturers and OEM partners that secure classified compatibility are positioned to capture replacement and retrofit spend with lower go-to-market friction.
- M&A and partnerships: Market concentration trends point to attractive bolt-on opportunities for tier-two manufacturers seeking distribution or technology access, and for incumbents seeking faster route-to-market in key end-use channels.
- Supply-chain resilience: Dependency on copper, steel and specialized polymers exposes manufacturers to raw-material volatility — hedging and nearshoring/local assembly strategies will materially affect margin and delivery risk in 2026.
- Regulatory and channel risk: Certification timelines and third-party classified pathways mean compliance strategy and channel partnerships (loadcenter manufacturers, electrical distributors, and retrofit specialists) are central to gaining share.
What’s in the full PW Consulting report (practical, transaction-ready content)
- High‑resolution market sizing and scenario models (base year 2025; historical 2020–2025; forecasts 2026–2032) with downloadable Excel sheets and sensitivity toggles for price, volume and raw-material shocks.
- Demand-driver analysis and adoption curves for digital/smart circuit breakers, retrofit cycles, and grid-modernization projects.
- Supply-chain heatmaps highlighting critical nodes (components, subassembly, and regional assembly footprints) and a risk-index with mitigations for 2026 procurement planning.
- Regulatory tracker centered on UL-Classified interchangeability, testing bottlenecks and anticipated certification timelines by product family.
- Competitive benchmarking and vendor scorecards (product breadth, classified compatibility, channel coverage, R&D roadmap, and financial positioning) for leading global suppliers.
- Go-to-market playbooks for OEMs, aftermarket suppliers and distributors: positioning, pricing ladders, channel incentives, and sample commercial templates.
- M&A and partnership shortlist with valuation frameworks and integration checklists tailored for acquirers and targets in the classified breaker space.
- Use-case driven case studies (residential retrofit programs, commercial retrofitting portfolios, industrial maintenance playbooks) and implementation roadmaps.
Note: this preview intentionally omits granular regional and application splits; the full tables and interactive maps are provided exclusively in the paid report package.
Worldwide Classified Circuit Breaker Market
Data-driven narrative: 2020–2032 market evolution
The classified circuit breaker market has demonstrated both cyclicality and resilience across the 2020–2025 period. After an initial slowdown, the market recovered as retrofit cycles resumed, new compliance work pushed replacement demand, and early-stage adoption of smart breakers accelerated. PW Consulting’s bottom‑up modeling aggregates panel retrofit activity, new builds, and aftermarket replacement cycles to produce annual point estimates and scenario ranges. The 2025 market size of USD 540.0 Million reflects that recovery; our base case projects continued expansion to USD 578.6 Million in 2026 and to USD 811.96 Million by 2032 under a 6.0% CAGR.
Worldwide Classified Circuit Breaker Market
Growth is supported by three structural dynamics: (1) utility and commercial grid modernization and increased distributed generation penetration, which raise demand for protective and remotely manageable devices; (2) an aftermarket driven by safety-driven replacement and retrofit cycles enabled by UL-Classified interchangeability; and (3) the rapid emergence of digitally-enabled breakers that deliver telemetry and remote trip/restore capabilities. Each dynamic has different timing and margin profiles; the report dissects these to quantify addressable revenue and margin pools for product and channel strategies.
Market structure and concentration — what it means for entrants and incumbents
Market concentration is notable: the top three global suppliers control a majority share of the classified breaker market, and the top five command a substantially larger portion. This structure favors established manufacturers with broad distribution, classification expertise and compatibility across a range of loadcenters, but it also creates pockets of opportunity for nimble specialists and regional assemblers to win retrofit and localized supply contracts.
For corporate strategy teams, this implies a dual approach: defend core revenue streams through continuous compatibility updates and certification investments, while pursuing targeted, lower‑capex growth via partnerships, localized assembly and value-add services (installation, digital monitoring subscriptions).
Competitive landscape: strategic profiles and implications
- Eaton Corporation — Strength: arguably the broadest UL‑classified compatibility set and extensive loadcenter coverage, positioning Eaton as the go-to for broad retrofit compatibility. Strategic implication: incumbents and challengers must account for Eaton’s compatibility moat when targeting retrofit channels.
- Connecticut Electric — Strength: focused UL-classified replacement solutions with a keen replacement-market orientation. Strategic implication: specialized catalog and distribution relationships make them a resilient aftermarket player in targeted geographies.
- Siemens — Strength: global reach and suite of classified replacement options (e.g., QD replacements), combined with a deep installed base of panels. Strategic implication: Siemens’ global OEM footprint makes it a defender in industrial/commercial specifications.
- ABB Ltd — Strength: comprehensive portfolio across voltage classes and strong industrial/utility presence. Strategic implication: ABB competes where system-level integration and service contracts matter most.
- Schneider Electric — Strength: Square D brand compatibility and broad channel relationships. Strategic implication: retaining loadcenter OEM relationships remains central to maintaining share in residential/commercial retrofit programs.
- General Electric (GE Vernova) — Strength: integrated offer of breakers and loadcenters amenable to classified replacements. Strategic implication: cross-selling into existing GE channel relationships is a core advantage.
- CHINT Group — Strength: aggressive international expansion and recent investments in local assembly (announced at FEICON 2026). Strategic implication: nearshoring and localized assembly reduce lead times and import risk for regional buyers.
- Mitsubishi Electric, LS Electric, Fuji Electric — Strengths: industrial-grade portfolios and strong APAC presence. Strategic implication: these suppliers are natural partners for industrial and utility-scale projects requiring robust, higher-spec protection.
Recent industry activity underscores two themes: (1) local assembly and regional presence are being prioritized to mitigate logistics and tariff risks (e.g., CHINT’s Brazil announcement), and (2) digitalization is moving from prototype to pre-commercial launches (as demonstrated by product showcases at Light + Building and Hannover Messe). PW Consulting’s vendor scorecards and technology maturity curves in the full report quantify these moves and their likely commercial timing.
Practical recommendations for 2026 (for leadership, BD, procurement and M&A teams)
- Prioritize classification compatibility as a product- and channel-entry requirement; plan certification timelines into 2026 roadmaps.
- Lock strategic supply agreements or local assembly partnerships for copper, steel and polymer components to stabilize gross margins under raw-material volatility.
- Invest selectively in smart-breaker features that enable recurring revenue (monitoring, analytics, firmware updates) rather than chasing hardware-only volume.
- Pursue bolt-on acquisitions or distribution partnerships in regions where incumbent compatibility creates entry barriers — aim for targets with proven certified products or localized assembly footprints.
- Implement scenario-based pricing and inventory strategies using the report’s downloadable models to stress-test procurement decisions under material price shocks and regulatory delays.
How to get the full report and supporting models
This press preview presents high‑level strategic conclusions and selected market metrics to inform 2026 planning. PW Consulting’s full report contains the comprehensive regional and application breakdowns, interactive Excel models, vendor benchmarking matrices, and the M&A shortlist that underpin the recommendations above. For immediate access to the complete dataset, implementation playbooks and the vendor scorecards referenced here, contact PW Consulting’s research team or visit our report page to request the complete Worldwide Classified Circuit Breaker Market report package.
PW Consulting — Bringing rigorous, actionable market intelligence to leaders shaping the next generation of electrical protection and distribution strategies.
For detailed analysis of this topic, please visit the official page: Worldwide Classified Circuit Breaker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


