



Category: market research
PW Consulting: Worldwide Photosensitive Resin Market Poised to Surge with a 12.45% CAGR Through 2032
By PW Consulting, 2026-08-05
Worldwide Photosensitive Resin Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting’s forthcoming market study on the Worldwide Photosensitive Resin Market provides an evidence-based playbook for executives, R&D leaders, procurement officers, and investors who must make decisions in 2026 that position their organizations for the next growth wave. Drawing on a consistent historical baseline (2020–2025) and a detailed forecast horizon (2026–2032), the study synthesizes market sizing, concentration dynamics, technology inflection points, supply-chain risk, and actionable go-to-market strategies—while deliberately reserving granular segmentation data for subscribers and report purchasers.
Worldwide Photosensitive Resin Market
Why 2026 Is a Pivotal Year
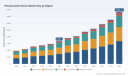
The photosensitive resin market is transitioning from a phase of tool-driven adoption into one shaped by materials innovation and regulatory pressure. The market expanded from a multi-billion-dollar industry in 2020 to a materially larger market in 2025, with our base-year estimate for 2025 at USD 6,750.5 million. At a robust compound annual growth rate (CAGR) of 12.45% across the 2026–2032 forecast window, total market value is projected to more than double by 2032. That trajectory makes 2026 a strategic inflection point for firms that wish to scale capacity, accelerate product differentiation, or consolidate position through targeted M&A before competition intensifies.
Worldwide Photosensitive Resin Market
What the Report Delivers — Practical, Decision-Ready Content
- Market architecture and growth drivers: a narrative that connects end-market demand drivers (e.g., additive manufacturing, electronics miniaturization, medical device adoption) with materials innovation and regulatory dynamics.
- Risk and resilience diagnostics: scenario-based stress testing of supply chains under raw-material price volatility and regional capacity shifts, and playbooks to reduce exposure.
- Technology roadmaps: comparative assessment of next-generation formulations (e.g., high-temperature, flexible, biobased photoresists, and two-photon polymerization chemistries), development timelines, and go/no-go criteria for in-house development vs. partnerships.
- Commercial strategies: pricing and channel models aligned to evolving regulatory requirements, certification timeframes, and customer willingness-to-pay for low-toxicity and recyclable formulations.
- Actionable M&A and partnership targets: investment filters anchored to market concentration metrics, capability adjacencies, and manufacturing footprint optimization.
- Regulatory and sustainability playbook: roadmap to achieve certifications and to commercialize lower-toxicity or biomass-derived products without sacrificing performance or margins.
Market Dynamics: Growth Drivers, Constraints, and Structural Signals
Three structural forces are defining the near-term market environment:
Worldwide Photosensitive Resin Market
- Rapid end-market adoption and product diversification. Adoption in high-growth applications has materially increased addressable demand, and manufacturers continue to launch new grades. In 2024 alone, more than 120 new photopolymer grades were introduced—ranging from heat-resistant formulations rated above 150°C to flexible chemistries demonstrating elongations up to 25%—expanding the solution set available to OEMs and service bureaus.
- Raw-material volatility and capacity dynamics. Key feedstocks, notably acrylate monomers, experienced pronounced price swings (cited volatility reached ~40% in 2023), placing immediate stress on gross margins for producers who lack hedging or diversified supply. Conversely, upstream expansions—particularly capacity growth in Asia Pacific—moderated some input-cost pressure in 2025 but did not eliminate short-term spikes. These opposing movements mean procurement strategy and inventory policy will materially affect 2026 P&Ls.
- Regulatory and sustainability pressure. Stricter environmental and safety standards in major markets (U.S., EU) are accelerating adoption of lower-toxicity and higher-recyclability formulations. Parallel innovation efforts are underway to monetize sustainability: notable advances include development of biomass-derived photoresists intended for next-generation semiconductor patterning, signaling new premium product lanes for manufacturers that can secure provenance and performance simultaneously.
Competitive Landscape: Who’s Shaping the Market
Industry concentration is meaningful but not prohibitive—the top three players account for a significant portion of market share (CR3 ~38.4%), while the top five approach a majority position (CR5 ~52.15%). This structure creates both scale advantages for incumbents and opportunity windows for nimble specialists.
Our competitive analysis profiles a cross-section of market participants—from global chemicals majors to materials-first startups—and evaluates their strategic positioning across technology, manufacturing footprint, channel reach, and regulatory footholds. Highlights include:
- Materials-first specialists (e.g., Resione, Zicai Chemical, U-Sunny/Youyang): typically focused on LCD/MSLA/DLP resin families and tailored chemistries for popular 3D printing platforms. Their strengths are rapid product iteration, close OEM partnerships, and price-competitive supply chains anchored in Asia.
- Platform and system integrators with in-house resin portfolios (e.g., Formlabs, 3D Systems): combine endpoint device sales with certified resin ecosystems—this integration supports premium pricing and sticky customer relationships, especially in dental and medical segments where regulatory clearance is a barrier to entry.
- High-performance and specialty-material innovators (e.g., UpNano, Liqcreate): focused on niche, performance-driven formulations such as two-photon polymerization resins or tough industrial grades. These players compete on specification and application fit rather than raw cost.
- Electronics and semiconductor materials leaders (e.g., Asahi Kasei, TOK, JSR, Shin-Etsu, Fujifilm Electronics Materials): control critical product lines for photoresists and ultra-high-performance photosensitive materials, with deep customer validation in semiconductor and display markets and long sales cycles tied to process qualification.
Recent corporate moves underscore where value is concentrating. Examples include expanded UV-curable sales channels from a specialty resins firm in 2025; notable growth in recycled-content resin volumes reported by a regional chemical distributor; advances in biomass-based photoresist development by a diversified materials conglomerate; and targeted regulatory clearances for dental resins by a leading desktop 3D printing vendor. These developments illustrate multiple parallel routes to value: scale channels, circular-chemistry differentiation, and regulation-enabled premiumization.
Strategic Recommendations for 2026 Decision-Makers
PW Consulting recommends executives align 2026 priorities across five levers to capture growth while managing risk.
- Supply resilience and procurement sophistication. Implement dual-sourcing or strategic inventory frameworks for volatile monomers and photoinitiators; negotiate longer-term purchase agreements that include indexation and force-majeure protections tied to quality metrics.
- Product differentiation through compliance and sustainability. Prioritize development and certification pathways for lower-toxicity or recyclable resins; accelerate pilots for biomass-derived formulations where regulatory tailwinds exist, while protecting IP through selective partnerships.
- Go-to-market integration vs. specialization: choose your model. Integrated players should leverage device-plus-resin ecosystems to lock-in customers in high-value niches (e.g., dental, medical). Pure-play materials firms should double down on formulation agility and cost leadership for commodity-grade volumes.
- M&A and capability buys. With mid-market concentration and a projected market expansion underpinned by double-digit growth, 2026 is attractive for bolt-on acquisitions that add regulatory certifications, novel chemistries, or regional manufacturing capacity. Use CR3/CR5 metrics to size targets and avoid overpaying in crowded subsegments.
- Commercial and pricing playbook. Given the market’s strong CAGR and product premiumization trends, implement value-based pricing for certified, sustainability-linked grades and dynamic pricing for commodity categories—ensuring gross margin protection against raw-material swings.
What the Full Report Unlocks
For organizations that require executable plans, the full PW Consulting report supplies:
- Detailed scenario models that quantify P&L exposure under alternate raw-material and regulatory trajectories.
- Step-by-step certification timelines and cost estimates across major regulatory regimes.
- An annotated list of near-term M&A and partnership targets with rationale and integration risk scores.
- Benchmarking tools to compare capability across formulation chemistry, manufacturing scale, and channel reach.
We purposefully withhold granular segmentation tables and some proprietary competitive metrics in this preview—to preserve the report’s subscriber value and to encourage targeted follow-up conversations. That said, the macro picture is clear: after growing to an estimated USD 6,750.5 million in 2025, the photosensitive resin market is forecast to grow at a 12.45% CAGR in the 2026–2032 window, leading to substantial value creation opportunities for those who act strategically in 2026.
Next Steps
PW Consulting invites procurement heads, R&D chiefs, and corporate strategists to request the full report and the accompanying decision-support tools. For teams prioritizing 2026 investments, we offer bespoke briefings that translate the market-level forecasts into company-specific implications—covering margin scenarios, capex timing, and M&A prioritization. Contact PW Consulting to schedule a customized consultation and obtain the full dataset, including regional and application-level segmentation tables that are intentionally omitted from this preview.
For detailed analysis of this topic, please visit the official page: Worldwide Photosensitive Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Multi-Sensor and Multi-Directional Security Camera Market to Grow at 15.26% CAGR, Reaching USD 3,911.82 Million by 2032
By PW Consulting, 2026-08-05
Worldwide Multi-Sensor and Multi-Directional Security Camera Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market research briefing on the Worldwide Multi-Sensor and Multi-Directional Security Camera Market synthesizes technical, commercial, and regulatory intelligence into an actionable decision framework for enterprise and public-sector leaders preparing budgets, procurement strategies, and pilot programs in 2026. This preview highlights the report’s strategic value and core themes; full datasets, segmentation tables, and vendor scorecards are available in the complete report.
Worldwide Multi-Sensor and Multi Directional Security Camera Market
Executive summary: why this market matters in 2026
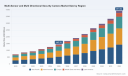
Multi-sensor and multi-directional camera architectures are transitioning from niche wide-area solutions to foundational components of modern security and operations platforms—integrated with edge AI, cloud management, and standardized network ecosystems. The market has already shown sustained expansion, rising from USD 712.45 million in 2020 to USD 1,447.53 million in 2025. PW Consulting’s forecast places the market at approximately USD 1,695.4 million in 2026, with a projected trajectory that reaches USD 3,911.82 million by 2032, implying a robust compound annual growth rate (CAGR) of 15.26% across the forecast period (2026–2032).
Worldwide Multi-Sensor and Multi Directional Security Camera Market
For technology strategy, procurement, and security operations leaders, 2026 represents an inflection point: organizations that align procurement with the maturation of on-device AI, multisensor fusion, and compliance discipline will capture outsized benefits in coverage efficiency, analytics fidelity, and total cost of ownership.
Worldwide Multi-Sensor and Multi Directional Security Camera Market
What the report delivers — practical, board-ready intelligence (overview)
- Executive briefings and investment theses tailored to corporate security, transportation, and smart-city portfolios.
- Market sizing and trend diagnostics (2020–2025 historical base plus scenario-driven forecasts to 2032), with sensitivity analyses reflecting supply chain and regulatory shocks.
- Vendor assessment framework (technology, integration, compliance, global support) that ranks suppliers across capability vectors—mapping product architectures to enterprise use cases.
- Implementation playbooks covering architecture selection (panoramic vs. multi-adjustable vs. hybrid PTZ multisensor), deployment models (edge-first vs. cloud-managed), and migration pathways from legacy single-sensor systems.
- Procurement templates and ROI models for CAPEX/OPEX planning, including PoE/PoE++ infrastructure scenarios and serverless vs. server-based AI designs.
The goal is not merely to state market direction but to equip leaders with repeatable processes: vendor short-listing checklists, pilot success criteria, and a compliance checklist (including NDAA and interoperability standards) that can be executed within typical procurement cycles.
Market trajectory and investment implications
The steep growth implied by the 15.26% CAGR reflects three reinforcing dynamics: commoditization of multi-imager hardware, rapid assimilation of edge AI engines into camera housings, and accelerating demand from wide-area and complex environments (transportation hubs, commercial campuses, and smart-city initiatives). The market’s mid-decade momentum (2024–2026) is supportive of near-term investments in pilot projects that emphasize analytics-driven outcomes—its size and growth profile justify re-prioritizing security capex toward fewer, higher-capability devices that lower overall device count while improving coverage and actionable insight delivery.
From a capital allocation perspective, PW Consulting advises a staged adoption approach in 2026: validate edge-AI use cases in constrained pilots (30–90 days), then scale using standardized integration templates to contain systems integration costs. The report includes discounted cash-flow and payback horizon models calibrated to typical deployment footprints.
Technology and integration dynamics to watch
- Edge AI convergence: Vendors are embedding increasingly powerful inference engines (including partner ecosystems around GPU-accelerated modules) to enable serverless analytics, on-camera tracking, and object classification that reduces bandwidth and back-end processing needs.
- Sensor fusion and flexible optics: Multi-angle and multi-lens form factors enable single-device coverage of complex fields—trading off single-point resolution for comprehensive situational awareness. Hybrid models that combine fixed multisensors with adjustable PTZ elements are emerging as a pragmatic compromise for mixed-demand sites.
- Systems interoperability: ONVIF and similar interoperability standards remain essential for reducing vendor lock-in; cloud-managed platforms that support standard APIs accelerate integration with VMS, access control, and analytics ecosystems.
- Infrastructure and power: The broader adoption of PoE++ and centralized power provisioning simplifies installation at scale but requires early coordination between facilities and IT teams. The report includes wiring topologies and BOM templates for common campus and roadway scenarios.
Competitive landscape — capability clusters (what to look for)
Our vendor analysis maps leading suppliers into capability clusters rather than market share rankings, enabling procurement teams to match solution archetypes to strategic objectives. Key archetypes include:
- AI-centric, serverless solutions: Firms integrating onboard AI accelerators and offering high-efficiency inference engines for serverless recording and analytics. Representative capabilities include NVIDIA Jetson-class integrations and optimized on-camera models that reduce back-end compute.
- Panoramic and stitched imaging specialists: Vendors with refined image-stitching, motorized lens arrays, and high-resolution panoramic sensors designed for continuous 180°–360° monitoring of open spaces.
- Cloud-managed multisensor platforms: Providers that combine multi-sensor hardware with cloud-native management, enabling remote repositioning, health monitoring, and scalable licensing models.
- Compliance-focused suppliers: Manufacturers that emphasize regulatory compliance (NDAA options, export-aware supply chains) and long-term firmware support for public-sector procurements.
Notable industry participants exemplify these archetypes. Examples include vendors known for AI-enabled, industry-grade multi-sensor models and on-device inferencing; panoramic specialists with advanced stitching and motorized optics; cloud-first entrants offering simple, scalable management and PoE++ deployments; and legacy and OEM suppliers updating product lines to meet procurement compliance and NDAA requirements. The report provides side-by-side capability matrices, integration risk scores, and deployment case studies for each archetype.
Regulatory and supply-chain risk: compliance is a project risk, not a checkbox
Two regulatory dynamics are especially material in 2026. First, NDAA-style compliance requirements continue to constrain sourcing options in certain public and enterprise deployments—forcing buyers to embed compliance checks into the early stages of vendor selection. Second, export controls and national security policies influence component sourcing, firmware provenance, and long-term support contracts.
Operationally, this means procurement teams must treat compliance as a project-level deliverable (with verification milestones) rather than an afterthought. The report’s compliance playbook includes NDAA verification templates, supplier attestations, and a list of red flags that should trigger legal and supply-chain escalation.
Recent industry developments and their implications
- Hanwha Vision’s release of multi-channel AI multi-sensor models integrated with NVIDIA Jetson-class processing demonstrates the commercial viability of serverless edge analytics—allowing deployments to shift processing from centralized servers to device-level inference without sacrificing analytic depth.
- Manufacturers updating product catalogs to emphasize NDAA-compliant multi-sensor lines reflect a broader pivot toward public-sector and regulated enterprise contracts; this trend increases the importance of validated compliance in vendor selection.
- Ongoing product matrix refreshes among mid-tier suppliers indicate a maturing product lifecycle: customers can expect shorter refresh cadences but must plan for firmware and lifecycle support costs when evaluating TCO.
How to use this report in 2026 decision cycles
- Board-level allocation: Use the market forecast and scenario analyses to justify reallocation of security CAPEX towards fewer, higher-capability devices that lower lifecycle costs.
- Pilot design: Adopt the report’s pilot blueprint to validate edge-AI use cases, interoperability tests, and compliance verification in 30–90 day cycles calibrated to enterprise procurement timelines.
- Vendor short-listing: Apply the report’s vendor assessment framework—technology fit, integration risk, compliance posture, and support footprint—to reduce RFP cycles and accelerate contracting.
- M&A and partnership strategy: Private equity and strategic acquirers can use the market concentration diagnostics and capability mappings to identify acquisition targets or partnership opportunities that fill capability gaps.
Final note — a trailer with depth
This briefing surfaces the strategic contours PW Consulting sees as critical for 2026 planning: accelerated edge AI adoption, a practical migration toward multi-sensor consolidation, and an operating environment where regulatory compliance materially shapes sourcing. The complete report contains the detailed time-series market model (2020–2032), scenario-adjusted forecasts, granular vendor scorecards, and implementation templates designed for immediate adoption by security and technology leaders.
For the full intelligence package—complete datasets, segmented forecasts, vendor matrices, and downloadable procurement templates—please access the report on PW Consulting’s publications page.
For detailed analysis of this topic, please visit the official page: Worldwide Multi-Sensor and Multi Directional Security Camera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide 5G NR Antenna Market to Expand from USD 28,900 Million (Base Year 2025) to USD 80,113.5 Million by 2032 at a 15.68% CAGR, Led by Asia‑Pacific (USD 12,584.71 Million)
By PW Consulting, 2026-08-05
Worldwide 5G NR Antenna Market: Strategic Imperatives for 2026 — PW Consulting Preview
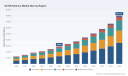
As mobile networks enter a new phase of densification and spectrum reallocation, PW Consulting’s upcoming Worldwide 5G NR Antenna Market report provides a strategic lens for executives preparing decisions in 2026. The market has moved from a nascent expansion into a structurally significant category: total industry revenue reached USD 28,900 Million in 2025 and, under our central scenario, is projected to grow at a compound annual growth rate (CAGR) of 15.68% to exceed USD 80,100 Million by 2032. This brief previews the report’s practical intelligence — showing the analytical depth that underpins our recommendations while intentionally withholding detailed segment-level datapoints to encourage direct access to the full study.
Worldwide 5G NR Antenna Market
Market snapshot: momentum and structure
-
Five-year momentum. The 2020–2025 period established the commercial runway: investment cycles, spectrum auctions, and the first large-scale massive MIMO rollouts catalyzed rapid value creation. That trajectory is the foundation for our 2026–2032 forecast, which anticipates sustained double-digit expansion across base-station antennas, distributed antenna systems (DAS), and integrated active antenna units (AAUs).
Worldwide 5G NR Antenna Market -
Concentration and competitive dynamics. The market exhibits moderate concentration: the top three firms control just under half the market, and the top five approach two-thirds — a landscape that supports both entrenched incumbents and specialist challengers. This structure creates bespoke opportunities for consolidation, alliances, and differentiated go-to-market plays.
Worldwide 5G NR Antenna Market -
Technology vectors. Growth is being driven by multiple technology vectors — active antenna integration, massive MIMO scaling, mmWave densification, and indoor DAS — each with distinct procurement and deployment economics. Our report delivers technology-adoption timelines and supplier-performance overlays to align investment timing with technical maturity.
Why this matters for decisions taken in 2026
-
Timing spectrum and capital allocation. With regulatory moves (including upper C‑band auctions and broader spectrum pipelines) reshaping operator priorities, 2026 is a pivotal year for capex allocation. The interplay between spectrum availability and antenna architectures will determine where incremental spend yields highest return on network performance.
-
Supply-chain and cost pressure. Fiber and optical components — essential for 5G backhaul/fronthaul — face elevated price and lead‑time volatility. Early 2026 saw continued price pressure on bend-insensitive, high-density fiber, increasing build-out trade-offs between fiber-heavy macro strategies and more fiber-efficient small-cell or radio-lean approaches.
-
Regulatory constraints shaping design. 3GPP’s Release 19 introduced new over‑the‑air spatial emission requirements affecting upper-6 GHz operation. Antenna vendors and operators must account for OTA emission testing, certification complexity, and potential mitigation costs when specifying multi-band arrays or deploying in adjacent-satellite environments.
What the PW Consulting report delivers — operational, actionable intelligence
-
Decision-ready models. Financial models that translate antenna architecture choices into multi-year TCO outcomes for macro, small-cell, and in-building scenarios — with sensitivity analyses for spectrum band, backhaul cost, and fiber pricing volatility.
-
Vendor scorecards. Deep supplier assessments combining product roadmaps, manufacturing footprints, compliance posture, and price/lead-time benchmarking. Each vendor is profiled to indicate where they are most competitive (e.g., large-scale AAUs, passive panel solutions, DAS integration), and where risks persist.
-
Regulatory and test-risk matrix. A practical matrix mapping new standards (e.g., OTA spatial emissions from Release 19), national auction timetables, and certification requirements — showing which deployments require design changes or additional testing overheads.
-
Deployment playbooks. Step-by-step procurement and deployment checklists for operators and towercos covering site acquisition, site-sharing opportunities, hybrid active-passive deployments, and capex-opex tradeoffs for 2026 rollouts.
-
M&A and partnership signals. Target identification and strategic fit assessments for buyers seeking scale in AAUs, DAS, or passive antenna portfolios — including integration risk profiles and expected synergies.
Competitive dynamics — where incumbents and specialists position
-
Ericsson (Stockholm). Strong in massive MIMO and hybrid active-passive base-station antennas, with noteworthy integration experience via Kathrein technologies. Ericsson’s strengths are in macro high-capacity sites and global service reach.
-
Nokia (Espoo). Focused on scalable AirScale mMIMO and hybrid designs that appeal to operators seeking modular radio access solutions across macro and small cell footprints.
-
Huawei (Shenzhen). A major force in ultra-wideband AAUs and multi-band massive MIMO, particularly where energy‑efficiency and tight vendor integration are decisive for dense urban rollouts.
-
Samsung (Suwon). Emphasizes high-throughput massive MIMO radios and is notable for collaborations in non‑terrestrial networking (NTN) testing — a relevant consideration for future NTN-enabled deployments.
-
ZTE (Shenzhen). Offers large-format AAUs that balance coverage and capacity with practical hybrid designs — attractive to regions prioritizing cost-effective macro coverage.
-
Infrastructure specialists (CommScope, Amphenol Antenna Solutions, Tongyu, PROSE). These firms supply passive and hybrid antennas and bring manufacturing scale and sustainability credentials — often the preferred partners for towercos and neutral-host deployments.
-
DAS and in-building leaders (Corning, JMA Wireless, SOLiD). Distributed antenna systems remain critical for venues and enterprise markets where mmWave and sub‑6 GHz indoor coverage demands integrated optical and RF solutions.
The net effect: incumbents lead on scale and integration; specialists excel in verticalized solutions (DAS, optical integration, sustainable passive arrays). Our report profiles each vendor’s addressable opportunity and provides a playbook for supplier selection depending on strategic priorities.
Regulatory, test, and infrastructure noise that will shape 2026 choices
-
Spectrum policy. Recent US legislative direction and FCC actions (renewed auction authority and spectrum identification across sub-6 to mid-band ranges) accelerate operator timelines for capacity expansion. Operators must weigh auction outcomes against deployment window and antenna procurement lead times.
-
Standards and testing. 3GPP Release 19’s OTA spatial emission limits in the upper 6 GHz band introduce additional compliance steps for antenna vendors and system integrators. Early adopters should anticipate incremental testing and potential redesign for beamforming arrays operating near satellite bands.
-
Supply-side shocks. Elevated fiber prices and constrained optical component supply change the economics of certain architectures, making fiber-efficient topologies and integrated optical-RF designs commercially attractive.
-
Emerging certification pathways. Milestones such as the first PTCRB NTN RF test certifications signal that device and antenna ecosystems are preparing for non-terrestrial use cases, expanding potential product requirements for future antenna designs.
Strategic imperatives for 2026 — recommended actions by stakeholder
-
For operators: prioritize modularity. Procure radio/antenna stacks that allow phased upgrades (e.g., AAU shells that accept incremental RF module upgrades). Use the PW Consulting deployment playbook to sequence macro and enterprise rollouts around known auction timelines.
-
For vendors: operationalize compliance-first design. Build Release 19 OTA test readiness into product roadmaps and accelerate partnerships with test houses. Where possible, provide fiber-efficient interfaces and options that mitigate optical price volatility.
-
For towercos and neutral hosts: develop flexible hosting packages that bundle active, passive, and optical infrastructure with clear SLA and upgrade corridors that reduce operator switching costs.
-
For investors and M&A teams: target capabilities, not just scale. Look for targets that fill gaps in DAS, optical integration, or specialized AAU expertise — areas where consolidation yields non-linear synergies given the current market concentration dynamics.
-
For regulators and policymakers: calibrate auction timetables and interference mitigation guidance to reduce retrofitting risk and encourage vendor compliance investments that support long‑term network health.
Conclusion — the tactical value of timely, informed decisions
2026 represents a strategic inflection: operators are balancing auction-driven spectrum choices, supply-chain cost dynamics, and new compliance regimes while vendors race to deliver higher-performing, lower-footprint antenna solutions. PW Consulting’s Worldwide 5G NR Antenna Market report is designed to convert market momentum into executable plans: it quantifies the upside (and downside) across architectures, profiles supplier strengths, and provides procurement-ready tools that reduce execution risk.
To access the full dataset, detailed segmentation, supplier scorecards, and the decision-support models referenced in this preview, PW Consulting invites readers to consult the complete report. The report’s level of granularity is tailored to inform board-level capital allocation, procurement negotiations, and product roadmaps for executives preparing for 2026 network investments.
For detailed analysis of this topic, please visit the official page: Worldwide 5G NR Antenna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Environmentally Friendly Gas‑Insulated Switchgear Market to Climb from USD 2,850 Million in 2025 to USD 4,931.7 Million by 2032 at an 8.15% CAGR, Led by Europe and Asia Pacific
By PW Consulting, 2026-08-05
Worldwide Environmentally Friendly Gas Insulated Switchgear Market: Strategic Imperatives for 2026 — PW Consulting Insight
As energy transition timelines compress and decarbonization targets harden, operators and equipment manufacturers face a pivotal inflection point in grid infrastructure procurement. PW Consulting’s new market study on the Worldwide Environmentally Friendly Gas Insulated Switchgear (GIS) market — covering 2020–2025 history and a 2026–2032 forecast horizon — translates market scale, technological evolution, regulatory pressure and supplier dynamics into concrete decision levers for 2026 planning cycles.
Worldwide Environmentally Friendly Gas Insulated Switchgear Market
Headline market trajectory (what decision‑makers must know)
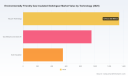
- The global environmentally friendly GIS market has moved from a nascent niche to a multi‑billion dollar market. Our modelling shows the market expanding from approximately USD 2.85 billion in 2025 to nearly USD 4.93 billion by 2032, tracking an 8.15% compound annual growth rate (CAGR) through the forecast period.
- Growth is underpinned by three concurrent forces: regulatory accelerants that limit or ban SF6 in new equipment, utility modernization and resilience programs, and accelerated commercialization of SF6‑free or reduced‑GWP insulation technologies.
- Market structure is moderately concentrated: the top three vendors account for roughly half of the market, while the top five control well over two‑thirds — an important consideration for procurement and partnership strategies.
Why 2026 is a strategic inflection year
Several market realities converge in 2026 to make it a decision‑critical year for OEMs, utilities, and investors:
Worldwide Environmentally Friendly Gas Insulated Switchgear Market
- Regulatory trigger points: Major jurisdictions are moving from guidance to enforcement on SF6 use in distribution and transmission equipment. Procurement timelines that begin in 2026 will determine fleet compositions for the next decade.
- Commercial viability of alternatives: Multiple SF6‑free or SF6‑reduced platforms are now commercially deployed at operational voltage ratings that matter to grid planners. This shifts the debate from “if” to “how and which” technologies to adopt.
- Cost trade‑offs crystallize: Eco‑efficient units still command a premium over legacy SF6 designs. That premium, combined with lifecycle operating costs and carbon accounting, will frame Total Cost of Ownership (TCO) decisions in 2026 budgeting cycles.
Competitive landscape: who’s shaping supply and how
Our competitive review synthesizes product roadmaps, recent commercial wins, and strategic positioning across global OEMs. The market’s current leadership is defined less by geography and more by the breadth of alternative‑gas portfolios, deployment track record, and system integration capability.
Worldwide Environmentally Friendly Gas Insulated Switchgear Market
- GE Vernova (USA) — Focused leadership in g3 gas‑based GIS solutions. Recent high‑voltage commissioning projects demonstrate the ability to scale g3 into backbone transmission applications, validating performance at the highest operational demands.
- Siemens Energy (Germany) — Commercial portfolio centered on synthetic, fluorine‑free “clean air” solutions for medium and higher voltage classes; recent major system awards show continued utility confidence in their Blue GIS approach.
- Hitachi Energy (Switzerland) — Aggressive cross‑voltage strategy with an SF6‑free EconiQ lineup; grid connections in European markets underscore its transition from pilot to mainstream supply for operators upgrading substations.
- ABB (Switzerland) — Builds on an eco‑efficiency brand with updated product releases certified for higher voltage ranges; combines broad service capabilities with a range of gas mixture options.
- Schneider Electric (France), Mitsubishi Electric (Japan) and Toshiba Energy Systems & Solutions (Japan) — Each offers differentiated MV/HV approaches, including vacuum switching, solid insulation and CO2‑based gases, with varying commercialization progress across markets.
Recent vendor developments in late 2024 and early 2025 — from UK 420 kV g3 commissioning to multiple contract awards and catalog upgrades — signal a rapid move from demonstration to procurement. For buyers, this changes negotiation dynamics: supply alternatives exist, but lead times, certification paths and lifecycle service networks remain critical selection criteria.
Regulatory and supply‑chain dynamics that will shape vendor and buyer strategies
- Policy enforcement is real and immediate in several regions. Regulations banning SF6 in new medium‑voltage equipment and setting concentration limits in installations mean that replacement and new‑build specifications must be reviewed now to align capital plans with compliance windows.
- Global refrigerant and HFC policy trends (including phasedowns) indirectly affect the availability and cost of fluorinated gas alternatives. Technology choices are therefore influenced not only by performance but by anticipated regulatory trajectories on gas chemistries.
- Raw material and component economics matter. Alternative gas chemistries, sealing systems and vacuum technologies carry an upfront premium; however, when combined with reduced leakage risk and lower carbon penalties, the lifetime economics can favor environmentally friendly GIS in many procurement scenarios.
- Funding and subsidy windows (public R&D and pilot grants) are accelerating field demonstrations. These programs reduce deployment risk for utilities and enable suppliers to scale manufacturing and certification investments more quickly.
What PW Consulting’s report delivers — practical assets for 2026 decision cycles
Designed as an operational playbook for executives and planners, the report translates macro trends into actionable tools. Highlights include:
- Scenario‑based demand modelling calibrated to policy, capex cycles and technology adoption curves — so buyers can stress‑test procurements against conservative, base and accelerated transition scenarios.
- Vendor scorecards and supplier risk matrices — assessing maturity of alternative gas technologies, field track record, service footprint, warranty terms and aftermarket integration risks.
- Procurement playbooks — model RFP language, acceptance test templates and interoperability checklists to de‑risk specification and contracting of SF6‑free or reduced‑SF6 GIS.
- Lifecycle total cost of ownership (TCO) templates — incorporating capital premium, leakage risk exposure, carbon cost sensitivity and service costs to compare like‑for‑like across vendor offerings.
- Regulatory readiness checklists — for in‑house counsel and compliance teams to align fleet renewal programs with jurisdictional ban dates, reporting thresholds and emissions accounting rules.
- Case studies and pilot lessons — granular operational learnings from early high‑voltage and medium‑voltage deployments that surface retrofitting constraints, commissioning issues and best‑practice maintenance regimes.
How buyers, OEMs and investors should act in 2026
- For utilities: treat 2026 procurements as strategic portfolio decisions. Prioritize piloting in long‑lead, high‑impact nodes (e.g., critical transmission corridors) while leveraging procurement templates to secure competitive options across gas technologies.
- For OEMs: accelerate certification and field performance documentation. Scale partnerships with gas suppliers, stamping suppliers, and integrators to shorten lead times and lower the incremental premium curve.
- For investors and asset owners: evaluate capital allocation toward vendors demonstrating repeatable commercial deployments and diversified technology stacks. The market’s concentration metrics favor suppliers with scale and service networks, but modular entrants can succeed where niche performance or cost advantages exist.
Signal intelligence we track going into 2026
- Policy rollouts that create procurement cliffs.
- Commercial deployments that prove equivalence at higher voltage classes.
- Component supply bottlenecks or cost normalization that compress or widen the premium for eco‑efficient GIS.
- Consolidation activity among medium and niche technology vendors that could reshape supplier choice and bargaining power.
Why PW Consulting’s report is strategically valuable right now
Decision cycles launched in 2026 will lock in asset configurations and supplier relationships for years. Our study combines a rigorous market sizing and growth path (from USD ~2.85 billion in 2025 to nearly USD 4.93 billion by 2032 at an 8.15% CAGR) with operational playbooks, vendor intelligence and regulatory readiness tools that procurement, engineering, and strategy teams need to act with confidence.
We deliberately present a high‑resolution strategic narrative here while withholding granular segment share tables and per‑region/application valuations in this release. Those core sub‑segment datasets — which drive procurement optimization, capex forecasting and M&A diligence — are available within the full report and our interactive dashboard.
Next steps
- Download the full report to access the sub‑segment data, regional demand curves, supplier share matrices and our interactive scenario modeller.
- Engage with PW Consulting for a tailored briefing: our advisory packages include vendor shortlist workshops, procurement template customization and live TCO run‑throughs tied to your asset inventory.
Contact PW Consulting to schedule a 2026 planning workshop and obtain the full Worldwide Environmentally Friendly GIS Market report and dashboards. Timebound regulatory triggers and accelerating commercial deployments make 2026 the year that separates cautious observers from decisive adopters.
For detailed analysis of this topic, please visit the official page: Worldwide Environmentally Friendly Gas Insulated Switchgear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide HIFU Lipoplasty Devices Market Set to Grow at 8.01% CAGR, Fueling a Surge in Aesthetic Treatments
By PW Consulting, 2026-08-05
Worldwide High-Intensity Focused Ultrasound (HIFU) Lipoplasty Devices Market: Strategic Preview for 2026 Decision‑Making
PW Consulting’s latest market study on Worldwide HIFU Lipoplasty Devices distills seven years of market evolution and a forward-looking, commercially oriented forecast to empower device manufacturers, strategic investors, clinical operators, and payers as they plan for 2026 and beyond. The market has moved from an emergent niche in 2020 to a clear commercial growth trajectory driven by procedural acceptance, regulatory pathway maturation, and incremental technology enhancements. Our base-year calibration (2025) and the report’s projection through 2032 capture this transition: the market is on track to exceed USD 595.0 Million in 2026 and is modeled to reach just over USD 900 Million by the end of the forecast window, reflecting a compounded annual growth rate of approximately 8.0% across the forecast period.
Worldwide High-Intensity Focused Ultrasound (HIFU) Lipoplasty Devices Market
Why this matters for 2026 strategic planning
-
Market inflection point: The HIFU lipoplasty market is no longer early-stage hobbyist territory. Structural growth, improving reimbursement clarity in select geographies, and a steady pipeline of clinical evidence are creating a repeatable, investable market. This is the moment for product and commercial leaders to move from experimentation to scaled-market approaches.
Worldwide High-Intensity Focused Ultrasound (HIFU) Lipoplasty Devices Market -
Regulatory and reimbursement regimes are converging toward predictability — but not uniformity. HIFU devices commonly proceed via the FDA 510(k) Class II pathway in the U.S., while EU regulatory requirements under the Medical Device Regulation present a different post‑market commitment profile. On reimbursement, established CPT coding has enabled clearer revenue mechanics for providers, with average Medicare reimbursement levels in the U.S. providing a tangible baseline for business models.
Worldwide High-Intensity Focused Ultrasound (HIFU) Lipoplasty Devices Market -
Technology differentiation is intensifying. Vendors are moving beyond single‑use claims to platform-level differentiation — deeper targeting transducers, multi-pass transducer architectures, and hybrid energy combinations that pair HIFU with adjunctive modalities for synergistic outcomes. These product choices will determine the winners in device adoption curves and consumables economics.
-
Commercial models are evolving from capital-sales only to hybrid capture of consumable and service economics. As clinical protocols converge on repeatable treatment regimens, long‑term revenue from cartridges, upgrades, and training packs becomes material to valuation and unit economics.
What the PW Consulting report delivers (practical, decision-ready content)
-
Quantified market sizing and demand modeling calibrated to 2025 base-year performance and extended through 2032, including alternative scenarios that stress regulatory tightening, reimbursement expansion, and technological disruption.
-
Commercial segmentation maps (by device architecture and end‑user channel) with demand drivers and elasticity analysis — designed to inform product roadmap prioritization and go‑to‑market allocations. Note: granular splits are reserved for the full report.
-
Competitive benchmarking and vendor scorecards covering product functionality, regulatory clearance status, clinical evidence depth, service models, and price architecture.
-
Regulatory playbook and time-to-market checklists by jurisdiction, including a practical interpretation of FDA 510(k) expectations, EU MDR post-market surveillance obligations, and practical steps to accelerate clearance without compromising compliance.
-
Reimbursement modeling and “per-treatment” economics for clinic and hospital operators, showing how varying reimbursement scenarios affect ROI, break-even periods, and channel economics.
-
M&A and partnership advisory frameworks with target screening criteria and integration checklists tailored to strategic acquirers seeking product, geographic, or channel expansion within energy-based aesthetic devices.
-
Operational playbooks for providers: patient selection, protocol optimization, marketing messaging that balances clinical outcomes with regulatory-compliant claims, and consumable management to maximize lifetime value.
Competitive landscape: tactical implications from recent moves
The market structure is best described as moderately concentrated: the leading handful of companies together control a meaningful share of revenue, but there remains ample room for challengers with differentiated technology or superior commercial execution. Recent strategic moves from established vendors illustrate the two-speed nature of competition — incumbents iterating platforms and newer entrants pushing modularity and service-led models.
-
Liposonix (Hologic) occupies an important place in the narrative and technology lineage for HIFU-based lipoplasty, although legacy product availability has shifted over time. Historical presence has shaped clinical expectations and set a bar for non‑invasive abdominal fat reduction claims.
-
Merz Aesthetics’ Ultherapy program continues to broaden indications following regulatory success, including recent clearances that expand submental treatment claims. This underlines a strategic path where strong clinical data and conservative regulatory strategy unlock new treatment adjacencies.
-
InMode’s iterative product launches — including recent transducer upgrades — highlight the competitive emphasis on hardware modularity and transducer-level performance as a route to better clinical efficacy and improved operator ergonomics.
-
Hironic’s renewal of European certifications with deeper‑targeting cartridges signals how vendors can use incremental product development to re-enter or strengthen their position in regulated markets.
Collectively, these developments signal a shift from one‑off devices to platform strategies where upgradeability, consumables economics, and clinical-supported indications determine market share gains. For investors and acquirers, the implication is clear: target companies with scalable platform roadmaps rather than limited single‑use playbooks.
Top strategic priorities for 2026
-
For device OEMs: prioritize modular architectures and a clear consumables roadmap. Winning products will balance capital affordability with a predictable consumables revenue stream and a clear clinical value proposition.
-
For clinical operators: adopt a data-driven protocol playbook. Standardize outcome tracking and align clinical messaging with reimbursement codes to accelerate payer acceptance and attract referral volume.
-
For investors and acquirers: evaluate targets on four axes — regulatory clearance durability, consumables capture potential, service and training capabilities, and clinical evidence depth. Small, well-positioned players with strong upgrade pathways are attractive bolt‑on targets.
-
For payers and policymakers: anticipate heterogenous adoption and design reimbursement pilots that link payment to measurable patient‑reported outcomes and safety metrics to contain cost while enabling innovation.
Scenario planning: three plausible 2026 entry paths
-
Baseline growth track: steady adoption among aesthetic clinics and select hospital centers, with gradual expansion of indications and reimbursement recognition, supporting the projected mid‑single-digit to low‑double‑digit CAGR across the forecast.
-
Regulatory tightening scenario: extended clinical data requirements and more onerous post‑market surveillance in major jurisdictions compress near‑term margins and slow new product launches, advantaging larger players with regulatory infrastructure.
-
Technology leap scenario: a breakthrough in transducer efficiency or combined modality therapy delivers clinically superior outcomes, accelerating adoption and shifting market share rapidly toward first movers with validated real‑world evidence.
How to use the full PW Consulting report
The published executive preview is deliberately selective: it surfaces strategic insights and near-term imperatives while preserving granular market splits, vendor share matrices, unit shipment forecasts, and scenario-specific financial models for subscribers. The full report contains:
-
Detailed regional and device‑type revenue splits, with unit economics and pricing ladders.
-
End‑user segmentation with adoption curves and clinic-level ROI calculators.
-
Vendor scorecards with feature-level comparisons, regulatory timelines, and aftermarket strategies.
-
Robust sensitivity analyses and downloadable financial models to stress-test product, reimbursement, and regulatory assumptions.
These deliverables are designed to be operational tools you can plug directly into 2026 budgeting, go‑to‑market planning, and M&A diligence workflows.
Final takeaways for 2026 decision-makers
The HIFU lipoplasty market presents a pragmatic growth opportunity: not a land‑grab overnight, but a field where disciplined product development, evidence generation, and commercially savvy reimbursement engagement create durable advantage. The market’s projected expansion to roughly the high‑hundreds of millions of USD by the early 2030s at a mid‑single‑digit CAGR offers a compelling backdrop for targeted investment — particularly for players who can convert clinical differentiation into a sticky consumables and services ecosystem.
For leaders planning 2026 moves, the immediate questions are operational: which product architectures to prioritize, how to finance clinical programs that unlock broader indications, and which go‑to‑market mix will maximize share while preserving margin. PW Consulting’s full report provides the tactical roadmaps and quantitative tools needed to convert these strategic hypotheses into executable plans.
Next steps
To access the full report, scenario models, and vendor playbooks — or to commission a bespoke strategic workshop tailored to your organization’s 2026 objectives — contact PW Consulting’s Healthcare Devices practice. Our advisory team will help translate market intelligence into measurable business outcomes and a prioritized action plan for the coming year.
For detailed analysis of this topic, please visit the official page: Worldwide High-Intensity Focused Ultrasound (HIFU) Lipoplasty Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Natural Aroma Chemicals Market Set to Expand at a 6.8% CAGR Through 2032
By PW Consulting, 2026-08-05
Worldwide Natural Aroma Chemicals Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study, "Worldwide Natural Aroma Chemicals Market (Base Year: 2025; Forecast: 2026–2032)," synthesizes five years of historical tracking (2020–2025) and a forward-looking scenario analysis to equip executives with the insight required to shape commercial strategy in 2026. The global natural aroma chemicals market reached approximately USD 2,504 million in 2025 and, under our central projection, will expand at a compound annual growth rate (CAGR) of 6.8% through 2032 to approach USD 3,969 million. This release functions as a strategic trailer: it distills the high-conviction implications of the research while intentionally withholding the full granular breakdowns to prompt direct consultation of the full report for transaction-grade figures and segment models.
Worldwide Natural Aroma Chemicals Market
Why this study matters for 2026
-
Timing: 2026 is the inflection year when sustainability-driven sourcing shifts intersect with new trade and regulatory dynamics — companies that recalibrate now will capture outsized share in the next planning cycle.
Worldwide Natural Aroma Chemicals Market -
Scale: the market growth trajectory (6.8% CAGR to 2032) implies persistent demand across food & beverage, personal care, and specialty fragrance channels; however, growth is non-uniform and conditioned by feedstock supply, regulatory constraints, and biotechnological adoption.
Worldwide Natural Aroma Chemicals Market -
Concentration: market concentration is moderate — our CR3 sits at 28.5% and CR5 at 42.15% — indicating meaningful opportunities for nimble challengers while leaving advantage to incumbent innovators with scale and integrated sourcing.
Executive takeaways for 2026 planning
-
Strategic sourcing must become scenario-driven. Essential oils remain the principal feedstock; the global essential oils market alone was valued at roughly USD 28.3 billion in 2025 and is expected to increase further into 2026. That scale masks acute exposure to agricultural cycles, vegetable oil price swings (our inputs show index readings materially higher year-on-year into mid-2025), and tariff corridors introduced during 2025. Procurement teams should adopt multi-scenario contracts (short-term forward buys, indexed volumes, and option structures) and expand supplier bases across botanical and biotech channels.
-
Biotech is no longer fringe — it is a commercial lever. Precision fermentation and other biotechnological routes are moving from pilot to commercial scale, yielding high-purity molecules with lower carbon intensity. Our study highlights licensing and co-development as faster routes to a differentiated product slate than build-alone CAPEX programs, particularly for firms targeting low-carbon product claims in personal care and beverage segments.
-
Regulatory trajectory reshapes product portfolios. IFRA and REACH-driven reformulation continues to push formulators toward clean-label, natural, and low-risk aroma ingredients. Companies must prioritize regulatory intelligence and pre-emptive safety dossiers to shorten time-to-market for reformulated SKUs.
-
Supply-chain resilience is a competitive differentiator. Recent policy shifts — including new reciprocal tariffs introduced by the U.S. in 2025 — have reintroduced border risk into the next-tier supplier model. Leading companies are reallocating working capital toward buffer inventories for critical botanical intermediates and investing in near-shore and biotech-enabled manufacturing options.
What PW Consulting’s report delivers — practical, actionable outputs
This study is structured to be operational for commercial, R&D, and M&A teams. Key deliverables include:
-
A validated market-sizing model (2020–2025 historical; 2026–2032 forecast) with scenario toggles for raw material volatility, tariff regimes, and adoption curves for biotechnological production.
-
Demand-driver matrices mapping end-market pull (food & beverage, personal care, household care, and specialty segments) against formulation constraints and regulatory risk.
-
Supply-side playbook covering botanical sourcing, essential oil volatility, and contract structures; forward-looking cost curve analysis for biotech-derived ingredients under alternate feedstock cost scenarios.
-
Competitive landscaping with profiles and capability maps for the industry’s strategic players, plus an M&A readiness assessment highlighting likely targets and valuation sensitivities.
-
A practical 90-day action plan for commercializing low-carbon and biotech-derived aroma ingredients that includes proof-of-concept KPIs, go-to-market sequencing, and claim substantiation checklist for sustainability labeling.
Competitive landscape — what the major players are doing
The market’s competitive dynamic combines global flavour & fragrance majors, specialty natural houses, and regional processors. PW Consulting’s analysis profiles both scale and niche players and highlights three strategic archetypes: Integrated Innovators, Specialist Naturals, and Contract/Regional Suppliers.
-
Integrated Innovators — Examples include Givaudan SA (Vernier, Switzerland) and International Flavors & Fragrances Inc. (IFF, New York, USA). These firms combine global distribution, deep R&D in sustainable sourcing, and increasing biotech partnerships to drive product differentiation for multinational CPG clients.
-
Technology-forward majors — Companies such as BASF SE (Ludwigshafen, Germany), Symrise AG (Holzminden, Germany), and DSM-Firmenich (Kaiseraugst, Switzerland) are accelerating biotech and fermentation routes. Recent BASF launches (including an L-Menthol with reduced Product Carbon Footprint in April 2025 and a high-purity fermentation-derived alpha-Farnesene announced in October 2025) and DSM-Firmenich’s new facility in France underscore this shift from pilot to production scale.
-
Specialist naturals and regional suppliers — Firms such as Mane SA, Robertet Group, Privi Speciality Chemicals, Citrus & Allied, and others preserve critical botanical expertise and supply relationships needed for premium and clean-label formulations. Their value is heightened where provenance and traceability commands price premium.
Our report includes company capability matrices and a forward-looking competitiveness score that combines innovation capacity, sustainability credentials, and supply-chain robustness. These tools allow corporate strategists to model partnership, co-investment, or acquisitive routes to bolster capability gaps.
Recent developments that matter for 2026
-
BASF’s rPCF (reduced Product Carbon Footprint) launches and Isobionics® fermentation-derived portfolio expansions indicate a near-term commercialization pathway for lower-carbon aroma ingredients — this validates decision frameworks that prioritize carbon-intensity as a commercial variable.
-
DSM-Firmenich’s facility expansion for pine-based bio-sourced ingredients and biodegradable musk underscores the rising commercial relevance of bio-sourced musks and specialty pine intermediates for sustainable perfumery.
-
Macro input dynamics — the essential oils market’s large scale and recent price movements in vegetable oil indices — necessitate active hedging and alternative feedstock planning for 2026 procurement cycles.
-
Policy noise — new tariff measures and tightened regulatory regimes — require scenario-based supply-chain redesigns and customs cost modeling to prevent margin leakage in 2026 product launches.
How to translate insights into a 2026 playbook
-
Prioritize a dual-sourcing roadmap: secure critical botanical supplies while establishing pilot biotech partnerships to mitigate feedstock risk and shorten certification timelines.
-
Rewire pricing models to reflect carbon and provenance premiums; embed clause-based pass-throughs for feedstock-driven cost variability and tariff impacts.
-
Fast-track regulatory dossiers for reformulated SKUs targeting IFRA/REACH-constrained markets; invest in toxicology and claim substantiation now to avoid delayed launches.
-
Use M&A selectively to acquire capability (fermentation scale-up, traceable botanical supply chains, or niche chemistries) rather than broad consolidation; the CR3/CR5 dynamics suggest that targeted acquisitions can materially enhance competitiveness without necessitating megadeals.
What we’re intentionally not disclosing here — and why
In keeping with the “trailer” principle of this release, we are presenting the strategic implications and high-level market sizing that will influence 2026 choices while withholding the report’s full segment-by-segment revenue tables, regional share matrices, and application-by-type line-item forecasts. These granular data sets (region, type, application splits and underlying supplier-level volumes) are essential for transaction diligence, procurement contracting, and precise pricing decisions — they are included in the full report and interactive model package.
Next steps for executives
-
Download the full report model to run your scenarios: customize commodity price paths, tariff scenarios, and biotech adoption curves to reveal P&L and supply-chain outcomes for 2026 planning.
-
Engage our advisory team for a 4-week rapid diagnostic: we will align the report’s scenarios to your portfolio, identify three near-term quick wins, and a mid-term roadmap for capability build or acquisition.
-
Book a briefing to review the report’s competitive matrices and M&A valuation sensitivities before your 2026 budget and strategic-planning cycles close.
PW Consulting’s "Worldwide Natural Aroma Chemicals Market" report is designed to be the operative intelligence layer that informs procurement strategy, R&D prioritization, and corporate development decisions in 2026. For access to the full dataset, interactive forecast model, and tailored strategy engagements, please consult the report landing page or contact our advisory desk.
For detailed analysis of this topic, please visit the official page: Worldwide Natural Aroma Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global SGP Interlayer Films Market to Jump from USD 306.7 Million in 2025 to USD 525.6 Million by 2032 at an 8% CAGR — Structural Glazing, North America Lead
By PW Consulting, 2026-08-05
Worldwide SGP Interlayer Films Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market intelligence on the Worldwide SGP (ionoplast) interlayer films market is designed as a strategic primer for executive teams planning for 2026. Anchored on a 2025 base year with historical coverage from 2020–2025 and a forecast window to 2032, our analysis synthesizes demand dynamics, competitive positioning, regulatory and trade shocks, and actionable playbooks that translate market signals into capital, procurement, and go‑to‑market decisions. This release is a deliberate industry “trailer”: we show the structural insights and decision frameworks that matter to leaders while reserving the granular segment tables and proprietary model outputs for the full report.
Worldwide SGP Interlayer Films Market
Market snapshot: growth trajectory and concentration
The global SGP interlayer films market is at an inflection point. From a clearly documented base in 2025, the market registers robust expansion driven by structural glazing, safety & security mandates, and growing demand from transport and specialty applications. PW Consulting’s model places the 2025 market at USD 306.69 Million (base year) with a compound annual growth rate of 8.0% across the 2026–2032 forecast window; the model projects continued acceleration in absolute terms early in the forecast horizon. The industry’s commercial topology is markedly concentrated — a small number of incumbent suppliers account for the majority of capacity and influence — a fact that materially shapes pricing, product roadmaps, and channel strategies.
Worldwide SGP Interlayer Films Market
Why this matters for 2026 planning
- Capital allocation and capacity planning: With mid‑single‑digit to high‑single‑digit CAGR and concentrated supplier control, small shifts in demand or capacity add materially to lead times and price power. Firms contemplating plant expansions, outsourcing, or contract buyouts must align capex timelines with the market’s next 12–18 month inflection points.
- Procurement and margin protection: Feedstock volatility and tariff regimes have raised the cost of ownership for finished films. Procurement teams need hedging and supplier diversification strategies that reflect tighter margins and episodic supply shocks.
- Regulatory compliance as market access: Certification and harmonized testing now determine which projects suppliers can service — particularly in overhead, load‑bearing, and safety‑critical glazing — making product certification an operational imperative, not a marketing nicety.
- M&A and partnership windows: High concentration and growing demand create selective opportunities for bolt‑on acquisitions, strategic alliances with fabricators, and exclusive distribution arrangements that can rapidly scale market presence in targeted geographies.
Competitive landscape — who moves the market
The market is dominated by a handful of well‑capitalized players with differentiated technology and established distribution channels. Leading participants include global manufacturers and specialized processors whose product, certification, and capacity moves set the competitive cadence. Recent notable developments underscore divergent strategies:
Worldwide SGP Interlayer Films Market
- Trosifol (Wiesbaden) continues to leverage brand and product innovation, expanding the aesthetic and performance envelope of SGP with recently launched colored SGP variants aimed at decorative structural glazing.
- Kuraray (Tokyo), as a developer and manufacturer of leading SGP ionoplast technology, has fortified applications credentials through updated certifications for overhead use — extending addressable project types for certified partners.
- Everlam (Halen) has focused on capacity agility, announcing a capacity expansion to meet structural glass demand in key European projects — a reminder that manufacturing scale and service levels matter when architects and façade engineers set project specifications.
- Glastrotech (Dallas) exemplifies the channel play: authorized distribution plus pre‑laminated panel offerings that shorten the value chain for North American façade integrators.
Given the market’s concentration, incumbents retain pricing leverage and can accelerate adoption through certification, product diversification, and selective capacity investments. New entrants or smaller players should prioritize partnerships, niche technical differentiation, and service models that reduce ordering friction for large projects.
Supply chain and raw material pressure
Raw input dynamics are a near‑term strategic risk. Spot prices for key feedstocks — polyvinyl butyral (PVB) and ionomer resins — experienced an appreciable uplift in late 2024 amid upstream monomer constraints. That price movement compresses margins at the film level unless companies adopt differentiated pass‑through strategies, cost efficiency programs, or vertical integration. Procurement teams must reconcile longer lead times with price volatility and consider structured contracts, strategic inventory, and supplier diversification to de‑risk project pipelines.
Regulatory and trade environment — practical implications
Regulation and tariffs are shaping supply routes and cost stacks. The EU’s Construction Products Regulation (CPR) and the associated CE marking and post‑breakage vision testing requirements now influence product specifications on load‑bearing and overhead installations. Compliance timelines and testing costs introduce gating items for project bids and should be built into qualification roadmaps. Concurrently, certain environmental restrictions on plasticizers have tightened formulation windows — an advantage for ionoplasts positioned as non‑PVC alternatives, but a compliance burden for firms reliant on legacy chemistries.
On trade, existing tariff measures — such as duties affecting imports of SGP interlayers in some markets — remain a tangible factor for sourcing decisions. Even when temporary, tariff uncertainty elevates the value of localized capacity or qualified third‑party processing relationships.
What PW Consulting’s full report delivers (practical, operational, confidential)
For strategy teams preparing 2026 budgets, our full Worldwide SGP Interlayer Films Market report offers the working materials and decision tools finance, commercial, supply chain, and technology leads need to act:
- Proprietary 2020–2032 demand model with sensitivity scenarios that stress test raw material shocks, tariff changes, and certification adoption curves.
- Commercial playbooks for incumbents and challengers: premium product positioning, channel strategies, and contract flavors that win façade vs. retrofit vs. transport bids.
- Regulatory compliance checklist and certification cost estimator for CE/pRAVE and other major regional requirements.
- Supplier and customer heatmaps, including provider capability matrices, authorized distributor networks, and a qualified‑fabricator index to speed partner selection.
- Transaction support materials: valuation benchmarks, consolidation scenarios, and integration templates that reflect the market’s high concentration dynamic.
- Capex and ROI templates for lamination lines and pre‑laminated panel capacities, calibrated to lead time sensitivity and batch economics.
Note: To preserve the strategic value of our models for paying clients and to drive efficient executive engagement, detailed segment share tables, region‑level revenue splits, and project‑level competitive overlays are available exclusively in the full report and accompanying data workbook.
Top strategic moves to prioritize in 2026
- Fix supply risk immediately: Implement multi‑tier contracts for ionomer and PVB inputs with price collars or indexed pricing; evaluate short‑term inventory buffers where warranted.
- Certify and qualify now: Allocate resources to achieve project‑critical certifications (including overhead and post‑breakage testing) ahead of multi‑year tenders to gain first‑mover advantage on lucrative structural glazing projects.
- Localize selectively: Where tariff or lead time risk threatens margin, evaluate partnerships or contract manufacturing to create quasi‑local supply at lower capex commitment.
- Product and channel differentiation: Pursue product variants that meet aesthetic and functional demands (e.g., colored SGP, ultra‑thick lamination) coupled with pre‑laminated panel offerings to shorten procurement cycles for façade contractors.
- Prepare for consolidation plays: Use the high concentration backdrop to scan for bolt‑on acquisitions and strategic alliances that expand capacity or route‑to‑market in priority geographies.
- Lock in project pipelines: Sales teams should target early specification influence with architects, façade engineers, and glazing consultants to embed SGP in project Bill of Materials before competitive bids narrow.
How PW Consulting supports execution
Beyond the report, PW Consulting offers bespoke advisory packages for 2026 implementation, including supplier negotiation support, certification program management, technical due diligence for M&A, and a tailored go‑to‑market sprint for product launches. Our empirical models can be adapted to client balance sheets and procurement constraints so leaders can translate forecast scenarios into investment decisions with measurable P&L impact.
For procurement officers, the report’s cost‑to‑serve mapping will speed contract renegotiations. For corporate development teams, our valuation matrices and consolidation scenarios provide a short list of targets that deliver capacity, tech, or geographies at attractive multiples. For product teams, the intersection of certification pathways and recent product launches reveals differentiated white space ready for commercialization.
Conclusion — preparing for a decisive 2026
The SGP interlayer films market in 2026 will reward disciplined, informed action: early moves on certification and localized supply, tactical capacity choices aligned to demand trajectories, and commercial models that capture the premium associated with certified, high‑performance interlayers. PW Consulting’s Worldwide SGP Interlayer Films Market report is structured to shorten the path from insight to execution. We have intentionally showcased strategic frameworks and summary market mechanics here while reserving the granular, transaction‑grade datasets and segmental allocations for the full report and data workbook.
To access the complete forecast files, segmented demand tables, and our proprietary scenario models that directly support 2026 capital and commercial decisions, consult the full report on PW Consulting’s website or contact our industry practice for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide SGP Interlayer Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Omni‑channel and Warehouse Management Systems Market Poised for a 13.98% CAGR Through 2032
By PW Consulting, 2026-08-05
Worldwide Omni-channel and Warehouse Management Systems Market: Strategic Imperatives for 2026 — PW Consulting
PW Consulting today releases its authoritative market briefing, Worldwide Omni-channel and Warehouse Management Systems Market — an actionable intelligence product designed to shape enterprise decisions in 2026. Drawing on a rigorous base-year analysis (2025) and a seven-year forecast window (2026–2032), the report codifies the forces that will determine winners and losers across supply chain execution platforms. At the macro level, the global market is growing at a near-14% compound annual growth rate (CAGR) and is projected to expand from roughly USD 5.0 billion in 2025 to in excess of USD 12.4 billion by 2032, a scale that underwrites both waves of strategic investment and sustained vendor consolidation.
Worldwide Omni-channel and Warehouse Management Systems Market
What PW Consulting’s report delivers — practical intelligence, not platitudes
- Comprehensive market sizing and scenario-based forecasts calibrated to 2026 planning cycles and extending to 2032.
- Decision frameworks for technology selection: vendor-fit matrices, use-case mapping (omni-channel retail, 3PL, regulated industries), and a procurement scorecard that senior IT and supply chain leaders can operationalize immediately.
- Implementation playbooks covering cloud migration, phased rollouts, automation integration (WCS/WES/WMS orchestration), and change management templates that reduce deployment risk.
- Commercial tools including TCO/ROI models, benchmark KPIs, and negotiation playbooks tailored to multi-site rollouts and software-as-a-service contracts.
- Competitive landscape analysis and vendor positioning intelligence — including strengths, differentiation levers, and partnership ecosystems — with tactical implications for partner selection and M&A monitoring.
- Regulatory, security, and compliance checklists designed for highly regulated verticals (pharma, food & beverage, healthcare) and cross-border operations.
Note: this release highlights strategic conclusions and practical guidance; the full report contains the proprietary, granular segmentation and vendor scoring that enterprise buyers use to finalize RFPs and investment cases.
Worldwide Omni-channel and Warehouse Management Systems Market
Why 2026 is an inflection year
- Cloud acceleration: Our market intelligence confirms cloud-native WMS has reached critical mass in 2026, capturing approximately half of new deployments. Cloud economics — lower upfront capital requirements, elastic scalability, continuous feature delivery — make cloud the default for organizations scaling omni-channel fulfillment.
- Integration drives value: Leading buyers now expect WMS to play as part of a broader execution stack (TMS, WES, OMS, ERP). Recent strategic moves by vendors to bundle or integrate transportation and execution layers remove planning silos and materially improve end-to-end responsiveness.
- Labor and automation economics: Advanced platforms are delivering measurable throughput and uptime gains, which in many cases offset rising labor costs and chronic staffing shortages. Buyers must quantify these gains in financial terms before committing to capital-intensive automation projects.
- Regulatory and security overlay: Stricter traceability mandates and heightened data-protection expectations mean WMS selection is equally a compliance decision. Cloud platforms that bake audit trails, automatic compliance updates, and robust role-based controls into the stack present lower regulatory risk.
- Concentration and competitive dynamics: The market is moderately concentrated among a handful of major providers, but specialist vendors and mid-market focused suites continue to find routes to growth. The balance creates both partnership opportunities and acquisition targets for strategic buyers and financial sponsors.
Competitive landscape — what enterprise buyers should infer
Our vendor analysis blends product capability assessment with go-to-market posture and recent strategic developments. A few high-level takeaways:
Worldwide Omni-channel and Warehouse Management Systems Market
- Platform-first leaders: Vendors that offer cloud-native, modular execution platforms with embedded omni-channel orchestration are the natural partners for large, multi-channel retailers and global distributors seeking unified order streams and real-time visibility.
- AI and orchestration differentiators: Firms that incorporate advanced orchestration — workforce optimization, returns management, AI-enabled slotting and order streaming — unlock disproportionate operational gains for complex networks.
- ERP-integrated suites: Major ERP providers that embed EWM into a broader enterprise ecosystem remain attractive to companies seeking single-vendor roadmaps and tighter transactional coherence with finance and procurement.
- Mid-market and specialist value: Cost-effective, Microsoft-based and web-native suites targeted at SMB and mid-market manufacturers/distributors continue to outcompete larger suites when simplicity, speed of deployment, and price sensitivity dominate procurement criteria.
Selected vendor strategic profiles (high-level):
- Manhattan Associates — strong cloud-native WMS with deep omni-channel fulfillment, labor management and integrations to transportation and distributed order management; recognized repeatedly in industry analyst evaluations.
- Blue Yonder — mature functional WMS with workforce and returns capabilities and a focus on AI-driven orchestration for complex distribution networks.
- SAP SE — EWM embedded in a broad ERP and supply chain stack, appealing to enterprises seeking consolidated transactional systems and global process consistency.
- Oracle — Fusion Cloud WMS and NetSuite WMS offerings that emphasize cloud scalability, mobile operations and tight ERP integration for large and mid-market buyers.
- Infor — tier-1 cloud WMS capabilities targeting manufacturing, distribution and F&B verticals with added 3PL functionality.
- Körber (Infios) — significant portfolio consolidation and strategic TMS integration following recent acquisitions, moving toward comprehensive execution suites that pair WMS, WCS and TMS.
- Specialists (Made4net, Softeon, Tecsys, Deposco, Mecalux, Generix, Logistics Reply, Hardis) — a diverse set of pragmatic solutions, each bringing particular strengths in mid-market deployments, verticalized functionality, or fast-to-value cloud offerings; many have recently expanded partnerships with automation and cloud infrastructure providers.
Recent corporate moves substantiate the strategic trends we surface. Notable developments include platform rebrandings and portfolio integration to unify WMS, WCS and TMS; cloud WES product introductions for real-time orchestration; and channel expansions supported by alliances with cloud hyperscalers and automation OEMs. These events accelerate a market shift from point-product selection toward platform alignment and ecosystem strategies.
Actionable recommendations for 2026 decision-makers
- Shift from feature checklists to outcome-based procurement. Define target KPIs (throughput, inventory accuracy, fill rate, lead-time) and require vendors to price outcomes or provide performance guarantees tied to pilot metrics.
- Adopt modular, API-first architectures. Prioritize vendors with clear integration roadmaps for OMS, TMS, WES, and automation controllers to avoid future rip-and-replace cycles.
- Quantify labor and automation ROI up front. Use the report’s benchmark models to stress-test scenarios—improvements of 15–25% in throughput and as much as 30% reduction in downtime are achievable; structure contracts to de-risk the path to those outcomes.
- Make compliance and security a gating factor. For regulated industries require demonstrated batch/serial tracking, automated audit trails, and evidence of continuous compliance updates as part of the value proposition.
- Leverage the market’s consolidation dynamics. Use CR-level intelligence and competitive pressure to extract commercial concessions and faster delivery timelines; evaluate partnership or acquisition targets among specialists if vertical depth is strategic.
- Plan for cloud total cost of ownership, not just license fees. Include hosting, integration, change management, and ongoing optimization in the five-year financial model.
- Start small, scale fast. Select a pilot site aligned to the most complex fulfillment flows; use it as a governed learning lab before wider rollouts.
Measuring success and de-risking investments
Executives must move beyond simple implementation checklists and insist on a measurable business case. PW Consulting’s ROI templates translate operational KPIs into P&L impacts and cash-flow profiles suitable for capital approval. Security and privacy readiness assessments, together with automated compliance capabilities, reduce regulatory exposure while enabling faster international expansion.
How to obtain the full intelligence
This briefing is a strategic preview. The full Worldwide Omni-channel and Warehouse Management Systems Market report contains proprietary segmentation, vendor scoring, country-level guidance, and download-ready RFP templates that procurement teams and C-suite leaders rely on to finalize 2026 budgets and transformation roadmaps. The report’s base year is 2025, forecasts span 2026–2032, and our methodology blends market transactions, primary interviews, and vendor filings to ensure actionable fidelity.
PW Consulting invites supply chain leaders, CIOs, and investment professionals to request the executive summary or full report package to access the detailed datasets and vendor comparatives required to execute on the 2026 agenda. The public synopsis above is intentionally selective — the full data will enable immediate operational and commercial action.
For detailed analysis of this topic, please visit the official page: Worldwide Omni-channel and Warehouse Management Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide ESD Packing Market Set for Robust 8.1% CAGR Through 2032, Report Finds
By PW Consulting, 2026-08-05
Worldwide ESD Packing Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive summary
The global market for electrostatic discharge (ESD) protective packing is transitioning from a niche compliance segment into a strategic frontier for electronics, semiconductor, automotive-electronics and regulated industries. Our latest Worldwide ESD Packing Market study — with 2025 as the base year — finds the market reached approximately USD 5,035 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 8.1% through the 2026–2032 forecast window, reaching roughly USD 8,685 Million by 2032. Market concentration remains moderate: the three largest firms account for just over 32% of sales, while the top five reach near 46%, leaving meaningful opportunity for differentiated players.
Worldwide ESD Packing Market
Why this matters for 2026 corporate decisions
- Acceleration of upstream and downstream risk management: Procurement, product engineering and sustainability teams must treat ESD packing not only as a cost item but as a leverage point to secure supply chains and meet incoming producer responsibility mandates.
- Regulatory inflection points require proactive capital allocation: Emerging EPR (extended producer responsibility) laws in multiple U.S. states and tightening international recycling targets will materially influence material selection, packaging architecture and end-of-life strategies.
- Commercial differentiation through material innovation: Novel ESD substrates and combined functionality (e.g., ESD + VCI corrosion inhibitors; ESD paper alternatives) are reshaping supplier value propositions and creating premium pockets for suppliers that can deliver validated, circular solutions at scale.
Market dynamics: what is driving growth — and what will reshape it in 2026
Growth through 2025 has been supported by broad-based expansion in electronics manufacturing and regional reshoring activities that increase the need for protective logistics and handling. From 2026 onward, three structural dynamics will be particularly decisive:
Worldwide ESD Packing Market
- Regulatory pressure and producer responsibility. Jurisdictions are moving from aspirational recycling targets to enforceable EPR schemes with fees and compliance obligations. California’s SB 54, new state-level EPR laws, and recently operational programs elsewhere are creating an explicit regulatory cost for non-recyclable single-use packaging. Organizations that anticipate compliance costs can convert them into competitive advantage by redesigning packaging and entering recycling partnerships now.
- Material innovation and cost structure. Polyethylene remains the dominant raw material due to cost and availability, but the premium associated with conductive fillers and specialized polymer blends raises production costs relative to conventional packaging. New entrants and incumbents alike are investing in paper-based ESD treatments, VpCI-integration, and higher recycled-content films. These innovations balance lifecycle impacts with unit-cost pressures; strategic trade-offs will determine winners.
- Demand-side complexity. The need to protect higher-value, static-sensitive content from semiconductors to advanced automotive modules, combined with increasing emphasis on supply chain traceability and circularity, is shifting procurement criteria from “lowest-cost bag” to “validated protective system.” Companies that can demonstrate dual benefits — static control plus corrosion inhibition, recyclability or reclaimed feedstock use — will secure longer-term contracts.
Competitive landscape: positioning the key players
The market features a mix of specialized ESD suppliers, large diversified packaging groups, and niche innovators. Our research synthesizes public disclosures, product launches, and primary interviews to map competitive archetypes:
Worldwide ESD Packing Market
- Specialist ESD manufacturers (e.g., companies with deep product portfolios in static-dissipative and conductive films and thermoformed trays). These firms compete on technical validation, customization and speed-to-market for production lines with tight handling tolerances.
- Packaging champions with scale and sustainability roadmaps (large corrugated and flexible-packaging groups). Their strength lies in supply-chain reach and the ability to integrate ESD-safe corrugated and paper-based alternatives into global logistics programs.
- Material innovators and hybrid solution providers (companies combining ESD protection with VpCI or paper-based ESD innovations). Recent product launches demonstrate a push toward recyclable or PCR-containing films and ESD-treated paper solutions.
Notable recent product and portfolio moves — which illustrate strategic currents in the market — include the emergence of recyclable ESD pouches and paper-based ESD options, and combined ESD + corrosion protection films. These events are enabling new supplier claims around circularity while increasing technical validation requirements from OEMs and contract manufacturers.
What the report delivers — practical, buyer-ready tools
Our report is structured to move stakeholders from insight to action. Highlights include:
- Market sizing and scenario modeling: robust bottom-up model calibrated to 2020–2025 historicals and three strategic scenarios for 2026–2032 that stress-test demand and regulatory outcomes.
- Supplier scorecards: performance and capability assessments across materials expertise, sustainability credentials, technical validation, geographic footprint and customization capability.
- Unit-cost and total-cost-of-ownership (TCO) frameworks: a practitioner’s toolkit to compare incumbent PE-based solutions versus alternative substrates (paper-based, VpCI hybrid films, high-PCR content films) including sensitivity to polymer commodity prices and conductive-filler premiums.
- Regulatory impact toolkit: templates and cost-estimation models for EPR compliance, including producer-fee scenarios and roadmap for transitioning to compliant packaging by 2032 timelines.
- Go-to-market and procurement playbooks: actionable strategies for supplier consolidation, qualification protocols, pilot-to-scale pathways, and commercialization checklists for new ESD materials.
- M&A and partnership screeners: a pragmatic shortlist of acquisition targets and JV models aligned with capability gaps — from thermoforming expertise to validated VpCI technology or circular-material supply chains.
Strategic implications and recommended moves for 2026
For executive teams responsible for packaging, procurement, and product engineering, the next 12–18 months are a window to convert compliance risk into strategic advantage. Our top recommendations:
- Initiate a material-risk audit by Q2 2026. Map current ESD packing spend by material family and assess exposure to jurisdictional EPR obligations and polymer supply volatility.
- Fund two parallel pilots: one focused on high-recyclability paper-based ESD alternatives for lower abrasion handling, another on high-PCR film solutions that preserve ESD performance. Ensure pilots include lifecycle and handling testing under real logistics conditions.
- Create a supplier tiering strategy that values technical validation and circularity outcomes over unit price alone. Engage multiple archetype suppliers: a technical-specialist for complex assemblies and a scaled-packager for distributed logistics.
- Embed EPR and end-of-life clauses into supplier contracts. Shift a portion of procurement evaluation to include takeback, recycling credits or closed-loop commitments.
- Invest in in-house validation labs or partner with accredited third parties to reduce qualification timelines for novel ESD media. Time-to-qualification will be a gating factor for adoption at scale.
- Prepare M&A and partnership playbooks aimed at modular capabilities: thermoforming capacity, VpCI chemistry, paper-treatment expertise, and recycling partnerships that can be integrated into existing packaging operations.
- Price and commercial strategy: model the premium customers will accept for verified dual-function solutions (e.g., ESD + corrosion control) and for demonstrably recyclable ESD packaging. Use this to design margin-preserving migration pathways.
Where PW Consulting adds unique value
Our report is built to be a decision-enabler for 2026: not just market forecasts, but executable roadmaps. Clients gain access to a data-driven market model that ties regulatory scenarios to unit-cost outcomes, supplier capability matrices linked to operational KPIs, and prioritized investment pathways designed to minimize compliance and supply-chain risk while capturing growth in higher-value packaging segments.
Next steps — how to convert insight into advantage
This preview outlines the structural shifts and the strategic choices facing firms in 2026. For companies preparing 2026 operating plans, the full Worldwide ESD Packing Market report provides the granular scenario outputs, supplier-by-capability assessments, and the regulatory-cost worksheets necessary to create defensible budgets and go-to-market plans. PW Consulting also supports clients with bespoke workshops to translate these findings into procurement RFx criteria, pilot designs and M&A diligence templates.
To access the full findings, proprietary segmentation, and the operational playbooks referenced here, please visit the report page linked from our corporate portal. The public preview intentionally omits detailed segment tables and contract-level numbers to preserve the analytical value reserved for licensed users and client engagements.
For detailed analysis of this topic, please visit the official page: Worldwide ESD Packing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Electric Ambulance Stretchers Market to Hit USD 979.19 Million by 2032 as 8.31% CAGR Lifts Value from USD 560.0 Million in 2025
By PW Consulting, 2026-08-05
Worldwide Electric Ambulance Stretchers Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest market intelligence on the Worldwide Electric Ambulance Stretchers market delivers a focused, decision-ready briefing for executives planning fleet, procurement, and product investment strategies in 2026. The global market, which expanded from the low hundreds of millions in 2020 to an estimated USD 560.0 Million in the 2025 base year, is projected to continue a robust growth path through the forecast horizon — reaching roughly USD 979.2 Million by 2032 at a compound annual growth rate of 8.31% (2026–2032). This trajectory reflects accelerating replacement cycles, technology-led upgrades, and institutional procurement programs in emergency medical services and hospital systems worldwide.
Worldwide Electric Ambulance Stretchers Market
Why 2026 is a Pivotal Year
Two convergent forces make 2026 a strategic inflection point for organizations that buy, specify, or manufacture ambulance stretchers. First, an emerging wave of fleet modernization programs — driven by operational safety mandates, ergonomics and caregiver injury prevention, and electrification of pre-hospital equipment — is converting latent demand into near-term procurement activity. Second, rapid advancements in battery systems, load-sensing hydraulics, vehicle-to-equipment interface standards, and telematics are creating a richer product set but also increasing procurement complexity. Decisions made in 2026 about platform selection, supplier diversification, and service-network contracting will determine cost of ownership and operational resilience for the next decade.
Worldwide Electric Ambulance Stretchers Market
Macro Drivers and Market Dynamics
-
Fleet Renewal Pressure: Many EMS fleets and hospital systems are entering scheduled replacement windows; combined with rising attention to manual-handling injuries, this is accelerating purchases of powered cots and stretchers.
Worldwide Electric Ambulance Stretchers Market -
Standards and Certification: Compliance demands — including dynamic crash testing and medical electrical safety standards — are raising the bar for product design and validation. Key normative references currently shaping procurement specifications include dynamic crash standards, national ambulance equipment norms, and IEC electrical safety frameworks.
-
Technology Differentiation: Suppliers compete on battery chemistry and management, load-sensing hydraulics, operator ergonomics, integrated fastening systems, and connected features for fleet analytics. The market is moving beyond basic power assistance to systems that promise measurable reductions in caregiver strain and dispatch turnaround times.
-
Procurement Pathways: Public-sector and institutional buyers increasingly use formalized schedules and multi-stage RFPs to manage risk (including national contract vehicles in certain geographies). Performance-based contracting and lifecycle service agreements are becoming common procurement constructs.
Regulatory and Standards Context
Understanding the regulatory landscape is a prerequisite for strategic sourcing and product development. Powered wheeled stretchers are subject to a range of technical standards and procurement norms. Importantly, under current regulatory interpretations, some powered stretchers are exempt from premarket notification requirements that apply to other device classes, while still needing to demonstrate compliance with dynamic crash testing protocols and electrical safety (among other requirements). PW Consulting’s report maps these obligations and shows how compliance intersects with liability, procurement scoring, and warranty design.
Competitive Landscape — What Leading Suppliers Bring to the Table
The supply base spans large multinational medical-device OEMs and regional specialized manufacturers. Leading players differentiate through engineered system features, validated safety credentials, and broad service footprints. Highlights from competitor analysis include:
-
Stryker Corporation (Kalamazoo, Michigan): Market leader in high-end powered cots, offering connected ambulance cots with one-button height control, load-sensing hydraulics, lithium‑ion power, and embedded fleet-management capabilities. Their models prioritize integration with vehicle retention systems and adherence to multiple crash standards.
-
Ferno-Washington, Inc. (Wilmington, Ohio): Deep EMS heritage and a portfolio of electric stretchers designed to reduce operator injury risk. Recent large-scale fleet contract awards and iterative product documentation updates indicate strong field validation and procurement readiness.
-
Kartsana S.L. (Spain): European specialist focused on hydraulic/electric hybrid systems engineered to reduce technician effort while meeting regional safety norms; strengths include ergonomic design and localized compliance expertise.
-
Chinese and regional manufacturers (several firms based in Jiangsu province and other industrial clusters): Offer cost-competitive powered and semi-powered stretchers with features such as automatic loading and adjustable payload capacity — competitive options for price-sensitive institutional buyers and international distributors.
PW Consulting’s competitive benchmarking evaluates supplier differentiators across product safety, operational ergonomics, telematics, service coverage, warranty structures, and supply-chain resilience — equipping buyers to weight trade-offs beyond headline unit price.
Recent Market Signals
-
Large fleet procurement awards and inclusion of specific models in authoritative market surveys are consolidating purchaser confidence in a narrow set of validated products. Recent contract awards to established OEMs demonstrate buyer willingness to invest in proven platforms after comprehensive RFP testing and acceptance trials.
-
Manufacturers are updating technical documentation and user manuals to reflect new maintenance regimes and battery management practices, signaling maturation of product support and aftermarket services.
-
Independent survey programs and government-sponsored equipment evaluations are increasingly influential in public procurement decisions, functioning as third‑party validation for buyers and suppliers alike.
Supply Chain and Procurement Implications
Decision-makers must reconcile three tensions: performance vs. price, local service responsiveness vs. global manufacturing efficiency, and short-term availability vs. long-term total cost of ownership (TCO). Key implications include:
-
Service Network: Evaluate suppliers on network density, SLA response times, and availability of certified technicians — not just initial delivery lead times.
-
Battery Lifecycle Management: Battery technology is a core determinant of lifecycle cost and operational uptime. Procurement specifications should explicitly define battery performance thresholds, warranty terms, and end‑of‑life replacement processes.
-
Interoperability and Retention Systems: Compatibility with existing vehicle-mounted fasteners, retention rails, and ambulance interiors reduces retrofit costs and adoption friction; buyers should validate physical compatibility during pilots.
-
Geopolitical and Sourcing Risk: Manufacturers clustered in specific industrial regions can offer competitive pricing but introduce supply concentration risk; diversification strategies and consigned spare inventories are practical mitigations.
Actionable Playbook for 2026
For executives who must convert market intelligence into operational decisions this year, PW Consulting recommends the following prioritized actions.
-
Initiate a two‑track pilot program: run comparative pilots that test ergonomic outcomes, loading/retention compatibility, and in-situ battery performance across candidate platforms before committing to large-scale purchases.
-
Adopt performance-based RFPs: move from lowest-unit-price procurement to TCO-weighted evaluations that include downtime cost, warranty coverage, and maintenance response time.
-
Build a battery and telematics clause into contracts: require suppliers to provide telemetry APIs and battery-health reporting to enable predictive maintenance and to quantify fleet-level benefits.
-
Layer risk controls in supplier selection: include secondary-sourcing provisions, inventory consignment options, and scheduled replenishment to guard against lead‑time shocks.
-
Design phased fleet modernization: prioritize high-utilization assets and ambulances serving high-acuity routes to accelerate safety and labor-savings ROI.
-
Negotiate upgrade pathways: secure options for modular upgrades (e.g., battery packs, telematics modules) to preserve capital flexibility as technologies evolve.
-
Use third-party validation: require compliance evidence and third‑party test results for dynamic crash tests and electrical safety as tender pre-qualification criteria.
What PW Consulting’s Report Delivers (Practical, Writable Outputs)
The full PW Consulting report is structured to be operationally actionable for procurement, clinical engineering, fleet management, and M&A teams. Key deliverables include:
-
Market-size and growth modeling with scenario planning (base, downside, and accelerated adoption pathways).
-
Supplier scorecards and payback/TCO models customized to buyer usage profiles.
-
Contract and RFP templates that codify performance metrics, service levels, and upgrade pathways.
-
Technical compliance matrix mapping stretchers to applicable crash, electrical and flammability standards.
-
Operational pilots and acceptance-test batteries designed to de-risk large-scale rollouts.
-
M&A and partnership advisory guidance for strategic entrants and incumbents considering consolidation or capability buys.
Note: This release highlights strategic themes, macro sizing, and practicable next steps to inform 2026 planning cycles. Detailed segmentation tables, regional share breakdowns, unit-price curves, and the supplier-specific revenue splits are intentionally omitted from this summary to preserve the full analytical value of the core report.
Next Steps for Leaders
If your organization is preparing a procurement cycle, planning capital investments, or evaluating supplier partnerships in 2026, PW Consulting can provide tailored briefings and the full dataset/models underlying this summary. Our proprietary TCO models and supplier evaluation tools convert industry signals into defensible procurement choices and implementation roadmaps.
Contact PW Consulting to schedule a strategy briefing and to obtain the complete Worldwide Electric Ambulance Stretchers market report, including the full analytical annex, supplier scorecards, and executable procurement templates.
— PW Consulting, Senior Strategy and Industry Analysis Team
For detailed analysis of this topic, please visit the official page: Worldwide Electric Ambulance Stretchers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


