



Category: market research
PW Consulting: Worldwide Phenolic Foam Insulation Sheet Market to Reach USD 2,368.39 Million by 2032 at 5.85% CAGR — 2025 Base Market USD 1,590.81M; Europe (USD 613.84M) and Aluminum Foil‑Faced (USD 833.76M) Lead
By PW Consulting, 2026-08-05
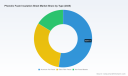
Worldwide Phenolic Foam Insulation Sheet Market — Strategic Briefing for 2026 Decision-Making
PW Consulting's latest market research report on the Worldwide Phenolic Foam Insulation Sheet market provides a focused, decision-ready intelligence package for executives navigating the next phase of industry evolution. Built on a base year of 2025 and calibrated against five years of historical performance (2020–2025), the study delivers demand forecasting through 2032, scenario-based stress tests, and actionable supplier and product strategies that matter for capital allocation, sourcing, and go-to-market planning in 2026.
Worldwide Phenolic Foam Insulation Sheet Market
Executive snapshot: growth trajectory and what it means
The phenolic foam insulation sheet market has shown resilient expansion through the early 2020s — rising from a market size near USD 1.21 billion in 2020 to USD 1.59 billion in 2025 (USD Million). Looking forward, our model projects compound annual growth of approximately 5.85% over the 2026–2032 forecast window, with the market approaching roughly USD 2.37 billion by 2032. That growth profile positions phenolic foam as a high-priority segment for stakeholders focused on energy-efficiency, fire-safety retrofits, and premium building-envelope solutions.
Worldwide Phenolic Foam Insulation Sheet Market
Why this report is strategically valuable for 2026
- Decision timing aligned with policy windows: 2026 marks a tightening regulatory and procurement environment in many major markets; our report maps the exact regulatory milestones and code adoption timelines that will drive near-term specification changes.
- Supply-cost trigger points: The analysis identifies the raw-material cost thresholds and supply-side constraints that will compress or expand margins across different producer classes — information critical for pricing, hedge planning, and contract negotiations.
- Scenario-based capital planning: Three investment scenarios (base, accelerated decarbonization, and protectionist trade shocks) translate top-line forecasts into CAPEX timelines and ROI windows so CFOs can prioritise plants, automation, or product diversification in 2026.
- Supplier-sourcing playbook: The report synthesizes the market concentration dynamics and company capabilities into procurement strategies for securing continuity and negotiating better commercial terms.
Key demand drivers and structural trends
Several structural factors underpin the market’s mid-single-digit CAGR. First, global energy-efficiency mandates and building retrofit programmes are increasing demand for high-performance insulation with low thermal conductivity and compact board thickness. Second, tighter fire-safety requirements across building codes elevate materials that can demonstrate both thermal performance and superior reaction-to-fire characteristics. Third, industrial and HVAC sectors continue to favour closed-cell phenolic systems for their combination of thermal, moisture-resistant and long-term dimensional stability benefits.
Worldwide Phenolic Foam Insulation Sheet Market
These demand drivers are tempered by two important dynamics: the sensitivity of manufacturers to phenolic resin feedstock swings, and evolving indoor-air-quality regulations that require low-emission formulations. Both dynamics create short- and medium-term windows where nimble producers can gain share by aligning product chemistry, compliance documentation, and stock strategies ahead of competitors.
Raw-material and cost dynamics — what procurement teams must track
Phenolic resin — the primary feedstock for phenolic foam manufacturing — has experienced notable price and supply volatility, linked to benzene and methanol feedstock cycles and regional logistics pressures. Recent market checks indicate elevated resin pricing levels and tighter availability compared with pre-pandemic norms, and—importantly—geographic differentials remain material for landed cost calculations.
Procurement strategies that will matter in 2026 include:
- Diversified sourcing contracts with volume bands and flexible take-or-pay terms to smooth cost exposure.
- Hedging options and index-linked price clauses tied to relevant petrochemical inputs.
- Partnerships with resin suppliers on sustainability initiatives (e.g., bio-based resin lines) to capture premium specification opportunities and mitigate regulatory risk.
Regulation and standards — compliance is a commercial lever
Regulatory frameworks and building-code tests underpin product acceptance in critical markets. Phenolic foam benefits from well-established fire performance classifications — including Euroclass and ASTM/BS test regimes — and must meet evolving low-emission requirements under regulatory instruments such as regional formaldehyde and VOC mandates. Additionally, product standards specific to phenolic thermal insulation set factory-manufacturing, performance, and testing requirements that buyers and engineers increasingly reference at specification stage.
For commercial teams, the implication is clear: verified test certifications, low-emission formulation documentation, and pre-approval by major code authorities materially reduce project-level friction and shorten sales cycles. Our report maps the most consequential standards and specifies the evidence buyers will demand in 2026–2028 procurements.
Competitive landscape — concentrated but with room for nimble players
The competitive structure shows moderate concentration among a handful of global producers and a broader tail of regional fabricators and specialty suppliers. The three- and five-firm concentration ratios indicate a market where leading manufacturers hold significant influence over pricing and standard-setting, but where regional and application-specific specialists retain opportunities to win niche business through service, fabrication capability, and local approvals.
Highlighted company archetypes and strategic considerations:
- Large integrated manufacturers: Firms with global scale and branded product lines are increasingly focused on premium performance claims (thermal, fire, low-emission). They are best positioned to invest in R&D, global approvals, and backward integration into resin supplies.
- Regional champions and fabricators: Independent fabricators and regional mills compete on lead-time, bespoke fabrication (curved segments, pipe sections), and local code approvals; these players can capture retrofit and replacement-work packages where fast response and local relationships matter.
- Chemicals and resin suppliers: New resin formulations and bio-based alternatives are mobility vectors — suppliers who can partner with foam producers to co-develop low-emission or bio-based offerings create commercial pull for their customers’ product lines.
Notable recent developments include bio-based resin launches from major chemical firms — a development that will matter both for sustainability positioning and for reformulating product portfolios to meet tightening formaldehyde/VOC expectations. Our competitive profiles cover leading producers’ positioning, technical differentiators, capacity footprints, and likely next moves for 2026–2028.
What the PW Consulting report contains — practical, executable modules
- Market sizing and outlook: Annualised historical dataset (2020–2025) and a detailed forecast to 2032 with scenario overlays and sensitivity analysis to raw-material and trade-shock events.
- Application and product diagnostics: Demand drivers by application cluster, product-performance thresholds specified by buyers, and win-loss analysis from recent tenders (anonymised).
- Cost and margin modeling: Bottom-up cost build-ups for representative phenolic sheet products, including resin, additives, energy, and labour, together with margin simulations under different resin-price scenarios.
- Regulatory and standards matrix: Mapping of the most consequential codes and test requirements by market, plus a compliance checklist that reduces specification friction on project tenders.
- Competitive and supplier intelligence: Profiles for leading global manufacturers and a taxonomy of regional fabricators, including capability maps, likely strategic moves, and partnership/leverage opportunities.
- Strategic playbook: Actionable growth paths for producers, fabricators, distributors, and raw-material suppliers covering product innovation, M&A triggers, channel strategies, and risk mitigation steps for 2026 decisions.
Practical recommendations for executives planning in 2026
- Procurement leaders: Lock in multi-year but flexible resin supply agreements, and prioritise suppliers offering low-emission resin technology to pre-empt regulatory or project-level demands.
- Product and R&D heads: Accelerate validation of low-emission and bio-based formulations; secure third-party fire and VOC testing early in 2026 to shorten project approval cycles.
- Commercial leaders: Recalibrate pricing strategies to reflect rising total-cost-of-supply while protecting contract margins via indexation clauses and service-level premiums.
- Investors and corporate development: Use the report’s scenario outputs to test M&A or greenfield timing — target assets that provide fabrication flexibility, local approvals, or access to resilient resin supply chains.
Why a “trailer” perspective — and what you’ll get from the full report
This briefing demonstrates the analytical depth and practical orientation of PW Consulting’s full study while intentionally withholding granular segment-level allocations and sensitive breakouts to preserve client value. The full report contains the proprietary segmentation tables, regional demand split, application-level forecasts, and model files that allow you to run your own what-if scenarios (including contract-level margin simulations and project-level ROI calculators).
For executives preparing procurement strategies, product roadmaps, or investment cases in 2026, the full dataset and scenario models are critical. They convert high-level market direction into specific action steps: when to adjust prices, where to allocate CAPEX, which partnerships to prioritise, and how to structure commercial terms to protect margins and market share.
Next steps
PW Consulting can provide an executive briefing, a data-licence for the model outputs, or a bespoke workshop to translate the study into a 90-day plan tailored to your organisation. For teams that require immediate tactical support, we offer focused modules on resin-sourcing optimisation, low-emission product validation, and regulatory approval acceleration.
Access to the full report and the interactive forecast model is available through our publication page. Senior leaders seeking a private walk-through or custom modelling should contact PW Consulting to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Phenolic Foam Insulation Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Chemical Industry DCS Market Hits USD 6,510 Million in 2025, Set for 5.5% CAGR in 2026–2032
By PW Consulting, 2026-08-05
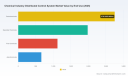
Worldwide Chemical Industry Distributed Control System Market: Strategic Intelligence Briefing for 2026 Decision-Makers
PW Consulting’s new market research briefing on the Worldwide Chemical Industry Distributed Control System (DCS) market arms executives with the pragmatic intelligence needed to make high-stakes technology, procurement, and capital-allocation decisions in 2026. Built on a base year of 2025 and covering historical trends (2020–2025) and forward-looking forecasts to 2032, the report combines rigorous market sizing with actionable playbooks for modernization, migration and vendor selection—without sacrificing commercial sensitivity. This release highlights the strategic value of the research while intentionally preserving granular segment-level figures to encourage stakeholders to consult the full study for proprietary data.
Worldwide Chemical Industry Distributed Control System Market
Why this report matters in 2026
-
An increasingly software-led DCS market: The global DCS market for chemical applications has demonstrated steady growth, expanding from USD 5,825 Million in 2023 to USD 6,510 Million in 2025, and is projected to reach approximately USD 9,470 Million by 2032 at a compound annual growth rate (CAGR) of 5.5% over the forecast period. That trajectory reflects accelerated investment in software-defined automation, edge/cloud architectures, and digitized lifecycle services.
Worldwide Chemical Industry Distributed Control System Market -
Technology and regulation are co-driving change: Advances in software-defined DCS platforms, AI-assisted operations, and tighter cybersecurity expectations are reshaping vendor value propositions—while regulatory developments (for example, the U.S. EPA phasedown of certain high-GWP HFCs under the AIM Act) are forcing operational and equipment-level adjustments across chemical plants.
Worldwide Chemical Industry Distributed Control System Market -
Vendor consolidation with differentiated service plays: The market remains moderately concentrated—top vendors maintain strong footholds, but competition is intensifying around lifecycle services, upgrade/retirement playbooks and open-standards interoperability.
What executives will gain from the PW Consulting briefing
-
Decision-ready market context: Clear, validated market sizing and a 2026–2032 growth roadmap that supports CapEx planning, M&A screening and technology sourcing.
-
Commercially actionable benchmarks: Vendor positioning matrices, procurement scorecards, and vendor TCO templates to compare license, maintenance, services and lifecycle costs across alternative migration strategies.
-
Implementation blueprints: Stepwise migration playbooks for brownfield modernization, hybrid control architectures, and phased replacement of legacy DCS assets to minimize downtime and regulatory exposure.
-
Risk and compliance overlays: Scenario analysis demonstrating how regulatory actions and supply-chain constraints materially influence operational decisions and total cost of ownership.
-
Executive-ready recommendations: Prioritized initiatives and near‑term KPIs for technology, operations and procurement teams to execute in 2026.
Market dynamics shaping strategy
-
Software-defined automation (SDA) is becoming strategic: 2025–2026 product introductions from major suppliers show a clear pivot to software-first architectures. These platforms promise faster feature rollouts, easier integration with analytics and a path toward subscription-based commercial models—changing traditional CapEx/Opex trade-offs for owners and EPCs.
-
OT/IT convergence accelerates value capture: Integration of DCS with plant analytics, digital twins and enterprise systems is producing measurable gains in yield, asset utilization and predictive maintenance. Organizations that link DCS modernization to digital use cases capture ROI faster than those pursuing systems upgrades in isolation.
-
Cybersecurity and regulatory compliance are non-negotiable: Recent regulatory moves (e.g., phasedowns under environmental mandates) and the growing cyber threat landscape mean compliance-ready architectures and vendor-provided security controls are procurement must-haves in 2026.
-
Service-led differentiation: With hardware commoditization on certain fronts, vendor differentiation is increasingly delivered through migration services, lifecycle support, and industry-specific control libraries—areas where long-term contracts and field-service capabilities matter most.
Competitive landscape — who matters and why
-
Major incumbent vendors maintain leadership through integrated control suites and deep chemical-industry expertise. Several suppliers are actively evolving their platforms toward software-defined architectures and expanded services portfolios. This strategic repositioning is reflected in recent product and update launches across the supplier base and underscores a competition axis that favors openness, cybersecurity and lifecycle economics over raw feature lists.
-
Notable vendor moves in 2025–2026 include: major releases and upgrades positioning vendors to capture modernization projects through enhanced connectivity (e.g., OPC UA), software-defined capabilities, and greater automation intelligence. These moves materially affect vendor selection criteria—especially for brownfield modernization projects where interoperability and long-term service commitments reduce transition risk.
-
Market concentration remains meaningful: the leading groups control a substantial portion of the market, creating advantages in global support networks, spare-parts logistics and upgrades. However, the competitive landscape is dynamic—new software-centric entrants and existing automation firms pursuing software-first strategies can disrupt incumbency if they demonstrate superior lifecycle economics and cybersecurity assurances.
Recent vendor developments that change procurement calculus
-
Software-defined DCS introductions and upgrades: Several major vendors unveiled or updated platforms aimed at reducing automation cost-per-node, improving data visibility and embedding cybersecurity features—moves that materially influence total cost of ownership and migration sequencing.
-
New releases emphasizing autonomous operations and plant-level intelligence: Vendors are embedding capabilities for autonomous control, batch optimization and AI-assisted diagnostics—features that alter value capture timelines for digital transformation projects.
-
Enhanced field device integration and standardized communications: Upgrades that support open protocols and tighter field integration simplify the integration burden on EPCs and owners and accelerate deployment of advanced control strategies.
Strategic recommendations for 2026
-
Adopt a staged modernization roadmap: Avoid one-time rip-and-replace. Use the report’s migration playbooks to sequence software-first upgrades, targeted hardware refreshes and phased decommissioning to protect production and cash flow.
-
Prioritize open standards and modular architectures: Require interoperability (e.g., open protocol support and modular interfaces) in vendor contracts to reduce lock-in risk and enable multi-vendor ecosystems for analytics and cybersecurity tools.
-
Embed cybersecurity and regulatory impact into procurement: Include compliance testing, patching SLAs and regulatory scenario clauses (e.g., phasedown-related process changes) in RFPs to mitigate downstream retrofit costs.
-
Negotiate outcome-based commercial models: Explore contracts that combine product supply with performance guarantees and shared-savings clauses to align vendor incentives with operational KPIs.
-
Bias towards vendors with comprehensive lifecycle services: For brownfield projects especially, emphasize global support, spare-parts availability and documented migration experience to reduce project risk.
-
Use CapEx/Opex scenario planning: Align investment timing with the report’s 5.5% CAGR outlook and perform sensitivity analysis across commodity cycles and regulatory scenarios to prioritize projects with the fastest payback.
-
Build an internal integration center of excellence (CoE): Create a cross-functional team to own vendor relationships, digital use-case prioritization and the adoption of analytics—this speeds time-to-value from DCS modernization.
Report contents — what’s inside (operational focus)
-
Validated market sizing and a 2026–2032 forecast model with scenario sensitivities calibrated to regulatory and technology adoption vectors;
-
Vendor benchmarking and strategic profiles covering product roadmaps, global delivery capability, and service economics;
-
Technology heatmaps and adoption timelines for software-defined DCS, edge/cloud integration, AI-assisted control and cybersecurity technologies;
-
Migration playbooks, execution timelines, and TCO models tailored to brownfield and greenfield chemical plants;
-
Procurement scorecards, sample RFP language, contract negotiation levers and recommended KPIs for supplier SLAs;
-
Regulatory impact assessments and remediation pathways that translate new standards and phasedowns into operational actions and cost estimates;
-
Deal flow and M&A screening tools to identify acquisition targets and partnership opportunities within the DCS ecosystem.
How to use this intelligence
Leaders in operations, engineering, and procurement should treat this briefing as the strategic framing for 2026 spending cycles. Use the market growth trajectory and vendor dynamics to stress-test budgets, accelerate high-value pilots, and renegotiate long-term service agreements. For teams planning modernization, the combination of TCO templates and migration playbooks provides a disciplined roadmap to reduce transition risk and optimize lifetime value.
PW Consulting’s full report includes the granular segment and regional detail, proprietary vendor scoring, and downloadable tools referenced above. For organizations that require a bespoke executive briefing, scenario workshops or a tailored vendor short‑list informed by site-level constraints and regulatory exposures, PW Consulting offers advisory engagements that translate the market-level intelligence into executable programs.
To access the full study and the supporting decision‑support tools, please visit the PW Consulting market portal for the Worldwide Chemical Industry Distributed Control System Market report.
For detailed analysis of this topic, please visit the official page: Worldwide Chemical Industry Distributed Control System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Disposable Surgical Electrodes Market at USD 1,770.45 Million in 2025, Poised to Reach USD 2,747.64 Million by 2032 at a 6.48% CAGR
By PW Consulting, 2026-08-05
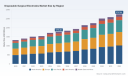
Worldwide Disposable Surgical Electrodes Market: Strategic Intelligence for 2026
Executive snapshot
PW Consulting’s new market brief on the Worldwide Disposable Surgical Electrodes market synthesizes five years of historical performance (2020–2025) with a robust forecast window (2026–2032) to give healthcare executives a decision-grade perspective entering 2026. The market expanded from roughly USD 1.32 billion in 2020 to about USD 1.77 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 6.48% through our forecast horizon, reaching an anticipated USD 2.75 billion by 2032. These headline dynamics mask meaningful structural shifts — regulatory tightening, new-device clearances, raw-material innovation, and changing procurement models — that will shape winner-take-more outcomes in the next three years.
Worldwide Disposable Surgical Electrodes Market
Why this matters for 2026 planning
-
Momentum and optionality: The market’s mid-single-digit CAGR creates runway for product-line investments, but it is not so large as to absorb unfocused capital. Strategic allocation matters.
Worldwide Disposable Surgical Electrodes Market -
Portfolio and channel decisions: With moderate market concentration among leading players, nimble manufacturers and private-label partners can create disruptive value through targeted clinical claims, differentiated materials, and channel-led pricing.
Worldwide Disposable Surgical Electrodes Market -
Regulatory and procurement inflection points: Class II device dynamics, evolving IEC compliance expectations, and variations in reimbursement by setting mean that market access and total-cost-of-ownership arguments will increasingly determine adoption.
What the PW Consulting report delivers (practical, actionable content)
-
Transparent market sizing and scenario models — base year 2025, historical series 2020–2025 and scenario-driven forecasts for 2026–2032 — enabling CFOs to stress-test revenue plans under conservative, base, and upside assumptions.
-
Go-to-market playbook for 2026: segmented commercial strategies for hospital procurement, ambulatory surgical centers, and specialty clinics; pricing elasticity models; and channel optimization guidance that includes private-label and distributor partnership options.
-
Regulatory & quality quick-reference: decision trees mapping 510(k) pathways, relevant IEC standards (electrical safety and performance), and sterilization/packaging compliance considerations that shorten time-to-market for new single-use electrodes.
-
Supplier and cost-mapping: upstream raw-material sensitivity analysis (including PTFE coating adoption), contract-manufacturing options, and inventory/sterility logistics to minimize EO sterilization bottlenecks and shelf-life risk.
-
Competitive intelligence dossier: capability maps, innovation positioning, and M&A/partnership priorities for leading and fast-emerging players — enabling deal teams to prioritize targets and integration risks.
-
Clinical & reimbursement impact matrix: how device claims (e.g., non-stick coatings, reduced eschar, ergonomic pencil designs) translate to CPT-billing differentials and purchasing committees’ ROI thresholds in hospital versus office settings.
-
Twenty-page annex of primary research: interview extracts with procurement officers, OR nurses, clinical engineers, and regulatory leads across three continents, covering procurement decision drivers and unmet product needs.
Competitive landscape: what leading firms are doing and why it matters
The competitive field combines several multinational medical-device platforms with specialized small- and mid-cap manufacturers. The market’s current structure favors organizations that can pair broad surgical-energy portfolios with high-quality single-use electrodes, while lower-cost manufacturers focus on high-volume procedure segments and adjacent specialties.
-
Large medtech platforms (e.g., Medtronic, Johnson & Johnson MedTech / Ethicon): These firms leverage integrated surgical-energy ecosystems and brand trust to bundle disposables with capital systems, capture installed-base economics, and support complex hospital procurement cycles. Their strategic advantages include scale manufacturing, global regulatory teams, and deep relationships with system-level purchasers.
-
Electrosurgery specialists (e.g., CONMED, ERBE): These players often compete on technical breadth, offering extensive disposables portfolios (monopolar and bipolar variants, pencils, and specialty tips). They win where clinical preference and device performance carry weight — for example, in specialty operating suites and teaching hospitals.
-
Precision and niche innovators (e.g., Kirwan Surgical, Progressive Medical): These companies focus on procedural ergonomics and material science (PTFE coatings, non-stick surfaces) to reduce OR time and consumable waste. Their propositions are attractive to cost-conscious surgical teams focused on clinical outcomes.
-
End-market challengers from Asia (several China- and Taiwan-headquartered manufacturers): These firms compete aggressively on price and increasingly on feature parity. Rapid product introductions and targeted regulatory clearances in select jurisdictions have amplified competition in mid-to-low price tiers.
Market concentration metrics indicate a moderately concentrated sector: the cumulative share of the top three and top five players reflects significant, but not insurmountable, market power. For 2026 decisions, that means regional and procedural niches remain fertile for entrants that can demonstrate clinical differentiation and supply reliability.
Regulatory, standards, and clinical-environment dynamics
-
Regulatory baseline: Disposable electrosurgical electrodes are typically regulated as Class II devices requiring 510(k) clearance in the U.S. Manufacturers must build regulatory timelines into product launches; incremental design changes can trigger new submissions.
-
Standards and sterilization: Compliance with IEC 60601-series standards (electrical safety and performance) is table stakes for hospital adoption. Most sterile single-use electrodes utilize EO gas sterilization and commonly carry multi-year shelf-life claims; packaging and sterilization validation are recurring points of regulatory scrutiny.
-
Clinical practice and billing: Reimbursement for electrosurgical procedures follows specialty-specific CPT coding rules, with payments varying by care setting. Commercial strategies that reduce OR time or complication rates can be framed in total-cost-of-care models that resonate with hospital value committees.
Recent innovation signals (select examples)
-
2025–2026 FDA clearances demonstrate ongoing product flow: multiple 510(k) clearances were recorded for single-use electrodes and system-integrated disposables across dermatologic, arthroscopic, and rehabilitation applications. These events underscore continued regulatory throughput for well-documented safety and performance claims.
-
Material innovation: Adoption of PTFE coatings to reduce eschar build-up and improve non-stick performance is a visible trend among suppliers aiming to differentiate clinically and reduce procedure delays.
Commercial implications and competitive playbook for 2026
-
Price vs. performance stratification: Manufacturers must choose where to compete — as premium, clinical-differentiated suppliers or as cost-efficient high-volume vendors. Hybrid strategies (e.g., premium features in targeted specialties; commoditized SKUs for volume channels) can protect margins while expanding footprint.
-
Channel sophistication: Direct-sell remains important for strategic accounts, but distributor partnerships and private-label agreements are accelerating in markets where procurement centralization favors bundled contracts.
-
Procurement intelligence: Hospitals are increasingly requiring total-cost-of-ownership analyses, including sterile waste handling and OR throughput impact. Vendors that present robust evidence (clinical, economic, and usability data) win contract renewals.
-
M&A and partnering lens: With a mid-sized market growing at ~6.5% CAGR, acquirers will prioritize bolt-on technologies (e.g., novel electrode coatings, ergonomic pencils) and access plays (regional distributors, OEM manufacturing capacity) rather than large transformational deals.
Top-line strategic recommendations (how to use this intelligence in 2026)
-
For incumbent global players: Double down on integrated value propositions that tie disposables to capital systems, while allocating targeted R&D to coatings and ease-of-use improvements that justify price premiums.
-
For mid-size innovators: Prioritize regulatory-ready design dossiers and pursue focused clinical studies that validate OR time savings or complication reductions; use these outcomes to accelerate hospital formulary inclusion.
-
For private-equity and corporate development teams: Target tuck-ins that bring proven regulatory clearances, manufacturing scale in key geographies, or unique materials expertise. Structure earn-outs around commercial milestones tied to hospital adoption rates.
-
For procurement and hospital system leaders: Adopt a clinically anchored procurement framework that quantifies OR-time savings, infection-control benefits, and lifecycle costs rather than relying on per-unit price alone.
How to access the full intelligence
This press release is a strategic preview. PW Consulting’s full report expands the themes summarized here into detailed models, a full vendor matrix, primary interview findings, regulatory appendices, and downloadable financial models that can be adapted to your organization’s assumptions. For teams making 2026 budget allocations, the report is designed to convert market insight into an actionable three-year plan that aligns commercial, regulatory, and manufacturing efforts.
Final note
As disposable surgical electrodes continue to evolve at the intersection of material science, regulatory oversight, and procurement discipline, 2026 will be a year for decisive positioning. PW Consulting’s research is engineered to help executives choose between incremental optimization and strategic reshaping — and to execute the operational moves that translate market growth into durable advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Disposable Surgical Electrodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pharma‑Grade Ibrutinib Market Poised to Climb from USD 954.91 Million in 2025 to USD 1,246.34 Million by 2032 at a 3.88% CAGR
By PW Consulting, 2026-08-05
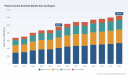
Worldwide Pharma Grade Ibrutinib Market — Strategic Brief for 2026 Decision‑Makers
PW Consulting’s latest market study on the worldwide pharma grade ibrutinib market provides an evidence‑based roadmap for commercial, regulatory, and supply‑chain decisions in 2026. Built on a 2020–2025 historical series with 2025 as the base year and a scenario‑driven forecast window spanning 2026–2032, the report delivers a granular, decision‑ready view of the market in which revenue grows from an estimated USD 954.91 million in 2025 toward a projected USD 1,246.34 million by 2032 — an overall trajectory that translates into a mid‑single‑digit compound annual growth rate (CAGR) of 3.88% over the forecast period. This brief highlights the strategic implications embedded in that trajectory while intentionally withholding our proprietary subsegment tables to preserve the “trailer” view; access to the full dataset and model is available on the report page.
Worldwide Pharma Grade Ibrutinib Market
Why this study matters for 2026 strategic choices
- Timing is central. The market’s near‑term expansion sits alongside a clustered set of regulatory and pricing inflection points — from patent cliffs and exclusivity expiries to reimbursement reforms — that will materially shape competitive dynamics through this decade.
- Revenue resilience masks structural change. Although the aggregate market grows modestly through 2032, our analysis shows that the composition of revenue, channel economics, and clinical usage patterns are likely to shift significantly. The winners will be organizations that read the change drivers early and align manufacturing, regulatory, and commercial moves to distinct scenarios.
- Concentration raises strategic fragility. Market concentration is meaningful: the top three players account for a majority share, and the top five further consolidate control. That concentration provides incumbents with commercial leverage but also creates predictable targets for entrants, payers, and policy scrutiny — particularly where price and access interact with public reimbursement reforms.
Regulatory, clinical, and reimbursement inflection points to watch in 2026
- Patent and exclusivity timeline: Public filings indicate that the U.S. composition‑of‑matter patent for ibrutinib is expected to expire in 2027, with pediatric regulatory exclusivity extending into 2028. Additional secondary patents have been cited as delaying effective generic entry in the United States until early in the next decade. These overlapping protections create a multi‑year window during which branded strategies can be optimized, but they also require active lifecycle management and legal monitoring.
- Regional nuances matter: Patent expiries and the resulting generic approvals are not synchronous globally. For example, local filings and approvals in large Asian markets have already altered competitive dynamics regionally. Companies must therefore make geographically differentiated plans rather than assuming a single global timing for generic substitution.
- Reimbursement pressure: Under U.S. policy changes, the Medicare Part D negotiated price construct will materially compress list pricing for high‑cost oral oncology therapies starting January 2026. This shift materially alters revenue per unit in the largest single payer market and forces sponsors to reassess price, rebate, and access strategies, with ripple effects into private payers and international pricing benchmarks.
- Clinical evidence that redefines use patterns: Late‑stage clinical data released in recent major hematology forums — including a large Phase 3 study evaluating fixed‑duration combinations versus continuous therapy — introduces credible pathways to reduce cumulative drug exposure for certain patient cohorts. Such shifts would change lifetime drug spend per patient and therefore alter total addressable market assumptions for both branded and generic suppliers.
Supply‑side economics: manufacturing, pricing and concentration
- Supplier landscape: A diverse set of dedicated API manufacturers and vertically integrated generic players has emerged across South Asia, Eastern Europe, and China. These firms vary in scale, GMP accreditation, and dossier maturity. Our intelligence shows an active race to secure API capacity, validate formulations, and file for approvals in high‑value markets where patent and exclusivity conditions permit.
- Concentration metrics: The market exhibits material concentration at the top, which has two strategic consequences — it underpins incumbent margin power today, and it focuses regulatory and commercial attention on the largest suppliers as candidates for partnerships, divestitures, or competitive attack.
- Cost and raw material risk: While ibrutinib’s finished product economics depend on complex inputs and multi‑step synthesis, buyers should expect variability in API availability and quote lead times tied to demand windows, export controls, and quality audits. Vertical integration and multi‑sourcing strategies therefore remain best practice for manufacturers and large purchasers alike.
Competitive positioning: incumbents, challengers, and their playbooks
The competitive map is multi‑tiered. At the center are the innovator partners that jointly developed and commercialize the branded oral BTK inhibitor — an incumbent franchise with a comprehensive product portfolio including capsules, tablets and an oral suspension formulation, and an active lifecycle program to protect usage and expand label claims. Recent corporate actions include label refinements and high‑visibility clinical data presentations that have implications for treatment algorithms and duration of therapy debates.
Worldwide Pharma Grade Ibrutinib Market
Surrounding the incumbent are two visible strategic cohorts: (1) India‑based API and generic pharmaceutical groups that are scaling GMP capacity, securing dossier approvals and pursuing tentative approvals where permissible; and (2) regionally focused manufacturers in Eastern Europe and China who are active in markets with earlier patent expiries. Tentative approvals and regulatory filings in the United States and major export markets prove the intent of many challengers, but actual commercial entry will remain contingent on patent law outcomes, litigation, and settlements.
Worldwide Pharma Grade Ibrutinib Market
What the full report contains — practical deliverables
- Proprietary market model (2020–2032) with base year 2025, including scenario modules for alternative patent, pricing, and clinical‑practice outcomes.
- Consolidated supplier scorecards: API capacity, GMP certification status, dossier maturity and likely time‑to‑market by jurisdiction.
- Commercial playbooks for incumbents and challengers: pricing levers, channel strategies, formulary access approaches, and likely response timelines to Medicare and payer reforms.
- Regulatory and IP timeline with litigation risk grading and event‑driven forecast adjustments.
- Deal and M&A prioritization matrix that aligns asset types, regions and entry timing with expected returns under multiple scenarios.
- Risk heatmap and mitigation options for supply disruption, price compression, and adverse clinical data outcomes.
Note: To preserve the strategic value of our proprietary analysis and to comply with a “teaser” publication approach, we are deliberately withholding the detailed subsegment tables (regional shares, application splits, and per‑segment pricing ladders) in this release. The full report contains those tables, downloadable models, and interactive scenario tools.
Strategic playbook recommendations for 2026
- Recalibrate pricing and contracting now. Anticipate lower net prices in major public programs beginning in 2026 and model the operational breakpoints at which volume incentives, bundled pricing, and patient support services change profitability dynamics.
- Prioritize supply‑chain resilience rather than shortest‑cost sourcing. Secure multi‑source API agreements and consider near‑shoring options for finished‑dosage manufacturing ahead of any surge in demand or litigation‑driven supplier exits.
- Design flexible launch sequences. For companies planning to commercialize generics, align regulatory filings in markets with immediate openings while hedging investments in markets where patent litigation or exclusivities may delay entry.
- Prepare clinical narrative and real‑world evidence to protect or reclaim share. If new data projects shorter treatment durations or fixed‑duration regimens, incumbents can offset price pressure by demonstrating superior outcomes, patient‑reported benefits, or cost offsets tied to reduced total therapy duration.
- Use M&A and partnerships tactically. With the top tier controlling a large share of today’s market, smaller players should evaluate asset consolidation to build scale and dossier breadth — while larger players should consider bolt‑on acquisitions that improve supply security or expand into complementary oral oncology portfolios.
How executives should use this report in Q1–Q2 2026
- Executive teams: validate portfolio and pricing assumptions using our scenario outputs to set 2026 budgets and reimbursement negotiations.
- Business development: target partner discussions and competitive diligence toward suppliers and regional players that our supplier scorecards identify as most likely to enable rapid scale‑up.
- Manufacturing and regulatory: sequence capacity investments and dossier submissions in line with the patent and exclusivity timelines mapped in our report.
- Market access: deploy payer‑facing value dossiers that reflect the new reimbursement environment and incorporate real‑world cost offsets tied to evolving clinical practice.
Concluding perspective
The pharma grade ibrutinib market in 2026 is characterized by a stable but evolving top‑line trajectory: meaningful aggregate growth underpinned by concentrated market shares, intersecting patent and exclusivity timelines, rapidly shifting reimbursement realities, and an active set of challengers building API and finished‑dose capacity. For decision‑makers, the imperative is clear — move beyond headline revenue forecasts to synchronized plans across legal, clinical, manufacturing, and commercial functions. PW Consulting’s full report supplies the granular segmentation, scenario models, and supplier intelligence required to operationalize that synchronization.
For access to the full dataset, interactive models, and a detailed supplier directory (including our assessment of capability, dossier status, and likely time‑to‑market), please visit the report page to download the complete Worldwide Pharma Grade Ibrutinib Market study and the accompanying decision‑support toolkit.
For detailed analysis of this topic, please visit the official page: Worldwide Pharma Grade Ibrutinib Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 5.86% CAGR for Worldwide Lapis Lazuli Pendant Market Through 2032
By PW Consulting, 2026-08-05
PW Consulting Releases Strategic Brief: Worldwide Lapis Lazuli Pendant Market — Actionable Insights for 2026 Decision-Makers
The Worldwide Lapis Lazuli Pendant Market report from PW Consulting presents an evidence-driven, strategy-oriented view of a specialty gemstone segment whose dynamics are reshaping sourcing, retail, and manufacturing choices across jewelry supply chains. Built on a 2020–2025 historical analysis with 2025 as the base year and forward-looking scenarios through 2032, the study projects the market to expand at a compound annual growth rate (CAGR) of 5.86% across the 2026–2032 forecast window (figures are stated in USD Million). This briefing summarizes the report’s strategic value for corporate leaders preparing budgets, procurement strategies, and go-to-market plans in 2026 while intentionally withholding core segmented datapoints to encourage stakeholders to consult the full report for transaction-ready detail.
Worldwide Lapis Lazuli Pendant Market
Why this report matters for 2026 strategy
-
Validated growth trajectory: With multi-year historical tracking and a modeled continuation into 2032, the report gives leadership teams confidence in setting medium-term investment horizons for product development, inventory allocation, and supplier commitments.
Worldwide Lapis Lazuli Pendant Market -
Practical decision frameworks: Beyond market sizing, the study translates macro signals into prioritized actions — e.g., inventory staging by risk tolerance, supplier diversification thresholds, and price-indexing approaches tailored to lapis-based offerings.
Worldwide Lapis Lazuli Pendant Market -
Regulatory and logistics foresight: The analysis integrates near-term trade and transit developments that are already altering landed costs and time-to-market, enabling procurement and legal teams to preempt compliance-related surprises in 2026.
Market trajectory and what it implies for business plans
Our base-year analysis places 2025 as a pivotal year in which demand patterns and supply-side shifts converged to create a stable, growth-oriented base. The projected CAGR of 5.86% across 2026–2032 reflects a market recovering from short-term disruptions and responding to sustained interest from both heritage and contemporary jewelry segments. For commercial teams, this trajectory supports moderate expansion plans rather than aggressive capacity bets: allocate incremental inventory and manufacturing capacity to test new product families, while preserving financial flexibility for mid-cycle adjustments.
Pricing strategies will need to be nuanced. The report models multiple price-pressure scenarios driven by raw-material variations and tariff regimes. We recommend embedding a dynamic pricing mechanism for lapis-laden assortments that maps to a supplier-indexed cost of goods sold (COGS) and routes margin buffers into new collection launches rather than across-the-board discounts.
Primary demand drivers and supply-side constraints
-
Consumer tastes: Lapis lazuli pendants remain prized for both artisanal authenticity and fine-jewelry aesthetics. The market exhibits bifurcated demand — consumers seeking provenance and craftsmanship versus buyers focused on design-led, plated-metal price points.
-
Raw material dynamics: Increased production and investment in key lapis-producing areas have improved availability but introduced quality and certification heterogeneity. Forward-buying and supplier-qualified stock programs can mitigate short-term volatility.
-
Logistics and transit corridors: International transit routes that historically supported lapis exports continue to matter; firms need contingency plans for corridor-level disruptions and to optimize shipment batching to keep landed costs predictable.
Regional dynamics — strategic highlights (qualitative)
The report presents a nuanced, regionally informed narrative: each market geography exhibits a distinct mix of consumer preference, retail distribution structure, and sourcing relationships. Rather than surface-level comparisons, the study diagnoses the operational levers that matter locally — trade facilitation, artisanal networks, and retail format evolution — and converts these into tactical recommendations for market entry, expansion, or retrenchment. For confidentiality and to preserve the report’s commercial value, detailed regional splits are available in the full dossier.
Regulatory and trade environment: immediate considerations for 2026
Two regulatory realities require action now. First, certain import jurisdictions introduced duties and documentation requirements for colored gemstones and set jewelry that have already affected landed costs and clearance timelines. Procurement teams must update vendor contracts to reflect country-of-origin verification protocols and revise incoterms to control customs risk.
Second, transparency and ethical sourcing expectations are gaining traction with consumers and regulators alike. Where provenance claims are part of the value proposition, retailers and brands should expect to invest in traceability workflows and audit-ready supplier documentation to support claims and reduce reputational risk.
Raw-material and geopolitics — what changed and what to do
-
Supply-side opportunity: Production increases in certain mining regions are creating supply opportunities that translate into competitive advantage for buyers who can commit to forward-offtake arrangements or engage in development partnerships.
-
Corridor resilience: Key transit corridors remain operational and continue to facilitate exports, but companies should stress-test their logistics plans against corridor-specific disruptions and consider secondary routing options.
-
Rural economic impact: Enhanced extraction activity in producing regions is translating into broader socio-economic effects. Ethical sourcing programs that incorporate community benefits can create positive brand differentiation while stabilizing supply relationships.
Competitive landscape — how to position against established players
The pendant segment is characterized by a mix of family-owned specialty importers, artisan platforms, wholesale manufacturers, and regionally focused exporters. The market remains fragmented — the three-largest firms account for a modest portion of total market turnover while the top five collectively still leave significant share to be captured by agile challengers. This fragmentation creates both risks and opportunities: incumbents can be outmaneuvered through superior curation and storytelling, whereas scale players can exert purchasing leverage to tighten margins.
-
Lapis Lazuli World (United States): A family-owned importer with tightly managed overseas operations, known for authentic Chilean-sourced pendants and direct supplier oversight.
-
925 Silver Shine & Silver Star Jewellery (India): High-volume manufacturers with capacity to serve wholesale and private-label needs, attractive for retailers seeking sterring-silver designs at scale.
-
Lapis Village Company (Afghanistan): A direct-source exporter rooted in Badakhshan supply chains — a strategic partner for companies prioritizing natural, mine-to-market relationships.
-
Quartzsite Minerals & NOVICA (United States): Online-first suppliers and artisan platforms enabling rapid market access for boutique and retail audiences, with ethical sourcing propositions.
-
Akrati Jewels Inc. (India) & Bernd Wolf (Germany): Represent distinct pathways — competitive manufacturing capabilities and high-end European artisanal craftsmanship, respectively.
Our competitive analysis combines capability mapping, supplier risk scores, and scenario-based cost curve modeling to help procurement and strategy teams select the optimal partner mix for their brand ambitions. The full report includes a supplier short-listing tool and a negotiation playbook tailored for 2026 contracting cycles.
What’s inside the full report: operational assets for immediate use
-
Market sizing and validated forecast model (2020–2032) with downloadable projections in USD Million, sensitivity testing, and scenario toggles for alternative macro environments.
-
Supplier due-diligence templates and a scoring matrix to compare provenance, capacity, ethical credentials, and lead-time reliability.
-
Price-index series and procurement hedging strategies for managing short-term spikes and planning medium-term sourcing commitments.
-
Trade and compliance checklist that aligns contract clauses, invoicing practices, and labeling for key import markets as of 2025–2026.
-
Retail and channel playbook setting out assortment rationales for online marketplaces, specialty jewelry stores, and department-store partners (including margin and promotional levers).
-
Strategic M&A and partnership screening guide for buyers and investors assessing consolidation opportunities in a fragmented market.
Recommended 90-day action plan for executives
-
Week 1–4: Run a cost-to-serve audit for lapis-containing SKUs and map supplier exposure to regulatory change. Engage legal and customs to update documentation requirements.
-
Week 5–8: Initiate supplier qualification pilots with at least two partners representing distinct sourcing models (direct-mining vs. artisan platform) and run small-batch assortments online to validate customer response and margin performance.
-
Week 9–12: Finalize a sourcing mix policy and launch a traceability pilot for premium collections; set KPIs for lead-time, quality yield, and ethical compliance to inform 2026 procurement commitments.
M&A and partnership themes to watch
Given the market’s fragmentation, acquisition targets fall into three strategic buckets: upstream raw-material specialists that secure supply; platform-based artisan marketplaces that expand direct-to-consumer reach; and specialized manufacturers that deliver margin-enhancing private-label capabilities. The report models valuation scenarios under varying growth and margin assumptions — a critical tool for corporate development teams considering bolt-on acquisitions or minority investments.
How to access the full analysis
This briefing is designed as a strategic teaser: it outlines the major implications and actionable next steps for 2026, while preserving the granular data and operational templates that constitute the report’s commercial value. For procurement scorecards, region-by-region demand curves, and downloadable financial models (USD Million), please consult the full Worldwide Lapis Lazuli Pendant Market report on PW Consulting’s research portal.
For bespoke briefings, executive workshops, or assistance integrating the report’s tools into 2026 planning cycles, PW Consulting’s jewelry practice is available to provide tailored advisory support.
For detailed analysis of this topic, please visit the official page: Worldwide Lapis Lazuli Pendant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Aircraft Windows Market to Expand at a 4.25% CAGR in 2026–2032 Forecast
By PW Consulting, 2026-08-05
Worldwide Aircraft Windows Market — Strategic Briefing for 2026 Decisions
PW Consulting today releases an executive briefing tied to our full market research report on the Worldwide Aircraft Windows Market (base year 2025). Synthesizing five years of historical performance (2020–2025) and forward-looking scenario modelling across 2026–2032, the analysis quantifies a resilient market trajectory with a compound annual growth rate (CAGR) of 4.25% and material upside tied to broader commercial fleet growth and accelerating retrofit cycles. This briefing outlines the strategic implications for OEMs, Tier‑1 suppliers, MRO operators, investors, and procurement leaders as they finalize budgets and strategic priorities for 2026.
Worldwide Aircraft Windows Market
Why this market matters in 2026
-
Clear demand corridor: Passenger traffic recovery and long-term growth expectations underpin sustained new-build demand for transparencies, while regulatory-driven safety cycles support aftermarket and MRO volumes. Our models show the market expanding steadily from the 2025 baseline toward the 2032 horizon, reflecting both new aircraft deliveries and recurring replacement activity.
Worldwide Aircraft Windows Market -
Balanced growth drivers: The combination of OEM production (notably narrowbody deliveries in the late 2020s), regulatory replacement cadence from authorities such as FAA and EASA, and the rising use of advanced materials and coatings create parallel pathways for revenue — new-build, retrofit, and aftermarket.
Worldwide Aircraft Windows Market -
Concentration and supplier dynamics: The transparency market exhibits a mid-to-high level of supplier concentration — the three largest suppliers capture a majority share and the top five consolidate near seven in ten units of market influence. For strategic sourcing and partnership decisions, this concentration materially affects negotiation power, lead times, and technology access.
-
Technology and materials inflection: Lightweight polymer alternatives and advanced multilayer coatings are shifting product specifications and lifecycle economics. These technology shifts are creating targeted windows of opportunity for materials specialists, coating innovators, and niche OEMs to capture premium aftermarkets and retrofit programs.
Key takeaways for executive teams
-
Prioritize MRO and retrofit playbooks: Regulatory scrutiny of windshield replacement and safety-driven inspection regimes means aftermarket demand will remain a predictable revenue stream. MRO providers and component specialists should accelerate capacity planning and certification roadmaps for high-turnaround services.
-
Reassess material strategies by use-case: Glass laminates continue to command preference where optical fidelity is critical, while engineered polymers (acrylics, polycarbonate composites) are gaining ground where weight and fuel-economy trade-offs dominate procurement decisions. Sourcing strategies should be tailored by platform and mission profile rather than one-size-fits-all specification changes.
-
Embed coatings and systems thinking into product roadmaps: UV-blocking and anti-reflective coatings, pre-integrated sensor ports, and damage-tolerant designs are differentiators for both OEM supply contracts and aftermarket conversions. Investments in proprietary coatings or partnership agreements with coating specialists can create defensible margins.
-
Map supplier concentration to risk: With a significant portion of market influence concentrated among a handful of players, contingency planning — dual-sourcing, long-term offtake, and strategic inventory positioning — reduces program exposure for large operators and OEMs.
-
Explore strategic partnerships in emerging platforms: New entrants in electric regional and urban air mobility platforms are creating opportunities for advanced transparencies (e.g., lightweight, large-area windows with novel mounts). Strategic partnerships, design wins, and integrations (including ongoing partnerships between legacy suppliers and eVTOL OEMs) are early indicators of where durable IP and aftermarket annuities will form.
What the PW Consulting report delivers — practical assets for 2026 planning
-
Granular market sizing and validated forecasts — anchored to a 2025 base year and modelled through 2032 — including scenario runs that stress-test delivery slippages, regulatory tightening, and raw-material price shocks.
-
Supplier ecosystem maps and capability matrices — supplier footprints, core competencies (materials, coatings, transparency systems), certification readiness, and aftermarket service capacity, enabling rapid supplier selection and partnership decisioning.
-
Commercial & procurement playbooks — negotiation levers, inventory hedging strategies for acrylics and specialty laminates, and contract structures tailored to manufacturers, airlines, and MROs.
-
Technology roadmaps and R&D gap analysis — comparative assessment of coatings, laminated glass vs. polymer trajectories, and sensor-ready transparency architectures that inform product development priorities.
-
Regulatory impact simulations — quantified implications of evolving FAA/EASA guidance on replacement intervals, inspection regimes, and certification timelines for new transparency types.
-
Risk heat maps and supply continuity plans — raw-material exposure, supplier concentration risks, and recommended mitigation scenarios tied to lead-time and capacity constraints.
-
Revenue-at-risk and margin impact models — customizable tools that let finance and strategy teams model the P&L impact of material substitutions, coating uplifts, and MRO pricing strategies.
Competitive landscape — capabilities and commercial implications
-
PPG Aerospace (United States): A market leader in original-equipment transparencies and aftermarket coatings. PPG’s advanced coating systems — designed to improve UV protection and durability — are increasingly central to OEM specifications and aftermarket differentiation.
-
GKN Aerospace (United Kingdom): A dominant position in military transparency systems and a strong second in commercial transparencies. GKN’s installed base and coated window platforms provide a strategic advantage in both new-build contracts and retrofit campaigns.
-
Saint‑Gobain Aerospace (France): A trusted supplier of windows and windshields to multiple OEMs, and an active partner in next-generation platforms. Recent strategic partnerships with electric aircraft developers underscore the company’s ability to transition legacy capability into emerging segments.
-
Lee Aerospace (Wichita, Kansas, United States): Specialist in FAA‑approved transparencies for business and general aviation, with a robust aftermarket program and targeted upgrade offerings aimed at fractional ownership and high-utilization corporate fleets.
-
The NORDAM Group (United States): Integrated MRO and manufacturing capabilities for transparencies, offering scale in repair‑overhaul operations that are essential to airline continuity plans and regional MRO ecosystems.
-
Gentex Corporation (United States): Focused on advanced optical and protective systems, enabling product differentiation in cockpit and specialized transparency applications where integrated systems and sensors are value‑drivers.
-
Key regional and specialist players (e.g., L.P. Aero Plastics, Perkins Aircraft Windows, Cee Bailey’s, Llamas Plastics): These firms supply critical FAA‑PMAs, bespoke solutions for light and general aviation platforms, and rapid-turn replacement services — an often overlooked but profitable segment of the market.
Notable recent development: in 2025 Saint‑Gobain confirmed an active partnership to supply transparencies for a high‑profile electric aircraft program, illustrating how legacy transparency manufacturers are leveraging traditional competencies into next‑generation platforms.
Strategic recommendations — tactical moves for 2026
-
Lock in tiered sourcing agreements for high-risk materials and coatings to reduce lead-time exposure while preserving flexibility for specification changes.
-
Capitalize on aftermarket predictability: invest in fast‑turn MRO centers with digital inspection tools to convert regulatory-driven replacement cycles into service revenue growth.
-
Invest selectively in coatings and polymer R&D: prioritize technologies that reduce lifecycle maintenance costs or enable new certification envelopes (e.g., scratch resistance, UV protection, integrated health monitoring).
-
Negotiate long‑term strategic partnerships with concentrated suppliers where design wins are required, but preserve contingency capacity through vetted secondary suppliers for critical components.
-
Pursue targeted go‑to‑market plays in emerging air mobility: early collaboration on design requirements yields long-term aftermarket capture and preferred supplier status.
Data integrity, assumptions and how to get the full intelligence
Our models use a 2025 base year and draw a validated historical series for 2020–2025, projecting through 2032 under multiple scenarios. All financials are presented in USD (Revenue unit: Million). The headline growth trajectory reported here — a 4.25% CAGR across the forecast window — is the result of blended modeling that integrates fleet delivery programs, passenger traffic projections, regulatory replacement frequency, raw-material cost sensitivities, and supplier capacity constraints.
In keeping with the “trailer” principle for this briefing, we have intentionally showcased the analytical depth and the strategic conclusions while withholding detailed segment tables, region-by-region splits, and line-item pricing that are included in the full dataset. The full PW Consulting report contains the comprehensive segmentation, granular regional and platform breakdowns, supplier-by-supplier market shares, and downloadable financial models that operational teams use to finalize 2026 plans.
Next steps
-
Procurement & Sourcing leaders: use the report’s supplier capability matrix and risk heat map to finalize 2026 supplier contracts and inventory buffers.
-
Product & Technology teams: adopt the technology roadmap and materials benchmarks to prioritize R&D and certification timelines.
-
Investors and corporate development teams: leverage the supplier financial assessments and concentration metrics to inform M&A and partnership diligence.
PW Consulting’s Worldwide Aircraft Windows Market report is available for licensing and enterprise advisory engagements. For access to the full datasets, segmentation tables, and customizable forecasting models that underpin the conclusions summarized here, please contact PW Consulting’s industry practice or visit our reports portal to request the complete study.
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft Windows Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Power EMS Market Poised to Expand at a 13.52% CAGR Through 2032, New Report Finds
By PW Consulting, 2026-08-05
Worldwide Power Energy Management System (EMS) Market: Strategic Imperatives for 2026 Decision‑Making
PW Consulting’s latest market intelligence brief — the Worldwide Power Energy Management System (EMS) Market Report (base year 2025, historical 2020–2025, forecast 2026–2032) — reframes how energy executives, utility planners, and industrial strategists should set priorities for the coming planning cycle. Our model shows the global EMS market accelerating from the mid‑2025 baseline to a substantially larger opportunity by 2032, driven by utility modernization, distributed energy resource (DER) aggregation, electrification, and software‑first orchestration. The market’s compound annual growth rate sits at 13.52%, reflecting structurally higher demand for digital grid control and advanced energy optimization. PW Consulting prepared this release to arm 2026 decision‑makers with precise strategic pathways while preserving detailed segmental data in the full report to support transaction‑grade choices.
Worldwide Power Energy Management System (EMS) Market
Why this report matters for 2026
2026 will be a pivotal year for capital allocation in the power sector. Regulators are redefining EMS boundaries, transmission owners are reimagining grid topologies, and large energy consumers are reshaping procurement to secure resilience and cost predictability. Our report translates these shifts into executable options for boards and investors by combining forward‑looking market sizing, scenario stress‑testing, and vendor benchmarking into one deliverable.
Worldwide Power Energy Management System (EMS) Market
- Decision relevance: Align capital plans and procurement timelines to a market trajectory that accelerates through the late 2020s, enabling earlier capture of efficiency and flexibility benefits.
- Risk management: Map regulatory changes and DER penetration scenarios to operational and financial contingency plans.
- Go‑to‑market clarity: Prioritize product and service investments that convert near‑term demand into sustainable revenue streams.
Top‑line market context
PW Consulting’s global model shows continued expansion from the 2025 baseline into a materially larger market by the end of the 2032 forecast, consistent with a 13.52% CAGR over the forecast window. This growth profile is not uniform; it is shaped by technology cycles, standards evolution, and infrastructure investment programs. While the headline figures set the size and pace of opportunity, the strategic nuance that separates winners from laggards lies in product architectures, integration capabilities, and customer outcome propositions — elements we analyze in depth.
Worldwide Power Energy Management System (EMS) Market
Regulatory and macro drivers reshaping demand
Three classes of external forces are compounding EMS demand:
- Standards and code evolution. The 2026 National Electrical Code (NEC) reclassification of EMS provisions (relocated to Article 130) and clarified distinctions between Energy Management Systems and Power Control Systems materially affect product specifications, procurement language, and compliance pathways.
- DER aggregation and VPP ambition. Policy updates, including public roadmaps for Virtual Power Plants that target very large aggregated DER capacities by 2030, raise the technical bar for EMS solutions tasked with secure, real‑time orchestration across heterogeneous resources.
- Grid modernization investments. Major transmission and distribution upgrade programs, together with large industrial electrification projects and data‑center related load growth, are expanding the addressable market for EMS technologies that deliver operational optimization and resilience.
Recent programmatic events exemplify these drivers: system operators approving EMS upgrade programs, major vendors committing capital to regional manufacturing and digital service expansion, and standard‑setting organizations updating code language to reflect new PCS/EMS boundaries. Those developments are discussed in the report with sources and timelines to support procurement and compliance planning.
Technology trajectories and product strategy implications
EMS is evolving from a largely control‑centric offering into a layered architecture where software, edge devices, and services converge to deliver continuous optimization. Key technical shifts include:
- Software‑first orchestration: Cloud/edge hybrids that enable rapid feature deployment while preserving deterministic control paths for mission‑critical functions.
- AI and analytics: Predictive maintenance, probabilistic load forecasting, and adaptive control strategies that improve asset utilization and reduce dispatch errors.
- Interoperability and standards compliance: Increased commercial value from solutions that can integrate heterogeneous DERs, legacy SCADA, and advanced market interfaces under evolving code requirements.
- Outcome‑based services: Movement from product sales to energy‑as‑a‑service models where vendors monetize verified performance improvements.
For product leaders, the implication is clear: prioritize modular, standards‑aligned software layers and build services capabilities to monetize performance outcomes. Procurement teams should require auditable performance guarantees and interoperability proof points in RFPs to avoid lock‑in and to protect system operators’ ability to adapt as codes and market rules change.
Competitive landscape — what to watch
The competitive set is a mix of long‑standing industrial automation incumbents and digitally oriented platform providers. PW Consulting’s qualitative and quantitative assessments highlight differentiated strengths across the vendor cohort:
- Siemens AG: Strong in utility‑scale grid control with mature transmission and generation EMS platforms focused on large‑system optimization and renewable integration.
- Schneider Electric SE: Competitive in building and facility‑level EMS integrated with digital services and recent capital commitments to expand manufacturing and service capacity.
- ABB Ltd: Emphasizes real‑time monitoring and industrial applications with platforms that bridge plant efficiency and grid interactions.
- GE Vernova: Concentrates on transmission and generation asset digital twins and grid‑scale monitoring tools.
- Honeywell, Eaton, Emerson: Offer industrial and infrastructure‑grade EMS solutions with strengths in process integration, power distribution, and reliability.
- Johnson Controls, Rockwell Automation, Mitsubishi Electric, Yokogawa, Hitachi Energy: Provide complementary solutions across building, industrial, and generation domains with varying emphases on controls, services, and system integration.
Market concentration metrics show a moderate level of aggregation: the top three vendors account for roughly a third of market activity and the top five capture just over half. This structure supports continued competition around services and software differentiation — and leaves room for niche players and new entrants to scale through partnerships and focused vertical plays.
Practical deliverables in the PW Consulting report
For executives building strategy in 2026, the report is organized around practical decision tools rather than only descriptive analysis. Highlights include:
- Global market model with annualized totals (USD million) from 2020 through 2032 and multiple scenario variants for policy and DER adoption sensitivities.
- Procurement and RFP playbooks, including contract clauses that reflect the NEC 2026 distinction between EMS and PCS functionality.
- Vendor evaluation framework (technology, services, delivery risk) and a reproducible scoring template to accelerate vendor selection workshops.
- Deployment checklists and integration roadmaps covering on‑prem/cloud hybrids, cybersecurity baselines, and data governance for EMS rollouts.
- TCO and ROI calculators for capex/opex trade‑offs and energy‑as‑a‑service pilots.
- Regulatory and policy briefs for major markets, mapping compliance timelines to procurement cycles.
To preserve the report’s value as a transaction‑grade planning tool, we intentionally withhold the full disaggregated regional, application and vendor share tables from this press summary. These granular splits, vendor scores, and downloadable models are available only in the full report and data package.
Actionable recommendations for 2026
- Reframe procurement around outcomes: Insist on measurable performance KPIs in contracts (availability, ramp rates, energy savings) with financial alignment between vendor and customer.
- Prioritize interoperability testing: Require DER simulators and third‑party validation in the procurement cycle to avoid integration surprises.
- Invest in software talent and data ops: Successful EMS rollouts will be as much about data management and analytics as about control hardware.
- Pilot VPP and DER aggregation use cases: Use constrained pilots to validate commercial models and grid services monetization prior to large‑scale rollouts.
- Update compliance playbooks: Align engineering and procurement teams with the NEC 2026 code changes and ISO energy management expectations to avoid rework.
- Scan for partnerships and bolt‑on capabilities: Given market concentration and rapid feature development, consider alliances or targeted M&A to close capability gaps quickly.
Conclusion — the strategic edge for 2026
As EMS becomes the control plane for a decarbonized, decentralized power system, the companies and agencies that combine robust, standards‑aware platforms with outcome‑oriented services will capture disproportionate value. PW Consulting’s Worldwide Power EMS Market Report offers the empirical basis and tactical playbooks leaders need to make defensible 2026 commitments — from capital allocation and vendor selection to regulatory compliance and workforce planning. For transaction‑ready intelligence, including the granular regional and application splits, vendor scorecards and downloadable financial models, access the full report package through PW Consulting’s publication channel.
For detailed analysis of this topic, please visit the official page: Worldwide Power Energy Management System (EMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide CRPG Games Market Set to Grow at a 6.48% CAGR Through 2032
By PW Consulting, 2026-08-05
Worldwide CRPG Games Market: Strategic Intelligence for Executive Decisions in 2026
Executive Snapshot
As studios, publishers, investors, and platform operators set strategic priorities for 2026, understanding the commercial trajectory of the computer role‑playing game (CRPG) segment is non‑negotiable. Our Worldwide CRPG Games Market report (base year 2025; forecast period 2026–2032) synthesizes a decade of observed dynamics and forward scenario analysis to translate market movement into boardroom‑grade decisions. The market reached an estimated USD 2,540.0 Million in 2025 and is projected to expand through the forecast window at a compound annual growth rate (CAGR) of 6.48%. Our year‑on‑year trajectory highlights both cyclical harvesting opportunities and structural shifts that will determine winners and losers across development, distribution, and live‑service operations.
Worldwide CRPG Games Market
Why this matters in 2026
-
Timing of investment and M&A: With mid‑single‑digit CAGR and uneven short‑term growth pulses, 2026 will be a year for selective capital deployment—prioritizing studios with demonstrable live‑ops retention, modding ecosystems, or exclusive IP pathways that extend lifetime value.
Worldwide CRPG Games Market -
Platform and distribution strategy: The CRPG audience remains platform‑diverse and sentiment‑sensitive. Strategic choices about platform exclusivity, multi‑platform launches, and distribution mix materially affect unit economics and long‑term community health.
Worldwide CRPG Games Market -
Operational resilience: Infrastructure costs, data localization rules, and hardware availability will influence cloud‑dependent features (co‑op, cross‑platform saves, AI‑assisted NPCs). These external factors require contingency planning that goes beyond traditional development roadmaps.
Market Dynamics — Interpreting the Numbers
The headline growth rate signals a sector that is expanding steadily but not explosively; this is a market where product craftsmanship, player retention, and intelligent live‑service design compound revenue more effectively than broad user acquisition campaigns alone. Our historical series (2020–2025) shows a recovery and acceleration phase after mid‑cycle disruptions, with forward forecasts (2026–2032) indicating steady expansion supported by recurring revenue mechanisms and renewed consumer appetite for narrative‑first experiences.
Concentration metrics suggest a moderately consolidated landscape—top firms exert meaningful influence over distribution terms and platform relationships, but a healthy mid‑market and active independent scene preserve creative variety. This combination elevates the importance of strategic partnerships and IP licensing in 2026 as firms seek to scale without shouldering full production risk.
Operational and Infrastructure Headwinds
-
Data center capacity and cost: Hyperscale demand continues to reshape availability and pricing of cloud infrastructure. Capacity growth has been strong, but record low vacancy in primary markets constrains large, immediate expansions. As CRPGs integrate online features and cloud‑enabled services, developers must forecast higher distribution and operational costs into their release economics.
-
Regulatory friction: Data sovereignty and privacy regimes are raising the cost of cross‑border feature delivery. For studios planning cloud saves, regional leaderboards, or hosted narrative experiences, localized deployments and edge strategies will be prerequisites rather than luxuries.
-
Hardware and AI compute: Export controls and chip availability can affect studio roadmaps for AI‑assisted development tools and in‑game systems. Firms that diversify compute partners and design scalable AI fallbacks will mitigate risk to release timelines.
What the Report Delivers — Practical Inputs for 2026 Strategy
This report is designed as an actionable playbook, not an abstract forecast. Key deliverables include:
-
Robust market sizing and validated forecasting models (base year 2025; forecast 2026–2032), with scenario sensitivity for demand shocks and platform disintermediation.
-
Revenue architecture templates for CRPG titles—covering launch monetization, post‑launch content calendars, modding economies, and subscription/season pass permutations—enabling finance teams to stress‑test LTV assumptions.
-
Go‑to‑market playbooks that align release windows with platform windows, influencer cadence, and regional marketing spend optimization across a segmented audience framework.
-
Regulatory and infrastructure impact assessment—detailing how data center constraints, sovereignty rules, and hardware controls shift product architecture and distribution strategies.
-
Competitive intelligence dossiers with strategic positioning maps, pipeline tracking, and scenario analyses for leading studios and publishers—designed to inform M&A diligence and partnership outreach.
-
Market concentration and supplier power analyses that identify leverage points for negotiating platform fees, distribution deals, and cloud contracts.
-
Executive dashboards and model deliverables in native spreadsheet form to enable rapid localization of assumptions and re‑run scenarios for internal committees.
Competitive Landscape — Strategic Archetypes and Near‑Term Moves
The CRPG ecosystem is populated by distinct strategic archetypes—independent auteur studios, legacy triple‑A houses, niche specialist developers, and platform‑centric publishers. Each archetype brings different risk profiles and levers for 2026 strategy:
-
Independent auteur studios (e.g., studios recognized for narrative depth and player choice) continue to punch above their weight by marrying strong IP with engaged communities and modding support. Their post‑launch support and community governance have turned single releases into long‑tail revenue streams.
-
Veteran story studios maintain relevance through franchise stewardship and community‑first expansions. Their primary challenge in 2026 is balancing cinematic ambition with recurring engagement mechanics to sustain ARR (annual recurring revenue).
-
Large open‑world developers and publishers command distribution scale but must ration capital across larger portfolios, increasing the value of co‑investment, licensing, and third‑party live‑ops partnerships.
-
Niche and license‑driven developers exploit recognizable IP to reduce marketing friction but face pipeline risks tied to license cycles and platform holder negotiations.
Recent market signals reinforce these archetypes in action: certain mid‑sized studios announced sequels that expand scope and worldbuilding to capture a broader audience; other teams are doubling down on post‑launch support and mod tooling to maintain active player bases. These moves underscore a wider strategic truth for 2026—scale and community engagement are complementary, not opposing strategies.
Strategic Recommendations for 2026
-
Prioritize live‑ops and community‑centric KPIs at the earliest design stages. Retention multipliers are the primary drivers of sustainable revenue growth in a market with measured CAGR.
-
Hedge infrastructure risk by diversifying cloud and edge partners and baking in regional deployment plans to satisfy data sovereignty requirements without materially increasing latency for core gameplay.
-
Adopt staged monetization frameworks—soft launch small regions to validate progression loops and monetize thereafter with calibrated season pass content that rewards long‑term play.
-
Use strategic partnerships and IP licensing to accelerate time‑to‑market while preserving in‑house capabilities for franchise stewardship.
-
Build acquisition and integration playbooks that target studios with proven community retention and mod ecosystems rather than purely IP‑centric valuations.
How to Use This Report
For 2026 planning cycles, executive teams should use the report as the central reference for: investment memos, product roadmaps, quarterly scenario updates, and M&A target shortlists. The deliverables include ready‑to‑use financial models, competitive heatmaps, and infrastructure risk matrices—enabling cross‑functional teams to align on prioritized initiatives within 30–60 days.
Next Steps
This article provides a strategic preview of our full analysis. The complete Worldwide CRPG Games Market report contains granular segmentation, proprietary demand curves by platform and distribution channel, downloadable datasets, and full company profiles with validated pipeline milestones. To access the exhaustive datasets, segmentation tables, and the interactive dashboard that underpins our recommendations, please visit the full report landing page.
For detailed analysis of this topic, please visit the official page: Worldwide CRPG Games Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Differential Electrochemical Mass Spectrometry (DEMS) Market to Rise from USD 52.45 Million in 2025 to USD 97.43 Million by 2032 at a 9.25% CAGR — Asia Pacific Leads with USD 21.53M
By PW Consulting, 2026-08-05
Worldwide Differential Electrochemical Mass Spectrometry (DEMS) Market — Strategic Outlook for 2026
Executive summary
As DEMS transitions from a niche laboratory tool to a strategic instrumentation class for energy materials and electrocatalysis research, 2026 will be the year executive teams must convert observational insight into operational decisions. PW Consulting’s latest market study — the Worldwide Differential Electrochemical Mass Spectrometry Market — combines a multi-year historical series with a forward-looking model to deliver an evidence-based roadmap for procurement, R&D prioritization, partnership screening, and M&A screening through 2032.
Worldwide Differential Electrochemical Mass Spectrometry Market
Market trajectory at a glance
Our model, anchored on 2025 as the base year, traces a clear growth profile for the DEMS market. The market grew steadily through the 2020–2025 period and enters a sustained expansion phase in the forecast window, driven by accelerating activity in battery R&D, electrocatalysis, CO2 conversion research, and an expanding base of academic and industrial labs. The global market recorded progressive annual growth from 2020 to 2025 and the forecast path through 2032 implies a compound annual growth rate of approximately 9.25% — a rate that signals structural opportunity rather than short-term cyclical demand.
Worldwide Differential Electrochemical Mass Spectrometry Market
- Historical baseline (2020–2025): the market moved from a sub‑forty‑million USD footprint to a mid‑fifty‑million USD scale by the 2025 base year, reflecting increasing instrument adoption and recurring service/reagent spending in advanced laboratories.
- Forecast (2026–2032): the model shows continued uplift across the forecast period, with year‑on‑year growth accelerating as commercial R&D and pilot‑scale electrosynthesis activities expand.
Why 2026 is a pivot year for corporate strategy
Three converging dynamics make 2026 the moment for decisive action:
Worldwide Differential Electrochemical Mass Spectrometry Market
- Acceleration in application demand. Battery lifecycle studies, catalyst screening for fuel cells and CO2 conversion, and early-stage electrosynthesis pilots are increasing instrument utilization and creating need for higher throughput, automation, and integrated data workflows.
- Hardware and integration constraints. Key technical chokepoints — most notably the membrane or nanoporous interface that mediates gas/volatile transfer into the MS vacuum — introduce service and reliability risk that materially affects total cost of ownership and uptime economics.
- Concentration and supplier specialization. The vendor landscape is consolidated at the top end, creating both dependency risk and opportunity for strategic partnerships, aftermarket services, and niche product plays.
Strategic implications for 2026 decision‑making
Our analysis distills five actionable priorities for companies that rely on DEMS-based insight or are contemplating entry into adjacent markets (instruments, consumables, software, or services):
- Embed DEMS into R&D roadmaps with explicit KPIs. Quantify how real‑time gaseous product data will shorten discovery cycles or de‑risk scale‑up experiments. Convert those benefits into headcount and capital allocations for 2026 budgets.
- Lock in operational resilience. Negotiate multi‑year service and consumables contracts that prioritize membrane replacement, rapid swaps, and preventative maintenance. Given the documented susceptibility of membrane interfaces to clogging, service uptime has outsized value relative to initial capex.
- Pursue modularity and software integration. Favor systems designed for in‑situ synchronization with potentiostats and lab data infrastructure. Standardized cabling and software synchronization between potential/current traces and mass signals are now de‑facto expectations for reproducible experiments and automated workflows.
- Design partnership and sourcing strategies. Explore vendor co‑development, shared test‑beds, or preferred supplier agreements to hedge concentration risk and obtain early access to product roadmaps, especially for high‑resolution or integrated in‑situ modules.
- Model service and consumable economics. When calculating ROI, include membrane lifetime, vacuum component maintenance cycles, and software licensing; these line items can dominate lifetime cost for high‑utilization labs.
Competitive landscape — who to watch and why
The competitive set combines established instrument houses and focused innovators offering complementary architectures. Market concentration is meaningful: the top three vendors account for a significant share of revenue, and the top five control an even larger portion, creating differentiated supplier power and potential entry barriers for newcomers.
- Hiden Analytical (Warrington, UK): Known for integrated membrane‑inlet mass spectrometers paired with modular electrochemical cells, Hiden’s product family emphasizes real‑time synchronization of electrochemical parameters and gas/volatile analysis. The vendor’s recent showcase of an electrochemical cell series underlines a push toward tighter instrument‑to‑cell integration and enhanced synchronization with potentiostats.
- Spectro Inlets (Denmark): Specialist systems focused on quantifiable EC‑MS for battery gas evolution and solid‑electrolyte interphase (SEI) studies. Their technical positioning addresses battery R&D labs that demand reproducible gas quantification linked to cycling protocols.
- Liquid Loop (Europe): Modular, microfluidic and thin‑layer architectures targeted at electrocatalysis workflows. Their compact, modular approach is attractive for labs seeking flexible cell formats and rapid reconfiguration between chemistries.
- Shanghai Linglu Instruments (China): Supplier of in‑situ DEMS systems serving both battery DEMS and classical electrochemical cells; competitive on price and regional support for Asian R&D hubs.
Recent product developments — including Hiden Analytical’s early‑2026 product series showcase — demonstrate supplier intent to deepen cell‑to‑MS integration and to reduce friction in time‑synchronized data capture. That trend favors vendors with strong application engineering capabilities and software interoperability with widely used potentiostats and data infrastructure.
Technology and standards dynamics
From a risk and deployment perspective, four technical and regulatory observations matter to corporate planners:
- Membrane interface is the primary hardware bottleneck. Pervaporation and nanoporous membranes are critical but failure‑prone components in volatile electrolyte environments; maintenance strategy and design choices here materially affect uptime.
- Software and cabling standardization is a practical enabler. Integration with potentiostats (for example, leading commercial potentiostat platforms) requires standardized interfaces and synchronization protocols to ensure the temporal alignment of electrochemical and mass signals.
- No DEMS‑specific ISO regime exists today. Usage remains governed by general laboratory, mass spectrometry, and electrochemistry safety guidelines rather than a sectoral ISO standard — a fact that increases the importance of supplier audits and internal SOPs for regulated customers.
- Research‑use‑only positioning. DEMS instruments are explicitly research tools; they are not intended for clinical diagnostics or production‑scale continuous monitoring without additional validation and engineering changes.
What the PW Consulting report contains (practical, operational value)
We designed the report as a decision‑orientated playbook for executives, procurement teams, and R&D leaders. Key deliverables include:
- Market model and scenario analysis: a bottom‑up revenue model from 2020 through 2032 with alternative uptake scenarios and sensitivity to hardware reliability and lab deployment rates.
- Vendor benchmarking: qualitative and quantitative supplier profiles, product architecture mapping, integration readiness assessments, and a service‑capability scorecard.
- Procurement and CAPEX templates: total cost of ownership calculators customized to high‑, medium‑, and low‑utilization lab profiles, including consumables, service, and downtime cost layers.
- Use‑case playbooks: deployment blueprints for battery R&D, electrocatalysis screening, and CO2 conversion experiments, each with recommended cell formats, throughput estimates, and expected data outputs.
- Risk and mitigation matrices: practical mitigations for membrane failure, vacuum pumps, software interoperability, and supplier concentration, plus a three‑level escalation ladder for operational incidents.
- Deal and partnership playbook: templates for supplier‑cofunded R&D, evaluation lab agreements, and structured supplier roadmaps to secure preferential access to beta instruments and prioritized support.
How to use this intelligence in 90, 180, and 365 days
- 90 days — Audit and baseline: complete an inventory of existing DEMS assets, map utilization, and calculate current total cost of ownership using our provided template.
- 180 days — Negotiate and pilot: issue RFPs that include service uptime SLAs and membrane replacement clauses; launch a pilot with a preferred vendor to validate integration with lab data systems.
- 365 days — Scale and secure: finalize multi‑year service agreements, implement automated data synchronization with potentiostats, and evaluate forward integration (e.g., custom cells or co‑development) for strategic advantage.
Trailer note: what we’re withholding here and why
In keeping with the “trailer” principle — provide substantive, actionable intelligence while preserving the proprietary depth of our full dataset — this public summary omits the granular regional and application split tables, detailed revenue-per‑vendor line items, and the full sensitivity matrices. Those datasets and downloadable templates are available only in the complete report and interactive spreadsheet package.
Conclusion and next steps
DEMS is evolving from a specialist measurement technique into a strategic enabler for energy and electrosynthesis R&D. The market’s mid‑single‑digit to low‑double‑digit CAGR and the observed supplier concentration imply both risk and structured opportunity for companies that act deliberately in 2026. PW Consulting’s report converts complexity into executable choices — from procurement and maintenance strategies to vendor selection and partnership design — enabling organizations to capture scientific insight as a persistent competitive advantage.
To access the complete dataset, vendor scorecards, and the executable toolset referenced above, please consult the full PW Consulting report or contact our industry practice for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Differential Electrochemical Mass Spectrometry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Grinding Machine with Moving Table Market to Reach USD 4,309.35 Million by 2032 at a 4.62% CAGR — Asia‑Pacific Leads with USD 1,384.02 Million
By PW Consulting, 2026-08-05
Worldwide Grinding Machine With Moving Table Market — Strategic Outlook for 2026: A PW Consulting Preview
As companies plan capital allocation, factory modernization, and M&A strategies for 2026, PW Consulting’s latest market research on the Worldwide Grinding Machine With Moving Table market delivers an indispensable, action-oriented intelligence package. This preview highlights the research’s strategic value for executives and investors while deliberately preserving the detailed segmentation tables and proprietary split analytics that are available only in the full report.
Worldwide Grinding Machine With Moving Table Market
Why this market matters in 2026
Grinding machines with moving tables remain a cornerstone technology for high-precision metalworking in heavy industry, automotive, aerospace, energy and medical device supply chains. Our analysis shows a steady recovery and modernization cycle following 2020–2025, driven by renewals of installed bases, reshoring of critical manufacturing, and increasing demand for tight-tolerance components suitable for automated and unattended production. With base-year 2025 coverage and a forecast horizon to 2032, the report positions decision‑makers to align capex, service networks, and product roadmaps against realistic growth paths and risk scenarios.
Worldwide Grinding Machine With Moving Table Market
Market snapshot — clear trajectory, defined pace
Using historical data (2020–2025) as the foundation, PW Consulting projects the global market to expand at a compound annual growth rate (CAGR) of approximately 4.62% through 2026–2032. On an absolute basis, the market grows from an assessed level in 2025 to a materially larger footprint by 2032, reflecting continued investment in precision grinding capacity and the replacement of legacy equipment with digitally enabled, energy‑efficient systems. This steady, mid-single-digit growth underpins a competitive environment where both incumbents and focused challengers can win by executing on technology, aftermarket services and systems integration.
Worldwide Grinding Machine With Moving Table Market
Key dynamics shaping supplier and buyer strategy
- Raw-material and input-cost volatility: Iron and steel input prices and scrap market fluctuations have direct bearing on OEM bill-of-materials and the pricing of cast beds and tables. Supply chain tightness and recycled-metal availability are forcing both design optimization and strategic sourcing reviews across the value chain.
- Industry 4.0 and automation: Adoption of connected controls, predictive maintenance, and digital twins is transitioning grinders from purely mechanical assets into data-rich nodes of smart factories. Buyers prioritizing unattended operation and cycle-time consistency are premium customers for OEMs with proven IoT stacks and integration partners.
- Energy and sustainability mandates: Energy-efficiency requirements and customers’ carbon targets are accelerating the development of lower-power drives, optimized cooling circuits, and material-light structural designs. These factors are influencing purchase criteria and total cost of ownership (TCO) calculations.
- Service and lifecycle monetization: With the installed base aging in many mature markets, aftermarket services, retrofits, and digital up‑grades represent outsized profit pools. Suppliers that bundle hardware, lifecycle services and subscription software gain recurring revenue and closer customer lock-in.
Actionable implications for 2026 decision-making
- OEMs: Prioritize modular platforms that support hybrid operations (grinding + turning/milling) and retrofit pathways for legacy customers. Investing selectively in hydrostatic bearings, high‑stiffness beds and connected controls will pay off when bidding for higher-margin aerospace, energy and medical programs.
- Component suppliers: Lock in long-term contracts for castings and specialty steel while pursuing partnerships to offer certified recycled-material options. Material sourcing resilience is now a strategic differentiator, not just a cost issue.
- Manufacturers / end users: Emphasize TCO modeling that internalizes energy consumption, predictive maintenance savings and the value of reduced downtime from unattended grinding. For buyers, choosing platforms with clear upgrade paths mitigates obsolescence risk over multi-year programs.
- Investors & M&A advisors: Look for targets with strong aftermarket positions, proven digital offerings and niche precision capabilities. Market concentration is meaningful but not prohibitive — mid-sized specialists with differentiated technology or service models can scale through platform plays and geographic expansion.
Competitive landscape — who matters and why
The market is characterized by a mix of specialized niche manufacturers and broader machine tool groups. Market concentration metrics show a modestly consolidated top tier, but still leave room for regional champions and technology-focused entrants to expand. PW Consulting profiles the competitive set to surface where capability overlaps, white-space opportunities and collaboration prospects exist. Highlights include:
- Danobat (Elgoibar, Spain) — Known for vertical grinding machines with moving table designs that enable hybrid operations (grinding, hard turning, milling and drilling in a single setup). Danobat emphasizes large workpiece handling and sub-micron precision, making it a pick for gear and large-component manufacturers. Recent customer deliveries in early 2026 underscore continued demand from precision gearmakers.
- Herkules (Siegen, Germany) — Specializes in roll grinders and heavy-duty travelling-table designs with automation for loading/unloading and steady-rest systems. Strength lies in high‑precision grinding of large rolls and cylindric components for steel, paper and rubber industries.
- Robbi Group (Zimella, Italy) — Offers cylindrical grinding with moving tables and options for robot integration; a flexible partner for medium-series precision grinding in diverse workshops.
- Morara / Grinding Technology (Italy) — Supplies heavy-duty external/internal cylindrical grinding machines; well-positioned for railway axle and similar applications where robustness and throughput are critical.
- HMT Machine Tools (Bengaluru, India) — Competes on cost-to-performance in horizontal spindle reciprocating table surface grinders; attractive to price-sensitive regional markets undergoing modernization.
- JTEKT Machinery (Japan / Americas) — Brings high-production precision grinders and moving-table compatible cylindrical models, with performance and accuracy suited to automotive and bearing production lines.
- European specialists (Gioria, AZ spa, Kehren, UNITED GRINDING / MÄGERLE) — These firms collectively cover a spectrum from conventional table-moving cylindrical grinders to large rotary-table centers with hydrostatic tables and multi-ton capacities for turbine and coupling components.
- Smaller and regional players (Dowell, LGB Scop, others) — Offer adaptable rotary table and vertical spindle variants; typically compete on local service, price, or niche capability.
Our competitive analysis combines capability benchmarking, product roadmaps, installed‑base assessment, and aftermarket strength. A notable recent development — a March 2026 Danobat customer expansion — illustrates the continuing relevance of high‑spec universal OD grinders in precision gearmaking, reinforcing themes of targeted fleet upgrades and modular multiprocess capability.
What PW Consulting’s full report delivers (operationally useful)
- Verified historical dataset (2020–2025) and forward-looking market sizing to 2032 with scenario variants and sensitivity to input-price shocks and automation adoption rates.
- Material-cost stress-testing models that quantify impacts of iron and scrap price moves on OEM cost structures and equipment ASPs.
- Technology adoption curves for Industry 4.0 features: connectivity, condition monitoring, and automation readiness assessments for leading product lines.
- Vendor capability matrices summarizing machine class (vertical/horizontal, cylindrical/surface), load capacities, precision features, and retrofit pathways — with executive recommendations for supplier selection by buyer type.
- Aftermarket and services playbook: margin profiles, service-bundling strategies, refurbishment and retrofit economics, and go-to-market templates.
- Acquisition targets and partnership candidates mapped by strategic need: digital capability, geographic footprint, or sector specialization.
How to use the preview and next steps
This press summary is a strategic preview designed to inform planning conversations and frame board-level questions for 2026. It demonstrates the depth of our modelling, scenario analysis and vendor intelligence while withholding the proprietary segmentation matrices and exact split data that are core to tactical procurement and M&A execution. To translate this intelligence into prioritized action — including customized TCO models, supplier shortlists, and integration roadmaps — PW Consulting recommends commissioning a tailored workshop or purchasing the full market study.
Final recommendations for executives
- Start 2026 by aligning capex and retrofit budgets to multi-year replacement curves rather than short-term price cycles; incremental innovation in controls and energy efficiency yields outsized TCO improvements.
- Assess suppliers not only on machine specs but on digital roadmaps and aftermarket capability — who can deliver predictive maintenance and unattended operation at scale?
- Consider strategic vertical plays: retaining in-house competence for hard-to-outsource processes (e.g., aerospace components) while outsourcing high-volume, lower-complexity volumes to partners that offer integrated automation.
- Use the full PW Consulting dataset to stress-test acquisition targets and to structure earn-outs that align vendor incentives with aftermarket service expansion.
For complete datasets, actionable segment splits, vendor scorecards and bespoke advisory options, PW Consulting’s full Worldwide Grinding Machine With Moving Table Market report provides the next step. Contact our research team to access the report and schedule a briefing tailored to your 2026 strategic priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Grinding Machine With Moving Table Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


