



Category: market research
PW Consulting Predicts 6.5% CAGR for Worldwide Complicated UTI Treatment Market Through 2032
By PW Consulting, 2026-08-05
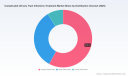
Worldwide Smart Solar Urban Equipment Market — Strategic Preview for 2026
PW Consulting’s newest market study, Worldwide Smart Solar Urban Equipment Market (base year 2025; forecast 2026–2032), equips executives with the operational intelligence they need to convert market momentum into defensible growth. The market is entering an inflection window: after expanding from roughly USD 510 million in 2020 to USD 1,142.8 million in 2025, our modeled trajectory reaches an expected USD 1,342.9 million in 2026 and continues to accelerate to roughly USD 3,043.7 million by 2032, implying a 2026–2032 compound annual growth rate (CAGR) of 15.02% (USD, revenue in Millions). For leaders planning 2026 investments, this is not a slow-and-steady trend — it is a scale-up opportunity that rewards timely, disciplined choices in product design, procurement, partnerships and policy engagement.
Worldwide Smart Solar Urban Equipment Market
Why this preview matters for 2026 decisions
-
Action window: 2026 is the first full planning year after our 2025 base — budgets, pilot cycles and procurement pipelines that start this year will capture the most value as the market compounds beyond the USD 1.3 billion mark.
Worldwide Smart Solar Urban Equipment Market -
Strategic inflection: rapid unit deployment, hardware-as-a-service models and IoT-enabled monetization are converging. Firms that align product roadmaps with urban authorities’ financing cycles can convert earlier adopter pilots into city-wide rollouts.
Worldwide Smart Solar Urban Equipment Market -
Risk-reward imbalance: supply chain friction and regulatory headwinds mean cost and timeline contingencies must be baked into 2026 plans — the upside is material, but so are avoidable execution failures.
What PW Consulting’s report delivers — practical outputs for 2026 execution
-
Executive decision packs: concise investment memos and board-ready slide decks that translate market growth scenarios into capital allocation recommendations and ROI timelines.
-
Go-to-market playbooks: target-account frameworks, pilot-to-scale pathways, procurement specs for municipalities, and standardized KPIs for performance-based contracts.
-
Vendor & technology scorecards: comparative assessments of product families, IoT platforms, warranty structures, and total cost of ownership (TCO) models for both capex and service-led commercial models.
-
Supply chain & sourcing playbook: component sourcing maps, concentration risk heatmaps, hedging strategies for PV module and battery volatility, and supplier qualification checklists.
-
Regulatory and incentive navigator: translated implications of trade measures, local grants, and permitting friction — including mapping of relevant incentive programs and grant windows for municipal projects.
-
Pilot design kits and procurement templates: modular pilot bundles, measurement & verification (M&V) protocols, and contract language aligned with public procurement rules to accelerate award and deployment.
-
Scenario modeling tools: sensitivity analyses incorporating raw material price variance, duty scenarios, and installation labor constraints so finance teams can stress-test business cases.
Note: the full report contains detailed regional/type/application splits, granular vendor revenue benchmarks and segment-level price curves. Consistent with our “preview” approach, those core subsegment figures are available in the full report and are intentionally withheld here to guide you to the source for actionable, licensed data.
Macro dynamics shaping 2026 strategy
-
Component pricing and margins: module and battery markets stabilized in 2025–2026 versus prior volatility, yet regional price differentials persist. Public utility-scale benchmarks and module spot prices reported by recognized research bodies remain essential inputs for procurement clauses and long-lead sourcing.
-
Trade and regulation: import duties and anti-dumping measures are active levers in several markets. Duty regimes that changed in 2025 create procurement leakage and timing considerations for 2026 tenders; procurement teams must model duty exposure into bid evaluation.
-
Deployment scale and urban demand: municipal infrastructure modernization, rising urban sustainability mandates, and demand for resilient off-grid lighting and urban furniture are primary demand generators. Funding windows and stimulus mechanisms — local grants and technical assistance programs — materially change project bankability at the municipal level.
-
Service and data monetization: IoT-enabled assets (connectivity, sensors, ad/sponsorship surfaces) are creating new recurring-revenue pathways that can transform low-margin hardware into attractive service businesses.
Competitive landscape — positioning the key players
The market remains fragmented: our concentration metrics indicate the top three vendors account for a modest share of global revenues (CR3 ~21.4%), and the top five reach roughly a third of the market (CR5 ~32.65%). This fragmentation reflects a healthy innovation ecosystem but also signals consolidation potential as projects up-size and integrated solutions gain preference.
-
EnGoPlanet Energy Solutions LLC (New York, USA) — Strengths: integrated IoT stacks, value-added services (Wi‑Fi, environmental sensors, security cameras) and subscription-based lighting-as-a-service models. Strategic implication: incumbents with platform capabilities will be prime partners for city digital twin initiatives; vendors should prioritize platform interoperability and recurring-revenue contracts to deepen lifecycle margins.
-
SOLTECH LLC (Emeryville, CA, USA) — Strengths: high-efficacy off-grid lighting optimized for reliability and rapid deployment. Recent catalog emphasis on event-scale, fast-deploy installations highlights a go-to-market niche (events, temporary urban upgrades). Strategic implication: suppliers targeting infrastructure integrators should emphasize proven reliability and reduced civil works.
-
Archasol (global supplier) — Strengths: broad portfolio of solar urban furniture for mains-free public spaces. Strategic implication: channel partnerships and OEM relationships will accelerate adoption in regions with limited grid access or high street furniture demand.
-
SEEDiA (Poland) — Strengths: bench-based IoT platform (InCity.io) and integrated asset management. Strategic implication: platform-enabled vendors can cross-sell into transit and shelter programs; look for M&A or white-label partnerships to scale software monetization.
-
Sunna Design (France / North America) — Strengths: energy management systems and autonomous street lighting solutions with proven rural and urban deployments. Strategic implication: leaders with system-level energy management capabilities will win large municipal tenders that prize lifecycle performance and resilience.
-
Strawberry Energy (Serbia) — Strengths: modular, highly customizable benches and urban furniture with strong design differentiation. Strategic implication: design-led differentiation retains traction in high-visibility urban projects where aesthetics and user experience matter.
-
Finbin (Finland) — Strengths: solar-powered smart waste bins with compacting and sensing capabilities. Strategic implication: adjacent smart-city verticals (waste, parking, micro-mobility) are logical routes to broaden addressable market and create bundled procurement offers.
Recommended 2026 playbook for market leaders and new entrants
-
Prioritize pilots that validate both hardware performance and recurring software revenue. Design pilots with procurement-friendly success metrics (uptime, energy yield, sensor fidelity) and defined scale triggers.
-
Adopt dual sourcing and price-indexed contracts for critical PV and battery components. Use multi-year supply agreements with contingent volume tiers to balance cost and inventory risk.
-
Build product families around services: offer basic hardware, premium IoT management, and a pure service (lighting-as-a-service) tier to capture diverse municipal procurement preferences.
-
Invest in interoperability and open APIs. Cities prioritize solutions that integrate with existing smart city platforms; platform lock-in is a barrier to procurement and to long-term value creation.
-
Engage regulators and local funders early. Where grant windows and local incentive programs exist, structured engagement (coding technical assistance offers into bids, co-financing proposals) accelerates award likelihood.
-
Use design and urban engagement to justify premium pricing in visible urban corridors. For commoditized corridors, compete on lifecycle cost and warranty-backed performance.
-
Prepare M&V and data governance frameworks prior to deployment. Cities will demand transparency on performance; vendors that demonstrate measurable outcomes and privacy-compliant data handling will win trust faster.
Immediate tactical moves for Q1–Q3 2026
-
Lock in long-lead PV and battery volumes with flexible delivery clauses tied to duty scenarios — this reduces exposure to trade actions while maintaining competitive pricing.
-
Run two parallel pilot tracks: one for rapid-deploy, high-visibility assets and one for high-throughput municipal infrastructure pilots measuring TCO over 24 months.
-
Establish at least one strategic partnership with an IoT platform or public works integrator to accelerate municipal procurement approvals.
-
Allocate R&D spend to modular product lines that enable faster localization and lower installation time — time-to-service is increasingly a procurement differentiator.
Closing: capture growth without overexposure
The smart solar urban equipment market presents a compelling growth runway: a return-to-scale trajectory that rewards speed, platform orientation, and disciplined risk management. For 2026, PW Consulting recommends a balanced program of selective scale pilots, supplier hedging, platform partnerships and targeted regulatory engagement. Our full report provides the granular segmentation, vendor scorecards, dynamic scenario models and procurement templates that enable teams to operationalize these recommendations and validate project-level business cases.
For access to the complete dataset, proprietary segment-level forecasts and PW Consulting’s ready-to-deploy procurement templates, visit the full report page. The preview above is curated to guide your immediate strategic choices; the licensed report contains the detailed figures and tools your procurement, product and finance teams will need to execute with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Solar Urban Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Non‑Filtering Cloth Vacuum Filters Market to Grow from USD 254.4 Million in 2025 to USD 378.74 Million by 2032 at a 5.85% CAGR
By PW Consulting, 2026-08-05
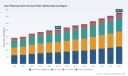
Worldwide Ovum Egg Banking Market: Strategic Imperatives for 2026 — PW Consulting Insights
PW Consulting today publishes a strategic briefing drawn from its new Worldwide Ovum Egg Banking Market report (base year 2025, forecast 2026–2032). The global ovum egg banking sector is moving from niche clinical service to an investable, technology-enabled healthcare vertical. Our analysis quantifies a clear growth trajectory—anchored by a 12.48% CAGR across the forecast window—and translates that trajectory into actionable choices for corporate leaders, investors, and clinical operators preparing strategy for 2026 and beyond.
Worldwide Ovum Egg Banking Market
Why 2026 is a Strategic Pivot
-
Macro momentum is converging with micro catalysts. After robust expansion through 2020–2025, total industry revenue crosses important scale thresholds in 2025 and is projected to more than double by the end of our forecast period. This creates a widened opportunity set for platform plays, specialized providers, and adjacent healthcare companies seeking to enter reproductive specialties.
Worldwide Ovum Egg Banking Market -
Regulatory and clinical legitimacy is strengthening. Professional society guidance and practice-documents issued in the 2025–2026 window clarify the role of planned oocyte cryopreservation and fertility preservation, reducing clinical uncertainty and supporting broader adoption among patients and referring clinicians.
Worldwide Ovum Egg Banking Market -
Market structure invites consolidation and differentiation. Measured concentration remains low compared with mature medtech and specialty pharma markets, signaling acquisition targets and strategic partnerships for scale-driven operators.
Key Quantitative Signals (headline-level)
-
Base-year validation: PW Consulting’s model uses 2025 as the analytical anchor year, integrating historical trends (2020–2025) and a bottom-up build to inform forward estimates.
-
Growth profile: The sector is modeled to expand at a compound annual growth rate (CAGR) of 12.48% across the 2026–2032 forecast period, reflecting rising uptake, improved outcomes, and expanding payer and employer interest in fertility preservation services.
-
Scale implications: With revenue scale increasing materially during the forecast window, investors should expect larger deal sizes, more institutional capital flows, and greater interest from healthcare platform consolidators by 2026–2028.
What the Report Contains — Practical, Transaction-Focused Intelligence
-
Robust market model: Our proprietary model provides a consolidated market-size curve, sensitivity scenarios, and revenue levers modeled across clinical demand drivers, technology adoption, and payer behavior (reported in USD Million).
-
Decision-grade forecasts: Scenario-based forecasts (base, upside, downside) calibrated to regulatory shifts, reimbursement scenarios, and patient adoption curves to support investment memos and board-level decision-making.
-
Competitive benchmarking: Strategic profiles, capability maps, and relative positioning across clinical service providers, cryobanks, and integrated fertility networks to identify white-space and defensive priorities.
-
Go-to-market playbooks: Practical recommendations for clinic networks, cryobanks, and new entrants covering pricing strategy, channel partnerships, employer and payer engagement, and telehealth-enabled patient acquisition.
-
M&A and partnership framework: Target identification criteria, valuations guidance (multiples frameworks and revenue sensitivities), integration risks, and five defensive and offensive deal archetypes.
-
Regulatory & reimbursement navigator: A pragmatic matrix of jurisdictional considerations, coding inputs, and reimbursement touchpoints to support commercialization planning.
-
Operational excellence tools: Recommendations for laboratory standardization, cold-chain logistics, quality management, and patient data capture that drive unit-economics improvements.
Dynamics Shaping 2026 Strategy
-
Clinical authority and ethics: Recent updates from professional bodies have reframed oocyte cryopreservation from experimental to a recognized option under both medical and elective contexts. PW Consulting’s report examines how this evolving guidance changes referral patterns, informed consent practices, and clinical counseling — critical inputs for 2026 patient acquisition plans.
-
Reimbursement friction and coding: Reimbursement remains uneven. While procedural CPT codes exist for cryopreservation and thawing (including widely used codes for mature oocyte cryopreservation and thawing), donor egg procurement and donor-bank fees are often out-of-pocket for recipients. Our advisory identifies where payer pilots, employer fertility benefits, and state-level mandates can materially alter revenue mix and unit economics.
-
Fragmentation-to-consolidation runway: Concentration metrics indicate a fragmented competitive field — a dynamic that favors early consolidators or well-funded platforms that can invest in standardized lab processes, digital patient engagement, and multi-clinic logistics to capture scale advantages.
-
Clinical outcomes and evidence generation: Clinical milestones being reported by active banking programs — births from frozen oocytes and annual cycle volumes — serve as credibility multipliers. Our research highlights how operators can use outcomes data to negotiate reimbursement, drive referral relationships, and command premium pricing.
Competitive Landscape — Who Matters
PW Consulting’s competitive analysis profiles the leading clinical networks, dedicated cryobanks, and hybrid service providers operating at scale. Representative names include long-established international cryobanks, US-based cryopreservation firms, integrated fertility networks, and clinic-led banking programs. Each profile in the report addresses business model, geographic reach, channel strategy, and capability gaps that create near-term opportunity.
-
Cryos International A/S — an international donor egg banking specialist with distribution capabilities that illustrate cross-border logistics and regulatory coordination as a commercial advantage.
-
California Cryobank — a US-headquartered provider combining donor services with cryopreservation offerings, representing a model of brand-led market access.
-
Donor Egg Bank USA and Fairfax EggBank — specialized donor-focused players with searchable databases and clinic distribution networks.
-
ReproTech and Cryo-Cell International — providers that underline the importance of long-term storage infrastructure and compliance rigor.
-
Clinic networks such as CCRM Fertility, IVIRMA Global, Shady Grove Fertility, Kindbody, Boston IVF, Monash IVF Group, Genea, and others — these clinic-led programs demonstrate the integrated care model where egg banking sits alongside broader fertility offerings and patient acquisition channels.
-
Extend Fertility — an example of a consumer-facing model emphasizing affordability and employer benefit integration.
Strategic Playbook for 2026
-
For investors: Prioritize targets with standardized lab protocols, digital patient funnels, and contractual relationships with clinic networks. Look for assets where incremental capital can materially compress costs per storage unit and expand distribution reach.
-
For clinic operators: Invest in outcome-data capture and interoperable IT that supports referrals and reimbursement conversations. Consider hybrid partnerships with dedicated cryobanks to achieve scale in storage and logistics while maintaining clinical control.
-
For cryobanks: Differentiate through vertical integration (logistics + storage + registry services) and value-added offerings such as specimen analytics and long-term follow-up. These services improve retention and create upsell pathways.
-
For payers/employers: Design pilots with outcome-linked contracting and bundled pricing for fertility preservation in oncology pathways and high-risk medical indications to accelerate evidence generation and cost predictability.
Risks and Mitigations
-
Regulatory variability: Jurisdictional differences in practice scope and donor regulation can affect cross-border models — mitigate through localized compliance playbooks and staged market entry.
-
Reimbursement exposure: Out-of-pocket dependence for donor egg procurement compresses addressable market — mitigate via employer benefit integrations and payer pilots.
-
Operational risk: Laboratory quality and long-duration cold-chain reliability are single points of failure — prioritize investments in quality management systems, redundancy, and certification.
-
Reputational risk: Ethical scrutiny around elective preservation necessitates transparent patient counseling and outcome reporting aligned with professional society guidance.
How PW Consulting’s Report Helps Executives in 2026
-
Fast-track decisions: Use our scenario models and sensitivity tables to stress-test investment theses in under an hour, instead of months of primary due diligence.
-
Pinpoint growth levers: Identify which commercial initiatives (employer benefits, clinic partnerships, international distribution) are likely to move the needle for your business model.
-
Structure deals: Access valuation frameworks and integration checklists calibrated to the egg banking value chain.
-
Operationalize compliance: Leverage our regulatory navigator to prioritize markets and minimize time-to-launch risk.
Final Observations and Next Steps
The ovum egg banking market is at a rare inflection: clinical validation and patient demand are aligning with scalable business models and technology-enabled logistics. For organizations that move decisively in 2026—whether through targeted M&A, partnership builds, or product and process investments—the payoff is likely to be significant as the market scales at a mid-double-digit CAGR.
PW Consulting’s full report contains the complete datasets, models, granular market segmentation, company benchmarking tables, and step-by-step execution guidance designed to support boardroom decisions in 2026. To access the complete intelligence and the appendices (including detailed methodology, sensitivity models, and company profiles), please visit PW Consulting’s report page for the Worldwide Ovum Egg Banking Market.
For detailed analysis of this topic, please visit the official page: Worldwide Ovum Egg Banking Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Cooling Apparel Market Poised for Rapid Growth at 8.99% CAGR, New Report Shows
By PW Consulting, 2026-08-05
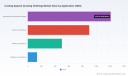
PW Consulting: Strategic Preview — Worldwide Cooling Apparel Market Report (2026 Outlook)
PW Consulting today publishes an executive preview of its in-depth market study on the Worldwide Cooling Apparel market, designed to equip senior executives, product leaders, and corporate strategists with the actionable intelligence required to make high-consequence decisions in 2026. The market is moving rapidly: from a mid-sized segment in 2020 it expanded materially through 2025 and, under PW Consulting’s baseline forecast, is projected to more than double by the end of the 2026–2032 forecast window. Our analysis shows the market accelerating with a compound annual growth rate (CAGR) of 8.99% across the forecast period, reflecting a structural shift in consumer behavior, occupational requirements, and climate-driven demand.
Worldwide Cooling Apparel (Cooling Clothing) Market
Why this matters for 2026 strategic planning
-
Risk and Opportunity Converge: The intersection of more frequent heatwaves, stricter chemical regulations, and material-cost volatility requires firms to simultaneously de-risk supply chains and pursue new revenue streams.
Worldwide Cooling Apparel (Cooling Clothing) Market -
Acceleration of Commercialization: What was once a niche performance category is entering mainstream adoption across consumer sportswear, industrial PPE, healthcare, and defense procurement cycles—raising stakes for first-mover advantage and rapid scale execution.
Worldwide Cooling Apparel (Cooling Clothing) Market -
Technology Diversity: Multiple technological pathways—evaporative systems, phase-change materials (PCMs), air-cooled systems, and active liquid approaches—create a multi-modal competitive field where product architecture and system integration matter as much as textile formulation.
Headline market trajectory (macro view)
Our topline sizing captures both the historical ramp and near-term outlook. The sector grew steadily through the early 2020s and reached a clear inflection point by 2024–2025 as product portfolios broadened and distribution channels matured. PW Consulting’s modeling places the market on a sustained growth path from the 2026 base year into 2032, achieving a projected market size that underscores meaningful commercial scale for suppliers, licensors, and OEMs.
Key demand drivers and dynamics
-
Climate and public health: Frequency of heatwave events has risen sharply since 2020—our synthesis of climate and consumer-data sources indicates environment-driven demand is one of the primary growth vectors, with notable adoption among outdoor professionals, industrial workers, and organized sports.
-
Occupational safety and regulation: Industrial purchasers are beginning to specify cooling capabilities as part of heat-stress mitigation protocols; this creates recurring B2B demand distinct from consumer fashion cycles.
-
Material and cost pressure: Raw material volatility—illustrated by recent polyester staple-fiber price increases—directly impacts cost structures for crop-to-garment OEMs and can squeeze margins absent tactical procurement responses.
-
Regulatory friction: Regulatory changes (for example, restrictions on certain microencapsulated PCMs under current chemical frameworks) raise product-compliance costs and development timelines. These tailwinds and headwinds make compliance strategy central to commercialization planning.
-
Labor and sourcing shifts: Rising manufacturing wages in key hubs and geopolitical supply-chain reconfiguration are accelerating conversations on nearshoring, capacity diversification, and automation adoption.
Report contents — what executives will find inside
PW Consulting’s full report is designed to be operational from day one. Highlights include:
-
Proprietary market sizing and 2020–2032 forecasts, with scenario models that stress-test demand under thermal-climate and regulatory permutations.
-
Technology roadmaps and adoption timelines for evaporative fabrics, PCMs, air-cooled apparel, and liquid-cooling systems—plus an assessment of technical integration risk and certification requirements.
-
Commercial playbooks: go-to-market segmentation by channel, pricing templates for OEM/B2B contracts, recommended margin strategies across direct-to-consumer and institutional channels.
-
Supply-chain playbook: supplier shortlists, dual-sourcing templates, cost-pass-through models, and nearshoring decision frameworks tailored to 2026 procurement priorities.
-
Regulatory and compliance dossier addressing REACH-like regimes, testing protocols for encapsulated technologies, and steps to mitigate intellectual-property exposure.
-
M&A and partnership intelligence: prioritized opportunity maps for consolidation, strategic minority investments, and licensing collaborations—backed by valuation sensitivities tied to unit economics and market-share scenarios.
-
Operational tools: RFP templates, pilot-program design checklists, and an innovation-evaluation scorecard to shorten vendor selection cycles.
Competitive landscape — synthesis and strategic implications
The competitive set is a composite of global sportswear giants, specialist niche brands, and technology-focused apparel makers. Large footwear and apparel incumbents bring marketing scale and distribution reach, while specialized players own differentiated technical IP or niche channel relationships. Recent product moves illustrate the direction of travel:
-
Legacy sportswear brands continue to invest in fabric science and high-visibility product launches to protect and extend core brand equity. These firms use performance lines to defend market share in mass channels and to anchor premium pricing tiers.
-
Mid-market specialists and start-ups are winning penetration in targeted verticals—industrial PPE, military contracts, and endurance sports—by pairing focused technical claims with rapid iteration and lean manufacturing partnerships.
-
Notable product actions in 2025 underscore this bifurcation: major brands announced next-generation cooling fabrics at global trade shows, while niche players extended lightweight, water-activated products emphasizing sustainability and price accessibility.
-
From a strategic vantage, incumbents are likely to pursue three parallel moves in 2026: expand proven performance lines, selectively acquire or partner with technology providers, and use channel segmentation to separate mass-market and institutional offerings.
Operational risks and near-term strategic choices
-
Material-cost volatility: Companies that hedge raw material costs, diversify fiber sources, or redesign product constructions to reduce high-cost inputs will protect margins better than peers.
-
Regulatory compliance: Firms relying on encapsulated PCMs or emerging nanoparticle-based agents should prioritize compliance testing and consider migration pathways to accepted alternatives to avoid product delisting risk in regulated markets.
-
Channel and margin management: The shift from single-season consumer skews to recurring institutional procurement requires reconfigured sales organizations and pricing models to capture lifecycle value.
-
IP and partner selection: Licensing or co-development agreements can accelerate time-to-market but require disciplined IP governance to prevent technology leakage and commoditization.
Strategic recommendations for 2026
-
Build a modular technology stack: Avoid exclusive dependence on one cooling mechanism. A multi-technology product portfolio increases resilience to regulation and raw-material shocks.
-
Prioritize industrial and institutional B2B pipelines: These channels offer higher-volume, lower-marketing-cost sales and can be a stabilizing revenue base as consumer cycles fluctuate.
-
Lock down compliance early: Invest in third-party testing, toxicology reviews, and pre-submission consultations with regulators in priority markets.
-
Optimize procurement and manufacturing footprint: Run dual-sourcing pilots and evaluate nearshoring for critical SKUs to reduce lead times and currency/transportation exposure.
-
Adopt an M&A playbook: For firms seeking rapid scale or technology access, prioritize tuck-ins that supply manufacturable IP and immediate channel access over speculative platform plays.
How PW Consulting’s report helps decision-makers
This report is purpose-built to shorten strategy cycles. It converts raw market growth signals into prioritized actions: what to pilot this quarter, what to hedge in procurement, and which partners to approach for co-development before a major procurement window. We layer quantitative forecasts with qualitative supplier intelligence and executable templates so that leaders can move from insight to contract within weeks—not months.
Call to action
PW Consulting’s full Worldwide Cooling Apparel market report contains the complete data tables, regional and application-level segmentation, supplier scorecards, and downloadable scenario models required to operationalize the 2026 strategy outlined above. The preview you’ve just read demonstrates the type of strategic depth and pragmatic toolset included; the full report retains detailed subsegment figures, country-level breakdowns, and proprietary vendor benchmarking that are intentionally withheld here to preserve client value.
For organizations planning product launches, sourcing reconfigurations, or targeted M&A in 2026, the full report is the recommended next step. Contact PW Consulting to request the full report package, a tailored executive briefing, or a 90-minute strategy workshop to translate these findings into a 12-month executable roadmap.
For detailed analysis of this topic, please visit the official page: Worldwide Cooling Apparel (Cooling Clothing) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Email Address Verification Service Market Set to Expand at a 13.45% CAGR Through 2026–2032, Boosting Global Data Accuracy
By PW Consulting, 2026-08-05
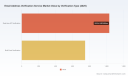
PW Consulting Releases Strategic Preview: Worldwide Email Address Verification Service Market (Base Year 2025) — What Decision‑Makers Need for 2026
Why this report matters now: accelerated growth, regulatory pressure, and the operational imperative for cleaner identity data
PW Consulting’s latest market study on the Worldwide Email Address Verification Service Market (base year 2025) arrives at a critical inflection point for enterprises that rely on email as a core channel for customer engagement, lead generation, and identity verification. The market is expanding rapidly: our model shows the market growing from a mid‑2020s base into a multi‑billion dollar opportunity by the end of the decade, driven by a compounded annual growth rate (CAGR) of approximately 13.45% through the 2026–2032 forecast window. That pace of expansion, combined with mounting privacy and cybersecurity obligations, makes 2026 a year for decisive strategy — for technology selection, sourcing, compliance budgeting, and M&A consideration.
Worldwide Email Address Verification Service Market
What this preview reveals — and what we intentionally withhold
This announcement summarizes the strategic conclusions and practical implications from the full PW Consulting report while deliberately withholding the granular segmentation tables and proprietary unit‑level forecasts that corporate buyers and investors depend on. We aim to demonstrate the analytical rigor underpinning our recommendations and to show how the macro trends will shape supplier and buyer behavior in 2026 — while reserving the complete, actionable segment data behind the report paywall for subscribers.
Worldwide Email Address Verification Service Market
Key macro takeaways
- Market momentum: After a steady increase through the early 2020s, the market crosses a notable inflection in 2026 as higher deliverability expectations, tighter data controls, and broader adoption of automated validation APIs accelerate vendor adoption across sectors.
- Scale and concentration: The market exhibits moderate concentration — the top three players account for roughly one‑third of value, and the top five approach half the market — creating a competitive landscape where mid‑tier innovators can scale quickly if they demonstrate superior accuracy, compliance posture, or integration economics.
- Regulatory overlay: Regulation remains a primary structural driver. GDPR enforcement and enhanced CCPA rules (including expanded monetary damages and cybersecurity audit expectations) materially increase the cost of non‑compliance for service providers and buyers alike. For SMEs engaging in list hygiene, initial GDPR alignment costs can fall in a notable low‑to‑mid range in the first year, making managed or accredited verification offerings attractive.
Market trajectory (high‑level)
Using 2025 as our analytical base, PW Consulting’s forecast models demonstrate sustained double‑digit growth through the forecast horizon. Demand expands both from existing email‑centric use cases (marketing deliverability, CRM hygiene, outbound sales) and from adjacent identity and fraud use cases where validated email is used as a signal in multi‑factor decisioning. By 2032 the market is projected to be multiple times the mid‑2020s baseline, reflecting recurring revenues from API‑driven verification and higher value services like predictive deliverability scoring, AI‑enhanced risk detection, and compliance‑certified processing.
Worldwide Email Address Verification Service Market
Strategic implications for 2026 decision‑makers
- Procurement and vendor selection: 2026 procurement cycles should prioritize providers that pair measurable accuracy with demonstrable compliance credentials (ISO, SOC, GDPR mapping) and open integration points for marketing automation, CRM, and identity orchestration platforms. Price per verification remains important, but total cost of ownership — factoring false positives, bounce costs, and compliance risk — is the decisive metric.
- Platform architecture: Organizations building or re‑architecting identity or marketing platforms should treat verification as a service with clearly defined SLAs, telemetry, and retriable workflow patterns. Embrace hybrid approaches: real‑time APIs for transactional flows and scheduled bulk processing for list hygiene and analytics.
- Risk and compliance budgeting: Expect compliance obligations to push buyers toward vendors that can produce repeatable evidence of lawful processing. For smaller organizations, anticipate one‑time GDPR alignment costs in the range reported by industry studies; for larger enterprises, plan for continuous controls, vendor audits, and integration of verification logs into privacy compliance platforms.
- M&A and partnership focus: Investors should watch for tuck‑ins that add AI scoring, multi‑channel contact resolution, or privacy certifications. Given the market’s mid‑range concentration, acquisition multiples will increasingly differentiate on data quality, unique signal sets, and enterprise sales motion.
Competitive landscape: who to watch and why
The market combines global cloud‑native challengers with regionally focused specialists. PW Consulting’s qualitative benchmarking highlights a set of companies that exemplify the competing value propositions you’ll face in procurement evaluations:
- Accuracy and analytics leaders: Vendors emphasizing real‑time validation paired with deliverability analytics (e.g., providers with fine‑grained scoring and campaign-level diagnostics) are positioned to win enterprise marketing and sales budgets.
- Compliance and security specialists: Firms that publish compliance artefacts (ISO certifications, security whitepapers) and invest in catch‑all detection and secure processing are attractive to regulated industries and European buyers.
- Price and scale plays: High‑volume focused vendors competing on credits and non‑expiring packages will remain popular with agencies and high‑throughput senders where predictable unit economics matter most.
Selected company exemplars analyzed in the report (profiles and positioning only — full vendor scorecards are in the report) include established validators and newer entrants that demonstrate differentiated features such as integrated email finding, AI‑powered scoring, and enterprise integrations. Recent vendor moves underscore the contest between product innovation and compliance signaling: some providers have released AI enhancements for predictive deliverability and risk detection; others have strengthened ISO and audit narratives to win security‑sensitive customers.
Regulatory and operational dynamics shaping supplier choice
- Enhanced enforcement: European fines and expanded U.S. state privacy frameworks have raised the bar for processors of personal data (email addresses). Buyers must demand contractual assurances and operational evidence that verification is lawful and that processing is limited to stated purposes.
- Auditability and logging: Successful vendors provide immutable audit trails, redaction options, and retention policies that align with data minimization principles. These capabilities materially reduce downstream legal and remediation costs.
- SME considerations: For smaller organizations, third‑party verification can be a cost‑effective route to compliance if vendors provide templated data processing agreements and straightforward onboarding that keep initial privacy compliance efforts within the typical low‑to‑mid first‑year spend ranges reported by independent studies.
What the full PW Consulting report delivers (practical, operational content)
- Detailed market sizing and validated forecast models at the global level and by major segments (note: granular segment tables and unit pricing matrices are available only in the full report).
- Vendor scorecards and feature‑level comparison across accuracy, integrations, compliance posture, and enterprise readiness.
- Procurement playbooks with RFP templates, contract clauses for data protection, and SLA examples tailored for verification services.
- Technical integration guides that map verification flows into common ESPs, CRMs, and identity orchestration stacks, plus a checklist for hybrid real‑time vs bulk deployment strategies.
- Scenario‑based ROI tools that model deliverability lift, bounce cost reduction, and compliance cost avoidance under alternate vendor choices.
Investment, M&A and product innovation lens
From an investor standpoint, the market’s moderate concentration and high growth rate create attractive market dynamics for both strategic acquirers and growth equity. Targets that can combine robust data signals, enterprise sales capability, and verifiable compliance controls command price premiums. Product innovation will center on three vectors: improved signal fusion (email + behavioral + identity data), predictive scoring via machine learning, and embedded compliance automation (contractual and technical controls). Expect partnerships between verification specialists and identity orchestration or anti‑fraud platforms to accelerate.
2026 tactical checklist for executives
- Re‑baseline your deliverability KPIs and quantify the cost of poor address hygiene in your ecosystem (bounces, reputational impact, deliverability penalties).
- Require verifiable compliance evidence from preferred providers and incorporate audit rights into engagements.
- Design your architecture for both API latency and bulk throughput: treat verification as a service with observable SLAs.
- Pilot AI‑enhanced scoring on a representative segment of transactional flows before performing broad rollouts.
- For M&A, prioritize targets with unique signal sets, existing enterprise contracts, and certified security postures.
How to access the full intelligence
This release is a strategic preview intended to inform 2026 planning cycles and procurement decisions. The full PW Consulting Worldwide Email Address Verification Service Market report contains the complete data tables, segmented forecasts, vendor scorecards, and the downloadable procurement playbook that organizations use to execute on the recommendations summarized here. Our report preserves the depth and reproducibility of our models; if your team is preparing a sourcing event, or evaluating M&A opportunities, the complete document and our advisory services provide the operational detail you will need.
PW Consulting stands ready to support tailored briefings, vendor selection workshops, and model walkthroughs that translate the report’s findings into executable roadmaps for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Email Address Verification Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Hypersomnia Drug Market Poised for Rapid Expansion — Forecasted 10.5% CAGR Through 2026–2032
By PW Consulting, 2026-08-05
Worldwide Hypersomnia Drug Market — Strategic Preview for 2026 Decisions
PW Consulting today publishes a strategic preview of our forthcoming Worldwide Hypersomnia Drug Market report (base year 2025, forecast 2026–2032). This release is designed as an executive “trailer”: it demonstrates the analytical depth and decision-usefulness of our full study while preserving the core segmented intelligence for subscribers. Below we synthesize the macro trajectory, highlight the competitive and regulatory inflection points that will shape 2026 decisions, and outline the practical deliverables inside the full report that senior executives and investors will need to act with confidence.
Worldwide Hypersomnia Drug Market
Market snapshot — a rapidly expanding opportunity
The hypersomnia drug market has moved from a niche specialty category into a materially larger and more investable therapeutic space. Using USD and reporting revenue in millions, our standardized market model shows growth from approximately 3,120 million USD in 2020 to roughly 5,001 million USD in 2025. The market is forecast to expand at a compounded annual growth rate (CAGR) of 10.5% across the 2026–2032 window, reaching an expected total market size on the order of 10,060 million USD by 2032 under the base scenario.
Worldwide Hypersomnia Drug Market
This secular expansion is neither accidental nor cosmetic: it is being driven by a convergence of clinical innovation (new mechanisms such as orexin receptor agonists and optimized oxybate formulations), regulatory developments that shape product labeling and controlled‑substance management, and commercial dynamics including generic/authorized generic entry that reshapes pricing and access. For executives planning 2026 budgets, portfolio prioritization, or M&A activity, these macro metrics quantify a market with both high upside and concentrated competitive dynamics.
Worldwide Hypersomnia Drug Market
What the full PW Consulting report delivers (practical, actionable contents)
- Transparent market-sizing methodology, with reconciled top‑down and bottom‑up models and sensitivity scenarios (base/optimistic/conservative).
- 7‑year product‑level forecasting tools (2026–2032) that incorporate regulatory milestones, clinical readout probabilities, and payer uptake curves.
- Competitive landscape dossiers for active players and late‑stage pipeline sponsors, including capability maps and commercial readiness scores.
- Regulatory and access playbooks adapted to controlled‑substance considerations and REMS complexities.
- Pricing and reimbursement simulation modules and payer segmentation analysis to stress‑test launch and lifecycle strategies.
- Go‑to‑market templates: launch sequencing, field force sizing, and KOL engagement calendars tied to country and channel priorities.
- M&A and licensing decision frameworks with valuation drivers and integration risk checklists.
Competitive dynamics and the 2026 strategic inflection points
The market is concentrated: the top three commercial incumbents account for a substantial share of revenue, and the top five concentrate even more. High concentration underscores why 2026 will be decisive—small shifts in clinical readouts, regulatory approvals, or generic entry will produce outsized commercial and valuation consequences.
- Oxybate franchise dynamics: Branded oxybates remain foundational for symptomatic management, but authorized generics and recent ANDA approvals have materially altered the pricing and access landscape in key geographies. Market participants must now plan for segmented pricing strategies that reflect both branded clinical differentiation and increased generic availability.
- Extended‑release and low‑sodium formulations: Several once‑nightly and extended‑release oxybate formulations are advancing through regulatory pathways. These formulations aim to address patient convenience and safety narratives (e.g., reduced sodium exposure), and their approval timelines will influence substitution patterns across channel partners.
- Orexin receptor agonists and novel mechanisms: The emergence of oral selective orexin 2 receptor agonists and other orexin pathway agents represents the single largest mechanism-based inflection for the category. Breakthrough designations, positive Phase 3 readouts, or priority review outcomes for these agents would recalibrate long‑term demand and payer willingness to reimburse premium products.
- Non‑stimulant wake‑promoting agents and generics: Established wake‑promoters and authorized generics continue to support symptomatic control; however, their relative role is evolving as novel therapies target underlying pathophysiology.
Recent industry events that matter for 2026 decisions
- Major M&A activity into the orexin space is already reshaping the competitive map and accelerating scale‑up commitments by large pharma acquirers.
- Late‑stage clinical and regulatory milestones are clustered in 2026: several Phase 3 readouts and PDUFA decisions will create binary valuation moments for pipeline sponsors and potential licensors.
- Regulatory controls remain salient: oxybate products are handled under controlled‑substance frameworks with associated REMS requirements, creating both access friction and differentiation opportunities for safer, lower‑sodium, or extended‑release formulations.
Implications for corporate strategy — what to decide in 2026
Below are the practical strategic choices PW Consulting clients are already evaluating. Each recommendation is tied to discrete, model‑backed triggers included in the full report.
- R&D and portfolio prioritization: Rebalance late‑stage investment toward mechanisms with durable disease‑modifying potential (e.g., orexin agonists) while rationalizing incremental expenditures on me‑too formulations unless they demonstrate clear payer or patient adherence advantages.
- Commercial and access planning: Prepare multi‑tiered launch scenarios that reflect both premium launch uptake (if clinical outcomes are differentiated) and a rapid‑entry competitive price band driven by generics. Early payer engagement and real‑world evidence plans will be decisive for formulary positioning.
- M&A and partnering: Use the concentrated market structure and finite number of high‑quality orexin assets to inform opportunistic acquisitions or bolt‑on licensing. Establish trigger‑based bid limits tied to clinical readout probabilities and modeled synergies.
- Manufacturing and supply chain: Reassess supply commitments for controlled‑substance raw materials and third‑party fill/finish capacity. Contingency plans for scaling or contracting should be aligned with both optimistic and conservative uptake scenarios.
- Regulatory and compliance: Invest in REMS infrastructure and patient support programs that reduce friction to access while managing diversion risk—these investments materially influence payer coverage and real‑world adherence.
Competitive case studies (high-level)
To illustrate decision tradeoffs, the full report includes company‑level case studies that synthesize public filings, clinical timelines, and commercial positioning. Examples featured at a high level include:
- Established oxybate originators and authorized generic entrants: strategies to defend share through formulation enhancements, patient support, and differentiated messaging.
- Specialty innovators pursuing orexin agonists: go/no‑go criteria tied to Phase 3 endpoints and payer coverage thresholds.
- Large pharma entrants and consolidators: how strategic acquisitions accelerate scale and alter negotiation dynamics with payers and distribution partners.
Scenario planning — watchlist for 2026
PW Consulting’s scenario engine flags six leading indicators to monitor through 2026. These serve as operational triggers for tactical moves (e.g., ramp manufacturing, adjust launch sequencing, accelerate BD outreach):
- Key Phase 3 and regulatory readouts and their statistical robustness.
- PDUFA/approval outcomes and labeling language nuances that affect indications and reimbursement.
- Authorized generic and ANDA entry timing in primary markets.
- Payer guideline updates and major formulary decisions in target geographies.
- Material M&A transactions that shift competitive concentration or rare disease platforms.
- Real‑world safety signals and REMS-related compliance developments.
Why PW Consulting’s report is operationally different
Many reports describe trends. PW Consulting’s deliverable is an operational toolkit. Subscribers receive an editable forecasting model calibrated to multiple clinical and commercial levers, a decision matrix for BD/M&A with preset valuation multipliers, payer negotiation playbooks, and a launch‑readiness checklist linked to specific timelines and resource allocations. Crucially, the full report preserves the segmented intelligence—product by product, country by country, channel by channel—that underpins the top‑level numbers summarized above. That granular segmentation is intentionally reserved for report subscribers because it is the tactical currency required for executable strategies.
Next steps for executives and investors
For leadership teams developing 2026 budgets, the next 90 days are critical. Several clinical readouts and regulatory milestones are scheduled in the first half of the year; outcomes will materially affect valuation, partner interest, and payer positioning. PW Consulting recommends immediate actions for market players: align resource allocation with scenario triggers, accelerate payer evidence generation, and prepare flexible manufacturing contracts. The full report provides the decision matrices and templates needed to operationalize these recommendations.
To access the granular forecasts, segmented market maps, and proprietary models that drive these strategic prescriptions, please consult the full PW Consulting Worldwide Hypersomnia Drug Market report. The complete study is designed to convert market intelligence into executable 2026 plans for R&D, commercial, and corporate development teams.
For detailed analysis of this topic, please visit the official page: Worldwide Hypersomnia Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Composite Railroad Tie Market Set to Expand at a 6.12% CAGR Through 2032, New Report Reveals
By PW Consulting, 2026-08-05
Worldwide Composite Railroad Tie Market — Strategic Imperatives for 2026
PW Consulting’s latest market study on the Worldwide Composite Railroad Tie Market (base year 2025; historical 2020–2025; forecast 2026–2032) is released as operators, infrastructure owners, and capital allocators make capex and sourcing decisions that will define track economics for decades. The report synthesizes market-sizing (USD, Million), a 6.12% CAGR across the forecast window, longitudinal performance data and field-validated supplier intelligence into an actionable strategy playbook tailored for 2026 procurement cycles and multi-year asset renewal programs.
Worldwide Composite Railroad Tie Market
Executive summary — why this matters in 2026
Railroad stakeholders face a moment of inflection. Composite ties have moved beyond experimental pilot stages into large-scale field deployment and strategic supplier partnerships. Between 2020 and 2025 the market expanded materially — reflecting accelerating adoption driven by lifecycle-cost economics, environmental regulation and the industrialization of recycled-plastic manufacturing processes. Our forecast shows continued expansion in 2026 and beyond, with the market expected to cross the billion-dollar mark early in the forecast window and grow to materially larger levels by 2032, underpinned by a sustained compound annual growth rate of 6.12%.
Worldwide Composite Railroad Tie Market
For decision-makers in 2026, the implications are straightforward: the choice between traditional timber, concrete, and composite solutions is no longer purely technical; it is strategic — impacting total cost of ownership, network resilience, ESG commitments and supply chain risk. The PW Consulting report focuses on the intelligence practitioners need to move from rhetoric to procurement-ready programs while preserving optionality as standards, approvals and large-railroad trials evolve.
Worldwide Composite Railroad Tie Market
Market trajectory and macro takeaways
-
Momentum: The composite-tie market has grown from an identifiable base in 2020 to a significantly larger market by 2025, and the first year of the forecast (2026) shows clear expansion as early adopters scale installations.
-
Scale and timing: The market crosses critical scale thresholds in the near term — a signal to manufacturers, recyclers and logistics partners to align capacity, capital and commercial strategies now if they aim to be in the prime vendor set for 2027–2030 replacement cycles.
-
Unit economics: Composite solutions are being adopted not solely on purchase price but on demonstrated lifecycle advantages in high-decay and high-maintenance operating environments. Several product families report design lives that substantially exceed typical timber lifecycles, shifting procurement evaluation toward lifecycle cost and service models.
Dynamics reshaping demand in 2026
-
Raw material and circularity: Leading composite ties leverage post-consumer plastics (e.g., polyolefins, HDPE) reinforced with glass fibers. This linkage to plastic recycling creates both opportunity and exposure — access to stable supply of feedstock, regulatory incentives for circular materials and reputational benefits are balanced by the need to hedge quality variability and commodity shocks.
-
Regulation and procurement policy: Policy shifts (including bans or phase-outs of creosote-treated timber in some jurisdictions) are accelerating institutional procurement of composite alternatives. For network owners with explicit climate or biodiversity commitments, composite ties offer a tangible mitigation pathway that eases regulatory compliance and DOC/ESG reporting.
-
Standards and performance validation: Commercial-grade composite products increasingly meet or exceed established railway standards. Some manufacturers have attained formal industry certifications and long-term service-life claims supported by laboratory and field data — an important commercial inflection that changes how specifiers evaluate risk.
-
Class I adoption and field evidence: Large-scale trials and installations with major freight and passenger operators are demonstrating constructability and installation rates comparable to conventional ties. These operational validations are reducing implementation uncertainty for late-adopter networks planning phased replacements.
Competitive landscape — who matters now
The competitive map is a mix of specialized recyclers and composite innovators, traditional infrastructure suppliers extending portfolios, and global engineering OEMs forming distribution and field service alliances. Key companies profiled in the report include:
-
Evertrak LLC (St. Louis, Missouri, USA) — Known for the Evertrak 7000 product family, Evertrak combines recycled-plastic formulations with GFRP reinforcement. Products are positioned for heavy-haul and high-decay regions and carry industry certifications that reduce buyer approval friction.
-
Sicut Enterprises (United Kingdom, with US operations) — A supplier with deep approvals across European networks. Sicut’s full product approvals with major rail authorities illustrate a successful route-to-market for suppliers engaging public-sector procurement frameworks.
-
Pioonier GmbH (Germany) — Focused on patented processing technologies and recyclable plastics, Pioonier emphasizes durability and sustainable material cycles aligned with European operator requirements.
-
TieTek (EFG TieTek) (Houston, Texas, USA) — A long-standing market participant since the mid-1990s, with a track record of delivering composite ties and grade crossings; its legacy in product engineering remains influential across North American specifications.
-
AGICO (China) — A high-volume manufacturer offering cost-competitive composite solutions for metro and specialty applications; evidence of significant activity in Asian metro systems.
-
Triton Group (Triton Ties) (St. Louis, Missouri, USA) — Produces fiber-reinforced polymer ties and has commenced strategic commercial linkages with larger OEMs to scale distribution and credibility in Class I trials.
-
Progress Rail (Caterpillar) (Albertville, Alabama, USA) — An infrastructure scale player that has recently established distribution and marketing arrangements to accelerate composite tie market reach.
-
Other notable players — Lankhorst Mouldings, Sekisui Chemical, Axion Structural Innovations, IntegriCo Composites and Vossloh are active competitors, each bringing specific strengths in manufacturing scale, historical product approvals or system integration capabilities.
Recent market-moving events
-
Partnerships to scale distribution: In 2026, a major OEM entered a supply-and-marketing agreement with a composite-tie manufacturer, combining materials expertise with global sales reach to accelerate global deployments.
-
Large-scale field validation: In 2025, an extensive Class I trial installed tens of thousands of glass-reinforced polymer composite ties from multiple suppliers, reporting high installation success and operational compatibility with conventional installation workflows.
-
Strategic investment activity: Private and strategic investors are funding manufacturing expansion for GFRP and recycled-plastic composite producers to meet the expected demand lift in North America and other regions.
-
Procurement policy shifts: Network-level decisions to move away from creosote-treated timber have opened procurement windows for fully approved composite alternatives in regulated markets.
What PW Consulting’s report delivers — practical content for 2026 decisions
-
Robust market sizing and scenario models (USD, Million) covering 2020–2032 that enable capital planners to stress-test procurement timing, volume phasing and supplier capacity assumptions against realistic adoption curves.
-
Operational playbooks for procurement teams — including tender language templates, approval-path checklists, installation rate benchmarking and maintenance planning assumptions to reduce procurement and operational risk.
-
Supplier scorecards and diligence frameworks that combine technical certifications, field performance records, production scalability and financial resilience into procurement shortlists.
-
ROI and lifecycle-total-cost-of-ownership (TCO) calculators designed to be populated with project-specific input data; these tools translate manufacturer claims and field-trial performance into network-level financial outcomes.
-
Case studies and installation audits that document constructability, rework rates, and operator feedback from major trials and early-adopter installations — objective evidence to inform approval committees.
-
Risk matrices covering feedstock availability, regulatory shifts, warranty frameworks and end-of-life recycling logistics to support board- and executive-level investment approvals.
Strategic playbook — actions for rail networks, suppliers and investors in 2026
-
For network owners and operators: Implement staged replacement pilots in representative climate and traffic sectors, using PW Consulting’s TCO templates to capture real-world maintenance savings and service-life performance data.
-
For procurement and supply chain teams: Engage suppliers early on capacity commitments and feedstock traceability. Negotiate warranty and performance-linked commercial terms rather than relying on procurement based purely on unit price.
-
For suppliers and OEMs: Scale manufacturing and verticalize recycling partnerships to secure consistent feedstock quality. Prioritize approvals and transparent third-party test data to shorten approval cycles in regulated markets.
-
For investors and infrastructure funds: Use market sizing and scenario outputs to evaluate the timing of capital deployment. Prioritize companies with demonstrable field installations, diversified approval footprints and strategic OEM or distribution partnerships.
-
For policymakers and regulators: Encourage transparent performance metrics and lifecycle accounting in tender evaluations to internalize environmental benefits and long-term network resilience gains.
Closing — why the report is essential for 2026 planning
Our analysis shows that 2026 is a decisive year: operational validation is converging with procurement policy shifts and strategic commercial partnerships. These forces together accelerate the transition from pilot projects to mainstream procurement. PW Consulting’s Worldwide Composite Railroad Tie Market report packages market-scale forecasts (USD, Million), actionable procurement playbooks, supplier due-diligence frameworks and hands-on ROI tools that turn macro trends into defensible investment choices.
To preserve competitive advantage, organizations should move from contemplation to controlled execution: pilot, measure, scale. The full report contains the segmented datasheets, supplier scorecards, project-level case studies and downloadable decision-support models intentionally omitted from this release to protect the analytical core — access those materials on our website to operationalize your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Composite Railroad Tie Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Sauna Steam Generator Market — Strategic Outlook for 2026: A PW Consulting Preview
As global wellness and experiential hospitality rebound, the sauna steam generator market is entering a phase of measured expansion and operational reconfiguration. PW Consulting’s latest market study — grounded in a 2020–2025 historical base and projecting through 2032 — shows the total market rising from about USD 707 million in 2025 to approximately USD 1.11 billion by 2032, corresponding to a compound annual growth rate (CAGR) of roughly 6.6% across our 2026–2032 forecast window. This briefing summarizes the strategic implications our clients must weigh when setting 2026 priorities, while intentionally omitting the granular segment tables available in the full report to preserve decisive commercial value for subscribers.
Worldwide Sauna Steam Generator Market
Why 2026 Is a Make-or-Break Year
-
Regulatory inflection: Tighter energy and safety requirements in key markets are shortening the timeline for product compliance investments and product withdrawals from shelf. Notably, European efficiency standards and emerging national-level mandates are forcing manufacturers to accelerate energy-efficiency upgrades and certification roadmaps.
Worldwide Sauna Steam Generator Market -
Demand tailwinds: Robust growth in global wellness tourism and renewed capital spend in hospitality and premium residential upgrades are creating a sustained commercial replacement cycle and new-install pipeline that favors differentiated, higher-margin systems.
Worldwide Sauna Steam Generator Market -
Supply-side cost pressure: Raw-material and labor-cost dynamics are compressing gross margins for conventional product architectures while opening opportunities for value capture through design-for-cost, vertical supply agreements, and service-led revenue models.
Market Trajectory — What the Numbers Mean for Strategy
The headline market scale and CAGR indicate healthy expansion with clear room for premiumization, especially in commercial, hospitality and high-end residential channels. However, aggregate growth masks important structural shifts: customers increasingly prize digital controls, energy efficiency and integrated wellness experiences over commodity pricing; competition is consolidating at the top but remains fragmented overall (the top three firms account for under 40% of the market, and the top five about half), creating distinct avenues for both incumbents and challengers.
For leadership teams, the implication is straightforward: prioritize investments that compound competitive advantage (certified high-efficiency platforms, digital user experiences, and scalable service operations) and defer broad catalog expansions that increase exposure to commodity volatility.
Key Strategic Priorities for 2026
-
Compliance-first product roadmaps: Accelerate testing and certification pipelines to meet imminent efficiency thresholds in regulated markets. The cost of late compliance (product delistings, retrofit programs, or forced rebates) will outweigh near-term R&D savings.
-
Supply resilience and cost engineering: Lock in critical inputs through multi-year contracts and alternate-source qualification. Even modest increases in stainless-steel costs and specialized component lead times materially affect installed-product economics; firms that redesign for lower material intensity while retaining durability will win.
-
Service-driven monetization: Build recurring revenue through installation, preventive maintenance, extended warranties and performance-as-a-service contracts. Skilled-installation shortages in mature markets suggest a premium for bundled service offerings.
-
Digital differentiation: Integrate app-controlled features, predictive maintenance, and interoperability with broader building-management or hospitality platforms. Intelligent controls are becoming a purchaser expectation — not a luxury feature.
-
M&A and partnership focus: Target bolt-on acquisitions that shore up certification expertise, fast-track energy-efficient product lines, or add regional service capacity. Given moderate market concentration, well-chosen deals can generate scale benefits without triggering major antitrust scrutiny.
Competitive Landscape — Who Matters and Why
PW Consulting’s competitive assessment highlights several established players whose strategic moves will set market tone in 2026:
-
Steamist (Long Island City, NY) — A broad product range across residential and commercial systems. Strengths: scalable manufacturing and broad capacity range. Strategic consideration: streamline the top-selling SKUs and prioritize energy-efficiency upgrades to protect margin.
-
Mr. Steam (Hauppauge, NY) — Strong brand in luxury and digitally controlled systems. Recent product launches emphasize Bluetooth and app-driven controls. Strategic consideration: leverage brand to expand services and enterprise integrations with hotel chains seeking differentiated guest experiences.
-
Amerec (Woodinville, WA) — Known for robust mid-range and commercial designs emphasizing reliability. Strategic consideration: accelerate certification and energy-efficiency claims to defend commercial accounts in regulated jurisdictions.
-
TyloHelo (Hillerstorp, Sweden) — European leader with integrated sauna systems and strong trade-show presence. Strategic consideration: capitalize on channel relationships to upsell energy-efficient and eco-focused models into European retrofit programs.
-
Harvia (Muurame, Finland) — Well-positioned for commercial installs and exports, with recent catalog updates targeting energy performance. Strategic consideration: move beyond catalog refreshes to modular platforms that reduce SKU proliferation.
-
KLAFS GmbH (Schwäbisch Gmünd, Germany) — Specialist in hotel and spa wellness systems aligned to European safety standards. Strategic consideration: pursue integration partnerships with HVAC and building automation providers.
-
Saunacore (Richmond Hill, ON) — Custom commercial steam generators and stainless-steel expertise. Strategic consideration: scale the custom business through production platformization and export-focused compliance readiness.
Recent corporate activity reinforces the priority themes above: product launches highlighting app-control and user experience, trade-show rollouts of energy-focused units, and catalog updates emphasizing efficiency. These moves validate that product differentiation and compliance will be competitive battlegrounds through at least 2028.
Report Deliverables — What PW Consulting Provides
Our full study is designed as a practical playbook for executives. Key deliverables include:
-
A calibrated market model with historical (2020–2025) validation and 2026–2032 scenarios (base, upside and downside), including sensitivity to raw-material price swings, labor-cost shocks, and regulatory acceleration.
-
Go-to-market frameworks for residential, commercial-spa and hospitality channels — including route-to-market tactics, margin staircases, and distributor scorecards.
-
Supplier-risk matrix and cost-to-serve heatmaps to identify where redesigns or vertical integration yield the highest ROI.
-
Competitive intelligence dossiers for leading and challenger firms (product roadmaps, patents, channel strategies), plus an M&A target short-list aligned to three buyer archetypes: platform acquirers, service consolidators, and capability buyers.
-
Operational playbooks (manufacturing optimization, certification checklists, and field-service scaling guides) to compress time-to-compliance and protect margin.
-
Executive dashboards for board-level scenario planning and a TCO calculator that quantifies lifecycle energy and service costs under multiple regulatory regimes.
Risks & Scenario Planning
We identify three principal downside risks that should shape 2026 capital allocation:
-
Regulatory acceleration: Stricter-than-expected energy or safety mandates could trigger retrofits or product removals; firms without rapid compliance plans face disproportionate disruption.
-
Input-cost inflation: Steel and specialized components remain vulnerable to supply shocks; firms that cannot hedge or redesign will see margin erosion.
-
Installation capacity constraints: Certified technician shortages in mature markets elevate installation timelines and labor rates, pushing customers toward bundled-installation providers or modular plug-and-play solutions.
Our scenario modelling quantifies the impact of each risk on revenues, margins and total cost of ownership across product families; the model is included with the full report subscription and is configurable for firm-specific assumptions.
Practical Recommendations — A 90-Day Action Plan for 2026
-
Week 1–4: Audit product lines vs. imminent efficiency and safety standards; prioritize certification timelines for top revenue SKUs.
-
Month 2: Secure multi-source procurement agreements for critical raw materials and components; start engineering-for-cost workshops to identify quick wins.
-
Month 3: Pilot a service bundle in a target hospitality region to validate pricing, SLAs and technician training programs; parallel-run a marketing test for digital-control premium features.
FAQ — Quick Answers from the Study
-
Is consolidation underway? Market concentration is moderate: the top three firms account for under 40% of market value, and the top five collectively approximately half, which creates both defensive and opportunistic M&A dynamics.
-
How material are compliance costs? Very. Regional energy-efficiency directives require meaningful product re-engineering and formal certification. Firms should treat certification pipelines as multi-quarter product milestones.
-
What certifications are critical? For U.S. commercial sales, recognized safety standards (e.g., UL-related certifications addressing overheating risk) are a precondition for market access; Europe also requires specific energy and safety verifications.
-
Are installation and service margins sizeable? Yes — shortage-driven labor rates in certain markets materially enhance the economics of bundled service offerings and recurring revenue models.
Concluding View — Where to Play and How to Win in 2026
Against a backdrop of steady market growth and structural change, the winners will be those who synchronize product compliance, supply resilience and service monetization before regulatory and labor pressures tighten further. PW Consulting’s study equips decision-makers with the quantitative scenarios, operational playbooks and competitive intelligence necessary to make decisive 2026 investments — whether the objective is to defend market share, accelerate premiumization, or pursue acquisitive scale.
This preview highlights the strategic contours; the full report contains the granular market model, channel-level playbooks, and configurable scenario tools that executives need to convert insights into measurable outcomes. For access to the datasets, dashboards, and the actionable annexes referenced here, please visit our report page or contact PW Consulting’s industry desk to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Sauna Steam Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Methylparaben Market Poised for Steady Expansion with 4.5% CAGR
By PW Consulting, 2026-08-05
Worldwide Methylparaben Market 2026 Strategic Preview — What Decision‑Makers Must Know Now
PW Consulting’s new market study on the Worldwide Methylparaben Market (base year 2025, forecast 2026–2032) delivers an executive-grade briefing for boards, commercial leaders, procurement teams and regulatory affairs functions preparing strategy for 2026. The global market, recovering from a short-term dip, is projected to follow a steady upward trajectory with a compound annual growth rate (CAGR) of 4.5% through the forecast window. Our baseline analysis pegs the market at approximately USD 82.45 Million in 2025, rising into the low‑90s in 2026 and reaching an anticipated USD 112.19 Million by 2032 under the central forecast scenario.
Worldwide Methylparaben Market
Why this matters for 2026 planning
- Resilience with volatility: The market has shown resilience—recovering from a near‑term contraction to re‑accelerate—highlighting both demand persistence and sensitivity to episodic supply shocks.
- Margin and sourcing pressure: Raw material dynamics and regulatory constraints are creating asymmetric cost and access risks that will materially influence supplier economics and customer margins in 2026.
- Consolidation and concentration: The market exhibits moderate concentration (the top three and top five supplier groups control a meaningful share of industry supply), which increases the strategic importance of supplier selection, dual‑sourcing and long‑term offtake agreements.
Data‑driven snapshot (high level)
Key macro datapoints from our study that executives should carry into boardrooms and planning sessions:
Worldwide Methylparaben Market
- Base year: 2025 (market size ~USD 82.45 Million).
- Forecast period: 2026–2032 with a central CAGR of 4.5%.
- 2026 year‑on‑year outlook: an expected rebound to the low‑90s (USD millions) underpinning strategic investment windows.
- Long‑term trajectory: steady growth to a seven‑figure (USD millions) market value by 2032 under our baseline model.
What’s driving growth and where the risk is concentrated
Our analysis identifies three structural growth engines and two primary risk categories that should define 2026 strategy:
Worldwide Methylparaben Market
- End‑market demand stability: Cosmetics & personal care and pharmaceuticals continue to be the primary demand centers; product formulations and safety perceptions shape purchasing patterns more than cycle timing.
- Regulatory overlay: Regulatory constraints—particularly in the EU and certain Asian markets—are shaping permissible use and labeling requirements for methylparaben. This creates product re‑formulation incentives and selective demand migration toward compliant grades.
- Feedstock and trade dynamics: Tightness in key intermediates (notably p‑hydroxybenzoic acid) and trade measures have produced episodic material cost inflation and geopolitical sourcing complexity, resulting in near‑term price volatility and procurement risk.
Regulatory and supply‑chain signals to watch in 2026
- Regulatory tightening on consumer safety labeling and concentration limits continues to drive incremental compliance costs and reformulation activity; this is particularly relevant for product lines sold into jurisdictions with precautionary rules.
- Raw material price shocks—our modelling captured a notable price jump in the key feedstock during late‑2024—which translates into margin stress unless pass‑through mechanisms or hedging are in place.
- Trade measures and anti‑dumping actions create sourcing premiums for certain origins and necessitate agile procurement strategies (duty exposure and footprint diversification are now material P&L considerations).
Competitive landscape — strategic map and implications
The methylparaben supply base combines global chemical majors, specialty producers, and regional exporters. The market’s moderate concentration implies that the actions of a handful of suppliers will materially affect supply balances and terms in 2026.
- Eastman Chemical Company (USA) — Eastman positions methylparaben within a broader cosmetic and industrial ingredients portfolio. Recent REACH compliance updates strengthen its EU market credentials. Strategic implication: Eastman is a natural choice for customers prioritizing regulatory assurance and global distribution networks; expect pricing stability but limited room for aggressive discounts.
- Spectrum Chemical Mfg. Corp. (USA) — A focused supplier of USP/NF‑grade methylparaben catering to pharmaceutical and laboratory markets. Strategic implication: Spectrum is a high‑assurance supplier for regulated pharmaceutical supply chains; customers requiring batch traceability and pharmacopeial compliance will prioritize Spectrum despite potential premium pricing.
- Celanese Corporation (USA) — Operating through its cellulose derivatives and specialty chemicals platforms, Celanese has expanded low‑impurity grades targeted at pharma. Strategic implication: Product innovation (low‑impurity grades) creates differentiation opportunities and supports customers’ reformulation requirements driven by tighter regulatory scrutiny.
- Nippon Shokubai Co., Ltd. (Japan) — Offers high‑purity grades and strong reach in Asia. Strategic implication: Nippon’s Asia‑centric footprint and technical service make it a preferred partner for formulators in the region, particularly where premium purity and customer support are value drivers.
- Shanghai Trustin Chemical Co., Ltd. & Wanxiang Jingliu Chemical Co., Ltd. (China) — These producers focus on industrial and cosmetic grades for global export. Strategic implication: Chinese exporters remain competitive on cost and volume; however, exposure to trade measures and feedstock price swings increases counterparty risk—mitigants include audited supply chains and contingency sourcing.
Recent supplier developments flagged in our research are directional for 2026 decisions: a major supplier’s REACH certification update improves EU access; another large supplier expanded low‑impurity grades addressing pharmaceutical demand. These moves compress the differentiation window for commodity grades and widen it for specialty, regulatory‑compliant products.
Report contents — practical value for decision‑makers
PW Consulting’s report is designed as an operational toolkit for 2026 strategy execution, not just an academic exercise. Major deliverables include:
- Demand and supply model with scenario runs (base, downside, upside) to quantify the financial impact of feedstock shocks, regulatory changes and market access restrictions.
- Supplier scorecards and a procurement playbook that rank vendors on regulatory compliance, quality (including pharmacopeial certifications), capacity flexibility and geopolitical risk.
- Price pass‑through and margin impact analysis calibrated to real feedstock price moves and typical contractual clauses used in the industry.
- Regulatory tracker and reformulation impact matrix that maps jurisdictional constraints into likely product strategy responses for cosmetics, pharmaceuticals and food applications.
- M&A and vertical integration playbook with valuation ranges, target archetypes and integration checklists tailored to the methylparaben value chain.
- Commercial scenarios and go‑to‑market templates for suppliers and buyers including new product commercialization roadmaps for specialty grades.
How to use this insight in 2026 decisions
Executives told to prepare for 2026 should prioritize three actions derived from our analysis:
- Hedge and diversify procurement: Convert stochastic feedstock risk into managed exposure through multi‑sourcing, longer‑dated contracts with embedded price adjustment clauses, and qualified secondary suppliers from low‑risk jurisdictions.
- Invest selectively in regulatory compliance and product differentiation: Premium, low‑impurity grades and documented compliance with key markets will unlock pricing power and reduce customer churn in regulated segments.
- Embed scenario planning into commercial and R&D budgets: Create trigger‑based playbooks that specify when to accelerate reformulation, when to temporarily limit exposure to a supplier, and criteria for strategic inventory build‑outs.
What the preview purposefully withholds
In accordance with our “trailer” approach, this release surfaces strategic findings and high‑level quantitative direction but intentionally withholds proprietary granular splits (detailed region‑by‑region and application‑by‑application percentage breakdowns, full price ladders and supplier revenue shares). These fine‑grain datasets and interactive models are available exclusively in the full report and online data portal, enabling clients to run customized scenario permutations against their own balance sheets.
Client use cases — who benefits and how
- Consumer goods manufacturers: Validate reformulation roadmaps and supplier transition plans to maintain shelf presence in jurisdictions with tightened labeling.
- Pharmaceutical purchasers: Secure pharmacopeial‑grade supply while optimizing total landed cost under volatile feedstock pricing.
- Suppliers and investors: Identify white spaces for specialty grade investment, cross‑border trade opportunities, and acquisition targets to strengthen market position.
- Regulatory and compliance teams: Use the regulatory tracker to prioritize product registrations and label updates to minimize market access interruptions.
Next steps and access
For teams preparing 2026 budgets and strategic plans, the full PW Consulting report provides the actionable datasets, supplier analytics and scenario tools necessary to translate the directional insights above into executable strategies. To obtain the full report, interactive models and supplier scorecards—each containing the detailed segmentation, price forecasts and regional exposure matrices referenced but not disclosed in this preview—please visit our Worldwide Methylparaben Market report page or contact your PW Consulting representative.
Concluding perspective
The methylparaben market is entering a phase where regulatory nuance and feedstock dynamics will drive differentiation between commodity and specialty supply. For companies that proactively align procurement, product development and regulatory strategy in 2026, the environment offers both defensive risk reduction and selective opportunities for premium positioning. PW Consulting’s study arms decision‑makers with the scenario‑driven intelligence required to prioritize near‑term mitigations and longer‑term value creation—without disclosing the proprietary segment matrices that clients rely on to make confident, capital‑intensive moves.
For detailed analysis of this topic, please visit the official page: Worldwide Methylparaben Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 14.5% CAGR for Global 2'-Fucosyllactose Market, Forecasting USD 812.7 Million by 2032
By PW Consulting, 2026-08-05
Worldwide Multi-Point Ground Flares (MPGF) Market — Strategic Preview for 2026 Decision Makers
PW Consulting’s latest industry briefing previews the full Worldwide Multi-Point Ground Flares (MPGF) Market study and distills the specific, actionable intelligence that senior executives, project sponsors, EPC firms, and investors need to prioritize through 2026. This article follows a “trailer” approach: it demonstrates the methodological depth and strategic insights contained in the full report while intentionally preserving core segment and regional detail to drive qualified traffic to the source for complete data and annexes.
Worldwide Multi-Point Ground Flares (MPGF) Market
Market snapshot — where the opportunity stands
At the macro level, the MPGF market is in an unmistakable growth phase. Using 2025 as the report’s base year, our modeled market size stands at USD 346.48 Million. Our forecast, based on historical trends (2020–2025), industry project pipelines, regulatory trajectories, and technology adoption rates, projects a compound annual growth rate (CAGR) of 6.52% across the 2026–2032 horizon, with the global market reaching approximately USD 539.12 Million by 2032.
Worldwide Multi-Point Ground Flares (MPGF) Market
This steady expansion is driven by converging forces: heightened regulatory scrutiny on flaring emissions and visible plumes; operational imperatives for smokeless, low-visibility solutions at high and variable waste-gas flow rates; continuing petrochemical and LNG infrastructure development; and increasing demand for turnkey, low-footprint, and remotely monitored flare systems. The market dynamics favor established OEMs with proven smokeless combustion technologies, reliable staging and ignition systems, and the capacity to deliver project-level guarantees under strict environmental and safety specifications.
Worldwide Multi-Point Ground Flares (MPGF) Market
What the full report delivers (practical, transaction-grade content)
- Robust market sizing and a transparent forecast model (base year 2025), including sensitivity scenarios tied to oil & gas CAPEX cycles, LNG project sanctions, and tightening emissions limits.
- Vendor benchmarking and a decision matrix that scores suppliers across 60+ criteria: technical performance, turndown range, smokeless/noise/radiation controls, lifecycle O&M burden, spare-parts lead times, and service footprint.
- Procurement playbook for owners and EPCs — standard RFP language, warranty formulations, performance guarantees, and contract de-risking clauses specific to MPGF deployment and retrofits.
- Techno-economic models that juxtapose capital expenditures, operating fuel/assist gas consumption, and lifecycle emissions costs to quantify payback under multiple regulatory regimes.
- Compliance and monitoring framework aligned to ISO/API standards and U.S. regulations (including references to legacy AMEL approvals and 40 CFR requirements) to reduce approval friction and accelerate permitting.
- Site selection and retrofit decision trees that help prioritize where MPGF delivers highest value versus alternative flaring solutions.
- Risk register and mitigation playbook — from ignition reliability and assist-gas logistics to community visibility, noise, and radiant heat management.
- M&A and partnership playbook highlighting where strategic acquisitions, JV structures, or licensing can secure aftermarket revenues and shorten market entry timelines.
Regulatory and standards context — a non-negotiable constraint
Regulation is a primary adoption lever for MPGFs. Notable precedents — such as EPA’s Alternative Means of Emission Limitation (AMEL) approvals for pressure-assisted MPGFs at major petrochemical sites — demonstrate that regulators will accept alternative flare technologies when accompanied by rigorous monitoring, performance guarantees, and documented destruction efficiency. In parallel, ISO/API standards (including ISO 23251 / API 521 references and other applicable API standards) frame design and operational expectations, while U.S. rules such as 40 CFR 60.18 remain operational touchstones for flare control and reporting. Manufacturers and buyers must design procurement and commissioning strategies around this regulatory envelope to avoid costly rework or permit delays.
Competitive landscape — vendor positioning and strategic bets
The MPGF vendor field is dominated by a mix of specialized combustion firms and wider industrial suppliers that have integrated MPGF offerings into broader process portfolios. Our qualitative assessment in the full report covers capability gaps, product roadmaps, and go-to-market strategies for tier-one and niche providers. Highlights:
- Zeeco, Inc. ( https://www.zeeco.com) — Zeeco positions MPGF as a solution for highly variable waste-gas volumes with a focus on safe, smokeless, and low-visibility flaring. Their strength lies in proven combustion engineering and site-specific customization for pressure, flow, radiant heat, and noise control. Recent product promotions emphasize these attributes, reinforcing their brand in operator-oriented sales cycles.
- John Zink Hamworthy Combustion ( https://www.johnzink.com) — John Zink’s LRGO™ MPGF lineup competes on demonstrated destruction efficiency, high turndown via staged systems, and turnkey delivery. Their product messaging emphasizes reliability and lifecycle performance, which resonates with risk-averse owners seeking long-term O&M predictability.
- Aereon (part of Cimarron) ( https://aereon.com) — Aereon focuses on array-enclosed configurations for very large flows with multi-stage operation and assist gas strategies for smokeless performance at low regimes. Their technical emphasis is attractive for projects with extreme variability in waste gas.
- Honeywell UOP Callidus ( https://uop.honeywell.com) — Honeywell’s strength is integration: staged high-pressure burners and controls that align with upstream and midstream process automation, aimed at large gas and petrochemical applications where systemic interoperability and reduced radiation are priorities.
- Encore Combustion ( https://encorecombustion.com) — Encore’s enclosed combustion MPGF offerings target ground-based smokeless combustion for large hydrocarbon volumes, leveraging proprietary burner designs and a focus on reliable ignition and maintenance simplicity.
Recent market moves illustrate the interplay of vendor marketing, operator vigilance, and project execution. Examples include Zeeco’s mid-2025 emphasis on MPGF capabilities, operator-led monitoring upgrades (an owner in Pennsylvania added an additional camera to MPGF monitoring in early 2025), and recent large-scale project supplies by specialty providers. These actions confirm two trends: operators are increasingly focused on continuous monitoring and visibility control, and vendors are commercializing turnkey and service-led propositions rather than stand-alone hardware.
Strategic implications for 2026 decision cycles
For executives setting 2026 priorities, the MPGF market presents distinct choices that will affect CapEx scheduling, vendor selection, and operational risk profiles:
- Owners and operators should treat MPGF procurement as a system buy — specifying performance-based outcomes (visibility, destruction efficiency, noise/radiation limits) rather than detailed component lists. This creates accountability and incentivizes vendor innovation on assist gas, staging, and remote diagnostics.
- EPCs must integrate MPGF selection early in FEED to avoid costly layout and utilities rework. Pre-approved vendor lists and standardized interface packages reduce bogging at tender stage.
- OEMs and suppliers should prioritize modular, serviceable designs and expand remote-monitoring as-a-service offerings. Aftermarket services and spare-parts subscriptions will be pivotal revenue streams as site operators seek to minimize downtime and guarantee compliance.
- Investors and project financiers should require demonstrable compliance paths and vendor performance guarantees as conditions precedent to funding — particularly where permitting relies on alternative emission limitation approvals.
- Regulators and community engagement teams should expect MPGFs to be evaluated against the same transparency principles applied to other emission control assets: continuous monitoring, public-friendly data disclosure, and traceable destruction-efficiency metrics.
How buyers should use PW Consulting’s report
The full PW Consulting MPGF report is built to be operational: not just market numbers but buy-side decision support. Subscribers will receive downloadable procurement templates, vendor scorecards, risk-mitigation checklists, and techno-economic spreadsheets calibrated to multiple gas quality and flow variability scenarios. The annexes contain vendor contact matrices, compliance checkpoints mapped to international standards, and worked examples that show when retrofits dominate over new-build MPGF procurement from a total-cost-of-ownership perspective.
Because this piece is a strategic preview, core segment-level splits and granular regional allocation tables are intentionally omitted here. Those detailed worksheets, sensitivity tables, and raw model files are included exclusively in the licensed report and the online data portal.
Concluding guidance — three action steps for 2026
- Prioritize compliance-first specifications: make performance guarantees and monitoring requirements the primary procurement levers to reduce approval and operational risk.
- Adopt a modular supplier strategy: combine a primary OEM with a validated secondary source for critical spares and commissioning support to mitigate single-source risk.
- Monetize the aftermarket: suppliers should launch service subscription models for remote monitoring, predictive maintenance, and regulatory reporting to capture recurring revenue and differentiate bids.
PW Consulting’s full Worldwide MPGF Market report provides the quantitative templates, vendor-level assessments, and regulatory mapping that decisionmakers need to operationalize these steps. For procurement teams, finance committees, and strategic planners preparing for 2026, the report is designed to shorten decision cycles and reduce execution uncertainty. To access the complete data, supplier scorecards, and downloadable procurement toolkits, visit our report portal and license the full study.
For detailed analysis of this topic, please visit the official page: Worldwide Multi-Point Ground Flares (MPGF) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Agar Resin Market to Grow at 9.24% CAGR Through 2032 as Affinity Chromatography and Biopharmaceutical Production Drive Demand
By PW Consulting, 2026-08-05
Worldwide Agar Resin Market: Strategic Playbook for 2026
As PW Consulting’s lead industry analyst, I present an executive briefing drawn from our new Worldwide Agar Resin Market report — a concise, decision-oriented synthesis designed to inform executive choices in 2026. The market for agar-derived resins has entered a new phase: after a period of steady expansion through 2020–2025, the sector is expected to continue robust growth across the 2026–2032 forecast window. Our analysis quantifies that momentum and translates it into clear, actionable pathways for commercial, procurement, R&D and M&A teams. This is a high-level preview intended to demonstrate analytical depth; core segment tables and granular figures are intentionally withheld here to drive senior teams to the full report for due diligence and transaction support.
Worldwide Agar Resin Market
Market trajectory at a glance
Between 2020 and our base year 2025 the global agar-resin market expanded materially, reflecting accelerating uptake across biopharmaceutical purification, diagnostics, and research applications. The report’s baseline shows the market at USD 312.45 Million in 2025 and projects continued expansion at a compound annual growth rate (CAGR) of approximately 9.24% through the 2026–2032 forecast period. By the close of the projection window, total market value is modeled to approach USD 580 Million — a near doubling in under a decade.
Worldwide Agar Resin Market
What this trajectory signals to executives: structural demand is strengthening, and the economics of scale and differentiation will increasingly determine value capture. Growth is not uniform — pockets of higher demand and supply fragility create tailwinds and risks that require targeted, rather than generic, strategic responses.
Worldwide Agar Resin Market
Supply-side dynamics: raw materials and manufacturing constraints
-
Feedstock sensitivity: Seaweed-based feedstock (notably Gelidium and Gracilaria species) remains the single largest source-side vulnerability. Global aquaculture tonnage has risen in recent years, yet high-grade feedstock suitable for premium agarose remains susceptible to climate variability and ocean temperature fluctuations. These ecological drivers create intermittent supply constraints and price volatility that cascade through processor margins and lead times.
-
Input price pressure: Regional market signals, particularly in Asia, showed sustained upward pressure on agar-agar pricing in 2025 driven by competing demand from food and pharma channels. Procurement teams must plan for continued short-to-medium term cost volatility.
-
Manufacturing economics: Thin processing margins at raw-agar processors mean that inventory management and working-capital discipline are critical. Seasonal harvest cycles and limited cultivation scalability put a premium on upstream vertical integration and contract structures that share risk.
Competitive landscape — what senior leadership needs to know
The industry blends legacy commodity suppliers with specialized technology vendors that supply agarose beads, pre-activated grades and chromatography resins used in bioprocessing. Key profiles and strategic implications include:
-
Hispanagar S.A. (Burgos, Spain) — A leading European supplier of high-quality agar and agarose, well-positioned for customers seeking traceability and value-added grades. Their positioning matters for supply reliability and high-grade downstream applications.
-
Meron Group / Marine Hydrocolloids (Kochi, India) — Significant capacity in commodity and bacteriological grades, servicing large-volume food and related markets. Their scale makes them a force in price-setting and spot availability in Asia.
-
B&V srl (The Agar Company, Italy) — Offers custom formulations across food, pharma, and technical grades; a supplier of choice for bespoke product requirements and fast product development cycles.
-
Indonesian producers (e.g., PT Agarindo Bogatama, PT Surya Indoalgas) — Key exporters leveraging local cultivation and extraction; these firms are vital partners for diversification and near-term capacity assurance.
-
Global BioIngredients (Doral, Florida, with partners) — A commercial model that blends sourcing partnerships and regional manufacturing to serve global demand with premium grades for tissue culture and bioprocessing.
-
Bio-Works Technologies AB (Sweden) — Technology-focused vendor producing agarose-based chromatography resins (WorkBeads). Notably, in January 2024 the company was granted a patent for a greener bead-manufacturing method using vegetable oils, illustrating how process innovation can unlock premium positioning and regulatory/ESG advantages.
-
Agarose Bead Technologies (ABT, Spain) — Growing presence and capacity expansion through 2025–2026 underscore the industry’s shift to scale up higher-performance agarose resin manufacturing for bioprocessing applications.
Recent industry developments and strategic inference
-
Capacity expansions: Announcements of expanded agarose resin capacity in late 2025 reflect supplier responses to anticipated biopharma demand and a move to de-risk lead-times. For buyers, this reduces the urgency of reactive sourcing but raises competitive pressure on differentiation.
-
Process innovation and sustainability: Patent activity and green manufacturing initiatives (e.g., replacement of fossil-based oils with vegetable alternatives in bead manufacturing) are early signals that ESG-driven product premiums will form part of contract negotiations and product roadmaps.
-
Raw material market noise: Persistent feedstock volatility and price increases in Asia during 2025 emphasize the need for structured procurement and supplier development programs.
What the PW Consulting report contains (practical tools for 2026 decision-making)
Our full report is structured to be a playbook for immediate and medium-term action. It includes:
-
Revenue and demand modeling across 2020–2032 with scenario variants (base, downside, upside), calibrated to macro life-science investments and diagnostic adoption curves.
-
End-to-end supplier mapping and a proprietary supplier-risk scoring matrix that combines feedstock exposure, geographic risk, capacity elasticity and innovation index.
-
Commercial benchmarking and pricing frameworks to support negotiation playbooks for multi-year contracts, toll-manufacturing, and spot/pipeline mixes.
-
Technology and process dossiers covering bead manufacturing approaches, pre-activation chemistries, and sustainability innovations — with implications for cost-to-serve and regulatory compliance.
-
M&A and partnership thesis templates — where to look for upstream cultivation assets, niche resin manufacturers, or tolling partners to secure supply and accelerate differentiation.
-
Operational playbooks: inventory-sizing rules, hedging instruments, and capex decision models tuned to the sector’s seasonality and working-capital profiles.
Strategic implications for 2026 — recommended actions by function
For 2026, organizations should convert market momentum into durable advantage. Below are prioritized actions, sequenced for timing and impact.
-
Procurement: Immediately implement dual-track sourcing — secure multi-year contracts with premium-grade suppliers while maintaining a calibrated spot buffer. Build supplier scorecards that capture feedstock origin, quality controls and climate risk exposure.
-
Supply chain & operations: Deploy inventory optimization tied to harvest seasonality. Evaluate tolling or co-manufacturing agreements to expand flexible capacity without heavy capex commitments. Where margins permit, pilot upstream investments in seaweed cultivation partnerships to stabilize feedstock flows.
-
Commercial & product: Prioritize product segmentation that leverages premium attributes (e.g., ESG-verified beads, traceable agarose) and defend margins via technical services and regulatory support packages.
-
R&D & sustainability: Invest selectively in bead-manufacturing innovations and green chemistries; patents and process differentiation will command pricing power in regulated bioprocessing channels.
-
M&A & corporate development: Targeted acquisitions of regional processors or cultivation assets can be an efficient route to secure supply and capture margin. Use the report’s valuation and synergy templates to prioritize targets with both feedstock control and technical bead capability.
Timing and governance — a calendar for 2026 decisions
-
Q1–Q2 2026: Finalize multi-year supplier contracts, deploy supplier scorecards, and run a stress-test of inventory models under adverse feedstock scenarios.
-
Q2–Q3 2026: Execute pilot tolling/co-manufacturing agreements; begin targeted R&D pilots on greener bead manufacturing if not already underway.
-
Q3–Q4 2026: Assess M&A opportunities identified in our screening; negotiate preferred-supplier terms and align commercial roadmaps to newly secured capacity.
Why consult the full PW report
This article intentionally omits segmented tables and specific regional/application breakdowns: those are the tactical levers you will want behind a non-disclosure or subscription wall when negotiating suppliers, pricing, or transactions. The full report provides the detailed splits, supplier scorecards, contract language examples, and valuation templates that commercial and corporate development teams need to act decisively in 2026.
Decision-makers who read only the headlines risk mispricing risk, under-allocating working capital, or missing windows for strategic deals. Our full dataset — built from bottom-up supplier models, primary interviews, and proprietary procurement surveys — is optimized to convert the macro growth (CAGR ~9.24% and a projected market approaching USD 580M by 2032) into executable plans.
Concluding note
The agar-resin market offers a rare confluence of strong demand growth and material supply-side fragility. That creates both upside for differentiated suppliers and downside for players reliant on commodity sourcing. In 2026, the winners will be those who pair disciplined procurement and supply-chain hedges with targeted investments in product and process innovation. PW Consulting’s Worldwide Agar Resin Market report is designed to be the operational roadmap for that outcome.
Contact PW Consulting to schedule a briefing and obtain the full report, which includes all tables, supplier profiles, contractual templates and the proprietary models referenced above. Our team is prepared to support scenario modeling, supplier negotiations, and M&A advisory to convert insight into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Agar Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


