



Category: market research
PW Consulting: 3D Optical Surface Profilers Market to Reach USD 237.6M by 2032 at 3.83% CAGR
By PW Consulting, 2026-08-02
3D Optical Surface Profilers (Profilometers) Market — Strategic Insights for 2026 Decision‑Makers
As the metrology layer that underwrites quality, yield and certification across precision manufacturing, 3D optical surface profilometry is transitioning from a niche laboratory capability to a mission‑critical production discipline. Our latest PW Consulting market study — anchored on a 2025 base year and projecting through 2032 — finds that the global market has demonstrated steady expansion over the 2020–2025 period and is positioned to continue growing at a compound annual growth rate of 3.83% in the forecast window. By 2025 the market reached a clear six‑figure magnitude in USD Million terms and is modeled to approach a substantially larger figure by 2032, reflecting measurable demand acceleration in select use cases and a maturing supplier landscape.
3D Optical Surface Profilers (Profilometers) Market
Why this analysis matters for corporate strategy in 2026
-
Investment prioritization: Capital allocation toward R&D, factory automation and aftermarket services must be informed by a market that is growing modestly overall but unevenly across product types and end‑use intensity.
3D Optical Surface Profilers (Profilometers) Market -
M&A and partnership scouting: A concentrated supplier base combined with pockets of capability gaps presents targeted acquisition and alliance opportunities to accelerate access to software, in‑line integration, and service networks.
3D Optical Surface Profilers (Profilometers) Market -
Product roadmap decisions: Differentiation is shifting from pure hardware performance to measurement software, standards compliance and workflow integration — a shift that should drive product development priorities in 2026 and beyond.
-
Supply chain and production risk mitigation: Raw material constraints and component price volatility now pose a crystallized risk to capacity expansion and time‑to‑market for new metrology systems.
-
Regulatory and customer compliance: Standards and regulation (notably ISO 25178 and region‑specific device regulations) are altering procurement specifications — buyers increasingly treat areal surface texture as a contractual requirement, not an optional capability.
High‑level market dynamics — what is driving change
Four structural forces are shaping the market’s trajectory in 2026:
-
Standards and regulatory elevation. Areal surface texture standards such as ISO 25178 are being embedded into engineering drawings and quality specifications, while semiconductor industry roadmaps and medical device regulations mandate advanced 3D metrology for process control and device safety. These developments are creating non‑optional demand for certified measurement traceability and repeatability.
-
Technology convergence. Suppliers who combine optical hardware with robust surface analytics, automation for sub‑micron repeatability, and industry‑specific measurement libraries are pulling ahead. Buyers increasingly value systems that integrate seamlessly into automated production lines and factory data environments.
-
Supply‑side friction. Component shortages and raw material price volatility are constraining some vendors’ ability to scale production quickly. Strategic buyers and suppliers must assume lead‑time variability and diversify procurement to protect critical launches and contractual commitments.
-
Consolidation and concentration. The market exhibits high concentration among a small set of incumbent players, driving premium pricing for trusted, field‑proven systems and creating both barriers and opportunities for challengers seeking to enter via software, service, or niche application specialization.
Competitive landscape — who matters and how they compete
The competitive field blends large instrumentation houses, specialized metrology firms and agile niche players. The market’s concentration metrics indicate a dominant share commanded by a few leaders (top‑three and top‑five concentration levels are materially high), which has strategic implications for pricing power, channel control and warranty/service economics.
-
Bruker Corporation (Billerica, MA). Bruker’s offering emphasizes precision measurement across materials and semiconductor workflows, pairing established interferometric platforms with growing analytics ecosystems. Their strength lies in cross‑portfolio integration and strong field service footprints.
-
Zygo Corporation (Middlefield, CT). Zygo continues to be positioned around high‑accuracy interferometry for optical manufacturing. Recent trade show activity reinforced their focus on non‑contact surface measurement for precision optics and semiconductor inspection workflows.
-
Taylor Hobson (Leicester, UK). With a long history in surface and form metrology, Taylor Hobson is advancing automation and setup speed for aspheric and freeform measurements — a 2026 product update introduced automatic centre and level features that accelerate throughput in optical production.
-
Sensofar (Barcelona, Spain). Sensofar is notable for flexible, application‑focused systems targeted at industrial research and production, emphasizing software‑driven measurement recipes for surface texture and defect analysis.
-
Onto Innovation / 4D Technology (Tucson, AZ). Combining interferometric and wavefront metrology competencies, Onto Innovation competes on high‑precision solutions for semiconductor and optical fabs where integration with process control is critical.
-
Mahr GmbH (Göttingen, Germany). Mahr leverages a strong European installed base and focuses on industrial metrology solutions that marry robust hardware with serviceability and factory integration.
-
Nanovea (Irvine, CA). Nanovea’s value proposition emphasizes flexible profilometry for both laboratory and shop‑floor use, with modular systems that address diverse material types and testing standards.
-
Evident (Olympus) (Tokyo, Japan). Evident’s portfolio targets materials science and industrial microscopy applications where 3D surface data supplements imaging and failure analysis workflows.
-
Keyence Corporation (Osaka, Japan). Keyence offers integrated measurement and automation platforms that appeal to high‑volume manufacturing customers seeking rapid, rugged measurement on the production line.
-
Michelyne (France) and FRT GmbH (Germany). These specialist suppliers focus on tailored metrology solutions for surface characterization, often serving regional niches or high‑precision research markets.
Recent vendor activity in early 2026 — including product updates that reduce setup time for complex optics and trade‑show showcases of next‑generation non‑contact profilers — underlines an industry pivot toward throughput, ease of use and production readiness.
Strategic playbook — eight practical moves for 2026
-
Map compliance to product roadmaps. Align new product development to ISO 25178 parameter coverage and semiconductor/metrology chapter recommendations; make certification and traceable reporting a sales enabler, not an afterthought.
-
Invest in software and workflow IP. Differentiate on measurement analytics, automated reporting and API‑level integration to factory execution systems — buyers now prize turnkey measurement recipes as much as optical resolution.
-
Prioritize supply‑chain resilience. Lock long‑lead components, qualify secondary suppliers and build inventory buffers for critical optical and electronic subassemblies to avoid production disruption.
-
Design for modularity and serviceability. Offer modular instrument architectures that can be upgraded in the field to protect customer investment and create recurring aftermarket revenue.
-
Pursue targeted M&A or partnerships. Consider tuck‑ins that add analytics, software or regional service reach rather than broad, unfocused acquisitions; bolt‑on capabilities accelerate go‑to‑market faster than greenfield builds.
-
Monetize data and calibration services. Develop subscription models for data analytics, remote diagnosis and calibration services that capture higher lifetime value per install.
-
Segment go‑to‑market by use case. Industrial buyers in high‑mix, low‑volume sectors value flexibility and service; high‑volume semiconductor and optics fabs prioritize throughput and automation — tailor sales motions accordingly.
-
Build standards leadership. Contribute to standards bodies and publish white papers and validated measurement protocols to shape buyer requirements and lower procurement friction.
What PW Consulting’s full report delivers
This research is designed for boards, corporate strategy teams, product leaders and M&A professionals who need decision‑ready intelligence for 2026. Key practical deliverables include:
-
Market sizing and scenario modeling (2020–2032) with baseline and upside/downside cases that reflect component constraints and regulatory shifts.
-
Vendor scorecards and positioning maps that assess technology differentiation, service networks, and go‑to‑market DNA without compromising confidentiality of proprietary benchmarks.
-
Application playbooks with buyer decision criteria, procurement checklists and CapEx templates tailored for semiconductor, optical, medical device and transportation OEMs.
-
Technology roadmaps for interferometry, confocal and hybrid approaches, including maturity curves and integration levers for automation and AI‑based analysis.
-
Supply‑chain risk heatmaps and mitigation playbooks that translate component volatility into concrete sourcing and inventory tactics.
-
Strategic M&A screening matrices and valuation heuristics calibrated to the market’s concentration realities and service‑led revenue potential.
-
Actionable recommendations for sales, service and product teams to convert standards compliance and certification investments into measurable revenue uplift.
Closing — how to use this insight in 2026
For companies that manufacture, integrate or buy 3D optical profilometers, 2026 is a year to translate recognition of metrology’s strategic importance into disciplined execution: shore up supply chains, double down on software and services, and align product investments with rising regulatory and industry measurement requirements. This market is concentrated enough that targeted moves — whether a partnership, an acquisition of analytics IP, or an operational pivot to modularity — can materially change competitive position.
PW Consulting’s report functions as a tactical roadmap and a strategic radar: it reveals the direction of travel and equips leaders with the tools needed to convert metrology requirements into competitive advantage. For the full suite of segmentation tables, granular regional‑and‑application demand analysis, vendor financial proxies and the downloadable vendor scorecards that underpin our recommendations, please consult the full report on our publication page.
For detailed analysis of this topic, please visit the official page: 3D Optical Surface Profilers (Profilometers) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Audiometers Market to Reach USD 302.56M by 2032 at 5.2% CAGR
By PW Consulting, 2026-08-02
Medical Audiometers (Diagnostic Audiometer) Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a concise, insight-driven preview of our new Medical Audiometers (Diagnostic Audiometer) Market study. This preview is designed to communicate the strategic value of the full report for corporate leaders planning resource allocation, product roadmaps, regulatory strategy, and M&A in 2026 — while preserving the detailed, commercially sensitive segment-level data that we reserve for the full publication.
Medical Audiometers (Diagnostic Audiometer) Market
Why this report matters for 2026
The diagnostic audiometer market is at an inflection point where steady clinical demand, evolving reimbursement and regulatory frameworks, and incremental technology innovation converge. Our modeling shows a resilient market with a compound annual growth rate (CAGR) of 5.2% over the 2026–2032 forecast window, built on a historical base that spans 2020–2025. The market size increased from USD 153.75 Million in 2020 to USD 215.0 Million in 2025 (base year), and our outlook projects continued expansion through 2032, with modeled year-by-year projections reflecting both steady baseline demand and upside from telehealth-enabled services and device modernization. Executives who prioritize evidence-driven strategy in 2026 will use the report to translate these macro trajectories into investment priorities and go-to-market choices.
Medical Audiometers (Diagnostic Audiometer) Market
Market trajectory snapshot (contextual numbers)
- Historical context (2020–2025): The sector grew from USD 153.75 Million in 2020 to USD 215.0 Million in 2025, demonstrating recovery and incremental adoption during the latter half of the historical window.
- Near-term outlook (2026–2032): Using 2025 as the base year, our forecast anticipates market expansion at a 5.2% CAGR through 2032, with year-specific model points that reflect conservative and aggressive adoption scenarios for digital audiometry, cloud-enabled deployments, and hybrid business models.
- Concentration dynamics: Market concentration is moderate—our CR3 and CR5 metrics indicate that the top three and top five firms hold a meaningful but not dominant share of the market (CR3: 47%, CR5: 57%), signaling both entrenched incumbency and continued opportunities for mid-sized challengers and specialized new entrants.
How PW Consulting’s report supports 2026 strategic choices
- Portfolio prioritization: We translate market trajectories into a decision matrix that helps product and corporate strategists choose where to accelerate R&D (e.g., advanced diagnostic platforms, integrated OAEs, or portable tele-audiometry kits) and where to rationalize SKUs.
- Regulatory and reimbursement readiness: The report maps near-term regulatory changes and reimbursement pathways so device manufacturers can timetable submissions, audits, and labeling updates with precision.
- M&A and partnership playbooks: We identify target archetypes, valuation heuristics, and integration risk factors that are actionable for corporates and financial sponsors evaluating tuck-ins or platform acquisitions.
- Market-entry and commercial tactics: For companies expanding geographically or into adjacent clinician- and consumer-facing service models, we provide go-to-market sequencing and pricing frameworks tailored to 2026 market realities.
Key industry dynamics that change the game in 2026
Several regulatory and reimbursement developments crystallize as critical inputs to near-term strategy:
Medical Audiometers (Diagnostic Audiometer) Market
- Regulatory simplifications and controls: Historical shifts (e.g., past FDA reclassifications) have reduced certain premarket burdens for select hearing-related devices. At the same time, a significant procedural change takes effect beginning February 2, 2026: PMA and HDE submissions and related preapproval inspections will be evaluated against an ISO 13485-based Quality Management System Regulation. This elevates QMS alignment as a gating factor for advanced device approvals and requires companies to prioritize systems-level compliance investments.
- CPT code overhaul and telehealth permanence: The American Medical Association’s code restructuring (effective January 1, 2026) that replaced older audiology codes with a new suite of professional service codes materially alters billing pathways for hearing device-related professional services. Complementing this, proposed CMS rules for 2026 include the permanent inclusion of certain telehealth audiology codes (e.g., CPT 92622), which increases the commercial attractiveness of tele-audiology-enabled devices and subscription services.
- 510(k) throughput and clearance patterns: The FDA continues to process a high volume of device submissions (CDRH authorized over 3,200 510(k)s in 2025), reflecting an active clearance environment. Manufacturers should anticipate both steady review activity and heightened scrutiny tied to QMS expectations.
Competitive landscape — what the report reveals (high level)
The market structure comprises established clinical audiology device manufacturers, regional specialists, and emergent software-enabled entrants. Our competitive module evaluates market positioning, product portfolios, commercial channels, and strategic initiatives for each named player — allowing readers to assess competitive threats and partnership opportunities without disclosing granular market-split figures.
- Grason-Stadler (Eden Prairie, MN): Longstanding reputation in diagnostic audiometers, tympanometry, and OAE devices. Strengths include clinician trust and clinical-grade product lines; watch for moves to integrate cloud data workflows and service bundles.
- MAICO Diagnostics (Eden Prairie, MN): Broad portfolio spanning diagnostic and screening audiometry. Their channel depth in public health and occupational screening makes them a natural partner for scaled screening deployments.
- MedRx (Largo, FL): Noted for comprehensive diagnostic series (e.g., AVANT A2D lineage). Product engineering and modularity are strategic assets for facilities seeking integrated ENT test suites.
- Amplivox (United Kingdom): Recently launched the Model 270+ (May 2025), which emphasizes accuracy across air, bone, and speech audiometry. Product refreshes such as this are reshaping clinical expectations for measurement precision and workflow efficiency.
- Sibelmed (Sabadell, Spain): Offers compact diagnostic platforms focused on clinician ergonomics and noise-robust testing, appealing to outpatient clinics and private practices across target regions.
- Happersberger Otopront (Hohenstein, Germany): Positioned in the advanced ENT diagnostic segment, with strengths in engineering and integration for hospital-grade audiology suites.
Our competitor analysis synthesizes public disclosures, product launches (such as Amplivox’s May 2025 release), and Q4/2025–Q1/2026 commercial signals to build scenario-based threat maps. The report’s annex contains head-to-head product feature matrices, patent landscaping, and channel-margin benchmarks (available only in the full report).
What the full report contains — practical components for immediate use
- Detailed market sizing and forecast model (historical 2020–2025; base year 2025; forecast 2026–2032) with downloadable model inputs to run custom scenarios.
- Segmental analysis by device type, application, and region, each presented with demand drivers, adoption hurdles, and upside risk cases. (Segment tables and regional splits are reserved for the full report.)
- Competitive profiles and product mapping for the leading suppliers, plus capability assessments and acquisition targets.
- Regulatory and reimbursement playbook, translating code changes, QMS expectations, and telehealth policy into tactical timelines for product labeling, clinical trials, and payer engagement.
- Commercial playbooks for direct sales, distributor partnerships, and hybrid subscription models—complete with pricing elasticity tests and launch checklists.
- Supply chain risk register that flags single-source components, calibration instrument dependencies, and logistics vulnerabilities that commonly affect audiometer manufacturers.
- Executive decision tools: M&A scoring matrix, internal investment prioritization framework, and a one-page board-ready strategic recommendation.
Executive takeaways — priorities for 2026
- Invest in QMS maturity now. With ISO 13485-based evaluation anchored in regulatory review processes beginning in early 2026, QMS readiness is not optional for companies seeking PMA/HDE pathways or international market access.
- Embed telehealth capabilities into product value propositions. Permanent inclusion of tele-audiology billing codes materially increases the market for remote diagnostic solutions and recurring service revenue models.
- Monitor clearance backlog and 510(k) trends. Clearance throughput remains robust; plan submission timing and premarket evidence generation to minimize time-to-market slippage.
- Targeted product refreshes beat broad proliferation. Given moderate market concentration and the continued importance of clinician trust, prioritizing upgrades that materially improve measurement accuracy, workflow, or tele-integration will yield better returns than broad SKU expansion.
- Use M&A selectively to fill capability gaps. Mid-sized M&A can accelerate access to software platforms, telehealth delivery models, or regional channels—our report provides a shortlist of archetypal targets and valuation guidance.
Where the trailer leads
This preview has demonstrated the methodological rigor and practical orientation of our full Medical Audiometers market study: credible base-year calibration (2025 = USD 215.0 Million), transparent historical series (2020–2025), and a robust forecast that reflects a 5.2% CAGR through 2032. It surfaces regulatory inflection points, competitive motions, and near-term commercial levers that matter to leaders in 2026. For CFOs, Heads of Product, BD teams, and Corporate Development officers, the full report converts these insights into executable actions and ready-to-use financial models.
To access the segment-level forecasts, regional and application splits, granular competitor benchmarking, and proprietary scenario model downloadable files, please refer to the full PW Consulting study. The complete deliverable is designed to be used at the board level and in operational planning cycles across 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Medical Audiometers (Diagnostic Audiometer) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sodium Percarbonate Market to Reach USD 705M by 2032 at 4.5% CAGR
By PW Consulting, 2026-08-02
Sodium Percarbonate Market 2026: Strategic Imperatives for Decision-Makers
Executive snapshot
As PW Consulting’s lead industry analyst, I present a concise, decision-focused view of the sodium percarbonate landscape to inform 2026 corporate strategy. Our market model—anchored to a 2025 base year and spanning historical data from 2020–2025 with forecasts through 2032—shows the market has strengthened materially over the past half-decade and is expected to continue expanding at a steady mid-single-digit cadence (CAGR 4.5% over the forecast window). From recovery and rebalancing following 2020–2021 disruptions to renewed demand traction in 2024–2025, the market’s macro momentum and structural attributes create distinct opportunities and hazards for producers, downstream formulators, and investors planning moves in 2026.
Sodium Percarbonate Market
Why this study matters for 2026 strategic choices
-
Timing matters: With the market already larger in 2025 than in prior years and projections extending growth toward the end of the decade, 2026 is a pivotal year for capacity, pricing and partnership decisions that will lock in relative competitive position for the next planning cycle.
Sodium Percarbonate Market -
Profitability under pressure: Feedstock volatility and regional demand swings are squeezing margins episodically; near-term cost management and commercial tactics will determine which players convert volume growth into sustainable earnings.
Sodium Percarbonate Market -
Regulatory and trade policy noise is elevated: Chemical registration, anti-dumping actions and evolving environmental expectations are reshaping sourcing and market access strategies—requiring proactive compliance and country-level playbooks.
-
Consolidation potential: The market concentration profile indicates that a relatively small number of firms capture a meaningful share of global supply—creating both acquisition targets and strategic scale advantages for incumbents and entrants.
Market trajectory: what the numbers tell us (high-level)
Our topline market model tracks a clear expansion from the early-2020 baseline through a firm 2025 base year, followed by steady growth across the forecast period. This trajectory—underpinned by a 4.5% compound annual growth rate—reflects a combination of durable household and commercial demand, incremental industrial use cases, and an ongoing shift toward higher-value, stabilized product grades within detergent and cleaning formulations. For executives, the implication is simple: volume growth is real, but margin capture depends on product mix, channel strategy and cost control.
Report contents — practical, action-first deliverables
Our full study is built for practitioners who must act in 2026. It includes:
-
Topline market sizing and demand-driver analysis (2020–2025 history; 2026–2032 scenarios) with sensitivity runs around feedstock and pricing.
-
Segmentation frameworks by form and application that map to supply chain, logistics and margin pools—presented in a way that supports SKU-level commercial decisions (note: detailed splits and unit-level price curves are available in the full report).
-
Channel and end-customer mapping, highlighting how detergent makers, industrial launderers, water treatment operators and household product OEMs procure and value differentiated grades.
-
Cost-to-serve models and break-even analyses to support pricing and make-versus-buy choices.
-
Regulatory matrix and trade-risk heatmap, cross-referenced to likely compliance actions and fast-deploy remediation pathways.
-
Competitor playbooks and inorganic opportunities: due diligence checklists, valuation benchmarks and a prioritized target list for bolt-on or transformative acquisitions.
Dynamics shaping 2026 — what to watch
-
Feedstock volatility: Sodium percarbonate production is sensitive to sodium carbonate and hydrogen peroxide availability and pricing. During 2025 feedstock trends were uneven, and our monitoring shows continued volatility into 2026—requiring hedging and flexible procurement arrangements for producers and formulators alike.
-
Short-term price movement in China: In Q1 2026 the domestic price index registered a quarter-over-quarter uptick driven by export demand and restocking. Such short-run price moves can compress margins or, if managed via contractual adjustments, can be converted into improved returns.
-
Regulatory scrutiny and compliance: European registration dossiers remain active for established trade names, emphasizing dossier hygiene, REACH-aligned testing, and forward-looking substitution evaluations for downstream customers that increasingly prioritize compliant sources.
-
Trade remedies: Anti-dumping measures in certain markets have altered competitive dynamics and redirected trade flows—an ongoing variable that companies must incorporate into supply and go-to-market strategies.
Competitive landscape — how to interpret positioning
The sodium percarbonate supplier base combines established global majors, regional champions and specialized niche players. Market concentration is meaningful: the top three suppliers collectively capture a majority of the market’s supply, while the top five increase that coverage substantially—creating clear scale advantages but also room for focused challengers.
-
Solvay (Brussels, Belgium): Global footprint and branded high-stability grades make it a go-to supplier for premium laundry and industrial bleaching customers. Their strength lies in global logistics and R&D-backed formulations.
-
Evonik (Essen, Germany): Competes on technology-enabled grades geared to cold-water washing and eco-detergent trends—positioning that aligns well with western detergent innovation agendas.
-
OCI (Seoul, South Korea): Large-scale capacity and a focus on detergent and bleaching markets provide cost and supply security advantages, particularly in Asia-Pacific corridors.
-
Specialists such as Kandelium and Chinese producers: These firms offer deep product know-how and cost-competitive supply, with strong positions in coated and tailored grades; they are important partners or rivals depending on regional market access and quality requirements.
-
Other regional players (Turkey, India, China): These firms support local industrial, textile and water treatment demand and have export ambitions; they are often the flexible swing suppliers in spot markets.
Strategic implications and recommended 90-day actions for 2026
-
Immediate procurement hedges and supplier diversification: Lock flexible offtake terms with multiple origins to weather feedstock-driven spikes. Short-term index-linked contracts combined with conditional volume agreements reduce exposure.
-
Prioritize higher-margin, differentiated grades: Accelerate development and commercialization of stabilized/coated grades where technical barriers and brand trust allow price premium capture.
-
Regulatory readiness: Update dossiers, engage early with authorities in target markets, and build an evidentiary base for eco-claims—this reduces market-access latency and supports premium positioning.
-
M&A and partnership screening: Use market concentration and capacity maps to identify bolt-ons that either shore up regional supply or add specialized product lines.
-
Commercial playbook refresh: Re-segment customers by margin-to-serve and technical requirements; deploy targeted pricing and logistics offers to strategic OEMs and formulators.
-
Scenario and contingency planning: Model downside stress cases for feedstock shocks and trade disruptions; prepare temporary production re-routing plans and emergency inventory protocols.
What we leave for the full report (and why)
True to the “trailer” principle of this introduction, we have showcased the strategic depth required to act in 2026 while deliberately withholding the granular segmentation tables, SKU-level pricing decks, region-by-region breakdowns and confidential company share matrices that materially affect tactical decisions. These datasets are compiled in the full report and are essential for precise commercial modelling, buyer-specific negotiations and M&A valuation work.
How PW Consulting supports your 2026 execution
We combine a quantified market model, primary-sourced procurement intelligence and transaction advisory experience to convert the insights above into executable programs. Whether you need a rapid supply-security retrofit, a tailored product commercialization plan, or a buy-side diligence package, our team delivers integrated workstreams that tie forecast scenarios to P&L impact and implementation milestones.
Next step
If you are considering capacity moves, pricing resets, or acquisitive growth in 2026, request the full Sodium Percarbonate Market report for detailed segmentation tables, company share analytics, price decks and the defensive playbooks that are omitted from this preview. The full toolkit is designed to convert the macro picture and competitive intelligence above into immediate actions that protect margin and accelerate market share.
For detailed analysis of this topic, please visit the official page: Sodium Percarbonate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vaccine Refrigerators Market to Reach USD 932 Million by 2032 at 8.5% CAGR
By PW Consulting, 2026-08-02
Vaccine Refrigerators Market — Strategic Outlook and Decision Framework for 2026
As global immunization agendas accelerate and health systems prioritize resilient cold chains, the vaccine refrigerators market has entered a sustained growth phase. After expanding from a historical base of approximately USD 350 million in 2020 to a 2025 market size of USD 525 million, the sector is positioned to nearly double by the end of the 2026–2032 forecast window. Our modeling indicates a compound annual growth rate of roughly 8.5% across the forecast period, reflecting a mix of replacement demand, programmatic expansion in emerging markets, and technology-driven upgrades in mature markets. For executive teams planning capital allocation, product roadmaps, go-to-market pivots, or M&A activity in 2026, this landscape requires finely-tuned strategy that balances regulatory compliance, service economics, and supply-chain resilience.
Vaccine Refrigerators Market
Why this Report Matters for 2026 Decision-Making
- Translates macro momentum into operational choices: We map where growth is most durable and what capabilities (certifications, energy profiles, service networks) convert market tailwinds into revenue.
- Reduces technical and regulatory uncertainty: With WHO PQS and CDC guidelines increasingly shaping procurement, the report clarifies compliance thresholds that materially affect win rates in institutional tenders and international immunization programs.
- Prioritizes capital-efficient product development: We identify product attributes and service models that maximize lifetime value (LTV) under realistic OPEX and labor-cost scenarios.
- Supports M&A and partnership screening: The analysis highlights target profiles, integration risks, and value-creation levers for roll-up or cross-border alliance plays.
Report Contents — Practical, Actionable, and Executable
- Market sizing and topline projections from 2020 through 2032, with scenario analysis calibrated to regulatory shifts, energy-cost volatility, and programmatic funding cycles.
- Market dynamics and segmentation logic that explain where and why demand concentrates — without exposing proprietary client-level splits in the public summary.
- Regulatory and standards matrix: PQS, CDC/NSF guidance, annual verification cycles, and their procurement implications across buyer types.
- Competitive benchmarking and product scorecards covering temperature performance, freeze-protection, energy use, solar-direct-drive readiness, and serviceability.
- Commercial playbooks: pricing strategies, tender bid-shaping, LRP (long-range planning) for spare parts, and aftermarket service-as-a-product models to improve margins.
- Supply-chain vulnerability assessment and mitigation strategies for critical inputs (e.g., insulation formulations) and logistics to remote installations.
- Investment thesis and M&A screening templates, including stress-tested valuations under three demand scenarios.
- Implementation roadmaps with KPIs, operating models, and pilot design templates for 12–24 month execution cycles.
Market Dynamics and Near-Term Catalysts
Three structural forces are converging to define the market through 2026 and beyond. First, public-health funding and routine immunization programs continue to expand, driving baseline demand for certified storage capacity. Second, mature markets are accelerating replacement cycles to meet more stringent energy- and safety-related standards, elevating the share of higher-specification units. Third, off-grid immunization efforts and remoteness considerations are increasing demand for solar-capable and robust solar-direct-drive designs.
Vaccine Refrigerators Market
Regulatory frameworks are a critical gating factor. WHO PQS performance specifications (notably for E003-category refrigerators) now emphasize Grade A freeze protection and solar compatibility — a requirement that directly influences product architectures and supplier selection for many international tenders. In parallel, CDC guidance in the United States continues to set behaviorally binding expectations for vaccine storage, requiring purpose-built solutions that meet defined standards.
Vaccine Refrigerators Market
On the input side, material and labor dynamics are non-trivial. Polyurethane foam insulation remains a core material, and supply-chain pressure has driven OEMs to innovate toward more energy-efficient formulations that reduce both material costs and operating energy. Additionally, the labor-intensive nature of installation and maintenance in remote geographies increases total deployment costs, making service models and local partnerships a decisive competitive advantage.
Competitive Landscape — Profiles and Strategic Implications
- Helmer Scientific (Noblesville, Indiana) — Purpose-built medical-grade refrigerators and freezers designed to meet CDC recommendations. Helmer’s emphasis on temperature uniformity and recovery positions it well in high-regulation clinical and hospital channels. Recent product introductions into ultra-low temperature segments expand their addressable market and reinforce a hospital- and research-focused distribution footprint. ( https://www.helmerinc.com/)
- B Medical Systems (Hosingen, Luxembourg) — Offers a broad portfolio including ice-lined and solar direct-drive options compliant with WHO guidelines and PQS certification paths. Their recent product releases add capacity and water-pack freezer options, signaling a push into higher-volume, program-oriented tenders. ( https://www.bmedicalsystems.com/)
- PHC Europe B.V. (PHCbi) (Etten-Leur, Netherlands) — Pharmaceutical-grade cold solutions with emphasis on precise temperature control and energy efficiency, appealing to pharmaceutical companies, central labs, and academic research sites. ( https://www.phchd.com/)
- Haier Biomedical (Qingdao, China) — A full-range provider targeting both commercial and programmatic cold-chain systems, including solar and integrated system solutions for immunization programs. Their manufacturing scale and integrated product lineup make them a natural partner in large rollouts. ( https://www.haiermedical.com/)
- Vestfrost Solutions (Esbjerg, Denmark) — Specialized in PQS-approved self-regulating refrigerators suitable for professional and tropical use. Recent PQS prequalification further validates their suitability for international procurement programs. ( https://www.vestfrostsolutions.com/)
- Aucma (Qingdao Aucma Global Medical) — WHO PQS-certified offerings and designated supplier status for certain immunization equipment categories; their presence signals continued competition from scale-oriented Asian OEMs. ( https://www.aucmamedicalglobal.com/)
The competitive structure is moderately concentrated: the top three firms capture a meaningful but not dominant share of the market, and the top five increase concentration further. This opens room for specialist players to win in focused niches (e.g., ultra-low temperature, solar-direct-drive for off-grid markets, or high-service-margin hospital channels) while larger OEMs drive scale-based advantages in price and distribution.
Strategic Playbook for 2026
- For OEMs: Accelerate PQS and equivalent certifications; prioritize modular designs that enable local assembly and reduce freight costs; develop adjustable service contracts with predictive maintenance and remote monitoring to convert CAPEX buyers into recurring revenue streams.
- For investors and acquirers: Target mid-sized specialists with proven PQS/NSF compliance and established local-service footprints. Value creation can be realized by combining product portfolios, centralizing spare-parts logistics, and cross-selling managed services.
- For procurement agencies and NGOs: Shift evaluation criteria from purchase price to total cost of ownership and serviceability, with explicit scoring for freeze-protection, energy efficiency, and solar readiness. Prioritize suppliers with demonstrated compliance histories and local maintenance partners.
- For service providers: Invest in remote telemetry, field-service training programs, and bundled spare-part subscriptions — particularly for deployments in regions where labor and logistics are costly.
- For materials and components suppliers: Explore long-term supply agreements and co-development of lower-GWP, higher-performance insulation blends to meet both regulatory and energy objectives.
Operational Levers and Risk Mitigation
Decision-makers should stress-test plans against four primary risks: raw-material volatility (insulation and refrigerants), labor and installation cost escalation in remote installs, tightening or evolving regulatory standards (including annual PQS re-evaluations), and the risk of technology obsolescence as energy-efficiency expectations rise. Mitigation measures include dual sourcing for key materials, modular product platforms to enable rapid certification updates, local-assembly partnerships to reduce logistics burdens, and piloting service-as-a-product models with built-in telemetry to reduce onsite visits and accelerate issue resolution.
How PW Consulting’s Study Enhances Your 2026 Playbook
Our full study blends quantitative forecasts with practical tools — procurement scorecards, certification checklists, supplier due-diligence templates, and investment case models — designed to be used directly by product leaders, procurement heads, and investors. We maintain a clear separation between strategic narrative and proprietary segment-level datasets; the former is provided here to inform immediate choices, while the latter is bundled in the full report to enable transaction-level and bid-level decision-making.
In summary, 2026 represents a pivotal year: the broader market momentum (8.5% CAGR across the forecast) provides attractive upside, but realization of that upside will be uneven and dependent on certification readiness, service capability, and supply-chain agility. Organizations that operationalize the recommendations in this report — prioritizing compliance, modularity, service monetization, and strategic partnerships — will be best positioned to capture the most profitable growth pockets.
Next Steps
- Access the complete PW Consulting Vaccine Refrigerators Market report for regional and application-level forecasts, supplier scorecards, and downloadable decision templates.
- Engage with our advisory team for a tailored briefing and a 6–12 month implementation roadmap aligned to your organization’s objectives and risk tolerance.
For the detailed datasets, granular regional and application breakdowns, and the full competitive scorecards referenced in this executive preview, please visit our report page or contact PW Consulting’s life sciences practice for a confidential briefing.
For detailed analysis of this topic, please visit the official page: Vaccine Refrigerators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Roof Coating Market to Grow 3.8% CAGR to USD 3,350M by 2032
By PW Consulting, 2026-08-02
Roof Coating Market 2026: Strategic Imperatives and Decision-Ready Insights
Executive summary — why this study matters to boardrooms and deal teams in 2026
As organizations reassess capital allocation and product strategies for the post‑pandemic recovery, the roof coating market presents a mix of steady growth, supply‑side stressors and regulatory uncertainty that will materially influence near‑term commercial outcomes. PW Consulting’s latest Roof Coating Market study (base year 2025; historical series 2020–2025; forecast 2026–2032) synthesizes quantitative trend lines and qualitative, actionable intelligence to help executives make high‑confidence decisions on pricing, sourcing, product positioning, and M&A through 2026 and beyond.
Roof Coating Market
Key macro anchors from the study: global market value climbed from roughly USD 2,200 Million in 2020 to an estimated USD 2,570 Million in 2025, and PW Consulting’s scenario modelling indicates expansion toward the low‑to‑mid USD 3,000 Millions by the early 2030s, riding a compound annual growth rate (CAGR) of about 3.8% over the forecast window. Market structure is moderately concentrated (CR3 ≈ 55%, CR5 ≈ 72%), which creates both incumbent power and opportunity for focused challengers.
Roof Coating Market
How this research converts to 2026 decisions
- Procurement & supply strategy: The report maps supplier risk across raw materials and polymer chemistries, enabling procurement teams to prioritize dual‑sourcing and hedging strategies where margin exposure and supply disruption risk are highest.
- R&D and product road‑mapping: With regulatory pressure on VOCs and hazardous constituents intensifying, the report identifies priority reformulation pathways that balance performance, compliance, and cost.
- Commercial & pricing playbooks: Dynamic pricing scenarios and price‑elasticity modelling in the study give commercial leaders the tools to test price moves against volume, margin, and warranty exposure.
- M&A and portfolio moves: The concentration profile and company‑level value drivers spotlight pockets where bolt‑on acquisitions or capability purchases can deliver disproportionate returns.
- Go‑to‑market optimization: The research overlays product, channel and end‑user logic to recommend where to invest in contractor incentives, specification campaigns, or OEM partnerships.
Market trajectory & implications
Growth over the past five years has been steady but nonlinear. Recovery patterns in construction activity, periodic raw material price shocks, and pronounced changes in building‑performance requirements have created distinct windows of opportunity for technology upgrades and higher‑value coatings. The study’s baseline projection (CAGR ~3.8% for 2026–2032) reflects a market that favors incremental innovation, selective premiumization, and regulatory‑driven product migration rather than explosive expansion.
Roof Coating Market
For 2026 decision cycles this implies three practical imperatives: prioritize margin resilience through supply chain and product design; align new product introductions with tightening emissions and chemical regulations; and focus channel investments where specification and retrofit demand converge.
Critical dynamics shaping 2026 outcomes
- Raw material pressure: Tight supplies of methyl methacrylate (PMMA) and silicone resin feedstocks are generating upward price pressure and longer lead times for certain formulation pathways. The report quantifies supplier concentration, lead‑time variability and sensitivity of different product classes to these inputs, enabling supply‑chain mitigation planning.
- Regulatory acceleration: National and regional authorities are advancing rules on volatile organic compounds (VOCs) and hazardous chemical content. The report includes a regulatory impact matrix that translates pending rules into shelf‑level formulation and labelling implications for 2026 product launches.
- Consolidation and competitive positioning: With a mid‑range market concentration profile, scale and specialty chemistry matter. The study’s competitive framework explains why certain global players can defend margins through integrated supply chains while niche manufacturers can succeed by optimizing life‑cycle cost performance for specific roofing systems.
Competitive landscape — what incumbents and challengers are doing
The study provides a granular, decision‑oriented assessment of incumbent strategies and challenger playbooks. PW Consulting evaluated a cross‑section of leading manufacturers, from large diversified chemical and coatings groups to regionally focused specialists. The analysis highlights business models, channel focus, technical differentiation, and near‑term strategic moves that will determine competitive advantage in 2026.
- Specialty silicone-focused manufacturers: Firms that produce OH‑functional silicone polymers and related elastomeric technologies are positioned to capture premium retrofit and high‑performance commercial segments—subject to securing resilient silicone feedstock supply chains.
- Performance coatings groups and diversified players: Large coatings and chemical companies leverage scale in R&D, distribution and integrated raw material sourcing to defend share across multiple product families. Their ability to internalize raw‑material volatility and amortize regulatory compliance investments is a key advantage.
- Regionally focused manufacturers and installers: Companies that combine in‑house manufacturing with installation services can capture lifetime value via warranty extensions and maintenance contracts; they also face unique working‑capital dynamics and concentration risk in local supply ecosystems.
To illustrate how the competitive analysis is structured, the full report includes company profiles (headquarters, core value propositions, and go‑to‑market orientation) for major players, alongside an assessment of their strategic strengths, vulnerabilities and likely 12‑24 month plays. As an example, Progressive Materials is profiled for its silicone roof coatings and trade show engagement; similarly, a set of global chemical and coatings groups are evaluated for their product platforms and supply integration. The report synthesizes public developments and interview intelligence to produce strategic theses for each firm.
Report contents — operational modules that executives use
PW Consulting’s Roof Coating Market study is constructed as an operational toolkit rather than a pure data dump. Key modules include:
- Demand modelling (scenario‑based) that ties macro drivers—new construction, retrofits, roofing lifecycles—to product demand and revenue outcomes across 2026–2032;
- Price‑and‑cost sensitivity analyses exposing margin exposure to key feedstocks, freight and energy;
- Supply‑chain heatmaps and supplier scorecards with mitigation playbooks for critical raw materials and specialty polymers;
- Regulatory impact matrix linking pending rules to formulation, labelling and testing requirements in priority markets;
- Competitive benchmarking and strategic option maps (organic R&D, partnerships, acquisitions) tailored to different company archetypes;
- Go‑to‑market playbooks segmented by channel (contractors, specifiers, distributors) and commercial model (product vs. product+service);
- Innovation and sustainability roadmap that prioritizes reformulation, circularity and warranty design to meet customer willingness‑to‑pay and compliance thresholds;
- Deal screening and valuation addenda for M&A teams, spotlighting acquisition targets, synergy sources and integration risk.
Each module is designed to be extracted into board materials, investor memos or 100‑day integration plans—delivering both the “what” and the “how” to act. Importantly, the report intentionally refrains from publishing some core sub‑segment datapoints in summary outlets; PW Consulting’s source portal houses the full split‑level datasets and model access for clients.
Practical recommendations for 2026 action plans
- Immediately: stabilize feedstock exposure. Activate alternative sourcing, strategic inventory buffers, and contractual protections for PMMA and silicone resins where your formulations are most exposed.
- Next 90 days: compliance readiness sprint. Use the report’s regulatory matrix to triage SKUs for reformulation, testing and labelling ahead of new VOC and hazardous‑content rules.
- Within 6 months: refine product and channel mix. Reallocate commercial investments toward higher margin segments and specification channels identified in the study’s demand modelling outputs.
- Over 12–18 months: pursue capability M&A selectively. Target acquisitions that deliver raw‑material access, formulation know‑how, or contractor channel control—using the report’s deal screening filters to prioritize targets with the fastest path to accretion.
Data integrity and methodology
PW Consulting’s approach combines primary interviews with manufacturers, distributors and major contractors; bottom‑up revenue mapping; and cross‑validation with trade‑level shipment and raw‑material flow data. The study’s market size time series (2020–2025 historical and 2026–2032 forecast) is expressed in USD Million and is anchored to a 2025 base year to align corporate planning cycles for 2026. Scenario sensitivity tests and a transparent assumptions appendix enable clients to re‑run the core model under bespoke internal hypotheses.
Closing — a strategic invitation
For executives, the question is not whether the roof coating market will grow—our baseline shows ongoing expansion at a mid‑single‑digit CAGR—but how to capture durable value in a market defined by raw‑material tightness, regulatory change, and a mix of scale and niche competition. PW Consulting’s Roof Coating Market study translates these macro truths into a practical, priority‑ranked playbook for 2026 actions: stabilise supply, de‑risk compliance, reprice with discipline, and pursue capability buys where integration economics are clear.
To access the full dataset, detailed sub‑segment analytics and the company‑level decision memos that are intentionally withheld from summary briefings, visit the PW Consulting client portal or contact our industry team. The intelligence in the report is designed to be the operational backbone for the next 18 months of strategic choices—equipping CEOs, CFOs, and business unit leaders to convert market transparency into competitive advantage.
For detailed analysis of this topic, please visit the official page: Roof Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Sprocket Market Outlook 2026: Strategic Imperatives from Our 2025 Base-Year Study
As firms prepare budgets, M&A roadmaps, and product strategies for 2026, the ability to translate validated market signals into targeted choices will be the differentiator between opportunistic gains and costly missteps. PW Consulting’s latest Sprocket Market study—anchored on a 2025 base year and a rigorous 2020–2025 historical analysis—provides that translation. In short: the market is sizeable, recovering from near-term cyclical noise, and positioned for steady expansion at a mid-single-digit compound annual growth rate through 2032. This briefing outlines the strategic value of the study for 2026 decision-making while intentionally preserving our segmented intelligence behind the report paywall.
Sprocket Market
Why this study matters for 2026
Decision cycles in 2026 will be dominated by three realities: constrained capital allocation, supply-chain reconfiguration, and accelerating product differentiation driven by materials and manufacturing technology. Stakeholders need a single, defensible view of demand drivers, supplier economics, and concentration dynamics to prioritize actions. Our report synthesizes primary interviews, demand modelling, cost mapping, and scenario stress-tests into a practical guide for executives, corporate development teams, procurement officers, and R&D leaders.
Sprocket Market
- Validated market trajectory: Using 2025 as the base year, we show the market’s recovery after a brief softening and its expected expansion through the forecast horizon—culminating in an estimated market size in 2032 that confirms durable mid-term growth at a 6.8% CAGR.
- Decision-focused outputs: Rather than broad commentary, the study provides explicit levers—sourcing, pricing, product mix, and partnership playbooks—that can be executed within an 18–24 month planning horizon.
- Risk-first scenarios: Multiple macro- and micro-scenarios quantify downside and upside outcomes for capital-intensive moves (e.g., new plant builds, acquisitions), enabling contingency planning that is realistic and actionable for 2026 budgets.
Market trajectory: what the macro numbers tell you
Our consolidated market model places the industry at a clear inflection point. After tracking historical output through 2020–2025, the market stabilized into 2025—reflecting a mix of demand rebounds in certain end-markets and cost pressures elsewhere. From this position, the market is forecast to grow at a compound annual growth rate of 6.8% over the 2026–2032 forecast window, reaching a materially larger size by the end of the period.
Sprocket Market
For executives, two interpretations matter. First, sustained mid-single-digit growth supports selective capacity expansion, particularly where differentiated product or service models can realize premium pricing. Second, the pace of growth is not so rapid as to eliminate the value of consolidation and efficiency plays; disciplined inorganic moves and operational optimization remain compelling.
Concentration and competition: reading the market structure
Market concentration in the Sprocket sector is moderate. The top three players capture a meaningful share of revenue, and the top five widen that lead further—indicators of established incumbency yet also of accessible share for well-executed challengers. Specifically, the three-firm concentration and five-firm concentration metrics validate a market where scale matters but niche specialization and service differentiation can still create defensible positions.
- Implication for M&A: Targets should be assessed not only on immediate revenue synergies but on capability adjacencies that accelerate time-to-premium (e.g., coatings, higher-tolerance machining, aftermarket services).
- Implication for suppliers: Tiered procurement strategies that blend strategic partnerships with agile spot sourcing will reduce supply disruption risk without eroding margin capture.
- Implication for new entrants: Entry opportunities exist where product-performance improvements or logistics/service models materially change customer economics.
Key dynamics shaping strategy in 2026
- End-market oscillation: Automotive and industrial demand patterns are diverging in pace and quality of demand. Firms must map product portfolios to the elasticity of each end-market and avoid one-size-fits-all pricing or capacity decisions.
- Material-technology push: Advances in metallurgy, surface engineering, and precision manufacturing are compressing lifecycle costs for premium offerings. R&D investments focused on weight, durability, and lifecycle serviceability will unlock margin expansion.
- Supply-chain resilience: Geographic diversification of critical suppliers, nearshoring of key processes, and digital traceability are no longer optional—they are a requirement to maintain customer trust and preserve contractual penalties in tighter delivery ecosystems.
- Service and aftermarket: Monetization beyond initial sale—spare parts, predictive maintenance, and integration services—is a high-leverage channel to stabilize revenues as capital spending cycles fluctuate.
From insight to action: four tactical priorities for 2026
Based on our modeling and interviews, PW Consulting recommends four tactical priorities to ensure 2026 initiatives are high-impact and low-regret.
- Calibrate capacity investments to validated demand pockets: Use the report’s localized demand scenarios to sequence CAPEX. Prioritize flexible lines and modular tooling that allow quick shifts between product families.
- Reprice with value, not cost: Implement a value-based pricing framework for product tiers that captures technical differentiation and aftermarket potential. Our workshop templates show how to convert performance delta into price premiums with customer segmentation.
- Accelerate supply-partner consolidation where it reduces complexity: Consolidate low-value transactional relationships and build strategic alliances with vendors who can co-invest in resilience and quality improvement programs.
- Make targeted M&A bets for capability, not scale alone: Look for bolt-ons that close capability gaps (e.g., proprietary coatings, localized logistics hubs) rather than acquisitions that merely add symmetrical capacity without improving margin mechanics.
What the full PW Consulting Sprocket Market study includes
To make these recommendations executable, the full report contains a comprehensive package of practical deliverables. Highlights include:
- Granular demand forecasts across region, material, and application dimensions (historic and forecast), including sensitivity ranges and lead indicators to watch in real time;
- Detailed cost-to-serve and supplier economics models that allow buyers to stress-test contract terms and identify immediate cash-saving levers;
- Value-chain maps with supplier risk scores, interchangeability assessments, and recommended near-term mitigations;
- Commercial playbooks: go-to-market strategies for premiumization, aftermarket growth, and geographic rollout—each articulated with P&L impact estimates and implementation checklists;
- M&A playbook: target screening matrix, valuation multipliers calibrated to current market multiples, and integration checklists designed to capture synergies in 12–18 months;
- Interactive dashboards and downloadable datasets to allow teams to run custom scenarios aligned to internal KPIs.
Note: While we preview the report’s architecture here, the granular segment-level forecasts and the downloadable datasets are made available exclusively within the full report package to ensure confidentiality and integrity of our models.
How to use the report in your 2026 planning cycle
The study is structured to slot directly into typical corporate planning workflows. Tactical usage patterns we recommend:
- Q4 2025 / Q1 2026 budgeting: Use the base-case scenario and sensitivity bands to set conservative vs. aggressive budget lines for revenue and CAPEX.
- M&A diligence: Apply our target-screening criteria and valuation frameworks during initial screening to avoid overpaying for scale without capability uplift.
- Procurement renegotiations: Deploy the supplier economics models in supplier scorecards and renegotiation playbooks to secure firm, resilient commitments.
- R&D prioritization: Map product development pipelines against the forecasted premium segments to rationalize investments that will pay back within a 24–36 month window.
Closing perspective: where opportunity and discipline meet
The Sprocket market today presents a classic strategic trade-off: measured growth and moderate concentration reward both scale and focused differentiation. For 2026, success will be defined neither solely by the size of a firm’s balance sheet nor by aggressive capacity expansion, but by its ability to invest selectively—locking in capabilities and partnerships that convert moderate demand growth into lasting competitive advantage.
PW Consulting’s study is engineered to be the operating manual for that choice process. It combines a defensible macro view—anchored to the 2025 base year and articulated through a 6.8% CAGR forecast—with the tactical playbooks and datasets teams need to act quickly and confidently.
Next steps
For immediate access to the full segmented forecasts, company-level profiles, interactive dashboards, and implementation materials referenced above, visit the PW Consulting report page. If you prefer a tailored briefing, our consulting team can run a 90-minute executive workshop to translate the study’s findings into a 12–24 month action plan calibrated to your organization’s priorities.
For detailed analysis of this topic, please visit the official page: Sprocket Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: X-ray Inspection Market Set to Grow at 5.73% CAGR to USD 3.86B by 2032
By PW Consulting, 2026-08-02
X-ray Inspection Systems Market: Strategic Imperatives for 2026 — An Executive Preview
PW Consulting presents a focused industry primer to accompany our full X-ray Inspection Systems Market study. This briefing is designed to orient senior leaders — CEOs, heads of product, BD and regulatory affairs — to the forces that will shape capital allocation, M&A, and go-to-market decisions in 2026. It highlights why the market matters, where strategic risks and opportunities concentrate, and how our full report turns data into executable choices.
X-ray Inspection Systems Market
Why this market matters in 2026
X-ray inspection systems sit at the intersection of quality assurance, regulatory compliance, and production automation. Across medical devices, pharmaceuticals, automotive, and electronics manufacturing, X‑ray technologies (from high-resolution micro-CT to inline 2D imaging) are shifting from “nice-to-have” validation tools to mission‑critical production controls. The commercial signal is clear: after growing from under USD 2.0 Billion in 2020 to approximately USD 2.61 Billion by the 2025 base year, the market is projected to continue expanding through the forecast window. By 2032 total industry revenues approach the high‑single‑digit billions under a mid‑cycle CAGR of approximately 5.73%. That steady, technology-driven expansion creates predictable runway for targeted investments while exposing firms to differentiated competitive and regulatory pressures.
X-ray Inspection Systems Market
What the full PW Consulting study delivers (practical, action-oriented)
- Market sizing and validated forward curves (historical 2020–2025; forecast 2026–2032) calibrated to real equipment replacement cycles and factory automation roadmaps.
- Scenario-based demand models that translate macro drivers into unit-volume and service-revenue outcomes under three realistic adoption trajectories.
- Regulatory and reimbursement impact assessments (including recent FDA and Medicare shifts) with decision trees and compliance-cost estimates tied to product classes.
- Vendor landscaping with competitive positioning maps, capability heatmaps (hardware, software/AI, services), and M&A readiness scoring.
- Commercial playbooks for incumbents and challengers: channel strategies, bundling recommendations, and pricing levers optimized for capital equipment and recurring service economics.
- Procurement and supply‑chain resilience diagnostics, including lead-time stress tests and single‑sourcing risk matrices.
- Operational KPI dashboards and a step‑by‑step implementation guide for piloting inline and CT inspection solutions in high-mix production lines.
- Appendices: primary interviews, methodology, and an anonymized database of procurement tenders and equipment spec-level requirements across end markets.
Key market dynamics shaping 2026 choices
- Technology convergence. Higher-resolution detectors, faster reconstruction algorithms, and on-device AI are increasing the scope of defects that can be automated for real‑time reject decisions. This improves throughput but requires tighter integration across hardware, edge compute, and MES/ERP systems.
- Regulation is tightening. The U.S. Quality Management System Regulation (QMSR), effective February 2, 2026, embeds ISO 13485:2016 into device CGMP expectations — raising the bar for validation, traceability and supplier audits for solutions used in medical device inspection.
- Reimbursement and care‑delivery models matter for portable systems. Pending Medicare analyses tied to HCPCS codes for portable X‑ray services will materially influence buyer economics for mobile units used in remote care and hospital-at-home settings.
- Concentration and value capture. The market shows a moderate to high degree of concentration at the top — a structural feature that favors firms with integrated product-service offerings and global support footprints. This has implications for pricing power, partnership strategies, and M&A valuation multiples.
- End-market divergence. Demand drivers in medical device QA, consumer electronics, and automotive are asynchronous: medical adoption is regulatory-bound but high-value per unit; electronics and automotive prioritize throughput and inline integration. Effective product roadmaps will segment offerings accordingly.
Competitive landscape — who matters and why
The competitive field blends specialized inspection innovators with large industrial automation and metrology players. Leading manufacturers remain differentiated on three axes: imaging physics (microfocus, CT vs. 2D), software/analytics (3D recon & AI detection), and aftermarket support (service, calibration, training). Notable incumbents profiled in our study include:
X-ray Inspection Systems Market
- North Star Imaging — a specialist in industrial CT and non‑destructive testing for micro-components and implants, with deep application engineering for 3D imaging challenges.
- Nikon Metrology — offers large‑envelope CT capacity and microfocus tubes tailored to implantables and additively manufactured parts, leveraging optics and precision engineering heritage.
- Nordson Corporation — provides both manual and automated series inspection platforms with strong integration options for production lines.
- YXLON International — microfocus X‑ray and CT systems focused on medical device QA for small parts and implants.
- Mettler Toledo — supplies X‑ray systems tuned for pharmaceutical and medical device packaging integrity and contaminant detection.
- Viscom AG — specializes in 3D AXI and MXI systems for series inspection of medical electronics and modules.
- HEUFT Systemtechnik — delivers pulsed X‑ray systems optimized for inline foreign object and package-quality detection.
Recent regulatory milestones — such as FDA 510(k) clearances for advanced stationary and portable systems — are accelerating market entry for new device classes and expanding clinical use cases. Our competitive assessment emphasizes relative strengths (e.g., clinical approvals, service network breadth, software ecosystems) rather than headline revenue figures; the full report includes an actionable vendor selection matrix for procurement teams.
Strategic implications for decision-makers in 2026
For leaders making budget and product decisions in 2026, three high‑priority implications emerge from our analysis:
- Prioritize regulatory alignment and documentation now. With QMSR effective in early 2026 and ongoing FDA device clearances reshaping clinical use, firms should accelerate ISO-aligned quality programs, supplier audits, and traceability systems to avoid market access delays.
- Design product portfolios along two axes — high-value, compliance-heavy systems (medical & pharma) and high-volume, throughput-optimized inline solutions (electronics, automotive). Each requires distinct sales motions, support economics, and upgrade paths.
- Monetize services and data. As installed bases grow, service, calibration, and software subscriptions become the main margin lever. Build remote diagnostics and predictive maintenance into contracts and consider outcome-based pricing pilots for tier‑1 OEMs and system integrators.
Recommended immediate moves (first 90–180 days)
- Run a regulatory gap assessment mapped to QMSR/ISO 13485 for all inspection products and supply partners.
- Initiate a channel and partner audit to identify weaknesses in aftersales coverage and spare‑parts logistics for priority markets.
- Test a bundled hardware+software offering in one pilot customer segment (medical QA or electronics inline) to quantify churn reduction and service ARPU uplift.
- Establish a reimbursement monitoring cell focused on HCPCS code developments and hospital procurement trends for mobile X‑ray adoption.
- Screen strategic M&A targets using our five‑factor readiness score (technology fit, service footprint, regulatory posture, customer overlap, cultural compatibility).
What the full report will let you do
Accessing PW Consulting’s full X-ray Inspection Systems Market study gives you the granular inputs and executable tools you need to convert insights into decisions: procurement scorecards, supplier shortlists, capex sensitivity matrices, and a prioritized roadmap of product changes keyed to regulatory timelines. We deliberately preserve confidential sub‑segment tables and client-level data in the paid report to protect commercial value; the executive summary here surfaces the strategic signals without releasing those granular splits.
How PW Consulting supports execution
Beyond analysis, we offer hands-on engagement packages tailored to the typical 2026 agenda: compliance readiness sprints, go‑to‑market pilots, M&A diligence and integration playbooks, and field service optimization projects. Our approach couples the market intelligence in this report with implementation teams that translate recommendations into measurable P&L outcomes.
Closing — the decision moment
For executives evaluating capital allocations in 2026, the choice is framed by predictability and differentiation. The market’s steady compound growth provides a reliable horizon for investment; the differentiator will be how quickly firms align product roadmaps to regulatory shifts, convert installed bases into service revenue, and embed AI-enabled analytics into inspection workflows. PW Consulting’s full report gives you the actionable detail to prioritize investments, de‑risk execution, and capture the greatest value as the X‑ray inspection market enters its next growth chapter.
To obtain the full dataset, proprietary segmentation tables, and vendor selection tools referenced in this preview, please contact PW Consulting for access to the complete X-ray Inspection Systems Market report and advisory services.
For detailed analysis of this topic, please visit the official page: X-ray Inspection Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Traffic Marking Paints market to reach USD 321.9 Million by 2032 (5.2% CAGR)
By PW Consulting, 2026-08-02
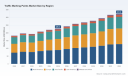
Traffic Marking Paints Market: Strategic Outlook for 2026 Decision-Making
As cities accelerate infrastructure renewal, highways demand higher durability, and sustainability rules tighten, the traffic marking paints market occupies an outsized role in municipal planning, highway concession economics, and coatings portfolios. PW Consulting’s latest study—anchored on a 2025 base year and projecting through 2032—provides the strategic intelligence executives need to act decisively in 2026. The market, measured in USD (Million), has shown a resilient recovery across 2020–2025 and is projected to grow at a compound annual growth rate (CAGR) of 5.2% from 2026 onwards, reaching an anticipated market size by 2032 that makes the category a non-trivial contributor to specialty coatings growth agendas.
Traffic Marking Paints Market
Why this intelligence matters for corporate strategy in 2026
- Resource allocation and portfolio prioritization. With predictable mid-single-digit growth, senior management can set capital allocation rules for R&D, production upgrades, and market-entry pilots with greater confidence. The report translates growth trajectories into investment thresholds that preserve margin while enabling product differentiation.
- Procurement and supply-chain resilience. Volatility in key inputs—most notably titanium dioxide and specialty resins, which together can represent a dominant share of manufacturing cost—means procurement strategies materially impact gross margin. Our analysis converts raw-material exposure into hedging and vendor diversification playbooks.
- Regulatory and sustainability positioning. Stricter low-VOC expectations in many jurisdictions require actionable reformulation and compliance roadmaps. The study maps regulatory trajectories against product portfolios to highlight where incremental reformulation investments yield outsized market access benefits.
- M&A and commercial plays. The market’s competitive structure supports both bolt-on consolidation and regional roll-up strategies. Our scenario models help identify the economic thresholds at which acquisition creates immediate scale economics versus when organic growth is superior.
What the report delivers: practical, action-oriented modules
Beyond forecasting, our study is organized to facilitate decision-making across functions. Key operational and strategic deliverables include:
Traffic Marking Paints Market
- Dynamic market model: a buildable model that converts macro drivers and scenario levers (e.g., urbanization rates, highway capex, VOC regulation timelines) into demand and revenue outputs.
- Cost-sensitivity and margin diagnostics: SKU-level margin maps that isolate the impact of titanium dioxide, resin type, and glass bead quality on unit economics, plus suggested pricing ladders across product lifecycles.
- Regulatory readiness checklist: jurisdiction-by-jurisdiction actions tied to R&D timelines for low-VOC and waterborne technologies, including recommended testing protocols and certification roadmaps.
- Competitive scorecards: comparative analyses of incumbent and challenger suppliers on technical performance, channel coverage, production footprint, and innovation trajectories—designed to inform partner selection and M&A prioritization.
- Go-to-market playbooks: tender and specification strategies for winning public contracts, trial deployment plans for long-life thermoplastic solutions, and specification language that procurement teams can use to capture total cost of ownership advantages.
- Implementation-ready pilot designs: practical testing frameworks for proving long-life or low-VOC products on a municipal scale, with KPI templates and failure-mode monitoring.
Competitive landscape: actionable insights on leading players
The traffic marking paints sector combines global coatings majors with specialized regional manufacturers and system providers. Our analysis synthesizes recent strategic moves and capability sets of the most consequential participants to outline threats, opportunities, and likely next moves in 2026:
Traffic Marking Paints Market
- Global coatings leaders: Companies with broad coatings portfolios bring compelling advantages in distribution, R&D scale, and raw-material procurement. Recent product launches focused on extreme-weather durability and longer service life demonstrate their intent to push premium-priced, differentiated lines that reduce life-cycle repainting needs.
- Specialist marking companies: Niche players that concentrate on thermoplastic systems or zone-marking products retain strong customer intimacy and technical know-how, making them natural partners for joint innovation or attractive targets for roll-up strategies that deliver immediate route-to-market benefits.
- Technology and material innovators: Suppliers expanding eco-friendly waterborne solutions and enhanced retroreflective thermoplastics are engineering the next performance bar. Portfolio expansions and product launches during 2025–2026 signal a two-track market: premium durability claims and low-VOC sustainability claims will compete for procurement preference.
Notable industry moves tracked in the study include launches of high-durability and eco-friendly product lines as well as targeted market expansions tied to smart-city and highway modernization projects. These developments highlight an industry actively reshaping product value propositions around durability, environmental impact, and retroreflective performance.
Market structure and strategic implications
The market displays moderate fragmentation: leading firms do not yet command very high concentration ratios, leaving room for strategic consolidation and local leadership plays. This structure creates a dual strategic pathway for incumbents and entrants alike—either invest to capture premium segments through product differentiation or pursue geographical/segment roll-ups to achieve scale benefits in procurement and distribution.
Raw-material price dynamics and margin pressure
Raw-material inputs are a dominant determinant of manufacturing economics. Independent data points indicate that titanium dioxide and specialty resins can account for a large share of total costs, and thermoplastic formulations exhibit a wide price band driven by resin quality and glass-bead specifications. The practical implications for 2026 are clear:
- Price volatility in TiO2 and resins can rapidly compress margins; companies should operationalize cost pass-through clauses for public tenders and institute flexible pricing mechanisms for private contracts.
- Product engineering focused on reducing TiO2 intensity or substituting with lower-cost binders—without sacrificing retroreflectivity—can produce durable competitive advantage.
- Vertical partnerships with glass-bead suppliers and resin producers can stabilize supply and enable joint value propositions emphasizing longevity and safety performance.
Strategic imperatives and a 12-month action plan for 2026
To convert market visibility into commercial advantage, the following priority actions are recommended for the next 12 months:
- Launch targeted pilot programs for waterborne and low-VOC lines in jurisdictions signaling stricter environmental norms; use early wins to secure specification language in municipal tenders.
- Institute a raw-material risk dashboard that ties TiO2 and resin exposure to product margin by SKU and flags hedging or inventory actions when risk thresholds are crossed.
- Develop an M&A filter: target specialty producers with strong regional contracts or unique thermoplastic recipes that materially extend repaint cycles.
- Redesign tender bid templates to emphasize total cost of ownership (TCO) and service-life metrics rather than lowest upfront price; back claims with third-party durability data from controlled pilot deployments.
- Invest in product certification and lab capacity to accelerate time-to-market for eco-friendly and high-retroreflective products; consider co-funded demonstration projects with cities and highway authorities.
- Create channel partnerships with road-services contractors and airport operators to embed products into lifecycle service agreements, increasing recurring revenue and near-term adoption.
KPIs to monitor through 2026
- Market share movement in targeted geographies and application verticals (tracked quarter-on-quarter).
- Average service life improvements (months or years) attributable to premium formulations.
- VOC intensity per SKU and compliance milestones achieved versus regulatory timelines.
- Gross margin resilience against raw-material price shocks; frequency and efficacy of price pass-throughs.
- Number and size of specification wins in municipal and highway tenders linked to product pilots.
What we intentionally withhold in this preview
To preserve the commercial utility of the full intelligence package, this article omits granular, segment-level revenue tables, region-by-region split figures, individual SKU price matrices, and detailed supplier revenue shares. The complete report contains those datasets, alongside interactive modeling tools that allow clients to test bespoke scenarios (e.g., different reformulation investment levels, tender-win rates, and raw-material cost projections) and receive tailored P&L impacts.
Next steps: how to use this study in board-level decision cycles
For boards and executive teams planning 2026 actions, the report is structured to slot directly into strategic reviews. Use it to:
- Inform capital allocation decisions for coatings R&D and production line upgrades;
- Define procurement risk tolerances and contract language for raw-material supply;
- Prioritize markets and product categories for M&A and organic investment;
- Set measurable KPIs for sustainability and specification wins in public infrastructure projects.
In a market growing at an expected mid-single-digit CAGR and presenting both margin pressure from raw-material exposure and upside from premium performance claims, 2026 represents a tactical window to re-engineer product portfolios, secure specification-led revenues, and lock in long-term partnerships. PW Consulting’s full Traffic Marking Paints Market study is designed to move teams from insight to implementation—equipping leaders with the models, scorecards, and playbooks necessary to convert the sector’s trajectory into realized competitive advantage.
For detailed analysis of this topic, please visit the official page: Traffic Marking Paints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High-Selenium Yeast Market Poised for 4.8% CAGR Through 2032
By PW Consulting, 2026-08-02
High Selenium Yeast: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive snapshot
As the High Selenium Yeast market moves from niche supplement to strategic ingredient across animal nutrition and functional foods, 2026 will be a pivotal year for executives who must reconcile regulatory complexity, supply-chain constraints and product premiumization. PW Consulting’s forthcoming full report — built on a base year of 2025 and an explicit forecast horizon of 2026–2032 — shows a steady, investment-grade market trajectory with compound annual growth of 4.8%. The market has expanded consistently through 2020–2025 and our models project continued growth into the early 2030s, underscoring predictable upside for companies that align R&D, regulatory and commercial execution now.
High Selenium Yeast (High-Selenium Yeast) Market
Why this matters for 2026 decision-makers
2026 will be the year when strategic moves crystallize into structural advantage. Several dynamics that have been maturing across the supply chain and regulatory landscape converge to make near-term decisions high-leverage:
High Selenium Yeast (High-Selenium Yeast) Market
- Regulatory clarity: Recent authorizations and government recognitions in major markets have reduced a key source of uncertainty that previously inflated go-to-market timelines.
- Demand articulation: The ingredient’s transition from an ancillary micronutrient to a differentiated technology input (for antioxidant support, animal health and human functional foods) is driving higher-margin opportunities.
- Supply-side normalization: Raw-material cost volatility has eased relative to earlier cycles, enabling predictable procurement and more confident margin modeling.
Market trajectory in context
PW Consulting’s topline model tracks the market through a full five-year historical run (2020–2025) and delivers scenarios into 2032. The market has shown stepwise expansion year-over-year and our baseline forecast envisions steady growth through the forecast window at an annualized rate of 4.8%. For commercial leaders, this predictability enables multi-year investments in formulation, route-to-market and brand positioning that previously would have been considered premature.
High Selenium Yeast (High-Selenium Yeast) Market
Key growth drivers and headwinds
- Premiumization of feed and functional food formulations: As nutritionists and formulators seek higher bioavailability and traceability, demand is shifting toward standardized, well-documented yeast-based selenium solutions that can be justified on health outcomes and feed efficiency metrics.
- Regulatory momentum: Recent official recognitions and approvals in geographies that previously required lengthy local data packages have shortened commercialization windows for compliant suppliers.
- Clinical and translational evidence: A modest but growing corpus of peer-reviewed and industry-sponsored studies supports claims for bioavailability and functional benefits, encouraging adoption in targeted applications.
- Supply-chain steadiness: After periods of commodity-driven input volatility, selenium supply and logistics have stabilized, lowering one barrier to scale. However, capacity constraints for high-selenium yeast manufacturing still demand strategic supplier relationships and contingency planning.
- Commercial fragmentation: The competitive field remains fragmented enough to favor focused players with technical differentiation, but concentrated enough in some subsegments that partnerships and alliances remain meaningful routes to scale.
Competitive landscape — strategic takeaways
Our competitive analysis focuses on incumbent ingredient specialists and vertically integrated animal-nutrition firms. The following are synthesis-level insights drawn from company profiles, product positioning and recent regulatory events; detailed market-share and segment-level metrics are available in the full report.
- Lallemand Inc. (Montreal, Canada): Lallemand’s high-selenium yeast offering has achieved regulatory traction in key jurisdictions and is positioned as a premium, standardized additive with assured selenomethionine content. The company’s strength lies in regulatory know-how and a track record of gaining approvals across complex markets — a capability that shortens commercialization timelines for customers who value compliance certainty.
- Alltech Inc. (Nicholasville, USA): Alltech couples proprietary yeast technology with extensive feed and farm channel relationships. Their product emphasis on animal well-being and antioxidant support reflects an integrated go-to-market that leverages farm-level outcomes and nutritional consulting — a model that drives adoption where advisors influence procurement.
- Cypress Minerals Inc. (Fresno, USA): Cypress positions a standardized, gluten-free high-selenium yeast product that has been used in clinical settings. The company’s differentiation is technical purity and use-case specificity, attractive to functional food formulators and clinical researchers seeking controlled inputs for trials.
Recent regulatory developments — notably the authorization of Lallemand’s premium product in European markets and regulatory green lights in large Asian markets — materially change the competitive calculus. These events make regulatory readiness a table-stakes capability for 2026.
What PW Consulting’s full report delivers (practical content)
The full PW Consulting study is designed as an operational playbook for executives. It includes:
- Detailed market-size modeling (historical series and scenario-based forecasts), with embedded sensitivity analyses to test price, adoption and regulatory timing assumptions.
- Go-to-market matrices that map channel economics across feed, dietary supplements and functional food pathways — highlighting margin pools, lead times and typical buyer decision cycles.
- Supply-chain diagnostics that identify concentration risks at raw-material and manufacturing stages, and prescribe procurement hedges and inventory-buffer strategies.
- Regulatory heat maps and pathway playbooks for prioritized jurisdictions, including dossier templates, expected timelines and evidence requirements for feed and food approvals.
- Competitive benchmarking and M&A scouting: profiles of incumbent suppliers, assessment of technological differentiators, and transaction criteria for bolt-on acquisitions to accelerate capability gaps.
- Commercial test-and-learn pilots and an A/B playbook for pricing, claims architecture and distributor incentives — enabling rapid validation with measurable KPIs.
Actionable strategic moves for 2026
Executives should view the coming 12–18 months as a window to build asymmetric advantages. Recommended moves we articulate in the report include:
- Prioritize regulatory “fast tracks”: Allocate resources to secure authorizations in jurisdictions where approvals materially expand addressable demand — engage early with regulators, and pre-position robust safety and efficacy dossiers.
- Lock in supplier partnerships: Negotiate multi-year offtake and capacity agreements with certified manufacturers to protect margins and ensure continuity as demand scales.
- Invest in clinical evidence selectively: Fund targeted trials that align with high-value use cases (e.g., reproductive performance in livestock, specific functional-food endpoints) to unlock premium pricing and label claims.
- Design go-to-market pilots with outcome-based pricing: Partner with lead customers to co-finance pilots that tie price to observable improvements (e.g., feed conversion ratios or biomarker improvements), lowering buyer risk and accelerating adoption.
- Evaluate bolt-on capabilities: Use M&A to acquire critical capabilities — such as specialized fermentation, analytics for organic selenium speciation, or niche distribution networks — where time to scale via build is prohibitive.
How to use the report in your 2026 planning cycle
Use our report as the central input to three enterprise processes:
- Commercial planning: Translate demand scenarios into SKU-level revenue plans and distributor incentive structures.
- R&D roadmapping: Prioritize formulations and analytic investments that maximize differentiation and reduce regulatory friction.
- Corporate development: Define acquisition screens and partnership scorecards focused on technical fit, regulatory dossiers and channel access.
Why PW Consulting’s approach matters
We combine macro forecasting with practical, executable playbooks. The market’s steady compound growth and improving regulatory clarity reduce structural investment risk, but success hinges on execution across three dimensions: regulatory foresight, manufacturing certainty and clinical differentiation. Our preview here surfaces directional insights; the full study contains the granular models, scenario matrices and action templates that your leadership team will need to operationalize these strategies.
Next steps
This article follows the “preview” principle: it demonstrates the analytical depth needed to build confidence while preserving the report’s proprietary segmentation, granular regional and application-level forecasts, and downloadable model files for subscribers. For those preparing 2026 budgets and strategic initiatives, access to the full report will translate high-level conviction into executable plans with quantifiable ROI.
To obtain the complete High Selenium Yeast market study with detailed segment economics, regulatory playbooks and transaction scouting lists, please visit the PW Consulting publication page.
For detailed analysis of this topic, please visit the official page: High Selenium Yeast (High-Selenium Yeast) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: CNG ISO Tank Market to Reach USD 266.96M by 2032 at 5.63% CAGR
By PW Consulting, 2026-08-02
CNG ISO Tank Container Market — Strategic Imperatives for 2026
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present a focused strategic primer on the compressed natural gas (CNG) ISO tank container market intended to orient executive decision-making for 2026. This piece synthesizes our quantitative outlook, competitive reading, and actionable playbooks without disclosing the proprietary, granular splits and scenarios contained in the full study. Consider this the trailer: enough insight to recalibrate strategy and priorities now, but intentionally reserved to drive engagement with the full PW Consulting deliverable for transaction‑grade detail.
CNG ISO Tank Container Market
Market snapshot: trajectory and structural signal
Our base-year analysis (2025) and historical review (2020–2025) show a market that has grown steadily and is positioned for continued expansion through our forecast window (2026–2032). The global CNG ISO tank container market reached a meaningful milestone in 2025, having advanced materially since 2020, and we model a compound annual growth rate (CAGR) of 5.63% over the forecast period. Under PW Consulting’s central scenario, the market expands progressively into the early 2030s—driven primarily by rising CNG adoption across vehicle fleets and industrial propulsion, coupled with incremental modernization of intermodal transport assets.
CNG ISO Tank Container Market
Two structural signals emerge from the top-line analysis. First, demand is broadening: buyers are no longer concentrated in a single application niche but are increasingly deploying standardized, high-pressure ISO solutions across multiple use-cases. Second, supply-side consolidation and product differentiation are intensifying, creating both scale advantages and distinct technology/IP vectors for leading vendors.
CNG ISO Tank Container Market
Why this matters for 2026 decision-making
-
CapEx and capacity planning: With a predictable mid-single-digit CAGR and clear seasonality in procurement cycles, manufacturers and fleet operators must sync investment timetables with the market’s multi‑year ramp. A delayed capacity investment can mean missed market share; an oversized bet risks underutilized assets. Our modeling helps you size phased expansions and decide between in-house production vs. contract manufacturing.
-
Product strategy & differentiation: Safety and pressure-handling capabilities have emerged as product axes. New higher-pressure designs and safety-focused architectures are moving from R&D to commercialization. Winning vendors will balance incremental innovation with certification time — the latter can materially affect go-to-market timing.
-
Sourcing and cost resilience: Carbon steel remains the dominant raw material due to its strength and cost profile. Price volatility in steel markets therefore transmits directly to unit economics. Procurement teams should establish dual-sourcing, indexed contracts, and forward-purchase strategies; operations leaders should evaluate design changes that reduce steel intensity without compromising safety or certification.
-
Regulatory compliance as a market gate: ISO 1496-series compliance and related testing for intermodal transport govern market access. Certification timelines materially affect time-to-revenue and should be built into product launch plans and acquisition due diligence.
-
M&A and partnership timing: With mid-to-high market concentration and clear global leaders, strategic acquisitions and OEM partnerships remain viable routes to scale and geographic expansion. However, premium multiples for proven certification, backlog, and manufacturing capacity can compress the arbitrage window; acting in 2026 requires pre-validated integration playbooks and regulatory checklists.
What PW Consulting’s full study delivers (practical, transaction‑ready tools)
The PW Consulting CNG ISO Tank Container study combines a transparent forecasting engine with pragmatic execution tools designed for corporate leadership, investors, and supply-chain managers. Highlights include:
- Scenario-based demand models (base, upside, downside) covering 2026–2032 with editable assumptions so your team can stress-test strategies under alternative energy and macro setups.
- Comprehensive TCO (total cost of ownership) models for owner-operators and lessors that incorporate capital, certification, maintenance, and logistics components.
- Supplier scorecards and manufacturing benchmarking packs to accelerate vendor selection and audit prioritization.
- Regulatory heatmaps and certification timelines keyed to ISO 1496 and relevant regional approvals, with a practical checklist to compress approval cycle time.
- CapEx planning templates and sensitivity analyses, including steel-price pass-through levers and margins under different procurement arrangements.
- Go‑to‑market and commercial playbooks for OEMs, integrators, and leasing businesses (pricing guidance, bundling strategies, and channel design).
- Targeted M&A screening methodology and a confidential shortlist workflow to identify and value bolt-on manufacturing, IP, or channel assets.
Competitive landscape — concentration, players, and tactical moves
The market exhibits moderate-to-high concentration: our concentration metrics indicate material share aggregation among the top three and top five suppliers. That concentration produces asymmetric advantages in pricing, certification throughput, and channel relationships, but it also opens exploitable niches for nimble competitors focused on specific product attributes or service models.
Profiles of representative, strategically significant suppliers illustrate current competitive dynamics:
-
TGE Gas Engineering (France) — Specialist in high‑pressure, safety‑optimized ISO tank solutions. Recent product launches targeted at higher-pressure applications and sustained trade-show engagement (notably in 2024–2025) signal a deliberate commercialization push to capture premium segments.
Website: https://tge-gas.com
-
SinoCleansky Technologies Corporation (China) — Focused on long-tube skid containers and ISO-certified tank units for transport and storage. The company’s certification breadth (ISO/ASME) supports export orientation and competitive participation in global supply pools.
Website: https://www.sinocleansky.com
-
Luxi New Energy Equipment Group (China) — Manufacturer of long-tube skid and ISO-compliant tanks with strong domestic manufacturing scale. Their product mix accentuates cost competitiveness in volume applications.
Website: https://www.luxixny.com
Strategic implication: incumbents with integrated certification capabilities and demonstrated product evolution will increasingly command higher margins. New entrants must either find narrow, defensible niches (e.g., ultra-high safety platforms, leasing-as-a-service) or partner with established players to achieve scale rapidly.
Supply‑chain and raw‑material playbook
Carbon steel’s predominance creates a predictable vulnerability: when steel swings, unit economics do too. Practical mitigations that we recommend and that are modeled in the full report include:
- Indexed supply agreements and capped corridor pricing to smooth cost volatility.
- Design-to-cost initiatives to reduce steel intensity while preserving certification and safety margins.
- Geographic diversification of fabrication footprints to balance freight, labor, and tariff exposure.
- Strategic inventory buffering calibrated to working-capital cost and lead-time risk tolerance.
Regulatory & standards context — operational levers
ISO 1496-series standards and related intermodal testing are not administrative hurdles but determinant commercial factors. Certification timelines should be explicitly accounted for in go‑to‑market sequencing, and compliance-driven design choices will frequently determine which customer segments a product can serve. For 2026 launches, the executives we advise build certification paths in parallel with prototype testing to compress the overall commercialization schedule.
Recommended execution roadmap: 90‑day and 12‑month priorities
-
90‑day (stabilize & prioritize): validate backlog and orderbook quality, secure critical steel forward positions for the next two quarters, initiate certification pre-submissions for any new pressure-class product, and run a rapid supplier scorecard to identify single‑source risks.
-
12‑month (scale & differentiate): complete pilot runs of higher-pressure containers with concurrent third-party certification; finalize at least one strategic partnership (manufacturing or channel) to accelerate market access; deploy TCO-based commercial pilots with key fleet customers to lock in early-adopter references.
Conclusion — what to do next
The CNG ISO tank container market presents a clear, measurable growth runway through 2032 underpinned by rising CNG adoption and structural supply-side consolidation. For 2026, the strategic priority is simple: marry disciplined capacity and procurement decisions with accelerated certification and customer‑facing TCO tools. That alignment converts favorable market growth into sustained competitive advantage.
PW Consulting’s full study provides the granular segmentations, interactive models, and asset-level diligence materials needed to operationalize these priorities. To access the complete market dataset, regional and application splits, and bespoke scenario tools that inform transaction-level decisions, contact our advisory team or visit the PW Consulting report page for a confidential briefing.
For detailed analysis of this topic, please visit the official page: CNG ISO Tank Container Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


