



Category: market research
PW Consulting: Water Recycling & Reuse Market to Reach USD 47,349.62M by 2032 (11.25% CAGR)
By PW Consulting, 2026-07-13
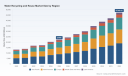
Water Recycling and Reuse Market — 2026 Strategic Preview
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused, decision-grade preview of our full Water Recycling and Reuse Market study — designed to fast-track C-suite and corporate strategy teams in 2026. This piece demonstrates the depth of our analysis and the concrete strategic implications emerging today, while preserving proprietary segment-level intelligence to encourage direct access to the full report and interactive tools.
Water Recycling And Reuse Market
Market Snapshot: Scale, Trajectory, and the Investment Imperative
The global water recycling and reuse market has transitioned from a niche sustainability play to a major infrastructure and industrial investment theme. Our base-year assessment shows the market reached approximately USD 22.45 billion in 2025. Under a central-case projection, the market expands at a compound annual growth rate (CAGR) of 11.25% across our 2026–2032 forecast horizon, nearly doubling to an estimated USD 47.35 billion by 2032. This trajectory reflects the combined effect of policy acceleration, industrial demand for closed-loop water systems, urban-scale recycling programs, and growing commercial viability of advanced treatment technologies.
Water Recycling And Reuse Market
Strategic Drivers That Will Shape Corporate Decisions in 2026
- Regulatory acceleration and mandate-driven demand. New policy frameworks and standards are proliferating. Notable examples include the US EPA’s Water Reuse Action Plan 2.0, which explicitly targets industry verticals such as data centers and energy; state-level mandates increasing reuse of produced water in oil & gas; and adoption of testing/qualification standards for onsite reuse systems. These create predictable demand corridors for firms able to meet compliance thresholds and demonstrate validated treatment performance.
- Large-scale municipal and industrial projects as market pull. Major programmes — from municipal purified-recycled-water initiatives to industrial reuse facilities built under long-term O&M contracts — are crystallizing the market into investable, bankable assets. Project milestones in 2025–2026 have converted theoretical demand into executable pipelines.
- Technology maturation and cost dynamics. Membrane-based systems, modular MBRs, and multi-barrier tertiary treatment are now proven at scale. Capital-intensity remains a consideration: industry benchmarks continue to quote capital cost ranges for membrane bioreactor systems and advanced tertiary treatment in per-gallon terms, which materially affect project-level IRR and procurement choice between centralized and decentralized architectures.
- Commercial models shifting to services and outcomes. The value pool is moving from equipment sales toward integrated offerings — performance guarantees, long-term service contracts, and digital-enabled lifecycle optimization. Acquirers and platform investors are seeking recurring-revenue streams tied to O&M and analytics.
- Fragmented supplier base with rising consolidation pressure. Market concentration metrics show meaningful room for consolidation: leading vendors account for a material but not dominant share, leaving strategic space for M&A, roll-up plays, and strategic partnerships between technology specialists and global operators.
What the PW Consulting Report Delivers — Actionable, Not Academic
Our full report is structured to convert market intelligence into executable initiatives. Highlights include:
Water Recycling And Reuse Market
- Proprietary market sizing and three scenario-based forecasts (conservative, central, disruption) with sensitivity analysis to policy and capital-cost variables.
- Demand-driver mapping by use-case (municipal programs, industrial reuse, produced water, onsite greywater), translating regulatory signals and capital cycles into addressable opportunity curves.
- Technology assessment framework that ranks treatment pathways by total cost of ownership, regulatory fit, footprint, and time-to-deploy — with deployment playbooks for centralized vs. decentralized models.
- Supplier and competitive intelligence, including strategic profiles and capability heatmaps for global and regional challengers. (Profiles of core companies included in the public synopsis; full comparative matrices are in the report.)
- Investment and procurement toolkits: project-level financial models, contractor RFP templates, O&M contracting options, risk allocation matrices, and a regulatory tracker for major markets.
- Ten detailed case studies that distill lessons from recent project wins, large-scale municipal programs, and industrial ZLD implementations — each with implementation timelines and supplier ecosystem maps.
Competitive Landscape — Who Matters and Why
The market is competitive and strategically diverse: global operators with integrated water-management capabilities are competing alongside specialized membrane and modular-system vendors. Key players we profile in depth include Veolia, Xylem Inc., SUEZ Water Technologies & Solutions, Ecolab (Nalco Water), DuPont Water Solutions, Pentair, Aquatech, Kubota, ALFA LAVAL, Hitachi, Siemens, Fluence, Kurita, Culligan, and Consolidated Water. Our report evaluates each firm across three strategic vectors: technology stack and IP, go-to-market model (project EPC vs. recurring O&M vs. product sales), and corporate capability to scale across geographies and verticals.
- Veolia continues to leverage its project-development and long-term O&M expertise to secure consortium-scale industrial reuse contracts, exemplified by large industrial plant agreements signed in 2025.
- Xylem’s platform expansion via acquisition is a defining move — combining fluid-handling, membranes, and analytics shifts the value proposition toward integrated lifecycle services and data-driven performance guarantees.
- SUEZ and Ecolab remain strong in modular solutions and customized industrial programs; their strength lies in multi-barrier approaches and chemical/biological process integration.
- Specialists — from membrane manufacturers to ZLD system integrators and modular decentralized providers — are the most likely acquisition targets or partners for larger engineering and services firms seeking rapid capability scaling.
Recent, tangible developments underscore these dynamics: a major acquisition completed in early 2026 that enlarged a membranes-and-analytics platform; milestone project agreements and contract awards for large-scale industrial and municipal plants in 2025–2026; and municipal programs advancing environmental approvals — all of which convert stated strategies into near-term addressable revenue.
Strategic Playbook for Executives in 2026
- Prioritize use cases with policy-backed demand. Immediate priorities should be projects and contracts anchored to regulatory mandates or long-term municipal programmes. These are the highest-confidence revenue streams for capex deployment and investor pitches.
- Design offerings around lifecycle economics, not just capex. Given the capital intensity of advanced treatment, winning in 2026 requires service-centric pricing, performance guarantees, and ability to reduce total cost of ownership through predictive maintenance and process optimization.
- Pursue targeted M&A and partnerships. Buyers should acquire modular-treatment specialists, membrane IP, or analytics providers to create bundled solutions. Sellers should seek strategic buyers that can deliver large-scale O&M contracts to convert product revenues into recurring streams.
- Use pilots to derisk and prove commercial models. Structure limited pilots with clear KPIs and scale-up triggers tied to financing milestones; consider shared-risk, incentive-aligned contracts to accelerate customer adoption.
- Embed digital to monetize performance data. Invest in remote monitoring and analytics to enable outcome-based contracts and to protect margins as hardware becomes commoditized.
- Monitor cost benchmarks and procurement timing. Capex-per-unit benchmarks for membrane bioreactors and tertiary treatment remain central inputs to bid strategy and ROI calculations — incorporate these ranges into tender pricing and lifecycle models.
- Engage regulators early and shape standards. Proactive engagement on standards and testing protocols will accelerate approvals and give first-mover advantages in nascent reuse categories (e.g., industrial reuse for data centers, produced water mandates).
Why PW Consulting’s Report is Valuable for 2026 Decisions
This study is not an academic compendium; it is a hands-on, transaction-oriented playbook. It gives corporate strategists and investment committees the forecasts, vendor scorecards, and risk-adjusted financial models needed to: prioritize capital allocation, design deals that convert projects into annuity-like income, position organizations for consolidation waves, and operationalize regulatory change. We surface where policy and project execution intersect to create bankable opportunities — and where capability gaps will determine winners and losers.
For decision-makers preparing budgets, negotiating partnerships, or evaluating M&A opportunities in 2026, the choice is twofold: rely on high-level public narratives — or equip your team with the granular scenarios, commercial templates, and supplier assessments that materially improve project selection, pricing discipline, and negotiation outcomes. Our report delivers the latter.
Next Steps
Access to the full PW Consulting Water Recycling and Reuse Market report provides the detailed, segment-level models, vendor matrices, and interactive ROI tools referenced above. For executives ready to convert the 2026 market dynamics into a clear growth agenda — whether through organic investment, partnership, or acquisition — the report is the operational map and the decision support system you need.
For detailed analysis of this topic, please visit the official page: Water Recycling And Reuse Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Selective Soldering Market to Hit USD 922.6M by 2032 at 6.8% CAGR
By PW Consulting, 2026-07-13
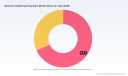
Selective Soldering Equipment Market: Strategic Intelligence for Executive Decisions in 2026
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present an incisive preview of our latest Selective Soldering Equipment Market study — a practical briefing designed to inform capital allocation, product strategy, supply-chain prioritization, and M&A decision-making throughout 2026. This article emphasizes the strategic value of the research while deliberately withholding the granular sub-segment figures that reside in the full report to preserve the incentive to engage with our complete analysis.
Selective Soldering Equipment Market
Executive snapshot: why this matters to 2026 decision-makers
Selective soldering is no longer a niche workshop capability; it is a foundational technology for high-reliability, mixed-technology PCB assembly across automotive electrification, advanced industrial controls, telecom infrastructure and increasingly demanding consumer electronics. Our base-year view (2025) positions the global selective soldering equipment market at approximately USD 582.1 Million, with a projected 2026 market step-up to roughly USD 663.2 Million and a compound annual growth rate (CAGR) of 6.8% through our 2026–2032 forecast window. Those topline numbers quantify a recovery and acceleration trajectory that corporate leaders must internalize when planning CAPEX cycles, equipment refresh programs, and factory modernization roadmaps in 2026.
Selective Soldering Equipment Market
Market trajectory and the mechanics behind the growth
-
Recovery and momentum: The market exhibited pandemic-era volatility during 2020–2022, followed by stabilization and renewed investment through 2023–2025. The forecast to 2032 anticipates steady expansion driven by miniaturization, lead-free requirements, and rising complexity in mixed-technology assemblies.
Selective Soldering Equipment Market -
Consolidation and concentration: Market concentration is non-trivial: the leading three suppliers control close to half the market, while the top five approach two-thirds of market share. This balance of scale and specialized engineering capacity shapes pricing, service coverage and innovation cycles for buyers and investors.
-
Structural demand drivers: Adoption is being propelled by three structural shifts — miniaturized components that require focused heat control, regulatory and lead-free soldering mandates, and the growth of electric vehicle (EV) and ADAS electronics which demand selective accuracy and low-void solder joints.
Why 2026 is a pivot year for equipment and operations strategy
For OEMs, EMS providers, and equipment vendors, 2026 represents a decision inflection: deferment of equipment investment risks falling behind in throughput and process yield versus competitors; premature replacement risks under-utilized assets and eroded returns. Our study frames that tradeoff through three executable decision lenses:
-
Capital allocation: Use forward-looking demand curves and scenario stress-tests to time major inline selective soldering investments. Short-cycle production needs can still be met with modular or standalone platforms, while strategic high-volume lines justify integrated, multi-station in-line systems.
-
Operational efficiency: Selective soldering’s cost profile (notably lower flux and solder consumption and reduced nitrogen use) can materially alter TCO compared with conventional wave soldering — a critical lever when margins are under pressure.
-
Quality & compliance: The technology supports compliance with IPC-level industry standards and can achieve void and reliability targets necessary for aerospace, medical and automotive electronics, making selective soldering a risk-management investment as much as a throughput play.
Practical, actionable content inside the full report
Our Selective Soldering Equipment Market study was assembled specifically for operational leaders and strategic investors. Key pragmatic deliverables include:
-
Decision-ready financial models — TCO calculators that contrast CAPEX, OPEX, consumables, and service across equipment classes and production profiles.
-
Vendor scorecards — engineering, aftermarket support, global service footprint, and retrofit compatibility metrics to accelerate shortlisting and procurement.
-
Technology roadmaps — comparative analysis of inline multi-station architectures versus standalone/batch systems, including modular upgrade paths and automation integration considerations.
-
Scenario playbooks — three to five demand and supply scenarios with sensitivity analysis for raw-material price swings, labor constraints, and regulatory tightening.
-
M&A and partnership lenses — playbooks for strategic and financial buyers highlighting integration risks, service-synergy opportunities, and quickly accretive bolt-ons.
-
Service & spares optimization — inventory policies and aftermarket strategies to reduce downtime and guarantee process repeatability across multi-site rollouts.
Competitive landscape: who matters and why
The competitive field blends long-established OEMs with focused niche specialists. Our study contains detailed vendor profiles, but the strategic highlights follow.
-
Kurtz Ersa GmbH (Germany) — A market leader with modular VERSAFLOW and ECOSELECT platforms. Strengths: broad platform range from entry-level to high-volume, electromagnetic pump technology and multi-nozzle adaptability that supports throughput scaling.
-
Nordson SELECT (United States) — Offers a complete spectrum (standalone, inline, multi-station) with a deep global service network. Competitive edge: turnkey solutions and aftermarket coverage for high-volume electronics manufacturers.
-
SEHO Systems GmbH (Germany) — Strong in integrated fluxing, preheating and soldering zones aimed at productivity and yield. Notable for platform-level engineering to support higher first-pass yields.
-
Pillarhouse International Ltd (UK) — Pioneer of selective soldering with a high-patent count; competitive in high-engineering-standard, reliability-focused segments.
-
JUKI Corporation & Apollo Seiko (Japan) — Provide batch and inline platforms, respectively, with particular relevance to through-hole legacy transitions and dual-pot innovations for precision soldering.
-
US and regional specialists (DDM Novastar, RPS Automation, TM Soldering Solutions, Hentec, VennTek-SASinno, INERTEC) — Offer cost-effective, niche and retrofit solutions that improve access to selective soldering across small and medium-sized EMS providers.
Recent vendor movements underscore competitive dynamics: multiple product launches and trade show showcases in late 2025 and early 2026 signal accelerating feature competition and an emphasis on throughput and modularity. Our full profiles catalog disclosed product launches, service expansions and regional go-to-market tactics in granular detail.
Key operational and regulatory context
-
Raw materials: The solder flux market — a critical consumable for selective processes — was estimated at roughly USD 3.12 billion in 2025 and is itself a growth market. Understanding flux segmentation and supply-chain concentration is essential for reliable OEE planning.
-
Process efficiency: Empirical process studies and vendor claims point to substantial reductions in solder usage and nitrogen consumption for selective soldering versus wave approaches. These efficiencies directly influence operating margins and environmental footprint.
-
Standards & reliability: Selective soldering is a practical enabler of compliance with IPC-level requirements and lower void percentages demanded by aerospace, medical and automotive assemblies — translating into lower warranty risk and higher product reliability.
Risk factors and scenario planning
While demand fundamentals remain constructive, 2026 strategies must include contingency playbooks addressing:
-
Raw-material volatility and supply chain disruptions for fluxes and specialty alloys.
-
Geopolitical shifts affecting capital-equipment sourcing and service footprints.
-
Rapid technology substitution or unexpected shifts in production architectures — for instance, a faster-than-anticipated move to fully automated inline cells that renders some legacy standalone investments sub-optimal.
Actionable strategic recommendations for 2026
-
For OEMs and Tier-1 manufacturers: Prioritize selective soldering investments on product lines where reliability premiums or regulatory compliance deliver quantifiable margin uplift. Use staged adoption: start with pilot inline cells on critical SKUs before committing to full-line conversions.
-
For EMS providers: Build a flexible equipment portfolio that mixes compact standalone systems for short runs and modular inline stations for predictable, high-volume customers. Strengthen service contracts and spare-parts availability to turn uptime into a competitive differentiator.
-
For equipment vendors: Invest in service orchestration, remote diagnostics, and modular upgradeability. Product differentiation will hinge on throughput scaling, ease-of-retrofit, and lifecycle service economics.
-
For investors & M&A teams: Seek targets that offer either niche technological IP (e.g., unique pump or nozzle technologies) or service-reach that can be rapidly integrated into a global aftermarket network; focus on assets that improve gross margin predictability in rolling 12–24 month horizons.
What the full PW Consulting report unlocks
The complete study contains the operational models, supplier scorecards, and scenario analytics required to convert these strategic signals into executable plans. To respect proprietary value and maintain the “selective” nature of this preview, we have withheld the granular regional and application splits from this article — those tables and the interactive modeling tools are available within the full report package and on our data portal.
Next steps
If you are responsible for CAPEX planning, factory modernization, procurement of selective soldering systems, or evaluating investment targets in 2026, the PW Consulting Selective Soldering Equipment Market study provides the operational blueprints and financial models you need. Contact our team or visit the report landing page to obtain the full dataset, vendor scorecards, and the TCO calculator.
For detailed analysis of this topic, please visit the official page: Selective Soldering Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cloud Logistics Software Market to Reach USD 58,052.5M by 2032 (14.5% CAGR)
By PW Consulting, 2026-07-13
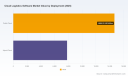
Cloud Logistics Software Market 2026: Strategic Imperatives for Enterprise Decision‑Makers
Executive snapshot
As organizations reset supply‑chain priorities for the post‑pandemic, AI‑enabled decade, cloud logistics software has moved from “nice to have” to a board‑level imperative. PW Consulting’s latest study—anchored on a 2025 base year and a six‑year historical run (2020–2025) with a forward forecast covering 2026–2032—documents a market that has more than doubled in momentum over the past half‑decade and is set to expand at a sustained compound annual growth rate of approximately 14.5% through the forecast horizon. This research synthesizes macro sizing, competitive dynamics, regulatory forces, and operational playbooks into a single, execution‑focused reference for CIOs, supply‑chain chiefs, and procurement leaders planning for 2026.
Cloud Logistics Software Market
Why this research matters for decisions in 2026
-
Investment timing and ROI: With rapid growth and rising vendor sophistication, enterprise buyers must align procurement windows, pilot cadences, and migration budgets to capture both short‑term efficiency and medium‑term strategic advantage.
Cloud Logistics Software Market -
Risk management: Escalating cloud hosting cost pressure and evolving regulatory requirements (data transfer documentation, AI transparency mandates, and heightened vendor risk expectations) are reshaping total cost of ownership and contractual terms.
Cloud Logistics Software Market -
Vendor selection and ecosystem planning: The market is large and growing fast, but remains only moderately concentrated—creating choices between integrated platform plays, best‑of‑breed specialists, and new entrants focused on AI or last‑mile orchestration.
Market trajectory and macro dynamics
Our topline sizing places the cloud logistics software market firmly in a high‑growth category as we enter 2026. After a period of accelerated adoption across transport management, warehousing, freight forwarding, and visibility services, the market’s baseline in 2025 provides the springboard for robust expansion through 2032—driven by rising e‑commerce volumes, omnichannel fulfillment complexity, and the application of AI/advanced analytics to network optimization.
Two external forces deserve special emphasis because they will materially affect vendor economics and enterprise deployment decisions in 2026:
-
Cloud hosting and infrastructure cost pressure: Major cloud and hardware suppliers signaled notable price adjustments in late‑stage 2025 and into 2026. Enterprises evaluating SaaS offers must treat host‑cost volatility as a line‑item risk when modelling multi‑year TCO and when negotiating pass‑throughs or fixed‑price elements in vendor agreements.
-
Regulatory and compliance tightening: GDPR enforcement continuity around cross‑border transfers, plus the operational demands of the EU AI Act for systems that process personal data, mean that buyers and vendors must now bake transfer impact assessments, SCC documentation, and model‑level transparency into contracts and implementation plans.
What the full report delivers (practical, operational, and boardroom ready)
PW Consulting designed this study to do more than describe trends; it is built to be applied. The full deliverable includes:
-
Topline market sizing and validated demand model (historical 2020–2025, forecast 2026–2032) with scenario stress‑testing for macroeconomic and cost‑inflation paths.
-
A market concentration and competitive landscape assessment enabling go‑to‑market targeting and M&A diligence, including CR3/CR5 concentration context to frame consolidation risk and white‑space opportunities.
-
Vendor scorecards and capability matrices mapping functional depth (TMS, WMS, freight forwarding, visibility), cloud‑native maturity, data fabric architectures, and partner ecosystems—useful for shortlisting and RFP design.
-
Implementation playbooks and migration roadmaps tailored to enterprise archetypes (global manufacturers, retailers, 3PLs, and asset‑light freight forwarders), including phased KPIs, integration patterns, and change‑management checklists.
-
Procurement templates: contract clauses for cloud cost pass‑throughs, service credits tied to delivery and event metrics, data governance and AI transparency obligations, and vendor exit/portability provisions.
-
Financial models and TCO templates (capex/opex tradeoffs, incremental margin impact, and sensitivity to hosting price inflation) that can be dropped into internal capital asks.
-
Security and compliance controls: zero‑trust architecture recommendations, third‑party risk assessment checklists, and operational controls aligned with current regulatory expectations.
Competitive landscape: how to read vendor differentiation
The vendor ecosystem in cloud logistics can be viewed through three pragmatic lenses: integrated ERP clouds, best‑of‑breed logistics suites, and specialist freight/forwarding platforms. Each category follows distinct commercial and technical tradeoffs buyers must weigh against their operating model.
-
Integrated ERP clouds (examples among incumbents): These providers leverage broad installed bases and offer end‑to‑end enterprise process continuity—from order to cash through logistics execution. Their strengths are in unified data models and single‑vendor support; tradeoffs include potential slower innovation cycles on logistics‑specific features and higher switching costs.
-
Best‑of‑breed logistics suites: Vendors focused on warehouse, transportation, and optimization bring deeper operational functionality and faster release cadences for logistics innovation. Their differentiation often lies in domain expertise, flexible deployment, and partner ecosystems for execution (carrier integrations, TMS/TM). However, integration effort and cross‑functional coordination are procurement considerations.
-
Freight‑forwarding and niche specialists: Platforms optimized for forwarding, customs, and cross‑border documentation deliver workflow efficiency and compliance strength for international trade flows. They can be attractive to freight forwarders and 3PLs but may require more extensive ERP interfaces for global shippers.
Notable competitive cues from recent market activity and our vendor review:
-
Longstanding logistics software vendors continue to defend enterprise footprints through integrated suites and ecosystem play—pushing customers toward bundled cloud‑managed offerings.
-
Cloud‑native, AI‑first entrants are accelerating capabilities for last‑mile orchestration and dynamic routing, intensifying competition in urban delivery and final‑mile SLAs.
-
Recognition and award activity among niche vendors underscores the continuing market appetite for specialized solutions that deliver rapid time‑to‑value in focused use cases such as freight forwarding and trade compliance.
-
Overall concentration metrics indicate meaningful market share for leading players, but enough fragmentation remains to permit strategic partnerships, regional champions, and acquisition opportunities.
Recent signals: product launches, recognition, and what they imply
Our monitoring of industry developments through early 2026 highlighted two signals worth noting for strategy teams:
-
A prominent last‑mile platform unveiled a unified AI‑driven logistics system that consolidates execution, analytics, and automation in a single cloud‑native stack—an explicit bet on bringing orchestration and optimisation closer to the delivery edge.
-
Specialist forwarding platforms continue to receive industry recognition for product maturity and customer satisfaction, emphasizing that vertical depth and executional fit still win deals, particularly for complex cross‑border flows.
Procurement and implementation counsel for 2026
Enterprises preparing to select or renew cloud logistics solutions in 2026 should institutionalize six practices immediately:
-
Treat hosting cost volatility as procurement risk—require transparent pass‑through mechanisms, caps, or multi‑year fixed elements where possible, and simulate cost shocks in TCO models.
-
Demand AI model documentation and risk assessments as part of RFP responses—this anticipates regulatory expectations and reduces downstream remediation costs.
-
Define composable integration boundaries—standardize on APIs and data models to avoid lock‑in and to enable best‑of‑breed composition.
-
Adopt zero‑trust and continuous monitoring requirements in security annexes, and make third‑party audit evidence a contractual prerequisite.
-
Prioritize early wins with focused pilots (e.g., route optimization, dock scheduling, customs automation) that generate measurable ROI within 6–9 months.
-
Preserve exit optionality—require structured data exports, runbook transfer support, and interoperability guarantees to safeguard future strategic pivots.
Strategic scenarios and recommended next steps
Based on our scenario modeling, enterprises should align vendor choices to one of three strategic paths:
-
Defensive consolidation: For firms seeking single‑vendor simplicity and deep ERP alignment, prioritize integrated clouds with defined roadmaps for logistics capability growth.
-
Operational differentiation: For companies competing on fulfillment speed and cost, adopt best‑of‑breed logistics suites and invest in API‑first integration and data fabrics.
-
Edge innovation: For urban delivery and last‑mile leaders, pilot AI‑driven orchestration platforms and develop carrier/partner networks that can be orchestrated through a single control tower.
Conclusion and how to use this briefing
This introduction provides the strategic framing enterprise leaders need to prioritize cloud logistics investments for 2026. The full PW Consulting report expands each of these themes with granular models, vendor scorecards, contractual language, and implementation templates that operational teams can use immediately. If your goal is to accelerate time‑to‑value while controlling cost and regulatory risk, the complete research package and downloadable tools will provide the practitioner‑level detail you need to act in 2026—without the need to reinvent frameworks or rebuild financial models from scratch.
To access the full dataset, segmentation models, and actionable playbooks referenced here, please consult the PW Consulting report portal for the Cloud Logistics Software Market 2026 edition.
For detailed analysis of this topic, please visit the official page: Cloud Logistics Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High Purity Tungsten Market to 2032 — USD 1,001.64M, 6.5% CAGR
By PW Consulting, 2026-07-13
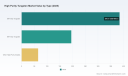
High Purity Tungsten Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s latest High Purity Tungsten Market study is designed as a decision‑grade intelligence package for corporate strategists, procurement leaders, and investors gearing up for the 2026 planning cycle. Built on a full historical series (2020–2025) and a forward forecast (2026–2032), the analysis combines a robust demand model, supply‑side mapping, and scenario stress‑tests to translate commodity dynamics into executable business options.
High Purity Tungsten Market
Why this study matters in 2026
-
Strategic inflection. The high purity tungsten market is transitioning from a niche industrial material into a strategic raw material for advanced electronics, semiconductor sputtering targets, and select aerospace/medical applications. That transition creates both volatility and structurally higher long‑term value—requiring distinct strategic choices for suppliers, consumers, and financiers.
High Purity Tungsten Market -
Policy and trade shocks. Recent policy moves—tariff increases and export controls—have altered supply economics and rendered previously robust sourcing strategies fragile. Procurement teams and corporate strategists must reconcile short‑term price volatility with longer term supply security objectives.
High Purity Tungsten Market -
Capital allocation decisions. With the market on a growth trajectory and increasing interest in upstream project development, 2026 is a pivotal year to decide on greenfield investments, offtake agreements, and M&A plays that will determine access to high‑purity feedstocks for the decade ahead.
Market snapshot — the macro view
Our macro model tracks the high purity tungsten market from roughly USD 462 million in 2020 to approximately USD 645 million in 2025, driven by stronger electronics demand and constrained feedstock flows. We project the market to expand at a compound annual growth rate (CAGR) of about 6.5% over the 2026–2032 forecast window, reaching roughly USD 1.0 billion by 2032 under the baseline scenario. These headline numbers mask significant structural shifts beneath the surface—changes in buyer concentration, grade mix, feedstock sourcing, and the role of geopolitical policy—that materially affect margin pools across the value chain.
Key market dynamics reshaping strategy
-
Feedstock tightness and price volatility. Ammonium paratungstate (APT), the primary intermediate for high purity production, experienced acute price moves driven by supply controls and trade measures—creating immediate margin pressure for processors and downstream buyers. Rotterdam and domestic price indicators tracked sharp increases through 2025–2026, underscoring the need for explicit raw‑material risk management in contracts and forecasting.
-
Regulatory and trade interventions. Major jurisdictional actions—most notably increased tariffs on imports from China in the U.S., and Chinese export controls on selected tungsten intermediates—have elevated the cost basis for cross‑border flows and accelerated regionalization of processing capacity. These interventions change commercial calculus for sourcing and capital projects and require continuous monitoring in supplier selection frameworks.
-
Supply response and new project pipeline. The supply side is responding: new mining production and advanced project developments in multiple jurisdictions, together with targeted public funding for domestic capacity in several markets, will change availability over the medium term. However, upstream lead times and metallurgy constraints mean that supply elasticity will remain limited in the near term.
-
Consolidation and concentration. The market exhibits moderate concentration: incumbent manufacturers and integrated material houses retain dominant shares of high‑purity manufacturing capabilities. This concentration supports pricing discipline but also raises counterparty risk for large raw‑material consumers.
What the PW Consulting report delivers (practical, operational modules)
-
Interactive demand model — build your own scenarios by application, purity grade, and procurement horizon (baseline, upside, downside).
-
Supply chain map — from concentrate to ultra‑high purity metal and finished components, identifying single points of failure and alternative routing options.
-
Price and feedstock sensitivity matrices — quantify margin exposure across realistic APT price trajectories and tariff permutations.
-
Regulatory watchlist and export‑control matrix — jurisdictional rules and likely policy pathways that impact trade flows and permitting timelines.
-
Company profiles and capability heatmap — strengths, technological differentiators, capacity footprints, and counterparty risk indicators (detailed supplier dossiers included for leading market participants).
-
Project evaluation templates — capex/opex heuristics, payback thresholds, and blended cost of supply models tailored for greenfield and brownfield investments.
-
Commercial playbooks — procurement levers, hedging blueprints, offtake negotiation frameworks, and M&A screening criteria focused on 2026 execution.
Competitive landscape — strategic reads on core participants
-
Elmet Technologies LLC (Lewiston, ME, USA) — Fully integrated U.S. manufacturer with reduction‑based powder making and downstream mill products. Elmet’s integration gives it defensible margin control and fast response times to North American demand surges. Strategic implication: attractive partner for short‑term offtake and for firms seeking to shorten supply lines, but scale limitations may constrain large program commitments without capacity expansion.
-
Buffalo Tungsten Inc. (Depew, NY, USA) — Independent specialist focused on ultra‑high purity powders and tungsten carbide powders. Buffalo’s product purity and niche customer relationships make it a preferred supplier for high‑value electronics work; however, independents remain exposed to feedstock cost shocks and freight disruptions.
-
Global Tungsten & Powders (GTP) — Plansee Group affiliate — A major integrated materials house with broad downstream capabilities, positioned to capture value across the chain (powder, chemicals, components). GTP’s global footprint and downstream product mix reduce single‑point exposure, making it a logical counterparty for OEMs seeking supply continuity and technical partnerships.
-
H.C. Starck / Plansee Group / A.L.M.T. / JX Nippon / Xiamen / Chongyi Zhangyuan / Masan High‑Tech — A mix of European, Japanese, Chinese and Southeast Asian manufacturers covering a range of technological capabilities—from specialty powders and wires to large‑scale powder production. The competitive set presents a spectrum of tradeoffs between cost, quality, speed, and geopolitical exposure. Strategic buyers must weigh price against security and qualification lead times for critical applications.
Recent developments that change the game
-
Project momentum in exploration and development has picked up—new staking and land expansions in North America and project approvals in Europe create optionality for future feedstock supply lines.
-
Trade and regulatory measures enacted since late 2024 and into 2025 have meaningfully tightened cross‑border flows of key intermediates and prompted buyers to re‑evaluate sourcing and inventory policies.
-
Public funding and strategic programs in mine jurisdictions are reducing some sovereign risk, but not eliminating short‑term price spikes driven by immediate constraints in processing and transport.
Actionable plays for corporate leaders in 2026
-
Adopt a two‑tier procurement strategy: secure a core of qualified, long‑term suppliers (to cover critical needs) and maintain a flexible margin of opportunistic purchasing to exploit spot dislocations.
-
Hedge selectively using contract structures that share raw‑material risk—indexation clauses, blended pricing corridors, and multi‑year offtake with escape provisions for extreme policy moves.
-
Prioritize qualification pipelines: accelerate qualification of alternative suppliers and regional sources (even at a premium) for mission‑critical components to shorten response time in supply shocks.
-
Assess vertical integration selectively: for manufacturers with scale, upstream processing or strategic equity stakes in concentrate projects can be accretive—model conservatively and stress‑test on delayed ramp scenarios.
-
Target bolt‑on M&A where it reduces counterparty risk or speeds time‑to‑market for higher‑purity grades; for investors, look for platform assets with repeatable processing technology and locked‑in offtake.
-
Invest in materials R&D that substitutes high‑cost grades or improves recovery—small improvements in yield or downstream processing can materially change unit economics over multi‑year production runs.
Why PW Consulting’s study is different
Beyond conventional market sizing, our study ties macro dynamics to micro decisions through an integrated demand/supply/risk model and an actionable toolkit for 2026. We combine granular supplier intelligence, a dynamic pricing sensitivity engine, and regulatory scenario mapping so that commercial, procurement, and corporate development teams can run "what‑if" strategies and produce investment‑grade outputs suitable for Board review.
Note: this briefing emphasizes strategic takeaways and constrained disclosure by design. Core subsegment tables, granular regional shares, and application‑level revenue splits are intentionally withheld from this public overview to preserve the report’s commercial integrity. Full access to the segmentation, supplier dossiers, and interactive models is available through the PW Consulting report portal.
Immediate next steps for readers
-
Procurement & Supply Chain leads — request the report’s procurement playbook and the supplier risk heatmap to incorporate into 2026 sourcing cycles.
-
Corporate Strategy & M&A teams — schedule a scenario workshop to test acquisition and investment hypotheses against our baseline and downside cases.
-
Investors & Project Developers — use the project evaluation templates and offtake framework to fast‑screen opportunities in the new supply pipeline.
For organizations that need to convert market signals into executable plans in 2026, this study provides the models, vendor intelligence, and tactical playbooks to act with conviction. Access to the full study, including the underlying segmentation tables, supplier dossiers, and the interactive forecast model, is available via PW Consulting’s report portal.
For detailed analysis of this topic, please visit the official page: High Purity Tungsten Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Recovered Carbon Black (RCB) Market to Grow at 11.5% CAGR (2026–2032)
By PW Consulting, 2026-07-13
Recovered Carbon Black (rCB) Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
Recovered carbon black (rCB) has moved rapidly from niche sustainability pilots into a commercially material segment of the carbon black industry. Our PW Consulting Recovered Carbon Black Rcb Market study—anchored on a 2025 base year and a 2026–2032 forecast horizon—documents a clear, investment-grade growth trajectory: the rCB market expanded materially between 2020 and 2025 and is projected to compound at a double-digit clip (11.5% CAGR) into the early 2030s. By 2025 the market reached a level that demands serious strategic attention from tire makers, masterbatch formulators, coatings companies and raw-material traders; by 2032 the market is expected to be more than double the size it was in 2020.
Recovered Carbon Black Rcb Market
Why this matters for 2026 corporate strategy
-
Supply security & cost resilience: rCB introduces a new upstream vector that can reduce exposure to fossil-derived feedstock pricing cycles. For companies deciding 2026 procurement strategies, rCB supply agreements and feedstock partnerships can be structured to complement traditional carbon black sourcing while de‑risking long-term cost volatility.
Recovered Carbon Black Rcb Market -
Regulatory arbitrage and market access: policy moves—most notably European recognition of tire pyrolysis as a recovery process and the emergence of ISCC PLUS for circular carbon—create a compliance and commercial pathway for rCB to be treated as a non‑waste, tradeable input. Firms adjusting product specifications or sustainability claims in 2026 will need to embed certification prerequisites into procurement contracts.
Recovered Carbon Black Rcb Market -
Product strategy and margin management: rCB’s current material properties (purity levels that are lower than top‑grade virgin carbon black) create both opportunity and constraint. 2026 decisions will hinge on pragmatic product segmentation—where to deploy rCB blends without compromising performance, and where to retain virgin carbon black for high‑stress applications.
-
M&A and capex prioritization: the rCB value chain is consolidating but far from mature (market concentration shows leading groups do not yet dominate the sector). For corporates evaluating inorganic growth or greenfield investments in 2026, the market offers attractive bolt‑on and joint‑venture prospects, particularly for firms that can marry feedstock access to downstream integration.
Market trajectory — what the headline data says
Our modeling, which synthesizes historical data and primary interviews across the value chain, shows robust expansion from the early 2020s into the 2030s. After a multi‑year ramp from 2020 to 2025, the market’s compound annual growth rate during the forecast window points to sustained demand pull and accelerating commercialization. This macro momentum is driven by three structural forces: increasing tire and rubber recycling rates, industrial adoption for lower‑risk elastomer and non‑tire applications, and policy frameworks that reward circular inputs.
Competitive landscape — who to watch (and why)
The rCB competitive set is populated by technology‑led specialists and strategic initiatives from incumbent tyre and chemical players. Key profiles include:
-
Pyrolyx AG (Germany) — A commercial pyrolysis producer that has moved from demonstration to industrial production. Pyrolyx’s early plant commercialization provides practical evidence that scaled rCB supply can meet industrial reinforcement specifications, supporting integration strategies for downstream users.
-
Black Bear Carbon (Netherlands) / Michelin partnership — Backed by a major tire manufacturer, this operation is emblematic of the “buyer‑backed” approach to feedstock security and quality control. Strategic partnerships of this sort materially shorten commercialization timelines and reduce technical adoption risk for tyre makers.
-
Enviro AB (Sweden) — Focused on certification and compliance, Enviro’s attainment of circularity credentials demonstrates the importance of verified sustainability chains for market acceptance, especially in Europe.
-
Hi‑Green Carbon (India) — A lower‑cost regional producer whose ISCC‑certified production lines and proximity to feedstock pools illustrate the geographic arbitrage and trade flows that will shape regional supply dynamics.
Market concentration remains moderate: the top three and top five suppliers do not yet command an overwhelming share of the market, leaving room for new entrants and consolidation. That balance favors strategic buyers who can secure preferential supply or form joint ventures without paying monopoly premia.
Regulatory and technical dynamics impacting 2026 decisions
-
Regulatory recognition and certification: The EU Waste Framework’s treatment of pyrolysis outputs and the adoption of ISCC PLUS establish a compliance framework that allows rCB to be commercially used and marketed as circular. Companies planning 2026 product claims must lock in certified supply and ensure mass‑balance bookkeeping.
-
Purity and application scope: rCB purity presently sits below the highest‑performance virgin grades. This technical constraint will dictate a phased adoption: early wins will be in non‑critical rubber goods, some plastics/masterbatch formulations and selected coatings/inks, with gradual penetration into higher‑performance tire compounds as R&D advances.
-
Trade and tariffs: Regional fiscal treatments (including import duties in certain jurisdictions) will influence global sourcing strategies. These are tangible near‑term considerations for companies designing 2026 cross‑border procurement programs.
What our report delivers — practical outputs for 2026 action
The PW Consulting Rcb Market report is intentionally built for decision makers who need executable recommendations, not just high‑level commentary. Key deliverables include:
-
Global market model with scenario and sensitivity analysis—enabling buyers and investors to stress‑test demand, feedstock availability and price pathways without exposing proprietary segment splits in this preview.
-
Supplier due‑diligence and scorecard toolkit—covering technology maturity, certification status, feedstock security, and commercial reliability to accelerate vendor selection.
-
Procurement playbook—templates for offtake agreements, quality acceptance criteria, and contract provisions that incorporate certification and traceability clauses.
-
Commercial adoption roadmap—segment‑by‑segment go‑to‑market sequencing, pilot design checklists, and KPI frameworks to measure performance during 2026 rollouts.
-
CapEx and investment decision matrix—an interactive framework for evaluating greenfield vs. JV vs. supplier partnerships, with trigger thresholds for investment readiness calibrated to market growth and concentration dynamics.
-
Regulatory and certification checklist—practical steps to achieve ISCC compliance, engage with authorities and ensure claims are auditable across multiple jurisdictions.
Case actions for 2026 (recommended)
-
Secure short‑to‑mid term offtake: Negotiate staggered offtake volumes with certified suppliers to de‑risk supply while preserving optionality as product acceptance evolves.
-
Embed certification requirements: Make ISCC (or equivalent) certification a contractual condition for sustainability claims and corporate reporting.
-
Run targeted formulation pilots: Prioritize non‑critical rubber and plastics applications where rCB performance parity is closest, then scale into higher‑risk tire applications only after validated performance data and lifecycle assessments.
-
Design a blended sourcing strategy: Combine regional low‑cost producers with strategic local partners to balance price, logistics and regulatory exposure.
-
Allocate a small strategic M&A war chest: Use it to secure minority stakes in technology‑proven producers or recycling networks that provide privileged access to feedstock.
Where the uncertainty lies—and how the report helps
-
Feedstock price volatility and competition for scrap tires: Increased recycling demand can drive feedstock costs. Our forecast scenarios quantify impacts on margin and recommend hedging and vertical integration strategies.
-
Technical parity with virgin carbon black: Current purity gaps limit some tyre tread applications. The report includes an R&D prioritization guide and blending decision matrix to minimize performance tradeoffs.
-
Policy tailwinds and trade friction: Divergent regional treatments create both arbitrage and compliance complexity; our regulatory matrix maps actions by jurisdiction to keep 2026 strategies compliant and efficient.
Final thoughts — the 2026 strategic inflection
Recovered carbon black is no longer a speculative sustainability experiment; it is a maturing industrial commodity with clear pathways to scale and meaningful implications for cost structures, product positioning and sustainability claims. The macro indicators point to rapid expansion through the remainder of the decade, but the commercial story will be written in 2026 by firms that move from assessment to disciplined operational execution—locking in certified supply, proving formulations in prioritized applications, and using structured procurement and investment frameworks to capture upside while managing purity and regulatory constraints.
Next step
This briefing is a curated preview designed to help senior leaders frame 2026 choices. Our full PW Consulting Recovered Carbon Black Rcb Market report contains the granular forecasting, supplier performance benchmarking, contractual templates and scenario models you will need to operationalize the recommendations above. Visit the report page to access the complete dataset, downloadable toolkits and supplier matrices that support immediate execution.
For detailed analysis of this topic, please visit the official page: Recovered Carbon Black Rcb Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Micro System Analyzer Market to Hit USD 431.2M by 2032 at 8.36% CAGR
By PW Consulting, 2026-07-13
Micro System Analyzer Market — Strategic Outlook for 2026 Decision‑Making
Executive summary
The Micro System Analyzer (MSA) market sits at an inflection point. After a steady recovery and expansion through the early 2020s, the global market escalated from a modest base in 2020 to a substantially larger industry by 2025, and our forecast shows continued acceleration through 2032. PW Consulting’s baseline model projects a compound annual growth rate (CAGR) of 8.36% across the 2026–2032 forecast horizon, reflecting rising demand for non‑contact optical characterization, tighter product qualification cycles, and broader adoption across high‑value end markets. In absolute terms, the market nearly doubles over the next several years under our central scenario, driven by technology maturation, higher test-throughput requirements at wafer and device level, and expanding applications that demand precise dynamic and topographic measurement.
Micro System Analyzer Market
Why this research matters for 2026 corporate decisions
-
Timing for capital allocation: An 8%+ structural growth trajectory means executives must decide whether to accelerate capital deployment in test equipment, or to pursue capacity-light options (contract test services, partnerships) to capture growth without over-investment.
Micro System Analyzer Market -
R&D and product roadmap prioritization: As measurement capabilities move from single-point probing to integrated, non-contact optical workstations, product teams must weigh embedding measurement-friendly features (test hooks, design-for-measurement) against system cost and manufacturability tradeoffs.
Micro System Analyzer Market -
M&A and partnership strategies: A market with noticeable concentration at the top creates premium for bolt-on capabilities—companies can buy optics competency, software analytics, or expand into wafer-level quality assurance through targeted acquisitions or co-development agreements.
-
Regulatory and reimbursement posture for medical applications: Non-contact dynamic characterization is gaining acceptance in medical device development workflows. Decision makers in med‑tech need to integrate validated measurement protocols early to shorten clinical and regulatory cycles.
What PW Consulting’s Micro System Analyzer Market report delivers
Our study is designed as a practical playbook for leaders making investment, product, and market entry decisions in 2026. The report combines proprietary market sizing and scenario-driven forecasts with market structure diagnostics and tactical tools for execution. Highlights include:
-
A transparent market model—historical time series (2020–2025) and forward-looking scenarios for 2026–2032—allowing financial planners to stress test capital plans against upside/downside demand trajectories.
-
Technology deep dives that decode performance envelopes (frequency, spatial resolution, throughput) and map product families to typical use cases (R&D, wafer‑level inspection, reliability testing).
-
Action-oriented go‑to‑market modules—buyer personas, procurement decision trees, and commercial playbooks for OEMs, test houses, and academic labs.
-
Competitive benchmarking and capability matrices that identify where incumbents dominate and where white‑space exists for new entrants or adjacent players.
-
Investment and M&A scoring tools that rank targets against integration risk, time‑to‑market contribution, and margin accretion potential.
-
Risk registers and mitigation roadmaps covering supply chain fragility, software validation, and evolving regulatory scrutiny—especially for biomedical applications.
To preserve the value of the dataset for our subscribers, this public overview purposely omits granular regional and application segment figures. The full report includes those breakdowns alongside downloadable financial models and primary‑research transcripts.
Competitive landscape: focus on Polytec and market structure
Market structure matters for strategy. Our concentration analysis indicates the market is neither highly fragmented nor monopolized—top vendors capture a meaningful share of demand, creating advantages in scale, installed base, and aftermarket services. That balance produces both stability for incumbent margins and windows of opportunity for innovative entrants.
Polytec GmbH emerges as the most visible incumbent in the MSA category. The company’s MSA series—positioned as all‑in‑one, optical, non‑contact workstations—serves static and dynamic three‑dimensional characterization needs across MEMS and microsystems development. Key strategic implications from Polytec’s footprint:
-
Product breadth and depth: Polytec’s lineup spans instruments optimized for high‑frequency vibration analysis through to comprehensive surface topography mapping. For buyers, this creates a compelling single‑vendor option for multi‑stage workflows (R&D → wafer test → reliability).
-
Clinical and biomedical relevancy: Polytec explicitly supports non‑contact characterization of biomedical samples and medical MEMS devices. For med‑tech firms, the ability to validate dynamic behavior without mass loading is a material advantage for device verification and regulatory filing strategies.
-
Channel and service moat: Mature instrumentation vendors like Polytec typically benefit from installed‑base lock‑in via calibration, software updates, and training—elements that increase switching costs for key R&D and production customers.
-
Competitive posture: New entrants should plan to undercut incumbents on either cost or data‑centric features (analytics, integration with PLM/ALM systems). Incumbents will likely respond by deepening software ecosystems and expanding test services.
Key market dynamics and risks to model into 2026 planning
-
Adoption versus commoditization: As optical and data‑processing components scale, certain measurement functions may commoditize, compressing hardware margins but raising value of software and services.
-
Regulatory tailwinds and constraints: Non‑contact measurement supports medical device validation without introducing measurement artifacts—a strategic benefit—but it also introduces scrutiny over traceability and validation protocols. Companies must prepare for tighter documentation and auditability in clinical pathways.
-
Supply chain concentration: Specialized opto‑electronic components and high‑precision mechanics remain concentrated among a handful of suppliers. Procurement strategies should include multi‑sourcing or long‑lead contracting for critical parts.
-
Consolidation dynamics: Given meaningful share captured by leading vendors, strategic acquisition activity is likely around software analytics, automated inspection integration, and wafer‑level throughput improvements.
2026 playbook: recommended actions for executives
-
Integrate measurement strategy into product design cycles. Treat non‑contact characterization capabilities as first‑class design requirements to reduce iteration and accelerate qualification.
-
Prioritize pilot deployments with clear KPIs. Run small, cross‑functional pilots that pair MSA vendors with manufacturing test engineers to validate throughput, yield impact, and process integration before scaling procurement.
-
Hedge hardware risk by buying modularity. Specify instruments with modular optics and upgradeable software so you can extend useful life and protect against early obsolescence.
-
Evaluate M&A or partnership for rapid capability acquisition. For those seeking near‑term entry into wafer‑level testing, acquiring analytics or service capabilities offers faster path to market than in‑house development.
-
Lock in regulatory certainty early. For medical device programs, mandate validated measurement protocols and traceable calibration practices during preclinical stages to de‑risk later submission delays.
How to use this report in Q1 2026
Leadership teams should treat the report as an execution tool rather than a theoretical brief. Immediate uses include: model-driven capital budgeting that ties equipment buys to revenue scenarios; configuration checklists for procurement that articulate must‑have technical specs; target lists for M&A screening; and regulatory playbooks for medical device qualification. Each deliverable in the report is paired with templates—RFP language, ROI calculators, and pilot test plans—to move from decision to deployment within a single fiscal quarter.
Conclusion and next steps
The Micro System Analyzer market offers disciplined growth and strategic leverage for organizations that decide early and design measurement strategy into their product and production lifecycles. PW Consulting’s research synthesizes market sizing, technology assessment, competitive insight, and executable playbooks to shorten the path from insight to impact in 2026.
Note: this overview highlights our core findings while intentionally withholding the granular regional and application split data and downloadable financial models that subscribers receive. To access the full dataset, vendor matrices, and the scenario financial model that powers our CAGR and forecast, please visit the report landing page or contact PW Consulting’s industry practice for a demo and sample worksheets.
For detailed analysis of this topic, please visit the official page: Micro System Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Synthetic Diamond Grit Market — 5.2% CAGR to USD 3,065M by 2032
By PW Consulting, 2026-07-13
Synthetic Diamond Grit Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s latest Synthetic Diamond Grit Market study provides a focused, decision-ready view for companies preparing strategy, sourcing, and investment plans in 2026. At a market level, the industry demonstrates steady, resilient growth: from an estimated USD 2,150.5 Million in 2025 to a projected USD 3,065.05 Million by 2032, representing a 5.2% compound annual growth rate across the 2026–2032 forecast window. Our research draws on a 2020–2025 historical baseline and a 2026 forward-looking modelling framework (base year 2025), combining primary interviews, plant-level economics, and trade/regulatory scenario analysis to produce operationally relevant guidance.
Synthetic Diamond Grit Market
Why this matters for 2026
- Market momentum. The mid-single-digit CAGR underlines an industry moving beyond cyclical volatility into structural demand drivers tied to infrastructure, precision manufacturing, and high-performance materials.
- Timing of choices. Capital allocation, capacity expansions, and supply-contract renegotiations executed in 2026 will determine competitive positioning for the next seven years of growth reflected in our forecast.
- Complex levers. Price exposure (feedstock and freight), regulatory shifts, and evolving end-use requirements (from heavy sawing to semiconductor polishing) create a narrow window where operational agility converts to market share gains.
Market trajectory and what the numbers imply
The market’s recent trajectory shows consistent year-on-year expansion through 2025, with the structural drivers expected to sustain growth into the 2030s. Our scenario modelling incorporates baseline demand for industrial abrasives, incremental gains from advanced polishing in electronics, and cyclical influences from construction and mining. While headline figures indicate attractive growth, strategic implications differ by value chain node: raw-material sourcing and energy intensity are critical for producers; supply reliability and product-grade diversification matter most to toolmakers and OEMs.
Synthetic Diamond Grit Market
Competitive landscape — what to watch
The synthetic diamond grit ecosystem includes global leaders with diversified technical portfolios and vertically integrated producers focused on volume and cost. The market exhibits moderate concentration (CR3 and CR5 metrics indicate a cluster of established multinationals alongside numerous regional specialists), which creates both partnership and consolidation opportunities.
Synthetic Diamond Grit Market
- Global technology leaders: Established players with HPHT and CVD capabilities continue to push technical differentiation into electronics and precision grinding applications. New product launches aimed at high-value polishing segments are shifting value away from commodity grit supplies.
- Regional manufacturers: Several Asia-based manufacturers drive scale in construction- and stone-processing grades. Their strengths lie in cost competitiveness and proximity to heavy end markets.
- Specialist suppliers: Firms focusing on high-strength or application-specific grades (e.g., thermal-stable grits for high-speed sawing or high-purity pellets for semiconductor polishing) are capturing premium niches.
Recent notable corporate moves include new high-purity products for semiconductor polishing, capacity expansions targeted at stone-processing demand, and launches of thermally stable grades for high-speed sawing—each signaling where profitable growth is emerging. Our competitive assessment maps these developments against technology roadmaps and customer procurement cycles to identify likely winners and vulnerable incumbents.
Supply chain, cost drivers and operational risk
Three supply-side dynamics will dominate strategic choices in 2026:
- Feedstock and energy intensity. Graphite—which remains a principal feedstock for HPHT synthesis—has shown price volatility; supply-chain sensitivities and feedstock sourcing strategies materially affect production cost curves. HPHT production’s energy consumption is non-trivial and has been highlighted in regulatory and carbon-accounting frameworks.
- Transport and logistics. Ocean freight volatility is impacting landed costs for continent-spanning supply chains. Recent freight-rate increases materially raise shipment economics for low-value, high-weight consignments and alter the optimum location for inventory and toll-processing facilities.
- Trade and regulatory regimes. Tariff regimes and chemical-materials regulations create pricing and compliance layers that must be modelled into sourcing decisions. Import duties and nano-material registration requirements can change go-to-market math quickly for cross-border flows.
Regulatory and environmental dynamics — implications for 2026 planning
Regulatory developments are not peripheral; they reshape cost structures and market access. Key dynamics to account for in strategic planning include:
- Nanomaterial registration requirements in major markets, which affect formulations and mixture approvals for certain abrasive products.
- Tariff and trade measures that can materially alter landed costs for imports from specific countries—necessitating alternative sourcing or local footprint adjustments.
- Energy and carbon accounting frameworks that increasingly influence the competitiveness of HPHT versus alternative synthesis routes and may drive relocation or investment in low-carbon energy at scale.
Sector-specific demand signals
Different end-use sectors present distinct growth, margin, and product-quality profiles:
- Construction and stone-processing remain volume anchors; price sensitivity and delivery reliability govern vendor selection.
- Automotive and aerospace require tighter specifications and traceability, presenting opportunities for premium pricing where certification and supplier quality systems are demonstrable.
- Electronics and semiconductor polishing represent the highest margin growth corridor, but require rigorous R&D, long qualification cycles, and tight supply security.
What PW Consulting’s report delivers — practical, operable outputs
We structure the deliverables to support the decision calendar of C-suite, commercial, and procurement teams in 2026:
- Strategic scenarios and playbooks: three actionable pathways (scale, specialize, partner) with trigger points and capex/ROI sensitivities modelled under alternative cost and regulatory scenarios.
- Commercial tactics: customer-segment scorecards, value-capture levers by application, and pricing playbooks that integrate freight and tariff overlays.
- Supply-chain diagnostics: supplier scorecards, recommended hedging strategies for feedstock, and a roadmap for nearshoring vs. offshore procurement backed by landed-cost modelling.
- M&A and partnership screening: a prioritized list of acquisition and JV archetypes, integration risk profiles, and suggested due-diligence metrics focused on technology, quality systems, and energy footprint.
- Operational benchmarks: plant-level throughput, energy consumption norms, and productivity KPIs to inform capital investment sizing and retrofit decisions.
How to use this research in 2026
Senior leaders should treat the report as a tactical blueprint for the year ahead:
- Procurement teams: re-run supplier TCO with updated freight and compliance assumptions; implement short-term hedges where exposure is highest.
- Business development and R&D: prioritize qualification efforts in semiconductor and high-precision grinding segments where premium margins and long-term contracts justify development spend.
- Finance and strategy: stress-test capital projects against carbon-accounting scenarios and tariff contingencies; use our scenario outputs to set hurdle rates and staging conditions for expansions.
- M&A teams: use the target archetypes and integration playbooks to accelerate screening and reduce transaction timelines.
Risks and early-warning indicators
Key early-warning indicators to monitor through 2026 that would necessitate tactical course corrections:
- Feedstock and energy price spikes or regional supply disruptions.
- New or tightened regulatory requirements for nano-component registration or carbon-embedded tariffs in major consuming regions.
- Sharp freight-rate shifts or port congestion that push landed costs beyond threshold economics.
- Acceleration of technical substitution in specific applications (e.g., new abrasive chemistries or tool designs that reduce diamond consumption per unit).
Competitive watch-list (what we tracked)
Our coverage includes proprietary profiling and strategic positioning for major industry participants—global technology leaders, regional high-volume manufacturers, and specialist suppliers. Recent corporate moves observed in the market include launches of high-purity polishing products targeted at semiconductor applications, capacity expansions focused on stone-processing demand, and new grades engineered for thermal stability in high-speed sawing. These activity clusters highlight where R&D and capex are being deployed, and where partnership or M&A interest is likely to concentrate over the next 12–24 months.
Next steps — how PW Consulting helps you operationalize insight
The full PW Consulting study provides the underlying data tables, sensitivity models, and supplier scorecards required to convert high-level insight into executable plans—without disclosing client-sensitive segmentation or proprietary contract levers in this preview. If your 2026 plan includes capacity decisions, supplier consolidation, or entry into premium polishing markets, our bespoke advisory services can translate the study’s scenarios into a detailed implementation roadmap, including commercial negotiation tactics, capex phasing, and integration checklists.
Closing
The synthetic diamond grit market presents a classic choice for 2026 leaders: commit to selective investment and capability-building now to capture a disproportionate share of the forecast growth window, or risk margin compression as energy, trade, and regulatory realities reshape competitiveness. PW Consulting’s report equips decision-makers with the frameworks and operational tools to make that choice with confidence. For full access to the segmented modelling, supplier-level analysis, and implementation templates referenced here, please consult the complete report on our publication platform.
For detailed analysis of this topic, please visit the official page: Synthetic Diamond Grit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Heavy Industry Hydraulic Systems Market to Grow at 4.85% CAGR (2026–2032)
By PW Consulting, 2026-07-13
Heavy Industry Hydraulic System Market — Strategic Intelligence for 2026 Decision-Makers
As capital budgets reopen and heavy industry operators accelerate decarbonization and digitalization plans, hydraulic systems remain an indispensable element of the global heavy equipment value chain. PW Consulting’s new market study — anchored on a 2025 base year and projecting through 2032 — quantifies that importance and translates it into executable strategic options. The market is set to expand at a steady mid-single-digit pace (4.85% CAGR for the 2026–2032 forecast window), moving from a large multi‑billion-dollar base in 2025 toward materially higher aggregate revenue by 2032. For C-suite leaders, corporate strategists, and business development teams, the practical question in 2026 is not whether hydraulics matter, but how to allocate scarce capital and talent to capture resilient, margin-accretive growth while managing rising regulatory and input-cost volatility.
Heavy Industry Hydraulic System Market
Why this study matters in 2026
-
Timing and trajectory: The forecast period (2026–2032) captures a decisive phase in the heavy-equipment refresh cycle. Capex programs, electrification pilots, and retrofit projects that are decided in 2026 will reach execution or scale within our forecast horizon — making early strategic choices high-leverage.
Heavy Industry Hydraulic System Market -
Policy and standards acceleration: New standards such as ISO 18464:2025, together with energy-efficiency mandates, materially change product design constraints. Manufacturers that internalize these constraints now will reduce rework and margin erosion later.
Heavy Industry Hydraulic System Market -
Input-cost and supply risk: Steel-price volatility and concentrated raw-material supply chains continue to pressure component costs and supplier reliability. Procurement and product-design strategies developed this year will determine the robustness of supply for the next 5–7 years.
-
Technology inflection: The industry is balancing proven hydraulic architectures with hybrid and electrified options (including electrified hydraulic power units — eHPUs) and increasingly connected control layers. The pace and economics of these transitions are uneven across application classes; our study provides the decision frameworks to prioritize investments.
Market structure and competitive dynamics — what to watch
Our analysis shows a market that blends global incumbents with regionally strong specialists. Market concentration is moderate: the top three firms account for roughly one-third of the market while the top five capture under half. This structure creates a dual pathway for competitive advantage — scale-based plays from the leading incumbents and focused differentiation opportunities for nimble specialists.
Key established players continue to set technology and quality benchmarks: large engineering OEMs and system integrators are investing in connected controls, higher-pressure architectures, and energy-optimization packages. Select independent suppliers are pursuing narrow but deep plays on filtration and wear-resistant components, or on integrated electro-hydraulic subsystems tailored to off-highway and mining applications. Newer entrants and regional champions accelerate adoption through trade-show launches and targeted OEM partnerships — recent product reveals and awards in major 2026 shows demonstrate the ongoing innovation cycle.
-
Strategic positioning matters more than ever: firms that combine systems engineering, software-enabled controls, and service-based revenue models will capture a disproportionate share of aftersales and lifecycle margin.
-
M&A and partnership activity will be selective: buyers are targeting capabilities in electrified power units, system integration, and digital services more than low-margin commodity components.
-
Regional go-to-market remains relevant: global scale helps with R&D and supply chain resilience, but local engineering and aftermarket presence determine success in heavy industries with site-specific requirements.
Technology and regulatory tailwinds that shape winners
Three linked trends will define competitive outcomes across the forecast horizon:
-
Energy efficiency and compliance: With ISO 18464:2025 and strengthening emissions/efficiency mandates, product roadmaps must incorporate energy-optimized circuit design and loss-reduction technologies. Early adopters can exploit first-mover advantages in bidding for large retrofit and greenfield projects.
-
Electrification and hybrid architectures: eHPUs and hybrid hydraulic-electric drivetrains reduce on-site emissions and offer lifecycle cost benefits in many duty cycles. Commercial viability depends on component reliability, integration skill, and TCO-based sales models that account for fuel, maintenance, and downtime.
-
Digitally enabled reliability: Predictive maintenance, remote diagnostics, and control-layer optimization translate into lower OPEX and higher attachment uptime — and thus into monetizable service contracts. Companies that marry hydraulic expertise with software platforms will be best positioned to grow aftermarket revenues.
Recent market signals — what the shows and awards reveal
Targeted industry events in early 2026 offered useful directional signals. Several exhibitors showcased next-generation mobile hydraulics and purpose-built cylinder and pump solutions at major North American trade shows; an electrified hydraulic power unit secured a top new-product award at a leading agricultural expo. These public demonstrations — from both established suppliers and newer specialists — confirm rising customer interest in electrified subsystems, application-specific performance tuning, and integrated testing platforms. For strategists, these signals imply that product maturity, customer validation, and price points are aligning to enable broader commercial adoption in the near term.
What the PW Consulting report delivers (practical contents)
Our study is designed to be hands-on and decision-oriented for 2026 corporate planning cycles. Highlights include:
-
Transparent market sizing and forecast methodology, including base-year reconciliation and scenario-based projections across a 2026–2032 forecast horizon.
-
End-user demand drivers and procurement behavior profiles: capital vs. operating cost sensitivities, retrofit decision triggers, and service-interval economics.
-
Technology deep dives: comparative TCO analyses for conventional hydraulics, hybrid architectures, and electrified hydraulic power units; control-layer integration and cybersecurity considerations for connected systems.
-
Value-chain mapping and supplier risk assessment that identify choke points (raw materials, filtration, control semiconductors), mitigation levers, and strategic sourcing playbooks.
-
Competitive benchmarking and capability matrices across system suppliers, component specialists, and OEM integrators, coupled with M&A and partnership screening templates.
-
Commercial playbooks for market entry and scale: channel strategies, aftermarket enhancement tactics, pricing frameworks, and retrofit program designs tailored to heavy-industrial customers.
-
Executive-ready decision tools: investment prioritization frameworks, sensitivity analyses for steel-price shocks and regulatory tightening, and phased implementation roadmaps for 2026 capital plans.
Note: The full report contains granular splits, component- and regional-level scenarios, proprietary segmental tables and financial templates that are intentionally omitted from this preview to preserve the report’s exclusive value.
How to convert insight into 2026 actions
-
Rebalance R&D toward integration: Shift incremental R&D budgets from component improvement to system-level integration (electro-hydraulic controls, eHPU uptime, and digital diagnostics) to increase capture of lifecycle value.
-
Hedge raw-material exposure: Implement a two-tier procurement approach — strategic long-term steel contracts for core production and tactical spot positions for opportunistic sourcing — and update bill-of-materials designs to reduce steel intensity where feasible.
-
Prioritize retrofit economics: Develop retrofit bundles that emphasize short payback for high-utilization assets in mining and infrastructure — backed by financing or outcome-based contracts to lower buyer resistance.
-
Build aftermarket-as-a-service propositions: Monetize predictive-maintenance insights through subscription models that combine remote monitoring, parts-on-demand logistics, and uptime guarantees.
-
Design M&A with capability inflection in mind: Target acquisitions that offer direct capability jumps in electrified subsystems, software platforms, or specialized filtration and wear components rather than pure-volume roll-ups.
Final takeaways for 2026 strategic planning
Hydraulics will remain central to heavy-industry productivity through 2032, but the basis of competition is shifting. Firms that integrate energy-efficient engineering, electrified subsystems, and software-enabled lifecycle services will win premium returns. Conversely, players relying on commodity differentiation face margin compression and acquisition vulnerability unless they pursue structural change. The market’s moderate concentration means there is room for both scale plays and focused specialists, but successful execution requires clarity on regulatory scenarios, raw-material risk, and the economics of electrified alternatives.
PW Consulting’s Heavy Industry Hydraulic System Market study provides the empirical foundation — robust market sizing, scenario modeling, and operational playbooks — to convert these insights into action. For executives preparing 2026 capital allocations, technology roadmaps, or M&A targets, the study offers a pragmatic, prioritized path to secure competitive advantage in a market growing at a 4.85% CAGR through 2032.
To access the full set of segment-level intelligence, competitive scorecards, and investment-ready templates, visit the PW Consulting report page for this study.
For detailed analysis of this topic, please visit the official page: Heavy Industry Hydraulic System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Biomass Power Equipment Market to reach USD 201.46B by 2032 (6.99% CAGR)
By PW Consulting, 2026-07-13
Biomass Power Equipment Market — Strategic Outlook for 2026 Decision-Making
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused preview of our full Biomass Power Equipment Market study — a practical intelligence package designed to inform capital allocation, partnership selection, and technology choices as organizations finalize strategies for 2026. Our analysis is grounded in a comprehensive market model (base year 2025, forecast 2026–2032) and shows the global market expanding from USD 125,458.26 Million in 2025 to USD 201,458.54 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.99%. This trajectory, and the structural dynamics behind it, will materially influence project economics, procurement timelines, and M&A activity over the next three years.
Biomass Power Equipment Market
Why 2026 Is an Operational and Strategic Inflection Point
- Policy-driven demand acceleration. Recent and prospective policy interventions—ranging from strengthened renewable targets in major economic blocs to tax incentives and investment credits—have created a near-term window for project developers and OEMs to lock in favorable financing and subsidy conditions. Timing investments to capture these policy windows is a high-return move in 2026.
- Carbon and energy-market economics are reshaping fuel choice. Elevated carbon prices in emissions trading systems and more aggressive national decarbonization roadmaps increase the economic case for biomass retrofit and replacement of fossil-fired capacity in jurisdictions where sustainability credentials are accepted for biomass feedstocks.
- Feedstock and component cost volatility matters. Commercial wood pellet and other biomass feedstock prices, plus the unit costs for key equipment (e.g., grate stoker systems), have shown meaningful bid-ask spreads in recent project tenders; supply-chain negotiations and contracting strategies in 2026 will materially affect long-term project IRRs.
- Technology performance is advancing quickly. Efficiency improvements and hybridization strategies demonstrated by incumbent OEMs compress payback periods for higher-capex, higher-efficiency solutions. Buyers that optimize for lifecycle cost rather than first-cost will capture superior margins or lower levelized cost of energy (LCOE).
What PW Consulting’s Full Report Delivers (Practical, Implementable)
- Robust top-down market sizing and forecast: granular annual modeling from 2026–2032 with scenario variants tied to policy and commodity shocks.
- Technology and feedstock decision frameworks: actionable matrices that map technology archetypes (combustion, fluidized bed, gasification, anaerobic digestion) to typical plant scales, operational profiles, and feedstock elasticity — enabling quick narrowing of viable options for a given project mandate.
- Procurement & CapEx/O&M playbooks: standardized bid templates, cost benchmarking, and assembly-level component cost ranges to accelerate vendor selection and negotiate fixed-price EPC contracts.
- Policy & incentive integration tools: jurisdictional incentive trackers and templates that translate headline subsidies and tax credits into project-level cashflow impacts and investor-return scenarios.
- Supply chain risk maps: prioritized mitigation strategies for feedstock sourcing, component lead times, and logistics, including contingency procurement paths that preserve project timelines.
- Commercial and contracting models: off-take, tolling, and co-generation commercial term sheets, plus model financial covenants that reflect biomass-specific risks.
- M&A and partnership playbook: valuation frameworks for bolt-on acquisitions and JV structures that accelerate market entry while de-risking supply and permitting exposures.
The above deliverables are designed as executable tools — not just narrative — so commercial teams can move from strategy to procurement and execution with clarity and speed. To preserve competitive value and to respect client confidentiality thresholds, the public preview intentionally omits certain segment-level monetary and regional share tables; the full report contains those stratified datasets and downloadable models.
Biomass Power Equipment Market
Competitive Landscape: Players, Positions, and Tactical Moves to Watch
- Valmet (Espoo, Finland) — Strengths: full-plant capability spanning boilers, turbines, and flue gas cleaning for multiple combustion platforms. Tactical implication: attractive partner for developers seeking turnkey delivery and advanced emissions compliance. Recent commissioning of a biomass-fired CHP plant demonstrates continued commercial execution on mid-to-large scale projects.
- ANDRITZ (Graz, Austria) — Strengths: fluidized bed combustion expertise and turnkey deliveries. Tactical implication: suited for projects focused on efficient biomass utilization and fuel flexibility; maintain ANDRITZ on shortlists where fuel variability is expected, as evidenced by recent European orders.
- Babcock & Wilcox (Akron, USA) — Strengths: grate and hybrid stoker technologies optimized for co-firing and dedicated biomass. Tactical implication: strong candidate for retrofit projects and for clients prioritizing modular staging; recent grid connections validate commercial reliability.
- Mitsubishi Power (Yokohama, Japan) — Strengths: integrated high-efficiency steam turbines and advanced combustion systems. Tactical implication: preferred where top-tier thermal efficiency and long-term performance guarantees are procurement priorities; recent efficiency milestones highlight R&D-to-market velocity.
- Siemens Energy (Munich, Germany) & GE Vernova (Cambridge, USA) — Strengths: turbine optimization and systems integration for variable fuel inputs and hybrid configurations. Tactical implication: ideal partners where integration with broader grid assets or hybrid gas/steam cycles is envisioned.
- Kraftwerke Mannheim (Mannheim, Germany) — Strengths: operator-supplier model with European co-generation experience. Tactical implication: partner of choice for utilities and municipalities pursuing operational know-how and O&M excellence.
- Zibo Zichai New Energy (Zibo, China) — Strengths: cost-competitive gasifiers and equipment for small-to-medium plants. Tactical implication: strong contender for distributed generation projects where capital efficiency and local content are decisive.
Market concentration metrics indicate an industry that remains moderately fragmented, leaving room for consolidation and alliance strategies. Incumbents are using a mix of turnkey project wins, efficiency innovations, and selective geographic plays to expand footprints — presenting opportunities for M&A, technology licensing, and OEM-developer partnerships.
Biomass Power Equipment Market
Key Dynamics That Will Drive 2026 Decisions
- Policy and incentives: National investment credits and renewable targets materially change the NPV calculus for new-build projects and repowering initiatives. Structuring bids to capture those windows is critical.
- Carbon pricing: Elevated allowance prices increase the competitiveness of biomass solutions against fossil alternatives; buyers should model carbon-price sensitivities across 5–10 year horizons.
- Feedstock markets: Feedstock cost and availability will be a gating factor for project sizing and contract tenors. Hedging, vertical integration, or long-duration supply agreements should be prioritized in 2026 procurement strategies.
- Component supply and CapEx: Equipment lead times and the unit economics of core systems (e.g., grate stoker modules) will shape project schedules and financing structures; early procurement windows reduce schedule risk.
- Operational efficiency and retrofits: Efficiency upgrades and hybridization pathways materially change lifetime returns — businesses should evaluate retrofit options for existing assets as potential quick wins.
Actionable Strategic Imperatives for Executives
- Prioritize feedstock security through long-term contracts, strategic inventories, or upstream investments. Short-term savings on feedstock can erode returns if supply reliability is compromised.
- Opt for technology decisions that align with long-term fuel availability and grid-service requirements; favor solutions that offer modular scalability and retrofit pathways.
- Lock in EPC and major-equipment lead times in 2026 to avoid inflationary and supply-chain exposure; consider contractor-financed milestones tied to performance guarantees.
- Design financing structures that capture available tax credits and grants, and stress-test models for carbon-price volatility and fuel-cost inflation scenarios.
- Use M&A and JV structures to accelerate entry in fragmented markets where local operating know-how and permitting relationships are decisive.
Decision Scenarios — How to Use This Intelligence
- Utility decarbonization track: Prioritize high-efficiency steam turbines and long-term feedstock contracts; evaluate retrofits to existing coal plants as a near-term emissions reduction lever.
- Independent power producer track: Emphasize modular plant options and flexible off-take agreements; structure financing to capture available investment tax credits and subsidies.
- OEM and equipment supplier track: Focus R&D on fuel flexibility and emissions control, and pursue strategic alliances to offer turnkey solutions that reduce buyer integration risk.
Each of these scenarios is supported in the full report by modelled P&L, sensitivity runs, supplier scorecards, and a prioritized action list for the next 12–18 months.
Next Steps — Where This Preview Leaves You
This preview synthesizes the high-level market trajectory, competitive patterns, and tactical pathways that will shape biomass power equipment investment and procurement decisions in 2026. It intentionally highlights strategic levers and refrains from publishing the full segment-level figures and regional breakouts — those detailed tables, downloadable financial models, and supplier scorecards are part of the full PW Consulting report.
If your team is preparing capital plans, supplier RFPs, or M&A strategies for 2026, the full report will accelerate decision-making by providing the calibrated models and operational playbooks necessary to convert strategy into executable projects. Visit our report page to access the complete dataset, scenario models, and procurement templates (full access includes editable financial models and vendor evaluation tools).
For detailed analysis of this topic, please visit the official page: Biomass Power Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Corn Flour Market to Reach USD 8.63 Billion by 2032 at 4.25% CAGR
By PW Consulting, 2026-07-13
Corn Flour Market 2026: Strategic Imperatives for Decision-Makers — PW Consulting Industry Brief
By PW Consulting — Senior Strategic Advisor & Chief Industry Analyst
Corn Flour Market
Executive snapshot
The global corn flour market is entering a period of steady, structurally-driven growth. After a multi-year historical review (2020–2025), our baseline analysis identifies the market at approximately USD 6.45 Billion in 2025 (base year). Under conservative demand- and supply-side assumptions, the market is projected to expand to roughly USD 8.63 Billion by 2032, reflecting a compound annual growth rate (CAGR) of about 4.25% over the 2026–2032 forecast window.
Corn Flour Market
This industry brief previews the full PW Consulting Corn Flour Market study and translates our quantitative findings into pragmatic strategic guidance for 2026 corporate decision-making. We intentionally reveal directional market dynamics, methodology rigor, and practical use cases while withholding detailed sub-segmentation datapoints to preserve the study’s exclusive value for subscribers.
Corn Flour Market
Why this matters for 2026 strategy
- Portfolio prioritization: Growth is predictable but not uniform — stable mid-single-digit expansion means firms must choose where to invest for higher returns versus protecting volume-driven businesses.
- Capex & capacity planning: Manufacturers and ingredient suppliers need forward-looking demand curves and input-price scenarios to time mill upgrades, capacity expansions, or contract manufacturing partnerships without overexposure to cyclical inventory risk.
- Procurement & price risk: Corn price dynamics remain a primary margin lever; procurement strategies (fixed contracts, indexed purchasing, hedge overlays) will materially influence 2026 earnings sensitivity.
- Innovation & premiumization: Premium, specialty, and functional applications offer margin uplift — but they require R&D, labeling, and targeted distribution investments aligned to consumer trends.
- Regulatory & trade-readiness: Recent regulatory shifts and tariff developments mean supply-chain flexibility and compliance readiness are non-negotiable for exporters and multinational processors.
What the full report delivers — practical, action-oriented content
Our full Corn Flour Market report is structured to convert macro insight into executable initiatives. Key deliverables include:
- Transparent market-sizing methodology with bottom-up and top-down reconciliations, sensitivity testing, and alternate scenarios for high/low demand outcomes.
- Seven-year forecasting models (2026–2032) with monthly-to-annual cadence options for demand planning and capex phasing.
- Supply-chain maps by milling configuration and logistics archetype, highlighting lead times, critical bottlenecks, and cost-to-serve benchmarks.
- Input-price scenario suite: spot, forward, and stress-case trajectories for corn and energy that feed margin-scenario matrices for manufacturers and ingredient buyers.
- Go-to-market playbooks for ingredients (e.g., industrial, retail, foodservice), including route-to-market options, co-manufacturing criteria, and private-label risk assessments.
- M&A & partnership target screening framework: a scored universe of strategic fits based on product portfolio, geography, capacity, and ESG alignment.
- Regulatory compliance checklist and labeling implications across key jurisdictions, plus an assessment of how trade-policy shifts could alter sourcing economics.
- Operational improvement diagnostics: recommendations for yield uplift at wet- and dry-milling operations, energy optimization, and waste valorization opportunities.
Market dynamics shaping 2026 choices
Several ongoing dynamics will determine which players capture disproportionate value in 2026 and beyond:
- Input-price volatility: USDA’s projection of a season-average corn price for 2025/26 and contemporaneous futures pricing indicate continued sensitivity to harvest outcomes and macro demand (including feed and ethanol). Firms must model procurement under both normalized and stress-price regimes.
- Regulatory clarity: Standards of identity and labeling requirements (e.g., national food codes) remain a structural constraint for product reformulation and cross-border trade. Compliance-driven reformulation timelines must be built into product-development roadmaps.
- Trade-policy friction: Recent tariff activity and legal rulings have injected uncertainty into import/export economics; supply-chain reworking (nearshoring, multi-sourcing) is a prudent defensive measure.
- Sustainability and traceability: Buyer preference is accelerating toward regenerative sourcing, lower-carbon milling, and documented supply chains. Sustainability credentials are increasingly table stakes for large retail and foodservice contracts.
Competitive landscape — who to watch and what they signal
The corn flour market sits at the intersection of large agribusiness integrators, specialized ingredient innovators, and regional/heritage millers. Each cohort brings distinct capabilities and strategic intent that will influence competition, partnership opportunities, and consolidation dynamics in 2026.
- Global processors (Archer Daniels Midland, Cargill, Bunge): These firms leverage scale, integrated origination, and diversified end markets. Their strengths are in supply security, contract logistics, and large-scale food-ingredient solutions. Recent sustainability initiatives and new-plant investments reflect a dual focus on decarbonization and feedstock-to-fuel economics — moves that can compress supplier risk for buyers but also escalate competitive intensity in commoditized channels.
- Ingredient specialists (Ingredion, Grain Millers): These companies compete on formulation expertise, functional performance, and ingredient customization. They are natural partners for consumer-packaged goods firms seeking clean-label texture and shelf-life solutions. Expect continued product development around texturizing functionalities and starch-protein blends that enable reformulation away from higher-cost inputs.
- Heritage and nixtamal-focused producers (Gruma, Azteca Milling, Minsa): With deep know-how in traditional masa and nixtamalized flours, these players dominate cultural and premium segments. Their IP in processing and recipe adaptation creates high barriers for entrants aiming at heritage categories, and they are attractive targets for CPGs aiming to secure authenticity credentials.
- Specialty and retail-focused mills (Bob’s Red Mill, King Arthur Baking, regional millers): These firms command premium positioning through organic, non-GMO, and gluten-free claims. They are well positioned to capture retail and specialty foodservice premiums, though scale limitations may prompt contract manufacturing or distribution alliances to meet broader demand.
- Regional & contract processors (SEMO Milling, LifeLine Foods, Mittal Cornezza): These players offer flexible tolling, private-label, and B2B supply solutions. Their value lies in agility and cost-competitive regional fulfillment; they often form the backbone of contingency supply strategies for larger buyers.
The mix of scale, specialty, and regional players suggests a market where strategic collaborations — rather than pure acquisitions — may deliver the most immediate value in 2026. Examples include co-located milling partnerships with retailers, sustainability-linked offtake agreements, and joint R&D on functional flours.
Recent developments with strategic implications
- Major processor sustainability programs — for example, large global processors introducing regeneratively sourced flours milled with renewable electricity — will accelerate buyer requirements for origin verification and may shift premium capture toward vertically integrated suppliers.
- New downstream or adjacent-capacity announcements (e.g., processing and ethanol facilities) can alter local corn balances and logistics flows; firms should re-evaluate feedstock availability and tolling economics in affected corridors.
- Commodity-price signals and futures levels through early 2026 emphasize the value of dynamic hedging frameworks and flexible supply contracts to protect margins during price swings.
- Trade-policy and court rulings that modify tariff regimes create windows for import growth in some supply-constrained markets — an opportunity for agile exporters and tolling providers.
Strategic recommendations for 2026 (prioritized)
- Build adaptive sourcing playbooks: Implement multi-tier supplier strategies that combine long-term offtake with short-term spot levers and hedges tied to price triggers.
- Invest selectively in premium innovation: Allocate R&D and commercial resources to high-margin, specialty blends and labeling claims favored by retail and foodservice channels.
- Partner for sustainability: Form origin-level partnerships to secure regenerative or low-carbon inputs; align commercial incentives with farm-level practices to lock in premiums.
- Operationalize scenario planning: Use the report’s forecast and stress scenarios to sequence capex, manage working capital, and design contingency logistics pathways.
- Explore targeted alliances: For mid-size players, pursue co-manufacturing, distribution-sharing, or minority investments with specialty millers to access capabilities without full integration risk.
How PW Consulting’s study supports execution
Our full report operationalizes the above recommendations with the tools procurement, finance, and commercial teams need to act in 2026: granular forecasting models, supplier-scorecard templates, scenario-ready P&L impacts, and a screened M&A/partnership universe. Subscribers receive both the evidence base and the execution checklists required to move from strategy to measurable outcomes within twelve months.
Next steps
PW Consulting’s Corn Flour Market study is designed as a decision-support asset for 2026. If your organization is evaluating capacity investments, re-shaping procurement, launching premium products, or exploring M&A in the corn value chain, the full report will provide the detailed segmentation, financial models, and supplier-level diligence you need. Contact our client services team to arrange a briefing, data-room access, or a tailored advisory workshop that maps findings to your strategic priorities.
Note: This preview emphasizes high-level market sizing, growth trajectory, competitive positioning, and actionable implications while withholding detailed sub-segment data reserved for the full report subscription.
For detailed analysis of this topic, please visit the official page: Corn Flour Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


