



Category: market research
PW Consulting: Hydroxyacetic Acid (Glycolic Acid) Market to Reach USD 628.84M by 2032 at 6.8% CAGR
By PW Consulting, 2026-07-12
Hydroxyacetic Acid (Glycolic Acid, CAS 79-14-1): Strategic Intelligence for 2026 Decision-Making
Executive snapshot
Glycolic acid (hydroxyacetic acid) has moved from a niche specialty chemical to a strategically relevant input across personal care, specialty industrial cleaners, textiles, and select pharmaceutical and food-processing applications. Our PW Consulting market study, with a 2025 base year and a forecast window through 2032, captures this transition: the global market has expanded from the low‑hundreds of USD Million in 2020 to an estimated USD 415.0 Million in 2025, and our modeled trajectory shows sustained acceleration through the forecast period, underpinned by a compound annual growth rate of 6.8% (2026–2032).
Hydroxyacetic Acid (Glycolic Acid) (CAS 79-14-1) Market
Why this study matters for 2026 decisions
- Timing of investment and capacity moves: The market’s mid‑single‑digit CAGR masks pockets of faster growth tied to bio‑based supply innovations and higher‑purity grades for pharma and electronics. For corporate boards and investors evaluating brownfield or greenfield capacity in 2026, the study translates market growth into realistic utilization ramp profiles and payback windows under multiple feedstock scenarios.
- Risk calibration in procurement: Recent feedstock volatility—illustrated by upward pressure on oxalic acid and ethylene glycol prices and regional spikes in formaldehyde costs—means procurement strategies calibrated in 2026 must emphasize hedging, supplier diversification, and qualification of alternative chemistries. Our analysis provides actionable procurement stress tests and switching cost matrices.
- Regulatory and ESG alignment: Environmental compliance costs have risen materially for downstream European users; 2025 saw a notable increase in compliance‑related spending. Managers planning 2026 product roadmaps need to prioritize lower‑impact grades and bio‑based sourcing to future‑proof market access and avoid margin erosion from tightening environmental standards.
What the macro picture reveals
At an aggregate level, glycolic acid exhibits steady expansion: the market size climbed from approximately USD 315 Million in 2020 to USD 415 Million in 2025, and our baseline forecast anticipates it continuing to grow to the high hundreds by the end of the decade. That expansion is not uniform—growth in certain high‑purity segments and end‑use niches outpaces the headline number—but the 6.8% CAGR for the forecast window provides a robust planning anchor for capital allocation and product strategy in 2026.
Hydroxyacetic Acid (Glycolic Acid) (CAS 79-14-1) Market
Market structure and competitive dynamic
The competitive landscape is characterized by a mix of global leaders with advanced manufacturing platforms, national champions focused on cost‑competitive supply, and regional specialists targeting niche applications. Market concentration is moderate: the top three players account for roughly one‑third of the market, while the top five approach half. This structure creates space for both scale players to pursue capacity and innovation plays, and for agile suppliers to carve out specialty niches.
Hydroxyacetic Acid (Glycolic Acid) (CAS 79-14-1) Market
- Scale & technology leaders: Producers leveraging continuous manufacturing, high‑purity process control, and bio‑based feedstock technology are positioned to serve pharmaceutical, electronics, and specialty chemicals demand with differentiated pricing power and higher margins.
- Volume & cost players: Fine‑chem manufacturers and chemical intermediates producers remain critical to volume supply for industrial applications. Their strategy centers on operational efficiency and logistics optimization to protect margins when feedstock prices spike.
- Regional specialists and contract manufacturers: Strategic partnerships between high‑purity technology owners and regional contract manufacturers are emerging as a repeatable model to combine technology leadership with local market access and regulatory compliance.
Notable recent developments and what they imply
- Bio‑based pilot capacity comes online: The commissioning of new bio‑based glycolic acid pilots signals a potential inflection point in feedstock sourcing. Producers and buyers should evaluate how bio‑based sourcing affects long‑term cost curves, sustainability claims, and route‑to‑market for premium grades.
- Product portfolio upgrades for high‑purity markets: New technical‑grade offerings targeting electronics etching and pharmaceutical use highlight a bifurcation in the market: standard industrial grades versus value‑added high‑purity products. This bifurcation has strategic implications for plants, QA regimes, and certification investments initiated in 2026.
- Commercial partnerships and co‑development: Recent alliances between high‑purity manufacturers and contract manufacturing organizations reduce time‑to‑market for pharmaceutical suppliers while protecting IP and capital. Corporates pursuing growth should consider partnership roadmaps as an alternative to direct investment.
Raw materials, cost dynamics and supply risk
Feedstock volatility is a real and present driver of margin volatility. Since late‑2024 and into 2026 we have observed pockets of tightness and price migration across oxalic acid, ethylene glycol, and formaldehyde—each of which can transmit to glycolic acid producers depending on their synthetic route. In practice, buyers and sellers must model multiple price paths and plan working capital accordingly. Our full report provides linked price‑path scenarios and margin sensitivities that are essential for 2026 contract negotiation and capex approvals.
Strategic implications by stakeholder
- Producers (large & medium): Reassess the trade‑off between volume and quality: investing in high‑purity process capability or bio‑based feedstock can create differentiated growth, but requires longer lead times and stricter regulatory compliance. Use our scenario models to map investment timing to expected ROI under conservative and aggressive market cases.
- Private equity and strategic investors: Market concentration and predictable growth create attractive roll‑up opportunities, provided integration plans address quality assurance, regulatory exposure, and feedstock risk. Our M&A playbook identifies value levers, typical synergies, and integration pitfalls observed across recent transactions.
- Downstream formulators: For cosmetics and specialty cleaners, there is a near‑term imperative in 2026 to qualify multiple sources and secure long‑term supply agreements with grade‑specific quality metrics. The report offers supplier shortlists and qualification templates tailored to cosmetic and pharmaceutical quality regimes.
- Procurement and risk managers: Adopt a tiered sourcing strategy that blends spot, term, and alliance‑based supply; use hedging where appropriate; and incorporate environmental compliance cost pass‑throughs into supplier contracts. Our standard contract clauses and risk allocation templates can be implemented immediately.
What the PW Consulting report delivers — practical, transaction‑grade content
Beyond strategic narrative, the report is designed for commercial and operational decision‑makers who need executable outputs in 2026. It includes:
- Transparent market sizing methodology and reconciled top‑down/bottom‑up estimates for 2020–2025 and projected 2026–2032 trajectories.
- Scenario models (base, downside, upside) with sensitivity to feedstock price paths, purity mix, and regulatory tightening.
- Price benchmark matrices and contract negotiation playbooks for term and spot purchasing.
- Supply‑chain maps and constraint analyses identifying concentration points and logistical choke points under multiple disruption scenarios.
- Actionable go‑to‑market playbooks for launching high‑purity and bio‑based product lines, including sample QA/QC checklists and regulatory prerequisites by jurisdiction.
- Detailed company profiles and competitive positioning for major players, including technology differentiators, capacity footprints, and recent strategic moves.
- M&A target screens, valuation ranges, and integration checklists tailored to roll‑up and bolt‑on strategies.
- Regulatory and sustainability matrix highlighting compliance cost drivers and mitigations that matter for 2026 procurement and product approvals.
Competitive highlights — what to watch in 2026
We track three strategic playbooks among market participants: (1) technology/quality leadership built around continuous and high‑purity manufacturing platforms; (2) cost‑focused volume producers leveraging scale and regional feedstock advantages; and (3) integrated partnerships pairing technology owners with contract manufacturers to accelerate commercialization while limiting capital exposure.
Key incumbents exemplify these playbooks. Some are market leaders in high‑purity production through proprietary continuous manufacturing; others are established fine‑chemical exporters serving industrial demand. Recent capacity and product launches by leading European and global chemical players, combined with strategic partnerships, are worth monitoring as catalysts that could shift supply dynamics and price realization over the next 18–36 months.
How to use this intelligence in 2026
- Start with a short‑form sensitivity run: model your exposure to a 10–20% feedstock shock using our provided templates to see whether margins compress to unacceptable levels and whether price pass‑through is viable.
- For capex proposals, deploy our scenario models to stress‑test payback periods under conservative demand adoption rates for premium grades.
- Use the supplier shortlists and qualification templates to compress supplier onboarding timelines from months to weeks—critical when negotiating 2026 term contracts.
- If pursuing M&A, apply our target architecture and integration checklist to evaluate targets quickly and prioritize actions that de‑risk quality and regulatory exposures.
Final note — the trailer principle
This article is intentionally selective: it surfaces the strategic contours, competitive dynamics, and prioritized actions that matter for making defensible decisions in 2026. To preserve analytical traction and the commercial integrity of actionable sub‑segment data (region‑by‑region demand curves, grade‑specific pricing, and detailed supplier revenue splits), we reserve those tables, models, and raw datasets for the full report and its downloadable datasets.
For a thorough, transaction‑ready pack—complete with financial models, supplier scorecards, contract clause templates, and the granular segmentation that supports confident 2026 execution—please consult the full PW Consulting Hydroxyacetic Acid (Glycolic Acid) market study. The report delivers the level of detail required to convert strategic intent into measurable outcomes in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Hydroxyacetic Acid (Glycolic Acid) (CAS 79-14-1) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Gaming Market 2026: Strategic Signals from PW Consulting’s Market Research Preview
As organizations prepare their 2026 strategic roadmaps, the global gaming market presents a unique mix of scale, velocity and structural change. PW Consulting’s latest market research — rooted in an audited base year of 2025 — shows the industry expanding from approximately USD 130 billion in 2020 to USD 189 billion in 2025, and poised to approach USD 355 billion by 2032 under our base-case outlook. This trajectory implies a compound annual growth rate of roughly 9.43% across the forecast horizon. For decision-makers, that macro momentum matters — but the critical value lies in understanding where growth, consolidation and disruption will intersect, and how to translate those inflections into executable moves in 2026.
Gaming Market
Why this report matters for 2026 decision-making
-
Orientation in a fast-growing market: With sustained high single-digit CAGR, leaders must choose between doubling down on core franchises, scaling platform plays, or entering adjacencies. The report isolates the strategic trade-offs each path entails.
Gaming Market -
Operational translation, not just forecasts: Beyond top-line projections, the research provides playbooks for product roadmaps, live-ops economics, talent sourcing, and supply-chain resilience — all essential to convert market tailwinds into durable cashflow.
Gaming Market -
Regulatory and macro foresight: The study synthesizes recent regulatory signals and macro shocks (tariffs, shifting consumer protections, and adjacent gambling market dynamics) into risk-adjusted scenarios for product launches and market entry.
-
M&A and competitive positioning: With market concentration that favors large incumbents yet leaves opportunity for focused challengers, the report guides buyers and sellers on valuation levers and integration priorities.
What the research delivers — practical components of the report
-
Robust market sizing and forecasting model: Transparent assumptions link historical performance (2020–2025) to a set of scenarioled forecasts (2026–2032) that can be stress-tested for client-specific use.
-
Segment and channel playbooks: Actionable GTM templates for platform strategies (hardware, console ecosystems, PC, and mobile), developer economies, and third-party distribution without publishing sensitive granular splits in this preview.
-
Competitive benchmarking: Outcome-focused scorecards for major platform owners and leading publishers covering product pipeline, monetization quality, R&D productivity, and partner ecosystems.
-
Monetization and retention toolkit: Standardized live-ops KPIs, cohort analysis templates, and scenario-based LTV/CAC models to prioritize investment across content and user acquisition.
-
Regulatory & supply-chain risk register: Prioritized mitigations for tariffs, import disruptions, and emergent regulatory threats with playbooks for pricing, localization and lobbying posture.
-
M&A playbook and valuation levers: Checklist for target screening, synergies, and integration sequencing tailored to the gaming value chain.
-
Executive workshops and decision dashboards: Ready-to-use board materials and a 90-day implementation roadmap for rapid strategy execution.
Competitive landscape — what executives need to know now
The industry’s structure combines powerful platform owners with influential first- and third-party content creators. Concentration metrics indicate meaningful scale at the top, but the market remains sufficiently fragmented to allow nimble entrants and specialist studios to capture disproportionate returns if they assemble the right assets.
-
Nintendo: The recent hardware cycle — marked by the launch of Nintendo’s next-generation console in 2025 — reshapes platform dynamics. Rapid uptake of new hardware compresses the time window for content monetization and elevates the value of exclusive IP and family-friendly ecosystems.
-
Sony Interactive Entertainment & Microsoft: Both continue to balance hardware innovation with cloud-service and subscription strategies that blur lines between console ownership and service access. Their playbooks highlight bundling economics, first-party exclusives and backwards compatibility as leverage points.
-
Valve: With its Steam ecosystem and handheld hardware initiatives, Valve illustrates the power of distribution platforms to influence PC and handheld lifecycles; distribution governance and developer revenue shares are strategic battlegrounds.
-
SEGA & SEGA SAMMY CREATION: These players showcase diversification — from consoles and IP to arcade and venue-based entertainment — offering lessons in multi-channel monetization and brand extension.
-
Major publishers (Take-Two, EA, Ubisoft, Epic): Content owners remain central. Their investments in live services, proprietary engines, and cross-media IP exploitation underscore the premium on long-term engagement models over one-off title sales.
Recent product launches and collaborations materially affect planning horizons: a fast-selling new console compresses product roadmaps; high-profile content or hardware tie-ins reshape consumer expectations; and cross-industry moves (e.g., branded collaborations or venue-based launches) redefine addressable markets. These developments, coupled with an uneven regulatory backdrop, argue for scenario-driven, flexible strategies rather than deterministic plans.
Five strategic imperatives for 2026
-
Design for cross-platform engagement and modular IP: Prioritize architectures and content design that enable simultaneous monetization across hardware generations, cloud services and mobile touchpoints.
-
Embed live-ops and analytics into product development: Shift investment from episodic releases to continuous engagement, supported by real-time data flows that drive retention and incremental monetization.
-
Hedge supply-chain and price exposure: The report’s analysis correlates import-tariff risk to consumer pricing sensitivity. Sophisticated procurement strategies, localized manufacturing, and dynamic pricing can preserve margins when hardware costs spike.
-
Operationalize regulatory readiness: With a significant portion of executives viewing unregulated prediction markets and regulatory uncertainty as major threats, firms must develop compliance playbooks, lobbying strategies and adaptable product features to mitigate legal and reputational risk.
-
Adopt a disciplined M&A posture: Use buy-versus-build frameworks to capture IP, talent and platform capabilities. Prioritize targets that accelerate live-ops competencies, platform interoperability, or unlock underserved monetization vectors.
Scenario thinking and KPIs — converting outlook into measurable action
Our baseline forecast uses the 9.43% CAGR to map a credible path to 2032. From that baseline, the report provides two alternate scenarios: a policy-constrained downside, and an accelerated-adoption upside tied to cloud, 5G and adjacent-vertical convergence. Each scenario contains tailored KPI sets and budget reallocation templates.
-
Suggested strategic KPIs: retention by cohort (D30/D90), ARPU by monetization stream, CAC payback period, content engagement per DAU, hardware attach rate (where applicable), and partner revenue share.
-
Investment triggers: thresholds for additional spend on live-ops, platform subsidies, or M&A integration based on early funnel conversion and LTV attainment.
Using the full report — next steps
This preview is intended to equip executives with the directional insights needed to prioritize 2026 initiatives. The full PW Consulting report contains the granular segmentations, regional playbooks, proprietary Excel models and annexed data tables that underpin these recommendations. PW’s consulting team also offers customized workshops that translate the report’s scenarios into a tailored 90-day strategic plan and a one-year transformation roadmap.
Immediate, practical next steps we recommend for leadership teams are:
-
Run a one-day executive alignment session using the supplied decision dashboards to pick a primary and secondary strategic axis for 2026.
-
Authorize a 60–90 day pilot to operationalize a live-ops hypothesis or a supply-chain hedging strategy informed by the report’s models.
-
Commission a rapid M&A screen mapping potential tuck-ins that accelerate access to critical capabilities identified in the report.
In a market that is scaling materially — nearly doubling in under a decade under our baseline — the winners will be those who combine rigorous scenario planning with fast execution. PW Consulting’s full research package captures that balance: precise enough to drive confident investment, and practical enough to support immediate action. For the granular segment data, regional breakdowns, and downloadable financial models that you’ll need to finalize 2026 budgets and M&A strategies, please refer to the full report.
For detailed analysis of this topic, please visit the official page: Gaming Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aseptic Filling Machine Market to Hit USD 1.99B by 2032 at 7.26% CAGR
By PW Consulting, 2026-07-12
Pharmaceutical Aseptic Filling Machine Market: Strategic Imperatives for 2026
As capital allocation, regulatory enforcement and product pipelines converge in 2026, procurement and strategy teams at pharmaceutical manufacturers, contract development and manufacturing organizations (CDMOs), original equipment manufacturers (OEMs) and private equity investors face one immutable fact: aseptic fill-finish capability is now a strategic bottleneck. Our new PW Consulting market study on the Pharmaceutical Aseptic Filling Machine market provides an actionable playbook for decision-makers who must balance compliance, capacity and cost under accelerating timelines.
Pharmaceutical Aseptic Filling Machine Market
Why this study matters for 2026 decisions
The market for aseptic filling machines is recovering from pandemic-era surges and entering a structurally higher-growth phase driven by biologics, single-dose injectables and global regulatory harmonization. With a base-year market sizing anchored in 2025 and a forecast horizon extending through 2032, the study quantifies how the market expands under realistic regulatory and technology adoption scenarios. The headline: the market, measured in USD Billion, has strengthened materially since 2020 and—at a compounded annual growth rate (CAGR) of 7.26%—is projected to approach USD 2.0 Billion by 2032. That macro trajectory frames investment timing, procurement cadence and service-model design in your capital planning cycles.
Pharmaceutical Aseptic Filling Machine Market
What the market trajectory tells strategic planners
-
Acceleration in capital spend: The market size has grown steadily since 2020 and reached a new structural baseline in 2025. The combination of capacity rebuild, greenfield biomanufacturing and replacement of legacy lines means demand is less cyclical and more driven by strategic capacity additions.
Pharmaceutical Aseptic Filling Machine Market -
Predictable expansion window: With a 7.26% CAGR baked into our base case, organizations that commit to capacity upgrades in 2026–2028 position themselves to capture the mid-cycle demand that peaks later in the decade.
-
Investment scale and ROI timing: Modern isolator-based, gloveless and integrated filling lines require meaningful upfront capex and validation lead times. Planning a 2026 procurement implies production upside in 2028–2029; delaying procurement risks extended qualification windows and lost production opportunities.
Regulatory and operational dynamics that shape tactical choices
-
Annex 1 and global alignment: The revised EU GMP Annex 1 continues to drive adoption of isolator-based or RABS solutions with continuous environmental monitoring. This regulation is a de facto baseline for multinational manufacturers and contract providers serving EU markets.
-
US FDA design expectations: By 2026, FDA guidance and expectations emphasize modern cleanroom design, separative equipment and integrated material transfers—factors that materially affect line architecture and validate effort.
-
Capital intensity and scale constraints: Independent analyses and industry surveys indicate that installation and validation costs for fully automated aseptic lines commonly exceed multimillion‑dollar thresholds, constraining adoption among smaller manufacturers and creating demand for modular, phased deployments.
-
Infrastructure preference: High initial capex has catalyzed demand for modular, scalable designs and for service-driven business models (equipment-as-a-service, managed capacity) that reduce up-front spending while preserving compliance and yield.
Competitive landscape — positioning and implications
The competitive field remains moderately fragmented: the three largest firms account for a meaningful share of installed capacity, and the top five increase that concentration further. This structure creates differentiated opportunities for incumbents and challengers alike.
-
Syntegon Technology (Stuttgart) — Known for integrated liquid filling and isolator-based RTU solutions, Syntegon competes on system integration and global service footprints. Their modular lines appeal to multinational players needing consistent validation packages.
-
Bausch+Ströbel (Ilshofen) — Specialist in aseptic cleaning, filling and stoppering; strength in turnkey lines and complex high-speed vial applications. Their engineering-driven approach suits high-volume manufacturing.
-
Dara Pharma (Spain) — A focused supplier of complete aseptic lines with nimble customization capabilities; attractive to regional producers and CDMOs seeking rapid configuration.
-
Groninger (Crailsheim) — Strong in RTU containers and fully integrated process lines; emphasis on packaging compatibility and downstream automation.
-
IMA Group & Marchesini Group (Italy) — Broad portfolios across liquid and powder processing; Marchesini’s strategic manufacturing stakes and partnerships broaden its access to North American clinical and commercial customers.
-
OPTIMA Pharma (Schwaebisch Hall) and Tofflon (Shanghai) — Deliver turnkey isolator and lyophilization-capable systems. OPTIMA emphasizes turnkey projects and freeze-drying integration; Tofflon competes on cost-competitive, rapidly deployed systems for liquid and lyophilized products.
-
Rommelag — Pioneer of Blow-Fill-Seal technology with differentiated solutions for aseptic bottling and semisolid applications, often selected where BFS offers throughput and sterility advantages.
-
AST (Tacoma) — Known for adaptive, compact filling systems used across clinical and small commercial runs; attractive to organizations that need flexible, high‑quality small-batch capability.
Recent industry developments underscore consolidation and capacity alliances. A notable 2026 strategic move saw Marchesini Group expand its equity and operational integration with AST, creating a stronger combined capability in fill-finish—an instructive example of how manufacturers and suppliers are using equity and partnership strategies to secure downstream manufacturing capacity. Separately, major equipment installations by established OEMs at regional CDMOs demonstrate how rapid automation contracts can materially increase batch capacity and shorten time-to-market for sterile products.
Where the real opportunities — and risks — lie for 2026
-
For manufacturers and CDMOs: Prioritize modular, validated platforms that enable phased capacity adds. Where capital is constrained, negotiate capacity-sharing agreements or outcome-based contracts with OEMs to de‑risk upfront spend.
-
For OEMs and system integrators: Differentiate through lifecycle services, digital monitoring and remote validation tools. Aftermarket revenue and spare-parts optimization materially improve lifetime customer economics.
-
For investors and acquirers: Target assets that combine engineering differentiation with service businesses and recurring revenue—companies that can monetize validation packages, spare parts and remote support are higher-margin and more defensible.
-
For regulators and quality organizations: Expect inspection focus to shift toward integrated monitoring, data integrity across process controls and supply-chain traceability; equipment architects should design with auditability as a first-class requirement.
How our report turns insight into action
PW Consulting’s full study is built as a practical decision-support toolkit for executives who must act in 2026. Key deliverables include:
-
Market-size and demand-models (2020–2025 historical; 2026–2032 forecast) with scenario sensitivity to regulatory change and biologics adoption rates.
-
Procurement playbooks and a capital planning template that translate validation timelines, installation phasing and regulatory milestones into cash‑flow and ROI projections in USD Billion terms.
-
Supplier benchmark matrix combining technical fit, geographic service coverage and lifecycle costs—designed to shorten vendor selection from months to weeks.
-
Technical gap assessment and validation checklist for isolator, RABS and BFS architectures, enabling rapid internal audits prior to vendor engagement.
-
M&A and partnership screens that identify potential bolt-ons (technology or service-oriented) and provide integration roadmaps focused on compliance retention and customer retention.
-
Risk heat maps mapping regulatory, supply-chain and labor-cost scenarios to mitigation actions and financial contingencies.
We intentionally preserve granular segment-level splits, explicit regional percentage shares and line-item market shares for the full report to ensure our clients receive controlled, validated inputs for tender and M&A processes. The analysis presented here is designed to demonstrate the strategic depth and actionable framing we provide—while the full dataset and vendor-specific metrics are available in the report package.
Recommended actions for Q3–Q4 2026
-
Fast-track technical due diligence on any planned isolator or RABS procurement; expect 6–12 month lead times for delivery and a similar window for qualification.
-
Model three procurement scenarios (CAPEX-heavy, hybrid-service and full-service) and compare net-present-value and time-to-volume outcomes for each product line requiring sterile fill.
-
Pursue strategic supplier partnerships that include capacity reservation clauses and service SLAs to hedge against industry backlogs.
-
Prioritize digital retrofit investments for installed lines—real-time monitoring and remote diagnostics reduce downtime and regulatory friction.
-
If pursuing M&A, focus on targets with strong aftermarket revenues and validated client contracts—these assets are more resilient to equipment cycle shifts.
Final note
The aseptic filling equipment market in 2026 is not just a procurement decision; it is a strategic lever that affects product timelines, regulatory risk and unit economics for sterile pharmaceuticals. Our PW Consulting study equips leaders with the foresight, templates and competitive intelligence required to convert market growth—projected at a 7.26% CAGR into 2032 and approaching USD 2.0 Billion—into durable strategic advantage. For the complete dataset, vendor-level benchmarking and the downloadable procurement toolkit, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Pharmaceutical Aseptic Filling Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Instant Noodles Market to Hit USD 98.46B by 2032 at 6.19% CAGR
By PW Consulting, 2026-07-12
Instant Noodles Market — 2026 Strategic Preview
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a forward-looking interpretation of our Instant Noodles Market research tailored for executive decision-making in 2026. This briefing synthesizes the study’s most consequential signals — growth trajectory, competitive posture, regulatory inflection points, and tactical options — while reserving the report’s granular segment tables and proprietary models for subscribers and licensed clients. Think of this as the strategic trailer: substantive, directional, and intentionally non-exhaustive to focus boardroom debate and immediate priorities.
Instant Noodles Market
Market Snapshot: growth you can bank on
The instant noodles category re-entered a phase of robust expansion after pandemic-era volatility. On a macro basis, global retail value climbed from roughly USD 49.2 billion in 2020 to about USD 64.7 billion in 2025, reflecting resilient demand across price tiers and formats. With base-year 2025 as our operational anchor, the market is projected to grow through the 2026–2032 forecast window at a compound annual growth rate of 6.19%, reaching an upper-nine-figure industry value by 2032.
Instant Noodles Market
Why does this matter for 2026 planning? A mid-single-digit CAGR in a consumer staples category translates into predictable topline expansion that still accommodates significant product churn, channel disruption, and margin reallocation. In practice that means: stable category demand allows room to invest in premiumization and sustainability, but market share shifts can be rapid where incumbents fail to adapt to new regulatory or health-driven expectations.
Instant Noodles Market
Why 2026 is an inflection year
- Regulatory acceleration: Multiple jurisdictions are moving from voluntary guidance to mandatory front-of-package and recyclability mandates that will materially affect formulation, labeling, and packaging supply chains. Players that pre-empt these changes will shorten time-to-shelf and preserve promotional flexibility.
- Premiumization and health modernization: Demand for fortified, lower-sodium, plant-based, and chef-driven variants is converting value into higher-margin sub-categories. Reformulation and credible health claims will be a gating factor for shelf- and e-commerce assortment.
- Channel bifurcation: Traditional grocery and convenience operations remain important but co-exist with accelerated direct-to-consumer and modern-trade strategies that reward brand storytelling and variant breadth.
- Supply-chain concentration risks: Ingredient sourcing, packaging inputs, and single-source OEM capacity create asymmetric risk. Recent product recalls and quality events underscore the need for tightened traceability and contingency capacity.
What PW Consulting’s full Instant Noodles Study delivers
The report is structured to convert market intelligence into operational action across strategy, commercial, and supply functions. Key deliverables include:
- Validated historical market series (2020–2025) and a detailed 2026–2032 forecast model with scenario toggles for pricing, raw-material shocks, and premium mix shifts.
- SKU-level pricing and elasticity matrices derived from retail scanner and e-commerce datasets, enabling SKU rationalization and promotional optimization.
- Channel-centric playbooks for grocery, convenience, and direct-to-consumer launch plans, including digital microsite templates and trade promotion best-practices.
- Packaging and sustainability impact assessment tied to regulatory milestones and sourcing timelines, plus vendor scorecards for recycled-content suppliers.
- Competitor dossiers and strategic option maps for key global and regional players, accompanied by M&A and JV opportunity heatmaps.
- Operational toolkits: short-term crisis response, recall mitigation checklist, and a 12–18 month execution calendar.
To protect the commercial integrity of the dataset we have omitted granular region/application shares and SKU-by-SKU values from this preview. These are available in the full report and via our interactive subscriber dashboard.
Key market dynamics and strategic implications
- Premiumization opportunity: Consumers are trading up within the category — seeking restaurant-quality, artisanal, and fortified options. Brands that combine authentic flavor narratives with improved nutrition profiles can capture incremental margin and retailer premium space.
- Health and labeling as market shapers: Mandatory front-of-package systems and country-specific nutrient labeling timelines will force reformulation cycles and alter promotional claims. Companies delaying compliance face both market access and reputational risk.
- Sustainability is table-stakes: Upcoming recycled-content and traceability mandates necessitate early supplier development and packaging redesign. Brands that embed circularity claims with transparent QR-driven traceability will win shelf preference without sacrificing speed-to-market.
- Channel sophistication: E-commerce and D2C platforms reward assortment depth and storytelling; in contrast, mass retail prioritizes price/promotional efficiency and SKU rationalization. A hybrid go-to-market that segments SKUs by channel converts assortment complexity into commercial ROI.
- Moderate-to-high branded concentration: The category exhibits a notable branded leadership cluster that controls a large share of value — yet the market remains porous for local champions and agile challengers, particularly in regions with strong regional taste preferences.
Competitive landscape — strategic takeaways
Our competitive analysis synthesizes product strategy, geographic footprint, innovation focus, and vulnerability exposures across major players. Highlights:
- Nissin Foods Holdings (Tokyo): A pioneer with a strong innovation pipeline in convenience and health-forward cup formats. Their experiential sampling tactics signal a continued focus on demand stimulation at point of consumption.
- PT Indofood (Jakarta): A dominant regional brand operator with deep local flavor IP and distribution muscle. Their playbook emphasizes local-market taste leadership and cost-efficient mass production.
- Uni-President (Taiwan): Diverse portfolio management and fortified options position them well in markets prioritizing nutrition claims.
- Nongshim & Samyang (South Korea): Leaders in spicy and premium positioning, with aggressive export strategies targeting global spicy-food demand.
- Toyo Suisan / Maruchan (Japan/US): Strong in seafood and limited-edition flavors; recent retail expansion shows strategic attention to North American mass distribution.
- Regional challengers (Vietnam, Thailand, Russia, etc.): Local producers blend authenticity and cost advantage, making them attractive partners or acquisition targets for global entrants aiming faster market access.
Recent corporate actions underscore two themes: proactive demand activation (e.g., experiential sampling and targeted retail expansion) and operational vulnerability (several high-profile recalls in 2025–2026). These developments amplify the importance of integrated quality-control and crisis communication capabilities in any 2026 plan.
Scenario planning: three operational pathways for 2026 board decisions
- Baseline (Most likely): Continued mid-single-digit growth. Priorities: SKU rationalization, conservative capex for line-extension in premium formats, pilot recycled-content packaging, and strengthened QC for high-volume SKUs.
- Upside (Premium acceleration): If premium/health variants outpace expectations, accelerate NPD pipelines, expand higher-margin cup formats, and allocate incremental distribution funding to modern trade and D2C.
- Downside (Regulatory or quality shock): Prioritize recall readiness, accelerate supplier dual-sourcing, and tighten traceability. Delay non-critical expansion capital and preserve working capital for promotional defense.
12–18 Month Execution Playbook (high-impact tactical moves)
- Quick-win SKU rationalization: eliminate low-velocity SKUs and redeploy spend to hero premium SKUs that span channels.
- Reformulation sprints: prioritize sodium, saturated fat reductions and plant-based noodle options with minimal cost disruption.
- Packaging pivot: pilot recycled-content packaging on top-tier SKUs and roll out QR-based provenance labeling ahead of local mandates.
- Trade-lift programs: negotiate category resets with major retailers and secure premium shelf placements tied to new-product exclusives.
- Digital-first D2C trials: subscription bundles and limited-edition flavor drops to gather consumer data and test price elasticity.
- Supplier resilience: audit highest-risk inputs and establish dual-sourcing contracts with capacity options.
- Quality & recall playbook: implement cross-functional rapid response drills and a consumer-communications template library.
- M&A screen: shortlist regional brands with strong flavor IP and manufacturing footprint for bolt-on acquisition.
- Consumer insight cadence: deploy monthly tracker for flavor trends, health claims, and pack-preference signals in core markets.
- Governance & compliance: assign a cross-border regulatory lead to map labeling and packaging mandates against SKU timelines.
Why PW Consulting’s dataset matters for 2026 decisions
Our study combines a validated historical series (2020–2025), a forward-looking 2026–2032 forecast envelope, and scenario-based financial sensitivities — all calibrated to retail scanner, e-commerce, and manufacturer-sourced inputs. Subscribers gain access to the underlying model so they can: stress-test price promotions, simulate reformulation cost impact, and quantify the ROI for packaging investments over a 3–5 year horizon.
This preview intentionally omits the detailed regional, format, and channel splits that are the commercial core of the dataset. Those segment tables are the decision-grade inputs procurement, commercial, and M&A teams rely on. If your 2026 planning cycle requires actionable slices (SKU by channel by market), our interactive report and consulting workshops convert the intelligence into executable workstreams within 30 days.
Next steps for executives
- Prioritize compliance and quality: assign budget and leadership to packaging compliance and traceability now.
- Run a rapid SKU portfolio audit to free up promotional budget for premium launches.
- Engage PW Consulting for a tailored workshop that maps our forecast scenarios to your P&L and supply chain tolerances.
In an industry characterized by steady macro expansion but high tactical churn, 2026 is the year to align product, channel, and compliance strategies. Treat the category’s predictable growth as permission to invest — but structure investments to survive regulatory shifts and quality shocks. For access to the full dataset, proprietary segmentation, and our interactive forecast model, please consult the complete Instant Noodles Market report or contact PW Consulting’s market team for a licensed briefing.
For detailed analysis of this topic, please visit the official page: Instant Noodles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Semiconductor Chip Handler Market — USD 680M in 2025, 4.7% CAGR (2026–2032)
By PW Consulting, 2026-07-12
Semiconductor Chip Handler Market — Strategic Briefing for 2026 Decisions
Executive snapshot
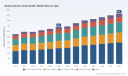
The semiconductor chip handler market is maturing into a mission-critical enabler of advanced packaging and high-throughput test flows. From a base of USD 550 Million in 2020 the market expanded to USD 680 Million by the 2025 base year and is forecast to reach approximately USD 928 Million by 2032. The medium-term trajectory implies a compound annual growth rate of 4.7% across the 2026–2032 forecast window. Market concentration is material: the top three firms capture roughly two-thirds of revenue (CR3 ≈ 65%), while the five largest firms approach three quarters (CR5 ≈ 75%).
Semiconductor Chip Handler Market
Why this matters for 2026 corporate decision-making
- Capital planning: a modest, steady expansion at ~4.7% CAGR signals predictable capacity needs rather than explosive replacement cycles—useful for capex phasing and leasing strategies.
- Supplier strategy: high concentration creates both dependency risks and supplier-bargaining asymmetries; buyers should prioritize supplier resilience and flexible contracts.
- Technology roadmap alignment: handler innovation (automation, thermal control, vision systems, AI-driven maintenance) is tightly coupled with packaging trends and test flow automation—decisions on internal development vs. third-party integration will materially affect time-to-volume for new products.
- Regulatory & geopolitical risk: export controls and incentive programs change the calculus for regional sourcing and capacity expansion—2026 is a pivot year for aligning commercial plans with policy constraints and funding opportunities.
What PW Consulting’s Semiconductor Chip Handler Study delivers (practical, decision-ready content)
This research is structured as a working toolkit for 2026 strategy execution rather than a purely descriptive market paper. Core deliverables include:
Semiconductor Chip Handler Market
- Robust market-sizing and trend narrative from 2020–2025 (historical) and a seven-year forecast (2026–2032) with scenario analysis (base, upside, downside) to stress-test capex plans.
- Buy-side decision frameworks: a supplier selection scorecard, total cost of ownership (TCO) template, and retrofit vs. greenfield decision trees for handler investments.
- Vendor diagnostics and competitive playbooks: strategic profiles, capability maps, and partner-fit matrices that translate vendor capabilities into procurement requirements by test-type and packaging architecture.
- Supply-chain mapping: critical upstream inputs, single-point-of-failure analysis, and mitigations for raw-material and labor constraints relevant to handler OEMs and subsystem suppliers.
- Operational KPIs and deployment playbooks: throughput modeling, thermal-management validation steps, and an AI-enabled predictive-maintenance pilot plan that can be executed in 90–180 days.
- M&A and partnership roadmaps: valuation heuristics, capability-acquisition checkpoints, and integration milestones for buyers seeking rapid access to advanced handler technologies or regional service networks.
- Primary intelligence: interviews with OEMs, OSATs, IDMs, and service providers; field-validated case studies showing real-world TCO outcomes and yield impacts post-handler upgrades.
Note: the full report contains gated, granular segmentation tables (by handler type, function, application, and region) and proprietary quantitative splits—these are intentionally withheld here to direct readers to the full dataset and vendor scorecards.
Semiconductor Chip Handler Market
Competitive landscape — how to read vendor behavior in 2026
The handler market is dominated by a small set of specialists and systems integrators. Understanding each player’s strategic vectors is essential when shaping supplier portfolios or evaluating partner investments.
- Advantest Corporation (Tokyo) — Strengths: high-throughput platforms and a clear focus on AI/HPC test stacks. Strategic implications: best partner for buyers prioritizing scale and front-line test automation for logic and memory at advanced nodes. Recent visibility at SEMICON events underscores continued product and ecosystem investments.
- Cohu, Inc. (San Diego) — Strengths: modular handler architectures and thermal-control subsystems. Strategic implications: candidates for integration when thermal management and flexible reconfiguration across device families are priority objectives.
- ASMPT (Singapore) — Strengths: breadth across assembly and test automation; tight fit to advanced packaging flows. Strategic implications: attractive for OSATs and IDMs seeking turnkey assembly-to-test solutions and tighter interface engineering across process stages.
- TESEC Corporation (Tokyo) — Strengths: niche capabilities in discrete, MEMS, and power IC handlers. Strategic implications: strong fit for specialized high-reliability device lines where test mechanics differ from commodity ICs.
- Boston Semi Equipment (USA) — Strengths: agile product development in pick-and-place and SLT lines; recent product-line expansions broaden the addressable final-test portfolio. Strategic implications: potential supplier for mid-volume lines and custom automation projects.
- SRM Integration (Penang) — Strengths: high-speed IC handlers and custom automation for final test. Strategic implications: regional advantage in Southeast Asia for buyers co-locating with back-end assembly clusters.
- HON. PRECISION (Taichung) — Strengths: Taiwan-based engineering depth for flash/memory and MEMS test handlers. Strategic implications: logical partner for memory-oriented test lines and nearshore support to Taiwanese fabs and OSATs.
- Pentamaster (Penang) — Strengths: integration of vision systems and pick-and-place automation for final test and power modules. Strategic implications: good fit where vision-enabled inspection and automation yield are prioritized.
- NS Technologies (Kanematsu Group, Japan) — Strengths: throughput-oriented handlers supporting logic, memory, and automotive chips. Strategic implications: a viable partner for scale-out initiatives where global service and high throughput are required.
Recent vendor moves—exhibitions, product launches, and demo roadmaps—confirm the market’s focus on AI-enabled optimization, thermal precision, and modular architectures suitable for mixed-technology lines. These tactical shifts are summarized in the full report alongside vendor scorecards and risk matrices.
Industry dynamics and risk factors shaping 2026 outcomes
- Regulatory overlays: U.S. export controls on advanced compute chips and related equipment introduce conditionality for some sales channels and OEMs. Buyers and suppliers must embed compliance checkpoints into procurement and partnership agreements.
- Policy tailwinds: CHIPS Act funding and allied programs materially influence capital availability for domestic expansion in the U.S.—this creates windows for co-investment and subsidy-aligned capacity planning in 2026.
- Raw-material dependencies: substrates and mechanical components rely on epoxy resins, metal alloys, and ceramics; volatility or quality constraints in these inputs directly affect handler lead times and retrofit feasibility.
- Labor and automation: handler adoption continues to accelerate as firms mitigate labor scarcity and raise throughput. Investments in semi- and fully-automatic handlers should be benchmarked against labor cost curves and expected yield improvements.
- Energy and operational efficiency: leading handlers are embedding AI-driven predictive maintenance and software-defined optimization to reduce energy consumption and operating expense—key for sustainability targets and OPEX reduction in 2026.
Recommended 90–180 day actions for decision-makers
- Execute a supplier resilience stress test: map single-source dependencies, validate alternate vendors, and negotiate short-term capacity options tied to clear service-level metrics.
- Initiate a pilot for AI-enabled predictive maintenance: select one high-volume line, instrument key handler assets, and run a 90–day trial to quantify downtime reduction and energy savings.
- Align CAPEX with scenario outputs: reserve growth-capex tranches tied to the forecast scenarios in this report so that expansion is triggered by measurable demand or incentive milestones.
- Embed export-control and subsidy compliance into contracts: add clauses that account for licensing regimes and CHIPS program commitments to de-risk cross-border procurement and co-investments.
- Prioritize retrofitability in specs: when issuing RFPs, score vendors not only on throughput but on modular retrofit capability, software APIs, and spare-parts logistics to reduce TCO over a 7–10 year horizon.
- Explore targeted partnerships or tuck-ins: use M&A heuristics in the full report to evaluate small-cap acquisitions that accelerate advanced-packaging handler capabilities or regional service footprints.
Conclusion — the strategic value of this intelligence
For executives drawing 2026 capital and sourcing roadmaps, the handler market offers predictable growth with concentrated supplier power and meaningful technological differentiation. The strategic choices made this year—vendor selection, automation pilots, subsidy-aligned expansions, and compliance embedding—will determine whether companies capture yield and throughput gains or suffer extended ramp cycles. PW Consulting’s full Semiconductor Chip Handler Market study transforms the macro narrative above into executable roadmaps, procurement tools, and vendor playbooks designed for immediate use by strategy, operations, and procurement teams.
Access the full report to retrieve the gated segment-level forecasts, vendor scorecards, and the operational playbooks necessary to convert insight into 2026 action.
For detailed analysis of this topic, please visit the official page: Semiconductor Chip Handler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Perfluoroalkoxy (PFA) Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused industry preview designed to orient executive teams for the pivotal decisions of 2026. This briefing synthesizes macro dynamics, competitive moves, regulatory noise and cost pressures shaping the Perfluoroalkoxy (PFA) market — while preserving the proprietary segmentation and granular datasets that our full report delivers. Use this as a strategic compass: it signals where value and risk concentrate, how leading suppliers are positioning, and which playbooks will matter as companies allocate capital and commercial effort over the next planning cycle.
Perfluoroalkoxy (PFA) Market
Market Trajectory: The Macro Baseline
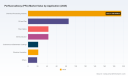
PFA has demonstrated steady expansion through the 2020–2025 historical window, growing from USD 368.44 Million in 2020 to USD 427.83 Million in the base year 2025. Our forecast horizon (2026–2032) models a mid-single-digit expansion, anchored by a compound annual growth rate (CAGR) of approximately 4.5%. Under our central scenario the market climbs to roughly USD 580.81 Million by 2032, with intermittent volatility driven by raw-material pricing and regulatory tightening. This pace reflects continued demand from high-purity industrial applications — notably semiconductor processing, chemical handling, and specialty tubing — even as incremental end-market adoption unfolds more gradually than in narrative-led projections.
Perfluoroalkoxy (PFA) Market
Why this matters for 2026 decisions
-
Portfolio prioritization: With moderate aggregate growth, 2026 is a year to refine product portfolios — doubling down on high-margin, high-purity grades while pruning lower-return commodity exposures.
Perfluoroalkoxy (PFA) Market -
Supply-chain strategy: The interplay of feedstock volatility and regulatory-driven process upgrades elevates supply-risk as a strategic variable; procurement and supply security will determine margin preservation.
-
CapEx and M&A timing: Investors should treat 2026 as a tactical inflection point to deploy capital into surfactant-free production, traceability systems and targeted bolt-on assets that accelerate access to regulated customers.
Key Market Dynamics and Structural Drivers
Several structural forces converge to define opportunity and exposure in 2026:
-
Regulatory acceleration: The U.S. EPA’s May 2026 proposed rules on PFAS in drinking water — including compliance timelines that in one option extend to 2031 — create a layered compliance landscape. Even where transitional provisions exist, lead customers and large OEMs are shortening their internal timelines, effectively accelerating demand for PFAS-compliant process technologies and documentation.
-
Manufacturing evolution toward surfactant-free processes: Suppliers such as Syensqo and AGC have publicly committed to or demonstrated surfactant-free manufacturing approaches. For buyers, supplier roadmaps on fluorosurfactant elimination are fast becoming a procurement gate.
-
Raw-material and cost pressure: TFE feedstock experienced meaningful price volatility in early 2026 and PFA production saw an 8% cost step-up in 2023 tied to compliance and material price shifts. These inputs magnify the importance of dynamic pricing clauses and hedging strategies in supply contracts.
-
Demand concentration: The market exhibits high supplier concentration at the top end; our concentration analysis signals that the top-tier players control a dominant share of supply, which reinforces the strategic importance of supplier relationships and long-term agreements for downstream integrators.
Competitive Landscape: What leading suppliers are doing
The competitive set is active on product innovation, capacity reconfiguration and application-specific high-purity positioning. Highlights of strategic relevance:
-
The Chemours Company (Wilmington, Delaware). Chemours has expanded and refined its high-purity PFA portfolio — including launches tailored to semiconductor requirements — signaling a supplier intent on defending premium niches where certification, traceability and contaminant control are decisive.
-
Daikin Industries, Ltd. (Osaka). With its NEOFLON series tailored for melt-molding and high-purity tubing, Daikin emphasizes technology transfer to electronics and semiconductor supply chains that prioritize consistent melt flow and minimal extractables.
-
AGC Inc. (Tokyo). AGC’s surfactant-free manufacturing process, announced in recent years, positions it as an operator-focused option for customers seeking PFAS exposure mitigation across their supplier base.
-
Syensqo (Brussels). Syensqo’s disclosure of PFA-free FFKM options and commitments to fluorosurfactant elimination reflect a differentiated sustainability message that resonates with battery and semiconductor OEMs.
-
Regional and niche specialists (e.g., Hubei Everflon, Zeus, RTP). These players are concentrated on dispersions, high‑purity tubing and compound formulations respectively; they compete on flexibility, localized supply and tailored product platforms for medical and semiconductor end-uses. Recent product introductions — including Zeus’s 2026 PFX platform for medical catheters — demonstrate where tactical innovation sits relative to broader capacity investments.
Recent Developments to Watch
-
Product launches and platform innovations (2025–2026) show incumbents defending technical moats around high-purity and extrusion capabilities.
-
Public commitments to eliminate fluorosurfactants (Syensqo, AGC) accelerate non-product regulatory mitigation strategies across the value chain.
-
Raw-material volatility and the 2023 cost step-up underscore the need for active pricing governance and supply‑chain resilience planning in supplier negotiations for 2026 contracts.
What our full report delivers (practical outputs)
PW Consulting’s full PFA Market study contains the operational and decision-grade tools you need for 2026 planning. Key deliverables include:
-
Market sizing and validated historical series (2020–2025) and forward projection models (2026–2032) with scenario toggles for regulatory stringency and feedstock shocks.
-
Supplier scorecards and capacity maps that integrate technology readiness, surfactant elimination timelines and contractual flexibility metrics.
-
Segment-level playbooks (product, application and route-to-market) that translate demand forecasts into prioritized commercial actions and SKU rationalization recommendations. Note: granular segment-level outputs are available in the full report; this preview intentionally omits those line-by-line splits to protect the analytical IP and to guide you to the source for detailed positioning work.
-
Raw-material sensitivity models and pricing pass‑through frameworks enabling rapid stress testing of margin outcomes under alternative TFE pricing scenarios.
-
Regulatory impact matrices with mitigation pathways — from process redesign and certification to customer communication templates and remediation CapEx estimates.
-
Targeted M&A and partnership scouting lists, including integration risk scoring and time-to-benefit estimates for bolt-on capacity or technology acquisitions focused on high‑purity and regulatory-compliant offerings.
-
Commercial negotiation playbook and model supply agreements for 2026 contracting cycles — incorporating indexation, force majeure considerations for regulatory changes, and sustainability commitments.
Strategic Imperatives for Executives in 2026
-
Pursue supplier risk diversification and lock key volumes with conditionality for regulatory-driven process changes. Where possible, insist on supplier roadmaps for surfactant elimination as a contracting KPI.
-
Prioritize high-purity product investments and certification pathways that align with semiconductor and battery customer specifications; these segments are the most durable under regulatory pressure.
-
Deploy dynamic pricing and hedging instruments to manage TFE exposure — establish internal triggers for price renegotiation and pass‑through clauses tied to validated cost indices.
-
Accelerate regulatory scenario planning: integrate the EPA proposed rule options into capital expenditure timing, and stage compliance investments to preserve optionality if timelines extend to 2031 under certain regulatory options.
-
Use targeted M&A to fill capability gaps (e.g., dispersion chemistry, surfactant-free processes, high‑purity extrusion) rather than generic scale buys; integration speed matters more than scale in a concentrated market.
Final note: why this preview — and why now
This briefing signals the contours of strategic choice in a market that is structurally concentrated and increasingly shaped by regulatory and feedstock volatility. The aggregate trajectory is constructive — modest, steady expansion at a roughly 4.5% CAGR through the 2026–2032 forecast window — but the distribution of value and risk within the market is shifting fast. That is why 2026 is a decisive planning year: contractual decisions, CapEx commitments and supplier selections made now will disproportionately determine competitive positions throughout the forecast period.
PW Consulting’s full PFA Market report packages the precise segmentation tables, supplier-level metrics and executable playbooks required to convert this strategic preview into operational plans. For decision-makers preparing budgets, negotiating supply contracts or evaluating M&A opportunities in 2026, the detailed datasets and scenario tools in the full study are essential to move from insight to action.
For detailed analysis of this topic, please visit the official page: Perfluoroalkoxy (PFA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Animal Feed Ingredients to hit USD 52.9B by 2032 at a 3.6% CAGR
By PW Consulting, 2026-07-12
Animal Feed Ingredients Market 2026: Strategic Briefing for Executive Decision-Making
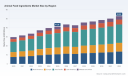
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, forward-looking briefing designed to equip C-suite and business-unit leaders with the strategic context they need to make high-confidence decisions in 2026. Our full Animal Feed Ingredients Market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — synthesizes hard market sizing, competitive dynamics, regulatory shifts, and raw-material risk to convert market intelligence into executable options. The market we track expanded from roughly USD 29.7 billion in 2020 to about USD 41.3 billion in the 2025 base year, and it is forecast to grow at a compound annual growth rate of 3.6% toward the 2032 horizon (reaching an estimated USD 52.9 billion). This macro trajectory frames the near-term choices executives must confront in 2026.
Animal Feed Ingredients Market
Why this briefing matters for 2026 decisions
-
Timing and resource allocation: With the market in a mid-cycle growth phase, managers face trade-offs between volume-led expansion and margin-protection investments (e.g., precision additives, quality assurance, logistics). Our study clarifies the return profiles of those alternatives under multiple price and regulation scenarios.
Animal Feed Ingredients Market -
Innovation window: Recent regulatory acceleration in several jurisdictions has shortened approval timelines for microbiome- and emissions-related additives, compressing the window for first-mover advantage. Companies that strategically align R&D, regulatory affairs, and commercialization will capture disproportionate value from premium additives and differentiated formulations.
Animal Feed Ingredients Market -
Supply-chain choreography: Volatility in grains and oilseed markets, coupled with evolving trade policy in priority export markets, means procurement strategy is now a competitive lever rather than a back-office function. Executives must decide whether to double down on vertical integration, secure offtakes, or diversify supplier bases in 2026.
Topline market dynamics
The animal feed ingredients market shows resilient, steady growth: from roughly USD 29.7 billion in 2020 to USD 41.3 billion in our 2025 base year and continuing upward to an estimated USD 52.9 billion by 2032 under our central-case projection (CAGR ~3.6%). This is not a hyper-growth theme, but it is large, strategic, and increasingly sophisticated — where incremental improvements in feed conversion, animal health, and regulatory compliance translate directly into meat, dairy, and aquaculture producers’ margins.
Three structural forces shape outcomes in 2026:
-
Cost pass-through pressure and raw-material cycles: Grain and oilseed price dynamics remain the primary determinant of short-run margin swings for conventional ingredient classes. Commodity prices moderated in 2025, and 2026 projections show continued stability in certain grains — an opportunity for processors and integrated suppliers to optimize mix and capture margin.
-
Shift from commodity to specialty: Growth in value-added feed additives, enzymes, amino acids, and targeted premixes is outpacing commodity volumes in many channels as producers seek productivity and sustainability gains. Regulatory facilitation of microbiome-focused solutions further accelerates adoption.
-
Regional policy inflections: Trade and fiscal policy moves in key import and export markets are re-shaping logistics economics — creating new export corridors while compressing margins in previously protected niches.
Regulation and raw-material signals you cannot ignore in 2026
-
Shortened approval timelines for gut- and emissions-focused inputs: A recent regulatory initiative has materially reduced time-to-market for products that meaningfully alter the gut microbiome or reduce enteric emissions. For strategy teams, this changes pipeline prioritization — invest in categories with accelerated approval and first-to-market potential.
-
Grain and oilseed pricing context: Stable-to-moderate grain prices observed in 2025 and similar 2026 projections create a favorable backdrop for demand recovery in sensitive livestock segments. However, soybean meal price volatility remains a persistent input risk; hedging and diversified sourcing should be part of any procurement playbook.
-
Trade policy shifts: Fiscal and tariff policy changes in selective emerging markets are opening up export opportunities and altering landed cost calculations. Firms with nimble commercial teams can exploit these short-term arbitrage windows to secure new customers and long-term contracts.
What the full report delivers (practical, executable content)
PW Consulting’s comprehensive report is designed to be immediately operational for strategy, commercial, and procurement teams. Highlights include:
-
Top-down and bottoms-up market sizing with historical validation and scenario-based forecasts to 2032 — enabling capital planning and revenue targets aligned to market trajectories.
-
Product and channel playbooks that translate technical ingredient trends (from commodity to specialty) into commercial tactics for pricing, bundling, and field support.
-
Regulatory impact matrix and go/no-go decision trees for product registration and market entry, reflecting shortened approval timelines for microbiome and emissions innovations.
-
Raw-material sensitivity models and procurement options analysis (hedging, vertical integration, strategic offtake), calibrated to recent grain and oilseed price paths.
-
Competitive heatmaps, capability benchmarking, and M&A candidate screens to inform inorganic growth strategies and partnership prioritization.
-
Client-ready slide decks and an executive dashboard for ongoing monitoring of price, policy, and demand indicators.
Competitive landscape — what to watch in 2026
The market displays moderate concentration: the top three players account for a little over half of global revenue, while the top five capture roughly two-thirds. This structure creates a balance — large incumbents retain scale economics and distribution reach, while mid-sized and specialty players lead on innovation and niche solutions. For 2026, the following competitive moves merit attention:
-
Scale players (global traders and processors): Firms with upstream origination and processing capabilities continue to leverage logistics and distribution networks to secure volume contracts and stabilize supply. Investments in regional production assets remain a key defensive and offensive lever.
-
Specialty ingredient and additive firms: Companies focused on enzymes, amino acids, probiotics, and mycotoxin solutions are the primary innovation engines. Their agility in registrational pathways and formulation expertise positions them to capture premium value as producers shift toward productivity-enhancing inputs.
-
Integrated animal nutrition divisions: Vertically integrated feed companies and divisions of larger agri-business players are experimenting with bundled offers (ingredients + premixes + advisory services), seeking to lock in lifetime customer value.
Notable corporate developments in the recent 12–18 months illustrate these dynamics. Strategic acquisitions in specialty additives have consolidated capabilities in gut health and mycotoxin mitigation, while partnerships and capital infusions into animal nutrition businesses reinforce the focus on scale plus innovation. Investments in regional manufacturing assets — exemplified by new, high-capacity feed plants — demonstrate that global players continue to optimize local supply footprints to serve fast-growing consumption corridors.
Operational and M&A implications for 2026
-
Prioritize capability fills over broadscale M&A: In a market where regulation accelerates category adoption, acquiring specific formulation, regulatory, or application expertise is often higher-return than chasing topline expansion via commodity bets.
-
Optimize go-to-market by livestock segment: Different livestock classes react to price and productivity levers in distinct ways. Tailored commercial models — from performance-based contracts to bundled advisory services — will prove decisive.
-
Secure supply: Use a mix of long-term contracts, strategic stocks, and selective integration to manage commodity cycles. For 2026, locking favorable offtakes in regions where fiscal changes remove import frictions presents an immediate arbitrage opportunity.
-
Pivot R&D roadmaps: Re-allocate a portion of R&D budgets toward microbiome and emissions-reducing solutions that now face shortened regulatory pathways. Fast-follower strategies can work where first-mover clinical data is scarce but registration is expedited.
Three actionable recommendations for 2026
-
Implement a short-cycle product commercialization track: Create a fast-track path that coordinates regulatory, manufacturing scale-up, and field trial teams to exploit accelerated approval windows for targeted additives.
-
Undertake a targeted supplier diversification program: Identify two to three strategic suppliers per major input category and negotiate mixed hedging/profiled contracts to reduce P&L volatility without sacrificing flexibility.
-
Build partnership and bolt-on acquisition pipelines: Focus on specialty players with differentiated science and registrational momentum; these assets are both defensive (protecting margin) and offensive (driving premium product sales).
Conclusion — how to use this intelligence in 2026
The animal feed ingredients market in 2026 is a large, steady-growth arena where marginal improvements in product performance, regulatory agility, and supply resilience compound into sizable commercial advantage. Executives who combine disciplined procurement, targeted innovation investment, and selective inorganic moves will secure outsized returns. PW Consulting’s full report provides the granular, proprietary segmentation, supplier profiles, and scenario tools necessary to operationalize the strategies summarized here — including the region- and ingredient-level detail and financial models that we intentionally reserve for the full product.
For teams preparing budgets, evaluating acquisition targets, or refreshing product roadmaps this year, the report is designed to be a decision-ready playbook: not just what’s happening, but what to do next. Visit our report page to access the complete dataset, interactive dashboards, and bespoke advisory options that will convert insight into 2026 outcomes.
For detailed analysis of this topic, please visit the official page: Animal Feed Ingredients Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Native Starches Market Reaches USD 24.71 Billion in 2025
By PW Consulting, 2026-07-12
Native Starches Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As companies prepare strategy roadmaps for 2026, native starches sit at the intersection of food innovation, industrial reformulation, and sustainability-driven supply chain transformation. PW Consulting’s forthcoming Native Starches Market study (base year 2025; forecast 2026–2032) synthesizes market dynamics, competitor moves, and risk vectors into an actionable framework for C-suite and corporate development teams. This preview outlines the strategic value of the full study, highlights the high-level market trajectory, and summarizes competitive and operational flashpoints that will determine winners in the next planning cycle — while preserving the granular segment intelligence available in the full report.
Native Starches Market
Why this study matters for 2026 decision-making
-
Clear market momentum: Between the historical window and the forecast horizon, the native starches market exhibits steady expansion underpinned by demand in food and adjacent industrial applications. The study’s baseline shows multi-year growth culminating in a robust outlook through 2032, driven by product reformulation, label-friendly ingredient demand, and selective industrial uptake.
Native Starches Market -
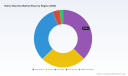
Actionable foresight for capital allocation: With a compounded annual growth rate of approximately 5.05% across the forecast window, the market is neither commodity-tame nor hyper-volatile — a profile that favors disciplined capacity investments, targeted R&D, and partnership-led expansion over indiscriminate greenfield buildouts.
Native Starches Market -
Competitive and regulatory inflection points: Fragmented market structures, certification trends, and raw-material cost variability create pockets of premium opportunity (e.g., label-friendly, non-GMO, sustainably certified starches) and downside risk (emissions, compliance, input-price shocks). The report prioritizes these themes for 2026 planning cycles.
Market trajectory at a glance
PW Consulting’s consolidated market model charts a recovery-and-growth arc. The market expanded through the early 2020s, accelerating toward the 2025 baseline. From that base, our forecast anticipates steady growth through 2032, driven by incremental gains across food, industrial, and specialty use-cases. The model is built from bottom-up demand drivers, price and volume scenarios, and supply-side capacity adjustments — producing a mid-case consistent with the ~5% CAGR noted above. Readers should treat this preview as directional; the full report contains the underlying sensitivity analyses and scenario permutations used to derive the headline projection.
What’s in the full report — practical content for executives
-
Executive dashboard: concise KPIs, market sizing and growth drivers, and three investment-case archetypes for roll-up decisions in 2026 (capacity-led, specialty-led, or channel-led).
-
Methodology and data appendix: transparent sourcing, modeling assumptions, and reconciliation of global trade versus domestic consumption flows for robust valuation work.
-
Segment playbooks: go-to-market playbooks for core product types and end-use clusters, with recommended pricing strategies, technical dossier checklists, and customer segmentation matrices.
-
Supply chain deep dives: supplier maps, procurement levers and hedging templates, cold-chain and processing bottleneck analysis, and a procurement playbook tailored to agricultural-commodity input risk.
-
Regulatory & sustainability toolkit: certification pathways (including renewable-carbon and mass-balance schemes), emissions compliance checklists, and cost-benefit analysis for sustainability investments.
-
Competitive intelligence: company profiles, recent developments, an M&A radar, and a 12–24 month action calendar you can apply directly to business development and investor outreach.
-
Scenario & sensitivity analyses: upside and downside market scenarios tied to raw-material price shocks, substitution trends, and rapid adoption of label-friendly alternatives.
Competitive landscape — what incumbents and challengers are doing
The native starch arena is characterized by a mix of global ingredient houses, regionally strong cooperatives, and specialized processors. Overall market concentration remains modest; leading groups do not fully dominate the space, leaving room for agile competitors and niche specialists to capture premium segments. The CR3 and CR5 metrics we track underscore a marketplace where scale matters for raw-material access and cost-efficiency, but where differentiation and technical capabilities deliver outsized margins.
-
Cargill, Incorporated — A large-scale integrator with broad native-starch capabilities across multiple botanical sources. Cargill’s strength lies in its upstream raw-material footprint and its ability to integrate starch offerings into broader food-ingredient platforms for texturizing and thickening.
-
Roquette Frères — A major product innovator with a wide native starch portfolio and a strategic tilt toward label-friendly and plant-based credentials. Recent product introductions and certification achievements evidence Roquette’s push into differentiated native starch formats tailored to confectionery and coating applications.
-
AGRANA Beteiligungs AG — A producer focused on potato, corn, and wheat pathways, recently active on capacity expansion through partnership models. AGRANA’s joint-venture approach illustrates how mid-sized processors can scale selectively to serve European and export markets.
-
Emsland Group, Royal Avebe, KMC Ingredients, and MGP Ingredients — Collectively, these companies represent the cooperative and specialist cohort, leveraging botanical expertise and regional supply chains to serve both food and industrial needs with focused portfolios.
These profiles demonstrate three broad competitor archetypes: integrated multinationals that prioritize scale and cross-product bundling; specialty processors that win on botanical or process expertise; and cooperative models that secure raw-material reliability. Each archetype implies distinct strategic levers for 2026 — from vertical integration and long-term supply contracts to premium product development and co-investment with growers.
Recent developments that shape 2026 tactics
-
Product innovation is accelerating. A notable example is the launch of thermally soluble, label-friendly starches designed for confectionery and coatings — a category that opens reformulation opportunities for FMCG manufacturers seeking cleaner labels without sacrificing functionality.
-
Certification and sustainability credentials are becoming table stakes. Leading producers are securing renewable-carbon and mass-balance certifications to access sustainability-driven procurement programs and to mitigate buyer-level ESG risk.
-
Capacity expansion via partnerships: joint ventures and capacity-sharing agreements indicate a preference for capital-light scaling when demand is uncertain. Such structures are efficient ways to increase throughput while preserving financial flexibility.
-
Compliance and legacy environmental liabilities remain an operational risk. Historical regulatory actions in related processing segments serve as reminders that emissions and permitting exposures can carry balance-sheet and reputational costs if not proactively managed.
Operational levers for 2026 — what we recommend
-
Prioritize product differentiation over scale-first plays. Invest in label-friendly formulations and specialty botanical formats where margin expansion is demonstrable.
-
Lock in raw-material security with hybrid sourcing: combine long-term contracts, local cooperative partnerships, and strategic inventory buffers to reduce exposure to agricultural volatility.
-
Make certification a commercial enabler. ISCC-style and similar certifications are increasingly embedded in buyer specs; the incremental cost of certification often pays back through access to higher-margin customers.
-
Evaluate partnerships for capacity flexibility. JVs and tolling arrangements offer a lower-risk path to expand capacity into new geographies or product formats.
-
Embed emissions and compliance due diligence into M&A and capex approvals to avoid legacy liabilities that erode ROI.
-
Run a price–volume sensitivity analysis for product portfolios to understand margin resilience under input-price spikes — and design pass-through mechanisms for key customers.
How PW Consulting supports execution
Our full Native Starches Market study is designed as an execution tool, not just an analytical document. Clients receive modular deliverables that can be deployed directly into investment committees, procurement negotiations, or R&D prioritization workshops. Deliverables include a one-page investment memo, a 12-month commercialization sprint plan, supplier scorecards, and a tailored risk-heatmap aligned with corporate risk tolerances.
This preview intentionally omits the granular regional and application-level split tables, price-by-origin matrices, and the full company-level financial comparatives that our subscribers rely on for transaction and operational work. Those elements are available within the full report package to preserve the commercial value of proprietary modeling.
Next steps — using the preview to inform 2026 plans
-
Use the headline CAGR and trajectory to update medium-term demand assumptions in your strategic planning cycle, replacing ad-hoc estimates with a scenario-based approach.
-
Leverage competitor archetypes to stress-test your capability gaps: where do you compete on scale, where do you compete on specialty, and where should you consider partnerships?
-
Institute a short-term tactical plan (90–180 days) to shore up raw-material sourcing and to scope certification projects that can be operational by late 2026.
-
Contact PW Consulting for an executive briefing and a customized extraction of the report’s playbooks — including the confidential segmentation tables and price-sensitivity models that will be decisive for M&A and capex decisions.
In sectors where small formulation benefits compound across thousands of SKUs, having the right market intelligence is the difference between margin recovery and margin erosion. PW Consulting’s Native Starches Market study gives you that intelligence packaged for decision-making in 2026 — rigorous, operational, and calibrated to the realities of agricultural sourcing and ingredient innovation.
For detailed analysis of this topic, please visit the official page: Native Starches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AWG Market to Reach USD 300 Million by 2032 at 8.5% CAGR
By PW Consulting, 2026-07-12
Arrayed Waveguide Grating (AWG) Market: Strategic Outlook for 2026 Decision‑Makers
As AWG-enabled photonics moves from niche telecom applications into mainstream data‑center interconnects, coherent optics, and integrated photonic platforms, 2026 will be a pivotal year for corporate strategy. This briefing — drawn from PW Consulting’s latest AWG Market research (base year 2025; historical 2020–2025; forecast 2026–2032) — synthesizes the practical intelligence executives need to convert technical signals into commercial advantage.
Arrayed Waveguide Grating (AWG) Market
Data‑driven snapshot you can act on
-
Measured in USD (Million), the AWG market expanded materially through the early 2020s, growing from the low‑hundreds of millions to a base‑year size of USD 170 Million in 2025.
Arrayed Waveguide Grating (AWG) Market -
Our forecast horizon (2026–2032) assumes a compound annual growth rate (CAGR) of 8.5%, with the market tracking toward an approximate USD 300 Million size by 2032 under the base scenario.
Arrayed Waveguide Grating (AWG) Market -
Market concentration remains moderate: the top three suppliers account for roughly 30% of global share, while the top five reach about 45% — a structure that favors nimble specialists and opportunistic consolidation alike.
These headline metrics are intended to inform capital allocation, product roadmaps, and M&A screening in 2026. The full report contains the granular segmentation, pricing bands, and channel economics required to convert these directional numbers into executable plans.
Why this research matters for 2026 decisions
-
Standards and regulation are converging on AWG performance thresholds. Recent standards work (e.g., channel grids and spacing) and operator specifications for insertion loss and crosstalk are establishing pass/fail gates that will determine which modules scale in hyperscale deployments.
-
Thermal management is a commercial battleground. Athermal AWG solutions remove active temperature control from the bill of materials and operations, creating a durable OPEX advantage for outdoor and uncontrolled environments. The implications span product engineering, procurement, and field operations.
-
Manufacturing complexity and labor intensity remain high. Wafer‑scale AWG fabrication requires cleanroom capacity, specialized photonic engineers, and strict process control — a barrier that constrains rapid commoditization and shapes supplier selection.
-
Growth is uneven across end‑use drivers. Internet backbone upgrades, data center interconnects, and enterprise optical fabric programs are each on different adoption curves. Strategic planners must align product features (e.g., channel spacing, athermal behavior, uniformity) with the precise requirements of target use cases.
Key dynamics shaping 2026–2032
-
Standards alignment: ITU‑T grids and Ethernet developments (e.g., large‑bandwidth datacenter optics) are driving demand for specified channel spacings and filter performance. Suppliers that pre‑qualify products to these standards shorten buying cycles and reduce qualification risk.
-
Regulatory and procurement requirements: Data center interconnect specifications increasingly mandate low insertion‑loss uniformity and stringent crosstalk limits for cascaded AWG chains. These technical barometers are now commercial gates for hyperscalers and telecom operators.
-
Technology tradeoffs: Substrate choice (silica, PLC, polymer, silicon photonics) defines the trade space: cost, thermal behavior, channel density, and integration potential. Different substrates appeal to different buyers — and companies that can span more than one technology stack have new cross‑selling opportunities.
-
Manufacturing and supply risk: High precision fabrication concentrates value around foundries with appropriate tooling and skills. Outsourcing strategies, IP protection, and dual‑sourcing are critical levers for manufacturing‑heavy players.
Competitive landscape — what to watch in 2026
The AWG supplier ecosystem is composed of distinct archetypes: silicon‑photonics integrators, PLC and silica module specialists, polymer/SoS athermal vendors, and niche optics houses. Below we summarize strategic postures for key players featured in our global coverage.
-
Aloe Semiconductor (Middletown, NJ, USA) — Focused on silicon photonic integrated circuits that embed AWG functions alongside active components. Strengths: integration density, roadmap alignment with coherent optics and transceiver OEMs. Strategic risks: foundry dependences and thermal sensitivity at scale.
-
Bright Photonics (Eindhoven, Netherlands) — IP and prototyping specialist offering AWG cores and modules for custom foundry runs. Strengths: rapid prototyping, access to European photonic ecosystems, and IP flexibility. Strategic play: act as an innovation bridge between universities/foundries and systems OEMs.
-
Agilechip Photonics (Zhongshan, China) — Manufactures PLC‑based AWGs, including athermal variants for DWDM, CWDM, and data‑center optics. Strengths: manufacturing scale and cost competitiveness in high‑volume segments. Watch: globalization efforts and customer qualification timelines outside local markets.
-
SENKO Advanced Components (Japan) — Producer of polymer and SoS athermal AWG modules with a focus on DWDM mux/demux uniformity. Strengths: field‑proven athermal designs and strong OEM relationships in Asia. Opportunity: lead in outdoor/uncontrolled deployments where OPEX matters most.
-
AC Photonics (United States) — Silica‑on‑silicon athermal AWG specialist targeting 100/150 GHz DWDM coherent markets. Strengths: high channel uniformity and alignment to coherent telecom requirements. Strategic runway: move up the value chain into subsystem integration for coherent transceivers.
-
engionic Fiber Optics (Germany) — Niche high‑performance photonic component specialist. Strengths: deep engineering capabilities and tailored solutions for demanding optical subsystems. Strategic fit: attractive partner for customized, high‑margin applications.
Collectively, these players demonstrate the sector’s heterogeneity: technology specialization, geography, and business model diversity. For buyers and investors in 2026, supplier selection will hinge on technology fit, qualification velocity, and the supplier’s ability to manage manufacturing and supply risk.
What PW Consulting’s full report contains (practical deliverables)
-
Market sizing and forward forecasts (2026–2032) with scenario sensitivity analyses that stress test CAGR assumptions against supply disruptions, standard shifts, and hyperscaler adoption — enabling realistic upside/downside planning.
-
Segmented demand drivers by use case, with a procurement playbook for qualifying AWG modules against operational KPIs (including insertion loss uniformity and crosstalk thresholds mandated by data center specifications).
-
Technology maps that compare substrate tradeoffs (silicon photonics, silica, PLC, polymer/SoS), product roadmaps, and cost drivers to inform product‑level decisions and make/buy debates.
-
Supplier scorecards, benchmarking, and a prioritized M&A target list — with commercial due diligence templates and red‑flag indicators for intellectual property, foundry access, and qualification backlog.
-
Operational guidance: sample RFP language, test‑plan checklists tethered to IEEE/ITU‑T norms, and capex/OPEX models that quantify the lifetime savings of athermal modules in uncontrolled environments.
-
Scenario playbooks for 2026 procurement cycles: supplier negotiation levers, dual‑sourcing roadmaps, and pilot program designs to de‑risk deployment at scale.
Actionable recommendations for 2026
-
For OEMs and subsystem integrators: prioritize athermal solutions where the lifetime energy and thermal management cost outweigh incremental BOM savings. Pre‑qualify at least two substrate technologies to avoid single‑technology risk.
-
For hyperscalers and carriers: insist on supplier compliance to industry performance gates and include staged acceptance tied to field metrics (insertion loss, crosstalk) to accelerate vendor accountability.
-
For investors and private equity: target consolidation candidates that own differentiated IP or exclusive foundry access. The market’s CR3/CR5 profile indicates room for bolt‑on value creation without competing on low‑margin commoditized products.
-
For foundries and contract manufacturers: invest in wafer‑scale process control and workforce development — these are persistent supply constraints that will command premium contracting terms with OEMs.
Intentional withholding — why you should read the full study
In keeping with our “trailer” approach, this article deliberately highlights strategy, dynamics, and actionable themes while withholding granular subsegment tables, regional breakdowns, and unit‑price banding that are essential for procurement negotiation and precise financial modeling. The full PW Consulting AWG Market report supplies those confidential line items, detailed supplier cost models, and buyer‑specific scenario outputs to convert strategic intent into executable plans.
Next steps
-
Use the high‑level intelligence here to set internal priorities for 2026 (standards alignment, athermal pilots, supplier due diligence).
-
Engage PW Consulting for a tailored briefing that maps the report’s granular data to your product roadmap, procurement calendar, and M&A thesis.
AWG technology is no longer a peripheral component — it is a gating factor for future optical architectures. In 2026, the right combination of standards readiness, manufacturing resilience, and product differentiation will separate leaders from followers. PW Consulting’s full study provides the segmented facts and decision tools you need to act with conviction.
For detailed analysis of this topic, please visit the official page: Arrayed Waveguide Grating (AWG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vehicle-to-Grid (V2G) Market 2026: Strategic Imperatives for Corporates — A PW Consulting Preview
As the energy transition accelerates, Vehicle-to-Grid (V2G) has moved from niche pilots to the threshold of commercial scale. Our PW Consulting Vehicle-to-Grid Market study (base year 2025) synthesizes quantitative forecasting, policy overlays, commercial pilots and supplier due diligence into a decision-grade guide for corporate leaders planning capital allocation, product roadmaps, and market entry in 2026. This preview explains why V2G should be on every energy, mobility and asset-management executive’s 2026 agenda — and how our full study equips organizations to act with confidence.
Vehicle-to-Grid (V2G) Market
Why 2026 is the Inflection Year
Two converging forces create a unique window for V2G value capture in 2026: regulatory standardization and improving economics. Binding technical requirements that mandate bidirectional communication in new/renovated charging infrastructure are scheduled to take effect across major jurisdictions, effectively turning “nice to have” bidirectionality into a compliance and market-access requirement. Separately, recent policy moves — for example the removal of double grid fees in key markets — materially improve the commercial case for exporting vehicle-stored energy back to the network.
Vehicle-to-Grid (V2G) Market
Price signals are supportive. Global residential electricity rates and wholesale futures in 2026 have produced realistic revenue pathways for aggregate V2G fleets to monetize arbitrage and ancillary services. These conditions convert theoretical V2G value into executable business cases for utilities, aggregators, OEMs and large fleet owners.
Vehicle-to-Grid (V2G) Market
Market Momentum — The Macro Picture
Our bottom-up model traces the V2G market from early commercial traction in 2020 through the 2025 base year, and projects forward across a 2026–2032 forecast horizon. The market expanded from the low hundreds of millions (USD, revenue unit: Million) in 2020 to roughly USD 215.0 Million by the 2025 base year; projected growth accelerates thereafter, reaching an estimated USD 344.8 Million by 2032. The forecast is driven by a compound annual growth rate (CAGR) of approximately 6.98% over the modeled forecast period — a pace signaling steady, platform-enabled adoption rather than exponential consumer-led uptake.
Two implications follow: first, V2G is not a rapid, consumer-driven gold rush; it is a multi-stakeholder systems play that rewards strategic positioning and partnerships. Second, early movers who secure grid access, aggregation capacity, and regulatory alignment will capture durable, higher-margin revenue streams as the market matures.
Competitive Landscape — Who Matters and Why
The V2G ecosystem today is characterized by meaningful technical differentiation and a fragmented supplier base. Market concentration metrics confirm a low consolidation state: the top-three and top-five providers hold modest combined shares, reflecting room for partnership, consolidation and regional champions. For corporates this means the competitive battlefield will be defined less by price alone and more by integration capability, regulatory footprint, and data/aggregation competence.
- Technology providers and aggregators: Players such as Nuvve (GIVe platform) and Virta emphasize fleet aggregation, bidirectional control stacks and virtual power plant services — capabilities essential for monetizing grid services. Recent organizational moves (e.g., Nuvve’s deployments and local leadership appointments in Japan in 2026) underscore a push into critical new geographies.
- Hardware and industrial integrators: ABB and The Mobility House specialize in bidirectional charging hardware and integrated systems — from chargers to V2G control software — enabling scale deployments for commercial, industrial and fleet customers. Standalone hardware competence without software and aggregation partnerships will limit addressable value.
- OEMs and ecosystem partners: Vehicle manufacturers and utilities (e.g., Nissan launching affordable bidirectional charging solutions, and energy groups such as E.ON and Enel) are closing the loop between vehicles, tariffs and customer propositions. Examples in early 2026 show OEMs and energy companies bringing market-ready bundles to residential and commercial customers.
- Retail energy innovators: New tariff and platform experiments by energy retailers (e.g., Octopus Energy’s Powerloop) illustrate the consumer-facing business model evolution: V2G as a differentiated retail product combining hardware incentives, smart tariffs and customer engagement.
These firms are all active in the field through product launches, deployments and commercial pilots — but none alone dominates the space today. That presents an opening for thoughtful strategic engagement, whether through JV models, white-label partnerships, or targeted M&A focused on aggregation, software IP and market access.
What the PW Consulting Report Contains — Practical Deliverables
Our full study is designed as an executable toolkit for 2026 decision-making. Highlights include:
- Forecast model with scenario branches (baseline, accelerated policy adoption, and slow consumer uptake) and sensitivity levers for energy prices, vehicle-to-charger adoption rates, and tariff structures.
- End-to-end value chain analysis mapping revenue pools by use case (e.g., residential arbitrage, ancillary services, demand-side management), supplier roles, and margin profiles.
- Commercial playbooks: go-to-market options for OEMs, utilities, fleet operators and retailers including pricing templates, partner scorecards, pilot-to-scale transition checklists, and B2B contract clauses for aggregation and energy settlement.
- Regulatory and compliance matrix tied to product design — including implementation pathways for ISO 15118-20 and jurisdictional fee structures — to accelerate product certification and tariff approval processes.
- Technology assessment and interoperability map: charger and vehicle compatibility matrices, cyber-security best practices, and data governance frameworks required for grid services participation.
- Vendor diligence annex: comparative profiles, recent developments, patent and IP snapshots, and M&A heatmaps identifying likely consolidation targets.
- Financial tools: TCO calculators for fleet and residential deployments, capital expenditure planning templates, and investment cases capturing bidirectional hardware costs, software-as-a-service revenue, and O&M assumptions.
The full report contains granular regional and application splits, vendor scorecards and downloadable models. In this preview we intentionally withhold those segmented figures to preserve the value of the detailed datasets and proprietary scoring methods included in the subscription edition.
Practical Strategic Recommendations for 2026 Decision-Makers
- Utilities and system operators: Prioritize partnership pilots with aggregators that can demonstrate real-time dispatch and settlement capability. Use 2026 commercial pilots to validate revenue stacking (ancillary + arbitrage + capacity) and to influence tariff design that supports bidirectional participation.
- OEMs: Embed V2G capability into product roadmaps where it aligns to customer value and regional regulation. Consider white-label charging partnerships and enable flexible warranty/maintenance models for bidirectional hardware to lower customer adoption friction.
- Fleet operators and large energy buyers: Test aggregation contracts that offer predictable revenue streams; use short-term procurement to build operational experience and refine fleet management practices before committing to large-scale capital expenditure.
- Charge-point operators and hardware vendors: Invest in software layers and open APIs for marketplace participation. Hardware-only strategies are increasingly fragile: the monetizable economics of V2G come from orchestration, settlement and QoS guarantees.
- Investors and corporate development: Focus M&A on companies that combine aggregation software with documented grid revenue performance and regulatory footprints in priority markets. Early-stage investments should prioritize IP around bidirectional control algorithms, cyber-resilient communications, and settlement engines.
Risk & Mitigation — What to Watch in 2026
- Regulatory timing and implementation risk: Mandates and technical standards are evolving; companies should build flexible architectures that can adapt to ISO 15118-20 implementations and AFIR timelines without costly hardware retrofits.
- Revenue stacking dependence on price signals: V2G returns are sensitive to electricity price volatility and ancillary market design. Mitigation: secure pre-commercial agreements with grid operators and explore revenue guarantee structures during pilot stages.
- Interoperability and cybersecurity: As multiple vendors and vehicle platforms interact, interoperability failures or breaches could stall deployments. Recommended mitigation includes vendor certification requirements, layered security designs, and third-party interoperability testing.
- Customer acceptance and behavioral risk: Residential adoption depends on perceived battery degradation risk and simplicity of proposition. Transparent warranty terms and intuitive tariffing are essential.
Signals from the Field — 2026 Developments Worth Noting
- OEM-led consumer product launches (e.g., Nissan’s affordable bidirectional chargers in early 2026) are shifting V2G from research labs into retail channels.
- Energy-utility collaborations (e.g., BMW/E.ON residential V2G commercial offers launched in Germany) demonstrate how tariff innovation can accelerate customer take-up when paired with OEM hardware commitments.
- Localized deployments (for example, bidirectional charger installations using Quasar 2 technology) show real-world interoperability tests between hardware vendors and vehicle models — useful early lessons for scale rollouts.
- Corporate moves into key markets (e.g., Nuvve’s organizational expansion in Japan) reveal where operator confidence in local market structures is rising.
Conclusion — What PW Consulting Recommends for 2026
V2G in 2026 is a strategic opportunity best pursued with a systems view. The macro trajectory — reflected in our forecasted growth to the end of the decade and a near-7% CAGR — favors orchestrators who can align vehicle OEMs, charge-point vendors, energy retailers, and grid operators. For executives deciding budgets and partnerships this year, PW Consulting recommends a three-track approach: (1) secure pilot-level technical and commercial proof points in priority markets; (2) build or partner for aggregation and settlement capabilities; and (3) embed regulatory foresight into product design to avoid costly rework when standards take effect.
Our full report provides the actionable segmentation, vendor scorecards, and financial models necessary to translate these strategic imperatives into procurement decisions and investment theses. For teams preparing 2026 capital plans, the report functions as both roadmap and risk register — designed to shorten time-to-value while preserving optionality as the market consolidates.
Next Steps
Contact PW Consulting to access the complete V2G Market study, including the downloadable forecast model, regional and application splits, detailed vendor profiles and custom advisory options tailored for executives preparing 2026 strategies. The market is at an inflection point — firms that prepare now will be best positioned to convert nascent grid services into recurring, defensible revenue streams.
For detailed analysis of this topic, please visit the official page: Vehicle-to-Grid (V2G) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


