



Category: market research
Pipe Joints Market — 2026 Strategic Preview for Corporate Decision‑Makers
PW Consulting presents a concentrated strategic preview of our forthcoming Pipe Joints Market report — a practical briefing designed to shape capital allocation, sourcing, product and regulatory strategies for the year ahead. The market, measured on a base year of 2025, sits at approximately USD 228.6 Million and is forecast to expand at a compound annual growth rate (CAGR) of 5.35% through the 2026–2032 horizon, reaching roughly USD 328 Million by 2032. This trajectory reflects steady, structurally driven demand and meaningful pockets of opportunity for manufacturers, system integrators and large buyers. The purpose of this preview is to surface the decision‑critical themes and tactical playbooks contained in the full study while reserving the granular sub‑segment data for the full report and interactive dashboards.
Pipe Joints Market
Why this briefing matters for 2026 decision cycles
-
Capital planning: The modest but reliable market growth and clear technology clustering (mechanical couplings, restrained joints, expansion assemblies) change the payback calculus for plant retrofits, specification changes in new builds, and inventory rationalization.
Pipe Joints Market -
Procurement and supplier strategy: With raw material costs moderating in 2026 and product unit prices ranging broadly by spec (general metal joints commonly priced in the low tens to low hundreds of dollars, with high‑spec alloy units commanding up to the low thousands), procurement teams can redesign sourcing agreements to capture savings while insulating against volatility.
Pipe Joints Market -
Regulatory compliance and risk management: Recent fire‑safety regulations affecting nonmetallic joint approvals are already reshaping specification windows for building and sprinkler systems. Compliance readiness has become as material to project timelines as lead‑time control.
-
M&A and partnership targeting: The market remains fragmented — top sellers control a modest share of demand (the three‑firm and five‑firm concentration ratios are low‑to‑moderate), making targeted acquisitions and channel partnerships a fast route to capability expansion and geographic reach.
What the full report contains (practical deliverables)
-
Transparent market sizing and validated forecast model (historical 2020–2025; forecast 2026–2032) with scenario toggles for raw material, regulatory and capex cycles.
-
Go‑to‑market playbooks: product specification checklists by system class, procurement negotiation levers, installation labor reduction case studies and retrofit decision trees.
-
Supply chain heatmaps and supplier scorecards: lead time breakouts, near‑term sourcing risks, and an inputs‑to‑cost bridge that isolates steel, elastomers and specialty alloys for targeted hedging.
-
Competitive benchmarking and strategic options: capability matrices for mechanical couplings, restrained joints, expansion joints and polymer fittings; potential M&A candidates and integration synergies.
-
Regulatory tracker and certification roadmap: actionable steps to ensure product approvals under recent code updates and an audit checklist for installation compliance.
-
Interactive commercial tools: total cost of ownership (TCO) calculators, SKU rationalization simulators and procurement timing models designed to be used in board‑level capital deliberations.
Market dynamics snapshot — what’s driving demand and cost in 2026
-
Infrastructure and retrofit momentum: Spend on water systems, urban utilities and industrial maintenance continues to underpin steady demand. The full study maps demand drivers against investment cycles to indicate where replacement and new‑build opportunities cluster.
-
Material and cost dynamics: Steel prices have moderated in 2026 after prior volatility; this normalization reduces immediate margin stress for metal‑focused manufacturers but amplifies competition on delivery and technical differentiation.
-
Specification shifts and safety codes: New fire‑safety requirements and installation standards are prompting architects, contractors and owners to revise product lists and installation practices, accelerating adoption of certified mechanical systems in higher‑risk applications.
-
Installation productivity as a product differentiator: Solutions that materially shorten onsite labour time — grooved systems, pre‑fabricated couplings, and modular joint assemblies — are being prioritized by contractors seeking certainty on schedule and cost.
Competitive landscape — what leading vendors reveal about strategy
The competitive set combines specialist manufacturers, broad system suppliers and component specialists. The market’s fragmentation (three‑firm and five‑firm concentration ratios are consistent with a low‑to‑moderate level of consolidation) implies that focused investments or partnerships can rapidly change a vendor’s standing.
-
Northwest Pipe Company — Positioning: engineered steel water pipe with integrated watertight joint systems. Strategic implications: strength in engineered, long‑lead water projects and the ability to bundle pipe + joint as a specification advantage in municipal and large‑scale water programs.
-
Victaulic — Positioning: global leader in grooved mechanical couplings emphasizing rapid installation and system safety. Strategic implications: Victaulic’s product innovation (including recent rigid‑joint sprinkler coupling introductions) highlights the premium buyers place on labor savings and standardized systems — a competitive vector others must address.
-
Teekay Couplings — Positioning: UK‑manufactured mechanical couplings across an extensive diameter range focused on installation efficiency and weight savings. Strategic implications: regional manufacturing and breadth of diameters create advantages in projects where logistics and weight constraints matter.
-
American Cast Iron Pipe Company — Positioning: restrained joints for ductile iron pipe with a focus on preventing endwise separation under thrust. Strategic implications: product specialization that supports utility and heavy‑civil specifications; attractive partner for consortium bids on large water infrastructure programs.
-
Holz Rubber Company — Positioning: custom and standard expansion joints designed to absorb thermal movement and misalignment. Strategic implications: elastic joint systems are complementary to rigid coupling providers; cross‑sell and integration opportunities exist for firms that marry mechanical and elastomeric technologies.
Recent market activity — from product launches to trade fairs — underscores two tactical realities: suppliers continue to compete on installation efficiency and compliance credentials, while trade‑show circuits remain key for procurement discovery and specification shifts. Examples include a spring 2026 product launch focused on rigid sprinkler joints and high‑visibility trade fairs where global suppliers showcased new couplings and fittings.
Immediate strategic actions for executive teams in 2026
-
Reprice and renegotiate supply contracts now that steel costs have moderated. Capture savings through indexed contracts that retain upside protection against raw material re‑spikes.
-
Prioritize certification and installation compliance for nonmetallic and hybrid systems where codes have tightened. Fast‑tracking approvals shortens lead times for projects tied to new safety standards.
-
Run a 90‑day SKU and specification audit to identify where modular couplings or pre‑assembled joints can reduce onsite labour by 15–30% (case estimates documented in the full study).
-
Develop an M&A/partnership shortlist: target small‑to‑mid players with complementary installation technologies or regional manufacturing that can be integrated quickly to improve service and margins.
-
Implement the TCO toolkit from the report: move procurement conversations from unit price to lifecycle cost, factoring in installation time, maintenance intervals and failure‑risk premiums.
-
Design a compliance monitoring cadence: align engineering, procurement and legal teams to ensure product specs remain compliant as local codes evolve.
How PW Consulting supports your 2026 strategy
PW Consulting’s full Pipe Joints Market report delivers the data, models and practical playbooks required to convert market insight into executable plans. The deliverables include downloadable datasets, interactive scenario models, supplier‑level briefings, and a short‑form board presentation tailored to capital approval cycles. The full report contains the granular sub‑segment breakouts, regional demand dashboards and unit‑price matrices that our preview intentionally holds back to guide readers to the full, interactive resource.
If your 2026 agenda includes supply‑chain realignment, targeted M&A, specification revision or capex reprioritization in piping systems, the intelligence in the full report reduces risk and accelerates decision timelines. PW Consulting’s advisory team is prepared to run focused workshops using the report’s tools to convert insights into a 90‑day action plan customized for your footprint.
Summary: the pipe joints market offers manageable growth with clear levers for value creation in 2026 — procurement reshaping, compliance acceleration and targeted capability builds offer the highest near‑term returns. The full PW Consulting study contains the empirical detail and implementation templates required to make these moves with confidence.
For detailed analysis of this topic, please visit the official page: Pipe Joints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Progressing Cavity Pumps Market to Hit USD 2036.03M by 2032 (CAGR 5.55%)
By PW Consulting, 2026-07-12
Progressing Cavity Pumps Market — Strategic Preview for 2026 Decision Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present an executive preview of our in-depth Progressing Cavity Pumps (PCP) market study — a practical briefing designed to sharpen corporate actions in 2026. This article synthesizes the market’s macro trajectory, competitive dynamics, supply-chain pressures and regulatory inflections that will determine winners and losers in the coming planning cycle. Think of this as the film trailer: authoritative context, clear strategic signposts, and a compelling invitation to access the full dossier for the underlying data, segmented forecasts and executable playbooks.
Progressing Cavity Pumps Market
Market trajectory at a glance
The PCP market has expanded steadily through the early 2020s, reflecting resilience across oil & gas, water treatment, chemicals and food processing uses. Our base-year calibration (2025) sits on a market size of approximately USD 1,393.2 Million, up from roughly USD 1,061.5 Million in 2020. From 2026 onward, we expect sustained expansion underpinned by replacement demand, aftermarket services and targeted OEM adoption. The report’s forecast horizon (2026–2032) projects growth at a compounded annual growth rate (CAGR) of 5.55%, with the market moving from an estimated USD 1,422.6 Million in 2026 to about USD 2,036.0 Million by 2032 under the central scenario.
Progressing Cavity Pumps Market
Why this research matters for 2026 corporate strategy
- Investment timing: Clarifies where to prioritize CAPEX vs. M&A to capture mid-decade tailwinds without overexposure to short-term raw material cycles.
- Product roadmap validation: Identifies which technological attributes (hermetic sealing, hygienic design, digital controls, multiphase handling) are moving from differentiators to table-stakes.
- Commercial resource allocation: Informs market-entry sequencing, channel investments and aftermarket-service expansion to maximize lifetime revenue per pump.
- Cost and procurement playbooks: Quantifies exposure to elastomer and specialized polymer volatility and proposes practical hedging and supplier-partnership tactics.
- Risk-adjusted forecasting: Supplies scenario-based demand curves for portfolio stress-testing and three-tier contingency planning.
What the full PW Consulting report delivers (practical, take-to-action components)
- Robust market sizing and trend decomposition from 2020–2025 and modeled forecasts through 2032, with high-, base-, and low-case scenarios calibrated to commodity, regulatory and adoption variables.
- Detailed segmentation frameworks (by application, product variant and geography) paired with an interactive model (spreadsheet) that executives can run with internal assumptions; note — segment-level figures are reserved for the full report to preserve the “trailer” integrity of this preview.
- Competitive benchmarking matrix and playbooks covering pricing behavior, distribution footprints and technology stack comparisons for leading OEMs and prominent regional players.
- Aftermarket and service economics: maintenance intervals, spare-part cascades, and optimized service contract models that lift gross margins and customer retention.
- Procurement and supplier risk assessment: supplier concentration mapping, elastomer/polymers cost sensitivity simulations, and recommended contracting structures to mitigate quarter-to-quarter price volatility.
- Regulatory and standards roadmap: interpretation of hygienic, safety and hermetic-seal developments with implementation checklists for compliance and product positioning.
- Actionable M&A and partnership targets annotated by strategic fit, integration risk and second-order service synergies.
Competitive landscape — who matters in 2026
The PCP vendor universe remains a mix of global OEMs, specialized regional manufacturers and systems suppliers focused on artificial-lift and hygienic processing niches. Market concentration is moderate: the three largest firms account for roughly one-third of the market, and the top five approach just under 40% — a structure that supports both scale plays and differentiated niche strategies.
Progressing Cavity Pumps Market
- PCM Group (France) — A recognized leader with a broad product set (EcoMoineau MX, HyCare, Moineau A series) spanning oil & gas, food and industrial sectors. PCM’s emphasis on maintenance-in-place designs and hygienic certifications positions it well where uptime and regulatory compliance are prioritized. Recent announcements in early 2026 highlight application-specific solutions for oily water treatment and hygienic meat transfer for pet food production, and PCM leveraged IFAT to showcase water/wastewater innovations.
- NETZSCH Pumps & Systems (Germany) — Known for the NEMO progressing cavity range, NETZSCH continues to push hermetic sealing solutions that materially reduce emission and handling risks for toxic media — a rapid-response feature to tightened safety and environmental rules.
- SEEPEX (Germany) — A specialist in standard progressive cavity pumps and hopper designs, SEEPEX combines rugged mechanical platforms with digital control electronics to address abrasive and shear-sensitive fluids across industrial verticals.
- NOV Process & Flow Technologies (USA), Weatherford International (USA), ChampionX (USA) — These suppliers have concentrated capabilities in artificial lift and downhole PCP systems. Their strengths are field-proven high-sand and heavy-oil deployments and integrated service offerings for producers pursuing cost-effective artificial-lift optimization.
- Sulzer, Roto Pumps, ITT Bornemann, Nova Rotors, Flexon-All — Regional champions and specialists deliver niche technical variants (high-pressure units, hygienic sanitary models, grinders and API-compliant offerings) that are important for operators needing tailored solutions rather than off-the-shelf products. Nova Rotors’ recent participation in the Cibus Tech exhibition in 2026 underscores the continued importance of food-industry channels.
Market dynamics and near-term risks
Four interlocking dynamics will shape near-term performance and strategic choice:
- Raw material price volatility. Elastomer and specialized polymer inputs used for stators drive meaningful cost swings. Stator cost represents a non-trivial share of pump manufacturing cost, and we observe 5–10% typical annual swings in elastomer pricing with episodes of up to 15% change within a quarter due to supply disruptions. These movements directly compress OEM margins unless captured through pricing, hedging or supplier integration.
- Regulatory and safety evolution. Advances in hermetic sealing and the migration of hygienic design standards (EHEDG/FDA compliance for food, cosmetic and pharmaceutical applications) are rapidly redefining acceptable design baselines and are creating near-term retrofit and replacement demand.
- Operational economics and serviceability. Designs that minimize removal downtime — for example, maintenance-in-place architectures — materially reduce field labor and operational cost. Vendors exploiting these advantages can capture higher aftermarket revenues and reduce total cost of ownership for end-users.
- Technology adoption and digitalization. Variable-speed drives, integrated condition monitoring and pump-systems optimization are shifting buyer priorities from upfront CapEx cost to lifecycle efficiency and predictive maintenance, opening new monetization models (subscription, performance contracts).
Strategic imperatives for 2026
For executive teams planning budgets and M&A pipelines in 2026, we recommend a balanced set of strategic moves tailored to capability and appetite for integration:
- Prioritize product lines that embed safety and hygienic compliance as standard; this reduces go-to-market friction in regulated sectors and increases sell-through velocity.
- Lock in elastomer and polymer supply through multi-year agreements or backward integration where scale permits; use price-indexed contracts to limit margin erosion during quarter-to-quarter volatility.
- Expand aftermarket service packages and consider outcome-based contracts (uptime guarantees, performance SLAs) to leverage installed-base revenue and improve predictability.
- Accelerate digital retrofit offerings (VSDs, condition monitoring) that can be upsold to existing customers and create recurring revenue streams.
- Scan for bolt-on acquisitions in niche hygienic, grinder and multiphase PCP technologies to rapidly close capability gaps without incurring long R&D timelines.
- Design regional go-to-market plays that favor service density over pure product shipments — aftermarket presence often trumps new-unit sales in margin contribution.
Methodology and confidence
The full PW Consulting study is built on a mixed-methods approach: primary interviews with OEMs, end-users and distributors; trade-show and product-announcement monitoring; proprietary price-tracking of critical elastomers/polymers; and a bottoms-up equipment/aftermarket revenue model. Base-year normalization is to 2025, historical assessment covers 2020–2025, and forecasts extend 2026–2032 under scenario analysis. We surface sensitivity ranges so that CFOs and business-unit heads can stress-test P&L implications under different raw-material and regulatory outcomes.
Where to go next
This preview is intended to focus your 2026 strategy conversations on the levers that matter: product architecture, supply resilience, aftermarket economics and targeted inorganic moves. The full report contains the segmented market tables, regional and application-level forecasts, downloadable financial models and an actionable M&A shortlist. For teams preparing Q3 budgets, tender bids, or M&A diligence, those detailed inputs will materially accelerate decision velocity and reduce execution risk.
Access the full Progressing Cavity Pumps Market study and the supporting scenario models at our research portal to unlock the granular segmentation, supplier scorecards and the decision playbooks that will convert insight into measurable competitive advantage in 2026.
For detailed analysis of this topic, please visit the official page: Progressing Cavity Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hearables Market to Reach USD 344.8 Million by 2032 at 6.98% CAGR — PW Consulting
By PW Consulting, 2026-07-12
Hearables Market 2026: Strategic Preview for Executive Decision‑Making
As PW Consulting’s senior strategic advisor and industry lead, I present a focused preview of our latest Hearables Market study — a research product designed to convert market intelligence into immediate strategic choices for 2026. This briefing frames why hearables have moved from a product category to a strategic vector across consumer electronics, health tech and enterprise communications, and explains how the numbers and dynamics in our full report should shape near‑term corporate decisions.
Hearables Market
Executive snapshot: growth, concentration and the decision horizon
The hearables market remains a growth engine: from a multi‑hundred‑million dollar base in 2025, the category is projected to expand at a compound annual growth rate of 6.98% across our 2026–2032 forecast window, reaching the high hundreds of millions by 2032 under the base scenario. That steady expansion is accompanied by modest market concentration — the top three to five players account for a minority share of total value — creating a landscape that is simultaneously competitive and opportunity‑rich for incumbents and challengers alike. For 2026, these structural facts translate into a clear imperative: move quickly to lock in ecosystem advantages while safeguarding margin through supply‑chain resilience.
Hearables Market
Why this matters for 2026 corporate strategy
-
Product portfolio vs. platform play: Hearables are no longer only hardware. Companies that win will package signals from sensors, ANC/AI stacks, and subscription services into bundled value propositions that drive recurring revenue.
Hearables Market -
Channel economics and price elasticity: Growth expectations provide cover for premiumization in select segments, but sustained adoption will be conditional on perceived value — manufacturers must validate feature ROI at the point of purchase.
-
M&A and partnership timing: Fragmentation and growth create attractive bolt‑on opportunities to acquire niche IP (ANC, bone‑conduction, hearing health algorithms) and to scale distribution quickly.
-
Regulation and supply chain stress tests: Tariff shifts and component availability are no longer hypothetical. Executives must allocate 2026 capital to dual‑sourcing, regional assembly, and active policy tracking.
Market dynamics shaping 2026 moves
-
Feature convergence and segmentation pressure: High‑end audio, hearing‑health capabilities, and open‑ear safety solutions are converging. Expect consumer choice to consolidate around platforms that integrate hardware, software and services.
-
Component constraints and cost inflation: A disrupted MEMS microphone supply chain has compressed lead times and driven cost increases for critical acoustic components. Trade measures and tariffs have further accelerated the trend toward regional sourcing — a factor that will materially affect 2026 gross margins unless mitigated.
-
Trade policy volatility: The industry is operating with a new tariff and policy overlay. While recent executive actions have begun to unwind specific integrated‑circuit tariffs, broader protectionist measures enacted in prior years have already altered supplier footprints and buying behavior.
-
Fragmented competitive structure: With limited share concentration among the largest players, corridor opportunities exist for differentiated entrants and OEMs willing to invest in differentiated silicon, ANC and form‑factor innovation.
Competitive landscape: what key players are signaling for 2026
Our competitive scan identifies a set of feature and go‑to‑market archetypes. The following synthesis focuses on strategic positioning rather than raw share figures — a deliberate lens designed to highlight where competitive battles will be fought in 2026.
-
Apple — Platform leverage and ecosystem lock: Apple continues to push integrated user experiences (hardware, OS integration, health data pathways). Product advances emphasize next‑generation silicon and sensor fusion that deepen user lock‑in.
-
Bose — Experience differentiation via signal processing: Bose’s roadmap is anchored in advanced ANC and openness for spatial audio experiences, targeting premium listeners and professionals who prioritize audio fidelity and comfort.
-
Samsung — AI tuning plus device ecosystem: Samsung is scaling AI optimization for diverse listening contexts and leveraging device breadth to bundle services and drive volume adoption across price tiers.
-
Sony — High‑fidelity engineering: Sony’s strength lies in high‑fidelity reproduction and class‑leading noise cancellation — attributes that sustain premium positioning and justify price premiums for discerning consumers.
-
Anker (Soundcore) — Cost‑effective innovation: Anker competes on value, integrating long battery life, fit innovation and emerging compute concepts to challenge incumbent price points.
-
Shokz — Open‑ear and sports dominance: Bone‑conduction and TÜV‑certified noise reduction position Shokz as a specialist in safe, situational audio for active users — a niche that is growing in strategic importance.
-
Jabra — Enterprise and pro audio convergence: Jabra’s emphasis on unified communications integrations makes it a key player where hearables cross into workplace endpoints.
-
Sennheiser — Premium audio heritage: Sennheiser’s focus on premium sound quality and audiophile credentials sustains its appeal in top‑tier segments and licensing contexts.
-
Philips — Health integration: Philips’ movement toward integrating hearing‑aid features with consumer hearables signals a convergence between clinical and consumer value chains.
-
Airoha/MediaTek — Silicon enablement: Companies that control reference SoCs and Bluetooth audio platforms remain strategic enablers; silicon innovation will be a gating factor for form‑factor and battery improvements through 2026.
Recent signals to watch (product and policy)
-
Product launches at major trade shows are accelerating open‑ear and safety innovations, illustrating a practical route to growth in sports and commuting use cases.
-
Tariffs and related import costs imposed in recent years materially influenced 2025 vendor margins and sourcing choices; subsequent policy reversals for some integrated circuits in early 2026 are easing specific pressures, but a permanently altered supplier map is the more likely baseline.
-
Component shortages driven by geopolitical events have increased the value of silicon‑level partnerships and long‑term contracts with MEMS suppliers.
Strategic playbook for 2026 (prioritized actions)
-
Secure acoustic supply chains: Move from single‑source MEMS and PCB suppliers to a multi‑tier sourcing strategy and establish assembly redundancy in at least two regions to reduce tariff and logistics exposure.
-
Invest in software moat: Prioritize investments in ANC, hearing health algorithms, and over‑the‑air personalization layers that can be monetized via subscriptions or enterprise licensing.
-
Segment for clarity, not complexity: Reduce SKU proliferation by designing modular platforms where premium features are enabled or disabled by firmware and services rather than separate SKUs.
-
Plan M&A around capability gaps: Target acquisitions that fill immediate strategic gaps (bone‑conduction IP, low‑power AI audio chips, enterprise UC integrations) rather than scale alone.
-
Model margin sensitivity to tariff scenarios: Use scenario testing against our baseline CAGR to understand breakpoints for price increases, subsidy strategies and promotional cadence.
-
Regulatory & compliance readiness: Build a regulatory monitoring cell focused on health‑adjacent features; certification pipelines vary between markets and will determine time‑to‑market for hearing‑health enabled devices.
What our full hearables report delivers (operationally oriented)
The full PW Consulting Hearables Market study goes beyond narrative to deliver the practical tools that executives need to act in 2026. Highlights include:
-
Proprietary market sizing and a scenario suite (base, upside, downside) calibrated to 2020–2025 historicals and our 2026–2032 forecasts.
-
Competitive dashboards that map product roadmaps, channel strategies, and engineering beats for leading vendors (including the profiles summarized above).
-
Supply‑chain sensitivity models that quantify margin impacts under tariff, shortage and logistics stress scenarios, with recommended hedging levers.
-
Go‑to‑market playbooks for penetrating the premium, active/sports and health segments — including bundling, pricing buckets and channel incentives.
-
M&A trigger maps and valuation heuristics for priority targets (IP‑rich component suppliers, niche form‑factor innovators, and service/OS plays).
-
Regulatory checklists and certification timelines tailored to flagship markets to accelerate time‑to‑revenue for health‑adjacent innovations.
Note: this preview intentionally omits granular subsegment tables, regional splits and competitor share tables that are included in the full report. Those datasets are essential to execution and are available in the complete deliverable.
Implications for the 2026 budget cycle
Executives setting 2026 budgets should align capital allocation to three priorities: fortify supply‑chain resilience (short‑term), accelerate software and silicon differentiation (medium‑term), and pursue targeted inorganic moves where capability gaps threaten platform parity (medium‑to‑long term). With a projected market trajectory that supports sustainable growth, the optimal mix balances defensive plays against tariffs and shortages with offensive investments in services, ecosystems and M&A.
Final perspective: converting growth into durable advantage
The hearables category in 2026 is less a single market and more a set of adjacent markets — premium audio, active/sports, enterprise communications and consumer health — that will recombine around software and silicon. Our baseline growth outlook provides a favorable macro tailwind, but the margin of victory will belong to organizations that treat hearables as platforms rather than commoditized hardware. The PW Consulting Hearables Market study equips leaders with the metrics, scenarios and executable playbooks required to convert a forecast into a defensible, profitable strategy.
To access the detailed subsegment data, supplier matrices, and scenario models referenced above, review the full report on our site or contact PW Consulting for a briefing. The datasets and executable templates there are designed to be plugged directly into boardroom planning and 2026 operating plans.
For detailed analysis of this topic, please visit the official page: Hearables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Luxury Packaging Market Poised for 5.23% CAGR Through 2032
By PW Consulting, 2026-07-12
Luxury Packaging Market: Strategic Primer for 2026 Decision-Makers
As global luxury brands recalibrate product and sustainability strategies, packaging has become a decisive battlefield for differentiation, cost control and regulatory compliance. PW Consulting’s new Luxury Packaging Market introduction frames the operational and strategic choices that will matter most in 2026 — and why teams that act with data-led clarity will capture disproportionate value. This primer outlines the study’s macro trajectory, strategic implications for next-year planning, the practical deliverables inside the full report, and a concise read on competitive dynamics and near-term risks. It deliberately sketches opportunities and trade-offs while withholding granular segmentation tables and transactional figures to encourage review of the source report for full operational metrics.
Luxury Packaging Market
Where the market is heading: a data-driven snapshot
Between 2020 and 2025 the luxury packaging market recorded sustained growth, rising from the low hundreds of millions (USD, base-year 2025) to a larger base in 2025. Our model projects continued expansion through the 2026–2032 forecast window at a compound annual growth rate of approximately 5.23%, reaching a markedly higher market size by 2032. This steady, mid-single-digit CAGR reflects a combination of premiumization of end products, resilient demand in key luxury categories, and incremental price pressure driven by raw-material and energy cost dynamics.
Luxury Packaging Market
Market concentration remains low-to-moderate: the top three and top five players account for under a third of industry revenues, indicating a fragmented landscape where regional specialists and design-driven boutiques coexist with large fiber and board producers. That structure both complicates procurement for global brands and creates acquisition and partnership pathways for scale-oriented players.
Luxury Packaging Market
Why this matters for 2026 strategy
- Operational resilience and supplier strategy: Elevated paper and polymer input costs, alongside logistics volatility, make supplier diversification, hedging, and nearshoring practical levers. Procurement teams should move from transaction-based sourcing to integrated supplier risk-management programs that combine capacity mapping, stress-testing and contingency playbooks.
- Regulatory-first product development: New packaging regulations in major markets are accelerating design constraints (for example, mandates to reduce over-packaging and higher producer responsibilities). Brands that factor regulatory pathways into packaging briefs — balancing minimalism with perceived value — will avoid rework costs and expedited compliance expenses in 2026.
- Premiumization vs. sustainability trade-offs: Luxury consumers expect both exquisite tactile experiences and credible sustainability claims. The strategic decision is no longer binary: it is about articulating net environmental benefit across lifecycle stages and embedding circularity into the value proposition without eroding perceived luxury.
- Innovation timing and capital allocation: The mid-single-digit expansion sets a growth corridor for targeted investments — innovation centers, pilot lines for alternative substrates, and digital embellishment capabilities. Capital allocation should prioritize platforms with demonstrable scale-up pathways and short-to-medium-term payback under multiple pricing scenarios.
Actionable takeaways for C-suite and functional leaders
- CEOs / Strategy Heads: Revisit portfolio-level packaging mandates: identify line items where premium packaging materially influences willingness-to-pay, and separate those from categories where lean luxury can protect margin.
- CMOs / Brand Teams: Define the narrative architecture for sustainability claims — lifecycle evidence, return logistics, and consumer-facing storytelling — before design partners propose costly specialty materials.
- Procurement / Operations: Implement a three-tier supplier segmentation: strategic long-term partners, flexible regional capacity partners, and niche craft producers. Add scenario-driven pricing models that account for raw-material inflation and regulatory levies.
- R&D / Packaging Engineers: Prioritize material substitution pilots (fiber-based solutions, bio-based coatings, mono-material structures) that are compatible with existing filling and fulfillment lines, reducing retrofit CAPEX.
The report: practical deliverables and how they support 2026 decisions
Our full Luxury Packaging Market study is designed as an operational playbook for 2026. It combines strategic context with tools and templates that enable execution:
- Market sizing and forward-looking scenarios (base-year 2025, forecast to 2032) with sensitivity to material-price and regulatory shocks.
- Segment-level diagnostic framework (by substrate, format and end-use) that prioritizes opportunities based on margin impact and regulatory exposure — detailed segment tables are available in the full report.
- Competitive benchmark and capability matrix for packaging suppliers, assessing design sophistication, sustainability credentials, geographic footprint, and production agility.
- Supply chain risk map and supplier-concentration heatmaps coupled with mitigation playbooks and sample contractual clauses to secure capacity.
- Cost-to-serve and price-elasticity models adapted for premium SKUs, enabling scenario-based pricing decisions under different material-cost and demand assumptions.
- Go-to-market playbooks for launching sustainable luxury packaging lines, including commercialization timelines, sample merchandising concepts, and consumer testing protocols.
- M&A and alliance screening toolkit highlighting targets and partnership archetypes for scale, technology or regional access — with a shortlist of candidate profiles.
Competitive landscape: what leading suppliers are doing
The sector blends large-scale fiber-and-board players with specialist luxury producers and regional ateliers. Major incumbents continue to invest in sustainable materials, automation for complex constructions, and premium finishing capabilities. Recent industry moves illustrate the direction of travel:
- Leading fiber and board companies are showcasing circular, fiber-based luxury concepts at high-profile trade events, signaling rapid commercialization of recycled and mono-fiber luxury substrates.
- Innovation-focused firms have expanded R&D footprints in European design hubs, accelerating the translation of advanced materials into manufacturable products suitable for luxury positioning.
- Regional production specialists in Asia remain competitive on complex rigid structures and fast-turn prototyping, servicing fashion and accessories segments where structural design is a differentiator.
Noteworthy corporate profiles in the competitive review include a mix of European and North American firms focused on premium paperboard solutions, design-driven houses specializing in high-end rigid boxes, and emerging players from Asia with strengths in structural complexity and cost-efficient scale. The market’s fragmentation (top-three and top-five concentration remaining below one-third) creates openings for consolidation, platform plays and brand-supplier strategic partnerships.
Near-term signals and industry noise to monitor
- Material price volatility: Paper and polymer costs are elevated compared with pre-pandemic norms and susceptible to energy and feedstock disruptions. This erodes margins for undifferentiated packaging and amplifies the value of substitution pilots.
- Regulatory momentum: New packaging regulations in major markets are actively discouraging over-packaging and raising producer accountability. Brands should expect compliance timelines that compress design-to-shelf windows.
- Trade shows and innovation hubs: Recent exhibitions have highlighted smart-packaging integrations and novel fiber technologies — both are moving quickly from concept to commercial trials, creating first-mover advantages for brands that co-invest with suppliers.
- Plastic supply chain pressure: Contract uplifts for commodity resins have translated into renewed commercial interest in mono-material systems and coated papers as pragmatic stop-gaps.
Risks, blind-spots and the value of primary data
Three common blind-spots undermine packaging strategies:
- Underestimating integration costs: Material substitution pilots often assume seamless compatibility with filling and logistics. The real cost of retrofits and supply requalification can exceed material savings if not modeled end-to-end.
- Over-reliance on sustainability narratives without lifecycle evidence: Consumers and regulators are increasingly scrutinous. Claims unsupported by credible lifecycle assessment invite reputational and regulatory risk.
- Misreading regional regulatory nuance: Packaging rules are diverging across jurisdictions. A one-size-fits-all approach to compliance will create pockets of non-conformance and emergency capex later in 2026.
PW Consulting’s full report includes primary interviews, plant-level capacity data and a differentiated risk-index that surfaces these hidden costs and compliance gaps; these empirical inputs are why the complete study is essential for executable plans.
Recommended next steps for 2026 planning cycles
- Commission a 90-day material-and-cost deep-dive using the report’s supplier matrix and cost models to identify two immediate pilots: one sustainability-first option and one margin-preservation retrofit.
- Run a regulatory impact workshop for 2026–2027 to align product roadmaps and marketing claims with forthcoming rules and producer responsibilities.
- Engage with two strategic packaging partners under conditional pilot agreements that include capacity guarantees and shared innovation milestones.
- Adopt the report’s scenario toolkit to stress-test pricing, mix and investment plans under at least three material-cost and demand scenarios.
Conclusion — the strategic horizon
Luxury packaging in 2026 will be defined by three converging forces: consumer expectations for elevated experiences, regulatory pressure to reduce environmental footprint, and cost dynamics driven by raw materials and energy. Success will favor companies that move beyond aesthetics to treat packaging as a cross-functional lever — one that can protect margin, amplify brand promises and reduce future regulatory drag.
PW Consulting’s full Luxury Packaging Market report delivers the granular segmentation tables, supplier-level benchmarks, and executable playbooks that translate the strategic direction outlined here into operational plans. Accessing the complete study will give you the metrics and templates needed to convert 2026 uncertainty into competitive advantage.
For detailed analysis of this topic, please visit the official page: Luxury Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Hose Market Poised for 6.98% CAGR Through 2032
By PW Consulting, 2026-07-12
Industrial Hose Market — Strategic Briefing for 2026 Decision-Makers
As capital allocation cycles reset and supply-chain strategies are reworked for 2026, industrial hose manufacturers, OEMs, distributors, and large end-users face a market that is growing steadily but unevenly across types, applications, and geographies. PW Consulting’s new Industrial Hose Market study (base year 2025) synthesizes five years of historical performance (2020–2025) with a robust forecast (2026–2032) to deliver the actionable intelligence leaders need to convert growth into competitive advantage.
Industrial Hose Market
Market at a glance
Our analysis shows the global industrial hose market reached an estimated USD 14,352 Million in 2025. Underlying demand drivers and structural recovery dynamics support a multi-year upswing: the model projects a compound annual growth rate (CAGR) of 6.98% across the 2026–2032 forecast window, taking the market to a materially larger size by 2032. While headline growth is healthy, market concentration remains low—three- and five-firm concentration ratios are modest—indicating fragmentation, niche specialization, and multiple windows for consolidation or scale-driven advantage.
Industrial Hose Market
What the report delivers (practical, action-oriented contents)
- Executive summary with investment implications tailored to board-level and corporate development audiences.
- Macro-to-micro forecasts including base-year calibration, scenario analysis, and sensitivity testing to raw material and demand shocks.
- Strategic playbooks for procurement, manufacturing footprint optimization, aftermarket service expansion, and sales-channel transformation.
- Competitive landscaping with profiles, strategic positioning, and capability maps for the major global and regional players.
- Supply-chain stress-testing: raw-material cost pass-through simulations, inventory strategies, and dual-sourcing blueprints.
- Regulatory and standards impact assessment (including the latest standards relevant to hose construction and workplace safety), plus compliance checklists for product managers and QA teams.
- Proprietary financial model and downloadable datasets (exclusive segment-level metrics, price/tariff scenarios, and M&A valuation comparables) to plug directly into internal decision frameworks.
Why this study matters for 2026 strategic choices
Three strategic realities converge in 2026: sustained demand growth, margin pressure from raw-material volatility, and a fragmented supplier landscape. Each of these has distinct implications for the way companies should prioritize investments this year.
Industrial Hose Market
- Portfolio prioritization: With the overall market on a nearly 7% CAGR, companies must sharpen product prioritization based on technical differentiation and service economics, not just historical revenue share. The study identifies where premiumization (higher-spec hoses, engineered assemblies with embedded sensors, longer-life materials) produces disproportionate margin gains versus volume plays that are capital intensive.
- Manufacturing footprint and reshoring calculus: Our scenario work shows that small shifts in freight costs or raw-material availability can rapidly change the cost-benefit of regional manufacturing. The report provides an optimization framework for deciding when to localize production, invest in modular lines, or leverage toll-manufacturing partners.
- Aftermarket and service monetization: Given the mature and fragmented nature of the market, aftermarket services (inspection, certified rework, extended warranties) become high-return attachments. We quantify addressable aftermarket pools and provide templates for service contracts that improve retention and margins.
Supply chain, raw materials, and pricing pressure
Raw material dynamics are a near-term strategic lever and a medium-term risk. Input price movements—particularly in metals and elastomers—are impacting cost structures across hydraulic, chemical, and specialty hoses. For example, stainless steel and rubber price trends are already influencing manufacturing economics and sourcing decisions. The report walks through pass-through strategies, hedging approaches, and formulates a tactical procurement playbook that procurement chiefs can deploy in Q1–Q2 2026.
Regulation and standards — operational and go-to-market implications
Standards and workplace-safety rules have immediate implications for product design, testing regimes, and aftermarket liabilities. Our study examines recent updates to specifications for reinforced hydraulic hoses and assembly practices, and maps how they affect certification timelines, product labeling, and distributor responsibilities. We also provide a compliance checklist tailored to procurement, product, and field-service functions to close implementation gaps without slowing product launches.
Competitive landscape — positioning the key players
The market’s modest concentration indicates both opportunity and complexity for players at scale and newcomers seeking niche leadership. The report contains detailed company profiles and strategic diagnostics for major participants, including (but not limited to) Parker Hannifin Corporation, Gates Corporation, Danfoss, Continental AG, Kuriyama of America, Flexaust Inc., Southeastern Hose, and NRP Jones.
- Parker Hannifin Corporation (Cleveland, Ohio) — Strengths include global distribution reach, systems-level capabilities, and deep aftermarket service networks. For strategic buyers, Parker’s platform offers a benchmark for integrated solutions and assembly-level margins.
- Gates Corporation (Denver, Colorado) — Noted for product engineering and multi-standard compliance, Gates is a compelling comparables set for pricing discipline and global channel management.
- Danfoss (Nordborg, Denmark) — A player to watch where specialized industrial solutions intersect with energy efficiency and electromechanical systems; attractive in portfolios seeking exposure to higher-spec industrial segments.
- Continental AG (Hanover, Germany) — Durable-product emphasis and a broad industrial footprint make Continental a model for performance-led differentiation and marine/commercial applications.
- Kuriyama, Flexaust, Southeastern Hose, NRP Jones — These companies illustrate regional specialization, rapid-response assembly capabilities, and niche product leadership—critical dynamics in a fragmented market where customer proximity and customization matter.
Our competitive chapter does more than profile: it maps capability gaps, identifies likely consolidation targets, and quantifies the valuation premia associated with scale vs. specialization in industrial-hose M&A scenarios.
Recent industry signals and implications
Trade-show activity and product showcases in early 2026 reflect both demand confidence and a shift in go-to-market strategies. Leading fabricators and manufacturers increased presence at major events, underlining an emphasis on OEM partnerships, application-specific demonstrations, and aftermarket service offerings. These field signals are triangulated with our proprietary data to identify emerging demand pockets and buyer priorities before they become visible in public financials.
Scenario outlook and key uncertainties (2026–2032)
Our forecast embeds three scenarios—Base, Upside, and Systemic-Stress—anchored to sensitivities in raw-material pricing, capital spending in infrastructure-intensive end-markets, and regulatory shifts. The base scenario uses the 6.98% CAGR as the central path, but decision-makers should use the adjacent scenarios to stress-test capital plans, inventory policies, and M&A timing. We provide trigger-based decision rules (e.g., when to fast-track capacity vs. delay based on price thresholds or order-book indicators) so strategy teams can move from passive monitoring to pre-committed action.
How to use the full report
This article is a strategic preview: it demonstrates methodology, directional sizing, and the kinds of operational and commercial levers that matter in 2026. The full PW Consulting Industrial Hose Market study contains the granular segment and regional tables, downloadable financial models, and step-by-step implementation blueprints intentionally withheld here to preserve the value of the source intelligence. For procurement directors, M&A teams, and product leaders, the full dataset will materially shorten the time from insight to decision.
Final recommendation
Executives should treat 2026 as a decision window: allocate resources to three parallel tracks—(1) protect margins through disciplined procurement and selective hedging, (2) capture higher-margin product adjacencies and service contracts, and (3) evaluate bolt-on M&A that closes capability gaps or extends last-mile service footprints. The PW Consulting study equips teams with the quantitative and playbook-level tools to execute on those tracks with precision.
To access the full dataset, scenario models, and the operational playbooks referenced above, please consult the PW Consulting Industrial Hose Market report page where the in-depth segment tables and proprietary forecasts are available.
For detailed analysis of this topic, please visit the official page: Industrial Hose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
2‑In‑1 Laptops Market — Strategic Preview for 2026 Decision‑Makers
As enterprises and device manufacturers set strategy for 2026, understanding where the 2‑in‑1 laptop market is heading is no longer optional — it is foundational. This preview, prepared by PW Consulting’s Senior Strategy Team, distills the essential macro trajectory, competitive dynamics, and risk vectors that will determine winners and losers over the coming investment cycle. It intentionally reveals the high‑level intelligence you need to prioritize actions while withholding the granular subsegment tables that form the core of our paid analysis — the exact splits and micro‑metrics that materially affect tactical decisions are available in the full report.
2-In-1 Laptops Market
Why this study matters for 2026 strategic decisions
-
Market momentum: The 2‑in‑1 market has demonstrated consistent growth through the early 2020s and is positioned for continued expansion. From the early‑2020 baseline, the market expanded to a mid‑2020s base year and is forecast to accelerate through the 2026–2032 horizon at a mid‑single‑digit compound annual growth rate (CAGR) of 7.0%.
2-In-1 Laptops Market -
Investment signals: That trajectory means that capital allocation decisions made in 2026 — on product R&D, factory capacity, and go‑to‑market programs — will compound through the decade. Firms that act on forward‑looking scenario analysis will capture asymmetrical returns versus those reacting to last year’s trends.
2-In-1 Laptops Market -
Portfolio optimization: For OEMs and channel partners, the study provides the strategic lens to rationalize SKUs, prioritize form factors (convertible vs detachable), and align inventory strategies with projected demand curves and component lead‑time dynamics.
Market trajectory — a data‑driven snapshot
From an industry vantage, the 2‑in‑1 market has grown from roughly USD 2.6 billion in 2020 to just over USD 3.3 billion in the base year of 2025. Our forecast indicates continued expansion, with the market approaching the mid‑USD 3.6 billion mark in 2026 and progressing toward more than USD 5.3 billion by 2032 under the central case — driven by product renewal cycles, AI‑enabled user experiences, and sustained demand in both consumer and commercial channels.
This trajectory is underpinned by three structural forces: improving component integration (notably displays and NPUs), diversification of CPU/accelerator architectures, and the gradual normalization of supply chains following geopolitically‑induced dislocations. While the headline CAGR of 7.0% is valuable, the sector’s true inflection points occur at the component and regional level — details that the full dataset and scenario matrices unpack in actionable form.
Competitive landscape — who matters and why
The market shows a relatively concentrated supplier set: the largest OEMs collectively control a material share of industry revenue (CR3 in the high‑sixties percent range). That concentration creates predictable competitive dynamics — scale advantages in components procurement, marketing reach for channel rollout, and the ability to fund platform‑level AI investments.
-
Dell — leverages enterprise relationships and breadth of 2‑in‑1 SKUs. Dell’s focus on Intel Core Ultra‑based platforms and pen/touch integration keeps it relevant across corporate fleets that prioritize manageability and security.
-
HP — blends enterprise product reliability with consumer innovation. HP’s Elite and OmniBook lines push OLED screens and embedded AI features, strengthening positions in hybrid work and premium consumer segments.
-
ASUS — differentiates through display and performance variants. With lines that span ProArt to ROG and Chromebook, ASUS exploits form‑factor flexibility and display technology leadership (high‑res OLED options and 360° hinges).
-
Acer — driving aggressive silicon diversification. Recent product introductions emphasize Snapdragon‑based platforms and long battery life, an important wedge in mobility‑centric enterprise and education deployments.
-
Lenovo — strong portfolio depth from consumer Yoga to enterprise Think‑class alternatives. Lenovo’s adoption of AI‑centric OS features (e.g., Copilot integrations) is accelerating differentiation on user productivity.
-
Samsung — capitalizing on AMOLED and system‑level integration. Samsung’s Galaxy Book 2‑in‑1 family marries display quality with AI PC capabilities — a clear play for high‑value creative and premium segments.
-
Microsoft — the benchmark in detachable innovation. Surface Pro lines and high‑end detachable devices set expectations for detachable performance, design, and OS‑level AI experiences.
Collectively, these firms are converging on three common battlegrounds: display quality and touch/pen fidelity, AI/NPU acceleration at the edge, and supply chain resilience. Our full competitive module includes vendor scorecards, SKU‑level margin proxies, and partner maps that are essential for channel and OEM negotiation strategies — material intelligence that we withhold from this public preview.
Dynamics and risk vectors shaping 2026 outcomes
Several external dynamics will materially affect 2026 decisions. These are not abstract — they change unit economics, time‑to‑market, and strategic timing for launches and capacity investments.
-
Geopolitical trade friction: Export controls and tariffs have forced manufacturers to diversify component sourcing and accelerate localization. This is reshaping supplier selection and influencing the preferred locations for assembly and sub‑assembly closer to end markets.
-
Component shortages and semiconductor risk: Ongoing trade tensions amplify lead‑time volatility for advanced semiconductors and displays. Firms that model multi‑tier sourcing alternatives and maintain strategic buffer inventories gain negotiating power and reduce stock‑out costs.
-
Raw material and input cost inflation: Retaliatory tariff cycles and logistic disruptions have driven significant cost pressure on finished device pricing. Price elasticity and channel promotion planning are therefore critical to preserve market share without eroding margins.
-
Regulatory procurement impacts: Public sector procurement authorities note longer lead times and elevated costs in laptop categories; vendors targeting government and education buyers must factor compliance and SLA adjustments into bids.
Two recent industry developments exemplify these dynamics: Acer’s May 2026 launch of a Snapdragon‑based Swift Spin 14 AI (highlighting the high‑performance ARM ecosystem and multi‑day battery claims) and a February 2026 ramp of OLED touch controller ICs by a display component specialist — both signals that component roadmaps and platform choices are rapidly evolving.
How senior executives should use this research in 2026
-
Product roadmap prioritization: Use our scenario outputs to decide which form factors and feature sets to fund in 2026 R&D budgets. Prioritize investments that increase perceived differentiation (display, pen UX, AI edge performance) without disproportionately raising BOM risk.
-
Procurement and supply‑chain hedging: Implement a supplier risk matrix and alternative sourcing playbook derived from our lead‑time and cost simulations to protect critical launches.
-
Channel and pricing strategy: Align promotional cadence and inventory targets by integrating our demand seasonality models and price‑elasticity analysis — especially where education and enterprise refresh cycles drive volume.
-
M&A and partnership screening: Apply our vendor scorecards and technology roadmaps to shortlist acquisition targets or strategic equity partnerships that accelerate access to OLED, NPU, or modem capabilities.
-
Regulatory and procurement readiness: Use our policy impact assessments to construct compliant bid strategies for public sector opportunities, where lead‑time and origin constraints are now binding.
What the full PW Consulting report delivers (practical contents)
The full research package is designed as a boardroom‑ready decision tool. Key deliverables include:
-
Comprehensive market model (historical 2020–2025; forecast 2026–2032) with scenario ranges, sensitivity tables, and demand drivers by macro segment.
-
Detailed competitive intelligence: SKU‑level maps, product launch timelines, go‑to‑market matrices, and vendor scorecards that quantify technology and channel advantages.
-
Supply‑chain heatmaps and mitigation playbooks, including alternate sourcing ladders, contract negotiation levers, and lead‑time optimization tactics.
-
Commercial playbooks for OEMs and channel partners — pricing tactics, bundle strategies, and promotional calendars tailored to education, enterprise, and premium consumer buyers.
-
Investment and M&A screening tools: proprietary valuation benchmarks for target selection, plus integration risk checklists tied to component availability and IP ownership.
-
Executive‑ready briefings and slide decks customizable for investor relations, board meetings, and sales enablement.
Note: This preview deliberately omits the granular region‑by‑region and application‑by‑application splits and unit‑level price tables — those constitute the core, monetizable intelligence in the subscription report. If your team requires subsegment KPIs and the underlying datasets to operationalize these recommendations, the full report contains downloadable Excel models and interactive dashboards.
Conclusion — what to act on now
Decisions made in 2026 will lock in product portfolios and supply‑chain commitments for multiple years. The macro outlook is favorable — mid‑single‑digit CAGR and a market that nearly doubles over the forecast horizon — but upside capture requires targeted investments in AI‑enabled UX, display quality, and resilient sourcing. For firms that can combine product differentiation with multi‑tier supply strategies, the coming windows offer meaningful growth and margin expansion.
To convert these insights into a 90‑day action plan tailored to your organization, request the full PW Consulting 2‑In‑1 Laptops Market report and our accompanying scenario workbench. The preview is sufficient to inform strategic intent; the full intelligence package is required to execute with conviction.
For detailed analysis of this topic, please visit the official page: 2-In-1 Laptops Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Micronized Rubber Powder Market to Reach USD 279.34 Million by 2032 at 6.5% CAGR
By PW Consulting, 2026-07-12
Micronized Rubber Powder Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s senior strategic advisor and industry analyst, I present an executive preview of our latest Micronized Rubber Powder (MRP) Market study — a decision-oriented intelligence product tailored for executives preparing capital, commercial and M&A moves in 2026. This preview demonstrates the analytical depth and operational focus you will find in the full study while intentionally withholding core sub-segment datapoints that are reserved for subscribers and clients.
Micronized Rubber Powder Market
Why this study matters for 2026
-
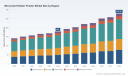
A compact but fast-growing market. The MRP market has expanded from an estimated USD 142 million in 2020 to USD 180 million in the base year 2025, and our forecast models project a compound annual growth rate (CAGR) of 6.5% over 2026–2032. Under baseline assumptions, the market is expected to reach approximately USD 279 million by 2032, with the 2026 opening-year projection at roughly USD 193 million.
Micronized Rubber Powder Market -
Decision window for capacity and partnerships. The combination of steady growth and tightening feedstock/regulatory dynamics means that investment choices made in 2026 will materially shape competitive position through the 2026–2032 horizon.
Micronized Rubber Powder Market -
From compliance to competitive advantage. Beyond volume demand, high-value attributes — including particle morphology, product traceability, and lifecycle credentials — are the new battlegrounds for margin and adoption in downstream applications such as asphalt modification, polymer compounding and specialty coatings.
What the PW MRP study delivers (practical, transaction-ready intelligence)
-
Market sizing & validated forecast model: detailed historical series (2020–2025) and multi-scenario forecasts (2026–2032) with sensitivity levers for feedstock costs, regulatory adoption rates and product mix shifts.
-
Segment playbooks: actionable value-creep maps for particle-size strategies, application use-cases, and regional go-to-market priorities (note: full sub-segment metrics are available in the paid report).
-
Production economics and cost curves: bottom-up cost models for cryogenic and ambient processing lines, with breakouts for capex, energy, labor and critical consumables.
-
Supply-chain and feedstock risk matrix: mapping of tyre collection networks, logistics bottlenecks, and feedstock quality variance — with mitigation options (offtake contracts, co-located collection hubs, and pre-processing partnerships).
-
Lifecycle & sustainability dossier: LCA benchmarking templates, carbon-intensity levers, and certification pathways (EPD, product declarations) tailored to asphalt and construction end-markets.
-
Competitive landscaping and capability matrix: granular profiles of incumbent and emerging producers, their processing technologies, IP positions and commercial strategies.
-
M&A and partnership targets: screened targets across geographies and technologies, with valuation frameworks and integration risk checklists.
-
Commercial playbook and contracts library: sample offtake agreements, pricing models indexed to feedstock and energy, and specification templates for customers and regulators.
Key dynamics that will define 2026 strategies
-
Cost structure centers on nitrogen and energy. For cryogenic MRP producers, liquid nitrogen is a significant variable cost driver — industry data indicates it often represents roughly 28–35% of variable production cost. Recent process improvements have reduced nitrogen usage per ton by an estimated 15–20% over the last five years, but operators remain sensitive to spot nitrogen and energy price volatility.
-
Premium for cryogenic product attributes. Cryogenic-grade MRP consistently commands a price premium over ambient-produced grades — reflecting superior particle morphology and surface area that aid compatibility with polymer matrices. Market evidence suggests a meaningful premium range, which makes technology choice (and process optimization) a primary determinant of margin strategy.
-
Regulation and circularity are demand multipliers. Regulatory pressure on end-of-life tyre management and public procurement requirements for recycled content continue to create higher-value outlets for MRP. European frameworks and product-level disclosures (e.g., EPDs) are already influencing procurement in construction and public infrastructure projects.
-
Moderate market concentration leaves room for scale players. The market concentration profile shows a moderately fragmented industry: the top three players account for around one-third of market volume, and the top five just over two-fifths. This structure favors consolidation, strategic alliances, and technology-based differentiation.
Competitive snapshot — what incumbents signal about strategic trajectories
-
Lehigh Technologies (Michelin Group): a technology-driven leader with a clear upstream–downstream integration play; recent lifecycle assessment work underscores a push to monetize carbon-reduction benefits in asphalt and polymer applications.
-
Genan: large-scale EOL tyre recycling specialist with focus on ultra-fine powders and premixed asphalt solutions; product certification moves indicate a strategy to command specification-driven uptake in infrastructure projects.
-
Tinna Rubber & Infrastructure: integrated producer with strong regional collection networks and high mesh capability; its scale in certain geographies creates cost and feedstock advantages.
-
Entech Inc.: long-tenured U.S. operator offering breadth across particle sizes and services — a playbook focused on customer intimacy and integrated services (hauling to compounding).
-
Rubberjet Group: differentiates via high-pressure water-jet technology, targeting morphology-sensitive applications and alternative feedstock profiles.
Recent industry moves underscore the strategic themes above: Lehigh’s October 2025 LCA publication seeks to translate carbon credentials into premium pricing and procurement wins, while Genan’s October 2025 EPD certification for an asphalt premix product shows the path from certification to specification-driven demand.
Strategic plays we recommend for 2026 (practical, prioritized)
-
Invest selectively in cryogenic capability where margin delta and off-take economics justify the premium. Use a staged-capex approach (demo → modular lines → scale) to de-risk and accelerate time-to-market.
-
Secure feedstock via hybrid models: a mix of long-term collection agreements, co-invested collection hubs and partnerships with tyre dealers. Prioritize quality consistency clauses to reduce processing variability.
-
Monetize sustainability credentials: implement EPDs/LCA claims early, use those credentials in bid strategies for infrastructure contracts, and develop carbon or circularity premium pricing where spec-driven purchasing exists.
-
Diversify technology exposure: pair cryogenic capability with ambient or water-jet processing to serve distinct application tiers and improve asset utilization.
-
Value chain integration: for mid-sized players, evaluate vertical integration into compounding or asphalt premix blending to capture downstream margin and reduce sensitivity to spot pricing.
-
M&A and alliances: pursue bolt-on acquisitions to secure regional feedstock or proprietary processing IP; alternatively, structure JV agreements with offtakers to derisk demand and capex.
-
Commercial sophistication: adopt indexed pricing contracts linking MRP prices to feedstock and energy baskets, include quality-based premiums, and provide technical support packages to accelerate adoption in new end-markets.
Scenario planning, KPIs and what to track in 2026
-
Scenarios we model: baseline growth consistent with a 6.5% CAGR (2026–2032), a policy-accelerated upside (faster adoption tied to procurement mandates and certifications), and a downside (feedstock/logistics shocks or commodity-price shocks). Each scenario includes NPV, IRR and payback estimates for greenfield lines, retrofits and strategic acquisitions.
-
Operational KPIs to monitor: specific production cost per ton (with nitrogen and energy lines), product yield by particle-size distribution, feedstock quality variance, on-time delivery to offtakers, and certification status (EPD/LCAs).
-
Market KPIs to monitor: specification wins in target sectors (e.g., asphalt mixes and polymer compounding), contract tenor and price realization relative to spot, and share shifts among top players (watch CR3/CR5 movement as a proxy for consolidation).
Closing — how PW Consulting can accelerate your 2026 plan
This preview demonstrates the strategic vantage offered by our full Micronized Rubber Powder Market study: a fusion of market forecasting, production economics, certification roadmaps, competitor intelligence and transaction-ready playbooks. In 2026, executives must navigate a market where operational efficiency (notably nitrogen and energy management), product differentiation (morphology and LCA), and feedstock security will determine winners.
To unlock the full dataset, granular regional and application splits, and executable annexes (including financial models, contract templates and target lists), access the complete report and advisory engagement options on our website. The full report contains the precise sub-segment metrics and scenario spreadsheets needed to finalize capex decisions, structure partnerships and execute M&A with confidence.
For detailed analysis of this topic, please visit the official page: Micronized Rubber Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Heating Furnace Market Poised for 5.5% CAGR Through 2032
By PW Consulting, 2026-07-12
Heating Furnace Market — Strategic Preview for 2026 Decision-Makers
As Pw Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a high-level briefing on our Heating Furnace Market study that positions executive teams to make decisive, risk-calibrated moves in 2026. Built on a robust historical window (2020–2025) and a detailed forecast horizon (2026–2032), this analysis synthesizes macro growth trajectories, regulatory inflection points, raw-material pressures, competitive positioning, and product/technology vectors that will determine winners and laggards through the end of the decade.
Heating Furnace Market
Market at a Glance — What the Numbers Tell Us
The heating furnace market reached a substantive base in 2025, and our model projects a compound annual growth rate (CAGR) of 5.5% through 2032 under the central scenario. That pace reflects a mix of retrofit activity, new construction demand, technology upgrades driven by energy-efficiency standards, and selective industrial investment in advanced heating technologies. By 2032 the market is forecast to be meaningfully larger than the 2025 baseline, creating a multi-billion dollar opportunity pool for suppliers, integrators, and service specialists who align product roadmaps and channel strategies to the emerging regulatory and fuel-price landscape.
Heating Furnace Market
Why This Report Matters to 2026 Strategy
-
Actionable timing: The 2026–2032 forecast period overlays a critical regulatory cascade and commodity cycle that will drive product obsolescence and create windows for premiumization. Companies that allocate capex and R&D in 2026 with these timelines in mind will capture disproportionate share in the early-adoption tranche.
Heating Furnace Market -
Policy-driven premiums: New efficiency mandates and updated industry standards are reshaping product architectures. Our study translates those mandates into product-level technical requirements, compliance timelines, and estimated retrofit volumes — enabling procurement, product and regulatory teams to prioritize investments that protect margin.
-
Supply chain resilience: Rising commodity costs and supply constraints for key inputs (notably steel) are compressing supplier margins. The report provides scenario-tested procurement strategies and supplier-sourcing playbooks that reduce exposure while maintaining launch schedules.
-
Competitive intelligence: We map winners by capability (high-efficiency combustion platforms, induction heating for industrial users, and digital-integrated solutions for the residential channel) and identify whitespace where late entrants can establish new footholds.
Report Contents — Practical Deliverables (Summary)
-
Market sizing and growth drivers: historical decomposition and bottom-up forecast models capturing demand levers across channels and end-markets for 2026–2032.
-
Regulatory impact analysis: scenario modeling of efficiency standards, codes, and guidance (including major published rules and ASHRAE guidance) and their timing impacts on product lifecycles and cost pass-through.
-
Technology and product roadmaps: competitive benchmarking of combustion, electric, induction, and hybrid heating technologies, with R&D priorities and cost-to-performance trajectories.
-
Go-to-market playbooks: channel segmentation, pricing strategies, aftermarket and service monetization blueprints, and digital value propositions for 2026 rollouts.
-
Supply-chain and procurement risk maps: critical-input exposure assessments, hedging strategies, and alternative sourcing scenarios tuned to 2026 supply dynamics.
-
M&A and partnership pipeline: prioritized target archetypes, valuation heuristics, and integration risks for roll-up or capability-acquisition plays.
-
Decision-support tools: ROI calculators, sensitivity analyses, and playbook checklists designed for board-level decision cycles in 2026.
Competitive Landscape — Forces Shaping Market Structure
The market exhibits moderate concentration: the leading three firms account for under one third of market share, while the top five remain below the 40% threshold. This structure favors firms capable of scale in manufacturing, differentiated product platforms, or superior channel access — but it also leaves meaningful room for regional specialists and engineered-solution providers to disrupt.
-
Carrier — a leader in high-efficiency gas and electric furnaces, leveraging variable-speed technology and ENERGY STAR positioning. Carrier’s strength is in system-level integration and channel reach; their playbook for 2026 should emphasize lifecycle services and bundled efficiency solutions for premium segments.
-
Trane Technologies — through the Trane and American Standard brands, they emphasize reliability, high AFUE performance, and integrated smart controls. The strategic lever for Trane is pushing system integration with building controls, enabling recurring revenues via service and controls subscriptions.
-
Lennox International — known for premium, quiet, and modulating models. Lennox’s advantage lies in differentiated product performance; defensive moves in 2026 should include expanding value-added installation training and optimizing compressor/electronics supply chains to protect margin on high-end SKUs.
-
Rheem Manufacturing — a value-to-performance player offering durable constructions across gas and electric lines. Rheem can increase share by streamlining aftermarket parts availability and reinforcing installer loyalty programs in growth geographies.
-
Goodman Manufacturing — competes on affordability and dependable performance. Goodman’s strategic opportunity in 2026 is to couple cost leadership with modular, upgradable electronics that enable an eventual premium services attach without undermining price positioning.
-
Inductotherm Group — a specialist in industrial induction heating for metal processing. Inductotherm benefits from capital-equipment tailwinds where energy efficiency and process repeatability are mission-critical; their 2026 play should focus on digital process monitoring and vertical partnerships with metal processors.
Recent Industry Moves and Their Strategic Bearings
-
Product launches at industry shows in 2025 signaled a push toward next-generation burners, compact system furnaces, and installation/diagnostic tools — all pre-positioning vendors for retrofit waves and stricter efficiency expectations. These launches create short-term differentiation but will be table stakes if regulations tighten as expected.
-
Commodity-pressure events in 2025 increased unit cost volatility for steel and other inputs. Tactical purchasing strategies and contract renegotiations are essential in 2026 to preserve gross margins without sacrificing availability.
-
Published standards and guidance from regulatory bodies and ASHRAE are converging toward uniform efficiency and safety practices. The timing of these policies creates predictable windows for product obsolescence and forced retrofits — windows that can be exploited for margin-rich replacement cycles if firms are operationally prepared.
Key Strategic Imperatives for 2026
-
Prioritize compliance-led product refreshes: Prepare engineering and supply chains in 2026 to meet impending efficiency thresholds. Delaying retooling beyond 2026 risks compressed timetables and elevated replacement costs.
-
Monetize services and digitalization: Build subscription and predictive-maintenance offers tied to smart controls and diagnostics. These revenue streams insulate firms from cyclical capex swings and enhance customer retention.
-
Hedge raw-material exposure: Implement layered sourcing, strategic stockpiling for critical components, and supplier partnerships that include cost-sharing mechanisms to absorb short-term price spikes.
-
Invest selectively in electrification and induction capabilities: While gas-fired solutions remain central today, the long-term vector favors electrified and induction offerings in select industrial and premium residential segments. Early entrants to hybrid platforms will secure attractive pricing power.
-
Optimize channel economics: Rebalance investments between direct-installation programs, contractor incentives, and OEM distribution to ensure profitable installation throughput as retrofit demand accelerates.
-
Use M&A to plug capability gaps: Targets that expand controls, digital services, or induction expertise will accelerate time-to-market and are generally less capex-intensive than greenfield R&D investments.
Risk Factors and Contingencies
-
Regulatory timing risk — accelerated or delayed adoption of efficiency mandates materially affects replacement cadence and inventory strategies.
-
Fuel-price dynamics — projected shifts in relative electricity vs gas pricing alter total-cost-of-ownership calculations and customer switching behavior; companies should stress-test pricing and product mixes against both higher and lower electricity-to-gas scenarios.
-
Supply-chain shocks — single-source dependence for critical components elevates vulnerability; diversification is a priority.
Next Steps — How Executives Should Use This Preview
This briefing outlines the strategic shape of the market and the levers that leaders must pull in 2026 to create defensible growth. Our full report contains the granular segmentation, regional and application breakdowns, product-level compliance requirements, and executable 90–180–360 day playbooks that are intentionally withheld from this preview to preserve proprietary insights. For teams developing 2026 budgets, crafting M&A pipelines, or revising R&D roadmaps, the full dataset and scenario models are indispensable.
Pw Consulting is prepared to walk leadership teams through tailored briefings, readiness assessments, and rapid-deployment playbooks grounded in the report’s findings. For those prioritizing decisive action in 2026, the time to translate scenario visibility into execution capability is now.
For detailed analysis of this topic, please visit the official page: Heating Furnace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vein Finder Market to Hit USD 574M by 2032 at 5.15% CAGR — PW Consulting
By PW Consulting, 2026-07-12
Vein Finder Market 2026: Strategic Imperatives for Decision-Makers
Executive snapshot
As health systems globally seek to reduce procedural failure rates, improve patient throughput and lower per-procedure costs, the vein finder market has moved from niche adjunct to operationally material medical device category. Our PW Consulting Vein Finder Market research (base year 2025; historical 2020–2025; forecast 2026–2032) shows the market achieving steady expansion at a compound annual growth rate (CAGR) of 5.15%. Measured in USD millions, the market is recorded at USD 405.0 Million in 2025 and is modeled to progress meaningfully through the forecast window, reflecting steady clinical adoption and incremental technology improvements.
Vein Finder Market
Why this study matters for 2026 decisions
- Timing: 2026 is the first full year after multiple supplier refreshes and regulatory milestones that materially alter supplier capacity and product availability. Procurement cycles that began in 2024–25 will be assessed and renewed this year—making 2026 strategy decisions pivotal.
- Operational impact: Incremental improvements in imaging fidelity and device ergonomics are unlocking new use cases (e.g., emergent vascular access in high-throughput departments) that directly influence capital allocation and staffing models.
- Market structure clarity: Our market concentration analysis shows a market in which the top three firms control a plurality but not a monopoly (CR3 ≈ 47.3%), and the top five account for a clear majority (CR5 ≈ 61.9%), creating a competitive environment where scale matters but agility and product differentiation can still win.
Market trajectory and structural implications
The Vein Finder market’s steady CAGR reflects a classic medical-technology maturation curve: sustained clinical validation, gradual price erosion on legacy technologies, and a steady stream of incremental innovations that expand addressable use cases. Between 2020 and 2025 the market expanded consistently, and our forecasts through 2032 anticipate continued growth as hospitals embed vein visualization into standard vascular access protocols and as outpatient and home-care settings adopt portable solutions.
Vein Finder Market
For executives, the practical takeaway is twofold. First, strategic investments—whether in product development, sales infrastructure, or clinical education—must be planned on a multi-year horizon to capture compounded returns. Second, scale remains an advantage for pricing and distribution, but differentiated product characteristics (battery life, imaging depth, ease of disinfection, integration with EHR/workflow) can overturn incumbency in targeted clinical pockets.
Vein Finder Market
Technology and clinical adoption dynamics
- Modular innovation: Near-infrared (NIR) and transillumination technologies continue to be the primary performance vectors. Recent device launches emphasize improved imaging algorithms, longer battery and field durability, and easier sterilization protocols—attributes that shorten training curves and reduce total cost of ownership.
- Shifting use cases: While vascular access remains the dominant clinical application driving unit uptake, secondary use cases (dermatology, surgical planning, pediatric and geriatric care) are growing. Adoption is often incremental—starting with high-volume wards and expanding laterally as clinicians gain confidence.
- Form factor segmentation: Handheld and portable systems are taking share in ambulatory and emergency care settings due to flexibility and lower upfront procurement friction; stationary, projection-based systems retain an advantage in procedural suites and specialized departments where integration and multi-user access are priorities.
Competitive landscape — what to watch in 2026
The competitive field contains a mix of established specialty vendors and nimble regional players. Core competitors in the space include long-standing specialists that have introduced next-generation systems, as well as newer entrants focused on localized regulatory approvals and cost-competitive portfolios.
- AccuVein Inc. continues to invest in next-gen handheld NIR systems, launching an AV600 model in early 2026 that emphasizes enhanced imaging and field durability—an explicit signal that incumbents are prioritizing product robustness for clinical throughput environments.
- Christie Medical Holdings retains its presence with projection-style systems tailored to high-volume procedural settings; attention to cleaning and compatability instructions in its device guides signals an operational focus required by large hospital clients.
- TransLite and other transillumination specialists keep competing on simplicity and focused performance for specific clinical niches such as EMS and pediatric use.
- China-based manufacturers and other regional players (including those updating catalogs or securing local regulatory clearances) are expanding addressable markets by offering competitive price-performance tradeoffs—which will accelerate adoption in emerging markets and price-sensitive channels.
Recent industry events in early-to-mid 2026—product launches, catalog updates and first-mover regulatory clearances in emerging markets—are reshuffling procurement conversations. Companies that can couple product improvements with clear clinical evidence and robust service models will command leverage in hospital negotiations.
Regulatory and procurement environment
- Regulatory posture: Many non-contact projection and certain LED-based visualization devices continue to qualify for lower-risk regulatory pathways in major markets, which reduces time-to-market for new entrants. Simultaneously, device-specific cleaning compatibility and hospital infection-control expectations are becoming decisive procurement filters.
- Procurement dynamics: Hospitals are shifting from unit-by-unit purchases to portfolio-level sourcing—favoring vendors who offer predictable maintenance, integrated training programs, and demonstrable throughput improvements. Pricing discussions are increasingly tied to service-level metrics and failure-rate reductions rather than hardware list price alone.
- Emerging-market nuance: Local regulatory clearances in high-growth countries are enabling domestic manufacturers to compete effectively on price and distribution speed; multinational suppliers must decide between direct investment, distribution partnerships, or licensing strategies to maintain presence.
Actionable strategic playbook for 2026
PW Consulting’s analysis produces a set of high-confidence actions for executives who need to convert market intelligence into deliverables this year.
- Prioritize clinical evidence tied to operational KPIs. Sponsor and publish cohort studies that quantify first-attempt success improvements, procedure-time reductions and downstream cost avoidance. These metrics win procurement conversations faster than imaging-resolution specifications alone.
- Segment go-to-market by clinical workflow, not by department names. Target high-throughput wards (e.g., emergency, dialysis, pediatric floors) with tailored propositions—bundled devices, training and service commitments—rather than one-size-fits-all offers.
- Design differentiated pricing models. Introduce outcome-linked pricing for high-volume clients and subscription-based models for outpatient chains. These reduce procurement friction and align incentives for device uptime and service performance.
- Invest selectively in product robustness and cleaning compatibility. Hospital infection-control requirements and device longevity directly affect total cost of ownership and purchasing decisions—make these explicit selling points backed by test data.
- Establish regional playbooks. For emerging markets, consider licensing or local manufacturing relationships to accelerate regulatory clearances and meet price-performance expectations. For mature markets, double down on integration, bundled service and clinical training.
- M&A and partnering discipline. With CR5 around 61.9%, there is room for bolt-on acquisitions that extend clinical reach or broaden portfolio breadth. Prioritize targets with complementary clinical data, robust service networks, or unique form-factor IP over purely geographical roll-ups.
What the PW Consulting report delivers (practical components)
This study is crafted to be directly actionable for product, commercial, and corporate development teams. Deliverables include:
- A robust market model (historical 2020–2025; forecast 2026–2032) with scenario toggles for adoption rates, price erosion and service revenue assumptions;
- A competitive playbook detailing product positioning, service propositions and go-to-market templates for both mature and emerging markets;
- Regulatory and procurement risk-mapping by market cluster, including recommended mitigations for device cleaning, classification and local registration timelines;
- Commercial templates—provider ROI calculators, contract language frameworks and clinical-evidence study protocols—designed to shorten sales cycles and strengthen negotiation positions.
Importantly, while this introduction highlights directional insights and strategic implications, detailed sub-segment tables and confidential supplier share estimates are intentionally reserved for the full report. Those granular views are essential for transaction-level decisions and are accessible through our research portal.
How to use this intelligence in Q2–Q4 2026
- Rapid portfolio review: Use the market model to stress-test product roadmaps against conservative and optimistic adoption curves, then prioritize R&D and capital accordingly.
- Commercial pilots: Launch high-impact pilots in targeted clinical pockets where you can demonstrate measurable throughput benefits within 90–180 days.
- Regulatory pathway alignment: If entering new jurisdictions, map registration timelines to procurement cycles to avoid missed contracting windows.
- M&A readiness: Prepare an acquisition checklist that emphasizes clinical evidence dossiers, service coverage maps and IP transferability to accelerate deal execution in a moderately consolidated market.
Closing — the strategic value of evidence-led action
The vein finder market offers predictable, above-inflation growth driven by practical clinical benefits and a wave of incremental product innovation. For 2026, success will flow to organizations that combine rigorous evidence generation, targeted commercial execution and operational readiness to support clinicians. PW Consulting’s Vein Finder Market research provides the modeling, competitive context and executable tools to translate these market dynamics into defensible strategic moves—while leaving the detailed, transaction-critical sub-segment datasets to the full report for subscribers and clients.
For organizations preparing budgets, evaluating M&A opportunities, or planning product launches in 2026, this study is designed to shorten decision cycles and reduce execution risk.
For detailed analysis of this topic, please visit the official page: Vein Finder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Car Audio Speakers Market to Hit USD 10.27B by 2032 at 7.21% CAGR
By PW Consulting, 2026-07-12
Car Audio Speakers Market — Strategic Brief for 2026 Decisions
PW Consulting’s latest market study on Car Audio Speakers (base year 2025; historical window 2020–2025; forecast 2026–2032) is designed as a decision-grade intelligence package for executive teams planning moves in 2026. The market is expanding at a steady compound annual growth rate (CAGR) of 7.21%, having grown from a multi-billion-dollar global base in 2020 to an estimated USD 6,310 Million in 2025, and is projected to exceed USD 10 Billion by 2032. This brief summarizes the strategic value of that research, highlights the commercial inflection points executives must address this year, and previews the actionable workstreams contained in the full report — while deliberately withholding the granular segment tables and region/application splits to encourage direct access to the underlying models.
Car Audio Speakers Market
Why 2026 Is a Critical Decision Window
-
Consolidation and concentration: Market concentration is meaningful — the largest three players control a substantial share and the top five an even larger portion — creating both barriers for scale and openings for focused differentiation. This structural reality shapes pricing power, channel leverage, and M&A calculus.
Car Audio Speakers Market -
Product premiumization meets platform integration: OEMs are increasingly looking for speaker solutions that are tuned for vehicle interiors and integrated into factory audio stacks. At the same time, aftermarket demand is bifurcating between value-oriented upgrades and high-end, experience-driven systems (high-resolution audio, advanced subwoofers, and tunable component arrays).
Car Audio Speakers Market -
Trade and supply volatility: Recent tariff actions, changing import duties, and supply pressure on critical components have already prompted pricing adjustments across the supply base. These dynamics are feeding margin pressure and are forcing suppliers and OEMs to revisit sourcing strategies and pricing models in 2026.
-
Technology and vehicle trends: Electrification, increased in-cabin time, and greater on-board compute enable richer audio features (active filtering, software-defined equalization, and vehicle-level sound staging). Manufacturers who translate acoustics into perceived in-cabin value will capture premium dollars.
What the Full Report Delivers (Operational Contents)
-
Proprietary market sizing and forecast model (2020–2032) with scenario toggles for tariff, material-cost, and EV-adoption trajectories. The model is provided in a downloadable workbook so commercial teams can re-run forecasts against their own assumptions.
-
Demand-driver diagnostics: a layered view of consumer and OEM drivers, elasticities across price tiers, and a short-list of high-impact product attributes that change purchase intent.
-
Competitive and product benchmarking: product family mapping, value propositions across price tiers (entry, mid, premium), and a vendor capability matrix focused on engineering, distribution, and OEM relationships.
-
Go-to-market playbooks for OEM-supply and aftermarket channels, including channel economics, recommended margin structures, and sample commercial terms for 12-, 36-, and 60-month engagements.
-
Supplier risk heatmap and sourcing strategies identifying node-level exposure (tariffs, single-source parts, lead-time sensitivity) with recommended hedging and dual-sourcing approaches.
-
M&A and partnership screening framework: prioritized target profiles, valuation heuristics, and integration checklists tailored to capture incremental shelf-space in premium OEM programs and aftermarket distribution.
Competitive Dynamics — What Leading Vendors Are Doing
Industry leaders are executing distinct but overlapping plays. Some are doubling down on OEM integration and factory-fit programs; others are sharpening aftermarket propositions with series-level product families engineered for specific use cases.
-
Pioneer and Alpine are positioning around complete system offerings that serve both factory-fit and upgrade scenarios. Their product roadmaps show emphasis on system-level integration and interior tuning.
-
High-performance brands like Rockford Fosgate and JL Audio continue to stress power handling and fidelity for enthusiasts and install-heavy aftermarket segments.
-
Consumer electronics incumbents (e.g., Sony) leverage brand recognition and high-resolution audio credentials to move upmarket within factory-specified programs.
-
Specialist premium audio firms (e.g., Focal, Hertz) focus on timbre accuracy and plug-and-play high-fidelity kits, often targeted at premium OEM trims and performance-oriented aftermarket customers.
Recent industry moves underscore this dynamism: Hertz introduced compact and sport-tuned models in early-to-mid 2026, Pioneer announced a flagship integrated interior audio system in March 2026, and Sony refreshed its GS speaker and subwoofer lineup in 2025. These product actions illustrate how vendors are responding to both engineering demands and channel opportunities.
Strategic Implications for 2026 Decision-Makers
-
Portfolio prioritization: Firms must decide whether to compete on system integration, niche/high-fidelity performance, or cost-driven aftermarket solutions. Our report’s product-level profitability matrices help prioritize SKUs and engineering investment through 2028.
-
Channel strategy: With OEMs seeking tightly integrated systems and aftermarket channels fragmenting by specialty stores and e-commerce, manufacturers should adopt differentiated channel mixes with dedicated SKUs and pricing to avoid channel conflict.
-
Sourcing and pricing under tariff uncertainty: Short-term pricing actions taken in 2025–2026 reflect supplier constraints and tariff responses. The report provides hedging playbooks and scenario pricing that finance teams can use to renegotiate long-term contracts and rebalance landed-cost exposure.
-
M&A and partnerships: Where scale matters (distribution, OEM relationships), bolt-on acquisitions and licensing partnerships can accelerate access. We provide an acquisition target heatmap and integration milestones to de-risk such moves.
-
R&D and feature roadmap: Investment in tuning tools, software-defined audio features, and scalable subwoofer/component architectures will yield differentiated propositions — particularly for EV platforms where cabin acoustics differ materially from ICE vehicles.
How Executives Should Use This Research in 2026
-
Run the provided financial model against three internal scenarios (base, tariff-stress, high-EV-adoption) and translate outcome deltas into prioritized capex and commercial milestones for the next 18 months.
-
Use vendor benchmarking and supplier heatmaps to renegotiate supply agreements; prioritize contingency capacity or dual-sourcing for high-exposure components identified in our risk mapping.
-
Adopt a two-track product strategy: protect OEM relationships with integration-ready platforms while investing in a modular aftermarket line that can be rapidly deployed through e-commerce and specialty channels.
-
Prepare preemptive M&A diligence on targets that unlock distribution, engineering IP, or specialized fabrication capabilities — the report’s acquisition heatmap narrows this list to the highest-value targets for fast follow-up.
Where This Brief Fits in Your 2026 Planning Cycle
This document is an executive primer: it synthesizes the macro trajectory (7.21% CAGR and a market expected to surpass USD 10 Billion by 2032), competitive moves, and the near-term commercial variables that will shape profitability in 2026 and beyond. The full PW Consulting report contains the granular segmentations, region- and application-level breakdowns, SKU-level price elasticity matrices, and vendor scorecards you will need to operationalize strategy. Those detailed datasets are intentionally gated to ensure clients extract maximum commercial advantage from the analysis.
Next Steps — How to Access the Full Intelligence
For teams preparing budget submissions, supplier renegotiations, or M&A screening in 2026, the complete report and the accompanying financial model are practical tools that turn insight into executable plans. Reach out to PW Consulting to obtain the full study, unlock the segmentation tables, and receive a tailored briefing that maps findings directly to your P&L and product roadmap.
PW Consulting’s Car Audio Speakers Market study is built to be a working document for leadership teams — not a static read. In a market where product refreshes, trade policy, and vehicle platform changes can shift outcomes quickly, access to a validated model and prioritized action lists is the difference between reacting and leading.
For detailed analysis of this topic, please visit the official page: Car Audio Speakers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


