



Category: market research
LAN Access Point Market: Why Wi-Fi 7, 9.18% CAGR, and Enterprise Demand Are Redefining Growth
By PW Consulting, 2026-09-18
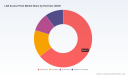
Strategic Trends and Commercial Opportunities in the Worldwide LAN Access Point Market
Market Landscape: Navigating Growth Amidst Structural Shifts
The Worldwide LAN Access Point Market is experiencing a period of robust expansion, characterized by a significant upward trajectory in revenue over the past half-decade. Valued at approximately $8.15 billion in 2020, the market has climbed to a projected $12.45 billion in 2025. This growth is not merely a recovery from pandemic-era disruptions but reflects a fundamental shift in how organizations deploy and manage wireless infrastructure. Looking forward, the market is anticipated to sustain a compound annual growth rate of 9.18% through 2032, potentially reaching $23.02 billion. This expansion underscores the critical role that reliable, high-speed local area networking plays in the broader digital economy, serving as the backbone for enterprise operations, educational institutions, and public sector services.
Despite the optimistic revenue figures, the industry stands at a critical juncture defined by several key challenges. First, the transition to next-generation standards is creating a bifurcation in the market. While newer protocols are gaining traction, a substantial portion of the installed base remains reliant on legacy technologies, creating a complex environment for vendors managing support, compatibility, and upgrade paths. Organizations must balance the immediate need for connectivity with the long-term necessity of future-proofing their infrastructure, often amidst constrained budgets.
Second, infrastructure readiness presents a notable hurdle. The performance benefits of advanced access points are inherently tied to the quality of the wired backhaul supporting them. In many regions, the existing copper or fiber infrastructure requires significant upgrades to handle the throughput and low latency promised by newer wireless standards. This dependency adds a layer of complexity and cost to deployment projects, potentially slowing adoption rates in areas where civil works or cabling upgrades are prohibitively expensive or logistically challenging.
Worldwide WLAN Access Points Market
Finally, market concentration remains high, with the top three players controlling a significant majority of the revenue share. This consolidation creates barriers to entry for smaller innovators and can lead to pricing pressure or reduced differentiation in mature segments. However, it also suggests that the market is moving towards standardized, mature solutions where network effects and ecosystem integration become more valuable than standalone hardware specifications. Decision-makers must navigate this concentrated landscape by evaluating not just hardware capabilities, but the broader manageability and security ecosystems offered by dominant providers.
Key Drivers Fueling Market Expansion
Technological Innovation and the Wi-Fi 7 Transition
The primary engine driving market growth is the rapid technological evolution from Wi-Fi 6 and 6E towards Wi-Fi 7. This shift represents more than a incremental speed increase; it is a fundamental change in network architecture designed to support higher density and lower latency. Wi-Fi 7 introduces features such as multi-link operation and wider channel bandwidths, which are critical for modern enterprise applications requiring consistent performance across diverse devices. Early commercial deployments in 2025 indicated a swift uptake, with next-generation protocols capturing a significant portion of revenue in the dependent access point segment by the end of the year. Vendors have responded by accelerating product roadmaps, releasing tri-band access points that maximize throughput for high-density environments. This technological leap is compelling organizations to reconsider their refresh cycles, moving from periodic maintenance upgrades to proactive infrastructure modernization to support AI-driven workloads and high-bandwidth applications.
Regulatory Mandates and Public Infrastructure Investment
Policy and regulatory environments are increasingly shaping demand dynamics. In early 2025, legislative moves such as the European Union's 'Connected Continent' regulation mandated Wi-Fi coverage in public buildings and transport hubs. Such policies directly stimulate procurement in the government and public sector verticals, transforming wireless LAN access from a discretionary IT expense into a compliance requirement. Beyond regulation, broader infrastructure investment trends are creating a supportive backdrop. Global spending on data center infrastructure is projected to grow substantially over the next five years, with significant implications for the connectivity required to support wireless access points. As organizations invest heavily in AI-ready facilities, the demand for robust LAN access points that can seamlessly integrate with high-performance backend networks increases. This correlation between broader digital infrastructure spending and LAN access point deployment suggests that public and private investment cycles will remain a strong tailwind for the market.
Shifting Demand Patterns in Enterprise and SMB Segments
Demand-side behavior is evolving as organizations recognize wireless not just as a convenience, but as a primary access medium. Enterprises are prioritizing high-density deployments to support hybrid work models, IoT integration, and real-time data analytics. The expectation for seamless connectivity has raised the baseline for Service Level Agreements (SLAs), pushing IT leaders towards solutions that offer AI-driven management and automated troubleshooting. Simultaneously, the Small and Medium Business (SMB) and prosumer segments are seeing increased sophistication in requirements. Affordable, scalable solutions utilizing mesh architectures and Wi-Fi 7 capabilities are becoming standard even in smaller environments, driven by the proliferation of high-bandwidth consumer devices and smart home ecosystems. This democratization of high-performance wireless technology expands the total addressable market, allowing vendors to capture growth in segments previously dominated by legacy or lower-tier products.
Supply Chain Dynamics and Infrastructure Costs
The cost structure of deploying LAN access points is influenced by broader supply chain and infrastructure economics. While hardware costs have stabilized, the total cost of ownership is increasingly tied to the underlying network infrastructure. For instance, the cost of building data centers capable of supporting high-density wireless networks has risen, with AI-ready facilities commanding significantly higher investment per megawatt compared to standard builds. These infrastructure cost pressures ripple through to deployment budgets, requiring stakeholders to justify LAN access point investments through clear ROI metrics related to productivity and operational efficiency. Furthermore, the expansion of fiber optic networks, with over 60% of homes in key markets passed by fiber, provides the essential wired backhaul necessary for optimal access point performance. This synergy between fiber expansion and wireless deployment reduces bottlenecks and enables the full realization of new Wi-Fi standards, reinforcing the supply-side readiness for market growth.
Worldwide Wireless Acess Point Controller Market
Competitive Landscape and Strategic Positioning
The market is defined by a mix of entrenched infrastructure giants and agile challengers, each pursuing distinct strategies to capture share. Cisco Systems currently maintains a leadership position in revenue share, particularly in the early adoption of Wi-Fi 7 indoor access points. Their strategy relies on aggressive pricing relative to previous generations and leveraging their massive installed base to drive faster adoption rates during refresh cycles. By integrating access points deeply with their broader networking and security portfolio, Cisco creates a sticky ecosystem that appeals to large enterprises seeking unified management and support.
Hewlett Packard Enterprise (Aruba) represents another pillar of strength, particularly following its acquisition of Juniper Networks. This integration brought Juniper's Mist AI-driven wireless portfolio into the Aruba fold, significantly enhancing capabilities in automated, high-performance LAN access. The focus here is on user experience and operational efficiency, using AI to predict and resolve issues before they impact users. This differentiation is crucial in verticals like education and hospitality, where downtime directly correlates to revenue or learning outcomes. CommScope, through Ruckus Networks, continues to differentiate through reliability in challenging and dense environments, catering to enterprises that require robust performance in difficult physical layouts.
A distinct trend in the competitive landscape is the rise of security-converged networking. Fortinet, for example, integrates its access points into a broader Security Fabric, offering converged networking and advanced security capabilities. This approach addresses the growing concern over network perimeter security, appealing to organizations that prefer a unified threat management approach over siloed security and networking tools. Meanwhile, cost-effective challengers like Ubiquiti, TP-Link, and Netgear are capturing significant volume in the SMB and prosumer spaces. TP-Link's launch of whole-home mesh systems supporting Wi-Fi 7 illustrates how these players are bringing enterprise-grade features to smaller deployments at accessible price points, putting pressure on incumbents to justify premium pricing in lower-tier segments.
The market is evolving through both consolidation and fragmentation. The merger of major players like HPE and Juniper indicates a trend towards consolidation to achieve scale and integrate AI capabilities. However, fragmentation persists in the lower end of the market and in specialized use cases, such as fixed wireless or specific outdoor deployments where niche players like Cambium Networks operate. New entrants or existing players are increasingly competing on software value—management interfaces, analytics, and security—rather than just radio frequency performance. The battleground is shifting from "who has the fastest radio" to "who provides the most reliable and secure operational environment."
Future Outlook: Trends Shaping 2026-2030
Looking ahead, the convergence of AI and network management will likely become the default standard rather than a differentiator. As networks become more complex with the introduction of Wi-Fi 7 and the proliferation of connected devices, manual management will become untenable. Access points will increasingly function as sensors, providing data that feeds into AI models to optimize traffic flow, predict failures, and enhance security posture autonomously. Organizations that adopt infrastructure capable of supporting this AI-driven management layer will see operational efficiencies, while those sticking to legacy manual paradigms may face higher operational costs and reliability gaps.
Another critical trend is the deepening integration of LAN access points with broader cloud and edge computing architectures. As edge computing grows, the access point becomes a key gateway for data moving between endpoints and edge servers. This will drive demand for access points with higher computational capabilities or tighter integration with edge nodes. Furthermore, the regulatory push for public connectivity will likely expand beyond Europe, prompting governments in other regions to consider similar mandates. This could open substantial public sector opportunities, though it also introduces the risk of procurement delays and compliance complexities that vendors must navigate.
However, uncertainties remain. The pace of Wi-Fi 7 adoption could face headwinds if the cost of required infrastructure upgrades—such as cabling and switching—outpaces the perceived immediate benefit for some organizations. Additionally, geopolitical factors affecting supply chains could impact hardware availability and pricing. Security threats will also continue to evolve, requiring access point vendors to stay ahead of vulnerabilities that could exploit wireless vectors. The ability to balance innovation with security and cost-effectiveness will define the winners in the next cycle.
Strategic Actions for Decision Makers
For enterprise leaders and IT planners, the immediate priority should be aligning refresh cycles with the Wi-Fi 7 transition. Delaying upgrades risks falling behind on density and latency capabilities required for modern applications. When evaluating vendors, focus on the software ecosystem and management capabilities rather than hardware specifications alone. AI-driven operations and security integration offer long-term value that outweighs marginal differences in throughput. Procurement teams should also assess the readiness of their wired backhaul infrastructure to avoid bottlenecks that negate the benefits of new access points.
Investors looking at the networking sector should monitor companies that are successfully integrating AI and security into their wireless portfolios. The value creation in this market is shifting towards recurring revenue models based on management software and services, rather than one-off hardware sales. Companies with strong positions in high-growth verticals like education and government, driven by regulatory demand, also present attractive opportunities. Conversely, reliance on legacy hardware without a clear path to next-generation standards poses a risk.
For manufacturers and vendors, differentiation through reliability in challenging environments and specialized vertical solutions remains a viable path against the giants. Expanding into adjacent markets where fiber backhaul is expanding rapidly can also unlock growth. Collaboration with infrastructure providers to ensure seamless integration between wireless access points and fiber networks will be key to reducing deployment friction.
Navigating the LAN access point market requires a nuanced understanding of technology roadmaps, regulatory shifts, and competitive dynamics. While the headline growth figures are encouraging, the real opportunities lie in the details of segmentation, adoption curves, and vendor-specific strategies. Stakeholders seeking to capitalize on these trends should consider accessing granular data to refine their investment theses or procurement strategies. Comprehensive research reports provide the detailed breakdown of regional performance, specific vendor market shares, and deep-dive analysis into sub-segments necessary for precise planning. Engaging with such detailed intelligence ensures that strategic decisions are grounded in the latest market realities rather than generalized assumptions.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide LAN Access Point Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Graphene Aerogel Market 2026: Decoding the 16.52% CAGR and 637 Million USD Growth Path
By PW Consulting, 2026-09-18
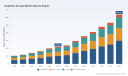
Navigating the Global Graphene Aerogel Market: Strategic Trends and Commercial Opportunities
The worldwide graphene aerogel market has entered a period of accelerated expansion, transitioning from laboratory curiosity to a commercially viable material class with cross-industry applications. Valued at approximately $105.34 million in 2020, the market reached $218.42 million by 2025, reflecting a compound annual growth rate of 16.52% through 2032. By the end of the forecast period, annualized revenue is projected to approach $636.92 million. This trajectory is not merely a function of incremental demand growth; it signals a structural shift in how advanced porous materials are integrated into energy, electronics, and environmental systems.
Despite the compelling growth narrative, producers and buyers alike face persistent headwinds. First, scaling laboratory-grade synthesis to industrial volumes remains a bottleneck. Traditional supercritical drying and freeze-drying methods are energy-intensive and difficult to standardize across batches, creating quality variance that delays qualification in precision applications. Second, the supply chain for high-purity graphite precursors is tightening. As downstream demand rises, upstream concentration in specific geographic regions exposes manufacturers to pricing volatility and logistics friction. Third, end-users in regulated sectors require extensive validation before adoption. Thermal durability, long-term mechanical stability, and compatibility with existing manufacturing lines often become gatekeeping requirements that slow commercial rollout. These challenges do not negate the market's momentum; rather, they define the competitive terrain where execution discipline will determine winners.
A third inflection point lies in the evolving regulatory and trade environment. Shifts in tariff structures, export licensing requirements, and chemical classification frameworks are reshaping how raw materials and finished aerogel products move across borders. Companies that previously operated with a single-region supply model are now re-evaluating sourcing portfolios, while buyers are building redundancy into their procurement strategies. The net effect is a market that rewards flexibility, transparent compliance practices, and diversified production footprints. The question for decision-makers is no longer whether graphene aerogel will scale, but which players can navigate the intersection of technical complexity, supply chain constraints, and regulatory change most effectively.
Strategic Implications for Market Participants
Growth at this pace rarely translates into uniform opportunity. Margins, qualification timelines, and customer acquisition costs vary significantly by application and region. Producers that treat aerogel as a general-purpose material often struggle against competitors who align product specifications, processing routes, and certification support with the exact requirements of target end markets. For buyers, the key is distinguishing between early-stage promise and repeatable, supply-stable performance. The next phase of market development will separate companies that build defensible positions from those that simply ride the volume wave.
Key Drivers Shaping Market Trajectory
Several interdependent forces are accelerating adoption and reshaping competitive dynamics. Understanding these drivers is essential for evaluating where value will concentrate over the next five to seven years.
Technical Innovation and Process Maturation
The most consequential driver is the steady improvement in manufacturing scalability and property control. Researchers and commercial producers have progressively reduced the cost and complexity of creating low-density, high-surface-area structures while preserving mechanical integrity. Advances in ambient-pressure drying, template-assisted synthesis, and composite integration are narrowing the gap between bench-scale performance and factory-floor reproducibility. Equally important is the ability to tune pore structure, conductivity, and compressibility for specific applications. When aerogel can be engineered to meet thermal, electrical, or adsorption requirements without excessive over-engineering, total system cost declines and adoption becomes more practical.
This technical maturation is particularly visible in energy storage and thermal management. In battery and supercapacitor architectures, aerogel-based electrodes and intercalation layers can support faster charge transport and improved structural resilience. In thermal management, the material's low conductivity and flexibility enable insulation solutions that are difficult to achieve with conventional foams or mineral fibers. The strategic takeaway is that innovation is no longer limited to discovering new properties; it increasingly centers on making those properties accessible at scale and in forms that downstream manufacturers can integrate without major retooling.
Policy, Regulation, and Trade Environment
Regulatory clarity and trade policy are becoming decisive variables in global sourcing and investment. In Europe, the European Chemicals Agency concluded that graphene, graphene flakes, and few-layer graphene do not warrant harmonized classification for specific target organ toxicity or germ cell mutagenicity. This determination reduces a layer of uncertainty for downstream users developing formulations and components in regulated industries. It does not eliminate the need for responsible handling and product stewardship, but it does simplify the compliance narrative for many commercial applications.
At the same time, trade policy is reshaping cost structures and supply routes. The United States has moved to increase Section 301 tariffs on imports of natural graphite and synthetic graphite from China to 25%, effective January 1, 2026. Alongside this, China requires export licenses for graphite and related products with purity above 99.95% carbon and specifications for battery use, effective December 1, 2023. These measures create a more guarded environment for high-purity precursor flows, particularly for battery-related supply chains. For aerogel producers, the implication is twofold: sourcing strategies must account for tariff exposure and licensing friction, and qualification programs may need to incorporate alternative precursor routes or regional production options to maintain continuity.
Demand-Side Shifts in Energy, Electronics, and Environmental Applications
Demand is being pulled by structural needs rather than cyclical promotions. In energy storage, the push for higher power density, longer cycle life, and improved thermal safety is encouraging exploration of advanced porous materials that can supplement or replace conventional electrode architectures. In electronics and electromagnetic interference shielding, miniaturization and higher performance thresholds are driving interest in lightweight materials that combine conductivity control with mechanical flexibility. Environmental remediation represents another expanding demand channel, where high surface area and adsorption characteristics support water treatment, contaminant capture, and separation processes.
What ties these demand segments together is a common requirement: performance must be delivered within cost and integration constraints. End-users are increasingly unwilling to accept material superiority if it comes with unpredictable supply, difficult processing, or unclear total-cost economics. As a result, adoption is accelerating in channels where suppliers can provide not only the material itself, but also application-specific guidance, sample availability, and compatibility data. This shifts the competitive emphasis from product features alone to solution readiness.
Supply Chain and Cost Structure Evolution
Cost dynamics remain a central driver of market behavior. Graphite feedstock pricing has moved in response to demand expansion and regional supply concentration. For example, prices for Chinese fine-flake graphite with 95% carbon content and 300-mesh specification averaged around $1,200 per metric ton in December 2023 amid rising demand. While this figure reflects a specific grade and window, it illustrates the sensitivity of precursor economics to demand cycles and regional availability. Aerogel manufacturers that depend heavily on a narrow set of feedstock specifications can experience margin pressure when input costs shift or when preferred grades become less accessible due to export or licensing constraints.
In response, the supply chain is gradually diversifying. Producers are evaluating alternative precursor grades, blended formulations, and regional sourcing partnerships to reduce single-point exposure. At the same time, downstream buyers are increasingly factoring resilience into procurement decisions, sometimes accepting modest cost premiums in exchange for predictable availability and reduced compliance risk. This recalibration is changing how value is negotiated across the chain and encouraging longer-term supply relationships rather than purely transactional purchasing.
Competitive Landscape and Leading Strategies
The competitive environment is shaped by a mix of specialized producers, application-focused suppliers, and regional material companies pursuing different routes to value. Rather than competing on a single dimension, leading players are building positions around product format, application alignment, and supply reliability.
Differentiated Positioning Among Established Players
The Sixth Element (Changzhou) Materials Technology Co., Ltd. operates from Changzhou, Jiangsu, China, and has developed a profile centered on graphene aerogel composite insulation materials, including blankets and felts for high-temperature thermal insulation and aerospace applications. This positioning reflects a clear strategic choice: target demanding thermal and specialty environments where performance and reliability justify premium positioning. By focusing on composite formats rather than powder alone, the company aligns more directly with end-use integration requirements in sectors where processing compatibility and thermal endurance are decisive.
ACS Material LLC, based in Alhambra, California, USA, supplies graphene aerogel powder with densities ranging from 2 to 10 mg/cm³ for research, energy storage, and thermal management applications. This format-oriented approach serves a market segment that values specification transparency, density tunability, and accessibility for development work. The strategy is well suited to customers who need material flexibility for prototyping and early-stage product design, particularly in energy storage and thermal management. It also positions the company as a provider of enabling inputs rather than finished assemblies, allowing it to serve a broader set of downstream developers.
Cheap Tubes Inc., located in Braselton, Georgia, USA, provides graphene aerogel products optimized for supercapacitors, insulation, and adsorption applications. By explicitly connecting product offerings to application categories, the company emphasizes use-case relevance over generic material supply. This is an effective way to shorten evaluation cycles for buyers who want to understand suitability before committing to larger-scale testing. In practice, application-oriented messaging can reduce the friction between material acquisition and engineering validation, especially in fast-moving development environments.
Structural Evolution in the Market
The broader market structure appears to be moving along multiple paths simultaneously. One path is consolidation around players who can combine consistent quality, application support, and supply continuity. In high-stakes sectors such as aerospace, energy storage, and regulated electronics, customers often prefer fewer, more reliable suppliers over a long list of low-cost options. This creates an incentive for producers to invest in process control, certification readiness, and customer-facing technical support.
A second path is fragmentation in research-grade and early-commercial segments, where a wider range of suppliers compete on density options, packaging, lead time, and application notes. This level of the market is important as an input channel for innovation, but it also tends to reward producers who can maintain reproducible specifications while keeping access convenient for development teams. The presence of multiple US-based and China-based suppliers illustrates how regional specialization and format differentiation can coexist within the same overall market.
A third dynamic is the potential for new entrants to emerge at the intersection of precursor supply, processing technology, and application integration. Companies that can bridge the gap between raw material economics and finished-product performance may find opportunities in niche segments where incumbents are too general in their offerings or too slow to adapt to changing compliance and trade conditions. At the same time, new entrants face real barriers in scale-up, qualification, and customer trust, meaning that success will depend on targeted positioning rather than broad market coverage.
What Differentiates Executing Players
Across these competitive patterns, several capability themes recur. Producers that can deliver repeatable density and pore characteristics, offer formats aligned with downstream processing, and navigate trade and compliance complexity are better positioned to convert demand into durable revenue. Equally important is the ability to support customer evaluation with clear technical documentation and application-relevant sample programs. In a market where performance claims are easy to make and harder to validate, evidence and consistency become competitive assets. For buyers, the operational lesson is to evaluate suppliers not only on unit price, but on the total cost of integration, qualification, and supply continuity.
Forward Outlook: Trends and Commercial Implications
Looking ahead to the 2026–2032 window, a few trends are likely to shape where growth concentrates and where risk accumulates.
Worldwide Organic Aerogel Market
- Application-led scaling will outpace generic volume growth. The strongest commercial momentum is expected in energy storage, electronics and shielding, and environmental remediation, where the material's properties map directly onto system-level needs. Producers that align capacity expansion with specific application requirements are more likely to capture higher-value demand than those pursuing undifferentiated volume.
- Supply chain reconfiguration will become a strategic necessity. With tariff escalation, export licensing, and regional precursor concentration all influencing cost and availability, companies will increasingly design sourcing structures around resilience. This may mean multi-region procurement, alternative precursor pathways, or closer integration with downstream customers to reduce cycle time and uncertainty.
- Regulatory clarity will lower friction in some regions while trade policy raises it in others. The absence of harmonized toxicity classification for certain graphene forms in Europe is favorable for commercial development in that jurisdiction. Meanwhile, evolving US-China trade measures and licensing requirements will continue to affect cross-border material flows. The net outlook is one of uneven terrain: opportunity is expanding, but it is not identically distributed across regions and supply routes.
These trends create actionable commercial opportunities. Manufacturers can gain advantage by doubling down on application-specific formats, investing in process consistency, and building compliance-aware sourcing strategies. Investors can focus on companies with credible scale-up roadmaps, defensible customer relationships, and exposure to demand segments where performance justifies premium economics. Procurement teams can use the current environment to negotiate more resilient supply arrangements, qualify alternative sources, and reduce dependence on single-region feedstock pathways. At the same time, risk remains. Scale-up shortfalls, quality variability, and sudden policy shifts can disrupt timelines and compress margins, especially for players with narrow supply exposure or underdeveloped customer validation capabilities.
Aerogel Market
Strategic Actions for Decision-Makers
For manufacturers, the priority is to link product development to real integration requirements. That means defining target applications early, engineering formats that fit downstream processing, and investing in the documentation and sample support that shorten customer qualification cycles. It also means building sourcing flexibility before disruptions force reactive changes.
For investors, due diligence should go beyond headline growth rates and examine the operating mechanics behind them: repeatability of production, readiness for regulated end markets, exposure to tariff and export constraints, and the depth of customer relationships beyond pilot-scale trials. Companies that can demonstrate a credible path from lab performance to reliable commercial supply are better positioned to capture long-term value.
For procurement and engineering leaders, the practical move is to treat graphene aerogel as a strategic input rather than a spot purchase. Qualify multiple sources, map tariff and licensing exposure across regions, and evaluate total cost against performance, lead time, and supply continuity. Building optionality now reduces vulnerability later, particularly in applications where qualification lead times are long and substitution is difficult.
PW Consulting
Market intelligence that combines segment-level demand trends, competitor positioning, regulatory updates, and supply chain cost dynamics can materially improve planning quality. For organizations seeking deeper segmentation detail, regional breakdowns, application-specific sizing, and tailored scenario analysis, the full PW Consulting market study provides a more granular basis for investment, sourcing, and product strategy decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Graphene Aerogel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Railway Expansion Joints Market: Why 5.14% CAGR and Asia Pacific Lead Reshape Strategy
By PW Consulting, 2026-09-18
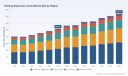
Strategic Trends and Commercial Opportunities in the Global Railway Expansion Joints Market
The global railway expansion joints market has transitioned from a steady demand-driven sector to a strategically dynamic space shaped by infrastructure modernization, technical specialization, and supply chain volatility. In 2025, the market crossed the 520 million USD threshold, extending a five-year trajectory that has consistently moved upward despite cyclical pressures in raw materials and project pipelines. Projections point to a compound annual growth rate of approximately 5.14 percent through 2032, a pace that signals durable expansion rather than short-term recovery. This trajectory is not uniform across geographies or applications. Instead, value creation is concentrating in segments where movement capacity, ballast retention, and certification requirements push buyers toward differentiated engineering rather than commodity procurement. Market concentration data underscores this shift: the top three and top five players together account for a meaningful share of revenue, reflecting buyer preference for suppliers with proven qualification records and global installation experience.
Pipe Joints Market
The current environment is defined by several interdependent challenges. First, raw material cost volatility continues to pressure margins, particularly for steel-intensive expansion joints exposed to fluctuating rebar and alloy benchmarks. Second, procurement cycles are lengthening in publicly funded railway programs, where certification, qualification testing, and compliance documentation can delay project timelines and compress installation windows. Third, the divergence between maintenance-driven replacement demand and new-build expansion projects is creating uneven revenue patterns across segments. Buyers are increasingly asking for components that can handle higher movement ranges, minimize ballast seepage, and maintain performance under variable weather and load conditions. These requirements are reshaping supplier selection criteria, elevating technical documentation and regional approval records to core decision factors.
For executives and investors, the implication is clear. The market is no longer a simple volume play. Growth is increasingly tied to engineering credibility, qualification breadth, and the ability to offer solutions that align with specific bridge, track, and high-speed rail requirements. Companies that rely on standardized offerings without documented performance in relevant operating conditions face mounting pressure to justify pricing and installation value. Conversely, suppliers with localized approval records, modular variants, and proven movement capacities are capturing a larger share of complex orders. The next phase of market development will be decided by how effectively participants convert technical differentiation into repeatable project wins and stable order books.
Key Drivers Shaping Market Dynamics
The expansion of railway infrastructure investment is the most visible driver in this market. Public and private operators are committing capital to track surfacing, undercutting, viaduct reinforcement, and capacity expansion, all of which increase demand for reliable expansion joints. Recent corporate capital plans illustrate this pattern, with multiple operators budgeting billions for infrastructure renewal and capacity-building projects. These investments are not cosmetic. They reflect the need to maintain network availability, reduce maintenance interruptions, and prepare corridors for higher traffic density or heavier axle loads. In practical terms, this means expansion joints are being specified not only for new alignments but increasingly for refurbishment programs where existing joints must be replaced with components that match modern movement requirements and long-term reliability expectations.
Regulatory and qualification frameworks are equally important. Approval pathways have become a competitive differentiator. Where operators require manufacturer-related product qualification or alignment with national railway specifications, suppliers with documented approvals gain a distinct advantage in sourcing decisions. This is especially true in markets where ballast bed load transfer, compliance with recognized design rules, and performance under weather and repeated load cycles are scrutinized during procurement. The effect is twofold. First, qualification becomes a barrier to entry that favors experienced players and disciplined engineering teams. Second, it raises the value of technical documentation, testing evidence, and field performance records. Suppliers that can provide clear, repeatable qualification information reduce procurement risk for operators and shorten evaluation cycles, which translates into faster conversion of project pipelines into awarded contracts.
Technological differentiation is reshaping product value. Expansion joints are moving beyond basic gap accommodation toward engineered systems that manage ballast retention, corrosion resistance, movement range, and load distribution. Certain suppliers emphasize stainless steel construction to improve durability in aggressive environments, while others focus on modular or mat-style designs that simplify installation and align with specific bridge geometries. Movable switch configurations and extended movement capacities are becoming more relevant where heavy-duty transport and variable thermal cycles create higher expansion demands. At the same time, manufacturers are increasingly tailoring product families to short-to-medium extensions versus high-range applications, allowing buyers to match joint specifications more precisely to project conditions. This specialization reduces over-engineering in simpler installations and improves fit-for-purpose selection in complex bridge and viaduct work.
PW Consulting
Supply chain and cost structure shifts are an additional pressure point. Steel and alloy prices have exhibited mixed, range-bound behavior in recent quarters, driven by raw material costs, construction demand recovery, and inventory adjustments. Rebar benchmarks have remained elevated in some regions, creating periodic margin stress for steel-intensive products. These fluctuations matter because they affect both pricing strategies and lead-time planning. Suppliers that manage material procurement more proactively, balance product mix toward higher-value engineered systems, and maintain transparent documentation on cost drivers are better positioned to preserve profitability without sacrificing competitiveness. For buyers, this environment increases the importance of total-cost evaluation, including installation complexity, maintenance expectations, and lifecycle performance rather than unit price alone.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a set of established engineering and infrastructure suppliers, with strong representation from European manufacturers and meaningful participation from North American and Asian players. Freyssinet has built a reputation around railway expansion joints designed to prevent ballast seepage into joint gaps on bridge decks, with solutions covering movement ranges up to 900 mm and extensive global installation experience on railway structures. This positioning reflects a strategic emphasis on high-movement applications and long-term field credibility. Voestalpine Railway Systems offers rail expansion joints with movable switch rails for short to medium extensions, and a heavier-duty model engineered for transport applications with axle loads up to 30 t and extension capacity up to ±600 mm. This dual approach allows the company to address both standard trackwork and more demanding heavy-duty use cases.
In the bridge segment, MAURER provides mat expansion joints with movement capacities up to ±130 mm and load transfer via ballast bed, supported by manufacturer-related product qualification for German Federal Railways. The company's recent technical documentation update reinforces performance claims under weather and load conditions, an example of how qualification clarity and documentation discipline can strengthen a supplier's competitive position. Mageba contributes ballast-retaining railway expansion joints made of stainless steel, with models designed for railway bridges and installed by major rail operators. D.S. Brown Company brings over 50 years of experience in engineered steel and rubber products for transportation infrastructure, offering bridge expansion joint systems adaptable to railway applications. Vossloh provides bridge joints and expansion rail joints in multiple configurations, including manganese and all-rail designs, while L.B. Foster supports rail infrastructure solutions with insulated rail joints and related trackwork components. CMI Promex rounds out the field with rail expansion joints for standard and embedded track, designed for measured expansion ranges suitable to specific installation contexts.
Across this group, the clearest pattern is strategic differentiation through fit-for-purpose engineering rather than broad price competition. Leaders position around movement capacity, ballast retention, certification records, and installation experience. Some concentrate on bridge-specific requirements with documented load transfer behavior. Others emphasize heavy-duty axle loads, short-to-medium extension ranges, or material durability in corrosive environments. The result is a market where value is captured by suppliers who can demonstrate that their offerings match the operational and regulatory conditions of the target segment. This is also where buyer risk is reduced, because qualification evidence and product-specific installation guidance make evaluation more straightforward and reduce ambiguity during project planning.
Looking ahead, the market structure is likely to evolve through selective consolidation, deepening specialization, and cautious new entry. Established players with global installation footprints and approval records are well placed to absorb complex demand and expand into adjacent corridor projects. Smaller or regional suppliers may compete by targeting niche movement requirements, specific track configurations, or cost-sensitive replacement programs, but they will need credible qualification or field performance to win larger contracts. New entrants face a meaningful barrier in certification and installation track record, which favors incremental expansion over disruptive displacement. At the same time, procurement teams are becoming more deliberate, weighing total installed value, maintenance exposure, and documentation quality. This environment rewards suppliers that combine engineering clarity with reliable execution, and it pressures those that compete primarily on price without a differentiated technical story.
Forward-Looking Trends and Commercial Opportunities
One clear trend for the next three to five years is the continued shift toward application-specific expansion joints rather than generic replacements. As more rail corridors undergo modernization and operators seek to reduce maintenance interruptions, projects will increasingly call for joints with documented movement capacity, ballast retention behavior, and approval alignment with local railway requirements. This trend creates commercial opportunity for suppliers that can present clearly segmented product families and provide transparent installation and qualification guidance. The practical upside is stronger conversion rates on technically complex bids and reduced reliance on commodity price competition.
Concrete Expansion Joint Market
A second trend is the growing importance of lifecycle value in procurement decisions. Unit pricing will remain relevant, but it will be weighed against installation complexity, expected service life, corrosion and wear performance, and total maintenance burden. Stainless steel options, modular designs, and mat-style systems that simplify load transfer are likely to gain attention where operators want to limit long-term intervention. For suppliers, this means communicating performance evidence in ways that procurement teams can compare across alternatives. For investors, it suggests that margin resilience will favor companies with engineered, higher-value product mixes rather than undifferentiated volume lines.
A third trend is the continued impact of material cost volatility on pricing and project economics. Steel and alloy benchmarks may remain range-bound with periodic spikes, and procurement teams will increasingly manage this risk through earlier specification, flexible sourcing, and lifecycle cost assessments. Suppliers with disciplined material planning and transparent cost communication will have an advantage in maintaining stable pricing relationships. At the same time, operators may accelerate replacement programs when maintenance disruptions or reliability concerns become more costly than the capital investment, creating episodic demand surges tied to operational pressure rather than pure expansion.
These trends carry inherent uncertainty. Certification requirements may evolve, project pipelines can shift with budget cycles, and raw material volatility can compress margins if not managed proactively. Still, the direction of travel remains favorable for suppliers who can convert technical credibility into repeatable project wins. The commercial opportunity lies in aligning product strategy with qualification evidence, installation practicality, and lifecycle value communication, so that expansion joints are evaluated as engineered solutions rather than interchangeable components.
Strategic Actions for Decision Makers
For manufacturers, the priority is to sharpen product segmentation around movement capacity, ballast retention, and certification relevance. Rather than competing broadly, focus technical messaging on the applications where documented performance and approval records reduce buyer risk. Invest in clear technical documentation, installation guidance, and qualification evidence that procurement teams can use directly during evaluation. Where material costs are volatile, strengthen procurement planning and communicate cost drivers transparently to protect pricing relationships without eroding competitiveness.
For investors, the key question is whether a supplier's portfolio is aligned with higher-value, application-specific demand or dependent on commodity replacement cycles. Favor companies with diversified product families across bridge, standard track, and heavy-duty use cases, and with credible qualification or installation records that support margin resilience. Monitor how effectively management converts engineering differentiation into repeat project wins, because that is a stronger indicator of durable growth than headline order announcements.
For procurement and project leaders, the practical move is to evaluate expansion joints on total installed value and documented performance rather than unit cost alone. Specify movement requirements, load transfer expectations, and approval criteria early, and request evidence that matches the intended operating conditions. This approach shortens evaluation cycles and reduces risk in complex bridge and trackwork projects. Detailed segmentation data, regional demand patterns, and supplier-by-supplier qualification breadth can further sharpen sourcing decisions, and a comprehensive market report can help internal teams benchmark alternatives before commitments are made.
For detailed analysis of this topic, please visit the official page: Worldwide Railway Expansion Joints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Long Range Baby Monitor Market: Why Global Expansion Beyond a 7.82% CAGR Changes Everything
By PW Consulting, 2026-09-18
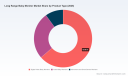
Worldwide Long Range Baby Monitor Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The worldwide long range baby monitor market has evolved from a niche accessory into a structured consumer electronics segment valued at approximately USD 485.6 million in 2025, with projected revenue expanding to USD 822.56 million by 2032. This trajectory reflects a compound annual growth rate of 7.82 percent, signaling steady demand expansion rather than speculative hype. The market's resilience stems from a combination of durable purchasing cycles, incremental technology upgrades, and shifting parental preferences toward connectivity options that balance range, privacy, and usability. As households increasingly treat baby monitors as essential safety tools rather than optional gadgets, vendors have had to adapt product roadmaps, distribution strategies, and quality assurance processes to meet expectations that extend well beyond basic audio transmission.
Despite the positive top-line momentum, the industry faces structural challenges that will shape competitive outcomes over the next several years. One of the most pressing issues is the tension between range performance and secure, reliable transmission. Many long range monitors rely on non-WiFi radio protocols to deliver coverage across large homes, outdoor spaces, or multi-unit dwellings, yet maintaining consistent signal quality while avoiding interference remains technically demanding. This challenge is compounded by growing consumer sensitivity to data privacy and electromagnetic exposure, which pushes manufacturers to justify transmission choices without compromising usability. The result is a market where technical differentiation matters, but engineering claims must be supported by real-world performance and transparent communication.
A second critical challenge involves supply chain volatility and component availability. Recent dynamics in semiconductor memory pricing, rare earth export policy shifts, and broader trade-related scrutiny have introduced uncertainty into production planning for electronic consumer goods. Companies that depend on tightly optimized bill-of-materials structures are exposed when lead times extend or input costs fluctuate unexpectedly. This environment rewards manufacturers with flexible sourcing strategies, prudent inventory positioning, and the ability to adjust product specifications without eroding core functionality. It also raises the stakes for product safety and compliance, as even minor design weaknesses can become costly when production volumes are high and recall management is complex.
The third major turning point is the growing expectation that long range monitors should integrate into wider smart-home and parenting ecosystems without becoming dependent on internet connectivity. Consumers want practical features such as extended battery life, clear video or audio capture, night vision, temperature awareness, and dependable two-way communication, but they also want the freedom to use products offline when preferred. Balancing localized functionality with optional smart features is becoming a defining product strategy question. Taken together, these challenges suggest that the market's next phase of growth will be determined less by headline range numbers and more by reliability, regulatory readiness, and the ability to deliver consistent user experiences across diverse living environments.
Key Drivers Shaping Market Growth
Technological innovation remains the most visible driver of long range baby monitor demand. Advances in radio frequency transmission, image processing, and low-power display design have made it possible to offer broader coverage while preserving picture clarity and battery duration. Several manufacturers now emphasize stable non-WiFi transmission in the range of 1,000 feet or more, with select models extending further under favorable conditions. This matters because range is not only a specification; it is a practical enabler for larger homes, backyard monitoring, and multi-room caregiving arrangements. At the same time, improved image sensors, night vision performance, and audio noise reduction are raising the baseline expectations for what a monitor should deliver. The competitive edge increasingly belongs to products that combine dependable transmission with clean, interpretable visuals and intuitive controls.
The second major driver is changing consumer behavior, especially around privacy, safety, and usability. Many buyers are actively searching for options that do not rely on continuous internet connectivity, either to reduce exposure to potential network vulnerabilities or to avoid subscription-linked dependence. This preference has elevated the importance of local transmission, onboard storage, and straightforward parental controls. At the same time, parents are looking for monitors that fit naturally into daily routines. Features such as temperature monitoring, two-way communication, pan-and-tilt control, and interchangeable lenses are no longer treated as premium extras in every segment; they are increasingly viewed as practical indicators of product maturity. As a result, demand is being shaped by a blend of peace-of-mind purchasing and feature-driven comparison, which encourages vendors to articulate clearly why one transmission approach or design architecture is better suited to certain user profiles than another.
Regulatory and safety considerations are also influencing market development. High-visibility recall events have reminded industry participants that battery behavior, charging design, and parent unit thermal management can become decisive trust factors. When safety issues attract regulatory attention, they affect more than a single product line; they reshape consumer confidence across the category and prompt closer scrutiny of quality assurance practices. This environment is pushing manufacturers to prioritize rigorous testing, clearer usage guidance, and traceable aftermarket support. It also creates a practical incentive to design products with fault tolerance and serviceability in mind, rather than treating safety as a downstream compliance task. In a market where word-of-mouth and retail reputation travel quickly, durability and safe operation are becoming strategic assets.
Supply-side dynamics further reinforce these demand trends. Fluctuations in semiconductor availability, memory pricing, and critical mineral policy have added pressure to electronics manufacturing schedules and cost structures. Companies must now consider not only how to build a capable monitor, but how to do so with enough supply resilience to withstand procurement delays or material cost swings. This has encouraged greater attention to component commonality, alternative sourcing pathways, and product architectures that can tolerate substitutions without compromising performance. For vendors that manage these constraints effectively, there is an opportunity to maintain margin stability while competitors face disruptions. For the broader market, the implication is that reliable long range monitors will increasingly be defined by operational discipline as much as by feature lists.
Competitive Landscape and Leading Strategies
The competitive field in the long range baby monitor market is mixed, with established consumer electronics players, specialty monitor brands, and emerging private-label or direct-to-consumer entrants all pursuing distinct positions. VTech Communications Inc. continues to hold relevance through a broad portfolio of long range non-WiFi monitors that emphasize range, battery endurance, and multiple video or audio configurations. Its strategy reflects scale, distribution reach, and the ability to offer families a range of price points and form factors. Infant Optics has carved out a differentiated position by focusing on video quality, lens flexibility, and active noise reduction, while also relying on secure transmission architecture. Its product narrative appeals to buyers who want more control over what they see and how the device performs in everyday use. Eufy, through Anker Innovations, has leveraged its broader consumer electronics credibility to deliver monitors that combine long range local transmission with high-resolution video and extended battery life, positioning the category within a larger smart-home context without making internet dependency a requirement.
PW Consulting
Other participants illustrate how segmentation strategy varies across the market. Babysense, under Hisense Ltd., has emphasized higher-resolution split-screen capabilities and a premium video experience, though recent safety-related recall activity has underscored the operational risks that can accompany high-volume product lines. Momcozy has pursued dual-mode and extended-range designs with local storage and no-WiFi options, while HelloBaby has concentrated on accessible pricing, clear core features, and practical value. Bonoch has leaned into higher video resolution, wide viewing angles, and encryption-oriented messaging for privacy-conscious users. Motorola Solutions, drawing on its broader professional communications heritage, has signaled reliability and strong indoor/outdoor signal performance in certain models. Bebcare has focused on audio-centric designs built around low-EMF transmission and long range, and Arenti has emphasized tested coverage and straightforward reliability in open-space conditions. Taken together, these profiles show that the market is not converging on a single winning formula; rather, different brands are winning by solving different user priorities.
The most successful strategies appear to be those that pair technical credibility with clear consumer messaging. Range claims alone are no longer enough; buyers want to understand how a monitor performs in realistic settings, how securely it transmits, and how safely it operates over time. Companies that communicate test-backed performance, transparent usage conditions, and dependable parent-unit design are better positioned to earn trust. Several players also distinguish themselves through product architecture choices, such as interchangeable lenses, local storage, or low-EMF audio designs, giving them a cleaner narrative for specific customer segments. This fragmentation is healthy in the near term because it expands choice, but it also signals that the market is ripe for consolidation among brands that can combine reliable execution with broader retail and e-commerce presence.
Worldwide Multifunction Baby Monitors Market
Market evolution is likely to remain a mix of differentiation and consolidation. Entrants that focus exclusively on price may find it difficult to sustain margins if component costs remain volatile and safety expectations continue to rise. At the same time, established players with strong distribution, brand recognition, and engineering discipline can use their scale to standardize high-performing architectures and expand into adjacent feature sets. Private-label and regional brands may thrive by targeting underserved price bands or specific feature preferences, but long-term advantage will likely go to those that can demonstrate repeatable quality, efficient sourcing, and a coherent value proposition. The strategic lesson for competitors is that long range capability is now a baseline expectation, while differentiation will be determined by reliability, safety assurance, and alignment with the way families actually use monitors at home.
Future Trends and Commercial Implications
Over the next three to five years, one of the clearest trends will be the continued prioritization of secure, non-internet-dependent long range transmission. As more households seek tools that function reliably without constant cloud connectivity, products that deliver strong local range, stable video or audio, and privacy-conscious design will likely capture a larger share of attention. This trend opens commercial opportunities for vendors that can articulate practical advantages in plain language, supported by consistent performance rather than exaggerated specifications. It also favors product lines that can serve both technophobic buyers and more connected users through optional smart features without forcing a single dependency model.
A second trend will be higher expectations for integrated functionality and safety assurance. Buyers are increasingly treating monitors as part of a broader caregiving setup, which means they value features such as clear night vision, temperature awareness, two-way communication, and robust parent-unit construction. At the same time, the market is likely to see more rigorous attention to battery behavior, charging safety, and product traceability. Companies that invest early in quality systems and transparent communication can convert these expectations into brand trust, while those that treat safety and usability as afterthoughts may face sharper reputational and operational consequences.
Baby Monitoring System Market
A third trend is the growing importance of supply chain resilience and cost strategy. If semiconductor availability, memory pricing, and critical material policy remain fluid, manufacturers with diversified sourcing and disciplined product planning will be better positioned to hold margins and fulfillment stability. This creates an opportunity for brands that can maintain feature consistency despite input volatility, and it raises the barrier for entrants that depend on fragile procurement models. The commercial implication is that future winners may be distinguished as much by operational reliability as by product innovation.
Potential risks remain significant. Overcrowded feature claims could blur consumer understanding and make it harder to justify premium pricing. Recall exposure, regulatory scrutiny, and shifting trade conditions could disrupt production planning or damage category confidence. In addition, if long range performance is marketed without clear real-world context, dissatisfaction may rise and pressure brands to compete on specifications alone. The most durable opportunities will belong to organizations that align product design, safety practices, and messaging with realistic usage scenarios.
Strategic Actions for Decision-Makers
For manufacturers, the priority should be to strengthen product reliability and safety validation while keeping long range performance grounded in real-world conditions. Engineering roadmaps should emphasize stable transmission, durable parent-unit design, and battery/charging safety, supported by clear usage guidance and responsive after-sales support. Sourcing flexibility and component planning should be treated as strategic capabilities, not back-office tasks, because they directly affect margin resilience and time-to-market.
For investors, the most interesting signals are not simply top-line growth estimates but evidence of operational discipline, distribution strength, and consistent quality control. Brands that can demonstrate repeatable manufacturing outcomes, prudent sourcing, and credible differentiation are better positioned to withstand recall risk, component volatility, and competitive pressure. Due diligence should pay close attention to product safety history, supply chain exposure, and the clarity of each company's value proposition.
For retailers, procurement teams, and channel partners, careful evaluation of range claims, safety records, and feature authenticity can reduce returns, protect shelf reputation, and improve customer satisfaction. Selecting monitors with transparent specifications, dependable transmission, and strong support structures is likely to pay off in lower service burden and stronger consumer trust. In a category where reliability and safety increasingly drive purchasing decisions, timely access to detailed market, product, and regulatory intelligence can help decision-makers move with more confidence. For those seeking deeper segmentation, competitive benchmarks, and tailored scenario planning, PW Consulting's complete research package offers a more detailed basis for action.
For detailed analysis of this topic, please visit the official page: Worldwide Long Range Baby Monitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Wireless Communication Systems: The Forces Behind 12.48% CAGR Growth
By PW Consulting, 2026-09-18
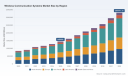
Worldwide Wireless Communication Systems Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The worldwide wireless communication systems market has evolved from a connectivity utility into a strategic infrastructure layer that underpins digital transformation across industries. Valued at approximately 1.45 billion USD in 2025, the market has demonstrated consistent expansion over the past five years and is projected to accelerate through the 2032 horizon. The compound annual growth rate of 12.48 percent reflects a structural shift rather than a cyclical upturn, driven by the maturation of fifth-generation networks, the gradual retirement of legacy fourth-generation deployments, and the increasing integration of satellite and short-range wireless architectures into unified communication ecosystems.
Despite this robust trajectory, the sector is navigating a set of interconnected challenges that will shape competitive positioning and capital allocation decisions in the near term. The first challenge lies in the physical and economic density of next-generation infrastructure. Deploying advanced radio access networks and backhaul systems requires substantial upfront investment, and operators are under continuous pressure to justify site-level economics while expanding coverage and capacity. This tension is particularly pronounced in regions where population density, terrain complexity, and regulatory approval timelines intersect, forcing vendors and service providers to rethink deployment models and cost-sharing frameworks.
The second challenge centers on fragmentation in standards, interoperability, and vendor ecosystems. The industry is moving toward disaggregated architectures and open interface frameworks, which promise greater flexibility and lower switching costs. At the same time, this transition introduces integration complexity, testing overhead, and the need for new operational competencies. Organizations that cannot manage multi-vendor interoperability or align their hardware and software roadmaps with evolving interface specifications risk higher total cost of ownership and slower time-to-market for new services.
A third challenge is the shifting regulatory and geopolitical landscape. Spectrum allocation decisions, export controls on advanced semiconductors, and platform interoperability mandates are increasingly influencing where and how wireless systems can be designed, manufactured, and deployed. These dynamics are not uniform across regions, which means global players must operate with greater architectural flexibility and regional adaptation. The market's overall concentration, with the top three participants holding roughly 38.45 percent and the top five holding about 52.12 percent, indicates that scale, portfolio breadth, and ecosystem relationships remain decisive, but it also leaves room for specialized players that can deliver differentiated technology or cost advantages in targeted segments.
PW Consulting
Key Drivers Shaping Market Dynamics
Technology Innovation and Architectural Shift
The transition from fourth-generation systems to fifth-generation and emerging fifth-generation advanced capabilities is the most visible driver of market expansion. This is not simply a matter of faster peak speeds; it is an architectural shift that enables network slicing, lower latency, and more granular service differentiation. Recent commercial activity illustrates how quickly these capabilities are being operationalized. In early 2025, Ericsson was selected by Deutsche Telekom to upgrade the 5G standalone core across Germany, signaling a move toward fully independent core architectures that can support diverse enterprise and consumer workloads. Around the same period, Nokia deployed 5G advanced equipment for China Mobile across multiple provinces, reinforcing the industry's push toward higher-throughput radio systems and more efficient resource utilization.
At the device and component level, the innovation curve is extending beyond traditional smartphones and base stations. Qualcomm's introduction of a new 5G modem-RF platform designed to support reduced-capability devices and lightweight wireless standards points to a broader vision in which lower-power, cost-sensitive endpoints can participate in advanced wireless networks. This expands the addressable base beyond high-end mobile devices and creates new pathways for industrial sensors, wearables, and specialized telemetry equipment. Huawei's launch of a 5.5G solution with 10Gbps peak speeds for commercial trials in Asia further underscores the industry's focus on pushing throughput boundaries while preparing networks for denser traffic patterns and more demanding applications.
Policy, Spectrum, and Regulatory Environment
Policy decisions continue to shape both the pace and geography of wireless investment. Spectrum availability remains a foundational enabler, and recent auction activity demonstrates how aggressively operators are securing mid-band and other valuable frequencies. In one notable allocation, the FCC awarded 102 licenses in the 3.45-3.55 GHz band, raising 1.82 billion USD and highlighting the strategic value of mid-band spectrum for balancing coverage and capacity. At the same time, regulatory frameworks are increasingly addressing the broader digital ecosystem rather than wireless infrastructure in isolation. The restoration of net neutrality rules under Title II classification in the United States and the enforcement of interoperability requirements for gatekeeper platforms in the European Union both signal a more interventionist stance on how networks and platforms interact.
These regulatory moves matter because they influence service design, traffic management, and the commercial models that operators and enterprises can build on top of wireless systems. For vendors, regulatory certainty can reduce planning risk, while sudden policy shifts can alter demand forecasts and regional prioritization. For enterprises, clearer rules around interoperability and traffic treatment can lower integration risk and make wireless-dependent solutions more predictable from a compliance standpoint.
Demand-Side Transformation Across Sectors
Demand is no longer concentrated solely in traditional telecommunications services. Industrial operations, consumer devices, and mobility applications are all generating new requirements for reliable, scalable, and often low-latency wireless connectivity. Industrial environments are increasingly adopting private and hybrid network models to support automation, asset tracking, and real-time control, which places a premium on predictable performance and integration with operational technology. Consumer electronics continue to expand the base of connected endpoints, but the more strategically important shift is the growing expectation that devices and services should work seamlessly across cellular, Wi-Fi, and short-range networks depending on context and cost.
In transport and automotive applications, wireless systems are enabling vehicle-to-infrastructure communication, fleet telemetry, and in-cabin connectivity, all of which depend on a combination of coverage, resilience, and spatial reuse. This diversification of end users means that wireless communication systems are becoming multi-purpose platforms rather than single-use networks. The strategic implication is that suppliers must design for flexibility: the same infrastructure should be able to serve mobile operators, enterprises, and vertical industries with different service levels and operational constraints.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by both infrastructure economics and component-level constraints. The average cost of deploying a 5G base station, typically ranging from 100,000 to 300,000 USD per site, remains a meaningful barrier to rapid dense deployment, especially when operators are balancing capital expenditure against uncertain revenue uplift in certain areas. This cost pressure is encouraging experimentation with virtualized radio architectures, centralized processing, and more efficient site designs that can reduce per-location expenditures or improve utilization.
Worldwide Underwater Communication System Market
At the same time, export controls on advanced semiconductors have introduced new uncertainty into the supply of high-performance chips used in both network equipment and end-user devices. Restrictions imposed on semiconductor exports to Huawei in late 2023, for example, illustrate how geopolitical considerations can affect product roadmaps, regional availability, and competitive dynamics. These supply-side factors are pushing companies to diversify sourcing, design for component flexibility, and in some cases re-evaluate where critical manufacturing and integration activities are located.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a mix of established infrastructure incumbents, semiconductor and platform specialists, and regional players with strong execution capabilities in specific markets. Ericsson and Nokia remain central to the carrier-grade infrastructure conversation, with portfolios that span radio access, core networks, and cloud-aligned platforms. Ericsson's recent core upgrade work with Deutsche Telekom emphasizes end-to-end control of the standalone architecture, which can be a differentiator for operators seeking to standardize on a single vendor's ecosystem for manageability and service orchestration. Nokia's deployment of 5G advanced equipment for China Mobile highlights a strategy centered on scaling proven radio and baseband technologies across large operator networks while supporting next-generation features such as massive MIMO and advanced antenna systems.
Samsung and Qualcomm illustrate a different but complementary axis of competition. Samsung's expanded Open RAN 5G network work with Verizon in the US Midwest reflects a push toward virtualized and open-interface infrastructure that can reduce dependence on single-vendor stacks and broaden integration options for operators. Qualcomm's modem-RF platforms anchor much of the device-side ecosystem, and its continued investment in reduced-capability and lightweight wireless standards shows a strategy aimed at broadening the range of connectable devices and use cases beyond premium smartphones. This device-to-network alignment is increasingly important because wireless system value is shaped not only by infrastructure performance but also by the diversity and capability of endpoints.
Huawei, ZTE, NEC, Fujitsu, Cisco, and CommScope each occupy distinct strategic positions. Huawei's full-stack 5G approach and emphasis on AI-driven optimization and high-capacity base stations position it as an integrated solution provider, even as export controls and regional restrictions shape where and how its offerings can be deployed. ZTE's focus on macro and small-cell radio systems with carrier aggregation supports operators seeking capacity gains through dense site architectures. NEC's microwave and radio systems serve backhaul and fronthaul needs, which remain critical as traffic grows and fiber availability varies by region. Fujitsu's RIC and O-RAN compliant base stations align with the broader move toward programmable, disaggregated networks. Cisco continues to strengthen its role in enterprise wireless LAN environments by integrating Wi-Fi 6 and 6E access points with SD-WAN and broader networking fabrics, while CommScope provides radio and antenna solutions for small cells and macro sites, addressing the physical-layer realities of densification.
Wireless Communication Intelligent Module Market
What ties these strategies together is a gradual re-balancing between integration and openness. Leading players are investing in platforms that can operate across proprietary and open interfaces, and they are positioning themselves as enablers of hybrid architectures rather than as single-stack vendors. Market concentration remains significant, but the landscape is also becoming more modular, which creates opportunities for specialized suppliers in radios, antennas, control software, device platforms, and integration services. The companies most likely to sustain advantage are those that can combine technical performance with deployment efficiency, multi-vendor compatibility, and the ability to tailor solutions to regional spectrum, cost, and regulatory conditions.
Future Trends and Strategic Implications
Over the next three to five years, one clear trend is the continued convergence of cellular, short-range, and satellite wireless capabilities into more unified service experiences. Networks will increasingly be evaluated not only on peak throughput but on how effectively they can hand off traffic, prioritize critical sessions, and support varied device classes without fragmenting the user or enterprise experience. This creates opportunities for providers that can offer orchestration layers, cross-domain management, and service assurance across heterogeneous environments.
A second trend is the acceleration of virtualized and software-defined radios and cores, which will make networks more adaptable but also increase the importance of integration, automation, and security. As functions become more software-centric, the competitive edge will shift toward operational efficiency, lifecycle management, and the ability to introduce new capabilities without costly hardware replacement cycles. Vendors and operators that invest early in automation, telemetry, and standardized interfaces are likely to gain an advantage in total cost of ownership and service velocity.
A third trend is the widening of use-case diversity across industrial, automotive, and consumer segments, which will increase demand for tailored connectivity profiles rather than one-size-fits-all network designs. This opens commercial opportunities for private network solutions, vertical-specific service bundles, and endpoint platforms optimized for power, cost, and specialized performance. The main uncertainty lies in how quickly standards, spectrum, and regulatory frameworks will align to support these differentiated offerings at scale. Geopolitical constraints, spectrum affordability, and deployment economics could slow adoption in some regions, while more favorable conditions may enable faster commercialization elsewhere. Companies that can model these variables and adapt their architectures accordingly will be better positioned to capture value as the market matures.
Actionable Guidance for Decision Makers
For infrastructure manufacturers and technology suppliers, the priority is to design for flexibility without sacrificing performance. This means investing in architectures that can support both integrated and open interfaces, building portfolios that address a broad range of device classes and deployment scenarios, and reducing the integration cost of multi-vendor environments. Suppliers that can demonstrate lower site-level deployment complexity, efficient spectrum use, and credible interoperability will be better placed to compete in a market where cost pressures and regulatory diversity are both rising.
For investors, the most valuable signal is where capital is flowing across the stack. Interest is likely to remain strong in core modernization, virtualized and open-interface infrastructure, device platforms that expand the addressable endpoint base, and enabling technologies for backhaul, small cells, and enterprise wireless environments. Portfolio decisions should account for regional exposure, since spectrum policy, export controls, and interoperability mandates are creating uneven competitive conditions across geographies. Diversification into integration, orchestration, and specialized vertical solutions may offer more durable returns than betting solely on generic hardware cycles.
For procurement leaders and enterprise adopters, the focus should be on total lifecycle economics and service assurance rather than on headline specifications alone. Selecting wireless systems that can integrate with existing IT and operational technology environments, support evolving interface standards, and provide predictable performance across cellular, Wi-Fi, and short-range networks will reduce risk as use cases expand. Building internal capability for network management, security, and vendor coordination is increasingly as important as the equipment selection itself.
Given the speed at which spectrum decisions, deployment economics, and regulatory frameworks are evolving, decision makers benefit from maintaining a continuous view of segment-level demand, regional policy shifts, and vendor roadmaps. Detailed segmentation data, region-specific deployment economics, and company-level strategic assessments can sharpen capital allocation, product planning, and sourcing decisions in a market that is expanding rapidly but becoming more complex to navigate.
For detailed analysis of this topic, please visit the official page: Worldwide Wireless Communication Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Otolaryngology Endoscopy Market: Why 6.52% CAGR and Shifting Dynamics Redefine Growth
By PW Consulting, 2026-09-18
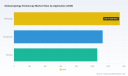
Navigating the Global Otolaryngology Endoscopy Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The global otolaryngology endoscopy market has demonstrated consistent expansion, reaching an estimated valuation in 2025 before progressing toward a projected valuation by 2032. This trajectory reflects a compound annual growth rate of approximately 6.52 percent across the forecast horizon. Such growth underscores the procedure's central role in modern ear, nose, and throat care, driven by procedural volume increases and procedural complexity. The market structure reveals notable concentration, with the top three players commanding nearly half of total revenue and the top five entities controlling over sixty percent. This consolidated landscape suggests established incumbents hold significant sway over pricing, distribution channels, and technological standards, while smaller specialized firms navigate limited whitespace without strategic partnerships or niche differentiation.
Several structural headwinds currently shape market dynamics. First, supply chain fragility continues to pressure manufacturers, particularly for precision optics, specialized sensors, and medical-grade polymers. Component shortages and logistics disruptions have historically extended lead times and inflated production costs, forcing companies to reassess inventory strategies and supplier diversification. Second, reimbursement environments remain uneven across regions and procedure codes. While certain automated delivery systems and advanced visualization techniques have secured favorable payment classifications, many health systems face budget constraints that delay capital equipment upgrades. This reimbursement uncertainty directly influences procurement cycles and limits the speed at which newer technologies diffuse into clinical practice. Third, the sector faces a talent and training bottleneck. Advanced endoscopic procedures demand specialized clinical proficiency, yet training infrastructure often lags behind equipment availability. Hospitals and ambulatory surgery centers must invest in simulation programs, credentialing pathways, and continuous education to realize the full value of modern endoscopic platforms, creating an adoption friction point that manufacturers and service providers must address holistically.
Key Growth Drivers: Technology, Policy, Demand, and Supply Chain Dynamics
Technological innovation remains the most visible accelerator of market evolution. Visualization quality has improved markedly through enhanced depth-of-field optics, higher-resolution video processors, and integrated imaging workflows. Recent regulatory clearances for systems featuring extended depth of field capabilities and towerless hybrid architectures illustrate how engineering advances translate into procedural efficiency. These platforms reduce setup complexity, improve surgeon ergonomics, and support faster turnover between cases, which matters greatly in high-volume ENT practices. At the same time, single-use flexible endoscopy has matured from a niche concept into a credible alternative for diagnostic procedures. Single-use devices lower cross-contamination risk, streamline reprocessing workflows, and reduce downstream costs associated with sterilization and instrument maintenance. This shift aligns with institutional priorities around infection control and operational simplification, particularly in outpatient settings where throughput and patient turnover are critical metrics.
Regulatory and reimbursement developments are reshaping commercial pathways. Recent clearance activity has expanded the procedural envelope for both diagnostic and therapeutic endoscopy, including indications that support transoral approaches for select oropharyngeal conditions and novel navigation systems designed for cranial and sinus applications. Clearer procedural indications reduce commercial uncertainty and encourage earlier adoption by demonstrating acceptable safety and performance profiles. On the payment side, the assignment of national payment rates to specific procedural codes for automated tube delivery and localized anesthesia techniques signals a broader willingness to recognize technology-enabled efficiency. When reimbursement frameworks explicitly value automation and precision delivery, hospitals gain fiscal justification to invest in compatible capital equipment, creating a virtuous cycle of device uptake and procedural standardization.
Demand-side behavior is shifting as care delivery models evolve. Patients and providers alike increasingly favor minimally invasive diagnostics that can be performed in office-based settings rather than operating rooms. Office-based endoscopy reduces facility fees, shortens wait times, and supports same-day decision-making, making it attractive for both health systems and payers. This preference accelerates demand for portable, high-quality visualization tools and single-use scopes suited to ambulatory workflows. Simultaneously, hospital operators continue to allocate substantial capital toward infrastructure modernization. Large health networks have outlined multi-year capital expenditure programs that explicitly include imaging and endoscopy system upgrades, reflecting a strategic intent to standardize platforms, improve surgical precision, and support expanded service lines. When capital budgets align with clinical priorities, procurement cycles accelerate and multi-year platform agreements become more common.
Laryngoscope Market
Supply chain and cost structures are undergoing parallel transformation. Manufacturers are rebalancing toward regional sourcing, dual-supplier strategies, and modular component designs that allow faster production adjustments when demand shifts. These approaches help mitigate volatility in optical elements, display components, and disposable materials. At the same time, the cost equation for end-users is changing. While advanced visualization platforms require meaningful upfront investment, total cost of ownership arguments increasingly account for reduced reprocessing labor, fewer repair events, and improved case throughput. Buyers are therefore evaluating purchases not solely on sticker price but on workflow integration, service availability, and clinical outcomes. This more sophisticated evaluation framework rewards vendors that can demonstrate measurable operational benefits rather than device features in isolation.
Competitive Landscape and Strategic Positioning
The market is defined by a mix of large diversified conglomerates, focused endoscopy specialists, and emerging innovators targeting specific procedural niches. Established players have built strong positions through broad product portfolios, global distribution networks, and long-standing relationships with surgical teams. Their advantage lies in the ability to offer integrated solutions spanning rigid and flexible scopes, video processors, navigation platforms, and related instruments. This comprehensiveness simplifies purchasing for health systems that prefer fewer vendor interfaces and standardized service contracts. Differentiation among incumbents increasingly depends on workflow integration, image quality, and the degree to which platforms connect with navigation or robotics ecosystems. Companies that can unify planning, visualization, and instrument control within a coherent clinical workflow create meaningful switching costs and support recurring revenue through servicing and consumables.
Several strategic themes distinguish the competitive field. First, single-use and hybrid device strategies are expanding. Some manufacturers have introduced disposable flexible video rhinolaryngoscopes tailored for diagnostic and therapeutic use, while others have brought forward hybrid systems that combine rigid and flexible capabilities within a single platform. These moves address two distinct demands: infection control and reprocessing simplification on one hand, and procedural versatility on the other. Second, navigation and robotics integration is becoming a competitive battleground. Advanced navigation platforms designed for sinus and skull base procedures, along with systems that unify planning and instrument guidance, are gaining regulatory clearances and clinical visibility. These technologies appeal to centers treating complex pathologies where precision and anatomical orientation directly influence outcomes. Third, smaller innovators are carving opportunities through specialized navigation features, steerable flexible platforms for nasal and upper airway applications, and streamlined towerless designs that reduce footprint in crowded procedure rooms. Such entrants often compete on agility, focused clinical claims, and faster iteration cycles.
Market structure appears to be moving along two parallel tracks. Consolidation remains likely as larger organizations seek to expand procedural coverage, geographic reach, and consumables attach rates through acquisitions or partnership arrangements. At the same time, segmentation is intensifying. Different care settings—large academic hospitals, community surgical centers, and office-based practices—have distinct requirements for portability, reprocessing capacity, and capital tolerance. This divergence encourages vendors to develop tiered offerings, where high-end integrated systems serve complex surgical environments while streamlined portable units and single-use options address outpatient and ambulatory demand. New entrants that can demonstrate clear clinical utility, regulatory compliance, and a credible reimbursement pathway stand a realistic chance of gaining footholds, even in a concentrated market, provided they solve a specific workflow pain point rather than competing broadly on general specifications.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
One defining trend is the continued blurring of diagnostic and therapeutic endoscopy. As imaging clarity improves and instrument channels become more capable, clinicians increasingly move from visualization to intervention within the same procedural session. This evolution favors platforms that support smooth transitions from diagnosis to treatment, including compatible instruments, reliable suction and irrigation, and integrated navigation where anatomical complexity warrants it. Companies that design for this continuum—rather than treating diagnosis and therapy as separate product lines—will be better positioned to capture recurring procedural volume and consumables demand.
A second trend is the institutionalization of single-use endoscopy for selected indications. As clinical evidence matures and cost models are refined, single-use flexible scopes are likely to claim a growing share of diagnostic examinations, particularly where turnaround time, sterility assurance, and space constraints matter. The commercial implication is a shift in revenue mix: lower per-unit pricing for disposable devices must be offset by higher volumes, streamlined supply agreements, and reliable distribution. Manufacturers that can standardize specifications, ensure consistent quality, and align with facility procurement cycles will benefit most. At the same time, hybrid strategies that pair durable capital systems with consumable accessories and selected disposables may become the dominant economic model for many providers.
A third trend involves deeper integration of navigation, planning tools, and data-enabled workflow support. Rather than viewing endoscopy as an isolated visualization task, leading centers increasingly treat it as part of a broader procedural ecosystem that includes pre-operative planning, intra-procedural guidance, and post-procedural documentation. This trajectory opens opportunities for software-driven differentiation, interoperable device ecosystems, and analytics that help hospitals benchmark throughput, complication rates, and instrument utilization. The associated risk is that integration requirements raise the barrier to entry and increase dependency on a small number of platform providers. Buyers may consequently demand greater interoperability, transparent data ownership provisions, and flexible service terms to avoid lock-in while still capturing clinical benefits.
Worldwide Respiratory Endoscope Market
Actionable Implications for Decision-Makers
For manufacturers and technology developers, the priority is to build modular yet integrated solutions that serve multiple care settings without sacrificing clinical performance. Portfolio strategy should balance advanced visualization and navigation for complex surgical environments with portable, low-footprint, and single-use options for office-based and ambulatory use. Equally important is aligning product roadmaps with reimbursement realities: devices that help standardize procedures, reduce reprocessing burden, or enable office-based care will find stronger adoption pathways when paired with clear payment logic and clinical evidence. Companies should also invest in training and service ecosystems, since adoption friction often hinges on clinician confidence and operational readiness rather than hardware specifications alone.
For investors, the most promising signals sit at the intersection of workflow simplification and procedural expansion. Capital allocation should favor platforms that demonstrate genuine integration benefits, recurring consumables potential, and credible clearances for expanded indications. It is also prudent to monitor suppliers and sub-systems where supply chain resilience is improving, as component reliability increasingly determines which vendors can scale consistently. Careful attention to reimbursement developments and hospital capital expenditure guidance can provide early indicators of procurement momentum, especially in markets where payment classification changes have recently improved the economics of technology-enabled procedures.
For procurement leaders and health system executives, the strategic question is less about buying a scope than about selecting a platform that fits long-term service lines and operational goals. Evaluations should weigh image quality and instrument compatibility alongside reprocessing demands, training requirements, service coverage, and interoperability with existing navigation or imaging infrastructure. Where possible, pilot programs and structured clinical assessments can reduce uncertainty before multi-year commitments. As the market continues to evolve, organizations that secure detailed, up-to-date intelligence on segment dynamics, pricing structures, and regulatory trajectories will be better equipped to time investments, negotiate terms, and build procurement strategies aligned with both clinical needs and fiscal constraints.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Otolaryngology Endoscopy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cast Aluminum Cookware Market: Why 5.24% CAGR & Asia Pacific Shift Change Everything
By PW Consulting, 2026-09-18
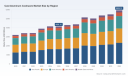
Global Cast Aluminum Cookware Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The worldwide cast aluminum cookware market has demonstrated consistent expansion, with revenue reaching approximately 4.15 billion USD in 2025. The sector has navigated a period of steady growth from 2020 through 2025, transitioning into a forecast period that extends to 2032. Projections indicate the market will approach the 6 billion USD threshold by the end of the forecast window, supported by a compound annual growth rate of 5.24 percent. This trajectory reflects a mature yet evolving industry where volume expansion increasingly depends on value differentiation rather than raw capacity additions.
Several structural shifts are reshaping the competitive baseline. First, regulatory pressure around chemical coatings is accelerating formulation changes across the supply chain. Jurisdictions such as California have moved to restrict cookware containing intentionally added PFAS, effective from early 2025. This creates compliance complexity for manufacturers relying on traditional nonstick chemistries and pushes brands toward alternative surface technologies, reformulated coatings, or uncoated hard-anodized variants. Second, input cost volatility remains a persistent pressure point. Primary aluminum transaction prices have experienced notable swings, and dependence on concentrated production hubs exposes downstream cookware makers to supply disruptions and currency effects. These dynamics compress margins for undifferentiated products while rewarding manufacturers that secure stable sourcing arrangements or pass cost efficiency into premium positioning. Third, channel fragmentation is altering how value is captured. Online commerce has grown its share of distribution, but offline retail still commands substantial volume, particularly in mass-market and regional segments. Companies must balance channel economics, inventory risk, and brand visibility without diluting price discipline.
These challenges are not purely headwinds. They function as filters that reward scale, technical competence, and regulatory readiness. Firms that treat compliance, material sourcing, and channel strategy as integrated design choices are better positioned to convert market growth into durable margin expansion.
Key Demand and Supply Drivers
Technology innovation continues to redefine product value. Advances in nonstick coating formulations, induction-compatible base structures, and multilayer casting methods are enabling lighter cookware with improved heat distribution and durability. Pressure-casting techniques and recycled aluminum integration are also gaining traction, allowing producers to reduce weight, improve consistency, and address sustainability expectations without sacrificing performance. These improvements matter because they expand the addressable use cases for cast aluminum beyond traditional cost-sensitive applications and into premium residential and multi-cooktop environments.
Aluminum Casting Market
Policy and regulatory environments are increasingly shaping product roadmaps. Beyond PFAS-related restrictions, trade policy is affecting landed costs and sourcing decisions. Additional duties on certain aluminum products imported from China have added complexity to cost planning for brands that rely on cross-border supply chains. At the same time, stricter environmental expectations are encouraging material traceability, recycled content, and longer product lifecycles. The combined effect is a market where regulatory and trade dynamics are not external noise but core inputs to product design, supplier selection, and pricing architecture.
On the demand side, consumer behavior is tilting toward convenience, health-conscious messaging, and cookware compatibility with modern kitchens. Households are investing in fewer, higher-quality pieces that work across gas, electric, and induction surfaces. In commercial settings, foodservice operators prioritize dent resistance, consistent heating, and low maintenance, especially in high-volume environments where downtime and replacement frequency directly affect cost control. These divergent requirements create distinct value propositions within the same material category, supporting both premium and value-tier segments simultaneously.
Supply chain and cost structure changes reinforce the importance of flexibility. Primary aluminum production remains geographically concentrated, and regional price disparities can create arbitrage opportunities or exposure depending on sourcing strategy. Manufacturers that combine localized finishing or assembly with disciplined raw material procurement are better equipped to manage tariff exposure, lead times, and working capital. Meanwhile, the shift toward e-commerce and direct-to-consumer models is altering inventory positioning and packaging requirements, making agility in demand forecasting and channel mix a competitive advantage.
Stainless Steel Cookware Market
Competitive Landscape and Leading Strategies
The industry is characterized by a mix of established multinational players, specialized premium brands, and high-volume regional producers. Market concentration remains moderate, indicating that share gains are still achievable through differentiation rather than consolidation alone. Companies are competing on multiple fronts at once: coating performance, induction readiness, aesthetic design, durability claims, and channel reach. The result is a landscape where positioning is increasingly specific rather than generic.
Several strategic archetypes are evident. Premium-focused brands emphasize advanced nonstick surfaces, induction compatibility, and high-temperature oven safety, targeting consumers who value performance and design and are willing to pay for durable, multifunctional products. These players often use trade exhibitions and retail partnerships to reinforce credibility and visibility. Value-oriented manufacturers compete on price, practicality, and broad foodservice suitability, offering standard nonstick lines, woks, saute pans, and steam table components that meet commercial durability expectations without premium pricing. In parallel, brands built around consumer franchises or lifestyle identities use set configuration, hard-anodized exteriors, and accessible price points to capture mainstream retail demand.
Commercial specialists remain critical to the overall market. Suppliers serving foodservice prioritize dent-resistant bottoms, consistent heat transfer, and ease of cleaning, recognizing that total cost of ownership matters more than upfront price in professional kitchens. Their product lines are often optimized for repeated use, high-temperature service, and compatibility with common commercial cooktops and ovens. This commercial segment provides a stable demand base that can offset volatility in consumer discretionary spending.
Recent exhibition activity illustrates how companies are using visible market moments to reinforce product direction. In early 2024, multiple manufacturers showcased cast aluminum skillets, griddles, and nonstick collections at major trade events, highlighting pressure-cast construction, induction readiness, and reformulated surface technologies. These presentations are not merely promotional; they signal where brands are placing bets on future demand, particularly around multifunctionality and compliance-friendly materials.
The competitive trend appears to be moving toward segmentation with overlapping competition. Premium and value tiers are both expanding, but they are not converging quickly because the underlying performance and cost requirements differ. New entrants can succeed by targeting underserved application niches, such as specific induction configurations, commercial durability at mid-range pricing, or region-specific retail preferences. Incumbents, meanwhile, are strengthening moats through coating expertise, sourcing reliability, and brand trust. M&A and partnership activity may increase where scale in sourcing or distribution can convert into margin advantage, but differentiation will remain the primary battleground.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, two to three trends are likely to shape opportunity sets. First, compliance-driven coating innovation will become a standard product requirement rather than a niche advantage. As restrictions on certain chemical additives broaden and consumer sensitivity increases, brands that can deliver durable nonstick performance without relying on restricted chemistries will command stronger shelf positioning and lower regulatory risk. This creates openings for coating specialists, material scientists, and manufacturers that can validate performance claims with consistent test data and transparent sourcing narratives.
PW Consulting
Second, induction compatibility and multifunctionality will increasingly serve as baseline expectations, especially in regions where appliance mix is shifting. Cookware that works reliably across cooktop types and can transition from stovetop to oven expands consumer utility and reduces replacement cycles. The commercial implication is clear: product lines should be designed for interoperability, not just for a single cooking environment. This is especially relevant where kitchen upgrades are accompanied by appliance changes, since cookware compatibility often becomes a purchase criterion at the point of replacement.
Third, supply chain regionalization and cost management will matter more as trade policy and input prices continue to fluctuate. Companies that diversify sourcing, secure longer-term aluminum supply agreements, or adapt product geometry to optimize material use can protect margins more effectively than those dependent on single-channel procurement. There is also opportunity in recycled content and lighter-gauge engineering where performance allows, both to manage cost and to align with sustainability expectations.
These trends carry uncertainty. Regulatory timelines can shift, enforcement intensity may vary by region, and raw material prices can change quickly enough to disrupt planning horizons. Brands that treat these variables as dynamic inputs rather than fixed assumptions will be better prepared to adjust product mixes, pricing, and sourcing without losing market momentum.
Actionable Recommendations for Decision-Makers
Manufacturers should prioritize integrated product design that combines compliance-ready coatings, induction compatibility, and durable base construction. Where possible, investment in coating validation, material traceability, and channel-specific packaging can protect differentiation and reduce exposure to regulatory or trade disruptions. Aligning product roadmaps with both residential convenience and commercial durability requirements can broaden addressable demand without fragmenting brand identity.
Investors should assess exposure to regulatory transitions, input cost sensitivity, and channel mix when evaluating opportunities. Businesses with stable sourcing, clear compliance positioning, and resilient commercial demand tend to offer more predictable operating profiles than those dependent on single-material sourcing or price-led competition. Commercial foodservice-oriented suppliers and brands with strong multifunction performance can provide defensibility even when discretionary consumer spending softens.
Procurement and retail buyers should weigh total cost of ownership, compatibility with existing cooktops, and compliance documentation alongside upfront price. Diversifying across coating technologies and supplier geographies can reduce risk while maintaining product quality. In commercial procurement, prioritizing dent resistance, ease of cleaning, and consistent heating can lower replacement frequency and service interruptions over time.
For organizations seeking a deeper view of segment sizing, regional dynamics, pricing patterns, and competitive benchmarks, the full PW Consulting market study provides detailed segmentation data and tailored scenario analysis to support planning across product, channel, and sourcing decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Cast Aluminum Cookware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
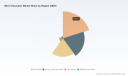
Global Micro Excavator Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global micro excavator market has demonstrated steady expansion over the past five years, evolving from a niche equipment segment into a critical component of urban infrastructure development. Valued at approximately 1,435 million USD in 2025, the market has grown from 1,120 million USD in 2020, reflecting a compound annual growth rate of 5.19 percent projected through 2032. This trajectory indicates a maturation phase where volume growth is increasingly driven by technological differentiation and regulatory compliance rather than purely by population or economic expansion.
Structural shifts within the market reveal diverging growth paths across segments. The zero tail swing category has gained significant ground against traditional tail swing designs, reflecting operator preferences for equipment that maximizes maneuverability in constrained environments. Application-wise, construction and demolition remains the dominant use case, but landscaping and agriculture sectors are exhibiting accelerated adoption rates as property developers and municipal contractors seek compact solutions for precision work. Public utilities represent a stable but slower-growing segment, benefiting from consistent infrastructure maintenance budgets rather than explosive expansion.
Despite positive momentum, the market faces three interconnected challenges that will define competitive battles over the next five years. First, supply chain volatility continues to pressure manufacturing costs. Raw material pricing, particularly for steel components essential to hydraulic systems and chassis construction, has shown variability that complicates long-term pricing strategies. Second, regulatory fragmentation across major markets creates compliance complexity. Emissions standards, safety certifications, and import duties vary significantly between regions, forcing manufacturers to maintain multiple production configurations or absorb compliance costs. Third, labor dynamics are reshaping demand patterns. Persistent skill shortages in construction sectors are accelerating automation requirements, pushing buyers toward equipment with advanced operator aids and telematics capabilities while simultaneously constraining the available workforce to operate even compact machinery.
These challenges do not undermine the market outlook but rather reshape how value is created and captured. Companies that navigate these friction points effectively will secure disproportionate market share, while those relying on legacy product architectures risk margin erosion and customer attrition.
Key Drivers Shaping Market Evolution
Technological Innovation and Equipment Differentiation
Technological advancement stands as the primary catalyst for market growth, transforming micro excavators from simple mechanical tools into connected, precision instruments. Manufacturers are investing heavily in hydraulic system optimization, cab ergonomics, and control interface design. The introduction of joystick controls, improved visibility cabins, and counter-rotation steering mechanisms reflects a broader industry focus on reducing operator fatigue and increasing work efficiency in confined spaces.
Recent product launches illustrate this innovation trajectory. Leading manufacturers have introduced ultra-short tail swing models with enhanced hydraulic responsiveness, enabling tighter turning radii and better access to urban job sites. Updated micro excavator ranges showcased at major industry events have incorporated refined cabin designs that improve operator comfort during extended shifts, directly addressing retention challenges in the construction labor market. New compact excavator models with improved cab comfort have entered the market, targeting contractors who prioritize operator retention alongside equipment performance. Additionally, zero tail swing models compliant with stringent emissions standards have been released, demonstrating how regulatory requirements can coexist with operational efficiency improvements.
Beyond mechanical improvements, digital integration is becoming a competitive differentiator. Telematics platforms that monitor equipment utilization, fuel consumption, and maintenance schedules are increasingly standard features rather than premium add-ons. This connectivity supports fleet management optimization and provides data that contractors use to justify equipment investments through measurable productivity gains.
Policy and Regulatory Environment
Regulatory frameworks are simultaneously constraining and enabling market growth. Emissions standards, particularly in Europe and North America, have compelled manufacturers to redesign engine systems and exhaust treatment components. While compliance adds upfront costs, it also creates barriers to entry that consolidate market positions among established players with sufficient engineering resources and certification infrastructure.
PW Consulting
The European Union Stage V emissions standards, which mandate reduced nitrogen oxide and particulate matter outputs for non-road diesel engines, have been in effect since 2021 and continue to shape product development roadmaps. Manufacturers that achieve compliance efficiently gain access to regulated markets without disruption, while those lagging face shipment delays and potential market exclusion. Similar regulatory pressures exist in other regions through varying mechanisms, creating a complex compliance landscape that rewards manufacturers with global engineering capabilities and diversified production footprints.
Beyond emissions, safety regulations and import policies influence market access. Tariff structures on certain origin countries affect competitive pricing dynamics, with duties on Chinese-origin equipment over specific value thresholds altering the cost advantage that some importers previously enjoyed. These trade policies encourage regional manufacturing investments and supply chain localization strategies among major players seeking to maintain price competitiveness in key markets.
Demand-Side Shifts and Construction Sector Dynamics
Changes in how construction projects are executed and funded are driving sustained equipment demand. Global construction output expanded by 3.5 percent in 2024, supported by infrastructure investments exceeding 10 trillion USD annually. This capital flow into roads, utilities, urban redevelopment, and commercial construction creates consistent demand for compact equipment that can operate in space-constrained environments where larger machinery cannot function effectively.
A critical demand-side dynamic involves labor availability. The construction sector in the United States alone faced a shortage of approximately 500,000 workers in 2024. This labor gap is accelerating demand for compact automation equipment that reduces manual labor requirements and increases individual operator productivity. Contractors are increasingly willing to invest in higher-specification micro excavators with operator aids, improved hydraulics, and telematics because these features help maximize output from smaller crews and reduce reliance on multiple personnel for tasks that compact equipment can handle more efficiently.
Urbanization trends further support demand. As cities expand and existing infrastructure requires renovation, demolition and rebuilding activities increasingly occur in dense neighborhoods where large equipment faces access restrictions, noise limitations, and safety constraints. Micro excavators fit precisely into this operational paradigm, enabling contractors to work in alleys, residential zones, and interior spaces without the logistical burden of larger machines.
Supply Chain and Cost Structure Dynamics
Cost pressures and supply chain stabilization efforts are reshaping manufacturing strategies. Raw material pricing for construction machinery inputs, including hot-rolled steel coils, averaged around 650 USD per metric ton in the fourth quarter of 2024 amid gradual supply chain stabilization. While this represents improvement from earlier volatility, cost management remains a strategic priority as manufacturers balance material expenses with competitive pricing expectations.
Manufacturers are responding through multiple approaches: optimizing component design to reduce material usage, negotiating long-term supplier agreements to lock in pricing, and exploring alternative material specifications where performance requirements allow. Regional production strategies are also gaining traction, with companies establishing or expanding manufacturing footprints closer to end markets to reduce logistics costs, mitigate tariff impacts, and improve supply chain resilience.
The cost structure evolution is not purely defensive. Efficient supply chain management and localized production can become competitive advantages, enabling manufacturers to offer more consistent pricing, faster delivery times, and improved after-sales support. These operational capabilities increasingly factor into procurement decisions alongside equipment specifications.
Competitive Landscape and Leading Strategies
The market features a diverse competitive field spanning established global manufacturers, specialized compact equipment producers, and regional players with strong local presence. Market concentration metrics indicate that the top three companies capture approximately 38.5 percent of revenue, while the top five hold roughly 52.8 percent. This concentration level suggests a moderately consolidated landscape where leading players exert significant influence but substantial share remains available for well-positioned competitors.
Leading manufacturers have adopted distinct strategic positioning approaches. Major equipment companies with broad product portfolios leverage their brand recognition, global service networks, and financial strength to offer micro excavators as part of comprehensive fleet solutions. These players emphasize telematics integration, dealer support infrastructure, and the ability to supply equipment across multiple size classes, appealing to large contractors who value single-source procurement and standardized maintenance processes.
Japanese manufacturers have carved out strong positions through specialization in compact and micro segments. Their product architectures emphasize zero tail swing designs, fuel-efficient engine systems, and refined operator interfaces tailored to precision work. These companies often compete on reliability, maneuverability, and segment-specific engineering rather than broad portfolio breadth. Their focus on micro excavators as a core competency rather than a peripheral offering enables deep optimization of weight, size, and functionality for targeted applications.
European and American players contribute through varied approaches. Some emphasize electrification alongside diesel options, offering zero-emission alternatives for urban environments with noise or air quality restrictions. Others focus on GPS integration and grade control technologies that enhance precision for landscaping and utility work. These technology-forward strategies appeal to contractors operating in regulated urban zones or those seeking to differentiate through higher-precision outputs.
Chinese manufacturers have expanded their presence through competitive pricing and increasingly sophisticated feature sets. Their product ranges target emerging markets and cost-sensitive segments while incorporating intelligent control systems and efficiency improvements that narrow the perceived quality gap with established brands. Trade policy dynamics, including tariff structures on certain origin equipment, influence the competitive balance in specific regions, prompting some Chinese manufacturers to pursue regional assembly strategies or partner with local distributors to navigate trade barriers.
Strategic differentiation is evolving along several dimensions. Electrification represents a growing battleground, with manufacturers offering electric micro excavators under specific weight thresholds for applications where indoor operation, noise sensitivity, or emissions restrictions favor battery-powered alternatives. Telematics and data connectivity are becoming standard expectations rather than differentiators, pushing competition toward deeper integration with contractor fleet management systems and predictive maintenance capabilities.
Excavator Attachments Market
Market evolution trends point toward continued consolidation pressure alongside ongoing fragmentation in niche segments. Larger players may pursue acquisitions to gain specialized technology, regional distribution networks, or product line completeness. At the same time, specialized manufacturers with strong micro excavator expertise can thrive by serving specific applications or geographic markets with focused value propositions. New entrants face high barriers due to engineering complexity, certification requirements, dealer network development costs, and the need to establish reliability reputations, but opportunities exist for companies that bring distinctive technology or serve underserved application niches.
Future Trends and Commercial Implications
Looking toward 2032, several trends will shape market trajectories and create distinct commercial opportunities. The first and most consequential is the acceleration of electrification and alternative powertrain adoption. While diesel micro excavators will remain dominant in the near term, electric models are gaining traction for specific use cases where operational restrictions, urban noise ordinances, or corporate sustainability commitments favor zero-emission equipment. As battery technology improves and charging infrastructure expands, electric micro excavators will capture growing share in landscaping, indoor construction, and municipal applications. Manufacturers that develop robust electric platforms with competitive runtime, fast charging options, and integrated energy management will position themselves advantageously for regulated urban markets and sustainability-focused contractors.
The second trend involves deepening digital integration and data-driven equipment management. Telematics will evolve from basic utilization tracking to predictive maintenance, remote diagnostics, and performance optimization recommendations. Contractors will increasingly expect equipment that integrates seamlessly with their digital workflows, providing data that supports operational decisions, reduces downtime, and improves resource allocation. Companies that offer open data architectures, compatible fleet management software, and responsive remote support will differentiate themselves as the market shifts from evaluating individual machine specifications to assessing total fleet intelligence capabilities.
Excavator Market
The third trend relates to continued urbanization and infrastructure renewal driving sustained demand for compact, maneuverable equipment. As cities densify and renovation activities displace new ground-up construction in many developed markets, the operational niche for micro excavators will expand. Contractors will require equipment that navigates confined spaces, complies with noise and emissions restrictions, and delivers precision work without the logistical complexity of larger machinery. This environment favors manufacturers with strong zero tail swing designs, versatile attachment compatibility, and configurations optimized for urban job site constraints.
These trends carry both opportunities and risks. Electrification promises market expansion but introduces uncertainty around battery costs, charging logistics, and performance parity in demanding applications. Digital integration enhances value but raises expectations for software reliability, cybersecurity, and ongoing technical support that smaller manufacturers may struggle to meet consistently. Urban demand growth is robust but depends on continued infrastructure spending and regulatory environments that sustain construction activity. Economic cycles, interest rate fluctuations, and shifts in government investment priorities could moderate growth rates, particularly in segments dependent on discretionary development rather than essential infrastructure maintenance.
Commercial opportunities will accrue to companies that align product development with these trajectories. Manufacturers can capture growth by expanding electric model ranges, enhancing telematics integration, and optimizing products for urban constraints. Investors can evaluate companies based on their technology roadmaps, regional market access, and ability to navigate regulatory and trade complexity. Procurement professionals can focus on total cost of ownership considerations that include operator efficiency, maintenance predictability, and compliance assurance rather than initial purchase price alone.
Strategic Recommendations for Decision Makers
Manufacturers should prioritize technology roadmaps that balance emissions compliance, electrification capabilities, and digital integration while maintaining cost competitiveness. Investing in zero tail swing architectures, operator comfort improvements, and telematics platforms will address the key purchase drivers identified by contractors. Companies should also evaluate regional production and supply chain strategies to navigate tariff dynamics and raw material cost variability, ensuring that pricing remains attractive while margins are protected through operational efficiency and localized support infrastructure.
Investors evaluating opportunities in this market should focus on companies with clear technological differentiation, strong regional market access, and capabilities to manage regulatory complexity. The moderate market concentration suggests room for growth, but sustained value creation will favor players that can execute on product innovation, service network development, and strategic geographic positioning. Assessing a company's electrification roadmap, data integration maturity, and ability to adapt to trade policy shifts will provide insight into long-term competitive positioning beyond current revenue performance.
Procurement teams and contractors should approach equipment selection with a total cost of ownership mindset that accounts for operator productivity, maintenance predictability, compliance assurance, and fleet integration capabilities. The labor shortage environment makes operator efficiency and retention increasingly valuable, supporting investment in equipment with improved ergonomics, automation aids, and telematics that reduce downtime and simplify fleet management. Evaluating suppliers based on their ability to deliver consistent product availability, responsive service support, and compliance with regional emissions standards will mitigate operational risk and support long-term project execution.
For stakeholders seeking detailed segment-level data, regional analysis, competitive benchmarking, and customized strategic recommendations, comprehensive market research reports provide the depth required for precise planning. Access to granular data across product types, application segments, regional dynamics, and company profiles enables more informed decisions regarding market entry, investment allocation, product development priorities, and procurement strategies tailored to specific business contexts.
For detailed analysis of this topic, please visit the official page: Worldwide Micro Excavator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Diesel Lubricity Improver Market: Why 4.2% CAGR Upsets Old Growth Narratives
By PW Consulting, 2026-09-18
Worldwide Diesel Lubricity Improver Market: Strategic Trends and Commercial Opportunities (2025–2032)
1. Market Snapshot and Core Challenges
The global diesel lubricity improver market has evolved from a compliance-driven niche into a strategically significant segment within the broader fuel additives landscape. Valued at approximately $475 million in 2020, the sector expanded steadily through the mid-2020s, reaching roughly $585 million by 2025. Forward-looking projections place the market on a trajectory to exceed $780 million by 2032, supported by a compound annual growth rate of around 4.2 percent. This growth reflects a structural shift rather than a cyclical uptick, as refiners, additive formulators, and engine manufacturers navigate the persistent tension between emissions reduction mandates and equipment durability. The consistent upward trajectory underscores how lubricity management has become embedded in fuel specification compliance, supply chain planning, and downstream performance expectations across multiple geographies and end-use sectors.
Behind the headline figures, the industry confronts three interconnected challenges that will shape competitive positioning over the next several years. First, the regulatory baseline continues to tighten. Standards such as EN 590 and GB 19147 mandate a maximum HFRR wear scar diameter of 460 μm at 60°C, which effectively compels the use of lubricity enhancers in ultra-low sulfur diesel formulations. While this creates steady baseline demand, it also compresses the value proposition for basic compliance products, pushing suppliers to differentiate through multi-functional performance rather than single-attribute improvement. Second, feedstock economics introduce volatility into cost structures. The production of diesel lubricity improvers commonly relies on fatty acid derivatives and esters, whose pricing is influenced by upstream vegetable oil markets and crude oil-derived feedstocks. Fluctuations in these input costs ripple through manufacturing economics, squeezing margins for formulators that lack robust hedging strategies or diversified sourcing networks. Third, the transition toward advanced combustion technologies and higher biofuel blending rates is altering the performance envelope. Deposit control, oxidation stability, and cold-flow behavior are increasingly intertwined with lubricity requirements, meaning that legacy stand-alone improvers face pressure to integrate into broader additive packages that deliver synergistic engine protection.
For executives and strategists, these dynamics translate into a market where volume growth is relatively predictable but margin and differentiation trajectories are highly contingent on formulation strategy, supply chain agility, and regulatory interpretation. Companies that treat lubricity improvement as a commodity compliance exercise risk being squeezed by price competition and feedstock exposure, while those that position their offerings as integrated performance solutions capture greater resilience and pricing power. The next section examines the drivers intensifying these shifts.
2. Key Drivers Reshaping the Market
Technological Innovation and Formulation Evolution
Advancements in additive chemistry are redefining what a lubricity improver can deliver beyond baseline wear protection. Formulators are increasingly designing molecules and blends that address HFRR wear scar requirements while simultaneously contributing to deposit mitigation, corrosion resistance, and compatibility with higher biofuel content. This multi-functional approach is particularly relevant as engine manufacturers optimize fuel injection systems for efficiency and emissions control, demanding fuels that protect precision components without compromising combustion cleanliness. Recent product launches illustrate this trajectory. In February 2025, TotalEnergies introduced the RUBIA OPTIMA diesel lubricity improver, tailored for ultra-low sulphur diesel engines in Europe. The launch signals a broader industry pattern: rather than offering narrow lubricity additives, leading suppliers are packaging performance attributes that align with real-world operating conditions and regional fuel specifications. For engine and vehicle manufacturers, this evolution means a growing preference for additive partners that can validate performance across multiple parameters, reducing the burden of multi-supplier qualification and simplifying fuel quality assurance.
Policy and Regulatory Environment
Regulation remains the most reliable demand anchor for diesel lubricity improvers. The widespread adoption of ultra-low sulfur diesel has eliminated naturally occurring sulfur compounds that historically contributed to fuel lubricity, making additives essential for protecting fuel pumps, injectors, and cylinder components. Global fuel standards codify this need through measurable HFRR thresholds, creating a consistent compliance pull across mature and emerging markets. In parallel, environmental agencies maintain oversight of additive formulations to ensure that lubricity enhancements do not undermine emissions performance or air quality objectives. The U.S. EPA, for example, maintains a registered diesel additives list updated as of March 2025 that includes multiple approved lubricity improver formulations for commercial use. This registration framework increases transparency for end-users but also raises the bar for product documentation, testing, and ongoing compliance management. For suppliers, the regulatory environment rewards those with established testing infrastructure, clear homologation pathways, and the ability to adapt formulations as regional standards evolve.
Demand-Side Shifts in Vehicle and Industrial Use
Demand patterns are diverging by application, creating distinct opportunity pockets. Heavy-duty vehicles continue to represent the largest application segment, driven by long-haul logistics, commercial fleet operations, and the durability requirements of high-pressure common-rail injection systems. Passenger vehicles, while smaller in absolute volume, benefit from increasing fuel quality expectations and the persistence of diesel in certain regional markets, particularly where total cost of ownership remains favorable. Industrial and stationary engines constitute another meaningful demand base, especially in power generation, agricultural equipment, and remote-site operations where fuel storage duration and variable operating conditions amplify the need for wear protection. Across these segments, the common thread is that lubricity management is no longer a standalone concern; it is integrated into broader fuel reliability and asset-protection strategies. Fleet operators and industrial buyers are increasingly evaluating total cost of ownership, maintenance intervals, and warranty implications, which broadens the relevance of additive performance beyond immediate wear metrics.
Supply Chain and Cost Structure Dynamics
Cost structures in the lubricity improver market are closely tied to raw material availability and pricing. Fatty acids and ester-based feedstocks form the backbone of many formulations, linking production economics to agricultural commodity cycles and petroleum-derived intermediates. When these input costs fluctuate, manufacturers face pressure on margins unless they can adjust blend architectures, optimize process efficiency, or pass through cost changes without losing volume. The implication is clear: competitive advantage is shifting toward companies with geographically diversified sourcing, long-term supplier agreements, and formulation flexibility that allows substitution among functionally equivalent chemistries. Refineries and terminal operators also influence demand patterns through blending economics and logistics. Additive inclusion decisions at the terminal stage can vary by region, season, and fuel specification, meaning that distribution and partnership models matter as much as molecular performance. Suppliers that can integrate technical service, blending guidance, and inventory alignment into their commercial offerings reduce friction for customers and strengthen retention in a market where switching costs are sometimes lower than the operational risk of inconsistent fuel quality.
PW Consulting
3. Competitive Landscape and Leading Strategies
The competitive map in diesel lubricity improvers is characterized by a blend of global specialty chemical companies, fuel additive specialists, and integrated energy suppliers. Market concentration metrics indicate that a limited number of players command a substantial share of revenues, with the top three holding approximately 45.2 percent and the top five reaching around 62.4 percent. This footprint suggests a market where scale, technical credibility, and customer relationships create meaningful barriers, but it also leaves room for regional specialists and application-focused entrants in underserved niches.
Infineum International Limited, headquartered in the United Kingdom, operates as a major global supplier of diesel fuel additives, with dedicated lubricity improvers formulated for ultra-low sulfur diesel to meet HFRR standards such as EN 590 and equivalent specifications. Its strength lies in broad formulation expertise and a global technical support footprint that helps refiners and distributors align additive programs with regional fuel quality requirements. The Lubrizol Corporation, based in the United States, provides comprehensive diesel performance additive packages with lubricity improvers targeting fuel injection equipment protection in low-sulfur diesel fuels. Lubrizol’s differentiation often comes from packaging lubricity within broader performance solutions, giving customers a streamlined route to multi-attribute fuel improvement. Afton Chemical Corporation, also U.S.-based, offers the HiTEC series lubricity improvers and multi-functional diesel additives designed to restore lubricity in ULSD while meeting global fuel specifications. Afton’s emphasis on brand recognition and application-specific formulations supports a strategy centered on validated performance and customer education.
European chemical majors contribute scale and regional regulatory fluency. BASF SE supplies diesel fuel additives including acidic and non-acidic lubricity improvers for automotive, commercial, and industrial diesel applications, leveraging its broad chemical portfolio to support customized solutions. Evonik Industries AG produces performance additives including lubricity enhancers for low-sulfur diesel fuels used in transportation and industrial sectors, combining specialty chemistry capabilities with application engineering. LANXESS AG and Clariant AG further round out the European field, with LANXESS providing chemical additives for fuels, including lubricity improvement solutions for diesel, and Clariant supplying a fuel additives portfolio containing lubricity improvers compliant with global diesel fuel quality standards. These companies often compete on technical depth, compliance documentation, and the ability to support large-volume programs across multiple jurisdictions.
In the United States, Innospec Inc. develops and markets diesel lubricity improvers such as OLI series products for ULSD and biofuel blends to ensure compliance with wear scar diameter requirements, positioning itself around assurance of specification compliance and compatibility with evolving blending trends. Chevron Oronite Company LLC specializes in fuel additives with lubricity improvers for diesel fuels, supporting refinery and terminal blending to meet international lubricity standards. Its refinery-facing orientation reinforces a strategy built on technical service at the point of fuel production and distribution. Baker Hughes Company delivers fuel additives via its specialty chemicals segment, including lubricity improvers for diesel fuel systems, reflecting the broader trend of large industrial groups using diversified platforms to address fuel performance needs.
Regional and emerging-market players add another dimension to the landscape. Dorf Ketal Chemicals, based in India, offers specialized diesel lubricity improvers and fuel treatment chemicals focused on ULSD applications in emerging markets. Its positioning highlights a growing opportunity set in regions where fuel quality improvement programs are expanding, infrastructure is modernizing, and cost-sensitive formulators seek reliable performance at competitive price points. TotalEnergies SE complements this dynamic from the integrated energy side, marketing diesel additives and lubricity improvers through its additives and special fuels division, including products for ultra-low sulfur diesel. Its February 2025 launch of the RUBIA OPTIMA diesel lubricity improver for ultra-low sulphur diesel engines in Europe demonstrates how integrated energy companies can use product updates to reinforce performance positioning in regulated markets.
Strategically, the leaders differentiate along several axes: multi-functional formulation capability, regulatory compliance infrastructure, technical service depth, and supply chain resilience. Some compete by offering broad additive packages that reduce the number of suppliers a customer must manage. Others emphasize application-specific validation for heavy-duty, passenger, or industrial use. A third group focuses on regional execution, tailoring products and service models to local fuel standards, logistics, and price sensitivity. The market is likely to see continued consolidation among players seeking scale and portfolio breadth, while also witnessing targeted entry or expansion by companies that serve specific geographies or application niches with lean, high-value propositions. For customers, this means more choices but also greater importance in evaluating total value rather than price per kilogram alone.
4. Forward Trends for 2026–2032
Looking ahead, three trends are likely to shape the diesel lubricity improver market over the next several years. The first is the shift from single-attribute lubricity additives to integrated performance packages. As engine equipment becomes more sensitive to deposits, corrosion, and compatibility with renewable blends, customers will increasingly favor formulations that address multiple performance parameters in a single addition step. This favors suppliers that can demonstrate cross-attribute synergy and provide validated testing for real-world operating conditions, opening opportunities for premium positioning and longer-term customer partnerships.
Lubricant Viscosity Index Improvers Market
The second trend is the continued expansion of lubricity improvement demand in regions where fuel quality standards are tightening or where biofuel blending is increasing. Regulatory baselines such as EN 590 and GB 19147 provide a durable anchor in established markets, while emerging economies pursuing fuel quality upgrades and cleaner diesel programs create incremental volume opportunities. Suppliers with strong regional technical presence, flexible formulation options, and credible compliance documentation are best placed to capture this growth. At the same time, the relationship between lubricity enhancers and higher biofuel blends remains an area of active development, as oxygenated components and varying oxidation behaviors can influence both wear performance and storage stability.
The third trend is cost discipline and supply chain adaptability becoming competitive differentiators. With feedstock exposure to fatty acid derivatives and petroleum-linked inputs, companies that can manage input volatility through diversified sourcing, formulation flexibility, and efficient blending operations will protect margins more effectively than those dependent on narrow supply paths. This dynamic may accelerate supplier consolidation in some segments while encouraging niche players to compete on agility, localized service, and rapid response to regional specification changes. A related uncertainty is the pace and shape of fuel transition strategies. If diesel demand in certain passenger segments declines faster than expected, growth may concentrate even more heavily in heavy-duty, industrial, and backup power applications, requiring suppliers to align product roadmaps with where durable diesel use persists. Regulatory interpretations, additive registration updates, and sustainability expectations for feedstocks also introduce variability, making scenario planning essential for both manufacturers and buyers.
5. Strategic Guidance for Decision-Makers
For additive manufacturers and formulators, the priority is to move beyond compliance-only positioning and build demonstrable multi-functional value. Invest in testing that connects lubricity performance with deposit control, engine protection, and compatibility with higher biofuel blends, and align product documentation with the regulatory expectations of key markets. Strengthening supply chain flexibility and feedstock diversification will also be critical to protecting margins amid input cost volatility. Building technical service capabilities that help customers optimize blending and fuel handling can create stickier relationships and reduce exposure to pure price competition.
Fuel Additives Market
For investors, the most compelling opportunities lie in companies with credible formulation differentiation, established compliance infrastructure, and exposure to durable demand in heavy-duty, industrial, and regions undergoing fuel quality upgrades. Evaluate cost structure resilience, sourcing strategy, and the ability to scale multi-functional products as indicators of long-term competitiveness. Monitor how product portfolios evolve relative to biofuel blending trends and regional specification shifts, as these will influence both volume growth and margin profiles. Companies that can balance global reach with regional execution are likely to outperform in a market where local fuel standards and logistics matter.
For procurement and fuel quality stakeholders, the focus should be on total value rather than unit price alone. Compare additive programs on HFRR compliance assurance, compatibility with existing fuel handling practices, storage stability, and the supplier’s ability to support blending optimization and documentation needs. Where possible, consolidate supply around partners that can deliver consistent performance across applications and provide reliable technical support during specification changes or feedstock transitions. Treat supplier selection as a risk-management decision that affects maintenance costs, warranty exposure, and operational reliability over time. For those seeking a more granular view of regional dynamics, application splits, and formulation-level segmentation, the full market research report provides detailed breakdowns and tailored recommendations to support planning and procurement decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Diesel Lubricity Improver Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
How Asia Pacific's 8.2B Lead and 6.15% CAGR Are Redefining the AC Motor Controllers Market
By PW Consulting, 2026-09-18
Worldwide AC Motor Controllers Market: Strategic Trends and Commercial Opportunities (2025–2032)
Market Landscape and Core Challenges
The global AC motor controllers market has matured into a critical enabler of industrial efficiency and electrification. Between 2020 and 2025, the sector expanded from approximately USD 13.7 billion to USD 18.5 billion, reflecting a compound annual growth rate of 6.15% through 2032, when it is projected to reach USD 28.1 billion. This trajectory is not merely incremental; it signals a structural shift where motor control infrastructure is moving from a maintenance-driven commodity to a strategic asset for energy management, process optimization, and automation.
Despite this robust expansion, the industry faces three interconnected challenges that will define competitive positioning in the coming years. First, supply chain fragmentation and component volatility are testing margin resilience. While wide-bandgap semiconductor pricing has shown periodic relief, other critical inputs such as copper-based PCB materials have experienced sharp cost escalations, forcing manufacturers to balance pricing power against volume commitments. Second, regulatory complexity is accelerating fragmentation across regional compliance frameworks. Safety and efficiency mandates are no longer optional; they dictate design architectures, certification pathways, and time-to-market. Firms that treat compliance as an afterthought face escalating rework costs and delayed commercialization. Third, the integration of advanced control algorithms with legacy infrastructure creates deployment friction. End users increasingly expect plug-and-play interoperability, yet many facilities operate mixed-vendor environments with varying communication protocols and cybersecurity baselines. Bridging this gap requires more than hardware performance; it demands ecosystem-level compatibility and lifecycle support.
These pressures are reshaping how value is captured. Companies that can standardize compliance, stabilize component sourcing, and simplify integration are gaining share, while those relying on fragmented product lines or reactive supply strategies are seeing margin compression. The market is no longer growing uniformly; growth is concentrating around application segments that deliver measurable energy savings, process reliability, and scalability.
Key Drivers Shaping Market Dynamics
Technological Innovation and Control Architecture Evolution
The most visible driver is the maturation of intelligent control architectures that embed optimization directly into drive hardware and firmware. Recent product introductions highlight a shift toward self-tuning parameters, adaptive torque control, and built-in energy management functions that reduce the need for external supervisory systems. At major industry exhibitions, manufacturers have demonstrated drives with integrated optimization features that adjust operating profiles based on load conditions, reducing energy waste without requiring extensive re-engineering of existing lines. This evolution lowers the barrier to adoption for mid-tier industrial users and expands the addressable base beyond high-performance automation.
Cybersecurity and functional safety are now first-class design requirements rather than add-on certifications. Updated drive platforms have begun incorporating hardened communication stacks and secure update pathways, responding to the reality that connected motor control systems are increasingly exposed to operational technology threats. As facilities integrate drives into broader industrial networks, vendors that provide verifiable security baselines and clear lifecycle patching policies are differentiating themselves in procurement evaluations.
Policy and Regulatory Momentum
Regulatory frameworks are acting as a powerful demand catalyst, particularly where energy efficiency mandates directly influence equipment selection. Efficiency standards that require higher performance classes for AC motors above defined power thresholds have accelerated the replacement of fixed-speed setups with variable-speed solutions. In parallel, safety regulations for adjustable speed power drive systems remain mandatory across multiple jurisdictions, shaping both product certification and system integration practices. These requirements are not uniform; they vary by region and application, which creates compliance complexity but also rewards vendors with global certification portfolios and regionalized support capabilities.
The cumulative effect is a regulatory tailwind that favors controllers capable of delivering measurable efficiency gains while meeting stringent safety and interoperability criteria. Procurement teams are increasingly aligning equipment specifications with compliance roadmaps, turning regulation from a constraint into a selection filter that narrows the field to vendors with proven adherence and documentation rigor.
Demand-Side Shifts in Industrial and Commercial End Users
On the demand side, operational resilience and total cost of ownership are driving procurement behavior. Industrial operators are prioritizing motor control solutions that reduce maintenance downtime, improve process consistency, and offer remote diagnostics. HVAC and water management sectors are similarly focused on energy consumption reduction, where variable-speed control delivers fast payback through reduced fan, pump, and compressor loads. Meanwhile, electrification trends in mobility and material handling are expanding the use of precision motor control in applications that require responsive torque and regenerative capabilities.
These demand patterns are shifting the evaluation criteria from unit price to lifecycle value. End users are more willing to invest in controllers that provide clearer visibility into operating conditions, predictive maintenance signals, and integration with existing control ecosystems. The result is a market where software-enabled features, service agreements, and deployment support increasingly influence purchasing decisions alongside hardware specifications.
Supply Chain and Cost Structure Realignment
Cost structures are being reshaped by both component dynamics and trade policy. On the input side, power semiconductor pricing has experienced periodic declines due to expanded production capacity, easing pressure on bill-of-materials costs for certain drive categories. However, this relief is uneven; other materials critical to drive construction have seen price increases tied to mining disruptions and logistics constraints. These fluctuations require proactive sourcing strategies, dual-sourcing arrangements, and design flexibility to substitute components without compromising performance or certification status.
Trade policy adds another layer of complexity. Tariff adjustments on specific import categories have altered regional cost comparisons, prompting manufacturers and distributors to reassess sourcing footprints and regional assembly strategies. Companies that maintain diversified supply chains and clear regional compliance documentation are better positioned to navigate these shifts, while those heavily dependent on single-source imports face greater exposure to cost volatility and lead-time risk.
Competitive Landscape and Leading Strategies
The competitive field is defined by a blend of multinational incumbents with broad automation portfolios and specialized players with deep application expertise. Leading firms are pursuing differentiation through a combination of platform breadth, application-specific tuning, and ecosystem integration. Rather than competing solely on hardware specifications, top vendors are expanding their value proposition to include deployment services, firmware lifecycle management, and interoperability with prevailing control architectures.
Strategic positioning varies by company focus. Large industrials leverage integrated drive-and-control platforms to serve complex automation environments, emphasizing precision, scalability, and engineering support. In contrast, specialists often concentrate on high-volume application segments such as HVAC, pumping, and wastewater, where energy efficiency and ease of commissioning drive adoption. Recent product updates have reinforced these strategies: revised drive lines with enhanced security features, expanded low-voltage options, and catalog updates that broaden compatibility with common industrial use cases. Trade show introductions have also highlighted optimization capabilities and process-industry refinements, signaling a market where performance is increasingly defined by how well a controller fits into a specific operational context.
Distribution and regional reach are becoming equally important. Appointment of new distribution partners in key growth regions reflects a deliberate push to improve local availability, technical support, and faster fulfillment. This is particularly relevant where end users expect shorter lead times and on-the-ground application engineering. As a result, competitive advantage is shifting toward vendors that can combine global product consistency with regional responsiveness.
Market consolidation and specialization are unfolding simultaneously. Larger players are strengthening their positions through portfolio alignment and cross-selling into adjacent automation and energy management offerings. At the same time, niche suppliers continue to gain traction by focusing on specific applications, cost-sensitive segments, or unique integration requirements. New entrants face high barriers in certification, reliability validation, and channel development, but opportunities remain in underserved application pockets and regions where localized support is scarce. The overall trend is toward a layered competitive structure: broad-platform leaders at the top, application-focused specialists in the middle, and regional distributors or system integrators extending reach and tailoring solutions to local requirements.
AC Servo Motor Market
Future Outlook: Trends and Commercial Implications
Looking ahead to the 2026–2032 period, three trends are likely to shape commercial opportunity. First, intelligent optimization and edge-level analytics will become standard expectations rather than premium features. Drives that can autonomously adjust operating parameters, flag degradation signatures, and communicate efficiently with supervisory systems will be favored in procurement processes. This creates opportunities for vendors that can package control hardware with actionable diagnostics, simplified configuration tools, and clear data interfaces.
Second, regulation-driven adoption will continue to expand the addressable market, especially where efficiency mandates accelerate retrofit and replacement cycles. Regions with active ecodesign and motor efficiency policies will see sustained demand for variable-speed solutions, while safety and interoperability standards will push system designers toward platforms that simplify compliance documentation and multi-vendor integration. Commercial winners will be those that translate regulatory requirements into turnkey deployment pathways rather than leaving end users to assemble compliance pieces independently.
Third, supply chain and cost dynamics will reward agility. Component price cycles will remain uneven, and trade policy will continue to influence regional cost structures. Firms that invest in design modularity, diversified sourcing, and regional inventory positioning will be better equipped to protect margins and maintain service levels. For buyers, this environment favors suppliers with transparent lead-time communication, flexible configuration options, and clear roadmaps for component lifecycle management.
PW Consulting
Potential risks include the possibility that component cost relief could be temporary, that regulatory divergence could increase certification burden for global players, and that rapid feature expansion could outpace end-user readiness for integration and training. Companies that assume uniform adoption or stable input costs may face margin surprises. Conversely, organizations that prepare for variability and invest in deployment simplicity will be better positioned to convert market growth into sustainable commercial gains.
Strategic Recommendations for Decision-Makers
For manufacturers and product leaders, the priority is to align hardware roadmaps with the shifting basis of competition. This means investing in control features that reduce commissioning complexity, strengthening cybersecurity and safety documentation, and building modular designs that can accommodate component substitutions without re-certification delays. Differentiators will increasingly come from how quickly a solution can be deployed, how clearly it communicates operating status, and how well it fits into existing automation ecosystems.
For investors, the market offers opportunities in companies that demonstrate platform cohesion, regional channel strength, and disciplined cost management. Valuation and growth potential will depend less on headline volume and more on the ability to protect margins amid input price fluctuation, expand in regulation-driven segments, and capture share through application-focused solutions. Monitoring product launch cadence, distributor expansion, and compliance readiness provides early signals of competitive momentum.
For procurement and operations leaders, the focus should shift from unit price to total lifecycle value. Evaluation criteria ought to include energy performance under real load profiles, integration effort with current control infrastructure, support availability in the region, and the vendor’s ability to sustain firmware and security updates over the asset life. Supplier diversity and clear service-level expectations can reduce exposure to supply disruptions and configuration delays.
Timely access to detailed segmentation data, regional cost structures, and application-level demand patterns can sharpen these decisions and reduce execution risk. For organizations seeking a deeper view of the market, including component-level cost dynamics, regional policy timelines, and competitive positioning across application segments, a comprehensive market report can provide the granular context needed to align strategy with the next phase of growth.
Electric Vehicle Motor Controller Market
For detailed analysis of this topic, please visit the official page: Worldwide AC Motor Controllers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


