



Category: market research
PW Consulting: Manual Motor Starter Market to Hit $857M by 2032, 4.5% CAGR
By PW Consulting, 2026-09-07
Unlocking Market Intelligence: Inside the Manual Motor Starters Landscape for 2026 and Beyond
The global industrial landscape is undergoing a profound transformation, driven by the dual pressures of operational efficiency and stringent safety compliance. Within this intricate ecosystem, the Manual Motor Starters Market remains a critical cornerstone. These electromechanical devices are not mere components; they are the primary interface for manual isolation, control, and overcurrent protection in a vast array of electrical installations. For strategic planners, investors, and industry executives, understanding the trajectory of this market is no longer optional—it is a prerequisite for risk mitigation and opportunity capture.
Worldwide Fiber Expansion Joints Market
PW Consulting is pleased to introduce a comprehensive market research study that dissects the current state and future potential of the global Manual Motor Starters sector. This article serves as a strategic overview, highlighting the key dynamics, competitive tensions, and growth vectors that define the landscape between 2026 and 2032. While we provide high-level context here, the full granularity of our analysis is reserved for the detailed report, available exclusively through our platform.
Worldwide Clock Chip Market
The Macro Trajectory: Growth Amidst Stability
When evaluating the historical performance of the Manual Motor Starters Market, the data reveals a story of steady resilience rather than volatile spikes. Following a trajectory that began at a substantial baseline in the early 2020s, the market has demonstrated consistent appreciations in value year over year. From a valuation in 2020, the market grew to cross significant thresholds by 2025, reflecting the underlying demand from industrial manufacturing, infrastructure development, and energy sectors.
AI Visual Intelligent Analysis Solution Market
Looking forward, our forecast models indicate a continued positive trend. The Compound Annual Growth Rate (CAGR) projected for the period through 2032 underscores a moderate but reliable expansion. This growth is not merely a function of population increase, but rather a structural shift towards modernizing aging electrical infrastructure and adhering to updated safety standards globally. The cumulative revenue value over the forecast period represents a significant opportunity for stakeholders who can position themselves correctly within the supply chain.
Strategic Value for 2026 Decision-Making
Why does this matter specifically for decisions being made in 2026? The answer lies in the timing of capital expenditure cycles. As industries plan for upgrades and expansions in the mid-decade, the procurement of motor protection and control units must align with long-term reliability goals. A reactive approach to sourcing manual motor starters can lead to procurement inefficiencies, compatibility issues, and compliance risks.
This research is designed to turn uncertainty into actionable intelligence. By analyzing the market size evolution and the drivers behind it, executives can better allocate resources. The study moves beyond simple top-line numbers to explore the structural forces reshaping the demand side. Understanding the velocity of adoption in critical sectors allows decision-makers to anticipate volume shifts before they impact supply availability or pricing power.
Core Market Dynamics and Regulatory Tailwinds
The operational environment for manual motor starters is heavily influenced by technical standards and regulatory frameworks. These devices are fundamentally defined by their ability to provide manual isolation, control, and overcurrent protection in strict accordance with IEC and UL standards. This rigorous requirement creates a high barrier to entry for non-compliant manufacturers and ensures that safety remains a primary market differentiator.
Furthermore, the technical specifications of these devices are becoming increasingly demanding. Manufacturer specifications often require compliance with short-circuit breaking capacity requirements up to 100 kA at 400 VAC. This technical ceiling dictates the engineering roadmap for vendors and influences the pricing tiers of high-performance units. On the hazardous side of operations, specific product lines, such as factory-sealed manual motor starters, are engineered for use in hazardous locations including Class I, Division 1 and 2 areas. These niche requirements carve out specialized segments within the broader market, where consistent supply and certified safety take precedence over pure cost competition.
Pricing dynamics also play a critical role in market accessibility. The average selling price for industrial-grade manual motor starters typically ranges from $150 to $450, depending largely on the current rating, which can span from 10A to 100A, and the sophistication of protection features. This pricing sensitivity means that procurement strategies must carefully balance specification requirements against budget constraints, a tension this report analyzes in depth.
Competitive Landscape: The Titans and the Challengers
The market is not a free-for-all; it is defined by a specific set of established players and regional specialists. Our analysis identifies key companies that are driving innovation and market share acquisition. The competitive structure is moderately concentrated, with the top players commanding significant influence over product roadmaps and pricing standards.
Leading the charge is ABB, headquartered in Zurich, Switzerland. ABB has long been recognized for its robust portfolio of motor protection and control. Their specific offering for the Manual Motor Starters Market includes the MS116, MS132, MS165, MO132, and MO165 series. These units are designed to provide comprehensive motor protection and control within compact units, appealing to customers who value space efficiency and integrated functionality.
Schneider Electric, based in France, continues to exert strong influence through its TeSys Deca GV2 and GV3 series. These manual starters and protectors are widely deployed in industrial applications where modularity and ease of integration are paramount. In late 2025, the company released the TeSys Catalog 2026, featuring TeSys Deca Advanced and new Motor Starter Solutions, signaling a continued commitment to product line evolution and catalog expansion.
Eaton, with its headquarters in Dublin, Ireland, offers a diverse range of solutions including the PKZM series, MS series, and Cutler-Hammer B100 manual motor starters. Their breadth of branding allows them to address different legacy system requirements across multiple geographies. Siemens, from Munich, Germany, remains a formidable presence with its 3RV2 series manual motor starters, often embedded in larger automation and machine-building contexts.
Beyond the European and American giants, the landscape includes specialized players contributing to regional stability and product diversity. NOARK Electric, based in Pomona, California, USA, recently released the Ex9S80 Manual Motor Starter as part of the Ex9S series, adding to their lineup of Ex9S series manual motor starters known for built-in fault indication. Fuji Electric, from Tokyo, Japan, provides the Duo Series and Fuji Duo MMS manual motor starters, targeting high reliability in demanding environments. Appleton Electric, located in Marion, Illinois, USA, offers the EDS series factory-sealed manual motor starters, a crucial product for specific hazardous applications. Finally, LS Electric, headquartered in Anyang, South Korea, competes with its Metasol MMS series manual motor starters, emphasizing robust performance and regional supply chain advantages.
The competitive dynamics are not static. They shift with every product release and catalog update. For instance, the sequencing of a new release by a major player in the summer, followed by a catalog expansion by another competitor in the winter, highlights the continuous innovation cycle that defines this market. Stakeholders must monitor these cadence shifts to stay ahead in procurement negotiations and technology adoption.
Segmentation Insights: Beyond the Surface
To truly navigate this market, one must understand the distinct branches of the value tree. The report provides a deep dive into segmentation that goes far beyond simple categorization. We examine the dominance of different technological types, specifically the contrast between Alternating Current and Direct Current based manual motor starters. Each type serves a distinct utility profile, and the volume split reveals much about the current state of industrial electrification.
Additionally, the application landscape is a key determinant of demand stability. Industrial manufacturing remains a primary driver, but sectors such as Oil & Gas, Water & Wastewater, and Mining exhibit unique procurement behaviors and specification requirements. The "Others" category aggregates various secondary applications that often provide early signals of emerging trends. The report analyzes how these applications interact with regional economic activity to create varying demand curves.
Geographically, the market exhibits a fragmented distribution. Demand is not uniform across the globe. Different regions demonstrate varying levels of market maturity and investment in electrical infrastructure. Our analysis breaks down the performance across major territories, including North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. This geographical nuance is essential for companies with global supply chains or those looking to enter new markets, as it reveals where growth pockets are forming relative to saturated zones.
The Strategic Imperative of Market Concentration
Understanding the structure of competition is vital for assessing risk. In markets with high concentration, a few players can dictate terms, whereas fragmented markets offer more procurement flexibility but potentially lower quality assurance. Our data suggests a moderate level of concentration, implying a balanced but competitive oligopoly. This structure benefits the end-user by providing multiple viable suppliers without diluting the collective R&D investment needed to meet evolving safety standards. The ratio of market share held by the top players indicates a healthy level of rivalry that drives product improvements and service enhancements.
What’s Inside the Full Report?
This overview scratches the surface of a comprehensive analytical effort. The full report, "Manual Motor Starters Market," is an exhaustive resource designed for high-level strategy and detailed operational planning. It contains actionable intelligence that cannot be gleaned from press releases or standard industry news.
Readers of the full document will find:
- Detailed historical expenditure analysis from the base year 2025, tracing back to 2020 to establish robust trend lines.
- A granular forecast extending through 2032, detailing the expected trajectory of the 2026 market valuation and its progression into the future.
- In-depth segmentation analysis that correlates specific product types with geographical demand, providing a matrix of opportunity.
- Application-specific buyer power analysis, distinguishing the procurement drivers in heavy industry versus infrastructure sectors.
- Company profiles that go beyond product lists to analyze market positioning, strategic shifts, and competitive responses.
- Regulatory impact assessments, detailing how compliance requirements are shaping the operational landscape for manufacturers and users alike.
- Supply chain and pricing sensitivity models based on current rating specifications and protection feature sets.
The report is built to serve as a reference point for boardroom discussions, R&D planning, and supply chain optimization. It connects the dots between raw regulatory facts, technical specifications, and economic reality.
Conclusion: Positioning for the Future
The Manual Motor Starters Market is at a juncture where safety, efficiency, and technological evolution converge. The projected growth trajectory suggests that demand will continue to rise, supported by the relentless need to protect and control industrial motors across diverse global sectors. For companies operating in or adjacent to this space, the ability to interpret these signals accurately is a competitive advantage.
Relying on high-level headlines is insufficient for the complex decisions of 2026 and beyond. You need the depth. You need the segmentation. You need the competitive nuance. The full scope of this intelligence is available in our detailed market research report. We invite you to explore the complete analysis to equip your organization with the insights necessary to navigate the future of electrical motor protection and control with confidence.
For detailed analysis of this topic, please visit the official page: Manual Motor Starters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AFIS Market to Hit $566M by 2032 with 7.5% CAGR from 2026-2032
By PW Consulting, 2026-09-07
Navigating the Next Decade: A Strategic Preview of the Automated Fingerprint Identification Systems Market
The global security infrastructure is undergoing a fundamental transformation, driven by the escalating demand for precise identity verification and the rapid integration of biometric technologies into critical public and private sectors. As we move beyond the baseline of 2025, the Automated Fingerprint Identification Systems (AFIS) market stands at the intersection of technological evolution and regulatory necessity. PW Consulting has recently finalized a comprehensive market research study focused on the trajectory of this sector from 2026 through 2032. This article serves as a strategic executive preview, outlining the macroeconomic currents, competitive dynamics, and operational imperatives that define this landscape. For enterprise leaders, government contractors, and investment stakeholders, understanding the velocity of this market is no longer optional; it is a prerequisite for informed decision-making in an era where digital identity is the new currency of security.
Worldwide Manual Feeding System Market
The purpose of this insight piece is to delineate the strategic value embedded within our latest report. While the following narrative highlights the structural trends and key players shaping the industry, the full depth of our quantitative analysis—including specific volume projections and structural breakouts—remains exclusive to the complete research document. This approach ensures that our clients receive unfiltered, high-fidelity intelligence necessary for formulating robust strategies in the coming years. The market is not merely growing; it is evolving in complexity, requiring a nuanced understanding of regional variances, technological shifts, and the consolidating nature of the vendor landscape.
Unified Commerce Service Market
Macroeconomic Trajectory and Market Vitality
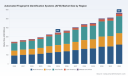
The historical performance of the AFIS sector over the past half-decade provides a robust foundation for future forecasting. Between 2020 and 2025, the market demonstrated consistent resilience and expansion, reflecting the broader adoption of biometric solutions across government and commercial verticals. Our analysis tracks the revenue progression from a baseline of 245.0 million USD in 2020, marking a steady climb to 348.0 million USD by the base year of 2025. This historical arc underscores a fundamental shift where fingerprint identification has moved from a niche forensic tool to a cornerstone of modern identity management infrastructure.
Worldwide Gasoline Lawn Mower Market
Looking forward, the forecast period from 2026 to 2032 suggests an acceleration in valuation. The market is projected to reach 368.96 million USD in 2026, immediately following the base year, and continue its upward trajectory to culminate at 566.0 million USD by 2032. This growth path implies a Compound Annual Growth Rate (CAGR) of 7.5 percent over the forecast horizon. Such a rate indicates a healthy, maturing market that is expanding beyond initial adoption curves into widespread integration phases. For strategists, this CAGR is not just a number; it represents the pace at which capital must be allocated to R&D, partnership development, and market entry strategies to capture value before the growth curve stabilizes.
It is crucial to note that this top-line valuation aggregates diverse revenue streams ranging from hardware procurement to software licensing and maintenance services. The sheer scale of the projected 566.0 million USD endpoint suggests that the addressable market is becoming increasingly crowded. Organizations entering this space must recognize that organic growth will likely need to be supplemented by strategic consolidation or differentiation through algorithmic superiority. The transition from the 348.0 million USD mark in 2025 to the final forecast figures reflects not only volume growth but also potential price erosion due to competition, balanced against premium pricing for advanced AI-driven matching capabilities.
Technological Segmentation and Structural Drivers
The internal architecture of the AFIS market is defined by distinct operational types and application vectors, each carrying different implications for deployment complexity and customer acquisition costs. Our research distinguishes between Live Scan AFIS, Offline AFIS, and other emerging types, highlighting how the mode of capture influences downstream processing speeds and integration requirements. The industry is witnessing a pronounced tilt toward solutions that offer seamless connectivity and real-time processing capabilities. While our detailed report provides the specific revenue attribution for each type, the strategic implication is clear: solutions that bridge the gap between physical capture and digital analysis without latency are commanding the most attention from end-users.
Live scan technologies, which allow for the digital capture of fingerprints without ink and paper, continue to dominate the operational mindset of law enforcement and border control agencies. However, offline systems retain relevance in specific archival and forensic contexts where digital infrastructure may be limited or where retroactive analysis of physical latent prints is required. The balance between these types is shifting as cloud infrastructure becomes more reliable and secure. The move toward cloud-native architectures allows for scalable database management, which is essential as national and international biometric databases expand in size.
Application-wise, the market is primarily anchored by Law Enforcement and Security agencies, which remain the steadfast backbone of AFIS adoption. Criminal investigations utilize these systems for suspect identification and case resolution, while border and immigration authorities leverage them for traveler verification and identity fraud prevention. The interplay between these applications creates a complex demand signal. For instance, increased border security protocols often drive demand for higher throughput scanners, whereas criminal investigation needs prioritize accuracy and latent print matching capabilities. Our report delves into the operational requirements of each segment, helping buyers understand which solution architecture aligns with their specific use case without disclosing the precise share splits that could compromise competitive intelligence within the document.
Furthermore, the integration of multi-modal biometrics is becoming a standard expectation rather than a differentiator. Modern AFIS platforms are increasingly expected to interoperate with facial recognition and iris scanning systems to create a holistic view of identity. This convergence reduces false acceptance rates and enhances security postures. Vendors who fail to adapt their AFIS offerings to support multi-biometric environments risk obsolescence, particularly in high-security government contracts where layered verification is mandated. The strategic takeaway for 2026 and beyond is that standalone fingerprint solutions are losing ground to integrated identity platforms.
Competitive Landscape and Vendor Dynamics
The vendor ecosystem within the AFIS market is characterized by a mix of established multinational technology giants and specialized biometric firms. Our analysis identifies a market concentration that suggests a moderately consolidated environment, where a handful of key players command significant influence over pricing and technology standards. The CR3 and CR5 metrics within our full report quantify this concentration, but qualitatively, it is evident that the battle for market share is being fought on the grounds of algorithmic accuracy, scalability, and global support networks.
NEC Corporation, headquartered in Tokyo, remains a formidable presence with its Integra-ID AFIS/ABIS platform. Their focus on advanced fingerprint matching algorithms for law enforcement and border security positions them as a preferred partner for government-grade contracts. Similarly, Fujitsu Limited leverages its strong IT infrastructure background to provide cloud-based AFIS platforms. By integrating AI-enhanced matching for financial institutions and public security, Fujitsu addresses the dual need for high security and scalable cloud architecture, appealing to sectors beyond traditional policing.
IDEMIA, based in Courbevoie, France, continues to push the boundary with its STORM ABIS cloud-native system and Case AFIS for latent fingerprint identification. Their emphasis on multibiometric searches aligns with the industry trend toward comprehensive identity solutions. HID Global Corporation, operating out of Austin, Texas, takes a hardware-centric approach with modular AFIS/ABIS solutions. Their FBI-certified scanners and livescan management software are critical for government and law enforcement clients who require certified hardware interoperability. These three entities, among others, define the upper tier of the competitive hierarchy.
In the European and emerging markets, companies like DERMALOG Identification Systems GmbH in Hamburg contribute specialized high-speed matching algorithms for civil and criminal identification. Meanwhile, Papillon Systems in Moscow supplies AFPIS multibiometric AFIS with support for palmprint and fingerprint, catering specifically to forensic and law enforcement needs in specific geographic zones. The presence of diverse players such as Sonda Technologies Ltd. from the Republic of Korea and M2SYS Technology from Chennai, India, highlights the global nature of the supply chain. M2SYS, for instance, focuses on scalable cloudABIS platforms with hyper-threaded matching servers, targeting large-scale biometric databases that require heavy computational resources.
Crossmatch Technologies Inc. and SUPREMA from South Korea represent the hardware and integration stronghold. Crossmatch manufactures fingerprint scanners and AFIS integration solutions certified for FBI NGI systems, ensuring compliance with stringent US federal standards. SUPREMA provides BioMini and other fingerprint scanners alongside AFIS-compatible solutions for ID and border control, reinforcing the importance of end-to-end compatibility. Innovatrics in Bratislava adds to this mix with high-performance ABIS featuring multimodal support for enterprise biometric identification. The competitive landscape is not static; it is defined by ongoing technological upgrades and the ability of these companies to navigate local regulatory environments while maintaining global interoperability. For a buyer, selecting a partner involves weighing these specific capabilities against long-term support viability and integration costs.
Regional Dynamics and Deployment Considerations
Geography plays a critical role in the deployment and adoption rates of AFIS technologies. While global growth is positive, the drivers vary significantly by region. North America typically maintains a strong position due to established federal and state-level investment in biometric infrastructure and the presence of key industry players. Europe follows with rigorous data privacy regulations that shape how AFIS solutions are implemented, often requiring localized data handling and strict compliance frameworks. The Asia Pacific region represents a high-growth vector, driven by expanding digital identity programs, smart city initiatives, and increasing security expenditures across both public and private sectors.
Emerging regions in Latin America and the Mideast and Africa present unique opportunities and challenges. In these markets, the adoption of AFIS is often linked to international aid projects, border security enhancements, and modernization of legacy law enforcement systems. The growth potential here is significant, but it is accompanied by infrastructure constraints and varying levels of regulatory maturity. Our full report provides a detailed breakdown of revenue performance across these regions, allowing strategists to pinpoint where capital expenditure is most likely to yield returns. However, the strategic overview indicates that a one-size-fits-all approach is ineffective. Deployment strategies must be localized, considering connectivity issues, power stability, and local legal mandates regarding biometric data storage and processing.
The regional analysis also extends to supply chain considerations. With manufacturing hubs distributed across Japan, the United States, Europe, India, and South Korea, logistics and trade dynamics influence the availability and cost of hardware components. Import regulations and technology transfer restrictions can impact the ability of vendors to deploy solutions in certain jurisdictions. Understanding these geographic friction points is essential for multinational corporations planning to roll out AFIS solutions across multiple continents. The market research provides the necessary context to navigate these complexities, ensuring that deployment timelines are realistic and compliant with local trade and security laws.
Strategic Implications for 2026 and Beyond
For stakeholders formulating strategies in 2026, the AFIS market offers clear signals regarding where value is being created. The first implication is the necessity of cloud integration. As databases grow from millions to billions of records, on-premise solutions may struggle to offer the required scalability and update cadence. Vendors and buyers alike must prioritize architectures that support hybrid or full-cloud environments to ensure long-term viability. The second implication is the critical importance of AI and machine learning in matching algorithms. As the volume of data increases, manual verification becomes impossible. Automated, AI-driven matching that reduces false positives and negatives is the key performance indicator that will differentiate winning solutions from legacy systems.
Investment decisions should also account for the trend toward modal convergence. Projects that propose AFIS as a standalone silo may face scrutiny during budget approvals. Instead, positioning fingerprint identification as part of a broader biometric identity suite aligns better with current procurement trends in both the public and private sectors. This positioning also mitigates risk; if one modality faces technical limitations, others can compensate, ensuring continuous security operations.
Furthermore, compliance and certification remain non-negotiable hurdles. The FBI NGI system certifications and other regional regulatory standards act as gatekeepers to significant market segments. Companies must maintain rigorous compliance schedules to remain eligible for government contracts. For investors, this means due diligence must include an assessment of a vendor's regulatory track record and their capacity to maintain certifications amidst changing standards. The market is rewarding vendors who view compliance not as a burden but as a value proposition that guarantees trust and interoperability.
Finally, the concentration of the market suggests that partnership or acquisition strategies may be more effective than pure organic growth for new entrants. The barrier to entry regarding algorithm development and hardware certification is high. Collaborating with established players or acquiring niche technology firms can accelerate time-to-market. The detailed segmentation data in our full report will help identify which sub-segments are ripe for consolidation and where white spaces might exist for disruptive innovation.
Conclusion and Access to Complete Intelligence
The Automated Fingerprint Identification Systems market is poised for significant expansion through 2032, underpinned by robust technological adoption and enduring security needs across the globe. The journey from 348.0 million USD in 2025 to a projected 566.0 million USD in 2032 represents more than just revenue growth; it signifies a deepening integration of biometric identity into the fabric of societal security and operational efficiency. The 7.5 percent CAGR indicates that this is a sector where sustained attention and strategic positioning are required to capture value. While the macroeconomic overview and competitive landscape presented here offer a valuable starting point, they are merely the surface layer of the intelligence available.
PW Consulting's full market research report goes far beyond these high-level insights. It contains the granular data necessary to build financial models, assess specific regional risks, evaluate vendor capabilities against detailed specifications, and identify precise growth vectors within each segmentation category. The report includes comprehensive profiles of the key companies driving the market, detailed analysis of recent developments, and a breakdown of concentration metrics that inform merger and acquisition strategies. For decision-makers who need to move from observation to action, the complete document is the essential tool.
We invite industry leaders, investors, and strategic planners to access the full report to equip themselves with the exact data points needed to navigate this evolving landscape. In a market defined by precision and trust, relying on partial information is a risk that can be avoided. The complete research provides the clarity required to make informed investments, forge the right partnerships, and deploy technologies that will stand the test of time in the global security infrastructure. The strategic value of this intelligence lies in its ability to turn complex market dynamics into actionable roadmaps for 2026 and the years beyond.
For detailed analysis of this topic, please visit the official page: Automated Fingerprint Identification Systems (AFIS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Long-Term Care Software Market to Reach $642.7M by 2032, Growing at 8% CAGR
By PW Consulting, 2026-09-07
Strategic Horizons in Long-Term Care Software: A 2026 Market Intelligence Brief
The long-term care software market has entered a decisive phase of structural transformation. For executives navigating care delivery, technology procurement, and capital allocation, the question is no longer whether digital infrastructure will reshape post-acute and senior care operations, but how quickly the competitive landscape will consolidate around platforms that can reconcile regulatory complexity, reimbursement volatility, and clinician workflow demands. The latest PW Consulting market research on the Long-term Care Software Market is designed to answer that question with empirical rigor and actionable strategic framing.
Worldwide Non-Slip Floor Covering Market
Drawing on historical momentum through 2025 and extending our forecast horizon to 2032, the research establishes a clear trajectory of expansion. The market has consistently moved upward from 2020 through 2025, reflecting sustained institutional demand for integrated electronic health records, revenue cycle management, and ancillary operational modules. Over the forecast period, the analysis projects a compound annual growth rate of 8.0 percent, with total market size climbing from the mid-400 million range in 2026 toward a scale exceeding 640 million by the close of the decade. These figures are not merely indicators of volume; they signal a compounding shift in how care organizations digitize documentation, optimize reimbursement, and coordinate transitions of care. For leadership teams, the strategic implication is straightforward: software selection and integration roadmaps now carry enterprise-level financial and operational consequences.
Worldwide Tetrachloroethene Market
What elevates this research beyond headline metrics is the deliberate focus on decision-grade architecture. The report is built to support scenario planning, vendor evaluation, and resource allocation under conditions of regulatory uncertainty and platform competition. It provides a comprehensive map of the market’s structural layers, including type-based segmentation, application-driven demand patterns, and regional distribution of value creation. Crucially, while the executive brief you are reading highlights the scale and direction of the market, the full study preserves the granular splits, detailed segmentation values, and region-specific revenue dynamics that executives require for precise budgeting, go-to-market modeling, and competitive benchmarking. Those deeper figures are available through the complete research portal, where they can be cross-referenced with your internal forecasting assumptions.
Worldwide Scalable Clinical Chemistry Analyzers Market
Why Long-term Care Software Is a Strategic Imperative in 2026
The operational environment for long-term care providers has become significantly more demanding. Reimbursement frameworks are being recalibrated, compliance obligations are tightening, and clinical teams are under sustained pressure to reduce documentation burden while improving care continuity. Software platforms that once functioned primarily as record-keeping tools are now expected to serve as the connective tissue between clinical documentation, reimbursement accuracy, quality reporting, and operational decision-making.
Several regulatory and policy developments reinforce that expectation. CMS released an FY 2026 PDPM ICD-10 mapping tool with 34 changes effective October 1, 2025, directly affecting MDS and RAI coding as well as reimbursement calculations in long-term care settings. Alongside that, the FY 2026 Skilled Nursing Facility PPS Final Rule updated quality reporting and case-mix requirements, creating additional compliance responsibilities that long-term care software must support. At the same time, new HIPAA Security Rule amendments effective in 2026 mandate 72-hour breach reporting and biannual vulnerability scanning for in-scope systems used in long-term care EHR platforms. Together, these shifts mean that software capabilities are now tightly coupled to both financial performance and regulatory exposure.
For executives, the implication is that technology investment decisions can no longer be optimized around feature checklists alone. The market is rewarding platforms that can adapt to code changes, support accurate case-mix capture, streamline reimbursement workflows, and maintain compliance without adding friction to clinical documentation. This is precisely the environment in which detailed market research becomes a guiding instrument: it helps organizations distinguish between incremental product updates and structural competitive advantage.
What the Research Delivers: Structure, Applications, and Practical Intelligence
The PW Consulting study is organized to support multi-layered decision-making. It begins with a macro-level view of market growth and then drills into the components that drive revenue composition and adoption behavior. The research covers the principal software categories shaping the long-term care space, including electronic health records, revenue cycle management, and a broad set of supporting solutions that together form the operational backbone of care facilities and home-based services. Rather than presenting these categories as static silos, the report analyzes how demand for each segment interacts with organizational priorities, compliance needs, and reimbursement models.
The application dimension is equally important. Demand is distributed across nursing homes, assisted living facilities, and home healthcare agencies, with each setting carrying distinct workflow requirements, staffing models, and regulatory touchpoints. The study evaluates how software adoption differs across these environments and what that means for implementation complexity, integration priorities, and long-term value capture. Executives evaluating expansion, partnership, or procurement strategies can use this framing to determine where software capabilities must be most robust and where standardization can create efficiency gains.
Beyond structure, the report provides practical intelligence for vendor assessment and internal planning. It maps the capabilities that matter most in the current cycle, including MDS and RAI support, billing and reimbursement optimization, quality reporting, care transitions, and clinician productivity tools. It also examines how cloud deployment, data interoperability, and AI-assisted workflows are reshaping expectations around scalability and administrative burden. The goal is to give leadership teams a coherent framework for comparing solutions not only by feature sets, but by operational outcomes and compliance resilience.
Competitive Landscape: Platform Differentiation and Consolidation Signals
The long-term care software market is characterized by a moderately concentrated competitive field, with a limited number of leading providers accounting for a substantial share of revenue. This concentration creates both risk and opportunity. On one hand, a small group of dominant platforms can shape pricing, integration norms, and buyer expectations. On the other, it intensifies the importance of differentiation through AI-enabled workflows, reimbursement tooling, and domain-specific compliance support. The research systematically examines how the leading companies are positioning themselves within this environment.
PointClickCare, based in Chicago, has built its long-term care offering around an AI-powered EHR platform designed for skilled nursing, senior living, and post-acute care. Its emphasis on real-time data, transitions of care, and reimbursement optimization reflects the market’s growing need to connect clinical documentation with financial performance. MatrixCare, headquartered in Bloomington, focuses on EHR and home health solutions for both facility-based and home-based care organizations, with support for MDS/RAI, billing, and quality reporting. WellSky, located in Overland Park, offers a Long-Term Care EHR alongside its SkySense AI solution, targeting operational efficiency, documentation quality, and clinician productivity in skilled nursing and post-acute settings.
Netsmart Technologies, based in Cleveland, provides myUnity and GEHRIMED EHR platforms for post-acute and long-term care providers, spanning senior living, home health, and value-based care coordination. American HealthTech, headquartered in Ridgeland, has historically delivered EHR solutions for long-term care facilities with an emphasis on MDS/RAI automation, case-mix optimization, and reimbursement tools, and its acquisition by PointClickCare signals continued consolidation among major platforms. Optimus EMR contributes a cloud-based EHR system for skilled nursing and long-term care facilities, while HealthMEDX focuses on EHR solutions specifically for skilled nursing and long-term care providers. Collectively, these firms illustrate a competitive landscape in which domain specialization, reimbursement tooling, and workflow automation are becoming central to market positioning.
Recent developments reinforce that trajectory. In February 2026, WellSky expanded SkySense AI into Long-Term Care and Skilled Nursing Facilities, embedding AI capabilities within the Long-Term Care EHR to improve operational efficiency, documentation quality, and clinician productivity. In March 2026, PointClickCare launched a next-generation EHR for practice groups, integrating AI-driven workflows such as Ambient Scribe to streamline senior care documentation and reduce administrative burden. These moves are not isolated product updates; they reflect a broader industry push to use AI and automation to address documentation fatigue, compliance complexity, and reimbursement accuracy simultaneously.
For organizations evaluating the market, the strategic takeaway is that vendor selection increasingly depends on how well a platform integrates compliance support, reimbursement functionality, and clinician-facing efficiency tools into a single operating environment. The full research report profiles these competitive dynamics in greater depth, including capability comparisons and strategic implications for buyers, investors, and incumbent vendors. The detailed assessments are available through the complete study, where they can be used to support due diligence and procurement decisions.
Regulatory Pressure and the Reimburse-to-Compliance Nexus
One of the defining themes of the current market cycle is the convergence of reimbursement mechanics and compliance obligations. Long-term care software is no longer evaluated solely on usability or record-keeping fidelity; it is assessed on its capacity to support accurate case-mix capture, adapt to coding changes, and maintain audit-ready documentation under evolving regulatory expectations. This is why regulatory developments must be treated as market drivers rather than background noise.
The FY 2026 PDPM ICD-10 mapping changes are particularly significant because they alter the coding foundation used for reimbursement calculations and MDS/RAI workflows. Software platforms that can accommodate mapping updates efficiently, reduce manual rework, and preserve reimbursement accuracy gain a direct operational advantage. Similarly, the FY 2026 Skilled Nursing Facility PPS Final Rule’s updates to quality reporting and case-mix requirements raise the compliance bar for software vendors and the organizations that depend on them. In practice, this means that long-term care software must support not only day-to-day clinical workflows, but also the reporting and documentation structures that determine payment and regulatory standing.
At the same time, the HIPAA Security Rule amendments effective in 2026 add another layer of operational responsibility. The requirement for 72-hour breach reporting and biannual vulnerability scanning places greater emphasis on security governance within in-scope EHR platforms. For providers, this creates a dual mandate: systems must enable efficient care and reimbursement workflows while also meeting heightened security and monitoring expectations. The market research accounts for these pressures by analyzing how software capabilities align with compliance risk, implementation burden, and long-term total cost of ownership. Detailed regulatory impact analysis and its implications for procurement timing are included in the full study.
Strategic Takeaways for Executives and Investors
For leaders operating in or around the long-term care software market, the research supports several high-level strategic conclusions. First, the market’s growth trajectory indicates that digital transformation in post-acute and senior care is moving from adoption to maturation. Organizations that delay integration, standardization, or vendor consolidation may find themselves carrying higher administrative costs and greater compliance exposure over time. Second, reimbursement-linked functionality is becoming a primary differentiator. Platforms that strengthen MDS/RAI accuracy, case-mix optimization, and billing efficiency are well positioned because they directly affect revenue integrity and operational predictability.
Third, AI-enabled documentation and workflow tools are shifting from innovation narratives to practical expectations. Recent product launches from major vendors show that the market is beginning to reward systems that reduce administrative load, improve documentation quality, and support clinician productivity without compromising compliance. Fourth, the competitive field’s concentration suggests that strategic buyers should evaluate not only current capabilities, but also the likely direction of platform consolidation, integration ecosystems, and post-acquisition product roadmaps. These considerations have direct bearing on procurement strategy, contract negotiation, and long-term planning.
Finally, the research underscores that market intelligence in this sector must be both broad and precise. Executives need a clear view of overall momentum while still being able to interrogate the specific segmentation and regional dynamics that shape local demand and vendor positioning. The full PW Consulting report is structured to provide that balance, preserving the macro narrative while making deeper data available for detailed analysis and internal modeling.
Accessing the Full Intelligence Set
This executive brief has outlined the strategic direction of the Long-term Care Software Market, the regulatory forces shaping demand, the competitive dynamics among leading platforms, and the practical decision-making value embedded in the research. To move from directional insight to precise planning, organizations need access to the complete market study, where detailed segmentation values, regional distributions, application-level demand patterns, and vendor-level assessments are presented in full. Those deeper figures, including region-specific market sizes, type-based revenue splits, and application-driven breakdowns, are available through the full research portal and can be aligned with internal forecasting models, procurement timelines, and investment theses.
For teams preparing decisions in 2026, the market is sending a clear message: long-term care software is now central to compliance resilience, reimbursement performance, and clinician workflow sustainability. The organizations that act on that message with disciplined analysis will be best positioned to navigate the next phase of market evolution.
For detailed analysis of this topic, please visit the official page: Long-term Care Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Copper Strips Market Hits $126.6M in 2025, Poised to Reach $180M by 2032 at 5.24% CAGR
By PW Consulting, 2026-09-07
Strategic Intelligence for the Copper Strips Market: Navigating Growth, Margin Pressure, and Competitive Shifts in 2026
The global copper strips industry stands at a critical inflection point. As electrification accelerates across transportation, energy infrastructure, and consumer electronics, demand for high-conductivity rolled copper products continues to outpace broader industrial growth. Yet beneath the surface of record prices and multi-year expansion lies a complex matrix of margin compression, regional supply realignment, regulatory trade dynamics, and rapid product innovation. For executives, procurement leaders, and strategy teams operating in or adjacent to this space, understanding the structural forces shaping copper strips from 2026 onward is no longer optional—it is a prerequisite for resilient capital allocation and market positioning.
Private Business Valuation Service Market
PW Consulting has published a comprehensive market research study designed to cut through noise and deliver actionable intelligence for boards, investors, and operational leaders. This overview outlines the strategic rationale behind the study, previews its analytical architecture, and demonstrates how the 2026–2032 forecast horizon can inform near-term planning without exposing the granular, proprietary data that drive defensible competitive advantage. Readers seeking complete regional breakdowns, application-level share metrics, forecasting models, and company-level benchmarking are invited to access the full report.
Worldwide High-capacity Battery Market
Why a Dedicated Copper Strips Study Matters in 2026
Copper strips occupy a unique position in the metals value chain. As semi-finished rolled products, they bridge upstream smelting and refining with downstream fabrication, component manufacturing, and end-use assembly. Their technical performance—conductivity, formability, surface quality, and alloy-specific strength—directly influences product reliability in electrical equipment, automotive wiring harnesses, heat exchangers, and precision electronic assemblies. At the same time, strips are highly sensitive to raw material pricing, refining economics, logistics, and trade policy. That dual exposure makes them both a barometer of industrial demand and a focal point for margin management.
Worldwide Graphic Novel Publishing Platform Market
Recent market conditions underscore the urgency of informed decision-making. Global copper prices reached historic levels, briefly exceeding USD 14,500 per tonne in early 2026 and sustaining elevated levels through the first quarter. Q1 2026 averages climbed to approximately USD 12,822 per metric tonne, a sharp rise from Q4 2025 baselines. Simultaneously, the LME copper cash price approached USD 13,842 per metric tonne by March 2026, with arbitrage remaining relatively tight. These price regimes reflect robust pull from electric vehicle production, renewable energy build-out, and broader electrification, but they also introduce volatility into procurement planning and build-to-order supply contracts.
Compounding the price environment are midstream margin pressures and policy-driven distortions. Smelter treatment and refining charges (TC/RCs) fell to all-time lows even as spot prices soared, signaling that value capture is unevenly distributed across the chain. In the United States, tariffs on semi-finished copper products—while exempting refined copper—meant that COMEX next-active contract pricing moved from roughly USD 4.03 per pound in January 2025 to USD 5.82 per pound by July 2025, eventually peaking near USD 6.06 per pound in March 2026. These dynamics reshuffle competitive advantages across regions, alter make-versus-buy calculations, and create both risks and opportunities for firms that can anticipate where the value will accrue.
Against this backdrop, a disciplined, data-rich market study becomes a strategic asset. It enables teams to stress-test assumptions, quantify demand trajectories by application family, assess supply-side capacity additions, and understand how leading manufacturers are repositioning their strip portfolios for higher-performance requirements. The 2026–2032 forecast window is particularly valuable because it captures the maturation of multiple secular trends—decarbonization, vehicle electricalization, grid modernization, and electronics miniaturization—while also accounting for near-term cyclicality and policy shifts.
Market Trajectory: A Multi-Year Growth Arc with Nuanced Drivers
The study’s baseline trajectory positions the copper strips market on a steady growth path, supported by expanding industrial end-use demand and incremental capacity additions across major producing regions. Historical data from 2020 through 2025 shows consistent expansion, with the market scaling from just above USD 102.45 million in 2020 to approximately USD 126.6 million in 2025. This progression reflects not only recovery from earlier disruption but also structural demand growth across key verticals.
Looking forward, the forecast indicates continued expansion through 2032, with 2026 estimated demand reaching roughly USD 136.64 million and the market surpassing the USD 180 million threshold by the end of the period. The implied compound annual growth rate across the 2026–2032 horizon sits at approximately 5.24 percent, a rate that is neither explosive nor complacent. It is the kind of growth profile that rewards strategic patience, targeted capacity investments, and disciplined product-mix optimization. For operators, this trajectory suggests that volume growth will be meaningful but must be paired with margin discipline and differentiated offerings to outperform.
A nuanced reading of the revenue arc reveals more than headline expansion. Year-over-year movement between 2026 and 2028, for example, shows a mid-period transition where growth decelerates modestly before re-accelerating toward the end of the decade. Such patterns often reflect capacity ramp timing, product launch cycles, and regional demand synchronization. The study unpacks these inflection points so that planners can avoid over-extrapolating near-term momentum or underestimating later-cycle demand pull from electronics and electrical infrastructure.
Segmentation and Application Dynamics: Where Value Is Created and Captured
Copper strips are not a monolithic product category. Their economics and growth drivers differ materially by region, application, and end-use configuration. The report provides a structured segmentation framework that maps demand across geographies and application families, allowing readers to identify where incremental volume is most likely to emerge and where competitive intensity may compress returns.
Regionally, the study captures a global demand footprint that is broadly distributed but clearly weighted toward Asia Pacific, with North America and Europe representing substantial, mature demand bases, and Latin America and the Middle East & Africa contributing growing, albeit smaller, shares. Rather than treating regional figures as static snapshots, the analysis treats them as dynamic ecosystems influenced by local industrialization, vehicle program timing, infrastructure investment cadence, and trade flows. This perspective is essential for companies evaluating market entry, capacity siting, export strategy, or localized supplier relationships.
By application, the report differentiates demand across electrical equipment, automotive wiring, electronic devices, construction, and other applications. Each segment carries distinct technical requirements and purchasing behaviors. Electrical equipment and automotive wiring dominate the demand profile in aggregate, reflecting the centrality of copper in power distribution, motor windings, connectors, and vehicle harness systems. Electronic devices form a high-value, specification-sensitive segment where strip dimensions, surface finish, and alloy selection directly influence performance. Construction and other applications round out the demand mix with more cyclical and regionally variable patterns. The study avoids oversimplifying these segments; instead, it evaluates how shifting product standards, miniaturization trends, and electrification requirements are reshaping volume and value within each family.
End-use segmentation further clarifies the demand picture by mapping consumption across automotive, electrical, electronics, and other end-use categories. This layer is particularly useful for understanding how indirect demand—driven by equipment manufacturers and system integrators—translates into strip procurement. The report examines how end-use growth vectors interact with supply chain practices such as just-in-time delivery, quality certifications, and technical co-development, helping readers anticipate not only how much demand will grow but also what kind of supplier capabilities will be rewarded.
Competitive Landscape: Consolidating Incumbents, Expanding Capacity, and Advancing Product Technology
Market concentration in copper strips remains moderate but meaningful. The study reports that the top three participants hold approximately 35.2 percent of market share, while the top five account for around 52.1 percent. This concentration pattern suggests a landscape where established players command significant position, yet room remains for specialized suppliers, regional champions, and new entrants that can win on technology, service, or cost. For strategists, the implication is clear: competitive advantage increasingly depends on execution in product development, capacity efficiency, and customer intimacy rather than scale alone.
Several leading companies exemplify the strategic diversity shaping the sector. Europe continues to host technically sophisticated manufacturers with deep metallurgical capability and broad industrial customer bases. Germany-based Aurubis AG operates as a leading global non-ferrous metals producer and recycler, integrating copper strip offerings within its broader portfolio of rolled copper products. Its positioning reflects the value of combining upstream recycling and refining expertise with downstream semi-finished product availability, an integration that can support cost stability and supply assurance for industrial buyers. KME Germany GmbH & Co. KG, also headquartered in Germany, focuses on rolled copper and copper alloy preliminary and semi-finished products, with strips designed for industrial applications. Its profile highlights the importance of alloy breadth, dimensional consistency, and application-specific engineering in sustaining long-term customer relationships.
In Asia, Mitsubishi Materials Corporation from Tokyo has established a strong reputation for wrought copper products, including oxygen-free copper strips, multi-gauge strips, and high-performance alloys targeting automotive and electronics demand. The company’s product emphasis on high-purity strips and multi-gauge flexibility speaks to the growing need for heat dissipation solutions and contact applications that can be served with a single material platform. In Europe, Wieland-Werke AG from Ulm operates as a specialist supplier of semi-finished copper and copper alloy rolled products, with dedicated strip, sheet, and plate offerings. Its focus on precision rolled products reinforces the premium that certain end-users place on tight tolerances, surface quality, and alloy performance in demanding applications.
Recent corporate activity demonstrates that the competitive frontier is moving quickly. In late 2025, Mitsubishi Materials Corporation introduced a new high-strength and high-heat-resistance oxygen-free copper MOFC™-HR multi-gauge strip, engineered to allow the production of heat dissipation and contact areas using the same material. This innovation signals how product-led differentiation is becoming a strategic priority in segments where thermal management and durability requirements are intensifying. Around the same period, KME Germany advanced its capacity footprint, inaugurating a second refining furnace at its Osnabrück site in May and September 2025, reinforcing its commitment to domestic refining and rolled product capability. Most recently, in January 2026, Wieland-Werke AG broke ground on a major expansion in Northwest Ohio, a move that aligns with growing North American demand and reflects a broader pattern of capacity repositioning closer to key end-use markets.
These developments are not isolated news items. They indicate how incumbents are balancing three strategic imperatives simultaneously: expanding or relocating capacity to reduce logistical friction and tariff exposure, investing in refining and rolling capability to improve margin resilience, and advancing product grades that unlock higher-value applications. The report’s competitive analysis places these moves in context, allowing readers to assess where capacity is likely to add, where product specifications are heading, and how supplier selection criteria may evolve in the next planning cycle.
Macro and Regulatory Dynamics: Navigating Volatility, Trade Policy, and Margin Realities
A market study is only as useful as its treatment of external forces. The copper strips sector is being shaped by an overlapping set of upstream, midstream, and regulatory dynamics that can alter both demand timing and cost structures. The report integrates these forces into a coherent narrative so that strategy teams can separate transient price noise from structural change.
On the raw material side, recent price behavior illustrates how strong secular demand can push copper to record levels while also creating volatility that complicates procurement planning. Price spikes above USD 14,500 per tonne, Q1 2026 averages near USD 12,822, and LME cash levels around USD 13,842 by March 2026 reflect an environment where demand for electrification-driven copper is colliding with tightening availability and investor positioning. For strip producers and consumers alike, such conditions affect hedging strategies, contract structures, inventory policies, and the relative attractiveness of substitutes or design alternatives. The study examines how these price regimes influence downstream purchasing behavior and how they may stabilize or recur over the forecast window.
Trade policy adds another layer of complexity. Tariffs on semi-finished copper products in the United States, while excluding refined copper, have influenced domestic versus imported pricing differentials and COMEX contract behavior. The climb from roughly USD 4.03 per pound in early 2025 to a March 2026 peak near USD 6.06 per pound shows how policy can reshape regional cost bases and redirect trade flows. The study analyzes how such tariffs interact with capacity location decisions, supplier diversification strategies, and the economics of local sourcing for North American manufacturers.
Midstream economics present a paradox that many observers miss. Even with high spot copper prices, refinery margins measured by treatment and refining charges have fallen to historically low levels. This dynamic implies that the economic benefit of elevated copper prices is not being uniformly captured along the chain. Instead, value is being redistributed across producers, traders, and downstream processors depending on contract terms, hedging positions, and vertical integration. For strip manufacturers and buyers, the practical implication is that raw material price alone is an incomplete indicator of cost pressure. Margin analysis must account for refining economics, feedstock sourcing, and the extent to which firms can buffer volatility through recycling content, long-term supply arrangements, or integrated production.
The report treats these dynamics holistically. It considers how price levels, tariffs, refining charges, and logistics costs interact to shape regional competitiveness and end-use adoption. It also explores how firms can use scenario planning to prepare for multiple futures, including continued price elevation, tariff adjustments, supply expansions that ease tightness, or demand shifts from adjacent sectors such as data center build-out and renewable energy deployment.
What the Study Delivers: Operational Rigor for Strategy, Procurement, and Investment
The PW Consulting Copper Strips Market research is built to support multiple decision contexts. It is structured not merely as a data compendium but as an analytical framework that translates market behavior into practical guidance for planning and execution.
First, the study provides a clear demand and revenue trajectory anchored in historical performance and extended through 2032. It distinguishes near-term momentum from longer-term structural growth, helping organizations set realistic volume expectations and budget assumptions. Rather than presenting a single deterministic series, the analysis highlights transition points and drivers that can accelerate or moderate growth, allowing readers to map assumptions to their own operational realities.
Second, the report delivers detailed segmentation across regions, applications, and end uses. This multidimensional view is designed to support market prioritization, product-mix decisions, and sales segmentation. Executives can identify which geographies and application families are most aligned with their capabilities, while procurement teams can better anticipate where demand concentration is likely to persist and where supplier diversification may be necessary.
Third, the study includes a focused competitive assessment of leading firms and recent strategic moves. By linking product innovation, capacity actions, and market positioning to broader demand trends, the analysis helps readers evaluate who is gaining traction, where differentiation is being created, and what capabilities will likely matter more in the next phase of the market’s evolution. This is especially valuable for benchmarking, partnership evaluation, and supplier risk assessment.
Fourth, the report situates the market within its macro and regulatory environment. It addresses price behavior, tariff impacts, refining economics, and trade flow shifts in a way that connects directly to operational decisions. For instance, procurement and supply chain teams can use the analysis to inform hedging posture, contract term selection, and sourcing geography, while finance teams can incorporate scenario-driven margin sensitivity into capital planning.
Finally, the study is intended to be practical at the working level. Sales leaders can use segmentation insights to refine territory and account strategies; product managers can align development roadmaps with application requirements that are gaining share; and strategy teams can use the competitive and macro layers to stress-test expansion, partnership, or acquisition hypotheses. By combining revenue forecasts with qualitative drivers and corporate developments, the report creates a common analytical language for cross-functional decision-making.
How to Use This Research for 2026 Decision-Making
The strategic value of the study lies in its ability to support decisions across time horizons. In the immediate term, the 2026 baseline and first-year forecast provide a reference point for annual planning, procurement budgeting, and capacity utilization assumptions. The analysis helps teams interpret whether current demand signals are consistent with a stable growth path or represent a transitional phase that warrants caution or opportunism.
In the medium term, the 2026–2032 trajectory supports investment prioritization and product strategy. Organizations considering capacity additions, technology upgrades, or market entry can use the segmentation and competitive layers to assess where incremental returns are most probable and where competitive intensity is likely to rise. The inclusion of recent corporate moves—such as multi-gauge strip innovation, refining furnace expansions, and major site development in North America—offers a practical lens on how incumbents are positioning themselves and where gaps might still exist for new or differentiated offerings.
In the policy and risk domain, the study’s treatment of tariffs, price volatility, and refining economics helps organizations move beyond reactive price tracking. By understanding how regulatory settings and midstream margins shape effective cost structures, leaders can design sourcing strategies that are more resilient to shock and better aligned with long-term value creation. This is particularly relevant for firms exposed to international trade flows or those balancing imported versus domestic supply options.
Conclusion: Turn Insight into Advantage
The copper strips market is expanding within a landscape defined by strong electrification-driven demand, elevated raw material prices, tightening midstream margins, and active capacity and product investment by leading manufacturers. Growth at an implied rate near 5.24 percent over 2026–2032 is meaningful, but the real strategic opportunity lies in understanding where within that growth curve value will accrue, which applications and regions will lead, and how competitive positions will shift as incumbents expand, innovate, and reconfigure supply footprints.
This PW Consulting market research study is designed to equip decision-makers with that understanding. It translates historical performance and forward-looking projections into a structured view of demand, segmentation, competitive dynamics, and macro risk, while keeping the most granular intelligence reserved for clients who need the full picture to act with precision. For teams preparing 2026 budgets, evaluating supplier strategies, or assessing market entry and expansion options, the report provides a defensible foundation for planning in a market that rewards clarity, technical alignment, and disciplined execution.
To access the complete regional and application-level breakdowns, detailed forecast series, competitive benchmarking, and scenario analysis, request the full Copper Strips Market report and ensure your next strategic decisions are informed by the most comprehensive intelligence available.
For detailed analysis of this topic, please visit the official page: Copper Strips Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Hydraulic Bolt Tensioner Market to Reach $304.27M by 2032 at 5.5% CAGR
By PW Consulting, 2026-09-07
Strategic Precision in an Evolving Industrial Landscape The 2026 Hydraulic Bolt Tensioner Market Outlook
The industrial bolting sector stands at a critical juncture where operational safety, structural integrity, and capital efficiency converge. Hydraulic bolt tensioners have emerged as indispensable tools for achieving controlled axial force across demanding applications ranging from offshore oil and gas infrastructure to wind turbine foundations and heavy industrial assemblies. For engineering leaders and procurement strategists, understanding the trajectory of this specialized equipment market is no longer optional; it is a prerequisite for informed capital allocation, vendor selection, and long-term maintenance planning. PW Consulting latest market research delivers a comprehensive, data-grounded view of the hydraulic bolt tensioner landscape, calibrated to support enterprise decision-making throughout 2026 and beyond.
Hockey Protective Equipment Market
This introduction outlines the strategic architecture of the report, highlights the macroeconomic and competitive forces reshaping the sector, and explains how the full intelligence package equips organizations to navigate procurement cycles, technology adoption, and regional expansion with confidence. Rather than offering a superficial survey, the analysis traces the operational realities of tensioning systems across topside, subsea, and wind configurations, while mapping the evolving capabilities of established manufacturers and emerging specialists. Readers will gain a clear understanding of where the market has been, why it is moving in its current direction, and how to translate those insights into actionable strategies before the next procurement or infrastructure development cycle begins.
Angle Impact Wrench Market
Market Trajectory and Structural Growth Dynamics
The hydraulic bolt tensioner market has demonstrated consistent expansion over the past half-decade, driven by a combination of aging infrastructure renewal, stringent flange management standards, and the accelerating deployment of large-scale renewable energy assets. Historical revenue data from 2020 through 2025 reflects steady upward movement, with total market valuation progressing from 163.15 million USD to 211.1 million USD. This trajectory has established a reliable baseline for forward-looking projections, and the forecast period extend from 2026 through 2032 indicates continued compounding growth at a CAGR of 5.5 percent. By 2032, the sector is positioned to approach a valuation near 304.27 million USD, underscoring the durability of demand for precision tensioning equipment.
Worldwide Structural Biology Service Market
Several structural factors underpin this growth. First, the ongoing push toward higher pressure ratings in oil and gas processing facilities and the expansion of subsea production systems require tensioning solutions capable of delivering repeatable preload without compromising bolt yield thresholds. Second, wind farm development, particularly the transition to larger turbine foundations and more constrained installation environments, has increased the reliance on specialized single-stage and multi-stage tensioners that can apply simultaneous preload under restricted site conditions. Third, industrial end-users across steel fabrication, mining, and heavy construction are prioritizing labor efficiency and worker safety, which favors spring-return, auto-retract, and manual-return designs that reduce on-site exposure during critical bolting operations.
The market concentration profile further clarifies the competitive environment. With the top three players holding approximately 35.0 percent of total revenue and the top five representing roughly 45.0 percent, the sector remains moderately consolidated while leaving meaningful room for regional specialists and application-focused manufacturers. This balance creates a dynamic procurement landscape in which buyers can evaluate both established global suppliers and niche innovators depending on their technical requirements, lead time constraints, and service expectations. PW Consulting report captures these dynamics in detail, enabling organizations to benchmark supplier capabilities and assess the strategic implications of vendor selection across different operating contexts.
Report Architecture and Operational Intelligence
The full research package is structured to provide practical, decision-ready intelligence rather than abstract market commentary. The analysis opens with a macro-level assessment of revenue progression, growth drivers, and the competitive framework, then moves into pricing behavior, procurement cycles, and end-user specifications. A core strength of the report lies in its integration of regulatory and technical context. Hydraulic bolt tensioners must align with evaluation frameworks such as ISO 898-1:1999 and ASTM A490M standards, ensuring controlled axial force application and adherence to yield strength limits. The report examines how these compliance requirements influence product design, certification pathways, and supplier qualification processes, giving procurement and engineering teams a clearer view of the technical gatekeeping that shapes purchasing decisions.
Material selection and construction approaches are also treated as strategic variables. Subsea tensioners, for example, frequently require high-strength stainless steel construction to meet corrosion resistance demands in offshore operations, which directly affects component costs and total cost of ownership. At the same time, spring-return and auto-retract configurations are reducing manual labor exposure during industrial and wind turbine maintenance, shifting the value proposition from purely mechanical performance to operational efficiency and risk reduction. The research connects these technical realities to segment-level demand patterns, helping organizations interpret why certain designs command premium positioning in specific environments.
The report additionally includes a thorough review of recent industry developments that signal the direction of product innovation. Manufacturers have been updating design and analysis resources, expanding on-site bolting tool catalogs, and publishing practical guidance for resolving recurring tensioner issues to improve reliability in critical applications. In parallel, specialized solutions for wind energy have been introduced to address halyard and structural tensioning requirements, reflecting the broader crossover between precision bolting technologies and renewable infrastructure. These developments are not treated as isolated news items; they are incorporated into a forward-looking assessment of how product roadmaps, after-sale support, and application expertise are likely to influence buyer preferences throughout the forecast period.
Competitive Landscape and Supplier Differentiation
The hydraulic bolt tensioner market features a diverse set of manufacturers whose capabilities span standard topside systems, subsea-rated assemblies, wind turbine models, and heavy-duty industrial tools. PW Consulting competitive analysis goes beyond organizational profiles to examine how each supplier configures its product families, addresses application-specific constraints, and positions itself within different procurement environments. This approach allows buyers to evaluate not only what a manufacturer offers, but how well those offerings align with operational realities such as flange configurations, bolt size ranges, pressure class requirements, and maintenance access limitations.
Several established suppliers illustrate the breadth of current market offerings. Hydrodynamic and bolting specialists such as HYTORC and TorqLite provide hydraulic tensioner systems with interchangeable adapters and multi-stud configurations, supporting bolt ranges that cover common industrial and infrastructure applications. Their portfolios include topside standard models, subsea variants, and wind-oriented designs, with emphasis on spring return, composite seal integration, and custom foundation tensioning solutions. Atlas Copco contributes a wide-ranging equipment suite that spans topside, subsea, and wind turbine tensioning platforms alongside associated pumps, appealing to organizations seeking integrated tensioning and pressure supply ecosystems. Hydratight and Hi-Force offer series-based tensioner families designed for ANSI, ASME, and API flanges, with interchangeable bridges, quick-fit release features, and manual return designs that prioritize field flexibility and serviceability.
European and Asian manufacturers add further differentiation. FPT Fluid Power Technology produces single-stage and multi-stage tensioners engineered for Norsok, Vector, slip-on, and weld neck flanges, using serial hydraulic connections to streamline multi-stud operations. Hi-Force shares similar field-oriented strengths through STS, SBT, SRT, and STU series that address subsea deployment, manual return requirements, and overstroke prevention. From the Indian manufacturing base, Tritorc and Technotorc bring high-pressure axial force systems, pneumatic pump platforms, and multi-stage tensioner designs aimed at critical oil and gas, steel, mining, and heavy industrial applications. WREN Hydraulics rounds out the competitive field with ultra-high pressure tensioners integrated into broader bolting solution portfolios.
Recent supplier activities reinforce the practical orientation of this market. Design and analysis updates have emphasized load cell accuracy, hydraulic pump output, and subsea application considerations, while enhanced catalogs have focused on on-site bolting tools for critical joint integrity. Complementary technical guidance addressing common operational issues has been published to support reliability in industrial settings. In the wind segment, new tensioning solutions have entered the market to support structural and foundation preload requirements. Collectively, these activities indicate that suppliers are not merely expanding product lines, but refining them around accuracy, maintainability, and application-specific performance. The full report translates these strategic signals into a structured evaluation framework so buyers can compare suppliers on the dimensions that most influence procurement outcomes.
Regional Demand Patterns and Application Segmentation Logic
Market growth is distributed across multiple regions, each with distinct procurement rhythms, infrastructure priorities, and technical requirements. North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa region all contribute to the overall demand profile, but their relative weighting and growth trajectories differ according to local industrial activity, energy transition investments, and offshore development programs. Rather than isolate regional percentages in a static table, the report examines how regional demand is shaped by project pipelines, maintenance schedules, and the deployment intensity of specific asset classes.
The same analytical approach applies to application segmentation. Oil and gas remains a foundational demand driver, supported by continuous requirements for flange management, critical joint integrity, and high-pressure system maintenance. Wind and power generation has become an increasingly significant application area as turbine scale and site complexity increase, demanding tensioners that can handle simultaneous preload in restricted environments. Industrial applications continue to draw consistent demand from sectors such as steel, mining, and heavy construction, where productivity and operator safety influence the adoption of labor-reducing tensioning designs. Other applications contribute additional demand from adjacent infrastructure and specialty assembly contexts. The report maps these application flows to supplier portfolios and procurement behaviors, helping organizations understand where pricing pressure, specification requirements, and lead time expectations are likely to intensify.
Strategic Implications for 2026 Decision-Making
The hydraulic bolt tensioner market in 2026 is defined by a blend of steady demand growth, application-driven specification complexity, and supplier differentiation around precision, safety, and service support. For enterprises planning procurement, capacity expansion, or fleet standardization, the strategic question is not simply which tensioner to purchase, but how to align tensioning technology with operational risk, total cost of ownership, and long-term asset integrity goals. PW Consulting research provides the analytical foundation to answer that question with clarity. It connects historical performance and forecast momentum to the real-world requirements of topside, subsea, wind, and industrial applications, while framing the competitive landscape in terms of practical buyer considerations.
Organizations that integrate this intelligence into their planning processes are better positioned to evaluate supplier proposals, anticipate regional demand shifts, and select tensioning systems that match both current project needs and future maintenance cycles. The report also supports scenario planning around labor exposure, compliance requirements, corrosion-related material costs, and the operational advantages of spring-return or auto-retract configurations. By absorbing these insights before procurement decisions are finalized, engineering and sourcing teams can reduce specification friction, improve vendor negotiation outcomes, and align tensioning investments with broader infrastructure and energy transition objectives.
The full report expands each of these themes into a complete, actionable intelligence package. Readers who need detailed segment analysis, supplier evaluation criteria, procurement timing insights, and region-level demand logic will find the complete study designed for immediate operational use. We invite you to access the source page to review the full dataset, competitive breakdowns, and strategic recommendations that accompany this market research. The complete analysis is available to support your 2026 planning cycle with the depth and precision required for confident, data-informed decisions.
For detailed analysis of this topic, please visit the official page: Hydraulic Bolt Tensioner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Modular Data Centers to Hit $36.37B in 2025, Growing at 17.11% CAGR to 2032
By PW Consulting, 2026-09-07
The Modular Data Centers Market: Strategic Intelligence for 2026 and Beyond
The global infrastructure landscape is undergoing a profound transformation, driven by the insatiable demand for computational power, the proliferation of edge computing, and the urgent need for agile deployment models. In this context, modular data centers have emerged not merely as an alternative construction method, but as a critical strategic asset for enterprises seeking to balance speed, scalability, and operational efficiency. PW Consulting is proud to introduce our latest comprehensive market research report on the Modular Data Centers Market, designed to equip decision-makers with the foresight necessary to navigate the complexities of the 2026-2032 forecast period.
Semiconductor Grade Mixed Bed Resin Market
This analysis serves as a strategic compass for C-suite executives, infrastructure architects, and investment stakeholders. By examining the trajectory from 2020 through the projection horizon, we uncover the dynamics shaping an industry poised for exponential growth. The following insights preview the depth of our findings, highlighting the market's robust expansion, the competitive maneuvers of key players, and the regulatory shifts redefining deployment standards. To access the full granularity of segmentation data, regional revenue breakdowns, and detailed company profiles, we invite you to explore the complete report on our platform.
Internet Real-time Captioning Service Market
Market Trajectory and Strategic Magnitude
The modular data center market has demonstrated remarkable resilience and acceleration over the past five years. Our historical analysis from 2020 to 2025 reveals a consistent upward curve, reflecting the industry's shift away from traditional, time-intensive construction toward prefabricated and containerized solutions. In 2020, the market established a solid foundation, and by 2025, the total revenue had grown substantially, signaling a mature yet rapidly expanding ecosystem.
Worldwide Metal Spinning Lathes Market
Looking forward, the growth narrative becomes even more compelling. The forecast period from 2026 to 2032 projects a robust Compound Annual Growth Rate (CAGR) of 17.11 percent. This rate underscores the critical role modular solutions play in addressing the infrastructure gaps created by AI workloads, telecommunications expansion, and distributed enterprise needs. The market size is expected to escalate significantly, moving from the 2026 baseline toward a substantial valuation by 2032. Such trajectory indicates that modular data centers are transitioning from a niche solution to a dominant infrastructure paradigm.
For strategic planners, this growth rate is not just a number; it represents a window of opportunity for market entry, capacity expansion, and technology integration. Organizations that align their capital allocation with this growth curve can secure first-mover advantages in regions and sectors where demand outpaces traditional supply. The revenue projections suggest that by the end of the forecast period, the market will have more than doubled its 2025 stature, highlighting the urgency for stakeholders to finalize their modular strategies now.
Core Applications and Sectoral Shifts
The demand for modular data centers is not uniform; it is driven by distinct sectoral requirements that prioritize speed, density, and location flexibility. Our research delves into the key application verticals that are propelling this market forward. Telecommunications remains a primary driver, as network operators seek to deploy edge nodes rapidly to support 5G infrastructure and low-latency services. The financial sector, with its stringent requirements for security and high-performance computing, is increasingly adopting modular designs to scale trading infrastructure and data resilience without the delays of conventional construction.
Healthcare and education sectors are also witnessing a surge in modular adoption. In healthcare, the need for remote data processing, telemedicine support, and secure patient data management is driving deployments that can be installed quickly in sensitive environments. Similarly, educational and research institutions are leveraging modular units to create high-performance computing clusters for academic and scientific workloads, benefiting from the scalability that modular architectures provide.
Beyond these primary verticals, a diverse range of other applications contributes significantly to the market volume. This includes industrial IoT, retail edge computing, and government infrastructure projects. The breadth of applications indicates that modular data centers are becoming a versatile infrastructure tool, adaptable to varied environmental and operational constraints. Understanding which sectors are accelerating their investment cycles is crucial for vendors and investors aiming to target high-growth niches within the broader market.
Competitive Dynamics and Key Player Strategies
The competitive landscape of the modular data center market is characterized by a mix of established infrastructure giants and specialized solution providers. Our report provides a detailed analysis of the key companies shaping this ecosystem, examining their product portfolios, strategic positioning, and recent moves that signal future market directions.
Vertiv, headquartered in Lewisville, Texas, continues to emphasize its prefabricated modular solutions that integrate power, cooling, and IT modules. Their focus on rapid deployment for AI and high-performance computing workloads positions them as a critical partner for organizations scaling compute-intensive infrastructure. Similarly, Schneider Electric, based in Boulogne-Billancourt, France, leverages its EcoStruxure Modular Data Center solutions to offer adaptable high-performance designs. Their approach addresses complex infrastructure needs across diverse locations, highlighting the importance of interoperability and management software in modular deployments.
ABB, from Zurich, Switzerland, focuses on modular, scalable, and prefabricated solutions that accelerate colocation data center deployment and ROI. Their strategy emphasizes flexible scaling for future demand, a key consideration for colocation providers facing unpredictable growth patterns. Eaton, headquartered in Dublin, Ireland, offers SmartRack modular data center solutions that combine IT rack, cooling, and service enclosures in a single unit. This integration aims to optimize performance and reduce deployment time, catering to enterprises seeking streamlined infrastructure packages.
Flex, based in Sunnyvale, California, is making significant strides with its AI infrastructure platform. Their pre-engineered modular designs integrate power, cooling, and compute, promising accelerated deployment speeds that are critical in the race to deploy AI factories. Dell Technologies, from Round Rock, Texas, provides modular data center solutions that deploy modularized integrated racks outside traditional constraints, targeting edge and high-density environments where space and power density are paramount.
M.C. Dean, located in Alexandria, Virginia, specializes in modular data center support rack systems and installation methods for overhead-mounted components. Their innovation in installation methods addresses the logistical complexities of large-scale deployments. Haskell Modular Solutions, from Greenville, South Carolina, offers custom modular data center solutions with factory-controlled fabrication, emphasizing efficiency, flexibility, and scalability through controlled manufacturing environments.
Recent Strategic Movements and Product Innovations
The market is dynamic, with key players frequently announcing developments that reshape competitive advantages. Our research tracks these movements to provide context for current market positioning. In January 2026, Eaton expanded its modular data center offering in collaboration with Flexnode, targeting rapid AI factory deployment. This collaboration includes power backup, racks, and cable management, reportedly reducing deployment schedules by 35 percent on average. Such partnerships highlight a trend toward ecosystem collaboration to solve deployment bottlenecks.
In August 2025, Vertiv launched the Vertiv OneCore global solution for high-performance data centers. This modular design supports deployments ranging from 5 MW to 50 MW, specifically optimized for AI and HPC market needs. This launch signals a push toward higher capacity modular units capable of serving hyperscale requirements. Earlier, in June 2025, Siemens introduced a new turnkey modular Edge data center in collaboration with Cadolto Datacenter and Legrand Data Center Solutions. This solution supports deployment within six to 12 months for both permanent and interim operations, reinforcing the value proposition of speed in edge infrastructure.
These developments illustrate that the market is moving toward integrated solutions that promise not just hardware, but guaranteed deployment timelines and performance outcomes. For buyers, these innovations reduce risk and improve predictability, key factors in procurement decisions for critical infrastructure.
Regulatory, Standardization, and Supply Chain Dynamics
Beyond competitive moves, the market is influenced by evolving regulatory frameworks and standardization efforts that dictate how modular data centers are designed, tested, and deployed. The revised UL 2755:2025 Outline of Investigation for Prefabricated Modular Data Center Systems and Related Modular Units was released to address evolving safety requirements for modern prefabricated modular data centers and AI-driven workloads. This update is critical for ensuring that rapid deployment does not compromise safety or reliability, particularly as power densities increase with AI applications.
Innovation is also protected and driven by intellectual property. M.C. Dean was issued a United States Patent for its Modular Data Center Support Rack System and Installation Method, aimed at streamlining electrical configuration and accelerating delivery on large-scale data center campuses. Such patents indicate a competitive moat based on engineering efficiency and installation methodology.
Standardization efforts are also gaining traction. The Open Compute Project Modular Data Center sub-project focuses on designs enabling OCP hardware use in power, cooling, IT, and all-in-one modules. This initiative aims to improve data center deployment speed and efficiency by promoting open standards, which can reduce vendor lock-in and foster a more competitive hardware ecosystem. Furthermore, modular data center deployments are increasingly recognized for their ability to enable quick construction and deployment for changing site demands, offering lower construction risk in regions facing supply chain constraints. This supply chain resilience is a significant strategic advantage in an era of global logistical volatility.
Market Concentration and Competitive Intensity
Understanding the concentration of market share is vital for assessing competitive risk and partner viability. Our analysis indicates a moderately concentrated market structure. The top three competitors hold a significant portion of the market revenue, while the top five players extend their collective influence further. This concentration suggests that while there are dominant players with extensive resources and global reach, there remains sufficient space for specialized providers and regional champions to thrive, particularly in niche applications or specific geographic territories.
For enterprises selecting partners, this landscape requires careful due diligence. Partnering with a highly concentrated player may offer global scale and comprehensive support, but specialized providers may offer greater flexibility or innovation in specific modular configurations. The balance between scale and specialization is a key strategic consideration for 2026 procurement strategies.
Strategic Implications for 2026 Decision Makers
As organizations plan their infrastructure roadmaps for 2026, the modular data center market offers several strategic imperatives. First, speed to deployment is no longer a luxury but a necessity. With AI and edge workloads demanding immediate compute capacity, the ability to deploy infrastructure in months rather than years is a competitive differentiator. Investing in modular solutions that guarantee rapid deployment schedules can accelerate time-to-value for digital initiatives.
Second, scalability must be designed into the architecture from the outset. The modular approach allows organizations to start with a baseline capacity and expand incrementally as demand grows. This pay-as-you-grow model reduces upfront capital risk and aligns infrastructure investment with actual usage patterns. Decision-makers should evaluate vendors based on their ability to support seamless scaling without significant re engineering.
Third, integration and interoperability are paramount. As modular data centers become more complex, integrating power, cooling, and IT management into a cohesive system is essential. Solutions that offer open standards and compatibility with existing management tools will reduce operational overhead and improve long-term sustainability. The trend toward OCP standards and integrated ecosystem partnerships underscores the importance of future-proofing investments.
Finally, risk mitigation through supply chain resilience and regulatory compliance cannot be overlooked. Choosing vendors who adhere to updated safety standards like UL 2755:2025 and who have robust supply chain strategies can protect organizations from project delays and compliance issues. The modular model inherently offers some protection against construction risks, but vendor reliability remains a critical factor.
Conclusion: The Value of Deep Intelligence
The Modular Data Centers Market is at an inflection point, driven by technological demand, regulatory evolution, and competitive innovation. For stakeholders aiming to capitalize on this growth, surface-level data is insufficient. The strategic value lies in understanding the nuances of market segmentation, regional dynamics, and the specific capabilities of competitive players.
PW Consulting's full market research report provides the detailed intelligence required to make informed decisions. From precise regional revenue breakdowns and segment-specific growth rates to comprehensive company profiles and SWOT analyses, the complete report equips you with the tools to navigate this complex landscape. We invite you to access the full study to unlock the granular data and strategic insights that will define your success in the modular data center era. The future of infrastructure is modular, and the time to strategize is now.
For detailed analysis of this topic, please visit the official page: Modular Data Centers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Greenhouse Soil Market to Reach $6.86 Billion by 2032 with 5.5% CAGR: PW Consulting Insights
By PW Consulting, 2026-09-07
Strategic Intelligence for the Decade Ahead: Inside the 2026 Greenhouse Soil Market Outlook
The global greenhouse soil market is entering a decisive inflection point. As agricultural systems worldwide confront tightening environmental regulations, volatile raw material supply chains, and accelerating demand for controlled-environment production, the soil substrates that anchor greenhouse cultivation are no longer mere inputs. They are strategic assets. PW Consulting’s newly released Greenhouse Soil Market research report delivers a comprehensive, data-grounded navigation framework for executives, procurement leaders, and investors who must position their organizations for resilience and growth through 2032.
Silicone Sprayer Market
This analysis draws on verified historical performance from 2020 through 2025, extends a rigorously modeled forecast across the 2026–2032 horizon, and integrates the latest regulatory, competitive, and macroeconomic developments reshaping the sector. For enterprise decision-makers, the report is engineered not as a retrospective summary but as a forward-looking intelligence asset. It is designed to answer the questions that keep senior leadership awake at night: Where will commercial volume concentrate? Which substrate architectures will survive the next wave of policy mandates? How are incumbent specialists and agile innovators restructuring their portfolios, partnerships, and pricing architectures in response to structural cost pressures?
Worldwide Underwater Hull Antifouling Coating Market
Market Architecture and the Trajectory of Commercial Value
The commercial landscape of greenhouse soils has demonstrated steady expansion over the past half-decade, driven by the compounding effects of urbanized food production, precision horticulture, and the substitution of field soils with engineered growing media. Historical revenue performance from 2020 to 2025 illustrates a market that has consistently compounded in value, reflecting both volume growth and structural pricing power across specialist formulations. That trajectory reaches a measured baseline in 2025, positioning the sector for a forecast window in which the overall market is projected to expand at a compound annual growth rate of 5.5 percent through 2032.
Worldwide Anti-adhesion Composite Mesh Market
Revenue multiples across the forecast horizon reveal a market that does not merely grow—it re-rates. The expansion curve reflects several converging forces: rising adoption of high-yield greenhouse architectures, sustained investment in controlled-environment agriculture, and the gradual premiumization of substrate performance as growers demand higher consistency, reduced disease pressure, and improved water-holding dynamics. The 2032 valuation endpoint underscores a sector that is transitioning from steady commodity growth to a more nuanced, performance-differentiated commercial environment. For executives, this means the near-term operating window is defined less by aggregate demand than by the velocity at which companies can adapt their product architectures, supply commitments, and pricing strategies to a market that is simultaneously expanding and fragmenting around new material paradigms.
Segmentation Dimensions That Shape Commercial Strategy
Behind the headline growth figures lies a market structure that rewards precision. The report decomposes commercial activity across multiple operational lenses, allowing leadership teams to isolate where margin pools are forming, where volume is migrating, and where competitive intensity is intensifying. By product architecture, the market reflects a hierarchy of specialized growing media, with potting mixes and garden soils commanding material share of commercial activity, while mulch and topsoil segments serve distinct landscaping and cultivation utilities. This architecture signals that greenhouse operators and commercial growers are not purchasing generic earth; they are acquiring engineered performance substrates tailored to moisture retention, aeration, microbial stability, and transplant readiness.
Geographically, the market reflects pronounced regional specialization. North America and Europe together account for the largest share of commercial activity, reflecting mature greenhouse infrastructure, well-established horticultural supply chains, and advanced substrate formulation capabilities. Asia Pacific, Latin America, and the Middle East and Africa each represent differentiated growth vectors, with demand patterns shaped by local cultivation practices, import dependency for premium substrates, and the pace at which controlled-environment agriculture is scaling beyond traditional field-based systems. Crucially, the divergence in regional demand profiles means that a single distribution or formulation strategy cannot be uniformly applied; commercial teams must calibrate their go-to-market architecture to regional substrate preferences, logistics constraints, and regulatory environments.
By end-use application, commercial greenhouse cultivation, lawn and landscaping, and indoor gardening each represent sizable demand centers, but their growth drivers differ sharply. Commercial greenhouse activity is governed by yield optimization, disease management, and substrate longevity across multiple cropping cycles. Landscaping and lawn applications are shaped by aesthetic consistency, seasonal demand, and municipal procurement standards. Indoor gardening reflects consumer behavior, residential horticulture trends, and the growing popularity of controlled indoor growing environments. The report maps these application vectors against performance requirements and purchasing cycles, enabling procurement and product teams to align formulation roadmaps with the specific economics of each demand center.
Regulatory Fault Lines and the Rewiring of Input Economics
No market analysis in this sector is complete without confronting the regulatory and cost architecture that is actively rewriting substrate economics. Policy interventions are no longer peripheral concerns; they are restructuring the competitive baseline. In the United Kingdom, the nursery sector is implementing a phased government peat ban, with a 100 percent peat reduction mandated by 2025 for the hobby segment and by 2030 for professional growing media used in greenhouses. This regulatory arc is forcing substrate suppliers and growers alike to accelerate the transition toward peat-reduced and peat-free formulations well ahead of the legal deadline, compressing the timeline for reformulation, supplier qualification, and grower acceptance.
Parallel pressures are emerging across Northern Europe. In Finland, a greenhouse cooperative has mandated that all soil mixes for greenhouse production contain less than 30 percent peat, a threshold that has already forced multiple legacy vendors off supplier lists. This is a representative signal of a broader trend: commercial grower groups are converting environmental mandates into procurement specifications, and suppliers that cannot demonstrate viable alternative substrate performance are being excluded from consideration regardless of legacy relationships. The European Union’s peatland protection policies are simultaneously accelerating peat reduction in growing media, prompting a shift toward alternative substrates such as wood fiber and coir in greenhouse applications. These shifts are not cosmetic; they alter the material cost structure, the technical specification envelope, and the supplier qualification pathway.
At the same time, macroeconomic pressures are compounding the challenge. Rising fuel and transportation costs for peat moss and perlite components have increased labor and material expenses for preparing greenhouse soil mixes, squeezing margins across the value chain. Suppliers must absorb higher inbound logistics costs, while growers face steeper input pricing that erodes the economics of marginal cropping decisions. Yet the regulatory environment is not solely restrictive. In the United States, USDA Inflation Reduction Act funding supports climate-smart practices that include greenhouse soil amendments for soil carbon sequestration and emission reduction. This subsidy architecture opens a parallel commercial pathway: substrates and amendments that can document measurable environmental performance may become eligible for financial incentives, effectively turning compliance into a margin support mechanism rather than a pure cost center.
The strategic implication is clear. Companies that treat substrate development as a static formulation exercise will find themselves outpaced by rivals that are engineering products to meet simultaneously the performance specifications of commercial growers and the documentation requirements of subsidy programs and regulatory frameworks. The market is splitting between legacy material dependence and forward-positioned alternative substrate portfolios, and the window for repositioning is narrowing.
Competitive Positioning and the Emerging Battleground for Substrate Authority
The competitive landscape is defined by a core group of specialists that have built entrenched positions around material expertise, regional distribution, and cultivation-specific formulation. Scotts Miracle-Gro Company, headquartered in Marysville, Ohio, remains a major producer of organic and conventional greenhouse soil mixes and potting substrates for professional growers, leveraging brand recognition and broad distribution to anchor share in both retail and professional channels. Sun Gro Horticulture, based in Vancouver, Canada, operates as the largest North American producer of horticultural peat moss and bark-based growing media blends for greenhouses, giving it a distinctive advantage in raw material sourcing and blend engineering.
In Europe, Klasmann-Deilmann GmbH, headquartered in Geeste, Germany, stands as a leading manufacturer of peat-based and alternative growing media substrates optimized for greenhouse cultivation, with a portfolio that reflects deep technical specialization and a growing emphasis on substrates adapted to shifting regulatory expectations. Premier Tech Ltd., based in Rivière-du-Loup, Canada, supplies specialized growing media and greenhouse substrates tailored for commercial horticulture, positioning itself at the intersection of formulation science and large-scale grower support. In the United States, FoxFarm Soil and Fertilizer Co, headquartered in Arcata, California, produces organic greenhouse soil amendments and ready-to-use potting mixes that serve both professional and enthusiast segments, while Michigan Peat Company, based in Houston, Texas, remains a key producer of peat-based greenhouse soil mixes and custom horticultural substrates.
Espoma Company, headquartered in Millville, New Jersey, manufactures natural and organic greenhouse soil products and blends, building share in the organic and consumer-aligned segments. Good Earth Horticulture, operating in Oregon, provides high-performance greenhouse soil solutions for commercial growers, with a product focus that emphasizes cultivation reliability and regional supply responsiveness. Florentaise, based in Quebec, Canada, supplies specialized greenhouse and nursery growing media substrates that address the demands of intensive propagation and container production. ASB Greenworld, based in the Netherlands, serves as a European producer of peat and bark-based growing media for greenhouses, offering formulation capability aligned with the technical expectations of professional controlled-environment operations.
This competitive set illustrates a market where leadership is being contested across multiple axes: raw material access, formulation science, regional supply reliability, and the ability to navigate the transition toward reduced-peat and alternative substrates. The recent activity in the sector confirms that incumbents and challengers alike are restructuring their commercial footprint. In April 2025, Griffin Greenhouse Supplies announced a master distributor agreement with Hortus U.S.A. for growing media products including greenhouse soil substrates, expanding distribution reach and broadening the substrate options available to commercial buyers. In September 2025, HydraFiber introduced HydraTerra, a new formulation combining HydraFiber Advanced Substrate and Sunterra Canadian Sphagnum Peat for greenhouse growers, signaling ongoing investment in engineered blend architectures that seek to balance performance with evolving material constraints.
Market concentration metrics reinforce the strategic stakes. The three largest firms account for approximately 25.2 percent of the market, and the five largest reach roughly 28.4 percent. This mid-range concentration indicates a sector where scale confers meaningful advantages in supply chain leverage, formulation investment, and commercial reach, but where a broad field of capable specialists remains active and willing to compete on performance, service, and regional responsiveness. For enterprise buyers and investors, the concentration profile suggests that supplier relationships, formulation partnerships, and distribution agreements will be decisive variables in securing reliable access to high-performing substrates as demand patterns evolve.
Report Architecture and the Intelligence Organizations Need Now
This research is structured to convert complex market dynamics into actionable decision support. Rather than presenting static tables divorced from commercial context, the report is organized around the operational questions that procurement, product development, and strategic planning teams face when allocating capital and negotiating supply commitments. It traces the historical market through 2025, establishes the current baseline, and maps the forecast trajectory through 2032, enabling leadership to test growth assumptions against multiple adoption scenarios and material transition timelines.
The segmentation analysis provides granular visibility into how product architectures, regional demand profiles, and end-use applications interact to shape volume and margin. Instead of leaving executives to interpret isolated data points, the report frames each segmentation dimension in operational terms: what the split means for formulation priorities, what it implies for distribution planning, and where competitive overlap is likely to intensify. This approach allows teams to identify which segments are likely to command premium pricing for performance differentiation and which are more exposed to commodity substitution and logistics-driven cost pressure.
The competitive assessment goes beyond corporate descriptions to examine the strategic posture of the leading specialists and the implications of their product portfolios, regional footprints, and recent commercial moves. By mapping the competitive field against regulatory trajectories and raw material economics, the report helps organizations assess which suppliers are best positioned to sustain performance under tightening peat-reduction mandates and which are actively engineering alternative substrate pathways. The inclusion of recent developments, such as the Griffin Greenhouse Supplies distributor agreement and the HydraFiber product launch, grounds the competitive analysis in the market’s present momentum, showing how distribution alliances and formulation innovation are actively reshaping access and differentiation.
Equally important, the report situates the market within its wider environment. Regulatory timelines, subsidy pathways, transportation cost dynamics, and alternative substrate trends are analyzed not as background color but as drivers of commercial behavior. For procurement leaders, this means the research can inform supplier qualification criteria, contract structures, and multi-year sourcing strategies. For product and R&D teams, it provides a structured view of where formulation investment is most likely to yield competitive advantage. For executives and investors, it offers a consolidated view of where value is accumulating, where risk is concentrating, and where strategic agility will determine market standing over the forecast horizon.
Why This Intelligence Matters for 2026 Decision-Making
Enterprise decisions made in 2026 will be judged against the market’s structural evolution over the following years. Substrate selection is no longer a routine purchasing function; it is a strategic lever that touches yield stability, compliance readiness, cost predictability, and the ability to qualify for incentive programs. Suppliers and growers alike must navigate a landscape in which legacy material reliance is being penalized by both policy and procurement specification, while alternative substrate architectures are being validated through performance trials and commercial scaling. The organizations that succeed will be those that treat substrate strategy as a continuous capability—one that integrates formulation science, supply chain resilience, regulatory monitoring, and commercial partnerships.
The report’s forecast window is particularly valuable because it translates trajectory into planning context. The projected growth path through 2032 is not a guarantee of uniform opportunity; it is a map of where volume, margin, and competitive intensity are likely to concentrate. By aligning internal forecasts with the market’s modeled trajectory, organizations can stress-test capacity commitments, assess the timing of formulation or sourcing transitions, and identify the segments where advance positioning is most likely to protect share and margin.
For procurement and supply chain leaders, the research clarifies which supplier relationships and formulation categories are best aligned with the coming regulatory and cost environment. For commercial teams, it reveals where distribution and product messaging should be sharpened to capture performance-driven demand. For executive leadership, it provides a consolidated intelligence base to evaluate capital allocation, partnership strategy, and risk exposure across a market that is expanding even as it reconfigures around new material and policy realities.
Access the Full Strategic Blueprint
The greenhouse soil market is not simply growing; it is recalibrating around performance specifications, alternative material architectures, and a regulatory environment that is converting environmental intent into commercial specification. PW Consulting’s comprehensive market research report delivers the analytical architecture required to navigate that transformation with confidence. The full study provides the detailed breakdown, competitive depth, and forward-looking modeling that enterprise teams need to convert market complexity into deliberate strategy.
To obtain the complete segmentation analysis, full forecast trajectory, regional and application-level breakdowns, competitive positioning detail, and the full set of regulatory and macroeconomic assessments, request access to the complete report through the official research portal. The executive summary presented here outlines the strategic shape of the market, but the operative detail—the specific data, scenario analysis, and supplier-level intelligence that underpin confident 2026 and beyond decision-making—resides in the full publication. Explore the complete Greenhouse Soil Market research to secure the intelligence required to plan, source, and compete with clarity through 2032.
For detailed analysis of this topic, please visit the official page: Greenhouse Soil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Guitar Amp Market to Reach $182.7M by 2032, Growing at 2.11% CAGR
By PW Consulting, 2026-09-07
Corporate Strategy in a Resonant Market: The 2026–2032 Guitar Amplifier Landscape
1. Executive Context: Why This Study Matters Now
The guitar amplifier market is entering a period of structural recalibration. Between 2020 and 2025, the industry expanded from 119.5 million USD to 142.0 million USD, reflecting a steady but uneven recovery trajectory shaped by shifting instrument retail behavior, professional audio upgrades, and the gradual normalization of global supply chains. Looking forward, the forecast window from 2026 through 2032 projects the market to reach 182.7 million USD, with a compound annual growth rate of 2.11 percent. While the headline growth rate may appear measured, the underlying dynamics—regulatory pressure, component scarcity, technological hybridization, and concentrated competitive positioning—are creating disproportionate strategic stakes for manufacturers, distributors, and downstream commercial players.
Pet Injection Molded Toys Market
PW Consulting’s latest Guitar Amplifier Market research study is designed not as a static snapshot, but as a decision architecture for executives who must allocate capital, price strategically, plan product roadmaps, and anticipate supply-side volatility in a 2026 operating environment. This preview outlines the analytical framework, the competitive contours, and the operational tensions the full report dissects in granular detail. The objective is straightforward: give leadership teams enough structural clarity to validate investment hypotheses, while reserving the segment-level data, regional splits, and scenario modeling that underpin precise commercial planning for the complete intelligence package.
LED Flexible Circuit Board Film Market
2. Macro Trajectory and the Strategic Meaning of a 2.11% CAGR
A 2.11 percent CAGR across a seven-year forecast horizon is neither a stagnation signal nor a runaway expansion narrative. It is, instead, a diagnostic indicator. Markets that grow at this pace rarely do so through uniform volume expansion. More often, they are shaped by product-mix shifts, pricing power battles, replacement-cycle dynamics, and selective category outperformance. In the guitar amplifier sector, the historical data underscores this pattern: revenue moved from 122.78 million USD in 2021 to 136.68 million USD in 2023, experienced a minor dip to 136.11 million USD in 2024, and then rebounded to 142.0 million USD in 2025. That sequence suggests a market that is consolidating demand, recalibrating inventory, and beginning a new growth cycle rather than simply extending a legacy trend.
Intelligent Central Control System Market
The forward projection reinforces this interpretation. The baseline forecast steps from 147.85 million USD in 2026 to 155.63 million USD in 2027, then to 160.78 million USD in 2028, before a brief moderation in 2029 and a renewed climb toward 178.0 million USD in 2031 and 182.7 million USD in 2032. For strategy teams, this contour matters because it implies that the most consequential strategic opportunities will not come from chasing aggregate growth alone, but from understanding where value is migrating inside the total. Product architectures, channel economics, and regional cost structures will increasingly determine which organizations can convert modest market growth into margin expansion.
It is equally important to recognize what this study deliberately does not do in its public preview. The complete report contains segment-level revenue breakdowns, subcategory penetration rates, and regional contribution analysis that reveal how specific product families and application environments are outperforming or lagging behind the aggregate trend. Those data points are essential for pricing architecture, SKU rationalization, and geographic prioritization. They are not included here because their full strategic utility depends on being read alongside competitive mapping, cost-structure assumptions, and regulatory scenario planning—all of which the full report integrates.
3. Market Dynamics: Tariffs, Transformer Scarcity, and Supply Chain Tension
Any 2026 strategy for the guitar amplifier market must be built on an honest assessment of cost-side disruption. The industry is currently navigating a convergence of tariff exposure, component scarcity, and prolonged lead-time risk that is reshaping both boutique and mid-volume production economics. Recent trade policy developments have introduced new cost layers for imported amplifier sets and tube-based components. In particular, a 25 percent surtax on certain electric sound amplifier sets originating from Canada, alongside broader tariff actions on imports from Mexico and Canada, has materially altered the landed-cost structure for some manufacturers. Industry commentary has noted that these measures can add meaningful cost to boutique amplifier heads, changing the feasible pricing corridors for companies that depend on cross-border sourcing or finished-goods imports.
The European dimension adds another constraint. EU member states have imposed a 15 percent tariff on receiver and amplifier tubes for US-origin goods under the Harmonized Tariff Schedule, which directly affects manufacturers whose tube-amp lines rely on transatlantic component flows. This is not a marginal retail tariff issue; it becomes a design-and-sourcing problem when tube availability, tube pricing, and final-assembly geography are tightly coupled. For companies that position around authentic tube architectures, the regulatory environment is now a strategic variable rather than a compliance footnote.
Equally significant is the transformer supply picture. Electrical component market reporting indicates that transformer prices for guitar amplifier power and output units have risen substantially, with high-voltage models experiencing lead times extending to approximately three years. This is a structural bottleneck, not a transitory one. In a market where tube amplifier credibility depends heavily on power delivery, headroom characteristics, and signal-chain integrity, transformer availability influences not only cost but also product launch sequencing, custom-order fulfillment, and the feasibility of certain high-gain or high-wattage designs. Strategy teams that treat component lead times as a procurement detail rather than a product-planning constraint will likely face margin compression or schedule slippage during the forecast period.
The full report models these dynamics more explicitly by mapping how cost pressure interacts with pricing power across different amplifier architectures, and by identifying which operational levers—such as supplier diversification, hybrid design transitions, localized assembly, or SKU selectivity—offer the most resilient countermeasures. That analysis is necessarily detailed, because tariff and component risk do not affect every company uniformly. Their impact depends on product mix, sourcing geography, and the degree to which a brand can shift cost exposure without eroding perceived value.
4. Competitive Architecture: Incumbents, Boutique Builders, and the Hybridization Battle
The competitive landscape in guitar amplification remains concentrated but differentiated. Market concentration metrics indicate that the top three players account for approximately 45 percent of revenue, while the top five reach roughly 55 percent. That level of concentration suggests a market where brand equity, product lineage, and channel control still matter enormously, even as new product architectures and modeling technologies broaden the competitive field. The full report provides a company-by-company assessment of strategic positioning, but several competitive patterns are already visible well before the segment-level detail is integrated.
Fender Musical Instruments Corporation continues to anchor its amplifier strategy in a broad portfolio that spans tube, modeling, and digital architectures, including flagship lines such as the Hot Rod Deluxe and Tone Master series. The company’s 2026 product announcements, including a 30th anniversary update to the Hot Rod Deluxe, illustrate a familiar but powerful strategic logic: reinvest in legacy recognition while expanding the technological basis of the lineup. For competitors, the implication is that heritage brands can use product anniversaries and catalog refreshes to defend shelf presence and pricing while simultaneously migrating customers toward newer architectures.
Gibson Brands, Inc. presents a different strategic posture. With deep historical roots in amplifier production and current affiliation with Epiphone and Squier lines, Gibson’s market relevance is reinforced by its announced amplifier relaunch plans. In a concentrated market, relaunch narratives can be strategically potent because they re-activate brand associations without requiring a full platform-scale investment in every subcategory. The success of such a strategy depends, however, on whether production execution, component availability, and channel readiness align with the brand message.
Marshall Amplification remains a defining force in high-gain tube and hybrid amplification. Its market influence is tied less to catalog breadth than to iconic sound signatures and durable professional reputation. That profile gives Marshall a distinct pricing and positioning latitude, but it also ties the brand’s fortunes more closely to tube-centric demand and the regulatory and supply dynamics that affect it. PRS Guitars, by contrast, has been extending its amplifier presence through signature and combo models, including the David Grissom DGT 15 combo amplifier and new SE Series models. This approach reflects a strategy of incremental amplifier expansion tied to artist identity and differentiated combo form factors rather than broad platform substitution.
Boutique and specialty builders are shaping the market from the opposite end of the spectrum. Friedman Amplification has been pushing the boundaries of boutique tube and hybrid design, most recently with the PX20 watt amplifier developed in collaboration with Phil X and incorporating IR-Load technology. Benson Amps continues to emphasize hand-wired all-tube construction, an offering that directly trades on craftsmanship and tonal authenticity. These companies compete not on scale but on differentiation, and they are especially exposed to transformer lead-time risk and tariff-driven cost escalation because their value propositions depend on specific component and construction characteristics. At the same time, their prominence raises the strategic ceiling for the entire category by reinforcing consumer willingness to pay for tonal distinctions.
Beyond the core amplifier OEMs, adjacent players influence the ecosystem in ways that strategy teams should not overlook. Hammond Manufacturing supplies replacement power and output transformers for tube guitar amplifiers, making it a critical part of the maintenance, repair, and extended-life economics of the tube market. Orange Amplification contributes British-style tube and solid-state options that broaden the stylistic range available to buyers. BOSS Corporation’s Katana series and related modeling products, including upgraded mini amplifier formats with Bluetooth and effects integration, illustrate how digital-modeling logic is scaling downward into compact and accessible form factors. Peavey Electronics Corporation continues to operate with a professional-grade orientation and has been expanding production capacity in the Asia-Pacific region, a move that has direct implications for cost structure, lead-time management, and geographic exposure.
The full report translates these company profiles into a competitive map that shows where scale advantages, brand leverage, technological transitions, and cost exposure intersect. In a market with this level of concentration, competitive strategy is rarely about matching every move; it is about understanding which moves are defensive, which are offensive, and where differentiation can be protected long enough to support margin.
5. Strategic Segmentation Themes: Combo, Head, Commercial, and Household Demand
The study’s segmentation architecture is built to show how product form and usage context interact with the broader market trajectory. Combo amplifiers and head amplifiers represent two distinct product philosophies with different purchasing drivers, installation contexts, and price expectations. The complete report quantifies the relative scale of each category and traces how their demand profiles evolve across the forecast period, but even without disclosing the precise splits here, the strategic implication is clear: the balance between combo and head architectures shapes everything from retail merchandising to gigging-pro procurement to home-player convenience.
Similarly, the market’s division between commercial and household application environments provides a lens on demand quality, replacement cycles, and channel behavior. Commercial usage tends to imply professional or institutional demand patterns, where reliability, tonal consistency, and serviceability can be as important as outright price. Household usage typically reflects a broader and more price-sensitive buyer base, with purchasing decisions influenced by convenience, setup simplicity, and the blending of amplifier features with effects, connectivity, and portability. These two demand environments do not simply add together; they compete for manufacturing focus, inventory allocation, and go-to-market energy. The full report assesses how each application environment contributes to the total and where strategic emphasis is likely to generate the strongest return.
A recurring theme across both product-type and application segmentation is hybridization. Modeling technology, digital signal processing, and tube-logic approaches are increasingly used to bridge the gap between authenticity and flexibility. This is not just a product-feature story. It is a strategic story about how companies can manage component exposure, expand addressable use cases, and reposition legacy lines without fully abandoning the aesthetic expectations that underpin premium pricing. The report examines these transitions in detail, including how they affect the competitive positioning of established tube-centric brands and the threat they pose to more traditional architectures.
Again, the specific regional and application-level figures are reserved for the full intelligence package because their value is maximized when read together with cost assumptions, regulatory exposure, and competitive capability analysis. A standalone percentage tells a reader what the market looks like; the full study tells leadership what to do about it.
6. What the Full Study Delivers: Decision-Ready Analysis for 2026 Planning
This preview is intentionally structured as a strategic doorway rather than a complete deliverable. The complete PW Consulting Guitar Amplifier Market report is designed to support concrete decisions in the 2026 planning cycle and beyond. It includes a detailed revenue trajectory through 2032, segment-level analysis by product type and application, regional demand patterns, competitive profiling of the core market participants, and an integrated assessment of the regulatory and supply-chain forces that are reshaping cost structures.
The report also translates market structure into operational implications. It addresses how manufacturers can think about product-mix optimization in the face of transformer lead-time risk, how brands can evaluate pricing corridors under new tariff regimes, and how distributors and retailers can interpret demand shifts across commercial and household channels. Where relevant, it maps recent product announcements and strategic moves to the broader market logic, allowing readers to distinguish between one-off launches and structural repositioning.
For executives, the study is built to answer a set of linked questions: Where is growth actually originating within the total market? Which product architectures and application environments are best positioned to withstand cost and regulatory pressure? How concentrated is the market really, and what does that concentration mean for pricing, channel negotiation, and competitive response? Which company strategies are likely to be durable, and which depend on assumptions that may be vulnerable over the forecast horizon? The full report provides the data and the analytical scaffolding to answer those questions with precision.
7. Conclusion: From Market Signal to Strategic Action
The guitar amplifier market is not defined by explosive growth, but by meaningful structural complexity. A 2.11 percent CAGR over the 2026–2032 forecast period masks important internal shifts in product architecture, application demand, component availability, and regulatory exposure. For organizations operating in this space, the strategic challenge is not simply to track the top-line number but to identify where value creation is becoming more sensitive to sourcing decisions, design choices, and brand positioning. The market concentration profile, the visible tension between tube authenticity and hybridization, and the ongoing cost pressures from tariffs and transformer scarcity all point to a market in which disciplined strategy will increasingly outperform reactive product expansion.
PW Consulting’s full market study offers the deeper intelligence required to translate these signals into actionable plans. It provides the segment detail, regional context, competitive analysis, and scenario-aware framing that allow leadership teams to move from awareness to execution. For decision-makers preparing for the 2026 operating environment and the forecast window ahead, the complete report is the difference between understanding the market’s outline and being able to act on its specifics.
For detailed analysis of this topic, please visit the official page: Guitar Amplifier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cold Mix Asphalt Additives Market to Hit $701M by 2032, Growing at 4.92% CAGR
By PW Consulting, 2026-09-07
Strategic Intelligence for Infrastructure Leaders: The Cold Mix Asphalt Additives Market Outlook 2026–2032
Infrastructure development stands at a critical crossroads where operational efficiency, environmental compliance, and supply chain resilience must converge. For contractors, material suppliers, and municipal procurement teams, the question is no longer whether cold mix technologies will gain traction, but how quickly the supporting chemical ecosystem will mature. As a senior strategic advisor tracking construction materials across multiple cycles, I view this transition as one of the most actionable opportunities in the broader pavement management sector. The newly released PW Consulting analysis of the Cold Mix Asphalt Additives Market translates complex demand signals, formulation shifts, and regulatory pressures into a structured decision framework for 2026 planning.
Hydrogeology Consulting Service Market
This market has moved beyond niche experimentation. Ambient-temperature application formulations now enable substantial energy savings and measurable emission reductions compared with conventional hot mix processes, a shift that aligns procurement mandates with long-term lifecycle economics. At the same time, feedstock volatility, regional compliance requirements, and evolving sustainability expectations introduce cost structures and launch timelines that many organizations still underestimate. A disciplined market assessment is therefore essential, not merely for top-line forecasting but for proactive portfolio design, sourcing strategies, and competitive positioning.
Worldwide Small Scale Bioreactor Market
The purpose of this article is to provide a curated preview of the intelligence embedded in our full study. It highlights the structural forces reshaping demand, outlines the analytical depth available to subscribers, and explains how the findings can be operationalized during 2026 budgeting, product development, and market entry decisions. Core segmentation figures, regional breakdowns, and detailed pricing data are intentionally reserved for the complete report so that executives can evaluate the full scope before committing resources.
Worldwide Cross Door Refrigerator Market
Why 2026 Is a Defining Year for Cold Mix Asphalt Additives
The next several quarters will separate organizations that merely observe sustainability trends from those that embed them into procurement and formulation strategy. Several converging forces make 2026 a pivotal reference point for decision-makers in this space.
From niche option to mainstream infrastructure solution
Cold mix asphalt additives have transitioned from seasonal repair tools to year-round enabling chemistries. Their ability to support installation under ambient conditions reduces dependence on high-temperature plant operations, cuts transport and placement energy requirements, and expands the practical window for pavement interventions. This is particularly relevant for agencies and contractors managing aging networks, emergency pothole remediation, and remote or low-volume road programs where hot mix logistics impose heavy cost premiums.
Regulatory pressure as a demand catalyst
Green procurement mandates introduced by national and municipal authorities across Europe, North America, and Oceania are increasingly incentivizing or requiring lower-emission construction methods. In parallel, chemical compliance frameworks such as European REACH, California Proposition 65 requirements, and analogous regimes in Australia and Canada demand substantial toxicological testing and documentation for additives used in cold mix systems. The net effect is a dual dynamic: faster adoption where environmental credentials are rewarded, but higher compliance overhead for suppliers seeking to launch or scale products internationally. Understanding where those friction points will land is now a core strategic task.
Cost volatility and formulation economics
Feedstock economics remain a persistent variable. Volatility in crude oil and petrochemical inputs directly influences the production cost of bitumen emulsifiers, amine-based anti-stripping agents, and petroleum-derived adhesion promoters. This exposes manufacturers and buyers to margin compression if pricing, substitution, or hedging strategies are not anticipated. At the same time, bio-based alternatives to conventional petroleum-derived additives command a recognizable price premium, reflecting their sustainability positioning. That premium is not simply a sales tactic; it is a market signal that buyers are increasingly willing to evaluate against emissions targets, regulatory exposure, and long-term liability.
These dynamics call for a forward-looking rather than reactive posture. Organizations that interpret the interplay between environmental mandates, chemical compliance burdens, and feedstock risk will be better positioned to price intelligently, secure supply, and shape specifications in their favor.
Market Trajectory and the Strategic Signals Behind It
Our forecast window runs from 2026 through 2032, anchored by historical performance spanning 2020 to 2025. The overall market in current-year terms reached approximately USD 501.05 million in 2025, and the projected trajectory points to continued growth with a forecast compound annual growth rate of 4.92 percent. Looking ahead, the market is expected to reach roughly USD 519.91 million in 2026, advancing toward around USD 701.0 million by 2032.
Rather than treating these figures as static headline numbers, it is more useful to read them as expressions of underlying structural change.
- The upward path reflects the gradual institutionalization of cold mix formulations within both repair and new paving workflows, supported by energy and emissions advantages at the application stage.
- The forecast gradient suggests a market that is expanding steadily enough to justify capacity and portfolio investment, but not so explosively that short-term hype should override disciplined planning.
- Mid-period fluctuations in the broader projection remind us that growth is not smooth; regulatory shifts, feedstock shocks, and regional adoption patterns can alter pacing. That is why scenario-aware planning matters more than single-point targets.
From a strategic standpoint, the most important takeaway is that the market is moving from a repair-centric narrative to a broader construction and rehabilitation ecosystem. This has implications for product design, go-to-market sequencing, and the relative attractiveness of different formulation families. Executives evaluating 2026 budgets should therefore think in terms of demand durability, specification influence, and supply chain flexibility rather than in terms of one-off project spikes.
Inside the Report: Practical Intelligence for Decision-Makers
The full PW Consulting study is designed to move beyond macro commentary and into execution-ready analysis. It combines market sizing, segmentation logic, competitive profiling, and regulatory mapping into a single operational reference. Below is a structured overview of what the report delivers and how each component can be applied during planning cycles.
Market sizing and trajectory architecture
The report presents a calibrated trajectory across the forecast horizon, supported by historical calibration that ties recent performance to forward assumptions. It does not simply extend past growth; it integrates formulation adoption curves, procurement momentum, and likely demand intensity under different policy and cost environments. Readers gain a basis for budgeting, investment staging, and revenue planning that accounts for both base-case momentum and plausible deviations.
Structural segmentation analysis
A significant portion of the study is devoted to understanding how demand is distributed across product types, application modes, and geographic markets. The report explains which formulation families are aligned with which use cases, why certain applications favor specific adhesive or moisture-resistant properties, and how regional procurement realities shape uptake. Regional variations in volume concentration, infrastructure funding patterns, and specification practices are examined so that commercial teams can prioritize where to allocate sales effort, technical support, and distribution resources. The analysis also distinguishes between stockpile-oriented cold patch demand and continuous paving-oriented cold mix demand, since the underlying purchasing drivers, performance expectations, and seasonal patterns differ materially.
Competitive landscape and strategic positioning
The competitive section profiles the organizations that are defining the commercial and technical direction of the market. It maps company headquarters, product logic, and the strategic intent behind recent launches. This allows readers to compare not just who is present, but how firms are attempting to differentiate.
- Arkema SA, based in Courbevoie, France, emphasizes cold mix asphalt additives and adhesion promoters through its ColdGrip® offering. Its value proposition centers on improving cold patch longevity by displacing water and enhancing adhesion, an approach that directly addresses durability and moisture-related failure modes in repair and maintenance applications.
- Cargill, headquartered in Minneapolis, Minnesota, United States, has advanced Anova cold mix additives with polymer-modified, bio-based formulations. Its product direction highlights up to 100 percent RAP incorporation, low VOC performance, year-round applicability, and improved viscosity and moisture resistance, signaling a broader push toward high recycled content and environmental compatibility.
Recent market activity reinforces the strategic significance of these moves. In May 2025, Cargill introduced Anova cold mix additives with polymer-modified bio-based formulations enabling up to 100 percent RAP incorporation, low VOCs, and year-round application. In August 2025, Verde Resources unveiled a biochar-infused cold-mix asphalt designed to sequester CO₂ while remaining durable under traffic. These launches illustrate two parallel competitive vectors: formulation chemistry aimed at performance and recycled content, and material innovation aimed at emissions and sustainability storytelling. The full report assesses how such developments reshape customer evaluation criteria and competitive barriers.
Regulatory, cost, and procurement dynamics
A major strength of the study is its integration of external pressures into market logic rather than treating them as isolated footnotes. Compliance burdens such as toxicological documentation requirements and regional chemical restrictions are assessed for their impact on launch timing, market access, and total cost of ownership. Feedstock-linked cost exposure is analyzed to show where margin sensitivity is highest and where substitution pathways may emerge. Green procurement mandates are examined as structural demand accelerators, especially where specifiers can tie material selection to emissions and lifecycle considerations. The report also addresses the pricing premium associated with bio-based alternatives and explains how sustainability credentials are being translated into commercial value rather than merely marketing claims.
Actionable planning outputs
To make the intelligence usable, the report includes frameworks that help executives convert analysis into decisions. These include guidance on market entry sequencing, supplier evaluation criteria, formulation investment priorities, and risk mitigation around feedstock and compliance exposure. The aim is to support concrete actions such as revising specification language, adjusting sourcing contracts, prioritizing regional expansion, or restructuring product roadmaps in response to where demand intensity and competitive pressure are likely to concentrate.
Competitive Dynamics: Differentiation, Compliance, and the Green Premium
The competitive environment in this market is not defined solely by volume share; it is increasingly defined by performance credibility, regulatory readiness, and sustainability positioning. Three interconnected themes deserve attention as organizations plan for 2026 and beyond.
Performance differentiation as the baseline expectation
Cold mix additives must resolve practical failure modes that historically limited the reliability of ambient-temperature pavement solutions. Moisture infiltration, adhesion loss, and short service life in patch and paving applications remain central concerns. Suppliers that can demonstrate measurable improvements in adhesion promotion, water displacement, and durability under real traffic conditions are likely to gain stronger specification influence. In this context, product claims need to be supported by application-relevant evidence, not only laboratory characterization. The market is moving toward an expectation that additives should improve workability and placement flexibility without sacrificing field performance.
Regulatory readiness as a competitive moat
Chemical compliance regimes are raising the cost and complexity of product introduction. Documentation requirements, toxicological testing, and region-specific restrictions mean that international launches are not merely logistical exercises; they are compliance-intensive undertakings that can determine market access speed. Companies that invest early in regulatory alignment, documentation rigor, and region-specific formulation adaptation may gain an advantage in markets where buyers are increasingly risk-averse about material selection. This trend also favors suppliers that can present compliance as part of a broader value proposition, reducing hesitation among public-sector and large contractor buyers.
Sustainability positioning and the economic reality of the green premium
Bio-based and low-emission formulations are gaining visibility, but their commercial role depends on how buyers weigh the premium against measurable benefits. The premium associated with bio-based alternatives reflects not only formulation cost but also the value buyers attach to emissions reduction, recycled content, and regulatory or reputational alignment. For some applications, this creates a legitimate differentiation path; for others, it creates a purchasing tension that must be managed through lifecycle costing, specification incentives, or supplier-backed performance data. The report examines where this premium is likely to be absorbed, where it may constrain volume adoption, and how suppliers can structure offerings so sustainability features translate into defensible market position.
Translating Insights into 2026 and Beyond
Market intelligence in the construction materials space becomes valuable only when it informs concrete choices. For 2026 planning, there are several strategic actions that the full report is designed to support.
- Align product roadmaps with specification trends. If green procurement mandates and lower-emission methods continue to gain institutional traction, then formulation development and marketing should emphasize not only workability but also emissions-related benefits, moisture resistance, and compatibility with high recycled content where applicable.
- Stress-test cost models against feedstock risk. Because petroleum-derived inputs can shift production economics quickly, buyers and suppliers alike should map exposure points, evaluate substitution options, and consider pricing architecture that protects margins under volatility.
- Use compliance strategy as a launch lever. Organizations seeking international expansion should treat regulatory documentation and toxicological readiness as part of commercial strategy, not as an afterthought. Earlier investment here can reduce market-entry friction and increase credibility with risk-conscious buyers.
- Prioritize regional focus based on demand logic. Regional infrastructure funding patterns, procurement style, climate-driven maintenance needs, and specification maturity differ substantially. The report helps identify where effort should be concentrated and where a more measured entry is appropriate.
- Evaluate competitive moves with a clear framework. New launches in bio-based formulations, high RAP incorporation, and CO₂-sequestering material concepts are shaping customer expectations. Decision-makers should assess whether these developments alter specification criteria, expand the acceptable performance envelope, or create pricing pressure in specific segments.
The strategic synthesis is straightforward: the cold mix asphalt additives market is maturing into a structurally important segment of pavement management, but its growth path is being shaped by formulation performance, regulatory complexity, feedstock economics, and sustainability expectations simultaneously. Organizations that prepare for all four forces will extract more value from the opportunity than those that respond to only one.
How to Use This Study for Board-Level and Operational Decisions
The report is built to serve multiple audiences within an organization. Executive teams can use it to frame market direction, investment sequencing, and risk exposure. Commercial leaders can use segmentation and competitive analysis to refine territory priorities, value propositions, and launch timing. Technical and procurement teams can use the dynamics sections to anticipate compliance burdens, feedstock sensitivity, and specification shifts that affect sourcing decisions.
To get the most out of the study, readers should approach it as a planning instrument rather than a static market snapshot. The core macro trajectory provides shared context, while the segmentation, competitive, and regulatory analyses support internal scenario building. When combined with internal data on project pipelines, regional activity, and procurement calendars, the report can help convert broad momentum into specific 2026 actions and resource allocation choices.
Conclusion: A Market Where Preparation Determines Advantage
The Cold Mix Asphalt Additives Market is entering a phase in which credibility, compliance, and formulation intelligence matter as much as volume growth. The trajectory through 2032 indicates continued expansion, but the more strategic question is where value will accrue, which product families will be favored in which applications, and how regulatory and cost dynamics will shape competitive positioning. Organizations that anticipate these forces will be able to design better product strategies, protect margins, and influence specifications before demand patterns become fully established.
This article has provided a substantive preview of the framework behind the full PW Consulting study. The complete report develops the underlying segmentation detail, competitive assessment, regional logic, and dynamic analysis in far greater depth, enabling decision-makers to move from directional understanding to specific, defensible plans for 2026 and beyond. For teams that require the full intelligence set—including detailed market sizing context, segmentation logic, competitor profiles, and regulatory-cost mapping—the complete study is available through our source page.
For detailed analysis of this topic, please visit the official page: Cold Mix Asphalt Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Calcium Sulfate Market to Hit $385.32M by 2032 with 4.2% CAGR
By PW Consulting, 2026-09-07
Strategic Imperatives in the Calcium Sulfate Market: Navigating Growth and Complexity Through 2032
Executive Overview: The Foundation of Industrial and Agricultural Stability
Calcium sulfate remains a cornerstone mineral commodity across multiple vertically integrated industries, serving as a critical functional additive, structural component, and soil amendment. As global supply chains recalibrate and regulatory frameworks tighten around material sourcing, waste repurposing, and grade-specific purity standards, enterprises operating in or adjacent to the calcium sulfate value chain must adopt a sharper, data-informed strategic posture. The latest market intelligence from PW Consulting examines the full trajectory of this sector, tracing historical demand elasticity from 2020 through 2025 and projecting structural expansion across the 2026 to 2032 forecast window. This analysis is engineered to equip procurement leaders, product developers, and corporate strategists with the contextual depth required to anticipate volume shifts, pricing pressures, and competitive repositioning before they materialize in quarterly performance metrics.
Worldwide Lateral Hydraulic Damper Market
The calcium sulfate ecosystem is defined by its dual identity: a commodity-grade industrial and agricultural input, and a highly regulated specialty ingredient in food, pharmaceutical, and personal care formulations. This duality creates distinct growth vectors, risk profiles, and margin structures that cannot be managed through aggregate market assumptions alone. Decision-makers require granular visibility into how grade specifications, regional sourcing dynamics, and end-use substitution trends interact to shape realized demand. Our comprehensive market study delivers precisely that framework, translating historical procurement patterns and forward-looking regulatory signals into an actionable strategic lens.
Worldwide Micromobility Market
Historical Trajectory and Forward Growth Architecture
Macro Market Evolution: From Recovery Dynamics to Sustained Expansion
The calcium sulfate market has demonstrated a clear pattern of baseline recovery followed by methodical, structurally supported growth. Over the 2020 to 2025 historical period, total revenue climbed from approximately 235.18 million USD to 288.9 million USD, reflecting a market that absorbed post-pandemic demand normalization while navigating supply-side adjustments in raw material availability. This upward arc was not linear; interim year-to-year movements reveal how construction activity cycles, agricultural input demand, and specialty-grade procurement behaved under shifting macroeconomic and regulatory conditions. The historical dataset captures the exact inflection points where volume expansion diverged from price-led revenue movements, providing a validated baseline for forecasting reliability.
Worldwide Medical Imaging Remote Diagnosis Service Market
Looking ahead across the 2026 to 2032 forecast horizon, the market is positioned to expand to an estimated 385.32 million USD. This trajectory reflects a compound annual growth rate of 4.2 percent, a pace that underscores durable utilization across core verticals rather than speculative demand surges. The sustainability of this expansion is anchored in several structural drivers: ongoing renovation and infrastructure activity supporting construction-grade consumption, expanding agricultural programs that leverage calcium sulfate as both a soil conditioner and secondary nutrient carrier, and steady incorporation of technical, food, and pharmaceutical grades into manufacturing workflows where purity consistency and regulatory compliance are non-negotiable.
Translating Forecast Data into Decision Architecture
Aggregate market size and CAGR figures are necessary but insufficient for executive planning. The true strategic value lies in understanding how growth distributes across product forms, grade specifications, and application verticals. The calcium sulfate market is bifurcated between dihydrate and anhydrous variants, each carrying distinct handling characteristics, processing requirements, and end-market suitability. Similarly, grade segmentation delineates fundamentally different buyer profiles and purchasing criteria. Technical-grade demand responds primarily to volume and cost efficiency in industrial and construction workflows, while food-grade and pharmaceutical-grade revenue streams are governed by certification pathways, traceability expectations, and formulation-specific performance thresholds.
Application-side dynamics further complicate procurement planning. Construction remains a dominant consumption channel, but growth in agricultural supplementation, industrial processing, and personal care formulations introduces portfolio diversification opportunities that many market participants are still learning to capture. The forecast period will likely reward companies that align sourcing strategies with application-specific grade transitions rather than relying on undifferentiated bulk procurement. Our full research deliverable unpacks these interrelationships in operational detail, providing scenario-based volume and revenue frameworks that allow teams to model procurement commitments against multiple demand pathways.
Competitive Landscape: Positioning Among Established Specialists
Market Concentration and Strategic Implications
The competitive structure of the calcium sulfate market reflects moderate consolidation coupled with a persistent presence of regional and specialized suppliers. Market concentration metrics indicate that a limited set of leading participants controls a substantial share of overall revenue, with the top three firms accounting for approximately 58.0 percent and the top five expanding that share to about 62.0 percent. This concentration pattern suggests that scale, origination capability, and grade-certification infrastructure confer meaningful competitive advantage, particularly for buyers prioritizing supply reliability and specification consistency. At the same time, the remaining market share distributed across regional processors and niche-grade producers indicates that differentiated service models, localized formulation expertise, and application-specific technical support continue to create viable competitive entry points.
Core Participants Shaping Supply and Application Innovation
Several established organizations illustrate the operational diversity shaping current market behavior. CB Minerals operates from Mamaroneck, New York, offering calcium sulfate across dihydrate, hemihydrate, and anhydrous forms with sourcing origins in both the United States and China. Its positioning serves industrial and agricultural markets where flexible form availability and origin diversification matter for procurement resilience. The Kish Company, based in Mentor, Ohio, functions as a supplier and processor of anhydrous and dihydrate calcium sulfate, emphasizing use as industrial mineral extenders and additives. Its profile highlights the importance of secondary processing and functional integration in higher-specification industrial supply chains.
On the specialty and export-oriented side, Hebei Xingtai Shuanghua Gypsum Products Co., Ltd., headquartered in Xingtai, Hebei, China, manufactures and exports food-grade, anhydrous, and related calcium sulfate products. Its activity extends into baking ingredients, tofu coagulation, and pharmaceutical applications, illustrating how grade purity and regional production scale can support cross-border specialty demand. Meanwhile, SUL4R-PLUS in Illinois has directed its capabilities toward granular calcium sulfate fertilizer blends designed to deliver secondary nutrients, particularly calcium and sulfur, for agricultural programs. This specialization demonstrates how calcium sulfate-based products can be engineered for agronomic performance rather than treated solely as bulk mineral inputs.
Recent Developments and the Signal Value for Procurement Strategy
Recent operational activity reinforces the importance of monitoring capacity expansion and supply-chain localization trends. In April 2025, SUL4R-PLUS opened a new calcium sulfate fertilizer plant in Marissa, Illinois, converting a former Quad County Ready Mix site near the Prairie State power plant. The facility was commissioned with an annual capacity of 100,000 tons, signaling a deliberate push into higher-volume, application-specific agricultural supply. This kind of development matters beyond the immediate production figure; it reflects how regional production assets can strengthen distribution efficiency, reduce lead-time variability, and enable closer alignment with cropping cycles and nutrient management programs. For procurement teams, such capacity additions reshape regional availability and can alter the relative attractiveness of long-haul sourcing versus localized supply partnerships.
Market Dynamics: Regulation, Feedstock Transitions, and Operational Realities
Regulatory Guidance and the Reuse Imperative
Regulatory developments continue to reshape calcium sulfate handling, sourcing, and downstream utilization. In January 2025, India’s Central Pollution Control Board issued handling and management guidance for flue gas desulfurization gypsum, with the stated intent of supporting its agricultural and industrial reuse while improving environmental compliance. This type of regulatory intervention is strategically significant because it directly affects the legitimacy, traceability, and operating expectations associated with secondary gypsum streams. For industry participants, the guidance creates both opportunity and oversight burden: it can broaden acceptable reuse pathways while simultaneously demanding documentation, handling protocols, and downstream quality assurance that may not have been standard practice in earlier market cycles.
Such regulatory clarity can also influence procurement preferences. Buyers increasingly evaluate not only price and specification fit but also the compliance posture of their suppliers and the regulatory status of the feedstock from which finished calcium sulfate products are derived. This creates a competitive premium for organizations that can demonstrate controlled handling, documented origin, and application-appropriate material stewardship. Our research framework examines how these compliance expectations intersect with grade requirements and regional market practices, offering a structured view of where regulatory risk is most likely to translate into cost or availability implications.
Feedstock Transitions and Supply-Side Constraints
On the supply-side, feedstock availability remains a critical dynamic. Synthetic gypsum production has experienced decline linked to the closure of coal-fired power plants, reducing the availability of this secondary calcium sulfate feedstock. This transition affects more than nominal volume; it alters the composition of available supply, shifts reliance toward alternative sources, and can introduce variability in material characteristics depending on origin and processing pathway. For downstream users, the implications can include changes in procurement lead times, reformulation considerations where synthetic gypsum was historically integrated, and heightened attention to source diversification.
The interaction between feedstock transitions and grade-specific demand is particularly important. Where agricultural, construction, and industrial applications have historically benefited from the availability of secondary gypsum streams, tightening supply can reshape relative pricing and availability across product forms. At the same time, specialty-grade applications that depend on controlled purity and consistent specification may be less directly affected by synthetic gypsum availability shifts but could still experience indirect effects through broader supply competition. Understanding these linkages requires a supply-chain lens that goes beyond total market size and into origin mix, processing capacity, and end-use substitution behavior.
Building Forward-Ready Strategy With PW Consulting Intelligence
What the Research Delivers for Operating and Planning Teams
This market study is designed as an operational reference for teams that must convert uncertain market conditions into defensible planning assumptions. Rather than presenting calcium sulfate as a single homogeneous market, the research breaks down the structural forces shaping revenue formation, volume movement, and competitive repositioning across the 2026 to 2032 period. The report integrates historical performance context, forecast architecture, segmentation logic, regulatory updates, and company-level activity into a coherent narrative that supports multiple use cases, including category strategy, supplier evaluation, capacity planning, and product portfolio prioritization.
The analytical content is structured to help users answer applied questions: how demand intensity differs across grade and application contexts, where regional supply realignment is most consequential, how regulatory guidance alters procurement criteria, and which operational signals indicate shifting competitiveness among established players. By mapping these elements together, the study enables leadership teams to distinguish between transient noise and durable structural change. It also supports scenario planning by clarifying which segments exhibit greater stability and which are more exposed to feedstock transitions, regulatory recalibration, or regional sourcing disruption.
Why This Study Matters Now for 2026 Decision-Making
The 2026 market environment demands a more sophisticated reading of calcium sulfate dynamics than aggregate growth figures alone can provide. A positive compound annual growth trajectory does not guarantee uniform opportunity across product lines, regions, or buyer segments. Some channels may experience stronger volume retention, others may face margin compression from feedstock realignment, and specialty applications may see disproportionate value creation if procurement teams can secure specification-ready supply with reliable compliance documentation. The ability to anticipate these divergences is a strategic differentiator.
This is precisely where PW Consulting’s market research adds practical value. The report provides the depth required to support procurement negotiations, product development roadmaps, regional expansion assessments, and risk evaluation around supply concentration and regulatory change. It is built to serve as an internal decision-support asset that can be referenced by commercial, supply chain, and strategy functions without requiring additional interpretation overhead.
- Comprehensive historical-to-forecast revenue mapping that establishes a trusted baseline for planning assumptions
- Grade, product, and application-level analysis that clarifies where growth drivers are most concentrated and where supply competition is intensifying
- Regulatory and feedstock context that connects policy and supply-side shifts to operational procurement implications
- Competitive landscape review grounded in company profiles, product forms, origin strategies, and recent capacity activity
- Actionable frameworks for evaluating supplier selection, regional sourcing, and grade-specific demand alignment across the forecast window
Next Steps: Accessing the Complete Market Intelligence
The calcium sulfate market is entering a period in which strategic advantage will belong to organizations that can align procurement, product development, and compliance awareness with a precise understanding of how demand and supply are evolving. Historical momentum, forecast direction, competitive concentration, and regulatory change all point to a market that rewards preparation and penalizes reactive decision-making. Our full market research report expands on every dimension outlined here, providing the detailed segmentation, scenario structure, and sourcing dynamics that enterprise teams need to make confident 2026 and beyond planning decisions.
For a complete view of the segmentation breakdowns, regional and application-level analysis, and the full competitive and regulatory context, we invite you to access the complete PW Consulting Calcium Sulfate Market study. The source report contains the detailed intelligence necessary to translate this high-level strategic overview into actionable procurement, investment, and product strategy.
For detailed analysis of this topic, please visit the official page: Calcium Sulfate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


