



Category: market research
PW Consulting: Attapulgite Market Hits $300M in 2025, Projected 2.8% CAGR Through 2032
By PW Consulting, 2026-09-07
Strategic Imperatives in a Maturing Attapulgite Landscape: A 2026 Decision-Maker’s Preview
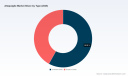
The global market for attapulgite clay has entered a phase of measured expansion, reflecting broader industrial trends where performance materials are increasingly valued for specificity rather than volume alone. Over the historical period from 2020 to 2025, the sector demonstrated steady growth, with total revenue climbing from approximately 250 million USD to 300 million USD. As we project forward through the 2026 to 2032 forecast window, the trajectory points toward a compound annual growth rate of 2.8 percent, suggesting that while the underlying demand is not explosive, it is structurally resilient. For executives navigating supply chain optimization, regulatory compliance, and end-market positioning, these macro indicators are merely the opening frame. What truly separates leading organizations from the rest is a granular understanding of how technological refinement, application-specific performance requirements, and regional supply dynamics intersect. Our newly released Attapulgite Market research study was designed precisely for that purpose: to convert broad industry signals into actionable strategic intelligence.
Worldwide Thermal Ablation System Market
In an environment where raw material availability, processing sophistication, and end-use certification increasingly dictate competitive advantage, a surface-level view of the market is insufficient. This research preview outlines how our comprehensive analysis equips leadership teams with the foresight needed to allocate capital efficiently, evaluate partnership opportunities, and anticipate regulatory shifts that could reshape sourcing strategies. Rather than presenting static snapshots, the study constructs a decision-oriented narrative that maps historical performance, forecasts structural shifts, and dissects the operational realities of the companies that define the competitive frontier.
Worldwide Railway Expansion Joints Market
Why the 2026 Outlook Demands a Refined Analytical Lens
The transition from the 2025 baseline into the 2026 horizon marks a critical inflection point for attapulgite stakeholders. The market’s historical expansion underscores a consistent appreciation for attapulgite’s rheological, sorptive, and structural properties across industrial and specialty applications. Yet the projected path forward reveals more than a linear continuation of past trends. It highlights a market where growth is increasingly driven by differentiated grades, application-specific performance validation, and tighter quality control frameworks that align with evolving end-user expectations. For procurement leaders, R&D directors, and strategic planners, the central challenge is no longer simply securing volume but ensuring that the material specifications, traceability standards, and cost structures align with mission-critical operational goals.
Worldwide Multi-Currency Checker Market
This is where high-resolution market intelligence becomes indispensable. The forecast window through 2032 reveals a landscape in which demand patterns are expected to shift in response to both technical innovation and broader industrial prioritization. Understanding which application verticals will anchor near-term consumption, how regional supply chains will adapt to traceability and performance requirements, and which product grades will capture disproportionate value requires a structured, data-rich analytical framework. Our report delivers exactly that: a multi-dimensional view that connects market sizing with competitive behavior, regulatory context, and operational developments, enabling decision-makers to separate transient market noise from durable growth drivers.
Beyond the Headline Numbers: What Strategic Decision-Makers Actually Need
While top-line revenue figures provide essential context, they rarely answer the questions that matter most to executives. A responsible market assessment must go further, interrogating the structural composition of demand, the concentration of supply, and the operational moves that signal where value will accrue. Our study approaches the attapulgite market with that discipline, ensuring that every analytical layer serves a clear strategic purpose.
The report is built around several core analytical pillars that together create a complete operational picture:
- Historical market reconstruction that contextualizes recent performance and isolates the factors that shaped revenue evolution over the 2020 to 2025 period.
- Forward-looking modeling that translates macro trends into a structured forecast framework, helping organizations test assumptions against a range of demand scenarios.
- A segmentation lens that distinguishes between product-grade dynamics and application-driven consumption patterns, enabling more precise alignment between sourcing strategy and end-market requirements.
- A regional perspective that maps how geographic demand clusters interact with supply logistics, regulatory environments, and manufacturing footprints.
- A competitive and concentration analysis that evaluates market structure, key player positioning, and the strategic implications of consolidated supply.
This architecture is deliberately designed for application, not just observation. Rather than leaving readers with isolated statistics, the study connects each analytical dimension to operational implications: how a shift in grade-level demand might affect procurement mix, how regional demand balances could influence logistics planning, and how evolving product introductions may reshape competitive thresholds. The result is a decision-support tool that can be integrated directly into strategic planning, investment evaluation, and market-entry assessments.
Segment Architecture and the Shift Toward Grade-Specific Value
One of the most consequential dimensions of the attapulgite market lies in the distinction between product characteristics and the applications they serve. Not all attapulgite is functionally equivalent. Differences in particle morphology, surface activity, and processing refinement create clear divides in performance, acceptable use cases, and ultimately, commercial value. Our research unpacks these distinctions by examining how market demand distributes across colloidal and sorptive grades, and how those grades map to the industrial and specialty sectors that depend on them.
The colloidal segment represents a domain where processing precision directly enables performance in formulations that require thickening, suspension stability, and controlled rheology. In parallel, sorptive-grade attapulgite serves application environments where absorption capacity, chemical stability, and structural integrity are paramount. The balance between these two domains reveals far more than a simple product split; it reflects how end users are prioritizing functionality, certification, and formulation reliability. For companies evaluating production capabilities or supply commitments, understanding this grade-level architecture is essential because it shapes both pricing dynamics and qualification barriers.
On the demand side, the report explores how consumption patterns extend across multiple verticals, including oil and gas operations, pet waste absorbent products, agricultural applications, paints and coatings formulations, and medical and pharmaceutical uses. Each of these sectors imposes different specification thresholds, regulatory scrutiny, and performance expectations. The strategic implication is clear: growth in attapulgite demand will not be evenly distributed across applications. Some segments will be propelled by functional necessity and substitution resistance, while others will depend on formulation innovation and regulatory alignment. Our study identifies the structural logic behind these consumption patterns, giving readers the context needed to anticipate where attapulgite’s value proposition is strongest and most durable.
Regional Dynamics and Supply-Chain Realities
Geography remains a defining variable in the attapulgite market, not only because demand is distributed unevenly but also because supply logistics, manufacturing proximity, and regulatory frameworks vary substantially across regions. The study maps the global footprint of attapulgite consumption and evaluates how regional markets differ in terms of intensity, application mix, and operational expectations.
In North America, the market has historically reflected deep integration with industrial absorbent demand and established extraction and processing infrastructure. Europe presents a different profile, where performance specifications, pharmaceutical-grade quality expectations, and traceability requirements often shape procurement decisions more than volume considerations alone. Asia Pacific stands out as a region where expanding industrial activity and application diversification are creating new demand pathways, while also placing pressure on supply reliability and consistency. Latin America and the Middle East and Africa, though smaller in absolute scale, contribute meaningful context to the global picture, particularly where regional industrial needs intersect with import dependency and logistics constraints.
The regional analysis does more than describe where demand exists; it examines how regional characteristics influence sourcing strategy. For instance, supply chain resilience, export-import dynamics, and local processing capacity can determine whether a manufacturer can meet specification consistency at scale. The report connects these geographic realities to practical planning considerations, allowing organizations to evaluate whether regional demand patterns justify nearshoring, partnership development, or specification adjustments in procurement contracts.
Competitive Intensity and the Structure of Market Leadership
The attapulgite market is characterized by a concentrated supply base, where a limited number of established producers hold a disproportionately large share of total market activity. The report examines this concentration directly, analyzing how market structure affects pricing flexibility, qualification barriers, and the strategic leverage available to both incumbents and new entrants. A concentrated landscape often translates into higher switching costs for buyers seeking certified, consistent material, while also rewarding suppliers that can demonstrate process control, product repeatability, and application-specific documentation.
Several key companies define the competitive rhythm of this sector. Active Minerals International LLC operates from Houston, Texas, and is recognized for producing and supplying gel-quality attapulgite clay, including grades designed for rheology modification, suspension, and absorption applications. Oil-Dri Corporation of America, based in Chicago, Illinois, supplies attapulgite clay as a functional absorbent and rheology modifier, serving industrial, pet care, and drilling-related applications. Clariant AG, headquartered in Muttenz, Switzerland, provides colloidal attapulgite clay for pharmaceutical, cosmetic, and specialty absorbent uses, emphasizing refined grades aligned with stricter end-use requirements. BASF SE, located in Ludwigshafen, Germany, supplies attapulgite-based products for coatings, adhesives, and industrial rheology modification, positioning itself within formulation-intensive markets where performance consistency matters.
The strategic significance of these players extends beyond their product portfolios. Their location, operational focus, and end-market orientation reveal how value is being partitioned across the supply chain. Companies that invest in grade specialization, application documentation, and supply reliability are better positioned to defend margin and customer loyalty in a concentrated market. At the same time, customers benefit from understanding which suppliers are most aligned with their technical and regulatory needs, reducing qualification risk and improving long-term sourcing stability.
Recent Developments That Signal Where the Market Is Heading
Competitive positioning is not static; it is continuously reshaped by product launches, partnership announcements, and evolving compliance expectations. Two recent developments stand out for their strategic relevance. In December 2025, Clariant introduced Pharmasorb™ Colloidal attapulgite clay, a highly refined pulverized grade intended for cosmetic and pharmaceutical applications and produced under Current Good Manufacturing Practice guidelines. This move underscores how attapulgite suppliers are increasingly aligning product development with stringent quality regimes, particularly where human-use and regulated formulations are involved.
Shortly before that, in October 2025, Active Minerals International LLC announced a supply partnership with the RBH Group to provide reliable, traceable high-performance attapulgite clay supply chains for European and Asian manufacturers. Rather than a simple sales arrangement, this kind of collaboration signals a broader industry shift toward traceability, specification transparency, and supply assurance across key regions. These developments matter because they illustrate how competitive advantage is being defined: not merely by material availability, but by verifiable quality, documented supply integrity, and the ability to support regulated and performance-sensitive applications.
The report situates these events within the larger market context, including relevant regulatory and industry references such as the role of US fuller's earth in the absorbents segment and the broader production and consumption tracking documented in recent mineral commodity summaries. By connecting discrete corporate actions to macro-level industry signals, the study helps readers interpret what such moves imply for future supply behavior, qualification requirements, and competitive thresholds.
How to Use This Research as a Decision Framework
A strong market study should not simply inform; it should enable action. The Attapulgite Market research is structured to support multiple strategic use cases. Procurement and supply chain teams can use the segmentation and regional analysis to evaluate sourcing diversification, specification alignment, and logistics exposure. R&D and product development groups can leverage the grade-specific and application-focused insights to assess where attapulgite can deliver differentiated performance and where substitution risk may be higher. Competitive intelligence teams can draw on the market concentration and company profiles to benchmark positioning, anticipate supplier strategy, and identify partnership or acquisition logic. Executive planners can use the forecast framework to test growth assumptions against realistic market behavior rather than extrapolating from headline figures alone.
Equally important, the report is designed to be referenced, not just read. By organizing the analysis around decision-relevant themes, it supports scenario testing, risk assessment, and internal alignment across functions that must coordinate around material strategy. In that sense, the research acts as a shared analytical foundation for cross-functional planning.
Accessing the Full Strategic Intelligence
This preview offers a structured introduction to the market logic, competitive dynamics, and analytical priorities that define our Attapulgite Market study. It is intended to demonstrate the depth of the framework and the practical orientation of the research, while preserving the detailed breakdowns that carry the most operational value. The complete report extends far beyond this overview, providing the comprehensive segmentation detail, regional and application-level intelligence, and competitive profiling that decision-makers need to act with confidence.
For leaders responsible for material sourcing, formulation strategy, or market planning in 2026 and beyond, the full study delivers the precision and context required to move from general awareness to informed execution. The deeper data architecture, scenario-based forecast context, and company-level strategic reading are available through the complete market research package. We invite you to access the full report to secure the complete intelligence set and integrate it into your strategic planning process.
For detailed analysis of this topic, please visit the official page: Attapulgite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Acupuncture Needles Market Hits $215M in 2025, Projects 6.98% CAGR to 2032
By PW Consulting, 2026-09-07
Navigating the Next Wave: Strategic Imperatives in the Global Acupuncture Needles Market
The global healthcare landscape is undergoing a profound transformation, driven by an increasing integration of traditional and complementary therapies into mainstream medical practice. Among these, acupuncture stands out as a cornerstone of pain management and holistic wellness, creating a robust demand for high-quality, precise instrumentation. For industry stakeholders, investors, and supply chain strategists, understanding the trajectory of the acupuncture needles market is no longer optional—it is a critical component of future-proofing business decisions in 2026 and beyond.
Skid Steer Loader Tire Market
This article serves as a strategic preview of our latest comprehensive market research report. It is designed to equip leadership teams with the macro-level intelligence necessary to identify growth vectors, mitigate regulatory risks, and understand the competitive forces shaping the industry. While we highlight the key trends and structural dynamics here, the full depth of quantitative intelligence remains exclusive to our detailed publication, guiding you toward data-driven actions that secure market share.
Worldwide Hematology Calibrators Market
Macro Market Trajectory: Resilience and Expansion
The acupuncture needles market has demonstrated remarkable resilience over the past five years, evolving from a niche sector into a significant component of the broader medical device industry. Our analysis tracks the market evolution from 2020 through the forecast horizon ending in 2032, revealing a consistent upward trajectory that underscores the growing acceptance of acupuncture therapies globally.
Quartz Sand、Quartz Grit and Quartz Slab Market
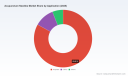
Historical data indicates a steady compounding of revenue, with the market valuation climbing from approximately 163.15 million USD in 2020 to an estimated 215.0 million USD in 2025. This growth is not merely a recovery from global disruptions but reflects a structural shift in healthcare consumption. As we look toward 2026, market revenues are projected to reach 227.99 million USD, signaling strong momentum as the industry enters the forecast period.
The long-term outlook remains highly favorable. Forecasts suggest that by 2032, the market could expand to 344.8 million USD. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 6.98 percent during the 2026-2032 forecast period. Such a rate indicates that the sector is outperforming many traditional medical device segments, driven by factors including an aging population, increased prevalence of chronic pain conditions, and the widening insurance coverage for complementary therapies in key economies.
- Historical Stability: Consistent revenue growth from 2020 to 2025 establishes a reliable baseline for forecasting.
- Future Upside: The projection to 344.8 million USD by 2032 highlights significant untapped potential in emerging applications.
- Growth Velocity: A CAGR nearing 7 percent suggests that early movers in supply chain optimization and product innovation will capture disproportionate value.
Segmentation Dynamics: Where Value Is Created
Understanding the anatomy of market revenue is essential for strategic positioning. The market is not a monolith; it is fragmented across product types, end-user applications, and geographical regions, each with distinct growth drivers and competitive intensities. Our report dissects these segments to reveal where capital efficiency and demand density are highest.
Product Type and Material Considerations
The product landscape is primarily divided into disposable and non-disposable needles, alongside other specialized variants. Disposable needles currently represent the dominant revenue stream, reflecting a global shift toward sterility, safety, and convenience in clinical settings. This preference is reinforced by regulatory mandates and patient expectations regarding hygiene. Non-disposable needles maintain a presence, particularly in specific traditional practice contexts, but the trend line favors single-use solutions.
Material science also plays a pivotal role. Surgical-grade stainless steel wire remains the dominant material due to its biocompatibility and autoclave compatibility. However, innovations such as siliconized stainless steel needles are gaining traction for their ability to reduce insertion friction and enhance patient comfort. Manufacturers who invest in surface treatment technologies and precision manufacturing processes are distinguishing themselves in a crowded field.
Application and End-User Ecosystems
Demand is heavily concentrated among hospitals and clinics, which serve as the primary procurement hubs for acupuncture instruments. Hospitals drive volume due to integrated pain management departments and rehabilitation centers incorporating acupuncture into multimodal treatment protocols. Clinics, including specialized TCM practices and private wellness centers, contribute significantly to the revenue base, often demanding higher variety and customization in product lines.
The billing environment influences application growth. In many jurisdictions, the cost of needles is included in the acupuncture service billing rather than submitted separately. For instance, under CPT codes such as 97810 and 97811, separate submission of needle costs may be denied. This reimbursement structure incentivizes providers to select cost-effective yet high-quality needles that align with service billing frameworks, impacting purchasing decisions at the institutional level.
Geographical Growth Vectors
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. While mature markets in North America and Europe maintain steady demand driven by established healthcare infrastructure and reimbursement policies, the Asia Pacific region presents compelling growth opportunities due to the deep cultural roots of traditional medicine and expanding manufacturing capabilities. Latin America and the Middle East and Africa are emerging as incremental growth zones, where regulatory harmonization and distribution network development are key prerequisites for market entry.
Our detailed analysis maps the revenue contributions across these regions, identifying specific countries where regulatory changes or demographic shifts are creating inflection points for demand. The full regional breakdown provides the granularity needed to allocate marketing budgets and distribution resources effectively.
Regulatory Landscape and Compliance Imperatives
Operating in the acupuncture needles market requires rigorous adherence to a complex web of regulatory standards. Compliance is not merely a legal checkbox; it is a competitive moat that determines market access and brand reputation. Our report provides a deep dive into the regulatory frameworks governing the design, manufacturing, and distribution of acupuncture needles.
In the United States, the FDA classifies acupuncture needles as Class II medical devices under 21 CFR 880.5580. This classification mandates requirements for sterility, single-use labeling, and biocompatibility for licensed practitioners. Manufacturers must navigate premarket notification pathways and maintain robust quality management systems to ensure ongoing compliance. The FDA MAUDE database also serves as a critical monitoring tool, recording adverse event reports such as serious injury incidents involving foreign body retention, which underscore the importance of product reliability and post-market surveillance.
Internationally, ISO 13485 certification is a prerequisite for manufacturers seeking to sell acupuncture needles in markets including the European Union and various Asian countries. This standard specifies requirements for a quality management system where an organization needs to demonstrate its ability to provide medical devices and related services that consistently meet customer and regulatory requirements. Held certifications such as CE marking and TGA approval further validate product safety and facilitate cross-border trade.
- FDA Classification: Class II device status requires sterility, single-use labeling, and biocompatibility compliance.
- ISO Standards: ISO 13485 is essential for international market access, covering quality management for medical devices.
- Adverse Event Monitoring: Reports like the FDA MAUDE database entry regarding foreign body retention highlight the need for rigorous quality control.
- Reimbursement Nuances: Understanding billing codes ensures that product pricing aligns with provider reimbursement realities.
Competitive Landscape: Leaders and Emerging Players
The competitive environment is characterized by a mix of established global leaders, regional manufacturers with strong domestic footprints, and specialized distributors. Market concentration analysis indicates a moderately fragmented landscape, with the top three companies holding a combined market share of approximately 24.6 percent and the top five reaching 26.2 percent. This structure suggests that while scale players exist, there is room for specialized and agile competitors to thrive through niche innovation and strategic partnerships.
Key Incumbents and Differentiators
Seirin Corporation, headquartered in Shizuoka, Japan, stands as a worldwide leader in painless acupuncture needles since 1978. The company offers a comprehensive portfolio including J-Type, L-Type, G-Type, and Pyonex disposable lines, leveraging automated precision manufacturing and ISO/CE certifications to serve global markets. Their reputation for quality and painless insertion technology sets a high benchmark for the industry.
AcuMedic, based in London, UK, operates as a key distributor and provider specializing in Seirin and other premium acupuncture needles. Their focus on sterile single-use and reusable formats for clinical and professional use positions them as a vital link in the supply chain for Western practitioners seeking trusted brands.
In China, Suzhou Medical Appliance Factory, known for the Hwato brand, represents the country's oldest and largest acupuncture needle manufacturer, with origins dating back to the 1850s. They produce Hwato and TONY sterile disposable needles and hold a suite of international certifications including FDA 510(k), CE, TGA, and ISO 13485. Their ability to supply international distributors makes them a formidable force in global procurement.
Dongbang Medical (DBC), located in Woorim, South Korea, produces siliconized stainless steel acupuncture needles under the DBC brand. They supply CE/FDA/ISO-certified lines for global distribution, covering hand, body, and intradermal types. Their focus on siliconization addresses the demand for reduced insertion resistance and enhanced patient comfort.
Wuxi Jiajian Medical Instrument Co., Ltd., another Chinese manufacturer, differentiates through color-coded handles and conductive options. Holding ISO and CE certifications with products listed in FDA establishment registration, they actively engage in international trade platforms. Asiamed Needle Co., Ltd. also contributes to the competitive mix as an Asian supplier focusing on sterile disposable single-use options with international quality certifications.
Recent Strategic Movements
The competitive dynamics are further shaped by recent strategic developments that signal shifting alliances and market expansion efforts. In October 2025, TCMzone, LLC announced a distribution partnership with Suzhou Medical Appliance Factory to distribute Hwato-brand acupuncture needles to licensed US practitioners. This move expands the reach of a legacy manufacturer into the US market through an established distribution channel, potentially intensifying competition among US-based suppliers.
In May 2025, Wuxi Jiajian Medical Instrument Co., Ltd. participated as an exhibitor at MEDICA 2025 in Düsseldorf, Germany. By showcasing acupuncture needles and related medical instruments at one of the world's largest medical trade fairs, the company demonstrated its commitment to international visibility and B2B networking, reinforcing the trend of Chinese manufacturers actively pursuing global market share through direct engagement.
- Seirin: Global leader with painless technology and broad disposable lines.
- AcuMedic: Premium distributor bridging Asian manufacturing with Western clinical demand.
- Hwato (Suzhou): Historic manufacturer with broad international certifications and new US distribution partnership.
- DBC: Korean innovator in siliconized needles with global certification suite.
- Wuxi Jiajian & Asiamed: Active players leveraging certifications and trade shows to expand global footprint.
Strategic Outlook for 2026 Decision Makers
As we move deeper into 2026, the acupuncture needles market offers a landscape rich with opportunity but contingent on strategic agility. The convergence of regulatory stringency, reimbursement complexities, and evolving clinical preferences requires stakeholders to adopt a multidimensional approach to strategy. Success will not come from price competition alone but from value creation through quality, compliance, and channel excellence.
For manufacturers, the imperative is to maintain rigorous adherence to ISO 13485 and FDA requirements while investing in product differentiation. Innovations in needle tip geometry, surface treatment, and handle ergonomics can command premium positioning. Furthermore, establishing robust post-market surveillance mechanisms to monitor adverse events is critical for maintaining trust and regulatory standing.
For distributors and retailers, the focus should be on curating product portfolios that align with the billing realities of end-users. Given that needle costs are often bundled into service billing under CPT codes, providing a range of options that meet clinical standards without inflating overhead is key. Strategic partnerships, such as the recent distribution agreements seen in the industry, can unlock access to verified markets and accelerate growth.
Investors and analysts should pay close attention to the growth velocity in the Asia Pacific region and the expanding presence of certified manufacturers from China and South Korea in Western markets. The moderate market concentration leaves space for consolidation or for specialized players to carve out niches in high-growth application segments like hospital-integrated pain management.
Supply chain resilience is another critical theme. Ensuring consistent access to surgical-grade stainless steel wire and maintaining capacity for automated precision manufacturing will be vital as demand scales toward the 344.8 million USD mark projected for 2032. Disruptions in raw material sourcing or quality deviations can have outsized impacts in a market where product reliability is paramount.
Deep Dive Awaits: Unlocking Full Market Intelligence
This overview provides a strategic snapshot of the forces shaping the acupuncture needles market, highlighting the growth trajectory, segmentation nuances, regulatory hurdles, and competitive maneuvers that define the industry. However, the full continuum of insights—including precise regional revenue splits, detailed segment valuations, consumer behavior analysis, and granular competitive benchmarking—is contained within our comprehensive report.
For executives and strategists who need to quantify market entry opportunities, optimize pricing strategies, or assess competitor threats with precision, the detailed data tables and proprietary forecasts are indispensable. The report offers actionable intelligence designed to support investment theses, product development roadmaps, and go-to-market strategies with confidence.
We invite you to access the full market research publication to leverage the complete dataset and analytical frameworks. In a market growing at a CAGR of 6.98 percent toward a 344.8 million USD horizon, the depth of your intelligence will directly correlate with the sharpness of your strategic execution. Stay ahead of the curve by grounding your 2026 decisions in the most rigorous analysis available.
Contact our research team or visit the source page to secure your copy of the full report and begin transforming market data into decisive competitive advantage.
For detailed analysis of this topic, please visit the official page: Acupuncture Needles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automatic Platform Screen Door Market To Hit $2,025M by 2032 at 8.5% CAGRPW Consulting: Emotion Analytics Market to Hit $4.75B by 2032, Growing at 15.5% CAGR
By PW Consulting, 2026-09-07
Strategic Imperatives in the Automatic Platform Screen Door Market: A 2026 Outlook
The global transit infrastructure landscape is undergoing a fundamental transformation, driven by urbanization pressures, safety regulations, and the relentless pursuit of operational efficiency. At the heart of this evolution lies the Automatic Platform Screen Door (APSD) market, a critical subset of railway and metro safety systems. As we move through 2026, the strategic importance of understanding this market cannot be overstated. For stakeholders ranging from metro operators to infrastructure investors, the ability to navigate the shifting dynamics of platform safety technology is a decisive competitive advantage.
Worldwide Outdoor Camping Cookware Market
This article serves as a precursor to the comprehensive market research report recently published by PW Consulting. Our objective is to outline the strategic value of this intelligence for enterprise decision-making in the current fiscal year and beyond. By synthesizing historical trends with forward-looking projections, we provide a framework for understanding where value is created, where risks lie, and how competitive forces are reshaping the industry.
Stainless Steel Buzzer Market
Market Trajectory and Growth Fundamentals
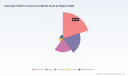
The Automatic Platform Screen Door sector has demonstrated resilience and consistent expansion over the past half-decade. Based on our analysis covering the historical period from 2020 to 2025, the market has transitioned from a niche safety intervention to a standard requirement in modern transit development. In 2020, the global market valuation stood at 812.65 Million USD. By the base year of 2025, this figure had climbed to 1196.0 Million USD. This growth trajectory reflects not only the retrofitting of legacy systems but also the integration of APSDs into new rail lines and airport transit links worldwide.
Worldwide Fluorine Resin Market
Looking ahead, the forecast period spanning 2026 to 2032 suggests continued momentum. The market is projected to reach 1268.0 Million USD in 2026, with expectations to surge toward 2025.0 Million USD by the end of the forecast window in 2032. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 8.5 percent. Such a rate indicates a healthy, sustained demand environment, though it also implies that competition for market share will intensify as the total addressable market grows.
For strategic planners, these numbers are more than mere statistics; they represent capital allocation signals. An 8.5 percent CAGR suggests that the sector is outpacing many traditional infrastructure segments, driven by specific tailwinds including safety mandates and passenger throughput requirements. However, realizing value in this market requires more than acknowledging growth; it requires understanding the structural components that drive it.
The Strategic Value of Granular Intelligence
While macro trends provide the compass, detailed segmentation provides the map. Our full report delves deep into the operational realities of the market, offering insights that generic analyses often overlook. The strategic value of this research lies in its ability to reduce uncertainty for investment and operational planning.
Comprehensive Coverage and Scope
The report is constructed to provide a 360-degree view of the industry. It encompasses a robust analytical framework that covers:
- Historical data analysis from 2020 through 2025 to establish baseline performance and volatility patterns.
- A detailed forecast model extending to 2032, allowing for long-term capacity planning and ROI calculations.
- Deep dives into manufacturing technologies, supply chain logistics, and end-user procurement behaviors.
- Regional assessments that account for local regulatory environments and infrastructure spending cycles.
By integrating these elements, the report enables stakeholders to move beyond speculation. For instance, understanding the shift in demand between different door configurations or the specific procurement cycles of metro authorities can dictate inventory strategy and production scheduling for manufacturers. The intelligence provided is designed to be actionable, translating data points into operational directives.
Risk Mitigation and Regulatory Compliance
The APSD market is heavily influenced by safety standards and regulatory codes. Our research incorporates the latest regulatory developments that impact market entry and product certification. In 2025 and 2026, new standards have come into effect or are being implemented across major regions. For example, China introduced GB/T 46749-2025, specifying requirements for urban rail transit platform screen door systems. Simultaneously, standards such as UNE-EN 17168 govern PSD platform screen doors in Spain.
Navigating this regulatory mosaic is critical. A failure to comply with local safety certifications can halt deployments or lead to costly retrofits. Our report analyzes how these regulations shape market access and influence the competitive balance between local and international suppliers. Understanding the timing and strictness of these regulations allows companies to anticipate certification bottlenecks and align their R&D pipelines accordingly.
Competitive Landscape and Key Players
The market structure is moderately concentrated, with a CR3 of 42.5 percent and a CR5 of 55.2 percent. This indicates that while top players hold significant influence, there remains ample room for specialized providers and regional specialists to compete effectively. The competitive dynamics are shaped by technological differentiation, particularly in control systems and modular design capabilities.
Leading Entities and Strategic Positioning
The landscape features a mix of established European manufacturers and emerging players in Asia, each bringing distinct capabilities to the table.
In Europe, specifically Spain, there is a strong cluster of expertise. Masats S.A. produces PSD Platform Screen Doors for metro and rail stations, offering modular barrier systems synchronized with train doors. Their focus on synchronization technology is critical for operational safety. Similarly, Grupsa supplies Platform Screen Doors (PSD) and Automatic Platform Gates (APG) for metro, train, bus, and tram terminals, showcasing a versatility that appeals to multi-modal transit hubs. Manusa manufactures automatic platform screen doors with modular configurations for new and renovated stations, positioning itself as a flexible partner for both greenfield and brownfield projects. Polarteknik also contributes to this ecosystem by designing and supplying interior train door systems including automatic fire and barrier doors for rail, complementing the platform-side safety infrastructure.
In the realm of safety control systems, ClearSy from France provides SIL3/SIL4 safety-critical PSD control systems for metro stations. Their recent developments highlight the importance of software and control logic in the physical hardware market. In April 2024, ClearSy launched the COPPILOT SIL3/SIL4 PSD control system. This system was deployed in a Paris metro test period and installed in Sao Paulo Metro with 7 stations in service and 2 under deployment in 2024. Achieving SIL3/SIL4 safety certification for metro applications is a significant barrier to entry that strengthens the moat for established control system providers.
Emerging markets are also becoming hubs for innovation and cost-effective manufacturing. Toshi Automation in India supplies automatic platform screen doors for metro stations, including custom designs for Indian railway traffic. Their ability to adapt to specific local traffic conditions demonstrates the need for localized engineering solutions. In China, Zhejiang Rongchen Technology Co., Ltd. manufactures metro safety platform screen doors for passenger safety at station platforms. As domestic rail expansion continues in Asia, manufacturers like Zhejiang Rongchen are poised to capture significant volume, influencing global pricing dynamics.
Implications for Competitive Strategy
For companies operating in this space, the key takeaway is that competition is not solely based on price. Safety certification, modularity, and integration capabilities with existing train control systems are paramount. The presence of specialized control system providers like ClearSy indicates a trend toward decoupling hardware from high-level safety logic, or conversely, a need for tight integration that only certified partners can provide. Strategic partnerships or vertical integration may be necessary to secure high-value contracts in stringent regulatory environments like Europe or major metro systems in South America.
Dynamics Shaping the 2026 Horizon
Several converging dynamics will define the market trajectory in 2026 and the subsequent forecast period. Understanding these forces is essential for scenario planning.
Urbanization and Capacity Constraints
As urban populations densify, metro systems face increasing pressure to maximize throughput while maintaining safety. Platform screen doors serve a dual purpose: preventing accidents and improving energy efficiency by reducing tunnel air conditioning loads. This dual value proposition strengthens the investment case for APSDs even in markets where initial capital expenditure is a concern. The growth from 1196.0 Million USD in 2025 to projected figures exceeding 2000 Million USD by 2032 reflects this enduring utility.
Technological Integration and Smart Transit
The future of platform doors is not just mechanical; it is digital. The integration of IoT sensors, real-time monitoring, and advanced control systems is becoming standard. The deployment of systems like COPPILOT suggests a move toward smarter, safer integration where the door system communicates seamlessly with train arrival data to minimize dwell times. Companies that can offer connected solutions with predictive maintenance capabilities will likely command premium positioning in the market.
Regional Regulatory Divergence
While safety is a universal goal, the path to compliance varies. The divergence between standards like GB/T 46749-2025 in China and UNE-EN 17168 in Spain requires manufacturers to maintain flexible production lines or region-specific certification tracks. For global suppliers, this increases complexity but also creates barriers for smaller competitors who lack the resources to manage multiple regulatory frameworks. This dynamic may lead to further consolidation or the formation of regional joint ventures to share compliance costs.
Retrofitting vs. New Construction
The market is driven by both new metro lines and the modernization of existing infrastructure. The historical data from 2020 to 2025 shows steady growth, implying that retrofit projects are a significant contributor. As legacy systems age, the opportunity for upgrading to automatic, safety-certified doors increases. This segment often has different procurement cycles and budget constraints compared to new builds, requiring tailored sales strategies.
Why This Report is Critical for 2026 Decision Making
In an environment where capital is finite and project timelines are tight, blind spots in market intelligence can lead to costly strategic errors. This report is designed to eliminate those blind spots.
By quantifying the market size and growth rates, we provide the baseline for financial modeling. By analyzing the competitive landscape, we highlight where consolidation is likely and where niche opportunities exist. By examining the regulatory environment, we warn of potential compliance hurdles before they impact project viability.
For investors, the report offers a clear view of the revenue potential and the concentration risks associated with key suppliers. For manufacturers, it provides insight into competitor capabilities and customer requirements. For operators, it aids in vendor selection and long-term infrastructure planning.
The data presented in the executive summary offers a glimpse into the magnitude of the opportunity, but the true strategic advantage lies in the details. The specific segmentation data, the detailed company profiles, and the granular regional analysis contained in the full report are essential for crafting a winning strategy. General knowledge of an 8.5 percent CAGR is useful, but knowing which type of door system is driving that growth in specific transit applications is vital for product development.
Conclusion and Call to Action
The Automatic Platform Screen Door market is at a pivotal juncture. With a clear growth trajectory toward 2032 and evolving safety standards reshaping the competitive field, the need for precise, up-to-date intelligence has never been greater. The insights provided in this overview confirm the sector's health and importance, but they only scratch the surface of what is required to navigate the complexities of 2026 successfully.
PW Consulting's full market research report goes further. It provides the depth, the specific segmentation splits, and the detailed competitive profiles necessary to make informed decisions with confidence. Whether you are looking to enter the market, expand your footprint, or optimize your supply chain, the complete intelligence package is the tool you need.
To access the full dataset, including detailed revenue breakdowns by region, type, and application, as well as comprehensive company profiles and regulatory impact analyses, please visit the source webpage to download the complete report. Equip your organization with the strategic clarity required to lead in the evolving landscape of global transit safety.
For detailed analysis of this topic, please visit the official page: Automatic Platform Screen Door Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Organic Honey Market Hits $1.4B in 2025, Projected 7.2% CAGR to $2.28B by 2032
By PW Consulting, 2026-09-07
Strategic Intelligence in the Organic Honey Sector: Navigating the 2026–2032 Growth Horizon
The global organic honey market is entering a phase of accelerated, value-driven expansion. Rather than relying on volume alone, industry participants are increasingly aligning their portfolios with premiumization, traceability, and clean-label positioning. Our latest Organic Honey Market research is designed to give executives a precise, forward-looking view of this transition. Drawing on historical data from 2020 through 2025 and extending a detailed forecast horizon to 2032, the study converts macro momentum into actionable strategy for sourcing, product architecture, pricing, and competitive positioning.
Steam Dishwasher Market
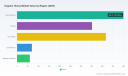
Between 2020 and 2025, revenue in the sector moved decisively beyond the seven-figure threshold measured in millions of U.S. dollars, with the 2025 base year establishing a firm foundation above one billion. Looking ahead, the trajectory through 2032 suggests sustained, compounding growth rather than a short-lived cycle. The market is projected to reach a materially higher revenue level by the end of the forecast window, reflecting longer-term shifts in consumer preference, retail shelf strategy, and ingredient substitution. A seven-point-two percent compound annual growth rate captures this forward arc, signaling an environment where early structural positioning can compound advantage across multiple planning cycles.
Worldwide Centralized Monitoring Market
This is not a story of uniform expansion. Growth is uneven across product tiers, use cases, and geographies, and the strategic implications differ sharply depending on whether a company competes in retail-ready formats, industrial ingredient supply, or specialty functional positioning. The report treats these layers not as isolated statistics, but as interlocking decision variables that influence margin design, supply commitment, and brand architecture.
PET High Reflective Film Masterbatch Market
The Strategic Case for This Study in 2026 Decision-Making
For leadership teams planning capital allocation, portfolio expansion, or supplier renegotiation in 2026, the timing of this research is deliberate. The market is at an inflection point where consumer demand signals, certification pathways, and regulatory friction are all moving simultaneously. Strategic plans that rely on backward-looking benchmarks risk misjudging the pace of premium adoption, the volatility of raw intake pricing, and the extent to which packaging and assessment frameworks will reshape landed-cost models.
Our study is built to support three immediate corporate use cases. First, it helps commercial leaders calibrate whether to invest in organic honey as a core revenue driver or as a strategic complement to broader clean-label portfolios. Second, it assists supply chain and procurement teams in evaluating sourcing geography, certification risk, and the implications of domestic organic constraints alongside import-dependent supply models. Third, it gives strategy and corporate development teams a structured basis for assessing competitive overlap, white-space opportunities, and partnership design across food, personal care, and pharmaceutical value chains.
Rather than functioning as a static market snapshot, the report is structured to translate forecast logic into planning discipline. The objective is to reduce the gap between market narrative and operational execution, enabling teams to anchor decisions in a coherent view of what is expanding, what is consolidating, and where margins are likely to be defended or eroded.
Market Trajectory and Structural Shifts
The historical record from 2020 through 2025 shows a market that has shed earlier stagnation and is now participating in a broader shift toward ingredient transparency and premium sweeteners. Revenue growth over this period has not come from a single driver; it reflects a combination of category elevation, stronger retail placement, and increasing willingness to pay for certified organic and functionally differentiated honey products. The 2025 base year crystallizes this shift, with the market positioned at a materially higher revenue level than at the start of the decade.
The forecast period from 2026 through 2032 suggests that this momentum is not peaking. Instead, it is moving into a more mature but still dynamic stage, in which growth is increasingly tied to product innovation, geographic rebalancing, and segmentation choices. A 7.2 percent CAGR implies that the market will continue to outpace many conventional food-ingredient categories, but it also indicates that outperformance will depend on execution quality. The organizations that convert this growth into durable advantage will be those that understand how demand is fragmenting across premiumized types, application-specific benefit claims, and regional purchasing patterns.
Crucially, the structure of the market is not purely demand-led. Supply-side realities, including the geographic concentration of certified organic sources and the economics of raw honey procurement, impose their own discipline on pricing, margin architecture, and product formulation. Strategic planning that ignores these constraints tends to overestimate agility and underestimate exposure. This study explicitly connects demand forecasts with supply logistics and certification pathways so that revenue expectations can be tested against operational feasibility.
Competitive Dynamics and Corporate Positioning
The competitive field is defined by players that have invested early in USDA Organic credibility, international sourcing relationships, and increasingly, functional differentiation. Nature Nate's illustrates a strategy centered on convenience and specialty expansion, moving beyond core retail jars into on-the-go formats and certified functional offerings. Its recent moves into organic honey minis and UMF-certified manuka lozenges point to a broader industry effort to capture consumers in transitional consumption moments while also anchoring the brand in higher-value wellness positioning.
Other leading companies are pursuing parallel but distinct strategic paths. Some emphasize clean-label verification and bulk-and-retail versatility, using certifications such as QAI, True Source, and Non-GMO to reinforce trust across ingredient and consumer channels. Others build on long-standing USDA Organic credentials, leveraging multi-country sourcing footprints that span North America, Canada, Brazil, and New Zealand. Several players differentiate through sourcing narratives tied to wild hives, glyphosate-free assurance, or sustainable beekeeping practices, using transparency as a competitive lever rather than merely a compliance exercise.
These profiles matter because the organic honey market is not a commodity race to the bottom. It is a credibility market, where sourcing provenance, certification integrity, and product-specific claims influence both retail shelf velocity and B2B ingredient acceptance. Companies that can harmonize authentic sourcing stories with operational scale are best positioned to defend pricing and expand share. Those that depend on price positioning alone face a more difficult environment, especially as packaging assessment frameworks, import dependencies, and raw cost variability reshape the economics of participation.
Recently, competitive intensity has also been shaped by certification milestones, product innovation from regional producers, and CSR-linked honey launches that broaden the notion of what an organic honey brand can represent. These developments reinforce the value of monitoring not only the largest branded players, but also cooperative movements, specialty producers, and localized innovation efforts that can influence sourcing norms, consumer expectations, and category storytelling over time.
Segmentation Logic and Strategic Implications
Segmentation is where strategy becomes tangible. The market can be understood through three primary lenses: product type, application, and region. Each lens carries a different strategic weight, and each creates a distinct set of trade-offs for sourcing, branding, and channel design.
In product type, the mix ranges from mass-facing blended organic offerings to more premiumized specialty categories and regional varietal expressions. The strategic question is not simply which segment is largest, but which segments generate defensible margin structures and which require continuous promotional support. Specialty and high-credibility positions, such as manuka and other functionally associated varieties, can command stronger value perception, but they also depend on certification integrity and supply reliability. Blended organic honey can provide broader volume reach, but its strategic advantage depends on consistent quality, clean-label alignment, and efficient supply execution. Wildflower and other varietal expressions often support storytelling and regional identity, which can be valuable in premium retail and gourmet channels.
In application, food and beverages remain a major commercial engine, but personal care, cosmetics, and pharmaceutical uses introduce different demand logic. Ingredient honey in food and beverage often competes on flavor, clean-label substitution, and functional positioning. In personal care and cosmetics, the emphasis shifts toward purity, formulation compatibility, and consumer-facing benefit narratives. In pharmaceutical contexts, the conversation becomes more precise, with stricter expectations around consistency, documentation, and claim support. Companies that treat these applications as interchangeable risk underinvesting in the specific capabilities each channel requires. Those that map product architecture to application-specific requirements are better positioned to expand across categories without diluting brand integrity or operational focus.
Regional structure adds another layer of complexity. The market does not behave as a single pool of demand. Different regions reflect different retail maturity, consumer willingness to pay for organic claims, import reliance, and certification expectations. Some markets are shaped by strong domestic branding and retail ecosystems; others depend more heavily on cross-border supply and export-quality alignment. Because sourcing geography and demand geography do not always coincide, successful regional strategies require a clear view of where certification is credible, where logistics create friction, and where consumer expectations favor domestic origin versus imported premiumization.
The report analyzes these segmentation dimensions as a connected system. That approach matters because margin, volume, and risk often move in different directions across segments. A portfolio that appears balanced in total revenue may still be exposed if it depends too heavily on a single application channel, a narrow set of sourcing origins, or a region with rising regulatory or logistics pressure.
Regulatory, Sourcing, and Operational Dynamics
No near-term organic honey strategy can ignore regulatory and operational dynamics. Several forces are actively reshaping cost structures, compliance requirements, and sourcing options.
One important variable is the assessment framework affecting honey packers and importers. Assessment rates have moved through scheduled adjustments, with the rate structure transitioning upward around mid-2026. For companies operating at scale, this changes the calculus of landed cost and margin planning, especially in categories where packaging, distribution, and retail markup already compress profitability. Strategic responses may include reformulating pack sizes, adjusting channel mix, renegotiating supplier terms, or re-evaluating whether premium positioning can absorb the added cost burden without eroding velocity.
On the sourcing side, the organic certification environment introduces structural constraints that many planning exercises underestimate. Certified organic honey cannot simply be produced domestically in the continental United States under current foraging-radius realities; instead, certified supply is primarily associated with imported sources, with meaningful volumes originating from regions such as Brazil, Mexico, and Uruguay. This dependency gives sourcing geography a strategic significance far beyond procurement logistics. It affects certification credibility, supply continuity, currency exposure, and the narrative a brand can responsibly make to consumers and retail partners.
Raw honey pricing also remains a planning variable. Prices paid to beekeepers for extracted unprocessed honey have reflected a meaningful range for light amber varieties in major producing states. Even where final products are positioned as premium, underlying intake costs can shift the economics of scaling, reformulation, or private-label expansion. Companies that rely on static cost assumptions risk being surprised by margin compression, especially when combined with packaging assessments, export demand shifts, and geopolitical or supply-chain disruptions.
International flow dynamics further complicate the picture. For example, shifts in Mexican organic honey exports to certain European markets have been associated with supply-chain pressure and changing organic hive numbers. Such movements illustrate how regional supply health, certification standards, and trade conditions can alter availability and pricing far from the end consumer. For global sourcing strategies, this reinforces the need for diversified origin planning and a realistic view of how organic supply capacity can change over time.
Taken together, these dynamics mean that organic honey strategy cannot be reduced to consumer trend analysis alone. It must include certification architecture, assessment exposure, raw-material sensitivity, and geographic sourcing logic. The report integrates these elements so that revenue scenarios can be evaluated alongside operational constraints, rather than in isolation.
What the Report Delivers
The study is structured to give executives a practical decision toolkit rather than a narrow market summary. It combines market sizing and forecasting with competitive profiling, segmentation logic, regulatory context, and operational reality checks. The result is a document that can be used directly in strategy workshops, product roadmapping, sourcing reviews, and investment discussions.
Key deliverables include:
- A multi-year market view that links historical performance from 2020 through 2025 to a detailed forecast through 2032, providing a coherent basis for planning, scenario-building, and long-range targeting.
- Market structure analysis that explains how size, growth, and concentration interact, helping leadership interpret where scale advantages exist and where fragmentation or consolidation is likely to shape competitive outcomes.
- Segment-level strategic framing across product type, application, and region, enabling teams to prioritize the most profitable or defensible paths rather than treating the category as a uniform opportunity.
- Competitive and corporate profiles that describe how leading players position themselves through sourcing, certification, product format, and functional differentiation, with attention to recent launches, certifications, and innovation moves.
- Operational and regulatory context covering assessment adjustments, organic sourcing dependencies, raw intake pricing, and international supply shifts, all of which influence margin design and supply continuity.
- Practical interpretation guidance for commercial, supply chain, and corporate development teams, translating analytical findings into the kinds of questions that should be asked before committing capital, capacity, or brand resources.
Importantly, the report preserves confidentiality of the most sensitive strategic breakdowns while still giving enough depth to support real decisions. The objective is to provide a credible, analytically rigorous foundation that helps teams ask better questions before committing to sourcing contracts, product launches, or channel investments.
How to Use This Research for 2026 Decisions
The most valuable use of this study is not passive reading; it is structured internal application. For product and brand leaders, the report supports decisions about which formats, certifications, and claim structures are most likely to hold pricing power in a market where consumers are increasingly literate about organic and clean-label distinctions. For procurement and supply chain leaders, it provides context for evaluating sourcing diversification, certification risk, and the sensitivity of cost models to assessment changes and raw-price variation. For corporate strategy teams, it offers a framework for identifying where competitive overlap is intensifying, where white space may still exist, and where partnership or M&A could accelerate access to credible sourcing or application-specific capabilities.
It also supports risk management. In a market where regulatory frameworks, import dependencies, and raw-material economics are all in motion, decisions made without supply-side awareness can create hidden exposure. Conversely, decisions that integrate regulatory timing, sourcing logistics, and segmentation reality can create a more durable position, even in a competitive environment.
Conclusion
The organic honey market in 2026 is not merely growing; it is reorganizing around credibility, premiumization, and operational discipline. The companies that will benefit most are those that treat market size and growth rate as starting points, not conclusions. They will need a clear view of how segmentation shapes margin, how sourcing geography shapes compliance and narrative, and how regulatory and packaging economics shape cost structures.
Our Organic Honey Market research is designed to provide that view. It connects forward-looking market trajectory with the practical realities of competition, certification, and supply, giving leadership teams a stronger basis for strategy in the years ahead. For decision-makers who need to move beyond headline numbers and understand where value is actually created and defended, the full report offers the depth required to act with confidence.
For detailed analysis of this topic, please visit the official page: Organic Honey Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Power Sports Market Hits $215M in 2025, Projected to Grow at 6.8% CAGR Through 2032
By PW Consulting, 2026-09-07
Power Sports Market Strategic Intelligence Report 2026: Navigating Growth and Transformation
The global power sports industry stands at a pivotal juncture as we move through 2026. Characterized by a resilient demand for recreational vehicles and a rapid technological evolution, the market presents both significant opportunities and complex challenges for stakeholders. This article serves as an introduction to the latest Power Sports Market Market Research published by PW Consulting. Our comprehensive analysis is designed to equip executives, investors, and strategic planners with the actionable intelligence required to make informed decisions in this dynamic landscape. By dissecting historical trends, forecasting future trajectories, and evaluating the competitive environment, this report offers a roadmap for sustainable growth. We invite you to delve into the details that follow, understanding that the full depth of our proprietary data is available within the complete study.
Gasoline & Electric Hybrid Powered Drones Market
Market Trajectory and Sizing Overview
Understanding the macroeconomic footprint of the power sports sector is the first step in strategic planning. Our research utilizes a robust methodology that examines historical performance to validate forecasting models. The data indicates a clear upward trajectory in market valuation over the past half-decade, reflecting consistent consumer interest and expansion in key verticals. Starting from a baseline in 2020, the market has demonstrated steady appreciation, reaching a significant milestone by 2025. This historical momentum provides a strong foundation for the forecast period extending from 2026 to 2032.
Smart Guitar Market
The Compound Annual Growth Rate (CAGR) projected for the forecast period underscores the sector's resilience and potential for expansion. This growth is not merely a function of inflation but is driven by genuine increases in unit sales, product mix improvements, and emerging market penetration. The valuation metrics are presented in USD Millions, offering a standardized view for international comparison. Stakeholders reviewing the full report will find detailed year-over-year breakdowns that highlight acceleration points and potential saturation risks. However, the core takeaway for decision-makers is the sustained positive momentum that defines the current cycle. This trajectory suggests that capital allocation toward power sports assets remains a viable strategy, provided it is guided by granular insights into regional performance and vehicle type preferences.
Worldwide Vacuum Wine Stopper Market
Segmentation Dynamics and Vehicle Type Performance
The power sports market is not a monolith; it is a collection of distinct segments, each with its own demand drivers and consumption patterns. Our analysis breaks down the market by vehicle type, revealing which categories are leading the charge in terms of revenue generation. All-Terrain Vehicles (ATVs) continue to hold a prominent position, driven by their versatility in both recreational and utility applications. Utility Task Vehicles (UTVs) are also seeing substantial engagement, particularly among users seeking side-by-side capabilities for diverse terrains.
Other vehicle categories, including snowmobiles, heavyweight motorcycles, and personal watercraft, contribute to the diversified revenue stream. Each segment responds differently to seasonal variations, regulatory changes, and technological advancements. For instance, winter-specific vehicles face different supply chain constraints compared to year-round motorcycles. The report provides a deep dive into these segment-level dynamics, helping clients identify where their specific product portfolios fit within the broader ecosystem. By understanding the relative size and growth rate of each vehicle type, companies can optimize their production schedules and inventory management. The full study excludes generalized assumptions, offering instead specific performance indicators for each category that allow for precise benchmarking.
Regional Landscape and Distribution Channels
Geography plays a critical role in the distribution and consumption of power sports vehicles. The market exhibits varying levels of maturity across different regions, influenced by local regulations, economic conditions, and cultural affinity for outdoor recreation. North America and Europe remain traditional strongholds with established dealer networks and high consumer awareness. Meanwhile, the Asia Pacific region represents a high-growth frontier, where urbanization and rising disposable incomes are creating new demand pockets.
Latin America and the Middle East and Africa also contribute to the global total, though their market structures may differ significantly from the developed economies. Our report analyzes the revenue distribution across these regions without relying on simplistic generalizations. We examine the infrastructure supporting sales, the prevalence of organized retail versus independent dealers, and the impact of import tariffs or local manufacturing incentives. For multinational corporations, understanding the regional revenue mix is essential for balancing risk and maximizing return on investment. The complete analysis includes nuanced discussions on market entry barriers and localization strategies that are not fully detailed in this summary. Readers are encouraged to consult the full report for specific regional revenue figures and growth rankings.
Competitive Landscape and Key Player Strategies
The power sports market is characterized by a mix of specialized manufacturers and diversified conglomerates. Competition is intense, driven by product innovation, brand loyalty, and the ability to navigate supply chain disruptions. Our report profiles the key companies that Shape the industry, analyzing their strategic positioning and recent moves.
Polaris Inc. , based in Minneapolis, continues to be a dominant force with a broad portfolio encompassing ATVs, UTVs, snowmobiles, and motorcycles. Their strategy often focuses on expanding the utility aspects of recreational vehicles while maintaining high performance standards. In a recent development, Polaris announced the 2026 RZR Pro R, featuring a 10.4-inch touchscreen display and Dynamix Active Suspension. This launch highlights their commitment to integrating advanced technology and comfort into utility vehicles, signaling a shift toward smarter off-road experiences.
BRP Inc. , headquartered in Valcourt, Canada, is another major player known for Ski-Doo snowmobiles, Can-Am ATVs and UTVs, and Spyder motorcycles. BRP has been aggressive in exploring electrification and performance enhancements. Their launch of the 2026 Can-Am Outlander Electric ATV with Rotax E-Power powerpack demonstrates a strategic pivot toward sustainable mobility without compromising on towing capacity or ride modes. This move positions them as a leader in the electric utility segment.
Yamaha Motor Corporation , from Iwata, Japan, maintains a strong global presence with motorcycles, ATVs, and snowmobiles. Their focus on engineering precision and rider connectivity is evident in the 2026 YZ450FX Cross Country motorcycle, which features ECU lock functions and smartphone integration via the Power Tuner app. Yamaha's strategy leverages their extensive manufacturing capabilities to cater to both recreational and competitive riders.
Honda Motor Co., Ltd. , based in Tokyo, remains a powerhouse in motorcycles and recreational power sports equipment. Their ability to scale production while maintaining quality gives them a competitive edge in volume-driven markets. Harley-Davidson, Inc. , from Milwaukee, holds a unique position focused on motorcycles and related power sports vehicles, often emphasizing brand heritage and lifestyle. Their launch of the 2026 Pan America 1250 Limited with Adaptive Ride Height and Skyline OS interface shows their push into adventure touring with high-tech features.
The report further analyzes market concentration metrics, noting that the top three and top five players hold specific shares of the market. This concentration level suggests that while there is room for niche players, the majority of revenue is contested by these giants. Strategic partnerships, acquisitions, and regional expansions are common tactics employed by these firms to solidify their positions.
Industry Dynamics: Regulation, Materials, and Technology
The operating environment for power sports businesses is shaped by external forces that can alter demand patterns and operational costs. Regulatory changes are a constant factor. For the 2026 season, significant updates have been observed. Helmets with ECE 22.05 certification are no longer allowed in certain contexts, necessitating changes in equipment specifications for dealers and consumers. Additionally, OEM co-op program changes for 2026 are shifting toward digital advertising and original content creation across major brands, reflecting the broader migration of marketing spend to digital channels.
Government investment also plays a role. In January 2026, the Interior Department unveiled a USD 254 million investment decision for local parks. Such investments can indirectly boost the power sports market by improving access to recreational areas and enhancing public interest in outdoor activities. However, companies must monitor these policy shifts to anticipate changes in land usage regulations or access fees.
Raw material dynamics and application trends also influence the market. Recreational applications hold a significant share of the market in 2026, indicating that leisure remains the primary driver of demand. Supply chain stability regarding raw materials for engines, chassis, and electronics is critical. Fluctuations in material costs can impact pricing strategies and margin profiles. The report details how these dynamics interact to shape the profitability of different market participants.
Scope and Utility of the Full Research Report
This article provides a high-level overview, but the true value of PW Consulting's Power Sports Market Market Research lies in the depth and granularity of the full document. The report is structured to support various strategic functions, from market entry feasibility to product line optimization.
Data Coverage and Methodology: The study covers the historical period from 2020 to 2025 and the forecast period from 2026 to 2032. The base year for analysis is 2025. Our methodology combines top-down and bottom-up approaches to ensure accuracy. The full report includes detailed data tables, charts, and visual representations that make complex data accessible for presentation and internal reporting.
Segmentation Analysis: Beyond the macro splits, the report breaks down the market by region and vehicle type with specific revenue contributions. It explores the interplay between different segments, such as how the growth in UTVs might correlate with specific regional trends. It also distinguishes between off-road and on-road applications, providing clarity on where consumer spending is concentrated.
Competitive Intelligence: The company profiles extend beyond basic descriptions. They include analysis of recent developments, such as product launches and strategic shifts, as seen with Harley-Davidson, Polaris, BRP, Yamaha, and Honda. The report evaluates their market share, pricing strategies, and distribution reach. It also identifies emerging players who may disrupt the status quo.
Strategic Recommendations: The report concludes with actionable insights. For manufacturers, this might involve recommendations on R&D focus areas, such as electrification or connectivity. For investors, it provides risk assessment frameworks. For distributors, it offers guidance on regional expansion opportunities. The goal is to translate data into decisions.
Strategic Value for 2026 Decision-Making
In the current economic climate, decisions based on intuition are increasingly risky. The power sports market, while growing, is subject to volatility in supply chains, shifting consumer preferences, and regulatory headwinds. This research report serves as a critical tool for mitigating uncertainty.
For executives planning capital expenditure for the remainder of 2026 and beyond, the forecast data offers a evidence-based projection of market size. Knowing that the market is projected to reach specific valuation milestones by 2032 helps in long-term capacity planning. The CAGR informs expectations for return on investment timelines. Furthermore, understanding the regional revenue distribution allows companies to allocate marketing budgets more effectively, focusing on high-growth areas rather than saturated ones.
The competitive analysis helps in benchmarking. If a company is launching a new ATV, knowing the features introduced by competitors like the Polaris RZR Pro R or the BRP Outlander Electric allows for a competitive feature set analysis. It helps in positioning the product correctly in the market. The regulatory insights ensure compliance and risk management, preventing costly issues related to certification standards or marketing program restrictions.
Ultimately, the report is designed to be a living resource for strategic teams. It provides the context needed to interpret daily news and market fluctuations within a broader analytical framework. By integrating historical data, current dynamics, and future predictions, it empowers stakeholders to act with confidence.
Conclusion: Accessing the Full Intelligence
The power sports sector offers substantial opportunities for those who can navigate its complexities. The growth trajectory indicated by the data suggests a healthy expanding market, but success depends on execution and insight. PW Consulting's Power Sports Market Market Research is built to provide that insight. It goes beyond surface-level summaries to deliver the specific data points and strategic analyses required for high-stakes decision-making.
We have outlined the macro trends, the key players, and the dynamic forces at play. However, the specific segmentation values, detailed regional breakdowns, and precise market share percentages are reserved for the full report. This approach ensures that our clients receive exclusive, high-value intelligence that is not publicly disseminated. To access the complete dataset, including the full year-over-year forecasts, detailed company profiles, and strategic frameworks, we invite you to obtain the full report. This document will serve as a cornerstone for your strategic planning, ensuring your organization is aligned with the realities of the 2026 market and prepared for the growth expected through 2032.
For detailed analysis of this topic, please visit the official page: Power Sports Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bollards Market to Reach $4,852.89M by 2032 With 7.95% CAGR
By PW Consulting, 2026-09-07
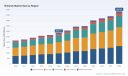
Navigating the Bollards Market Outlook 2026: Strategic Intelligence for Infrastructure, Security, and Urban Resilience
The global bollards market has evolved far beyond its traditional roots in perimeter marking and basic traffic demarcation. Today, bollards function as critical components within broader security, traffic management, and urban design ecosystems. As cities grapple with rising vehicle-related threats, expanding smart infrastructure deployments, and increasingly complex regulatory frameworks, the demand for purpose-engineered bollard solutions has accelerated. PW Consulting’s latest Bollards Market research study delivers a comprehensive, data-grounded assessment of this trajectory, providing executive teams, procurement strategists, and infrastructure planners with the foresight needed to align capital allocation, supply chain planning, and product portfolio decisions through 2032.
Worldwide Open Cell Aluminum Foam Market
This article serves as a strategic preview of the full report. It outlines the macroeconomic arc of the market, the structural dynamics reshaping competitive positioning, and the practical analytical frameworks embedded in the study. In keeping with our commitment to actionable intelligence, we present the strategic architecture of the research while reserving the granular segmentation, regional valuation breakdowns, and project-level case analyses for the complete deliverable. Decision-makers who require precise quantification of opportunity pools, share-shift patterns, and forecasting sensitivities are encouraged to access the full study for complete market intelligence.
Worldwide Thermoplastic Carbon Fiber Medical Composites Market
Market Trajectory and the Strategic Context for 2026 Decision-Making
The bollards market has demonstrated steady expansion over the past half-decade, reflecting a compound growth profile that underscores both resilience and structural demand. Historical valuation data from 2020 through 2025 reveals consistent upward momentum, with the market progressing from approximately 2,156.75 million USD to an estimated 2,865.57 million USD by the 2025 base year. Looking forward, the forecast horizon spanning 2026 to 2032 projects sustained growth, with the market anticipated to reach roughly 3,084.29 million USD in 2026 and continue advancing toward an estimated 4,852.89 million USD by the close of the forecast period.
Worldwide Tissue Culture Flask Market
Central to this outlook is a projected compound annual growth rate of 7.95 percent across the forecast window. This growth cadence is not merely a reflection of incremental procurement cycles; it signals a broader realignment in how organizations approach physical security, traffic orchestration, and public-space design. For enterprise strategists, the implications are twofold. First, the forecast affirms that bollard adoption is being driven by durable, long-cycle investment themes rather than short-term discretionary spending. Second, the rate of expansion suggests that competitive differentiation will increasingly hinge on performance certification, integration readiness, lifecycle cost modeling, and regional supply responsiveness rather than commodity pricing alone.
The full report unpacks these trajectory patterns through layered forecasting models that account for demand elasticity, substitution dynamics, and scenario-based sensitivity testing. By isolating the structural drivers behind the growth curve and mapping them against procurement calendars and infrastructure funding cycles, the study equips leadership teams with a defensible basis for capacity planning, vendor selection, and geographic expansion prioritization.
Core Segmentation Axes and Application Realities
The bollards market is structured around three primary analytical dimensions: product type, end-use application, and geographic deployment. Each axis presents distinct commercial considerations, and the interplay between them often determines which solutions win in specific procurement environments. The research examines how fixed installations, retractable systems, and alternative configurations compete across varying threat profiles, aesthetic requirements, and operational flexibility needs. Rather than treating these categories as static buckets, the study evaluates them as dynamic choices shaped by load-bearing requirements, installation footprint constraints, maintenance expectations, and certification standards.
On the application side, demand is distributed across traffic control functions, security and perimeter protection objectives, and a range of supplementary use cases. The report analyzes how these application segments diverge in specification criteria, approval pathways, and stakeholder alignment. Traffic-oriented deployments tend to prioritize visibility, durability, and integration with broader roadway systems, while security-focused installations require rigorous impact performance, threat-level alignment, and compliance with recognized testing protocols. The study further explores how hybrid requirements are pushing suppliers to offer modular designs, cover systems, and adaptable mounting configurations that can satisfy both functional and aesthetic mandates without compromising protective performance.
A key strength of the full report is its refusal to present segmentation as a simple proportional snapshot. Instead, it contextualizes each segment through demand triggers, specification evolution, and procurement behavior patterns. This approach enables buyers and suppliers alike to anticipate where specification upgrades are likely to occur, which product attributes are becoming table stakes, and where whitespace may still exist for specialized offerings.
Competitive Landscape: Structural Realities among Leading Firms
The bollards market features a diverse cohort of manufacturers and specialists, ranging from broad-line steel and concrete fabricators to security-focused integrators and design-centric suppliers. The research profiles a representative set of companies whose product strategies illuminate the broader competitive contours of the market. These include Vestil Manufacturing Corp., Reliance Foundry Co. Ltd., Justrite Manufacturing Company LLC, The Bollard Company, Ameristar Security Products, Barrier1 Systems LLC, Beacon Industries Inc., L.K. Goodwin Co., Frontier Pitts Ltd., BollardsUSA, Post Guard, Dark Horse Metals, Bollards Plus, and Selcom Manufacturing Inc.
Collectively, these firms illustrate a market where differentiation is emerging along several axes. Some competitors emphasize removable ornamental and steel pipe safety bollards, positioning around flexibility, visual integration, and reversible deployment. Others concentrate on concrete and crash-rated solutions, leveraging material robustness and recognized impact performance for high-exposure environments. A further group focuses on specialized security bollards, shallow-mount configurations, and modular cover systems that address retrofits, aesthetic upgrades, and rapid installation constraints. The presence of stainless steel security offerings, coated and fabricated steel variations, and high-density polyethylene options further demonstrates how material selection has become a strategic lever rather than a purely engineering decision.
The study evaluates how these product philosophies intersect with supply chain realities, regional distribution capabilities, and specification penetration. It also examines the market concentration structure, where the top three firms account for an estimated 29.4 percent of combined share and the top five reach approximately 34.1 percent. This level of concentration suggests a competitive environment that is neither fully fragmented nor tightly consolidated. In practice, it means that scale advantages exist, but they are counterbalanced by the importance of application-specific expertise, regional service networks, and the ability to meet increasingly detailed performance specifications.
Rather than offering a static ranking, the report maps competitive positioning through lenses that matter to buyers: certification readiness, product breadth, customization capacity, lead-time reliability, and post-installation support. For suppliers, these same dimensions serve as a diagnostic for identifying where portfolio gaps, pricing architectures, and go-to-market messaging should evolve.
Market Dynamics and the Forces Reshaping Procurement Behavior
Several intersecting dynamics are reshaping how bollard solutions are specified, sourced, and deployed. Regulatory and standards-based expectations continue to elevate the importance of measurable performance. Notably, the ASTM F3016 standard, introduced in 2014, has steadily reinforced the need for defined performance criteria for bollards intended to protect pedestrians, storefronts, and public spaces. As specification communities and procurement teams become more familiar with such frameworks, the bar for demonstrated impact resistance and documented testing is rising, particularly in security-sensitive deployments.
Material cost conditions are also exerting renewed pressure on planning assumptions. Industry reporting from early 2026 indicates that steel prices remain on an upward trajectory, with manufacturers noting continued cost escalation. At the same time, bollard steel pipe pricing is being affected by supply chain disruptions and broader raw material fluctuations. These dynamics are not merely tactical procurement concerns; they influence total cost of ownership calculations, project phasing decisions, and the relative attractiveness of alternative material or design approaches. The full report integrates these dynamics into its strategic assessment, exploring how cost volatility interacts with specification choices, inventory strategies, and regional sourcing options.
Recent market events further illustrate how the bollards ecosystem is being shaped by demonstration, guidance, and real-world implementation. In May 2025, crash-tested bollards were exhibited at the International Security Expo, reinforcing the industry’s emphasis on verified performance and visible security engineering. In June 2025, Post Guard published guidance explaining ASTM F3016 bollards and addressing the performance characteristics of traditional bollard designs, contributing to broader specification literacy among buyers and installers. By September 2025, the City of New Orleans advanced a notable project delivery milestone, upgrading the Bourbon Street bollard system with new removable stainless-steel bollards. These developments, among others, reflect a market in which product credibility, standards communication, and municipal-scale deployment experience are increasingly intertwined with commercial success.
The study situates these dynamics within a broader analytical framework, allowing readers to assess how regulatory familiarity, material cost trends, and high-profile project implementations are likely to influence demand timing, specification rigor, and supplier selection criteria over the forecast period.
What the Full Report Delivers: Operational Intelligence for Strategy and Execution
The complete PW Consulting Bollards Market study is designed as an operational companion for strategic planning, not simply a summary of market size and growth. It provides a structured set of analyses intended to support decisions across product development, competitive positioning, procurement strategy, and geographic prioritization. Key components of the report include:
- A detailed demand forecast that extends through 2032, anchored in historical data from 2020 to 2025 and structured to support multi-year planning cycles.
- An assessment of the primary market segmentation axes, with analytical context around how type, application, and regional deployment patterns interact in real procurement environments.
- A competitive landscape evaluation that examines how leading manufacturers and specialists position their offerings, where differentiation is accumulating, and what specification attributes are becoming decisive.
- A review of market concentration and share structures, offering perspective on the balance between scale-driven competition and niche specialization.
- Contextual analysis of the regulatory, materials, and project-level dynamics that are shaping specification behavior, cost planning, and implementation feasibility.
- Practical frameworks for interpreting forecast sensitivities, demand triggers, and substitution possibilities across fixed, retractable, and alternative bollard configurations.
The report is structured to serve multiple internal audiences. Strategy and business development teams can use it to assess whitespace, prioritize segments, and align product roadmaps with evolving specification expectations. Procurement and operations leaders can leverage its dynamic analysis to better anticipate cost pressures, lead-time considerations, and the implications of standards-driven procurement. Investors and market entrants can draw on the study’s structural assessment to understand where competitive intensity is increasing and where durable differentiation remains achievable.
Importantly, the full study does not stop at aggregate trends. It connects the macro growth story to practical decision variables, including how application requirements influence product selection, how regional deployment characteristics shape sourcing logic, and how recent standards communication and project implementations are likely to affect buyer confidence and specification velocity. By integrating these threads, the report provides a basis for decisions that are both analytically rigorous and operationally relevant.
Why This Research Matters for 2026 Strategy
The 2026 decision environment calls for clarity on where demand is structurally anchored and where competitive conditions are shifting. The bollards market sits at the intersection of infrastructure investment, physical security expectations, and urban design priorities, which makes it sensitive to both long-cycle funding patterns and shorter-term specification changes. A forecast CAGR of 7.95 percent, set against a market already advancing toward the 3 billion USD threshold in 2026 and projected to climb further by 2032, indicates that the opportunity is substantial and that the basis for competition is becoming more refined.
In this context, the value of the full report lies in its ability to translate broad market movement into decision-ready intelligence. It helps organizations anticipate which specification attributes will carry more weight, how material cost and standards dynamics may alter procurement timing, and how the competitive field is shaping up across different product philosophies and application contexts. For enterprises planning capability investments, vendor negotiations, or regional expansion, the study offers a structured view of the forces that will determine performance over the next several years.
This preview has outlined the strategic architecture of the research and the market logic that underpins it. The complete study contains the detailed segmentation values, regional assessments, company-level analyses, and scenario frameworks necessary for precise planning. Decision-makers seeking the full quantitative picture and the accompanying interpretive depth are invited to access the full PW Consulting Bollards Market research for comprehensive market intelligence.
For detailed analysis of this topic, please visit the official page: Bollards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hookah Tobacco Market Hits $215M in 2025, Projects 6.98% CAGR Through 2032
By PW Consulting, 2026-09-07
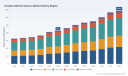
Navigating the Hookah (Shisha) Tobacco Market: Strategic Insights for 2026 and Beyond
The global landscape for waterpipe tobacco is undergoing a period of significant transformation, driven by evolving consumer preferences, regulatory shifts, and a competitive arena that rewards innovation. As industry stakeholders prepare their strategic frameworks for the upcoming fiscal cycles, having access to precise, data-backed intelligence is no longer a luxury; it is a necessity. This article serves as an introduction to our latest comprehensive market research on the Hookah (Shisha) Tobacco Market, designed to equip executives, investors, and product strategists with the foundational knowledge required to make informed decisions in 2026.
Worldwide API Process Development and Manufacturing Market
Our analysis covers a vast historical window and projects forward with rigorous modeling, offering a clear view of where the industry stands and where it is heading. For decision-makers, the value lies not just in the numbers, but in the contextual depth that explains why those numbers matter and how they translate into actionable business intelligence.
Worldwide Baby Cleaning Swabs Market
Market Trajectory and Growth Dynamics
Understanding the macroeconomic pulse of the Hookah (Shisha) Tobacco Market is the first step toward strategic planning. The sector has demonstrated consistent upward momentum over the past half-decade, reflecting a resilient consumer base and expanding distribution channels. According to our baseline analysis, the market valuation has escalated from 163.15 million USD in 2020 to a projected 231.26 million USD in 2026. This trajectory underscores a compound annual growth rate (CAGR) of 6.98 percent throughout the forecast period extending to 2032.
Worldwide LCD Backlighting Market
This growth is not merely linear; it represents a structural expansion fueled by demographic shifts and cultural integration of hookah consumption in new regions. The forecast indicates that by 2032, the market will reach approximately 344.8 million USD. Such figures suggest that the industry is moving beyond niche status into a more mature phase of commercialization, where scale economies and supply chain optimization become critical differentiators for market participants.
However, raw top-line figures only tell part of the story. To truly grasp the opportunities, one must understand how these aggregates break down across key dimensions. Our research dissects the market along multiple axes, revealing the nuanced drivers behind the overall expansion. While we will highlight the primary categories here, the granular segmentation splits and their corresponding revenue contributions are reserved for the full report, ensuring that deep-dive analysts can leverage the complete dataset for their specific modeling needs.
Segmentation Architecture: Product, Geography, and End-Use
The market is structurally diverse, and strategic success depends on identifying which segments offer the highest margin potential or the fastest adoption rates. Our research categorizes the landscape into distinct typologies, regional clusters, and application verticals.
Product Types and Material Composition
The industry is primarily anchored by specific manufacturing formats that cater to different consumption experiences. Key product categories include premium polyolefin-based blends, polyester variants, and other specialized forms. Each type commands a different level of market penetration based on flavor retention, smoke quality, and cost structures. The dominant category holds a significant share of the total volume, but the relative positioning of the secondary and tertiary segments offers critical clues about manufacturing trends and potential white-space opportunities for new entrants. Detailed revenue attribution for each type is a core component of the full analysis.
Regional Distribution and Demand Centers
Geographically, the demand is widespread, yet it is heavily influenced by cultural heritage, regulatory environments, and import-export dynamics. Major regions under scrutiny include North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each zone presents a unique risk-reward profile. For instance, established markets may be transitioning toward premiumization, while emerging regions could be experiencing rapid volume growth driven by urbanization and social leisure trends. The complete report maps out the specific market size and growth velocity for each region, allowing stakeholders to prioritize market entry or expansion efforts with precision.
Application Verticals and Consumer Usage
Beyond the physical product, the end-use context shapes purchasing behavior. A substantial portion of the market is tied to semiconductor wafer manufacturing and related industrial applications, reflecting the specialized nature of certain tobacco processing technologies and materials. Simultaneously, other application segments capture diverse consumer and commercial use cases. Understanding the interplay between these verticals is essential for companies that operate across multiple channels or are considering diversification strategies. The full study provides a breakdown of application-specific revenue streams without disclosing the precise percentages that form the basis of our competitive benchmarking.
Competitive Landscape: Key Players and Strategic Posturing
The Hookah (Shisha) Tobacco Market is characterized by a mix of legacy brands with strong regional loyalty and agile competitors that leverage product innovation to capture share. Our analysis profiles the core entities that are shaping the competitive dialogue, examining their headquarters, product philosophies, and global reach.
Al Fakher Tobacco Factory , based in Ajman, United Arab Emirates, remains a cornerstone of the premium segment. The company focuses on high-quality tobacco blends spanning fruit, mint, and grape flavors, and continues to expand its appeal through new fantasy blends and strategic collaborations. Its commitment to innovation is evident in its recent activity, including a notable product launch in November 2025 where Al Fakher partnered with Snoop Dogg to unveil exclusive new hookah flavors. This move underscores the brand's strategy of leveraging cultural icons to drive consumer engagement and attract a younger demographic.
Adalya Tobacco , headquartered in Izmir, Turkey, has carved a niche with premium fruity blends and black tobacco variants, complemented by its Aqua Mentha line. The company maintains a robust global export network, positioning itself as a reliable supplier for international distributors seeking consistent quality and flavor diversity.
On the other side of the Atlantic, Fumari , operating out of San Diego, United States, emphasizes small-batch premium tobacco packaged in flavor-lock pouches. Their product messaging highlights new mint-forward and dessert flavors, aligning with trends that favor intensity and freshness. In July 2025, Fumari released a Pink and Orange Gummi Bear flavor, demonstrating a continued push into playful, dessert-inspired profile categories that resonate with social lounges and home users alike.
Afzal Shisha , based in India, stands as one of the world's largest hookah tobacco producers. The company offers Paan and fruity blends, and periodically releases special edition products, such as the Special Edition PaanDemic fruity flavor commemorating the 2020 pandemic period. This ability to blend cultural memory with flavor innovation helps reinforce brand loyalty in a crowded marketplace.
Nakhla Tobacco Company , rooted in Cairo, Egypt, brings a strong heritage component to the market. It delivers traditional and premium shisha tobacco with a significant export presence, catering to consumers who value authenticity and time-tested recipes alongside modern quality standards.
Mujeeb Sons , located in Moradabad, India, differentiates itself by offering flavored shisha tobacco alongside a notable focus on 100 percent tobacco-free substitutes. This dual approach addresses the growing demand for alternatives that mimic the hookah experience without the traditional tobacco content, a segment that is gaining attention as regulatory and health-conscious trends evolve.
Al Waha (METCO) , operating from Zarka, Jordan, focuses on premium flavored molasses and tobacco blends, serving a customer base that prioritizes rich, aromatic profiles for both casual and dedicated sessions.
In the United States, Starbuzz Tobacco , based in Lake Forest, continues to influence the market with exotic and premium shisha flavors, including the White Grape and Buzz series. The brand's emphasis on distinctive flavor profiles ensures it remains a recognizable name in specialty retail environments and lounges.
Beyond individual profiles, our research assesses market concentration to understand the competitive density. The industry exhibits a competitive but not overwhelmingly consolidated structure, with the top three players accounting for a combined share of approximately 24.6 percent and the top five reaching around 26.2 percent. This indicates room for mid-tier and niche players to thrive through differentiation, provided they can navigate supply chain and regulatory hurdles effectively.
Industry Dynamics and Regulatory Shifts in 2025-2026
No strategic assessment of the Hookah (Shisha) Tobacco Market is complete without addressing the external forces that reshape operational feasibility and market access. The period from 2025 to 2026 has introduced several pivotal developments that demand attention from leadership teams.
Regulatory and Taxation Amendments
In the United States, the regulatory environment has seen targeted adjustments that directly affect cost structures and compliance pathways. The Hookah Clarification Act of 2025 amends U.S. tax classification for waterpipe tobacco, setting a rate of 0.5662 USD per pound, distinct from standard pipe tobacco. This clarification, enacted in July 2025, creates a more defined fiscal framework but also introduces administrative considerations for importers and manufacturers who must align their labeling and reporting processes accordingly.
Furthermore, state-level legislation continues to influence market access. The California Flavored Tobacco Sales Law of 2026 permits the sale of flavored shisha only at hookah lounges and retailers meeting specific conditions. Enforced from May 2026, this law effectively channels flavored product distribution through controlled venues, potentially benefiting lounge-centric business models while constraining broader retail availability. Such localized regulations can create uneven competitive playing fields across regions and must be factored into any market entry or expansion plan.
Price Adjustments and Product Launch Cadence
Pricing dynamics remain fluid as companies respond to input costs, demand elasticity, and competitive pressure. In October 2025, Eastern Tobacco announced a price increase for hookah tobacco effective March 2025, signaling that some industry participants are recalibrating their pricing strategies to maintain margin integrity. Such moves can trigger ripple effects across the value chain, influencing consumer purchasing frequency and brand switching behavior.
Product launch velocity also remains high. Beyond the collaborations and flavor releases mentioned earlier, the industry is witnessing a continuous stream of new introductions aimed at refreshing the consumer experience. Companies that can sustain a robust pipeline while managing inventory risk are better positioned to capture share during periods of market growth.
Strategic Implications for Decision Makers in 2026
The convergence of growth, segmentation complexity, competitive maneuvering, and regulatory evolution creates a landscape where generic strategies are unlikely to succeed. Our research is structured to help leaders move from broad awareness to precise action.
Identifying High-Potential Segments
With a projected CAGR of 6.98 percent and a 2032 market size approaching 344.8 million USD, the opportunity is substantial, but it is unevenly distributed. Decision makers need to pinpoint which product types, geographic territories, and application verticals offer the most attractive return on investment relative to their capabilities. The full report provides the detailed segmentation splits that allow for sensitivity analysis and scenario planning without exposing the intermediate figures that form the analytical backbone.
Navigating Regulatory Complexity
Companies operating in or entering the North American market must account for the new tax classification and state-specific sales restrictions. Strategies may include adjusting supply chain configurations, aligning product labeling with updated compliance requirements, or exploring partnership models with venue-based retailers in constrained jurisdictions. Understanding the interplay between federal and local regulations is critical to avoiding costly missteps.
Competitive Positioning and Differentiation
With a competitive field that includes major producers from the Middle East, South Asia, and North America, differentiation is paramount. Brands are leveraging collaborations, limited-edition flavors, tobacco-free alternatives, and packaging innovations to stand out. The research profiles these strategies in depth, offering benchmarks that can inform your own product roadmap. Whether you are considering a premiumization play, a volume-driven approach, or a niche alternative like tobacco-free substitutes, the competitive context provided in the study helps validate your positioning assumptions.
Supply Chain and Raw Material Considerations
The rise of alternative products, such as 100 percent tobacco-free shisha substitutes, highlights the importance of raw material strategy. Companies that can secure reliable sources of specialized ingredients and maintain quality consistency will have an advantage as consumer preferences diversify. The report examines how key players like Mujeeb Sons and others are addressing this aspect of the value chain, providing insights that can inform supplier negotiations and inventory planning.
What the Full Report Delivers
This article offers a strategic preview, but the complete market research study goes much further. It is designed as a practical toolkit for executives who need to translate market intelligence into operational decisions. Here is a glimpse of the operational content included:
- Comprehensive Market Sizing and Forecasting: Year-by-year projections from the base year through 2032, enabling financial modeling and long-range planning.
- Detailed Segmentation Analysis: Granular breakdowns by region, type, and application, with revenue contributions that support targeted go-to-market strategies.
- Competitive Intelligence Profiles: In-depth company assessments covering product offerings, geographic footprint, and recent strategic moves, including partnerships and product launches.
- Regulatory and Policy Tracker: A curated summary of key legislative and tax developments, with implications for compliance, pricing, and distribution.
- Market Concentration and Competitive Intensity Metrics: Data on concentration ratios and structural dynamics to inform M&A considerations and competitive response planning.
- Industry Context and Trend Analysis: Integration of raw material trends, product innovation patterns, and consumer-facing developments that shape demand trajectories.
By consolidating these elements into a single, coherent analysis, the report eliminates the need for stakeholders to piece together disparate sources. It provides a unified reference point that aligns finance, marketing, supply chain, and regulatory affairs around a common set of facts and forward-looking projections.
Conclusion
The Hookah (Shisha) Tobacco Market is at a juncture where thoughtful strategy can yield significant competitive advantage. The combination of steady top-line growth, a diversified segmentation framework, an active competitive field, and a regulatory environment that is becoming more defined creates both opportunities and obstacles. Success in 2025 and beyond will belong to organizations that can interpret these dynamics with precision and act decisively.
Our market research is built to support that objective. It offers the depth required to validate strategic hypotheses and the breadth needed to explore alternative pathways. For those ready to move beyond high-level overview and into the specifics that drive planning, the full report provides the complete intelligence architecture. Explore the detailed findings, segment breakdowns, and competitive analyses by visiting the source publication, where the full dataset and executive summaries are available for immediate review.
For detailed analysis of this topic, please visit the official page: Hookah (Shisha) Tobacco Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Anti-Counterfeiting Packaging Market to Hit $497.86M by 2032, 11.79% CAGR
By PW Consulting, 2026-09-07
Strategic Imperatives in Anti-Counterfeiting Packaging: Navigating the 2026 Market Landscape
In an era where supply chain integrity defines brand equity, the anti-counterfeiting packaging market stands at a critical inflection point. As counterfeit operations grow more sophisticated and global regulatory frameworks tighten, enterprises across pharmaceuticals, food and beverage, personal care, and electronics must treat packaging security not as a compliance afterthought, but as a core strategic capability. This comprehensive market research report delivers the analytical rigor required to navigate this shifting terrain, offering decision-makers a structured view of market trajectories, competitive dynamics, and technology deployment pathways through 2032.
Scenario-Based Healing Marketing Solution Market
The baseline data underscores a market in sustained acceleration. From a 2020 valuation of 133.86 million USD, the sector expanded to 231.89 million USD by 2025, reflecting compound annual growth that has consistently outpaced broader packaging benchmarks. Looking ahead, our forecast models project the market will reach 254.79 million USD in 2026 and continue its upward trajectory to 497.86 million USD by 2032. This expansion is anchored by a forecast period CAGR of 11.79 percent, a figure that signals durable investment momentum rather than a transient spike. The consistency of growth across the historical window and the projected decade ahead reflects structural demand drivers that extend well beyond short-term regulatory compliance cycles.
Pet Luxury Products Market
The Strategic Architecture of the Market Study
A market research report only delivers value when it translates macro trends into actionable intelligence. Our study is engineered to serve that exact purpose, bridging high-level market sizing with granular operational insights that procurement, R&D, and commercial leadership teams can deploy immediately. The analytical framework is built around three interconnected pillars: technology segmentation, application mapping, and competitive positioning, each examined through the lens of deployment feasibility, total cost of ownership, and regulatory alignment.
Sound Mixing Tool Market
Coverage Beyond Surface-Level Sizing
The report moves past headline valuations to dissect how security technologies are actually deployed across supply chains. Rather than treating the market as a monolith, we examine how holographic credentials, RFID integration, tamper-evident architectures, and forensic marker systems interact with different product categories, lifecycle requirements, and verification ecosystems. The analysis also maps where each technology type creates the strongest deterrence-to-cost ratio, enabling leaders to prioritize investments that match their risk profile and brand protection objectives.
Forecast Methodology and Scenario Modeling
Forecasting in a market shaped by regulatory change, raw material volatility, and rapidly evolving counterfeit tactics requires more than linear extrapolation. Our projections incorporate historical momentum from 2020 through 2025, then extend forward with scenario-aware adjustments that reflect likely shifts in enforcement intensity, sustainability mandates, and authentication technology adoption. Decision-makers gain not only a central growth path, but also the contextual reasoning behind inflection points, allowing them to stress-test internal planning assumptions against plausible market outcomes.
Operational and Tactical Decision Support
The research is designed to inform concrete business actions. It identifies where security packaging should be integrated at the component level, where label-based verification creates the strongest consumer-facing trust signal, and where integrated digital authentication can reduce downstream inspection costs. The study also examines how packaging architectures can be designed to support serialization mandates, traceability workflows, and lifecycle data requirements without compromising production throughput or cost discipline.
Competitive Landscape: Incumbents, Innovators, and Strategic Positioning
The anti-counterfeiting packaging market is characterized by a fragmented but increasingly differentiated vendor landscape. Market concentration metrics show a CR3 of 24.6 percent and a CR5 of 26.2 percent, indicating that while leading players hold meaningful share, no single organization dominates the entire ecosystem. This structure favors buyers who can evaluate suppliers based on technology specialty, geographic reach, and compatibility with existing packaging lines, rather than defaulting to scale alone.
Technology-Led Differentiation Across Leading Firms
Several companies illustrate how competitive advantage is being built through focused technical positioning. AlpVision S.A., headquartered in Switzerland, concentrates on covert digital anti-counterfeiting solutions such as Cryptoglyph and AlpVision Fingerprint, designed to be verifiable through standard smartphones. This approach reflects a broader shift toward accessible verification that does not require specialized hardware at the point of use. Origin Pharma Packaging, based in the United Kingdom, anchors its offering in ISO 15378 compliant pharmaceutical primary packaging with tamper-evident and child-resistant features, aligning security directly with regulated healthcare supply chain requirements.
Quantum Base, also based in the United Kingdom, occupies a different frontier by developing Q-ID quantum-secure optical tags and a matching scanner for packaging authentication. The emphasis on unbreakable authentication positions the company within high-assurance use cases where the cost of verification failure is particularly steep. Shosky Security, operating from China, focuses on customized tamper-evident strips, tapes, labels, bags, and materials for high-security packaging, providing a more material-centric approach for organizations seeking physical deterrence and customization flexibility. NovaVision Inc., in the United States, specializes in holographic security labels, tamper-evident tapes, seals, and bags, combining visible deterrence credentials with practical packaging protection.
Holostik India Limited has built its profile around holographic films, tamper-proof labels, security holograms, and shrink sleeves for packaging, extending its relevance across both protection and aesthetic packaging needs. Precintia, based in Spain, focuses on passive security seals, tamper-evident products, and traceability solutions, serving applications where seal integrity and chain-of-custody assurance are paramount. ProAmpac, headquartered in the United States, emphasizes recyclable secure and tamper-evident flexible packaging solutions, reflecting a growing convergence between security performance and sustainability commitments.
Recent Developments Reshaping Vendor Capabilities
Recent corporate activity highlights how these players are translating strategy into market-facing capability. In May 2026, Holostik India Limited launched an eco-friendly Paperogram hologram and sustainable anti-counterfeiting packaging innovations targeting the pharma and FMCG sectors. Around the same period, the company showcased sustainable anti-counterfeiting packaging solutions at Labelexpo Europe 2025 and the 12th Speciality Films and Flexible Packaging Global Business Summit, signaling a deliberate alignment between security credibility and environmental positioning. In March 2026, Holostik also updated its product catalog for holographic shrink sleeves and custom anti-counterfeiting packaging for mono cartons and flexible packaging, expanding the scope of deployable formats for brand owners.
ProAmpac participated in Interpack 2026 with sustainable packaging solutions designed for secure consumer goods, reinforcing its emphasis on recyclable structures that still meet tamper-evident and protection expectations. These moves matter because they show how leading vendors are responding to dual pressure: the need for stronger authentication and the demand for packaging systems that support circular economy goals without compromising integrity. For procurement and packaging engineering teams, this convergence is becoming a key selection criterion, not a secondary preference.
Regulatory and Sustainability Forces Redefining the Market
The growth trajectory of anti-counterfeiting packaging cannot be understood apart from the regulatory environment shaping it. Across major markets, authorities are tightening requirements around product authentication, material accountability, and packaging lifecycle transparency. These mandates do more than increase baseline demand; they alter the economics of packaging design and push security features closer to the core of product development rather than treating them as add-ons.
In the European Union, the packaging regulatory landscape is evolving in ways that directly affect secure packaging strategies. The EU Packaging Regulation mandates increasing recycled content in plastic packaging, while extended producer responsibility schemes continue expanding accountability for producers of anti-counterfeiting and tamper-evident packaging. At the same time, the EU Falsified Medicines Directive requires serialization and tamper-evident features on pharmaceutical packaging for all prescription medicines sold in Europe, embedding security requirements into the pharmaceutical supply chain at a foundational level. Alongside these measures, EU Digital Product Passport regulations require on-pack codes linking to lifecycle data and material composition for secure packaging, creating a new expectation that packaging not only protects against counterfeiting but also supports verified product identity and material traceability.
Regulatory direction is only one part of the equation. Material innovation is also reshaping what secure packaging can look like in practice. Faller Packaging introduced recyclable fibre-based tamper-evident labels using sustainable cellulose fibres for pharmaceutical packaging, illustrating how security and sustainability can be integrated at the label level. Berry Global launched the Pical Pouring Closure made from lightweight HDPE for tamper-evident packaging in edible oils and sauces, designed to ensure compliance with EU single-use plastics regulations. These examples demonstrate that raw material choices are increasingly evaluated through a combined lens of regulatory compliance, brand protection, and environmental performance, and that suppliers are responding with solutions built for that more complex evaluation.
Segmentation Dynamics and Demand Drivers
While the overall market growth path is clear, the real strategic value lies in understanding where demand is concentrating and why. The report examines how segmentation patterns reflect different risk profiles, regulatory exposure, and consumer-facing authentication expectations across regions and applications. This matters because not all security investments generate the same return. A credentialing strategy that works for a high-value pharmaceutical product may be misaligned for a fast-moving consumer goods category, and a visibility-focused solution may deliver stronger deterrence in one market while a covert verification mechanism is more effective in another.
Application-Level Demand Patterns
Demand patterns differ sharply by product category, driven by the consequences of counterfeiting and the regulatory burden attached to each sector. Pharmaceutical applications represent the most security-intensive segment, where brand protection, patient safety, and serialization requirements converge. Food and beverage applications follow, where tamper evidence and consumer trust signals play an essential role in protecting both reputation and safety. Personal care and electronics applications also contribute meaningful demand, though each brings distinct constraints around cost, production speed, and verification complexity. The study explores how these application differences influence technology selection, packaging architecture, and the balance between visible deterrence and covert verification.
Technology Adoption Pathways
Technology adoption is not uniform because counterfeit threats are not uniform. Holographic credentials continue to play an important role where visible authentication and brand recognition reinforce consumer trust. RFID integration offers traceability and automated verification advantages in environments where supply chain visibility and electronic handover are priorities. Tamper-evident designs remain essential wherever physical integrity must be proven at the point of use. Forensic markers provide a finer-grained authentication layer for applications that require laboratory-level differentiation or very high-assurance verification. The report evaluates how these technology types are positioned relative to one another, where they overlap, and where hybrid approaches are becoming the more practical choice for complex packaging programs.
Regional Market Structure and Strategic Implications
Regional dynamics shape both demand volume and the competitive priority of local vendors. North America reflects a substantial share of current market activity, supported by strong demand in consumer goods, electronics, and regulated product categories. Europe’s market footprint is reinforced by stringent pharmaceutical and packaging regulations, along with active sustainability mandates that influence packaging design and material selection. Asia Pacific remains an important demand center, particularly as local supply chains scale and brand protection needs expand across both domestic and export-oriented production. Latin America and the Middle East and Africa represent smaller but strategically relevant markets, often tied to specific distribution risks, import dependency patterns, and emerging enforcement environments. Our analysis frames these regional differences in terms of deployment priorities and vendor selection logic rather than simply ranking markets by size.
What Decision-Makers Will Gain from the Full Study
The market data and competitive context summarized here provide the opening frame, but the full report delivers the deeper intelligence required for confident strategic planning. The complete study is built to help teams move from awareness to execution by aligning market evidence with operational decision points.
Integrated Intelligence for Packaging and Brand Protection Strategy
Executives and category leaders will find a structured basis for evaluating where anti-counterfeiting packaging should be treated as a compliance necessity, where it can serve as a brand differentiation lever, and where it can reduce downstream risk exposure. The study connects market size evolution and forecast direction with the practical realities of packaging design, supplier selection, and verification strategy, allowing leadership to make investment decisions with a clearer sense of where value is being created and where it is being eroded.
Supplier Evaluation and Negotiation Context
The competitive analysis provides a practical context for evaluating vendors beyond marketing claims. By examining how leading companies position their technologies, the report helps procurement and packaging engineering teams assess fit across factors such as verification method, regulatory alignment, material compatibility, customization requirements, and sustainability considerations. This context is especially valuable in a fragmented market where scale alone does not determine the best partner for a given program.
Future-Proofing Packaging Investments
Because the market is being shaped simultaneously by technology innovation, regulatory momentum, and raw material evolution, packaging decisions made today can have long-term consequences. The study helps organizations identify where current choices may create future constraints, where flexible verification architectures can reduce adjustment costs later, and where sustainability-linked requirements should be integrated into security planning from the outset. This forward-looking orientation is essential for organizations that want to avoid rework, reselection, or compliance gaps as mandates and consumer expectations continue to evolve.
Anti-counterfeiting packaging is no longer a peripheral concern for risk and compliance teams alone. It is now a strategic element of brand integrity, supply chain resilience, and regulatory readiness. The market’s steady expansion, the rising sophistication of authentication technologies, and the tightening of legal and sustainability requirements all point in the same direction: organizations that build a clear, evidence-based approach to secure packaging will be better positioned to protect product value and customer trust through the rest of the decade.
To access the complete market sizing, segmentation analysis, forecast assumptions, and vendor evaluation framework, readers are invited to explore the full report. The comprehensive study provides the detailed intelligence required to convert high-level market momentum into precise, executable strategy across procurement, R&D, regulatory affairs, and commercial leadership.
For detailed analysis of this topic, please visit the official page: Anti-Counterfeiting Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cellulose Acetate Market to Hit $8.37 Billion by 2032 at 4.6% CAGR From 2026-2032
By PW Consulting, 2026-09-07
Cellulose Acetate Market Outlook 2026: Strategic Intelligence for Sustainable Growth and Competitive Positioning
Unlocking Value in a Maturing yet Dynamic Market
The global Cellulose Acetate (CA) market stands at a critical inflection point. Formerly characterized by stable growth and predictable demand cycles, the industry is now experiencing a profound transformation driven by sustainability imperatives, raw material volatility, and shifting end-user preferences. For executives, procurement leaders, and strategic planners, navigating this landscape requires more than historical hindsight. It demands forward-looking intelligence that connects macroeconomic trajectories with granular operational realities. Our latest research publication, the Cellulose Acetate Market Report 2026, is designed precisely for this moment. It translates complex market signals into actionable strategic frameworks, enabling organizations to make evidence-based decisions from 2026 through 2032 and beyond.
Hand-held Polisher Market
The broader market trajectory reflects a steady expansion path, with total revenue climbing from 4.85 billion USD in 2020 to an estimated 6.06 billion USD in 2025. Looking ahead, the market is projected to reach 8.37 billion USD by 2032, supported by a consistent compound annual growth rate of 4.6 percent over the 2026 to 2032 forecast period. These figures are not merely statistical markers; they represent a structural shift in how cellulose acetate is sourced, formulated, and deployed across industries. Understanding the forces behind this numerical progression is essential for capturing market share, optimizing product portfolios, and mitigating exposure to supply chain and regulatory disruptions.
Lavalier Microphone Systems Market
This report delivers exactly that depth. Rather than offering surface-level summaries, it unpacks the operational, technological, and competitive dynamics that will shape corporate performance over the next seven years. Readers will find a carefully constructed analytical architecture that bridges macro market sizing with segment-level behavior, regional demand migration, and company-specific strategic positioning. The following sections outline how the report is structured, what operational intelligence it provides, and why it should be a foundational reference for 2026 strategic planning.
Worldwide Bioprocess Automation Software Market
Market Trajectory and Structural Shifts
The historical record from 2020 to 2025 reveals a market that has demonstrated resilience amid fluctuating raw material costs and evolving end-market demand. Revenue progression from 5.05 billion USD in 2021 to 5.51 billion USD in 2023, and further to 5.99 billion USD in 2024, signals a demand environment that is expanding beyond traditional reliance on legacy applications. By 2025, the market settled at 6.06 billion USD, establishing a robust base year for forward projections. The forecast window from 2026 to 2032 paints a picture of measured but deliberate expansion, with annual revenue expected to climb through the late 2020s and accelerate toward the end of the decade, culminating at 8.37 billion USD in 2032.
This trajectory is not linear in execution. Growth is being shaped by a combination of incremental volume gains, formulation innovation, and a pronounced shift toward bio-based and sustainable grades. Cellulose acetate has historically benefited from its renewable feedstock origin, but the market is now being asked to prove its environmental credentials across the full value chain. That pressure is reshaping procurement strategies, influencing product development roadmaps, and redefining what it means to be a competitive supplier in a market where differentiation increasingly depends on sustainability performance as much as on cost and consistency.
At the same time, the industry is navigating a period of heightened input cost sensitivity. The broader acetyl chain ecosystem has experienced price fluctuations that directly affect production economics for cellulose acetate manufacturers. These dynamics have prompted strategic adjustments across the competitive landscape, including portfolio re-pricing, capacity optimization, and selective investment in alternative feedstock routes. The report examines how these pressures are being absorbed, distributed, and ultimately priced into downstream applications, offering decision-makers a clearer view of where margin resilience can be built and where exposure should be actively managed.
Competitive Landscape and Strategic Posturing
The cellulose acetate market is defined by a concentrated yet globally distributed competitive structure. With a CR3 of 45.8 percent and a CR5 of 68.3 percent, the industry reflects meaningful market share held by a core group of established producers while leaving room for specialized and regional players to capture differentiated niches. Dominance in such a structure does not automatically translate into uniform strategic advantage. Instead, competitive success increasingly depends on application specialization, regional supply chain proximity, and the ability to offer sustainable or high-performance variants that align with end-user specifications.
Several leading enterprises exemplify the strategic diversity shaping the market. Eastman Chemical Company continues to position itself across fibers, plastics, films, and sustainable bio-based grades, serving textile, filtration, and specialty applications with a focus on formulation versatility and downstream integration. Celanese Corporation maintains a leading global role in cellulose acetate flake and tow, particularly for cigarette filters, textiles, and industrial uses, leveraging scale and process expertise to serve high-volume demand channels. Daicel Corporation contributes high-quality cellulose acetate for textile fibers, films, and specialty derivatives, reinforcing a reputation for consistency and application-tuned product performance.
Solvay S.A. supplies cellulose acetate flake and derivatives for filter tow, automotive, and industrial uses, aligning its portfolio with sectors that demand durability, regulatory compliance, and specialized chemical performance. Mitsubishi Chemical Holdings Corporation operates as a producer of cellulose acetate products and derivatives for textile, film, and specialty applications, drawing on broader material science capabilities to support differentiated end-use solutions. Cerdia International GmbH brings more than a century of experience in sustainable cellulosic solutions, serving as a global supplier of cellulose acetate and derivatives with an emphasis on long-standing expertise and eco-conscious product stewardship.
In Asia, Sichuan Push Acetate Co., Ltd. has emerged as a notable leader in China, producing all commercial grades of cellulose acetate for industrial and fiber applications. Its regional scale and grade breadth illustrate how localized manufacturing strength can support both domestic demand and broader export dynamics. Sappi Limited extends its material portfolio into cellulose acetate and derivatives for specialty papers, films, and sustainable materials, connecting fiber-based heritage with advanced application development. Rayonier Advanced Materials Inc. focuses on specialty cellulose derivatives including acetate for filtration, nonwovens, and high-performance applications, emphasizing tailored performance rather than commodity volume. Borregaard ASA supplies high-purity specialty cellulose suitable for cellulose acetate production in filters, yarn, and plastics, supporting the upstream foundation of the value chain with precision and quality control.
These companies are not merely competing on price. They are actively shaping the market through product introductions, portfolio adjustments, and responses to raw material conditions. Recent developments highlight this strategic momentum. In February 2026, Eastman Chemical Company introduced Naia Lyte sustainable cellulose acetate fiber at Première Vision Paris, targeting high-performance textiles and apparel. That launch reflects a broader industry push toward renewable, performance-oriented fibers that meet evolving apparel and textile specifications. In March 2026, Celanese Corporation implemented a global price increase across its entire Acetyl Chain product portfolio, including cellulose acetate, to address rising raw material costs and supply chain disruptions. This move underscores how cost pressures are being actively managed and passed through the value chain, with implications for buyer planning, contract structures, and competitive pricing dynamics.
The report maps these and other strategic moves within a structured competitive framework, allowing readers to compare regional footprints, application focus, product breadth, and likely responses to market shocks. It provides the analytical context required to interpret competitor behavior not as isolated events, but as signals within a broader competitive rhythm.
What the Report Delivers: Operational Depth for Strategic Planning
This research is built for practitioners who need more than market size estimates. The report is organized to support real-world decision-making across strategy, sourcing, product development, and risk management. It offers an integrated view of how demand is forming, how supply is adapting, and where competitive advantages are being created or eroded. The following elements represent the core value of the publication.
- Comprehensive market sizing and forecast architecture that connects historical performance with forward projections, giving executives a reliable baseline for scenario planning and investment prioritization.
- Segment-level analysis that explains how different product categories and application channels are contributing to growth, where demand concentration is forming, and which use cases are gaining strategic relevance without exposing sensitive percentage splits or absolute sub-market figures.
- Regional demand exploration that examines how market activity is distributed across key geographies, highlighting relative importance, demand migration patterns, and the structural factors influencing local market development.
- Competitive benchmarking that places leading suppliers in context, comparing strategic orientation, application coverage, regional presence, and likely reactions to cost pressures, regulatory shifts, and sustainability requirements.
- Supply chain and raw material insight that connects upstream cost dynamics to downstream pricing behavior, offering a framework for interpreting supplier announcements, procurement risk, and inventory strategy.
- Regulatory and policy context that identifies measures and announcements capable of altering trade flows, input availability, and compliance obligations, helping organizations anticipate rather than react to external changes.
- Practical strategic implications for capacity planning, product portfolio decisions, partnership selection, and market entry or expansion considerations, ensuring the analysis is anchored in executable business logic.
By combining these layers, the report enables readers to move from observation to action. Instead of treating market growth as a single number, decision-makers can see how that growth is composed, where it is most durable, and which variables are most likely to influence results over the forecast horizon.
Raw Material Pressures and Supply Dynamics
No analysis of the cellulose acetate market is complete without a clear understanding of input economics. The acetyl chain sits at the center of production cost structures, and recent trends show that price behavior in this segment can materially influence manufacturer margins and downstream pricing strategies. In March 2026, acetic anhydride prices in Northeast Asia reached 0.65 USD per kilogram, up 20.4 percent from December, driven by strong demand from cellulose acetate and pharmaceutical sectors alongside rising acetic acid feedstock costs. In Europe, acetic anhydride prices reached 0.95 USD per kilogram in the same period, up 11.8 percent from December, supported by firm demand from cellulose acetate manufacturing and constrained import supply.
These shifts are not isolated cost fluctuations. They represent a broader pattern in which feedstock availability, regional demand intensity, and logistics constraints interact to shape production economics. For buyers, such movements affect contracting timing, inventory strategy, and supplier negotiations. For producers, they influence pricing architecture, grade prioritization, and the pace at which cost recovery can be achieved without damaging customer relationships. The report places these dynamics in a structured interpretive context, helping organizations distinguish between temporary volatility and more persistent structural pressure.
Importantly, the analysis also considers how raw material conditions interact with strategic responses already underway in the competitive landscape. When major suppliers adjust pricing or launch sustainable product lines, they are often reacting to a combination of input costs, customer expectations, and differentiation opportunities. Understanding that interplay gives executives a more accurate basis for forecasting supplier behavior and planning their own procurement or product strategies.
Regulatory Signals and Cross-Market Sensitivities
Regulatory developments can reshape market behavior quickly, especially when they affect raw material availability or trade conditions. The cellulose acetate industry does not operate in a vacuum; it is exposed to broader policy measures that influence chemical supply chains, export conditions, and regional manufacturing economics. Recent regulatory actions illustrate the kind of external signals that informed operators must monitor.
In April 2025, the China Ministry of Commerce issued Announcement No.18 of 2025, implementing export control on certain medium and heavy rare earth items effective immediately. While this measure directly targets rare earth commodities, it reflects a wider policy environment in which export controls and industrial resource management can affect downstream material flows and supply chain confidence. In November 2025, China's MOFCOM and GAC issued Announcement No.70 of 2025, temporarily suspending multiple export control measures on key raw materials including rare earths, lithium batteries, and diamonds until November 10, 2026. These actions demonstrate the fluid nature of trade regulation and the importance of tracking policy timelines that may influence input availability, logistics planning, and regional sourcing assumptions.
Even when such measures do not directly name cellulose acetate, they contribute to the operating environment in which chemical manufacturers, converters, and end-users make decisions. Regulatory uncertainty can affect supplier selection, inventory buffering, and regional procurement strategy. The report incorporates this regulatory awareness into its broader market narrative, ensuring that readers understand how policy signals can intersect with raw material conditions, competitive behavior, and application demand.
Why This Study Matters for 2026 Decision-Making
Strategic planning in 2026 requires an evidence base that is both current and structured for application. Market participants face simultaneous pressures: the need to align with sustainability expectations, the challenge of managing input cost volatility, the imperative to interpret competitor moves with precision, and the responsibility to prepare for regulatory and trade dynamics that can shift quickly. A superficial market overview cannot support these decisions. What is needed is a detailed, operationally relevant analysis that shows not only where the market is going, but why it is moving that way and what that means for specific business choices.
This report is designed to meet that requirement. It provides a cohesive framework for interpreting market size, growth rate, competitive concentration, segment behavior, and external shocks in a unified narrative. It supports multiple functions: corporate strategy teams can use it to prioritize growth avenues and assess competitive positioning; procurement and sourcing leaders can use it to frame supplier negotiations and risk mitigation; product and R&D teams can use it to identify application trends and sustainable formulation opportunities; and regional executives can use it to understand relative market importance and demand migration patterns.
Just as importantly, the report respects the complexity of the industry. It does not reduce the cellulose acetate market to a single story. Instead, it presents a multi-layered view in which historical performance, forecast trajectory, raw material conditions, regulatory developments, and competitor actions are examined together. That integrated perspective is what makes the analysis useful for 2026 planning and beyond.
Explore the Full Intelligence Architecture
The insights summarized here represent only the opening layer of the full study. To support rigorous decision-making, the complete report extends far beyond headline figures and company profiles. It delivers detailed segmentation analysis, regional demand evaluation, competitive benchmarking, raw material and pricing context, regulatory timelines, and practical strategic recommendations tailored to the realities of the 2026 to 2032 forecast window.
For organizations that need to anticipate demand shifts, assess supplier strength, interpret cost pressures, and align product or sourcing strategies with market direction, the full report provides the depth required to act with confidence. It is structured to serve as both a strategic reference and a working intelligence asset, enabling teams to move from high-level awareness to detailed, defensible planning.
The Cellulose Acetate Market Report 2026 is built for leaders who want more than a snapshot. It offers a comprehensive view of an industry in transition and a practical foundation for the decisions that will define competitive performance over the next several years. We invite you to access the complete publication and explore the full intelligence architecture behind the market's projected path to 8.37 billion USD by 2032.
For detailed analysis of this topic, please visit the official page: Cellulose Acetate (CA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Stereo Bluetooth Headsets Market Hits $1.98B in 2025, 8.95% CAGR Forecast to 2032
By PW Consulting, 2026-09-07
Beyond the Audio Curve: Strategic Intelligence for the Stereo Bluetooth Headsets Market in 2026
Navigating the Next Wave of Audio Connectivity
The global wireless audio landscape is approaching a critical inflection point. As enterprises evaluate capital allocation, product roadmaps, and supply chain resilience for the coming fiscal year, the Stereo Bluetooth Headsets Market has emerged as a bellwether for broader consumer electronics, gaming, and professional communication trends. At PW Consulting, we recognize that the decisions made in 2026 will be shaped not by surface-level hype but by rigorous, forward-looking intelligence that distinguishes cyclical fluctuations from structural growth. This market research introduction is designed to provide executives, product strategists, and investment committees with the analytical scaffolding required to anticipate demand shifts, assess competitive intensity, and align operational capabilities with emerging opportunity sets.
Worldwide High Quality Australian Beef Market
Over the historical window of 2020 through 2025, the sector demonstrated sustained expansion, reflecting a compound trajectory that accelerated as true wireless architectures matured and premium feature sets became mainstream expectations. The baseline year of 2025 anchors a forecast horizon extending through 2032, during which the market is projected to realize a CAGR of 8.95% in USD Million terms across the overall addressable universe. This growth is not merely a continuation of past momentum; it reflects the layering of new product architectures, regional supply reconfiguration, and deepening integration of advanced audio technologies into everyday professional and leisure use cases.
Worldwide Human-machine Collaboration Market
For leaders operating in 2026, the strategic question is no longer whether the category will grow, but how to position portfolios, procurement strategies, and channel investments to capture disproportionate value as the market scales toward higher revenue thresholds by the end of the decade.
Unmanned Aerial Vehicle Interception Equipment Market
Macro Trajectory and the 2026 Decision Window
Historical Momentum Meets Forecast Discipline
The historical arc from 2020 to 2025 illustrates consistent revenue expansion, with the overall market climbing from approximately 1,200 million in 2020 to a baseline of 1,980 million in 2025. This progression captures the compounding effects of adoption maturation, feature-led upgrades, and expanding relevance across both consumer and enterprise end-users. Looking forward, the forecast period from 2026 through 2032 maps a clear upward path, with projected revenue stepping through successive milestones and reaching substantially higher valuations by the close of the forecast window.
What makes this trajectory strategically significant for 2026 decision-makers is not the headline number alone, but the cadence of growth implied across the multi-year horizon. The progression from the 2026 forecast point through the terminal year reflects a market that continues to add value at a rate well above static replacement cycles. This implies that product planners and category managers must think in terms of sustained iteration, not single-generation wins. Pricing architecture, feature sequencing, and inventory horizons all need to be calibrated to a market where premiumization and functional differentiation are likely to remain central growth drivers rather than temporary tactical levers.
Structural Drivers Shaping the Next Cycle
Several interlocking forces underpin the forward growth profile. First, the broader true wireless stereo ecosystem continues to command a dominant position within premium audio preferences, favored for its immersive separation and its compatibility with advanced feature sets. Second, the integration of active noise cancellation, spatial audio capabilities, and refined touch-gesture interfaces has shifted the value proposition from baseline connectivity to experiential differentiation. Third, the category's average selling price dynamics reflect higher functionality and brand value relative to mono alternatives, reinforcing a premium-tier pull that benefits manufacturers able to execute on acoustic performance, design language, and ecosystem integration.
From an operational perspective, these drivers require a decision framework that balances innovation velocity against cost discipline. The market's expansion into 2026 and beyond is not uniform across all product architectures or usage contexts. Leaders who treat the category as a single block risk misallocating resources; those who decompose the opportunity by form factor, application relevance, and regional supply dynamics will be better positioned to capture margin and share gains. Our research is built to support exactly that decomposition, translating top-line growth into actionable segmentation logic without exposing the granular figures until readers engage with the full intelligence suite.
Competitive Intensity and Portfolio Positioning
A Fragmented yet Differentiated Field
The competitive landscape for Stereo Bluetooth Headsets is characterized by a mix of global audio specialists, consumer technology giants, and ergonomic-focused enterprise vendors. Market concentration metrics indicate a moderately fragmented structure, with the top three players holding a combined share in the mid-twenties and the top five extending into the mid-thirties. This level of concentration suggests that while brand leadership and distribution scale remain important, there is still meaningful room for targeted differentiation, regional resonance, and vertical-specific positioning.
Sony continues to push the premium true wireless segment with its WF-1000XM5 True Wireless Stereo Bluetooth Headphones, emphasizing acoustic refinement and noise management for audio-focused audiences. Bose reinforces its QuietComfort Ultra Earbuds with active noise cancellation for stereo Bluetooth audio, leveraging its established reputation for comfort and isolation in high-attention environments. Apple's AirPods Pro (2nd generation) represent a tightly integrated true wireless offering that benefits from ecosystem alignment and consistent feature cadence, while Samsung's Galaxy Buds3 Pro extend the same logic within a mobile-centric device strategy.
Beyond the consumer-premium axis, professional and hybrid-use positioning remains strategically important. Jabra's Evolve2 75 and Evolve2 85 True Wireless Stereo Bluetooth Headsets target professional communication requirements, where voice clarity, call stability, and workplace ergonomics carry distinct weight. Poly (HP) contributes with Poly Voyager Focus 2 and Poly Voyager Surround Stereo Bluetooth Headsets, reinforcing a business-grade emphasis on remote and hybrid work usability. Logitech complements this trajectory with the Zone True Wireless Stereo Bluetooth Headsets for business, underscoring the continued relevance of conferencing-grade audio in enterprise deployments.
In parallel, the mid-tier and value-conscious segments remain active with players such as Anker, whose Soundcore Life P3 True Wireless Stereo Bluetooth Headphones illustrate the push toward feature-rich offerings at accessible price points, and Sennheiser, whose MOMENTUM True Wireless 4 Stereo Bluetooth Headphones reflect a continued emphasis on authentic audio character and design credibility. JBL enters the premium wireless conversation through its Live Pro 2 True Wireless Stereo Bluetooth Headphones, balancing lifestyle appeal with feature adoption. The result is a competitive field in which differentiation is increasingly defined by the alignment of acoustic promise, feature integration, and use-case relevance rather than by connectivity alone.
Product Innovation Cadence and Feature Prioritization
The Acceleration of New Product Development
Innovation activity in the category has intensified markedly. Between 2023 and 2024, new product development in stereo Bluetooth headsets surged, with true wireless stereo-based innovations comprising the majority of all new launches. This shift signals that the category's center of gravity has moved firmly toward architectures that support richer stereo separation and advanced feature integration. Bluetooth 5.3+ technology was integrated into a substantial share of headsets introduced during the period, indicating that connectivity improvements are no longer incremental footnotes but core enablers of latency control, pairing stability, and power efficiency.
At the same time, active noise cancellation-enabled product development grew at a strong pace, reflecting sustained demand for immersive listening and improved focus in both consumer and professional environments. Touch-gesture control features were increasingly included in premium models, while AI-powered audio enhancement tools featured in a meaningful portion of newly released SKUs. Taken together, these patterns suggest that manufacturers are competing on a multi-dimensional feature frontier: acoustic quality, environmental adaptation, interface sophistication, and intelligent audio processing.
For 2026 planning, this innovation cadence has direct implications. Product teams must evaluate whether their roadmaps are responsive to the true wireless premiumization trend, whether their engineering investments in Bluetooth version adoption and ANC integration are aligned with buyer expectations, and whether their software and algorithm capabilities can support AI-based enhancement without eroding cost structures. The companies that win in this environment will be those that can sequence feature introduction in a way that matches both consumer appetite and production feasibility.
Supply Chain Realities and Operational Resilience
Component Pressure and Lead-Time Volatility
Growth aspirations must be evaluated against operational constraints. Supply chain disruption and semiconductor shortages have remained ongoing challenges, with Bluetooth headphones relying heavily on lithium-ion batteries, Bluetooth chips, and micro-electromechanical sensors. These components faced production slowdowns during the 2023–2024 period, and the resulting component cost increases affected final product pricing and delivery schedules. Shipping delays also extended average lead times across several regions, compounding planning uncertainty for brands, distributors, and enterprise buyers.
In response, manufacturers are diversifying suppliers and building local assembly plants to mitigate risk. This shift is strategically significant because it suggests that regional supply reconfiguration is becoming a structural element of category competitiveness, not simply a short-term mitigation tactic. For 2026, procurement leaders need to evaluate supplier concentration, buffer inventory assumptions, and assembly footprint decisions as part of a broader resilience strategy. Where product plans assume uninterrupted component flow, margin and service levels are exposed; where plans incorporate supplier diversification and regional assembly options, organizations can better protect launch timing and pricing integrity.
India's electronics manufacturing incentives are also relevant to this regional diversification theme, attracting component suppliers to major industrial zones and enabling supply alternatives beyond traditional concentration points. This evolution supports a broader narrative in which supply chain strategy is increasingly intertwined with regional market access, tariff exposure, and lead-time reliability. The businesses that treat supply configuration as a strategic variable, rather than an operational afterthought, will be better positioned to convert demand growth into dependable fulfillment.
Regulatory and Geopolitical Context
Compliance, Standardization, and Regional Realignment
Market strategy cannot be separated from the regulatory environment. The EU common charger requirements now apply to a broad set of portable electronics, including headphones and headsets, introducing new considerations for packaging, accessory design, and product lifecycle planning. The Commission's ongoing review of radio equipment categories eligible for common charging requirements adds a further layer of forward uncertainty, with an initial report expected in the near term. For stereo Bluetooth headset manufacturers, these developments affect not only conformance costs but also product architecture decisions, accessory bundling, and regional go-to-market configurations.
Geopolitical dynamics reinforce the need for regional adaptability. Policy-driven manufacturing incentives are pulling supply relationships into new geographies, altering the economics of component sourcing and final assembly. This realignment does not eliminate dependency risk, but it expands the set of feasible sourcing and production strategies. For executives planning 2026 product launches, channel expansion, or private-label partnerships, the regulatory and geopolitical backdrop should be treated as a design constraint that shapes cost models, compliance timelines, and market entry sequencing. Our research integrates these dynamics so that decision-makers can evaluate demand potential alongside the practical limits imposed by compliance and supply geography.
Inside the PW Consulting Stereo Bluetooth Headsets Market Research
A Practical, Decision-Ready Structure
This market research is designed to move beyond aggregate narratives and into the operational detail that senior teams need for 2026 planning. The full study provides a comprehensive mapping of overall market size and forecast progression in USD Million terms, with historical and forward data structured to support demand modeling, revenue planning, and scenario comparisons. Rather than leaving leaders to infer implications from top-line figures alone, the report examines the market through segmentation logic that distinguishes form factor architectures, application contexts, and regional demand distributions, while preserving the precision required for portfolio and channel decisions.
Readers will find detailed analysis of how Over Ear, On Ear, and In Ear headset architectures divide the addressable market, how Consumer Electronics, Gaming, and Professional Communication applications shape volume and value patterns, and how regional demand varies across markets with distinct adoption drivers and purchasing behaviors. The study also incorporates competitive profiles for the companies shaping the category, including their headquarters, product-level emphasis, and positioning within the broader stereo Bluetooth headset landscape. These profiles are not generic company summaries; they are calibrated to illustrate how specific offerings relate to the market's premiumization trend, professional-use requirements, and true wireless innovation cadence.
Beyond segmentation and competitive mapping, the research integrates recent developments in new product activity, supply chain conditions, and market outlook signals. This includes examination of the surge in true wireless innovation, the role of Bluetooth 5.3+ adoption, the growth in ANC-enabled development, the rise of touch-gesture controls and AI-powered audio tools, and the continuing pressure from component shortages and lead-time extensions. By combining these threads, the study enables readers to assess where growth is coming from, how it is being built, and where execution risk is concentrated.
The report also addresses market concentration and the strategic implications of a moderately consolidated yet still highly contested competitive field. For M&A evaluation, partnership screening, and channel strategy, this structure supports a more nuanced reading of share dynamics than headline revenue alone can provide. For product strategy, it clarifies which architecture-application combinations merit deeper investment. For supply and operations planning, it connects demand assumptions to the realities of component dependency, regional assembly, and compliance-driven design changes.
Why 2026 Demands a Higher-Order Reading of the Category
The decision environment for 2026 is defined by a tension that is familiar but increasingly consequential: demand potential is strong, but the operational and competitive conditions for capturing that potential are more complex than ever. The market's projected growth trajectory through the early 2030s indicates that the category will continue to expand at a pace that rewards organizations capable of disciplined differentiation. Yet the simultaneous pressures of component volatility, lead-time elongation, regulatory standardization, and rapid feature iteration mean that growth is not self-executing.
In this context, the Stereo Bluetooth Headsets Market should be evaluated as a portfolio of interdependent choices. How should premium versus accessible product tiers be balanced? Which form factors and application contexts deserve the most engineering and marketing attention? Where should supply relationships be diversified, and what local assembly or supplier options are credible? How should EU common charger compliance and other regulatory reviews reshape accessory strategy and regional packaging? How should competitive positioning respond to the combined influence of Sony, Bose, Apple, Samsung, Jabra, Poly, Logitech, Sennheiser, Anker, and JBL, each of which is competing on a slightly different axis of value?
These questions cannot be answered by intuition alone. They require segment-level visibility, competitive context, supply chain realism, and forward forecast discipline. That is the purpose of this research introduction and the fuller study it previews. Executives who engage with the complete analysis will be able to move from general confidence in market growth to specific, defensible decisions about product sequencing, geographic prioritization, supplier strategy, and brand positioning.
Access the Complete Intelligence Suite
This introduction has outlined the strategic landscape shaping the Stereo Bluetooth Headsets Market as organizations prepare for 2026 and beyond. It has highlighted the macro growth trajectory, the innovation cadence surrounding true wireless architectures and advanced feature sets, the competitive diversity across premium consumer and professional-use offerings, and the operational and regulatory realities that influence execution. What it has not done, by design, is release the full segmented figures, regional breakdowns, application splits, and detailed forecast tables that turn strategic direction into precise planning inputs.
Those details are available in the complete PW Consulting market research. The full report delivers the segmented market sizes, application and architecture splits, regional demand distributions, competitive profiles, and recent development analysis required for scenario modeling, pricing strategy, channel planning, and product roadmap alignment. For teams that need to translate category momentum into executable 2026 decisions, the full study provides the depth and structure necessary to act with confidence. We invite you to access the complete intelligence suite through the source webpage to obtain the comprehensive data, segmentation detail, and competitive context that will support your next cycle of strategic planning.
For detailed analysis of this topic, please visit the official page: Stereo Bluetooth Headsets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


