



Category: market research
PW Consulting: Global Cloud CDN Market Hits $11.7B in 2025, Projected to Reach $28.49B by 2032
By PW Consulting, 2026-09-07
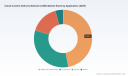
Unlocking the Edge: Strategic Imperatives in the Cloud Content Delivery Network Market Through 2032
The digital infrastructure landscape is undergoing a profound transformation. As enterprises accelerate their migration to cloud-native architectures and consumers demand instantaneous content delivery across geographies, the Cloud Content Delivery Network Market has emerged as a critical backbone of global digital commerce. Our latest comprehensive market research report provides a definitive analysis of this sector, offering senior decision-makers the intelligence required to navigate investment, procurement, and competitive positioning through the forecast period ending 2032. This article serves as a strategic preview of the findings, highlighting the macroeconomic trajectory, the evolving competitive architecture, and the operational dynamics that will define enterprise success in the coming years.
Worldwide Self-propelled Feeding System Market
Market Trajectory and Macroeconomic Context
The historical performance of the Cloud Content Delivery Network sector demonstrates sustained resilience and accelerating adoption. Between 2020 and 2025, the market expanded from a base valuation of 6.5 billion USD to 11.7 billion USD, reflecting a compound annual growth trajectory that underscores the infrastructure criticality of edge delivery networks. This growth has been fueled by parallel trends: the exponential increase in video streaming consumption, the performance demands of modern web applications, and the rising need for API acceleration across distributed microservices environments.
Worldwide Custom Piano Market
Looking forward, our forecast modeling projects the market to reach 13.74 billion USD in 2026, with momentum carrying through to a projected valuation of 28.49 billion USD by 2032. This forward curve implies a compound annual growth rate of 13.5 percent across the forecast horizon. Such a rate places cloud CDN infrastructure among the more dynamic segments of the broader cloud services ecosystem, outpacing many traditional IT spend categories. The growth is not merely a function of organic expansion but reflects structural shifts in how enterprises architect their digital presence. Edge computing capabilities are increasingly bundled with security, serverless compute, and real-time analytics, transforming CDN from a passive content cache into an active application delivery plane.
Worldwide Cosmetics Regulatory Consultant Market
For enterprise strategists, these aggregate figures provide essential context for budget planning and capacity modeling. However, the headline numbers represent only the surface layer of actionability. The true strategic value of our research lies in the decomposition of these trends across technology types, application verticals, and regional deployment patterns. Decision-makers must understand where capital is flowing, which workloads are driving procurement, and how geopolitical and regulatory variables will reshape regional demand curves. Our report dissects these dimensions without obscuring the underlying mechanics, enabling executives to test scenarios against granular data rather than relying on top-down extrapolations.
Competitive Architecture: Navigating a Concentrated yet Dynamic Landscape
The competitive structure of the cloud CDN market presents a nuanced picture for both investors and enterprise buyers. Market concentration metrics indicate that the top three providers command approximately 65 percent of total revenue, while the top five entities extend their collective share to roughly 80 percent. This concentration reflects the economies of scale inherent in operating globally distributed edge networks, the high barriers to entry associated with peering agreements and Points of Presence deployment, and the enterprise preference for vendors with proven reliability at scale.
Within this consolidated framework, several incumbent and specialized players continue to differentiate through platform architecture and strategic pivots. Akamai Technologies Inc., headquartered in Cambridge, Massachusetts, has long anchored the market through its Akamai Connected Cloud platform, which integrates a massively distributed edge network with cloud computing, security, and content delivery services. The company's strategic positioning extends beyond traditional CDN caching into broader cloud infrastructure services, a pivot validated by recent financial disclosures and landmark enterprise commitments. In early 2026, Akamai reported full-year 2025 revenue of 4.208 billion USD, representing a 5 percent year-over-year increase, with Cloud Infrastructure Services revenue growing 25 percent to 630 million USD. Subsequent developments reinforced this trajectory, including a seven-year, 1.8 billion USD commitment from a leading U.S.-based frontier model provider, marking the largest customer deal in the company's history. Alongside these growth signals, Akamai has navigated cost-side pressures by notifying customers and partners of a 3 percent interim surcharge effective April 2026, with potential adjustments up to 10 percent on contract renewals tied to rising expenses for servers, RAM, SSDs, and energy. Regulatory and security positioning has also advanced, with Akamai on track to achieve FedRAMP High and DOD Impact Level 4 and 5 accreditations in 2026, while simultaneously announcing an intent to acquire LayerX to enforce AI usage control across browser environments.
Cloudflare, Inc., based in San Francisco, California, continues to press its differentiation through the Workers and edge compute platform, which delivers a global network purpose-built for content delivery, security, and application performance. The company's recent financial results underscore strong momentum, with Q1 2026 revenue reaching 639.8 million USD, a 34 percent year-over-year increase, alongside non-GAAP income from operations of 73.1 million USD. This performance reflects the growing appeal of edge compute platforms that allow developers to run logic closer to end users, reducing latency and centralizing security policy enforcement at the perimeter.
Fastly, Inc., also headquartered in San Francisco, has carved a distinct niche with its Compute@Edge platform, emphasizing high-performance content delivery and serverless application execution. The company reported record Q1 2026 financial results, with revenue of 173.02 million USD and an adjusted gross margin of 65.1 percent. Remaining performance obligations expanded 63 percent year-over-year, signaling strong forward demand and contract visibility. Fastly's trajectory highlights the ongoing relevance of specialized, developer-centric edge platforms even within a market increasingly dominated by hyperscale and diversified cloud providers.
The hyperscale cloud providers maintain a significant presence through integrated CDN offerings that align closely with broader cloud ecosystems. Amazon Web Services, Inc., headquartered in Seattle, Washington, operates Amazon CloudFront, a global edge network designed for content delivery and streaming services, tightly coupled with AWS storage and compute primitives. Microsoft Corporation, based in Redmond, Washington, provides Azure CDN and Front Door for optimized content delivery within cloud environments, enabling enterprises to leverage existing Azure investments while extending performance to the edge. Alphabet Inc., headquartered in Mountain View, California, offers Google Cloud CDN for global edge delivery and streaming optimization, integrating with Google's broader network infrastructure and analytics capabilities. These hyperscaler offerings benefit from procurement consolidation advantages and ecosystem lock-in, though they also face competitive pressure from independent providers that emphasize neutrality, multi-cloud portability, and specialized edge compute capabilities.
Our report provides detailed company profiles, strategic positioning matrices, and capability comparisons across these key players. We examine how each vendor's architecture, pricing philosophy, security posture, and geographic footprint influence enterprise selection criteria. The analysis extends to recent developments, including pricing adjustments, accreditation achievements, and strategic acquisitions that signal where each competitor is placing its bets. By mapping these dynamics, the report equips procurement teams and strategy leaders with a comparative lens to evaluate vendor fit beyond brand recognition.
Market Segmentation Dynamics: Workloads, Types, and Regional Variation
Understanding where demand originates within the cloud CDN market is essential for aligning technology investments with revenue-generating workflows. Our segmentation analysis distinguishes three primary frameworks: by type, by application, and by region. Each lens reveals distinct growth drivers and procurement behaviors that aggregate figures obscure.
By type, the market encompasses Video Streaming, Web Performance, and API Acceleration workloads. Video Streaming represents the largest revenue concentration, reflecting the persistent growth of on-demand media, live event delivery, and user-generated content platforms that require low-latency, high-throughput edge distribution. Web Performance remains a foundational category, as enterprises optimize page load times, reduce bounce rates, and improve search rankings through edge caching and content optimization. API Acceleration addresses the rising complexity of distributed application architectures, where microservices, mobile backends, and third-party integrations demand consistent low-latency communication across global user bases. The interplay among these categories varies by vendor capability and enterprise maturity, and our report details how workload mix influences pricing, contract structure, and service level expectations.
By application, demand concentrates across Media and Entertainment, E-commerce, Gaming, and Others. Media and Entertainment organizations rely on CDN infrastructure to manage bursty traffic patterns, global audience distribution, and rights-managed content delivery. E-commerce platforms depend on edge performance to reduce checkout friction, protect against traffic spikes during promotional events, and maintain brand credibility through fast, secure experiences. Gaming operators utilize CDN capabilities to distribute updates, manage matchmaking latency, and support real-time content delivery for both cloud gaming and traditional title distribution. The Others category captures a growing set of enterprise use cases, including SaaS delivery, financial services compliance-driven caching, and IoT telemetry aggregation at the edge. Our segmentation analysis provides relative revenue contributions across these application areas, enabling readers to benchmark their industry's position and anticipate cross-industry adoption patterns.
Regional variation introduces additional strategic complexity. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each present distinct procurement dynamics shaped by infrastructure maturity, regulatory environments, and enterprise digital transformation pacing. North America maintains the largest revenue share, reflecting the concentration of hyperscale cloud providers, high enterprise IT spend, and early adoption of edge compute use cases. Europe demonstrates strong demand driven by data localization requirements, multilingual content delivery, and regulatory frameworks influencing data routing and caching strategies. Asia Pacific represents a high-growth region characterized by rapid mobile adoption, diverse language and content requirements, and expanding cloud infrastructure investment across both developed and emerging markets. Latin America and the Middle East and Africa, while smaller in absolute terms, offer meaningful growth opportunities as enterprises in these regions accelerate their digital presence and as global vendors extend Points of Presence to improve latency and local compliance. Rather than presenting static percentage allocations that age quickly, our report frames regional dynamics through growth trajectories, deployment drivers, and the strategic implications of vendor network expansion. This approach allows decision-makers to assess market entry timing, partnership opportunities, and capacity planning with greater precision.
Industry Dynamics: Pricing, Regulation, and Infrastructure Pressure
Beyond the structural growth narrative, the cloud CDN market is navigating a period of operational and regulatory intensity that directly affects enterprise planning. Cost pressures on infrastructure providers are translating into pricing adjustments that procurement teams must anticipate. As noted in recent industry communications, infrastructure vendors have signaled interim surcharges and renewal price adjustments linked to rising costs for servers, memory, storage components, and energy. These adjustments reflect broader supply chain dynamics and the capital intensity of maintaining globally distributed edge networks. Enterprises should incorporate such pricing variability into total cost of ownership models and negotiate contract structures that account for potential mid-cycle adjustments.
Regulatory and accreditation developments are simultaneously reshaping eligibility and deployment options for government, defense, and regulated industry workloads. Advancements in security accreditations, including trajectories toward FedRAMP High and defense impact level accreditations, expand the addressable market for providers that can demonstrate compliance with stringent security controls. For enterprises operating in regulated sectors, the availability of accredited edge infrastructure influences vendor selection, data residency strategies, and risk management frameworks. Our report examines how these regulatory developments intersect with CDN deployment models and what they imply for enterprise compliance roadmaps.
Pricing transparency and interconnect dynamics also warrant attention. Cloud providers continue to refine pricing for peering, interconnect, and carrier services, with list price adjustments effective across major regions. These changes affect the cost structure of hybrid and multi-cloud delivery architectures, particularly for enterprises that rely on direct peering or carrier partnerships to optimize traffic routing. Understanding the direction and magnitude of such pricing shifts helps enterprises forecast egress and interconnection costs, evaluate alternative routing strategies, and assess whether vendor consolidation or diversification better serves cost management objectives.
Strategic acquisitions and product expansions further signal where the market is heading. Moves to extend edge platforms into browser-based AI usage control, serverless compute, and advanced security enforcement illustrate the convergence of content delivery with broader application and security capabilities. Enterprises evaluating CDN investments should consider these expansions not as peripheral features but as indicators of how vendors intend to deepen platform stickiness and expand the scope of edge-mediated workloads. Our report analyzes these developments within the context of vendor roadmaps and competitive differentiation.
What the Full Report Delivers: Operational Intelligence for Decision-Makers
This preview highlights the strategic shape of the market, but the complete research study provides the depth required for concrete action. The report is structured to support multiple decision contexts, from enterprise procurement and vendor selection to investment analysis and competitive strategy. It includes detailed market sizing across historical and forecast periods, decomposed across type, application, and region, with methodology notes that clarify assumptions and data sources. Readers gain access to segmentation splits that quantify revenue contributions without reducing the analysis to static snapshots, allowing for scenario testing and demand forecasting aligned to specific enterprise contexts.
The competitive analysis section delivers company profiles for the leading providers, with emphasis on platform offerings, recent financial results, strategic announcements, and operational developments. These profiles are paired with concentration analysis and positioning commentary that help readers interpret market share in the context of capability depth, pricing philosophy, and ecosystem integration. The report also incorporates industry context on pricing adjustments, regulatory accreditations, and infrastructure cost dynamics, mapping these factors to practical implications for contract negotiation, compliance planning, and total cost of ownership assessment.
For technology leaders, the report provides actionable guidance on evaluating edge platform capabilities, understanding the trade-offs between hyperscale integrated offerings and independent specialized providers, and aligning CDN procurement with broader cloud and security architectures. For investors and analysts, the study offers a structured view of growth drivers, concentration risks, and the operational variables that will influence margin trajectories and competitive positioning through 2032. For procurement teams, segmentation and regional analysis support demand planning, multi-vendor strategy evaluation, and negotiation preparation informed by market-wide pricing and cost dynamics.
We have deliberately reserved the most granular data points, scenario models, and detailed vendor comparison matrices for the full report. This approach ensures that readers who engage with the complete study receive actionable intelligence rather than generalized observations. The preview presented here establishes the strategic context and demonstrates the analytical rigor of the research, while the full publication delivers the specific figures, segmentation breakdowns, and competitive assessments needed to translate market intelligence into decisive action.
Strategic Takeaways for Enterprise Decision-Makers
As enterprises plan for the 2026 to 2032 horizon, several priorities emerge from the market dynamics outlined in this research. First, organizations should treat cloud CDN infrastructure as a strategic application delivery layer rather than a commodity caching service. The convergence of edge compute, security enforcement, and content delivery means that vendor selection increasingly influences developer productivity, security posture, and user experience outcomes. Second, procurement strategies should account for pricing variability and infrastructure cost pressures by incorporating flexibility into contract terms, evaluating multi-vendor approaches where appropriate, and modeling total cost of ownership against workload-specific performance requirements. Third, regulatory and accreditation developments should be factored into compliance roadmaps, especially for enterprises operating in government, defense, and regulated industry contexts where accredited edge infrastructure expands or constrains vendor options.
Finally, the concentration of market share among leading providers does not diminish the relevance of specialized platforms or the importance of differentiation in procurement decisions. Enterprises with unique performance, latency, or multi-cloud portability requirements may find that specialized edge compute platforms or independent CDN providers offer capabilities that align more closely with their architectural goals. Conversely, organizations prioritizing procurement consolidation and ecosystem integration may benefit from hyperscale offerings that simplify operations and align with existing cloud investments. The optimal path depends on workload mix, geographic distribution, compliance needs, and long-term platform strategy, all of which our full report examines in detail.
The Cloud Content Delivery Network Market is positioned for sustained expansion, driven by the structural demands of digital content, application performance, and edge-mediated security. Our research provides the intelligence framework to navigate this growth with clarity, enabling decision-makers to move beyond aggregate market narratives and engage with the segmentation, competitive, and operational details that shape real-world outcomes. We invite readers to access the complete study for the full breadth of data, analysis, and strategic guidance required to make informed decisions in this evolving market.
For detailed analysis of this topic, please visit the official page: Cloud Content Delivery Network (CDN) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tufting Machine Market Hits $202.04M in 2025, Projected 6.9% CAGR Through 2032
By PW Consulting, 2026-09-07
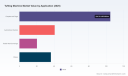
Strategic Imperatives in the Tufting Machine Market: Navigating Growth and Complexity in 2026
The global textile manufacturing landscape is undergoing a significant transformation, driven by shifting consumer preferences, technological advancements, and macroeconomic pressures. Within this ecosystem, the tufting machine market stands out as a critical bellwether for industrial textile production. As businesses plan their capital expenditure and capacity expansion strategies for the remainder of the decade, understanding the nuanced dynamics of this sector is no longer optional—it is a strategic necessity. PW Consulting's latest comprehensive study on the Tufting Machine Market offers a definitive roadmap for stakeholders aiming to capitalize on emerging opportunities while mitigating inherent risks.
Worldwide Sprocket Gear Hob Market
This analysis serves as an introduction to the depth and breadth of our findings. It is designed to highlight the strategic value of the report for executive decision-makers, investors, and industry analysts. While we outline the overarching trends and structural components here, the specific data points required for precise modeling and benchmarking are detailed within the full publication.
Intermodal Cranes Market
Market Trajectory and Historical Context
The tufting machine industry has demonstrated remarkable resilience and growth over the past half-decade. Based on our aggregated data covering the period from 2020 through 2025, the market has evolved from a post-pandemic recovery phase into a period of sustained expansion. The historical revenue stream illustrates a consistent upward trajectory, reflecting renewed confidence in textile infrastructure investments.
Smart Hand Dryer Market
Looking forward, our forecast period extends from 2026 to 2032. The projected growth rate during this interval suggests a robust market environment. Our analysis indicates a Compound Annual Growth Rate (CAGR) that underscores the sector's vitality. This growth is not merely a function of inflation but is rooted in tangible increases in production capacity and adoption rates across various manufacturing hubs. While the headline CAGR of 6.9% provides a macro-level view, the true strategic insight lies in understanding the velocity of growth across different phases of the forecast period. Early years may show steady increments, but later years could reflect acceleration driven by new technology adoption cycles.
For a firm planning a five-year capital strategy, knowing the aggregate market size is useful, but understanding the inflection points within that timeline is invaluable. Our report dissects these phases, allowing planners to align procurement and investment cycles with market peaks and troughs. Without access to the full granular data, stakeholders risk misaligning their expansion plans with actual market absorption rates.
Segmentation Dynamics and Operational Implications
One of the most critical aspects of strategic planning in the tufting industry is understanding where demand is concentrated. The market is not a monolith; it is fractured into distinct segments based on machine type, application, and geography. Each segment carries its own risk profile, margin structures, and growth drivers.
Machine Type Stratification
The market is dominated by specific categories of machinery, each serving different production needs. High-volume broadloom production relies heavily on specific cut pile technologies, while decorative and specialized textile applications often require loop pile or multi-level loop configurations. Our report provides a detailed breakdown of how revenue is distributed across these categories. Understanding the revenue unit distribution among Cut Pile, Loop Pile, Multi-Level Loop Pile, and Other machine types is essential for manufacturers deciding which technological lines to prioritize. For instance, a shift in consumer preference toward high-pile interiors might favor specific loop technologies, whereas industrial flooring might sustain demand for cut pile systems. The full report details the relative market weight of each category, enabling equipment vendors to tailor their R&D and manufacturers to optimize their floor layout.
Application End-Uses
Demand for tufting machines is derivative of demand for the final products. The primary application remains carpets and rugs, representing the largest share of the consumption basket. However, other sectors such as automotive interiors and textile wall coverings are gaining traction. The automotive sector, in particular, presents a unique value proposition due to the higher quality specifications required for vehicle interiors. Textile wall coverings represent a growing niche driven by interior design trends in commercial spaces.
Our analysis explores the revenue units associated with each application vertical. We examine how the 104.79 million USD revenue unit baseline for carpets and rugs compares to the 40.71 million USD unit interest in automotive interiors, and how these figures are projected to evolve. For a machinery supplier, knowing which application segment is growing fastest helps in targeting sales channels. For a producer, it helps in diversifying revenue streams. The complete report elaborates on the specific growth catalysts within each application segment, including regulatory changes in automotive materials and design trends in residential housing.
Regional Landscape
Geography plays a pivotal role in market dynamics. Manufacturing hubs in Asia Pacific, established markets in North America and Europe, and emerging regions in Latin America and the Mideast and Africa all contribute to the global total. The revenue units are distributed across these regions, with North America showing significant activity at 66.05 million USD units, followed closely by Europe at 56.17 million USD units, and Asia Pacific at 55.15 million USD units.
However, raw revenue numbers do not tell the whole story. Production costs, labor availability, and logistical infrastructure vary wildly between these regions. A strategic investor needs to know not just where the revenue is generated, but where the capacity is being installed. Our regional analysis goes beyond top-line figures to discuss installation rates and capacity utilization trends. We advise clients on where to locate distribution centers or assembly plants based on these nuanced regional insights. The full document provides the specific regional breakdowns necessary for localization strategies.
Competitive Landscape and Vendor Positioning
The tufting machine market is characterized by a mix of established legacy manufacturers and agile new entrants. Market concentration is a key metric for assessing competitive risk. Our data indicates a moderately concentrated landscape, where the CR3 stands at 52.0 percent and the CR5 at 61.0 percent. This suggests that while there are dominant players, there is still ample room for specialized competitors to thrive.
Key Industry Players
Several companies define the current competitive arena. Tuftco Corporation, headquartered in Chattanooga, Tennessee, remains a cornerstone of the industry. Their focus on integrated tufting machines with full production lines from yarn to finished carpet allows them to serve carpet mills worldwide with a comprehensive solution. This vertical integration offers clients reduced complexity but may come with higher capital entry barriers.
Similarly, Card-Monroe Corp. (CMC), also based in Chattanooga, competes heavily in the high-speed segment. Their machinery supports broadloom carpet, patterned carpet tiles, and synthetic turf, with a presence spanning 38 countries. Their ability to operate across diverse geographies makes them a benchmark for global service capabilities.
In Europe, Vandewiele NV represents the high-tech end of the spectrum. Their tufting division utilizes advanced patterning technology such as ICN, Myriad, and Colortec. This positions them strongly in markets where design complexity and customization are premium drivers, such as high-end carpets and turf.
On the other end of the spectrum, companies like Tuft Love in the USA focus on durability and performance for residential use, catering to a different customer base than the industrial mills served by Tuftco or CMC. Meanwhile, the Asian manufacturing sector is represented by players like TMT Machinery and Haochuan Group. TMT Machinery emphasizes high-speed machines with enhanced automation and energy efficiency, a critical factor in regions with rising energy costs. Haochuan Group offers a range from automatic CNC rug machines to tufting guns, bridging the gap between industrial production and custom artisanal work.
Technology and Innovation Trends
Innovation is the primary differentiator in this market. Recent developments highlight the pace of change. For example, Card-Monroe Corp. and Vandewiele Group both showcased their latest technologies at the ICFE 2026 exhibition in Istanbul, Turkey. These trade shows are critical barometers for industry direction. In late 2025, TMT Machinery launched its new TMT-8600 high-speed carpet tufting machine at the INDEX Saudi Arabia textile exhibition, signaling a push toward high-efficiency hardware in the Middle East region.
Furthermore, product launches such as the AK-V tufting gun by Tufting Europe in 2024 demonstrate continuous refinement in tooling precision and noise reduction. These incremental improvements accumulate to create significant productivity gains over the lifecycle of the machinery. Our report analyzes how these technological shifts impact total cost of ownership and output quality. We assess which technologies are becoming commoditized and which remain proprietary advantages. Understanding the adoption curve of technologies like CNC automation and energy-efficient motors is crucial for long-term asset planning.
Industry Dynamics and External Pressures
Macroeconomic and regulatory factors exert significant pressure on the tufting machine market. Strategic planners must account for variables beyond simple demand and supply.
Raw Material Volatility
The cost of inputs is a perpetual concern. Recent industry data indicates that polypropylene prices increased by 34 percent year-to-date through April 2026, driven by rising crude oil and naphtha costs. Since tufted carpets and textiles are heavily reliant on synthetic fibers, this cost pressure trickles down to machine utilization rates. If material costs rise too high, production volumes may contract, affecting the frequency of machine replacement or upgrade cycles. Our analysis models various commodity price scenarios to help clients stress-test their investment plans against raw material volatility.
Regulatory and Classification Standards
Compliance is another layer of complexity. The HS code 8447.90 for tufting machines is in effect worldwide, but regulatory landscapes are shifting. Expected US HTS mandates and EU Combined Nomenclature refinements in 2025 require manufacturers and importers to stay vigilant regarding classification and tariff structures. Misclassification can lead to significant cost penalties or supply chain delays. Our report includes a regulatory watchlist that tracks these changes, ensuring that clients remain compliant as they expand across borders.
Labor and Automation
Labor costs continue to drive the adoption of automation. There is a macro trend showing increasing demand for residential and commercial carpets driving nearly 40 percent growth in tufting machine adoption. This demand surge often coincides with tightness in skilled labor markets. Consequently, the value proposition of fully automatic and CNC-controlled machines increases. Tuftco, for instance, supplied over 4,500 high-speed tufting machines in 2023, contributing to the production of 6.7 million square meters of tufted carpets. This scale of output highlights the efficiency gains possible with modern machinery compared to manual or semi-automatic processes. Our report quantifies the labor savings and productivity improvements associated with different machine tiers, assisting HR and operations directors in building business cases for automation.
The Strategic Value of Comprehensive Intelligence
In a market defined by complex segmentation, volatile input costs, and rapid technological iteration, intuition is insufficient. Decisions regarding capital expenditure, market entry, or vendor selection require robust data. PW Consulting's Tufting Machine Market report is designed to fill the information gap between general industry knowledge and actionable intelligence.
The report provides a structured framework for analysis. It begins with the executive summary, offering a high-level view of the market health and key takeaways. It then dives into the methodology, ensuring transparency in how data was collected and modeled. The detailed market overview section dissects the historical and forecast data, providing the specific revenue units and growth rates needed for financial modeling. The segmentation analysis offers the breakdowns discussed earlier, allowing users to isolate specific niches rather than viewing the market as a whole.
Furthermore, the competitive landscape section does more than list companies; it analyzes their strategic positioning, recent developments, and potential vulnerabilities. This is crucial for mergers and acquisitions activity or for identifying potential partners. The industry dynamics section contextualizes the data within the broader economic and regulatory environment, ensuring that predictions are grounded in reality rather than optimism.
Why This Report Matters for 2026 Decision-Making
As we move through 2026, the window for strategic positioning is narrowing. Companies that wait for the market to fully mature may find themselves priced out of key segments or lagging in technology adoption. Conversely, those who invest without clear data risk overcapacity in shrinking segments.
Our report allows you to:
- Validate Capacity Expansion: Use precise forecast data to justify new machinery purchases to stakeholders.
- Identify High-Growth Niches: Pinpoint specific machine types or applications that offer the best return on investment.
- Assess Competitive Threats: Understand the capabilities of key rivals like Tuftco, CMC, and Vandewiele to anticipate market shifts.
- Mitigate Risk: Account for raw material price swings and regulatory changes in your long-term planning.
- Optimize Supply Chains: Leverage regional insights to determine the best locations for manufacturing or distribution.
The difference between a good strategy and a great one often lies in the quality of the underlying data. While this article provides a snapshot of the market's direction, the full report contains the depth required to execute strategy. It transforms abstract trends into concrete metrics.
Conclusion
The tufting machine market is poised for continued growth, underpinned by steady demand in core applications and emerging opportunities in specialized sectors. However, navigating this growth requires more than a surface-level understanding. It demands a deep dive into segmentation data, competitive moves, and macroeconomic drivers. The interplay between rising raw material costs, regulatory adjustments, and technological advancements creates a complex environment where information is a primary asset.
PW Consulting remains committed to providing the clarity needed to thrive in this environment. Our Tufting Machine Market research is the tool designed to empower your leadership team with the confidence to make bold, data-backed decisions. We invite you to explore the full findings of this study to unlock the detailed intelligence necessary for securing your position in the evolving textile manufacturing landscape. The future of tufting is not just about making carpets; it is about engineering efficiency and precision in a demanding global market. Ensure your strategy is built on the most comprehensive foundation available.
For detailed analysis of this topic, please visit the official page: Tufting Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AMOLED Revenue Hits $25B in 2025, Forecast to Surge to $47.75B by 2032 at 9.75% CAGR
By PW Consulting, 2026-09-07
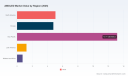
The AMOLED Market in 2026: Strategic Imperatives and the Road to 2032
The global display industry is entering a decisive inflection point. As mobile devices, wearables, automotive cabins, and consumer electronics converge toward richer visual experiences, AMOLED technology has evolved from a premium differentiator into a structural requirement for product competitiveness. For executives navigating capital allocation, supply chain resilience, and product roadmaps, the ability to separate durable growth from cyclical noise is now a strategic necessity.
Worldwide Automotive Electric Heating Film Market
Our newly released AMOLED Market research study provides a comprehensive view of this landscape, anchoring executive decision-making in rigorous historical analysis and forward-looking modeling. Covering the historical period from 2020 to 2025 and extending through the forecast horizon of 2026 to 2032, the study quantifies how the market has scaled from approximately 12.45 billion USD in 2020 to an estimated 25.0 billion USD in 2025. Looking ahead, the market trajectory reflects a compound annual growth rate of 9.75 percent, with projected revenue reaching 27.78 billion USD in 2026 and advancing toward 47.75 billion USD by 2032. These headline figures provide the framework, but the real strategic value lies in the underlying mechanics: how technology transitions, application diversification, regional supply footprints, and competitive concentration shape opportunity and risk.
Non-Slip Fitness Mat Market
This article offers a preview of the study's strategic logic. It demonstrates the analytical depth that executives can rely on, while deliberately withholding the granular segmentation data that forms the backbone of actionable planning. The full report remains the essential instrument for teams that need to convert market intelligence into investment decisions, sourcing strategies, and product positioning.
Worldwide Industrial Flow Sensor Market
Why 2026 Is a Strategic Reckoning Year for AMOLED
The 2026 landscape is shaped by simultaneous advances on multiple fronts: panel generation upgrades, foldable form factor maturation, automotive display expansion, and an increasingly complex materials and intellectual property environment. Against this backdrop, high-level market sizing is necessary but insufficient. Decision-makers need to understand how revenue flows across technology variants, which applications absorb volume and value at different stages of adoption, and where geographic concentration creates pricing leverage or exposure.
The study's base year of 2025 and forecast window through 2032 were selected precisely because they capture the period in which AMOLED transitions from smartphone-led dominance toward broader application absorption. Over the historical 2020 to 2025 cycle, the market demonstrated a pattern of accelerating adoption punctuated by supply constraints and premiumization effects. The forecast period continues that momentum, though with a critical nuance: growth will not be uniform across segments or geographies. Some application categories will expand rapidly as attachment rates rise, while others will remain niche but strategically important as platform differentiators.
Because the full segmentation breakdown is reserved for the complete report, organizations that rely only on top-line numbers risk misreading where future margin pools and volume drivers will concentrate. The study's architecture is designed to resolve that ambiguity by mapping market size against type, application, and regional supply dynamics in a way that supports internally consistent scenario planning.
Inside the Research: What the Study Delivers
Our AMOLED Market report is built for strategy, procurement, finance, and product leadership teams that need defensible assumptions rather than generic market narratives. The study combines historical reconstruction with forward modeling, and it organizes the market in a way that mirrors the actual operating logic of the display supply chain.
Scope and Structural Design
The report aligns its analytical framework with the core dimensions that determine competitive exposure and commercial opportunity:
- Historical reconstruction from 2020 through 2025, establishing the actual growth path behind the headline market size
- Forecast modeling from 2026 through 2032, anchored on the 9.75 percent CAGR and a revenue trajectory measured in billions of USD
- Segmentation by technology type, enabling readers to understand how rigid, flexible, foldable, and transparent AMOLED panels contribute differently to overall market value
- Segmentation by application, distinguishing the roles of smartphones, wearables, televisions, automotive, and emerging use cases in shaping demand
- Regional breakdown across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa
- Market concentration analysis, revealing how consolidated the competitive field is and where pricing power may reside
Rather than presenting isolated figures, the study integrates these dimensions so that leadership teams can examine consistency across layers. For example, the relationship between premium device adoption and flexible or foldable panel demand is analyzed in context, not as an abstract trend. The same applies to automotive display integration, where design cycles, qualification requirements, and regional vehicle production patterns influence the pace of AMOLED uptake.
Actionable Outputs for Decision-Making
The report translates market modeling into tools that support concrete decisions. Readers can use the analysis to:
- Benchmark internal forecasts against externally validated market trajectories and identify where assumptions diverge
- Assess segment-level attractiveness without relying on fragmentary industry anecdotes
- Evaluate supply-side concentration and the implications for sourcing, negotiation leverage, and continuity risk
- Frame product roadmap choices around the technologies and applications most likely to drive value over the decade
- Prepare for input cost volatility and structural materials constraints that influence panel economics
Importantly, the study does not treat regional or application splits as static snapshots. It contextualizes them within the broader competitive and technology environment so that executives can understand not just where the market is, but how it is likely to move.
Competitive Landscape: Concentration, Capability, and Recent Shifts
One of the most strategically significant features of the AMOLED market is the degree of concentration among leading manufacturers. The study examines market concentration through the lens of controlled share among the top players, with the top three accounting for approximately 55.0 percent of market revenue and the top five reaching roughly 72.0 percent. This level of concentration has direct implications for pricing dynamics, qualification pathways, and the degree of dependence that downstream brands and OEMs may face.
The competitive environment is anchored by a set of companies with distinct technological positioning and geographic advantages. Samsung Display, headquartered in Yongin, South Korea, remains the world's largest AMOLED producer by volume and revenue. Its portfolio spans flexible, rigid, QD-OLED, and foldable AMOLED panels for smartphones, wearables, laptops, and automotive applications, making it a central reference point for the entire industry. LG Display, based in Seoul, South Korea, is a major AMOLED panel supplier with particular strength in WOLED and tandem OLED panels for smartphones, TVs, and automotive displays. In China, BOE Technology Group in Beijing has emerged as a key AMOLED manufacturer producing flexible, foldable, and rigid AMOLED panels for smartphones, wearables, and automotive applications. AUO Corporation, located in Hsinchu, Taiwan, is an active producer of AMOLED and OLED panels for consumer electronics and automotive displays, while Visionox, headquartered in Shenzhen, China, supplies AMOLED displays including foldable and high-resolution panels for smartphones and wearables.
These companies are not merely participants in a static market; they are actively reshaping it through capacity expansion, product launches, and technology licensing relationships. The report evaluates the strategic significance of recent developments rather than simply listing them. For instance, Samsung Display's start of AMOLED display sample production at its 8.6-Gen IT production line in Asan in January 2026 represents a meaningful shift in production scale and application targeting, with mass production verified and samples shipped to customers including Apple for 2026 MacBook Pro laptops. That development matters because it signals the extension of AMOLED into larger IT devices, a category where display economics, thermal management, and substrate requirements differ materially from smartphones.
Similarly, Samsung Display's March 2026 launch of its latest foldable AMOLED panel series, featuring enhanced durability and ultra-thin form factors targeting premium smartphones and automotive dashboards, illustrates how foldable technology is moving beyond early adopters into higher-reliability use cases. At the same event ecosystem level, BOE showcased a new foldable flexible OLED display at AWE 2026 with structural refinement and material innovation for seamless form factors, reinforcing the competitive intensity around foldable implementations and the increasing importance of material and structural engineering.
These developments are not isolated product news; they are indicators of where value and differentiation are being created. The study contextualizes them within broader competitive dynamics, including the licensing environment. For example, Samsung Display has been granted non-exclusive license rights under various patents owned or controlled by Samsung Electronics to BOE for manufacturing and selling OLED displays. This kind of arrangement affects not only direct competition but also the overall pace at which new entrants can scale differentiated products without being constrained by proprietary barriers.
Segment Dynamics, Materials, and the Cost of Premium Performance
Technology segmentation is central to understanding both the upside and the limits of AMOLED growth. The report separates the market into rigid AMOLED, flexible AMOLED, foldable AMOLED, and transparent AMOLED, because each category carries different manufacturing complexity, cost profiles, and end-market fit. Rigid panels may offer scale and maturity in certain applications, while flexible and foldable approaches unlock design freedoms that are strategically attractive but technically demanding. Transparent AMOLED adds another layer of differentiation with specialized use cases, though typically at a smaller scale relative to mainstream display categories.
The materials layer is equally important. Premium AMOLED performance depends on substrate quality and process precision, and those requirements translate directly into cost. OLED glass substrates command a 30 to 60 percent price premium over LCD equivalents due to tighter surface roughness specifications below 0.5 nm Ra. This premium is not a minor input detail; it shapes panel economics, influences the relative attractiveness of different device categories, and affects the pace at which cost-sensitive applications can adopt AMOLED at volume.
On the materials front, Corning Incorporated introduced a next-generation ultra-thin glass substrate for foldable smartphones in 2024, an advance that highlights the ongoing push to reconcile durability with thinness and weight. Such substrate innovations matter because foldable adoption is not simply a question of consumer preference; it is also a function of reliability, hinge engineering, and the supply base's ability to produce consistent panels at scale. The study incorporates these kinds of material-level shifts into its interpretation of segment growth rather than treating them as peripheral technical news.
Because segment-level detail is one of the areas where organizations most often need precision, the full report provides the specific breakdowns that allow teams to evaluate where rigid, flexible, foldable, and transparent AMOLED are likely to generate the most value. That level of detail is essential for anyone making architecture choices, sourcing commitments, or portfolio prioritization decisions.
Regional Supply Footprints and Structural Risk Factors
Geography remains a defining feature of AMOLED market strategy. The study maps regional distribution across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, not as a set of disconnected percentages, but as a framework for understanding where demand concentration, production capability, and supply risk converge. Asia Pacific, in particular, stands out as a major axis of activity given its concentration of panel manufacturing, device assembly, and consumer electronics demand. Yet the strategic story is not simply about which region is largest; it is about how regional dynamics interact with technology transitions and competition.
Regional planning becomes more complex when supply chains are exposed to trade policy and materials control risks. US-China trade restrictions on advanced materials and potential export controls on high-purity glass precursor chemicals represent systemic supply chain risk. For companies that depend on specialized substrates, precursor chemicals, and tightly controlled process inputs, these risks affect not only cost but also continuity of supply and the feasibility of certain sourcing strategies.
The study treats these risks as strategic variables rather than background noise. It examines how regional concentration may amplify or mitigate exposure, how qualification cycles influence sourcing flexibility, and how companies can position themselves against disruptions that may not appear in a single year's forecast but can have outsized effects over a multi-year planning horizon. For that reason, the regional analysis in the report is designed to support scenario-based resilience planning, not just opportunity sizing.
How to Use the Full Study in 2026 Planning
The preview above outlines the analytical framework and the strategic logic behind the study. What it cannot do, by design, is replace the full report. The real decision-grade value lies in the segmentation detail, the consistency checks across type, application, and region, and the competitive interpretations that connect recent developments to longer-term positioning. Organizations that need to align product strategy, sourcing, capacity planning, and investment cases will find that the complete study offers the specificity required to move from directional confidence to executable assumptions.
In practice, the report is most valuable when used as a shared reference point across functions. Strategy teams can use it to test growth narratives; procurement and supply chain teams can use it to evaluate supplier concentration and materials exposure; finance can use it to calibrate revenue and cost trajectories; and product teams can use it to weigh the timing and commercial logic of technology adoption. The 9.75 percent CAGR and the headline progression from 25.0 billion USD in 2025 toward 47.75 billion USD by 2032 provide the macro frame, but the segmented structure is what turns that frame into an operational tool.
The study also helps leadership teams avoid the common mistake of treating AMOLED as a single homogeneous category. The distinctions among rigid, flexible, foldable, and transparent formats, and among smartphone-led, wearable, television, automotive, and other applications, are not cosmetic. They determine where scale is achievable, where premium pricing can be defended, and where new entrants or incumbents can build durable advantage.
Conclusion: From Market Awareness to Decision Advantage
The AMOLED market in 2026 is large, growing, and increasingly contested. The combination of strong historical momentum, a clear forward CAGR, and active technology development across major manufacturers creates a landscape rich with opportunity, but also rich with complexity. Concentration among leading producers, premium materials requirements, licensing relationships, and geopolitical supply risks all shape the practical meaning of the market's growth trajectory.
Our AMOLED Market research is designed to help executives interpret that complexity with discipline. It provides the historical grounding, the forecast structure, the segmentation logic, and the competitive context needed to make informed decisions in 2026 and beyond. The macro story is clear; the operational story is where real advantage is created. For that operational story, the full report is the essential source, offering the detailed segmentation and competitive intelligence that turn market awareness into decision advantage.
For detailed analysis of this topic, please visit the official page: AMOLED Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electric Truck Market to Hit $10.16B by 2032, 29.5% CAGR Through 2032
By PW Consulting, 2026-09-07
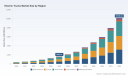
Electric Trucks Market 2026: Strategic Intelligence for Executive Decision-Making
The commercial transportation sector stands at a definitive inflection point. As regulatory mandates tighten and total cost of ownership models shift in favor of electrification, the transition from diesel to electric powertrains is no longer a question of if, but how fast. For logistics executives, fleet operators, and investors, the ability to navigate this transition with precision is the difference between capturing market share and being left behind by competitors who have already locked in supply chains, charging infrastructure, and regulatory compliance pathways.
Portable Vlogging Camera Market
PW Consulting's latest Electric Trucks Market research report provides a comprehensive, data-driven foundation for these critical decisions. Spanning a historical analysis from 2020 through 2025 and a detailed forecast period extending to 2032, this study offers the granularity required to allocate capital efficiently, mitigate supply chain risk, and position organizations ahead of the regulatory curve. The following overview outlines the strategic landscape, the macroeconomic forces at play, and the competitive dynamics that define the electric truck ecosystem in 2026 and beyond.
WBG Semiconductor Material (SiC-GaN) Market
Market Trajectory and Scale: A Decade of Accelerated Adoption
The historical data underscores a pattern of exponential growth that has fundamentally altered the baseline for commercial vehicle forecasting. From a market valuation of approximately 392.3 million USD in 2020, the sector expanded to 1,662.14 million USD by 2025. This represents a compound annual growth trajectory that reflects not merely incremental adoption but a structural reordering of the commercial vehicle market. The momentum is projected to sustain through the forecast period, with the market expected to reach 2,118.75 million USD in 2026 and continue its ascent to 10,158.53 million USD by 2032.
Optical Glass Inspection Services Market
Such growth rates, underpinned by a forecast compound annual growth rate of 29.5 percent, signal that electrification is moving from early-adopter phases into mainstream commercial deployment. For enterprise strategists, this implies that the window for establishing first-mover advantages in fleet conversion, charging network partnerships, and regional regulatory compliance is rapidly narrowing. The report's forecast model accounts for the interplay of battery cost trajectories, infrastructure rollout rates, and policy enforcement timelines, providing a realistic range of scenarios for capacity planning and investment timing.
It is critical to recognize that this expansion is not uniform across all segments or geographies. The research dissects the market into distinct operational categories, propulsion architectures, and regional demand centers, enabling decision-makers to identify where volume concentrations will emerge and where regulatory or infrastructural friction may alter adoption curves. The following sections distill the structural components of this landscape.
Segmentation Dynamics: Powertrain Architectures and Duty Cycles
The electric truck market is not a monolithic entity. It is bounded by duty cycles, payload requirements, and charging feasibility, which collectively dictate the viability of specific propulsion technologies. The report segments the market by propulsion type, capturing the distinct characteristics of battery electric, plug-in hybrid, and fuel cell electric configurations. Battery electric vehicles dominate the current revenue share, reflecting the maturity of lithium-ion supply chains and the operational suitability of battery architectures for regional haul and urban delivery cycles. Plug-in hybrid solutions represent a transitional bridge for applications where range anxiety or insufficient charging infrastructure remains a constraint, while fuel cell electric platforms are carving out niches in heavy-duty long-haul operations where rapid refueling and high vehicle utilization are paramount.
By vehicle type, the market is stratified into heavy-duty, medium-duty, and light-duty categories. Heavy-duty trucks command the largest share of revenue, driven by the high cost of diesel assets in long-haul and regional distribution networks and the substantial fuel savings achievable through electrification. Medium-duty trucks, encompassing step vans, box trucks, and municipal service vehicles, represent a high-growth segment fueled by last-mile delivery expansion and municipal zero-emission mandates. Light-duty electric trucks serve specialized commercial applications, including service fleets and proprietary delivery operations, where payload flexibility and maneuverability are prioritized over maximum range.
Battery pricing dynamics are a critical variable in the unit economics of these segments. Industry data indicates that average battery prices for electric vehicles declined by 8 percent in 2025, driven by manufacturing efficiency gains and shifts in battery chemistries. This cost compression directly improves the total cost of ownership for fleet operators and expands the addressable market for electric trucks in segments where upfront capital costs have historically been a barrier. The report quantifies how these cost curves intersect with vehicle utilization rates, charging time availability, and residual value assumptions to produce segment-specific ROI profiles.
Regional Demand Centers and Policy-Driven Deployment
Geographic demand for electric trucks is shaped by a combination of regulatory ambition, industrial density, and infrastructure readiness. North America, Europe, and Asia Pacific represent the three primary demand centers, each governed by distinct policy frameworks and market structures. In North America, the U.S. Advanced Clean Trucks Rule mandates that manufacturers sell an increasing percentage of zero-emission trucks as an increasing percentage of annual sales from model year 2025 through 2035. This regulatory signal has catalyzed fleet procurement strategies and infrastructure investments across major logistics corridors. Similarly, New Jersey's Advanced Clean Trucks Rule requires manufacturers producing vehicles over 8,500 pounds GVWR to sell increasing percentages of zero-emission trucks, reinforcing the regulatory momentum at the state level.
In Europe, the push toward decarbonization is equally pronounced, with fleet operators aligning procurement strategies to meet national and supranational emissions targets. The region's dense urban environments and well-developed charging networks in key industrial corridors provide a favorable backdrop for medium-duty and heavy-duty electric truck deployment. Asia Pacific presents a differentiated landscape, with electric truck sales more than doubling in 2025 worldwide and reaching 9 percent of all truck sales. Nearly 30 percent of the Chinese market has been captured by new Chinese manufacturers, illustrating the intensity of domestic competition and the speed at which local supply chains have scaled. The Chinese electric truck market is almost exclusively served by Chinese manufacturers using local batteries, with one provider supplying a dominant share of the total cell capacity. This concentration highlights the strategic importance of localized battery supply and the competitive insulation that domestic manufacturers enjoy in their home markets.
Latin America and the Middle East and Africa, while currently smaller in absolute revenue terms, are emerging as monitoring zones for future policy adoption and pilot deployments. The report provides detailed regional revenue trajectories that allow strategists to assess where policy tailwinds or infrastructure investments may unlock secondary demand centers within the forecast horizon.
Competitive Landscape: Incumbents, Challengers, and Technology Positioning
The electric truck market features a diverse mix of established commercial vehicle manufacturers, technology-driven entrants, and regional specialists. This competitive mosaic is defined by differing approaches to vehicle architecture, battery integration, charging ecosystem partnerships, and geographic focus. Understanding the positioning of key participants is essential for assessing supply risk, partnership opportunities, and potential market consolidation.
Volvo Trucks North America has solidified its presence in the North American market with the VNR Electric series and next-generation FH, FM, and FMX Electric trucks. In April 2026, Volvo launched the FH Aero Electric with a range of up to 700 km, alongside next-generation FH, FM, and FMX Electric models with improved flexibility and ranges up to 470 km. The following month, Volvo expanded capabilities for the VNR Electric in North America with new configurations and supporting infrastructure. With over 750 units operating in North America, Volvo has built a substantial operational footprint that provides real-world performance data and a template for enterprise fleet integration.
Daimler Truck has expanded its e-truck portfolio with the Mercedes-Benz eActros 600 long-haul electric truck and additional variants. In April 2026, Daimler showcased the eActros Lowliner variant and the eActros 600 Expedition vehicle at trade exhibitions, signaling a strategy of broadening the application envelope of its electric platforms. The eActros 600 is positioned as a solution for long-haul operations, a segment where range and payload have historically been the primary constraints on electrification.
Tesla is preparing to commence volume production of the Tesla Semi electric semi-truck in 2026. The entry of a technology company with significant vertical integration capabilities into the heavy-duty truck segment introduces a new competitive dynamic, particularly around battery efficiency, software-defined vehicle architecture, and direct-to-customer sales models. The timing of volume production aligns with a period of heightened fleet interest in long-haul electrification.
MAN Truck & Bus has brought the eTGX, eTGS, eTGM, and eTGL electric truck series to series production active since 2025, complemented by the Charge&Go charging service. This integrated approach to vehicle and charging infrastructure reflects a growing industry trend where manufacturers are expanding their value proposition beyond the vehicle itself to include energy management solutions.
Harbinger Motors has focused on medium-duty electric and hybrid-electric trucks and vans, leveraging in-house motor and battery manufacturing. In October 2025, Harbinger launched medium-duty electric vehicle sales in Canada through a dealer network with upfitter partnerships, extending its market reach beyond the United States. This expansion underscores the growing cross-border demand for medium-duty electrification and the importance of dealer and upfitter relationships in scaling deployment.
Workhorse Group produces the W56 electric step vans and commercial delivery trucks, with 100-unit orders and promotional pricing active in 2026. This focused approach to the step van and delivery segment targets a specific operational niche where predictable routes and centralized charging can maximize the economic benefits of electrification.
BYD Company Ltd. continues to leverage its integrated Chinese battery supply chain to produce electric heavy-duty trucks and commercial vehicles at scale. The company's ability to vertically integrate battery production with vehicle manufacturing provides a cost and supply chain advantage in markets where local battery sourcing is a strategic priority. Tata Motors produces electric commercial and heavy-duty trucks in India and global markets, positioning itself to capitalize on the growing electrification demand in emerging economies where total cost of ownership sensitivity is high and policy incentives are evolving.
Scania AB maintains an active e-truck lineup with regional projects that demonstrate the practical deployment of electric heavy-duty vehicles in structured fleet operations. Rivian produces electric commercial and work vehicles including electric trucks, extending its technology platform from consumer vehicles into the commercial segment. Slate Auto is targeting deliveries of affordable electric pickup trucks for late 2026, expanding the definition of commercial electrification into the light-duty pickup segment where fleet adoption for service and construction applications is growing.
The market concentration reflects a moderately fragmented competitive environment. The top three participants account for 38.0 percent of market revenue, while the top five hold 42.0 percent. This concentration level suggests that while scale advantages exist, there is significant room for specialized entrants and regional players to capture value in specific duty cycles or geographies. The report's competitive analysis includes detailed company profiles, product positioning, and strategic assessments that enable readers to evaluate supply chain resilience and partnership potential.
Fleet Deployment Milestones and Infrastructure Realities
The transition from pilot programs to scaled fleet deployment is a defining characteristic of the 2026 market landscape. In January 2026, GMA Trucking Procurement enabled the largest known Class 8 battery-electric truck deployment in Texas with 40 trucks by Nevoya for the Houston-Dallas corridor. This deployment represents a significant operational validation of battery-electric heavy-duty trucks in a major logistics corridor, providing real-world data on range performance, charging logistics, and maintenance requirements under commercial service conditions.
Such deployments are critical for the broader market because they generate the operational evidence that fleet managers, regulators, and financiers require to accelerate adoption. The report examines the infrastructure requirements associated with these deployments, including depot charging capacity, grid connection feasibility, and the role of public and semi-public charging networks in supporting regional haul operations. The interplay between vehicle range, charging time, and route structure is analyzed to provide practical guidance on fleet sizing, charging station placement, and energy procurement strategies.
The decline in battery prices by 8 percent in 2025 is a supportive factor for these deployments, but infrastructure constraints, permitting timelines, and utility interconnection processes remain operational risks that must be managed proactively. The research provides a framework for assessing these risks and developing mitigation strategies that align fleet rollout schedules with infrastructure readiness.
Regulatory Tailwinds and Market Signal Interpretation
Regulatory mandates are a primary driver of electric truck adoption, but their impact varies by jurisdiction and vehicle class. The U.S. Advanced Clean Trucks Rule and state-level implementations such as New Jersey's Advanced Clean Trucks Rule create a structured demand signal that manufacturers must respond to through product portfolio adjustments and production planning. For fleet operators, these mandates translate into procurement requirements that influence vehicle replacement cycles and fleet composition planning.
The International Energy Agency Global EV Outlook 2026 reports that electric truck sales more than doubled in 2025 worldwide, reaching 9 percent of all truck sales, with nearly 30 percent of the Chinese market captured by new Chinese manufacturers. This global acceleration provides context for the regional dynamics discussed in the report and highlights the divergent competitive structures that are emerging across markets. In regions where domestic manufacturers have strong battery supply chain integration, competitive intensity is higher and pricing pressure is more pronounced. In markets where international manufacturers are gaining traction, differentiation through vehicle performance, service networks, and financing solutions becomes a critical success factor.
For strategic planners, the key insight is that regulatory targets are not static. They represent ratcheting requirements that will continue to tighten through the forecast period. The report models the interaction between regulatory compliance timelines and fleet turnover rates, enabling organizations to anticipate the timing of mandate-driven procurement needs and to structure leasing, purchasing, and infrastructure investments accordingly.
Operational Insights and Decision Frameworks Within the Report
The full research report delivers a depth of operational intelligence that goes beyond headline market figures. It provides detailed segmentation analysis across regions, vehicle types, and propulsion technologies, allowing users to construct scenario-based demand forecasts that reflect their specific operational context. The report includes company profiles for the leading participants in the market, covering their product offerings, geographic presence, and strategic positioning. These profiles are designed to support supplier evaluation, partnership due diligence, and competitive benchmarking.
Recent developments are tracked and contextualized, including product launches, market expansions, and fleet deployments. These events are integrated into the broader market narrative to illustrate how individual company actions contribute to market evolution and to identify emerging best practices in vehicle specification, charging infrastructure planning, and fleet integration. The research also examines the supply chain dynamics that underpin vehicle production, including battery cell sourcing, motor manufacturing, and component localization trends.
For finance and investment teams, the report provides the revenue trajectory data and segment-level context needed to assess market opportunity sizing, capital allocation priorities, and the risk-return profile of electric truck exposure across different value chain positions. The forecast period through 2032 allows for multi-year planning horizons that align with fleet replacement cycles and infrastructure investment payback periods.
Strategic Imperatives for 2026 and Beyond
As the electric truck market enters a phase of accelerated scaling, the strategic implications for enterprises are clear. First, the timing of fleet electrification decisions must account for the ratcheting nature of regulatory mandates and the lead times required for vehicle procurement, charging infrastructure installation, and driver and maintenance training. Early planning reduces the risk of being forced into rushed procurement decisions at unfavorable pricing or with limited vehicle availability.
Second, the competitive landscape is evolving rapidly, with established manufacturers expanding their electric portfolios, technology entrants moving toward volume production, and regional specialists capturing niche opportunities. Understanding the strengths, limitations, and strategic intentions of each participant is essential for making informed supplier selection and partnership decisions. The report's competitive profiles and recent development tracking provide the basis for this analysis.
Third, the total cost of ownership calculus for electric trucks is improving, driven by battery cost declines and the increasing cost of diesel and compliance with emissions regulations. However, the economics remain segment-specific and route-dependent. The report's segmentation analysis and operational insights enable organizations to identify the applications where electrification delivers the strongest financial and strategic returns, and to prioritize those applications in their fleet transition plans.
Fourth, infrastructure readiness is a critical enabler of scaled deployment. The report's examination of charging requirements, grid considerations, and real-world deployment examples such as the Houston-Dallas corridor provides practical guidance for aligning vehicle rollout with infrastructure development. This alignment is essential for avoiding operational disruptions and maximizing the utilization of electric assets.
Fifth, the global nature of the market means that strategies must account for regional differences in competitive intensity, regulatory frameworks, and supply chain structures. The report's regional analysis supports the development of market-specific strategies that reflect local conditions while maintaining alignment with global corporate objectives.
Accessing the Full Strategic Intelligence
The electric truck market in 2026 presents a complex environment defined by rapid growth, evolving competition, regulatory acceleration, and shifting technology economics. Navigating this environment requires more than headline market figures. It requires a detailed, structured understanding of segment dynamics, regional demand patterns, competitive positioning, and the operational realities of fleet deployment.
PW Consulting's Electric Trucks Market research report provides this comprehensive intelligence. The full report contains the detailed segmentation data, company profiles, recent development tracking, and scenario-based forecasts that enterprise decision-makers need to allocate resources, manage risk, and capture opportunity in the electric truck transition. The macro-level trajectory, competitive landscape, and market dynamics summarized here are intended to demonstrate the scope and rigor of the research, while the complete dataset and analytical frameworks remain available through the full report.
To access the complete market size breakdowns, regional revenue trajectories, segment-level growth rates, company profiles, and forecast models, we invite you to explore the full report on the PW Consulting website. The detailed intelligence contained within is designed to support strategic planning, investment decisions, and operational execution across the 2026 to 2032 forecast horizon.
The transition to electric commercial vehicles is reshaping the logistics and transportation industry. Organizations that invest in rigorous market intelligence today will be better positioned to make informed decisions, build resilient supply chains, and capitalize on the growth opportunities that this transformation creates. PW Consulting's Electric Trucks Market report is built to provide that foundation, combining historical analysis, forward-looking forecasts, and competitive intelligence into a single, actionable resource for executive decision-making.
For detailed analysis of this topic, please visit the official page: Electric Trucks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pediatric Hearing Aids Market to Reach $3.39M by 2032 at 6.3% CAGR
By PW Consulting, 2026-09-07
Navigating the Next Wave: Strategic Intelligence for the Global Pediatrics Hearing Aids Market (2026-2032)
The pediatric hearing aids sector is undergoing a profound transformation, driven by converging forces of technological innovation, evolving reimbursement frameworks, and an expanding recognition of early auditory intervention as a cornerstone of child development. For corporate strategists, investors, and healthcare market leaders, understanding the trajectory of this specialized market is no longer optional it is a strategic imperative. PW Consulting is pleased to introduce our latest comprehensive research study, meticulously crafted to equip decision-makers with the precision intelligence required to navigate the 2026-2032 forecast horizon.
Highly Transparent Synthetic Hydrotalcite Market
Built upon a rigorous analytical foundation spanning 2020 through 2025 historical data, this report maps a highly structured forecast period that extends through 2032. At the macro level, the global pediatric hearing aids market has demonstrated consistent, measurable expansion. Revenue growth has accelerated steadily over the past half-decade, with the market surpassing the two-billion-dollar threshold in 2025 and continuing its upward trajectory into 2026. The compounded annual growth rate projected across the forecast window stands at 6.3 percent, reflecting both underlying demographic realities and the accelerating commercialization of child-specific auditory technologies. By the close of the forecast period, the market is positioned to reach a substantially elevated revenue baseline, underscoring the long-term structural demand that stakeholders must prepare for.
Worldwide Nursing Underwear Market
This executive overview is designed as a strategic preview. It highlights the analytical architecture, competitive intelligence, and market dynamics that will be unpacked in full within the complete study. Readers will gain a clear understanding of how the research connects macro-level momentum to actionable corporate strategy, while preserving the granular segmentation, regional breakdowns, and pricing matrices that form the core value proposition of the full report.
Eco-friendly Camping Tableware Market
The Strategic Imperative for 2026 Decision-Making
Market entrants, incumbents, and allied healthcare stakeholders face a uniquely complex landscape in 2026. Unlike mature adult hearing aid segments, the pediatric market operates at the intersection of clinical necessity, parental decision-making, pediatric audiologist preferences, school-based screening programs, and highly regulated reimbursement pathways. These intersecting variables create both formidable barriers to entry and highly defensible positioning opportunities for organizations equipped with precise market intelligence.
The strategic value of this research lies in its ability to translate broad growth trajectories into decision-ready frameworks. For product developers, the report decodes where innovation investment yields the strongest clinical adoption and where engineering complexity must be balanced against pediatric usability and durability requirements. For commercial and sales leadership, the analysis illuminates the procurement behaviors of audiologists, hospital networks, and early intervention programs, mapping the influence pathways that ultimately drive prescription and fitting volumes. For policy and market access teams, the study contextualizes how recent coding updates, state-level coverage adjustments, and regulatory clearances are reshaping the commercial environment for pediatric auditory devices.
A critical insight emerging from the 2026 environment is the growing premium on child-specific differentiation. Generic adaptations of adult hearing aid architectures increasingly fail to meet the functional, aesthetic, and acoustic demands of younger patients. Stakeholders that recognize this shift and align their development roadmaps, clinical training investments, and reimbursement positioning accordingly will be better positioned to capture share in a market where trust, clinical efficacy, and ease of use are decisive purchase drivers.
Furthermore, the forecast period coincides with heightened scrutiny around access, early detection, and equitable intervention. Organizations that anticipate these macro trends and embed them into their commercial planning will gain a structural advantage. This report is engineered to support that anticipation, providing a disciplined, evidence-based foundation for scenario planning, resource allocation, and competitive positioning.
Decoding the Market Architecture: Structure, Momentum, and Concentration
The pediatric hearing aids market exhibits a distinctive structural profile that differentiates it from broader adult and general audiology segments. Understanding this architecture is essential for any organization evaluating product sequencing, channel strategy, or clinical partnership development. The market is shaped by technology formats that balance acoustic performance, physical fit, and pediatric suitability, by clinical typologies of hearing loss that dictate intervention pathways, and by geographic realities that influence screening infrastructure, reimbursement maturity, and adoption velocity.
Historical revenue performance across the 2020-2025 window reflects a market that has consistently expanded, albeit with variations in pace tied to broader healthcare access dynamics and technology adoption cycles. The upward trajectory has brought the market firmly into a multi-billion-dollar revenue tier, with 2025 establishing a clear inflection point as more refined pediatric product lines and stronger clinical awareness converged. The forecast sequence that follows carries this momentum forward, projecting continued expansion through 2032 at a sustained compounded annual rate of 6.3 percent. This rate is neither speculative nor aggressive it is grounded in observed adoption patterns, product pipeline maturity, and the structural importance of early auditory intervention in pediatric care pathways.
From a concentration standpoint, the market remains moderately consolidated. The three largest players collectively account for approximately 42 percent of revenue, while the top five extend that share to roughly 48 percent. This level of concentration signals a competitive environment where scale, brand trust, and clinical engagement matter significantly, yet where meaningful share remains accessible to specialized entrants and regionally focused players who can deliver differentiated value. The implication for corporate strategy is clear: competitive advantage will not be derived from scale alone, but from the precision with which organizations align product offerings, clinical education, and reimbursement navigation to the specific needs of pediatric care delivery.
The segmentation architecture explored in the full report provides the granular lens required for targeted strategy. Product design variations reflect differing priorities in acoustic performance, retention, aesthetics, and pediatric adaptability, each appealing to distinct clinical and parental preferences. Hearing loss typologies further differentiate clinical demand, influencing the type of intervention most appropriate for a given patient profile and shaping the product mix that audiologists and implant specialists recommend. Geographic distribution adds another layer of strategic relevance, as regional differences in screening initiatives, healthcare financing, and provider density influence both volume potential and route-to-market design. In the complete study, these dimensions are fully mapped, enabling stakeholders to evaluate where to concentrate investment, where to adapt positioning, and where to expect competitive friction.
Competitive Landscape: Navigating an Innovator-Driven Arena
The competitive field in pediatric hearing aids is characterized by a blend of established audiology leaders, specialized technology developers, and implantable solution providers, each pursuing pediatric relevance through distinct strategic lenses. Rather than competing solely on price or general hearing performance, leading organizations are investing heavily in child-specific engineering, clinical engagement, and reimbursement-aligned service models. This has produced a landscape where differentiation is increasingly defined by the depth of pediatric understanding embedded in product design and commercial execution.
Several major players have built dedicated pediatric portfolios that reflect a deliberate commitment to this segment. Sonova Holding AG has advanced a focused pediatric offering with models engineered for children experiencing mild-to-profound hearing loss, signaling a clear strategy of pediatric specialization within a broader portfolio. William Demant Holding A/S, operating through its Oticon brand, has moved toward AI-enhanced sound processing and user-intent sensing tailored to younger users, aligning premium technology development with pediatric usability. Starkey Hearing Technologies has concentrated on pediatric-friendly solutions and program structures designed to meet the needs of children across varied age groups, emphasizing accessibility and tailored support. GN Store Nord A/S supplies pediatric instruments and infant-appropriate models, reinforcing the importance of early-life intervention within its commercial architecture. WS Audiology has extended its Signia platform into pediatric use with child-oriented series, while Widex A/S has developed offerings spanning babies, infants, and older children, reflecting a comprehensive age-range approach.
Beyond conventional hearing aid manufacturers, the competitive field also includes implantable and bone conduction specialists whose pediatric applications expand the intervention continuum. MED-EL develops both implantable and non-implantable hearing solutions with pediatric applications, while Cochlear Limited manufactures implantable cochlear systems designed specifically for pediatric patients. Oticon Medical AB contributes pediatric bone conduction and implant solutions, illustrating how regulatory clearances and implant-based technologies are extending the competitive perimeter beyond traditional air conduction devices. ReSound, operating under the GN Store Nord umbrella, further reinforces the pediatric hearing aid style landscape with models designed for children across age ranges.
What unites these competitors is a recognition that pediatric adoption depends on more than technical specification. Clinical education, fitting workflows, parental confidence, durability in active use environments, and integration with early intervention programs all influence prescription behavior. The full report analyzes these behavioral drivers in detail, examining how each major player positions itself within the pediatric ecosystem, where their product development focus lies, and how their commercial activities shape the competitive dynamic. This competitive mapping is critical for stakeholders evaluating partnership opportunities, competitive response strategies, or market entry pathways.
Recent product activity further underscores the pace of innovation. In April 2026, Oticon Inc. introduced a pediatric hearing aid family featuring second-generation AI-powered sound processing and 4D user-intent sensors, positioning the launch as a differentiated advance in pediatric auditory technology. Developments of this kind signal a broader industry direction: the convergence of intelligent sound processing, contextual sensing, and child-appropriate design is becoming an increasingly important battleground for competitive differentiation.
Market Dynamics and the Evolving Operating Environment
Strategic planning in the pediatric hearing aids market cannot be separated from the regulatory, reimbursement, and operational dynamics that shape commercial viability. In 2026, stakeholders are operating within an environment where policy updates, coding changes, and coverage adjustments directly influence access, prescribing behavior, and the economic calculus of pediatric intervention.
One significant regulatory development is the release of updated procedural coding frameworks that include new hearing device services codes effective from early 2026. These changes affect how pediatric hearing aid fittings, follow-up services, and related clinical activities are documented and billed, with downstream implications for provider workflows, reimbursement predictability, and the commercial economics of pediatric audiology practices. For manufacturers and market access teams, such coding shifts create both implementation requirements and opportunities to align service models with emerging billing realities.
Reimbursement landscapes are also evolving at the state and program level. In California, for example, the Department of Health Care Services updated its 2026 action plan related to hearing aid coverage for children, reflecting ongoing efforts to refine access pathways and coverage structures for pediatric patients. Adjustments of this nature matter because pediatric hearing aid adoption is highly sensitive to out-of-pocket exposure, public program coverage, and the clarity of reimbursement processes for families and providers. Organizations that monitor and anticipate these changes can better align pricing strategies, clinical support resources, and patient assistance frameworks.
Regulatory clearances for pediatric-relevant technologies continue to expand the intervention toolkit. The FDA clearance of a pediatric-relevant bone conduction hearing system through a 510(k) submission illustrates how implant-adjacent and bone conduction options are becoming more embedded in pediatric care considerations. Such clearances broaden the clinical options available for specific hearing loss profiles and can influence how specialists evaluate intervention pathways for younger patients. They also introduce new competitive dynamics for companies operating across both conventional and implantable solution categories.
On the commercial side, cost remains a central consideration for families, providers, and program administrators. Pediatric hearing aids typically carry a meaningful per-unit expense, with average costs broadly ranging from one thousand to four thousand dollars. This price reality reinforces the importance of reimbursement navigation, value-based communication, and durable product design that can withstand the wear-and-tear associated with pediatric use. For commercial leaders, it also highlights the need to articulate clinical and lifestyle value in ways that resonate with audiologists, parents, and funding bodies alike.
Taken together, these dynamics create an operating environment that rewards organizations capable of integrating regulatory awareness, reimbursement strategy, and product innovation into a coherent commercial plan. The full report provides the structured analysis required to translate these moving parts into practical strategy, including the implications for channel design, clinical engagement, and market access positioning.
What the Full Study Delivers: A Practical Intelligence Framework
This research study is built to support concrete decision-making rather than abstract market commentary. The complete report provides a structured, evidence-based framework that connects high-level market trajectory to the operational questions faced by product, commercial, clinical, and market access teams. It is designed to serve as a reference point for strategic planning, competitive assessment, and investment prioritization across the 2026-2032 horizon.
At the core of the study is a detailed market sizing and forecast architecture that traces historical performance and projects forward with methodological transparency. This foundation enables stakeholders to evaluate growth momentum, identify inflection points, and align internal planning assumptions with externally validated trajectories. Beyond headline figures, the report examines how different product types, hearing loss categories, and regional environments shape demand patterns and adoption pathways, providing the segmentation depth required for targeted strategy.
The competitive analysis component translates company profiles and recent developments into an actionable landscape view. Rather than presenting static corporate summaries, the study assesses how major players position themselves within the pediatric space, where their product emphasis lies, how they engage clinical stakeholders, and what their recent activity suggests about future strategic direction. This approach helps readers evaluate competitive vulnerability, identify white-space opportunities, and anticipate likely responses to market shifts.
In addition to structural and competitive analysis, the report incorporates the regulatory and reimbursement context that shapes commercial execution. It examines how coding changes, coverage updates, and regulatory clearances influence access dynamics and provider behavior, offering practical context for market access planning and clinical partnership development. Cost considerations are addressed within this framework, connecting pricing realities to reimbursement pathways, parental affordability, and the broader value proposition that must be communicated across the care ecosystem.
The full study also integrates forward-looking scenario considerations that help organizations stress-test their strategies against alternative market conditions. By connecting product innovation trajectories, clinical adoption factors, and policy evolution to potential demand outcomes, the report equips readers to plan with greater confidence in an environment where multiple variables evolve simultaneously. This scenario orientation is especially valuable for organizations evaluating new product introductions, geographic expansion, or partnership structures in a specialized and rapidly evolving segment.
Conclusion: Aligning Strategy with the Next Phase of Pediatric Auditory Care
The pediatric hearing aids market is entering a phase defined by stronger clinical emphasis on early intervention, accelerating technology differentiation, and an evolving reimbursement and regulatory backdrop. Growth is no longer solely a function of population dynamics or general audiology expansion it is increasingly shaped by how effectively organizations design for pediatric needs, engage clinical stakeholders, and navigate access pathways. In this environment, strategic intelligence is a decisive advantage.
PW Consulting’s full market research study offers the depth, structure, and competitive context required to make informed decisions in 2026 and beyond. It is intended for leaders who need more than directional trends they need a rigorous, decision-ready understanding of market size dynamics, segmentation behavior, competitive positioning, and the policy and reimbursement forces that shape commercial outcomes. The preview presented here highlights the strategic architecture of the study while reserving the detailed segmentation, regional breakdowns, and pricing intelligence for the complete report.
For organizations preparing product roadmaps, commercial plans, market access strategies, or investment evaluations, the full study provides the precision intelligence necessary to move from awareness to action. We invite strategic decision-makers to access the complete report and leverage its insights to strengthen positioning, refine execution, and align capabilities with the next phase of growth in the global pediatric hearing aids market.
For detailed analysis of this topic, please visit the official page: Pediatrics Hearing Aids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Intelligence in the ANPR Cameras Market: Why 2026 Decisions Require More Than Surface Data
The global landscape for Automatic Number Plate Recognition (ANPR) cameras is shifting from a niche surveillance utility to a foundational component of intelligent infrastructure. Traffic management, law enforcement, toll collection, and access control are no longer operating in silos. They are converging under a single technological umbrella where vehicle identification, real-time data processing, and automated decision-making intersect. For executives, procurement leaders, and strategy teams navigating 2026 and beyond, understanding where this market is heading is not optional. It is a prerequisite for capital allocation, partnership selection, and regulatory compliance.
Worldwide Wall Mounted Thermometer Market
At PW Consulting, our latest in-depth study on the ANPR Cameras Market is designed to serve as a decision-grade intelligence asset. Rather than offering surface-level generalizations or recycled market narratives, this report maps the structural forces shaping revenue trajectories, competitive positioning, and deployment patterns across the forecast horizon. It is built for leaders who need to separate meaningful signal from market noise and make targeted moves in an environment where technological capability, regulatory compliance, and regional dynamics are evolving simultaneously.
Worldwide Drone Controller Market
What follows is a strategic preview of the market architecture, the operational implications for enterprises, and the competitive landscape that will define the ANPR sector through 2032. The intent is to demonstrate the analytical rigor and practical utility embedded in the full study, while preserving the granular segmentation that organizations can only access by engaging with the complete research.
Glass Straw Market
From Reactive Surveillance to Predictive Vehicle Intelligence
Over the past several years, ANPR technology has graduated beyond fixed checkpoints and reactive enforcement. Modern deployments increasingly rely on integrated recognition software, AI-accelerated processing, and sensor architectures designed to function under real-world conditions: poor lighting, high vehicle speeds, multi-lane traffic, and varying weather. The result is a market that is expanding not only in unit volume but in functional scope.
Historical revenue data reflects this evolution clearly. Between 2020 and 2025, global market revenue grew from approximately 2.09 billion USD to 4.09 billion USD, signaling more than a doubling of commercial scale in half a decade. That momentum is not flattening. The forecast period extending to 2032 points to continued expansion, supported by a compound annual growth rate of 9.7 percent. By 2032, total revenue is projected to reach 7.83 billion USD. These figures are not abstract totals. They represent sustained investment in intelligent transportation systems, cybersecurity-conscious access control, and public-safety infrastructure that requires reliable vehicle identification at scale.
For decision-makers, the strategic question is not whether ANPR adoption will keep growing. It is where the fastest value creation will occur, which deployment models will dominate in specific operational contexts, and how vendors will differentiate as the installed base widens. Those questions require a deeper reading of segmentation, end-use priorities, and regional demand signatures than high-level market headlines can deliver.
Why 2026 Is a Pivotal Decision Year
2026 sits at a meaningful inflection point. Several forces are converging at once: maturing AI recognition accuracy, broader integration with cloud-based security platforms, increasing pressure on government fleets and highway authorities to modernize legacy systems, and a regulatory environment that is tightening expectations around data handling and automated decision-making. Organizations that delay strategic evaluation risk entering procurement cycles behind the curve, relying on outdated assumptions about performance, interoperability, or compliance readiness.
This is precisely why the timing of a structured market intelligence effort matters. A report such as ours is not intended to be read once and shelved. It is intended to shape near-term planning across multiple functions:
- Technology and procurement teams can align camera specifications, software requirements, and integration pathways with realistic deployment scenarios.
- Business development groups can identify where partner ecosystems are forming and which vendor capabilities are becoming table stakes.
- Risk, legal, and compliance leaders can better anticipate how data governance expectations may influence system design and vendor selection.
- Investors and corporate strategy teams can assess market concentration, competitive intensity, and the differentiation potential of specialized players against broader platform vendors.
In short, the report is built to support decisions, not just inform them.
Inside the ANPR Cameras Market Research: What the Report Delivers
This study combines historical reconstruction with forward-looking analysis to provide a comprehensive operating picture of the ANPR cameras market. It is structured to help readers move from macro trends to actionable intelligence without losing sight of commercial reality. The full report covers the following core dimensions.
Market Size, Growth Path, and Structural Momentum
The report traces revenue progression across the historical period and projects performance through the forecast window. It translates overall market scale into a clear growth narrative, emphasizing the rate of expansion and the continuity of demand drivers behind it. Rather than presenting numbers in isolation, the analysis embeds them within a broader operational context: how enforcement priorities, toll modernization, parking automation, and enterprise access control collectively shape buying behavior over time.
Segmentation Architecture Without the Blind Spots
A major strength of the research lies in its segmentation design. The study evaluates the market across multiple structural lenses, enabling readers to understand how demand splits by technology type, application environment, and regional deployment patterns. This is where many market summaries stop at averages. Our report goes further by framing each segment in terms of operational fit, adoption drivers, and competitive implications. Organizations evaluating cameras for fixed sites, mobile operations, traffic corridors, or restricted-access facilities can use the segmentation framework to assess where their requirements intersect with broader market demand.
Competitive Landscape and Company Profiling
The ANPR market is characterized by a mix of large, platform-oriented security manufacturers, specialized recognition vendors, and software-centric solution providers. The report profiles the companies shaping this landscape and organizes them by strategic relevance, product orientation, and deployment fit. Rather than presenting a simple directory, the analysis captures how each player positions itself across traffic enforcement, parking, access control, public safety, and enterprise security.
Several firms stand out for the breadth of their ANPR-integrated offerings. Hikvision emphasizes high-performance cameras for traffic enforcement, parking, and security applications, with recognition software embedded in the solution design. Dahua Technology supplies ANPR and LPR cameras targeted at intelligent traffic surveillance, access control, and enforcement use cases. Uniview Technologies focuses on high-precision cameras using large-format sensors for real-time plate recognition in traffic monitoring scenarios. Axis Communications approaches the market through ANPR-enabled network cameras that incorporate AI acceleration for automated plate verification and enforcement workflows. Hanwha Vision integrates ANPR into its BLAZE platform, linking vehicle tracking with access control capabilities. Avigilon serves enterprise and public-safety customers with LPR/ANPR cameras designed for retail security, access management, and organized crime prevention. Bosch Security Systems contributes deep-learning-based recognition through its VECTOR3 ANPR cameras, with emphasis on multi-lane performance under difficult conditions. Adaptive Recognition offers specialized hardware such as Vidar, Einar, and MicroCAM for high-speed traffic and parking applications. QRO Solutions provides Harrier ANPR cameras associated with high-speed tolling and traffic enforcement performance. Sunell Security focuses on starlight sensors and high-frame-rate imaging for intelligent traffic surveillance. Flock Safety differentiates with solar-powered LPR cameras designed for rapid deployment in law enforcement and public safety settings. Insight LPR manufactures edge-oriented cameras such as Matrix Edge and Defender for real-time alerts and highway-speed recognition. 3dEYE Inc. supports law enforcement and enterprise use cases through its ALPR systems. iOmniscient Corporation delivers real-time vehicle identification through its camera and system portfolio. Tattile combines ANPR with laser and radar integration, supported by controller software for mobility-oriented solutions. Verkada integrates ANPR into cloud-based security cameras for enterprise and government environments. Mirasys provides ANPR integration paths for existing IP cameras within VMS ecosystems. Optiview offers IP-based ANPR cameras oriented to entrance and exit management. Plate Recognizer expands flexibility by supplying ALPR software that can be paired with a wide range of IP cameras for ANPR deployments.
This competitive breadth matters because buyer requirements rarely align neatly with a single product category. Some organizations need rugged, fixed-site recognition for high-speed corridors. Others seek mobile or rapidly deployable units for policing or temporary access control. Still others prioritize software interoperability, cloud connectivity, or VMS integration. The report translates this complexity into a usable competitive map, making it easier to see where capabilities are concentrated and where differentiation is emerging.
Recent Deployment Patterns That Signal Market Direction
One of the most practical elements of the study is its coverage of recent operational moves across public agencies, airports, transportation authorities, and vendors. These developments provide an on-the-ground read on how ANPR is being adopted in real time.
In mid-2025, the Telangana Regional Transport Authority decided to deploy ANPR cameras across 17 check posts throughout the state, reflecting a structured, large-scale use of vehicle identification for transport oversight. Around the same time, Salem City Police announced plans to install eight ANPR cameras at key junctions and national highway locations to support speeding enforcement. The Delhi Government moved to implement ANPR cameras at every border entry point in order to limit the influx of end-of-life vehicles, a policy-driven deployment that ties recognition technology to regulatory enforcement. Nagpur local authorities installed AI-enabled ANPR cameras as part of a substantial integrated intelligent traffic management system, illustrating how recognition hardware is being embedded within broader city infrastructure programs.
On the tolling side, the Ministry of Road Transport and Highways announced a pilot deployment combining ANPR with FASTag-based barrier-free tolling at select national highway plazas. That move is strategically significant because it points toward hybrid identification architectures, where camera-based recognition and electronic toll mechanisms can reinforce one another. In the aviation and access-control domain, London Stansted Airport deployed a new automatic number plate recognition system to support barrier-free entry and exit, demonstrating how ANPR continues to expand beyond roadways into controlled facilities.
On the vendor side, Tattile announced new ANPR camera releases at a major industry event, signaling continued product-cycle momentum and an active competitive road map. Collectively, these developments show that ANPR is being deployed in a wide variety of operational settings, each with different performance expectations, integration requirements, and policy motivations.
Regulatory Context as a Strategic Variable
Technology adoption in this market does not occur in a vacuum. Data governance, retention expectations, automated decision-making rules, and sector-specific surveillance guidance are increasingly shaping procurement and deployment decisions. The report treats regulation not as a compliance footnote but as a market dynamic that influences design choices, vendor suitability, and long-term system viability.
For example, recent legal updates in certain jurisdictions have modified provisions related to data processing, automated decision-making, and retention in ANPR systems. In parallel, public guidance continues to reinforce expectations around the operational use of surveillance camera systems by government and law enforcement bodies. In other markets, regulatory attention has extended toward how ANPR-related data intersects with broader consumer and credit reporting frameworks. While the specifics differ by region, the overarching trend is clear: organizations deploying or purchasing ANPR solutions need to anticipate a more formalized environment for data handling, accountability, and operational transparency.
A strong market study must help leaders interpret that environment rather than simply list it. The report connects regulatory developments to practical implications for system architecture, integration planning, and vendor evaluation.
Reading the Market Concentration Signal
Market structure is a crucial piece of strategic context. The ANPR cameras market is not defined by extreme dominance from a single vendor, nor is it so fragmented that differentiation loses meaning. Instead, the analysis points to a moderately concentrated competitive landscape in which leading players hold meaningful but not overwhelming shares.
The report notes that the top three companies account for roughly 25.5 percent of market revenue, while the top five reach about 32.0 percent. Those figures tell an important story. They suggest room for specialized vendors to compete effectively in targeted segments, while also reflecting the scale advantage of larger manufacturers with broader security and surveillance portfolios. For buyers, this environment creates a strategic choice: whether to align with broader platform ecosystems that offer cross-product integration and global support, or to prioritize best-fit ANPR specialists with deep recognition expertise for specific use cases.
For vendors and investors, the concentration profile indicates that growth will likely come through a combination of portfolio expansion, software integration, regional reach, and vertical-specific tuning rather than through a single winner-take-all dynamic. The full study explores these implications in greater detail, with company-level context that helps explain how differentiation is being built in practice.
Where the Market Is Moving
Looking across the historical trajectory, recent deployments, vendor activity, and regulatory evolution, several strategic themes emerge.
First, ANPR is increasingly treated as part of a wider intelligent-infrastructure stack rather than a standalone camera acquisition. That means recognition accuracy, edge processing capability, connectivity options, and software interoperability matter as much as hardware durability. Second, mobile and rapidly deployable solutions are gaining relevance in contexts where enforcement, safety, or access management needs to be established without long lead times. Third, the combination of ANPR with tolling, traffic management, and cloud-based security workflows suggests that integrated ecosystems will become more important over the forecast period.
At the same time, the market remains broad enough that different segments will follow different maturation paths. Traffic management, law enforcement, toll collection, and other application areas each carry distinct performance requirements and procurement cycles. Regional demand will also diverge based on infrastructure priorities, policy mandates, and budget timing. Capturing these nuances requires a segmentation view that goes beyond headline totals.
This is where the full report is designed to add the most value. It does not flatten the market into a single growth curve. It examines how the curve is built from multiple demand sources, how competitive positioning differs across them, and what that means for organizations making investment and sourcing decisions in 2026 and beyond.
Why the Full Study Matters for Executive Decision-Making
A market overview can tell leadership that ANPR is expanding. It cannot, on its own, tell a procurement team how to evaluate fixed versus mobile requirements, a business development group where partnership opportunities are forming, or a strategy function how to interpret competitive concentration without losing sight of specialized entrants. The report is built to close that gap.
It offers a structured basis for assessing market timing, vendor fit, and deployment relevance. It connects revenue growth to operational drivers and regulatory conditions rather than leaving the numbers floating in isolation. It profiles companies in a way that reflects both their strategic positioning and the practical contexts in which they compete. And it tracks recent real-world deployments that reveal how ANPR is being used right now, not just how it might be used in theory.
For organizations that need to move from general market awareness to executable strategy, that level of detail is not a luxury. It is the difference between a directional guess and a defensible plan.
Turning Market Intelligence into 2026 Advantage
The ANPR cameras market is entering a phase where strategic clarity pays measurable dividends. Demand is expanding, deployment models are diversifying, and competitive offerings are becoming more specialized even as larger platform players continue to scale. In that environment, the organizations that act with precision will be the ones that understand the market at the right level of depth.
This report is intended to provide that depth. It combines historical analysis, forecast trajectory, competitive profiling, application-level insight, and regulatory context into a single strategic reference. It is designed to support more informed decisions across procurement, technology, compliance, partnerships, and corporate planning.
The high-level numbers and structural themes outlined here offer a credible starting point, but the real strategic advantage lies in the full segmentation architecture, company-level assessment, and deployment analysis that the complete study delivers. For leaders who need to decide where to invest, what to buy, whom to partner with, and how to prepare for the next phase of ANPR adoption, the full research provides the intelligence required to move with confidence.
For detailed analysis of this topic, please visit the official page: ANPR (Automatic Number Plate Recognition) Cameras Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: GRP & GRE Pipe Market to Hit $6,078.59M by 2032, 5.55% CAGR
By PW Consulting, 2026-09-07
Strategic Intelligence for 2026: Navigating the GRP and GRE Pipe Market Dynamics
As we move deeper into 2026, the industrial infrastructure sector faces a complex landscape defined by shifting raw material costs, evolving regulatory frameworks, and sustained demand for corrosion-resistant piping solutions. For executives, investors, and supply chain strategists, understanding the trajectory of the Glass Reinforced Plastic (GRP) and Glass Reinforced Epoxy (GRE) pipe market is no longer optional—it is a critical component of risk management and growth planning.
Worldwide Myotonic Dystrophy Type 1 (DM1) Market
PW Consulting is pleased to introduce our latest comprehensive market research study, designed specifically to equip decision-makers with the actionable intelligence needed to navigate this evolving environment. This report moves beyond surface-level statistics to provide a granular analysis of market mechanics, competitive pressures, and future growth vectors through 2032.
Pet Medical Insurance Market
Executive Summary: Market Trajectory and Scale
The global demand for composite piping solutions has demonstrated resilience over the past half-decade. Based on historical data tracked from 2020 through 2025, the market has consistently expanded, reflecting the broader industrial shift toward durable, low-maintenance infrastructure materials. The base year valuation for 2025 establishes a significant baseline, indicating a mature yet growing ecosystem.
Ultra-wide Bandgap Semiconductor Market
Looking ahead, our forecast period spanning 2026 to 2032 projects a steady compound annual growth rate (CAGR) of approximately 5.55 percent. This growth trajectory suggests that while the market is not experiencing explosive volatility, it offers reliable expansion opportunities for stakeholders who can optimize operational efficiency and capture share in high-demand segments. The projected revenue scale by the end of the forecast period underscores the enduring relevance of GRP and GRE technologies in civil engineering, energy, and chemical processing sectors.
However, raw market size numbers only tell part of the story. The true value of this research lies in dissecting the drivers behind these figures and understanding the friction points that could alter the path. Our analysis integrates macroeconomic indicators with on-the-ground industry developments to provide a holistic view of the market health.
Critical Market Dynamics Influencing 2026 Decisions
Decision-making in 2026 cannot be done in a vacuum. Several external factors are currently exerting pressure on the supply chain and pricing structures within the GRP and GRE sector. Our report dedicates significant attention to these dynamics, ensuring that clients understand not just where the market is going, but what forces are pushing it there.
Raw Material Volatility and Supply Chain Risks
Input costs remain a primary concern for manufacturers and buyers alike. Recent industry data indicates that ortho resin prices experienced an upward shift in early 2026, driven by supply concerns originating in the Middle East. This region remains a critical hub for upstream feedstock, and any escalation there tends to ripple through the global composite supply chain. Conversely, glass fibre prices have shown more stability, with some indications of slight decreases amid weaker demand signals. Understanding the net effect of these divergent trends on final product pricing is essential for budgeting and contract negotiations.
Regulatory and Trade Environment
Trade policies continue to shape market accessibility. Recent adjustments to reciprocal tariff rates on imported GRP/GRE pipes and composite materials in the United States are expected to impact end-use market pricing. For multinational corporations or exporters targeting the North American region, these tariff structures could alter competitive positioning. Furthermore, environmental regulations such as styrene reduction initiatives in Europe may influence resin pricing structures in the medium term. Our report analyzes how these regulatory nuances affect regional cost structures and compliance requirements.
Comprehensive Report Scope and Methodology
To support robust strategic planning, our research methodology combines top-down market modeling with bottom-up company profiling. This dual approach ensures that the high-level forecasts are grounded in realistic operational capabilities and competitive realities.
The report covers a detailed historical review from 2020 to 2025, allowing stakeholders to benchmark recent performance against long-term trends. This historical context is crucial for validating the assumptions used in our 2026 to 2032 forecast model. By analyzing the growth rates year-over-year, we identify inflection points where market behavior shifted, providing lessons for future scenario planning.
We examine the market across multiple dimensions without exposing the proprietary segmentation data reserved for full report subscribers. The analysis considers the breakdown by product type, distinguishing between the standard GRP and GRE categories that dominate the landscape, as well as niche variants. Similarly, the application landscape is scrutinized, covering critical sectors such as oil and gas infrastructure, municipal sewage systems, agricultural irrigation, and chemical processing plants. Each application vertical presents unique demand drivers and regulatory hurdles, which are thoroughly explored.
Geographic coverage is another pillar of this study. We assess performance and outlook across key regions including Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa. While specific regional revenue shares are detailed in the complete intelligence package, the narrative analysis highlights which markets are acting as growth engines versus those facing maturity or regulatory headwinds.
Competitive Landscape: Key Players and Strategic Moves
The market structure exhibits moderate concentration, with the top three players holding a significant share of total revenue and the top five firms commanding a slightly larger portion of the market. This concentration suggests that while there is room for mid-sized players, scale advantages and technological moats are increasingly important. Our report profiles several key companies that are defining the competitive standards in this space.
- Kuzeyboru: Based in Turkey, this manufacturer operates a significant facility in Malatya focused on continuous fiber winding technology. They produce GRP pipes ranging from 300 to 4000 mm, targeting infrastructure, sewerage, and industrial applications. Recent activity includes the shipment of 800 mm diameter GRP pipes and fittings to Pescara, Italy, for a sewerage infrastructure project, highlighting their reach into European markets.
- Amiantit: Headquartered in Saudi Arabia, Amiantit is a major producer of GRP and GRE systems, including their proprietary AMIPOX technology. They serve water management, infrastructure, and extreme wear applications. In September 2026, the group launched Flowtite Orange, a new GRP pipe technology designed specifically for extreme abrasion and erosion conditions, demonstrating ongoing investment in product differentiation.
- Future Pipe Industries: Operating out of the UAE, this company manufactures GRE, GRP, and GRV pipes up to 4000 mm. Their portfolio serves oil and gas, offshore, power, and infrastructure sectors, leveraging advanced composite technologies to meet high-pressure and corrosive environment standards.
- Amiblu Holding GmbH: An Austrian specialist focusing on GRP pipe systems for water, sewerage, irrigation, and industrial use. They utilize Hobas centrifugal casting and Flowtite filament winding technologies, offering a dual-technology approach to serve diverse customer requirements.
- Fibrex: Based in the USA, Fibrex produces GRP and FRP pipes tailored for chemical plants, chlor-alkali, and industrial corrosive environments. Their focus on high-resistance materials positions them strongly within the chemical processing vertical.
- Abu Dhabi Pipe Factory: A key UAE manufacturer producing GRP, GRV, and GRE pipes and fittings up to 3000 mm. They utilize dual helical and continuous filament winding techniques to support Gulf infrastructure projects.
- Advanced Piping Solutions: Also based in Saudi Arabia, this firm produces GRP and GRE pipes ranging from 25 to 1200 mm for water, sewerage, power, and industrial sectors using continuous filament winding.
- Chemical Process Piping Pvt. Ltd.: An Indian manufacturer focusing on GRP, GRE, and thermoplastic-lined FRP piping systems. Their applications span chemical, power, oil and gas, desalination, and water treatment, reflecting the diverse needs of the Asian market.
- Hill & Smith PLC: A UK-based supplier that provides GRP composites, pipe supports, and related infrastructure products, offering a broader ecosystem of support materials alongside core piping solutions.
Beyond company profiles, the report analyzes recent strategic developments. For instance, the shipment activities by Kuzeyboru in mid-2026 and the product launch by Amiantit in late 2026 serve as case studies for how competitors are maintaining momentum. These events are not just news items; they are indicators of capacity utilization, technological advancement, and market expansion strategies that inform our competitive intensity assessments.
Strategic Value for 2026 Decision-Making
Why is this report critical for your organization in 2026? The answer lies in the intersection of opportunity and risk. With ortho resin prices fluctuating and trade tariffs shifting, procurement strategies need to be agile. Our analysis helps procurement leaders anticipate cost pressures and evaluate supplier viability. For example, understanding the stability of glass fibre pricing versus resin volatility can inform material sourcing decisions and inventory planning.
For investors and private equity firms, the market concentration data and company profiles provide a clear view of the competitive moats. Companies with proprietary technology, such as Amiantit's Flowtite Orange or Amiblu's dual casting methods, may possess stronger pricing power in niche segments. Our report helps identify which capabilities are becoming table stakes versus which ones offer genuine differentiation.
Infrastructure developers and engineering firms will benefit from the application-specific insights. Whether planning a new sewage network in Europe or an oil and gas pipeline in the Middle East, knowing the regional supply dynamics and leading manufacturers can reduce project risk. The report details which players have the capacity and technological fit for specific project scales, from small diameter industrial lines to large-scale municipal infrastructure.
Navigating Regional Complexities
The global market is not a monolith. Regional dynamics vary significantly due to local infrastructure spending, regulatory environments, and supply chain maturity. Asia Pacific currently represents a substantial portion of global volume, driven by rapid industrialization and infrastructure development. Europe faces its own set of challenges and opportunities, particularly regarding environmental regulations like styrene reduction initiatives which could reshape cost structures over the coming months.
North America remains a critical market, especially given the recent adjustments to reciprocal tariff rates on imported composite materials. These policy changes could reshape the competitive landscape for domestic manufacturers versus importers. Our report provides the context needed to interpret these policy shifts without making speculative claims, focusing instead on the potential impact on pricing and market share distribution.
Meanwhile, regions like Latin America and the Middle East and Africa, while smaller in total volume compared to the major hubs, present specific opportunities linked to energy infrastructure and water management projects. Understanding the specific demand drivers in these regions is key to evaluating market expansion potential.
Conclusion: Turning Data into Strategy
The GRP and GRE pipe market offers a stable growth outlook with a projected CAGR of 5.55 percent through 2032, but realizing value in this environment requires more than just acknowledging the growth rate. It requires a deep understanding of the material cost dynamics, regulatory shifts, and competitive technologies that define the market structure.
PW Consulting's new market research report is designed to be that strategic bridge. By combining historical performance data from 2020 to 2025 with a forward-looking forecast to 2032, and enriching this with detailed company profiles and real-time industry developments, we provide a comprehensive toolkit for strategic planning.
We invite you to leverage this intelligence to refine your market entry strategies, optimize supply chain contracts, and identify high-potential investment targets. The full report contains the specific segmentation data, regional revenue breakdowns, and detailed competitive matrices necessary to execute these strategies with precision.
To access the complete intelligence package and secure your competitive edge in the 2026 GRP and GRE Pipe Market, please visit our official research portal. There you will find the full dataset, interactive forecasts, and deep-dive analysis ready to support your critical decisions.
Contact PW Consulting today to request the full report or schedule a briefing with our industry analysts.
For detailed analysis of this topic, please visit the official page: GRP & GRE Pipe Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Epichlorohydrin Market Hits $2.83B in 2025, Poised for 5.3% CAGR to Reach $4B by 2032
By PW Consulting, 2026-09-07
Navigating the Epichlorohydrin Market: Strategic Imperatives for 2026 and Beyond
The global epichlorohydrin (ECH) market stands at a critical inflection point as industry stakeholders navigate the 2026 landscape. Following a trajectory that saw the overall market size reach an estimated 2,825.0 million USD in 2025, the sector is poised to advance toward 4,039.0 million USD by 2032. This growth, underpinned by a compound annual growth rate (CAGR) of 5.3 percent across the forecast period of 2026-2032, is not merely a statistical projection. It represents a complex interplay of raw material volatility, strategic capacity adjustments, and a accelerating pivot toward bio-based alternatives. For corporate leaders, procurement directors, and investors, understanding the granular drivers behind these numbers is not optionalit is a prerequisite for securing supply chains and capitalizing on competitive advantages.
Worldwide Animal Sourced Casings Market
Our latest comprehensive market research report on the Epichlorohydrin Market offers a definitive strategic roadmap. This analysis moves beyond top-line figures to dissect the operational realities, competitive maneuvers, and regional nuances that will define profitability and market share in the coming years. By integrating historical data from 2020 through 2025 with forward-looking projections, this study provides the intelligence necessary to make informed decisions in a market characterized by both robust demand and significant structural shifts.
Cancer Gene Testing Service Market
Market Trajectory: From Recovery to Sustained Expansion
The historical arc of the ECH market reveals a story of resilience and gradual recovery. After stabilizing at 2,497.46 million USD in 2023, the market demonstrated renewed momentum, climbing to 2,633.22 million USD in 2024 and further to 2,825.0 million USD in 2025. This upward trajectory reflects recovering industrial activity and steady demand from downstream sectors. The forecast period beginning in 2026 anticipates a continuation of this growth, with the market size projected to reach 2,961.76 million USD in 2026 and escalating to 3,308.07 million USD by 2028.
Worldwide Digital Mine Market
However, the path to 4,039.0 million USD by 2032 is rarely linear. The projection highlights the importance of understanding the underlying dynamics that can accelerate or dampen growth. Market participants must look past the aggregate numbers to recognize how capacity expansions, feedstock economics, and regional demand shifts will interact. The 5.3 percent CAGR serves as a benchmark, but achieving or exceeding this growth requires a nuanced grasp of the specific segments and geographies that are outperforming or facing headwinds. Our report provides the analytical depth to navigate these variations, offering a clear view of where growth is most attainable and what risks may impede progress.
Segmentation Dynamics: Oil-Based Dominance and Bio-Based Momentum
A closer examination of the market structure reveals a landscape where traditional feedstocks maintain a commanding presence while renewable alternatives gain strategic relevance. In 2025, the oil-based segment accounted for a substantial 2,467.71 million USD, reflecting its entrenched role in large-scale industrial applications. This segment continues to drive volume, supported by established supply chains and cost efficiencies in regions with ample petrochemical infrastructure. Yet, the bio-based segment, valued at 357.29 million USD, is emerging as a critical area of innovation and regulatory alignment.
The divergence between oil-based and bio-based ECH is becoming a defining feature of the competitive environment. As sustainability mandates tighten and customers in coatings, composites, and advanced materials seek greener credentials, the bio-based pathway is attracting significant investment and technological refinement. Companies leveraging renewable feedstocks are positioning themselves to capture premium pricing and long-term contracts from environmentally conscious buyers. Our report delves into the technological and economic factors shaping both segments, analyzing how cost structures, feedstock availability, and application requirements are influencing the balance between conventional and bio-based production. Understanding this duality is essential for stakeholders evaluating capacity investments, sourcing strategies, and product portfolio alignment.
Regional Inflection Points and Growth Centers
Geographic distribution of demand and supply remains a cornerstone of ECH market strategy. Asia Pacific has emerged as a dominant force, with a 2025 market valuation of 1,653.2 million USD, underscoring the region's role as a primary consumption hub. This concentration is driven by robust manufacturing activity, expanding infrastructure, and growing demand for epoxy resins and specialty chemicals across multiple downstream industries. North America, valued at 379.82 million USD, and Europe, at 592.81 million USD, represent mature markets where growth is increasingly tied to product differentiation, regulatory compliance, and supply chain resilience rather than sheer volume expansion.
Latin America and the Middle East and Africa, with valuations of 142.83 million USD and 56.34 million USD respectively, present distinct opportunities and challenges. These regions are characterized by evolving industrial bases and varying degrees of integration into global supply networks. The strategic importance of each region extends beyond current market size. It lies in the ability to anticipate shifts in trade flows, feedstock dynamics, and localized demand patterns. Our analysis maps these regional landscapes in detail, highlighting where capacity additions are aligning with demand growth and where market participants may face intensifying competition or margin pressure. By understanding the regional architecture, stakeholders can optimize their geographic footprint and mitigate exposure to localized disruptions.
Application Landscape: Epoxy Resins Lead, Diversified Demand Emerges
The application spectrum of ECH is anchored by epoxy resins, which accounted for 2,433.6 million USD in 2025. This dominance reflects the material's critical role in coatings, adhesives, composites, and electrical applications, sectors that continue to benefit from infrastructure development, automotive lightweighting, and renewable energy expansion. The sheer scale of epoxy resin demand ensures that fluctuations in this segment have a pronounced impact on overall market dynamics. However, a comprehensive strategy requires attention to the broader application mix.
Synthetic glycerin, valued at 317.56 million USD, and water treatment chemicals, at 73.84 million USD, represent specialized but strategically important end uses. Synthetic glycerin serves as a versatile intermediate with applications spanning personal care, pharmaceuticals, and food ingredients, while water treatment chemicals address growing environmental and regulatory needs. The interaction between these application segments and ECH supply is multifaceted, influenced by substitution possibilities, regulatory frameworks, and downstream industry cycles. Our report provides an in-depth assessment of these application drivers, exploring how demand variability, product specifications, and market trends are shaping the utilization of ECH across different end-use markets. This granular perspective enables stakeholders to identify high-value niches and align their product offerings with evolving customer requirements.
Competitive Landscape: Concentration, Capacity Shifts, and Strategic Positioning
The ECH market is defined by a concentrated competitive structure, with the top three players holding approximately 45 percent of market share and the top five commanding around 65 percent. This level of concentration underscores the importance of scale, technological capability, and strategic agility in securing a competitive position. Major producers are actively reshaping the landscape through capacity investments, technology transitions, and operational adjustments, creating a dynamic environment where enterprise moves can ripple through supply and pricing.
Olin Corporation remains a cornerstone of the global supply base, with capacity exceeding 450,000 metric tons per year across facilities in Freeport, Texas, and Stade, Germany. Its extensive footprint and integrated operations position it as a key supplier to epoxy resin and downstream industries, reinforcing the importance of scale and geographic diversification. Formosa Plastics Corporation leverages its integrated chemical operations in Taiwan to produce ECH as a key intermediate for epoxy resins and specialty materials, benefiting from synergies within a broader petrochemical portfolio. Sumitomo Chemical Co., Ltd. contributes to the Asian supply network with ECH as a core intermediate in its chemical portfolio, supporting downstream derivatives and regional demand. LOTTE Fine Chemical Co., Ltd. operates integrated production in Ulsan, South Korea, supplying epoxy resins and specialty applications, while Hexion Inc. in the United States employs bio-based glycerin-to-ECH technology to serve coatings and composites markets, reflecting a growing emphasis on renewable pathways.
In Europe, Solvay S.A. has advanced its Epicerol technology to produce ECH from renewable feedstocks, supplying large-scale volumes for epoxy resins and advanced materials. This technological positioning aligns with the broader industry trend toward sustainability and offers a differentiated value proposition in markets where green credentials are increasingly valued. INEOS Group operates facilities in Tavaux, France, using both glycerine- and propylene-based processes to supply merchant and captive markets, demonstrating the flexibility required to navigate feedstock volatility and demand variations. The competitive picture is further shaped by significant capacity actions that are altering supply balances. Westlake Corporation's temporary mothballing of its allyl chloride and ECH units at the Pernis site in the Netherlands, effective through 2025, has removed volume from the European market and influenced regional pricing dynamics. Similarly, the permanent closure of ECH and chlorine units at INEOS's Rheinberg plant in Germany, following a works council decision in October 2025, marks a structural shift in European production capacity.
India has emerged as a focal point of capacity expansion. DCM Shriram Limited, based in Delhi, has fully commissioned its expanded ECH facility at the Jhagadia chemical complex in Gujarat, reaching a total capacity of 52,000 TPA following Phase I commissioning of 35,000 TPA in October 2025 and the subsequent addition of 17,000 TPA. This expansion underscores the strategic importance of India as a growing production hub and highlights the company's focus on liquid epoxy resins and advanced materials. Aditya Birla Chemicals, headquartered in Mumbai, is also strengthening its presence through ECH and chlor-alkali derivatives production at its Vilayat complex, with commissioning activities aligned to support specialty polymers and epoxy applications. Grasim Industries, part of the Aditya Birla Group, has progressed with the commissioning of its ECH plant at Vilayat, reflecting a coordinated push to expand domestic and export-facing capacity. Meghmani Finechem Limited, based in Vadodara, has similarly advanced its ECH production via glycerin-based renewable technology under the TechnipFMC EPICEROL license, supplying domestic and export markets from its Dahej plant. These developments illustrate a broader trend of capacity growth in India, driven by favorable cost structures, growing downstream demand, and strategic investments in both conventional and bio-based routes.
Raw Material Dynamics and Price Volatility
Feedstock economics remain a primary driver of ECH market behavior, with propylene and chlorine costs exerting direct influence on production economics and pricing. In the first quarter of 2026, the interplay of upstream costs produced divergent regional outcomes. In Northeast Asia, strong upstream propylene and chlorine feedstock costs supported a 10.6 percent price increase for ECH, reflecting tight supply conditions and elevated input expenses. This price movement highlights the sensitivity of the Asian market to feedstock fluctuations and the resulting impact on manufacturer margins and customer pricing.
In contrast, Europe experienced a 2.1 percent price decline in the same period, as easing upstream propylene and chlorine costs provided relief to producers and downstream buyers. This divergence illustrates the localized nature of feedstock markets and the importance of monitoring regional cost structures when assessing profitability and competitive positioning. North America saw a 2.2 percent price rise in Q1 2026, driven by strong upstream propylene and chlorine feedstock costs, reinforcing the link between input prices and market pricing in that region. These fluctuations underscore the need for proactive feedstock management and pricing strategies. Our report provides a detailed analysis of these dynamics, examining how raw material costs interact with capacity changes, demand shifts, and regional market conditions to shape ECH pricing trends. Understanding these relationships is critical for developing resilient sourcing strategies and mitigating exposure to cost volatility.
Strategic Insights and Decision Framework for 2026
The convergence of capacity expansions, feedstock volatility, regulatory pressures, and sustainability trends creates a complex decision environment for ECH market participants. Success in this landscape requires more than a high-level view of market size and growth rates. It demands a deep understanding of the operational, competitive, and regional factors that influence performance at the enterprise level. The insights contained in our full report are designed to support a wide range of strategic decisions, from capacity planning and technology selection to supplier evaluation and market entry analysis.
Stakeholders must consider how capacity additions in India and adjustments in Europe and North America will affect supply availability and pricing over the forecast horizon. The balance between oil-based and bio-based production is likely to evolve as technology matures and customer preferences shift, presenting both opportunities and risks for producers and buyers. Regional demand patterns will continue to be shaped by downstream industry cycles, infrastructure investment, and regulatory frameworks, making geographic analysis a vital component of strategic planning. Additionally, the concentration of market share among leading players means that competitive moves by major producers can have swift and significant impacts on market dynamics, requiring continuous monitoring and agile response.
Our report equips decision-makers with the analytical tools and data-driven insights needed to navigate these complexities. By synthesizing historical performance, current market conditions, and forward-looking projections, the study offers a comprehensive view of the forces shaping the ECH market through 2032. The analysis goes beyond descriptive trends to provide actionable intelligence, enabling stakeholders to identify growth opportunities, assess risks, and formulate strategies that align with their organizational objectives. Whether the goal is to optimize procurement, evaluate investment options, or strengthen competitive positioning, the depth and rigor of this research provide a solid foundation for informed decision-making.
Inside the Report: Content Architecture and Analytical Depth
The Epichlorohydrin Market research report is structured to deliver both breadth and precision, ensuring that readers gain a holistic understanding of the market while retaining access to the specific data points required for strategic action. The report begins with an executive summary that distills key findings, market drivers, and strategic implications, providing a high-level overview for executives and senior planners. This is followed by a detailed market overview that sets the context, defining the scope of the analysis and outlining the methodology used to generate forecasts and assessments.
A core component of the report is the segmentation analysis, which breaks down the market by region, type, and application. This section provides a nuanced view of how demand and supply are distributed across different segments, highlighting growth rates, share dynamics, and the factors influencing each category. The regional analysis examines the performance of Asia Pacific, North America, Europe, Latin America, and the Middle East and Africa, offering insights into local demand drivers, competitive intensity, and supply chain characteristics. The type analysis explores the oil-based and bio-based segments, assessing technological trends, cost structures, and market adoption. The application analysis delves into epoxy resins, synthetic glycerin, and water treatment chemicals, evaluating demand patterns, end-use trends, and the interplay between application requirements and ECH properties.
The competitive landscape section provides a thorough assessment of key market participants, including their production capacities, technological capabilities, geographic footprints, and strategic initiatives. Profiles of major companies such as DCM Shriram Limited, Olin Corporation, Formosa Plastics Corporation, Aditya Birla Chemicals, Solvay S.A., Sumitomo Chemical Co., Ltd., LOTTE Fine Chemical Co., Ltd., INEOS Group, Meghmani Finechem Limited, Hexion Inc., and Westlake Corporation offer a detailed view of the players shaping the market. This section also analyzes recent developments, capacity changes, and strategic moves that are influencing market dynamics, providing context for understanding competitive positioning and future market evolution.
In addition to segmentation and competition, the report includes an in-depth examination of market dynamics, covering raw material trends, pricing behavior, regulatory influences, and technological developments. This section integrates data on feedstock costs, price movements, and capacity adjustments to provide a comprehensive picture of the forces driving market performance. The forecast section presents projections for the 2026-2032 period, based on a rigorous analysis of historical data, current trends, and anticipated market developments. These forecasts are designed to support planning and decision-making by offering a clear view of the expected trajectory of the market and the key variables that may influence outcomes.
The report also features strategic recommendations and scenario analyses, helping stakeholders interpret the data in the context of their specific objectives and constraints. By considering multiple scenarios and evaluating the potential impact of different market conditions, readers can develop robust strategies that are adaptable to changing circumstances. The inclusion of detailed data tables, charts, and supplementary materials ensures that users have access to the information they need to conduct further analysis and support internal presentations and planning processes.
Conclusion: The Imperative for Deep Market Intelligence
The Epichlorohydrin Market in 2026 is defined by a combination of steady growth, regional complexity, technological transition, and competitive intensity. With the market projected to expand from 2,961.76 million USD in 2026 to 4,039.0 million USD by 2032 at a CAGR of 5.3 percent, the opportunities for value creation are significant. However, realizing these opportunities requires a sophisticated understanding of the market's underlying dynamics, from the interplay of oil-based and bio-based production to the impact of capacity changes in key regions and the volatility of raw material costs.
Our comprehensive market research report provides the depth and precision needed to navigate this landscape with confidence. By integrating historical data, current market intelligence, and forward-looking analysis, the study offers a valuable resource for stakeholders seeking to make informed strategic decisions. The insights contained in the report are designed to support a wide range of applications, from capacity planning and sourcing strategy to competitive analysis and investment evaluation. For those seeking to stay ahead in the ECH market, the full report delivers the detailed intelligence necessary to translate market trends into actionable strategy.
For detailed analysis of this topic, please visit the official page: Epichlorohydrin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Synthetic Fabrics Market to Hit USD 159.58 Billion by 2032, Driven by 5.78% CAGR
By PW Consulting, 2026-09-07
Navigating the Synthetic Fabrics Landscape: Strategic Intelligence for 2026 and Beyond
Executive Overview
The global synthetic fabrics market has entered a phase of mature expansion defined by structural resilience and shifting demand patterns. As enterprises finalize their strategic roadmaps for 2026, understanding the trajectory of this sector is no longer optional. PW Consulting recent market research delivers a comprehensive, data-driven analysis designed specifically to inform capital allocation, supply chain positioning, and product development strategies through the end of the decade.
Digtal Body Composition Monitors Market
This introduction outlines the strategic architecture of our latest study, highlighting the analytical frameworks, competitive intelligence, and real-time industry dynamics embedded within the full report. While we present the foundational market metrics and structural themes here, the complete intelligence package—including granular segmentation breakdowns, proprietary forecasting models, and actionable strategic recommendations—is available exclusively through our dedicated research portal. The purpose of this preview is to demonstrate analytical rigor, establish methodological credibility, and clarify exactly how this research translates into executable corporate strategy.
Worldwide Vertical Mixing Tank Market
Macro Market Trajectory and Structural Context
The synthetic fabrics sector has demonstrated consistent upward momentum over the past half-decade, driven by consumer preference shifts, industrial material substitution, and the ongoing modernization of textile manufacturing capabilities. Historical revenue data from 2020 through 2025 establishes a clear baseline of expansion, with market valuation progressing from the mid-eighty-billion range to exceed the one-hundred-eight-billion threshold by the base year. This trajectory reflects both volume growth and sustained pricing power across core product categories.
Worldwide Air Purification Sensor Market
Our forecasts extend through 2032, mapping a steady growth curve that carries the overall market toward the one-hundred-fifty-nine-billion mark by the terminal forecast year. The projected compound annual growth rate of approximately 5.78 percent underscores a market that is not experiencing explosive disruption but rather achieving disciplined, compounding expansion. This growth profile is particularly valuable for strategic planners because it suggests predictable demand fundamentals, allowing organizations to model capacity investments, inventory strategies, and geographic expansion with higher confidence intervals.
It is important to recognize that these aggregate figures serve as the analytical anchor for deeper segmentation dissection. The full report deconstructs how specific product architectures, end-use verticals, and regional manufacturing ecosystems interact to produce the headline numbers. By isolating the underlying drivers rather than relying on top-line projections alone, enterprise strategists can identify which value pools will expand most rapidly, which segments face margin compression, and where substitute-material competition is likely to reshape pricing dynamics.
Report Architecture: Core Analytical Modules
Our Synthetic Fabrics Market research is engineered to function as a desktop reference for multiple corporate functions simultaneously. The publication is structured around interconnected analytical modules, each designed to answer a distinct strategic question while feeding into the broader market narrative.
Demand-Side Segmentation Analysis
The report dissects consumption patterns across major application channels, including apparel, home furnishing, automotive interiors, healthcare textiles, and diversified industrial categories. Rather than presenting static market share snapshots, our analysis maps the evolution of demand drivers within each vertical. For example, the study tracks how performance requirements in automotive seating and interior trim are shifting toward lighter, more durable synthetic variants, while healthcare applications continue to prioritize antimicrobial and moisture-management synthetic constructs. The full publication provides detailed volume and revenue trajectories for each application channel, alongside sensitivity scenarios that account for consumer spending shifts, regulatory mandates, and supply chain restructuring.
Product-Type and Material Architecture
Material composition remains the fundamental axis of competitive differentiation. Our research categorizes the market by primary synthetic fiber types and evaluates how relative pricing, technical performance, and sustainability attributes influence procurement decisions. The study examines the dominance of mainstream polyester volumes, the specialized positioning of nylon and acrylic variants, and the expanding footprint of polyolefin-based constructs. Each material segment is assessed for its cost structure, processing requirements, and end-use compatibility. The report further cross-references material choices against regional manufacturing capabilities, allowing readers to understand where local production advantages or feedstock advantages create structural moats.
Regional Manufacturing and Demand Ecosystems
Geography continues to shape competitive positioning, logistics strategy, and tariff exposure. The research maps demand concentration and production capacity across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Rather than offering simple regional revenue splits, the full study investigates the industrial infrastructure, trade flow dynamics, and policy environments that define each geography. This includes analysis of port logistics, duty regimes, local content requirements, and the relative maturity of domestic synthetic fiber manufacturing. Strategists can use this framework to evaluate market entry timing, sourcing reconfiguration, and export opportunity sizing.
To preserve analytical exclusivity and encourage direct engagement with the complete dataset, precise regional percentage distributions and isolated application-level revenue breakdowns are intentionally withheld from this preview. The full research deliverable contains the complete segmentation matrices required for detailed financial modeling and market entry planning.
Raw Material Economics and Supply Chain Dynamics
The profitability and pricing flexibility of synthetic fabric producers are deeply tied to upstream feedstock economics. Our research integrates real-time commodity intelligence to map how shifts in raw material pricing cascade through the value chain. Recent monitoring indicates notable cost pressure in key precursor markets. In Northeast Asia, adipic acid pricing reached levels above 1.23 USD per kilogram in March 2026, reflecting a substantial increase from the prior year-end period. This movement has been attributed to rising cyclohexane and nitric acid feedstock costs, directly influencing the cost base for nylon and related synthetic intermediates.
Simultaneously, acrylic acid pricing in North America climbed to approximately 1.71 USD per kilogram by May 2026, driven by escalating propylene and energy costs. These upstream fluctuations introduce margin volatility for fabric producers who lack diversified sourcing or hedging frameworks. Our report incorporates scenarios that project how sustained feedstock cost escalation could compress industry margins, accelerate consolidation, and incentivize material substitution in cost-sensitive applications. The analysis also evaluates which manufacturers possess the scale, backward integration, or contractual flexibility to absorb cost shocks more effectively than competitors.
Competitive Landscape and Strategic Positioning
The synthetic fabrics market exhibits moderate concentration, with the top three firms collectively representing a substantial share of industry revenue and the top five approaching majority coverage. This structure creates a landscape where scale, technological differentiation, and vertical integration determine competitive outcomes. Our research provides detailed corporate profiles, strategic capability assessments, and competitive positioning maps for the sector leading enterprises.
DuPont de Nemours maintains a distinctive competitive identity through its focus on high-performance synthetic constructs, most notably Kevlar aramid fibers and Nomex flame-resistant fabrics. The company strategic emphasis on protective and industrial applications positions it to benefit from regulatory-driven demand in safety-critical sectors. The full report evaluates DuPont pricing strategies, application expansion initiatives, and how its specialty material portfolio withstands cyclical downturns in general apparel demand.
Toray Industries anchors its competitive strategy in broad-spectrum synthetic textile production spanning polyester, nylon, and acrylic fibers. Its portfolio includes differentiated constructs such as silky polyester variants designed for premium apparel, alongside composite materials tailored for industrial uses. The research assesses Toray manufacturing scale, regional customer relationships, and the company ability to leverage material science expertise to capture value at both the commodity and specialty ends of the spectrum.
Teijin Limited has carved a strong position in high-performance synthetic fibers, with particular emphasis on ultra-fine polyester nanofiber fabrics and technical materials engineered for advanced applications. Recent technological advancements in separability and fiber fineness have expanded the functional envelope of its product lines, allowing incorporation into lightweight technical textiles and specialized performance requirements. The report examines how Teijin innovation cadence compares against industry peers, and where its technical material capabilities create defensible differentiation.
Lenzing AG occupies a strategically interesting position by offering wood-based, synthetic-like lyocell fibers that serve as sustainable alternatives within breathable fabric and stretch applications. The perception of environmental compatibility has become a commercially meaningful attribute, particularly as downstream brands face pressure to reduce synthetic carbon footprints and improve circularity narratives. Our study explores how Lenzing certification achievements and fiber performance characteristics influence procurement preferences among sustainability-oriented end-users.
INVISTA continues to emphasize spandex elastane and nylon 6,6 fibers as foundational inputs for performance synthetic fabrics in both apparel and technical textile applications. The company strategic focus on stretch, recovery, and structural performance attributes aligns with ongoing demand for functional apparel and engineered textile solutions. The full report analyzes INVISTA market share dynamics, formulation advantages, and how its core product lines interact with broader textile construction trends.
Regulatory Catalysts and Sustainability-Driven Demand
Regulatory developments and certification milestones are increasingly shaping market structure, procurement criteria, and brand communication strategies. Our research integrates these regulatory signals to assess how compliance requirements and voluntary sustainability standards redirect demand and alter competitive positioning.
In early 2026, Lenzing lyocell fibers received TÜV AUSTRIA certification for biodegradability across soil, freshwater, and marine environments. This regulatory validation strengthens the commercial narrative around bio-based synthetic alternatives and provides downstream brands with credible claims that resonate with sustainability commitments. The full report evaluates how this certification influences procurement decisions, price elasticity, and competitive pressure on conventional synthetic fiber suppliers.
On the innovation frontier, Teijin Frontier advanced its new sea and island separable fiber technology, enabling production of ultra-fine polyester nanofiber fabrics with fiber dimensions around 700 nanometers. Advancements of this caliber expand the technical boundaries of synthetic textiles, enabling new performance characteristics in filtration, protective garments, and high-end fabric finishes. The research tracks how such technological milestones translate into commercial adoption timelines, licensing opportunities, and market segmentation shifts.
Sustainability regulation, circular material mandates, and carbon disclosure expectations continue to influence procurement specifications across major consumer and industrial buyers. The report maps the intersection of regulatory pressure, certification availability, and material substitution trends to help strategists anticipate which product attributes will become procurement requirements in the coming years.
Strategic Implications for 2026 Decision-Making
Enterprises approaching 2026 planning cycles need intelligence that goes beyond headline forecasts. The Synthetic Fabrics Market research is designed to support concrete strategic actions across several decision domains.
First, the study provides the baseline data required to evaluate capacity expansion timing. With aggregate market growth trending toward the one-hundred-fifty-nine-billion range by 2032 and a mid-single-digit growth rate, organizations must determine whether incremental capacity additions, acquisition-driven scale expansion, or regional capacity relocation offers the most favorable risk-adjusted returns. Our analysis clarifies which segments justify dedicated capacity and which remain better served through contract manufacturing arrangements.
Second, the research supports sourcing strategy reassessments. Raw material cost volatility, feedstock concentration risks, and shifting tariff environments require dynamic supplier portfolio management. The report identifies structural cost drivers, regional price differentials, and the implications of upstream commodity trends for procurement resilience. This enables sourcing leaders to balance cost optimization with supply security.
Third, competitive positioning and product portfolio strategy benefit directly from the segmentation analysis. Organizations can use the full dataset to determine whether to compete on volume, performance, or sustainability differentiation, and to quantify the market opportunity associated with each strategic orientation. The report also highlights where convergence between apparel performance expectations and technical textile requirements is creating cross-vertical demand opportunities.
Finally, the research supports investor-facing and corporate development narratives by providing defensible market sizing, growth drivers, and competitive benchmarking. Whether the objective is market entry justification, partnership evaluation, or portfolio rationalization, the study supplies the analytical scaffolding needed to defend strategic decisions internally and externally.
Why This Research Pays for Itself
Many market summaries offer high-level numbers without the analytical architecture required for strategic execution. PW Consulting report is built to function as a working intelligence asset rather than a static reference document. It combines macro forecasting, segmentation depth, raw material tracking, competitive profiling, and regulatory monitoring into a single integrated framework. This allows strategists to trace the lifecycle of a market trend from upstream cost signals through material selection, regional demand, competitive response, and downstream procurement behavior.
The full report also includes scenario modeling capabilities, enabling users to adjust assumptions around feedstock pricing, consumer demand elasticity, and regulatory adoption curves. By providing this flexibility, the research becomes a living tool for quarterly strategy reviews, budget preparation, and tactical market response rather than a one-time read.
Accessing the Complete Intelligence Package
This preview demonstrates the analytical depth, structural rigor, and strategic relevance embedded in our latest Synthetic Fabrics Market research. While the macro trajectory, competitive profiles, raw material dynamics, and regulatory catalysts introduced here illustrate the scope of the study, the complete deliverable contains the granular segmentation data, detailed regional and application-level breakdowns, and full competitive benchmarking matrices necessary for precise strategic planning.
To obtain the complete dataset, scenario models, and proprietary market estimates, enterprise decision-makers should access the full report through our dedicated research portal. The publication is structured to be immediately actionable for strategy, sourcing, product development, and corporate development teams seeking to align their 2026 plans with a clear, evidence-based view of the synthetic fabrics market.
For detailed analysis of this topic, please visit the official page: Synthetic Fabrics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pheromones Market to Hit $366.2M by 2032 with 8.45% CAGR
By PW Consulting, 2026-09-07
Strategic Olfaction: Navigating the Pheromone Market Trajectory Through 2032
The global pheromones market stands at a critical inflection point where biochemical innovation intersects with urgent agricultural sustainability mandates. As conventional pesticide resistance escalates and regulatory frameworks tighten around chemical residues, semiochemical-based solutions have transitioned from niche alternatives to central pillars of integrated pest management. Our latest comprehensive research delivers a granular, forward-looking assessment of this rapidly maturing sector, equipping executives, investors, and product strategists with the analytical rigor required to position portfolios for sustained advantage. The following overview outlines the strategic architecture of the study, highlights the macroeconomic forces reshaping supply and demand, and demonstrates how data-driven foresight translates directly into 2026决策 frameworks.
Worldwide Hybrid Cloud Platform Market
The Macro Landscape: A Decade of Structural Expansion
Historical performance patterns reveal a sector that has consistently outperformed broader agrochemical benchmarks. From a baseline valuation in 2020, the industry has navigated through periods of supply chain recalibration, formulation breakthroughs, and accelerated farmer adoption across diverse crop systems. By 2025, market revenue crossed a pivotal threshold, demonstrating resilience even amid volatile input costs and shifting trade architectures. Looking ahead, the forecast horizon through 2032 projects a compound annual growth rate of 8.45 percent, a trajectory underpinned by expanding application matrices, regulatory tailwinds for non-toxic controls, and sustained capital deployment into scalable synthesis platforms. This growth cadence is not linear; it reflects shifting intensity across crop categories, geographic penetration rates, and technology adoption curves that our research isolates through multi-variable modeling.
Worldwide Classic Steak Cuts Market
The forward revenue mapping illustrates how early adoption cycles compound into mainstream integration. By the mid-2020s, established distribution networks and proven efficacy data begin driving annualized volume expansions that outpace traditional chemical segments. As formulation economics improve and manufacturing scale deepens, the revenue architecture transitions from experimental deployment to routine agronomic planning. Understanding where these inflection points materialize, which crop profiles accelerate uptake, and how pricing structures evolve across maturity phases requires the kind of segmented forecasting embedded in our methodology. Executives leveraging these projections can align R&D pipelines, inventory planning, and channel partnerships with the precise windows where investment yields compound most efficiently.
3-Amino-1-adamantanol Market
Report Architecture: Translating Complexity Into Actionable Intelligence
A market research deliverable only earns executive shelf space when it bridges analytical depth with operational deployment. Our study is structured to serve multiple decision-making functions without forcing leaders to navigate redundant or superficial content. The core framework spans demand-side adoption drivers, supply-side synthesis economics, competitive positioning matrices, and scenario-based forecasting that stress-tests assumptions against regulatory shifts, raw material volatility, and trade policy recalibration.
Operational sections are designed for immediate translation into corporate planning cycles:
- Executive dashboards that consolidate baseline valuations, growth vectors, and concentration metrics for rapid board-level alignment.
- Segmentation analyses that map how different product categories and application methodologies diverge in velocity, margin structure, and regional penetration.
- Supply chain diagnostics examining precursor sourcing, synthesis bottlenecks, formulation scalability, and the impact of trade policy on cost structures and lead times.
- Competitive profiling that evaluates incumbent scale, specialty positioning, partnership architectures, and emerging disruptor pipelines.
- Scenario modeling that projects how tariff adjustments, regulatory approvals, and input cost fluctuations alter revenue trajectories across alternative macro environments.
Each analytical module is cross-referenced with primary market signals and secondary validation sources, ensuring that projections are grounded in observable adoption behavior rather than speculative extrapolation. The result is a reference document that can inform capital allocation, market entry timing, partnership strategy, and risk hedging simultaneously.
Competitive Architecture: Scale, Specialization, and Strategic Collaboration
The competitive landscape reflects a blend of established chemical manufacturers, specialized pheromone producers, and agile innovators repositioning biological controls into mainstream crop protection portfolios. Market concentration metrics indicate that the top three players capture approximately 35.7 percent of aggregate revenue, while the top five collectively account for roughly 48.9 percent. This distribution suggests a sector where leadership is substantial but not impenetrable, leaving meaningful room for differentiated technology, localized manufacturing, and partnership-driven market access.
Established participants illustrate distinct strategic postures. Russell IPM has built recognition around pheromone-based monitoring and control systems, emphasizing precision deployment and agronomic integration. Shin-Etsu Chemical approaches the category through its specialty chemicals and functional materials platform, leveraging broader chemical engineering capabilities to support formulation consistency and scale. Trécé operates through a portfolio of recognized brands that span pest management, monitoring, and storage protection, positioning pheromone solutions within broader integrated systems rather than as standalone products. FMC Corporation has advanced pheromone production through yeast fermentation pathways, expanding the viability of mating disruption for row crops at commercial scale. ISCA Technologies and Koppert Biological Systems both emphasize semiochemical and biological integration, aligning pheromone deployment with wider ecological management strategies. Suterra and Pacific Biocontrol continue to refine dispenser design and crop-specific application protocols, while Provivi has focused pioneering work on mating disruption technologies that reduce reliance on broad-spectrum chemical interventions.
Recent corporate activity demonstrates that the sector is moving beyond standalone product launches toward ecosystem-building strategies. In early 2025, FMC Corporation secured its first product registration for a pheromone targeting fall armyworm, a milestone that signals regulatory pathway maturation for fermentation-derived mating disruption in high-pressure pest environments. Shortly thereafter, a biodegradable dispenser line entered the market for organic pome, stone, and chestnut applications, reflecting growing demand for compliant, residue-conscious delivery systems. Strategic alliances have also accelerated geographic expansion: a notable partnership in late 2024 introduced rice and corn dispenser solutions in India, combining local distribution capabilities with advanced formulation expertise. In parallel, a landmark distribution agreement in mid-2024 positioned a sprayable pheromone solution for Western corn rootworm across European markets, illustrating how channel partnerships can compress time-to-market for specialized application formats.
These developments are not isolated events; they are indicators of structural change. Companies that pair proprietary synthesis or dispenser technology with localized regulatory navigation and distribution partnerships are gaining asymmetric advantages in regions where pest pressure, cropping intensity, and sustainability mandates intersect. Our report dissects these positioning patterns to help stakeholders identify where collaboration, acquisition, or differentiated R&D will generate the highest marginal returns.
Macroeconomic and Regulatory Forces Reshaping Supply and Demand
No pheromone market strategy can be isolated from the broader trade and input-cost environment. The period following 2024 introduced a cascade of policy adjustments and supply chain reorientations that directly affect chemical input availability, formulation economics, and regional pricing architecture. In early 2025, US chemical imports experienced a sharp pre-tariff surge as buyers accelerated procurement ahead of reciprocal trade measures, disrupting short-term inventory planning and temporarily elevating landed costs. Subsequent policy actions imposed aggressive reciprocal tariffs effective in April 2025, with select chemical categories facing duties that reached meaningful levels, particularly for sourcing channels tied to China. The resulting import contraction was substantial, with year-on-year declines in the second quarter of 2025 reflecting both price sensitivity and deliberate supply diversification.
These trade dynamics have practical implications for pheromone producers and downstream users alike. Effective tariff rates on chemical imports moved into a higher structural band after reciprocal adjustments took effect, altering the cost basis for precursor materials and finished formulations that depend on cross-border chemical flows. Simultaneously, raw material inputs used in pheromone production experienced sustained price escalation over the preceding years due to the specialized nature of chemical synthesis and the tightening of qualified supplier networks. When synthesis complexity combines with trade friction, margin management becomes a function of formulation efficiency, regional sourcing strategy, and manufacturing footprint optimization rather than simple procurement negotiation.
On the demand side, regulatory momentum continues to strengthen the case for semiochemical-based controls. Restrictions on broad-spectrum residues, increasing retailer and consumer expectations around residue-conscious production, and farmer willingness to adopt mating disruption in high-value cropping systems all reinforce adoption trajectories. Yet adoption is not uniform. Regions with mature IPM frameworks, strong extension services, and accessible subsidy or certification incentives exhibit faster uptake, while markets with limited technical support or fragmented distribution show slower conversion. Understanding these adoption gaps, and the specific interventions required to close them, is central to realistic forecasting and market-entry planning.
Strategic Applications for 2026 Decision-Making
As organizations prepare their 2026 operating plans, the pheromone sector offers a uncommon combination of growth visibility and strategic optionality. The key is converting market trajectory into precise portfolio moves rather than broad directional bets. Our research is designed to support that translation through several decision lenses.
For product and R&D leadership, the report isolates where formulation complexity, dispenser reliability, and application convenience converge to drive farmer adoption. Not all pest systems respond equally to pheromone-based control; some require mating disruption at scale, others benefit from monitoring-triggered interventions, and still others gain most from mass trapping in concentrated deployment zones. Mapping these use-case distinctions against manufacturing feasibility and regulatory pathways allows teams to prioritize development efforts where performance differentiation is both technically achievable and commercially defensible.
For commercial and channel strategy, the analysis examines how distribution architectures, local registration capability, and partnership models influence market penetration speed. In regions where trade policy and input costs create volatility, local formulation or dispersal partnerships can reduce landed-cost exposure and accelerate regulatory clearance. In markets with strong organic or residue-conscious certification pathways, biodegradable dispensers and sprayable formats can unlock premium positioning and tighter alignment with sustainability mandates. The strategic question is not simply where demand exists, but which commercial model converts that demand into durable share.
For supply chain and procurement planning, the research provides the context needed to stress-test sourcing assumptions against synthesis bottlenecks, precursor pricing trends, and tariff-induced rerouting. Companies that model multiple procurement and production scenarios can better evaluate whether to consolidate synthesis internally, diversify precursor sourcing, or adjust finished-product manufacturing geography to preserve margin integrity under shifting trade conditions. The ability to anticipate cost-structure inflection points is a direct source of competitive resilience.
For investors and corporate development teams, the market concentration profile and recent partnership activity highlight where consolidation, capability acquisition, or venture engagement may generate outsized returns. The presence of both scaled incumbents and agile innovators means that transaction opportunities span a wide spectrum, from niche formulation assets to regional distribution platforms and advanced dispenser technologies. Identifying which assets carry durable moats versus transient positioning requires the kind of segmented demand and competitive analysis embedded in the full study.
Why the Full Study Is Essential for Forward Planning
Market summaries and headline growth figures can orient a strategy discussion, but they rarely provide the resolution required to commit capital, redesign product roadmaps, or restructure channel partnerships. The complete research deliverable closes that gap by offering detailed segmentation navigation, scenario-tested forecasts, competitive capability mapping, and supply-side cost diagnostics that collectively support precise decision-making. It connects macro trajectory to segment-level behavior, enabling leaders to distinguish between temporary demand blips and durable structural shifts. It also contextualizes recent corporate developments within longer technology and regulatory cycles, helping teams separate marketing momentum from execution-ready opportunity.
Most importantly, the study is built to be used. Its analytical layers are organized so that strategy, commercial, supply chain, and investment functions can extract the specific inputs they need without reconstructing the underlying assumptions. Whether the objective is to time a market entry, prioritize a formulation platform, structure a distribution alliance, or hedge against input-cost volatility, the report's architecture supports those choices with evidence rather than intuition.
Positioning for the Next Phase of Market Evolution
The pheromones sector is entering a phase where technological maturation, regulatory alignment, and farmer adoption reinforce each other more consistently than in prior cycles. That convergence creates opportunity, but only for organizations that can read the underlying mechanics rather than the surface narrative. Growth will continue to be shaped by synthesis scalability, dispenser and application innovation, regional regulatory pathways, and the ability to integrate pheromone-based controls into broader crop management systems. Companies that treat these factors as interconnected variables rather than isolated market features will be best positioned to capture the forward revenue trajectory projected through the end of the decade.
Our comprehensive market research provides the structured intelligence required to navigate that complexity with confidence. By combining baseline valuation context, forecast modeling, competitive profiling, and trade-and-input dynamics into a single decision-ready framework, the study transforms market movement into actionable strategy. For leaders preparing 2026 plans and beyond, the distinction between incremental participation and strategic advantage will depend on how precisely they can align their portfolios with the segment-level forces that actually drive value creation. The full report delivers that resolution, enabling informed commitments rather than speculative positioning.
For detailed analysis of this topic, please visit the official page: Pheromones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


