



Category: market research
PW Consulting: Hemp-Based Foods Market Hits $160M in 2025, Projected 6.5% CAGR to 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for the Hemp-Based Foods Market: Navigating Growth, Volatility, and Competitive Shifts in 2026
Market Trajectory and the Strategic Imperative for 2026
The global hemp-based foods market has transitioned from a niche wellness segment to a structurally significant category within the broader plant-based and functional nutrition landscape. According to PW Consulting’s latest market research, the sector has demonstrated consistent expansion across the historical review period, with industry revenue climbing from approximately 100.0 million USD in 2020 to an estimated 160.0 million USD in 2025. This upward trajectory reflects sustained consumer interest in nutrient-dense, sustainably sourced ingredients, as well as progressive regulatory normalization in several key markets.
Worldwide Standalone UPS Market
Looking ahead, the forecast period from 2026 through 2032 signals a measured but durable growth pathway. The research projects a compound annual growth rate of 6.5 percent, positioning the market to reach approximately 246.41 million USD by the close of the forecast window. These macro-level indicators do more than chart a growth curve; they provide strategic leaders with a foundational reference for capacity planning, ingredient sourcing commitments, and product pipeline prioritization. Yet, as with any fast-evolving category, the headline figures only tell part of the story. The real strategic value lies in understanding how regional demand patterns, application-driven consumption, and ingredient-type dynamics interact to shape competitive advantage.
Gas Proportional Valve Market
For executives evaluating market entry, portfolio allocation, or partnership opportunities in 2026, this research is designed to convert high-level growth signals into actionable intelligence. Rather than offering generic category commentary, the report maps the operational and commercial levers that will determine which organizations can scale efficiently, protect margins amid commodity fluctuations, and capture share in a market that remains relatively fragmented at the top.
Intra-city Logistics Market
Why This Research Matters for Enterprise Decision-Making
Market research in emerging food ingredient categories often falls into one of two traps: it either stays too abstract to guide operational planning, or it buries decision-makers in disconnected data points. The PW Consulting Hemp-Based Foods Market study is built to bridge that gap. It is structured as a decision-support instrument, meaning each section is intended to feed directly into strategic workflows such as go-to-market planning, supplier evaluation, pricing architecture, and competitive benchmarking.
One of the most immediate applications of the report is in scenario planning. Because the category sits at the intersection of agriculture, food manufacturing, and evolving consumer wellness trends, organizations need a clear view of how historical performance sets the baseline for future forecasting. The research provides a connected view of market sizing across the review and forecast years, enabling leaders to test assumptions around demand elasticity, product launch timing, and channel expansion. This is particularly relevant for companies that must align capital expenditures with realistic adoption curves rather than optimistic narratives.
Equally important, the report is designed to help teams separate structural growth from short-term promotional spikes. In categories where retail visibility can shift quickly, it is easy to mistake temporary shelf momentum for durable demand. By grounding analysis in a multi-year framework, the research allows executives to evaluate whether observed trends are likely to persist, intensify, or normalize. That distinction can determine whether a company overcommits to inventory, underinvests in product development, or sequences its market engagement with greater precision.
Report Architecture and Operational Content
The study is organized to support a wide range of internal use cases, from board-level market overviews to category-manager-level tactical planning. Its architecture moves from macro foundations to more granular commercial analysis, while maintaining a consistent focus on practical application. The core components include:
- A connected market sizing framework that traces historical performance and extends through the forecast horizon, giving organizations a unified reference for trend analysis and planning assumptions.
- A structural breakdown of the market by region, type, and application, intended to clarify where demand is forming, how product formats are differentiating, and which consumption pathways are driving volume.
- Competitive landscape profiling that examines the strategies, positioning, and operational focus of leading companies shaping the category.
- An assessment of market concentration and competitive dispersion, helping leaders understand the balance between established incumbents and the room available for new entrants or niche innovators.
- Dynamic market drivers and constraints, including pricing behavior, retail visibility shifts, ingredient availability considerations, and the regulatory and labeling environment that influences product development and consumer trust.
Each section is intended to be modular, so that strategy, sales, supply chain, and innovation teams can extract the relevant insights without needing to parse an undifferentiated block of analysis. The report does not simply describe what is happening; it provides a conceptual framework for why it matters and how different stakeholders can act on it. For example, pricing and retail-advertising trends are discussed not as isolated data points, but as indicators of promotional intensity, channel momentum, and potential margin pressure. Similarly, segmentation analysis is presented to help identify where product-formulation opportunities and demand concentration are most likely to create differentiated value.
Competitive Landscape: Navigating a Fragmented but Evolving Field
A defining characteristic of the hemp-based foods market is the presence of a diverse set of participants spanning ingredient supply, branded consumer products, and integrated processors. PW Consulting’s research profiles several companies that illustrate the different strategic postures now competing for share. These include organizations such as Nutiva, based in Berkeley, California, which has built its identity around organic hemp seed oil and hemp protein powder within the broader hemp-based foods space. Manitoba Harvest, headquartered in Winnipeg, Manitoba, operates as a producer and marketer of hemp seeds, protein powders, and related food products and is part of Tilray Brands. Canada Hemp Foods Ltd. serves as a supplier of hemp seed hearts, oil, and bulk ingredients for hemp-based foods and recipes, while Hemp Foods Australia provides organic hemp protein powder, seed oil, and hemp-based foods in its regional market.
The competitive field also includes upstream and processing-oriented players that support the broader value chain. Agropro operates as an upstream supplier of high-quality hemp seeds and ingredients for food manufacturers. Hempco functions as a hemp processing and ingredients provider for food applications. Elixinol is engaged in hemp ingredients and hemp-based food product development, and The Cool Hemp Company serves as a hemp seed and food ingredient supplier. Fresh Hemp Foods Ltd. has an early-mover profile as a developer and supplier of hulled hemp seed, hemp seed protein powder, and hemp seed oil for foods. Together, these profiles reflect a market in which ingredient quality, processing capability, and brand positioning can each become decisive differentiators.
From a strategic standpoint, the research uses these company profiles not as a simple directory, but as a lens into competitive logic. Some organizations compete primarily through organic positioning and consumer brand trust. Others compete through supply reliability, ingredient consistency, and the ability to serve industrial and food-manufacturing customers at scale. The report examines how these differing value propositions interact with market fragmentation and concentration patterns. In particular, the analysis highlights that the top three competitors account for approximately 22.5 percent of market revenue, while the top five represent roughly 28.0 percent. This dispersion suggests that while recognizable brands and established processors hold meaningful influence, the category still contains substantial headroom for specialized players, regional leaders, and product-formulation innovators.
For 2026 decision-making, this competitive structure matters because it shapes both opportunity and risk. In a market where no single entity dominates, companies can still face intense competition on formulation, price perception, and shelf visibility. At the same time, the dispersion creates openings for organizations that can move faster on product innovation, build credible sourcing narratives, or secure advantageous supply arrangements. The report’s competitive analysis is therefore designed to help leaders identify which battles are worth fighting, which partnerships may accelerate scale, and where differentiation is most defensible.
Market Dynamics: Pricing Signals, Retail Behavior, and Category Momentum
Beyond structure and competition, the hemp-based foods market is shaped by a set of operational dynamics that can materially affect margins, campaign planning, and product architecture. Recent retail pricing and advertising signals captured in USDA AMS Specialty Crops Market News illustrate how quickly category visibility and price perception can shift. In May 2026, the National Weekly Hemp Report recorded a national weighted average price for hemp protein in 16 oz packages at 13.61 USD, hemp seeds in 8 oz packages at 8.36 USD, and organic hemp seeds in 7 oz packages at 10.87 USD. The same report noted that the advertising total rose sharply, with multiple retailers featuring hemp items during the reporting period.
Earlier in the year, the January 2026 reporting showed a different pattern: organic hemp seeds in 12 oz and 7 oz packages decreased by 12 percent, while the overall advertising total increased 47 percent week-over-week. This combination of unit-price movement and rising promotional visibility is strategically informative. It suggests that retail engagement with hemp-based foods can expand even as per-unit pricing adjusts, a dynamic that can influence both consumer accessibility and retailer commitment to shelf space. For manufacturers and brand owners, these movements are not just background noise; they are early indicators of how the category is being positioned in the trade environment.
Such dynamics also underscore the importance of separating short-term promotional effects from underlying demand trends. When advertising totals jump and price points move in tandem, it can be tempting to read the moment as either strong adoption or temporary discounting. The report contextualizes these signals within the broader market framework so that executives can interpret them with more discipline. Are retailers experimenting with hemp products as a growth adjacency? Are price reductions intended to build trial, clear inventory, or respond to input-cost pressure? Is the category gaining structural placement in certain retail formats, or is visibility concentrated in promotional cycles? These are the kinds of questions the research is built to help leadership teams answer more decisively.
Segmentation Logic as a Strategic Planning Tool
Segmentation is often treated as a descriptive exercise, but in a category like hemp-based foods it can serve as a practical planning tool. The market can be understood through multiple lenses, including geography, product type, and application. Each lens reveals a different aspect of where value is created and where execution risks may arise.
Regional analysis helps decision-makers recognize that demand does not develop uniformly across markets. Different regions can exhibit different adoption speeds, retail structures, and ingredient supply realities. The research uses regional segmentation to support judgments about where to prioritize market development efforts, where distribution partnerships may be most valuable, and where regulatory or consumer-education hurdles could alter timelines. Rather than presenting region as a static ranking, the report frames it as a strategic map for sequencing investment and managing expectations.
Type-based segmentation provides a complementary view by distinguishing among product formats and ingredient expressions. Edible hemp products, beverages, and other hemp-based foods each carry different formulation challenges, usage occasions, and consumer expectations. A company’s exposure to one format versus another can influence everything from sourcing strategy to packaging decisions to channel selection. By analyzing these type distinctions within a connected market framework, the report helps organizations understand how product architecture choices may affect growth potential and competitive positioning.
Application-based segmentation further sharpens the picture by separating human consumption from industrial uses. This distinction matters because the demand drivers, purchasing processes, and margin structures associated with each pathway are not interchangeable. Human consumption typically aligns with consumer-brand dynamics, retail visibility, and taste or wellness positioning, while industrial uses often depend on ingredient consistency, supply reliability, and manufacturing integration. The research uses this application lens to help leaders evaluate whether their strategy should lean closer to consumer-facing product development or to ingredient supply and B2B relationships. In practice, the most resilient strategies often reflect a clear understanding of which application pathway offers the best fit for a company’s capabilities and capital posture.
Using the Forecast Period to De-Risk 2026 Planning
Forecasting in a developing food category is never about predicting a single fixed future. It is about building a usable range of expectations that can inform budgeting, hiring, sourcing, and product investment. The forecast window in this research extends from 2026 through 2032, allowing organizations to examine not only the near-term year but also the sequence of growth that may shape medium-term strategy. That longer view is especially valuable for companies that must make today’s decisions in anticipation of future category saliency, retail readiness, and ingredient supply maturity.
For 2026 specifically, the forecast provides a reference point for evaluating whether current operational plans are aligned with the likely pace of category expansion. If a company’s growth assumptions are substantially more aggressive than the market trajectory, the discrepancy may signal the need to clarify what additional advantages—such as exclusive supply, superior formulation, or accelerated retail placement—would be required to outperform the broader category. Conversely, if assumptions are overly conservative, the organization may be underinvesting in an opportunity that warrants a more deliberate push. The research is designed to make these comparisons explicit so that leadership can calibrate ambition against evidence.
The forecast also helps frame portfolio decisions. In a market growing at a steady but not explosive pace, the winners are often not simply those who chase the largest headline number, but those who align their product mix, cost structure, and channel strategy with the segments and dynamics most likely to compound over time. By providing a multi-year view, the report gives executives a better basis for judging whether a product launch, capacity upgrade, or market-entry move is appropriately timed. Timing errors are costly in food categories, where shelf resets, retailer conversations, and consumer trial patterns can be difficult to accelerate artificially.
Who Should Use This Research and How
This study is intended for a broad but focused audience of strategic decision-makers. Corporate strategy teams can use it to frame market-entry evaluations, portfolio prioritization, and long-range planning assumptions. Commercial and category leaders can draw on it to assess where hemp-based foods are gaining traction, how product formats are differentiating, and what retail dynamics may influence launch timing. Supply chain and procurement teams can use the competitive and dynamic sections to better understand supplier positioning, ingredient flow considerations, and the pricing context that affects sourcing negotiations. Innovation and product development teams can use the segmentation and application analysis to identify formulation pathways with the strongest strategic fit.
The report is also useful for investors and partners seeking a structured view of the category beyond surface-level headlines. Because it connects historical sizing, forward-looking growth, competitive dispersion, and market dynamics, it provides a more complete foundation for evaluating opportunity and risk. Rather than treating the market as either a breakout phenomenon or a marginal trend, the research supports a more disciplined interpretation of where hemp-based foods stand today and what kind of execution will matter most in 2026 and beyond.
Conclusion: Turning Category Intelligence into Competitive Advantage
The hemp-based foods market is entering a phase in which strategic clarity matters more than ever. Growth is real, but it is not automatic. Companies that succeed will be those that understand not just the size of the opportunity, but the structure of the market, the behavior of key competitors, the influence of pricing and retail dynamics, and the segmentation choices that shape product and channel strategy. PW Consulting’s Hemp-Based Foods Market research is built to provide that understanding in a form that can be used directly in executive planning and operational decision-making.
For leaders preparing for 2026, the report offers a practical way to move from informed curiosity to precise action. It establishes the macro context, maps the competitive field, and examines the dynamics that can alter margins and momentum. What it deliberately does not do is replace the need for deeper commercial due diligence where specific segmentation values, regional breakdowns, and detailed application splits matter most. Those precision-level insights are reserved for the full study, where they can be reviewed in the context required for high-stakes planning.
In a category where the difference between a good decision and a great one often comes down to granularity, the full report is designed to give decision-makers the complete picture. For organizations serious about positioning themselves in hemp-based foods, the next step is to access the comprehensive analysis and translate these strategic signals into a concrete plan for growth, resilience, and competitive differentiation.
For detailed analysis of this topic, please visit the official page: Hemp-based Foods Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Touch Probes Market Hits $215M in 2025, Forecasts 4.5% CAGR to 2032
By PW Consulting, 2026-09-07
Strategic Imperatives in the Touch Probes Market: A 2026 Leader's Guide to Capitalizing on Metrology Evolution
The precision manufacturing ecosystem is undergoing a subtle yet profound transformation. While macro-economic headwinds often dominate headlines, the machinery sector responsible for dimensional accuracy is experiencing steady, structural expansion. For enterprise decision-makers, understanding the trajectory of the Touch Probes Market is no longer a niche concern; it is a critical component of supply chain resilience, quality assurance strategy, and capital expenditure planning. Our latest comprehensive market research, covering historical performance through 2025 and projecting forward to 2032, provides the granular intelligence required to navigate this landscape.
Worldwide PV Interconnect Wires Market
This article serves as a strategic overview, outlining the macro-economic forces, competitive dynamics, and regulatory currents shaping the sector. By contextualizing the broader market trajectory, we aim to demonstrate why deep-dive intelligence is essential for 2026 planning. While we outline the structural reality here, the precise segmentation data and forward-looking quantitative models remain exclusive to our full report. Acquiring the complete intelligence is the only way to secure a definitive edge in your specific operational context.
Worldwide Unbleached Parchment Market
Market Trajectory and Macro Economic Indicators
The historical data from 2020 through 2025 reveals a market characterized by resilience and moderate but consistent growth. Following a period of volatility in the early 2020s, the market demonstrated a clear ability to recover and stabilize, reaching a baseline revenue of 215.0 Million USD in 2025. This foundational strength sets the stage for a forecast period from 2026 to 2032 that analysts have identified as critical for infrastructure modernization and automated integration.
Worldwide Multifunctional Wheelchair Market
Projecting forward, the industry is expected to grow at a Compound Annual Growth Rate of 4.5 percent. This outpaces many traditional mechanical hardware sectors, driven primarily by the increasing adoption of in-process inspection and the reduction of manual measurement errors. The market valuation is anticipated to climb from 219.05 Million USD in 2026 to 292.37 Million USD by 2032. This growth path suggests that while the market is mature, it is not saturated; rather, it is evolving through technological differentiation and regional economic shifts.
For strategic leaders, these numbers tell a clear story: the touch probe market is a stable growth engine within the broader metrology and machining ecosystem. However, aggregate numbers alone are insufficient for capital allocation. Understanding which sub-segments are driving this CAGR, identifying regional hotspots with the highest velocity, and distinguishing between mature product lines and emerging technologies requires the detailed breakdown provided in our full proprietary model.
Segmentation Dynamics: Navigating Growth Vectors
Type-Based Differentiation and Product Evolution
The market structure is defined by clear distinctions between product types, each serving specific operational needs within the precision manufacturing workflow. The revenue landscape is currently fragmented across several key categories, with a notable emphasis on advanced dimensional measurement solutions. While 3D Touch Probes currently command a significant portion of revenue due to their versatility in on-machine kinematics and complex surface inspection, the market maintains a robust demand for legacy 2D systems in high-volume, repetitive machining environments.
Specialized instrument categories, such as Tool-length Measuring Probes and Tool Touch-off Probes, offer niche but essential functionalities for machine tool protection and setup efficiency. The interplay between these categories is shifting. As automation becomes more prevalent in CNC operations, the demand dynamics are tilting towards probes that integrate seamlessly with machine controllers and allow for automated tool setting without operator intervention.
While exact revenue splits between these types are detailed in our complete dataset, the strategic implication is clear: investment in automated setup tools correlates with long-term efficiency gains. However, the specific adoption rates and revenue potential for each type vary significantly by region and vertical, details that are critical for targeted product launches or procurement strategies.
Application Verticals: From CNC Machining to Specialized Processes
The application of touch probes is anchored heavily in Numerical Control operations, but the depth of penetration varies across specific process types. CNC Machining represents the dominant application sphere, driven by the need for repeatable accuracy in complex part production. CNC Turning constitutes another substantial pillar, where probes are essential for compensating tool wear and ensuring diameter tolerances in rotational symmetry. Meanwhile, diversified applications in grinding, milling, and specialized metrology represent a growing 'Others' category, fueled by the expansion of precision requirements into non-standard manufacturing tasks.
Each application vertical has different pain points, different integration requirements, and different regulatory constraints. For instance, the throughput needs in high-speed turning differ vastly from the precision requirements in complex multi-axis machining. Our research dissects these verticals to show exactly where the volume and margin opportunities lie, providing a roadmap for aligning probe technology with specific manufacturing workflows.
Regional Performance and Geographic Shifts
Geography plays a pivotal role in market performance. The Asia Pacific region stands out as a primary volume driver, underpinned by massive manufacturing capacity and an increasing focus on domestic supply chain sovereignty. North America and Europe maintain strong market positions, driven not merely by volume but by high-value manufacturing sectors such as aerospace, medical devices, and automotive. Emerging markets in Latin America and the Middle East and Africa offer niche opportunities characterized by lower volume but specific infrastructure development needs.
Understanding the regional weight and growth rates is essential for multinational operations. A strategy that works for a high-cost, high-precision environment in Western Europe may not translate directly to a high-volume export hub in Asia. Our report provides the nuanced regional breakdowns required to tailor supply chain and sales strategies effectively, moving beyond generic global averages to actionable local intelligence.
Competitive Landscape: Battlegrounds Among Renishaw, Hexagon, and Peers
The touch probes market is characterized by a moderate level of concentration, with the top firms holding a significant but not monopolistic share. The top three players command approximately 24.6 percent of the total market revenue, while the top five control roughly 26.2 percent. This structure indicates a healthy competitive environment where market leaders coexist with specialized challengers. Success in this landscape often depends on technological differentiation rather than pure price competition.
Strategic Profiles of Key Market Participants
A deep analysis of the incumbent players reveals distinct strategic positioning. Renishaw plc , headquartered in the United Kingdom, remains a formidable presence with a focus on standard-accuracy machine tool touch probes designed for automated workpiece setup and inspection in precision manufacturing. Their established distribution networks and long-standing reputation in industrial measurement make them a benchmark for reliability.
Hexagon AB , based in Sweden, continues to leverage its strength in industrial metrology. Their offering centers on Absolute Arm measurement systems and smart probes aimed at high-precision industrial metrology, positioning them as a leader in integration between offline inspection and on-machine data collection.
Marposs S.p.A. , from Italy, carves out a strong niche with specialized in-process monitoring and thermal compensation probes. These are particularly valued in grinding and turning machines where thermal errors can compromise precision, highlighting the importance of environment-specific probing solutions.
Blum-Novotest GmbH , operating from Germany, represents the technical edge in 3D probing. Their compact TC52 and TC62 3D touch probes are engineered for on-machine kinematics measurement and process-integrated inspection. This focus on kinematic integration appeals to advanced CNC users looking to close the loop on machining accuracy.
The German engineering ecosystem also features prominently with Dr. Johannes Heidenhain GmbH offering ultra-rigid probes designed for on-machine environments with high collision tolerance, catering to harsh shop floors where durability is non-negotiable. Meanwhile, Mitutoyo Corporation in Japan brings its reputation for precision to the tactile probes for CRYSTA family CMM lines in general metrology, bridging the gap between dedicated probing stations and on-machine solutions.
On the high-end side, Carl Zeiss Industrial Metrology GmbH delivers sub-micron PRISMO probe systems for laboratory-grade precision, targeting the most demanding metrology standards where marginal accuracy determines product viability.
Furthermore, Haff & Schneider GmbH & Co. OHG serves niche precision probes for high-accuracy machining applications, demonstrating how specialized players can thrive by serving high-compliance, high-tolerance segments. Finally, Optical Gaging Products (OGP) from the United States offers a hybrid approach with tactile probes integrated with video systems for precision inspection, combining optical and tactile data for comprehensive quality analysis.
These competitive dynamics suggest that procurement decisions should be driven by specific machine integration requirements and tolerance stacks. A full overview of the competitive positioning, market shares by region, and strategic responses from each firm is available in the complete competitive analysis section of our report.
Market Dynamics: Regulatory Tailwinds and Industry Evolution
Regulatory Pressures as Adoption Catalysts
While economic factors drive general demand, regulatory frameworks are increasingly acting as a forcing function for technology adoption. In the medical device sector, compliance requirements are reshaping how manufacturers approach dimensional inspection. Standards such as ISO 13485 dictate stringent quality management systems, and when combined with traceability requirements for dimensional measurements, they push manufacturers towards automated, documented measurement processes. Touch probe systems provide the digital traceability that manual inspection often lacks, making them a strategic compliance asset as much as a productivity tool.
Furthermore, regulations like FDA 21 CFR Part 11 impose strict electronic record and signature requirements, which influence how measurement data is captured and stored. These regulatory layers drive adoption of touch probe systems in metrology because the systems can inherently log data in accordance with electronic compliance standards. Similarly, CE marking and FDA 510(k) clearances for precision machining equipment incorporating touch probes ensure compliance in medical device manufacturing. The requirement for stricter ISO 13485 certification for suppliers using touch probes in the production of orthopedic implants and surgical instruments further cements the technology's role in regulated industries.
For component suppliers and machine builders, failing to account for these regulatory currents can result in market exclusion. The strategic implication is that touch probe integration is becoming a baseline requirement for tapping into high-value regulated supply chains.
Industry Noise and Operational Realities
Beyond regulation, the operational environment dictates technology choices. Factors such as machine tool rigidity, coolant resistance, cycle time sensitivity, and operator skill levels all interact with probe selection. The trend is moving towards probes that are more collapsible or robust to prevent damage during collisions, and easier to install for rapid changeovers. These practical dynamics, while not always headline-grabbing, are critical for ROI calculations. Our research captures these operational drivers and maps them against the competing technologies to help you align the solution with the shop floor reality.
Why This Research is Critical for 2026 Strategic Planning
The forecasting period from 2026 to 2032 presents a convergence of factors. On one hand, organizations must optimize existing assets and reduce variability in production. On the other hand, they must invest in capabilities that meet future regulatory and quality standards. The accuracy of these decisions depends entirely on the quality of the intelligence guiding them.
What The Full Report Delivers
Our comprehensive market research goes beyond the macro overview to provide actionable intelligence. The report includes detailed segmentation analysis across types, applications, and regions, revealing exactly where the growth capital should flow. We provide a rigorous assessment of the competitive landscape, including detailed profiles of key companies like Renishaw, Hexagon, and Marposs, analyzing their specific offerings such as Blum's TC52/TC62 3D probes and Zeiss's sub-micron PRISMO systems, allowing you to benchmark your technology stack against the market leaders.
Crucially, the report quantifies the impact of regulatory drivers, mapping compliance requirements like ISO 13485 and FDA traceability back to procurement opportunities. It offers forward-looking estimates based on rigorous model assumptions, enabling accurate budgeting and capacity planning. You will gain clarity on the revenue potential of 3D versus 2D solutions, the specific CAGR by region, and the exact market concentration dynamics that inform partnership and acquisition strategies.
However, the rich detail behind these models is curated for subscribers. The specific regional market sizes, the precise breakdown of revenue by each application vertical, and the detailed forecast tables are available exclusively in the full dataset. Relying on summary figures misses the nuances necessary for precise execution.
Call to Action for Decision Makers
The touch probes market is not just growing; it is maturing into a sophisticated ecosystem of measurement intelligence. Leaders who rely on generic market data risk misallocating resources or missing regulatory-driven opportunities. By accessing the complete Touch Probes Market report, you gain the granular insights needed to navigate the competitive pressure from players like Heidenhain and Mitutoyo, align with regulatory shifts, and capture the projected growth from 219.05 Million USD in 2026 towards the 292.37 Million USD mark in 2032 with precision.
To secure the full strategic roadmap, detailed segmentation data, and the competitive intelligence required for your 2026 planning, we invite you to access our complete market research. The macro trends are clear, but the path to outperformance lies in the details.
For detailed analysis of this topic, please visit the official page: Touch Probes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydroxyapatite Market Hits $215M in 2025, Forecasts 6.85% CAGR to $344.8M by 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for the Decade Ahead: Navigating the Hydroxyapatite Market Landscape (2026–2032)
The global biomaterials sector is undergoing a structural transformation, driven by an aging population, the rising prevalence of orthopedic and dental conditions, and a regulatory environment that is increasingly favoring biocompatible, bioactive solutions. At the center of this shift lies hydroxyapatite (HA), a calcium phosphate mineral that closely mimics the inorganic component of human bone. Its unique ability to integrate with living tissue—known as osteoconductivity—has cemented its role across medical implants, dental care, regenerative therapies, and even consumer cosmetics.
Worldwide GC Liner Market
As we move deeper into 2026, enterprise leaders, investors, and R&D strategists require more than surface-level trend spotting. They need actionable, granular intelligence that maps market trajectories, competitive positioning, regulatory inflection points, and supply-chain vulnerabilities. This article serves as an executive preview of our latest comprehensive study on the hydroxyapatite market. It outlines the strategic rationale for the research, distills the macro-level market architecture, highlights the competitive forces reshaping the landscape, and examines the dynamic regulatory and raw-material developments that will define the 2026–2032 forecast period. Readers seeking full quantitative breakdowns, segment-level revenue mapping, and detailed company deep-dives are directed to the complete report, where the full intelligence architecture is laid out for immediate operational use.
Men No-Show Socks Market
Market Architecture: Tracing the Trajectory from Historical Growth to Forecast Expansion
Hydroxyapatite has evolved from a niche biomedical material into a multi-application ingredient with cross-industry relevance. The past half-decade has demonstrated steady, compounding growth, reflecting both incremental adoption in established medical segments and emerging demand in dental care, plastic surgery, and advanced consumer formulations. Our historical analysis (2020–2025) captures this momentum, showing a market that has broadened its revenue base while gradually professionalizing its supply ecosystem.
Gamma Ray Monitoring System Market
Looking forward, the forecast period from 2026 through 2032 points to sustained expansion. The market is projected to advance from an estimated 231.4 million USD in 2026 to approximately 344.8 million USD by 2032, supported by a compound annual growth rate of 6.85 percent. This trajectory signals more than mere continuation of past patterns. It reflects an inflection in adoption intensity, particularly where material performance, regulatory clarity, and clinical evidence converge.
For decision-makers, this forecast framework matters because it reframes hydroxyapatite from a discretionary R&D input into a strategic procurement and innovation pathway. Companies that treat the market as a static commodity space risk misaligned capacity planning, underinvestment in product differentiation, or missed timing on regulatory-enabled demand surges. By contrast, organizations that anchor their planning in a forward-looking, data-rich market model can prioritize applications with the highest value capture, align supply investments with demand centers, and anticipate substitution threats before they materialize.
Importantly, the broad market revenue curve does not tell the full story by itself. The real strategic value lies in understanding how revenue is distributed across material types, application verticals, and geographic theaters. Our report deconstructs these layers without diluting them into oversimplified averages. Instead, it maps where growth is concentrated, which sub-segments are accelerating or plateauing, and how regional demand patterns intersect with manufacturing footprints, regulatory regimes, and distribution channels. This level of disaggregation is essential for scenario planning, whether a company is evaluating market entry, portfolio expansion, or potential consolidation opportunities.
Structural Segmentation: How Material Form, Application, and Geography Shape Revenue Flows
Hydroxyapatite is not a monolithic material category. Its commercial value depends heavily on physical form, purity, particle morphology, and intended application. Nano-sized variants, for example, have gained traction in settings where surface reactivity, bioresorption profiles, or incorporation into advanced coatings and composite scaffolds is critical. Micro-sized and larger particle formats continue to serve established implant, bone graft, and industrial coating applications, each with distinct processing requirements and performance thresholds.
Similarly, the application spectrum spans from high-volume orthopedic and dental use cases to more specialized plastic surgery procedures and a growing set of adjacent applications. Each vertical carries its own clinical evidence requirements, procurement cycles, regulatory pathways, and price sensitivity. Orthopedic and dental segments remain foundational, but the dispersion of demand across other medical and consumer-facing applications introduces both diversification benefits and complexity. Decision-makers must understand where incremental volume is likely to emerge, where substitution risk is highest, and how material specifications translate into competitive differentiation.
Geography adds another layer of strategic nuance. Demand is not evenly distributed, and neither are manufacturing capabilities, certification pathways, or end-user purchasing behaviors. Some regions are characterized by mature clinical adoption and well-established distribution networks, while others are experiencing faster growth due to expanding healthcare access, rising disposable income, or local regulatory shifts. Understanding these geographic dynamics enables companies to calibrate go-to-market strategies, optimize production and logistics footprints, and anticipate reimbursement or standards-related risks that vary by market.
In the full report, these segmentation dimensions are examined in depth. We avoid presenting broad proportional breakdowns in isolation; instead, we integrate them into a contextual analysis of what they imply for capacity planning, R&D prioritization, pricing architecture, and market-entry sequencing. This approach is designed to support operational decisions rather than passive observation.
Competitive Landscape: Mapping the Players Shaping the Hydroxyapatite Ecosystem
The hydroxyapatite market is shaped by a mix of specialized biomaterials manufacturers, larger medical device and implant companies, and suppliers that serve adjacent industries such as chromatography, life sciences, and industrial coatings. This diversity matters because competition in HA is not purely price-based. It is increasingly defined by material quality, certification portfolios, application-specific formulations, manufacturing scale, and the ability to meet rigorous medical and regulatory standards.
A number of companies stand out for their focused expertise in hydroxyapatite. APS Materials Inc., headquartered in Dayton, Ohio, produces HA orthopedic implant coatings using plasma spray technology for titanium implants, illustrating how surface engineering and coating processes can create defensible value in the implant space. Berkeley Advanced Biomaterials, part of GNI Group Ltd. and based in Berkeley, California, supplies high-purity HA powders and custom forms for medical and research applications, highlighting the importance of purity and customization in high-specification end markets. Bio-Rad Laboratories Inc., located in Hercules, California, offers HA for chromatography resins and life science applications, demonstrating how the material’s functional properties extend beyond direct medical use into laboratory and bioprocessing workflows.
In Asia, CGbio in South Korea manufactures HA biomaterials for orthopedic and dental implants, reflecting the region’s growing capability in medical-grade biomaterials. Fluidinova S.A., based in Odivelas, Portugal, specializes in synthetic HA and tricalcium phosphate materials under its nanoXIM® brand, underscoring the strategic relevance of proprietary formulations and material branding. SigmaGraft Biomaterials, operating in the USA, supplies HA biomaterials for bone graft and implant applications, while Granulab Sdn. Bhd. in Malaysia produces and supplies HA for biomedical applications, pointing to a broader Southeast Asian manufacturing presence.
Japanese firms also represent a notable cluster of capability and standardization focus. Taihei Chemical Industrial Co. Ltd. manufactures HA and related calcium phosphate products, while Tomita Pharmaceutical Co., Ltd. produces high-purity HA conforming to ASTM standards for medical use, an emphasis on standardized quality that can be a significant barrier to entry and a trust signal for procurement teams. SANGI CO., LTD. specializes in HA products for medical, regenerative, and oral care applications, showing how certain players extend across multiple end-use domains from clinical to consumer-facing markets.
On the commercial implant side, Zimmer Biomet, based in Warsaw, Indiana, incorporates HA in implants and bone grafts, aligning material strategy with large-scale clinical distribution and surgeon relationships. Himed, in the USA, manufactures MATRIX HA® HA coatings for dental and medical implants, while Stanford Advanced Materials supplies HA powder for thermal spraying and industrial coatings, and The Lubrizol Corporation provides HA and calcium phosphate additives for lubricants and industrial use. Together, these players demonstrate that the HA market spans highly regulated medical segments as well as industrial and specialty applications, each with its own value drivers.
Our report analyzes this competitive field in structured detail. It examines how these companies position themselves across material types and applications, what competencies are becoming increasingly important, and where customer procurement decisions are likely to lean toward incumbents with certified quality systems and application-specific expertise. Rather than presenting a static company list, the study maps strategic adjacency, potential partnership logic, and the conditions under which new entrants or consolidation could alter market concentration.
Regulatory Dynamics and Raw-Material Context: The Forces Reshaping Demand and Cost Structures
No strategic assessment of the hydroxyapatite market is complete without attention to regulation and input economics. Both have become more influential in recent years, not only in determining what products can be sold and where, but also in shaping formulation strategies, packaging claims, and R&D roadmaps.
One significant development is the evolving regulatory posture toward nano-hydroxyapatite in consumer-facing applications. In 2025, the Scientific Committee on Consumer Safety issued an approval allowing higher nano-hydroxyapatite concentration limits in cosmetics, enabling up to 29.5 percent in toothpaste and 10 percent in mouthwash. The European Chemicals Agency subsequently issued a final opinion confirming the safety of nano-hydroxyapatite in toothpaste and mouthwash at those specified concentrations. EU Regulation 2024/858 also set limits on nano-HA in toothpaste and mouthwash, reinforcing a regulatory environment that is more defined, though still conditional on adherence to concentration thresholds and safety documentation.
These regulatory signals matter because they expand the commercially viable design space for dental care and oral hygiene formulations while also raising the bar for compliance, testing, and documentation. Companies that can align product development with these parameters may unlock new usage levels and consumer-facing claims, provided they can demonstrate consistency, purity, and safety. Conversely, firms that underestimate the documentation burden or fail to anticipate future revisions may face reformulation costs or market-access delays.
On the supply side, raw-material dynamics have introduced notable volatility. Phosphate rock prices spiked 25 percent in 2022 due to supply disruptions, affecting downstream calcium phosphate costs and reminding the industry how tightly upstream commodity conditions can influence biomedical and specialty material economics. Tricalcium phosphate prices have also shown regional variation, with ranges observed from approximately 935 USD per metric ton in China to around 1,090 USD per metric ton in the USA in the third quarter of 2025. Such differentials create opportunities for regional sourcing strategies, but they also require careful scrutiny of quality consistency, logistics costs, and contractual risk allocation.
A parallel trend is the emergence of bio-derived alternatives and the pursuit of certification pathways that can broaden market acceptance. Shell Apatite powder derived from Japanese scallops, for instance, debuted in local dental clinics and is pursuing CE certification, with the certification effort advancing further after the clinic debut. This trajectory reflects a broader industry interest in sustainable sourcing narratives and alternative raw-material routes, provided they can meet regulatory and clinical performance expectations. These developments are not mere anecdotes; they signal how sourcing innovation, regulatory clearance, and early commercial validation can combine to open new market niches.
Integrating these dynamics into strategy is essential. If a company is evaluating product roadmaps, it must account for regulatory ceilings and openings, raw-material price exposure, and the strategic implications of bio-derived or region-specific sourcing. If it is assessing supply resilience, it needs to understand where concentration risks exist and how alternative feedstocks or supplier relationships might mitigate disruption. The report captures these interdependencies and translates them into practical considerations for procurement, R&D, compliance, and commercial planning.
What the Report Delivers: An Operational Framework for Strategy and Investment Decisions
This study is designed as a decision-support instrument rather than a descriptive overview. It brings together market sizing, segmentation architecture, competitive profiles, regulatory and raw-material context, and forward-looking scenario thinking in a format built for internal alignment and external engagement. The objective is to help teams answer practical questions: Where is the market going, and with what level of confidence? Which material forms and applications offer the most resilient growth? How should a company position itself relative to incumbents and emerging niche players? What regulatory or sourcing risks should be monitored over the forecast horizon?
To support those questions, the report combines quantitative structure with qualitative interpretation. It maps historical performance to establish baseline momentum, then links that baseline to the forecast period so that leadership can distinguish cyclical variation from structural expansion. It examines how product specifications and application requirements influence purchasing decisions, pricing tolerance, and adoption speed. It profiles key companies not simply by description, but by strategic lens: where they compete, what capabilities they emphasize, and how they might evolve as regulation, sourcing, and demand patterns shift.
The study also integrates recent industry developments as strategic signals rather than isolated news items. Regulatory approvals and limits, certification progress, raw-material price movements, and sourcing innovations are assessed for their implications on market access, formulation strategy, and cost structures. By doing so, the report helps teams anticipate not just where the market is today, but where the pressure points and opportunities will intensify over the next several years.
For executives, commercial leaders, R&D managers, and investors, this synthesis reduces the friction between market information and strategic action. It provides a shared framework for discussing prioritization, resource allocation, and risk management. It also establishes a basis for more precise internal modeling, since the full dataset and segment-level detail are available for teams that need to build bottom-up forecasts, run sensitivity analyses, or prepare investment committee materials.
Why This Study Matters for 2026 Decision-Making
2026 is a pivotal year for biomaterials strategy. Demand is expanding, regulatory frameworks are becoming more specific, and competitive differentiation is increasingly tied to material performance, certification strength, and application-specific value propositions. In such an environment, broad narratives are insufficient. Organizations need to know not only that hydroxyapatite demand is growing, but how that growth is distributed, what assumptions underpin the forecast, where competitive pressure is likely to intensify, and which external developments could alter the trajectory.
This report is built to meet that need. It frames the hydroxyapatite market as a dynamic, multi-segment ecosystem and equips decision-makers with the context required to act with greater precision. Whether the goal is to enter new applications, strengthen supplier relationships, refine product specifications, evaluate partnership or acquisition targets, or prepare for regulatory and sourcing shifts, the study provides a structured foundation for those choices.
The complete report offers the full quantitative and qualitative architecture behind this preview, including detailed market sizing through 2032, segment-level analysis across type, application, and region, company profiles with strategic context, and an integrated assessment of regulatory and raw-material dynamics. For teams that need to move from high-level insight to executable planning, that depth is where the real operational value lies.
Conclusion: From Market Awareness to Strategic Readiness
Hydroxyapatite is no longer a peripheral biomaterials topic. It sits at the intersection of clinical need, material science, regulatory evolution, and supply-chain complexity. The market’s projected growth from 231.4 million USD in 2026 to approximately 344.8 million USD by 2032, at a CAGR of 6.85 percent, is a useful headline, but the strategic implications are found in the details beneath it: how material forms differentiate value, how applications shape adoption, how regulations redefine feasible product designs, and how raw-material volatility affects cost and resilience.
Our full market study is intended to give organizations the clarity to navigate that complexity with confidence. By combining rigorous market structure with current industry signals and competitive context, it helps leaders convert information into decision-ready intelligence. For those preparing strategy, investment, or product plans for the 2026–2032 period, the complete report provides the depth needed to move beyond observation and into actionable positioning.
For detailed analysis of this topic, please visit the official page: Hydroxyapatite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Egg Protein Powder Market Hits $93M in 2025, Projects 5.3% CAGR to 2032
By PW Consulting, 2026-09-07
Strategic Horizons in the Egg Protein Powder Market: Navigating Growth, Innovation, and Supply Chain Realities Through 2032
The global egg protein powder market stands at a critical inflection point. Shaped by concurrent forces of nutritional demand expansion, supply chain volatility, and a wave of biotechnological disruption, the sector is evolving from a traditional agricultural ingredient into a sophisticated commodity that sits at the intersection of food science, health and wellness, and advanced manufacturing. For executives, procurement leaders, and product developers, understanding the trajectory of this market is no longer optional—it is a prerequisite for resilient strategy.
Vessel Towing Pins Market
Our latest market research on the Egg Protein Powder Market provides a comprehensive, forward-looking intelligence framework designed to support high-stakes decision-making throughout the forecast period. Drawing on rigorous historical analysis from 2020 through 2025 and extending detailed projections through 2032, this study translates complex market signals into actionable strategic insights. What follows is a deep dive into the forces shaping the landscape, the structural characteristics of the competitive arena, and the operational intelligence embedded in this report—all curated to help your organization capture value in a market projected to reach 133.66 Million USD by the close of the forecast horizon.
Worldwide Domino Car Wiper Blade Market
The Macro Arc: From Recovery to Sustained Expansion
The last half-decade has witnessed a remarkable recovery and subsequent acceleration in global demand for egg protein powders. Between 2020 and 2022, the market moved from 72.36 Million USD to 82.6 Million USD, a period characterized by pandemic-driven shifts in food consumption patterns, heightened consumer focus on immune health and protein intake, and initial supply chain recalibrations across egg processing networks. As industrial activity normalized, the market continued its ascent, reaching 84.34 Million USD in 2023 and further expanding to 91.22 Million USD in 2024. The base year of 2025 sits at an estimated 93.0 Million USD, reflecting both the residual momentum of post-pandemic reformulation trends and the early adoption of egg-derived protein fractions in emerging functional food applications.
Worldwide In Vitro Safety Pharmacology Profiling Market
Looking forward, the market is positioned to deliver a compound annual growth rate of 5.3 percent over the forecast period. Starting from an estimated 95.7 Million USD in 2026, the trajectory points toward steady, compounding expansion, with valuations anticipated to cross the 100 Million USD threshold in 2027 and continue climbing through the end of the decade. The projections for 2028, 2029, and 2030 track progressive increases, followed by continued growth into 2031 and 2032, where the market is expected to surpass 130 Million USD. This upward arc is not merely statistical; it reflects deep-seated shifts in how manufacturers, formulators, and consumers view egg protein as a versatile, high-quality ingredient.
For strategic planners, this growth profile carries important implications. A sustained CAGR above 5 percent signals that the market is unlikely to plateau in the near term, even amid macroeconomic headwinds. However, growth will not be uniform across all players or regions. The organizations that thrive will be those that proactively align their portfolios, pricing strategies, and supply partnerships with the structural demand drivers underpinning this expansion—drivers that the full report dissects in granular detail.
Market Architecture: Concentration, Segmentation, and Structural Shifts
Behind the headline growth numbers lies a market structure that rewards scale, specialization, and supply chain foresight. The competitive landscape is moderately concentrated, with the top three firms commanding approximately 52.0 percent of total market revenue and the top five collectively accounting for around 58.0 percent. This concentration pattern suggests that while the market remains accessible to mid-tier and niche players, the largest participants enjoy meaningful advantages in procurement leverage, regulatory navigation, and downstream distribution relationships. At the same time, the presence of specialized manufacturers and emerging precision-fermentation entrants indicates that competitive differentiation is increasingly driven by technological capability, formulation expertise, and brand positioning rather than volume alone.
The report's segmentation analysis reveals a multi-dimensional market architecture that executives must navigate with precision. On the type front, distinct product categories have established their own demand profiles, usage contexts, and pricing dynamics. The full study examines how these subcategories interact with broader formulation trends, cost structures, and consumer preferences—without relying on simplistic volume tables. Instead, the analysis focuses on the strategic implications of each segment's positioning, the drivers of substitution or complementarity among product types, and how manufacturers can optimize their portfolio mix to capture margin across multiple channels.
From an application perspective, the market's demand is distributed across several core end-use domains, each with its own growth cadence, regulatory environment, and competitive intensity. The report explores how application-specific requirements are reshaping sourcing strategies, quality specifications, and go-to-market approaches. Whether the priority is securing consistent feedstock for large-scale food manufacturing, meeting the demanding purity standards of dietary supplement formulators, or developing clean-label positioning for retail-facing products, the underlying application landscape dictates very different strategic postures. Our research unpacks these dynamics systematically, giving decision-makers the context needed to align product development roadmaps with the most attractive demand pockets.
Geographic distribution further complicates—and enriches—the strategic picture. The report maps regional demand patterns, procurement behaviors, and regulatory frameworks across major global markets, highlighting where growth is most pronounced, where import dependencies create vulnerability, and where local manufacturing presence confers a durable competitive moat. Executives operating across multiple territories will find the regional intelligence particularly valuable for capacity planning, partnership selection, and tariff or compliance risk assessment. To protect the analytical integrity of the complete study, we deliberately withhold granular regional and application-level splits in this summary; those figures, along with their strategic interpretations, are fully detailed in the final report.
Competitive Battleground: Incumbents, Innovators, and Disruptive Approaches
The competitive field in egg protein powder is characterized by a blend of long-established agricultural processors, specialized supplement manufacturers, and a new wave of biotechnology-driven entrants pursuing animal-free and fermentation-derived alternatives. This mixture creates a dynamic environment where traditional competitive advantages—such as flock management, processing infrastructure, and long-standing supply contracts—must now be weighed against innovations in precision fermentation, downstream purification, and novel protein functionality.
Among the incumbents and established specialists, several organizations have built recognizable positions around product quality, application versatility, and supply reliability. Companies such as All American Foods, Inc., operating out of Mankato, Minnesota, have focused on egg replacement and substitution powders designed for food applications that demand functional parity with whole egg ingredients. Rembrandt Foods has carved out a strong export-oriented footprint, producing egg white powders for food, nutrition, and industrial uses. In the dietary supplement and retail channel, NOW Foods and Bulk Supplements serve as prominent suppliers of high-quality egg white protein products, catering to both end consumers and bulk functional ingredient buyers. Makers Nutrition operates at the intersection of custom formulation and private labeling, enabling brands to access tailored egg white protein solutions without building in-house manufacturing capability. Egg+ rounds out this cohort with a focus on 100 percent egg white protein powder sourced from antibiotic-free, hormone-free eggs and processed in NSF-certified facilities, a positioning that resonates strongly with clean-label and sports nutrition segments.
At the same time, the competitive frontier is being actively reshaped by companies pioneering precision fermentation and bio-manufacturing approaches. The EVERY Company has gained considerable attention for its OvoPro™ platform, which produces animal-free egg proteins suitable for baked goods and functional applications without relying on conventional poultry supply chains. Onego Bio has pursued a parallel trajectory with its Bioalbumen® ingredient, a fermentation-derived egg protein powder that aims to deliver the functional attributes of traditional egg protein while eliminating dependence on hen-based production. These ventures illustrate a broader strategic question facing the industry: to what extent will fermentation-derived alternatives complement, compete with, or eventually displace conventional egg-derived powders in specific applications? The answer will depend on cost curves, regulatory pathways, sensory performance, and the speed at which large-scale manufacturing capacity comes online.
Recent Developments Shaping Competitive Dynamics
Several recent corporate events underscore the pace of change and the strategic priorities currently driving market participants. In March 2025, Onego Bio selected Jefferson County, Wisconsin, as the flagship manufacturing site for its Bioalbumen® fermentation-derived egg protein powder, securing a 25.9-acre footprint within the Food and Beverage Innovation Campus. This facility decision reflects a calculated bet on midwestern infrastructure, access to specialized talent, and proximity to food innovation ecosystems.
Later in the year, The EVERY Company closed a 55 million USD Series D funding round in November 2025, earmarking the capital to expand manufacturing capacity and accelerate commercialization of its precision-fermented egg proteins, including animal-free egg white powder alternatives. This funding milestone signals strong investor confidence in the scalability of fermentation-based protein platforms and highlights the capital intensity required to move from pilot-scale success to commercial-grade supply reliability.
On the conventional and hybrid side, June 2025 brought multiple indicators of brand and operational momentum. Gaspari Nutrition reinforced the market position of its Proven Egg egg white protein powder, which remained a top-selling product on Amazon, supported by a broad flavor portfolio that included an unflavored variant designed for cooking and food applications. This multi-use positioning illustrates how supplement brands are increasingly leveraging functional versatility to expand beyond the gym channel. Meanwhile, Kewpie Corporation announced an expansion of its protein processing operations and an improvement in powder purity levels by approximately 18 percent, aimed at strengthening its appeal to sports nutrition and functional food manufacturers. Rose Acre Farms, in December 2025, introduced clean-label egg white protein products with reduced additive usage, targeting health-conscious supplement buyers and aligning with the broader retail shift toward ingredient transparency.
Collectively, these developments illustrate a market in which competitive differentiation is emerging from multiple vectors: manufacturing scale, purity and quality benchmarks, clean-label positioning, distribution channel strength, and the ability to serve both supplement-native and food-manufacturing use cases. Our full competitive analysis goes beyond event summaries, evaluating each key player's strategic posture, likely capacity trajectory, and vulnerability to substitution or regulatory shifts.
Industry Dynamics: Volatility, Compliance, and Structural Cost Pressures
No strategic assessment of the egg protein powder market would be complete without confronting the operational realities that shape margins, supply reliability, and market entry conditions. Industry participants are currently navigating a confluence of cost, regulatory, and supply-side pressures that directly influence competitive positioning and long-term planning.
On the raw material and cost front, volatility in egg supply and pricing remains a persistent concern. Disease outbreaks, fluctuations in feed costs, and evolving regulatory pressures have repeatedly disrupted production economics for egg processing facilities. These shocks do not simply raise input costs in the short term; they also complicate capacity planning, long-term contracting, and the ability to guarantee consistent specifications for downstream buyers. Layered atop this, labor shortages and elevated housing and operational requirements contributed to an approximate twofold increase in egg production costs over the 2022–2024 period, according to official U.S. government reporting. For processors and powder manufacturers, such structural cost escalation erodes margin unless offset by higher-value product differentiation, efficiency gains, or strategic hedging through supply diversification.
Regulatory and compliance requirements add another layer of strategic complexity. Import pathways for egg protein powder are tightly controlled, with USDA and FSIS guidance restricting eligible establishments to countries that maintain equivalent inspection systems, such as Canada and the Netherlands. This import architecture shapes not only the cost and feasibility of cross-border sourcing but also the geographic footprint of reliable supply partnerships. Meanwhile, FDA export mechanisms require specific HS code-based certification for shipments to key markets including China, adding documentation and compliance burdens that can disproportionately affect smaller exporters or those without established regulatory support functions.
Packaging and labeling obligations further influence cost structures and market access. Strict allergen labeling regulations across North America, Europe, and parts of Asia increase compliance and packaging expenditures for manufacturers targeting children, clinical nutrition, or mass retail channels. These requirements are not static; they evolve with consumer expectations and public health policy, meaning that future-proofing packaging and labeling strategies is increasingly a strategic, not merely operational, concern.
Taken together, these dynamics create a market environment in which operational resilience is a genuine source of competitive advantage. Companies that can manage raw material exposure, maintain regulatory compliance across multiple jurisdictions, and communicate product quality credibly are better positioned to sustain margins and defend customer relationships through cycles of supply stress. The complete report integrates these dynamics into a broader strategic framework, linking risk factors to specific strategic response options for procurement, supply chain design, and market entry.
What the Full Study Delivers: A Decision-Ready Intelligence Toolkit
This market research was built to translate complex market information into usable strategic guidance. Rather than functioning as a static data repository, the report is structured as a decision-support toolkit, with each section designed to answer specific questions that executives, product leaders, and supply chain planners face in day-to-day strategy work. The following elements define the scope and practical value of the full study:
- Comprehensive historical reconstruction and forward-looking forecasts that anchor planning assumptions in a consistent, methodology-driven baseline, with market valuations traced from 2020 through 2032 and key inflection points identified for scenario planning.
- Segment-level strategic interpretation that moves beyond simple category splits to examine how type, application, and regional demand patterns interact, where substitution risks are most acute, and which demand pockets offer the most favorable combination of growth and margin potential.
- Competitive profiling of leading market participants, including established processors, supplement-focused suppliers, private-label formulators, and precision-fermentation innovators, with attention to positioning, manufacturing strategy, and likely trajectories under different market scenarios.
- Event-driven analysis of recent corporate developments, funding rounds, facility launches, product introductions, and operational upgrades, interpreted not as isolated news items but as signals about where capital, capability, and attention are flowing within the industry.
- Dynamics and risk assessment covering raw material volatility, labor and cost pressures, regulatory import and export requirements, allergen labeling obligations, and the strategic implications of each factor for pricing, sourcing, and market access.
- Strategic recommendations and scenario considerations that help leadership teams evaluate capacity commitments, partnership choices, geographic prioritization, and product roadmap decisions in the context of a market that is expanding but also increasingly contestable.
To illustrate the kind of actionable clarity the report aims to provide, consider how it approaches the intersection of growth and disruption. Rather than treating conventional and fermentation-derived proteins as entirely separate markets, the study examines where their demand curves may converge, which applications are most sensitive to cost-versus-functionality trade-offs, and how incumbents can position themselves relative to emerging alternatives. Similarly, the analysis of regulatory frameworks does not stop at compliance checklists; it connects import eligibility, export certification requirements, and labeling obligations to real decisions about which supply partnerships are sustainable, which markets are worth prioritizing, and where compliance investment yields the highest strategic return.
Because the market's value lies not just in size but in structure, the full study also pays close attention to concentration dynamics and the strategic implications of operating in an environment where top firms hold a meaningful share while specialized and innovative entrants continue to test the boundaries of product capability. Understanding how these layers interact is essential for anyone evaluating white-space opportunities, assessing competitive threats, or deciding where to allocate limited R&D and commercial resources.
Where Leadership Teams Should Focus as the Forecast Unfolds
As the market advances from its 2026 starting point toward the later years of the forecast period, several strategic priorities are likely to separate the organizations that capture disproportionate value from those that merely participate. First, supply resilience will remain a defining competitive variable. Companies that treat raw material volatility, labor cost escalation, and regulatory complexity as background noise rather than strategic design parameters will face repeated margin compression and supply disruption. Those that invest in diversified sourcing, robust compliance infrastructure, and flexible manufacturing or formulation capabilities will be better equipped to sustain performance through cycles of stress.
Second, the product strategy conversation is increasingly multi-dimensional. Decision-makers must weigh the relative appeal of conventional egg-derived powders, clean-label and reduced-additive offerings, application-tailored variants, and emerging fermentation-based alternatives. There is no single correct answer across all applications; the optimal portfolio posture depends on target customers, formulation requirements, channel dynamics, and tolerance for technology risk. The report provides the analytical scaffolding to make these trade-offs explicit rather than intuitive.
Third, geographic and channel strategy will reward precision. The presence of strong regional demand centers, unevenly distributed import eligibility, and distinct regulatory regimes means that broad, undifferentiated expansion is less effective than targeted, insight-led prioritization. The study's regional and application intelligence is designed to support that prioritization without overgeneralizing from aggregate numbers.
Finally, the competitive field will continue to reward organizations that can articulate and prove product quality, functional performance, and brand credibility in ways that matter to specific buyer segments. Whether the priority is sports nutrition, bakery formulation, industrial food manufacturing, or private-label supplement solutions, the ability to match claims with verifiable specifications and consistent supply will increasingly determine who wins preference in a crowded and fast-moving market.
Accessing the Full Intelligence Package
The egg protein powder market is expanding, but expansion alone does not guarantee advantage. The real strategic question is how to position your organization to benefit from growth while managing volatility, regulatory constraints, and the disruptive potential of new production technologies. This market research is designed to answer that question with specificity, giving leadership teams the evidence base and interpretive framework needed to make confident decisions across procurement, product development, competitive strategy, and geographic planning.
For those who require the complete dataset, segmentation breakdowns, competitive profiles, and scenario-based interpretations, the full report is available through our research portal. The consolidated analysis includes all historical and forecast valuations, detailed segment and regional context, comprehensive profiles of the key companies shaping the industry, and an integrated discussion of the operational dynamics that directly affect margin, compliance, and supply continuity. We invite executives and strategy teams to access the full study and use its findings to stress-test current assumptions, identify overlooked opportunities, and build a market position that is resilient through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Egg Protein Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Unveils UHMWPE Sheet Market to Hit $344.8M by 2032 at 6.98% CAGR
By PW Consulting, 2026-09-07
Strategic Imperatives in the UHMWPE Sheet Market: Navigating Growth Trajectories Through 2032
The Ultra-High Molecular Weight Polyethylene (UHMWPE) sheet market stands at a critical inflection point. As industries demand materials that combine extreme wear resistance, low friction, and biocompatibility, UHMWPE has transitioned from a niche engineering plastic to a foundational component in high-stakes sectors ranging from medical implants to heavy-duty material handling. For stakeholders navigating this landscape in 2026, the ability to discern between transient market noise and structural growth drivers will define competitive advantage. Our latest comprehensive study on the UHMWPE Sheet Market provides the granular intelligence required to turn these material dynamics into actionable corporate strategy.
Worldwide Reactive M Dyes Market
This analysis serves as a strategic briefing, outlining the macroeconomic forces, competitive pressures, and technological shifts that will shape decision-making over the next seven years. It is designed to equip procurement leaders, product development executives, and investment committees with the contextual framework needed before diving into the full data repository.
Email Newsletter Tool Market
Macroeconomic Trajectory and Market Valuation
Understanding the scale of the opportunity is the first step in resource allocation. The market has demonstrated consistent resilience and expansion over the historical review period. From a valuation of approximately 163.15 million USD in 2020, the market climbed steadily to an estimated 215.0 million USD by the base year of 2025. This historical growth underscores a compounding demand curve that outpaces many traditional polymer segments.
AI Servers for Internet Market
Looking forward, the forecast period from 2026 to 2032 projects a robust expansion trajectory. The market is expected to reach 236.81 million USD in 2026, accelerating towards 344.8 million USD by 2032. This growth is underpinned by a projected Compound Annual Growth Rate (CAGR) of 6.98 percent. For enterprise planners, this figure is not merely a statistical expectation but a signal of sustained capital inflow into polymer processing and downstream fabrication capabilities.
It is important to note that while the aggregate numbers indicate health, the distribution of value across the value chain is uneven. The forecast suggests that late-period years will see an acceleration in value capture, likely driven by the commercialization of specialized grades and higher-margin applications that move beyond commodity substitution.
Segmentation Dynamics and Value Distribution
Product Types and Material Grades
The market is stratified by material origin and functional modification, each serving distinct performance requirements. The landscape includes Virgin UHMWPE Sheets, Reprocessed UHMWPE Sheets, and Anti-Static UHMWPE Sheets. Virgin grades remain the cornerstone for high-performance applications where molecular consistency and mechanical integrity are non-negotiable, particularly in medical and aerospace contexts.
Reprocessed sheets represent a growing niche driven by sustainability mandates and cost optimization in less critical industrial wear applications. Meanwhile, Anti-Static variants address specific operational hazards in electronics manufacturing and sensitive processing environments. The strategic selection between these types often hinges on the total cost of ownership rather than initial material cost, a nuance explored in depth within the full report.
Application Verticals
Demand is driven by several high-intensity application verticals. Medical Devices represent a dominant force, fueled by the biocompatibility of UHMWPE and its prevalence in orthopedic implants and surgical tools. Food Processing is another critical vertical, where low friction and FDA compliance are table stakes for conveyor components and cutting boards.
Conveying Equipment rounds out the primary demand drivers, particularly in mining, agriculture, and logistics sectors where abrasion resistance directly correlates to operational uptime. Each vertical possesses unique procurement cycles, regulatory hurdles, and failure-mode tolerances. Our research dissects the specific revenue contribution and growth velocity of each segment without relying on broad generalizations, allowing clients to pinpoint where their specific portfolio fits within the broader ecosystem.
Regional Performance
Geographically, the market spans North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Each region presents a distinct maturity profile. Developed economies in North America and Europe show stable demand anchored by established industrial bases and stringent regulatory environments regarding material safety and recycling.
Asia Pacific continues to exhibit dynamic growth characteristics linked to industrialization and infrastructure development. Latin America and the Mideast and Africa offer emerging opportunities, often tied to specific resource extraction or infrastructure projects. The report provides a localized view of procurement hubs and manufacturing footprints, enabling supply chain strategists to optimize logistics and mitigate regional risk exposure.
Competitive Landscape and Strategic Positioning
The UHMWPE sheet market is characterized by a mix of multinational resin producers, specialized fabricators, and regional distributors. The competitive intensity is moderate, with a CR3 of 24.6 percent and a CR5 of 26.2 percent, indicating that while major players hold influence, the market remains accessible to specialized entrants who can differentiate on service, customization, or niche grade performance.
Key Industry Participants
Several companies define the current operational standards and innovation benchmarks within this sector.
- Sangir (China): Focuses on specific industrial offerings such as Nova Strong UHMWPE sheets in standard sizes like PE-300, PE-500, and PE-1000, emphasizing high impact strength and FDA compliance.
- A&C Plastics (USA): Operates as a distributor and processor, supplying sheets in various thicknesses and colors for wear strips, chute liners, and custom fabrication projects.
- Polymershapes (USA): Fabricates and supplies UHMW sheets from leading manufacturers, offering virgin, bearing, ceramic-filled, and FDA-approved grades in multiple colors and sizes.
- Curbell Plastics (USA): Specializes in UHMW plastic sheets for wear strips, chute liners, star wheels, and fabricated parts, leveraging low friction properties and FDA compliance.
- TSE Industries (USA): Manufactures and supplies UHMWPE sheets and rods tailored for industrial, marine, and heavy-duty applications.
- Crown Plastics (USA): Produces UHMWPE sheets and rollstock primarily for packaging and broader industrial uses.
- Mitsubishi Chemical Advanced Materials (Japan): Supplies high-performance UHMWPE sheets and plates designed for rigorous engineering and structural applications.
- Asahi Kasei (Japan): Produces UHMWPE resins and sheets for medical, industrial, and high-value applications, including compression-molded products.
- LyondellBasell (USA): Offers Lupolen UHMWPE resins processed into sheets, plates, and rods for compression molding and various industrial uses.
- dsm-firmenich (Netherlands): Provides UHMWPE grades for medical and industrial sheets, holding ISO 5834 certification for orthopedic and high-performance uses.
- Celanese Corporation (USA): Manufactures GUR UHMWPE for sheets, rods, and plates used in industrial components and medical implants.
- Braskem (Brazil): Supplies UHMWPE powders and processed sheets for engineering plastics in industrial and consumer goods.
- Teijin (Japan): Produces Endumax UHMWPE sheets with enhanced properties specifically targeting marine and transportation equipment.
- Avient Corporation (USA): Supplies UHMWPE products including sheets through the Dyneema brand for composites and industrial applications.
- Röchling (Germany): Offers TKG UHMWPE plates and bars processed into sheets for heavy-duty engineering applications.
- Sinopec Yizheng Chemical Fibre Limited (China): Produces UHMWPE resin and sheets for industrial and engineering plastics sectors.
- Shandong Lijiu New Material Co., Ltd. (China): Manufactures UHMW sheets, rods, and liners for general industrial use.
- Polyreflex (China): Supplies UHMWPE sheets with high impact and abrasion resistance for industrial and ice rink applications.
- Abosn (Dezhou) New Material Co., Ltd. (China): Produces UHMWPE sheets, ground protection mats, and marine fenders.
The competitive dynamic is not solely based on price. Many of these players compete on technical support, customization capabilities, and the ability to navigate certification regimes. For a detailed breakdown of market share adjacencies and specific competitive moats, the full report provides a comparative matrix.
Recent Industry Developments and Capacity Shifts
The period leading into 2026 has seen significant activity regarding capacity and product innovation, signaling where capital is being deployed.
- Celanese Corporation (December 2024): Expanded sheet and rod compression molding capacity to meet rising OEM demand in material handling and food processing sectors.
- LyondellBasell (December 2024): Expanded medical-grade polyethylene resin production at Wesseling and Houston facilities supporting orthopedic device manufacturers.
- dsm-firmenich (December 2024): Expanded virgin-grade resin production for medical applications, reinforcing the high-value end of the spectrum.
- Mitsui Chemicals (June 2025): Launched a recyclable ultra high molecular weight polyethylene grade designed for easier recovery and reprocessing in industrial and medical applications.
- Teijin (July 2025): Commercialized the Endumax Beyond series featuring UHMWPE sheets with vastly improved adhesion properties for marine and transportation equipment.
These developments highlight a dual strategy in the market: expanding volume for established industrial uses while simultaneously engineering higher-performance grades for specialized sectors. The move towards recyclability by key players also suggests that sustainability will become a differentiating factor in procurement specifications over the forecast period.
Industry Dynamics and External Pressures
Raw Material Volatility
The economics of UHMWPE production are inextricably linked to feedstock availability and pricing. For instance, global ethylene prices increased by 6.8 percent in the first week of July 2025 in the US, driven by tight supply and refinery maintenance. Such fluctuations can compress margins for processors who lack hedging strategies or vertical integration. Our analysis includes sensitivity modeling to help finance teams anticipate how raw material shocks might impact sheet pricing and procurement budgets.
Regulatory and Certification Standards
Compliance remains a barrier to entry and a loyalty driver in key verticals. dsm-firmenich received ISO 5834 certification for UHMWPE resin agreements with orthopedic implant manufacturers in the United States and Europe. Similarly, Celanese expanded Ticona engineered materials UHMWPE capacity in 2024 to support food processing and material handling OEM customer demand growth, aligning production with regulatory expectations for food contact.
Additionally, Mitsui Chemicals expanded compression molding capacity for precision sheet applications in 2024, and LyondellBasell expanded medical-grade polyethylene resin production to support orthopedic device manufacturer procurement growth. These moves indicate that regulatory alignment is not just a compliance checkbox but a strategic enabler for scaling in high-margin segments.
Strategic Recommendations for 2026 Decision Makers
Based on the trajectory and dynamics outlined above, several strategic actions merit consideration for organizations operating in or adjacent to this market.
1. Diversify Grade Portfolios: Reliance on a single type of UHMWPE sheet exposes firms to segment-specific risks. Balancing virgin grades for high-performance clients with reprocessed options for cost-sensitive industrial accounts can stabilize revenue streams.
2. Monitor Capacity Announcements: The expansions by Celanese, LyondellBasell, and dsm-firmenich suggest tightening supply in specific high-grade categories. Procurement teams should secure long-term agreements or qualify alternative suppliers to prevent bottlenecks.
3. Invest in Application Engineering: As seen with Teijin's adhesion improvements and Mitsui's recyclability focus, value is shifting towards functionalized properties. Suppliers who can offer technical assistance on integration rather than just material sales will capture greater wallet share.
4. Evaluate Geographic Hedging: With regional variations in ethylne pricing and manufacturing capacity, supply chain resilience may require sourcing strategies that span multiple geographies, particularly for critical medical or food-grade components.
5. Prepare for Sustainability Mandates: The introduction of recyclable grades indicates a regulatory and customer push towards circular economy principles. Early adoption of these materials or development of in-house reprocessing capabilities could become a competitive differentiator.
Conclusion: The Value of Deep Intelligence
The UHMWPE Sheet Market is poised for significant expansion, driven by a CAGR of 6.98 percent and a projected valuation reaching 344.8 million USD by 2032. However, realizing value in this environment requires more than tracking top-line growth. It demands an understanding of the interplay between raw material volatility, regulatory certification, capacity shifts, and the specific performance requirements of verticals like medical devices and food processing.
This briefing has outlined the structural components of the market and the key players defining its trajectory. Yet, the specific segmentation splits, detailed regional revenue breakdowns, and precise forecast models for each application vertical contain the actionable intelligence needed to finalize investment and procurement strategies.
To access the complete dataset, including the full segmentation analysis, competitive benchmarking matrices, and risk assessment models, we invite you to consult the full UHMWPE Sheet Market Research Report. The detailed intelligence within is designed to convert these macro insights into micro-level execution plans for your organization.
For detailed analysis of this topic, please visit the official page: UHMWPE Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electronic Packaging Materials Market to Hit $3,729.9M by 2032, Growing at 7.8% CAGR
By PW Consulting, 2026-09-07
Navigating the Next Wave: Strategic Intelligence for the Electronic Packaging Materials Market (2026–2032)
As the global electronics industry enters a defining phase of architectural transformation, the materials that enable miniaturization, thermal management, and signal integrity are no longer peripheral inputs—they are strategic assets. The electronic packaging materials sector has moved beyond incremental improvement into a period of structural realignment, where material science, regulatory pressure, and assembly-node migration intersect simultaneously. Our newly published market research synthesizes five years of historical performance with a seven-year forward view, giving corporate strategists, procurement leaders, and R&D directors the evidence base needed to act decisively through 2032.
Unified Commerce Platform Market
For decision-makers operating in 2026, the question is no longer whether the packaging materials landscape will change, but how to position supply chains, product roadmaps, and partnership portfolios ahead of the curve. This analysis translates macroeconomic signals, competitive realignments, and emerging regulatory economics into actionable strategic context, while deliberately preserving granular segmentation insights for the full report. The objective is straightforward: equip leadership teams with the framing required to allocate capital, prioritize supplier relationships, and anticipate margin pressures before they become competitive disadvantages.
Worldwide Reproductive System Anatomical Model Market
Market Trajectory and the Architecture of Growth
The electronic packaging materials market has demonstrated a pronounced expansion pattern over the historical review window, with revenues rising from approximately $1,800.5 million in 2020 to $2,215.0 million in 2025. That progression was not linear, of course; short-term adjustments reflected broader electronics demand cycles, material availability constraints, and shifting semiconductor packaging priorities. Yet the underlying trajectory has converged toward a sustained upward slope, and our forecast modeling extends that momentum through 2032, with the total market projected to reach $3,729.9 million by the terminal year of the outlook period.
The implied compound annual growth rate over the 2026–2032 forecast window stands at 7.8 percent, a figure that places the sector above the broader industrial materials baseline and signals durable demand aggregation. Growth at that pace does not emerge from a single application surge or one regional engine; it reflects compounding contributions across device complexity, substrate innovations, and packaging format transitions. For enterprise planners, a 7.8 percent CAGR is a meaningful benchmark when evaluating capacity planning, long-term supplier commitments, and R&D investment horizons. It also underscores that material categories tied closely to advanced assembly and interconnection will likely outpace legacy substitution flows, creating asymmetrical opportunity zones within an otherwise unified market structure.
Worldwide MTB Helmet Market
Strategically, this trajectory matters because it reframes packaging materials from a commodity-adjacent category into a growth-supported input sector. Companies that continue to treat electronic packaging materials purely through the lens of unit cost optimization risk missing the structural value migration that accompanies format migration and node scaling. The full research report dissects how growth is distributed across material classes and end-use contexts, allowing procurement and product strategy teams to align sourcing decisions with forward demand concentration rather than backward price benchmarks.
Competitive Architecture and Strategic Positioning
Fragmented yet Focused: How Concentration Shapes Market Dynamics
One of the most operationally important findings in the 2026 outlook is the market’s concentration profile. The top three participants collectively account for roughly 18.5 percent of total sector revenue, while the top five reach approximately 25.6 percent. Those numbers tell a clear story: this is a market with recognized incumbents and specialized material specialists, but it is far from an oligopoly. Dispersion of that kind creates both opportunity and execution risk.
On the opportunity side, fragmentation means that technology differentiation, regional distribution strength, and application-specific formulation expertise can still generate meaningful premium positioning. It also means that midstream manufacturers and assembly operators have a real choice in supplier architecture—single-source dependency is not structurally forced by market economics alone. On the execution-risk side, the same dispersion requires disciplined supplier qualification, technical validation, and compliance monitoring. The firms that convert fragmentation to advantage are typically those that build portfolio relevance across multiple packaging formats while maintaining deep capability in one or two material technology families.
Incumbents at the Forefront: Profiles and Strategic Implications
Across the competitive landscape, several organizations have established themselves as reference points for capability and scale. Their activities through early 2026 provide useful signals for anyone evaluating partnership pathways or benchmarking technology roadmaps.
- 3M Company, headquartered in St. Paul, Minnesota, continues to anchor its electronics materials presence around chip packaging and interconnection solutions alongside semiconductor production materials. Its most recent 10-K filing for the fiscal year ended December 31, 2025 confirms the continued operation of its Electronics Materials Solutions segment with chip packaging and interconnection offerings, signaling that this capability set remains a defined business-line priority rather than a residual product line.
- Henkel AG & Co. KGaA, based in Düsseldorf, Germany, maintains a strong focus on epoxy-based structural adhesives, underfill materials, and packaging solutions. Its half-year financial report for 2025 described continued growth in industrial adhesives and specialty materials, including electronics packaging, which reinforces the strategic relevance of adhesive and underfill chemistry in current packaging architectures.
- Heraeus Holding GmbH, located in Hanau, Germany, provides materials and material systems for assembly and advanced semiconductor packaging. Its 2024 financial report highlighted growth within its Semiconductor & Electronics business platform, specifically in advanced packaging materials—an indicator that high-performance material systems remain an active investment and revenue focus.
- NAMICS Corporation, operating out of Japan, concentrates on advanced materials for semiconductor devices and packages. The company’s positioning reflects the broader demand pull for precision materials that support tighter tolerance assembly and higher thermal and mechanical reliability requirements.
- PacTech USA Packaging Technologies, Inc., with its operational base in Germany, focuses on wafer-level bumping and packaging technologies and services. That service-and-technology orientation matters because it bridges material supply with process integration, an increasingly important combination as packaging formats become more customized and node-specific.
Together, these profiles illustrate a market where chemical formulation, substrate interface engineering, and process-level packaging expertise all carry strategic weight. The competitive environment rewards firms that can align material supply with application-specific process needs, and it pressures laggards that rely on generic catalog selling without application engineering depth. Our report goes further into each company’s positioning, strategic moves, and likely implications for sourcing strategy and technical collaboration, but the immediate takeaway for 2026 planning is clear: supplier selection is becoming less about price lists and more about capability alignment across advanced assembly requirements.
Macro Pressure Points: Materials, Regulation, and Cost Architecture
Raw Material Signals and the Cost Environment
Cost discipline in electronic packaging materials cannot be separated from upstream material economics. Throughout early 2026, pricing indicators for polymer-based inputs have sent mixed but strategically relevant signals. According to the U.S. Bureau of Labor Statistics, the Producer Price Index for plastic materials and resin manufacturing registered 329.454 in April 2026, up from 312.442 in March 2026. That month-over-month movement points to near-term price volatility in resin-dependent supply chains. At the same time, broader annual tracking reported by IbisWorld showed the Producer Price Index for plastic materials and resin declining to 285.0 in 2026, a 9.5 percent decrease from the prior year. Taken together, these data points highlight a market where short-term monthly swings can coexist with a longer-term easing or repricing trend, depending on basis, timing, and material grade.
For procurement teams, the practical implication is not to anchor budgets on a single index printout, but to build contracting and inventory strategies that can accommodate both directionality and volatility. In a market growing at a mid-to-high single-digit CAGR, even modest raw material repricing can alter margin expectations across packaging material categories. The full report links these macro cost signals to segment-level exposure, helping leaders identify where resin-linked categories, specialty formulations, or high-performance compounds may face more pronounced cost transmission.
Regulatory Reconfiguration: Compliance as a Competitive Variable
Regulatory developments are reshaping the packaging materials economic equation in ways that go well beyond environmental compliance. The Packaging and Packaging Waste Regulation entered into force on 11 February 2025 and applies generally from 12 August 2026, introducing requirements for increased recycled plastic content in packaging. While this regulation is not exclusively about electronic packaging materials, it intersects with material sourcing strategies wherever plastic-based packaging solutions are part of the supply chain or product delivery architecture. The compliance timeline means that companies must already be operationalizing sourcing adjustments, supplier documentation, and content verification as they move through 2026.
In parallel, several U.S. states including Oregon and Maine have launched extended producer responsibility packaging programs with fees calculated by weight beginning in 2026. These state-level mechanisms expand the financial footprint of packaging decisions and increase the importance of weight efficiency, material choice, and packaging minimization in total cost modeling. For companies that consume electronic packaging materials in broader product distribution or device packaging chains, EPR fees introduce another variable into landed-cost and lifecycle cost calculations.
Strategically, regulation should not be treated as a compliance footnote. When recycled-content mandates and weight-based EPR fees begin affecting material selection and packaging geometry, they also influence supplier prioritization, qualification cycles, and long-term cost structure. The market study incorporates these dynamics into its forward assessment so that strategists can gauge where regulatory exposure may reinforce or disrupt existing sourcing preferences.
What the Research Delivers for 2026 Decision-Making
Operational Depth Behind the Outlook
A market overview can describe direction; it cannot, by itself, support procurement strategy, technology roadmapping, or competitive benchmarking. The full report is built to bridge that gap. It combines historical reconstruction, forward modeling, segment-level analysis, and company-specific profiling into a single decision-support structure. Rather than stopping at headline totals, the research maps the structural logic behind growth, identifies where material classes and application contexts diverge in growth intensity, and traces the competitive behavior of firms that are actively shaping the market’s next phase.
Practically, the report is designed for teams that need to answer questions such as:
- Where is demand concentration most likely to intensify across material types and end-use contexts through 2032?
- Which supplier capabilities are becoming more valuable as packaging formats become more application-specific?
- How should raw material volatility and regulatory cost mechanisms be incorporated into sourcing and pricing strategies?
- What company-level developments signal near-term shifts in technology emphasis or capacity orientation?
- How does market concentration shape negotiation leverage, qualification strategy, and supply continuity risk?
These are not abstract planning questions. In a market expanding from roughly $2.3 billion in 2026 to nearly $3.7 billion by 2032, the allocation of limited technical, procurement, and capital resources will determine which organizations capture value and which merely follow it. The report provides the structured intelligence needed to make those allocation calls with greater confidence.
Why 2026 Is a Strategic Inflection Point
The current year is especially consequential because multiple forces are converging at once. Demand growth remains robust enough to justify capacity and technology investment, but raw material pricing is showing both near-term volatility and longer-term directional change. Regulatory frameworks are moving from policy language to operational enforceability, and they are doing so while companies are still adjusting supply chains to advanced packaging requirements. At the same time, the competitive field remains sufficiently dispersed that differentiation is possible, but concentrated enough that technology leadership and application expertise can create durable advantages.
In that environment, the most effective strategic move is to replace assumption-based sourcing and reactive compliance with evidence-based planning. That means understanding not only the total market size and growth rate, but also where growth is concentrated, which material and application pathways are most exposed to cost and regulatory shifts, and how leading participants are aligning their portfolios with advanced packaging needs. Our research is structured to support exactly that decision sequence.
From Signal to Strategy: Accessing the Full Intelligence
The figures and developments summarized here establish the strategic backdrop; the complete report delivers the operational architecture behind them. While this preview highlights macro trajectory, concentration dynamics, competitive profiles, and regulatory-material pressure points, the full publication contains the segmentation detail, company benchmarking, and segment-level exposure analysis required to translate strategy into execution.
For teams building sourcing strategies, evaluating supplier partnerships, aligning R&D priorities, or preparing for regulatory-driven cost shifts, the difference between headline awareness and segment-specific intelligence can be substantial. The research was designed to close that gap. It provides a rigorous view of how the electronic packaging materials market is likely to evolve through 2032, which participants are shaping that evolution, and what cost and compliance variables will influence margin and sourcing outcomes along the way.
The strategic message for 2026 is clear: this market is expanding at a pace and with a structural complexity that rewards informed positioning. Organizations that incorporate forward-looking market intelligence into supplier selection, material qualification, and cost strategy will be better placed to manage volatility, meet compliance expectations, and capture growth where it is most concentrated. Those that rely on backward-looking assumptions will face a more difficult alignment problem as advanced packaging requirements and regulatory economics continue to reshape the field.
For the complete segmentation analysis, competitive benchmarking, and region- and application-level intelligence that supports precise 2026 decision-making, the full Electronic Packaging Materials Market research report is available through our official market research page.
For detailed analysis of this topic, please visit the official page: Electronic Packaging Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EVA Resin Market Hits $112.02M in 2025, Projected 8.83% CAGR Through 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for the EVA Resin Market: Navigating Growth, Volatility, and Competitive Shifts Through 2032
The global ethylene-vinyl acetate resin market is entering a decisive growth phase, shaped by converging forces in packaging, renewable energy, and sustainable material innovation. For executives planning 2026 budgets, capacity investments, and product roadmaps, the landscape demands more than surface-level trend tracking. It requires a disciplined, data-grounded view of where value is accumulating, which applications will drive the next wave of demand, and how supply-side dynamics will compress or expand margins in the years ahead. PW Consulting’s latest EVA Resin Market research is designed precisely for that purpose: a structured, decision-ready intelligence package that translates historical performance and forward-looking projections into actionable strategy.
Worldwide Projection Display Chip Market
This market study covers the trajectory from 2020 through 2032, with 2025 established as the base year and a full forecast window extending to 2032. The market, measured in millions of USD, moved from 87.51 in 2020 to 92.52 in 2021, then climbed to 94.29 in 2022, 99.52 in 2023, and 110.15 in 2024. The momentum continued into 2025 with a recorded size of 112.02, followed by a projected 125.56 in 2026, 132.54 in 2027, 144.11 in 2028, 159.3 in 2029, 168.6 in 2030, 182.73 in 2031, and 199.92 in 2032. This progression underpins a forecast CAGR of 8.83 percent, signaling a market that is expanding at a pace well above cyclical commodity norms and reflecting structural demand rather than one-off spikes.
Worldwide Laminated Shim Market
The strategic importance of these numbers lies not in the figures themselves, but in what they imply for portfolio planning. A market advancing from just over 112 near-term to nearly 200 by the end of the forecast period requires leaders to answer a different set of questions: where will volume concentrate, which application segments will capture disproportionate share, and how should sourcing and capacity decisions be sequenced to protect margin against raw material volatility? The research addresses these questions with a framework built for operating decisions rather than abstract market narration.
왜 이 연구가 2026 년 의사결정의 기준이 되는가
2026 년은 EVA 수지 공급망에서 단순한 연간 계획이 아니라 전환점이 될 가능성이 높습니다. 수요 구조는 포장재와 태양광 캡슐화를 중심으로 성숙하고 있으며, 발포체와 핫멜트 접착제 역시 용도별 기술 차별화가 본격화되고 있습니다. 동시에 에틸렌 기반 원재료 가격의 변동은 생산원가의 구조적 변수로 작용하고 있어, 구매 전략과 재고 설계, 장기 계약 조건을 통합한 접근이 필요합니다.
이 보고서는 각 의사결정 단계에 맞춘 인사이트 경로를 제공합니다. 먼저 시장 규모와 성장률의 시계열 흐름을 통해 현재 단계가 회복 국면인지, 구조적 확장 국면인지 판단할 수 있도록 구성했습니다. 다음으로 유형, 용도, 지역별 흐름을 종합해 어느 축에서 수요가 더 빠르게 형성되는지 확인할 수 있으며, 경쟁 강도 및 집중도 지표를 통해 신규 진출, 제휴, 또는 차별화 포지셔닝의 현실성을 점검하도록 설계했습니다. 마지막으로 최근 공급 확대와 제품 출시, 규제 환경 변화를 함께 다루어 수량적 전망만이 아니라 운영 리스크와 기회 요인을 동시에 읽을 수 있게 했습니다.
실무적으로 이 연구는 다음과 같은 질문에 답하는 데 활용됩니다.
- 2026 년 이후 성장 속도가 빨라지는 구간과 상대적으로 완만하게 움직이는 구간을 어떻게 구분할 것인가
- 포장, 태양광, 발포, 접착제 등 주요 용도 중 우선순위 투자 대상은 어디이며, 그 판단의 근거는 무엇인가
- 원재료 가격 변동과 공급 차질이 마진에 미치는 영향을 완화하기 위해 조달, 생산, 배합 전략을 어떻게 재설계할 것인가
- 지역별로 다른 규제, 관세, 인증 요건이 사업성 평가에 어떤 차이를 만들며, 어떤 시장 진입 방식이 현실적인가
- 경쟁사가 최근 발표한 설비 확장이나 신규 등급 출시가 자사 포지션에 어떤 영향을 주는가
핵심은 수치를 나열하는 것이 아니라, 수치를 전략 언어로 바꾸는 데 있습니다. 보고서가 제시하는 전망은 단순한 목표치가 아니라, 투자 타이밍, 제품 믹스 조정, 공급망 재편의 기준으로 쓰일 수 있도록 구성되어 있습니다.
보고서의 실전형 구성: 무엇을 담고 있는가
이 시장 연구는 경영진, 사업 개발, 조달, 연구개발, 영업 전략 담당자가 각각 필요로 하는 깊이를 한 문서 안에서 접근할 수 있도록 설계되었습니다. 중심에는 장기 시장 궤적과 성장 동인이 있으며, 그 주변으로 유형 체계, 용도 구조, 지역 분포, 경쟁 구도, 그리고 외부 환경 변수가 유기적으로 연결됩니다.
먼저 시장 규모 시리즈는 2020 년부터 2032 년까지의 흐름을 연속적으로 제시해 기준 연도 대비 현재 위치와 향후 확장 폭을 함께 확인할 수 있게 합니다. 이를 통해 2026 년을 기점으로 본격화되는 성장 경로 상에서 어느 구간이 가장 큰 증분 수요를 만들어내는지, 어떤 타이밍에 선제적 대응이 필요한지 해석할 수 있습니다. 성장률 지표 역시 단순 산출값이 아니라, 시장 성숙도와 수요 전환 속도를 함께 고려하는 관점에서 해석되도록 정리되어 있습니다.
유형별 분석에서는 저밀도, 중밀도, 고밀도 EVA 의 용도 적합성과 수요 형성 방식이 어떻게 다른지 다룹니다. 각 유형은 동일한 수지 범주에 속하면서도 포장재 적합성, 접착 성능, 발포 특성, 태양광 모듈 요구사양 등 각기 다른 기술적 매력과 비용 구조를 갖습니다. 보고서는 이러한 차이가 실제 수요와 가격 협상력에 어떤 영향을 주는지 이해할 수 있도록 구성되어 있으며, 특정 세부 수치보다는 유형별 전략적 의미를 읽도록 돕습니다.
용도 측면에서는 포장재 필름, 태양광 셀 캡슐화, 발포체, 핫멜트 접착제, 기타 응용으로 나누어 수요 동인과 성장 조건을 설명합니다. 포장재는 물량 기반과 유통·소비재 드라이빙이 강한 영역이고, 태양광 캡슐화는 모듈 보급과 신뢰성 요구 측면에서 구조적 수요가 형성되는 영역입니다. 발포체와 접착제는 가공 특성과 최종 용도 집단의 요구사항에 따라 차별화 기회가 존재하는 영역입니다. 보고서는 각 용도의 성장률이 단순한 시장 점유율이 아니라 제품 사양, 규제 반응, 공정 효율, 대체재 압력과 어떻게 연결되는지 보여주도록 구성되어 있습니다.
지역 분석에서는 북미, 유럽, 아시아 태평양, 라틴아메리카, 중동 및 아프리카를 아우르며 지역별 성장 배경과 수요 중심, 공급망 접근성의 차이를 비교합니다. 어느 지역이 단기 확대 기회가 큰지, 어느 지역이 규제나 현지화 요건 때문에 진입 방식이 달라지는지, 어느 지역이 생산 거점이나 조달 거점으로 기능할 수 있는지에 대한 판단을 지원하도록 정리되어 있습니다. 세부 지역별 수치보다는 상대 위치와 성장 조건, 리스크 요인의 차이를 읽는 데 초점을 둡니다.
경쟁 구도 부문에서는 참여 기업의 제품 포트폴리오와 최근 움직임을 함께 검토해 시장의 집중도와 차별화 가능성을 평가합니다. 보고서의 경쟁 분석은 단순 기업 목록이 아니라, 각사가 어떤 응용 축을 중심으로 역량을 쌓고 있는지, 최근 설비 확장이나 바이오 기반 등급 출시가 어떤 전략적 방향성과 연결되는지 해석하도록 설계되어 있습니다.
마지막으로 시장 동학 섹션에서는 원재료 가격 상관성, 공급 차질, 관세와 규제 요건, 환경 기준과 컴플라이언스 이슈가 EVA 수지의 원가와 수요에 미치는 영향을 다룹니다. 특히 에틸렌과 비닐 아세테이트 관련 흐름이 생산원가에 미치는 영향, 지역별 관세 스케줄과 협정에 따른 수입 조건 변화, VOC 및 미세플라스틱 관련 규제와 reformulation 압력이 제품 설계와 공급 전략에 어떤 제약을 주는지 설명합니다. 이는 재무 모델링과 운영 계획을 동시에 검토할 때 필요한 배경입니다.
경쟁 구도와 최근 움직임의 전략적 의미
EVA 수지 시장은 상위 기업들의 집중도가 높은 구조로 이해할 필요가 있습니다. 시장 집중도 지표는 상위 3 개사 기준 65.0 퍼센트, 상위 5 개사 기준 85.0 퍼센트로 보고되며, 이는 신규 진입이나 범용 물량 경쟁만으로는 구조적 이점을 확보하기 어렵다는 점을 시사합니다. 결과적으로 경쟁 우위는 규모 그 자체보다 용도 적합성, 공급 안정성, 기술 차별성, 그리고 지속가능성 기반 제품 전략에서 형성될 가능성이 큽니다.
주요 참여 기업들을 살펴보면, 각사는 서로 다른 응용 축과 브랜드 자산을 중심으로 시장을 공략하고 있습니다. Dow Inc. 는 ELVAX™를 비롯한 EVA 공중합체 수지를 중심으로 포장, 접착제, 전선 및 케이블, 태양광 캡슐화 응용을 다루고 있으며, 폭넓은 응용 커버리지를 기반으로 다양한 가공 요건에 대응하는 포지션을 취하고 있습니다. ExxonMobil Corporation 은 폴리올레핀 플랜트를 통해 포장, 태양광, 폴리올레핀 응용용 EVA 공중합체를 공급하고 있으며, 최근 Baytown 폴리올레핀 플랜트의 가동 확대로 포장 및 태양광용 EVA 공중합체 생산능력을 확장한 바 있습니다.
Celanese Corporation 은 Ateva® 브랜드 EVA 수지를 통해 핫멜트 접착제, 코팅, 태양광 캡슐런트 중심의 응용에 접근하고 있으며, 접착과 코팅 성능을 요구하는 용도에서 기술 기반 차별화가 가능한 구조를 갖추고 있습니다. LG Chem Ltd. 는 신발, 포장, 산업용 응용을 위한 EVA 공중합체를 생산하며, 아시아 기반의 공급 역량과 다용도 포트폴리오를 통해 지역별 수요와 연결하는 전략을 취하고 있습니다. Lotte Chemical Corporation 은 접착제, 포장, 건설용 EVA 수지를 공급해 산업 전반의 수요층을 폭넓게 포괄하는 방향을 지향합니다.
Hanwha Solutions Corporation 은 포장 및 필름 응용용 EVA 수지를 다루며 필름 가공과 포장 용도에서의 적용성을 강조합니다. Braskem S.A. 는 사탕수수 기반의 I'm green™ 바이오 EVA 수지를 통해 지속가능성 중심 제품군에서 존재감을 구축하고 있으며, 원재료 소싱과 탄소 관련 차별화 측면에서 주목을 받고 있습니다. Formosa Plastics Corporation 은 다양한 산업용으로 EVA 공중합체를 제조하며, 범용 응용에서의 공급 안정성과 폭넓은 가공 대응이 강점 영역으로 볼 수 있습니다.
여기에 최근 발표된 사업 움직임이 시장 방향을 더 선명하게 만듭니다. Borealis 는 2025 년 5 월 신발 중창용 Borenewables EVA 등급을 출시하며 지속가능성 이니셔티브를 강화했고, 2025 년 10 월에는 조류 유래 소재와 EVA 를 혼합한 Bloom Materials 라인을 도입해 친환경 소재 포트폴리오를 확장했습니다. ExxonMobil 은 2024 년 4 월 발표 이후 2025 년까지 이어지는 Baytown 폴리올레핀 플랜트의 신규 운영을 통해 포장 및 태양광용 EVA 공중합체 생산능력을 확대했습니다.
이러한 움직임은 몇 가지 공통된 전략적 신호를 줍니다. 첫째, 용량 확대는 단순한 물량 증가가 아니라 포장재와 태양광이라는 수요 강세 응용에 대한 공급 안정화 의도를 담고 있습니다. 둘째, 바이오 기반 및 혼합 소재 등급의 출시는 규제 환경과 고객 요구 변화에 선제적으로 대응하는 차별화 경로로 볼 수 있습니다. 셋째, 지역별 기업 구성이 다양하게 형성되어 있어, 아시아 기반의 공급 역량과 미주·유럽 기반의 기술·브랜드 포트폴리오가 서로 다른 경쟁 축으로 작동하고 있습니다. 보고서는 이러한 개별 움직임을 시장 전체 맥락에서 해석해, 어떤 기업의 전략이 단기 물량 확보에 가까운지, 어떤 움직임이 중장기 포지셔닝에 가까운지 구분할 수 있도록 돕습니다.
원재료, 규제, 공급 리스크가 비즈니스에 미치는 영향
EVA 수지 사업의 수익성과 운영 안정성은 결국 원재료 흐름과 규제 환경의 조합에서 결정됩니다. 산업 데이터에 따르면 글로벌 에틸렌 가격은 원유 가격과 높은 상관관계를 유지하며, 2022 년 이후의 에너지 crisis 영향이 지속되면서 EVA 공중합체 생산원가에 직접적인 변동성을 초래하고 있습니다. 에틸렌과 VAM 은 통상 생산원가의 70~80 퍼센트 수준을 차지하므로, 이 구간의 가격 움직임은 판매 가격 협상, 계약 구조, 재고 전략, 생산 스케줄링에 직접적인 영향을 줍니다.
공급 측면에서는 중국과 중동 지역의 지정학적 긴장과 플랜트 셧다운이 비닐 아세테이트 모노머 공급에 차질을 일으켜 2024~2025 년 동안 가격 변동과 계약 조정으로 이어졌습니다. 이는 단순히 원재료 가격 문제가 아니라, 계약 조건 재설계, 대체 소싱 경로 확보, 생산 계획의 유연성 확보라는 운영 과제로 연결됩니다. 특히 수요가 빠르게 확장되는 구간에서는 공급 안정성이 가격 경쟁력만큼 중요해질 수 있어, 조달 전략의 재점검이 필요합니다.
규제 환경은 지역별로 차별화되어 있으며, 같은 수지라도 적용되는 요건과 비용이 달라질 수 있습니다. 일본 관세 스케줄에서는 에틸렌-비닐 아세테이트 공중합체가 HS 390130 으로 분류되며 4.1 퍼센트의 기본 세율이 적용되고, RCEP 요건 충족 수입품에는 2.8 퍼센트의 경감 세율이 적용됩니다. 이는 수입 경로 설계, 원산지 관리, 협정 활용 여부에 따라 실효 비용 구조가 달라질 수 있음을 의미합니다. EU REACH 및 관련 지침은 플라스틱 소재의 VOC 배출에 대한 더 엄격한 제한을 부과하고 있어, 포장 및 자동차 부문에서 EVA 기반 제품의 reformulation 노력이 촉발되고 있습니다.
미국과 유럽의 규제 동향도 간과할 수 없습니다. 미국 EPA 와 ECHA 는 EVA 유래 소재의 VOC 및 미세플라스틱 배출 관련 모니터링과 규제를 계속하고 있으며, 북미와 유럽에서의 생산에 컴플라이언스 요건이 영향을 미치고 있습니다. 규제 대응은 단순한 법적 준수를 넘어 제품 배합, 포장 설계, 고객과의 사양 협의, 그리고 장기적으로는 제품 포지셔닝과 차별화 방식까지 연결될 수 있습니다.
이러한 동학은 EVA 수지 시장을 단순한 성장 시장으로 보기보다, 원가 구조와 규제 대응력, 공급 안정성이 함께 작용하는 복합 경쟁 시장으로 이해해야 한다는 점을 보여줍니다. 보고서는 이 요소들을 시장 전망 및 경쟁 분석과 분리해 설명하지 않고, 서로 어떻게 겹치는지 읽을 수 있도록 배치해 경영 판단의 일관성을 높이도록 구성했습니다.
어떤 의사결정을 위해 이 연구를 활용해야 하는가
이 연구의 가치는 전망 수치 자체보다, 그 수치를 어떤 의사결정 프레임에 넣고 활용할 수 있는지에 있습니다. 2026 년을 포함한 중기 계획을 세우는 조직이라면 다음과 같은 활용 경로를 고려할 수 있습니다.
- 사업 포트폴리오 검토 시, 어떤 용도 또는 지역이 더 높은 성장 탄력성을 보이는지 확인하고 우선순위 조정 근거로 활용한다
- 공급망 및 조달 전략 수립 시, 원재료 가격 상관성과 공급 차질 사례를 반영해 계약 구조, 재고 수준, 대체 소싱 가능성을 재설계한다
- 생산능력 및 투자 검토 시, 수요 성장 경로와 경쟁사의 용량 확대가 장기적으로 어떤 수급 균형을 만들 수 있는지 가정 검증에 활용한다
- 제품 개발 및 reformulation 계획에서 규제 변화와 고객 요구 변화를 반영해 예상 비용, 인증, 시장 수용성을 함께 검토한다
- 경쟁 대응 전략 설계 시, 주요 기업의 브랜드, 응용 커버리지, 최근 제품 출시 패턴을 기준으로 우리 포지션의 차별 지점을 정의한다
특히 중요한 점은 세부 수치의 단순 확보가 아니라, 수치가 의미하는 전략적 결론을 추출하는 일입니다. 예를 들어 특정 유형의 점유율이나 특정 용도의 절대 금액이 아니라, 그 흐름이 우리 제품 라인, 고객사 구조, 생산 거점, 규제 노출과 어떻게 맞닿아 있는지를 함께 읽어야 실제 의사결정에 활용할 수 있습니다. 이 보고서는 바로 그 연결을 돕도록 설계되어 있습니다.
결론: 성장 전망보다 중요한 것은 해석의 정밀도와 실행 연결성
EVA 수지 시장은 2026 년 이후 2032 년까지 확장 궤도를 이어갈 가능성이 높으며, 그 과정에서 포장, 태양광, 발포, 접착제 등 주요 용도의 수요 동인과 원재료·규제 환경의 변화가 복합적으로 작용합니다. 시장이 커지는 국면일수록 기회는 넓어지지만, 경쟁은 더 정교해지고 원가 구조는 더 민감해집니다. 따라서 성장률은 출발점일 뿐이며, 실제로는 유형 선택, 용도 집중, 지역 진입 방식, 공급 안정성, 규제 대응, 그리고 경쟁사의 최근 행보가 함께 평가되어야 합니다.
PW Consulting 의 EVA Resin Market 연구는 이러한 다차원 판단을 지원하기 위해, 시장 규모 시계열과 성장 경로, 유형·용도·지역의 구조, 경쟁 집중도와 주요 기업 전략, 그리고 원재료 및 규제 동학을 하나의 일관된 프레임으로 정리했습니다. 세부 구간별 수치, 세부 지역별 비중, 세부 용도별 금액과 같은 핵심 분할 데이터는 전체 그림을 이해하는 데 필수적이지만, 실제 전략 수립 단계에서는 보다 정밀한 비교와 내부 데이터와의 결합이 필요합니다. 이 연구의 fuller insights, full segmentation breakdowns, and complete scenario detail 은 하단 링크를 통해 확인하실 수 있습니다.
Access the full EVA Resin Market report and detailed market intelligence here
이 소개 글은 연구의 범위와 방향, 그리고 2026 년 의사결정에 주는 의미를 개괄적으로 보여드리기 위한 것입니다. 실제 실행 가능한 판단과 내부 계획 수립을 위해서는 시장 구조, 경쟁 위치, 원가·규제 변수를 함께 포함한 전체 보고서를 검토하시기를 권장합니다.
For detailed analysis of this topic, please visit the official page: EVA Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Magnetic Couplings Market Hits $215M in 2025, Projected 6.98% CAGR
By PW Consulting, 2026-09-07
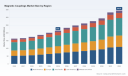
Strategic Intelligence: Navigating the Magnetic Couplings Market in 2026 and Beyond
The industrial landscape of 2026 is defined by a singular imperative: the integration of efficiency, safety, and reliability into core operational machinery. For senior executives and strategic planners, understanding the trajectory of enabling technologies is no longer optional; it is a prerequisite for resilient supply chain management and capital allocation. The Magnetic Couplings Market represents a critical nexus in this evolution, bridging the gap between traditional mechanical drive systems and the demands of modern, hermetic, and energy-efficient industrial processes.
Worldwide Hydraulic Servo Drive Market
PW Consulting is pleased to present a comprehensive market study designed to equip stakeholders with the foresight necessary to navigate this dynamic sector. This article serves as a strategic overview, highlighting the macroeconomic trends, competitive tensions, and operational drivers that define the market landscape from 2026 through 2032. It is intended to demonstrate the depth of our analysis while respecting the proprietary nature of the granular data contained within the full report.
Worldwide Mini Pleat HEPA Filter Market
Market Trajectory and Historical Context
Understanding where the market is going requires a clear view of where it has been. The Magnetic Couplings Market has exhibited consistent growth over the past half-decade, driven by a steady shift toward non-contact torque transmission solutions. In 2025, the market established a significant baseline, reflecting the cumulative impact of industrial automation upgrades and stricter environmental compliance measures across chemical and process industries.
Dust-Free Bag Vacuum Cleaner Market
Our analysis tracks this evolution from 2020 through the base year of 2025, providing a robust historical dataset that validates growth trends. The momentum has carried forward into 2026, where the market value is projected to reach new heights. This trajectory is not merely linear; it reflects compounding adoption rates in key verticals where leakage prevention and maintenance reduction are paramount. Looking ahead, the forecast period extends to 2032, offering a long-term view for investment planning. The compound annual growth rate observed over this forecast horizon underscores a sustained expansion phase, suggesting that magnetic couplings are transitioning from niche components to standard considerations in drive engineering.
For strategic decision-makers, these top-line figures validate the sector's stability. However, the true value lies in understanding the velocity of this change. The progression from the 2025 baseline to the 2032 outlook indicates a market that is maturing but still possesses significant runway for penetration. Companies that align their product development and market entry strategies with this growth curve stand to capture disproportionate value.
Drivers of Adoption and Market Dynamics
The expansion of the magnetic couplings sector is not happening in a vacuum. It is propelled by a confluence of macroeconomic trends, regulatory pressures, and technological necessities. In 2026, three distinct forces are shaping the demand landscape.
First, the push for energy efficiency remains a dominant theme. Industrial operations are under increasing pressure to reduce carbon footprints and operational expenditures. Magnetic couplings offer a pathway to optimized drive systems that minimize friction losses and enable variable speed control without the wear associated with mechanical contact. This is particularly relevant in sectors where pump and mixer operations run continuously, such as in chemical processing and water management.
Second, safety and environmental regulations are tightening globally. Industries handling hazardous materials, including petrochemicals and pharmaceuticals, face stricter requirements for hermetic sealing and leakage prevention. Magnetic couplings provide the necessary barrier-free separation between motor and pump shafts, eliminating the risk of seal failure and subsequent hazardous emissions. Compliance with these evolving standards is becoming a critical driver for procurement teams evaluating replacement and new installation projects.
Third, the broader trend toward industrial automation and robotics is creating new application niches. As manufacturing processes become more sophisticated, the demand for precise, contactless torque transmission increases. This extends beyond traditional heavy industry into medical devices and precision instrumentation, where reliability and cleanliness are essential. The market dynamics reflect this diversification, with demand signals strengthening across multiple application verticals.
Supply Chain and Raw Material Considerations
While demand drivers paint a positive picture, the supply side presents complexities that strategic leaders must monitor closely. The manufacturing of magnetic couplings, particularly those utilizing high-performance permanent magnets, is deeply tied to the rare-earth materials market.
Recent industry data indicates that raw material costs can account for a substantial majority of the total cost structure for neodymium-based magnetic couplings. Specific elements such as neodymium, praseodymium, and dysprosium represent the lion's share of these expenses. This concentration of cost means that price volatility in the rare-earth sector directly impacts the profitability and pricing strategies of coupling manufacturers.
Furthermore, geopolitical factors have come into sharp focus following regulatory changes in key producing regions. Notably, restrictions implemented in late 2025 regarding rare-earth and magnet exports have introduced fluctuations in global supply availability. Market participants witnessed a decline in export volumes during this period, which rippled through the supply chain. For companies relying on global sourcing strategies, these disruptions highlight the importance of supply chain security and diversification.
In response, some manufacturers are emphasizing localized production capabilities and engineered solutions that reduce dependency on volatile imports. This shift is influencing the competitive landscape, favoring firms with robust supply chain management and the ability to offer stable pricing despite market fluctuations. Strategic procurement and long-term supplier partnerships are becoming differentiating factors in this environment.
Competitive Landscape and Industry Players
The market is characterized by a mix of established engineering firms and specialized magnet manufacturers. Our analysis identifies a concentrated competitive environment where key players hold significant market share. The data suggests a moderate to high level of concentration, indicating thatwhile the market is open to innovation, scale and technical expertise remain critical barriers to entry.
Several companies are defining the standards for performance and application integration. In Europe, firms such as DST Dauermagnet-SystemTechnik GmbH and KTR Systems GmbH are recognized for their specialized permanent magnetic couplings designed for hermetic separation in demanding process industries. KTR's MINEX series, for instance, highlights the focus on pumps and agitators where leak prevention is critical. Similarly, mayr power transmission GmbH integrates magnetic couplings with safety brakes and torque limiters, addressing the needs of automation and robotics applications.
In the United States, companies like Magnetic Technologies Ltd. and MagnaDrive Corporation focus on custom solutions for seal-less pumps and energy-efficient drives. MagnaDrive's emphasis on torque-limiting couplings for mining and power generation illustrates the diversification of applications into heavy infrastructure. Dexter Magnetic Technologies brings expertise in synchronous and hysteresis couplings for high-precision fields such as medical devices and aerospace, showcasing the technology's reach beyond traditional industrial uses.
The presence of established industrial groups also shapes the landscape. EagleBurgmann provides magnetic coupling solutions specifically for hydrocarbon pumps in petrochemical and nuclear industries, leveraging deep domain knowledge in sealing technology. Eclipse Magnetics and Magnet Applications contribute by offering bespoke magnet assemblies and engineered solutions, with a noted emphasis on U.S.-based manufacturing to support supply chain security.
In Asia, SDM Magnetics Co., Ltd. represents the manufacturing capacity available in the region, focusing on sintered neodymium and custom assemblies for industrial automation. This global distribution of players ensures that supply capabilities exist across major regions, though logistics and trade policies continue to influence regional availability.
Recent Developments and Product Innovation
The pace of innovation remains high as companies seek to differentiate their offerings in a growing market. Recent activity in 2026 demonstrates a continued focus on showcasing integrated solutions and launching specific product lines tailored to emerging needs.
At major industry events such as ConExpo 2026, larger transmission groups like Regal Rexnord showcased integrated power transmission solutions that included magnetic couplings. This visibility at high-profile trade shows signals the technology's increasing relevance in broader power transmission ecosystems. Simultaneously, component specialists like Miki Pulley introduced contactless link magnetic couplings designed specifically for non-contact torque transmission, highlighting ongoing refinement in core product designs.
Further back in the recent timeline, Magnetic Technologies Ltd. announced new coupling models aimed at precision industrial applications, reinforcing the trend toward higher specification requirements. These developments indicate that competitors are not merely copying existing architectures but are actively engineering improvements to handle more demanding torque profiles and environmental conditions.
For buyers and partners, keeping track of these product launches is essential. The introduction of new models often signals shifts in capabilities, such as higher torque limits, improved thermal stability, or easier integration with motor systems. These incremental innovations can accumulate to create significant operational advantages over the lifecycle of the equipment.
Strategic Segmentation Insights
Understanding the market requires breaking it down by key dimensions, though the specific weightings often hold the proprietary key to investment timing. Our report delves into segmentation by region, type, and application, providing the granularity needed to identify high-potential pockets of growth.
Regionally, the market is distributed across major global economies. North America, Europe, and Asia Pacific represent significant bases of activity, each with distinct regulatory and industrial drivers. While aggregate figures show robust activity across these regions, the relative strength varies based on local manufacturing density and environmental mandate strictness. Latin America and the Middle East and Africa also contribute, often driven by specific large-scale infrastructure projects in petrochemical and water treatment sectors.
By product type, the market is anchored by disc-type and synchronous couplings, which handle the bulk of transactional volume in industrial settings. Disc-type couplings are broadly used for their simplicity and effectiveness in torque transmission, while synchronous types offer precise speed matching for specialized applications. Other types cater to niche requirements, ensuring that the technology can be adapted to a wide range of mechanical interfaces.
In terms of application, underwater environments represent a significant use case, driven by the need for reliable, sealed systems in subsea operations. The petrochemical sector remains a foundational application area, where safety regulations mandate hermetic solutions for pumps and mixers. The electronic sector, while smaller in volume terms, represents a high-growth niche where precision and miniaturization are key. Understanding which segments are outpacing the general market trend is vital for portfolio strategy.
Market Concentration and Competitive Intelligence
The competitive structure of the magnetic couplings market influences pricing power and innovation speed. Our analysis highlights a concentrated market environment, where a core group of firms commands a substantial portion of revenue. This concentration suggests that relationships with top-tier suppliers are critical for end-users seeking compliance and reliability.
For new entrants or those looking to expand, the concentration levels imply that competing on price alone is insufficient. Differentiation through customization, service support, and supply chain reliability is necessary to erode the share of incumbents. The presence of both specialized magnetic firms and large industrial conglomerates creates a dual dynamic where niche expertise competes with broad solution integration.
Strategic players are increasingly leveraging their ability to offer end-to-end solutions. By combining magnet manufacturing expertise with coupling design and integration services, leading companies reduce friction for customers who prefer single-source accountability. This trend is expected to continue, reinforcing the position of firms with comprehensive capabilities.
The Strategic Value of Comprehensive Market Intelligence
While the overview provided here captures the essential currents of the Magnetic Couplings Market, the complexities of 2026 and beyond require deeper data. Executive decisions regarding capital investment, supplier selection, and market entry demand precision that only a structured market study can provide.
The full PW Consulting report offers detailed breakdowns of market size and forecast figures across the entire forecast period. It unpacks the segmentation data to reveal which specific regions and applications are offering the highest return potential. This level of detail allows strategists to move beyond general trends and identify actionable opportunities.
Furthermore, the report provides a comprehensive competitive profiling section that goes beyond public summaries. It analyzes recent developments, product launches, and strategic moves in detail, offering a timeline of activity that helps predict competitor behavior. Understanding the impact of raw material fluctuations and regulatory changes on specific company supply chains is also part of the deep dive available in the full document.
Access to this level of intelligence reduces risk. It allows procurement leaders to anticipate price shifts driven by rare-earth costs. It enables product managers to align R&D with the most promising application verticals. It supports sales teams in targeting regions where regulatory tailwinds are strongest. In a market where concentration is high and supply chains are sensitive, information asymmetry is a significant advantage.
Conclusion: Positioning for 2026 and Beyond
The Magnetic Couplings Market is poised for continued expansion, underpinned by irreversible trends in energy efficiency, safety regulation, and automation. The forecast data projects a steady climb in market value through 2032, offering a stable growth environment for those who can navigate supply chain complexities and competitive intensity.
Success in this sector will belong to organizations that combine technological aptitude with strategic market awareness. They must understand not just the performance of the coupling, but the economics of the materials that build it and the regulatory frameworks that mandate its use. With moderate market concentration and a diverse player base, there are opportunities for both established players to defend share and agile firms to capture niche segments.
This article serves as a primer to the extensive analysis available in our latest market research. To fully equip your organization with the data required to make informed 2026 decisions, we invite you to explore the complete report. The detailed segmentation splits, granular forecast trajectories, and deep competitive profiles contained within will provide the actionable intelligence necessary to secure a strategic foothold in this evolving industry.
For access to the full market study and comprehensive data tables, please visit the source page to download the complete intelligence package. Equip your team with the precision data needed to turn market dynamics into strategic advantage.
For detailed analysis of this topic, please visit the official page: Magnetic Couplings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wall Mounted Gas Boiler Market Hits $6,277M in 2025, Projections Hit $9,099M by 2032 at 5.49% CAGR
By PW Consulting, 2026-09-07
Navigating the Wall Mounted Gas Boiler Market: Strategic Intelligence for 2026 and Beyond
The global heating infrastructure sector is undergoing a structural transformation driven by tightening efficiency mandates, evolving fuel compatibility requirements, and a decisive shift toward space-optimized thermal solutions. Within this landscape, the wall mounted gas boiler market has emerged as a critical battleground for manufacturers, distributors, and policy-aware investors. As operational footprints narrow and regulatory ceilings tighten, enterprise leaders require more than high-level trend statements. They need granular, forward-looking intelligence that maps technological inflection points, regional demand elasticity, and competitive positioning into actionable decision frameworks. This market research study is designed precisely for that purpose, offering a comprehensive analytical foundation to navigate the 2026–2032 forecast horizon with confidence.
Worldwide Aluminum Ski Poles Market
Drawing on a rigorous historical baseline spanning 2020 through 2025 and extending into a detailed forward projection, the study captures the market's compounding trajectory. Total revenue has progressed from approximately 4,257.8 million USD in 2020 to an estimated 6,277.15 million USD in 2025, reflecting a sustained expansion pattern that has consistently outpaced broader building equipment benchmarks. The forecast period anticipates continued growth, with projected valuations climbing toward 6,754.87 million USD in 2026, advancing to 7,217.42 million USD in 2027, and reaching approximately 9,099.16 million USD by 2032. This progression corresponds to a compound annual growth rate of 5.49 percent, a figure that signals resilient underlying demand rather than speculative short-term momentum. For executives calibrating capital allocation, capacity planning, and product portfolio roadmaps, these directional indicators provide a necessary anchor. Yet macro trajectories alone do not capture where value is concentrating, which product architectures are gaining share, or how competitive dynamics will reshape pricing and distribution models. That deeper layer of analysis resides within the full report.
Ludus Duodecim Scriptorum Market
Why the 2026 Decision Window Demands Specialized Market Intelligence
The current operating environment for wall mounted gas boilers is defined by simultaneous regulatory pressure, technological maturation, and supply chain recalibration. Since January 2025, EU Member States have been restricted from subsidizing or incentivizing stand-alone fossil fuel boiler sales, while updated energy efficient product design rules have begun systematically phasing out the least-efficient models from commercial channels. Concurrently, all newly installed gas boilers in the EU must now achieve a minimum efficiency rating of 92 percent under ErP standards, a threshold that aligns with broader revisions to the Energy Performance of Buildings Directive. These regulatory shifts are not isolated compliance checkboxes; they are actively restructuring demand patterns, accelerating the replacement cycle for older non-condensing units, and elevating the strategic importance of high-efficiency condensing architectures. Furthermore, EU legislation requires Member States to prepare for a complete phase-out of fossil fuel boilers by 2040, a long-horizon mandate that is already influencing product development cycles, investor expectations, and channel partner strategies in the present day.
Worldwide Shared Kitchen Market
For enterprise decision-makers, the implication is clear: generalized industry commentary cannot substitute for structured, data-backed analysis. Capacities must align with efficiency-driven replacement demand rather than speculative volume growth. Product roadmaps must integrate modulating burner technologies, hydrogen-compatible readiness pathways, and heat exchanger material strategies that balance performance with longevity. Distribution and installation ecosystems must adapt to pre-commissioned, low-noise, compact designs that reduce on-site labor and improve seasonal efficiency outcomes. The 2026 forecast year represents a critical inflection point where these factors converge, making this study's timing strategically relevant for procurement leaders, product managers, regional expansion planners, and competitive intelligence teams.
Research Architecture: From Macro Trajectory to Operational Playbooks
This study is constructed to bridge high-level market directionality with operational specificity. Rather than presenting static data tables, the report translates historical performance, forward estimates, and structural segmentation into decision-ready narratives. The analytical framework moves systematically through market sizing, segmentation logic, competitive profiling, regulatory impact mapping, and emerging product architecture trends. Each section is designed to surface implications for pricing strategy, capacity investment, channel development, and technology adoption timelines.
The report's operational utility is reinforced by a structured breakdown of market composition across key dimensions. Historical and projected revenue trajectories are contextualized within type, application, and regional demand patterns, allowing readers to identify where volume concentration is forming and which segments are experiencing the strongest efficiency-driven substitution effects. The study also examines market concentration dynamics, providing context around competitive density and the strategic positioning of dominant players. Throughout, the analysis deliberately avoids oversimplified regional or application percentage breakdowns in this preview, preserving the more granular, intersectional insights for the full dataset where they can be properly contextualized against pricing environments, installation infrastructure maturity, and policy implementation timelines.
Beyond quantitative mapping, the report integrates qualitative assessments of product architecture evolution. This includes an evaluation of condensing versus non-condensing technology adoption, the material science considerations shaping heat exchanger durability, and the performance implications of modulating output ranges, intelligent combustion adaptation, and pre-commissioned installation designs. These technology-level observations are directly linked to efficiency compliance pathways, seasonal performance outcomes, and end-user total cost of ownership, creating a practical bridge between engineering decisions and commercial strategy.
Competitive Landscape and Strategic Positioning Dynamics
The wall mounted gas boiler market is characterized by a concentrated but highly differentiated competitive field. Leading manufacturers have invested heavily in efficiency optimization, footprint reduction, installation speed, and future fuel compatibility. The report provides in-depth company profiles that move beyond generic brand recognition to examine specific product architectures, efficiency claims, and strategic development trajectories.
European manufacturers continue to anchor the upper tier of the market with engineered condensing platforms designed to meet stringent efficiency thresholds. Vaillant Group has emphasized intelligent combustion adaptation and high seasonal efficiency within its ecoTEC plus gas condensing wall-hung portfolio, while also advancing H2-ready capability pathways that align with long-term decarbonization expectations. Viessmann Manufacturing Company has focused on compact, pre-commissioned quick-install design through its Vitodens series, with recent developments reinforcing the strategic importance of small-footprint, low-noise units that deliver Class A efficiency outcomes. Robert Bosch GmbH has positioned its high-efficiency wall-hung condensing boilers around modulating burner technology, extending performance flexibility while also developing hydrogen-ready options that anticipate shifting fuel infrastructure requirements.
Parallel momentum is evident among other globally active players. Ariston Holding N.V. has advanced its Clas ONE and Alteas ONE+ series by integrating patented XtraTech stainless steel heat exchangers with strong ErP ratings, emphasizing durability and efficiency in residential and light commercial applications. Navien Inc. has expanded its presence through NHB-H and NCB-H series wall-hung condensing combi boilers that combine high-capacity modulating output with Wi-Fi control options, targeting installations where flexible output management and remote monitoring are commercially valuable. In the broader European manufacturing base, Ferroli S.p.A. continues to push high-output wall-hung condensing solutions such as the Force W line, supporting residential and cascade installations with capacities reaching substantial kW ranges, while also showcasing hydrogen-ready product developments at major trade platforms. Immergas S.p.A. has strengthened its competitive profile through Victrix Superior and Victrix Pro series units that leverage Aqua Celeris technology and emphasize sanitary comfort ratings alongside condensing performance. BDR Thermea Group has continued to refine its Quinta Ace wall-hung condensing line, offering aluminium or stainless-steel heat exchanger options tailored to both residential and commercial deployment scenarios.
These competitive profiles are not evaluated in isolation. The report situates each player within broader strategic themes: how product efficiency claims map to regulatory thresholds, how installation-friendly design features influence channel adoption, how hydrogen-ready development paths may shape future portfolio premiums, and where heat exchanger material selection affects lifecycle reliability and warranty economics. Recent milestones illustrate these dynamics in action. In February 2026, Viessmann launched the compact Vitodens 025-W wall-mounted gas condensing combi boiler with 24 kW and 28 kW outputs, achieving ERP efficiency of 92 percent (Class A) with seasonal efficiency up to 98 percent, a small footprint, low noise profile, and pre-commissioned unit configurations. Earlier, in June 2025, BDR Thermea Group introduced the Quinta Ace S wall-hung boiler series, combining advanced characteristics of its prior Quinta Ace platform with improved efficiency for residential applications. Around the same period, Ferroli highlighted its Force W wall-hung condensing boilers through touring van showcases and signaled new hydrogen-ready product developments, signaling an active transition toward future-compatible system designs.
This preview intentionally frames competitive positioning at a strategic level while reserving detailed share comparisons, technology adoption intensity metrics, and product-level performance cross-references for the full report. The goal is to give decision-makers enough structural clarity to recognize where competitive pressure is intensifying and which capability sets are becoming table stakes, without diluting the proprietary segmentation depth that supports precise benchmarking.
Market Dynamics: Regulation, Materials, and the Efficiency Imperative
Market dynamics in the wall mounted gas boiler segment are increasingly shaped by the intersection of policy compliance, material performance, and installation economics. Efficiency mandates are no longer peripheral considerations; they are central drivers of product eligibility, channel acceptance, and end-user replacement behavior. As noted, updated EU rules require newly installed gas boilers to achieve a minimum efficiency rating of 92 percent ErP, and the broader policy trajectory points toward the systematic removal of lower-efficiency models from active sale channels. This regulatory environment reinforces demand for condensing architectures that can consistently meet or exceed seasonal efficiency expectations while maintaining compact form factors suitable for wall mounting in space-constrained residential and commercial settings.
At the component level, material selection is exerting a meaningful influence on product durability and competitive differentiation. Sector analysis indicates that stainless steel heat exchangers have achieved dominant adoption in condensing boilers, accounting for approximately 68 percent of use cases, owing to superior corrosion resistance and extended lifespan in condensing operating environments. This material preference is not merely a technical detail; it affects warranty structures, service interval expectations, total cost of ownership calculations, and the commercial credibility of efficiency claims over the product lifecycle. Manufacturers that align heat exchanger engineering with condensing duty cycles gain an advantage in both performance reliability and downstream service economics, factors that increasingly matter as installation volumes shift toward higher-efficiency replacements and repeat purchase cycles lengthen.
Installation and operational behavior also shape demand trajectories. Pre-commissioned designs, low-noise operation, compact footprints, and integrated control capabilities are becoming commercially relevant because they reduce on-site labor complexity, improve fit within constrained mechanical spaces, and support smarter building integration. These attributes are especially important as distributors and installers prioritize products that minimize commissioning time while meeting stringent efficiency standards. The study examines how these dynamics interact with regional installation infrastructure maturity, channel training requirements, and the pace at which legacy non-condensing units are being replaced by condensing alternatives.
To support structured evaluation, the report outlines the strategic dimensions that enterprise teams should monitor throughout the forecast period:
- Regulatory alignment pathways and how efficiency thresholds influence product eligibility, promotional eligibility, and replacement cycle acceleration
- Technology substitution patterns between condensing and non-condensing architectures, including the performance and commercial implications of modulating output and intelligent combustion adaptation
- Material and durability considerations, particularly the role of stainless steel heat exchangers in extending service life and supporting long-term efficiency claims
- Installation ecosystem factors such as pre-commissioned design, footprint compression, noise reduction, and control integration that affect channel preference and end-user adoption
- Future fuel compatibility developments, including hydrogen-ready design strategies that position product portfolios for longer-horizon infrastructure transitions
These dynamics are not treated as isolated trends. The study maps their interaction across product development, distribution strategy, and regional deployment conditions, helping readers identify where operational readiness must be strengthened and where market opportunities are likely to concentrate.
Strategic Takeaways for 2026 Planning Cycles
The wall mounted gas boiler market is entering a phase where efficiency compliance, installation efficiency, and future fuel compatibility converge to redefine competitive advantage. Historical growth from 2020 through 2025 demonstrates a market that has consistently expanded under real demand conditions, while the 2026–2032 forecast horizon suggests continued momentum with a compound annual growth rate of 5.49 percent. Total revenue projections moving from an estimated 6,754.87 million USD in 2026 toward approximately 9,099.16 million USD by 2032 reflect a trajectory that rewards organizations capable of aligning product architecture, channel execution, and regulatory foresight.
Yet the strategic value of this study lies in what it enables beyond the headline numbers. It provides a structured basis for evaluating where condensing technology adoption is most advanced, which efficiency and material strategies are becoming commercially decisive, how leading manufacturers are differentiating through modulating output, pre-commissioned installation, and hydrogen-ready development, and where regional and application-level demand patterns are likely to influence capacity and distribution decisions. These insights are essential for teams planning product portfolio adjustments, regional expansion, competitive benchmarking, and investment prioritization.
This preview is intentionally designed to demonstrate analytical depth while reserving the most actionable segmentation data, detailed company comparisons, and intersectional market breakdowns for the complete report. The full study delivers the precision that enterprise decision-makers need to move from broad directional awareness to targeted strategic execution. For leaders who require a reliable foundation for 2026 planning and beyond, the complete market research offers the detailed intelligence necessary to translate market dynamics into informed, confident action.
For detailed analysis of this topic, please visit the official page: Wall Mounted Gas Boiler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Trypsin Market Hits USD 96.5M in 2025, Projects 5.5% CAGR to Reach USD 140.75M by 2032
By PW Consulting, 2026-09-07
Strategic Navigation in the Global Trypsin Market: 2026 Outlook and Decision Intelligence
The global trypsin market stands at a critical inflection point as industrial biotechnology, pharmaceutical manufacturing, and advanced diagnostics converge around increasingly stringent performance and regulatory expectations. Market intelligence compiled by PW Consulting indicates that the sector expanded from approximately 75.0 million USD in 2020 to 96.5 million USD in 2025, reflecting a disciplined yet accelerating trajectory shaped by bioprocessing scale-up, cell-based therapeutics, and the maturation of recombinant production platforms. The forecast period spanning 2026 to 2032 points toward sustained momentum, with a projected compound annual growth rate of 5.5 percent and a market valuation expected to reach 140.75 million USD by the close of the outlook window. For executives, procurement leaders, and R&D strategists, these figures are not merely summary statistics. They represent a structural realignment in how enzymes are sourced, qualified, and integrated into production workflows. This introduction outlines the strategic architecture of our newest report, demonstrates how macro-level intelligence can be operationalized, and clarifies the decision-grade content that awaits inside the full study.
Worldwide Granules Packing Machine Market
From Historical Trajectory to Forward-Looking Commitment
The market's historical arc from 2020 through 2025 illustrates a pattern of resilience punctuated by incremental but compounding growth. Annual revenue moved from 75.0 million USD in 2020 to 76.92 million USD in 2021, 81.49 million USD in 2022, 84.02 million USD in 2023, 89.51 million USD in 2024, and 96.5 million USD in 2025. This sequence signals a market that has moved beyond the post-pandemic stabilization phase and entered a period of deliberate expansion. Buyers no longer treat trypsin as a commoditized laboratory reagent. Instead, they evaluate it as a process-critical input whose purity profile, supply reliability, and regulatory posture directly affect batch success rates, downstream purification economics, and time-to-clinic for advanced therapies.
Intelligent Communication Software Market
The forecast landscape reinforces this shift. Revenue is projected to advance to 102.28 million USD in 2026, 105.51 million USD in 2027, 114.94 million USD in 2028, 118.85 million USD in 2029, 122.2 million USD in 2030, 131.51 million USD in 2031, and 140.75 million USD in 2032. The 5.5 percent CAGR is not an abstract figure; it is a decision parameter. It shapes capital allocation for capacity expansion, informs supplier diversification strategies, and helps R&D organizations align enzyme qualification roadmaps with long-term manufacturing plans. Leaders who internalize this growth rhythm can time sourcing commitments, negotiate contract structures with better visibility, and anticipate the competitive intensity that accompanies a maturing supply base.
Worldwide Cone Pizza Machine Market
Why This Research Matters for 2026 Decision-Making
Strategic decisions in the trypsin market are increasingly cross-functional. Procurement must balance cost discipline against the risk of supply interruption; R&D must reconcile experimental flexibility with the need to lock in GMP-grade formats for commercial programs; quality and regulatory teams must interpret evolving expectations around animal-origin-free alternatives and batch consistency; and business development teams must gauge which applications are accreting share versus plateauing. Our report was constructed to serve this cross-functional reality. Rather than offering a single-dimensional volume estimate, it delivers a modular intelligence framework that can be layered into sourcing strategy, pipeline planning, competitive benchmarking, and scenario modeling.
For 2026, the most consequential decisions revolve around format selection, supplier qualification, and application alignment. Recombinant and animal-origin-free variants are gaining traction precisely because they reduce exposure to biological variability and simplify the regulatory narrative. At the same time, legacy animal-derived forms continue to serve specific laboratory and process niches. Understanding where each format creates advantage, and under what compliance or cost conditions, is central to competitive positioning. The report translates these choice points into actionable analysis, helping teams avoid over-indexing on price alone or under-investing in qualification lead time.
Competitive Architecture at a Glance
The trypsin market exhibits moderate concentration, with the top three firms accounting for roughly 28.0 percent of revenue and the top five firms reaching approximately 35.0 percent. This structure indicates a landscape where established life-science and specialty enzyme players maintain meaningful influence, while specialized manufacturers and technology-focused entrants continue to carve out differentiated positions. Competitive advantage is no longer defined solely by catalog breadth. It is increasingly determined by the ability to deliver consistently qualified material, offer application-specific formulations, and align product architecture with regulatory expectations in biomanufacturing and diagnostic workflows.
Several flagship organizations illustrate how differentiated strategies are unfolding in practice. Novo Nordisk Pharmatech A/S, headquartered in Køge, Denmark, has focused its trypsin offering on high-purity animal-free recombinant materials produced via E. coli fermentation under GMP conditions, with supply directed toward biomanufacturing, cell dissociation, and vaccine production. In October 2024, the company launched TrypsiNNex®, a GMP-grade animal-free recombinant trypsin featuring more than 70 percent beta-trypsin content and batch variability below 5 percent, validated for biopharmaceutical manufacturing. This launch signals a broader move toward controlled, scalable recombinant supply for mission-critical process steps.
Thermo Fisher Scientific Inc., based in Waltham, Massachusetts, continues to anchor its trypsin portfolio around porcine-derived materials alongside animal-origin-free alternatives such as TrypLE, supporting cell culture dissociation and bioprocessing applications. The company’s breadth of infrastructure and integrated bioprocessing ecosystem positions it as a multi-format enabler for organizations that need to bridge research and commercial production without fragmenting their supplier base. Promega Corporation, located in Madison, Wisconsin, emphasizes high-performance formats for analytical and proteomics workflows, including sequencing-grade modified trypsin, Trypsin Gold, Trypsin Platinum in recombinant form, and immobilized variants tailored for mass spectrometry. Its positioning reflects the growing importance of enzyme quality in generating reproducible analytical data and advancing proteomics pipelines. Merck KGaA, through Sigma-Aldrich in Darmstadt, Germany, remains a reference point for laboratory-grade cell culture trypsin and associated research products, reinforcing the continued role of established reagent channels in early-stage development and scientific supply chains.
Beyond these core players, recent product and regulatory activity shows that the competitive field is being reshaped by formulation innovation and safety evaluations. In February 2026, EFSA adopted a safety opinion concluding that there were no safety concerns for the food enzyme serine protease, or trypsin, derived from a genetically modified Fusarium venenatum strain. That determination, published in the EFSA Journal in March 2026, broadens the regulatory conversation around recombinant enzyme acceptance and underlines how safety qualification can unlock new application pathways. Meanwhile, c‑LEcta expanded the recombinant supply landscape in October 2025 with the launch of CellTrypase, a GMP-grade recombinant animal-free trypsin-like enzyme validated for major biopharmaceutical production cell lines. Together, these developments point to an environment in which format credibility, regulatory clearance, and cell-line compatibility are becoming decisive competitive factors.
Market Dynamics Under the Microscope
The contemporary trypsin market is governed by a set of interacting forces that directly affect sourcing strategy and product planning. One of the most consequential is the regulatory drift toward recombinant and animal-origin-free formats for cell-therapy inputs and advanced biomanufacturing. Guidance endorsed by the European Medicines Agency in 2025 elevated recombinant trypsin to preferred status for cell-therapy inputs, reinforcing a directionality that procurement and quality teams can no longer treat as optional. In parallel, recombinant suppliers are expected to demonstrate compliance with stringent FDA 21 CFR 211 and ISO 13485 requirements, and to provide evidence of batch-to-batch consistency below 5 percent variability. These expectations reshape the value proposition of enzyme selection: consistency, documentation, and traceability now carry commercial weight comparable to unit pricing.
A second dynamic concerns the practical limits of animal-derived sourcing. Extraction from porcine and bovine sources is accompanied by complex purification steps and yield losses that commonly range from 5 to 15 percent, driven by variability in raw biological material. This inherent variability has implications for both cost predictability and process control, especially when manufacturers require tight lot-to-lot reproducibility. As a result, many organizations are reassessing the trade-off between legacy supply convenience and the longer-term advantages of controlled recombinant platforms. The trend does not imply the elimination of animal-derived trypsin, but it does encourage selective deployment where its characteristics are genuinely advantageous and where supply risk can be managed.
A third dynamic is the widening of application relevance. Trypsin is increasingly embedded in workflows that extend beyond traditional cell culture dissociation. Its role in biomanufacturing, vaccine production, proteomics, and advanced diagnostics connects enzyme supply to broader value chains where downstream success depends on upstream material performance. This linkage raises the stakes for qualification strategy and creates opportunities for suppliers that can provide application-validated formats, robust technical support, and clear regulatory alignment. Market growth is therefore not simply a function of demand volume; it is also a function of how effectively the supply base can answer cross-application requirements without sacrificing consistency or compliance.
What the Report Delivers: Decision-Grade Content Overview
The full report is organized to convert market intelligence into operational clarity. It provides a detailed assessment of market size and growth behavior across the historical and forecast periods, with a structured lens on the forces that shape expansion and the conditions that may accelerate or moderate it. The analysis includes a thorough segmentation review by region, by type, and by application, allowing readers to evaluate where demand is concentrating, which formats dominate specific use contexts, and how application portfolios are evolving. Importantly, the report avoids superficial breakdown by offering interpretive commentary alongside segment structure, so that buyers and strategists can understand the practical significance of each grouping rather than reading isolated share figures in isolation.
The study also contains a competitive analysis section that examines the strategic behavior of leading participants. Company-specific profiles describe the trypsin-related offerings, production philosophies, and application focus that define each player’s market position. These profiles are paired with an assessment of recent developments, including product launches, safety evaluations, and regulatory actions that alter the competitive field. By linking product architectures to market events, the report helps readers anticipate which suppliers are strengthening their position in biomanufacturing, which are deepening their analytical and proteomics relevance, and which are expanding the recombinant supply envelope for GMP environments.
Operational content extends to supply chain and procurement considerations. The report addresses raw material variability, purification complexity, format transition risk, and the practical implications of qualification requirements. It also maps regulatory context, including the implications of recent guidance and safety opinions for sourcing choices and compliance planning. For organizations that must align R&D flexibility with commercial readiness, this material supports a more disciplined approach to supplier selection, contract design, and specification lock-in. Readers will find scenario-oriented commentary that connects market growth to supply strategy, helping executive teams translate trajectory data into procurement timing, supplier diversification, and capacity planning decisions.
Translating Market Intelligence into 2026 Action
For companies making sourcing, investment, or product decisions in 2026, the strategic value of the report lies in its ability to connect external market behavior with internal decision processes. Leaders can use the growth projection as a checkpoint for whether to lock in long-term supply agreements, diversify across format types, or accelerate qualification of recombinant options. The competitive analysis supports supplier evaluation by clarifying what each major player emphasizes and where differentiation is emerging. The dynamics section helps quality, regulatory, and operations teams anticipate the requirements that will shape vendor qualification and batch acceptance. And the segmentation framework enables teams to identify which applications and format families warrant deeper engagement, without being distracted by granular share details before the proper internal review is complete.
The most effective use of this intelligence is not passive consumption but active integration. Procurement teams can compare supplier narratives against consistency requirements and application validation needs. R&D leaders can map enzyme format transitions onto pipeline milestones and clinical-readiness timelines. Business and strategy leaders can use the market trajectory to test assumptions about capacity expansion, geographic focus, and portfolio investment. In each case, the report is designed to support, not replace, internal judgment, providing a credible external baseline against which internal plans can be calibrated.
Why the Full Study Deserves a Place in Your Decision Process
Trypsin may appear at first glance to be a narrow reagent category, but its market behavior reflects broader shifts in biotechnology, pharmaceutical manufacturing, and diagnostics. As the sector moves from 2026 into the latter half of the decade, companies that treat enzyme supply as a strategic variable rather than a routine purchase will be better positioned to manage consistency risk, align with evolving regulatory expectations, and capture share in applications where material performance matters most. The full PW Consulting report offers the depth required to make those choices with confidence. It pairs market-size and growth analysis with segmentation insight, competitor profiling, regulatory context, and operational implications, all structured to support real-world decision workflows.
The preview above establishes the analytical foundation and the strategic relevance of the market, but the complete intelligence is contained in the full study. Inside, readers will find the detailed regional, type, and application breakdowns, the extended competitive assessment, and the decision frameworks needed to convert growth signals into sourcing and planning actions. For teams preparing for 2026 commitments and beyond, the report offers a structured lens on where the trypsin market is heading and how to position accordingly.
For detailed analysis of this topic, please visit the official page: Trypsin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


