



Category: market research
PW Consulting: Neuropathy Pain Treatment Market to Hit $12.94 Billion by 2032, Driven by 7.64% CAGR
By PW Consulting, 2026-09-07
Strategic Horizon 2026: Navigating the Neuropathy Pain Treatment Market
The global landscape for neuropathy pain treatment is undergoing a profound transformation, driven by an aging population, the rising prevalence of diabetes, and significant advancements in pharmacological understanding. As we approach 2026, the decision-making window for pharmaceutical leaders, healthcare investors, and strategic planners is narrowing. Understanding the trajectory of this market is no longer optional; it is a critical imperative for capitalizing on emerging opportunities and mitigating regulatory risks. PW Consulting's latest market research offers a comprehensive lens through which to view these dynamics, providing the granular intelligence necessary to navigate a sector defined by both robust growth and complex therapeutic challenges.
Worldwide Air Traffic Control Hardware Solutions Market
The convergence of chronic disease management and pain mitigation has created a fertile ground for investment. However, the heterogeneity of neuropathic conditions requires a nuanced approach to market entry and portfolio expansion. This report serves as a strategic compass, detailing the economic contours and competitive forces that will define the industry over the next half-decade. By dissecting the market from multiple analytical angles, we provide stakeholders with the foresight needed to align their commercial strategies with the evolving demands of clinicians and patients alike.
Worldwide Compound Extruder Market
Market Trajectory and Economic Outlook
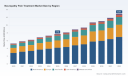
The historical data from 2020 through 2025 establishes a clear precedent of steady expansion, setting the stage for accelerated growth in the forecast period. The market has demonstrated resilience even amidst global supply chain disruptions and shifting healthcare priorities. In the base year of 2025, the overall market revenue reached 7.76 Billion USD. This figure represents a significant accumulation of value over the preceding five years, reflecting the increasing adoption of standardized pain management protocols and the broadening of therapeutic indications.
Worldwide Head Mounted Transmitter Market
Looking forward to the forecast period spanning 2026 to 2032, the momentum is projected to sustain and even intensify. The Compound Annual Growth Rate (CAGR) is estimated at 7.64 percent, signaling a healthy expansion rate that outpaces many traditional therapeutic sectors. By the end of the forecast horizon in 2032, the market is expected to surpass the 12.94 Billion USD mark. This trajectory implies a substantial increase in total addressable market size, offering lucrative avenues for stakeholders who can position themselves effectively ahead of this curve.
For corporate strategists, these macroeconomic figures are more than just statistics; they represent the scale of opportunity available for new product launches, pipeline acquisitions, and geographic expansion. The growth from 8.14 Billion USD in 2026 to nearly 13 Billion USD by 2032 suggests that demand will not be limited to mature markets but will increasingly draw from emerging economies where healthcare infrastructure is improving. The consistent year-over-year increments indicate a stable demand environment, reducing the volatility risk often associated with niche therapeutic areas.
Therapeutic Segments and Clinical Drivers
The utility of this research lies in its ability to deconstruct the aggregate market numbers into actionable therapeutic insights. The landscape is dominated by distinct drug classes that cater to different physiological mechanisms of pain. Anticonvulsants remain a cornerstone of treatment, holding a significant portion of the market share due to their established efficacy in managing nerve pain. Antidepressants also constitute a major pillar, particularly for patients where pain coexists with mood disorders, a common comorbidity in chronic neuropathy cases.
Beyond these mainstream categories, specialized formulations including opioids and capsaicinoids serve specific patient profiles where first-line treatments may be insufficient or contraindicated. The segmentation by drug class reveals a diversified ecosystem where innovation is not confined to a single molecule type. This diversity allows pharmaceutical companies to strategize based on their existing intellectual property portfolios or licensing capabilities. For instance, companies with strong anticonvulsant pipelines can leverage the dominant position of this class, while those focused on novel delivery mechanisms might target the capsaicinoid segment for localized pain relief solutions.
Equally critical is the breakdown by indication, which maps the revenue potential to specific disease states. Diabetic neuropathy continues to be the primary driver of demand, reflecting the global diabetes epidemic. Chemotherapy-induced neuropathy represents a growing segment, driven by advancements in oncology treatments that extend survival rates but leave patients managing long-term side effects. Postherpetic neuralgia and sciatic neuropathy further fragment the market, requiring targeted marketing and clinical engagement strategies. Understanding the revenue weight of each indication allows businesses to prioritize resources toward the highest value patient populations without neglecting niche areas that may offer premium pricing opportunities.
- Drug Class Dynamics: Evaluation of anticonvulsants, antidepressants, opioids, capsaicinoids, and other emerging classes.
- Indication Focus: Analysis covering diabetic neuropathy, chemotherapy-induced neuropathy, postherpetic neuralgia, sciatic neuropathy, and other conditions.
- Clinical Guidelines: Integration of current therapeutic recommendations influencing prescribing behaviors.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a moderate level of concentration, suggesting room for both established giants and agile niche players to compete. The top three companies collectively hold approximately 45.2 percent of the market, while the top five firms account for 58.3 percent. This concentration indicates that while market leaders exert significant influence through brand recognition and formulary access, a substantial portion of the revenue remains distributed among secondary competitors. This distribution creates opportunities for companies to carve out specific niches or acquire assets to consolidate their position.
Key industry players are actively shaping the competitive environment through product lifecycle management and generic entry strategies. Pfizer, headquartered in New York, continues to leverage its flagship products such as Lyrica and Lyrica CR, maintaining a strong presence in diabetic peripheral neuropathy and postherpetic neuralgia treatments. Meanwhile, companies like Eli Lilly and Company focus on antidepressant-based solutions like Cymbalta for diabetic peripheral neuropathy, diversifying the pharmacological approaches available to prescribers.
The generic segment is equally dynamic, with manufacturers like Torrent Pharmaceuticals Limited and Sunshine Biopharma expanding access to essential medications. Torrent produces generic pregabalin, offering cost-effective alternatives to branded options, while Sunshine Biopharma has recently entered the space with generic gabapentin products. Almatica Pharma LLC further complements this landscape by managing a portfolio of gabapentin products including Neurontin, Gralise, and Horizant. These companies collectively ensure that price competition remains a factor, influencing overall market pricing strategies and reimbursement negotiations.
- Brand Leaders: Strategies employed by major pharmaceutical firms to protect market share through extended-release formulations and new indications.
- Generic Entrants: The impact of ANDA approvals and generic launches on pricing pressure and market accessibility.
- Portfolio Diversification: How companies are balancing branded innovation with generic volume to maximize revenue streams.
Regulatory and Reimbursement Dynamics
Navigating the regulatory environment is as critical as understanding the clinical science. Recent regulatory actions have set new standards for drug development and labeling, particularly in complex areas like chemotherapy-induced peripheral neuropathy. In January 2025, the FDA issued a guidance document specifically addressing the development of drug and biological products for the prevention and treatment of this condition. This move signals a heightened regulatory focus on oncology-related neuropathic pain, potentially accelerating the approval pathways for targeted therapies in this segment while raising the bar for clinical evidence requirements.
Simultaneously, reimbursement policies and therapeutic guidelines are shaping prescribing habits at the point of care. In January 2025, the Texas Health and Human Services Commission updated its therapeutic drug class review, categorizing pregabalin and gabapentin as first-line agents for neuropathic pain. Additionally, duloxetine and milnacipran are recognized as additional first-line options. These classifications directly influence formulary decisions and insurance coverage, making compliance with regional health authority guidelines a prerequisite for market success. Companies must ensure their value propositions align with these preferred status designations to secure favorable reimbursement terms.
Controlled substance regulations also remain a pivotal consideration. Pregabalin is classified as a Schedule V controlled substance under federal regulations, requiring strict prescription protocols. This classification impacts distribution logistics, pharmacy stocking decisions, and patient access pathways. Strategic planners must account for these regulatory constraints when designing supply chain networks and sales force training programs. The interplay between efficacy, safety, and regulatory control creates a complex operating environment where compliance is not just a legal necessity but a competitive differentiator.
Strategic Implications for 2026 Decision Makers
As organizations prepare their strategies for 2026, the insights contained in this report offer several critical takeaways. First, the projected growth to over 12.94 Billion USD by 2032 underscores the importance of long-term capacity planning and R&D investment. Companies that hesitate to enter or expand within this space risk ceding share to competitors who are already positioning themselves for the upcoming wave of demand. Second, the segmentation data highlights the need for precision marketing. A one-size-fits-all approach is insufficient when the revenue drivers vary significantly across drug classes and indications.
Third, the competitive analysis suggests that partnership and licensing opportunities may be more viable than de novo development for certain players. Given the concentration levels and the activity of generic manufacturers, acquiring existing pipelines or partnering with generic producers can accelerate time-to-market. Finally, the regulatory updates regarding chemotherapy-induced neuropathy and controlled substance scheduling require immediate attention. Strategic plans must incorporate compliance workflows and advocacy efforts to navigate these evolving requirements successfully.
The timing of market entry is also paramount. With recent product launches such as Sunshine Biopharma's generic gabapentin in June 2025, the window for establishing a foothold in certain generic segments is narrowing. Early movers who can secure distribution agreements and clinician loyalty before the market becomes saturated will gain a distinct advantage. Conversely, late entrants must offer distinct value propositions, such as improved delivery systems or combination therapies, to justify their presence.
Navigating the Data Depth
While this overview provides a high-level strategic framework, the full scope of opportunity requires a deeper dive into the specific data points that drive these conclusions. The aggregate figures and trends discussed here are derived from a comprehensive dataset that includes detailed regional performance, granular revenue splits by segment, and extensive company profiles. Understanding the specific market share percentages, regional revenue distributions, and precise forecast models for each sub-segment is essential for building a robust business case.
For instance, while we have discussed the dominance of North America and the growth potential in Asia Pacific at a conceptual level, the exact revenue contributions and growth rates for each territory are crucial for investment allocation. Similarly, the specific valuation of each drug class and indication segment informs pricing strategies and portfolio prioritization that cannot be fully appreciated without the complete dataset. The nuances hidden within the segmentation splits determine where the highest margins lie and which customer segments are most resilient to pricing pressure.
To access the complete intelligence required for definitive strategic planning, stakeholders are encouraged to consult the full Neuropathy Pain Treatment Market research report. The full document contains the granular tables, detailed methodological explanations, and proprietary forecasts that transform general insights into actionable business intelligence. In a market moving toward 12.94 Billion USD, having the precise data behind the trends is the difference between a good strategy and a great one.
Conclusion
The neuropathy pain treatment market stands at a pivotal juncture in 2026. With a solid historical foundation, a robust CAGR of 7.64 percent, and a complex mix of regulatory and competitive forces, the sector offers significant potential for growth. However, realizing this potential requires more than general awareness; it demands precise, data-driven decision-making. From the dominance of anticonvulsants and antidepressants to the regulatory nuances of Schedule V substances and FDA guidance, every factor plays a role in shaping the commercial landscape.
PW Consulting's analysis provides the necessary depth to navigate this environment, offering a clear view of the market concentration, key player strategies, and therapeutic shifts. By leveraging these insights, organizations can align their resources with the highest value opportunities, mitigate regulatory risks, and capture share in a market destined for substantial expansion. The path forward is clear for those equipped with the right intelligence, making this research an indispensable tool for leaders aiming to define their position in the next era of pain management.
For detailed analysis of this topic, please visit the official page: Neuropathy Pain Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Device Polymers Market to Reach $18.49 Billion by 2032, Growing at 7.8% CAGR
By PW Consulting, 2026-09-07
Navigating the Next Wave of Growth: Strategic Imperatives in the Polymers for Medical Devices Market
Executive Preview from PW Consulting
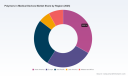
The global healthcare infrastructure is undergoing a material transformation. As medical device manufacturers push for lighter, more durable, and increasingly patient-specific solutions, the polymers that form the structural and functional backbone of these products have become a critical strategic battleground. PW Consulting’s latest in-depth market assessment tracks this evolution across a seven-year forecast horizon, translating macroeconomic shifts into actionable decision intelligence for executives, product developers, and supply chain leaders. This article outlines the strategic architecture of the research, highlights the structural forces reshaping competitive positioning, and demonstrates why a disciplined, data-grounded approach to polymer sourcing and R&D allocation will define market winners through the end of the decade.
Auxiliary Photosensitive Chemicals Market
Decision-makers evaluating capital allocation, supplier partnerships, or new product portfolios require more than headline figures. They need to understand how regulatory cadence, regional manufacturing footprints, and high-performance material substitution patterns intersect to create margin opportunities and compliance bottlenecks. The research framework presented here is designed precisely for that purpose: it maps observable market growth against the operational realities of medical-grade compounding, sterilization validation, and cleanroom conversion, while deliberately leaving the granular breakdowns for the complete dataset available on our source portal.
Big Data Replication Software Market
Macro Trajectory and the Strategic Opening for 2026 Decision-Making
The polymers incorporated into medical devices have moved from supporting roles into primary design determinants. Over the historical window, the sector demonstrated sustained expansion as device complexity increased and single-use architectures gained prevalence. The most recent baseline year reflects a consolidated global revenue level that underscores how deeply polymer selection is now embedded in device economics. Looking forward, the forecast period extends through the early 2030s, projecting a compound annual growth rate in the high-single-digit range. This trajectory is not uniform: it is conditioned by sterilization requirements, implant-grade validation cycles, and the pace at which manufacturers transition from legacy materials to engineered alternatives.
Worldwide Solvent Based Fire Retardant Coating Market
For 2026 planning cycles, the strategic implication is clear. The growth corridor offers room for suppliers to capture share through differentiated biocompatibility profiles, regional supply resilience, and faster qualification pathways. It also creates risk for OEMs that treat polymer procurement as a commoditized line item rather than a design-and-compliance decision. Executives who integrate the full segmentation logic, regional supply constraints, and application-specific qualification timelines into their budget models will be positioned to mitigate lead-time volatility and secure preferential access to medical-grade lots during periods of constrained conversion capacity.
What the Research Delivers: Actionable Intelligence Beyond Headline Growth
A robust market study must bridge the gap between aggregate revenue projections and the operational questions that procurement, regulatory, and R&D teams face daily. The PW Consulting report is structured to serve as a working reference rather than a static snapshot. Its architecture combines historical normalization, forward modeling, and qualitative benchmarking so that readers can stress-test assumptions against multiple scenarios.
- Historical trajectory analysis spanning the 2020 to 2025 window, aligning revenue evolution with known demand shocks, supply chain disruptions, and material substitution cycles.
- Forward modeling through the forecast horizon, with year-by-year progression that allows planners to map procurement peaks, capacity ramp schedules, and milestone gate reviews.
- Segmentation logic that separates material families, application contexts, and geographic demand clusters, enabling targeted sensitivity analysis rather than blunt aggregate planning.
- Competitive benchmarking across principal suppliers, including product-line positioning, specialty resin portfolios, and geographic manufacturing footprints.
- Regulatory and compliance cross-references that tie material selection to biocompatibility testing regimes, sterilization validation expectations, and change-control documentation requirements.
- Scenario-ready architecture, allowing users to adjust assumptions around regional capacity, conversion bottlenecks, and premium-grade pricing dynamics without rebuilding the model from scratch.
Each section is designed to feed directly into budgeting, supplier qualification, and product roadmap decisions. The complete dataset, including granular regional splits and application-level breakdowns, is reserved for the full report environment so that subscribers can run internal comparisons without relying on second-hand summaries.
Competitive Architecture: Seven Supplier Archetypes Shaping the Field
The market’s competitive structure reflects the technical demands of medical-grade production. High-performance thermoplastics, biostable elastomers, and emerging biodegradable systems each require specialized compounding, documentation, and conversion capabilities. The companies highlighted in the research illustrate how supplier strategies diverge across engineering excellence, regional localization, and sustainability-aligned material development.
Specialized Implant and High-Performance Resin Providers
Several European and American incumbents anchor the premium segment through implant-grade polymers and surgical tool materials. One German specialty supplier has built recognition around bioresorbable polymer systems and PEEK-based implantable solutions, complemented by filaments engineered for additive manufacturing workflows. A Belgian high-performance materials leader contributes PEEK, PPSU, and broader PAEK families that target long-term implant contact, sterilization resilience, and tooling applications where thermal and chemical stability are non-negotiable. These players compete not merely on resin chemistry but on qualification support, lot traceability, and the ability to co-develop formulations that reduce device-level validation burden.
Engineering Plastics and Device-Touch Materials
Another tier of competitors focuses on medical-grade engineering plastics that balance mechanical performance with manufacturability. A large German chemical group supplies polymer families tailored to surgical instruments, fluid handling components, and patient-contact parts, emphasizing formulations designed for sterilization compatibility and dimensional stability. A separate German materials company has expanded its device-touch portfolio with polycarbonate and thermoplastic polyurethane lines for intravenous systems, wearable platforms, and sterilization-resistant assemblies. A U.S.-based specialty firm extends this logic with polyesters, polyacetal, ultra-high-molecular-weight polyethylene, and liquid crystal polymers that support precision components, injection delivery systems, and orthopedic applications.
Tubing, Conversion, and PVC-Alternatives Specialists
Not all competitive advantage resides in resin synthesis. Conversion and tubing specialists translate medical-grade polymers into finished or semi-finished components under cleanroom conditions, where process control and regulatory documentation are integral to product value. One German converter has concentrated on thermoplastic and silicone processing for tubing, catheters, and injection systems, reflecting how downstream capability can become a differentiator when device makers seek to shorten assembly complexity. Alongside this, a U.S.-based polymer supplier has pushed styrenic block copolymers and related elastomeric systems as flexible, non-PVC options for tubing and component designs, aligning with broader sustainability and solubility concerns in disposable architectures.
Recent Developments That Signal Strategic Direction
Recent events reinforce the direction of travel. A major materials group localized production of a medical-grade thermoplastic polyurethane at a Taiwan site to strengthen regional supply for device manufacturers. A separate high-performance materials company introduced a white PPSU resin aimed at medical devices, surgical instruments, and biopharma workflows, expanding the palette of visually inspectable, high-purity resins. On the regulatory side, a light-activated polymer formulation received clearance for a 3D-printed nerve repair cuff device, illustrating how additive manufacturing and novel resin chemistry are converging in clinical applications. In parallel, a biomedical materials partner entered a co-development arrangement to advance next-generation bioresorbable systems for devices and drug delivery, signaling that biodegradable and bioresorbable pathways remain an area of active investment. Another supplier introduced a medical-grade polyurethane tailored for wearable devices with enhanced biocompatibility, reinforcing how wearable and patient-monitoring architectures are pulling material requirements toward skin-contact performance and long-term comfort.
Regulatory and Operational Dynamics That Redefine Competition
The market’s growth ceiling is not determined by demand alone. It is defined by the compliance environment surrounding polymeric materials used in direct patient contact, terminally sterilized assemblies, and implantable systems. Biocompatibility expectations under internationally recognized testing series shape material selection at the design stage. Packaging integrity and microbial barrier performance require validation pathways that influence how medical-grade polymers are integrated into finished device architectures. For implantable and long-term contact applications, manufacturers must operate under production control expectations that include change-notification discipline and supply continuity planning. These requirements introduce a structural premium on suppliers that can maintain lot-to-lot consistency, provide robust documentation, and support change management without triggering re-qualification delays.
The operational layer adds further nuance. Specialized conversion and compounding for medical-grade polymers typically depends on cleanroom environments and skilled operators to preserve biocompatibility and regulatory adherence. This means that raw resin availability does not automatically translate into device-ready supply. Lead times, conversion capacity, and qualification readiness often matter more to device OEMs than headline pricing. At the same time, regulatory encouragement around biodegradable polymers in disposable devices and packaging is reinforcing sustainability-oriented material substitution, particularly where waste reduction and single-use optimization intersect with clinical workflow improvements. Together, these dynamics create a market in which technical compliance and supply resilience are competitive advantages, not overhead.
Strategic Priorities for 2026 Planning
Given the interaction between growth momentum, regulatory constraints, and supplier specialization, several priorities emerge for executives shaping 2026 strategy.
- Treat medical-grade polymer selection as a design-and-compliance decision. Material performance, sterilization tolerance, and documentation readiness should be evaluated alongside cost, because qualification timelines can dominate total program economics.
- Map regional supply resilience against conversion capacity. Raw resin forecasts are necessary but insufficient; cleanroom conversion, tubing extrusion, and device-level assembly readiness can become the binding constraint during demand surges.
- Monitor high-performance and biodegradable substitution patterns. As implantable, surgical, and wearable applications continue to expand, premium resin families and bioresorbable systems are shaping new value pools that reward early qualification and specification leadership.
- Build supplier partnerships around change control and traceability. In categories where notification procedures and lot consistency matter, relationship depth and documentation capability can reduce downstream risk more effectively than transactional sourcing.
- Integrate sustainability drivers without over-indexing on narrative. Regulatory encouragement, packaging optimization, and PVC-alternative adoption are real demand signals, but strategic advantage comes from verifying material performance, sterilization compatibility, and supply continuity before scaling commitments.
Why the Complete Dataset Changes the Decision
Aggregated growth figures establish direction, but the operational decisions that determine outcomes live in the segmentation details. Regional demand distribution, application-level concentration, and material-family splits shape where margin pools form, where qualification bottlenecks emerge, and how supplier portfolios should be weighted in a sourcing strategy. The full report environment provides that structure without sacrificing analytical rigor, allowing teams to compare scenarios internally while preserving confidentiality and decision speed.
For organizations preparing for 2026 budgeting, product roadmap reviews, or supplier qualification cycles, the complete intelligence set offers a practical bridge between market growth and execution readiness. The research has been built to support those conversations with a clear, testable, and continuously relevant view of how polymers in medical devices are likely to evolve across the forecast horizon.
Accessing the Full Intelligence
The complete market assessment is available through our source portal, where subscribers can access the full segmentation architecture, regional and application-level breakdowns, supplier benchmarking tables, and the scenario-ready forecast models that underpin this analysis. Given the technical specificity of medical-grade polymer sourcing and the pace of regulatory and product developments, the most valuable use of this research is interactive: teams can test assumptions against the detailed splits, align procurement calendars with regional capacity signals, and prioritize qualification investments where material substitution and compliance risk intersect.
PW Consulting’s Polymers in Medical Devices Market study is designed for decision-makers who need more than directional confidence. It provides the structural detail required to translate market growth into sourcing strategy, R&D prioritization, and regulatory readiness. For executives preparing for the 2026 planning cycle, the complete dataset offers the precision necessary to move from headline growth to executable advantage.
For detailed analysis of this topic, please visit the official page: Polymers in Medical Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High Silica Zeolite Market Hits $1.19M in 2025, Projects 1.2% CAGR to 2032
By PW Consulting, 2026-09-07
Navigating the High Silica Zeolite Market: Strategic Intelligence for 2026 Decision Makers
Introduction: The Intersection of Stability and Niche Growth
The High Silica Zeolite market represents a specialized segment within the broader industrial catalyst and adsorbent landscape. For executives and strategists operating in 2026, understanding the trajectory of this market is not merely about tracking commodity prices; it is about anticipating shifts in refining efficiency, petrochemical throughput, and environmental compliance standards. As global industries pivot towards more sustainable operational frameworks, the demand for high-performance molecular sieves becomes increasingly critical. This market research briefing serves as a foundational tool for organizations seeking to align their supply chains, R&D investments, and partnership strategies with the evolving realities of the high silica zeolite sector.
Worldwide Elderly Hearing Aids Market
Our analysis covers the period from 2020 through 2032, providing a robust historical baseline alongside a forward-looking forecast. The data indicates a market that is mature yet resilient, characterized by steady progression rather than volatile spikes. By examining the interplay between technological specifications, regional manufacturing capabilities, and key corporate maneuvers, stakeholders can derive actionable insights that mitigate risk and identify emerging opportunities.
Worldwide Elderly Culture and Entertainment Market
Market Size and Trajectory: A Long-Term Perspective
Understanding the macroeconomic contours of the high silica zeolite market is essential for long-term capital allocation. The market has demonstrated a consistent presence over the past half-decade, maintaining a stabilized revenue profile in million USD terms. Historical data from 2020 to 2025 shows a market that has navigated various economic cycles while preserving its core value proposition. As we move into the forecast period extending to 2032, the growth trajectory suggests a gradual expansion.
Email Newsletter Tool Market
The compound annual growth rate (CAGR) projected for the forecast period stands at 1.2 percent. While this figure may appear modest compared to high-growth technology sectors, it reflects the mature nature of the industrial catalyst market. For investors and corporate planners, this steady growth rate indicates a lower-risk environment where value is derived from efficiency gains, product differentiation, and strategic consolidation rather than pure volume expansion. The forecast model anticipates fluctuations in yearly revenue, highlighting specific periods of consolidation followed by moderate upticks. This granular temporal analysis allows clients to prepare for inventory management and capacity planning with greater precision.
It is crucial to note that while the overall market size provides the umbrella view, the real strategic value lies in understanding the underlying drivers that sustain this trajectory. The stability observed in the 2020 to 2025 window was supported by consistent demand from downstream industries, even as global supply chains faced disruptions. The forecast to 2032 suggests that this demand will persist, albeit shaped by new regulatory pressures and technological advancements in catalyst formulation.
Segmentation Dynamics: Types, Applications, and Regional Influence
A superficial view of market size is insufficient for tactical decision-making. The true complexity of the high silica zeolite market lies in its segmentation. Our research dissects the market across type, application, and region, revealing where value is actually generated and consumed.
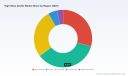
From a product type perspective, the market is stratified among several key zeolite variants. The dominance of specific types, such as ZSM-5, reflects their entrenched position in established refining processes. However, the presence of other types like USY and Beta indicates a diversified demand structure. Understanding the proportion of revenue attributed to each type helps manufacturers decide where to focus production capabilities. For instance, a type with a higher share of the market mix may require different scaling strategies compared to a niche variant with specialized performance characteristics. The report details the revenue splits across these categories without exposing the specific percentage breakdown here, encouraging a deeper dive into the full dataset for precise modeling.
Application-wise, the market is heavily influenced by the petroleum and petrochemical sectors. These industries remain the primary consumers of high silica zeolites due to their reliance on cracking and alkylation processes. However, the report also captures the remainder of the market, which includes emerging applications that may offer higher margins or growth potential. Identifying the weight of these application segments is vital for suppliers looking to diversify their client base beyond traditional refining customers.
Regionally, the market exhibits distinct characteristics. North America, Europe, and Asia Pacific represent significant portions of the market landscape. Each region presents unique regulatory environments, manufacturing hubs, and consumption patterns. For example, regulatory shifts in Europe regarding emissions and efficiency can drive demand for specific high-performance zeolites differently than in Asia Pacific, where industrial output growth might be the primary driver. The report segments the market by these geographic zones to help companies tailor their go-to-market strategies. Specific regional revenue splits are reserved for the comprehensive report to maintain the precision of our competitive intelligence.
Competitive Landscape: Key Players and Strategic Positioning
The high silica zeolite market is not a commodity free-for-all; it is defined by a select group of sophisticated manufacturers who command significant influence. Our analysis identifies key companies that shape the industry dynamics, ranging from specialized zeolite producers to large chemical conglomerates. The market concentration metrics indicate that while the market is not overly monopolized, there is a clear tier of leaders who drive pricing and innovation standards.
Tosoh Corporation, headquartered in Tokyo, stands as a leading producer of HSZ-series high silica zeolites. Their focus on SiO2/Al2O3 ratios above 10 positions them strongly in petroleum refining and petrochemical hydrocracking. Recent developments highlight the volatility inherent in this sector; for instance, in August 2025, Tosoh reported decreased HSZ shipments for automotive applications in both domestic and European markets. This kind of company-specific intelligence is crucial for competitors analyzing market share shifts and for customers assessing supply reliability.
Zeolyst International, based in Pennsylvania, operates as a global supplier of synthetic high-silica zeolite powders. Their positioning spans petroleum refining, petrochemicals, and emission control, making them a versatile player. Similarly, W.R. Grace & Co. in Maryland continues to manufacture high-performance catalysts for refining processes, leveraging decades of chemical engineering expertise. These US-based entities compete closely with European giants such as Clariant AG and BASF SE. Clariant, located in Muttenz, supplies synthetic high silica zeolites for industrial catalyst and adsorbent applications, while BASF in Ludwigshafen produces zeolite catalysts including high-silica variants for refining and petrochemical sectors.
Honeywell International Inc., through its UOP division in Charlotte, supplies high-silica zeolite catalysts for petroleum refining and chemical processes, integrating zeolite technology into broader process solutions. Additionally, Zeochem AG in Rotkreuz, Switzerland, manufactures high-silica zeolites for catalysts and adsorbents in refining and petrochemical industries. The interactions between these companies—whether through competition, patent landscapes, or supply chain dependencies—define the market's competitive intensity. Understanding the headquarters, operational focus, and recent shipment trends of these entities allows strategists to map out potential partnership opportunities or competitive threats.
Industry Dynamics: Raw Materials and Regulatory Pressures
Market dynamics are often driven by factors external to the zeolite production itself. Raw material availability and pricing form the bedrock of cost structures. According to data from the USGS in February 2026, US natural zeolite production rose to an estimated 81,000 tons in 2024, with ex-works unit values averaging $145 per metric ton. While natural zeolites differ from synthetic high silica variants, the broader zeolite ecosystem influences supply chain logistics and raw material sourcing strategies for chemical manufacturers. Fluctuations in natural zeolite production can signal broader geological or economic trends affecting the mineral sector.
Furthermore, regulatory environments play a pivotal role in shaping demand. The same USGS report noted that US natural zeolite production and sales increased due to growing demand for animal feed, odor control, soil amendment, and water purification applications. While these are not the primary focus of high silica synthetic zeolites, they illustrate the regulatory push towards environmental stewardship and resource efficiency that permeates the entire industry. For high silica zeolite manufacturers, this translates into pressure to develop catalysts that enable cleaner refining processes or more efficient chemical conversions. Compliance with emission standards and the drive for energy efficiency in petrochemical plants are indirect but powerful drivers of demand for advanced zeolite materials.
Operational noise in the industry, such as shipment variations reported by major players like Tosoh, underscores the importance of real-time monitoring. A decrease in automotive application shipments in specific regions can ripple through the supply chain, affecting inventory levels and pricing strategies. Our report integrates these dynamic factors to provide a living view of the market, rather than a static snapshot.
Report Content Overview: Operational Intelligence for Execution
To translate these high-level insights into execution, our comprehensive market research report provides a detailed operational toolkit. The document is structured to support various functional teams within an organization, from strategy and finance to operations and sales.
The scope of the analysis covers the historical period from 2020 to 2025 and the forecast period from 2026 to 2032. All financial data is presented in USD millions, ensuring consistency for global reporting standards. The report includes detailed segmentation splits that allow users to isolate specific market niches. By breaking down the market by region, type, and application, clients can benchmark their own performance against the broader industry averages.
Beyond market sizing, the report delves into company profiles for the key industry participants. These profiles include headquarters locations, corporate URLs, and summary assessments of their product portfolios and market focus. This information is invaluable for vendor selection, partnership due diligence, and competitive benchmarking. The inclusion of recent developments, such as shipment updates and product launches, ensures that the intelligence is current and relevant for immediate decision-making.
Additionally, the report contextualizes the market within the broader industry environment by incorporating data on raw materials and regulatory trends. This holistic approach ensures that users understand not just the 播报 numbers, but the forces that influence them. The concentration metrics, such as CR3 and CR5 percentages, provide insight into market competitiveness and barrier to entry. By understanding the level of consolidation, new entrants can assess the viability of market participation, while incumbents can evaluate the risk of disruption.
Strategic Imperatives for 2026 and Beyond
As organizations plan their strategies for the remainder of the decade, several imperatives emerge from this market analysis. First, maintaining supply chain resilience is paramount. Given the specialized nature of high silica zeolite production and the concentration of key manufacturing hubs, disruptions can have outsized effects. Diversifying sourcing channels and understanding the capacity limits of key suppliers like Tosoh or Zeolyst can prevent operational bottlenecks.
Second, innovation in catalyst formulation remains a key differentiator. With the market growing at a steady CAGR, volume growth alone may not suffice to capture significant value. Companies that invest in developing zeolite variants with higher efficiency, longer lifecycle, or better adaptability to new refining technologies will likely command premium positioning. The report's segmentation data helps identify which types and applications are yielding the most value, guiding R&D investment priorities.
Third, regulatory compliance should be viewed as a strategic opportunity rather than a cost center. As environmental regulations tighten globally, the demand for catalysts that enable cleaner processes will rise. Aligning product development with these regulatory trends can open up new revenue streams. The industry context regarding environmental applications, even in adjacent sectors like natural zeolites, signals a broader shift towards sustainability that high silica zeolite producers can leverage.
Finally, competitive intelligence must be continuous. The actions of major players, such as shipment adjustments or shifts in focus areas, provide leading indicators of market trends. Monitoring the activities of companies like Honeywell UOP or BASF allows strategists to anticipate shifts in pricing, availability, and technology standards. Our report provides the framework for this ongoing monitoring by establishing a baseline of company capabilities and recent performance.
Conclusion: Accessing Comprehensive Intelligence
The High Silica Zeolite Market is a complex, mature ecosystem where strategic advantages are gained through depth of knowledge rather than broad generalizations. The steady growth trajectory, combined with the specialized nature of the product segments and the influence of key corporate players, requires a nuanced approach to planning. This briefing has outlined the macro landscape, the competitive forces, and the operational dynamics that define the sector. However, the full value of this research lies in the detailed data tables, specific segmentation percentages, and granular forecast models that support precise financial modeling and strategic planning.
For organizations ready to deepen their understanding and secure their position in this market, accessing the full comprehensive report is the logical next step. The detailed intelligence contained within allows for scenario planning, precise market entry analysis, and robust competitive benchmarking. In a market where margins and efficiency are critical, having access to verified, granular data is the ultimate competitive asset. We invite stakeholders to explore the complete findings to ensure their 2026 decisions are built on the most accurate and actionable industry intelligence available.
For detailed analysis of this topic, please visit the official page: High Silica Zeolite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Card Fare Markets to Reach $2.43B by 2032, Driven by 9.1% CAGR
By PW Consulting, 2026-09-07
Smart Cards Automated Fare Collection Systems Market: A Strategic Compass for 2026 Decision-Making
The global transit landscape is undergoing a fundamental transformation, driven by the convergence of smart card technology, open-loop payment ecosystems, and the urgent demand for seamless multimodal mobility. As municipal authorities and transport operators accelerate their digital modernization agendas, the Smart Cards Automated Fare Collection Systems Market has emerged as a critical battleground for technology providers, systems integrators, and public sector stakeholders. Our latest market research publication offers a rigorous, data-grounded examination of this evolving sector, delivering the strategic intelligence required to navigate the opportunities and complexities that will define the 2026–2032 forecast horizon.
Environmentally Friendly Recycled Plastic Solution Market
This article serves as a strategic preview of the full report. It highlights the macro trajectory, the structural dynamics reshaping competitive positioning, and the operational insights embedded within our analysis. Readers seeking precise segment valuations, regional breakdowns, and granular competitor benchmarking will find the complete dataset exclusively available through the full research publication.
Backgammon Market
The Macro Trajectory: Sustained Expansion at a Defining Inflection Point
Analyzing historical performance from 2020 through the 2025 base year, the market has demonstrated consistent upward momentum, with total revenue expanding from approximately 0.85 billion USD to 1.32 billion USD over the six-year observational window. This trajectory reflects not only steady deployment cycles across mature transit networks but also the accelerating adoption of contactless smart card interfaces in markets previously reliant on legacy paper ticketing or fragmented validation systems.
Worldwide Acoustic Module Market
Looking ahead, the forecast period spanning 2026 to 2032 projects a compound annual growth rate of 9.1 percent, positioning the sector for robust expansion. By the close of the forecast window in 2032, aggregate market revenue is projected to reach 2.43 billion USD. This growth is underpinned by several structural drivers: the continued shift toward cashless and account-based ticketing architectures, the integration of mobile wallet and biometric validation modalities, and the broader modernization of rail and bus networks in both developed and emerging economies.
The momentum observed from 2024 to 2025—where revenue climbed from 1.21 billion USD to 1.32 billion USD—signals a market that is transitioning from early-adoption capitalization to a more mature, scale-driven phase. Organizations evaluating procurement timelines, technology roadmaps, or partnership strategies must recognize that the next several years will reward those who align their investment cycles with this projected acceleration. Our research dissects the inflection points within this curve, mapping where demand concentration is likely to intensify and which deployment models will capture disproportionate share.
Market Architecture and Operational Realities
Automated fare collection ecosystems are inherently multifaceted, comprising hardware deployments, software platforms, and backend settlement infrastructures that must interoperate across diverse operational environments. The market is structured across distinct hardware and software categories, including farebox installations, ticket vending machines, and onboard and off-board validators, each carrying different capital intensity profiles and lifecycle replacement schedules.
Hardware components such as fare gates, validators, and ticket vending machines require substantial investment, and industry data indicates that approximately 47 percent of transit agencies face financial limitations during system implementation. This cost reality introduces a critical strategic variable: procurement decisions are increasingly evaluated not merely on technical compatibility but on total cost of ownership, vendor financing flexibility, and the ability to phase deployments without disrupting service continuity. Our report examines how these budget constraints are reshaping vendor selection criteria, inflationary pressure on component supply chains, and the growing preference for modular, upgradeable architectures over monolithic turnkey installations.
On the regulatory and standards front, the push toward open-loop payment interoperability has gained decisive traction. National transportation authorities are completing nationwide open-loop EMV roll-outs across rail networks, with road-vehicle extensions planned in follow-on phases. For operators and technology vendors alike, this regulatory trajectory demands preparation for costs that extend beyond hardware procurement to encompass network integration, security certification, and ongoing transaction settlement reconciliation. Agencies rolling out open-loop payments must plan for equipment upgrades and backend connectivity that meet emerging security and interoperability benchmarks. Our analysis isolates the regulatory timelines, compliance requirements, and risk vectors that decision-makers must factor into multi-year capital planning.
Competitive Landscape: Concentration, Capability, and Strategic Positioning
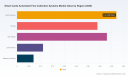
The market exhibits moderate concentration, with the top three players capturing approximately 26.5 percent of aggregate revenue and the top five firms accounting for roughly 29.4 percent. This concentration profile suggests a landscape that is neither overwhelmingly consolidated nor excessively fragmented—an environment where scale advantages coexist with meaningful room for specialized technology providers to differentiate through niche capabilities, regional partnerships, or modular product architectures.
Several established leaders define the competitive frontier. Cubic Corporation, headquartered in San Diego, California, continues to operate as a leading provider of integrated turnkey automated fare collection systems for public transport, offering full NFC and contactless smart card interfaces alongside fare processing engines, central computer systems, card management frameworks, and outsourcing services spanning bus, rail, and multimodal operations. Thales Group, based in Paris, functions as a global systems integrator delivering contactless smart card automatic fare collection systems, fare gates, validators, card readers, account-based ticketing platforms, and mobile wallet integration for mass transit and public transport ticketing. Scheidt & Bachmann GmbH, headquartered in Braunschweig, Germany, provides advanced fare collection systems using smart card technology, including account-based ticketing solutions such as the Fare Go Suite for seamless secure mobility with smart cards, mobile apps, contactless cards, and biometric options. Atos SE, located in Bezons, France, delivers complete mobility solutions for public transport including contactless payment systems, smart ticketing technology, transit fare management software, and integrated automated fare collection platforms.
At the component and semiconductor level, NXP Semiconductors, headquartered in Eindhoven, Netherlands, supplies secure NFC and RFID ICs, smart card interfaces, and contact readers for automated fare collection systems, including MIFARE Plus and RAIN RFID solutions enabling hands-free access and interoperable public transport ticketing. Omron Corporation, based in Kyoto, Japan, provides station device systems, transportation IC card solutions, and fare collection equipment supporting contactless smart cards and seamless validation for rail and public transport networks. Siemens AG, headquartered in Munich, Germany, offers integrated public transport ticketing solutions enabling cashless payments with tokens such as smart cards or barcodes linked to user accounts for seamless fare collection in bus, rail, and multimodal systems. These players collectively represent the spectrum of capability that operators evaluate when designing or upgrading fare collection infrastructures.
Our report maps each key company’s product portfolio, geographic footprint, partnership ecosystems, and recent strategic moves, enabling readers to assess where capability overlap exists, where white-space opportunities may emerge, and which vendors are best positioned to support specific deployment scenarios. The full publication provides detailed competitive profiling that goes beyond surface-level descriptions to examine integration complexity, certification portfolios, and service-level execution track records.
Recent Market Developments: Signals of Acceleration
Recent operational milestones illustrate the pace at which transit authorities are recalibrating their fare collection strategies. In March 2026, MARTA began upgrading its fare collection equipment and payment options to enable open payment using bank cards and mobile wallets while continuing to support existing Breeze smart cards. This simultaneous support for legacy smart cards and new open-loop channels reflects a pragmatic transition posture—operators must protect existing rider bases while expanding payment accessibility. Around the same period, Saint Louis Metro introduced next-generation fare collection with upgraded digital tools, new ticket vending machines, and state-of-the-art validators at all stations, signaling the continued relevance of on-site hardware refresh cycles even as backend payment architectures evolve.
Beyond North American deployments, international developments underscore the global nature of this modernization wave. In July 2025, the Land Bank of the Philippines launched a pilot automated fare collection system for MRT-3 enabling EMV payments and serving as a payment-gateway integrator for nationwide settlements. This initiative exemplifies the convergence of banking infrastructure, transit operations, and national payment standardization—a model with implications for other markets seeking to unify settlement rails across transport modes.
These events, among many others documented in the full report, are not isolated announcements; they are indicators of a structural shift. Transit agencies and operators have made real progress in modernizing fare collection through contactless and open-loop payment systems, yet the pace of adoption varies significantly by geography, regulatory environment, and capital availability. Our research contextualizes these developments within broader deployment patterns, helping stakeholders distinguish between headline announcements and actionable trend signals.
What the Full Report Delivers: Operational Intelligence for 2026 Planning
The complete Smart Cards Automated Fare Collection Systems Market research publication is designed as a decision-support tool rather than a static data repository. It integrates quantitative forecasting with qualitative industry analysis to answer the questions that procurement leaders, investment analysts, and technology strategists face when evaluating market entry, expansion, or partnership opportunities.
The report covers the following operational dimensions in depth:
- Historical market sizing from 2020 through the 2025 base year, with year-over-year revenue movement contextualized against deployment cycles, technology refresh patterns, and macroeconomic influences on transit capital budgets.
- A forward-looking forecast spanning 2026 to 2032, presenting revenue projections that account for expected adoption curves, hardware replacement timelines, and the diffusion of account-based and open-loop payment models across different operational environments.
- Segment-level analysis across hardware and software categories, including farebox installations, ticket vending machines, and validators deployed in onboard and off-board configurations. The full report examines how these categories interact, where capital intensity differs, and how lifecycle replacement schedules create recurring revenue opportunities for solution providers.
- Regional market dynamics that reflect distinct regulatory frameworks, infrastructure maturity, and transit ridership patterns. Decision-makers will find contextual analysis that explains why certain regions exhibit different adoption velocities and what that means for vendor go-to-market strategies.
- Competitive profiling of the key companies shaping the market, with attention to product architectures, integration capabilities, geographic presence, and recent strategic developments that indicate future positioning.
- Industry context analysis covering infrastructure cost realities, regulatory mandates such as open-loop EMV roll-outs, and the practical implications of network integration and equipment upgrade requirements for agencies transitioning to open payment environments.
- Strategic recommendations that translate market data into actionable guidance for technology vendors, systems integrators, transit operators, and investment stakeholders evaluating the sector’s growth trajectory and risk profile.
By combining macro revenue projections with segment-level structural analysis and competitive benchmarking, the report enables readers to model scenarios, prioritize investment targets, and anticipate where vendor capabilities will need to evolve to meet emerging operator requirements. The dataset underlying these insights is constructed to support both top-down market sizing and bottom-up segment evaluation, giving users the flexibility to approach the market from multiple analytical angles.
Why This Research Matters for 2026 Decisions
The 2026 to 2032 period will reward organizations that can distinguish between temporary deployment spikes and durable structural shifts. Smart card-based automated fare collection is no longer a niche transit function; it is a core component of the broader mobility payment infrastructure, intersecting with banking networks, mobile platforms, and national digital identity initiatives. Companies that underestimate the pace of open-loop integration, the capital constraints facing transit agencies, or the competitive intensity among established integrators risk misallocating resources or missing partnership windows.
Conversely, organizations that ground their strategy in rigorous market intelligence can identify where demand is concentrating, which deployment models are gaining traction, and how regulatory timelines are compressing decision cycles. The market’s 9.1 percent projected CAGR reflects genuine growth momentum, but growth at this scale also intensifies competition for contracts, accelerates technology obsolescence, and raises the bar for integration reliability. Our research equips decision-makers with the context needed to navigate these pressures rather than react to them after the fact.
For technology vendors and component suppliers, the report clarifies where product roadmaps should prioritize interoperability, where certification and security compliance will become gating factors, and how regional demand variation should influence go-to-market sequencing. For transit operators and public authorities, the analysis supports more informed procurement planning by highlighting the cost realities of hardware deployment, the integration complexity of open-loop transitions, and the vendor ecosystems best aligned with specific operational requirements. For investors and market analysts, the publication offers a structured view of market concentration, growth drivers, and competitive differentiation that supports valuation models and sector allocation decisions.
Accessing the Full Intelligence
This preview has outlined the strategic framework and macro contours of the Smart Cards Automated Fare Collection Systems Market as analyzed in our latest research publication. The complete report expands on every dimension introduced here, providing the detailed segment valuations, regional revenue distributions, competitor benchmarking matrices, and deployment scenario analyses that organizations require to make confident, evidence-based decisions.
Precise segmentation data, including regional revenue splits, type-specific market shares, and application-level breakdowns, is available exclusively within the full report. Readers seeking to evaluate specific market opportunities, benchmark vendors against defined criteria, or model forecast scenarios for internal planning should consult the complete publication to access the underlying dataset and accompanying analytical commentary.
The transit sector’s migration toward contactless, interoperable, and account-based fare collection is accelerating. The organizations that will capture value in this environment are those that combine strategic foresight with rigorous market intelligence. Our Smart Cards Automated Fare Collection Systems Market research is built to provide that foundation, enabling stakeholders to act with clarity as the 2026 to 2032 forecast period unfolds.
For detailed analysis of this topic, please visit the official page: Smart Cards Automated Fare Collection Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Orthopedic Surgical Power Tools Market Hits $194M in 2025, Forecast to $263M by 2032
By PW Consulting, 2026-09-07
Navigating the Next Decade: Strategic Imperatives in the Orthopedic Surgical Power Tools Market
The landscape of orthopedic surgery is undergoing a quiet but profound transformation. As surgical precision becomes increasingly linked to patient outcomes, the reliability and performance of surgical power tools have moved from being mere utilities to critical strategic assets. For stakeholders operating within the medical technology sector, understanding the trajectory of the Orthopedic Surgical Power Tools Market is no longer optional—it is a prerequisite for sustainable growth. Our latest market research provides a comprehensive lens through which to view these dynamics, offering a roadmap for navigating the complexities of the period from 2026 through 2032.
Worldwide Yaw Gear Box for Wind Power Market
This analysis serves as an introduction to the deeper intelligence contained within our full report. While the broader trends provide context, the specific data points required for precise forecasting and competitive positioning are detailed in the complete study. Here, we outline the macro-economic environment, the competitive forces at play, and the regulatory currents that will define the industry over the next decade.
Worldwide Hard Cover Making Machine Market
Market Trajectory and Historical Context
To understand where the market is going, one must first appreciate where it has been. The period from 2020 to 2025 established a baseline of resilience and gradual expansion. Over this historical window, the global revenue for orthopedic surgical power tools climbed from 165.0 million USD to approximately 194.0 million USD. This growth was not linear; it reflected the broader challenges and recoveries within the global healthcare infrastructure during recent years. The stabilization observed in 2023 followed by renewed momentum in 2024 and 2025 signals a maturing market that is absorbing shocks and returning to a growth trajectory.
Wood Clear Finish Market
Looking forward, the forecast period from 2026 to 2032 projects a continued upward trend. The market is expected to expand from an estimated 207.96 million USD in 2026 to 263.9 million USD by 2032. This progression represents a Compound Annual Growth Rate (CAGR) of 4.45 percent. While this rate may appear moderate compared to emerging technology sectors, it is significant within the context of regulated medical devices. It suggests steady demand driven by procedural volume increases rather than volatile speculative investment. For business leaders, this consistency implies that long-term capital allocation decisions can be grounded in predictable demand fundamentals, provided that product portfolios remain aligned with evolving surgical needs.
Core Drivers and Industry Dynamics
Several underlying factors are propelling this market expansion. The aging global population continues to drive demand for joint replacement and trauma repair procedures, which are primary use cases for orthopedic power tools. Furthermore, the shift toward minimally invasive surgery (MIS) places higher demands on the precision and ergonomics of surgical instrumentation. Surgeons require tools that offer consistent torque and control in tighter surgical fields, pushing manufacturers to innovate beyond traditional mechanical designs.
However, growth is not solely a function of demand; it is also constrained and shaped by operational realities. Reusable orthopedic surgical power tools require routine sterilization and maintenance, contributing to higher hospital costs compared to single-use alternatives. This dynamic creates a complex decision matrix for healthcare providers. While reusable instruments offer longevity, the associated labor and sterilization costs, including autoclave monitoring per AAMI ST-79 standards, must be weighed against the convenience of disposable options. This tension influences procurement strategies and product design roadmaps.
Regulatory compliance remains a critical gatekeeper. All orthopedic surgical power tools require FDA 510(k) clearance or CE marking under EU MDR. Compliance with ISO 13485 quality management and ANSI/AAMI standards is mandatory for orthopedic surgical power tools. These requirements ensure safety but add layers of complexity to product launches and market entry. Additionally, reimbursement landscapes are shifting. The 2026 CPT code updates include new codes for osteotomy procedures with externally controlled intramedullary lengthening devices effective January 1, 2026. Such updates can alter the economic viability of specific procedures, thereby influencing the demand for the tools used to perform them.
Competitive Landscape and Strategic Positioning
The market is characterized by a consolidated structure where major players hold significant sway. Market concentration data indicates that the top three companies hold a 62.0 percent share, while the top five control 75.0 percent of the market. This level of concentration suggests that competitive moves by industry giants ripple quickly through the ecosystem, affecting pricing, supply chain dynamics, and innovation pacing.
Several key companies define the current competitive terrain, each with distinct strategic focuses:
- Stryker Corporation: Based in Kalamazoo, Michigan, Stryker continues to reinforce its position through targeted product launches. In June 2026, the company launched the TPX HD premium small bone power tool for demanding orthopaedic procedures including total joint revisions, minimally invasive surgery, and oral maxillofacial cases. This move highlights a strategy focused on high-performance tools for complex revisions and specific specialties.
- Zimmer Biomet Holdings, Inc.: Located in Warsaw, Indiana, Zimmer Biomet emphasizes modularity in its approach. Their X Series Power System serves hip, knee, trauma, and shoulder procedures with modular design. This flexibility allows healthcare providers to standardize across different procedure types, potentially locking in long-term contracts.
- DePuy Synthes: Headquartered in West Chester, Pennsylvania, DePuy Synthes focuses on consistent power in demanding applications. Their orthopaedic power tool systems are designed to withstand the rigors of high-volume surgical environments.
- CONMED Corporation: Based in Largo, Florida, CONMED offers Hall Power tools for large and small bone procedures. Their strategy often centers on reliability and broad applicability across different orthopedic needs.
- B. Braun Melsungen AG: From Melsungen, Germany, this company provides integrated surgical power tools for orthopedic applications, leveraging its broader European presence to influence regional standards and adoption.
- MicroAire Surgical Instruments: Located in Charlottesville, Virginia, MicroAire focuses on powered instruments including PAL handpiece and Series 7000 for orthopedic procedures, catering to niche requirements within the broader tool category.
- ACF Medical: Based in Yunusemre, Manisa, Turkey, ACF Medical offers CE-certified battery-powered systems and saw blades for arthroplasty and trauma, representing the competitive pressure from emerging manufacturing hubs.
- Advanced Orthopaedic Solutions, Inc.: From Torrance, California, this firm focuses on technologically superior instruments for minimally invasive and precise orthopedic procedures, aligning closely with the macro trend toward MIS.
The competitive environment is not static. Companies are constantly balancing R&D investment against the need for regulatory approval. The launch of new tools like the TPX HD indicates a competitive race toward higher precision and better ergonomics. However, the high barriers to entry created by regulatory standards and established distribution networks protect incumbents while making it difficult for new entrants to gain significant traction without differentiated technology.
Segmentation Nuances and Regional Considerations
While the overall market size provides the headline numbers, the true strategic value lies in understanding how this value is distributed across different segments. The market is not a monolith; it is composed of distinct categories such as surgical drills, surgical saws, and other instruments and accessories. Demand varies significantly depending on the specific surgical application, ranging from large bone procedures to small bone and high-speed orthopedic power tools. Each segment carries its own growth drivers and competitive intensity.
Geography also plays a pivotal role in market dynamics. Revenue generation is not evenly distributed across the globe. Certain regions demonstrate higher adoption rates due to established healthcare infrastructure and reimbursement frameworks, while others offer growth potential due to improving access and increasing surgical volumes. However, detailed regional breakdowns, including specific percentage splits and revenue amounts for regions such as North America, Europe, and Asia Pacific, are critical data points that require careful analysis. These details form the backbone of any localized market entry or expansion strategy.
Similarly, the balance between different instrument types influences inventory planning and R&D focus. Some tool categories see consistent demand due to their ubiquity in standard procedures, while others may experience faster growth linked to specific technological advancements or surgical technique shifts. Understanding the revenue contribution of each type and application is essential for optimizing product mix. Our full report contains the granular segmentation data necessary to dissect these variances and identify high-value opportunities within each category.
Strategic Recommendations for 2026 and Beyond
For executives and strategists, the insights derived from this market analysis point to several actionable imperatives. First, product development must align with the dual demands of precision and durability. As surgical techniques evolve toward minimally invasive approaches, tools must offer enhanced torque and ergonomics without compromising reliability. The recent industry moves toward premium small bone power tools exemplify this direction.
Second, regulatory strategy cannot be an afterthought. With FDA 510(k) clearance and EU MDR requirements setting the baseline, companies must build compliance into their design controls early. The mandatory nature of ISO 13485 quality management means that quality systems are a competitive differentiator as well as a license to operate. Companies that can demonstrate superior quality management may gain preference in procurement processes where risk mitigation is prioritized by hospital groups.
Third, cost considerations for end-users must be factored into value propositions. The ongoing debate between reusable and single-use alternatives affects total cost of ownership calculations for hospitals. Manufacturers need to articulate the economic benefits of their tools, whether through longevity, reduced maintenance costs, or improved surgical outcomes that reduce readmission rates. The impact of sterilization processes and maintenance requirements on hospital budgets is a key talking point for sales and marketing teams.
Fourth, monitoring reimbursement trends is vital. Changes such as the 2026 CPT code updates can shift procedure volumes overnight. Strategic planning should include scenario modeling based on potential reimbursement shifts to ensure that product portfolios remain viable under different payment structures. Understanding which procedures are financially favored by payers allows companies to tailor their marketing and development efforts toward supported indications.
Finally, competitive intelligence should be continuous. With market concentration remaining high, tracking the product launches and strategic moves of the top players is essential. A launch by a market leader often demands a response, whether through innovation, partnership, or targeted marketing. Keeping abreast of developments such as new product introductions in the upper half of 2026 ensures that strategies remain relevant and responsive.
Conclusion: The Value of Comprehensive Intelligence
The Orthopedic Surgical Power Tools Market presents a landscape of steady growth tempered by regulatory and operational complexities. The projected expansion to 263.9 million USD by 2032 offers a compelling opportunity, but realizing value within this market requires more than a surface-level understanding of the trends. It demands a deep dive into segmentation, regional nuances, and competitive specific strategies.
The data provided in this overview sets the stage, highlighting the macro trajectory and the key players defining the industry. However, the specific percentage splits, regional revenue breakdowns, and detailed segment analysis hold the keys to precise strategic planning. These details allow for accurate forecasting, targeted market entry, and optimized resource allocation.
Our comprehensive report unlocks this deeper layer of intelligence. It provides the detailed segmentation data by region, type, and application that is necessary to move from general strategic direction to specific tactical execution. For organizations committed to leading in this space, accessing the full dataset is the next logical step. The full report contains the granular breakdowns required to validate assumptions and refine forecasts for the 2026 to 2032 period.
In an industry where precision defines success, your market intelligence should be equally precise. We invite you to explore the complete study to secure the detailed competitive and segment-level data required to navigate the upcoming decade with confidence.
For detailed analysis of this topic, please visit the official page: Orthopedic Surgical Power Tools Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Blackout Curtains Market to Hit $344.8M by 2032, Growing at 6.98% CAGR
By PW Consulting, 2026-09-07
Strategic Intelligence for the Blackout Curtains Market: Navigating Growth, Innovation, and Competitive Dynamics in 2026
In an era defined by shifting consumer preferences, evolving regulatory standards, and rapid material innovation, the window treatments sector has emerged as a critical battleground for home goods manufacturers, commercial interior suppliers, and retail strategists. At the heart of this transformation lies the blackout curtains market, a segment that has quietly but steadily captured significant market share over the past half-decade. As enterprises prepare their portfolio expansions, channel strategies, and sustainability initiatives for the 2026-2032 horizon, understanding the underlying forces shaping this category is no longer optional. It is a strategic imperative.
Worldwide Centralized Monitoring Market
Our latest comprehensive market study delivers precisely the kind of actionable intelligence that executive teams, product developers, and commercial leaders require to make confident, forward-looking decisions. Built upon a rigorous five-year historical foundation and extended through a seven-year forecast window, this report maps the structural inflection points, competitive maneuvers, and demand-side shifts that will dictate profitability and market positioning in the years ahead. Below, we outline the strategic contours of the analysis and demonstrate why it serves as an essential reference for stakeholders operating across household, commercial, and specialized applications.
Special Zirconium Beads For Electronic Materials Market
Market Trajectory and the Macroeconomic Foundation
The blackout curtains market has demonstrated consistent upward momentum, reflecting a confluence of urbanization trends, heightened awareness of sleep health, energy efficiency mandates, and the growing premiumization of interior environments. Historical revenue patterns from 2020 through 2025 reveal a steady expansion trajectory, with the broader category advancing from approximately 163.15 million USD at the start of the period to a baseline valuation of 215.0 million USD by 2025. This compounding growth underscores a market that has successfully moved beyond cyclical volatility and established a durable demand base.
Worldwide Process Pressure Gauge Market
Looking ahead, the forecast period spanning 2026 through 2032 projects a sustained compound annual growth rate of 6.98 percent. Such a trajectory signals not merely incremental expansion but a structural re-rating of the category's commercial significance. By the close of the forecast window, the market is positioned to reach a substantially elevated revenue threshold, reflecting both volume-driven consumption and value-added pricing strategies enabled by material innovation, certification differentiation, and premium design positioning. For enterprises evaluating production scaling, inventory planning, or geographic rollout, this growth framework provides a reliable baseline against which to model capacity investments and channel allocation.
Critically, the expansion is not uniformly distributed across all demand vectors. The report disentangles the structural drivers that are accelerating adoption in specific end-use environments while identifying the friction points that moderate growth in others. Household applications continue to anchor the category, benefiting from residential renovation cycles, remote-work lighting adjustments, and heightened consumer sensitivity to light pollution and thermal comfort. Commercial deployments, meanwhile, are increasingly influenced by workplace wellness standards, hospitality renovation programs, and specialized facility requirements. Transportation and niche operational settings represent a more specialized but strategically important demand pool, often driven by performance specifications that go well beyond basic aesthetic considerations.
Competitive Architecture and Strategic Positioning
The competitive landscape of the blackout curtains market is characterized by a fragmented yet increasingly sophisticated player base. Market concentration metrics indicate a relatively dispersed structure, with the top three firms holding a combined share that reflects the absence of a single dominant gatekeeper. This fragmentation creates both opportunity and risk: it enables agile entrants to capture niche segments through specialization, while simultaneously compelling established manufacturers to invest continuously in product differentiation, channel access, and brand credibility.
Several companies have emerged as focal points of competitive activity, each pursuing distinct strategic pathways that illustrate the breadth of approaches available in this market. Sun Zero has built its positioning around a rigorous performance narrative, marketing specialty room-darkening and true blackout curtains that emphasize 100 percent light-blocking capability validated through independent laboratory testing. This commitment to third-party verification has become a differentiating asset in a category where consumer trust is frequently undermined by inconsistent product claims.
Eclipse has pursued a distribution-centric model, producing thermal and blackout curtain lines that are scaled through major retail partnerships. Its strategy highlights the enduring importance of shelf presence, brand recognition, and volume-oriented merchandising in segments where accessibility and price competitiveness remain decisive purchase drivers. Quince, by contrast, has carved a direct-to-consumer pathway that emphasizes material provenance and certification transparency, offering European linen and cotton true blackout curtains backed by OEKO-TEX certification. This approach resonates with consumers who prioritize non-toxic materials, sustainable sourcing, and minimalist design language.
Blackoutcurtains.com operates as a specialized provider targeting commercial and studio environments, where precise light-control requirements demand tailored solutions rather than standardized consumer-grade offerings. Sleepout has introduced a portable, instant-install concept that aligns with the growing mobility of living and work arrangements, while simultaneously differentiating itself through PFAS-free formulations and OEKO-TEX certification. The presence of manufacturing-focused players such as Zhuji Tenzo Textile Co., Ltd. illustrates the critical role of upstream fabric producers in supplying half-blackout and full-blackout textiles to a broader ecosystem of brand owners and private-label developers. At the broader premium end of the window treatments spectrum, Hunter Douglas Inc. continues to leverage its global production capabilities and established distribution networks to integrate blackout curtain lines within a more extensive portfolio of architectural shading solutions.
This diversity of strategic postures is not merely descriptive. It reflects the underlying economic logic of the market: performance claims, certification credibility, channel strategy, material composition, and end-use specialization are all levers that companies can adjust to capture disproportionate value within their chosen segments. The report analyzes how these levers interact, which combinations are proving most resilient under current market conditions, and where emerging entrants are most likely to disrupt incumbent positions.
Industry Dynamics Shaped by Certification, Material Innovation, and Consumer Expectations
One of the most consequential shifts shaping the blackout curtains market is the accelerating emphasis on health, safety, and environmental performance. Certification frameworks have evolved from peripheral marketing claims into decisive purchase criteria, particularly among household consumers, interior designers, and commercial procurement teams that operate under stringent indoor air quality and material safety requirements. Recent product documentation and independent testing data indicate that multiple leading offerings now carry OEKO-TEX certification, with several also achieving GREENGUARD Gold recognition or PFAS-free formulations. The convergence of these standards is reshaping competitive benchmarks, as manufacturers that fail to align with non-toxic and low-emission expectations face growing reputational and commercial headwinds.
Simultaneously, material science and textile engineering continue to expand the functional envelope of blackout products. Yarn-dyed woven constructions, flame-retardant variants, and high-customization light-blocking fabrics are increasingly visible at major trade exhibitions, signaling that performance differentiation is moving beyond simple opacity metrics. Recent exhibition activity has highlighted dedicated zones where manufacturers showcased 100 percent blackout fabrics, specialized flame-retardant formulations, and advanced woven structures designed for both aesthetic refinement and rigorous light control. These developments suggest that the category is maturing toward a more technical, specification-driven identity, particularly in commercial and institutional contexts where compliance and durability requirements are non-negotiable.
Consumer expectations are also being reshaped by the broader interior wellness narrative. Sleep quality, circadian lighting management, and thermal regulation are no longer niche concerns; they are increasingly central to residential purchasing decisions. This cultural shift amplifies the strategic relevance of products that can articulate clear, verifiable performance benefits. At the same time, it raises the stakes for brand communication, because the market is saturated with contradictory claims regarding light-blocking efficacy, fabric composition, and environmental safety. Companies that invest in transparent testing, recognizable certifications, and consistent product storytelling are better positioned to convert awareness into repurchase and recommendation behavior.
What the Report Delivers: Operational Intelligence for Decision-Makers
This study is designed to translate high-level market dynamics into a practical decision-support framework. Rather than stopping at aggregate trend commentary, the report constructs a multi-layered analytical architecture that enables stakeholders to evaluate opportunities, anticipate risks, and calibrate execution strategies with precision. The following elements represent the core operational value of the research:
- Comprehensive historical reconstruction and forward-looking revenue modeling that contextualizes past performance while projecting plausible growth pathways through the end of the decade.
- Granular segmentation analysis that isolates the structural drivers, demand intensity, and competitive characteristics shaping distinct product categories, application environments, and regional markets.
- End-use deployment insights that differentiate household purchasing behavior from commercial procurement logic and specialized operational requirements, enabling more targeted product development and channel planning.
- Detailed competitive profiling that examines how key participants position themselves across performance claims, distribution models, material sourcing, certification strategy, and pricing architecture.
- Certification and regulatory tracking that maps the evolving landscape of OEKO-TEX standards, PFAS-free formulations, GREENGUARD recognition, and other compliance frameworks influencing purchase decisions.
- Trade show and innovation monitoring that distills emerging fabric technologies, customization trends, and product launches into actionable signals for R&D and portfolio management.
- Market concentration and structural analysis that clarifies the degree of fragmentation, the influence of leading firms, and the strategic opening available to new entrants or niche specialists.
Each of these components is integrated into a cohesive narrative that connects demand-side behavior with supply-side execution. The objective is not simply to describe what is happening, but to explain why it matters, where the leverage points are located, and how organizations can align their strategies to capture durable advantage.
Strategic Applications for 2026 Executive Decision-Making
For organizations operating in or adjacent to the blackout curtains market, the 2026 decision environment presents a distinctive set of priorities. Capacity planning must account for sustained demand growth without assuming uniform expansion across all segments. Product roadmaps need to balance performance differentiation with cost discipline, especially as certification requirements and non-toxic material expectations become more entrenched. Channel strategy must reconcile the pull of major retail distribution with the precision targeting enabled by direct-to-consumer models and specialized commercial procurement pathways. Brand positioning must navigate an increasingly crowded field of performance claims by anchoring messaging in verifiable testing and recognized certifications.
The report is structured to support these decisions at multiple levels of organizational responsibility. Executive leadership can use the macro growth framework and structural analysis to validate investment theses and set long-range strategic direction. Product and innovation teams can draw on the segmentation and certification insights to prioritize development initiatives and ensure that new offerings align with emergent consumer and procurement criteria. Commercial and sales leaders can leverage the competitive profiling and end-use distinctions to refine targeting, adjust pricing architecture, and strengthen channel partnerships. Procurement and supply chain teams can benefit from the analysis of upstream fabric ecosystems and material trends that influence cost structures and availability constraints.
Why the Full Report Is Essential
While the strategic outline above captures the analytical direction of the study, the complete report contains the detailed segmentation data, regional demand patterns, application-specific revenue breakdowns, and company-level strategic assessments that transform high-level insight into execution-ready intelligence. The aggregate figures provide the necessary context, but the true strategic value lies in the disaggregated analysis that reveals where growth is concentrated, which competitive tactics are outperforming, and how certification and material innovations are reshaping purchase criteria across different customer groups.
Accessing the full report enables decision-makers to move beyond directional awareness and into precise strategic calibration. It offers the depth required to benchmark internal performance, evaluate market entry or expansion scenarios, and identify the specific segments where competitive differentiation can be most effectively established. For teams that need to justify resource allocation, prioritize product development, or restructure commercial approaches in response to evolving consumer expectations, the detailed intelligence within the complete study provides the evidentiary foundation necessary for confident action.
Conclusion: Positioning for the Next Phase of Market Evolution
The blackout curtains market is entering a phase in which growth is no longer the only measure of success. Differentiation, credibility, compliance alignment, and channel precision are becoming equally decisive in determining which companies capture sustainable value. The trajectory observed from 2020 through 2025, combined with the projected expansion through 2032, indicates that the category will continue to attract attention from both established players and emerging specialists. Yet the competitive advantage will belong to those who can translate market momentum into targeted execution, using verified performance claims, material innovation, and strategic positioning to stand out in a crowded field.
Our full market research study is engineered to support that transition from observation to action. By combining rigorous quantitative modeling with deep qualitative analysis of competitive behavior, certification dynamics, and end-use demand shifts, the report equips stakeholders with the intelligence required to make informed, resilient decisions in 2026 and beyond. For organizations ready to move from strategic awareness to strategic advantage, the complete analysis offers the comprehensive perspective necessary to navigate the next chapter of this evolving market with clarity and confidence.
For detailed analysis of this topic, please visit the official page: Blackout Curtains Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: ATC Equipment Market Hits $1.12 Billion in 2025, Surging 8.39% CAGR to $1.97 Billion by 2032
By PW Consulting, 2026-09-07
Navigating the Skies of Innovation: Strategic Insights for the 2026 Air Traffic Control Equipment Market
The global aviation infrastructure stands at a pivotal juncture. As airspace becomes increasingly congested and the demand for safer, more efficient travel grows, the backbone of this evolution lies in advanced Air Traffic Control (ATC) equipment. For stakeholders operating within the aerospace, defense, and aviation services sectors, understanding the trajectory of this market is not merely an academic exercise—it is a critical imperative for strategic planning in 2026 and beyond.
Commercial and Household Paper Shredder Market
The ATC Equipment Market has demonstrated remarkable resilience and growth over the past half-decade. Valued at approximately 500 million USD in 2020, the sector has surged to an estimated 1,120 million USD by 2025. This trajectory underscores a compound annual growth rate (CAGR) of 8.39 percent projected through 2032, signaling a sustained expansion phase driven by technological modernization and regulatory mandates. This article serves as a strategic preview of our comprehensive market research, designed to equip decision-makers with the high-level intelligence needed to navigate the complexities of this evolving landscape. While we delve into the macro drivers and competitive forces here, the precise segmentation data and granular forecasts are reserved for our full report.
Worldwide Spinal Fusion Cage Market
The Macro Economic Trajectory and Growth Drivers
The growth narrative of the ATC equipment market is inextricably linked to the broader health of the global aviation industry. Following a period of disruption, the sector has rebounded with vigor. The market size climbed from 704.57 million USD in 2022 to 805.41 million USD in 2023, and further to 918.04 million USD in 2024. This consistent upward momentum suggests that investment in airspace management is being treated as a priority rather than a discretionary expenditure.
Worldwide Multi-Currency Checker Market
Looking toward the forecast period from 2026 to 2032, the market is expected to reach 1,967 million USD. This expansion is fueled by several converging factors. First, the aging infrastructure in major aviation markets requires urgent upgrades to maintain safety standards and operational efficiency. Second, the shift toward digitalization and remote tower technologies is opening new avenues for cost-effective management of air navigation services. Finally, regulatory bodies are increasingly mandating modern surveillance and communication systems to handle the integration of unmanned aircraft systems and increased flight densities.
For enterprise strategists, understanding these top-line figures is essential for capacity planning and investment allocation. However, the nuanced drivers behind regional performance and application-specific demand require a deeper dive. Our full analysis dissects these variables to provide a clear picture of where capital is flowing and which segments offer the highest return on investment in the coming cycle.
Regulatory Pressures and Infrastructure Modernization
Government policy and regulatory frameworks are among the most potent forces shaping the ATC equipment landscape. In the United States, the Federal Aviation Administration (FAA) has committed significant resources to modernization efforts. Notably, the FAA committed 6 billion USD by the end of 2025 for ATC upgrades under a 12.5 billion USD congressional authorization. This funding focuses heavily on telecommunications, radar surveillance, and data management systems. Such large-scale public investment creates a ripple effect across the supply chain, influencing vendor selection and procurement timelines globally.
However, challenges remain. Despite the authorization, FAA Facilities and Equipment account funding has remained approximately 3 billion USD annually, flat in real terms due to inflation. This constraint complicates the sustainment of legacy systems even as new technologies are deployed. Furthermore, reports indicate that aging National Airspace System (NAS) infrastructure risks service discontinuance by major carriers up to two years earlier than planned. This risk profile is prompting an accelerated transition to fiber and satellite networks to replace legacy copper infrastructure, aiming to support high-speed ATC data links and reduce obsolescence risks.
In April 2026, the FAA selected three AI-powered management system competitors, including Thales, for the SMART airspace routing trajectories program. This move highlights a clear strategic pivot toward intelligent automation and AI-driven routing to optimize traffic flow. For equipment manufacturers and system integrators, these regulatory signals are blueprints for product development and partnership opportunities. Our report details how these regulatory shifts specifically impact procurement cycles and technology adoption rates across different jurisdictions.
Competitive Landscape: Key Players and Strategic Moves
The ATC equipment market is characterized by a moderate level of concentration, with a CR3 of 24.6 percent and a CR5 of 26.2 percent. This fragmentation suggests that while major players dominate significant contracts, there is ample room for specialized innovators and regional partners to thrive. The competitive dynamics are defined by large-scale integrations, technology launches, and strategic partnerships aimed at securing long-term service agreements.
Several key companies are driving the industry forward. Thales Group, headquartered in Paris, provides integrated ATC systems including TopSky automation, radar surveillance, and digital towers for global air navigation service providers. In May 2025, Thales was awarded a modernization contract for nine ATC radar systems in Brazil by Omnisys, demonstrating its strong foothold in emerging markets. Similarly, L3Harris Technologies, Inc., based in Melbourne, Florida, offers FAA telecommunications infrastructure upgrades, ADS-B surveillance, tactical ATC systems, and digital voice solutions, positioning itself as a critical partner for US domestic upgrades.
Indra Sistemas S.A. from Madrid delivers air traffic management automation, surveillance radars, digital tower platforms, and airport operations systems. In a significant move toward cloud integration, Indra partnered with a major cloud provider in June 2025 for a scalable secure cloud platform supporting remote tower solutions. This partnership underscores the industry trend toward leveraging cloud computing for scalability and security in remote operations.
RTX Corporation (Collins Aerospace) in Arlington, Virginia, supplies STARS terminal automation, next-generation radars, digital tower systems, and common automation platforms. Their portfolio is essential for terminal area management. Meanwhile, Frequentis AG, based in Vienna, leads in ATC voice communication systems and integrated OneATM platforms supporting over 40 area control centres. In November 2025, Frequentis launched the TowerX unified automation platform to simplify tower operations with integrated modules, reflecting a push toward operational simplicity.
Leonardo S.p.A. from Rome provides ATC systems, integrated sensors, radars, and ground operations management for civil and military aviation, bridging the gap between defense and civil infrastructure needs. Beyond these incumbents, significant developments are reshaping the terrain. In December 2025, the FAA and DOT announced that Peraton was selected as the prime integrator for a Brand New Air Traffic Control System with 12.5 billion USD in modernization funding for radar replacement, fiber upgrades, and new centers. This massive contract award signals a new phase of procurement that favors large-scale system integration capabilities.
Understanding the specific contract values and market share nuances of these players is vital for competitive benchmarking. The full report provides a detailed competitive heat map that correlates company capabilities with regional demand spikes.
Technology Trends: Digital Towers and AI Integration
The technological frontier of the ATC market is defined by the move toward remote and digital tower modules and the integration of artificial intelligence. The shift from traditional concrete towers to remote digital solutions allows for centralized management of multiple airports, reducing operational costs and improving situational awareness for controllers. This transition is supported by the broader move to digital fiber and satellite networks replacing legacy copper infrastructure.
The integration of AI into airspace routing, as seen in the SMART program, represents a leap forward in efficiency. AI-powered systems can analyze vast datasets to predict congestion, optimize flight paths, and reduce fuel consumption. For equipment vendors, this means a shift in value proposition from hardware-centric solutions to software and service-oriented platforms. The ability to offer interoperable, software-defined systems is becoming a key differentiator.
Furthermore, surveillance technologies are evolving. ADS-B and next-generation radars are becoming standard requirements, pushing legacy surveillance equipment toward obsolescence. Companies that can offer seamless migration paths from legacy radar to modern surveillance suites will capture significant market share. These technological shifts are not uniform across all regions or application types. Our detailed segmentation analysis reveals which technologies are gaining traction in specific geographic zones and among different aircraft categories, providing a roadmap for R&D focus.
Strategic Implications for 2026 Decision Makers
For executives and strategy teams planning for 2026, the ATC equipment market offers both opportunities and risks. The clear growth trajectory suggests a favorable environment for sales and expansion. However, the complexity of procurement cycles, influenced by government funding timelines and regulatory approvals, requires careful navigation. Companies must align their product roadmaps with the specific modernization priorities outlined by bodies like the FAA and their international counterparts.
Supply chain resilience is another critical factor. With the accelerated transition to digital networks and the replacement of legacy infrastructure, the demand for specialized components and secure communication modules is rising. Delays in component availability can stall major modernization contracts. Additionally, the moderate market concentration implies that partnerships and consortiums may be necessary to bid for the largest system integration projects, such as the recent Peraton-led initiative.
Investment in AI and cloud capabilities is no longer optional for vendors aiming to remain competitive. The partnerships seen with Indra and the procurement preferences shown by the FAA indicate that scalability and intelligence are key purchase criteria. Firms that can demonstrate secure, scalable cloud integration for remote towers or AI-driven routing efficiencies will be better positioned to win contracts in the latter half of the decade.
Risk management also extends to geopolitical factors. Changes in defense spending and civil aviation budgets in key regions can alter the demand landscape quickly. Monitoring the balance between military and commercial aviation needs is essential, as many equipment suppliers serve both sectors. The interplay between these sectors often dictates the prioritization of dual-use technologies.
Conclusion: The Value of Deep Intelligence
The Air Traffic Control Equipment Market is undergoing a transformation defined by digitalization, AI integration, and massive infrastructure investment. The macro data indicates strong growth, but the real strategic value lies in understanding the underlying currents that drive this expansion. From regulatory funding constraints to the specific technological preferences of major prime contractors, the details matter.
This article has outlined the broad strokes of the market landscape, highlighting the key players, regulatory dynamics, and technological trends that define the 2026 outlook. However, to fully capitalize on these insights, organizations need granular data on segmentation splits, regional revenue distributions, and application-specific growth rates. The nuances of how commercial, military, and private aircraft sectors contribute to the total market volume require precise analysis to inform targeted strategies.
Our comprehensive report offers this depth. It moves beyond aggregate figures to provide actionable intelligence on market concentration, competitive positioning, and detailed forecast models. For organizations looking to secure a competitive advantage in the ATC equipment sector, access to this level of detailed intelligence is indispensable. We invite you to access the full market research study to unlock the specific data points and strategic recommendations necessary for informed decision-making in the year ahead.
For detailed analysis of this topic, please visit the official page: Air Traffic Control (ATC) Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cloud Database Market Hits $17.1B in 2025, 16.5% CAGR Forecasts $50B by 2032
By PW Consulting, 2026-09-07
Navigating the Cloud-Based Database Revolution: Strategic Intelligence for 2026 Enterprise Decisions
The landscape of enterprise data management has undergone a seismic shift in the first quarter of 2026. What was once considered an infrastructure utility has evolved into a critical strategic asset, driving everything from artificial intelligence integration to real-time regulatory compliance. As organizations worldwide accelerate their digital transformation agendas, the cloud-based database market stands at the forefront of this technological renaissance. PW Consulting recognizes that understanding the nuances of this market is no longer optional for C-suite executives and IT strategists; it is a fundamental requirement for sustainable growth.
Worldwide Industrial Pneumatic Brake Market
Our latest comprehensive market study, covering the historical trajectory from 2020 through 2025 and projecting forecast dynamics out to 2032, provides an unparalleled lens into this rapidly evolving sector. This article serves as an introduction to the depth of intelligence contained within the full report, highlighting the macro-level trends that define the industry while underscoring the operational specifics that only a detailed analysis can reveal. The numbers tell a compelling story of expansion, but the strategic implications lie in the intersection of technology, regulation, and competitive maneuvering.
B2B E-commerce Platform Tool Market
Market Trajectory and Growth Forecasts
The historical data from 2020 to 2025 illustrates a period of aggressive expansion for cloud-based database solutions. Starting at 8.85 billion USD in 2020, the market demonstrated resilience and upward momentum, reaching 10.17 billion USD in 2021 and continuing to climb through 2022 and 2023. By 2024, the market valuation had surged to 14.22 billion USD, reflecting the accelerated adoption of remote work infrastructures and the subsequent need for accessible, scalable data solutions. As we closed the base year of 2025, the market reached an estimated 17.1 billion USD, signaling a robust foundation for the forecast period.
Worldwide Energy Saving Air Conditioner Market
Looking forward to the forecast period of 2026 through 2032, the growth trajectory appears even more steep. The market is projected to reach 19.94 billion USD in 2026, followed by steady increments through 2027 and 2028, where valuations are expected to approach 27.31 billion USD. By the end of the decade in 2030, the market could touch 37.09 billion USD, culminating in a significant milestone of 50.0 billion USD by 2032. This expansion corresponds to a Compound Annual Growth Rate of 16.5 percent, a figure that underscores the high velocity of investment and adoption in this sector. Such growth rates are not merely statistical; they represent a fundamental restructuring of how enterprises store, manage, and derive value from their data assets.
However, raw market size and CAGR figures only scratch the surface. The true value for decision-makers lies in understanding the drivers behind this growth. Our full report dissects the contributing factors across different deployment models and database types, revealing which segments are fueling the bulk of this revenue expansion and which are poised for disruptive innovation. Readers of the complete study will find granular breakdowns that clarify where capital is flowing and where opportunity lies for both incumbents and new entrants.
Competitive Landscape and Key Players
The cloud-based database ecosystem is characterized by a high degree of market concentration, with a few dominant players commanding a significant share of the revenue. Our analysis indicates that the top three competitors hold approximately 65.0 percent of the market, while the top five extend their influence to 78.5 percent. This concentration suggests that while the market is growing, the battle for enterprise lock-in and multi-cloud interoperability is fierce among the leaders.
Amazon Web Services remains a pivotal force, leveraging a suite that includes Amazon Aurora, RDS for SQL Server, and DynamoDB to serve scalable relational, NoSQL, and serverless workloads. Their infrastructure continues to set the benchmark for availability and integration with broader cloud services. Microsoft competes closely with its Azure ecosystem, providing Azure SQL Database, Cosmos DB, and managed solutions for PostgreSQL and MySQL, often differentiating through built-in AI and security features that appeal to enterprise clients seeking integrated stacks. Google LLC has strengthened its position with Cloud SQL, Bigtable, Firestore, AlloyDB, and Spanner, focusing on cloud-native databases optimized for analytics, real-time applications, and deep AI integration.
Oracle Corporation continues to defend its stronghold in the enterprise relational space through Oracle Database Cloud Service, Autonomous Database, and Exadata on Cloud@Customer, now enhanced with AI capabilities. Meanwhile, Snowflake Inc. has carved a distinct niche with its cloud data platform, emphasizing native database and data sharing capabilities that allow for secure, scalable analytics without data movement. MongoDB, Inc. drives the NoSQL segment through MongoDB Atlas, a fully managed service designed for document-based workloads with multi-cloud support. IBM Corporation offers Db2 and Informix on Cloud, targeting hybrid environments that demand high availability and AI integration.
SAP SE provides SAP HANA Cloud for in-memory analytics and real-time business applications, crucial for large enterprises running ERP systems. Databricks, Inc. is gaining traction with its Lakehouse platform and integrated Delta Lake database, unifying data engineering and analytics in cloud environments. In the Asia-Pacific region, Tencent Cloud and Alibaba Cloud are significant players, offering TKEngine, Cloud Database services, RDS, and AnalyticDB tailored for regional enterprises and global scalability. Nutanix, Inc. and Couchbase, Inc. round out the competitive field with offerings focused on hybrid multicloud management and serverless NoSQL performance respectively.
The strategic moves made by these companies in early 2026 highlight the intensifying focus on AI integration. Google LLC announced managed, remote Model Context Protocol servers for its suite of databases, making them generally available for AI agents to connect securely to enterprise data as of April 2026. Oracle Corporation unveiled AI Database Agentic Innovations for Business Data and released enhancements for Oracle AI Database@Google Cloud in March 2026. Nutanix, Inc. released a complete agentic AI platform with Smart Tiering expansion in February 2026. These developments signal a shift from passive storage to active, intelligent data interfaces.
Segmentation Dynamics and Deployment Trends
Understanding how the market splits across different dimensions is crucial for targeting product strategies and investment decisions. The deployment landscape is divided among Public Cloud, Private Cloud, and Hybrid Cloud models. While the public cloud segment continues to capture the majority of attention due to its scalability and lower upfront costs, the hybrid and private cloud segments retain relevance for organizations with stringent data sovereignty or latency requirements. The full report provides specific revenue distributions across these deployment types, allowing strategists to gauge the relative maturity and growth potential of each model.
Similarly, the database type segmentation reveals the shifting preferences between Relational, NoSQL, and NewSQL technologies. Relational databases maintain a strong foundation, particularly for transactional integrity, but NoSQL solutions are expanding rapidly to handle unstructured data and high-velocity workloads. NewSQL represents an emerging frontier, promising the scalability of NoSQL with the consistency of SQL. Each type serves different use cases, and the revenue split between them indicates where developer preferences are trending.
End-user analysis further divides the market between SMEs and Large Enterprises. Large enterprises typically drive significant revenue due to the scale of their contracts and complex requirements, but SMEs represent a growing volume segment as managed services lower the barrier to entry. The report details the value contribution of each end-user category, offering insights into pricing strategies and service packaging that resonate with different organizational sizes.
Industry Dynamics and External Pressures
Market growth does not occur in a vacuum. Several external dynamics are shaping the cloud-based database market in 2026, creating both headwinds and tailwinds for industry participants. One significant factor is the labor market. Skilled database administrators and cloud infrastructure technicians command premium wages due to the rapid proliferation of managed cloud database deployments and AI-driven data processing demands. This labor cost pressure is influencing organizations to seek more automated, managed solutions that reduce the reliance on specialized human intervention, thereby feeding back into the demand for cloud-based database services.
Regulatory environments are also evolving rapidly. The EU Data Act, which came into force in September 2025, requires cloud providers to implement technical and organizational measures to prevent unlawful non-EU government access to non-personal data stored in Europe. This regulation impacts how providers architect their storage solutions and market their compliance capabilities to European clients. Concurrently, the U.S. CLOUD Act enables U.S. authorities to compel American cloud providers to provide access to data stored abroad, creating ongoing compliance challenges for European enterprises using these platforms. These cross-jurisdictional tensions require enterprises to carefully evaluate their cloud provider choices based on data residency and legal protection guarantees.
Infrastructure costs present another layer of complexity. U.S. data centers consumed 4 percent of total electricity in 2024, with demand projected to more than double by 2030 amid surging cloud database and AI workloads. This energy demand translates into operational costs and sustainability concerns that are increasingly becoming part of enterprise procurement criteria. Providers that can demonstrate energy efficiency or carbon-neutral operations may gain a competitive edge in specific segments of the market.
Security standards remain critical. ISO/IEC 27001 and related cloud security standards, along with 12 new global certifications achieved in 2025 for Oracle Database@Google Cloud, remain vital for enterprise adoption. Compliance is not just a checkbox; it is a currency of trust in the B2B market. Companies that fail to maintain or communicate their compliance posture risk losing ground to competitors who can guarantee higher levels of security assurance.
Strategic Value of the Full Report
While this overview provides a high-level map of the terrain, the full PW Consulting report offers the compass and detailed coordinates necessary for strategic navigation. The study goes beyond macro trends to offer actionable intelligence on pricing structures, vendor evaluation frameworks, and implementation roadmaps. For executives planning their 2026 budget allocations, the report provides the context needed to justify investments in cloud database migration or modernization.
The analysis includes deep dives into recent product releases and their implications. For instance, the launch of MariaDB Enterprise Platform 2026 in October 2025 as a unified cloud database platform uniting transactional, analytical, and AI vector workloads represents a significant consolidation trend. Understanding how such launches affect the competitive balance requires more than a press release summary; it requires an assessment of market reception and technical viability compared to established rivals.
Furthermore, the report addresses the supply chain and infrastructure constraints hinted at by energy consumption data. It explores how providers are mitigating risks associated with data center capacity and how enterprises can plan for potential latency or cost fluctuations driven by infrastructure scarcity. These operational details are critical for risk management strategies that extend beyond the IT department into supply chain and facilities planning.
Conclusion and Next Steps
The cloud-based database market in 2026 is defined by rapid growth, intense competition, and a complex regulatory environment. With a projected market size reaching 50.0 billion USD by 2032 and a CAGR of 16.5 percent, the sector offers substantial opportunities for organizations that can align their technology stacks with emerging trends. However, capitalizing on this growth requires more than general knowledge; it demands specific, data-backed insights into vendor capabilities, market share dynamics, and segment-specific growth rates.
PW Consulting's full market research report is designed to equip decision-makers with this precise intelligence. It transforms raw data into strategic narratives, helping organizations anticipate shifts in vendor dominance, regulatory compliance requirements, and technology adoption curves. For those ready to move beyond surface-level analysis and make informed, high-stakes decisions regarding their data infrastructure, the complete study is an essential resource. We invite you to access the full report to unlock the detailed segmentation data, competitor profiling, and forward-looking scenarios that will define the next era of cloud-based data management.
For detailed analysis of this topic, please visit the official page: Cloud-based Database Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Personal Dosimeter Market Hits $296.87M in 2025, Projects 7.06% CAGR to 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for Radiation Safety: Navigating the Personal Dosimeter Market Through 2032
The landscape of occupational radiation safety is undergoing a subtle but decisive transformation. As healthcare systems expand imaging capabilities, nuclear energy programs modernize legacy fleets, and industrial manufacturing adopts increasingly sophisticated containment protocols, the demand for precise, real-time personal dosimetry has shifted from compliance-driven procurement to strategic infrastructure investment. The newly released Personal Dosimeter Market study from PW Consulting maps this evolution across a seven-year forecast horizon, capturing the technical, regulatory, and commercial forces that will shape enterprise purchasing decisions through 2032.
Worldwide Cable Testing and Diagnostics Market
For executives navigating capital allocation, supply chain resilience, or product portfolio strategy, this report is designed less as a static reference and more as a decision operating system. It connects macro trajectory signals with on-the-ground procurement realities, translating historical inflection points into forward-looking procurement and R&D roadmaps. The analysis deliberately operates at the intersection of compliance architecture, clinical engineering priorities, and industrial safety economics, giving leadership teams a shared vocabulary for evaluating vendor partnerships, technology refresh cycles, and regional deployment sequencing.
Worldwide Thermoplastic Carbon Fiber Medical Composites Market
Why 2026 Represents a Structural Inflection Point
The personal dosimeter market has moved steadily upward over the past half-decade, with 2025 closing at approximately $296.87 million and 2026 projections reaching $319.14 million. This trajectory is not merely a function of incremental volume growth. It reflects a compounding set of operational realities: aging radiation protection frameworks requiring modernization, expanding occupational exposure monitoring mandates, and a gradual migration from passive badge-based workflows toward connected electronic systems capable of continuous dose logging, centralized analytics, and rapid incident response.
Worldwide Light Dump Trailer Market
The study's forecast period, spanning 2026 through 2032, positions leadership teams at a moment where procurement commitments made today will lock in exposure monitoring capabilities for the better part of a decade. The trajectory toward 2032, where market volume is projected to approach $477.22 million, signals an environment where dosimetry is increasingly embedded into broader radiation safety ecosystems rather than treated as isolated point solutions. Organizations that approach this window with granular vendor evaluation criteria, clear integration requirements, and realistic total-cost-of-ownership models will be better positioned to avoid fragmented deployments and vendor lock-in scenarios.
A compound annual growth rate of roughly 7.06 percent across the forecast horizon underscores both the resilience and the selectivity of this market. Growth will not distribute evenly across all product categories, application contexts, or geographies. The divergence between high-volume nuclear operations, broad-based clinical exposure monitoring, and specialized industrial use cases creates distinct purchasing cycles, different approval pathways, and varying sensitivity to price versus feature differentiation. This report's strategic value lies in clarifying where those divergences matter most for sourcing strategy and risk management.
What the Study Delivers: Operational Content Designed for Procurement and Product Teams
The report is organized to support translation from high-level market mapping to concrete procurement and product strategy. It does so by examining the ecosystem through three interlocking lenses: technology type, application environment, and deployment geography. Each lens is analyzed not simply for size, but for the operational dynamics that drive buying behavior, replacement cadence, and vendor evaluation criteria.
- Technology type coverage examines the functional trade-offs between electronic personal dosimeters, thermo luminescent badges, optically stimulated luminescence systems, film badge workflows, and emerging accessory types. The analysis connects measurement accuracy, read-out latency, reusability economics, and data management requirements to real procurement decisions in clinical and industrial settings.
- Application segmentation maps how exposure monitoring requirements differ across nuclear power operations, healthcare environments, industrial manufacturing sites, and specialized use cases. Each application context carries distinct compliance expectations, staffing models, and integration needs that influence whether organizations prioritize real-time alerting, archival dose records, multi-modal radiation detection, or streamlined badge exchange logistics.
- Regional deployment patterns are examined for how regulatory frameworks, procurement structures, and local radiation protection cultures shape demand. The report highlights where centralized hospital group purchasing, national nuclear operator standardization, and decentralized industrial safety programs create different competitive dynamics for suppliers and different negotiation leverage for buyers.
Beyond segmentation, the study includes a structured competitive landscape assessment, detailed profiles of leading manufacturers, and an operational scan of the regulatory and reimbursement environments that constrain or accelerate purchasing. These sections are intended to support vendor shortlisting, due diligence checklists, and internal business case development. The report also embeds raw material and capital expenditure context, including how hospital investment in radiation equipment and dosimetry integration frameworks influences product refresh timing and bundled procurement expectations.
Competitive Landscape: Ten Companies Shaping the Next Cycle
The market's competitive architecture is concentrated, with the top three and top five players each holding a substantial share of the overall landscape. That concentration does not imply a monolithic market, however. The field remains differentiated by product architecture, software integration depth, geographic service networks, and vertical specialization. The report profiles ten influential organizations whose product strategies and deployment footprints shape purchasing comparisons across medical, nuclear, and industrial environments.
Mirion Technologies, headquartered in Atlanta, Georgia, anchors its commercial emphasis on advanced wireless personal dosimetry with on-demand display capabilities and supporting dose management software. Its portfolio orientation illustrates the broader market drift toward connected read-out, centralized data workflows, and clinical-grade monitoring for X-ray, gamma, and beta environments. This product philosophy resonates in hospital and clinical procurement teams that prioritize rapid visibility and administrative workflow efficiency.
LANDAUER, based in Glenwood, Illinois, remains closely associated with optical and thermo luminescent badge ecosystems for occupational monitoring across medical, dental, and hospital facilities. Its market presence reflects the durability of badge-based programs where regulatory documentation, standardized exchange cycles, and long-established service relationships continue to drive repeat purchasing.
Tracerco, operating from Billingham in the United Kingdom, emphasizes real-time personal electronic dosimetry for gamma, beta, and neutron monitoring, with relevance across medical and life sciences applications. Its product direction highlights the growing importance of multi-modal detection in environments where exposure scenarios are less predictable and faster alarm response is operationally valuable.
Polimaster, from the Vilnius district in Lithuania, concentrates on active personal dosimetry for medical and healthcare settings. Its footprint demonstrates the continued regional diversification of supply options and the role of compact active monitoring tools in facilities seeking real-time staff dose awareness without full-scale system overhaul.
Unfors RaySafe, located in Hovås, Sweden, develops electronic personal dosimeters aligned with X-ray and gamma monitoring in medical imaging and clinical settings. Its positioning reflects the close coupling between imaging department workflow design and personal monitoring requirements, particularly where dose optimization initiatives place additional emphasis on accurate staff exposure tracking.
Thermo Fisher Scientific, headquartered in Waltham, Massachusetts, contributes to the market through electronic personal dosimetry platforms designed for gamma, beta, and neutron monitoring in hospital and medical contexts. Its broader instrumentation ecosystem gives it a distinct integration advantage in organizations that prefer aligning dosimetry purchases with existing laboratory, imaging, or safety infrastructure.
ATOMTEX, based in Minsk, Belarus, supplies personal dosimeters and radiation monitoring instruments with relevance in medical applications. Its presence in the profiled competitive set underscores the importance of understanding regional supplier capabilities, especially where service responsiveness, calibration logistics, and localized support influence vendor evaluation beyond spec-sheet comparisons.
Ludlum Measurements, from Sweetwater, Texas, focuses on personal radiation dosimeters and detectors for medical and hospital personnel exposure monitoring. Its profile reflects sustained demand for rugged, application-specific detection tools in settings where reliability and straightforward operational use remain decisive buying criteria.
Saphymo, operating from Massy, France, engages in radiation monitoring solutions including personal dosimetry for medical and nuclear medicine use. This positioning shows how specialized clinical workflows, especially in nuclear medicine, create requirements that differ from general radiology environments and often reward vendors with targeted workflow integration and isotope-aware monitoring approaches.
QuartaRad, based in Fair Lawn, New Jersey, offers compact personal Geiger counter and dosimeter solutions for medical and clinical radiation safety. Its inclusion in the competitive landscape highlights the enduring role of portable, point-and-read tools in supplemental monitoring, spot checks, and environments where simplicity and immediate feedback are prioritized.
Collectively, these companies illustrate a market where differentiation is less about presence versus absence and more about measurement modality, data integration, service model, and vertical fit. The study uses these profiles not as endorsements but as comparison scaffolding, enabling procurement teams to map product philosophies against internal requirements, compliance obligations, and long-term operating costs.
Regulatory Anchors and Reimbursement Realities Shaping Demand
Market growth in personal dosimetry does not happen in a vacuum. It is bounded and accelerated by regulatory expectations, occupational safety standards, and reimbursement or policy frameworks that influence how frequently monitoring is required, who bears the cost, and what documentation standards must be met. The report integrates these forces as live market dynamics rather than background footnotes.
In clinical settings, personal dosimetry is governed by a mix of employer obligations, occupational safety guidance, and device clearance requirements. FDA 510(k) clearances and CE Mark certifications continue to shape the commercial path for dosimeter devices sold in the U.S. and EU markets, affecting product launch timing, documentation burdens, and market access strategies for manufacturers. At the operational level, NIOSH and OSHA requirements influence how medical radiation environments structure monitoring programs, which in turn affects recurring demand for badges, electronic dosimeters, and supporting data management services.
Regulatory momentum is not static. Updated Ionizing Radiation Ordinance provisions have reinforced employer responsibilities for ensuring medical radiation workers wear personal dosimeters, which strengthens the compliance baseline for purchasing programs and narrows the window for informal or inconsistent monitoring practices. Such mandates matter strategically because they convert dosimetry from a discretionary safety enhancement into a defined operational obligation, making procurement continuity, calibration reliability, and service coverage more consequential than headline price comparisons.
Reimbursement constraints can also shape clinical demand indirectly. For example, certain provider policies limit basic radiation dosimetry calculation units over defined periods and constrain special dosimetry usage as well. While these policies do not eliminate monitoring requirements, they influence budgeting behavior, service intensity, and how clinical administrators justify equipment and monitoring spend. The study treats these dynamics as decision context, helping organizations distinguish between structural demand drivers and near-term administrative limits that may alter purchasing cadence without changing long-term necessity.
Implications for 2026 Enterprise Decision-Making
For leadership teams planning around 2026, the market's signals point toward several practical strategic priorities.
First, procurement strategy should be evaluated against integration requirements rather than device-only specifications. As dosimetry data becomes more central to radiation safety reporting, vendor selection increasingly depends on software interoperability, archiving practices, alerting logic, and the burden placed on safety officers and clinical staff. Products that offer cleaner data flow and simpler administrative handling often outperform on total operational value even when unit pricing appears less aggressive.
Second, the divergence between electronic and badge-based approaches should be assessed as a lifecycle question. Electronic personal dosimeters offer real-time visibility and stronger operational responsiveness, but their value depends on maintenance workflows, battery management, calibration cadence, and user adoption. Badge-based workflows remain relevant where documentation stability, standardized exchange programs, and long service relationships reduce administrative overhead. The right choice varies by site, staffing model, and the regulatory texture of the operating environment.
Third, regional procurement dynamics require differentiated sourcing strategies. In some markets, large centralized safety programs and institutional purchasing groups create volume leverage and standardization opportunities. In others, fragmented facility ownership and varied regulatory enforcement create a need for flexible service models and strong local support. The report's regional analysis is designed to help buyers anticipate where price competition is most intense, where service quality is the primary differentiator, and where compliance documentation requirements will dominate the evaluation process.
Fourth, capital expenditure planning should incorporate dosimetry as part of broader radiation equipment investment rather than as a standalone line item in isolation. Hospital budgets that sustain investment in radiation equipment increasingly expect dosimetry integration frameworks to align with imaging systems, safety programs, and personnel monitoring workflows. Vendors and buyers alike benefit from anticipating that linkage early, since it influences product selection, deployment sequencing, and multi-year service planning.
How to Use the Full Study
This preview is intended to demonstrate the analytical depth and decision relevance of the complete report while preserving the granular figures, segment breakdowns, and comparative employer-level insights for the full publication. The full study provides the detailed segment values, technology-level comparisons, region-specific demand patterns, and competitive positioning detail needed to support vendor shortlists, budget justifications, compliance planning, and product roadmap decisions.
Organizations evaluating radiation safety procurement for 2026 and beyond will find the complete edition useful for converting market direction into actionable criteria: which technology families align with specific application contexts, where regional dynamics create procurement advantages or risks, how the leading manufacturers differentiate their service and integration models, and what regulatory developments are likely to tighten or expand purchasing requirements.
The Personal Dosimeter Market report is built for teams that need more than aggregated growth numbers. It is designed to support decisions where accuracy, compliance durability, service reliability, and integration readiness determine whether a monitoring program delivers operational value over a multi-year horizon. For leaders preparing for 2026 commitments and planning toward 2032 capacity, the full study offers the structured intelligence required to move from market awareness to confident, evidence-based action.
For detailed analysis of this topic, please visit the official page: Personal Dosimeter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: High-Performance Electric Motorcycle Market to Hit $1.42 Billion by 2032, Growing at 11.8% CAGR
By PW Consulting, 2026-09-07
Navigating the High-Performance Electric Motorcycle Market: A Strategic Blueprint for 2026 and Beyond
The global mobility landscape is undergoing a paradigm shift, where performance is no longer the exclusive domain of internal combustion engines. High-performance electric motorcycles represent the vanguard of this transformation,merging exhilarating power delivery with sustainable technology. For industry stakeholders, investors, and strategic planners, understanding the trajectory of this segment is not merely an academic exercise; it is a critical imperative for navigating the opportunities and challenges of the coming years. Our latest market research publication offers a comprehensive dissection of the High-Performance Electric Motorcycle Market, providing the analytical rigor required to make informed decisions in 2026 and beyond.
Acoustics Service Market
This report serves as a strategic compass, designed to illuminate the path from the immediate present through the medium-term forecast horizon. By synthesizing historical performance data with forward-looking indicators, we equip decision-makers with the insights necessary to capitalize on emerging trends, mitigate risks, and identify high-value avenues for growth. The following overview encapsulates the depth, scope, and strategic utility of this analysis, offering a glimpse into the intelligence available within the full publication.
Three-proof Ruggedized Laptop Market
Market Trajectory and Growth Potential
The momentum behind high-performance electric motorcycles is underpinned by a robust upward trajectory in market revenue. Based on our extensive data modeling, the market has demonstrated consistent expansion over the historical review period, driven by technological breakthroughs in powertrain efficiency, battery energy density, and shifting consumer preferences toward zero-emission performance vehicles. In our base year, the global market generated approximately 0.65 billion USD in revenue, marking a significant step up from the estimated 0.37 billion USD recorded in 2020. This nearly doubling of market value over a five-year span highlights the accelerating adoption rates and the increasing commercial viability of premium electric two-wheelers.
Worldwide Hard Cover Making Machine Market
Looking ahead, the growth narrative remains compelling. The forecast period projects a sustained Compound Annual Growth Rate (CAGR) of 11.8 percent. This growth rate reflects a market that is maturing yet still possesses substantial room for expansion as infrastructure improves and product portfolios diversify. By the end of the forecast horizon in 2032, market revenue is projected to reach an estimated 1.42 billion USD. This trajectory suggests that the high-performance electric motorcycle segment is poised to transition from a niche enthusiast market to a more mainstream component of the broader electric mobility ecosystem, driven by continuous innovation and competitive pressure among leading manufacturers.
It is crucial to note that this growth is not uniform across all dimensions. The expansion is fueled by distinct dynamics in product types, application segments, and regional adoption patterns. While specific regional breakdowns and granular segment percentages are detailed within the full report to preserve the integrity of our proprietary analytics and to provide actionable nuance, the overarching theme is one of diversification. Demand is being shaped by a combination of individual consumer enthusiasm for thrill and speed, alongside commercial interests in fleet electrification and specialized utility applications, all of which are thoroughly analyzed in the study.
Product Segmentation: Performance Archetypes and Application Drivers
The high-performance electric motorcycle landscape is characterized by distinct product archetypes that cater to divergent rider expectations and usage scenarios. Our analysis categorizes the market based on vehicle type and application, revealing how manufacturers are tailoring engineering solutions to meet specific performance benchmarks. The market encompasses street-legal sportbikes designed for on-road dominance, as well as off-road machines engineered for rugged terrain, motocross, and enduro challenges. Each category demands unique approaches to power delivery, torque management, weight optimization, and suspension dynamics.
In the street segment, the focus is on rapid acceleration, top-speed capability, and advanced rider aids that integrate seamlessly with digital interfaces and connectivity features. These machines are competing directly with their gasoline-powered counterparts, offering instant torque and reduced maintenance requirements. The off-road segment, conversely, emphasizes agility, durability, and power-to-weight ratios that excel in technical environments. This includes trials, enduro, and dual-sport applications where electric powertrains offer advantages in packaging, low-end torque, and precise throttle control.
Application segmentation further delineates the market's growth vectors. Individual consumers remain a significant driver of demand, seeking high-performance machines for recreation, commuting, and brand affiliation. Simultaneously, commercial applications are emerging as a strategic growth pillar, encompassing uses such as specialized delivery, security patrols, and fleet operations where total cost of ownership, reliability, and operational efficiency are paramount. Our report provides a deep-dive analysis of these applications, evaluating the specific value propositions, purchasing criteria, and adoption barriers associated with each use case, enabling stakeholders to refine their market entry or expansion strategies.
Competitive Landscape: Innovation as the Primary Battlefield
The high-performance electric motorcycle sector is defined by a fiercely competitive environment where technological differentiation is the key to market leadership. The market structure exhibits a moderate level of concentration, reflecting the presence of established players leveraging brand equity and engineering heritage, alongside agile innovators disrupting the status quo with proprietary technologies. Our analysis profiles the key companies shaping this competitive arena, examining their strategic positioning, technological moats, and recent developments that signal future market directions.
Among the notable participants is Zero Motorcycles, headquartered in Santa Cruz, California. Zero has established itself as a pioneer in the electric performance space, utilizing its proprietary Z-Force electric powertrain combined with rigid, aircraft-grade aluminum frames. This engineering philosophy prioritizes lightweight construction and rapid off-the-line acceleration, delivering a superior riding experience that resonates with performance-oriented riders. Their continued focus on refining powertrain efficiency and frame integrity underscores a commitment to maintaining a competitive edge in the street and off-road segments.
Verge Motorcycles, based in Finland, represents the cutting edge of electric superbike engineering. The company has introduced patented hubless donut motors and claims first-to-market solid-state battery packs, technologies that enable record torque outputs and enhanced charging capabilities. By addressing critical pain points such as range anxiety and charging speed through proprietary hardware innovations, Verge is positioning itself as a leader in the high-end performance niche. Their approach highlights the importance of battery chemistry and motor design as differentiators in a market where performance specifications are increasingly scrutinized by sophisticated buyers.
Lightning Motorcycle, operating in the United States, has garnered attention for its high-performance sportbikes, including the LS-218 model. Engineered to rival the performance of gas counterparts, Lightning focuses on industry-leading fast charging capabilities and reduced maintenance needs. Their development trajectory emphasizes practicality alongside performance, targeting riders who demand the thrill of electric power without compromising on usability or downtime. This balance of performance and operational efficiency is a recurring theme among successful entrants in this market.
Energica Motor Company, based in Italy, specializes in high-performance electric motorcycles spanning superbike and sport models, such as the Ego Sport series. Energica's portfolio is characterized by zero-emission powertrains that deliver exceptional acceleration, with 0-60 mph times under 2.5 seconds for select models. Their expertise in high-output powertrains and comprehensive vehicle integration positions them as a benchmark for performance metrics in the European and global markets, appealing to enthusiasts who prioritize raw power and dynamic handling.
Harley-Davidson has entered the fray through its LiveWire division, bringing the weight of a legacy brand to the high-performance electric segment. The LiveWire S2 series exemplifies this approach, featuring advanced power delivery systems and modern connectivity features tailored for enthusiasts. By leveraging established manufacturing capabilities and brand recognition, Harley-Davidson is expanding the addressable market for electric performance motorcycles, bridging the gap between traditional motorcycle culture and electric mobility.
Stark Future, headquartered in Barcelona, Spain, focuses on motocross and dual-sport applications, emphasizing agile, torque-rich performance platforms. Their recent strategic partnership, announced in April 2026, with MOTOREX for lubrication expertise illustrates the nuanced collaborations required to optimize performance at racing, production, and product development levels. This move underscores the complexity of electric drivetrain lubrication and thermal management, areas where specialized knowledge can provide a tangible competitive advantage.
Electric Motion, based in Saint-Brès, France, specializes in high-performance electric motorcycles for trials, enduro, and off-road segments. Their focus on specialized powertrains and lightweight designs addresses the unique demands of off-road performance, where power-to-weight ratios and durability are critical. Electric Motion's presence highlights the vitality of the off-road niche, where electric propulsion is unlocking new possibilities for rider engagement and competitive racing formats.
These companies, among others, are engaged in a dynamic race to innovate, differentiate, and capture market share. Our report provides detailed competitive profiling, including headquarters locations, product strategies, and technological differentiators, offering a holistic view of the competitive ecosystem. Understanding the strengths, weaknesses, and strategic moves of these key players is essential for benchmarking, partnership identification, and competitive response planning.
Technological Dynamics and Market Enablers
The viability and growth of the high-performance electric motorcycle market are inextricably linked to advancements in raw materials, battery technology, and regulatory frameworks. Our analysis integrates these critical dynamics to provide a comprehensive understanding of the factors influencing market evolution. Battery technology remains the cornerstone of electric motorcycle performance, with lithium-ion and emerging solid-state battery packs playing a pivotal role in enhancing power-to-weight ratios, extending range, and reducing charging times. The transition toward solid-state batteries, as exemplified by developments in the industry, represents a potential breakthrough in energy density and safety, enabling longer ranges and higher performance without compromising vehicle weight.
Raw material sourcing and design innovations also contribute significantly to market capabilities. The use of aircraft-grade aluminum frames is a prevalent strategy for achieving lightweight construction, which is essential for high-performance handling and acceleration. Such material choices directly impact the overall vehicle architecture and performance characteristics, making supply chain resilience and material science advancements relevant considerations for manufacturers and investors.
Regulatory environments are increasingly shaping market incentives and product specifications. Standards such as EU Regulation 134/2014 Annex VII, which standardizes the measurement of electric motorcycle energy consumption and range, provide a framework for comparability and consumer transparency. Adherence to such regulations not only ensures market access but also drives manufacturers to optimize efficiency and accuracy in performance claims. Furthermore, zero-emission requirements and environmental regulations are accelerating the adoption of high-performance electric motorcycles, creating a supportive policy backdrop that aligns with sustainability goals and urban mobility strategies.
These technological and regulatory dynamics create a complex interplay that influences product development cycles, cost structures, and competitive positioning. Our report dissects these factors to reveal their implications for market growth, investment risks, and strategic opportunities, ensuring that readers are equipped with a nuanced understanding of the external forces at play.
Strategic Applications and Decision-Making Framework
The insights contained in this research report are designed to support a wide array of strategic applications for executives, investors, and product planners. Whether the objective is to enter the market, expand an existing product portfolio, identify partnership opportunities, or assess competitive threats, the analysis provides a solid foundation for evidence-based decision-making.
For manufacturers and technology providers, the report offers granular insights into segmentation drivers, consumer preferences, and performance benchmarks. This enables the refinement of product development roadmaps, ensuring that engineering investments align with market demand and competitive expectations. Understanding the relative importance of street versus off-road performance, the specific requirements of individual versus commercial applications, and the regional variations in adoption patterns allows for more targeted resource allocation and market prioritization.
Investors and financial analysts can leverage the market sizing, growth projections, and competitive landscape analysis to evaluate the potential return on investment and risk profile of ventures within the high-performance electric motorcycle sector. The detailed data on revenue trends, CAGR, and market concentration provides the quantitative basis for valuation models and scenario planning. Additionally, the identification of key technological and regulatory drivers assists in assessing the long-term viability and scalability of market participants.
For strategic planners within automotive and mobility organizations, the report serves as a tool for benchmarking and competitive intelligence. The profiles of leading companies, combined with an analysis of recent developments such as strategic partnerships and technological introductions, offer early warning signals of shifting competitive dynamics. This intelligence can inform M&A strategies, joint venture explorations, and positioning strategies to ensure relevance in an evolving market landscape.
It is important to emphasize that the full strategic value of this research lies in the depth and granularity of the data provided. While this overview highlights the macro-level trends and key players, the complete report contains essential details regarding regional market dynamics, precise segment shares, and specific application-driven demand factors. These elements are critical for fine-tuning localized strategies and uncovering niche opportunities that may not be apparent from aggregate figures alone. Access to the full dataset ensures that decision-makers have the complete picture required to execute with precision.
Why This Report is Essential for 2026 Strategic Planning
As we move through 2026, the high-performance electric motorcycle market is at an inflection point where acceleration in adoption, technological maturity, and competitive intensity are converging. Strategic decisions made now will have a lasting impact on market positioning and financial outcomes over the forecast period. This research report is structured to meet the demands of this critical juncture by delivering actionable intelligence that bridges the gap between high-level market trends and executable strategy.
The forecast period from 2026 to 2032 offers a substantial window for growth, but realizing this potential requires navigating a landscape characterized by rapid innovation and evolving consumer expectations. Companies must be agile in their response to technological breakthroughs, such as advancements in battery chemistry and motor design, while also addressing the practicalities of charging infrastructure, maintenance ecosystems, and regulatory compliance. Our analysis provides the context and data necessary to anticipate these changes and prepare accordingly.
Furthermore, the competitive landscape is dynamic, with new entrants and established players continually reshaping the battlefield through product launches, partnerships, and technological claims. Staying ahead requires a thorough understanding of who the key players are, what technologies they are pursuing, and how they are positioning themselves relative to the broader market. This report consolidates that intelligence, saving stakeholders the time and resources required to gather and synthesize disparate sources of information.
By integrating market sizing, segmentation analysis, competitive profiling, and technology assessment into a cohesive narrative, the report enables a holistic approach to strategy. It helps organizations align their internal capabilities with external opportunities, identify gaps in the market, and prioritize initiatives that offer the highest strategic return. Whether the focus is on product innovation, market expansion, or competitive defense, the insights provided serve as a catalyst for informed action.
Conclusion: Accessing the Full Intelligence Picture
The High-Performance Electric Motorcycle Market presents a compelling opportunity for stakeholders who are prepared to engage with its complexities and capitalize on its growth trajectory. With a projected CAGR of 11.8 percent and a market size poised to exceed 1.4 billion USD by 2032, the potential rewards for strategic foresight are significant. However, success in this environment demands more than a superficial understanding of trends; it requires detailed, data-driven insights that reveal the underlying mechanics of demand, competition, and technology.
This research publication is designed to be that definitive resource. It combines rigorous quantitative analysis with qualitative assessments of the competitive and technological landscape, offering a multi-dimensional view of the market. From the nuances of street versus off-road segmentation to the strategic implications of recent developments like Stark Future's partnership with MOTOREX, the report provides a level of detail that is essential for high-stakes decision-making.
To fully leverage the strategic value of this research, we invite you to access the complete report. The full publication contains the comprehensive data tables, detailed regional and segment breakdowns, in-depth company profiles, and forward-looking analysis that form the backbone of this overview. By obtaining the complete intelligence package, you will gain the clarity and confidence needed to navigate the high-performance electric motorcycle market with precision, identify the most promising avenues for growth, and secure a competitive advantage in the years to come.
The journey toward electrification in the performance two-wheeler sector is accelerating. Equip your organization with the insights necessary to lead, adapt, and thrive. Explore the full report to unlock the detailed market intelligence and strategic recommendations that will guide your path forward in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: High-Performance Electric Motorcycle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


