High Bandwidth Memory Market to Reach USD 34.1 Billion by 2035 as AI Infrastructure Accelerates Demand
By benziminkarare, 2026-09-25
High Bandwidth Memory Market to Reach USD 34.1 Billion by 2035
The High Bandwidth Memory Market is projected to reach USD 34.1 billion by 2035, rising from an estimated USD 3.8 billion in 2026 at a CAGR of 27.7%. According to Dimension Market Research , the market is gaining momentum as artificial intelligence infrastructure, high-performance computing, cloud data centers and advanced graphics processing increase demand for faster and more energy-efficient memory solutions.
HBM uses vertically stacked DRAM dies, through-silicon vias and advanced packaging to deliver substantially higher memory bandwidth while supporting efficient data movement between processors and memory. The technology is increasingly important for AI accelerators, GPUs, high-performance computing platforms, networking systems and data center infrastructure.
AI Infrastructure Strengthens HBM Market Growth
The rapid expansion of artificial intelligence is one of the primary factors supporting High Bandwidth Memory Market growth. Generative AI, machine learning, foundation models and AI inference workloads require large volumes of data to move quickly between processors and memory. HBM addresses these requirements by providing high bandwidth and lower latency in advanced computing architectures.
- AI accelerators are driving substantial HBM demand.
- Data centers require higher memory bandwidth for AI workloads.
- HBM3E is gaining adoption in next-generation AI chips.
- HBM4 represents an emerging opportunity for advanced processors.
- Advanced packaging supports higher memory density and performance.
The AI accelerator segment is projected to account for approximately 41.6% of the market in 2026, reflecting the growing deployment of AI computing infrastructure. Data Centers & Cloud Infrastructure is also expected to lead end-use demand with approximately 47.2% market share in 2026.
Request a Free PDF Brochure (latest forecast include) - Download Now
HBM3E and HBM4 Shape the Technology Outlook
HBM3E is expected to hold a significant position in the High Bandwidth Memory Market, with an estimated 44.8% share in 2026. Its combination of higher bandwidth, capacity and energy efficiency makes it suitable for AI accelerators, GPUs and hyperscale computing infrastructure.
HBM4 is emerging as an important technology opportunity as semiconductor manufacturers, processor developers and advanced packaging companies invest in next-generation memory architectures. Improvements in stack density, thermal management, packaging integration and interface performance are expected to influence future HBM adoption.
Asia Pacific Leads the HBM Market
Asia Pacific is expected to remain the leading regional market, accounting for approximately 56.4% share in 2026. The region benefits from established semiconductor manufacturing capabilities, memory production, advanced packaging facilities and a strong electronics manufacturing ecosystem.
North America is expected to record the fastest growth during the forecast period, supported by AI infrastructure investment, hyperscale data centers, semiconductor development and increasing deployment of AI accelerators.
The US HBM market is estimated at USD 900 million in 2026, while Europe's market is estimated at USD 570 million. Japan's HBM market is projected at approximately USD 342 million in 2026, supported by semiconductor manufacturing expertise, materials technology and advanced packaging development.
HBM Market Opportunities and Challenges
The expansion of AI data centers represents a major opportunity for HBM manufacturers and semiconductor ecosystem participants. Increasing AI adoption across cloud computing, enterprise applications, analytics and autonomous technologies is creating sustained requirements for high-bandwidth memory.
At the same time, HBM manufacturing presents significant challenges. Wafer processing, die stacking, bonding, packaging and testing require sophisticated technology and substantial capital investment. These requirements create high barriers to entry and make manufacturing capacity, yield improvement and advanced packaging important competitive factors.
- AI data center expansion creates new HBM opportunities.
- Advanced packaging remains critical to HBM development.
- Manufacturing complexity increases capital requirements.
- Thermal management is important for higher-density HBM stacks.
- Supply capacity is becoming strategically important.
Report Also Cover
What is the High Bandwidth Memory Market size?
The High Bandwidth Memory Market is estimated at USD 3.8 billion in 2026 and is projected to reach USD 34.1 billion by 2035 , representing a 27.7% CAGR.
What is driving High Bandwidth Memory Market growth?
Rapid growth in artificial intelligence infrastructure, AI accelerators, high-performance computing, GPUs and cloud data centers is driving demand for high-bandwidth memory.
Which HBM technology is leading the market?
HBM3E is projected to hold a significant market position in 2026, supported by adoption in AI accelerators, GPUs and hyperscale computing systems.
What is the fastest-growing HBM application?
High-performance computing is expected to experience strong growth as scientific research, simulations, weather forecasting and other data-intensive workloads expand.
Which end-use segment dominates the HBM market?
Data Centers & Cloud Infrastructure is projected to lead the market, supported by hyperscale AI infrastructure, cloud computing and high-performance servers.
Which region leads the High Bandwidth Memory Market?
Asia Pacific is expected to lead with an estimated 56.4% market share in 2026 due to its semiconductor, memory manufacturing and advanced packaging ecosystem.
What is the outlook for the US HBM market?
The US High Bandwidth Memory Market is estimated at USD 900 million in 2026 and is expected to grow at a 28.1% CAGR during the forecast period.
What opportunities exist in the HBM industry?
Expansion of AI data centers, advanced processors, cloud computing and high-performance computing creates opportunities for HBM manufacturers and semiconductor ecosystem companies.
What are the major challenges in HBM production?
Complex wafer processing, die stacking, advanced packaging, testing requirements and high capital expenditure are key challenges affecting HBM production.
Which companies participate in the HBM ecosystem?
Major companies identified in the research include SK hynix, Samsung Electronics, Micron Technology, NVIDIA, AMD, Intel, Broadcom, Marvell Technology, TSMC, ASE Technology and Amkor Technology.
Browse more reports:
- Manufacturing Operations Management Platforms Market
- Japan Industrial Vision Market
- Temperature Data Logger Market
About Us
Dimension Market Research (DMR) is a global market intelligence and consulting firm delivering data-driven insights that help organizations make informed strategic decisions. With expertise across 12+ industries and global markets, DMR provides syndicated reports, custom research, competitive analysis, white space analysis, and business strategy consulting.
Our research solutions combine analytical rigor, industry expertise, and forward-looking intelligence to identify opportunities, reduce risks, and support sustainable growth. Trusted by clients across diverse sectors, DMR is committed to delivering accurate, actionable insights that enable businesses to navigate evolving market landscapes with confidence.
Contact Us
Phone USA : +17323699777
Phone India : +919310023843
E-mail : enquiry@dimensionmarketresearch.com
Address USA : 957 Route 33, Suite 12 #308, Hamilton Square, NJ-08690
Address India : D44, Sector 6, Noida 201301, India
The US High Temperature and Low Sag (HTLS) Conductor Market to Reach USD 1,289.9 Million by 2035
According to Dimension Market Research , The US High Temperature and Low Sag (HTLS) Conductor Market is projected to reach USD 631.2 million in 2026 and grow to approximately USD 1,289.9 million by 2035, expanding at a CAGR of 8.3% from 2026 to 2035. Market growth is being supported by grid modernization, aging transmission infrastructure, renewable energy integration, electricity demand growth, and increasing adoption of advanced overhead conductors for transmission capacity upgrades.
High Temperature and Low Sag conductors are gaining importance as U.S. electric utilities seek ways to increase transmission capacity without developing entirely new transmission corridors. HTLS conductor technology allows existing power lines to carry higher electrical loads while limiting conductor sag at elevated operating temperatures. This makes the technology particularly relevant for grid reconductoring, renewable energy interconnections, urban transmission upgrades, and congestion relief.
Key Highlights of the US HTLS Conductor Market
- 2026 market size: USD 631.2 million
- 2035 forecast: USD 1,289.9 million
- 2026 to 2035 CAGR: 8.3%
- ACCC is projected to hold 34.1% share in 2026
- Composite core materials are expected to hold 36.1% share
- Grid reconductoring remains a major application
- Electric utilities represent the leading end-use segment
- Renewable integration continues to increase HTLS demand
Request a Free PDF Brochure (latest forecast include) - Download Now
Grid Modernization Is Driving HTLS Conductor Demand
A substantial portion of the U.S. transmission network was developed several decades ago, creating a growing requirement for infrastructure replacement and capacity enhancement. Utilities are increasingly evaluating advanced conductors, overhead transmission conductors, composite core conductors, ACCC conductors, ACSS conductors, and high-temperature transmission lines as alternatives to conventional conductor systems.
Reconductoring can allow utilities to increase power transfer capability across existing rights-of-way while reducing the need for new towers and transmission corridors. This becomes especially valuable in regions where permitting, land acquisition, environmental approvals, and construction timelines make greenfield transmission projects difficult.
Regional transmission organizations and independent system operators, including PJM, MISO, ERCOT, and CAISO, are also managing growing transmission congestion and generation interconnection requirements. Higher-capacity conductors can help transmission owners increase line utilization and address bottlenecks across constrained power networks.
Renewable Energy Integration Creates New Opportunities
Rapid deployment of utility-scale solar, wind energy, battery storage, and other distributed and centralized energy resources is increasing the need for transmission capacity across the United States. Many renewable projects are located far from major electricity demand centers, increasing dependence on high-capacity transmission infrastructure.
HTLS technologies provide an efficient option for connecting renewable energy zones with existing grid infrastructure. Advanced conductor technologies can support higher current carrying capacity while maintaining required ground clearance.
Major conductor technologies used across high-capacity transmission projects include:
- Aluminum Conductor Composite Core, or ACCC
- Aluminum Conductor Composite Reinforced, or ACCR
- Gap-type ACSR conductors
- Aluminum Conductor Invar Reinforced, or ACIR
- Aluminum Conductor Steel Supported, or ACSS
- Thermal-resistant aluminum alloy conductors
ACCC Conductors Hold a Major Market Position
Aluminum Conductor Composite Core is projected to account for approximately 34.1% of the U.S. HTLS conductor market by conductor type in 2026 . ACCC technology benefits from lightweight composite cores, low thermal expansion, high-temperature performance, and reduced conductor sag.
These characteristics enable transmission owners to increase line capacity using existing infrastructure. ACCC conductors are particularly relevant for congested transmission corridors, renewable energy integration projects, urban load centers, and grid capacity expansion programs.
Composite core materials are also projected to account for 36.1% of the market by material in 2026 . Their favorable strength-to-weight ratio, corrosion resistance, thermal stability, and low sag characteristics make them suitable for demanding transmission applications.
Grid Reconductoring Supports Market Expansion
Grid reconductoring and transmission capacity upgrades represent important applications for HTLS conductors. Instead of developing entirely new transmission lines, utilities can replace conventional conductors installed on existing structures with higher-performance conductors.
This approach can help address transmission congestion, improve infrastructure utilization, accommodate rising electricity loads, and enable renewable energy interconnection.
- Existing transmission corridors can support higher capacity
- HTLS solutions can reduce thermal sag
- Utilities can improve power transfer capability
- Reconductoring can reduce reliance on new rights-of-way
- Advanced conductors support renewable grid connections
Electric Utilities Lead HTLS Conductor Adoption
Electric utilities represent the major end-use industry for HTLS conductor systems because investor-owned utilities, public power authorities, electric cooperatives, transmission operators, and infrastructure developers manage extensive transmission assets.
Growing electricity consumption from industrial facilities, data centers, electrification, transportation, and expanding urban centers is increasing pressure on the power grid. Utilities are therefore prioritizing grid reliability, transmission efficiency, resilience, and capacity expansion.
Federal and state infrastructure initiatives are also supporting investment in grid modernization and clean energy transmission systems.
Competitive Landscape
The U.S. HTLS conductor market includes global cable manufacturers, specialized advanced conductor companies, transmission technology providers, and materials companies. Market participants compete through conductor performance, manufacturing capabilities, utility relationships, material innovation, transmission efficiency, reliability, and project support.
Prominent participants include:
- Southwire Company, LLC
- CTC Global Corporation
- LS Cable & System Ltd.
- Nexans S.A.
- Prysmian S.p.A.
- Midal Cables Ltd.
- ZTT International Limited
- Lamifil N.V.
- Hengtong Group
- Sumitomo Electric Industries, Ltd.
- Fujikura Ltd.
The competitive environment is expected to evolve as transmission operators place greater emphasis on advanced composite materials, improved ampacity, reduced sag, lower transmission losses, and long-term grid reliability.
Future Outlook for the US HTLS Conductor Market
The outlook for The US High Temperature and Low Sag (HTLS) Conductor Market remains closely linked to transmission modernization, renewable energy development, grid congestion management, aging power infrastructure, and electricity demand growth.
Technological advancement in composite core conductors, thermal-resistant aluminum alloys, dynamic line rating, grid monitoring, and conductor engineering is expected to broaden the role of HTLS technology in U.S. transmission networks.
As utilities seek faster and more practical methods of increasing transmission capacity, high-temperature low-sag conductors are expected to remain an important component of power grid modernization strategies through 2035.
Report Also Cover
What is the US High Temperature and Low Sag (HTLS) Conductor Market size?
The U.S. HTLS conductor market is projected to reach USD 631.2 million in 2026 and approximately USD 1,289.9 million by 2035 .
What is the expected CAGR of the US HTLS Conductor Market?
The market is projected to grow at a CAGR of 8.3% between 2026 and 2035 , supported by transmission upgrades, renewable integration, and grid modernization.
What is driving demand for HTLS conductors in the United States?
Key growth factors include aging transmission infrastructure, grid congestion, renewable energy integration, electricity demand growth, and the need for higher transmission capacity.
Which conductor type leads the US HTLS Conductor Market?
Aluminum Conductor Composite Core, or ACCC, is projected to lead the conductor type segment with approximately 34.1% market share in 2026 .
Why are HTLS conductors used in transmission lines?
HTLS conductors enable higher current capacity while reducing thermal sag, allowing utilities to increase transmission capability using existing towers and rights-of-way.
Which material leads the US HTLS conductor industry?
Composite core materials are projected to account for approximately 36.1% of the market in 2026 , supported by their strength, thermal stability, and low sag characteristics.
What is grid reconductoring?
Grid reconductoring involves replacing existing transmission conductors with higher-capacity conductors to increase electricity transfer capability without constructing an entirely new transmission corridor.
Who are the major buyers of HTLS conductors in the United States?
Electric utilities, transmission operators, renewable energy developers, infrastructure companies, and power project developers represent important buyers and users of HTLS conductor technologies.
How does renewable energy support HTLS conductor demand?
Utility-scale wind and solar development requires greater transmission capacity between generation areas and demand centers, encouraging utilities to adopt advanced high-capacity conductors.
Who are the major companies in the US HTLS Conductor Market?
Key market participants include Southwire, CTC Global, LS Cable & System, Nexans, Prysmian, Midal Cables, ZTT International, Lamifil, Hengtong Group, and Sumitomo Electric Industries.
Similar reports:
- KSA High Temperature and Low Sag Conductor Market
- Japan High Temperature and Low Sag (HTLS) Conductor Market
- High Temperature and Low Sag (HTLS) Conductor Market
- Europe High Temperature and Low Sag (HTLS) Conductor Market
About Us
Dimension Market Research (DMR) is a global market intelligence and consulting firm delivering data-driven insights that help organizations make informed strategic decisions. With expertise across 12+ industries and global markets, DMR provides syndicated reports, custom research, competitive analysis, white space analysis, and business strategy consulting.
Our research solutions combine analytical rigor, industry expertise, and forward-looking intelligence to identify opportunities, reduce risks, and support sustainable growth. Trusted by clients across diverse sectors, DMR is committed to delivering accurate, actionable insights that enable businesses to navigate evolving market landscapes with confidence.
Contact Us
Phone USA : +17323699777
Phone India : +919310023843
E-mail : enquiry@dimensionmarketresearch.com
Address USA : 957 Route 33, Suite 12 #308, Hamilton Square, NJ-08690
Address India : D44, Sector 6, Noida 201301, India
Powder Coating Industry Growth Driven by Automotive and Green Coatings
By benziminkarare, 2026-09-15
Powder Coating Industry Overview
The Global Powder Coating Industry is projected to reach USD 31.5 billion by 2034, rising from USD 15.5 billion in 2025 at a CAGR of 8.2%. According to Dimension Market Research , increasing demand for durable, corrosion-resistant and environmentally responsible coatings is supporting market expansion across automotive, construction, consumer goods, furniture, appliances, aerospace and industrial applaications.
Powder coating is a dry finishing technology in which electrically charged powder particles are applied to a substrate and then cured using heat. The process creates a durable decorative or protective surface with strong resistance to corrosion, chemicals, abrasion and environmental exposure. Growing preference for low-VOC coating solutions is also strengthening demand as manufacturers pursue sustainability and regulatory compliance.
Key Powder Coating Industry Highlights
- Global market value is projected to reach USD 31.5 billion by 2034.
- Market growth is estimated at an 8.2% CAGR from 2025 to 2034.
- Asia-Pacific accounted for 41.1% market share in 2025.
- Thermoset resins held a 53.1% share in 2025.
- Consumer electronics represented 32.2% of the market in 2025.
- The U.S. market is projected to reach USD 8.9 billion by 2034.
- Electrostatic spray remains a leading coating method.
- Automotive and appliances remain important demand-generating sectors.
Get free sample copy of report - https://dimensionmarketresearch.com/request-sample/powder-coating-market/
Powder Coating Industry Growth Drivers
The automotive and consumer goods industries are among the major contributors to Powder Coating Industry growth . Automotive manufacturers use powder coatings on wheels, chassis, components and other parts because of their durability, corrosion resistance and attractive finish. The growing electric vehicle industry is creating additional opportunities for coatings that can withstand demanding operating and environmental conditions.
Consumer appliances, electronics and furniture manufacturers are also adopting powder coatings for their scratch resistance, color retention, chemical resistance and surface quality. Rising disposable income and demand for premium finished products in emerging economies are further supporting market opportunities.
Environmental regulations are another important market driver. Powder coatings generally contain little to no volatile organic compounds compared with many conventional solvent-based coatings. Regulatory initiatives and sustainability programs are encouraging manufacturers to reduce emissions, improve resource efficiency and adopt lower-impact coating technologies.
Powder Coating Industry Trends and Opportunities
Sustainability is becoming a central trend in the global powder coating industry. Manufacturers are investing in low-temperature curing technologies, recyclable formulations, bio-based materials and advanced coating solutions designed to reduce energy consumption and environmental impact.
Technological development is also expanding the application range of powder coatings. Advances in formulation technology are improving durability, UV resistance, antimicrobial performance, corrosion protection and surface appearance. Low-temperature curing powders could help address some limitations associated with coating heat-sensitive substrates such as plastics, composites and wood.
Renewable energy infrastructure presents another significant opportunity. Solar installations, wind power equipment and electric vehicle charging infrastructure require coatings capable of resisting UV exposure, chemicals, moisture and changing weather conditions. This creates additional demand for high-performance powder coating solutions.
Powder Coating Industry Regional Outlook
Asia-Pacific is expected to maintain its position as the leading regional market, supported by its extensive manufacturing base and growing automotive, construction, appliance and consumer goods industries. China, India, Japan and South Korea remain important contributors to regional demand.
North America is expected to record strong growth during the forecast period. Demand is supported by environmental regulations, manufacturing modernization, electric vehicle production, automation and increasing adoption of sustainable coating technologies. The United States remains an important market because of its advanced manufacturing infrastructure and continued investment in powder coating technology.
Powder Coating Industry Competitive Landscape
The powder coating industry remains competitive, with established global manufacturers and regional companies investing in product development, capacity expansion, partnerships, acquisitions and advanced production technologies. Companies are focusing on improved formulations, specialized applications, sustainable products and automated coating processes to strengthen their market positions.
Prominent companies include Akzo Nobel N.V., PPG Industries Inc., BASF SE, Jotun, The Sherwin-Williams Company, DSM, Arkema, Bayer AG, TCI Powder, Berger Paints India Limited, Nippon Paint Holdings Co. Ltd and Asian Paints PPG Pvt Limited.
Report Also Cover
What is the current Powder Coating Industry size?
According to Dimension Market Research, the global Powder Coating Industry is expected to reach USD 15.5 billion in 2025 and is projected to reach USD 31.5 billion by 2034.
What is the Powder Coating Industry forecast?
The market is forecast to expand at a CAGR of 8.2% between 2025 and 2034, supported by industrial applications, sustainability requirements and demand for durable coatings.
What factors are driving Powder Coating Industry growth?
Automotive production, construction activity, consumer appliances, environmental regulations, manufacturing expansion and demand for durable low-VOC coatings are major growth factors.
Which region dominates the Powder Coating Industry?
Asia-Pacific is projected to remain the leading regional market, accounting for 41.1% of global market revenue in 2025.
Which Powder Coating Industry segment is leading by resin?
Thermoset resins are projected to lead the resin category, accounting for 53.1% of the global market in 2025.
What are the major Powder Coating Industry applications?
Major applications include consumer goods, architectural products, furniture, automotive components, general industrial equipment and other manufactured products.
What is driving demand for sustainable powder coatings?
Stricter environmental regulations, lower VOC requirements, sustainability goals and growing interest in low-waste manufacturing are increasing adoption of powder coatings.
What opportunities exist in the Powder Coating Industry?
Emerging markets, renewable energy infrastructure, electric vehicles, automated production and advanced coating formulations offer significant growth opportunities.
Who are the major Powder Coating Industry players?
Key companies include Akzo Nobel, PPG Industries, BASF, Jotun, Sherwin-Williams, Arkema, Bayer, Berger Paints, Nippon Paint Holdings and Asian Paints PPG.
What does the Powder Coating Industry report cover?
The report covers market size, historical data, forecasts, CAGR, resin types, coating methods, applications, regional markets, market dynamics, competitive landscape, key players and recent industry developments.
Market Scope
The Powder Coating Industry report provides historical data from 2019 to 2024 and forecast data covering 2026 to 2034. The analysis examines the market by resin, coating method, application and region, providing businesses and industry decision-makers with insights into market growth, competitive positioning and emerging opportunities.
For companies evaluating investments, product strategies, geographic expansion or competitive positioning, understanding Powder Coating Industry size, industry trends, demand patterns and future growth opportunities can support more informed business decisions.
Related Report:
- Industrial Coatings Market
- Protective Coatings Market
- Antimicrobial Coating Market
- Polysiloxane Coating Market
About Us
Dimension Market Research (DMR) is a global market intelligence and consulting firm delivering data-driven insights that help organizations make informed strategic decisions. With expertise across 12+ industries and global markets, DMR provides syndicated reports, custom research, competitive analysis, white space analysis, and business strategy consulting.
Our research solutions combine analytical rigor, industry expertise, and forward-looking intelligence to identify opportunities, reduce risks, and support sustainable growth. Trusted by clients across diverse sectors, DMR is committed to delivering accurate, actionable insights that enable businesses to navigate evolving market landscapes with confidence.
Contact Us
Phone USA : +17323699777
Phone India : +919310023843
E-mail : enquiry@dimensionmarketresearch.com
Address USA : 957 Route 33, Suite 12 #308, Hamilton Square, NJ-08690
Address India : D44, Sector 6, Noida 201301, India
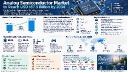
Analog Semiconductor Market to Reach USD 187.9 Billion by 2034
The global Analog Semiconductor Market is projected to reach USD 108.1 billion in 2025 and expand at a 6.3% CAGR to USD 187.9 billion by 2034 , according to Dimension Market Research. Increasing demand for electric vehicles, consumer electronics, industrial automation, connected devices, telecommunications infrastructure and energy-efficient power systems is creating new growth opportunities across the analog semiconductor industry.
Analog semiconductors process continuous real-world signals such as sound, temperature, light and pressure and convert them into electrical signals that electronic systems can understand. They are essential components in power management, signal conditioning, data conversion, amplification, sensing and communication systems. Their ability to connect physical inputs with digital processing makes analog integrated circuits critical to modern electronics.
Analog Semiconductor Market Growth Drivers
The market is benefiting from the increasing electronic content of vehicles, connected consumer products and industrial systems. Electric and hybrid vehicles require analog semiconductor components for battery monitoring, motor control, power conversion, sensor interfaces and advanced driver assistance systems.
Consumer electronics is another major demand center. Smartphones, laptops, wearables, smart appliances and IoT devices depend on analog chips for audio, display, charging, power management and signal conversion. Growing demand for smaller, connected and energy-efficient products is encouraging semiconductor manufacturers to develop compact and low-power solutions.
- Automotive electrification is increasing analog chip demand.
- IoT devices require efficient sensing and signal processing.
- Power management remains a major analog semiconductor function.
- Renewable energy projects are creating new power electronics demand.
- Mixed-signal integration is improving device efficiency and performance.
Get free sample data of the report - https://dimensionmarketresearch.com/request-sample/analog-semiconductor-market/
Technology and Application Trends
The increasing integration of analog and digital functions is one of the key trends shaping the industry. Mixed-signal semiconductor solutions can reduce component count, size and power consumption while improving system performance. This trend is particularly relevant to consumer electronics, automotive electronics, industrial automation and connected devices.
CMOS technology is expected to maintain a leading position, accounting for 53.8% of the market in 2025 . Its low power consumption, integration capabilities and cost advantages make it suitable for increasingly compact electronic systems.
Power management is also expected to remain a significant device function, with a 30.6% share in 2025 . Demand is being supported by electric vehicles, battery-powered electronics, renewable energy systems and industrial equipment.
Consumer electronics represents another important application, accounting for 27.5% of the market in 2025 . Automotive applications are expected to experience strong growth as vehicles incorporate more sensors, connectivity, safety systems and electrified powertrains.
Regional Analog Semiconductor Market Outlook
Asia Pacific is the leading regional market, representing 44.2% of global revenue in 2025 . Strong semiconductor manufacturing capabilities, consumer electronics production, automotive demand and telecommunications investment support the region's position. China, Japan, South Korea and Taiwan remain important centers for semiconductor production and technology development.
The US Analog Semiconductor Market is projected to reach USD 22.0 billion in 2025 , supported by technology innovation, semiconductor research, advanced manufacturing and strong demand across automotive, industrial and communications applications.
Europe is projected to reach USD 21.7 billion in 2025 , with automotive electronics, industrial automation, energy efficiency and renewable energy supporting market development.
Japan is projected to reach USD 10.8 billion in 2025 , while its analog semiconductor industry benefits from precision manufacturing, automotive electronics, robotics and advanced consumer devices.
- Asia Pacific leads with a 44.2% revenue share.
- US market value is projected at USD 22.0 billion in 2025.
- Europe is projected to reach USD 21.7 billion in 2025.
- Japan is projected to reach USD 10.8 billion in 2025.
- MEA offers emerging opportunities in smart infrastructure.
Opportunities and Industry Challenges
Renewable energy and smart grid development are opening new opportunities for analog semiconductor manufacturers. Power conversion, voltage regulation, energy monitoring and storage systems all require efficient analog components. Healthcare electronics is another promising area, with medical monitors, diagnostic equipment, imaging systems and wearable devices requiring accurate signal processing.
However, manufacturers face challenges including high production complexity, specialized equipment requirements, lengthy development cycles and supply chain vulnerabilities. Material availability, geopolitical uncertainty and capacity constraints can also affect production costs and delivery schedules.
Artificial intelligence is emerging as another important influence. AI-assisted design can accelerate analog circuit development, while AI-driven manufacturing analytics can help identify defects, improve yields and optimize production processes.
Analog Semiconductor Market Competitive Landscape
The competitive environment includes established semiconductor manufacturers and specialized technology companies competing through product innovation, energy efficiency, manufacturing capabilities and application-specific solutions. Major companies include Texas Instruments, Analog Devices, Infineon Technologies, STMicroelectronics, NXP Semiconductors, onsemi, Renesas Electronics, Microchip Technology, Skyworks Solutions, ROHM Semiconductor, Broadcom, Qorvo, Silicon Labs, Marvell Technology, Semtech, Monolithic Power Systems, Vicor, Diodes Incorporated and Power Integrations .
The market is also seeing innovation in analog IC design automation and AI-assisted semiconductor development, which could help shorten design cycles and accelerate the introduction of specialized analog solutions.
Report Also Cover
What is the Analog Semiconductor Market size?
The global Analog Semiconductor Market is projected to reach USD 108.1 billion in 2025 and USD 187.9 billion by 2034, expanding at a 6.3% CAGR during the forecast period.
What is driving the Analog Semiconductor Market?
Electric vehicles, consumer electronics, IoT devices, industrial automation, telecommunications, renewable energy and advanced power management are major market growth drivers.
Which region leads the Analog Semiconductor Market?
Asia Pacific leads the global market, accounting for an estimated 44.2% revenue share in 2025 due to its manufacturing ecosystem and strong electronics demand.
What is the US Analog Semiconductor Market size?
The US Analog Semiconductor Market is projected to reach USD 22.0 billion in 2025, supported by semiconductor innovation, advanced manufacturing and technology demand.
Which technology leads the market?
CMOS is expected to lead the technology segment with a 53.8% share in 2025, supported by its power efficiency, integration capabilities and cost advantages.
Which application holds the largest share?
Consumer electronics is projected to hold the largest application share at 27.5% in 2025, supported by demand for smartphones, laptops, wearables and connected devices.
Why are electric vehicles important to analog semiconductors?
Electric vehicles require analog components for battery management, power conversion, motor control, sensor interfaces and safety systems, increasing semiconductor content per vehicle.
What opportunities exist in renewable energy?
Solar, wind, energy storage and smart grid projects require analog components for power conversion, voltage regulation, monitoring and energy management.
Who are the major analog semiconductor companies?
Leading companies include Texas Instruments, Analog Devices, Infineon Technologies, STMicroelectronics, NXP Semiconductors, onsemi, Renesas and Microchip Technology.
What does the Analog Semiconductor Market report cover?
The report covers market size, forecast, growth drivers, restraints, opportunities, trends, technology, device function, applications, end-user industries, regional markets and competitive analysis.
Similar reports:
About Us
Dimension Market Research (DMR) is a global market intelligence and consulting firm delivering data-driven insights that help organizations make informed strategic decisions. With expertise across 12+ industries and global markets, DMR provides syndicated reports, custom research, competitive analysis, white space analysis, and business strategy consulting.
Our research solutions combine analytical rigor, industry expertise, and forward-looking intelligence to identify opportunities, reduce risks, and support sustainable growth. Trusted by clients across diverse sectors, DMR is committed to delivering accurate, actionable insights that enable businesses to navigate evolving market landscapes with confidence.
Contact Us
Phone USA : +17323699777
Phone India : +919310023843
E-mail : enquiry@dimensionmarketresearch.com
Address USA : 957 Route 33, Suite 12 #308, Hamilton Square, NJ-08690
Address India : D44, Sector 6, Noida 201301, India