

Blogs
Quality plays a critical role in industries where operational reliability, worker safety, and regulatory compliance must remain consistently high. Businesses in manufacturing, construction, utilities, and energy rely on well defined quality processes to complete projects successfully, maintain dependable assets, and prevent costly errors. Yet many organizations continue to manage inspections and testing through spreadsheets, extended email conversations, and disconnected document repositories. These fragmented approaches can take considerable time as employees search for records, chase approvals, verify information, and move between multiple systems.
A modern Inspection & Testing platform provides a more structured approach by bringing quality activities into a centralized digital environment. Instead of relying on scattered tasks and manual follow ups, organizations can manage inspection activities through a clearly defined workflow. Every inspection event follows an established process where information can be captured, reviewed, approved, and retained consistently. ToolKitX’s Inspection & Testing module applies this approach to help organizations simplify inspection management, improve compliance oversight, and connect quality activities with everyday operational processes.
The Role of a Modern Inspection & Testing Solution
A modern Inspection & Testing platform is designed to do much more than store inspection documents. It provides a structured framework for managing the entire inspection lifecycle, from initial preparation and field execution through review, approval, and final completion. Bringing these activities into a controlled workflow creates clearer accountability while ensuring that inspection information remains traceable throughout the process.
Critical quality information such as Inspection & Test Plans (ITPs), checklists, witness points, hold points, acceptance criteria, certifications, nonconformance records, and supporting evidence can be routed through predefined approval stages. Field teams can complete inspections directly from mobile devices while capturing photographs, videos, measurements, and instrument readings at the point where work occurs. Supervisors and authorized approvers can review submitted information electronically, increasing visibility while preserving detailed records of approval activity. At the same time, quality managers can monitor inspection performance across projects, contractors, assets, and operating locations without waiting for manually compiled reports.
Why Modernizing Inspection & Testing Is Important
Quality issues rarely remain limited to the original problem. A defect that appears minor at first can eventually result in additional work, schedule disruption, compliance concerns, increased costs, or greater operational exposure. When inspections are inconsistent, difficult to track, or inadequately documented, organizations have fewer opportunities to identify weaknesses and resolve them before they develop into larger problems.
A digital Inspection & Testing framework gives teams greater control over inspection activities and helps them identify potential issues earlier. By improving visibility, consistency, and documentation, organizations can strengthen quality outcomes while reducing the potential downstream consequences of inspection failures.
Key benefits include:
- Stronger compliance oversight through digitally approved, version controlled, and time stamped records that provide dependable audit trails.
- More standardized inspections through reusable templates, consistent processes, and clearly defined acceptance requirements.
- Faster review and approval through automated workflows, notifications, and escalation mechanisms that reduce manual follow ups.
- Improved operational coordination by connecting inspection information with assets, permits, and work orders.
- Ongoing audit readiness through real time visibility into compliance conditions across projects, locations, contractors, and different risk classifications.
Capabilities That Enable Operational Excellence
An effective Inspection & Testing system should simplify quality execution while enabling organizations to maintain consistent inspection practices across projects, sites, and operational teams.
Core capabilities include:
- Flexible ITP management that allows organizations to develop reusable Inspection & Test Plan templates containing sampling requirements, acceptance criteria, hold points, witness points, and relevant reference information.
- Digital inspection forms featuring dynamic checklists, conditional workflows, evidence requirements, measurement capture, and QR or barcode scanning capabilities.
- Integrated NCR and CAPA workflows for recording nonconformances, investigating root causes, implementing corrective actions, and verifying that issues have been properly closed.
- Certification and calibration management for maintaining equipment records, tracking expiration dates, and supporting ongoing calibration compliance.
- Punch list and commissioning functionality that enables teams to document outstanding items, allocate responsibility, track deadlines, and monitor completion.
- Secure electronic approvals with role based access controls that ensure approval activities are performed only by authorized personnel.
- Offline mobile capabilities that allow inspections to continue in locations with limited or unreliable connectivity, with information synchronized automatically once a connection is restored.
- Real time reporting and analytics for monitoring inspection activity, generating reports, and identifying recurring quality trends.
- Enterprise integrations that connect inspection workflows with Asset Management, Permit to Work, Work Order Management, Quality Management, ERP, and CMMS systems through APIs.
Business Advantages of a Unified Inspection Platform
Organizations that manage inspection and testing through a centralized, controlled platform can create significant improvements in day to day operations. Clearly defined workflows and established acceptance requirements can support better first time quality, while reducing defects and rework can help lower the costs associated with poor quality.
Review and approval activities can also become more efficient because evidence is captured directly at the worksite and automatically routed to the appropriate reviewers. Audit preparation becomes more straightforward when inspection records, certifications, corrective actions, nonconformance reports, and supporting evidence are organized within a single environment rather than scattered across different systems and repositories.
The value of a unified platform is not limited to saving time. Quality teams can gain a broader view of performance across projects, contractors, assets, and operating locations. Having this information readily accessible makes it easier to identify recurring issues, examine their underlying causes, and respond before developing patterns create more significant operational challenges.
Moving from Manual Processes to a Connected Quality Environment
Organizations that continue to depend on spreadsheets, email communication, and separate document repositories can face avoidable delays, coordination challenges, and limited visibility into quality performance. Transitioning to a structured Inspection & Testing solution offers a more consistent, controlled, and transparent approach to managing quality activities throughout the organization.
ToolKitX’s Inspection & Testing module helps organizations standardize inspection processes, streamline approvals, and maintain readiness for compliance requirements through connected, automated workflows. By connecting Inspection & Testing with Permit to Work, Asset Management, and Quality Management processes, the solution establishes a unified operational environment where quality information remains accessible, traceable, and integrated throughout the different stages of work.
Book a free demo @ https://toolkitx.com/campaign/inspection-and-testing/
Browse More
https://toolkitx.com/campaign/asset-management/
https://toolkitx.com/campaign/elearning/
https://toolkitx.com/campaign/employee-scheduling/
PW Consulting: Privacy Management Software Market Hits $7.36B in 2025, Projected to Surge at 37.4% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Privacy Management Software Market: Strategic Intelligence for 2026 and Beyond
The privacy technology landscape has entered a decisive inflection point. Organizations are no longer treating compliance as a periodic checklist or a back-office function. Instead, privacy management has become a core operational capability, intrinsically linked to customer trust, risk mitigation, and scalable digital transformation. Our latest Privacy Management Software Market research report translates this structural shift into a clear, actionable intelligence framework designed specifically for enterprise strategy teams, procurement leaders, and technology architects planning their 2026 roadmaps.
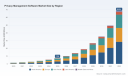
Drawing on a rigorous historical baseline spanning 2020 through 2025, the analysis extends its forward-looking lens through 2032. Over the past five years, the sector has witnessed a remarkable acceleration in capital allocation and vendor maturation. Market revenue grew from 1.5 billion USD in 2020 to 7.36 billion USD in 2025, underscoring how quickly privacy has evolved from a niche regulatory response into a mainstream enterprise priority. The trajectory does not flatten in the near term. Forecasts project continued expansion to 10.21 billion USD in 2026, with sustained momentum carrying the market toward 68.04 billion USD by 2032. Driving this expansion is a forecasted compound annual growth rate of 37.4 percent, a figure that signals far more than incremental adoption. It reflects a fundamental redesign of how organizations discover, classify, govern, and operationalize data across increasingly complex regulatory and technological environments.
For decision-makers navigating 2026, these numbers translate into critical strategic realities. Budgets are no longer discretionary. Privacy software is transitioning into a foundational layer of enterprise architecture, demanding careful evaluation of integration pathways, automation maturity, and long-term vendor viability. The research report is built to cut through marketing noise and equip leaders with the analytical rigor required to allocate resources, prioritize implementation sequences, and future-proof compliance operations.
Privacy Management Software Market
Market Dynamics Reshaping Enterprise Priorities
No enterprise privacy strategy can be designed in isolation from the regulatory and operational pressures shaping today’s compliance environment. Enforcement intensity has become a defining market catalyst. According to the GDPR Enforcement Tracker, 2026 alone has already recorded 143 fines, contributing to a cumulative total of over €6.29 billion across 3,186 recorded actions since 2018. This enforcement cadence is not merely a legal statistic; it is a direct signal that supervisory authorities are operationalizing privacy obligations with escalating precision and financial consequence.
In parallel, regional regulatory bodies are expanding the scope of obligations beyond traditional data handling. The California Privacy Protection Agency issued its first enforcement advisory on data minimization in April 2024, paired with ongoing proposed updates to the CCPA and CPRA frameworks, including forthcoming rules on automated decision-making technology. These developments illustrate a broader trend: regulators are no longer only scrutinizing static compliance artifacts. They are increasingly focused on how organizations architect data flows, manage consent dynamically, and govern emerging data processing activities in real time.
The operational strain of this expanding landscape is measurable. The PwC Global Compliance Survey from 2025 reveals that 77 percent of companies report negative business impact stemming from compliance complexity across multiple growth areas. When privacy obligations intersect with product innovation, M&A activity, cross-border data transfers, and third-party ecosystems, fragmented toolsets and manual workflows quickly become strategic bottlenecks. This is precisely where modern privacy management software enters as a structural enabler rather than a reactive safeguard.
What the Research Delivers: Operational Intelligence, Not Surface-Level Forecasts
This report is engineered for practitioners who must convert market intelligence into tangible operational decisions. Rather than presenting static snapshots, the analysis provides a comprehensive examination of how privacy management software is deployed across enterprise workflows, how solution categories diverge in capability, and where integration complexity most frequently derails implementation timelines.
The research maps the functional architecture of the market across its dominant solution types. Organizations are increasingly investing in regulatory compliance management as a central orchestration layer, while data discovery and mapping capabilities serve as the foundational prerequisite for accurate inventory, classification, and downstream governance. Risk assessment and management modules are gaining traction as boards and audit functions demand quantified exposure frameworks, while consent and preference management, incident and breach response, and other emerging capabilities round out the operational continuum. The report also examines how these capabilities converge within applied use cases, including privacy impact assessment and reporting, data subject request fulfillment, vendor and third-party risk oversight, and governance around incident response.
Beyond functional taxonomy, the study delivers a granular view of deployment considerations, vendor evaluation criteria, and implementation readiness factors. It investigates how enterprises are aligning privacy platforms with existing data governance structures, security operations, and customer experience architectures. Readers will find structured analysis on procurement pathways, integration dependencies, scalability thresholds, and the operational maturity required to transition from fragmented point solutions to unified privacy orchestration.
Critically, the report is designed to support scenario planning. It frames adoption trajectories within the context of organizational size, data environment complexity, regulatory exposure, and internal capability maturity. This allows strategy teams to model investment pacing, prioritize capability acquisition, and anticipate where automation will deliver the highest return on compliance efficiency.
Competitive Landscape: Platform Evolution and the Rise of Agentic Automation
The vendor ecosystem has matured rapidly, with leading providers differentiating through automation depth, data connectivity breadth, and cross-jurisdictional compliance orchestration. Market concentration currently reflects a moderately dispersed landscape, with the top three providers accounting for 26.2 percent of revenue and the top five capturing 39.5 percent. This structure indicates both vigorous competition and room for specialized innovators to gain footholds in high-value operational niches.
Several established and emerging players define the current competitive frontier. OneTrust, headquartered in Atlanta, Georgia, has advanced as an AI-ready governance platform emphasizing privacy automation, consent management, data subject rights fulfillment, and multi-jurisdictional compliance workflows. BigID, based in New York, has positioned its data security and privacy platform around AI-driven discovery, classification, and governance for sensitive data spanning cloud, on-premises, and AI systems. TrustArc, operating from Walnut Creek, California, provides a privacy management and consent platform supported by certification capabilities, DPIA automation, and global compliance tooling. DataGrail, in San Francisco, offers an agentic data privacy platform focused on consent management, data subject rights fulfillment, and risk assessment workflows. Transcend, also based in San Francisco, functions as a compliance layer for customer data, delivering consent management, data subject request automation, and preference management. Ketch, likewise headquartered in San Francisco, delivers enterprise privacy orchestration software spanning consent, data subject access requests, data mapping, assessments, and AI-ready data governance. IBM contributes through its broader enterprise portfolio, with Guardium Data Protection supporting data discovery, classification, and compliance across hybrid environments aligned with frameworks such as GDPR, CCPA, and PCI.
Recent product movements underscore how quickly the market is shifting toward automation intensity and AI-augmented governance. In March 2026, BigID introduced a unified privacy management platform expansion covering preference portals, deletion workflows, and AI data governance across structured and unstructured data assets. A few months later, in May 2026, Ketch launched the Ketch Agent Network, a multi-agent AI orchestration layer designed to support agentic data mapping, risk management, and assessment workflows within privacy programs. These releases illustrate a broader industry trajectory: privacy software is no longer confined to policy documentation or manual task routing. The frontier is now defined by orchestrated, intelligent workflows that reduce manual burden, accelerate response cycles, and embed compliance logic closer to operational data systems.
Legal Practice Management Software Market
Strategic Implications for 2026 Decision-Making
The convergence of enforcement pressure, regulatory expansion, and automation-driven platform evolution creates a clear mandate for enterprise leaders. Privacy management software is no longer a tactical purchase; it is a strategic capability that directly influences operational agility, risk exposure, and cross-functional coordination. Organizations that approach procurement with fragmented intent risk compounding complexity, while those that evaluate platforms through the lens of architectural fit, automation depth, and long-term scalability are better positioned to convert compliance obligations into competitive advantage.
This research report provides the analytical scaffolding required to make those evaluations with confidence. It illuminates where market growth is concentrated, how solution capabilities are diverging, and what implementation maturity looks like in practice. It also frames the vendor landscape in a way that supports comparative assessment without reducing complex platforms to superficial feature checklists.
For executives planning 2026 investments, the most valuable insight is structural rather than numerical. The market is scaling at a pace that rewards early architectural clarity. Enterprises that define privacy orchestration requirements, data discovery dependencies, and automation priorities now will face fewer integration bottlenecks, lower total cost of ownership, and stronger alignment between compliance operations and business objectives. Delaying that clarity until after procurement often results in reactive vendor selection, overlapping toolsets, and diminished returns on compliance investment.
The complete analysis extends well beyond the macro trajectory and competitive snapshots outlined here. Detailed segmentation intelligence, vendor evaluation frameworks, deployment sequencing models, and forward-looking scenario insights are provided in the full report. Readers seeking a comprehensive, decision-ready view of the Privacy Management Software Market are encouraged to access the complete research on the source page, where deeper segmentation breakdowns, vendor profile comparisons, and implementation pathway guidance are available in full.
For detailed analysis of this topic, please visit the official page: Privacy Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Thermoplastic Edgeband Market Hits $2.96B in 2025, Forecast 7.2% CAGR to $4.82B by 2032
By PW Consulting, 2026-09-16
Navigating the Thermoplastic Edgeband Market: Strategic Intelligence for 2026 and Beyond
The global furniture and interior design industries are undergoing a material transformation, driven by aesthetics, durability requirements, and increasingly complex regulatory environments. At the heart of this shift lies the thermoplastic edgeband sector, a critical component in cabinetry and surface finishing that bridges the gap between raw substrates and premium visual appeal. As we move through 2026, understanding the trajectory of this market is no longer optional for stakeholders; it is a fundamental necessity for securing competitive advantage. PW Consulting's latest comprehensive market research report offers an unprecedented deep dive into the thermoplastic edgeband landscape, providing the quantitative rigor and qualitative analysis needed to navigate the coming years with confidence.
This report is not merely a collection of statistics; it is a strategic roadmap designed to inform capital allocation, supply chain optimization, and product development strategies. By synthesizing historical performance with forward-looking projections, we equip decision-makers with the clarity required to mitigate risk and capitalize on emerging opportunities. The following analysis outlines the key themes, growth drivers, and competitive dynamics explored in detail within our full study.
Market Trajectory and Growth Projections
The thermoplastic edgeband market has demonstrated robust resilience and steady expansion over the past half-decade. Our analysis tracks historical performance from 2020 through 2025, establishing a solid baseline for future forecasting. The market has evolved from a valuation of approximately 2100 Million USD in 2020 to an estimated 2955 Million USD by 2025. This historical growth underscores the consistent demand for high-quality finishing solutions across residential and commercial sectors.
Thermoplastic Edgeband Market
Looking ahead, our forecast period spans 2026 to 2032, projecting a continued upward trajectory. We anticipate the market revenue will surpass the 3100 Million USD mark in 2026, growing to reach nearly 4817 Million USD by the end of the forecast window. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 7.2 percent. Such growth rates indicate a healthy, maturing market that is expanding in line with broader construction and furniture manufacturing trends, yet still possesses significant headroom for innovation-led gains.
However, raw top-line numbers only tell part of the story. The true value of this research lies in dissecting the variables that influence this growth. Fluctuations in raw material costs, shifting regulatory landscapes, and geopolitical tensions all play pivotal roles in shaping the net profitability and operational stability of industry players. Our report contextualizes these macroeconomic factors against market volume to provide a nuanced view of potential returns on investment.
Strategic Drivers Influencing Market Dynamics
Several critical dynamics are currently reshaping the supply and demand equilibrium within the thermoplastic edgeband industry. Understanding these forces is essential for any strategic planning exercise in 2026.
One of the most pressing challenges identified in our sector analysis is the volatility of raw material pricing. For instance, polypropylene, a primary feedstock for many thermoplastic solutions, saw price increases of over 19 percent between 2021 and 2023. This surge significantly impacted production costs, squeezing margins for manufacturers who lacked hedging strategies or vertical integration. Furthermore, nearly 42 percent of manufacturers report ongoing challenges due to the combination of fluctuating raw material prices and tightening environmental regulations, particularly concerning PVC usage.
Regulatory pressure is driving a material shift in preferences across certain geographies. In Europe, ABS edgebands are increasingly favored as a chlorine-free alternative to PVC, especially given their incinerability in authorized facilities. This regulatory divergence creates distinct market realities that require localized strategies. Meanwhile, trade policies continue to introduce friction. Recent U.S. tariffs, including new 25 percent duties on goods from Mexico and Canada and 10 percent on Chinese imports, have directly raised the costs of imported edge banding materials, forcing companies to reconsider their sourcing maps.
Geopolitical instability further complicates the supply chain. The fallout from the Russia-Ukraine conflict has disrupted European polymer production through sanctions on Russian oil and gas, leading to increased ethylene costs which are a key feedstock for PVC. These intersecting pressures highlight the need for robust risk management frameworks, a core component of our analytical methodology.
Regional Growth Patterns and Demand Centers
The global market is not a monolith; it is a collection of distinct regional ecosystems with unique growth drivers. Our report provides a granular view of how demand is distributed across key geographies, based on the latest historical data from 2025.
Thermoplastic Composites Market
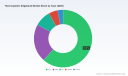
North America remains a dominant force in the market, reflecting a strong domestic furniture manufacturing base and significant consumption in interior design projects. Asia Pacific also represents a massive volume center, driven by rapid urbanization and a booming middle class in key economies. Europe continues to hold a substantial share, supported by its strong tradition of cabinetry and a regulatory environment that pushes for specific material standards. Meanwhile, emerging regions such as Latin America and the Middle East and Africa, while currently smaller in absolute volume, offer high-growth potential as infrastructure projects and consumer markets develop.
Strategic decision-makers must understand not just the size of these regions, but the velocity of their growth and the specific barriers to entry present in each. Our full report details the specific volume contributions of each region to help clients prioritize market entry or expansion strategies.
Application and Type Segmentation Insights
Demand is not evenly distributed across applications or material types. Our segmentation analysis reveals where the highest value concentrations lie. Furniture manufacturing remains the primary application driver, consuming the lion's share of market volume as manufacturers seek durable, aesthetically pleasing edges for cabinetry and casegoods. Interior design follows as a significant secondary application, where aesthetic versatility is paramount. Construction applications, while smaller in relative volume, offer steady demand driven by commercial fit-outs and modular building solutions.
On the material side, PVC continues to hold a significant position due to its cost-effectiveness and versatility. However, ABS is gaining traction, particularly in markets sensitive to environmental regulations or where specific processing advantages are required. PP and PMMA segments serve niche but important roles, offering specific performance characteristics such as flexibility or high-gloss finishes. Understanding the trade-offs between these materials regarding cost, processing technology, and end-of-life characteristics is vital for product portfolio management.
Competitive Landscape and Corporate Strategy
The market is characterized by a moderate level of concentration, with the top three companies capturing approximately 58 percent of the market share, and the top five holding around 68 percent. This structure suggests that while large incumbents hold significant sway, there is still room for specialized players and regional champions to thrive by focusing on niche technologies or superior service levels.
Leading the pack is SURTECO, headquartered in Buttenwiesen, Germany. With over 50 years of extrusion experience, SURTECO is a leading manufacturer of thermoplastic edgebands, offering PVC, ABS, and circular or sustainable designs. Their extensive international distribution network makes them a critical benchmark for global reach. Similarly, REHAU Group, based in Reinbek, Germany, stands as a powerhouse in the sector. They produce a wide array of thermoplastic edgebands including PVC, ABS, PP, PMMA, and specialty variants like FlexEdge and 3D variants. REHAU's unmatched color-matching technology and laser-edge capabilities position them at the forefront of innovation.
MKT, also based in Germany, specializes in premium ABS and PP thermoplastic edgebands. Their ALPHA-TAPE® line, featuring woodgrains, mirror gloss, and anti-fingerprint finishes, along with zero-joint technology solutions, targets high-end applications where finish quality is non-negotiable. In Turkey, ROMA PLASTIK has established itself as a major producer and leading export manufacturer. Headquartered in Gebze, they offer extensive decor catalogs covering PVC, ABS, and PMMA, leveraging their logistical advantages to serve both regional and export markets. Finally, Döllken-Kunststoffverarbeitung GmbH in Gladbeck, Germany, provides a comprehensive range of PVC, ABS, PP, and PMMA edgebands. Their focus on low static charge, high processing suitability, and Greenguard certification options appeals to clients with strict environmental and quality standards.
Recent Corporate Moves and Capacity Shifts
The competitive landscape is dynamic, with recent corporate activities signaling where investment is flowing. In May 2026, Wilsonart LLC announced a targeted expansion at its Temple, Texas facility specifically for ABS edge band production. This move is designed to serve the U.S. healthcare furniture market, indicating a strategic pivot towards specialized verticals with stringent hygiene and durability requirements.
Also in May 2026, REHAU Group expanded its digital decor printing capacity at its Viechtach plant. The addition of two high-resolution inkjet printing lines focuses on 3D-texture edge bands with haptic finishes, reinforcing their commitment to aesthetic innovation and customization. In a move to strengthen market presence in Central Asia, SURTECO participated in MebelExpo 2025 in Tashkent, Uzbekistan, showcasing their thermoplastic edgeband systems and highlighting the growing importance of emerging markets in product distribution strategies.
Capacity expansion is also occurring in Asia. E3 Edge Band inaugurated a new production plant in Andhra Pradesh, India, in May 2025 to expand PVC edge banding capacity, responding to local demand growth and potentially serving as an export hub. Furthermore, Roma Plastik invested in a new logistics centre in Gebze with a €23 million investment in May 2025 to support expanded edgeband production and distribution, underscoring the importance of supply chain efficiency in maintaining competitiveness.
The Strategic Value of Comprehensive Intelligence
In an environment defined by raw material volatility, regulatory fragmentation, and aggressive competitive maneuvering, intuition is insufficient. Success in the thermoplastic edgeband market requires data-driven precision. PW Consulting's report goes beyond surface-level trends to provide actionable intelligence. We analyze the interplay between feedstock costs and final pricing, the impact of trade tariffs on landed costs, and the technological differentiators that command premium pricing.
The report details the specific capacity expansions, product launches, and strategic partnerships that are reshaping the competitive field. It offers a critical assessment of market concentration metrics and identifies the vulnerabilities and strengths of key players. By understanding the specific dynamics of regions such as North America, Europe, and Asia Pacific, clients can tailor their go-to-market strategies to local realities rather than relying on global averages.
Conclusion: Making Informed Decisions for 2026
The thermoplastic edgeband market presents significant opportunities for growth, but realizing them requires a sophisticated understanding of the underlying forces at play. From the 7.2 percent CAGR driving overall expansion to the specific challenges posed by PVC regulations and raw material inflation, the landscape is complex. The strategic moves by key players like REHAU, SURTECO, and Wilsonart demonstrate where the industry is heading in terms of technology and capacity.
To access the complete dataset, including detailed segmentation splits, regional volume breakdowns, and deep-dive company profiles, stakeholders are invited to consult the full PW Consulting market research report. This document is designed to be a central reference for strategic planning, procurement, and investment decisions throughout 2026 and the forecast period to 2032. Equip your organization with the depth of insight necessary to lead in this evolving market.
For detailed analysis of this topic, please visit the official page: Thermoplastic Edgeband Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
From 2020 to 2035, the global radial heavy-duty tires market is expected to register steady growth, with revenue expanding from $9,500 million in 2020 to $14,500 million by 2025, and reaching $27,200 million by 2035. This upward trajectory is underpinned by increased infrastructural activities and rapid industrialization, especially in APAC and North America. The replacement and aftermarket segment is projected to accelerate growth, buoyed by technological advances and digital sales transformation. Manufacturers’ continued focus on durable, high-performance tire solutions will foster sustained value generation throughout the forecast period.
Read More - https://bussinessinsights.com/research-report/global-radial-heavy-duty-tires
Construction represents the largest application segment for radial heavy-duty tires, covering 35% of the global market share in 2025. Mining holds the second largest segment at 25%, while agriculture stands at 20%. The remaining 20% is shared among transport, military, and industrial applications. Demand is significantly driven by ongoing infrastructure upgrades and major construction projects worldwide. The mining sector also continues to be a crucial consumer due to harsh operability requirements and bulk procurement patterns. Meanwhile, the agricultural domain’s adoption of heavy-duty tires is propelled by mechanization trends and rising farm equipment sales in developing regions.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-radial-heavy-duty-tires
Frequently Asked Questions
Who are the key players in Global Radial Heavy-Duty Tires industry?
The key players in the Global Radial Heavy-Duty Tires market include Bridgestone Corporation, Michelin, Goodyear Tire & Rubber Company, Continental AG, and Pirelli & C. S.p.A. These companies are renowned for their strong global presence, extensive product portfolios, innovation in tire technology, and robust supply chains serving multiple industries.
What is the Global Radial Heavy-Duty Tires growth?
The Global Radial Heavy-Duty Tires market has exhibited steady growth, driven by increasing infrastructure projects and expansion in mining and construction sectors. In 2023, Bridgestone reported a strategic production capacity expansion in Asia-Pacific to meet rising demand, underlining the market’s positive outlook.
Which segment accounted for the largest Global Radial Heavy-Duty Tires share?
The construction and mining application segment holds the largest share in the Global Radial Heavy-Duty Tires market. Heavy machinery and equipment in these sectors require durable, high-performance tires capable of handling challenging terrains and loads, driving substantial demand for radial heavy-duty tires worldwide.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
The global ConstructionDrone market is anticipated to increase from USD 2,100 Million in 2020 to USD 8,650 Million by 2035, reflecting robust adoption across regions and applications. This upward trend is attributed to rapid technological advancements and escalating demand for automation in construction. The consistent increase in revenue underscores the transformation within the construction sector as drones become standard tools for efficiency and safety.
Read More - https://bussinessinsights.com/research-report/global-constructiondrone
Surveying & Mapping represents the largest share of application in the ConstructionDrone market for 2025, accounting for nearly half of all deployments due to the core demand in site planning and project validation. Inspection applications, including safety and structural checks, closely follow as projects prioritize risk mitigation and operational safety. Material delivery, though a niche segment, is showing steady growth as companies pilot autonomous logistics solutions. Other applications such as progress monitoring and security continue to grow bolstered by integrated analytics.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-constructiondrone
Frequently Asked Questions
Who are the key players in Global ConstructionDrone industry?
The top 5 players in the Global Construction Drone industry are DJI, Parrot SA, 3D Robotics, Trimble Inc., and Yuneec. DJI dominates with a broad product range for aerial mapping. Parrot SA is known for its innovation, while 3D Robotics, Trimble, and Yuneec focus on professional-grade drone solutions for construction.
What is the Global ConstructionDrone growth?
The Global Construction Drone market has witnessed robust growth, driven by increased adoption of smart technologies. In 2023, DJI reported expanding partnerships with construction firms, facilitating efficient site management. The market’s CAGR is projected at over 15% (2023-2028), with automation and real-time data boosting investments.
Which segment accounted for the largest Global ConstructionDrone share?
The aerial surveying and mapping segment holds the largest share in the Construction Drone market. Construction companies extensively use drones for topographic mapping, site monitoring, and progress tracking. Accurate data collection and improved project planning helped this segment lead, with applications in megaprojects and urban development.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Karaoke Machines Market to Hit $344.8M by 2032 at 6.98% CAGR
By PW Consulting, 2026-09-16
Unlocking the Rhythm of Growth: Strategic Insights from the 2026 Karaoke Machines Market Intelligence Report
The global karaoke machine market is currently undergoing a significant transformation, driven by shifting consumer habits, technological integration, and evolving entertainment preferences. As we move through the 2025-2032 forecast period, the industry is poised for steady expansion, presenting both opportunities and challenges for stakeholders across the entertainment hardware value chain. This executive summary outlines the strategic landscape of the karaoke machines market, derived from a comprehensive market research study designed to inform high-level decision-making in 2026 and beyond.
For business leaders, understanding the trajectory of this market is no longer optional; it is a prerequisite for capital allocation, product development, and competitive positioning. The following analysis leverages historical data and forward-looking projections to frame the current state of play. However, to maintain the integrity of proprietary forecasting models, specific granular breakdowns regarding regional revenue shares and segment-specific dollar values are reserved for the full report. Here, we focus on the strategic implications of the broad trends reshaping the industry.
Market Trajectory and Historical Context
The market has demonstrated resilience and consistent growth over the past half-decade. Historical data from 2020 through 2025 indicates a clear upward trend in revenue generation. Starting from a base of USD 163.15 million in 2020, the market scaled gradually each year, reaching USD 194.68 million by 2024. This growth trajectory accelerated in 2025, with valuations hitting USD 215.0 million. Such performance underscores a robust demand environment that has outlasted initial pandemic-induced fluctuations, transitioning from a recovery phase to a growth phase.
Looking ahead, the forecast period from 2026 to 2032 suggests continued expansion. Projections indicate the market value will climb to USD 230.86 million in 2026 and further escalate to USD 344.8 million by 2032. This long-term outlook is supported by a Compound Annual Growth Rate (CAGR) of 6.98 percent. This rate of growth implies that the market is outpacing many traditional consumer electronics segments, fueled by innovations in wireless connectivity and portable form factors. For investors and manufacturers, this CAGR serves as a benchmark for evaluating potential returns on investment in manufacturing capacity or marketing spend.
Competitive Landscape and Key Players
The competitive environment is characterized by a fragmented yet dynamic mix of established manufacturers and agile tech innovators. The market concentration remains relatively moderate, with the top three companies holding a CR3 of 24.6 percent and the top five firms accounting for a CR5 of 26.2 percent. This indicates that while there are dominant players, a significant portion of market share is distributed among smaller or regional entities, leaving room for disruption.
Several key companies are defining the current standards of product quality and innovation. The Singing Machine Company, Inc., headquartered in Fort Lauderdale, Florida, remains a pivotal player. They manufacture a wide range of all-in-one karaoke machines, portable systems, and microphones. Their recent strategic moves include the launch of the Carpool Karaoke Mic 2.0 in June 2026, featuring dual microphones and improved wireless connectivity. This product launch highlights their focus on leveraging brand partnerships and enhancing user experience through hardware refinements.
Ikarao, based in New York, distinguishes itself through portable smart karaoke machines with built-in screens and KaraFun integration. Their presence at CES 2025, where they dazzled audiences with all-in-one karaoke technology, signals a strong commitment to integrating software ecosystems with hardware. Meanwhile, Tonor, headquartered in Hong Kong, focuses on wireless karaoke machines with LED lights and Bluetooth connectivity. Their release of the K20 Wireless Karaoke Machine in March 2026, which offered enhanced mood lighting and portable design, demonstrates an emphasis on aesthetic appeal and party functionality.
JYX, also based in Hong Kong, competes directly in the portable speaker and karaoke machine segment. Their introduction of the T17T and S8 models in November 2025, which boasted improved sound quality and longer battery life, reflects the industry-wide push towards mobility and endurance. These companies collectively illustrate the divergence in strategy, from premium branded partnerships to budget-friendly, feature-rich portable units. Understanding the specific strengths and go-to-market strategies of these competitors is essential for any firm looking to gain share in this ecosystem.
Market Segmentation and Demand Drivers
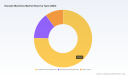
The market is segmented by type, application, and region, each offering distinct growth vectors. In terms of product type, the landscape is divided among portable, desktop, and other variants. The breadth of segmentation suggests that manufacturers cannot rely on a single form factor to capture the total market. Portable devices, in particular, have seen significant shipment increases, with data indicating an 18 percent rise in the first half of 2026 driven by demand for on-the-go entertainment.
Application-wise, the usage patterns have shifted noticeably. While commercial use remains a steady revenue stream, the share of karaoke machines used for home family gatherings surged in 2026. Internal data points to an increase from 52 percent in 2025 to 68 percent in 2026. This shift implies that product design and marketing should increasingly target home entertainment ecosystems rather than solely relying on commercial venue contracts. Portability, ease of setup, and aesthetic integration into home environments are becoming critical decision factors for consumers.
Regional dynamics also play a crucial role. The market spans North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique regulatory environments and consumer preferences. For instance, regulatory bodies such as the US Federal Communications Commission issued updated guidelines in April 2026 for Bluetooth karaoke devices to ensure safer audio output levels. Compliance with such regulations is a non-negotiable aspect of market entry and product certification in key jurisdictions. Ignoring these dynamics can lead to significant delays in product launches or recall risks.
Industry Dynamics and Operational Challenges
Navig 2026 requires a keen awareness of external pressures affecting supply chains and operations. One notable challenge is the cost volatility of raw materials. In the first quarter of 2026, prices for plastic and electronic components used in portable karaoke machines saw a 12 percent increase due to global semiconductor shortages. This cost pressure impacts margins for manufacturers who have not secured long-term supply contracts or diversified their supplier base. Strategic sourcing and inventory management are now critical components of operational planning.
Furthermore, the regulatory landscape is evolving. Beyond the FCC guidelines on audio output, manufacturers must stay abreast of varying safety standards and import-export regulations across different geographies. The fragmentation of regulations means that a product compliant in one region may require significant modification for another, impacting time-to-market and overall profitability.
Karaoke Machines Market
Slot Machines Market
Consumer habits continue to evolve alongside technology. The integration of wireless connectivity and app-based song libraries is no longer a luxury but an expectation. Devices that lack seamless connectivity or a robust library integration risk obsolescence. The trend towards smart features, as seen in recent product launches by key players, suggests that hardware specifications alone are insufficient to drive sales. The user experience, including interface design and library access, is becoming a primary differentiator.
Strategic Value of Comprehensive Market Intelligence
Given the complexity of these dynamics, relying on anecdotal evidence or outdated reports is a strategic risk. A dedicated market research report provides the granularity needed to make informed decisions. The full version of this study offers deep dives into segmentation splits, detailed company profiles with financial and operational highlights, and precise forecast models.
Access to the complete data allows stakeholders to identify high-growth niches within the broader market. For example, while aggregate numbers show growth, understanding the specific revenue contribution of portable versus desktop units, or the exact revenue distribution across regions, enables targeted marketing and production planning. It also allows for a more accurate assessment of competitor moves. While public announcements indicate product launches, the full report contextualizes these moves within market share shifts and pricing strategies.
Moreover, the report includes an in-depth analysis of industry barriers to entry, regulatory compliance checklists, and supply chain risk assessments. These operational insights complement the financial forecasts, providing a holistic view of the market environment. For investors, this translates to better risk-adjusted return profiles. For manufacturers, it means optimized product roadmaps. For distributors, it ensures inventory alignment with regional demand patterns.
The strategic value lies in the ability to anticipate rather than react. With the market projected to reach USD 344.8 million by 2032, the window for establishing a dominant position is open but narrowing. Companies that leverage detailed intelligence to navigate raw material cost fluctuations, comply with emerging regulations, and align product features with the 68 percent home-usage trend will be best positioned to capture value.
In conclusion, the karaoke machines market offers a compelling growth story backed by solid fundamentals and evolving consumer preferences. However, realizing the potential requires more than just observing the upward trend. It demands a nuanced understanding of the forces driving that trend, from semiconductor availability to FCC guidelines, and from competitive product launches to shifts in home entertainment habits. The roadmap to 2032 is clear, but the path to success depends on the quality of intelligence guiding your next move. To access the complete dataset, detailed segmentation analysis, and proprietary forecasts that underpin these insights, we invite you to explore the full report.
For detailed analysis of this topic, please visit the official page: Karaoke Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Many organizations continue to treat the permit to work (PTW) process as a procedural formality that must be finished before work begins. In many cases, permits are primarily seen as records that prove internal rules, regulatory expectations, or audit requirements have been followed. Compliance certainly matters, but viewing PTW only as documentation misses much of what the process can accomplish. When supported by a capable digital platform, permit to work can serve as a practical operational framework for preparing, coordinating, and controlling high risk activities.
A modern PTW solution creates a defined workflow for planning, reviewing, authorizing, executing, and documenting critical work. Instead of relying on separate procedures and disconnected records, organizations can establish consistent workflows, clarify responsibilities, reduce variation, and avoid unnecessary delays. This level of structure becomes particularly valuable for organizations operating multiple facilities, where safety practices and operational discipline need to remain consistent across locations. It can support activities ranging from hot and cold work to confined space entry, electrical isolation, and simultaneous operations.
The Role of a Permit to Work System
A permit to work system formally authorizes specific work and confirms that essential conditions have been addressed before the activity starts. Before work begins, relevant hazards should be identified, risks evaluated, and appropriate controls checked. Following this sequence provides a structured way to protect workers, equipment, other assets, and the surrounding environment.
PTW also creates a common understanding among the people involved in the job. Supervisors, permit requesters, approvers, and field workers can access important details about the activity, including the work being performed, its location, responsible personnel, and the period for which the authorization is valid. Keeping this information visible and organized strengthens coordination and reduces the chance of misunderstandings during execution.
With digital management, PTW becomes more than a collection of separate documents. It can operate as a connected workflow in which permits are associated with isolation details, gas testing records, inspections, and supporting checklists. Bringing these records together reduces the risk of misplaced paperwork, missing information, and delays caused by systems that operate independently.
How Digital PTW Systems Improve Efficiency
Traditional paper based permit processes can demand considerable administrative time and create bottlenecks. Employees may need to locate physical records, collect several signatures, enter identical information more than once, or wait for an approval before the next stage can proceed. Besides slowing work, these manual steps can increase the possibility of omissions and mistakes.
Digital PTW platforms address these challenges by combining automation, standardized procedures, and immediate visibility into permit status.
Key advantages include:
- Centralized work management: Permits, risk assessments, isolation details, and gas testing records can be stored together, making it easier for authorized personnel to find and review the information they need.
- Quicker approval workflows: Requests can be routed to the appropriate people automatically, while notifications and alerts can help limit unnecessary waiting.
- Real time operational visibility: Supervisors can identify permits awaiting approval, activities currently underway, completed jobs, and work that may be delayed. Field teams can also view the activities that have been authorized.
- Reduced errors and rework: Automated validation can identify missing details, expired qualifications, or incomplete lockout/tagout steps before a permit advances for approval.
Key Features of an Effective Digital PTW Platform
A capable digital permit to work platform should not simply reproduce a paper form on a screen. It should support the entire permit lifecycle while placing appropriate safety controls within the workflow.
- Standardized Permit Templates
Organizations can develop predefined templates for recurring activities such as hot work, confined space entry, excavation, electrical work, and work at height. Using consistent templates makes required precautions and verification steps easier to apply across similar tasks.
- Embedded Risk Management Controls
Integrated risk assessment tools, required safeguards, and questions tailored to working conditions can guide users through hazard identification and evaluation before work begins. Structuring the assessment process can encourage a more consistent and complete approach to managing risk.
- Isolation and Lockout/Tagout Integration
Permit workflows can include isolation details, equipment status, lockout activities, tagging requirements, and verification steps as part of the same process. Keeping these elements connected can make isolation activities easier to coordinate and manage reliably.
- Simultaneous Operations Management
When several jobs are occurring within the same area, visibility of overlapping activities can help teams recognize potential conflicts before work starts. This supports better coordination of concurrent tasks and improves management of interactions between different activities.
- Competency and Qualification Verification
Automated checks can help establish whether assigned personnel possess the necessary training, certifications, and qualifications for specific activities. This helps organizations ensure that specialized or higher risk work is assigned to appropriately qualified workers.
- Mobile Access for Field Teams
Field personnel should be able to access digital PTW functions through mobile devices while working. Depending on platform capabilities, users may approve permits, capture and attach photographs, enter gas testing results, or document toolbox talks from the work location. Offline capability can be particularly useful in remote areas or locations where connectivity is inconsistent.
- Audit and Reporting Capabilities
Detailed audit trails, dependable timestamps, and comprehensive reporting can provide clearer visibility into permit performance. They can also simplify compliance reviews and audit preparation by making records of decisions and activities easier to access and examine.
A Four Step Approach to PTW Implementation
Adopting a digital PTW platform involves more than installing software. Organizations also need practical processes and employee engagement to make the system part of everyday operations and achieve lasting results.
Step 1: Establish Standardized Processes
Develop consistent permit templates, authorization paths, and governance practices that can be used across facilities. At the same time, standards should leave appropriate flexibility for genuine site specific requirements where those differences are necessary.
Step 2: Prioritize High Risk Work Activities
Begin with activities where stronger controls can provide significant immediate value, including hot work and confined space entry. Concentrating first on higher risk categories can help organizations establish stronger safety and operational controls during the early stages of implementation.
Step 3: Connect PTW with Existing Operations
Integrate permit management with related processes such as maintenance planning, asset information, and shift handovers. Connecting these activities can reduce duplicate data entry, strengthen information sharing, and create a smoother movement of information between teams and departments.
Step 4: Use Practical, Scenario Based Training
Training should mirror the situations employees face during normal operations instead of concentrating only on software functions. Scenario based exercises allow users to practice applying the platform to realistic work situations. Monitoring adoption and relevant performance measures can then reveal where additional support or improvement is needed.
Evaluating the Effectiveness of Digital PTW
One important benefit of digital permit management is the ability to evaluate process performance using operational data. Organizations can examine indicators such as:
- Average time from permit submission to approval
- Percentage of permits receiving correct approval during the initial review
- Number of simultaneous operations conflicts identified before work begins
- Corrective actions raised while permits remain active and the time required to close them
- Reduction in time and effort needed for audits because records are complete and searchable
These measures offer tangible evidence of how the permit process is functioning. They can also expose areas where additional attention, adjustment, or process improvement may be needed.
Turning PTW Data into Continuous Improvement
When permit approvals, actions, changes, and verification activities are recorded automatically, PTW can deliver value well beyond meeting safety or compliance requirements. The data produced through the process can become a meaningful source of operational insight.
Reviewing that information can help organizations identify recurring approval delays, safeguards that are repeatedly missed, and areas where employees may require further training. It can also point to opportunities to refine procedures or introduce stronger engineering controls. Over time, these insights can support ongoing improvements in both workplace safety and operational efficiency.
A digital permit to work system should therefore be viewed as more than paperwork that must be completed before a task can begin. When implemented effectively, it can become a proactive framework for managing work. It provides greater control over high risk activities, supports safer execution, improves productivity, strengthens accountability, and turns permit information into operational insight that can support continuous improvement throughout the organization. It also gives decision makers a clearer view of where work stands at each stage, helping teams respond to issues sooner and maintain a more predictable flow of authorized activities without relying on repeated manual follow up across busy operations and changing work conditions throughout each facility and shift as well.
Book a free demo @ https://toolkitx.com/blogsdetails.aspx?title=How-a-permit-to-work-system-improves-efficiency-(and-safety)
Browse More
https://toolkitx.com/blogsdetails.aspx?title=Refinery-tank-farms-management:-the-digital-imperative-for-safety-and-profit
https://toolkitx.com/blogsdetails.aspx?title=What-is-a-Confined-Space-Entry-Permit-A-Simple-Guide
Global Compact ConstructionEquipment Market Size, Share & Forecast Report, 2034
By Manisha , 2026-09-16
The worldwide compact construction equipment market is projected to experience substantial revenue growth from 2020 through 2035. Revenue is expected to increase from approximately USD 34,500 million in 2020 to USD 69,300 million by 2035, reflecting consistent annual gains driven by urban infrastructure initiatives, increasing need for automated and sustainable equipment, and rising construction investments globally. The upward trajectory underscores robust market fundamentals and positive long-term outlook.
Read More - https://bussinessinsights.com/research-report/global-compact-constructionequipment
Residential construction constitutes the largest application segment for compact construction equipment in 2025, capturing the highest market share due to ongoing urban expansion and renovation activities. Commercial construction follows, propelled by investments in offices, retail, and institutional projects using compact and efficient machines. The agriculture and landscaping sectors are also rapidly adopting these machines for utility and cost-effectiveness, while industrial construction maintains a steady uptake. The dynamic residential and commercial construction environment is expected to remain the central growth engine for the segment throughout the forecast period.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-compact-constructionequipment
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Global Intelligent Vending Refrigerator Market Size, Share & Forecast Report, 2034
By Manisha , 2026-09-16
Between 2020 and 2035, the global intelligent vending refrigerator market is projected to grow at a steady compound annual growth rate (CAGR), driven by rising investments in automation and global expansion of retail infrastructure. Market revenue was estimated at USD 1,280 Million in 2020 and is forecasted to reach approximately USD 5,750 Million by 2035. The surge is attributed to widespread adoption across diverse industries, technological advancements, and consumer demand for convenient, contactless services. Year-on-year increments underscore the sector's resilient trajectory and innovation-led momentum.
Read More - https://bussinessinsights.com/research-report/global-intelligent-vending-refrigerator
Retail remains the leading application for intelligent vending refrigerators in 2025, as businesses leverage automated retail for improved convenience and operational efficiency. The food & beverage sector follows closely, driven by evolving consumer habits and demand for fresh, ready-to-eat options. Healthcare demonstrates increasing adoption, especially for secure medical storage and 24/7 pharmaceutical access. The education, transportation, and hospitality sectors are expanding their uptake, tapping into the trend of unmanned, automated services for students, travelers, and guests respectively.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-intelligent-vending-refrigerator
Frequently Asked Questions
Who are the key players in Global Intelligent Vending Refrigerator industry?
The key players in the Global Intelligent Vending Refrigerator industry include Sanden Holdings, Fuji Electric, Crane Merchandising Systems, Sielaff, and Royal Vendors. These companies are recognized for their innovative vending solutions, advanced payment systems, energy-efficient designs, and expansive product portfolios across global markets.
What is the Global Intelligent Vending Refrigerator growth?
The Global Intelligent Vending Refrigerator market has exhibited substantial growth, driven by technological advancements and expanding applications. For example, Crane Merchandising Systems reported significant revenue increases in 2023, fueled by rising demand for contactless payment integration and smart inventory management solutions.
Which segment accounted for the largest Global Intelligent Vending Refrigerator share?
The beverages segment accounted for the largest share in the Global Intelligent Vending Refrigerator market. This dominance is attributed to increasing demand for chilled drinks on-the-go, particularly in urban areas and transportation hubs, with companies like Fuji Electric focusing on advanced beverage vending solutions.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Navigating the Next Wave: Strategic Intelligence for the Autoclaved Aerated Concrete Market (2026–2032)
The built environment is undergoing a structural realignment. Decarbonization mandates, shifting material cost dynamics, and an accelerating preference for lightweight, high-thermal-performance solutions have propelled Autoclaved Aerated Concrete (AAC) from a niche alternative to a mainstream strategic consideration. As corporate decision-makers plan capital allocation, supply chain positioning, and geographic expansion for 2026 and beyond, the AAC market has emerged as a critical intersection of construction demand, regulatory tailwinds, and operational efficiency gains. Our latest research publication provides a comprehensive, decision-grade mapping of this trajectory across the forecast horizon through 2032.
The foundation of this outlook is built on a clear historical arc. From a base of USD 178.5 Million in 2020, the market progressed to USD 227.8 Million by 2025, reflecting compounding annual growth even amid intermittent supply chain friction and raw material price volatility. Moving into the forecast period, the trajectory accelerates into a robust growth corridor, with the market expected to cross the USD 244.0 Million threshold in 2026, continue upward through the mid-to-late 2020s, and approach USD 359.4 Million by 2032. Underlying this expansion is a forecast-period CAGR of 6.98 percent, a figure that signals sustained, structurally supported demand rather than a short-lived cyclical spike. For executives evaluating capacity planning, technology licensing, distributor partnerships, or regional entry strategies, these macro indicators establish the baseline for scenario modeling and investment prioritization.
Yet macroeconomic aggregates alone do not dictate competitive success. The strategic value of this research lies in its translational architecture: rather than presenting abstract totals, the study decomposes growth drivers into actionable dimensions that align with corporate planning cycles. Decision-makers are guided through a structured evaluation of how market momentum bifurcates across product formats, end-use applications, and regional ecosystems, enabling targeted positioning instead of broad, unfocused exposure. The report is designed to bridge the gap between market observation and execution, translating demand signals into procurement roadmaps, capacity expansion logic, and partnership criteria.
What the Report Delivers: Actionable Intelligence for 2026 Decisions
This publication is structured as an operational toolkit rather than a passive market summary. The analytical framework is engineered to support cross-functional teams—strategy, operations, supply chain, and business development—in validating assumptions and stress-testing strategic initiatives. Key components include:
- Historical Reconstruction and Baseline Calibration: A granular review of market evolution from 2020 through 2025, isolating inflection points, recovery patterns, and the structural factors that shaped volume and value trends. This retrospective anchors all forward-looking estimates and establishes the credibility of the forecast model.
- Forecasting Architecture for 2026–2032: A multi-variable projection framework that incorporates demand-side drivers, supply-side capacity dynamics, and regulatory pacing. The forecast does not rely on linear extrapolation; instead, it integrates sector-specific momentum to map a realistic growth corridor for the next seven years.
- Segment-Level Strategic Decomposition: Detailed analysis across product categories and application verticals, enabling readers to identify where value creation is concentrating, which formats are scaling most efficiently, and how end-use demand patterns are shifting in response to construction practices and building performance expectations.
- Regional Ecosystem Mapping: An assessment of how geographic markets differ in maturity, adoption intensity, regulatory influence, and competitive saturation. The analysis clarifies where demand is emergent, where it is consolidating, and where strategic entry or expansion may yield disproportionate returns.
- Competitive Positioning and Capability Benchmarking: A panoramic view of the operating landscape, including established manufacturers, technology providers, licensed plant operators, and distribution-focused players. Profiles are evaluated against production tenure, geographic footprint, product breadth, and strategic moves that signal future competitive intent.
- Industry Dynamics and Vulnerability Mapping: Targeted examination of the forces shaping margins and operational resilience, including raw material pricing behavior, policy interventions, and certification-driven procurement shifts. These insights allow organizations to anticipate cost pressure, evaluate substitution trends, and align sourcing strategies accordingly.
Collectively, these elements form a decision-support ecosystem. Rather than leaving readers with isolated data points, the report constructs a continuous logic chain: from historical evidence, through structural drivers, to competitive reality, and finally to strategic implication. The objective is to enable leaders to ask sharper questions—about capacity timing, product mix optimization, distributor alignment, and regional prioritization—and to answer them with evidence that withstands scrutiny.
Market Dynamics: Regulatory Acceleration, Material Realities, and Demand Reconfiguration
The AAC market's expansion is not occurring in a vacuum. It is being reshaped by intersecting forces that alter both the demand curve and the cost structure of production. One of the most consequential shifts involves regulatory and certification environments. In several advanced construction markets, green building certification frameworks have increasingly favored materials that combine structural utility with lightweight characteristics and thermal insulation performance. This has translated into higher procurement visibility for AAC within project specification processes, particularly where energy efficiency targets are tightening and where building envelopes must satisfy stricter performance thresholds. Parallel policy mechanisms in parts of Europe have further reinforced this trajectory, as energy codes and retrofit mandates effectively position AAC as a pragmatic solution for both new builds and renovation programs seeking measurable thermal gains.
At the same time, material-side dynamics are introducing a more complex operating environment. The core input architecture of AAC manufacturing—dependent on cement and lime as primary binding agents—remains exposed to pricing volatility. Seasonal fluctuations, regional supply constraints, and broader commodity cycles have periodically pressured input costs, affecting margin stability across block and panel producers. This has elevated the importance of sourcing strategy, formulation flexibility, and vertical coordination for manufacturers seeking to protect unit economics. In certain markets, policy-driven substitution initiatives have begun reshaping input dependency by encouraging alternative material pathways, lowering embodied carbon intensity and altering the traditional cost equation for AAC production. These regulatory and material intersections are not peripheral concerns; they are central to understanding where competitive advantage will be earned or eroded over the forecast period.
Autoclaved Aerated Concrete (AAC) Market
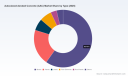
On the demand side, the configuration of end-use adoption is evolving as construction priorities shift. Residential applications continue to reflect substantial demand, supported by housing activity cycles and the material's suitability for efficient wall systems. Commercial development contributes a distinct demand layer, where speed of assembly, weight reduction, and building performance specifications influence material selection. Infrastructure and industrial applications, while representing smaller share tiers in aggregate, introduce specialized requirements that reward product consistency, durability, and tailored engineering profiles. The report evaluates these demand streams not merely as volume contributors, but as strategic segments where specification influence, purchasing behavior, and competitive differentiation diverge meaningfully.
Competitive Landscape: Established Players, Regional Expansion, and Strategic Signaling
The competitive architecture of the AAC market reflects a blend of long-entrenched manufacturers, technology-and-licensing operators, distribution-centric participants, and newer entrants expanding capacity to capture demand momentum. In North America, the landscape is anchored by producers with substantial operational tenure and established supply relationships. One of the region's oldest manufacturers has built a multi-decade presence in AAC blocks and panels, reinforcing channel depth and regional familiarity. Alongside it, another significant North American supplier has sustained production and market participation for over two decades, contributing to a competitive base that values reliability and specification acceptance. More recent activity has also brought newer manufacturing capacity into the region, with production commencing in 2022, signaling that market growth is attracting additional investment rather than consolidation alone.
In Europe, the competitive picture is shaped by a mix of manufacturers, structural system suppliers, and technology providers operating through licensed plant networks. A major Northern European producer has established scale across Estonia and Latvia, positioning itself as a leading regional manufacturer of blocks and panels. In Poland and broader Eastern Europe, additional producers are reinforcing regional supply, while in the UK, a manufacturer and supplier continues to extend structural wall system offerings across domestic and international channels. Technology-and-licensing operators also play an important role, enabling production capacity beyond the boundaries of vertically integrated manufacturers and expanding the market's geographic reach through partnership-based models.
Asia introduces a different dynamic, characterized by capacity expansion and diversified participation. In India, the sector has seen meaningful manufacturing scale-up, with one major producer completing a phased capacity expansion to a substantial annualized volume for blocks, bricks, and panels. Another significant player has moved into AAC production through a dedicated product line launched in 2025, reflecting the strategic use of broader cement and building materials portfolios to enter or deepen participation in lightweight concrete segments. Additional Indian manufacturers continue to build out block and panel output, underscoring the region's role as a focal point for both volume growth and operational scaling.
Distribution-focused participants further complicate and enrich the competitive fabric. In several markets, distributors act as critical intermediaries, sourcing and supplying AAC blocks and panels to construction projects where manufacturing presence may be limited or where project-specific procurement logistics favor intermediary scale. This dual structure—manufacturers building capacity and distributors extending reach—creates multiple pathways for market participation and complicates simplistic views of competitive intensity. The report evaluates these roles in context, highlighting where manufacturing control, technology licensing, or distribution capability constitutes the more decisive strategic asset.
Strategic Implications for 2026 Planning
For organizations entering 2026 with AAC exposure or considering it, the strategic implications fall into several priority areas. First, the growth trajectory justifies disciplined capacity and supply chain planning, but only when paired with segment-specific demand intelligence. Broad market growth does not automatically translate into uniform opportunity across product types or application verticals. Decisions regarding which formats to prioritize, which applications to target, and where to locate or expand production should be informed by the segmentation patterns revealed in the full study.
Second, competitive positioning will increasingly depend on how well firms manage the tension between demand tailwinds and input cost variability. Companies that can stabilize cost structures, optimize formulation strategies, or align sourcing with regional pricing behavior will be better positioned to preserve margins while scaling. Similarly, firms that understand where regulatory and certification pressures are converting into procurement preference will be able to align product specifications and marketing positioning more effectively.
Third, the competitive landscape suggests that market access is not uniform. In some regions, established manufacturing presence, specification history, and channel relationships create meaningful barriers. In others, licensed production models, distributor networks, and new capacity additions are loosening those barriers and opening room for strategic entry. Evaluating which pathway is most viable—direct manufacturing, technology partnership, or distribution alignment—requires a clear view of regional saturation, demand cadence, and incumbent behavior, all of which are examined in depth in the complete report.
Closing Perspective: The Case for Full Intelligence
The AAC market is entering a phase in which strategic advantage will belong to those who can interpret momentum with precision rather than approximation. The headline growth path outlines an attractive opportunity, but the real decision architecture lies beneath it: in the interplay of segment concentration, regional heterogeneity, regulatory pacing, input cost volatility, and competitive maneuvering. This research is built to expose those layers systematically, giving leadership teams a structured basis for planning capital, refining product strategy, and choosing where to commit operational resources.
The analysis presented here is intended as a strategic preview. It establishes the scale, direction, and structural logic of the market, and it highlights the operational realities that will shape execution in 2026 and beyond. For the full segmentation breakdown, regional demand mapping, competitive benchmarking detail, and the complete forecast tables that support internal modeling, we invite you to access the full report. The complete study provides the depth required to convert market visibility into concrete, defensible action.
Worldwide Cellular Concrete Market
For detailed analysis of this topic, please visit the official page: Autoclaved Aerated Concrete (AAC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com