

Blogs
Medical Cyclotron Market: How 6.9% CAGR and Diagnostic Imaging Demand Reshape Growth by 2032
By PW Consulting, 2026-09-21
Medical Cyclotron Market: Strategic Trends and Commercial Opportunities
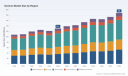
The medical cyclotron sector is entering a period of structural expansion. Historical data shows a steady rise from approximately $189 million in 2020 to $252 million in 2025, with a projected compound annual growth rate of 6.9 percent through 2032, pushing the market toward $398 million. This trajectory is not merely a reflection of steady capital equipment demand; it signals a shift in how radiopharmaceuticals are produced, distributed, and integrated into clinical pathways. For executives and investors, the market is moving from a niche imaging-support segment to a foundational component of precision diagnostics and targeted therapy ecosystems. Understanding why growth is accelerating, where competition is concentrating, and how demand-side behavior is reshaping procurement decisions will determine which organizations capture durable value.
Market Snapshot and Structural Shifts
The revenue trend over the 2020-2025 period demonstrates resilience through clinical adoption cycles and supply chain volatility. Demand has broadened beyond traditional PET tracer production, with oncology therapies and specialized diagnostic protocols expanding the addressable base for on-site isotope generation. The forecast period through 2032 suggests continued expansion, but not uniformly across use cases. Growth is being steered by applications that tie imaging to therapeutic decision-making, as well as by production models that favor localized isotope generation over centralized distribution. This structural shift is altering demand patterns, vendor selection criteria, and capital planning timelines.
Three challenges define the current inflection point. First, the industry is navigating a policy environment that is becoming more explicit about production traceability, quality documentation, and reimbursement coding for cyclotron-dependent isotopes. Regulatory attention to process validation and isotope sourcing is raising the bar for operators and suppliers alike. Second, the market remains concentrated, with a small group of manufacturers commanding the majority of share. Concentration creates short-term stability but also intensifies competition around product differentiation, service models, and installation flexibility. Third, demand is being reshaped by clinical adoption of theranostic protocols, which require reliable isotope supply and production capacity aligned to treatment schedules rather than episodic imaging volumes. These pressures are forcing vendors and buyers to rethink operating models rather than simply adding units.
Worldwide Positron Emission Tomography Devices Market
Key Drivers Shaping the Market
Technology innovation remains the clearest catalyst for change. Manufacturers are increasingly focusing on compact designs, higher output efficiency, and dedicated configurations for specific isotope families. Recent product launches illustrate this direction, including instruments engineered for routine production of alpha-emitter isotopes with automated irradiation control and reduced operator exposure. At the same time, high-output platforms continue to evolve for PET and SPECT applications, expanding the range of clinical sites that can support localized production. The strategic implication is straightforward: performance differentiation is moving from raw beam capability to workflow integration, footprint constraints, and compliance-ready operation.
Regulatory and reimbursement dynamics are reinforcing that shift. Authorities have been clarifying pathways for cyclotron-based isotope production in both diagnostic and therapeutic settings, with notable approvals and coding decisions that tie production methods to billing and clinical use. Examples include cleared production processes for Ga-68-based diagnostics, PDUFA action dates for cyclotron-prepared diagnostic kits, and therapy approvals that depend on reliable isotope production for radioligand treatments. These developments are not abstract regulatory milestones; they affect commercialization timelines, reimbursement certainty, and the economics of on-site production versus generator or centralized supply.
Demand-side behavior is changing as well. Hospitals, research centers, and specialized radiopharmacies are seeking more control over supply continuity and production timing, especially where therapeutic workflows depend on synchronized imaging and treatment. On-site cyclotron capability is increasingly viewed as a strategic asset for centers building out precision medicine programs. At the same time, expansion projects are being planned around manufacturing capacity and service responsiveness. New dedicated production facilities, installation milestones at academic and clinical sites, and multi-unit setups at manufacturing locations all point to a market where deployment speed, local support, and operational reliability are becoming as important as instrument performance.
Cost structure and supply chain considerations are also influencing purchasing strategy. Capital expenditure decisions are being evaluated against total cost of ownership, including servicing, consumables, staffing requirements, and regulatory compliance burdens. Suppliers that reduce installation complexity, streamline operational training, and provide clearer service coverage gain an advantage in procurement discussions. For buyers, the question is no longer only whether a cyclotron can produce a required isotope, but whether the broader operating model supports predictable uptime, qualified personnel, and integration with existing radiopharmacy workflows.
Competitive Landscape and Strategic Positioning
The market is led by a set of globally positioned manufacturers with distinct strategic angles. One established leader continues to emphasize breadth across medical cyclotron families and targeted alpha therapy production, including configurations designed for routine isotope output with minimized operator exposure. Another large diversified player anchors its offering around PETtrace platforms, linking on-site isotope production to diagnostic and therapy-related applications through hospital and research installations. A specialist manufacturer focused on high-output systems has been expanding its footprint, including investments in production capacity to support global nuclear medicine demand. A compact superconducting cyclotron developer is positioning around smaller footprints and integrated radiopharmaceutical manufacturing solutions. A Japanese industrial producer continues to compete with compact HM-series systems, emphasizing reliable support and delivery for PET tracer production. These profiles reveal a landscape where scale, specialization, and application focus coexist.
PW Consulting
The strategic differentiation among leaders is becoming clearer along three lines. First, product architecture matters: dedicated high-energy configurations for specific isotope families compete alongside flexible general-purpose platforms, and buyers increasingly evaluate which architecture best fits their isotope roadmap. Second, service and deployment models are a growing battleground, with vendors competing on installation speed, site readiness, commissioning support, and ongoing operational reliability. Third, application breadth is being used as a positioning lever, with some suppliers emphasizing alpha therapy production, others emphasizing PET and SPECT output, and still others connecting cyclotron capability to broader radiopharmaceutical manufacturing services. In practice, this means competitive advantage is less about a single specification and more about how well a vendor aligns instrument design with clinical workflow, compliance, and supply chain expectations.
Market structure is evolving through both consolidation pressure and fragmentation risk. Concentration in the hands of a few incumbents creates a high barrier to entry for general-purpose platforms, but it also opens space for specialized entrants in compact systems, superconducting architectures, or application-specific production lines. At the same time, recent installation activity by both manufacturers and end users reflects a pattern where multi-vendor environments and site-specific procurement choices are becoming more common. Some leading radiopharmaceutical operations are installing instruments from different suppliers to diversify production capability and support parallel diagnostic and therapeutic pipelines. This suggests the competitive battleground is shifting toward ecosystem value: how effectively equipment, isotope workflows, service coverage, and regulatory alignment fit together in a real operating environment.
Worldwide Negative Ion Cyclotron Market
Forward Outlook: Trends and Commercial Implications
Over the next three to five years, the market is likely to be shaped by three interrelated trends. The first is continued specialization around isotope families that connect diagnostics with therapy, particularly where production reliability directly affects treatment scheduling and clinical throughput. This trend favors vendors and operators that can demonstrate consistent output, documented quality processes, and flexible configurations for specific therapeutic and imaging isotopes. The commercial opportunity lies in aligning equipment selection with isotope roadmaps, not just current production needs.
The second trend is greater emphasis on site-integrated deployment. As more centers invest in precision medicine infrastructure, the value proposition of a cyclotron is increasingly tied to facility planning, staffing, and workflow integration rather than standalone instrument performance. Suppliers that offer simpler siting requirements, clearer commissioning pathways, and stronger local service coverage will have an advantage in competitive procurement processes. For operators, the opportunity is to plan capital investments as part of a broader production and service model, reducing downtime risk and improving utilization.
The third trend is regulatory and reimbursement clarity continuing to influence adoption velocity. As more production processes, diagnostic kits, and therapy pathways become explicitly linked to cyclotron-based isotope supply and billing codes, procurement decisions will be more directly connected to commercialization risk and operational compliance. This creates both opportunity and uncertainty. Where coding and approval pathways stabilize, demand can accelerate around established isotope families. Where regulatory timelines or reimbursement changes remain fluid, adoption may pause while buyers await clearer economics. Organizations that monitor policy milestones and reimbursement updates will be better positioned to time investments and avoid overcommitting to supply models that depend on uncertain coding outcomes.
Actionable Guidance for Decision-Makers
The market is expanding, but value capture will depend on how well organizations align strategy with isotope production realities, regulatory direction, and procurement dynamics. For manufacturers, the priority is to strengthen differentiation beyond instrument specifications by tightening the link between platform design, service coverage, and compliance-ready workflows. Product roadmaps should reflect the growing importance of specific isotope families, installation flexibility, and operational support, especially as centers plan multi-unit or multi-isotope environments. Competitive advantage will increasingly belong to suppliers that can demonstrate not only output capability but also reduced operational friction and reliable site readiness.
For investors, the practical question is where durable demand is forming and which segments are most exposed to rapid adoption or policy-driven uncertainty. Growth is strongest where production reliability supports both diagnostic imaging and therapeutic protocols, and where sites are willing to invest in localized isotope generation. At the same time, reimbursement coding and regulatory approvals can accelerate or delay commercialization timelines for specific isotopes and kits. Due diligence should focus on product fit to likely isotope roadmaps, the strength of service and deployment models, and the sensitivity of demand to policy milestones. Portfolio exposure should account for both the upside from theranostic adoption and the timing risk from evolving approval and billing pathways.
For procurement teams and radiopharmacy operators, the decision calculus is shifting from instrument capability alone to total operating suitability. Evaluating vendors now requires attention to siting constraints, staffing demands, commissioning support, service responsiveness, and alignment with planned isotope mixes. Multi-vendor environments and parallel production lines are becoming more relevant where organizations need flexibility across diagnostics and therapeutics. Procurement planning should also incorporate the impact of regulatory and reimbursement changes on isotope economics, since production method and coding status can materially affect the business case for on-site cyclotron investment.
Strategic decisions in this market carry long lead times and depend on details that are not always visible in high-level market sizing. Segment-level demand patterns, vendor-specific deployment metrics, policy timelines, and reimbursement developments will shape which opportunities convert into durable advantage. For teams that need a sharper view of these factors, the full research report provides deeper segmentation data, regional and application-level context, and customized guidance tied to specific operating model and investment objectives.
For detailed analysis of this topic, please visit the official page: Medical Cyclotron Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Ferulic Acid Market: Strategic Trends and Commercial Opportunities in a Growing Antioxidant Economy
Market Landscape and Core Challenges
The ferulic acid market has entered a phase of sustained expansion, driven by the compound's dual role as a potent antioxidant and a functional ingredient across multiple end-use sectors. Over the historical period from 2020 to 2025, the market demonstrated consistent upward momentum, with revenue climbing from approximately 100 million USD at the start of the decade to around 130 million USD by 2025. This trajectory reflects a compound annual growth rate of roughly 7 percent over the base period, a pace that signals healthy demand absorption rather than speculative hype. Forecasts extending through 2032 project the market to surpass the 205 million USD threshold, indicating that the growth runway remains intact even as the base widens.
Such figures, however, only tell part of the story. Behind the headline growth lies a market that is structurally evolving, with shifting cost dynamics, regulatory clarifications, and changing buyer expectations reshaping how value is created and captured. The expansion is not uniform across all value chains; it is concentrated in specific purity grades, sourcing paradigms, and application verticals that command premium pricing or faster volume growth. At the same time, the market exhibits moderate concentration, with the top three players accounting for approximately 45 percent of revenue and the top five reaching around 50 percent. This level of concentration suggests that incumbents possess meaningful scale and distribution advantages, yet it also leaves room for specialized challengers to carve out niches through differentiation in purity, sourcing origin, or regulatory positioning.
Natural Ferulic Acid (CAS 1135-24-6) Market
Several core challenges and inflection points are testing the industry's resilience. First, raw material volatility is exerting persistent pressure on production economics. Rice bran and wheat bran serve as the primary upstream feedstocks for ferulic acid extraction and refining, and the prices of these agricultural inputs fluctuate in response to harvest cycles, weather patterns, and competing demand from food and feed industries. When feedstock costs spike, manufacturers face difficult margin calculations, especially for price-sensitive segments that cannot easily pass through cost increases. Over time, this dynamic favors players with integrated sourcing arrangements, long-term supply contracts, or access to byproduct streams that lower effective input costs.
Second, regulatory clarity is both a catalyst and a constraint. Food-grade ferulic acid must meet quality standards approved by bodies such as the FDA, which increases compliance costs for manufacturers but also raises barriers to entry for less rigorous competitors. At the same time, the FDA's approval of ferulic acid usage in pharmaceutical formulations up to certain levels provides manufacturers with legal protection and stimulates product development in higher-margin therapeutic and nutraceutical contexts. The net effect is a bifurcated market where compliance capability becomes a competitive asset rather than a mere overhead expense. Companies that invest early in documentation, testing protocols, and quality management systems are better positioned to access premium channels, while those treating compliance as an afterthought risk exclusion from regulated supply chains.
Third, the market is experiencing a sourcing and purity divergence that is reshaping procurement behavior. Natural ferulic acid derived from agricultural byproducts is gaining traction in cosmetics and nutraceuticals, where clean-label positioning and traceable sourcing resonate with end consumers. Synthetic variants continue to serve applications where consistency, cost efficiency, and scalable supply are paramount. On the purity axis, high-purity material at 98 percent and above commands a disproportionate share of revenue compared with lower-purity grades, reflecting the premium that formulators place on performance reliability, color stability, and regulatory acceptability. This split creates strategic tension: producers must decide whether to compete on volume and cost in lower-purity tiers or to invest in purification capability, certification, and technical service to capture value in higher-purity segments.
Key Drivers Shaping the Market
Technological Innovation and Process Breakthroughs
Process innovation is a critical lever for expanding margins and unlocking new application potential. Extraction and purification technologies that improve yield from rice bran and wheat bran feedstocks directly reduce unit costs and improve the economic viability of natural ferulic acid. Advanced purification methods, including refined crystallization and chromatography-based approaches, enable manufacturers to consistently achieve high-purity specifications, which in turn opens doors to pharmaceutical and sensitive cosmetic formulations. These technical advances are not merely incremental; they alter the cost curve of the entire value chain, allowing producers to offer premium grades at prices that remain attractive to buyers who previously faced trade-offs between quality and affordability.
PW Consulting
In parallel, formulation science is expanding the functional scope of ferulic acid. Its antioxidant synergy with other ingredients, such as vitamins and UV filters, enhances product efficacy in personal care and cosmetics, reinforcing its appeal to brand owners seeking substantiated performance claims. As research continues to clarify stability profiles and delivery mechanisms, the compound's value proposition in topical applications strengthens, creating a virtuous cycle where better formulation outcomes drive greater demand, which in turn justifies further investment in supply quality.
Policy and Regulatory Environment
The regulatory landscape is moving from ambiguity toward structured acceptance, with meaningful implications for market participants. The FDA's stance on ferulic acid in pharmaceutical formulations, including approval for use up to specified levels, provides a clearer pathway for developers and reduces the regulatory risk associated with incorporating the ingredient into drug products. This legal certainty encourages research and development teams to explore ferulic acid in new therapeutic contexts, knowing that compliant use is definable and defensible. For manufacturers, this translates into a more predictable demand environment in the pharmaceutical segment, where formulation cycles are long but contract value and margin profiles can be substantial once approved products reach commercialization.
Simultaneously, food-grade regulations are raising the floor for quality. Meeting FDA-recognized quality standards for food applications increases compliance costs, but it also filters out under-resourced entrants and consolidates supply relationships around manufacturers with robust quality systems. The result is a market where regulation functions as a competitive filter: it adds cost, yes, but it also rewards those who treat quality infrastructure as strategic capability. Over the next several years, as regulatory expectations continue to crystallize across regions, the ability to provide traceable, well-documented material will become a prerequisite for access to premium buyers rather than a differentiator reserved for a few.
Demand-Side Shifts in Consumer and Business Behavior
On the demand side, the most visible shift is the accelerating emphasis on clean-label and plant-derived ingredients in personal care and cosmetics. Consumers and brand owners alike are increasingly scrutinizing ingredient origin, sustainability credentials, and transparency. Ferulic acid sourced from rice bran and similar agricultural byproducts aligns well with these preferences, offering a narrative of upcycling and natural efficacy that resonates in marketing and product positioning. This demand-side pressure is not cosmetic; it influences procurement decisions, as formulators seek ingredients that support brand claims without compromising performance.
A parallel shift is occurring in pharmaceuticals and nutraceuticals, where the focus on antioxidant support, skin health, and metabolic wellness continues to expand the functional ingredient pipeline. In this context, ferulic acid's established antioxidant properties and growing body of application research make it a candidate for inclusion in formulations that target specific health and wellness outcomes. The demand here is less about consumer-facing branding and more about evidence-based functionality, which places a premium on purity, consistency, and regulatory compliance. Together, these demand-side trends are pulling the market in two complementary directions: one emphasizing natural origin and storytelling in cosmetics, the other emphasizing specification reliability and compliance in pharmaceutical and nutraceutical channels.
Supply Chain and Cost Structure Evolution
Supply chain dynamics are reshaping where value accrues. Because rice bran and wheat bran are the primary upstream feedstocks, the economics of ferulic acid production are tied to agricultural commodity markets and the logistics of bran collection, storage, and processing. Volatility in these inputs affects production costs, but it also creates opportunities for players who can secure stable, cost-effective feedstock through regional partnerships, integrated processing facilities, or access to milling byproducts that would otherwise be underutilized. In effect, feedstock advantage is becoming a strategic moat, not just a procurement detail.
Cost structures are also evolving as manufacturers invest in higher-purity output and compliance infrastructure. The revenue skew toward 98 percent and above purity grades indicates that buyers are willing to pay for assurance, and that premium pricing can offset some of the cost burden associated with advanced purification and quality systems. For suppliers, the strategic question is whether to absorb these costs to gain access to higher-margin channels or to remain in lower-spec tiers where competition is more price-driven. The answer increasingly favors those who can couple technical capability with customer-facing service, such as formulation support, documentation packages, and reliable batch-to-batch consistency, because these elements turn a commodity ingredient into a value-added partnership.
Competitive Landscape and Leading Strategies
The competitive field in ferulic acid reflects a mix of regional specialization, sourcing heritage, and regulatory positioning. Tsuno Rice Fine Chemicals Co., Ltd., based in Wakayama, Japan, anchors its offering in rice bran-derived natural ferulic acid and related rice bran products used as source material for extraction into antioxidant ingredients for cosmetics and nutraceuticals. This positioning leverages a clear sourcing narrative and a heritage in rice bran processing, which can be compelling for buyers seeking traceable natural origin and a well-defined upstream story. The strategic implication is that Tsuno competes on provenance and specialty sourcing rather than on pure commodity scale, making its value proposition strongest in applications where ingredient origin carries commercial weight.
Vigon International, located in East Stroudsburg, Pennsylvania, USA, focuses on natural ferulic acid supplied for cosmetic formulations at greater than 98 percent purity. This combination of natural sourcing and high-purity specification targets a premium segment where formulators demand both clean-label alignment and performance reliability. The strategic logic is clear: by pairing natural origin with high purity, Vigon addresses a buyer need that sits at the intersection of marketing and functionality, allowing it to command attention in cosmetic supply chains that are increasingly discerning about both claims and specifications.
Spectrum Chemical Manufacturing Corp., based in Gardena, California, USA, offers ferulic acid powder meeting cGMP standards for pharmaceutical and research use. This positioning emphasizes quality systems and regulatory alignment, which are critical in pharmaceutical and research contexts where documentation, consistency, and compliant manufacturing practices are non-negotiable. Spectrum's strategy illustrates how compliance capability can serve as a market access key, enabling participation in higher-value channels where trust in quality is a prerequisite rather than a nice-to-have.
Indofine Chemical Company, situated in Belle Mead, New Jersey, USA, supplies ferulic acid for pharmaceutical, agricultural, and life science industries. This multi-sector orientation suggests a diversification strategy that spreads demand exposure across related verticals, reducing dependence on any single end-market while leveraging common quality and supply capabilities. Such diversification can stabilize revenue streams during cyclical shifts in any one sector, though it also requires the operational flexibility to serve differing specification and documentation requirements across industries.
On the natural ingredient side, Shaanxi LonierHerb Bio-Technology Co., Ltd., based in Xi'an, Shaanxi, China, provides natural ferulic acid as a herbal extract for food additives, cosmetics, and functional ingredients. This offering aligns with the broader trend of plant-derived ingredient demand and positions the company to serve buyers looking for herbal extract framing across multiple application categories. Similarly, Sichuan Benepure Pharmaceutical Co., Ltd., in Chengdu, Sichuan, China, offers ferulic acid as a botanical extract and active pharmaceutical ingredient for pharmaceutical, cosmetic, and nutraceutical applications. Benepure's dual framing as both botanical extract and API reflects an intent to span the gap between nutraceutical and pharmaceutical demand, which can be a powerful positioning if supported by appropriate quality and regulatory infrastructure.
Taken together, these players illustrate several patterns in the competitive landscape. First, sourcing origin and purity specification are central axes of differentiation. Companies that combine natural sourcing with high purity, or that pair compliance certifications with reliable supply, create defensible positions that are not easily replicated by generic producers. Second, there is a geographic spread that includes both established players in Japan and the United States and growing capabilities in China. This dispersion suggests that supply is not monolithically concentrated in one region, and that buyers have options based on their requirements for origin, certification, scale, and technical service. Third, the market is showing signs of both integration and specialization: larger or more diversified players can span multiple sectors and purity grades, while specialists can thrive by owning a narrow but valuable niche, such as cosmetic-grade natural ferulic acid at high purity or cGMP-compliant material for pharmaceutical use.
The evolution of the landscape is likely to continue along these lines. Incumbents with scale, certification, and long-standing customer relationships will seek to protect share by reinforcing quality credentials and expanding application support. New entrants and regional challengers will look for gaps where specific sourcing narratives, purity capabilities, or regulatory alignments can create entry points. Consolidation may occur where scale and compliance become increasingly decisive, particularly in pharmaceutical and food-grade channels, while fragmentation may persist in cosmetics and nutraceuticals where branding, origin, and specialized grades create room for multiple viable suppliers. The strategic winners are likely to be those who can articulate a clear value proposition along one or more of these axes and back it with consistent execution.
Future Trends and Commercial Opportunities
Looking ahead three to five years, several trends are poised to shape the ferulic acid market and create actionable commercial opportunities. The first trend is the deepening of high-purity demand as formulators across cosmetics and pharmaceuticals increasingly prioritize specification reliability. As products become more complex and claims more scrutinized, the tolerance for batch variability diminishes. Suppliers that can reliably deliver 98 percent and above purity, supported by robust documentation and consistent quality, will find expanded opportunities to serve as preferred partners rather than interchangeable sources. For businesses, this means that investments in purification capability, quality systems, and customer-facing technical support can translate into longer-term contracts and improved margin profiles.
Fumaric Acid Market
The second trend is the continued rise of natural and plant-derived positioning in cosmetics and nutraceuticals, amplified by clean-label consumer preferences and brand differentiation strategies. Ferulic acid sourced from rice bran and wheat bran is well placed to benefit from this trajectory, particularly where suppliers can provide traceable origin stories and substantiate sustainability or upcycling narratives. The commercial opportunity here lies not only in selling the molecule but in enabling brand owners to communicate value to end consumers. Suppliers that can package origin, purity, and technical performance into a coherent offering will be better positioned to capture premium demand than those competing solely on price.
The third trend is the gradual formalization of regulatory acceptance across applications, which is likely to reduce uncertainty and encourage product development in pharmaceutical and food contexts. The FDA's approval of ferulic acid usage in pharmaceutical formulations up to certain levels, alongside ongoing quality standard expectations for food-grade material, points toward a more structured environment where compliance capability becomes a market access determinant. For forward-looking businesses, this trend suggests that early investment in regulatory documentation, quality management, and application-specific testing can create a timing advantage as new formulations move from research to commercialization. The opportunity is to be an established, trusted supplier when demand materializes, rather than scrambling to qualify during a product launch window.
These trends are not without risks and uncertainties. Raw material volatility in agricultural feedstocks remains a persistent threat to cost stability, and any prolonged spike in bran prices could compress margins or trigger price resistance in sensitive segments. Regulatory environments can also shift, and while current signals are favorable, changes in quality expectations or jurisdictional requirements could raise compliance burdens unexpectedly. In addition, the growing interest in ferulic acid could attract new entrants, intensifying competition in specific grades or regions and pressuring pricing where differentiation is weak. Companies that rely on a single feedstock source, a single application channel, or a single geographic market may find themselves more exposed to these dynamics than those with diversified supply and demand bases.
Strategic Recommendations for Decision-Makers
For manufacturers and suppliers, the priority is to clarify which value axis to own and to invest accordingly. If the strategy is to compete in premium cosmetic or pharmaceutical channels, then high-purity capability, compliance infrastructure, and technical service should be treated as core assets rather than optional enhancements. If the strategy is to serve volume-driven segments, then securing stable, cost-effective feedstock through integrated or long-term supply relationships becomes the critical lever. In either case, it is advisable to avoid undifferentiated commodity positioning, because the market's revenue skew toward higher-purity grades and its increasing regulatory selectivity reward specificity. Manufacturers should also stress-test their cost models against raw material volatility and consider hedging strategies, regional diversification of feedstock sources, or byproduct integration to reduce exposure.
For investors evaluating opportunities in this space, the key is to distinguish between structural growth and cyclical pricing noise. The market's projected expansion through 2032, supported by demand in cosmetics, pharmaceuticals, and food and beverages, indicates a foundational growth trend rather than a transient surge. However, value creation will be uneven, and returns are likely to concentrate among players with clear differentiation in sourcing origin, purity, or compliance capability. Due diligence should therefore focus on the durability of a company's positioning: whether its sourcing advantages are defensible, whether its quality and regulatory infrastructure can support premium channels, and whether its customer relationships are based on specification and service rather than price alone. Monitoring regulatory developments, particularly around food-grade standards and pharmaceutical usage approvals, will also be important, as these factors can accelerate or constrain demand in specific segments.
For procurement and R&D leaders in cosmetics, pharmaceutical, and food and beverage companies, the strategic imperative is to treat ferulic acid sourcing as a partnership decision rather than a transactional purchase. Given the divergence between natural and synthetic offerings, and between lower- and higher-purity grades, procurement teams should align ingredient selection with product positioning, regulatory requirements, and performance needs. This means specifying not only the molecule but also the origin, purity, documentation package, and supply reliability that matter for the end application. Building relationships with suppliers that can provide consistent quality, clear traceability, and formulation support reduces the risk of downstream issues and strengthens the ability to make credible claims in marketing and regulatory contexts. It also pays to qualify multiple suppliers across different sourcing and purity profiles, so that supply strategies can adapt if feedstock costs shift or if application requirements evolve.
Across all these roles, timely access to detailed market intelligence remains a decisive advantage. The ferulic acid market is moving on multiple fronts at once, from feedstock economics and purification technology to regulatory acceptance and clean-label demand. Decisions made without a clear view of how these forces interact risk being reactive rather than proactive. More granular data on segment dynamics, purity-grade revenue splits, sourcing cost structures, and company-level positioning can sharpen strategy and reveal where to commit resources for the highest return. For those seeking a deeper, more customized view of the market, an expanded research report can provide the segmentation detail, competitive benchmarking, and scenario analysis needed to translate these high-level trends into concrete action plans.
For detailed analysis of this topic, please visit the official page: Ferulic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hot Roll Slitter Market Forecast: Technological Advancements, Growth Trends, and Future Opportunities 2023–2032
By preeti mmr, 2026-09-21
Market Overview
The Hot Roll Slitter Market was valued at approximately US$ 2.71 billion in 2025 and is expected to reach nearly US$ 3.48 billion by 2032 , expanding at a CAGR of 3.6% during the forecast period 2026–2032 . The market is experiencing steady development as manufacturers across steel processing, automotive, construction, packaging, paper, and industrial manufacturing increasingly require accurate and efficient material-conversion technologies.
Request Sample Link for More Details: https://www.maximizemarketresearch.com/request-sample/118980/
Hot roll slitters are specialized machines designed to divide wide rolls or coils into narrower strips while maintaining consistent dimensions, controlled tension, and acceptable edge quality. The equipment is particularly important in downstream manufacturing operations where material utilization, production speed, and dimensional precision influence overall manufacturing costs. As industrial producers seek to reduce scrap and improve throughput, modern slitting systems are becoming increasingly integrated with automated control, monitoring, and material-handling technologies.
The continued expansion of steel-processing activities is an important factor supporting market demand. Automotive components, construction materials, industrial equipment, packaging products, and other fabricated goods require processed metal and other roll-based materials in specific widths. Hot roll slitting systems enable manufacturers and service centers to convert larger master rolls into application-specific widths, supporting flexible production and inventory management.
Industrial modernization is also contributing to market development. Steel service centers and converting facilities are increasingly replacing conventional machinery with automated equipment capable of operating at higher speeds while maintaining consistent product quality. Advancements in tension control, knife positioning, blade technology, computerized monitoring, and automated material handling are improving machine performance and reducing production losses.
However, the market faces challenges associated with high initial investment, maintenance requirements, specialized technical expertise, and limitations related to processing different materials. Despite these constraints, increasing manufacturing capacity and modernization initiatives across emerging economies are expected to create sustained opportunities for hot roll slitter manufacturers through 2032.
Market Drivers and Trends
One of the major drivers of the Hot Roll Slitter Market is the growing demand for precision material processing . Manufacturers increasingly require narrower strips with controlled widths and consistent edges to meet downstream production specifications. Slitting machines provide an efficient method of converting large rolls into multiple smaller-width rolls, supporting improved material utilization and streamlined production.
Request Sample Link for More Details: https://www.maximizemarketresearch.com/request-sample/118980/
The expansion of the automotive industry is another important growth factor. Automotive manufacturers and component suppliers use processed metal materials for various body, structural, electrical, and mechanical components. As automotive production expands across Asia-Pacific and other industrial regions, demand for efficient coil-processing and material-conversion equipment is expected to increase.
Infrastructure development is also supporting demand. Construction projects require significant quantities of steel and other processed materials, while infrastructure investment encourages expansion of steel-processing and fabrication facilities. As service centers seek to improve processing capacity and respond to increasingly customized orders, investment in slitting equipment can support operational flexibility.
Automation and digitalization represent another important market trend. Modern hot roll slitting systems increasingly incorporate automated tension control, computerized settings, monitoring systems, precision knife positioning, and advanced safety features. These technologies help reduce operator intervention, improve repeatability, and support consistent output. Integration with factory automation and production-management systems is also creating opportunities for more connected processing environments.
Material optimization is becoming increasingly important as manufacturers seek to reduce waste and production costs. Rewind slitting technology enables large master rolls to be converted into smaller rolls according to customer requirements. This approach can support improved inventory utilization and more flexible order fulfillment.
The packaging and converting industries are also creating opportunities for slitting machinery. Growth in flexible packaging, printed materials, coated substrates, and other roll-based products is increasing demand for equipment capable of precise cutting and rewinding. At the same time, sustainability initiatives are encouraging manufacturers to reduce material losses and improve production efficiency.
Primary Market Constraints
Despite positive growth prospects, several factors may restrain the expansion of the Hot Roll Slitter Market. High capital expenditure is a significant challenge, particularly for small and medium-sized manufacturers. Advanced slitting systems equipped with automated controls, high-speed processing capabilities, and integrated material-handling systems can require substantial investment.
Maintenance requirements represent another constraint. Slitter machines contain precision components, cutting blades, tension-control systems, motors, bearings, and other mechanical and electronic components that require regular inspection and maintenance. Downtime caused by equipment failure can affect production schedules and increase operating costs.
Another limitation is the material-specific nature of slitting equipment . A single machine configuration may not be suitable for processing every material or substrate. Different materials can require different blade configurations, tension settings, machine specifications, and handling arrangements. Consequently, manufacturers working with multiple material types may need additional equipment or customized machine configurations.
The availability of skilled technical personnel can also influence adoption. Operating and maintaining high-precision slitting systems requires knowledge of machine settings, blade positioning, tension management, safety procedures, and production optimization. In regions where specialized technical expertise is limited, companies may face additional training and operational costs.
Key Market Segments
Based on Type , the Hot Roll Slitter Market is segmented into Log Slitting and Rewind Slitting .
The Rewind Slitting segment is expected to maintain a significant market position through 2032. Rewind slitting machines allow large master rolls to be unwound, divided into narrower widths, and rewound into smaller rolls. This capability makes them particularly suitable for manufacturers and converting facilities that need multiple finished roll sizes from a single master roll.
The growing emphasis on production flexibility, material utilization, and customized roll sizes is supporting demand for rewind slitting systems. Manufacturers can process large master rolls and produce multiple smaller rolls according to customer specifications, reducing the need for separate production runs and improving operational efficiency.
Based on Application , the market is segmented into Paper and Pulp, Printing and Packaging, Non-Woven Fabric, and Others .
The Printing and Packaging segment is expected to experience notable growth during the forecast period. Packaging manufacturers increasingly require accurate cutting, rewinding, coating, laminating, and converting processes. Growth in flexible packaging and printed packaging products is creating demand for machinery capable of maintaining consistent dimensions and production quality.
The Paper and Pulp segment also represents an important application area because paper products are frequently manufactured and processed in large rolls before being converted into smaller widths. Slitting systems support the downstream conversion of these materials into formats suitable for different industrial and commercial applications.
The Non-Woven Fabric segment is supported by expanding applications of non-woven materials across packaging, filtration, healthcare, hygiene, automotive, and industrial products. As manufacturers expand production capacity, precision roll-processing technologies can support improved material conversion and product consistency.
Request Sample Link for More Details: https://www.maximizemarketresearch.com/request-sample/118980/
Regional Market Insights
North America is expected to remain an important regional market through 2032. The region benefits from established industrial infrastructure, advanced manufacturing capabilities, and a strong presence of steel-processing and industrial production facilities. Modernization of manufacturing plants and the adoption of automated processing equipment are contributing to demand for advanced slitting systems.
The Asia-Pacific region is also expected to represent a major growth opportunity. Countries across the region have significant steel production capacity, expanding manufacturing industries, and increasing investments in automotive, construction, packaging, and industrial infrastructure. The growth of manufacturing facilities and the modernization of existing plants are supporting demand for efficient material-processing machinery.
China, Japan, India, and other developing industrial economies are important contributors to regional demand. Increasing industrialization, expanding domestic manufacturing capabilities, and growing investments in infrastructure are encouraging manufacturers to improve processing efficiency.
Europe remains an important market because of its established automotive, engineering, steel-processing, and industrial manufacturing sectors. Demand for precision machinery, production automation, and resource-efficient manufacturing processes supports the adoption of modern slitting technologies.
Major Industry Players
The competitive landscape of the Hot Roll Slitter Market includes established manufacturers and specialized machinery companies serving different industrial applications. Key players identified in the market include:
- Greer Steel
- BlueSky Machine
- Grand Steel Products
- ARK Industries
- KingJime Machine
- HPL-Group
- Lifetime Products
- H. R. (Paper) Machinery Private Limited
- Ghezzi & Annoni
- Hariram Engineering
- Svegea
- Rosenthal MFG
- Oteman
- CMC Converting Machinery Cevenini Srl
- Orion Graphic Machinery
- Windmoller & Holscher Machinery k.s.
Companies operating in the market are focusing on machinery performance, automation, precision cutting, production speed, material handling, and customized equipment configurations. Product development and technology integration are expected to remain important competitive factors as end users seek higher productivity and lower material waste.
Frequently Asked Questions
1. What is the projected market size of the Hot Roll Slitter Market by 2032?
The global Hot Roll Slitter Market is expected to reach approximately US$ 3.48 billion by 2032 .
2. What was the Hot Roll Slitter Market size in 2025?
The market was valued at approximately US$ 2.71 billion in 2025 .
3. What is the expected CAGR of the Hot Roll Slitter Market?
The market is projected to grow at a CAGR of 3.6% during 2026–2032 .
4. Which segment is expected to hold a significant share by type?
The Rewind Slitting segment is expected to hold a significant market share through 2032 because of its ability to unwind, slit, and rewind master rolls into smaller finished rolls.
5. Which applications are covered in the Hot Roll Slitter Market?
The market is segmented by application into Paper and Pulp, Printing and Packaging, Non-Woven Fabric, and Others .
Market Outlook
The Hot Roll Slitter Market is positioned for steady expansion as industrial manufacturers prioritize precision, automation, production flexibility, and material efficiency. The market's growth from US$ 2.71 billion in 2025 to approximately US$ 3.48 billion by 2032 reflects continued investment in downstream material-processing capabilities.
Connect With Us:
MAXIMIZE MARKET RESEARCH PVT. LTD.
2nd Floor, Navale IT park Phase 3,
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India.
+91 9607365656
sales@maximizemarketresearch.com
About Maximize Market Research:
Maximize Market Research is one of the fastest-growing market research and business consulting firms serving clients globally. Our revenue impact and focused growth-driven research initiatives make us a proud partner of majority of the Fortune 500 companies. We have a diversified portfolio and serve a variety of industries such as IT & telecom, chemical, food & beverage, aerospace & defense, healthcare and others.
Strategic Trends & Commercial Opportunities in the Tyre Curing Press Market
The tyre manufacturing sector is undergoing a quiet but consequential transformation, and the curing press sits at the center of that shift. Over the past five years, global demand for curing equipment has expanded from roughly $163 million to $215 million, and the trajectory suggests continued growth toward $345 million by 2032. The forward path is anchored by a compound annual growth rate of approximately 4.15 percent through the end of the decade. These figures do not describe a mature, static market. They describe an industry in the middle of a technology transition, a regulatory tightening cycle, and a geographic realignment that is reshaping how manufacturers source, spec, and operate curing systems. For executives planning capital expenditures, investors evaluating industrial equipment exposure, and procurement teams negotiating long-cycle orders, the direction of the market matters more than any single quarter. The next five years will favor players who align equipment strategy with energy efficiency, compliance readiness, and regional demand patterns rather than those who compete purely on price per unit.
Market Overview and Core Challenges
The current market structure reflects a steady but uneven expansion. Base-year sizing places the sector at $215 million, with historical data showing a clear acceleration after 2022. The jump from $172.69 million in 2022 to $193.7 million in 2023, followed by continued movement toward $201.23 million in 2024, indicates a post-pandemic normalization combined with fresh capital spending in tyre production capacity. From there, the forecast builds steadily, with the market crossing $222.74 million in 2026 and reaching $344.8 million by 2032. The consistency of this growth curve is significant: it suggests that curing press demand is being driven by structural factors rather than temporary capacity spikes. At the same time, the market is not concentrated in the hands of a few dominant players. A CR3 of 24.6 percent and a CR5 of 26.2 percent point to a broad competitive field, which reinforces price and technology differentiation as the main differentiators instead of oligopolistic advantage.
PW Consulting Automotive & Machinery Research Center
This broad landscape is also where the central tensions emerge. Three challenges define the current turning point.
- Technology substitution is accelerating, but not uniformly. Hydraulic systems continue to hold meaningful share, while hybrid and electric variants are gaining attention in specific production environments. The market is not eliminating mechanical presses, but it is shifting expectations around cycle consistency, energy draw, and process control.
- Regulatory scrutiny is intensifying around safety, traceability, and plant-level emissions. tyre identification requirements, compliance labeling, and environmental permitting have moved from administrative concerns to operational constraints. Manufacturers and equipment suppliers need to treat compliance as part of product design and deployment, not as a downstream paperwork exercise.
- Regional demand is uneven, creating both overcapacity risk in some areas and supply opportunities in others. Tire production growth, retreading activity, and replacement cycles are not moving in lockstep across geographies, which complicates demand forecasting for equipment suppliers and buyers alike.
For decision makers, the implication is straightforward: curing press strategy must be multifaceted. A unit that performs well in one plant may not be the right answer for another if energy costs, labor availability, regulatory exposure, or end-product mix differ materially. The market is rewarding flexibility and penalizing one-size-fits-all assumptions.
Key Drivers Shaping the Market
Technology Innovation and Process Control
The most consequential driver in the near term is the evolution of curing technology itself. The emergence of modular hydraulic and electric solutions, including next-generation curing platforms and post-cure inflation options, reflects a broader push toward tighter process control and reduced energy intensity. Manufacturers are not simply replacing old machines; they are rethinking the curing step as a variable that affects throughput, quality consistency, and operating cost. The trend is visible in the product mix, where hydraulic equipment leads in value and electric and hybrid formats are expanding their footprint in higher-value or more customized applications.
Trade show activity reinforces the point. Recent appearances by major equipment providers at international tyre and rubber events have highlighted advances in curing technology, manufacturing inspection, and sustainable production methods. These showcases are more than marketing events. They signal where engineering teams and end-users are converging on priorities: repeatable cure profiles, safer operator environments, and equipment that can integrate with automated line architectures. HF GROUP’s ongoing exhibition presence across Vienna, Chennai, and tyre technology events in 2026, along with its earlier participation in India Rubber Expo communications, underscores how suppliers are using live demonstrations to position curing solutions within broader sustainability and productivity narratives.
The commercial takeaway is that equipment choice is increasingly a process decision, not just a mechanical purchase. Plants that pair curing equipment with better control systems and predictive maintenance can reduce scrap, improve throughput, and adapt more easily to product mix changes. That makes the value proposition of advanced curing platforms more defensible than simple unit pricing.
Policy, Compliance, and Permitting Environments
Regulatory dynamics are becoming a more visible market driver than many equipment buyers assume. Traceability and compliance labeling requirements for tyres have created concrete consequences for producers and equipment integrators. Recent federal-level actions involving tire information numbering and curing press identification symbols illustrate how compliance failures can affect product acceptance and market access. This is not an abstract risk. It connects curing press configuration and plant recordkeeping directly to regulatory adherence.
At the same time, environmental permitting at the plant level is influencing where and how new equipment is installed. In several regions, permitting activity for rubber processing facilities and curing presses has been part of broader emissions and operational control frameworks. Authorized installations during 2025 and 2026 reflect a market in which environmental compliance is an integral part of capacity expansion. This matters for suppliers because it shapes the specifications buyers request, and for purchasers because it affects project timelines, operating conditions, and long-run operating costs.
One notable equipment-level example is the introduction of automatic curing press ranges with enhanced safety features, precise control, and mold compatibility for retreading and tyre manufacturing. Such product launches show how suppliers are responding to the dual pressure of operational performance and regulatory or safety expectations. The market is increasingly rewarding equipment that reduces operator risk and supports repeatable, auditable processes.
Demand-Side Shifts in Tire Types and Production Patterns
On the demand side, the market is shaped by what tyres are being produced and where. Passenger vehicle tyres remain the dominant application, supported by replacement demand, new vehicle production, and regional tyre manufacturing footprints. Commercial vehicle tyres, aircraft tyres, and other specialty formats make up meaningful but smaller segments, and they often carry different technical requirements for curing equipment. The mix matters because curing presses are increasingly evaluated by the range of tyre sizes and types they can handle without compromising cycle times or uniformity.
Demand for retreading and specialty tyre production also influences equipment choice. Automatic curing press solutions designed for retreading applications demonstrate how end-use diversification is creating additional demand vectors. Plants that serve both new tyre production and retreading markets need equipment that can switch configurations efficiently while maintaining product integrity. This trend favors flexible platforms and complicates buying decisions for organizations that previously treated curing presses as single-purpose assets.
Supply Chain and Cost Structure Dynamics
Cost structure is evolving as manufacturers balance capital expenditure discipline with operating efficiency. Energy consumption is a recurring theme in curing press evaluations, especially in facilities where electricity costs, cooling requirements, and cycle frequency significantly affect total cost of ownership. Suppliers have responded with press series designed to reduce energy consumption and optimize process control, and those features are becoming more prominent in buying criteria. For capital-intensive equipment, the conversation is shifting from sticker price to lifecycle economics.
Supply chain expansion is another relevant force. Acquisitions and integration moves in the hydraulic sector show how equipment makers are strengthening their capabilities to support broader system requirements. These moves are less about symbolic corporate growth and more about securing technical depth and service support. Buyers benefit when suppliers can deliver integrated hydraulic, mechanical, and automated components with tighter calibration and faster local support. The trend also suggests that the market is moving toward more bundled offerings rather than standalone press purchases, which has implications for vendor selection and contract scope.
Competitive Landscape and Leading Strategies
The market is populated by a diverse set of international players, each with a distinct strategic position. Rather than competing on identical terms, leading companies are building differentiation around product breadth, application focus, and regional presence.
- HF GROUP has built its position around modular hydraulic and electric curing solutions, including established curing platforms, classic press models, and post-cure inflation equipment, with extensive global deployment. Its strategy appears centered on demonstrating innovation through live exhibitions and maintaining a broad installed base that supports serviceability and product evolution.
- Uzer Makina focuses on floating column hydraulic presses and frame-type and mechanical options across a wide size range for passenger, light truck, truck, off-the-road, and agricultural tyre applications. Its recent expansion through acquisition in the hydraulic sector suggests a push toward deeper system capability and broader service support.
- Larsen & Toubro maintains a mechanical tyre curing press range that spans a wide application set, from two-wheelers to passenger cars, light trucks, trucks, tractors, and off-the-road equipment. This breadth positions the company to serve diverse markets, particularly where mechanical press familiarity and application coverage are valued.
- HERBERT Maschinenbau offers hydraulic and mechanical curing presses across passenger to off-the-road sizes, along with post-cure inflators and mold-related equipment. Its introduction of a press series emphasizing reduced energy consumption and optimized process control illustrates a clear response to efficiency and control requirements.
- SCPT Machinery provides tire curing press machines and vulcanizing equipment for varied tyre production needs, supporting a broad equipment portfolio that can appeal to producers seeking standardized vulcanization solutions.
- Cima Impianti markets automatic curing presses, including a product range oriented toward retreading and tyre manufacturing with emphasis on safety, control, and mold compatibility. This positioning addresses both production and aftermarket segments.
- ŽĎAS specializes in tyre curing presses for trucks, tractors, and building machines, reflecting a focused application strategy that serves heavier-duty and industrial tyre segments.
Taken together, the competitive landscape is not coalescing into a single dominant model. Instead, it is differentiating into several strategic approaches: technology-forward modular platforms, application-specific coverage, broader system integration through acquisitions, and sustainability- or efficiency-oriented product lines. This fragmentation is important because it creates choice for buyers, but it also raises the burden of evaluation. Procurement teams need to compare not just press price and capacity, but integration readiness, compliance support, service coverage, and fit with current and future product mixes.
The market evolution is likely to continue along two paths in parallel. In one, larger incumbents will deepen their offerings through product complexity, automation compatibility, and service networks. In the other, specialized suppliers will continue to compete by dominating particular tire types, regional demand patterns, or process configurations. The result is a market where consolidation will be selective rather than sweeping, and where the winners will be those who can articulate a clear operational value proposition rather than those who merely expand factory output.
Future Trends and Commercial Opportunities
Broader Adoption of Efficiency-Focused Curing Platforms
Over the next three to five years, efficiency and control will move from desirable features to baseline expectations. Curing presses that combine reduced energy consumption, predictable cycle management, and safer operation will become more central to procurement decisions, especially in facilities facing tighter operating margins and stricter environmental oversight. The commercial opportunity here is twofold. Equipment suppliers can capture value by selling lifecycle performance rather than commodity machinery, and manufacturers can reduce operating variability while improving throughput consistency. The key uncertainty is the pace at which energy cost volatility and regulatory expectations will accelerate replacement cycles in different regions.
Growth in Segmented and Application-Diverse Demand
Demand will increasingly be segmented by tyre type, production scale, and end-use cycle. Passenger vehicle tyres will continue to anchor volume, but commercial, aircraft, specialty, and retreading formats will create niches where equipment flexibility matters more than headline capacity. This creates opportunities for suppliers that can offer adaptable press configurations and for buyers who plan for mixed-product environments rather than single-line optimization. The risk is that overinvestment in narrowly optimized equipment may leave plants exposed to product mix changes, while underinvesting in flexibility can erode quality and consistency when lines need to switch applications.
Press Machine Market
Closer Integration of Compliance and Plant Equipment Strategy
As traceability, labeling, and permitting issues become more embedded in tyre manufacturing operations, curing press selection and plant strategy will be more tightly linked to compliance readiness. Future investments are likely to incorporate identification protocols, documentation compatibility, and environmental operating constraints as part of the equipment specification process. This trend opens opportunities for suppliers who design compliance-friendly architectures and for buyers who treat equipment planning as part of a broader regulatory strategy. The uncertainty lies in how quickly compliance requirements will change across jurisdictions and how consistently they will be enforced.
Strategic Recommendations for Decision Makers
The market is not simply expanding; it is becoming more conditional. The right curing press strategy depends on the role a company plays in the value chain and the operating pressures it faces. The following actions are most relevant across the three core audiences.
For Manufacturers and Equipment Buyers
- Evaluate curing systems on total operating economics, including energy use, cycle consistency, maintenance burden, and changeover flexibility, rather than on first-cost alone.
- Align press selection with the expected mix of tyre types and production cycles, including new tyre output and retreading activity where relevant, to avoid over-specialized equipment.
- Build compliance and traceability considerations into equipment specifications early, so that curing press configuration supports product identification, documentation, and permitting requirements without later retrofit costs.
For Investors and Strategic Planners
- Watch for differentiation that is tied to real operating gains, such as energy reduction, process control, and integrated service coverage, because those features are more likely to support durable competitive advantage than price-based competition.
- Track regional demand shifts and permitting activity, since market growth may be uneven and driven by local production expansion, environmental approvals, and replacement demand rather than by a uniform global cycle.
- Assess whether targets are building meaningful system capability and service depth or merely broadening product names, because integration and support quality will increasingly determine customer retention and aftermarket economics.
For Procurement and Operations Leaders
- Treat curing press sourcing as a multi-year operating decision, not a transactional purchase. Establish clear criteria for safety, control, mold compatibility, and service response, and use them consistently across bids.
- Prioritize suppliers whose product roadmaps align with your plant’s efficiency and compliance trajectory, especially if you expect tighter energy budgets or stronger environmental oversight in the coming years.
- Use pilot programs and reference installations to validate process outcomes where possible, because curing performance differences can be subtle in specifications but material in daily operations.
The tyre curing press market will continue to expand, but growth alone will not define winners. The companies that navigate this period well will be those that understand how technology transitions, compliance pressures, demand segmentation, and cost structures interact inside real production environments. Broad market sizing and directional trends are useful, but they rarely answer the specific questions that determine capital deployment, vendor selection, and operating risk. Manufacturers planning line upgrades, investors comparing equipment exposures, and procurement teams structuring long-cycle purchases need detailed segmentation data, regional demand context, and company-level capability mapping to move from general direction to actionable decision-making. For that level of detail, the full research report provides a deeper breakdown of market segments, competitive positioning, and development timelines that can support more granular strategy work.
Hydraulic Press Market
For detailed analysis of this topic, please visit the official page: Tyre Curing Press Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Dextran Market 2026: Why 5.5% CAGR and Asia Pacific Growth Redefine Strategy
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Dextran Market: A 2032 Outlook
The global dextran market is navigating a period of structural transition, balancing steady growth with evolving clinical preferences and supply chain recalibrations. Valued at approximately $131.0 million in 2025 and projected to reach $188.0 million by 2032, the market is expanding at a compound annual growth rate of around 5.5 percent. This trajectory reflects a sector that is neither explosive nor stagnant; rather, it is maturing under the influence of clinical guideline shifts, manufacturing modernization, and regional demand migration. For executives and investors, the opportunity lies not in chasing headline growth figures but in understanding where value is being created, which formulations are gaining or losing clinical traction, and how leading players are positioning themselves to capture margin and share.
The historical record from 2020 through 2025 reveals a market that has recovered from pandemic-era disruptions, rebounded with renewed procurement cycles, and now faces a more disciplined demand environment. Growth is no longer driven solely by volume expansion in traditional plasma expander applications. Instead, the market is being reshaped by formulation upgrades, derivative diversification, and regional capacity investments that aim to shorten delivery cycles and reduce logistics friction. This evolution creates a clearer divide between commodity-oriented production and clinically differentiated, compliance-backed offerings. The companies that thrive will be those that can align manufacturing reliability with therapeutic relevance, particularly as procurement teams increasingly weigh total cost of ownership against clinical outcomes and supply resilience.
One of the most pressing challenges is the clinical repositioning of certain high-molecular-weight formulations. Dextran 70, while still approved for volume expansion in hypovolemia, is used less frequently in modern practice due to recognized risks such as anaphylaxis, renal impairment, and coagulopathy. This does not eliminate the category, but it does shift demand toward formulations with improved safety profiles and toward derivative products that extend dextran’s utility beyond volume expansion. A second challenge lies in raw material exposure. Sucrose remains the dominant biological feedstock for microbial fermentation production, and its price volatility directly affects cost structures and pricing flexibility. Manufacturers with integrated sourcing, long-term contracts, or alternative feedstock strategies are better positioned to protect margins during input cost swings. A third challenge is regulatory and quality assurance intensity. Pharmaceutical-grade dextran operates under strict pharmacopoeial monographs, and both the FDA and EMA maintain a continuous focus on quality, safety, and traceability for excipient and active pharmaceutical ingredient applications. Compliance is not merely a barrier to entry; it is increasingly a competitive differentiator that influences hospital formulary decisions and procurement trust.
Key Drivers Reshaping Market Direction
The market’s next phase of growth will be shaped by a combination of technological progress, regulatory clarity, demand-side behavior change, and supply chain redesign. Each driver reinforces the others, creating a landscape in which incremental improvements can translate into meaningful share shifts.
Technological Innovation and Formulation Breakthroughs
Innovation in dextran has moved beyond basic polymer production toward targeted formulation and derivative engineering. The introduction of DEAE-Dextran as part of an expanded biopolymers portfolio illustrates how manufacturers are broadening the functional footprint of dextran beyond conventional volume expansion. In parallel, newer Dextran 20 formulations are being designed with enhanced biocompatibility for advanced surgical applications, addressing long-standing concerns around compatibility and patient response. These product-level improvements matter because they create clinically defensible reasons for hospitals and surgical centers to prefer specific offerings over generic alternatives. For commercial teams, the implication is clear: differentiation is increasingly tied to formulation quality, biocompatibility data, and the ability to support specific procedural use cases rather than price alone.
Policy, Regulation, and Reimbursement Dynamics
Regulatory expectations continue to elevate the importance of quality documentation and pharmacopoeial compliance. The sustained focus on monographs for pharmaceutical dextran means that suppliers must demonstrate consistent manufacturing standards, batch-to-batch reliability, and robust safety profiles. At the same time, reimbursement environments are influencing procurement decisions. Public and private payers are scrutinizing average prices and utilization patterns, which places pressure on suppliers to justify value through clinical performance and supply reliability. In this context, products that can demonstrate clear therapeutic benefit, predictable availability, and strong quality credentials are more likely to secure favorable formulary positioning. Reimbursement scrutiny is not a deterrent to growth; it is a filter that rewards disciplined manufacturers and penalizes undifferentiated commodity positioning.
Demand-Side Shifts in Healthcare and Biotechnology
Demand is being reshaped by changing clinical protocols and expanding application breadth. In hospital settings, the balance between traditional plasma expanders and alternative resuscitation strategies continues to evolve, influenced by safety considerations and institutional preferences. This shift encourages manufacturers to invest in formulations that align with modern surgical and emergency care pathways. Beyond direct infusion applications, derivative portfolios are gaining relevance across pharmaceutical and biotech workflows, where dextran-based materials support a wider array of process and formulation needs. The practical consequence is that demand is becoming more application-specific, and suppliers that can map their portfolio to distinct clinical and industrial use cases are better positioned to sustain predictable order flow.
Supply Chain, Logistics, and Cost Structure Realignment
Cold-chain logistics remain a critical enabler for sensitive dextran formulations used in plasma expanders and excipients. As product portfolios become more specialized, the cost and reliability of temperature-controlled distribution increasingly influence both margin and market access. Regional manufacturing expansion is one response, designed to reduce delivery times, lower logistics complexity, and improve service levels for local markets. At the same time, sucrose-driven feedstock costs require continuous attention to procurement strategy, fermentation efficiency, and yield optimization. Companies that combine localized capacity with disciplined input cost management can offer a more stable value proposition, particularly in markets where supply interruptions or prolonged lead times would otherwise disrupt clinical operations.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a moderate concentration level, with a core group of established manufacturers holding meaningful but not prohibitive share. This structure leaves room for differentiation through quality, regional service, and formulation expertise rather than through scale alone.
Profiles of Core Players and Strategic Positioning
Pharmacosmos stands out as an active large-scale manufacturer and global leader in pharmaceutical-grade dextran production. Its portfolio spans Dextran 40, Dextran 70, and derivatives, with supply of APIs, excipients, and clinical-grade dextran supported by FDA and EDQM approvals. This positions the company as a compliance-centric supplier for pharma and healthcare uses, where regulatory credibility and product consistency are central purchasing criteria. Its recent introduction of DEAE-Dextran under GMP certification from the Danish Medicines Agency signals a deliberate expansion into specialized biopolymer applications, reinforcing a strategy that combines regulatory strength with portfolio breadth.
Nagase Viita, formerly Hayashibara, is an active manufacturer of microbial polysaccharides including dextran and derivatives for pharmaceutical and biotech applications. Its long-standing presence in high-quality dextran polymer production reflects deep process knowledge and a focus on consistent polymer characteristics. For customers that prioritize manufacturing reliability and polymer quality across pharmaceutical and biotechnology workflows, this heritage provides a credible basis for long-term sourcing relationships.
What Differentiates the Leaders
The leading players are not competing solely on price; they are competing on trust, compliance, and application fit. Key differentiators include:
Dextrins Market
- Regulatory and quality credentials that simplify procurement validation and support formulary inclusion
- Portfolio breadth that covers both established infusion-grade products and derivatives for broader pharmaceutical use
- Manufacturing reliability and batch consistency that reduce supply risk for hospitals and biotech users
- Regional service capabilities that shorten lead times and improve responsiveness in key demand centers
These advantages matter because buyers in this market are increasingly risk-averse. A supplier that can demonstrate documented quality, predictable availability, and clinically relevant formulation options is more likely to retain share during periods of procurement consolidation or guideline changes.
PW Consulting
Evolution of the Market Structure
The landscape is evolving through a mix of expansion, product specialization, and selective capacity moves. Manufacturing expansion in Southeast Asia aimed at increasing Dextran 20 production capacity reflects a regionalization strategy designed to improve service levels and reduce delivery times. Product launches with enhanced biocompatibility for advanced surgical applications indicate a shift toward higher-value use cases in European hospitals. Regulatory approvals for Dextran 20–based plasma expanders in emergency trauma protocols underscore the continued relevance of dextran in acute care, while also highlighting the importance of timely regulatory clearance and clinical alignment. Taken together, these moves suggest a market that is neither consolidating into a single dominant model nor fragmenting into undifferentiated commodity competition. Instead, it is bifurcating: one pathway emphasizes compliance, clinical differentiation, and regional service, while another remains more price-sensitive and volume-oriented. The most resilient players will be those that can operate effectively across both pathways without diluting their quality positioning.
Future Trends and Commercial Implications
Looking ahead to the 2026–2032 period, three trends are likely to shape commercial outcomes.
Cyclodextrin Market
Trend One: Application Refinement Over Broad Volume Expansion
Growth will increasingly be driven by formulation upgrades and application-specific demand rather than undifferentiated volume gains. Dextran 40 and Dextran 70 will remain important, but their commercial relevance will depend on clinical acceptance, safety perception, and the availability of improved variants. Dextran 20 is likely to see continued interest where enhanced biocompatibility and surgical utility are valued, especially as regional capacity supports faster availability. For commercial teams, this means that portfolio strategy should prioritize applications with clear clinical justification and documented performance benefits, rather than relying on category-wide tailwinds.
Trend Two: Regional Capacity Build-Out and Logistics Optimization
Regional manufacturing and distribution improvements will become a more visible competitive lever. Investments that shorten delivery times, reduce cold-chain complexity, and improve local service can create meaningful advantages in markets where procurement teams value supply certainty. At the same time, feedstock cost management and fermentation efficiency will remain important for protecting margins. Companies that align capacity investments with demand geography and logistics realities are more likely to convert growth into sustainable profitability.
Trend Three: Regulatory and Reimbursement Discipline as a Market Filter
Regulatory expectations and reimbursement scrutiny will continue to reward disciplined manufacturers. Strict pharmacopoeial monographs and ongoing quality and safety focus will raise the bar for market participation, while reimbursement dynamics will encourage buyers to prioritize value and reliability. This environment favors suppliers with strong documentation, consistent quality, and the ability to articulate clinical and operational value. It also introduces risk for those that depend on commoditized positioning without a clear quality or service advantage.
These trends create tangible commercial opportunities. Manufacturers can pursue differentiated formulations and derivative expansions that align with evolving clinical needs. Investors can look for suppliers with credible regulatory standing, regional service strategies, and cost discipline. Procurement and hospital systems can benefit from suppliers that combine compliance, reliability, and application-specific support. The principal uncertainty lies in the pace of clinical guideline evolution and the degree to which safety considerations continue to shift demand away from certain formulations. Any misstep in quality, availability, or regulatory compliance can quickly erode trust in a market where reputation and consistency are central to purchasing decisions.
Actionable Guidance for Decision Makers
Different stakeholders should focus on distinct priorities, but all share a common need: timely, granular insight into where demand is moving, which formulations are gaining traction, and how competitors are adjusting their capacity and portfolio strategies.
For Manufacturers
- Strengthen formulation differentiation by investing in biocompatibility, derivative development, and application-specific support rather than competing primarily on price
- Align capacity and logistics with regional demand centers to reduce lead times and improve service reliability, especially for sensitive formulations that depend on cold-chain distribution
- Protect margin resilience through disciplined sucrose sourcing, fermentation efficiency, and long-term input cost planning, while maintaining rigorous quality documentation to support regulatory trust
For Investors
- Evaluate companies on regulatory credibility, quality systems, and the ability to sustain compliance across pharmaceutical-grade and excipient applications, since these attributes increasingly determine formulary access and procurement stability
- Assess regional expansion and service capabilities as indicators of competitive positioning, particularly where delivery speed and local availability can influence share in surgical and emergency care settings
- Monitor formulation mix and derivative growth as signals of portfolio health, because reliance on a narrow set of legacy products may expose a business to guideline-driven demand shifts
For Procurement and Hospital Systems
- Prioritize suppliers with strong pharmacopoeial compliance, documented quality consistency, and clear clinical support for the specific applications you use most frequently
- Evaluate total cost of ownership rather than unit price alone, including logistics reliability, cold-chain integrity, and the risk of supply interruption for sensitive formulations
- Track formulation updates and regulatory approvals that affect safety and compatibility, since product-level improvements can materially influence clinical outcomes and procurement decisions
Given the pace of formulation innovation, regulatory refinement, and regional capacity change, decision makers benefit from access to detailed segmentation data, competitor tracking, and scenario-based forecasts that go beyond aggregate market size. The broader market trajectory points toward moderate, disciplined growth, but the real value lies in understanding how share, margins, and application mix are shifting at the segment level. For teams that need deeper segmentation data and customized strategic recommendations, PW Consulting’s full Dextran Market research report provides the detailed breakouts and forward-looking analysis required to translate these trends into concrete business decisions.
For detailed analysis of this topic, please visit the official page: Dextran Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automotive Ambient Lighting Market: Why 10.5% CAGR Signals a $5.9B Design Shift
By PW Consulting, 2026-09-21
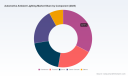
Illuminating the Path: Strategic Shifts and Commercial Opportunities in the Automotive Ambient Lighting Market
Market Architecture and Defining Headwinds
The automotive ambient lighting market has transitioned from a discretionary cabin furnishing element to a structured, technology-intensive segment that now demands dedicated strategic attention. Over the historical period, the market has expanded steadily, building on a multi-year trajectory that reflects both volume growth and rising content per vehicle. Looking ahead through the forecast horizon, the sector is projected to sustain a robust compound annual growth rate, indicating that ambient lighting is becoming a baseline consideration rather than a niche upgrade. This growth is underpinned by broader vehicle production increases, higher trim penetration, and the gradual migration of ambient systems from premium showcases to mass-market platforms.
The current landscape, however, is defined less by simple expansion and more by structural inflection points. Suppliers and OEMs are navigating a period in which volume growth no longer guarantees margin expansion. Several forces are compressing traditional economics and forcing a recalibration of how ambient lighting is sourced, specified, and monetized.
The first challenge is the erosion of unit economics through persistent component price deflation. As LED module pricing continues to decline at a steady annual pace, suppliers must absorb cost reductions while delivering increasingly sophisticated features such as multi-zone control, color accuracy, and seamless OEM integration. The margin structure that once rewarded scale alone is being replaced by a performance-driven model in which differentiation and system-level value capture determine profitability.
Automotive LED Lighting Market
The second challenge is the shifting center of gravity in the passive environment. Interior lighting, once treated as a low-risk styling decision, is now subject to evolving safety and visibility expectations. Regulatory expectations for interior illumination standards are reshaping specification requirements and forcing manufacturers to treat cabin lighting as a compliance-adjacent function rather than an optional aesthetic feature. This creates additional validation cycles, testing burdens, and design constraints that affect both cost and time-to-market.
The third challenge lies in supply chain geography and cost volatility. LED components, substrates, driver electronics, and interconnect materials remain heavily concentrated in a small set of manufacturing regions. That concentration offers scale and maturity, but it also exposes program schedules and bill-of-materials costs to geopolitical friction and tariff escalation. For vehicle assembly operations in North America and Europe, these dynamics can materially alter sourcing strategies and require deliberate redundancy planning rather than single-source reliance.
Four Forces Reshaping the Value Chain
The most consequential force shaping the market is the pace of component and system-level innovation. Ambient lighting is no longer about a single color strip hidden behind a trim panel; it is becoming a coordinated cabin interface that balances aesthetics, perception, and electrical architecture. Intelligent LED driver solutions with integrated color calibration, optimized pulse-width modulation control, and automotive-grade qualification are reducing the complexity of multi-zone implementations. At the same time, these advances allow OEMs to design zonal lighting experiences that are more dynamic, consistent, and easier to calibrate across trims and cabin configurations. This shift is significant because it moves differentiation upstream, away from mechanical placement and toward electronic control, software-defined behavior, and integrated validation.
Policy and regulation are emerging as a parallel driver of change. As interior lighting standards become more explicit for new vehicle types in major markets, ambient lighting is increasingly evaluated through the lens of occupant visibility, glare control, and predictable operational behavior. Compliance expectations do not necessarily eliminate customization; instead, they impose structure on it. Manufacturers that design cabin lighting with regulatory foresight can convert standards into a competitive advantage by building systems that satisfy both aesthetic goals and safety-related performance criteria without re-engineering at the end of the program cycle.
Consumer and commercial demand are also evolving in ways that matter for product strategy. In passenger vehicles, ambient lighting is increasingly tied to perceived quality, brand expression, and cabin personalization. The expectation is not simply that a vehicle has lighting, but that it can deliver a coherent sensory environment across different drive modes, times of day, and user profiles. For light and heavy commercial vehicles, the value case is slightly different: better cabin visibility, improved ergonomic perception, and stronger fleet branding can support operator comfort and brand differentiation. As these expectations mature, ambient lighting is becoming more of a functional and experiential layer than a pure styling add-on.
Cost structure and supply chain dynamics complete the set of core drivers. The combination of declining LED pricing and concentrated component sourcing creates a dual challenge: suppliers must keep innovating to defend margins while also managing exposure to trade policy and logistics risk. That means sourcing architectures are becoming more strategic, with greater attention to regional balance, qualification redundancy, and design flexibility. In practical terms, the market is rewarding participants who can decouple value creation from pure component cost competition and instead offer integrated electrical architecture, validated multi-zone control, and predictable program execution.
PW Consulting Automotive & Machinery Research Center
Competitive Positioning and Landscape Evolution
The competitive environment reflects a mix of established Tier-1 suppliers, lighting specialists, and electronics-focused manufacturers, each pursuing a different angle on cabin illumination. Some players compete by offering fully integrated ambient lighting systems with strong OEM integration and multi-zone capability. Others focus on advanced LED technology and smart control electronics that enable personalization, multi-color effects, and tighter electrical integration. A further group emphasizes precision LED modules and emitter-level innovation, delivering components that meet demanding color calibration, reliability, and automotive qualification requirements. There are also suppliers that embed ambient lighting within broader interior systems, electrical architecture, or full-vehicle module offerings, allowing them to capture value through system-level bundling rather than component-only sales.
The differentiation that matters most is shifting from lamp count or color variety toward integration confidence and system performance. Players with strong competency in driver ICs, calibrated color behavior, and EMC-optimized control are gaining leverage because they simplify OEM design work and reduce validation risk. Suppliers that can deliver ambient solutions as part of a broader interior or electrical integration package also enjoy an advantage in programs where packaging, harness strategy, and controller architecture must be solved together. On the other end of the spectrum, manufacturers that compete primarily on volume hardware without a clear integration or electronics advantage face increasing pressure as pricing continues to compress.
The landscape is evolving along several identifiable directions. One is consolidation of capability, where OEMs and Tier-1 suppliers favor partners that can reduce the number of distinct integration points across the cabin. Another is increasing specialization at the component and electronics level, especially around intelligent drivers and calibrated emitters that make multi-zone implementations more practical. At the same time, new entrants and expanding incumbents are exploring adjacent opportunities in optical design, software-controlled lighting behavior, and cabin experience personalization. The result is a market that is not simply becoming more crowded, but more functionally layered, with competition intensifying around integration depth, validation reliability, and the ability to support both premium customization and high-volume repeatability.
Forward Outlook: Three Trends That Will Shape the Next Cycle
The next several years are likely to be defined by a move toward more software-influenced cabin lighting strategies. As intelligent control components and multi-zone architectures mature, ambient lighting will increasingly support adaptive color, mode-based scenes, and more refined calibration across vehicle variants. This trend opens commercial opportunities for suppliers that can offer configurable lighting behavior without adding undue complexity to the electrical architecture. It also creates value for OEMs seeking distinct cabin identities without engineering a separate hardware stack for each trim. The strategic implication is that ambient lighting will become more of a configurable experience platform than a static part number, rewarding players who can balance flexibility with production discipline.
A second trend is the continued integration of ambient lighting into broader interior and electrical system strategies. Cabin illumination is increasingly considered alongside dashboard lighting, console illumination, footwell effects, door ambient features, and center console aesthetics as part of a unified interior experience. That integration encourages suppliers to think in terms of system reliability, connector strategy, thermal behavior, and validation coverage rather than isolated decorative strips. For procurement and program teams, it means ambient lighting decisions should be made with visibility into overall interior architecture, because late-stage changes in one zone can cascade into control logic, packaging, and cost across adjacent areas.
A third trend is the growing importance of supply chain resilience and regional sourcing balance. As tariff exposure and component concentration remain salient concerns, manufacturers will place greater value on partners who can provide supply continuity, transparent cost structures, and flexible qualification footprints. This trend favors suppliers with credible alternatives, disciplined program management, and the ability to maintain performance while adapting to changing trade and logistics conditions. The commercial opportunity lies in making ambient lighting programs less sensitive to single-point disruptions and more capable of meeting predictable cost and timing targets across multiple vehicle programs.
These trends carry inherent risks. Over-customization can increase validation burden and complicate cost control. Regulatory evolution may require recalibration of lighting performance assumptions, particularly where interior standards continue to tighten. And if pricing pressure persists without offsetting value capture through integration, electronics, or service-level differentiation, the market can reward scale while penalizing undifferentiated hardware suppliers. Navigating these risks will require discipline in architecture choices, sourcing strategy, and the pace at which customization is introduced into high-volume programs.
Strategic Actions for Different Decision-Makers
For manufacturers and Tier-1 suppliers, the priority should be to shift competitive positioning from component price to system and integration value. That means investing in control electronics, calibration reliability, multi-zone feasibility, and validated integration paths that reduce OEM development friction. Suppliers that can demonstrate predictable performance across zones, lower validation rework, and clearer electrical architecture integration will be better placed to defend margins even as individual component costs continue to decline. It is equally important to build sourcing resilience, not as a reactive hedge but as a planned element of program design, so that trade and logistics volatility does not become a recurring margin leak.
For investors, the more useful lens is value capture rather than headline volume. The strongest commercial prospects are likely to be found where suppliers combine intelligent control, qualification maturity, and integration relevance with credible cost discipline. Investments in companies that can support software-influenced cabin lighting, reduce fragmentation in OEM programs, and manage supply chain exposure may be better aligned with the next phase of market growth than exposure to undifferentiated LED hardware alone. Evaluating portfolio exposure should also account for how regulation, trade policy, and component concentration could affect regional program economics over the forecast period.
Automotive Lighting Market
For procurement and OEM program teams, the strategic task is to manage ambient lighting as a system decision rather than a late-stage styling add-on. Early alignment on zones, control architecture, color calibration expectations, and interior integration can prevent costly rework and improve the odds of consistent cabin experience across variants. Procurement strategies should also explicitly address sourcing diversity and tariff sensitivity, because the cost and continuity of ambient lighting programs are increasingly tied to the broader electrical and optical supply base. Treating cabin lighting decisions in isolation tends to create downstream risk; treating them as part of the interior and electrical plan tends to create more predictable outcomes.
For decision-makers seeking sharper segmentation detail, competitive benchmarking, pricing sensitivity analysis, and region-specific program implications, more comprehensive market research can provide the additional granularity needed to translate these trends into operational plans. Deep-dive coverage that breaks down component, vehicle-type, and regional dynamics in greater detail supports more precise scenario planning and more confident sourcing or investment decisions. In a market where margin creation depends on integration, qualification, and supply chain resilience, timely access to structured intelligence can make the difference between reacting to change and shaping it.
For detailed analysis of this topic, please visit the official page: Automotive Ambient Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Metal Cutting Fluids Market: Why 3.7% CAGR Acceleration Through 2032 Redefines Competitive Strategy
By PW Consulting, 2026-09-21
The Metal Cutting Fluids Market: Navigating the Strategic Crossroads
The global metal cutting fluids market has reached a pivotal inflection point. With the market valued at approximately USD 158.0 million in 2025 and projected to grow to USD 202.06 million by 2032, the sector is expanding at a compound annual growth rate of 3.7 percent. This trajectory reflects a mature yet dynamically evolving landscape where incremental volume growth must be balanced against mounting structural pressures. Historical data shows consistent expansion from USD 121.85 million in 2020, underscoring steady demand anchored in traditional machining and metalworking activities. Yet the forward-looking period introduces complexity: growth is no longer a simple function of industrial output. It is increasingly mediated by regulatory shifts, formulation innovation, supply chain volatility, and the strategic choices of dominant players who collectively command significant market share. For executives, investors, and procurement leaders, the central question is no longer whether the market will expand, but how value will be captured amid transforming operational and compliance realities.
Market Snapshot and Defining Characteristics
The current market environment is defined by moderate, predictable growth that masks deeper structural recalibration. Pricing power remains constrained by cost transparency and buyer scrutiny, while volume expansion is unevenly distributed across industrial regions and application segments. The competitive landscape exhibits meaningful concentration, with the top three players controlling roughly 57 percent of industry revenue and the top five capturing approximately 68 percent. This consolidation pattern signals entrenched supplier relationships, high switching costs for end-users, and the financial weight required to sustain innovation, technical service networks, and regulatory compliance programs. At the same time, the market’s growth cadence hints at emerging friction points. Certain forecast intervals show marginal deceleration, suggesting that traditional volume-driven expansion is encountering headwinds from material costs, formulation restrictions, and shifts in machining intensity across key end-use sectors.
Key Challenges and Inflection Points
Three interconnected challenges are reshaping how participants compete and how buyers evaluate fluid programs. First, environmental and occupational safety regulations are accelerating reformulation cycles. Restrictions on certain chlorinated paraffins and intensifying scrutiny of chemical exposure are compelling manufacturers to redesign formulations, validate alternative additive packages, and manage the operational disruption that accompanies product transitions. Second, raw material volatility continues to pressure margins. Base oil and specialty additive pricing remains sensitive to crude oil production cycles and geopolitical instability, making cost forecasting and contract structuring more difficult for both suppliers and industrial consumers. Third, the economics of spent fluid management are becoming a shared burden. Disposal requirements governed by environmental frameworks such as the U.S. Resource Conservation and Recovery Act and EU waste directives are elevating the total cost of ownership for cutting fluid programs, pushing manufacturers and end-users alike to consider longer fluid life, easier separation, and circular handling practices. Together, these factors are shifting competitive advantage away from pure price competition and toward reliability, compliance, and lifecycle efficiency.
Metal Cutting Tools Market
Innovation as a Core Growth Lever
Technological progress is redefining what metal cutting fluids must deliver. Modern machining environments increasingly demand fluids that can manage heat, protect tooling, and maintain surface quality under higher speeds, heavier loads, and more aggressive cutting parameters. This has elevated the strategic importance of advanced synthetic and water-miscible formulations with enhanced lubricity, improved stability, and better compatibility with diverse metal substrates. Equally significant is the rise of fluid management systems that integrate real-time monitoring, analytics, and concentration control. By moving from periodic manual checks toward continuous visibility, operators can reduce overuse, maintain consistent performance, and extend service intervals. These capabilities are not merely incremental improvements; they directly influence tooling costs, downtime, and waste generation. In an environment where manufacturing productivity is under constant pressure, fluid performance and fluid management are becoming inseparable elements of process optimization.
Regulatory and Sustainability Forces Reshaping Formulation Strategy
Policy and compliance dynamics are now central to product planning rather than peripheral considerations. Regulatory attention on chemical safety, worker exposure, and disposal obligations is pushing the industry toward more environmentally acceptable alternatives. Reformulation is no longer a reactive exercise; it is a strategic investment that affects performance validation, customer acceptance, and supply chain readiness. At the same time, sustainability expectations are extending beyond compliance. Industrial buyers are increasingly interested in fluids that support safer workplaces, reduce hazardous waste, and align with broader environmental goals without compromising process results. This dual pressure—regulations on one side and corporate sustainability objectives on the other—is creating a differentiation opportunity for suppliers that can demonstrate credible performance, transparent composition, and practical disposal or recovery pathways.
Demand-Side Shifts in Metalworking and Manufacturing
Demand is being reshaped by how manufacturers organize production and manage cost. Metalworking operations continue to be a primary consumption base, while automotive and general manufacturing segments remain substantial users of cutting and forming fluids. However, the character of demand is changing. Many producers are prioritizing process consistency, tool life, and surface finish over nominal fluid cost, particularly where high-value components and precision machining are involved. There is also growing interest in fluids that can support flexible production schedules, reduce maintenance interruptions, and simplify plant handling. As a result, purchasing decisions are increasingly influenced by operational reliability and total program cost rather than by initial price per unit alone. This shift favors suppliers that can provide technical support, application guidance, and robust performance validation alongside product supply.
Supply Chain Volatility and Cost Structure Realignment
The cost structure of metal cutting fluids is exposed to multiple external forces, making supply chain resilience a competitive necessity. Base oil pricing fluctuates with broader energy markets, while additives and specialty intermediates introduce additional variability. These dynamics affect not only supplier margins but also the predictability of customer operating costs. Companies that can stabilize input costs through forward contracting, reformulated value tiers, or smarter inventory management gain an advantage in a market where price shocks can disrupt procurement plans. On the buyer side, the response has been to seek greater transparency, longer-term agreements with defined adjustment mechanisms, and fluid programs designed to reduce waste and overuse. In practice, this means the commercial conversation is moving toward shared risk management and lifecycle economics rather than transactional spot purchasing.
Metal Working Fluids (Metalworking Fluids) Market
Competitive Landscape and Strategic Positioning
The market’s leadership group reflects a mix of global industrial fluid specialists, major energy and chemical companies, and focused specialty formulators. Each brings a different strategic posture. Quaker Houghton operates with a broad industrial process fluids footprint spanning water-based and synthetic solutions, metal removal fluids, and fluid management systems, supported by a strong presence in automotive, aerospace, and heavy equipment applications. Its recent acquisition activity illustrates a deliberate consolidation strategy aimed at expanding geographic reach and application coverage. In March 2025, the company acquired Dipsol Chemicals Co., Ltd., a supplier of surface treatment and plating solutions primarily serving automotive and industrial markets. In April 2025, it completed two additional acquisitions: Natech, Ltd., a UK-based metalworking fluids and lubricants supplier, and Chemical Solutions & Innovations (Pty) Ltd., a South African provider in the same category. These moves extend regional service capability and broaden the technology and customer base. Later in September 2025, Quaker Houghton commercialized QH Fluid Intelligence 2.0, a fluid management system driven by real-time analytics, signaling an intent to compete not only on formulations but also on operational visibility and process control.
ExxonMobil maintains a strong position through high-performance synthetic water-miscible fluids, most notably the Mobilcut™ series, which emphasizes enhanced lubricity additives for a wide range of metals. Its September 2025 product launch introduced an advanced line of synthetic metalworking fluids engineered for heavy-load, high-speed machining, reinforcing a strategy centered on extreme-condition performance and application-specific engineering. BP, through its Castrol portfolio, continues to supply branded metal cutting fluids and lubricants tailored for metal removal operations in automotive and industrial sectors, leveraging brand recognition and broad distribution channels. TotalEnergies complements this profile with an integrated energy company heritage and a dedicated metalworking fluid portfolio that includes cutting oils and coolants for industrial machining. FUCHS PETROLUB SE offers a comprehensive range of water-based, semi-synthetic, and synthetic cutting fluids for machining and metal forming, positioning itself as a full-spectrum specialty chemical producer. Blaser Swisslube AG focuses on high-performance cutting and forming fluids across multiple industries, while Idemitsu Kosan Co., Ltd. serves automotive and industrial metalworking applications with advanced fluids and lubricants. The Lubrizol Corporation contributes additive systems and complete formulations, emphasizing formulation science and customization. Valvoline Inc. extends its reach into metalworking through product lines such as Erozol for cutting, forming, and metal processing. Master Fluid Solutions formulates specialty water-soluble and neo-synthetic fluids, including TRIM products for aerospace and hard metal machining. Tower Metalworking Fluids provides advanced lubricants and cooling-focused formulations, such as SAF-T-VANISH, for rust prevention and metal forming and cutting. Petrofer GmbH has built a long-standing reputation around tool life extension, surface finish, and sustainable solutions. Schaeffer Manufacturing Company supplies heavy-duty fluids for drilling, cutting, forming, and shaping operations. Halocarbon expanded its presence with three advanced metalworking fluid formulations under its InfinX line, made available through its e-commerce platform in December 2025, reflecting a push toward direct digital distribution and product accessibility.
Consolidation, Differentiation, and the New Entry Calculus
The dominant strategic theme across the competitive set is differentiation through capability rather than scale alone. Leaders are building advantage along several axes: application-specific performance, fluid management and analytics, regional service density, formulation science, and compliance readiness. The acquisition activity led by Quaker Houghton demonstrates how inorganic growth is being used to compress geographic gaps, deepen application coverage, and strengthen service continuity for multinational and regional customers. At the same time, product launches from ExxonMobil and Halocarbon suggest parallel efforts to capture demand for higher-performance formulations and more accessible purchasing channels. The market is not fragmenting into low-cost commodity competition; rather, it is stratifying into tiers where performance, technical service, and regulatory compliance determine positioning. New entrants face meaningful barriers because success requires formulation expertise, validation capability, distribution reach, and the financial stamina to navigate raw material volatility and regulation-led reformulation cycles. Consequently, the most plausible disruptive pressure will come less from brand-new players and more from specialized formulators that can target underserved applications, advanced machining requirements, or sustainability-oriented programs with differentiated value propositions.
PW Consulting
Near-Term Trajectory: Three Forces Shaping the Next 3–5 Years
The next few years are likely to be shaped by the convergence of performance, compliance, and digital management. First, high-performance synthetic and water-miscible fluids will continue to gain relative importance where machining intensity, precision requirements, and tool life concerns are acute. These formulations will be increasingly paired with monitoring and control systems that help manufacturers stabilize concentration, reduce waste, and maintain consistent process conditions. The commercial implication is that fluid programs will be evaluated more like engineered process solutions than consumable inputs. Second, regulatory pressure will keep pushing reformulation and disposal management into core product planning. Suppliers that can provide credible, lower-hazard alternatives while preserving performance will be better positioned to retain and expand share, especially in regions with strict chemical and waste frameworks. Third, cost volatility will encourage more structured procurement and greater emphasis on total cost of ownership. Buyers will seek formulations and management approaches that reduce overuse, extend life, and simplify handling, while suppliers will look for greater supply chain flexibility and clearer pricing mechanisms. These forces together point toward a market where value accrues to participants that can integrate product performance with operational efficiency and compliance confidence.
Associated Opportunities and Residual Risks
The clearest opportunity lies in transforming fluid supply from a transactional category into a managed performance partnership. Suppliers that combine advanced formulations with real-time management tools, technical service, and credible sustainability attributes can unlock differentiated pricing and longer customer retention. End-users that adopt disciplined fluid management can reduce downtime, extend tool life, and lower waste handling costs, thereby improving overall process economics. A second opportunity emerges in regional market development, where service density, localized formulation support, and responsive supply can create durable advantages in segments that are underserved by global portfolios. At the same time, uncertainty persists. Regulatory interpretations may evolve faster than formulation and validation cycles, creating transition risk for both suppliers and buyers. Raw material price swings can compress margins or disrupt contract stability if not managed with transparent mechanisms. There is also execution risk in scaling digital management tools across diverse plant environments, where integration complexity and change management can slow adoption. Participants that treat these uncertainties as manageable variables rather than external shocks will be better equipped to convert market growth into sustainable advantage.
Actionable Directions for Decision-Makers
Manufacturers and machining operations should reassess fluid programs as part of broader process strategy rather than as a standalone procurement line. This means evaluating formulations for performance under actual operating conditions, considering fluid management systems that provide concentration and condition visibility, and incorporating disposal and handling costs into total cost assessments. Suppliers and formulators should prioritize application-specific validation, compliance transparency, and service continuity, while pursuing selective geographic or application expansion that reinforces differentiation. Procurement leaders should shift negotiation focus toward lifecycle economics, quality consistency, and risk sharing, using longer-term agreements with clearly defined adjustment mechanisms where appropriate. Investors evaluating exposure to this market should look beyond headline growth and assess which participants have durable formulation capabilities, credible management-tool platforms, and the balance-sheet flexibility to absorb volatility while investing in compliance and innovation. In a market where competitive outcomes depend on technical reliability, regulatory readiness, and operational integration, timely access to detailed segmentation data, company-level case evidence, and scenario analysis can materially improve strategic choices. The full study provides that granularity, enabling stakeholders to map growth by region and application, compare formulation and service strategies in greater depth, and align investment or procurement decisions with a clearer view of where value is likely to concentrate through 2032.
For detailed analysis of this topic, please visit the official page: Metal Cutting Fluids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
MVR Compressor Market: How Asia Pacific’s 5.6% CAGR Redefines Global Growth
By PW Consulting, 2026-09-21
MVR Compressor Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The mechanical vapor recompression (MVR) compressor market has entered a phase of sustained expansion, with global revenue surpassing $1 billion in 2025 and continuing to climb through the end of the decade. The trajectory reflects a compound annual growth rate of 5.6 percent across the forecast horizon, signaling steady demand rather than cyclical spikes. This growth pattern emerges from a combination of long-term capital planning in process industries and accelerating adoption of energy-recovery systems that reduce reliance on external utilities.
PW Consulting
Historical progression reveals a market that rebounded decisively after a brief contraction in 2023, when revenue dipped before regaining momentum. The 2024 to 2025 period delivered the strongest consecutive gain in recent years, driven by replacement cycles, greenfield installations, and stricter thermal-efficiency expectations across chemical, pharmaceutical, and food-processing sectors. By 2026, the market crosses into a higher revenue tier, and the upward slope remains intact through 2032, positioning MVR compressors as a structural component of industrial energy management rather than a niche optimization tool.
Despite the constructive outlook, three challenges shape how quickly value can be captured across the value chain. The first is intensifying efficiency expectations. Operators no longer treat MVR compressors as passive heat-recovery equipment; they demand a higher share of latent heat reuse, lower parasitic losses, and tighter integration with upstream and downstream separation units. Compressors that fall short of these benchmarks face displacement during retrofit cycles or lose out in competitive bids for new facilities.
The second challenge is material and fabrication complexity. High-speed impellers and housings must withstand corrosive condensates, thermal cycling, and sustained rotational loads. Specifications increasingly call for specialized stainless steels, titanium alloys, nickel-based superalloys, and advanced ductile alloys. Sourcing these materials with consistent metallurgical quality and managing fabrication tolerances adds cost and lead-time pressure, particularly for large-diameter or custom-configured units.
The third challenge lies in integration and lifecycle economics. An MVR compressor delivers value only when it is correctly matched to the evaporation temperature, vapor composition, and downstream process constraints. Misalignment leads to underperformance, higher maintenance burdens, and compromised energy savings. This dynamic is pushing buyers toward suppliers that can offer more than rotating equipment, favoring partners capable of system-level design, commissioning support, and long-term service arrangements.
Together, these forces are reshaping procurement logic. Buyers evaluate total steam and electricity consumption, not just headline compressor price. Manufacturers respond with higher-efficiency rotor designs, modular system architectures, and closer coupling of compressors with thermal separation skids. The result is an environment where competitive advantage increasingly depends on engineering depth and integration capability, not just production scale.
Key Drivers Shaping the Market
Technology Innovation and Efficiency Gains
Advancements in rotor aerodynamics, bearing systems, and sealing technologies are steadily lifting compressor efficiency and expanding the range of viable operating conditions. Modern MVR configurations increasingly rely on precision impeller geometries, improved surface treatments, and optimized flow paths that reduce internal recirculation and friction losses. These improvements translate directly into lower external energy requirements, which remains the central economic case for MVR adoption.
Efficiency has become a multi-dimensional race. Some suppliers emphasize specialized blower and compressor platforms designed for high thermal recovery rates, while others focus on material and impeller variations that extend service life under aggressive process conditions. The competitive edge is shifting toward designs that maintain stable performance across variable vapor loads and tolerate contaminants more effectively. This is particularly relevant in applications where condensate quality fluctuates or where occasional carryover places additional stress on rotating components.
At the same time, integration engineering is maturing. Suppliers are bundling compressors with evaporators, crystallizers, and control systems to reduce design risk for end users. This trend lowers the barrier to adoption for operators that lack in-house thermal-separation expertise and accelerates project timelines by minimizing interface complexity. As a result, technology leadership is no longer defined solely by the compressor itself, but by the ability to deliver a reliable, pre-engineered thermal process module.
Policy and Regulatory Environment
Energy-efficiency mandates and decarbonization expectations are strengthening the commercial case for MVR technology across multiple industries. Regulatory frameworks and internal sustainability targets are pressuring manufacturers to reduce fossil-based steam consumption, cut electricity intensity, and improve overall thermal productivity. MVR systems address these objectives by recirculating latent heat within the process, which directly reduces utility demand and lowers operating expenditure over the asset lifecycle.
The policy environment is also indirectly shaping technology preferences. Facilities facing stricter emissions reporting and energy audits are prioritizing equipment that delivers measurable, verifiable efficiency gains. This favors MVR compressors with documented performance curves, robust instrumentation, and predictable maintenance profiles. In turn, suppliers are investing more in application documentation, commissioning data, and lifecycle service packages to support compliance-related decision-making.
Demand-Side Shifts in Process Industries
Demand for MVR compressors is being reinforced by broad changes in how process plants are designed and operated. Pharmaceutical, chemical, food, and beverage manufacturers are increasingly seeking closed-loop evaporation and concentration solutions that minimize solvent loss, protect product quality, and stabilize operating costs. In many cases, these objectives align with the core strengths of MVR technology, particularly where low-temperature evaporation and gentle thermal handling are critical.
A notable demand-side development is the expansion of MVR relevance into emerging industrial applications beyond traditional evaporation and drying. Carbon capture and utilization projects, for example, are creating new compressor requirements where CO2-rich streams must be handled with materials compatible with specific gas chemistries and operating pressures. This diversifies the addressable market and introduces new specification priorities, including material compatibility, sealing integrity, and process control robustness. Customized thermal separation solutions are also gaining traction in regions where local operating conditions, utility costs, and labor constraints make standardized equipment less attractive.
From a buyer behavior perspective, procurement cycles are becoming more strategic. Operators are planning MVR installations alongside broader plant modernization programs, which means compressor selection is increasingly evaluated in the context of long-term energy budgets, expansion plans, and process flexibility. This creates stronger demand visibility for vendors that can align equipment offerings with multi-year capital roadmaps.
Supply Chain and Cost Structure Dynamics
Cost structures in the MVR compressor market are influenced by material availability, specialized manufacturing capacity, and the economics of high-performance alloys. Impeller fabrication and precision machining remain concentrated in environments that can maintain tight tolerances and consistent metallurgical quality. Fluctuations in alloy pricing, along with lead-time variability for specialized grades, can affect project scheduling and margin management for both equipment makers and system integrators.
At the same time, regional manufacturing footprints are becoming more relevant to cost and responsiveness. Local production and application engineering can shorten delivery timelines, simplify after-sales support, and improve alignment with regional design preferences. This is especially important where large-scale industrial projects require closely coordinated supply, installation, and commissioning. Suppliers that can balance global technical capability with regional execution are better positioned to manage total installed cost and project risk.
Cost dynamics are also being reshaped by service and digital support models. Predictive maintenance, performance monitoring, and remote diagnostics can reduce unplanned downtime and help operators sustain efficiency over time. While these capabilities add upfront complexity, they can improve the economic calculus of MVR adoption by protecting the long-term value of the equipment and reducing hidden operating costs.
A practical illustration of how demand-side expansion is translating into commercial activity is the recent sign of contract activity linking MVR compressors to carbon-related industrial projects in Europe. Such developments indicate that the market is broadening beyond traditional thermal separation use cases and that suppliers with specialized gas-handling capabilities are gaining incremental relevance. This kind of application diversification reinforces the view that MVR compressors will continue to find new demand pockets even as core evaporation and crystallization markets mature.
Competitive Landscape and Leading Strategies
The competitive environment is moderately concentrated, with a limited group of established players capturing a substantial share of high-value projects. This structure reflects the technical barriers to entry associated with high-speed rotating equipment, specialized materials, and system integration. It also means that differentiation is heavily dependent on technology pedigree, application expertise, and the ability to support complex installations from design through commissioning.
One clear competitive theme is technology specialization. Several leading suppliers have built reputations around specific efficiency claims, rotor technologies, or product platforms that emphasize thermal recovery performance. These vendors compete by demonstrating measurable efficiency advantages, broad global installation references, and application support that reduces operational risk. Their strategic positioning tends to center on reliability, proven field performance, and the ability to match equipment behavior to demanding process conditions.
Another theme is material and application versatility. Some manufacturers differentiate by offering impeller options in stainless steel, titanium, and special alloys, allowing them to adapt to more corrosive or chemically challenging service. This flexibility broadens the addressable opportunity and supports projects where standard materials would not meet longevity or compliance expectations. In parallel, a subset of suppliers focuses on fully integrated compression systems that pair compressors with evaporators and crystallizers, reducing interface complexity and helping customers achieve a more streamlined installation.
Regional strength and customization capability also shape competition. Leading Indian and Chinese manufacturers have expanded their presence by offering customized thermal separation solutions and localized engineering support. Their approach often emphasizes application-specific configuration, shorter response times, and cost-effective delivery for regional projects. This reflects a broader market trend in which end users increasingly value partners who can tailor equipment to local operating conditions and provide ongoing service within the same geography.
A further competitive vector is application expansion into new industrial domains. Some suppliers are positioning themselves around specialized compression needs tied to carbon management and other emerging process streams. This direction allows them to move beyond saturated traditional segments and capture projects where gas composition, pressure requirements, and material compatibility create a more bespoke engineering challenge. Such moves indicate that competitive differentiation is increasingly linked to the breadth of application coverage as much as to core compressor performance.
Looking at market evolution, the landscape appears to be moving along two parallel paths. One is consolidation of technical authority among suppliers that can deliver high-efficiency rotating equipment, specialized alloys, and integrated system designs. The other is fragmentation of application-specific niches, where regional manufacturers and specialized engineering firms compete by customizing solutions for local industries and project types. New entrants are most likely to succeed where they bring a clear technical angle, such as a distinct efficiency claim, a differentiated material strategy, or a strong regional service model, rather than competing solely on volume.
In practice, the winning strategy is becoming more holistic. Suppliers that combine efficiency, material flexibility, system integration, and regional execution are better equipped to secure large contracts and retain long-term service relationships. Buyers, in turn, are placing greater weight on reference installations, commissioning support, and lifecycle economics, which raises the stakes for manufacturers that rely on product-only positioning.
Worldwide Barrel Compressor Market
Future Trends and Commercial Implications
Over the next three to five years, the MVR compressor market is likely to be shaped by a small number of reinforcing trends that carry clear commercial implications.
The first trend is the continued prioritization of efficiency and integration as a bundled value proposition. Demand will increasingly favor suppliers who can demonstrate that their compressors reduce external energy requirements while fitting cleanly into the broader process train. This means more emphasis on pre-engineered module configurations, application-specific performance data, and service agreements that protect long-term efficiency. For manufacturers, the opportunity lies in packaging mechanical performance with engineering support and for buyers, the opportunity lies in selecting equipment that simplifies operation rather than adding integration risk.
The second trend is application diversification beyond conventional evaporation and drying. As industrial projects expand into carbon management, specialty chemical processing, and other streams with specific gas and material requirements, MVR compressor demand will gain additional drivers. This diversification can create higher-margin opportunities for suppliers with the right material expertise and process knowledge, but it also raises the bar for qualification, testing, and field validation. Projects in these areas may require more customized engineering, which can improve differentiation but also lengthen sales cycles.
The third trend is the growing importance of regional execution and lifecycle service. As projects become more distributed and operating teams more cost-conscious, local manufacturing, commissioning capability, and responsive after-sales support will become stronger competitive differentiators. Suppliers that can reduce lead-time risk, simplify spare-parts logistics, and deliver localized engineering will be better positioned to win repeat business. At the same time, operators will increasingly judge MVR investments through total cost of ownership, making service quality and reliability central to commercial success.
These trends carry both upside and uncertainty. The upside is that efficiency mandates, process modernization, and application expansion create a durable demand base for high-performance MVR compressors. The uncertainty lies in material price volatility, specialized manufacturing bottlenecks, and the risk that some projects may be delayed or redesigned if integration challenges are underestimated. In addition, application diversification may introduce new specification complexity that only a subset of suppliers can manage effectively. Companies that prepare for this mix of opportunity and volatility will be better placed to capture value as the market matures.
Mechanical Vapor Recompression (MVR) Evaporators Market
Actionable Recommendations for Decision-Makers
For Manufacturers and Technology Providers
Focus on the intersections where efficiency, material adaptability, and integration support reinforce one another. Investments in rotor and sealing technologies that improve efficiency under variable loads can strengthen competitive positioning, especially when paired with clear application documentation. Equally important is expanding the ability to specify and supply suitable alloy options for demanding service conditions without compromising lead times or quality consistency. Manufacturers should also treat integration support and commissioning capability as core products, because buyers are increasingly selecting partners who can reduce design risk and protect long-term performance.
For Investors and Strategic Allocators
Evaluate exposure to MVR compressor demand in the context of broader energy-efficiency and process-modernization spending, rather than treating it as a stand-alone equipment cycle. The most resilient opportunities are likely to appear where suppliers combine technical differentiation with regional execution and where end-use applications extend beyond mature evaporation segments into newer industrial needs. When assessing companies, look for evidence of recurring service revenue, strong reference bases, and the capability to address specialized material and gas-handling requirements. Diversification into application-specific niches can be attractive, but only if supported by engineering depth and qualification readiness.
For Procurement and Plant Operators
Structure evaluation around total operating impact, not just initial capital cost. The most valuable MVR compressor choices are those that align with the actual vapor conditions, material environment, and integration constraints of the plant. Prioritize suppliers that can provide credible performance data, realistic commissioning support, and a clear service pathway over the asset life. Where projects involve non-standard gas compositions or aggressive process conditions, request explicit material and sealing strategies rather than assuming standard configurations will suffice. Early engagement with suppliers during process design can reduce integration risk and improve the economics of the installed system.
Strategic decisions in this market increasingly depend on detailed understanding of application mix, regional dynamics, material specifications, and the service models that protect long-term value. Decision-makers seeking deeper segmentation, company-level positioning, and customized scenario analysis will benefit from more granular intelligence that maps these variables to their own project pipelines and investment priorities.
For detailed analysis of this topic, please visit the official page: MVR Compressor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Infusion Pump Software Market Forecast: Digital Healthcare Innovation, Trends, and Market Opportunities 2026–2032
By preeti mmr, 2026-09-21
Market Overview
The Infusion Pump Software Market was valued at approximately USD 1.14 billion in 2025 and is expected to reach nearly USD 1.89 billion by 2032 , registering a CAGR of 7.27% during the forecast period from 2026 to 2032 . The market is experiencing steady expansion as healthcare providers increasingly adopt software-enabled infusion systems designed to improve medication accuracy, patient safety, clinical workflow efficiency, and connectivity across healthcare environments.
Request Sample Link for More Details: https://www.maximizemarketresearch.com/request-sample/164151/
Infusion pump software is an essential component of modern infusion systems used to administer medications, nutrients, fluids, insulin, chemotherapy drugs, analgesics, and other therapies at controlled and programmable rates. Modern software platforms can manage pumping parameters, drug libraries, dose limits, alarm functions, user interfaces, clinical workflows, and data exchange with hospital information systems.
The growing adoption of smart infusion pumps is transforming traditional infusion practices. Healthcare organizations are increasingly moving toward systems that combine infusion hardware with dose error reduction software (DERS), interoperability capabilities, analytics, and electronic medical record connectivity. These developments are supporting more standardized medication administration while reducing reliance on manual programming.
The market is also benefiting from increasing healthcare expenditure, expansion of hospital infrastructure, rising chronic disease prevalence, and growing demand for technology-enabled medication management. In addition, the movement of certain infusion therapies from hospitals toward ambulatory and home-care environments is creating opportunities for software developers to design more flexible and remotely manageable infusion platforms.
Market Drivers and Trends
Growing Demand for Advanced Infusion Pump Software
The increasing adoption of smart infusion pumps is one of the major factors supporting the growth of the infusion pump software market. Healthcare providers are placing greater emphasis on medication safety and accurate intravenous drug administration. Software-enabled pumps can incorporate drug libraries, hard and soft dose limits, clinical alerts, and standardized programming protocols.
Request Sample Link for More Details: https://www.maximizemarketresearch.com/request-sample/164151/
Dose Error Reduction Software has become particularly important because it can help healthcare professionals identify potentially unsafe infusion settings before medication administration. Hospitals are increasingly integrating these capabilities into medication safety programs, particularly in intensive care, oncology, anesthesia, pediatrics, and other high-acuity settings.
Continuous development of software engineering, verification methods, simulation technologies, and model-based development is also supporting innovation. Manufacturers and technology providers are investing in testing and validation processes designed to improve software reliability and usability.
Increasing Prevalence of Chronic Diseases
The rising prevalence of chronic diseases is another important growth factor. Conditions such as cancer, diabetes, neurological disorders, and other long-term diseases often require repeated or continuous medication administration.
Infusion pumps allow healthcare professionals to administer medications and fluids at precisely programmed rates, making them valuable in chemotherapy, insulin therapy, pain management, critical care, and other applications. As the number of patients requiring long-term treatment increases, demand for reliable infusion systems and associated software is expected to rise.
The aging population is also contributing to demand for chronic disease management and long-term care services. This trend is encouraging healthcare organizations to explore infusion technologies that can support treatment outside conventional hospital environments.
Rising Demand for Ambulatory and Home Infusion
The shift toward ambulatory and home-based healthcare is creating additional opportunities for the infusion pump software market. Ambulatory infusion pumps can support chemotherapy, pain management, total parenteral nutrition, and other therapies while allowing patients to receive treatment outside traditional inpatient settings.
Healthcare providers are increasingly exploring site-of-care models that can reduce hospital utilization and provide greater flexibility for patients. This transition is encouraging manufacturers to develop software that supports portable pumps, remote monitoring, simplified interfaces, connectivity, and data management.
Increasing Interoperability and Connected Healthcare
Interoperability is emerging as an important trend in infusion pump software. Integration with EMR and EHR systems can enable infusion information to move between connected clinical systems, helping reduce manual data entry and improving documentation.
Connected infusion platforms can also support centralized drug library management, device fleet monitoring, analytics, maintenance management, and enterprise-wide standardization. As hospitals modernize their digital infrastructure, demand for interoperable infusion software is expected to increase.
Primary Market Constraints
Stringent Regulatory Requirements
Stringent regulatory requirements represent a major challenge for infusion pump software manufacturers. Because infusion systems directly influence medication administration, software development, validation, cybersecurity, usability, and quality assurance must comply with extensive regulatory and safety requirements.
The lengthy development and approval process can increase costs and delay commercialization of new software-enabled infusion technologies. Manufacturers must also continuously update their products to address identified software vulnerabilities, usability concerns, safety issues, and changing regulatory expectations.
Product Recalls and Software-Related Safety Concerns
Software errors, programming issues, alarm-related problems, and manufacturing defects can negatively affect the adoption of infusion technologies. Historical product recalls involving infusion pumps and drug-library systems have highlighted the importance of comprehensive software validation and quality control.
The complexity of modern infusion pump interfaces can also create usability challenges. Incorrect programming or incomplete configuration may increase the risk of medication administration errors. As a result, manufacturers are increasingly focusing on human-centered design, usability testing, verification, and continuous software improvement.
Market Opportunity
Increasing R&D for Home Infusion Systems
The growing cost of hospital-based care and the increasing number of patients requiring long-term therapies are creating opportunities for home infusion software. Manufacturers are investing in technologies that can support portable infusion devices, remote monitoring, connectivity, and simplified patient interfaces.
The expansion of home healthcare, specialty infusion centers, and ambulatory treatment models is expected to create new demand for software capable of managing infusion data across multiple care environments.
The market also presents opportunities through cloud-based deployment, analytics, cybersecurity, artificial intelligence-supported monitoring, and interoperability with healthcare information systems. These technologies can help healthcare organizations manage larger fleets of connected infusion devices while improving visibility into performance and medication administration.
Key Market Segments
By Software Type
Based on software type, the market is segmented into Dose Error Reduction Software, Clinical Workflow Software, Interoperability Software, Tracking and Billing Software, Analytics and Continuous Quality Improvement Software, and Closed-Loop Control Software .
Among these, Dose Error Reduction Software is expected to account for a significant share of market revenue. Its adoption is supported by the growing emphasis on medication safety, drug-library compliance, standardized dosing, and reduction of programming variability. DERS capabilities are particularly relevant in hospitals and high-acuity departments where precise medication administration is essential.
By Delivery Method
The market is divided into Wired and Wireless delivery methods. Wireless technologies are gaining attention as healthcare providers increasingly seek connected medical device ecosystems, centralized management, and flexible device deployment.
By Integration
Based on integration, the market includes Standalone, EMR Integrated, EHR Integrated, Pharmacy Information System Integrated, Alarm Notification Platform Integrated, and Asset Tracking System Integrated solutions.
Integrated solutions are becoming increasingly important as healthcare facilities pursue digital transformation and seek to connect infusion pumps with broader clinical information systems.
By Deployment Mode
The market is segmented into On-Premise, Cloud-Based, and Hybrid deployment models. Cloud-based and hybrid solutions are gaining interest because of their potential to support centralized administration, remote updates, analytics, and multi-site device management.
By Application
Applications include Pain and Anesthesia Management, General Infusion, Insulin Infusion, Chemotherapy, Enteral Infusion, Critical Care Infusion, Neonatal and Pediatric Infusion, Ambulatory Infusion, and Others .
Pain and anesthesia management represented a major application area in 2025, supported by the need for accurate and controlled medication administration in surgical, perioperative, postoperative, and critical-care environments. Chemotherapy and insulin infusion also remain important application areas because of the need for controlled and continuous drug delivery.
By End User
The market is segmented into Hospitals, Clinics, Ambulatory Surgical Centers, Home Care Settings, Specialty Infusion Centers, and Others . Hospitals represent a major end-user category due to their extensive use of infusion pumps across critical care, oncology, surgery, emergency care, and general inpatient departments.
Request Sample Link for More Details: https://www.maximizemarketresearch.com/request-sample/164151/
Regional Analysis
North America dominated the Infusion Pump Software Market in 2025 and is expected to maintain a significant position throughout the forecast period. The region benefits from extensive adoption of smart infusion pumps, advanced hospital infrastructure, strong healthcare IT integration, and increasing emphasis on medication safety.
The United States represents a major contributor to regional demand. Healthcare organizations are increasingly investing in connected infusion platforms, electronic medical record integration, drug-library standardization, and centralized device management. The presence of established medical technology companies and continuous product development further supports regional market activity.
Europe is also expected to experience continued growth, supported by healthcare digitization, medication safety initiatives, and adoption of connected medical devices. Meanwhile, Asia Pacific is anticipated to offer significant opportunities due to expanding healthcare infrastructure, increasing healthcare expenditure, rising patient populations, and growing adoption of advanced medical technologies in countries such as China, Japan, India, and South Korea.
Major Industry Players
The competitive landscape includes established pharmaceutical, medical technology, and healthcare technology companies. Major players identified in the market landscape include Baxter International Inc., Baxter, Fresenius Kabi, ICU Medical, Inc., B. Braun, and other healthcare technology providers involved in infusion systems, software, drug libraries, interoperability, and medication safety solutions.
The broader competitive environment is characterized by product development, regulatory clearances, software upgrades, strategic collaborations, interoperability enhancements, and expansion of connected infusion platforms.
Recent industry developments include Baxter's FDA 510(k) clearance for its Novum IQ Large Volume Infusion Pump with Dose IQ Safety Software in April 2024. Fresenius Kabi also continued updates to its Agilia Partner software environment, while ICU Medical received FDA 510(k) clearances in May 2025 for Plum Solo, updated Plum Duo, and updated LifeShield infusion safety software as part of its IV Performance Platform.
These developments demonstrate the industry's continued focus on integrating hardware and software to improve medication safety, workflow efficiency, connectivity, and scalability.
Frequently Asked Questions
What is the size of the Infusion Pump Software Market in 2025?
The Infusion Pump Software Market was valued at approximately USD 1.14 billion in 2025 .
What is the expected market size by 2032?
The market is expected to reach nearly USD 1.89 billion by 2032 .
What is the expected CAGR of the Infusion Pump Software Market?
The market is projected to expand at a CAGR of 7.27% from 2026 to 2032 .
Which software type is expected to hold a significant market position?
Dose Error Reduction Software is expected to remain a major software type because of increasing emphasis on medication safety, drug-library management, and controlled infusion programming.
Conclusion
The Infusion Pump Software Market is entering a period of continued technological development as healthcare providers increasingly prioritize medication safety, interoperability, automation, and efficient clinical workflows. With the market projected to increase from USD 1.14 billion in 2025 to nearly USD 1.89 billion by 2032 , software is becoming an increasingly important component of modern infusion systems.
Connect With Us:
MAXIMIZE MARKET RESEARCH PVT. LTD.
2nd Floor, Navale IT park Phase 3,
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India.
+91 9607365656
sales@maximizemarketresearch.com
About Maximize Market Research:
Maximize Market Research is one of the fastest-growing market research and business consulting firms serving clients globally. Our revenue impact and focused growth-driven research initiatives make us a proud partner of majority of the Fortune 500 companies. We have a diversified portfolio and serve a variety of industries such as IT & telecom, chemical, food & beverage, aerospace & defense, healthcare and others.
Ultra Fine Aluminium Hydroxide Market: Why 6.5% CAGR Bets on Flame Retardant Demand
By PW Consulting, 2026-09-21
The Strategic Shift: Navigating the Ultra Fine Aluminium Hydroxide Market Through 2032
The global market for ultra fine aluminium hydroxide has reached a critical inflection point. With a projected market value approaching 407.5 million USD by 2032 and a compound annual growth rate of 6.5 percent over the forecast period, the industry is transitioning from a mature specialty chemicals segment into a strategically vital enabler of next-generation materials safety, energy storage, and polymer performance. Between 2020 and 2025, the market expanded from 212.0 million USD to 278.8 million USD, reflecting steady underlying demand that has now accelerated into a multi-year growth trajectory. This expansion is not uniform across all value drivers; it is being reshaped by regulatory urgency, technological refinement in particle engineering, and a supply base that is simultaneously consolidating and regionalizing. For executives, investors, and procurement leaders, understanding the structural forces behind this trajectory is essential to positioning portfolios, pricing strategies, and long-term sourcing commitments.
Mapping the Market Trajectory
The revenue curve across 2020 through 2032 reveals a market that has moved past cyclical volatility and is now anchored by structural demand shifts. Growth from 2023 to 2025 alone added roughly 33.6 million USD in incremental revenue, signaling that end-use adoption is no longer limited to legacy flame retardant applications. The forecast period through 2032 projects continued expansion, with the steepest absolute gains expected between 2028 and 2032, when annual revenue additions will be driven by manufacturing scale-up, cross-sector substitution, and the commercialization of ultra-fine grades in higher-value performance matrices. This trajectory suggests that the market is entering a phase where capacity investments, rather than short-term pricing cycles, will define competitive positioning.
Concentration Dynamics and Strategic Implications
Market concentration remains a defining characteristic of the industry. The top three participants collectively command approximately 65 percent of revenue, while the top five account for around 82 percent. This concentration does not indicate a stagnant oligopoly; rather, it reflects a landscape where incumbents have built deep technical credibility in particle size control, surface treatment, and application-specific formulation support. Yet concentration also masks underlying fragmentation in sub-segments, particularly where regional producers are closing the quality gap and capturing localized demand without competing directly on global scale. The implication for buyers is a dual-layer marketplace: global specialists offer consistency, technical service, and regulatory documentation, while regional facilities increasingly provide cost-competitive access for standard-grade requirements.
Ultra Fine Copper Powder Market
Current Structural Challenges
Three interlocking challenges are forcing the industry to recalibrate its operating assumptions. First, the physical and regulatory constraints around transporting fine powdered chemicals are raising logistics costs. Containment protocols for powdered material have increased per-ton transport expenses by an average of 18 percent, compressing trade flexibility and making proximity to end-use clusters a more decisive competitive factor. Second, raw material inputs are undergoing both volume and price shifts. Bauxite consumption estimates for 2025 reached approximately 1.7 million tons, a 4 percent increase over the prior year, while the landed value of imported crude dry bauxite and metallurgical-grade alumina for U.S. consumption rose by 4 percent and 9 percent respectively in the first eight months of 2025 compared with the same period in 2024. Even with absolute dollar values in the tens of millions, these movements signal tightening upstream economics that will eventually transmit into ultra-fine production margins. Third, the demand environment is shifting from generic filler substitution toward specification-driven performance requirements. Buyers are no longer purchasing by bulk weight alone; they are demanding tight particle size distributions, consistent surface reactivity, and documented safety performance, which raises the barrier to entry for undifferentiated capacity.
PW Consulting
Key Drivers Reshaping the Landscape
Regulatory Substitution as a Demand Anchor
The most durable demand catalyst is the regulatory displacement of halogenated flame retardants. As of 2023, more than 53 countries had enforced restrictions on halogenated formulations, creating a structural pull toward halogen-free alternatives in sectors where safety certification, lifecycle compliance, and public acceptance are non-negotiable. Public transport, building interiors, and consumer electronics have become priority adoption zones, where ultra fine aluminium hydroxide serves not merely as a filler but as an active smoke suppressant and intumescent co-agent. This regulatory environment transforms the product from a commodity additive into a compliance-critical input, lengthening qualification cycles but also increasing switching costs once a grade is approved. The commercial consequence is a demand base that grows through specification lock-in rather than spot purchasing, rewarding suppliers who can support audit-ready documentation, consistent lot-to-lot performance, and application engineering.
Particle Engineering and Performance Differentiation
Technological progress in precipitation control, micronization, and surface modification is redefining what buyers consider a premium grade. The market now segments around particle size thresholds that directly influence dispersion quality, polymer clarity, rheological behavior, and flame retardant efficiency. Below-1-micron grades are increasingly favored where투명성, low haze, and high surface area reactivity are required, while 1-to-1.5-micron ranges remain strong in applications balancing reinforcement and processability. The competitive advantage has shifted from volume production alone to the ability to hold narrow size distributions at scale, manage agglomeration, and tailor surface chemistry for specific resin systems. Facilities investing in automated micronization and closed-loop precipitation are reporting meaningful capacity leverage; certain producers have expanded sub-1.5-micron output with double-digit percentage capacity increases to serve coatings, paints, and flame retardant blends. This technical layer raises the value of process IP and operational discipline, making consistent quality a more powerful moat than route selection alone.
Downstream Demand Shifts Toward Safety and Energy Applications
Demand-side behavior is moving beyond traditional polymer compounding toward applications where thermal safety, electrical insulation, and weight efficiency intersect. Automotive interiors and component housings are increasingly specified with halogen-free systems to align with regional safety expectations and OEM sustainability targets. Electronics enclosures and battery-adjacent components are driving interest in grades that combine filler functionality with smoke reduction and thermal stability. At the same time, higher-purity ultra-fine grades are finding roles in advanced ceramics and technical coatings, where trace impurities and particle morphology directly affect final performance. These shifts expand the addressable market beyond volume-driven filler substitution and create pricing resilience for grades that are certified and engineered for specific end-use environments.
Cost Structure and Upstream Realities
The cost equation is being reshaped on two fronts. On the raw material side, the reported increase in bauxite consumption and the higher import benchmarks for alumina point to an environment where input economics are less predictable than in prior years. Even when absolute commodity values remain modest, percentage movements in traded benchmarks affect planning assumptions for integrated and non-integrated producers alike. On the operating side, the logistics cost premium for powdered chemical transport is now a structural component of delivered pricing, especially for long-haul movements across regulatory jurisdictions. This dynamic is pushing regionalization of supply, localized blending and packaging, and greater emphasis on total landed cost rather than ex-works price. Manufacturers that can align capacity with demand clusters, or that offer stable formulation support to reduce re-qualification, are better positioned to manage these cost layers than suppliers competing solely on headline pricing.
Competitive Landscape and Strategic Positioning
Differentiated Advantage Among Leading Participants
The competitive field shows a clear divide between global specialists with deep application portfolios and regional operators focused on scale and cost efficiency. German and U.S. headquartered producers have built recognition around sub-micron particle engineering, flame-retardant efficacy, and smoke suppression in polymers and coatings. Their portfolios emphasize grades optimized for specific resin systems and regulatory environments, supported by technical service and consistent documentation. Japanese manufacturers have extended their relevance through high-performance polymer compatibility and water-based system formulations, where dispersion stability and purity profiles matter. Another German specialist has carved a distinct position in high-purity grades for advanced ceramics and technical applications, trading volume for specification precision. On the regional side, Chinese producers have been expanding automated micronization capacity and targeting paints, coatings, rubber, and plastics grades with sub-1.5-micron outputs and higher content formulations. A U.S. diversified chemical company has signaled a broader push into ultra-fine grades for automotive and electronics, paired with announced capacity expansion to meet rising demand in automotive, electronics, and energy storage sectors. Together, these participants illustrate a market where differentiation comes from either application engineering, purity control, or regional cost positioning.
Recent Moves That Signal Strategic Intent
Recent corporate activity clarifies how incumbents are shaping the next phase of competition. One major diversified producer announced a significant expansion of ultra-fine production facilities to meet rising demand across automotive, electronics, and energy storage applications, indicating a bet that downstream specification requirements will sustain volume growth beyond legacy uses. Around the same period, another leading manufacturer acquired assets tied to ultra-fine grades to strengthen its flame retardant and smoke suppressant portfolio, consolidating technical capability and market access in a segment where qualification inertia favors integrated offerings. These moves point to two converging strategies: capacity build-out where demand visibility is strong, and portfolio consolidation where application breadth and regulatory support create stickier customer relationships.
Market Evolution: Consolidation, Regionalization, and Selective Entry
The market structure is evolving along three vectors. Consolidation is occurring where scale, technical documentation, and global service networks create advantages in qualification-heavy end markets. Regionalization is accelerating as logistics costs and proximity requirements reward suppliers located near major polymer, coatings, and automotive clusters. Selective entry remains possible, but the barrier is rising: new capacity must demonstrate particle size control, surface consistency, and application support rather than competing purely on throughput. The likely outcome is a layered competitive map. Global specialists retain leadership in high-specification, certification-sensitive applications. Regional producers gain share in standard and semi-specification grades where logistics and price sensitivity dominate. In between, a small set of agile operators capture opportunities by offering targeted grades for coatings, rubber, and plastics with reliable consistency and responsive service. For buyers, this means the optimal sourcing strategy is increasingly hybrid, balancing specification assurance with regional cost dynamics.
Forward Outlook: Trends Shaping the Next Three to Five Years
Trend One: Specification-Led Demand as the Growth Engine
The next growth cycle will be defined less by raw volume expansion than by specification adoption across new end-use environments. As safety regulations continue to favor halogen-free systems and as OEMs embed thermal and smoke performance requirements deeper into component design, ultra fine aluminium hydroxide will move from a supporting additive to a defined performance parameter in material specifications. The commercial opportunity lies in grades that can be pre-qualified for multiple resin systems and that carry documented performance data across smoke suppression, thermal stability, and dispersion behavior. Suppliers that invest in application test matrices, regulatory dossiers, and customer co-development will capture longer qualification cycles and lower churn, translating into more stable revenue streams even as input costs fluctuate.
High Purity Boehmite Market
Trend Two: Capacity Realignment Around Demand Clusters
Production geography will increasingly align with demand concentration. The logistics cost premium for powdered transport makes long-distance shipments less attractive for price-sensitive grades, encouraging regional capacity, localized packaging, and regional blending operations. At the same time, higher-specification grades will remain globally traded where technical service and certification support justify the logistics burden. This bifurcation suggests that the market will develop distinct regional price equilibria, with nominal premiums for proximity and service, and narrower spreads for commodity-style grades where logistics and input volatility dominate. Investors and manufacturers evaluating expansion should prioritize demand adjacency, regulatory documentation capability, and the ability to serve multiple downstream formats over pure scale alone.
Trend Three: Purity, Morphology, and Cross-Sector Portability
A third trend is the growing relevance of purity and particle morphology across sectors that historically had limited overlap. High-purity ultra-fine grades are gaining traction in technical coatings and advanced ceramics, while consistent sub-micron distributions are becoming valuable in electronics-adjacent applications where dispersion and surface effects influence final properties. The opportunity is portability: grades engineered with controlled impurity profiles and repeatable morphology can be positioned across multiple segments, reducing the need for highly fragmented product lines. The risk is that purity and morphology targets are demanding and unforgiving, requiring disciplined process control and analytical support. Producers that treat these attributes as core capabilities, rather than niche features, will be better positioned to defend margins when volume growth moderates in any single segment.
Implications and Actions for Decision Makers
For Manufacturers and Material Formulation Teams
Lead with specification support and total cost management rather than volume pricing alone. As logistics costs and input benchmarks become more variable, competitiveness will depend on demonstrating consistent particle performance, reducing re-qualification friction, and aligning capacity with regional demand clusters. Invest in application data that connects particle size, surface behavior, and dispersion outcomes to end-use safety and processing metrics. Where possible, structure supply relationships to include documentation readiness and lot traceability, since these attributes increasingly influence retention in certified programs.
For Investors and Portfolio Strategists
Prioritize assets and operators that combine process control with application-facing capability. Capacity expansion is meaningful only when it is matched to demand visibility in safety-driven and performance-driven segments. Look for evidence of technological discipline in micronization and precipitation, stable customer relationships supported by technical service, and exposure to multiple downstream formats that reduce dependence on any single cycle. Regional cost advantages are valuable, but they are most durable when paired with consistent quality and the ability to serve specification-led demand without heavy re-qualification overhead.
For Procurement and Sourcing Leaders
Move from transactional price comparison to a total landed cost and qualification-cost framework. The logistics premium for powdered transport, the variability in upstream benchmarks, and the hidden cost of re-qualification all argue for a sourcing model that balances specification assurance with regional availability. Where standard grades are sufficient, regional suppliers can improve cost predictability; where certification and performance consistency matter, global specialists with documented application support reduce downstream risk. Build flexibility into contracts to accommodate input and logistics shifts without triggering costly requalification cycles.
Closing Perspective
The ultra fine aluminium hydroxide market is entering a period where technical consistency, regulatory alignment, and regional supply logic will matter more than headline volume alone. Growth through 2032 is anchored by halogen-free substitution, specification-driven adoption, and expanding relevance in automotive, electronics, and technical coatings, while cost realities in logistics and raw materials are reshaping where and how capacity is most effective. For organizations operating in or adjacent to this market, the strategic question is no longer whether demand will grow, but how to position grades, supply relationships, and portfolio exposure to capture value from specification lock-in and regional demand clustering. Detailed segmentation data, regional demand breakdowns, and customized scenario modeling can sharpen these decisions further, and PW Consulting’s full research report provides the granular visibility required to translate these trends into concrete sourcing, investment, and product strategy choices.
For detailed analysis of this topic, please visit the official page: Ultra Fine Aluminium Hydroxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com