

Blogs
The global Mandelic Acid Market is experiencing transformative growth, driven by a paradigm shift toward sensitive and inclusive dermatological formulations. According to a newly published report by Stellar Market Research , the market was valued at USD 0.31 Billion in 2025 and is projected to reach USD 0.79 Billion by 2032 . This trajectory highlights the strategic importance of mandelic acid as a high-value active pharmaceutical ingredient (API) and a foundational element in next-generation personal care.
Key Findings from the Report
-
Robust Market Expansion: The market is poised to grow at a staggering 14% CAGR during the 2026–2032 forecast period, reflecting high adoption rates across both cosmetic and medical channels.
-
Dominant Segment: The DL-Mandelic Acid segment held the largest market share in 2025, serving as a critical dual-action ingredient for anti-aging and acne-treatment pharmaceuticals.
-
Key Application Revenue: Cosmetics & Personal Care alongside Pharmaceutical applications account for the vast majority of demand, leveraging the acid’s exfoliating and antibacterial efficacy.
-
Leading Geography: North America dominated the market in 2025, fueled by advanced pharmaceutical drug manufacturing, extensive R&D investments, and dynamic skincare trends.
-
Emerging Supply Hub: India continues to establish itself as a vital strategic player, currently ranking as the world’s second-largest exporter of DL-Mandelic Acid to key western markets like the US and Germany.
For further information, click the following link: https://www.stellarmr.com/report/req_sample/Mandelic-Acid-Market/1945
Market Drivers and Restraints
-
Driver 1: Surging Demand for Inclusive Personal Care. The shift toward gentle AHAs that cater safely to sensitive and melanated skin types (Fitzpatrick IV-VI) is exponentially increasing mandelic acid integration in global skincare lines.
-
Driver 2: Pharmaceutical Antibacterial Applications. Rising advancements in API manufacturing are heavily utilizing mandelic acid for its reliable antibacterial and anti-inflammatory properties in topical drug formulations.
-
Driver 3: Green Chemistry Adoption. An increasing industry emphasis on environmental sustainability is driving innovations in green synthesis, solvent recycling, and waste reduction during mandelic acid production.
-
Restraint 1: Raw Material Price Volatility. Fluctuating petrochemical feedstock and crude oil prices impact the cost of synthesis, compressing profit margins for manufacturers.
-
Restraint 2: Stringent Regulatory Compliance. Navigating complex, evolving global standards for cosmetic ingredient purity, safety, and labeling requires continuous, capital-intensive compliance measures.
Technology, Regulation, and Sustainability Trends:
The mandelic acid supply chain is undergoing an operational transformation to meet modern ESG (Environmental, Social, and Governance) criteria. Manufacturers are actively pivoting toward greener chemistry principles—optimizing reaction conditions, recycling synthetic solvents, and reducing hazardous chemical reliance to align with strict FDA and EMA ecological guidelines. Concurrently, regulatory transparency is reshaping product labeling, requiring brands to educate consumers accurately on pH concentrations, multi-acid blending safety, and sun-sensitivity protocols, effectively standardizing global quality benchmarks.
Regional Insights:
North America leads the global landscape, underpinned by a highly agile cosmetic sector and a well-funded pharmaceutical infrastructure capable of rapid product commercialization. The U.S. remains the primary consumption hub for both indie beauty brands and clinical dermatological products. Meanwhile, the Asia Pacific region—spearheaded by India and China—is emerging as the powerhouse of global supply and export. India’s strategic capacity expansions and cost-effective manufacturing capabilities position it as a critical node in maintaining western supply chain stability, especially as K-Beauty trends originating in South Korea drive regional consumer demand for gentle exfoliants.
Recent Industry Developments
-
The Inkey List (2026): Expanded its accessible-actives portfolio with new Mandelic Acid and PHA serum extensions, directly targeting the gentle-acid tier and driving high-volume consumer adoption in the global mass-market segment.
-
Evonik and BASF (2026): Strategically adapted supply chain and inventory models for D-Mandelic Acid to mitigate crude oil price volatility, ensuring stabilized production of specialty chemical intermediates for global buyers.
-
Topicals (2026): Leveraged mandelic acid in targeted product extensions positioned specifically for melanated skin, successfully mitigating post-inflammatory hyperpigmentation (PIH) risks and capturing a highly underserved inclusive beauty segment.
-
By Wishtrend (2025): Scaled the global distribution of its category-defining Mandelic Acid 5% Skin Prep Water, solidifying K-Beauty's footprint in western markets and establishing the ingredient as a standard for gentle multi-acid routines.
-
Prequel Skin (2025): Launched advanced multi-acid formulations integrating mandelic acid with hydrating agents for barrier repair, capitalizing on the rising consumer demand for low-irritation exfoliants among the sensitive-skin demographic.
Competitive Landscape:
The market is highly competitive and characterized by strategic partnerships, portfolio expansions, and sustainability initiatives. Key global players include BASF, Evonik, Keyuan Biopharm, Cayman Chemical, Thermo Fisher Scientific, and MedChemExpress. On the consumer-facing front, skincare giants and indie disruptors such as Paula’s Choice, The Ordinary, and The Inkey List are aggressively formulating mandelic acid-anchored products. Manufacturers are increasingly focusing on securing stable raw material sourcing and expanding their eco-friendly production capacities to secure dominant market positioning.
Analyst Commentary:
"As consumer demographics demand more inclusive and sensitive-skin-friendly formulations, mandelic acid has transitioned from a niche cosmetic active to a foundational chemical ingredient," said a Senior Research Analyst at Stellar Market Research. "Its unique large-molecule structure minimizes irritation while delivering potent antibacterial benefits, making it an indispensable asset for the future of both dermatological cosmetics and complex pharmaceutical therapeutics."
Future Outlook
Looking through 2032, the Mandelic Acid Market is expected to see robust capital inflow from both the beauty and pharmaceutical sectors. As precision skincare becomes the industry standard, formulations blending mandelic acid with complementary actives (like PHAs and ceramides) will dominate product pipelines. Furthermore, continued advancements in sustainable chemical synthesis and strategic trade pathways between Asian exporters and Western consumers will successfully buffer the market against macroeconomic volatility.
For further information, click the following link: https://www.stellarmr.com/report/req_sample/Mandelic-Acid-Market/1945
About Stellar Market Research
Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Address
Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041
Email
sales@stellarmr.com
Mobile
+91 9607365656
Preparing for a trade show involves more than booking exhibition space and arranging products. Your stand needs to represent your brand, welcome visitors, and support your team throughout the event. A well-planned exhibition space can provide the right environment for product demonstrations, business meetings, and customer conversations.
An experienced Exhibition Stand Builder can help manage this process from the initial idea through to the completed installation.
Understand Your Exhibition Objectives
Before starting the design, define what you want your stand to achieve. Your goals could include introducing a new product, meeting existing customers, generating business enquiries, or increasing brand awareness.
Sharing these objectives with an Exhibition Stand Builder Company gives the design team a better understanding of what the stand needs to accomplish.
Develop a Practical Stand Layout
The layout is one of the most important parts of an exhibition project. Visitors should be able to enter, move around, view products, and speak with your team comfortably.
Professional Exhibition Stand Designs can include dedicated areas for reception, product displays, demonstrations, private meetings, storage, and hospitality. Each area should have a clear purpose without making the stand feel crowded.
Turn Ideas Into Professional Exhibition Stand Designs
Creative design can help your stand attract attention from across the exhibition hall. However, visual elements should support your brand message rather than distract from it.
An experienced Exhibition Stand Design Company can combine graphics, lighting, structures, furniture, digital displays, and architectural features to create a unified environment.
3D design presentations can also help you understand the proposed stand before fabrication begins. Changes can be discussed during this stage, making the final production process more organized.
Focus on Brand Visibility
Your exhibition stand should make your company easy to recognize. Large-format graphics, clear signage, branded counters, illuminated logos, and carefully positioned messaging can improve visibility.
A professional Exhibition Stand Builder can ensure these branding elements are incorporated into the overall design instead of being added as separate elements.
Manage Production and Installation
After the design is approved, fabrication begins. Materials and components are produced according to the agreed specifications.
Experienced Exhibition Stand Builder Companies can coordinate production, transportation, venue requirements, installation, and dismantling. This can make the project easier to manage, particularly when an exhibition has strict setup schedules.
Choose the Right Exhibition Partner
When comparing Exhibition Stand Builder Companies , consider more than the initial quotation. Look at their portfolio, previous exhibition projects, design process, construction capabilities, project management, and installation support.
It is also important to discuss deadlines and venue requirements early. Good communication between the exhibitor and builder can help prevent unnecessary delays during the project.
Create a Stand That Supports Visitor Interaction
A successful stand should provide opportunities for meaningful conversations. Comfortable seating, demonstration counters, product displays, meeting areas, and interactive technology can encourage visitors to spend more time at your space.
The design should also leave enough open area for visitors to enter without feeling that the stand is difficult to approach.
Complete Support From One Team
Working with a capable Exhibition Stand Design Company and builder can bring different stages of the project together. From the first sketch to 3D visualization, fabrication, graphics, installation, and dismantling, each stage can be planned around the same concept.
This approach helps maintain consistency between the approved design and the finished exhibition stand.
Make Your Next Exhibition Stand Count
A well-planned exhibition stand can become an important part of your trade show presence. The combination of clear objectives, thoughtful Exhibition Stand Designs , strong branding, practical layout, and professional construction can create a space that represents your company effectively.
By working with the right Exhibition Stand Builder , you can turn your exhibition space into a professional environment designed for product presentation, visitor interaction, and business conversations.
Silica Sand Market to Reach USD 43.16 Billion by 2032 as Glass, Construction, Solar and Industrial Applications Accelerate Demand
Global Silica Sand Market Outlook
The Silica Sand Market was valued at USD 27.77 billion in 2025 and is projected to reach nearly USD 43.16 billion by 2032, expanding at a CAGR of 6.5% during 2025–2032. Silica sand is increasingly important as a high-purity industrial raw material globally now for glass manufacturing, construction, foundry operations, filtration, chemicals, ceramics, oil and gas. Growth is supported by urbanization, infrastructure development, flat and container glass production, renewable-energy installations, and demand for specialty silica. Opportunities are expanding around tighter-purity grades, sustainable mining, digitalized processing and long-term supply agreements. Rising demand for solar photovoltaic glass, specialty glass, electronics-related materials and engineered construction products is encouraging producers to improve purification, processing efficiency and resource security.
U.S. Market Trends and Investment
The United States remains a major silica sand market because of its established oil and gas, construction, glass and industrial manufacturing base. During 2025, U.S. frac-sand demand remained relatively resilient despite a moderate decline in North American proppant demand, as longer horizontal wells and higher sand volumes per lateral foot supported consumption. In December 2025, Iron Oak Energy Solutions acquired Superior Silica Sands, adding more than three million tons per year of production capacity and expanding its Eagle Ford footprint to more than six million tons annually. Meanwhile, U.S. producers are broadening beyond energy toward glass, filtration, building products and other industrial applications.
Request a Sample PDF of the Market Report : https://www.maximizemarketresearch.com/request-sample/66769/
Market Segmentation: Largest Share
By end-use industry, Glass Manufacturing held the largest share of the global Silica Sand Market. Silica sand is essential for flat glass, container glass and specialty glass production. Demand is supported by construction, automotive glazing, solar photovoltaic glass and energy-efficient buildings. The shift toward higher-purity silica is creating opportunities for suppliers capable of delivering consistent chemical composition and particle-size specifications.
Competitive Analysis
Sibelco is a leading global silica sand supplier and is expanding its resource base and geographic reach. Its strategic commitment of AUD 49 million to Diatreme Resources covers equity investment and a silica sand joint venture in Queensland, supporting low-iron silica resources for solar PV and other high-value applications.
U.S. Silica has a diversified portfolio spanning industrial silica, oilfield proppants and specialty minerals. Following its acquisition by Apollo Funds in 2024, the company entered a new ownership phase focused on growth. Its processing and logistics capabilities support glass, chemicals, foundry, building products, filtration and energy applications.
Covia strengthened product development in 2025 by opening a roughly 20,000-square-foot innovation center in Concord, North Carolina. The facility supports product development, application testing and customer engagement across coatings, polymers, engineered stone and sports applications, helping expand higher-value mineral solutions.
Quarzwerke Group maintains high-grade quartz resources and supplies wet sand, dry sand and milled quartz. Its focus on high-purity deposits and processing supports applications requiring consistent mineral quality.
JFE Mineral & Alloy Company operates across mineral products and functional materials, including silica-related resources and processing. Its diversified materials capabilities support specialty glass, electronics-related materials and other advanced industrial applications where purity and processing performance matter.
Regional Analysis: United States and China
The United States is a major national market within the global silica sand industry today and dominates North American consumption and production. Oil and gas, glass manufacturing, construction, foundry applications and filtration support demand. U.S. government trade data reports USD 882.1 million of silica and quartz sand exports in 2024, with China representing a substantial destination, highlighting the country’s role in international supply chains.
China is a major force in Asia-Pacific because of its large glass, construction and photovoltaic manufacturing industries. Renewable-energy investment and solar manufacturing create sustained demand for high-quality silica-related inputs. In 2025, China published a national standard for high-purity sand used inside quartz crucibles for photovoltaic monocrystalline silicon growth, effective from December 2025. The standard reflects the increasing importance of consistent high-purity material specifications in advanced solar manufacturing.
Why This Market Matters Now
Silica sand is moving beyond its traditional role as a bulk industrial mineral and becoming an increasingly important input for high-value manufacturing. Glass demand, solar expansion, infrastructure development, energy production and advanced materials are changing purchasing priorities. Producers increasingly compete on purity, consistency, processing technology, logistics and sustainable resource management. These shifts are creating opportunities across high-purity silica, specialized processing, resource development and supply-chain integration.
Key Players
Badger Mining Corporation; Covia Holdings LLC; Euroquarz GmbH; JFE Mineral & Alloy Company, Ltd.; Mitsubishi Corporation; PUM GROUP; Sibelco; Sunstate Sand Bundaberg Pty. Ltd.; TOCHU CORPORATION; VRX Silica Limited; Australian Silica Quartz Group Ltd.; U.S. Silica Holdings, Inc.; Quarzwerke GmbH; Preferred Sands; Pattison Sand; Aggregate Industries; Hi-Crush Inc.; Capital Sand Company Inc.; Zhuzhou Kibing Group Co., Ltd.; Shandong Shanyuan New Material Co., Ltd.; and Smart Sand, Inc.
Explore More Related Reports
Resistivity Meters Market https://www.maximizemarketresearch.com/market-report/resistivity-meters-market/146819/
Global Aluminumextruded Products Market https://www.maximizemarketresearch.com/market-report/global-aluminum-extruded-products-market/25996/
About Maximize Market Research
Maximize Market Research Pvt. Ltd. (MMR) is a global market research and consulting company that provides reliable, data-focused, and practical business insights. The firm serves a wide range of industries, including healthcare, pharmaceuticals, technology, automotive, electronics, chemicals, personal care, and consumer goods. Through market forecasts, competitive analysis, strategic consulting, and industry impact assessments, MMR helps organizations understand changing market conditions, identify growth opportunities, and make informed business decisions for long-term success.
Contact Us
2nd Floor, Navale IT Park Phase 3
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India
+91 9607365656
sales@maximizemarketresearch.com
How Connected Tank Management Improves Safety, Visibility, and Efficiency
From the outside, tank terminals may appear orderly, controlled, and easy to predict. Inside the facility, however, daily activity is constantly changing. Inventory quantities shift throughout the day, products move between locations, inspections occur according to planned schedules, and trucks and marine vessels arrive and depart continuously to keep materials flowing. Managing all of this requires precision, discipline, and clear communication because a seemingly small error can create delays, financial consequences, or safety issues. The situation becomes more difficult when important information is scattered across spreadsheets, paper records, and disconnected applications. Staff may spend hours searching for details, warning signs can be missed, regulatory tasks can become harder to coordinate, and the likelihood of expensive errors increases. A cloud based tank farm platform can help overcome these problems by bringing operations, maintenance, HSSE, and commercial functions together in a secure digital environment supported by one centralized information source.
With multiple teams working around the clock, timely access to dependable information becomes especially important. A shared digital environment can make responsibilities clearer, reduce repeated data entry, and help employees work from the same operational picture while maintaining stronger coordination between departments and supporting functions.
A complete tank management system provides the operational backbone for this connected approach. It gathers current data from field equipment, including tank levels, temperatures, pressures, and other telemetry, then connects those readings with the business activities that rely on them. Instead of keeping operational measurements separate from administrative and commercial work, the platform links data with schedules, nominations, transfers, approvals, records, and billing processes. Standardized digital workflows create greater consistency across routine planning and execution. Built in controls can reinforce established practices for tanks, pipelines, and marine operations, reducing dependence on constant manual oversight. Since the solution is delivered through SaaS, information stays aligned across departments, while the platform can expand from one terminal to several facilities without creating unnecessary operational complexity.
Bringing operational information together also turns real time visibility into a useful part of daily decision making. Dashboards can combine current inventory positions, equipment status, and pending activities within one view. When unusual situations appear, such as unexpected product movements, possible contamination, or readings outside defined operating limits, appropriate personnel can receive timely alerts. Seeing these conditions earlier gives teams additional time to examine the situation and correct it before an emerging issue develops into an interruption, incident, or product loss. Customers can gain greater transparency as well. Secure access to inventory balances, allocation details, custody records, and supporting documentation reduces dependence on manually prepared reports and cuts down on repeated information requests. Terminal personnel can consequently devote more time to valuable operational and strategic work.
Storage and transfer activities carry several risks, from contamination and incorrect routing to errors during lineup operations. An integrated digital platform can reduce these risks by guiding employees through established procedures, verification activities, and operational controls. Approved movement plans, controlled configurations, and structured checks support accurate execution while limiting opportunities for human error. Mobile capabilities add another level of control by enabling field personnel to conduct inspections, take photographs, document observations, and scan equipment identifiers at the work location. If connectivity is weak or unavailable, information can be captured offline and synchronized once the connection returns. Field work can therefore continue without unnecessary interruption while maintaining a complete and dependable audit trail.
Safety and regulatory activities can become more effective when required tasks are embedded directly within ordinary operating workflows. Rather than depending mainly on paper forms or static instructions, organizations can use digital procedures that lead employees through each necessary action. Overfill prevention checks, shutdown confirmations, VOC monitoring, and incident reporting can become part of routine execution instead of separate administrative exercises. Finished actions can be automatically documented with timestamps and confirmation details, producing dependable evidence of what happened and when. The same digital environment can also support management focused business analysis. Dashboards can show throughput, utilization, profitability, and performance across products, customers, and operating areas. Connecting the platform with ERP systems can strengthen commercial processes by supporting more accurate billing and helping teams spot revenue discrepancies earlier.
Product movements can likewise be handled through controlled and validated workflows from initial receipt through final dispatch. Materials arriving by truck, vessel, pipeline, barge, or ISO container can pass through processes designed to confirm capacity, coordinate schedules, verify credentials, and collect necessary measurements. Internal transfers, blending activities, and pipeline movements can follow defined rules that consider operational requirements, including fill limitations and interface management. Barcode based tracking can improve control over packaged products, while value added activities such as heating and additive injection can be captured automatically. Recording these services systematically helps make sure relevant charges are documented correctly and applied consistently.
Noticeable operational improvements can begin appearing soon after implementation. Stronger controls can help limit product losses and operating expenses, while predictive maintenance practices can lower the possibility of unexpected equipment failures and support improved energy efficiency. Immediate access to inventory data, compliance records, and performance indicators also enables quicker, better informed decisions. Rather than waiting for manually compiled reports that may already be outdated, managers can view current information when action is required. Preconfigured industry templates can help reduce deployment time, while secure cloud infrastructure allows authorized users to reach relevant information from almost anywhere. Supervisors can review and approve activities remotely, and senior leaders can follow terminal performance in real time instead of relying solely on scheduled reporting cycles.
A connected digital platform can consequently create value across the broader organization. Operations teams receive clearer visibility into ongoing activities and work within more consistent processes. HSSE teams gain stronger oversight and dependable records that can help demonstrate compliance. Maintenance personnel can track equipment conditions more effectively while reducing the administrative effort tied to maintenance work. Finance teams gain access to reliable commercial information that can improve both the speed and quality of financial decisions. Customers can also gain greater confidence through better transparency, dependable documentation, and more consistent access to operational information that matters to their business.
Choosing a SaaS platform is therefore more than an effort to replace an existing software application. It can represent a wider strategic move toward centralized operational management, stronger safety performance, improved regulatory control, and greater commercial visibility. Organizations can preserve site specific procedures and requirements while removing disconnected applications and aging manual processes. The result is an operating environment that is more connected, efficient, resilient, and manageable. Whether deployed at one terminal or extended across a broader network of facilities, a unified digital platform can provide the practical foundation needed to support consistent performance and sustained operational excellence.
Book a free demo @ https://toolkitx.com/campaign/tank-management/
Browse More
https://toolkitx.com/blogsdetails.aspx?title=Chemical-work-permit-%E2%80%93-definition,-requirements-and-best-practices
https://toolkitx.com/blogsdetails.aspx?title=Key-responsibilities-of-an-HSE-officer-in-high-risk-industries:-what-every-safety-leader-must-know
https://toolkitx.com/blogsdetails.aspx?title=HSE-management-system-explained:-elements,-benefits,-examples-and-how-to-implement-it-right
Why Digital Permit to Work Is Transforming Hazardous Work Management
Controlling high risk work requires far more than gathering signatures or completing routine paperwork. Its real purpose is to stop incidents before they happen by recognising hazards, considering their potential consequences, and putting effective controls in place before work starts. A digital Permit to Work (PTW) system strengthens this approach by bringing scattered manual activities into one organised platform, improving accountability, visibility, and consistency. Rather than relying on paper documents, emails, and separate records, teams use a common system, responsibilities are assigned clearly, and actions are captured automatically from beginning to end.
Understanding the Role of a Permit to Work System
Activities including hot work, confined space entry, excavation, electrical isolation, and working at height can involve serious hazards, making careful assessment essential before work begins. A permit provides a formal barrier against uncontrolled activity by demonstrating that hazards have been reviewed, suitable precautions established, and required approvals completed by authorised personnel. Digital PTW systems strengthen this protection by embedding safety requirements directly into the workflow. Standardised permit templates encourage users to provide complete, relevant details, while mandatory steps reduce the likelihood that critical checks will be skipped. Supporting records, including risk assessments and isolation documentation, can be required before a permit advances for approval. Defined roles also make administration clearer by showing who is responsible for preparing, reviewing, authorising, and closing each permit.
Why Businesses Are Replacing Paper PTW
Managing paper permits becomes increasingly difficult as organisations add more teams, contractors, sites, and work areas. Records can be lost or delayed, approvals may take longer, and supervisors can struggle to maintain a reliable picture of activities currently in progress. A digital PTW system brings permit information into one accessible environment. Approvals, hazard information, drawings, evidence, and supporting documents can stay together and be retrieved when required. Supervisors can see which permits are active, waiting for approval, or affected by changing workplace conditions. Management also gains a reliable historical record of decisions, dates, approvals, and operational details that can be reviewed once work has been completed.
Core Capabilities of a Digital PTW Platform
A capable PTW platform should provide more than an electronic copy of a paper form. It functions as a broader safety management solution that enables organisations to prepare, control, and oversee hazardous work. Permit templates can be configured for different work categories so employees provide appropriate information and complete checks suited to the activity. Embedded guidance can help teams recognise hazards, verify isolations, and confirm that required protective measures are available. Automated approval routes send permits to the correct personnel while creating time stamped records of decisions and completed actions. Live dashboards provide an up to date view of ongoing work, supporting coordination, smoother shift handovers, and fewer unnecessary interruptions. Permits can also be associated with particular assets, locations, photographs, drawings, procedures, and other supporting resources. This gives workers and supervisors access to the context they need before the task begins. A secure audit trail records activity across the workflow, creating traceability from initial preparation through final permit closure.
How the Digital PTW Process Works
The workflow generally begins with defining the proposed activity, its location, associated hazards, and the controls needed to manage them. Relevant documents can then be attached, while guided steps support risk assessments and help identify isolation arrangements, protective measures, and other required precautions. When preparation is finished, the permit can move automatically through its designated approval route. Before work is released, information such as worker competence, toolbox talks, PPE verification, and required test results can be recorded within the platform. While work is underway, authorised users can monitor permit status and activity in real time. If workplace conditions change, the permit can be updated, extended, or temporarily suspended without losing control or visibility. Once the task is completed, isolations can be removed, evidence of completion documented, and the work area returned to a safe condition. Observations, findings, and lessons learned can also be recorded to help strengthen future activities.
Maintaining Consistency Without Ignoring Site Needs
A major benefit of digital PTW is the ability to establish consistent controls without forcing every site to follow an inflexible process. Organisations can set common permit templates, approval routes, and validation requirements across locations while allowing individual sites to introduce controls suited to their own conditions and risks. This approach helps businesses maintain common safety expectations across the organisation while preserving enough flexibility to respond to circumstances associated with particular sites, tasks, or work environments.
Benefits Across Different Teams
Digital PTW can support the different groups involved in controlling hazardous work. Operations teams can benefit from faster approvals and fewer administrative bottlenecks, allowing planned activities to move forward with less avoidable delay. Safety teams gain greater visibility into work occurring across locations, making compliance monitoring and audit preparation easier to manage. Asset owners can achieve more consistent working practices, improved contractor oversight, and clearer awareness of operational activities. Contractors may also find permit requirements easier to understand because information is presented more clearly and communication with site personnel follows a more structured process. This can reduce confusion while improving coordination among everyone involved.
Creating a Digital PTW Environment
Organisations do not need to digitise every permit process at once. Implementation can begin with activities carrying the greatest risk, such as hot work, confined space work, and electrical isolation. After these workflows are established, the platform can gradually extend to related processes including lockout tagout activities, inspections, and training records. Mobile field access enables workers and supervisors to manage permits where the work actually occurs. This can reduce unnecessary waiting and allow teams to respond to issues more quickly. Reporting and analytics can reveal recurring issues, developing performance trends, and areas where current controls may need strengthening. Over time, these insights can help organisations build a more consistent safety management framework while encouraging continuous operational improvement. Clear digital records also make it easier to trace responsibilities, confirm whether required actions were completed, and identify gaps that might otherwise remain hidden within disconnected paperwork. This creates a stronger foundation for learning, accountability, and more dependable control of hazardous work activities.
Book a free demo @ https://toolkitx.com/campaign/permit-to-work/
Browse More
https://toolkitx.com/blogsdetails.aspx?title=COSHH-explained:-a-practical-guide-for-oil-and-gas,-construction-and-utilities
https://toolkitx.com/blogsdetails.aspx?title=Common-HSE-Challenges-in-the-Workplace-And-How-Modern-Organizations-Overcome-Them
How Centralized Maritime Monitoring Can Improve Operational Awareness
Maritime environments can change in a matter of minutes. Visibility may deteriorate, weather conditions can shift, and nighttime operations can introduce additional challenges for crews and operational personnel. During these situations, having dependable information at the right moment becomes critical. When operational updates are scattered across different systems, teams may have to piece together information manually, making it harder to understand what is happening. This can slow communication, delay decisions, and increase uncertainty around people, equipment, assets, and essential maritime activities.
ToolKitX brings maritime information into a centralized operational environment. Its cloud based platform provides continuous visibility, real time awareness, and a common view of activity across an organization. Rather than requiring teams to switch between multiple applications or work with isolated information, organizations involved in ports, offshore wind, marine logistics, coastal operations, and energy related maritime activities can work from synchronized information in one location. Bringing these details together helps teams respond faster, reduce uncertainty, and make operational decisions with greater clarity.
Built to function as a modern operational command center, ToolKitX organizes information relating to vessels, offshore equipment, and coastal operations. Information from AIS, ADS B, GPS, radar, and other tracking sources can be consolidated and presented through integrated nautical maps. This provides teams with a live operational picture that is practical and easy to interpret. Instead of overwhelming users with every available data point, intelligent filtering and rules based processing can highlight the events and conditions that require attention.
Early identification of developing issues can provide teams with additional time to respond before a minor deviation becomes a larger operational problem. ToolKitX can recognize situations including vessels moving toward controlled zones, assets approaching one another too closely, speeds exceeding established limits, and vessels moving away from approved routes. Identifying these conditions as they occur allows responsible teams to coordinate their response, notify the relevant personnel, and address deviations before they develop into serious incidents. A shared operational picture can also improve coordination among different stakeholders by reducing misunderstandings and fragmented communication.
Near real time vessel tracking provides information on position, direction, speed, movement, and operational status through an interactive map available to both offshore and onshore personnel. Geofencing provides another important layer of operational control. Organizations can create virtual boundaries around ports, offshore installations, wind farms, restricted zones, and environmentally sensitive areas. Once these boundaries and associated rules are configured, vessel activity can be continuously checked against them. If a vessel enters a restricted location, exceeds a specified speed, breaks a timing condition, or crosses an authorized boundary without approval, automated workflows can issue appropriate alerts.
Notifications can reach personnel through desktop applications, mobile devices, email, or connected systems, helping critical information reach the people responsible for responding to it. Alert distribution can also be aligned with individual roles and responsibilities, so employees receive notifications that are relevant to their work. This can help reduce unnecessary interruptions and manage the potential effects of excessive alerts. Alongside real time monitoring, ToolKitX keeps a detailed historical record of operational activity. Vessel movements, alerts, events, and behavioral information can be securely retained for audits, investigations, insurance assessments, compliance activities, and internal reviews.
Key Capabilities
Continuous Tracking and Historical Replay
Teams can monitor extensive operational areas or focus attention on a particular vessel when detailed observation is required. Historical replay can cover periods of up to 90 days and include information such as routes and vessel speeds. These records can assist with operational reviews, compliance checks, incident investigations, and analysis of near miss events.
Intelligent Rules Based Geofencing
ToolKitX expands geofencing beyond basic location boundaries. Organizations can create rules based on speed thresholds, specific time conditions, proximity requirements, or combinations of different operational criteria. When configured conditions are met, alerts can automatically reach relevant stakeholders, including HSE teams, contractors, and regulators. This provides greater operational oversight without requiring personnel to deal with an unnecessary volume of notifications.
Integrated Weather Awareness
Weather conditions, including wind speed and sea conditions, can be assessed alongside established operating limits. Decision makers can use this combined operational picture when considering whether offshore work, personnel transfers, or other higher risk activities should continue, be temporarily suspended, or be rescheduled according to current conditions.
Proactive Collision Risk Detection
An integrated CPA engine can help identify developing collision risks before they become critical. Potential encounters can be detected and monitored while creating a structured record of the event. This information can later contribute to investigations, assessments, and ongoing efforts to strengthen maritime safety practices.
Unified Asset and Workforce Management
ToolKitX provides organized records covering vessels, aviation assets, operational equipment, and crew certification requirements. Automated reminders and notifications can help organizations keep certifications and operational requirements up to date. This reduces dependence on manual follow up and supports continued operational readiness.
Mobile Support for Remote Operations
The mobile application supports personnel working in remote or field environments where connectivity may not always be reliable. Teams away from central facilities can access relevant alerts, check recent vessel positions, and manage geofencing activities while continuing their operational responsibilities from remote locations.
Why Organizations Choose ToolKitX
Organizations can use ToolKitX to move away from fragmented operational systems and establish a more consistent source of information. Bringing AIS, radar, GPS, and ADS B information together allows marine operators, logistics personnel, and HSE teams to maintain a shared understanding of ongoing activity. Notifications relating to unauthorized access, excessive speeds, or CPA concerns can support efforts to reduce operational exposure, safeguard assets, minimize disruption, and maintain business continuity.
The platform can also support compliance and reporting activities by making historical information, exportable reports, and structured audit trails available for investigations and regulatory reviews. Whether an organization needs to oversee a smaller fleet or manage a complex operation involving numerous marine and offshore assets, ToolKitX can support different operational requirements while allowing controlled access for different groups of users.
Security and compliance are incorporated into the operational workflow. Vessel movements, alerts, and user activities are recorded, while encryption helps protect information both while it is transmitted and when it is stored. Before deployment, organizations can also model operational scenarios involving shipping routes, ports, offshore wind developments, and transit corridors. Teams can use these scenarios to test and refine rules and workflows before implementation, helping align the platform with practical operational requirements from the outset. This preparation can establish clearer response processes, reduce uncertainty, and encourage more consistent execution as maritime conditions evolve.
Book a free demo @ https://toolkitx.com/campaign/gps-tracking/
Browse More
https://toolkitx.com/blogsdetails.aspx?title=RIDDOR-Reporting:-What-Must-Be-Reported-and-How
https://toolkitx.com/blogsdetails.aspx?title=Oil-and-Gas-Hazard-Identification:-The-10-Most-Overlooked-Risks
https://toolkitx.com/blogsdetails.aspx?title=Daily-Workplace-Safety-Checklist-for-Construction-and-Utilities
EAS System Market Beyond 4.66% CAGR: Shifts Redefining Security by 2032
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Electronic Article Surveillance (EAS) System Market
The Electronic Article Surveillance (EAS) System Market has evolved from a simple theft-deterrence mechanism into a foundational component of retail loss prevention and inventory intelligence. Valued at 1,325.0 million USD in 2025, the market has grown steadily from 1,081.5 million USD in 2020, reflecting a compound annual growth rate of 4.66% projected through 2032. This trajectory is not merely a reflection of rising retail sales; it signals a structural shift in how retailers, manufacturers, and supply chain operators approach security, compliance, and operational efficiency. As the market expands toward 1,820.14 million USD by 2032, stakeholders must recognize that EAS is no longer a standalone hardware purchase—it is an integrated technology stack shaped by regulation, labor economics, and data analytics.
The growth pattern reveals a mature but still evolving landscape. Despite consistent revenue expansion, the market faces mounting pressure to justify capital expenditure through measurable operational outcomes. Retail environments are experiencing unprecedented shrinkage, while labor shortages and wage inflation are forcing operators to reconsider legacy security models. In this context, EAS systems are being evaluated not only on detection reliability but on their ability to reduce false alarms, integrate with broader store networks, and provide actionable insights that extend beyond the exit door. The market’s forward path will be defined by how quickly technology providers, component suppliers, and end users can align on interoperability, data sharing, and source-tagging adoption.
Key Challenges and Inflection Points
One of the most pressing challenges is the false-alarm burden that has historically undermined EAS reliability. Traditional detection systems often misread tagged items or environmental interference, creating operational frustration and eroding staff confidence in security infrastructure. Retailers are increasingly unwilling to deploy systems that require constant manual overrides or that disrupt the customer experience at entrances. This has accelerated demand for intelligent detection architectures that can distinguish between genuine tag activations and benign signal events, a shift that is reshaping product development priorities across the industry.
A second inflection point centers on the shifting economics of retail labor. Workforce constraints and rising wage costs are making manual tag application and in-store security monitoring less sustainable. Retailers are under pressure to reduce labor-intensive processes while maintaining or improving loss prevention outcomes. This dynamic is pushing the market toward upstream tagging strategies and automated detection solutions that minimize in-store handling. When tagging responsibility moves closer to manufacturing or distribution, the value proposition of EAS changes from a reactive security tool to a proactive supply chain enabler.
A third challenge lies in the fragmentation of tagging standards and interoperability expectations. As more retailers, brands, and suppliers adopt source-tagging requirements, the need for consistent encoding, chip compatibility, and system responsiveness becomes critical. Inconsistent tag formats or detection protocols can create blind spots, increase integration costs, and slow deployment at scale. The market is therefore entering a phase where technical compatibility and industry coordination are as important as raw detection performance.
Key Drivers of Market Change
Technology Innovation and Intelligence Integration
The most significant driver of market evolution is the infusion of intelligence into EAS hardware and tag ecosystems. Detection systems are increasingly incorporating edge processing and analytics capabilities that improve signal discrimination and reduce false alarms. This transition is transforming EAS from a binary alarm mechanism into a data-generating component of store operations. Recent deployments of edge-AI smart antennas have demonstrated meaningful reductions in false-alarm rates across large store networks, illustrating how software-defined improvements can enhance the value of existing detection infrastructure.
At the component level, miniaturization and chip advancements are expanding the range of products that can be tagged without compromising packaging, aesthetics, or sterilization requirements. Smaller inlays and labels enable tagging in categories that were previously difficult to secure, including cosmetics, pharmacy items, and healthcare products. These advances are particularly relevant for retailers and brand owners seeking to broaden protection coverage while maintaining a positive shopper experience. The combination of smarter detection and more versatile tagging is creating a feedback loop: better tags improve system accuracy, and better systems increase the return on tagging investment.
Regulatory and Compliance Pressure
Regulatory developments are reshaping the market by mandating or incentivizing source tagging and traceability. Policy frameworks that require product-level identification are pushing manufacturers and suppliers to embed tags earlier in the value chain. This shift reduces the labor burden on retailers while improving inventory visibility and enabling gray-market detection. Compliance-driven tagging also strengthens the case for interoperable encoding standards, as fragmented tag data can undermine the intended benefits of traceability and loss prevention.
In parallel, large retail chains are issuing supplier mandates that effectively set de facto industry standards. When major retailers require RFID-enabled EAS tags in categories such as home goods and electronics, they accelerate adoption across the supply base and create scale effects that lower component costs over time. These mandates also shift the commercial conversation from whether to tag to how to tag efficiently, consistently, and in ways that are compatible with downstream detection systems.
Demand-Side Shifts in Retail and Loss Prevention
Shrinkage trends are fundamentally altering demand patterns for EAS solutions. Retailers are reporting sharp increases in shoplifting incidents compared with pre-pandemic levels, which intensifies the need for reliable, scalable security infrastructure. At the same time, loss prevention is no longer viewed purely as a cost center. Retail executives are increasingly interested in systems that can contribute to inventory accuracy, operational insights, and customer flow management. This broader value proposition supports investment in EAS technologies that integrate with existing store networks and provide analytics beyond simple alarm events.
The demand picture is also being shaped by category expansion. While apparel and fashion accessories remain a core application area, growth is emerging in grocery, pharmacy, and cosmetics segments where product value, return rates, and theft vulnerability create strong adoption incentives. As detection systems become more adaptable and tags more discreet, EAS is moving into environments where traditional hard tags were impractical, widening the addressable market and encouraging cross-category deployment strategies.
Supply Chain and Cost Structure Dynamics
Cost structures in the EAS market are being influenced by upstream sourcing, chip availability, and the economics of large-scale tagging programs. Supplier mandates and standardized encoding guidelines are helping to create more predictable demand for inlays, labels, and detachers, which can improve production efficiency and reduce per-unit costs over time. At the same time, the shift toward hybrid RFID-EAS deployments is changing procurement models, as retailers and integrators evaluate total cost of ownership rather than hardware price alone.
Another important dynamic is the growing role of software and analytics in system value. As detection hardware becomes more standardized, differentiation increasingly comes from integration capabilities, cloud-based reporting, and loss-insight tools. This means that supply chain decisions now extend beyond physical components to include data architecture, compatibility with store IT environments, and the ability to support multi-site deployment with minimal customization. Companies that can align component supply with software-enabled services are better positioned to capture recurring value in a market where capital equipment purchases are increasingly tied to operational outcomes.
Competitive Landscape and Leading Strategies
Strategic Positioning of Major Players
The competitive environment is defined by a mix of detection-system specialists, tag and label suppliers, and broader retail technology providers. Leaders are differentiating not only through detection technology but through ecosystem breadth, integration depth, and the ability to translate EAS data into operational insights. Several strategic positions are emerging:
- Precision-calibrated detection with analytics overlays is becoming a strong differentiator for companies that can reduce false alarms while extracting category-level shrink insights from existing infrastructure.
- RFID-centric EAS platforms are gaining traction where item-level recognition, open-entrance detection, and cloud software integration are prioritized, especially in retailers seeking unified visibility across security and inventory functions.
- Tag and inlay suppliers are expanding their role by offering sterilization-compatible labels, compact HF/NFC inlays, and chip configurations optimized for EAS compatibility, enabling wider adoption in sensitive product categories.
- Multi-technology providers are positioning around flexibility, offering RF, AM, and RFID options within a single ecosystem to serve retailers with varied store formats and legacy equipment.
These positions reflect a market where hardware performance is necessary but not sufficient. Differentiation is increasingly tied to deployment scalability, data interoperability, and the ability to support both loss prevention and inventory intelligence objectives.
Recent Developments Shaping the Field
Recent product launches and deployment activity illustrate how the market is moving toward smarter, more integrated EAS solutions. Sensormatic Solutions introduced a category-level shrink insights ecosystem that leverages existing EAS infrastructure for intelligent loss-prevention analytics, signaling a shift toward software-driven value creation on established hardware footprints. Nedap expanded its RFID-based EAS footprint through large-scale store rollouts and a pan-European grocery deployment, reinforcing the appeal of item-level recognition and open-entrance detection in high-traffic retail environments.
Avery Dennison has been active in broadening the tag ecosystem with compact inlays, enhanced chip compatibility, and sterilization-ready RFID inlays for healthcare applications. These developments matter because they extend EAS feasibility into categories that require careful handling, small form factors, or compatibility with processing methods that previously limited tagging options. Collectively, these moves show a market where detection, tagging, and analytics are converging rather than evolving in isolation.
Rf Eas Label Market
Market Structure and Evolution Trends
Market concentration remains moderate, with leading players holding meaningful but not dominant shares. This creates room for both consolidation and specialized differentiation. Over the next several years, three structural trends are likely to shape the landscape:
- Integration and platformization will accelerate as retailers prefer fewer vendor relationships that can deliver detection, tagging, and analytics within a coherent architecture.
- Component specialists will continue to gain influence where miniaturization, sterilization compatibility, and chip-level compatibility create clear advantages in high-value or sensitive categories.
- New entrants and niche providers may find opportunities in edge-AI antennas, interoperability services, and vertical-specific solutions, particularly where legacy systems create upgrade bottlenecks.
The overall effect is a market that is becoming more solution-oriented. Winners will be those who can demonstrate measurable reductions in false alarms, labor efficiency, and shrink visibility while supporting the tagging standards and IT integration requirements that modern retail operations increasingly expect.
Future Trends and Commercial Opportunities
From Detection to Intelligence-Led Loss Prevention
Over the next three to five years, EAS systems are likely to be evaluated increasingly on their ability to generate actionable intelligence rather than simply trigger alarms. Edge processing, analytics dashboards, and integration with store data environments will turn detection points into sources of shrink insight, category comparison, and operational feedback. The commercial opportunity here lies in offerings that help retailers convert existing infrastructure into measurable loss-prevention improvements without requiring full hardware replacement. Providers that can package analytics with detection hardware, or enhance legacy systems through software upgrades, will be well positioned to capture demand from cost-conscious retailers seeking performance gains.
PW Consulting
Upstream Tagging and Ecosystem Standardization
Source tagging is expected to deepen as supplier mandates, compliance requirements, and labor economics continue to push tagging earlier in the supply chain. This creates opportunities for tag manufacturers, inlay developers, and integration partners who can deliver compatible, durable, and cost-effective tagging at scale. Standardization efforts around encoding and interoperability will further reduce deployment friction and support cross-retailer consistency. Companies that align their product portfolios with emerging tagging standards and can demonstrate compatibility with major detection systems will benefit from broader adoption and repeat procurement cycles.
Category Expansion and Hybrid Deployments
Growth is likely to broaden beyond traditional apparel and fashion as EAS becomes viable in grocery, cosmetics, pharmacy, and healthcare contexts. Miniaturized tags, sterilization compatibility, and hybrid RFID-EAS architectures will enable protection in categories where detection was previously limited. For retailers and integrators, this opens new deployment models that combine loss prevention with inventory accuracy and customer flow insights. The opportunity lies in designing category-specific tagging and detection strategies that balance security, aesthetics, and operational practicality.
Risks and Uncertainties
Despite the positive trajectory, several uncertainties merit attention. If false-alarm performance or interoperability issues persist, retailer confidence in large-scale EAS investments could slow. Regulatory requirements may also evolve in ways that change tagging obligations or compliance costs, creating short-term disruption for suppliers and retailers adjusting their sourcing strategies. Labor market conditions will continue to influence the economics of in-store tagging and monitoring, meaning that adoption speed may vary by region and retail format. Finally, as analytics become more central to EAS value, data privacy, IT integration complexity, and vendor lock-in concerns could affect purchasing decisions, particularly in consolidated retail environments.
Strategic Implications for Decision-Makers
For Manufacturers and Technology Providers
Companies operating in the EAS market should prioritize interoperability, false-alarm reduction, and analytics compatibility as core product priorities. The ability to support standardized encoding, integrate with major detection platforms, and offer software-enabled insights can differentiate a portfolio in a market where hardware specifications alone are increasingly insufficient. Investment in miniaturization, sterilization-compatible labeling, and chip configurations that align with prevailing EAS requirements will also expand addressable categories and strengthen supply chain partnerships.
Electronic Shelf Label (ESL) Market
For Investors
Investment attention should focus on providers that demonstrate a clear path from hardware to recurring value through analytics, integration services, and scalable tagging ecosystems. Businesses that can monetize intelligence layers, reduce deployment friction, and support upstream tagging requirements are better positioned to capture long-term growth than those dependent solely on equipment replacement cycles. It is also important to monitor consolidation signals, standardization progress, and large retailer mandates, as these factors can reshape competitive dynamics and margin structures across the value chain.
For Retailers and Procurement Leaders
Procurement decisions should evaluate EAS investments against total operational impact, including false-alarm reduction, labor efficiency, inventory visibility, and compatibility with existing store IT environments. Source-tagging requirements and supplier mandates should be factored into vendor selection, as upstream compatibility can materially affect deployment speed and ongoing maintenance costs. Hybrid and multi-technology options may be appropriate where store formats, product mixes, or legacy systems vary, but standardization and integration should remain central to avoid fragmented deployments that increase complexity without delivering proportional benefits.
The market’s trajectory suggests that the most valuable decisions will be those aligned with broader retail operating models rather than isolated security purchases. Stakeholders that act early on interoperability, intelligent detection, and upstream tagging strategies will be better prepared to manage shrink, labor constraints, and compliance expectations as the market moves toward 2032.
For decision-makers seeking detailed segmentation data, competitive benchmarks, and customized scenario planning, the full PW Consulting research report provides a deeper examination of regional dynamics, application trends, and vendor-level positioning. Access to the complete study can help translate these strategic themes into specific procurement, investment, and product-development choices tailored to your operating context.
For detailed analysis of this topic, please visit the official page: Electronic Article Surveillance (EAS) System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Digital Logbooks: A Better Way to Capture and Manage Operations
Managing operational records can become unexpectedly complicated when information is scattered across notebooks, spreadsheets, emails, sticky notes, whiteboards, and individual devices. Employees may feel that critical details are being recorded, yet reconstructing exactly what took place during routine operations can be much harder than anticipated. One employee may remember an event without knowing every detail, another may have the relevant image saved on a phone, while someone else could waste valuable time digging through outdated email conversations for information that was never formally recorded. A review that should take only a few minutes can quickly turn into a time consuming exercise of assembling information from several disconnected sources.
A digital logbook offers a more structured approach to managing these records. Rather than keeping observations, updates, images, and operating conditions in separate locations, teams can maintain them within one centralized environment. ToolKitX Log Books provide a searchable chronological history of operational activity, helping employees find relevant information more easily throughout the organization. Whether teams are operating from a control room, working in the field, or accessing records through mobile devices where connectivity is unreliable, essential operational information can remain accessible when needed.
How Digital Logbooks Have Changed
Today's digital logbooks have moved well beyond simply replacing handwritten notebooks with electronic versions. They have become useful operational centers where teams can record shift updates, incidents, observations, and handover details as work progresses. Employees no longer need to rely solely on memory or postpone documentation until later. Events can be recorded at the time they occur, producing records with reliable timestamps that provide greater context about the situation.
ToolKitX extends this approach through capabilities such as tagging, approvals, and analytics, turning documentation into an active part of operational management instead of treating it merely as a historical record. Electronic signatures can reinforce accountability, while organized categories make it easier to locate particular information. Analytical capabilities can help expose recurring problems, communication gaps between shifts, and developing risks before they become larger operational concerns. With information consolidated in one place, teams can remain informed without repeatedly switching between communication channels or wondering whether a significant event was properly recorded.
Why Fast and Reliable Information Matters
Round the clock industries such as energy, utilities, offshore operations, and large construction projects can produce substantial amounts of information during every shift. As the volume of records increases, locating one specific piece of information at the right moment can become increasingly challenging. When access to important details is delayed, decisions may take longer, responses can become less effective, and relatively minor operational issues may have more opportunity to develop.
ToolKitX is designed to manage increasing quantities of operational information while keeping records structured and accessible. Users can organize, filter, and examine information according to changing operational needs. Instead of manually working through lengthy records, employees can use search capabilities to find the information relevant to them. Analytical tools can also highlight unusual activity, recurring patterns, and emerging trends, helping teams recognize possible concerns sooner. Notifications can be directed to the personnel responsible for taking action, allowing important information to reach the appropriate people more efficiently.
Supervisors can examine records, approve activities, leave comments, escalate issues, or carry out follow up tasks while maintaining a visible history of the decisions and actions associated with an event. This provides a clearer link between what was originally reported, how the issue was addressed, and what occurred afterward.
Key Benefits for Operational Teams
Digital logging can provide greater operational visibility through dashboards that consolidate information across different shifts, departments, and locations. Managers and supervisors can develop a broader view of current activities, making it easier to recognize effective performance while identifying recurring difficulties that may need further attention.
Recording information can also become considerably easier. Employees can select an appropriate asset or location, establish priorities, enter notes through text or voice, and attach relevant photographs or documents without navigating complicated procedures. Simplified workflows and intelligent defaults can reduce the effort involved in documenting routine activities. This allows logging to become part of the normal work process instead of feeling like a separate administrative responsibility.
Digital logbooks can also strengthen shift handovers. Conventional handovers may rely heavily on conversations, short meetings, or informal messages, increasing the possibility that important details will be overlooked. ToolKitX can organize information that incoming personnel need, such as unresolved risks, incomplete work, active permits, and outstanding follow up actions. Digital acknowledgments allow employees to confirm that responsibilities and information have been received, helping create a more consistent and accountable handover process.
Supporting Different Operational Workflows
Operational teams do not all follow identical procedures or require the same documentation. Maintenance teams, HSE personnel, supervisors, project managers, and field workers may each need to capture different information. ToolKitX supports these varying requirements through configurable templates, fields, and categories that can be adjusted to individual operational needs while keeping information within a connected environment.
Additional details can also be recorded alongside individual log entries. Weather conditions, for example, can be associated with an operational event, giving future reviewers additional context when examining delays, restrictions, or safety related decisions. Records may also connect with permits, inspections, work orders, and asset information. Employees can therefore move between related details while retaining a broader view of the circumstances surrounding an event.
Increasing Efficiency and Supporting Compliance
Moving away from paper records and repetitive manual processes can help organizations reduce the time employees spend on administrative activities. Personnel can avoid repeatedly entering identical information, handling physical documents, or preparing reports manually. Security controls can also help protect operational records through authentication, automated backups, and measures intended to limit unauthorized changes or reduce the risk of data loss.
Automated reporting can reduce administrative effort further by generating professional summaries that can be distributed to relevant stakeholders when necessary. Integrations can also make information sharing between departments more efficient, reducing isolated data and helping teams maintain a more consistent view of operational activities.
Using Daily Records for Continuous Improvement
Digital logging does not necessarily require employees to maintain a continuous internet connection. Supported devices can allow personnel to create records while offline, documenting events as they happen and synchronizing the information once connectivity returns. Analytical capabilities can then help organize operational activity, identify exceptions, and uncover patterns that may not be immediately obvious.
Reports can transform everyday records into useful insight regarding incidents, delays, performance measures, and operational results. These insights can contribute to improved planning, stronger safety processes, and better informed decisions. Rather than waiting until an issue occurs and examining it afterward, organizations can use the information already being collected to recognize potential difficulties sooner and make ongoing improvements to how work is carried out.
Who Can Use Digital Logbooks?
Digital logbooks can support operations managers, supervisors, control room personnel, and field teams across industries such as energy, utilities, offshore operations, and construction. By placing everyday operational information into a more organized and accessible structure, they can improve visibility, support smoother shift transitions, and preserve records that can be reviewed whenever questions or concerns arise.
When operational information needs to be reviewed, confirmed, or validated, relevant details can be found together rather than being distributed across multiple sources. Photographs, timestamps, weather information, approvals, follow up activities, and acknowledgments can remain organized within the same record environment. This provides organizations with a clearer account of what happened, which decisions were made, and what actions followed, supporting greater operational accountability whenever reliable documentation is required.
Book a free demo @ https://toolkitx.com/campaign/logistic-planning/
Browse More
https://toolkitx.com/blogsdetails.aspx?title=Incident-Management-Process:-Step-by-Step-Guide-to-Improve-Workplace-Safety-and-Compliance
https://toolkitx.com/blogsdetails.aspx?title=loto-failures-real-industrial-incidents
https://toolkitx.com/blogsdetails.aspx?title=job-hazard-analysis-vs-task-risk-assessment
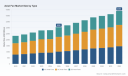
Axial Fan Market: Strategic Trends and Commercial Opportunities Beyond the Efficiency Mandate
The axial fan market finds itself at a structural inflection point. From 2020 through 2025, the global market expanded from roughly $2.33 billion to an estimated $3.05 billion, reflecting a compound annual growth rate of approximately 5.5 percent across the forecast horizon through 2032. By the end of that forecast window, revenue is projected to approach $4.4 billion. These headline figures, however, only capture the quantitative surface of a deeper transformation. The market is no longer growing purely on installation volume or incremental replacement cycles. Growth is being reshaped by efficiency regulations, motor technology migration, regional supply chain realignment, and the growing expectation that airflow systems must operate as intelligent, energy-optimized components rather than standalone mechanical parts.
For executives and investors, the central question is no longer whether demand will continue, but where margin and differentiation will accrue. The market remains moderately fragmented, with the top three players holding roughly a quarter of total revenue and the top five closer to a third. That concentration level suggests both room for consolidation and persistent competition from specialized manufacturers who compete on application expertise rather than scale alone. The companies that will capture disproportionate value are those that can align product architecture with regulatory timelines, control component cost exposure, and convert efficiency mandates into commercial advantage rather than compliance cost.
Market Status and Core Challenges
The current market environment is defined by three intersecting challenges that are altering how axial fan manufacturers plan product roadmaps, pricing, and geographic exposure.
Efficiency Regulation as a redesign Imperative
Regulatory pressure is moving from incremental tightening to mandatory step changes. The EU ErP 2026 framework raises mandatory efficiency requirements for axial fans and cooling towers, while California Title 24 2025 standards increase efficacy expectations for axial-fan cooling towers in nonresidential applications. These are not marginal adjustments. They effectively reset the minimum performance baseline for new equipment in key commercial and industrial segments. Manufacturers that have historically competed on price or basic airflow capacity now face a redesign window in which motor type, blade geometry, and control logic must be evaluated together. The practical challenge is timing: product development cycles that are too slow will miss market entry points, while premature launches risk non-compliance or retrofit friction.
Cost Structure Exposure in a Volatile Input Environment
Axial fans rely on steel housings, aluminum blades, and electric motors as core components, which means manufacturers are directly exposed to commodity price movements and trade policy shifts. Recent US trade measures introduce additional duties on steel and aluminum articles, affecting imports of structural and mechanical components used in fan assembly. Even when manufacturers source from diversified suppliers, the cumulative effect shows up in landed cost, margin stability, and quotation reliability. For companies that operate on fixed-price downstream contracts, the risk is not simply higher material costs; it is the difficulty of passing through cost changes without eroding competitiveness or delaying orders.
Application Complexity and the Shift from Component to System Thinking
The market is increasingly evaluated through system-level performance rather than isolated fan specifications. HVAC, industrial ventilation, cooling towers, and electronics cooling each place distinct demands on airflow, noise, space, and control integration. End users and OEMs are less interested in standalone air movement and more focused on whether the fan solution integrates cleanly into broader thermal management, energy, or automation architectures. This creates a strategic challenge for manufacturers that remain organized around discrete fan models rather than application bundles, controls, and service pathways. The market is rewarding those who can reduce integration friction and improve operating efficiency after installation, not just at the point of sale.
Key Drivers Reshaping the Market
Motor Architecture Evolution and EC/DC Technology Adoption
The most significant technical driver is the continued migration toward electronically commutated and DC motor platforms in axial fans. EC and DC architectures enable higher part-load efficiency, variable speed control, and more granular performance tuning than traditional AC designs in many applications. That matters because efficiency is no longer measured only at peak output; real-world operation increasingly values performance across duty cycles, startup behavior, and controllability. Manufacturers expanding EC and DC portfolios are positioning themselves for a market where efficiency compliance and operational flexibility become bundled value propositions. The broader implication is that motor technology is becoming a strategic differentiator, not simply a component choice.
Policy-Driven Demand and Retrofit Economics
Policy and building performance standards are creating both new equipment demand and retrofit activity. As efficiency thresholds rise, a portion of the market shifts toward replacement and upgrade cycles, especially in nonresidential HVAC, commercial ventilation, and cooling tower environments where compliance deadlines interact with capital planning. At the same time, stringent energy expectations in key regions influence procurement criteria, making efficiency class and total cost of ownership more prominent in purchasing decisions. Demand is therefore being shaped not only by end-market growth, but by regulatory-driven renewal cycles and the economics of replacing lower-efficiency installed base equipment.
Application Demand Diversification Across End-Use Segments
Demand continues to broaden across multiple usage contexts rather than concentrating in a single dominant application. HVAC remains a major axis of demand, supported by building climate control needs and system modernization. Industrial ventilation adds another layer, where airflow reliability, durability, and integration with process environments matter as much as efficiency. Residential cooling and commercial building ventilation contribute additional demand streams with different price sensitivity, specification cycles, and channel dynamics. Meanwhile, automotive and adjacent applications provide smaller but technically demanding niches where performance consistency and long-life operation are critical. The strategic implication is that growth is not monolithic; each application segment has its own regulatory exposure, specification cadence, and competitive intensity.
Supply Chain Realignment and Regional Cost Dynamics
Supply chain considerations are becoming more strategic as manufacturers evaluate where to source motors, blades, housings, and electronic controls. Trade measures affecting steel and aluminum inputs, combined with the broader shift toward more localized or diversified sourcing, are influencing cost structures and lead-time planning. In this environment, manufacturers that can balance regional production footprints, manage component standardization, and maintain flexibility in assembly locations gain a practical advantage. The market is increasingly sensitive to the intersection of compliance, cost, and supply reliability, especially for companies serving multiple regions with different regulatory and procurement expectations.
Competitive Landscape and Leading Strategies
The competitive landscape is anchored by a group of manufacturers with strong engineering reputations, application-focused portfolios, and increasingly divergent strategic postures. Several patterns stand out.
Electric Fan Market
Efficiency Leadership through EC and Modular Platforms
German and European manufacturers such as Ziehl-Abegg and ebm-papst are widely recognized for their focus on high-efficiency EC motors and axial fans tailored to HVAC, industrial, and precision control applications. Their value proposition centers on combining energy savings with controllability and application-specific engineering. Multi-Wing has built a reputation as a global leader in modular axial fans and impellers for condenser, heat exchanger, HVAC, and industrial cooling environments, where modularity and application breadth support rapid configuration across end markets. These companies illustrate a common strategic theme: efficiency leadership is increasingly expressed through platform design, not just motor choice.
Regional Scale, OEM Integration, and Cooling System Footprints
Other players compete through strong regional presence and deep integration with specific downstream systems. Rosenberg and Airmaster Fan Company combine German engineering with a US commercial and industrial focus, while Delta Electronics and Sanyo Denki emphasize EC, DC, and DC axial fan series for electronics cooling and performance-intensive environments. In the United States, companies such as New York Blower Company, SPX Cooling Technologies, Evapco, and Baltimore Aircoil Company concentrate on in-line, custom, and cooling-tower-integrated axial fan solutions. This group demonstrates that competitive advantage is not only about fan efficiency in isolation, but about embedding the fan into larger system architectures where reliability, service, and specification support matter.
Consolidation and Portfolio Expansion
Corporate activity suggests the market is entering a more active phase of consolidation and capability building. Nidec Corporation's acquisition of an axial fan division expanded its production capabilities and reinforced its position across industrial and HVAC applications with EC and AC motor-based axial fans. At the same time, product and event activity from other manufacturers is signaling active portfolio refresh in response to upcoming efficiency requirements. Multi-Wing introduced ErP 2026-compliant axial fan series and DCmax series exceeding EU energy efficiency regulations, while also preparing to showcase its offering at the IVT Expo in Cologne. ebm-papst announced AxiTone and AxiEco plug-in axial fans for HVAC applications. Taken together, these moves indicate that leading players are using product launches, trade presence, and selective acquisitions to strengthen both technical credibility and market coverage ahead of regulatory implementation.
Strategic Implications of the Current Landscape
The competitive environment favors manufacturers that can combine several capabilities at once: efficiency compliance readiness, application-specific configuration, motor and control integration, and supply chain resilience. Pure price competition is becoming harder to sustain as regulatory floors rise and input costs remain volatile. At the same time, the moderate concentration of the market leaves space for both consolidation among larger players and continued niche strength among specialists. New entrants face a meaningful barrier unless they bring a clear advantage in motor efficiency, system integration, or a specific regional application niche. The more probable trajectory is continued differentiation, selective M&A, and a growing divide between platform-driven leaders and application-focused specialists.
Forward Trends and Commercial Implications
Efficiency Compliance Becomes a Market-Filtering Event
Over the next three to five years, efficiency regulation will increasingly function as a market filter rather than a generic compliance task. As ErP 2026 and related regional standards take hold, procurement specifications are likely to narrow the field of acceptable products in regulated segments, particularly in commercial HVAC, cooling towers, and nonresidential ventilation. The commercial opportunity lies in positioning product lines that not only meet the new thresholds, but offer clear advantages in part-load performance, controllability, and integration. Manufacturers that can document compliance and translate it into operating savings will have stronger specification leverage. The risk is that companies with slower redesign cycles may face shrinking addressable demand in regulated channels, especially where replacement decisions are tied to compliance deadlines.
Growth Concentrates Where System Integration and Intelligence Add Value
A second trend is the growing importance of intelligent airflow management and system-level compatibility. Axial fans are increasingly evaluated alongside controls, sensors, and broader thermal or ventilation strategies. That creates opportunities for manufacturers that offer configurable solutions, compatible control interfaces, and lower integration complexity. In HVAC and industrial ventilation especially, the value shift is moving toward solutions that help reduce energy consumption across real operating conditions rather than at nominal ratings alone. The corresponding risk is that product portfolios remain fragmented, making it harder to scale cross-application platforms and to support customers who want standardized efficiency and control behavior across sites or projects.
Cooling Fan Market
Regional Divergence in Sourcing, Pricing, and Specification Cycles
The third trend is regional divergence in both cost dynamics and specification behavior. Trade measures affecting steel and aluminum inputs, combined with different regional regulatory timelines, mean that manufacturers cannot assume a uniform cost or compliance pathway across markets. Some regions may see faster replacement activity driven by building performance standards, while others may be more sensitive to input cost pressure and import exposure. This divergence creates opportunities for companies that can adapt sourcing, regional product configurations, and service coverage to local requirements. The uncertainty lies in how quickly trade conditions, material costs, and compliance enforcement will evolve, and whether manufacturers can maintain margin stability while adjusting regional strategies.
PW Consulting
Actionable Considerations for Decision Makers
For manufacturers, the priority is to treat efficiency compliance as a product strategy event rather than a certification task. That means aligning motor architecture, blade and housing design, and control capabilities with the regulatory timeline in each target market, while also reducing dependency on exposed input categories where possible. Companies should assess whether their portfolio is concentrated in application segments facing the sharpest compliance shifts and whether modular or configurable platforms can help them respond faster to specification changes. In parallel, building stronger system-integration support and documentation can improve specification win rates in segments where total cost of ownership matters more than unit price.
For investors, the market suggests a preference for companies with credible efficiency roadmaps, application breadth, and some degree of supply chain or geographic diversification. The moderate concentration level indicates room for consolidation, but value creation will likely depend on whether acquisitions and internal investments translate into compliant, differentiated platforms rather than simply adding volume. Investors should pay attention to how quickly manufacturers are converting regulatory pressure into new product launches, how exposed they are to steel and aluminum cost dynamics, and whether their growth is anchored in segments with durable replacement cycles and system-level demand.
For procurement and engineering leaders, the practical implication is to broaden evaluation criteria beyond nominal airflow and initial price. Efficiency class, part-load behavior, motor type, lifecycle cost, and compatibility with existing control or ventilation architecture are becoming more relevant as compliance expectations rise and operating environments grow more complex. Where projects intersect with regulated nonresidential or cooling-tower applications, early alignment with compliant product options can reduce redesign risk and specification delays. Procurement teams should also weigh supply continuity and regional sourcing exposure, particularly for programs with multi-year rollout plans or standardized equipment lists.
Conclusion
The axial fan market is moving from broad-based growth to a more selective, efficiency-driven expansion path. The combination of regulatory tightening, motor technology migration, application diversification, and input-cost volatility is reshaping where competitive advantage comes from. Manufacturers that treat compliance as a platform opportunity, invest in integration and control readiness, and manage material exposure strategically will be better positioned to capture margin and specification share. For investors and buyers, the most valuable intelligence is increasingly at the level of segment readiness, regional cost dynamics, and product roadmap alignment rather than aggregate market size alone. Detailed segment breakdowns, regional comparisons, and customized scenario analysis can sharpen these decisions further, especially for organizations planning capital allocation, product investment, or multi-region procurement strategies in the 2026 to 2032 window.
For detailed analysis of this topic, please visit the official page: Axial Fan Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Baby Bottles Market 2025-2032: 5.32% CAGR Growth Drives Regional and Material Shifts
By PW Consulting, 2026-09-21
The Baby Bottles Market: Navigating Growth, Safety, and Innovation Through 2032
The baby bottles market stands at a critical inflection point, shaped by steady demand growth, evolving safety expectations, and a competitive landscape where material science, regulatory scrutiny, and clinical performance increasingly determine market success. With total revenue projected to reach approximately 2,760.0 million USD in 2025 and expand to roughly 3,938.0 million USD by 2032, the sector is positioned for a long-term growth trajectory at a 5.32% CAGR across the 2026-2032 period. The historical record from 2020 through 2025 shows an uneven but ultimately upward path, with 2022 marking a brief plateau before accelerated expansion resumed in 2023-2025. This pattern reflects more than demographic tailwinds; it reveals a category reshaping itself around functionality, safety certification, and brand trust.
PW Consulting Health Care Research Center
For executives, investors, and strategic planners, the strategic question is no longer whether demand will persist. The question is where value will accumulate as safety incidents, material substitution, and formulation-led differentiation raise the bar for entry and retention.
Market Snapshot and Core Challenges
The market's size and trajectory provide a backdrop of resilience, but the underlying dynamics point to structural pressure points. Revenue has moved from 2,271.0 million USD in 2020 to 2,760.0 million USD in 2025, and forward estimates suggest continued expansion into the late 2030s. Growth is broad-based, but concentration remains meaningful: the top three players hold about 47.5% of the market, while the top five account for roughly 52.0%. This level of concentration indicates that leading brands still command significant shelf presence, channel leverage, and consumer recognition, yet it also leaves substantial room for specialized entrants and regional challengers to gain traction through focused value propositions.
Three strategic challenges define the current environment.
- Safety and material credibility have become decisive purchase criteria. Incidents involving lead detection, peeling plastic shells, and decal contamination have heightened scrutiny from regulators, retail buyers, and informed parents. Trust is now earned through testable material specifications, certification transparency, and rapid corrective action, not simply brand heritage.
- Anti-colic functionality and feeding performance are narrowing the gap between commodity and premium offerings. As clinicians, caregivers, and retail recommendations increasingly emphasize reduced spit-up, better airflow, and nipple designs that mimic natural feeding rhythms, products that fail to demonstrate functional benefit face eroding relevance regardless of price position.
- Regulatory divergence across regions is adding complexity to launch planning and production consistency. Different markets apply varying standards for materials, device safety, and labeling, which means global portfolios must balance scale efficiencies with localized compliance and testing. Any lapse can trigger recalls, retail delistings, or reputational damage that takes months to repair.
These challenges are not obstacles to dismiss; they are filters that are reallocating share toward manufacturers that can prove safety, performance, and consistency at scale.
Key Demand and Supply Drivers
Several interlocking forces are shaping the market's direction. Their combined effect is pushing the category toward higher-performing materials, more rigorous certification, and more clinically grounded product claims.
Technology Innovation and Material Advancement
Material choice has moved from a cost decision to a positioning decision. The market is no longer split simply between plastic and glass; silicone, stainless steel, and advanced thermoplastics each carry distinct tradeoffs in durability, weight, thermal behavior, and perceived safety. Recent developments illustrate how material upgrades are becoming a visible brand asset. One notable example is the adoption of high-performance thermoplastic in manufacturing to improve durability and safety consistency, signaling that material sourcing can be used as a competitive differentiator rather than a hidden supply decision. Similarly, hybrid constructions that combine the clarity and feel of glass with the impact resistance of plastic have gained attention by attempting to address the breakage concerns that limit glass adoption in certain channels.
Innovation is also advancing in venting and nipple geometry. Bottom-vent designs, internal vent systems, and gradual-slope nipples aim to reduce air ingestion, manage flow, and support more natural sucking patterns. Where these features are supported by clinical data or documented reduction in colic symptoms and spit-up, they move from marketing claims to product proof points. That proof matters increasingly in a market where caregivers compare options based on observable outcomes and peer recommendations.
Policy and Regulatory Environment
Regulators are tightening expectations around product safety, and the consequences of non-compliance have become highly visible. Voluntary recalls tied to choking hazards, peeling shells, and contamination concerns have underscored the importance of proactive quality control and post-market surveillance. In parallel, some jurisdictions have imposed bans on certain self-feeding devices due to choking, aspiration, and suffocation risks, reflecting a broader willingness to restrict product forms that do not meet safety thresholds.
These regulatory signals have two practical implications. First, they raise the baseline for what qualifies as an acceptable product in major markets, favoring manufacturers with robust testing protocols and traceable production processes. Second, they create reputational ripple effects: a recall in one category or brand can heighten consumer caution across the category, making transparent certification and rapid remediation essential for defending shelf space. Companies that can demonstrate compliance through recognized testing agencies and maintain clear documentation are better positioned to sustain retail relationships and consumer confidence.
Demand-Side Shifts in Consumer Behavior
Caregivers are making decisions with greater information and higher expectations. The modern purchase journey often involves comparing anti-colic performance, material safety, ease of cleaning, compatibility with breast pumps, and brand responsiveness to safety concerns. Parents are also increasingly receptive to products that offer functional benefits beyond basic containment, such as reduced gas, easier temperature control, or designs that support transition between breastfeeding and bottle feeding.
At the same time, brand trust is being re-evaluated. Hospital-trusted positioning, clinical data, and visible certification have gained influence because they help cut through ambiguity. Premiumization is evident in segments where consumers accept higher price points for perceived safety, comfort, or design refinement, but value remains important in price-sensitive channels. This bifurcation means that brands must be explicit about their value proposition rather than relying on generic category demand.
Supply Chain and Cost Structure Dynamics
Material availability, manufacturing consistency, and compliance testing all influence cost structures. As advanced materials and specialized components become more common in premium products, producers must manage the balance between performance gains and input costs. The market's concentration profile suggests that scale players still benefit from procurement leverage and distribution reach, but targeted investment in material quality and testing can allow smaller brands to compete on credibility rather than price alone.
Supply-side resilience is also increasingly tied to safety performance. A single quality failure can disrupt production schedules, retail orders, and brand perception simultaneously. Manufacturers that invest in process control, batch traceability, and pre-market testing reduce the likelihood of costly corrections later. In practice, the cost of prevention is often lower than the cost of a recall, a retailer audit, or a prolonged trust deficit.
Competitive Landscape and Leading Strategies
The market features a mix of established multinational brands, regionally strong players, and newer entrants focused on performance and certification. The strategic positions vary, but several patterns are clear.
Philips Avent has built a strong identity around anti-colic and Natural Response bottles, with AirFree venting technology and orthodontic nipples as core elements of its value proposition. Its positioning leans on functionality and familiarity, reinforced by broad retail availability and a recognizable brand footprint. BIBS represents the premium Danish approach, combining BPA-free polypropylene and borosilicate glass options with anti-colic valves, appealing to consumers who prioritize material clarity and design. Dr. Brown's differentiates through its Original Internal Vent System and clinical colic reduction data, giving it a credibility anchor in a category where caregivers look for demonstrable outcomes.
NUK continues to benefit from hospital-trusted associations and anatomically shaped nipples, with both glass and plastic options that cater to consumers seeking traditional trust signals and material choice. Evenflo, with more than a century of manufacturing history, uses its long track record and balance flow nipples to maintain relevance across classic and anti-colic segments. Tommee Tippee has leaned into eco-conscious positioning with Closer to Nature bottles and plant-based material options, aligning with consumers who weigh environmental considerations alongside feeding performance. Chicco addresses breakage concerns directly through hybrid unbreakable glass-to-plastic constructions using Invinci-glass technology, targeting the segment that wants glass-like aesthetics without the fragility risk.
Pigeon and Lansinoh both emphasize natural-feel feeding experiences through gradual slope nipples, with Lansinoh particularly aligned to breastfeeding-focused users. TOMY has historically offered reusable bottle systems with convenience-oriented features, though recent safety events have shown how quickly product reputation can shift when quality issues emerge. Thyseed's recent activity illustrates the opportunity for newer entrants to compete through clinically oriented design and certification strength, including bottom-vent anti-colic design and multi-test safety validation.
Several strategic themes cut across these profiles.
- Performance validation is becoming a yes-or-no gate. Brands that can connect product design to reduced colic, less spit-up, or improved feeding comfort are better positioned to command attention in both premium and recommendation-driven channels.
- Material strategy is a brand signal. Glass, silicone, advanced plastic, and hybrid constructions each communicate a different promise. The most effective portfolios do not merely offer choices; they explain why each material matters for a specific user need.
- Certification and transparency reduce friction. In an environment where recalls and contamination concerns have raised caution, documented testing and clear compliance positioning help protect both retail relationships and consumer trust.
- Speed of response matters more than before. When quality issues arise, the ability to pause sales, investigate, update designs, and communicate clearly can determine whether a brand recovers quickly or loses momentum for an extended period.
The competitive landscape is evolving through both consolidation and fragmentation. Established brands continue to hold meaningful share, but the presence of specialized entrants with focused certifications and targeted anti-colic claims suggests that fragmentation can persist where differentiation is credible. At the same time, retail consolidation and channel gatekeeping can favor brands that already meet stringent compliance and performance expectations, nudging the market toward a smaller set of trusted suppliers in certain segments. The long-term outcome is likely to be a layered market: dominant brands in broad distribution, specialized leaders in performance- and safety-focused segments, and periodic newcomer success where design and validation create a clear jump in perceived value.
Strategic Outlook: 2026-2032
Looking ahead, three trends are likely to shape where value is created and where risk concentrates.
Trend 1: Safety and certification will increasingly define premium positioning
As caregivers and retail buyers become more attuned to material safety, testing documentation, and post-market performance, certification is moving from a compliance requirement to a commercial asset. Brands that proactively validate materials, communicate test results, and maintain rigorous quality controls will be better equipped to defend price points and shelf placement. This trend also raises the stakes for any product that relies on weaker documentation or outdated materials, particularly as consumer awareness of contamination and choking hazards continues to grow.
The commercial opportunity lies in turning safety into a differentiated narrative. This does not mean overclaiming; it means clearly linking material selection, testing protocols, and design choices to practical outcomes such as durability, chemical stability, and reduced failure risk. In practice, the brands that win here will be the ones that make safety legible to consumers and buyers without relying on fear-based messaging.
Trend 2: Anti-colic and feeding-performance innovation will reshape segment boundaries
Functional innovation is likely to remain one of the strongest drivers of upgrade behavior. Bottom-vent systems, internal venting, nipple geometry, and material combinations that reduce air intake or improve latch feel will continue to influence purchasing decisions, especially where claims are supported by data or strong user feedback. As these features become more common, the market may see a shift in which basic bottles face greater pressure to justify their value, while functionally advanced products gain share among consumers seeking measurable comfort improvements.
The strategic implication is that product roadmaps should prioritize validated performance over feature count. A single well-executed venting or nipple design with credible evidence can outperform a broader set of unexamined features. Companies that can demonstrate clinically meaningful or user-verified reductions in colic symptoms and spit-up are better positioned to capture attention in both premium and recommendation-led channels.
Trend 3: Regional divergence and channel complexity will reward focused portfolios
Because regulatory expectations, material preferences, and channel dynamics differ by region, global one-size-fits-all portfolios will face growing tension. Some markets will emphasize material safety and device restrictions more heavily, while others will prioritize price accessibility or specific design preferences. Retailers and distributors are likely to continue consolidating their supplier base where trust, compliance, and performance are easiest to verify.
This environment creates opportunity for companies that design regionally informed portfolios rather than simply exporting a single product architecture. It also increases the value of local certification, localized consumer insight, and channel-specific packaging or messaging. Brands that can align product specifications with regional expectations while maintaining consistent quality standards will be better placed to scale without triggering compliance or reputation friction.
Potential risks and uncertainties remain significant. Recalls and contamination incidents can quickly reshape consumer perceptions and retailer confidence. Regulatory changes may restrict certain product forms or raise testing requirements, affecting both cost and time-to-market. Material substitution can create new performance benefits but also introduces validation burdens. In addition, competitive intensity may increase as new entrants use certification and functional claims to break into established segments, while larger brands respond with portfolio breadth and distribution strength. Companies that assume category growth alone will protect them risk being overtaken by rivals that convert safety and performance into clearer consumer value.
Implications for Decision Makers
Different stakeholders will extract value from the market in different ways, but the underlying requirements are similar: credible differentiation, verifiable safety, and disciplined execution.
For Manufacturers and Brand Leaders
Treat material and venting design as strategic decisions rather than engineering details. The brands gaining ground are those that can articulate why a specific material, venting system, or nipple shape matters for comfort, safety, or durability, and then back that claim with testing or clinical support. Portfolio design should also reflect the tension between scale and specialization. A broad range of products can capture more usage scenarios, but only if each variant has a clear purpose and consistent quality controls. Finally, post-market responsiveness should be built into operating routines, because the speed and clarity of response to a safety issue can be as important as the product design itself.
Worldwide Baby Glass Bottles Market
For Investors and Strategic Partners
Focus on companies with defensible proof points and operational discipline. Revenue growth is meaningful, but in a market where recalls and contamination concerns can disrupt reputation quickly, the quality of a company's testing infrastructure, certification posture, and corrective-action capability is equally important. Preference should go to brands that combine functional differentiation with documented safety validation and clear compliance processes, especially where they can sustain retail relationships and consumer trust over time. Diversification across materials and price points can be valuable, but only when each segment has a coherent value proposition rather than overlapping, undifferentiated SKUs.
For Procurement, Retail, and Channel Buyers
Use safety documentation and performance claims as part of sourcing criteria, not as optional background information. Asking for material specifications, testing results, and evidence of post-market monitoring can help reduce exposure to product failures and subsequent disruptions. It is also worth weighing portfolio breadth against accountability: a smaller set of well-documented, performance-validated suppliers may offer more predictable shelf performance than a larger group of weakly differentiated options. In channels where consumer caution is high, brands that communicate transparency and respond quickly to issues are likely to generate fewer interruptions and stronger end-consumer confidence.
Feeding Bottle Market
The baby bottles market is not simply expanding; it is being re-sorted by trust, performance, and material credibility. That re-sorting creates clear winners and losers among brands that look similar on the shelf but differ sharply in how they validate safety and demonstrate feeding benefit. The most valuable insights for any stakeholder come from understanding which product attributes, certification standards, and launch strategies will hold up under scrutiny, and where the next wave of differentiation will emerge as regulations, materials, and consumer expectations continue to evolve. Detailed segment data, company-level tracking, and customized scenario analysis can sharpen these priorities further for organizations preparing specific product, investment, or sourcing decisions.
For detailed analysis of this topic, please visit the official page: Baby Bottles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com