

Blogs
Automotive Ambient Lighting Market: Why 10.5% CAGR Signals a $5.9B Design Shift
By PW Consulting, 2026-09-21
Illuminating the Path: Strategic Shifts and Commercial Opportunities in the Automotive Ambient Lighting Market
Market Architecture and Defining Headwinds
The automotive ambient lighting market has transitioned from a discretionary cabin furnishing element to a structured, technology-intensive segment that now demands dedicated strategic attention. Over the historical period, the market has expanded steadily, building on a multi-year trajectory that reflects both volume growth and rising content per vehicle. Looking ahead through the forecast horizon, the sector is projected to sustain a robust compound annual growth rate, indicating that ambient lighting is becoming a baseline consideration rather than a niche upgrade. This growth is underpinned by broader vehicle production increases, higher trim penetration, and the gradual migration of ambient systems from premium showcases to mass-market platforms.
The current landscape, however, is defined less by simple expansion and more by structural inflection points. Suppliers and OEMs are navigating a period in which volume growth no longer guarantees margin expansion. Several forces are compressing traditional economics and forcing a recalibration of how ambient lighting is sourced, specified, and monetized.
The first challenge is the erosion of unit economics through persistent component price deflation. As LED module pricing continues to decline at a steady annual pace, suppliers must absorb cost reductions while delivering increasingly sophisticated features such as multi-zone control, color accuracy, and seamless OEM integration. The margin structure that once rewarded scale alone is being replaced by a performance-driven model in which differentiation and system-level value capture determine profitability.
Automotive LED Lighting Market
The second challenge is the shifting center of gravity in the passive environment. Interior lighting, once treated as a low-risk styling decision, is now subject to evolving safety and visibility expectations. Regulatory expectations for interior illumination standards are reshaping specification requirements and forcing manufacturers to treat cabin lighting as a compliance-adjacent function rather than an optional aesthetic feature. This creates additional validation cycles, testing burdens, and design constraints that affect both cost and time-to-market.
The third challenge lies in supply chain geography and cost volatility. LED components, substrates, driver electronics, and interconnect materials remain heavily concentrated in a small set of manufacturing regions. That concentration offers scale and maturity, but it also exposes program schedules and bill-of-materials costs to geopolitical friction and tariff escalation. For vehicle assembly operations in North America and Europe, these dynamics can materially alter sourcing strategies and require deliberate redundancy planning rather than single-source reliance.
Four Forces Reshaping the Value Chain
The most consequential force shaping the market is the pace of component and system-level innovation. Ambient lighting is no longer about a single color strip hidden behind a trim panel; it is becoming a coordinated cabin interface that balances aesthetics, perception, and electrical architecture. Intelligent LED driver solutions with integrated color calibration, optimized pulse-width modulation control, and automotive-grade qualification are reducing the complexity of multi-zone implementations. At the same time, these advances allow OEMs to design zonal lighting experiences that are more dynamic, consistent, and easier to calibrate across trims and cabin configurations. This shift is significant because it moves differentiation upstream, away from mechanical placement and toward electronic control, software-defined behavior, and integrated validation.
Policy and regulation are emerging as a parallel driver of change. As interior lighting standards become more explicit for new vehicle types in major markets, ambient lighting is increasingly evaluated through the lens of occupant visibility, glare control, and predictable operational behavior. Compliance expectations do not necessarily eliminate customization; instead, they impose structure on it. Manufacturers that design cabin lighting with regulatory foresight can convert standards into a competitive advantage by building systems that satisfy both aesthetic goals and safety-related performance criteria without re-engineering at the end of the program cycle.
Consumer and commercial demand are also evolving in ways that matter for product strategy. In passenger vehicles, ambient lighting is increasingly tied to perceived quality, brand expression, and cabin personalization. The expectation is not simply that a vehicle has lighting, but that it can deliver a coherent sensory environment across different drive modes, times of day, and user profiles. For light and heavy commercial vehicles, the value case is slightly different: better cabin visibility, improved ergonomic perception, and stronger fleet branding can support operator comfort and brand differentiation. As these expectations mature, ambient lighting is becoming more of a functional and experiential layer than a pure styling add-on.
Cost structure and supply chain dynamics complete the set of core drivers. The combination of declining LED pricing and concentrated component sourcing creates a dual challenge: suppliers must keep innovating to defend margins while also managing exposure to trade policy and logistics risk. That means sourcing architectures are becoming more strategic, with greater attention to regional balance, qualification redundancy, and design flexibility. In practical terms, the market is rewarding participants who can decouple value creation from pure component cost competition and instead offer integrated electrical architecture, validated multi-zone control, and predictable program execution.
PW Consulting Automotive & Machinery Research Center
Competitive Positioning and Landscape Evolution
The competitive environment reflects a mix of established Tier-1 suppliers, lighting specialists, and electronics-focused manufacturers, each pursuing a different angle on cabin illumination. Some players compete by offering fully integrated ambient lighting systems with strong OEM integration and multi-zone capability. Others focus on advanced LED technology and smart control electronics that enable personalization, multi-color effects, and tighter electrical integration. A further group emphasizes precision LED modules and emitter-level innovation, delivering components that meet demanding color calibration, reliability, and automotive qualification requirements. There are also suppliers that embed ambient lighting within broader interior systems, electrical architecture, or full-vehicle module offerings, allowing them to capture value through system-level bundling rather than component-only sales.
The differentiation that matters most is shifting from lamp count or color variety toward integration confidence and system performance. Players with strong competency in driver ICs, calibrated color behavior, and EMC-optimized control are gaining leverage because they simplify OEM design work and reduce validation risk. Suppliers that can deliver ambient solutions as part of a broader interior or electrical integration package also enjoy an advantage in programs where packaging, harness strategy, and controller architecture must be solved together. On the other end of the spectrum, manufacturers that compete primarily on volume hardware without a clear integration or electronics advantage face increasing pressure as pricing continues to compress.
The landscape is evolving along several identifiable directions. One is consolidation of capability, where OEMs and Tier-1 suppliers favor partners that can reduce the number of distinct integration points across the cabin. Another is increasing specialization at the component and electronics level, especially around intelligent drivers and calibrated emitters that make multi-zone implementations more practical. At the same time, new entrants and expanding incumbents are exploring adjacent opportunities in optical design, software-controlled lighting behavior, and cabin experience personalization. The result is a market that is not simply becoming more crowded, but more functionally layered, with competition intensifying around integration depth, validation reliability, and the ability to support both premium customization and high-volume repeatability.
Forward Outlook: Three Trends That Will Shape the Next Cycle
The next several years are likely to be defined by a move toward more software-influenced cabin lighting strategies. As intelligent control components and multi-zone architectures mature, ambient lighting will increasingly support adaptive color, mode-based scenes, and more refined calibration across vehicle variants. This trend opens commercial opportunities for suppliers that can offer configurable lighting behavior without adding undue complexity to the electrical architecture. It also creates value for OEMs seeking distinct cabin identities without engineering a separate hardware stack for each trim. The strategic implication is that ambient lighting will become more of a configurable experience platform than a static part number, rewarding players who can balance flexibility with production discipline.
A second trend is the continued integration of ambient lighting into broader interior and electrical system strategies. Cabin illumination is increasingly considered alongside dashboard lighting, console illumination, footwell effects, door ambient features, and center console aesthetics as part of a unified interior experience. That integration encourages suppliers to think in terms of system reliability, connector strategy, thermal behavior, and validation coverage rather than isolated decorative strips. For procurement and program teams, it means ambient lighting decisions should be made with visibility into overall interior architecture, because late-stage changes in one zone can cascade into control logic, packaging, and cost across adjacent areas.
A third trend is the growing importance of supply chain resilience and regional sourcing balance. As tariff exposure and component concentration remain salient concerns, manufacturers will place greater value on partners who can provide supply continuity, transparent cost structures, and flexible qualification footprints. This trend favors suppliers with credible alternatives, disciplined program management, and the ability to maintain performance while adapting to changing trade and logistics conditions. The commercial opportunity lies in making ambient lighting programs less sensitive to single-point disruptions and more capable of meeting predictable cost and timing targets across multiple vehicle programs.
These trends carry inherent risks. Over-customization can increase validation burden and complicate cost control. Regulatory evolution may require recalibration of lighting performance assumptions, particularly where interior standards continue to tighten. And if pricing pressure persists without offsetting value capture through integration, electronics, or service-level differentiation, the market can reward scale while penalizing undifferentiated hardware suppliers. Navigating these risks will require discipline in architecture choices, sourcing strategy, and the pace at which customization is introduced into high-volume programs.
Strategic Actions for Different Decision-Makers
For manufacturers and Tier-1 suppliers, the priority should be to shift competitive positioning from component price to system and integration value. That means investing in control electronics, calibration reliability, multi-zone feasibility, and validated integration paths that reduce OEM development friction. Suppliers that can demonstrate predictable performance across zones, lower validation rework, and clearer electrical architecture integration will be better placed to defend margins even as individual component costs continue to decline. It is equally important to build sourcing resilience, not as a reactive hedge but as a planned element of program design, so that trade and logistics volatility does not become a recurring margin leak.
For investors, the more useful lens is value capture rather than headline volume. The strongest commercial prospects are likely to be found where suppliers combine intelligent control, qualification maturity, and integration relevance with credible cost discipline. Investments in companies that can support software-influenced cabin lighting, reduce fragmentation in OEM programs, and manage supply chain exposure may be better aligned with the next phase of market growth than exposure to undifferentiated LED hardware alone. Evaluating portfolio exposure should also account for how regulation, trade policy, and component concentration could affect regional program economics over the forecast period.
Automotive Lighting Market
For procurement and OEM program teams, the strategic task is to manage ambient lighting as a system decision rather than a late-stage styling add-on. Early alignment on zones, control architecture, color calibration expectations, and interior integration can prevent costly rework and improve the odds of consistent cabin experience across variants. Procurement strategies should also explicitly address sourcing diversity and tariff sensitivity, because the cost and continuity of ambient lighting programs are increasingly tied to the broader electrical and optical supply base. Treating cabin lighting decisions in isolation tends to create downstream risk; treating them as part of the interior and electrical plan tends to create more predictable outcomes.
For decision-makers seeking sharper segmentation detail, competitive benchmarking, pricing sensitivity analysis, and region-specific program implications, more comprehensive market research can provide the additional granularity needed to translate these trends into operational plans. Deep-dive coverage that breaks down component, vehicle-type, and regional dynamics in greater detail supports more precise scenario planning and more confident sourcing or investment decisions. In a market where margin creation depends on integration, qualification, and supply chain resilience, timely access to structured intelligence can make the difference between reacting to change and shaping it.
For detailed analysis of this topic, please visit the official page: Automotive Ambient Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Metal Cutting Fluids Market: Why 3.7% CAGR Acceleration Through 2032 Redefines Competitive Strategy
By PW Consulting, 2026-09-21
The Metal Cutting Fluids Market: Navigating the Strategic Crossroads
The global metal cutting fluids market has reached a pivotal inflection point. With the market valued at approximately USD 158.0 million in 2025 and projected to grow to USD 202.06 million by 2032, the sector is expanding at a compound annual growth rate of 3.7 percent. This trajectory reflects a mature yet dynamically evolving landscape where incremental volume growth must be balanced against mounting structural pressures. Historical data shows consistent expansion from USD 121.85 million in 2020, underscoring steady demand anchored in traditional machining and metalworking activities. Yet the forward-looking period introduces complexity: growth is no longer a simple function of industrial output. It is increasingly mediated by regulatory shifts, formulation innovation, supply chain volatility, and the strategic choices of dominant players who collectively command significant market share. For executives, investors, and procurement leaders, the central question is no longer whether the market will expand, but how value will be captured amid transforming operational and compliance realities.
Market Snapshot and Defining Characteristics
The current market environment is defined by moderate, predictable growth that masks deeper structural recalibration. Pricing power remains constrained by cost transparency and buyer scrutiny, while volume expansion is unevenly distributed across industrial regions and application segments. The competitive landscape exhibits meaningful concentration, with the top three players controlling roughly 57 percent of industry revenue and the top five capturing approximately 68 percent. This consolidation pattern signals entrenched supplier relationships, high switching costs for end-users, and the financial weight required to sustain innovation, technical service networks, and regulatory compliance programs. At the same time, the market’s growth cadence hints at emerging friction points. Certain forecast intervals show marginal deceleration, suggesting that traditional volume-driven expansion is encountering headwinds from material costs, formulation restrictions, and shifts in machining intensity across key end-use sectors.
Key Challenges and Inflection Points
Three interconnected challenges are reshaping how participants compete and how buyers evaluate fluid programs. First, environmental and occupational safety regulations are accelerating reformulation cycles. Restrictions on certain chlorinated paraffins and intensifying scrutiny of chemical exposure are compelling manufacturers to redesign formulations, validate alternative additive packages, and manage the operational disruption that accompanies product transitions. Second, raw material volatility continues to pressure margins. Base oil and specialty additive pricing remains sensitive to crude oil production cycles and geopolitical instability, making cost forecasting and contract structuring more difficult for both suppliers and industrial consumers. Third, the economics of spent fluid management are becoming a shared burden. Disposal requirements governed by environmental frameworks such as the U.S. Resource Conservation and Recovery Act and EU waste directives are elevating the total cost of ownership for cutting fluid programs, pushing manufacturers and end-users alike to consider longer fluid life, easier separation, and circular handling practices. Together, these factors are shifting competitive advantage away from pure price competition and toward reliability, compliance, and lifecycle efficiency.
Metal Cutting Tools Market
Innovation as a Core Growth Lever
Technological progress is redefining what metal cutting fluids must deliver. Modern machining environments increasingly demand fluids that can manage heat, protect tooling, and maintain surface quality under higher speeds, heavier loads, and more aggressive cutting parameters. This has elevated the strategic importance of advanced synthetic and water-miscible formulations with enhanced lubricity, improved stability, and better compatibility with diverse metal substrates. Equally significant is the rise of fluid management systems that integrate real-time monitoring, analytics, and concentration control. By moving from periodic manual checks toward continuous visibility, operators can reduce overuse, maintain consistent performance, and extend service intervals. These capabilities are not merely incremental improvements; they directly influence tooling costs, downtime, and waste generation. In an environment where manufacturing productivity is under constant pressure, fluid performance and fluid management are becoming inseparable elements of process optimization.
Regulatory and Sustainability Forces Reshaping Formulation Strategy
Policy and compliance dynamics are now central to product planning rather than peripheral considerations. Regulatory attention on chemical safety, worker exposure, and disposal obligations is pushing the industry toward more environmentally acceptable alternatives. Reformulation is no longer a reactive exercise; it is a strategic investment that affects performance validation, customer acceptance, and supply chain readiness. At the same time, sustainability expectations are extending beyond compliance. Industrial buyers are increasingly interested in fluids that support safer workplaces, reduce hazardous waste, and align with broader environmental goals without compromising process results. This dual pressure—regulations on one side and corporate sustainability objectives on the other—is creating a differentiation opportunity for suppliers that can demonstrate credible performance, transparent composition, and practical disposal or recovery pathways.
Demand-Side Shifts in Metalworking and Manufacturing
Demand is being reshaped by how manufacturers organize production and manage cost. Metalworking operations continue to be a primary consumption base, while automotive and general manufacturing segments remain substantial users of cutting and forming fluids. However, the character of demand is changing. Many producers are prioritizing process consistency, tool life, and surface finish over nominal fluid cost, particularly where high-value components and precision machining are involved. There is also growing interest in fluids that can support flexible production schedules, reduce maintenance interruptions, and simplify plant handling. As a result, purchasing decisions are increasingly influenced by operational reliability and total program cost rather than by initial price per unit alone. This shift favors suppliers that can provide technical support, application guidance, and robust performance validation alongside product supply.
Supply Chain Volatility and Cost Structure Realignment
The cost structure of metal cutting fluids is exposed to multiple external forces, making supply chain resilience a competitive necessity. Base oil pricing fluctuates with broader energy markets, while additives and specialty intermediates introduce additional variability. These dynamics affect not only supplier margins but also the predictability of customer operating costs. Companies that can stabilize input costs through forward contracting, reformulated value tiers, or smarter inventory management gain an advantage in a market where price shocks can disrupt procurement plans. On the buyer side, the response has been to seek greater transparency, longer-term agreements with defined adjustment mechanisms, and fluid programs designed to reduce waste and overuse. In practice, this means the commercial conversation is moving toward shared risk management and lifecycle economics rather than transactional spot purchasing.
Metal Working Fluids (Metalworking Fluids) Market
Competitive Landscape and Strategic Positioning
The market’s leadership group reflects a mix of global industrial fluid specialists, major energy and chemical companies, and focused specialty formulators. Each brings a different strategic posture. Quaker Houghton operates with a broad industrial process fluids footprint spanning water-based and synthetic solutions, metal removal fluids, and fluid management systems, supported by a strong presence in automotive, aerospace, and heavy equipment applications. Its recent acquisition activity illustrates a deliberate consolidation strategy aimed at expanding geographic reach and application coverage. In March 2025, the company acquired Dipsol Chemicals Co., Ltd., a supplier of surface treatment and plating solutions primarily serving automotive and industrial markets. In April 2025, it completed two additional acquisitions: Natech, Ltd., a UK-based metalworking fluids and lubricants supplier, and Chemical Solutions & Innovations (Pty) Ltd., a South African provider in the same category. These moves extend regional service capability and broaden the technology and customer base. Later in September 2025, Quaker Houghton commercialized QH Fluid Intelligence 2.0, a fluid management system driven by real-time analytics, signaling an intent to compete not only on formulations but also on operational visibility and process control.
ExxonMobil maintains a strong position through high-performance synthetic water-miscible fluids, most notably the Mobilcut™ series, which emphasizes enhanced lubricity additives for a wide range of metals. Its September 2025 product launch introduced an advanced line of synthetic metalworking fluids engineered for heavy-load, high-speed machining, reinforcing a strategy centered on extreme-condition performance and application-specific engineering. BP, through its Castrol portfolio, continues to supply branded metal cutting fluids and lubricants tailored for metal removal operations in automotive and industrial sectors, leveraging brand recognition and broad distribution channels. TotalEnergies complements this profile with an integrated energy company heritage and a dedicated metalworking fluid portfolio that includes cutting oils and coolants for industrial machining. FUCHS PETROLUB SE offers a comprehensive range of water-based, semi-synthetic, and synthetic cutting fluids for machining and metal forming, positioning itself as a full-spectrum specialty chemical producer. Blaser Swisslube AG focuses on high-performance cutting and forming fluids across multiple industries, while Idemitsu Kosan Co., Ltd. serves automotive and industrial metalworking applications with advanced fluids and lubricants. The Lubrizol Corporation contributes additive systems and complete formulations, emphasizing formulation science and customization. Valvoline Inc. extends its reach into metalworking through product lines such as Erozol for cutting, forming, and metal processing. Master Fluid Solutions formulates specialty water-soluble and neo-synthetic fluids, including TRIM products for aerospace and hard metal machining. Tower Metalworking Fluids provides advanced lubricants and cooling-focused formulations, such as SAF-T-VANISH, for rust prevention and metal forming and cutting. Petrofer GmbH has built a long-standing reputation around tool life extension, surface finish, and sustainable solutions. Schaeffer Manufacturing Company supplies heavy-duty fluids for drilling, cutting, forming, and shaping operations. Halocarbon expanded its presence with three advanced metalworking fluid formulations under its InfinX line, made available through its e-commerce platform in December 2025, reflecting a push toward direct digital distribution and product accessibility.
Consolidation, Differentiation, and the New Entry Calculus
The dominant strategic theme across the competitive set is differentiation through capability rather than scale alone. Leaders are building advantage along several axes: application-specific performance, fluid management and analytics, regional service density, formulation science, and compliance readiness. The acquisition activity led by Quaker Houghton demonstrates how inorganic growth is being used to compress geographic gaps, deepen application coverage, and strengthen service continuity for multinational and regional customers. At the same time, product launches from ExxonMobil and Halocarbon suggest parallel efforts to capture demand for higher-performance formulations and more accessible purchasing channels. The market is not fragmenting into low-cost commodity competition; rather, it is stratifying into tiers where performance, technical service, and regulatory compliance determine positioning. New entrants face meaningful barriers because success requires formulation expertise, validation capability, distribution reach, and the financial stamina to navigate raw material volatility and regulation-led reformulation cycles. Consequently, the most plausible disruptive pressure will come less from brand-new players and more from specialized formulators that can target underserved applications, advanced machining requirements, or sustainability-oriented programs with differentiated value propositions.
PW Consulting
Near-Term Trajectory: Three Forces Shaping the Next 3–5 Years
The next few years are likely to be shaped by the convergence of performance, compliance, and digital management. First, high-performance synthetic and water-miscible fluids will continue to gain relative importance where machining intensity, precision requirements, and tool life concerns are acute. These formulations will be increasingly paired with monitoring and control systems that help manufacturers stabilize concentration, reduce waste, and maintain consistent process conditions. The commercial implication is that fluid programs will be evaluated more like engineered process solutions than consumable inputs. Second, regulatory pressure will keep pushing reformulation and disposal management into core product planning. Suppliers that can provide credible, lower-hazard alternatives while preserving performance will be better positioned to retain and expand share, especially in regions with strict chemical and waste frameworks. Third, cost volatility will encourage more structured procurement and greater emphasis on total cost of ownership. Buyers will seek formulations and management approaches that reduce overuse, extend life, and simplify handling, while suppliers will look for greater supply chain flexibility and clearer pricing mechanisms. These forces together point toward a market where value accrues to participants that can integrate product performance with operational efficiency and compliance confidence.
Associated Opportunities and Residual Risks
The clearest opportunity lies in transforming fluid supply from a transactional category into a managed performance partnership. Suppliers that combine advanced formulations with real-time management tools, technical service, and credible sustainability attributes can unlock differentiated pricing and longer customer retention. End-users that adopt disciplined fluid management can reduce downtime, extend tool life, and lower waste handling costs, thereby improving overall process economics. A second opportunity emerges in regional market development, where service density, localized formulation support, and responsive supply can create durable advantages in segments that are underserved by global portfolios. At the same time, uncertainty persists. Regulatory interpretations may evolve faster than formulation and validation cycles, creating transition risk for both suppliers and buyers. Raw material price swings can compress margins or disrupt contract stability if not managed with transparent mechanisms. There is also execution risk in scaling digital management tools across diverse plant environments, where integration complexity and change management can slow adoption. Participants that treat these uncertainties as manageable variables rather than external shocks will be better equipped to convert market growth into sustainable advantage.
Actionable Directions for Decision-Makers
Manufacturers and machining operations should reassess fluid programs as part of broader process strategy rather than as a standalone procurement line. This means evaluating formulations for performance under actual operating conditions, considering fluid management systems that provide concentration and condition visibility, and incorporating disposal and handling costs into total cost assessments. Suppliers and formulators should prioritize application-specific validation, compliance transparency, and service continuity, while pursuing selective geographic or application expansion that reinforces differentiation. Procurement leaders should shift negotiation focus toward lifecycle economics, quality consistency, and risk sharing, using longer-term agreements with clearly defined adjustment mechanisms where appropriate. Investors evaluating exposure to this market should look beyond headline growth and assess which participants have durable formulation capabilities, credible management-tool platforms, and the balance-sheet flexibility to absorb volatility while investing in compliance and innovation. In a market where competitive outcomes depend on technical reliability, regulatory readiness, and operational integration, timely access to detailed segmentation data, company-level case evidence, and scenario analysis can materially improve strategic choices. The full study provides that granularity, enabling stakeholders to map growth by region and application, compare formulation and service strategies in greater depth, and align investment or procurement decisions with a clearer view of where value is likely to concentrate through 2032.
For detailed analysis of this topic, please visit the official page: Metal Cutting Fluids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
MVR Compressor Market: How Asia Pacific’s 5.6% CAGR Redefines Global Growth
By PW Consulting, 2026-09-21
MVR Compressor Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The mechanical vapor recompression (MVR) compressor market has entered a phase of sustained expansion, with global revenue surpassing $1 billion in 2025 and continuing to climb through the end of the decade. The trajectory reflects a compound annual growth rate of 5.6 percent across the forecast horizon, signaling steady demand rather than cyclical spikes. This growth pattern emerges from a combination of long-term capital planning in process industries and accelerating adoption of energy-recovery systems that reduce reliance on external utilities.
PW Consulting
Historical progression reveals a market that rebounded decisively after a brief contraction in 2023, when revenue dipped before regaining momentum. The 2024 to 2025 period delivered the strongest consecutive gain in recent years, driven by replacement cycles, greenfield installations, and stricter thermal-efficiency expectations across chemical, pharmaceutical, and food-processing sectors. By 2026, the market crosses into a higher revenue tier, and the upward slope remains intact through 2032, positioning MVR compressors as a structural component of industrial energy management rather than a niche optimization tool.
Despite the constructive outlook, three challenges shape how quickly value can be captured across the value chain. The first is intensifying efficiency expectations. Operators no longer treat MVR compressors as passive heat-recovery equipment; they demand a higher share of latent heat reuse, lower parasitic losses, and tighter integration with upstream and downstream separation units. Compressors that fall short of these benchmarks face displacement during retrofit cycles or lose out in competitive bids for new facilities.
The second challenge is material and fabrication complexity. High-speed impellers and housings must withstand corrosive condensates, thermal cycling, and sustained rotational loads. Specifications increasingly call for specialized stainless steels, titanium alloys, nickel-based superalloys, and advanced ductile alloys. Sourcing these materials with consistent metallurgical quality and managing fabrication tolerances adds cost and lead-time pressure, particularly for large-diameter or custom-configured units.
The third challenge lies in integration and lifecycle economics. An MVR compressor delivers value only when it is correctly matched to the evaporation temperature, vapor composition, and downstream process constraints. Misalignment leads to underperformance, higher maintenance burdens, and compromised energy savings. This dynamic is pushing buyers toward suppliers that can offer more than rotating equipment, favoring partners capable of system-level design, commissioning support, and long-term service arrangements.
Together, these forces are reshaping procurement logic. Buyers evaluate total steam and electricity consumption, not just headline compressor price. Manufacturers respond with higher-efficiency rotor designs, modular system architectures, and closer coupling of compressors with thermal separation skids. The result is an environment where competitive advantage increasingly depends on engineering depth and integration capability, not just production scale.
Key Drivers Shaping the Market
Technology Innovation and Efficiency Gains
Advancements in rotor aerodynamics, bearing systems, and sealing technologies are steadily lifting compressor efficiency and expanding the range of viable operating conditions. Modern MVR configurations increasingly rely on precision impeller geometries, improved surface treatments, and optimized flow paths that reduce internal recirculation and friction losses. These improvements translate directly into lower external energy requirements, which remains the central economic case for MVR adoption.
Efficiency has become a multi-dimensional race. Some suppliers emphasize specialized blower and compressor platforms designed for high thermal recovery rates, while others focus on material and impeller variations that extend service life under aggressive process conditions. The competitive edge is shifting toward designs that maintain stable performance across variable vapor loads and tolerate contaminants more effectively. This is particularly relevant in applications where condensate quality fluctuates or where occasional carryover places additional stress on rotating components.
At the same time, integration engineering is maturing. Suppliers are bundling compressors with evaporators, crystallizers, and control systems to reduce design risk for end users. This trend lowers the barrier to adoption for operators that lack in-house thermal-separation expertise and accelerates project timelines by minimizing interface complexity. As a result, technology leadership is no longer defined solely by the compressor itself, but by the ability to deliver a reliable, pre-engineered thermal process module.
Policy and Regulatory Environment
Energy-efficiency mandates and decarbonization expectations are strengthening the commercial case for MVR technology across multiple industries. Regulatory frameworks and internal sustainability targets are pressuring manufacturers to reduce fossil-based steam consumption, cut electricity intensity, and improve overall thermal productivity. MVR systems address these objectives by recirculating latent heat within the process, which directly reduces utility demand and lowers operating expenditure over the asset lifecycle.
The policy environment is also indirectly shaping technology preferences. Facilities facing stricter emissions reporting and energy audits are prioritizing equipment that delivers measurable, verifiable efficiency gains. This favors MVR compressors with documented performance curves, robust instrumentation, and predictable maintenance profiles. In turn, suppliers are investing more in application documentation, commissioning data, and lifecycle service packages to support compliance-related decision-making.
Demand-Side Shifts in Process Industries
Demand for MVR compressors is being reinforced by broad changes in how process plants are designed and operated. Pharmaceutical, chemical, food, and beverage manufacturers are increasingly seeking closed-loop evaporation and concentration solutions that minimize solvent loss, protect product quality, and stabilize operating costs. In many cases, these objectives align with the core strengths of MVR technology, particularly where low-temperature evaporation and gentle thermal handling are critical.
A notable demand-side development is the expansion of MVR relevance into emerging industrial applications beyond traditional evaporation and drying. Carbon capture and utilization projects, for example, are creating new compressor requirements where CO2-rich streams must be handled with materials compatible with specific gas chemistries and operating pressures. This diversifies the addressable market and introduces new specification priorities, including material compatibility, sealing integrity, and process control robustness. Customized thermal separation solutions are also gaining traction in regions where local operating conditions, utility costs, and labor constraints make standardized equipment less attractive.
From a buyer behavior perspective, procurement cycles are becoming more strategic. Operators are planning MVR installations alongside broader plant modernization programs, which means compressor selection is increasingly evaluated in the context of long-term energy budgets, expansion plans, and process flexibility. This creates stronger demand visibility for vendors that can align equipment offerings with multi-year capital roadmaps.
Supply Chain and Cost Structure Dynamics
Cost structures in the MVR compressor market are influenced by material availability, specialized manufacturing capacity, and the economics of high-performance alloys. Impeller fabrication and precision machining remain concentrated in environments that can maintain tight tolerances and consistent metallurgical quality. Fluctuations in alloy pricing, along with lead-time variability for specialized grades, can affect project scheduling and margin management for both equipment makers and system integrators.
At the same time, regional manufacturing footprints are becoming more relevant to cost and responsiveness. Local production and application engineering can shorten delivery timelines, simplify after-sales support, and improve alignment with regional design preferences. This is especially important where large-scale industrial projects require closely coordinated supply, installation, and commissioning. Suppliers that can balance global technical capability with regional execution are better positioned to manage total installed cost and project risk.
Cost dynamics are also being reshaped by service and digital support models. Predictive maintenance, performance monitoring, and remote diagnostics can reduce unplanned downtime and help operators sustain efficiency over time. While these capabilities add upfront complexity, they can improve the economic calculus of MVR adoption by protecting the long-term value of the equipment and reducing hidden operating costs.
A practical illustration of how demand-side expansion is translating into commercial activity is the recent sign of contract activity linking MVR compressors to carbon-related industrial projects in Europe. Such developments indicate that the market is broadening beyond traditional thermal separation use cases and that suppliers with specialized gas-handling capabilities are gaining incremental relevance. This kind of application diversification reinforces the view that MVR compressors will continue to find new demand pockets even as core evaporation and crystallization markets mature.
Competitive Landscape and Leading Strategies
The competitive environment is moderately concentrated, with a limited group of established players capturing a substantial share of high-value projects. This structure reflects the technical barriers to entry associated with high-speed rotating equipment, specialized materials, and system integration. It also means that differentiation is heavily dependent on technology pedigree, application expertise, and the ability to support complex installations from design through commissioning.
One clear competitive theme is technology specialization. Several leading suppliers have built reputations around specific efficiency claims, rotor technologies, or product platforms that emphasize thermal recovery performance. These vendors compete by demonstrating measurable efficiency advantages, broad global installation references, and application support that reduces operational risk. Their strategic positioning tends to center on reliability, proven field performance, and the ability to match equipment behavior to demanding process conditions.
Another theme is material and application versatility. Some manufacturers differentiate by offering impeller options in stainless steel, titanium, and special alloys, allowing them to adapt to more corrosive or chemically challenging service. This flexibility broadens the addressable opportunity and supports projects where standard materials would not meet longevity or compliance expectations. In parallel, a subset of suppliers focuses on fully integrated compression systems that pair compressors with evaporators and crystallizers, reducing interface complexity and helping customers achieve a more streamlined installation.
Regional strength and customization capability also shape competition. Leading Indian and Chinese manufacturers have expanded their presence by offering customized thermal separation solutions and localized engineering support. Their approach often emphasizes application-specific configuration, shorter response times, and cost-effective delivery for regional projects. This reflects a broader market trend in which end users increasingly value partners who can tailor equipment to local operating conditions and provide ongoing service within the same geography.
A further competitive vector is application expansion into new industrial domains. Some suppliers are positioning themselves around specialized compression needs tied to carbon management and other emerging process streams. This direction allows them to move beyond saturated traditional segments and capture projects where gas composition, pressure requirements, and material compatibility create a more bespoke engineering challenge. Such moves indicate that competitive differentiation is increasingly linked to the breadth of application coverage as much as to core compressor performance.
Looking at market evolution, the landscape appears to be moving along two parallel paths. One is consolidation of technical authority among suppliers that can deliver high-efficiency rotating equipment, specialized alloys, and integrated system designs. The other is fragmentation of application-specific niches, where regional manufacturers and specialized engineering firms compete by customizing solutions for local industries and project types. New entrants are most likely to succeed where they bring a clear technical angle, such as a distinct efficiency claim, a differentiated material strategy, or a strong regional service model, rather than competing solely on volume.
In practice, the winning strategy is becoming more holistic. Suppliers that combine efficiency, material flexibility, system integration, and regional execution are better equipped to secure large contracts and retain long-term service relationships. Buyers, in turn, are placing greater weight on reference installations, commissioning support, and lifecycle economics, which raises the stakes for manufacturers that rely on product-only positioning.
Worldwide Barrel Compressor Market
Future Trends and Commercial Implications
Over the next three to five years, the MVR compressor market is likely to be shaped by a small number of reinforcing trends that carry clear commercial implications.
The first trend is the continued prioritization of efficiency and integration as a bundled value proposition. Demand will increasingly favor suppliers who can demonstrate that their compressors reduce external energy requirements while fitting cleanly into the broader process train. This means more emphasis on pre-engineered module configurations, application-specific performance data, and service agreements that protect long-term efficiency. For manufacturers, the opportunity lies in packaging mechanical performance with engineering support and for buyers, the opportunity lies in selecting equipment that simplifies operation rather than adding integration risk.
The second trend is application diversification beyond conventional evaporation and drying. As industrial projects expand into carbon management, specialty chemical processing, and other streams with specific gas and material requirements, MVR compressor demand will gain additional drivers. This diversification can create higher-margin opportunities for suppliers with the right material expertise and process knowledge, but it also raises the bar for qualification, testing, and field validation. Projects in these areas may require more customized engineering, which can improve differentiation but also lengthen sales cycles.
The third trend is the growing importance of regional execution and lifecycle service. As projects become more distributed and operating teams more cost-conscious, local manufacturing, commissioning capability, and responsive after-sales support will become stronger competitive differentiators. Suppliers that can reduce lead-time risk, simplify spare-parts logistics, and deliver localized engineering will be better positioned to win repeat business. At the same time, operators will increasingly judge MVR investments through total cost of ownership, making service quality and reliability central to commercial success.
These trends carry both upside and uncertainty. The upside is that efficiency mandates, process modernization, and application expansion create a durable demand base for high-performance MVR compressors. The uncertainty lies in material price volatility, specialized manufacturing bottlenecks, and the risk that some projects may be delayed or redesigned if integration challenges are underestimated. In addition, application diversification may introduce new specification complexity that only a subset of suppliers can manage effectively. Companies that prepare for this mix of opportunity and volatility will be better placed to capture value as the market matures.
Mechanical Vapor Recompression (MVR) Evaporators Market
Actionable Recommendations for Decision-Makers
For Manufacturers and Technology Providers
Focus on the intersections where efficiency, material adaptability, and integration support reinforce one another. Investments in rotor and sealing technologies that improve efficiency under variable loads can strengthen competitive positioning, especially when paired with clear application documentation. Equally important is expanding the ability to specify and supply suitable alloy options for demanding service conditions without compromising lead times or quality consistency. Manufacturers should also treat integration support and commissioning capability as core products, because buyers are increasingly selecting partners who can reduce design risk and protect long-term performance.
For Investors and Strategic Allocators
Evaluate exposure to MVR compressor demand in the context of broader energy-efficiency and process-modernization spending, rather than treating it as a stand-alone equipment cycle. The most resilient opportunities are likely to appear where suppliers combine technical differentiation with regional execution and where end-use applications extend beyond mature evaporation segments into newer industrial needs. When assessing companies, look for evidence of recurring service revenue, strong reference bases, and the capability to address specialized material and gas-handling requirements. Diversification into application-specific niches can be attractive, but only if supported by engineering depth and qualification readiness.
For Procurement and Plant Operators
Structure evaluation around total operating impact, not just initial capital cost. The most valuable MVR compressor choices are those that align with the actual vapor conditions, material environment, and integration constraints of the plant. Prioritize suppliers that can provide credible performance data, realistic commissioning support, and a clear service pathway over the asset life. Where projects involve non-standard gas compositions or aggressive process conditions, request explicit material and sealing strategies rather than assuming standard configurations will suffice. Early engagement with suppliers during process design can reduce integration risk and improve the economics of the installed system.
Strategic decisions in this market increasingly depend on detailed understanding of application mix, regional dynamics, material specifications, and the service models that protect long-term value. Decision-makers seeking deeper segmentation, company-level positioning, and customized scenario analysis will benefit from more granular intelligence that maps these variables to their own project pipelines and investment priorities.
For detailed analysis of this topic, please visit the official page: MVR Compressor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Infusion Pump Software Market Forecast: Digital Healthcare Innovation, Trends, and Market Opportunities 2026–2032
By preeti mmr, 2026-09-21
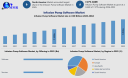
Market Overview
The Infusion Pump Software Market was valued at approximately USD 1.14 billion in 2025 and is expected to reach nearly USD 1.89 billion by 2032 , registering a CAGR of 7.27% during the forecast period from 2026 to 2032 . The market is experiencing steady expansion as healthcare providers increasingly adopt software-enabled infusion systems designed to improve medication accuracy, patient safety, clinical workflow efficiency, and connectivity across healthcare environments.
Request Sample Link for More Details: https://www.maximizemarketresearch.com/request-sample/164151/
Infusion pump software is an essential component of modern infusion systems used to administer medications, nutrients, fluids, insulin, chemotherapy drugs, analgesics, and other therapies at controlled and programmable rates. Modern software platforms can manage pumping parameters, drug libraries, dose limits, alarm functions, user interfaces, clinical workflows, and data exchange with hospital information systems.
The growing adoption of smart infusion pumps is transforming traditional infusion practices. Healthcare organizations are increasingly moving toward systems that combine infusion hardware with dose error reduction software (DERS), interoperability capabilities, analytics, and electronic medical record connectivity. These developments are supporting more standardized medication administration while reducing reliance on manual programming.
The market is also benefiting from increasing healthcare expenditure, expansion of hospital infrastructure, rising chronic disease prevalence, and growing demand for technology-enabled medication management. In addition, the movement of certain infusion therapies from hospitals toward ambulatory and home-care environments is creating opportunities for software developers to design more flexible and remotely manageable infusion platforms.
Market Drivers and Trends
Growing Demand for Advanced Infusion Pump Software
The increasing adoption of smart infusion pumps is one of the major factors supporting the growth of the infusion pump software market. Healthcare providers are placing greater emphasis on medication safety and accurate intravenous drug administration. Software-enabled pumps can incorporate drug libraries, hard and soft dose limits, clinical alerts, and standardized programming protocols.
Request Sample Link for More Details: https://www.maximizemarketresearch.com/request-sample/164151/
Dose Error Reduction Software has become particularly important because it can help healthcare professionals identify potentially unsafe infusion settings before medication administration. Hospitals are increasingly integrating these capabilities into medication safety programs, particularly in intensive care, oncology, anesthesia, pediatrics, and other high-acuity settings.
Continuous development of software engineering, verification methods, simulation technologies, and model-based development is also supporting innovation. Manufacturers and technology providers are investing in testing and validation processes designed to improve software reliability and usability.
Increasing Prevalence of Chronic Diseases
The rising prevalence of chronic diseases is another important growth factor. Conditions such as cancer, diabetes, neurological disorders, and other long-term diseases often require repeated or continuous medication administration.
Infusion pumps allow healthcare professionals to administer medications and fluids at precisely programmed rates, making them valuable in chemotherapy, insulin therapy, pain management, critical care, and other applications. As the number of patients requiring long-term treatment increases, demand for reliable infusion systems and associated software is expected to rise.
The aging population is also contributing to demand for chronic disease management and long-term care services. This trend is encouraging healthcare organizations to explore infusion technologies that can support treatment outside conventional hospital environments.
Rising Demand for Ambulatory and Home Infusion
The shift toward ambulatory and home-based healthcare is creating additional opportunities for the infusion pump software market. Ambulatory infusion pumps can support chemotherapy, pain management, total parenteral nutrition, and other therapies while allowing patients to receive treatment outside traditional inpatient settings.
Healthcare providers are increasingly exploring site-of-care models that can reduce hospital utilization and provide greater flexibility for patients. This transition is encouraging manufacturers to develop software that supports portable pumps, remote monitoring, simplified interfaces, connectivity, and data management.
Increasing Interoperability and Connected Healthcare
Interoperability is emerging as an important trend in infusion pump software. Integration with EMR and EHR systems can enable infusion information to move between connected clinical systems, helping reduce manual data entry and improving documentation.
Connected infusion platforms can also support centralized drug library management, device fleet monitoring, analytics, maintenance management, and enterprise-wide standardization. As hospitals modernize their digital infrastructure, demand for interoperable infusion software is expected to increase.
Primary Market Constraints
Stringent Regulatory Requirements
Stringent regulatory requirements represent a major challenge for infusion pump software manufacturers. Because infusion systems directly influence medication administration, software development, validation, cybersecurity, usability, and quality assurance must comply with extensive regulatory and safety requirements.
The lengthy development and approval process can increase costs and delay commercialization of new software-enabled infusion technologies. Manufacturers must also continuously update their products to address identified software vulnerabilities, usability concerns, safety issues, and changing regulatory expectations.
Product Recalls and Software-Related Safety Concerns
Software errors, programming issues, alarm-related problems, and manufacturing defects can negatively affect the adoption of infusion technologies. Historical product recalls involving infusion pumps and drug-library systems have highlighted the importance of comprehensive software validation and quality control.
The complexity of modern infusion pump interfaces can also create usability challenges. Incorrect programming or incomplete configuration may increase the risk of medication administration errors. As a result, manufacturers are increasingly focusing on human-centered design, usability testing, verification, and continuous software improvement.
Market Opportunity
Increasing R&D for Home Infusion Systems
The growing cost of hospital-based care and the increasing number of patients requiring long-term therapies are creating opportunities for home infusion software. Manufacturers are investing in technologies that can support portable infusion devices, remote monitoring, connectivity, and simplified patient interfaces.
The expansion of home healthcare, specialty infusion centers, and ambulatory treatment models is expected to create new demand for software capable of managing infusion data across multiple care environments.
The market also presents opportunities through cloud-based deployment, analytics, cybersecurity, artificial intelligence-supported monitoring, and interoperability with healthcare information systems. These technologies can help healthcare organizations manage larger fleets of connected infusion devices while improving visibility into performance and medication administration.
Key Market Segments
By Software Type
Based on software type, the market is segmented into Dose Error Reduction Software, Clinical Workflow Software, Interoperability Software, Tracking and Billing Software, Analytics and Continuous Quality Improvement Software, and Closed-Loop Control Software .
Among these, Dose Error Reduction Software is expected to account for a significant share of market revenue. Its adoption is supported by the growing emphasis on medication safety, drug-library compliance, standardized dosing, and reduction of programming variability. DERS capabilities are particularly relevant in hospitals and high-acuity departments where precise medication administration is essential.
By Delivery Method
The market is divided into Wired and Wireless delivery methods. Wireless technologies are gaining attention as healthcare providers increasingly seek connected medical device ecosystems, centralized management, and flexible device deployment.
By Integration
Based on integration, the market includes Standalone, EMR Integrated, EHR Integrated, Pharmacy Information System Integrated, Alarm Notification Platform Integrated, and Asset Tracking System Integrated solutions.
Integrated solutions are becoming increasingly important as healthcare facilities pursue digital transformation and seek to connect infusion pumps with broader clinical information systems.
By Deployment Mode
The market is segmented into On-Premise, Cloud-Based, and Hybrid deployment models. Cloud-based and hybrid solutions are gaining interest because of their potential to support centralized administration, remote updates, analytics, and multi-site device management.
By Application
Applications include Pain and Anesthesia Management, General Infusion, Insulin Infusion, Chemotherapy, Enteral Infusion, Critical Care Infusion, Neonatal and Pediatric Infusion, Ambulatory Infusion, and Others .
Pain and anesthesia management represented a major application area in 2025, supported by the need for accurate and controlled medication administration in surgical, perioperative, postoperative, and critical-care environments. Chemotherapy and insulin infusion also remain important application areas because of the need for controlled and continuous drug delivery.
By End User
The market is segmented into Hospitals, Clinics, Ambulatory Surgical Centers, Home Care Settings, Specialty Infusion Centers, and Others . Hospitals represent a major end-user category due to their extensive use of infusion pumps across critical care, oncology, surgery, emergency care, and general inpatient departments.
Request Sample Link for More Details: https://www.maximizemarketresearch.com/request-sample/164151/
Regional Analysis
North America dominated the Infusion Pump Software Market in 2025 and is expected to maintain a significant position throughout the forecast period. The region benefits from extensive adoption of smart infusion pumps, advanced hospital infrastructure, strong healthcare IT integration, and increasing emphasis on medication safety.
The United States represents a major contributor to regional demand. Healthcare organizations are increasingly investing in connected infusion platforms, electronic medical record integration, drug-library standardization, and centralized device management. The presence of established medical technology companies and continuous product development further supports regional market activity.
Europe is also expected to experience continued growth, supported by healthcare digitization, medication safety initiatives, and adoption of connected medical devices. Meanwhile, Asia Pacific is anticipated to offer significant opportunities due to expanding healthcare infrastructure, increasing healthcare expenditure, rising patient populations, and growing adoption of advanced medical technologies in countries such as China, Japan, India, and South Korea.
Major Industry Players
The competitive landscape includes established pharmaceutical, medical technology, and healthcare technology companies. Major players identified in the market landscape include Baxter International Inc., Baxter, Fresenius Kabi, ICU Medical, Inc., B. Braun, and other healthcare technology providers involved in infusion systems, software, drug libraries, interoperability, and medication safety solutions.
The broader competitive environment is characterized by product development, regulatory clearances, software upgrades, strategic collaborations, interoperability enhancements, and expansion of connected infusion platforms.
Recent industry developments include Baxter's FDA 510(k) clearance for its Novum IQ Large Volume Infusion Pump with Dose IQ Safety Software in April 2024. Fresenius Kabi also continued updates to its Agilia Partner software environment, while ICU Medical received FDA 510(k) clearances in May 2025 for Plum Solo, updated Plum Duo, and updated LifeShield infusion safety software as part of its IV Performance Platform.
These developments demonstrate the industry's continued focus on integrating hardware and software to improve medication safety, workflow efficiency, connectivity, and scalability.
Frequently Asked Questions
What is the size of the Infusion Pump Software Market in 2025?
The Infusion Pump Software Market was valued at approximately USD 1.14 billion in 2025 .
What is the expected market size by 2032?
The market is expected to reach nearly USD 1.89 billion by 2032 .
What is the expected CAGR of the Infusion Pump Software Market?
The market is projected to expand at a CAGR of 7.27% from 2026 to 2032 .
Which software type is expected to hold a significant market position?
Dose Error Reduction Software is expected to remain a major software type because of increasing emphasis on medication safety, drug-library management, and controlled infusion programming.
Conclusion
The Infusion Pump Software Market is entering a period of continued technological development as healthcare providers increasingly prioritize medication safety, interoperability, automation, and efficient clinical workflows. With the market projected to increase from USD 1.14 billion in 2025 to nearly USD 1.89 billion by 2032 , software is becoming an increasingly important component of modern infusion systems.
Connect With Us:
MAXIMIZE MARKET RESEARCH PVT. LTD.
2nd Floor, Navale IT park Phase 3,
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India.
+91 9607365656
sales@maximizemarketresearch.com
About Maximize Market Research:
Maximize Market Research is one of the fastest-growing market research and business consulting firms serving clients globally. Our revenue impact and focused growth-driven research initiatives make us a proud partner of majority of the Fortune 500 companies. We have a diversified portfolio and serve a variety of industries such as IT & telecom, chemical, food & beverage, aerospace & defense, healthcare and others.
Ultra Fine Aluminium Hydroxide Market: Why 6.5% CAGR Bets on Flame Retardant Demand
By PW Consulting, 2026-09-21
The Strategic Shift: Navigating the Ultra Fine Aluminium Hydroxide Market Through 2032
The global market for ultra fine aluminium hydroxide has reached a critical inflection point. With a projected market value approaching 407.5 million USD by 2032 and a compound annual growth rate of 6.5 percent over the forecast period, the industry is transitioning from a mature specialty chemicals segment into a strategically vital enabler of next-generation materials safety, energy storage, and polymer performance. Between 2020 and 2025, the market expanded from 212.0 million USD to 278.8 million USD, reflecting steady underlying demand that has now accelerated into a multi-year growth trajectory. This expansion is not uniform across all value drivers; it is being reshaped by regulatory urgency, technological refinement in particle engineering, and a supply base that is simultaneously consolidating and regionalizing. For executives, investors, and procurement leaders, understanding the structural forces behind this trajectory is essential to positioning portfolios, pricing strategies, and long-term sourcing commitments.
Mapping the Market Trajectory
The revenue curve across 2020 through 2032 reveals a market that has moved past cyclical volatility and is now anchored by structural demand shifts. Growth from 2023 to 2025 alone added roughly 33.6 million USD in incremental revenue, signaling that end-use adoption is no longer limited to legacy flame retardant applications. The forecast period through 2032 projects continued expansion, with the steepest absolute gains expected between 2028 and 2032, when annual revenue additions will be driven by manufacturing scale-up, cross-sector substitution, and the commercialization of ultra-fine grades in higher-value performance matrices. This trajectory suggests that the market is entering a phase where capacity investments, rather than short-term pricing cycles, will define competitive positioning.
Concentration Dynamics and Strategic Implications
Market concentration remains a defining characteristic of the industry. The top three participants collectively command approximately 65 percent of revenue, while the top five account for around 82 percent. This concentration does not indicate a stagnant oligopoly; rather, it reflects a landscape where incumbents have built deep technical credibility in particle size control, surface treatment, and application-specific formulation support. Yet concentration also masks underlying fragmentation in sub-segments, particularly where regional producers are closing the quality gap and capturing localized demand without competing directly on global scale. The implication for buyers is a dual-layer marketplace: global specialists offer consistency, technical service, and regulatory documentation, while regional facilities increasingly provide cost-competitive access for standard-grade requirements.
Ultra Fine Copper Powder Market
Current Structural Challenges
Three interlocking challenges are forcing the industry to recalibrate its operating assumptions. First, the physical and regulatory constraints around transporting fine powdered chemicals are raising logistics costs. Containment protocols for powdered material have increased per-ton transport expenses by an average of 18 percent, compressing trade flexibility and making proximity to end-use clusters a more decisive competitive factor. Second, raw material inputs are undergoing both volume and price shifts. Bauxite consumption estimates for 2025 reached approximately 1.7 million tons, a 4 percent increase over the prior year, while the landed value of imported crude dry bauxite and metallurgical-grade alumina for U.S. consumption rose by 4 percent and 9 percent respectively in the first eight months of 2025 compared with the same period in 2024. Even with absolute dollar values in the tens of millions, these movements signal tightening upstream economics that will eventually transmit into ultra-fine production margins. Third, the demand environment is shifting from generic filler substitution toward specification-driven performance requirements. Buyers are no longer purchasing by bulk weight alone; they are demanding tight particle size distributions, consistent surface reactivity, and documented safety performance, which raises the barrier to entry for undifferentiated capacity.
PW Consulting
Key Drivers Reshaping the Landscape
Regulatory Substitution as a Demand Anchor
The most durable demand catalyst is the regulatory displacement of halogenated flame retardants. As of 2023, more than 53 countries had enforced restrictions on halogenated formulations, creating a structural pull toward halogen-free alternatives in sectors where safety certification, lifecycle compliance, and public acceptance are non-negotiable. Public transport, building interiors, and consumer electronics have become priority adoption zones, where ultra fine aluminium hydroxide serves not merely as a filler but as an active smoke suppressant and intumescent co-agent. This regulatory environment transforms the product from a commodity additive into a compliance-critical input, lengthening qualification cycles but also increasing switching costs once a grade is approved. The commercial consequence is a demand base that grows through specification lock-in rather than spot purchasing, rewarding suppliers who can support audit-ready documentation, consistent lot-to-lot performance, and application engineering.
Particle Engineering and Performance Differentiation
Technological progress in precipitation control, micronization, and surface modification is redefining what buyers consider a premium grade. The market now segments around particle size thresholds that directly influence dispersion quality, polymer clarity, rheological behavior, and flame retardant efficiency. Below-1-micron grades are increasingly favored where투명성, low haze, and high surface area reactivity are required, while 1-to-1.5-micron ranges remain strong in applications balancing reinforcement and processability. The competitive advantage has shifted from volume production alone to the ability to hold narrow size distributions at scale, manage agglomeration, and tailor surface chemistry for specific resin systems. Facilities investing in automated micronization and closed-loop precipitation are reporting meaningful capacity leverage; certain producers have expanded sub-1.5-micron output with double-digit percentage capacity increases to serve coatings, paints, and flame retardant blends. This technical layer raises the value of process IP and operational discipline, making consistent quality a more powerful moat than route selection alone.
Downstream Demand Shifts Toward Safety and Energy Applications
Demand-side behavior is moving beyond traditional polymer compounding toward applications where thermal safety, electrical insulation, and weight efficiency intersect. Automotive interiors and component housings are increasingly specified with halogen-free systems to align with regional safety expectations and OEM sustainability targets. Electronics enclosures and battery-adjacent components are driving interest in grades that combine filler functionality with smoke reduction and thermal stability. At the same time, higher-purity ultra-fine grades are finding roles in advanced ceramics and technical coatings, where trace impurities and particle morphology directly affect final performance. These shifts expand the addressable market beyond volume-driven filler substitution and create pricing resilience for grades that are certified and engineered for specific end-use environments.
Cost Structure and Upstream Realities
The cost equation is being reshaped on two fronts. On the raw material side, the reported increase in bauxite consumption and the higher import benchmarks for alumina point to an environment where input economics are less predictable than in prior years. Even when absolute commodity values remain modest, percentage movements in traded benchmarks affect planning assumptions for integrated and non-integrated producers alike. On the operating side, the logistics cost premium for powdered chemical transport is now a structural component of delivered pricing, especially for long-haul movements across regulatory jurisdictions. This dynamic is pushing regionalization of supply, localized blending and packaging, and greater emphasis on total landed cost rather than ex-works price. Manufacturers that can align capacity with demand clusters, or that offer stable formulation support to reduce re-qualification, are better positioned to manage these cost layers than suppliers competing solely on headline pricing.
Competitive Landscape and Strategic Positioning
Differentiated Advantage Among Leading Participants
The competitive field shows a clear divide between global specialists with deep application portfolios and regional operators focused on scale and cost efficiency. German and U.S. headquartered producers have built recognition around sub-micron particle engineering, flame-retardant efficacy, and smoke suppression in polymers and coatings. Their portfolios emphasize grades optimized for specific resin systems and regulatory environments, supported by technical service and consistent documentation. Japanese manufacturers have extended their relevance through high-performance polymer compatibility and water-based system formulations, where dispersion stability and purity profiles matter. Another German specialist has carved a distinct position in high-purity grades for advanced ceramics and technical applications, trading volume for specification precision. On the regional side, Chinese producers have been expanding automated micronization capacity and targeting paints, coatings, rubber, and plastics grades with sub-1.5-micron outputs and higher content formulations. A U.S. diversified chemical company has signaled a broader push into ultra-fine grades for automotive and electronics, paired with announced capacity expansion to meet rising demand in automotive, electronics, and energy storage sectors. Together, these participants illustrate a market where differentiation comes from either application engineering, purity control, or regional cost positioning.
Recent Moves That Signal Strategic Intent
Recent corporate activity clarifies how incumbents are shaping the next phase of competition. One major diversified producer announced a significant expansion of ultra-fine production facilities to meet rising demand across automotive, electronics, and energy storage applications, indicating a bet that downstream specification requirements will sustain volume growth beyond legacy uses. Around the same period, another leading manufacturer acquired assets tied to ultra-fine grades to strengthen its flame retardant and smoke suppressant portfolio, consolidating technical capability and market access in a segment where qualification inertia favors integrated offerings. These moves point to two converging strategies: capacity build-out where demand visibility is strong, and portfolio consolidation where application breadth and regulatory support create stickier customer relationships.
Market Evolution: Consolidation, Regionalization, and Selective Entry
The market structure is evolving along three vectors. Consolidation is occurring where scale, technical documentation, and global service networks create advantages in qualification-heavy end markets. Regionalization is accelerating as logistics costs and proximity requirements reward suppliers located near major polymer, coatings, and automotive clusters. Selective entry remains possible, but the barrier is rising: new capacity must demonstrate particle size control, surface consistency, and application support rather than competing purely on throughput. The likely outcome is a layered competitive map. Global specialists retain leadership in high-specification, certification-sensitive applications. Regional producers gain share in standard and semi-specification grades where logistics and price sensitivity dominate. In between, a small set of agile operators capture opportunities by offering targeted grades for coatings, rubber, and plastics with reliable consistency and responsive service. For buyers, this means the optimal sourcing strategy is increasingly hybrid, balancing specification assurance with regional cost dynamics.
Forward Outlook: Trends Shaping the Next Three to Five Years
Trend One: Specification-Led Demand as the Growth Engine
The next growth cycle will be defined less by raw volume expansion than by specification adoption across new end-use environments. As safety regulations continue to favor halogen-free systems and as OEMs embed thermal and smoke performance requirements deeper into component design, ultra fine aluminium hydroxide will move from a supporting additive to a defined performance parameter in material specifications. The commercial opportunity lies in grades that can be pre-qualified for multiple resin systems and that carry documented performance data across smoke suppression, thermal stability, and dispersion behavior. Suppliers that invest in application test matrices, regulatory dossiers, and customer co-development will capture longer qualification cycles and lower churn, translating into more stable revenue streams even as input costs fluctuate.
High Purity Boehmite Market
Trend Two: Capacity Realignment Around Demand Clusters
Production geography will increasingly align with demand concentration. The logistics cost premium for powdered transport makes long-distance shipments less attractive for price-sensitive grades, encouraging regional capacity, localized packaging, and regional blending operations. At the same time, higher-specification grades will remain globally traded where technical service and certification support justify the logistics burden. This bifurcation suggests that the market will develop distinct regional price equilibria, with nominal premiums for proximity and service, and narrower spreads for commodity-style grades where logistics and input volatility dominate. Investors and manufacturers evaluating expansion should prioritize demand adjacency, regulatory documentation capability, and the ability to serve multiple downstream formats over pure scale alone.
Trend Three: Purity, Morphology, and Cross-Sector Portability
A third trend is the growing relevance of purity and particle morphology across sectors that historically had limited overlap. High-purity ultra-fine grades are gaining traction in technical coatings and advanced ceramics, while consistent sub-micron distributions are becoming valuable in electronics-adjacent applications where dispersion and surface effects influence final properties. The opportunity is portability: grades engineered with controlled impurity profiles and repeatable morphology can be positioned across multiple segments, reducing the need for highly fragmented product lines. The risk is that purity and morphology targets are demanding and unforgiving, requiring disciplined process control and analytical support. Producers that treat these attributes as core capabilities, rather than niche features, will be better positioned to defend margins when volume growth moderates in any single segment.
Implications and Actions for Decision Makers
For Manufacturers and Material Formulation Teams
Lead with specification support and total cost management rather than volume pricing alone. As logistics costs and input benchmarks become more variable, competitiveness will depend on demonstrating consistent particle performance, reducing re-qualification friction, and aligning capacity with regional demand clusters. Invest in application data that connects particle size, surface behavior, and dispersion outcomes to end-use safety and processing metrics. Where possible, structure supply relationships to include documentation readiness and lot traceability, since these attributes increasingly influence retention in certified programs.
For Investors and Portfolio Strategists
Prioritize assets and operators that combine process control with application-facing capability. Capacity expansion is meaningful only when it is matched to demand visibility in safety-driven and performance-driven segments. Look for evidence of technological discipline in micronization and precipitation, stable customer relationships supported by technical service, and exposure to multiple downstream formats that reduce dependence on any single cycle. Regional cost advantages are valuable, but they are most durable when paired with consistent quality and the ability to serve specification-led demand without heavy re-qualification overhead.
For Procurement and Sourcing Leaders
Move from transactional price comparison to a total landed cost and qualification-cost framework. The logistics premium for powdered transport, the variability in upstream benchmarks, and the hidden cost of re-qualification all argue for a sourcing model that balances specification assurance with regional availability. Where standard grades are sufficient, regional suppliers can improve cost predictability; where certification and performance consistency matter, global specialists with documented application support reduce downstream risk. Build flexibility into contracts to accommodate input and logistics shifts without triggering costly requalification cycles.
Closing Perspective
The ultra fine aluminium hydroxide market is entering a period where technical consistency, regulatory alignment, and regional supply logic will matter more than headline volume alone. Growth through 2032 is anchored by halogen-free substitution, specification-driven adoption, and expanding relevance in automotive, electronics, and technical coatings, while cost realities in logistics and raw materials are reshaping where and how capacity is most effective. For organizations operating in or adjacent to this market, the strategic question is no longer whether demand will grow, but how to position grades, supply relationships, and portfolio exposure to capture value from specification lock-in and regional demand clustering. Detailed segmentation data, regional demand breakdowns, and customized scenario modeling can sharpen these decisions further, and PW Consulting’s full research report provides the granular visibility required to translate these trends into concrete sourcing, investment, and product strategy choices.
For detailed analysis of this topic, please visit the official page: Ultra Fine Aluminium Hydroxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The High Performance Apparel Market: Strategic Shifts and Commercial Opportunities Through 2032
The high performance apparel market has evolved from a specialized niche serving elite athletes into a broad commercial category driven by everyday consumers, occupational requirements, and technological advancement. Between 2020 and 2025, global revenue climbed from 90.0 million USD to 141.0 million USD, reflecting sustained demand across multiple consumer segments. The trajectory forward indicates continued expansion, with the market projected to reach 280.0 million USD by 2032 and a compound annual growth rate of 10.4 percent across the 2026 to 2032 forecast period. This growth rate places the sector among the more dynamic segments within the broader textile and apparel industry, signaling that performance-driven design, material science, and functional differentiation are no longer optional features but central competitive requirements.
The pace of expansion, however, does not imply uniform opportunity across all participants. Market concentration remains notable, with the top three competitors accounting for approximately 60.0 percent of total revenue and the top five reaching 62.0 percent. This concentration indicates that scale advantages in brand recognition, distribution networks, and product development pipelines continue to shape outcomes. At the same time, the category's breadth—spanning synthetic and natural fiber systems, multiple application contexts, and diverse regional demand profiles—creates room for targeted positioning, specialized fabric innovation, and regional or segment-specific growth strategies.
Market Structure and the Current Inflection Point
The current market environment reflects a transition from volume-led expansion toward value-led differentiation. Early growth in the category was fueled by rising participation in fitness activities, growing awareness of moisture management and comfort benefits, and the gradual blending of athletic aesthetics into everyday wear. As adoption has widened, the challenge has shifted toward maintaining differentiation when performance claims become increasingly common across price tiers. Brands that once stood apart through basic functional benefits now face a market where consumers and procurement teams expect more precise performance outcomes, improved durability, and clearer evidence of value.
A second inflection point involves the tension between material performance and cost accessibility. Advanced textile technologies often require substantial research and development investment, specialized manufacturing processes, and tighter quality controls. These factors can elevate product cost and limit accessibility for a broader consumer base. At the same time, pricing pressure and volatile raw material costs across synthetic fabric manufacturing operations constrain adoption, particularly for price-sensitive segments and cost-driven purchasing organizations. The result is a market in which innovation and affordability must be managed simultaneously, rather than treated as separate priorities.
A third structural challenge emerges from supply chain timing and responsiveness. As performance apparel becomes more closely associated with seasonal demand patterns, sports calendars, and rapidly changing consumer preferences, lead time and inventory allocation have become strategic issues. Excess production can erode margins, while insufficient availability can weaken brand credibility during peak demand windows. This dynamic is especially relevant for companies balancing promotional calendars, performance launches, and wholesale commitments across multiple channels.
Key Drivers Shaping the High Performance Apparel Market
Technological Innovation and Material Performance
Material innovation remains the most visible engine of competitive change. Synthetic fiber systems continue to dominate functional apparel because of their moisture-wicking capability, durability, and relatively lower manufacturing cost. Within this environment, polyester maintains a substantial share of the materials landscape, supported by its performance characteristics and cost structure. Yet the strategic conversation is moving beyond basic fiber selection toward engineered fabric architectures, knit structures, and integrated performance features that respond to specific use conditions.
PW Consulting
Recent product activity illustrates this shift. In early 2026, Nike introduced Aerogami performance-apparel technology intended to improve breathability precisely when needed, signaling an emphasis on adaptive comfort rather than uniform ventilation. Later in the year, the company expanded its digital retail ecosystem with advanced demand forecasting tools designed to improve inventory allocation and reduce overproduction for performance apparel. These moves reflect a broader pattern in which material advancement and commercial sophistication are increasingly linked. Performance is not only a fabric attribute; it is also a function of product timing, channel execution, and demand visibility.
Similarly, Lululemon introduced a training apparel collection featuring body-hugging activewear built with Ultralu fabric technology, reinforcing the industry's focus on stretch, breathability, and comfort-focused fabrics for training and movement-based wear. This type of launch highlights how performance language is now extending beyond outdoor or competition contexts into routine fitness, travel, and lifestyle applications. The practical implication is that performance apparel is becoming more segmented by use case, even as the overall category continues to expand.
Policy, Regulation, and Sustainability Expectations
Regulatory expectations and sustainability considerations are reshaping product development priorities and sourcing decisions. While policy pressure varies by region, the broader direction points toward greater scrutiny of material sourcing, manufacturing practices, and environmental impact. In response, some leading companies are repositioning their product lines around reduced environmental footprint and recycled or bio-based inputs. For example, Adidas launched a new line of performance apparel utilizing bio-based and recycled materials to reduce environmental impact. This move reflects an increasing alignment between performance messaging and sustainability positioning, particularly when both can be communicated through tangible product attributes.
The commercial relevance of this trend extends beyond public relations. Sustainability-related sourcing choices can affect cost structures, supplier relationships, and product roadmaps. They can also influence procurement decisions among buyers who are themselves subject to internal sustainability targets or customer expectations. A practical challenge is that cutting-edge textile technologies often entail significant research and development investment and complex manufacturing processes, resulting in elevated product costs. Companies therefore need to determine where sustainability and performance can reinforce each other, and where trade-offs require clearer prioritization.
Demand-Side Shifts in Consumer and Enterprise Behavior
Demand is increasingly shaped by functional expectations that cross traditional category boundaries. In the application landscape, sportswear represents the largest demand pool, while protective clothing reflects a meaningful and operationally distinct segment. The sportswear side continues to benefit from participation in training, running, and general fitness, along with the broader adoption of activity-based apparel in everyday settings. The protective clothing side, by contrast, is driven by occupational requirements, safety standards, and durability expectations, where performance is measured not only by comfort but also by protection, longevity, and compliance.
What unites these segments is a stronger demand for purpose-built design. Consumers and institutional buyers are less interested in generic claims and more attentive to whether a garment's construction matches its intended use. This shift encourages brands to articulate performance more precisely, whether that means moisture control, stretch, breathability, insulation, or resistance to harsh conditions. It also encourages more differentiated product architecture, since a garment designed for high-intensity training may not satisfy the requirements of outdoor exposure or workplace protection.
Supply Chain and Cost Structure Dynamics
Cost and supply chain dynamics are becoming more central to strategic positioning. Raw material volatility, especially across synthetic fabric manufacturing operations, can constrain adoption by affecting both final pricing and margin stability. At the same time, the cost of advanced textile innovation remains a barrier for broader accessibility, which means that performance leadership is often correlated with companies that can fund research, manage manufacturing complexity, and still achieve commercial volume.
In this context, supply chain responsiveness has gained strategic importance. Inditex accelerated its nearshoring strategy with increased production capacity in Europe for performance apparel to reduce lead times. This type of capacity decision reflects a wider industry interest in shortening response cycles, improving availability, and reducing the risk of misaligned production plans. For performance apparel, where launch timing and demand spikes can be closely linked to seasonality and consumer attention windows, lead-time advantage can be as commercially important as product features.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a mix of global sportswear incumbents, technical outdoor specialists, and emerging performance-focused labels. The leading companies generally compete on a combination of brand equity, fabric technology, product specialization, and channel strength. The strategic question is not simply who has the strongest performance claims, but who can convert those claims into repeatable commercial advantage through design, manufacturing, and distribution.
Nike's profile reflects a broad performance apparel orientation centered on breathable, moisture-wicking, and performance fabrics for sports and fitness. Its recent activity suggests a dual focus: advancing fabric-level performance while also improving commercial execution through demand forecasting and inventory allocation. This pairing is notable because it links product innovation with operational discipline, an approach that can help manage the risk of overproduction while supporting more precise availability.
Adidas remains a major producer of high-performance sportswear with advanced fabrics and technologies for training and competition apparel. Its recent bio-based and recycled product launch indicates a strategy that ties performance to sustainability messaging, which can be especially relevant in markets where consumers and buyers evaluate environmental impact alongside functionality.
Under Armour specializes in high-performance athletic apparel featuring proprietary compression and moisture-control technologies. This specialization suggests a focus on function-specific differentiation, where proprietary technology and application fit play a larger role than broad lifestyle positioning. Puma, by contrast, supplies high-performance sportswear with emphasis on moisture-wicking and durable performance materials, indicating a strategy rooted in core functional reliability across active use cases.
Lululemon has built a position around high-performance activewear and training apparel with stretch, breathability, and comfort-focused fabrics. Its recent training collection launch shows continued attention to fabric feel and fit for movement-driven wear, appealing to consumers who want performance attributes without a purely competition-oriented aesthetic. Vuori similarly develops performance apparel and activewear with innovative knit and moisture-management technologies, reflecting the growing presence of brands that compete through fabric engineering andContemporary product experience rather than legacy sports marketing alone.
The outdoor and technical segment brings a different set of priorities. Columbia Sportswear produces high-performance outdoor and work apparel with advanced waterproofing and insulation technologies, while Patagonia manufactures high-performance outdoor apparel using recycled and durable materials for extreme conditions. Arc'teryx specializes in high-performance technical outerwear for alpine and extreme sports with advanced fabric engineering, and VF Corporation operates brands such as The North Face that offer high-performance technical outerwear and protective apparel. In this part of the market, durability, weather resistance, and specialized construction often matter as much as comfort or style.
The geographic diversity of the competitive field is also worth noting. FILA, headquartered in Seoul, produces high-performance sportswear and athletic apparel with focus on speed and durability fabrics, while ASICS Corporation, based in Kobe, supplies high-performance running and athletic apparel featuring advanced cushioning and breathable materials. Their presence underscores that performance apparel leadership is not confined to a single region or brand tradition; rather, different markets contribute distinct product philosophies and manufacturing strengths.
Strategic Positioning and Differentiation
Across these companies, differentiation tends to cluster around several strategic approaches. One is fabric-led innovation, where the brand emphasizes proprietary materials, knit structures, or engineered performance features. Another is use-case specialization, where the product roadmap is organized around running, training, outdoor exposure, workwear protection, or lifestyle movement. A third is sustainability-aligned product design, where recycled or bio-based inputs are integrated into the performance narrative. A fourth is operational agility, where demand forecasting, inventory allocation, and production proximity are treated as part of the value proposition.
Worldwide Performance Golf Apparel Market
The most resilient positions usually combine more than one of these elements. A brand that offers advanced breathability but cannot manage inventory timing may lose sales during peak demand. A brand that promotes sustainability but cannot keep costs within a viable range may limit its addressable market. A brand that excels in technical outdoor performance may need a different go-to-market approach than one targeting everyday training apparel. In this sense, competitive advantage in high performance apparel is increasingly multidisciplinary.
Market Evolution: Consolidation, Fragmentation, and New Entry
The current landscape suggests a market that is simultaneously concentrated and open to targeted disruption. High share among leading global players indicates that scale, distribution, and brand recognition remain powerful advantages. At the same time, the wide range of performance needs—across sports, outdoor use, occupational protection, and casual activity—creates space for specialized entrants and sub-segment leaders. New entrants often succeed by focusing on a specific fabric advantage, a defined consumer occasion, or a strong product experience rather than attempting to compete across the full category from day one.
Consolidation pressure is likely to persist where scale improves access to research and development, supplier negotiations, and multi-channel distribution. Yet fragmentation may also continue where differentiation is strong enough to support brand loyalty and premium positioning. The practical outcome is a market in which incumbents must defend breadth and supply chain capability, while newer or smaller players attempt to win through precision, storytelling, and function-specific relevance.
Forward Trends and Commercial Implications
Adaptive Performance and Fabric Intelligence
Over the next three to five years, one of the clearest trends is likely to be a move toward more adaptive performance design. Rather than providing a single level of breathability, moisture management, or insulation across all conditions, future products may be engineered to respond more precisely to activity intensity, climate, and wear duration. This direction is already hinted at by product concepts focused on breathability precisely when needed and by fabric technologies that emphasize comfort, stretch, and movement. The commercial opportunity lies in products that can claim a better fit between garment behavior and user context, especially in training, travel, and all-day wear scenarios where comfort and function intersect.
A related implication is that performance communication will need to become more specific. Broad claims may continue to attract attention, but sustained purchasing decisions are more likely when brands can connect material properties to real use outcomes. This creates opportunities for companies that can demonstrate functional benefit in a credible, differentiated way.
Sustainability as a Performance Enabler, Not Just a Message
Sustainability is likely to become more deeply integrated into performance apparel strategy, not only as a compliance or reputation issue but also as a product development parameter. Bio-based and recycled inputs, durable construction, and material efficiency can support both environmental goals and long-term product value if they are engineered well. The challenge is that adoption of advanced textile technologies often entails significant research and development investment and complex manufacturing processes, resulting in elevated product costs. Companies that can manage this tension—by selecting materials that deliver both functional and sustainability benefits, or by redesigning processes to reduce cost while maintaining performance—will have an advantage in markets where buyers expect both.
One risk is that sustainability and performance goals may not always align easily at every price point. Another is that raw material volatility and pricing pressure can make sustainable input strategies more difficult to scale. Organizations will need to test where sustainability improves product value and where it primarily adds cost, then prioritize accordingly.
Supply Chain Speed and Production Geography
Supply chain configuration is likely to remain a strategic variable, particularly as brands seek to reduce lead times and improve responsiveness. Nearshoring and regional capacity expansion can support shorter production cycles and better alignment with demand fluctuations, which is especially relevant in performance categories where timing influences commercial outcomes. At the same time, regional shifts introduce their own cost and capability considerations, so the optimal structure will vary by brand, product type, and target market.
A practical uncertainty is whether regional production can be scaled efficiently enough to support both performance quality and cost competitiveness. Another is that demand forecasting tools and inventory systems, while helpful, cannot fully remove the risk of misforecasting in a category influenced by trends, seasonality, and changing consumer behavior. Companies will need to treat supply chain design as a continuous optimization problem rather than a one-time decision.
Actionable Guidance for Decision Makers
For Manufacturers and Brand Builders
Product strategy should increasingly separate genuine functional advantage from generic performance language. Brands that can define a clear use case and engineer fabric, fit, and construction around that use case are better positioned to defend margins and build repeat purchase behavior. It is also important to align innovation investments with manufacturing feasibility, since advanced textile technologies often entail complex processes and elevated product costs. Where possible, performance claims should be tied to measurable outcomes that matter to the target customer, whether that is moisture control during training, comfort across long wear periods, or protection in demanding conditions.
High Performance Fiber Market
Operationally, manufacturers should treat demand forecasting and inventory allocation as part of the product value proposition. Better visibility into demand patterns can reduce overproduction risk and improve availability during peak periods. This is especially relevant for companies launching performance collections with seasonal or event-driven demand cycles.
For Investors
Investment decisions in this market should weigh both category growth and competitive concentration. The projected expansion to 280.0 million USD by 2032 and a 10.4 percent compound annual growth rate suggest a favorable demand environment, but share concentration indicates that incremental growth may not be distributed evenly. Investors may want to distinguish between businesses that rely primarily on brand scale and those that have defensible fabric technology, specialized application focus, or superior supply chain execution.
It is also worth monitoring how sustainability-linked product strategies affect cost structures and consumer adoption. Bio-based and recycled material lines can strengthen positioning, but their commercial impact depends on whether they can be produced at scale without eroding margin or accessibility. Companies that manage that balance more effectively may be better placed for durable growth.
For Procurement and Buying Organizations
Buyers should evaluate performance apparel based on use-case fit, durability, and total cost of ownership rather than headline features alone. In sportswear procurement, moisture-wicking, breathability, and comfort during movement may be priorities, while in protective clothing contexts, durability and compliance may carry more weight. Because pricing pressure and volatile raw material costs can affect supply stability, buyers may benefit from diversifying sourcing options and clarifying which performance attributes are essential versus nice to have.
Sustainability expectations are also increasingly part of purchasing decisions. Where relevant, buyers should assess whether recycled or bio-based claims are supported by consistent product standards and whether those choices affect lead times or cost. Clear specifications can help align procurement goals with operational reality.
Conclusion
The high performance apparel market is entering a phase in which growth is supported by strong demand, but competitiveness is determined by precision: precision in fabric engineering, precision in use-case targeting, precision in sustainability integration, and precision in supply chain execution. The category's projected expansion through 2032 indicates that performance apparel will remain a central commercial segment, but the winners are likely to be those who can convert functional innovation into reliable product outcomes and efficient operations.
For organizations seeking deeper segmentation data, regional breakdowns, application-level detail, and customized strategic recommendations, the full PW Consulting research report provides a more granular view of the market landscape and the operational decisions behind it.
For detailed analysis of this topic, please visit the official page: High Performance Apparel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Pneumococcal Vaccination Market 2026: Why 5.3% CAGR & Shifting Demand Signal Sustained Growth
By PW Consulting, 2026-09-21
Strategic Insights into the Pneumococcal Vaccination Market: Growth Trajectories and Commercial Opportunities
Market Landscape and Core Challenges
A Maturing Industry with Steady Expansion
The global pneumococcal vaccination market has demonstrated consistent growth over the past half-decade, expanding from approximately $7.35 billion in 2020 to nearly $9.38 billion in 2025. This historical trajectory reflects sustained immunization efforts, expanding national schedule integration, and incremental product introductions. Looking ahead, the market is projected to progress from $10.20 billion in 2026 toward $13.26 billion by 2032, representing a compound annual growth rate of 5.3%. While the growth rate is moderate compared to pandemic-era vaccine segments, it underscores a structural shift from emergency response to routine, high-coverage immunization programs with broader age-group inclusion.
Revenue concentration remains high, with the top three manufacturers accounting for roughly 85% of market value and the top five capturing about 92%. This concentration signals strong barriers to entry, primarily driven by complex conjugate chemistry, stringent regulatory pathways, and established procurement relationships with government agencies and multilateral organizations. At the same time, it suggests that differentiation increasingly depends on valency breadth, age-specific indications, and supply reliability rather than on basic vaccine availability.
Key Challenges at the Current Inflection Point
Three structural challenges define the current market environment. First, pricing and reimbursement dynamics remain highly bifurcated. In high-income markets, private-sector procurement prices for conjugate vaccines can range from $100 to $150 per dose, while subsidized doses in lower- and middle-income countries can reach as low as $3.50 through multilateral mechanisms. This gap creates tension between volume expansion and margin sustainability, especially as global health institutions push for broader access without proportionally increasing procurement budgets.
Second, cold chain logistics continue to constrain last-mile delivery and inventory flexibility. All pneumococcal conjugate vaccines require storage between 2 and 8 degrees Celsius, with stability limited to approximately four days at temperatures up to 40 degrees Celsius. This requirement elevates operational costs for remote outreach, increases wastage risk, and places pressure on manufacturers and distributors to improve packaging, monitoring, and contingency planning.
Third, reimbursement and coverage policy shape demand signals across regions. In the United States, Medicare Part B covers pneumococcal vaccines at 95% of average wholesale price, with geographically adjusted rates updated in 2025. While this supports predictable uptake among older adults, it also ties commercial performance to periodic policy updates and formulary decisions. Any lag in coverage alignment, particularly for newer higher-valent products targeting adult populations, can slow adoption even when clinical differentiation is clear.
Key Drivers Shaping Market Direction
Technology Innovation and Valency Evolution
The most visible driver is the ongoing expansion in valency coverage and target-population specificity. The launch of broader conjugate formulations reflects a deliberate effort to address serotype coverage gaps, particularly in adult populations where disease burden is rising and serotypes not covered by earlier formulations remain clinically relevant. A concrete example is the positive CHMP opinion received in March 2025 for Capvaxive, a 21-valent pneumococcal conjugate vaccine designed for adults. This milestone signals regulatory momentum for higher-valency products and indicates that differentiation is increasingly linked to serotype selection, immunogenicity, and age-specific clinical data rather than to conjugate technology alone.
Beyond new formulations, technology leadership also depends on manufacturing capability. Operations that can scale conjugate production efficiently, maintain lot consistency, and manage fill-finish throughput gain a meaningful advantage in a market where supply interruptions can immediately affect national procurement schedules. The establishment of a dedicated North Carolina site and custom fill-finish line for pneumococcal vaccines in 2026 illustrates how capacity building is becoming a strategic priority, not merely an operational detail.
Policy and Regulatory Dynamics
Regulatory pathways and procurement policy are becoming more granular. Multi-valency approvals for adults, pediatric indications, and regional licensing decisions all influence the speed at which new products reach the market. The growing emphasis on adult immunization reflects a broader policy recognition that pneumococcal disease burden spans age groups, and that coverage targets cannot be achieved through pediatric programs alone. In parallel, procurement forums such as the PAHO Revolving Fund continue to structure access in ways that blend affordability with local production goals. The January 2025 agreement for local PCV20 production in Argentina demonstrates how policy and manufacturing strategy can converge to support both supply security and regional capacity building.
At the same time, regulatory expectations on quality, stability, and post-market surveillance remain high. These requirements do not only affect launch timing; they shape long-term commercial viability by raising the minimum bar for manufacturing excellence and lifecycle management. Companies that treat regulatory compliance as a strategic capability, rather than a procedural hurdle, are better positioned to maintain access across diverse buyer environments.
Demand-Side Behavior and Immunization Priorities
Demand is being reshaped by broader public-health awareness, adult vaccination initiatives, and growing emphasis on equitable access. Pediatric demand remains substantial and is supported by routine immunization schedules, but the adult segment is gaining attention as health systems seek to reduce hospitalizations and complications linked to pneumococcal disease in older populations. This shift matters commercially because adult programs often involve different procurement channels, reimbursement structures, and provider education requirements compared with pediatric campaigns.
Another demand-side dynamic is the increasing preference for supply resilience. Procurement entities are more attentive to manufacturing location, backup capacity, and risk-sharing terms, especially after recent global disruptions across healthcare supply chains. Buyers are not simply evaluating price and valency; they are also assessing whether a supplier can deliver predictably across multiple seasons and geographies. For manufacturers, this means that commercial strategy increasingly includes operational credibility as a differentiator.
Cost Structure and Supply Chain Considerations
Cost structures remain highly sensitive to manufacturing complexity, serotype mix, and procurement segmentation. The large spread between high-income private pricing and subsidized multilateral pricing means that companies must manage product portfolios with different margin profiles and volume expectations. In that environment, efficiency in upstream production and downstream distribution has direct commercial implications. Even modest improvements in yield, fill-finish throughput, or packaging design can significantly affect net performance across high-volume, lower-margin segments without disrupting high-value markets.
Cold chain constraints also interact with cost structure. Temperature-stable packaging innovations, extended monitoring tools, and distribution planning can reduce wastage and broaden reach in harder-to-serve settings. These improvements are not only logistical; they influence the economic feasibility of expanding coverage in regions where the value case depends on reliable delivery rather than on vaccine availability alone.
Competitive Landscape and Leading Strategies
Strategic Positioning of Major Players
The competitive field is anchored by large multinational manufacturers and an emerging group of regional and cost-competitive suppliers. Leading multinationals typically compete through comprehensive pneumococcal portfolios spanning multiple valencies and age groups. For example, one major manufacturer markets a 20-valent conjugate vaccine and a 15-valent conjugate vaccine across infant and adult indications, while another maintains a portfolio that includes a well-established 13-valent conjugate vaccine, a 23-valent polysaccharide vaccine, and a newer 21-valent adult-focused conjugate vaccine. This breadth allows them to address different clinical needs and procurement categories while leveraging established brand recognition, regulatory experience, and global distribution capabilities.
Regional and affordability-oriented suppliers are positioned differently. Some focus on pneumococcal conjugate products intended for pediatric use, often in formulations that align with specific national immunization needs or cost constraints. One notable example is a 10-valent conjugate vaccine distributed for pediatric use and prequalified for broader access, while another manufacturer in India has brought a 14-valent conjugate vaccine into the market with WHO prequalification. These products illustrate how competitive advantage can be built through access-friendly pricing, regulatory prequalification, and fit-for-purpose formulations, especially in markets where procurement decisions weigh cost and supply continuity heavily.
China-based manufacturers also play an important role in domestic and regional supply, particularly with 13-valent conjugate vaccines for pediatric use. Their strategic relevance lies in serving high-volume local demand and potentially expanding into adjacent markets where regulatory alignment and pricing structures support competitor diversification.
Differentiation in a Concentrated Market
In a market where the top three and top five firms hold the large majority of value, differentiation tends to emerge in four areas:
- Valency and indication breadth: Products that address adult and pediatric populations with improved serotype coverage can command stronger positioning if supported by clinical evidence and reimbursement alignment.
- Manufacturing and supply reliability: Capacity investments, fill-finish specialization, and regional production partnerships create credibility with procurement entities that prioritize continuity and risk mitigation.
- Access strategy: Price-tier strategies, multilateral engagement, and local production arrangements can open volume opportunities in price-sensitive markets while preserving higher-margin segments elsewhere.
- Lifecycle and pipeline momentum: Companies advancing next-generation candidates, such as a 25-valent pediatric program, signal long-term intent and can influence formulary and procurement decisions well before launch.
These dimensions matter because the market is no longer defined solely by who has a conjugate vaccine. It is increasingly defined by who can deliver the right valency to the right population, at the right cost structure, with dependable operations and policy-aware market access.
Evolving Market Structure: Integration, Diversification, and New Entry
The market structure is evolving along several lines. Large players continue to reinforce positions through portfolio breadth, global procurement relationships, and pipeline advancement. At the same time, the industry is seeing targeted partnerships and regional manufacturing initiatives that could gradually diversify supply sources. The Argentina-based local production arrangement for PCV20, supported by a multinational partner and a regional procurement fund, shows how access and supply resilience can be pursued through coordinated partnerships rather than through wholly independent vertical integration.
New entry remains difficult, but not impossible. Entrants that can secure regulatory prequalification, demonstrate manufacturing quality, and align with multilateral or government procurement channels may find viable niches, especially where serotype coverage needs or cost thresholds create room for alternative suppliers. Conversely, entrants without clear cost advantages, differentiated valency coverage, or credible supply commitments will face steep headwinds in a market that already rewards scale, experience, and operational reliability.
Future Trends and Commercial Implications
Trend One: Adult-Focused Higher-Valency Adoption Will Accelerate
Over the next three to five years, adult immunization is likely to become a stronger growth driver as higher-valency conjugate options and supportive policy signals gain traction. This trend is commercially significant because adult programs can expand total addressable demand, encourage updated formulary placement, and create new procurement patterns distinct from pediatric routines. Vaccines with adult-specific indications and broader serotype coverage may benefit most, especially if reimbursement frameworks continue to support predictable access.
The business implication is that manufacturers and buyers alike should prepare for more segmented adult demand, with greater emphasis on provider education, scheduling logistics, and coverage alignment. Companies that can demonstrate real-world effectiveness, efficient adult dosing pathways, and reliable supply will be better positioned to capture share in this expanding segment.
Trend Two: Supply Resilience and Regional Production Will Become Strategic Assets
Another likely trend is the continued emphasis on supply security through regional production, dedicated fill-finish capacity, and procurement partnerships. As buyers place more weight on continuity, the ability to demonstrate manufacturing presence, contingency planning, and localized production potential may become a competitive advantage. This is not only about responding to shortages; it is about aligning with procurement preferences that increasingly treat supply reliability as a core requirement.
Commercial opportunities here include partnerships that combine technology, capacity, and procurement access; investment in flexible fill-finish infrastructure; and manufacturing strategies designed to serve multiple price-tier markets without undermining quality or delivery performance. For buyers, this shift creates opportunities to reduce concentration risk and improve long-term affordability through diversified supply arrangements.
Pertussis Vaccine Market
Trend Three: Pricing Pressure and Access Optimization Will Coexist
The third trend is the persistence of pricing divergence across markets. High-income private pricing and subsidized procurement will continue to coexist, which means that portfolio management and market access strategies will remain central to commercial success. Companies will need to navigate the tension between volume growth in lower-price segments and margin preservation in higher-price segments. This is likely to reinforce interest in efficiency improvements, targeted access programs, and differentiated formulations that can justify pricing based on clinical value and service reliability.
A related opportunity lies in optimizing the pathway between product value and reimbursement. In settings where coverage policy shapes adoption speed, alignment with payer expectations, formulary status, and provider workflows can be as important as clinical differentiation. Firms that integrate market access considerations earlier in product planning will be better equipped to convert innovation into commercial traction.
Risk Considerations
Several uncertainties could alter the pace or pattern of growth. Regulatory timing for new higher-valency products may vary by region, affecting how quickly adult and pediatric segments adopt next-generation formulations. Cold chain constraints and last-mile delivery costs may continue to limit coverage expansion in certain environments, especially where infrastructure is limited or seasonal demand spikes strain supply systems. Pricing and reimbursement updates can also change demand dynamics, particularly if policy adjustments reduce reimbursement levels or shift procurement toward more competitive contracting. Finally, the high concentration of market value means that competitive responses by leading players, such as pricing maneuvers, portfolio expansions, or supply agreements, can materially influence the landscape for smaller participants and new entrants.
Worldwide Multivalent Pneumococcal Conjugate Vaccine Market
Actionable Recommendations for Decision Makers
For Manufacturers and Developers
Focus on differentiating through valency relevance, age-specific evidence, and operational credibility. For adult-focused products, ensure that clinical positioning supports reimbursement alignment and provider adoption. For pediatric and mixed-population offerings, emphasize supply reliability and manufacturing maturity as part of the commercial proposition. Consider regional production or partnership models that improve access credentials and supply resilience without sacrificing quality. Build lifecycle plans that anticipate not only new formulations but also procurement expectations, cold chain realities, and price-tier management across markets.
For Investors and Strategic Partners
Evaluate opportunities based on three questions: whether a candidate or asset addresses a clear serotype or population gap, whether the operating model supports dependable supply at scale, and whether the market access pathway is realistic in the target geography. Higher-valency adult programs, dedicated fill-finish capacity, and access-oriented partnerships are areas where strategic value may be particularly sensitive to execution quality. At the same time, assess concentration risk in the supply base and the potential for procurement policy shifts to change volume or pricing assumptions. In this market, value creation often depends less on speculative demand than on execution of differentiation, reliability, and access.
For Procurement Leaders and Health System Decision Makers
Prioritize contracts and procurement strategies that balance cost, coverage, and continuity. Where possible, diversify supply sources for critical pneumococcal programs and require evidence of cold chain capability, contingency planning, and delivery reliability. For adult immunization programs, align procurement decisions with reimbursement and provider workflows to reduce adoption friction. For pediatric programs, emphasize predictable supply and formulation fit with national schedules. As higher-valency options become available, evaluate them not only on price but also on serotype relevance, target-population coverage, and total program reliability.
PW Consulting Health Care Research Center
Timely, detailed intelligence is especially valuable in a market where commercial outcomes depend on the interaction of regulation, procurement policy, manufacturing capacity, and product differentiation. Decision makers who monitor pipeline milestones, regional production developments, reimbursement updates, and procurement trends are better positioned to anticipate shifts rather than react to them. For those seeking deeper segmentation detail, scenario analysis, and tailored recommendations, the full research report offers a more granular view of regional dynamics, product-level positioning, and market-access considerations across buyer environments.
For detailed analysis of this topic, please visit the official page: Pneumococcal Vaccination Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Zinc Borate Market: The Real Drivers Behind 6.98% CAGR and $345M Growth
By PW Consulting, 2026-09-21
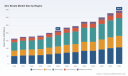
Strategic Trends and Commercial Opportunities in the Zinc Borate Market: 2025–2032 Outlook
The zinc borate market has entered a phase of steady, structurally supported expansion. Valued at approximately $215 million in 2025, the market is projected to grow at a compound annual growth rate of 6.98 percent through 2032, reaching just under $345 million. This trajectory reflects a broader shift in how industrial formulators balance performance, compliance, and supply chain resilience. Zinc borate has long been recognized as a reliable flame retardant and smoke suppressant, but the market no longer rewards commodity positioning alone. The next growth cycle will be shaped by technological refinement, regulatory recalibration, and geographic realignment. For executives and investors, the question is no longer whether demand will rise, but where value will concentrate and which capabilities will separate winners from marginal players.
Market Status and Core Challenges
The market's expansion over the past five years has been consistent rather than explosive. Annual revenue climbed from $163.15 million in 2020 to $215 million in 2025, with the forward forecast pointing to a clear upward slope through the early 2030s. Growth is broad-based across regions and end-use sectors, but the distribution of value is uneven. North America, Europe, and Asia Pacific account for the largest revenue shares, while Latin America and the Middle East and Africa represent smaller but increasingly strategic volumes. In terms of application, construction remains the dominant demand anchor, driven by building codes, fire safety mandates, and the substitution of higher-cost or more constrained flame retardant chemistries. Textiles and other specialty applications contribute smaller but high-margin segments where product consistency and regulatory documentation matter as much as price.
Three structural challenges define the current inflection point. First, raw material volatility continues to pressure cost predictability. Boric acid, the primary feedstock for zinc borate production, has experienced price swings tied to supply chain disruptions and the geographic concentration of boron resources. When feedstock costs fluctuate, manufacturers face difficult choices between absorbing margin compression, passing costs downstream, or adjusting formulation specifications. Second, regulatory scrutiny is tightening across multiple jurisdictions. Boric acid and its salts have been added to restricted substance lists in cosmetic applications in Canada, and related risk management scopes under environmental legislation now classify certain boron compounds as substances with potential immediate or long-term harmful effects. While zinc borate itself is not uniformly categorized in the same way, the broader regulatory environment around boron chemistry is shifting, and formulators are increasingly cautious about downstream compliance exposure. Third, trade friction is altering landed costs and import flows. Reciprocal tariff actions introduced in 2025 affected zinc borate imports into the United States, raising costs for certain importers and prompting a wider re-evaluation of sourcing strategies. Together, these forces are pushing the market away from price-only competition and toward a model where supply reliability, compliance readiness, and application support carry more weight.
Zinc Sulfate Market
Key Demand Drivers
The market's trajectory is being pulled by a combination of technical, regulatory, demand-side, and supply-side forces that reinforce one another.
Technology and product refinement. Innovation in zinc borate applications centers less on entirely new chemistries than on grade optimization, particle engineering, and formulation compatibility. Higher-purity grades are gaining traction in applications where consistency, low moisture sensitivity, and controlled smoke suppression are critical. Standard grades continue to serve cost-sensitive polymer and rubber formulations, but the margin opportunity increasingly lies in tailored products that integrate more cleanly into complex polymer matrices and meet tighter performance thresholds. This is especially visible in wire and cable, automotive components, and electronics-adjacent applications, where formulators need additives that do not compromise processing or mechanical properties. The practical effect is a market that rewards technical differentiation and application engineering more than bulk volume alone.
PW Consulting
Policy and regulatory environment. Regulation is acting as both a constraint and a catalyst. Stricter fire safety expectations in construction and transportation continue to support demand for halogen-free or low-halogen flame retardant systems, where zinc borate remains a practical option. At the same time, boron-related regulatory updates are making downstream buyers more attentive to documentation, substance tracking, and formulation risk. This does not eliminate zinc borate demand, but it raises the bar for suppliers that can provide clear compliance support, stable quality, and transparent sourcing. In practice, regulatory pressure is helping consolidate demand toward suppliers with stronger technical service capabilities and established regulatory files, while squeezing out less differentiated commodity positioning.
Demand-side behavior. End-user preferences are shifting toward safer, more durable, and more compliant materials. In construction, fire performance requirements and insulation-driven material choices are expanding the use of flame retardant additives in polymer-based building components. In industrial manufacturing, compounders are seeking additives that reduce smoke generation and improve material performance without disrupting processing economics. This demand-side evolution favors products that can demonstrate consistent performance across batches and offer formulation guidance. Buyers are less willing to treat zinc borate as an interchangeable input; they want reassurance that the grade they select will behave predictably in their specific polymer system and regulatory context.
Supply chain and cost structure. The supply side is being reshaped by capacity expansion, geographic sourcing decisions, and feedstock dynamics. New production capacity has come online in regions with access to boron resources and lower-cost manufacturing bases, while established producers in other markets have invested in higher-purity lines to capture premium demand. At the same time, boric acid price volatility and trade policy adjustments have made landed cost a more variable factor. These conditions are encouraging buyers to diversify sourcing, reconsider near-term inventory strategies, and evaluate total cost of ownership rather than unit price alone. For producers, the implication is that scale advantages matter, but they must be paired with reliability, technical support, and regulatory readiness to defend margin.
Competitive Landscape and Leading Strategies
The competitive field is moderately concentrated, with the top three firms accounting for roughly 24.6 percent of market revenue and the top five reaching about 26.2 percent. This level of concentration suggests a market where established players hold meaningful share but fragmentation remains sufficient for regional specialists and application-focused entrants to compete on performance, service, or cost positioning. The strategic differences among leading companies are instructive.
Large established producers have built their positions around brand recognition, broad application coverage, and consistent quality. U.S. Borax, for example, has emphasized specific flame retardant and smoke suppressant grades for polymers, wire and cable, and construction uses. Its strategic advantage lies in a recognized product portfolio and the ability to support regulated applications with established technical credibility. In a market where buyers increasingly value reliability and compliance documentation, this kind of positioning provides a defensive moat, especially in North American and global supply chains that prioritize proven performance over incremental cost savings.
Regional producers with access to boron resources are pursuing a different logic: capacity expansion and targeted high-purity offerings. Akdeniz Chemson began producing hydrated zinc borate flame retardants with a first-phase plant capacity of 3,000 tonnes per year, and its recent capacity expansion reflects a deliberate move to capture rising demand. Eti Maden has taken a similar path, expanding production capacity with a facility dedicated to high-purity zinc borate to address global demand growth and improve supply chain efficiency. Turkey's broader role in boron resource availability gives these producers structural cost and supply advantages, but their commercial success depends on converting resource access into consistent quality, export reach, and application support.
European and Asian specialists are generally leaning into purity, sector-specific requirements, and regulatory alignment. Societa Chimica Larderello focuses on high-purity grades for automotive, electrical, and coatings sectors with REACH compliance. Sakai Chemical Industry positions premium high-purity zinc borate for electronics, automotive, and demanding Asian markets. These strategies target segments where buyers are less price-sensitive and more focused on performance consistency, documentation, and long-term supply assurance. In contrast, several Chinese producers serve domestic polymer processors and export to price-sensitive markets with standard-grade products. This is a commercially rational approach in volume-driven segments, but it also exposes those players to tighter margin dynamics and greater sensitivity to feedstock volatility and trade policy shifts.
Technical service and formulation support are emerging as differentiators across the landscape. Royce Global and Wallace FR illustrate a service-oriented model built around technical advisory, regulatory compliance documentation, and support for polymer compounders operating under regulated conditions. This matters because zinc borate performance is highly application-dependent. Buyers in wire and cable, construction polymers, and specialty coatings often need help optimizing loading levels, understanding interaction with other additives, and navigating documentation requirements. Suppliers that can reduce formulation risk and accelerate time to compliance are increasingly able to command preference even when unit pricing is not the lowest.
The competitive landscape is likely to evolve along three axes. Consolidation will continue where scale, resource access, and regulatory files provide durable advantages. Differentiation will intensify around purity, application support, and compliance readiness, especially in higher-value segments. New and expanding entrants will pursue specific niches, such as high-purity grades, regional cost advantages, or specialized technical service. The broader trend is not toward a single dominant model, but toward a layered market in which value capture depends on aligning product grade, service capability, and geographic reach with the right end-use segments.
Zinc Oxide Market
Future Trends and Commercial Opportunities
Over the next three to five years, three interconnected trends are likely to shape how value is created and captured in this market.
Trend one: premiumization within a growing volume base. As demand expands, a larger share of growth is expected to come from higher-purity and application-tailored grades rather than undifferentiated standard products. Construction and industrial polymer applications will continue to drive volume, but the most durable margin opportunities will belong to suppliers that can provide consistent quality, controlled particle characteristics, and formulation support. The commercial opportunity here is to move up the value chain within zinc borate itself: invest in grade development, quality assurance, and technical service so that the product becomes a defining element of the buyer's formulation rather than a replaceable commodity.
Trend two: compliance and documentation as competitive infrastructure. Regulatory attention around boron-related substances is unlikely to fade. Even where zinc borate remains acceptable for core flame retardant uses, downstream buyers will continue to demand clearer documentation, traceability, and proactive compliance support. This creates an opportunity for suppliers to treat regulatory readiness as part of the product offering rather than an administrative add-on. Companies that can supply robust compliance files, transparent sourcing information, and application-specific guidance will be better positioned to retain customers in regulated polymer, construction, and electrical applications. The risk is that suppliers with weaker documentation or less consistent quality will face growing exclusion from sensitive supply chains.
Trend three: geographic realignment and sourcing diversification. Trade policy, tariff effects, and feedstock concentration are encouraging buyers to diversify supply sources and reconsider inventory and sourcing strategies. At the same time, capacity expansion in resource-adjacent regions is changing the balance of available volume. The opportunity lies in matching supply positioning to buyer risk tolerance. Some customers will prioritize regional supply security and technical support, while others will pursue cost-optimized sourcing where documentation and quality consistency are still acceptable. Producers that can operate across these demand profiles, or that deliberately choose a clear positioning, will be better equipped to manage volume and margin than those stuck in the middle.
These trends point to a market where growth is real but not uniformly distributed. The most attractive opportunities will be in segments where flame retardant performance, smoke suppression, and compliance intersect with demanding applications. The most significant risks involve feedstock price volatility, regulatory uncertainty around boron chemistry, and trade-driven cost fluctuations that can quickly erode margin for poorly positioned players. Executives should therefore treat the market as one where strategic choices about grade mix, service capability, and sourcing geography matter as much as overall demand growth.
Actionable Recommendations for Decision Makers
For manufacturers and formulators, the priority is to align product and sourcing strategies with the way value is shifting in the market. Evaluate zinc borate grades not only by price, but by how reliably they perform in the intended polymer system, how well they support regulatory documentation, and whether the supplier can provide formulation guidance. Where applications are performance-sensitive or regulation-intensive, the total cost of ownership argument often favors more consistent, better-supported grades over the lowest headline price. At the same time, review sourcing exposure to feedstock volatility and trade-related cost changes, and consider whether a diversified supplier base or a more deliberate regional sourcing strategy reduces risk without sacrificing performance.
For investors and corporate development teams, the appeal lies in companies that combine resource access or scale with premium grade development and compliance readiness. Capacity expansion alone is not a sufficient thesis; the more durable opportunities are in producers that can capture higher-value segments, serve regulated applications with credible documentation, and offer technical support that reduces customer risk. Watch for signposts such as continued investment in high-purity lines, expansion in regions with resource advantages, and growing emphasis on application engineering rather than bulk commodity sales. Conversely, exposure to undifferentiated price competition in highly tariff-sensitive or feedstock-volatile channels should be assessed carefully, as margin durability may be limited.
For procurement and supply chain leaders, the strategic task is to balance cost, reliability, and compliance in a market where each can shift independently. Multi-source sourcing may be prudent for high-volume applications, but the goal should be to qualify suppliers that meet consistent quality and documentation expectations rather than simply alternating between the lowest-cost options. Build compliance and traceability requirements into supplier qualification early, especially for applications entering regulated construction, electrical, or automotive supply chains. In practice, the buyers who will gain the most leverage are those who define performance and documentation requirements clearly, then evaluate suppliers against those criteria instead of treating zinc borate as a fungible input.
The timing of these decisions matters. The market is moving toward greater differentiation in grades, stronger expectations around compliance support, and more deliberate sourcing strategies. Companies that wait for the landscape to settle risk paying higher costs later, both in supply disruption and in lost positioning. More detailed segmentation, regional dynamics, and company-level benchmarking can help translate these directional insights into specific operating choices. The full research report provides deeper granularity on market splits, demand patterns, and competitive benchmarks for organizations that need to move from strategic direction to implementation.
For detailed analysis of this topic, please visit the official page: Zinc Borate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Organic PVC Stabilizers Market Transforms as Construction & Asia Pacific Drive Sustained Growth
By PW Consulting, 2026-09-21
Navigating the Organic PVC Stabilizers Market: Strategic Trends and Commercial Opportunities (2025–2032)
The global organic PVC stabilizers market is entering a phase of structural transition, where growth is no longer defined solely by volume expansion but by a complex interplay of regulatory pressure, raw material volatility, and strategic buyer behavior. Over the historical period from 2020 to 2025, the market moved through uneven cycles, reflecting broader macroeconomic shocks, supply chain recalibration, and shifting demand patterns across key downstream sectors. Looking ahead to the forecast window of 2026 through 2032, the trajectory points toward a compound annual growth rate of 2.2%, with the overall market expected to expand from a base value in 2025 to a significantly larger scale by the end of the projection period. While the absolute figures suggest steady expansion, the real story lies in how value is being redistributed across chemistry types, application verticals, and geographic corridors.
For executives and investors tracking this space, the headline growth rate masks a market where competitive positioning increasingly depends on formulation innovation, compliance readiness, and the ability to manage input cost swings. The organic stabilizers segment is being reshaped by forces that extend well beyond conventional polymer additive economics, and companies that treat this as a commodity-driven category risk missing the strategic inflection points now taking shape.
Market Structure and the Core Challenges Ahead
The organic PVC stabilizers market is characterized by a moderately concentrated competitive field, with the top three players accounting for roughly half of overall revenue and the top five capturing approximately sixty percent. This level of concentration suggests that scale advantages, formulation IP, and established customer relationships still matter, but it also leaves meaningful room for specialized entrants and regional specialists to compete on performance, service, and sustainability credentials. The revenue base is anchored by methyltin chemistry, which commands the largest share, followed by butyltin and octyltin systems, with other formulations making up the remainder. On the application side, construction materials and packaging materials together form the backbone of demand, while medical instruments and other end-use segments contribute smaller but strategically important volumes. Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, with no single region dominating to the point of eliminating regional differentiation.
Worldwide Plastic Stabilizer Market
Against this backdrop, several structural challenges are redefining how participants operate and plan.
- Lead substitution is no longer a compliance checkbox but a market reality. Regulatory frameworks such as EU REACH and China’s GB standards are accelerating the displacement of traditional lead-based systems in favor of organic and bio-based alternatives. This shift is irreversible in most high-value applications, forcing both incumbents and new entrants to invest in lead-free architectures rather than treating them as optional upgrades.
- Raw material cost pressure is compressing margins and forcing formulation strategy adjustments. Since the first quarter of 2023, calcium-based compounds used in organic stabilizer systems have experienced price increases in the range of forty-two percent, while zinc derivatives have seen cost increases around thirty-seven percent amid global supply chain disruptions. These movements are not temporary blips; they are reshaping cost structures and pushing buyers to weigh total cost of ownership against unit price.
- The willingness to pay for performance and longevity is being tested by buyers with tighter procurement budgets. Organic PVC stabilizer systems typically command a price premium of twenty-five to forty percent over traditional lead-based alternatives, a gap that can be justified by extended service life and regulatory safety, but only when value communication is clear and consistent across the value chain.
These challenges converge into a single strategic message: the market is moving from a price-and-specification dynamic toward one where compliance, lifecycle value, and supply resilience determine competitive outcomes. Companies that continue to compete purely on unit cost are likely to face shrinking headroom as regulatory expectations and input volatility become more entrenched.
Key Drivers Reshaping the Market
The forward direction of the organic PVC stabilizers market is being shaped by four interconnected forces: chemistry innovation, regulatory momentum, demand-side behavior changes, and supply chain restructuring. Each driver carries implications that extend beyond incremental growth and into the question of which business models will be durable over the next several years.
Technology and formulation innovation remain the most powerful lever for differentiation. The move away from petroleum-based thiols toward bio-based ligands derived from vegetable oils, castor oil, and agricultural residues is gaining traction as part of a broader push to reduce dependency on fossil feedstocks while maintaining stabilization performance. This is not a purely academic exercise; it responds directly to downstream buyers who are under pressure to lower the carbon footprint of their own products and who increasingly view additive origins as part of their sustainability reporting. At the same time, high-efficiency heat stabilizer architectures continue to improve for PVC pipes, fittings, rigid film, and exterior-grade applications, enabling formulators to achieve better processing stability and longer service life without reverting to older chemistries. The practical impact is that innovation is becoming a credibility signal as much as a performance advantage.
Policy and regulatory pressure is acting as a hard boundary for legacy solutions. The substitution toward bio-based and organic stabilizers is being reinforced not by a single regulation but by a converging set of standards and buyer expectations. In markets where lead-based systems were once economically attractive, the compliance cost of continuing with them is rising faster than the cost of switching, particularly for applications that intersect with consumer-facing, food-contact, or construction safety regimes. This is changing the conversation from “what is cheapest today” to “what can remain viable through the next audit cycle and customer specification review.”
PW Consulting
Demand-side behavior is evolving as both consumers and enterprises become more attentive to material safety and lifecycle durability. Construction specifiers, packaging converters, and medical device manufacturers are not simply looking for pass/fail compliance; they are increasingly interested in systems that reduce long-term degradation, simplify material declarations, and align with broader ESG narratives. This creates a market where organic stabilizer suppliers can win on value storytelling and technical support, especially when they can demonstrate extended service life and consistent performance under demanding conditions.
Supply chain and cost structure changes are forcing both procurement and R&D to adapt simultaneously. The sharp increases in calcium and zinc-based inputs have exposed the vulnerability of formulations that depend heavily on specific commodity derivatives. In response, some players are pursuing broader supplier diversification, dual-sourcing strategies, and formulation flexibility that allows partial substitution without sacrificing critical performance attributes. The strategic implication is that resilience is becoming a design parameter, not just a sourcing concern. Formulators that can adjust to input volatility while preserving specification integrity are gaining an advantage that goes beyond short-term margin protection.
Taken together, these drivers indicate a market where winners will be those who integrate compliance, formulation science, and cost-aware supply strategy rather than treating them as separate functions.
Competitive Landscape and Leading Strategies
The competitive field in organic PVC stabilizers includes both global and regional players with distinct strategic orientations. PMC Group Inc., based in the United States, has positioned itself around organotin stabilizers spanning methyltin, butyltin, and octyltin variants, with a focus on high-efficiency heat stabilizers for PVC pipe, fittings, rigid film, and exterior applications. Its profile suggests a strategy built on application-specific performance and reliability for demanding extrusion and film use cases. In China, Henan Shunbang Chemical Industry Co., Ltd. manufactures organic PVC stabilizers, including lead salt and compound organic types, serving PVC pipes, sheets, and food packaging. This points to a broad product footprint that balances cost-competitive offerings with application coverage across pipe and packaging channels. Guangdong Sky Bright Group Co., Ltd., also in China, emphasizes organic PVC stabilizers such as high heat resistance tin stabilizers for hard PVC and food-grade applications, suggesting a more targeted emphasis on performance grades aligned with stricter end-use requirements.
Akcros Chemicals Limited, operating in the United Kingdom as part of Valtris Specialty Chemicals, supplies sustainable and bio-based organic PVC stabilizers as part of lead-free systems. Its positioning reflects a sustainability-led value proposition that resonates with buyers seeking to reduce reliance on traditional feedstocks while meeting evolving regulatory expectations. REAGENS S.p.A. in Italy provides organic and calcium-zinc PVC stabilizers for construction and industrial applications, an indication of strength in systems that balance performance with familiar, widely accepted chemistries. Pau Tai Industrial Corporation in Taiwan manufactures organic PVC stabilizers for PVC pipe and profile extrusion, aligning with the structural demand coming from construction-related shaping and extrusion processes.
Several strategic patterns emerge from this landscape. First, differentiation is increasingly formulated around application fit and regulatory readiness rather than chemistry alone. High-efficiency organotin systems for pipes, fittings, and exterior use compete on processing performance and durability, while bio-based and calcium-zinc systems compete on sustainability alignment and broader acceptance in lead-free environments. Second, regional specialization remains important because downstream demand patterns, regulatory baselines, and cost structures differ meaningfully across markets. Third, suppliers that can offer reliable food-grade or construction-grade certifications, combined with application support, are better positioned to capture premium value than those relying solely on volume pricing.
The market is also likely to see continued integration and selective fragmentation. Concentration at the top suggests scope for consolidation among players seeking scale in formulation capacity, distribution, and technical service, especially in regions where compliance complexity is rising. At the same time, fragmentation is possible around specialized bio-based, high-performance, or region-specific formulations where smaller players can build defensible niches. New entrants that bring innovation in ligand design, feedstock sourcing, or cost-efficient production could further re-sort the landscape, particularly if they address the dual requirements of performance and regulatory acceptability.
Future Trends and Commercial Implications
Looking across the forecast period, three trends are likely to shape how the organic PVC stabilizers market evolves and where commercial opportunities will concentrate.
Worldwide Methyl Tin Stabilizer Market
The first trend is the deepening of lead-free and bio-based substitution as a default expectation rather than a premium option. As regulatory standards tighten and customer specifications mature, organic stabilizer systems built on renewable or bio-derived inputs will become increasingly relevant in packaging, construction, and medical-adjacent applications. The commercial opportunity lies in building formulations that can match or exceed the performance expectations of legacy systems while offering a cleaner compliance profile. The associated risk is that feedstock availability, formulation scalability, and price stability may lag behind the pace of specification change, creating temporary supply gaps or margin pressure for early adopters.
The second trend is a shift toward value-based procurement that rewards extended service life and total cost of ownership. Because organic stabilizer systems typically carry a meaningful price premium, buyers will become more rigorous in evaluating whether that premium is offset by reduced failure rates, longer replacement cycles, or easier compliance management. Here, the opportunity belongs to suppliers that can quantify lifecycle benefits, provide application-specific performance data, and support downstream users in specification decisions. The risk is that in cost-constrained purchasing environments, value arguments may be discounted unless they are supported by strong technical credibility and consistent field results.
The third trend is greater formulation flexibility and supply resilience as a competitive requirement. With calcium-based and zinc-based input costs having risen sharply, companies that can manage volatility through diversified sourcing, modular formulation design, and responsive production planning will be better positioned to protect margins and maintain supply continuity. The commercial upside is the ability to offer customers more stable pricing behavior and fewer disruption-driven specification changes. The uncertainty is that prolonged input volatility could compress profitability across the board and reward only those participants with enough scale or innovation to offset cost pressure without eroding quality.
These trends suggest that the next few years will reward players who can align chemistry, compliance, and commercial execution rather than those who excel in only one dimension. The market is unlikely to reward purely transactional strategies, but it will offer meaningful openings for companies that can translate technical and regulatory change into practical value for downstream buyers.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to treat formulation strategy as a business strategy, not just a technical function. Investments in bio-based ligand development, lead-free systems, and application-specific high-efficiency stabilizers should be paired with supply diversification and cost-aware design so that performance gains are not eroded by input volatility. Companies should also strengthen technical support and documentation capabilities, because in a market where compliance and lifecycle value matter, the ability to prove and explain performance can be as important as the performance itself.
For investors, the opportunity lies in identifying participants that combine regulatory readiness with durable differentiation. The most resilient businesses are likely to be those with clear positioning in high-value applications, credible sustainability or performance narratives, and the operational flexibility to navigate raw material swings. Due diligence should examine not only current product breadth but also formulation roadmap, feedstock strategy, and exposure to regions where compliance change is advancing fastest.
For procurement and buying organizations, the practical move is to evaluate stabilizer suppliers on a broader scorecard that includes compliance trajectory, supply resilience, and total cost of ownership, rather than anchoring decisions on unit price alone. Where organic stabilizer systems can extend service life or reduce compliance risk, the premium should be assessed against downstream consequences of specification failures, audit exposure, and replacement costs. Engaging early with suppliers on formulation direction can also help align future specifications with evolving regulatory and sustainability expectations.
For decision-makers who need a deeper, more granular view of how these dynamics will play out across chemistry types, application segments, and regional demand patterns, the full research report provides detailed breakdowns, scenario context, and customized guidance that can be mapped directly to internal planning and investment decisions. The market is moving quickly enough that relying on aggregate trends alone may leave strategic questions unanswered, especially where regulatory timelines, raw material exposure, and application-specific value claims intersect. A more detailed analysis can help translate these interconnected forces into actionable next steps for your specific operating context.
For detailed analysis of this topic, please visit the official page: Organic PVC Stabilizers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Laser Capture Microdissection Market: Why 8.55% CAGR Changes Everything
By PW Consulting, 2026-09-21
Navigating the Laser Capture Microdissection Market: Strategic Trends and Commercial Opportunities
The Laser Capture Microdissection (LCM) market has moved past its early-adopter phase and is now entering a period of structured expansion. From 2020 through 2025, market revenue grew from approximately $178 million to $230 million, reflecting steady adoption across life sciences and clinical research settings. The trajectory through 2032 points to sustained momentum, with revenue projected to reach $383 million and a compound annual growth rate of roughly 8.55 percent. This scale is not merely a reflection of instrument sales; it signals a broader shift in how heterogeneous biological samples are interrogated. As molecular profiling becomes more precise, the ability to isolate pure cell populations from complex tissues has transitioned from a niche capability to a foundational workflow step. For executives and investors, the growth curve suggests a maturing market where differentiation, workflow integration, and reimbursement clarity will determine which players capture disproportionate share.
The market structure reveals meaningful concentration. A small group of established vendors holds a combined share exceeding half of total revenue, with the top three firms controlling roughly 52.5 percent and the top five reaching 64.2 percent. This concentration reflects the capital-intensive nature of LCM platforms, the importance of application-specific validation, and the long sales cycles tied to core facilities and reference laboratories. At the same time, the breakdown between instruments and consumables, along with the split between research and diagnostics applications, underscores a dual-engine market. Instruments anchor initial adoption, while recurring consumable purchases and diagnostic revenue streams create the long-term economics that sustain vendors. For decision-makers, this structure implies that competitive advantage will increasingly come from total cost of ownership, workflow compatibility, and service ecosystems rather than from hardware specifications alone.
Worldwide Tissue Microarray Market
Market Snapshot and Core Challenges
The LCM market sits at an inflection point where technical capability, operational constraints, and commercial policy intersect. Growth has been durable, but several structural challenges are shaping how quickly new customers adopt platforms and how efficiently existing users scale their workflows.
The first challenge is the persistent tension between capability and accessibility. LCM instruments remain capital-intensive, with acquisition costs that can create meaningful barriers for laboratories in emerging regions or smaller academic settings. This dynamic reinforces a concentrated adoption pattern, where well-funded core facilities and larger institutions lead deployment while smaller groups rely on shared resources or outsource isolation steps. The practical effect is a market where installed base expansion is gated not only by scientific interest but also by budget cycles, space constraints, and the availability of trained operators. As a result, vendors that can reduce operational friction—through automation, simplified sample handling, or flexible deployment models—are better positioned to extend reach beyond flagship institutions.
The second challenge is workforce and operational readiness. Even as demand for cell-specific molecular analysis rises, staffing shortages and training bottlenecks continue to temper the pace of adoption. LCM workflows require microscopy expertise, careful sample preparation, and disciplined downstream handling. In core facilities and high-throughput environments, the need for skilled personnel can become a limiting factor, especially when instrument utilization is high and turnaround expectations are tight. This operational reality is reshaping purchasing criteria. Laboratories increasingly weigh not just image quality or laser precision, but also reproducibility, ease of training, and the ability to standardize isolation protocols across users and shifts. Vendors that invest in workflow simplification, guided operation, and robust application support are effectively addressing a barrier that hardware specs alone cannot solve.
The third challenge lies in the gap between scientific utility and commercial realization. LCM has long been valued in research, but translating that value into diagnostics and reimbursed workflows has required regulatory clarity, standardization, and payer recognition. Progress is underway, but adoption in clinical settings still depends on demonstrating consistent analytical performance, integrating LCM into established pathology and molecular pipelines, and aligning with reimbursement frameworks that recognize the incremental value of targeted cell isolation. Until these elements are firmly in place, the market will continue to see a divide between research-driven demand and diagnostics-driven scale. For commercial teams, bridging that divide is less about selling instruments and more about enabling validated, repeatable workflows that meet clinical-grade expectations.
PW Consulting
Key Demand Drivers
The LCM market is being shaped by a set of reinforcing drivers that extend beyond incremental improvements in laser technology. Each driver alters the value proposition in a way that expands use cases, influences purchasing behavior, and changes the competitive basis across regions and application segments.
Technological innovation remains the most visible driver. Advances in laser control, optical integration, and automation are steadily improving precision, throughput, and contamination control. Modern systems are increasingly designed to isolate single cells, small clusters, or subcellular components with greater consistency, which directly supports downstream genomic, transcriptomic, and proteomic analyses. Equally important is the trend toward workflow integration. LCM is no longer evaluated as a standalone instrument; it is assessed as part of a larger sample-to-answer chain that includes staining, capture, nucleic acid extraction, and molecular profiling. Vendors that offer tighter compatibility with common laboratory workflows, flexible collection methods, and software tools that reduce manual steps are gaining an edge in environments where reproducibility and throughput matter. The practical implication is that innovation is shifting from pure hardware performance to integrated solutions that reduce variability and make LCM more accessible to a broader range of operators.
Regulatory and reimbursement developments are becoming a meaningful demand catalyst, particularly in the diagnostics direction. Recognition of specific billing codes for oncology-related semiquantitative analysis that includes laser capture microdissection has improved the commercial logic for clinical adoption. When payers formally acknowledge the role of LCM in enabling more precise diagnostic evaluation, laboratories gain a clearer path to justify investment and operational cost. This does not automatically unlock mass adoption, but it strengthens the business case for sites that are already considering LCM for molecular pathology, biomarker stratification, and tumor microenvironment studies. For manufacturers and service providers, this shift makes application-specific validation and documentation more valuable. The market reward increasingly goes to those who can support standardized protocols, demonstrate consistency across sample types, and help laboratories navigate the interface between research-grade flexibility and clinical-grade reliability.
Demand-side behavior is also evolving. Researchers and clinical laboratories are under growing pressure to extract more information from limited or heterogeneous samples. In oncology, neuroscience, and developmental biology, the ability to isolate defined cell populations enables analyses that would otherwise be diluted by surrounding tissue. This need is amplified by the broader move toward single-cell and spatially informed molecular methods, where sample purity and representation directly affect interpretation. At the same time, core facilities and service laboratories are facing higher expectations for turnaround, data quality, and protocol standardization. As a result, purchasing decisions are driven less by novelty and more by practical fit: the system must match the laboratory's sample volume, operator capacity, and downstream application. Laboratories that once treated LCM as a specialized tool are now evaluating it as part of a longer-term molecular strategy, which favors vendors that can support scalable, repeatable operations.
Supply-side and cost-structure dynamics add another layer of influence. The capital cost of LCM instruments remains a significant consideration, and this cost structure interacts with regional purchasing power, service availability, and consumable economics. In higher-budget markets, adoption is often driven by the availability of dedicated funding, shared infrastructure, or clinical programs that can absorb upfront investment. In lower-budget environments, the decision is more sensitive to total cost of ownership, maintenance requirements, and the availability of consumables over time. This divergence is encouraging a more pragmatic competition. Vendors are increasingly differentiating through service models, consumable pricing, training support, and regional availability of application specialists. The operational lesson is that durable market success depends on aligning pricing and support with the realities of laboratory budgets, staffing, and local infrastructure.
Competitive Landscape and Leading Strategies
The LCM market is defined by a relatively concentrated group of established players, each pursuing a distinct positioning strategy. While the leaders share core capabilities in laser-based isolation, their differentiation lies in how they connect hardware, software, consumables, and application support to specific customer needs.
Thermo Fisher Scientific has a long-standing presence in the space through its Arcturus LCM systems, kits, reagents, and slides designed for isolating specific cells from heterogeneous tissue via infrared and ultraviolet laser approaches. The commercialization of the Arcturus business by Laxco illustrates an important dynamic in this market: brand, distribution, and application support can be as influential as the original instrument design. For end users, the value often comes from the availability of compatible consumables, proven protocols, and a reliable supply chain. Thermo Fisher's broader commercialization strength gives it a structural advantage in reaching large laboratory networks, integrating LCM into wider procurement relationships, and supporting standardized workflows across multiple sites.
Worldwide Laser Capture Microdissection (LCM) Market
Molecular Machines & Instruments has positioned itself around precision and contamination-free isolation, with CellCut systems and automated CellRobot options that support single cells, cell clusters, or subcellular components across varied tissue types. This emphasis on automation and contamination control targets laboratories where reproducibility, clean handling, and throughput are central concerns. The strategic message is clear: LCM is not only about capturing the right cells, but also about doing so in a way that minimizes variability and protects downstream analysis. In highly controlled research and clinical environments, that positioning can be a strong differentiator.
Carl Zeiss and Leica Microsystems both leverage deep optical heritage, but they apply it in slightly different ways. Zeiss's PALM systems are integrated with microscopes for cutting and recovering viable cells from tissue cultures and fixed material, emphasizing integration with established imaging workflows in life sciences and research. Leica's LMD6 and LMD7 systems focus on high-precision lasers for cutting and collecting defined microscopic areas into collection vessels for downstream molecular analysis. Leica's continuing investment in demonstrations and user engagement, including recent on-site demonstrations at academic imaging cores, reflects a strategy centered on hands-on validation, trusted relationships with core facilities, and visible support for active research environments. This approach reinforces the idea that LCM adoption is influenced not only by specifications, but also by local proof points, operator familiarity, and the credibility of application support.
Laxco has carved out a position around accessible infrared laser capture with the Accuva Cellect system, emphasizing isolation of cells of interest while preserving adjacent cell integrity. This focus on selective capture and sample preservation speaks to laboratories that need clean separation without compromising the broader specimen context. For some users, that balance is a practical requirement, especially when comparative morphology or adjacent tissue architecture remains relevant to interpretation. Laxco's trajectory also highlights how specialized commercial entities can compete by narrowing the value proposition to specific workflow benefits rather than trying to match broader portfolio scale.
The competitive landscape is evolving along several axes. One is integration versus specialization. Larger players with broad laboratory portfolios can bundle LCM into wider purchasing relationships and offer broader service coverage, while specialized firms can move faster on niche workflow needs and application-specific optimization. Another axis is automation and reproducibility. As laboratories scale LCM use, automation, standardized collection, and software-assisted operation become more valuable, which favors vendors that can reduce operator dependence and support consistent output across users. A third axis is commercial execution in diagnostics. Companies that can help laboratories align LCM workflows with clinical expectations, documentation, and reimbursement considerations are likely to gain advantage as the diagnostic segment matures.
Market consolidation and partnership activity are plausible as the segment matures. The presence of commercialized product lines, the importance of consumables, and the need for strong application support all create incentives for strategic alignment. At the same time, new entrants may find opportunities in adjacent capabilities such as software-driven workflow management, automated sample handling, or integrated extraction and analysis pipelines. The real differentiation in the next phase will likely come from end-to-end reliability: how well a vendor can support the scientific question, the operational environment, and the commercial constraints that laboratories face at the same time.
Future Trends and Commercial Implications
Over the next three to five years, the LCM market is likely to be shaped by three interconnected trends. Each carries clear commercial implications and introduces uncertainties that decision-makers should monitor.
The first trend is the shift from instrument-centric adoption to workflow-centric adoption. As LCM becomes embedded in more standardized molecular pipelines, customers will evaluate systems less as isolated hardware and more as part of a complete process that spans sample prep, targeting, capture, extraction, and downstream analysis. This shift favors vendors that can deliver compatible consumables, repeatable protocols, and software that reduces variability. It also raises the importance of service, training, and application documentation. For manufacturers, the commercial opportunity lies in building defensible recurring relationships through consumables, support contracts, and workflow packages. For laboratories, the opportunity is faster turnaround, more consistent results, and better utilization of skilled staff. The risk is that vendors who compete only on hardware features may face increasing pressure from integrated solutions that lower operational friction.
The second trend is the gradual expansion of LCM into more clinically oriented workflows. Reimbursement recognition and the demand for precise cell-level analysis in oncology and other complex diseases create a path toward broader diagnostic relevance. However, clinical adoption will depend on standardized validation, robust documentation, and alignment with laboratory operations and payer expectations. The commercial upside is meaningful, because diagnostics can create more predictable demand and strengthen the economic case for LCM in high-value settings. The uncertainty is equally important: clinical pathways are regulated, payer policies vary, and laboratory adoption can be slow unless the workflow fits existing pathology and molecular routines. Companies that invest early in application validation, clinical-grade consistency, and practical integration are better positioned to capture this opportunity than those that assume research demand alone will carry the transition.
The third trend is the broadening of access through automation, shared infrastructure, and more flexible deployment. Staffing constraints and capital costs will continue to shape where LCM is deployed, but automation and simplified operation can reduce the dependency on highly specialized operators. Core facilities, reference laboratories, and service providers are likely to remain important adoption hubs, especially in regions where individual laboratories cannot justify standalone systems. This creates an opportunity for vendors to design for multi-user environments, shared scheduling, and scalable utilization. It also opens space for new business models centered on service, outsourcing, and regional support. The potential risk is that automation and simplification may raise expectations for throughput and consistency, making performance shortfalls more visible. In that environment, vendor credibility will depend on dependable operation as much as on feature lists.
Strategic Recommendations for Decision-Makers
For manufacturers and vendors, the most effective strategy is to strengthen the full workflow value proposition rather than competing solely on laser performance or optical specifications. That means prioritizing consumables ecosystems, application-specific protocols, training pathways, and service reliability. Companies should also invest in automation and software features that reduce operator dependence and improve reproducibility across users and sites. In diagnostics-adjacent segments, validated workflows, documentation, and reimbursement-aligned messaging will become increasingly important. The commercial goal should be to make LCM easier to adopt, easier to operate, and easier to sustain over time, because those attributes drive both initial sales and long-term recurring revenue.
For investors, the market offers a profile of steady growth with concentration risk and meaningful operational dependencies. The durable CAGR and expanding use cases support a constructive long-term view, but returns will likely depend on which companies can capture recurring consumable demand, expand into clinically relevant applications, and manage service and support efficiently. Pay close attention to reimbursement developments, staffing dynamics, and the pace at which automation reduces adoption barriers. Companies that demonstrate strong application support, reliable supply chains, and credible clinical or core-facility relationships are better positioned than those relying primarily on hardware differentiation. As always, the key is not just market growth, but which players convert growth into defensible economics.
For procurement leaders and laboratory managers, the priority should be to evaluate LCM systems against operational reality rather than headline specifications. Total cost of ownership, consumable availability, training burden, multi-user support, and compatibility with downstream molecular workflows should carry substantial weight. Where internal staffing is limited, shared-facility access, service contracts, and automation features may outweigh marginal performance gains. Where diagnostic or high-stakes research applications are involved, protocol validation, repeatability, and vendor support should be treated as core purchasing criteria. The best outcome comes from selecting a platform that fits the laboratory's actual throughput, personnel profile, and downstream needs, rather than one that simply offers the most impressive technical feature set.
The LCM market is moving from specialized capability to a more mainstream enabler of precise molecular analysis. That transition creates opportunities for vendors who can integrate hardware, consumables, and support into reliable workflows, for investors who understand where recurring value is being built, and for laboratories that can align adoption with operational and clinical realities. Given the pace of reimbursement change, automation progress, and competitive repositioning, a detailed look at region-specific dynamics, application splits, pricing structures, and vendor-specific benchmarks can make the difference between a good strategic decision and a great one. For a more complete view of the segment data, competitive benchmarks, and forward scenarios, exploring the full PW Consulting research report can provide the level of detail needed to shape procurement plans, investment theses, and product strategy with greater confidence.
For detailed analysis of this topic, please visit the official page: Laser Capture Microdissection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com