

Blogs
ESP Market 2026–2032: Why 6.4% CAGR and Power Generation Dominance Redefine Strategy
By PW Consulting, 2026-09-21
Navigating the Electrostatic Precipitators Market: Strategic Trends and Commercial Opportunities Through 2032
The electrostatic precipitator (ESP) market is entering a phase of measured but meaningful expansion, driven by tightening emissions standards, aging infrastructure demands, and incremental technological upgrades. Between 2020 and 2025, the global market grew from 6,500.0 million USD to 8,300.0 million USD, reflecting steady demand across utility and industrial sectors. Looking ahead to the 2026-2032 forecast period, the trajectory points toward a compound annual growth rate of 6.4%, with revenue projected to reach 12,790.0 million USD by 2032. This growth is not uniform. It is concentrated among a handful of established players, as reflected in a CR3 of 38.2% and CR5 of 55.0%, indicating that scale, technical expertise, and long-term service relationships continue to shape competitive dynamics. The market’s structure favors firms that can deliver not only hardware but also lifecycle support, performance upgrades, and integration with broader emission control systems.
Behind the headline numbers lie structural tensions that will define how companies position themselves over the next several years. The first challenge centers on the balance between capital intensity and operational efficiency. Advanced ESP configurations increasingly rely on digital control modules, corrosion-resistant materials, and hybrid filtration approaches, all of which raise upfront investment. At the same time, electrical energy consumption in large-scale installations remains substantial, translating into ongoing operating costs that plant operators must justify against performance gains. The second challenge is regulatory fragmentation. While federal and regional standards continue to push particulate limits downward, the pace and specifics of compliance requirements vary by jurisdiction and by industrial application, creating uneven demand cycles and complicating long-term planning. The third challenge involves the shift from greenfield installations to retrofit and rebuild activity. Many existing plants are prioritizing incremental upgrades that restore or exceed original collection efficiency without full system replacement, reshaping procurement patterns and service expectations.
Market Structure and the Shift Toward Service-Enabled Solutions
The ESP market’s evolution is increasingly defined by how suppliers manage the entire asset lifecycle rather than by initial equipment sales alone. Rebuild contracts, performance optimization, and integration with flue gas treatment systems are gaining weight in commercial negotiations. Companies that can demonstrate consistent collection efficiency, lower operating expenditure, and predictable maintenance intervals are finding stronger positioning in both utility and industrial segments. This shift is visible in recent contract activity and network expansion moves, where the emphasis is on extending service reach, supporting existing installations, and delivering measurable efficiency improvements. For decision-makers, the implication is clear: competitive advantage is moving from hardware specification to total cost of ownership and performance reliability over time.
Key Drivers Reshaping the ESP Market
Regulatory Pressure as a Baseline Demand Catalyst
Emissions regulations are the most consistent force behind ESP demand, and recent regulatory actions reinforce that trajectory. In the United States, the EPA’s Mercury and Air Toxics Standards require coal-fired power plants to contain filterable particulate emissions at 0.03 lb/MMBtu, accelerating the deployment of ESP systems that can meet or exceed those limits. At the same time, federal regulations on particulate matter emissions from industrial sources continue to compel facilities to adopt ESP technologies for compliance. These requirements do not merely create one-time purchase cycles; they establish a compliance floor that encourages operators to invest in systems capable of sustained performance, particularly where future tightening is anticipated. For suppliers, this environment rewards proven high-efficiency collection capability and the ability to document compliance outcomes.
Technological Innovation: Efficiency, Control, and Integration
Technological progress in ESP systems is increasingly focused on improving collection efficiency while moderating energy use and simplifying integration with downstream gas cleaning. High-efficiency collection up to 99.9% is now a benchmark that several leading providers reference, and achieving that level consistently often depends on advanced electrode design, better discharge management, and refined control logic. Equally important is the move toward smarter operation. AI-enhanced control systems and digital monitoring are being embedded into ESP platforms to adjust operating parameters in response to load changes, dust characteristics, and process conditions. This reduces wasted energy, stabilizes performance, and improves predictability for plant operators. Integration with flue gas conditioning and NOx reduction technologies further extends the value of ESP installations, especially in coal-fired utility settings where multi-pollutant control is a priority.
Recent developments illustrate how these innovations are being commercialized. Babcock & Wilcox secured more than 18 million USD in wet and dry ESP rebuild contracts for utility and industrial plants across the U.S. and Europe, emphasizing collection efficiency up to 99.9%, a clear signal that performance-led upgrades remain commercially attractive. FLSmidth expanded its service center network with a new facility in Dammam, Saudi Arabia, to support advanced emission control technologies including electrostatic precipitators, reflecting a strategy of positioning service capability closer to key industrial demand centers. Mitsubishi Heavy Industries delivered an ESP unit for a 700,000-tonne chemical pulp project in China, while Valmet shipped electrostatic precipitators to Nordic Paper’s Swedish Backhammar recovery boiler with completion targeted by the end of 2025. These activities show that demand is not limited to power generation; pulp and paper, chemical pulp production, and broader industrial recovery systems are also active deployment areas where ESP performance matters.
Demand-Side Shifts Across Power and Industrial Applications
Demand for ESP systems continues to be anchored by power generation, particularly where coal-fired and biomass-linked facilities must meet strict particulate limits or extend the viable operating life of existing assets. Beyond power, industrial applications are expanding the addressable market. Cement and lime processing, waste-to-energy and biomass, chemical and petrochemical operations, and specialized sectors such as pulp and paper recovery boilers all present distinct dust characteristics and operating conditions that shape ESP selection. The commercial implication is that a single ESP architecture rarely fits all applications. Suppliers that can tailor electrode design, gas flow management, and cleaning methods to specific process environments are better positioned to capture demand across multiple verticals. This is also where wet and dry system choices become strategically important, with selection driven by dust properties, moisture content, and downstream process constraints.
PW Consulting
Cost, Energy, and Supply Chain Considerations
Despite the positive demand outlook, cost and energy dynamics remain central to commercial decision-making. High capital and maintenance costs for advanced ESP systems incorporating digital control modules, corrosion-resistant materials, and hybrid filtration technologies require substantial upfront investment. Electrical energy consumption in electrostatic precipitators can also be substantial, with resulting high operating costs for large-scale installations. These factors encourage a more disciplined approach to procurement, where operators evaluate not only collection performance but also energy profile, maintenance intervals, and 부품 or material availability over the system’s lifespan. Supply chain considerations are becoming more prominent as well, particularly for specialized materials and control hardware. Providers that can streamline sourcing, localize support, and reduce downtime through predictable maintenance planning are likely to gain preference in competitive bidding situations.
Competitive Landscape and How Leading Players Differentiate
The ESP market is moderately concentrated, with a limited group of established companies holding meaningful share and long-standing relationships across utility and industrial markets. Market leadership is less about unit volume alone and more about the breadth of application coverage, demonstrated efficiency, service reach, and the ability to offer integrated emission control solutions. Several firms have built their positioning around high-efficiency systems, rebuild and retrofit capabilities, and sector-specific expertise. For example, some leaders emphasize wet and dry ESP systems for utility and industrial power generation with global installation experience, while others specialize in advanced ESP technologies integrated with gas cleaning systems for industrial emission control. Custom wet and dry ESP manufacturing for power, cement, and steel applications remains a differentiator for firms serving heavy industrial environments, and AI-enhanced control systems are increasingly part of the value proposition for providers targeting cement and industrial applications.
Worldwide Dry Electrostatic Precipitator Market
Company activity over the past two years highlights three strategic themes. First, performance-led rebuilds are a commercially meaningful pathway, as shown by major rebuild contracts focused on restoring or improving collection efficiency in existing plants. Second, geographic and service expansion is being used to reduce response times and strengthen relationships in important demand regions, including the Middle East. Third, sector-specific project wins in pulp, chemical pulp, and recovery boiler environments indicate that specialization can open doors beyond the largest power generation markets. Together, these moves suggest a market where incumbents are reinforcing their positions through service proximity, proven efficiency claims, and application-specific execution rather than relying solely on equipment pricing.
Consolidation, Fragmentation, and Entry Dynamics
The ESP market is not experiencing dramatic consolidation at the top, but it is showing signs of functional consolidation around capabilities. Buyers increasingly value suppliers that can handle design, installation, commissioning, and ongoing optimization under a coordinated framework. At the same time, niche players remain relevant where specialized applications, local support needs, or custom engineering demands create room for focused offerings. New entry is challenging but not impossible, especially where a company brings a clear technical advantage, such as a novel control approach, improved energy management, or a distinctive material solution that lowers lifecycle cost. In practice, the most resilient competitors are those that combine technical credibility with commercial flexibility, allowing them to serve both large-scale utility projects and smaller industrial retrofits without losing operational focus.
Forward Outlook: Trends Likely to Shape the Next 3-5 Years
Trend 1: Efficiency and Energy Management Will Become the Central Battleground
As regulations tighten and operating costs remain under scrutiny, the most important competitive differentiator will be the ability to deliver high collection efficiency without inflating energy consumption. Systems that can modulate power use intelligently, sustain efficiency across variable loads, and integrate with broader plant controls will be favored in both new installations and upgrades. This trend creates commercial opportunities for providers that can quantify energy savings, reduce maintenance burden, and show compliance durability over time. It also raises the stakes for suppliers still relying on static operating profiles, since plants are increasingly reluctant to accept high operating costs as a fixed requirement.
Electrostatic Chucks (ESCs) Market
Trend 2: Retrofit, Rebuild, and Life Extension Will Outweigh Greenfield Demand in Many Markets
In many regions, the near-term opportunity lies less in replacing entire systems and more in restoring performance, adapting to new fuel or process conditions, and extending service life. Rebuild contracts and targeted upgrades are likely to remain a significant share of activity, especially where plants need to meet current standards or prepare for future limits without committing to full replacement. This shift rewards vendors with strong field service capabilities, modular upgrade paths, and the ability to diagnose existing installations efficiently. For investors and manufacturers, it suggests that service-oriented revenue streams and upgrade kits may be as strategically important as flagship new-system sales.
Trend 3: Regional Service Footprints and Application Specialization Will Determine Access to Demand
Demand is geographically and sectorally uneven, and access to projects will increasingly depend on local presence and application knowledge. Expansion of service centers, local support teams, and region-specific engineering capacity can reduce friction in procurement and commissioning while improving responsiveness during operation. At the same time, companies that understand the dust and process nuances of specific industries will be better positioned to win in segments such as cement, waste-to-energy, chemical, and pulp and paper applications. The commercial opportunity here is to build repeatable sector playbooks rather than treating each project as a standalone customization exercise.
Risks and Uncertainties to Monitor
Several uncertainties could alter the pace or shape of market growth. Regulatory timelines may shift, particularly if compliance deadlines are adjusted or if enforcement emphasis changes across jurisdictions. Energy pricing and availability can affect operating economics, especially for large installations where power use is a major cost element. Material availability and lead times for specialized components may influence project scheduling and total cost. Finally, changes in fuel mix, plant retirement decisions, and the balance between coal, biomass, and alternative generation pathways can reshape where ESP demand appears and how quickly it materializes. Companies that monitor these variables closely will be better prepared to adjust pipeline planning and service capacity.
Strategic Recommendations for Decision-Makers
For ESP Manufacturers and Solution Providers
- Prioritize total-cost-of-ownership positioning by documenting efficiency outcomes, energy behavior, and maintenance predictability, not just collection performance at a point in time.
- Invest in service and rebuild capabilities, since retrofit and upgrade activity is likely to remain a durable source of revenue and customer contact.
- Build application-specific engineering playbooks for cement, waste-to-energy, chemical, and pulp and paper environments, where process conditions shape system selection and value claims.
For Investors and Strategic Partners
- Evaluate providers based on their ability to sustain high-efficiency claims in the field, expand service reach, and capture multi-pollutant integration opportunities rather than equipment scale alone.
- Watch for commercial signals in rebuild activity, regional service expansion, and sector project wins, as these often indicate where demand is becoming more concrete.
- Assess exposure to energy-intensive operating profiles and specialized material supply, since these factors influence margin stability and project execution risk over the forecast period.
For Plant Operators and Procurement Teams
- Select ESP solutions with a clear view of lifecycle cost, including energy consumption, maintenance intervals, and the feasibility of future upgrades as regulations or processes change.
- Use rebuild and retrofit pathways where feasible to meet current compliance targets while preserving capital flexibility for other plant priorities.
- Request performance evidence tied to operating conditions similar to your own, especially for dust characteristics, load variability, and integration with existing gas treatment systems.
The ESP market is moving toward a more performance-intensive, service-oriented, and application-aware phase of growth. That shift rewards companies that can combine proven collection efficiency with smarter operation, local support, and credible lifecycle economics. For organizations seeking to navigate this environment with greater precision, deeper segmentation data, company-level benchmarks, and customized strategic guidance can clarify where to commit resources and how to sequence next steps. Access the full PW Consulting report on the Electrostatic Precipitators market to explore detailed segmentation, competitive profiles, and forward-looking scenarios built for planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Electrostatic Precipitators (ESP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Chemotherapy Induced Peripheral Neuropathy Treatment Market: 6.5% CAGR from 2026-2032
By PW Consulting, 2026-09-21
Chemotherapy-Induced Peripheral Neuropathy Treatment Market: Strategic Trends and Commercial Opportunities
The chemotherapy-induced peripheral neuropathy (CIPN) treatment market has reached a critical inflection point. With a total market value of approximately $1.46 billion in 2025 and a projected trajectory to exceed $2.28 billion by 2032, the sector reflects a compound annual growth rate of 6.5 percent over the 2026-2032 period. This expansion is not merely a function of rising oncology volumes. It represents a structural shift in how the pharmaceutical industry approaches symptom management, neurological preservation, and quality-of-life endpoints in cancer care. Chemotherapy remains one of the most widely deployed modalities in oncology, and neuropathy stands among its most persistent and debilitating side effects. Patients receiving platinum-based agents, taxanes, and vinca alkaloids frequently experience progressive sensory loss, pain, balance impairment, and treatment-limiting dose reductions. The market for interventions addressing these outcomes has evolved from a fragmented landscape of off-label symptomatic therapies into a structured pipeline of mechanism-targeted candidates, increasingly shaped by regulatory guidance and clinical evidence standards.
Yet the scale of opportunity is matched by complexity. Stakeholders approaching this space must navigate a market where clinical differentiation, regulatory pathways, pricing dynamics, and oncology practice patterns intersect in non-linear ways. The next phase of growth will likely reward players who can translate mechanism plausibility into robust trial design, align with evolving oncology workflows, and articulate value propositions that resonate beyond symptom relief alone. Understanding where the market stands today, what forces are reshaping it, how competitors are positioning themselves, and where strategic opportunities are likely to emerge provides a necessary foundation for informed decision-making.
Market Landscape and Core Challenges
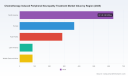
The CIPN treatment space is characterized by moderate market concentration and a therapeutic mix that still leans heavily on existing symptomatic classes, particularly antidepressants and anticonvulsants, alongside a smaller but strategically important segment of narcotics and emerging alternatives. This composition reflects both historical prescribing habits and the limited number of approved, mechanism-specific interventions. While the broader market size demonstrates steady expansion, the underlying structure reveals a sector that is simultaneously mature in its standard-of-care elements and early-stage in its innovation pipeline. That duality creates both stability and uncertainty, as legacy therapies continue to anchor clinical practice while newer candidates attempt to redefine therapeutic expectations.
A first challenge lies in clinical endpoint definition and trial design. CIPN presents across a spectrum of sensory, motor, and autonomic symptoms, and the field has historically struggled to standardize how improvement, stabilization, or prevention should be measured. Different chemotherapy regimens, cumulative dosing patterns, and patient baseline risk profiles complicate the creation of uniform trial populations. Sponsors that rely on broad symptom scales without mechanistic alignment or clearly defined responder thresholds risk generating data that is difficult to position clinically or commercially. The challenge is not simply demonstrating statistical change. It is demonstrating clinically meaningful change that oncologists, neurologists, and payers can act upon.
A second challenge is the persistent alignment gap between existing symptomatic classes and the underlying neurobiology of nerve injury. Current treatments often address perceived symptom pathways without directly interrupting axonal degeneration, ion channel dysfunction, or inflammatory signaling associated with specific chemotherapeutic agents. As understanding of CIPN mechanisms matures, therapies that are not linked to a plausible biological rationale may face growing pressure in clinical discussion and formulary positioning. This does not render all symptomatic options obsolete, but it does raise the bar for differentiation. The market increasingly favors interventions that can articulate not only what they treat, but why they should work in a particular chemotherapy context.
PW Consulting Health Care Research Center
A third challenge involves the oncology treatment environment itself. Dose adjustments, regimen substitutions, and individualized risk-benefit calculations can influence both the incidence of neuropathy and the perceived value of adjunctive interventions. In practice, neuropathy management does not exist in isolation. It competes for attention alongside tumor response, survival endpoints, and other supportive care priorities. Treatments that can integrate into existing oncology workflows, offer predictable safety profiles, and demonstrate a credible link to preserving chemotherapy delivery are more likely to gain adoption than those positioned as standalone neurological interventions with limited integration into cancer care pathways.
Key Drivers Shaping the Market
Several interconnected factors are accelerating momentum in the CIPN treatment market, and their influence is likely to intensify over the next several years. Rather than acting independently, these forces are reinforcing one another, reshaping both pipeline priorities and commercial expectations.
One of the most consequential drivers is the shift toward mechanistic and targeted approaches. A growing portion of the pipeline is focused on molecular pathways with clearer links to nerve injury, signaling dysregulation, or peripheral nerve repair. Candidates addressing specific ion channels, receptor-mediated protective pathways, and topical delivery strategies reflect an effort to move beyond nonspecific symptom modulation. This trend matters commercially because it creates opportunities for sharper messaging, more defensible clinical narratives, and potential differentiation in a crowded supportive care environment. At the same time, it raises the technical requirement for biomarker strategy, subgroup definition, and endpoint clarity. Sponsors that can connect a mechanism to a meaningful clinical readout are better positioned to justify investment and partnership interest.
Regulatory guidance and pathway signals are a second major driver. The issuance of FDA draft guidance for developing drug and biological products for the prevention and treatment of CIPN has helped establish a more explicit framework for expectations around trial design, population definition, and outcome measurement. Complementary regulatory actions, including Fast Track designations and IND clearances for candidates targeting CIPN, indicate that the agency is engaging with the area more actively. This environment reduces some ambiguity for developers and can improve the perceived credibility of programs that are designed with regulatory expectations in mind. For commercial stakeholders, the implication is that programs aligned early with guidance are more likely to navigate development with fewer late-stage surprises and clearer dialogue with regulators.
A third driver is the changing demand profile within oncology. As cancer therapies improve and patients live longer, the burden of chronic treatment-related effects is becoming more visible. Neuropathy that persists beyond active chemotherapy or limits future treatment options carries significant downstream implications for physical function, independence, and quality of life. This has increased attention to interventions that can prevent symptomatic progression, reduce dose-limiting toxicity, or support patients through longer treatment courses. Demand is not only coming from patient advocacy and clinician concern. It is also being shaped by the broader oncology goal of preserving treatment continuity and minimizing long-term functional impairment.
Supply-side and reimbursement dynamics also play a role, though often in less visible ways. The relative availability of generic symptomatic therapies exerts competitive pressure on pricing and adoption for newer agents, while reimbursement expectations increasingly favor evidence that connects treatment to functional outcomes, reduced downstream costs, or maintained chemotherapy delivery. Cost structures are therefore influenced by both the competitive shadow of established options and the evidentiary requirements of payers and health systems. Programs that can demonstrate practical value in real-world oncology settings are more likely to achieve sustainable market positioning than those relying solely on clinical signals without integration into care economics.
Competitive Landscape and Leading Strategies
The competitive environment reflects a spectrum of developmental maturity and strategic focus. Some companies are advancing candidates with clearer regulatory momentum or later-stage clinical activity, while others are operating in earlier phases or have paused further development after earlier signals. What distinguishes the more strategically positioned players is not only the stage of their programs, but the coherence of their therapeutic rationale, the alignment of their trial design with oncology context, and their ability to use regulatory or partnership leverage to accelerate confidence in their approach.
Dogwood Therapeutics illustrates a company building momentum through a combination of clinical progress and strategic licensing activity. The Halneuron program has moved forward in Phase 2b with reported interim findings and substantial enrollment progress, while the SP16 program has advanced through licensing from Serpin Pharma with IND clearance and planned Phase 1b activity. This dual-track structure suggests an emphasis on diversifying mechanism exposure while maintaining forward progress in a lead candidate. From a strategic standpoint, the company appears to be positioning around both clinical data generation and partnership-enabled capability expansion, which can be valuable in a market where single-asset dependence carries execution risk.
Asahi Kasei Pharma’s ART-123 program takes a prevention-oriented approach in a defined oncology population, focusing on sensory symptom prevention in colorectal cancer patients receiving oxaliplatin. This positioning is strategically notable because prevention can be harder to demonstrate than treatment, but it may also offer stronger clinical integration if the evidence supports a clear reduction in neuropathy burden within a specific chemotherapy context. Targeting a well-defined regimen and patient group can reduce some of the heterogeneity challenges that complicate broader CIPN studies, though it also narrows the initial commercial footprint.
Neuropathy Pain Treatment Market
Sironax’s SIR2501 program has drawn attention through Fast Track designation, signaling regulatory recognition of potential unmet need and development efficiency value. In a market where endpoint complexity can slow progress, regulatory designations can provide useful leverage for development planning, clinical engagement, and partnership conversations. WinSanTor’s topical pirenzepine program, meanwhile, reflects an alternative delivery strategy and a broader peripheral neuropathy focus, with ongoing work extending beyond CIPN. Topical approaches may be attractive if they can reduce systemic exposure or offer localized benefit, but adoption will depend on evidence that supports clinical differentiation and practical usability.
Serpin Pharma’s SP16 program reinforces the growing importance of early-stage financing and academic or institutional support in shaping pipeline viability. The receipt of grant funding to support a Phase 1b trial highlights how non-dilutive resources can help earlier programs reach critical developmental checkpoints. For investors and partners, this is a reminder that the CIPN market includes meaningful activity not only from large-scale commercial developers, but also from smaller, mechanism-focused groups whose evolution may influence future licensing and acquisition dynamics.
Across these players, a few competitive themes emerge. First, there is a clear trend toward programs that are more tightly tied to specific mechanisms or delivery modalities, with the intent of differentiating from nonspecific symptom management. Second, regulatory engagement and guidance alignment are increasingly part of strategic positioning, particularly for companies looking to reduce development risk or improve the credibility of their programs in clinical and investor discussions. Third, the landscape remains open enough for new entrants to find niches, but crowded enough that differentiation must be supported by more than mechanistic plausibility. Credible clinical design, context-specific positioning, and practical integration into oncology care will likely determine which programs translate into durable commercial advantage rather than short-term pipeline interest.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, several trends are likely to shape the direction of the CIPN treatment market. These are not mutually exclusive, and each carries distinct commercial implications.
One likely trend is a sharper separation between prevention-focused and treatment-focused interventions. As clinical programs mature, stakeholders may increasingly differentiate between agents intended to reduce the onset or progression of neuropathy during chemotherapy and those intended to manage established symptoms. This distinction matters for trial design, regulatory positioning, and clinical adoption. Prevention programs may target specific regimens or high-risk populations, while treatment programs may need to demonstrate meaningful benefit in patients with existing neurological impairment. The commercial implication is that value propositions will need to be tailored more precisely to the clinical context in which the intervention is used. Broad, undifferentiated claims may be less effective than narrowly supported, use-case-specific positioning.
A second trend is the increasing importance of topical and targeted delivery approaches alongside systemic therapies. Topical strategies may gain attention if they can offer focused benefit with favorable tolerability or reduced systemic exposure, especially in a population where polypharmacy and cumulative toxicity are concerns. However, clinical adoption will depend on whether these approaches can demonstrate consistent efficacy, ease of use, and integration into oncology supportive care routines. The commercial opportunity is not just in developing a new formulation. It is in proving that the delivery method creates meaningful clinical or operational advantages that clinicians and patients will accept in practice.
A third trend is growing pressure to connect CIPN interventions with functional and care-continuity outcomes. As payer and health system expectations evolve, evidence that goes beyond symptom scores may become more important. Demonstrating associations with maintained chemotherapy dosing, reduced supportive care utilization, or improved day-to-day function could strengthen commercial viability for certain programs. The risk is that companies relying solely on conventional symptom endpoints without a clear link to broader outcomes may find adoption more difficult or reimbursement discussions more complex. This creates a strategic imperative to design evidence generation around the full clinical and economic context of use.
At the same time, uncertainty remains. Trial results may vary by chemotherapy class, baseline risk, and endpoint definition, and not every mechanistic hypothesis will translate into durable clinical benefit. Competitive dynamics may also shift through partnerships, licensing, or consolidation, particularly as earlier-stage programs reach pivotal milestones. Stakeholders should therefore plan for a market that is growing but fragmented in credibility, where selection of partners, programs, or investment targets requires careful assessment of trial design, intended use case, and alignment with oncology practice.
Strategic Recommendations for Decision-Makers
For manufacturers and developers, the priority is to design programs with clear clinical context and regulatory alignment from the outset. This includes defining the intended chemotherapy setting, the relevant patient population, and the endpoint strategy in a way that supports both clinical credibility and commercialization. Mechanism-based differentiation is valuable, but it must be paired with evidence that can withstand scrutiny in real-world oncology settings. Developers should also consider how they will position their intervention relative to existing symptomatic options and whether they can articulate a distinct value proposition around tolerability, delivery, or care integration.
For investors, the opportunity lies in distinguishing programs with defensible execution roadmaps from those that depend primarily on early enthusiasm. Attention should be paid to enrollment feasibility, endpoint clarity, regulatory engagement, and the strength of clinical rationale within a specific chemotherapy context. Programs that combine mechanism interest with sound trial design and credible milestones may offer stronger risk-adjusted prospects than those that emphasize scientific promise without a clear path to clinically actionable evidence. Early-stage licensing and partnership activity may also create optionality, particularly if it enables better-capitalized or more operationally experienced groups to accelerate development.
For procurement and formulary decision-makers, the focus should be on evidence that supports practical adoption and value relative to current care patterns. This means evaluating not only efficacy signals but also safety, ease of integration, and any demonstrated impact on treatment continuity or functional outcomes. As new agents emerge, structured assessment frameworks can help determine which interventions warrant adoption, under what conditions, and where further evidence is needed before broader use. The availability of more standardized guidance and maturing clinical data should support more disciplined evaluation over time.
Worldwide Advanced Cancer Pain Management Market
In a market expanding toward $2.28 billion by 2032, the strategic question is not whether demand for effective CIPN intervention will continue to grow, but which programs, partnerships, and evidence strategies will separate durable value creation from transient pipeline interest. Detailed segmentation data, pipeline benchmarking, and scenario analysis can help organizations move from general market awareness to specific, actionable decisions. Readers interested in deeper breakdowns of market segments, competitive benchmarks, and customized strategic implications can explore the full report available through PW Consulting for more detailed segmentation data and tailored guidance.
For detailed analysis of this topic, please visit the official page: Chemotherapy Induced Peripheral Neuropathy Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Insect Feed Market: How 16.4% CAGR and Aquaculture Demand Reshape 2032 Outlook
By PW Consulting, 2026-09-21
The Insect Feed Market: Strategic Trends and Commercial Opportunities Through 2032
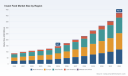
The insect feed sector is transitioning from niche sustainability play to mainstream protein infrastructure. With the global market valued at approximately $147 million in 2025 and projected to reach $425.8 million by 2032, the sector is expanding at a compound annual growth rate of 16.4 percent. This trajectory reflects more than incremental demand growth. It signals a structural recalibration of animal nutrition supply chains, driven by regulatory opening, substrate economics, and the scaling of bioconversion technology. For executives and investors, the question has shifted from whether insect protein will gain traction to how capital, capability, and partnerships will be allocated as the market matures.
Market Landscape and Core Challenges
The revenue arc over the past half-decade illustrates steady acceleration, with growth compounding as production capacity converts from pilot scale to commercial throughput. By the close of the forecast window, the market is on a path toward nearly triple its 2025 baseline. That expansion is uneven rather than uniform, shaped by regional regulatory readiness, feed formulation economics, and the pace at which manufacturing networks achieve cost parity with conventional protein sources. Understanding where the market is heading requires looking past headline figures to the structural constraints that will determine which players capture value.
Navigating Structural Constraints
Several inflection points are shaping the operational reality of the industry. First, substrate sourcing and waste-stream consistency remain foundational bottlenecks. Insect feed production depends on upcycled organic inputs such as food processing byproducts, and the economics of collection, pretreatment, and contamination control vary widely by geography and season. While this model can reduce material costs substantially relative to conventional protein sourcing, the operational discipline required to maintain consistent substrate quality across multiple intake streams is non-trivial. Facilities that fail to standardize input quality encounter downstream variability in yield, nutrient profiles, and regulatory compliance.
Second, regulatory adoption is advancing but remains fragmented. In the European Union, rules governing insect protein in aquaculture are established, and approval pathways for poultry and swine applications have progressed under updated feed frameworks. In the United States, regulatory clearances have extended for select insect proteins in poultry and pet food categories. The pace and scope of these approvals differ by jurisdiction and protein type, creating uneven commercialization timelines. Companies that can navigate multiple regulatory regimes simultaneously, or that align product development with the fastest-opening categories, gain a meaningful time advantage.
Aqua Feed Market
Third, scaling biology is as much an engineering challenge as a biological one. Temperature control, humidity management, disease mitigation, and harvesting logistics all influence yield stability and unit economics. Early-stage producers often underestimate the capex intensity of climate-controlled environments and the operational complexity of continuous rearing systems. As the market moves toward larger facilities, the gap between companies with proven process control and those still refining biological workflows will become more visible in margin performance and supply reliability.
Key Drivers Reshaping the Sector
Several forces are converging to accelerate adoption and reshape competitive dynamics. These drivers are not isolated; they reinforce each other and create a clearer line of sight to commercial scale for operators who align technology, compliance, and customer demand.
Bioconversion and Process Technology
The most consequential technical progress lies in improving rearing efficiency, feedstock flexibility, and downstream processing consistency. Proprietary rearing systems, automation in harvesting and separation, and process controls that stabilize larval growth cycles are reducing variability in protein and lipid outputs. This matters because feed formulators require repeatable nutrient profiles, contamination thresholds, and functional properties. Companies that treat insect production as a manufacturing process rather than an agricultural experiment are gaining credibility with B2B buyers who evaluate suppliers on reliability as much as sustainability credentials.
The commercial significance of this shift is clear when viewed alongside recent market activity. Innovafeed has expanded its operational footprint with a U.S. facility in Decatur, Illinois, marking a step toward localized production in a market where feedstock availability and regulatory timing support scale-up. This move illustrates how technology-enabled producers are positioning themselves closer to end markets in order to reduce logistics friction and respond more quickly to regional demand signals.
Regulatory Opening and Category Expansion
Regulation remains the central gatekeeper for category expansion. Approvals for aquaculture have already enabled commercial use of insect proteins in fish feed, while newer regulatory movements in the EU and U.S. have extended possibilities into poultry and swine nutrition and, in certain contexts, pet food. These changes do not merely open new addressable segments; they reshape feed formulation economics by creating alternatives to soy and fishmeal in categories where substitution pressure is strongest.
The regulatory trajectory also influences procurement behavior. Feed manufacturers and integrators that have been waiting for regulatory clarity are now beginning to test inclusion rates, evaluate supply continuity, and negotiate multi-year arrangements. Protix, for example, signed a multi-year supply agreement with Skretting for black soldier fly meal in salmon feed formulations, a move that signals how regulatory maturity is translating into committed offtake and category-specific product development.
Demand-Side Shifts in Animal Nutrition and Pet Care
Demand is being pulled by multiple end-use pressures. In aquaculture, the need for sustainable protein inputs continues to intensify as marine ingredient supply faces volatility and environmental scrutiny. In poultry and swine nutrition, producers are exploring insect protein not only for sustainability positioning but also for functional benefits and supply diversification. In pet food, consumer interest in novel protein sources and premium formulation is expanding the addressable market for insect-based ingredients, particularly where regulatory clearance and brand acceptance progress together.
This diversification matters strategically because it reduces dependence on any single category’s adoption cycle. Companies with portfolios that span aquaculture, livestock nutrition, and pet food can shift commercialization emphasis as regulatory timing and customer readiness vary by region. The effect is a more resilient demand base and a stronger foundation for long-term contract structures.
Cost Structure and Substrate Economics
The economic case for insect feed is closely tied to substrate cost and plant efficiency. Because insect production can utilize upcycled organic waste streams, input costs can be materially lower than those of conventional protein sources when collection and pretreatment are managed effectively. Life cycle assessments comparing insect-based inputs with soy or fishmeal indicate substantial differences in land and water requirements and lower associated greenhouse gas emissions, reinforcing the sustainability narrative that supports procurement decisions.
However, cost advantage is not automatic. It depends on logistics networks, preprocessing capability, and the ability to maintain consistent substrate composition at scale. Facilities that integrate substrate procurement, pretreatment, and rearing into a coordinated operational model are better positioned to protect margins as volumes increase. This is where competitive differentiation increasingly emerges: not simply in the insect species used, but in the industrial design of the entire value chain.
Competitive Landscape and Leading Strategies
The market remains moderately concentrated, with a small group of established producers accounting for a meaningful share of revenue and an expanding set of regional and specialized entrants competing on niche formulations, geography, or substrate strategies. The strategic posture of leading companies reveals how value is being captured in a market still defining its standards.
Differentiation Through Scale, Technology, and Of ftake
Several patterns distinguish the more advanced players. Protix has built a profile around high-quality insect solutions spanning feed, pet food, aquaculture, and plant care, with a focus on black soldier fly larvae and broad application coverage. Its multi-year agreement with Skretting illustrates a strategy centered on committed customer relationships and category-specific formulation support, which helps stabilize demand and fund capacity expansion.
Innovafeed has emphasized proprietary rearing technology and geographic expansion, including its U.S. facility in Illinois. This reflects a strategy of combining technical differentiation with direct market access, reducing reliance on export logistics and positioning closer to large North American feed markets. Entobel has pursued a similar operational discipline, with long-standing production in Vietnam and a recent certification milestone that reinforces its positioning around sustainability and governance as commercial signals for B2B buyers.
Pet Food Insect Protein Market
Other companies are carving distinct lanes. Beta Hatch has focused on mealworm-based production within a regenerative agriculture framing, highlighting a different species and system design from the black soldier fly-dominant core of the market. Nutrition Technologies, now operating under the Sentara Group name following expansion, has continued to build around black soldier fly ingredients for aquaculture, agriculture, and animal feed, illustrating how rebranding and organizational scaling can accompany capacity growth. Hexafly and nextProtein have emphasized the bioconversion of food waste into protein, oil, and fertilizer, aligning product portfolios with circular-economy value propositions that appeal to customers seeking integrated sustainability outcomes.
Market Evolution: Consolidation, Specialization, and New Entry
The competitive landscape is evolving along several axes. Scale industrialization is concentrating production among companies able to fund large facilities, standardize processes, and secure stable substrate supply. At the same time, specialization remains viable in niches such as pet food formulations, functional ingredients, plant care products, and regional supply arrangements where logistics and regulatory timing favor local production.
New entry continues, but the bar is rising. Early entrants could often compete on concept and pilot output; newer entrants must demonstrate process reliability, regulatory compliance, cost control, and defensible customer relationships. This dynamic is likely to reward operators that combine biological capability with manufacturing discipline and commercial execution. It also suggests that partnerships, offtake agreements, and integration with existing feed supply chains will become more important than standalone brand positioning.
Forward Outlook: Three Strategic Trends for 2026–2032
Looking ahead, several trends are likely to define how value accrues in the insect feed market over the next several years.
Trend 1: Regional Production Clusters and Feedstock-Proximity Manufacturing
Production is likely to consolidate around feedstock availability, regulatory readiness, and end-market demand rather than forming a single global center of gravity. Regions with strong waste-stream infrastructure, supportive feed regulations, and large aquaculture or livestock sectors will attract capacity. This has direct commercial implications: companies that align facility siting with substrate economics and customer proximity will lower logistics costs and improve supply reliability, while those dependent on long-distance substrate or product movement may face margin pressure as the market scales.
Trend 2: Formulation Integration and Category-Specific Product Design
Insect ingredients will increasingly be valued not simply as generic protein but as formulated inputs tailored to specific species, life stages, and functional requirements. As feed manufacturers gain experience with inclusion rates and nutrient performance, demand will shift toward consistent specifications, traceability, and technical support. The commercial opportunity lies in building product architectures around customer formulations rather than selling undifferentiated bulk ingredients. Suppliers that invest in application engineering and quality assurance will be better positioned to defend pricing and deepen relationships.
Trend 3: Regulatory Normalization and Procurement Mainstreaming
As approvals expand and standards mature, insect protein is likely to move from special-case procurement to routine supplier evaluation. That transition will favor operators with established compliance records, auditable quality systems, and supply continuity. It also introduces risk: regulatory timing can shift, inclusion limits can change, and category approvals may not proceed uniformly. Companies that assume a linear regulatory path without scenario planning may misallocate capacity or overcommit to segments that open more slowly than expected.
Associated uncertainties include substrate consistency at scale, biological process control during rapid expansion, and the risk that sustainability narratives alone will not sustain procurement decisions if cost or performance gaps remain. The market’s trajectory is strong, but execution quality will determine which participants convert growth into durable margins.
Implications and Actions for Decision Makers
For executives and investors evaluating the insect feed market, the strategic task is to match ambition with operational readiness and to prioritize the decisions that convert market momentum into competitive advantage.
PW Consulting Health Care Research Center
For Producers and Technology Developers
- Prioritize process control and substrate logistics as the foundation of scale-up. Consistent quality and cost stability matter more to B2B buyers than incremental sustainability claims, so investment should flow toward rearing consistency, harvesting efficiency, and integrated feedstock management.
- Align capacity deployment with regional regulatory timing and customer demand. Expanding too quickly into segments with uncertain approval pathways can create underutilized assets, while sequencing expansion around opening categories supports revenue absorption and learning-curve gains.
- Build formulation support and application data. As customers move from trial to routine use, technical service capability becomes a differentiator. Developing species-specific and application-specific evidence strengthens customer retention and pricing power.
For Investors and Capital Allocators
- Evaluate biological capability alongside manufacturing discipline. The most attractive opportunities are likely to be with teams that can demonstrate repeatable yield, contamination control, and cost trajectory rather than concept-level promise.
- Assess demand visibility through offtake structure and customer diversification. Contracts, pilot-to-commercial conversion rates, and exposure across aquaculture, livestock, and pet food can indicate resilience if one category’s adoption slows.
- Model regulatory and substrate scenarios, not just base-case growth. Because approvals, inclusion limits, and feedstock availability can vary by region, sensitivity analysis around timing and input costs is essential for realistic return expectations.
For Procurement and Feed Formulators
- Treat insect ingredients as part of a supply diversification and sustainability strategy, but validate them through performance trials and supply reliability assessment. The strategic value lies in reducing exposure to conventional ingredient volatility while maintaining nutrient specification and consistency.
- Engage early with suppliers on specification design and traceability. Collaboration on inclusion rates, quality parameters, and auditability can accelerate integration and reduce reformulation risk.
- Structure sourcing with regulatory awareness. Procurement plans should account for category-specific approvals and potential changes in inclusion limits so that supply commitments align with regulatory reality in each market.
Closing Perspective
The insect feed market is entering a phase where growth is increasingly determined by execution rather than narrative. The revenue trajectory through 2032 points to a substantial expansion in addressable demand, but the distribution of value will depend on how effectively companies manage substrate economics, regulatory complexity, process control, and customer integration. For organizations building, funding, or sourcing from this sector, the opportunity is not simply to participate in a high-growth category but to shape a supply chain that can deliver consistent quality at competitive cost while meeting the sustainability expectations of modern animal nutrition. Detailed segmentation, regional dynamics, and company-level benchmarking can sharpen these decisions further, and a full research report can provide the supporting data and structured frameworks needed for planning at the segment and facility level.
For detailed analysis of this topic, please visit the official page: Insect Feed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Robotic Polishing Machine Market: Why the 12.6% Growth Trajectory Redefines Competition
By PW Consulting, 2026-09-21
Robotic Polishing Machine Market: Strategic Shifts, Competitive Dynamics, and Value Creation Horizons
The global market for robotic polishing machines is entering a phase of accelerated structural transformation. Between 2020 and 2025, market revenue expanded from approximately $163 million to $215 million, reflecting sustained adoption across precision manufacturing and surface finishing workflows. The trajectory forward indicates a compound annual growth rate of 12.6% through 2032, with projected revenue approaching $345 million by the end of the forecast horizon. This growth is not merely a function of incremental automation adoption; it reflects a fundamental rethinking of how surface quality, throughput, and labor constraints interact in modern production environments. For executive teams and capital allocators, the implication is clear: robotic polishing is transitioning from a niche productivity tool to a strategic capability that shapes product quality, operational resilience, and competitive positioning.
Market Snapshot and Structural Challenges
The market’s expansion over the past half-decade has been broad-based, with steady year-over-year increases that signal deepening integration rather than speculative cycles. Revenue climbed from roughly $174 million in 2021 to nearly $208 million in 2024, before stabilizing near $215 million in 2025. The forward path suggests continued momentum, with the market expected to cross $250 million by 2027 and approach $290 million around 2030. Yet this headline trajectory masks a more nuanced reality. Growth is uneven across use cases, and the market is navigating several inflection points that will separate winners from laggards.
One of the most pressing challenges is the tension between standardization and application-specific customization. Polishing requirements vary dramatically by material, geometry, tolerance thresholds, and finish specifications. A solution that performs exceptionally on high-volume automotive components may struggle with delicate electronics housings or irregularly shaped stone surfaces. Manufacturers are therefore forced to balance the cost efficiencies of modular, repeatable systems against the precision demanded by specialized workflows. This creates a strategic fork: companies that over-index on rigid automation risk losing high-margin niches, while those that overengineer custom solutions may sacrifice scalability and total cost of ownership advantages.
A second challenge lies in workforce transition and operational integration. Deploying robotic polishing is not simply a hardware purchase; it requires reconfiguration of upstream and downstream processes, recalibration of quality control protocols, and upskilling of operators who must interface with systems that blend mechanical execution with sensor-driven adaptation. Facilities with strong internal automation competency are absorbing these transitions relatively smoothly, but organizations with fragmented production planning or limited engineering bandwidth are experiencing longer payback periods and higher initial friction. The market is increasingly rewarding operators who treat robotic polishing as a process transformation initiative rather than a point solution.
A third challenge is the evolving regulatory and safety environment. Industrial robotics deployments are subject to stringent operational safety requirements, and robotic polishing systems introduce additional complexity due to dynamic force application, tool wear, and interaction with delicate or irregular workpieces. Compliance frameworks now emphasize risk assessments, protective measures, and system-level integration checks. While these standards are essential for safe, scalable deployment, they also raise the barrier to entry for smaller integrators and increase the importance of designing for compliance from the outset rather than retrofitting it after the fact.
Core Drivers Reshaping the Market
Several interconnected forces are accelerating the shift toward robotic polishing, and each carries distinct strategic implications for how companies should position themselves.
Technology Innovation and Adaptive Control
The most consequential technical shift is the move from static, pre-programmed finishing routines to adaptive, sensor-informed polishing. Advanced systems increasingly combine multi-axis motion with force control, vision-based inspection, and closed-loop feedback that adjusts pressure, speed, and tool engagement in real time. This capability directly addresses one of the long-standing limitations of automation in surface finishing: the inability to maintain consistent quality when workpieces vary or when tool wear introduces drift. AI-enabled platforms are pushing this further by scanning surfaces, mapping deviations, and automating path generation without extensive manual programming. The result is faster setup, reduced rework, and more repeatable finishes on complex geometries. For manufacturers, the strategic takeaway is that value is increasingly created not just by the robot arm itself, but by the intelligence layer that governs how polishing decisions are made during production.
Regulatory and Safety Expectations
As robotic systems become more capable and more widely deployed, safety and compliance expectations are becoming a defining element of market acceptance. Governing standards for industrial robots now require structured risk assessments and protective measures that account for force-controlled interactions, tool changes, and human proximity in shared workspaces. This is particularly relevant in polishing applications where unpredictable material response and tool wear can create operational variability. Systems designed with integrated safety logic, documented risk controls, and modular compliance features are gaining preference, especially in regulated industries and in deployments where multiple stakeholders must validate automation before scaling. Compliance is no longer a checkbox; it is becoming a competitive differentiator that influences procurement decisions, deployment speed, and long-term operational risk.
Demand-Side Shifts in Quality, Throughput, and Consistency
On the demand side, manufacturers are under increasing pressure to deliver higher consistency at lower defect rates while maintaining throughput. Automotive production, electronics assembly, hardware tooling, and household product manufacturing all place distinct demands on surface finish, but they share a common requirement: quality cannot be treated as a variable that is inspected in at the end of the line. It must be engineered into the process. Robotic polishing supports this shift by reducing dependence on manual skill variability, enabling repeatable finishes across shifts and facilities, and freeing skilled workers for higher-value tasks. At the same time, end customers and OEM partners are increasingly specifying finish tolerances and appearance standards that are difficult to meet reliably with manual or semi-automated methods. This demand-side pressure is expanding the addressable use case set beyond high-volume commodity finishing into precision and brand-sensitive applications where finish quality directly affects perceived value and downstream performance.
Supply Chain and Cost Structure Dynamics
Cost structures are also evolving in ways that reshape ROI calculations for automation. Labor availability, wage dynamics, and training burdens continue to push manufacturers toward solutions that reduce dependence on highly skilled manual finishing labor. At the same time, improvements in component availability, tooling ecosystems, and system integration practices are gradually lowering the total cost of deployment for well-scoped projects. The most compelling economics are emerging where robotic polishing is used not only to replace labor but to compress cycle times, reduce scrap and rework, and stabilize output quality across production runs. Companies that evaluate ROI narrowly through headcount replacement often underestimate the operational value of consistency, uptime, and reduced quality leakage. The market is increasingly favoring deployments that are justified through a broader set of operational benefits rather than labor cost alone.
Competitive Landscape and Leading Strategies
The competitive environment is shaped by a mix of established automation suppliers, specialized tooling and finishing companies, and newer entrants bringing software-centric approaches to surface finishing. Several firms stand out for the way they are positioning their offerings around different value propositions.
Acme Manufacturing has built a strong focus on robotic polishing machines with advanced belt polishing heads, targeting high-volume producers that need repeatable finishes on complex shapes. Its strategic emphasis is on throughput and consistency for demanding production environments, where the ability to maintain finish quality across large batches is a core purchasing driver. This positioning reflects a broader trend: in high-volume segments, reliability and repeatability are often more valuable than flexibility, and suppliers that can demonstrate proven performance at scale gain traction.
Mirka Ltd offers a more complete system view, combining robotic polishing and sanding systems with tools and automation solutions for industrial surface finishing. By presenting an integrated tool-plus-automation proposition, Mirka addresses customers who want fewer integration handoffs and a more coordinated hardware ecosystem. This approach reduces ambiguity in tool selection, process setup, and maintenance planning, which can be especially valuable for organizations that prefer to simplify supplier complexity and standardize finishing workflows.
GrayMatter Robotics has differentiated itself with AI-powered robotic polishing systems that scan surfaces and automate polishing to support manufacturing capacity and quality enhancement. This software-led approach centers on reducing programming effort and enabling faster adaptation to variation, which appeals to environments where part diversity or setup changeovers make conventional programming costly. The strategy highlights a growing market segmentation: systems that emphasize intelligence, scanning, and automated path generation are gaining relevance wherever flexibility and responsiveness are prioritized over fixed, high-volume routines.
Dinosaw Machine manufactures 6-axis robotic arms and systems for stone grinding and polishing, with a focus on force control and precision tooling. Its emphasis on precision control and material-specific applications illustrates the importance of domain specialization. In materials such as stone, where structural variability and surface behavior can differ significantly from metallic or synthetic workpieces, force-controlled accuracy and tooling precision are central to performance. This specialization also aligns with the broader regulatory and safety expectations for industrial robots, where force control and protective integration are increasingly viewed as prerequisites for reliable deployment.
American Siepmann Corporation supplies automated CNC polishing machines and robotic systems for high-precision industrial finishing. Its positioning reflects demand for tightly controlled processes in environments where tolerance, repeatability, and integration with CNC workflows matter. The company’s focus on precision industrial finishing underscores the fact that robotic polishing is not a single market but a family of use cases, each with its own performance priorities and procurement logic.
Recent market developments reinforce these strategic directions. In late 2025, Dinosaw Machine presented a detailed analysis of stone polishing robot technology, emphasizing 6-axis force control and safety integration. That activity reflects a broader industry emphasis on controlling force dynamically while meeting safety expectations for industrial robotics. Meanwhile, Mirka Ltd updated its robotic solutions materials to highlight automated polishing, sanding, and grinding systems, signaling continued investment in integrated finishing offerings and a desire to make automation more accessible across a wider set of applications. These kinds of moves suggest that leading players are expanding system completeness, reinforcing safety and control capabilities, and refining the way they communicate value to customers who are evaluating automation across multiple use cases.
PW Consulting
The market structure itself is moderately concentrated, with the top firms accounting for a majority of revenue. This concentration does not imply stagnation; rather, it suggests that scale, integration depth, and brand trust still matter in a market where deployment risk and process reliability are significant concerns. At the same time, the landscape is open enough to permit differentiation through technology depth, application specialization, and software-enabled flexibility. New entrants and niche specialists can compete by solving specific finishing problems better than broader incumbents, particularly in high-value or technically demanding segments. Consolidation is likely to continue where larger players seek to broaden their system capabilities, but fragmentation will persist where application diversity and regional manufacturing patterns reward localized specialization.
Outlook: Key Trends for the Next Three to Five Years
Looking ahead, several trends are likely to shape how the market evolves and where commercial opportunities will concentrate.
-
Adaptive, intelligence-led finishing will become a baseline expectation rather than a premium feature. Systems that can scan, measure, and adjust polishing behavior in real time will increasingly be favored because they reduce programming burden, improve robustness to variation, and support faster changeovers. Over the next few years, the strategic question will shift from whether to adopt robotic polishing to how much adaptive control is necessary for a given application and how to integrate that capability into quality workflows.
-
Application specialization will intensify, with suppliers and end users aligning solutions more tightly to material and process requirements. Polishing for automotive components, electronics, hardware tools, household products, and stone or specialty materials each carries distinct demands. Companies that build deep domain expertise, tool ecosystems, and demonstration cases in specific verticals are likely to earn stronger customer trust and pricing power than those that attempt to serve all segments with generic solutions. This trend creates opportunities for focused innovators and for established players that can credibly claim leadership in a defined application set.
-
Integration and compliance will increasingly operate as joint value drivers. As deployments scale, customers will care not only about the polishing module but about how it connects to upstream machining, downstream inspection, tooling maintenance, and operational safety. Systems that are designed with documented safety integration, risk-control logic, and interoperability in mind will face lower deployment friction and will be easier to scale across facilities. In practice, this means that the most successful offerings will be those that reduce the total integration burden rather than simply optimizing a single machine’s performance.
These trends create clear commercial opportunities, but they also carry risks. One risk is overinvestment in automation before process maturity is sufficient to absorb it. Facilities that lack stable upstream processes, clear quality specifications, or operational discipline may experience disappointing results even with capable hardware. Another risk is market fragmentation driven by application diversity: too much customization can erode scalability, while too little can leave high-value segments underserved. A third risk is the pace of regulatory and safety expectations, which may continue to evolve and raise the standard for what counts as a deployable system. Organizations that treat safety, integration, and process design as afterthoughts will face higher costs and slower adoption curves.
Strategic Implications for Decision Makers
For manufacturers evaluating robotic polishing, the first priority should be to define the operational problem with precision. The strongest business cases typically emerge where finishing variability, rework, or throughput constraints are well understood and where automation can be introduced into a process that already has clear quality targets and stable upstream conditions. Rather than starting with the hardware, leaders should start with the finish specification, the tolerance for variation, the frequency of changeovers, and the cost of quality leakage. That framing makes it easier to determine whether a repeatable high-volume system, an adaptive AI-driven platform, or a precision-focused CNC-integrated solution is the better fit.
For investors and strategic planners, the opportunity lies in identifying where value is being created along the chain. Revenue growth is meaningful, but the more important question is where margins, differentiation, and recurring value are forming. Companies that control the combination of hardware, tooling, adaptive software, and integration know-how are likely to capture more durable value than those competing primarily on unit pricing. Equally important is the ability to demonstrate measurable outcomes in targeted applications. Investors should favor exposure to players that can connect their technology to defensible use cases, repeatable deployments, and clear operational benefits, rather than to broad claims that are not anchored in specific finishing problems.
Worldwide Glass Polishing Powder Market
For procurement and operations leaders, the emphasis should be on total deployment risk rather than initial sticker price. That means evaluating tooling ecosystems, programming and changeover burden, safety and compliance posture, and the service and maintenance model alongside the core machine. A system that appears marginally more expensive may offer materially lower integration risk and faster ramp-up if it reduces programming time, simplifies tooling management, or embeds safety and quality logic more effectively. Procurement decisions that incorporate these factors tend to produce more reliable outcomes and fewer hidden costs after deployment.
For all of these audiences, the value of detailed, current market intelligence is rising. The market is moving quickly enough that broad assumptions about adoption, pricing, and competitive positioning can become outdated within a short period. Segment-level demand patterns, technology substitutions, regulatory expectations, and supplier strategies can differ significantly across regions and applications, and these differences shape where opportunities are real and where they are overstated. Organizations that use detailed, structured intelligence to map their specific application, cost structure, and competitive environment are better positioned to calibrate investment timing, prioritize use cases, and avoid committing to solutions that do not fit their operational reality.
As the robotic polishing market continues its shift from incremental automation to capability-driven competitiveness, the leaders who benefit most will be those who approach it as a strategic decision rather than a tactical purchase. The combination of adaptive technology, application specialization, safety-aware integration, and disciplined ROI framing will determine which organizations capture durable value. For decision makers seeking a deeper view of segment-level dynamics, regional variation, and tailored scenario planning, the full PW Consulting research report on the robotic polishing machine market provides a more detailed foundation for those decisions.
Robotic Polishing Cells Market
For detailed analysis of this topic, please visit the official page: Robotic Polishing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fibrinogen Concentrates Market: Why a 5.96% CAGR Reshapes the $704.96M Outlook by 2032
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Fibrinogen Concentrates Market
The global fibrinogen concentrates market has evolved from a specialized niche into a strategically significant segment within the broader plasma-derived therapeutics landscape. Market valuation reached approximately USD 468.38 million in 2025, reflecting a compound annual growth rate of 5.96 percent over the historical evaluation period and positioning the sector for continued expansion through 2032, when projected revenues approach USD 705 million. This trajectory is not merely a function of demographic demand or clinical adoption; it reflects structural shifts in surgical standards, regulatory pathways, manufacturing efficiency, and the economics of hemostatic care. For executives navigating biologics markets, fibrinogen concentrates present a case study in how concentrated therapeutic classes can scale while navigating plasma supply constraints, reimbursement complexity, and competitive differentiation.
PW Consulting
At the same time, the market is not without friction. Growth trajectories must be weighed against manufacturing bottlenecks, cost barriers for end users, and the evolving reimbursement environment that determines real-world utilization. Understanding where value is being created, which strategic moves are compounding advantage, and where uncertainty remains is essential for companies allocating capital, shaping product roadmaps, or evaluating partnership and acquisition targets in hemostasis and plasma-derived therapies.
Market Dynamics and Core Challenges
The current market structure reflects a mature but still expanding therapeutic category. Demand is distributed across surgical bleeding management, congenital fibrinogen deficiency, and a broad set of acquired and specialized applications. The product mix continues to favor powdered formulations, while liquid presentations are gaining incremental traction as reconstitution and storage considerations are addressed through formulation innovation. Geographically, developed markets continue to anchor the largest revenue shares, but the growth profile increasingly depends on expanded access in regions where hemophilia and bleeding disorder infrastructure is maturing.
Human Fibrinogen Market
Several forces are converging to define the near-term inflection points for the industry:
- Plasma supply and fractionation economics remain the dominant cost constraint. Fibrinogen-rich plasma inputs account for more than half of total production costs, which means that supply chain resilience, yield optimization, and donor plasma economics directly influence pricing power and margin stability.
- Reimbursement and coding frameworks are evolving rapidly in key markets. Recent HCPCS designations and expanding clinical approvals are reshaping the administrative and financial pathways that hospitals and payers use to authorize fibrinogen concentrate use, influencing both volume and substitution patterns.
- Clinical adoption is expanding beyond congenital indications into acquired fibrinogen deficiency and acute bleeding settings, but evidence requirements, institutional protocols, and cost consciousness create uneven adoption curves across health systems.
These dynamics create a market that rewards operators who can align product formulation, regulatory strategy, and market access planning rather than treating each as a separate silo. The ability to navigate plasma cost volatility while securing reimbursement clarity is becoming a competitive differentiator rather than a baseline expectation.
Key Drivers Shaping the Market
Technological Innovation and Formulary Differentiation
Innovation in fibrinogen concentrates is increasingly centered on presentation formats, viral inactivation robustness, reconstitution convenience, and indication expansion. Manufacturers are advancing refined purification and pathogen reduction processes that support confidence in efficacy and safety, while new packaging options are designed to meet the operational needs of surgical theaters and emergency settings. The introduction of specialized gram-level presentations reflects a broader trend toward tailoring product formats to clinical workflows and dosing requirements. These advances are not cosmetic; they affect procurement decisions, storage logistics, dosing precision, and the speed with which fibrinogen can be deployed in time-sensitive bleeding scenarios.
From a commercial standpoint, formulation and presentation strategy has become a lever for market access. Products that reduce handling complexity, improve dosing flexibility, or support specific patient populations can gain preference even in a category where therapeutic class equivalence is often assumed. The practical implication is that innovation must be paired with evidence generation and reimbursement alignment to translate clinical value into market share.
Regulatory and Reimbursement Dynamics
Regulatory progress continues to expand the addressable patient population. Recent approvals in the United States have broadened the use of fibrinogen concentrates for acquired fibrinogen deficiency and acute bleeding episodes, while separate regulatory actions have reinforced product-specific coding pathways. These developments matter because they influence prescribing confidence, hospital procurement policies, and payer coverage decisions. A product that moves from a narrower congenital indication into acquired and acute bleeding settings can unlock substantially larger utilization, provided the supporting evidence and coding environment enable consistent reimbursement.
The same regulatory environment introduces complexity. Stringent plasma collection, testing, and fractionation requirements raise the barrier to entry and increase the operational burden for manufacturers. Simultaneously, payers and health systems are scrutinizing cost-effectiveness, dosing efficiency, and the relationship between fibrinogen concentrate use and broader hemostatic management protocols. Companies that proactively shape clinical evidence, real-world utilization data, and coding narratives are better positioned to mitigate reimbursement friction and sustain volume growth.
Demand-Side Transformation in Surgical and Bleeding Care
Demand for fibrinogen concentrates is being shaped by several interrelated clinical and institutional trends. Surgical bleeding management remains a central application, supported by growing recognition of fibrinogen’s role in perioperative hemostasis and the desire to reduce transfusion-related risks and complications. At the same time, congenital fibrinogen deficiency continues to anchor a consistent base of demand, while acquired fibrinogen deficiency is emerging as an area of expanding clinical interest across trauma, cardiac, obstetric, and critical care settings.
Hospital procurement behavior is also shifting. Procurement teams are increasingly balancing clinical efficacy, supply reliability, presentation convenience, and total cost of care. In many institutions, formulary decisions are not made solely on price per gram; they incorporate workflow fit, stability, reconstitution requirements, and the availability of dosing options that match patient weight and bleeding severity. This suggests that demand growth will not be uniform across products or settings. Instead, adoption will favor manufacturers who can demonstrate clinical reliability, practical usability, and a clear value proposition relative to alternatives in the hemostatic toolkit.
Supply Chain and Cost Structure Pressures
Cost structure remains a defining feature of the market. The economics of plasma fractionation mean that plasma acquisition and processing represent the largest share of manufacturing cost, with fibrinogen-rich materials contributing a substantial portion of total expense. This creates sensitivity to plasma supply variability, donor availability, fractionation yields, and overhead associated with compliance and testing. For manufacturers, the challenge is not simply reducing unit cost; it is managing a cost stack that is partially exposed to external supply dynamics while maintaining consistent product availability and quality.
The cost implication for end users is equally important. At typical dosing levels, fibrinogen concentrate therapy can represent a meaningful expense for hospitals, particularly in lower-income regions or resource-constrained settings. That pricing pressure does not eliminate demand, but it shapes substitution decisions, protocol design, and the pace at which fibrinogen concentrate use expands beyond well-resourced centers. Commercial strategies that account for tiered access, presentation efficiency, and strong pharmacoeconomic justification are more likely to sustain growth across diverse market conditions.
Competitive Landscape and Leading Strategies
The market is characterized by a concentrated group of established plasma-derived biologics manufacturers alongside regional players seeking to establish or expand fibrinogen concentrate offerings. Leading organizations differentiate themselves through combinations of indication breadth, presentation options, regulatory milestones, manufacturing scale, and market access positioning. Rather than competing on a single dimension, successful players are aligning product portfolios with clinical workflows and reimbursement realities.
Several strategic positions are evident in the current landscape:
- Indication expansion as a growth lever. Companies that secure approvals for acquired fibrinogen deficiency or acute bleeding episodes broaden the clinical contexts in which their products can be used, increasing the addressable volume beyond congenital deficiency alone.
- Presentation flexibility as an operational advantage. Introducing dosing options and formulations tailored to specific settings can reduce friction in procurement, compounding, and bedside administration, strengthening hospital preference and formulary retention.
- Regulatory and coding alignment as a commercial enabler. Clear coding pathways and reimbursement language can reduce administrative barriers and accelerate institutional adoption, especially when paired with clinical evidence that supports appropriate use.
- Plasma-derived manufacturing credibility and supply resilience. Established fractionation capabilities and robust quality systems matter in a category where consistency, safety, and supply continuity are paramount for both clinicians and purchasers.
Recent developments illustrate how regulatory and product-level moves are reshaping competitive positioning. In late 2025, a major plasma therapeutics company secured FDA approval for a fibrinogen concentrate in acute bleeding episodes for pediatric and adult patients with congenital fibrinogen deficiency. Shortly thereafter, in early 2026, another key player gained FDA approval for a new 2-gram presentation of its fibrinogen concentrate for bleeding patients with acquired fibrinogen deficiency, building on earlier expanded approval activity in the prior year. These milestones are not isolated product events; they signal a broader shift toward wider clinical use, more flexible dosing formats, and increased competitive intensity around indication coverage and market access.
The market concentration profile suggests that scale and regulatory experience still matter, with a relatively concentrated share structure among leading participants. However, the landscape is also evolving through targeted launches, indication-specific differentiation, and regional capacity development. New entrants and regional manufacturers can compete by focusing on specific geographies, cost-efficient presentations, or locally relevant indications, particularly where access gaps remain or where procurement dynamics favor regional supply resilience. Consolidation may continue over time as larger players seek to strengthen portfolio depth and manufacturing reach, but differentiation through formulation, indication strategy, and market access capability will remain central to winning share.
Future Trends and Commercial Implications
Broader Clinical Use Will Drive Volume, but Distribution Will Be Uneven
Over the next three to five years, the most consequential trend is likely to be the continued migration of fibrinogen concentrate use beyond narrowly defined congenital indications into acquired deficiency and acute bleeding management. This broadening reflects both regulatory momentum and clinical interest in targeted fibrinogen replacement. The commercial implication is that total volume potential increases, but adoption will depend on local protocols, evidence dissemination, and reimbursement clarity. Markets with mature bleeding disorder infrastructure and established surgical hemostasis pathways are likely to absorb new indications faster, while regions where plasma-derived therapy access remains constrained will see more gradual uptake. Companies that invest in clinical education, guideline engagement, and site-level implementation support can convert indication expansion into sustained utilization more effectively than those relying on label expansion alone.
Presentation Innovation and Workflow Fit Will Influence Preference
As the category matures, product format will increasingly serve as a differentiator. Liquid formulations, specialized gram presentations, and packaging designed for rapid deployment in surgical and emergency settings can reduce logistical friction and improve fit within institutional workflows. This does not eliminate the importance of clinical efficacy and safety, but it adds a practical layer to procurement and formulary decisions. The trend favors manufacturers that treat product design as part of the value proposition, aligning presentation choices with real-world usage patterns. For hospitals and health systems, the opportunity lies in standardizing fibrinogen concentrate use in a way that supports both clinical outcomes and operational efficiency.
Cost, Access, and Reimbursement Will Remain Strategic Variables
Cost pressures are unlikely to disappear. Plasma-dependent manufacturing economics will continue to expose the category to input cost volatility, while high per-dose treatment costs will keep affordability and pharmacoeconomic justification in focus for payers and hospital administrators. The trend here is not a simple price war; it is a more sophisticated market access environment in which coding, coverage, evidence, and total cost of care arguments influence adoption. For manufacturers, the strategic response should include robust health economics support, dosing efficiency narratives, and proactive engagement with reimbursement frameworks. For investors, the durability of margins will depend on yield management, supply resilience, and the ability to secure favorable access arrangements rather than on volume growth alone.
Hemodialysis Concentrates Market
Potential Risks and Uncertainties
Several uncertainties could alter the pace or shape of growth. Plasma supply disruptions, donor availability constraints, or fractionation bottlenecks can affect availability and cost. Reimbursement changes, stricter utilization management, or shifts in payer policy could slow expansion in specific settings. Competitive intensity may increase as new presentations, regional entrants, or alternative hemostatic therapies influence treatment choices. In addition, clinical evidence expectations may evolve, requiring more robust real-world data to support use outside traditional indications. These risks do not negate the growth outlook, but they highlight the need for contingency planning around supply, access, and evidence strategy.
Actionable Guidance for Decision Makers
The fibrinogen concentrates market rewards strategic discipline across product, regulatory, and access dimensions. For executives and investors, four priorities stand out.
- For manufacturers, align formulation innovation with indication strategy and reimbursement planning. Product launches should be built around clinical workflow fit, dosing flexibility, and a credible market access narrative, not solely around regulatory milestones.
- For investors, focus on supply resilience, fractionation efficiency, and access-enabled growth. Companies that can manage plasma cost exposure, maintain consistent availability, and convert indication expansion into reimbursed utilization are better positioned for durable value creation.
- For procurement and clinical leaders, evaluate fibrinogen concentrate options based on total workflow impact and total cost of care, including presentation efficiency, dosing suitability, and evidence supporting appropriate use in relevant patient populations.
- For all stakeholders, treat market access and evidence development as ongoing capabilities. Reimbursement pathways, coding frameworks, and clinical adoption patterns are shifting quickly, and timely intelligence can reduce execution risk and improve planning accuracy.
Given the pace of regulatory updates, presentation innovation, and reimbursement evolution, decisions made on incomplete market intelligence carry avoidable risk. For organizations that need deeper segmentation, pricing and reimbursement detail, competitive benchmarks, and scenario planning across regions and indications, more granular analysis can help translate these trends into actionable plans. Detailed data sets, company-specific evaluations, and tailored commercial scenarios are available through PW Consulting’s full Fibrinogen Concentrates Market report, which provides the structured intelligence needed to support product strategy, investment decisions, and procurement planning with greater precision.
For detailed analysis of this topic, please visit the official page: Fibrinogen Concentrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Polyphenylene Sulfide Fibers Market: How 4.7% CAGR and Filtration Demand Reshape 2032
By PW Consulting, 2026-09-21
The Polyphenylene Sulfide Fibers Market: Strategic Trends and Commercial Opportunities in a High-Performance Materials Landscape
The global market for polyphenylene sulfide fibers has entered a phase of steady, value-driven expansion. Valued at approximately 151.2 million USD in 2020 and reaching roughly 189.6 million USD by 2025, the market is projected to grow to around 259.8 million USD by 2032, reflecting a compound annual growth rate of 4.7 percent over the forecast period. This trajectory signals a mature yet resilient industry where demand is increasingly tied to high-performance applications rather than volume-led commoditization. For executives, investors, and procurement leaders, the question is no longer whether PPS fibers will grow, but how the competitive landscape, cost structure, and regulatory environment will reshape who captures value in the next cycle.
Despite the consistent growth profile, the market is navigating several structural inflection points. First, margin compression is becoming a reality as energy-intensive production collides with tightening environmental controls and rising utility costs. Second, geopolitical and trade dynamics are introducing uncertainty around cross-border sourcing, particularly as major economies reassess anti-dumping frameworks and regional supply dependencies. Third, demand is shifting from generic filtration uses toward more specialized, specification-driven applications that reward technical differentiation and consistent quality. These forces are redefining the baseline for competitive performance and forcing companies to rethink scale, innovation, and supply chain architecture.
Innovation at the Fiber Level: Performance Trumps Volume
Technical advancement remains the most powerful growth lever in this market. The industry is moving beyond baseline heat and chemical resistance toward engineered fiber architectures that solve specific operational pain points. Trilobal cross-section designs, for example, have demonstrated measurable improvements in dust collection efficiency for filtration systems, while new flame-retardant grades are opening pathways into high-voltage electrical insulation where safety margins are non-negotiable. Simultaneously, bio-based feedstock initiatives are beginning to reshape the sustainability narrative, offering a credible route for buyers under pressure to reduce embodied carbon without sacrificing performance. These innovations are not incremental tweaks; they are creating application-specific value pools that command pricing resilience and longer-term customer lock-in.
Regulatory Realignment and the Trade Policy Variable
Policy and regulatory shifts are becoming a decisive factor in sourcing strategy. Environmental controls in key production regions have already influenced raw material pricing, with p-dichlorobenzene costs rising sharply in 2024 as tightened standards constrained supply. At the same time, trade policy dynamics are entering a new phase. The initiation of a sunset review investigation into anti-dumping measures on imports of polyphenylene sulfide from Japan and other countries signals that tariff and duty environments may be recalibrated in the near term. For multinational buyers and producers alike, this creates a dual challenge: maintaining supply continuity while preparing for potential cost volatility and redirected logistics. Companies that treat compliance and trade exposure as strategic variables rather than administrative hurdles will be better positioned to navigate procurement disruptions.
Demand-Side Transformation: From Filtration Dominance to High-Performance Diversification
End-use demand continues to be anchored by filtration applications, which remain the largest consumption segment. Bag filters in industrial dust collection and emission control systems represent a core demand driver, supported by stricter air quality standards and the need for durable, high-temperature-resistant media. However, the most notable shift is the growing interest in insulation materials and engineering applications where PPS fibers are being evaluated for thermal stability, chemical resistance, and long service life. Procurement behavior is also evolving: buyers are increasingly specification-driven, evaluating total cost of ownership rather than unit price alone. This change rewards suppliers that can demonstrate consistent grade quality, technical support, and application engineering capability. It also creates an opening for fiber producers to expand into adjacent high-performance segments where differentiation is achievable.
Cost Structure and Supply Chain Pressure
The economics of PPS fiber production are increasingly sensitive to energy intensity and raw material availability. Producing one metric ton of PPS requires approximately 3,200 kWh of electricity, which places a premium on regional energy tariffs and grid reliability. In markets with high or volatile electricity costs, this translates directly into margin pressure and can influence plant location decisions, capacity timing, and pricing strategies. At the same time, the supply chain is experiencing selective consolidation and regional rebalancing. Capacity expansions and targeted acquisitions are being used to strengthen local market access and reduce exposure to long logistics chains. These moves reflect a broader industry recognition that resilience and proximity to key end markets are becoming as important as scale alone.
Competitive Landscape and Strategic Positioning
The market is moderately concentrated, with the top three players accounting for roughly 35.8 percent of share and the top five reaching approximately 42.6 percent. This concentration suggests a landscape where scale and brand recognition matter, yet enough fragmentation remains to allow differentiated entrants to compete on technical performance, regional presence, or application specialization. Leadership in this market is increasingly defined by how effectively a company aligns product architecture, capacity strategy, and regional access with the evolving needs of specification-driven buyers.
Japanese and European Incumbents: Engineering Heritage and Application Depth
Several established manufacturers have built strong positions by emphasizing application-specific fiber grades and long-standing technical credibility. Leading PPS fiber producers have focused on high-temperature and chemical-resistant grades tailored for bag filters and insulation, reinforcing their relevance in industrial filtration and demanding engineering environments. Other major players offer PPS fiber variants with superior heat, chemical, and hydrolysis resistance across yarn, fabric, and non-woven formats, broadening their reach into both filtration and high-performance industrial uses. A notable differentiator in the market has been the development of trilobal cross-section fibers designed specifically to improve dust collection efficiency, a clear example of structural innovation translating into measurable performance gains. European suppliers have also maintained a presence with fiber grades suitable for monofilament and multifilament extrusion in high-performance engineering applications, positioning themselves in niches where precision and consistency are critical.
Phosphorus Pentasulfide Market
Regional Expansion and Capacity Strategy
Capacity and supply chain strategy are becoming central to competitive positioning. Recent activity includes the completion of an acquisition of a regional PPS fiber manufacturing plant in Southeast Asia, a move aimed at strengthening supply chain resilience and improving market access. In parallel, capacity expansions by major producers in China are signaling a continued push to serve both industrial and automotive-adjacent demand more efficiently. These developments point to a market that is not only growing but also reconfiguring its geographic footprint. For buyers and investors, regional capacity additions can reduce lead times and logistics risk, but they also intensify local competition and may pressure margins in oversupplied segments.
Product Innovation as a Competitive Moat
Recent product launches illustrate how innovation is being used to defend and extend market position. One major Japanese manufacturer introduced a new flame-retardant PPS fiber grade specifically designed for high-voltage electrical insulation, targeting an application space where reliability and safety certification create strong barriers to entry. Meanwhile, a European supplier announced an eco-friendly PPS fiber line using bio-based feedstocks, aligning product development with sustainability goals in markets where procurement teams face increasing pressure to document lifecycle impacts. In a related high-performance direction, a partnership between a global chemical company and an aerospace OEM has focused on co-developing ultra-high-performance nanocomposite PPS fibers, suggesting that the upper end of the market is moving toward tailored, application-engineered materials rather than standardized grades.
PPS Resin Market
Market Structure Evolution: Consolidation, Differentiation, and New Entrants
The competitive trajectory appears to be moving toward a hybrid structure. On one side, consolidation and capacity acquisitions are strengthening the scale and regional reach of incumbents. On the other, product differentiation and application specialization are enabling companies to compete without relying solely on volume. New and expanding entrants, particularly in China, are increasing production capacity for filtration and industrial uses, which broadens available supply but also raises the importance of quality consistency and technical support. Over the next few years, the market is likely to reward players that can combine reliable scale with clear application advantages, while those competing primarily on price in commoditized segments may face intensifying pressure.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
The next phase of growth will be shaped by the interaction of technical differentiation, cost resilience, and regulatory uncertainty. Three trends stand out as particularly consequential for commercial strategy.
PW Consulting
Trend 1: Application-Specific Value Pools Will Outperform Generic Segments
As buyers increasingly prioritize total cost of ownership and performance reliability, specification-driven applications are expected to capture a disproportionate share of margin growth. High-voltage insulation, advanced filtration media, and engineered industrial textiles are likely to see stronger demand for premium grades that solve clear operational problems. This trend favors producers with strong application engineering capabilities and consistent grade control, and it creates opportunities for companies that can demonstrate measurable performance advantages in targeted use cases. The broader implication is that growth will be less about expanding volume across all segments and more about winning in high-value niches where customers are willing to pay for proven performance.
Trend 2: Cost and Energy Dynamics Will Drive Regional Strategy Decisions
Given the electricity intensity of PPS production and ongoing raw material price volatility, regional cost structures will increasingly influence where capacity is added, how production is scheduled, and which suppliers are preferred in tender processes. Producers in regions with stable, cost-competitive energy and efficient logistics may gain a structural advantage, while high-energy-cost regions could see margin pressure unless offset by premium product positioning or local demand strength. For downstream buyers, this trend underscores the importance of multi-region sourcing strategies and scenario planning for energy and input cost fluctuations. It also suggests that near-market capacity expansions could become a differentiator for suppliers seeking to reduce lead times and improve supply assurance.
Trend 3: Sustainability and Regulatory Compliance Will Become Commercial Inputs
Sustainability is transitioning from a reputational consideration to a procurement requirement in several end markets. Bio-based feedstock development and other eco-aligned product initiatives are likely to gain traction among buyers who need to document environmental performance across their supply chains. At the same time, trade and regulatory reviews will continue to shape cross-border sourcing, potentially altering duty exposure and supply routes. The commercial implication is clear: sustainability claims and regulatory readiness will increasingly influence supplier selection, especially in sectors where compliance, safety, and lifecycle documentation carry operational weight. Companies that can provide credible, verifiable product attributes and maintain agile sourcing options will be better positioned to retain and expand share.
Risks and Uncertainties to Monitor
Despite the constructive growth outlook, several risks warrant attention. Continued raw material price volatility, especially for key precursors, could compress margins if not managed through pricing strategy or supply contracts. Energy cost escalation in certain regions may affect production economics and plant utilization decisions. Trade policy reviews and potential duty adjustments could introduce short-term sourcing disruption and pricing uncertainty. Finally, the risk of overcapacity in specific regional segments could intensify price competition, particularly in more commoditized filtration applications. Navigating these risks will require a combination of technical differentiation, flexible sourcing, and disciplined capacity planning.
Strategic Implications for Decision-Makers
For manufacturers, the priority is to align product development with the applications that command the strongest performance requirements and willingness to pay. Investing in grade consistency, application-specific fiber architectures, and credible sustainability attributes can create meaningful differentiation. At the same time, capacity and energy strategy should be evaluated in the context of regional cost structures and customer proximity, rather than scale alone. Companies that can combine reliable supply with clear technical advantage will be best placed to defend pricing and expand into higher-value segments.
For investors, the market offers a profile of steady growth with pockets of higher-margin opportunity in specialized applications. Due diligence should focus on the durability of product differentiation, the exposure of production costs to energy and raw materials, and the ability of target companies to navigate trade and regulatory shifts. Regional capacity moves and acquisitions may improve supply chain resilience, but they also require scrutiny around utilization, local competition, and end-market demand quality. Selective exposure to engineered fiber segments and application-led growth appears more attractive than undifferentiated volume plays.
For procurement and supply chain leaders, the strategic task is to reduce exposure to single-source dependency and price-only purchasing logic. Evaluating suppliers on the basis of grade consistency, technical support, energy and regulatory resilience, and sustainability documentation can lower total risk and improve long-term cost stability. Building multi-region sourcing options and maintaining visibility into trade policy developments will help mitigate disruption if duty environments or input costs shift. In practice, procurement strategies that treat PPS fibers as a performance-critical input rather than a commodity are more likely to secure reliable supply and better commercial outcomes.
The market is entering a period where technical value, cost resilience, and regulatory readiness will separate durable participants from price-takers. For decision-makers seeking a deeper, segment-level view of demand dynamics, competitive positioning, and scenario-based planning parameters, a more detailed research compendium can provide the granularity needed to translate these strategic trends into specific operational choices.
For detailed analysis of this topic, please visit the official page: Polyphenylene Sulfide Fibers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Surgical Blades & Scalpels Market 2026: Why 5.2% CAGR and Disposable Blades Reshape Strategy
By PW Consulting, 2026-09-21
The Surgical Blades & Scalpels Market: Strategic Trends and Commercial Opportunities Through 2032
The global market for surgical blades and scalpels has entered a phase of steady, structurally supported expansion. Valued at approximately $172.5 million in 2020, the market reached $219.8 million in 2025 and is projected to climb to $312.3 million by 2032, reflecting a compound annual growth rate of 5.2 percent. This trajectory mirrors broader shifts in surgical practice, infection control standards, and procurement economics. While the product category itself is mature, the competitive and operational dynamics beneath the surface are evolving quickly. For executives, investors, and procurement leaders, the market presents a paradox: top-line growth is predictable, yet margin structures, channel control, and innovation pathways are being reshaped by regulation, safety mandates, and regional supply chain reconfiguration.
The market is heavily concentrated. The top three players account for roughly 60 percent of revenue, and the top five capture about 72 percent. This concentration signals scale advantages in manufacturing, sterilization, distribution, and compliance management. Yet the remaining share is fragmented across regional manufacturers, specialty blade producers, and safety-focused innovators, creating both pressure and opportunity depending on a company's positioning. The following analysis examines the core challenges, demand and supply drivers, competitive strategies, and forward-looking opportunities that will shape decision-making through the end of the decade.
Market Landscape and Core Challenges
A Mature Category Operating Under Structural Efficiency Pressure
The surgical blades and scalpels market is not experiencing explosive growth, but it is benefiting from persistent procedural volume expansion, a shift toward single-use sterile disposables, and tightening safety standards. The overall revenue path from 2020 through 2032 shows consistent year-over-year gains, with the steepest incremental increases expected in the latter half of the forecast period. This pattern is consistent with a category where volume growth, product mix shifts, and regional procurement changes compound rather than spike.
One of the most pressing challenges is the tension between cost containment and safety compliance. Hospitals and surgical centers are under sustained pressure to reduce indirect costs, yet regulatory and occupational safety expectations continue to favor single-use sterile blades and safety scalpels. The result is a procurement environment where price sensitivity exists alongside mandatory or strongly encouraged adoption of safety-engineered products. Manufacturers that can deliver standardized, compliant, and competitively priced disposable blades are better positioned than those relying on premium differentiation alone.
PW Consulting
A second challenge lies in the regulatory asymmetry across regions. In the United States, scalpel blades and scalpels are generally classified as Class I exempt devices, meaning most models do not require a premarket submission, but establishments must still register and list with the appropriate authorities. Manufacturing facilities are expected to meet ISO 13485 quality management expectations, and EU markets impose stricter single-use validation protocols under the Medical Device Regulation framework. This duality creates a compliance burden for companies selling across multiple jurisdictions, especially when validation documentation, sterilization records, and traceability requirements differ. The cost of maintaining multi-region compliance can erode margins for smaller producers while reinforcing the position of established players with mature quality systems.
A third challenge is the absence of dedicated reimbursement codes for blades and scalpels. Costs are typically embedded within global surgical procedure fees rather than billed as standalone items. This structure pushes procurement decisions toward total cost of procedure rather than device-level price comparisons, and it places a premium on reliability, inventory turnover, and integration with broader perioperative workflows. Suppliers that can demonstrate predictable availability, reduced sharps injury risk, and compatibility with existing surgical workflows gain leverage in a reimbursement environment that does not isolate blade economics.
Key Demand and Supply Drivers
Safety Standards and the Shift Toward Single-Use Sterile Disposables
A major driver of market evolution is the continued migration from reusable blades to single-use sterile disposables. This shift is reinforced by occupational safety mandates and international standards for safety scalpels, which aim to reduce sharps injuries among surgical staff. Facilities are increasingly standardizing on disposable sterile blades not only for clinical reasons but also to streamline infection control protocols and minimize reprocessing costs. The practical effect is a product mix that tilts toward disposable blades in many general surgery settings, while reusable blades retain relevance in specific use cases where reprocessing infrastructure and cost equations remain favorable.
Double Edges Blades Market
The commercial implication is clear: manufacturing capacity, sterilization capability, and distribution reliability for disposable blades are becoming strategic assets. Companies that can scale sterile disposable production while maintaining tight dimensional tolerances and consistent sharpness profiles are better positioned to capture share in a market where safety standards are accelerating adoption. At the same time, safety scalpel designs and retractable or shielded options are gaining attention in procurement specifications, giving an edge to suppliers with differentiated safety portfolios.
Regulatory Classification and Quality System Expectations
Regulatory classification shapes both entry barriers and operating economics. The Class I exempt status of most scalpel blades and scalpels in the United States lowers the premarket submission burden for many models, but it does not remove the need for establishment registration, listing, and robust quality management. ISO 13485 certification is effectively a baseline expectation for manufacturing facilities, and EU requirements add further validation rigor for single-use devices. These conditions favor manufacturers with mature quality infrastructure and disciplined documentation practices.
Worldwide Surgical Saw Blades Market
This environment also affects innovation incentives. Since many conventional blade models face a lighter regulatory pathway, competition often centers on manufacturing consistency, packaging, sterilization reliability, and supply continuity rather than dramatic product redefinition. By contrast, safety-engineered scalpels and specialty micro blades can involve more complex design validation, creating a higher barrier but also a stronger differentiation opportunity for companies that can demonstrate clinical and operational value.
Procurement Economics and the Embedded Cost Reality
Because blades and scalpels are generally absorbed into broader surgical procedure costs rather than reimbursed under dedicated codes, procurement decisions are influenced by total procedure economics. Surgical teams and purchasing departments evaluate availability, standardization, waste reduction, and injury prevention alongside unit price. This creates an environment where bundling compatibility, inventory management support, and safety alignment can be as important as the blade itself.
Demand-side behavior reflects this embedded cost reality. Hospitals seek to minimize variation across surgical service lines, which encourages standardization on a limited set of blade and handle configurations. At the same time, specialty procedures and microsurgical applications sustain demand for precision blades and ophthalmic knives. The net effect is a market where volume flow favors standardized disposable products, while higher-value niches reward precision engineering and application-specific design.
Manufacturing Scale, Regional Sourcing, and Cost Structure Dynamics
Cost structure remains a decisive competitive lever. Blade manufacturing requires precise metallurgy, controlled edge geometry, reliable sterilization, and consistent packaging. Companies with integrated production and quality systems can manage unit costs more effectively, while smaller or regionally focused producers must compete on flexibility, local service, or niche applications. Regional sourcing strategies are gaining importance as procurement teams look to reduce logistics risk, improve lead-time predictability, and align with local compliance expectations.
Recent distribution developments illustrate how channel strategy is evolving. For example, in early 2025, a Canadian distribution agreement expanded exclusive coverage for a major blade and scalpel portfolio, signaling a push to strengthen regional availability and service reliability. Moves like this reflect a broader pattern: established manufacturers are investing in distribution density and localized support to protect share in regulated, service-intensive markets, while emerging producers pursue export growth and selective partnerships to enter new regions.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Players
The competitive field combines long-established multinational manufacturers, precision-focused producers, and regional exporters with growing scale. The leading companies differentiate along several axes: product range breadth, safety portfolio depth, metallurgical precision, sterilization and sterile packaging capability, and integration into broader perioperative or specialty workflows.
Several strategic profiles are visible across the market. One group emphasizes heritage, broad blade and handle ranges, and comprehensive sterile disposable offerings. These players often compete on consistency, distribution reach, and the ability to serve General Surgery and multiple specialty segments with standardized products. Another group focuses on precision manufacturing and high-sharpness stainless steel products, with particular attention to safety scalpel lines and micro blade options. This positioning appeals to surgical specialties that require fine edge control and reliable performance in delicate procedures.
A third profile is built around regional export strength and cost-competitive sterile disposable manufacturing. These companies have expanded their footprint by offering full lines of carbon steel and stainless steel blades and scalpels, targeting price-sensitive procurement environments while meeting international quality expectations. A fourth profile lies in specialty focus, where ophthalmic surgical knives, micro blades, and dental-oriented scalpel systems create differentiated value in narrower but higher-specification applications. Finally, some broader perioperative solution providers incorporate scalpel blades and handles into integrated surgical workflows, using device availability and service continuity as part of a larger institutional relationship.
Market Structure Evolution: Consolidation Pressure and Targeted Expansion
The high concentration at the top of the market indicates that scale, compliance, and distribution maturity matter. Larger players benefit from the ability to standardize quality systems, manage sterilization at volume, and maintain inventory across multiple regions. At the same time, the long tail of smaller and regional manufacturers remains active, particularly where localized service, flexible order sizes, or specialty products create room for differentiation.
The evolution of the landscape is likely to continue along two tracks. First, established manufacturers will keep strengthening distribution partnerships and regional coverage to protect share and improve service levels. Second, targeted expansion by efficient regional producers and specialty innovators will pressure incumbents in specific segments, especially where disposable adoption is rising and procurement is open to alternative suppliers that can meet compliance requirements at competitive cost. M&A and rebranding activity also reshape the landscape indirectly, as companies reposition portfolios to emphasize safety, specialty precision, or perioperative integration.
Given the embedded cost structure and safety-driven adoption trends, competitive advantage increasingly comes from the ability to deliver standardized sterile disposables with reliable lead times, consistent quality, and safety-aligned design features. In specialty niches, the advantage shifts toward precision, application fit, and clinical trust. Companies that can operate effectively across both tracks—scale-driven standard products and higher-specification specialty offerings—are best placed to defend and expand their positions.
Forward Trends and Commercial Opportunities Through 2032
Continued Mix Shift Toward Sterile Disposable and Safety-Aligned Products
Over the next three to five years, the product mix is expected to keep moving toward single-use sterile disposables and safety-oriented scalpels where protocols and procurement specifications allow. This trend is supported by safety standards, infection control expectations, and the operational simplicity of disposables in high-volume surgical environments. For suppliers, the opportunity lies in scaling sterile disposable capacity, improving packaging and traceability, and aligning product lines with the safety expectations that hospitals are increasingly embedding into purchasing criteria.
A related opportunity is the expansion of safety scalpel adoption in settings that have historically relied on conventional blades. Education, workflow integration, and cost acceptance will influence the pace of adoption, but the direction of travel favors designs that reduce handling risk and support standardized disposal procedures.
Regional Growth and Supply Chain Localization
Regional dynamics will continue to shape growth patterns. North America remains the largest market, supported by established surgical volumes, safety adoption, and mature distribution. Europe follows with substantial demand and stricter validation expectations that reinforce quality and traceability requirements. Asia Pacific represents a meaningful growth path, driven by expanding surgical capacity, increasing procurement professionalism, and growing export competitiveness among efficient manufacturers. Latin America and the Middle East and Africa remain smaller in absolute terms but offer incremental opportunities where access, service, and compliance alignment improve.
Commercially, this points to a strategy of regional reinforcement rather than uniform global rollout. Companies that invest in localized distribution, predictable lead times, and documentation readiness for multiple regulatory environments can capture share more effectively than those relying solely on product price. For investors, regional scalability and channel control are likely to be critical indicators of long-term resilience.
Precision, Specialty, and Workflow-Integrated Positioning
While standardized disposables drive volume, specialty applications sustain higher-margin opportunities. Ophthalmic knives, micro blades, and application-specific scalpel systems require tighter tolerances and greater clinical confidence, which can support differentiated pricing when performance and reliability are demonstrable. At the same time, broader perioperative providers can create value by integrating blade and scalpel availability into larger surgical workflow solutions, making supply reliability and service continuity part of the value proposition.
This bifurcation suggests a practical strategic path: maintain a strong core in standardized sterile disposables to capture volume and safety-driven adoption, while building or strengthening specialty lines that serve precision procedures and specialized surgical workflows. The risk is spreading too thin across unrelated segments; the opportunity is to align precision and workflow integration with genuine clinical need rather than broad but shallow expansion.
Risks and Uncertainties
Several uncertainties could alter the trajectory. Regulatory and validation expectations may tighten further in certain markets, raising compliance costs and slowing the pace at which new entrants can scale. Procurement pressure could intensify if hospitals prioritize cost over safety features in specific budget cycles, temporarily dampening the shift toward premium safety designs. Supply chain disruptions, raw material cost volatility, and sterilization capacity constraints could also affect margin stability and service levels. Finally, because reimbursement does not isolate blade costs, demand can be indirectly affected by changes in surgical procedure volumes, service line economics, and broader healthcare spending patterns.
Strategic Implications for Decision Makers
For Manufacturers
Prioritize the operational foundations that convert market growth into defensible share. That means investing in sterile disposable capacity, quality system maturity, and distribution reliability, while maintaining enough precision capability to serve specialty segments. Standardize core blade and handle configurations where hospital procurement favors consistency, but preserve differentiated safety and micro blade options where clinical value supports them. Build regional channel strength through partnerships or localized service capacity, especially in markets where lead time and documentation readiness influence purchasing decisions.
For Investors
Evaluate businesses on their ability to manage compliance, scale sterile production, and control distribution across regions. Concentration in the market indicates that scale and quality infrastructure matter, but growth opportunities also exist for efficient producers and specialty innovators that can meet safety expectations at competitive cost. When assessing potential investments or partnerships, look for evidence of ISO 13485-aligned quality systems, reliable sterilization and traceability processes, and channel strategies that reduce reliance on a single geography or customer type. Also consider exposure to procedural volume cycles, since blade demand is tied to surgical activity even though reimbursement does not itemize the device separately.
For Procurement and Supply Chain Leaders
Treat blade and scalpel selection as part of total procedure economics rather than an isolated unit-price exercise. Standardize where clinical workflows allow, but preserve access to safety-aligned disposables and precision options for specialties that require them. Evaluate suppliers on consistency, injury-prevention design, inventory reliability, and documentation readiness as much as on price. Where possible, align purchasing specifications with occupational safety standards and infection control goals to reduce downstream operational risk.
Closing Perspective
The surgical blades and scalpels market is moving through a period where growth is steady, safety expectations are rising, and competitive advantage depends on execution quality as much as product design. The mix shift toward sterile disposables, the regulatory and validation environment, and the embedded cost structure of surgical procedures all point in the same direction: future success will belong to organizations that can combine scale, compliance discipline, and targeted precision where it matters most. For leaders navigating this landscape, the most valuable next step is to ground strategy in detailed, segment-level intelligence—covering regional demand patterns, product mix economics, channel dynamics, and competitor positioning—so that decisions on capacity, portfolio focus, and market entry are calibrated to the opportunities and risks that lie ahead.
For detailed analysis of this topic, please visit the official page: Surgical Blades & Scalpels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Agarose Market 2032: Why the 6.98% CAGR Trajectory Signals Strategic Shifts in Life Sciences
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Agarose Market
Market Overview and Core Challenges
The global agarose market has demonstrated consistent expansion over the past half-decade, establishing itself as a critical component within the broader life sciences and bioprocessing supply chain. Starting from a valuation of approximately 153.44 million USD in 2020, the market has grown steadily to reach an estimated 215.0 million USD in 2025. This trajectory reflects a compound annual growth rate of 6.98 percent, with projections indicating continued expansion through 2032. By the end of the forecast period, the market is expected to surpass 344 million USD, signaling sustained demand across research and industrial applications.
This growth is not merely a function of population or academic output increases; it represents a structural shift in how biological materials are processed and analyzed. The market has moved from a niche consumable model toward a more integrated industrial supply dynamic. However, this expansion faces headwinds that strategic planners must account for. The period from 2025 to 2032 will not be defined solely by volume growth but by how players navigate supply chain fragility and regulatory divergence.
Three critical challenges define the current inflection point for industry stakeholders. First, raw material security remains a persistent vulnerability. Agarose is primarily derived from seaweed, linking market stability directly to marine agriculture and geopolitical trade flows. Recent data indicates that geopolitical tensions between major seaweed-producing nations and key import markets like the European Union and the United States have triggered higher import/export tariffs. These barriers have increased operational costs for producers, squeezing margins on standard grades while complicating long-term capacity planning.
Second, regulatory uncertainty in key regions is altering demand patterns. In 2024, China introduced classification rules for bio-stimulant products such as seaweed extracts that created inspection delays and price fluctuations. While this specifically impacts biostimulants, it signals a broader trend of tighter oversight on seaweed-derived materials that can spill over into industrial and laboratory-grade agarose supply chains. Additionally, the new French national roadmap launched in March 2025 aims to triple domestic seaweed production by 2027. While this enhances sector resilience in Europe, it also shifts regional supply dynamics and may alter competitive advantages for producers reliant on specific geographic sources.
Third, the market is experiencing a bifurcation in demand quality. Standard agarose continues to drive volume, but high-performance variants such as low melting point agarose are gaining strategic importance in specialized applications. This divergence forces manufacturers to choose between competing on cost efficiency in commoditized segments or investing in differentiation for high-value niches. Companies that fail to align their product portfolios with this shift risk exposure to margin compression as standard-grade pricing comes under pressure from rising input costs.
For executives and investors, these challenges underscore the need to look beyond top-line growth figures. The market size trajectory is positive, but the underlying economics are tightening. Success in the next cycle will depend on supply chain agility, regulatory foresight, and the ability to capture value in differentiated segments rather than competing solely on volume.
Gracilaria Agarose and Gelidium Agarose Market
Key Growth Drivers
Understanding the forces propelling the agarose market requires examining the intersection of technological advancement, regulatory evolution, demand-side shifts, and cost structures. Each driver influences not only the pace of growth but also where value is created within the market ecosystem.
Technological Innovation and Performance Breakthroughs
Innovation in agarose chemistry and manufacturing processes is reshaping application boundaries. Advances in purification and gel characterization have enabled products that deliver higher resolution and reproducibility for nucleic acid analysis. More importantly, the development of specialized resins for bioprocessing has opened new commercial pathways. Manufacturers are increasingly engineering agarose-based matrices tailored for affinity purification and monoclonal antibody processing, where performance consistency directly impacts downstream therapeutic production.
Recent market activity illustrates this trajectory. In February 2024, Purolite, part of Ecolab, commercially launched Praesto CH1, a 70-micron agarose-based affinity resin developed in partnership with Repligen for specialized monoclonal antibody purification. This launch highlights how agarose is moving beyond traditional laboratory electrophoresis into high-value bioprocessing workflows. Such developments expand the addressable market and create pricing power for suppliers capable of meeting stringent performance and regulatory standards for biological drug manufacturing.
Policy and Regulatory Environment
Regulatory frameworks are acting as both constraints and catalysts. On one hand, trade policies and tariffs are raising input costs and complicating cross-border sourcing. On the other, government initiatives aimed at strengthening domestic production capacity are creating new opportunities. The French national roadmap to triple seaweed production by 2027 exemplifies this dual dynamic. By supporting local cultivation, the policy reduces dependency on imported raw materials and enhances supply chain resilience for European processors.
At the same time, regulatory clarity around product classification remains uneven. The 2024 Chinese regulatory adjustments for seaweed-derived biostimulants caused temporary market disruptions, demonstrating how policy ambiguity can ripple through related supply chains. For agarose producers, this signals the importance of monitoring regulatory developments in bothsource and destination markets. Proactive engagement with policy trends can help companies anticipate sourcing shifts and position their product lines to comply with evolving standards for laboratory and industrial-grade materials.
Demand-Side Shifts in Research and Biomanufacturing
End-user behavior is evolving as laboratory workflows become more automated and throughput requirements increase. In academic and clinical research settings, the demand for reliable DNA and RNA isolation and gel electrophoresis remains foundational. However, the scale and standardization expectations are rising. Laboratories are increasingly seeking precast solutions and certified powders that reduce variability and preparation time. This shift favors suppliers who can offer consistent quality and integrated product systems rather than bulk commodity powders alone.
Simultaneously, the biopharmaceutical sector's expansion is driving demand for agarose-based chromatography media. As monoclonal antibody therapies and advanced biologics continue to scale, manufacturers require purification resins that can handle larger volumes while maintaining binding capacity and flow properties. This demand is less price-sensitive than routine research applications and more focused on performance validation and supply reliability. Companies that can demonstrate batch-to-batch consistency and offer technical support for process integration are capturing a growing share of this higher-value demand segment.
Supply Chain and Cost Structure Dynamics
Cost pressures are reshaping competitive positioning across the value chain. Rising fuel prices and trade barriers since 2024 have increased the cost of seaweed extract biostimulants and related upstream resources used in agarose production. These input cost increases affect both raw material procurement and logistics. Producers with diversified sourcing strategies or localized supply networks are better positioned to absorb these shocks compared to those relying on single-source or long-distance procurement models.
At the same time, the cost structure is encouraging consolidation and specialization. Smaller players may struggle to invest in the capacity expansions or quality systems required to meet bioscience-grade standards, while larger entities can leverage scale and integration to maintain margins. This dynamic is pushing the market toward a structure where competitive advantage is increasingly tied to supply chain robustness, technical service capabilities, and the ability to offer graded product portfolios that match distinct end-user requirements.
Competitive Landscape and Leading Strategies
The agarose market is characterized by a mix of specialized manufacturers and broader life sciences companies, each pursuing distinct strategic positions. Market concentration data shows that the top three companies hold approximately 35 percent of the market, while the top five account for around 48 percent. This moderate concentration suggests a landscape where established leaders maintain meaningful share but room remains for niche players and regional specialists to compete on differentiation.
Thermo Fisher Scientific and Bio-Rad Laboratories represent the large-cap life sciences segment, offering certified agarose powders and precast gel systems optimized for routine and high-throughput nucleic acid analysis. Thermo Fisher's UltraPure powders and E-Gel precast systems cater to laboratories seeking consistency and workflow efficiency, while Bio-Rad's certified molecular biology powders and precast gels serve similar demand with a strong reputation in research and teaching environments. Their strategic advantage lies in brand trust, distribution scale, and integrated product ecosystems that reduce user variability.
Lonza occupies a specialized position with products such as SeaKem and NuSieve grades tailored for nucleic acid gel electrophoresis. Its focus on high-clarity and specialized gel formulations addresses applications where resolution and reproducibility are paramount. By maintaining a dedicated product architecture for electrophoresis, Lonza competes on technical performance rather than volume pricing, appealing to users with demanding analytical requirements.
Agarose Bead Technologies (ABT) and Purolite represent the bioprocessing-oriented flank of the market. ABT, based in Spain, specializes in high-performance custom agarose resins for bioprocessing applications including monoclonal antibody purification and advanced therapies. Its strategy emphasizes customization and capacity investment. In October 2024, ABT completed a 1,000 square meter addition to its Burgos facility, increasing agarose resin production capacity to 100,000 liters annually. This expansion signals a commitment to scaling supply for bioprocessing demand. ABT's participation in Analytica 2026 in Munich further underscores its focus on showcasing agarose-based resins and custom chromatography solutions to a global bioprocessing audience.
Purolite, operating across the UK and US under Ecolab, leverages patented jetting technology for agarose-based chromatography resins used in bioprocessing and affinity purification. Its partnership-driven approach, exemplified by the Praesto CH1 launch in collaboration with Repligen, illustrates how resin suppliers are building ecosystems around specific therapeutic manufacturing needs. This model allows Purolite to align product development with customer process requirements and capture value in the antibody purification workflow.
Worldwide Agar Resin Market
The competitive landscape is evolving along two axes: integration and specialization. Larger life sciences companies are expanding their agarose offerings through brand extension and precast system integration, competing on workflow convenience and global reach. Specialized manufacturers are deepening their technical focus on custom resins, high-performance grades, and bioprocessing applications, competing on performance, customization, and supply reliability for advanced therapies. New entrants are most likely to succeed by targeting underserved niches, such as regional supply optimization, tailored resin specifications, or cost-efficient production of standard grades with consistent quality. Mergers and partnerships may increase as companies seek to combine upstream raw material access with downstream application expertise.
PW Consulting
Future Trends and Commercial Implications
Looking ahead to the 2026 to 2032 period, several trends are likely to shape market direction and create distinct commercial opportunities. These trends are grounded in current data trajectories and recent industry developments, offering a basis for strategic planning.
Trend 1: Premiumization and Workflow-Integrated Solutions
The market is likely to see continued growth in high-performance and low melting point agarose variants as laboratories and bioprocessors prioritize reproducibility, speed, and integration. Demand for precast gels, certified powders, and resins with validated performance characteristics will expand as users seek to reduce preparation variability and accelerate throughput. This trend favors suppliers that can offer complete workflow solutions, technical documentation, and application support. Commercial opportunities lie in bundling products with service offerings, developing application-specific grades, and building partnerships with equipment and automation providers to embed agarose solutions into standardized workflows.
Trend 2: Regional Supply Restructuring and Sourcing Diversification
Policy initiatives such as France's push to triple domestic seaweed production and ongoing trade tensions affecting import/export tariffs will encourage regional supply chain restructuring. Producers and buyers alike will increasingly value diversified sourcing strategies and localized processing capabilities to mitigate tariff risks and input cost volatility. Over the next few years, expect more investment in regional cultivation partnerships, alternative sourcing routes, and capacity located closer to key demand centers. Companies that secure resilient raw material access and can offer transparent sourcing will gain a competitive edge, particularly in Europe and North America where supply security is becoming a strategic priority.
Trend 3: Convergence of Research and Bioprocessing Demand
As biomanufacturing scales and research workflows become more standardized, the boundary between laboratory-grade and bioprocessing-grade agarose applications may continue to blur in certain segments. Advanced therapies and biologics production require high-purity, consistent resins, while research labs increasingly adopt precast and certified products that mirror industrial quality expectations. This convergence creates opportunities for suppliers that can span both domains with appropriate quality tiers and regulatory documentation. It also raises the bar for quality systems, traceability, and technical support, rewarding companies that can bridge research and production requirements without compromising cost efficiency.
Potential risks and uncertainties accompany these trends. Regulatory ambiguity in key seaweed-producing and consuming markets could resurface, causing supply disruptions or reclassification of products that affect demand. Geopolitical tensions and fuel price volatility may continue to pressure input costs, particularly if trade barriers persist or intensify. Additionally, oversaturation in standard-grade segments could intensify price competition, eroding margins unless companies successfully differentiate through quality, service, or application-specific value. Strategic planners should stress-test their assumptions around sourcing stability, regulatory clarity, and pricing power in commoditized segments.
Actionable Insights for Decision Makers
For manufacturers, the priority is to align product portfolios with the shift toward differentiation and workflow integration. Investing in high-performance grades, precast systems, and custom resin capabilities can protect margins and capture higher-value demand. At the same time, strengthening supply chain resilience through diversified sourcing, regional partnerships, or localized processing can reduce exposure to tariffs and input cost volatility. Manufacturers should also evaluate whether capacity expansion aligns with demand concentration in bioprocessing or whether a regional strategy better serves market needs. Technical service capabilities and application support should be treated as core competitive assets rather than ancillary functions, as end-users increasingly value validation, consistency, and process integration.
For investors, the market offers attractive structural growth supported by a steady CAGR and expanding demand across research and bioprocessing. However, due diligence should focus on supply chain robustness, regulatory exposure, and product mix. Companies with diversified sourcing, clear quality systems, and a balanced portfolio of standard and premium products are better positioned to navigate input cost pressures and regulatory uncertainty. Interest in specialized bioprocessing resins and custom chromatography solutions is likely to remain a value-creation driver, particularly as monoclonal antibody and advanced therapy production scales. Evaluating capacity expansion plans against realistic demand trajectories and regional policy developments can help identify companies with sustainable competitive positioning.
For procurement and supply chain leaders, securing reliable supply while managing cost volatility requires proactive supplier engagement and sourcing diversification. Qualifying multiple suppliers across regions, establishing clear quality and documentation requirements, and exploring partnerships with manufacturers that offer transparent sourcing and capacity visibility can reduce risk. Buyers should also assess the total cost of ownership beyond unit price, considering workflow efficiency, reproducibility, and technical support, especially for critical applications where variability can impact results or production timelines. Monitoring regulatory developments in source and destination markets enables earlier adjustments to sourcing strategies and reduces the likelihood of disruption from classification changes or trade policy shifts.
Accessing detailed segmentation data, regional demand patterns, and customized strategic recommendations can sharpen decision-making in this evolving landscape. Comprehensive market intelligence that breaks down growth trajectories by application, product type, and region, along with scenario analysis for regulatory and supply chain variables, provides the granularity needed to turn high-level trends into actionable plans. For organizations seeking to optimize sourcing, prioritize product development, or evaluate investment and partnership opportunities, a deeper data-backed view of the agarose market is an essential input to strategic planning.
For detailed analysis of this topic, please visit the official page: Agarose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Lab Glassware Market 2026: The 4.7% CAGR Trajectory and What It Reveals
By PW Consulting, 2026-09-21
Navigating the Laboratory Glassware Market: Strategic Trends and Commercial Imperatives
The laboratory glassware market is entering a phase of structural transformation, driven by technological refinement, evolving regulatory expectations, and shifting procurement behaviors across end-user segments. Valued at approximately USD 185.0 million in 2025, the market has expanded from USD 140.5 million in 2020, reflecting steady compounding growth over the post-pandemic period. Forward projections indicate a trajectory toward USD 253.28 million by 2032, with a compound annual growth rate of 4.7 percent across the forecast horizon. This expansion is not merely incremental; it reflects a market responding to heightened precision requirements, supply chain recalibration, and the integration of traceability and standardization into routine laboratory operations. For executives, investors, and procurement leaders, the window to align product portfolios, capital allocation, and sourcing strategies with these underlying shifts is opening now.
Market Snapshot: Growth Trajectory and Structural Realities
The market’s historical performance from 2020 through 2025 demonstrates a consistent upward curve, with annual revenue crossing the USD 160 million threshold in 2022 and accelerating into the USD 170–185 million range by mid-decade. The forecast period from 2026 to 2032 projects continued expansion, though the growth path is not uniform. The transition from USD 185.0 million in 2025 to the projected USD 253.28 million in 2032 implies that demand generation will increasingly depend on application-specific precision, regulatory compliance, and regional capacity dynamics rather than broad volume expansion alone.
At the structural level, the market operates with moderate concentration. The top three participants collectively command roughly 45 percent of total revenue, while the top five extend that share to approximately 60 percent. This concentration pattern indicates that established manufacturers retain meaningful pricing power and distribution leverage, yet the remaining 40 percent of the market remains fragmented across regional players, specialty suppliers, and cost-focused producers. Such a landscape creates both defensive moats for incumbents and entry points for well-positioned challengers, particularly where customization, compliance documentation, or supply chain reliability becomes a differentiating factor rather than a baseline expectation.
The market is also characterized by a clear hierarchy of product and application relevance. Volumetric measurement tools and general containment vessels continue to anchor demand, while pipettes and precision dispensing instruments represent a growing precision segment. In application terms, pharmaceutical and biotechnology workflows consume the largest share of glassware volumes, followed by academic and research environments, clinical diagnostic settings, and ancillary use cases. This distribution indicates that demand is increasingly tied to regulated, high-throughput, or quality-sensitive environments where measurement accuracy, material consistency, and documentation traceability carry direct operational and compliance implications.
Defining Challenges and Inflection Points
Despite the favorable growth baseline, the industry faces several interconnected challenges that will shape competitive outcomes over the next three to five years.
Precision Standards and Calibration Expectations
The laboratory glassware sector is moving toward tighter standardization for measurement-critical items, particularly in one-mark volumetric instruments. Updated international requirements are reinforcing calibration consistency, marking accuracy, and manufacturing repeatability. For producers, this translates into higher compliance costs, more rigorous quality control protocols, and the need to align product specifications with evolving normative references. Laboratories and procurement teams, in turn, are placing greater weight on certification documentation and conformance assurance, raising the barrier for sellers that cannot demonstrate consistent specification integrity across batches.
Material Consistency and Thermal Performance Requirements
Borosilicate glass remains the dominant material foundation because of its thermal shock resistance and chemical durability. While this dominance provides stability, it also constrains rapid material substitution and heightens sensitivity to raw material quality, melting consistency, and forming precision. Variability in feedstock composition or furnace control can affect wall thickness uniformity, dimensional tolerance, and long-term reliability in temperature-cycling applications. Manufacturers that treat material consistency as a core process capability rather than a commodity input will be better positioned to capture demand from environments where thermal stress and chemical exposure are routine.
Traceability, Documentation, and Procurement Digitalization
A quiet but consequential shift is underway in how laboratories track, verify, and manage glassware inventory. The introduction of QR-coded product items, enhanced batch traceability, and digital catalog integration reflects growing demand for item-level identification and audit-ready documentation. This trend is especially relevant in regulated environments where lot traceability, usage history, and replacement scheduling influence both operational efficiency and compliance reviews. Suppliers that enable faster verification, clearer product identification, and smoother integration with laboratory inventory systems can reduce friction in the procurement cycle while strengthening supplier-of-choice positioning.
Core Drivers Reshaping the Market
Regulatory Alignment and Standardization Momentum
The push toward harmonized international standards is one of the most consequential forces in the market. Updated normative references for one-mark volumetric flasks are establishing clearer expectations for dimensional accuracy, marking, and conformity testing. Rather than treating standards as static compliance checkboxes, leading manufacturers are using them as product development anchors, aligning tooling, inspection routines, and documentation with anticipated certification expectations. For buyers, the practical implication is that specification sheets and conformity evidence are becoming more comparable across suppliers, which can compress differentiation based solely on branding and shift attention toward reliability, lead-time consistency, and technical support.
Innovation in Safety and Durability Features
Product-level innovation is increasingly focused on reducing breakage risk, improving handling safety, and extending service life in demanding workflows. Coated laboratory bottles with enhanced shatter protection illustrate this direction, addressing both workplace safety and total cost of ownership concerns. In settings where glassware is handled frequently, moved across benches, or used in environments with vibration, temperature variation, or incidental impact, safety-oriented design features can differentiate a product line and influence purchasing decisions beyond base price comparisons. Innovation is also extending to interchangeability, filtration-compatible configurations, and specialized vessel geometries that reduce workflow adaptation time.
Demand-Side Shifts in Regulated and Research Workflows
End-user behavior is evolving as laboratory workflows become more standardized, auditable, and throughput-sensitive. Pharmaceutical and biotechnology environments continue to absorb the largest share of demand because measurement precision, contamination control, and reproducibility carry direct implications for development timelines and quality outcomes. Academic and research institutions remain a substantial demand base, but their procurement patterns are increasingly influenced by budget cycles, shared instrumentation models, and the need for broad compatibility across teaching and research labs. Clinical diagnostic settings add another layer of complexity, where glassware usage is tied to laboratory service delivery and reimbursement frameworks that do not always map cleanly onto individual product codes. This fragmentation in reimbursement and procurement pathways means that suppliers must navigate both technical specifications and institutional purchasing logic.
Supply Chain and Cost Structure Pressures
Cost dynamics in the market are influenced by raw material availability, energy intensity in glass melting and forming, and logistics complexity across regions. Borosilicate glass production requires controlled high-temperature processing, which makes energy pricing and furnace utilization relevant to cost structure. At the same time, regional demand patterns are reshaping sourcing strategies. North American and European markets maintain substantial demand bases, while Asia Pacific represents a growing volume center supported by expanding research infrastructure, manufacturing capacity, and domestic consumption. The result is a supply environment in which regional presence, export capability, and inventory positioning increasingly matter for competitive responsiveness. Companies that can combine consistent production output with dependable distribution and clear compliance documentation are gaining an advantage in tenders and recurring procurement programs.
Competitive Landscape and Strategic Positioning
The competitive environment blends incumbent scale, regional manufacturing strength, and niche specialization. Companies with established brand portfolios and broad product ranges are using brand trust, specification consistency, and application coverage to defend share. At the same time, regional manufacturers are gaining relevance by offering competitive cost profiles, adaptable production runs, and growing conformity to local certification expectations. This dual dynamic creates a market where scale and reputation matter, but they no longer guarantee automatic preference if a competitor can match specifications and improve traceability, lead time, or safety features.
Differentiation Patterns Among Leading Players
Several strategic positioning patterns are evident across the competitive set.
-
Brand-led premium positioning: Multi-brand manufacturers leverage well-known product lines and long-standing laboratory recognition to anchor trust in precision measurement and material quality. Their differentiation often rests on specification consistency, broad application coverage, and established distribution relationships.
-
Customization and specialty systems: Some suppliers emphasize custom configurations, reaction systems, and application-specific geometries. This approach is particularly relevant for research environments that require non-standard vessel dimensions, specialized port configurations, or integrated handling solutions.
-
Standards-aligned volume manufacturing: Regional producers focus on USP, ASTM, and local certification alignment, offering general laboratory glassware and consumables at competitive cost points. Their relevance grows where procurement teams prioritize specification compliance, batch consistency, and pricing predictability.
Glassware Market -
Traceability and catalog modernization: Suppliers introducing QR-coded items, updated catalogs, and improved identification systems are reducing friction in inventory verification and lot tracking. This is becoming a practical value-add, especially for repeat purchasers managing large SKU counts or regulated usage environments.
-
Safety-enhanced product extensions: Manufacturers introducing shatter-protection coatings, coated bottles, and handling-safety features are targeting total cost of ownership and workplace risk reduction. This positioning resonates in environments where breakage-related disruptions, cleanup, and replacement frequency influence operating costs.
PW Consulting
Evolution of the Competitive Structure
The market is unlikely to consolidate into a single dominant configuration over the near term. Instead, the structure appears to be evolving through selective integration, regional capacity expansion, and specialization by workflow. Incumbents are defending core positions by strengthening product reliability, demonstration value at major industry events, and application-aligned product launches. Regional producers are expanding relevance by combining cost efficiency with growing conformity to certification and standards expectations. At the same time, new entrants and expanders can gain traction by addressing unmet needs in traceability, safety, specialized geometries, or regional service responsiveness. The practical outcome is a landscape where competitive advantage is increasingly defined by the intersection of specification integrity, documentation readiness, and operational convenience rather than by brand alone.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
Trend 1: Standards-Driven Harmonization of Precision Glassware
Over the next several years, the emphasis on harmonized requirements for measurement-critical items is likely to intensify. One-mark volumetric instruments will continue to serve as a focal point for calibration discipline, and suppliers that proactively align manufacturing controls, inspection protocols, and documentation with evolving normative expectations will face fewer friction points in regulated procurement. The commercial implication is that quality documentation and specification consistency will become more central to supplier selection, and companies that treat conformance as a design and process priority rather than an after-the-fact certification activity will be better positioned for repeat business in quality-sensitive environments.
Trend 2: Safety, Durability, and Total-Cost-of-Ownership Framing
Demand for safety-enhanced and durability-oriented products is expected to grow as laboratories and procurement teams evaluate glassware not only by unit price but by handling risk, breakage frequency, replacement cycles, and workflow interruption. Coated bottles, protective designs, and improved handling characteristics can shift purchasing conversations toward operational outcomes. This trend creates opportunity for manufacturers that can demonstrate measurable benefits in safety and lifecycle performance, especially where laboratory staffing constraints, training variability, or high-throughput handling increase exposure to breakage and handling errors.
Trend 3: Digital Traceability and Procurement System Integration
QR-enabled identification, updated product catalogs, and improved traceability are early indicators of a broader move toward inventory digitization and audit-readiness. As laboratories seek faster verification, clearer lot history, and easier integration with procurement and inventory systems, suppliers that provide machine-readable identification and well-structured product data will reduce administrative burden and improve buyer confidence. This trend is particularly relevant for recurring procurement programs, multi-site institutions, and regulated settings where documentation continuity matters. The opportunity lies not only in labeling, but in supporting buyers with data consistency, clear product hierarchy, and compatibility with modern procurement workflows.
Risks and Uncertainties to Monitor
Several risks could temper or redirect these trends. Regulatory and standards implementation can vary by region and by procurement cycle, creating uneven adoption timelines. Raw material and energy cost volatility may pressure margins, particularly for producers with limited pricing flexibility or high exposure to energy-intensive forming processes. Reimbursement and procurement structures in diagnostic and clinical service settings remain complex, which can obscure demand signals and slow purchasing decisions. In addition, the fragmented portion of the market can intensify price competition, especially where differentiation is limited to specification parity and brand recognition. Companies that fail to strengthen traceability, documentation, and safety value propositions may find themselves competing primarily on price in an increasingly demanding specifications environment.
Actionable Guidance for Decision-Makers
For Manufacturers and Brand Owners
Strengthen the link between product design and compliance readiness. Where measurement-critical items are concerned, investment in process control, inspection discipline, and conformity documentation can reduce friction in regulated procurement and improve repeat-order reliability. Equally important is the differentiation path beyond base specifications: safety coatings, handling improvements, traceability features, and application-specific geometries can shift purchasing conversations toward operational value. Manufacturers should also evaluate regional certification expectations and determine where local compliance, service responsiveness, or cost-positioning can open access to growing demand centers. Participation in major industry exhibitions and consistent product demonstration can reinforce visibility, but the durable advantage will come from repeatable conformance, clear documentation, and the ability to reduce buyer risk across the ordering and use cycle.
For Investors and Strategic Allocators
Evaluate exposure through the lens of specification integrity, regional capacity, and value-added differentiation rather than aggregate volume alone. Segments tied to precision measurement, safety-enhanced products, and traceability-enabled catalog systems are likely to see stronger demand resilience because they address compliance, handling risk, and procurement efficiency. It is also important to assess the regional balance of demand and production capacity, since energy intensity, raw material access, and logistics can shape margin durability. Companies that combine stable production quality with clear documentation and differentiated product features may offer more defensible positioning than those reliant on undifferentiated commodity supply. In addition, investors should monitor how reimbursement and procurement structures evolve in diagnostic-linked settings, since those frameworks influence demand timing even when the product itself is not directly coded.
For Procurement Leaders and Laboratory Operators
Expand evaluation criteria beyond unit price to include specification conformance, documentation completeness, handling safety, and traceability support. In precision-sensitive workflows, the cost of measurement uncertainty, replacement delays, and compliance friction can outweigh small differences in list price. Suppliers that provide clearer product identification, reliable conformity evidence, and efficient replenishment processes can reduce administrative burden and improve continuity. Procurement teams should also consider total cost of ownership when breakage, handling risk, and replacement frequency are material, since safety-enhanced options may lower downstream disruptions even if upfront pricing differs. Where multi-site or regulated environments are involved, standardized product data and traceable lot management can simplify audit preparation and inventory control.
From Insight to Execution
The laboratory glassware market is moving from a period of steady expansion to one where differentiation is increasingly determined by precision discipline, safety enhancement, traceability readiness, and regional execution. The baseline growth trajectory remains constructive, but the more valuable question for decision-makers is not whether the market will continue to grow, but which capabilities will earn preference as specifications tighten and procurement becomes more documentation-driven. Manufacturers that align product development with standards expectations, reinforce material and process consistency, and reduce operational friction for buyers can convert market-wide growth into share gains. Investors and procurement leaders, meanwhile, can use these signals to prioritize exposure, negotiate with clearer evaluation criteria, and reduce hidden cost risks in precision-sensitive workflows.
Worldwide Laboratory Glass Container Market
For organizations that need a granular view of regional demand splits, product-type dynamics, application-level consumption patterns, and company-specific competitive positioning, a more detailed research view can help translate these high-level trends into segment-specific strategy. Access to the full breakdown supports scenario planning, sourcing decisions, and portfolio prioritization with finer granularity than is possible in a market overview alone.
For detailed analysis of this topic, please visit the official page: Laboratory Glassware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
LPO Market at 22.91% CAGR: What’s Really Driving the $125.85B Surge to 2032
By PW Consulting, 2026-09-21
The Legal Process Outsourcing Market: Strategic Shifts and Growth Horizons (2025–2032)
The legal process outsourcing (LPO) sector has transitioned from a cost-arbitrage experiment into a core operational function for corporations, law firms, and compliance teams worldwide. Over the past five years, the market has demonstrated consistent expansion, with revenues climbing from approximately 11.0 billion USD in 2020 to nearly 30 billion USD by 2025. The trajectory continues upward, with annual growth momentum expected to push the sector past 125 billion USD by 2032. At a compound annual growth rate of roughly 22.9 percent across the 2026–2032 forecast window, LPO is outpacing many adjacent professional services categories, reflecting a structural recalibration of how legal work is sourced, managed, and delivered.
This growth is not merely a function of volume expansion. It reflects a deeper transformation in how organizations approach legal capacity, regulatory complexity, and technology integration. For executives, investors, and procurement leaders, the LPO landscape now offers a mix of established scale players, specialized capability providers, and emerging technology-driven models. Navigating this environment requires a clear understanding of where value is being created, where operational friction persists, and which strategic moves are separating consistent performers from the rest of the field.
Healthcare BPO Market
Market Realities and Core Challenges
The LPO market has reached a scale where traditional outsourcing playbooks no longer apply uniformly. Organizations today are leveraging external legal operations for everything from high-volume document review to regulatory monitoring, contract lifecycle management, and specialized intellectual property support. The breadth of services has expanded significantly, and the revenue base now spans multiple service categories with varying maturity levels. Litigation support and e-discovery workflows remain a substantial portion of the service mix, while contract management, regulatory and compliance services, and legal research functions have grown in strategic importance as internal legal teams face increasing workloads and tighter budgets.
Despite the strong growth profile, the industry faces several structural challenges that will shape its next phase of development.
- Quality and consistency at scale. As volumes increase and service delivery crosses multiple jurisdictions, maintaining consistent quality standards becomes more difficult. Legal work is inherently high-stakes, and errors in contract review, compliance monitoring, or discovery processes can carry significant financial and reputational consequences. Vendors must balance speed and cost efficiency with rigorous quality controls, which often requires layered review processes, specialized training, and robust performance metrics.
- Data security, privacy, and cross-jurisdictional compliance. Legal outsourcing frequently involves transferring sensitive information across borders, which introduces regulatory complexity. Data protection requirements, industry-specific confidentiality obligations, and evolving cross-border data transfer rules create operational hurdles for providers and clients alike. Delivery models must be designed with security architecture, access controls, and compliance monitoring built in from the start rather than treated as add-ons.
- Talent availability and capability gaps. The LPO sector depends on a blend of legal knowledge, process discipline, and increasingly technical skills. Demand for professionals who can operate across legal workflows, data analytics, and AI-assisted tools is rising, but supply remains uneven across regions. Provider organizations that can develop, retain, and continuously upskill talent gain a meaningful advantage, while those relying on purely labor-cost arbitrage face growing pressure as automation absorbs more routine tasks.
These challenges are not static barriers; they are becoming strategic differentiators. Providers that design their operating models around quality assurance, secure data handling, and talent development are better positioned to capture higher-value work, while those that compete primarily on price are likely to face margin compression and client churn as buyers become more sophisticated.
Core Drivers Reshaping the Market
The expansion of the LPO sector is being driven by a combination of technological, regulatory, demand-side, and cost-structure forces. These drivers interact with one another, creating feedback loops that accelerate adoption in certain segments while reshaping competitive expectations across the broader market.
Technology Innovation as a Core Enabler
Artificial intelligence and automation are no longer peripheral tools in legal operations; they are increasingly embedded in how work is scoped, executed, and reviewed. Machine-assisted document review, contract analysis, legal research, and compliance monitoring are reducing turnaround times and allowing provider teams to focus on higher-judgment tasks. The shift is not simply about replacing manual effort. It is about re-architecting workflows so that technology handles the repetitive, high-volume components while human expertise is applied where nuance, interpretation, and client-specific context matter most.
Recent industry activity illustrates how seriously providers are investing in this direction. Several leading firms have moved to strengthen their AI-enabled service lines and data capabilities, integrating legal operations support with more advanced analytics, contract management platforms, and compliance workflows. In parallel, partnerships aimed at deploying end-to-end platforms with stronger security and compliance controls are becoming more common, particularly where cross-border data handling is involved. These moves signal that technology is now a competitive baseline rather than a differentiator reserved for a few early adopters.
Regulatory Complexity and Monitoring Demands
The regulatory environment for large corporations and regulated industries continues to become more demanding. Environmental, social, and governance expectations, data privacy regimes, sector-specific compliance obligations, and cross-border operational requirements have all increased the volume and urgency of legal and compliance work. This is pushing organizations to seek external support not only for episodic litigation or transaction work, but also for ongoing monitoring, reporting, and risk management.
A notable example is the introduction of managed services focused on ESG compliance, including real-time regulatory monitoring and reporting. Such offerings reflect a broader trend: clients increasingly want continuous, structured support rather than ad hoc project-based assistance. As regulatory expectations become more dynamic, providers that can combine legal knowledge with operational monitoring and reporting capabilities are well placed to capture recurring revenue streams.
Demand-Side Shifts in Legal Capacity and Procurement
Internal legal departments are under growing pressure to manage expanding workloads with constrained headcount and budgets. At the same time, corporate procurement and legal operations teams are becoming more deliberate about how they source external support. The conversation has evolved from simple cost reduction to total value, including speed, quality, predictability, security, and the ability to scale up or down as needs change. This has encouraged a shift toward managed services and longer-term partnerships rather than one-off engagements.
The result is a more diverse buyer profile. Some organizations are building hybrid models in which internal teams oversee strategy and high-judgment work while external providers handle volume-driven processes. Others are using LPO providers to fill capability gaps in specialized areas, such as multilingual litigation support, intellectual property analytics, or jurisdiction-specific compliance. In both cases, the common theme is flexibility: buyers want providers who can adapt to changing caseloads, regulatory demands, and internal priorities without sacrificing control or consistency.
Cost Structure and Delivery Model Evolution
Cost remains a foundational driver, but the way cost advantage is achieved is changing. Pure labor-cost arbitrage is increasingly insufficient in segments where quality, turnaround speed, and technology integration matter most. Providers are restructuring delivery around a blend of onshore, nearshore, and offshore locations, with secure facilities and specialized centers supporting specific legal domains or jurisdictional requirements. This geographic diversification helps manage cost while also addressing data residency, language, and legal system familiarity.
At the same time, operational efficiency is being improved through process standardization, workflow automation, and better portfolio management. Organizations that treat legal outsourcing as a managed operation—complete with governance, performance tracking, and continuous improvement—are more likely to realize durable savings and service reliability than those that rely on transactional, project-by-project purchasing.
Competitive Landscape and Leading Strategies
The LPO market remains moderately fragmented, with the top three providers accounting for a combined share in the high twenties and the top five reaching just over a third of total market revenue. This structure implies that while scale players have meaningful presence, there is still substantial room for specialization, regional strength, and capability-based differentiation. The competitive dynamic is less about a single dominant model and more about how providers combine scale, technology, domain expertise, and delivery footprint.
Strategic Positioning Among Key Players
Several established providers illustrate different pathways to competitive advantage.
- Integreon Managed Solutions has focused on AI-powered legal operations support spanning contract management, document review, legal research, and compliance services. Its recent strategic collaboration with PwC for legal managed services in the EMEA region, along with the opening of a new secure delivery center in Cape Town to support offshore outsourcing with an emphasis on English common law jurisdictions, reflects a strategy centered on both geographic expansion and partnership-driven scale.
- Elevate Services has positioned itself around AI-powered legal services that include litigation support, contract management, legal operations consulting, and managed services. Its acquisition of a specialist in Chinese, Japanese, and Korean language support for litigation, together with a legal data and AI consulting company, demonstrates a push to deepen multilingual capability and data/AI advisory strength in a single move.
- QuisLex has built its offering on managed services for document review, contract management, compliance, litigation support, and legal spend optimization. Its launch of a managed service focused on ESG compliance with real-time regulatory monitoring and reporting shows an effort to move beyond traditional litigation-support work into recurring, compliance-driven engagements.
- Epiq Global continues to emphasize technology-enabled legal and compliance services, including e-discovery, class actions, bankruptcy, and outsourcing for law firms and corporations. Its profile reflects the importance of scale infrastructure and specialized case-type expertise in high-volume, process-intensive work.
- Axiom Law has carved out a position around on-demand legal talent, secondments, and AI-enabled services supporting in-house legal teams and complex projects. This model highlights the value of flexible talent deployment and close integration with internal legal functions, especially for organizations that want external support without fully handing off operational control.
- UnitedLex has focused on data-driven legal and litigation support services, including e-discovery, patent analytics, and case management. Its strategic partnership with a major cloud provider to deploy an advanced end-to-end e-discovery platform with enhanced data security and cross-border compliance capabilities underscores the increasing importance of secure technology infrastructure in competitive positioning.
How the Landscape Is Evolving
Three patterns are evident in the current competitive environment.
- Capability-driven consolidation. M&A and strategic partnerships are being used to add multilingual capacity, data and AI consulting, and broader managed-service portfolios. This suggests a market in which buyers increasingly want integrated solutions rather than narrow point services.
- Geographic and jurisdictional specialization. Providers are expanding or refining delivery centers to align with common law frameworks, language requirements, and regional compliance expectations. This reflects a recognition that legal outsourcing is not a uniform global service; jurisdictional familiarity and data handling rules shape where and how work can be performed.
- Platform and security as competitive foundations. Partnerships and platform investments focused on secure, end-to-end processing are becoming more prominent, particularly for e-discovery and other data-sensitive workflows. In a market where information security and regulatory compliance are central concerns, technology infrastructure is increasingly part of the value proposition rather than a back-office utility.
For new entrants, the bar is rising. Pure cost-based entry is harder to sustain as automation reduces the advantage of low-cost labor alone, and buyers are more capable of evaluating quality, security, and service design. New players that can bring specialized domain expertise, strong technology integration, or a clear regional and jurisdictional fit have a more credible path than those offering only generalized volume services.
Forward Trends and Commercial Opportunities
Looking ahead across the next three to five years, several trends are likely to shape how the LPO market develops and where commercial opportunities emerge.
AI-Embedded Legal Operations Become Standard Configuration
The integration of AI and automation into legal workflows is expected to deepen, moving from selected use cases to broader operational baselines. Document review, contract abstraction, legal research, compliance monitoring, and matter management are all candidates for increased automation, with human reviewers focusing on exception handling, strategic judgment, and client-specific interpretation. For providers, this trend creates opportunities to redesign service offerings around technology-assisted efficiency, predictable turnaround times, and measurable quality outcomes. For buyers, it opens the possibility of scaling legal support without proportionally increasing headcount, provided vendor selection emphasizes workflow design and governance rather than tool presence alone.
Compliance and ESG-Linked Services Grow as Recurring Revenue Engines
As regulatory expectations continue to expand, managed services tied to regulatory monitoring, compliance reporting, and ESG-related obligations are likely to become more prominent. Unlike episodic litigation or transaction support, these engagements can create more predictable, recurring demand. Providers that can combine real-time monitoring, structured reporting, and cross-functional coordination with legal and compliance teams are well positioned to capture this demand. For enterprises, the opportunity lies in moving from reactive compliance support to continuous operational oversight, reducing the risk of late responses to regulatory changes and improving internal accountability.
Regional Rebalancing and Jurisdiction-Focused Delivery Models
The geographic distribution of LPO activity is expected to remain dynamic. While some regions already account for a substantial share of market activity, others are positioned for faster growth during the forecast period as legal demand, regulatory complexity, and delivery infrastructure evolve. Western Europe, for example, is widely expected to emerge as one of the fastest-growing regions during the forecast window, reflecting expanding compliance needs and increasing adoption of external legal operations support. At the same time, Asia Pacific continues to hold a leading share, underscoring the region’s established role in global legal service delivery. For providers, this environment favors deliberate investment in regional capabilities, language coverage, and jurisdiction-specific expertise. For buyers, it creates options for aligning delivery location with legal framework familiarity, data residency requirements, and cost considerations.
Legal Practice Management Software Market
Risks and Uncertainties to Monitor
Despite the strong growth outlook, several uncertainties could affect the pace and shape of market development. Regulatory changes around data transfer, privacy, and cross-border operations may increase compliance costs and slow certain delivery models if requirements become more restrictive. Security incidents or quality failures in high-stakes legal work could also shift buyer caution and raise due-diligence requirements. In addition, rapid automation could compress margins for providers that have not reinvested in workflow redesign, talent development, or higher-value service capabilities. Finally, macroeconomic fluctuations may influence how aggressively organizations expand external legal support, even if the underlying structural drivers remain intact.
Implications for Decision-Makers
The current LPO environment rewards deliberate strategy over reactive purchasing. Executives, investors, and procurement leaders each face a distinct set of priorities, but all benefit from a clearer view of where the market is heading and how to position accordingly.
For Corporations and Legal Operations Leaders
- Move from project-based buying to managed service design. Where possible, structure engagements around governance, service-level expectations, quality metrics, and continuous improvement. This reduces variability and makes it easier to scale support as workload fluctuates.
- Define security and compliance requirements before sourcing. Data handling, jurisdiction, access controls, and reporting expectations should be part of the initial scoping process, not negotiated after the fact. Providers with built-in secure infrastructure and cross-border compliance capabilities will be easier to integrate into sensitive workflows.
- Use external support to build capability, not just capacity. The most valuable engagements often combine volume handling with knowledge transfer, process improvement, and access to specialized expertise. This helps internal teams evolve while maintaining strategic control over high-judgment work.
For Investors and Strategic Allocators
- Focus on models with durable differentiation. Sustainable advantage is increasingly tied to technology integration, quality systems, multilingual and jurisdiction-specific capability, and recurring compliance-oriented services rather than labor-cost advantage alone.
- Watch consolidation and partnership activity as signals. Acquisitions and collaborations that add language coverage, data and AI advisory strength, or platform security capabilities often indicate where the market is heading and which capability gaps are being closed.
- Evaluate exposure to regulatory-driven demand. Segments tied to ongoing compliance monitoring, ESG reporting, and data-sensitive discovery workflows may offer more predictable demand profiles, though they also carry higher expectations for security, accuracy, and operational discipline.
For Procurement and Sourcing Professionals
- Evaluate total value, not just unit cost. Speed, quality, security, scalability, and the ability to manage changing requirements can matter as much as price, especially in complex or high-volume legal work.
- Build vendor portfolios by capability, not by brand alone. Different providers are stronger in different areas, such as litigation support, contract management, IP analytics, or compliance monitoring. A diversified sourcing approach can match work types to the most suitable providers.
- Embed performance management into ongoing relationships. Regular review of quality, turnaround, cost predictability, and security compliance helps maintain alignment and reduces the risk of service drift over time.
Conclusion
The legal process outsourcing market is entering a phase defined by greater technological integration, more demanding compliance expectations, and a growing preference for managed, scalable service models. Growth momentum remains strong, but the competitive edge is shifting toward providers that can combine secure infrastructure, quality assurance, jurisdictional awareness, and AI-enabled workflows with the ability to support recurring legal and compliance needs. For organizations seeking to use LPO strategically, the priority is no longer simply finding lower-cost support. It is selecting partners and service designs that improve speed, control, and resilience while allowing internal teams to focus on the work that most requires judgment and accountability.
PW Consulting
For decision-makers needing a more detailed view of service-line dynamics, regional trajectories, competitive positioning, and custom sourcing implications, the full research report provides a deeper breakdown of market segments, company-level developments, and forward scenarios. It is designed to support more granular planning, from service portfolio design and vendor evaluation to investment prioritization and risk assessment.
For detailed analysis of this topic, please visit the official page: Legal Process Outsourcing (LPO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com