

Blogs
Asia-Pacific Software Defined Radio (SDR) Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-07
From 2020 to 2035, the Asia-Pacific SDR market is forecasted to grow at a strong CAGR, with revenues rising from $1,920 Million in 2020 to over $7,850 Million by 2035. Key inflection points include substantial upticks in 2025 with $3,200 Million driven by 5G rollouts, and rapid acceleration post-2030 owing to defense communications upgrades. This trajectory reflects evolving digitalization in public and private sectors, with continued investments projected during the period.
Read More - https://bussinessinsights.com/research-report/asia-pacific-software-defined-radio-(sdr)-market
By 2025, military applications dominate the Asia-Pacific SDR market, representing 38% of the total share due to military modernization and secure communications. Telecommunication follows with 26%, reflecting the region’s 5G and network transformation. Public safety and disaster response constitute 14%, fueled by government funding for resilient emergency communication systems. The contribution of these applications strengthens SDR’s value in both national security and civilian infrastructure, highlighting the dynamism of the region’s communications landscape.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-software-defined-radio-(sdr)-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Software Defined Radio (SDR) Market industry?
Key players in the Asia-Pacific SDR market include Leonardo S.p.A., Thales Group, L3Harris Technologies, BAE Systems, and Rohde & Schwarz. These companies are industry leaders, specializing in advanced communications systems, military and commercial SDR solutions, and continuous research and development to enhance connectivity, interoperability, and performance across defense and commercial sectors.
What is the Asia-Pacific Software Defined Radio (SDR) Market growth?
The Asia-Pacific SDR market is experiencing significant growth, driven by increased defense modernization and digitalization. For instance, Thales Group recently expanded its SDR deployments with new contracts in Australia and India, contributing to the region's projected CAGR of over 8% during the forecast period.
Which segment accounted for the largest Asia-Pacific Software Defined Radio (SDR) Market share?
The defense application segment held the largest market share in the Asia-Pacific SDR market. SDRs are increasingly adopted by defense organizations for secure military communications, tactical interoperability, and real-time data sharing, primarily driven by ongoing modernization programs in countries like India, China, and Australia.
Thanks & Regards,
priya
sales@bussinessinsights.com
Asia-Pacific In-Vehicle Networking Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-07
The Asia-Pacific in-vehicle networking market is poised for substantial growth, with revenue projected to rise from $2,950 Million in 2020 to $6,880 Million by 2035. The growth trajectory is driven by evolving automotive technologies, expanding electric vehicle production, and the surging demand for connectivity features. The compounded momentum between 2025 and 2030 is expected as regulatory and technological enablers converge, empowering both premium and mass-market segments in APAC.
Read More - https://bussinessinsights.com/research-report/asia-pacific-in-vehicle-networking-market
Powertrain and Safety applications collectively command a major share of in-vehicle networking adoption, driven by increasing regulatory norms and the push toward electrification. Infotainment & Communication systems also account for a considerable proportion, aligning with consumer demand for connectivity and personalized experience. Other application domains such as body electronics and chassis modules are projected to gain share steadily as vehicle automation matures.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-in-vehicle-networking-market
Frequently Asked Questions
Who are the key players in Asia-Pacific In-Vehicle Networking Market industry?
The top 5 players in the Asia-Pacific In-Vehicle Networking Market are NXP Semiconductors, Robert Bosch GmbH, Broadcom Inc., Texas Instruments Inc., and Infineon Technologies AG. These companies lead the market by offering advanced networking solutions, such as CAN, LIN, and Ethernet, that enable efficient vehicle communication and improved safety features.
What is the Asia-Pacific In-Vehicle Networking Market growth?
The Asia-Pacific In-Vehicle Networking Market is experiencing rapid growth, driven by increased automotive production and rising demand for connected vehicle technologies. In 2023, companies like NXP Semiconductors reported strong regional revenue, reflecting surging investments in autonomous and electric vehicle platforms across China, Japan, and South Korea.
Which segment accounted for the largest Asia-Pacific In-Vehicle Networking Market share?
The passenger vehicles segment held the largest market share in the Asia-Pacific In-Vehicle Networking Market. This is attributed to the growing adoption of advanced infotainment, driver assistance, and safety features in passenger cars, particularly in emerging economies like China and India, where consumer demand for connected vehicles continues to accelerate.
Thanks & Regards,
Priya
sales@bussinessinsights.com
Asia-Pacific Class D Audio Amplifier Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-07
The Asia-Pacific Class D Audio Amplifier market is projected to expand steadily from a market size of 1,130 Million USD in 2020 to 4,210 Million USD in 2035. This impressive trajectory is supported by continuous investment in R&D, growing consumer base, and rapid technological advancements in amplifier efficiency and integration. Market growth is anticipated to be particularly strong between 2025 and 2035, as both consumer electronics and automotive sectors witness digital transformation and rising demand for high-performance audio solutions. Government support for local manufacturing and innovation in countries like China and India is expected to fuel additional growth in coming years.
Read More - https://bussinessinsights.com/research-report/asia-pacific-class-d-audio-amplifier-market
Consumer electronics represent the largest segment for Class D audio amplifiers in the Asia-Pacific market in 2025, primarily driven by relentless growth in smartphone, wireless earbud, and smart home device sales. Automotive applications hold a significant portion due to rising integration of advanced sound systems, particularly in electric and hybrid vehicle models across China, Japan, and South Korea. Industrial & retail segments, including public announcement systems and professional audio installations, continue to present stable demand. This highlights how diversified application areas are supporting robust market expansion and helping manufacturers achieve economies of scale through multi-vertical products.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-class-d-audio-amplifier-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Class D Audio Amplifier Market industry?
Top players include Texas Instruments, Infineon Technologies, NXP Semiconductors, STMicroelectronics, and ON Semiconductor. These companies lead the market by offering innovative and energy-efficient Class D audio amplifier solutions, strong R&D capabilities, and a broad product portfolio catering to consumer electronics, automotive, and professional audio equipment manufacturers.
What is the Asia-Pacific Class D Audio Amplifier Market growth?
The Asia-Pacific Class D Audio Amplifier Market is witnessing robust growth, driven by increasing demand for consumer electronics and advancements in automotive audio systems. For example, Infineon Technologies reported significant growth in amplifier sales in 2023, accelerated by rising adoption in smartphones, smart TVs, and connected vehicles.
Which segment accounted for the largest Asia-Pacific Class D Audio Amplifier Market share?
Consumer Electronics applications, notably in smartphones, tablets, and smart TVs, accounted for the largest market share in the region. Growing popularity of portable devices with high-quality sound output, along with innovations by companies like Samsung and Sony, are fueling demand for Class D audio amplifiers.
Thanks & Regards,
Priya
sales@bussinessinsights.com
The Asia-Pacific Precision Farming Market has shown consistent growth from 2020 and is expected to accelerate significantly through 2035. In 2025, market revenues are projected at $2,950 million, up from $1,200 million in 2020. This upward trajectory is driven by digital transformation in agri-business, increased adoption of smart farm techniques, and government-backed modernization initiatives. By 2035, revenue is anticipated to exceed $10,900 million, as technology penetration accelerates across key APAC markets.
Read More - https://bussinessinsights.com/research-report/asia-pacific-precision-farming-market
Yield monitoring remains the dominant application in 2025, fueled by demand for real-time crop performance insights. Field mapping is also significant, enabling spatial analysis and enhanced decision-making. Variable rate application, utilizing data-driven tools for precise field input management, is rapidly growing as farmers seek to minimize input costs and environmental impacts. These top applications reflect Asia-Pacific's focus on increasing farm productivity through smart data utilization and environmentally conscious farming practices.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-precision-farming-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Precision Farming Market industry?
Key players include Trimble Inc., Deere & Company, AGCO Corporation, Kubota Corporation, and Topcon Corporation. These companies provide advanced solutions in precision agriculture, such as GPS guidance systems, sensors, autonomous equipment, and farm management software, driving technological adoption and efficiency across the Asia-Pacific agricultural landscape.
What is the Asia-Pacific Precision Farming Market growth?
The Asia-Pacific Precision Farming Market is experiencing robust growth, driven by increasing adoption of smart farming technologies. For example, in 2023, Trimble expanded its offerings in India and China to address rising demand for data-driven agriculture, helping farmers enhance productivity and resource efficiency.
Which segment accounted for the largest Asia-Pacific Precision Farming Market share?
The yield monitoring segment holds the largest market share in the Asia-Pacific Precision Farming Market. Farmers and agribusinesses widely adopt yield monitoring systems to collect real-time data during harvest, enabling better management decisions, increased productivity, and improved crop quality across major agricultural economies like China and Australia.
Thanks & Regards,
Priya
sales@bussinessinsights.com
Executive Summary: Navigating the Pea Starch Market in 2026 and Beyond
The global pea starch market has entered a decisive inflection point. Between 2020 and 2025, the industry expanded from $107.0 million to an estimated $165.0 million in annual revenue, reflecting a compound trajectory that underscores shifting consumer preferences, formulation innovation, and supply chain realignment across multiple verticals. As we look toward the forecast window of 2026 through 2032, the market is projected to reach $288.0 million, sustained by a long-term growth rate of 8.4 percent. These figures are not merely statistical markers; they represent a structural reallocation of ingredient strategies across food and beverage, animal feed, and industrial applications.
OBC+DC/DC Integrated On-board Charger Market
This strategic overview is designed to equip decision-makers with the contextual intelligence required to navigate an increasingly competitive landscape. The purpose of this piece is to preview the analytical architecture of our newly released Pea Starch Market research report while demonstrating the depth of insight available to subscribers. Rather than offering a superficial scan of surface-level trends, the full study dissects the operational, regulatory, and competitive forces that will shape procurement strategies, product development roadmaps, and market entry decisions throughout the remainder of the decade.
UHPLC Packing Materials Market
The following sections outline the macro trajectory, segmentation dynamics, competitive positioning, and regulatory environment that define the current market moment. Where granular breakdowns, regional weightings, and proprietary scenario models are required for precise planning, this preview intentionally withholds the exact figures and segment allocations. Those data points are embedded within the full report and structured to support direct integration into corporate forecasting workflows.
Wafer Grade Micro Lens Array (MLA) Market
Market Trajectory and Growth Architecture
The revenue arc from 2020 to 2025 demonstrates consistent acceleration, with year-over-year expansion reflecting both volume growth and value migration toward higher-functioning starch formats. The 2025 baseline of $165.0 million sets the stage for a forecast period in which incremental gains are expected to compound at a measured but persistent pace. By 2026, the market is anticipated to reach $180.06 million, and the climb continues through 2027 at $199.09 million, 2028 at $203.01 million, and 2029 at $226.94 million. The latter half of the forecast horizon shows further expansion toward $244.0 million in 2030, $272.54 million in 2031, and $288.0 million in 2032.
Several structural drivers underpin this trajectory. First, the clean-label movement continues to reshape ingredient specifications across categories where native starches and modified starches must satisfy both functional performance and consumer transparency expectations. Second, the expansion of plant-based and gluten-free product lines has elevated pea starch from a niche texturizer to a mainstream formulation backbone. Third, industrial and animal feed applications are incorporating pea-derived inputs at increasing rates as processors seek alternative carbohydrate sources that align with sustainability targets and supply diversification strategies.
Our full report decomposes this growth into forward-looking scenarios that account for pricing volatility, raw material availability, processing yield improvements, and regional demand shifts. Rather than presenting a single linearized forecast, the analysis provides a range of outcomes tied to plausible macroeconomic and supply-side conditions, enabling procurement and strategy teams to model exposure and opportunity with greater precision.
Segmentation Dynamics: Type, Application, and Regional Balance
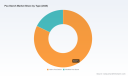
The market is organized around two principal product categories: native pea starch and modified pea starch. Native formats continue to command the larger revenue share, reflecting their broad compatibility with clean-label positioning, straightforward processing requirements, and established demand in food and beverage formulations. Modified variants, while smaller in absolute terms, are gaining traction in applications that require enhanced stability, textural control, or thermal solubility without sacrificing label simplicity. The interplay between these two categories is a central theme of the report, particularly as manufacturersExperiment with hybrid formulations and process innovations that blur the traditional boundary between native and modified performance profiles.
In terms of end-use, food and beverage applications represent the largest demand pool, followed by animal feed and industrial applications. The food and beverage segment benefits from continuous reformulation activity, especially in baked goods, confectionery, dairy alternatives, and plant-based meat analogues, where pea starch contributes to texture, moisture retention, and clean-label ingredient decks. Animal feed applications leverage pea starch as a functional carbohydrate source within optimized nutrition formulations, while industrial uses span adhesives, coatings, and specialty processing aids that require predictable viscosity and binding characteristics.
Regional demand is distributed across multiple geographies, with mature markets in North America and Europe maintaining strong consumption bases, while Asia Pacific, Latin America, and the Middle East and Africa contribute increasingly important growth nodes. The full study maps these regional profiles without reducing them to static share percentages, instead focusing on the drivers that differentiate demand intensity, procurement patterns, and distribution infrastructure across each territory. This approach allows strategists to identify where near-term volume opportunities are most concentrated and where longer-term capacity investments may yield competitive advantage.
To preserve the analytical value of the segmentation exercise, the report avoids publishing exhaustive sub-segment figures in public summaries. Instead, it provides structured frameworks that show how type, application, and regional variables interact, along with the conditions under which share shifts are most likely to occur. Subscribers gain access to the complete allocation tables, sensitivity analyses, and scenario overlays needed to translate these dynamics into operational plans.
Competitive Landscape: Eight Profiles and the Shape of Rivalry
The pea starch market is characterized by a moderately concentrated competitive structure. The three-firm concentration ratio stands at 42.0 percent, while the five-firm concentration ratio reaches 52.0 percent. This configuration suggests a market in which a core group of established producers commands a substantial portion of revenue, yet sufficient fragmentation remains to allow specialist players, regional suppliers, and innovation-driven entrants to compete on formulation quality, sustainability credentials, and customer-specific service models.
Several companies illustrate the strategic diversity shaping the market. Roquette Frères, headquartered in Lestrem, France, produces both native and modified pea starch, including the AMYSTA™ L 123 label-friendly thermally soluble pea starch and organic pea starch for food, nutraceutical, and confectionery applications. Ingredion Incorporated, based in Westchester, Illinois, USA, offers PURITY® P native pea starch and HOMECRAFT Pulse PG 100 for clean-label texturizing in baked goods, gluten-free products, and plant-based applications. Emsland Group, located in Lingen, Germany, manufactures native and modified pea starch from yellow peas for food, pet nutrition, and industrial uses with clean-label profiles.
Cosucra Groupe Warcoing, based in Warcoing, Belgium, produces NASTAR™ native pea starch and pre-gel instant pea starch for food ingredients with a sustainability focus. The Scoular Company, headquartered in Omaha, Nebraska, USA, supplies premium pea starch from yellow peas for food manufacturing, pet food, and plant-based formulations with gluten-free and clean-label properties. Vestkorn Milling AS, in Vestfold, Norway, is a leading European producer of pea starch and concentrates from dry and wet processing for food and industrial applications. Nutri-Pea Limited, in Portage la Prairie, Manitoba, Canada, is a North American manufacturer of pea starch and functional ingredients from Canadian yellow peas with local sourcing. PURIS, based in Dawson, Minnesota, USA, produces upcycled pea starch in North America for alternative meats, supplements, and clean-label food applications.
These profiles point to a competitive environment where differentiation is increasingly tied to processing technology, label compatibility, regional sourcing advantages, and the ability to serve adjacent verticals such as pet nutrition and nutraceuticals. The report evaluates each company’s product architecture, geographic footprint, and strategic posture, then situates them within a broader rivalry map that highlights where consolidation pressure, capacity expansion, or technology-led disruption is most probable. Rather than offering a simple ranking, the analysis clarifies the competitive levers available to each player and the conditions under which market share may migrate.
Recent Developments and the Innovation Signal
Product innovation remains a powerful indicator of where the market is heading. In October 2025, Roquette Frères introduced AMYSTA™ L 123, described as the first label-friendly thermally soluble pea starch using an enzyme- and chemical-free process for clean-label beverages, soups, and sauces. This launch is significant not only for the product itself but for what it signals about the industry’s direction: a growing emphasis on thermal solubility, label simplicity, and process cleanliness in categories where formulation transparency is a decisive purchasing criterion.
The introduction of such a solution expands the functional envelope of pea starch in liquid and semi-liquid applications, potentially accelerating adoption in beverage and sauce formulations that previously relied on more complex starch modification or non-pea inputs. It also illustrates how leading suppliers are investing in process engineering to reconcile performance requirements with clean-label expectations, a tension that continues to shape product development across the category.
The full report examines this launch within a wider set of recent developments, connecting product-level moves to broader strategic implications for formulation teams, procurement managers, and competitors evaluating whether to follow with comparable offerings. By mapping the innovation pipeline against demand patterns and regulatory context, the study helps organizations anticipate where functional gaps may close, where substitution risk may rise, and where first-mover advantages can be sustained.
Regulatory Tailwinds and the Efficiency Imperative
Regulatory activity is adding a new layer of strategic relevance to pea starch processing and industrialization. Commission Implementing Regulation (EU) 2026/916 of 27 April 2026 amends Implementing Regulation (EU) 2025/2144 to support research and industrialization for improving pea starch separation efficiency using indigenous lactic acid. This development underscores a policy environment that encourages process optimization, resource efficiency, and technological upgrading within the value chain.
For manufacturers and downstream users, the practical implication is that separation efficiency gains may translate into cost structure improvements, yield stability, and reduced processing complexity over time. It also suggests that regulatory frameworks are increasingly aligned with industrial goals that favor higher-utilization feedstocks and cleaner processing routes. In a market where margins can be sensitive to raw material availability and processing economics, such policy-supported efficiency improvements can influence competitive positioning and capacity planning.
The report integrates this regulatory context into a broader discussion of market dynamics, linking policy signals to operational variables such as capital investment timing, technology adoption curves, and regional competitiveness. By tracing how regulation interacts with innovation and supply-side economics, the study provides a more complete picture of the forces that will shape industry profitability and structural change through the forecast period.
What the Full Report Delivers: Actionable Intelligence for 2026 Decision-Making
The public preview above is intended to demonstrate the analytical rigor and strategic relevance of the full Pea Starch Market research study. Subscribers receive a comprehensive, decision-oriented package that moves beyond high-level description into the operational specifics required for planning, sourcing, and competitive positioning.
The report includes detailed segmentation analysis that breaks down type, application, and regional demand patterns with the granularity needed to support product planning and market-entry evaluation. It provides historical trend reconstruction from 2020 through 2025 alongside the 2026–2032 forecast, enabling users to benchmark current performance against projected trajectories and identify inflection points. Competitive profiling extends beyond company summaries to include strategic posture assessment, product architecture mapping, and scenario-based share dynamics.
In addition, the study incorporates market concentration metrics and interprets their implications for pricing behavior, capacity utilization, and partnership strategy. It examines demand-side drivers across food and beverage, animal feed, and industrial applications, with attention to formulation trends, clean-label requirements, and cross-category substitution risk. Regulatory developments are analyzed for their potential impact on processing efficiency, supply economics, and regional competitiveness.
Strategically, the report is designed to support multiple decision contexts. For procurement teams, it offers a structured basis for evaluating supplier options, anticipating cost and availability shifts, and aligning sourcing strategies with formulation roadmaps. For product development organizations, it clarifies where functional demand is expanding and which starch formats are best positioned to meet emerging label and performance requirements. For corporate strategists and investors, it maps concentration dynamics, innovation signals, and regulatory tailwinds to identify where value creation is most likely to accrue over the forecast horizon.
Crucially, the full study reserves its most decision-sensitive data for subscribers, including the complete segmentation allocations, regional detail, and scenario overlays that cannot be responsibly summarized without losing analytical precision. This design ensures that the report functions as a practical planning tool rather than a general market overview, giving organizations the specific intelligence needed to act with confidence in 2026 and beyond.
Strategic Imperatives for the Next Planning Cycle
As the market moves from $165.0 million in 2025 toward $288.0 million by 2032, the strategic question is not whether pea starch will continue to gain relevance, but how companies should position themselves to capture value amid intensifying competition, evolving formulation standards, and regulatory-supported efficiency gains. Organizations that treat pea starch as a static commodity input risk underpricing its strategic importance in clean-label, plant-based, and diversified supply-chain strategies. Organizations that invest in formulation alignment, supplier partnership quality, and process-aware procurement are better positioned to convert market growth into durable advantage.
The competitive map suggests that differentiation will increasingly depend on the ability to deliver label-friendly functionality, thermal solubility where needed, and reliable supply from transparent sourcing bases. Concentration metrics indicate that while a core group of producers holds substantial market weight, the presence of multiple capable players creates both partnership opportunities and substitution risks. Recent innovation signals and regulatory developments point to a market in which processing efficiency and clean-label compatibility are moving from desirable attributes to essential requirements.
For decision-makers preparing for the 2026 planning cycle, the immediate priority is to ground strategy in a clear view of where demand is expanding, which product formats are gaining traction, and how competitive and regulatory forces are likely to reshape supply economics. The full Pea Starch Market report provides that view in a structured, forecast-linked format designed for direct use in commercial planning, procurement strategy, and product development decision-making.
This preview has outlined the market’s macro trajectory, segmentation logic, competitive structure, innovation direction, and regulatory context to demonstrate the depth of analysis available in the complete study. The specific figures, segment allocations, and scenario models that enable precise planning are reserved for the full report, where they are presented in a form that supports actionable interpretation rather than passive reading. Organizations that engage with the full dataset will be better equipped to anticipate shifts, allocate resources, and build formulations and sourcing strategies that align with the market’s next phase of growth.
For detailed analysis of this topic, please visit the official page: Pea Starch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Asia-Pacific Acoustic Wave Sensor Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-07
The Asia-Pacific acoustic wave sensor market was valued at USD 755 Million in 2020 and has exhibited robust growth, reaching USD 1,430 Million by 2025. Consistent innovation and adoption in automotive, healthcare, and industrial automation sectors have powered this double-digit CAGR. The revenue trend remains upward through 2035, with forecasts suggesting USD 5,020 Million as developers leverage advancements in MEMS technology and expand into new IoT and smart city use cases.
Read More - https://bussinessinsights.com/research-report/asia-pacific-acoustic-wave-sensor-market
The automotive sector represents the largest share in application, propelled by regulatory mandates for TPMS and advanced driver assistance systems. Healthcare follows closely due to expanding uses in biosensing and medical diagnostics. Consumer electronics ranks third as wearable devices and IoT applications proliferate. Industrial automation and environmental monitoring are experiencing robust year-on-year growth, driven by Industry 4.0 investments and smart factory initiatives, while military & defense continues to sustain steady demand for high-reliability, passive sensor technologies.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-acoustic-wave-sensor-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Acoustic Wave Sensor Market industry?
The top 5 players in the Asia-Pacific Acoustic Wave Sensor market are Siemens AG, Murata Manufacturing Co., Ltd., Honeywell International Inc., Kyocera Corporation, and Teledyne Technologies. These companies are known for their innovation and broad product portfolios, spanning applications in automotive, industrial, and healthcare sectors.
What is the Asia-Pacific Acoustic Wave Sensor Market growth?
The Asia-Pacific Acoustic Wave Sensor Market is witnessing robust growth, driven by increasing adoption in consumer electronics and automotive sectors. For instance, Murata Manufacturing announced expanded investments in acoustic sensor production in 2023 to meet rising demand in connectivity and safety applications.
Which segment accounted for the largest Asia-Pacific Acoustic Wave Sensor Market share?
The automotive application segment accounted for the largest market share in the Asia-Pacific Acoustic Wave Sensor Market. Rapid advances in vehicle safety, infotainment, and emission control systems have drastically increased the integration of acoustic wave sensors by leading automotive manufacturers in the region.
Thanks & Regards,
Priya
sales@bussinessinsights.com
Asia-Pacific Track Geometry Measurement System Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-07
The Asia-Pacific TGMS market displays a strong upward revenue trajectory, reflecting ongoing rail infrastructure development and technological convergence. Market size reached $1,320 Million in 2025, propelled by government investments and private sector participation. By 2035, revenues are projected to grow at a CAGR of 9.8%, surpassing $3,380 Million. The rise is attributed to increased adoption of digital rail solutions, new metro and high-speed rail projects, and the proliferation of no-contact systems. Consistent expansion in Southeast Asian and Pacific nations further bolsters the revenue outlook, making the region a global growth hotspot.
Read More - https://bussinessinsights.com/research-report/asia-pacific-track-geometry-measurement-system-market
Railway track applications account for the largest market share in 2025, as national railways and metro operators invest in regular monitoring to improve safety and performance. Metro track applications follow, fueled by rapid urbanization and new metro projects in major APAC cities. High-speed rail track measurement is the fastest-growing segment as countries like China and Japan expand high-speed networks. Heavy haul, light rail, and others represent niche yet essential use cases, particularly in resource-centric economies. TGMS deployment is now considered a core operational requirement for most major rail infrastructure programs.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-track-geometry-measurement-system-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Track Geometry Measurement System Market industry?
The top five players in the Asia-Pacific Track Geometry Measurement System Market include Amberg Technologies, Trimble Inc., Fugro, Ensco, and MERMEC Group. These companies offer advanced rail track inspection solutions, leveraging innovative technologies and comprehensive service portfolios to serve rail operators, infrastructure owners, and government agencies across the Asia-Pacific region.
What is the Asia-Pacific Track Geometry Measurement System Market growth?
The Asia-Pacific Track Geometry Measurement System Market has experienced significant growth, driven by rapid rail infrastructure expansion and modernization projects. For instance, Trimble Inc. witnessed increased adoption of its rail solutions in 2023, aligning with government investments in smart transportation systems and stringent track safety requirements across countries like China, India, and Japan.
Which segment accounted for the largest Asia-Pacific Track Geometry Measurement System Market share?
The largest market share is held by the conventional railway applications segment. This dominance is due to extensive rail network upgrades and frequent inspections needed for passenger and freight routes. The demand for safety, operational efficiency, and reduced maintenance costs has led operators to adopt sophisticated geometry measurement solutions in conventional railways.
Thanks & Regards,
Priya
sales@bussinessinsights.com
The Asia-Pacific eye tracking market is forecasted to demonstrate strong growth from 2020 to 2035, with market revenue rising from USD 305 Million in 2020 to an estimated USD 560 Million in 2025 and reaching USD 1,020 Million by 2035. The majority of the expansion is attributed to the widespread integration in automotive safety systems, healthcare diagnostics, and the proliferation of AR/VR consumer applications. The compound annual growth rate (CAGR) is expected to be 17.2% over the forecast period. Investments in AI-driven analytics, portable platforms, and regulatory support for accessibility are key revenue drivers, solidifying Asia-Pacific as a growth engine in the global eye tracking ecosystem.
Read More - https://bussinessinsights.com/research-report/asia-pacific-eye-tracking-market
Research applications lead the Asia-Pacific eye tracking market in 2025, accounting for 36% of the total share, propelled by demand in academic, neurological, and consumer behavior studies. Human-computer interaction (HCI) captures 28%, closely followed by assistive technology at 18%. Automotive safety and driver monitoring contribute 10%, while consumer devices hold an 8% share. The sector's dominance in research is a testament to the technology's value in understanding cognitive processing and behavior. Meanwhile, HCI and assistive technologies benefit from rapid tech adoption in education, enterprise, and healthcare. As awareness grows and deployment costs drop, the spread of eye tracking into UX, AR/VR, and daily-use devices is expected to further transform user experience and inclusivity across APAC.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-eye-tracking-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Eye Tracking Market industry?
The top 5 players in the Asia-Pacific Eye Tracking Market include Tobii AB, SR Research, Seeing Machines, EyeTech Digital Systems, and Smart Eye AB. These companies are recognized for their advanced technology, comprehensive product portfolios, and significant regional presence, contributing to the widespread adoption of eye tracking solutions in various sectors.
What is the Asia-Pacific Eye Tracking Market growth?
The Asia-Pacific Eye Tracking Market has shown robust growth, driven by increasing adoption across healthcare, automotive, and research sectors. For instance, in 2023, Smart Eye AB reported a surge in demand for its driver monitoring systems, highlighting the region’s accelerated technological advancements and investment in human-computer interaction technologies.
Which segment accounted for the largest Asia-Pacific Eye Tracking Market share?
The research and healthcare application segment holds the largest share in the Asia-Pacific Eye Tracking Market. Eye tracking is extensively used for psychological studies, neuromarketing, and medical diagnostics, as demonstrated by the growing partnerships between academic institutions and solution providers such as Tobii AB.
Thanks & Regards,
Priya
sales@bussinessinsights.com
PW Consulting: Instant Adhesive Market to Hit $344.8M by 2032, 6.58% CAGR Amid 2025's $215M Growth
By PW Consulting, 2026-09-07
Projecting the Instant Adhesive Market: A Strategic Blueprint for 2026 and Beyond
Introduction: The Adhesive Imperative in Modern Manufacturing
In the contemporary industrial landscape, bonding technologies have evolved from simple assembly aids to critical engineering components that dictate product performance, durability, and design flexibility. The instant adhesive market stands at the forefront of this transformation, serving as an essential enabler across sectors ranging from high-precision electronics to heavy-duty transportation manufacturing. As organizations navigate an increasingly complex global environment characterized by supply chain recalibrations, stringent environmental regulations, and shifting consumer expectations, the ability to make informed, data-driven decisions regarding adhesive procurement and investment has never been more vital.
Escape Door Control Unit Market
This comprehensive market research study examines the historical trajectory and future projections of the instant adhesive industry, offering a rigorous analytical framework designed to support executive decision-making through 2032. By synthesizing macroeconomic trends, competitive intelligence, raw material dynamics, and regulatory pressures, this report provides stakeholders with the actionable intelligence needed to position their organizations advantageously in a market projected to experience sustained growth.
Gasket Structure Keyboard Market
Market Trajectory: Navigating Growth Amid Volatility
The instant adhesive market has demonstrated remarkable resilience and expansion over the past half-decade, establishing a robust foundation for continued momentum. Historical data from 2020 through 2025 reveals a market that has not only recovered from disruptions but has accelerated its growth trajectory, reaching approximately 215.0 Million USD in the base year of 2025. This represents a significant evolution from the 163.15 Million USD recorded in 2020, underscoring the compound annual growth rate that has characterized the industry's maturation.
Worldwide Switch Expansion Joints (SEJ) Market
Looking ahead, the forecast period spanning 2026 through 2032 projects a compound annual growth rate of 6.58 percent, a figure that reflects both steady demand expansion and the industry's capacity to adapt to emerging technological and regulatory requirements. By 2026, market revenue is anticipated to reach 230.33 Million USD, climbing progressively to 344.8 Million USD by the close of the forecast horizon in 2032. This upward trajectory signals more than mere volume growth; it indicates a maturing market where value creation is increasingly tied to product innovation, application-specific formulations, and strategic geographic expansion.
Several structural factors underpin this growth outlook. The ongoing transition toward lightweight materials in transportation and automotive manufacturing continues to drive demand for high-performance bonding solutions that can replace traditional mechanical fasteners. Simultaneously, the electronics industry's relentless miniaturization and the medical sector's push for biocompatible, rapid-curing adhesion technologies create sustained pull factors across multiple end-use verticals. Companies that recognize these cross-industry demand signals and align their product development pipelines accordingly will be best positioned to capture disproportionate market share in the coming years.
Structural Composition: Demand Drivers Across Key Verticals
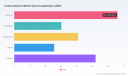
Understanding where instant adhesive demand concentrates is essential for strategic resource allocation and market entry timing. The application landscape reveals a diverse but clearly hierarchical set of consumption patterns that reflect broader industrial trends. Electronics represents a dominant consumption segment, driven by the sector's need for precise, high-speed bonding in component assembly, consumer devices, and increasingly sophisticated wearable technologies. The woodworking sector, while historically associated with slower-curing formulations, has embraced instant adhesive solutions for applications requiring rapid turnaround and strong initial tack in furniture manufacturing and cabinetry production.
Transportation applications continue to expand as original equipment manufacturers seek weight-reduction strategies and design flexibility that instant adhesives facilitate. This includes both traditional automotive manufacturing and the rapidly growing electric vehicle segment, where battery assembly and lightweight structural components demand specialized bonding chemistries. The medical sector represents another critical growth vector, with demand fueled by surgical device assembly, wound closure applications, and the development of increasingly sophisticated diagnostic equipment. Industrial applications broadly encompass manufacturing assembly, maintenance repair operations, and specialty bonding tasks that require rapid setting times without compromising ultimate bond strength.
From a product type perspective, the market is anchored by two principal categories. Cyanoacrylate-based instant adhesives command the largest share of the product landscape, reflecting their widespread adoption across consumer, industrial, and medical end uses due to their rapid curing characteristics and strong bonding performance on a variety of substrates. Epoxy-based instant adhesive formulations constitute a complementary segment, particularly valued in applications requiring higher temperature resistance, greater structural integrity, or specialized chemical resistance profiles. The interplay between these product categories creates a dynamic where formulators must continuously innovate to meet the diverging requirements of performance, safety, and cost-efficiency.
Geographic Distribution and Regional Dynamics
The geographic footprint of instant adhesive consumption reflects both established industrial bases and emerging growth corridors. North America represents a substantial revenue contributor, supported by mature manufacturing sectors, a strong electronics industry presence, and a healthcare market that demands advanced bonding solutions. Europe maintains a parallel position of significance, driven by its robust automotive and industrial manufacturing ecosystems, alongside increasing regulatory emphasis on environmental compliance that shapes product formulation strategies across the region.
Asia Pacific emerges as a particularly notable region in terms of market scale, reflecting the concentration of electronics manufacturing, rapid industrialization, and growing consumer markets across multiple economies. The region's expansive production capacity and increasing domestic consumption create a complex competitive environment where both multinational formulators and regional players vie for share. Latin America and the Middle East and Africa represent additional geographic dimensions, with growth potential tied to infrastructure development, industrial modernization initiatives, and gradually expanding manufacturing bases in select economies.
Regional dynamics are further complicated by divergent regulatory environments, varying raw material access, and differing labor cost structures that influence both product pricing and formulation priorities. Strategic market entry or expansion decisions require nuanced understanding of these regional characteristics rather than one-size-fits-all approaches. Companies that develop region-specific product portfolios and distribution strategies will find themselves better equipped to navigate the heterogeneous demands of global instant adhesive markets.
Competitive Landscape: Architects of Market Evolution
The instant adhesive market operates within a moderately concentrated competitive structure. Analysis of the competitive landscape reveals a market environment where the top three players command approximately 19.4 percent of total revenue, while the top five collectively account for roughly 22.5 percent. This concentration profile suggests a market that accommodates both established multinational corporations with extensive research and development capabilities and smaller, specialized formulators that compete through niche application expertise, regional distribution strength, or proprietary formulation technologies.
Among the prominent organizations shaping this landscape, Henkel AG and Co KGaA stands as a defining presence through its Loctite-branded instant adhesive and cyanoacrylate portfolio, which serves industrial, medical, and automotive applications with a reputation for performance reliability. The company's global distribution network and sustained investment in application-specific product development reinforce its position as a benchmark competitor. 3M Company maintains a parallel stature through its Scotch-Weld and Super-Fast instant adhesive lines, catering to electronics, industrial bonding, and medical use cases with a portfolio that emphasizes both performance and accessibility across diverse customer segments.
Huntsman Corporation contributes to the competitive ecosystem by supplying instant adhesive resins and solutions tailored for general industrial and construction bonding applications, leveraging its broader materials science expertise to support large-scale manufacturing customers. H.B. Fuller Company markets a diversified portfolio of instant adhesives designed for quick-bonding industrial and specialty applications, with recent strategic moves underscoring its commitment to capacity expansion and regional market servicing. Bostik SA, operating under the Arkema Group umbrella, develops and supplies instant engineering adhesives including the Born2Bond series, positioning its offerings for demanding environments that require robust performance under stress or temperature variation.
Toagosei Co Ltd brings specialized expertise in cyanoacrylate instant adhesives through its Aron Alpha brand, targeting industrial manufacturing markets with formulations optimized for production-line efficiency. Pidilite Industries Limited extends its reach across consumer, industrial, and craft bonding segments through the Fevikwik instant adhesive line, demonstrating the brand strength that can emerge from effective product positioning in both professional and retail channels. Permabond LLC, with its North American operations anchored from a UK base, specializes in high-performance instant adhesives designed for engineering and industrial use cases where bond reliability is paramount. Dymax Corporation rounds out the competitive array with its focus on UV and light-cure instant adhesives, particularly serving electronics and medical assembly applications where curing precision and speed are critical operational requirements.
Recent corporate developments highlight the strategic dynamism within this competitive field. In May 2026, H.B. Fuller Company executed significant capacity expansion initiatives, opening a new state-of-the-art facility in Cairo, Egypt, that adds manufacturing capacity for pressure-sensitive and non-pressure-sensitive adhesives serving over thirty market segments, including industrial adhesives. Concurrently, the company expanded its site in the United Arab Emirates to enhance manufacturing capabilities for waterproofing, woodworking, and industrial adhesives. These investments signal a deliberate strategy to strengthen regional manufacturing presence, reduce supply chain vulnerabilities, and position the company to capture growth in emerging markets with localized production capabilities.
The competitive dynamics extend beyond corporate strategy to encompass the broader forces that shape market access and product differentiation. Formulators must balance the imperative to innovate with the practical constraints of cost management and regulatory compliance, creating an environment where competitive advantage is increasingly derived from integrated solutions rather than commodity product offerings alone.
Raw Material Dynamics and Cost Structure Considerations
The economics of instant adhesive production are fundamentally shaped by raw material cost structures and supply chain volatility. Industry data indicates that raw material prices account for approximately 86 percent of the final instant adhesive product price, a proportion that makes feedstock cost management a central concern for profitability and pricing strategy. Monomer cost swings, in particular, exert significant influence on pack pricing, requiring manufacturers to maintain agile procurement strategies and, where feasible, hedging mechanisms to mitigate exposure to commodity price fluctuations.
During March 2026, stable but firm feedstock costs, particularly for methanol and acetone, contributed to steady firm pricing of cyanoacrylate in the USA market. This pricing environment reflects the interplay between raw material availability, production capacity utilization, and demand strength, creating conditions where margin preservation depends on operational efficiency and value-added product positioning rather than simple volume expansion. Companies that have invested in vertical integration, long-term supplier agreements, or alternative feedstock sourcing strategies are better insulated against the periodic cost pressures that characterize this segment of the materials market.
The sensitivity of final product pricing to raw material inputs also shapes competitive dynamics in meaningful ways. Larger, well-capitalized manufacturers may possess advantages in procurement scale and supply chain diversification, while smaller players may need to compete through service differentiation, specialized technical support, or regional market focus. Understanding these cost structure dynamics is essential for competitive analysis, pricing strategy development, and investment planning across the instant adhesive value chain.
Regulatory Pressures and Formulation Evolution
The instant adhesive industry operates within an increasingly complex regulatory environment that influences product formulation, market access, and compliance cost structures across multiple geographies. In the United States, Canada, and Australia, strict volatile organic compound regulations and occupational-health requirements compel formulators to develop low-VOC and low-odor instant adhesives, raising compliance costs while simultaneously creating opportunities for companies that can deliver compliant products without sacrificing performance. These regulatory pressures are not static; they evolve as governments and regulatory bodies refine their approaches to chemical safety, emissions control, and workplace health protection.
Across global markets, formulators are shifting toward low-VOC and REACH-compliant instant adhesives to meet tightening environmental standards. This shift represents more than a compliance exercise; it reflects a broader industry movement toward sustainable chemistry and environmentally responsible manufacturing practices that resonate with downstream customers and end consumers alike. Companies that proactively invest in compliant formulation development and maintain robust regulatory monitoring capabilities will find themselves with competitive advantages in markets where environmental compliance is increasingly a prerequisite for supply chain participation.
The medical sector introduces an additional regulatory dimension. New medical-grade cyanoacrylate formulations are being developed without CMR ingredients to comply with safety requirements for heat-resistant medical device applications. This formulation evolution addresses the stringent biocompatibility and safety standards that govern medical device manufacturing, creating specialized product opportunities for formulators with the technical expertise and regulatory documentation capabilities to serve this demanding segment. The intersection of regulatory compliance and product performance in medical applications underscores the value of specialized knowledge and the premium that sophisticated customers place on reliably compliant solutions.
These regulatory trends have strategic implications beyond product development. They influence market entry timing, geographic expansion feasibility, and the competitive positioning of companies with varying levels of regulatory infrastructure and expertise. Organizations that treat regulatory compliance as a strategic capability rather than a peripheral concern will be better equipped to navigate the evolving landscape and capitalize on the opportunities created by regulatory-driven product differentiation.
What This Report Delivers: Analytical Depth and Strategic Utility
This market research study is structured to provide executives, strategic planners, and industry analysts with a comprehensive yet actionable understanding of the instant adhesive market's current state and future trajectory. The report integrates macroeconomic market sizing and growth projections with detailed segmentation analysis, competitive intelligence, and an examination of the regulatory and raw material dynamics that shape market conditions. By situating quantitative data within a qualitative framework of industry forces, the study enables readers to move beyond surface-level market observations toward a nuanced grasp of the strategic factors that will drive performance over the forecast period.
The report's segmentation analysis provides visibility into how revenue distributes across product types, application verticals, and geographic regions, enabling readers to identify where demand concentration creates opportunities and where fragmentation requires targeted strategies. The competitive landscape assessment goes beyond company profiles to examine strategic positioning, recent corporate developments, and the structural characteristics of market concentration that influence competitive behavior and market access. The inclusion of raw material dynamics and regulatory trend analysis ensures that readers understand the cost and compliance environments that underpin product economics and market entry feasibility.
Importantly, this report is designed to support decision-making rather than merely describe market conditions. The analytical framework presented enables stakeholders to assess growth opportunities, evaluate competitive threats, plan capacity investments, and develop product strategies aligned with market realities. Readers seeking a comprehensive understanding of the instant adhesive market's opportunities and challenges will find the full report's detailed data sets, segmentation breakdowns, company profiles, and forward-looking analysis essential to formulating informed strategic responses.
Positioning for 2026 and the Decade Ahead
The instant adhesive market enters the 2026 to 2032 forecast period with a foundation of established growth, evolving competitive dynamics, and a regulatory and cost environment that demands strategic agility. The projected compound annual growth rate of 6.58 percent reflects sustained demand across multiple industrial sectors, but realizing the benefits of this growth requires more than passive market participation. Organizations must actively monitor raw material cost trajectories, adapt product portfolios to meet regulatory and performance requirements, and position themselves within the competitive landscape in ways that leverage their specific capabilities and market access advantages.
The companies that thrive in this environment will be those that treat market intelligence as a strategic asset, integrating deep understanding of segmentation trends, regional dynamics, raw material economics, and regulatory developments into coherent decision-making frameworks. Whether evaluating market entry opportunities, assessing competitive threats, planning capacity investments, or developing product innovation pipelines, access to comprehensive and timely market intelligence proves indispensable. This report is designed to provide exactly that foundation, offering the analytical rigor and strategic perspective needed to navigate the instant adhesive market with confidence through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Instant Adhesive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Golf GPS Market Valued at USD 215M in 2025, Projected to Grow at 6.98% CAGR Through 2032
By PW Consulting, 2026-09-07
The 2026 Golf GPS Market: Strategic Intelligence for Corporate Decision-Making
The global golf GPS and rangefinder sector stands at a inflection point. As course layouts become increasingly digitized, consumer expectations shift toward real-time analytics, and regulatory frameworks tighten around device certification, enterprises operating in this space must navigate a landscape defined by both opportunity and operational complexity. Our latest comprehensive market research on the Golf GPS Market delivers the analytical rigor required to transform uncertainty into actionable strategy for 2026 and beyond.
Shaving Pen Market
This report is not merely a retrospective on past sales figures or a generic projection of industry growth. It is a decision-grade intelligence asset designed for executive teams, product strategists, supply chain planners, and market entry analysts who require a clear line of sight into demand trajectories, competitive positioning, and structural market shifts. By synthesizing historical performance patterns, forward-looking demand signals, and granular product-category dynamics, the study constructs a multidimensional view of where value will be created, consolidated, or disrupted over the coming forecast horizon.
Online File-Sharing Platforms Market
Macro Trajectory and Structural Market Signals
Over the assessment window from 2020 through 2025, the global Golf GPS Market demonstrated consistent expansion, with revenue scales maturing across successive annual cycles. The trajectory reflects a market that has moved past early adoption volatility and entered a phase of stabilized growth driven by broader participation in golf, technological refinement in navigation hardware, and increasing integration of performance analytics into consumer devices. Looking ahead to the 2026-2032 forecast period, the research models a compound annual growth rate of 6.98%, anchored in baseline valuations established at the close of the historical review window. Revenue projections for the opening forecast year indicate continued upward momentum, with subsequent annual milestones reflecting an accelerating expansion curve as hardware ecosystems mature and software-enabled value propositions gain traction across diverse user segments.
Worldwide Proxy Server Reporting Software Market
The forecast architecture within the study isolates key inflection variables that will shape mid-decade performance. These include shifts in hardware form-factor preferences, the monetization pathways of companion applications, course-level data licensing models, and the pacing of professional versus recreational adoption cycles. By mapping these variables against regional demand intensity and competitive supply dynamics, the report enables stakeholders to anticipate revenue concentration patterns, evaluate the timing of category saturation, and calibrate investment horizons accordingly.
Importantly, the research treats market size not as a static endpoint but as a dynamic function of ecosystem readiness. High consumer spending environments have historically supported sustained expansion in golf technology categories, and the study isolates the demand-side conditions that will determine whether growth remains linear or accelerates through cross-category bundling, subscription-enabled analytics, and course-operator partnerships. The resulting analytical framework equips decision-makers with scenario-ready inputs rather than rigid single-point predictions.
Operational and Regulatory Dynamics Shaping the Competitive Field
The operating environment for golf GPS manufacturers and distributors has grown increasingly multifaceted. On the demand side, durable consumer spending capacity has underpinned category resilience through recent assessment years, allowing manufacturers to sustain launch cadences, expand accessory ecosystems, and invest in elevated data-capture capabilities without sacrificing margin stability. However, the supply and compliance pathway is undergoing structural adjustment. Recent regulatory developments require heightened attention from importers, assemblers, and channel partners. Beginning mid-2026, consumer product imports, including golf GPS devices, must electronically file certificates of compliance with U.S. Customs and Border Protection. This procedural shift introduces new administrative obligations that will affect lead times, customs clearance workflows, and cost structures for companies with cross-border supply chains.
Simultaneously, the regulatory footprint of established manufacturers continues to expand. Public registration data indicates that more than 1,200 GPS device models from a leading hardware manufacturer have been recorded for U.S. compliance, including specialized golf GPS configurations. This concentration of registered intellectual property and certified product variants underscores a broader industry reality: scale players are not only competing on feature sets and brand equity but also on the institutional capacity to navigate certification pipelines at volume. For smaller entrants and regional distributors, understanding compliance architecture is increasingly a strategic prerequisite rather than a back-office administrative task.
These dynamics interact with product strategy in meaningful ways. Manufacturers that integrate compliance readiness into early-stage design, localization, and channel planning will gain speed advantages in market entry and product refresh cycles. Conversely, organizations that treat regulatory filing as an afterthought may encounter friction in inventory turnover, regional rollout sequencing, and partnership negotiations with course operators who increasingly demand certified, auditable equipment for course management applications.
Research Architecture and Decision-Ready Content
The study is constructed to translate raw market intelligence into operational clarity. Readers will encounter a layered analytical structure that moves from overarching demand modeling to category-level differentiation, from regional intensity mapping to firm-level competitive positioning. Each section is designed to answer a specific strategic question that executives face when allocating capital, prioritizing product roadmaps, or evaluating partnership and distribution opportunities.
The report delivers detailed segmentation analysis across device categories, usage contexts, and geographic demand zones. Rather than presenting abstract totals, the research isolates the structural drivers behind each segment, including feature preferences, price-point elasticity, adoption barriers, and the role of accompanying software or analytics services. This approach allows readers to identify which sub-categories are experiencing incremental maturation, which are being reshaped by technological substitution, and where latent demand remains under-served by current product portfolios.
Competitive profiling is embedded within the analytical framework rather than appended as a standalone directory. The report examines how leading manufacturers position their offerings across precision distance measurement, on-course navigation, swing and shot analytics, and pace-of-play management. It evaluates product architecture choices, ecosystem lock-in strategies, content partnerships with course databases, and the extent to which brands leverage tradition, performance credibility, or digital convenience as differentiation levers.
Additionally, the study incorporates recent corporate activity to illustrate how strategy is being executed in near-real time. Product launches, display presentations at industry events, and brand campaign shifts are analyzed not as isolated news items but as indicators of strategic intent. By mapping these developments against broader category trends, the report helps readers distinguish between tactical promotions and genuine portfolio pivots.
Competitive Landscape: Positioning, Differentiation, and Strategic Signaling
The competitive field in golf GPS and related precision navigation hardware reflects a blend of established outdoor technology brands, specialized golf-performance companies, and regional specialists expanding their footprint through feature innovation and channel development. Several firms illustrate the dominant strategic archetypes shaping market evolution.
Garmin Ltd. continues to extend its footprint through integrated GPS ecosystems that span wearable devices, handheld units, and application-linked analytics. Recent product activity underscores a dual focus: advancing performance telemetry for engaged players while broadening accessibility for younger or entry-level users. The introduction of a touchscreen-enabled GPS handheld with expanded radar metrics and putting features signals investment in richer on-course data capture. At the same time, a junior-oriented GPS watch emphasizing skill-based tee positioning and pace management reflects a strategic interest in cultivating long-term user relationships and addressing slow-play concerns that affect course throughput and player experience.
Bushnell Corporation, operating through its golf division, maintains a strong association with precision distance measurement and performance compensation features. Its recent rangefinder introduction highlights continued emphasis on slope processing and display modernization, reinforcing the brand's positioning around accuracy, course management utility, and tournament-adjacent credibility. The firm's portfolio approach blends handheld optics, GPS-enabled wearables, and tracking devices, allowing it to address both traditional rangefinder buyers and users migrating toward multi-function performance tools.
Voice Caddie and Shot Scope Technologies exemplify the analytics-forward segment of the market, where hardware serves as a conduit for deeper performance insights. Voice Caddie's emphasis on OLED touchscreen interfaces and advanced swing analytics indicates a product philosophy that prioritizes on-device readability and post-round performance interpretation. Shot Scope Technologies has pursued a similarly data-centric direction, combining GPS hardware with app-linked performance tracking and AI-informed analytics. Its recent launch monitor collaboration and global brand campaign signal an effort to translate performance data into narrative-driven consumer engagement while expanding visibility in key demand regions.
Other participants reflect the breadth of specialization within the category. TecTecTec and Canmore Electronics focus on portable distance measurement and on-course navigation tools, serving users who prioritize compact form factors and straightforward distance feedback. iGolf Solutions contributes embedded GPS and Doppler-based solutions relevant to simulation environments and handheld applications, illustrating the convergence between on-course navigation and off-course practice technology. Precision Pro Golf's emphasis on audible guidance and speaker-integrated navigation highlights an alternative interaction model for players who prefer voice-assisted course management. Tagmarshal's cart-based GPS systems and pace-of-play software represent the course-operator side of the market, where device intelligence is leveraged to manage flow, scheduling, and operational efficiency rather than individual shot data alone.
Collectively, these profiles reveal a market in which differentiation is increasingly multidimensional. Hardware precision remains essential, but competitive advantage is now shaped by ecosystem integration, analytics usability, course database coverage, certification capacity, and the ability to address both recreational and operational stakeholder needs. The report's competitive analysis maps these dimensions systematically, enabling readers to evaluate where incumbents have structural advantages and where emerging players may find viable entry or disruption pathways.
Strategic Implications for 2026 Decision-Makers
For enterprises formulating 2026 strategies, the Golf GPS Market research provides several actionable implications. First, growth planning must account for the interaction between hardware refresh cycles and software-enabled value creation. Devices are no longer isolated purchase events; they are entry points into broader data, analytics, and course-commerce ecosystems. Companies that design roadmaps around companion services, subscription potential, and data interoperability will be better positioned to capture recurring value and extend product lifecycles.
Second, distribution and compliance strategy require proactive design. With evolving import-certification requirements and a heavily registered compliance landscape among scale players, market entrants and expanders must evaluate supply chain architectures for resilience, documentation readiness, and regional clearance efficiency. Organizations that integrate compliance planning into product localization and inventory sequencing will reduce operational friction and protect launch timing.
Third, competitive positioning should be evaluated through the lens of stakeholder coverage. The market now spans individual players seeking distance and performance insights, training-focused users seeking swing and strategy improvement, tournament-adjacent environments demanding precision and reliability, and course operators seeking flow management and operational visibility. Firms that align product features, communication narratives, and channel partnerships with the specific priorities of each stakeholder group will differentiate more effectively than those competing solely on generic navigation functionality.
Fourth, regional demand intensity and segment maturity patterns should inform market entry sequencing. The research isolates where demand is concentrated, where adoption curves are steepening, and where product-category preferences indicate preference for handheld devices, wearables, or application-based solutions. These insights help strategists prioritize geographic rollout, tailor product-mix decisions, and allocate marketing investment toward the most receptive demand environments.
Finally, the study supports risk-aware scenario planning. By connecting historical demand behavior, forecast trajectory, competitive concentration, and regulatory shifts, it provides decision-makers with a structured basis for stress-testing assumptions about pricing, channel access, product substitution, and compliance cost exposure. This is particularly valuable in a market where major players hold substantial concentration, making new entry or portfolio expansion dependent on clear strategic differentiation and operational preparedness.
Why This Research Is Built for Action
The report is intended to serve as a working reference for strategy formulation, not merely a one-time read. It combines macro market modeling with segment-level interpretation, competitive profiling with recent corporate event analysis, and regulatory context with supply-chain relevance. By maintaining a consistent focus on decision applicability, the study ensures that every analytical component ties back to a practical strategic question.
Readers will find structured coverage of market size evolution, forecast progression, segmentation behavior across device types, usage contexts, and regional demand, as well as detailed profiles of key companies and their strategic offerings. The integration of recent product launches, campaign activity, and compliance dynamics enables a near-term view of how competitive momentum is being generated and where operational friction may emerge.
Access the Complete Intelligence Package
The narrative above previews the analytical orientation and strategic relevance of the full study. To support precise planning, the complete research provides the underlying segmentation detail, competitive benchmarking, regional demand patterns, and forecast structures necessary for rigorous decision-making. These components are designed to be referenced during product planning cycles, market entry evaluations, partnership assessments, and capital allocation reviews.
For executive teams seeking a comprehensive, decision-grade view of the Golf GPS Market through 2026 and across the extended forecast horizon, the full report delivers the depth, structure, and strategic context required to move from observation to action.
Discover the complete market research and access detailed segmentation, competitive analysis, and forecast intelligence tailored for strategic planning.
For detailed analysis of this topic, please visit the official page: Golf GPS Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com