



Category: Chemical & Materials
Pharmaceutical Grade Sodium Chloride: Asia Pacific’s 67% Share and 5.6% CAGR Reshape Growth
By PW Consulting, 2026-09-21
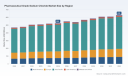
Pharmaceutical Grade Sodium Chloride Market: Strategic Trends and Commercial Opportunities in a Shift-Driven Landscape
Market Snapshot: Growth Trajectory and Structural Realities
The pharmaceutical grade sodium chloride market has settled into a steady expansion phase, with revenue reaching approximately $525 million in 2025 and projected to approach $630 million by 2032. The implied compound annual growth rate of 5.6 percent reflects a market that is growing not through explosive demand surges, but through gradual capacity additions, formulation complexity, and sustained healthcare consumption across mature and emerging regions alike. Historical data from 2020 through 2025 shows a relatively smooth upward trajectory, punctuated by modest step changes rather than sharp inflection points, suggesting that core demand drivers have remained resilient even as feedstock costs, logistics, and regulatory expectations have shifted.
What makes this market structurally interesting is its concentration profile. The top three players account for roughly 28.5 percent of revenue, while the top five capture about 35.2 percent. That level of fragmentation, combined with steady growth, signals a landscape where scale advantages exist but are not insurmountable. Regional and application splits reveal clear concentration patterns: the Asia Pacific region represents the largest revenue pool, while the market is bifurcated by type between active pharmaceutical ingredient grade sodium chloride and hemodialysis grade material. On the application side, injections and hemodialysis dominate the demand base, with oral rehydration salts, osmotic agents, and other uses contributing meaningful but smaller shares. Rather than focusing on individual share percentages, the strategic takeaway is that high-value clinical applications and large-volume therapeutic uses are pulling the market in different directions, each with distinct quality, logistics, and margin expectations.
Several structural challenges and transition points are shaping how participants navigate this growth. First, regulatory scrutiny around impurity profiles, traceability, and batch documentation continues to intensify, especially for materials used in parenteral and dialysis applications where patient safety margins are narrow. Second, cost volatility in energy, purification inputs, and distribution has compressed margins for suppliers that lack integrated quality systems or flexible sourcing models. Third, regional demand growth is uneven, with mature markets facing price discipline and capacity rationalization, while high-growth regions require localized compliance readiness, consistent specification management, and stronger technical support. These dynamics mean that growth alone is not enough; suppliers must convert volume into dependable, specification-grade supply with clear quality differentiation.
Key Drivers Reshaping Demand and Competitive Positioning
Technical Innovation in Purification and Controlled Manufacturing
Advances in purification technology, crystallization control, and analytical verification are redefining what suppliers can reliably deliver at pharmaceutical grade. Improvements in trace metal control, endotoxin management, and particle size consistency have become increasingly important for injection-grade and dialysis-grade applications, where even minor deviations can affect downstream processing or clinical performance. Manufacturers that have invested in closed-loop handling, validated cleaning protocols, and robust quality documentation are better positioned to serve customers who require tight specification adherence across multiple batches. For buyers, this shift means that technical capability is increasingly evaluated not just by certificate compliance, but by the consistency of lot-to-lot performance, the transparency of testing, and the supplier’s ability to support troubleshooting when formulations are adjusted.
Worldwide Pharmaceutical Grade Calcium Hydroxide Market
The innovation curve also extends to packaging, storage, and transport conditions that preserve material integrity. Moisture control, contamination prevention, and shelf-life stability are gaining attention as supply chains become more distributed and inventory strategies more cautious. This matters because pharmaceutical grade sodium chloride is often treated as a commodity input, yet its downstream use can be highly sensitive. Suppliers that align processing improvements with practical logistics and documentation benefits are creating a more defensible value proposition than those competing purely on price.
Regulatory and Policy Environment: Stricter Expectations, Higher Barriers
Policy and regulatory expectations continue to evolve in ways that raise the quality bar and increase the cost of market entry for lower-capability players. Pharmaceutical grade materials sit at the intersection of industrial chemical production and healthcare compliance, which means they are subject to rigorous documentation, quality system expectations, and increasingly detailed impurity surveillance. In practical terms, this environment favors suppliers that can demonstrate controlled manufacturing, reliable audit readiness, and clear traceability from raw source to finished batch. It also reinforces the importance of harmonization across regions, since multinational buyers increasingly seek consistent specifications regardless of sourcing location.
The regulatory backdrop is not solely a constraint; it is also a competitive filter. As compliance expectations rise, suppliers with mature quality infrastructure and experienced regulatory support gain an advantage in securing long-term supply agreements, especially with larger pharmaceutical and dialysis operators that prioritize supply reliability over spot pricing. At the same time, buyers are becoming more discerning about vendor qualification, testing protocols, and change-control management, which raises the stakes for suppliers that treat quality systems as administrative rather than operational capabilities.
Demand-Side Evolution: Clinical Complexity, Volume Growth, and Formulation Strategy
On the demand side, the market is being shaped by a combination of steady clinical consumption and evolving formulation needs. Injections and hemodialysis applications remain central demand pillars because sodium chloride is integral to solution preparation, dilution, and dialysis fluid composition. As healthcare delivery expands and treatment volumes increase, especially in regions scaling hospital infrastructure and outpatient services, demand for dependable pharmaceutical grade material continues to grow. At the same time, formulation strategies are becoming more nuanced, with manufacturers seeking materials that integrate smoothly into multi-component preparations and meet tighter internal quality standards.
Another demand-side development is the growing emphasis on supply assurance. Buyers are less willing to accept variability in lead times, specification consistency, or documentation completeness, particularly when production downtime or batch deviation carries high cost or clinical risk. This is changing purchasing behavior: procurement teams are placing more weight on supplier reliability, technical responsiveness, and continuity planning than on headline price alone. The result is a market where differentiated service and quality assurance can support stronger commercial positioning, especially when tied to long-term supply arrangements.
PW Consulting Chemical & Energy Research Center
Supply Chain and Cost Structure: Energy, Sourcing, and Logistics Pressure
Cost structures in this market are influenced by energy usage, purification requirements, source material variability, and distribution complexity. Because pharmaceutical grade sodium chloride requires controlled processing and verification, it is more sensitive than industrial-grade equivalents to fluctuations in operating costs and transport conditions. Suppliers that can manage energy intensity, source consistent inputs, and minimize handling risk gain a margin advantage, while those exposed to fragmented sourcing or less controlled processing face greater volatility.
Logistics further complicates the cost picture. Pharmaceutical-grade materials often require careful storage, contamination control, and documentation handoffs across borders or regions. In markets where import dependence is high or where regulatory clearance adds time and cost, lead-time reliability becomes a commercial differentiator. This environment pushes companies toward either regional sourcing strategies, integrated production and supply models, or stronger partnerships with distributors that can support compliance and traceability requirements. The broader implication is that cost competitiveness in this market is increasingly about operational discipline and supply continuity, not simply unit pricing.
Competitive Landscape: Positioning, Differentiation, and the Shape of Consolidation
Established Players and Differentiated Strategies
The competitive field includes a broad set of global and regional players with distinct strategic orientations. Large diversified chemical and salt producers bring advantages in scale, sourcing breadth, and distribution reach. Their positioning often emphasizes dependable volume supply, multi-region availability, and established quality systems that support pharmaceutical customer qualification. For these companies, the opportunity lies in converting broad salt-production expertise into a controlled pharmaceutical-grade offering that can compete on reliability as well as cost.
Alongside these broader players, specialized producers and regional manufacturers focus on tighter specification control, local compliance readiness, and closer technical engagement with buyers. Their differentiation typically comes from product consistency, responsive documentation, and the ability to serve specific customer segments such as injection preparation, hemodialysis fluids, or regional formulation needs. These companies often compete by demonstrating that they can reduce variability and support tighter integration into customer processes, which is valuable when procurement teams prioritize risk reduction over purely transactional pricing.
A third group of participants operates with a niche or application-specific orientation, serving laboratory, specialty formulation, or highly regulated use cases where documentation, purity thresholds, and batch control are paramount. Their commercial leverage often depends on technical trust, reproducibility, and the ability to maintain stringent handling standards. In a market where the top three and top five players hold only modest combined shares, these specialized positions can remain viable if they deliver clearly differentiated quality and service.
How Leading Companies Are Structuring Advantage
Across the competitive set, several strategic themes recur. One is the focus on controlled processing and quality documentation as a commercial asset. Suppliers that can show consistent impurity control, validated manufacturing practices, and complete traceability are better positioned to win and retain pharmaceutical customers who treat material qualification as a multi-year decision rather than a periodic purchase. Another theme is the alignment of product grades with end-use requirements. Because API-grade and hemodialysis-grade sodium chloride serve different functional and regulatory contexts, companies that clearly articulate grade-specific capabilities and test data can reduce friction in buyer evaluation and strengthen their positioning in targeted segments.
A third recurring strategy is the use of technical service as a differentiator. Suppliers that provide formulation support, specification clarity, troubleshooting assistance, and reliable change-control communication can create stickier customer relationships. This is especially relevant in applications where sodium chloride must integrate with other ingredients or where patient-facing formulations demand high consistency. In practice, competitive advantage is increasingly built on the combination of material quality, documentation reliability, and the supplier’s ability to reduce operational risk for the buyer.
Market Evolution: Fragmentation, Selective Consolidation, and New Entrants
The market’s concentration profile suggests ongoing fragmentation rather than dominance by a small number of incumbents. That structure creates space for both consolidation and new entry, depending on capabilities and regional positioning. Consolidation is likely to occur where scale, quality infrastructure, and regional coverage can be combined to serve multinational buyers more efficiently. In contrast, new entrants may find footholds by addressing specific quality, specification, or service gaps that larger suppliers do not fully cover, particularly in regions where localized compliance and technical support are valued.
A practical evolution to watch is the growing importance of regional supply resilience. Buyers in multiple markets are increasingly attentive to sourcing diversification and continuity risk, which can benefit suppliers that offer dependable local or near-local supply with appropriate quality credentials. At the same time, multinational procurement standards are pushing the market toward greater consistency in documentation and testing expectations, which may pressure smaller players without strong quality systems. The net effect is a landscape where competitive success depends less on claiming general market presence and more on demonstrating reliable performance in the specific grade, application, and region that matters to the customer.
Looking Ahead: Three Trends That Will Shape the Next Three to Five Years
Trend One: Quality and Traceability Become Commercial Differentiators
Over the next several years, pharmaceutical grade sodium chloride is likely to be evaluated less as a routine chemical input and more as a quality-sensitive component whose consistency, documentation, and traceability directly affect buyer risk. As regulatory and internal quality expectations rise, suppliers with stronger analytical verification, controlled handling, and transparent batch records will be better positioned to secure long-term agreements and command more stable pricing. For manufacturers and procurement teams, this trend means that supplier selection should increasingly weigh quality reliability and documentation completeness alongside cost and lead time.
Trend Two: Regional Demand Growth Will Redefine Sourcing Strategies
Demand growth will remain uneven across regions, with larger revenue pools continuing to attract attention while high-growth areas require more localized readiness. This will encourage suppliers to develop region-specific quality alignment, distribution responsiveness, and technical support capacity. For buyers, the strategic implication is that sourcing decisions may increasingly balance global consistency with regional resilience, especially where supply interruptions or specification mismatches carry high operational risk. Companies that can provide predictable supply in the right region, with appropriate pharmaceutical-grade credentials, will have an advantage in winning disciplined, long-cycle procurement relationships.
Trend Three: Capacity, Cost Discipline, and Margin Pressure Will Separate Operators
As the market grows at a moderate pace, the competitive battleground will shift toward operating efficiency and cost discipline. Energy usage, purification intensity, logistics overhead, and waste control will matter more as buyers become more price-aware and suppliers compete for share in a fragmented market. Operators that can manage cost structures without compromising pharmaceutical-grade consistency will be better positioned to protect margins, while those with weaker process control may face pressure to lower prices or lose qualification status. The risk is that cost-cutting efforts erode the very quality attributes that justify pharmaceutical-grade positioning in the first place, so the winning approach will likely combine efficiency with rigorous quality assurance rather than sacrificing one for the other.
Sodium Chloride Injection Market
Risks and Uncertainties to Monitor
Several uncertainties could alter the pace or shape of growth. Regulatory expectations may tighten further in ways that raise compliance costs or change documentation requirements, especially for materials used in sensitive clinical applications. Cost volatility in energy and logistics could compress margins and shift sourcing preferences faster than suppliers can adapt. Demand patterns may also evolve if healthcare delivery models change, if formulation strategies shift away from certain uses, or if alternative sourcing models alter how buyers qualify and manage suppliers. Finally, regional supply disruptions or trade friction could expose vulnerabilities in concentrated sourcing strategies, making diversification and continuity planning more important than ever.
Actionable Guidance for Decision-Makers
For manufacturers and suppliers, the priority is to treat pharmaceutical-grade consistency as a growth lever rather than a compliance checkbox. Investing in purification control, analytical verification, and documentation reliability can improve qualification success and support longer contract cycles. Equally important is clarifying grade-specific capabilities so that customers can quickly see which applications a supplier is best equipped to serve. Companies that align product quality, technical support, and regional availability will be better positioned to convert steady market growth into durable share gains.
For investors, the key is to distinguish between suppliers that are scaling volume and those that are building defensible pharmaceutical-grade capability. Growth in this market is real, but value creation will favor operators with strong quality systems, controlled cost structures, and the ability to retain customers through reliability rather than price alone. Investment diligence should therefore focus on manufacturing discipline, regulatory readiness, traceability, and the company’s capacity to serve high-value applications without compromising specification integrity.
For procurement and supply chain leaders, the strategic imperative is to evaluate suppliers on a broader set of criteria than unit price alone. Lead-time reliability, lot-to-lot consistency, documentation completeness, change-control responsiveness, and continuity planning all matter when sodium chloride feeds into injections, dialysis fluids, or other sensitive applications. Diversifying supply where appropriate, qualifying suppliers with strong quality systems, and maintaining clear specification expectations can reduce operational risk while preserving cost discipline.
Given the range of regional, technical, and regulatory variables shaping this market, detailed segment-level data and tailored supply-chain assessment can make a meaningful difference in planning. For decision-makers seeking deeper visibility into volume patterns, application-specific demand, grade-level positioning, and supplier qualification dynamics, a more comprehensive market review can help translate these trends into concrete sourcing, investment, and production decisions.
For detailed analysis of this topic, please visit the official page: Pharmaceutical Grade Sodium Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hydrogen Peroxide Market: Why Asia Pacific's Dominance Changes Growth Through 2032
By PW Consulting, 2026-09-21
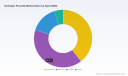
Hydrogen Peroxide Market: Strategic Trends and Commercial Opportunities Through 2032
The Market in Context: Growth Trajectory and Structural Challenges
Hydrogen peroxide (H2O2) continues to occupy a strategic position in industrial chemistry, evolving from a commodity chemical into a differentiated input with specialized grades, sustainability credentials, and expanding application breadth. The market has demonstrated consistent expansion over the past five years, moving from approximately 3,073.45 million USD in 2020 to 3,624.4 million USD in 2025. Forward projections indicate the market will cross 3,864.68 million USD in 2026 and reach 5,096.5 million USD by 2032, translating to a compound annual growth rate of 5.2 percent over the 2026–2032 period. This trajectory reflects steady demand expansion rather than a one-off surge, signaling that hydrogen peroxide is increasingly embedded in long-cycle industrial and consumer value chains.
PW Consulting Chemical & Energy Research Center
Despite the upward baseline, the market sits at a crossroads. Three structural challenges are reshaping how producers, buyers, and investors approach the sector. First, demand is fragmenting across increasingly specialized applications that require distinct purity specifications, packaging formats, and supply reliability standards. The days of treating hydrogen peroxide as a uniform bulk chemical are fading; buyers in electronics, food processing, and water treatment now demand grade-specific performance that standard inventories cannot consistently deliver. Second, regulatory frameworks are tightening and expanding simultaneously. Agencies are redefining permissible uses, safety thresholds, and environmental expectations, which forces producers to adapt formulations, documentation, and logistics while creating both compliance burdens and first-mover advantages. Third, cost structures remain exposed to energy intensity, transportation constraints, and regional capacity imbalances. Producers that fail to align asset footprints with demand geography or to manage logistics intelligently risk margin compression even as headline market growth persists.
For executives, the key takeaway is that aggregate growth can mask uneven operational realities. A 5.2 percent CAGR suggests broad expansion, but the strategic question is where incremental growth concentrates, which customer segments reward differentiation, and how quickly regulatory and technical shifts alter competitive positioning. Market participants that treat hydrogen peroxide as a standardized volume play may find themselves exposed to price volatility, margin erosion, and displaced share by suppliers who adapt faster to application-specific needs and regional demand patterns.
Core Drivers Reshaping Demand and Supply Dynamics
Technological Innovation and Grade Differentiation
The most consequential shift in the hydrogen peroxide market is the accelerating divergence between bulk grades and specialty grades with engineered performance profiles. High-purity and electronic-grade variants are increasingly critical for semiconductor fabrication, advanced water treatment, and sensitive processing environments where trace impurities can disrupt yield or compliance. This technical premium is not merely a laboratory concern; it has become a commercial differentiator that determines which suppliers win contracts in high-value downstream markets. Capacity expansions focused on electronic-grade output, including recent initiatives in China targeting semiconductor demand, illustrate how producers are aligning production capabilities with applications that command stronger margins and more durable customer relationships.
At the same time, process innovation is reshaping the cost and sustainability equation. Producers are experimenting with operational improvements, selective capacity debottlenecking, and integrated site strategies that reduce energy intensity and logistics friction. The commercial impact is twofold: differentiation improves pricing power in specialty segments, while process efficiency can cushion margins against input cost volatility. The practical implication for buyers is that supplier technical capability, quality consistency, and site-level reliability are becoming as important as the base chemical itself.
Policy, Regulation, and the Expanding Use-Case Horizon
Regulatory change is no longer a background issue; it is actively widening the addressable use cases for hydrogen peroxide while simultaneously raising compliance expectations. A notable example is the amendment of food additive regulations by the FDA, which expanded permitted uses of hydrogen peroxide as an antimicrobial agent, oxidizing and reducing agent, bleaching agent, and agent for removing sulfur dioxide in food production, including use in modified whey at very low concentrations. This type of adjustment changes the commercial calculus for food processors, sanitation operators, and ingredient suppliers, because it formalizes new application pathways that can increase demand while also requiring rigorous documentation, handling controls, and traceability.
Electronic Grade Hydrogen Peroxide Market
Beyond food applications, environmental and industrial regulations continue to influence demand for water treatment and disinfection solutions. As water quality standards tighten and industrial operators face greater scrutiny around effluents and process hygiene, hydrogen peroxide’s role as an oxidant and disinfectant becomes more strategically relevant. For competitors, the regulatory environment creates a dual opportunity: expanded use cases can lift volume, but only firms with strong compliance capability, clear safety messaging, and reliable grade certification can convert that potential into durable market share.
Demand-Side Shifts Across Industrial and Consumer Segments
Demand is being reshaped by the combined effect of industrial modernization, hygiene expectations, and downstream product innovation. Pulp and paper remains a foundational application area, but the market is no longer defined solely by traditional bulk bleaching cycles. Electronics manufacturing, water treatment, personal care, food and beverage processing, and mining are all creating incremental demand streams with distinct technical requirements. In particular, sectors that rely on process purity, contamination control, and consistent oxidative performance are increasing their dependence on differentiated hydrogen peroxide supplies.
On the consumer-facing side, expectations around sanitation, product safety, and ingredient transparency are influencing downstream formulations. Personal care and food-related applications are especially sensitive to grade reliability and handling standards. These demand-side shifts mean that hydrogen peroxide is increasingly evaluated not just as a reactive chemical but as a process enabler with reputational and operational implications. Buyers are paying closer attention to supply continuity, documentation, and the perceived risk profile of their supplier base, which favors producers that can deliver consistency across complex procurement cycles.
Supply Chain Geometry and Cost Structure Pressures
The geography of production and consumption is becoming a more important source of competitive advantage. Hydrogen peroxide is sensitive to transportation constraints, regional capacity balance, and local demand clustering. Where production capacity aligns with high-growth application demand, suppliers can reduce logistics exposure and improve responsiveness. Where misalignment exists, exporters and importers face higher cost, longer lead times, and greater vulnerability to disruption. This is especially relevant in markets where specialized grades are required, since routing the right grade to the right customer at the right time is more operationally demanding than bulk commodity distribution.
Cost structures are also being influenced by the interaction between energy use, capacity utilization, and product mix. Producers can improve resilience by shifting the portfolio toward higher-margin specialty grades while optimizing bulk operations for reliability and scale efficiency. For buyers, the strategic issue is that cost dynamics are no longer purely a function of raw material movements; they increasingly reflect supplier decisions about asset allocation, grade strategy, packaging, and service levels. This makes supplier selection a more nuanced strategic decision than simple price comparison.
Competition Landscape and Leading Strategies
Strategic Positionings Among Key Players
The competitive field reflects a mix of global scale producers and specialized manufacturers pursuing distinct value propositions. Solvay has reinforced its leadership emphasis on high-purity grades for demanding industrial and electronic applications, including a capacity expansion in Zhenjiang, China that doubled annual output of high-purity electronic-grade hydrogen peroxide to serve semiconductor demand. This move highlights a clear strategic intent: align capacity with high-value downstream markets where technical performance and supply reliability justify stronger positioning.
Arkema brings a long-standing global footprint with broad grade coverage across chemical synthesis, cleaning and disinfection, cosmetics, electronics, food, mining, pharmaceuticals, pulp and paper, and textiles. Its value proposition rests on product breadth, application experience, and certified operational standards that support a wide customer base. For many industrial and consumer-adjacent buyers, that combination translates into convenience, risk reduction, and multi-application sourcing.
Nouryon has positioned itself around sustainability-linked differentiation, including the launch of a low-carbon product line intended to lower the carbon footprint relative to conventional supply. In a market where downstream buyers increasingly face their own emissions targets and procurement expectations, such an offering can become a meaningful advantage, especially for customers who need to document supply chain footprint performance as part of their own reporting.
Mitsubishi Gas Chemical Company holds a prominent position in super-pure and high-purity hydrogen peroxide and has expanded its geographic footprint with production sites in Japan and the United States. Its strength lies in serving end markets where purity is non-negotiable, particularly semiconductors and electronics. In these segments, supplier qualification, consistency, and technical support can matter more than commodity price differentials.
Evonik continues to emphasize specialty applications, including solar cells, semiconductors, food packaging, and photovoltaics, and has moved forward with joint venture-aligned capacity in China. The 20,000-ton specialty facility targeting photovoltaics, semiconductors, and food packaging illustrates how producers are building dedicated capacity for segments where specification control and application focus create defensible commercial positions.
Other participants, including OCI Company Ltd, Sitara Peroxide Limited, Akzo Nobel, BASF, Gujarat Alkalies & Chemicals Ltd., and National Peroxide Limited, contribute important regional supply and application coverage, particularly in industrial, pulp and paper, textile, and bleaching contexts. Their roles often revolve around localized availability, segment specialization, and cost-competitive bulk supply. The strategic implication is that competition is not monolithic: some players compete on global grade breadth and technical reliability, while others compete on regional availability, segment focus, or cost efficiency.
Structural Evolution: Integration, Fragmentation, and Entry Risk
The market is simultaneously consolidating at the top tier and fragmenting at the application and regional levels. Market concentration remains meaningful, with the top three firms accounting for roughly 42 percent of revenue and the top five close to 52 percent. This level of concentration indicates that scale, integrated asset bases, and established grade portfolios still matter, particularly for large buyers seeking supply assurance. At the same time, the concentration figures also leave substantial share for regional and specialty players who can outperform by focusing on specific segments, geographies, or grade requirements.
The evolution of competitive strategy suggests three parallel dynamics. First, scale players are investing in ability to serve high-value segments rather than competing solely on bulk volume. Second, specialty and regional suppliers are building defensible niches by emphasizing grade specifics, compliance capability, or local responsiveness. Third, new entries and joint ventures are concentrating on application-linked demand, especially where semiconductor, electronics, photovoltaic, food packaging, or low-carbon differentiation create higher barriers to entry but also higher payoff for successful positioning. The overall trend is toward a more layered competitive environment, where the same chemical can be supplied through multiple business models with different margin profiles and customer relationships.
Forward Outlook: Three Trends to Watch Over the Next 3–5 Years
Trend 1: Specialty and High-Purity Grades Will Capture Disproportionate Value
Over the next several years, incremental revenue growth is likely to concentrate disproportionately in high-purity, electronic-grade, and sustainability-differentiated products rather than in undifferentiated bulk supply. The rationale is straightforward: demand in semiconductors, electronics, advanced water treatment, and sensitive processing environments rewards specification control, quality assurance, and supply reliability. As downstream industries modernize and become more sensitive to contamination, yield, and process control, the commercial premium for the right grade will become harder for commodity-focused suppliers to match. For producers, this means that portfolio strategy, site specialization, and technical service capability will be more important than volume alone. For buyers, it means procurement planning should account for grade specificity and qualification cycles rather than assuming interchangeable supply.
Trend 2: Application Expansion Will Be Shaped by Regulatory and Hygiene-Driven Demand
Regulatory developments and hygiene expectations are likely to keep broadening hydrogen peroxide’s role in food, water treatment, disinfection, and process sanitation. The expanded FDA scope for food-related uses is a concrete signal that applications can move from marginal to material when regulatory permissions align with functional need. In parallel, water treatment and industrial sanitation demands often grow as standards tighten and operating environments become more compliance-intensive. The strategic opportunity lies in anticipating where these use cases become recurring rather than opportunistic. The associated risk is that regulatory interpretation, documentation requirements, and approval timelines can vary by jurisdiction and application, meaning that entry into new use cases may require more than product availability; it may require qualification, support infrastructure, and consistent compliance positioning.
Trend 3: Regional Capacity Alignment Will Separate Resilient Suppliers from Exposed Ones
A third trend is the growing importance of matching production footprint to localized demand clusters, especially where specialty grades and responsiveness matter. Capacity expansions and joint ventures in regions with strong electronics, photovoltaic, food packaging, or industrial demand indicate that suppliers are betting on proximity advantages, reduced logistics friction, and faster service. Where regional alignment is achieved, suppliers can improve reliability and margin stability. Where it is not, firms may face higher exposure to transport constraints, lead-time variability, and cost pressure. For procurement organizations, this trend reinforces the importance of dual-sourcing strategies, regional backup options, and supplier assessment that goes beyond price into reliability and geographic fit.
Strategic Implications and Operational Priorities
Hydrogen peroxide is moving from a largely commoditized input to a portfolio of differentiated products with application-specific value. That transition has direct implications for how different stakeholders should position themselves.
For Manufacturers and Producers
- Align capacity investments with grade differentiation rather than treating all output as interchangeable. High-purity and specialty segments offer stronger differentiation potential, but only if supported by consistent quality systems, application knowledge, and qualification support.
- Build sustainability and compliance into product value propositions in a way that is verifiable. Low-carbon profiles, documented handling standards, and grade certifications can become purchasing criteria for downstream customers facing their own regulatory and emissions expectations.
- Optimize the asset footprint for regional demand responsiveness and logistics resilience. In a market where the right grade must reach the right customer with minimal friction, site strategy and distribution design can be as important as chemical production capability.
For Investors and Strategic Developers
- Assess exposure to application-linked demand rather than relying on headline market volume. Growth in electronics, food processing, water treatment, and sustainability-differentiated supply is likely to matter more than uniform bulk expansion.
- Look for evidence of defensible positioning: specialized grades, qualification trust, regional alignment, and the ability to support customer compliance needs. These attributes tend to correlate with more durable pricing power and customer retention.
- Monitor regulatory changes as demand-shaping events, not just compliance issues. Permitted-use expansions, sanitation expectations, and industrial standards can alter demand trajectories faster than traditional cyclical factors.
For Procurement, Operations, and Supply Chain Leaders
- Treat hydrogen peroxide sourcing as a specification and reliability decision, not only a cost decision. Grade consistency, documentation, lead-time reliability, and supplier responsiveness increasingly influence operational risk in sensitive applications.
- Evaluate supplier portfolios for regional coverage and backup capacity. Where application requirements are strict or production continuity is critical, multi-source strategies and geographic diversification can reduce exposure to disruption.
- Incorporate sustainability and regulatory compliance attributes into supplier evaluation where relevant. As downstream reporting and procurement expectations evolve, supply chain attributes may become purchasing criteria rather than optional considerations.
Why Detailed Segmentation Still Matters
Aggregate market growth provides only a partial map of where value is created and where risk concentrates. The commercial reality is that hydrogen peroxide demand behaves differently by region, application, and grade, and those differences shape pricing, qualification requirements, logistics cost, and competitive vulnerability. The broad expansion projected through 2032 masks the fact that some segments will migrate toward premium, specification-driven supply while others remain more cost-competitive and volume-sensitive. Understanding those dynamics requires segment-level clarity on demand drivers, grade requirements, regulatory exposure, and regional supply alignment.
Decision-makers who rely solely on headline figures risk misjudging where margins are durable, where new capacity will compete most effectively, and where procurement exposure is highest. A more granular view supports better capital allocation, supplier selection, and product strategy. For organizations that need to move from general market awareness to specific, actionable decisions, deeper segmentation and customized scenario analysis can help translate market direction into operational priorities.
PW Consulting maintains a detailed hydrogen peroxide market research service designed for executives, strategic planners, investors, and procurement leaders who need segment-level clarity on demand, competition, and forward risks. For readers interested in a closer look at regional dynamics, grade-specific demand patterns, and tailored strategic options, the full research report provides expanded data, company-level developments, and segmentation detail beyond this executive overview.
Hydrogen Market
For detailed analysis of this topic, please visit the official page: Hydrogen Peroxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
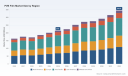
The PVB Film Market at a Strategic Inflection Point: Growth, Innovation, and Competitive Realignment
The poly vinyl butyral (PVB) film market has entered a phase of sustained expansion, with global revenue projected to climb from approximately 215.0 million USD in 2025 to 344.8 million USD by 2032, reflecting a compound annual growth rate of 6.98% across the 2026–2032 forecast window. This trajectory builds on a recovery and acceleration pattern observed from 2020 through 2025, during which the market moved from 163.15 million USD to its current scale despite intermittent supply chain disruptions and macroeconomic volatility. The underlying growth is not merely a bounce-back from pandemic-era constraints; it signals a structural shift driven by performance requirements, regulatory pressures, and evolving end-use expectations. For executives and investors, the PVB film sector presents a concentrated yet dynamically evolving landscape where technological differentiation, sustainability credentialing, and supply chain resilience are becoming the primary axes of competition.
At the same time, the market is not sailing into calm waters. Three interlocking challenges define the current operating environment. First, raw material volatility and input cost pressure continue to test margin structures. Key precursors for PVB film production, including butyraldehyde and polyvinyl alcohol, remain exposed to petrochemical price cycles, logistics friction, and currency translation effects. Recent disclosures indicate that exchange rate fluctuations and fuel cost movements have imposed material headwinds on operating profit for major producers, with one leading manufacturer reporting a negative impact quantified in the billions of its local currency during its most recent fiscal reporting period. Second, the industry is navigating a tightening sustainability and transparency mandate. Customers and regulators are increasingly scrutinizing the carbon footprint of interlayers, pushing producers to adopt certified bio-based or recycled content, renewable energy usage, and third-party verification frameworks. Third, demand is bifurcating across application segments, with some verticals demanding higher structural performance and others prioritizing aesthetic customization or cost efficiency. This divergence forces manufacturers to manage multiple product architectures simultaneously, complicating capacity planning and R&D allocation.
Navigating the Core Challenges
The margin challenge is not simply a cost-pass-through exercise. Producers that rely on undifferentiated standard PVB film face intensifying price sensitivity, especially in applications where interlayer performance requirements are modest. At the same time, the shift toward high-performance variants, which command premium positioning, requires incremental investments in formulation science, processing control, and application-specific validation. These investments are non-trivial, and the return profile depends on the ability to secure design wins in automotive programs, specification adoption in architectural projects, and qualification in photovoltaic laminates. The sustainability mandate adds another layer of complexity. Certification achievements and the integration of recycled resin content are becoming table stakes in certain customer conversations, particularly in Europe and North America, where procurement teams are embedding environmental criteria into supplier qualification processes. Producers that treat sustainability as a compliance checkbox rather than a product and process strategy risk losing specification relevance over time.
Demand bifurcation is equally consequential. Automotive applications continue to drive a substantial share of volume, propelled by evolving vehicle architectures, safety expectations, and the gradual redesign of interiors and glazing systems. Architectural usage remains a steady and growing contributor, supported by building codes, renovation activity, and a growing appetite for specialized visual effects in premium and commercial projects. The photovoltaic segment, while smaller in relative terms, is gaining attention as solar module makers explore improved encapsulation and durability characteristics. The strategic implication is clear: growth is available, but it is unevenly distributed, and capturing it requires targeted product roadmaps rather than broad-based volume plays.
Key Drivers Reshaping the PVB Film Market
Three to four core drivers are interacting to reshape the competitive and commercial dynamics of the PVB film market. These drivers do not operate in isolation; they reinforce one another and collectively raise the bar for what constitutes a viable market position.
Technological Innovation and Performance Breakthroughs
Performance differentiation is moving from a nice-to-have to a decisive purchase criterion. In laminated safety glass, the interlayer's role is expanding beyond basic structural bonding and optical clarity.Automotive OEMs and Tier suppliers are seeking interlayers that contribute to acoustic comfort, impact resistance, and shape retention under stress, while architectural specifiers are looking for films that enable thinner glass packages, improved load-bearing characteristics, and distinctive visual finishes. Recent product introductions illustrate this direction. In the spring of 2024, a major producer launched a next-generation interlayer engineered for improved structural capacity, resistance, toughness, and elasticity, signaling a push toward higher-performance standards in safety glass applications. Later in the year, another incumbent introduced a low-carbon film variant that incorporated recycled resin content and leveraged renewable energy in its production process. By the following year, a European-focused manufacturer unveiled a specialized interlayer designed to deliver a refined visual effect suited to minimalistic architectural designs. These launches collectively demonstrate that innovation is branching into both performance engineering and aesthetic customization, broadening the value proposition beyond traditional transparency and adhesion.
The strategic takeaway is that R&D is becoming a direct revenue lever. Manufacturers that can shorten qualification cycles, align product attributes with end-use validation protocols, and communicate performance benefits in customer-relevant terms are better positioned to secure long-term specification loyalty. Conversely, firms that stagnate on product architecture risk being squeezed between premium innovators and cost-oriented competitors.
Policy, Regulation, and Sustainability Credentials
Regulatory and sustainability dynamics are increasingly shaping procurement decisions and competitive access. Certification frameworks that verify the bio-based or recycled content of materials, as well as the sustainability of manufacturing operations, are gaining traction in customer qualification checklists. Recent certification milestones have covered PVB film products and major production sites across Europe, the United States, and Asia, reflecting a deliberate effort by leading players to institutionalize sustainability credentials across their global footprint. This is not merely a public relations exercise; it is becoming a gateway to certain projects and programs where environmental criteria are embedded in sourcing policy. At the same time, producers are deploying financial and operational instruments to manage input volatility, including derivative tools to hedge exposure on strategic raw materials. The combination of sustainability certification and cost-risk management is creating a more resilient operating model, but it also raises the investment threshold for staying competitive.
For decision-makers, the implication is that sustainability is converging with commercial risk management. Procurement teams are weighing not only price and performance but also the compliance and reputational risk associated with material sourcing. Manufacturers that can provide traceable, verified content and energy sourcing data are gaining an advantage in specification discussions, particularly in regions where regulatory and customer expectations are advancing most quickly.
Demand-Side Shifts in Automotive, Architecture, and Energy Applications
Demand-side behavior is evolving across the three primary application areas, each with distinct drivers. In automotive, glazing strategies are being influenced by vehicle electrification, interior redesign, noise and vibration refinement, and the ongoing push for lighter, safer, and more aesthetically cohesive cabin environments. These trends support continued demand for interlayers that can meet stricter performance profiles while enabling designers to achieve new visual and tactile outcomes. In architecture, the drivers are more varied: building energy codes, renovation and retrofit activity, security and safety requirements, and a growing interest in bespoke finishes for commercial and premium residential projects. The photovoltaic application, while representing a smaller share of current demand, is attracting attention as module manufacturers and integrators evaluate encapsulation options that can contribute to longevity, optical consistency, and processing compatibility. The common thread is that customers are becoming more application-literate and are expecting film suppliers to speak to specific use-case requirements rather than offering generic interlayer solutions.
This specificity changes the commercial dynamic. Winning in automotive often requires long lead times, rigorous testing, and program-aligned supply commitments. Winning in architecture frequently depends on specification relationships, visual and performance differentiation, and the ability to support architects and fabricators with consistent quality and aesthetic options. Winning in photovoltaic contexts depends on validation against module-level durability and processing requirements. Each path requires a tailored go-to-market model, and the firms that can orchestrate these models coherently are better positioned to convert demand into durable revenue.
Supply Chain and Cost Structure Evolution
The supply side is being reshaped by the interplay of input volatility, capacity decisions, and regional localization pressures. Key raw materials remain sensitive to petrochemical cycles and logistics costs, and currency movements can materially affect operating results for globally exposed producers. In response, leading manufacturers are pursuing a combination of hedging strategies, production optimization, and selective capacity expansion or rationalization. The objective is to protect margins without sacrificing service levels or quality consistency. There is also a growing emphasis on reducing the carbon intensity of production, which can involve energy sourcing changes, process efficiency improvements, and the integration of recycled or bio-based feedstocks where technically and commercially viable. These efforts are not isolated initiatives; they are increasingly woven into product positioning and customer discussions, blurring the line between operational efficiency and market-facing value creation.
The practical consequence is that cost leadership alone is becoming harder to sustain as a differentiator. While efficiency remains essential, the more durable advantages are emerging from the combination of performance innovation, verified sustainability attributes, and reliable supply assurance. Producers that can deliver this combination are able to command more favorable commercial terms and build deeper relationships with specifiers and procurement organizations.
Competitive Landscape and Leading Strategies
The PVB film market is characterized by a high degree of concentration, with the top three producers accounting for approximately 79% of market value and the top five representing around 85%. This concentration reflects the scale, technical know-how, and qualification infrastructure required to compete effectively across automotive and architectural applications. It also means that competitive dynamics are shaped by a relatively small number of players whose product portfolios, geographic reach, and sustainability commitments directly influence market direction.
Strategic Positioning of Leading Players
Several incumbent companies illustrate the divergent yet overlapping strategies now unfolding. One U.S.-based producer has built a strong association with laminated safety glass interlayers for both automotive and architectural markets, leveraging established brand recognition and a broad application footprint. Recent moves have combined product innovation with sustainability positioning, including the introduction of a low-carbon film variant that incorporates recycled resin content and uses renewable energy in production. The same company has also relied on derivative instruments to manage volatility in the cost of strategic raw materials, highlighting a dual focus on product differentiation and cost-risk control. Another major player, headquartered in Japan, maintains a globally recognized interlayer portfolio and has pursued a parallel path of performance and sustainability advancement. This includes the launch of a next-generation stiff interlayer designed for improved structural capacity and the achievement of sustainability certification covering products and major plants in Europe, the United States, and Asia. A Taiwanese producer contributes a distinct angle through its focus on polyvinyl butyral resins and film for safety glass interlayers, adhesives, and printing inks, reflecting a broader materials orientation that can support integrated supply advantages. A Belgium-based manufacturer has carved out a specialized position in high-quality PVB film for architectural laminated safety glass, with recent attention to refined visual effects tailored for minimalistic design contexts.
These profiles reveal a market in which leaders are not merely competing on volume but are differentiating along multiple axes: performance engineering, aesthetic customization, sustainability verification, and supply chain resilience. The strategic implication is that competitive advantage is becoming multidimensional. A single strength, such as cost efficiency or brand recognition, is less sufficient on its own than it once was. Instead, the most defensible positions combine at least two of the following: application-specific performance leadership, credible sustainability credentials, and reliable, localized supply capability.
Market Structure Evolution: Consolidation, Differentiation, and Entry Dynamics
Given the high concentration and the technical barriers associated with qualification, scale, and application validation, the market is likely to see continued consolidation pressure among smaller or less differentiated participants. At the same time, the bifurcation of demand and the emergence of specialized product attributes are creating space for targeted differentiation, even within a concentrated landscape. New entry remains challenging because of the need to secure design wins, pass validation protocols, and establish supply reliability across demanding customer segments. However, niche opportunities may arise in specialized architectural finishes, high-performance interlayers for specific automotive programs, or application-tailored solutions for photovoltaic encapsulation, where focused innovation and strong specification relationships can offset scale disadvantages. The broader trend is one of strategic segmentation: the market is not becoming uniformly consolidated into a single winners-take-all structure, but rather into a set of performance and application niches where distinct value propositions can command premium positioning.
VCI Film Market
For observers of competitive dynamics, the key question is not whether concentration will persist, but how value will be distributed within that concentrated structure. Leaders that can translate product innovation into specification wins and sustainability credentials into procurement preference will likely capture a disproportionate share of the incremental growth projected through the end of the decade and into the early 2030s.
Forward Outlook: Three Trends to Watch Over the Next Three to Five Years
Looking ahead, the PVB film market is likely to be shaped by trends that connect technological ambition, sustainability expectations, and application-specific demand. These trends carry both opportunity and risk, and they should inform near-term strategic planning.
Performance-Led Premiumization Accelerates
The push toward higher-performance interlayers is expected to intensify as automotive and architectural customers raise their expectations for structural capacity, acoustic behavior, durability, and design flexibility. This trend favors producers that can validate advanced attributes in relevant applications and secure design or specification wins early in program or project cycles. The commercial opportunity lies in building a portfolio of differentiated variants that address specific performance gaps, supported by technical service and application engineering. The risk is that premiumization outpaces the ability to scale qualified production or that customers resist premium pricing in cost-sensitive segments, forcing difficult trade-offs between margin and volume.
Sustainability Becomes a Specification Factor, Not a Differentiator
Sustainability credentials are on a trajectory from optional advantage to expected attribute in several regions and customer segments. Certification coverage across major production sites, the use of recycled or bio-based content, and renewable energy integration are increasingly part of supplier evaluations. The opportunity is to embed sustainability into product identity and process design in ways that are verifiable and customer-relevant, thereby reducing friction in qualification and strengthening preference in competitive bids. The uncertainty lies in the pace and uniformity of adoption. If expectations diverge significantly by region or application, producers may face complex portfolio and compliance decisions. If standards tighten faster than anticipated, firms that have not invested early may find themselves excluded from certain opportunities or forced into catch-up investments at higher cost.
Supply Chain Localization and Cost Discipline Reshape Competitive Resilience
Input volatility, currency exposure, and logistics complexity are likely to keep cost and supply resilience in focus. Producers will continue to pursue a mix of hedging, process efficiency, energy sourcing changes, and selective capacity adjustments. The opportunity for resilient operators is to combine cost discipline with reliable service and consistent quality, building trust with customers who are themselves managing procurement risk. The risk is that overinvestment in capacity in a softening segment or underinvestment in qualifying new variants can distort the portfolio and weaken competitive positioning. Additionally, regional cost structures and regulatory environments may create uneven profitability across geographies, requiring disciplined portfolio management rather than blanket expansion.
PW Consulting Chemical & Energy Research Center
Actionable Implications for Decision-Makers
For manufacturers, the priority is to align product roadmaps with the specific performance and aesthetic requirements of high-value applications while institutionalizing sustainability credentials across production sites. This means treating R&D as a commercial engine, not a back-office function, and ensuring that new variants are supported by validation data, technical service, and clear positioning. It also means building cost-risk management into the operating model, using hedging and process optimization to protect margins without compromising quality or service. Companies that can demonstrate measurable performance benefits and credible sustainability attributes are more likely to secure specification loyalty and defend premium positioning.
For investors, the strategic signal is that growth is real but unevenly distributed across applications and product tiers. The most attractive exposure is likely to be found in producers that combine application-relevant innovation with verified sustainability and disciplined cost management, rather than in undifferentiated volume plays. Due diligence should focus on qualification pipelines, certification coverage, raw material exposure, and the ability to convert product launches into specification wins. Portfolio valuation should account for the possibility that premiumization and sustainability adoption will accelerate in some regions and segments faster than others, creating divergence in growth and margin profiles across the competitive set.
For procurement and sourcing leaders, the practical guidance is to evaluate suppliers on a broader set of criteria that includes performance validation, sustainability verification, and supply assurance, not just unit price. The most resilient sourcing relationships will be those in which the supplier can demonstrate traceability, consistent quality, and the ability to support application-specific requirements over the life of a program or project. Engaging early in design and specification cycles, and aligning on sustainability and performance expectations upfront, can reduce downstream risk and improve total value.
For all of these audiences, the pace of change in the PVB film market argues for timely, granular intelligence. High-level growth figures and concentration ratios provide context, but the commercial decisions that matter most—program qualification, specification strategy, capacity allocation, sustainability investment, and sourcing commitments—depend on detailed segmentation data, regional demand patterns, and company-level trajectories. Accessing deeper, structured analysis can shorten the distance between market awareness and actionable strategy, enabling more precise prioritization of investments, partnerships, and risk mitigation.
PV Ribbon Market
For detailed analysis of this topic, please visit the official page: PVB Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Sodium Permanganate Market: Why 4.6% CAGR and Water Treatment Demand Change Everything
By PW Consulting, 2026-09-21
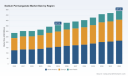
Sodium Permanganate Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The global sodium permanganate market is navigating a period of structural transformation, defined by steady expansion against a backdrop of regulatory tightening, raw material volatility, and evolving end-use requirements. Over the historical period spanning 2020 through 2025, market revenue demonstrated consistent upward movement, reflecting both post-pandemic industrial recovery and sustained investment in critical infrastructure. The base year of 2025 marks an inflection point where demand growth has begun to outpace earlier cyclical patterns, driven by capital expenditure programs in water infrastructure and electronics manufacturing. The forecast window through 2032 projects a compound annual growth rate of 4.6 percent, suggesting that the market will continue to expand at a moderate but resilient pace, supported by long-cycle investments rather than short-term discretionary spending.
Scale alone, however, does not define the strategic landscape. The market exhibits a pronounced concentration profile, with the top three firms controlling approximately seventy percent of revenue and the top five firms capturing roughly three-quarters of total share. This structure implies limited competitive fragmentation, high barriers to entry around certification and distribution networks, and a pricing environment where incumbents can exert meaningful influence over contract terms. At the same time, concentrated markets are vulnerable to supply shocks and regulatory adjustments that can cascade quickly through the value chain. The current environment presents several interrelated challenges that decision-makers must address.
First, raw material cost volatility has become a persistent pressure point. Manganese-based inputs underpin sodium permanganate production, and recent pricing movements in related chemical streams have introduced margin uncertainty. Quarter-over-quarter increases in manganese sulfate pricing, linked in part to higher sulfuric acid costs, illustrate how upstream inputs can compress profitability even when end-market demand remains robust. Second, supply disruptions tied to mining operations have reinforced the fragility of raw material availability. Weather-related interruptions at manganese-producing sites have periodically tightened supply, pushing ore prices higher and creating timing mismatches between procurement cycles and production schedules. These dynamics elevate the strategic importance of supplier diversification, inventory planning, and long-term contracting.
Third, regulatory frameworks are reshaping competitiveness in ways that go beyond simple compliance. Designations that elevate high-purity manganese to a strategic material status introduce new considerations around supply security, traceability, and alignment with broader policy priorities. In practice, this means procurement decisions increasingly factor in resilience and continuity alongside price and quality. Organizations that can demonstrate certified supply chains, documented compliance, and stable sourcing arrangements gain an advantage in bidding environments where reliability carries tangible commercial weight. Taken together, these challenges do not threaten the market’s trajectory, but they do reward firms that treat supply chain resilience and regulatory readiness as core capabilities rather than operational afterthoughts.
Key Drivers of Market Change
Technological Innovation and Product Differentiation
Innovation in sodium permanganate markets is less about radical chemistry shifts and more about precision, purity, and application fit. High-purity grades have gained traction in end-use segments where contamination sensitivity is critical, particularly in electronics manufacturing and specialized industrial processes. The availability of purity levels approaching ultra-high specifications reflects a broader trend toward customization: buyers are increasingly unwilling to accept commodity-grade solutions when performance margins and process reliability are at stake. This shift favors suppliers capable of delivering consistent quality with rigorous documentation and testing regimes.
Sodium Percarbonate Market
In parallel, liquid-formulation expertise continues to differentiate incumbents in water treatment applications. NSF-certified grades and compliance with AWWA standards have become baseline expectations in municipal and government procurement, not optional enhancements. Suppliers that can provide certified products, clear safety data documentation, and application support are better positioned to secure long-term contracts. The strategic implication is clear: technical credibility and certification infrastructure now function as competitive moats. In a concentrated market, the firms that invest early in quality systems and application-specific grade development are more likely to preserve pricing power and customer loyalty over time.
Policy and Regulatory Environment
Policy developments are increasingly influencing where capital flows and how supply chains are evaluated. The elevation of high-purity manganese within critical raw materials frameworks has made supply security a strategic priority for downstream industries and public-sector buyers alike. When manganese is explicitly recognized as a material important to supply security, procurement teams and project developers pay closer attention to sourcing origins, price stability, and the continuity of available grades. This does not simply add a compliance layer; it changes the decision calculus for large-volume contracts and infrastructure programs.
Simultaneously, government support for domestic production capacity in battery-grade and industrial manganese streams signals a longer-term shift toward supply localization in key geographies. Grant programs and policy incentives aimed at building production facilities reflect a broader emphasis on reducing dependence on imported inputs for strategic applications. For sodium permanganate markets, this creates a dual effect. On one hand, policy-driven investment in manganese production capacity could improve long-term availability and moderate input cost volatility. On the other hand, transitional periods may still be marked by tightness, regional disparities, and competition for intermediate materials. Companies that maintain visibility into these policy dynamics can better time procurement commitments, capacity planning, and partnership structures.
Manganese Sulphate Market
Demand-Side Shifts in Water Treatment and Electronics
Demand growth continues to be anchored by water treatment applications, where sodium permanganate remains a valued oxidizing agent for odor control, iron and manganese removal, and broader oxidation processes. Infrastructure budgets, public health priorities, and tightening water quality standards all contribute to sustained procurement needs in this segment. Importantly, large municipal and government contracts often follow multi-year planning cycles, meaning demand in this area is relatively stable but highly dependent on certification compliance, specification alignment, and trust in supplier reliability. Contract awards that reference NSF and AWWA standards exemplify how procurement processes reward documented conformity and supply consistency.
In the electronics segment, demand is shaped by process sensitivity and purity requirements rather than volume alone. High-specification applications reward suppliers capable of delivering tightly controlled grades with comprehensive quality documentation. As electronics manufacturing continues to emphasize reliability and contamination control, the value proposition of specialty-grade sodium permanganate strengthens. The broader demand picture includes additional application areas that add incremental growth and diversify end-use exposure, reducing reliance on any single vertical. For commercial strategy, the key insight is that demand-side strength varies by segment quality thresholds, procurement structures, and certification dependencies. Success depends on matching product architecture to the specific requirements of each major application rather than treating the market as a homogeneous whole.
Supply Chain and Cost Structure Dynamics
Cost structures in this market are heavily influenced by manganese availability, chemical input pricing, and the logistics of specialized distribution. Recent quarter-over-quarter increases in manganese sulfate pricing illustrate how quickly input economics can shift, especially when driven by higher costs for essential precursor chemicals such as sulfuric acid. These movements affect not only production costs but also the timing of contract negotiations and the structure of pricing terms. In concentrated markets, suppliers with established sourcing relationships and inventory buffers may be better positioned to manage short-term volatility without passing all costs downstream.
Supply disruptions from manganese mining operations further complicate cost planning. When production interruptions occur due to environmental incidents or operational constraints, ore prices can rise and availability can tighten, forcing downstream producers and distributors to adjust procurement strategies. Events such as mine suspensions linked to cyclone damage have shown how quickly physical supply conditions can change. The result is a market where resilience is increasingly priced into sourcing decisions. Buyers are willing to pay for assurance, and suppliers that can offer dependable continuity, transparent documentation, and proactive risk management gain leverage. Over time, this dynamic rewards organizations that treat supply chain design as a strategic function, integrating supplier diversification, contractual flexibility, and scenario planning into everyday operations.
Competitive Landscape and Leading Strategies
The competitive structure of the sodium permanganate market is defined by a small group of established U.S.-based producers and distributors with strong positioning in water treatment, government procurement, specialty-grade supply, and bulk distribution. This concentration reflects the importance of certification, application expertise, and supply reliability. Rather than competing primarily on price, leading firms differentiate through product grades, compliance documentation, distribution reach, and customer relationships built around recurring contract cycles.
Carus Corporation stands out as a major producer and supplier of liquid sodium permanganate for water treatment applications, including NSF-certified grades. Its strategic positioning centers on alignment with municipal and industrial water treatment requirements, where certification and product consistency are decisive. By maintaining a focus on certified grades and application-oriented supply, the company reinforces its role in high-value public-sector and industrial procurement environments. In a market where contract awards increasingly reference NSF and AWWA standards, that certification-oriented posture is a meaningful competitive asset.
Hawkins, Inc. operates as a domestic manufacturer, blender, and distributor with a B2B-only sales model focused on municipal and government water treatment. Its strategy emphasizes local production and distribution reliability, targeting customers that prioritize continuity of supply and direct commercial relationships. The B2B-only orientation allows the firm to concentrate on specification-driven buyers rather than broader retail-style channels. This model supports stable demand attachment to public-sector and institutional customers where procurement processes favor established distribution partners with documented compliance capabilities.
Valudor Products, LLC supplies 40 percent sodium permanganate solution certified for water treatment with full safety data documentation. Its differentiation is rooted in product specification clarity and documentation completeness, which matter in procurement settings where compliance and transparency are non-negotiable. Suppliers that make safety data sheets and certification information readily accessible reduce friction in the purchasing process and strengthen trust with buyers who must satisfy internal and external audit requirements. In concentrated markets, even incremental improvements in documentation and specification clarity can influence supplier selection.
American Elements positions itself around high-purity offerings, providing sodium permanganate at purity levels up to 99.999 percent for commercial, research, and industrial uses. This strategy targets segments where purity thresholds drive value rather than cost minimization alone. High-purity specialization creates a different competitive logic: customers in electronics and advanced industrial applications often prioritize grade integrity and documentation over bulk commodity pricing. By focusing on ultra-high purity capability, the company serves demand that is less sensitive to commodity price fluctuations and more sensitive to performance assurance.
Rock Chemicals, Inc. operates as a trusted bulk supplier with emphasis on reliable sourcing and compliance documentation. Its positioning reflects a practical, reliability-first value proposition: customers in bulk procurement environments value consistency, sourcing transparency, and the ability to meet compliance requirements without administrative delay. In a market where raw material volatility and supply interruptions are real risks, that emphasis on dependable sourcing and documentation provides a practical competitive edge, especially for procurement teams seeking to reduce uncertainty in recurring supply contracts.
Recent procurement activity highlights how these competitive dynamics play out in practice. Contract awards such as the 2025 supply agreement for sodium permanganate under NSF and AWWA standards demonstrate that public-sector buyers continue to prioritize certified compliance and specification alignment. Such contracts reinforce the value of firms that can meet documented standards and sustain reliable delivery. In a concentrated market, these wins are not merely transactional; they signal a broader pattern where certification readiness and procurement compatibility shape share dynamics over multi-year horizons. The competitive landscape is likely to evolve through selective integration, deeper specialization by purity or application, and the continued importance of distribution and documentation capabilities. New entrants will face steep barriers unless they can credibly replicate certification infrastructure, supply reliability, and customer trust.
Future Trends and Commercial Opportunities
Looking ahead over the next three to five years, several interconnected trends are likely to shape commercial strategy in sodium permanganate markets. The first is a reinforcement of certification and compliance as competitive drivers. As water infrastructure procurement remains anchored in public-sector standards and industrial buyers demand documented traceability, firms with robust certification portfolios and clear application-specific grades will be better positioned to win and retain contracts. The opportunity here lies in strengthening application alignment, expanding certified grade availability where feasible, and reducing friction in the buyer’s compliance review process. Organizations that can provide clearly documented, specification-matched products will find it easier to command premium positioning in procurement cycles where risk avoidance matters.
A second trend is the continued tension between demand resilience and raw material volatility. Infrastructure spending and electronics-related demand are expected to provide underlying support, but input cost fluctuations tied to manganese sulfate pricing and mining disruptions will likely remain a recurring theme. This creates commercial opportunities for firms that can secure longer-term sourcing arrangements, build inventory buffers where appropriate, and design pricing structures that balance stability with flexibility. For buyers, the opportunity is to reduce exposure through diversification, strategic contracting, and clearer visibility into upstream pricing signals. For suppliers, the opportunity is to differentiate through reliability, documentation, and service quality in a market where continuity can be as valuable as unit price.
The third trend is the growing influence of strategic raw material policy on supply chain behavior. As manganese gains recognition within critical materials frameworks and public investment supports domestic production development, procurement and production strategies may gradually shift toward greater supply security, regional diversification, and alignment with policy priorities. This creates opportunities for firms that can articulate supply resilience, traceability, and continuity as part of their commercial value proposition. At the same time, transitional uncertainty may persist, particularly during periods when new capacity is being developed but has not yet stabilized availability. Decision-makers should therefore plan for a market environment where policy, sourcing, and pricing interact more closely than in the past.
These trends carry potential risks and uncertainties. Raw material price swings can compress margins or trigger renegotiation pressure if contracts lack flexibility. Regulatory changes can alter compliance expectations faster than product or documentation systems can adapt. Supply disruptions may expose overreliance on limited sourcing channels. In addition, market concentration means that shifts in the strategy or capacity of a small number of incumbents can affect overall availability and pricing dynamics. The commercial opportunity is not simply to forecast growth, but to build operational and commercial buffers that allow firms to respond decisively when conditions change.
Actionable Guidance for Decision-Makers
For manufacturers and producers, the priority is to reinforce differentiation through grade specialization, certification readiness, and supply reliability. Investment in high-purity capability, certified water treatment grades, and rigorous documentation can support premium positioning in application-sensitive segments. Equally important is proactive management of input costs and sourcing risk. Diversifying supplier relationships, maintaining visibility into manganese-related pricing trends, and structuring contracts with appropriate flexibility can protect margins without sacrificing customer trust. Manufacturers should also consider how application-specific support, technical documentation, and compliance clarity can reduce friction in customer qualification processes, especially where procurement cycles are long and specification-driven.
For investors, the market presents a profile of steady growth with concentrated leadership and strategic sensitivity to raw material and regulatory dynamics. Due diligence should focus on supply chain resilience, certification positioning, and exposure to input cost volatility rather than on top-line growth alone. Companies with strong compliance documentation, recurring government or municipal contracts, and credible sourcing strategies are better equipped to withstand disruptions and defend pricing. At the same time, investors should monitor the pace of policy-driven capacity development and any shifts in manganese availability that could affect cost structures or regional supply patterns. In concentrated markets, competitive advantage often depends on reliability and credibility as much as scale, so qualitative assessments of operational maturity can be as important as financial metrics.
For procurement teams and buyers, the strategic priority is to reduce exposure to volatility while preserving quality and compliance. Diversifying approved suppliers, aligning purchasing cycles with upstream cost signals, and prioritizing vendors with robust certification and documentation can improve contract stability. Where possible, long-term agreements should incorporate mechanisms that address raw material price movements without sacrificing service quality or specification integrity. Procurement strategies should also account for the increasing importance of supply security and continuity in public-sector and industrial environments, where auditability and reliability can outweigh marginal price differences. In this context, detailed segment-level intelligence on grade demand, certification dependencies, and sourcing risk can materially improve sourcing decisions.
For organizations seeking a more granular view of segment dynamics, regional demand patterns, and contracting trends, deeper analysis can clarify where value is created and where risk concentrates. A detailed research report can provide the segmented data, competitive mapping, and scenario context needed to support pricing, capacity, and sourcing decisions with greater precision. Given the pace of regulatory and raw material developments, timely access to structured market intelligence is not merely an analytical exercise; it is a practical input to strategy execution. For decision-makers who need to translate market signals into procurement, investment, or product strategy, a fuller examination of the data and competitive dynamics can help ensure that action plans are grounded in current conditions rather than assumptions.
PW Consulting Chemical & Energy Research Center
For detailed analysis of this topic, please visit the official page: Sodium Permanganate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Flame Retardant Cable Market: The 4.5% CAGR Shift Reshaping 2032 Demand
By PW Consulting, 2026-09-21
Flame Retardant Cable Market: Strategic Trends and Commercial Opportunities for Forward-Looking Enterprises
The global market for flame retardant cable solutions has entered a phase of mature, steady expansion characterized by shifting regulatory emphasis and evolving end-user performance requirements. Valued at approximately USD 1.85 billion in 2025, the sector has demonstrated a compound annual growth rate of roughly 4.5 percent through the forecast period extending to 2032, with total revenue projected to approach USD 2.5 billion by the end of the decade. This trajectory reflects a market that is no longer driven primarily by volume growth in traditional construction wiring, but rather by incremental value creation through compliance, safety certification, and application-specific engineering. Growth is increasingly concentrated in segments where fire performance is non-negotiable, where circuit integrity must be preserved under extreme thermal load, and where building codes intersect with operational continuity concerns across transportation, energy, and industrial facilities.
Several structural features define the current landscape. Market concentration remains moderate, with the top three players capturing roughly one-third of total revenue and the top five collectively accounting for close to half. This distribution suggests an environment where scale advantages coexist with meaningful regional and technical differentiation, allowing specialized manufacturers to compete on certification portfolios, insulation chemistry, and application engineering rather than price alone. At the same time, the broader cable industry contends with raw material volatility across copper, plastics, rubber, and aluminum, which directly influences manufacturing economics for flame retardant formulations. These input cost dynamics, combined with rising compliance complexity, have raised the bar for execution and are filtering out operators without strong testing infrastructure or established certification relationships.
Against this backdrop, the market is navigating a series of pivotal challenges that will shape competitive positioning over the next several years. The first is the accelerating pace of regulatory revision across major codes. Ongoing updates to fire safety standards are tightening performance thresholds for emergency circuits, increasing concrete encasement requirements in certain jurisdictions, and aligning fire detection and alarm system expectations with more rigorous cable testing protocols. As building codes evolve toward 2026 and beyond, compliance is shifting from a checkbox exercise to a continuous engineering requirement, pressuring manufacturers to maintain up-to-date certification evidence and technical documentation for each installed base.
A second challenge lies in balancing smoke and toxicity management against mechanical and electrical performance. Low smoke zero halogen formulations and other advanced insulation systems are gaining prominence in enclosed transit environments, high-rise residential buildings, and data-centric facilities where occupant evacuation and equipment survivability are paramount. Yet these materials often require precise compounding, controlled curing, and specialized jacketing to achieve target flame propagation and circuit integrity metrics. The technical trade-offs between halogenated and halogen-free architectures, as well as between cost and fire-rated performance, are forcing suppliers to invest in application-specific validation rather than rely on generic product lines.
A third challenge is the growing alignment of fire safety expectations with operational resilience in mission-critical environments. As facilities such as AI data centers, semiconductor plants, and advanced manufacturing sites demand uninterrupted power under fault conditions, the value proposition of flame retardant cable is expanding beyond life safety toward business continuity. This shift introduces new testing requirements, supply chain rigor, and documentation standards that smaller players struggle to meet consistently, while incumbents leverage their engineering depth to secure long-term specification wins. The result is a market in which differentiation is increasingly earned through demonstrated performance under extreme temperatures, validated circuit survival, and reliable delivery of certified product into complex projects.
Key Drivers Shaping Market Momentum
Innovation in Fire-Resistant Insulation and Circuit Integrity Solutions
Technological progress continues to reshape what flame retardant cable can achieve under real-world fire conditions. Recent product commercialization illustrates how insulation chemistry, conductor shielding, and jacketing design can be integrated to sustain power delivery under severe thermal stress. A notable example is the launch of a medium-voltage fire-resistant cable capable of maintaining circuit function at temperatures up to 830°C, developed specifically for AI data centers and semiconductor plants and aligned with updated IEC 60331-4 standards. This type of capability redefines the performance ceiling for critical infrastructure wiring, where even brief loss of power can translate into significant operational and financial consequences.
Flame Retardant Fabric Market
At the same time, fire-resistant and low smoke zero halogen variants are being refined for high-rise residential, transit, and industrial applications where flame propagation control and circuit integrity are specified as part of project approval. Manufacturers that pair material science expertise with in-house testing and certification workflows are better positioned to convert code changes into specification opportunities. The practical implication for buyers and designers is that performance is no longer determined solely by nominal voltage or conductor size; it increasingly depends on validated behavior under fire exposure, which makes detailed technical comparison and certification evidence central to procurement decisions.
Regulatory Evolution and Compliance as a Specification Driver
Policy and code activity remains a primary force behind demand for compliant fire-resistant solutions. Revisions to widely referenced standards are raising the bar for how emergency circuits are installed and protected, including stronger concrete encasement expectations and enhanced testing alignment for fire detection and alarm systems. In parallel, construction product regulations in major markets require manufacturers to demonstrate compliance through documented testing and certification, adding a layer of traceability that influences both product development and sales cycles.
These regulatory dynamics create a dual effect. On the demand side, they increase the addressable scope for certified flame retardant cables by expanding the range of applications where fire performance must be proven. On the supply side, they raise the cost of entry and ongoing compliance, favoring organizations that can maintain current certifications, support specification teams with technical evidence, and adapt product portfolios quickly when standards are updated. For executives overseeing portfolio strategy, the takeaway is that regulatory tracking should be treated as a core commercial function rather than a back-office compliance task, because the timing and substance of code changes often determine which product variants win in upcoming project cycles.
Demand-Side Shifts Toward Resilience in Critical Facilities
End-user behavior is changing as digital infrastructure and advanced manufacturing become more central to economic activity. Data center operators, semiconductor fabricators, and energy facility managers are placing greater emphasis on continuity of supply under fault conditions, which elevates the importance of cables that can maintain function while resisting flame spread. This demand-side shift is not merely a safety preference; it is increasingly an operational requirement tied to uptime commitments, insurance considerations, and facility certification.
In building and construction, the trend is visible in specification practices that favor documented fire performance for vertical risers, transit interchanges, and enclosed public spaces. In automotive and industrial wiring, fire-resistant insulation options are being evaluated for applications where thermal events could compromise both safety and equipment integrity. Across these segments, the common thread is a growing willingness to pay for verified performance when the cost of failure is high. For suppliers, this creates an opportunity to move beyond commoditized pricing by offering application-engineered solutions with clear certification backing and technical support during the design and approval phases.
Supply Chain and Cost Structure Pressures
The economics of flame retardant cable production are being shaped by input cost volatility and the operational demands of maintaining certified product streams. Fluctuations in copper and polymer markets directly influence manufacturing costs, while the need to produce materials with consistent flame retardant and low smoke characteristics adds complexity to sourcing and compounding. These pressures are encouraging consolidation of production capability in facilities that can achieve scale, control quality tightly, and sustain certification evidence across batches.
Worldwide Flame Retardant Masterbatches Market
Capacity investments in specialized fire-resistant lines reflect this reality. For example, expansion of a fire-resistant LSZH cable production facility has increased annual capacity to better serve demand in high-rise residential and transit sectors, signaling that manufacturers are aligning capacity additions with the applications where compliance and performance requirements are most stringent. Such moves illustrate a broader pattern: investment is flowing toward product lines where specification wins are repeatable and where certification and engineering support can be monetized through long-term contracts and recurring project flow.
Competitive Landscape and the Strategies of Leaders
The market is shaped by a mix of global cable leaders and regionally strong specialists, each pursuing distinct strategic positioning. The leading organizations differentiate not only through scale, but through application focus, certification depth, and the ability to integrate fire safety into broader infrastructure solutions. Their recent actions provide a useful lens on how competitive advantage is being built in this segment.
One global group has concentrated on fire-resistant cables, including low smoke zero halogen variants designed for high-rise, transit, and industrial environments, with particular emphasis on circuit integrity and flame propagation compliance. Its recent capacity expansion in the UK demonstrates a deliberate alignment of production capability with demand in high-specification building and transit projects. This approach positions the company to compete on technical reliability and compliance documentation rather than on price alone, and it signals to specifiers that supply continuity for certified product is a priority.
A major European cable manufacturer has pursued a complementary strategy centered on fire-resistant and fire-retardant solutions for critical infrastructure, with an emphasis on the building and energy sectors. Its recent acquisition of a Spanish low-voltage cable producer specializing in fire-resistant building solutions illustrates a willingness to consolidate regional capability and broaden portfolio coverage where code-driven demand is intensifying. By combining organic standard upgrades with targeted acquisitions, this type of player seeks to secure both technical credibility and local specification relationships, which can translate into more resilient project pipelines.
A South Korean manufacturer has focused on high-performance fire-resistant cables that meet IEC 60331 standards, including medium-voltage and energy storage applications. Its commercialization of a medium-voltage fire-resistant cable designed for AI data centers and semiconductor plants highlights how advanced manufacturing and energy-adjacent demand can pull new performance classes into the market. This trajectory suggests that strategic differentiation can emerge from serving emerging high-value applications where fire safety intersects with power continuity and equipment survivability.
Other active participants extend the competitive picture into automotive and industrial wiring systems, where fire-resistant insulation options are increasingly specified, as well as into high- and low-voltage power cables with fire safety features for energy and infrastructure. An additional industrial and energy-focused player rounds out the landscape by supplying fire-resistant and flame-retardant cables for industrial and energy applications. Collectively, these companies illustrate a market where segmentation is blurring at the edges: players are no longer defined solely by commodity cable volume, but by their ability to deliver certified performance into specific end-use contexts.
The market structure is evolving along several axes. Consolidation is evident where acquirers seek to strengthen regional footprints and expand certified portfolios, particularly in segments tied to building infrastructure and energy. Differentiation is intensifying where manufacturers build technical narratives around circuit integrity, smoke management, and extreme-temperature performance. New entry or re-entry remains challenging because of the certification burden and testing requirements, which tend to favor incumbents with established compliance infrastructure. At the same time, mid-tier specialists can still compete effectively by concentrating on a narrow application set and delivering superior documentation, technical support, and delivery reliability.
Future Outlook: Three Trends to Watch
The next three to five years are likely to be defined by the convergence of stricter compliance expectations, higher performance thresholds, and a more selective allocation of capacity toward high-value applications. One trend to monitor is the continued elevation of certification and documentation as core commercial assets. As codes evolve and specification committees place greater weight on validated fire performance, products with current, well-maintained certification evidence and clear technical narratives will gain an advantage in competitive bids. This trend benefits manufacturers that invest in testing agility and transparent compliance communication, while increasing the risk for those that treat certification as episodic rather than operational.
A second trend is the migration of flame retardant cable requirements into mission-critical digital and energy infrastructure. Data centers, semiconductor facilities, and advanced energy installations are driving demand for solutions that preserve circuit function under severe thermal conditions. This shift expands the strategic relevance of medium-voltage and specialized fire-resistant variants, and it creates opportunities for suppliers that can align product capabilities with the continuity requirements of these facilities. The opportunity is not simply to sell cable, but to participate earlier in the design process and to offer performance data that supports specification and approval.
A third trend is the potential for regional divergence in code intensity and enforcement, which may influence where demand grows fastest and where localized compliance capability becomes a competitive necessity. Areas with accelerating construction of high-rise residential, transit, and critical infrastructure may see stronger pull for certified fire-resistant solutions, while regions with slower code adoption could experience more price-sensitive competition. Organizations operating across multiple markets will need to manage these differences carefully, balancing portfolio standardization with local specification readiness.
These trends carry risk. Raw material volatility can compress margins if pricing mechanisms lag cost movements. Regulatory pace and interpretation can vary by jurisdiction, creating uncertainty for product roadmaps and capacity planning. Supply chain disruptions can affect the availability of certified batches, which in turn can jeopardize project timelines and specification commitments. The commercial implication is that resilience depends on diversified sourcing, disciplined cost management, and the ability to sustain certification continuity even as inputs and standards shift.
Actionable Recommendations for Decision-Makers
For manufacturers and product leaders, the priority is to treat certification and application engineering as growth enablers rather than support functions. That means maintaining current alignments with evolving fire safety codes, investing in testing capacity that supports rapid validation of new formulations, and building documentation frameworks that help specification teams justify selection. Companies should also consider targeted capacity and portfolio moves toward applications where circuit integrity and extreme-temperature performance command willingness to pay, especially in data centers, semiconductor facilities, and critical building infrastructure. The guiding question is whether the organization can reliably deliver certified performance into the projects that matter most, and whether its technical narrative is clear enough to win in specification committees.
For investors evaluating exposure to this segment, the key is to distinguish between volume-driven commodity exposure and value-driven compliance exposure. Businesses with strong certification portfolios, application-specific engineering capability, and relationships in high-specification building, transit, and energy markets are better positioned to sustain margins through raw material cycles and code changes. Capacity expansions that target fire-resistant LSZH and medium-voltage fire-resistant lines should be assessed against the durability of demand in the intended end-markets. Due diligence should emphasize the quality of testing and certification processes, the stability of key specification wins, and the company’s ability to adapt product offerings as standards evolve.
For procurement and specification teams, the strategic task is to embed fire performance evidence into early design decisions rather than treating compliance as a last-stage requirement. That includes comparing cable options on validated circuit integrity, smoke and toxicity behavior, and the currency of certification, not just on nominal specifications. Procurement strategies should give weight to suppliers that can demonstrate consistent batch-to-batch compliance, provide timely technical support during approval cycles, and maintain supply continuity for certified product. In environments where downtime costs are high, selecting cable based on documented extreme-temperature performance and circuit survival can reduce operational risk in ways that are not visible on a unit price comparison.
PW Consulting Chemical & Energy Research Center
In a market where regulatory momentum, application criticality, and material economics are reshaping competitive rules, timely access to detailed segmentation data, regional demand signals, and company-level benchmarking becomes a practical necessity. Decision-makers who need granular breakdowns by insulation material, application mix, regional dynamics, and competitor positioning will find that deeper intelligence directly supports portfolio planning, capacity allocation, and specification strategy. For those seeking a more complete view of the Flame Retardant Cable Market—including detailed segmentation data, regional trends, and customized strategic recommendations—PW Consulting’s full research report offers expanded analysis and targeted guidance to support concrete business decisions.
For detailed analysis of this topic, please visit the official page: Flame Retardant Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Rubber Conveyor Belt Market: Why the 4.05% CAGR Path from 2026–2032 Redefines Strategy
By PW Consulting, 2026-09-21
Rubber Conveyor Belt Market: Strategic Trends and Commercial Opportunities (2026–2032)
1. Market Snapshot and Core Challenges
The global rubber conveyor belt market has transitioned from a post-pandemic recovery phase into a period of measured, structurally driven growth. Revenue reached approximately 3.38 billion USD in 2025, expanding from 2.80 billion USD in 2020 at a compound annual growth rate of 4.05 percent. The forecast period through 2032 projects the market to approach 4.46 billion USD, with growth trajectories reflecting both steady baseline demand and periodic accelerations tied to heavy industrial capital cycles. This trajectory signals a market that is no longer defined by volatile rebounds but by operational efficiency imperatives, material handling scale-up, and the gradual replacement of aging infrastructure across mature and emerging economies.
Despite this constructive outlook, the industry faces intersecting challenges that will separate agile operators from stagnant incumbents. First, raw material price volatility and supply chain fragmentation continue to compress margins, particularly for manufacturers reliant on synthetic rubber, carbon black, and steel cord inputs. Second, the regulatory and operational push toward energy efficiency and emissions reduction is forcing end-users to reassess belt specifications, favoring longer-life, lower-friction solutions that carry higher upfront costs but deliver measurable total cost of ownership benefits. Third, market concentration remains pronounced, with the top three players holding roughly 45 percent share and the top five approaching 60 percent. This concentration creates a dual dynamic: established leaders benefit from scale, technical credibility, and service networks, while smaller producers face pressure to differentiate through niche applications, regional agility, or cost-optimized manufacturing footprints.
For executives and investors, the implication is clear. The market is not simply growing; it is restructuring around performance metrics, service intensity, and regional demand shifts. Strategy that ignores these structural forces risks exposure to commoditization, whereas strategy that aligns product portfolios, supply chain resilience, and customer-facing value propositions with the new operating reality can capture disproportionate share.
PW Consulting Chemical & Energy Research Center
2. Key Drivers Reshaping the Market
Technological Innovation and Material Performance
The most consequential driver is the ongoing evolution of reinforcement technology and compound engineering. Steel-cord reinforcement, for example, is forecast to post a 6.05 percent CAGR through 2031, outpacing broader market growth. This acceleration is not a statistical artifact; it reflects a practical shift in how operators design material handling systems. Steel-cord belts provide high tensile strength and low elongation, enabling longer single-flight conveyors that lower energy consumption and reduce maintenance frequency. As mining, cement, and bulk logistics operators seek to minimize downtime and energy intensity, the specification conversation is moving from "replace like-for-like" to "optimize system performance." This shift favors manufacturers with advanced carcass design capabilities, consistent quality control, and the technical service infrastructure to support engineered solutions rather than commodity replacement.
Beyond reinforcement, innovation in cover compounds, abrasion resistance, and heat or oil resistance is expanding the addressable use cases for rubber belts in environments previously dominated by alternative materials. The commercial reality is that value is migrating toward performance-justified pricing, where buyers accept higher unit costs in exchange for extended service life, fewer belt related stoppages, and reduced total energy consumption. Manufacturers that can quantify these benefits and supply evidence-backed specifications will command better margins and stronger customer retention.
Regulatory and Operational Pressure on Efficiency and Safety
Policy and regulatory trends are not acting as blunt constraints; they are reshaping procurement logic. Environmental and workplace safety expectations are increasing scrutiny on dust generation, spillage, and maintenance-related exposure in bulk handling facilities. Simultaneously, energy cost awareness is driving procurement teams to evaluate conveyor systems through a lifecycle lens. In this environment, belt selection becomes a strategic variable rather than a tactical purchase. Industry recognition patterns reflect this shift: ContiTech was named Best Conveyor Belt Supplier for the third consecutive time in Chile in October 2025, with additional recognition for belt cleaners. Such recurring validation in demanding operating environments signals that leading suppliers are being rewarded not merely for product availability but for reliability, local operational support, and complementary system solutions that reduce material carryback and maintenance burden.
For decision-makers, the operational takeaway is that compliance and efficiency are converging. Regulations and corporate sustainability goals are increasingly aligned with the same outcome: fewer failures, less energy waste, and lower exposure to operational risk. Suppliers that can position their offerings within this combined narrative gain access to procurement conversations that were previously locked behind price negotiations.
Demand-Side Shifts in Mining, Manufacturing, and Logistics
Demand is being reshaped by the differing growth rhythms of core application sectors. Mining continues to anchor market volume, supported by bulk material movement in extractives and the need to transport ore, coal, and aggregates across increasingly large site layouts. Manufacturing and logistics and warehousing are expanding on the back of throughput optimization, automation compatibility, and the need for dependable internal material movement in high-lot operations. What unites these segments is a declining tolerance for unplanned downtime and a growing willingness to invest in belts that integrate cleanly with broader conveyor system design.
A notable demand-side change is the shift from reactive replacement to planned lifecycle management. Operators are increasingly aligning belt procurement with maintenance scheduling, conveyor redesign, and site expansion plans. This creates opportunities for suppliers that can offer application engineering, installation guidance, and failure analysis as part of the value proposition. It also raises the barrier for pure price-based competition, because buyers are comparing packages rather than unit prices alone.
Supply Chain and Cost Structure Evolution
Cost structures are being recalibrated by input volatility, logistics complexity, and the strategic reorganization of manufacturing footprints. In response, leading companies are pursuing consolidation of production assets, selective localization, and tighter control over critical inputs. Yokohama Rubber’s consolidation of its conveyor belt subsidiary in China illustrates this direction. The move was designed to further stabilize earnings under its Yokohama Transformation 2026 medium-term plan, reflecting a broader tendency to rationalize regional operations where scale, coordination, and margin stability can be improved. Rather than expanding everywhere, mature players are prioritizing operational coherence and earnings predictability.
At the same time, the supply base is being tested by the need to balance cost competitiveness with specification integrity. Lower-cost production can win short-term procurement rounds, but inconsistent quality creates hidden costs in the field. The market is therefore developing a clearer hierarchy: premium engineered belts for demanding applications, cost-competitive belts for less severe service, and a growing expectation that suppliers clearly differentiate these tiers rather than blur them. The companies that manage this tiering transparently will be better positioned to defend margins while retaining volume.
Heavy Duty Conveyor Belts Market
3. Competitive Landscape and Leading Strategies
Structural Positioning of Core Players
The competitive set reflects a blend of specialized European technology suppliers, large international rubber producers, and increasingly capable Asian manufacturers serving both domestic and export markets. SIG S.p.A. operates as a specialized manufacturer of rubber conveyor belts and elevator belts with textile and steel carcass construction for bulk material handling, positioning itself around application specificity and carcass expertise. ContiTech leverages its broader industrial rubber and materials handling heritage to supply energy-efficient and heavy-duty models for industrial, mining, and materials handling applications, with an emphasis on system-level performance and recognized field reliability.
In China, Zhejiang Double Arrow Rubber Co., Ltd. stands out as a leading producer of fabric, steel cord, solid woven, aramid, and specialized rubber conveyor belts, supported by global sales and ISO certifications. Qingdao Rubber Six Conveyor Belt Co., Ltd. similarly manufactures fabric, steel cord, and heavy-duty rubber conveyor belts under the Rubber Six and Zhonghua brands, reflecting the scale and range available within the Chinese supply base. On the Japan-linked side, The Yokohama Rubber Co., Ltd. manufactures rubber conveyor belts through its wholly owned subsidiary Shandong Yokohama Rubber Industrial Products Co., Ltd., while Bando Chemical Industries, Ltd. supplies conveyor belts and related rubber products for industrial power transmission and materials handling. Fenner Dunlop Conveyor Belting rounds out the landscape with durable rubber and PVC conveyor belts for mining, industrial, and heavy-duty applications, distributed across EMEA and the Americas.
These profiles matter because they reveal two competing axes of advantage. One axis is application depth: companies that emphasize carcass technology, cover compound engineering, and technically supported solutions. The other axis is reach and cost orchestration: companies that combine broad product ranges, certifications, and multi-region distribution with disciplined manufacturing. The strongest players increasingly operate along both axes by offering tiered portfolios, credible technical service, and recognizable reliability in demanding markets.
Differentiation and Strategic Themes
Several strategic themes differentiate the leaders from the rest of the field. First, engineered solution selling is becoming a margin defense mechanism. Suppliers that can size belts to conveyor geometry, material characteristics, and throughput targets reduce the likelihood of under-specification and over-specification, both of which create friction in procurement and maintenance. Second, recognition and repeatability in difficult operating environments build a form of credibility that is hard for new entrants to replicate quickly. Recurrent awards or customer validations in high-stress regions indicate that a supplier’s products and support infrastructure perform under real conditions, not just in specification sheets.
Third, organizational consolidation is becoming a strategic lever. Yokohama Rubber’s subsidiary consolidation in China demonstrates how companies can seek earnings stability and operational focus rather than pursuing undifferentiated geographic expansion. This pattern suggests that future competition will not only be about who has the broadest footprint, but about who manages its footprint with the greatest coherence, quality consistency, and capital discipline. Fourth, complementary system components are gaining attention. Belt cleaners and related accessories are increasingly part of the commercial conversation because they reduce carryback, improve cleanliness, and lower maintenance effort. Recognition of belt cleaner performance alongside belt supply signals a market that is progressively valuing integrated material handling outcomes.
Market Evolution: Consolidation, Fragmentation, and Entry Dynamics
The market is likely to evolve through selective consolidation among scale players seeking margin stability and operational efficiency, alongside continued fragmentation in regional and niche segments where local service, cost positioning, or specialized applications matter. New entry remains possible, but the barriers are rising in the premium engineered segment, where performance history, testing capability, and customer trust compound over time. In the value segment, entry and competition remain more fluid, though price competition alone is increasingly risky as buyers become more aware of lifecycle costs and specification sensitivity.
For manufacturers and investors, the strategic question is where competitive advantage is being created and preserved. In demanding mining and heavy industrial applications, advantage is being built through technical reliability, long-life designs, and service density. In broader industrial and logistics applications, advantage is increasingly tied to consistent quality, predictable delivery, and clear segmentation between duty levels. The companies that can articulate and deliver these distinctions will be better placed to sustain pricing power and customer loyalty.
4. Future Trends and Commercial Implications
Over the next three to five years, three trends are likely to shape commercial outcomes. The first is the continued shift toward steel-cord and high-performance reinforcement in applications where conveyor length, load intensity, and energy efficiency justify the specification. With steel-cord belts forecast to grow at a 6.05 percent CAGR through 2031, the commercial opportunity lies in application engineering, lifecycle justification, and service support that helps operators realize the intended efficiency gains. The revenue opportunity is not simply in selling more belts; it is in aligning product selection with system-level performance so that higher specification becomes a defensible investment rather than a premium price objection.
The second trend is the growing importance of recognized reliability and localized support in key operating regions. Recurring supplier recognition in challenging environments suggests that buyers increasingly value proof of performance and responsive service over generalized brand claims. This creates commercial opportunities for manufacturers that invest in regional technical presence, failure analysis capability, and fast response to field issues. It also raises the stakes for suppliers that depend on remote selling without sufficient local problem-solving capacity, because trust in demanding applications is difficult to build and easy to lose.
The third trend is the rationalization of manufacturing and service footprints around earnings stability and cost discipline. As seen in recent corporate moves to consolidate subsidiaries and focus on medium-term transformation plans, companies are likely to favor operational clarity over unchecked expansion. For buyers and investors, this can translate into more predictable supply, clearer product segmentation, and potentially stronger supplier commitment to quality and service in core markets. For exporters and smaller regional players, the implication is that scale, certification, and consistent execution will matter more than before, especially where buyers are under pressure to reduce total cost of ownership without sacrificing reliability.
Potential risks and uncertainties should be monitored closely. Raw material swings can undermine margin plans even when demand is healthy. Over-investment in heavy industrial capacity during cyclical upswings can create exposure if mining or cement activity soften. Regulatory and sustainability expectations may accelerate specification upgrades, which is favorable for premium suppliers but challenging for cost-focused operators with limited engineering support. Finally, the line between rubber and alternative belt materials in some applications may narrow if competing technologies improve on cost, weight, or maintenance characteristics. Competitive strategy will therefore require continuous reassessment of where rubber belts hold a durable advantage and where substitution risk is rising.
5. Strategic Actions for Decision-Makers
For Manufacturers and Suppliers
Develop a clearly segmented portfolio that separates engineered high-performance solutions from cost-competitive standard offerings, with transparent differentiation in duty, reinforcement, and expected service life. Build the technical service capability needed to justify higher specifications through application engineering, lifecycle analysis, and field failure insights. Prioritize operational coherence in key regions, focusing on quality consistency, delivery reliability, and recognized performance in demanding environments rather than pursuing growth that dilutes margin or control. Where complementary system components such as belt cleaners are relevant, evaluate whether bundling or coordinated solution selling can strengthen customer retention and differentiate from pure product suppliers.
For Investors
Assess exposure not only to top-line market growth, but to the structural forces that determine margin quality: reinforcement mix, application intensity, regional service density, and the ability to defend price through performance justification. Companies with disciplined manufacturing consolidation, credible field recognition, and a defensible position in steel-cord or other faster-growing reinforcement types are better aligned with the market’s direction than generic volume players. Monitor for cyclical risk in mining-anchored demand and for substitution pressure in less severe applications, and weigh these against the durability of engineering-led differentiation and regional reputation.
For Procurement and Operations Leaders
Shift evaluation criteria from unit price to total cost of ownership, incorporating energy efficiency, expected service life, downtime reduction, and maintenance burden. Use specification as a strategic lever: select belt types that match material characteristics and conveyor geometry, and request evidence-backed performance data rather than accepting generic claims. Strengthen supplier relationships where local support, failure analysis, and rapid response are available, because these capabilities increasingly determine operational resilience. Where possible, align belt procurement with planned maintenance and conveyor optimization programs to capture the full value of higher-specification solutions.
Conveyor Belts Market
For decision-makers seeking a deeper, segment-level view of growth trajectories, regional demand dynamics, duty-level breakdowns, and company-level strategic positioning, the full market research report provides the additional granularity needed to translate these trends into customized action plans. The broader market trajectory is clear; the practical advantage lies in the details that connect product strategy, sourcing decisions, and capital allocation to the operating realities shaping the next phase of demand.
For detailed analysis of this topic, please visit the official page: Rubber Conveyor Belt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Wire Enamels Market: Strategic Trends and Commercial Opportunities Through 2032
The global Wire Enamels Market has entered a phase of structural expansion, defined by steady revenue growth, technological differentiation, and shifting demand patterns across industrial and transportation sectors. From a baseline of approximately 952.5 million USD in 2020, the market scaled to 1287.75 million USD in 2025, reflecting an annualized growth trajectory that positions the segment for continued uplift. Projections for the forecast period spanning 2026 through 2032 indicate revenue will advance toward 2032.1 million USD by the end of the horizon, underpinned by a compound annual growth rate of 6.8 percent. The 2020 to 2025 historical window captured the market’s recovery from supply chain disruptions, followed by a demand rebound driven by motor manufacturing, transformer replacements, and the accelerating adoption of electric drivetrains. As the industry moves into the mid-to-late 2020s, the growth curve is no longer solely dependent on volume expansion; it is increasingly shaped by formulation performance, regulatory compliance, and regional capacity realignment. For executives and investors evaluating exposure to industrial coatings and electrical insulation materials, the market presents a structurally favorable environment, but one that requires disciplined positioning to navigate raw material volatility, evolving compliance mandates, and intensifying product differentiation.
Despite the positive macro trajectory, the industry is confronting a set of inflection points that will determine which participants capture disproportionate value over the next several years. The first challenge lies in balancing performance requirements with cost control. End-users in motors and automotive components increasingly demand insulation systems that withstand higher operating temperatures, improved thermal dissipation, and extended service life, while simultaneously pressuring suppliers for more predictable pricing. This tension is amplified by the second challenge: raw material cost dynamics. Fluctuations in resin feedstocks, pigment supplies, and specialty chemical intermediates have repeatedly raised production expenses across the value chain, prompting manufacturers to reassess procurement strategies and pricing architectures. The third challenge involves the regulatory environment. Stringent environmental standards on solvent-based formulations are accelerating the transition toward low-VOC and solvent-free solutions, forcing incumbents and new entrants alike to invest in reformulation, testing, and compliance documentation. Together, these forces are reshaping competitive benchmarks. Companies that can integrate advanced polymer chemistry, stabilize input costs through strategic sourcing, and align product portfolios with regulatory and performance expectations are best positioned to convert market growth into durable margin expansion.
Technological Innovation and Formulation Breakthroughs
Product innovation is becoming a primary vector of differentiation in the Wire Enamels Market, with advances centered on hybrid architectures, thermal stability, and application-specific reliability. Organic-inorganic hybrid polyamide-imide formulations have emerged as a notable development, offering enhanced insulation performance for high-demand electrical systems where thermal endurance and mechanical resilience are critical. These hybrid systems are particularly relevant for electric vehicle powertrains, wind turbine generators, and other high-performance electrical applications that push conventional enamel limits. Parallel progress in polyesterimide and polyamide-imide chemistries is enabling manufacturers to deliver tailored solutions for magnet wire coatings, allowing winding producers to optimize balance between dielectric strength, flexibility, and cure characteristics. The shift toward formulation precision is also supported by improved process control and closer collaboration between enamel suppliers and winding wire manufacturers. Rather than treating enamels as commodity coatings, leading participants are positioning them as engineered components within larger motor and transformer designs. This approach creates room for premium positioning, especially where customers seek to reduce failure rates, improve energy efficiency, or extend maintenance intervals. Innovation is therefore not only a technical storyline; it is a commercial strategy that links material performance directly to end-product value.
Policy and Regulatory Pressures Reshaping Formulation Paths
Regulatory momentum is exerting a powerful influence on product design and manufacturing choices. Environmental requirements targeting solvent-based wire enamels are encouraging a broader migration toward sustainable low-VOC solutions and solvent-free systems. This transition is not simply a compliance exercise; it affects formulation stability, application behavior, curing requirements, and downstream processing compatibility. Manufacturers must therefore coordinate changes in chemistry with customer production environments to ensure that new coatings perform reliably under real-world winding and impregnation conditions. In parallel, regulatory scrutiny around emissions, workplace safety, and chemical handling is increasing the importance of documentation, testing protocols, and transparent supply chain practices. Companies that proactively align their portfolios with evolving standards can reduce the risk of retrofit costs, specification changes, and market access delays. Conversely, late adaptation can leave suppliers exposed to customer qualification bottlenecks and regional compliance mismatches. The regulatory trajectory also intersects with customer expectations for sustainability, meaning that environmental performance is increasingly part of the purchasing rationale rather than a separate administrative issue.
Demand-Side Shifts in Motors, Automotive, and Electrical Equipment
Demand behavior is changing as end-use sectors reassess performance, reliability, and electrification goals. Motors remain the dominant demand anchor, reflecting their pervasive role in industrial machinery, HVAC systems, and increasingly efficient electric drives. Automotive components represent another high-growth demand center, where the expansion of electrified powertrains and the need for robust motor windings are elevating the importance of high-performance insulation materials. Beyond these segments, transformers and industrial equipment continue to contribute meaningfully, supported by grid infrastructure upgrades, industrial automation, and replacement cycles for aging equipment. Home appliances and other smaller-scale applications add breadth to the demand base, though they typically place different emphasis on cost and processing convenience versus extreme thermal or mechanical performance. A key demand-side trend is the growing preference for enamel solutions that can support higher efficiency and reliability without compromising manufacturability. This is prompting closer specification alignment between enamel suppliers and winding producers, as well as more rigorous qualification processes for new formulations. The commercial implication is clear: demand growth is increasingly tied to applications where insulation performance directly affects system outcomes, giving advanced products a stronger value proposition than in lower-specification settings.
Supply Chain Reconfiguration and Cost Structure Dynamics
Cost structure dynamics remain a central factor shaping competitiveness. Volatility in raw material inputs, including resin and pigment pricing, has increased production expenses and complicated margin planning for producers. This environment is encouraging more active procurement strategies, such as multi-source sourcing, long-term supply arrangements, and formulation adjustments that reduce exposure to volatile intermediates without sacrificing performance. Capacity decisions are also being revisited in response to regional demand patterns and cost considerations. Investments in production footprint expansion are being directed toward locations where demand growth is strongest and where manufacturers can better serve local winding wire producers and component manufacturers. At the same time, pricing actions are becoming more selective, with increases tied to specific chemical families and market conditions rather than applied uniformly across all products. These adjustments reflect a broader move toward disciplined portfolio management, where profitability depends on aligning cost recovery with value delivered in each application segment. Supply chain resilience is therefore not just a logistics concern; it is a strategic differentiator that affects pricing credibility, delivery reliability, and the ability to scale advanced formulations.
PW Consulting Chemical & Energy Research Center
Competitive Dynamics and Strategic Positioning
The competitive landscape features a mix of specialty coating manufacturers, large materials companies, and integrated wire and coating suppliers, with no single dominance pattern across all regions or application segments. Market concentration remains moderate, with the top three participants holding a combined share in the mid-twenties and the top five only slightly higher, indicating that differentiation, regional presence, and application-specific expertise still matter greatly. This fragmented-but-specialized structure creates opportunities for companies that can combine formulation strength with strong customer proximity and technical service capabilities. Several leading participants are pursuing distinct strategic angles. One established European-focused manufacturer has built a broad portfolio of high-performance enamels for magnet wire coatings, emphasizing global production sites and custom solutions for motors and electric vehicles. This provider has also taken steps to expand capacity in southern China to align supply with rising regional demand, while implementing selective price adjustments across major chemical families to reflect changing market conditions. Another major coatings company has advanced hybrid polyamide-imide solutions, including a recent launch of an organic-inorganic hybrid wire enamel recognized for its relevance to electric vehicles, wind turbines, and high-performance electrical systems. That product momentum signals a deliberate push into segments where insulation reliability is a critical purchasing criterion. A large U.S.-based materials company has supported its polyesterimide offering through capacity-related expansion tied to an acquisition, reinforcing its ability to supply electric vehicle and industrial motor applications. A Japanese specialist has focused on high-efficiency insulation materials developed in collaboration with electric vehicle component producers, illustrating the value of application-side partnerships in refining product fit. In parallel, an integrated wire and coating supplier serves winding wire manufacturers with enameled wire and enamel offerings, while another global materials producer provides resins and coating inputs that support high-temperature and motor applications. These varied strategies highlight a market where value capture depends on combining chemistry, capacity, and customer-facing engineering rather than competing on price alone.
Market Evolution Toward Integration, Differentiation, and Targeted Entry
The market structure is evolving along several directions at once. Consolidation pressure exists in regions where scale, regulatory compliance, and technical service requirements raise the barrier to effective competition, yet the moderate concentration levels suggest that specialization and regional strength remain viable paths. Differentiation is intensifying around performance classes, with high-performance polyesterimide, polyamide-imide, and hybrid formulations attracting greater attention than lower-specification alternatives in demanding applications. This creates a two-layer competitive environment: one where commodity-adjacent products compete on cost and supply reliability, and another where engineered coatings compete on thermal endurance, dielectric robustness, and application fit. New entry and expansion activity is likely to remain selective, favoring participants with existing chemical expertise, production know-how, and customer relationships in motors, transformers, or automotive components. At the same time, capacity additions are being shaped by regional demand centers, especially where electrification and industrial modernization are accelerating. The overall trend is toward a more segmented market in which success depends on matching product architecture to application requirements, maintaining dependable supply, and adapting to regulatory change without losing commercial momentum.
Outlook: Three Structural Trends Shaping 2026 to 2032
The next several years are likely to be defined by three reinforcing trends. First, high-performance and hybrid enamel formulations will continue to gain share in demanding applications as electric vehicle motors, wind power equipment, and advanced industrial drives push insulation requirements higher. This trend favors suppliers that can demonstrate measurable improvements in thermal resistance, reliability, and process compatibility, and it creates opportunities for premium pricing where performance outcomes are clearly valued by customers. Second, sustainability-driven reformulation and regulatory compliance will become standard elements of competitive capability rather than occasional initiatives. Low-VOC and solvent-free directions will increasingly influence specification decisions, procurement criteria, and regional market access, making formulation agility and compliance readiness a durable advantage. Third, regional capacity alignment will grow in importance as manufacturers seek to serve local demand more efficiently and reduce exposure to input cost disruptions and logistics constraints. Together, these trends suggest a market where growth is not uniform across products or geographies, but is concentrated in segments where performance, compliance, and supply reliability converge. The commercial opportunity lies in identifying those convergence points early and building the technical and operational capabilities required to serve them consistently.
Worldwide Retangular Enameled Wire Market
These trends also carry risks that warrant careful monitoring. Raw material volatility can compress margins if pricing mechanisms lag cost movements, especially in periods when resin and pigment inputs fluctuate sharply. Regulatory changes may outpace reformulation timelines, creating qualification gaps or regional mismatches that slow adoption of new products. Demand intensity can also vary by segment, with electrification-related applications potentially experiencing cyclical or project-driven swings that affect planning accuracy. Additionally, capacity expansion in high-growth regions may intensify competition if multiple suppliers pursue the same demand pockets simultaneously, placing pressure on both pricing and customer qualification cycles. Managing these uncertainties will require scenario-aware sourcing, disciplined product roadmaps, and close engagement with downstream customers to anticipate specification shifts before they become disruptive.
Strategic Actions for Different Decision-Maker Profiles
For manufacturers and product leaders, the priority is to sharpen formulation strategy around the applications that most value performance differentiation. This means investing in hybrid and high-temperature systems where insulation reliability translates into customer benefits, while maintaining a cost-competitive baseline for lower-specification segments. Equally important is building technical service capabilities that help winding wire producers and motor manufacturers integrate new enamels efficiently, since adoption often depends on processing compatibility and qualification support as much as on material properties. For investors and corporate development teams, the focal point should be the intersection of electrification-driven demand, regulatory-driven reformulation, and regional capacity shifts. Opportunities are likely to be strongest where suppliers can demonstrate both product leadership and supply resilience, especially in motors and automotive components. Evaluating exposure should therefore go beyond headline growth figures to include portfolio mix, pricing discipline, compliance readiness, and regional manufacturing alignment. For procurement and sourcing leaders, the practical goal is to balance performance, cost, and continuity risk by diversifying supply where possible, aligning specifications with sustainability and reliability requirements, and monitoring input cost trends that may affect pricing stability. Long-term supply agreements and early engagement on reformulation transitions can help reduce disruption risk while preserving access to advanced insulation materials.
The Wire Enamels Market is moving from steady growth toward a more performance-sensitive and regulation-shaped competitive environment. The companies that capture the most value will be those that align product architecture with demand intensity, operate with resilient cost structures, and respond quickly to compliance and application changes. For decision-makers seeking deeper segmentation detail, regional demand patterns, and customized scenario planning, the full PW Consulting research report provides the additional data and structured analysis needed to translate these strategic themes into precise commercial decisions.
Enameled Wire Market
For detailed analysis of this topic, please visit the official page: Wire Enamels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Composite Insulators Market: Why 6.98% CAGR Redefines 2032 Revenue Trajectory
By PW Consulting, 2026-09-21
Composite Insulators Market: Strategic Trends and Commercial Opportunities Through 2032
The composite insulators market has transitioned from a niche alternative to a mainstream component in high-voltage infrastructure, reflecting a structural shift in how utilities and OEMs approach reliability, weight, and maintenance economics. Valued at approximately 215.0 million USD in 2025 and projected to reach 344.8 million USD by 2032, the market follows a compound annual growth rate of 6.98 percent across the 2026–2032 forecast window. Growth from 163.15 million USD in 2020 to 215.0 million USD in 2025 illustrates a steady expansion trajectory, with momentum accelerating through the end of the decade. This trajectory is not simply volume-driven; it signals a maturing value proposition where polymer-based designs are increasingly selected for their durability in harsh environments, reduced creepage requirements, and compatibility with modular grid architectures.
Behind the headline numbers lies a market that is gaining confidence but not without friction. The sector is navigating raw material volatility, evolving certification expectations, and a competitive landscape that is consolidating around firms with differentiated manufacturing depth. For executives and investors, the question is no longer whether composite insulators will capture additional share, but where the highest-margin segments will form, which capabilities will separate winners from commoditized producers, and how supply chain and regulatory dynamics will shape returns over the next five years.
A Market at an Inflection Point
The current landscape is defined by three intersecting pressures that are reshaping strategy across the value chain. First, cost structures are increasingly sensitive to input price swings, particularly in resin and fiberglass, which directly influence pultrusion economics and margin stability. Second, international standards are tightening, raising the bar for sheath integrity, interface quality, and long-term performance validation. Third, the supplier base is undergoing selective consolidation, with larger multinational groups acquiring specialized production assets to secure technology, capacity, and certification portfolios. These forces are not isolated; together they are increasing the importance of process integration, quality assurance, and regional compliance readiness.
For market participants, the practical implication is that scale alone is no longer a sufficient advantage. Competitors that can control core manufacturing steps, align product designs with updated standards, and demonstrate consistent performance in demanding applications are better positioned to defend pricing and win long-term utility contracts. Firms that remain dependent on fragmented sourcing or minimal differentiation face greater exposure to price competition and specification-driven disqualification.
Core Drivers Reshaping Demand and Supply
Several structural drivers are underpinning the market’s expansion, and each carries distinct implications for product strategy and commercial positioning.
Technological innovation continues to broaden the applicability of composite insulators. Advances in silicone rubber formulations and hollow-core engineering are enabling lighter, more hydrophobic solutions that perform well in polluted or high-humidity environments. The release of new high-consistency silicone rubber for composite insulator production illustrates how material innovation is opening design space for manufacturers, especially where traditional porcelain or glass solutions carry weight, breakage, or maintenance penalties. At the same time, process technologies that improve interface quality and sheath uniformity are becoming more important as standards raise minimum performance thresholds.
Policy and regulatory evolution is sharpening the focus on compliance and interoperability. Updated frameworks such as IEC 61109 Edition 3.0 and EN IEC 62217:2025 are reinforcing expectations around sheath thickness, interface quality, and defined performance classes for polymeric high-voltage insulators. These revisions do more than set technical baselines; they reduce ambiguity for specifiers and create a more uniform path for manufacturers seeking to serve multiple regions. In practice, this is encouraging producers to invest in certification readiness and to design families of products that can be validated across transmission, substation, and distribution contexts.
Demand-side behavior is also changing. Utilities and industrial operators increasingly favor solutions that reduce footprint, simplify installation, and lower long-term maintenance burden. Composite insulators are gaining traction where their mechanical resilience and corrosion resistance translate into lower lifecycle risk, especially in remote corridors, coastal settings, or regions with aggressive atmospheric contamination. At the same time, the broader push toward grid modernization and expanded transmission capacity is lifting volumes across both overhead lines and substation equipment, broadening the addressable base beyond traditional replacement cycles.
PW Consulting Chemical & Energy Research Center
Supply chain and cost dynamics remain a critical variable. Pultruded fiberglass profiles for composite insulator cores generally cost between 5 and 15 USD per linear foot, or roughly 2 to 10 USD per pound depending on resin selection and customization. This range underscores how sensitive production economics are to glass fiber and resin pricing, and why manufacturers with integrated processes or disciplined procurement strategies can achieve more stable margins. When raw material prices fluctuate, the impact is not limited to input cost; it ripples through lead times, quotation reliability, and the ability to scale capacity without eroding unit economics.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of technologically specialized manufacturers, regionally concentrated producers, and multinational groups pursuing targeted expansion. Market concentration remains moderate, with the top three firms holding approximately 24.6 percent and the top five about 26.2 percent of the market. This fragmentation suggests room for both differentiation and consolidation, depending on the segment and geography.
Worldwide Low Voltage Insulators Market
Leading players are pursuing distinct strategic positions. Some manufacturers emphasize full vertical integration in hollow composite insulator production, building end-to-end control over core fabrication, housing, and final assembly. This model is particularly valuable where OEMs and utilities prioritize traceability, repeatability, and the ability to offer alternative gas or insulation options. Others compete on breadth of product families, covering suspension, line post, pin, tension, and bushing types across transmission, substation, and distribution networks. That breadth can be a strong commercial advantage when specifiers want a single source for multiple asset classes, especially in large-scale grid build-outs.
A third strategic theme is technology-led specialization. Certain producers focus on epoxy-resin glass fiber cylinders and high-temperature injection or advanced molding technologies that target substation and line applications requiring precise mechanical and electrical performance. These capabilities can support premium positioning when paired with rigorous qualification data and strong service networks. In parallel, manufacturers active in Asia and India continue to expand capacity and export reach, often competing on combination of cost, scale, and growing technical credibility. Their growth reflects both domestic demand and the broader international search for reliable supply alternatives.
Recent industry developments offer a clear window into how the landscape is evolving. The introduction of new silicone rubber materials for composite insulator production highlights the ongoing push to improve material consistency and processing efficiency. Meanwhile, corporate moves such as the acquisition of composite insulator production facilities by a larger group, including machinery and intellectual property, point to a strategy of securing specialized manufacturing assets and expanding capacity in established industrial regions. This kind of transaction suggests that controls over core processes, proprietary know-how, and certified production lines are becoming strategic assets rather than mere operational inputs.
Trade show participation and regional exhibition activity also indicate where companies are concentrating commercial effort. Exhibiting advanced high-voltage composite insulators at international grid equipment events and utility-focused conferences signals a continued emphasis on face-to-face specification engagement, particularly in markets where project pipelines are active and relationships with utilities, contractors, and system integrators matter.
Taken together, the competitive picture suggests three unfolding dynamics. First, differentiation is shifting toward process depth, materials expertise, and certification readiness rather than catalog breadth alone. Second, consolidation is likely to continue in pockets where complementary technologies, regional access, or specialized production assets create clear value. Third, new entrants and expanding regional manufacturers will keep pressure on pricing in commodity-adjacent segments, while more engineered applications remain open to firms with strong technical validation and application support.
Forward Outlook: Trends and Commercial Implications
Over the next three to five years, the market is likely to be shaped by the intersection of materials progress, standards-driven specification clarity, and selective consolidation. The first trend is the continued migration of composite insulators into higher-value applications where performance under stress, weight reduction, and maintenance savings justify the choice over traditional alternatives. This shift will not be uniform; it will concentrate in environments where contamination, humidity, vibration, or access limitations make polymer-based designs especially advantageous.
Composite Insulated Panels Market
The second trend is the growing importance of compliance as a commercial differentiator. As updated standards raise expectations for sheath quality, interface integrity, and consistent high-voltage performance, manufacturers that can demonstrate robust qualification processes and repeatable production control will gain an advantage in tender evaluations and OEM supply agreements. Certification readiness is becoming less of a back-office function and more of a market-access requirement, particularly for suppliers targeting multiple regions or working with large multinational buyers.
The third trend is the continued realignment of manufacturing capacity and ownership. Strategic acquisitions and capacity expansions in established production hubs indicate that scale, technology control, and localized capability will matter more as customers seek reliable supply and shorter qualification cycles. At the same time, raw material sensitivity will keep cost discipline and formulation flexibility in focus, especially where resin and fiberglass pricing can compress margins or disrupt quoting.
These trends create concrete commercial opportunities. There is room for product strategies that pair material consistency with application-specific design, enabling suppliers to serve both transmission and substation segments without diluting manufacturing focus. There is also opportunity in regional expansion where grid investment is accelerating and where localized support, certification alignment, and service responsiveness can outweigh pure price competition. For buyers, the opportunity lies in reducing lifecycle risk through more predictable performance and in consolidating the supplier base where quality assurance and technical support can be managed more efficiently.
Risks and uncertainties remain. Raw material volatility can quickly alter cost assumptions and erode the economics of capacity expansions if not managed with hedging, formulation options, or process efficiencies. Regulatory updates, while beneficial in the long run, can impose rework, retesting, or redesign costs if product families are not aligned early. In addition, intensified competition in volume-oriented segments may pressure margins even as premium segments expand, creating a bifurcated market where profitability depends heavily on positioning and execution.
Strategic Implications for Decision Makers
Manufacturers should prioritize capabilities that convert technical advantage into commercial advantage. That means investing in process integration where it strengthens quality, consistency, and traceability; aligning product families with updated standards before specification cycles lock in; and building formulation and procurement flexibility to absorb raw material swings. Where possible, firms should also consider targeted expansion of engineered product lines rather than undifferentiated catalog growth, since higher-value applications are likely to reward proven performance and application support more than breadth alone.
Investors should evaluate exposure not just to market growth but to the underlying drivers of margin durability. Capacity expansions, technology acquisitions, and regional entry decisions all look more attractive when paired with certification readiness, material expertise, and a clear route to utility or OEM demand. The most resilient opportunities are likely to emerge where operators can demonstrate control over critical production steps and where the customer base values reliability and lifecycle performance enough to support disciplined pricing.
Procurement and specification teams should treat composite insulator selection as a lifecycle decision rather than a unit-price comparison. Evaluating sheath quality, interface design, material consistency, certification status, and supplier process control can reduce installation risk and long-term maintenance exposure. Consolidating suppliers where supported by strong technical documentation and consistent qualification data may also improve procurement efficiency, especially across transmission, substation, and distribution programs with overlapping performance requirements.
Closing Perspective
The composite insulators market is entering a phase where growth is increasingly tied to technical credibility, standards alignment, and strategic control of manufacturing depth. The pathway from 215.0 million USD in 2025 to 344.8 million USD by 2032 will not be evenly distributed across every supplier or segment. Instead, value will accrue to participants that can combine material innovation, compliance readiness, and operational discipline with a clear focus on the applications where composite designs deliver the strongest economic and technical case. For organizations operating in or adjacent to this market, the most valuable next step is to map these shifts against specific product portfolios, regional pipelines, and procurement strategies, and to update assumptions as standards, materials, and ownership structures continue to evolve.
For detailed analysis of this topic, please visit the official page: Composite Insulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Wind Power Coating Market Surges 10.8% CAGR: What the Data Reveals About Real Drivers
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Wind Power Coating Market
The wind power coating market has reached an inflection point where material performance, regulatory pressure, and turbine scale converge to reshape competitive dynamics. Valued at approximately USD 1.54 billion in 2025, the market expanded from roughly USD 1.15 billion in 2020, reflecting a compound annual growth rate of 10.8 percent through 2032. This trajectory is not merely a function of turbine installation volumes; it signals a structural shift in how operators prioritize asset longevity, maintenance efficiency, and compliance with increasingly stringent environmental standards. For decision-makers, the market presents a clear mandate: coating systems are no longer commoditized afterthoughts but critical enablers of uptime, safety, and total cost of ownership.
Segmentation data underscores where value is concentrating. Polymer-based formulations continue to command the largest share, driven by their versatility in blade manufacturing and field repair applications. Ceramic and metal coatings occupy smaller but strategically important niches, particularly in high-temperature environments and structural corrosion protection. Onshore installations remain the dominant application channel, while offshore deployments are accelerating as projects move into deeper waters and more aggressive operating conditions. Understanding these structural realities is essential for positioning product portfolios, managing supply chain risk, and aligning R&D roadmaps with end-user expectations.
Operational Durability Meets Scale Expansion
One of the most pressing challenges facing the industry is the widening gap between turbine scale and coating durability. As rotor diameters increase and offshore sites expose assets to salt spray, ultraviolet radiation, and mechanical fatigue, traditional coating systems are being tested beyond their historical performance envelopes. Leading-edge erosion, micro-cracking, and delamination can compromise aerodynamic efficiency and force unplanned maintenance, which is especially costly in remote or marine environments. Operators are therefore demanding formulations that balance flexibility with abrasion resistance, while manufacturers face the pressure to reduce cure times and volatile organic compound emissions without sacrificing protection longevity.
A second challenge lies in navigating an evolving regulatory landscape. Regional frameworks targeting solvent-based chemistries and industrial emissions are progressively narrowing the formulation options available to coating producers. Compliance is no longer a static checkbox; it requires continuous reformulation, lifecycle assessment, and documentation that satisfies both manufacturing partners and end-users. This shift rewards companies that invest early in solvent-free or low-emission architectures, while penalizing those that treat regulatory adaptation as a reactive exercise.
A third structural challenge is raw material volatility. Petrochemical-linked inputs such as isocyanates, epoxy resins, and fluoropolymer intermediates have experienced unpredictable pricing and availability fluctuations. Because coating formulations often rely on precise resin blends and specialty additives, cost instability can compress margins and disrupt production scheduling. Companies that lack transparent supplier relationships or alternative material pathways are particularly exposed, making supply chain resilience a strategic priority rather than a back-office function.
Technology Innovation as a Performance Multiplier
Technological breakthroughs are redefining what coatings can deliver in wind turbine applications. Advanced polymer systems are increasingly engineered for faster in-mould curing, higher temperature tolerance, and improved adhesion under variable humidity conditions. These attributes directly translate into higher manufacturing throughput and reduced downtime during blade production. In parallel, elastomeric repair coatings are being reformulated to enable field-applied restoration of leading edges with significantly shorter application windows and enhanced resistance to rain erosion. Such innovations reduce the frequency of major interventions and help operators maintain power curve performance over longer inspection intervals.
Standardization is also accelerating the pace of innovation. New testing methodologies for ice adhesion and hail resistance are bringing greater rigor to coating qualification, particularly for sites in cold or high-storm-frequency regions. As these protocols mature, they create a clearer benchmark for performance claims and help procurement teams compare solutions on a more consistent basis. For coating suppliers, this environment favors those that invest in validated test data and can demonstrate repeatable results across multiple turbine platforms and operating conditions.
The practical implication for manufacturers and service providers is clear: performance differentiation is increasingly tied to quantifiable durability metrics rather than generic product claims. Companies that can show how a coating system performs under standardized erosion, corrosion, and environmental exposure tests will gain credibility with turbine OEMs and asset owners. This, in turn, shortens evaluation cycles and supports premium positioning in segments where failure costs are highest.
Policy and Regulatory Shifts Reshaping Formulation Choices
Policy signals are exerting a powerful influence on coating chemistry, application processes, and supplier selection. Directives targeting industrial emissions and chemical safety are progressively restricting solvent-based systems, steering the market toward high-solids, water-borne, and solvent-free alternatives. This transition is not uniform across regions, but the directional momentum is consistent: formulations that reduce emissions and simplify waste handling are gaining preference in both new-build and retrofit projects.
Worldwide Wind Turbine Blade Anti-Corrosion Coating Market
Corrosion protection standards for steel structures further shape purchasing behavior. Guidance frameworks that define protection system selection for tower and foundation assets encourage operators to specify coatings with documented service life expectations and compatible surface preparation requirements. In offshore contexts, where access for maintenance is expensive and weather-dependent, these specifications increasingly prioritize long-term protection over short-term cost savings. Suppliers that align their technical documentation with recognized standards can reduce friction in qualification processes and position their products as low-risk choices for engineering teams.
For businesses operating in or adjacent to the wind sector, these regulatory dynamics create both constraint and opportunity. Constraint comes from the need to reformulate, retest, and redesignated products to meet evolving requirements. Opportunity emerges for companies that can offer compliant systems without sacrificing application efficiency or durability. Early movers in solvent-free gelcoats, low-emission repair coatings, and standards-aligned corrosion packages are building moats that are difficult for late entrants to replicate quickly.
Demand-Side Shifts and Cost Structure Evolution
Demand-side behavior is changing as asset owners internalize the full lifecycle cost of coatings. Rather than selecting products based solely on unit price, operators are increasingly evaluating protection systems through the lens of maintenance frequency, blade performance retention, and repair logistics. Offshore projects, in particular, amplify this calculus because travel, weather windows, and specialized crew availability make downtime disproportionately expensive. As a result, coatings that extend inspection intervals or simplify field repairs are gaining traction even when their upfront cost is higher.
On the supply side, cost structures are being reshaped by material volatility, energy inputs, and logistics complexity. Petrochemical-derived intermediates remain central to many high-performance formulations, and their pricing sensitivity introduces unpredictability into both production planning and final pricing. At the same time, the push toward faster curing and lower-emission processes is altering energy and consumable requirements at manufacturing sites. Companies that diversify supplier bases, secure long-term feedstock agreements, or develop hybrid formulations with more stable input profiles are better positioned to protect margins through cyclical disruptions.
A notable demand signal is the growing emphasis on repairability. Leading-edge protection and blade restoration systems are attracting attention because they directly address one of the most common degradation modes in operational turbines. Products that enable faster on-site repair, broader application conditions, and improved erosion resistance reduce the total cost of ownership for operators and create recurring revenue streams for coating suppliers and service partners. This shift is expanding the market beyond initial manufacturing coatings into a more service-intensive, maintenance-driven value chain.
Competitive Positioning and Strategic Differentiation
The competitive landscape features a mix of global coating specialists, resin producers, and niche providers focused on blade repair and protection. Leading players are distinguishing themselves through combinations of application expertise, technical documentation, and regionally tailored service networks. One common differentiator is the ability to supply integrated systems that cover both manufacturing-stage protection and in-service maintenance, reducing the number of vendors an operator must manage across a turbine’s lifecycle.
Several companies have built strong associations with blade coatings and repair technologies, where performance claims around leading-edge protection, rain erosion resistance, and cure speed are closely scrutinized. Others emphasize corrosion protection for steel structures, towers, and foundations, aligning their portfolios with recognized corrosion guidance and offshore durability requirements. Resin and polymer suppliers occupy a critical upstream position by controlling key formulation inputs, giving them influence over the performance characteristics that downstream coating makers can deliver.
Recent product activity illustrates how competition is intensifying around application efficiency and compliance. One major coatings provider introduced a fast-curing, solvent-free epoxy in-mould gelcoat designed to support higher temperature applications and accelerate blade production cycles. A separate technical data sheet for the same system reinforced the emphasis on controlled processing and manufacturing optimization. In the repair segment, another specialist launched an improved white version of a leading-edge repair coating, engineered to deliver significantly faster application while enhancing rain erosion resistance and widening the usable application window. These moves reflect a broader industry push to reduce downtime, improve throughput, and meet stricter environmental expectations without compromising protection.
PW Consulting Chemical & Energy Research Center
The market is also showing signs of consolidation and specialization occurring simultaneously. Larger groups are leveraging scale to standardize core technologies across regions, while smaller firms are carving out niches in repair, leading-edge protection, or regional service delivery. New entrants face a high bar because qualification cycles are lengthy, performance data is increasingly standardized, and asset owners prefer suppliers with proven field track records. As a result, successful differentiation tends to come from deep application know-how, validated test results, and the ability to support customers through both manufacturing and operational phases.
Future Outlook: Three Trends Shaping the Next Three to Five Years
The first trend is the acceleration of solvent-free and low-emission coating architectures across both manufacturing and maintenance applications. As regulatory pressure and customer sustainability expectations continue to build, formulations that reduce volatile emissions and simplify handling will become the default choice in many projects. This trend will favor companies with established R&D pipelines in high-performance, low-emission chemistries and those that can demonstrate equivalent or superior durability relative to legacy solvent-based systems.
The second trend is the increasing importance of standardized durability testing as a commercial filter. With maturing protocols for ice adhesion, hail resistance, and corrosion system selection, procurement teams will rely more heavily on comparable performance data when shortlisting suppliers. This will reward firms that invest in robust testing programs and transparent documentation, while raising the cost of entry for players that cannot substantiate performance claims under recognized methods. Over time, this dynamic will likely concentrate share among suppliers that can consistently meet or exceed benchmark expectations.
The third trend is the expansion of service-linked coating business models. As operators seek to reduce maintenance frequency and protect power output, coatings that enable faster repairs and longer protection intervals will create recurring engagement opportunities. Expect more partnerships between coating suppliers, blade service providers, and turbine operators to co-develop repair protocols, train field teams, and optimize application conditions. This service dimension will make coatings a more integrated part of asset management strategies rather than a one-time purchase at commissioning.
Special Epoxy Resin for Wind Power Blades Market
Potential risks remain. Raw material price swings could compress margins if companies cannot adjust formulations or lock in feedstock stability. Regulatory divergence across regions may complicate product launches and require multiple formulation variants, increasing cost and time-to-market. In addition, if standardization efforts outpace the availability of validated products, qualification delays could slow adoption of advanced systems. Businesses should treat these risks as design parameters in their planning rather than external uncertainties to be monitored passively.
Strategic Recommendations for Decision-Makers
For turbine manufacturers and blade producers, the priority is to align coating selection with production efficiency and lifecycle durability. Evaluate solvent-free and fast-curing systems that can reduce mould cycle times while meeting environmental targets, and require suppliers to provide standardized test data for erosion, corrosion, and environmental exposure. Where possible, consolidate supply relationships for both manufacturing coatings and repair solutions to simplify qualification and improve consistency across turbine platforms.
For investors and portfolio managers, attention should focus on companies with differentiated formulation capabilities, strong technical documentation, and exposure to both manufacturing and maintenance segments. Businesses that can demonstrate recurring demand through repair and service offerings, or that control critical resin and polymer inputs, are better positioned to capture value as the market matures. Monitor regulatory trajectories in key regions, since compliance readiness will increasingly separate leaders from laggards.
For procurement teams and asset owners, the most effective approach is to shift evaluation criteria from unit price toward total cost of ownership. Prioritize coatings with documented performance under standardized tests, clear application guidance, and support for field repairs. Establish qualification criteria early in project planning, and request lifecycle-oriented documentation that connects coating performance to inspection intervals, maintenance logistics, and downtime costs. This discipline will help reduce operational risk and improve long-term asset economics.
For organizations seeking to move from strategic insight to execution, detailed segmentation data, regional granularity, and tailored competitive assessments can sharpen planning further. A comprehensive research report can provide the deeper breakdowns and scenario analysis needed to validate product roadmaps, pricing strategies, and market entry decisions. Engaging with that level of detail early enables teams to act with confidence rather than retrofit strategy after market conditions have already shifted.
For detailed analysis of this topic, please visit the official page: Wind Power Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Galvanized Steel Wire Market: 7.1% CAGR and $2.96B Outlook Shape Strategy
By PW Consulting, 2026-09-21
The Galvanized Steel Wire Market: Strategic Shifts, Competitive Dynamics, and Opportunities Through 2032
The galvanized steel wire market has entered a phase of measured but accelerating expansion, driven by a combination of structural demand, coating innovations, and evolving infrastructure priorities. From 2020 through 2025, total revenue climbed steadily, with the base year valuation reaching an estimated USD 1.83 billion. The forward trajectory points toward a compound annual growth rate of 7.1 percent across the 2026–2032 forecast window, tracking toward a market size that approaches USD 3 billion by the end of the period. This growth is not merely a continuation of historical patterns; it reflects a structural reorientation in how coated steel wire is specified, manufactured, and deployed across construction, agriculture, telecommunications, and infrastructure applications.
Beneath the headline growth trajectory lies a market that is consolidating around a handful of large producers while simultaneously fragmenting around application-specific performance requirements. The top three firms collectively control roughly 42 percent of global revenue, with the top five extending that share to just under half. Concentration of this magnitude suggests mature competitive dynamics, but it also masks meaningful divergence in technological positioning, geographic exposure, and product differentiation. For executives and investors, the operational implication is clear: scale alone no longer guarantees resilience. Competitive advantage is increasingly tied to coating chemistry, tensile performance, and the ability to align production capacity with localized demand signals.
Key Challenges and Inflection Points
Three structural challenges are reshaping how market participants plan capacity, pricing, and product roadmaps.
First, raw material volatility remains a persistent pressure on cost structures. Zinc price fluctuations continue to drive production cost variability for galvanized steel wire, forcing manufacturers to balance pass-through pricing with customer retention. This dynamic is particularly acute for producers reliant on conventional hot-dip galvanizing, where coating weight and zinc consumption are directly tied to input costs. Companies that cannot hedge exposure or transition toward more efficient coating architectures face margin compression during periods of commodity instability.
Second, the market is crossing an inflection point where traditional zinc coatings are no longer sufficient for demanding applications. Infrastructure projects, renewable energy installations, and high-stress structural uses are pushing beyond baseline corrosion protection thresholds. This creates a dual challenge: legacy product lines must be defended while next-generation coated wires require capital investment in new coating lines, quality control protocols, and technical sales capabilities. Firms that delay this transition risk ceding premium segments to competitors offering longer service life and higher strength-to-weight performance.
Third, the demand environment is becoming more application-diverse and regionally uneven. Construction remains a foundational demand pillar, but growth rates and specification requirements vary significantly across geographies and project types. Agricultural fencing, telecommunications infrastructure, and increasingly specialized industrial uses each impose distinct performance criteria. Navigating this fragmentation requires production flexibility, inventory strategies that align with project cycles, and commercial teams capable of translating technical specifications into procurement decisions.
Key Demand Drivers and Structural Forces
Technological Innovation in Coating and Wire Performance
Coating technology is moving from a commodity differentiator to a core value driver. The development of Zn-Al-Mg alloy coatings represents a meaningful departure from conventional hot-dip galvanizing, delivering corrosion protection that extends service life by roughly half again in demanding outdoor and marine-adjacent environments. This shift is not incremental; it changes the economics of infrastructure durability by reducing maintenance cycles and enabling wire specifications that withstand harsher exposure without thicker zinc layers. At the same time, high-tensile formulations are pushing mechanical performance upward, with newer products achieving yield strengths approaching 1,000 MPa alongside controlled zinc adhesion and uniform coating distribution.
The commercial significance of these advances lies in their ability to unlock premium pricing and application expansion. Offshore wind farm guy wires, highway safety barriers, seismic-resistant bridge cables, and solar panel frameworks are all environments where failure costs are high and replacement cycles are expensive. When a coated wire can deliver longer protection and higher structural performance, specifiers are more willing to accept elevated unit costs in exchange for lifecycle savings. Producers that have built technical demonstration capabilities, field validation data, and application-specific engineering support are gaining leverage in specification processes that historically defaulted to standard galvanized offerings.
Policy, Regulation, and Infrastructure Priorities
Regulatory and policy environments are shaping demand indirectly but powerfully by influencing project specifications, durability requirements, and public infrastructure spending priorities. Infrastructure programs that emphasize resilience, longer asset life, and reduced maintenance are creating a favorable backdrop for higher-performance coated wires. In parallel, safety standards for bridges, transportation corridors, and energy installations are tightening in ways that reward stronger materials with proven corrosion resistance. These dynamics are not uniform across regions, but they collectively reinforce a preference for coated steel wire that can meet more demanding engineering criteria.
The policy effect also intersects with renewable energy deployment and grid expansion. Solar frameworks, transmission conductors, and wind support infrastructure require materials that can operate reliably under outdoor exposure while maintaining structural integrity over decades. When procurement teams evaluate these applications, coating performance and tensile reliability increasingly enter the decision calculus alongside conventional considerations such as lead time and availability. This creates a tailwind for manufacturers that can document performance advantages and align product portfolios with infrastructure and energy-transition project requirements.
Demand-Side Shifts in End-Use Behavior
Demand patterns are being reshaped by how end users prioritize durability, total cost of ownership, and specification reliability. In construction and agricultural fencing, there is a growing tendency to specify wire based on anticipated service life and environmental exposure rather than lowest upfront price. This is especially visible where projects face corrosive soils, coastal conditions, or long maintenance cycles. In telecommunications and related infrastructure uses, reliability and consistency of supply are gaining weight as networks expand and installation schedules become more time-sensitive.
At the enterprise level, procurement behavior is shifting toward suppliers that can offer technical support, consistent coating quality, and predictable lead times. The commercial implication is that relationship-based selling and specification influence are becoming more valuable than price competition alone. Manufacturers that invest in application engineering, sample programs, and post-sale technical assistance are better positioned to capture and retain demand in segments where performance risk is high.
Supply Chain and Cost Structure Dynamics
Cost structures are being renegotiated by the interaction of raw material exposure, production efficiency, and capacity utilization. Zinc volatility remains a primary driver of production cost fluctuations, and producers are responding with a mix of procurement hedging, coating optimization, and selective pass-through strategies. The broader cost environment also reflects producer price trends in steel wire drawing and coated wire production, which have shown sustained elevation in recent readings. This reinforces the need for disciplined cost management and transparent pricing frameworks that preserve margin without alienating price-sensitive segments.
Supply chain resilience is also emerging as a differentiator. Industrial customers and infrastructure project teams increasingly value dependable availability and the ability to service large orders without disruption. Producers that maintain balanced capacity utilization, regional distribution reach, and responsive customer service can convert supply reliability into competitive advantage, particularly in applications where project timelines and installation schedules leave little room for delay.
Competitive Landscape and Leading Strategies
The market’s competitive architecture is defined by a mix of large integrated producers, specialized coated-wire specialists, and regional manufacturers with strong application footholds. The leading firms are not competing on a single dimension; rather, they are building differentiated positions around coating chemistry, tensile performance, geographic reach, and application-specific service models.
PW Consulting Chemical & Energy Research Center
ArcelorMittal has positioned itself around advanced coated wire solutions, including hot-dip galvanized steel wire and newer Zn-Al-Mg coated products designed for construction, infrastructure, and agricultural fencing. Its strategic emphasis on longer corrosion protection aligns with the broader shift toward durability-driven specifications. Nippon Steel Corporation has concentrated on high-strength galvanized and alloy-coated products, with particular relevance to offshore wind farm guy wires and highway safety barriers. This focus places the company in higher-performance segments where mechanical strength and coating resilience carry premium value.
Tata Steel has built a strong presence in low-carbon and high-tensile hot-dip galvanized wires for fencing, agriculture, and infrastructure, supported by capacity expansion that broadened output in its Jamshedpur facility. United States Steel Corporation has differentiated through specialized high-tensile galvanized offerings, including the ZincGuard® series developed for seismic-resistant bridge cables and solar panel frameworks. Its recent high-tensile product with 1,000 MPa yield strength and a 100 gsm zinc layer illustrates how targeted product engineering can serve demanding structural and energy-infrastructure applications.
Other notable participants include JFE Steel Corporation, which supplies galvanized and coated wire products for industrial and construction use; POSCO, with galvanized steel wire serving automotive components, infrastructure, and agricultural applications; Steel Authority of India Limited, active in hot-dip galvanized wire for fencing and construction; Bekaert, known for agricultural fencing, automotive components, and industrial cable applications; The Heico Companies, with wire mesh, fencing, and specialty industrial products; and Davis Wire Ltd., a producer focused on fencing and wire products.
The competitive landscape is evolving along two reinforcing trends. The first is consolidation of scale and technical capability among the largest producers, who are investing in advanced coatings, high-tensile processing, and application-focused commercial organizations. The second is continued differentiation in regional markets, where local producers maintain advantage through proximity, supply reliability, and familiarity with domestic specification practices. Strategic collaborations are also emerging as a way to commercialize advanced coating technologies more quickly, signaling that even well-resourced firms recognize the value of partnerships in accelerating technical deployment.
For companies evaluating competitive positioning, the strategic takeaway is that leadership is being redefined. It is no longer sufficient to be a low-cost galvanized wire supplier. The firms that are gaining strategic ground are those that can pair coating innovation with tensile performance, document lifecycle benefits, and align capacity with the most valuable end-use segments.
Strategic Implications of Recent Moves
Recent industry activity underscores how competitive advantage is being built. A major Indian producer expanded its galvanized steel wire production facility by 25 percent to increase output of low-carbon and high-tensile hot-dip galvanized wires, reinforcing a strategy centered on scale, cost efficiency, and expanded availability for fencing, agriculture, and infrastructure demand. A leading U.S. steelmaker launched a high-tensile galvanized wire with 1,000 MPa yield strength and a 100 gsm zinc layer aimed at seismic-resistant bridge cables, solar frameworks, and transmission conductors, illustrating a push into performance-oriented segments where specification influence matters. In parallel, a strategic collaboration between two major international producers focused on commercializing high-strength galvanized wires with advanced Zn-Al-Mg coatings, targeting 50 percent longer corrosion protection for offshore wind farm guy wires and highway safety barriers.
These developments collectively point to a market where capacity expansion, product premiumization, and technology partnerships are being used in combination. The pattern suggests that firms are preparing for a future in which demand growth is tied less to volume alone and more to value-added performance in applications where failure is costly and durability is prized.
Forward Outlook: Three Trends Shaping 2026–2032
Trend 1: Premium Coatings Gain Mainstream Relevance
Advanced alloy coatings and engineered zinc architectures are expected to move from niche applications into broader commercial use as infrastructure durability requirements intensify and maintenance costs become more visible in project economics. As specifiers compare total lifecycle cost rather than initial material price, coated wires offering longer corrosion protection and reliable adhesion will capture a growing share of high-value demand. The opportunity for manufacturers lies in building specification relationships early, providing field data, and aligning product lines with the environments where extended protection delivers measurable savings.
The associated risk is execution and adoption velocity. Premium coatings require new processing capabilities, quality assurance rigor, and customer education. If adoption is slower than anticipated, capacity investments in advanced lines may face underutilization, and price differentials may be difficult to sustain in price-sensitive segments.
Steel Wire Rope Market
Trend 2: High-Tensile Wire Expands Into Infrastructure and Energy Applications
High-tensile galvanized wire is poised to play a larger role in bridge cables, solar frameworks, transmission conductors, and safety barrier systems. The combination of higher strength and controlled coating performance allows engineers to reduce material mass while maintaining structural reliability, which is attractive in projects where span, load, and exposure conditions are demanding. Growth in this trajectory is likely to be reinforced by infrastructure modernization, renewable energy deployment, and transportation safety requirements.
The upside is meaningful, but it depends on consistent quality and proven performance in critical applications. Any quality inconsistency or field failure in high-stakes uses could slow specifier confidence and shift procurement toward more conservative choices, at least in the near term.
Trend 3: Regional Demand Divergence and Capacity Rebalancing
Demand growth will not be evenly distributed. Some regions will see stronger pull from construction activity, agricultural expansion, and infrastructure programs, while others will experience more modest growth or project cycle dependency. This divergence will encourage producers to rebalance capacity, adjust export strategies, and tailor product mixes to regional specification norms. Companies that can align regional capacity with local demand signals and maintain dependable supply chains are better positioned to capture disproportionate share in their served markets.
The uncertainty here lies in project timing, macroeconomic conditions, and policy implementation pace. If infrastructure spending or agricultural investment slows in key regions, near-term utilization may soften even as the longer-term growth trajectory remains intact. Producers with flexible capacity and diversified application exposure will be better equipped to manage that variability.
Strategic Actions for Decision Makers
For Manufacturers and Producers
Prioritize coating and tensile differentiation as the core of commercial strategy. The market is rewarding firms that can offer longer corrosion protection and higher mechanical performance in applications where lifecycle value justifies premium pricing. Invest in technical demonstration, field validation, and specification support so that sales teams can compete on performance rather than price alone. At the same time, manage zinc exposure and coating efficiency carefully, since raw material volatility will continue to pressure margins and require disciplined pricing and procurement practices.
Consider capacity decisions through the lens of application mix rather than aggregate volume. Expanding output is valuable only if it aligns with the segments where performance differentiation and reliable supply can be monetized. Where advanced coating or high-tensile lines are justified, ensure that quality control, customer technical support, and application engineering are scaled alongside production capacity.
For Investors
Evaluate exposure based on product positioning and end-use resilience rather than market-level growth alone. The most attractive risk-adjusted opportunities are likely to be found in firms with credible high-tensile and advanced coating portfolios, diversified application bases, and the ability to serve infrastructure, energy, and construction demand with differentiated specifications. Scale remains important, but it should be assessed alongside technological roadmap, margin defense against raw material volatility, and the strength of specification relationships in priority segments.
Watch for consolidation and partnership activity as signals of how the market is maturing. Collaborations around advanced coatings and capacity expansions in high-growth regions can reveal where value is being created and which technological pathways are gaining commercial traction.
Hot-dip Galvanized Steel Market
For Procurement and Supply Chain Leaders
Reassess specification criteria to reflect total cost of ownership, especially in applications exposed to corrosion, structural load, or long maintenance cycles. Where lifecycle performance matters, advanced coatings and high-tensile options may lower long-term risk even if unit costs are higher. Build procurement frameworks that allow for performance-based selection rather than defaulting to lowest initial price in every category.
Strengthen supplier relationships with an emphasis on quality consistency, coating reliability, and delivery dependability. In project-driven environments, supply assurance and technical support often matter as much as price. Diversifying sourcing where appropriate and maintaining visibility into supplier capacity and coating technology roadmaps can reduce risk during periods of raw material volatility or demand surges.
Navigating the Next Phase with Better Intelligence
The galvanized steel wire market is not simply expanding; it is restructuring around performance, durability, and application-specific value. Growth to nearly USD 3 billion by 2032 is plausible, but the distribution of that growth will favor firms and buyers who understand where premium coatings, high-tensile formulations, and regional demand patterns converge. For decision makers, the most valuable next step is to move from market-level awareness to segment-level clarity: which applications are shifting specifications fastest, where coating innovation is translating into commercial advantage, and how capacity and cost structures will evolve as raw material volatility and infrastructure priorities continue to interact.
A deeper dive into regional demand splits, type-level dynamics across hot-dip, electrogalvanized, and other coated wire categories, and application-level growth paths can sharpen strategic planning far beyond what headline figures reveal. Disaggregating the market by region, product type, and end use exposes where concentration risks lie, where premium segments are forming, and which capacity and procurement decisions are best timed now versus later. For executives and investors looking to translate market momentum into concrete action, that level of segmentation and forward scenario detail is where strategy becomes executable.
For detailed analysis of this topic, please visit the official page: Galvanized Steel Wire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


