

Blogs
PW Consulting: AC-DC EPS Market to Hit $9.83B in 2025, Growing at 5.3% CAGR to 2032
By PW Consulting, 2026-09-16
Powering the Next Decade: Strategic Intelligence for the AC-DC External Power Supply Market
The AC-DC External Power Supply (EPS) market is undergoing a structural transformation. From consumer electronics to industrial automation and healthcare devices, external power supplies remain the critical link between grid electricity and modern equipment. As regulatory frameworks tighten and efficiency requirements escalate, understanding the trajectory of this market is no longer optional for enterprise decision-makers. This article outlines the strategic value of our latest market research report, designed to equip stakeholders with the foresight needed to navigate the 2026-2032 forecast period and beyond.
Market Trajectory and Growth Dynamics
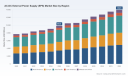
The global AC-DC EPS market has demonstrated consistent expansion over the past half-decade. Historical data from 2020 through 2025 reveals a market that has grown from approximately 7,700 million USD to nearly 9,830 million USD, reflecting a compound annual growth rate that underscores steady demand accumulation across multiple end-use sectors. Looking ahead, the forecast period from 2026 to 2032 projects a sustained CAGR of 5.3 percent, with revenue expected to approach 13,923 million USD by the end of the forecast horizon.
This growth is not merely a function of volume expansion. It represents a convergence of technological innovation, regulatory compliance pressures, and shifting application demands. The base year of 2025 serves as a critical inflection point, with the market crossing the 9,800 million USD threshold and setting the stage for accelerated adoption of high-efficiency, compact power solutions. Enterprises that understand the underlying drivers of this trajectory will be better positioned to allocate capital, plan product roadmaps, and identify partnership opportunities.
However, aggregate figures tell only part of the story. The true strategic value lies in dissecting the market across multiple dimensions—power output ranges, application verticals, and geographic regions—each of which presents distinct growth vectors, competitive intensities, and risk factors. Our report provides this granular dissection, enabling stakeholders to move beyond headline numbers and develop nuanced, segment-specific strategies.
Key Industry Dynamics Shaping the Landscape
Several macro-level forces are reshaping the competitive environment for AC-DC external power supplies. Understanding these dynamics is essential for anticipating market shifts and positioning products or investments accordingly.
- Regulatory Compliance压力 : Efficiency standards continue to evolve globally. The U.S. Department of Energy's Level VI requirements, ENERGY STAR Program Requirements for Single Voltage External AC-DC Power Supplies, and the EU Ecodesign framework (2025/2052) are mandating higher efficiency thresholds. Manufacturers must ensure their products meet these criteria to remain eligible for key markets. Additionally, Natural Resources Canada has implemented energy efficiency standards for single-voltage external AC-DC power supplies effective 2025, further expanding the compliance landscape. ENERGY STAR Partner Commitments also require manufacturers to adhere to strict eligibility criteria including efficiency testing protocols.
- Raw Material Volatility : Copper prices fluctuated within an 8,500 to 10,200 USD per ton range in 2025, driving bill of materials costs for power supply components up by nearly one-fifth. This volatility introduces margin pressure and necessitates strategic sourcing decisions, supplier diversification, and potentially redesigned architectures that optimize material usage.
- Technology Innovation : The adoption of wide-bandgap semiconductors such as silicon carbide (SiC) and gallium nitride (GaN) is enabling higher efficiency, reduced thermal losses, and miniaturization. Recent product launches from leading manufacturers demonstrate this shift, with GaN-based solutions and wide-range AC-DC modules entering the market at various power levels.
- Application Diversification : While consumer electronics remain a significant demand driver, industrial, automotive, healthcare, and telecommunications applications are expanding their share of the market. Each vertical imposes unique requirements around reliability, efficiency, form factor, and environmental durability, creating specialized niches that reward targeted engineering and market positioning.
Competitive Landscape: Key Players and Strategic Positioning
The AC-DC EPS market is characterized by a concentrated competitive structure. The top three firms command approximately 65 percent of market revenue, while the top five collectively hold around 80 percent. This concentration reflects the scale advantages, established customer relationships, and engineering capabilities that leading players have cultivated over time. However, the presence of numerous specialized manufacturers and regional players ensures that competition remains dynamic, particularly in segments where customization, rapid innovation, or cost optimization are paramount.
AC-DC External Power Supply (EPS) Market
Our report provides detailed profiles of the key companies shaping this landscape, examining their product portfolios, geographic reach, application focus, and recent strategic moves. Among the profiled firms are TDK-Lambda Americas, COSEL USA, Bel Fuse Inc., XP Power, Murata Manufacturing Co., Mean Well Enterprises Co. Ltd., FSP Technology Inc., Sparkle Power Incorporated, Advanced Energy Industries Inc., P-DUKE Technology Co. Ltd., Phihong USA, Acopian Power Supplies, and Pico Electronics.
These companies represent a diverse array of strategic positions. Some focus on high-performance solutions for medical and industrial applications, leveraging advanced technologies like SiC and GaN to deliver efficiency gains and compact form factors. Others emphasize broad portfolios spanning desktop and wall-plug adapters alongside enclosed AC-DC supplies for industrial and ITE applications. Several manufacturers have established strong presences in harsh-environment and factory automation segments, offering configurable and ruggedized solutions. The geographic spread of headquarters and manufacturing capabilities—from the United States and Japan to Taiwan and the United Kingdom—adds another layer of strategic consideration for supply chain resilience and market access.
Worldwide External Power Supplies (EPS) Market
Recent product launches and technological announcements provide valuable signals about where competitive intensity is building. In early 2026, multiple firms introduced new product lines emphasizing efficiency, power density, and application-specific optimization. These developments underscore the pace of innovation and the importance of monitoring competitor roadmaps to anticipate market shifts and identify whitespace opportunities. Our report captures these recent developments and contextualizes them within broader competitive trends.
Report Scope and Actionable Insights
This market research report is designed to serve as a comprehensive decision-support tool. It goes beyond descriptive market sizing to deliver actionable intelligence across multiple dimensions. Key components of the report include:
- Historical and Forecast Revenue Analysis : Detailed revenue breakdowns for the 2020-2025 historical period and the 2026-2032 forecast period, enabling trend analysis and growth rate validation at both aggregate and segment levels.
- Segmentation by Output Power : Analysis of market share and growth trajectories across power output ranges, from low-power solutions up to 10W through higher-power segments reaching 101W-400W. Each range presents distinct application profiles and competitive dynamics.
- Segmentation by Application : Deep dives into the major application verticals driving demand, including consumer electronics, industrial, automotive, healthcare, telecommunications, and others. The report examines the unique requirements, growth catalysts, and competitive intensity within each vertical.
- Segmentation by Region : Geographic revenue distribution and growth outlooks that help stakeholders assess market maturity, penetration opportunities, and regional regulatory considerations across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
- Company Profiles and Competitive Benchmarking : In-depth profiles of key market participants, covering their strategic focus, product offerings, recent developments, and positioning within specific segments. This enables competitive mapping and identification of potential partnership or acquisition targets.
- Regulatory and Technology Landscape : Synthesis of the evolving efficiency standards, energy certification requirements, and material cost dynamics that influence product design, compliance costs, and time-to-market decisions.
The report is structured to support multiple use cases. Product managers can leverage segment-level data to prioritize development resources and refine feature specifications. Supply chain and procurement teams can use geographic and cost dynamics insights to optimize sourcing strategies. Strategic planners and investors can rely on the forecast models and competitive analysis to evaluate market entry opportunities, partnership scenarios, and long-term growth potential.
Strategic Value for 2026 Decision-Making
As enterprises navigate the 2026 business environment, the AC-DC EPS market presents both opportunities and complexities. The combination of steady market growth, regulatory evolution, raw material volatility, and rapid technological advancement demands a data-driven approach to strategy formulation. This report is built to address those demands by providing:
- Forward-Looking Visibility : The 2026-2032 forecast period offers a clear window into expected market trajectories, helping organizations align investment cycles, capacity planning, and product launch calendars with anticipated demand patterns.
- Segment-Specific Intelligence : Rather than relying on aggregate market figures, decision-makers can drill into the segments most relevant to their business, understanding the competitive intensity, growth rate, and application requirements that define each space.
- Competitive Context : With a concentrated market structure and active innovation pipelines, knowing where key players are focusing their efforts is critical. The report maps competitor capabilities and recent developments to help identify gaps, overlaps, and potential areas for differentiation.
- Risk and Compliance Awareness : Regulatory requirements and material cost fluctuations can significantly impact product economics and market access. The report integrates these factors into the analysis, enabling proactive risk management and compliance planning.
The strategic questions facing organizations in this market are numerous. Which power output ranges offer the most attractive growth-to-competition ratios? How will regulatory changes reshape the competitive hierarchy over the forecast period? Where are the geographic markets with the strongest expansion potential, and what barriers exist to entry? How are technology shifts like wide-bandgap semiconductors altering product specifications and customer expectations? Our report provides the foundational data and analytical framework to address these questions with confidence.
Accessing the Full Intelligence
This article has outlined the strategic context and structural components of the AC-DC External Power Supply Market research report. The market is positioned for continued growth, driven by expanding application demands, efficiency-driven innovation, and a competitive landscape that rewards both scale and specialization. However, the full value of this research lies in the detailed segment breakdowns, comparative analysis, and forward-looking models that go beyond the high-level overview presented here.
Organizations seeking to make informed decisions in 2026 and beyond should consider accessing the complete report, which contains the granular revenue data, segment-level growth rates, regional distributions, application splits, and company-specific profiles necessary to build robust, evidence-based strategies. The combination of historical validation, forecast modeling, and competitive intelligence provides a comprehensive foundation for navigating the market's evolving dynamics.
For stakeholders ready to deepen their understanding and translate market intelligence into actionable strategy, the full report offers the depth, precision, and contextual analysis required to stay ahead in a competitive and rapidly changing landscape.
For detailed analysis of this topic, please visit the official page: AC-DC External Power Supply (EPS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Agritourism Market Hits USD 9.01 Billion in 2025, Forecasts 11.9% CAGR to 2032
By PW Consulting, 2026-09-16
Agritourism Market Outlook 2026: Capitalizing on the Experience Economy via Strategic Intelligence
The convergence of agricultural production and experiential travel has evolved from a niche diversification tactic into a structural growth engine for rural economies. As hospitality consumers increasingly seek authenticity, provenance, and direct connection to land-based operations, agritourism has matured into a standalone commercial discipline. Our latest market research synthesizes historical trajectories, forward-looking demand signals, and competitive positioning to equip executive teams with the institutional intelligence required to navigate this rapidly shifting landscape. With the global market expanding from 5.8 billion USD in 2020 to a projected 10.43 billion USD in 2026, and an anticipated compound annual growth rate of 11.9 percent through 2032, the sector presents both remarkable expansion potential and complex operational trade-offs. Leaders who base capital allocation, partnership strategies, and market entry decisions on fragmented or retrospective data risk misjudging regional regulatory friction, consumer preference volatility, and the pace of infrastructure development. This analysis outlines how a disciplined, data-driven framework transforms uncertainty into executable strategy.
Executive Snapshot: Macro Trajectory and Structural Shifts
The agritourism sector has demonstrated consistent upward momentum over the past half-decade, reflecting a broader consumer migration toward localized, immersive, and mission-aligned travel. Revenue streams have expanded across direct-to-consumer farm interfaces, curated educational programming, and recreational event models, creating a diversified commercial ecosystem that rewards operators capable of balancing agricultural functionality with hospitality-grade service standards. The baseline forecast indicates continued acceleration, yet the pace and profitability of growth will vary significantly depending on regional tourism infrastructure, municipal zoning frameworks, seasonal capacity utilization, and the degree to which operators can integrate value-added processing into their visitor experience. Market concentration metrics further signal an industry in consolidation, where established players hold disproportionate share while emergent regional operators compete by specializing in high-touch experiences, targeted demographic segments, or hybrid agricultural-servitization models. Understanding where scale advantages concentrate, and where agile niche execution can outpace incumbents, is essential for portfolio planning and competitive benchmarking.
Report Architecture: How This Study Maps to Operational Decision-Making
A market intelligence briefing only delivers strategic value when it translates high-level trends into operational levers. This study is designed around that translation layer, moving systematically from macro sizing to actionable execution pathways. The research framework encompasses historical performance baselines, multi-year forecast modeling across primary commercial vectors, and a granular assessment of the competitive landscape. It evaluates how distinct experiential formats are monetized, how hospitality expectations are reshaping traditional farm operations, and how regulatory environments influence site development, liability exposure, and partnership viability. Readers will find structured sections covering demand drivers, consumer segmentation behaviors, capital deployment considerations, and the operational requirements of scaling agritourism from seasonal add-on activity to a year-round revenue architecture. The report deliberately avoids superficial market commentary and instead focuses on the mechanics of growth: visitor acquisition channels, experience design optimization, service capacity constraints, and the financial modeling required to sustain occupancy and repeat visitation. By anchoring analysis in measurable market signals rather than aspirational narratives, the study provides a repeatable methodology for stress-testing strategic options across different risk profiles and capital environments.
Agritourism Market
Competitive Landscape: Benchmarking Established Operators and Sector Archetypes
Agritourism is not a homogenous market. It operates as a layered ecosystem where luxury hospitality brands, specialized tour operators, educational programming providers, and regional farm consortia compete on different value propositions. Leading operators illustrate the strategic diversity available within the sector. High-end integrated resorts demonstrate how agricultural land can be positioned as a premium hospitality asset, combining working farm operations with curated culinary journeys, outdoor programming, and multi-day accommodation models that command elevated per-guest valuations. By contrast, escorted agricultural tour providers focus on connective infrastructure, linking international and domestic visitors to producer networks, rural tourism operations, and behind-the-scenes farming experiences that emphasize authenticity and direct producer engagement. Specialist tour firms extend this model further by offering inspection-oriented and bespoke itineraries designed for associations, professional audiences, and organizations seeking structured exposure to agricultural systems. Custom group travel providers layer programming around rural site visits for professionals, students, and sector enthusiasts, while dedicated agri-technical and educational tour operators build repeatable B2B and institutional channels through association partnerships and organizational programming.
These archetypes reveal distinct strategic postures. Luxury and integrated hospitality models compete on exclusivity, service depth, and land-based brand narrative. Tour and facilitation operators compete on access, logistics reliability, and curated producer relationships. Educational and institutional operators differentiate through content authority, program design, and repeatable group frameworks. Each model carries its own growth requirements, staffing demands, risk profile, and margin structure. Executive teams evaluating entry or expansion must assess where their organizational capabilities align within these competitive clusters, which consumer segments justify premium pricing, and which operational components can be sourced through partnerships rather than built in-house. The competitive analysis in this report maps these dynamics in detail, outlining positioning strategies, brand differentiation paths, and the implications of operating at different points along the experience spectrum.
Regulatory Friction and Structural Dynamics Shaping Deployment Timelines
Growth in agritourism is increasingly mediated by policy environments, land-use frameworks, and liability architectures. Regulatory signals are no longer peripheral; they directly affect site development schedules, operational scope, insurance cost structures, and the feasibility of scaling visitor-facing activities on agricultural land. Recent guidance published by regional agricultural authorities has begun to establish clearer baselines for value-added processing and agritourism operations, signaling a move toward more formalized compliance expectations. At the same time, local planning proposals addressing gatherings on farmland demonstrate how municipal priorities can reshape allowable visitor experiences, parking logistics, event frequency, and nighttime operations. Executive teams planning capital deployment must treat regulatory analysis as a core planning variable rather than a post-investment compliance task. Strategic advantage increasingly belongs to organizations that map jurisdictional variance early, incorporate permitting lead times into rollout roadmaps, and design flexible experience modules that can adapt to changing land-use parameters without sacrificing core revenue logic. On the policy side, broader legislative frameworks influencing program eligibility and income classification have begun altering the economics of farm-based diversification, particularly for operators heavily reliant on direct marketing and visitor revenue. These developments highlight the importance of scenario planning, where growth strategies account not only for demand-side opportunity but also for the administrative cadence and compliance cost embedded in different jurisdictions.
Operations Momentum and the Institutionalization of Agritourism
The sector is also maturing through organized industry activity that is accelerating knowledge transfer, peer benchmarking, and professionalization. Anniversary conventions, regional tourism workshops, and inaugural global conferences are creating venues where operators exchange practical insights on product development, seasonal planning, partnership formation, and experience economy integration. These gatherings reflect a broader shift from ad hoc farm diversification to coordinated industry building, where operators invest in staff training, guest journey design, and repeatable program structures rather than relying solely on informal rural charm. Alongside event-based momentum, select operators are launching dedicated retreat-style offerings that emphasize working-farm immersion, animal engagement, heritage storytelling, and natural setting experiences. Such launches underline the growing commercial appeal of multi-day stays and curated agricultural immersion, reinforcing the need for operators to think beyond day-visit revenue models.
Federal and regional economic data further support the migration toward experience-led farm revenue. Agritourism and recreational service income have expanded materially over the past decade, with meaningful participation spread across counties and median outcomes indicating broad-based, not merely outlier-driven, adoption. This trajectory suggests durable structural demand rather than a temporary travel cycle effect. Yet scale remains uneven. Margin quality, seasonality management, and the ability to convert first-time visitors into repeat guests continue to differentiate high-performing operators from those that merely capture transient foot traffic. The strategic question is therefore not whether demand exists, but how organizations build the operational discipline required to monetize it consistently across weather cycles, staffing constraints, and shifting consumer expectations.
Translating Market Intelligence into 2026 Decision-Making
For executives entering 2026, the practical challenge is prioritization under uncertainty. Capital can be allocated toward destination development, experience packaging, marketing acquisition, partnership expansion, or regulatory navigation, but each path carries different payback horizons and risk exposures. The strategic value of a comprehensive market study lies in its ability to compress that decision space by clarifying where growth is most defensible, which formats align with target demographics, and where competitive white space remains under-monetized. Organizations that build strategy on partial information often overinvest in visible but saturated demand channels while underweighting the operational complexity of service delivery, permitting, and year-round occupancy. Conversely, leaders who ground their planning in sector-specific sizing, segmentation dynamics, and competitive benchmarking can sequence investments more effectively, aligning capability building with the customer segments and experience formats most likely to sustain revenue resilience.
The report accompanying this article is designed to support that disciplined approach. It consolidates historical performance signals, forecast trajectories, competitive archetypes, and structural dynamics into a unified reference framework. By focusing on the mechanics of growth rather than isolated statistics, it enables leadership teams to evaluate entry timing, partnership strategy, experience portfolio design, and regional expansion with greater confidence. Agritourism is increasingly a strategic business discipline rather than a secondary farm activity, and the organizations that treat it accordingly will be better positioned to convert experiential demand into durable commercial advantage.
Strategic Conclusion and Next Steps
The agritourism market is moving into a phase where differentiation, operational precision, and regulatory fluency determine competitive outcomes more than raw destination appeal alone. The projected expansion curve through 2032 underscores the magnitude of the opportunity, while the competitive and regulatory context underscores the need for careful execution. Executive teams seeking to convert this opportunity into measurable performance should treat market intelligence as an active planning instrument, integrating sizing context, segmentation logic, competitor positioning, and policy dynamics into a coherent investment thesis. The full study provides the depth required to pressure-test those decisions across multiple growth scenarios and operational assumptions. We invite leadership teams, investors, and strategy functions to engage with the complete research package to align their 2026 planning with the market realities shaping this sector.
Worldwide Culinary Tourism Market
For detailed analysis of this topic, please visit the official page: Agritourism Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The China Vibration Monitoring Market is projected to record a steady increase in revenue from approximately USD 570 million in 2020 to over USD 1410 million by 2035. This growth is attributed to the rapid integration of smart manufacturing technologies, the rise of Industry 4.0, and continuous investments in condition monitoring across multiple sectors. The period from 2025 onwards is especially robust, showcasing a compounded annual growth rate (CAGR) of 9.5%. Key players adopting AI-driven and cloud solutions further elevate market value and broaden the adoption base.
Read More - https://bussinessinsights.com/research-report/china-vibration-monitoring-market
The automotive sector leads in vibration monitoring adoption in China for 2025, accounting for the highest market share amidst increased automation and quality control initiatives. Oil & Gas follows, driven by stringent safety and environmental regulations, while Energy & Power industries benefit from the need for reliable operation of turbines and generators. Other sectors, such as food & beverages and pharmaceuticals, are gradually embracing vibration systems to meet compliance and efficiency goals. This distribution reflects both the industrial priorities and ongoing digital transformation in critical production environments.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-vibration-monitoring-market
Frequently Asked Questions
Who are the key players in China Vibration Monitoring Market industry?
The top 5 players in the China Vibration Monitoring Market include SKF Group, General Electric (Bently Nevada), Emerson Electric Co., Hansford Sensors, and Siemens AG. These companies are recognized for their advanced vibration monitoring solutions, strong R&D, broad product portfolios, and significant presence across key industrial sectors in China.
What is the China Vibration Monitoring Market growth?
The China Vibration Monitoring Market has experienced robust growth, especially with Emerson Electric Co. expanding its digital solutions in 2023. Increased focus on industrial automation, predictive maintenance, and reliability improvements by leading manufacturers are fueling rapid market expansion across various Chinese industries.
Which segment accounted for the largest China Vibration Monitoring Market share?
The manufacturing segment accounted for the largest share of the China Vibration Monitoring Market. Manufacturing facilities are increasingly adopting vibration monitoring systems to ensure equipment reliability, reduce downtime, and optimize maintenance schedules, driven by the need for high productivity and cost-efficiency.
Thanks & Regards,
priya
sales@bussinessinsights.com
Revenue in the China Portable Battery Pack Market reached USD 4,200 Million in 2025 and is projected to grow steadily, reaching USD 8,900 Million by 2030 and surpassing USD 13,800 Million by 2035. The robust growth reflects increased power requirements from proliferating smart devices and EVs, continuous advancements in battery technology, and expansive distribution across both online and offline retail channels. This upward trajectory underscores the market’s resilience to shifting consumer patterns and technological disruption.
Read More - https://bussinessinsights.com/research-report/china-portable-battery-pack-market
Smartphones remain the largest application segment, accounting for 45% of market share in 2025. Tablet and laptop use follows, comprising 25%, as remote work and e-learning accelerate electronics usage. Automotive applications, such as EV accessories and onboard electronics, capture 16%, while wearables and other segments represent 14%. This distribution highlights the market’s core dependence on personal electronics, with gradual diversification driven by automotive innovation and growth in IoT devices.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-portable-battery-pack-market
Frequently Asked Questions
Who are the key players in China Portable Battery Pack Market industry?
The top five players in the China Portable Battery Pack Market are Xiaomi, Anker Innovations, Romoss, Pineng, and Yoobao. Xiaomi is renowned for its innovative products; Anker excel in battery technology; Romoss is popular for high-capacity models; Pineng focuses on affordable, reliable packs; Yoobao offers versatile charging solutions.
What is the China Portable Battery Pack Market growth?
The China Portable Battery Pack Market is witnessing steady growth, primarily driven by increased smartphone and smart device penetration. In 2023, Xiaomi reported a surge in portable battery sales as consumers demanded faster, higher-capacity options. The market is projected to grow at a CAGR of around 9% during 2024-2029.
Which segment accounted for the largest China Portable Battery Pack Market share?
The smartphones and tablets application segment dominates the China Portable Battery Pack Market, accounting for the largest share. With the widespread use of mobile devices and growing reliance on continuous connectivity, demand for portable battery packs supporting mobile charging has risen significantly across urban and rural areas.
Thanks & Regards,
priya
sales@bussinessinsights.com
China Hall-Effect Current Sensor Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-16
The China Hall-Effect current sensor market revenue has seen consistent growth, beginning at $350 million in 2020 and projected to reach $1,175 million by 2035. The compound annual growth rate (CAGR) reflects rising demand across varied sectors: automotive, renewable energy, and industrial modernization. By 2025, market value is estimated at $540 million, with strong momentum expected as China’s electrification and automation initiatives broaden.
Read More - https://bussinessinsights.com/research-report/china-hall-effect-current-sensor-market
Automotive remains the leading application for Hall-Effect current sensors in China for 2025, with a 38% share driven by EV and hybrid market expansion. Industrial applications occupy 34% as factories modernize for energy efficiency and automation. Consumer electronics, thanks to miniaturized and energy-efficient sensors, make up 18%. Renewable energy and telecom contribute the remaining 10%, with the growing infrastructure demanding constant power monitoring and management.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-hall-effect-current-sensor-market
Frequently Asked Questions
Who are the key players in China Hall-Effect Current Sensor Market industry?
The key players in the China Hall-Effect Current Sensor Market include Allegro MicroSystems, LEM International, Asahi Kasei Microdevices, TDK Corporation, and Honeywell International. These companies lead the market by focusing on innovation, strategic partnerships, extensive distribution networks, and a broad portfolio catering to automotive, industrial, and energy sectors.
What is the China Hall-Effect Current Sensor Market growth?
The China Hall-Effect Current Sensor Market has witnessed significant growth, with an estimated CAGR of over 9% during 2022-2024. Recent growth is attributed to increasing adoption of electric vehicles and industrial automation, with Allegro MicroSystems expanding its production and collaborations in China to meet surging demand.
Which segment accounted for the largest China Hall-Effect Current Sensor Market share?
The automotive application segment accounted for the largest market share in China, driven by rising electric vehicle (EV) and hybrid vehicle production. Hall-Effect current sensors are extensively used for battery management, powertrain, and charging infrastructure, supported by government energy-saving initiatives and industry electrification trends.
Thanks & Regards,
priya
sales@bussinessinsights.com
China Micro-Electro-Mechanical System (MEMS) Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-16
The revenue trajectory of China’s MEMS market shows robust growth from 2020 to 2035, reflecting swift adoption in core sectors such as consumer electronics, automotive, and healthcare. In 2025, the market size reaches approximately USD 4,300 Million, fueled by the proliferation of IoT devices and increased MEMS integration into emerging technologies. Sustained investments and policy incentives are projected to drive revenue beyond USD 13,000 Million by 2035, bolstered by China’s strong manufacturing ecosystem and dedicated MEMS R&D programs.
Read More - https://bussinessinsights.com/research-report/china-micro-electro-mechanical-system-(mems)-market
The application landscape in 2025 witnesses Consumer Electronics leading with a dominant market share, trailed by Automotive and Healthcare sectors. The surge in smart gadgets, mobile devices, and IoT applications drive Consumer Electronics adoption. Automotive's rapid pace of becoming smarter with ADAS and infotainment systems heavily utilizes MEMS technologies, while Healthcare's diagnostic equipment increasingly incorporates MEMS for precision monitoring.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-micro-electro-mechanical-system-(mems)-market
Frequently Asked Questions
Who are the key players in China Micro-Electro-Mechanical System (MEMS) Market industry?
The key players in China’s MEMS market include Goertek Inc., AAC Technologies, Shanghai Silead Inc., MEMSensing Microsystems, and Suzhou Nanomicro Technology. These companies are recognized for their innovation in sensors, microphones, and accelerometers, supporting diverse applications from consumer electronics to automotive and medical devices.
What is the China Micro-Electro-Mechanical System (MEMS) Market growth?
China’s MEMS market has experienced robust growth, driven by rising demand in the consumer electronics and automotive sectors. In 2023, companies like Goertek Inc. reported increased MEMS sensor revenues, reflecting the market’s expansion at a CAGR of over 8% during recent years.
Which segment accounted for the largest China Micro-Electro-Mechanical System (MEMS) Market share?
Consumer electronics applications held the largest share of China’s MEMS market. Devices such as smartphones, wearables, and tablets integrate MEMS sensors for enhanced user experiences, including gesture recognition and motion sensing, making this segment dominant in both production and consumption.
Thanks & Regards,
priya
sales@bussinessinsights.com
China Augmented and Virtual Reality Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-16
The AR/VR market in China has demonstrated strong revenue expansion since 2020, with an estimated market size of USD 2,300 million in 2025 and a projected CAGR of 21% through 2035. The revenue chart indicates a steady upward trajectory, driven by technological advances, expanding consumer usage, and significant enterprise adoption across industries. By 2035, the market is anticipated to reach USD 15,600 million, highlighting the long-term investment potential and transformative impact of AR/VR technologies in the Chinese landscape.
Read More - https://bussinessinsights.com/research-report/china-augmented-and-virtual-reality-market
The application landscape in 2025 is led by the gaming segment, which holds a commanding 41% market share. Healthcare follows at 21%, reflecting strong adoption for training, surgery, and diagnostics. Education is the third-largest application, making up 18% of the market, driven by the increasing use of AR/VR tools in classrooms and training modules. Retail, manufacturing, and automotive collectively make up the remainder, each showing steady gains but not surpassing the top three applications. This distribution confirms the dominance of entertainment and essential services in driving AR/VR technology adoption across China.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-augmented-and-virtual-reality-market
Frequently Asked Questions
Who are the key players in China Augmented and Virtual Reality Market industry?
The top five players in China’s AR and VR market are Huawei, Xiaomi, Nreal, DPVR, and Tencent. Huawei leads in hardware innovation, Xiaomi focuses on affordable smart devices, Nreal is known for lightweight AR glasses, DPVR specializes in immersive VR headsets, and Tencent advances gaming and social AR/VR platforms.
What is the China Augmented and Virtual Reality Market growth?
The China AR and VR market is experiencing rapid growth, with double-digit annual expansion. In 2023, the market saw significant investment and soaring consumer adoption, especially with companies like Nreal launching mass-market AR glasses and Huawei introducing new VR devices, driving strong year-on-year market growth.
Which segment accounted for the largest China Augmented and Virtual Reality Market share?
Gaming and entertainment applications hold the largest market share in China’s AR and VR market. Popular platforms like Tencent VR and NetEase have witnessed widespread adoption as consumers increasingly use AR/VR for immersive gaming, interactive live streaming, and virtual social experiences, outpacing education and industrial applications.
Thanks & Regards,
priya
sales@bussinessinsights.com
China's security solutions market is projected to grow from USD 19,200 million in 2020 to USD 51,600 million by 2035. This remarkable rise is propelled by ongoing digitalization, mounting security challenges, and strong investments in both public and private sectors. The compound annual growth rate (CAGR) for the period 2025 to 2035 is estimated at approximately 10.1%, reflecting sustained technology adoption, urban expansion, and robust demand for advanced surveillance, access management, and integrated platforms.
Read More - https://bussinessinsights.com/research-report/china-security-solutions-market
Commercial applications hold the lion’s share (36%) of China’s security solutions market by application in 2025, as businesses prioritize safety against theft and cyber risks. Government and infrastructure projects contribute 21%, benefiting from large-scale public safety initiatives. Residential adoption stands at 18%, driven by smart home devices and rising urban incomes. Industrial (12%), transportation (8%), and healthcare (5%) complete the landscape. The dominance of the commercial and government segments highlights the country’s emphasis on robust security for public spaces, critical infrastructure, and corporate facilities.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-security-solutions-market
Frequently Asked Questions
Who are the key players in China Security Solutions Market industry?
The top five players in the China Security Solutions Market are Hikvision, Dahua Technology, Huawei, Uniview, and Zkteco. Hikvision and Dahua dominate in surveillance products, Huawei specializes in integrated security and network solutions, Uniview is a leader in IP video surveillance, and Zkteco is a top provider of biometric access control.
What is the China Security Solutions Market growth?
The China Security Solutions Market has experienced robust growth, with a CAGR of over 10% in recent years. In 2023, companies like Hikvision reported increased revenues driven by higher demand for smart surveillance and AI-based security systems across government, commercial, and residential sectors.
Which segment accounted for the largest China Security Solutions Market share?
Video surveillance remains the largest segment by application in the China Security Solutions Market, accounting for significant market share. This dominance is attributed to the mass adoption of CCTV, AI analytics, and network video monitoring in urban security, transportation, and critical infrastructure protection.
Thanks & Regards,
priya
sales@bussinessinsights.com
North America Environmental Sensor Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-16
From 2020 to 2035, the North America Environmental Sensor Market displays robust revenue growth, rising from USD 1,320 Million in 2020 to USD 2,155 Million in 2025, and on track to reach USD 6,980 Million by 2035. This growth is propelled by technological advancements, expanded smart city deployments, and industrial sector investments. Year-over-year increments reflect both increased sensor adoption and expanding application portfolios, particularly around IoT and predictive analytics-enabled solutions. Manufacturers, municipalities, and regulatory agencies are key contributors to this revenue acceleration.
Read More - https://bussinessinsights.com/research-report/north-america-environmental-sensor-market
Air Quality Monitoring leads the North America Environmental Sensor Market applications in 2025 with 32%, driven by government initiatives and corporate ESG mandates to tackle urban air pollution. Water Quality Monitoring accounts for 19%, reflecting rising concerns about industrial discharge and potable water safety. Weather Monitoring (17%) and Soil Monitoring (12%) are witnessing increased investments from agricultural and infrastructural agencies. Noise Measurement (10%) and Radiation Detection (10%) hold significant roles, especially as cities work to manage sound pollution and address radiological safety.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/north-america-environmental-sensor-market
Frequently Asked Questions
Who are the key players in North America Environmental Sensor Market industry?
The top 5 players include Honeywell International Inc., Texas Instruments Incorporated, STMicroelectronics, Sensirion AG, and Amphenol Advanced Sensors. These companies are renowned for their advanced sensor technologies, robust product portfolios, and strategic focus on R&D and innovation, enabling them to maintain leading positions in the highly competitive environmental sensor market.
What is the North America Environmental Sensor Market growth?
The North America Environmental Sensor Market has witnessed significant growth, driven by increasing adoption of IoT and smart environmental monitoring. For example, Honeywell reported robust demand for air quality sensors in 2023, supporting an overall market CAGR exceeding 7% from 2023 to 2028.
Which segment accounted for the largest North America Environmental Sensor Market share?
The air quality monitoring application segment holds the largest market share. Growing concerns regarding pollution and regulatory mandates have accelerated deployment of air quality sensors across industries, public infrastructure, and smart buildings to enable real-time monitoring and improved decision making for environmental safety.
Thanks & Regards,
priya
sales@bussinessinsights.com
The China Vibration Sensors Market is projected to rise from $750 million in 2021 to $1,210 million in 2025 and reach $2,860 million by 2035. This robust growth is underpinned by China’s rapid industrial modernization, increased implementation of Industry 4.0 standards, and heightened demand from automotive and electronics sectors. As companies invest in advanced manufacturing and smart factories, demand for optimized machinery health monitoring and safety compliance is propelling market revenues upwards.
Read More - https://bussinessinsights.com/research-report/china-vibration-sensors-market
Industrial Machinery holds the dominant share in application segmentation, accounting for over one-third of China’s vibration sensors market in 2025. This is driven by heavy focus on automation, predictive maintenance, and process efficiency in China’s large manufacturing base. Automotive applications represent the second largest segment due to the adoption of smart systems and EV development, while Consumer Electronics continues to grow due to the proliferation of connected devices. The diversification across sectors buffers the market against downturn in any single industry.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-vibration-sensors-market
Frequently Asked Questions
Who are the key players in China Vibration Sensors Market industry?
Key players in the China Vibration Sensors Market include Honeywell, TE Connectivity, Bosch, SKF, and Omron. These companies lead through extensive R&D, innovative sensor technologies, robust product portfolios, and strong local partnerships, driving advanced vibration monitoring solutions across manufacturing, automotive, and industrial applications.
What is the China Vibration Sensors Market growth?
The China Vibration Sensors Market has experienced robust growth, with a CAGR above 7% in recent years, propelled by rising industrial automation and predictive maintenance needs. For instance, SKF expanded its vibration monitoring solutions in 2023, catering to China’s demand for smart manufacturing technologies.
Which segment accounted for the largest China Vibration Sensors Market share?
The industrial machinery segment led the China Vibration Sensors Market, driven by increased demand for predictive maintenance and equipment health monitoring. Frequent use of vibration sensors in manufacturing lines has resulted in enhanced operational efficiency, particularly as factories pursue Industry 4.0 integration.
Thanks & Regards,
priya
sales@bussinessinsights.com