

Blogs
Party Balloon Market: Why 6.5% CAGR and Shifting Demand Reshape 2026–2032
By PW Consulting, 2026-09-21
Party Balloon Market: Strategic Trends and Commercial Opportunities in a Maturing Sector
The party balloon market has evolved from a simple seasonal commodity into a nuanced segment of the broader event and decorative products industry. What was once dominated by volume-driven latex sales is now shaped by sustainability mandates, supply chain reconfiguration, and a clear bifurcation between residential and commercial demand. For executives and investors, the sector presents a steady growth trajectory but demands strategic repositioning to capture value in a landscape that is increasingly defined by regulatory compliance, material innovation, and regional capacity shifts.
Market Snapshot and Core Challenges
A Baseline of Measured Expansion
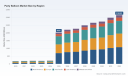
The overall market has demonstrated consistent growth over the past half-decade, with revenue climbing from roughly 180 million at the start of the period to more than 2.7 billion by the current baseline year. Forward projections indicate a compound annual growth rate of approximately 6.5 percent through the end of the forecast horizon, ultimately reaching nearly 3.15 billion in annual revenue. This expansion reflects both enduring consumer demand for decorative event products and a structural uplift from commercial applications, where balloon installations, themed retail displays, and corporate event styling contribute a larger share of revenue than residential use.
The geographic footprint remains broad but uneven. North America and Europe continue to anchor demand, supported by mature event cultures and retail infrastructure, while Asia Pacific has emerged as a meaningful growth engine, driven by rising disposable incomes, expanding middle-class consumption, and a growing professional event decoration sector. Latin America and the Middle East and Africa contribute smaller but steady portions of the total, often characterized by localized production, seasonal demand spikes, and price-sensitive consumer segments.
Within the product mix, latex balloons remain the dominant category, supported by their lower unit cost, versatility, and widespread acceptance in both retail and professional decoration channels. Foil balloons occupy the second position, valued for their longer float time, printed customization potential, and role in seasonal and commercial displays. Bubble balloons and other specialty formats represent a smaller but strategically important niche, appealing to premium event decorators and consumers seeking distinct visual effects. The commercial application segment has grown to a position of clear importance, reflecting how balloons are increasingly used as part of broader experiential marketing, hospitality, and retail environments rather than solely as casual household decorations.
Three Pressures Shaping the Market's Next Chapter
Despite the encouraging growth path, the sector is navigating three interconnected challenges that will define competitive outcomes over the next several years.
First, regulatory scrutiny around environmental impact is rewriting the rules of material choice and product use. Restrictions on non-biodegradable balloon manufacturing and release, alongside broader single-use plastic directives in major markets, have pushed manufacturers and distributors to reconsider formulations, end-of-life pathways, and public messaging. At the same time, multiple governments across the U.S., EU, UK, and Australia have limited the release of helium balloons due to environmental concerns. These measures are not only affecting how products are sold but also reshaping customer expectations around responsible decoration practices.
Second, cost volatility in core raw materials is eroding margin predictability. Natural rubber prices in Southeast Asia have shown upward movement, with recent readings above the two-dollar-per-kilogram threshold, adding pressure to input costs for latex-based products. In a market where many price points are already competitive and volume-driven, sustained raw material inflation can force difficult trade-offs between price maintenance, product quality, and supplier relationships.
Third, trade and classification friction is introducing new complexity into cross-border supply chains. Enhanced customs scrutiny around tariff classification for recreational items, including latex balloons, has increased compliance overhead and the risk of shipment delays. For manufacturers and traders that rely on multi-country sourcing, packaging, and distribution networks, this environment demands more rigorous documentation, better classification discipline, and potentially reshuffled sourcing maps.
Key Drivers Reshaping the Sector
Sustainability as a Strategic Filter, Not a Marketing Add-On
Environmental regulation and consumer sentiment are moving sustainability from a peripheral concern to a core strategic filter. The cumulative effect of single-use plastic directives and helium release restrictions has made biodegradability, material sourcing, and product behavior after use central considerations for both manufacturers and professional decorators. Companies that can credibly offer responsibly produced latex, clearer usage guidance, and alternatives that reduce environmental impact are better positioned to retain customers in markets where compliance and reputation increasingly overlap.
PW Consulting
This dynamic is also spurring product and process innovation. Some manufacturers are emphasizing professional-grade offerings with stronger quality consistency and a more defined sustainability narrative, which helps them command attention in event and retail channels where trust and differentiation matter. The shift is not simply about materials; it is about building a coherent story around responsible production, use, and disposal that aligns with customer expectations and regulatory requirements.
Commercial Demand and the Rise of Purpose-Built Applications
A major structural driver is the increasing importance of commercial applications. Balloons are no longer limited to spontaneous home celebrations; they are integrated into retail environments, hospitality venues, brand activations, and professional event styling. This shift favors products and formats that offer stronger visual impact, better durability, and reliable consistency across larger installations. Foil balloons, with their printed customization potential and longer display life, and bubble balloons, which create distinctive premium effects, are particularly relevant in these contexts.
For businesses serving this segment, the commercial channel changes the economics of the market. Repeat B2B relationships, volume orders, and the need for dependable supply become more important than one-off consumer purchases. It also raises the bar for product uniformity, packaging, and after-sales support. Companies that can standardize offerings and build dependable supply relationships are better placed to capture the higher-value commercial segment, which now accounts for a substantial portion of total revenue.
Supply Chain Reconfiguration and Capacity Expansion
Capacity investments are reshaping the supply landscape in ways that will influence cost structures and regional competitiveness. Recent expansion announcements signal a deliberate push to increase production throughput and strengthen proximity to key demand centers. One major latex manufacturer opened a new plant in Mexico with annual capacity reaching 400 million units, while another specialist in latex balloons added a new facility in Colombia, investing roughly 40 million dollars to add monthly capacity of 60 million balloons.
These moves point to a broader trend: producers are looking to scale efficiently, diversify geographic exposure, and reduce dependence on concentrated supply nodes. For downstream buyers, such expansion can translate into greater availability, more competitive pricing over time, and improved resilience against localized disruptions. At the same time, it raises the stakes for manufacturers that have not yet modernized capacity, automated production, or diversified their manufacturing footprint. The ability to meet growing demand while controlling costs will increasingly separate leaders from followers.
Retail Channel Dynamics and the Helium Factor
Helium availability and cost remain an underappreciated influence on market behavior. Restrictions on helium balloon releases, combined with the operational realities of sourcing helium for inflated products, are nudging both consumers and event professionals toward air-filled options, alternative materials, and display techniques that do not rely exclusively on floating effects. This is not a collapse of demand but a reorientation of how balloons are used. Retailers, decorators, and event planners are adapting with creative designs that prioritize visual impact, longevity, and practicality over floating duration alone.
For manufacturers, this environment rewards product portfolios that perform well in both air-filled and helium-filled applications, as well as packaging and presentation that help customers deploy balloons effectively in constrained conditions. The broader implication is that product utility is being redefined, and the winners will be those who can support new usage patterns without sacrificing the festive appeal that drives the category in the first place.
Competitive Landscape: Positioning, Differentiation, and Evolution
Diverse Leaders, Distinctive Value Propositions
The market's competitive field includes a mix of established manufacturers with broad regional reach, specialists focused on professional and retail channels, and producers leveraging automation or sustainability narratives to stand out. Several companies illustrate the range of strategic approaches now in play.
- Pioneer Balloon Company, based in Wichita, Kansas, manufactures high-quality latex, microfoil, and bubble balloons for professional event and party decoration. Its recent operational move to open a new latex plant in Mexico illustrates a capacity-forward strategy aimed at supporting scale and regional availability.
- Belbal, headquartered in Poland, focuses on premium natural latex balloons in a wide range of sizes, colors, and retail formats. Its positioning emphasizes product range and retail readiness, appealing to distributors and decorators who need consistent variety.
- Gemar Balloons, located in Casalvieri, Italy, combines latex and foil manufacturing with an emphasis on sustainability and professional-grade products. Its narrative links quality and environmental responsibility, a combination that resonates with events and commercial buyers seeking credible differentiation.
- CTI Industries, in the United States, produces both helium-filled and air-filled latex and foil balloons for retail and event use, aligning its offering with the practical needs of multiple channels and usage scenarios.
- Sempertex, based in Colombia, specializes in latex balloons for party and event decoration markets and has reinforced its expansion trajectory with a significant new facility investment, adding monthly output in the tens of millions of units.
- Balonevi, in Turkey, produces natural latex balloons with automated production for global party and event applications, highlighting the role of automation in meeting scale and consistency requirements.
- Anagram International, in the United States, is a leading manufacturer of foil and latex balloons for birthdays, parties, graduations, and events, reflecting a broad consumer-event orientation with strong brand recognition in key occasions.
- Latex Occidental, in France, manufactures latex balloons with global brand partnerships and private-label production, showing how contract and brand-aligned manufacturing can extend reach without necessarily building a consumer-facing brand of its own.
- Maple City Rubber Company, also in the United States, produces Tuftex latex balloons and related party balloon products, representing a long-standing manufacturing presence with a focus on latex-based product consistency.
How the Leaders Differentiate
Across these players, a few strategic themes emerge. Some compete primarily on scale and capacity, using production expansion and geographic diversification to secure supply advantages and cost leverage. Others lean into product quality and professional-grade consistency, targeting event decorators and commercial clients who value reliability and repeatability. A further group uses sustainability and responsible sourcing as a point of differentiation, aligning product attributes with regulatory trends and buyer preferences. Private-label and partnership-based models also remain relevant, allowing manufacturers to serve multiple channels without heavy consumer branding investment.
The implications are clear. No single formula dominates. Instead, competitive success depends on aligning the company's strengths with the segment it serves. A producer focused on retail volume will need a different set of capabilities than one built around professional event supply or B2B commercial contracts. The companies that perform best will be those that can combine reliable quality, sensible cost management, and a credible response to environmental and regulatory expectations.
Consolidation, Fragmentation, and the New Entrant Question
The market's concentration remains relatively modest, with the top few firms holding a minority share of total revenue. This fragmented structure suggests room for continued competition but also hints at potential consolidation over time, especially as capacity investments raise the cost of staying competitive and as buyers increasingly prefer suppliers that can meet broader requirements around volume, compliance, and consistency. At the same time, niche entry points exist for companies that serve specific regions, product formats, or premium event segments. New entrants that can offer differentiated materials, localized production, or specialized customer support may find opportunities even in a market where several established players already operate.
Party Supplies Market
One to watch is the interplay between capacity growth and raw material dynamics. Expanding production can improve availability and potentially moderate pricing pressure, but only if input costs and trade conditions are manageable. If raw material inflation persists or trade friction intensifies, capacity expansion alone will not guarantee margin health. Companies that pair investment with flexible sourcing and disciplined cost control will be better positioned to convert growth into profitable outcomes.
Three Trends to Watch and the Opportunities They Unlock
Trend One: Sustainability Moves From Compliance to Competitive Advantage
Over the next three to five years, sustainability will increasingly function as a competitive parameter rather than a compliance checkbox. Buyers in commercial and professional channels will likely favor suppliers that can demonstrate responsible material sourcing, clear usage guidance, and product characteristics aligned with environmental expectations. This opens opportunities for manufacturers that invest in credible sustainability practices, communicate them clearly, and integrate them into product design and packaging. It also creates room for innovation in biodegradable formulations, alternative material blends, and usage models that reduce environmental impact without sacrificing appeal.
The opportunity lies in turning a constraint into a point of differentiation. Companies that act early can build trust with event professionals, retail partners, and brand customers who are under their own pressure to demonstrate responsible sourcing and product choices. The risk is that vague or inconsistent claims will be scrutinized more closely, especially in markets where regulatory expectations are rising and customers are becoming more literate about material and environmental issues.
Trend Two: Commercial Applications Drive a Higher-Value Segment
As commercial use continues to grow in importance, the market will increasingly reward products and services tailored to B2B and professional environments. This includes stronger consistency across batches, formats suited to larger displays, packaging that supports professional handling, and service levels that meet the demands of repeat business. The commercial segment's growth also suggests opportunities in related services and support, such as design guidance, bulk ordering systems, and dependable logistics for time-sensitive events.
Businesses that recognize this shift can pursue higher-value relationships rather than competing solely on unit price. The associated risk is that commercial buyers will become more demanding over time, expecting suppliers to deliver on quality, timing, and compliance with little room for disruption. Suppliers that fail to adapt to these expectations may find themselves relegated to lower-margin, less differentiated transactions.
Party Costumes Market
Trend Three: Regional Capacity and Trade Realignment Will Shape Cost and Availability
Continued capacity additions in the Americas, combined with ongoing scrutiny of trade classification and customs processes, point to a period of regional realignment. Some production is likely to move closer to major demand centers, reducing exposure to long, complex supply routes and improving responsiveness. At the same time, raw material price movements, especially in natural rubber, will remain a swing factor for input costs and overall margin potential. These dynamics create opportunities for players that can manage regional sourcing intelligently, maintain flexible production, and plan for volatility rather than assuming a stable cost base.
For commercial strategy, this means that supply chain resilience will increasingly be part of the value proposition. Buyers will appreciate suppliers that can demonstrate reliable delivery, clear tariff and classification handling, and contingency planning for input cost swings. The uncertainty lies in the pace and direction of trade policy changes and raw material trends; businesses that build scenario flexibility into their sourcing and pricing approaches will be better prepared for whatever path emerges.
Strategic Actions for Decision-Makers
For Manufacturers and Brand Owners
- Align product portfolios with commercial demand by strengthening consistency, packaging, and formats suited to professional installations, while maintaining credible options for retail consumers.
- Treat sustainability as a core design and communication priority, ensuring that material choices, usage guidance, and product claims are coherent and defensible in regulated markets.
- Use capacity and geographic diversification strategically, balancing expansion with disciplined cost control and flexible sourcing to protect margins when raw materials and trade conditions move against you.
For Investors and Strategic Buyers
- Evaluate companies on the basis of their ability to convert capacity growth into profitable volume, not just on installed capacity alone. Margin resilience under raw material and trade pressure is a critical indicator of durability.
- Look for businesses with clear segment focus and credible differentiation, whether through quality, sustainability, commercial service, or regional reach, rather than undifferentiated volume plays.
- Monitor regulatory and trade developments closely, since shifts in classification, environmental rules, and helium-related practices can change the attractiveness of specific products and channels relatively quickly.
For Procurement and Channel Partners
- Prioritize suppliers that can demonstrate consistent quality, dependable delivery, and a clear approach to compliance and environmental expectations, especially when serving commercial or professional clients.
- Diversify sourcing where feasible to reduce exposure to concentrated supply or single-region risk, and maintain clear documentation around classification and customs requirements to avoid delays.
- Plan for input cost variability by combining long-term relationships with flexible purchasing strategies, and consider product alternatives that can preserve visual impact while reducing dependence on the most volatile inputs.
Navigating the Road Ahead
The party balloon market is moving through a period in which steady growth coexists with structural change. Demand remains healthy across residential and commercial channels, but the rules of competition are being rewritten by sustainability expectations, raw material dynamics, and supply chain realignment. Companies that treat these forces as strategic signals rather than background noise will be better placed to capture the next wave of growth.
For those seeking a more detailed view of the segment, including granular breakdowns and customized guidance, the full research report provides a deeper look at the data, regional and category dynamics, and scenario-based implications for different business models. It is designed to support practical decision-making with focused analysis that goes beyond the headline numbers.
For detailed analysis of this topic, please visit the official page: Party Balloon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Coronary Stents Market: How 6.5% CAGR and Drug-Eluting Dominance Redefine Growth
By PW Consulting, 2026-09-21
Beyond the Catheter Lab: Strategic Shifts Reshaping the Coronary Stents Market
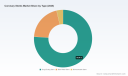
The coronary stents market has evolved from a volume-driven business into a precision-driven arena where clinical differentiation, reimbursement architecture, and regional procurement behavior intersect. With the global market reaching approximately USD 6,920 million in 2025 and projected to expand at a 6.5% CAGR through 2032, the industry is not merely scaling—it is restructuring around performance metrics, procedural economics, and patient stratification. This transformation carries distinct implications for manufacturers navigating R&D pipelines, investors evaluating portfolio risk, and health systems optimizing interventional cardiology programs. The following analysis maps the structural dynamics, competitive maneuvers, and forward-looking opportunities that will define the next phase of value creation in coronary stenting.
Market Landscape and Defining Challenges
The market's trajectory over the past half-decade reflects steady expansion with notable inflection points. From a base of roughly USD 5,800 million in 2020, revenue progression has been characterized by moderate annual growth, with accelerated movement in recent years as newer-generation platforms and procedural complexity drove uptake. The forecast horizon through 2032 points toward a market approaching the USD 10.7 billion range, sustained by procedural volume growth, technology upgrades, and shifting clinical protocols. This growth, however, is not uniform across segments; it is increasingly concentrated among manufacturers that can demonstrate improved deliverability, reduced late-stage complications, and alignment with reimbursement incentives.
PW Consulting Health Care Research Center
Three interlocking challenges are redefining strategic priorities:
- Clinical differentiation is narrowing the window for me-too launches. Operators now expect stents that perform predictably in complex anatomy, support rapid endothelialization, and minimize long-term inflammatory exposure. Devices that do not articulate a clear clinical or procedural advantage face intensifying scrutiny during formulary reviews and procurement tenders.
- Reimbursement architecture is shaping procedural economics. Pricing and coverage for stent placement are being influenced by procedural coding adjustments, bundled payment pressures, and payer attention to total cost of care. As coding structures evolve to recognize complexity, manufacturers must align product attributes with the economic signals that drive procedure selection and site-of-care decisions.
- Supply chain resilience and input cost volatility are reshaping margins. Material sourcing, manufacturing precision, and global logistics continue to introduce variability. Companies that can stabilize input costs while preserving quality and delivery timelines gain a structural advantage in both price negotiations and product availability.
These dynamics create a market where scale alone is insufficient. The ability to demonstrate differentiated clinical value, navigate reimbursement signals, and maintain cost discipline determines who captures share as the market moves toward the next billion-dollar milestone.
Core Drivers Shaping Value Creation
Technological Innovation and Clinical Performance
Innovation in coronary stents is increasingly focused on polymer science, scaffold architecture, and deliverability in complex lesions. The emphasis has shifted from simply maintaining vessel patency to reducing long-term inflammatory responses, accelerating endothelial healing, and improving trackability through tortuous anatomy. Recent product milestones underscore this direction. In early 2025, Medtronic secured regulatory clearance for an upgraded Resolute Onyx drug-eluting stent featuring an improved polymer designed to accelerate endothelial healing and lower thrombosis risk. Shortly thereafter, Boston Scientific received FDA approval for the SYNERGY XD bioabsorbable polymer stent, positioned to reduce long-term inflammation and thrombosis risks. Abbott followed with the launch of the XIENCE Sierra Flex, a newer-generation platform engineered for complex lesions with enhanced flexibility, improved deliverability, and faster endothelial healing.
These developments signal a broader industry pivot: the next wave of value will accrue to platforms that combine favorable acute procedural performance with durable long-term safety. For manufacturers, the implication is clear—R&D must prioritize endpoints that matter to operators and payers, including deliverability in challenging anatomy, healing profiles, and compatibility with complex percutaneous coronary intervention techniques. For investors, this environment rewards companies with credible pipelines and demonstrated regulatory execution rather than those relying on incremental feature sets.
Cardiac Stent Market
Policy and Regulatory Environment
Regulatory pathways continue to shape the pace and cost of market entry. Coronary drug-eluting stents classified as Class III devices require premarket approval submissions to the FDA Office of Cardiovascular Devices, reinforcing the importance of robust clinical data packages and predictable approval timelines. The regulatory environment also interacts with reimbursement structures in ways that influence adoption. For example, percutaneous transcatheter placement of intracoronary drug-eluting stent(s), with or without other therapeutic intervention, any method; single vessel is assigned to APC 0656 under CMS classification. Meanwhile, a new complex PCI code introduced for 2026 provides notably higher RVU credits for procedures involving two or more distinct lesions or bifurcation treatment. These coding and coverage dynamics create economic incentives that can accelerate the use of advanced platforms in higher-complexity cases, provided the devices and procedural workflows align with the intended indications and documentation requirements.
For companies, regulatory predictability and reimbursement alignment are strategic assets. Early engagement with regulatory expectations, combined with clear understanding of how procedural codes affect site economics, can reduce time-to-market friction and support smoother adoption trajectories. Conversely, misalignment in either dimension can slow uptake regardless of clinical promise.
Demand-Side Shifts in Clinical Practice
Cardiology practice patterns are evolving toward risk-tailored interventions, increased attention to high-bleeding-risk populations, and broader adoption of techniques that address complex lesion sets. Clinical teams are increasingly evaluating devices not only for acute results but also for their contribution to long-term outcomes and procedural efficiency. This shift is reinforcing demand for platforms that support reliable deployment across a spectrum of anatomies and patient profiles, including de novo lesions and patients with elevated bleeding risk where stent selection and adjunct therapy must be carefully balanced.
Demand is also being influenced by the growing importance of procedural complexity as a driver of value. As coding frameworks increasingly recognize multi-lesion and bifurcation work, operators are incentivized to select tools that can manage these scenarios effectively. The commercial consequence is a market where flexibility, deliverability, and procedural control are becoming central purchasing considerations, especially in centers that handle higher-acuity case mixes.
Supply Chain and Cost Structure Dynamics
Cost structures in stent manufacturing remain sensitive to material availability, quality control requirements, and the economics of global distribution. Polymer-based and metal-based scaffolds each carry distinct sourcing and processing considerations, and disruptions in either channel can affect lead times and margin profiles. At the same time, procurement teams in health systems and group purchasing organizations are placing greater emphasis on total cost of ownership, including device performance, procedural efficiency, and downstream complication risk. This environment favors manufacturers that can deliver consistent quality, predictable availability, and demonstrable value in complex procedures, rather than competing solely on unit price.
Strategic management of supply chain resilience, combined with clear communication of value propositions tied to procedural outcomes, is becoming a differentiator. Companies that can balance cost discipline with clinical credibility are better positioned to navigate both tender processes and direct hospital negotiations.
Competitive Landscape and Leadership Strategies
The coronary stents market is characterized by significant concentration, with a handful of global leaders commanding the majority of share. This structure places a premium on differentiated platforms, disciplined commercial execution, and strategic clarity around target patient populations. Abbott, Boston Scientific, and Medtronic remain central to the competitive conversation, each advancing distinct value propositions and recent product milestones that reflect differing strategic focal points.
Abbott continues to emphasize newer-generation drug-eluting systems, exemplified by the March 2025 launch of the XIENCE Sierra Flex designed for complex lesions with enhanced flexibility and improved deliverability. The company's focus on deliverability and endothelial healing underscores an approach that connects acute procedural performance with longer-term outcomes. Boston Scientific has been advancing platforms for complex lesions and in-stent restenosis, including the February 2025 FDA approval of SYNERGY XD bioabsorbable polymer stent aimed at reducing long-term inflammation and thrombosis risks. This reflects a strategy oriented toward addressing residual risks associated with long-term polymer exposure and expanding applicability in challenging clinical scenarios. Medtronic's trajectory centers on durable performance in de novo lesions and high-bleeding-risk patients, highlighted by the January 2025 CE clearance of an upgraded Resolute Onyx platform with an improved polymer intended to speed endothelial healing and lower thrombosis risk. Together, these three players illustrate how leaders are competing on the intersection of polymer technology, procedural handling, and patient stratification.
Beyond the largest players, a competitive tier of specialists and regional champions is shaping the market from different angles. Terumo and Biotronik continue to advance bioresorbable polymer and sirolimus-eluting platforms, reinforcing interest in healing-oriented designs. MicroPort, with its drug-eluting portfolio, reflects the growing influence of regional manufacturing strength and expanding commercial footprints in Asia and beyond. Smaller innovators such as Elixir Medical and Hexacath are exploring bioadaptor and bio-active approaches, while Cook Medical's covered stent systems underscore the continued relevance of specialized applications. These players demonstrate that differentiation can emerge from novel scaffold concepts, niche clinical use cases, or regional distribution advantages, even within a concentrated market.
Market structure is evolving in two complementary directions. Consolidation pressures remain present as larger platforms seek to broaden indication coverage and streamline portfolios, while differentiation pressures create space for targeted entrants that can address specific clinical gaps or regional procurement dynamics. The likely trajectory is not a simple shakeout but a layered landscape: dominant platforms competing on broad clinical credibility and procedural versatility, alongside focused innovators pursuing distinct mechanisms or regional advantages. For companies operating in this environment, strategy must address both ends—protecting broad footprint value while identifying where a specialized proposition can command premium positioning.
Forward-Looking Trends and Commercial Implications
Trend 1: Polymer and Scaffold Design as the New Battleground
The most consequential differentiation in the near term will likely come from polymer chemistry, scaffold architecture, and the balance between durability and bioabsorbability. As platforms demonstrate improved endothelial healing and reduced long-term inflammatory exposure, clinical teams will increasingly weigh these attributes in device selection, particularly for patients where late complications carry disproportionate risk. Commercially, this trend rewards manufacturers with credible data packages and clear narratives around healing profiles, and it creates opportunities for partnerships and licensing in polymer science. The risk side lies in the possibility that head-to-head clinical evidence narrows perceived differences, shifting competition toward cost and availability unless performance advantages remain clinically meaningful.
Trend 2: Coding and Reimbursement as Adoption Accelerators
Procedural coding and coverage decisions are becoming more influential in shaping adoption patterns, especially where complexity-based incentives are introduced. New complex PCI coding frameworks that provide higher RVU credits for multi-lesion or bifurcation procedures can make advanced platforms more economically attractive in high-acuity settings. Manufacturers that align their indications, training, and documentation support with these coding realities can benefit from faster integration into complex case workflows. The uncertainty lies in the pace and consistency of payer responses across regions, and in the potential for future adjustments that alter the economic calculus. Companies should monitor reimbursement signals as closely as clinical data, because economics can accelerate or constrain uptake regardless of device performance.
Trend 3: Complexity-Led Growth and Regional Divergence
Growth in the coming years is expected to be shaped by procedural complexity, patient risk profiles, and regional differences in access, procurement, and clinical practice. Markets with expanding interventional capacity and increasing treatment of complex lesion sets are likely to drive demand for flexible, deliverable platforms. At the same time, regional procurement models and health system economics will continue to influence the pace of adoption for premium-priced devices. This divergence creates opportunities for companies to tailor value propositions by setting, focusing on deliverability and procedural efficiency where complexity is rising, while emphasizing total value and consistency where procurement is price-sensitive. The main risk is that regional variability can slow global portfolio scaling if value narratives are not adapted to local economic and clinical priorities.
Strategic Recommendations for Decision-Makers
Manufacturers should prioritize platforms that connect acute deliverability with durable safety profiles, while investing in evidence generation that speaks to operator priorities and reimbursement realities. Portfolio decisions should be guided by the ability to address complex lesions and higher-risk patient groups, supported by clear training and procedural support that helps sites capture the value of new coding incentives. Supply chain stability and consistent quality should be treated as commercial advantages, not just operational concerns, because availability and reliability increasingly influence purchasing decisions alongside clinical features.
Investors should evaluate pipelines against regulatory execution, reimbursement alignment, and the credibility of differentiation claims. The market appears most rewarding for companies that can demonstrate meaningful clinical or procedural advantages and navigate approval pathways efficiently. Portfolio risk should be assessed with attention to concentration dynamics, the durability of polymer-related innovation claims, and exposure to regional procurement variability. Companies with broad footprint value and credible complexity-focused platforms are better positioned to sustain share as coding and clinical practice evolve.
Stent Grafts Market
Procurement leaders and health system decision-makers should focus on total value rather than unit price alone, weighing device performance in complex cases, procedural efficiency, and downstream complication risk. Engaging clinical teams early to identify the features that most affect outcomes in local case mixes can improve formulary decisions and tender positioning. Monitoring reimbursement updates and coding changes is equally important, because these signals can reshape the economics of procedure selection and the relative attractiveness of different device categories.
The coronary stents market is entering a phase where clinical nuance, procedural economics, and supply discipline jointly determine competitive outcomes. The leaders who capture the next wave of growth will be those who translate innovation into measurable value at the point of care, align with reimbursement architecture, and maintain reliable execution across global demand cycles. For organizations seeking more granular segmentation data, regional procurement patterns, and tailored scenario analysis, the full PW Consulting report provides a deeper quantitative and strategic foundation, including detailed market sizing, segmentation breakdowns, and company-level competitive assessments designed to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Coronary Stents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Rail Market Insights: Why 6.47% CAGR Through 2032 Signals a Structural Shift
By PW Consulting, 2026-09-21
Rail Market Strategic Trends and Commercial Opportunities Through 2032
The global rail market has entered a decisive growth phase, expanding from $142.5 billion in 2020 to an estimated $193.76 billion in 2025, with projections indicating continued acceleration toward $300.51 billion by 2032. This trajectory reflects a compound annual growth rate of 6.47% across the forecast period, positioning rail infrastructure and rolling stock as one of the more resilient segments within heavy industrial markets. The expansion is not merely cyclical recovery but structural growth driven by transportation decarbonization mandates, urban mobility shifts, and substantial infrastructure investment programs across multiple geographies. For executives and investors evaluating exposure to this sector, the question has shifted from whether rail markets will grow to how value will be distributed across the supply chain and which capabilities will capture disproportionate returns.
Understanding the current market architecture requires looking beyond headline figures to examine where capital is flowing, which segments are absorbing investment, and what structural constraints are shaping competitive dynamics. The market composition reveals a concentrated landscape where scale, technical certification, and regional presence create meaningful barriers, while simultaneously leaving openings for specialized players who can address niche performance requirements or integrate emerging technologies into legacy systems.
Market Architecture and Structural Challenges
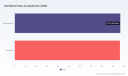
The rail market operates across multiple interconnected layers, from foundational track infrastructure and electrification systems to signaling architectures and rolling stock manufacturing. Revenue distribution across these components reflects both historical investment patterns and emerging priorities. Track systems continue to represent the largest share of market activity, followed by rolling stock and signaling infrastructure, with electrification and power supply representing a smaller but rapidly evolving segment. Application demand splits between passenger and freight operations, with both segments showing sustained capital deployment rather than one dominating at the expense of the other.
Three structural challenges define the current inflection point and will shape competitive outcomes over the next several years.
Supply Chain Fragmentation and Lead Time Volatility
Rail manufacturing remains heavily dependent on specialized steel production, precision casting, and complex assembly processes that span multiple jurisdictions. The industry has experienced recurring pressure from raw material pricing fluctuations, constrained capacity for long rail production, and uneven availability of certified components. These dynamics create execution risk for large infrastructure programs and compress margins for manufacturers who cannot optimize inventory positioning or secure forward commitments on critical inputs. The challenge is particularly acute for operators managing multi-year deployment schedules where supply interruptions cascade into operational delays and cost overruns.
Aging Infrastructure Versus Modernization Mandates
Much of the existing rail infrastructure in mature markets requires significant rehabilitation, while emerging markets are simultaneously expanding networks to support economic development. This dual pressure creates a complex investment environment where capital must be allocated between maintenance of legacy systems and deployment of next-generation components. The tension is especially visible in signaling and electrification, where upgrading existing corridors requires compatibility with operational continuity while meeting newer safety and capacity standards. Organizations that can deliver modular upgrade pathways rather than full corridor shutdowns gain a distinct advantage in winning procurement competitions.
Regulatory Alignment and Certification Complexity
Rail systems operate under stringent safety and interoperability requirements that vary across jurisdictions. While harmonization efforts continue, certification processes remain time-intensive and can delay market entry for new technologies or cross-border deployments. The regulatory environment is also evolving to accommodate automated operations, data-driven maintenance, and cybersecurity requirements for signaling and control systems. Companies navigating this landscape must balance innovation speed with compliance rigor, and those able to establish recognized certification pathways early position themselves to shape procurement specifications rather than react to them.
Key Demand Drivers Reshaping the Market
The market trajectory is being pulled by several reinforcing forces that extend beyond cyclical infrastructure spending. Understanding how these drivers interact helps identify where growth will concentrate and which capabilities will be most valued by buyers.
Technology Innovation and Operational Integration
Rail technology is moving from isolated component improvements toward integrated system performance. Automation, advanced diagnostics, and data analytics are increasingly embedded into both rolling stock and infrastructure management. Recent developments illustrate this shift clearly. Hitachi Rail opened a new advanced manufacturing facility in Hagerstown, Maryland, delivering railcars equipped with AI-powered video analytics for metro systems, including the D.C. Metro and Baltimore. This reflects a broader move toward smart fleet deployment where onboard intelligence supports maintenance forecasting, passenger safety monitoring, and operational efficiency. In parallel, Hitachi Rail partnered with DB Cargo to launch Europe’s first automated freight locomotive equipped with ATO and RTO technology, signaling that automation is expanding beyond passenger corridors into freight operations where labor constraints and throughput targets are intensifying interest in assisted and autonomous running.
For manufacturers and technology providers, the commercial implication is that value is shifting toward integrated solutions rather than standalone hardware. Companies that can combine physical components with software-enabled performance, predictive maintenance, and remote monitoring are better positioned to command premium positioning and longer-term service relationships.
Policy Momentum and Infrastructure Funding Cycles
Government investment programs and transportation policy frameworks continue to serve as powerful demand catalysts. Rail benefits from its alignment with decarbonization goals, congestion reduction targets, and supply chain reliability objectives. Public funding is increasingly tied to performance criteria, interoperability standards, and domestic manufacturing content, which shapes not only the volume of demand but also the composition of eligible suppliers. The policy environment also influences technology adoption, as procurement specifications increasingly reflect next-generation track circuit capabilities aimed at improving occupancy detection and broken rail identification, replacing legacy systems with more resilient monitoring architectures.
For industry participants, policy cycles create both opportunity and planning complexity. Multi-year funding commitments support capacity expansion and technology investment, but shifting regulatory emphasis and qualification requirements can alter competitive dynamics mid-cycle. Organizations that maintain active engagement with standards development and procurement evolution are better equipped to anticipate specification changes and align product roadmaps accordingly.
Demand-Side Shifts in Mobility and Freight Logistics
Passenger mobility patterns and freight logistics strategies are reshaping where rail demand emerges. Urban and regional passenger rail continues to attract investment as cities manage congestion and aim to expand mass transit capacity. At the same time, freight operators are evaluating rail as a component of broader logistics resilience, particularly where consistent volume movement and lower emissions intensity provide competitive advantage. The balance between passenger and freight investment suggests that both segments will remain significant demand centers, but with different procurement rhythms and specification priorities. Passenger projects tend to emphasize capacity, comfort, and integrated transit features, while freight procurement prioritizes durability, throughput, and total cost of ownership across heavy-use cycles.
This divergence matters for suppliers because it affects product mix, service models, and go-to-market strategy. Companies that can tailor solutions to distinct operating profiles, rather than offering uniform specifications across applications, are more likely to win segmented contracts and build repeat engagement.
Cost Structure Evolution and Manufacturing Efficiency
Cost competitiveness in rail increasingly depends on production scale, material efficiency, and process innovation. The ability to produce longer rail lengths with consistent dimensional quality reduces joint-related maintenance and improves installation efficiency, which directly affects lifecycle cost for operators. In North America, manufacturers are supplying hot-rolled finished rails in lengths up to 320 feet with strong dimensional consistency and surface finish, reflecting process maturity that supports both freight and industrial applications. At the same time, broader labor economics and event-driven industry engagement, such as large-scale rail exhibitions expected to draw thousands of attendees from dozens of countries, illustrate the continued importance of relationship networks, technical exchange, and supply chain coordination in this market.
Cost structure advantages are not limited to raw material pricing. They also emerge from design standardization, reduced assembly complexity, and the ability to serve multiple rail environments with adaptable components. Suppliers that can demonstrate lower installed cost, faster deployment, and reduced maintenance burden are increasingly competitive, especially in procurement environments where total lifecycle economics outweigh upfront price comparisons.
PW Consulting
Competitive Landscape and Strategic Positioning
The rail market features a mix of established multinational suppliers, regional specialists, and technology-forward operators expanding their manufacturing and service footprint. Market concentration remains meaningful, with the top three competitors holding approximately 52% of market share and the top five reaching around 58%. This concentration reflects the importance of scale, certification breadth, and long-standing customer relationships in winning major infrastructure and rolling stock programs. At the same time, the presence of focused specialists indicates that specialized capability and regional responsiveness continue to matter, particularly in complex trackwork, fastening systems, and tailored material solutions.
Railway Equipment Market
Several leading companies illustrate different strategic angles within the market. Pandrol operates as a global leader in rail fastening systems, aluminothermic welding, track construction equipment, electrification solutions, and resilient track infrastructure components, with deployments across more than 100 countries. Its breadth across mainline, heavy-haul, and urban applications demonstrates how a component-focused supplier can achieve scale by standardizing high-performance interfaces while adapting to varied operating environments. Vossloh AG supplies rails, turnouts, concrete sleepers, fastening systems, and rail and turnout maintenance solutions for freight, high-speed, and urban rail, positioning itself across both infrastructure and maintenance segments. This dual exposure allows the company to engage customers across the asset lifecycle rather than only at initial installation.
In North America, voestalpine Railway Systems Nortrak specializes in design, innovation, and manufacturing of special trackwork, turnouts, frogs, crossings, switches, concrete and turnout ties, castings, and mouldings for Class I, passenger transit, and industrial rail sectors. Its recent acquisition of Unitrac Railroad Materials assets from Wabtec to expand special trackwork capacity illustrates a consolidation strategy aimed at strengthening regional manufacturing footprint and broadening material offerings. Steel Dynamics Inc. operates as a North American manufacturer of hot-rolled steel rails, joint and splice bars, guard bars, and mine ties, with continuous welded rail production extending to 320-foot lengths. Its profile underscores the continuing importance of domestic steel production capability and long-rail manufacturing in serving freight and industrial demand.
Differentiation Paths in a Concentrated Market
Leading competitors generally pursue one or more of the following differentiation strategies.
-
Lifecycle coverage: Expanding from product supply into maintenance, monitoring, and service integration to deepen customer relationships and capture recurring revenue.
-
Regional scale and responsiveness: Investing in local manufacturing and material capacity to reduce lead times, simplify logistics, and meet content or sourcing preferences in key markets.
-
Technical specialization: Concentrating on high-complexity components such as special trackwork, fastening systems, or custom castings where certification, engineering support, and application expertise create barriers to substitution.
-
Technology-enabled performance: Embedding analytics, automation, and advanced diagnostics into rolling stock and infrastructure solutions to improve operational outcomes and differentiate on total system value.
The competitive landscape is evolving through both consolidation and targeted expansion. Asset acquisitions are being used to secure capacity, broaden portfolios, and enter adjacent specialties, while established players with manufacturing footprint and technology capabilities are extending into automation and smart system integration. At the same time, new entrants and technology providers are finding openings in software-driven maintenance, analytics, and automation layers where traditional hardware dominance is less absolute. The likely direction is a market in which large suppliers continue to hold substantial share, but competitive advantage increasingly depends on the ability to combine physical manufacturing strength with technology integration, regional execution, and lifecycle service models.
Forward Trends and Commercial Implications
Looking toward 2026 through 2032, several trends are likely to define where value is created and how competitive dynamics shift.
Trend 1: Integrated Automation and Smart Operations Become Procurement Norms
Automation and data-driven operation are moving from pilot programs to broader deployment across both passenger and freight rail. The launch of automated freight locomotives and AI-enabled metro railcars indicates that operational intelligence is becoming part of the core product proposition rather than an add-on. Over the next several years, procurement specifications will increasingly expect compatibility with remote monitoring, predictive maintenance, and assisted operation. Commercial opportunity will favor suppliers that can deliver not only hardware but also the sensing, software, and integration capabilities needed to support smarter operations. The risk is that organizations underestimating the operational change, training, and cybersecurity requirements associated with automated systems may face adoption friction or delay.
Trend 2: Lifecycle Value and Service Integration Outweigh Pure Equipment Pricing
As infrastructure ages and modernization programs expand, buyers will place greater weight on total cost of ownership, maintenance burden, and uptime performance. This favors suppliers that can offer durable components, easier replacement pathways, and service models that reduce operational disruption. The trend also supports business models where recurring service revenue becomes a larger share of supplier economics. Companies that remain strictly transactional in their engagement may find margin pressure intensifying, while those that build long-term performance accountability can secure more stable relationships. A key uncertainty is the pace at which operators are willing to transition from legacy maintenance practices to new monitoring and replacement regimes, which will affect the speed of adoption.
Trend 3: Regional Manufacturing and Supply Chain Resilience Shape Sourcing Decisions
Supply chain reliability, lead time predictability, and regional content expectations will continue to influence procurement decisions. The ability to produce long rail lengths with consistent quality, maintain local inventory of critical components, and respond quickly to project-specific requirements will remain valuable, particularly in large markets where infrastructure programs are scaling. This trend supports continued investment in regional manufacturing assets and may encourage further consolidation among suppliers seeking to achieve scale and coverage. The uncertainty lies in how raw material availability, energy costs, and trade dynamics evolve, since these factors can alter the economics of localized production versus broader supply networks.
Strategic Considerations for Decision Makers
Different stakeholders face distinct priorities, but several actionable themes apply across the board.
For Rail Manufacturers and Component Suppliers
-
Prioritize lifecycle capability alongside product performance. Engineering strength in a single component category remains important, but customers increasingly value suppliers who can support installation, maintenance, and performance monitoring across the asset life.
Worldwide Rail Components Market -
Invest in technology integration where it strengthens competitive positioning. Automation-compatible hardware, diagnostic interfaces, and analytics-ready designs can differentiate offerings and support higher-value contracts.
-
Use targeted acquisitions or capacity expansion to secure regional manufacturing presence and specialty material capabilities, especially where special trackwork, fastening systems, or long-rail production are strategically important.
For Investors Evaluating Rail Exposure
-
Focus on companies with diversified revenue across components, applications, or service layers, since reliance on a single product cycle can increase volatility in a market where procurement timing and specification changes matter.
-
Assess exposure to automation, maintenance services, and regional manufacturing scale as indicators of future margin resilience, rather than looking only at top-line growth potential.
-
Monitor consolidation activity and capacity moves as signals of where competitive concentration is increasing and where niche specialists may be gaining or losing ground.
For Procurement Leaders and Rail Operators
-
Evaluate suppliers on total lifecycle performance and integration capability, not only upfront unit cost. Compatibility with monitoring, maintenance, and automation roadmaps can materially affect long-term operating economics.
-
Plan upgrade pathways that maintain operational continuity while adopting next-generation signaling and track monitoring capabilities, since full corridor shutdowns can create cost and scheduling risk that outweighs technical benefits if not managed carefully.
-
Balance multi-source strategies with the need for technical coherence, ensuring that component interfaces, certification standards, and service support align across the system rather than optimizing individual purchases in isolation.
Closing Perspective
The rail market is entering a period in which growth is increasingly tied to technological integration, lifecycle performance, and supply chain reliability rather than simple capacity expansion. The projected path from $193.76 billion in 2025 toward $300.51 billion by 2032 reflects a market where demand is broadening across passenger and freight applications, where automation and analytics are becoming embedded in core offerings, and where scale and specialization coexist as viable competitive models. The organizations that will capture the most durable value are those that can align product capabilities with evolving procurement priorities, maintain regional execution strength, and integrate service and technology into their market positioning.
For decision makers navigating this environment, the most useful intelligence is not broad market sizing alone but detailed visibility into segment dynamics, competitive moves, technology adoption patterns, and region-specific procurement behavior. PW Consulting’s comprehensive rail market research report provides deeper segmentation data, competitive profiling, and customized strategic guidance to support execution planning across manufacturing, investment, and procurement decisions. Readers seeking a fuller view of market splits, regional nuances, and forward scenario detail can explore the complete report for a more granular basis to evaluate opportunities and risks in the rail sector.
For detailed analysis of this topic, please visit the official page: Rail Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electric Submeter Market: Why the 6.98% CAGR Path to 2032 Changes Everything
By PW Consulting, 2026-09-21
Electric Submeter Market: Strategic Trends and Commercial Opportunities Through 2032
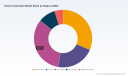
The electric submeter market has moved from a niche utility-billing adjunct to a core component of energy management, regulatory compliance, and operational efficiency across commercial, industrial, and residential sectors. Over the past half-decade, the sector has demonstrated steady expansion, with revenue climbing from approximately 163.15 million USD in 2020 to an estimated 215.0 million USD in 2025. The trajectory points toward a forecast period of 2026 through 2032, during which the market is projected to grow at a CAGR of 6.98 percent, reaching roughly 344.8 million USD by 2032. These figures reflect more than incremental hardware sales; they signal a structural shift in how facilities track, allocate, and optimize electricity consumption at a granular level.
For executives, strategists, and investors, the numbers provide a baseline, but the real value lies in understanding what is accelerating adoption, where friction points are accumulating, and which strategic moves will separate leaders from laggards. The following analysis maps the current market landscape, the forces reshaping demand and supply, the competitive dynamics among established and emerging players, and the trajectory likely to define the next several years.
Market Landscape and Core Challenges
The electric submeter market today sits at the intersection of regulatory mandates, building modernization cycles, and a growing appetite for data-driven energy accountability. Revenue growth over the historical period from 2020 to 2025 has been consistent, with the market surpassing the 200 million USD threshold as institutions and property operators increasingly treat submetering as a compliance and cost-management necessity rather than an optional upgrade. The forecast window through 2032 suggests continued expansion, though the pace will be shaped by how quickly standards, installation economics, and integration capabilities align across regions and building types.
Key Challenges and Inflection Points
Despite the upward trajectory, the market faces several structural challenges that will determine which segments scale efficiently and which encounter bottlenecks.
- Regulatory heterogeneity and compliance complexity. Submetering requirements are no longer uniform. Jurisdictions are introducing building-specific mandates, submetered-party inquiry procedures, and updated performance criteria that vary by application and geography. For technology providers and end users alike, navigating a patchwork of rules increases deployment risk, slows procurement cycles, and raises the cost of ensuring that installed systems remain compliant as regulations evolve.
- Installation economics and retrofit friction. Hardware cost is only one component of total cost of ownership. Retrofit installation expenses, which vary with building age, panel configuration, and labor availability, can materially affect project ROI. In older buildings, limited access to distribution panels and the need for customized routing can stretch timelines and budgets, making submetering less attractive unless the payback case is clearly quantified.
- Standardization and performance expectations. As submetering moves into revenue-grade and portfolio-level monitoring contexts, expectations around accuracy, interoperability, and data quality are rising. Updated metering codes and performance criteria are pushing vendors to demonstrate that devices can meet both operational monitoring needs and stricter billing-grade requirements. Companies that cannot align with evolving standards risk losing eligibility for public-sector evaluations and commercial contracts that increasingly reference recognized performance benchmarks.
These challenges are not stagnant barriers; they are inflection points. Markets that can reduce installation complexity, clarify compliance pathways, and demonstrate credible performance under updated standards will capture disproportionate share as procurement teams seek lower-risk deployments.
Core Drivers Reshaping the Market
The growth profile of the electric submeter market is being shaped by a combination of technology evolution, regulatory pressure, demand-side behavior shifts, and changing cost structures. Each driver reinforces the others, creating a feedback loop that is accelerating adoption in specific application areas while also raising the bar for product and service maturity.
Technology Innovation and Breakthroughs
Submetering technology is increasingly defined by real-time data capture, wireless deployment flexibility, and integration with analytics platforms. Devices that can deliver circuit-level visibility, tenant billing data, and portfolio energy monitoring are moving beyond simple consumption tracking to become operational tools for fault detection, load management, and energy reporting. The shift toward hardware-software bundles is particularly significant: organizations are looking for systems that not only measure electricity but also translate measurements into actionable insights, automated reporting, and centralized monitoring across multiple buildings.
This trend is visible in the growing emphasis on low-cost and revenue-grade options. Public-sector evaluations have highlighted submetering points at approximately 200 USD for standard accuracy and around 250 USD for revenue-grade accuracy, signaling that cost thresholds are becoming more defined and that competitive devices must balance affordability with performance. At the same time, installation cost benchmarks for retrofits—often ranging from 250 to 500 USD per unit depending on building age and panel configuration—mean that hardware price alone does not determine adoption. Solutions that reduce installation time, simplify wiring, or enable wireless architectures are gaining relevance because they lower the total friction of deployment.
Policy and Regulatory Environment
Policy is one of the strongest catalysts for submeter adoption. Mandates that require submeter installation in larger commercial spaces, along with updated rules for electricity and natural gas submetering, are expanding the addressable base of buildings that must measure consumption at a more granular level. In parallel, regulatory bodies are refining procedures related to submetered-party inquiries and system approvals, which increases transparency but also raises administrative expectations for metering providers and building operators.
Standard-setting activity is equally important. Updated codes for electricity metering that establish performance criteria for AC watthour meters, smart meters, and auxiliary devices are raising the baseline for what qualifies as a dependable metering solution. For commercial and public-sector buyers, alignment with recognized standards is increasingly a prerequisite rather than a differentiator. This regulatory momentum favors vendors that can document compliance, support auditable reporting, and adapt device performance to evolving test requirements.
Demand-Side Shifts in Consumer and Enterprise Behavior
End-user expectations are changing on two fronts. First, building owners and property operators are under greater pressure to manage operating expenses, allocate utility costs fairly, and demonstrate energy accountability to tenants and stakeholders. Submetering supports tenant billing, portfolio monitoring, and identification of inefficient loads, which makes it a practical tool for both cost control and sustainability narratives.
Second, the industrial and commercial sectors are demanding more circuit-level and system-level visibility. Facilities are not just asking whether total consumption is rising or falling; they want to know which circuits, tenants, or processes are driving usage. This demand is pushing submetering beyond aggregate measurement into diagnostic and operational use cases. In multifamily and commercial properties, the need for accurate billing and transparent usage data is particularly acute, while in industrial settings the focus is often on operational efficiency, load balancing, and integration with broader energy monitoring programs.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by the interplay of hardware pricing, labor costs, and the growing availability of low-cost metering options for public and commercial use. As reference points for submeter hardware prices become more established, procurement teams are increasingly able to benchmark offers and challenge vendors on total cost. This environment rewards providers that can deliver transparent pricing, predictable installation workflows, and bundled services that reduce hidden deployment expenses.
Labor and installation complexity remain sensitive variables. Retrofit projects in older buildings can incur higher costs because of panel access issues and customization requirements, while newer constructions may allow more streamlined deployments. The market is therefore seeing a divergence in adoption ease across building vintages and configurations. Suppliers that offer flexible installation models, clearer scopes of work, and services that minimize on-site disruption are better positioned to convert interest into completed projects.
Competitive Landscape and Leading Strategies
The electric submeter market is not dominated by a single archetype of competitor. Instead, it contains a mix of analytics-oriented providers, wireless and low-cost hardware specialists, circuit-level metering firms, established commercial utility submetering brands, and service-focused billing and installation companies. This diversity reflects the fact that buyers have different priorities: some want strong analytics and tenant billing integration, others prioritize low-cost wireless deployment, and still others value installation services or billing consultation.
Strategic Positioning and Differentiation
A few patterns stand out among the companies shaping the market.
- Real-time analytics and tenant billing focus. Some providers concentrate on real-time electrical submetering for tenant billing, portfolio energy monitoring, and data analytics in multifamily and commercial buildings. Their differentiation lies in turning meter data into billing-ready outputs and ongoing energy visibility, which appeals to property operators seeking both compliance and operational insight.
- Low-cost wireless and energy monitoring systems. Other companies emphasize low-cost wireless electrical submeters and energy monitoring for commercial and residential applications. This positioning targets cost-sensitive deployments and faster installation cycles, making it relevant for large-scale rollouts where hardware affordability and ease of deployment are decisive.
- Circuit-level and multi-utility measurement. A third group focuses on circuit-level electric submetering along with water, gas, and BTU meters, often with wireless deployment for commercial, industrial, and institutional facilities. This broader measurement scope supports facilities that want unified visibility across utilities rather than electricity alone.
- Hardware-plus-SaaS monitoring platforms. Some vendors combine submetering hardware with SaaS platforms for granular electricity, gas, and water monitoring, including automated reporting. The strategic advantage here is reduced manual reporting burden and continuous data availability, which is especially valuable for portfolios with many metered points.
- Commercial utility submetering and compliance-oriented product lines. Established suppliers with commercial utility submetering solutions and dedicated series for accurate energy monitoring in multifamily and commercial properties often compete on reliability, brand recognition, and documented compliance support.
- Service and billing-oriented models. Several companies focus on electric submetering solutions paired with utility billing services, custom system design, installation, maintenance, and consultation for multifamily and commercial facilities. In these cases, the value proposition is not just hardware but the operational support that keeps submetering programs functioning smoothly.
These positions are not mutually exclusive, but they illustrate how the market is segmenting around analytics, affordability, multi-utility coverage, platform integration, and service delivery. Companies that clearly define their target deployment context—and align product, pricing, and support accordingly—are more likely to win repeat business and public-sector evaluation interest.
Market Structure Evolution: Consolidation, Fragmentation, and New Entrants
The market structure appears moderately fragmented, with no single concentration dominance. This fragmentation creates room for specialized players to thrive in focused niches, but it also encourages consolidation pressure over time as buyers prefer fewer, more capable partners who can cover multiple building types, utilities, and reporting needs.
Several forces are likely to shape this evolution. Public-sector evaluations that assess device performance for federal facilities can accelerate preference for vendors with proven, documented results, effectively narrowing the field for certain procurement categories. Regulatory updates that standardize performance expectations and submetering procedures can raise entry barriers for products that cannot meet updated criteria, while also giving compliant incumbents a stronger footing. At the same time, new entrants may emerge from adjacent markets—energy analytics, wireless sensor networks, or building automation—bringing fresh capabilities but also facing the challenge of demonstrating metering-grade credibility.
Worldwide Distribution Meter Market
In this environment, differentiation is increasingly tied to three questions: Can the solution meet current accuracy and performance expectations? Can it be deployed without excessive installation friction? And can it deliver usable data outputs for billing, reporting, and operational decisions? Providers that answer all three convincingly will be best positioned as the market matures.
Worldwide Prepayment Meter Market
Future Trends and Commercial Opportunities
Looking ahead through the forecast period, several trends are likely to define the electric submeter market and create distinct commercial opportunities.
Trend 1: Standardization as a Market Filter
Updated metering codes and evolving regulatory requirements will increasingly act as a filter rather than a mere technical footnote. Devices and systems that align with recognized performance criteria will gain access to a wider set of commercial and public-sector opportunities, while those that lag may face procurement exclusion or higher scrutiny. The commercial opportunity here lies in building compliance documentation, test alignment, and auditable performance reporting into product strategy early, rather than treating them as after-the-fact certifications.
Trend 2: Lower-Friction Deployment Models
As installation economics remain a major determinant of project viability, the market will likely reward approaches that reduce onsite complexity. Wireless architectures, streamlined retrofit methods, and bundled service offerings can lower the total cost and time required to deploy submetering across multiple points or buildings. For manufacturers and service providers, this creates an opportunity to differentiate not just on device features but on deployment workflow, labor efficiency, and predictable project outcomes.
Trend 3: From Measurement to Operational Intelligence
Submetering is increasingly valued for what happens after measurement. Real-time monitoring, automated reporting, circuit-level diagnostics, and tenant or portfolio-level analytics are becoming part of the core purchase rationale. The commercial opportunity is to move beyond selling metering points toward selling outcomes: clearer billing, faster issue detection, better load visibility, and reduced manual reporting effort. Providers that integrate hardware with software workflows and demonstrate tangible operational benefits will have stronger leverage in competitive evaluations.
Risks and Uncertainties
These trends are not without risk. Regulatory divergence across jurisdictions can complicate product planning and slow multi-region rollouts. Installation cost variability can undermine projected ROI in older or complex buildings, especially if labor or access constraints are underestimated. In addition, as standards tighten, some existing devices may require updates or replacements to remain eligible for revenue-grade or compliance-sensitive applications. Buyers and vendors alike should treat submetering investments as part of a longer-term program, with attention to future-proofing, documentation, and service continuity.
PW Consulting
Actionable Guidance for Decision Makers
The electric submeter market offers meaningful opportunities, but capturing them requires decisions that are aligned with deployment context, compliance expectations, and total cost rather than hardware price alone. The following guidance is oriented toward three common stakeholder perspectives.
For Manufacturers and Technology Providers
- Prioritize compliance readiness and documentation. With updated metering codes and regulatory procedures gaining prominence, clear evidence of performance alignment can become a decisive advantage in commercial and public-sector evaluations.
- Reduce deployment friction. Hardware specifications matter, but installation efficiency can be equally important. Designing for easier retrofits, flexible wiring, or wireless deployment can expand addressable projects and improve win rates in cost-conscious segments.
- Bundle measurement with usable data workflows. Solutions that connect submetering to automated reporting, tenant billing support, or portfolio monitoring are better positioned to compete on outcomes rather than on points alone.
For Investors and Strategic planners
- Focus on segments where regulatory momentum and operational demand reinforce each other. Commercial, industrial, and multifamily settings with compliance drivers and cost-allocation needs are likely to sustain demand more reliably than purely optional installations.
- Evaluate total cost of deployment, not just device pricing. Installation variability, labor exposure, and service requirements can materially affect margin and scalability, especially in retrofit-heavy portfolios.
- Watch for consolidation signals. As buyers seek fewer, more capable partners, companies that can cover multiple utilities, building types, and reporting needs may gain strategic value, while narrow specialists may face pressure unless they maintain a strong niche advantage.
For Procurement and Operational Buyers
- Define the use case before evaluating hardware. Tenant billing, circuit-level diagnostics, portfolio monitoring, and compliance documentation have different requirements. Clear objectives help avoid over-specifying or under-specifying the system.
- Ask for total project economics. Include installation variability, labor exposure, and ongoing reporting or maintenance needs in the comparison, not just per-point hardware cost.
- Verify compliance and performance documentation early. Where regulations, standards, or public-sector evaluation criteria apply, confirm that proposed devices and processes align before committing to deployment timelines.
Closing Perspective
The electric submeter market is expanding within a context that rewards clarity, credibility, and operational usefulness. Growth is supported by regulatory mandates, rising demand for granular energy accountability, and a technology base that is increasingly capable of delivering real-time monitoring and actionable reporting. At the same time, the market is being shaped by installation economics, standardization pressure, and a competitive landscape that ranges from low-cost wireless specialists to analytics-driven platforms and service-oriented billing providers.
For organizations looking to act with confidence, the next step is to connect market-level direction with segment-specific detail: the relevant application context, regional regulatory nuances, pricing benchmarks, and vendor capabilities that matter for a particular deployment. Detailed segmentation data, company profiles, recent developments, and compliance-related updates provide the granularity needed to translate broad trends into concrete decisions. For decision makers seeking a deeper, data-backed view of submarket sizes, competitive positioning, and forward-looking scenarios, a comprehensive research report can offer the structured detail required to support planning, sourcing, and investment choices.
For detailed analysis of this topic, please visit the official page: Electric Submeter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
How to Choose the Right Exhibition Stand Builder Company for Your Next Event
By castlebooth, 2026-09-21
A well-designed exhibition stand can help your brand attract attention, present products clearly, and create a professional impression at a trade show. Choosing the right Exhibition Stand Builder is therefore an important part of your event planning.
An experienced Exhibition Stand Builder Company can manage the complete process, from the initial concept and Exhibition Stand Designs to production, installation, and dismantling. This allows exhibitors to focus on meeting visitors and achieving their event goals.
Why Choose a Professional Exhibition Stand Builder?
A professional builder understands how to make the best use of your available exhibition space. They consider your brand identity, products, visitor flow, lighting, graphics, meeting areas, storage, and presentation requirements when developing the stand.
Working with experienced Exhibition Stand Builder Companies can also make the project easier to manage. Instead of coordinating with several suppliers, you can work with one team for design, construction, logistics, installation, and dismantling.
Creative Exhibition Stand Designs
Good Exhibition Stand Designs should do more than look attractive. They should communicate your brand message and make it easy for visitors to understand what your company offers.
Depending on your requirements, your stand may include:
- Product display areas
- Private meeting rooms
- Reception counters
- Interactive screens
- Storage spaces
- LED lighting
- Branded graphics
- Demonstration areas
- Seating and hospitality spaces
The design should also match the size and location of your exhibition space.
What to Look for in an Exhibition Stand Design Company
Before selecting an Exhibition Stand Design Company , review its previous projects and experience. A reliable company should be able to understand your objectives and turn them into a practical stand concept.
Look for a team that offers clear communication, realistic timelines, quality materials, professional project management, and installation support. It is also useful to choose a company that can provide 3D visualizations before production begins.
From Design to Installation
The right Exhibition Stand Builder can support your project throughout the complete exhibition process. The work generally begins with understanding your brand, objectives, exhibition space, and budget.
The design team then develops the concept and prepares the Exhibition Stand Designs for approval. Once the design is finalized, the stand is fabricated and prepared for transportation. The team can then handle installation at the venue and dismantling after the event.
Make Your Exhibition Presence Count
Your exhibition stand is often one of the first things visitors notice about your company. A combination of thoughtful design, strong branding, practical layout, and professional construction can create a welcoming space for business conversations.
By choosing an experienced Exhibition Stand Builder Company , you can have a dedicated team handling the important details of your exhibition stand while you concentrate on your visitors, products, and business objectives.
Take time to compare Exhibition Stand Builder Companies , review their previous work, understand their services, and select a partner that can deliver a stand that fits your brand and exhibition requirements.
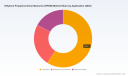
Strategic Trends and Commercial Opportunities in the EPDM Market: A 2025–2032 Outlook
Market Landscape and Core Challenges
The Ethylene Propylene Diene Monomer (EPDM) market has demonstrated consistent expansion over the past five years, evolving from a baseline of approximately 4,000.0 million USD in 2020 to an estimated 5,000.0 million USD in 2025. This trajectory reflects a compound annual growth rate of 5.0 percent, with projections indicating the market will reach 7,029.12 million USD by 2032. The growth pattern is not merely a function of incremental demand but rather a reflection of deepening integration across automotive manufacturing, infrastructure development, and industrial electrical systems. EPDM's unique combination of weather resistance, thermal stability, and chemical compatibility has cemented its position as a foundational elastomer in sectors where material failure carries significant operational or safety costs.
Ethylene Propylene Diene Rubber (EPDM) Market
Despite this favorable trajectory, the industry faces structural challenges that will shape competitive dynamics in the coming years. First, regulatory and fiscal scrutiny is intensifying around chemical substances used in large volumes. A petition filed in mid-2025 requesting that EPDM rubber be included in the Superfund Tax on Chemical Substances in the United States introduces uncertainty around cost structures and compliance burdens. While the outcome remains unresolved, the petition signals a broader shift in how policymakers evaluate polymer-based supply chains, particularly those with significant environmental persistence or complex disposal pathways.
Second, the push toward circularity is reshaping material expectations across end-use industries. The European Union's revised Directive on Packaging and Packaging Waste, which mandates 30 percent recycled content by 2030, has created regulatory pressure that extends well beyond packaging. Automotive and industrial sectors are now facing similar expectations to incorporate recycled or bio-derived content into elastomer applications. This creates a tension for EPDM producers and downstream formulators, who must balance performance requirements with sustainability targets that were not originally designed into the material's chemical architecture.
Third, supply chain resilience remains a critical vulnerability. Regional disparities in feedstock availability, energy costs, and manufacturing infrastructure mean that demand shocks or policy shifts in one geography can cascade through global pricing. The market's concentration, with the top three players holding approximately 45 percent of revenue and the top five accounting for 55 percent, reduces competitive fragmentation but also concentrates supply risk. Companies outside these tiers must navigate pricing power dynamics carefully, while leading firms must manage the operational and reputational implications of supply disruptions.
Key Drivers Shaping Market Trajectory
Technological Innovation and Material Performance
Advancements in EPDM formulation and compounding are expanding the material's addressable use cases beyond traditional sealing and roofing applications. Manufacturers are developing grades with improved resistance to ozone, UV degradation, and steam exposure, which directly benefits automotive cooling systems, outdoor building envelopes, and wire insulation in harsh environments. At the same time, innovations in processing technology are reducing cycle times and enabling more precise control over cross-link density, which improves consistency for high-volume industrial buyers. These technical improvements are not incremental; they are enabling EPDM to compete more effectively against alternative elastomers in applications where cost-performance trade-offs previously favored other materials.
The implications for commercial strategy are significant. Producers that can offer differentiated grades tailored to specific environmental or mechanical requirements create pricing premiums and deeper customer lock-in. Conversely, commoditized EPDM offerings face margin pressure as buyers gain access to broader supplier options. The trend favors firms that invest in application-specific R&D and maintain closer technical collaboration with downstream manufacturers.
Policy and Regulatory Environment
Regulatory developments are acting as both a constraint and a catalyst. The potential inclusion of EPDM in chemical tax frameworks raises the cost baseline for producers and can influence sourcing decisions, particularly in price-sensitive segments. At the same time, sustainability mandates are pushing innovation in recyclable and recycled-content elastomers. Companies that proactively align their formulations with emerging regulatory expectations position themselves to capture demand from customers facing compliance deadlines. In Europe, where regulatory leadership is most pronounced, early movers in sustainable EPDM variants stand to gain preferential access to automotive and construction supply chains that are under pressure to demonstrate credible environmental progress.
For decision-makers, the regulatory dimension requires scenario planning. A single policy shift can alter the economics of a product line or trigger requalification processes that take months. Engaging with regulatory trends early, rather than reacting after mandates take effect, reduces the risk of stranded inventory or lost contracts.
Demand-Side Shifts in Automotive and Construction
Automotive demand remains the largest application driver for EPDM, driven by the material's role in sealing systems, vibration damping, and weatherproofing components. As vehicle platforms evolve, EPDM continues to find relevance in both internal combustion and electrified architectures, though the specific component mix is shifting. Building and construction applications provide a second robust demand pillar, particularly in roofing membranes, window seals, and waterproofing systems where long service life and low maintenance requirements justify material selection. Growth in infrastructure investment across emerging economies, combined with renovation activity in mature markets, sustains steady consumption in this segment.
The Wire and Cable sector adds a complementary growth channel, especially where electrical systems must operate in outdoor or chemically aggressive environments. As industrial automation, renewable energy installations, and grid modernization expand, demand for durable insulation materials increases. These demand-side dynamics do not operate in isolation; they interact with energy prices, labor availability, and project financing cycles. Understanding where demand is most inelastic versus where it is sensitive to macro conditions helps buyers and sellers anticipate volume volatility.
Supply Chain and Cost Structure Evolution
Feedstock pricing, energy costs, and manufacturing scale are the core levers shaping EPDM economics. Regional production footprints determine exposure to logistical friction and local energy markets. Recent capacity announcements illustrate how producers are attempting to rebalance supply geography and reduce vulnerability. For example, in mid-2025, Dow Inc. announced plans to increase EPDM rubber production in the United States by restarting additional capacity at its Plaquemine, Louisiana site. This move reflects a broader industry pattern of reevaluating domestic manufacturing footprints to improve responsiveness, reduce exposure to trade disruptions, and align capacity with regional demand clusters.
Cost structure evolution is not only about raw material prices. It also encompasses the operational efficiency of polymerization and compounding processes, logistics optimization, and the ability to absorb regulatory or tax impacts without eroding competitiveness. Producers with integrated operations or long-term feedstock agreements tend to navigate cost volatility more effectively than those reliant on spot-market inputs. For downstream buyers, supplier stability and transparent cost drivers are becoming as important as unit price when qualifying long-term supply agreements.
Competitive Landscape and Leading Strategies
The EPDM market is characterized by a mix of global chemical majors and specialized elastomer producers, each pursuing distinct strategic positioning. ExxonMobil has established a strong presence through its Vistalon™ EPDM elastomers, emphasizing formulation consistency and broad application coverage that appeals to large industrial buyers seeking reliable supply across multiple end-use categories. Dow Inc. continues to compete aggressively with its NORDEL™ and NORDEL™ REN EPDM grades, differentiating through a combination of performance versatility and geographic manufacturing reach, including recent capacity reinforcement in North America.
Lanxess AG and ARLANXEO represent the European-centric strength in the market. Lanxess focuses on Buna®EP EPDM elastomers, leveraging technical service and specialty formulations that serve automotive and industrial customers with demanding performance criteria. ARLANXEO's Star™ EPDM products similarly emphasize application reliability and grade flexibility, supporting customers that require consistent properties across varied processing conditions. These European players benefit from proximity to automotive and construction hubs with stringent quality and sustainability expectations, and they often compete on technical support and qualification speed as much as on price.
Asian suppliers are expanding their influence through scale, cost competitiveness, and increasingly sophisticated product portfolios. SK Geo Centric Co., Ltd. and Kumho Polychem Co., Ltd. in South Korea, along with Mitsui Chemicals, Inc. in Japan, offer EPDM elastomers and rubber products that serve both domestic demand and export markets. PetroChina Company Limited brings substantial feedstock and production scale advantages in China, while Lotte Versalies Elastomers contributes specialized EPDM rubber offerings from its Seosan operations. These players are increasingly important in a market where regional demand growth in Asia Pacific outpaces many other geographies and where cost-conscious buyers prioritize value and delivery reliability.
PW Consulting Health Care Research Center
Versalis S.p.A. rounds out the competitive set with its own EPDM product lines, reflecting the continuing role of integrated petrochemical platforms in supplying elastomer intermediates and finished grades. Together, these companies illustrate a market where scale, technical differentiation, and regional presence determine competitive outcomes.
The strategic dynamics among these leaders are shifting in several ways. Integration and portfolio rationalization are leading some producers to concentrate on high-margin specialty grades, while others pursue capacity additions to capture volume growth in core segments. Differentiation is increasingly tied to sustainability credentials, application-specific performance, and supply reliability rather than price alone. New entrants face high barriers due to the technical qualification requirements of automotive and construction customers, but indirect competition can emerge from alternative elastomers or recycled-content substitutes if performance gaps narrow. Market fragmentation is unlikely in the near term given the concentration structure, but pressure from regulatory compliance costs and regional capacity shifts will test the margins of producers that lack scale or specialized application capabilities.
Future Trends and Commercial Implications (2026–2032)
Trend 1: Sustainability-Linked Product Architectures Gain Commercial Relevance
Over the next three to five years, EPDM offerings will increasingly be evaluated not only on mechanical performance but also on lifecycle attributes. The regulatory direction in Europe, combined with customer sustainability targets in automotive and construction, will accelerate demand for grades that can demonstrate recycled content, improved recyclability, or lower carbon intensity in production. Producers that develop credible sustainability narratives backed by verifiable data will find more opportunities to enter qualified supplier lists and negotiate favorable terms. This trend creates commercial openings for formulators who can blend performance with compliance, but it also raises the risk of greenwashing scrutiny if claims are not substantiated. Market participants should expect qualification processes to become more rigorous and documentation requirements to expand.
Trend 2: Regional Capacity Realignment and Supply Chain Localization
Capacity decisions announced in recent periods are likely to be followed by further adjustments as manufacturers respond to energy economics, trade policy, and demand geography. North American and European producers are likely to maintain or expand capacity where feedstock advantages and customer proximity justify investment, while Asian producers will continue to scale to serve regional demand growth and export opportunities. This realignment can reduce lead times and logistics exposure for some buyers, but it can also create pockets of tight supply if demand accelerates faster than capacity comes online. Commercial strategies that rely on single-source suppliers in vulnerable geographies will face greater risk, making multi-region sourcing and inventory buffering more attractive for critical applications.
Trend 3: Application Convergence and Material Substitution Pressures
As EPDM grades improve and alternative elastomers advance, the boundaries between material choices will continue to shift. In some automotive and industrial applications, performance gains in EPDM will expand its share of demanding use cases. In others, substitution pressure may increase where cost or sustainability targets favor competing materials. The net effect is that EPDM's growth will be driven less by universal expansion and more by targeted wins in applications where its weather resistance, thermal stability, and durability provide clear value. This dynamic rewards suppliers and buyers who understand application-specific trade-offs rather than treating EPDM as a uniform commodity. Companies that map where EPDM is structurally favored versus where it is vulnerable to substitution will make better sourcing and product development decisions.
Strategic Recommendations for Decision-Makers
For EPDM producers and compounders, the priority is to protect margins while building defensible differentiation. This means investing in application-linked grade development, strengthening technical service capabilities, and preparing for regulatory scenarios that could affect cost structures. Capacity decisions should be evaluated against regional demand trajectories and feedstock economics, with an emphasis on flexibility to adjust product mix as customer requirements evolve. Companies that can demonstrate consistent quality, transparent sustainability data, and reliable delivery will be better positioned to retain key accounts and expand into higher-value segments.
For investors and corporate development teams, the market offers opportunities tied to scale, specialization, and regional realignment. Interest should focus on producers with strong positions in automotive and construction demand centers, credible plans for sustainability-related product development, and supply chain configurations that reduce exposure to policy or logistical shocks. Valuation considerations should account for the impact of potential tax or regulatory changes on cost bases, as well as the upside from capacity additions that align with confirmed demand growth. Diversification across geographies and application segments can mitigate concentration risk, while exposure to highly commoditized segments without differentiation may limit return potential.
For procurement and supply chain leaders, the emphasis should be on resilience and qualification agility. Qualifying multiple suppliers across regions, understanding the cost drivers behind quoted prices, and maintaining visibility into regulatory developments can reduce disruption risk. Building collaborative relationships with suppliers on sustainability and performance expectations can shorten requalification cycles when material changes are needed. Procurement strategies that balance cost optimization with supply security and compliance readiness will be more durable as regulatory and market conditions evolve.
Conclusion and Next Steps for Deeper Market Intelligence
The EPDM market is entering a period where growth is supported by broad demand fundamentals but shaped decisively by regulatory pressure, sustainability expectations, and regional capacity decisions. The combination of steady compound annual growth, concentrated competitive structures, and evolving application requirements creates a market that rewards strategic foresight and detailed operational intelligence. Organizations that act on these dynamics early can secure supply advantages, align product portfolios with emerging demand, and manage cost and compliance risks more effectively.
Deeper segmentation data, granular regional forecasts, competitor benchmarking, and customized sourcing or investment scenarios can sharpen decision-making further. For readers seeking a more detailed view of volume dynamics, price trends, and segment-specific opportunities, the full PW Consulting research report provides an expanded dataset and proprietary analysis designed to support executive planning, investment evaluation, and supply chain strategy.
Isoprene Monomer Market
For detailed analysis of this topic, please visit the official page: Ethylene Propylene Diene Monomer (EPDM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Sugar Centrifugal Screens Market 2032: Beyond 6.5% CAGR, What Drives $275M Growth
By PW Consulting, 2026-09-21
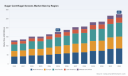
Sugar Centrifugal Screens Market: Strategic Trends and Commercial Opportunities for the Next Decade
The global sugar centrifugal screens market has established itself as a critical niche within industrial processing equipment, with total revenue reaching approximately $177.0 million in 2025 and an expected trajectory toward $275.0 million by 2032. This growth path reflects a compound annual growth rate of 6.5 percent across the forecast horizon through 2032, building on a recovery from the pandemic-era contraction seen between 2020 and 2021. The market's expansion is not merely a function of volume but of structural shifts in processing efficiency, material science adoption, and regional demand recalibration. For executives and investors evaluating industrial consumables and processing components, understanding the centrifugal screen segment requires looking beyond headline growth rates to the operational and competitive dynamics that shape margin realization and market access.
The sector's trajectory over the historical window from 2020 to 2025 demonstrates resilience and selective acceleration. Revenue moved from $130.0 million in 2020 to $135.6 million in 2021, followed by a pronounced step-up to $151.09 million in 2022 and a plateau near $151.18 million in 2023 before pushing to $163.96 million in 2024. The 2025 baseline of $177.0 million signals that the post-pandemic normalization has given way to sustained demand expansion. Forecasts project $188.41 million in 2026, $203.3 million in 2027, $207.03 million in 2028, $230.69 million in 2029, $234.03 million in 2030, $266.71 million in 2031, and $275.0 million in 2032. This progression suggests that the market is entering a phase where incremental efficiency gains and replacement cycles, rather than first-time capacity additions alone, will drive recurring revenue streams.
Centrifugal Pump Market
Market Conditions and Key Challenges
The centrifugal screen market operates at the intersection of heavy processing equipment renewal cycles and consumable component replacement dynamics. Screens function as critical separation elements within batch and continuous centrifuges, directly influencing crystal purity, throughput consistency, and downstream refining quality. Because these components interface with high-stress operational environments — abrasive sugar crystals, acidic or alkaline process liquors, and mechanical vibration — their performance dictates both production uptime and product specification compliance. The market's modest size relative to broader processing equipment categories belies its strategic importance, as screen performance can influence overall plant efficiency far beyond the component's standalone cost.
PW Consulting Automotive & Machinery Research Center
Three structural challenges currently shape the market environment. First, the tension between replacement frequency and total cost of ownership remains unresolved for many operators. Lower upfront cost options often impose higher downtime and more frequent change-outs, while premium materials carry higher initial pricing but extend service life. This calculus varies significantly by application intensity, plant scale, and regional labor cost structures, creating fragmented purchasing behavior rather than uniform specification standards. Second, procurement complexity is rising as end-users increasingly demand documented quality assurance, material traceability, and compatibility verification across multiple centrifuge brands and generations. Screens are not interchangeable commodities; dimensional tolerances, surface finish, and perforation geometry affect separation efficiency, which means specification errors can cascade into throughput losses or product quality deviations. Third, supply chain volatility for specialty materials — particularly high-purity nickel for electroformed screens and specific stainless steel grades for stamped or laser-drilled alternatives — introduces cost unpredictability that suppliers and buyers must actively manage through inventory strategy and long-cycle ordering.
The competitive structure reflects moderate concentration, with the top three participants accounting for roughly 45 percent of revenue and the top five capturing approximately 55 percent. This concentration level suggests a market where established suppliers hold meaningful share but where specialized performers can still compete on technical differentiation, regional service capability, and application-specific engineering support. The presence of both screen-only specialists and integrated centrifuge manufacturers creates a dual-channel dynamic: some buyers source screens directly from component specialists seeking maximum material performance, while others obtain screens through original equipment channels that emphasize compatibility assurance and unified maintenance support.
Core Growth Drivers and Influence Points
Several interdependent factors are shaping demand trajectories and supplier strategy in this market. The most consequential is the ongoing shift in material specification philosophy, moving from a narrow focus on initial purchase price toward lifecycle economics. Electroformed nickel screens have gained recognition for their corrosion resistance across a broad pH range, dimensional stability, and smooth surface characteristics that reduce crystal breakage during separation. These attributes matter in applications where sugar purity, particle integrity, and consistent flow rates are prioritized. At the same time, stainless steel and brass alternatives continue to serve segments where cost sensitivity is higher or where process conditions are less aggressive. The result is a bifurcated specification environment in which material selection is becoming more application-engineered rather than standardized across all use cases.
A second driver is the increasing emphasis on processing uptime and maintenance predictability. Screen failure in a centrifuge can interrupt batch cycles, force unscheduled cleaning, and disrupt downstream scheduling. Suppliers that can demonstrate extended service life under matched operating conditions, combined with predictable replacement intervals, are able to position their products as part of broader operational reliability programs rather than isolated component purchases. This framing aligns with operator priorities in environments where labor for unplanned maintenance carries significant cost and where throughput consistency is tied to contractual supply commitments. The practical implication is that screen suppliers with strong application data, installation guidance, and field performance documentation are gaining advantage in specification decisions, especially where multiple technically acceptable options exist.
A third factor is the regulatory and quality assurance environment surrounding export and compliance. Screens used in international sugar processing supply chains increasingly require documented test certificates aligned with recognized standards for corrosion resistance and dimensional stability. This requirement affects both suppliers and buyers: manufacturers must maintain certified quality systems and reproducible manufacturing processes, while end-users must verify that imported screens meet the specifications needed for their process chemistry and centrifuge design. Compliance is not merely a customs or procurement formality; it reduces the risk of performance deviations and supports consistent batch quality, which is especially relevant for exporters of refined sugar products subject to stringent customer specifications.
A fourth influence comes from regional demand recalibration and processing modernization. While mature markets continue to drive replacement and upgrade activity, emerging processing regions are expanding capacity and improving filtration and separation standards as part of broader quality and efficiency initiatives. This dynamic broadens the addressable base for screen suppliers, but it also introduces variation in technical requirements, procurement maturity, and service expectations. Suppliers that can adapt specification packages, provide application engineering support, and maintain reliable logistics to diverse markets are better positioned to capture growth without overextending into regions where service infrastructure is insufficient to protect performance claims.
Recent field activity reinforces these dynamics. In September 2024, a laser-drilled centrifugal screen deployment was documented at a major British sugar operation to address high-wear screen life issues. This case illustrates how customized perforation technology and targeted material application can resolve persistent wear problems in demanding operating environments, and it signals growing interest in solution-oriented screen configurations rather than generic catalog orders. Such deployments matter because they demonstrate that screen specification can be optimized to specific wear patterns, flow conditions, and maintenance constraints — reinforcing the trend toward application-tailored procurement.
Competitive Landscape and Strategic Positioning
The competitive field includes a mix of screen specialists, precision perforation manufacturers, and centrifuge OEMs that also supply compatible screens. This diversity creates a market where differentiation hinges on material expertise, perforation capability, application compatibility, and service responsiveness rather than on price alone. The most visible strategic positions cluster around three archetypes.
The first archetype is the electroformed nickel specialist. Manufacturers focused on high-purity nickel screens emphasize mirror-smooth surfaces, broad chemical resistance, and dimensional accuracy suitable for continuous and batch centrifuges across multiple major equipment brands. Their value proposition rests on performance durability, filtration consistency, and compatibility with internationally recognized specification frameworks. For operators running aggressive process chemistries or prioritizing minimal crystal damage, this positioning directly addresses lifecycle outcomes rather than initial unit cost. The export orientation of these suppliers also reflects an understanding that compliance documentation and repeatable manufacturing quality are prerequisites for serving dispersed global buyer bases.
The second archetype is the precision perforation and laser-drilling specialist. These suppliers focus on hole geometry control, slotted and round hole configurations, and wear mitigation through engineered perforation patterns. Their relevance grows in environments where standard perforation approaches have proven insufficient for screen life targets or where specific flow and retention characteristics are needed. Laser-drilled and precision-perforated screens can be particularly compelling where wear patterns are uneven or where crystal size distribution and throughput targets require tailored separation characteristics. The British Sugar case illustrates how this archetype can move from generic supply to problem-solving engagement.
The third archetype is the integrated centrifuge manufacturer or equipment supplier offering compatible screens as part of a broader system solution. For some buyers, this channel reduces specification risk, simplifies procurement, and aligns screen replacement with equipment maintenance planning. The strategic trade-off is between the convenience and compatibility assurance of an integrated supply channel and the potential performance optimization available through specialized screen suppliers. In practice, many larger operators maintain relationships across both channels, selecting component specialists for specific high-wear or high-specification applications while relying on equipment channels for standardization and service coordination.
The market is evolving along several structural lines. One is the gradual elevation of technical service and documentation as competitive requirements. Suppliers that can provide application engineering support, installation guidance, and performance data aligned to specific centrifuge types and process conditions are better positioned to defend share against lower-cost alternatives. Another is the continued relevance of multi-brand compatibility. Screens that can be specified across BMA, FCB, and other major centrifuge platforms reduce buyer friction and expand the addressable installed base, which is why compatibility claims appear prominently among leading screen suppliers. A third evolution is the potential for selective consolidation or partnership activity, as screen specialists seek broader geographic reach or as equipment manufacturers look to strengthen component supply reliability. New entry remains possible, particularly where a supplier brings a distinct perforation technology, a cost-advantaged manufacturing process, or a strong regional service model, but the barrier to meaningful share capture lies in demonstrating durable performance and building trust with specifying engineers and maintenance teams.
Forward Outlook: Three to Five-Year Trends
Looking ahead, three trends are likely to shape market outcomes through the late 2020s and into the early 2030s. The first is the continued migration toward specification based on total operating cost rather than initial price. As operators accumulate field experience comparing screen life, failure modes, and maintenance labor, the economic case for higher-durability materials in high-stress applications becomes more persuasive. This does not imply universal premiumization; rather, it implies more deliberate matching of material and perforation choice to application intensity. For suppliers, this trend rewards the ability to quantify performance differences, provide installation and maintenance guidance, and maintain consistency across production batches.
The second trend is growing emphasis on wear-optimized and application-specific screen configurations. As plants seek to reduce unplanned downtime and extend run lengths between change-outs, customized perforation geometry, material grade selection, and backing screen combinations are likely to receive more attention. The practical effect is a shift from catalogue purchasing toward engineered solutions in a meaningful subset of orders, especially where wear issues have already prompted operational frustration. This trend opens opportunities for suppliers with strong laser-drilling, precision perforation, or electroforming capabilities to engage earlier in specification discussions and to build reference installations that support broader adoption.
Centrifugal Separator Market
The third trend is the widening of geographic opportunity sets alongside increased buyer sophistication. As processing modernization continues across multiple regions, more facilities are adopting higher separation and filtration standards, which expands demand for screens that meet stricter quality and compatibility expectations. At the same time, buyers in these markets are increasingly aware of documentation, certification, and aftermarket support requirements. Suppliers that can combine product quality with reliable export compliance, technical support, and logistics resilience will be better positioned to convert regional growth into sustained account relationships.
These trends carry inherent uncertainties. Material cost volatility can compress margins for manufacturers and complicate pricing commitments for buyers, particularly when specialty nickel or specific steel grades are involved. Exchange rate movements can affect export competitiveness and import cost structures for screen procurement in different regions. On the demand side, sugar processing economics are influenced by raw material availability, energy costs, and end-market pricing, which can shift the pace of capacity expansion and the timing of equipment and component renewal. There is also the risk that overly aggressive standardization could understate application-specific needs, leading to premature wear or performance shortfalls that damage confidence in otherwise suitable technologies.
Strategic Implications for Decision Makers
Manufacturers and component suppliers should prioritize two areas. First, strengthen the evidence base that connects material and perforation choices to measurable operational outcomes. Field data on service life, wear patterns, and maintenance intervals — presented in a way that maps to specific centrifuge types and process conditions — is increasingly valuable in specification discussions. Second, invest in compatibility breadth and documentation rigor. Suppliers that can demonstrate multi-brand fit, maintain certified quality processes, and provide export-compliant test documentation reduce friction for international buyers and strengthen their position in markets where procurement teams are under pressure to de-risk supplier selection.
Investors evaluating participation in this market should focus on the durability of differentiation rather than on headline growth alone. Because the market is specialized and moderately concentrated, competitive advantage tends to come from manufacturing precision, material expertise, application engineering, and service responsiveness. Businesses that rely primarily on commoditized supply without technical differentiation face greater vulnerability to price competition and substitution. Conversely, suppliers with demonstrated field performance, strong reference installations, and the ability to serve demanding applications are better positioned to defend margins and grow share. Due diligence should therefore examine not only order books and capacity but also technical service capability, customer retention in high-specification segments, and exposure to material cost and export compliance risk.
Buyers and procurement leaders should approach screen specification as a lifecycle decision rather than a transactional purchase. The most effective procurement strategy matches material and perforation choice to actual operating intensity, establishes clear compatibility and documentation requirements before ordering, and balances standardization benefits against the performance gains available from application-tailored solutions. Where wear or downtime has been a recurring issue, engaging suppliers with precision perforation or high-durability material capabilities earlier in the specification process can reduce the cycle of trial and error. Where standardization and service simplicity are paramount, integrated supply channels can still play a valuable role, particularly when backed by reliable compatibility assurance and maintenance planning support.
For stakeholders seeking a more detailed view of regional demand structures, application-level splits, type-based revenue distribution, and company-by-company positioning, the full research report provides the granular segmentation and customized scenario analysis needed for planning. The commercial logic of the centrifugal screen market is increasingly defined by specification discipline, lifecycle economics, and the ability to deliver consistent performance across diverse processing environments. Organizations that align procurement, supply, and investment decisions with these realities are better placed to capture the value embedded in the market's projected growth path through 2032.
For detailed analysis of this topic, please visit the official page: Sugar Centrifugal Screens Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Lawn Mower Market 2026: Beyond the 6.1% CAGR Story—Robotics and Regional Dominance
By PW Consulting, 2026-09-21
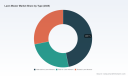
The Lawn Mower Market at an Inflection Point: Strategic Trends and Commercial Opportunities
The global lawn mower market has matured into a strategically complex landscape where steady top-line growth masks deep structural shifts beneath the surface. From a base year of 2025, the sector has expanded consistently over the 2020 to 2025 historical period, moving from approximately 169.5 million USD in 2020 to a 2025 valuation of 215.0 million USD. The forward trajectory through 2032 points to sustained momentum, with the market projected to reach 325.35 million USD by the close of the forecast period, reflecting a compound annual growth rate of 6.1 percent. These headline figures establish a baseline of reliability, but the real strategic value lies in understanding why that growth is unfolding unevenly across product categories, customer segments, and geographies, and what it means for organizations navigating procurement, production, and capital allocation decisions.
Several macro forces are compressing traditional vendor playbooks. Raw material input costs, particularly for steel and electronic components, are tracking upward as captured by recent Producer Price Index movements, placing margin pressure on manufacturers that rely on legacy cost structures. At the same time, regulatory scrutiny is tightening around consumer safety and emissions, creating compliance complexity that rewards operators with robust testing protocols and supply chain transparency. The result is a market where volume growth remains attractive but profitability is increasingly contingent on operational discipline, product differentiation, and the ability to anticipate customer preferences before they become mainstream.
Market Snapshot and Core Challenges
A Familiar Growth Curve with Uneven Momentum
The historical progression through 2020 to 2025 tells a clear story of recovery and expansion. The market moved from 169.5 million USD in 2020, through 173.76 million USD in 2021 and 184.87 million USD in 2022, before settling at 188.69 million USD in 2023 and accelerating to 201.55 million USD in 2024. By 2025, the figure reached 215.0 million USD, setting the stage for the forecast interval. From 2026 onward, projections indicate continued expansion: 221.49 million USD in 2026, a notable step-up to 247.23 million USD in 2027, followed by 249.22 million USD in 2028, 268.21 million USD in 2029, 298.57 million USD in 2030, 300.49 million USD in 2031, and 325.35 million USD in 2032. The cadence of growth is not perfectly linear; the 2026 to 2027 interval reflects a more pronounced acceleration, while subsequent years show a steadier climb. For decision makers, that pattern suggests the market is entering a phase where early-cycle product adoption and replacement demand are interacting with longer replacement cycles and seasonal purchasing behavior.
Underlying concentration further shapes how growth is distributed. A relatively small group of leading firms accounts for a combined share of 65.4 percent when looking at the top three players, and 78.2 percent when including the top five. This level of concentration indicates that scale advantages, channel relationships, and brand trust continue to matter, but it also signals that the remaining market is accessible to well-positioned challengers, particularly in categories where differentiation is possible through technology, service models, or regional specialization.
Three Pressing Challenges Reshaping the Landscape
First, compliance and safety regulation are becoming more operational, not just legal, considerations. Regulatory frameworks governing walk-behind power mowers and related outdoor equipment are evolving in ways that affect product design, testing documentation, and time-to-market. Manufacturers must treat certification and standards alignment as core engineering inputs rather than after-the-fact approvals, especially when launching across multiple jurisdictions or expanding into new applications.
Second, input cost volatility is testing pricing strategies and margin resilience. As steel and electronic component costs climb, companies face a delicate balance between absorbing costs, passing them through to customers, or redesigning products to reduce exposure. This challenge is particularly acute for manufacturers balancing multiple product lines with varying bill-of-materials profiles, because a shift in one cost driver can cascade across commercial and residential portfolios in different ways.
Third, the market is navigating a demand-side transition that is difficult to read in aggregate. Residential and commercial buyers are increasingly weighing convenience, noise considerations, and operating costs alongside traditional factors like durability and upfront price. That shift creates opportunities for differentiated offerings, but it also makes forecasting more complex because purchasing decisions are fragmenting across use cases, property sizes, and labor availability. Organizations that rely on a single product narrative risk missing where incremental growth is actually forming.
Key Drivers Reshaping the Lawn Mower Market
Technology Innovation and the Push Toward Automation
Technology is no longer an add-on feature; it is becoming a central battlefield for differentiation. Battery-powered platforms and automation tools are gaining visibility across both residential and commercial channels, with major industry equipment manufacturers scheduled to showcase new commercial-grade mowers, battery-powered models, and automation tools at Equip Exposition in October 2026. The strategic implication is straightforward: product roadmaps are expanding beyond mechanical refinement to include power architecture, connectivity, and labor-saving functionality. For manufacturers, that means engineering investment is increasingly tied to battery system performance, electronic component sourcing, and integration of automation features that reduce operator workload or improve consistency. For commercial buyers, the appeal lies in reduced downtime, lower noise profiles, and the potential to manage labor constraints more effectively.
Importantly, technology adoption is not uniform. Walk-behind and ride-on categories continue to anchor large portions of the market, while robotic solutions are carving a distinct position for properties and operations where autonomous operation delivers clear value. Companies that can match technology choices to specific customer workflows, rather than treating advanced features as generic upgrades, are likely to capture more resilient demand.
Regulatory and Emissions Pressure as a Design Constraint
Regulation is shaping product architecture in more direct ways than in past cycles. Safety standards for walk-behind power lawn mowers continue to require manufacturer certification through testing aimed at mitigating blade-contact injuries, and related outdoor power equipment standards are being maintained and reaffirmed across the industry. At the same time, regional emissions rules are influencing operating-season decisions for gasoline-powered equipment. For example, Colorado Regulation 29 restricts the use of gasoline-powered small hand-held lawn and garden equipment with internal combustion engines below 7 kW between June 1 and August 31 to reduce ground-level ozone formation.
For national and multi-regional players, these requirements create a compliance matrix that cannot be addressed with a single product design. Engineering teams must consider safety certification pathways, regional use restrictions, and variations in operating-season demand when planning product launches. In practice, this increases the value of modular platforms, flexible power options, and clear documentation that supports customer compliance. It also raises the stakes for companies expanding into regions where environmental rules are tightening faster than in established markets.
Demand-Side Behavior and the Labor Equation
Customer behavior is shifting in ways that reflect broader economic and operational pressures. Residential users are increasingly evaluating total cost of ownership, ease of use, and storage and maintenance implications, while commercial operators are paying closer attention to labor availability, operator training, and productivity per hour. These considerations are not new, but they are becoming more decisive as property owners and service providers weigh whether to maintain existing equipment, replace it with upgraded models, or move toward alternatives that reduce manual effort.
The commercial segment, in particular, is exposed to labor dynamics that can accelerate or delay equipment purchases. When crews are stretched, the appeal of equipment that improves efficiency or reduces physical strain strengthens. When budgets tighten, replacement cycles can lengthen and purchasing decisions become more selective. That combination makes demand in the commercial channel more sensitive to operational conditions than to macro growth narratives alone, and it reinforces the need for product and service offerings that map directly to productivity outcomes.
Cost Structure and Supply Chain Realities
The cost environment is forcing a more disciplined approach to sourcing and product design. Rising input costs for steel and electronic components are placing pressure on manufacturers that must balance material selection, production volume, and end-user pricing. This is not merely a purchasing challenge; it is a strategic design challenge. Companies that can standardize components across product families, reduce dependence on volatile materials, or shift features toward lower-cost electronic architectures where appropriate can protect margins while still delivering meaningful performance improvements.
Supply chain resilience also matters more than ever because product launches increasingly depend on electronic systems and battery components rather than purely mechanical assemblies. That shift changes the risk profile of new product introductions, since delays in electronic sourcing or testing can cascade into broader launch timelines. Organizations that treat supplier diversification, inventory strategy, and qualification processes as strategic capabilities rather than back-office functions are better positioned to sustain cadence in a more constrained environment.
Competitive Landscape and Leading Strategies
How the Leaders Are Positioned
The market features a mix of broad-platform manufacturers and specialists with strong commercial or residential focus. The Toro Company, based in Bloomington, Minnesota, is a leading manufacturer of commercial and residential zero-turn and riding lawn mowers, walk-behind mowers, and accessories. It also provides Exmark commercial zero-turn, walk-behind, and stand-on mowers, giving it a strong footprint across both professional and homeowner channels. Deere & Company, headquartered in Moline, Illinois, is a producer of durable riding lawn tractors and zero-turn mowers for residential and commercial use, emphasizing long-standing brand trust and broad application coverage. Husqvarna Group, from Stockholm, Sweden, supplies residential and commercial zero-turn mowers, robotic mowers, and walk-behind models, positioning itself across a wide range of use cases and including automation-oriented products.
Stanley Black & Decker, based in New Britain, Connecticut, offers Cub Cadet riding lawn mowers and zero-turn models for homeowners and landscapers, leveraging a portfolio that spans consumer-friendly brands and professional-grade offerings. Metalcraft of Mayville, located in Mayville, Wisconsin, manufactures Scag commercial zero-turn and walk-behind lawn mowers, focusing on commercial operators with an emphasis on productivity and durability. EGO Power+, headquartered in Naperville, Illinois, produces battery-powered self-propelled and walk-behind lawn mowers, representing a clear focus on cordless power platforms and the broader transition toward battery-driven outdoor equipment.
PW Consulting Health Care Research Center
These profiles show that the leaders are not competing on a single dimension. Some differentiate through commercial channel strength and professional-grade reliability, others through brand breadth and residential reach, and still others through power architecture and automation. That divergence matters because it indicates the market has room for distinct value propositions, and that the most effective strategies are tied to clearly defined customer segments and use cases rather than generic scale alone.
Strategic Differentiation and Shifting Patterns
Several patterns are emerging in how companies are competing. First, product platforms are becoming more important than standalone models. Organizations that can extend core architectures across walk-behind, ride-on, and battery-powered variants gain efficiency in engineering, parts commonality, and service support. That platform approach also helps companies respond to regulation and cost pressure more flexibly, because changes can be deployed across a broader set of products without redesigning every line from scratch.
Second, channel relationships and service ecosystems are increasingly part of competitive advantage. In commercial applications, the ability to support uptime, parts availability, and operator training can be as influential as the hardware itself. In residential channels, brand recognition, dealer networks, and ease of purchase and maintenance continue to shape preference. Companies that treat service and support as integral to product value, rather than a separate function, are better placed to protect share as buyers become more discerning.
Third, the landscape is showing signs of both consolidation and targeted specialization. High concentration among the largest players suggests that scale and distribution still confer meaningful advantages, but the presence of focused battery and automation-oriented entrants indicates that new competitive angles are opening, especially where power source transitions and labor-saving features align with customer priorities. New entrants and expanding specialists do not need to win everywhere; they need to win in scenarios where their technology or service model solves a specific problem better than a generalist alternative.
Future Trends and Commercial Opportunities
Trend One: Power Architecture Will Keep Rebalancing the Portfolio
Over the next three to five years, battery-powered and hybrid-ready platforms are likely to command a growing share of attention in product planning, particularly where noise, emissions, and labor considerations matter most. The commercial and residential segments will continue to diverge in how quickly they adopt alternative power sources, but the overall direction points toward more choice across the portfolio rather than a single standard. The commercial opportunity here lies in supplying equipment that matches the operating environment: operations with seasonal constraints, noise sensitivity, or labor pressures may prefer battery platforms, while others will continue to prioritize traditional durability and refueling simplicity. Manufacturers that can offer credible options without overcomplicating the supply chain or service model will be better positioned to capture demand as preferences evolve.
Trend Two: Automation and Labor-Saving Features Will Move from Niche to Mainstream Consideration
Automation tools and features that reduce operator workload are expected to gain broader visibility, especially as commercial buyers confront labor constraints and residential users seek convenience. This trend does not mean every buyer will move to fully autonomous solutions, but it does suggest that incremental automation, smarter cut quality, and features that reduce fatigue or simplify operation will become more important purchase criteria. For commercial service providers, the opportunity is to align equipment choices with crew productivity and training needs. For manufacturers, the opportunity is to integrate automation in ways that are reliable, maintainable, and understandable to end users, rather than treating it as a standalone novelty.
Automatic Lawn Mower Market
Trend Three: Regulation and Regional Variation Will Shape Product Roadmaps More Than Ever
The next several years will likely bring continued emphasis on safety certification, emissions-related operating restrictions, and standards alignment across markets. As a result, product planning will need to account for regional variation rather than assuming a uniform launch path. Companies that build flexibility into their platforms, maintain strong documentation and testing practices, and anticipate seasonal or jurisdictional constraints will navigate this environment with less friction. There is also a commercial opportunity in helping customers understand and manage compliance, particularly in regions where operating windows or equipment restrictions can affect usage patterns and purchasing decisions.
Risks and Uncertainties to Watch
The outlook carries real uncertainties. Input cost volatility could pressure margins faster than product pricing or redesign efforts can offset, especially if steel and electronic component costs remain elevated. Regulatory timelines and regional rule variations may shift faster than product development cycles, creating mismatch risk for launch planning. Demand patterns could also diverge more sharply between residential and commercial channels, making aggregate growth figures less useful as planning guides. Finally, technology adoption may advance unevenly, with some markets and segments embracing battery and automation features more quickly than others, creating execution risk for companies that over-index on a single transition narrative.
Lawn and Garden Equipment Market
Actionable Recommendations for Decision Makers
For manufacturers: Build product roadmaps around platform flexibility and clearly defined customer workflows. Prioritize engineering and sourcing strategies that reduce exposure to volatile input costs while maintaining credibility in safety certification and product testing. Where possible, align battery, automation, and service capabilities to distinct use cases rather than launching features without a clear operational fit. Evaluate channel and service support as part of the product value proposition, especially for commercial accounts where uptime and operator experience directly affect adoption.
For investors: Focus on the segments and capabilities likely to capture durable growth rather than the headline market expansion alone. Favor companies that demonstrate disciplined cost management, credible power-platform transitions, and strong commercial or residential positioning tied to real workflow advantages. Pay attention to regulatory readiness and regional adaptability as indicators of execution risk, because markets with concentrated leadership can still reward nimble product strategies and punish rigid ones. The most attractive opportunities may sit at the intersection of differentiation and operational resilience, where a company can defend share while expanding into higher-value use cases.
For procurement and commercial buyers: Evaluate equipment decisions against total operating cost, labor implications, and compliance requirements in the specific regions where equipment will be used. For commercial operations, prioritize solutions that reduce operator strain, improve cut consistency, and support service availability, since these factors often matter more than upfront price alone. For residential purchasing, weigh storage, maintenance, noise, and power-source fit alongside durability and brand support. In both cases, timing purchases around seasonal constraints and regulatory windows can affect both operating flexibility and total cost of ownership.
For decision makers who need deeper segmentation, regional dynamics, and company-level benchmarks to translate these trends into operational plans, the full PW Consulting research report provides the detailed breakdowns and customizable analysis required to support product planning, capital allocation, and procurement strategy.
For detailed analysis of this topic, please visit the official page: Lawn Mower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Management Consulting Services Market: Why 5.63% CAGR Redefines Competitive Dynamics
By PW Consulting, 2026-09-21
Management Consulting Services Market: Strategic Shifts and Commercial Opportunities in an AI-Reshaped Landscape
The global management consulting services market has entered a period of structural acceleration, with total revenue expanding from approximately $302.15 billion in 2020 to an estimated $391.68 billion in 2025. Projections indicate continued growth through 2032, with the market expected to reach $572.38 billion, sustaining a compound annual growth rate of 5.63 percent across the 2026 to 2032 forecast period. The trajectory reflects more than cyclical demand recovery; it signals a fundamental recalibration of how organizations procure, deploy, and measure advisory services. Growth is being concentrated in regions and segments where digital transformation, operational resilience, and regulatory complexity intersect, while traditional retainer-based engagements face mounting scrutiny over measurable outcomes. For executives and investors, the market is no longer simply expanding; it is reorganizing around new capability requirements, pricing models, and delivery architectures.
The expansion has been uneven across functional and industry dimensions, with operations-focused advisory and technology-adjacent consulting capturing disproportionate shares of incremental spend. At the same time, the market remains moderately concentrated, with the top three firms commanding roughly 52 percent of total revenue and the top five accounting for approximately 68 percent. This concentration masks a deeper fragmentation at the practice and sub-sector level, where specialized boutiques, technology-enabled delivery units, and cross-industry alliances are steadily redefining competitive boundaries. The persistence of concentration alongside rising specialization suggests that scale alone is no longer the primary competitive moat; instead, firms that can combine domain depth, implementation capacity, and technology integration are capturing the most durable growth.
1. Market Current State and Core Challenges
Redefining Value in a High-Expectation Environment
The consulting market is operating under a dual pressure: clients demand faster, more measurable impact while simultaneously questioning whether traditional advisory fare delivers sufficient differentiation. Several macroeconomic and structural forces have hardened this expectation. Organizations are navigating persistent cost discipline, supply chain reconfiguration, and a heightened focus on operational execution rather than purely strategic diagnosis. As a result, advisory engagements are increasingly judged against implementation readiness, technology integration, and the ability to embed change within legacy operating models. The consequence is a shift from episodic strategy projects to multi-year transformation partnerships, where value is measured in throughput gains, cost-to-serve improvements, and time-to-market for new products and channels.
This shift is colliding with a volatile cost environment for specialized talent. Specialized human labor costs within the sector have risen by an estimated 15 to 20 percent annually in 2025 and 2026, driven by demand for professionals who can combine domain expertise with AI-augmented advisory capabilities. Projected labor costs are anticipated to rise another 10 percent in 2026, reflecting shortages of skilled AI and digital transformation professionals. For consulting firms, this creates a margin equation that cannot be solved by headcount alone; productivity gains, automation of analytical workflows, and new delivery models are becoming essential to protect profitability while meeting rising client expectations.
Regulatory and Data-Privacy Complexity as a Delivery Constraint
Regulatory exposure is intensifying across multiple jurisdictions, with compliance requirements expanding around data privacy, algorithmic transparency, and the governance of technology-enabled advisory services. Recent assessments from US agencies and international bodies emphasize that management consulting services are increasingly subject to scrutiny when they intersect with sensitive client data, quantitative decision models, and AI-assisted recommendations. This adds a layer of operational complexity to engagement design, requiring stronger data handling protocols, auditability of analytical methods, and clearer boundaries between advisory input and client-controlled implementation. In practice, compliance costs are rising not only as a legal expense but as a design constraint that influences how engagements are scoped, delivered, and priced.
Concentration, Specialization, and the Hybridization of Delivery Models
While the market remains concentrated at the top, the competitive frontier is diversifying. Firms are blending strategy, operations, and technology advisory in ways that blur traditional category boundaries, while specialized players are gaining traction by focusing on high-complexity niches such as risk analytics, actuarial integration, and AI-enabled process redesign. The result is a market in which scale provides distribution and client access, but differentiation is increasingly driven by proprietary tools, implementation partnerships, and the ability to stand up large-scale transformation programs. New entrants and alliances are exploiting gaps where incumbents are either too broad to move quickly or too narrow to support end-to-end change. This hybridization is reshaping buyer behavior: organizations increasingly assemble portfolios of providers rather than relying on a single lead advisor, which rewards firms that can demonstrate interoperability, repeatability, and clear handoff to execution.
2. Key Drivers of Market Change
Technology Innovation and the Shift Toward Agentic AI
Technology is no longer a standalone consulting vertical; it is becoming the delivery backbone for strategy and operations alike. The integration of generative and agentic AI into advisory workflows is changing the economics of analysis, synthesis, and recommendation development. Rather than relying solely on manual research and bespoke modeling, firms are deploying AI agents to accelerate scenario analysis, benchmark extraction, process mapping, and unstructured data interpretation. This does not eliminate the need for senior judgment; it elevates it. The premium is moving toward professionals who can define the right problem frames, validate AI-generated outputs, and design human-in-the-loop processes that preserve accountability. The most consequential shift is operational: engagements are increasingly designed to leave behind reusable models, decision tools, and capability building rather than static decks.
Recent developments indicate that this transition is already at scale within leading firms. McKinsey & Company, for example, announced in January 2026 that it is deploying approximately 25,000 AI agents alongside roughly 40,000 human consultants to enhance productivity and client delivery. This combination signals a structural bet on blended delivery, where AI supports volume-intensive analytical tasks while human consultants concentrate on client interaction, synthesis, and implementation design. Similarly, Capgemini launched its Resonance AI Framework in July 2025 to help clients implement agentic AI at scale with human-AI collaboration for measurable business impact. These moves collectively suggest that AI is transitioning from an experimentation topic to a production-focused capability, with implications for pricing, staffing, and engagement timelines across the market.
Regulatory and Policy Environment as a Catalyst and Constraint
Policy dynamics are reshaping demand patterns in two directions. On one hand, emerging compliance obligations around data privacy, algorithmic accountability, and technology governance are prompting organizations to seek advisory support for risk assessment, control design, and transformation roadmaps. On the other hand, these same obligations constrain how consulting firms can collect, process, and reuse data across engagements. The July 2025 USITC report highlights that management consulting services face rising compliance requirements tied to data privacy and technological advancements, underscoring the regulatory weight now attached to advisory activities that involve sensitive information or automated decision support.
This environment favors firms with robust data governance, clear methodologies, and the ability to translate regulatory complexity into operational design. Sectors such as financial services, healthcare, and public-sector adjacent services are particularly exposed, which in turn shapes where demand is most resilient. For buyers, regulatory pressure is also changing procurement behavior: engagements increasingly require demonstrable compliance with data handling standards, clearer separation of advisory from implementation liability, and documented methodological rigor. The net effect is a market in which regulation is simultaneously expanding demand for advisory services and raising the bar for what qualifies as a credible engagement.
Demand-Side Shifts in Enterprise and Consumer Behavior
Client organizations are reevaluating what they expect from advisory relationships. There is growing skepticism toward generic strategy narratives, especially in environments where execution capacity is constrained by talent shortages or cost pressure. Buyers are increasingly prioritizing engagements that are tied to specific operating improvements, customer value creation, and technology-enabled change. This is reflected in a broader shift toward outcome-oriented commercial models, where pricing and success metrics are linked to measurable business impact rather than time and materials alone. In parallel, consumer-facing industries are pushing firms to integrate experience design, channel optimization, and data-driven personalization into their transformation agendas, while industrial and service sectors are focusing on productivity, asset utilization, and supply chain resilience.
This demand-side evolution is also driving fragmentation in spend patterns. Organizations are allocating more budget to capabilities that directly support execution, including process redesign, workforce change management, and digital operating model design. At the same time, the appetite for pure diagnostic work is becoming more selective, reserved for moments of strategic redirection, market entry, or major capital allocation decisions. For consulting providers, the implication is that durable demand will come from firms that can connect upstream insight to downstream execution, rather than from those offering isolated point solutions.
Cost Structure and Supply Dynamics in a Talent-Constrained Market
The supply side of the market is being reshaped by talent scarcity and cost escalation. The rising premium for professionals with AI, digital transformation, and domain-specific expertise is altering the cost structure of advisory delivery. With specialized labor costs rising sharply, firms are under pressure to improve throughput without diluting quality. This has accelerated interest in labor-mixing strategies, where routine analytical tasks are delegated to automation or lower-cost pools while senior professionals focus on high-leverage decisions and client relationships. It has also intensified the search for repeatable methodologies, modular deliverables, and knowledge assets that can be reused across clients to reduce marginal cost.
On the supply frontier, geography and capability availability are increasingly intertwined. Regional demand is growing in areas where industrial transformation, digital adoption, and regulatory change converge, but the ability to deliver depends on access to skilled talent and implementation partners. This is creating a two-sided constraint: demand is strong where transformation is urgent, but execution capacity is uneven. Firms that can mobilize blended teams, leverage alliances, and scale delivery through standardized toolkits are gaining an advantage, while those dependent on bespoke, high-cost teams risk margin compression and slower responsiveness.
3. Competitive Landscape and Leading Strategies
Strategic Positioning Across Different Firm Archetypes
The competitive map is defined less by uniform scale than by differentiated positioning along strategy, operations, technology, and industry depth. At one end are global strategy-oriented firms that compete on thought leadership, senior client access, and cross-functional problem framing. These firms typically build their reputations on high-stakes decisions, corporate strategy, and transformation direction-setting. At another end are firms with strong implementation credentials, where consulting is integrated with technology services, systems integration, or outsourcing capabilities. These players compete on end-to-end delivery, scale, and the ability to transition recommendations into operational reality. A third archetype includes specialized boutiques that win through depth in narrow domains, such as private equity value creation, risk and actuarial advisory, or growth strategy in particular industries.
The largest players illustrate these strategic choices clearly. McKinsey & Company positions around strategy, digital transformation, and operations advisory, and is actively reinforcing that model with large-scale AI deployment to improve productivity and client delivery. Boston Consulting Group emphasizes strategy, corporate finance, and digital innovation, with a focus on business and government clients, suggesting a balanced orientation toward high-level problem formulation and digital execution. Bain & Company leans into strategy, private equity, and operations, aligning its brand with value creation and performance-focused engagements. Accenture differentiates through the integration of consulting with technology and digital transformation solutions, making implementation capacity a core part of its advisory proposition. Deloitte, PwC, EY, and KPMG each offer management consulting within broader professional services portfolios, allowing them to connect advisory work with audit, tax, technology, and risk capabilities. Oliver Wyman, Booz Allen Hamilton, Capgemini, L.E.K. Consulting, and Kearney further diversify the landscape through specialized strengths in risk management, government and technology solutions, AI-enabled operations, growth advisory, and strategy-operations integration.
Business Management Consulting Service Market
Differentiation Through Capability, Alliance, and Delivery Models
The most sustainable advantages in this market are emerging from three sources. The first is proprietary capability that can be scaled, including AI-enabled analysis, decision-support tools, and reusable transformation frameworks. The second is ecosystem positioning, where alliances and partnerships extend a firm’s reach into adjacent domains such as actuarial risk, systems integration, or industry-specific implementation. The third is delivery architecture, where firms design engagements to leave behind capabilities, governance, and measurement systems rather than one-off recommendations. These advantages matter because clients increasingly evaluate providers on repeatability, speed, and the ability to transfer knowledge into the organization.
Recent moves highlight how these differentiators are being operationalized. Oliver Wyman’s April 2026 strategic partnership with Actuarial teams under Marsh McLennan is an example of extending strategy and risk advisory capabilities through specialized integration, strengthening the firm’s position where financial, operational, and risk considerations intersect. Such alliances reflect a broader trend in which consulting firms expand credibility and coverage by partnering with domain specialists rather than building every competency internally. This pattern is likely to accelerate where complexity is high and where the cost of building proprietary depth in every niche would be prohibitive.
Toward Consolidation, Fragmentation, and Selective New Entry
Market structure is evolving along multiple axes at once. Concentration at the top remains significant, which implies that scale, brand, and global client access continue to confer advantages in large enterprise accounts and multi-year transformation programs. At the same time, the front edge of competition is fragmenting as practice-level specialization, regional capability centers, and technology-led delivery models create new competitive dynamics. New entrants and mid-tier challengers are gaining relevance where they can offer speed, niche depth, or more flexible commercial terms, particularly in engagements that require rapid mobilization or deep operational involvement.
The likely trajectory is not simple consolidation or fragmentation, but selective combination. Larger firms will continue to acquire reach and cross-functional breadth, but they will also face pressure to modularize services and improve delivery economics. Specialized players will seek to scale through partnerships, productized offerings, or targeted expansion into adjacent capabilities. Meanwhile, technology providers and implementation-centric firms will continue to blur the line between consulting and execution, creating hybrid competition that traditional strategy firms must either match or complement through alliances. For buyers, this means that provider selection is becoming more multidimensional, with evaluation criteria that include capability depth, delivery model, technology enablement, and the ability to integrate with internal teams.
4. Future Trends and Commercial Implications
Trend One: AI-Augmented Advisory Becomes the Delivery Default
Over the next three to five years, AI-augmented advisory is expected to shift from a differentiator to a baseline expectation. The combination of agentic AI, advanced analytics, and human judgment will become embedded in problem definition, scenario design, benchmarking, and implementation planning. The commercial implication is significant: engagements that rely solely on manual analysis will face growing cost and speed disadvantages, while firms that can operationalize AI safely and effectively will be able to scale insight generation and improve throughput. The opportunity lies not in replacing consultants, but in reconfiguring the value chain so that human expertise concentrates on judgment, client alignment, and implementation design while AI supports volume-intensive analytical tasks. The risk is execution discipline: firms that deploy AI without strong governance, validation, and client-ready explainability may expose themselves to quality and trust issues, especially in regulated or high-stakes contexts.
Trend Two: Outcome-Oriented Commercial Models Gain Ground
Commercial models are likely to continue shifting toward measurable outcomes, with pricing and incentives tied more closely to business impact, adoption metrics, and sustained operating improvements. This trend will be reinforced by rising labor costs and client demand for greater accountability. Advisory engagements will increasingly need to define success in operational terms, such as improved throughput, reduced cost-to-serve, faster decision cycles, or stronger customer outcomes. For providers, this creates both opportunity and risk. The opportunity is to build repeatable frameworks that connect strategy to execution and to develop measurement systems that demonstrate value over time. The risk is that outcome-based models require deeper client integration, stronger change management, and the ability to navigate implementation complexity, which may not suit all engagement types or all buyers.
Trend Three: Regulatory and Compliance Complexity Drives Demand for Governance-Led Transformation
Regulatory and compliance complexity is expected to remain a structural driver of demand, particularly in sectors where data usage, technology deployment, and decision automation are accelerating. Organizations will increasingly seek advisory support not only for growth and efficiency, but for governance design, risk integration, and compliance-ready operating models. This opens commercial opportunities for firms that can connect strategy, operations, and technology with clear accountability and auditability. At the same time, it introduces uncertainty: regulatory trajectories differ across regions, and expectations around data privacy and technology governance may evolve quickly. Firms that can maintain methodological rigor while adapting to local requirements will be better positioned than those relying on one-size-fits-all frameworks. A further uncertainty is the potential for regulatory fragmentation to slow cross-border delivery models or increase the cost of data reuse across engagements.
Uncertainty and Risk Factors to Monitor
Several factors could alter the trajectory of growth and competitive dynamics. Continued escalation in specialized labor costs may compress margins for firms that cannot offset them through productivity improvements or delivery redesign. Talent shortages in AI and digital transformation could constrain the speed at which firms scale new capabilities, particularly in regions where skilled professionals are scarce. Regulatory developments may raise compliance costs or limit the reuse of data and models across engagements, affecting both economics and speed. In addition, client budget discipline could shift spend toward a smaller number of higher-conviction initiatives, intensifying competition for large mandates while reducing appetite for exploratory work. These risks do not negate growth, but they suggest that the market will reward firms that manage cost, compliance, and capability deployment with discipline.
5. Strategic Actions for Decision Makers
For Transformation Leaders and Operating Executives
Treat advisory selection as an execution decision, not just a strategy purchase. When evaluating providers, prioritize those that can demonstrate how insight will translate into operating change, including clear handoff to implementation, reusable tools, and measurable success criteria. Favor engagements that are designed to build internal capability and leave behind decision-support assets rather than static deliverables. Given rising labor costs and talent constraints, also assess whether a provider’s delivery model uses automation, knowledge reuse, and blended teams in ways that protect speed and quality without inflating cost.
For Investors and Portfolio Managers
Evaluate consulting exposure with attention to delivery economics and positioning, not only revenue scale. Firms that combine domain depth with AI-enabled productivity, implementation alliances, and outcome-oriented commercial models are better placed to sustain margins in a cost-escalating environment. Monitor concentration carefully, but also watch the specialized and hybrid players that are gaining traction in high-complexity niches. The most useful signals will come from evidence of repeatable delivery, credible governance around data and AI, and the ability to win engagements where execution—not just diagnosis—is the primary value driver.
PW Consulting
For Procurement and Commercial Teams
Use the shifting supply landscape to improve commercial terms and risk allocation. Expect greater variation in pricing models, delivery approaches, and liability structures, which creates room to negotiate outcome-linked components, clearer data-handling obligations, and stronger handoff arrangements. Where possible, assemble multi-provider portfolios that separate strategy, implementation, and specialist risk or technology work, allowing each partner to play to its strengths. Ensure that procurement criteria include governance standards, methodological transparency, and evidence of capability transfer, since these will increasingly determine whether an engagement creates durable value or remains a short-term intervention.
Computer Consulting Services Market
The trajectory of the management consulting services market is being shaped by the convergence of technology-enabled delivery, regulatory complexity, rising talent costs, and a client base that is more demanding in return for its spend. These forces are not simply expanding the market; they are redefining where value is created and how competitive advantage is earned. For decision makers seeking to act with precision—whether in provider selection, investment allocation, or transformation planning—the value of detailed segment-level data, competitive mapping, and customized scenario analysis is substantial. A comprehensive research report can provide deeper visibility into regional and functional splits, company-level positioning, and forward scenarios that support more targeted execution.
For detailed analysis of this topic, please visit the official page: Management Consulting Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Organic Elemental Analyzer Market: What the 6.98% 2032 Growth Path Really Means
By PW Consulting, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Organic Elemental Analyzer Market
The global market for Organic Elemental Analyzers (OEA) has entered a phase of sustained, structurally driven expansion. Valued at approximately USD 215.0 million in 2025, the sector has demonstrated consistent upward momentum over the past half-decade, building from a baseline of USD 163.15 million in 2020. The trajectory is projected to accelerate through the forecast horizon, reaching an estimated USD 344.8 million by 2032. This translates to a compound annual growth rate of 6.98 percent, a figure that places the market above the broader analytical instrumentation sector average. Growth is not merely cyclical; it reflects a fundamental recalibration in how laboratories, manufacturers, and regulatory bodies approach material characterization, quality assurance, and environmental compliance.
The expansion narrative, however, cannot be reduced to aggregate numbers. The market is navigating a complex landscape where technological capabilities, supply chain realities, and end-user expectations are intersecting. Below the headline growth rate lies a competitive environment shaped by consolidation pressures, regional demand divergence, and rapid innovation in combustion and detection methodologies. Stakeholders who understand the underlying mechanics of this expansion will be better positioned to allocate capital, design product roadmaps, and negotiate procurement strategies with confidence.
Market Architecture and the Friction Points Defining the Next Cycle
The current market architecture is characterized by a moderate degree of concentration. The three largest players collectively account for roughly 24.6 percent of total revenue, while the top five firms control approximately 26.2 percent. This distribution suggests a market that remains sufficiently fragmented to allow specialized entrants and regional champions to compete on niche capabilities, yet consolidated enough that incumbents hold meaningful pricing power, distribution leverage, and service network advantages. The gap between the top three and top five is notably narrow, indicating that mid-tier competitors are increasingly closing the performance and commercial coverage gap through targeted product development rather than broad-spectrum expansion.
Several structural challenges are simultaneously acting as inflection points. First, the cost and complexity of analytical workflows continue to pressure end-user budgets, particularly in mid-sized laboratories and contract research organizations operating under tight capital expenditure constraints. High-caliber OEA systems require robust sample preparation protocols, calibrated reference materials, and specialized maintenance routines. When total cost of ownership rises faster than budget allocations, procurement cycles elongate and buyers increasingly scrutinize return on investment at the application level rather than the instrument level.
Total Organic Carbon (TOC) Analyzer Market
Second, the industry is grappling with a skills and operational expertise gap. Modern elemental analyzers integrate sophisticated combustion chambers, automated gas handling, and advanced detection optics. While automation has reduced manual intervention, operators still require training in method validation, baseline drift management, and cross-application method transfer. Institutions that cannot staff adequately or upskill existing personnel face throughput bottlenecks, which in turn dampen the perceived utility of higher-throughput systems and slow replacement cycles for legacy assets.
Third, supply chain volatility for high-purity reagents, specialized catalysts, and precision-machined components has introduced uncertainty into both manufacturing lead times and service-level commitments. Even as logistics networks normalize following earlier disruptions, the underlying dependency on tightly specified consumables and calibration standards means that any regional constraint or pricing shift can ripple through deployment schedules and affect near-term revenue recognition for manufacturers.
These challenges are not merely obstacles; they are forcing functions that are reshaping competitive priorities. Manufacturers that can decouple performance from consumables consumption, streamline software-driven calibration, and offer application-specific validation packages are gaining traction. Buyers that internalize total cost of ownership calculations and align instrument selection with validated workflow requirements are reducing unexpected downtime and improving analytical consistency across campaigns.
Key Drivers Accelerating Market Trajectory
Technical Innovation as the Primary Growth Engine
The most consequential driver of market expansion is the steady progression of combustion and detection technologies. Contemporary OEA platforms increasingly deliver simultaneous determination of carbon, hydrogen, nitrogen, sulfur, and oxygen within unified analytical runs, reducing the need for sequential testing and minimizing sample consumption. This capability is particularly valuable in environments where throughput, repeatability, and sample scarcity intersect. High-throughput modules, automated sample introduction, and software-assisted method selection have lowered the operational burden for routine analyses while expanding the range of matrices that can be processed reliably.
A notable example of this direction is found in the FlashSmart Elemental Analyzer and the FLASH 2000 Series, which are engineered to provide simultaneous CHNS/O determination tailored for pharmaceutical workflows and analytical laboratories. These systems illustrate how modern architectures prioritize streamlined sample handling, integrated data processing, and robust baseline stability to meet the documentation and reproducibility standards expected in regulated environments. By compressing the time between sample loading and validated output, such platforms directly address the throughput and consistency pressures that laboratories face when scaling analytical operations.
Policy and Regulatory Mandates Expanding the Addressable Base
Regulatory frameworks and compliance requirements continue to broaden the applications for which elemental analysis is indispensable. In pharmaceutical and fine chemical manufacturing, stringent impurity profiling, identity confirmation, and batch consistency checks depend on reliable carbon, nitrogen, and sulfur determinations. Environmental testing and waste characterization protocols similarly require accurate organic composition data to support reporting, risk assessment, and remediation planning. As jurisdictions tighten reporting standards and enforcement diligence, laboratories and industrial quality teams are compelled to formalize their analytical capabilities rather than rely on ad hoc testing or outsourced services.
This regulatory tailwind does not simply increase volume; it changes the purchasing calculus. Buyers seek instruments with traceable method documentation, validated performance characteristics, and service support that can withstand audit scrutiny. The compliance dimension elevates the importance of vendor reputation, application support, and long-term availability of consumables and software updates. In many procurement scenarios, the decision to standardize on a particular platform is as much about risk management and audit readiness as it is about analytical performance.
Demand-Side Shifts in Quality Assurance and Advanced Materials
Demand patterns are evolving as end-users place greater emphasis on predictive quality and material consistency. Semiconductor-related manufacturing and advanced packaging workflows, for example, require rigorous control over organic residues, process contaminants, and material purity indicators. While the OEA category spans diverse end uses, the semiconductor wafer manufacturing segment has emerged as a substantial demand driver, reflecting the industry's need for precise characterization of materials that influence device yield and reliability. IC packaging activities also contribute meaningfully, as miniaturization and heterogeneous integration increase the sensitivity of final device performance to surface chemistry and organic contamination profiles.
Beyond electronics, food, feed, and organic matrix testing remain significant application areas where carbon, hydrogen, nitrogen, and protein determinations underpin nutritional labeling, authenticity verification, and quality control. The 828 Series macro combustion analyzer, focused on carbon, hydrogen, nitrogen, and protein in food, feeds, and organic matrices, reflects how instrument design is being adapted to application-specific throughput and sample-scale requirements. When analytical platforms align closely with the sample type, throughput expectations, and reporting formats of a given industry, adoption friction decreases and replacement cycles accelerate.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by the interplay between instrument capability, consumables intensity, and regional service economics. Manufacturers are increasingly differentiating on the basis of how efficiently their systems consume reagents and reference materials, how predictable maintenance intervals are, and how quickly field service can restore operational status. In parallel, regional service density and local technical support availability have become decisive factors for buyers in markets where downtime carries high cost. Companies that build or partner into responsive service networks, localize consumable supply where feasible, and provide remote diagnostics and software-based troubleshooting are strengthening their commercial resilience.
The vario EL cube platform, which offers simultaneous CHNS with oxygen, chlorine, and total inorganic carbon determination across micro to macro sample ranges, demonstrates how expanded parameter coverage and flexible sample handling can command premium positioning. By consolidating multiple analytical objectives into a single workflow, such systems reduce fragmentation in laboratory inventories and simplify method management. This value proposition is especially relevant for organizations that seek to standardize instrumentation across multiple sites or consolidate legacy platforms onto a modern, software-integrated architecture.
Competitive Landscape and the Logic of Differentiation
Incumbent Positioning and Capability Mapping
The competitive field is anchored by a group of established manufacturers with distinct strategic orientations. Thermo Fisher Scientific, based in Waltham, Massachusetts, competes through integrated analytical portfolios that emphasize simultaneous CHNS/O determination and laboratory workflow compatibility, particularly in pharmaceutical and analytical lab settings. The company's positioning leverages broad commercial coverage, established service infrastructure, and the ability to embed elemental analysis into wider laboratory information and quality management ecosystems.
LECO Corporation, headquartered in St. Joseph, Michigan, has built recognition around macro combustion analysis for carbon, hydrogen, nitrogen, and protein applications in food, feeds, and organic matrices. Its strategic emphasis reflects deep application focus, robust engineering tradition in combustion analysis, and a commercial approach that prioritizes method reliability and throughput for high-volume routine testing. This application specialization enables the firm to serve buyers whose primary concern is consistency across large sample populations rather than maximally broad elemental coverage.
Elementar Analysensysteme, located in Langenselbold, Germany, addresses the market with platforms that combine simultaneous CHNS capability with oxygen, chlorine, and total inorganic carbon determination for micro to macro sample analysis. The strategic logic here centers on analytical flexibility, parameter expansion within a single instrument, and the ability to serve laboratories that need to consolidate multiple characterization tasks. European manufacturing heritage, precise engineering, and configurable sample handling contribute to a value proposition that appeals to organizations seeking method consolidation and enhanced data continuity.
OEA Laboratories, based in Exeter, United Kingdom, occupies a complementary position by focusing on supplies and products designed for use with OEA and EA-IRMS instruments. Rather than competing directly on complete instrument platforms, the company supports the consumables, accessories, and application ecosystem that surround elemental analysis workflows. This positioning can be strategically valuable for buyers that prioritize supply reliability, application-specific consumables optimization, and ecosystem compatibility across different instrument brands.
PerkinElmer, also headquartered in Waltham, Massachusetts, competes through established analytical instrumentation offerings such as the 2400 CHNS/O Organic Elemental Analyzer for total carbon, nitrogen, hydrogen, and sulfur determination. Its market presence benefits from a broad instrument portfolio, longstanding relationships in analytical laboratories, and integration pathways that connect elemental analysis with other characterization and quality control functions within laboratory environments.
Strategic Patterns in a Consolidating yet Accessible Market
The market is not trending toward extreme concentration; instead, it is evolving toward functional specialization and ecosystem-based competition. The relatively narrow gap between the top three and top five firms suggests that competitive advantage is increasingly derived from application-specific validation, software-enabled workflow simplification, service responsiveness, and consumables efficiency rather than from sheer scale alone. Incumbents with broad portfolios can leverage cross-selling and service density, while focused competitors can gain share by solving a narrowly defined problem exceptionally well and building reference installations that propagate through industry networks.
New entrants and regional specialists continue to find viable niches, particularly where local service expectations, language and compliance requirements, or application-specific sample types create friction for global platforms that are not sufficiently localized. At the same time, acquisition activity and partnership strategies are quietly reshaping the landscape. Larger players seek to strengthen application coverage, consumables supply chains, and geographic service reach, while mid-tier firms explore agreements that expand their parameter coverage or software capabilities without undertaking full-platform development programs.
For procurement leaders and investors, the strategic implication is that vendor evaluation should extend beyond headline specifications. The durability of a purchasing decision depends on the alignment between instrument architecture and validated workflows, the predictability of consumables and service costs, the availability of method support for the specific matrices in use, and the likelihood that the platform can evolve as application requirements change. Competitors that invest in these dimensions are building switching costs that are based on operational reliability and data continuity rather than on lock-in alone.
PW Consulting
Forward Outlook: Trends Shaping the Next Three to Five Years
Trend One: Workflow Consolidation and Software-Defined Analysis
Over the next several years, the market is likely to reward platforms that reduce the complexity of method selection, calibration management, and data interpretation. Software-defined workflows that guide users from sample preparation through validated result reporting will become more important as laboratories seek to standardize operations across sites and reduce dependence on highly specialized operators. The commercial opportunity lies not only in instrument sales but in the recurring value of software subscriptions, method libraries, remote configuration support, and training ecosystems that lower the operational burden for buyers. Organizations that can demonstrate measurable reductions in setup time, method transfer errors, and result variability will capture disproportionate share in regulated and high-throughput environments.
A risk to monitor is the potential for software complexity to outpace user readiness. If interface design and validation tools are not intuitive, the promised efficiency gains may be undermined by longer adoption cycles and increased reliance on external support. Vendors that invest in user experience, documentation clarity, and role-based access will differentiate themselves in a segment where operational simplicity is becoming a competitive requirement.
Trend Two: Regional Demand Divergence and Service-Led Growth
Demand is expected to continue diverging by region, with Asia Pacific representing a substantial share of market expansion, North America sustaining strong adoption driven by pharmaceutical, analytical, and advanced manufacturing demand, and Europe maintaining robust activity shaped by regulatory and industrial testing requirements. Latin America and the Middle East and Africa will likely grow from smaller bases, with adoption shaped by the pace of laboratory modernization, regulatory formalization, and the availability of localized service support. The commercial opportunity for manufacturers is to align regional go-to-market strategies with local application priorities, establish service density where downtime is costly, and offer financing or managed-service models that reduce upfront capital barriers for mid-sized buyers.
A key uncertainty is the degree to which macroeconomic fluctuations and currency volatility affect procurement timing in emerging markets. Even when underlying demand is strong, budget cycles and foreign exchange dynamics can delay deployment. Companies that build flexible commercial terms and maintain reliable local consumables availability will be better positioned to convert demand into installed base over time.
Trend Three: Application Convergence and Cross-Industry Method Transfer
As analytical requirements become more tightly integrated into quality systems, there will be increasing interest in platforms capable of supporting method transfer across applications and sites with minimal revalidation burden. Laboratories that serve multiple industries or that operate shared analytical facilities will favor instruments that can accommodate diverse matrices while maintaining consistent performance characteristics. This trend creates opportunities for vendors that provide robust application libraries, cross-method validation guidance, and consumables configurations optimized for multi-application environments. The strategic benefit will accrue to organizations that can reduce the friction of moving methods between development, quality control, and contracted testing workflows.
The primary risk is that application diversity can also fragment demand if instruments are perceived as too specialized or too generalized. Vendors must strike a balance between parameter coverage, sample-scale flexibility, and the clarity of application-specific support. Overreach into configurations that dilute ease of use or inflate consumables overhead can weaken adoption, while overly narrow designs may miss cross-selling opportunities in laboratories with expanding analytical portfolios.
Strategic Actions for Decision Makers
For Manufacturers and Product Leaders
Product strategy should prioritize the intersection of analytical performance and operational simplicity. Investments in simultaneous multi-parameter determination, predictable consumables consumption, and software-assisted method management are likely to yield the strongest competitive returns. Equally important is the development of application-specific validation packages and service models that reduce total cost of ownership for buyers in regulated and high-throughput environments. Manufacturers that can articulate measurable improvements in throughput, repeatability, and method transfer efficiency will strengthen their positioning against both broad-portfolio incumbents and focused niche competitors.
Commercial strategy should emphasize regional service density and local application support where downtime and compliance scrutiny are significant concerns. Aligning consumables supply, calibration standards, and remote diagnostics with the realities of local procurement cycles can improve both win rates and long-term retention. For organizations considering portfolio expansion, targeted acquisitions or partnerships that add parameter coverage or software capabilities may deliver faster market impact than full-platform development programs.
For Investors and Strategic Allocators
Investment theses should account for the market's moderate concentration and the enduring role of application specialization. Recurring revenue streams tied to consumables, service agreements, and software support are valuable complements to instrument sales, particularly where buyers prioritize predictable operating costs and rapid issue resolution. When evaluating opportunities, diligence should examine not only technological specifications but also the depth of application validation, the reliability of consumables supply, and the credibility of regional service networks. Companies that can demonstrate durable customer relationships in regulated or high-volume applications are better positioned to sustain growth through procurement cycles and regional volatility.
Portfolio diversification across application areas and regions can reduce exposure to localized demand shocks, but only if the underlying commercial model supports effective service delivery and consumables management. Investors should also monitor the pace of consolidation and partnership activity, as these dynamics can reshape competitive advantages in parameter coverage, service reach, and software ecosystems faster than organic product roadmaps alone.
For Procurement Leaders and Laboratory Managers
Procurement decisions should be anchored in validated workflow fit rather than nominal specification comparisons. Evaluate platforms against the specific matrices, throughput requirements, documentation standards, and reporting formats that your operations demand. Assess total cost of ownership with explicit consideration of consumables consumption, calibration frequency, maintenance intervals, and the availability of local service and remote diagnostics. Where possible, structure evaluations around method transfer scenarios and multi-application use cases to ensure that the selected platform can support evolving analytical needs without excessive revalidation burden.
Worldwide Automatic Elemental Analyzer Market
Negotiation strategies should account for software support, training, and consumables predictability as value levers alongside hardware pricing. Establishing clear expectations for service response times, software update continuity, and application support can reduce operational risk and improve long-term return on investment. In multi-site organizations, standardizing on platforms that simplify method management and deliver consistent performance across locations can yield operational savings that exceed the apparent price differential between alternatives.
Why Detailed Market Intelligence Remains Essential
The Organic Elemental Analyzer market is expanding along a credible growth trajectory, but the most consequential decisions will be made at the level of application fit, service economics, and workflow integration rather than at the level of aggregate demand. The segmentation of demand across regions, instrument types, and application contexts matters because it determines where competitive advantage is created and where procurement risk is concentrated. Detailed breakdowns of regional dynamics, product-type adoption patterns, and application-level volume distribution provide the granularity needed to calibrate product strategy, service investments, and purchasing decisions with precision.
Executive teams, strategic planners, and investors who require that level of granularity can benefit from the full research report, which provides comprehensive segmentation data, company profiles, and forward-looking scenario analysis. Access to detailed submarket data and tailored strategic recommendations enables more disciplined capital allocation, more confident procurement negotiations, and more targeted product development priorities. For organizations seeking to act on the trends outlined here with specificity and speed, the complete research resource offers the depth required to translate market intelligence into executable strategy.
For detailed analysis of this topic, please visit the official page: Organic Elemental Analyzer (OEA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com