

Blogs
PW Consulting: Micronized Rubber Powder Market to Hit $279.34M by 2032 at 6.5% CAGR
By PW Consulting, 2026-09-16
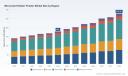
Strategic Intelligence Brief: The Micronized Rubber Powder Market Outlook 2026-2032
Executive Summary: A Market Poised for Structural Transformation
The global micronized rubber powder (MRP) industry is navigating a pivotal inflection point. As sustainability mandates intensify and circular economy principles transition from regulatory ideal to commercial necessity, the demand for high-performance recycled rubber solutions has accelerated. Our latest comprehensive research publication provides a granular analysis of this dynamic landscape, offering decision-makers the clarity required to navigate market volatility, supply chain constraints, and competitive disruptions across the forecast period of 2026 to 2032.
For strategic planners, procurement leaders, and investment committees, the window to secure advantageous positioning is narrowing. This article serves as a foundational overview of the market mechanics, growth trajectories, and competitive architectures detailed in our full report. It is designed to demonstrate the analytical rigor and operational relevance of our research while preserving the proprietary data necessary for precise strategic modeling. To access the complete segmentation matrices, pricing elasticity curves, and forecast scenario models, readers are invited to consult the full market brief directly.
The market has demonstrated consistent resilience over the past half-decade, evolving from a niche recycling byproduct segment into a specialized materials market characterized by technological differentiation and stringent performance standards. Understanding the forces propelling this evolution is essential for any organization seeking to capitalize on the opportunities embedded within end-of-life tire valorization and advanced polymer modification.
Historical Trajectory and Baseline Valuation (2020-2025)
Our retrospective analysis covering the period from 2020 through 2025 reveals a market that has steadily expanded despite macroeconomic headwinds, supply chain uncertainties, and fluctuating raw material costs. Over this six-year horizon, the industry consolidated its foundation, driven by increasing adoption of MRP in high-value applications and growing acceptance of recycled content mandates across key industrial sectors. The baseline valuation at the end of the historical period stands at a recorded level, reflecting a mature and increasingly sophisticated market ecosystem.
This historical growth was not uniform. It was shaped by diverging regional adoption rates, varying degrees of regulatory enforcement on tire disposal, and the gradual maturation of processing technologies. The data indicates a clear trajectory of value accumulation, with early adopters of fine-particle processing technologies capturing disproportionate margins compared to producers relying on conventional ambient grinding methods. The historical record establishes a credible foundation for forward-looking projections and underscores the importance of timing in capacity expansion and technology investment decisions.
Forward Outlook: Growth Catalysts for 2026-2032
Looking ahead, the forecast period anticipates a robust compound annual growth rate that outpaces many traditional industrial materials segments. This growth is underpinned by a convergence of structural drivers that are likely to persist throughout the decade. Regulatory frameworks worldwide are tightening requirements for tire recycling, mandating higher recovery rates and penalizing landfill disposal. Simultaneously, infrastructure spending programs in multiple economies are creating immediate demand pull for asphalt modifiers and construction additives derived from recycled rubber.
Technological advances are also reshaping the supply side. Improvements in cryogenic processing efficiency have progressively reduced energy intensity, mitigating one of the historically significant cost burdens associated with fine-particle production. At the same time, the industrial preference for powders with superior surface area and morphology is elevating the commercial relevance of specialized grades, creating pricing tiers that reward producers with advanced milling and classification capabilities. These dynamics suggest that the market of 2032 will look materially different from the market of 2026, with greater emphasis on product specification, traceability, and environmental certification.
Market Structure, Segmentation, and Value Migration
The Particle Size Dimension: Technical Differentiation as a Margin Driver
Particle size is not merely a physical specification; it is a fundamental determinant of end-use eligibility and pricing power. The market segmentation by particle size reveals a clear hierarchy of value, with finer fractions commanding preferential positioning in applications that demand intimate polymer interaction, uniform dispersion, and enhanced mechanical performance. Coarser fractions continue to serve bulk-modification roles, but the margin differential between fine and coarse grades has become increasingly pronounced as downstream formulators optimize formulations for performance and sustainability credentials.
Worldwide Micronized Silica Market
This technical segmentation has strategic implications for capacity planners. Investment in fine-grinding capability requires higher capital intensity and more complex operational control, but it opens access to application segments with lower price elasticity and stronger competitive moats. Our full report dissects the capacity allocation trade-offs across these size categories and provides scenario analysis on how shifting application preferences may alter relative demand shares over the forecast horizon.
Application Ecosystems: Where Demand Converges and Diverges
The application landscape of MRP spans multiple industrial domains, each with distinct procurement cycles, specification requirements, and growth trajectories. The automotive sector has historically represented the largest demand pool, leveraging MRP for vibration damping, component lightweighting, and recycled content integration. Construction-related applications, particularly asphalt modification and paving compounds, have emerged as a high-growth vector, supported by public-sector sustainability procurement and the demonstrated performance benefits of rubber-modified surfaces.
Industrial manufacturing, coatings, and specialty uses constitute additional demand pillars, each responding to different drivers such as polymer compounding trends, adhesive formulation requirements, and consumer-facing sustainability messaging. The interplay between these application segments creates a diversified demand base that can buffer the market against sector-specific downturns, but it also complicates forecasting, as relative demand shares shift with technological substitution, raw material pricing, and regulatory emphasis. Our detailed analysis maps these interdependencies and identifies the segments most likely to generate incremental volume growth in the coming years.
Micronized Rubber Powder Market
Regional Dynamics and Geographic Arbitrage
Geographic distribution of demand and production capacity reflects a complex interplay of regulatory environments, tire generation rates, processing infrastructure density, and logistics economics. Different regions exhibit markedly different adoption curves, with some markets leading in per-capita recycled content integration while others remain in earlier stages of capacity development. Understanding these regional asymmetries is critical for companies evaluating export opportunities, local processing investments, or strategic partnerships.
The full research publication provides a comprehensive geographic breakdown that maps demand intensity against supply availability, identifies logistics bottlenecks, and evaluates the economic viability of regional trade flows. This geographic intelligence is essential for optimizing footprint strategy and for anticipating where regulatory or infrastructure developments may create the next wave of regional demand spikes.
Competitive Architecture and Strategic Positioning
Market Concentration and the Scale Advantage
The MRP industry exhibits a moderate concentration profile, with a defined set of leading producers holding meaningful shares of global output. Competitive positioning is increasingly determined by technology tenure, processing capability, and the ability to supply certified, specification-grade materials at scale. Producers that have invested in proprietary milling technologies, integrated recycling loops, or advanced quality assurance systems are better positioned to capture premium segments and defend against commoditization pressure.
Market leaders such as Lehigh Technologies, a Michelin Group subsidiary operating from Tucker, Georgia, exemplify the integration of advanced cryogenic turbo mill technology with a diversified application portfolio spanning tires, plastics, asphalt, and construction materials. Their emphasis on lifecycle assessment and circular economy messaging aligns with the credentialing demands of downstream customers. Genan Holding A/S, headquartered in Denmark and recognized as a leading global end-of-life tire recycler, has built a reputation around ultra-fine powder production and ambient granulates, with recent product certifications reinforcing the environmental value proposition of their asphalt premix offerings.
Tinna Rubber & Infrastructure Limited, based in India, has established itself as a large-scale producer with deep integration from radial truck and bus tire feedstock through to crumb rubber modifiers, reclaim rubber, and polymer applications. Their scale and vertical integration illustrate a distinct competitive model centered on feedstock control and cost-efficient processing. Entech Inc., operating from Middlebury, Indiana, brings long operational tenure dating back to the mid-1990s, offering a broad size range of MRP and crumb rubber products complemented by integrated hauling, processing, and compounding services.
The Rubberjet Group, based in Italy, represents a different technological pathway, utilizing proprietary high-pressure water-jet technology to produce micronized rubber powder and granules from medium and large end-of-life tires and rubber tracks. Their approach underscores the ongoing innovation in processing methods and the differentiation potential that alternative milling technologies can create.
Recent Competitive Signals and Industry Developments
Recent announcements from key players illustrate the intensifying focus on environmental credentialing and product certification. In late 2025, Lehigh Technologies released a lifecycle assessment study quantifying CO2 reduction and circular economy benefits associated with their micronized powders used in asphalt modification, signaling a strategic emphasis on evidence-based sustainability claims. Concurrently, Genan Holding A/S secured Environmental Product Declaration certification for its GENAN ROAD+ PREMIXED asphalt premix, reinforcing the market trend toward third-party verified environmental performance in construction applications.
These developments are not isolated marketing events; they reflect a structural shift in procurement decision-making, where environmental documentation and performance validation are becoming prerequisites for entry into premium application segments. Companies that invest early in measurement, certification, and transparent reporting are likely to gain preferential access to specification-driven demand.
Structural Dynamics Shaping Margin and Viability
Cost Architecture and the Cryogenic Premium
The economics of MRP production are heavily influenced by process technology choice and the associated variable cost structure. For cryogenic producers, liquid nitrogen represents a significant share of variable production costs, making energy efficiency and nitrogen consumption management critical levers for margin protection. Over the past five years, improvements in cryogenic processing efficiency have materially reduced per-ton nitrogen consumption, easing a persistent cost pressure and enhancing the competitiveness of fine-grade output.
At the same time, the market has demonstrated willingness to pay a meaningful price premium for cryogenic-grade material, reflecting the functional benefits associated with superior particle morphology and surface area. This premium creates a clear economic rationale for producers to invest in or maintain cryogenic capability, but it also raises the stakes for operational execution. Cost mismanagement in the cryogenic process can quickly erode the margin advantage that the premium is meant to deliver.
Regulatory Tailwinds and Circular Economy Alignment
Policy frameworks continue to play a decisive role in shaping demand. The inclusion of natural rubber on the European Commission list of critical raw materials has heightened attention on alternative material sourcing and recycling pathways. Simultaneously, recycling regulations targeting end-of-life tires are reinforcing demand for high-value MRP as a compliant, value-adding circular economy solution. These regulatory signals are not uniform across jurisdictions, but the overall trajectory favors increased recovery, higher-value reuse, and greater documentation of environmental impact.
Organizations seeking to align their strategies with these regulatory currents must look beyond headline compliance requirements and understand the specification expectations, certification pathways, and procurement preferences emerging in regulated markets. Our report provides the detailed regulatory mapping and interpretation needed to translate policy signals into actionable commercial strategy.
Strategic Implications for 2026 Decision-Making
For executives planning allocations, capacity decisions, partnership structures, and competitive positioning in 2026, the MRP market offers both opportunity and complexity. The growth trajectory is favorable, but the distribution of value is increasingly concentrated among producers with advanced technology, certified product portfolios, and the ability to serve specification-driven applications. Companies that treat MRP as a commoditized byproduct risk ceding margin and market access to competitors who have built differentiation into their operational and commercial models.
Our full market research publication delivers the depth and granularity required to execute informed strategy. It includes detailed segmentation analysis, forward-looking volume and value projections, competitive benchmarking, cost structure evaluation, regulatory interpretation, and scenario modeling across multiple demand and supply variables. The complete dataset, including regional breakdowns, application-level demand shares, particle size valuations, and concentration metrics, is available in the full report and forms the analytical backbone for strategic planning.
To explore the full research suite, access detailed segmentation data, and obtain the complete forecast models for 2026 through 2032, request the complete Micronized Rubber Powder Market research publication. The insights within are structured to support immediate strategic action and long-range planning in a market that is rapidly redefining the value of recycled rubber materials.
For detailed analysis of this topic, please visit the official page: Micronized Rubber Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Smart Doorbell Market to Hit $1.88B by 2032 at 17.9% CAGR, Says PW Consulting Report
By PW Consulting, 2026-09-16
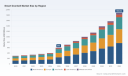
Navigating the Smart Doorbell Market: Strategic Intelligence for 2026 and Beyond
The smart doorbell market has evolved from a niche accessory into a cornerstone of the broader connected home and physical security ecosystem. As we move deeper into 2026, enterprises, investors, and technology strategists must look beyond surface-level adoption narratives and understand the structural forces shaping revenue trajectories, competitive positioning, and regulatory readiness. Our latest market research delivers precisely that analytical architecture. Built on a rigorous historical foundation spanning 2020 through 2025 and extended through a detailed forecast window to 2032, this study transforms fragmented industry signals into a cohesive decision-making framework. For executive teams navigating product roadmaps, channel strategy, or M&A evaluation, the report functions as both a compass and a calibration tool.
Macro Trajectory and the 2026 Inflection Point
The market's expansion over the past half-decade demonstrates a consistent upward arc, but the true strategic significance lies in how momentum accelerates rather than merely sustains. Historical revenue climbed steadily from approximately $300 million in 2020 to $401.26 million in 2024, reflecting mature consumer electronics adoption curves and incremental smart home penetration. The 2025 baseline of $595 million marks a pronounced step-change, signaling that market maturation has triggered a new growth regime rather than a plateau. Looking ahead, our forecast maps a clear trajectory toward $710.07 million in 2026, accelerating through $1.005 billion around 2028, and ultimately approaching $1.884 billion by 2032.
Underpinning this expansion is a forecasted compound annual growth rate of 17.9 percent across the 2026 to 2032 horizon. For strategic planners, this figure is not merely a growth statistic; it is a timing signal. An expansion rate at this level implies that early-mover advantages in ecosystem integration, manufacturing scale, and regional compliance infrastructure will compound rapidly. Enterprises that treat 2026 as a baseline planning year rather than a continuation of prior-year assumptions will find themselves either capturing disproportionate share or scrambling to retrofit capabilities under tighter margin conditions.
Competitive Architecture: Differentiating in a Crowded Field
The smart doorbell landscape is defined by a diverse set of players, each anchoring their offerings to distinct technological philosophies and ecosystem strategies. Analyzing these positions is essential because competitive advantage in this category no longer stems from hardware specifications alone; it emerges from how product architecture aligns with customer retention models, subscription economics, and interoperability expectations.
Amazon-owned Ring continues to leverage its dominant consumer footprint through both battery-powered and wired video doorbells, emphasizing two-way audio, package detection, and seamless integration within the Amazon retail and services ecosystem. Its scale and brand recognition create a persistent reference point against which rivals measure market entry and feature parity. Meanwhile, TP-Link has pushed differentiation through its Tapo series, offering dual-powered 2K+ video doorbells with AI detection while explicitly addressing a growing consumer preference for no-subscription cloud options.
Ubiquiti Inc. occupies a different strategic niche. The UniFi G4 Doorbell Pro targets prosumer and integrated security environments with advanced package detection, an integrated chime, and tight coupling with the UniFi Protect ecosystem. This positioning reflects a broader market split between mass-market plug-and-play solutions and infrastructure-oriented deployments that value centralized management. REOLINK follows a similar practical differentiation path, offering WiFi and PoE models with 2K+ resolution, local NVR storage, and AI features that eliminate recurring subscription dependencies.
In the residential and smart-home automation segment, Lumi United Technology Co., Ltd. has advanced its Aqara Video Doorbell G4 with facial recognition capabilities, local storage architecture, and HomeKit Secure Video support. This aligns with a consumer base that prioritizes privacy, interoperability within Apple-centric households, and reduced reliance on third-party cloud infrastructure. Anker Innovations Co., Ltd. has pursued a complementary strategy through its eufy Video Doorbell E340 and related models, featuring a dual-camera setup and local storage to appeal to users seeking broader field coverage without recurring fees.
Amazon's Blink brand continues to extend its reach with an emphasis on long battery life, two-way talk, and Alexa integration, while SimpliSafe, Inc. connects its Video Doorbell Pro to professional monitoring and no-contract security system compatibility, effectively bridging DIY smart home devices with traditional security service expectations. Arlo Technologies, Inc. rounds out this competitive field with its 2K Video Doorbell emphasizing wide-angle lens design, color night vision, and Arlo Secure cloud storage.
What makes this competitive mosaic strategically significant is that rivalry no longer operates along a single axis. Differentiation now spans power architecture, storage philosophy, ecosystem lock-in versus openness, professional monitoring compatibility, and privacy-conscious design. The winners in 2026 and beyond will be those capable of aligning product architecture with a clearly defined customer segment rather than attempting to dominate across all dimensions simultaneously.
Market Dynamics: Regulation, Supply Chain, and the Compliance Premium
The operational environment surrounding smart doorbells is increasingly shaped by regulatory and structural forces that reward preparedness and penalize reactive design. Spectrum management remains a foundational consideration, as FCC regulation continues to govern spectrum allocation for Wi-Fi and Bluetooth in smart doorbell devices, requiring manufacturers to prevent interference across the 2.4 GHz and 5 GHz bands. For hardware engineering and product certification teams, this is not a background detail; it is a design constraint that directly affects time-to-market, regional deployment flexibility, and interoperability performance.
Doorbell Market
Data protection requirements have become equally central to commercial strategy. GDPR and data sovereignty laws now require end-to-end encryption and local storage options for smart doorbell video feeds within the European Union. This regulatory posture shifts the competitive calculus for vendors targeting European customers. Companies that have embedded privacy-by-design architectures and local storage pathways into their product roadmaps can position those capabilities as market access enablers, whereas those retrofitting compliance under deadline pressure face both technical and reputational friction.
Cybersecurity management standards further reinforce this compliance premium. The widespread adoption of ISO/IEC 27001 standards across smart home devices, including video doorbells, signals that enterprise-grade security governance is becoming table stakes rather than a differentiator reserved for specialized verticals. For market participants, this means that product security, certification readiness, and transparent data handling are increasingly intertwined with brand trust and channel acceptability.
On the manufacturing and cost side, sector analysis indicates that assembly and testing labor costs for smart doorbell hardware are elevated in regions with skilled electronics manufacturing supply chains. This dynamic has strategic implications for sourcing decisions, margin planning, and product localization. Companies must weigh the trade-offs between manufacturing proximity, labor cost structures, quality consistency, and logistics efficiency, especially as competition intensifies and pricing pressure increases in the mass-market segment.
A recent product-launch signal further illustrates how these dynamics play out in real time. In May 2026, Blink debuted a second-generation video doorbell featuring an expanded field of view and enhanced person detection. This release demonstrates how incumbents continue to iterate on core detection quality and visual coverage to defend share, while also reflecting the broader industry push toward more accurate on-device intelligence. For competitors, such launches are both an operational benchmark and a reminder that feature escalation alone will not sustain differentiation without clear segmentation and ecosystem alignment.
What the Full Research Delivers: Operational Intelligence, Not Just Forecasts
A market summary can establish direction, but enterprise decision-making requires structured, actionable detail. Our Smart Doorbell Market research is designed to convert high-level trajectory into implementable intelligence across product, commercial, and risk functions. The report maps historical performance and forward-looking forecasts within a consistent methodological framework, allowing readers to validate growth assumptions against segmented demand drivers, regional adoption patterns, and application-specific purchasing behavior.
Beyond aggregate sizing, the study dissects how the market is structured across type-based and application-based demand, giving strategists visibility into where wired and wireless architectures are gaining traction and how residential versus commercial use cases shape product requirements, pricing tolerance, and channel expectations. Regional demand distribution is similarly examined to identify where growth concentration, competitive intensity, and compliance environments diverge, enabling more precise go-to-market prioritization rather than broad, undifferentiated global assumptions.
The report also includes competitive profiling that goes beyond corporate descriptions. It situates each key player within a strategic context, connecting product features, ecosystem integration, storage and subscription philosophy, and monitoring or security compatibility to the segments they are best positioned to serve. This approach allows business leaders to benchmark their own product strategy against peer positioning, identify white-space opportunities, and anticipate where competitive pressure is likely to intensify.
Equally important, the research integrates regulatory and operational dynamics into the market narrative rather than treating them as peripheral footnotes. By examining the interplay between spectrum regulation, data sovereignty expectations, cybersecurity standards, and manufacturing cost structures, the study helps organizations assess readiness across multiple dimensions simultaneously. For product teams, this means clearer visibility into design constraints and certification pathways. For commercial teams, it means more realistic margin modeling and market-entry sequencing. For leadership, it means a consolidated view of where operational risk and strategic opportunity converge.
Why This Research Matters for 2026 Decision-Making
Markets that expand at a double-digit CAGR do not reward passive observation. They reward organizations that can convert structural growth into targeted execution. In the smart doorbell category, 2026 sits at a point where historical momentum, regulatory maturation, and competitive fragmentation intersect. The companies that navigate this inflection successfully will be those that treat product strategy, compliance architecture, and segmentation discipline as interconnected rather than sequential concerns.
Our research is built for that challenge. It is intended for executives who need to evaluate whether to deepen existing product lines, enter adjacent segments, restructure supply and cost assumptions, or reposition against ecosystem-driven competitors. It is also intended for investors and advisors who require a defensible view of where demand is concentrating, which competitive models are proving durable, and which operational hurdles will separate scalable players from those constrained by compliance gaps or misaligned product philosophy.
Smart Doorbell Market
The complete report provides the segmented data, competitive benchmarking, regional breakdowns, and forward-looking scenario structure necessary to move from strategic intent to operational plan. If your team is preparing for 2026 planning cycles, channel allocation, product roadmap prioritization, or competitive response planning, the full study offers the granularity required to make those decisions with confidence.
The market trajectory is clear. The strategic question is how precisely your organization intends to meet it.
For detailed analysis of this topic, please visit the official page: Smart Doorbell Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The global mobile elevator market’s revenue trajectory illustrates a steady upward progression between 2020 and 2035. Driven by expanding construction and warehousing applications, coupled with technology upgrades, the market value is projected to rise from approximately USD 7,300 million in 2020 to more than USD 15,800 million by 2035. Strategic investments in innovation, electrification, and emerging market penetration are expected to sustain this growth. Big players like JLG Industries and Sinoboom continue to lead in revenue generation by leveraging advanced product launches and forging large-scale distribution partnerships. The market demonstrates resilience despite cyclical challenges related to raw material costs and economic slowdowns.
Read More - https://bussinessinsights.com/research-report/global-mobile-elevator
Construction applications hold the largest share within the global mobile elevator market, reflecting the ongoing global boom in infrastructure development. Industrial applications remain the second largest, supported by stringent workplace efficiency and safety demands within manufacturing and logistics. Warehousing is also a significant segment, leveraging specialized lifts for vertical transport in high-density storage environments. As industries focus on automation and rapid turnaround, the application mix is expected to gradually migrate toward tech-integrated and multi-functional solutions targeting diverse use-cases, with maintenance & repair as well as events & exhibitions also accounting for notable market presence.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-mobile-elevator
Frequently Asked Questions
Who are the key players in Global Mobile Elevator industry?
The top five players in the Global Mobile Elevator industry are Otis Elevator Company, Schindler Group, KONE Corporation, Thyssenkrupp AG, and Mitsubishi Electric Corporation. These companies lead the market due to their extensive product portfolios, global reach, investment in R&D, and continued innovation in mobile elevator technologies.
What is the Global Mobile Elevator growth?
The Global Mobile Elevator market has witnessed significant growth, with an estimated CAGR of over 5% from 2022 to 2024. Recent growth is attributed to rising construction and infrastructure development, with Otis Elevator Company expanding its mobile solutions portfolio to meet heightened demand in emerging economies.
Which segment accounted for the largest Global Mobile Elevator share?
The construction segment accounted for the largest share of the Global Mobile Elevator market. Mobile elevators are extensively used in construction and maintenance projects due to their flexibility, ease of transport, and ability to reach varying heights, supporting growing urbanization and infrastructure expansion worldwide.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Coal Tar Pitch Market to Hit $3,044.1 Million by 2032, 4.85% CAGR
By PW Consulting, 2026-09-16
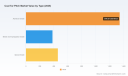
Navigating the Carbon Binders Landscape: Strategic Imperatives for the Coal Tar Pitch Market Through 2032
The global coal tar pitch market stands at a critical inflection point. As foundational carbon binders underpin both primary aluminum production and advanced graphite manufacturing, industry participants must reconcile steady demand growth with tightening environmental regulations and evolving feedstock dynamics. Our latest research evaluates the market across a comprehensive 2026 through 2032 forecast window, building on a rigorously validated historical baseline spanning 2020 to 2025. This analysis is designed to equip procurement leaders, strategy executives, and investment committees with the structural clarity required to allocate capital, secure supply corridors, and align product portfolios with long-term industrial trajectories.
Over the historical period, revenue patterns reflected a combination of cyclical demand recovery, capacity rationalization in mature regions, and gradual migration toward higher-performance grades. The market advanced from a baseline of 1,765.2 million USD in 2020 to 2,185.5 million USD in 2025, with the trajectory demonstrating both resilience and episodic volatility driven by downstream construction cycles and metallurgical output adjustments. Looking forward, the forecast horizon projects sustained expansion, positioning total market revenue near 3,044.1 million USD by 2032. This growth is anchored by a compound annual growth rate of 4.85 percent, signaling a mature yet persistently expanding addressable market rather than a speculative surge. For corporate planners, this trajectory underscores the importance of modeling demandelasticity against macro industrial indicators, rather than relying on static volume assumptions.
Market Framework and Structural Segmentation
A rigorous understanding of coal tar pitch requires disaggregating the market across both product architecture and end-use demand profiles. The report maps the landscape across multiple type categories, capturing the distinct operational requirements that separate aluminum-grade binders from impregnation and specialty variants. Aluminum-grade pitch continues to represent the dominant share of revenue, reflecting its indispensable role in carbon anode formulation for primary smelting operations. Binder and impregnation grades serve a more specialized set of downstream applications, where softening points, coking values, and rheological characteristics dictate procurement specifications. Special-grade formulations address niche performance thresholds in advanced carbon materials and refractory systems, creating a higher-margin yet technically demanding segment for producers with differentiated processing capabilities.
Coal Tar Pitch For Graphite Electrodes Market
Demand concentration across applications follows a similarly hierarchical pattern. Aluminum smelting remains the foundational consumption pillar, while graphite electrode manufacturing sustains a substantial secondary channel tied to electric-arc furnace steelmaking and industrial carbon processing. Additional application channels, including roofing formulations and specialty industrial uses, provide supplementary revenue streams that help balance cyclical volatility in the core metallurgical segments. The report examines how these application pathways interact with regional processing capacity, logistics constraints, and customer specification requirements, enabling readers to identify where supply-demand balance is most likely to tighten or loosen over the forecast period.
Regional analysis in the study is structured to highlight where manufacturing footprints, trade flows, and regulatory environments shape competitive positioning. The market is not uniformly distributed; instead, it concentrates around established carbon-processing clusters and emerging refining hubs that can offer both scale and grade flexibility. The research details how regional pricing differentials, freight exposure, and local compliance requirements influence buyer-seller dynamics, helping strategists evaluate which geographies present durable advantages and which are more susceptible to regulatory friction or feedstock disruption.
Competitive Landscape and Enterprise Positioning
The coal tar pitch sector remains moderately concentrated, with established producers leveraging integrated distillation assets, long-term customer relationships, and technical service capabilities to defend market positions. Our analysis identifies the core enterprise cohort shaping competitive dynamics, including Koppers Holdings Inc., Rain Carbon Inc., Himadri Speciality Chemical Ltd., Deza, a.s., and Shree Shyam Chemicals. Each occupies a distinct strategic niche shaped by feedstock access, geographic footprint, and grade specialization.
Coal Tar Pitch Market
Koppers Holdings Inc., headquartered in Pittsburgh, Pennsylvania, operates as an integrated producer of carbon pitch derived from coal tar distillation, with primary offerings focused on binding agents for carbon anodes serving aluminum smelters and for graphite electrodes used by electric-arc furnace steel producers. Rain Carbon Inc., based in Stamford, Connecticut, has established itself as a global leader in coal tar and petroleum distillation, manufacturing coal tar pitch with varying softening points for carbon anodes, graphite electrodes, specialty graphite, and refractory materials. Himadri Speciality Chemical Ltd., operating from Kolkata, India, stands out as a vertically integrated producer with annual pitch capacity exceeding 600,000 metric tons, offering coal tar pitch grades for aluminum, graphite electrode, and carbon black sectors, including liquid and export variants. Deza, a.s., in the Czech Republic, produces coal tar pitch and related distillation products, supplying binder-grade and impregnating grades for carbon and specialty applications. Shree Shyam Chemicals, based in Bhilai, Chhattisgarh, manufactures coal tar pitch, coal tar, and related chemicals, serving industrial-grade requirements across aluminum, graphite, chemical, and pharmaceutical sectors.
Recent Developments Shaping Supply and Corridor Strategy
Beyond structural positioning, the report tracks recent operational moves that reveal where capital is flowing and how supply arrangements are evolving. In January 2025, Rain Carbon Inc. announced a new coal tar distillation and pitch processing facility in APSEZ, Anakapalli, Andhra Pradesh, India. The initial phase targets 50,000 metric tons per year and addresses graphite, battery, and aluminum markets, with further expansion planned, signaling a deliberate push to diversify processing geography and capture demand growth in South Asia. In November 2025, Epsilon Carbon Private Limited signed a non-binding MoU with Aluminium Bahrain for the long-term supply of liquid coal tar pitch, aimed at supporting aluminum smelting demand and strengthening export security for a key downstream customer. In December 2025, Himadri Speciality Chemical Ltd. executed its first-ever liquid coal tar pitch export of 3,600 tonnes to the Middle East from the New Mangalore Port terminal, establishing a new supply corridor and demonstrating the increasing importance of logistics-enabled grade differentiation.
These developments are not isolated events. Collectively, they point to a market in which supply reliability, grade customization, and corridor diversification are becoming as strategically consequential as raw production volume. The report examines how such moves reshape competitive pressure, influence customer negotiation leverage, and alter regional import-dependency profiles for buyers seeking to de-risk procurement.
Regulatory Dynamics and the Compliance Premium
Regulatory scrutiny represents one of the most consequential variables for coal tar pitch strategy, particularly where polycyclic aromatic hydrocarbon exposure intersects with pavement applications, industrial emissions standards, and chemical handling requirements. The analysis incorporates multiple regulatory signals that are reshaping demand quality and compliance economics. Minnesota prohibits the sale and use of coal tar sealant products containing coal tar, coal tar pitch volatiles, or CAS 65996-93-2/65996-89-6 on asphalt-paved surfaces, effective January 1, 2014. New York State has proposed legislation, Senate Bill 2025-S3179A, to tighten the PAH limit in the state's coal tar ban for pavement products. Under the EU REACH framework and related directives, strict PAH controls apply to coal tar pitch production and use, with compliance costs rising for legacy grades. Tightening PAH emission and wastewater norms in Canada and New York State continue to drive compliance-driven capacity considerations and low-PAH grade development.
These regulatory threads matter because they create a structural divergence between commodity-grade volumes and specification-driven demand. As jurisdictions tighten limits on certain applications and emissions profiles, producers and buyers alike must navigate higher compliance burdens, reformulation requirements, and potential substitution pressure in affected end-use channels. The report assesses how these dynamics influence grade architecture, regional demand elasticity, and the relative attractiveness of processing investments that can accommodate tighter specifications without sacrificing cost competitiveness.
Feedstock Volatility and Industrial Demand Shifts
In addition to regulation, market participants must contend with raw material uncertainty. Coal tar feedstock volatility and shifts toward electric-arc furnace steel production continue to constrain coal tar availability for pitch distillation. This constraint is significant because it links the coal tar pitch market not only to aluminum and graphite demand, but also to broader metallurgical technology transitions and upstream coke and tar supply conditions. Where tar availability tightens, grade allocation, pricing behavior, and customer qualification timelines can all become more volatile, making supply-chain visibility and flexible contracting models increasingly valuable. The study evaluates how these pressures interact with regional availability, refining capacity utilization, and downstream qualification cycles, helping stakeholders anticipate where bottlenecks may emerge and which procurement strategies are best suited to mitigate them.
What the Full Study Delivers
This executive overview highlights the strategic contours of the coal tar pitch market, but the full research provides the operational depth that decision-makers need to convert insight into action. Our report delivers a comprehensive market sizing and forecasting framework covering historical performance and forward projections through 2032. It includes detailed segmentation analysis by type and application, together with regional evaluation that situates demand growth within local regulatory and logistical realities. The study maps the competitive landscape across key producers, examining capacity structures, product orientation, and recent developments that signal changing market power. It also assesses the regulatory and raw-material environment shaping compliance costs, feedstock constraints, and demand quality.
For executives responsible for procurement, production planning, or market entry assessments, the research is structured to answer practical questions: which grade families offer the most durable growth under tightening compliance regimes, where regional demand expansion is likely to be most consistent, how supply corridor development may affect import dependency, and what operational factors distinguish resilient producers in a concentrated market. The analysis avoids superficial generalizations in favor of scenario-aware interpretation, allowing readers to integrate findings into internal forecasting models, sourcing strategies, and investment evaluations.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle is unlikely to resolve into a single dominant trend. Instead, leaders will need to manage multiple overlapping forces: steady structural demand growth, a moderately concentrated producer base, regulatory tightening across key jurisdictions, and feedstock availability linked to broader metallurgical transitions. In that environment, strategic advantage will accrue to organizations that can distinguish durable growth from temporary cyclical noise, align grade portfolios with shifting specification requirements, and secure supply access before capacity reallocations intensify.
Our coal tar pitch market research is designed to support that process by combining macro market visibility with segment-level interpretation. It provides the evidence base needed to evaluate whether to expand supply relationships, pursue qualification in higher-specification grades, or reassess exposure to applications facing heightened regulatory scrutiny. Just as importantly, it offers a structured competitive lens for interpreting the significance of recent capacity expansions, supply agreements, and corridor developments that may reshape buyer leverage over the coming planning cycles.
The full report contains the detailed regional, type, and application breakdowns, the extended competitive profiles, and the scenario discussion that decision-makers require for rigorous 2026 and beyond planning. Readers seeking the complete dataset and analysis are encouraged to access the full study page, where the comprehensive market intelligence is available in a format designed for strategic integration and executive review.
For detailed analysis of this topic, please visit the official page: Coal Tar Pitch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Luxury Packaging Market to Hit $253.71M by 2032 Amid 5.23% CAGR
By PW Consulting, 2026-09-16
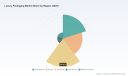
Strategic Horizons: Navigating the Luxury Packaging Market in 2026 and Beyond
The luxury packaging sector stands at a critical inflection point. As consumer expectations evolve and regulatory pressures intensify, brands are no longer treating packaging as a mere container but as a strategic asset that communicates value, reinforces sustainability commitments, and protects brand equity. Understanding the trajectory of this market is essential for executives making capital allocation, product development, and supply chain decisions in 2026. This publication presents a comprehensive analysis of the luxury packaging landscape, offering the intelligence required to navigate an increasingly complex environment.
Worldwide Luxury Cosmetics Packaging Market
The global luxury packaging market has demonstrated consistent growth over the past half-decade. Valued at approximately 143.92 million USD in 2020, the sector expanded steadily to reach 178.23 million USD by the base year of 2025. Looking forward, the market is projected to climb to 186.79 million USD in 2026, continuing its upward trajectory through the forecast period ending in 2032, where it is expected to surpass 253.71 million USD. This expansion is underpinned by a compound annual growth rate of 5.23 percent, reflecting sustained demand across high-end consumer segments. However, aggregate figures only tell part of the story. The real strategic opportunities lie in understanding the structural shifts, material innovations, and regional dynamics that are reshaping competitive positions.
Our latest market research goes beyond top-line projections. It provides a granular examination of the forces driving growth, the constraints limiting expansion, and the strategic maneuvers required to capture value in a fragmented yet consolidating industry. For decision-makers operating in 2026, this report serves as a vital compass, illuminating pathways for investment, partnership, and innovation.
Decoding the Competitive Landscape
The luxury packaging ecosystem is characterized by a mix of established multinational players and specialized niche manufacturers. Our analysis maps the strategic positioning of key companies that are defining the market's direction, examining their operational focus, geographic reach, and innovation pipelines.
Market Leaders and Specialized Innovators
Several prominent organizations are setting the pace for the industry. DS Smith plc, headquartered in London, has cemented its reputation through a strong focus on paper-based luxury rigid boxes and premium packaging solutions. Similarly, Smurfit Westrock plc, based in Dublin, continues to advance paperboard and rigid luxury packaging while integrating sustainability innovations into its core offerings. In Milan, Pusterla 1880 S.p.A. specializes in luxury rigid boxes and premium cardboard packaging, catering to brands that demand both aesthetic excellence and structural integrity.
The Asia-Pacific region contributes significant manufacturing capabilities, exemplified by Topsion Packaging in Dongguan, China, which focuses on structurally complex rigid boxes for premium luxury applications. European fiber-based solutions are championed by Stora Enso Oyj in Helsinki, whose emphasis on circular solutions aligns with growing environmental mandates. International Paper Company, operating from Memphis, USA, provides premium paperboard and secondary paper luxury packaging at scale. Mondi plc, also headquartered in London, drives the market forward with advanced materials and designs tailored for luxury packaging. Complementing these larger entities are specialized firms such as HH Deluxe Packaging Ltd. in London, which concentrates on high-end luxury packaging and presentation solutions, and Winter and Company AG in Zug, Switzerland, known for luxury gift boxes and premium packaging. BDMO, based in Belgium, rounds out this competitive cohort with a focus on luxury cardboard packaging for cosmetics and gifts.
The competitive landscape is moderately consolidated. The top three players command a combined market share of 24.6 percent, while the top five extend their influence to 26.2 percent. This concentration indicates that while dominant players hold significant sway, substantial room remains for specialized competitors and regional leaders to carve out profitable niches. Understanding the specific strengths and strategic vulnerabilities of each competitor is essential for positioning your own offerings effectively.
Market Dynamics and Structural Shifts
Material Economics and Supply Chain Pressures
The cost environment for luxury packaging materials has become increasingly volatile. Paper prices remain elevated due to sustained global demand, higher energy costs for production, and increased reliance on recycled fibre. This pressure is compounded by regulatory and market forces affecting alternative materials. Plastic prices have risen notably, with contract increases of nearly 20 percent for polyethylene and polypropylene used in packaging. These cost dynamics directly impact margin structures and force brands to make difficult trade-offs between material choice, aesthetic quality, and cost efficiency.
Regulatory Headwinds and Opportunities
Regulatory frameworks are reshaping the operational landscape. The European Union's Packaging and Packaging Waste Regulation targets over-packaging with mandates for reduced material use in luxury segments. Compliance is no longer optional; it is a strategic imperative that influences design specifications, material sourcing, and end-of-life considerations. In the United Kingdom, Extended Producer Responsibility fees for 2025-2026 set producer charges at 192 pounds per tonne for glass and 196 pounds per tonne for paper and card. These fee structures incentivize material optimization and circular design approaches, rewarding companies that can reduce weight without compromising perceived quality.
Innovation in Action: Recent Developments Defining the Market
The pace of innovation in luxury packaging is accelerating, driven by sustainability mandates, consumer demand for experiences, and technological advancements. Recent milestones highlight the industry's commitment to redefining what luxury packaging can achieve.
Showcasing Circular Solutions
At the Luxe Pack Shanghai trade show in May 2026, Stora Enso showcased innovative fiber-based packaging solutions redefining circular luxury. This demonstration underscored the growing viability of sustainable materials that do not sacrifice the tactile and visual qualities expected in premium segments. Meanwhile, Luxe Pack New York returned with record-breaking figures, featuring premium materials, smart packaging, and a strong sustainability focus. These events signal that the intersection of luxury and sustainability is no longer a niche interest but a mainstream expectation.
Investment in Capabilities
Infrastructure investments are reinforcing the industry's innovation capacity. In April 2026, Mondi inaugurated a new innovation center in Milan dedicated to advanced materials and designs for luxury packaging. This facility will serve as a hub for developing next-generation solutions that meet evolving brand and regulatory requirements. Earlier in the year, in January 2026, James Cropper secured funding to expand production capacity for luxury packaging papers, addressing the growing demand for high-quality fiber-based substrates. These developments illustrate that leading players are committing significant resources to staying ahead of market trends.
Strategic Implications for 2026 Decision-Makers
The luxury packaging market offers substantial growth potential, but realizing that potential requires more than passive observation. Executives must adopt a proactive stance, leveraging data-driven insights to inform strategy across multiple dimensions.
Aligning Material Strategy with Regulatory and Cost Realities
With raw material costs under pressure and regulations tightening, brands must reassess their material portfolios. The shift toward fiber-based and recycled solutions is gaining momentum, but the transition must be managed carefully to maintain premium perception. Understanding the cost implications of different material choices, including regulatory fees and supply chain risks, is critical for maintaining profitability while meeting sustainability targets.
Capitalizing on Regional and Application-Specific Opportunities
Growth is not uniform across all segments. Certain applications and regions are outpacing others, driven by consumer wealth, brand investment, and cultural preferences. Identifying where demand is concentrated and which customer segments are most willing to pay for premium packaging enables more targeted product development and marketing efforts. The ability to tailor offerings to specific luxury sub-segments, whether in cosmetics, fashion, or premium beverages, can significantly enhance competitive differentiation.
Leveraging Competitive Intelligence for Strategic Positioning
The moderately consolidated nature of the market means that both large players and specialized firms have opportunities to thrive. Understanding competitor capabilities, innovation pipelines, and strategic focus areas allows companies to identify gaps in the market and position themselves effectively. Whether through partnerships, acquisitions, or organic innovation, strategic Positioning requires a clear view of the competitive terrain.
Preparing for the Future
The forecast period extending to 2032 suggests that the luxury packaging market will continue its expansion, but the composition of that growth will evolve. Companies that invest now in flexible manufacturing capabilities, sustainable material portfolios, and customer-centric design processes will be best positioned to capture long-term value. Those that delay adaptation risk being squeezed by cost pressures, regulatory constraints, and shifting consumer expectations.
Why This Research Matters Now
In a market defined by rapid change, incomplete information is a liability. The insights contained in this report are designed to equip executives with the knowledge needed to make confident, forward-looking decisions. From material economics and regulatory impacts to competitive dynamics and innovation trends, every aspect of the luxury packaging ecosystem is examined with the rigor required for high-stakes strategy development.
The data presented here represents only a fraction of what is available. Our full market research provides detailed segmentation analysis, granular regional breakdowns, application-specific growth drivers, and comprehensive competitor profiles. It includes actionable recommendations for supply chain optimization, product portfolio strategy, and market entry or expansion planning. For organizations serious about competing in the luxury packaging sector, this depth of intelligence is indispensable.
Your Next Step
The luxury packaging market is evolving at an accelerating pace. The decisions made in 2026 will shape competitive positioning for years to come. To access the complete analysis, including detailed segmentation data, regional market sizes, application breakdowns, and in-depth competitor evaluations, we invite you to explore our full market research report. Equip your organization with the strategic intelligence needed to navigate this dynamic landscape and capture the value that lies ahead.
Luxury Packaging Market
For detailed analysis of this topic, please visit the official page: Luxury Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Portable Polishing Machine Market Size, Share & Forecast Report, 2034
By Manisha , 2026-09-16
Market revenue has shown consistent growth from 2020 to 2025, reflecting increasing industrial demand and technological progress. Projections indicate the market size will reach $2,050 Million in 2025 and is expected to double by 2035, driven by innovation and expansion in emerging markets.
Read More - https://bussinessinsights.com/research-report/global-portable-polishing-machine
Automotive applications account for the highest market share owing to the industry’s demand for surface finishing, restoration, and refurbishment. Metalworking constitutes the second-largest segment, while electronics and construction are emerging as significant contributors due to the trend towards miniaturization and infrastructure development. Aerospace and household applications are showing steady, niche growth.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-portable-polishing-machine
Frequently Asked Questions
Who are the key players in Global Portable Polishing Machine industry?
The top 5 players in the Global Portable Polishing Machine industry are 3M, Bosch, Dewalt, Hitachi, and Makita. These companies are recognized for their innovative technologies, strong distribution networks, and broad product portfolios, driving consistent advancement and competitive pricing in the market worldwide.
What is the Global Portable Polishing Machine growth?
The Global Portable Polishing Machine market has experienced significant growth, with a CAGR of around 7% in recent years. This surge is driven by increasing demand in automotive and construction industries, with companies like Bosch launching advanced models catering to efficiency and user safety.
Which segment accounted for the largest Global Portable Polishing Machine share?
The automotive industry segment holds the largest share of the Global Portable Polishing Machine market. Polishing machines are essential for car maintenance, repair, and detailing — making them indispensable tools in auto shops and service centers, which continually drive the adoption of these portable machines.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Pressure Sensors Market to Hit $22.88B by 2032 at 6.5% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Pressure Sensors Market: Navigating 2026 and Beyond
Executive Overview
The global pressure sensors market stands at a critical inflection point as we move through 2026. Following a trajectory of consistent expansion from 2020 through 2025, the sector has matured into a complex landscape where technological differentiation, supply chain resilience, and regional dynamics converge to shape competitive outcomes. Our latest market research provides decision-makers with a comprehensive, data-backed roadmap to navigate this evolving environment, offering actionable intelligence that extends far beyond superficial market summaries.
Understanding the pressure sensors market requires more than tracking headline numbers. It demands a granular appreciation of how type-specific demand shifts, application-driven procurement cycles, regional adoption patterns, and competitive maneuvers interact to create both risk and opportunity. This report is designed for executives, product strategists, procurement leaders, and investors who require precision intelligence to allocate capital, prioritize R&D pipelines, and position portfolios against structural market shifts.
While broader market indicators provide essential context for strategic planning, the true value of this research lies in its operational depth. We examine the underlying drivers that will determine which organizations capture disproportionate value in the years ahead, and which risk being displaced by more agile, technologically adept competitors.
Medical Pressure Sensors Market
Macro Trajectory and Strategic Context
The pressure sensors market has demonstrated robust growth over the past half-decade, with total market revenue expanding from approximately 10.8 billion USD in 2020 to an estimated 14.75 billion USD by 2025. This expansion reflects sustained demand across industrial automation, automotive electrification, medical device innovation, and infrastructure modernization. Looking forward, the market is projected to continue its upward trajectory through the 2026 to 2032 forecast period, with a compound annual growth rate of 6.5 percent. By 2032, total market revenue is anticipated to reach 22.88 billion USD, underscoring the sector's long-term structural momentum.
Such macroeconomic visibility is valuable, but it is only the starting point for informed strategy. Growth rates mask significant variation in how different sensor categories perform, how regional markets evolve at divergent paces, and how application-specific procurement behaviors reshape purchasing patterns. Executives who rely solely on aggregate forecasts risk misallocating resources or misjudging the timing of market entry and exit decisions. Our research dissects these layers of complexity, enabling leaders to build plans grounded in segment-level reality rather than top-line approximation.
Pressure Sensors Market
The forecast period also coincides with a phase of heightened industry volatility. Supply chain reconfiguration, raw material cost pressures, regulatory certification burdens, and tariff-driven production economics are simultaneously reshaping cost structures and competitive positioning. Organizations that anticipate these dynamics and embed flexibility into their operating models will be better equipped to preserve margins and accelerate time-to-market, even as the broader environment grows more challenging.
Key Industry Dynamics Shaping 2026
-
Reciprocal tariff policies across major economies have introduced new cost pressures and forced supply chain reconfiguration decisions for pressure sensor manufacturers. Producers must now weigh the trade-offs between localized production, diversified sourcing, and inventory strategy in ways that directly affect unit economics and delivery reliability.
-
Silicon wafer availability and broader semiconductor material supply constraints continue to influence production timelines for piezoresistive pressure sensor manufacturing. These disruptions ripple through component lead times, capacity planning, and qualification cycles, particularly for organizations dependent on high-volume MEMS fabrication.
-
Stainless steel and ceramic pressure sensor cells face mounting price erosion and margin compression as elevated material and labor costs intersect with high-volume production demands. This environment rewards manufacturers that can optimize bill-of-materials efficiency, streamline assembly processes, and differentiate through performance rather than commodity cost alone.
-
Hazardous area certifications such as ATEX and IECEx add 20 to 30 percent to product development costs for industrial pressure sensors. For companies targeting process industries, oil and gas, and utility applications, certification strategy and time-to-certification have become critical determinants of commercial viability and competitive reach.
These dynamics do not affect every segment equally. Some categories benefit from resilience in high-precision or specialized applications, while others experience intensified price competition as commoditized solutions encounter cost headwinds. The research unpacks which segments are most exposed, which are insulated by technical barriers, and how leading players are adjusting their portfolios to navigate the new cost and compliance reality.
Competitive Landscape and Strategic Positioning
The pressure sensors market features a diverse field of established multinational manufacturers, specialized engineering firms, and technology-focused innovators. Competitive advantage in this environment is increasingly defined not by scale alone, but by the ability to combine material science expertise, packaging innovation, application-specific calibration, and compliance readiness into solutions that reduce total cost of ownership for end users.
Several core companies illustrate the range of strategic approaches shaping the market. Honeywell International Inc. continues to strengthen its industrial, transportation, and HVAC portfolio through heavy-duty pressure sensors, board-mount solutions such as the ABP series, and high-pressure transducers leveraging piezoresistive technology. Its recent introduction of a 13MM pressure sensor tailored for cleanroom semiconductor environments highlights how targeted product development can open doors in highly specialized, standards-driven applications.
TE Connectivity Ltd. maintains a broad technology footprint spanning board-level devices, media-isolated sensors, and pressure transducers built on piezoresistive MEMS and silicon strain gauge architectures. Its ability to serve medical, industrial, automotive, and aerospace sectors with pressure ranges spanning from ultra-low to extremely high values demonstrates the commercial power of versatile platform technologies. Merit Sensor complements this landscape with surface-mount piezoresistive sensors and modules focused on ultra-low-pressure differential and gage measurement for industrial use, reflecting a strategy centered on precision in demanding control environments.
In the industrial and utility segment, ABB Ltd. has expanded its offering with a new P-Series pressure transmitter portfolio designed for high-precision measurement, reinforcing its emphasis on robust, chemically resistant, and ingress-protected devices. Gems Sensors & Controls, Setra Systems, Ashcroft Inc., and SSI Technologies each contribute ruggedized designs and application-focused engineering, targeting demanding fluid measurement, HVAC, material handling, and high-accuracy industrial environments. These firms illustrate how physical durability, environmental resilience, and tailored form factors remain decisive in sectors where failure costs are high.
High-temperature and extreme-environment capability represents a distinct competitive frontier. Sentek Instrument has advanced its position through the NovaPT-E sapphire pressure sensor, which has demonstrated reliable operation at pulse temperatures up to 1500 degrees Celsius and demodulation at frequencies up to 60 kHz. Its recent contract win to supply high-temperature sensors to a major jet engine manufacturer for applications above 1000 degrees Celsius underscores the growing importance of extreme-environment measurement in aerospace and advanced propulsion systems.
On the component and integration side, Amphenol Corporation, Microsensor Corporation, MPI Melt Pressure, and several semiconductor-centric players contribute specialized capabilities ranging from leadless miniature packages to custom melt-pressure measurement solutions. Meanwhile, Bosch Sensortec, NXP Semiconductors, and STMicroelectronics embed pressure sensing functionality within broader IC and MEMS platforms, particularly for automotive and consumer applications. This segmentation between discrete sensor specialists and integrated semiconductor suppliers creates distinct value chains, each with its own cost structure, innovation cadence, and customer engagement model.
Market concentration remains moderate, with the top three firms and top five firms collectively holding meaningful but not dominant shares of total revenue. This structure suggests that while scale advantages and distribution reach matter, there is substantial room for specialized players to win on performance, certification, customization, and service. The research evaluates how these concentration patterns are likely to evolve as consolidation, partnerships, and technology platform strategies reshape competitive boundaries.
Report Scope and Actionable Intelligence
This market research is built for operational decision-making. It moves beyond descriptive analysis to deliver the kind of structured intelligence that product leaders, strategy teams, and commercial executives can translate directly into planning and execution. The report's content is designed to answer the questions that matter most when allocating resources and defining market strategy in 2026 and beyond.
What the Report Covers
-
Market sizing and forecast architecture across the full 2020 to 2032 timeline, with a focused 2026 to 2032 forecast window that supports near-term budget planning and longer-term portfolio strategy.
-
Detailed segmentation analysis by type, application, and region, enabling readers to identify where demand is strengthening, where saturation risk is rising, and where white space remains for differentiated offerings.
-
Competitive profiling of major participants, including technology positioning, product capabilities, geographic reach, and recent strategic actions that signal where each company is placing its bets.
-
Recent industry developments, including product launches, contract wins, and milestone achievements that illustrate the pace of innovation and the practical direction of market demand.
-
Regulatory, certification, and compliance considerations that affect development timelines, cost structures, and market access in industrial, medical, and hazardous-area applications.
-
Supply chain and input-cost dynamics, with attention to materials, semiconductor dependencies, labor economics, and tariff exposure that influence margin outcomes and sourcing strategy.
-
Strategic frameworks for interpreting segment attractiveness, prioritizing investment, and aligning product roadmaps with the most resilient demand vectors.
Who Should Use This Research
-
Corporate strategy and business development teams seeking to assess market entry, expansion, partnership, or acquisition opportunities.
-
Product managers and R&D leaders responsible for sensor portfolio planning, feature prioritization, and technology roadmapping.
- Procurement and supply chain executives evaluating supplier options, cost risk, and resilience strategies in a shifting materials and tariff environment.
-
Investors and market analysts requiring structured, defensible market intelligence to support valuation, due diligence, and sector monitoring.
-
Engineering and operations leaders in end-user industries who need to understand sensor capability trends, compliance requirements, and integration implications.
Why This Research Matters for 2026 Decisions
The pressure sensors market in 2026 is not simply larger than it was five years ago; it is more structurally complex. Growth persists, but the sources of growth are spreading across different sensor types, applications, and regions at uneven rates. At the same time, cost pressures from materials, labor, tariffs, and certification requirements are compressing the economics of commoditized segments while elevating the strategic importance of performance, reliability, and application-specific engineering.
In this environment, effective decision-making depends on understanding not just where the market is going, but why it is going there and what that implies for competitive positioning. A forecast number can inform revenue targets, but only a detailed segmentation and competitive analysis can reveal which product lines deserve investment, which customer segments warrant deeper engagement, and which supply chain assumptions need to be stress-tested.
Our research is designed to provide exactly that level of clarity. It gives executives the evidence needed to challenge assumptions, prioritize initiatives, and reduce uncertainty in planning cycles. By linking market size and growth trajectories to segment-level mechanics and real-world competitive moves, the report helps organizations align strategy with the realities of demand, cost, and technology development.
The complete analysis contains the detailed segmentation data, company-by-company competitive evaluation, and scenario-sensitive interpretation needed to support high-stakes decisions. Readers who require the full depth of market sizing, segment breakdowns, and strategic benchmarking are encouraged to access the complete report through our source page, where the full intelligence package is available for immediate use in strategic planning.
Conclusion
The pressure sensors market offers substantial opportunity for organizations that can combine technological credibility, supply chain discipline, and segment-focused strategy. With sustained growth projected through 2032 and a competitive landscape that rewards differentiation, the window for proactive positioning is open, but it is not unlimited. Tariff exposure, material constraints, certification costs, and evolving end-user requirements will continue to test companies that rely on generic product strategies or rigid operating models.
This report provides the strategic foundation needed to act with confidence in 2026. By translating market-scale trends into operational insight, it enables leaders to make sharper investment decisions, build more resilient supply strategies, and target the applications and regions where the next wave of value creation will emerge. The full research details are available through our source page for teams ready to move from awareness to action.
For detailed analysis of this topic, please visit the official page: Pressure Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Market revenue for global water filter cartridges reached $6,820 million in 2020 and is forecast to grow to $8,150 million by 2025 and $16,100 million by 2035, representing a consistent upward trajectory over the next decade. This sustained growth is attributed to escalating applications across household, industrial, and municipal sectors, coupled with technological advancements and heightened regulatory standards for water safety. The increasing adoption of advanced filtration technologies will be pivotal in driving future revenue, especially in emerging markets.
Read More - https://bussinessinsights.com/research-report/global-water-filter-cartridges
Residential applications dominate the global water filter cartridges market in 2025, capturing 45% of the total share, driven by rising consumer demand for clean drinking water. Industrial and commercial segments collectively represent a substantial part of demand, with growth attributed to regulatory compliance and the need for process water purification. Healthcare and municipal applications, while smaller, are benefiting from tailored solutions targeting specific water quality requirements. The growth across these segments underscores the crucial role of filtration cartridges in maintaining health and safety standards across varying end-user categories.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-water-filter-cartridges
Frequently Asked Questions
Who are the key players in Global Water Filter Cartridges industry?
The top five players in the global water filter cartridges market are Pentair, 3M, Culligan, Brita, and GE Appliances. These companies are recognized for their extensive R&D, global distribution networks, innovative product developments, and a strong presence in both residential and commercial filtration solutions worldwide.
What is the Global Water Filter Cartridges growth?
The global water filter cartridges market has seen robust growth, with a compound annual growth rate (CAGR) of over 6% from 2021 to 2024. Companies like Pentair have reported increased sales, driven by rising consumer awareness of water quality and health, as well as expanding urbanization.
Which segment accounted for the largest Global Water Filter Cartridges share?
The residential segment holds the largest market share in the global water filter cartridges market. This is due to the increasing demand for clean drinking water at home, coupled with growing health concerns and the adoption of water filtration systems in urban households worldwide.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Pool Cleaners Market Hits $115M in 2025, Set to Hit $197.09M by 2032, Growing at 6.23% CAGR
By PW Consulting, 2026-09-16
Navigating the Blue Economy: Strategic Insights from the 2026 Pool Cleaners Market Intelligence Report
The landscape of aquatic maintenance is undergoing a profound transformation, driven by converging technological innovations and shifting consumer expectations. As industry leaders prepare for the remainder of the decade, access to precise, forward-looking intelligence is no longer merely advantageous; it is essential for sustained competitive advantage. This article serves as a strategic preview of our latest comprehensive research initiative, designed to equip stakeholders with the analytical clarity required to navigate the Pool Cleaners Market through 2032. By synthesizing historical performance with forward-looking projections, this report constructs a robust framework for capital allocation, product development, and market positioning.
Pool Cleaners Market
Macro Trajectory and Structural Growth Dynamics
The global pool cleaning equipment sector has demonstrated remarkable resilience and steady expansion over the past half-decade. Historical analysis reveals a consistent upward trajectory, with market valuation climbing from 85.0 million USD in 2020 to approximately 115.0 million USD by the 2025 base year. This growth reflects broader macroeconomic trends, including rising disposable incomes in mature markets, increased installation of private swimming facilities, and a growing emphasis on automated home maintenance solutions. Looking ahead, the forecast period spanning 2026 through 2032 indicates sustained momentum, with the market projected to reach 197.09 million USD by the terminal forecast year. This expansion corresponds to a compound annual growth rate of 6.23 percent, signaling a stable, moderately paced growth environment rather than a speculative boom.
It is important to recognize that such aggregate figures represent more than simple linear expansion. They embody a structural evolution in how consumers and facility managers approach water quality, chemical reduction, and time allocation. The steady CAGR underscores a mature yet innovation-driven ecosystem where incremental improvements in engineering, user experience, and energy efficiency compound over time. For executive teams, understanding this trajectory means recognizing that market share gains will increasingly depend on product differentiation, brand trust, and the ability to anticipate regional purchasing behaviors rather than on volume-driven price competition alone.
Technological Inflection Points and Product Evolution
The past eighteen months have witnessed a pronounced shift toward intelligent, connected, and highly autonomous cleaning systems. CES 2026 served as a visible showcase for this evolution, with multiple industry participants unveiling next-generation platforms that leverage artificial intelligence, advanced navigation protocols, and hybrid power architectures. These product launches are not isolated marketing events; they reflect a broader industry consensus that the next phase of value creation will be captured by manufacturers who successfully integrate smart diagnostics, adaptive cleaning patterns, and user-centric design into mainstream offerings.
Pool Chemical Market
Robotic systems have emerged as a particularly dynamic segment, increasingly favored for their operational efficiency and reduced reliance on external plumbing or manual intervention. Simultaneously, traditional suction and pressure-side categories continue to evolve, benefiting from refined filtration compatibility and enhanced durability. The interplay between these product architectures creates a complex but highly actionable landscape for engineering leaders and product managers. Our research dissects the innovation cadence across these categories, analyzing how feature adoption curves align with consumer willingness to pay, installation complexity tolerances, and long-term maintenance expectations.
Competitive Landscape and Strategic Positioning
The market exhibits a moderately concentrated structure, with the top three participants collectively commanding approximately 42.5 percent of total revenue and the top five entities holding roughly 58.0 percent. This concentration suggests an environment where established brands leverage distribution networks, service infrastructure, and brand recognition to maintain defensive moats, while newer entrants and specialized manufacturers pursue aggressive differentiation through software-driven features and cordless form factors. Understanding the equilibrium between incumbent stability and challenger agility is critical for businesses evaluating partnership opportunities, acquisition targets, or internal R&D prioritization.
Key players such as Maytronics Ltd., operating from its Israeli headquarters with a strong focus on its Dolphin-branded residential and commercial robotic systems, continue to invest heavily in navigation and propulsion refinements. Hayward Industries, Inc., based in North Carolina, maintains a broad portfolio spanning robotic and traditional cleaning categories, often emphasizing brand versatility and installer familiarity. Pentair plc, headquartered in Minnesota, provides a comprehensive suite of cleaning solutions that integrate seamlessly with wider aquatic ecosystems. Fluidra S.A., headquartered in Barcelona, leverages a portfolio encompassing Polaris, Zodiac, and Aquabot offerings, with a particular emphasis on European and global distribution channels. Aiper Intelligent LLC, operating from the United States, has positioned itself at the forefront ofcordless and AI-assisted robotic cleaners, emphasizing smart navigation and consumer usability. Meanwhile, NingBo Poolstar Pool Products Co., Ltd., based in China, functions as a significant OEM/ODM partner, supporting both branded and private-label demand across multiple product categories.
Recent product activity reinforces the intensity of this competitive environment. In January 2026, Aiper Intelligent LLC introduced the Scuba V3 and Scuba V3 Pro platforms at CES, highlighting advanced artificial intelligence and smart operational capabilities. During the same event, Maytronics Ltd. launched the Dolphin EON robotic cleaner, featuring JetIQ propulsion technology, SmartMap navigation, and a hybrid power configuration. By February 2026, iGarden, under the Fairland Group umbrella, released the M1 Pro Max bionic dual-vision robotic cleaner, an initiative that was subsequently recognized as a CES 2026 Innovation Award honoree. These developments illustrate a market where engineering differentiation, rather than pure scale, increasingly determines premium positioning.
Regulatory Pressures and Supply Chain Considerations
Beyond product innovation and competitive maneuvering, external macro-forcing mechanisms are actively reshaping cost structures and sourcing strategies. As of March 2025, the United States implemented new tariff measures affecting imported raw materials and chemicals, including a twenty-five percent tariff on steel and aluminum and a ten percent tariff on Chinese-origin imports. These policy adjustments have direct ramifications for pool equipment manufacturers, component suppliers, and assembled product importers, introducing volatility into input costs and prompting strategic reevaluation of domestic versus overseas production footprints.
Such regulatory dynamics interact with broader supply chain considerations, including freight logistics, alternative material substitution, and regional manufacturing flexibility. Companies that proactively map these cost drivers into their pricing architectures, inventory planning, and vendor diversification strategies will be better positioned to preserve margins without sacrificing market accessibility. Our analysis incorporates these external pressures into a holistic assessment of market resilience, enabling decision-makers to model scenarios that account for tariff impacts, currency fluctuations, and shifting sourcing patterns.
Probing Beyond the Surface: What This Research Delivers
While the macroeconomic trajectory and competitive framing provide a necessary foundation, the true strategic value of this research lies in its granular, decision-oriented architecture. The full study is engineered to support cross-functional teams with actionable intelligence across multiple dimensions. Key components include:
- A comprehensive segmentation analysis that isolates performance drivers across product architectures, installation environments, and geographic demand clusters, allowing leadership to identify high-conviction growth pathways without relying on generic market narratives.
- Detailed demand behavior profiling that examines purchase frequency, feature prioritization, installer influence, and post-sale service expectations, helping product and marketing teams align development roadmaps with real-world adoption patterns.
- Competitive intelligence mapping that evaluates brand positioning, innovation pacing, distribution reach, and strategic response patterns among leading manufacturers and emerging challengers, enabling precise benchmarking and gap identification.
- Supply chain and cost-structure assessments that contextualize input volatility, component dependency, and regional manufacturing considerations, supporting procurement and financial planning under varying tariff and logistics scenarios.
- Scenario-based forecasting frameworks that translate historical performance and forward indicators into actionable revenue expectations, capacity planning inputs, and market entry timing assessments.
Each analytical module is designed to answer specific strategic questions: Which product developments command premium acceptance in high-growth demand clusters? How are incumbent brands defending share against software-led entrants? Where do distribution partnerships and regional service networks create the most durable competitive advantages? By addressing these questions with methodological rigor and clearly sourced data, the study transforms raw market signals into executable strategic guidance.
Implications for 2026 Decision-Making
Entering the second half of the decade, businesses operating in or adjacent to this sector face a defining set of choices. The convergence of artificial intelligence-driven cleaning routines, cordless engineering, tariff-sensitive supply chains, and evolving consumer expectations creates an environment where reactive strategies will be quickly outpaced by proactive, data-informed positioning. Organizations that treat market intelligence as a continuous input rather than a periodic report will be better equipped to time product launches, allocate marketing spend, negotiate supplier contracts, and evaluate partnership or acquisition opportunities.
This research publication is specifically structured to serve that purpose. It provides executive teams, strategy directors, product leaders, and investment analysts with a consolidated, high-fidelity view of market mechanics, enabling them to separate structural growth from temporary noise. By grounding strategic planning in clearly delineated trend lines, competitive benchmarks, and segment-level demand dynamics, stakeholders can construct more resilient operating plans and reduce the uncertainty associated with capital deployment.
Strategic Access and Forward Engagement
The complete research deliverable extends well beyond the high-level trajectory outlined here. It contains the detailed segmentation breakdowns, competitive playbooks, regional performance context, and forecasting methodologies necessary to translate awareness into execution. For organizations seeking to calibrate product roadmaps, refine pricing architectures, evaluate market entry timing, or benchmark against the most active industry participants, the full report offers the depth required to make those decisions with confidence.
This preview demonstrates the analytical rigor and strategic orientation embedded in our research methodology. To access the complete segmentation matrices, company-specific competitive assessments, scenario-driven forecasts, and the full spectrum of data-driven insights, we invite you to visit the official source webpage and obtain the complete Pool Cleaners Market research publication. In a market defined by steady expansion, accelerating technological iteration, and shifting regulatory cost structures, precision intelligence is the most effective differentiator for businesses committed to long-term growth and market leadership.
For detailed analysis of this topic, please visit the official page: Pool Cleaners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Rolling Ring Turnings Crusher Market Size, Share & Forecast Report, 2034
By Manisha , 2026-09-16
Global revenues for rolling ring turnings crushers are forecasted to rise from $680 Million in 2020 to $1,430 Million by 2035, reflecting a strong CAGR driven by industrial automation, sustainability imperatives, and emerging market expansion. Key revenue surges in 2025 are linked to increased investments in green infrastructure and technological retrofits in existing plants, while gradual market maturation moderates later growth years.
Read More - https://bussinessinsights.com/research-report/global-rolling-ring-turnings-crusher
Metal recycling remains the primary application in 2025, commanding a 40% share, fueled by robust government regulations and sustainability drives. Mining holds 25% share due to continued commodity extraction, followed by Metallurgy at 18%. Usage in waste management, construction, and other sectors comprise the balance. This allocation underscores the sector's essential role in the lifecycle of metals, supporting circular economy ambitions and ongoing urbanization.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-rolling-ring-turnings-crusher
Frequently Asked Questions
Who are the key players in Global Rolling Ring Turnings Crusher industry?
The top five players in the global Rolling Ring Turnings Crusher industry include Metso Outotec, BHS Sonthofen, PRAB, Erdwich Zerkleinerungs-Systeme, and Shredwell Recycling. These companies specialize in advanced metal recycling solutions, focusing on high-efficiency crushers, innovative designs, global distribution networks, and strong after-sales services, driving sectoral competitiveness.
What is the Global Rolling Ring Turnings Crusher growth?
The global Rolling Ring Turnings Crusher market has experienced robust growth in recent years, fueled by rising metal recycling rates and expansion in the manufacturing sector. Metso Outotec, for instance, reported increased sales in metal recycling equipment in 2023, reflecting growing demand from automotive and heavy industries.
Which segment accounted for the largest Global Rolling Ring Turnings Crusher share?
The automotive scrap processing segment accounted for the largest share in the Rolling Ring Turnings Crusher market. This is due to the significant volume of metal turnings generated by automotive manufacturing and the growing emphasis on sustainability and metal reuse within the automotive value chain.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com