Agritourism Market to Witness Strong Growth Through 2034, Supported by Rising Demand for Rural Experiences
By Punampatil2001, 2026-11-20
Global Agritourism Market Overview
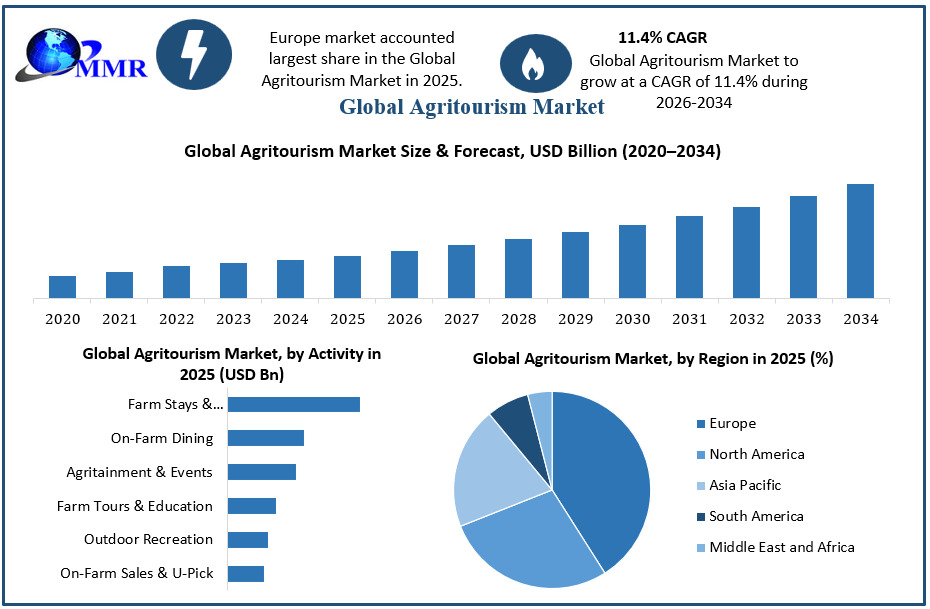
The Global agritourism market is experiencing significant growth as travellers increasingly seek authentic rural experiences, nature-based tourism and opportunities to understand agricultural activities. The global agritourism market was valued at USD 11.6 billion in 2025 and is projected to reach USD 30.6 billion by 2034 , registering a CAGR of 11.4% during 2026–2034 . The market is estimated to reach USD 12.9 billion in 2026, reflecting growing interest in farm-based tourism and diversified agricultural businesses.
Agritourism combines agricultural activities with tourism services, allowing visitors to experience farm stays, vineyard tours, fruit picking, farm-to-table dining, educational programmes and recreational activities. Farmers are increasingly adopting tourism as an additional revenue source to reduce their dependence on traditional agricultural income. Rising disposable incomes, changing travel preferences and growing interest in sustainable tourism are supporting market expansion. Digital booking platforms and social media are also helping small farms reach domestic and international tourists.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/330929/
Market Growth Drivers and Opportunities
Increasing demand for experiential tourism is one of the major factors driving the agritourism market. Modern travellers are showing greater interest in peaceful rural destinations, outdoor recreation, traditional food experiences and direct interaction with farming communities. Families, educational institutions and international tourists are increasingly choosing agricultural destinations for recreational and learning purposes.
Farm income diversification is another important growth driver. Fluctuating agricultural commodity prices, rising production costs and unpredictable weather conditions encourage farmers to develop additional revenue streams through accommodation, guided tours, agricultural workshops and farm retail. The expansion of premium farm stays, vineyard resorts, camping facilities and farm-to-table restaurants is creating attractive investment opportunities.
Furthermore, government initiatives supporting rural development, sustainable tourism and agricultural entrepreneurship are encouraging farmers to enter the tourism sector. Educational tourism, wellness retreats, organic farming experiences and digital booking solutions are expected to create new opportunities for market participants.
U.S. Agritourism Market: Latest Trends and Investments
The United States is witnessing growing demand for farm-based accommodation, agricultural entertainment, rural recreation and farm-to-table experiences. In September 2026, Airbnb partnered with American Farmland Trust to introduce the Farm to Stay Grant Program, offering eligible farmers and ranchers grants of up to USD 10,000 to establish or expand farm stays and visitor experiences. American farms on Airbnb generated nearly USD 120 million in 2025 through farm stays, highlighting the commercial potential of the sector. Additionally, USDA announced USD 32.4 million in funding under its Local Agriculture Market Program in April 2026, supporting local food enterprises and direct producer-to-consumer activities. These investments are expected to improve farm infrastructure, digital visibility and tourism opportunities across rural communities.
Agritourism Market Segmentation Analysis
The agritourism market is segmented by activity, farm type, tourist type, visitor group, booking channel and visit type.
By Activity: Farm Stays and Accommodation hold the largest revenue share. Overnight visitors generate higher spending through accommodation, meals and additional farm experiences compared with day visitors.
By Farm Type: Vineyards and Wineries represent an important high-value segment because wine tasting, premium dining, events and vineyard accommodation attract higher visitor spending.
By Tourist Type: Domestic tourists account for the largest number of visits, supported by accessible rural destinations, family travel and weekend tourism.
By Visitor Group: Families represent the leading visitor group, driven by demand for outdoor activities, educational experiences, animal interactions and recreational farm visits.
By Booking Channel: Direct Booking holds the largest share, supported by repeat customers, local visitors and direct relationships between farm operators and tourists.
By Visit Type: Day Visits dominate visitor volume, while short and extended stays contribute higher revenue through accommodation and bundled activities.
Competitive Analysis
The global agritourism market is fragmented, with online travel platforms, farm-stay marketplaces and specialised experience providers competing through digital distribution, customer engagement and unique rural experiences.
1. Airbnb, Inc.
Airbnb is expanding its farm-stay business through digital accommodation listings and agricultural experiences. Its partnership with American Farmland Trust introduced the Farm to Stay Grant Program in September 2026, providing financial support of up to USD 10,000 per eligible farm. This initiative can encourage more farmers to offer accommodation, workshops and agricultural tourism activities.
2. Booking Holdings Inc.
Booking Holdings is strengthening its travel technology through artificial intelligence, personalised recommendations and digital booking solutions. Booking.com's AI-powered Smart Filters, Property Q&A and review summaries help travellers identify suitable accommodation more efficiently. These innovations can improve the discovery of rural accommodation and farm-based tourism experiences.
3. Expedia Group, Inc.
Expedia Group is investing in artificial intelligence and travel-discovery technologies to improve customer experiences. In May 2025, the company introduced Expedia Trip Matching, which transforms Instagram travel reels into personalised, bookable travel recommendations. Its expanded technology platform also supports activities and experience bookings, creating opportunities for rural tourism operators to reach more customers.
4. Tripadvisor, Inc. (Viator)
Tripadvisor, through Viator, is strengthening its experiences marketplace by investing in product development, marketing and a wider selection of bookable activities. Its focus on mobile bookings, personalised recommendations and improved tools for experience providers can support the promotion of farm tours, food experiences and rural recreational activities.
5. GetYourGuide AG
GetYourGuide is expanding its digital experiences marketplace by improving the availability and discovery of bookable activities. In January 2026, the company announced that it had achieved more than €1 billion in revenue for FY2025, with over €4 billion in gross merchandise value and more than 33 million experiences booked. Its growing marketplace provides opportunities for specialised agricultural tours and authentic local experiences to reach international travellers.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/330929/
Regional Analysis
United States: The United States is a major agritourism market, supported by its extensive agricultural landscape and established tourism infrastructure. Farms generate revenue through pumpkin patches, corn mazes, wineries, fruit picking and farm accommodation. Government support through agricultural marketing grants and state-level agritourism liability protection encourages farm diversification and investment.
United Kingdom: The UK market benefits from established farm holidays, countryside accommodation, farm shops and educational tourism. Government support for rural business diversification and tourism development encourages farmers to introduce accommodation, recreational activities and local food experiences. Growing interest in countryside holidays is also supporting demand.
Germany: Germany has a well-developed rural tourism industry, supported by farm holidays, agricultural experiences and countryside accommodation. Its National Tourism Strategy focuses on improving tourism competitiveness, connectivity and reducing administrative burdens for tourism businesses. Strong domestic travel demand and interest in sustainable holidays support market development.
France: France benefits from its established agricultural heritage, vineyards, cheese production and culinary tourism. The Bienvenue à la Ferme network and Gîtes de France promote rural accommodation and farm-based experiences. Government support for rural development and agricultural diversification further encourages tourism activities.
Japan: Japan is developing agritourism through green tourism programmes that connect urban visitors with rural communities. Farm stays, traditional food experiences, fruit picking and agricultural workshops are attracting domestic and international tourists. Government initiatives supporting regional revitalisation and rural tourism are creating opportunities for small agricultural businesses.
China: China is witnessing growing demand for rural leisure tourism, supported by government-led rural revitalisation initiatives. Development of leisure agriculture villages, rural tourism routes and agricultural experience centres is encouraging investment. The country's large domestic travel market and increasing interest in traditional farming experiences are supporting sector expansion.
Europe holds the largest regional share of the global agritourism market, while Asia Pacific is the fastest-growing region. The six countries discussed above have different growth opportunities based on agricultural resources, tourism infrastructure and government support.
► Get to Know More About This Market Study: https://www.maximizemarketresearch.com/market-report/agritourism-market/330929/
Conclusion
The global agritourism market is expected to experience strong growth through 2034 as consumers increasingly prefer authentic rural holidays, sustainable tourism and agricultural experiences. The projected increase from USD 11.6 billion in 2025 to USD 30.6 billion by 2034 highlights the growing commercial importance of farm-based tourism.
In my view, the most significant growth opportunity lies in combining traditional agriculture with modern hospitality and digital booking technologies. Investment in premium farm stays, farm-to-table dining, educational tourism, organic farming experiences and year-round recreational activities can create additional income for farmers while strengthening rural economies. Government grants, improved rural infrastructure and partnerships with online travel platforms will further accelerate industry development. Companies that focus on authentic experiences, sustainable operations, customer satisfaction and digital accessibility are likely to benefit from the expanding global agritourism industry.
About Maximize Market Research:
Maximize Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Contact Maximize Market Research:
3rd Floor, Navale IT Park, Phase 2
Pune Banglore Highway, Narhe,
Pune, Maharashtra 411041, India
sales@maximizemarketresearch.com
+91 96071 95908, +91 9607365656
Global White Hydrogen Market to Witness Strong Growth Through 2034, Fueled by Natural Hydrogen Exploration
By Punampatil2001, 2026-11-20
Market Overview
The Global White Hydrogen Market is gaining significant attention as countries and energy companies explore naturally occurring hydrogen as an alternative source of clean energy. White hydrogen, also known as natural or geological hydrogen, is found naturally beneath the Earth's surface and can be extracted through drilling and specialised gas separation technologies. Unlike green hydrogen, which is produced through water electrolysis, white hydrogen occurs through natural geological processes such as serpentinization, radiolysis, volcanic activity and hydrothermal reactions. Its potential to provide low-carbon hydrogen without requiring energy-intensive manufacturing processes is attracting interest from the energy, chemical, refining, steel and transportation industries.
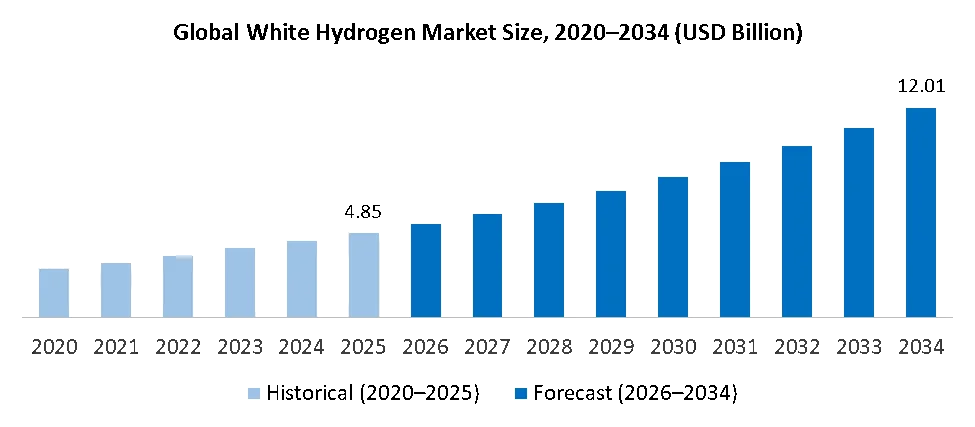
According to Maximize Market Research, the global White Hydrogen Market was valued at USD 4.85 billion in 2025 and is projected to reach USD 12.01 billion by 2034 , registering a CAGR of 10.60% during 2026–2034 . The market increased from USD 2.79 billion in 2020 to USD 4.85 billion in 2025, reflecting growing exploration activities and investment in geological hydrogen resources. Increasing demand for low-carbon fuels, rising net-zero commitments and the need for energy security are expected to strengthen market growth. Additionally, improvements in geological surveys, seismic imaging, reservoir modelling, drilling operations and hydrogen purification are creating new opportunities for commercial exploration and production.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/330589/
Growth Drivers and Market Opportunities
The increasing global focus on decarbonisation is one of the major factors supporting the growth of the White Hydrogen Market. Industries such as oil refining, ammonia production, methanol manufacturing and steelmaking require significant quantities of hydrogen. Currently, much of this demand is fulfilled through conventional fossil-fuel-based hydrogen production. Naturally occurring hydrogen offers an alternative pathway that could reduce dependence on carbon-intensive production methods.
Another important growth driver is the potential cost advantage of white hydrogen. Since it is naturally generated underground, it does not require conventional electrolysers or large renewable electricity supplies for hydrogen production. Existing oil and gas exploration expertise, drilling equipment and subsurface technologies can also be adapted for natural hydrogen exploration. However, actual production costs will depend on reservoir productivity, hydrogen concentration, extraction depth and purification requirements.
Growing investment in exploration licences, pilot drilling projects and geological research is creating further opportunities. Advanced geochemical detection, artificial intelligence-based geological modelling and improved seismic imaging can help identify underground hydrogen deposits more efficiently. The development of purification, compression, storage and transportation infrastructure will also support the transition from exploration to commercial production.
Market Segmentation Analysis
The global White Hydrogen Market is segmented by source, extraction technology and end use. Among these segments, the following categories held the largest market shares in 2025:
By Source: Serpentinization of olivine and pyroxene ultramafic rocks dominated the market with a 41% share in 2025. This process generates hydrogen through chemical reactions between water and iron-rich rocks, making it an important target for geological exploration.
By Extraction Technology: Direct extraction from underground reservoirs and natural gas fields held the largest share at 36% in 2025. The technology benefits from established drilling methods and existing oil and gas industry expertise.
By End Use: Oil and gas refining and upgrading accounted for the largest share at 31% in 2025. Refineries require substantial hydrogen for processing operations, and the transition towards lower-carbon hydrogen is supporting demand from this segment.
United States Market Trends and Investment
The United States is emerging as an important centre for white hydrogen exploration, supported by geological research, private-sector investment and the availability of established oil and gas infrastructure. The U.S. Geological Survey released its first publicly available geological hydrogen prospectivity map in January 2025, identifying areas with favourable geological conditions for natural hydrogen accumulation. This development is helping exploration companies identify promising locations and improve exploration strategies. In October 2026, Japan-based energy company JERA invested in US natural hydrogen developer Koloma through its corporate venture capital arm, JERA Ventures, to explore the potential of naturally occurring hydrogen as a future low-carbon energy source. Additionally, exploration activities in states such as Kansas and Nebraska are attracting industry attention. Government-supported geological research, regulatory developments and growing investment in advanced exploration technologies are expected to strengthen the US market.
Competitive Analysis
The global White Hydrogen Market includes specialised exploration companies, natural hydrogen developers and energy-sector investors. Five notable companies operating in this market include:
1. Koloma Inc.
Koloma is a US-based natural hydrogen exploration company focused on identifying and developing underground hydrogen resources. The company uses proprietary geological data, advanced subsurface expertise and specialised exploration tools to identify potential hydrogen deposits. In October 2026, JERA Ventures invested in Koloma to strengthen its understanding of natural hydrogen exploration and its future commercial potential. This strategic investment highlights growing interest from international energy companies in US-based natural hydrogen technologies.
2. Natural Hydrogen Energy LLC
Natural Hydrogen Energy is an exploration-focused company working on the discovery and development of naturally occurring hydrogen resources. Its activities in the United States contribute to the growing understanding of geological hydrogen reservoirs and their commercial potential. The company's participation in exploration projects and the use of geological assessment and drilling techniques support the development of the emerging natural hydrogen industry.
3. Hydroma Inc.
Hydroma is recognised for its natural hydrogen project in Bourakébougou, Mali, which has demonstrated the practical use of naturally occurring hydrogen for electricity generation. The project has supplied hydrogen-based electricity to a local village since 2012. Its operating experience provides valuable insights into natural hydrogen extraction, gas handling and potential commercial applications. Continued research into reservoir behaviour and production methods could help establish similar projects in other geological regions.
4. Gold Hydrogen Limited
Gold Hydrogen is an Australian company developing the Ramsay Natural Hydrogen Project on the Yorke Peninsula in South Australia. The company has invested in exploration drilling, well testing and advanced gas analysis to evaluate hydrogen and helium resources. In November 2026, it announced that natural hydrogen had flowed to the surface and been separated during appraisal testing at Ramsay 3. The company reported potential production of approximately 100 kg of natural hydrogen per day per well. Its work on horizontal well designs and possible green methanol production also creates opportunities for future industrial applications.
5. HyTerra Limited
HyTerra is an Australian natural hydrogen exploration company with activities in the United States and other international markets. Fortescue holds a 39.8% stake in the company, providing strategic backing for its exploration activities. HyTerra has focused on geological hydrogen exploration, appraisal drilling and the evaluation of potential commercial production. Its collaboration with ARA Natural Resources in March 2026 to evaluate geological hydrogen opportunities in Oman demonstrates its international expansion strategy. The company is also focusing on its Kansas exploration activities following the withdrawal from an early US project in November 2026 due to sub-commercial flow rates.
These companies are competing through exploration acreage, geological expertise, drilling capabilities, technological innovation and access to investment capital. However, the market remains at an early commercialisation stage, and publicly comparable company-level market-share percentages are not established.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/330589/
Regional Analysis
1. United States
The United States holds a leading position in the global White Hydrogen Market as part of North America's 36% regional market share in 2025 . The country benefits from established oil and gas infrastructure, advanced geological research and increasing private investment. Geological hydrogen prospectivity mapping and exploration activities in Kansas and Nebraska are supporting resource identification. Growing interest from energy companies and venture capital investors is expected to encourage further exploration and technological development.
2. United Kingdom
The United Kingdom is developing opportunities in natural hydrogen exploration through geological research and specialised exploration licences. Exploration companies are evaluating geological formations that could contain naturally occurring hydrogen. The country's wider hydrogen strategy, investment in clean energy technologies and research into alternative hydrogen resources provide a favourable environment for future market development. Exploration licensing and improved geological assessment could support future investment.
3. Germany
Germany represents an important potential market because of its strong industrial base and increasing demand for low-carbon energy. The country's Hydrogen Acceleration Act, effective from April 2026, introduced a clearer legal framework by classifying natural hydrogen as a freely mineable mineral resource under mining legislation. This development can facilitate exploration and future extraction activities. Industrial demand from steel, chemicals and manufacturing industries could create opportunities for natural hydrogen suppliers.
4. France
France is emerging as an important European centre for white hydrogen exploration. The country is encouraging natural hydrogen development through exploration permits, research programmes and financial support for innovative energy technologies. In May 2026, French exploration company Mantle8 secured €31 million in Series A funding, including investment through the Bpifrance-managed Ecotechnologies 2 fund. In June 2026, the French government also awarded an exclusive five-year exploration permit covering 739 square kilometres in the Pyrenees to a Mantle8 subsidiary. These developments highlight France's growing commitment to natural hydrogen exploration.
5. Japan
Japan is showing increasing interest in white hydrogen as part of its broader energy security and decarbonisation strategy. Since the country relies heavily on imported energy resources, alternative hydrogen sources could help diversify its future energy supply. Japan's Green Transformation framework and national hydrogen strategy encourage investment in low-carbon hydrogen technologies. Japanese industrial companies' interest in overseas exploration projects could support technology development and future supply partnerships.
6. China
China has significant potential for white hydrogen development because of its diverse geological formations, growing energy demand and expanding hydrogen industry. In September 2026, the China Geological Survey conducted its first dedicated geological survey for natural hydrogen resources, focusing on the Hegen Mountain region in Inner Mongolia and the Laji Mountain area in the South Qilian Mountains. The research developed new exploration methodologies and identified geological evidence of hydrogen generation. Government-supported geological research and advancements in resource assessment could create opportunities for future exploration and commercial development.
► Get to Know More About This Market Study: https://www.maximizemarketresearch.com/market-report/global-white-hydrogen-market/330589/
Conclusion
The global White Hydrogen Market is expected to experience substantial growth through 2034 as industries seek affordable and sustainable alternatives to conventional hydrogen production. Increasing exploration investment, geological discoveries, supportive government policies and technological advancements will be important factors influencing market expansion. The development of efficient drilling techniques, advanced reservoir identification, hydrogen purification and transportation infrastructure will create significant opportunities for market participants. In particular, successful pilot projects and confirmation of commercially viable underground hydrogen reserves could accelerate large-scale adoption. Companies investing in geological research, strategic partnerships and advanced extraction technologies are likely to gain competitive advantages. Overall, white hydrogen has the potential to become an important complementary source of low-carbon energy and contribute to global decarbonisation and long-term energy security.
About Maximize Market Research:
Maximize Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Contact Maximize Market Research:
3rd Floor, Navale IT Park, Phase 2
Pune Banglore Highway, Narhe,
Pune, Maharashtra 411041, India
sales@maximizemarketresearch.com
+91 96071 95908, +91 9607365656
UV Curing Systems Market to Advance Through High-Performance Curing Technologies and Green Manufacturing
By Punampatil2001, 2026-11-19
Global UV Curing Systems Market Overview
The Global UV Curing Systems Market is witnessing significant growth due to increasing demand for fast, energy-efficient and environmentally friendly curing technologies across various industries. The global UV Curing Systems Market is projected to reach USD 8.2 billion by 2034 , growing at a CAGR of 10.19% during the forecast period of 2026–2034 . UV curing systems use ultraviolet and visible light to initiate photochemical reactions that rapidly cure inks, adhesives, coatings and other materials. Unlike conventional drying methods, UV curing works through polymerization rather than evaporation, enabling faster production cycles, improved product quality and reduced processing time.
The increasing adoption of UV curing technologies in automotive manufacturing, consumer electronics, medical devices, printing, packaging and industrial machinery is a major factor driving market growth. Manufacturers are increasingly focusing on improving production efficiency, reducing operational costs and meeting environmental standards. UV curing systems offer advantages such as rapid curing, consistent surface finishing, strong adhesion and lower emissions of volatile organic compounds (VOCs). Additionally, growing demand for electric vehicles, electronic components, semiconductor devices and advanced medical equipment is creating new opportunities for UV curing equipment manufacturers. The development of UV LED technologies, automated production lines and high-performance curing systems is further expected to support market expansion.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/7189/

US Market Trends and Investments
The United States represents a major market for UV curing systems, supported by advanced manufacturing infrastructure, technological innovation and increasing demand from automotive, electronics, healthcare and printing industries. In 2024, manufacturers increasingly focused on developing high-performance UV LED curing solutions to improve production speed and energy efficiency. A significant development occurred in October 2024, when Excelitas Technologies introduced its Generation 8 Phoseon UV LED Fiber Curing System for optical fiber, electrical wire, structural wire and smart fabric applications. The new system incorporates a three-part reflector design that improves irradiance at the fiber by approximately 20%, enabling faster production speeds and improved curing performance. This innovation highlights the growing investment in advanced UV LED technology in the United States. Furthermore, increasing emphasis on sustainable manufacturing, industrial automation and reduced energy consumption is expected to create additional opportunities for UV curing system suppliers.
Market Segmentation Analysis
The UV Curing Systems Market is segmented based on technology, type, pressure, application and end-user industries. Among the technology segments, Mercury-Based UV Lamps are expected to hold a dominant market share due to their established use in industrial manufacturing and printing applications. These systems offer reliable curing performance and are widely adopted for high-speed production processes.
Based on type, the Spot Cure segment held the largest market share. Spot curing systems are extensively used in precision manufacturing, electronics assembly and industrial applications where localized and controlled UV exposure is required. By pressure, the High-Pressure segment is expected to maintain a dominant position because of its high-intensity output, which supports the curing of deeper coating layers in automotive, industrial and consumer electronics applications. The increasing demand for low-power, high-output (LPHO) lamps is also supporting segment growth.
Competitive Landscape and Top 5 Companies
The global UV curing systems industry is competitive, with manufacturers focusing on product innovation, energy efficiency, automation and advanced LED technologies.
1. Baldwin Technology
Baldwin Technology focuses on advanced UV and LED curing solutions for printing, packaging and converting industries. In May 2024, the company showcased its Unity LED system and QuadCure UV system at drupa 2024. These technologies were developed to improve production efficiency, printing quality and operational productivity while reducing investment requirements. Its continued focus on advanced curing equipment is expected to strengthen its market presence.
2. Dymax
Dymax is strengthening its position through innovative UV and LED curing equipment and light-curable adhesive technologies. In June 2024, the company introduced its upgraded UVCS V3.0 LED Conveyor, featuring an eight-inch touchscreen, programmable belt speed and adjustable LED intensity. In November 2024, Dymax also received a patent for its Hybrid Light-Curable (HLC) adhesive technology, which enables curing in both illuminated and difficult-to-reach areas. These developments support applications in electronics, medical devices and precision assembly.
3. Nordson Corporation
Nordson Corporation offers industrial UV curing equipment designed for coatings, adhesives, sealants and manufacturing applications. Its CoolWave 2 systems use microwave-powered UV technology to deliver reliable curing performance and flexible production integration. The company's focus on automated production lines, improved process control and efficient curing equipment creates opportunities in electronics, automotive, packaging and industrial manufacturing.
4. Excelitas Technologies
Excelitas Technologies is expanding its UV LED curing portfolio through advanced photonic technologies. In October 2024, the company launched the Generation 8 Phoseon Fiber Curing System for optical fiber and wire coating applications. Its three-part reflector design improves irradiance by 20%, supporting faster processing and consistent curing. The system also uses LED technology to reduce energy consumption and lower workpiece surface temperatures, strengthening its position in advanced industrial applications.
5. Heraeus Holding
Heraeus Holding is an established technology provider in industrial UV applications, offering UV lamp and curing solutions for manufacturing processes. The company focuses on improving lamp performance, energy efficiency and industrial process reliability. Its expertise in specialty lighting and advanced UV technologies provides opportunities in printing, coatings, electronics and industrial production. Continued development of efficient UV light sources can support manufacturers seeking reliable alternatives to conventional curing processes.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/7189/
Regional Analysis
United States: The United States represents a major market within North America, which accounted for the largest regional share of the global UV curing systems market in 2023. Growth is supported by advanced automotive manufacturing, electric vehicle production, semiconductor development and medical device manufacturing. Environmental regulations, including the Clean Air Act framework, encourage industries to control air pollutants and VOC emissions, creating opportunities for UV-based curing technologies.
United Kingdom: The UK market is supported by growing demand for sustainable industrial coatings, advanced printing technologies and electronics manufacturing. Environmental requirements and industrial emission-control standards encourage manufacturers to adopt radiation-curable inks, coatings and adhesives. The country's focus on energy-efficient production and advanced manufacturing is expected to support market expansion.
Germany: Germany represents an important European market due to its strong automotive, machinery, electronics and industrial manufacturing sectors. Demand for precision coating, high-performance adhesives and automated production equipment is supporting UV curing adoption. European industrial emission regulations also encourage the use of radiation-curable materials to reduce solvent consumption and VOC emissions.
France: France is witnessing opportunities through its automotive, aerospace, packaging and healthcare manufacturing industries. Increasing investment in industrial modernization, sustainable production and advanced surface-finishing technologies is encouraging manufacturers to consider UV curing solutions. The adoption of radiation-curable coatings and adhesives is also supported by European environmental requirements.
Japan: Japan is an important market due to its strong electronics, semiconductor, automotive and precision manufacturing industries. Demand for advanced electronic components and high-quality industrial coatings supports the adoption of UV curing technologies. Government initiatives supporting manufacturing innovation and research and development are creating opportunities for advanced LED curing equipment and automation.
China: China is expected to remain an important growth market because of its large electronics, automotive, semiconductor, packaging and industrial manufacturing base. Increasing production of consumer electronics, electric vehicles and electronic components is creating demand for efficient curing technologies. Government initiatives promoting advanced manufacturing, industrial modernization and green production are further encouraging the adoption of energy-efficient UV curing systems.
► Get to Know More About This Market Study: https://www.maximizemarketresearch.com/market-report/global-uv-curing-system-market/7189/
Conclusion
The Global UV Curing Systems Market is expected to experience strong growth through 2034, supported by increasing industrial automation, rising demand for high-quality coatings and adhesives, and the growing importance of environmentally friendly manufacturing technologies. The expansion of automotive, electronics, semiconductor, medical device and packaging industries will remain important demand drivers.
In my view, the most significant future opportunity lies in the development of advanced UV LED curing systems that offer higher energy efficiency, faster processing speeds, improved product quality and lower operating costs. Manufacturers investing in smart curing equipment, automated production integration and innovative UV-curable materials are likely to gain competitive advantages. Furthermore, increasing environmental awareness and stricter emission-control requirements will encourage industries to replace conventional curing processes with more sustainable alternatives. These factors are expected to create attractive long-term growth opportunities for UV curing equipment manufacturers worldwide.
About Maximize Market Research:
Maximize Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Contact Maximize Market Research:
3rd Floor, Navale IT Park, Phase 2
Pune Banglore Highway, Narhe,
Pune, Maharashtra 411041, India
sales@maximizemarketresearch.com
+91 96071 95908, +91 9607365656
Global Polyglycerol Market to Grow with Rising Demand for Sustainable Personal Care Ingredients
By Punampatil2001, 2026-11-18
Global Polyglycerol Market Overview
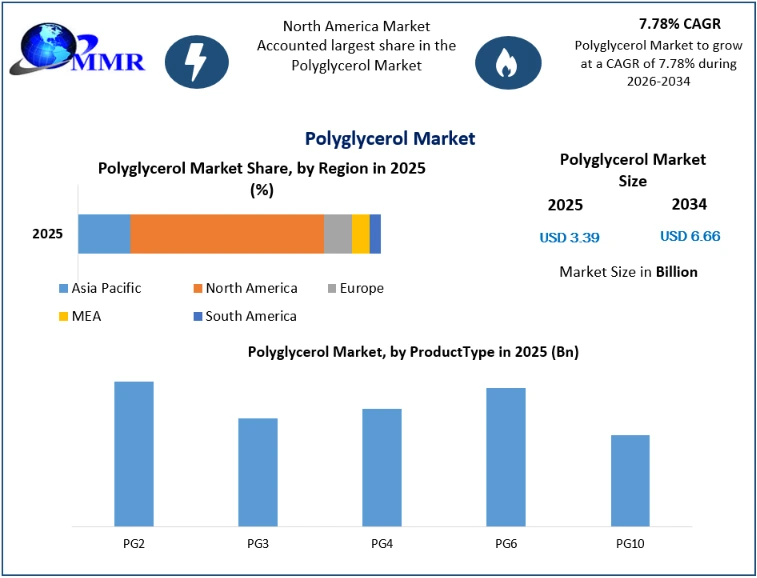
The Global polyglycerol market is witnessing significant growth, driven by increasing demand for multifunctional ingredients across personal care, food and beverages, pharmaceuticals, and specialty chemical industries. According to the market assessment, the global polyglycerol market was valued at USD 3.39 billion in 2025 and is projected to reach approximately USD 6.66 billion by 2034 , growing at a CAGR of 7.78% during the forecast period of 2026–2034 . Polyglycerol is a versatile chemical compound widely used in manufacturing emulsifiers, stabilizers, surfactants, and other specialty ingredients. Its ability to improve product stability, texture, moisture retention, and formulation performance makes it an important ingredient across several industries. Increasing consumer preference for natural, plant-derived, and environmentally friendly ingredients is further supporting market expansion. Manufacturers are focusing on developing advanced polyglycerol-based formulations to meet changing industrial requirements and consumer expectations.
Several factors are contributing to the expansion of the global polyglycerol market. Rising consumption of skincare, haircare, cosmetics, and personal hygiene products is increasing demand for polyglycerol-based emulsifiers and formulation ingredients. The growing popularity of clean-label food products, bakery items, chocolates, and confectionery products is also creating new opportunities for market participants. In the pharmaceutical industry, polyglycerol is increasingly used in specialized formulations and excipient applications because of its functional properties. Additionally, expanding oil and gas exploration, drilling fluid applications, textile lubricants, and wastewater treatment activities are creating opportunities for industrial-grade polyglycerol. However, fluctuating raw material prices and the availability of alternative chemical ingredients may create challenges for manufacturers. Investments in research and development, sustainable production processes, and bio-based raw materials are expected to generate new growth opportunities throughout the forecast period.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/27536/
United States Market Trends and Investments
The United States represents an important market for polyglycerol, supported by strong demand from the personal care, cosmetics, food processing, and pharmaceutical industries. In 2024, the market witnessed increasing interest in naturally derived emulsifiers, biodegradable surfactants, and sustainable cosmetic ingredients as manufacturers responded to changing consumer preferences. A notable industry development was the introduction of Geomulse by Arxada in April 2024 , featuring naturally derived polyglycerol ester-based non-ionic emulsifiers and surfactants. The product range was developed for personal care and beauty applications, including creams, cleansers, and other skincare formulations. Its plant-derived composition, PEG-free formulation, and compatibility with sustainability standards highlight the industry's movement toward environmentally conscious ingredients. Furthermore, Dow continued investments in manufacturing capacity and sustainable specialty chemical solutions during 2024, including projects supporting personal care applications. These developments demonstrate growing opportunities for polyglycerol-based ingredients in the US market, particularly in premium skincare, clean beauty, and sustainable formulation technologies.
Global Polyglycerol Market Segmentation Analysis
By Application: The personal care segment is expected to hold the largest share of the global polyglycerol market. Its leading position is supported by increasing consumption of skincare, haircare, cosmetics, and personal hygiene products. Polyglycerol-based ingredients are widely used as emulsifiers, stabilizers, and moisturizing agents in cosmetic formulations. Rising consumer awareness regarding skincare, growing disposable incomes, and increasing demand for premium beauty products are strengthening segment growth. Additionally, manufacturers are introducing naturally derived and mild formulation ingredients to meet the growing preference for sustainable personal care products.
By Product Type: PG2 and PG3 are identified as important product segments expected to experience increasing demand. Their applications across different industrial formulations and specialty ingredient manufacturing are supporting their market potential.
Competitive Analysis
The global polyglycerol market includes established chemical manufacturers and specialty ingredient suppliers focusing on product innovation, manufacturing capabilities, sustainable chemistry, and strategic investments. According to the companies listed in the market assessment, the five leading companies highlighted are:
1. Procter & Gamble: Procter & Gamble maintains a strong presence in personal care and consumer products. The company focuses on research, product innovation, and developing advanced formulations across beauty and personal care categories. Its continued emphasis on product performance, consumer preferences, and sustainable product development creates opportunities for polyglycerol-based ingredients in cosmetic and skincare formulations.
2. Solvay: Solvay is an established specialty chemicals manufacturer with expertise in advanced chemical materials and sustainable solutions. The company continues to focus on innovation, operational efficiency, and environmentally responsible chemical production. Its capabilities in specialty chemistry and formulation technologies support opportunities in applications requiring high-performance emulsifiers and functional ingredients.
3. Unilever Holdings: Unilever is a major global consumer goods company with an extensive portfolio of personal care, beauty, and hygiene products. In 2024, the company announced a €100 million investment to strengthen its fragrance capabilities, supporting product innovation and advanced formulation development. Its continued focus on premium beauty products, product differentiation, and consumer-driven innovation creates opportunities for specialty ingredients, including polyglycerol derivatives.
4. Godrej Industries Ltd: Godrej Industries is strengthening its position in oleochemicals, surfactants, and specialty chemicals through manufacturing expansion and research capabilities. Its chemical business focuses on sustainable chemistry and supplying ingredients for personal care, home care, food, and industrial applications. The company's acquisition of an ethoxylation manufacturing facility at Kheda, Gujarat, in 2024 strengthened its specialty chemical manufacturing capabilities and expanded its product portfolio.
5. Dow Chemical Company: Dow is focusing on advanced chemical technologies, sustainable materials, and specialty ingredient manufacturing. During 2024, the company brought several growth investment projects online, including capacity expansions supporting personal care and other industrial applications. Its development of bio-based polymers and plant-derived surfactants demonstrates its commitment to sustainable formulation technologies. These developments may support future opportunities for polyglycerol-related specialty ingredients.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/27536/
Regional Analysis
United States: The United States represents a major market for polyglycerol, supported by North America's leading regional position. Strong demand for cosmetics, personal care products, bakery items, and pharmaceutical formulations is supporting market expansion. Increasing interest in clean-label ingredients and sustainable chemical solutions is encouraging manufacturers to introduce advanced formulations.
United Kingdom: The United Kingdom market is supported by growing demand for premium skincare, cosmetics, and sustainable personal care products. The presence of established beauty and specialty chemical manufacturers encourages research into naturally derived emulsifiers. Increasing consumer preference for environmentally responsible ingredients is creating additional opportunities.
Germany: Germany is an important European market because of its well-established chemical manufacturing, cosmetics, pharmaceutical, and food processing industries. Strong industrial research capabilities and increasing attention to sustainable manufacturing are supporting the adoption of specialty ingredients. European environmental and chemical regulations, including REACH requirements, also encourage manufacturers to improve product safety and environmental performance.
France: France is witnessing opportunities in polyglycerol applications through its strong cosmetics, skincare, luxury beauty, and personal care industries. Demand for premium cosmetic formulations and naturally derived ingredients is encouraging manufacturers to invest in innovative emulsifier technologies. The country's established beauty industry provides opportunities for specialty polyglycerol ingredients.
Japan: Japan represents an important Asian market, supported by advanced cosmetics, food processing, and pharmaceutical industries. Increasing demand for high-quality skincare products, functional food ingredients, and innovative formulations is contributing to market development. Japanese manufacturers are also focusing on product quality, technological innovation, and efficient manufacturing processes.
China: China is emerging as a significant growth market because of its expanding cosmetics, food and beverages, pharmaceutical, and specialty chemical industries. Increasing urbanization, rising disposable incomes, and growing consumption of personal care products are supporting demand. Government initiatives promoting industrial modernization, green manufacturing, and technological development are further encouraging investment in advanced chemical production.
► Get to Know More About This Market Study: https://www.maximizemarketresearch.com/market-report/global-polyglycerol-market/27536/
Conclusion
The global polyglycerol market is expected to experience steady growth through 2034, supported by increasing applications across personal care, food and beverages, pharmaceuticals, and specialty chemicals. The market's projected growth from USD 3.39 billion in 2025 to USD 6.66 billion by 2034 highlights its expanding industrial importance. In my view, the personal care industry will remain a major growth contributor because of increasing demand for skincare products, premium cosmetics, and naturally derived ingredients. Furthermore, technological advancements in bio-based emulsifiers, sustainable manufacturing, and clean-label formulations will create attractive opportunities for manufacturers. Companies investing in research and development, production capacity, and innovative product formulations will be better positioned to strengthen their market presence. Overall, rising consumer awareness, industrial expansion, and the shift toward sustainable chemical solutions are expected to remain the major factors driving the global polyglycerol market during the forecast period.
About Maximize Market Research:
Maximize Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Contact Maximize Market Research:
3rd Floor, Navale IT Park, Phase 2
Pune Banglore Highway, Narhe,
Pune, Maharashtra 411041, India
sales@maximizemarketresearch.com
+91 96071 95908, +91 9607365656
Global Smart Luggage Market to Witness Strong Growth Driven by Rising Travel and Smart Technologies
By Punampatil2001, 2026-11-18
Market Overview
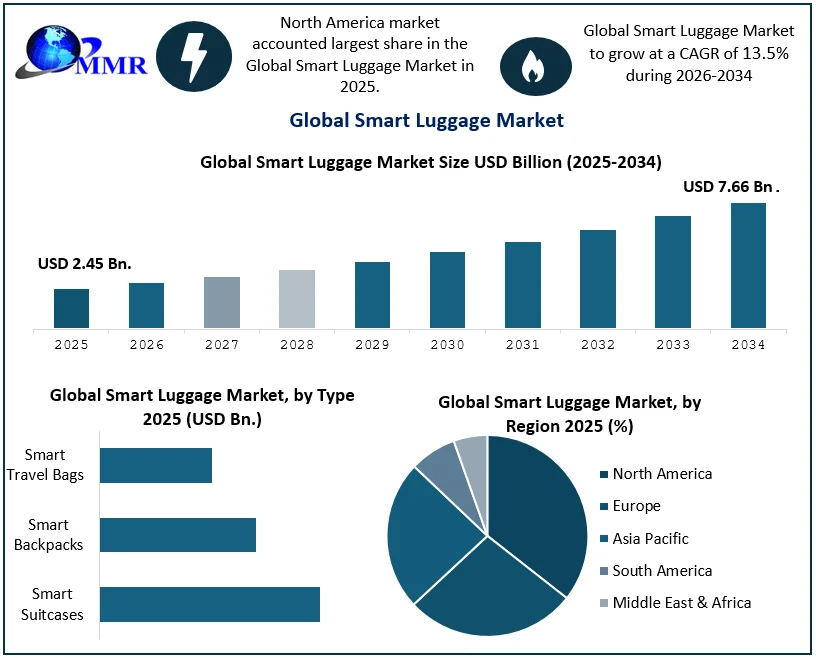
The Global Smart Luggage Market was valued at USD 2.45 billion in 2025 and is projected to reach USD 7.66 billion by 2034 , growing at a CAGR of 13.5% during the forecast period from 2026 to 2034 . The market is experiencing significant growth due to increasing international tourism, rising air passenger traffic, and growing consumer preference for technologically advanced travel accessories. Smart luggage integrates innovative features such as GPS tracking, Bluetooth connectivity, USB charging ports, biometric locks, digital security systems, and weight sensors. These technologies improve travel convenience, baggage monitoring, and personal security, making smart suitcases increasingly attractive to business travelers and frequent flyers.
The growing adoption of smartphones, Internet of Things (IoT) technology, and connected devices is creating new opportunities for smart luggage manufacturers. Consumers are increasingly choosing lightweight, durable, and multifunctional suitcases that offer real-time tracking and enhanced protection against luggage theft or loss. Additionally, expanding e-commerce platforms, increasing disposable incomes, and demand for premium travel accessories are supporting market expansion. However, high product costs, battery regulations imposed by airlines, and electronic maintenance concerns may restrict adoption. Manufacturers focusing on affordable pricing, removable batteries, sustainable materials, and improved tracking technologies are expected to gain significant opportunities.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/188058/
United States Market Trends and Investment
The United States represents an important market for smart luggage, supported by high air passenger traffic, strong purchasing power, and widespread adoption of connected technologies. In 2024, interest in GPS-enabled suitcases, Bluetooth tracking, anti-theft systems, and smart charging solutions continued to increase. A notable development was the January 2024 acquisition of a majority stake in Samsara Luggage Inc. by US-based Ilustrato Pictures International Inc., highlighting investment interest in technology-oriented luggage businesses. Manufacturers are also focusing on improved baggage security, removable battery systems, and mobile application integration. Growing domestic and international tourism is expected to create further investment opportunities.
Market Segmentation Analysis
The global smart luggage market is segmented by product type, technology, security feature, end-user, and distribution channel. Smart suitcases hold a leading position in the product category due to their advanced functionality and widespread adoption among frequent travelers. GPS tracking is an important technology segment because consumers increasingly prioritize real-time baggage monitoring and security. Business travelers represent a significant end-user segment due to frequent travel requirements and demand for premium luggage. Online stores account for a leading distribution channel position, supported by convenient shopping, product comparisons, and access to international brands.
Competitive Landscape
The major companies operating in the global smart luggage market include:
1. Samsonite International S.A.: Focuses on lightweight, durable luggage, innovative materials, and sustainable product development. Its technology-oriented travel accessories support changing consumer expectations.
2. Tumi Holdings Inc.: Concentrates on premium luggage for business and frequent travelers. Its FXT ballistic nylon, durable construction, and functional organizational features strengthen its market position.
3. Delsey Paris: Focuses on lightweight luggage and advanced security systems. Its SECURITECH anti-theft zipper technology and TSA-compatible locking systems improve baggage protection.
4. Rimowa GmbH: Specializes in luxury aluminum and polycarbonate luggage. Its investment in premium materials, lightweight engineering, and modern product designs supports its international presence.
5. Travelpro International Inc.: Focuses on professional travel luggage featuring durable fabrics, lightweight construction, advanced wheel systems, and practical organizational features.
These companies are expected to strengthen their competitive positions through investments in GPS tracking, biometric security, smart battery systems, innovative materials, and connected travel technologies.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/188058/
Regional Analysis
United States: The US market benefits from high air passenger traffic, strong consumer purchasing power, and advanced digital infrastructure. Growing demand for connected travel accessories and improved baggage security supports market development.
United Kingdom: The UK market is supported by international tourism, business travel, and established airport infrastructure. Demand for lightweight luggage, GPS tracking, and advanced security features is creating growth opportunities.
Germany: Germany benefits from strong manufacturing capabilities, international business travel, and consumer preference for durable, high-quality products. Sustainability initiatives and advanced manufacturing technologies encourage product innovation.
France: France's established tourism industry and premium travel accessories market support smart luggage adoption. Demand for luxury designs, lightweight suitcases, and advanced security systems contributes to market growth.
Japan: Japan's technological advancement, tourism activities, and consumer preference for innovative products support market expansion. Automated technologies, compact luggage designs, and advanced tracking solutions offer growth opportunities.
China: China's expanding middle class, increasing disposable income, growing tourism, and strong electronics manufacturing industry are supporting smart luggage demand. Investments in smart manufacturing and digital infrastructure also create opportunities for domestic manufacturers.
► Get to Know More About This Market Study: https://www.maximizemarketresearch.com/market-report/smart-luggage-market/188058/
Conclusion
The global smart luggage market is expected to experience significant growth as technological advancements transform the travel accessories industry. Increasing air travel, rising tourism, baggage security concerns, and growing demand for connected products will remain major growth drivers. In my view, the biggest opportunity lies in developing affordable, lightweight, and airline-compliant smart luggage with GPS tracking, biometric locks, removable batteries, and improved battery life. Manufacturers focusing on technological innovation, sustainable materials, competitive pricing, and e-commerce expansion are likely to strengthen their market positions and benefit from increasing global demand for convenient and secure travel solutions.
About Maximize Market Research:
Maximize Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Contact Maximize Market Research:
3rd Floor, Navale IT Park, Phase 2
Pune Banglore Highway, Narhe,
Pune, Maharashtra 411041, India
sales@maximizemarketresearch.com
+91 96071 95908, +91 9607365656
Global Tungsten Market to Reach USD 10.99 Billion by 2032, Driven by Industrial Growth and Technological Advancements
By Punampatil2001, 2026-11-18
Market Overview
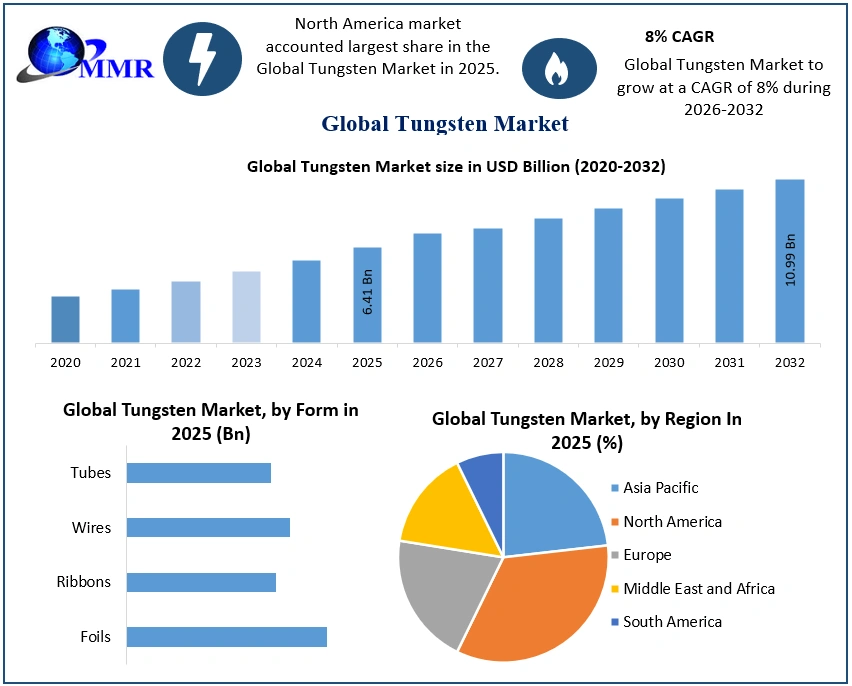
The Global Tungsten Market was valued at USD 6.41 billion in 2025 and is expected to reach approximately USD 10.99 billion by 2032, growing at a CAGR of 8% during the forecast period (2025–2032). Tungsten is a strategically important industrial metal known for its exceptional hardness, high melting point, strength, and resistance to wear and corrosion. These properties make it essential for manufacturing cutting tools, drilling equipment, electrical components, aerospace materials, and high-performance industrial machinery. Its extensive use in tungsten carbide products also supports demand from automotive, construction, mining, and metalworking industries.
The growing demand for advanced materials across industrial sectors is a major factor driving market expansion. Increasing investments in aerospace and defence manufacturing, automotive production, electronics, semiconductor equipment, and infrastructure development are creating new opportunities for tungsten manufacturers. Furthermore, the expansion of precision machining and the growing adoption of durable tungsten carbide tools are supporting consumption. Technological developments in powder metallurgy, advanced coatings, recycling, and sustainable metal processing are also expected to strengthen the market. However, fluctuating raw material prices, supply-chain limitations, export restrictions, and high processing costs remain important industry challenges.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/25066/
U.S. Market Trends and Investment Developments
The United States tungsten market is gaining importance due to increasing demand for critical minerals, defence equipment, advanced manufacturing, and domestic supply-chain security. The country depends significantly on imported tungsten because commercial tungsten mining has not taken place in the United States since 2015. According to the 2024 U.S. Geological Survey report, approximately 60% of domestic tungsten consumption was used in cemented carbide components for cutting and wear-resistant applications. A major development occurred on December 13, 2024, when the U.S. Department of Defense announced a USD 15.8 million investment in Fireweed Metals Corp. to accelerate the development of the Mactung tungsten project in Canada's Yukon region. The investment supports resource assessment, metallurgical testing, and feasibility studies to strengthen North American tungsten supply security. Such initiatives are expected to encourage further investments in mining, refining, recycling, and advanced tungsten processing technologies.
Tungsten Market Segmentation Analysis
Based on type, application, form, and product, the global tungsten market is divided into several segments. Among the type segments, Tungsten Carbide is expected to hold the largest market share due to its exceptional hardness, strength, durability, and resistance to high temperatures. It is extensively used in cutting tools, drilling equipment, mining machinery, industrial components, and precision engineering applications. Increasing demand for high-performance tools in automotive, construction, and metalworking industries continues to support this segment's leading position.
By application, the market includes aerospace and defence, automotive, electrical and electronics, machine tools and equipment, construction, healthcare, and others. By form, it includes foils, ribbons, wires, and tubes. The increasing use of tungsten-based products in industrial manufacturing and advanced engineering applications provides opportunities across these segments.
Competitive Landscape and Key Players
The global tungsten market is competitive, with major manufacturers focusing on production capacity, advanced processing technologies, recycling, product quality, and strategic partnerships.
1. China Minmetals Corporation
China Minmetals Corporation is an important participant in the global non-ferrous metals industry, with activities across mineral resources, processing, and metal production. Its integrated industrial operations support the availability of tungsten-based materials for manufacturing and industrial applications. The company's position in China's mineral supply chain provides opportunities to benefit from increasing demand for tungsten carbide, high-performance alloys, and industrial materials.
2. Almonty Industries Inc.
Almonty Industries is strengthening its position through investments in tungsten mining and supply-chain diversification. In 2024, the company advanced underground development at its Sangdong tungsten mine in South Korea, with ore extraction beginning in September. It also installed advanced processing equipment supplied by Metso to support future operations. These developments are important for increasing tungsten availability outside China and strengthening supply to global industrial and defence manufacturers.
3. Global Tungsten & Powders Corp.
Global Tungsten & Powders Corp. is a specialised manufacturer of tungsten metal powders, tungsten carbide powders, and related materials. The company serves industrial customers requiring high-quality materials for cutting tools, wear-resistant components, and advanced manufacturing. Improvements in powder production, material consistency, and specialised tungsten applications can help the company benefit from increasing demand for precision-engineered products.
4. Wolfram Company GmbH
Wolfram Company GmbH is involved in tungsten processing and the production of specialised tungsten materials. Its industrial capabilities support applications in hard metals, tools, and advanced engineering. Growing demand for reliable European raw-material supplies and sustainable processing technologies creates opportunities for the company to strengthen its market position.
5. H.C. Starck Tungsten GmbH
H.C. Starck Tungsten GmbH is a major producer of tungsten powders and specialised tungsten materials. An important corporate development took place in December 2024 when Mitsubishi Materials Corporation completed the acquisition of H.C. Starck Holding. The transaction created opportunities for greater technological cooperation, recycling capabilities, and integration across metal-processing operations. The company also introduced an innovative black-mass recycling process in June 2024, designed to improve material recovery while reducing energy and auxiliary material consumption. These developments support the transition towards more sustainable material production.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/25066/
Regional Analysis
United States: The United States is an important tungsten-consuming market, supported by aerospace, defence, automotive, and industrial manufacturing. Growing government initiatives to secure critical mineral supplies and reduce import dependence are encouraging investment in alternative mining and processing projects. Demand for tungsten carbide cutting tools and wear-resistant components further supports market development.
United Kingdom: The UK tungsten market benefits from aerospace engineering, defence manufacturing, automotive production, and advanced industrial applications. Government initiatives supporting critical mineral supply-chain resilience and domestic manufacturing create opportunities for tungsten suppliers. Demand for high-performance materials in precision engineering and industrial equipment is also supporting market development.
Germany: Germany is a significant European market due to its strong automotive, machinery, aerospace, and industrial manufacturing sectors. The country's advanced engineering industry creates demand for tungsten carbide tools and specialised metal products. The integration of H.C. Starck into Mitsubishi Materials in December 2024 also strengthens the potential for investment in tungsten processing, recycling, and sustainable material technologies.
France: France represents an important market because of its aerospace, defence, automotive, and advanced manufacturing industries. The growing requirement for durable materials in aircraft components, industrial machinery, and precision tools supports tungsten consumption. Government initiatives focused on industrial competitiveness, strategic materials, and sustainable manufacturing are creating additional opportunities.
Japan: Japan's tungsten market is supported by its advanced electronics, automotive, semiconductor, and precision manufacturing industries. Demand for high-quality tungsten powders, carbide tools, and specialised components is increasing with technological advancements. Mitsubishi Materials' acquisition of H.C. Starck also provides opportunities for greater integration of tungsten processing and recycling technologies across international operations.
China: China remains a major force in the global tungsten industry because of its substantial mineral reserves, established mining infrastructure, processing capabilities, and strong industrial demand. The country's automotive, electronics, machinery, and manufacturing industries consume significant quantities of tungsten-based materials. Government management of strategic mineral resources and export controls also influence international tungsten supply and pricing. Its established production ecosystem supports its competitive position in the global market.
► Get to Know More About This Market Study: https://www.maximizemarketresearch.com/market-report/global-tungsten-market/25066/
Conclusion
The global tungsten market is expected to experience considerable growth through 2032, supported by increasing industrial production, technological advancements, and demand for high-performance materials. Tungsten carbide, in particular, will remain an important growth segment because of its extensive applications in cutting tools, mining equipment, automotive components, and precision engineering. In my view, the major growth opportunity lies in developing alternative tungsten supply chains, expanding recycling facilities, and improving advanced powder-processing technologies. Investments in sustainable mining, strategic partnerships, and high-quality tungsten materials will also play an important role in future market expansion. Companies focusing on supply-chain security, material innovation, and resource efficiency are likely to strengthen their competitive positions in the global tungsten industry.
About Maximize Market Research:
Maximize Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Contact Maximize Market Research:
3rd Floor, Navale IT Park, Phase 2
Pune Banglore Highway, Narhe,
Pune, Maharashtra 411041, India
sales@maximizemarketresearch.com
+91 96071 95908, +91 9607365656
Global Textile Market to Experience Significant Growth, Driven by Rising Industrial Applications and Sustainable Fashion Trends
By Punampatil2001, 2026-11-18
Textile Market Overview
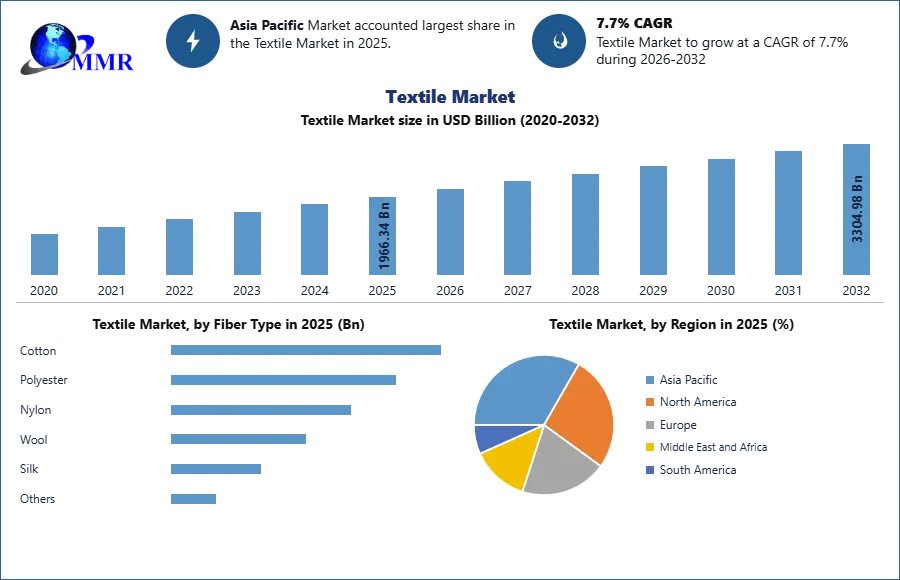
The Global Textile Market was valued at USD 1,966.34 billion in 2025 and is projected to reach approximately USD 3,304.98 billion by 2032, growing at a CAGR of 7.7% during the forecast period from 2026 to 2032. The market is experiencing significant growth due to increasing demand for apparel, home furnishings, industrial fabrics, and technical textiles across various industries. Rising disposable incomes, rapid urbanization, population growth, and changing fashion preferences are encouraging consumers to purchase a wider variety of textile products. Additionally, the expansion of the fashion and apparel industry, increasing e-commerce penetration, and growing demand for comfortable and durable fabrics are supporting global market expansion.
The growing adoption of sustainable manufacturing practices and advanced textile technologies is creating new opportunities for market participants. Manufacturers are increasingly investing in recycled polyester, organic cotton, biodegradable fibers, and other environmentally friendly materials to reduce environmental impact. Furthermore, innovations in smart textiles, automated manufacturing, digital printing, and advanced fiber processing are improving product quality and manufacturing efficiency. The increasing use of specialized textiles in healthcare, automotive, construction, aerospace, and defense applications is also expanding the industry's growth potential. However, fluctuating raw material prices, environmental concerns associated with dyeing and finishing processes, and supply chain disruptions remain important challenges for manufacturers.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/200298/
U.S. Textile Market Trends and Investments
The United States textile market is witnessing increasing investment in domestic manufacturing, advanced textile technologies, and sustainable production. In 2024, the U.S. Department of Commerce's Economic Development Administration announced an investment of USD 800,000 to support The Industrial Commons in Morganton, North Carolina, to strengthen local textile manufacturing through equipment and workforce development. Additionally, Welspun announced a USD 12.5 million investment in August 2024 to expand its U.S. manufacturing operations in Grove City, Ohio, adding production capabilities for towels, rugs, and bedding products. The U.S. textile industry is also focusing on reshoring manufacturing, recycling facilities, and high-performance materials to strengthen domestic production capabilities. These developments are expected to support innovation, employment, and long-term growth in the U.S. textile industry.
Textile Market Segmentation Analysis
Based on product, the market is segmented into polyester, natural fiber, nylon, and others. Among these, the polyester segment held the largest market share in 2025 and is expected to maintain its leading position during the forecast period. Polyester is widely used because of its durability, flexibility, wrinkle resistance, moisture resistance, and cost-effectiveness. Its applications extend across apparel, sportswear, home furnishings, automotive interiors, industrial fabrics, ropes, and construction materials. The availability of polyester in different forms, including filament yarns, staple fibers, and microfibers, further increases its commercial applications. Additionally, growing demand for recycled polyester and blended fabrics is encouraging manufacturers to develop more sustainable textile solutions.
Competitive Analysis
The global textile market is highly competitive, with leading manufacturers focusing on capacity expansion, sustainable materials, technological innovation, and strategic investments. The key companies highlighted in the market report include:
1. Toray Industries: Toray Industries focuses on advanced synthetic fibers, performance textiles, and sustainable materials. The company invests in research and development to improve fiber performance, durability, and environmental efficiency. Its advanced conjugate spinning technology, NANODESIGN, enables the development of specialized fibers with enhanced comfort and functional properties, supporting innovation in high-performance textiles.
2. Inditex: Inditex is strengthening its position through sustainable textile innovation and circular fashion initiatives. In October 2024, the company launched an approximately EUR 50 million investment fund to support startups developing innovative textile materials and technologies. Its investments include companies working on textile recycling and lab-grown cotton, supporting the development of lower-impact textile fibers and sustainable manufacturing.
3. Hengli Petrochemical: Hengli Petrochemical is a major manufacturer of polyester fibers and petrochemical-based materials. The company operates large-scale polyester filament production facilities and continues to strengthen its integrated manufacturing capabilities. Its investments in advanced polyester production and functional materials support the availability of synthetic fibers for apparel, industrial fabrics, and other textile applications.
4. Aditya Birla Group: Aditya Birla Group, through Grasim Industries and Birla Cellulose, focuses on sustainable cellulosic fibers, viscose, and specialty textile materials. The company is expanding its Lyocell fiber manufacturing capacity by 110 KTPA at Harihar, Karnataka, with the first phase of 55 KTPA planned for completion by mid-2027. Its GreenTrack technology also improves fiber traceability and sustainability verification, supporting demand for responsible textile materials.
5. Vardhman Textiles: Vardhman Textiles is strengthening its manufacturing capabilities through investments in spinning, fabric processing, technical textiles, and green energy. In May 2024, the company announced an investment of approximately INR 2,000 crore for capacity expansion and modernization. In November 2024, it further approved an investment of approximately INR 350 crore to increase processed fabric capacity by 31 million meters annually at its Budhni facility. These initiatives are expected to improve production efficiency and support growing domestic and international demand.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/200298/
Regional Analysis
United States: The United States represents an important textile consumption and manufacturing market. According to the report's 2020 international trade data, the country accounted for 12.6% of global textile imports. Demand for technical textiles, medical fabrics, protective clothing, and sustainable materials supports market growth. Government-backed manufacturing investments and domestic production initiatives are strengthening the industry.
United Kingdom: The United Kingdom accounted for approximately 3% of global textile imports in 2020. The market benefits from demand for fashion apparel, premium fabrics, home textiles, and sustainable clothing. Government-supported initiatives such as Textiles 2030 encourage businesses to adopt circular economy practices, improve resource efficiency, and reduce textile waste.
Germany: Germany is an important European textile market, supported by its automotive, industrial, healthcare, and technical textile sectors. Demand for high-performance fabrics and sustainable materials is encouraging manufacturers to invest in innovative production processes. European Union regulations, including the Sustainable and Circular Textiles Strategy, are supporting recyclable product design, longer-lasting fabrics, and improved waste management.
France: France's textile industry benefits from its established fashion, luxury apparel, and home furnishing sectors. Increasing consumer interest in sustainable fashion and premium-quality fabrics is supporting market development. European environmental regulations and circular economy initiatives are encouraging companies to adopt recycled materials and environmentally responsible manufacturing practices.
Japan: Japan accounted for approximately 3.3% of global textile imports in 2020. Its market growth is supported by demand for advanced synthetic fibers, functional clothing, technical textiles, and innovative fabric technologies. The Japanese government introduced textile resource-circulation initiatives in 2024, including guidelines for environmentally conscious textile design and resource recycling, encouraging sustainable production and consumption.
China: China is one of the world's leading textile producers and exporters, supported by its extensive manufacturing infrastructure, raw material availability, and established supply chains. The country accounted for approximately 3.9% of global textile imports in 2020, according to the report's trade data. Strong domestic consumption, large-scale polyester production, technological modernization, and government initiatives promoting advanced manufacturing and resource efficiency support the country's textile industry.
► Get to Know More About This Market Study: https://www.maximizemarketresearch.com/market-report/textile-market/200298/
Conclusion
The global textile market is expected to experience substantial growth through 2032, supported by rising demand for apparel, home textiles, industrial fabrics, and advanced technical materials. Increasing consumer awareness of sustainable products, technological advancements, and expanding applications across healthcare, automotive, construction, and aerospace industries will create significant growth opportunities. Polyester is expected to remain the leading product segment due to its versatility, durability, and wide industrial applications. Furthermore, investments in recycled fibers, smart textiles, automated manufacturing, and circular production systems will play an important role in shaping the industry's future. Companies focusing on sustainable materials, manufacturing efficiency, and innovative textile technologies are likely to strengthen their competitive positions and benefit from the expanding global market.
About Maximize Market Research:
Maximize Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Contact Maximize Market Research:
3rd Floor, Navale IT Park, Phase 2
Pune Banglore Highway, Narhe,
Pune, Maharashtra 411041, India
sales@maximizemarketresearch.com
+91 96071 95908, +91 9607365656
Global Tin Market to Reach USD 9.57 Billion by 2032, Driven by Electronics Demand
By Punampatil2001, 2026-11-18
Market Overview
The Global Tin Market was valued at approximately USD 7.57 billion in 2025 and is expected to reach nearly USD 9.57 billion by 2032, growing at a CAGR of 3.4% during the forecast period of 2026–2032. Tin is an important industrial metal widely used in electronics, automotive, packaging, construction, chemicals, and renewable energy applications. Its excellent corrosion resistance, electrical conductivity, malleability, and soldering properties make it an essential raw material for several manufacturing industries.
The increasing production of electronic devices, semiconductors, printed circuit boards (PCBs), and electric vehicles is supporting market expansion. Tin-based solder is extensively used to establish reliable electrical connections in electronic components. Additionally, the growing adoption of renewable energy technologies, solar panels, and energy storage systems is creating new opportunities for tin manufacturers. The development of advanced battery technologies, lead-free solder materials, and tin-based chemical products is further strengthening market demand. However, fluctuations in raw material prices, mining restrictions, geopolitical uncertainties, and supply chain disruptions may create challenges for market participants.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/57921/
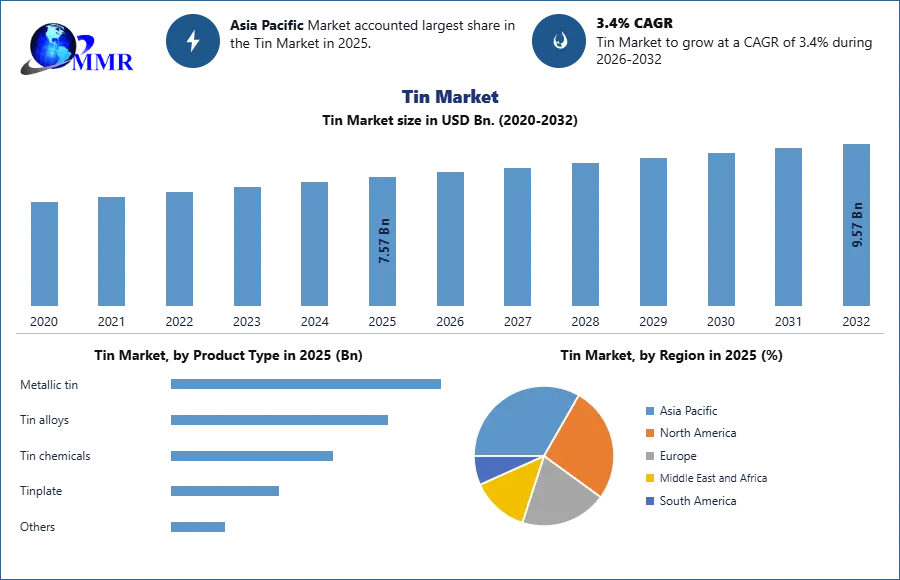
Growth Drivers and Opportunities
The growing demand for consumer electronics, smartphones, computers, automotive electronics, and semiconductor components is a major factor driving the global tin market. The transition towards electric mobility is also increasing the requirement for tin in battery systems, power electronics, charging infrastructure, and electrical connections. Furthermore, environmental regulations encouraging the replacement of lead-based solder with lead-free alternatives are creating significant opportunities for refined tin and specialized tin alloys.
The renewable energy sector offers additional growth potential through the increasing use of tin in solar energy technologies and next-generation batteries. Research into tin-based anodes for lithium-ion and sodium-ion batteries is attracting attention because of their potential for improved energy storage capacity. In addition, electronic waste recycling, recovery of used solder, and sustainable metal processing are creating opportunities to improve resource efficiency and reduce dependence on traditional mining activities.
US Market Trends and Investments
The United States tin market is witnessing increasing attention towards domestic production, recycling, and supply chain security. The country depends significantly on imported refined tin because domestic tin mining and primary smelting operations have been inactive for several decades. In September 2024, the US Department of Defense awarded USD 19 million to Nathan Trotter & Co. through the Defense Production Act Investment Program to establish a domestic tin processing facility in Coatesville, Pennsylvania. The proposed facility is designed to develop domestic tin smelting, refining, and recycling capabilities. This investment highlights the strategic importance of tin in semiconductors, electronic components, military equipment, and defence applications. Growing investment in domestic processing and recycling infrastructure is expected to strengthen the US tin supply chain and create opportunities for the market.
Market Segmentation Analysis
By Product Type: Metallic Tin dominated the global tin market in 2025, accounting for more than 55% of total market revenue. Its leading position is attributed to extensive applications in solder production, metal plating, electronic components, and industrial manufacturing. Its corrosion resistance, conductivity, and malleability make it an important material for electronics and automotive applications.
By Application: Soldering held the largest market share in 2025, accounting for approximately 50–51% of global tin consumption. The segment's dominance is supported by increasing electronics manufacturing, semiconductor assembly, PCB production, electric vehicle components, and renewable energy installations. The growing adoption of lead-free soldering materials is further supporting demand.
Competitive Analysis
The global tin market includes several established mining, smelting, and refining companies competing through production expansion, technological innovation, operational efficiency, and sustainable sourcing. The major companies include:
1. Yunnan Tin Company: Yunnan Tin is one of the world's leading refined tin producers. In August 2024, the company launched the Yunnan Tin and Indium Laboratory to strengthen research and development in advanced materials and improve technologies across the tin and indium value chains. Its focus on high-purity materials and technological development is expected to support future demand from electronics and semiconductor industries.
2. PT Timah Tbk: PT Timah is strengthening its global position through strategic partnerships and improvements in mining and processing technologies. In August 2024, the company established a strategic cooperation agreement with Yunnan Tin to improve mineral resource utilization, smelting, refining, international trading, and downstream product development. The collaboration is expected to increase production efficiency and expand international market access.
3. Minsur: Minsur is a major tin producer operating the San Rafael mining unit in Peru. The company focuses on improving mining productivity, resource management, and sustainable production practices. Its 2024 operating performance showed increased tin production, supported by higher output from its mining operations. Its investments in operational improvements and responsible sourcing strengthen its competitive position.
4. Malaysia Smelting Corporation Berhad: Malaysia Smelting Corporation (MSC) is focusing on improving tin recovery, processing capacity, and mining efficiency. The company has invested in upgrading its processing facilities, including a new ball mill and improvements at its RHT Tin Mine. It has also developed plans for a tailings processing facility to recover additional tin from mining waste. These initiatives support resource efficiency and sustainable production.
5. Thailand Smelting and Refining Co. Ltd. (Thaisarco): Thaisarco is an established tin smelting and refining company with a focus on responsible production and supply chain transparency. Its participation in the International Tin Code demonstrates its commitment to environmental responsibility, occupational safety, and responsible mineral sourcing. Such sustainability practices can strengthen customer confidence and support demand for responsibly sourced tin.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/57921/
Regional Analysis
United States: The United States is an important tin-consuming country, particularly in electronics, semiconductor manufacturing, defence, and packaging. The country relies heavily on imported refined tin, creating opportunities for domestic processing and recycling investments. The USD 19 million investment announced by the Department of Defense in September 2024 to establish a tin smelting, refining, and recycling facility highlights the government's focus on supply chain security. Increasing demand for electronic components and advanced manufacturing is expected to support market growth.
China: China is the largest tin-consuming country, accounting for approximately 50% of global tin demand. Its extensive electronics manufacturing industry, semiconductor production, PCB manufacturing, and electric vehicle supply chain are major contributors to consumption. Government support for advanced manufacturing, technological development, and strategic mineral security is strengthening the country's position. The establishment of the Yunnan Tin and Indium Laboratory in 2024 further demonstrates China's focus on research, innovation, and high-value tin applications.
United Kingdom: The UK tin market benefits from demand for electronic components, industrial manufacturing, renewable energy, and packaging materials. Government regulations, including the Restriction of Hazardous Substances (RoHS) framework and Waste Electrical and Electronic Equipment (WEEE) regulations, encourage safer materials and improved recycling practices. These initiatives support the adoption of lead-free solder and recovery of valuable metals from electronic waste.
Germany: Germany represents an important European market for tin because of its established automotive, electronics, engineering, and industrial manufacturing industries. The increasing production of electric vehicles, electronic systems, and advanced industrial equipment supports demand for tin-based solder and alloys. European environmental regulations promoting recyclable materials, restricted hazardous substances, and resource efficiency are also encouraging sustainable tin consumption.
France: France's tin market is supported by the automotive, aerospace, electronics, packaging, and renewable energy industries. Increasing investments in electric mobility, semiconductor technologies, and clean energy infrastructure are creating opportunities for tin-based materials. European environmental and recycling policies are further encouraging manufacturers to adopt lead-free soldering solutions and improve metal recovery from electronic waste.
Japan: Japan is an important market for tin due to its advanced electronics, semiconductor, automotive, and precision manufacturing industries. The growing production of electronic components, batteries, electric vehicles, and renewable energy equipment is supporting demand for high-purity tin. Government initiatives promoting semiconductor manufacturing, resource efficiency, and battery technology development are expected to create additional opportunities.
► Get to Know More About This Market Study: https://www.maximizemarketresearch.com/market-report/global-tin-market/57921/
Conclusion
The global tin market is expected to experience steady growth through 2032, supported by increasing electronics production, semiconductor development, electric vehicle adoption, and renewable energy investments. Metallic tin and soldering will remain the leading product and application segments because of their essential roles in electronic manufacturing and electrical connections. China will continue to play a significant role in global consumption and production.
In my view, the most important growth opportunity lies in the development of lead-free soldering materials, advanced battery technologies, and electronic waste recycling. Manufacturers investing in high-efficiency refining, sustainable mining, and advanced material research will be better positioned to benefit from changing industrial requirements. Furthermore, government support for domestic mineral processing and supply chain diversification will help reduce supply risks. Overall, technological innovation, sustainable sourcing, and growing demand from the electronics and clean energy sectors are expected to remain the major factors influencing the future growth of the global tin market.
About Maximize Market Research:
Maximize Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Contact Maximize Market Research:
3rd Floor, Navale IT Park, Phase 2
Pune Banglore Highway, Narhe,
Pune, Maharashtra 411041, India
sales@maximizemarketresearch.com
+91 96071 95908, +91 9607365656