Global Paralleling Switchgear Market to Reach USD 2.87 Billion by 2032
By Punampatil2001, 2026-11-18
Global Paralleling Switchgear Market Overview
The Global Paralleling Switchgear Market was valued at USD 1.77 billion in 2025 and is projected to reach USD 2.87 billion by 2032 , growing at a CAGR of 7.15% during the forecast period (2026–2032) . The market is experiencing growth due to rising demand for uninterrupted power supply, increasing industrialization, and expanding data center infrastructure. Paralleling switchgear connects and synchronizes multiple generators or power sources to ensure reliable electricity distribution across commercial, industrial, and critical infrastructure facilities.
Increasing investments in data centers, healthcare, manufacturing, and renewable energy projects are driving market demand. Technological advancements in automated synchronization, intelligent controllers, remote monitoring, and power management systems are creating new growth opportunities. Additionally, grid modernization, rising electricity consumption, and the need for efficient backup power solutions are expected to support market expansion.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/24270/

US Paralleling Switchgear Market: Latest Trends and Investments
The United States is witnessing increasing demand for paralleling switchgear due to expanding data centers, artificial intelligence infrastructure, and industrial electrification. In March 2024, Schneider Electric announced a USD 140 million investment in its US manufacturing operations to expand electrical equipment production. Similarly, Siemens announced a USD 36 million investment in its Wendell, North Carolina facility in September 2024 to increase manufacturing capacity. These investments support growing demand for advanced switchgear and reliable power distribution systems.
Global Paralleling Switchgear Market Segmentation Analysis
By Transition Type: The open-transition segment holds the largest market share due to its simple design, cost-effectiveness, and easy installation. It is widely used in commercial and industrial facilities for backup power applications.
By Voltage: The low-voltage segment dominates the market due to its extensive adoption in hospitals, commercial buildings, manufacturing facilities, and data centers.
By Application: The standby power segment holds the largest market share, accounting for more than 43% in 2023. Increasing demand for uninterrupted electricity in critical facilities is supporting its dominance.
By End User: The commercial and industrial segment dominates the market due to increasing electricity requirements, industrial automation, and the need for continuous operations.
Competitive Analysis: Top 5 Companies
1. ABB Ltd.
ABB Ltd. focuses on intelligent switchgear, digital monitoring, automation, and energy-efficient electrical systems. Its advanced electrification and smart power management technologies support reliable power distribution and operational efficiency.
2. Schneider Electric SE
Schneider Electric provides advanced switchgear, energy management, and automation solutions. Its USD 140 million US manufacturing investment announced in 2024 supports production expansion and increasing demand from data centers and critical infrastructure.
3. Siemens AG
Siemens AG develops intelligent switchgear, digital control systems, and electrical distribution technologies. Its USD 36 million investment in its North Carolina facility in 2024 supports manufacturing expansion and growing demand from data centers and industrial applications.
4. Eaton Corporation plc
Eaton provides power distribution, circuit protection, backup power, and electrical management solutions. In 2024, the company highlighted more than USD 1 billion in incremental capacity investments to support growing demand from industrial, utility, and data center markets.
5. General Electric Company (GE)
GE focuses on power generation, electrical infrastructure, power conversion, and grid modernization technologies. Its capabilities in advanced power management and renewable energy integration support opportunities in reliable electricity distribution.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/24270/
Regional Analysis
United States: The US market is driven by expanding data centers, industrial automation, healthcare infrastructure, and electricity network modernization. Government investments under the Infrastructure Investment and Jobs Act support grid improvements and advanced electrical infrastructure.
United Kingdom: The UK market is supported by renewable energy integration, industrial electrification, and electricity network modernization. Government net-zero initiatives encourage investments in efficient power distribution technologies.
Germany: Germany's strong manufacturing sector, industrial automation, and renewable energy expansion are driving demand. Government energy transition policies support modernization of electrical infrastructure.
France: France is witnessing increasing demand due to industrial modernization, renewable energy investments, and electricity network development. Government initiatives promoting energy efficiency are supporting market opportunities.
Japan: Japan's focus on energy security, disaster preparedness, and reliable electricity supply is supporting market growth. Investments in renewable energy and resilient infrastructure are encouraging advanced power management solutions.
China: China's rapid industrialization, urban development, and rising electricity consumption are driving demand. Government investments in smart grids, renewable energy, and power infrastructure modernization are supporting market expansion.
► Get to Know More About This Market Study: https://www.maximizemarketresearch.com/market-report/global-paralleling-switchgear-market/24270/
Conclusion
The Global Paralleling Switchgear Market is expected to experience steady growth through 2032, driven by increasing electricity consumption, data center expansion, industrial automation, and demand for uninterrupted power supply. Standby power applications and low-voltage systems will remain important growth segments. Investments in intelligent switchgear, digital monitoring, automated synchronization, and renewable energy integration will create significant opportunities. Increasing demand for reliable backup power and modernization of electrical infrastructure will remain the major factors supporting the market's long-term growth.
About Maximize Market Research:
Maximize Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Contact Maximize Market Research:
3rd Floor, Navale IT Park, Phase 2
Pune Banglore Highway, Narhe,
Pune, Maharashtra 411041, India
sales@maximizemarketresearch.com
+91 96071 95908, +91 9607365656
Global Railway Connectors Market Overview
The Global Railway Connectors Market is witnessing steady growth due to increasing railway electrification, modernization of transportation infrastructure, and rising demand for reliable passenger and freight transportation. Railway connectors are essential electrical and electronic components used for transmitting power, data, and signals across railway systems. They support critical operations involving traction systems, braking mechanisms, signaling equipment, lighting, and communication networks.
The global railway connectors market was valued at approximately USD 1.65 billion in 2022 and is projected to reach USD 2.44 billion by 2029, registering a CAGR of 5.8% during the forecast period (2023–2029).
The growing adoption of advanced railway technologies is a major factor supporting market expansion. Increasing urbanization, globalization, and international trade are encouraging governments to improve railway infrastructure and expand freight transportation networks. Additionally, rising passenger mobility, intercity travel, and demand for high-speed trains are increasing the requirement for durable and high-performance connectors. Railway operators are increasingly adopting fiber-optic, miniature, and ultra-resistant connectors to improve operational efficiency, safety, and communication reliability. However, high installation and maintenance costs, along with the technical complexity of railway systems, may restrict market growth. The development of compact, lightweight, vibration-resistant, and energy-efficient connectors presents significant opportunities for manufacturers.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/78032/

U.S. Railway Connectors Market: Latest Trends and Investments
The United States is an important market for railway connectors, supported by increasing investments in passenger rail modernization, freight transportation, and railway safety improvements. In 2024, the U.S. Department of Transportation announced more than USD 2.4 billion in funding through the Consolidated Rail Infrastructure and Safety Improvements (CRISI) Program to support 122 railway improvement projects across 41 states and Washington, D.C. The funding focuses on railway safety, track modernization, bridge rehabilitation, port connectivity, and locomotive improvements. Additionally, in November 2024, the government announced nearly USD 1.5 billion for 19 infrastructure projects along the Northeast Corridor. These investments are expected to increase demand for advanced power connectors, data connectors, and signaling components. The growing adoption of digital railway technologies, automated train control, and passenger information systems will further create opportunities for railway connector manufacturers in the United States.
Global Railway Connectors Market Segmentation Analysis
The Global Railway Connectors Market is segmented by application, connector type, and platform.
- By Application: The market includes Electric Multiple Units (EMUs), Diesel Multiple Units (DMUs), passenger coaches, subways/metros, and others. EMUs are expected to experience the highest growth due to increasing railway electrification and the transition toward environmentally friendly transportation systems.
- By Connector Type: The market is categorized into data connectors, power connectors, and broad-level connectors. Among these, data connectors hold the largest market share because of their extensive use in transmitting information between railway vehicles, signaling systems, communication networks, and control equipment. Increasing digitalization and real-time railway monitoring are further strengthening demand for these connectors.
- By Platform: The market is divided into rolling stock and signaling. The rolling-stock segment is benefiting from increasing demand for modern locomotives, electric trains, passenger coaches, and freight transportation vehicles.
The growing integration of electronic systems, advanced communication technologies, and safety equipment across railway networks is expected to support demand across all three segments.
Competitive Landscape and Top 5 Companies
The Global Railway Connectors Market includes several established manufacturers focusing on product innovation, technological advancement, product reliability, and international expansion.
1. Fischer Connectors
Fischer Connectors specializes in high-performance circular connectors and cable assemblies designed for demanding industrial environments. Its focus on compact, durable, and environmentally sealed connectivity solutions supports applications requiring resistance to vibration, moisture, and temperature variations. These technologies provide opportunities in modern railway communication and control systems.
2. TE Connectivity
TE Connectivity is a major global supplier of electrical and electronic connectivity solutions. Its railway-related product portfolio includes connectors and components designed for demanding transportation environments. The company's focus on reliable connectivity, advanced materials, and miniaturized electronic solutions supports railway electrification, data transmission, and signaling applications.
3. Sichuan Yonggui Science and Technology
Sichuan Yonggui Science and Technology develops electrical connectors and interconnection solutions for railway transportation and industrial applications. The company benefits from China's railway infrastructure expansion and increasing demand for high-speed railway equipment. Its focus on railway-specific connectivity products and domestic manufacturing capabilities provides opportunities in the growing Asian market.
4. Amphenol Corporation
Amphenol Corporation offers railway and mass-transit connectivity solutions, including rectangular connectors, RF connectors, and high-performance electrical components. Its railway products are designed to withstand vibration, environmental exposure, and demanding operating conditions. The company also offers lightweight composite connector solutions that comply with railway fire and smoke safety requirements. These developments support modern rolling-stock applications and railway communication systems.
5. Smiths Interconnect
Smiths Interconnect focuses on advanced connectivity technologies for high-reliability applications. In June 2024, the company introduced Hypertac Green Connect technology, which provides up to 90% more energy transfer than its existing offering and is designed for applications including electric transportation and rail. The technology also eliminates lead and beryllium from the product design. In July 2024, it introduced its Mini-Lock connector, supporting signal frequencies up to 110 GHz and offering improved resistance to vibration and shock. Such innovations demonstrate the potential for advanced connector technologies in future railway systems.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/78032/
Regional Analysis: Global Railway Connectors Market
United States: North America held the largest regional share in 2022. The United States benefits from government funding for railway modernization, freight transportation, and passenger rail infrastructure. Investments through the Bipartisan Infrastructure Law are supporting advanced railway equipment, signaling upgrades, and connectivity technologies.
United Kingdom: The UK railway connectors market is supported by railway modernization, electrification initiatives, and investments in passenger transportation infrastructure. Government support for railway operations and infrastructure improvements encourages demand for reliable connectors used in rolling stock, signaling, and communication systems.
Germany: Germany represents an important European railway market due to its advanced railway manufacturing ecosystem and extensive rail network. Deutsche Bahn reported approximately EUR 20.1 billion in spending on network expansion, renewal, stations, and energy systems during 2024. Infrastructure modernization and digital railway initiatives are creating opportunities for advanced electrical connectors and signaling technologies.
France: France is experiencing demand for railway connectors through investments in rail infrastructure, high-speed railway services, and urban transportation networks. Investment in transport infrastructure reached approximately EUR 27.5 billion in 2024, with railway infrastructure investment increasing by 3.4%. These developments support demand for advanced railway electrical and communication components.
Japan: Japan's railway connectors market benefits from its advanced railway technology, high-speed Shinkansen network, and strong emphasis on passenger safety and operational reliability. The country's railway electrification and technological expertise support demand for high-performance connectors used in train control, power transmission, and communication systems.
China: China is an important growth market because of its extensive high-speed railway expansion and government-backed infrastructure development. In 2024, China's railway fixed-asset investment reached approximately CNY 850.6 billion, increasing by 11.3% year-on-year. The country also opened more than 3,100 km of new railway lines during the year. These developments are increasing demand for railway connectors used in electric trains, signaling equipment, and advanced communication networks.
► Get to Know More About This Market Study: https://www.maximizemarketresearch.com/market-report/global-railway-connectors-market/78032/
Conclusion
The Global Railway Connectors Market is expected to experience consistent growth as countries increase investments in railway electrification, high-speed transportation, and infrastructure modernization. The projected growth to USD 2.44 billion by 2029 reflects the increasing importance of reliable connectivity solutions in modern railway operations.
In my view, the most significant growth opportunities will come from electric multiple units, advanced data connectors, fiber-optic communication, and lightweight, high-performance connector technologies. Manufacturers investing in improved energy efficiency, fire-resistant materials, vibration protection, and high-speed data transmission will be better positioned to benefit from changing railway requirements. Furthermore, government infrastructure funding and the expansion of digital railway networks will remain major factors influencing long-term market growth.
About Maximize Market Research:
Maximize Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Contact Maximize Market Research:
3rd Floor, Navale IT Park, Phase 2
Pune Banglore Highway, Narhe,
Pune, Maharashtra 411041, India
sales@maximizemarketresearch.com
+91 96071 95908, +91 9607365656
Norway Electric Car Market to Grow, Driven by Government Incentives and Zero-Emission Vehicle Demand
By Punampatil2001, 2026-11-17
Norway Electric Car Market Overview
The Norway Electric Car Market is witnessing significant growth as the country continues to lead the global transition towards sustainable transportation. Increasing environmental awareness, supportive government policies, expanding charging infrastructure, and technological advancements in electric vehicle (EV) batteries are driving market development. Norway has established itself as one of the world's leading electric car markets through long-term investments in clean mobility and attractive incentives for electric vehicle buyers.
The market is supported by Norway's commitment to reducing carbon emissions and promoting zero-emission transportation. The availability of renewable electricity, particularly hydropower, makes electric cars an environmentally attractive alternative to conventional petrol and diesel vehicles. Government initiatives, including tax advantages, reduced road charges, toll benefits, and investments in charging infrastructure, have encouraged consumers to adopt electric vehicles.
Furthermore, increasing demand for fuel-efficient vehicles, improvements in battery performance, longer driving ranges, and the introduction of affordable electric car models are creating new opportunities. The development of fast-charging networks, battery recycling technologies, and advanced vehicle software is also expected to support long-term market expansion.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/65503/
US Electric Car Market: Latest Trends and Investments in 2024
The United States electric car market experienced continued growth in 2024, supported by increasing consumer interest, government incentives, domestic manufacturing investments, and improvements in battery technology. Automakers are expanding their electric vehicle portfolios to meet rising demand for sustainable transportation. The EV manufacturing sector attracted substantial investment in battery production, vehicle assembly, and charging infrastructure. Federal support through the Inflation Reduction Act and Bipartisan Infrastructure Law encouraged domestic production and charging network development. These initiatives strengthened the electric vehicle supply chain and created opportunities for battery manufacturers and automotive technology companies.
Norway Electric Car Market Segmentation Analysis
The Norway Electric Car Market is segmented by technology, product, battery type, battery capacity, and end-user.
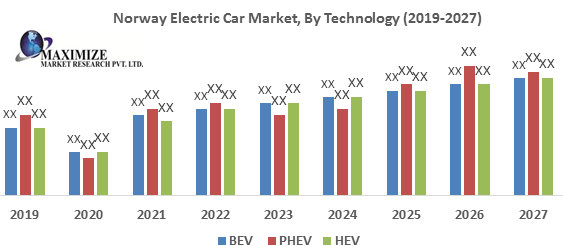
- By Technology: Battery Electric Vehicles (BEV), Plug-in Hybrid Electric Vehicles (PHEV), and Hybrid Electric Vehicles (HEV). BEVs represent the leading technology segment, supported by Norway's strong preference for fully electric transportation and extensive charging infrastructure.
- By Product: Hatchback, Sedan, SUV, and Others. SUVs represent an important product category because of their spacious interiors, driving comfort, versatility, and increasing availability in electric models.
- By Battery: Lithium Iron Phosphate (LFP), Lithium Nickel Manganese Cobalt (Li-NMC), and Others. Li-NMC batteries are important because of their high energy density and suitability for vehicles requiring longer driving ranges.
- By Battery Capacity: Above 201 Ah and Below 201 Ah. Higher-capacity batteries attract consumers seeking longer driving ranges and improved vehicle performance.
- By End-User: Shared Mobility Providers, Government Organizations, Personal Users, and Others. Personal users are a major consumer group due to increasing household adoption and government incentives.
Competitive Landscape and Top 5 Companies
The Norway Electric Car Market includes established international automotive manufacturers competing through vehicle innovation, battery development, product launches, and investments in electric mobility.
1. Tesla
Tesla is an important competitor in Norway's electric car industry, offering vehicles with advanced battery systems, software integration, and long driving ranges. Its Model Y and Model 3 have contributed to electric vehicle adoption. The company continues to develop battery efficiency, charging technology, and vehicle software to strengthen its competitive position.
2. BMW
BMW is strengthening its electric vehicle portfolio through advanced battery technology, efficient electric motors, and lightweight vehicle platforms. Its Neue Klasse development programme focuses on next-generation electric architecture, improved driving range, and charging performance. These innovations can improve the appeal of premium electric vehicles.
3. Renault
Renault is expanding its electric mobility business through its dedicated EV activities and Ampere platform. The company focuses on affordable electric vehicles, battery cost reduction, and improved vehicle efficiency. Its electric vehicle development strategy can support wider adoption among price-conscious consumers.
4. Hyundai Motor Company
Hyundai is investing in electric vehicle technology, battery development, and advanced mobility solutions. In August 2024, the company announced its Hyundai Way strategy, including plans for 21 EV models by 2030 and investment of KRW 120.5 trillion between 2024 and 2033. Its focus on affordable batteries, safety improvements, and electrification is expected to strengthen its market position.
5. Chevrolet
Chevrolet, a General Motors brand, is contributing to electric vehicle adoption through models designed for different customer requirements. The company is expanding its EV offerings and focusing on battery technology, vehicle affordability, and improved driving range. Its electric SUV portfolio can help increase consumer access to electric mobility.
Overall, these manufacturers are strengthening competition through improved battery performance, vehicle efficiency, software innovation, and wider product availability.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/65503/
Regional Analysis
1. United States: The United States is an important electric vehicle market, supported by federal tax incentives, domestic battery manufacturing investments, and charging infrastructure development. Electric vehicle adoption is increasing as consumers shift towards sustainable transportation.
2. United Kingdom: The UK electric car market is expanding through its Zero Emission Vehicle mandate, which came into force in January 2024. Government targets, charging infrastructure investments, and growing consumer awareness are supporting electric vehicle adoption.
3. Germany: Germany is an important automotive manufacturing hub with strong capabilities in electric vehicle engineering and battery technology. Government support, automotive research, and investments in advanced manufacturing are contributing to market development.
4. France: France is promoting electric mobility through environmental incentives, vehicle manufacturing investments, and emission-reduction policies. Government support and the development of affordable electric vehicle models are contributing to market expansion.
5. Japan: Japan is gradually expanding its electric vehicle industry through investments in battery technology, automotive research, and next-generation mobility solutions. Government support for clean transportation and advanced battery development offers opportunities for future growth.
6. China: China is the world's largest electric car market, supported by government incentives, consumer demand, domestic battery manufacturing, and competitive vehicle prices. Its extensive battery production capabilities and strong automotive supply chain are further strengthening its global position.
► Get to Know More About This Market Study: https://www.maximizemarketresearch.com/market-report/norway-electric-car-market/65503/
Conclusion
The Norway Electric Car Market is expected to maintain its strong position in the global transition towards sustainable transportation. Government incentives, increasing environmental awareness, renewable electricity availability, and continuous improvements in battery technology are the major factors supporting market development. Norway's electric vehicle adoption demonstrates how consistent government policies and investments in charging infrastructure can accelerate the transition from conventional vehicles to electric mobility.
Electric vehicles accounted for approximately 88% of new passenger car sales in Norway in 2024, demonstrating the country's advanced electric mobility ecosystem.
In the coming years, opportunities in fast-charging infrastructure, high-capacity batteries, affordable electric vehicles, battery recycling, and advanced vehicle technologies are expected to create new business opportunities. Automakers focusing on innovation, competitive pricing, energy efficiency, and improved driving range will be better positioned to benefit from market growth. Overall, continued technological advancement and supportive government policies will remain essential to the long-term development of the Norway Electric Car Market.
About Maximize Market Research:
Maximize Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Contact Maximize Market Research:
3rd Floor, Navale IT Park, Phase 2
Pune Banglore Highway, Narhe,
Pune, Maharashtra 411041, India
sales@maximizemarketresearch.com
+91 96071 95908, +91 9607365656
Agriculture Tire Market Overview
The Global Agriculture Tire Market was valued at approximately USD 8.34 billion in 2022 and is projected to reach USD 12.14 billion by 2027 , according to the market estimation presented by Maximize Market Research. The market is expected to grow at a compound annual growth rate (CAGR) of 5.51% during the forecast period 2023–2029 . Increasing agricultural mechanization, rising food consumption, expanding tractor production, and growing adoption of modern farming equipment are among the major factors supporting market growth. Agricultural tires play an essential role in improving vehicle stability, traction, load-bearing capacity, and operational efficiency across farming activities. These tires are manufactured using natural rubber, synthetic rubber, steel, polyester, and carbon black to provide durability under demanding agricultural conditions.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/128476/

Market Growth Drivers and Opportunities
The increasing global population and rising demand for food production are encouraging farmers to adopt mechanized farming practices. Tractors, harvesters, loaders, trailers, and other agricultural vehicles require specialized tires capable of handling heavy loads and different soil conditions. The growing use of advanced agricultural machinery for ploughing, sowing, irrigation, and harvesting is therefore creating significant demand for agricultural tires.
Technological advancements in tire manufacturing are another important growth driver. Innovations such as Increased Flexion (IF), Very High Flexion (VF), and improved lug technologies provide better traction, flexibility, durability, and reduced soil compaction. These technologies help farmers improve fuel efficiency and protect soil productivity. Government subsidies supporting agricultural mechanization, particularly in developing economies, are also encouraging equipment purchases. Furthermore, increasing awareness of tire maintenance and the growing replacement demand from existing agricultural vehicle owners are creating attractive opportunities for manufacturers. However, fluctuating raw material prices, weather-dependent agricultural activities, and high equipment costs may restrict market growth.
United States Market Trends and Investments
The United States represents an important market for agricultural tires because of its advanced farming infrastructure, large-scale agricultural operations, and adoption of technologically advanced farm equipment. U.S. farm tractor retail sales declined by approximately 13.2% in 2024 compared with 2023, reflecting weaker equipment demand amid high interest rates and uncertainty in the agricultural economy. Despite this temporary slowdown, manufacturers continued investing in advanced tire technologies. In August 2024, Firestone Ag introduced premium Bridgestone VX, VT, and VX-R tractor tire lines for farmers in the United States and Canada. The VX-TRACTOR tire offers up to 45% more wear life through advanced tread and lug designs, improving traction, durability, and road performance. Such innovations are expected to strengthen replacement demand and support the adoption of premium agricultural tires.
Agriculture Tire Market Segmentation
The market is segmented by tire type, application, and sales channel.
- By Tire Type: The bias tire segment holds the largest market share. Bias tires feature diagonally arranged fabric layers that provide strong load-bearing capacity and durability. Their suitability for tractors, trailers, sprayers, and other agricultural machinery supports their widespread adoption, particularly in developing agricultural markets.
- By Application: The tractor segment represents the leading application category, supported by the extensive use of tractors in land preparation, planting, cultivation, and transportation activities. Increasing tractor utilization across commercial and small-scale farming operations continues to generate demand.
- By Sales Channel: The aftermarket segment dominates the market, accounting for approximately 56% of the global market share . Lower replacement costs, wide product availability, and convenient purchasing options make aftermarket tires attractive to farmers seeking affordable maintenance solutions.
Competitive Analysis
The global agriculture tire market includes established manufacturers focusing on product innovation, manufacturing capabilities, distribution expansion, and improved tire performance. The key companies identified in the market report include Bridgestone, Alliance Tire Company, Birla Tires, Titan Tire Corporation, and Belshina.
1. Bridgestone: Bridgestone focuses on premium agricultural tire technology, improved durability, and advanced tread designs. Its Firestone Ag division introduced the VX, VT, and VX-R tractor tire ranges in 2024. The VX-TRACTOR provides up to 45% greater wear life, supporting longer operating periods and improved farm productivity.
2. Alliance Tire Company: Alliance, part of Yokohama Off-Highway Tires, focuses on agricultural, industrial, and construction tire solutions. Its Agriflex technology incorporates IF and VF tire designs, allowing tires to carry heavy loads at lower inflation pressures. These technologies help reduce soil compaction while maintaining traction and operational efficiency.
3. Birla Tires: Birla Tires is expanding its off-highway tire portfolio through research and development in advanced materials. Its innovation areas include nano-carbon composites, specialized resins, polymer grafting, and sustainable rubber compounds. These developments aim to improve tire life, traction, durability, and environmental performance.
4. Titan Tire Corporation: Titan International continues to strengthen its agricultural tire manufacturing capabilities. In March 2024, the company invested USD 2 million in its Des Moines, Iowa, facility, installing two new tire-curing presses to increase production capacity and improve supply availability. Its Low Sidewall (LSW) technology also helps reduce soil compaction, power hop, and fuel consumption.
5. Belshina: Belshina is an established tire manufacturer offering products for agricultural and industrial applications. Its agricultural tire opportunity is supported by demand for durable tires capable of operating under heavy loads and challenging field conditions. Product development focused on improved tread designs, traction, and wear resistance can strengthen its competitiveness in the replacement and original equipment markets.
Regional Analysis
United States: The United States accounted for more than 55% of the North American agricultural tire market in 2020. The North American market was valued at approximately USD 808.9 million in 2020 and was projected to grow at a CAGR of 5.2%. Advanced farming equipment, large agricultural operations, and demand for efficient machinery support market development. Government initiatives through the U.S. Department of Agriculture, including subsidized crop insurance and agricultural support programmes, contribute to the development of the farming sector.
United Kingdom: The UK agricultural tire market benefits from established agricultural machinery manufacturers, mechanized farming practices, and demand for efficient crop production. Government support through agricultural productivity and environmental programmes encourages farmers to invest in modern machinery and sustainable farming practices.
Germany: Germany is an important European market because of its advanced agricultural machinery industry and adoption of precision farming technologies. Government support for agricultural modernization and investments in efficient farming equipment create opportunities for premium radial tires, flexible tire technologies, and durable replacement products.
France: France's agricultural sector benefits from extensive crop cultivation and modern farm machinery. Agricultural modernization initiatives and sustainability-focused farming practices encourage the adoption of advanced tractors and harvesting equipment, supporting demand for high-performance agricultural tires.
Japan: Japan's agricultural tire market is supported by increasing automation and smart farming adoption. In 2024, Japan introduced its Smart Agriculture Technology Utilization Promotion Act, which came into force in October 2024. The legislation provides financial and other support for farmers and businesses investing in smart agricultural technologies, creating opportunities for advanced agricultural machinery and specialized tires.
China: China represents a significant agricultural tire market because of its large agricultural sector, growing mechanization, and increasing demand for modern farming equipment. In April 2024, China's Ministry of Agriculture and Rural Affairs and Ministry of Finance introduced the 2024–2026 agricultural machinery purchase and application subsidy programme. The initiative supports the purchase of advanced agricultural machinery, including high-performance planting and harvesting equipment, strengthening the long-term demand outlook for agricultural tires.
► Get to Know More About This Market Study: https://www.maximizemarketresearch.com/market-report/agriculture-tire-market/128476/
Conclusion
The global Agriculture Tire Market is expected to experience steady growth, supported by increasing farm mechanization, rising food production requirements, technological advancements, and expanding agricultural equipment adoption. The growing replacement market and demand for durable, high-performance tires will remain important contributors to industry expansion. Manufacturers investing in IF and VF technologies, improved rubber compounds, sustainable materials, and soil-friendly tire designs are likely to gain competitive advantages. The development of precision agriculture and advanced tractor technologies will create significant opportunities for tire manufacturers. Companies focusing on fuel efficiency, longer tire life, reduced soil compaction, and affordable replacement products will be well-positioned to capture future market opportunities.
About Maximize Market Research:
Maximize Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Contact Maximize Market Research:
3rd Floor, Navale IT Park, Phase 2
Pune Banglore Highway, Narhe,
Pune, Maharashtra 411041, India
sales@maximizemarketresearch.com
+91 96071 95908, +91 9607365656
Global Aircraft Switches Market Overview
The Global Aircraft Switches Market is witnessing steady growth, supported by increasing aircraft production, rising air passenger traffic, defence modernization programmes, and advancements in aviation technologies. According to Maximize Market Research, the global Aircraft Switches Market was valued at approximately USD 2.58 billion in 2025 and is projected to reach USD 3.4 billion by 2032 , registering a CAGR of 4.05% during the forecast period (2026–2032) .
Aircraft switches are essential electrical components used by pilots and crew members to control and monitor various aircraft operations, including lighting, navigation, communication, engine starting, power distribution, and cabin management systems.
The growing demand for commercial aircraft is one of the major factors supporting market expansion. Increasing passenger travel, airline fleet expansion, and replacement of ageing aircraft are encouraging aircraft manufacturers to increase production capacity. Additionally, the rising adoption of fly-by-wire technology and advanced avionics systems is creating demand for reliable and efficient switching components.
Furthermore, growing defence expenditure and military aircraft procurement are creating new opportunities for manufacturers. Countries are investing in advanced fighter aircraft, transport aircraft, helicopters, and unmanned aerial vehicles to strengthen their defence capabilities. The increasing integration of in-flight entertainment and connectivity (IFEC) systems is also generating demand for additional switches in aircraft cabins. Technological advancements in lightweight materials, durable electrical components, and automated switching systems are expected to create further opportunities during the forecast period.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/121023/

United States Market Trends and Investments
The United States represents an important market for aircraft switches, supported by its well-established aerospace manufacturing industry, commercial aviation network, and substantial defence expenditure. In 2024, the US aviation industry focused on improving aircraft manufacturing capabilities, strengthening supply chains, and upgrading aviation safety standards. The FAA Reauthorization Act of 2024, signed on May 16, 2024, authorized aviation programmes and investments through fiscal year 2028, supporting aviation safety, infrastructure modernization, workforce development, and emerging aviation technologies. Additionally, Honeywell completed its approximately USD 1.9 billion acquisition of CAES Systems in September 2024, strengthening its defence and aerospace technology portfolio. These developments, alongside increasing demand for aircraft avionics, electrical systems, and advanced cockpit technologies, are expected to support demand for aircraft switches in the United States.
Global Aircraft Switches Market Segmentation Analysis
The global Aircraft Switches Market is segmented by type, platform, application, and end-user.
- By Type: Manual switches dominated the market in 2025 and are expected to maintain their leading position during the forecast period. These switches include pushbutton, toggle, rocker, and rotary switches. Their extensive use in cockpit dashboards, lighting systems, communication equipment, and aircraft power controls supports their market dominance.
- By Platform: Fixed-wing aircraft represent an important market segment because of the extensive use of commercial passenger aircraft, military aircraft, and cargo aircraft. Their complex electrical architectures require multiple switching components for different operational functions.
- By Application: The commercial aircraft segment held the dominant market position in 2025. Increasing aircraft deliveries, growing passenger traffic, and the integration of in-flight entertainment and connectivity systems are generating demand for switches in aircraft cockpits and cabins.
- By End-User: The market is divided into OEM and aftermarket segments. Both segments benefit from aircraft production, component replacement, maintenance, and modernization requirements.
The dominance of manual switches and commercial aircraft highlights the importance of conventional cockpit controls and increasing aircraft manufacturing activity in the global market.
Competitive Analysis
The competitive landscape includes established aerospace manufacturers and electrical component suppliers. The following are five key companies listed in the market report.
1. Safran SA
Safran is strengthening its position in aircraft electrical systems through technological development and strategic acquisitions. Its acquisition of Thales' aeronautical electrical systems activities expanded its capabilities in electrical power generation, conversion, and motors for civil and military aircraft. In 2024, Safran reported total research and development expenditure of approximately EUR 1.98 billion, supporting advanced aerospace technologies and decarbonization initiatives. Its focus on aircraft electrification and efficient power management can create opportunities for advanced switching technologies.
2. Honeywell International Inc.
Honeywell is a major supplier of aerospace technologies, including avionics, flight controls, sensors, and electrical systems. In September 2024, the company completed its USD 1.9 billion acquisition of CAES Systems, strengthening its defence and aerospace electronics capabilities. In December 2024, Honeywell also signed a strategic agreement with Bombardier to provide advanced avionics, propulsion, and satellite communication technologies for current and future aircraft. These developments can strengthen its position in advanced aircraft control and switching applications.
3. Eaton Corporation plc
Eaton is strengthening its aerospace business through intelligent power management, electrical distribution, and advanced component technologies. Its 2024 annual report highlighted growth opportunities in commercial aerospace and defence markets, supported by increasing aircraft demand and electrification. The company reported aerospace segment sales of approximately USD 3.74 billion in 2024, compared with USD 3.41 billion in 2023. Its continued focus on reliable electrical power management and advanced aerospace components supports opportunities in aircraft switching systems.
4. TE Connectivity Corporation
TE Connectivity develops advanced connectivity, sensor, and electronic component solutions for aerospace and defence applications. Its expertise in high-performance electrical connectivity, miniaturized components, and reliable signal transmission supports the development of compact aircraft electrical systems. Increasing demand for lightweight aircraft components, advanced avionics, and reliable electrical connections provides opportunities for the company to strengthen its aerospace product portfolio.
5. RTX Corporation
RTX, through its Collins Aerospace business, is investing in advanced avionics, electrical power systems, and aircraft technologies. In February 2024, Collins Aerospace was selected to supply advanced avionics hardware for 140 Air India Boeing 737 MAX aircraft. In July 2024, it also announced progress in the Clean Aviation HECATE project, which aims to develop high-voltage electrical distribution technologies for future hybrid-electric aircraft. These developments support innovation in aircraft electrical management and create opportunities for advanced switching components.
Regional Analysis
United States: North America accounted for approximately 45% of the global Aircraft Switches Market in 2025, making it the leading regional market. The United States is a major contributor because of its established aircraft manufacturing industry, advanced defence programmes, strong aviation infrastructure, and presence of leading aerospace companies. Government support through the FAA Reauthorization Act of 2024 and investments in aviation safety and modernization are supporting industry development.
United Kingdom: The United Kingdom is an important aerospace manufacturing and engineering hub. Its established aviation supply chain, aircraft maintenance industry, and investments in aerospace research and development support demand for advanced aircraft electrical components. The development of hybrid-electric aviation technologies is also creating opportunities for innovative switching systems.
Germany: Germany's aerospace industry benefits from advanced engineering capabilities, aircraft component manufacturing, and strong research infrastructure. Government-supported aerospace innovation, industrial digitalization, and investments in sustainable aviation technologies are encouraging the development of efficient electrical systems and aircraft components.
France: France plays a significant role in the European aerospace industry through major aircraft manufacturers and equipment suppliers. The presence of Safran and its investments in aircraft electrical systems, power conversion, and electrification technologies supports the development of advanced aircraft switches. Government and European Union initiatives promoting sustainable aviation and aerospace research further strengthen market opportunities.
Japan: Japan's aircraft switches market benefits from its advanced electronics manufacturing capabilities, growing aviation industry, and investments in aerospace technology. Increasing demand for commercial aircraft, defence modernization, and aircraft maintenance activities is supporting the adoption of reliable electrical switching components.
China: China represents an important growth opportunity because of its expanding aviation sector, increasing passenger traffic, and investments in domestic aircraft manufacturing. Government initiatives supporting indigenous aerospace production and defence modernization are encouraging demand for aircraft electrical components. Growing commercial aircraft deliveries and the development of domestic aviation capabilities are expected to support long-term market expansion.
► Get to Know More About This Market Study: https://www.maximizemarketresearch.com/market-report/global-aircraft-switches-market/121023/
Conclusion
The global Aircraft Switches Market is expected to experience consistent growth through 2032, supported by increasing aircraft production, commercial aviation expansion, defence modernization, and technological advancements in aircraft electrical systems. Manual switches and commercial aircraft will remain important market segments, while increasing adoption of automated switching technologies and advanced avionics will create additional growth opportunities. North America's strong aerospace manufacturing base will continue to support its market leadership.
In my view, the major growth opportunity lies in the development of lightweight, durable, highly reliable, and advanced electrical switching solutions for next-generation aircraft. Manufacturers investing in smart switching technologies, aircraft electrification, improved safety systems, and efficient power management will be better positioned to capture emerging opportunities. Furthermore, increasing investments in hybrid-electric aircraft and military aviation modernization are expected to create new demand for innovative aircraft switching components over the coming years.
About Maximize Market Research:
Maximize Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Contact Maximize Market Research:
3rd Floor, Navale IT Park, Phase 2
Pune Banglore Highway, Narhe,
Pune, Maharashtra 411041, India
sales@maximizemarketresearch.com
+91 96071 95908, +91 9607365656
Global Automotive Natural Gas Vehicle Market to Reach USD 42.83 Million by 2029, Growing at 3.3% CAGR
By Punampatil2001, 2026-11-17
Global Automotive Natural Gas Vehicle Market Overview
The Global Automotive Natural Gas Vehicle (NGV) Market is witnessing steady growth as governments, automotive manufacturers, and transportation companies increasingly focus on reducing carbon emissions and improving fuel efficiency. The global Automotive Natural Gas Vehicle Market was valued at approximately USD 34.12 million in 2022 and is projected to reach USD 42.83 million by 2029, growing at a CAGR of 3.3% during the forecast period 2023–2029. The market estimation is presented in thousand units rather than conventional monetary value.
Natural gas vehicles use compressed natural gas (CNG) or liquefied natural gas (LNG) as alternative fuels to conventional petrol and diesel. These vehicles offer several advantages, including lower fuel costs, reduced emissions, improved fuel economy, and lower noise pollution. Natural gas is also widely available in several countries, supporting energy security and reducing dependence on imported petroleum products.
The growing adoption of alternative-fuel vehicles, increasing environmental awareness, and stringent government emission regulations are among the major factors driving market growth. Natural gas vehicles are particularly suitable for public transportation, logistics, waste collection, and long-distance commercial transportation. Furthermore, technological advancements in fuel storage systems, engine performance, and fuel injection technologies are creating new opportunities for manufacturers. The development of renewable natural gas (RNG), produced from organic waste, is also expected to strengthen the market by providing a lower-carbon alternative to conventional natural gas.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/16556/

US Market Trends and Investment Opportunities
The United States is witnessing increasing interest in renewable natural gas and alternative-fuel transportation, particularly in commercial vehicle fleets. In 2024, investment in renewable natural gas production continued to increase, supported by federal and state-level clean fuel initiatives. The Renewable Fuel Standard (RFS) and California's Low Carbon Fuel Standard (LCFS) have encouraged the production and use of renewable natural gas in transportation. Investment in clean transportation technologies and natural gas infrastructure has also supported market development. Additionally, Cummins continued advancing its X15N natural gas engine technology, designed to improve heavy-duty vehicle performance while meeting stringent emission requirements. These developments are creating opportunities for natural gas vehicle manufacturers, fuel suppliers, and infrastructure developers in the US market.
Market Segmentation Analysis
The market is segmented based on fuel type and vehicle type. Among fuel types, Compressed Natural Gas (CNG) held the largest market share in 2022 due to its affordability, availability, established refuelling infrastructure, and lower operating costs compared with conventional fuels. CNG is widely used in passenger cars, public transportation, and commercial vehicles. Its increasing adoption in countries with expanding natural gas distribution networks is expected to support segment growth.
By vehicle type, the passenger vehicle segment represents an important application area, supported by increasing consumer demand for economical transportation and government initiatives promoting cleaner fuels. Commercial vehicles also offer significant growth opportunities, particularly in heavy-duty transportation, logistics, public buses, and waste management fleets.
Competitive Landscape and Key Players
The Global Automotive Natural Gas Vehicle Market includes established automotive manufacturers, engine developers, and alternative-fuel technology providers.
1. Ford Motor Company
Ford Motor Company is a major automotive manufacturer offering alternative-fuel vehicle technologies and commercial transportation solutions. Its natural gas vehicle technologies include factory-prepared and alternative-fuel powertrain applications. The company's focus on improving vehicle efficiency, reducing emissions, and developing advanced commercial vehicle platforms supports the wider adoption of cleaner transportation solutions.
2. AB Volvo
AB Volvo is an important participant in the natural gas commercial vehicle industry. The company has developed LNG-powered heavy-duty trucks that support long-distance transportation and logistics operations. Its investments in alternative fuels, renewable fuels, and advanced engine technologies are strengthening its position in sustainable commercial transportation. Volvo's continued focus on reducing vehicle emissions and improving fuel efficiency is expected to create further opportunities in the NGV market.
3. CNH Industrial
CNH Industrial, through its commercial vehicle business and IVECO brand, has been actively developing natural gas-powered vehicles. IVECO offers natural gas and biomethane-compatible commercial vehicles for freight transportation and urban logistics. Its focus on biomethane technology provides opportunities to reduce the environmental impact of heavy-duty transportation while supporting the transition towards renewable fuels.
4. Cummins Inc.
Cummins is strengthening its position through investments in advanced natural gas engine technology. In September 2024, the company started full production of its X15N 15-liter natural gas engine at its Jamestown Engine Plant in the United States. The engine delivers up to 500 horsepower and 1,850 lb-ft of torque, making it suitable for heavy-duty and long-distance transportation. Its compatibility with renewable natural gas and advanced engine technologies is expected to improve the performance and environmental benefits of NGVs.
5. Volkswagen AG
Volkswagen has contributed to the development of natural gas-powered passenger vehicles through its CNG technology and TGI vehicle platforms. The company has focused on efficient engine systems and alternative fuel solutions to reduce conventional fuel consumption. Its experience in developing fuel-efficient automotive technologies supports the broader alternative-fuel vehicle industry.
Regional Analysis
United States: The US market is supported by renewable natural gas production, commercial fleet adoption, and clean transportation initiatives. Federal programmes such as the Renewable Fuel Standard and state-level low-carbon fuel policies encourage the use of renewable fuels. Growing applications in waste collection, freight transportation, and public transportation are creating opportunities for NGV manufacturers and fuel infrastructure providers.
United Kingdom: The UK market is influenced by government initiatives focused on reducing transportation emissions and improving air quality. Policies promoting cleaner commercial fleets and the use of biomethane provide opportunities for natural gas-powered heavy-duty vehicles. The development of renewable gas production and refuelling infrastructure can further support market expansion.
Germany: Germany is an important European market for alternative-fuel commercial transportation. Strict vehicle emission regulations and European Union clean transportation policies encourage manufacturers to develop lower-emission vehicle technologies. The availability of biomethane and advanced commercial vehicle engineering capabilities supports the adoption of natural gas-powered transportation solutions.
France: France is supporting the transition towards cleaner mobility through environmental regulations, alternative-fuel infrastructure, and renewable energy initiatives. The use of biomethane in commercial vehicles and public transportation creates opportunities for NGV adoption. Growing investments in sustainable logistics and low-emission transportation are expected to support the market.
Japan: Japan's NGV market is primarily driven by commercial applications, including trucks, buses, and waste collection vehicles. Approximately 80% of its natural gas vehicles are commercial vehicles. Government-supported low-carbon technology development and LNG refuelling projects are creating opportunities for natural gas transportation. In October 2024, LNG refuelling for LNG-powered trucks reached 3,000 cumulative refuelling operations in a Japanese demonstration project.
China: China is one of the most important markets for natural gas-powered heavy-duty vehicles. In 2024, the country's LNG truck adoption increased significantly due to competitive fuel prices, emission regulations, and government support. The National Development and Reform Commission's June 2024 natural gas utilisation measures identified heavy-duty transportation as a priority application for LNG. China also expanded its LNG vehicle refuelling infrastructure, supporting long-distance freight transportation.
► Get to Know More About This Market Study: https://www.maximizemarketresearch.com/market-report/global-automotive-natural-gas-vehicle-market-ngv/16556/
Conclusion
The Global Automotive Natural Gas Vehicle Market is expected to experience steady growth, supported by increasing demand for cost-effective and cleaner transportation solutions. The growing adoption of CNG and LNG vehicles in commercial transportation, logistics, public buses, and waste management fleets will remain important growth drivers. Among the major opportunities, the development of renewable natural gas, advanced natural gas engines, improved fuel storage systems, and expansion of refuelling infrastructure could significantly influence market growth. In particular, heavy-duty vehicles and long-distance freight transportation offer considerable opportunities because of their operational fuel requirements. Overall, continuous technological innovation, supportive government policies, and investments in renewable natural gas infrastructure are expected to strengthen the global NGV industry during the forecast period.
About Maximize Market Research:
Maximize Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Contact Maximize Market Research:
3rd Floor, Navale IT Park, Phase 2
Pune Banglore Highway, Narhe,
Pune, Maharashtra 411041, India
sales@maximizemarketresearch.com
+91 96071 95908, +91 9607365656
Global Automotive Air Conditioning Market to Reach USD 24.38 Billion by 2029
By Punampatil2001, 2026-11-17
Global Automotive Air Conditioning Market Overview
The Global Automotive Air Conditioning Market is witnessing steady growth due to increasing vehicle production, rising consumer demand for cabin comfort, and technological advancements in automotive cooling systems. According to Maximize Market Research, the market was valued at approximately USD 19.95 billion in 2022 and is expected to reach USD 24.38 billion by 2029 , growing at a CAGR of 2.9% during the forecast period (2023–2029).
Automotive air conditioning systems play an essential role in maintaining comfortable cabin temperatures, regulating humidity, and improving the overall driving experience in passenger and commercial vehicles.
The increasing demand for passenger cars, SUVs, and commercial vehicles is one of the major factors supporting market expansion. Growing disposable incomes, urbanization, and changing consumer preferences have encouraged automobile manufacturers to integrate advanced air conditioning systems into their vehicles. Additionally, rising temperatures across several regions and increasing awareness of passenger comfort are strengthening demand for efficient automotive cooling solutions.
Technological developments such as automatic climate control, intelligent temperature sensors, variable-speed compressors, and energy-efficient cooling systems are creating new opportunities. The growing adoption of electric vehicles (EVs) is also increasing demand for advanced thermal management systems that maintain cabin comfort while minimizing battery energy consumption. Manufacturers are focusing on lightweight components, improved refrigerants, and compact cooling technologies to enhance system efficiency and reduce environmental impact.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/27392/

US Automotive Air Conditioning Market: Latest Trends and Investments
The United States represents an important market for automotive air conditioning systems, supported by strong automobile production, high vehicle ownership, and increasing consumer expectations for advanced cabin comfort. In 2024, environmental sustainability and energy efficiency remained important industry priorities. The US Environmental Protection Agency's 2024 Automotive Trends Report highlighted the importance of improving automotive air conditioning efficiency because conventional systems can contribute to greenhouse gas emissions through refrigerant leakage and additional fuel consumption. The report also discussed performance credits for manufacturers implementing technologies that reduce air-conditioning-related emissions.
These developments are encouraging manufacturers to invest in improved refrigerants, efficient compressors, and advanced climate-control technologies. Furthermore, the increasing adoption of electric and hybrid vehicles is creating opportunities for electric compressors and integrated thermal management systems.
Market Segmentation Analysis
The Global Automotive Air Conditioning Market is segmented by vehicle type, sales channel, component, and region.
- By Sales Channel: The Original Equipment Manufacturer (OEM) segment is expected to hold the largest market share. OEMs play a significant role in supplying factory-installed air conditioning systems through partnerships with automobile manufacturers. Large-scale production, cost efficiency, customized product development, and integration of advanced cooling technologies support the segment's dominance.
- By Vehicle Type: The market is divided into passenger vehicles and commercial vehicles. Passenger vehicles represent an important demand category because of increasing personal vehicle ownership and growing consumer preference for comfortable driving experiences.
- By Component: The market includes compressors, evaporators, receivers, and condensers. These components work together to provide effective cooling, maintain cabin temperature, and ensure the efficient circulation of refrigerants.
- By Region: Asia Pacific is expected to dominate the global automotive air conditioning market, supported by increasing vehicle production and rising demand across China, India, and Japan.
Competitive Analysis: Leading Automotive Air Conditioning Companies
The competitive landscape includes established automotive component manufacturers focusing on product innovation, manufacturing expansion, strategic partnerships, and energy-efficient cooling technologies. The following five companies are among the leading players.
1. Denso Corporation
Denso Corporation is a major automotive technology supplier offering air conditioning systems, compressors, heat exchangers, and thermal management solutions. The company is focusing on advanced heating and cooling technologies for electric and hybrid vehicles. Its investments in electrification, heat management, and energy-efficient automotive air conditioning systems aim to improve cabin comfort while reducing energy consumption and supporting vehicle electrification.
2. Hanon Systems
Hanon Systems specializes in automotive thermal management solutions, including compressors, climate control systems, and heat exchangers. The company is focusing on compact and energy-efficient climate control technologies to meet changing automobile manufacturing requirements. Its product development strategy emphasizes improved cooling performance, reduced component weight, and advanced thermal management for electric vehicles.
3. Sanden Holding Corporation
Sanden Holding Corporation is strengthening its automotive air conditioning production capabilities through manufacturing investments and technological development. In March 2024, the company completed a production system in China with an annual capacity of 4.5 million HVAC units and started mass production. The expansion represented a 41% capacity increase compared with 2021. Sanden is also focusing on electric compressors and integrated thermal management systems to serve growing demand from electric vehicle manufacturers.
4. Mitsubishi Heavy Industries
Mitsubishi Heavy Industries is developing automotive air conditioning products with an emphasis on compact designs, lightweight materials, and energy efficiency. Its product portfolio includes HVAC modules, control panels, electric water heaters, and electric-driven compressors. The company is expanding its high-voltage electric compressor offerings to address increasing demand from electrified vehicles. Its innovative heat-pump technologies are expected to support improved vehicle energy efficiency.
5. MAHLE GmbH
MAHLE GmbH is investing in advanced automotive thermal management and electrification technologies. During 2024, the company invested approximately €425 million in tangible fixed assets, with a significant focus on thermal management and electric mobility. Its investments included expanding electric compressor production capacities in Europe and Asia and strengthening North American manufacturing operations. MAHLE also secured substantial orders for thermal management modules, battery cooling systems, and electric compressors.
Regional Analysis
United States: The United States is an important automotive air conditioning market because of its established automobile manufacturing industry, high vehicle ownership, and increasing demand for advanced climate control systems. Government initiatives through the Environmental Protection Agency encourage manufacturers to reduce greenhouse gas emissions associated with automotive refrigerants and improve air conditioning efficiency. The growing adoption of electric vehicles is also creating demand for advanced compressors and battery thermal management technologies.
United Kingdom: The UK automotive air conditioning market is supported by demand for passenger vehicles, electric vehicles, and energy-efficient automotive components. Government policies promoting vehicle electrification and the transition toward zero-emission vehicles are encouraging manufacturers to develop efficient climate control technologies. Refrigerant management requirements and environmental regulations are also supporting the adoption of lower-impact refrigerants and improved cooling systems.
Germany: Germany represents an important automotive manufacturing centre, with established automobile manufacturers and automotive component suppliers. Government support for electric mobility, vehicle electrification, and industrial innovation is encouraging investment in advanced thermal management systems. The country's strong automotive engineering capabilities and focus on energy-efficient vehicle technologies are supporting demand for innovative air conditioning solutions.
France: France's automotive air conditioning market benefits from its established automotive manufacturing industry and growing electric vehicle ecosystem. Government initiatives supporting low-emission mobility and sustainable transportation are encouraging manufacturers to develop efficient automotive cooling technologies. Companies are increasingly focusing on heat pumps, electric compressors, and environmentally friendly refrigerants to improve vehicle performance.
Japan: Japan is a major automotive technology and component manufacturing hub. The presence of established companies such as Denso, Sanden, and Mitsubishi Heavy Industries supports the development of advanced automotive air conditioning systems. Government initiatives promoting carbon neutrality and electric mobility are encouraging investment in energy-efficient compressors, heat pumps, and integrated thermal management solutions.
China: China is one of the most important markets for automotive air conditioning because of its large automobile production base and rapidly expanding electric vehicle industry. Government policies supporting new energy vehicles, domestic automobile manufacturing, and technological innovation are creating significant opportunities. Increasing demand for passenger vehicles and electric vehicles is encouraging manufacturers to expand production capacity and develop advanced HVAC systems. Sanden's 2024 expansion to 4.5 million annual HVAC units demonstrates the importance of China's automotive market.
► Get to Know More About This Market Study: https://www.maximizemarketresearch.com/market-report/global-automotive-air-conditioning-market/27392/
Conclusion
The Global Automotive Air Conditioning Market is expected to experience steady growth, supported by increasing vehicle production, rising consumer expectations for cabin comfort, and technological advancements in cooling systems. The market's projected growth from USD 19.95 billion in 2022 to USD 24.38 billion by 2029 highlights the continued importance of automotive air conditioning across passenger and commercial vehicle categories.
In my view, the growing electric vehicle industry will be one of the most important opportunities for market participants. Manufacturers investing in electric compressors, intelligent climate control, lightweight components, heat pumps, and environmentally friendly refrigerants will be better positioned to meet future automotive requirements. Additionally, expanding automobile production in China, Japan, and other emerging economies will create further opportunities for industry suppliers. Companies that prioritize energy efficiency, sustainable technologies, product innovation, and strategic manufacturing expansion are likely to strengthen their competitive positions and contribute significantly to the long-term development of the global automotive air conditioning market.
About Maximize Market Research:
Maximize Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Contact Maximize Market Research:
3rd Floor, Navale IT Park, Phase 2
Pune Banglore Highway, Narhe,
Pune, Maharashtra 411041, India
sales@maximizemarketresearch.com
+91 96071 95908, +91 9607365656
Automotive Differential System Market to Reach USD 35.67 Billion by 2032
By Punampatil2001, 2026-11-16
Global Automotive Differential System Market Overview
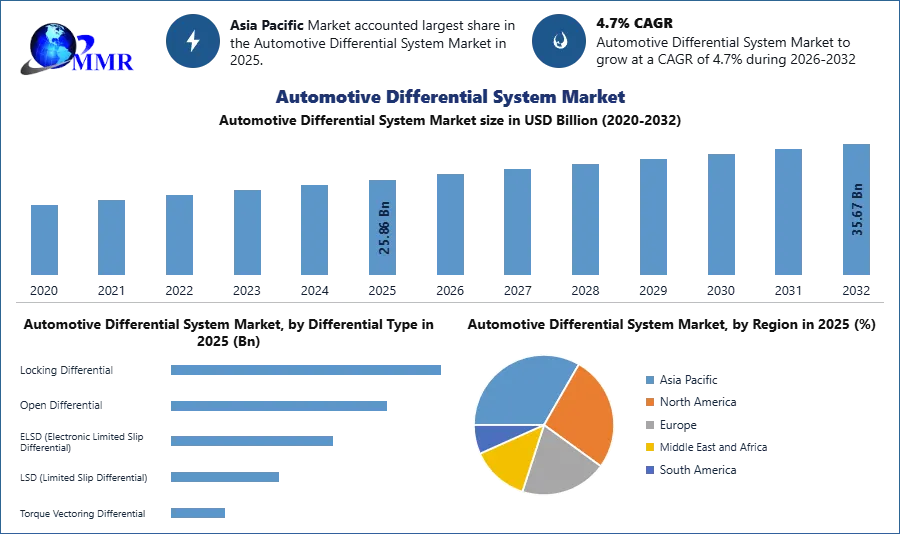
The Global Automotive Differential System Market is witnessing steady growth, supported by increasing vehicle production, rising demand for SUVs, and advancements in automotive drivetrain technologies. According to Maximize Market Research, the global automotive differential system market was valued at USD 25.86 billion in 2025 and is projected to reach USD 35.67 billion by 2032 , growing at a CAGR of 4.7% during the forecast period (2026–2032) . Automotive differential systems play an essential role in distributing engine power between vehicle wheels while allowing them to rotate at different speeds, particularly when cornering. These systems improve vehicle stability, traction, handling, and driving performance across different road conditions.
♦ Download Sample Report Here : https://www.maximizemarketresearch.com/request-sample/70396/
Market Estimation, Growth Drivers and Opportunities
The increasing popularity of sport utility vehicles (SUVs), luxury vehicles, and all-wheel-drive (AWD) and four-wheel-drive (4WD) vehicles is a major factor driving the automotive differential system market. Consumers are increasingly preferring vehicles that offer improved safety, driving comfort, off-road capabilities, and performance. Differential systems help distribute torque efficiently between wheels, improving traction on uneven, slippery, and challenging road surfaces. The expansion of automotive manufacturing, increasing disposable incomes, and infrastructure development are further supporting market demand.
The growing adoption of electric vehicles (EVs) is another important growth driver. Automotive manufacturers are developing advanced drivetrain technologies to improve vehicle efficiency, power distribution, and driving performance. Electronic limited-slip differentials (eLSDs) and torque-vectoring differentials are gaining importance because they provide better control over wheel torque. These technologies are particularly useful in high-performance vehicles, electric SUVs, and AWD electric vehicles. Furthermore, government initiatives promoting vehicle electrification and stringent vehicle emission standards are encouraging manufacturers to invest in advanced automotive technologies.
The market also offers significant opportunities through the development of intelligent differential systems, lightweight components, advanced gear materials, and electronically controlled torque-management technologies. Manufacturers focusing on improved durability, reduced friction, lower energy losses, and cost-effective production can strengthen their market position. Increasing demand for commercial vehicles, construction equipment, and off-highway vehicles is also expected to create new business opportunities.
United States Market Trends and Investments
The United States represents an important market for automotive differential systems because of its established automotive manufacturing industry and strong consumer demand for SUVs, pickup trucks, and performance vehicles. In 2024, manufacturers increasingly focused on developing electric drivetrain technologies and advanced torque-management systems. BorgWarner introduced its electric Torque Vectoring and Disconnect (eTVD) system for the Polestar 3 battery-electric SUV in 2024. The company also announced contracts to supply its electric cross differential (eXD) technology to three major global automotive manufacturers. These technologies improve vehicle traction, handling, stability, and energy efficiency. Such developments highlight increasing investment in electronically controlled differential technologies and create opportunities for the US automotive component industry.
Market Segmentation Analysis
The automotive differential system market is segmented by differential type, vehicle type, component, drive type, and application.
By Differential Type: The locking differential segment dominated the market, accounting for approximately 42% market share in 2025 . Its leadership is supported by increasing demand for off-road vehicles, all-terrain vehicles (ATVs), and advanced traction-control systems.
By Vehicle Type: Off-road vehicles represent an important leading segment because of their requirement for enhanced traction, vehicle stability, and performance across challenging terrains.
By Drive Type: AWD/4WD systems benefit from increasing adoption in SUVs, luxury vehicles, and off-road vehicles.
By Component: Differential gears, bearings, and differential cases are essential components supporting efficient torque distribution and drivetrain performance.
Competitive Analysis
The global automotive differential system market is competitive, with manufacturers focusing on product innovation, electrification, strategic partnerships, and advanced drivetrain solutions. Five prominent companies in the market include:
1. GKN PLC: GKN Automotive offers open differentials, limited-slip differentials, electronic differential locks, and electronic torque-management systems. Its electronically controlled limited-slip differential technology improves vehicle traction and handling. The company is also developing integrated eDrive and AWD solutions for electric and hybrid vehicles, creating opportunities in next-generation drivetrains.
2. Eaton: Eaton is a major manufacturer of automotive differential technologies, including electronic locking differentials and limited-slip systems. Its ELocker technology allows drivers to electronically switch between open and fully locked differential modes. The use of net-forged gears improves strength and durability, supporting applications in pickup trucks and off-road vehicles.
3. American Axle & Manufacturing Inc. (AAM): AAM focuses on advanced driveline systems, differential assemblies, electric drive units, and axle technologies. At CES 2024, the company showcased its next-generation 3-in-1 electric drive units, integrated e-Beam axles, and other electrification technologies. The company also expanded production of power-transfer units and rear-drive modules for AWD vehicle platforms during 2024.
4. JTEKT Corporation: JTEKT develops differential units, torque-control devices, and advanced drivetrain technologies. Its Ultra Compact Differential (JUCD) is designed for electric vehicle eAxles, offering a compact and durable alternative to conventional differential designs. Its technology supports improved packaging, reduced weight, and higher power density in electric drivetrains.
5. Dana Ltd.: Dana develops advanced driveline technologies, including axles, driveshafts, differentials, and electric propulsion systems. The company is expanding its electrification portfolio through integrated eAxles, electric drive systems, and advanced powertrain components. Its focus on improving drivetrain efficiency and supporting different vehicle architectures positions it to benefit from growing demand for electric and hybrid vehicles.
Regional Analysis
United States: The United States is an important automotive market, supported by established vehicle manufacturing facilities, demand for pickup trucks and SUVs, and investments in electric vehicle technologies. Government initiatives supporting vehicle electrification and stricter fuel-efficiency and emissions requirements encourage manufacturers to develop advanced drivetrain components.
United Kingdom: The UK automotive market benefits from its established automotive engineering industry and increasing adoption of electric and hybrid vehicles. Government policies supporting zero-emission vehicle adoption and investments in automotive research and development are creating opportunities for advanced differential technologies.
Germany: Germany represents a major European automotive manufacturing hub. The presence of leading automotive manufacturers and component suppliers, combined with strong engineering capabilities, supports demand for advanced differential systems. Government support for electric mobility, industrial innovation, and carbon-emission reduction is encouraging investment in efficient drivetrain technologies.
France: France's automotive differential system market is supported by established vehicle manufacturers, increasing electric vehicle production, and government initiatives promoting low-emission transportation. Investments in automotive electrification and advanced manufacturing technologies are expected to support market development.
Japan: Japan has a strong automotive manufacturing ecosystem and is home to major automotive component manufacturers. Companies are investing in compact differential systems, advanced gears, and electronically controlled torque-distribution technologies. Government support for carbon neutrality and next-generation mobility is encouraging innovation in hybrid and electric vehicle drivetrains.
China: China is a major contributor to the Asia Pacific automotive differential system market. According to the market report, Asia Pacific accounted for approximately 43.24% of the global market in 2020 , while China represented around 49.52% of the regional market by volume . Strong domestic vehicle production, expanding automotive manufacturing capabilities, and increasing demand for SUVs and electric vehicles support market growth. Government policies promoting new-energy vehicles, domestic manufacturing, and automotive technology development further strengthen China's position.
► Get to Know More About This Market Study: https://www.maximizemarketresearch.com/market-report/automotive-differential-system-market-2/70396/
Conclusion
The Global Automotive Differential System Market is expected to experience consistent growth through 2032, driven by increasing vehicle production, rising SUV and off-road vehicle demand, and the growing adoption of electric and hybrid vehicles. Technological advancements in electronic limited-slip differentials, locking differentials, and torque-vectoring systems will play an important role in improving vehicle safety, stability, and energy efficiency. The strongest long-term opportunity lies in developing compact, lightweight, and electronically controlled differential systems specifically designed for electric vehicle platforms. Manufacturers investing in advanced gear technologies, intelligent torque management, and strategic collaborations with automobile manufacturers are likely to strengthen their competitive positions and benefit from the evolving global automotive industry.
About Maximize Market Research:
Maximize Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Contact Maximize Market Research:
3rd Floor, Navale IT Park, Phase 2
Pune Banglore Highway, Narhe,
Pune, Maharashtra 411041, India
sales@maximizemarketresearch.com
+91 96071 95908, +91 9607365656