



PW Consulting: Chainsaw Chains Market Poised to Expand at a 4.5% CAGR as Industry Outlook Strengthens

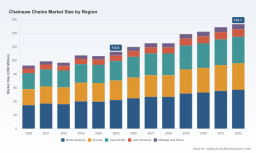
Chainsaw Chains Market 2026 Strategic Outlook — PW Consulting Industry Brief
Executive trailer
PW Consulting's Chainsaw Chains Market report (base year 2025) delivers a decision-grade intelligence package designed to inform corporate strategy, capital allocation, and commercial planning for 2026 and beyond. Anchored by a comprehensive historical review (2020–2025) and forward-looking projections through 2032, the analysis shows the market expanding at a compound annual growth rate (CAGR) of 4.5%. In practical terms, the market moves from an estimated USD 112.8 Million in 2025 to roughly USD 119.8 Million in 2026, and toward an expected USD 153.1 Million by 2032 — a trajectory that creates both clear growth opportunities and structural risks for incumbents and new entrants alike.
Chainsaw Chains Market
Why 2026 is pivotal for decision-makers
-
Regulatory inflection points are compressing time-to-action. Recent safety interventions — including a large-scale recall of battery-operated saws and tightened standards for replacement chains — have raised the bar for compliance and supply transparency. Firms that embed regulatory mitigation into product design and after-sales processes will materially reduce recall exposure and liability costs.
Chainsaw Chains Market -
Product innovation is accelerating premiumization in heavy-duty and professional segments. Tooling and carbide-enabled chain technologies are shifting value capture toward firms that can reliably scale hardened-edge manufacturing and offer validated lifecycle guarantees.
Chainsaw Chains Market -
Channel and aftermarket economics are shifting. As electrification and professionalization of end users change replacement cadences, firms must recalibrate inventory strategies, warranty terms, and channel incentives to sustain margins while protecting service levels.
-
Supply-chain resilience determines competitive runway. Raw-material volatility, machining capacity constraints, and quality-assurance bottlenecks will separate market winners from laggards in 2026 capacity planning cycles.
Key market dynamics shaping 2026–2032
-
Electrification vs. legacy power: The market is being rewired by the proliferation of battery-operated tools on one hand, and entrenched gasoline/professional applications on the other. Safety recalls in the electric chain segment have increased scrutiny, which in turn stimulates demand for higher-specification replacement chains and validated compatibility testing.
-
Material and manufacturing innovation: Advances such as tungsten-carbide toothings and automated heat-treatment deliver performance gains. Recent product launches targeting heavy-duty applications underscore that premium segments will command differentiated pricing and aftermarket loyalty.
-
Regulation and standards: Tighter standards for replacement chains and mandatory conformity testing shorten innovation cycles but raise market entry hurdles. Firms that pre-empt new compliance thresholds will benefit from first-mover trust among distributors and professional end-users.
-
Channel fragmentation and service monetization: Growth in professional services and equipment leasing increases the value of integrated maintenance and parts-supply contracts. Suppliers that can bundle technical training, predictive replacement schedules, and service-level guarantees will win share.
-
Geostrategic sourcing and nearshoring: Manufacturers are reassessing geographic footprints to reduce lead times and meet certification requirements. Strategic investments in regional finishing and distribution can cut working-capital needs and improve responsiveness.
Competitive landscape: what the largest players reveal about the market
The chainsaw chains industry remains a market where brand trust, manufacturing expertise, and channel reach matter. Our report profiles leading players and decodes strategic positioning for both OEM-focused and aftermarket-specialist companies. Two representative profiles illuminate broader competitive dynamics:
-
Oregon Tool, Inc. — an incumbent with deep manufacturing scale and channel breadth. Oregon’s global footprint and strong presence in both OEM supply and aftermarket distribution create durable advantages in purchasing power, R&D investment, and compliance execution. These attributes make the company a natural consolidator when quality and capacity constraints increase.
-
Andreas Stihl AG & Co. — a vertically integrated OEM with unique control over saw and chain design. Stihl’s approach of in-house chain production aligned with its engine platforms exemplifies how control over product-system interfaces can elevate safety performance and capture higher margin share within professional segments.
Beyond the largest firms, recent mid-market moves — including product introductions in heavy-duty carbide chains — demonstrate how focused innovation by smaller players can shift competitive dynamics within niche end-use segments. The market’s structure is best described as moderately concentrated: a handful of global leaders command significant influence, while an engaged base of mid-tier and regional players compete on specialization, service, and cost agility.
Actionable deliverables within the PW Consulting report
The report is deliberately structured to be implementation-focused for executive teams planning 2026 initiatives. Key sections include:
-
Verified market sizing and historical trend analysis (2020–2025) with a clear reconciliation to public and proprietary data sources.
-
Forward-looking forecasting through 2032 with scenario variants and sensitivity to commodity, regulatory, and electrification adoption rates.
-
Demand-driver deep dives that map end-user segments, replacement cycles, and value pools — with operational KPIs tied to channel economics.
-
Regulatory and safety risk matrix that quantifies recall exposure, compliance timelines, and certification costs across product classes.
-
Competitive benchmarking with capability heatmaps and strategic options for incumbents, new entrants, and private equity investors.
-
Go-to-market playbooks and eight executable initiatives — including SKU rationalization, tiered warranty models, and distributor incentive structures — prioritized by expected ROI and implementation complexity.
-
A downloadable financial model and Excel toolkit that allow users to test price, volume, and cost scenarios, and to evaluate M&A accretion under multiple synergy assumptions.
Note: detailed regional and application-level splits are intentionally withheld in this briefing to preserve the report’s role as the primary source for granular segmentation data and datasets.
Strategic imperatives for 2026 planning
-
Embed compliance into product roadmaps: Move regulatory impact assessment from legal review to product development sprints. Incorporate standardized testing, traceability, and diagnostic tagging into new SKUs to reduce recall risk and accelerate certification timelines.
-
Prioritize aftermarket capture strategies: Given evolving replacement dynamics, invest in service contracts, digital maintenance tools, and parts subscription offerings that extend customer lifetime value and stabilize demand.
-
Invest selectively in premium metallurgy and finishing: Target segments where performance differentiation justifies price premiums and supports long-term margin expansion.
-
Strengthen supply-chain optionality: Identify dual-sourcing options for critical inputs and build regional finishing nodes to shorten lead times and meet local certification demands.
-
Prepare for consolidation opportunities: With mid-market innovators generating valuable IP and channel access, 2026 is a prime window to pursue tuck-ins that accelerate product diversification without disrupting core operations.
Use cases: who should read the report and why
-
OEM product leaders — to design compliant, higher-margin chains aligned with evolving saw architectures.
-
Supply-chain and procurement teams — to model sourcing alternatives for key inputs and to evaluate nearshoring trade-offs.
-
Commercial directors and channel managers — to optimize SKU portfolios, rebate structures, and aftermarket value propositions.
-
Private equity and corporate development teams — to identify acquisition targets and synergy levers in a moderately concentrated market.
Call to action
PW Consulting’s Chainsaw Chains Market report is designed to be the working playbook for 2026 strategy cycles. For firms that cannot afford hindsight after a regulatory event or an unexpected supply shock, this is the primary resource to shape proactive decisions. Access to the full dataset — including granular segmentation, competitor profiles, and the financial model — is available through PW Consulting. The full report provides the detailed inputs you need to convert the strategic imperatives above into board-level initiatives and one- to three-year operating plans.
To protect the actionable value of the analysis, this brief highlights the high-level findings and strategic implications while reserving the complete segmented data and company-level financials for the full report.
For detailed analysis of this topic, please visit the official page: Chainsaw Chains Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


